Category: New Issues

New Issues

New Issue: CU FixedReset, 4.50%+369M450

Canadian Utilities Limited has announced (emphasis added):

it has entered into an agreement with a syndicate of underwriters co-led by BMO Capital Markets and RBC Capital Markets, and including TD Securities Inc., Scotiabank, CIBC, Canaccord Genuity Corp., and GMP Securities L.P. The underwriters have agreed to buy 4,000,000 4.50% Cumulative Redeemable Second Preferred Shares Series FF at a price of $25.00 per share for aggregate gross proceeds of $100,000,000. The proceeds will be used for capital expenditures, to repay indebtedness and for other general corporate purposes.

Canadian Utilities Limited has granted the underwriters an option to purchase at the offering price an additional 2,000,000 Series FF Preferred Shares exercisable in whole or in part at any time up to 7:00 AM (Calgary time) on the date that is two business days prior to closing. Should the option be fully exercised, the total gross proceeds of the Series FF Preferred Share offering will be $150,000,000.

The Series FF Preferred Shares will be issued to the public at a price of $25.00 per share and holders will be entitled to receive fixed cumulative preferential cash dividends, payable quarterly for an initial period of five years, as and when declared by the Board of Directors of the Company at an annual rate of $1.125 per share, to yield 4.50% annually.

Thereafter, the dividend rate will reset every five years to the then current 5-Year Government of Canada Bond yield plus 3.69%, and in any event, no less than 4.50%. On December 1, 2020, and on December 1 of every fifth year thereafter, the Company may redeem the Series FF Preferred Shares in whole or in part at par.

Holders may elect to convert any or all of their Series FF Preferred Shares into an equal number of Cumulative Redeemable Second Preferred Shares Series GG on December 1, 2020, and on December 1 of every fifth year thereafter. Holders of the Series GG Preferred Shares will be entitled to receive quarterly floating rate cumulative preferential cash dividends, as and when declared by the Board of Directors of the Company, equal to the then current 3-month Government of Canada Treasury Bill yield plus 3.69%. On December 1, 2025, and on December 1, of every fifth year thereafter, the Company may redeem the Series GG Preferred Shares in whole or in part at par. On any other date, the Company may redeem the Series GG Preferred Shares in whole or in part by the payment of $25.50 for each share to be redeemed.

The offering is being made only in the provinces of Canada by means of a prospectus supplement and the closing date of the issue is expected to be on or about September 24, 2015.

Assiduous Readers with sharp eyes will have noticed the bolding and murmured to themselves ‘oh, a minimum rate on reset guarantee! So that’s what the “M450” in the headline of this post means! It wasn’t a typo! Gee, I wish I hadn’t sent that vituperative eMail!’

The minimum rate guarantee seems to have been very popular, since later in the day they announced:

that as a result of strong investor demand for its previously announced offering of Cumulative Redeemable Second Preferred Shares Series FF, the size of the offering has been increased to 10,000,000 shares. The aggregate gross proceeds will now be $250,000,000.

It’s an interesting idea and I’m sure that investors will be demanding this feature for some time to come (images of stolen horses and barn doors come to mind!). But will the banks and insurers issue them? We can take a refreshing look at the Capital Adequacy Guidelines, Chapter 2, “Definition of Capital” for some hints … I don’t see anything that would stop them.

Item 2.1.2.1(11)(4) states:

Is perpetual, i.e. there is no maturity date and there are no step-ups [Footnote 14] or other incentives to redeem [Footnote 15].

Footnote 14 reads: A step-up is defined as a call option combined with a pre-set increase in the initial credit spread of the instrument at a future date over the initial dividend (or distribution) rate after taking into account any swap spread between the original reference index and the new reference index. Conversion from a fixed rate to a floating rate (or vice versa) in combination with a call option without any increase in credit spread would not constitute a step-up.

Footnote 15 reads: Other incentives to redeem include a call option combined with a requirement or an investor option to convert the instrument into common shares if the call is not exercised.

So I don’t think there’s a problem there – OSFI is worried about issuance of 2% century-wink-wink-nudge-nudge bonds that step up to 25% on the first call date, thereby giving the issuer a certain incentive to redeem. But that’s not the case here; there is a floor, but it will not necessarily be applied.

The other rule I thought of that might throw a monkey-wrench into bank issuance was item 2.1.2.1(11)(9):

The instrument cannot have a credit sensitive dividend feature, that is a dividend/coupon that is reset periodically based in whole or in part on the institution or organization’s credit standing [Footnote 18]

Footnote 18 reads: Institutions may use a broad index as a reference rate in which the issuing institution is a reference entity, however, the reference rate should not exhibit significant correlation with the institution’s credit standing. If an institution plans to issue capital instruments where the margin is linked to a broad index in which the institution is a reference entity, the institution should ensure that the dividend/coupon is not credit-sensitive. [BCBS FAQs #12, p.5]

So, while it was worth checking, that particular rule is very specific that increases in spread based on credit quality is prohibited, but increases in spread based on interest rates seems to be OK.

So I think this minimum rate guarantee structure will be permissible for banks. But I’m neither OSFI nor an underwriter nor a bank treasury analyst!

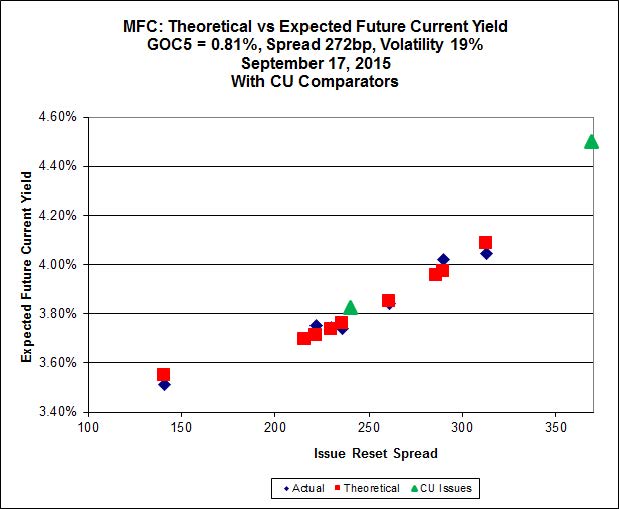
Update, 2015-9-17: This chart compares the CU issues to extant MFC issues. See the comments for discussion.
impVol_MFC_CU_150917
Click for Big
New Issues

BSC.PR.B Refunding Issue Moves Closer

The Bank of Nova Scotia has announced:

BNS Split Corp. II (the “Company”) announced today that the final condition required to extend the term of the Company for an additional five years to September 22, 2020, has been met as holders of 89.2% of Class A Capital Shares (“Capital Shares”) have elected to extend. Holders of Capital Shares previously approved the extension of the term of the Company subject to a minimum of 800,000 Capital Shares remain outstanding after giving effect to the special retraction right (the “Special Retraction Right”).

Under the Special Retraction Right, 137,506 Capital Shares were tendered to the Company for payment on September 22, 2015. The holders of the remaining 1,138,286 Capital Shares will continue to enjoy the benefits of a leveraged participation in the capital appreciation of the Company’s portfolio of common shares of The Bank of Nova Scotia while potentially deferring any capital gains tax liability which would otherwise be realized on the redemption of their Capital Shares.
The Company’s Class B Preferred Shares, Series 1 will be redeemed by the Company on September 22, 2015 in accordance with the redemption provisions at a price per share equal to the lesser of $18.85 and the Net Asset Value per Unit. In order to maintain the leveraged “split share” structure of the Company, the Company intends to create and issue a new series of Class B Preferred Shares to be called the Series 2 Preferred Shares, which are expected to be issued immediately following this redemption.

BNS Split Corp. II is a mutual fund corporation created to hold a portfolio of common shares of The Bank of Nova Scotia. Capital Shares and Preferred Shares of BNS Split Corp. II are listed for trading on The Toronto Stock Exchange under the symbols BSC and BSC.PR.B respectively.

… and the new issue was assigned a provisional rating of Pfd-2(low) by DBRS:

DBRS Limited (DBRS) has today assigned a provisional rating of Pfd-2 (low) to the Class B Preferred Shares, Series 2 (the Preferred Shares) to be issued by BNS Split Corp. II (the Company). The Preferred Shares will be issued as part of a share capital reorganization, which permits holders of Class A Capital Shares (the Capital Shares) to extend their investment in the Company beyond the redemption date of September 22, 2015, for an additional five years to September 22, 2020. The Preferred Shares will be issued to maintain the leveraged split share structure of the Company, so that the number of issued and outstanding Capital Shares are twice the number of issued and outstanding Preferred Shares. The Preferred Shares and Capital Shares will be redeemed by the Company on September 22, 2020.

There is a preliminary short form prospectus available on SEDAR dated August 25, which I am not permitted to link to directly since the Canadian Securities Administrators think it’s bad enough that investor scum have any access at all to public documents and are doing their level best to make access inconvenient.

The critical bits of information, such as coupon rate, have not yet been filled in but there are some items of interest:

The Series 2 Preferred Shares may be surrendered for retraction at any time by the holders. Retraction payments for Series 2 Preferred Shares will be made on the 22nd day of a month or, where such day is not a business day, on the preceding business day (a “Retraction Payment Date”) provided the Series 2 Preferred Shares have been surrendered for retraction no later than the first business day before the 8th day of that month.

A holder who surrenders a Series 2 Preferred Share for retraction will receive on the Retraction Payment Date the amount, if any, by which 95% of the Unit Value exceeds the aggregate of (i) the average cost to the Company, including commissions, of purchasing two Capital Shares in the market; and (ii) $1.00.

That’s a pretty awful retraction price; it won’t support the preferred share value very much in the event of a crash in the underlying portfolio of BNS common.

Any Series 2 Preferred Shares still outstanding on the Redemption Date will be redeemed by the Company on the Redemption Date at a price per share equal to the lesser of the issue price of a Series 2 Preferred Share and the Unit Value. See “Description of the Securities Distributed – Attributes of the Series 2 Preferred Shares”.

In addition, the Company may also redeem Series 2 Preferred Shares on any Annual Retraction Payment Date (defined herein) at a price per share equal to the issue price of a Series 2 Preferred Share. The Company will only redeem Series 2 Preferred Shares in these circumstances to the extent that unmatched Capital Shares have been tendered for retraction under the Special Annual Retraction (defined herein). Where less than all the Series 2 Preferred Shares are to be so redeemed, Series 2 Preferred Shares shall be redeemed on a pro rata basis or in such other manner as is approved by the Board of Directors of the Company. The Company may also redeem Series 2 Preferred Shares in the circumstances described under “Changes Affecting Portfolio Securities.”

In addition to the annual redemption right as described above, Series 2 Preferred Shares may be redeemed by the Company at any time prior to the Redemption Date at a price (the “Premium Redemption Price”) which, until September 2016, will equal
the issue price of the Series 2 Preferred Shares multiplied by a premium which will initially be 4% and which will decline by 1% each year to nil after September 22, 2019.

And that’s a pretty onerous redemption condition. Split Shares which can be redeemed annually at par are rarely a good investment unless they’re pretty well discounted, since there’s a lot of uncertainty about redemption and less possibility of capital gain.

There is no NAV test for Capital Unit distributions, but according to the July Information Circular:

Holders of Class A Capital Shares are entitled to receive dividends as declared by the Board of Directors.

The policy of the Board of Directors is to only pay a dividend on the Class A Capital Shares provided that the Unit Value ras herein described) at the time of declaration of such dividend is, after giving effect to the dividend, greater than or equal to the original issue price of the Series 1 Preferred Shares. The current running yield on the Class A Capital Shares is 2.97% based on the closing price of the Class A Capital Shares of $19.85 on June 26, 2015.

Policies are nice things to have. Contractual obligations are better.

New Issues

New Issue: CU Straight Perpetual, 5.25%

Canadian Utilities has announced:

it has entered into an agreement with a syndicate of underwriters co-led by BMO Capital Markets and RBC Capital Markets, and including TD Securities Inc., Scotiabank, CIBC, Canaccord Genuity Corp., and GMP Securities L.P. The underwriters have agreed to buy 5,000,000 5.25% Cumulative Redeemable Second Preferred Shares Series EE at a price of $25.00 per share for aggregate gross proceeds of $125,000,000. The proceeds will be used for capital expenditures, to repay indebtedness and for other general corporate purposes.

Canadian Utilities Limited has granted the underwriters an option to purchase at the offering price an additional 2,000,000 Series EE Preferred Shares exercisable in whole or in part at any time up to 7:00 AM (Calgary time) on the date that is two business days prior to closing. Should the option be fully exercised, the total gross proceeds of the Series EE Preferred Share offering will be $175,000,000.

The Series EE Preferred Shares will be issued to the public at a price of $25.00 per share and holders will be entitled to receive fixed cumulative preferential cash dividends, payable quarterly as and when declared by the Board of Directors of the Corporation at an annual rate of $1.3125 per share, to yield 5.25% annually. On or after September 1, 2020, the Corporation may redeem the Series EE Preferred Shares in whole or in part from time to time, at $26.00 per share if redeemed during the 12 months commencing September 1, 2020, at $25.75 per share if redeemed during the 12 months commencing September 1, 2021, at $25.50 per share if redeemed during the 12 months commencing September 1, 2022, at $25.25 per share if redeemed during the 12 months commencing September 1, 2023, and at $25.00 per share if redeemed on or after September 1, 2024.

The offering is being made only in the provinces of Canada by means of a prospectus supplement and the closing date of the issue is expected to be on or about August 7, 2015.

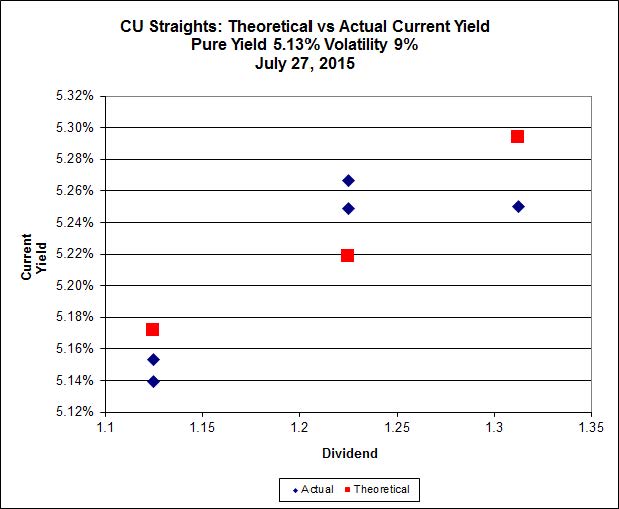
Implied Volatility theory suggests that this issue is somewhat expensive – the company has, as is often the case, priced the issue so that it yields the same as issues trading at a discount, thus assigning a value of zero to the ill effects of negative convexity.

impVol_CU_150727
Click for Big
New Issues

New Issue: BMO Straight Perpetual, 5.00%, NVCC

Bank of Montreal has announced:

a domestic public offering of $150 million of Non-Cumulative Perpetual Class B Preferred Shares, Series 35 (Non-Viability Contingent Capital (NVCC)) (the “Preferred Shares”). The offering will be underwritten on a bought-deal basis by a syndicate of underwriters led by BMO Capital Markets. The Bank has granted to the underwriters an option to purchase up to an additional $50 million of the Preferred Shares exercisable at any time up to 48 hours before closing.

The Preferred Shares will be issued to the public at a price of $25.00 per share. Holders will be entitled to receive non-cumulative preferential fixed quarterly dividends as and when declared by the board of directors of the Bank, payable in the amount of $0.3125 per share, to yield 5.00 per cent annually. Subject to regulatory approval, on or after August 25, 2020, the Bank may redeem the Preferred Shares in whole or in part at a declining premium.

The anticipated closing date is July 29, 2015. The net proceeds from the offering will be used by the Bank for general corporate purposes.

It’s very nice to see another Straight Perpetual being issued!

New Issues

New Issue: RY Straight Perpetual, 4.90%, NVCC

The Royal Bank of Canada has announced:

a domestic public offering of Non-Cumulative, Preferred Shares Series BI.

Royal Bank of Canada will issue 6 million Preferred Shares Series BI priced at $25 per share to raise gross proceeds of $150 million. The bank has granted the Underwriters an option, exercisable in whole or in part, to purchase up to an additional 2 million Preferred Shares Series BI at the same offering price.

The Preferred Shares Series BI will yield 4.90 per cent annually, payable quarterly, as and when declared by the Board of Directors of Royal Bank of Canada.

Subject to regulatory approval, on or after November 24, 2020, the bank may redeem the Preferred Shares Series BI in whole or in part at a declining premium.

The offering will be underwritten by a syndicate led by RBC Capital Markets. The expected closing date is July 22, 2015.

We routinely undertake funding transactions to maintain strong capital ratios and a cost effective capital structure. Net proceeds from this transaction will be used for general business purposes.

It’s very nice to see another Straight Perpetual coming out, but disappointing that it has the same coupon as RY.PR.W and RY.PR.N!

New Issues

New Issue: TD Straight 4.90%, NVCC

TD Bank has announced:

a domestic public offering of Non-Cumulative Fixed Rate Preferred Shares (non-viability contingent capital (NVCC)), Series 11 (the “Series 11 Shares”).

TD has entered into an agreement with a group of underwriters led by TD Securities Inc. to issue, on a bought deal basis, 6 million Series 11 Shares at a price of $25.00 per share to raise gross proceeds of $150 million. TD has also granted the underwriters an option to purchase, on the same terms, up to an additional 2 million Series 11 Shares. This option is exercisable in whole or in part by the underwriters at any time up to two business days prior to closing of the offering.

The Series 11 Shares will yield 4.90% annually, with dividends payable quarterly, as and when declared by the Board of Directors of TD. The Series 11 Shares will be redeemable in whole or in part by TD on or after October 31, 2020, subject to regulatory consent, at a declining premium.

The expected closing date is July 21, 2015. TD will make an application to list the Series 11 Shares as of the closing date on the Toronto Stock Exchange. The net proceeds of the offering will be used for general corporate purposes.

It’s nice to see another Straight Perpetual on the market!

New Issues

New Issue: HSE FixedReset, 4.60%+352

Husky Energy has announced that it:

has agreed to issue to a syndicate of underwriters led by RBC Capital Markets, BMO Capital Markets and Scotia Capital Inc. for distribution to the public 6,000,000 Cumulative Redeemable Preferred Shares, Series 7 (the “Series 7 Shares”).

The Series 7 Shares will be issued at a price of $25.00 per Series 7 Share, for aggregate gross proceeds of $150 million. Holders of the Series 7 Shares will be entitled to receive a cumulative quarterly fixed dividend yielding 4.60 percent annually for the initial period ending June 30, 2020. Thereafter, the dividend rate will be reset every five years at a rate equal to the five-year Government of Canada bond yield plus 3.52 percent.

Holders of Series 7 Shares will have the right, at their option, to convert their shares into Cumulative Redeemable Preferred Shares, Series 8 (the “Series 8 Shares”), subject to certain conditions, on June 30, 2020 and on June 30 every five years thereafter. Holders of the Series 8 Shares will be entitled to receive cumulative quarterly floating dividends at a rate equal to the 90-day Government of Canada Treasury Bill rate plus 3.52 percent.

Husky has granted the underwriters an option, exercisable in whole or in part prior to closing, to purchase up to an additional 2,000,000 Series 7 Shares at the same offering price. The Series 7 Shares will be offered by way of prospectus supplement to the short form base shelf prospectus of Husky Energy dated February 23, 2015.

The prospectus supplement will be filed with securities regulatory authorities in all provinces of Canada.

The net proceeds of the offering will be used for general corporate purposes which may include, among other things, the partial repayment of bank debt incurred by the Company to further advance its near-term heavy oil thermal projects.

The offering is expected to close on or about June 17, 2015 subject to customary closing conditions and receipt of required regulatory approvals.

The chart of Implied Volatility for the series of HSE FixedResets indicates that the new issue can be thought of as being a little cheap … not just because it’s above the theoretical yield for the series, but because the Implied Volatility seems a little high, indicating that there is, perhaps, a little bit more downside protection with the higher-spread issues than with the lower-spread issues.

impVol_HSE_150609
Click for Big
New Issues

New Issue: Loblaw 5.30% Straight

Loblaw Companies Limited has announced:

a domestic public offering of 6 million cumulative Second Preferred Shares, Series B (the “Preferred Shares Series B”) at a price of $25.00 per share, to yield 5.30% per annum, for an aggregate gross amount of $150 million.

Loblaw has agreed to sell the Preferred Shares Series B to a syndicate of underwriters co-led by RBC Capital Markets, Scotiabank and TD Securities Inc. on a bought deal basis. Loblaw has granted to the underwriters an option to purchase an additional $50 million of the Preferred Shares Series B at any time up to 48 hours prior to closing.

The Preferred Shares Series B will be offered by way of prospectus supplement under the short form base shelf prospectus of Loblaw dated March 19, 2015. The prospectus supplement will be filed with securities regulatory authorities in all provinces of Canada.

Loblaw also announced that it intends to redeem all of its outstanding Second Preferred Shares, Series A (TSX:L.PR.A) (the “Preferred Shares Series A”) for cash on July 31, 2015 (“redemption date”). The redemption price for each Preferred Share Series A will be $25.00. Holders of Preferred Shares Series A will separately receive all accrued and unpaid dividends outstanding on the redemption date. Loblaw intends to use the net proceeds of the issue of Preferred Shares Series B to partially fund the redemption of its Preferred Shares Series A. The offering is expected to close on or about June 9, 2015.

Later, they announced:

that as a result of strong investor demand for its offering that was announced earlier today, it has agreed to increase the size of the offering from 6 million to 9 million cumulative Second Preferred Shares, Series B (the “Preferred Shares Series B”) at a price of $25.00 per share, to yield 5.30% per annum, for an aggregate gross amount of $225 million. In addition, there will not be an underwriters’ option as was previously granted.

Loblaw has agreed to sell the Preferred Shares Series B to a syndicate of underwriters co-led by RBC Capital Markets, Scotiabank and TD Securities Inc. on a bought deal basis.

The Preferred Shares Series B will be offered by way of prospectus supplement under the short form base shelf prospectus of Loblaw dated March 19, 2015. The prospectus supplement will be filed with securities regulatory authorities in all provinces of Canada.

Loblaw also announced that it intends to redeem all of its outstanding Second Preferred Shares, Series A (TSX: L.PR.A) (the “Preferred Shares Series A”) for cash on July 31, 2015 (“redemption date”). The redemption price for each Preferred Share Series A will be $25.00. Holders of Preferred Shares Series A will separately receive all accrued and unpaid dividends outstanding on the redemption date. Loblaw intends to use the net proceeds of the issue of Preferred Shares Series B to partially fund the redemption of its Preferred Shares Series A. The offering is expected to close on or about June 9, 2015.

The redemption of L.PR.A has been reported previously.

It’s quite a treat to see another Straight issue being issued hard on the heels of the last one, although there are some among us who might mutter darkly that 40bp isn’t much of a spread for such a wide credit jump (Loblaw is Pfd-3 vs. Royal Bank’s Pfd-2, according to DBRS; P-3(high) vs. P-2, according to S&P).

This issue also looks a little rich when compared to the closest comparables – Straights from its parent, Weston:

WN Straights
Ticker Dividend Quote
2015-6-1
Bid YTW
WN.PR.A 1.45 25.29-35 Negative
(immediate call)
WN.PR.C 1.30 24.39-83 5.41%
WN.PR.D 1.30 24.79-95 5.32%
WN.PR.E 1.1875 23.68-71 5.08%

WN.PR.C appears to have lost its bid today; it was quoted at 24.81-90 on Friday May 29. Still, I think a 5.40% or 5.45% coupon would have been more appropriate, giving a tiny bit of compensation for a tiny amount of extra call risk, and 10bp as a new issue concession … but, with a 3% commission on sales, it’s doing well anyway!

Update, 2015-6-3: Rated Pfd-3 by DBRS.

New Issues

New Issue: RY 4.90% Straight, NVCC-Compliant

Royal Bank of Canada has announced:

a domestic public offering of Non-Cumulative, Preferred Shares Series BH.

Royal Bank of Canada will issue 6 million Preferred Shares Series BH priced at $25 per share to raise gross proceeds of $150 million.

The Preferred Shares Series BH will yield 4.90 per cent annually, payable quarterly, as and when declared by the Board of Directors of Royal Bank of Canada.

Subject to regulatory approval, on or after November 24, 2020, the bank may redeem the Preferred Shares Series BH in whole or in part at a declining premium.

The offering will be underwritten by a syndicate led by RBC Capital Markets. The expected closing date is June 5, 2015.

We routinely undertake funding transactions to maintain strong capital ratios and a cost effective capital structure. Net proceeds from this transaction will be used for general business purposes.

Well! It’s been a long time since we last saw a Straight Perpetual being issued … not since GWO.PR.S, paying 5.25%, announced 2014-5-13 and listed 2014-5-22.

I’m not sure what we can make of this … does this mean that RY’s treasury department thinks FixedResets are cheap? Their recently issued RY.PR.M, FixedReset, 3.60%+262, was hammered on the opening and they might be unwilling to risk a reprise. Or they may simply want to test the waters of the Straight Perpetual market with a small new issue. Or they might feel that they’ve got quite enough capital tied to five-year Canadas, thank you very much, and be willing to pay up a little for diversification of funding.

One way or another, it’s good to see. I’ve been saying for the past six years that I think Straights will always be the ‘little black dress’ of the preferred share market and it’s nice to see a bit of support for that idea.

Update, 2015-5-29: It’s also noteworthy that this issue has a great big fat first dividend, payable in November, that will go ex in late October. There might be some opportunities for dividend capture come October!

New Issues

New Issue: BMO FixedReset, 3.80%+271, NVCC-Compliant

Bank of Montreal has announced:

a domestic public offering of $200 million of Non-Cumulative 5-Year Rate Reset Class B Preferred Shares Series 33 (Non-Viability Contingent Capital (NVCC)) (the “Preferred Shares Series 33”). The offering will be underwritten on a bought-deal basis by a syndicate of underwriters led by BMO Capital Markets. The Bank has granted to the underwriters an option to purchase up to an additional $50 million of the Preferred Shares Series 33 exercisable at any time up to 48 hours before closing.

The Preferred Shares Series 33 will be issued to the public at a price of $25.00 per share. Holders will be entitled to receive non-cumulative preferential fixed quarterly dividends for the initial period ending August 25, 2020, as and when declared by the Board of Directors of the Bank, payable in the amount of $0.2375 per share, to yield 3.80 per cent annually.

Subject to regulatory approval, on or after August 25, 2020, the Bank may redeem the Preferred Shares Series 33 in whole or in part at par. On August 25, 2020, the dividend rate will reset and will reset thereafter every five years to be equal to the 5-Year Government of Canada Bond Yield plus 2.71 per cent. Subject to certain conditions, holders may elect to convert any or all of their Preferred Shares Series 33 into an equal number of Non-Cumulative Floating Rate Class B Preferred Shares Series 34 (Non-Viability Contingent Capital (NVCC)) (“Preferred Shares Series 34”) on August 25, 2020, and on August 25 of every fifth year thereafter. Holders of the Preferred Shares Series 34 will be entitled to receive non-cumulative preferential floating rate quarterly dividends, as and when declared by the Board of Directors of the Bank, equal to the then 3-month Government of Canada Treasury Bill Yield plus 2.71 per cent. Subject to certain conditions, holders may elect to convert any or all of their Preferred Shares Series 34 into an equal number of Preferred Shares Series 33 on August 25, 2025, and on August 25 of every fifth year thereafter.

The anticipated closing date is June 5, 2015. The net proceeds from the offering will be used by the Bank for general corporate purposes.

This issue comes with a great big fat first dividend, payable November 25, 2015, which should go ex sometime around the end of October. October might bring a few opportunities for dividend capture!

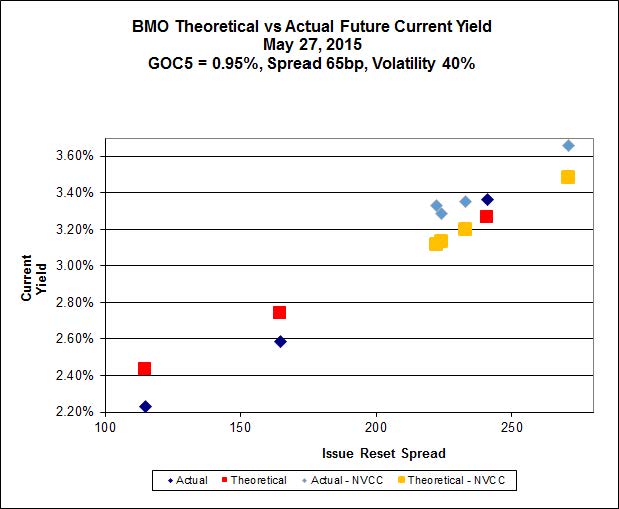
This issue actually looks reasonably good according to Implied Volatility theory:

impVol_BMO_150527
Click for Big

Note that the very high level of Implied Volatility is also calculated when only the NVCC-compliant issues are considered – for these issues alone, I get a spread of 93bp and Implied Volatility of 40%. This level of Implied Volatility is silly and will generally arise when the issues concerned are trading with an expectation of directionality in prices; I suggest that there are a lot of investors who figure that anything with the BMO brand name on it will trade somewhere near par forever.

This has the effect of making the lower spread issues vulnerable to a decline in credit quality and/or an increase in spreads; in other words, the higher-spread issues (such as this new issue) are getting a boatload of downside protection for free (when compared to other BMO issues ONLY!).