Category: Issue Comments

Better Communication, Please!

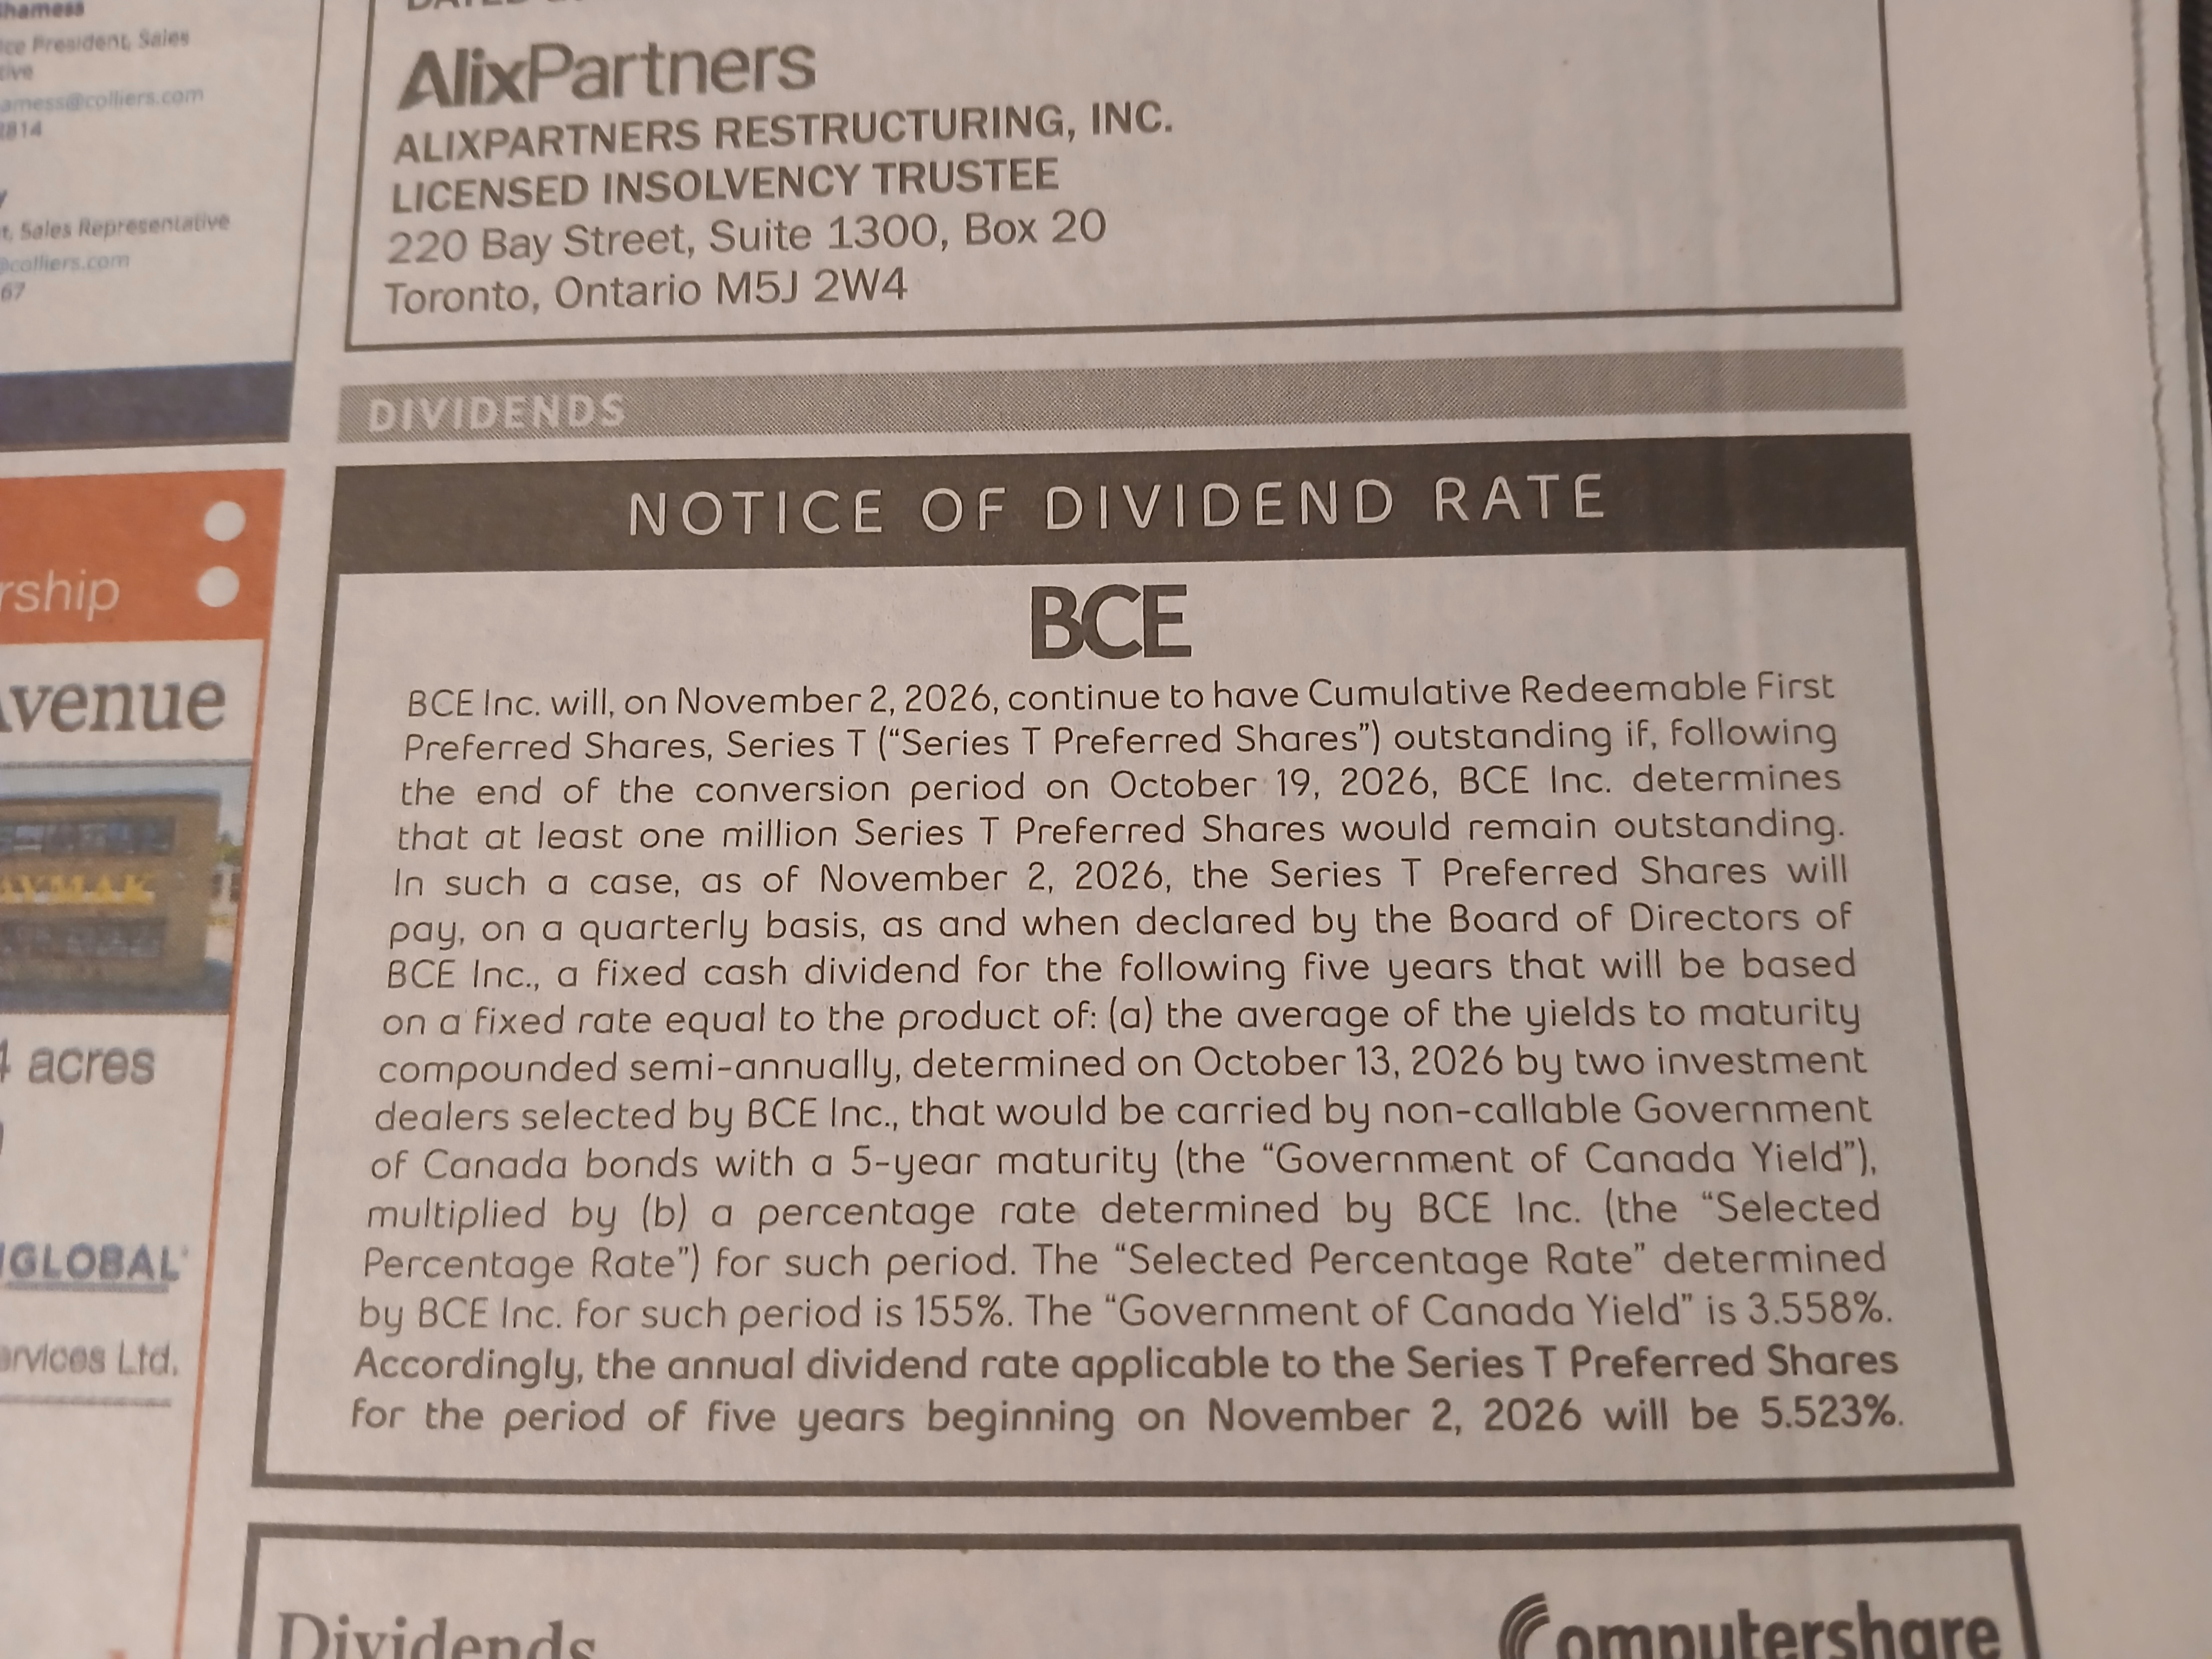
BCE.PR.T To Reset To 5.523%; Interconvertible with BCE.PR.S

BCE has announced:

The above image, you will observe, is a photo of the announcement in the Globe today – links are hard to come by for ‘Business Classified’ ads. The reset information is not yet on their website, a reprise of the BCE.PR.I fiasco. It’s very disappointing.

According to prefinfo.com, dividend resets for this issue over the past fifteen years have been:

  • 2011-11-01 dividend change: 1.1255->0.8482
  • 2016-11-01 dividend change: 0.8482->0.7548
  • 2021-11-01 dividend change: 0.7548->1.2475

Thanks to Assiduous Reader TopGear81 for bringing this to my attention!

Issue Comments

PVS.PR.N Settles Soft on OK Volume

Partners Value Split Corp. has announced (but not yet on their website because, my God, these people are lazy):

the completion of its previously announced offering of Class AA Preferred Shares, Series 18 (the “Series 18 Preferred Shares”). A total of 6,000,000 Series 18 Preferred Shares were issued at an offering price of $25.00 per Series 18 Preferred Share, raising gross proceeds of $150,000,000. The issuance included 1,000,000 Series 18 Preferred Shares issued pursuant to the exercise, in full, of the underwriters’ option granted by the Company to the underwriters in the offering. The Series 18 Preferred Shares carry quarterly fixed cumulative preferential dividends representing a 5.30% annualized yield on the offering price and have a final maturity of September 29, 2033. The Series 18 Preferred Shares have been listed and posted for trading on the Toronto Stock Exchange under the symbol PVS.PR.N.

PVS.PR.N is a SplitShare issued with a seven-year term and a 5.30% dividend rate, announced 2026-10-7. It has a long first coupon.

The issue traded 362,090 shares today (consolidated: 603,750) in a range of 24.79-90 before closing at 24.77-85. Vital statistics are:

PVS.PR.N SplitShare 362,091 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2033-09-29
Maturity Price : 25.00
Evaluated at bid price : 24.77
Bid-YTW : 5.48 %

DBRS confirmed the provisional Pfd-2 rating for this issue and confirmed the rating on PVS’ other issues (PVS.PR.H, PVS.PR.J, PVS.PR.K, PVS.PR.L and PVS.PR.M):

DBRS Limited (Morningstar DBRS) finalized its provisional credit rating of Pfd-2 on the Class AA Preferred Shares, Series 18 (the Series 18 Preferred Shares) issued by Partners Value Split Corp. (the Company). Morningstar DBRS also confirmed the credit ratings on the Class AA Preferred Shares, Series 10; the Class AA Preferred Shares, Series 12; the Class AA Preferred Shares, Series 13; the Class AA Preferred Shares, Series 14; the Class AA Preferred Shares, Series 15; the Class AA Preferred Shares, Series 16; and the Class AA Preferred Shares, Series 17 (collectively, the Class AA Preferred Shares) at Pfd-2.

The Series 18 Preferred Shares will be entitled to a fixed quarterly cumulative preferential dividend of $0.33125 per share to yield 5.30% per annum on the issue price of $25.00. The maturity date for the Series 18 Preferred Shares will be September 29, 2033. Prior to the issuance of the Series 18 Preferred Shares, the Company will subdivide the existing Capital Shares, so that after the closing of the offering, the aggregate number of preferred shares (Class AA Preferred Shares and Junior Preferred Shares) outstanding and the aggregate number of Capital Shares outstanding will be equal.

Issue Comments

BK.PR.A To Get Bigger

Quadravest has announced:

Canadian Banc Corp. (the “Company”) is pleased to announce it will undertake an offering of Preferred Shares (TSX: BK.PR.A) and Class A Shares (TSX: BK) of the Company. The offering will be led by National Bank Financial Inc.

The sales period of this overnight offering will end at 8:30 a.m. (Toronto time) on October 15, 2026. The offering is expected to close on or about October 22, 2026 and is subject to certain closing conditions including approval by the TSX.

The Preferred Shares will be offered at a price of $10.35 per Preferred Share and the Class A Shares will be offered at a price of $15.40 per Class A Share.

The closing price on the TSX of each of the Preferred Shares and Class A Shares on October 13, 2026 was $10.42 and $15.77, respectively.

Since inception of the Company, the aggregate dividends paid on the Preferred Shares have been $11.98 per share and the aggregate dividends paid on the Class A Shares have been $26.64 per share, for a combined total of $38.62 per unit. All distributions paid to date have been made in tax advantage eligible Canadian dividends or capital gains dividends.

The net proceeds of the offering will be used by the Company to invest in a portfolio consisting primarily of six publicly traded Canadian banks as follows:

Bank of Montreal Canadian Imperial Bank of Commerce Royal Bank of Canada
The Bank of Nova Scotia National Bank of Canada The Toronto-Dominion Bank

The Company’s investment objectives are:
Preferred Shares:
i. to provide holders with cumulative preferential floating rate monthly cash dividends at a rate per annum equal to the prevailing Canadian prime rate plus 1.50% (minimum annual rate of 5.0% and maximum annual rate of 8.0%) based on original $10 issue price; and
ii. on or about the termination date, currently December 1, 2028 (subject to further 5 year extensions and it has been extended in the past) to pay holders the original $10 issue price of those shares.

Class A Shares:
i. to provide holders with regular monthly cash distributions currently targeted to be at the annualized rate of 15% based upon the volume-weighted average trading price of the Class A Shares for the last three trading days of the preceding month; and
ii. on or about the termination date, currently December 1, 2028 (subject to further 5 year extensions and it has been extended in the past) to pay holders the original issue price of those shares.

Issue Comments

CU & EMA to Merge, Probably

Canadian Utilities has announced:

  • Emera and Canadian Utilities will combine in a merger of equals to form a Top 20 North American utility, with approximately $72 billion in combined enterprise value2, $45 billion in rate base3 and six million customers.
  • Creating a Canadian champion with greater financial strength, operating capabilities and investment capacity, the combined company is expected to benefit from improved credit rating thresholds, providing greater financial flexibility to better support its customers and communities.
  • The combined company plans to execute on a $32 billion capital plan through 2030, supporting expected average annual rate base growth of 7% to 8%, while continuing to pursue investments in growth opportunities driven by electrification, transmission, energy security and other major energy infrastructure needs across Canada, the United States and Australia.
  • Emera shareholders are expected to own approximately 60% of a substantially larger and more diversified company, with the transaction expected to be accretive to adjusted EPS in the first full year following closing, enhancing the combined company’s credit profile and supporting long-term earnings and dividend growth.
  • Canadian Utilities’ shareholders will receive approximately 40% ownership in the $72 billion larger combined company, while benefiting from an approximately 20% expected increase in dividend income.4
  • Both Canadian Utilities and Emera will benefit from greater geographic and regulatory diversification, enhanced financial flexibility and continued exposure to two of the fastest growth jurisdictions in North America – Florida and Alberta.
  • The combined company will operate as Emera and maintain its public company headquarters in Halifax and Canadian Utilities’ corporate and operational headquarters in Calgary, Edmonton and Perth, Australia. Emera CEO, Scott Balfour, will serve as CEO of the combined company and Canadian Utilities Executive Chair, Nancy Southern, will serve as Co-Chair of the Board with current Chair, Karen Sheriff.
  • In connection with the transaction, ATCO will spin off into a new publicly-traded industrial services leader made up of housing, defence and investments, including ports and retail energy. ATCO Chair and CEO, Nancy Southern, will serve as Chair and CEO of the new entity.
    ATCO shareholders will receive an interest in both the combined energy company, Emera and the purpose-built New ATCO with dedicated leadership, capital and strategic focus in both companies.

  • ATCO’s controlling shareholder, Sentgraf Enterprises Ltd., has signed a voting support agreement to support the transaction.
  • The transaction was approved following comprehensive reviews by all three Boards, including independent Special Committees for ATCO and Canadian Utilities, supported by independent financial and legal advice.

…
Voting support agreements

Sentgraf, which holds approximately 27% of the outstanding non-voting shares and all outstanding voting shares of ATCO, has entered into a voting support agreement pursuant to which it has irrevocably agreed to vote its ATCO shares in favour of the transaction, and against any competing acquisition proposals.

In addition, each of the directors and executive officers of ATCO, have entered into voting support agreements agreeing to vote their ATCO shares in favour of the continuance and the transaction.

ATCO, which holds approximately 37% of the outstanding non-voting shares and all outstanding voting shares of Canadian Utilities, has entered into a voting support agreement pursuant to which it has agreed to vote its Canadian Utilities shares in favour of the transaction, and against any competing acquisition proposals. In addition, each of the other directors and executive officers of Canadian Utilities, have entered into voting support agreements agreeing to vote their Canadian Utilities shares in favour of the transaction.

All directors and executive officers of Emera have entered into voting and support agreements pursuant to which they have agreed to vote their Emera shares in favour of the transaction.

Timing and conditions to closing

Completion of the transaction is subject to the satisfaction of customary conditions, including applicable shareholder, court and regulatory approvals. The transaction is expected to close in the third or fourth quarter of 2027.

Shareholder approvals

The transaction will be effected by way of a court-approved plan of arrangement under the Canada Business Corporations Act. The arrangement will require approvals from ATCO and Canadian Utilities securityholders at special meetings to be called in connection with the transaction. On each such resolution, all applicable ATCO and Canadian Utilities securityholders (including holders of non-voting shares, options and SARs) are entitled to one vote for each security held. In order to proceed, the arrangement must be approved by:

  • at least two-thirds of the votes cast by holders of ATCO Class I and Class II shares, voting together as a single class;
  • at least two-thirds of the votes cast by holders of ATCO Class I and Class II shares, ATCO options and ATCO SARs, voting together as a single class;
  • at least two-thirds of the votes cast by holders of Canadian Utilities Class A shares;
  • at least two-thirds of the votes cast by holders of Canadian Utilities Class B shares;
  • at least two-thirds of the votes cast by holders of Canadian Utilities Class A and Class B shares, Canadian Utilities options and Canadian Utilities SARs, voting together as a single class;
  • a simple majority of the votes cast by the holders of Canadian Utilities Class A shares, excluding votes required to be excluded under Multilateral Instrument 61-101 – Protection of Minority Security Holders in Special Transactions; and
  • a simple majority of the votes cast by Emera shareholders for the issuance of Emera shares in connection with the transaction

in each case by applicable holders present or represented by proxy at the applicable meeting, and such other approvals as may be required under applicable securities laws or by the Court of King’s Bench of Alberta in connection with the arrangement.

Fitch Ratings has announced:

Fitch Ratings has affirmed ATCO Ltd.’s (ATCO) Long-Term Issuer Default Ratings (IDR) at ‘BBB+’ and Canadian Utilities Limited (CUL)’s and CU Inc.’s Long-Term IDRs at ‘A-‌’‌. Fitch has placed ATCO’s and CUL’s Long-Term IDRs on Rating Watch Negative (RWN). CU Inc.’s Rating Outlook is Stable.

The RWN reflects Fitch’s expectation that ATCO and CUL will become intermediate holding companies when Emera Incorporated (BBB/Stable) and CUL complete their merger through all-share acquisitions of ATCO’s and CUL’s minority shares. Both companies will have limited or no independent access to external capital. Fitch expects to equalize their ratings with Emera’s.

CU Inc.’s Stable Outlook reflects Fitch’s expectation that its rating will remain above Emera’s consolidated credit profile. This reflects CU Inc.’s wholly regulated Alberta electricity and natural gas transmission and distribution operations and continued access to external debt markets. The ratings also reflect constructive regulatory environments in Alberta and Australia, which support credit metrics during an elevated capital expenditure cycle centered on the Yellowhead pipeline project.

At the same time, Fitch has placed ATCO’s unsecured notes rated ‘BBB+’ and fixed-to-floating subordinated notes rated ‘BBB-‌’ on RWN. Fitch has placed CUL’s senior unsecured debt rated ‘A-‌’‌, cumulative redeemable preferred shares and junior subordinated notes rated ‘BBB’, Short-Term IDR rated ‘F2’ and commercial paper (CP) program rated ‘F2’ on RWN. Fitch has affirmed CU Inc.’s senior unsecured debt at ‘A’, cumulative redeemable preferred shares rated ‘BBB+’, Short-Term IDR rated ‘F2’ and CP program rated ‘F2’.

Fitch expects to resolve the Rating Watch when the transaction closes. Given the expected closing timeline, the RWN may remain in place for more than six months.

S&P affirmed Emera:

  • Halifax, Nova Scotia-based Emera Inc. announced today it entered a definitive agreement to merge with Calgary, Alberta-based Canadian Utilities Ltd. (CUL) in an almost-all-share-backed transaction. Emera will remain the existing entity.
  • S&P Global Ratings expects the transaction will close by the end of 2027, pending approval from Emera and CUL shareholders, and U.S., Canadian, and Australian federal and provincial regulatory approvals.
  • We expect the merger to create a larger entity with enhanced regulatory and operating diversity and a group credit profile consistent with that for Emera.
  • We affirmed all our ratings on Emera, including the ‘BBB’ issuer credit rating, and the ‘BBB-’ rating on subsidiary Nova Scotia Power Inc. (NSPI) and ‘BBB+’ rating on subsidiary Tampa Electric Co. (TEC).
  • The stable outlook reflects our expectation that the combined entity’s financial measures will reflect funds from operations (FFO) to debt averaging 12% in fiscal years 2028 and 2029.

Several years ago, S&P withdrew their ratings on CU & CIU:

TORONTO (S&P Global Ratings) July 12, 2023–S&P Global Ratings withdrew its ‘BBB+’ long-term issuer credit ratings (ICRs) and all related debt issue ratings on ATCO Ltd. (ATCO) and subsidiary Canadian Utilities Ltd. (CUL) at their request. At the same time, we also withdrew our ‘A-‘ ICR and all related debt issue ratings on ATCO’s subsidiary CU Inc. (CUI) at their request. At the time of the withdrawal, the outlooks on the ratings on ATCO and subsidiaries were stable.

Moody’s affirmed Emera:

Moody’s Ratings (Moody’s) today affirmed Emera Inc.’s (Emera) Baa3 senior unsecured and Issuer ratings following the company’s announcement of an all-share combination with Canadian Utilities Limited (CUL). At the same time, we affirmed the ratings of Tampa Electric Company (Tampa Electric), including its A3 senior unsecured and Issuer ratings and P-2 short-term rating for commercial paper. The rating outlooks for both companies are stable.

We also affirmed the Baa3 senior unsecured ratings of Emera US Finance LP, Emera US Finance, LLC, and TECO Finance, Inc., along with the Ba1 junior subordinated ratings of Emera US Finance, LLC and EUSHI Finance, Inc. All of these entities’ debt obligations are guaranteed by Emera. The rating outlooks for these companies are stable.

So, it looks like we’re going to lose an investment-grade name. Again. But fear not, investment fans!

“Our goal is to create a Canadian champion,” said Scott Balfour, Emera’s chief executive officer, in an interview. He said the merger will create a company with the scale and financial strength needed to build networks that support projects such as data centres, new natural gas pipelines and integrated provincial electrical grids.

A “Canadian champion”, as far as I have ever been able to tell, is a company that gets lots of government financial and regulatory support, routed through schemes including networks that support projects such as data centres, new natural gas pipelines and integrated provincial electrical grids. A Canadian champion makes good money for its shareholders (and officers) through government protection shielding them from domestic competition, so they can more effectively rip off consumers by doing barely acceptable work for premium charges. The Toronto Stock Exchange, for example, is a Canadian champion. So are the banks, telecoms and airlines. The petite bourgeoisie whose opinion matters think it’s great because they’re all invested up to their eyeballs in these companies. It’s Canada’s version of state capitalism.

Affected issues are: CIU.PR.A, CIU.PR.C, CU.PR.C, CU.PR.D, CU.PR.E, CU.PR.F, CU.PR.G, CU.PR.H, CU.PR.J, CU.PR.K, EMA.PR.A, EMA.PR.C, EMA.PR.E, EMA.PR.F, EMA.PR.H, EMA.PR.J & EMA.PR.L,

Update, 2026-10-08: ATCO & CU under Review-Developing by DBRS:

DBRS Limited (Morningstar DBRS) placed Canadian Utilities Limited’s (CUL) Issuer Rating and Unsecured Debentures credit rating of “A,” Fixed-to-Fixed Rate Subordinated Notes credit rating of BBB (high), Commercial Paper credit rating of R-1 (low), and Cumulative Preferred Shares credit rating of Pfd-2 Under Review with Developing Implications. Concurrently, Morningstar DBRS placed ATCO Ltd.’s (ATCO) Issuer Rating and Senior Notes credit rating of A (low), as well as its Fixed-to-Floating Rate Subordinated Notes credit rating of BBB, Under Review with Developing Implications. These credit rating actions follow the October 6, 2026, announcement that Emera Inc. (Emera), CUL, and ATCO have entered into a definitive agreement for Emera to acquire CUL and ATCO (the Transaction), under which Emera will acquire all of CUL’s and ATCO’s issued and outstanding shares. ATCO’s nonutility businesses will be spun off into New ATCO, while the remaining businesses will become part of the combined Emera group. The Transaction is expected to close in Q3 2027 or Q4 2027, subject to customary approvals.

The Under Review with Developing Implications status reflects uncertainty regarding the Transaction’s ultimate impact on ATCO’s and CUL’s overall credit risk profiles. Morningstar DBRS expects the Transaction to result in significant changes to ATCO’s and CUL’s ownership, corporate, and financing structures. That said, at this juncture, Morningstar DBRS does not have sufficient information regarding the postmerger legal and financing structures, including the treatment of existing debt obligations and other capital instruments, to determine the Transaction’s ultimate impact on the companies’ credit risk profiles.

Morningstar DBRS expects to resolve the Under Review with Developing Implications status when there is sufficient clarity regarding ATCO’s and CUL’s post-Transaction corporate and financing structures. In its review, Morningstar DBRS will focus on (1) the allocation of ATCO’s assets and liabilities between New ATCO and the Emera group; (2) CUL’s role within the post-Transaction corporate structure, including whether it will remain a stand-alone financing entity; and (3) the treatment of ATCO’s and CUL’s existing debt obligations and other capital instruments. Morningstar DBRS will review additional information as it becomes available and provide an update if there is greater clarity in the direction of the credit ratings.
Issue Comments

FFN.PR.A Dividend Maintained At 7.50% For One Year

Quadravest has announced:

North American Financial 15 Split Corp. (the “Company”) is pleased to announce the Preferred Share dividend rate for the fiscal year beginning December 1, 2026.

Monthly distributions on the FFN.PR.A Preferred Shares will be maintained at $0.06250 per share, representing an annual yield of 7.50% based on the $10.00 redemption value.

This represents no change from the current dividend rate.

The Preferred Share dividend rate is subject to a minimum annual rate of 7.00% through the term ending December 1, 2029.

The Company invests in an actively managed, high quality portfolio consisting of financial services companies made up of Canadian and U.S. issuers as follows:

Bank of Montreal National Bank of Canada Bank of America Corporation
The Bank of Nova Scotia Manulife Financial Corporation Citigroup Inc.
Canadian Imperial Bank of Commerce Sun Life Financial Inc. Goldman Sachs Group, Inc.
Royal Bank of Canada Great-West Lifeco Inc. JPMorgan Chase & Co.
The Toronto-Dominion Bank   Wells Fargo & Company
Issue Comments

FTN.PR.A Dividend Maintained At 7.25% For One Year

Quadravest has announced:

Financial 15 Split Corp. (the “Company”) is pleased to announce the Preferred Share dividend rate for the fiscal year beginning December 1, 2026.

Monthly distributions on the FTN.PR.A Preferred Shares will be maintained at $0.06042 per share, representing an annual yield of 7.25% based on the $10.00 redemption value.

This represents no change from the current dividend rate.

The Preferred Share dividend rate is subject to a minimum annual rate of 6.00% through the term ending December 1, 2030.

The Company invests in an actively managed, high quality portfolio consisting of financial services companies made up of Canadian and U.S. issuers as follows:

Bank of Montreal National Bank of Canada Bank of America Corporation
The Bank of Nova Scotia Manulife Financial Corporation Citigroup Inc.
Canadian Imperial Bank of Commerce Sun Life Financial Inc. The Goldman Sachs Group, Inc.
Royal Bank of Canada Great-West Lifeco Inc. JPMorgan Chase & Co.
The Toronto-Dominion Bank   Wells Fargo & Company
Issue Comments

BPO.PR.R : No Conversion to FloatingReset

Brookfield Office Properties Inc., a subsidiary of Brookfield Property Partners L.P., has announced:

that after having taken into account all election notices received by the deadline for the conversion of the Class AAA Preference Shares, Series R (the “Series R Shares”) (TSX: BPO.PR.R) into Class AAA Preference Shares, Series S (the “Series S Shares”), the holders of Series R Shares are not entitled to convert their Series R Shares into Series S Shares. There were 24,640 Series R Shares tendered for conversion, which is less than the one million shares required to give effect to conversions into Series S Shares.

The Series R Shares will pay on a quarterly basis, for the five-year period beginning on October 1, 2026, as and when declared by the board of directors of Brookfield, a fixed dividend based on an annual dividend rate of 6.829% (C$0.4268125 per share per quarter).

BPO.PR.R was issued as a 5.10%+348 FixedReset that commenced trading 2011-9-2 after being announced 2011-8-25. The issue reset to 4.155% in 2016 and there was an 11% conversion to the FloatingReset BPO.PR.S. BPO.PR.R reset to 4.30% in 2021 and the FloatingResets were forcibly converted to the FixedResets. The issue reset to 6.829% in 2026; unusually – perhaps uniquely – the conversion election period was extended from the period originally announced.

Issue Comments

SLF.PR.K : Forced Conversion to SLF.PR.H

Sun Life Financial Inc. has announced:

that 1,400 of its 6,838,672 Class A Non-cumulative Rate Reset Preferred Shares Series 10R (the “Series 10R Shares”) have been elected for conversion on September 30, 2026, on a one-for-one basis, into Class A Non-cumulative Floating Rate Preferred Shares Series 11QR (the “Series 11QR Shares”), and 621,829 of its 1,161,328 Series 11QR Shares have been elected for conversion on September 30, 2026 on a one-for-one basis into Series 10R Shares.

Since there would be less than 1,000,000 Series 11QR Shares outstanding on September 30, 2026, after taking into account all such election notices received by the September 16, 2026 deadline for conversion, (i) Sun Life will automatically convert all remaining Series 11QR Shares into Series 10R Shares, on a one-for-one basis, on September 30, 2026, and (ii) the holders of Series 10R Shares are not entitled to convert their Series 10R Shares into Series 11QR Shares.

Consequently, on September 30, 2026, Sun Life will have 8,000,000 Series 10R Shares issued and outstanding and nil Series 11QR Shares issued and outstanding. The Series 10R Shares are listed on the Toronto Stock Exchange under the symbol SLF.PR.H.

As announced by Sun Life on August 31, 2026, commencing as of September 30, 2026, holders of Series 10R Shares will be entitled to receive non-cumulative preferential cash dividends on a quarterly basis, as and when declared by the Board of Directors of Sun Life and subject to the Insurance Companies Act (Canada). The dividend rate for the five-year period commencing on September 30, 2026 to but excluding September 30, 2031 will be 5.519% per annum or $0.344938 per share per quarter, being equal to the sum of the Government of Canada Yield, as defined in the terms of the Series 10R Shares, on Monday, August 31, 2026 plus 2.17%, as determined in accordance with the terms of the Series 10R Shares.

Subject to regulatory approval, Sun Life may redeem all or any part of the outstanding Series 10R Shares, at Sun Life’s option, by the payment of an amount in cash for each share so redeemed of $25.00, together with all declared and unpaid dividends to the date fixed for redemption, on September 30, 2031 and on September 30 in every fifth year thereafter.

SLF.PR.H was issued as a FixedReset, 3.90%+217, that commenced trading 2011-8-12 after being announced 2011-8-4. After notice of extension the issue reset to 2.842% in 2016 and there was a 14% conversion to the FloatingReset SLF.PR.K. The issue reset to 2.967% in 2021 and there was a 1% net conversion into the FloatingReset. The issue reset to 5.519% in 2026.

SLF.PR.K is a FloatingReset, Bills+217, that arose via a partial conversion from SLF.PR.H in 2016.

Thanks to Assiduous Reader FletcherLynd for bringing this to my attention!

Issue Comments

BPO.PR.R Conversion Election Period Extended

Brookfield Office Properties Inc., a subsidiary of Brookfield Property Partners L.P., has announced:

an extension to the conversion privilege on its Class AAA Preference Shares, Series R (“Series R Shares”) (TSX: BPO.PR.R) to September 23, 2026.

Holders of Series R Shares have the right, at their option, exercisable no later than 5:00 p.m. (Toronto time) on September 23, 2026, to convert all or part of their Series R Shares, on a one-for-one basis, into Class AAA Preference Shares, Series S (the “Series S Shares”), effective September 30, 2026.

As previously announced, if declared, the fixed quarterly dividends on the Series R Shares for the five years commencing October 1, 2026 and ending September 30, 2031 will be paid at an annual rate of 6.829000% ($0.4268125 per share per quarter).

The quarterly floating rate dividends on the Series S Shares have an annual rate, calculated for each quarter, of 3.48% over the annual yield on three-month Government of Canada treasury bills. The actual quarterly dividend rate for the October 1, 2026 to December 31, 2026 dividend period for the Series S Shares will be 1.454360% (5.770000% on an annualized basis) and the dividend, if declared, for such dividend period will be $0.363590 per share, payable on December 31, 2026.

Holders of Series R Shares are not required to elect to convert all or any part of their Series R Shares into Series S Shares.

As provided in the share conditions of the Series R Shares, (i) if Brookfield determines that there would be fewer than 1,000,000 Series R Shares outstanding after September 30, 2026, all remaining Series R Shares will be automatically converted into Series S Shares on a one-for-one basis effective September 30, 2026; and (ii) if Brookfield determines that there would be fewer than 1,000,000 Series S Shares outstanding after September 30, 2026, no Series R Shares will be permitted to be converted into Series S Shares. There are currently 9,946,218 Series R Shares outstanding.

When the BPO.PR.R reset to 6.829% was announced, the conversion election period was supposed to extend to 2026-09-15, but now it’s been extended to 2026-09-23. As mentioned by Assiduous Reader Sacha (who brought this to my attention), this is very peculiar. I can’t recall ever having seen an announcement like this before – there’s a wonderful story behind this somewhere, but we don’t know what it is …

BPO.PR.R was issued as a 5.10%+348 FixedReset that commenced trading 2011-9-2 after being announced 2011-8-25. The issue reset to 4.155% in 2016 and there was an 11% conversion to the FloatingReset BPO.PR.S. BPO.PR.R reset to 4.30% in 2021 and the FloatingResets were forcibly converted to the FixedResets. The issue reset to 6.829% in 2026.

Issue Comments

RS.PR.A Downgraded to Pfd-3 by DBRS

DBRS has announced that it:

downgraded the credit rating of the Preferred Shares issued by Real Estate Split Corp. (the Company) to Pfd-3 from Pfd-3 (high). The downgrade reflects a decline in downside protection, which has trended downward over the past three years, decreasing to 47.7% as of September 4, 2026, from 50.7% as of August 31, 2025. The reduction in downside protection was primarily driven by a decline in the portfolio’s net asset value (NAV), as the portfolio is heavily concentrated in real estate and real estate-related sectors.

The Company invests in an actively managed diversified portfolio composed of dividend-paying securities of issuers primarily operating in the real estate or related sectors, including real estate investment trusts, that Middlefield Limited (the Advisor), believes are well-positioned to benefit from low interest rates, the rapid adoption of e-commerce, the growth of data infrastructure as well as attractive valuations in various areas of the real estate sector. As of September 4, 2026, the Company held a portfolio of common shares (the Portfolio) issued by 27 entities. The investments were largely made in Canadian entities (85.0%) with a smaller amount in U.S. issuers (15.0%) and primarily invested in the real estate sector (96.2%), with a small portion allocated to the financial sector (3.8%). The Portfolio may include securities denominated in currencies other than the Canadian dollar (CAD), exposing the Preferred Shares to foreign currency risk. The Company has not hedged its current U.S. dollar (USD) exposure to currency fluctuations; however, it closely monitors USD/CAD currency movements. The Portfolio is actively managed in accordance with the Company’s investment objectives, strategy, and restrictions.

On August 13, 2025, the Company announced an extension of the maturity date of the Company for an additional 5-year term to December 31, 2030. On maturity, the holders of the Preferred Shares will be entitled to the value of the Portfolio up to the face value of the Preferred Shares and any accrued but unpaid dividends in priority to the holders of the Class A Shares. On October 28, 2025, the Company announced the distribution rate for the Preferred Shares for the new 5-year term starting from December 31, 2025, to December 31, 2030, will be $0.58 per annum (5.8% on the issue price of $10.00). The new distribution rate represents a 10.5% increase from the previous 5.25% distribution rate.

The Preferred shareholders are entitled to a quarterly distribution of $0.145 per Preferred Share, representing a yield of 5.80% per annum on the issue price of $10.0. The targeted monthly cash distributions to the Class A Shares are $0.13 per Class A Share, representing a yield of 10.4% per annum on the initial issue price of $15.0. No monthly distributions to the Class A Shares will be made if the dividends of the Preferred Shares are in arrears or the NAV per Unit falls to less than $15.0.

As of September 4, 2026, the downside protection available to holders of the Preferred Shares declined to 47.7% from 50.7% as of August 31, 2025. The dividend coverage ratio stood at 0.9 times (x), down from 1.1x a year ago, reflecting the increased Preferred Shares distribution rate. The dividend coverage below 1.0x indicates that the current dividend income earned by the Company is not enough to fully cover the Company’s targeted distributions on the Preferred Shares, which increases the reliance on the Manager to generate a high yield to meet distributions without having to liquidate portfolio securities. To supplement the Portfolio income, the Company may engage in covered call option writing on all or a portion of the shares held in the Portfolio. Without giving consideration to the capital appreciation potential or any source of income other than the dividends earned by the Portfolio, the Preferred Share distributions together with the current distributions on the Class A Shares are likely to create an average annual grind on the Portfolio’s NAV equivalent to 5.1% over the next five years.

Considering the decline in downside protection, dividend coverage below one time, term extension, increased Preferred Share distribution rate and the projected grind on the Portfolio, Morningstar DBRS downgraded the rating on the Preferred Shares to Pfd-3 from Pfd-3 (high).

The main constraints to the credit rating are the following:
— Market fluctuations could affect the Company’s NAV. Resulting volatility in prices, along with changes in the dividend policies of the underlying issuers, may result in significant reductions in the Preferred Shares’ dividend coverage or downside protection from time to time.
— Reliance on the Portfolio Manager to generate additional income, through option writing, to meet distributions and other trust expenses without having to liquidate the Portfolio’s securities.
— The high concentration of the Portfolio in one industry (real estate).
— Potential foreign-exchange risk because the income received on the Portfolio is not hedged all the time.
— Stated monthly distributions on the Class A Shares may create a grind on the Portfolio. This risk is mitigated by an asset coverage test of 1.5x that ensures sufficient levels of downside protection to the holders of the Preferred Shares.
— Preferred Shares dividend coverage is less than one time.

Morningstar DBRS’ credit rating on the Preferred Shares addresses the credit risk associated with the identified financial obligations in accordance with the relevant transaction documents. The associated financial obligations are the fixed cumulative preferential quarterly cash distributions and the return of the original issue price to holders of the Preferred Shares on the maturity date.

Morningstar DBRS’ credit rating does not address nonpayment risk associated with contractual payment obligations contemplated in the applicable transaction documents that are not financial obligations.

RS.PR.A was last mentioned on PrefBlog when it reset to 5.80% last October, effective 2025-12-31.