MAPF

MAPF Performance: October, 2026

Malachite Aggressive Preferred Fund’s Net Asset Value per Unit as of the close October 30, 2026, was $10.8074.

Unitholders who have started to think about their 2026 taxes should note that the current level of realized capital gains for the ten months ended October 30, 2026 amounts to about $0.55 per Unit. Note that this figure can be very volatile and may have little relation to the overall state of the market since it is dependent on how many of which issues get sold. Unrealized capital gains currently amount to about $0.48 per Unit.

Fund returns were adversely affected by TRP.PR.B (-1.53%) and CM.PR.S (-0.78% following last month’s outperformance) but benefitted from good performance by MFC.PR.B (+2.71% after counter-adjusting for the bad quote supplied by the Toronto Stock Exchange last month, following last month’s underperformance), PWF.PF.A (+3.09% following last month’s underperformance) and CU.PR.K (+4.46%); small holdings are not considered for individual mention here.

FixedResets continue to yield more than PerpetualDiscounts; on October 30, I reported median YTWs of 6.29% and 5.81%, respectively, for these two indices; compare with mean Current Yields of 5.78% and 5.74%, respectively.

Returns to October 30, 2026
Period MAPF TXPR*
Total Return
CPD – according to RBCGAM
One Month +1.00% +0.63% -%
Three Months -1.63% -1.65% -%
One Year +8.77% +6.61% +%
Two Years (annualized) +17.25% +13.11% N/A
Three Years (annualized) +24.42% +18.83% +%
Four Years (annualized) +17.30% +11.97% N/A
Five Years (annualized) +7.89% +5.65% +%
Six Years (annualized) +14.97% +9.20% N/A
Seven Years (annualized) +12.90% +8.17% N/A
Eight Years (annualized) +8.60% +6.05% N/A
Nine Years (annualized) +7.88% +5.39% N/A
Ten Years (annualized) +9.72% +6.41% +%
Eleven Years (annualized) +9.45% +6.28%  
Twelve Years (annualized) +6.74% +4.28%  
Thirteen Years (annualized) +6.95% +4.42%  
Fourteen Years (annualized) +6.35% +4.00%  
Fifteen Years (annualized) +6.66% +4.13%  
Sixteen Years (annualized) +6.39% +4.15%  
Seventeen Years (annualized) +7.21% +4.60%  
Eighteen Years (annualized) +9.91% +5.20%  
Nineteen Years (annualized) +9.03% +4.17%  
Twenty Years (annualized) +8.39%    
Twenty-One Years (annualized) +8.29%    
Twenty-Two Years (annualized) +8.20%    
Twenty-Three Years (annualized) +8.51%    
Twenty-Four Years (annualized) +9.20%    
Twenty-Five Years (annualized) +8.77%    
MAPF returns assume reinvestment of distributions, and are shown after expenses but before fees.
The BMO Capital Markets “50” Preferred Share Index is no longer being calculated. The final performance report incorporating this venerable index was published as of December, 2020.
“TXPR” is the S&P/TSX Preferred Share Index. It is calculated without accounting for fees, but does assume reinvestment of dividends.
CPD Returns are for the NAV and are after all fees and expenses. Reinvestment of dividends is assumed.
All fund and ETF returns shown below are after all fees and expenses
Figures for NBI Preferred Equity Income Fund, Series F [NBC780] (formerly Omega Preferred Equity) (which are after all fees and expenses) for 1-, 3- and 12-months are -%, -% and +%, respectively, according to National Bank Investments after all fees & expenses. Three year performance is +%; five year is +%; ten year is +%.

Figures from Morningstar are no longer conveniently available.

Manulife Preferred Income Class Adv has been terminated by Manulife. The performance of this fund was last reported here in March, 2018.
Figures for Horizons GlobalX Active Preferred Share ETF (HPR) (which are after all fees and expenses) for 1-, 3- and 12-months are -%, +% & +%, respectively. Three year performance is +%, five-year is +%, ten year is +%
Figures for NBI Preferred Equity Fund Series F [NBC710] (formerly Altamira Preferred Equity Fund) are -%, +% and +% for one-, three- and twelve months, respectively. Three year performance is +%; five-year is +%; ten-year is +%

Acccording to the fund’s fact sheet as of June 30, 2016, the fund’s inception date was October 30, 2015. I do not know how they justify this nonsensical statement, but will assume that prior performance is being suppressed in some perfectly legal manner that somebody at National considers ethical.

The last time Altamira Preferred Equity Fund’s performance was reported here was April, 2014; performance under the National Bank banner was first reported here May, 2014.

The figures for the NAV of BMO Laddered Preferred Share Index ETF (ZPR) is +% for the past twelve months. Two year performance is +%, three year is +%, five year is +%, ten year is +%

Note that analysis of ZPR shows some doubt as to whether this fund is either "laddered" or an "index fund". However, there was a remarkable improvement in the laddering in the six months following the publication of my analysis.

Figures for Fiera Canadian Preferred Share Class Cg Series F, (formerly Natixis Canadian Preferred Share Class Series F) (formerly NexGen Canadian Preferred Share Tax Managed Fund) are no longer available as the Fund is now the property of Canoe Financial. The last reported performance for the merged fund was May 2020.
Figures for BMO Preferred Share Fund (advisor series) are not available as the fund has been terminated. This is as per an announcement by the bank on 2024-5-28. The last performance report for this awful fund was as of July 31, 2024.
Figures for PowerShares Canadian Preferred Share Index Class, Series F (PPS) are no longer available since the fund has been terminated. Performance was last reported for the fund to month-end, March 2023
Figures for the First Asset Preferred Share Investment Trust (PSF.UN) are no longer available since the fund has merged with First Asset Preferred Share ETF (FPR).

Performance for the fund was last reported here in September, 2016; the first report of unavailability was in October, 2016.

Figures for Lysander-Slater Preferred Share Dividend Fund (Class F) according to the company are -%, +% and +% for the past one, three and twelve months, respectively. Three year performance is +%, five-year is +%, ten-year is +%.
Figures for the Desjardins Canadian Preferred Share Fund F Class (F Class), as reported by the company are -%, -% and +% for the past one, three and twelve months, respectively. Two year performance is +%, three-year is +%, five-year is +%, ten-year is +%
Figures for the RBC Canadian Preferred Share ETF (RPF) are reported as -%, +% and +% for the past one, three and twelve months, respectively. Three-year performance is +%, five-year is +%, ten-year is +%.
Figures for the Dynamic Active Preferred Shares ETF (DXP) are -%, -% and +% for the past one, three and twelve months, respectively. Three-year performance is +%; five-year is +%
Figures for the Purpose Canadian Preferred Share Fund (Class F) are -%, +% and +% for the past one, three and twelve months, respectively. Three-year performance is +%; four-year is +%; five-year is +%; seven-year is +%; ten-year is +%.
Figures for the TD Active Preferred Share ETF (TPRF) are -%, +% and +% for the past one, three and twelve months, respectively. Two-year performance is +%, three-year is +%; five-year is +%.

Note that “The TD ETF may also hold common shares, government and corporate bonds, and other income-producing securities. … The TD ETF may invest in foreign securities to an extent that will vary from time to time but is not typically expected to exceed 5% of its assets at the time that foreign securities are purchased.

The non-preferred share components of the portfolio are relatively minor – as of their year-end 2023 report, they had $1.6-million in Canadian Natural Resources Limited common, $1.8-million in RBC common, $1.6-million in SLF common, and $1.75-million in Fortis common, totalling $6.75-million in a $220-million portfolio.

I take the view that the purpose of this mandate is to destroy, or at least deprecate, comparability. Banks hate comparability.

So at the time of initial writing (2026-11-1) all of the comparator funds have not published returns to October month-end. I will, as usual, have to attempt to fill in the blanks prior to publishing the November PrefLetter. Remember, readers, if you want customer service, you have to go to a big firm like Hymas Investment Management Inc. – if you go to some tiny outfit like National Bank, you’ll find that they simply do not have the resources to publish returns promptly after each applicable month-end. They have published their prices and distributions, most of them: updating the performance numbers to reflect these data would be trivial programming work – if they cared to do it.

The five-year Canada yield was virtually unchanged over the month, with the five-year Canada yield (“GOC-5”) moving from 3.71% at September month-end to 3.58% at October month-end and 3-month bills moving from 2.40% to 2.52% over the month.

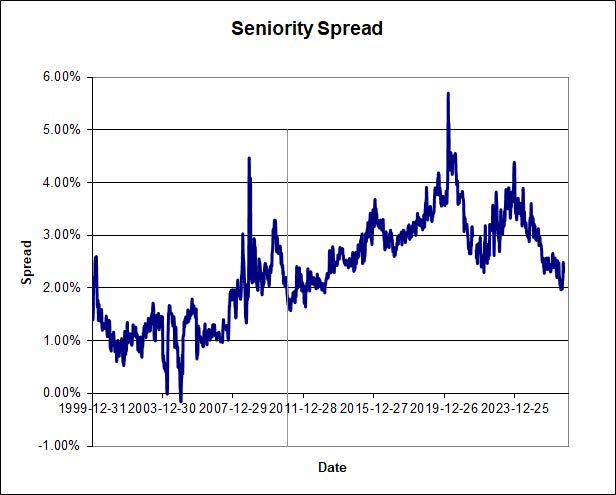
The Seniority Spread (between long-term corporate bonds and interest-equivalent PerpetualDiscounts) was 225bp on 2026-10-28, a dramatic narrowing from the 250bp on 2026-09-30 (chart end-date 2026-10=09).
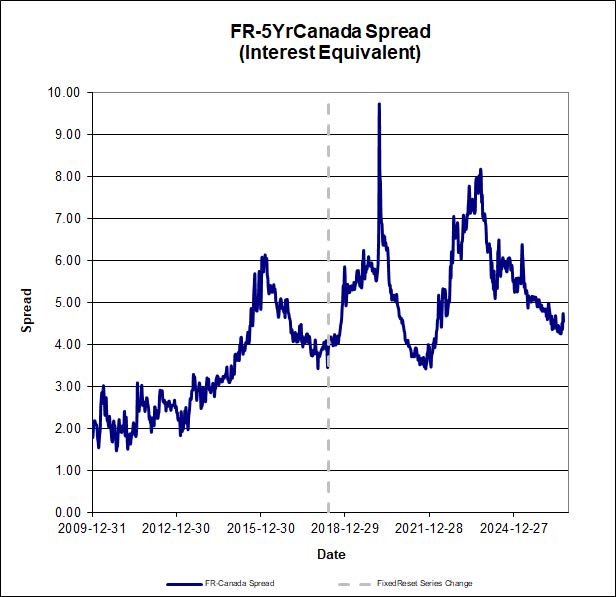
The situation with FixedResets is interesting, with the spread between GOC-5 and the interest-adjusted FixedReset (Discount) rate widening significantly (despite recent narrowing) from its 2021-11-10 low of 344bp to a level of 443bp (as of 2026-10-28)… (chart end-date 2026-10-09):
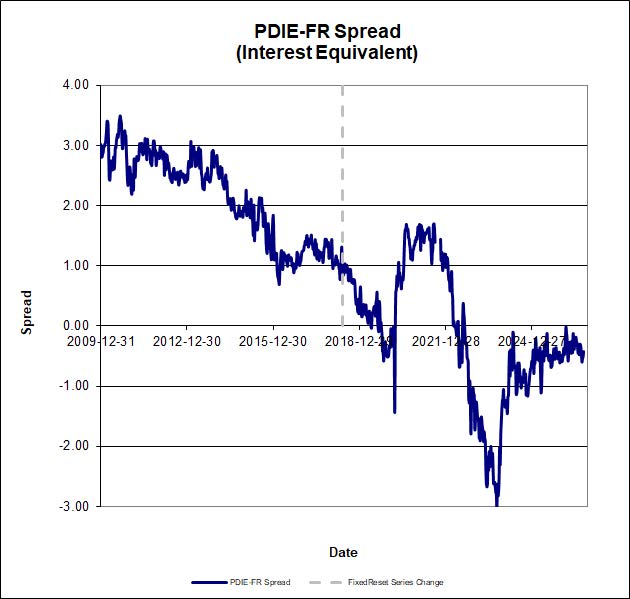
…while at the same time the interest-equivalent spread between FixedReset (Discounts) and PerpetualDiscounts has narrowed to -46bp (as of 2026-10-28) from its 2021-7-28 level of +170bp (chart end-date 2026-10-09):
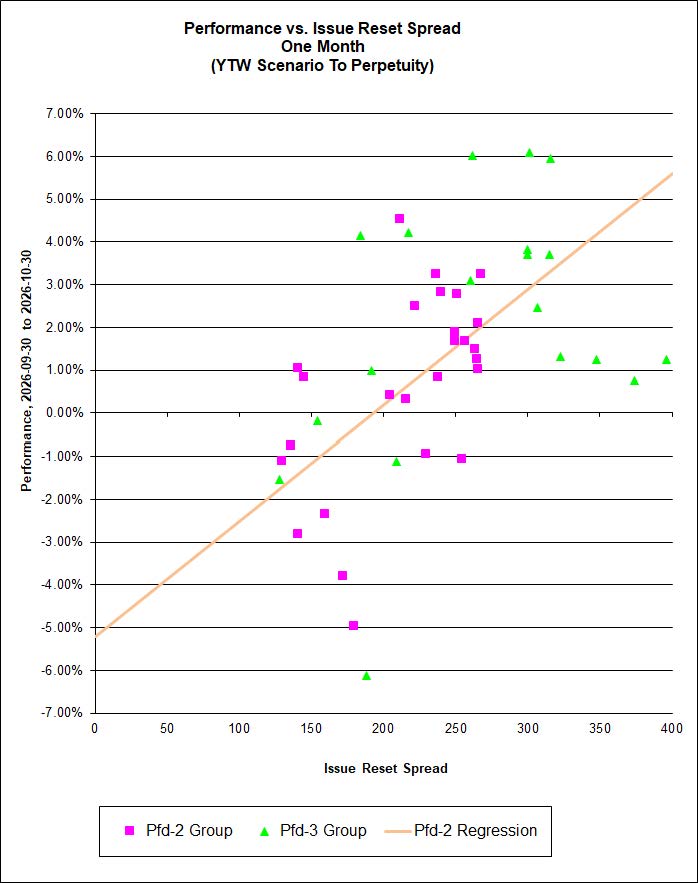
There is a correlation between the Issue Reset Spread and 1-month performance for discounted FixedResets for the Pfd-2 Group (29%) but not for the Pfd-3 Group issues.
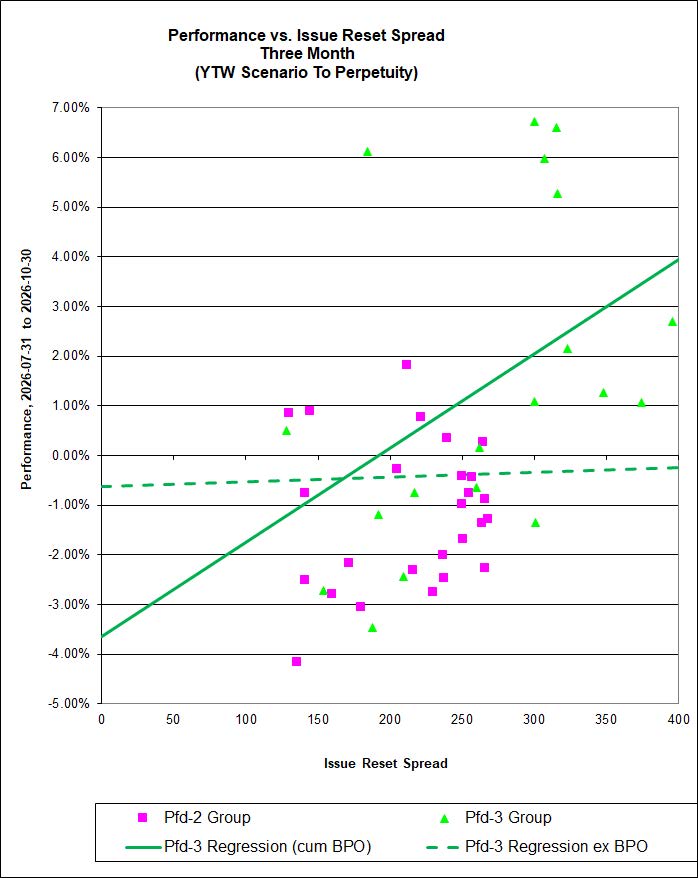
There is no correlation for the Pfd-2 group but there is a small, somewhat spurious one (14%) the Pfd-3 group between the Issue Reset Spread and 3-month performance for discounted FixedResets. The Pfd-3 group changes slope dramatically and the correlation declines to a minimal 11% when the BPO issues (high spread, high return, mostly) are discarded from the calculation.
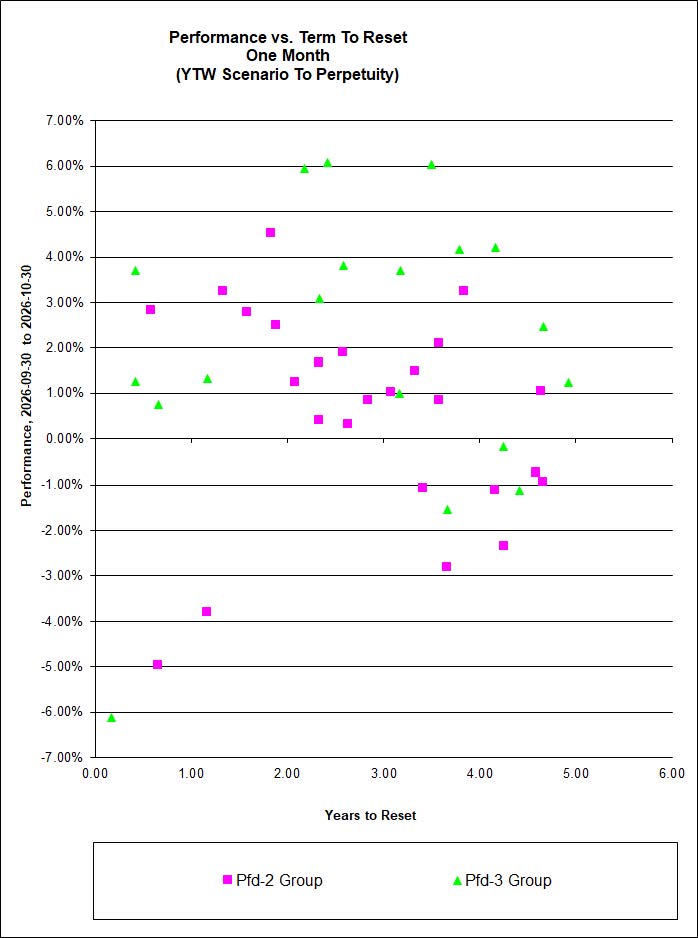
There is no correlations for either the Pfd-2 Group or the Pfd-3 Group for Term-to-Reset vs. 1-Month returnsL
… and the three-month returns vs. Term to Reset show no correlation for either the Pfd-2 Group or the Pfd-3 Group.
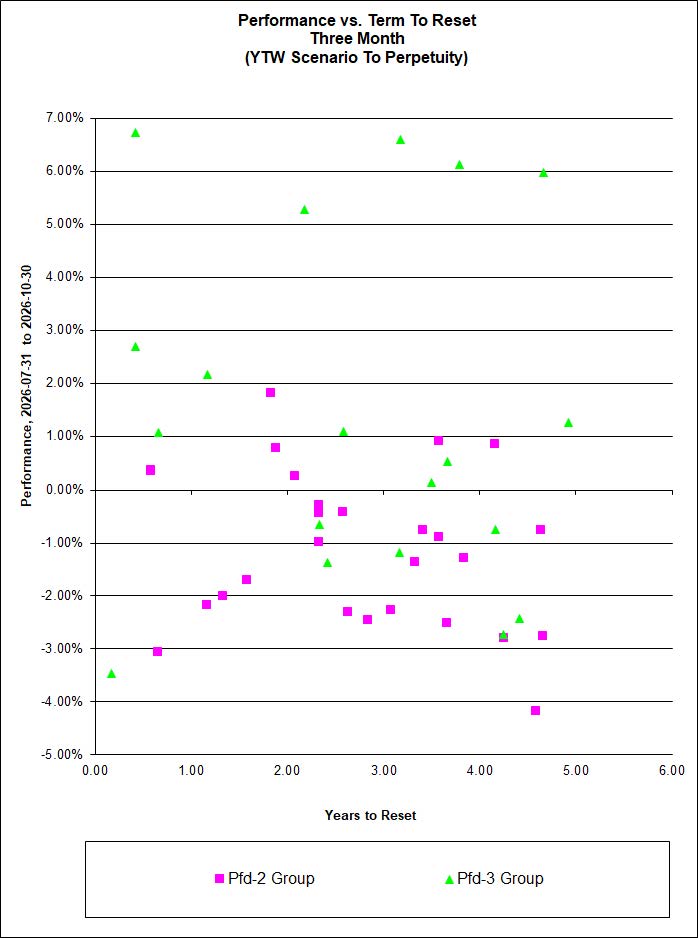
It should be noted that to some extent a dependence (of performance on term-to-reset) can be justified as the nearer-term issues will receive the benefit (adverse effects) of higher (lower) projected dividend rates sooner as a result of higher GOC-5 yields and therefore, perhaps, for longer. Equations for the relationship between correlation slope and change in GOC-5 were derived in the August 2022 PrefLetter.

Upward-sloping correlations of Performance vs. Term are to be expected when GOC-5 decreases.

I keep talking about ‘Sustainable Income’ when discussing the fund’s income projections. This is because Sustainable Income is the average yield-to-worst (YTW) of the portfolio when the YTW is calculated to perpetuity (or to redemption, of course, if the yield to redemption is lower), including resets at the current GOC-5 rate. The sharp increase in GOC-5 in the past few years caused the difference between YTW and Current Yield to skyrocket, but these two values have become much closer. We have to wait for the reset date of the MAPF portfolio securities before we see a change in actual cash receipts – and, of course, there is no guarantee whatsoever that the rate used for estimation purposes now will be used for the actual calculation in the future or that the portfolio composition at that time will be similar to the current state (chart prepared as of 2026-10-09).
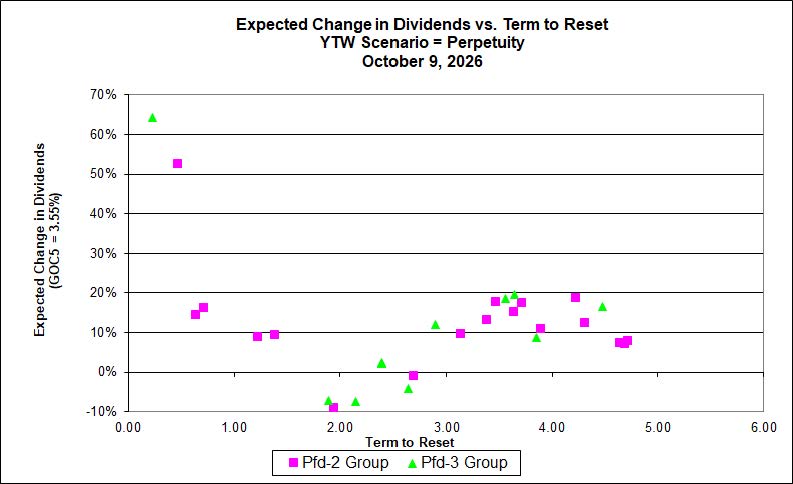
I will note that the fund’s current holdings of FixedResets are now paying dividends based on their previous reset at an average GOC-5 rate of 2.91% (for discounted FixedResets only, weighted by shares held), about 60bp below the current rate used for projections.

Calculation of MAPF Sustainable Income Per Unit
Month NAVPU Portfolio
Average
YTW
Leverage Divisor Securities Average
YTW
Capital Gains
Multiplier
Sustainable
Income per
Current
Unit
June, 2007 9.3114 5.16% 1.03 5.01% 1.552 0.3006
September 9.1489 5.35% 0.98 5.46% 1.552 0.3219
December, 2007 9.007 5.53% 0.942 5.87% 1.552 0.3407
March, 2008 8.8512 6.17% 1.047 5.89% 1.552 0.3359
June 8.3419 6.03% 0.952 6.34% 1.552 0.3407
September 8.1886 7.11% 0.969 7.34% 1.552 0.387
December, 2008 8.0464 9.24% 1.008 9.17% 1.552 0.4752
Mar, 2009 $8.83 8.60% 0.995 8.80% 1.552 0.5009
June 10.9846 7.05% 0.999 7.06% 1.552 0.4995
September 12.3462 6.03% 0.998 6.04% 1.552 0.4806
December, 2009 10.5662 5.74% 0.981 5.85% 1.306 0.4734
March, 2010 10.2497 6.03% 0.992 6.08% 1.306 0.4771
June 10.577 5.96% 0.996 5.98% 1.306 0.4846
September 11.3901 5.43% 0.98 5.54% 1.306 0.4832
December, 2010 10.7659 5.37% 0.993 5.41% 1.207 0.4824
March, 2011 11.056 6.00% 0.994 5.96% 1.207 0.5463
June 11.1194 5.87% 1.018 5.98% 1.207 0.5505
September 10.2709 6.10% 1.001 6.11% 1.207 0.5196
December, 2011 10.0793 5.63% 1.031 5.81% 1.172 0.4992
March, 2012 10.3944 5.13% 0.996 5.11% 1.172 0.4531
June 10.2151 5.32% 1.012 5.38% 1.172 0.4693
September 10.6703 4.61% 0.997 4.62% 1.172 0.421
December, 2012 10.8307 4.24% 0.989 4.29% 1.172 0.3962
March, 2013 10.9033 3.87% 0.996 3.89% 1.172 0.3615
June 10.3261 4.81% 0.998 4.80% 1.172 0.4229
September 10.0296 5.62% 0.996 5.64% 1.172 0.4829
December, 2013 9.8717 6.02% 1.008 5.97% 1.172 0.503
March, 2014 10.2233 5.55% 0.998 5.56% 1.172 0.4851
June 10.5877 5.09% 0.998 5.10% 1.172 0.4607
September 10.4601 5.28% 0.997 5.30% 1.172 0.4727
December, 2014 10.5701 4.83% 1.009 4.79% 1.172 0.4317
March, 2015 9.9573 4.99% 1.001 4.99% 1.172 0.4235
June 9.4181 5.55% 1.002 5.54% 1.172 0.4451
September 7.814 6.98% 0.999 6.99% 1.172 0.4658
December, 2015 8.1379 6.85% 0.997 6.87% 1.172 0.4771
March, 2016 7.4416 7.79% 0.998 7.81% 1.172 0.4956
June 7.6704 7.67% 1.011 7.59% 1.172 0.4965
September 8.059 7.35% 0.993 7.40% 1.172 0.509
December, 2016 8.5844 7.24% 0.99 7.31% 1.172 0.5356
March, 2017 9.3984 6.26% 0.994 6.30% 1.172 0.505
June 9.5313 6.41% 0.998 6.42% 1.172 0.5224
September 9.7129 6.56% 0.998 6.57% 1.172 0.5447
December, 2017 10.0566 6.06% 1.004 6.04% 1.172 0.5179
March, 2018 10.2701 6.22% 1.007 6.18% 1.172 0.5413
June 10.2518 6.22% 0.995 6.25% 1.172 0.5468
September 10.2965 6.62% 1.018 6.50% 1.172 0.5713
December, 2018 8.6875 7.16% 0.997 7.18% 1.172 0.5324
March, 2019 8.4778 7.09% 1.007 7.04% 1.172 0.5093
June 8.0896 7.33% 0.996 7.36% 1.172 0.5079
September 7.7948 7.96% 0.998 7.98% 1.172 0.5305
December, 2019 8.09 6.03% 0.995 6.06% 1.172 0.4183
March 5.5596 7.04% 1.006 7.00% 1.172 0.332
June 6.3568 6.10% 0.99 6.16% 1.172 0.3342
September 7.2852 5.32% 1 5.32% 1.172 0.3307
December, 2020 8.3947 4.46% 0.999 4.46% 1.172 0.3197
March, 2021 9.6473 4.48% 0.996 4.50% 1.172 0.3703
June 10.3712 3.92% 0.985 3.98% 1.172 0.3522
September 10.7572 4.08% 1.017 4.01% 1.172 0.3682
December, 2021 10.7432 4.31% 0.999 4.31% 1.172 0.3954
March, 2022 10.504 5.53% 1.004 5.51% 1.172 0.4937
June 9.3115 7.04% 0.993 7.09% 1.172 0.5633
September 8.4093 8.10% 0.997 8.12% 1.172 0.5829
December, 2022 7.9921 8.47% 0.996 8.50% 1.172 0.5799
March, 2023 8.0788 7.90% 0.997 7.92% 1.172 0.5462
June 8.0197 9.19% 1.003 9.16% 1.172 0.627
September 7.9922 9.86% 0.997 9.89% 1.172 0.6744
December, 2023 8.4715 8.14% 1.002 8.12% 1.172 0.5872
March,2024 9.5892 7.60% 1.006 7.56% 1.172 0.6181
June 9.8516 7.32% 0.999 7.33% 1.172 0.6159
September 10.3641 6.55% 0.99 6.62% 1.172 0.5851
December, 2024 11.0142 6.44% 0.992 6.49% 1.172 0.6101
March,2025 10.8891 6.22% 0.993 6.26% 1.172 0.582
June 11.4529 6.10% 0.997 6.12% 1.172 0.5979
September 11.7912 5.78% 1.002 5.77% 1.172 0.5803
December, 2025 10.5056 5.61% 1.016 5.52% 1 0.5801
March, 2026 10.4455 5.59% 1.002 5.58% 1 0.5827
June 10.8873 5.13% 0.999 5.140% 1 0.5596
September 10.7006 5.34% 0.992 5.38% 1 0.5760
October, 2026 10.8074 5.44% 1.002 5.429% 1 0.5867
NAVPU is shown after quarterly distributions of dividend income and annual distribution of capital gains.
Portfolio YTW includes cash (or margin borrowing), with an assumed interest rate of 0.00%
The Leverage Divisor indicates the level of cash in the account: if the portfolio is 1% in cash, the Leverage Divisor will be 0.99
Securities YTW divides “Portfolio YTW” by the “Leverage Divisor” to show the average YTW on the securities held; this assumes that the cash is invested in (or raised from) all securities held, in proportion to their holdings.
The Capital Gains Multiplier adjusts for the effects of Capital Gains Dividends. On 2009-12-31, there was a capital gains distribution of $1.989262 which is assumed for this purpose to have been reinvested at the final price of $10.5662. Thus, a holder of one unit pre-distribution would have held 1.1883 units post-distribution; the CG Multiplier reflects this to make the time-series comparable. Note that Dividend Distributions are not assumed to be reinvested.
Sustainable Income is the resultant estimate of the fund’s dividend income per current unit, before fees and expenses. Note that a “current unit” includes reinvestment of prior capital gains; a unitholder would have had the calculated sustainable income with only, say, 0.9 units in the past which, with reinvestment of capital gains, would become 1.0 current units.
DeemedRetractibles are comprised of all Straight Perpetuals (both PerpetualDiscount and PerpetualPremium) issued by BMO, BNS, CM, ELF, GWO, HSB, IAG, MFC, NA, RY, SLF and TD, which are not exchangable into common at the option of the company or the regulator (definition refined in May, 2011). These issues are analyzed as if their prospectuses included a requirement to redeem at par on or prior to 2022-1-31 (banks) or the Deemed Maturity date for insurers and insurance holding companies (see below)), in addition to the call schedule explicitly defined. See the Deemed Retractible Review: September 2016 for the rationale behind this analysis.

The same reasoning is also applied to FixedResets from these issuers, other than explicitly defined NVCC from banks.

In November, 2019, the assumption of DeemedRetraction for insurance issues was cancelled in the wake of the IAIS decision included in ICS 2.0. This resulted in a large drop in the yield calculated for these issues

The Deemed Maturity date for insurers was set at 2022-1-31 at the commencement of the process in February, 2011. It was extended to 2025-1-31 in April, 2013 and to 2030-1-31 in December, 2018. In November, 2019, the assumption of DeemedRetraction was cancelled in the wake of the IAIS decision included in ICS 2.0.
Yields for September, 2011, to January, 2012, were calculated by imposing a cap of 10% on the yields of YLO issues held, in order to avoid their extremely high calculated yields distorting the calculation and to reflect the uncertainty in the marketplace that these yields will be realized. From February to September 2012, yields on these issues have been set to zero. All YLO issues held were sold in October 2012.

These calculations were performed assuming constant contemporary GOC-5 and 3-Month Bill rates, as follows:

Canada Yields Assumed in Calculations
Month-end GOC-5 3-Month Bill
September, 2015 0.78% 0.40%
December, 2015 0.71% 0.46%
March, 2016 0.70% 0.44%
June 0.57% 0.47%
September 0.58% 0.53%
December, 2016 1.16% 0.47%
March, 2017 1.08% 0.55%
June 1.35% 0.69%
September 1.79% 0.97%
December, 2017 1.83% 1.00%
March, 2018 2.06% 1.08%
June 1.95% 1.22%
September 2.33% 1.55%
December, 2018 1.88% 1.65%
March, 2019 1.46% 1.66%
June 1.34% 1.66%
September 1.41% 1.66%
December, 2019 1.68% 1.68%
March, 2020 0.57% 0.21%
June 0.37% 0.21%
September 0.35% 0.14%
December, 2020 0.42% 0.08%
March, 2021 0.94% 0.09%
June 0.93% 0.13%
September 1.07% 0.13%
December, 2021 1.31% 0.16%
March, 2022 2.44% 0.53%
June 3.24% 2.11%
September 3.45% 3.60%
December, 2022 3.37% 4.35%
March, 2023 2.93% 4.44%
June 3.74% 5.00%
September 4.31% 5.21%
December, 2023 3.21% 5.13%
March, 2024 3.55% 5.06%
June 3.41% 4.71%
September 2.74% 3.94%
December, 2024 3.02% 3.19%
March, 2025 2.64% 2.66%
June 2.85% 2.68%
September 2.75% 2.45%
December, 2025 2.93% 2.18%
March, 2026 3.13% 2.33%
June 3.01% 2.27%
September 3.71% 2.40%
October, 2026 3.58% 2.52%
MAPF

MAPF Portfolio Composition: October, 2026

Turnover didn’t change much at 8% in October. Liquidity is generally very low and spreads on quotations are high.

Sectoral distribution of the MAPF portfolio on October 30, 2026, was:

MAPF Sectoral Analysis 2026-10-30
HIMI Indices Sector Weighting YTW ModDur
Ratchet 0% N/A N/A
FixFloat 0% N/A N/A
Floater 10.0% 5.67% 14.39
OpRet 0% N/A N/A
SplitShare 0% N/A N/A
Interest Rearing 0% N/A N/A
PerpetualPremium 0% N/A N/A
PerpetualDiscount 13.1% 5.81% 14.16
Fixed-Reset Discount 7.3% 6.50% 13.23
Insurance – Straight 23.8% 5.58% 14.53
FloatingReset 0% N/A N/A
FixedReset Premium 28.1% 4.81% 1.53
FixedReset Bank non-NVCC 0% N/A N/A
FixedReset Insurance non-NVCC 1.4% 5.81% 14.30
Scraps – Ratchet 0% N/A N/A
Scraps – FixedFloater 0% N/A N/A
Scraps – Floater 1.9% 5.67% 14.39
Scraps – OpRet 0% N/A N/A
Scraps – SplitShare 8.4% 4.59% 3.15
Scraps – PerpPrem 0% N/A N/A
Scraps – PerpDisc 0% N/A N/A
Scraps – FR Discount 6.2% 6.24% 13.83
Scraps – Insurance Straight 0% N/A N/A
Scraps – FloatingReset 0% N/A N/A
Scraps – FR Premium 0% N/A N/A
Scraps – Bank non-NVCC 0% N/A N/A
Scraps – Ins non-NVCC 0% N/A N/A
Cash -0.2% 0.00% 0.00
Total 100% 5.44% 9.75
Totals and changes will not add precisely due to rounding. Cash is included in totals with duration and yield both equal to zero.
The various “Scraps” indices include issues with a DBRS rating of Pfd-3(high) or lower and issues with an Average Trading Value (calculated with HIMIPref™ methodology, which is relatively complex) of less than $25,000. The issues considered “Scraps” are subdivided into indices which reflect those of the main indices.
DeemedRetractibles were comprised of all Straight Perpetuals (both PerpetualDiscount and PerpetualPremium) issued by BMO, BNS, CM, ELF, GWO, HSB, IAG, MFC, NA, RY, SLF and TD, which are not exchangable into common at the option of the company or the regulator. These issues are analyzed as if their prospectuses included a requirement to redeem at par on or prior to 2022-1-31 in the case of banks or normally in the case of insurers and insurance holding companies, in addition to the call schedule explicitly defined. See the Deemed Retractible Review: September 2016 for the rationale behind this analysis and IAIS Says No To DeemedRetractions for the recent change in policy with respect to insurers.

Note that the estimate for the time this will become effective for insurers and insurance holding companies was extended by three years in April 2013, due to the delays in OSFI’s providing clarity on the issue and by a further five years in December, 2018; the estimate was eliminated in November. However, the distinctions are being kept because it is useful to distinguish insurance issues from others.

The name of this subindex has been changed to “Insurance Straight” as of November, 2020

Calculations of yield and related attributes of resettable instruments are performed assuming a constant GOC-5 rate of 3.58%, a constant 3-Month Bill rate of 2.52% and a constant Canada Prime Rate of 4.70%

The “total” reflects the un-leveraged total portfolio (i.e., cash is included in the portfolio calculations and is deemed to have a duration and yield of 0.00.). MAPF will often have relatively large cash balances, both credit and debit, to facilitate trading. Figures presented in the table have been rounded to the indicated precision.

Credit distribution is:

MAPF Credit Analysis 2026-10-30
DBRS Rating MAPF Weighting
Pfd-1 0
Pfd-1(low) 0
Pfd-2(high) 37.0%
Pfd-2 32.6%
Pfd-2(low) 16.0%
Pfd-3(high) 5.8%
Pfd-3 5.6%
Pfd-3(low) 3.2%
Pfd-4(high) 0%
Pfd-4 0%
Pfd-4(low) 0%
Pfd-5(high) 0%
Pfd-5 0%
Cash -0.2%
Totals will not add precisely due to rounding.

Liquidity Distribution is:

MAPF Liquidity Analysis 2026-10-30
Average Daily Trading MAPF Weighting
<$50,000 21.7%
$50,000 – $100,000 40.9%
$100,000 – $200,000 28.1%
$200,000 – $300,000 4.7%
>$300,000 4.7%
Cash -0.2%
Totals will not add precisely due to rounding.

The distribution of Issue Reset Spreads is:

Range MAPF Weight
<100bp 0%
100-149bp 7.2%
150-199bp 0%
200-249bp 18.8%
250-299bp 3.2%
300-349bp 13.3%
350-399bp 0.4%
400-449bp 0%
450-499bp 0%
500-549bp 0%
550-599bp 0%
>= 600bp 0%
Undefined 57.0%

Distribution of Floating Rate Start Dates is shown in the table below. This is the date of the next adjustment to the dividend rate, if the issue is currently paying a fixed rate for a limited time; which in practice is successive terms of 5 years. Issues that adjust quarterly are considered “Currently Floating”.

Range MAPF Weight
Currently Floating 12.7%
0-1 Year 0.4%
1-2 Years 20.8%
2-3 Years 11.1%
3-4 Years 11.0%
4-5 Years 1.4%
5-6 Years 0%
>6 Years 0%
Not Floating Rate 42.7%

MAPF is, of course, Malachite Aggressive Preferred Fund, a “unit trust” managed by Hymas Investment Management Inc. Further information and links to performance, audited financials and subscription information are available the fund’s web page. The fund may be purchased directly from Hymas Investment Management. A “unit trust” is like a regular mutual fund, but are not sold with a prospectus This is cheaper, but means subscription is restricted to “accredited investors” (as defined by the Ontario Securities Commission). Fund past performances are not a guarantee of future performance. You can lose money investing in MAPF or any other fund.

Market Action

October 30, 2026

On the day before Hallowe’en, equities got spooked:

A sell-off in artificial intelligence stocks accelerated on Friday, as investors fretted about whether the industry’s debt-fueled spending spree still justified such high share prices.

The tech-heavy Nasdaq Composite index dropped 2.9 percent on the last trading session of the month, while the broader S&P 500 index shed 1.8 percent, the worst one-day showing since June for both.

The makers of computer chips were particularly hard hit. Intel plunged 29.2 percent after the chipmaker reported financial results that fell short of Wall Street’s expectations. The Philadelphia Semiconductor Index, a benchmark for the industry, fell 7.2 percent.

The shares of Amazon, Nvidia and other tech giants also fell.
…
Alphabet this week reported earnings that fell short of investors’ expectations, especially in light of the vast sums it is spending. Google’s parent company suffered its worst day in the stock market on Thursday, with its share price falling 12.6 percent and into negative territory for the year. Alphabet has slid roughly 30 percent since its peak in May, putting the company into a bear market, defined as a loss of 20 percent or more from a recent high. It shed another 1.4 percent on Friday.

Alphabet is one of five “hyperscalers” driving the A.I infrastructure build-out. Two of the others — Oracle and Meta — are also in a bear market. Amazon’s earnings report on Thursday sent its shares falling, leaving it up just 4.1 percent for the year. Microsoft is 7.9 percent higher, close to its high for the year.
…
As investors have reduced their growth expectations, Treasury yields, which are sensitive to such expectations, have also fallen. The 10-year Treasury yield dipped back below 5 percent this week, having peaked at 5.3 percent earlier in October.

The Great White North was not immune:

The S&P/TSX Composite Index ended down 629 points, or 1.74%, at 35,620.03, the lowest closing level since October ​14. For the month, the index was up ‌1.09% after falling 2.85% in September.

The TSX technology sector Friday fell 3%, with shares of e-commerce company Shopify down 5.7%.

The materials sector was down 4.8% as the price of ⁠gold fell 3.5%, hitting a one-year low. The precious metal typically comes under pressure when it appears U.S. interest rates are going to rise, sending investors to yield-paying securities instead of bullion.

Heavily weighted financials shed 1.6% and industrials ended 1.2% lower. Shares of TFI International tumbled 17.2% after the transportation and logistics company’s quarterly results missed estimates.

Just two of the 10 major TSX sectors ended higher, ​including energy. It rose 1.7% as US crude oil futures settled 2.1% higher at US$104.12 a barrel on the potential for escalation in the Iran war after the US midterm elections.

The five year Canada yield (GOC-5) was down about 2bp today to 3.52%

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.0680 % 2,769.8
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.0680 % 5,215.9
Floater 5.60 % 5.67 % 24,862 14.39 2 -0.0680 % 3,005.9
OpRet 0.00 % 0.00 % 0 0.00 0 0.0480 % 3,615.9
SplitShare 4.80 % 5.34 % 61,955 2.41 5 0.0480 % 4,318.2
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0480 % 3,369.2
Perpetual-Premium 0.00 % 0.00 % 0 0.00 0 0.4648 % 3,049.9
Perpetual-Discount 5.74 % 5.81 % 49,583 14.12 32 0.4648 % 3,281.8
FixedReset Disc 5.78 % 6.29 % 81,689 13.29 25 -1.2155 % 3,315.5
Insurance Straight 5.68 % 5.78 % 64,865 14.21 19 0.1392 % 3,167.3
FloatingReset 0.00 % 0.00 % 0 0.00 0 -1.2155 % 4,048.2
FixedReset Prem 6.05 % 5.03 % 73,854 1.94 24 -0.1646 % 2,609.7
FixedReset Bank Non 0.00 % 0.00 % 0 0.00 0 -1.2155 % 3,389.1
FixedReset Ins Non 5.64 % 5.78 % 46,212 13.94 13 -0.4415 % 3,227.9
Performance Highlights
Issue Index Change Notes
BN.PR.T FixedReset Disc -23.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-30
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 8.20 %
BN.PR.X FixedReset Disc -4.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-30
Maturity Price : 20.67
Evaluated at bid price : 20.67
Bid-YTW : 6.55 %
SLF.PR.G FixedReset Ins Non -2.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-30
Maturity Price : 20.70
Evaluated at bid price : 20.70
Bid-YTW : 5.89 %
GWO.PR.R Insurance Straight -2.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-30
Maturity Price : 20.26
Evaluated at bid price : 20.26
Bid-YTW : 6.00 %
BN.PR.R FixedReset Disc -1.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-30
Maturity Price : 22.31
Evaluated at bid price : 23.03
Bid-YTW : 6.29 %
IFC.PR.G FixedReset Ins Non -1.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-30
Maturity Price : 23.71
Evaluated at bid price : 25.10
Bid-YTW : 6.11 %
POW.PR.A Perpetual-Discount -1.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-30
Maturity Price : 23.70
Evaluated at bid price : 24.01
Bid-YTW : 5.87 %
SLF.PR.H FixedReset Ins Non -1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-30
Maturity Price : 23.00
Evaluated at bid price : 24.53
Bid-YTW : 5.78 %
PWF.PR.P FixedReset Disc -1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-30
Maturity Price : 20.91
Evaluated at bid price : 20.91
Bid-YTW : 6.05 %
MFC.PR.C Insurance Straight 1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-30
Maturity Price : 20.52
Evaluated at bid price : 20.52
Bid-YTW : 5.56 %
PWF.PR.R Perpetual-Discount 1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-30
Maturity Price : 23.32
Evaluated at bid price : 23.60
Bid-YTW : 5.85 %
PWF.PR.L Perpetual-Discount 1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-30
Maturity Price : 21.59
Evaluated at bid price : 21.85
Bid-YTW : 5.86 %
MFC.PR.B Insurance Straight 1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-30
Maturity Price : 21.19
Evaluated at bid price : 21.19
Bid-YTW : 5.57 %
PWF.PR.S Perpetual-Discount 2.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-30
Maturity Price : 20.80
Evaluated at bid price : 20.80
Bid-YTW : 5.81 %
CU.PR.D Perpetual-Discount 4.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-30
Maturity Price : 22.15
Evaluated at bid price : 22.43
Bid-YTW : 5.54 %
CU.PR.G Perpetual-Discount 10.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-30
Maturity Price : 21.00
Evaluated at bid price : 21.00
Bid-YTW : 5.45 %
Volume Highlights
Issue Index Shares
Traded
Notes
CU.PR.G Perpetual-Discount 141,162 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-30
Maturity Price : 21.00
Evaluated at bid price : 21.00
Bid-YTW : 5.45 %
BN.PF.N FixedReset Disc 128,900 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-30
Maturity Price : 23.08
Evaluated at bid price : 24.79
Bid-YTW : 5.71 %
FTS.PR.M FixedReset Disc 103,466 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2029-12-01
Maturity Price : 25.00
Evaluated at bid price : 25.15
Bid-YTW : 5.63 %
TD.PF.I FixedReset Prem 67,649 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2027-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.38
Bid-YTW : 4.75 %
TD.PF.A FixedReset Prem 39,192 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2029-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.15
Bid-YTW : 4.78 %
GWO.PF.A Perpetual-Discount 27,015 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-30
Maturity Price : 24.36
Evaluated at bid price : 24.75
Bid-YTW : 5.81 %
There were 10 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
See TMX DataLinx: ‘Last’ != ‘Close’ and the posts linked therein for an idea of why these quotes are so horrible.
Issue Index Quote Data and Yield Notes
BN.PR.T FixedReset Disc Quote: 18.00 – 23.45
Spot Rate : 5.4500
Average : 2.9411

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-30
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 8.20 %

GWO.PR.R Insurance Straight Quote: 20.26 – 21.90
Spot Rate : 1.6400
Average : 1.1260

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-30
Maturity Price : 20.26
Evaluated at bid price : 20.26
Bid-YTW : 6.00 %

BN.PR.X FixedReset Disc Quote: 20.67 – 21.67
Spot Rate : 1.0000
Average : 0.5846

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-30
Maturity Price : 20.67
Evaluated at bid price : 20.67
Bid-YTW : 6.55 %

FTS.PR.F Perpetual-Discount Quote: 22.24 – 23.50
Spot Rate : 1.2600
Average : 0.8589

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-30
Maturity Price : 22.01
Evaluated at bid price : 22.24
Bid-YTW : 5.59 %

SLF.PR.G FixedReset Ins Non Quote: 20.70 – 21.70
Spot Rate : 1.0000
Average : 0.6026

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-30
Maturity Price : 20.70
Evaluated at bid price : 20.70
Bid-YTW : 5.89 %

PWF.PR.P FixedReset Disc Quote: 20.91 – 22.00
Spot Rate : 1.0900
Average : 0.8003

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-30
Maturity Price : 20.91
Evaluated at bid price : 20.91
Bid-YTW : 6.05 %

Market Action

October 29, 2026

The US Personal Consumption Expenditures index picked up in September:

Prices, as measured by the Personal Consumption Expenditures index, increased 0.5 percent in September from a month earlier and 3.6 percent compared with the same time last year, according to a report released on Thursday by the Bureau of Economic Analysis.
…
“Core” prices, which exclude more volatile categories like food and energy, jumped 3.1 percent in September annually and rose 0.3 percent from a month earlier. That month-over-month increase was also 0.3 percent in August.
…
The data also showed that Americans’ personal income grew more slowly last month. Thursday’s release showed personal income increased 0.2 percent, less than the 0.3 percent increase reported in August.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.2044 % 2,771.6
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.2044 % 5,219.4
Floater 5.59 % 5.66 % 25,698 14.40 2 0.2044 % 3,008.0
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0320 % 3,614.2
SplitShare 4.80 % 5.34 % 58,938 2.41 5 -0.0320 % 4,316.1
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0320 % 3,367.6
Perpetual-Premium 0.00 % 0.00 % 0 0.00 0 -0.0551 % 3,035.8
Perpetual-Discount 5.77 % 5.81 % 48,734 14.11 32 -0.0551 % 3,266.6
FixedReset Disc 5.71 % 6.21 % 84,391 13.32 25 -0.1408 % 3,356.3
Insurance Straight 5.69 % 5.79 % 64,112 14.20 19 0.2864 % 3,162.9
FloatingReset 0.00 % 0.00 % 0 0.00 0 -0.1408 % 4,098.0
FixedReset Prem 6.04 % 5.01 % 74,998 1.92 24 0.0456 % 2,614.0
FixedReset Bank Non 0.00 % 0.00 % 0 0.00 0 -0.1408 % 3,430.8
FixedReset Ins Non 5.62 % 5.70 % 45,187 13.94 13 0.4919 % 3,242.2
Performance Highlights
Issue Index Change Notes
CU.PR.D Perpetual-Discount -4.97 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-29
Maturity Price : 21.40
Evaluated at bid price : 21.40
Bid-YTW : 5.83 %
PWF.PR.S Perpetual-Discount -1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-29
Maturity Price : 20.25
Evaluated at bid price : 20.25
Bid-YTW : 5.97 %
ENB.PF.G FixedReset Disc -1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-29
Maturity Price : 22.73
Evaluated at bid price : 23.70
Bid-YTW : 6.51 %
PWF.PR.P FixedReset Disc -1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-29
Maturity Price : 21.15
Evaluated at bid price : 21.15
Bid-YTW : 5.98 %
FTS.PR.J Perpetual-Discount -1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-29
Maturity Price : 21.30
Evaluated at bid price : 21.30
Bid-YTW : 5.68 %
BN.PR.X FixedReset Disc -1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-29
Maturity Price : 21.33
Evaluated at bid price : 21.60
Bid-YTW : 6.25 %
MFC.PR.B Insurance Straight -1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-29
Maturity Price : 20.90
Evaluated at bid price : 20.90
Bid-YTW : 5.64 %
GWO.PR.R Insurance Straight -1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-29
Maturity Price : 20.73
Evaluated at bid price : 20.73
Bid-YTW : 5.86 %
POW.PR.A Perpetual-Discount 1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-29
Maturity Price : 24.14
Evaluated at bid price : 24.39
Bid-YTW : 5.78 %
GWO.PR.P Insurance Straight 1.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-29
Maturity Price : 23.25
Evaluated at bid price : 23.55
Bid-YTW : 5.79 %
IFC.PR.G FixedReset Ins Non 1.59 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2028-06-30
Maturity Price : 25.00
Evaluated at bid price : 25.50
Bid-YTW : 5.09 %
POW.PR.B Perpetual-Discount 3.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-29
Maturity Price : 23.11
Evaluated at bid price : 23.37
Bid-YTW : 5.76 %
ENB.PF.C FixedReset Disc 3.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-29
Maturity Price : 22.83
Evaluated at bid price : 23.80
Bid-YTW : 6.43 %
MFC.PR.M FixedReset Ins Non 3.72 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2029-12-20
Maturity Price : 25.00
Evaluated at bid price : 25.10
Bid-YTW : 5.65 %
GWO.PR.G Insurance Straight 7.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-29
Maturity Price : 22.44
Evaluated at bid price : 22.70
Bid-YTW : 5.79 %
Volume Highlights
Issue Index Shares
Traded
Notes
SLF.PR.E Insurance Straight 76,400 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-29
Maturity Price : 20.36
Evaluated at bid price : 20.36
Bid-YTW : 5.59 %
BN.PF.N FixedReset Disc 53,750 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-29
Maturity Price : 23.07
Evaluated at bid price : 24.78
Bid-YTW : 5.71 %
PVS.PR.N SplitShare 36,438 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2033-09-29
Maturity Price : 25.00
Evaluated at bid price : 25.01
Bid-YTW : 5.34 %
ENB.PR.D FixedReset Disc 29,265 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-29
Maturity Price : 22.86
Evaluated at bid price : 23.32
Bid-YTW : 6.42 %
NA.PR.E FixedReset Prem 25,900 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2028-05-15
Maturity Price : 25.00
Evaluated at bid price : 25.29
Bid-YTW : 4.89 %
BILP.PR.A FixedReset Prem 25,500 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2031-10-01
Maturity Price : 25.00
Evaluated at bid price : 25.10
Bid-YTW : 5.80 %
There were 7 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
See TMX DataLinx: ‘Last’ != ‘Close’ and the posts linked therein for an idea of why these quotes are so horrible.
Issue Index Quote Data and Yield Notes
CU.PR.D Perpetual-Discount Quote: 21.40 – 22.99
Spot Rate : 1.5900
Average : 1.0262

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-29
Maturity Price : 21.40
Evaluated at bid price : 21.40
Bid-YTW : 5.83 %

CU.PR.K Perpetual-Discount Quote: 24.55 – 25.92
Spot Rate : 1.3700
Average : 1.0226

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-29
Maturity Price : 24.17
Evaluated at bid price : 24.55
Bid-YTW : 5.79 %

ENB.PR.P FixedReset Disc Quote: 24.25 – 24.93
Spot Rate : 0.6800
Average : 0.4252

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-29
Maturity Price : 23.20
Evaluated at bid price : 24.25
Bid-YTW : 6.31 %

PWF.PR.S Perpetual-Discount Quote: 20.25 – 20.99
Spot Rate : 0.7400
Average : 0.5244

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-29
Maturity Price : 20.25
Evaluated at bid price : 20.25
Bid-YTW : 5.97 %

GWO.PR.N FixedReset Ins Non Quote: 20.70 – 21.50
Spot Rate : 0.8000
Average : 0.5961

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-29
Maturity Price : 20.70
Evaluated at bid price : 20.70
Bid-YTW : 5.72 %

CU.PR.G Perpetual-Discount Quote: 19.00 – 21.20
Spot Rate : 2.2000
Average : 1.9976

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-29
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 6.03 %

Market Action

October 28, 2026

The Fed stood pat today:

The Federal Open Market Committee approved the following statement for release by a 10 – 2 vote:

The Committee decided to maintain the target range for the federal funds rate at 3-3/4 to 4 percent, in support of the Federal Reserve’s dual mandate. The Committee is continuing its policy of maintaining ample reserves in the banking system.

Economic activity is expanding at a strong pace. While uncertainty remains elevated owing, in part, to geopolitical developments, domestic spending has been resilient. Productivity growth is strong, and capital investment is robust. Job gains have kept pace with the workforce, and the unemployment rate has changed little.

Inflation remains elevated. The accumulation of more information will help the Committee determine the policy stance appropriate to ensure a timely return of inflation to the Committee’s 2 percent goal. The Committee will deliver price stability.

Voting against the monetary policy action were Lisa D. Cook and Beth M. Hammack, who preferred to raise the target range for the federal funds rate by 1/4 percentage point at this meeting.

I am pleasantly surprised to learn that there are whispers about Social Security during the mid-terms in that southern place:

Republican senators rarely endorse raising taxes, especially from under the lights of a debate stage. But Senator Roger Marshall, the Kansas incumbent seeking re-election, said he supported the idea to strengthen Social Security.

“I would eliminate the cap altogether,” Mr. Marshall said in a debate last Wednesday, referring to the $184,500 income ceiling on payroll taxes, the dedicated tax that finances the social insurance program. That means higher earners would be subject to taxes on a larger share of their income. His Democratic opponent, Adam Hamilton, supported raising the cap — though he wasn’t yet sure by how much.
…
Many Senate candidates in battleground states have clung to expected party lines and broad pledges to protect the program. But a growing number of Republican candidates, including Mr. Marshall, have said they’re open to the idea of subjecting more earned income to Social Security taxes. They join sitting Republican lawmakers including Senator Bernie Moreno of Ohio and Representatives Tom Cole of Oklahoma and Lloyd Smucker of Pennsylvania.
…
Social Security is financed through workers’ payroll taxes, a dedicated tax of 6.2 percent of earnings paid by both employees and employers (for a total of 12.4 percent). It’s applied to the first $184,500 of earnings in 2026 — that’s known as the taxable maximum, which rises with average wages.
…
In a recent analysis of 41 Senate candidates in competitive races (there are 35 races total), 20 candidates have endorsed raising or eliminating the cap, according to Jon Schwabish, an economist who focuses on retirement and tax policy issues and the founder of PolicyViz, a data analysis firm.
…
Eliminating the payroll cap altogether — without providing any corresponding rise in benefits to individuals paying more in taxes — would close about 58 percent of the financing gap over the next 75 years, according to Social Security’s projections, though other estimates vary. (Providing higher benefits to people who pay more in tax wouldn’t go quite as far in narrowing the gap.)
…
Raising taxes is not the only way to bolster the program: benefit reductions, slowing the cost-of-living adjustments, raising the retirement age or collecting other taxes are other options, some of which were also mentioned in recent political ads, debates or on candidates’ websites.

PerpetualDiscounts now yield 5.83%, equivalent to 7.58% interest at the standard conversion factor of 1.3x. Long corporates yielded 5.33% on 2026-10-21. Therefore the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) has widened slightly (and perhaps spuriously) to 225bp from the 220bp reported October 21.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.0340 % 2,766.0
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.0340 % 5,208.8
Floater 5.30 % 5.36 % 25,564 14.89 2 -0.0340 % 3,001.8
OpRet 0.00 % 0.00 % 0 0.00 0 0.1361 % 3,615.3
SplitShare 4.80 % 5.35 % 59,146 2.42 5 0.1361 % 4,317.5
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1361 % 3,368.7
Perpetual-Premium 0.00 % 0.00 % 0 0.00 0 0.0097 % 3,037.5
Perpetual-Discount 5.76 % 5.83 % 50,210 14.10 32 0.0097 % 3,268.4
FixedReset Disc 5.71 % 6.19 % 84,057 13.31 25 0.0034 % 3,361.0
Insurance Straight 5.71 % 5.78 % 65,421 14.22 19 -0.5504 % 3,153.9
FloatingReset 0.00 % 0.00 % 0 0.00 0 0.0034 % 4,103.8
FixedReset Prem 6.04 % 5.06 % 75,151 1.92 24 0.0897 % 2,612.9
FixedReset Bank Non 0.00 % 0.00 % 0 0.00 0 0.0034 % 3,435.6
FixedReset Ins Non 5.65 % 5.74 % 46,903 13.95 13 -0.4385 % 3,226.4
Performance Highlights
Issue Index Change Notes
GWO.PR.G Insurance Straight -7.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-28
Maturity Price : 21.15
Evaluated at bid price : 21.15
Bid-YTW : 6.23 %
IFC.PR.A FixedReset Ins Non -4.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-28
Maturity Price : 22.06
Evaluated at bid price : 22.70
Bid-YTW : 5.83 %
ENB.PF.C FixedReset Disc -3.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-28
Maturity Price : 22.40
Evaluated at bid price : 23.00
Bid-YTW : 6.67 %
POW.PR.B Perpetual-Discount -3.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-28
Maturity Price : 22.41
Evaluated at bid price : 22.67
Bid-YTW : 5.94 %
GWO.PR.P Insurance Straight -1.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-28
Maturity Price : 22.93
Evaluated at bid price : 23.20
Bid-YTW : 5.88 %
FTS.PR.J Perpetual-Discount -1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-28
Maturity Price : 21.28
Evaluated at bid price : 21.55
Bid-YTW : 5.59 %
PWF.PR.L Perpetual-Discount -1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-28
Maturity Price : 21.33
Evaluated at bid price : 21.60
Bid-YTW : 5.93 %
POW.PR.D Perpetual-Discount -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-28
Maturity Price : 21.75
Evaluated at bid price : 22.00
Bid-YTW : 5.72 %
IFC.PR.F Insurance Straight -1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-28
Maturity Price : 22.98
Evaluated at bid price : 23.25
Bid-YTW : 5.76 %
GWO.PR.Q Insurance Straight 1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-28
Maturity Price : 22.08
Evaluated at bid price : 22.36
Bid-YTW : 5.81 %
CU.PR.K Perpetual-Discount 2.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-28
Maturity Price : 24.05
Evaluated at bid price : 24.43
Bid-YTW : 5.82 %
CU.PR.E Perpetual-Discount 7.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-28
Maturity Price : 22.31
Evaluated at bid price : 22.58
Bid-YTW : 5.50 %
Volume Highlights
Issue Index Shares
Traded
Notes
BN.PF.N FixedReset Disc 39,900 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-28
Maturity Price : 23.09
Evaluated at bid price : 24.82
Bid-YTW : 5.70 %
BILP.PR.A FixedReset Prem 21,400 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2031-10-01
Maturity Price : 25.00
Evaluated at bid price : 25.06
Bid-YTW : 5.84 %
PWF.PR.F Perpetual-Discount 18,500 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-28
Maturity Price : 22.17
Evaluated at bid price : 22.45
Bid-YTW : 5.87 %
PVS.PR.N SplitShare 15,100 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2033-09-29
Maturity Price : 25.00
Evaluated at bid price : 25.00
Bid-YTW : 5.35 %
MFC.PR.F FixedReset Ins Non 14,500 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-28
Maturity Price : 21.20
Evaluated at bid price : 21.20
Bid-YTW : 5.85 %
PWF.PR.P FixedReset Disc 13,350 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-28
Maturity Price : 21.40
Evaluated at bid price : 21.40
Bid-YTW : 5.91 %
There were 2 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
See TMX DataLinx: ‘Last’ != ‘Close’ and the posts linked therein for an idea of why these quotes are so horrible.
Issue Index Quote Data and Yield Notes
GWO.PR.G Insurance Straight Quote: 21.15 – 22.83
Spot Rate : 1.6800
Average : 1.1621

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-28
Maturity Price : 21.15
Evaluated at bid price : 21.15
Bid-YTW : 6.23 %

CU.PR.G Perpetual-Discount Quote: 19.00 – 21.20
Spot Rate : 2.2000
Average : 1.7758

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-28
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 6.03 %

ENB.PF.C FixedReset Disc Quote: 23.00 – 24.00
Spot Rate : 1.0000
Average : 0.5853

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-28
Maturity Price : 22.40
Evaluated at bid price : 23.00
Bid-YTW : 6.67 %

CU.PR.J Perpetual-Discount Quote: 21.80 – 26.00
Spot Rate : 4.2000
Average : 3.8283

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-28
Maturity Price : 21.52
Evaluated at bid price : 21.80
Bid-YTW : 5.53 %

POW.PR.B Perpetual-Discount Quote: 22.67 – 23.75
Spot Rate : 1.0800
Average : 0.7179

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-28
Maturity Price : 22.41
Evaluated at bid price : 22.67
Bid-YTW : 5.94 %

IFC.PR.F Insurance Straight Quote: 23.25 – 24.49
Spot Rate : 1.2400
Average : 0.8995

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-28
Maturity Price : 22.98
Evaluated at bid price : 23.25
Bid-YTW : 5.76 %

Canada Prime

BoC Hikes Policy Rate 25bp to 2.50%; Prime Follows

The Bank of Canada has announced it has:

increased its target for the overnight rate by 25 basis points to 2.5%, with the Bank Rate at 2.75% and the deposit rate at 2.45%.

Since the July Monetary Policy Report, global economic activity has remained resilient, despite higher energy prices. In the United States, the economy continues to grow at a robust pace, supported by consumer spending and AI-related investment. Growth in the euro area has been resilient and broad-based. After slowing in the second quarter, Chinese growth rebounded in the third quarter, owing to strength in exports and a pickup in fiscal spending. With persistently elevated oil prices and refinery margins, inflation has risen in most countries.

Given the ongoing resilience of the global economy, the Bank has revised up global GDP growth slightly to 3.1% in 2026, while growth in 2027 and 2028 remains unchanged from the July projection at 3.2%.

Global financial conditions have tightened since July. Advanced economy sovereign bond yields are higher. Equity and credit markets have been volatile due to uncertainty about the outlook for the AI sector. The Canadian dollar had weakened somewhat on US-dollar strength but has since recovered to around 71 cents – the same as assumed in the July Report.

Growth picked up in Canada through the middle of the year. GDP growth was 3.3% in the second quarter, and recent indicators point to growth of about 2% in the third quarter. This is stronger than expected in the July Report. Consumer spending has been solid, even with slow population growth. Business investment rebounded, reflecting oil and gas sector activity and spending on machinery and equipment. Despite ongoing weakness in sectors affected by US tariffs, exports overall have strengthened, owing to robust US demand, higher energy production and increasing signs that businesses are adapting to the changing trade environment. The unemployment rate has been around 6½% for several months. A broad set of indicators continue to point to some excess supply in the economy.

Owing to new US tariffs, growth is expected to slow in the fourth quarter of 2026, before picking up again in 2027. This rebound is supported by business investment, exports and fiscal measures. Consumption growth is expected to moderate and housing to remain relatively weak.

The Canadian economy is expected to grow 1% in 2026, and 2% in 2027 and 2028. This is a somewhat stronger overall growth projection than the July Report. This forecast is still subject to considerable uncertainty, particularly regarding Canada-US trade relations.

Given persistently high oil prices, CPI inflation has been around 3% since April and is expected to rise to about 3½% by the end of the year. Excluding gasoline, inflation was 2.2% in September and measures of core inflation remain close to 2%. But cost pressures are building, with high fuel prices raising the costs of production and transportation. Imported industrial and electronics input prices have also increased. While businesses have mostly absorbed higher input costs so far, Bank surveys suggest cost pass-through will increase over the next year. Near-term household and business inflation expectations have risen, while longer-term inflation expectations remain well anchored.

The conflict in the Middle East is now in its eighth month and there is no clear path to resolution. The combination of higher-for-longer energy prices and increased pass-through adds to the persistence of inflation in the projection. CPI inflation is expected to average 3% in 2027, a percentage point above the July projection, then come down to 2% in the middle of 2028. The main sources of uncertainty around this forecast are developments in the Middle East and businesses’ responses to cost pressures.

In the outlook, inflation is higher and more persistent than in the July Report. Growth has picked up this year and is expected to recover further. Against this backdrop, Governing Council decided to increase the policy rate to reduce the risk that continuing high energy prices spread broadly to the prices of other goods and services. There could be a need to increase the policy rate further, but given uncertainties, Governing Council agreed to proceed carefully. The Bank remains committed to maintaining Canadians’ confidence in price stability.

Mark Rendell in the Globe comments:

Interest rate swap markets, which capture market expectations for monetary policy, are pricing in three more quarter-point rate hikes before the end of 2027, according to Bloomberg data, with a roughly 60-per-cent chance of another hike at the bank’s next meeting in December. Analysts are generally anticipating two to four more hikes.
…
Several hours after the Bank of Canada’s decision, the U.S. Federal Reserve announced that it was holding its benchmark rate steady following a rate hike last month. The hold was widely expected, not least because the decision landed only days before the U.S. midterms. Markets are betting the Fed will resume hikes in December.
…
The bank upgraded its forecast for annualized gross domestic product growth in the third quarter to 2 per cent from 1.5 per cent. It also raised its GDP forecast for 2027 and 2028 to 2 per cent in each year, from a previous forecast of 1.8 per cent in both years.

The bank noted high energy prices are spurring investment in the oil and gas sector, government spending is supporting growth and consumer spending remains robust, despite a slowdown in population growth.

The bank also released its Monetary Policy Report, which noted:

The nominal neutral interest rate in Canada is assumed to be at the midpoint of
its estimated range of 2.25% to 3.25%.

Prime followed:

Well, Rob Carrick and Ryan Siever will be mad – nothing on the way up, nothing on the way down and nothing so far on the way back up:

There’s a case to be made for banks giving borrowers a break when what is expected to be the biggest interest rate hike in 22 years is announced on Wednesday.

A brief flashback to 2015 is required to get the sense of this story. The economy back then was in the opposite shape of what it is now – weak enough to prompt the Bank of Canada to cut its trendsetting overnight rate by 0.25 of a percentage point in January and again in July.

The big banks hijacked part of that rate cut. While the overnight rate fell by a total 0.5 of a point, the banks cut their prime rate by cumulative 0.3 of a point. They held back the rest of the rate cut to build their revenues and profit.

There was a delay in reducing the prime when the Canada Overnight rate dropped 25bp to 0.75% in January 2015 and again when Canada Overnight dropped a further 25bp to 0.50% in July of that year.

Market Action

October 27, 2026

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.0680 % 2,766.9
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.0680 % 5,210.6
Floater 5.30 % 5.36 % 25,369 14.89 2 -0.0680 % 3,002.9
OpRet 0.00 % 0.00 % 0 0.00 0 0.0240 % 3,610.4
SplitShare 4.80 % 5.36 % 59,338 2.42 5 0.0240 % 4,311.6
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0240 % 3,364.1
Perpetual-Premium 0.00 % 0.00 % 0 0.00 0 -0.2434 % 3,037.2
Perpetual-Discount 5.76 % 5.82 % 49,912 14.12 32 -0.2434 % 3,268.1
FixedReset Disc 5.71 % 6.19 % 79,925 13.33 25 -0.0737 % 3,360.9
Insurance Straight 5.67 % 5.76 % 67,260 14.23 19 0.2832 % 3,171.3
FloatingReset 0.00 % 0.00 % 0 0.00 0 -0.0737 % 4,103.7
FixedReset Prem 6.05 % 4.97 % 76,448 1.92 24 -0.0522 % 2,610.5
FixedReset Bank Non 0.00 % 0.00 % 0 0.00 0 -0.0737 % 3,435.5
FixedReset Ins Non 5.62 % 5.73 % 48,305 13.95 13 0.6378 % 3,240.6
Performance Highlights
Issue Index Change Notes
CU.PR.G Perpetual-Discount -9.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-27
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 6.03 %
CU.PR.E Perpetual-Discount -6.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-27
Maturity Price : 21.04
Evaluated at bid price : 21.04
Bid-YTW : 5.93 %
PWF.PR.K Perpetual-Discount -2.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-27
Maturity Price : 21.05
Evaluated at bid price : 21.05
Bid-YTW : 5.92 %
GWO.PR.Q Insurance Straight -1.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-27
Maturity Price : 21.78
Evaluated at bid price : 22.03
Bid-YTW : 5.90 %
POW.PR.C Perpetual-Discount -1.37 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2026-11-26
Maturity Price : 25.00
Evaluated at bid price : 25.15
Bid-YTW : 0.81 %
BMO.PR.E FixedReset Prem -1.35 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2028-11-25
Maturity Price : 25.00
Evaluated at bid price : 26.26
Bid-YTW : 4.87 %
FTS.PR.F Perpetual-Discount 1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-27
Maturity Price : 22.22
Evaluated at bid price : 22.50
Bid-YTW : 5.52 %
PWF.PR.H Perpetual-Discount 1.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-27
Maturity Price : 24.29
Evaluated at bid price : 24.59
Bid-YTW : 5.87 %
GWO.PR.L Insurance Straight 2.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-27
Maturity Price : 24.19
Evaluated at bid price : 24.45
Bid-YTW : 5.84 %
MFC.PR.N FixedReset Ins Non 4.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-27
Maturity Price : 23.07
Evaluated at bid price : 24.34
Bid-YTW : 5.90 %
IFC.PR.A FixedReset Ins Non 4.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-27
Maturity Price : 23.27
Evaluated at bid price : 23.77
Bid-YTW : 5.57 %
GWO.PR.S Insurance Straight 5.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-27
Maturity Price : 22.49
Evaluated at bid price : 22.75
Bid-YTW : 5.83 %
POW.PR.H Perpetual-Discount 7.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-27
Maturity Price : 24.60
Evaluated at bid price : 25.01
Bid-YTW : 5.78 %
Volume Highlights
Issue Index Shares
Traded
Notes
BN.PF.N FixedReset Disc 47,950 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-27
Maturity Price : 23.12
Evaluated at bid price : 24.91
Bid-YTW : 5.68 %
PVS.PR.N SplitShare 37,800 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2033-09-29
Maturity Price : 25.00
Evaluated at bid price : 24.86
Bid-YTW : 5.45 %
FFH.PR.K FixedReset Prem 27,626 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2027-03-31
Maturity Price : 25.00
Evaluated at bid price : 25.20
Bid-YTW : 4.06 %
BILP.PR.A FixedReset Prem 18,800 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2031-10-01
Maturity Price : 25.00
Evaluated at bid price : 25.10
Bid-YTW : 5.79 %
SLF.PR.G FixedReset Ins Non 18,236 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-27
Maturity Price : 21.24
Evaluated at bid price : 21.24
Bid-YTW : 5.73 %
BN.PF.A FixedReset Prem 17,374 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2028-09-30
Maturity Price : 25.00
Evaluated at bid price : 25.43
Bid-YTW : 6.11 %
There were 8 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
See TMX DataLinx: ‘Last’ != ‘Close’ and the posts linked therein for an idea of why these quotes are so horrible.
Issue Index Quote Data and Yield Notes
CU.PR.G Perpetual-Discount Quote: 19.00 – 21.20
Spot Rate : 2.2000
Average : 1.3106

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-27
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 6.03 %

CU.PR.J Perpetual-Discount Quote: 21.80 – 26.00
Spot Rate : 4.2000
Average : 3.4208

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-27
Maturity Price : 21.52
Evaluated at bid price : 21.80
Bid-YTW : 5.52 %

CU.PR.E Perpetual-Discount Quote: 21.04 – 22.84
Spot Rate : 1.8000
Average : 1.2075

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-27
Maturity Price : 21.04
Evaluated at bid price : 21.04
Bid-YTW : 5.93 %

SLF.PR.D Insurance Straight Quote: 20.19 – 21.07
Spot Rate : 0.8800
Average : 0.6396

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-27
Maturity Price : 20.19
Evaluated at bid price : 20.19
Bid-YTW : 5.58 %

MFC.PR.M FixedReset Ins Non Quote: 24.27 – 25.27
Spot Rate : 1.0000
Average : 0.8567

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-27
Maturity Price : 23.07
Evaluated at bid price : 24.27
Bid-YTW : 6.06 %

PWF.PR.K Perpetual-Discount Quote: 21.05 – 21.56
Spot Rate : 0.5100
Average : 0.3667

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-27
Maturity Price : 21.05
Evaluated at bid price : 21.05
Bid-YTW : 5.92 %

Market Action

October 26, 2026

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.0340 % 2,768.8
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.0340 % 5,214.1
Floater 5.30 % 5.36 % 24,917 14.90 2 -0.0340 % 3,004.9
OpRet 0.00 % 0.00 % 0 0.00 0 0.2408 % 3,609.5
SplitShare 4.80 % 5.36 % 61,686 2.42 5 0.2408 % 4,310.6
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.2408 % 3,363.3
Perpetual-Premium 0.00 % 0.00 % 0 0.00 0 -0.2483 % 3,044.6
Perpetual-Discount 5.75 % 5.79 % 49,272 14.17 32 -0.2483 % 3,276.0
FixedReset Disc 5.70 % 6.19 % 80,115 13.33 25 0.2250 % 3,363.4
Insurance Straight 5.69 % 5.76 % 68,014 14.25 19 -0.2227 % 3,162.4
FloatingReset 0.00 % 0.00 % 0 0.00 0 0.2250 % 4,106.7
FixedReset Prem 6.04 % 5.01 % 77,604 1.92 24 -0.1612 % 2,611.9
FixedReset Bank Non 0.00 % 0.00 % 0 0.00 0 0.2250 % 3,438.0
FixedReset Ins Non 5.66 % 5.72 % 48,805 13.75 13 -0.0064 % 3,220.0
Performance Highlights
Issue Index Change Notes
POW.PR.H Perpetual-Discount -6.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-26
Maturity Price : 23.05
Evaluated at bid price : 23.35
Bid-YTW : 6.20 %
GWO.PR.S Insurance Straight -5.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-26
Maturity Price : 21.51
Evaluated at bid price : 21.51
Bid-YTW : 6.18 %
CU.PR.K Perpetual-Discount -4.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-26
Maturity Price : 23.29
Evaluated at bid price : 23.60
Bid-YTW : 6.03 %
MFC.PR.M FixedReset Ins Non -3.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-26
Maturity Price : 23.09
Evaluated at bid price : 24.30
Bid-YTW : 6.05 %
GWO.PR.L Insurance Straight -2.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-26
Maturity Price : 23.51
Evaluated at bid price : 23.78
Bid-YTW : 6.00 %
PWF.PR.H Perpetual-Discount -1.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-26
Maturity Price : 23.92
Evaluated at bid price : 24.18
Bid-YTW : 5.97 %
POW.PR.A Perpetual-Discount -1.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-26
Maturity Price : 23.85
Evaluated at bid price : 24.10
Bid-YTW : 5.85 %
CU.PR.E Perpetual-Discount 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-26
Maturity Price : 22.30
Evaluated at bid price : 22.57
Bid-YTW : 5.50 %
ENB.PR.H FixedReset Disc 1.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-26
Maturity Price : 23.41
Evaluated at bid price : 24.46
Bid-YTW : 5.94 %
MFC.PR.Q FixedReset Ins Non 2.24 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2028-06-19
Maturity Price : 25.00
Evaluated at bid price : 25.56
Bid-YTW : 4.93 %
POW.PR.G Perpetual-Discount 3.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-26
Maturity Price : 24.21
Evaluated at bid price : 24.50
Bid-YTW : 5.75 %
FTS.PR.J Perpetual-Discount 5.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-26
Maturity Price : 21.59
Evaluated at bid price : 21.85
Bid-YTW : 5.51 %
Volume Highlights
Issue Index Shares
Traded
Notes
BN.PF.N FixedReset Disc 100,000 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-26
Maturity Price : 23.13
Evaluated at bid price : 24.93
Bid-YTW : 5.67 %
FTS.PR.H FixedReset Disc 26,500 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-26
Maturity Price : 20.25
Evaluated at bid price : 20.25
Bid-YTW : 6.07 %
MFC.PR.F FixedReset Ins Non 23,400 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-26
Maturity Price : 21.15
Evaluated at bid price : 21.15
Bid-YTW : 5.86 %
ENB.PF.E FixedReset Disc 18,700 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-26
Maturity Price : 22.83
Evaluated at bid price : 23.85
Bid-YTW : 6.39 %
TD.PF.I FixedReset Prem 12,500 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2027-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.39
Bid-YTW : 4.66 %
BILP.PR.A FixedReset Prem 10,900 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2031-10-01
Maturity Price : 25.00
Evaluated at bid price : 25.05
Bid-YTW : 5.84 %
There were 0 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
See TMX DataLinx: ‘Last’ != ‘Close’ and the posts linked therein for an idea of why these quotes are so horrible.
Issue Index Quote Data and Yield Notes
CU.PR.J Perpetual-Discount Quote: 21.80 – 26.00
Spot Rate : 4.2000
Average : 2.5665

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-26
Maturity Price : 21.52
Evaluated at bid price : 21.80
Bid-YTW : 5.52 %

POW.PR.H Perpetual-Discount Quote: 23.35 – 25.07
Spot Rate : 1.7200
Average : 1.0021

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-26
Maturity Price : 23.05
Evaluated at bid price : 23.35
Bid-YTW : 6.20 %

GWO.PR.S Insurance Straight Quote: 21.51 – 22.94
Spot Rate : 1.4300
Average : 0.9129

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-26
Maturity Price : 21.51
Evaluated at bid price : 21.51
Bid-YTW : 6.18 %

CU.PR.K Perpetual-Discount Quote: 23.60 – 24.80
Spot Rate : 1.2000
Average : 0.8185

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-26
Maturity Price : 23.29
Evaluated at bid price : 23.60
Bid-YTW : 6.03 %

MFC.PR.M FixedReset Ins Non Quote: 24.30 – 25.30
Spot Rate : 1.0000
Average : 0.6995

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-26
Maturity Price : 23.09
Evaluated at bid price : 24.30
Bid-YTW : 6.05 %

FTS.PR.F Perpetual-Discount Quote: 22.27 – 23.35
Spot Rate : 1.0800
Average : 0.8148

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-26
Maturity Price : 22.04
Evaluated at bid price : 22.27
Bid-YTW : 5.58 %

Market Action

October 23, 2026

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.1019 % 2,769.8
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.1019 % 5,215.9
Floater 5.30 % 5.36 % 25,932 14.91 2 -0.1019 % 3,005.9
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0722 % 3,600.9
SplitShare 4.82 % 5.43 % 60,401 2.43 5 -0.0722 % 4,300.2
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0722 % 3,355.2
Perpetual-Premium 0.00 % 0.00 % 0 0.00 0 0.0165 % 3,052.2
Perpetual-Discount 5.73 % 5.77 % 51,211 14.17 32 0.0165 % 3,284.2
FixedReset Disc 5.71 % 6.29 % 83,438 13.26 25 0.0891 % 3,355.8
Insurance Straight 5.68 % 5.77 % 70,846 14.23 19 0.1967 % 3,169.4
FloatingReset 0.00 % 0.00 % 0 0.00 0 0.0891 % 4,097.5
FixedReset Prem 6.03 % 4.84 % 78,035 1.93 24 -0.2129 % 2,616.1
FixedReset Bank Non 0.00 % 0.00 % 0 0.00 0 0.0891 % 3,430.3
FixedReset Ins Non 5.66 % 5.83 % 48,467 13.62 13 -0.5924 % 3,220.2
Performance Highlights
Issue Index Change Notes
IFC.PR.A FixedReset Ins Non -4.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-23
Maturity Price : 22.06
Evaluated at bid price : 22.70
Bid-YTW : 5.93 %
POW.PR.G Perpetual-Discount -3.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-23
Maturity Price : 23.38
Evaluated at bid price : 23.67
Bid-YTW : 5.95 %
MFC.PR.N FixedReset Ins Non -3.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-23
Maturity Price : 22.54
Evaluated at bid price : 23.25
Bid-YTW : 6.29 %
GWO.PR.Z Insurance Straight -1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-23
Maturity Price : 24.17
Evaluated at bid price : 24.56
Bid-YTW : 5.85 %
ENB.PF.G FixedReset Disc -1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-23
Maturity Price : 22.73
Evaluated at bid price : 23.71
Bid-YTW : 6.58 %
POW.PR.B Perpetual-Discount -1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-23
Maturity Price : 23.15
Evaluated at bid price : 23.41
Bid-YTW : 5.75 %
SLF.PR.G FixedReset Ins Non -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-23
Maturity Price : 21.19
Evaluated at bid price : 21.19
Bid-YTW : 5.83 %
PWF.PR.Z Perpetual-Discount 1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-23
Maturity Price : 21.82
Evaluated at bid price : 22.06
Bid-YTW : 5.86 %
GWO.PR.R Insurance Straight 1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-23
Maturity Price : 20.91
Evaluated at bid price : 20.91
Bid-YTW : 5.81 %
BMO.PR.E FixedReset Prem 1.29 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2028-11-25
Maturity Price : 25.00
Evaluated at bid price : 26.60
Bid-YTW : 4.17 %
CU.PR.G Perpetual-Discount 1.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-23
Maturity Price : 20.95
Evaluated at bid price : 20.95
Bid-YTW : 5.46 %
PWF.PR.O Perpetual-Discount 2.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-23
Maturity Price : 24.47
Evaluated at bid price : 24.71
Bid-YTW : 5.89 %
MFC.PR.M FixedReset Ins Non 3.28 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2029-12-20
Maturity Price : 25.00
Evaluated at bid price : 25.19
Bid-YTW : 5.49 %
GWO.PR.H Insurance Straight 3.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-23
Maturity Price : 21.21
Evaluated at bid price : 21.21
Bid-YTW : 5.78 %
Volume Highlights
Issue Index Shares
Traded
Notes
BN.PF.N FixedReset Disc 117,779 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-23
Maturity Price : 23.12
Evaluated at bid price : 24.92
Bid-YTW : 5.74 %
PVS.PR.N SplitShare 13,600 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2033-09-29
Maturity Price : 25.00
Evaluated at bid price : 24.86
Bid-YTW : 5.43 %
BILP.PR.A FixedReset Prem 13,090 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2031-10-01
Maturity Price : 25.00
Evaluated at bid price : 25.05
Bid-YTW : 5.83 %
FTS.PR.H FixedReset Disc 12,700 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-23
Maturity Price : 20.25
Evaluated at bid price : 20.25
Bid-YTW : 6.16 %
SLF.PR.D Insurance Straight 10,940 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-23
Maturity Price : 20.17
Evaluated at bid price : 20.17
Bid-YTW : 5.58 %
SLF.PR.C Insurance Straight 10,021 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-23
Maturity Price : 20.14
Evaluated at bid price : 20.14
Bid-YTW : 5.59 %
There were 0 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
See TMX DataLinx: ‘Last’ != ‘Close’ and the posts linked therein for an idea of why these quotes are so horrible.
Issue Index Quote Data and Yield Notes
PWF.PR.P FixedReset Disc Quote: 21.40 – 25.00
Spot Rate : 3.6000
Average : 2.1169

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-23
Maturity Price : 21.40
Evaluated at bid price : 21.40
Bid-YTW : 5.99 %

ENB.PR.J FixedReset Disc Quote: 24.70 – 25.85
Spot Rate : 1.1500
Average : 0.6478

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-23
Maturity Price : 23.39
Evaluated at bid price : 24.70
Bid-YTW : 6.34 %

IFC.PR.A FixedReset Ins Non Quote: 22.70 – 23.89
Spot Rate : 1.1900
Average : 0.7349

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-23
Maturity Price : 22.06
Evaluated at bid price : 22.70
Bid-YTW : 5.93 %

MFC.PR.N FixedReset Ins Non Quote: 23.25 – 24.69
Spot Rate : 1.4400
Average : 1.0744

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-23
Maturity Price : 22.54
Evaluated at bid price : 23.25
Bid-YTW : 6.29 %

MFC.PR.B Insurance Straight Quote: 21.00 – 22.00
Spot Rate : 1.0000
Average : 0.6695

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-23
Maturity Price : 21.00
Evaluated at bid price : 21.00
Bid-YTW : 5.61 %

POW.PR.G Perpetual-Discount Quote: 23.67 – 24.57
Spot Rate : 0.9000
Average : 0.5765

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-23
Maturity Price : 23.38
Evaluated at bid price : 23.67
Bid-YTW : 5.95 %

Market Action

October 22, 2026

Interesting times for equities!

Stocks tumbled on Thursday and the Nasdaq posted its steepest daily drop since early June as a batch of high-profile earnings reports ignited fresh fears about the AI spending race, sending investors scurrying to the safety of the bond market. Yields on U.S. Treasuries, which move inversely to prices, saw some of their biggest one-day declines in years.
…
Meta Platforms’ results beat analyst expectations, but its stock slid 7.0% as the Facebook parent posted its first cash outflow in more than a decade due to ​its AI-related expenditures and announced plans to issue non-voting shares in a two-for-one split to ‌raise capital to spend on the nascent technology.
…
Domestically, markets are pricing in nearly 80% odds that the Bank of Canada will hike interest rates next week, in what would be its first move on rates in a year, as it fights off the inflationary impact of surging crude oil prices. Several economists, however, say the bank should stay on hold for now.

The yield on the benchmark US ⁠10-year Treasury note fell 19.3 basis points to 4.953%, its biggest daily drop since ​March 10, 2023. The yield had risen to 5.3645% on October 7, its highest since April 2002.
…
The Dow Jones Industrial Average rose 11.89 points, or 0.02%, to 52,867.98, the S&P 500 lost 93.74 points, or 1.21%, to 7,663.43 and the Nasdaq Composite lost 694.00 points, or 2.60%, to 26,008.86.

The S&P/TSX Composite Index ended down 351.54 points, or 1%, at 35,973.45. It posted on Wednesday its highest closing level since September 22.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.1018 % 2,772.6
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.1018 % 5,221.2
Floater 5.29 % 5.35 % 50,977 14.92 2 -0.1018 % 3,009.0
OpRet 0.00 % 0.00 % 0 0.00 0 -0.2640 % 3,603.5
SplitShare 4.81 % 5.43 % 60,822 2.43 5 -0.2640 % 4,303.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.2640 % 3,357.6
Perpetual-Premium 0.00 % 0.00 % 0 0.00 0 -0.1753 % 3,051.7
Perpetual-Discount 5.74 % 5.78 % 50,675 14.19 32 -0.1753 % 3,283.6
FixedReset Disc 5.72 % 6.33 % 84,171 13.26 25 -0.1436 % 3,352.8
Insurance Straight 5.69 % 5.77 % 71,726 14.21 19 -0.0456 % 3,163.2
FloatingReset 0.00 % 0.00 % 0 0.00 0 -0.1436 % 4,093.8
FixedReset Prem 6.02 % 4.81 % 77,694 1.93 24 -0.1395 % 2,621.7
FixedReset Bank Non 0.00 % 0.00 % 0 0.00 0 -0.1436 % 3,427.3
FixedReset Ins Non 5.62 % 5.77 % 48,801 13.70 13 -0.4685 % 3,239.4
Performance Highlights
Issue Index Change Notes
FTS.PR.J Perpetual-Discount -5.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-22
Maturity Price : 20.80
Evaluated at bid price : 20.80
Bid-YTW : 5.81 %
GWO.PR.H Insurance Straight -3.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-22
Maturity Price : 20.51
Evaluated at bid price : 20.51
Bid-YTW : 5.98 %
MFC.PR.M FixedReset Ins Non -3.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-22
Maturity Price : 23.12
Evaluated at bid price : 24.39
Bid-YTW : 6.11 %
PWF.PR.O Perpetual-Discount -2.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-22
Maturity Price : 23.93
Evaluated at bid price : 24.17
Bid-YTW : 6.02 %
GWO.PR.R Insurance Straight -2.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-22
Maturity Price : 20.65
Evaluated at bid price : 20.65
Bid-YTW : 5.88 %
BMO.PR.E FixedReset Prem -1.83 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2028-11-25
Maturity Price : 25.00
Evaluated at bid price : 26.26
Bid-YTW : 4.84 %
IFC.PR.G FixedReset Ins Non -1.61 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2028-06-30
Maturity Price : 25.00
Evaluated at bid price : 25.10
Bid-YTW : 6.03 %
CU.PR.E Perpetual-Discount -1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-22
Maturity Price : 21.97
Evaluated at bid price : 22.20
Bid-YTW : 5.60 %
BN.PR.T FixedReset Disc -1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-22
Maturity Price : 22.50
Evaluated at bid price : 23.45
Bid-YTW : 6.33 %
BN.PR.X FixedReset Disc -1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-22
Maturity Price : 21.33
Evaluated at bid price : 21.60
Bid-YTW : 6.35 %
PWF.PR.Z Perpetual-Discount -1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-22
Maturity Price : 21.56
Evaluated at bid price : 21.82
Bid-YTW : 5.92 %
IFC.PR.F Insurance Straight 1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-22
Maturity Price : 23.20
Evaluated at bid price : 23.50
Bid-YTW : 5.69 %
POW.PR.B Perpetual-Discount 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-22
Maturity Price : 23.38
Evaluated at bid price : 23.67
Bid-YTW : 5.68 %
PWF.PR.K Perpetual-Discount 1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-22
Maturity Price : 21.50
Evaluated at bid price : 21.50
Bid-YTW : 5.79 %
IFC.PR.E Insurance Straight 1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-22
Maturity Price : 22.82
Evaluated at bid price : 23.10
Bid-YTW : 5.68 %
ENB.PF.G FixedReset Disc 1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-22
Maturity Price : 22.87
Evaluated at bid price : 24.00
Bid-YTW : 6.49 %
FTS.PR.F Perpetual-Discount 1.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-22
Maturity Price : 22.34
Evaluated at bid price : 22.61
Bid-YTW : 5.49 %
GWO.PR.Z Insurance Straight 2.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-22
Maturity Price : 24.47
Evaluated at bid price : 24.88
Bid-YTW : 5.77 %
Volume Highlights
Issue Index Shares
Traded
Notes
BN.PF.N FixedReset Disc 466,011 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-22
Maturity Price : 23.13
Evaluated at bid price : 24.93
Bid-YTW : 5.74 %
PVS.PR.N SplitShare 161,767 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2033-09-29
Maturity Price : 25.00
Evaluated at bid price : 24.75
Bid-YTW : 5.51 %
CU.PR.G Perpetual-Discount 66,200 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-22
Maturity Price : 20.60
Evaluated at bid price : 20.60
Bid-YTW : 5.55 %
PVS.PR.H SplitShare 63,162 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2027-02-28
Maturity Price : 25.00
Evaluated at bid price : 25.06
Bid-YTW : 5.72 %
ENB.PR.B FixedReset Disc 58,900 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-22
Maturity Price : 22.99
Evaluated at bid price : 23.70
Bid-YTW : 6.45 %
ENB.PR.J FixedReset Disc 56,100 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-22
Maturity Price : 23.38
Evaluated at bid price : 24.68
Bid-YTW : 6.34 %
There were 5 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
See TMX DataLinx: ‘Last’ != ‘Close’ and the posts linked therein for an idea of why these quotes are so horrible.
Issue Index Quote Data and Yield Notes
SLF.PR.C Insurance Straight Quote: 20.11 – 21.95
Spot Rate : 1.8400
Average : 1.0611

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-22
Maturity Price : 20.11
Evaluated at bid price : 20.11
Bid-YTW : 5.59 %

FTS.PR.J Perpetual-Discount Quote: 20.80 – 22.15
Spot Rate : 1.3500
Average : 0.8969

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-22
Maturity Price : 20.80
Evaluated at bid price : 20.80
Bid-YTW : 5.81 %

MFC.PR.M FixedReset Ins Non Quote: 24.39 – 25.39
Spot Rate : 1.0000
Average : 0.6551

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-22
Maturity Price : 23.12
Evaluated at bid price : 24.39
Bid-YTW : 6.11 %

PWF.PR.O Perpetual-Discount Quote: 24.17 – 24.95
Spot Rate : 0.7800
Average : 0.4787

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-22
Maturity Price : 23.93
Evaluated at bid price : 24.17
Bid-YTW : 6.02 %

BMO.PR.E FixedReset Prem Quote: 26.26 – 26.96
Spot Rate : 0.7000
Average : 0.4088

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2028-11-25
Maturity Price : 25.00
Evaluated at bid price : 26.26
Bid-YTW : 4.84 %

GWO.PR.H Insurance Straight Quote: 20.51 – 21.40
Spot Rate : 0.8900
Average : 0.6070

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-10-22
Maturity Price : 20.51
Evaluated at bid price : 20.51
Bid-YTW : 5.98 %