Category: New Issues

New Issues

New Issue: EFN FixedReset, 6.50%+534 (EFN.PR.G)

Element Financial Corporation has announced:

it plans to sell, on a “bought deal” basis, $1,550 million of subscription receipts (“Subscription Receipts”), $500 million aggregate principal amount of extendible convertible unsecured subordinated debentures (“Debentures”) and $150 million cumulative 5-year rate reset preferred shares, Series G of Element (“Series G Preferred Shares”). The Company intends to use the net proceeds from the Offerings (as defined below) to fund future acquisitions.
…
Element has entered into an agreement to sell, on a bought deal basis, 6,000,000 Series G Preferred Shares at a price of $25.00 per Series G Preferred Share for gross proceeds of $150 million (the “Preferred Share Offering”, and with the Subscription Receipt Offering and the Debenture Offering, the “Offerings”). Holders of the Series G Preferred Shares will be entitled, if, as and when declared by the Board of Directors of Element, to receive a cumulative quarterly fixed dividend for the initial five-year period ending September 30, 2020 of 6.50% per annum. Thereafter, the dividend rate will reset every five years to an annual dividend rate equal to the 5-Year Government of Canada Bond Yield as quoted on Bloomberg on the 30th day prior to the first day of the relevant subsequent five year fixed rate period plus 5.34%.

Holders of the Series G Preferred Shares will have the right to convert their shares into cumulative floating rate preferred shares, Series H of Element (“Series H Preferred Shares”), subject to certain conditions and Element’s right to redeem the Series G Preferred Shares, on September 30, 2020 and on September 30 every five years thereafter. Holders of the Series H Preferred Shares will be entitled to receive a quarterly floating rate dividend, if, as and when declared by the Board of Directors of Element, equal to the then current three-month Government of Canada Treasury Bill plus 5.34%. Holders of the Series H Preferred Shares may convert their Series H Preferred Shares into Series G Preferred Shares, subject to certain conditions and Element’s right to redeem the Series H Preferred Shares, on September 30, 2025 and on September 30 every five years thereafter. The Series G Preferred Shares will not be rated. If an Eligible Transaction does not proceed, the net proceeds from the Preferred Share Offering will be used by Element for general corporate purposes.

The Preferred Share Offering is being led by BMO Capital Markets, CIBC World Markets Inc., National Bank Financial Inc., RBC Capital Markets, and TD Securities, and includes GMP Securities L.P., Cormark Securities Inc., Desjardins Securities Inc., Manulife Securities Inc., and Scotiabank (collectively, the “Preferred Share Underwriters”).

This issue joins EFN.PR.A (FixedReset, 6.60%+471); EFN.PR.C (FixedReset, 6.50%+481); and EFN.PR.E (FixedReset, 6.40%+472).

As with the three previous issues, this issue will not be tracked by HIMIPref™ on the grounds that it is not rated. This is not because I can’t come to my own views regarding credit quality, or because I worship the Credit Rating Agencies, but because I feel the threat of an imminent downgrade from a major agency does an excellent job of focussing the minds of the directors and management that they have a problem that really should be addressed. A ‘Review-Negative’ by Hymas Investment Management does not have quite the same effect.
New Issues

New Issue: TD FixedReset, 3.70%+287

The Toronto-Dominion Bank has announced:

a domestic public offering of Non-Cumulative 5-Year Rate Reset Preferred Shares, Series 9 (the “Series 9 Shares”).

TD has entered into an agreement with a group of underwriters led by TD Securities Inc. to issue, on a bought deal basis, 8 million Series 9 Shares at a price of $25.00 per share to raise gross proceeds of $200 million. TD has also granted the underwriters an option to purchase, on the same terms, up to an additional 2 million Series 9 Shares. This option is exercisable in whole or in part by the underwriters at any time up to two business days prior to closing.

The Series 9 Shares will yield 3.70% annually, with dividends payable quarterly, as and when declared by the Board of Directors of TD, for the initial period ending October 31, 2020. Thereafter, the dividend rate will reset every five years at a level of 2.87% over the then five-year Government of Canada bond yield.

Subject to regulatory approval, on October 31, 2020 and on October 31 every 5 years thereafter, TD may redeem the Series 9 Shares, in whole or in part, at $25.00 per share. Subject to TD’s right of redemption and certain other conditions, holders of the Series 9 Shares will have the right to convert their shares into Non-Cumulative Floating Rate Preferred Shares, Series 10 (the “Series 10 Shares”), on October 31, 2020, and on October 31 every five years thereafter. Holders of the Series 10 Shares will be entitled to receive quarterly floating rate dividends, as and when declared by the Board of Directors of TD, equal to the three-month Government of Canada Treasury bill yield plus 2.87%.

The expected closing date is April 24, 2015. TD will make an application to list the Series 9 Shares as of the closing date on the Toronto Stock Exchange. The net proceeds of the offering will be used for general corporate purposes.

The Bank, as previously announced, will redeem its outstanding Non-cumulative Redeemable Class A First Preferred Shares, Series R on May 1, 2015.

The redemption of TD.PR.R has been previously reported on PrefBlog.

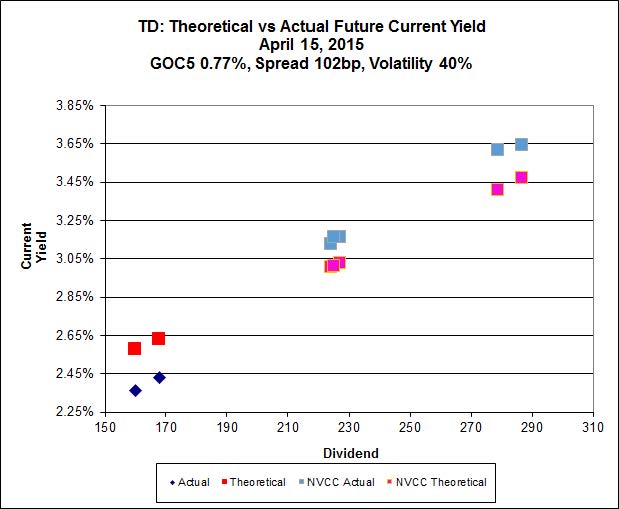
This new issue actually looks pretty reasonable. If we look at the standard Implied Volatility calculation …:

impVol_TD_150415_All
Click for Big

… we see that the Implied Volatility is very high, at 40%+, but that it appears that the (expected) relative richness of the NVCC non-compliant issues might be throwing off the calculation.

If the calculation is repeated using only the NVCC-compliant issues as sources of error …:

impVol_TD_150415_NVCC
Click For Big

… we see that our fears of material miscalculation are not realized: the Implied Volatility remains at 40%+.

This number is too high, ridiculously high. Although such high levels can be maintained for lengthy periods of time, they are associated with issues trading near par; the lowest price for a NVCC-compliant TD issues is 23.90 (for TD.PF.C, resetting 2020-1-31 at GOC-5 + 225bp), which is close enough to par that some people (I am sure) figure that it will always be close to par (an idea that has been dubbed the par always, shit forever hypothesis.

I conclude that the new issue is very attractively priced relative to the other TD NVCC FixedResets, as in the event of a spread-widening and consequent decline in price of each element of the series, the lower spread issues will significantly underperform as Implied Volatility declines to a more reasonable figure; of course, it is entirely possible and completely logical that the Implied Volatility will decline (flattening the curve) even in the absence of spread-widening for this series.

New Issues

New Issue: PPL FixedReset, 4.75%+391

Pembina Pipeline Corporation has announced:

that it has entered into an agreement with a syndicate of underwriters co-led by Scotiabank and RBC Capital Markets (together, the “Underwriters”) pursuant to which the Underwriters have agreed to purchase from Pembina 8,000,000 cumulative redeemable rate reset class A preferred shares, Series 9 (the “Series 9 Preferred Shares”) at a price of $25.00 per share for distribution to the public.

The holders of Series 9 Preferred Shares will be entitled to receive fixed cumulative dividends at an annual rate of $1.1875 per share, payable quarterly on the 1st day of March, June, September and December, as and when declared by the Board of Directors of Pembina, yielding 4.75 per cent per annum, for the initial fixed rate period to but excluding December 1, 2020. The first quarterly dividend payment date is scheduled for September 1, 2015. The dividend rate will reset on December 1, 2020 and every five years thereafter at a rate equal to the sum of the then five-year Government of Canada bond yield plus 3.91 per cent. The Series 9 Preferred Shares are redeemable by Pembina, at its option, on December 1, 2020 and on December 1 of every fifth year thereafter at a price of $25.00 per share plus accrued and unpaid dividends.

The holders of Series 9 Preferred Shares will have the right to convert their shares into cumulative redeemable floating rate class A preferred shares, Series 10 (the “Series 10 Preferred Shares”), subject to certain conditions, on December 1, 2020 and on December 1 of every fifth year thereafter. The holders of Series 10 Preferred Shares will be entitled to receive quarterly floating rate cumulative dividends, as and when declared by the Board of Directors of Pembina, at a rate equal to the sum of the then 90-day Government of Canada treasury bill rate plus 3.91 per cent.

Pembina has granted to the underwriters an option, exercisable at any time up to 48 hours prior to the closing of the offering, to purchase up to an additional 2,000,000 Series 9 Preferred Shares at a price of $25.00 per share.

Closing of the offering is expected on April 10, 2015, subject to customary closing conditions.

Proceeds from the offering will be used to reduce indebtedness under the Company’s credit facilities, which was incurred in connection with Pembina’s 2015 capital expenditure program.

The offering is being made by means of a prospectus supplement under the short form base shelf prospectus filed by the Company on March 18, 2015 in each of the provinces of Canada.

There is a whacking great first dividend on this, $0.4685, payable September 1, which will go ex around about maybe the end of July. There may be opportunities for dividend capture strategies in July!

Implied Volatility theory suggests that this issue is cheap relative to its peers – not because it is cheap to the fitted curve, but because the implied volatility is so large – ridiculously large, in fact – and the curve may therefore to be deemed likely to flatten.

impVol_PPL_150331
Click for Big

Update, 2015-4-6: Rated Pfd-3 by DBRS.

New Issues

New Issue: VSN FixedReset, 5.00%+427

Veresen Inc. has announced:

it has agreed to issue 8,000,000 Cumulative Redeemable Preferred Shares, Series E (“Series E Preferred Shares”) at a price of $25.00 per share for total gross proceeds of $200 million on a bought deal basis. The Series E Preferred Shares will be offered to the public through a syndicate of underwriters co-led by Scotiabank, TD Securities Inc. and RBC Capital Markets.

The holders of Series E Preferred Shares will be entitled to receive fixed cumulative dividends at an annual rate of 5.00%, representing $1.25 per share, payable quarterly for an initial period up to but excluding June 30, 2020, as and when declared by the Board of Directors of Veresen. The first quarterly dividend payment date is scheduled for June 30, 2015. The dividend rate will reset on June 30, 2020 and every five years thereafter at a rate equal to the sum of the then five-year Government of Canada bond yield plus 4.27%.

Subject to regulatory approval, the Series E Preferred Shares are redeemable by Veresen, in whole or in part, on June 30, 2020 and on June 30 of every fifth year thereafter at a price of $25.00 per share plus accrued and unpaid dividends.

The holders of Series E Preferred Shares will have the right to convert all or any part of their shares into Cumulative Redeemable Preferred Shares, Series F (“Series F Preferred Shares”), subject to certain conditions, on June 30, 2020, and on June 30 of every fifth year thereafter. The holders of Series F Preferred Shares will be entitled to receive quarterly floating rate cumulative dividends, as and when declared by the Board of Directors of Veresen, at a rate equal to the sum of the then 90-day Government of Canada Treasury Bill yield plus 4.27%.

The offering is expected to close on or about April 1, 2015, subject to customary closing conditions. Net proceeds from the offering will be used to repay amounts outstanding under the credit facility that Veresen entered into for purposes of financing its acquisition of a 50% convertible preferred interest in Ruby Pipeline Holding Company, L.L.C., the entity which indirectly owns the Ruby pipeline system.

The Series E Preferred Shares will be issued pursuant to a prospectus supplement that will be filed with the securities regulatory authority in each of the provinces of Canada under Veresen’s short form base shelf prospectus dated September 20, 2013. An application has been made to list the Series E Preferred Shares and the Series F Preferred Shares on the Toronto Stock Exchange.

This issue will join VSN.PR.A, a FixedReset 4.40%+292 that commenced trading 2012-2-14 and VSN.PR.E, a FixedReset 5.00%+301 that commenced trading 2013-10-21. One more and I can start calculating Implied Volatility!

Both extant issues were hit hard on the day: VSN.PR.A closed at 21.45-55, with the bid down 1.7% on the day, while VSN.PR.C closed at 24.00-12, with the bid down 3.7%.

New Issues

New Issue: RY FixedReset, 3.60%+262

Royal Bank of Canada has announced:

a domestic public offering of Non-Cumulative, 5-Year Rate Reset Preferred Shares Series BF.

Royal Bank of Canada will issue 12 million Preferred Shares Series BF priced at $25 per share to raise gross proceeds of $300 million. The bank has granted the Underwriters an option, exercisable in whole or in part, to purchase up to an additional 2 million Preferred Shares Series BF at the same offering price.

The Preferred Shares Series BF will yield 3.60 per cent annually, payable quarterly, as and when declared by the Board of Directors of Royal Bank of Canada, for the initial period ending November 24, 2020. Thereafter, the dividend rate will reset every five years at a rate equal to 2.62 per cent over the 5-year Government of Canada bond yield.

Subject to regulatory approval, on or after November 24, 2020, the bank may redeem the Preferred Shares Series BF in whole or in part at par. Holders of Preferred Shares Series BF will, subject to certain conditions, have the right to convert all or any part of their shares to Non-Cumulative Floating Rate Preferred Shares Series BG on November 24, 2020 and on November 24 every five years thereafter.

Holders of the Preferred Shares Series BG will be entitled to receive a non-cumulative quarterly floating dividend, as and when declared by the Board of Directors of Royal Bank of Canada, at a rate equal to the 3-month Government of Canada Treasury Bill yield plus 2.62 per cent. Holders of Preferred Shares Series BG will, subject to certain conditions, have the right to convert all or any part of their shares to Preferred Shares Series BF on November 24, 2025 and on November 24 every five years thereafter.

The offering will be underwritten by a syndicate led by RBC Capital Markets. The expected closing date is March 13, 2015.

We routinely undertake funding transactions to maintain strong capital ratios and a cost effective capital structure. Net proceeds from this transaction will be used for general business purposes.

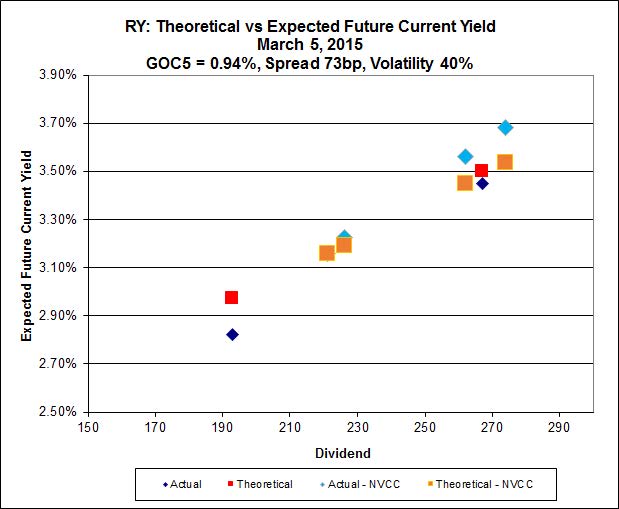
The issue will be NVCC compliant, so it will be treated as a true perpetual in the course of HIMIPref™ analysis.

The market’s certainty that anything issued by a Big Bank will keep its value, regardless of terms, is illustrated by the Implied Volatility chart – the Implied Volatility of 40%+ is completely unrealistic.

impVol_RY_150305
Click for Big
New Issues

New Issue: BIP FixedReset, 4.50%+356

Brookfield Infrastructure Partners L.P. has announced:

that it has agreed to issue 5,000,000 Cumulative Class A Preferred Limited Partnership Units, Series 1 (“Series 1 Preferred Units”) on a bought deal basis to a syndicate of underwriters led by CIBC, RBC Capital Markets, Scotiabank and TD Securities Inc. The Series 1 Preferred Units will be issued at a price of $25.00 per unit, for gross proceeds of $125,000,000. Holders of the Series 1 Preferred Units will be entitled to receive a cumulative quarterly fixed distribution at a rate of 4.50% annually for the initial period ending June 30, 2020. Thereafter, the distribution rate will be reset every five years at a rate equal to the 5-year Government of Canada bond yield plus 3.56%. The Series 1 Preferred Units are redeemable on or after June 30, 2020.

Holders of the Series 1 Preferred Units will have the right, at their option, to reclassify their Series 1 Preferred Units into Cumulative Class A Preferred Limited Partnership Units, Series 2 (“Series 2 Preferred Units”), subject to certain conditions, on June 30, 2020 and on June 30 every 5 years thereafter. Holders of Series 2 Preferred Units will be entitled to receive a cumulative quarterly floating distribution at a rate equal to the 90-day Canadian Treasury Bill yield plus 3.56%.

Brookfield Infrastructure has granted the underwriters an option, exercisable until 48 hours prior to closing, to purchase up to an additional 2,000,000 Series 1 Preferred Units which, if exercised, would increase the gross offering size to $175,000,000. The Series 1 Preferred Units will be offered in all provinces and territories of Canada by way of a supplement to Brookfield Infrastructure’s existing short form base shelf prospectus.

Brookfield Infrastructure intends to use the net proceeds of the issue of the Series 1 Preferred Units for general corporate purposes, including to fund new investments that were previously announced and repay amounts outstanding under its credit facilities. The offering of Series 1 Preferred Units is expected to close on or about March 12, 2015.

But have a look at the issuer! Brookfield Infrastructure Partners L.P.! LP, LP! For various tax reasons I am not competent to either judge or explain, this means that they cannot guarantee that the distributions will actually be dividends; instead, the distributions will be partially a return of capital and the “Certain Canadian Federal Income Tax Considerations” section of the prospectus will be more fraught with interest than otherwise might be the case.

For the past five years, the Return of Capital proportion of distribution with respect to ordinary units has been (starting with 2014) 1.60%, 76.90%, 47.03%, 63.44% and 79.00%, which many will consider gives rise to a pleasant deferral of tax (you eventually pay tax. Don’t worry about that! The ROC lowers the Adjusted Cost Base for capital gains purposes).

Just what the proportions might be in the future is for God to know and man to guess, but it appears that REI.PR.A and REI.PR.C and AX.PR.A, AX.PR.E and AX.PR.G, which also have this ROC structure now have some competition in the ‘deferred taxation’ space.

New Issues

New Issue: HSE FixedReset, 4.50%+357

Husky Energy has announced that it:

has agreed to issue to a syndicate of underwriters led by TD Securities Inc. and RBC Capital Markets for distribution to the public 6,000,000 Cumulative Redeemable Preferred Shares, Series 5 (the “Series 5 Shares”).

The Series 5 Shares will be issued at a price of $25.00 per Series 5 Share, for aggregate gross proceeds of $150 million. Holders of the Series 5 Shares will be entitled to receive a cumulative quarterly fixed dividend yielding 4.50 percent annually for the initial period ending March 31, 2020. Thereafter, the dividend rate will be reset every five years at a rate equal to the five-year Government of Canada bond yield plus 3.57 percent.

Holders of Series 5 Shares will have the right, at their option, to convert their shares into Cumulative Redeemable Preferred Shares, Series 6 (the “Series 6 Shares”), subject to certain conditions, on March 31, 2020 and on March 31 every five years thereafter. Holders of the Series 6 Shares will be entitled to receive cumulative quarterly floating dividends at a rate equal to the 90-day Government of Canada Treasury Bill rate plus 3.57 percent.

Husky has granted the underwriters an option, exercisable in whole or in part prior to closing, to purchase up to an additional 2,000,000 Series 5 Shares at the same offering price. The Series 5 Shares will be offered by way of prospectus supplement to the short form base shelf prospectus of Husky Energy dated February 23, 2015.

The prospectus supplement will be filed with securities regulatory authorities in all provinces of Canada.

The net proceeds of the offering will be used for the partial repayment of short term debt incurred in connection with the Company’s U.S. refining operations.

The offering is expected to close on or about March 12, 2015, subject to customary closing conditions and receipt of required regulatory approvals.

They later announced:

that the underwriters of its Cumulative Redeemable Preferred Shares, Series 5 (the “Series 5 Shares”) offering have exercised their option to increase the size to 8,000,000 shares, due to positive investor response.

The aggregate gross proceeds from the upsized offering will be $200 million. Closing of the offering is expected on or about March 12, subject to customary closing conditions and receipt of required regulatory approvals.

It astonishes me to report that the recently issued HSE.PR.C, a FixedReset 4.50%+313 resetting 2019-12-31 (a mere three months prior to the resetting of the new issue) was not more badly hurt by the news: yesterday it closed at 25.25-30 (3.94%-93) and today it closed at 24.84-93 ( ) on good volume of 77,500, which is far in excess of the turnover it saw in February. Come on, people! Surely rational expectations decree that a 44bp difference in reset rates should be worth more than that!

It might be, of course, that the market is asserting that the new issue is grossly underpriced and will pop as soon as it starts trading. This interpretation is consistent with the exercise of the underwriters’ option. And it is also possible that the market is asserting that Five-Year Canada yields in late 2019/early 2020 will be so high that a mere 44bp in dividend rates will be a mere bagatelle. And it is also possible that the market is asserting that the credit quality of HSE is so incredibly wonderful and adamantine that both issues are certain to be called on their first exchange dates and refinanced at a much cheaper rate.

Well, the market can assert whatever it likes. And it will.

After all, look at TRP.PR.E and TRP.PR.G, which show a bid price difference of $0.08 today, despite an Issue Reset Spread difference of 61bp, albeit with thirteen month difference in next Exchange Date. I suspect that eventually this recent spate of high-spread issues will force down the prices of the older, somewhat lower-spread issues (the very low spread issues have, I think, taken their hits already). But I’ve been wrong before and will be wrong again, so don’t mortgage the house.

New Issues

New Issue: TD FixedReset, 3.60%+279, NVCC

Toronto-Dominion Bank has announced:

a domestic public offering of Non-Cumulative 5-Year Rate Reset Preferred Shares, Series 7 (the “Series 7 Shares”).

TD has entered into an agreement with a group of underwriters led by TD Securities Inc. to issue, on a bought deal basis, 12 million Series 7 Shares at a price of $25.00 per share to raise gross proceeds of $300 million. TD has also granted the underwriters an option to purchase, on the same terms, up to an additional 2 million Series 7 Shares. This option is exercisable in whole or in part by the underwriters at any time up to two business days prior to closing.

The Series 7 Shares will yield 3.60% annually, payable quarterly, as and when declared by the Board of Directors of TD, for the initial period ending July 31, 2020. Thereafter, the dividend rate will reset every five years at a level of 2.79% over the then five-year Government of Canada bond yield.

Subject to regulatory approval, on July 31, 2020 and on July 31 every 5 years thereafter, TD may redeem the Series 7 Shares, in whole or in part, at $25.00 per share. Subject to TD’s right of redemption, holders of the Series 7 Shares will have the right to convert their shares into Non-Cumulative Floating Rate Preferred Shares, Series 8 (the “Series 8 Shares”), subject to certain conditions, on July 31, 2020, and on July 31 every five years thereafter. Holders of the Series 8 Shares will be entitled to receive quarterly floating dividends, as and when declared by the Board of Directors of TD, equal to the three-month Government of Canada Treasury bill yield plus 2.79%.

The expected closing date is March 10, 2015. TD will make an application to list the Series 7 Shares as of the closing date on the Toronto Stock Exchange. The net proceeds of the offering will be used for general corporate purposes.

The Bank, as previously announced, will redeem its outstanding Non-cumulative Redeemable Class A First Preferred Shares, Series P and Series Q on March 2, 2015. It is the intention of the Bank to exercise its right to redeem all of its outstanding 10 million Non-cumulative Redeemable Class A First Preferred Shares, Series R (the “Series R Shares”). The foregoing statement of intention does not constitute formal notice of redemption. Should the Bank exercise its right to redeem the Series R Shares, formal notice of redemption will be issued by the Bank in due course.

They later announced:

that, in connection with its recently announced public offering of 12,000,000 3.60% Non-Cumulative 5-Year Rate Reset Preferred Shares, Series 7 (the “Series 7 Shares”), the underwriters have exercised their option (the “Underwriters’ Option”) to purchase an additional 2,000,000 Series 7 Shares at a price of $25.00 per share. TD will receive additional gross proceeds of $50,000,000 from the exercise of the Underwriters’ Option, increasing the total size of the offering to $350,000,000. Closing of the Underwriters’ Option is expected to occur concurrent with the closing of the public offering on March 10, 2015.

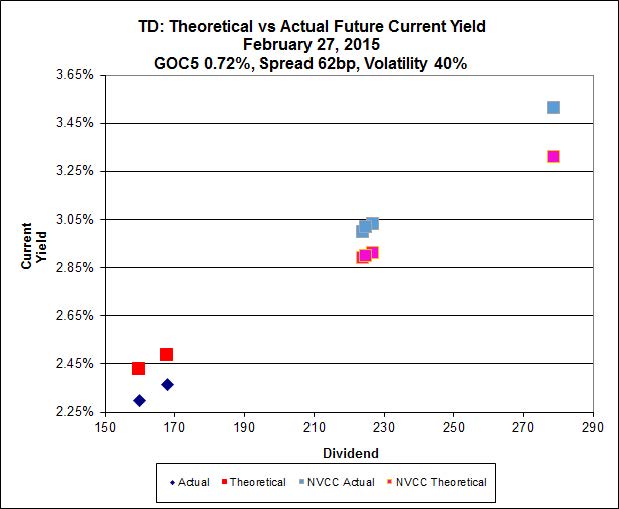
The Implied Volatility calculation has some points of interest:

impVol_TD_150227
Click for Big

Firstly, the market does not appear to be differentiated between the NVCC compliant and non-compliant issues, as the latter appear to be plotted on a line more or less defined by the former. Additionally, the Implied Volatility is very high – ridiculously high, for NVCC-compliant issues – so I would expect the new issue to outperform the three non-compliant issues (TD.PF.A, TD.PF.B and TD.PF.C) as the market comes to realize what the word “perpetual” means.

New Issues

New Issue: CM FixedReset, 3.60%+279

The Canadian Imperial Bank of Commerce has announced:

that it had entered into an agreement with a group of underwriters led by CIBC World Markets Inc. for an issue of 10 million Basel III-compliant Non-cumulative Rate Reset Class A Preferred Shares, Series 43 (the “Series 43 Shares”) priced at $25.00 per Series 43 Share to raise gross proceeds of $250 million.

CIBC has granted the underwriters an option to purchase up to an additional two million Series 43 Shares at the same offering price, exercisable at any time up to two days prior to closing. Should the underwriters’ option be fully exercised, the total gross proceeds of the financing will be $300 million.

The Series 43 Shares will yield 3.60% per annum, payable quarterly, as and when declared by the Board of Directors of CIBC, for an initial period ending July 31, 2020. On July 31, 2020, and on July 31 every five years thereafter, the dividend rate will reset to be equal to the then current five-year Government of Canada bond yield plus 2.79%.

Subject to regulatory approval and certain provisions of the Series 43 Shares, on July 31, 2020 and on July 31 every five years thereafter, CIBC may, at its option, redeem all or any part of the then outstanding Series 43 Shares at par.

Subject to the right of redemption, holders of the Series 43 Shares will have the right to convert their shares into Non-cumulative Floating Rate Class A Preferred Shares, Series 44 (the “Series 44 Shares”), subject to certain conditions, on July 31, 2020 and on July 31 every five years thereafter. Holders of the Series 44 Shares will be entitled to receive a quarterly floating rate dividend, as and when declared by the Board of Directors of CIBC, equal to the three-month Government of Canada Treasury Bill yield plus 2.79%.

Holders of the Series 44 Shares may convert their Series 44 Shares into Series 43 Shares, subject to certain conditions, on July 31, 2025 and on July 31 every five years thereafter.

The expected closing date is March 11, 2015. CIBC will make an application to list the Series 43 Shares as of the closing date on the Toronto Stock Exchange. The net proceeds of this offering will be used for general purposes of CIBC.

CIBC has two other series of FixedResets outstanding, CM.PR.O and CM.PR.P – sadly, insufficient to perform an Implied Volatility analysis.

I find it interesting that the issue won’t close until March 11 – two weeks is a relatively long marketing period for a major bank. The sluggishness of sales of current issues has been remarked upon both in comments on PrefBlog and elsewhere.

New Issues

New Issue: TRP FixedReset, 3.80%+296

TransCanada Corporation has announced:

that it will issue 10 million cumulative redeemable first preferred shares, series 11 (the “Series 11 Preferred Shares”) at a price of $25.00 per share for aggregate gross proceeds of $250 million on a bought deal basis to a syndicate of underwriters in Canada co-led by Scotiabank and RBC Capital Markets.

The holders of Series 11 Preferred Shares will be entitled to receive fixed cumulative dividends at an annual rate of $0.95 per share, payable quarterly on the last business day of February, May, August and November, as and when declared by the board of directors of TransCanada. The Series 11 Preferred Shares will yield 3.80 per cent per annum for the initial fixed rate period ending November 30, 2020 with the first dividend payment date scheduled for May 29, 2015. The dividend rate will reset on November 30, 2020 and on the last business day of November in every fifth year thereafter to a rate equal to the sum of the then five-year Government of Canada bond yield plus 2.96 per cent. The Series 11 Preferred Shares are redeemable by TransCanada, at its option, on November 30, 2020 and on the last business day of November in every fifth year thereafter at a price of $25.00 per share plus accrued and unpaid dividends.

The holders of Series 11 Preferred Shares will have the right to convert their shares into cumulative redeemable first preferred shares, series 12 (the “Series 12 Preferred Shares”), subject to certain conditions, on November 30, 2020 and on the last business day of November in every fifth year thereafter. The holders of Series 12 Preferred Shares will be entitled to receive quarterly floating rate cumulative dividends, as and when declared by the board of directors of TransCanada, at an annualized rate equal to the sum of the then 90-day Government of Canada treasury bill rate plus 2.96 per cent.

TransCanada has granted to the underwriters an option, exercisable at any time up to 48 hours prior to the closing of the offering, to purchase up to an additional two million Series 11 Preferred Shares at a price of $25.00 per share.

The anticipated closing date is March 2, 2015. The net proceeds of the offering will be used for general corporate purposes and to reduce short term indebtedness of TransCanada and its affiliates, which short term indebtedness was used to fund TransCanada’s capital program and for general corporate purposes.

Wonder of wonders, this issue actually looks cheap, continuing the brand new tradition set by the announcement of RY.PR.J (which is still cheap according to basic Implied Volatility theory, as far as that goes.

I don’t think this is due to any feelings of generosity amongst the issuers, however. It will be remembered that Implied Volatility theory (in its current stage of development) assumes a constant GOC-5 yield and does not incorporate the current coupon in its calculations (for which it has been harshly criticized).

If instead we look at the single closest comparable, TRP.PR.E, which is a FixedReset 4.25%+235 currently bid at 24.52, we see that it has an Expected Future Current Yield (EFCY) of 3.06%, which is equal to Par Value * (GOC-5 + IRS) / Bid = 25 * (0.65% + 235bp) / 24.52.

If we say that the new issue should have the same EFCY, then its Issue Reset Spread (IRS) should be 3.06% – 0.65% = 241bp. This is 55bp below the actual IRS, implying that the current coupon should also be 55bp below the actual coupon, so we conclude that if it was to trade even-yield with TRP.PR.E, then the new issue should actually carry terms of 3.25%+241. Note that if we were being more precise, the EFCY of the new issue should be a bit more than that of TRP.PR.E, as compensation for the greater negative convexity – call it about 20bp more, which certainly changes the numbers considerably, but not by enough to affect my argument.

The trouble for the issuers is, however, that a current coupon of 3.25% will bring with it a large amount of expected sticker shock for retail. I’m not sure if it would be possible for the underwriters to sell an issue at 3.25%+241 based on current market conditions – or even possible to sell it at 3.45%+261, accounting for negative convexity and volatility. You can be pretty sure they’d try it if they thought they could get away with it!

So what I think is happening is that the issuers are simply selling it based on current coupon and letting the chips fall where they may as far as the Issue Reset Spread is concerned. To a large extent it doesn’t matter much to them – if GOC-5 recovers in the next five years and spreads narrow, then they can just call it and reissue new paper.

This is much the same thing as what the banks did in 2009, with their enormous issuance of FixedResets with huge Issue Reset Spreads.

And all these suppositions break Implied Volatility theory, because – assuming that expectations are met and the market behaves as expected – then there is directionality in market prices and it is entirely possible that capital gains on the currently discounted issues will swamp any differential in coupon. But we will see! Check back in five years.

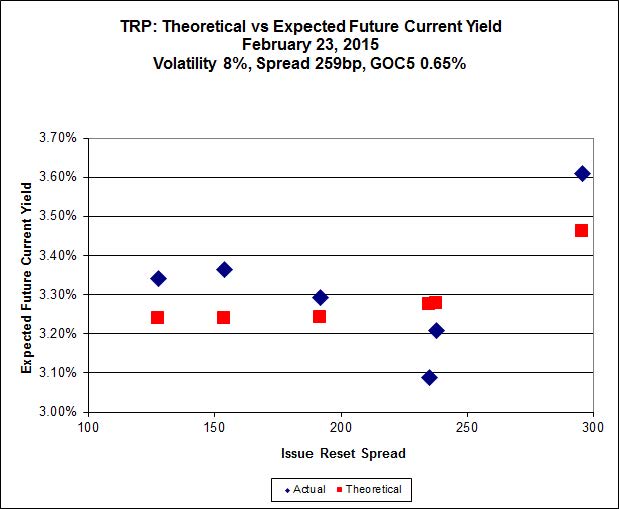
Still, for what it’s worth, here’s the Implied Volatility Chart for TRP FixedResets, incorporating the new issue at par:

impVol_TRP_150223
Click for Big

According to this analysis, the new issue would be fairly priced at $26.07.