Category: New Issues

New Issues

New Issue: EIT Retractible, 4.80%, 7-Year

Canoe EIT Income Fund has announced:

that it has entered into an agreement with a syndicate of underwriters (the “Underwriters”) led by Scotia Capital Inc. (“Scotia Capital”) to sell, 2,800,000 Cumulative Redeemable Series 2 Preferred Units (3,220,000 Cumulative Redeemable Series 2 Preferred Units if the over-allotment described below is exercised in full) of the Fund (“Series 2 Preferred Units”), on a “bought deal” basis, at a price of $25.00 per Series 2 Preferred Unit (the “Offering Price”) for gross proceeds of approximately $70 million (approximately $80.5 million if the over-allotment option is exercised in full) (the “Offering”).

Holders of the Series 2 Preferred Units will be entitled to fixed cumulative preferential cash distributions of $1.20 per Series 2 Preferred Unit per annum, as and when declared, which will accrue from the date of issue and will be payable quarterly on the 15th day of March, June, September and December in each year. On or after March 15, 2025, the Series 2 Preferred Units will be retractable for cash, at the option of the holder, for $25.00 per Series 2 Preferred Unit, together with any accrued and unpaid distribution in respect of such Series 2 Preferred Units, less any tax required by law to be deducted therefrom. The Series 2 Preferred Units are provisionally rated Pfd-2 (high) by Dominion Bond Rating Service Limited.

The Fund has agreed to grant the Underwriters an over-allotment option to purchase up to an additional 420,000 Series 2 Preferred Units at the Offering Price on the same terms and conditions, exercisable in whole or in part at any time for a period of up to 30 days following closing of the Offering.

The Fund intends to use the proceeds from the Offering in accordance with the investment objectives and investment strategies of the Fund, subject to the investment restrictions of the Fund.

DBRS has issued a provisional rating of Pfd-2(high):

DBRS Limited (DBRS) assigned a provisional rating of Pfd-2 (high) to the Cumulative Redeemable Series 2 Preferred Units (the Series 2 Preferred Units) to be issued by Canoe EIT Income Fund (the Fund) that will rank pari passu with the existing Cumulative Redeemable Series 1 Preferred Units (the Series 1 Preferred Units; collectively with the Series 2 Preferred Units, the Preferred Units). The Fund can issue an unlimited number of capital units (the Fund Units) and can also issue in series Preferred Units up to a maximum aggregate amount equal to 25% of the Fund’s total assets after giving effect to the proposed offering of Preferred Units

As of March 14, 2018, assuming no capital distributions or special dividends paid, the net asset value of the Fund would have to fall by approximately 81% for the holders of the Preferred Units to be in a loss position. The Series 1 Preferred Unit holders currently receive quarterly cumulative preferential cash distributions of $0.30 (or $1.20 annually), representing a 4.80% per-annum return on the issue price of $25.00. The holders of the Fund Units receive targeted monthly cash distributions of $0.10, amounting to $1.20 per annum. In addition, up to 10% of the aggregate outstanding Units may be redeemed at the option of the Unit holders each calendar year on a date determined by the Fund. The Series 1 Preferred Units are retractable for cash at the option of the holder on or after March 15, 2024.

In assigning the provisional rating, DBRS has considered the expected level of downside protection available to holders of the Series 2 Preferred Units and the composition and diversification of the portfolio. In addition, DBRS has taken into account the potential grind on the portfolio arising from the distributions to the Units and redemption rights, the potential foreign exchange risk because of some investments in foreign currencies not being hedged and the fact that the lenders under the Credit Facility have priority over the Fund’s assets up to the amount of credit outstanding. Because of the amount of the Credit Facility compared with the current total assets, DBRS does not consider the latter risk to be significant.

Investors should note that distributions will be a mix of eligible dividends, capital gains and return of capital. I anticipate that the following language from the EIT.PR.A prospectus will be essentially repeated:

A Holder will generally be required to include in computing the Holder’s income for tax purposes in each year the amount of income and net taxable capital gains, if any, paid or payable, or deemed to be paid or payable, to the Holder in the year by the Fund to the extent that the Fund deducts such amount in computing its income for tax purposes. The Fund’s income and net taxable gains for the purposes of the Tax Act will be allocated to the holders of Units and Preferred Units in the same proportion as the distributions received by such holders.

The amount of the non-taxable portion of any net realized capital gains of the Fund that is paid or payable to a Holder in a taxation year will not be included in computing the Holder’s income for the year. The Holder will not be required to reduce the adjusted cost base of the Holder’s Series 1 Preferred Units by such an amount.

Any other amount in excess of the income for tax purposes of the Fund that is paid or payable to a Holder in that year generally will not be included in the Holder’s income for the year, but the Holder will be required to reduce the adjusted cost base of the Holder’s Series 1 Preferred Units by that amount. To the extent that the adjusted cost base of a Series 1 Preferred Unit would otherwise be a negative amount, the negative amount will be deemed to be a capital gain and the adjusted cost base of the Series 1 Preferred Unit to the Holder will then be nil. The taxation of capital gains is described below (see “Capital Gains and Capital Losses”).

Provided that appropriate designations are made by the Fund, such portion of: (a) the net realized taxable capital gains of the Fund; (b) the foreign source income of the Fund and foreign taxes paid by the Fund eligible for the foreign tax credit; and (c) the taxable dividends (including eligible dividends) received, or deemed received, by the Fund on shares of taxable Canadian corporations, (including distributions from SIFT trusts or SIFT partnerships deemed to be taxable dividends under the SIFT Rules) as is paid or payable to a Holder will effectively retain their character and be treated as such in the hands of the Holder for purposes of the Tax Act. Amounts which retain their character in the hands of a Holder as taxable dividends on shares of taxable Canadian corporations will, in the case of a Holder who is an individual, be eligible for the normal gross-up and dividend tax credit rules under the Tax Act; and will, in the case of a Holder who is a corporation, generally be deducted in computing taxable income.

For the 2017 tax year the breakdown was:

EIT Distribution Taxation
2017
Actual Amount of Eligible Dividends 4.7%
Capital Gains 46.8%
Return of Capital 48.5%

Announcement of this issue knocked hell out of the trading price of EIT.PR.A, (also with a 4.8% coupon, retractible one year prior to the new issue) which commenced trading 2017-3-17 after being announced 2017-3-8 with marketting beginning 2017-2-22. It closed with a quote of 25.55-26.55 yesterday (last price 25.75) and today was 25.35-38, last price 25.28 on volume of 21,200. Today’s relative prices seem about right to me.
New Issues

New Issue: TD FixedReset 4.70%+270, NVCC

The Toronto-Dominion Bank has announced:

a domestic public offering of Non-Cumulative 5-Year Rate Reset Preferred Shares (non-viability contingent capital (NVCC)), Series 18 (the “Series 18 Shares”).

TD has entered into an agreement with a group of underwriters led by TD Securities Inc. to issue, on a bought deal basis, 10 million Series 18 Shares at a price of $25.00 per share to raise gross proceeds of $250 million. TD has also granted the underwriters an option to purchase, on the same terms, up to an additional 2 million Series 18 Shares. This option is exercisable in whole or in part by the underwriters at any time up to two business days prior to closing.

The Series 18 Shares will yield 4.70% annually, with dividends payable quarterly, as and when declared by the Board of Directors of TD, for the initial period ending April 30, 2023. Thereafter, the dividend rate will reset every five years at a level of 2.70% over the then five-year Government of Canada bond yield.

Subject to regulatory approval, on April 30, 2023 and on April 30 every 5 years thereafter, TD may redeem the Series 18 Shares, in whole or in part, at $25.00 per share. Subject to TD’s right of redemption and certain other conditions, holders of the Series 18 Shares will have the right to convert their shares into Non-Cumulative Floating Rate Preferred Shares (NVCC), Series 19 (the “Series 19 Shares”), on April 30, 2023, and on April 30 every five years thereafter. Holders of the Series 19 Shares will be entitled to receive quarterly floating rate dividends, as and when declared by the Board of Directors of TD, equal to the three-month Government of Canada Treasury Bill yield plus 2.70%.

The expected closing date is March 14, 2018. TD will make an application to list the Series 18 Shares as of the closing date on the Toronto Stock Exchange. The net proceeds of the offering will be used for general corporate purposes.

They later announced:

that as a result of strong investor demand for its previously announced domestic public offering of Non-Cumulative 5-Year Rate Reset Preferred Shares (non-viability contingent capital (NVCC)), Series 18 (the “Series 18 Shares”), the size of the offering has been increased to 14 million Series 18 Shares. The gross proceeds of the offering will now be $350 million. The offering will be underwritten by a group of underwriters led by TD Securities Inc.

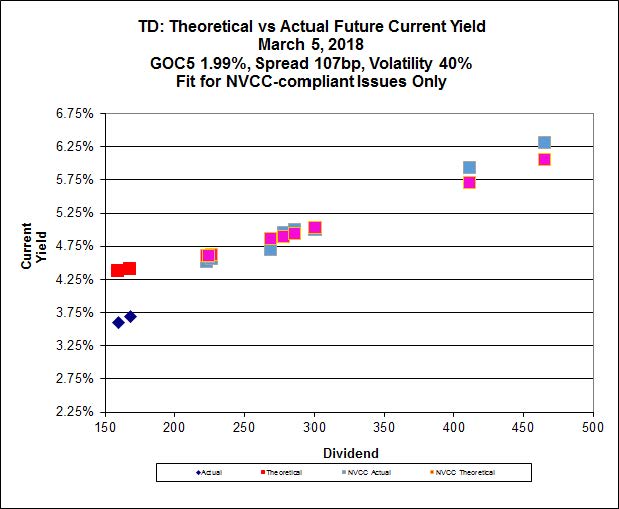
This issue looks quite expensive to me, according to Implied Volatility Analysis:

impvol_td_180305
Click for Big

We see in this chart many of the same features we saw when reviewing the recent BIP.PR.E, BEP.PR.M, CM.PR.S, NA.PR.E and MFC.PR.Q: the curve is very steep, with Implied Volatility equal to 40% (a ridiculously large figure).

The ludicrously high figure of Implied Volatility is something I take to mean that the underlying assumption of the Black-Scholes model, that of no directionality of prices, is not accepted by the market; the market seems to be taking the view that since things seem rosy now, they will always be rosy and everything will trade near par in the future.

I balk at ascribing a 100% probability to the ‘all issues will be called, or at least exhibit price stability’ hypothesis. There may still be a few old geezers amongst the Assiduous Readers of this blog who can still (faintly) remember the Great Bear Market of 2014-16, in which quite a few similar assumptions made earlier turned out to be slightly inaccurate. The extra cushion implied by an Issue Reset Spread that is well over the market spread is worth something, even if nothing gets called.

According to the analysis shown above, the fair value of this issue is 24.17. Careful Assiduous Readers will note that TD.PF.I, a FixedReset 4.50%+301 that commenced trading 2017-7-14, closed today at 25.04-20. The extra 20bp of initial dividend rate is worth $0.05 annually, or a total of a little over $0.20 extra for the new issue … but if they both reset then TD.PF.I will get – to the extent reset rates nine months apart are the same – $0.0775 p.a. more than the new issue. According to the Implied Volatility analysis above, the fair value of TD.PF.I is 24.91.

New Issues

New Issue: IAG FixedReset, 4.80%+275

Industrial Alliance Insurance and Financial Services Inc. has announced (emphasis from original) that it and:

PPI Management Inc. (PPI), a leading Canadian insurance marketing firm, today announced that they have reached an agreement for iA Financial Group to acquire PPI. The transaction is effective immediately.
…
The Company announces that it has today entered into an agreement pursuant to which a syndicate of underwriters co-led by TD Securities Inc. and National Bank Financial Inc. (the “Common Share Underwriters”) will purchase, on a bought deal basis, 2,500,000 common shares from iA Financial Group at a price of $54.10 per common share, representing aggregate gross proceeds of $135 million (the “Common Share Offering”).
…
Series I Preferred Share Offering
The Company announces that it today also entered into an agreement with a syndicate of underwriters co-led by TD Securities Inc. and National Bank Financial Inc. (the “Preferred Share Underwriters”), under which the Preferred Share Underwriters have agreed to buy, on a bought deal basis, 6,000,000 Non-Cumulative 5-Year Rate Reset Class A Preferred Shares Series I (the “Series I Preferred Shares”) from iA Financial Group at a price of $25.00 per Series I Preferred Share, representing aggregate gross proceeds of $150 million (the “Series I Preferred Share Offering” and, together with the Common Share Offering, the “Offerings”). iA Financial Group has also granted the Preferred Share Underwriters an option, exercisable in whole or in part at any time up to 48 hours prior to closing, to purchase up to an additional 2,000,000 Series I Preferred Shares at a price of $25.00 per share for additional aggregate gross proceeds of up to $50 million.

Holders of the Series I Preferred Shares will be entitled to receive a non-cumulative quarterly fixed dividend of $1.20 per Series I Preferred Share, yielding 4.80% per annum, as and when declared by the Board of Directors of iA Financial Group, for the initial period up to but excluding March 31, 2023. On March 31, 2023 and on March 31 every five years thereafter, the dividend rate will reset to be equal to the then current five-year Government of Canada bond yield plus 2.75%. Holders of the Series I Preferred Shares will have the right, at their option, to convert their shares into Non-Cumulative Floating Rate Class A Preferred Shares Series J (the “Series J Preferred Shares”), subject to certain conditions and the Company’s right to redeem the Series I Preferred Shares as described below, on March 31, 2023 and on March 31 every five years thereafter. Holders of the Series J Preferred Shares will be entitled to receive a quarterly non-cumulative floating rate dividend, as and when declared by the Board of Directors of iA Financial Group, equal to the 90-day Government of Canada Treasury Bill Rate plus 2.75%. Holders of the Series J Preferred Shares will have the right, at their option, to convert their shares into Series I Preferred Shares, subject to certain conditions and the Company’s right to redeem the Series J Preferred Shares as described below, on March 31, 2028 and on March 31 every five years thereafter.

The Series I Preferred Shares will not be redeemable by iA Financial Group prior to March 31, 2023. On March 31, 2023 and on March 31 every five years thereafter, iA Financial Group may, subject to certain conditions (including regulatory approval), redeem all or any part of the Series I Preferred Shares at a cash redemption price per share of $25.00 together with all declared and unpaid dividends. The Company may redeem all or any part of the Series J Preferred Shares at a cash redemption price per share of $25.00 together with all declared and unpaid dividends in the case of redemptions on March 31, 2028 and on March 31 every five years thereafter or $25.50 together with all declared and unpaid dividends in the case of redemptions on any other date after March 31, 2023.

The net proceeds of the Offerings will be used for general corporate purposes and to maintain and replenish iA Financial Group’s capital base, including after giving effect to the payment of the purchase price for the Acquisition.

On a pro forma basis, after giving effect to the Offerings (but without giving effect to any potential exercise of the over-allotment option under the Common Share Offering or the Preferred Share Underwriters’ option), the Company estimates that, as at December 31, 2017, its solvency ratio would increase by 12 percentage points, from 209% to 221%. After giving effect to the PPI acquisition completed today on February 26, 2018 (-8 percentage points) and the DAC acquisition completed earlier on January 23, 2018 (-8 percentage points), the solvency ratio would be 205%.

The Common Share Offering and the Series I Preferred Share Offering are each expected to separately close on or about March 7, 2018, subject to certain conditions, including Toronto Stock Exchange and other customary regulatory approvals. The Offerings will be made pursuant to separate prospectus supplements to iA Financial Group’s short form base shelf prospectus dated June 22, 2017, which will be filed with the Canadian securities regulatory authorities and will be available on SEDAR at www.sedar.com.

As this issue is not NVCC compliant and it is an insurance issue, it is analyzed as having a Deemed Retraction, effective 2025-1-31 (this date may change in the future).

This issue isn’t all that badly priced. IAG.PR.G, the only other FixedReset issued by the company, is currently described as 3.777%+285 and will reset 2022-6-30 – prior to the reset of this new issue. It closed today at 24.15-22. You’re losing about a point in dividends every year for the four years-odd until reset on a $25.00 par value, so that’s worth a buck; this correction means the issues are reasonably close to being fairly-priced relative to each other. The yields to the Deemed Maturity 2025-1-31 are 4.88% for IAG.PR.G and 4.82% for the new issue, after accounting for resets at the current GOC-5 level.

New Issues

New Issue: AX FixedReset, 6.00%+393M600, ROC

Artis Real Estate Investment Trust has announced:

that is [sic] has entered into an agreement to sell to a syndicate of underwriters led by TD Securities Inc., RBC Capital Markets and Scotiabank (collectively the “Underwriters”), on a bought deal basis, 4,000,000 Cumulative Minimum Rate Reset Preferred Trust Units, Series I (“Series I Units”) at a price of $25.00 per Series I Unit (the “Issue Price”) for gross proceeds of $100,000,000 (the “Financing”). Artis has also granted the Underwriters an option, exercisable at any time up to 48 hours prior to the closing of the Financing, to purchase a further 1,000,000 Series I Units at the Issue Price, which, if fully exercised, would result in additional gross proceeds of $25,000,000.

The Series I Units will pay fixed cumulative preferential distributions of $1.50 per Series I Unit per annum, yielding 6.00% per annum, payable on the last day of January, April, July and October of each year, as and when declared by the board of trustees of Artis, for the initial period ending on April 30, 2023. The first quarterly distribution, if declared, will be payable on April 30, 2018 and will be $0.3750 per Series I Unit, based on the anticipated closing date of the Financing on January 31, 2018. The distribution rate will be reset on April 30, 2023 and every five years thereafter at a rate equal to the greater of (i) the sum of the then five year Government of Canada bond yield and 3.93% and (ii) 6.00%. The Series I Units are redeemable by Artis, at its option, on April 30, 2023 and on April 30 of every fifth year thereafter.

Holders of Series I Units will have the right to reclassify all or any part of their Series I Units as Cumulative Floating Rate Preferred Trust Units, Series J (the “Series J Units”), subject to certain conditions, on April 30, 2023 and on April 30 of every fifth year thereafter. Such reclassification privilege may be subject to certain tax considerations (to be disclosed in the prospectus supplement for the Financing). Holders of Series J Units will be entitled to receive a floating cumulative preferential distribution, payable on the last day of January, April, July and October of each year, as and when declared by the board of trustees of Artis, at a rate equal to the sum of the then 90-day Government of Canada Treasury Bill yield plus a spread of 3.93%.

DBRS Limited has assigned a provisional rating of Pfd-3 (low) to the Series I Units.

The Financing is being made pursuant to the REIT’s base shelf prospectus dated August 8, 2016. The terms of the offering will be described in a prospectus supplement to be filed with Canadian securities regulators. The Financing is expected to close on or about January 31, 2018 and is subject to regulatory approval.

Artis intends to use the net proceeds from the Financing to redeem its existing U.S. dollar denominated cumulative redeemable preferred trust units, Series C and for general trust purposes.

They later announced:

that as a result of strong investor demand for its previously announced offering, the underwriters have exercised their option to increase the size of the offering to 5,000,000 Cumulative Minimum Rate Reset Preferred Trust Units, Series I (“Series I Units”) to be offered on a bought deal basis to a syndicate of underwriters led by TD Securities Inc., RBC Capital Markets and Scotiabank (collectively the “Underwriters”). The Series I Units will be issued at a price of $25.00 per unit, for gross proceeds of $125,000,000 (the “Financing”).

The Financing is being made pursuant to the REIT’s base shelf prospectus dated August 8, 2016. The terms of the offering will be described in a prospectus supplement to be filed with Canadian securities regulators. The Financing is expected to close on or about January 31, 2018 and is subject to regulatory approval.

Artis intends to use the net proceeds from the Financing to redeem its existing U.S. dollar denominated cumulative redeemable preferred trust units, Series C and for general trust purposes.

The issue they intend to redeem is AX.PR.U, a FixedReset, 5.25%+446 US PAY ROC announced 2012-09-11 which commenced trading 2012-9-18, and which is callable at par on 2018-3-31.

The new issue looks quite expensive to me, according to Implied Volatility Analysis:

impvol_ax_180122
Click for Big

This perceived richness has a different source than the other issues discussed here recently, such as the BEP.PR.M issue, the CM.PR.S issue and the NA.PR.E, since the calculated level of Implied Volatility, 11%, is actually quite reasonable.

In this case, the richness is due to the extraordinarily high value that retail – fighting the last war, as always – has placed on the minimum reset guarantee. If, like me, you consider the guarantee to have little or no value, you will expect the new issue to be trading near the price of AX.PR.A, which has an Issue Reset Spread of 406bp (and a current coupon of 5.662%). However, this issue closed today at 23.61, indicating that retail considers the minimum rate guarantee to be worth somewhere around $1.50. Wow! That’s nearly double the value of the call option in this analysis!

New Issues

New Issue: BIP FixedReset, 5.00%+300M500, ROC

Brookfield Infrastructure has announced:

that it has agreed to issue 8,000,000 Cumulative Class A Preferred Limited Partnership Units, Series 9 (“Series 9 Preferred Units”) on a bought deal basis to a syndicate of underwriters led by CIBC Capital Markets, BMO Capital Markets, RBC Capital Markets, Scotiabank, and TD Securities Inc. The Series 9 Preferred Units will be issued at a price of $25.00 per unit, for gross proceeds of $200,000,000. Holders of the Series 9 Preferred Units will be entitled to receive a cumulative quarterly fixed distribution at a rate of 5.00% annually for the initial period ending March 31, 2023. Thereafter, the distribution rate will be reset every five years at a rate equal to the greater of: (i) the 5-year Government of Canada bond yield plus 3.00%, and (ii) 5.00%. The Series 9 Preferred Units are redeemable on or after March 31, 2023.

Holders of the Series 9 Preferred Units will have the right, at their option, to reclassify their Series 9 Preferred Units into Cumulative Class A Preferred Limited Partnership Units, Series 10 (“Series 10 Preferred Units”), subject to certain conditions, on March 31, 2023 and on March 31 every five years thereafter. Holders of Series 10 Preferred Units will be entitled to receive a cumulative quarterly floating distribution at a rate equal to the 90-day Canadian Treasury Bill yield plus 3.00%.

Brookfield Infrastructure has granted the underwriters an option, exercisable until 48 hours prior to closing, to purchase up to an additional 2,000,000 Series 9 Preferred Units which, if exercised, would increase the gross offering size to $250,000,000.

The Series 9 Preferred Units will be offered in all provinces and territories of Canada by way of a supplement to Brookfield Infrastructure’s existing short form base shelf prospectus.

Brookfield Infrastructure intends to use the net proceeds of the issue of the Series 9 Preferred Units to fund a growing backlog of committed organic growth capital expenditure projects and an active pipeline of new investment opportunities, and for general working capital purposes. The offering of Series 9 Preferred Units is expected to close on or about January 23, 2018.

This issue looks quite expensive to me, according to Implied Volatility Analysis:

impvol_bip_180115
Click for Big

Well, it’s starting to get monotonous, but we see in this chart many of the same features we saw when reviewing last week’s BEP issue, the CM issue and NA issue:

  • The curve is very steep, with Implied Volatility equal to 40% (a ridiculously large figure), and
  • The extant issues are trading relatively near to, or well above par

The ludicrously high figure of Implied Volatility is something I take to mean that the underlying assumption of the Black-Scholes model, that of no directionality of prices, is not accepted by the market; the market seems to be taking the view that since things seem rosy now, they will always be rosy and everything will trade near par in the future.

I balk at ascribing a 100% probability to this outcome. There may still be a few old geezers amongst the Assiduous Readers of this blog who can still (faintly) remember the Great Bear Market of 2014-16, in which quite a few similar assumptions made earlier turned out to be slightly inaccurate.

For the long term, I suggest that any change in the slope of the curve will be a flattening, with a very high degree of confidence. This will imply that the higher-spread issues will outperform the lower-spread issues.

All told, though, I have no hesitation in slapping an ‘Expensive’ label on this issue – according to the Implied Volatility analysis shown above, the theoretical price of the new issue is 23.50. Mind you, the Implied Volatility cap rate of 40% is arbitrary; perhaps if I allowed 50% or so the new issue would sit on the curve … but in that case, Implied Volatility has become a completely arbitrary meaningless number.

New Issues

New Issue: NA FixedReset, 4.60%+258, NVCC-Compliant

National Bank of Canada has announced:

that it has entered into an agreement with a group of underwriters led by National Bank Financial Inc. for the issuance on a bought deal basis of 8 million non-cumulative 5-year rate reset first preferred shares series 40 (non-viability contingent capital (NVCC)) (the “Series 40 Preferred Shares”) at a price of $25.00 per share, to raise gross proceeds of $200 million.

National Bank has granted the underwriters an option to purchase, on the same terms, up to an additional 4 million Series 40 Preferred Shares. This option is exercisable in whole or in part by the underwriters at any time up to two business days prior to closing. The gross proceeds raised under the offering will be $300 million should this option be exercised in full.

The Series 40 Preferred Shares will yield 4.60% annually, payable quarterly, as and when declared by the Board of Directors of National Bank, for the initial period ending May 15, 2023. The first of such dividends, if declared, shall be payable on May 15, 2018. Thereafter, the dividend rate will reset every five years at a level of 258 basis points over the then 5-year Government of Canada bond yield. Subject to regulatory approval, National Bank may redeem the Series 40 Preferred Shares in whole or in part at par on May 15, 2023 and on May 15 every five years thereafter.

Holders of the Series 40 Preferred Shares will have the right to convert their shares into an equal number of non-cumulative floating rate first preferred shares series 41 (non-viability contingent capital (NVCC)) (the “Series 41 Preferred Shares”), subject to certain conditions, on May 15, 2023, and on May 15 every five years thereafter. Holders of the Series 41 Preferred Shares will be entitled to receive quarterly floating dividends, as and when declared by the Board of Directors of National Bank, equal to the 90-day Government of Canada Treasury Bill rate plus 258 basis points.

The net proceeds of the offering will be used for general corporate purposes and added to National Bank’s capital base. The expected closing date is on or about January 22, 2018. National Bank intends to file in Canada a prospectus supplement to its November 21, 2016 base shelf prospectus in respect of this issue.

They later announced:

that as a result of strong investor demand for its previously announced domestic public offering of non-cumulative 5-year rate reset first preferred shares series 40 (non-viability contingent capital (NVCC)) (the “Series 40 Preferred Shares”), the underwriters have exercised their option to purchase an additional 4,000,000 Series 40 Preferred Shares. The size of the offering has been increased to 12 million shares for gross proceeds of $300 million. The offering will be underwritten by a syndicate led by National Bank Financial Inc. The expected closing date is on or about January 22, 2018.

The net proceeds of the offering will be used for general corporate purposes and added to National Bank’s capital base.

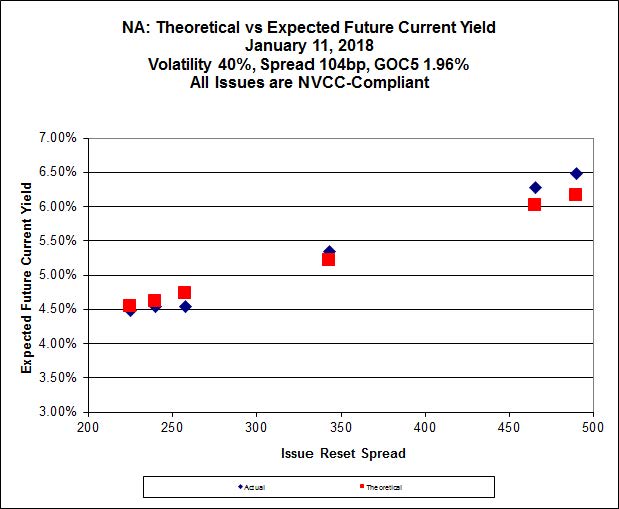
This issue looks quite expensive to me, according to Implied Volatility Analysis:

impvol_na_180111
Click for Big

We see in this chart many of the same features we saw when reviewing the recent BPO new issue and Tuesday’s BEP issue and yesterday’s CM issue:

  • The curve is very steep, with Implied Volatility equal to 40% (a ridiculously large figure), and
  • The extant issues are trading relatively near to, or well above par

The ludicrously high figure of Implied Volatility is something I take to mean that the underlying assumption of the Black-Scholes model, that of no directionality of prices, is not accepted by the market; the market seems to be taking the view that since things seem rosy now, they will always be rosy and everything will trade near par in the future.

I balk at ascribing a 100% probability to this outcome. There may still be a few old geezers amongst the Assiduous Readers of this blog who can still (faintly) remember the Great Bear Market of 2014-16, in which quite a few similar assumptions made earlier turned out to be slightly inaccurate.

For the long term, I suggest that any change in the slope of the curve will be a flattening, with a very high degree of confidence. This will imply that the higher-spread issues will outperform the lower-spread issues.

All told, though, I have no hesitation in slapping an ‘Expensive’ label on this issue – according to the Implied Volatility analysis shown above, the theoretical price of the new issue is 24.01.

New Issues

New Issue: CM FixedReset, 4.50%+245, NVCC-compliant

Canadian Imperial Bank of Commerce has announced:

that it had entered into an agreement with a group of underwriters led by CIBC Capital Markets for an issue of 16 million Basel III-compliant Non-cumulative Rate Reset Class A Preferred Shares Series 47 (Non-Viability Contingent Capital (NVCC)) (the “Series 47 Shares”) priced at $25.00 per Series 47 Share to raise gross proceeds of $400 million.

CIBC has granted the underwriters an option to purchase up to an additional two million Series 47 Shares at the same offering price, exercisable at any time up to two days prior to closing. Should the underwriters’ option be fully exercised, the total gross proceeds of the financing will be $450 million.

The Series 47 Shares will yield 4.5% per annum, payable quarterly, as and when declared by the Board of Directors of CIBC, for an initial period ending January 31, 2023. On January 31, 2023, and on January 31 every five years thereafter, the dividend rate will reset to be equal to the then current five-year Government of Canada bond yield plus 2.45%.

Subject to regulatory approval and certain provisions of the Series 47 Shares, on January 31, 2023 and on January 31 every five years thereafter, CIBC may, at its option, redeem all or any part of the then outstanding Series 47 Shares at par.

Subject to the right of redemption, holders of the Series 47 Shares will have the right to convert their shares into Non-cumulative Floating Rate Class A Preferred Shares Series 48 (Non-Viability Contingent Capital (NVCC)) (the “Series 48 Shares”), subject to certain conditions, on January 31, 2023 and on January 31 every five years thereafter. Holders of the Series 48 Shares will be entitled to receive a quarterly floating rate dividend, as and when declared by the Board of Directors of CIBC, equal to the three-month Government of Canada Treasury Bill yield plus 2.45%.

Holders of the Series 48 Shares may convert their Series 48 Shares into Series 47 Shares, subject to certain conditions, on January 31, 2028 and on January 31 every five years thereafter.

The expected closing date is January 18, 2018. CIBC will make an application to list the Series 47 Shares as of the closing date on the Toronto Stock Exchange. The net proceeds of this offering will be used for general purposes of CIBC.

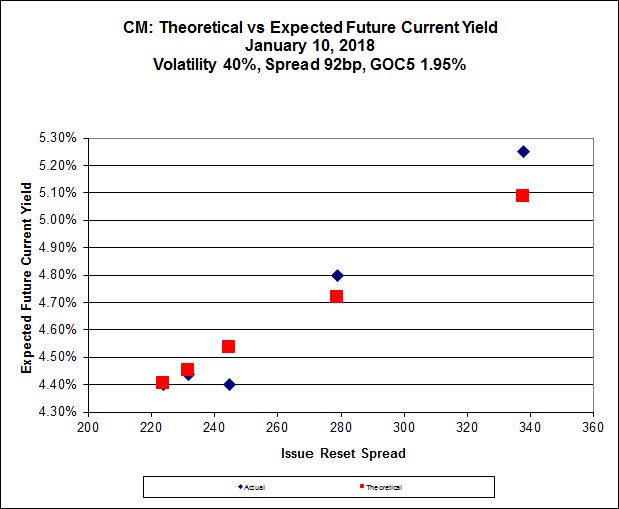
This issue looks quite expensive to me, according to Implied Volatility Analysis:

impvol_cm_180110
Click for Big

We see in this chart many of the same features we saw when reviewing the recent BPO new issue and yesterday’s BEP issue:

  • The curve is very steep, with Implied Volatility equal to 40% (a ridiculously large figure), and
  • The extant issues ar trading near par

The ludicrously high figure of Implied Volatility is something I take to mean that the underlying assumption of the Black-Scholes model, that of no directionality of prices, is not accepted by the market; the market seems to be taking the view that since things seem rosy now, they will always be rosy and everything will trade near par in the future.

I balk at ascribing a 100% probability to this outcome. There may still be a few old geezers amongst the Assiduous Readers of this blog who can still (faintly) remember the Great Bear Market of 2014-16, in which quite a few similar assumptions made earlier turned out to be slightly inaccurate.

For the long term, I suggest that any change in the slope of the curve will be a flattening, with a very high degree of confidence. This will imply that the higher-spread issues will outperform the lower-spread issues.

All told, though, I have no hesitation in slapping an ‘Expensive’ label on this issue – according to the Implied Volatility analysis shown above, the theoretical price of the new issue is 24.26.

New Issues

New Issue: BEP FixedReset 5.00%+300M500

Brookfield Renewable Partners L.P. has announced:

that it has agreed to issue 8,000,000 Cumulative Minimum Rate Reset Class A Preferred Limited Partnership Units, Series 13 (the “Series 13 Preferred Units”) on a bought deal basis to a syndicate of underwriters led by TD Securities Inc., BMO Capital Markets, CIBC Capital Markets, RBC Capital Markets and Scotiabank for distribution to the public. The Series 13 Preferred Units will be issued at a price of $25.00 per unit, for gross proceeds of $200,000,000.

Holders of the Series 13 Preferred Units will be entitled to receive a cumulative quarterly fixed distribution yielding 5.00% annually for the initial period ending April 30, 2023. Thereafter, the distribution rate will be reset every five years at a rate equal to the greater of (i) the 5-year Government of Canada bond yield plus 3.00%, and (ii) 5.00%. The Series 13 Preferred Units are redeemable on April 30, 2023 and on each Series 13 Reclassification Date (as defined below) thereafter.

Holders of the Series 13 Preferred Units will have the right, at their option, to reclassify their Series 13 Preferred Units into Cumulative Floating Rate Reset Class A Preferred Limited Partnership Units, Series 14 (“Series 14 Preferred Units”), subject to certain conditions, on April 30, 2023 and on April 30 every 5 years thereafter (each a “Series 13 Reclassification Date”). Holders of Series 14 Preferred Units will be entitled to receive a cumulative quarterly floating distribution at a rate equal to the 90-day Canadian Treasury Bill yield plus 3.00%.

Brookfield Renewable has granted the underwriters an option, exercisable until 48 hours prior to closing, to purchase up to an additional 2,000,000 Series 13 Preferred Units which, if exercised, would increase the gross offering size to $250,000,000.

The Series 13 Preferred Units will be offered in all provinces and territories of Canada by way of a supplement to Brookfield Renewable’s existing Canadian short form base shelf prospectus. The Series 13 Preferred Units may not be offered or sold in the United States or to U.S. persons absent registration or an applicable exemption from the registration requirements under the U.S. Securities Act.

Brookfield Renewable intends to use the net proceeds of the issue of Series 13 Preferred Units to repay indebtedness. The offering of Series 13 Preferred Units is expected to close on or about January 16, 2018.

They later announced:

that as a result of strong investor demand for its previously announced offering, the underwriters have exercised their option to increase the size of the offering to 10,000,000 Cumulative Minimum Rate Reset Class A Preferred Limited Partnership Units, Series 13 (the “Series 13 Preferred Units”) to be offered on a bought deal basis to a syndicate of underwriters led by TD Securities Inc., BMO Capital Markets, CIBC Capital Markets, RBC Capital Markets and Scotiabank. The Series 13 Preferred Units will be issued at a price of $25.00 per unit, for gross proceeds of $250,000,000.

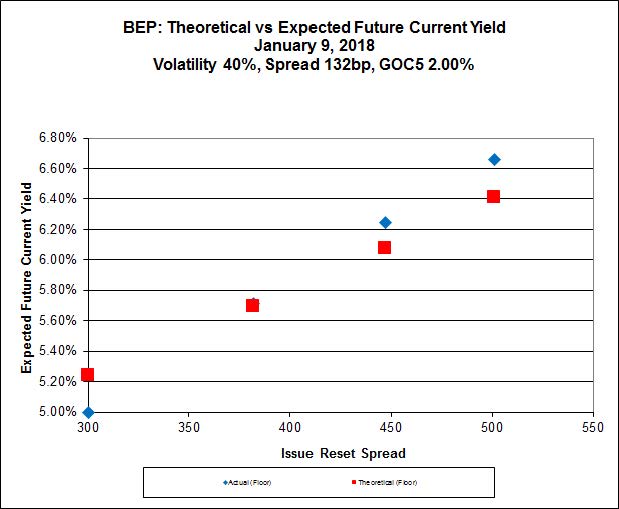
This issue looks quite expensive to me, but quantifying the degree of richness is difficult. According to Implied Volatility Analysis:

impvol_bep_180109
Click for Big

We see in this chart many of the same features we saw when reviewing the recent BPO new issue:

  • The curve is very steep, with Implied Volatility equal to 40% (a ridiculously large figure), and
  • Each of the extant issues is trading at a premium

The ludicrously high figure of Implied Volatility is something I take to mean that the underlying assumption of the Black-Scholes model, that of no directionality of prices, is not accepted by the market; in turn, I suggest that this reflects a rather touching faith that the existence of a minimum rate guarantee on reset also indicates that the issues will never, ever trade below par. There will be a lot of long faces when this test gets failed in the future!

However, for the long term, I suggest that any change in the slope of the curve will be a flattening, with a very high degree of confidence. This will imply that the higher-spread issues will outperform the lower-spread issues.

Complicating the above analysis is a high probability that the three extant issues will each be called at the first opportunity. I will certainly agree that this is likely to happen, but I balk at ascribing a 100% probability to this outcome. There may still be a few old geezers amongst the Assiduous Readers of this blog who can still (faintly) remember the Great Bear Market of 2014-16, in which quite a few similar assumptions made earlier turned out to be slightly inaccurate.

All told, though, I have no hesitation in slapping a ‘Very Expensive’ label on this issue.

New Issues

New Issue: KML FixedReset, 5.20%+351M520

Kinder Morgan Canada Limited has announced (although not yet on their website):

that it has entered into an agreement with a syndicate of underwriters led by CIBC Capital Markets, Scotiabank, RBC Capital Markets and TD Securities (together, the “Underwriters”) pursuant to which the Underwriters have agreed to purchase from the Company, 8,000,000 cumulative redeemable minimum rate reset preferred shares, Series 3 (the “Series 3 Preferred Shares”) at a price of $25.00 per share for distribution to the public.

The Company has granted to the Underwriters an option, exercisable at any time up to 48 hours prior to the closing of the offering, to purchase up to an additional 2,000,000 Series 3 Preferred Shares at a price of $25.00 per share.

The Company intends to use the proceeds from the offering to indirectly subscribe for preferred units in Kinder Morgan Canada Limited Partnership, which intends to subsequently use such proceeds to, directly or indirectly, finance the development, construction and completion of the Trans Mountain Expansion Project and Base Line Terminal project as well as potential future growth opportunities, to repay indebtedness and for general corporate purposes.

The holders of Series 3 Preferred Shares will be entitled to receive fixed cumulative dividends at an annual rate of $1.3000 per share, payable quarterly on the 15th day of February, May, August and November as and when declared by the Board of Directors of the Company, yielding 5.20 percent per annum at the issue price, for the initial fixed rate period to but excluding February 15, 2023 (the “Initial Fixed Rate Period”). The first quarterly dividend payment date is scheduled for February 15, 2018 and is anticipated to be in the amount of $0.22082 per share (assuming closing of the offering on December 15, 2017). The dividend rate will reset on February 15, 2023 and every five years thereafter at a rate equal to the sum of the then five-year Government of Canada bond yield plus 3.51 percent, provided that, in any event, such rate shall not be less than 5.20 percent per annum. The Series 3 Preferred Shares are redeemable by the Company, at its option, on February 15, 2023 and on February 15 of every fifth year thereafter at a price of $25.00 per share plus accrued and unpaid dividends.

The holders of Series 3 Preferred Shares will have the right to convert their shares into cumulative redeemable floating rate preferred shares, Series 4 (the “Series 4 Preferred Shares”), subject to certain conditions, on February 15, 2023 and on February 15 of every fifth year thereafter. The holders of Series 4 Preferred Shares will be entitled to receive quarterly floating rate cumulative dividends, as and when declared by the Board of Directors of the Company, at a rate equal to the sum of the then 90-day Government of Canada treasury bill rate plus 3.51 percent.

Closing of the offering is expected to occur on December 15, 2017, subject to customary closing conditions.

The offering is being made under a prospectus supplement to the base shelf prospectus of the Company dated July 28, 2017 (together, the “Prospectus”). Copies of the Prospectus may be obtained from Canadian Imperial Bank of Commerce, Commerce Court, Toronto, Ontario M5L 1A2, Telephone (416) 980-3096, The Bank of Nova Scotia, Scotia Plaza, 44 King Street West, Toronto, Ontario M5H 1H1, Telephone: (416) 866-3672, Royal Bank of Canada, 200 Bay Street, 4th Floor, North Tower, Toronto, Ontario, M5J 2W7, Telephone (416) 955-7803 and The Toronto-Dominion Bank, Toronto-Dominion Centre, Toronto, Ontario M5K 1A2, Telephone: (416) 308-6963. Investors should read the Prospectus, and the documents incorporated therein by reference, in their entirety, before making an investment decision.

The issue even made the Globe & Mail, presumably because of controversy about the Trans Mountain Pipeline:

Kinder Morgan Canada Ltd. is selling $200-million in shares even as the company dials back spending and warns of additional delays to its marquee Trans Mountain pipeline expansion.

The unit of Houston-based Kinder Morgan Inc. said Wednesday that it is selling eight million preferred units at $25 each in a bought deal to major banks, with proceeds earmarked to help finance the $7.4-billion pipeline expansion to Canada’s West Coast.

The offering comes despite warnings the 590,000-barrel-a-day expansion project could see oil shipments commence nine months later than originally planned. This week, the company said delays could extend beyond September, 2020, further driving up costs.

New Issues

New Issue: ENB FixedReset 4.90%+317M490

Enbridge Inc. has announced:

that it has entered into an agreement with a group of underwriters to sell $400 million Cumulative Redeemable Minimum Rate Reset Preference Shares, Series 19 (the “Series 19 Preferred Shares”) at a price of $25.00 per share for distribution to the public. Closing of the offering is expected on or about December 11, 2017.

The holders of Series 19 Preferred Shares will be entitled to receive fixed cumulative dividends at an annual rate of $1.225 per share, payable quarterly on the first day of March, June, September and December, as and when declared by the Board of Directors of Enbridge. The Series 19 Preferred Shares are expected to yield 4.90 percent per annum for the initial fixed rate period to, but excluding, March 1, 2023. The first quarterly dividend payment date is scheduled for March 1, 2018. The dividend rate will reset on March 1, 2023 and every five years thereafter at a rate equal to the sum of the then five-year Canadian Government bond yield plus 3.17 percent, provided that, in any event, such rate shall not be less than 4.90 percent per annum. The Series 19 Preferred Shares are redeemable by Enbridge, at its option, on March 1, 2023 and on March 1 of every fifth year thereafter.

The holders of Series 19 Preferred Shares will have the right to convert their shares into Cumulative Redeemable Preference Shares, Series 20 (the “Series 20 Preferred Shares”) on March 1, 2023 and on March 1 of every fifth year thereafter, subject to certain conditions. The holders of Series 20 Preferred Shares will be entitled to receive quarterly floating rate cumulative dividends, as and when declared by the Board of Directors of Enbridge, at a rate equal to the sum of the 90-day Government of Canada Treasury bill rate plus 3.17 percent.

Enbridge has granted to the underwriters an option to purchase up to an additional four million Series 19 Preferred Shares at a price of $25.00 per share, exercisable at any time up to 48 hours prior to the closing of the offering.

The offering is being made only in Canada by means of a prospectus supplement to the base shelf prospectus of the Company dated September 14, 2017. Proceeds are expected to be used to partially fund capital projects, to reduce existing indebtedness and for other general corporate purposes of the Company and its affiliates.

The syndicate of underwriters is led by Scotiabank, BMO Capital Markets, CIBC Capital Markets, and National Bank Financial.

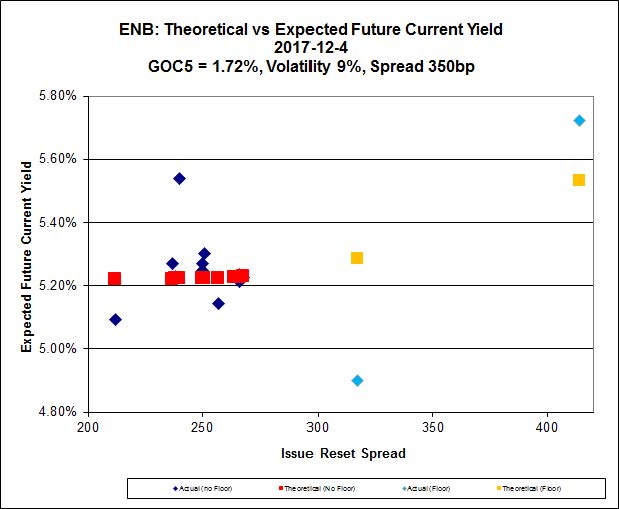
This issue looks extraordinarily expensive to me! According to Implied Volatility analysis:

impvol_enb_171204
Click for Big

With the parameters shown, the theoretical value of the new issue is 23.17, roughly equivalent to the BPO new issue. Critics will be quick to point out that in this calculation there is zero value assigned to the minimum rate guarantee … but I’d say that’s about right!