Category: Market Action

Market Action

April 13, 2020

Amidst all the gloom, it was interesting to see the details of a recent Scotia covered bond issue:

Bank of Nova Scotia (BNS) became the first bank outside Europe to issue a deeply negative yielding covered bond in a good size on Wednesday. The transaction provided a beacon for other issuers and was perfectly timed to benefit from a window of market stability between Monday’s and Thursday’s shocking volatility.

It’s Series CBL26, with details available on the Scotiabank covered bond page. The term sheet specifies:

Specified Currency or Currencies: €, EUR or EURO
…
Issue Price: 101.198% of the Aggregate Nominal Amount
…
Final Maturity Date: 18 March 2025
…
Rate(s) of Interest: 0.01% per annum payable annually in arrears on each Interest Payment Date
…
Indication of yield: -0.228% per annum

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -4.2670 % 1,408.4
FixedFloater 0.00 % 0.00 % 0 0.00 0 -4.2670 % 2,584.3
Floater 5.46 % 5.67 % 42,377 14.41 4 -4.2670 % 1,489.4
OpRet 0.00 % 0.00 % 0 0.00 0 -0.2090 % 3,262.3
SplitShare 5.09 % 6.28 % 86,727 3.95 7 -0.2090 % 3,895.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.2090 % 3,039.7
Perpetual-Premium 0.00 % 0.00 % 0 0.00 0 0.2689 % 2,756.4
Perpetual-Discount 6.08 % 6.32 % 90,181 13.47 35 0.2689 % 2,956.6
FixedReset Disc 6.67 % 5.75 % 199,915 13.99 83 0.1867 % 1,699.9
Deemed-Retractible 5.81 % 6.18 % 102,168 13.46 27 -0.3886 % 2,907.9
FloatingReset 3.22 % 4.78 % 31,613 14.44 4 -1.2768 % 1,694.6
FixedReset Prem 0.00 % 0.00 % 0 0.00 0 0.1867 % 2,350.9
FixedReset Bank Non 1.97 % 4.88 % 113,178 1.75 3 -0.4003 % 2,704.0
FixedReset Ins Non 7.07 % 6.13 % 125,076 13.43 22 0.7310 % 1,680.3
Performance Highlights
Issue Index Change Notes
TRP.PR.G FixedReset Disc -11.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 12.45
Evaluated at bid price : 12.45
Bid-YTW : 7.28 %
TRP.PR.H FloatingReset -10.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 7.72
Evaluated at bid price : 7.72
Bid-YTW : 4.96 %
BAM.PR.K Floater -6.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 7.52
Evaluated at bid price : 7.52
Bid-YTW : 5.75 %
HSE.PR.E FixedReset Disc -5.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 9.25
Evaluated at bid price : 9.25
Bid-YTW : 11.99 %
BAM.PR.C Floater -4.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 7.56
Evaluated at bid price : 7.56
Bid-YTW : 5.72 %
BAM.PR.B Floater -4.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 7.63
Evaluated at bid price : 7.63
Bid-YTW : 5.67 %
BAM.PR.Z FixedReset Disc -4.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 14.60
Evaluated at bid price : 14.60
Bid-YTW : 6.47 %
TRP.PR.B FixedReset Disc -3.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 8.25
Evaluated at bid price : 8.25
Bid-YTW : 5.69 %
MFC.PR.C Deemed-Retractible -3.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 6.33 %
GWO.PR.N FixedReset Ins Non -3.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 8.76
Evaluated at bid price : 8.76
Bid-YTW : 5.44 %
BIP.PR.E FixedReset Disc -3.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 19.40
Evaluated at bid price : 19.40
Bid-YTW : 6.51 %
SLF.PR.G FixedReset Ins Non -2.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 8.80
Evaluated at bid price : 8.80
Bid-YTW : 5.71 %
TRP.PR.A FixedReset Disc -2.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 11.60
Evaluated at bid price : 11.60
Bid-YTW : 6.04 %
TRP.PR.C FixedReset Disc -2.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 8.60
Evaluated at bid price : 8.60
Bid-YTW : 6.21 %
BIP.PR.D FixedReset Disc -2.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 19.50
Evaluated at bid price : 19.50
Bid-YTW : 6.48 %
IFC.PR.A FixedReset Ins Non -2.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 10.24
Evaluated at bid price : 10.24
Bid-YTW : 6.13 %
BIP.PR.F FixedReset Disc -2.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 20.01
Evaluated at bid price : 20.01
Bid-YTW : 6.44 %
HSE.PR.G FixedReset Disc -2.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 8.65
Evaluated at bid price : 8.65
Bid-YTW : 12.08 %
PWF.PR.A Floater -2.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 8.70
Evaluated at bid price : 8.70
Bid-YTW : 5.00 %
TRP.PR.K FixedReset Disc -2.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 21.05
Evaluated at bid price : 21.05
Bid-YTW : 5.91 %
CM.PR.R FixedReset Disc -2.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 16.50
Evaluated at bid price : 16.50
Bid-YTW : 6.13 %
SLF.PR.C Deemed-Retractible -1.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 18.41
Evaluated at bid price : 18.41
Bid-YTW : 6.10 %
CU.PR.C FixedReset Disc -1.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 14.37
Evaluated at bid price : 14.37
Bid-YTW : 5.35 %
BAM.PF.E FixedReset Disc -1.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 13.01
Evaluated at bid price : 13.01
Bid-YTW : 6.35 %
BNS.PR.H FixedReset Disc -1.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 21.50
Evaluated at bid price : 21.50
Bid-YTW : 5.58 %
IFC.PR.G FixedReset Ins Non -1.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 14.25
Evaluated at bid price : 14.25
Bid-YTW : 6.17 %
EIT.PR.B SplitShare -1.67 % YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2025-03-14
Maturity Price : 25.00
Evaluated at bid price : 23.50
Bid-YTW : 6.37 %
TRP.PR.D FixedReset Disc -1.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 13.05
Evaluated at bid price : 13.05
Bid-YTW : 6.14 %
IFC.PR.C FixedReset Ins Non -1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 13.31
Evaluated at bid price : 13.31
Bid-YTW : 6.16 %
RY.PR.W Perpetual-Discount -1.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 21.98
Evaluated at bid price : 22.21
Bid-YTW : 5.59 %
SLF.PR.E Deemed-Retractible -1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 18.65
Evaluated at bid price : 18.65
Bid-YTW : 6.09 %
EML.PR.A FixedReset Ins Non -1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 21.75
Evaluated at bid price : 22.20
Bid-YTW : 6.30 %
SLF.PR.D Deemed-Retractible -1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 18.52
Evaluated at bid price : 18.52
Bid-YTW : 6.07 %
NA.PR.A FixedReset Disc -1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 22.34
Evaluated at bid price : 22.75
Bid-YTW : 5.75 %
SLF.PR.A Deemed-Retractible -1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 19.65
Evaluated at bid price : 19.65
Bid-YTW : 6.10 %
IAF.PR.B Deemed-Retractible -1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 19.06
Evaluated at bid price : 19.06
Bid-YTW : 6.09 %
BNS.PR.Z FixedReset Bank Non -1.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.75
Bid-YTW : 4.88 %
BMO.PR.Y FixedReset Disc -1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 14.00
Evaluated at bid price : 14.00
Bid-YTW : 5.99 %
POW.PR.G Perpetual-Discount 1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 21.75
Evaluated at bid price : 22.07
Bid-YTW : 6.37 %
IAF.PR.I FixedReset Ins Non 1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 14.75
Evaluated at bid price : 14.75
Bid-YTW : 6.16 %
SLF.PR.J FloatingReset 1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 8.70
Evaluated at bid price : 8.70
Bid-YTW : 4.78 %
PWF.PR.E Perpetual-Discount 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 21.53
Evaluated at bid price : 21.79
Bid-YTW : 6.32 %
RY.PR.H FixedReset Disc 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 14.15
Evaluated at bid price : 14.15
Bid-YTW : 5.47 %
TD.PF.G FixedReset Disc 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 22.73
Evaluated at bid price : 23.26
Bid-YTW : 5.64 %
CU.PR.D Perpetual-Discount 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 20.98
Evaluated at bid price : 20.98
Bid-YTW : 5.93 %
PWF.PR.K Perpetual-Discount 1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 19.58
Evaluated at bid price : 19.58
Bid-YTW : 6.35 %
POW.PR.A Perpetual-Discount 1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 21.87
Evaluated at bid price : 22.11
Bid-YTW : 6.37 %
MFC.PR.H FixedReset Ins Non 1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 15.48
Evaluated at bid price : 15.48
Bid-YTW : 6.19 %
TRP.PR.F FloatingReset 1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 9.64
Evaluated at bid price : 9.64
Bid-YTW : 5.65 %
TRP.PR.J FixedReset Disc 1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 23.44
Evaluated at bid price : 23.95
Bid-YTW : 5.81 %
BMO.PR.W FixedReset Disc 1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 13.80
Evaluated at bid price : 13.80
Bid-YTW : 5.69 %
CU.PR.G Perpetual-Discount 1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 19.39
Evaluated at bid price : 19.39
Bid-YTW : 5.89 %
BMO.PR.T FixedReset Disc 1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 13.55
Evaluated at bid price : 13.55
Bid-YTW : 5.68 %
PWF.PR.S Perpetual-Discount 1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 19.25
Evaluated at bid price : 19.25
Bid-YTW : 6.26 %
IAF.PR.G FixedReset Ins Non 1.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 13.80
Evaluated at bid price : 13.80
Bid-YTW : 6.37 %
MFC.PR.K FixedReset Ins Non 1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 13.54
Evaluated at bid price : 13.54
Bid-YTW : 5.86 %
ELF.PR.H Perpetual-Discount 1.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 21.63
Evaluated at bid price : 21.95
Bid-YTW : 6.29 %
HSE.PR.C FixedReset Disc 1.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 9.18
Evaluated at bid price : 9.18
Bid-YTW : 11.39 %
BIP.PR.C FixedReset Disc 1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 21.41
Evaluated at bid price : 21.41
Bid-YTW : 6.31 %
BIP.PR.A FixedReset Disc 1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 14.25
Evaluated at bid price : 14.25
Bid-YTW : 7.35 %
BAM.PF.I FixedReset Disc 1.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 22.09
Evaluated at bid price : 22.38
Bid-YTW : 5.39 %
BAM.PF.H FixedReset Disc 1.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 22.71
Evaluated at bid price : 23.35
Bid-YTW : 5.36 %
W.PR.M FixedReset Disc 1.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 22.59
Evaluated at bid price : 23.00
Bid-YTW : 5.67 %
PWF.PR.L Perpetual-Discount 1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 20.25
Evaluated at bid price : 20.25
Bid-YTW : 6.32 %
MFC.PR.O FixedReset Ins Non 2.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 23.51
Evaluated at bid price : 24.00
Bid-YTW : 5.83 %
NA.PR.X FixedReset Disc 2.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 23.54
Evaluated at bid price : 24.05
Bid-YTW : 5.68 %
BAM.PR.R FixedReset Disc 2.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 11.50
Evaluated at bid price : 11.50
Bid-YTW : 6.35 %
MFC.PR.R FixedReset Ins Non 2.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 18.50
Evaluated at bid price : 18.50
Bid-YTW : 6.11 %
RY.PR.J FixedReset Disc 3.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 15.41
Evaluated at bid price : 15.41
Bid-YTW : 5.47 %
CU.PR.F Perpetual-Discount 3.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 5.71 %
MFC.PR.F FixedReset Ins Non 3.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 8.57
Evaluated at bid price : 8.57
Bid-YTW : 5.91 %
MFC.PR.G FixedReset Ins Non 3.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 14.30
Evaluated at bid price : 14.30
Bid-YTW : 6.24 %
MFC.PR.L FixedReset Ins Non 3.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 12.93
Evaluated at bid price : 12.93
Bid-YTW : 5.88 %
NA.PR.C FixedReset Disc 4.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 16.85
Evaluated at bid price : 16.85
Bid-YTW : 6.06 %
HSE.PR.A FixedReset Disc 4.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 5.91
Evaluated at bid price : 5.91
Bid-YTW : 9.96 %
MFC.PR.I FixedReset Ins Non 5.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 14.79
Evaluated at bid price : 14.79
Bid-YTW : 6.13 %
CM.PR.P FixedReset Disc 5.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 13.29
Evaluated at bid price : 13.29
Bid-YTW : 5.93 %
TRP.PR.E FixedReset Disc 7.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 12.90
Evaluated at bid price : 12.90
Bid-YTW : 6.15 %
RY.PR.M FixedReset Disc 20.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 14.46
Evaluated at bid price : 14.46
Bid-YTW : 5.65 %
Volume Highlights
Issue Index Shares
Traded
Notes
CM.PR.R FixedReset Disc 312,511 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 16.50
Evaluated at bid price : 16.50
Bid-YTW : 6.13 %
BNS.PR.H FixedReset Disc 297,922 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 21.50
Evaluated at bid price : 21.50
Bid-YTW : 5.58 %
TD.PF.J FixedReset Disc 103,846 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 16.71
Evaluated at bid price : 16.71
Bid-YTW : 5.29 %
TD.PF.A FixedReset Disc 79,417 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 13.76
Evaluated at bid price : 13.76
Bid-YTW : 5.56 %
RY.PR.Q FixedReset Disc 55,839 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 23.33
Evaluated at bid price : 23.85
Bid-YTW : 5.44 %
MFC.PR.G FixedReset Ins Non 45,799 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 14.30
Evaluated at bid price : 14.30
Bid-YTW : 6.24 %
There were 32 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
TD.PF.M FixedReset Disc Quote: 19.65 – 24.83
Spot Rate : 5.1800
Average : 2.7902

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 19.65
Evaluated at bid price : 19.65
Bid-YTW : 5.61 %

BAM.PF.A FixedReset Disc Quote: 15.75 – 21.00
Spot Rate : 5.2500
Average : 3.4390

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 15.75
Evaluated at bid price : 15.75
Bid-YTW : 6.12 %

TRP.PR.G FixedReset Disc Quote: 12.45 – 15.29
Spot Rate : 2.8400
Average : 2.1144

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 12.45
Evaluated at bid price : 12.45
Bid-YTW : 7.28 %

TD.PF.E FixedReset Disc Quote: 15.35 – 17.30
Spot Rate : 1.9500
Average : 1.4169

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 15.35
Evaluated at bid price : 15.35
Bid-YTW : 5.66 %

BAM.PF.I FixedReset Disc Quote: 22.38 – 23.84
Spot Rate : 1.4600
Average : 0.9772

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 22.09
Evaluated at bid price : 22.38
Bid-YTW : 5.39 %

TRP.PR.K FixedReset Disc Quote: 21.05 – 22.24
Spot Rate : 1.1900
Average : 0.8757

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-13
Maturity Price : 21.05
Evaluated at bid price : 21.05
Bid-YTW : 5.91 %

Market Action

April 9, 2020

unicorn_200409

cash_200408

Who needs jobs when we’ve got Central Banks?:

Global equity benchmarks moved higher on Thursday following signs of some success by governments and central banks which have taken additional steps to bolster their economies during the COVID-19 pandemic, while oil prices pulled back from an earlier surge.

Canada’s main stock index rose on Thursday as the U.S. Federal Reserve’s massive program to shore up the world’s largest economy overshadowed record domestic job losses in March.
…
However, bolstering investor sentiment was a broad, $2.3 trillion effort by the U.S. Federal Reserve to bolster local governments and small and mid-sized businesses in its latest move to keep the U.S. economy intact.

The Toronto Stock Exchange’s S&P/TSX composite index was unofficially up 240.92 points, or 1.73%, at 14,166.63.

Eight of the 11 major TSX sectors were higher, with materials leading gains with a 6.9% rise.

The sector, which mostly comprises of precious metal miners, was helped by a surge in prices, which jumped to their highest in a month on Thursday.

Energy stocks reversed course in afternoon trading and slid 2%.

Oil prices slumped on Thursday, giving back an earlier 10% surge as investors doubted the emerging supply-cut agreement between members of OPEC and its allies would adequately address the global fuel demand collapse caused by the coronavirus pandemic.

So, yes, the Fed took more action today:

The Federal Reserve on Thursday announced an expansive effort to help companies and state and local governments gain access to funding, ramping up its already extensive efforts to protect the economy and financial markets from the impact of a severe downturn.

The central bank said it could pump $2.3 trillion into the economy through the new and expanded programs. It rolled out the relief package just as the government announced that 6.6 million more Americans were newly jobless, laying bare the severe damage to the economy from the coronavirus pandemic.
…
The Fed’s new program makes use of funds recently authorized by Congress to buy municipal bonds and expand corporate bond-buying programs to include some lower-rated and riskier debt. Doing so will keep credit flowing through the economy, including to companies and state and local governments that might otherwise struggle to get access to it.

Mohamed El-Erian passes on a chart:

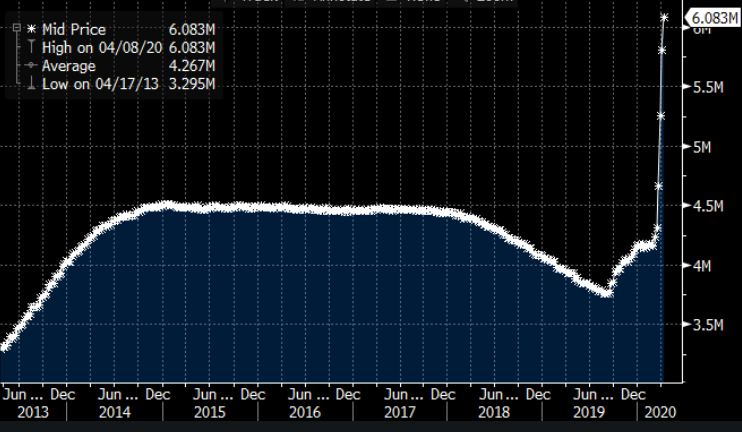
Here’s another astounding graph — also unthinkable just a few weeks ago — with another sharp and unprecedented spike in a very short period of time:

The Fed’s balance sheet has expanded to above $6 trillion … and it’s going much higher.

fedassets_200409
Click for Big

And the UK has taken a big step towards monetizing its debt:

The Treasury has announced it is to extend its overdraft facility at the Bank of England in a fresh sign of the mounting financial pressure on the government caused by the Covid-19-enforced lockdown of the economy.

Amid growing speculation that the quarantining will be extended next week, the Treasury said it needed extra firepower to support its cashflow and to ensure financial markets ran smoothly.

The Treasury has a long-established overdraft facility at the Bank through the “ways and means” facility. It currently stands at £400m but at times of crisis the chancellor can draw on it as a source of cash, and during the 2008 recession it rose to £19.8bn.

Canada had some horrific jobs numbers:

More than one million people in Canada lost their jobs in March and the unemployment rate climbed to 7.8 per cent, reflecting the first wave of layoffs resulting from the COVID-19 pandemic.

The March job losses easily surpassed a record one-month decline set in January of 2009 – when employment dropped by roughly 125,000 – according to Labour Force Survey data from Statistics Canada that dates back to 1976. March also saw the largest one-month increase of the country’s jobless rate, which had been 5.6 per cent in February.
…
Since Statscan’s survey week, layoffs have intensified as governments have implemented tighter restrictions on business operations and social interactions to curb the virus’s growth. Since March 16, more than 5 million Canadians have applied for emergency financial assistance with the federal government, a sign of unprecedented labour disruption.

As such, the April labour report (released early next month) is widely expected to show even worse job-loss figures.

There seems to be some progress towards an oil deal:

OPEC and it allies held talks on Thursday on record oil output curbs of 15 million to 20 million barrels per day (bpd), or 15 per cent to 20 per cent of global supplies, to support prices hammered by the coronavirus crisis, OPEC and Russian sources said.

They said the cuts included contributions of up to 5 million bpd from producers outside their group known as OPEC+ and could be made gradually, potentially overcoming resistance from the United States, whose involvement is seen as vital to win broad backing for an agreement.
…
Three OPEC+ sources said the group wanted non-members such as the United States, Canada, Norway and Brazil to contribute 5 million bpd to the overall cut, with OPEC+ would add at least another 10 million to 12 million bpd.

I do not support Canada joining the global oil cartel, however exciting it might be to rub shoulders with Big Men such as Putin and MBS. In extremis, I think, we should be imposing tariffs. The thought sticks in my craw, but there is little alternative that I can see; OPEC is simply another cartel and the current flood of oil should be viewed as simply another example of predatory pricing; OPEC would love to drive US shale oil and Canadian tar sands producers out of the game; once the western industry has been destroyed they will be free to jack prices up as far as they like.

There’s no global competition board to complain to; tariffs are the only solution. But please, keep them as low as possible. The objective should be to keep the Canadian oil industry on life-support, not to create a new class of welfare recipients.

And here’s some more on bank dividends:

During a bank CEO conference in early January, Canada’s banking regulator pledged to be more transparent about its work.

Assistant superintendent Jamey Hubbs said the Office of the Superintendent of Financial Institutions wants to build trust with Canadians. While he cautioned that OSFI has no plans to share top-secret information, he conceded that the regulator must do a better job of keeping regular folks informed.
…
Consequently, as regulators around the world free up hundreds of billions of dollars in capital reserves, and in some cases restrict banks from paying dividends, OSFI owes it to Canadians to be frank about how our banks compare with their international peers. That means providing clear answers about whether our banks are capitalized differently than those abroad, and whether it’s realistic to believe that dividends will remain sacrosanct throughout this crisis without a complete explanation about why regulators are sure lenders won’t need that money down the road.
…
Some banks have more latitude on how they meet capital requirements. The Big Six, for instance, use what’s known in industry parlance as the “advanced internal ratings-based approach” to calculate credit risk, which means they determine “all variables” for calculating risk weights. Risk-weighted assets are used to determine how much capital banks must set aside.

“The accuracy of measures of risk-weighted assets is a key concern especially for large banks in high-income OECD countries,” the World Bank Group stated in a 2019 policy research working paper.
…
It’s incumbent on OSFI and banks to explain whether their black-swan stress-testing scenarios are based on assumptions that mirror the conditions of this crisis.

Bay Street analysts say many levers can be pulled before dividends are cut, but they’re in the business of selling stock. Maintaining public confidence in Canada’s financial system requires clear answers from regulators, not a request for the unquestioning belief of the masses.

Clear answers? From OSFI? In my experience, they regard any question as a direct insult.

And now it’s time for PrefLetter.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 5.8387 % 1,471.2
FixedFloater 0.00 % 0.00 % 0 0.00 0 5.8387 % 2,699.5
Floater 5.23 % 5.40 % 43,108 14.85 4 5.8387 % 1,555.8
OpRet 0.00 % 0.00 % 0 0.00 0 1.6514 % 3,269.1
SplitShare 5.08 % 6.09 % 87,395 3.96 7 1.6514 % 3,904.0
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 1.6514 % 3,046.1
Perpetual-Premium 0.00 % 0.00 % 0 0.00 0 1.6271 % 2,749.0
Perpetual-Discount 6.10 % 6.34 % 92,850 13.48 35 1.6271 % 2,948.6
FixedReset Disc 6.68 % 5.77 % 204,851 13.98 83 2.7130 % 1,696.7
Deemed-Retractible 5.79 % 6.12 % 101,901 13.50 27 2.0050 % 2,919.3
FloatingReset 3.18 % 4.45 % 32,023 14.34 4 2.0130 % 1,716.5
FixedReset Prem 0.00 % 0.00 % 0 0.00 0 2.7130 % 2,346.5
FixedReset Bank Non 1.96 % 4.23 % 114,650 1.77 3 1.0460 % 2,714.9
FixedReset Ins Non 7.06 % 6.11 % 117,681 13.37 22 4.2493 % 1,668.1
Performance Highlights
Issue Index Change Notes
RY.PR.M FixedReset Disc -17.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 11.98
Evaluated at bid price : 11.98
Bid-YTW : 6.83 %
PWF.PR.P FixedReset Disc -6.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 9.00
Evaluated at bid price : 9.00
Bid-YTW : 6.10 %
BAM.PR.X FixedReset Disc -4.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 9.10
Evaluated at bid price : 9.10
Bid-YTW : 6.74 %
CM.PR.P FixedReset Disc -4.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 12.55
Evaluated at bid price : 12.55
Bid-YTW : 6.30 %
HSE.PR.G FixedReset Disc -3.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 8.85
Evaluated at bid price : 8.85
Bid-YTW : 11.78 %
HSE.PR.C FixedReset Disc -3.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 9.03
Evaluated at bid price : 9.03
Bid-YTW : 11.58 %
TRP.PR.E FixedReset Disc -1.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 12.00
Evaluated at bid price : 12.00
Bid-YTW : 6.62 %
CU.PR.F Perpetual-Discount -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 19.30
Evaluated at bid price : 19.30
Bid-YTW : 5.92 %
CM.PR.S FixedReset Disc 1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 14.47
Evaluated at bid price : 14.47
Bid-YTW : 5.71 %
TD.PF.K FixedReset Disc 1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 16.31
Evaluated at bid price : 16.31
Bid-YTW : 5.40 %
PVS.PR.D SplitShare 1.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2021-10-08
Maturity Price : 25.00
Evaluated at bid price : 24.26
Bid-YTW : 6.93 %
BNS.PR.Z FixedReset Bank Non 1.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.01
Bid-YTW : 4.23 %
MFC.PR.F FixedReset Ins Non 1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 8.26
Evaluated at bid price : 8.26
Bid-YTW : 6.13 %
TD.PF.A FixedReset Disc 1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 13.73
Evaluated at bid price : 13.73
Bid-YTW : 5.57 %
RY.PR.R FixedReset Disc 1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 23.86
Evaluated at bid price : 24.27
Bid-YTW : 5.62 %
RY.PR.F Deemed-Retractible 1.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.55
Bid-YTW : 5.87 %
RY.PR.A Deemed-Retractible 1.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.67
Bid-YTW : 5.58 %
GWO.PR.H Deemed-Retractible 1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 19.69
Evaluated at bid price : 19.69
Bid-YTW : 6.22 %
PWF.PR.G Perpetual-Discount 1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 22.69
Evaluated at bid price : 22.93
Bid-YTW : 6.44 %
CCS.PR.C Deemed-Retractible 1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 21.02
Evaluated at bid price : 21.02
Bid-YTW : 6.00 %
GWO.PR.Q Deemed-Retractible 1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 20.46
Evaluated at bid price : 20.46
Bid-YTW : 6.35 %
ELF.PR.G Perpetual-Discount 1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 18.85
Evaluated at bid price : 18.85
Bid-YTW : 6.34 %
GWO.PR.L Deemed-Retractible 1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 22.07
Evaluated at bid price : 22.30
Bid-YTW : 6.38 %
TD.PF.G FixedReset Disc 1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 22.51
Evaluated at bid price : 23.01
Bid-YTW : 5.70 %
NA.PR.W FixedReset Disc 1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 13.30
Evaluated at bid price : 13.30
Bid-YTW : 5.85 %
CM.PR.T FixedReset Disc 1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 18.25
Evaluated at bid price : 18.25
Bid-YTW : 5.77 %
GWO.PR.F Deemed-Retractible 1.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 23.32
Evaluated at bid price : 23.60
Bid-YTW : 6.30 %
TD.PF.F Perpetual-Discount 1.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 22.13
Evaluated at bid price : 22.50
Bid-YTW : 5.44 %
MFC.PR.J FixedReset Ins Non 1.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 14.52
Evaluated at bid price : 14.52
Bid-YTW : 6.04 %
RY.PR.N Perpetual-Discount 1.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 22.02
Evaluated at bid price : 22.35
Bid-YTW : 5.55 %
BAM.PF.D Perpetual-Discount 1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 19.60
Evaluated at bid price : 19.60
Bid-YTW : 6.31 %
TD.PF.B FixedReset Disc 1.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 13.85
Evaluated at bid price : 13.85
Bid-YTW : 5.55 %
BAM.PR.R FixedReset Disc 1.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 11.22
Evaluated at bid price : 11.22
Bid-YTW : 6.50 %
TRP.PR.J FixedReset Disc 1.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 23.12
Evaluated at bid price : 23.64
Bid-YTW : 5.88 %
BAM.PF.C Perpetual-Discount 1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 19.30
Evaluated at bid price : 19.30
Bid-YTW : 6.34 %
RY.PR.P Perpetual-Discount 1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 23.55
Evaluated at bid price : 24.00
Bid-YTW : 5.53 %
IFC.PR.E Deemed-Retractible 1.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 21.35
Evaluated at bid price : 21.35
Bid-YTW : 6.15 %
RY.PR.Q FixedReset Disc 1.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 23.40
Evaluated at bid price : 23.91
Bid-YTW : 5.42 %
PWF.PR.L Perpetual-Discount 1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 19.86
Evaluated at bid price : 19.86
Bid-YTW : 6.44 %
BIK.PR.A FixedReset Disc 1.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 21.68
Evaluated at bid price : 21.99
Bid-YTW : 6.70 %
RY.PR.O Perpetual-Discount 1.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 22.09
Evaluated at bid price : 22.45
Bid-YTW : 5.52 %
BMO.PR.E FixedReset Disc 1.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 16.80
Evaluated at bid price : 16.80
Bid-YTW : 5.44 %
PWF.PR.H Perpetual-Discount 1.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 22.24
Evaluated at bid price : 22.51
Bid-YTW : 6.40 %
RY.PR.S FixedReset Disc 1.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 16.92
Evaluated at bid price : 16.92
Bid-YTW : 5.05 %
CM.PR.O FixedReset Disc 1.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 13.16
Evaluated at bid price : 13.16
Bid-YTW : 5.94 %
POW.PR.D Perpetual-Discount 1.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 19.48
Evaluated at bid price : 19.48
Bid-YTW : 6.46 %
SLF.PR.D Deemed-Retractible 2.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 18.77
Evaluated at bid price : 18.77
Bid-YTW : 5.98 %
PWF.PR.O Perpetual-Discount 2.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 22.28
Evaluated at bid price : 22.55
Bid-YTW : 6.44 %
IAF.PR.I FixedReset Ins Non 2.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 14.60
Evaluated at bid price : 14.60
Bid-YTW : 6.22 %
BAM.PR.N Perpetual-Discount 2.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 18.92
Evaluated at bid price : 18.92
Bid-YTW : 6.34 %
W.PR.M FixedReset Disc 2.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 22.21
Evaluated at bid price : 22.57
Bid-YTW : 5.77 %
BMO.PR.Q FixedReset Bank Non 2.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.50
Bid-YTW : 5.45 %
PVS.PR.F SplitShare 2.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2024-09-30
Maturity Price : 25.00
Evaluated at bid price : 23.60
Bid-YTW : 6.41 %
TD.PF.C FixedReset Disc 2.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 14.10
Evaluated at bid price : 14.10
Bid-YTW : 5.57 %
GWO.PR.T Deemed-Retractible 2.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 20.50
Evaluated at bid price : 20.50
Bid-YTW : 6.34 %
GWO.PR.P Deemed-Retractible 2.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 21.44
Evaluated at bid price : 21.70
Bid-YTW : 6.27 %
GWO.PR.M Deemed-Retractible 2.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 22.71
Evaluated at bid price : 23.00
Bid-YTW : 6.35 %
BMO.PR.S FixedReset Disc 2.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 13.71
Evaluated at bid price : 13.71
Bid-YTW : 5.83 %
PWF.PR.F Perpetual-Discount 2.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 20.50
Evaluated at bid price : 20.50
Bid-YTW : 6.43 %
IAF.PR.G FixedReset Ins Non 2.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 13.60
Evaluated at bid price : 13.60
Bid-YTW : 6.46 %
BIP.PR.B FixedReset Disc 2.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 21.62
Evaluated at bid price : 22.00
Bid-YTW : 6.29 %
GWO.PR.R Deemed-Retractible 2.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 19.51
Evaluated at bid price : 19.51
Bid-YTW : 6.21 %
GWO.PR.G Deemed-Retractible 2.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 20.72
Evaluated at bid price : 20.72
Bid-YTW : 6.33 %
TD.PF.I FixedReset Disc 2.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 16.60
Evaluated at bid price : 16.60
Bid-YTW : 5.65 %
SLF.PR.J FloatingReset 2.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 8.61
Evaluated at bid price : 8.61
Bid-YTW : 4.82 %
MFC.PR.B Deemed-Retractible 2.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 19.46
Evaluated at bid price : 19.46
Bid-YTW : 6.04 %
POW.PR.B Perpetual-Discount 2.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 20.95
Evaluated at bid price : 20.95
Bid-YTW : 6.43 %
BAM.PR.M Perpetual-Discount 2.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 19.10
Evaluated at bid price : 19.10
Bid-YTW : 6.28 %
TD.PF.E FixedReset Disc 2.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 15.40
Evaluated at bid price : 15.40
Bid-YTW : 5.63 %
PWF.PR.K Perpetual-Discount 2.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 19.35
Evaluated at bid price : 19.35
Bid-YTW : 6.42 %
ELF.PR.H Perpetual-Discount 2.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 21.60
Evaluated at bid price : 21.60
Bid-YTW : 6.41 %
BMO.PR.Z Perpetual-Discount 2.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 23.02
Evaluated at bid price : 23.45
Bid-YTW : 5.39 %
BIP.PR.C FixedReset Disc 2.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 21.05
Evaluated at bid price : 21.05
Bid-YTW : 6.42 %
BMO.PR.C FixedReset Disc 2.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 5.96 %
TD.PF.L FixedReset Disc 2.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 18.85
Evaluated at bid price : 18.85
Bid-YTW : 5.54 %
NA.PR.S FixedReset Disc 2.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 13.51
Evaluated at bid price : 13.51
Bid-YTW : 5.98 %
MFC.PR.C Deemed-Retractible 2.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 18.60
Evaluated at bid price : 18.60
Bid-YTW : 6.12 %
PWF.PR.S Perpetual-Discount 2.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 18.98
Evaluated at bid price : 18.98
Bid-YTW : 6.35 %
GWO.PR.I Deemed-Retractible 2.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 18.22
Evaluated at bid price : 18.22
Bid-YTW : 6.23 %
IFC.PR.G FixedReset Ins Non 2.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 14.50
Evaluated at bid price : 14.50
Bid-YTW : 6.05 %
GWO.PR.S Deemed-Retractible 2.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 20.85
Evaluated at bid price : 20.85
Bid-YTW : 6.36 %
CM.PR.Q FixedReset Disc 2.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 13.94
Evaluated at bid price : 13.94
Bid-YTW : 6.07 %
MFC.PR.L FixedReset Ins Non 2.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 12.45
Evaluated at bid price : 12.45
Bid-YTW : 6.11 %
SLF.PR.B Deemed-Retractible 2.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 20.27
Evaluated at bid price : 20.27
Bid-YTW : 5.97 %
POW.PR.C Perpetual-Discount 2.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 22.44
Evaluated at bid price : 22.70
Bid-YTW : 6.42 %
PWF.PR.Z Perpetual-Discount 3.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 20.55
Evaluated at bid price : 20.55
Bid-YTW : 6.29 %
BMO.PR.D FixedReset Disc 3.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 16.60
Evaluated at bid price : 16.60
Bid-YTW : 5.89 %
CM.PR.R FixedReset Disc 3.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 16.85
Evaluated at bid price : 16.85
Bid-YTW : 5.99 %
POW.PR.A Perpetual-Discount 3.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 21.59
Evaluated at bid price : 21.85
Bid-YTW : 6.44 %
EIT.PR.A SplitShare 3.18 % YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2024-03-14
Maturity Price : 25.00
Evaluated at bid price : 24.00
Bid-YTW : 6.09 %
W.PR.K FixedReset Disc 3.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 21.88
Evaluated at bid price : 22.40
Bid-YTW : 5.87 %
PWF.PR.R Perpetual-Discount 3.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 21.57
Evaluated at bid price : 21.89
Bid-YTW : 6.29 %
POW.PR.G Perpetual-Discount 3.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 21.54
Evaluated at bid price : 21.85
Bid-YTW : 6.43 %
CU.PR.I FixedReset Disc 3.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 21.95
Evaluated at bid price : 22.50
Bid-YTW : 5.03 %
NA.PR.E FixedReset Disc 3.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 14.50
Evaluated at bid price : 14.50
Bid-YTW : 5.90 %
BMO.PR.F FixedReset Disc 3.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 19.55
Evaluated at bid price : 19.55
Bid-YTW : 5.64 %
BMO.PR.B FixedReset Disc 3.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 21.02
Evaluated at bid price : 21.02
Bid-YTW : 5.63 %
TD.PF.M FixedReset Disc 3.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 19.65
Evaluated at bid price : 19.65
Bid-YTW : 5.60 %
TRP.PR.F FloatingReset 3.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 9.52
Evaluated at bid price : 9.52
Bid-YTW : 5.72 %
BAM.PF.F FixedReset Disc 3.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 14.48
Evaluated at bid price : 14.48
Bid-YTW : 6.28 %
MFC.PR.Q FixedReset Ins Non 3.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 14.50
Evaluated at bid price : 14.50
Bid-YTW : 6.00 %
SLF.PR.E Deemed-Retractible 3.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 18.91
Evaluated at bid price : 18.91
Bid-YTW : 6.00 %
SLF.PR.A Deemed-Retractible 3.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 19.90
Evaluated at bid price : 19.90
Bid-YTW : 6.02 %
BAM.PF.A FixedReset Disc 3.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 15.71
Evaluated at bid price : 15.71
Bid-YTW : 6.13 %
SLF.PR.C Deemed-Retractible 3.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 18.77
Evaluated at bid price : 18.77
Bid-YTW : 5.98 %
BMO.PR.Y FixedReset Disc 3.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 14.15
Evaluated at bid price : 14.15
Bid-YTW : 5.92 %
TRP.PR.A FixedReset Disc 3.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 11.93
Evaluated at bid price : 11.93
Bid-YTW : 5.86 %
BAM.PF.H FixedReset Disc 3.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 22.21
Evaluated at bid price : 22.93
Bid-YTW : 5.45 %
TD.PF.H FixedReset Disc 3.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 21.30
Evaluated at bid price : 21.30
Bid-YTW : 5.55 %
BAM.PF.I FixedReset Disc 3.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 21.58
Evaluated at bid price : 21.98
Bid-YTW : 5.48 %
IFC.PR.A FixedReset Ins Non 3.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 10.50
Evaluated at bid price : 10.50
Bid-YTW : 5.96 %
BNS.PR.H FixedReset Disc 3.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 21.52
Evaluated at bid price : 21.89
Bid-YTW : 5.45 %
MFC.PR.M FixedReset Ins Non 4.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 13.00
Evaluated at bid price : 13.00
Bid-YTW : 6.20 %
MFC.PR.H FixedReset Ins Non 4.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 15.29
Evaluated at bid price : 15.29
Bid-YTW : 6.26 %
BAM.PF.G FixedReset Disc 4.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 13.77
Evaluated at bid price : 13.77
Bid-YTW : 6.27 %
MFC.PR.N FixedReset Ins Non 4.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 12.95
Evaluated at bid price : 12.95
Bid-YTW : 5.62 %
CM.PR.Y FixedReset Disc 4.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 19.38
Evaluated at bid price : 19.38
Bid-YTW : 5.76 %
BAM.PF.E FixedReset Disc 4.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 13.25
Evaluated at bid price : 13.25
Bid-YTW : 6.22 %
NA.PR.G FixedReset Disc 4.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 15.15
Evaluated at bid price : 15.15
Bid-YTW : 6.10 %
GWO.PR.N FixedReset Ins Non 4.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 9.05
Evaluated at bid price : 9.05
Bid-YTW : 5.26 %
BAM.PF.B FixedReset Disc 4.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 14.44
Evaluated at bid price : 14.44
Bid-YTW : 6.13 %
EML.PR.A FixedReset Ins Non 4.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 21.94
Evaluated at bid price : 22.50
Bid-YTW : 6.21 %
EIT.PR.B SplitShare 5.05 % YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2025-03-14
Maturity Price : 25.00
Evaluated at bid price : 23.90
Bid-YTW : 5.95 %
IAF.PR.B Deemed-Retractible 5.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 19.28
Evaluated at bid price : 19.28
Bid-YTW : 6.02 %
SLF.PR.I FixedReset Ins Non 5.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 13.77
Evaluated at bid price : 13.77
Bid-YTW : 6.16 %
BAM.PR.Z FixedReset Disc 5.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 15.25
Evaluated at bid price : 15.25
Bid-YTW : 6.18 %
TRP.PR.C FixedReset Disc 5.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 8.84
Evaluated at bid price : 8.84
Bid-YTW : 6.03 %
MFC.PR.K FixedReset Ins Non 5.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 13.34
Evaluated at bid price : 13.34
Bid-YTW : 5.95 %
BIP.PR.F FixedReset Disc 5.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 20.50
Evaluated at bid price : 20.50
Bid-YTW : 6.28 %
BNS.PR.E FixedReset Disc 5.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 22.12
Evaluated at bid price : 22.80
Bid-YTW : 5.59 %
MFC.PR.R FixedReset Ins Non 5.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 6.27 %
TRP.PR.D FixedReset Disc 5.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 13.26
Evaluated at bid price : 13.26
Bid-YTW : 6.03 %
CU.PR.C FixedReset Disc 5.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 14.65
Evaluated at bid price : 14.65
Bid-YTW : 5.25 %
BAM.PR.C Floater 5.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 7.93
Evaluated at bid price : 7.93
Bid-YTW : 5.45 %
BAM.PR.B Floater 5.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 7.99
Evaluated at bid price : 7.99
Bid-YTW : 5.41 %
PWF.PR.A Floater 5.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 8.89
Evaluated at bid price : 8.89
Bid-YTW : 4.89 %
BAM.PR.K Floater 5.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 8.00
Evaluated at bid price : 8.00
Bid-YTW : 5.40 %
BIP.PR.E FixedReset Disc 6.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 20.02
Evaluated at bid price : 20.02
Bid-YTW : 6.30 %
TRP.PR.H FloatingReset 6.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 8.60
Evaluated at bid price : 8.60
Bid-YTW : 4.45 %
BAM.PF.J FixedReset Disc 6.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 21.47
Evaluated at bid price : 21.83
Bid-YTW : 5.46 %
BIP.PR.D FixedReset Disc 6.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 6.31 %
TD.PF.D FixedReset Disc 6.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 15.26
Evaluated at bid price : 15.26
Bid-YTW : 5.54 %
MFC.PR.O FixedReset Ins Non 6.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 23.00
Evaluated at bid price : 23.50
Bid-YTW : 5.95 %
BIP.PR.A FixedReset Disc 6.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 14.00
Evaluated at bid price : 14.00
Bid-YTW : 7.48 %
BNS.PR.G FixedReset Disc 7.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 23.82
Evaluated at bid price : 24.25
Bid-YTW : 5.47 %
NA.PR.A FixedReset Disc 7.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 22.61
Evaluated at bid price : 23.05
Bid-YTW : 5.67 %
SLF.PR.G FixedReset Ins Non 7.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 9.06
Evaluated at bid price : 9.06
Bid-YTW : 5.54 %
NA.PR.X FixedReset Disc 7.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 22.97
Evaluated at bid price : 23.50
Bid-YTW : 5.81 %
TRP.PR.G FixedReset Disc 8.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 14.00
Evaluated at bid price : 14.00
Bid-YTW : 6.45 %
BAM.PR.T FixedReset Disc 9.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 11.85
Evaluated at bid price : 11.85
Bid-YTW : 6.31 %
IFC.PR.C FixedReset Ins Non 10.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 13.52
Evaluated at bid price : 13.52
Bid-YTW : 6.06 %
TRP.PR.B FixedReset Disc 10.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 8.59
Evaluated at bid price : 8.59
Bid-YTW : 5.46 %
SLF.PR.H FixedReset Ins Non 11.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 11.67
Evaluated at bid price : 11.67
Bid-YTW : 5.96 %
Volume Highlights
Issue Index Shares
Traded
Notes
HSE.PR.A FixedReset Disc 126,560 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 5.64
Evaluated at bid price : 5.64
Bid-YTW : 10.43 %
HSE.PR.E FixedReset Disc 92,592 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 9.80
Evaluated at bid price : 9.80
Bid-YTW : 11.27 %
HSE.PR.G FixedReset Disc 92,030 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 8.85
Evaluated at bid price : 8.85
Bid-YTW : 11.78 %
TD.PF.G FixedReset Disc 84,673 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 22.51
Evaluated at bid price : 23.01
Bid-YTW : 5.70 %
BAM.PF.E FixedReset Disc 83,001 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 13.25
Evaluated at bid price : 13.25
Bid-YTW : 6.22 %
PWF.PR.G Perpetual-Discount 63,800 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 22.69
Evaluated at bid price : 22.93
Bid-YTW : 6.44 %
There were 67 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
IAF.PR.G FixedReset Ins Non Quote: 13.60 – 20.00
Spot Rate : 6.4000
Average : 3.4653

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 13.60
Evaluated at bid price : 13.60
Bid-YTW : 6.46 %

NA.PR.W FixedReset Disc Quote: 13.30 – 19.00
Spot Rate : 5.7000
Average : 3.0448

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 13.30
Evaluated at bid price : 13.30
Bid-YTW : 5.85 %

MFC.PR.M FixedReset Ins Non Quote: 13.00 – 18.50
Spot Rate : 5.5000
Average : 2.9850

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 13.00
Evaluated at bid price : 13.00
Bid-YTW : 6.20 %

MFC.PR.N FixedReset Ins Non Quote: 12.95 – 15.88
Spot Rate : 2.9300
Average : 1.6402

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 12.95
Evaluated at bid price : 12.95
Bid-YTW : 5.62 %

RY.PR.M FixedReset Disc Quote: 11.98 – 15.00
Spot Rate : 3.0200
Average : 1.9063

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 11.98
Evaluated at bid price : 11.98
Bid-YTW : 6.83 %

BAM.PF.A FixedReset Disc Quote: 15.71 – 18.18
Spot Rate : 2.4700
Average : 1.4534

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-09
Maturity Price : 15.71
Evaluated at bid price : 15.71
Bid-YTW : 6.13 %

Market Action

April 8, 2020

unicorn_200408
Click for Big

There is more hope that the coronavirus is under control, or at least getting there:

The Toronto Stock Exchange’s S&P/TSX composite index was up 311.57 points, or 2.29%, at 13,925.71.

The energy sector climbed 4.2% as oil prices strengthened, buoyed by hopes that OPEC and its allies will strike a production cut agreement, shrugging off bearish signals from surging U.S. crude inventories.

Brent crude was up $1, or 3%, at $32.87. U.S. West Texas Intermediate (WTI) crude rose $1.55 cents to $25.18 a barrel.
…
Thursday’s video conference meeting between the Organization of the Petroleum Exporting Countries (OPEC) and allies including Russia – a group known as OPEC+ – was expected to be more successful than their gathering in March, which ended in a failure to extend supply cuts and a price war between Saudi Arabia and Russia.

TXPR closed at 488.19, up 1.13% on the day. Volume today was 4.06-million, the highest since March 26.

CPD closed at 9.73, up 0.21% on the day. Volume was 176,238, about average in the context of the past 30 trading days but the highest since March 26.

ZPR closed at 7.52, down 0.13% on the day. Volume of 442,451 was below average in the context of the past 30 trading days.

Five-year Canada yields were down 3bp to 0.65% today.

PerpetualDiscounts now yield 6.45%, equivalent to 8.38% interest at the standard equivalency factor of 1.3x. Long corporates now yield 3.84%, so the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) has spectacularly narrowed, to 455bp from the 515bp reported April 1. But we’re a little wider than the old record set on November 26, 2008 when trouble with the BCE buyout caused a short-lived spike in PerpetualDiscount bid yields, moving the Seniority Spread to 445bp.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 2.2427 % 1,390.0
FixedFloater 0.00 % 0.00 % 0 0.00 0 2.2427 % 2,550.6
Floater 5.53 % 5.73 % 43,594 14.34 4 2.2427 % 1,469.9
OpRet 0.00 % 0.00 % 0 0.00 0 1.7545 % 3,216.0
SplitShare 5.16 % 6.99 % 87,687 3.95 7 1.7545 % 3,840.6
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 1.7545 % 2,996.6
Perpetual-Premium 0.00 % 0.00 % 0 0.00 0 1.4318 % 2,705.0
Perpetual-Discount 6.19 % 6.45 % 93,048 13.31 35 1.4318 % 2,901.4
FixedReset Disc 6.86 % 5.98 % 203,266 13.62 83 1.2524 % 1,651.9
Deemed-Retractible 5.91 % 6.33 % 103,947 13.33 27 0.8789 % 2,861.9
FloatingReset 3.14 % 4.57 % 32,261 14.25 4 0.7556 % 1,682.6
FixedReset Prem 0.00 % 0.00 % 0 0.00 0 1.2524 % 2,284.6
FixedReset Bank Non 1.98 % 4.88 % 118,928 1.77 3 -0.4996 % 2,686.8
FixedReset Ins Non 7.37 % 6.45 % 117,884 12.90 22 1.2435 % 1,600.1
Performance Highlights
Issue Index Change Notes
TRP.PR.B FixedReset Disc -7.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 7.75
Evaluated at bid price : 7.75
Bid-YTW : 6.25 %
SLF.PR.H FixedReset Ins Non -6.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 10.50
Evaluated at bid price : 10.50
Bid-YTW : 6.76 %
HSE.PR.E FixedReset Disc -5.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 9.82
Evaluated at bid price : 9.82
Bid-YTW : 11.33 %
HSE.PR.G FixedReset Disc -3.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 9.18
Evaluated at bid price : 9.18
Bid-YTW : 11.52 %
SLF.PR.I FixedReset Ins Non -2.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 13.10
Evaluated at bid price : 13.10
Bid-YTW : 6.58 %
BIP.PR.A FixedReset Disc -2.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 13.10
Evaluated at bid price : 13.10
Bid-YTW : 8.11 %
HSE.PR.C FixedReset Disc -2.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 9.35
Evaluated at bid price : 9.35
Bid-YTW : 11.25 %
BMO.PR.Y FixedReset Disc -2.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 13.64
Evaluated at bid price : 13.64
Bid-YTW : 6.26 %
IFC.PR.C FixedReset Ins Non -2.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 12.23
Evaluated at bid price : 12.23
Bid-YTW : 6.82 %
TRP.PR.C FixedReset Disc -2.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 8.40
Evaluated at bid price : 8.40
Bid-YTW : 6.52 %
TRP.PR.D FixedReset Disc -1.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 12.55
Evaluated at bid price : 12.55
Bid-YTW : 6.48 %
TD.PF.D FixedReset Disc -1.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 14.30
Evaluated at bid price : 14.30
Bid-YTW : 6.02 %
BAM.PR.T FixedReset Disc -1.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 10.80
Evaluated at bid price : 10.80
Bid-YTW : 7.06 %
MFC.PR.M FixedReset Ins Non -1.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 12.50
Evaluated at bid price : 12.50
Bid-YTW : 6.55 %
GWO.PR.N FixedReset Ins Non -1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 8.65
Evaluated at bid price : 8.65
Bid-YTW : 5.68 %
BMO.PR.Q FixedReset Bank Non -1.46 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.01
Bid-YTW : 6.67 %
BAM.PR.X FixedReset Disc -1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 9.52
Evaluated at bid price : 9.52
Bid-YTW : 6.58 %
TRP.PR.J FixedReset Disc 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 22.75
Evaluated at bid price : 23.25
Bid-YTW : 5.98 %
CIU.PR.A Perpetual-Discount 1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 19.20
Evaluated at bid price : 19.20
Bid-YTW : 6.08 %
PVS.PR.D SplitShare 1.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2021-10-08
Maturity Price : 25.00
Evaluated at bid price : 24.00
Bid-YTW : 7.69 %
GWO.PR.F Deemed-Retractible 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 22.98
Evaluated at bid price : 23.25
Bid-YTW : 6.39 %
BAM.PF.B FixedReset Disc 1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 13.80
Evaluated at bid price : 13.80
Bid-YTW : 6.52 %
SLF.PR.C Deemed-Retractible 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 18.10
Evaluated at bid price : 18.10
Bid-YTW : 6.20 %
EIT.PR.A SplitShare 1.13 % YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2024-03-14
Maturity Price : 25.00
Evaluated at bid price : 23.26
Bid-YTW : 6.99 %
BAM.PF.D Perpetual-Discount 1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 19.30
Evaluated at bid price : 19.30
Bid-YTW : 6.41 %
TD.PF.A FixedReset Disc 1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 13.58
Evaluated at bid price : 13.58
Bid-YTW : 5.72 %
CU.PR.C FixedReset Disc 1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 13.86
Evaluated at bid price : 13.86
Bid-YTW : 5.65 %
PWF.PR.I Perpetual-Discount 1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 23.14
Evaluated at bid price : 23.40
Bid-YTW : 6.42 %
SLF.PR.B Deemed-Retractible 1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 19.69
Evaluated at bid price : 19.69
Bid-YTW : 6.15 %
BNS.PR.H FixedReset Disc 1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 21.05
Evaluated at bid price : 21.05
Bid-YTW : 5.76 %
CU.PR.D Perpetual-Discount 1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 20.75
Evaluated at bid price : 20.75
Bid-YTW : 5.99 %
GWO.PR.G Deemed-Retractible 1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 20.25
Evaluated at bid price : 20.25
Bid-YTW : 6.48 %
RY.PR.P Perpetual-Discount 1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 23.15
Evaluated at bid price : 23.60
Bid-YTW : 5.62 %
BAM.PR.K Floater 1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 7.55
Evaluated at bid price : 7.55
Bid-YTW : 5.73 %
BMO.PR.B FixedReset Disc 1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 20.32
Evaluated at bid price : 20.32
Bid-YTW : 5.90 %
ELF.PR.H Perpetual-Discount 1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 21.05
Evaluated at bid price : 21.05
Bid-YTW : 6.57 %
RY.PR.J FixedReset Disc 1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 15.00
Evaluated at bid price : 15.00
Bid-YTW : 5.72 %
GWO.PR.M Deemed-Retractible 1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 22.22
Evaluated at bid price : 22.50
Bid-YTW : 6.49 %
TD.PF.J FixedReset Disc 1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 16.45
Evaluated at bid price : 16.45
Bid-YTW : 5.45 %
PWF.PR.R Perpetual-Discount 1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 21.20
Evaluated at bid price : 21.20
Bid-YTW : 6.51 %
BMO.PR.W FixedReset Disc 1.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 13.49
Evaluated at bid price : 13.49
Bid-YTW : 5.91 %
BMO.PR.D FixedReset Disc 1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 16.11
Evaluated at bid price : 16.11
Bid-YTW : 6.15 %
TD.PF.K FixedReset Disc 1.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 16.14
Evaluated at bid price : 16.14
Bid-YTW : 5.53 %
NA.PR.A FixedReset Disc 1.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 21.50
Evaluated at bid price : 21.50
Bid-YTW : 6.17 %
PVS.PR.E SplitShare 1.46 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-10-31
Maturity Price : 25.00
Evaluated at bid price : 24.25
Bid-YTW : 7.05 %
TD.PF.G FixedReset Disc 1.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 22.06
Evaluated at bid price : 22.70
Bid-YTW : 5.83 %
CM.PR.R FixedReset Disc 1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 16.35
Evaluated at bid price : 16.35
Bid-YTW : 6.26 %
POW.PR.C Perpetual-Discount 1.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 21.81
Evaluated at bid price : 22.05
Bid-YTW : 6.61 %
TRP.PR.E FixedReset Disc 1.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 12.21
Evaluated at bid price : 12.21
Bid-YTW : 6.59 %
POW.PR.A Perpetual-Discount 1.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 21.20
Evaluated at bid price : 21.20
Bid-YTW : 6.65 %
BAM.PF.E FixedReset Disc 1.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 12.69
Evaluated at bid price : 12.69
Bid-YTW : 6.59 %
NA.PR.C FixedReset Disc 1.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 16.12
Evaluated at bid price : 16.12
Bid-YTW : 6.41 %
TD.PF.H FixedReset Disc 1.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 20.52
Evaluated at bid price : 20.52
Bid-YTW : 5.83 %
CM.PR.Y FixedReset Disc 1.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 18.57
Evaluated at bid price : 18.57
Bid-YTW : 6.08 %
BAM.PR.Z FixedReset Disc 1.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 14.50
Evaluated at bid price : 14.50
Bid-YTW : 6.60 %
PWF.PR.F Perpetual-Discount 1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 20.05
Evaluated at bid price : 20.05
Bid-YTW : 6.57 %
PWF.PR.G Perpetual-Discount 1.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 22.39
Evaluated at bid price : 22.65
Bid-YTW : 6.52 %
PWF.PR.Z Perpetual-Discount 1.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 19.95
Evaluated at bid price : 19.95
Bid-YTW : 6.48 %
PWF.PR.O Perpetual-Discount 1.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 21.86
Evaluated at bid price : 22.10
Bid-YTW : 6.57 %
TD.PF.F Perpetual-Discount 1.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 21.88
Evaluated at bid price : 22.16
Bid-YTW : 5.53 %
BAM.PR.B Floater 1.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 7.55
Evaluated at bid price : 7.55
Bid-YTW : 5.73 %
BIP.PR.D FixedReset Disc 1.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 18.75
Evaluated at bid price : 18.75
Bid-YTW : 6.73 %
BAM.PR.C Floater 1.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 7.50
Evaluated at bid price : 7.50
Bid-YTW : 5.76 %
BAM.PF.I FixedReset Disc 1.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 21.15
Evaluated at bid price : 21.15
Bid-YTW : 5.72 %
CM.PR.T FixedReset Disc 2.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 5.92 %
TD.PF.L FixedReset Disc 2.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 18.35
Evaluated at bid price : 18.35
Bid-YTW : 5.76 %
BMO.PR.Z Perpetual-Discount 2.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 22.50
Evaluated at bid price : 22.85
Bid-YTW : 5.53 %
GWO.PR.P Deemed-Retractible 2.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 21.23
Evaluated at bid price : 21.23
Bid-YTW : 6.42 %
ELF.PR.G Perpetual-Discount 2.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 18.60
Evaluated at bid price : 18.60
Bid-YTW : 6.42 %
MFC.PR.J FixedReset Ins Non 2.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 14.30
Evaluated at bid price : 14.30
Bid-YTW : 6.23 %
SLF.PR.D Deemed-Retractible 2.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 18.40
Evaluated at bid price : 18.40
Bid-YTW : 6.10 %
POW.PR.G Perpetual-Discount 2.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 21.15
Evaluated at bid price : 21.15
Bid-YTW : 6.66 %
TD.PF.M FixedReset Disc 2.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 18.99
Evaluated at bid price : 18.99
Bid-YTW : 5.86 %
NA.PR.X FixedReset Disc 2.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 21.50
Evaluated at bid price : 21.85
Bid-YTW : 6.33 %
IAF.PR.G FixedReset Ins Non 2.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 13.30
Evaluated at bid price : 13.30
Bid-YTW : 6.70 %
CU.PR.H Perpetual-Discount 2.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 21.70
Evaluated at bid price : 22.05
Bid-YTW : 6.02 %
MFC.PR.O FixedReset Ins Non 2.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 21.61
Evaluated at bid price : 22.00
Bid-YTW : 6.43 %
MFC.PR.H FixedReset Ins Non 2.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 14.70
Evaluated at bid price : 14.70
Bid-YTW : 6.61 %
IFC.PR.G FixedReset Ins Non 2.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 14.10
Evaluated at bid price : 14.10
Bid-YTW : 6.33 %
CU.PR.G Perpetual-Discount 2.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 19.20
Evaluated at bid price : 19.20
Bid-YTW : 5.95 %
BMO.PR.C FixedReset Disc 2.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 16.55
Evaluated at bid price : 16.55
Bid-YTW : 6.21 %
CU.PR.E Perpetual-Discount 2.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 20.80
Evaluated at bid price : 20.80
Bid-YTW : 5.98 %
NA.PR.W FixedReset Disc 2.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 13.12
Evaluated at bid price : 13.12
Bid-YTW : 6.02 %
MFC.PR.C Deemed-Retractible 2.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 18.10
Evaluated at bid price : 18.10
Bid-YTW : 6.29 %
NA.PR.G FixedReset Disc 2.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 14.50
Evaluated at bid price : 14.50
Bid-YTW : 6.47 %
BIP.PR.B FixedReset Disc 2.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 21.51
Evaluated at bid price : 21.51
Bid-YTW : 6.45 %
BNS.PR.G FixedReset Disc 2.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 22.03
Evaluated at bid price : 22.65
Bid-YTW : 5.91 %
CU.PR.F Perpetual-Discount 2.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 19.50
Evaluated at bid price : 19.50
Bid-YTW : 5.85 %
TD.PF.I FixedReset Disc 3.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 16.22
Evaluated at bid price : 16.22
Bid-YTW : 5.86 %
BIP.PR.F FixedReset Disc 3.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 19.45
Evaluated at bid price : 19.45
Bid-YTW : 6.62 %
CM.PR.Q FixedReset Disc 3.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 13.55
Evaluated at bid price : 13.55
Bid-YTW : 6.36 %
GWO.PR.L Deemed-Retractible 3.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 21.75
Evaluated at bid price : 22.00
Bid-YTW : 6.47 %
BAM.PF.A FixedReset Disc 3.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 15.15
Evaluated at bid price : 15.15
Bid-YTW : 6.45 %
PWF.PR.H Perpetual-Discount 3.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 21.85
Evaluated at bid price : 22.09
Bid-YTW : 6.52 %
BMO.PR.E FixedReset Disc 3.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 16.50
Evaluated at bid price : 16.50
Bid-YTW : 5.62 %
RY.PR.Q FixedReset Disc 3.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 22.98
Evaluated at bid price : 23.50
Bid-YTW : 5.58 %
TRP.PR.G FixedReset Disc 3.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 12.85
Evaluated at bid price : 12.85
Bid-YTW : 7.15 %
EML.PR.A FixedReset Ins Non 3.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 21.50
Evaluated at bid price : 21.50
Bid-YTW : 6.60 %
IFC.PR.I Perpetual-Discount 3.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 22.70
Evaluated at bid price : 23.05
Bid-YTW : 5.94 %
HSE.PR.A FixedReset Disc 3.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 5.60
Evaluated at bid price : 5.60
Bid-YTW : 10.76 %
PWF.PR.A Floater 3.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 8.40
Evaluated at bid price : 8.40
Bid-YTW : 5.18 %
PVS.PR.H SplitShare 3.74 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2027-02-28
Maturity Price : 25.00
Evaluated at bid price : 23.60
Bid-YTW : 5.80 %
MFC.PR.B Deemed-Retractible 3.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 6.19 %
RY.PR.Z FixedReset Disc 4.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 13.85
Evaluated at bid price : 13.85
Bid-YTW : 5.61 %
PVS.PR.G SplitShare 4.40 % YTW SCENARIO
Maturity Type : Option Certainty
Maturity Date : 2026-02-28
Maturity Price : 25.00
Evaluated at bid price : 23.75
Bid-YTW : 6.04 %
PWF.PR.T FixedReset Disc 4.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 13.27
Evaluated at bid price : 13.27
Bid-YTW : 6.25 %
BMO.PR.F FixedReset Disc 4.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 18.90
Evaluated at bid price : 18.90
Bid-YTW : 5.90 %
IAF.PR.I FixedReset Ins Non 5.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 14.30
Evaluated at bid price : 14.30
Bid-YTW : 6.45 %
TRP.PR.H FloatingReset 5.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 8.10
Evaluated at bid price : 8.10
Bid-YTW : 4.57 %
PWF.PR.P FixedReset Disc 6.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 9.60
Evaluated at bid price : 9.60
Bid-YTW : 5.86 %
RY.PR.M FixedReset Disc 7.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 14.50
Evaluated at bid price : 14.50
Bid-YTW : 5.73 %
TD.PF.E FixedReset Disc 12.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 15.02
Evaluated at bid price : 15.02
Bid-YTW : 5.87 %
MFC.PR.I FixedReset Ins Non 16.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 14.08
Evaluated at bid price : 14.08
Bid-YTW : 6.53 %
Volume Highlights
Issue Index Shares
Traded
Notes
HSE.PR.A FixedReset Disc 181,666 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 5.60
Evaluated at bid price : 5.60
Bid-YTW : 10.76 %
RY.PR.M FixedReset Disc 111,567 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 14.50
Evaluated at bid price : 14.50
Bid-YTW : 5.73 %
BMO.PR.F FixedReset Disc 92,933 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 18.90
Evaluated at bid price : 18.90
Bid-YTW : 5.90 %
BNS.PR.H FixedReset Disc 90,339 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 21.05
Evaluated at bid price : 21.05
Bid-YTW : 5.76 %
TD.PF.L FixedReset Disc 73,863 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 18.35
Evaluated at bid price : 18.35
Bid-YTW : 5.76 %
BMO.PR.C FixedReset Disc 62,857 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 16.55
Evaluated at bid price : 16.55
Bid-YTW : 6.21 %
There were 93 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
MFC.PR.K FixedReset Ins Non Quote: 12.67 – 18.10
Spot Rate : 5.4300
Average : 3.4621

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 12.67
Evaluated at bid price : 12.67
Bid-YTW : 6.39 %

EML.PR.A FixedReset Ins Non Quote: 21.50 – 23.39
Spot Rate : 1.8900
Average : 1.0905

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 21.50
Evaluated at bid price : 21.50
Bid-YTW : 6.60 %

GWO.PR.N FixedReset Ins Non Quote: 8.65 – 10.00
Spot Rate : 1.3500
Average : 0.7938

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 8.65
Evaluated at bid price : 8.65
Bid-YTW : 5.68 %

EIT.PR.B SplitShare Quote: 22.75 – 24.75
Spot Rate : 2.0000
Average : 1.5474

YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2025-03-14
Maturity Price : 25.00
Evaluated at bid price : 22.75
Bid-YTW : 7.11 %

BAM.PF.B FixedReset Disc Quote: 13.80 – 16.54
Spot Rate : 2.7400
Average : 2.2936

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 13.80
Evaluated at bid price : 13.80
Bid-YTW : 6.52 %

MFC.PR.G FixedReset Ins Non Quote: 13.70 – 19.17
Spot Rate : 5.4700
Average : 5.0422

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-08
Maturity Price : 13.70
Evaluated at bid price : 13.70
Bid-YTW : 6.61 %

Market Action

April 7, 2020

unicorn_200407
Click for Big

Globalism is getting a kicking. It began with export prohibitions of N-95 masks:

[Chaun] Powell, [vice president of strategic supplier engagement at North Carolina-based healthcare company] … Premier Inc., says that although China has not formally announced any embargoes on exports of personal protective equipment, he believes that no such gear has shipped out of China since mid-January. Other places, like Thailand, Taiwan and India have also restricted exports of masks to protect their domestic supply.

And then the anti-globalists in the White House got going, with Trump reportedly wanting exclusive rights to a vaccine:

German ministers have reacted angrily following reports US president Donald Trump offered a German medical company “large sums of money” for exclusive rights to a Covid-19 vaccine.

“Germany is not for sale,” economy minister Peter Altmaier told broadcaster ARD, reacting to a front page report in Welt am Sonntag newspaper headlined “Trump vs Berlin”.

The newspaper reported Trump offered $1bn to Tübingen-based biopharmaceutical company CureVac to secure the vaccine “only for the United States”.

… after which he banned export of N-95 masks and other material himself:

President Donald Trump said Friday the U.S. would ban export of critical N95 masks and other precious medical gear – as he blasted a manufacturer who criticized the administration for halting its shipment to Canada.

‘It includes everything,’ Trump said of a ban he has described of export of masks, gowns and other equipment.

Trump also tore into 3M Co, saying he was ‘not happy’ with the company after its CEO called the ban short-sighted and would harm the U.S. on a net basis. Trump had threatened the company with use of a defense production law earlier this week.

We’re also seeing plans for a more protectionist world:

As much of the rest of Canada has focused on immediate responses, Quebec has in recent days been talking more about its future once the health crisis subsides. Mr. Legault’s government says it has begun working on plans to increase the province’s self-sufficiency in health care and food, to make sure it has enough locally made medical equipment, medication and other supplies needed to weather a future crisis.

More broadly, Quebec has begun a detailed analysis of its trade balance in an attempt to prepare for a new economic reality once the peak of the global coronavirus pandemic has passed. The Premier is even evoking the possibility of using the province’s plentiful hydro power to warm indoor greenhouses in the winter and grow fruit and vegetables all year round instead of importing them.

… and now WHO, like the World Trade Organization, is under attack:

World leaders are putting the World Health Organization on notice if they don’t shape up. President Trump is threatening to cut 40 percent of U.S. funding from international organizations, while the United Kingdom released a report this week in which they say WHO must reform quickly or it “will result in decreased U.K. funding.”

Even with public health focus on threats such as the Zika and Ebola viruses, vaccines, and mental health, critics have accused the WHO of mission creep, putting resources into too many issues and not focusing enough on the important ones.

The journal Nature even took the unprecedented step of issuing an editorial demanding reform at the WHO, which they see as too bloated to tackle essential global health issues.

These are worrisome developments for Canada, as a small trading nation that has to gain whatever clout it can through participation in international bodies.

Don’t get me wrong; I’m not suggesting we place all our trust in open borders and hugs. By all means, let’s have a federal stockpile of equipment for forseeable disasters, backed up by an official body that would approve and publish open-source plans for things like 3-D printed ventilators; let’s have open tenders for contracts that would give companies an annual payment for a fixed term in exchange for the maintenance of an ability to manufacture X items per month on Y weeks notice. But if the isolationists win the coming battles, we will all lose.

Update, 2020-4-15 : I’m very pleased to see that the first part of my plan is being implemented in the States:

And it’s not just large universities and corporations who are getting involved in the effort. America Makes, a national accelerator for 3D printing (also known as additive manufacturing), has partnered with the Food and Drug Administration, Department of Veterans’ Affairs, and the National Institutes of Health to build a repository where manufacturers can upload their 3D-printable designs. The designs are reviewed and then fast-tracked to the NIH 3D Print Exchange, which is an open site for sharing designs.

This has allowed individuals and small-batch manufacturers to start producing protective face shields too. People like former Autodesk CEO Carl Bass have started producing face shields on their own, with the goal of making more than 20,000 to deliver to healthcare providers.

TXPR closed at 482.72, up 1.09% on the day. Volume today was 3.62-million, low in the context of the past thirty days but highest since March 26.

CPD closed at 9.71, up 1.68% on the day. Volume was 155,861, low in the context of the past 30 trading days but the highest since March 31.

ZPR closed at 7.53, up 1.62% on the day. Volume of 472,081 was below average in the context of the past 30 trading days.

Five-year Canada yields were up 3bp to 0.68% today.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -3.8986 % 1,359.5
FixedFloater 0.00 % 0.00 % 0 0.00 0 -3.8986 % 2,494.7
Floater 5.66 % 5.80 % 44,428 14.22 4 -3.8986 % 1,437.7
OpRet 0.00 % 0.00 % 0 0.00 0 0.6905 % 3,160.6
SplitShare 5.25 % 7.24 % 85,748 3.95 7 0.6905 % 3,774.4
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.6905 % 2,944.9
Perpetual-Premium 0.00 % 0.00 % 0 0.00 0 1.3106 % 2,666.8
Perpetual-Discount 6.25 % 6.52 % 92,035 13.17 35 1.3106 % 2,860.5
FixedReset Disc 6.93 % 6.10 % 201,101 13.42 83 1.3969 % 1,631.5
Deemed-Retractible 5.96 % 6.46 % 105,088 13.24 27 2.2203 % 2,837.0
FloatingReset 3.17 % 4.79 % 33,576 14.30 4 -0.6323 % 1,670.0
FixedReset Prem 0.00 % 0.00 % 0 0.00 0 1.3969 % 2,256.3
FixedReset Bank Non 1.97 % 4.87 % 118,375 1.77 3 0.1390 % 2,700.3
FixedReset Ins Non 7.46 % 6.50 % 116,592 12.83 22 1.3546 % 1,580.4
Performance Highlights
Issue Index Change Notes
MFC.PR.I FixedReset Ins Non -13.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 12.05
Evaluated at bid price : 12.05
Bid-YTW : 7.67 %
TD.PF.E FixedReset Disc -8.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 13.52
Evaluated at bid price : 13.52
Bid-YTW : 6.66 %
PWF.PR.A Floater -7.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 8.10
Evaluated at bid price : 8.10
Bid-YTW : 5.37 %
TRP.PR.H FloatingReset -6.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 7.68
Evaluated at bid price : 7.68
Bid-YTW : 4.82 %
TRP.PR.G FixedReset Disc -4.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 12.45
Evaluated at bid price : 12.45
Bid-YTW : 7.39 %
BAM.PR.C Floater -3.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 7.36
Evaluated at bid price : 7.36
Bid-YTW : 5.87 %
BNS.PR.G FixedReset Disc -3.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 21.60
Evaluated at bid price : 22.00
Bid-YTW : 6.10 %
BAM.PR.T FixedReset Disc -2.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 11.00
Evaluated at bid price : 11.00
Bid-YTW : 6.93 %
BAM.PR.B Floater -2.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 7.41
Evaluated at bid price : 7.41
Bid-YTW : 5.83 %
BIK.PR.A FixedReset Disc -2.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 21.52
Evaluated at bid price : 21.52
Bid-YTW : 6.86 %
NA.PR.G FixedReset Disc -2.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 14.09
Evaluated at bid price : 14.09
Bid-YTW : 6.67 %
BAM.PR.K Floater -1.97 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 7.45
Evaluated at bid price : 7.45
Bid-YTW : 5.80 %
RY.PR.Z FixedReset Disc -1.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 13.31
Evaluated at bid price : 13.31
Bid-YTW : 5.85 %
HSE.PR.A FixedReset Disc -1.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 5.40
Evaluated at bid price : 5.40
Bid-YTW : 11.16 %
BMO.PR.C FixedReset Disc -1.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 16.11
Evaluated at bid price : 16.11
Bid-YTW : 6.38 %
BAM.PF.A FixedReset Disc -1.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 14.70
Evaluated at bid price : 14.70
Bid-YTW : 6.66 %
BAM.PF.J FixedReset Disc -1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 20.52
Evaluated at bid price : 20.52
Bid-YTW : 5.84 %
CU.PR.H Perpetual-Discount -1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 21.55
Evaluated at bid price : 21.55
Bid-YTW : 6.18 %
EIT.PR.A SplitShare 1.05 % YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2024-03-14
Maturity Price : 25.00
Evaluated at bid price : 23.00
Bid-YTW : 7.31 %
BMO.PR.T FixedReset Disc 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 13.16
Evaluated at bid price : 13.16
Bid-YTW : 5.94 %
MFC.PR.J FixedReset Ins Non 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 14.00
Evaluated at bid price : 14.00
Bid-YTW : 6.37 %
PWF.PR.S Perpetual-Discount 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 18.61
Evaluated at bid price : 18.61
Bid-YTW : 6.59 %
BAM.PF.H FixedReset Disc 1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 21.62
Evaluated at bid price : 22.00
Bid-YTW : 5.71 %
IFC.PR.G FixedReset Ins Non 1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 13.75
Evaluated at bid price : 13.75
Bid-YTW : 6.50 %
RY.PR.C Deemed-Retractible 1.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.63
Bid-YTW : 5.82 %
RY.PR.Q FixedReset Disc 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 22.10
Evaluated at bid price : 22.77
Bid-YTW : 5.75 %
CM.PR.Q FixedReset Disc 1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 13.15
Evaluated at bid price : 13.15
Bid-YTW : 6.55 %
RY.PR.S FixedReset Disc 1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 16.44
Evaluated at bid price : 16.44
Bid-YTW : 5.28 %
CU.PR.D Perpetual-Discount 1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 20.50
Evaluated at bid price : 20.50
Bid-YTW : 6.06 %
MFC.PR.R FixedReset Ins Non 1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 16.90
Evaluated at bid price : 16.90
Bid-YTW : 6.77 %
BAM.PR.Z FixedReset Disc 1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 14.25
Evaluated at bid price : 14.25
Bid-YTW : 6.72 %
CM.PR.Y FixedReset Disc 1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 18.25
Evaluated at bid price : 18.25
Bid-YTW : 6.19 %
TD.PF.B FixedReset Disc 1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 13.97
Evaluated at bid price : 13.97
Bid-YTW : 5.70 %
POW.PR.B Perpetual-Discount 1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 20.35
Evaluated at bid price : 20.35
Bid-YTW : 6.62 %
NA.PR.W FixedReset Disc 1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 12.76
Evaluated at bid price : 12.76
Bid-YTW : 6.20 %
PWF.PR.K Perpetual-Discount 1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 19.04
Evaluated at bid price : 19.04
Bid-YTW : 6.65 %
PVS.PR.F SplitShare 1.32 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2024-09-30
Maturity Price : 25.00
Evaluated at bid price : 23.10
Bid-YTW : 6.95 %
SLF.PR.G FixedReset Ins Non 1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 8.41
Evaluated at bid price : 8.41
Bid-YTW : 6.15 %
BMO.PR.F FixedReset Disc 1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 18.02
Evaluated at bid price : 18.02
Bid-YTW : 6.20 %
SLF.PR.B Deemed-Retractible 1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 19.46
Evaluated at bid price : 19.46
Bid-YTW : 6.22 %
BIP.PR.D FixedReset Disc 1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 18.40
Evaluated at bid price : 18.40
Bid-YTW : 6.86 %
BAM.PF.F FixedReset Disc 1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 13.94
Evaluated at bid price : 13.94
Bid-YTW : 6.61 %
PWF.PR.E Perpetual-Discount 1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 21.50
Evaluated at bid price : 21.50
Bid-YTW : 6.54 %
BNS.PR.I FixedReset Disc 1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 16.18
Evaluated at bid price : 16.18
Bid-YTW : 5.35 %
IFC.PR.E Deemed-Retractible 1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 21.00
Evaluated at bid price : 21.00
Bid-YTW : 6.25 %
RY.PR.E Deemed-Retractible 1.46 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.30
Bid-YTW : 6.51 %
BAM.PF.D Perpetual-Discount 1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 19.08
Evaluated at bid price : 19.08
Bid-YTW : 6.48 %
GWO.PR.N FixedReset Ins Non 1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 8.78
Evaluated at bid price : 8.78
Bid-YTW : 5.59 %
RY.PR.F Deemed-Retractible 1.51 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.21
Bid-YTW : 6.67 %
SLF.PR.H FixedReset Ins Non 1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 11.17
Evaluated at bid price : 11.17
Bid-YTW : 6.35 %
GWO.PR.G Deemed-Retractible 1.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 6.56 %
CM.PR.R FixedReset Disc 1.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 16.10
Evaluated at bid price : 16.10
Bid-YTW : 6.36 %
RY.PR.M FixedReset Disc 1.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 13.46
Evaluated at bid price : 13.46
Bid-YTW : 6.18 %
TD.PF.C FixedReset Disc 1.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 13.95
Evaluated at bid price : 13.95
Bid-YTW : 5.84 %
IFC.PR.F Deemed-Retractible 1.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 21.35
Evaluated at bid price : 21.35
Bid-YTW : 6.26 %
BIP.PR.C FixedReset Disc 1.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 20.35
Evaluated at bid price : 20.35
Bid-YTW : 6.64 %
MFC.PR.C Deemed-Retractible 1.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 17.60
Evaluated at bid price : 17.60
Bid-YTW : 6.47 %
RY.PR.P Perpetual-Discount 1.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 22.89
Evaluated at bid price : 23.30
Bid-YTW : 5.70 %
BAM.PF.E FixedReset Disc 1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 12.48
Evaluated at bid price : 12.48
Bid-YTW : 6.70 %
BIP.PR.A FixedReset Disc 1.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 13.50
Evaluated at bid price : 13.50
Bid-YTW : 7.87 %
NA.PR.E FixedReset Disc 1.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 14.01
Evaluated at bid price : 14.01
Bid-YTW : 6.20 %
RY.PR.G Deemed-Retractible 1.84 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.30
Bid-YTW : 6.51 %
CU.PR.C FixedReset Disc 1.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 13.70
Evaluated at bid price : 13.70
Bid-YTW : 5.71 %
RY.PR.W Perpetual-Discount 1.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 22.25
Evaluated at bid price : 22.52
Bid-YTW : 5.51 %
BMO.PR.E FixedReset Disc 1.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 16.00
Evaluated at bid price : 16.00
Bid-YTW : 5.81 %
CM.PR.S FixedReset Disc 1.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 14.23
Evaluated at bid price : 14.23
Bid-YTW : 5.90 %
PWF.PR.I Perpetual-Discount 1.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 23.20
Evaluated at bid price : 23.50
Bid-YTW : 6.51 %
PWF.PR.L Perpetual-Discount 1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 19.75
Evaluated at bid price : 19.75
Bid-YTW : 6.60 %
SLF.PR.E Deemed-Retractible 1.97 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 18.10
Evaluated at bid price : 18.10
Bid-YTW : 6.27 %
SLF.PR.C Deemed-Retractible 1.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 17.90
Evaluated at bid price : 17.90
Bid-YTW : 6.27 %
IFC.PR.A FixedReset Ins Non 2.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 10.20
Evaluated at bid price : 10.20
Bid-YTW : 6.27 %
TD.PF.I FixedReset Disc 2.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 16.02
Evaluated at bid price : 16.02
Bid-YTW : 6.06 %
MFC.PR.N FixedReset Ins Non 2.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 12.50
Evaluated at bid price : 12.50
Bid-YTW : 5.95 %
TD.PF.G FixedReset Disc 2.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 22.07
Evaluated at bid price : 22.71
Bid-YTW : 5.94 %
CU.PR.G Perpetual-Discount 2.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 18.70
Evaluated at bid price : 18.70
Bid-YTW : 6.11 %
EML.PR.A FixedReset Ins Non 2.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 20.83
Evaluated at bid price : 20.83
Bid-YTW : 6.81 %
BNS.PR.H FixedReset Disc 2.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 20.80
Evaluated at bid price : 20.80
Bid-YTW : 5.83 %
RY.PR.O Perpetual-Discount 2.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 21.62
Evaluated at bid price : 21.96
Bid-YTW : 5.64 %
RY.PR.N Perpetual-Discount 2.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 21.86
Evaluated at bid price : 22.14
Bid-YTW : 5.60 %
PWF.PR.O Perpetual-Discount 2.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 21.81
Evaluated at bid price : 22.05
Bid-YTW : 6.71 %
MFC.PR.G FixedReset Ins Non 2.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 13.61
Evaluated at bid price : 13.61
Bid-YTW : 6.65 %
BAM.PR.N Perpetual-Discount 2.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 18.38
Evaluated at bid price : 18.38
Bid-YTW : 6.52 %
TD.PF.H FixedReset Disc 2.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 20.47
Evaluated at bid price : 20.47
Bid-YTW : 5.95 %
IAF.PR.G FixedReset Ins Non 2.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 13.00
Evaluated at bid price : 13.00
Bid-YTW : 6.86 %
BAM.PF.C Perpetual-Discount 2.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 18.84
Evaluated at bid price : 18.84
Bid-YTW : 6.50 %
PWF.PR.H Perpetual-Discount 2.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 21.52
Evaluated at bid price : 21.78
Bid-YTW : 6.74 %
BAM.PR.X FixedReset Disc 2.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 9.63
Evaluated at bid price : 9.63
Bid-YTW : 6.50 %
GWO.PR.P Deemed-Retractible 2.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 20.80
Evaluated at bid price : 20.80
Bid-YTW : 6.55 %
BAM.PR.M Perpetual-Discount 2.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 18.51
Evaluated at bid price : 18.51
Bid-YTW : 6.48 %
ELF.PR.H Perpetual-Discount 2.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 20.77
Evaluated at bid price : 20.77
Bid-YTW : 6.66 %
CIU.PR.A Perpetual-Discount 2.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 6.14 %
BMO.PR.Z Perpetual-Discount 2.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 22.07
Evaluated at bid price : 22.39
Bid-YTW : 5.65 %
TD.PF.K FixedReset Disc 2.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 16.20
Evaluated at bid price : 16.20
Bid-YTW : 5.64 %
NA.PR.S FixedReset Disc 2.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 13.10
Evaluated at bid price : 13.10
Bid-YTW : 6.27 %
HSE.PR.E FixedReset Disc 2.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 10.37
Evaluated at bid price : 10.37
Bid-YTW : 10.70 %
PWF.PR.T FixedReset Disc 2.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 12.95
Evaluated at bid price : 12.95
Bid-YTW : 6.58 %
NA.PR.A FixedReset Disc 2.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 21.19
Evaluated at bid price : 21.19
Bid-YTW : 6.26 %
TD.PF.L FixedReset Disc 2.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 18.30
Evaluated at bid price : 18.30
Bid-YTW : 5.91 %
ELF.PR.G Perpetual-Discount 2.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 18.21
Evaluated at bid price : 18.21
Bid-YTW : 6.56 %
GWO.PR.R Deemed-Retractible 2.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 19.10
Evaluated at bid price : 19.10
Bid-YTW : 6.34 %
BIP.PR.E FixedReset Disc 3.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 18.81
Evaluated at bid price : 18.81
Bid-YTW : 6.71 %
GWO.PR.S Deemed-Retractible 3.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 20.10
Evaluated at bid price : 20.10
Bid-YTW : 6.59 %
MFC.PR.M FixedReset Ins Non 3.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 12.73
Evaluated at bid price : 12.73
Bid-YTW : 6.42 %
HSE.PR.C FixedReset Disc 3.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 9.60
Evaluated at bid price : 9.60
Bid-YTW : 10.93 %
TD.PF.J FixedReset Disc 3.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 16.52
Evaluated at bid price : 16.52
Bid-YTW : 5.55 %
MFC.PR.Q FixedReset Ins Non 3.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 14.11
Evaluated at bid price : 14.11
Bid-YTW : 6.26 %
GWO.PR.L Deemed-Retractible 3.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 21.35
Evaluated at bid price : 21.35
Bid-YTW : 6.68 %
TRP.PR.A FixedReset Disc 3.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 11.40
Evaluated at bid price : 11.40
Bid-YTW : 6.25 %
TRP.PR.K FixedReset Disc 3.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 21.41
Evaluated at bid price : 21.74
Bid-YTW : 5.70 %
GWO.PR.T Deemed-Retractible 3.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 20.05
Evaluated at bid price : 20.05
Bid-YTW : 6.48 %
IFC.PR.C FixedReset Ins Non 3.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 12.54
Evaluated at bid price : 12.54
Bid-YTW : 6.65 %
GWO.PR.I Deemed-Retractible 3.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 17.75
Evaluated at bid price : 17.75
Bid-YTW : 6.40 %
MFC.PR.H FixedReset Ins Non 3.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 14.36
Evaluated at bid price : 14.36
Bid-YTW : 6.77 %
BMO.PR.Y FixedReset Disc 3.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 14.00
Evaluated at bid price : 14.00
Bid-YTW : 6.09 %
SLF.PR.J FloatingReset 3.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 8.40
Evaluated at bid price : 8.40
Bid-YTW : 4.79 %
BAM.PR.R FixedReset Disc 3.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 11.06
Evaluated at bid price : 11.06
Bid-YTW : 6.72 %
GWO.PR.H Deemed-Retractible 3.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 19.30
Evaluated at bid price : 19.30
Bid-YTW : 6.34 %
GWO.PR.Q Deemed-Retractible 3.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 20.06
Evaluated at bid price : 20.06
Bid-YTW : 6.48 %
CCS.PR.C Deemed-Retractible 3.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 20.85
Evaluated at bid price : 20.85
Bid-YTW : 6.05 %
HSE.PR.G FixedReset Disc 4.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 9.50
Evaluated at bid price : 9.50
Bid-YTW : 11.12 %
GWO.PR.F Deemed-Retractible 4.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 22.71
Evaluated at bid price : 23.00
Bid-YTW : 6.46 %
RY.PR.R FixedReset Disc 4.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 23.41
Evaluated at bid price : 23.86
Bid-YTW : 5.77 %
TD.PF.M FixedReset Disc 4.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 18.88
Evaluated at bid price : 18.88
Bid-YTW : 6.02 %
TRP.PR.C FixedReset Disc 4.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 8.61
Evaluated at bid price : 8.61
Bid-YTW : 6.36 %
TRP.PR.D FixedReset Disc 4.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 12.80
Evaluated at bid price : 12.80
Bid-YTW : 6.35 %
GWO.PR.M Deemed-Retractible 4.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 21.97
Evaluated at bid price : 22.20
Bid-YTW : 6.58 %
W.PR.K FixedReset Disc 5.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 21.36
Evaluated at bid price : 21.65
Bid-YTW : 6.08 %
W.PR.M FixedReset Disc 6.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 21.60
Evaluated at bid price : 22.00
Bid-YTW : 5.92 %
TD.PF.D FixedReset Disc 7.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 14.80
Evaluated at bid price : 14.80
Bid-YTW : 5.92 %
BIP.PR.F FixedReset Disc 7.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 18.88
Evaluated at bid price : 18.88
Bid-YTW : 6.82 %
PWF.PR.P FixedReset Disc 10.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 9.15
Evaluated at bid price : 9.15
Bid-YTW : 6.27 %
SLF.PR.I FixedReset Ins Non 10.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 13.50
Evaluated at bid price : 13.50
Bid-YTW : 6.38 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PF.B FixedReset Disc 116,274 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 13.97
Evaluated at bid price : 13.97
Bid-YTW : 5.70 %
TD.PF.H FixedReset Disc 93,644 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 20.47
Evaluated at bid price : 20.47
Bid-YTW : 5.95 %
HSE.PR.A FixedReset Disc 70,790 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 5.40
Evaluated at bid price : 5.40
Bid-YTW : 11.16 %
TD.PF.K FixedReset Disc 64,400 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 16.20
Evaluated at bid price : 16.20
Bid-YTW : 5.64 %
MFC.PR.H FixedReset Ins Non 61,700 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 14.36
Evaluated at bid price : 14.36
Bid-YTW : 6.77 %
NA.PR.S FixedReset Disc 49,450 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 13.10
Evaluated at bid price : 13.10
Bid-YTW : 6.27 %
There were 77 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
IFC.PR.G FixedReset Ins Non Quote: 13.75 – 17.60
Spot Rate : 3.8500
Average : 2.1699

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 13.75
Evaluated at bid price : 13.75
Bid-YTW : 6.50 %

PWF.PR.A Floater Quote: 8.10 – 12.00
Spot Rate : 3.9000
Average : 2.3416

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 8.10
Evaluated at bid price : 8.10
Bid-YTW : 5.37 %

MFC.PR.G FixedReset Ins Non Quote: 13.61 – 19.17
Spot Rate : 5.5600
Average : 4.5731

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 13.61
Evaluated at bid price : 13.61
Bid-YTW : 6.65 %

MFC.PR.I FixedReset Ins Non Quote: 12.05 – 14.36
Spot Rate : 2.3100
Average : 1.3753

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 12.05
Evaluated at bid price : 12.05
Bid-YTW : 7.67 %

SLF.PR.J FloatingReset Quote: 8.40 – 10.25
Spot Rate : 1.8500
Average : 1.1452

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 8.40
Evaluated at bid price : 8.40
Bid-YTW : 4.79 %

BAM.PF.B FixedReset Disc Quote: 13.65 – 15.95
Spot Rate : 2.3000
Average : 1.8041

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-07
Maturity Price : 13.65
Evaluated at bid price : 13.65
Bid-YTW : 6.59 %

Market Action

April 6, 2020

unicorn_200406

Portrait of an handsome smiling doctor

Doctors to the rescue!

Stocks rallied on Monday as investors seized on signals that the coronavirus outbreak may be peaking in some of the world’s worst-hit places.

The number of new confirmed deaths and infections is slowing in parts of Europe, and the number of deaths in New York has been steady for two days. In Italy and Spain, the total number of patients continues to climb, but the rate of new infections is no longer rising.

Wall Street analysts have been closely tracking the growth path of infections, with some spotlighting recent news as an indication that the outbreak could be near a peak in the United States. Analysts highlighted the tentative deceleration of infections in New York as a good sign for other virus hot spots in the country, as well as for stock market sentiment.
…
The optimism drove shares sharply higher. The S&P 500 rose 7 percent, its biggest gain since March 24, when it climbed more than 9 percent.

Some areas of the market that have been hit hardest by shutdowns of economic activity soared. The hotel chain Marriott and the casino company Wynn Resorts, for example, each rose more than 15 percent. Credit card companies also rallied, after being hammered by soaring unemployment in recent weeks, which makes people less likely to pay their bills. Capital One and Discover Financial both jumped more than 15 percent.

… and in Canada …:

Canada’s S&P/TSX Composite Index rose 5.1 per cent in a remarkably broad rally that included energy stocks (even though the price of oil fell sharply) and gold producers (even though gold is widely seen as a haven investment).
…
The price of crude oil fell though, as a much-anticipated meeting between Saudi Arabia and Russia to discuss oil production levels on Monday was postponed until Thursday. West Texas Intermediate oil, a U.S. benchmark, fell 6.9 per cent to US$26.39 per barrel.

Canadian energy stocks joined the rally, though. Suncor Energy Inc. rose 4.2 per cent and Canadian Natural Resources rose 1.5 per cent.

… and there are a lot of jobless:

More than three million Canadians have applied for jobless benefits and emergency income aid with the federal government since mid-March, the latest sign of historic levels of devastation in the labour market.

Government officials said Monday that 3.18 million people have applied for employment insurance and the Canada emergency response benefit since March 16. More than 794,725 Canadians filed for benefits on Monday alone, the launch day for CERB’s application system.

CERB is intended to capture workers affected by COVID-19 who aren’t covered by EI, such as the self-employed or those missing work because they’re caring for someone who is sick.

Once the damage is tallied, Canada’s job losses will likely be record-setting. The Conference Board of Canada on Monday said a combined 2.8 million jobs could be shed during March and April, equal to nearly 15 per cent of total employment.

Don’t make summer plans just yet:

Public-health officials, infectious disease experts and provincial data show that B.C.’s and Alberta’s efforts to flatten the curve may be starting to pay off. By contrast, Ontario and Quebec appear to be in an uphill battle.

The number of confirmed cases in B.C. was 1,266 on Monday, compared with 970 one week ago. Alberta reported 1,348 cases on Monday, up from 690 a week ago.

The changes in Ontario and Quebec are more dramatic. On Monday, Ontario reported 4,347 cases, more than 2.5 times the number of confirmed cases from a week earlier. In Quebec, there were 8,580 cases on Monday, a significant rise from 3,430 one week earlier.

… particularly if they involve the Shaw Festival:

Based on the Public Health Agency of Canada’s statement regarding mass gatherings, along with the guidance of the provincial and federal governments, the Shaw Festival has ceased all business on-site, including cancelling all public events and performances, with the intention of resuming on July 1, 2020. Mahabharata, scheduled to hit the stage in August, is cancelled for 2020 however we are committed to bringing it back in a future season.

And, as I so often reiterate, every portfolio manager is at the mercy of his clients. They sell, you sell.

Royal Bank of Canada’s asset management business saw $2.8-billion in net mutual fund redemptions last month as investors scrambled for cash and moved from longer-term funds into less volatile money market funds.

Mutual fund assets under management fell by 9.5 per cent in March, RBC Global Asset Management said Monday. Around 1 per cent of that drop was due to investors cashing out of their funds, said Doug Coulter, president of RBC’s asset management division. The rest of the drop was because of the decline in asset prices.

I love this line from a Globe article on pension plan funding:

“Given the massive drop in bond yields on government bonds, pension deficits should rise significantly, precisely at the wrong time when companies may have to face a potential economic downturn,” says Dimitry Khmelnitsky, an analyst at Veritas Investment Research Corp. who has authored the company’s reports on pension health at TSX-listed companies.

One would hope that this ‘wrong-way risk’ (a significant probability that two bad things will happen together, being highly correlated) would always be uppermost in the mind of any corporate treasurer having to address the issue.

TXPR closed at 477.53, up 2.76% on the day. Volume today was 3.54-million, low in the context of the past thirty days but highest since March 26.

CPD closed at 9.55, up 1.70% on the day. Volume was 113,608, very low in the context of the past 30 trading days.

ZPR closed at 7.41, up 1.51% on the day. Volume of 503,813 was below average in the context of the past 30 trading days.

Five-year Canada yields were up 6bp to 0.65% today.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 4.8521 % 1,414.7
FixedFloater 0.00 % 0.00 % 0 0.00 0 4.8521 % 2,595.9
Floater 5.44 % 5.69 % 45,204 14.40 4 4.8521 % 1,496.0
OpRet 0.00 % 0.00 % 0 0.00 0 1.5091 % 3,138.9
SplitShare 5.29 % 7.36 % 89,214 3.95 7 1.5091 % 3,748.5
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 1.5091 % 2,924.7
Perpetual-Premium 0.00 % 0.00 % 0 0.00 0 2.5647 % 2,632.3
Perpetual-Discount 6.33 % 6.64 % 92,730 12.99 35 2.5647 % 2,823.5
FixedReset Disc 7.03 % 6.26 % 199,292 13.29 83 3.1780 % 1,609.0
Deemed-Retractible 6.09 % 6.63 % 100,110 13.00 27 2.8245 % 2,775.3
FloatingReset 3.15 % 4.48 % 34,944 14.36 4 1.9376 % 1,680.7
FixedReset Prem 0.00 % 0.00 % 0 0.00 0 3.1780 % 2,225.2
FixedReset Bank Non 1.98 % 4.86 % 117,581 1.77 3 1.5366 % 2,696.5
FixedReset Ins Non 7.56 % 6.63 % 113,906 12.67 22 1.9323 % 1,559.3
Performance Highlights
Issue Index Change Notes
SLF.PR.I FixedReset Ins Non -2.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 12.20
Evaluated at bid price : 12.20
Bid-YTW : 7.08 %
RY.PR.E Deemed-Retractible 1.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.95
Bid-YTW : 7.36 %
MFC.PR.M FixedReset Ins Non 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 12.35
Evaluated at bid price : 12.35
Bid-YTW : 6.63 %
PWF.PR.K Perpetual-Discount 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 18.80
Evaluated at bid price : 18.80
Bid-YTW : 6.73 %
PVS.PR.H SplitShare 1.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2027-02-28
Maturity Price : 25.00
Evaluated at bid price : 22.75
Bid-YTW : 6.44 %
EIT.PR.B SplitShare 1.12 % YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2025-03-14
Maturity Price : 25.00
Evaluated at bid price : 22.50
Bid-YTW : 7.36 %
NA.PR.E FixedReset Disc 1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 13.76
Evaluated at bid price : 13.76
Bid-YTW : 6.32 %
RY.PR.A Deemed-Retractible 1.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.05
Bid-YTW : 7.06 %
MFC.PR.F FixedReset Ins Non 1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 8.10
Evaluated at bid price : 8.10
Bid-YTW : 6.43 %
BMO.PR.Z Perpetual-Discount 1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 21.53
Evaluated at bid price : 21.82
Bid-YTW : 5.80 %
BAM.PR.C Floater 1.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 7.60
Evaluated at bid price : 7.60
Bid-YTW : 5.69 %
BAM.PR.R FixedReset Disc 1.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 10.66
Evaluated at bid price : 10.66
Bid-YTW : 6.98 %
ELF.PR.H Perpetual-Discount 1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 20.25
Evaluated at bid price : 20.25
Bid-YTW : 6.83 %
GWO.PR.F Deemed-Retractible 1.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 21.85
Evaluated at bid price : 22.09
Bid-YTW : 6.73 %
PVS.PR.G SplitShare 1.57 % YTW SCENARIO
Maturity Type : Option Certainty
Maturity Date : 2026-02-28
Maturity Price : 25.00
Evaluated at bid price : 22.60
Bid-YTW : 7.04 %
CM.PR.Y FixedReset Disc 1.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 18.03
Evaluated at bid price : 18.03
Bid-YTW : 6.27 %
IAF.PR.B Deemed-Retractible 1.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 18.03
Evaluated at bid price : 18.03
Bid-YTW : 6.44 %
BNS.PR.E FixedReset Disc 1.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 21.43
Evaluated at bid price : 21.75
Bid-YTW : 5.94 %
PWF.PR.E Perpetual-Discount 1.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 21.20
Evaluated at bid price : 21.20
Bid-YTW : 6.63 %
BMO.PR.F FixedReset Disc 1.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 17.78
Evaluated at bid price : 17.78
Bid-YTW : 6.28 %
TRP.PR.D FixedReset Disc 1.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 12.25
Evaluated at bid price : 12.25
Bid-YTW : 6.64 %
PWF.PR.F Perpetual-Discount 1.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 19.98
Evaluated at bid price : 19.98
Bid-YTW : 6.72 %
MFC.PR.H FixedReset Ins Non 1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 13.85
Evaluated at bid price : 13.85
Bid-YTW : 7.02 %
IAF.PR.I FixedReset Ins Non 1.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 13.51
Evaluated at bid price : 13.51
Bid-YTW : 6.85 %
CM.PR.T FixedReset Disc 1.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 6.10 %
PWF.PR.Z Perpetual-Discount 1.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 19.77
Evaluated at bid price : 19.77
Bid-YTW : 6.66 %
RY.PR.R FixedReset Disc 1.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 22.48
Evaluated at bid price : 22.90
Bid-YTW : 6.02 %
TD.PF.G FixedReset Disc 1.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 21.78
Evaluated at bid price : 22.25
Bid-YTW : 6.07 %
BMO.PR.W FixedReset Disc 1.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 13.25
Evaluated at bid price : 13.25
Bid-YTW : 6.02 %
PWF.PR.S Perpetual-Discount 1.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 18.41
Evaluated at bid price : 18.41
Bid-YTW : 6.66 %
TRP.PR.A FixedReset Disc 1.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 11.01
Evaluated at bid price : 11.01
Bid-YTW : 6.48 %
RY.PR.P Perpetual-Discount 1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 22.56
Evaluated at bid price : 22.90
Bid-YTW : 5.80 %
NA.PR.S FixedReset Disc 2.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 12.76
Evaluated at bid price : 12.76
Bid-YTW : 6.44 %
MFC.PR.N FixedReset Ins Non 2.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 12.25
Evaluated at bid price : 12.25
Bid-YTW : 6.07 %
BAM.PF.C Perpetual-Discount 2.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 18.40
Evaluated at bid price : 18.40
Bid-YTW : 6.65 %
CU.PR.I FixedReset Disc 2.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 21.44
Evaluated at bid price : 21.75
Bid-YTW : 5.22 %
SLF.PR.H FixedReset Ins Non 2.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 11.00
Evaluated at bid price : 11.00
Bid-YTW : 6.45 %
PVS.PR.E SplitShare 2.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-10-31
Maturity Price : 25.00
Evaluated at bid price : 23.75
Bid-YTW : 7.94 %
BAM.PR.N Perpetual-Discount 2.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 17.96
Evaluated at bid price : 17.96
Bid-YTW : 6.67 %
PWF.PR.H Perpetual-Discount 2.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 21.26
Evaluated at bid price : 21.26
Bid-YTW : 6.92 %
ELF.PR.G Perpetual-Discount 2.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 17.70
Evaluated at bid price : 17.70
Bid-YTW : 6.75 %
CU.PR.G Perpetual-Discount 2.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 18.32
Evaluated at bid price : 18.32
Bid-YTW : 6.23 %
MFC.PR.Q FixedReset Ins Non 2.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 13.65
Evaluated at bid price : 13.65
Bid-YTW : 6.48 %
GWO.PR.M Deemed-Retractible 2.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 21.20
Evaluated at bid price : 21.20
Bid-YTW : 6.91 %
MFC.PR.I FixedReset Ins Non 2.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 13.91
Evaluated at bid price : 13.91
Bid-YTW : 6.61 %
BMO.PR.E FixedReset Disc 2.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 15.70
Evaluated at bid price : 15.70
Bid-YTW : 5.92 %
BIK.PR.A FixedReset Disc 2.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 21.69
Evaluated at bid price : 22.00
Bid-YTW : 6.70 %
BAM.PF.G FixedReset Disc 2.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 13.10
Evaluated at bid price : 13.10
Bid-YTW : 6.70 %
POW.PR.D Perpetual-Discount 2.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 19.08
Evaluated at bid price : 19.08
Bid-YTW : 6.59 %
PWF.PR.O Perpetual-Discount 2.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 21.28
Evaluated at bid price : 21.55
Bid-YTW : 6.87 %
BAM.PR.M Perpetual-Discount 2.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 18.06
Evaluated at bid price : 18.06
Bid-YTW : 6.64 %
TRP.PR.B FixedReset Disc 2.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 8.33
Evaluated at bid price : 8.33
Bid-YTW : 5.81 %
NA.PR.G FixedReset Disc 2.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 14.40
Evaluated at bid price : 14.40
Bid-YTW : 6.51 %
RY.PR.J FixedReset Disc 2.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 14.76
Evaluated at bid price : 14.76
Bid-YTW : 5.81 %
BMO.PR.C FixedReset Disc 2.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 16.40
Evaluated at bid price : 16.40
Bid-YTW : 6.26 %
TD.PF.H FixedReset Disc 2.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 6.09 %
TD.PF.L FixedReset Disc 2.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 17.79
Evaluated at bid price : 17.79
Bid-YTW : 6.09 %
CU.PR.E Perpetual-Discount 2.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 20.10
Evaluated at bid price : 20.10
Bid-YTW : 6.18 %
BMO.PR.B FixedReset Disc 2.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 5.99 %
PWF.PR.L Perpetual-Discount 2.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 19.37
Evaluated at bid price : 19.37
Bid-YTW : 6.73 %
IFC.PR.G FixedReset Ins Non 2.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 13.60
Evaluated at bid price : 13.60
Bid-YTW : 6.57 %
BMO.PR.S FixedReset Disc 2.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 13.20
Evaluated at bid price : 13.20
Bid-YTW : 6.15 %
GWO.PR.L Deemed-Retractible 2.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 20.65
Evaluated at bid price : 20.65
Bid-YTW : 6.91 %
RY.PR.Q FixedReset Disc 2.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 21.95
Evaluated at bid price : 22.52
Bid-YTW : 5.82 %
BAM.PF.D Perpetual-Discount 2.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 18.80
Evaluated at bid price : 18.80
Bid-YTW : 6.58 %
RY.PR.O Perpetual-Discount 2.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 21.50
Evaluated at bid price : 21.50
Bid-YTW : 5.79 %
BAM.PR.Z FixedReset Disc 2.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 14.08
Evaluated at bid price : 14.08
Bid-YTW : 6.80 %
TD.PF.K FixedReset Disc 2.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 15.78
Evaluated at bid price : 15.78
Bid-YTW : 5.80 %
POW.PR.B Perpetual-Discount 2.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 20.10
Evaluated at bid price : 20.10
Bid-YTW : 6.70 %
PWF.PR.I Perpetual-Discount 2.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 22.77
Evaluated at bid price : 23.05
Bid-YTW : 6.64 %
CIU.PR.A Perpetual-Discount 2.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 18.52
Evaluated at bid price : 18.52
Bid-YTW : 6.30 %
BNS.PR.H FixedReset Disc 2.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 20.37
Evaluated at bid price : 20.37
Bid-YTW : 5.95 %
BAM.PF.I FixedReset Disc 2.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 20.70
Evaluated at bid price : 20.70
Bid-YTW : 5.85 %
NA.PR.A FixedReset Disc 3.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 20.60
Evaluated at bid price : 20.60
Bid-YTW : 6.44 %
CU.PR.F Perpetual-Discount 3.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 18.80
Evaluated at bid price : 18.80
Bid-YTW : 6.07 %
MFC.PR.K FixedReset Ins Non 3.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 12.57
Evaluated at bid price : 12.57
Bid-YTW : 6.44 %
RY.PR.Z FixedReset Disc 3.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 13.56
Evaluated at bid price : 13.56
Bid-YTW : 5.73 %
SLF.PR.C Deemed-Retractible 3.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 17.55
Evaluated at bid price : 17.55
Bid-YTW : 6.40 %
PWF.PR.R Perpetual-Discount 3.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 21.30
Evaluated at bid price : 21.30
Bid-YTW : 6.60 %
BNS.PR.I FixedReset Disc 3.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 15.95
Evaluated at bid price : 15.95
Bid-YTW : 5.43 %
MFC.PR.G FixedReset Ins Non 3.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 13.30
Evaluated at bid price : 13.30
Bid-YTW : 6.81 %
BAM.PF.A FixedReset Disc 3.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 14.92
Evaluated at bid price : 14.92
Bid-YTW : 6.56 %
NA.PR.W FixedReset Disc 3.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 12.60
Evaluated at bid price : 12.60
Bid-YTW : 6.28 %
PWF.PR.G Perpetual-Discount 3.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 22.33
Evaluated at bid price : 22.60
Bid-YTW : 6.66 %
CU.PR.H Perpetual-Discount 3.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 21.50
Evaluated at bid price : 21.78
Bid-YTW : 6.10 %
RY.PR.W Perpetual-Discount 3.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 21.86
Evaluated at bid price : 22.10
Bid-YTW : 5.61 %
PWF.PR.T FixedReset Disc 3.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 12.60
Evaluated at bid price : 12.60
Bid-YTW : 6.77 %
TD.PF.I FixedReset Disc 3.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 15.70
Evaluated at bid price : 15.70
Bid-YTW : 6.19 %
GWO.PR.H Deemed-Retractible 3.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 18.60
Evaluated at bid price : 18.60
Bid-YTW : 6.58 %
TRP.PR.F FloatingReset 3.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 9.30
Evaluated at bid price : 9.30
Bid-YTW : 5.72 %
CU.PR.D Perpetual-Discount 3.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 20.26
Evaluated at bid price : 20.26
Bid-YTW : 6.14 %
BMO.PR.Q FixedReset Bank Non 3.37 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.30
Bid-YTW : 5.93 %
CM.PR.S FixedReset Disc 3.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 13.96
Evaluated at bid price : 13.96
Bid-YTW : 6.01 %
TRP.PR.J FixedReset Disc 3.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 22.40
Evaluated at bid price : 22.86
Bid-YTW : 6.08 %
GWO.PR.S Deemed-Retractible 3.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 19.50
Evaluated at bid price : 19.50
Bid-YTW : 6.80 %
BAM.PF.E FixedReset Disc 3.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 12.26
Evaluated at bid price : 12.26
Bid-YTW : 6.83 %
RY.PR.S FixedReset Disc 3.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 16.25
Evaluated at bid price : 16.25
Bid-YTW : 5.34 %
TRP.PR.C FixedReset Disc 3.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 8.25
Evaluated at bid price : 8.25
Bid-YTW : 6.64 %
IFC.PR.A FixedReset Ins Non 3.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 10.00
Evaluated at bid price : 10.00
Bid-YTW : 6.40 %
CM.PR.R FixedReset Disc 3.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 15.85
Evaluated at bid price : 15.85
Bid-YTW : 6.46 %
PVS.PR.F SplitShare 3.54 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2024-09-30
Maturity Price : 25.00
Evaluated at bid price : 22.80
Bid-YTW : 7.28 %
POW.PR.A Perpetual-Discount 3.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 20.71
Evaluated at bid price : 20.71
Bid-YTW : 6.80 %
TD.PF.C FixedReset Disc 3.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 13.73
Evaluated at bid price : 13.73
Bid-YTW : 5.93 %
MFC.PR.B Deemed-Retractible 3.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 18.30
Evaluated at bid price : 18.30
Bid-YTW : 6.43 %
BNS.PR.G FixedReset Disc 3.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 22.27
Evaluated at bid price : 22.68
Bid-YTW : 5.92 %
BIP.PR.D FixedReset Disc 3.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 18.15
Evaluated at bid price : 18.15
Bid-YTW : 6.95 %
MFC.PR.R FixedReset Ins Non 3.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 16.70
Evaluated at bid price : 16.70
Bid-YTW : 6.85 %
SLF.PR.B Deemed-Retractible 3.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 19.20
Evaluated at bid price : 19.20
Bid-YTW : 6.31 %
SLF.PR.E Deemed-Retractible 3.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 17.75
Evaluated at bid price : 17.75
Bid-YTW : 6.40 %
MFC.PR.J FixedReset Ins Non 3.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 13.85
Evaluated at bid price : 13.85
Bid-YTW : 6.44 %
GWO.PR.T Deemed-Retractible 3.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 19.35
Evaluated at bid price : 19.35
Bid-YTW : 6.72 %
GWO.PR.Q Deemed-Retractible 3.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 19.30
Evaluated at bid price : 19.30
Bid-YTW : 6.73 %
SLF.PR.D Deemed-Retractible 3.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 17.85
Evaluated at bid price : 17.85
Bid-YTW : 6.29 %
RY.PR.N Perpetual-Discount 3.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 21.64
Evaluated at bid price : 21.64
Bid-YTW : 5.75 %
BMO.PR.D FixedReset Disc 3.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 15.81
Evaluated at bid price : 15.81
Bid-YTW : 6.27 %
SLF.PR.A Deemed-Retractible 4.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 6.31 %
TD.PF.A FixedReset Disc 4.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 13.54
Evaluated at bid price : 13.54
Bid-YTW : 5.86 %
BMO.PR.T FixedReset Disc 4.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 13.02
Evaluated at bid price : 13.02
Bid-YTW : 6.01 %
POW.PR.G Perpetual-Discount 4.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 20.62
Evaluated at bid price : 20.62
Bid-YTW : 6.83 %
TD.PF.F Perpetual-Discount 4.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 21.64
Evaluated at bid price : 21.98
Bid-YTW : 5.66 %
TD.PF.B FixedReset Disc 4.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 13.80
Evaluated at bid price : 13.80
Bid-YTW : 5.77 %
BAM.PF.F FixedReset Disc 4.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 13.75
Evaluated at bid price : 13.75
Bid-YTW : 6.70 %
BAM.PR.X FixedReset Disc 4.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 9.40
Evaluated at bid price : 9.40
Bid-YTW : 6.66 %
MFC.PR.C Deemed-Retractible 4.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 17.30
Evaluated at bid price : 17.30
Bid-YTW : 6.58 %
CM.PR.P FixedReset Disc 4.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 12.90
Evaluated at bid price : 12.90
Bid-YTW : 6.20 %
POW.PR.C Perpetual-Discount 4.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 21.38
Evaluated at bid price : 21.65
Bid-YTW : 6.73 %
MFC.PR.L FixedReset Ins Non 4.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 12.10
Evaluated at bid price : 12.10
Bid-YTW : 6.39 %
RY.PR.H FixedReset Disc 4.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 13.95
Evaluated at bid price : 13.95
Bid-YTW : 5.63 %
GWO.PR.P Deemed-Retractible 4.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 20.30
Evaluated at bid price : 20.30
Bid-YTW : 6.71 %
BAM.PR.K Floater 4.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 7.60
Evaluated at bid price : 7.60
Bid-YTW : 5.69 %
TD.PF.E FixedReset Disc 4.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 14.70
Evaluated at bid price : 14.70
Bid-YTW : 6.11 %
GWO.PR.R Deemed-Retractible 4.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 18.56
Evaluated at bid price : 18.56
Bid-YTW : 6.53 %
BAM.PF.B FixedReset Disc 4.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 13.57
Evaluated at bid price : 13.57
Bid-YTW : 6.63 %
BAM.PF.J FixedReset Disc 5.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 20.75
Evaluated at bid price : 20.75
Bid-YTW : 5.77 %
CM.PR.O FixedReset Disc 5.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 12.83
Evaluated at bid price : 12.83
Bid-YTW : 6.19 %
BAM.PR.T FixedReset Disc 5.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 11.30
Evaluated at bid price : 11.30
Bid-YTW : 6.74 %
BIP.PR.C FixedReset Disc 5.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 20.01
Evaluated at bid price : 20.01
Bid-YTW : 6.75 %
BIP.PR.A FixedReset Disc 5.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 13.26
Evaluated at bid price : 13.26
Bid-YTW : 8.01 %
BIP.PR.B FixedReset Disc 5.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 21.00
Evaluated at bid price : 21.00
Bid-YTW : 6.61 %
TD.PF.J FixedReset Disc 5.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 16.00
Evaluated at bid price : 16.00
Bid-YTW : 5.74 %
GWO.PR.G Deemed-Retractible 5.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 19.69
Evaluated at bid price : 19.69
Bid-YTW : 6.66 %
BMO.PR.Y FixedReset Disc 5.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 13.50
Evaluated at bid price : 13.50
Bid-YTW : 6.32 %
GWO.PR.I Deemed-Retractible 5.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 17.12
Evaluated at bid price : 17.12
Bid-YTW : 6.63 %
GWO.PR.N FixedReset Ins Non 5.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 8.65
Evaluated at bid price : 8.65
Bid-YTW : 5.68 %
CM.PR.Q FixedReset Disc 6.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 13.00
Evaluated at bid price : 13.00
Bid-YTW : 6.62 %
TRP.PR.G FixedReset Disc 6.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 13.05
Evaluated at bid price : 13.05
Bid-YTW : 7.04 %
CCS.PR.C Deemed-Retractible 6.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 20.05
Evaluated at bid price : 20.05
Bid-YTW : 6.29 %
W.PR.K FixedReset Disc 6.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 20.60
Evaluated at bid price : 20.60
Bid-YTW : 6.41 %
BIP.PR.E FixedReset Disc 7.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 18.25
Evaluated at bid price : 18.25
Bid-YTW : 6.92 %
TRP.PR.H FloatingReset 7.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 8.25
Evaluated at bid price : 8.25
Bid-YTW : 4.48 %
NA.PR.C FixedReset Disc 7.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 15.70
Evaluated at bid price : 15.70
Bid-YTW : 6.58 %
RY.PR.M FixedReset Disc 10.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 13.25
Evaluated at bid price : 13.25
Bid-YTW : 6.28 %
W.PR.M FixedReset Disc 11.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 20.75
Evaluated at bid price : 20.75
Bid-YTW : 6.30 %
PWF.PR.A Floater 12.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 8.75
Evaluated at bid price : 8.75
Bid-YTW : 4.97 %
Volume Highlights
Issue Index Shares
Traded
Notes
SLF.PR.G FixedReset Ins Non 258,300 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 8.30
Evaluated at bid price : 8.30
Bid-YTW : 6.23 %
PWF.PR.L Perpetual-Discount 241,500 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 19.37
Evaluated at bid price : 19.37
Bid-YTW : 6.73 %
BAM.PR.B Floater 147,847 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 7.60
Evaluated at bid price : 7.60
Bid-YTW : 5.69 %
BAM.PR.X FixedReset Disc 114,270 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 9.40
Evaluated at bid price : 9.40
Bid-YTW : 6.66 %
BAM.PR.K Floater 109,300 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 7.60
Evaluated at bid price : 7.60
Bid-YTW : 5.69 %
CM.PR.S FixedReset Disc 59,405 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 13.96
Evaluated at bid price : 13.96
Bid-YTW : 6.01 %
There were 43 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
MFC.PR.G FixedReset Ins Non Quote: 13.30 – 19.17
Spot Rate : 5.8700
Average : 3.4910

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 13.30
Evaluated at bid price : 13.30
Bid-YTW : 6.81 %

W.PR.K FixedReset Disc Quote: 20.60 – 25.05
Spot Rate : 4.4500
Average : 2.6534

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 20.60
Evaluated at bid price : 20.60
Bid-YTW : 6.41 %

BMO.PR.C FixedReset Disc Quote: 16.40 – 19.48
Spot Rate : 3.0800
Average : 1.7140

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 16.40
Evaluated at bid price : 16.40
Bid-YTW : 6.26 %

PVS.PR.F SplitShare Quote: 22.80 – 25.35
Spot Rate : 2.5500
Average : 1.5250

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2024-09-30
Maturity Price : 25.00
Evaluated at bid price : 22.80
Bid-YTW : 7.28 %

POW.PR.B Perpetual-Discount Quote: 20.10 – 22.41
Spot Rate : 2.3100
Average : 1.3787

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 20.10
Evaluated at bid price : 20.10
Bid-YTW : 6.70 %

NA.PR.A FixedReset Disc Quote: 20.60 – 23.00
Spot Rate : 2.4000
Average : 1.5887

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-06
Maturity Price : 20.60
Evaluated at bid price : 20.60
Bid-YTW : 6.44 %

Market Action

April 3, 2020

Wow, no illustrations today! I can remember the halcyon days of my youth when that was normal!

The US jobs number recorded a big whoopsy today:

The longest stretch of job creation in American history came to a halt last month, the Labor Department reported Friday, another reflection of the coronavirus pandemic that has brought the economy to a virtual standstill.

Compared with the astounding numbers of people recently applying for unemployment benefits — nearly 10 million in the previous two weeks — the figure announced Friday was less striking: a loss of 701,000 jobs. But the data was mostly collected in the first half of the month, before stay-at-home orders began to cover much of the nation. With that, what had been a drip-drip-drip of job losses turned into a deluge.
…
The decline in employment last month represents the biggest monthly drop since the depths of the Great Recession in 2008-9. It was paced by a net loss of 459,000 jobs in the leisure and hospitality sector.

The Saudis are attempting to expand the oil cartel:

Saudi Arabia is calling on Canada and other countries to participate in oil-output cuts to help halt the slide in global crude prices that is taking a heavy toll on energy-producing economies already struggling with the COVID-19 crisis.

The official Saudi Press Agency reported that the kingdom urged members of the Organization of Petroleum Exporting Countries, Russia and other countries to seek an agreement to “restore equilibrium” in the oil market. Crude prices shot up 25 per cent on Thursday in response to that and to a comment from U.S. President Donald Trump that Saudi Arabia and Russia could be near a deal to end a price war that has flooded markets around the world.

A source within OPEC+, which comprises the cartel’s membership plus Russia, Mexico and other allied producers, said non-affiliated countries such as Canada and Brazil would need to join in any co-ordinated output cuts.

In the Credit Crunch, there were reports of mortgage servicers being reluctant to give anyone any kind of break on their mortgage, because they were at the end of a long ownership chain, contractually obliged to be tough on deadbeats unless they received instructions from somebody who needed to get instructions … it appears that the US has learned something from that:

The federal financial institution regulatory agencies and the state financial regulators issued a joint policy statement providing needed regulatory flexibility to enable mortgage servicers to work with struggling consumers affected by the Coronavirus Disease (referred to as COVID-19) emergency. The actions announced today by the agencies inform servicers of the agencies’ flexible supervisory and enforcement approach during the COVID-19 pandemic regarding certain communications to consumers required by the mortgage servicing rules. The policy statement and guidance issued today will facilitate mortgage servicers’ ability to place consumers in short-term payment forbearance programs such as the one established by the Coronavirus Aid, Relief, and Economic Security Act (CARES Act).

Under the CARES Act, borrowers in a federally backed mortgage loan experiencing a financial hardship due, directly or indirectly, to the COVID-19 pandemic, may request forbearance by making a request to their mortgage servicer and affirming that they are experiencing a financial hardship during the COVID–19 pandemic. In response, servicers must provide a CARES Act forbearance, that allows borrowers to defer their mortgage payments for up to 180-days and possibly longer.

The policy statement clarifies that the agencies do not intend to take supervisory or enforcement action against mortgage servicers for delays in sending certain early intervention and loss mitigation notices and taking certain actions relating to loss mitigation set out in the mortgage servicing rules, provided that servicers are making good faith efforts to provide these notices and take these actions within a reasonable time.

Cirque de Soliel has been declared in default by S&P:

  • We believe Montreal-based theatrical and live entertainment company Cirque Du Soleil Group did not make principal and interest payments due March 31 on its first-lien credit facility, and did not make the interest payment due March 31 on its second-lien credit facility, which constitutes a default under our criteria.
  • S&P Global Ratings is therefore lowering the issuer credit rating on the company to ‘D’ from ‘CCC-‘.
  • At the same time, we are lowering the issue-level rating on the first-lien debt to ‘D’ from ‘CCC’ to reflect the payment default. We are also lowering the rating on the second-lien debt to ‘D’ from ‘C’ to reflect the payment default.

But the show must go on:

Revenue at Cirque has plummeted to zero as all its 44 shows crashed to a sudden halt. Some 4,700 employees have been laid off. Cash is tight and about US$1-billion of debt sits on the balance sheet.

Still, Cirque’s existence is not in jeopardy, he says. He sees the firm as a global icon with nearly-unmatched ability to draw paying customers, a cultural cornerstone in Quebec that the province’s institutional power brokers will not abandon. Besides, he says, it’s profitable in normal times even if it faces a massive liquidity crunch now.

“We are one of the most amazing brands in the world,” Mr. Lamarre says. “No investor with a straight mind will let it go.”

Negotiations are now under way between shareholders, notably Texas-based private equity firm TPG Capital and pension fund giant Caisse de dépôt et placement du Québec, on a financial restructuring that will satisfy creditors and find a way out. The Quebec government is involved through its investment arm. A bankruptcy protection filing remains a possibility, Mr. Lamarre says. But the firm is also hoping it can soon reopen shows in carefully chosen markets as the pandemic wanes and get revenue flowing again.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.9220 % 1,349.2
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.9220 % 2,475.7
Floater 5.70 % 5.68 % 44,452 14.41 4 -0.9220 % 1,426.8
OpRet 0.00 % 0.00 % 0 0.00 0 -0.9630 % 3,092.2
SplitShare 5.37 % 7.79 % 84,264 3.94 7 -0.9630 % 3,692.8
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.9630 % 2,881.3
Perpetual-Premium 0.00 % 0.00 % 0 0.00 0 0.7409 % 2,566.5
Perpetual-Discount 6.49 % 6.79 % 93,838 12.81 35 0.7409 % 2,752.9
FixedReset Disc 7.24 % 6.29 % 200,939 13.10 83 0.2835 % 1,559.4
Deemed-Retractible 6.26 % 6.84 % 101,438 12.62 27 0.2011 % 2,699.1
FloatingReset 3.24 % 1.00 % 32,339 0.14 4 -0.1004 % 1,648.7
FixedReset Prem 0.00 % 0.00 % 0 0.00 0 0.2835 % 2,156.7
FixedReset Bank Non 2.00 % 5.35 % 118,731 1.77 3 -0.4062 % 2,655.7
FixedReset Ins Non 7.70 % 6.61 % 113,491 12.57 22 -0.5169 % 1,529.8
Performance Highlights
Issue Index Change Notes
TRP.PR.G FixedReset Disc -9.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 12.25
Evaluated at bid price : 12.25
Bid-YTW : 7.36 %
RY.PR.M FixedReset Disc -7.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 11.98
Evaluated at bid price : 11.98
Bid-YTW : 6.80 %
PWF.PR.P FixedReset Disc -7.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 8.31
Evaluated at bid price : 8.31
Bid-YTW : 6.70 %
W.PR.M FixedReset Disc -7.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 18.57
Evaluated at bid price : 18.57
Bid-YTW : 7.04 %
SLF.PR.I FixedReset Ins Non -5.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 12.56
Evaluated at bid price : 12.56
Bid-YTW : 6.74 %
HSE.PR.A FixedReset Disc -4.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 5.45
Evaluated at bid price : 5.45
Bid-YTW : 10.74 %
GWO.PR.N FixedReset Ins Non -3.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 8.20
Evaluated at bid price : 8.20
Bid-YTW : 5.78 %
NA.PR.C FixedReset Disc -3.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 14.56
Evaluated at bid price : 14.56
Bid-YTW : 6.99 %
BAM.PR.K Floater -3.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 7.25
Evaluated at bid price : 7.25
Bid-YTW : 5.96 %
SLF.PR.H FixedReset Ins Non -2.97 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 10.77
Evaluated at bid price : 10.77
Bid-YTW : 6.44 %
MFC.PR.G FixedReset Ins Non -2.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 12.89
Evaluated at bid price : 12.89
Bid-YTW : 6.90 %
BAM.PF.E FixedReset Disc -2.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 11.85
Evaluated at bid price : 11.85
Bid-YTW : 6.96 %
MFC.PR.R FixedReset Ins Non -2.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 16.10
Evaluated at bid price : 16.10
Bid-YTW : 7.01 %
BAM.PF.B FixedReset Disc -2.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 12.93
Evaluated at bid price : 12.93
Bid-YTW : 6.86 %
BAM.PR.R FixedReset Disc -2.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 10.50
Evaluated at bid price : 10.50
Bid-YTW : 6.92 %
EIT.PR.B SplitShare -2.20 % YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2025-03-14
Maturity Price : 25.00
Evaluated at bid price : 22.25
Bid-YTW : 7.61 %
TD.PF.D FixedReset Disc -2.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 13.80
Evaluated at bid price : 13.80
Bid-YTW : 6.23 %
W.PR.K FixedReset Disc -2.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 19.30
Evaluated at bid price : 19.30
Bid-YTW : 6.84 %
PVS.PR.F SplitShare -1.74 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2024-09-30
Maturity Price : 25.00
Evaluated at bid price : 22.02
Bid-YTW : 8.16 %
EIT.PR.A SplitShare -1.74 % YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2024-03-14
Maturity Price : 25.00
Evaluated at bid price : 22.60
Bid-YTW : 7.79 %
BMO.PR.Y FixedReset Disc -1.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 12.81
Evaluated at bid price : 12.81
Bid-YTW : 6.53 %
BMO.PR.F FixedReset Disc -1.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 6.31 %
MFC.PR.B Deemed-Retractible -1.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 17.66
Evaluated at bid price : 17.66
Bid-YTW : 6.66 %
MFC.PR.M FixedReset Ins Non -1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 12.22
Evaluated at bid price : 12.22
Bid-YTW : 6.59 %
GWO.PR.H Deemed-Retractible -1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 6.80 %
TRP.PR.A FixedReset Disc -1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 10.80
Evaluated at bid price : 10.80
Bid-YTW : 6.49 %
CU.PR.F Perpetual-Discount -1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 18.25
Evaluated at bid price : 18.25
Bid-YTW : 6.25 %
TD.PF.E FixedReset Disc -1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 14.02
Evaluated at bid price : 14.02
Bid-YTW : 6.29 %
BMO.PR.D FixedReset Disc -1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 15.21
Evaluated at bid price : 15.21
Bid-YTW : 6.42 %
IAF.PR.G FixedReset Ins Non -1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 12.60
Evaluated at bid price : 12.60
Bid-YTW : 6.95 %
MFC.PR.C Deemed-Retractible -1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 16.58
Evaluated at bid price : 16.58
Bid-YTW : 6.86 %
PVS.PR.E SplitShare -1.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-10-31
Maturity Price : 25.00
Evaluated at bid price : 23.25
Bid-YTW : 8.83 %
CCS.PR.C Deemed-Retractible -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 18.80
Evaluated at bid price : 18.80
Bid-YTW : 6.71 %
BIP.PR.B FixedReset Disc 1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 19.95
Evaluated at bid price : 19.95
Bid-YTW : 6.96 %
SLF.PR.A Deemed-Retractible 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 18.26
Evaluated at bid price : 18.26
Bid-YTW : 6.56 %
PWF.PR.S Perpetual-Discount 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 18.06
Evaluated at bid price : 18.06
Bid-YTW : 6.79 %
CIU.PR.A Perpetual-Discount 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 6.48 %
IFC.PR.G FixedReset Ins Non 1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 13.25
Evaluated at bid price : 13.25
Bid-YTW : 6.64 %
PWF.PR.G Perpetual-Discount 1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 21.65
Evaluated at bid price : 21.90
Bid-YTW : 6.87 %
GWO.PR.F Deemed-Retractible 1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 21.49
Evaluated at bid price : 21.75
Bid-YTW : 6.83 %
BIP.PR.C FixedReset Disc 1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 19.02
Evaluated at bid price : 19.02
Bid-YTW : 7.10 %
BIP.PR.E FixedReset Disc 1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 7.42 %
HSE.PR.E FixedReset Disc 1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 10.15
Evaluated at bid price : 10.15
Bid-YTW : 10.83 %
TD.PF.I FixedReset Disc 1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 15.20
Evaluated at bid price : 15.20
Bid-YTW : 6.30 %
BAM.PR.N Perpetual-Discount 1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 17.58
Evaluated at bid price : 17.58
Bid-YTW : 6.82 %
BAM.PF.C Perpetual-Discount 1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 18.02
Evaluated at bid price : 18.02
Bid-YTW : 6.79 %
BMO.PR.W FixedReset Disc 1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 13.00
Evaluated at bid price : 13.00
Bid-YTW : 6.03 %
BMO.PR.C FixedReset Disc 1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 16.00
Evaluated at bid price : 16.00
Bid-YTW : 6.32 %
BAM.PF.J FixedReset Disc 1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 19.75
Evaluated at bid price : 19.75
Bid-YTW : 6.06 %
PWF.PR.F Perpetual-Discount 1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 19.65
Evaluated at bid price : 19.65
Bid-YTW : 6.83 %
CM.PR.S FixedReset Disc 1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 13.50
Evaluated at bid price : 13.50
Bid-YTW : 6.11 %
BAM.PR.M Perpetual-Discount 1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 17.63
Evaluated at bid price : 17.63
Bid-YTW : 6.80 %
BAM.PF.F FixedReset Disc 1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 13.18
Evaluated at bid price : 13.18
Bid-YTW : 6.90 %
IAF.PR.B Deemed-Retractible 1.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 17.75
Evaluated at bid price : 17.75
Bid-YTW : 6.53 %
TD.PF.F Perpetual-Discount 1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 21.10
Evaluated at bid price : 21.10
Bid-YTW : 5.92 %
NA.PR.S FixedReset Disc 1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 12.50
Evaluated at bid price : 12.50
Bid-YTW : 6.46 %
TD.PF.L FixedReset Disc 1.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 17.35
Evaluated at bid price : 17.35
Bid-YTW : 6.16 %
BNS.PR.G FixedReset Disc 1.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 21.74
Evaluated at bid price : 22.20
Bid-YTW : 6.08 %
BNS.PR.I FixedReset Disc 1.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 15.76
Evaluated at bid price : 15.76
Bid-YTW : 5.55 %
RY.PR.W Perpetual-Discount 1.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 21.40
Evaluated at bid price : 21.40
Bid-YTW : 5.81 %
PWF.PR.K Perpetual-Discount 1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 18.60
Evaluated at bid price : 18.60
Bid-YTW : 6.80 %
MFC.PR.I FixedReset Ins Non 1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 13.60
Evaluated at bid price : 13.60
Bid-YTW : 6.65 %
IFC.PR.A FixedReset Ins Non 1.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 9.66
Evaluated at bid price : 9.66
Bid-YTW : 6.48 %
POW.PR.B Perpetual-Discount 1.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 19.55
Evaluated at bid price : 19.55
Bid-YTW : 6.88 %
SLF.PR.G FixedReset Ins Non 1.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 8.22
Evaluated at bid price : 8.22
Bid-YTW : 6.07 %
MFC.PR.O FixedReset Ins Non 1.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 21.20
Evaluated at bid price : 21.20
Bid-YTW : 6.61 %
PWF.PR.R Perpetual-Discount 1.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 20.66
Evaluated at bid price : 20.66
Bid-YTW : 6.80 %
BMO.PR.E FixedReset Disc 1.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 15.35
Evaluated at bid price : 15.35
Bid-YTW : 5.97 %
PWF.PR.Z Perpetual-Discount 1.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 19.43
Evaluated at bid price : 19.43
Bid-YTW : 6.77 %
PWF.PR.E Perpetual-Discount 2.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 20.87
Evaluated at bid price : 20.87
Bid-YTW : 6.73 %
BIK.PR.A FixedReset Disc 2.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 21.50
Evaluated at bid price : 21.50
Bid-YTW : 6.86 %
TD.PF.H FixedReset Disc 2.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 19.51
Evaluated at bid price : 19.51
Bid-YTW : 6.16 %
TD.PF.K FixedReset Disc 2.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 15.35
Evaluated at bid price : 15.35
Bid-YTW : 5.88 %
CU.PR.H Perpetual-Discount 2.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 21.10
Evaluated at bid price : 21.10
Bid-YTW : 6.31 %
CM.PR.T FixedReset Disc 2.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 17.20
Evaluated at bid price : 17.20
Bid-YTW : 6.12 %
BMO.PR.S FixedReset Disc 2.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 12.86
Evaluated at bid price : 12.86
Bid-YTW : 6.21 %
IFC.PR.F Deemed-Retractible 2.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 21.00
Evaluated at bid price : 21.00
Bid-YTW : 6.36 %
TRP.PR.D FixedReset Disc 2.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 12.05
Evaluated at bid price : 12.05
Bid-YTW : 6.64 %
BMO.PR.Z Perpetual-Discount 2.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 21.54
Evaluated at bid price : 21.54
Bid-YTW : 5.89 %
CU.PR.C FixedReset Disc 2.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 13.36
Evaluated at bid price : 13.36
Bid-YTW : 5.74 %
BIP.PR.F FixedReset Disc 2.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 7.36 %
BNS.PR.E FixedReset Disc 2.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 21.43
Evaluated at bid price : 21.75
Bid-YTW : 5.98 %
TRP.PR.K FixedReset Disc 3.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 20.90
Evaluated at bid price : 20.90
Bid-YTW : 5.95 %
BAM.PF.H FixedReset Disc 3.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 21.55
Evaluated at bid price : 21.55
Bid-YTW : 5.85 %
BMO.PR.B FixedReset Disc 3.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 19.50
Evaluated at bid price : 19.50
Bid-YTW : 6.06 %
BIP.PR.A FixedReset Disc 4.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 12.60
Evaluated at bid price : 12.60
Bid-YTW : 8.28 %
NA.PR.X FixedReset Disc 4.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 21.20
Evaluated at bid price : 21.20
Bid-YTW : 6.45 %
TRP.PR.E FixedReset Disc 5.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 12.08
Evaluated at bid price : 12.08
Bid-YTW : 6.55 %
TRP.PR.B FixedReset Disc 5.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 8.13
Evaluated at bid price : 8.13
Bid-YTW : 5.73 %
Volume Highlights
Issue Index Shares
Traded
Notes
BMO.PR.T FixedReset Disc 400,000 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 12.51
Evaluated at bid price : 12.51
Bid-YTW : 6.15 %
CM.PR.O FixedReset Disc 376,731 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 12.21
Evaluated at bid price : 12.21
Bid-YTW : 6.40 %
SLF.PR.D Deemed-Retractible 271,500 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 17.20
Evaluated at bid price : 17.20
Bid-YTW : 6.52 %
BMO.PR.S FixedReset Disc 181,743 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 12.86
Evaluated at bid price : 12.86
Bid-YTW : 6.21 %
MFC.PR.M FixedReset Ins Non 150,260 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 12.22
Evaluated at bid price : 12.22
Bid-YTW : 6.59 %
TRP.PR.C FixedReset Disc 106,550 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 7.97
Evaluated at bid price : 7.97
Bid-YTW : 6.65 %
There were 32 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BAM.PF.B FixedReset Disc Quote: 12.93 – 16.54
Spot Rate : 3.6100
Average : 2.1709

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 12.93
Evaluated at bid price : 12.93
Bid-YTW : 6.86 %

BAM.PF.J FixedReset Disc Quote: 19.75 – 22.47
Spot Rate : 2.7200
Average : 1.5983

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 19.75
Evaluated at bid price : 19.75
Bid-YTW : 6.06 %

MFC.PR.R FixedReset Ins Non Quote: 16.10 – 18.86
Spot Rate : 2.7600
Average : 1.9359

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 16.10
Evaluated at bid price : 16.10
Bid-YTW : 7.01 %

MFC.PR.K FixedReset Ins Non Quote: 12.20 – 16.17
Spot Rate : 3.9700
Average : 3.1874

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 12.20
Evaluated at bid price : 12.20
Bid-YTW : 6.52 %

RY.PR.M FixedReset Disc Quote: 11.98 – 14.20
Spot Rate : 2.2200
Average : 1.6119

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 11.98
Evaluated at bid price : 11.98
Bid-YTW : 6.80 %

W.PR.M FixedReset Disc Quote: 18.57 – 20.00
Spot Rate : 1.4300
Average : 0.8925

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-03
Maturity Price : 18.57
Evaluated at bid price : 18.57
Bid-YTW : 7.04 %

Market Action

April 2, 2020

Unicorn photo realistic

It was a good day for oil:

Canada’s main stock index rose on Thursday, led by energy shares as crude prices posted their biggest-one day gains on record on Thursday.

The Toronto Stock Exchange’s S&P/TSX Composite index finished unofficially up 221.39 points, or 1.72%, at 13,097.76.

Nine of the index’s 11 major sectors were higher, led by the energy sector, which climbed 9.3%.
…
Crude prices posted their biggest-one day gains on record on Thursday after President Donald Trump said he expects Russia and Saudi Arabia to announce a major oil production cut, and Saudi state media said the kingdom was calling an emergency meeting of producers to deal with the market turmoil.

Trump said he had spoken to Saudi Crown Prince Mohammed bin Salman, and expects Saudi Arabia and Russia to cut oil output by as much as 10 million to 15 million barrels, as the two countries signaled willingness to make a deal.
…
Brent soared as much as 47% during the session, its highest intraday percentage gain ever. WTI jumped as much as 35%, its second highest ever, after an intraday gain of 36% on March 19.

Oil prices pulled back from those highs as traders questioned whether Russia and Saudi Arabia could actually agree on such a big production cut.

A senior administration official told Reuters the United States does not know formal details of Saudi Arabian and Russian plans to reduce oil supply yet and will not ask U.S. domestic oil producers to chip in with their own cuts.

An article in the Globe is titled Why Canada’s banks have no plans to suspend dividends despite a global trend of cuts which has been a hot topic lately:

Canadian bank CEOs insist they will keep paying dividends, even as banks around the world have axed payouts under pressure from regulators to preserve capital within the banking system.
…
On Wednesday, the United Kingdom’s largest banks bowed to pressure from Britain’s financial regulator and suspended dividend payments. Several large European Banks, including Italy’s UniCredit and Dutch bank ING Group have also halted after a request from the European Banking Authority, and Mexico’s financial regulator followed suit on Thursday, saying that “it’s impossible to estimate how deep and how long the economic effects of the pandemic will be.”

Canada’s Office of the Superintendent of Financial Institutions, has told domestic banks not to increase dividends or buy back shares, but has made no effort to reduce payouts. And so far, bank executives are telling investors not to worry.
…
Banks are facing significant pressure from an anticipated spike in loan losses in the long run, as well as widespread demand from companies to draw down funds on credit lines immediately. But bankers and regulators are keenly aware that bank stocks are widely held by millions of Canadians, some of whom depend on them as retirement income. Some worry that cutting off dividends could worsen the economic hardship from the crisis.

“About 77 [per cent] to 80 per cent of our shareholders are Canadian, either institutional or retail, so the construct of our shareholder base is very different than would be a European bank,” said Bank of Nova Scotia CEO Brian Porter on Tuesday. Mr. Porter and Bank of Montreal CEO Darryl White both said they have no plans to slash their banks’ dividends.
…
And Canadian banks are in a different position politically, after some British banks needed government bailouts in the last crisis, said Laurence Booth, professor of finance at the University of Toronto’s Rotman School of Management.

“The Canadian banks do not have the bad reputation that the European and the U.K. banks have got, so it’s not like the government can lean on them and say, ‘Look, we’ve bailed you out, you’re bad guys, do what we say, you’ve got to rebuild your reputation,'” Mr. Booth said. “So that moral suasion component is missing in Canada.”

For what it’s worth, here was my response to a client inquiry:

I don’t think a governmentally requested suspension of bank dividends is in the cards.

Firstly, I don’t really see a good reason for it.

Secondly, bank stocks are the bedrock of a great many retirement portfolios and conniving at a suspension of the income would bring the government a great deal of grief.

Thirdly, the TSX/S&P index is about 32% Financials (see LINK ) compared to about 20% for the FTSE (see LINK ), a paltry 1.6% (!) in NZ, and 9.4% banks in Europe (with an additional 5.9% in insurance; see LINK ). You have probably read some of my rants about the harmful effects on Canada of having such a bloated financial sector … there’s a global comparison for you! And in this instance, bank dividends are ‘too big to fail’!

I’m not going to say it won’t ever happen. But I will say that we are not even close to the point where the possibility of mass suspension needs to be taken seriously.

I forgot to give him the link for the New Zealand data; such is life. I believe that in New Zealand they settle payments with sacks of wool and quarts of milk (“That’ll be three sacks and two quarts, ma’am”), but I may be wrong on that.

TXPR closed at 463.03, up 1.07% on the day. Volume today was 3.26-million, low in the context of the past thirty days but highest since March 26.

CPD closed at 9.21, up 2.22% on the day. Volume was 93,827, second-lowest of the past 30 trading days and only slightly more than the low set on April 1.

ZPR closed at 7.25, up 2.84% on the day. Volume of 364,785 was fourth-lowest of the past 30 trading days.

Five-year Canada yields were up 4bp to 0.58% today.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 1.1996 % 1,361.8
FixedFloater 0.00 % 0.00 % 0 0.00 0 1.1996 % 2,498.8
Floater 5.65 % 5.69 % 46,488 14.41 4 1.1996 % 1,440.1
OpRet 0.00 % 0.00 % 0 0.00 0 0.4902 % 3,122.3
SplitShare 5.32 % 7.34 % 84,521 3.95 7 0.4902 % 3,728.7
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.4902 % 2,909.3
Perpetual-Premium 0.00 % 0.00 % 0 0.00 0 1.1795 % 2,547.6
Perpetual-Discount 6.54 % 6.87 % 92,739 12.72 35 1.1795 % 2,732.6
FixedReset Disc 7.25 % 6.29 % 204,087 13.08 83 1.5563 % 1,555.0
Deemed-Retractible 6.28 % 6.94 % 104,102 12.65 27 0.7935 % 2,693.7
FloatingReset 3.24 % 1.26 % 33,555 1.80 4 0.8507 % 1,650.4
FixedReset Prem 0.00 % 0.00 % 0 0.00 0 1.5563 % 2,150.6
FixedReset Bank Non 1.99 % 5.22 % 120,569 1.77 3 0.7478 % 2,666.5
FixedReset Ins Non 7.66 % 6.70 % 115,039 12.68 22 1.5349 % 1,537.7
Performance Highlights
Issue Index Change Notes
RY.PR.M FixedReset Disc -3.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 13.01
Evaluated at bid price : 13.01
Bid-YTW : 6.26 %
BAM.PF.F FixedReset Disc -3.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 13.00
Evaluated at bid price : 13.00
Bid-YTW : 6.99 %
BAM.PR.X FixedReset Disc -2.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 9.00
Evaluated at bid price : 9.00
Bid-YTW : 6.79 %
BIK.PR.A FixedReset Disc -2.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 21.06
Evaluated at bid price : 21.06
Bid-YTW : 7.01 %
BMO.PR.Z Perpetual-Discount -2.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 21.00
Evaluated at bid price : 21.00
Bid-YTW : 6.04 %
PWF.PR.P FixedReset Disc -2.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 9.01
Evaluated at bid price : 9.01
Bid-YTW : 6.16 %
RY.PR.R FixedReset Disc -2.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 22.22
Evaluated at bid price : 22.61
Bid-YTW : 6.02 %
BIP.PR.D FixedReset Disc -1.97 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 17.45
Evaluated at bid price : 17.45
Bid-YTW : 7.23 %
NA.PR.X FixedReset Disc -1.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 20.70
Evaluated at bid price : 20.70
Bid-YTW : 6.74 %
BMO.PR.B FixedReset Disc -1.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 18.80
Evaluated at bid price : 18.80
Bid-YTW : 6.29 %
W.PR.K FixedReset Disc -1.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 19.70
Evaluated at bid price : 19.70
Bid-YTW : 6.70 %
BIP.PR.B FixedReset Disc -1.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 19.75
Evaluated at bid price : 19.75
Bid-YTW : 7.02 %
BAM.PF.G FixedReset Disc -1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 12.85
Evaluated at bid price : 12.85
Bid-YTW : 6.69 %
IFC.PR.G FixedReset Ins Non -1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 13.10
Evaluated at bid price : 13.10
Bid-YTW : 6.72 %
IFC.PR.F Deemed-Retractible -1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 20.51
Evaluated at bid price : 20.51
Bid-YTW : 6.51 %
BAM.PR.Z FixedReset Disc -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 13.73
Evaluated at bid price : 13.73
Bid-YTW : 6.86 %
BIP.PR.C FixedReset Disc -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 18.80
Evaluated at bid price : 18.80
Bid-YTW : 7.18 %
BAM.PF.J FixedReset Disc -1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 19.50
Evaluated at bid price : 19.50
Bid-YTW : 6.14 %
MFC.PR.B Deemed-Retractible 1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 17.93
Evaluated at bid price : 17.93
Bid-YTW : 6.55 %
ELF.PR.G Perpetual-Discount 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 17.43
Evaluated at bid price : 17.43
Bid-YTW : 6.85 %
TRP.PR.H FloatingReset 1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 7.68
Evaluated at bid price : 7.68
Bid-YTW : 4.88 %
MFC.PR.Q FixedReset Ins Non 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 13.39
Evaluated at bid price : 13.39
Bid-YTW : 6.50 %
IFC.PR.A FixedReset Ins Non 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 9.50
Evaluated at bid price : 9.50
Bid-YTW : 6.59 %
ELF.PR.H Perpetual-Discount 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 19.92
Evaluated at bid price : 19.92
Bid-YTW : 6.94 %
RY.PR.G Deemed-Retractible 1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.80
Bid-YTW : 7.68 %
PWF.PR.I Perpetual-Discount 1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 22.13
Evaluated at bid price : 22.41
Bid-YTW : 6.83 %
TD.PF.L FixedReset Disc 1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 17.10
Evaluated at bid price : 17.10
Bid-YTW : 6.26 %
BAM.PR.B Floater 1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 7.59
Evaluated at bid price : 7.59
Bid-YTW : 5.69 %
CM.PR.T FixedReset Disc 1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 16.80
Evaluated at bid price : 16.80
Bid-YTW : 6.27 %
RY.PR.F Deemed-Retractible 1.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.66
Bid-YTW : 7.98 %
GWO.PR.M Deemed-Retractible 1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 20.90
Evaluated at bid price : 20.90
Bid-YTW : 7.00 %
RY.PR.J FixedReset Disc 1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 14.40
Evaluated at bid price : 14.40
Bid-YTW : 5.83 %
CU.PR.H Perpetual-Discount 1.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 20.61
Evaluated at bid price : 20.61
Bid-YTW : 6.46 %
TD.PF.M FixedReset Disc 1.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 18.01
Evaluated at bid price : 18.01
Bid-YTW : 6.23 %
BMO.PR.F FixedReset Disc 1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 17.77
Evaluated at bid price : 17.77
Bid-YTW : 6.21 %
EIT.PR.A SplitShare 1.50 % YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2024-03-14
Maturity Price : 25.00
Evaluated at bid price : 23.00
Bid-YTW : 7.28 %
BMO.PR.E FixedReset Disc 1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 15.05
Evaluated at bid price : 15.05
Bid-YTW : 6.10 %
BIP.PR.F FixedReset Disc 1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 17.01
Evaluated at bid price : 17.01
Bid-YTW : 7.57 %
RY.PR.C Deemed-Retractible 1.60 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.07
Bid-YTW : 7.13 %
BAM.PR.R FixedReset Disc 1.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 10.75
Evaluated at bid price : 10.75
Bid-YTW : 6.76 %
BNS.PR.I FixedReset Disc 1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 15.51
Evaluated at bid price : 15.51
Bid-YTW : 5.64 %
GWO.PR.T Deemed-Retractible 1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 18.60
Evaluated at bid price : 18.60
Bid-YTW : 6.98 %
CU.PR.G Perpetual-Discount 1.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 18.06
Evaluated at bid price : 18.06
Bid-YTW : 6.32 %
BAM.PF.E FixedReset Disc 1.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 12.17
Evaluated at bid price : 12.17
Bid-YTW : 6.77 %
TD.PF.I FixedReset Disc 1.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 15.02
Evaluated at bid price : 15.02
Bid-YTW : 6.35 %
PVS.PR.H SplitShare 1.76 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2027-02-28
Maturity Price : 25.00
Evaluated at bid price : 22.50
Bid-YTW : 6.62 %
TRP.PR.E FixedReset Disc 1.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 11.50
Evaluated at bid price : 11.50
Bid-YTW : 6.90 %
PWF.PR.R Perpetual-Discount 1.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 20.27
Evaluated at bid price : 20.27
Bid-YTW : 6.93 %
PWF.PR.Z Perpetual-Discount 1.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 19.05
Evaluated at bid price : 19.05
Bid-YTW : 6.91 %
NA.PR.G FixedReset Disc 1.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 14.32
Evaluated at bid price : 14.32
Bid-YTW : 6.62 %
BMO.PR.Q FixedReset Bank Non 1.94 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.65
Bid-YTW : 7.50 %
BMO.PR.S FixedReset Disc 1.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 12.56
Evaluated at bid price : 12.56
Bid-YTW : 6.37 %
CU.PR.E Perpetual-Discount 1.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 19.50
Evaluated at bid price : 19.50
Bid-YTW : 6.37 %
MFC.PR.J FixedReset Ins Non 2.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 13.26
Evaluated at bid price : 13.26
Bid-YTW : 6.63 %
SLF.PR.D Deemed-Retractible 2.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 17.21
Evaluated at bid price : 17.21
Bid-YTW : 6.52 %
RY.PR.S FixedReset Disc 2.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 15.61
Evaluated at bid price : 15.61
Bid-YTW : 5.48 %
MFC.PR.N FixedReset Ins Non 2.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 12.01
Evaluated at bid price : 12.01
Bid-YTW : 6.04 %
PWF.PR.S Perpetual-Discount 2.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 17.86
Evaluated at bid price : 17.86
Bid-YTW : 6.87 %
CM.PR.P FixedReset Disc 2.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 12.38
Evaluated at bid price : 12.38
Bid-YTW : 6.37 %
PWF.PR.K Perpetual-Discount 2.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 18.30
Evaluated at bid price : 18.30
Bid-YTW : 6.91 %
BAM.PF.A FixedReset Disc 2.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 14.40
Evaluated at bid price : 14.40
Bid-YTW : 6.70 %
MFC.PR.H FixedReset Ins Non 2.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 13.75
Evaluated at bid price : 13.75
Bid-YTW : 6.95 %
PWF.PR.E Perpetual-Discount 2.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 20.45
Evaluated at bid price : 20.45
Bid-YTW : 6.87 %
GWO.PR.I Deemed-Retractible 2.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 16.36
Evaluated at bid price : 16.36
Bid-YTW : 6.94 %
BMO.PR.D FixedReset Disc 2.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 15.40
Evaluated at bid price : 15.40
Bid-YTW : 6.34 %
CU.PR.D Perpetual-Discount 2.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 19.64
Evaluated at bid price : 19.64
Bid-YTW : 6.33 %
GWO.PR.H Deemed-Retractible 2.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 18.26
Evaluated at bid price : 18.26
Bid-YTW : 6.70 %
IAF.PR.I FixedReset Ins Non 2.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 13.35
Evaluated at bid price : 13.35
Bid-YTW : 6.81 %
CM.PR.Q FixedReset Disc 2.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 12.35
Evaluated at bid price : 12.35
Bid-YTW : 6.83 %
IFC.PR.E Deemed-Retractible 2.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 20.50
Evaluated at bid price : 20.50
Bid-YTW : 6.39 %
MFC.PR.K FixedReset Ins Non 2.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 12.17
Evaluated at bid price : 12.17
Bid-YTW : 6.54 %
PWF.PR.F Perpetual-Discount 2.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 19.40
Evaluated at bid price : 19.40
Bid-YTW : 6.91 %
NA.PR.S FixedReset Disc 2.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 12.57
Evaluated at bid price : 12.57
Bid-YTW : 6.59 %
TD.PF.A FixedReset Disc 2.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 13.04
Evaluated at bid price : 13.04
Bid-YTW : 5.96 %
CM.PR.O FixedReset Disc 2.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 12.14
Evaluated at bid price : 12.14
Bid-YTW : 6.44 %
TRP.PR.F FloatingReset 2.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 9.00
Evaluated at bid price : 9.00
Bid-YTW : 5.96 %
EML.PR.A FixedReset Ins Non 2.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 20.20
Evaluated at bid price : 20.20
Bid-YTW : 6.93 %
NA.PR.E FixedReset Disc 2.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 13.90
Evaluated at bid price : 13.90
Bid-YTW : 6.30 %
TRP.PR.G FixedReset Disc 3.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 13.51
Evaluated at bid price : 13.51
Bid-YTW : 6.66 %
RY.PR.Z FixedReset Disc 3.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 13.18
Evaluated at bid price : 13.18
Bid-YTW : 5.79 %
BMO.PR.C FixedReset Disc 3.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 15.80
Evaluated at bid price : 15.80
Bid-YTW : 6.40 %
CU.PR.C FixedReset Disc 3.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 13.00
Evaluated at bid price : 13.00
Bid-YTW : 5.90 %
CU.PR.F Perpetual-Discount 3.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 18.50
Evaluated at bid price : 18.50
Bid-YTW : 6.17 %
MFC.PR.R FixedReset Ins Non 3.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 16.52
Evaluated at bid price : 16.52
Bid-YTW : 6.82 %
BNS.PR.H FixedReset Disc 3.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 6.09 %
TRP.PR.J FixedReset Disc 3.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 21.78
Evaluated at bid price : 22.26
Bid-YTW : 6.24 %
BAM.PR.K Floater 3.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 7.50
Evaluated at bid price : 7.50
Bid-YTW : 5.76 %
BMO.PR.Y FixedReset Disc 3.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 13.02
Evaluated at bid price : 13.02
Bid-YTW : 6.42 %
SLF.PR.E Deemed-Retractible 3.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 17.10
Evaluated at bid price : 17.10
Bid-YTW : 6.63 %
TD.PF.B FixedReset Disc 3.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 13.16
Evaluated at bid price : 13.16
Bid-YTW : 5.94 %
CM.PR.S FixedReset Disc 3.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 13.32
Evaluated at bid price : 13.32
Bid-YTW : 6.20 %
TD.PF.K FixedReset Disc 3.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 15.02
Evaluated at bid price : 15.02
Bid-YTW : 5.97 %
TD.PF.C FixedReset Disc 3.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 13.30
Evaluated at bid price : 13.30
Bid-YTW : 6.04 %
NA.PR.A FixedReset Disc 3.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 20.50
Evaluated at bid price : 20.50
Bid-YTW : 6.51 %
SLF.PR.I FixedReset Ins Non 3.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 13.25
Evaluated at bid price : 13.25
Bid-YTW : 6.38 %
TRP.PR.K FixedReset Disc 4.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 20.28
Evaluated at bid price : 20.28
Bid-YTW : 6.13 %
TD.PF.J FixedReset Disc 4.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 15.30
Evaluated at bid price : 15.30
Bid-YTW : 5.91 %
BMO.PR.T FixedReset Disc 4.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 12.62
Evaluated at bid price : 12.62
Bid-YTW : 6.09 %
RY.PR.H FixedReset Disc 4.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 13.31
Evaluated at bid price : 13.31
Bid-YTW : 5.81 %
BMO.PR.W FixedReset Disc 4.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 12.84
Evaluated at bid price : 12.84
Bid-YTW : 6.11 %
TD.PF.E FixedReset Disc 4.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 14.21
Evaluated at bid price : 14.21
Bid-YTW : 6.19 %
CM.PR.Y FixedReset Disc 5.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 17.60
Evaluated at bid price : 17.60
Bid-YTW : 6.35 %
TRP.PR.D FixedReset Disc 5.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 11.75
Evaluated at bid price : 11.75
Bid-YTW : 6.82 %
NA.PR.C FixedReset Disc 5.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 15.42
Evaluated at bid price : 15.42
Bid-YTW : 6.74 %
MFC.PR.G FixedReset Ins Non 6.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 13.26
Evaluated at bid price : 13.26
Bid-YTW : 6.70 %
CM.PR.R FixedReset Disc 6.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 15.25
Evaluated at bid price : 15.25
Bid-YTW : 6.61 %
TRP.PR.A FixedReset Disc 6.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 10.95
Evaluated at bid price : 10.95
Bid-YTW : 6.39 %
TD.PF.D FixedReset Disc 9.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 14.10
Evaluated at bid price : 14.10
Bid-YTW : 6.08 %
TRP.PR.B FixedReset Disc 10.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 7.70
Evaluated at bid price : 7.70
Bid-YTW : 6.05 %
IFC.PR.I Perpetual-Discount 11.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 21.93
Evaluated at bid price : 22.21
Bid-YTW : 6.16 %
BAM.PR.T FixedReset Disc 18.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 10.72
Evaluated at bid price : 10.72
Bid-YTW : 6.96 %
Volume Highlights
Issue Index Shares
Traded
Notes
TRP.PR.F FloatingReset 430,808 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 9.00
Evaluated at bid price : 9.00
Bid-YTW : 5.96 %
PWF.PR.Z Perpetual-Discount 162,500 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 19.05
Evaluated at bid price : 19.05
Bid-YTW : 6.91 %
BMO.PR.S FixedReset Disc 86,250 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 12.56
Evaluated at bid price : 12.56
Bid-YTW : 6.37 %
CM.PR.S FixedReset Disc 82,316 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 13.32
Evaluated at bid price : 13.32
Bid-YTW : 6.20 %
HSE.PR.A FixedReset Disc 70,000 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 5.68
Evaluated at bid price : 5.68
Bid-YTW : 10.29 %
CM.PR.R FixedReset Disc 57,409 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 15.25
Evaluated at bid price : 15.25
Bid-YTW : 6.61 %
There were 52 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
RY.PR.M FixedReset Disc Quote: 13.01 – 14.30
Spot Rate : 1.2900
Average : 0.9451

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 13.01
Evaluated at bid price : 13.01
Bid-YTW : 6.26 %

GWO.PR.F Deemed-Retractible Quote: 21.50 – 22.77
Spot Rate : 1.2700
Average : 0.9911

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 21.50
Evaluated at bid price : 21.50
Bid-YTW : 6.92 %

PVS.PR.E SplitShare Quote: 23.50 – 24.50
Spot Rate : 1.0000
Average : 0.7858

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-10-31
Maturity Price : 25.00
Evaluated at bid price : 23.50
Bid-YTW : 8.36 %

EIT.PR.B SplitShare Quote: 22.75 – 24.75
Spot Rate : 2.0000
Average : 1.8122

YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2025-03-14
Maturity Price : 25.00
Evaluated at bid price : 22.75
Bid-YTW : 7.08 %

TD.PF.F Perpetual-Discount Quote: 20.80 – 21.50
Spot Rate : 0.7000
Average : 0.5352

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 20.80
Evaluated at bid price : 20.80
Bid-YTW : 6.01 %

CIU.PR.A Perpetual-Discount Quote: 17.80 – 19.16
Spot Rate : 1.3600
Average : 1.2024

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-02
Maturity Price : 17.80
Evaluated at bid price : 17.80
Bid-YTW : 6.56 %

Market Action

April 1, 2020

mushroomcloud_200401

coronavirus_200401

Well, now that the horrors of March are done with, I’m sure we’re all very happy to start off a bright and shiny new … well, never mind:

Faced with grim new projections of the potential scale and economic ramifications of the coronavirus pandemic, investors dumped stocks on Wednesday. The S&P 500 fell more than 4 percent, bringing its decline over two days to 6 percent.

The drop, which followed a sell-off in Europe and Asia, came after President Trump said at a news conference on Tuesday that the United States would face a “very, very painful two weeks.” U.S. government scientists projected that the outbreak could kill up to 240,000 people in the country. On Wednesday, the United Nations warned of “enhanced instability, enhanced unrest and enhanced conflict.”
…
Airlines were the worst performing sector in the S&P 500 as government data showed a staggering drop in passenger traffic through airports. United Airlines fell 19 percent, and American Airlines dropped 12 percent.

Cruise operator Carnival was the worst performing stock in the S&P 500, with a decline of 33 percent, while rival Royal Caribbean fell 20 percent.

And in Canada:

The S&P/TSX Composite Index fell about 22 per cent in the first quarter, its biggest decline since 2008, but had showed some signs of steadying in recent days.

On Wednesday, the index closed down 3.8 per cent at 12,876.37, in a broad-based selloff that left only the gold sector with gains, as investors fled to the perceived safety of assets such as bullion, bonds and the U.S. dollar. Canadian banks were down about 5 per cent, with shares of security software company BlackBerry Ltd falling nearly 18 per cent after dismal quarterly results.
…
Automakers also reported sharp drops in U.S. sales for March, including a 43% plunge for Hyundai. Mortgage applications tumbled 24% from year-ago levels as open houses are all but shut down.
…
On this side of the border, the IHS Markit Canada Manufacturing Purchasing Managers’ index (PMI) fell to a seasonally adjusted 46.1 in March, the lowest in at least nine years. It indicated a contraction in factory activity.

The rugged free-marketers of Texas, well-known for their aversion to anything that smacks of socialism are clamouring for production quotas:

The U.S. shale industry is more worried about its future than ever. The unprecedented demand from the Texan companies to curtail production says as much. They have good reason to be fearful, because this downturn is not like the last one. Of course, prices will reverse course once economies reopen, but anyone betting on a quick leap to US$65 oil – the price before the COVID-19 crisis started – might be in for a rude shock.

There are very interesting real-estate negotiations going on:

Commercial property landlords are balking at requests for rent relief from big companies, saying they need to focus on helping vulnerable smaller tenants such as independent restaurants, clothing stores and barbershops that may not survive the huge losses from the coronavirus pandemic.
…
But many commercial landlords object strongly to those sort of requests from large tenants. “When a company that is well capitalized that has a legal obligation to pay rent, doesn’t pay rent, I think it is bad behaviour,” said Michael Cooper, chief executive with Dream Office REIT, which owns 32 office properties, mostly in Toronto.

“They hurt landlords’ ability to be able to help people that need it the most. If companies have the money, they have the legal obligation,” Mr. Cooper said. “If they don’t pay the rent, they are taking advantage of people in a very dire situation and that really is unseemly.”

Canadian Tire and other big names are able to flex their muscle because they are considered top tenants that can withstand economic downturns. Their tenancy often makes it easier for property owners to get lower mortgage rates and they can make a shopping centre more desirable because they draw more traffic to the property.

In return, landlords often ask for less rent and give into their demands, which they do not do with smaller businesses.

Speaking of Canadian Tire, they got downgraded by S&P yesterday:

  • S&P Global Ratings’ economists believe that due to the COVID-19 pandemic, a global and Canadian recession in 2020 is likely and, therefore, we expect consumer discretionary spending to slow.
  • As a result, at Toronto-based general merchandiser Canadian Tire Corp Ltd. (CTC), the COVID-19 pandemic is directly responsible for current store closures (except Canadian Tire Retail where store hours are curtailed) and government-mandated social distancing, which we believe will negatively affect revenue and EBITDA.
  • Therefore, S&P Global Ratings lowered its long-term issuer and issue-level ratings on CTC to ‘BBB’ from ‘BBB+’. At the same time, it affirmed the ‘A-2’ commercial paper rating on the company.
  • We also lowered our issuer credit rating on CT Real Estate Investment Trust (REIT) to ‘BBB’ from ‘BBB+’.
  • Finally, we forecast the company’s leverage to deteriorate close to 3.5x for the next 18-24 months, and have revised our financial risk profile on CTC to significant from intermediate.
  • The negative outlook reflects our expectation that, despite management’s steps to reduce costs and protect its balance sheet, there is increased risk that the company’s debt-to-EBITDA deteriorates above 3.5x, which we consider weak for our ratings, over the next 18-24 months.

But everybody with a business should be going after that government lolly:

Canada’s banks are preparing to start offering government-backed loans to small businesses as soon as next week amid a flood of requests for relief from business owners.

Banks have been rushing to roll out a program by which the federal government will guarantee loans of up to $40,000 interest-free until the end of 2022.
…
The federal government has promised $25-billion to guarantee the loans, removing the risk for banks. One quarter of each loan, up to $10,000, will be forgiven if businesses repay their balance before Dec. 31, 2022. If the loans aren’t repaid by that date, they can be converted into three-year term loans charging 5-per-cent interest, according to a CIBC statement.

TXPR closed at 458.15, down 2.25% on the day. Volume today was 2.25-million, lowest of the past thirty days, just a little lower than March 5.

CPD closed at 9.01, down 3.84% on the day. Volume was 89,774, lowest of the past 30 trading days and significantly lower than the previous low of March 5.

ZPR closed at 7.05, down 3.29% on the day. Volume of 203,971 was lowest of the past 30 trading days much lower than second place March 5.

Five-year Canada yields were down 5bp at 0.54% today.

PerpetualDiscounts now yield 6.92%, equivalent to 9.00% interest (!) at the standard equivalency factor of 1.3x. Long corporates continue to yield 3.87%, so the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) has widened to 515bp from the 500bp reported March 25. But we’re still way over the old record set on November 26, 2008 when trouble with the BCE buyout caused a short-lived spike in PerpetualDiscount bid yields, moving the Seniority Spread to 445bp.

Assiduous Reader Carrie will be pleased to note that the “Premium” indices are no longer populated!

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -2.1838 % 1,345.6
FixedFloater 0.00 % 0.00 % 0 0.00 0 -2.1838 % 2,469.2
Floater 5.71 % 5.74 % 48,484 14.28 4 -2.1838 % 1,423.0
OpRet 0.00 % 0.00 % 0 0.00 0 -1.1062 % 3,107.1
SplitShare 5.34 % 7.59 % 78,399 3.95 7 -1.1062 % 3,710.5
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -1.1062 % 2,895.1
Perpetual-Premium 0.00 % 0.00 % 0 0.00 0 -1.9547 % 2,517.9
Perpetual-Discount 6.62 % 6.92 % 92,899 12.66 35 -1.9547 % 2,700.8
FixedReset Disc 7.36 % 6.48 % 205,220 12.93 83 -2.8776 % 1,531.2
Deemed-Retractible 6.33 % 7.03 % 102,372 12.54 27 -2.9053 % 2,672.5
FloatingReset 3.27 % 1.41 % 34,017 1.81 4 -3.0059 % 1,636.4
FixedReset Prem 0.00 % 0.00 % 0 0.00 0 -2.8776 % 2,117.6
FixedReset Bank Non 2.01 % 5.33 % 125,487 1.77 3 0.2972 % 2,646.7
FixedReset Ins Non 7.78 % 6.72 % 115,509 12.45 22 -2.6217 % 1,514.5
Performance Highlights
Issue Index Change Notes
BAM.PR.T FixedReset Disc -21.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 9.02
Evaluated at bid price : 9.02
Bid-YTW : 8.31 %
TRP.PR.B FixedReset Disc -11.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 7.00
Evaluated at bid price : 7.00
Bid-YTW : 6.66 %
CU.PR.C FixedReset Disc -11.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 12.60
Evaluated at bid price : 12.60
Bid-YTW : 6.09 %
TRP.PR.F FloatingReset -9.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 8.76
Evaluated at bid price : 8.76
Bid-YTW : 6.11 %
TRP.PR.A FixedReset Disc -8.97 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 10.25
Evaluated at bid price : 10.25
Bid-YTW : 6.87 %
TRP.PR.D FixedReset Disc -7.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 11.09
Evaluated at bid price : 11.09
Bid-YTW : 7.24 %
BAM.PR.R FixedReset Disc -6.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 10.58
Evaluated at bid price : 10.58
Bid-YTW : 6.87 %
BAM.PF.A FixedReset Disc -6.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 14.09
Evaluated at bid price : 14.09
Bid-YTW : 6.86 %
RY.PR.H FixedReset Disc -6.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 12.71
Evaluated at bid price : 12.71
Bid-YTW : 6.09 %
BIP.PR.A FixedReset Disc -6.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 12.15
Evaluated at bid price : 12.15
Bid-YTW : 8.59 %
BMO.PR.Y FixedReset Disc -6.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 12.60
Evaluated at bid price : 12.60
Bid-YTW : 6.63 %
BAM.PR.X FixedReset Disc -5.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 9.25
Evaluated at bid price : 9.25
Bid-YTW : 6.60 %
SLF.PR.I FixedReset Ins Non -5.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 12.75
Evaluated at bid price : 12.75
Bid-YTW : 6.64 %
NA.PR.A FixedReset Disc -5.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 19.73
Evaluated at bid price : 19.73
Bid-YTW : 6.77 %
GWO.PR.Q Deemed-Retractible -5.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 18.32
Evaluated at bid price : 18.32
Bid-YTW : 7.09 %
NA.PR.C FixedReset Disc -5.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 14.55
Evaluated at bid price : 14.55
Bid-YTW : 7.15 %
MFC.PR.F FixedReset Ins Non -5.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 7.94
Evaluated at bid price : 7.94
Bid-YTW : 6.34 %
SLF.PR.E Deemed-Retractible -5.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 16.54
Evaluated at bid price : 16.54
Bid-YTW : 6.86 %
CM.PR.Y FixedReset Disc -5.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 16.75
Evaluated at bid price : 16.75
Bid-YTW : 6.68 %
GWO.PR.T Deemed-Retractible -5.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 18.30
Evaluated at bid price : 18.30
Bid-YTW : 7.10 %
TRP.PR.C FixedReset Disc -5.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 8.06
Evaluated at bid price : 8.06
Bid-YTW : 6.58 %
IFC.PR.A FixedReset Ins Non -5.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 9.40
Evaluated at bid price : 9.40
Bid-YTW : 6.67 %
GWO.PR.I Deemed-Retractible -5.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 16.00
Evaluated at bid price : 16.00
Bid-YTW : 7.09 %
GWO.PR.G Deemed-Retractible -4.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 18.56
Evaluated at bid price : 18.56
Bid-YTW : 7.07 %
IFC.PR.I Perpetual-Discount -4.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 6.87 %
HSE.PR.C FixedReset Disc -4.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 9.24
Evaluated at bid price : 9.24
Bid-YTW : 11.25 %
IFC.PR.C FixedReset Ins Non -4.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 12.15
Evaluated at bid price : 12.15
Bid-YTW : 6.72 %
GWO.PR.N FixedReset Ins Non -4.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 8.51
Evaluated at bid price : 8.51
Bid-YTW : 5.56 %
RY.PR.Z FixedReset Disc -4.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 12.78
Evaluated at bid price : 12.78
Bid-YTW : 5.98 %
TD.PF.B FixedReset Disc -4.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 12.71
Evaluated at bid price : 12.71
Bid-YTW : 6.16 %
MFC.PR.K FixedReset Ins Non -4.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 11.87
Evaluated at bid price : 11.87
Bid-YTW : 6.72 %
GWO.PR.P Deemed-Retractible -4.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 19.20
Evaluated at bid price : 19.20
Bid-YTW : 7.09 %
MFC.PR.G FixedReset Ins Non -4.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 12.51
Evaluated at bid price : 12.51
Bid-YTW : 7.11 %
BMO.PR.S FixedReset Disc -4.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 12.32
Evaluated at bid price : 12.32
Bid-YTW : 6.50 %
MFC.PR.B Deemed-Retractible -4.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 17.75
Evaluated at bid price : 17.75
Bid-YTW : 6.62 %
TRP.PR.H FloatingReset -4.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 7.60
Evaluated at bid price : 7.60
Bid-YTW : 4.91 %
GWO.PR.F Deemed-Retractible -4.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 21.40
Evaluated at bid price : 21.40
Bid-YTW : 6.95 %
GWO.PR.H Deemed-Retractible -4.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 17.84
Evaluated at bid price : 17.84
Bid-YTW : 6.85 %
GWO.PR.S Deemed-Retractible -3.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 18.65
Evaluated at bid price : 18.65
Bid-YTW : 7.10 %
BMO.PR.W FixedReset Disc -3.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 12.26
Evaluated at bid price : 12.26
Bid-YTW : 6.42 %
TD.PF.K FixedReset Disc -3.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 14.50
Evaluated at bid price : 14.50
Bid-YTW : 6.20 %
TD.PF.C FixedReset Disc -3.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 12.81
Evaluated at bid price : 12.81
Bid-YTW : 6.28 %
BIP.PR.F FixedReset Disc -3.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 16.75
Evaluated at bid price : 16.75
Bid-YTW : 7.68 %
CU.PR.E Perpetual-Discount -3.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 19.12
Evaluated at bid price : 19.12
Bid-YTW : 6.50 %
BAM.PR.K Floater -3.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 7.26
Evaluated at bid price : 7.26
Bid-YTW : 5.93 %
PVS.PR.H SplitShare -3.66 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2027-02-28
Maturity Price : 25.00
Evaluated at bid price : 22.11
Bid-YTW : 6.93 %
TD.PF.A FixedReset Disc -3.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 12.70
Evaluated at bid price : 12.70
Bid-YTW : 6.13 %
BAM.PR.Z FixedReset Disc -3.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 13.88
Evaluated at bid price : 13.88
Bid-YTW : 6.79 %
SLF.PR.D Deemed-Retractible -3.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 16.87
Evaluated at bid price : 16.87
Bid-YTW : 6.65 %
BAM.PF.F FixedReset Disc -3.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 13.50
Evaluated at bid price : 13.50
Bid-YTW : 6.73 %
SLF.PR.G FixedReset Ins Non -3.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 8.13
Evaluated at bid price : 8.13
Bid-YTW : 6.14 %
BMO.PR.T FixedReset Disc -3.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 12.07
Evaluated at bid price : 12.07
Bid-YTW : 6.39 %
BIP.PR.B FixedReset Disc -3.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 20.10
Evaluated at bid price : 20.10
Bid-YTW : 6.90 %
RY.PR.M FixedReset Disc -3.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 13.52
Evaluated at bid price : 13.52
Bid-YTW : 6.01 %
GWO.PR.M Deemed-Retractible -3.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 20.64
Evaluated at bid price : 20.64
Bid-YTW : 7.09 %
MFC.PR.R FixedReset Ins Non -3.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 16.00
Evaluated at bid price : 16.00
Bid-YTW : 7.05 %
POW.PR.B Perpetual-Discount -3.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 19.20
Evaluated at bid price : 19.20
Bid-YTW : 7.01 %
BIP.PR.D FixedReset Disc -3.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 17.80
Evaluated at bid price : 17.80
Bid-YTW : 7.08 %
NA.PR.X FixedReset Disc -3.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 21.10
Evaluated at bid price : 21.10
Bid-YTW : 6.61 %
GWO.PR.R Deemed-Retractible -3.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 17.75
Evaluated at bid price : 17.75
Bid-YTW : 6.82 %
TD.PF.I FixedReset Disc -3.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 14.76
Evaluated at bid price : 14.76
Bid-YTW : 6.47 %
RY.PR.S FixedReset Disc -3.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 15.30
Evaluated at bid price : 15.30
Bid-YTW : 5.60 %
BIP.PR.E FixedReset Disc -3.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 16.85
Evaluated at bid price : 16.85
Bid-YTW : 7.49 %
TD.PF.E FixedReset Disc -3.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 13.56
Evaluated at bid price : 13.56
Bid-YTW : 6.49 %
W.PR.M FixedReset Disc -3.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 20.05
Evaluated at bid price : 20.05
Bid-YTW : 6.52 %
NA.PR.G FixedReset Disc -3.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 14.05
Evaluated at bid price : 14.05
Bid-YTW : 6.76 %
TD.PF.F Perpetual-Discount -3.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 20.60
Evaluated at bid price : 20.60
Bid-YTW : 6.06 %
PVS.PR.G SplitShare -3.04 % YTW SCENARIO
Maturity Type : Option Certainty
Maturity Date : 2026-02-28
Maturity Price : 25.00
Evaluated at bid price : 22.30
Bid-YTW : 7.29 %
POW.PR.D Perpetual-Discount -3.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 18.51
Evaluated at bid price : 18.51
Bid-YTW : 6.79 %
BMO.PR.C FixedReset Disc -3.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 15.32
Evaluated at bid price : 15.32
Bid-YTW : 6.61 %
IFC.PR.F Deemed-Retractible -3.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 20.75
Evaluated at bid price : 20.75
Bid-YTW : 6.44 %
TRP.PR.K FixedReset Disc -2.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 19.50
Evaluated at bid price : 19.50
Bid-YTW : 6.38 %
MFC.PR.N FixedReset Ins Non -2.97 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 11.77
Evaluated at bid price : 11.77
Bid-YTW : 6.16 %
TRP.PR.G FixedReset Disc -2.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 13.10
Evaluated at bid price : 13.10
Bid-YTW : 6.87 %
BMO.PR.E FixedReset Disc -2.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 14.82
Evaluated at bid price : 14.82
Bid-YTW : 6.20 %
MFC.PR.Q FixedReset Ins Non -2.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 13.25
Evaluated at bid price : 13.25
Bid-YTW : 6.57 %
TRP.PR.J FixedReset Disc -2.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 21.55
Evaluated at bid price : 21.55
Bid-YTW : 6.48 %
BNS.PR.I FixedReset Disc -2.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 15.26
Evaluated at bid price : 15.26
Bid-YTW : 5.74 %
BAM.PF.B FixedReset Disc -2.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 13.30
Evaluated at bid price : 13.30
Bid-YTW : 6.67 %
CM.PR.R FixedReset Disc -2.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 14.32
Evaluated at bid price : 14.32
Bid-YTW : 7.04 %
TD.PF.M FixedReset Disc -2.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 17.75
Evaluated at bid price : 17.75
Bid-YTW : 6.32 %
SLF.PR.B Deemed-Retractible -2.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 18.45
Evaluated at bid price : 18.45
Bid-YTW : 6.56 %
MFC.PR.C Deemed-Retractible -2.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 16.81
Evaluated at bid price : 16.81
Bid-YTW : 6.77 %
BIK.PR.A FixedReset Disc -2.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 21.31
Evaluated at bid price : 21.60
Bid-YTW : 6.81 %
CU.PR.F Perpetual-Discount -2.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 17.92
Evaluated at bid price : 17.92
Bid-YTW : 6.37 %
IFC.PR.E Deemed-Retractible -2.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 6.55 %
BMO.PR.D FixedReset Disc -2.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 15.06
Evaluated at bid price : 15.06
Bid-YTW : 6.48 %
RY.PR.N Perpetual-Discount -2.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 20.75
Evaluated at bid price : 20.75
Bid-YTW : 5.99 %
PWF.PR.S Perpetual-Discount -2.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 7.01 %
PWF.PR.K Perpetual-Discount -2.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 17.92
Evaluated at bid price : 17.92
Bid-YTW : 7.06 %
PWF.PR.E Perpetual-Discount -2.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 7.03 %
TD.PF.J FixedReset Disc -2.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 14.70
Evaluated at bid price : 14.70
Bid-YTW : 6.17 %
SLF.PR.A Deemed-Retractible -2.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 6.65 %
IAF.PR.I FixedReset Ins Non -2.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 13.04
Evaluated at bid price : 13.04
Bid-YTW : 6.99 %
CU.PR.D Perpetual-Discount -2.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 19.20
Evaluated at bid price : 19.20
Bid-YTW : 6.47 %
MFC.PR.M FixedReset Ins Non -2.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 12.30
Evaluated at bid price : 12.30
Bid-YTW : 6.55 %
CM.PR.S FixedReset Disc -2.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 12.86
Evaluated at bid price : 12.86
Bid-YTW : 6.43 %
PWF.PR.G Perpetual-Discount -2.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 21.46
Evaluated at bid price : 21.46
Bid-YTW : 7.03 %
NA.PR.W FixedReset Disc -2.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 12.30
Evaluated at bid price : 12.30
Bid-YTW : 6.48 %
PWF.PR.A Floater -2.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 7.75
Evaluated at bid price : 7.75
Bid-YTW : 5.61 %
BAM.PR.N Perpetual-Discount -2.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 17.26
Evaluated at bid price : 17.26
Bid-YTW : 6.94 %
SLF.PR.J FloatingReset -2.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 8.05
Evaluated at bid price : 8.05
Bid-YTW : 5.04 %
GWO.PR.L Deemed-Retractible -2.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 20.26
Evaluated at bid price : 20.26
Bid-YTW : 7.03 %
CM.PR.O FixedReset Disc -2.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 11.82
Evaluated at bid price : 11.82
Bid-YTW : 6.62 %
POW.PR.A Perpetual-Discount -2.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 20.01
Evaluated at bid price : 20.01
Bid-YTW : 7.04 %
PWF.PR.P FixedReset Disc -2.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 9.21
Evaluated at bid price : 9.21
Bid-YTW : 6.03 %
TD.PF.L FixedReset Disc -2.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 16.90
Evaluated at bid price : 16.90
Bid-YTW : 6.33 %
POW.PR.G Perpetual-Discount -2.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 19.80
Evaluated at bid price : 19.80
Bid-YTW : 7.11 %
MFC.PR.J FixedReset Ins Non -2.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 13.00
Evaluated at bid price : 13.00
Bid-YTW : 6.77 %
IFC.PR.G FixedReset Ins Non -2.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 13.26
Evaluated at bid price : 13.26
Bid-YTW : 6.64 %
CM.PR.P FixedReset Disc -2.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 12.13
Evaluated at bid price : 12.13
Bid-YTW : 6.51 %
RY.PR.F Deemed-Retractible -2.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.37
Bid-YTW : 8.69 %
BAM.PF.C Perpetual-Discount -2.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 17.64
Evaluated at bid price : 17.64
Bid-YTW : 6.93 %
PWF.PR.I Perpetual-Discount -1.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 21.91
Evaluated at bid price : 22.15
Bid-YTW : 6.91 %
PWF.PR.F Perpetual-Discount -1.97 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 18.92
Evaluated at bid price : 18.92
Bid-YTW : 7.09 %
CM.PR.Q FixedReset Disc -1.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 12.05
Evaluated at bid price : 12.05
Bid-YTW : 7.00 %
BMO.PR.F FixedReset Disc -1.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 17.51
Evaluated at bid price : 17.51
Bid-YTW : 6.30 %
PWF.PR.H Perpetual-Discount -1.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 20.75
Evaluated at bid price : 20.75
Bid-YTW : 7.08 %
BNS.PR.E FixedReset Disc -1.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 21.10
Evaluated at bid price : 21.10
Bid-YTW : 6.18 %
MFC.PR.I FixedReset Ins Non -1.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 13.25
Evaluated at bid price : 13.25
Bid-YTW : 6.83 %
PWF.PR.Z Perpetual-Discount -1.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 18.70
Evaluated at bid price : 18.70
Bid-YTW : 7.04 %
PWF.PR.T FixedReset Disc -1.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 12.30
Evaluated at bid price : 12.30
Bid-YTW : 6.79 %
MFC.PR.H FixedReset Ins Non -1.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 13.45
Evaluated at bid price : 13.45
Bid-YTW : 7.11 %
RY.PR.P Perpetual-Discount -1.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 22.04
Evaluated at bid price : 22.41
Bid-YTW : 5.92 %
PWF.PR.O Perpetual-Discount -1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 20.90
Evaluated at bid price : 20.90
Bid-YTW : 7.09 %
MFC.PR.L FixedReset Ins Non -1.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 11.59
Evaluated at bid price : 11.59
Bid-YTW : 6.57 %
CU.PR.G Perpetual-Discount -1.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 17.75
Evaluated at bid price : 17.75
Bid-YTW : 6.43 %
W.PR.K FixedReset Disc -1.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 20.05
Evaluated at bid price : 20.05
Bid-YTW : 6.58 %
POW.PR.C Perpetual-Discount -1.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 20.75
Evaluated at bid price : 20.75
Bid-YTW : 7.03 %
BAM.PR.M Perpetual-Discount -1.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 17.31
Evaluated at bid price : 17.31
Bid-YTW : 6.92 %
PWF.PR.R Perpetual-Discount -1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 19.90
Evaluated at bid price : 19.90
Bid-YTW : 7.06 %
EIT.PR.A SplitShare -1.48 % YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2024-03-14
Maturity Price : 25.00
Evaluated at bid price : 22.66
Bid-YTW : 7.70 %
NA.PR.E FixedReset Disc -1.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 13.50
Evaluated at bid price : 13.50
Bid-YTW : 6.50 %
BAM.PR.C Floater -1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 7.50
Evaluated at bid price : 7.50
Bid-YTW : 5.74 %
CU.PR.H Perpetual-Discount -1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 20.32
Evaluated at bid price : 20.32
Bid-YTW : 6.55 %
PWF.PR.L Perpetual-Discount -1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 18.70
Evaluated at bid price : 18.70
Bid-YTW : 6.97 %
RY.PR.J FixedReset Disc -1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 14.21
Evaluated at bid price : 14.21
Bid-YTW : 5.91 %
BAM.PF.D Perpetual-Discount -1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 18.04
Evaluated at bid price : 18.04
Bid-YTW : 6.85 %
SLF.PR.C Deemed-Retractible -1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 16.85
Evaluated at bid price : 16.85
Bid-YTW : 6.66 %
SLF.PR.H FixedReset Ins Non -1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 11.00
Evaluated at bid price : 11.00
Bid-YTW : 6.30 %
NA.PR.S FixedReset Disc -1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 12.25
Evaluated at bid price : 12.25
Bid-YTW : 6.77 %
RY.PR.R FixedReset Disc -1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 22.66
Evaluated at bid price : 23.10
Bid-YTW : 5.89 %
CM.PR.T FixedReset Disc -1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 16.60
Evaluated at bid price : 16.60
Bid-YTW : 6.35 %
RY.PR.E Deemed-Retractible -1.18 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.44
Bid-YTW : 8.57 %
TD.PF.G FixedReset Disc -1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 21.50
Evaluated at bid price : 21.50
Bid-YTW : 6.23 %
BAM.PF.G FixedReset Disc -1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 13.01
Evaluated at bid price : 13.01
Bid-YTW : 6.61 %
PVS.PR.F SplitShare -1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2024-09-30
Maturity Price : 25.00
Evaluated at bid price : 22.50
Bid-YTW : 7.59 %
BAM.PR.B Floater -1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 7.50
Evaluated at bid price : 7.50
Bid-YTW : 5.74 %
RY.PR.A Deemed-Retractible -1.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.55
Bid-YTW : 8.24 %
BMO.PR.Q FixedReset Bank Non 1.00 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.22
Bid-YTW : 8.59 %
EIT.PR.B SplitShare 1.11 % YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2025-03-14
Maturity Price : 25.00
Evaluated at bid price : 22.75
Bid-YTW : 7.08 %
RY.PR.W Perpetual-Discount 1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 21.25
Evaluated at bid price : 21.25
Bid-YTW : 5.85 %
PVS.PR.E SplitShare 1.34 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-10-31
Maturity Price : 25.00
Evaluated at bid price : 23.51
Bid-YTW : 8.33 %
BAM.PF.J FixedReset Disc 1.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 19.70
Evaluated at bid price : 19.70
Bid-YTW : 6.07 %
HSE.PR.G FixedReset Disc 2.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 9.19
Evaluated at bid price : 9.19
Bid-YTW : 11.28 %
TD.PF.D FixedReset Disc 3.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 12.90
Evaluated at bid price : 12.90
Bid-YTW : 6.66 %
TRP.PR.E FixedReset Disc 8.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 11.30
Evaluated at bid price : 11.30
Bid-YTW : 7.02 %
Volume Highlights
Issue Index Shares
Traded
Notes
MFC.PR.F FixedReset Ins Non 100,500 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 7.94
Evaluated at bid price : 7.94
Bid-YTW : 6.34 %
GWO.PR.N FixedReset Ins Non 100,000 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 8.51
Evaluated at bid price : 8.51
Bid-YTW : 5.56 %
PWF.PR.P FixedReset Disc 51,616 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 9.21
Evaluated at bid price : 9.21
Bid-YTW : 6.03 %
MFC.PR.I FixedReset Ins Non 34,150 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 13.25
Evaluated at bid price : 13.25
Bid-YTW : 6.83 %
IAF.PR.G FixedReset Ins Non 32,610 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 12.80
Evaluated at bid price : 12.80
Bid-YTW : 6.84 %
MFC.PR.R FixedReset Ins Non 32,319 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 16.00
Evaluated at bid price : 16.00
Bid-YTW : 7.05 %
There were 26 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
MFC.PR.R FixedReset Ins Non Quote: 16.00 – 18.86
Spot Rate : 2.8600
Average : 2.1532

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 16.00
Evaluated at bid price : 16.00
Bid-YTW : 7.05 %

BAM.PR.T FixedReset Disc Quote: 9.02 – 11.08
Spot Rate : 2.0600
Average : 1.4770

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 9.02
Evaluated at bid price : 9.02
Bid-YTW : 8.31 %

MFC.PR.O FixedReset Ins Non Quote: 20.60 – 22.00
Spot Rate : 1.4000
Average : 0.8556

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 20.60
Evaluated at bid price : 20.60
Bid-YTW : 6.80 %

CU.PR.C FixedReset Disc Quote: 12.60 – 13.95
Spot Rate : 1.3500
Average : 0.9497

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 12.60
Evaluated at bid price : 12.60
Bid-YTW : 6.09 %

CM.PR.Q FixedReset Disc Quote: 12.05 – 13.44
Spot Rate : 1.3900
Average : 1.0567

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 12.05
Evaluated at bid price : 12.05
Bid-YTW : 7.00 %

RY.PR.H FixedReset Disc Quote: 12.71 – 13.70
Spot Rate : 0.9900
Average : 0.6929

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-04-01
Maturity Price : 12.71
Evaluated at bid price : 12.71
Bid-YTW : 6.09 %

Market Action

March 31, 2020

unicorn_200331

oilmoney_200331a

A nice day, for some:

The decimated energy sector has rallied hard off of 20-year lows, pushing Canadian stocks to a decent gain on a day that saw the U.S. market slip.

For the first time since the COVID-19 pandemic consumed global financial markets starting in early March, the S&P/TSX Composite Index meaningfully diverged from U.S. equity benchmarks, with a gain of 2.6 per cent on Tuesday. The S&P 500 index dropped by 1.6 per cent.

Canada’s biggest oil sands players led the advance, adding to a rebound that started on Monday. Over just two trading days, Canadian Natural Resources Ltd. shares have surged by 45 per cent, and Suncor Energy Inc. by 37 per cent.

Potential catalysts for the sudden reversal include expanded federal wage subsidies that would apply to energy sector employees, as well as Tuesday’s announcement that the long-delayed Keystone XL pipeline would go ahead with support from the province of Alberta.
…
For energy companies facing a liquidity crunch, there is hope that lenders will be flexible. “We’re seeing the banks be somewhat understanding,” Mr. Stelmach said. In some cases, lenders are offering extensions and renewals rather than calling in loans.

Loan guarantees are also expected to be included in a multibillion-dollar aid package for the oil patch, which Finance Minister Bill Morneau said last week was coming soon. These incremental developments are insufficient to explain the magnitude of the move in Canadian energy stocks so far this week, with the S&P/TSX Capped Energy Index rising by 30 per cent.

There was some talk in trading circles that a big U.S. investor has accumulated shares of Suncor and Canadian Natural Resources over the last couple of days.
…
Wall Street’s three major indexes tumbled on Tuesday, with the Dow registering its biggest quarterly decline since 1987 and the S&P 500 suffering its deepest quarterly drop since the financial crisis on growing evidence of massive economic damage from the coronavirus pandemic.

In one of the fastest turns into a bear market, the S&P 500 and the Dow both ended the first quarter more than 20% below the end of 2019, as the health crisis worsened in the United States and brought business activity to a standstill.

It was also the S&P’s biggest first-quarter decline on record as consumers were advised to stay at home, leading businesses to announce temporary closures and massive staff furloughs.
…
The Dow Jones Industrial Average fell 410.32 points, or 1.84%, to 21,917.16, the S&P 500 lost 42.06 points, or 1.60%, to 2,584.59 and the Nasdaq Composite dropped 74.05 points, or 0.95%, to 7,700.10.

Nevertheless:

Amid draconian efforts to contain the spread of the novel coronavirus, the avalanche of pink slips stemming from the COVID-19 pandemic has only begun. Some economists predict job losses will be nearly three times greater than they were during the Great Recession of 2008-09, and Canada’s unemployment rate could reach 9 per cent by summer.

The jarring disruptions caused by COVID-19 threaten to send many Canadian households into financial tailspins. In that scenario, a crisis many policymakers hoped would cause just a sharp but brief economic interruption could morph into a more painful, long-lasting collapse in aggregate demand, reverberating long after pandemic control measures have ended.

debt_200331
Click for Big

And quantitative easing is on the way:

The Bank of Canada is likely to buy about $200 billion of government debt after announcing its first quantitative easing program, which would nearly triple the amount of assets on the central bank’s balance sheet, bond strategists estimate.

Just a few weeks ago, Canada’s central bank was defying the global trend of monetary policy easing. But in a series of emergency interest rate cuts this month it has slashed its key interest rate to 0.25 per cent, the level it regards as the floor.

Quantitative easing, or large-scale buying of assets, is now the policy measure favored by the BoC to ease the economic impact of the coronavirus pandemic.

The bank plans to buy at least $5 billion a week of Government of Canada securities, starting on April 1, with the purchases continuing “until the economic recovery is well underway.”

Regrettably, easing is targetted on liquidity. It does not directly address solvency.

But there’s at least one group with no worries:

A tentative deal between Ontario’s public elementary school teachers and the government comes with an annual wage increase of just 1 per cent but allows boards to hire 434 more educators across the province to support students with special learning needs.

The Elementary Teachers’ Federation of Ontario (ETFO) shared details Monday evening of its recently negotiated deal, which includes a 4-per-cent bump in benefits in each year of the three-year offer – higher than the government originally wanted.

Now, if that’s not the classic contract in the education monopoly, I don’t know what is. A nice tough headline number for the politicians to brag about; a boatload of money slipped in through the back-door for the union to snicker about.

TXPR closed at 468.69, up 2.17% on the day. Volume today was 2.40-million, second-lowest of the past thirty days, ahead of only March 5.

CPD closed at 9.37, up 2.18% on the day. Volume was 161,128, below the average of the past 30 trading days.

ZPR closed at 7.29, up 1.96% on the day. Volume of 674,913 was low in the context of the past 30 trading days.

Five-year Canada yields were down 4bp at 0.59% today.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 3.4739 % 1,375.7
FixedFloater 0.00 % 0.00 % 0 0.00 0 3.4739 % 2,524.3
Floater 5.59 % 5.65 % 50,804 14.42 4 3.4739 % 1,454.8
OpRet 0.00 % 0.00 % 0 0.00 0 1.6423 % 3,141.8
SplitShare 5.28 % 7.30 % 79,171 3.96 7 1.6423 % 3,752.0
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 1.6423 % 2,927.5
Perpetual-Premium 6.67 % 6.87 % 105,336 12.68 12 2.6629 % 2,568.1
Perpetual-Discount 6.37 % 6.58 % 88,016 13.15 24 2.6737 % 2,754.6
FixedReset Disc 7.62 % 6.32 % 215,083 13.00 64 3.8063 % 1,576.6
Deemed-Retractible 6.14 % 6.69 % 103,246 12.98 27 3.0158 % 2,752.5
FloatingReset 5.16 % 5.10 % 60,812 15.25 3 6.0236 % 1,687.2
FixedReset Prem 6.23 % 6.18 % 208,665 13.56 22 2.8830 % 2,180.4
FixedReset Bank Non 2.01 % 5.09 % 130,409 1.78 3 -0.9671 % 2,638.9
FixedReset Ins Non 7.57 % 6.48 % 110,196 12.69 22 5.3041 % 1,555.2
Performance Highlights
Issue Index Change Notes
EMA.PR.F FixedReset Disc -11.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 11.75
Evaluated at bid price : 11.75
Bid-YTW : 7.67 %
BMO.PR.Q FixedReset Bank Non -3.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.00
Bid-YTW : 9.15 %
HSE.PR.G FixedReset Disc -2.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 9.00
Evaluated at bid price : 9.00
Bid-YTW : 11.52 %
TD.PF.D FixedReset Disc -2.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 12.41
Evaluated at bid price : 12.41
Bid-YTW : 6.93 %
TRP.PR.D FixedReset Disc -1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 12.01
Evaluated at bid price : 12.01
Bid-YTW : 6.66 %
BAM.PF.C Perpetual-Discount 1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 6.79 %
PWF.PR.A Floater 1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 7.95
Evaluated at bid price : 7.95
Bid-YTW : 5.47 %
RY.PR.A Deemed-Retractible 1.02 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.79
Bid-YTW : 7.63 %
RY.PR.F Deemed-Retractible 1.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.85
Bid-YTW : 7.48 %
PVS.PR.F SplitShare 1.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2024-09-30
Maturity Price : 25.00
Evaluated at bid price : 22.75
Bid-YTW : 7.30 %
BAM.PF.I FixedReset Prem 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 6.04 %
CM.PR.T FixedReset Disc 1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 16.80
Evaluated at bid price : 16.80
Bid-YTW : 6.27 %
RY.PR.G Deemed-Retractible 1.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.64
Bid-YTW : 8.06 %
TRP.PR.K FixedReset Prem 1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 20.10
Evaluated at bid price : 20.10
Bid-YTW : 6.18 %
BAM.PR.N Perpetual-Discount 1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 17.70
Evaluated at bid price : 17.70
Bid-YTW : 6.76 %
CCS.PR.C Deemed-Retractible 1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 6.63 %
EMA.PR.C FixedReset Disc 1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 13.84
Evaluated at bid price : 13.84
Bid-YTW : 6.53 %
BAM.PF.J FixedReset Prem 1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 19.39
Evaluated at bid price : 19.39
Bid-YTW : 6.17 %
RY.PR.P Perpetual-Premium 1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 22.49
Evaluated at bid price : 22.82
Bid-YTW : 5.82 %
RY.PR.W Perpetual-Discount 1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 21.00
Evaluated at bid price : 21.00
Bid-YTW : 5.92 %
RY.PR.Q FixedReset Prem 1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 21.43
Evaluated at bid price : 21.75
Bid-YTW : 5.96 %
BAM.PF.D Perpetual-Discount 1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 18.28
Evaluated at bid price : 18.28
Bid-YTW : 6.76 %
GWO.PR.N FixedReset Ins Non 1.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 8.93
Evaluated at bid price : 8.93
Bid-YTW : 5.30 %
GWO.PR.M Deemed-Retractible 1.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 21.35
Evaluated at bid price : 21.35
Bid-YTW : 6.85 %
SLF.PR.C Deemed-Retractible 1.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 17.07
Evaluated at bid price : 17.07
Bid-YTW : 6.57 %
ELF.PR.H Perpetual-Premium 1.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 19.80
Evaluated at bid price : 19.80
Bid-YTW : 6.98 %
BMO.PR.E FixedReset Disc 1.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 15.27
Evaluated at bid price : 15.27
Bid-YTW : 6.00 %
PWF.PR.G Perpetual-Premium 1.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 21.78
Evaluated at bid price : 22.02
Bid-YTW : 6.83 %
EIT.PR.B SplitShare 1.95 % YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2025-03-14
Maturity Price : 25.00
Evaluated at bid price : 22.50
Bid-YTW : 7.34 %
RY.PR.O Perpetual-Discount 1.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 20.90
Evaluated at bid price : 20.90
Bid-YTW : 5.95 %
PWF.PR.S Perpetual-Discount 1.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 6.81 %
PVS.PR.H SplitShare 2.00 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2027-02-28
Maturity Price : 25.00
Evaluated at bid price : 22.95
Bid-YTW : 6.27 %
EIT.PR.A SplitShare 2.09 % YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2024-03-14
Maturity Price : 25.00
Evaluated at bid price : 23.00
Bid-YTW : 7.27 %
TRP.PR.C FixedReset Disc 2.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 8.50
Evaluated at bid price : 8.50
Bid-YTW : 6.23 %
CU.PR.I FixedReset Prem 2.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 20.95
Evaluated at bid price : 20.95
Bid-YTW : 5.44 %
BAM.PF.H FixedReset Prem 2.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 20.80
Evaluated at bid price : 20.80
Bid-YTW : 6.05 %
PWF.PR.I Perpetual-Premium 2.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 22.33
Evaluated at bid price : 22.60
Bid-YTW : 6.77 %
PWF.PR.R Perpetual-Premium 2.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 20.20
Evaluated at bid price : 20.20
Bid-YTW : 6.95 %
PWF.PR.F Perpetual-Discount 2.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 19.30
Evaluated at bid price : 19.30
Bid-YTW : 6.95 %
IAF.PR.B Deemed-Retractible 2.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 17.60
Evaluated at bid price : 17.60
Bid-YTW : 6.59 %
IFC.PR.G FixedReset Ins Non 2.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 13.56
Evaluated at bid price : 13.56
Bid-YTW : 6.48 %
BIP.PR.F FixedReset Disc 2.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 17.40
Evaluated at bid price : 17.40
Bid-YTW : 7.39 %
PWF.PR.Z Perpetual-Discount 2.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 19.05
Evaluated at bid price : 19.05
Bid-YTW : 6.90 %
CU.PR.H Perpetual-Discount 2.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 20.61
Evaluated at bid price : 20.61
Bid-YTW : 6.46 %
BAM.PF.F FixedReset Disc 2.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 14.00
Evaluated at bid price : 14.00
Bid-YTW : 6.48 %
TRP.PR.J FixedReset Prem 2.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 21.74
Evaluated at bid price : 22.20
Bid-YTW : 6.26 %
EMA.PR.E Perpetual-Discount 2.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 18.46
Evaluated at bid price : 18.46
Bid-YTW : 6.19 %
IFC.PR.F Deemed-Retractible 2.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 21.40
Evaluated at bid price : 21.40
Bid-YTW : 6.24 %
TD.PF.I FixedReset Disc 2.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 15.25
Evaluated at bid price : 15.25
Bid-YTW : 6.25 %
SLF.PR.E Deemed-Retractible 2.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 17.46
Evaluated at bid price : 17.46
Bid-YTW : 6.49 %
CU.PR.D Perpetual-Discount 2.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 19.72
Evaluated at bid price : 19.72
Bid-YTW : 6.30 %
IFC.PR.E Deemed-Retractible 2.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 20.59
Evaluated at bid price : 20.59
Bid-YTW : 6.36 %
BIP.PR.D FixedReset Disc 2.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 18.40
Evaluated at bid price : 18.40
Bid-YTW : 6.85 %
PWF.PR.O Perpetual-Premium 2.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 21.28
Evaluated at bid price : 21.28
Bid-YTW : 6.96 %
BMO.PR.F FixedReset Disc 2.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 17.85
Evaluated at bid price : 17.85
Bid-YTW : 6.17 %
TD.PF.H FixedReset Prem 2.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 6.32 %
BMO.PR.C FixedReset Disc 2.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 15.80
Evaluated at bid price : 15.80
Bid-YTW : 6.40 %
CU.PR.F Perpetual-Discount 2.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 18.45
Evaluated at bid price : 18.45
Bid-YTW : 6.18 %
PWF.PR.K Perpetual-Discount 2.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 18.43
Evaluated at bid price : 18.43
Bid-YTW : 6.86 %
MFC.PR.O FixedReset Ins Non 2.97 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 20.45
Evaluated at bid price : 20.45
Bid-YTW : 6.85 %
TD.PF.L FixedReset Disc 2.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 17.30
Evaluated at bid price : 17.30
Bid-YTW : 6.18 %
BNS.PR.I FixedReset Disc 3.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 15.72
Evaluated at bid price : 15.72
Bid-YTW : 5.56 %
SLF.PR.J FloatingReset 3.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 8.25
Evaluated at bid price : 8.25
Bid-YTW : 4.92 %
SLF.PR.A Deemed-Retractible 3.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 18.50
Evaluated at bid price : 18.50
Bid-YTW : 6.47 %
RY.PR.S FixedReset Disc 3.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 15.80
Evaluated at bid price : 15.80
Bid-YTW : 5.41 %
BAM.PR.K Floater 3.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 7.54
Evaluated at bid price : 7.54
Bid-YTW : 5.71 %
BMO.PR.D FixedReset Disc 3.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 15.50
Evaluated at bid price : 15.50
Bid-YTW : 6.29 %
BNS.PR.E FixedReset Prem 3.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 21.50
Evaluated at bid price : 21.50
Bid-YTW : 6.06 %
TD.PF.F Perpetual-Discount 3.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 21.25
Evaluated at bid price : 21.25
Bid-YTW : 5.87 %
POW.PR.C Perpetual-Premium 3.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 21.10
Evaluated at bid price : 21.10
Bid-YTW : 6.91 %
BAM.PF.G FixedReset Disc 3.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 13.16
Evaluated at bid price : 13.16
Bid-YTW : 6.53 %
TD.PF.G FixedReset Prem 3.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 21.43
Evaluated at bid price : 21.75
Bid-YTW : 6.13 %
PVS.PR.G SplitShare 3.60 % YTW SCENARIO
Maturity Type : Option Certainty
Maturity Date : 2026-02-28
Maturity Price : 25.00
Evaluated at bid price : 23.00
Bid-YTW : 6.66 %
W.PR.K FixedReset Prem 3.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 20.40
Evaluated at bid price : 20.40
Bid-YTW : 6.47 %
PWF.PR.L Perpetual-Discount 3.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 18.96
Evaluated at bid price : 18.96
Bid-YTW : 6.87 %
BMO.PR.Z Perpetual-Discount 3.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 21.52
Evaluated at bid price : 21.52
Bid-YTW : 5.89 %
BMO.PR.W FixedReset Disc 3.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 12.75
Evaluated at bid price : 12.75
Bid-YTW : 6.16 %
TD.PF.J FixedReset Disc 3.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 15.11
Evaluated at bid price : 15.11
Bid-YTW : 5.99 %
TRP.PR.A FixedReset Disc 3.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 11.26
Evaluated at bid price : 11.26
Bid-YTW : 6.21 %
GWO.PR.L Deemed-Retractible 3.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 20.76
Evaluated at bid price : 20.76
Bid-YTW : 6.86 %
BAM.PR.X FixedReset Disc 3.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 9.83
Evaluated at bid price : 9.83
Bid-YTW : 6.20 %
SLF.PR.B Deemed-Retractible 3.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 6.36 %
IFC.PR.C FixedReset Ins Non 3.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 12.75
Evaluated at bid price : 12.75
Bid-YTW : 6.40 %
BAM.PR.B Floater 3.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 7.58
Evaluated at bid price : 7.58
Bid-YTW : 5.68 %
TRP.PR.G FixedReset Disc 3.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 13.50
Evaluated at bid price : 13.50
Bid-YTW : 6.67 %
BIP.PR.E FixedReset Disc 3.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 17.40
Evaluated at bid price : 17.40
Bid-YTW : 7.25 %
MFC.PR.Q FixedReset Ins Non 3.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 13.65
Evaluated at bid price : 13.65
Bid-YTW : 6.36 %
POW.PR.G Perpetual-Premium 3.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 20.26
Evaluated at bid price : 20.26
Bid-YTW : 6.95 %
SLF.PR.D Deemed-Retractible 3.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 6.41 %
TRP.PR.B FixedReset Disc 3.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 7.95
Evaluated at bid price : 7.95
Bid-YTW : 5.86 %
CIU.PR.A Perpetual-Discount 3.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 17.65
Evaluated at bid price : 17.65
Bid-YTW : 6.61 %
POW.PR.A Perpetual-Premium 3.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 20.50
Evaluated at bid price : 20.50
Bid-YTW : 6.87 %
GWO.PR.I Deemed-Retractible 4.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 16.85
Evaluated at bid price : 16.85
Bid-YTW : 6.73 %
GWO.PR.G Deemed-Retractible 4.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 19.51
Evaluated at bid price : 19.51
Bid-YTW : 6.72 %
BMO.PR.B FixedReset Prem 4.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 19.20
Evaluated at bid price : 19.20
Bid-YTW : 6.15 %
SLF.PR.G FixedReset Ins Non 4.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 8.43
Evaluated at bid price : 8.43
Bid-YTW : 5.92 %
PWF.PR.E Perpetual-Premium 4.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 20.56
Evaluated at bid price : 20.56
Bid-YTW : 6.83 %
RY.PR.J FixedReset Disc 4.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 14.40
Evaluated at bid price : 14.40
Bid-YTW : 5.83 %
RY.PR.N Perpetual-Discount 4.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 21.35
Evaluated at bid price : 21.35
Bid-YTW : 5.82 %
BMO.PR.T FixedReset Disc 4.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 12.50
Evaluated at bid price : 12.50
Bid-YTW : 6.15 %
W.PR.M FixedReset Prem 4.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 20.70
Evaluated at bid price : 20.70
Bid-YTW : 6.31 %
GWO.PR.H Deemed-Retractible 4.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 18.59
Evaluated at bid price : 18.59
Bid-YTW : 6.57 %
MFC.PR.C Deemed-Retractible 4.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 17.31
Evaluated at bid price : 17.31
Bid-YTW : 6.57 %
GWO.PR.F Deemed-Retractible 4.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 22.07
Evaluated at bid price : 22.30
Bid-YTW : 6.66 %
CM.PR.Q FixedReset Disc 4.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 12.29
Evaluated at bid price : 12.29
Bid-YTW : 6.86 %
BAM.PR.T FixedReset Disc 4.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 11.48
Evaluated at bid price : 11.48
Bid-YTW : 6.49 %
RY.PR.R FixedReset Prem 4.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 22.93
Evaluated at bid price : 23.38
Bid-YTW : 5.81 %
MFC.PR.B Deemed-Retractible 4.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 18.50
Evaluated at bid price : 18.50
Bid-YTW : 6.35 %
PWF.PR.T FixedReset Disc 4.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 12.53
Evaluated at bid price : 12.53
Bid-YTW : 6.65 %
PWF.PR.H Perpetual-Premium 4.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 21.15
Evaluated at bid price : 21.15
Bid-YTW : 6.94 %
NA.PR.S FixedReset Disc 4.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 12.40
Evaluated at bid price : 12.40
Bid-YTW : 6.68 %
POW.PR.D Perpetual-Discount 4.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 19.09
Evaluated at bid price : 19.09
Bid-YTW : 6.58 %
GWO.PR.R Deemed-Retractible 4.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 18.34
Evaluated at bid price : 18.34
Bid-YTW : 6.60 %
CM.PR.R FixedReset Disc 4.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 14.75
Evaluated at bid price : 14.75
Bid-YTW : 6.83 %
CM.PR.Y FixedReset Disc 4.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 17.67
Evaluated at bid price : 17.67
Bid-YTW : 6.32 %
TD.PF.K FixedReset Disc 4.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 15.07
Evaluated at bid price : 15.07
Bid-YTW : 5.95 %
GWO.PR.Q Deemed-Retractible 4.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 19.40
Evaluated at bid price : 19.40
Bid-YTW : 6.69 %
GWO.PR.S Deemed-Retractible 4.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 19.40
Evaluated at bid price : 19.40
Bid-YTW : 6.82 %
MFC.PR.K FixedReset Ins Non 4.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 12.41
Evaluated at bid price : 12.41
Bid-YTW : 6.40 %
SLF.PR.I FixedReset Ins Non 4.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 13.51
Evaluated at bid price : 13.51
Bid-YTW : 6.25 %
CM.PR.S FixedReset Disc 4.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 13.20
Evaluated at bid price : 13.20
Bid-YTW : 6.25 %
BAM.PR.R FixedReset Disc 4.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 11.37
Evaluated at bid price : 11.37
Bid-YTW : 6.38 %
BAM.PF.B FixedReset Disc 4.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 13.70
Evaluated at bid price : 13.70
Bid-YTW : 6.46 %
CM.PR.O FixedReset Disc 4.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 12.11
Evaluated at bid price : 12.11
Bid-YTW : 6.45 %
HSE.PR.C FixedReset Disc 4.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 9.70
Evaluated at bid price : 9.70
Bid-YTW : 10.67 %
GWO.PR.P Deemed-Retractible 4.97 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 20.05
Evaluated at bid price : 20.05
Bid-YTW : 6.79 %
MFC.PR.H FixedReset Ins Non 4.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 13.70
Evaluated at bid price : 13.70
Bid-YTW : 6.97 %
NA.PR.E FixedReset Disc 4.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 13.70
Evaluated at bid price : 13.70
Bid-YTW : 6.40 %
POW.PR.B Perpetual-Discount 5.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 19.85
Evaluated at bid price : 19.85
Bid-YTW : 6.77 %
TD.PF.M FixedReset Disc 5.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 18.28
Evaluated at bid price : 18.28
Bid-YTW : 6.13 %
IAF.PR.I FixedReset Ins Non 5.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 13.40
Evaluated at bid price : 13.40
Bid-YTW : 6.79 %
NA.PR.C FixedReset Disc 5.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 15.40
Evaluated at bid price : 15.40
Bid-YTW : 6.74 %
GWO.PR.T Deemed-Retractible 5.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 19.30
Evaluated at bid price : 19.30
Bid-YTW : 6.73 %
MFC.PR.I FixedReset Ins Non 5.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 13.50
Evaluated at bid price : 13.50
Bid-YTW : 6.70 %
CM.PR.P FixedReset Disc 5.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 12.40
Evaluated at bid price : 12.40
Bid-YTW : 6.35 %
RY.PR.H FixedReset Disc 5.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 13.60
Evaluated at bid price : 13.60
Bid-YTW : 5.67 %
MFC.PR.L FixedReset Ins Non 5.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 11.80
Evaluated at bid price : 11.80
Bid-YTW : 6.44 %
BMO.PR.S FixedReset Disc 5.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 12.85
Evaluated at bid price : 12.85
Bid-YTW : 6.21 %
MFC.PR.J FixedReset Ins Non 5.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 13.30
Evaluated at bid price : 13.30
Bid-YTW : 6.60 %
NA.PR.A FixedReset Prem 5.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 20.90
Evaluated at bid price : 20.90
Bid-YTW : 6.38 %
BIK.PR.A FixedReset Prem 5.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 21.86
Evaluated at bid price : 22.24
Bid-YTW : 6.61 %
TD.PF.A FixedReset Disc 5.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 13.18
Evaluated at bid price : 13.18
Bid-YTW : 5.89 %
TD.PF.C FixedReset Disc 5.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 13.31
Evaluated at bid price : 13.31
Bid-YTW : 6.03 %
MFC.PR.N FixedReset Ins Non 5.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 12.13
Evaluated at bid price : 12.13
Bid-YTW : 5.97 %
BIP.PR.A FixedReset Disc 5.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 13.00
Evaluated at bid price : 13.00
Bid-YTW : 8.02 %
CU.PR.E Perpetual-Discount 5.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 19.86
Evaluated at bid price : 19.86
Bid-YTW : 6.25 %
NA.PR.G FixedReset Disc 5.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 14.50
Evaluated at bid price : 14.50
Bid-YTW : 6.53 %
CU.PR.C FixedReset Disc 5.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 14.25
Evaluated at bid price : 14.25
Bid-YTW : 5.37 %
BAM.PR.C Floater 5.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 7.61
Evaluated at bid price : 7.61
Bid-YTW : 5.65 %
TRP.PR.F FloatingReset 6.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 9.68
Evaluated at bid price : 9.68
Bid-YTW : 5.52 %
MFC.PR.R FixedReset Ins Non 6.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 16.55
Evaluated at bid price : 16.55
Bid-YTW : 6.81 %
MFC.PR.G FixedReset Ins Non 6.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 13.05
Evaluated at bid price : 13.05
Bid-YTW : 6.81 %
TD.PF.B FixedReset Disc 6.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 13.30
Evaluated at bid price : 13.30
Bid-YTW : 5.87 %
RY.PR.Z FixedReset Disc 6.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 13.40
Evaluated at bid price : 13.40
Bid-YTW : 5.69 %
NA.PR.X FixedReset Prem 6.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 21.47
Evaluated at bid price : 21.81
Bid-YTW : 6.37 %
MFC.PR.F FixedReset Ins Non 6.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 8.40
Evaluated at bid price : 8.40
Bid-YTW : 5.99 %
EML.PR.A FixedReset Ins Non 6.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 19.80
Evaluated at bid price : 19.80
Bid-YTW : 7.07 %
RY.PR.M FixedReset Disc 6.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 13.99
Evaluated at bid price : 13.99
Bid-YTW : 5.81 %
IFC.PR.A FixedReset Ins Non 6.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 9.90
Evaluated at bid price : 9.90
Bid-YTW : 6.31 %
NA.PR.W FixedReset Disc 6.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 12.62
Evaluated at bid price : 12.62
Bid-YTW : 6.31 %
IAF.PR.G FixedReset Ins Non 7.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 12.70
Evaluated at bid price : 12.70
Bid-YTW : 6.89 %
TD.PF.E FixedReset Disc 7.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 14.00
Evaluated at bid price : 14.00
Bid-YTW : 6.28 %
HSE.PR.A FixedReset Disc 7.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 5.61
Evaluated at bid price : 5.61
Bid-YTW : 10.42 %
BNS.PR.H FixedReset Prem 8.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 19.52
Evaluated at bid price : 19.52
Bid-YTW : 6.24 %
PWF.PR.Q FloatingReset 8.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 9.00
Evaluated at bid price : 9.00
Bid-YTW : 5.10 %
BMO.PR.Y FixedReset Disc 9.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 13.45
Evaluated at bid price : 13.45
Bid-YTW : 6.21 %
MFC.PR.M FixedReset Ins Non 9.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 12.63
Evaluated at bid price : 12.63
Bid-YTW : 6.36 %
PWF.PR.P FixedReset Disc 10.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 9.43
Evaluated at bid price : 9.43
Bid-YTW : 5.88 %
SLF.PR.H FixedReset Ins Non 10.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 11.14
Evaluated at bid price : 11.14
Bid-YTW : 6.22 %
BAM.PF.A FixedReset Disc 18.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 15.10
Evaluated at bid price : 15.10
Bid-YTW : 6.37 %
Volume Highlights
Issue Index Shares
Traded
Notes
PWF.PR.E Perpetual-Premium 117,745 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 20.56
Evaluated at bid price : 20.56
Bid-YTW : 6.83 %
BMO.PR.F FixedReset Disc 70,279 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 17.85
Evaluated at bid price : 17.85
Bid-YTW : 6.17 %
RY.PR.S FixedReset Disc 55,343 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 15.80
Evaluated at bid price : 15.80
Bid-YTW : 5.41 %
RY.PR.Z FixedReset Disc 54,209 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 13.40
Evaluated at bid price : 13.40
Bid-YTW : 5.69 %
TD.PF.B FixedReset Disc 52,330 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 13.30
Evaluated at bid price : 13.30
Bid-YTW : 5.87 %
TD.PF.M FixedReset Disc 40,191 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 18.28
Evaluated at bid price : 18.28
Bid-YTW : 6.13 %
There were 57 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
MFC.PR.K FixedReset Ins Non Quote: 12.41 – 18.10
Spot Rate : 5.6900
Average : 4.6726

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 12.41
Evaluated at bid price : 12.41
Bid-YTW : 6.40 %

MFC.PR.R FixedReset Ins Non Quote: 16.55 – 18.86
Spot Rate : 2.3100
Average : 1.3783

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 16.55
Evaluated at bid price : 16.55
Bid-YTW : 6.81 %

EMA.PR.F FixedReset Disc Quote: 11.75 – 14.40
Spot Rate : 2.6500
Average : 1.8561

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 11.75
Evaluated at bid price : 11.75
Bid-YTW : 7.67 %

MFC.PR.G FixedReset Ins Non Quote: 13.05 – 19.17
Spot Rate : 6.1200
Average : 5.3345

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 13.05
Evaluated at bid price : 13.05
Bid-YTW : 6.81 %

TD.PF.D FixedReset Disc Quote: 12.41 – 14.58
Spot Rate : 2.1700
Average : 1.5280

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 12.41
Evaluated at bid price : 12.41
Bid-YTW : 6.93 %

BNS.PR.G FixedReset Prem Quote: 21.65 – 23.24
Spot Rate : 1.5900
Average : 1.0552

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-31
Maturity Price : 21.35
Evaluated at bid price : 21.65
Bid-YTW : 6.24 %

Market Action

March 30, 2020

unicorn_200330

gusher_200330

Oil action is in the news today:

Energy stocks led Canada’s main stock index higher on Monday, despite a plunge in crude prices as the market waits for news of support from Ottawa for the oil and gas industry.

The Toronto Stock Exchange’s S&P/TSX composite index was unofficially up 350.76 points, or 2.76%, at 13,038.50 The index fell as low as 12,548.96 in morning trading.

Nine of the index’s 11 major sectors were higher, paced by the energy sector, which rose 11.9%.

Global oil benchmark Brent crude plunged to its cheapest in almost 18 years on Monday and U.S. crude briefly tumbled below $20 per barrel on growing fears the global coronavirus shutdown could last months and demand for fuel will decline further.
…
Brent futures fell $2.17, or 8.7%, to settle at $22.76 a barrel, their lowest close since November 2002, while U.S. West Texas Intermediate (WTI) crude fell $1.42, or 6.6%, to $20.09, the lowest close since February 2002.
…
Economists expect a number of weak reports on the economy to come in through the week. The lowlight will likely be Friday’s jobs report, where economists expect to see the largest fall in the nation’s payrolls since the Great Recession.

But who knows? Maybe Trump will join OPEC with his pals MBS and Putin:

U.S. President Donald Trump and Russian President Vladimir Putin agreed during a phone call on Monday to have their top energy officials meet to discuss slumping global oil markets, the Kremlin said, as Trump called Russia’s price war with Saudi Arabia “crazy.”

The agreement marks a new twist in global oil diplomacy since a failed deal earlier this month between the Organization of the Petroleum Exporting Countries and Russia to cut production ignited the price war between Russia and OPEC’s de facto leader Saudi Arabia.
…
Shortly before Monday’s phone call, Trump said Saudi Arabia and Russia “both went crazy” in their oil-price war and that “I never thought I’d be saying that maybe we have to have an oil (price) increase, because we do.”

“The price is so low now they’re fighting like crazy over, over distribution and over how many barrels to let go,” Trump said in an interview on Fox News.

It would seem worthwhile to do something about US coronavirus testing costs:

The coronavirus bills passed so far — and those on the table — offer inadequate protection from a system primed to bill patients for all kinds of costs. The Families First Coronavirus Response Act, passed this month, says that the test and its related charges will be covered with no patient charge only to the extent that they are related to administering the test or evaluating whether a patient needs it.

That leaves hospital billers and coders wide berth. Mr. Cencini went to the E.R. to get a test, as he was instructed to do. When he called to protest his $1,622.52 for hospital charges (his insurer’s discounted rate from over $2,500 in the hospital’s billed charges), a patient representative confirmed that the E.R. visit and other services performed would be “eligible for cost-sharing” (in his case, all of it, since he’d not met his deductible).

This weekend he was notified that the physician charge from Emergency Care Services of New York was $1,166. Though “covered” by his insurance, he owes another $321 for that, bringing his out-of-pocket costs to nearly $2,000.

By the way, his test came back negative.

TXPR closed at 458.72, up 2.66% on the day. Volume today was 2.82-million, second-lowest of the past thirty days, ahead of only March 5.

CPD closed at 9.17, up 1.78% on the day. Volume was 140,404, well below the average of the past 30 trading days.

ZPR closed at 7.15, up 2.88% on the day. Volume of 803,406 was low in the context of the past 30 trading days.

Five-year Canada yields were unchanged at 0.63% today.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 2.2766 % 1,329.5
FixedFloater 0.00 % 0.00 % 0 0.00 0 2.2766 % 2,439.5
Floater 5.78 % 5.90 % 50,995 14.05 4 2.2766 % 1,405.9
OpRet 0.00 % 0.00 % 0 0.00 0 0.6805 % 3,091.1
SplitShare 5.37 % 7.79 % 80,184 3.96 7 0.6805 % 3,691.4
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.6805 % 2,880.2
Perpetual-Premium 6.85 % 7.11 % 107,103 12.44 12 3.0981 % 2,501.5
Perpetual-Discount 6.54 % 6.85 % 89,275 12.77 24 1.2080 % 2,682.9
FixedReset Disc 7.96 % 6.59 % 212,257 12.72 64 2.9732 % 1,518.8
Deemed-Retractible 6.33 % 6.96 % 103,546 12.63 27 2.2127 % 2,671.9
FloatingReset 5.47 % 5.56 % 61,644 14.49 3 0.6738 % 1,591.3
FixedReset Prem 6.40 % 6.37 % 208,289 13.27 22 3.2291 % 2,119.3
FixedReset Bank Non 1.99 % 5.32 % 126,550 1.78 3 0.8196 % 2,664.7
FixedReset Ins Non 7.97 % 6.98 % 114,676 12.17 22 2.6912 % 1,476.9
Performance Highlights
Issue Index Change Notes
BAM.PF.A FixedReset Disc -9.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 12.71
Evaluated at bid price : 12.71
Bid-YTW : 7.66 %
HSE.PR.G FixedReset Disc -5.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 9.25
Evaluated at bid price : 9.25
Bid-YTW : 11.20 %
SLF.PR.H FixedReset Ins Non -4.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 10.08
Evaluated at bid price : 10.08
Bid-YTW : 6.88 %
IFC.PR.A FixedReset Ins Non -2.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 9.28
Evaluated at bid price : 9.28
Bid-YTW : 6.76 %
BAM.PF.G FixedReset Disc -2.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 12.71
Evaluated at bid price : 12.71
Bid-YTW : 6.77 %
CIU.PR.A Perpetual-Discount -2.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 16.98
Evaluated at bid price : 16.98
Bid-YTW : 6.87 %
BNS.PR.H FixedReset Prem -1.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 6.77 %
TRP.PR.G FixedReset Disc -1.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 13.00
Evaluated at bid price : 13.00
Bid-YTW : 6.92 %
CU.PR.E Perpetual-Discount -1.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 18.78
Evaluated at bid price : 18.78
Bid-YTW : 6.62 %
SLF.PR.J FloatingReset -1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 8.00
Evaluated at bid price : 8.00
Bid-YTW : 5.07 %
HSE.PR.C FixedReset Disc -1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 9.25
Evaluated at bid price : 9.25
Bid-YTW : 11.23 %
BIP.PR.E FixedReset Disc 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 16.75
Evaluated at bid price : 16.75
Bid-YTW : 7.53 %
CU.PR.G Perpetual-Discount 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 6.34 %
GWO.PR.I Deemed-Retractible 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 16.20
Evaluated at bid price : 16.20
Bid-YTW : 7.00 %
BMO.PR.Z Perpetual-Discount 1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 20.75
Evaluated at bid price : 20.75
Bid-YTW : 6.11 %
RY.PR.W Perpetual-Discount 1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 20.70
Evaluated at bid price : 20.70
Bid-YTW : 6.00 %
TD.PF.I FixedReset Disc 1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 14.85
Evaluated at bid price : 14.85
Bid-YTW : 6.42 %
PWF.PR.H Perpetual-Premium 1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 20.25
Evaluated at bid price : 20.25
Bid-YTW : 7.26 %
BMO.PR.C FixedReset Disc 1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 15.35
Evaluated at bid price : 15.35
Bid-YTW : 6.59 %
W.PR.K FixedReset Prem 1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 6.72 %
POW.PR.C Perpetual-Premium 1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 20.40
Evaluated at bid price : 20.40
Bid-YTW : 7.15 %
RY.PR.E Deemed-Retractible 1.29 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.50
Bid-YTW : 8.39 %
PVS.PR.D SplitShare 1.34 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2021-10-08
Maturity Price : 25.00
Evaluated at bid price : 23.51
Bid-YTW : 9.01 %
BAM.PR.B Floater 1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 7.30
Evaluated at bid price : 7.30
Bid-YTW : 5.90 %
BAM.PR.K Floater 1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 7.30
Evaluated at bid price : 7.30
Bid-YTW : 5.90 %
BAM.PF.D Perpetual-Discount 1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 18.01
Evaluated at bid price : 18.01
Bid-YTW : 6.86 %
BAM.PR.C Floater 1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 7.18
Evaluated at bid price : 7.18
Bid-YTW : 6.00 %
BIP.PR.D FixedReset Disc 1.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 17.90
Evaluated at bid price : 17.90
Bid-YTW : 7.04 %
MFC.PR.C Deemed-Retractible 1.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 16.60
Evaluated at bid price : 16.60
Bid-YTW : 6.85 %
GWO.PR.Q Deemed-Retractible 1.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 18.53
Evaluated at bid price : 18.53
Bid-YTW : 7.01 %
POW.PR.G Perpetual-Premium 1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 19.50
Evaluated at bid price : 19.50
Bid-YTW : 7.22 %
PWF.PR.Z Perpetual-Discount 1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 18.60
Evaluated at bid price : 18.60
Bid-YTW : 7.07 %
GWO.PR.F Deemed-Retractible 1.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 21.38
Evaluated at bid price : 21.38
Bid-YTW : 6.96 %
TRP.PR.E FixedReset Disc 1.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 10.45
Evaluated at bid price : 10.45
Bid-YTW : 7.62 %
BMO.PR.S FixedReset Disc 1.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 12.20
Evaluated at bid price : 12.20
Bid-YTW : 6.56 %
GWO.PR.R Deemed-Retractible 1.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 17.55
Evaluated at bid price : 17.55
Bid-YTW : 6.89 %
RY.PR.A Deemed-Retractible 1.68 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.55
Bid-YTW : 8.21 %
SLF.PR.E Deemed-Retractible 1.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 6.67 %
GWO.PR.S Deemed-Retractible 1.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 18.53
Evaluated at bid price : 18.53
Bid-YTW : 7.14 %
SLF.PR.A Deemed-Retractible 1.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 17.92
Evaluated at bid price : 17.92
Bid-YTW : 6.68 %
BAM.PR.X FixedReset Disc 1.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 9.47
Evaluated at bid price : 9.47
Bid-YTW : 6.44 %
RY.PR.C Deemed-Retractible 1.85 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.68
Bid-YTW : 8.06 %
BAM.PF.I FixedReset Prem 1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 19.78
Evaluated at bid price : 19.78
Bid-YTW : 6.11 %
TD.PF.F Perpetual-Discount 1.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 20.55
Evaluated at bid price : 20.55
Bid-YTW : 6.08 %
RY.PR.N Perpetual-Discount 1.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 20.50
Evaluated at bid price : 20.50
Bid-YTW : 6.06 %
PWF.PR.K Perpetual-Discount 1.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 17.90
Evaluated at bid price : 17.90
Bid-YTW : 7.06 %
GWO.PR.T Deemed-Retractible 2.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 18.36
Evaluated at bid price : 18.36
Bid-YTW : 7.07 %
BIP.PR.B FixedReset Prem 2.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 20.70
Evaluated at bid price : 20.70
Bid-YTW : 6.70 %
BMO.PR.Q FixedReset Bank Non 2.02 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.70
Bid-YTW : 7.34 %
PWF.PR.P FixedReset Disc 2.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 8.57
Evaluated at bid price : 8.57
Bid-YTW : 6.48 %
PWF.PR.L Perpetual-Discount 2.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 18.29
Evaluated at bid price : 18.29
Bid-YTW : 7.12 %
ELF.PR.H Perpetual-Premium 2.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 19.45
Evaluated at bid price : 19.45
Bid-YTW : 7.10 %
GWO.PR.P Deemed-Retractible 2.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 19.10
Evaluated at bid price : 19.10
Bid-YTW : 7.13 %
IAF.PR.G FixedReset Ins Non 2.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 11.85
Evaluated at bid price : 11.85
Bid-YTW : 7.40 %
IFC.PR.C FixedReset Ins Non 2.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 12.28
Evaluated at bid price : 12.28
Bid-YTW : 6.65 %
NA.PR.E FixedReset Disc 2.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 13.05
Evaluated at bid price : 13.05
Bid-YTW : 6.74 %
TRP.PR.K FixedReset Prem 2.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 19.85
Evaluated at bid price : 19.85
Bid-YTW : 6.26 %
BIP.PR.A FixedReset Disc 2.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 12.30
Evaluated at bid price : 12.30
Bid-YTW : 8.48 %
BMO.PR.W FixedReset Disc 2.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 12.29
Evaluated at bid price : 12.29
Bid-YTW : 6.40 %
PWF.PR.R Perpetual-Premium 2.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 19.75
Evaluated at bid price : 19.75
Bid-YTW : 7.11 %
TD.PF.G FixedReset Prem 2.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 21.00
Evaluated at bid price : 21.00
Bid-YTW : 6.37 %
GWO.PR.N FixedReset Ins Non 2.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 8.79
Evaluated at bid price : 8.79
Bid-YTW : 5.38 %
POW.PR.B Perpetual-Discount 2.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 18.90
Evaluated at bid price : 18.90
Bid-YTW : 7.11 %
PWF.PR.S Perpetual-Discount 2.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 17.65
Evaluated at bid price : 17.65
Bid-YTW : 6.94 %
CU.PR.I FixedReset Prem 2.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 20.50
Evaluated at bid price : 20.50
Bid-YTW : 5.56 %
TD.PF.J FixedReset Disc 2.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 14.56
Evaluated at bid price : 14.56
Bid-YTW : 6.23 %
RY.PR.F Deemed-Retractible 2.56 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.60
Bid-YTW : 8.09 %
BAM.PF.J FixedReset Prem 2.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 19.12
Evaluated at bid price : 19.12
Bid-YTW : 6.26 %
PWF.PR.O Perpetual-Premium 2.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 20.70
Evaluated at bid price : 20.70
Bid-YTW : 7.16 %
PWF.PR.E Perpetual-Premium 2.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 19.75
Evaluated at bid price : 19.75
Bid-YTW : 7.11 %
NA.PR.W FixedReset Disc 2.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 11.80
Evaluated at bid price : 11.80
Bid-YTW : 6.77 %
CM.PR.R FixedReset Disc 2.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 14.11
Evaluated at bid price : 14.11
Bid-YTW : 7.15 %
MFC.PR.Q FixedReset Ins Non 2.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 13.14
Evaluated at bid price : 13.14
Bid-YTW : 6.63 %
TD.PF.L FixedReset Disc 2.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 16.80
Evaluated at bid price : 16.80
Bid-YTW : 6.37 %
PVS.PR.H SplitShare 2.74 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2027-02-28
Maturity Price : 25.00
Evaluated at bid price : 22.50
Bid-YTW : 6.62 %
GWO.PR.L Deemed-Retractible 2.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 7.12 %
NA.PR.C FixedReset Disc 2.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 14.65
Evaluated at bid price : 14.65
Bid-YTW : 7.10 %
BMO.PR.Y FixedReset Disc 2.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 12.34
Evaluated at bid price : 12.34
Bid-YTW : 6.77 %
MFC.PR.O FixedReset Ins Non 2.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 19.86
Evaluated at bid price : 19.86
Bid-YTW : 7.06 %
BAM.PR.Z FixedReset Disc 2.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 14.40
Evaluated at bid price : 14.40
Bid-YTW : 6.53 %
SLF.PR.B Deemed-Retractible 2.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 18.30
Evaluated at bid price : 18.30
Bid-YTW : 6.61 %
POW.PR.A Perpetual-Premium 2.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 19.72
Evaluated at bid price : 19.72
Bid-YTW : 7.14 %
CM.PR.Q FixedReset Disc 2.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 11.78
Evaluated at bid price : 11.78
Bid-YTW : 7.16 %
BAM.PF.H FixedReset Prem 3.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 20.35
Evaluated at bid price : 20.35
Bid-YTW : 6.19 %
IFC.PR.F Deemed-Retractible 3.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 20.84
Evaluated at bid price : 20.84
Bid-YTW : 6.41 %
ELF.PR.G Perpetual-Discount 3.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 17.25
Evaluated at bid price : 17.25
Bid-YTW : 6.92 %
NA.PR.S FixedReset Disc 3.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 11.87
Evaluated at bid price : 11.87
Bid-YTW : 7.00 %
CU.PR.C FixedReset Disc 3.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 13.45
Evaluated at bid price : 13.45
Bid-YTW : 5.70 %
GWO.PR.H Deemed-Retractible 3.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 17.83
Evaluated at bid price : 17.83
Bid-YTW : 6.86 %
RY.PR.Q FixedReset Prem 3.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 21.43
Evaluated at bid price : 21.43
Bid-YTW : 6.07 %
TD.PF.A FixedReset Disc 3.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 12.50
Evaluated at bid price : 12.50
Bid-YTW : 6.23 %
TRP.PR.A FixedReset Disc 3.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 10.85
Evaluated at bid price : 10.85
Bid-YTW : 6.46 %
CM.PR.Y FixedReset Disc 3.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 16.90
Evaluated at bid price : 16.90
Bid-YTW : 6.62 %
PWF.PR.Q FloatingReset 3.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 8.27
Evaluated at bid price : 8.27
Bid-YTW : 5.56 %
RY.PR.S FixedReset Disc 3.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 15.30
Evaluated at bid price : 15.30
Bid-YTW : 5.60 %
MFC.PR.R FixedReset Ins Non 3.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 15.60
Evaluated at bid price : 15.60
Bid-YTW : 7.23 %
PWF.PR.F Perpetual-Discount 3.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 18.87
Evaluated at bid price : 18.87
Bid-YTW : 7.11 %
EML.PR.A FixedReset Ins Non 3.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 18.62
Evaluated at bid price : 18.62
Bid-YTW : 7.52 %
BIP.PR.C FixedReset Prem 3.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 19.10
Evaluated at bid price : 19.10
Bid-YTW : 7.06 %
TD.PF.C FixedReset Disc 3.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 12.62
Evaluated at bid price : 12.62
Bid-YTW : 6.23 %
PWF.PR.I Perpetual-Premium 3.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 21.86
Evaluated at bid price : 22.10
Bid-YTW : 6.92 %
RY.PR.Z FixedReset Disc 3.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 12.61
Evaluated at bid price : 12.61
Bid-YTW : 6.07 %
RY.PR.M FixedReset Disc 3.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 13.15
Evaluated at bid price : 13.15
Bid-YTW : 6.18 %
RY.PR.O Perpetual-Discount 3.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 20.50
Evaluated at bid price : 20.50
Bid-YTW : 6.06 %
BAM.PF.F FixedReset Disc 3.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 13.65
Evaluated at bid price : 13.65
Bid-YTW : 6.65 %
BMO.PR.F FixedReset Disc 3.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 17.36
Evaluated at bid price : 17.36
Bid-YTW : 6.35 %
TD.PF.B FixedReset Disc 3.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 12.52
Evaluated at bid price : 12.52
Bid-YTW : 6.25 %
TD.PF.H FixedReset Prem 3.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 18.46
Evaluated at bid price : 18.46
Bid-YTW : 6.50 %
MFC.PR.K FixedReset Ins Non 3.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 11.85
Evaluated at bid price : 11.85
Bid-YTW : 6.73 %
GWO.PR.M Deemed-Retractible 3.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 21.00
Evaluated at bid price : 21.00
Bid-YTW : 6.96 %
IAF.PR.I FixedReset Ins Non 4.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 12.75
Evaluated at bid price : 12.75
Bid-YTW : 7.16 %
MFC.PR.I FixedReset Ins Non 4.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 12.84
Evaluated at bid price : 12.84
Bid-YTW : 7.05 %
GWO.PR.G Deemed-Retractible 4.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 18.75
Evaluated at bid price : 18.75
Bid-YTW : 6.99 %
RY.PR.H FixedReset Disc 4.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 12.92
Evaluated at bid price : 12.92
Bid-YTW : 5.99 %
BMO.PR.B FixedReset Prem 4.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 18.45
Evaluated at bid price : 18.45
Bid-YTW : 6.41 %
BMO.PR.T FixedReset Disc 4.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 12.00
Evaluated at bid price : 12.00
Bid-YTW : 6.42 %
TRP.PR.J FixedReset Prem 4.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 21.35
Evaluated at bid price : 21.64
Bid-YTW : 6.43 %
BAM.PF.B FixedReset Disc 4.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 13.07
Evaluated at bid price : 13.07
Bid-YTW : 6.79 %
RY.PR.J FixedReset Disc 4.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 13.83
Evaluated at bid price : 13.83
Bid-YTW : 6.07 %
MFC.PR.H FixedReset Ins Non 4.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 13.05
Evaluated at bid price : 13.05
Bid-YTW : 7.33 %
CM.PR.P FixedReset Disc 4.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 11.79
Evaluated at bid price : 11.79
Bid-YTW : 6.70 %
MFC.PR.G FixedReset Ins Non 4.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 12.30
Evaluated at bid price : 12.30
Bid-YTW : 7.23 %
RY.PR.P Perpetual-Premium 4.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 22.22
Evaluated at bid price : 22.50
Bid-YTW : 5.90 %
NA.PR.X FixedReset Prem 4.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 20.52
Evaluated at bid price : 20.52
Bid-YTW : 6.80 %
TD.PF.K FixedReset Disc 4.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 14.40
Evaluated at bid price : 14.40
Bid-YTW : 6.25 %
PWF.PR.A Floater 4.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 7.87
Evaluated at bid price : 7.87
Bid-YTW : 5.52 %
BNS.PR.G FixedReset Prem 4.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 21.42
Evaluated at bid price : 21.75
Bid-YTW : 6.21 %
BMO.PR.D FixedReset Disc 4.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 15.00
Evaluated at bid price : 15.00
Bid-YTW : 6.51 %
MFC.PR.J FixedReset Ins Non 5.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 12.62
Evaluated at bid price : 12.62
Bid-YTW : 6.98 %
BMO.PR.E FixedReset Disc 5.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 15.00
Evaluated at bid price : 15.00
Bid-YTW : 6.11 %
NA.PR.G FixedReset Disc 5.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 13.71
Evaluated at bid price : 13.71
Bid-YTW : 6.93 %
SLF.PR.I FixedReset Ins Non 5.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 12.90
Evaluated at bid price : 12.90
Bid-YTW : 6.55 %
PWF.PR.G Perpetual-Premium 5.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 21.33
Evaluated at bid price : 21.60
Bid-YTW : 6.96 %
CM.PR.T FixedReset Disc 5.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 16.60
Evaluated at bid price : 16.60
Bid-YTW : 6.35 %
BIK.PR.A FixedReset Prem 5.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 21.10
Evaluated at bid price : 21.10
Bid-YTW : 6.99 %
BNS.PR.E FixedReset Prem 5.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 20.80
Evaluated at bid price : 20.80
Bid-YTW : 6.27 %
CCS.PR.C Deemed-Retractible 5.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 18.75
Evaluated at bid price : 18.75
Bid-YTW : 6.72 %
RY.PR.R FixedReset Prem 5.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 21.87
Evaluated at bid price : 22.40
Bid-YTW : 6.07 %
MFC.PR.N FixedReset Ins Non 5.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 11.50
Evaluated at bid price : 11.50
Bid-YTW : 6.30 %
IFC.PR.I Perpetual-Premium 6.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 21.00
Evaluated at bid price : 21.00
Bid-YTW : 6.53 %
CM.PR.O FixedReset Disc 6.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 11.55
Evaluated at bid price : 11.55
Bid-YTW : 6.78 %
BNS.PR.I FixedReset Disc 6.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 15.25
Evaluated at bid price : 15.25
Bid-YTW : 5.74 %
MFC.PR.F FixedReset Ins Non 6.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 7.90
Evaluated at bid price : 7.90
Bid-YTW : 6.37 %
CM.PR.S FixedReset Disc 6.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 12.60
Evaluated at bid price : 12.60
Bid-YTW : 6.57 %
IFC.PR.E Deemed-Retractible 7.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 20.04
Evaluated at bid price : 20.04
Bid-YTW : 6.54 %
NA.PR.A FixedReset Prem 7.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 19.83
Evaluated at bid price : 19.83
Bid-YTW : 6.73 %
BAM.PR.T FixedReset Disc 7.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 11.00
Evaluated at bid price : 11.00
Bid-YTW : 6.77 %
TRP.PR.C FixedReset Disc 8.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 8.32
Evaluated at bid price : 8.32
Bid-YTW : 6.37 %
TRP.PR.D FixedReset Disc 26.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 12.25
Evaluated at bid price : 12.25
Bid-YTW : 6.52 %
BAM.PR.R FixedReset Disc 34.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 10.85
Evaluated at bid price : 10.85
Bid-YTW : 6.69 %
Volume Highlights
Issue Index Shares
Traded
Notes
HSE.PR.A FixedReset Disc 438,875 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 5.20
Evaluated at bid price : 5.20
Bid-YTW : 11.25 %
SLF.PR.A Deemed-Retractible 338,817 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 17.92
Evaluated at bid price : 17.92
Bid-YTW : 6.68 %
TD.PF.M FixedReset Disc 67,500 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 17.40
Evaluated at bid price : 17.40
Bid-YTW : 6.45 %
BMO.PR.D FixedReset Disc 45,935 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 15.00
Evaluated at bid price : 15.00
Bid-YTW : 6.51 %
BAM.PF.A FixedReset Disc 30,001 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 12.71
Evaluated at bid price : 12.71
Bid-YTW : 7.66 %
TD.PF.K FixedReset Disc 28,652 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 14.40
Evaluated at bid price : 14.40
Bid-YTW : 6.25 %
There were 35 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BMO.PR.Y FixedReset Disc Quote: 12.34 – 19.75
Spot Rate : 7.4100
Average : 4.3065

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 12.34
Evaluated at bid price : 12.34
Bid-YTW : 6.77 %

MFC.PR.K FixedReset Ins Non Quote: 11.85 – 18.10
Spot Rate : 6.2500
Average : 3.5571

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 11.85
Evaluated at bid price : 11.85
Bid-YTW : 6.73 %

MFC.PR.G FixedReset Ins Non Quote: 12.30 – 19.17
Spot Rate : 6.8700
Average : 4.4734

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 12.30
Evaluated at bid price : 12.30
Bid-YTW : 7.23 %

CIU.PR.A Perpetual-Discount Quote: 16.98 – 20.00
Spot Rate : 3.0200
Average : 1.8592

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 16.98
Evaluated at bid price : 16.98
Bid-YTW : 6.87 %

CU.PR.I FixedReset Prem Quote: 20.50 – 22.95
Spot Rate : 2.4500
Average : 1.4778

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 20.50
Evaluated at bid price : 20.50
Bid-YTW : 5.56 %

BAM.PF.A FixedReset Disc Quote: 12.71 – 15.15
Spot Rate : 2.4400
Average : 1.5150

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-03-30
Maturity Price : 12.71
Evaluated at bid price : 12.71
Bid-YTW : 7.66 %