Category: Market Action

Market Action

September 6, 2019

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 2.8928 % 1,889.8
FixedFloater 0.00 % 0.00 % 0 0.00 0 2.8928 % 3,467.7
Floater 6.32 % 6.46 % 51,326 13.13 4 2.8928 % 1,998.4
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0960 % 3,372.5
SplitShare 4.67 % 4.45 % 65,141 4.05 7 -0.0960 % 4,027.5
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0960 % 3,142.4
Perpetual-Premium 5.62 % -18.64 % 60,492 0.09 6 -0.0912 % 2,976.9
Perpetual-Discount 5.48 % 5.63 % 65,486 14.39 28 0.0765 % 3,120.5
FixedReset Disc 5.58 % 5.24 % 168,769 14.91 73 0.1197 % 2,051.1
Deemed-Retractible 5.29 % 6.08 % 78,093 7.91 27 0.1490 % 3,107.7
FloatingReset 4.58 % 6.82 % 62,277 8.00 3 0.9045 % 2,322.1
FixedReset Prem 5.26 % 4.02 % 137,906 1.63 14 -0.0196 % 2,574.9
FixedReset Bank Non 1.97 % 4.11 % 93,327 2.33 3 0.1805 % 2,669.1
FixedReset Ins Non 5.51 % 7.82 % 100,036 8.01 21 -0.0710 % 2,089.3
Performance Highlights
Issue Index Change Notes
HSE.PR.A FixedReset Disc -3.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-06
Maturity Price : 11.09
Evaluated at bid price : 11.09
Bid-YTW : 6.38 %
BAM.PR.T FixedReset Disc -2.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-06
Maturity Price : 14.42
Evaluated at bid price : 14.42
Bid-YTW : 6.11 %
BAM.PF.E FixedReset Disc -2.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-06
Maturity Price : 15.64
Evaluated at bid price : 15.64
Bid-YTW : 6.09 %
BAM.PF.G FixedReset Disc -2.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-06
Maturity Price : 17.02
Evaluated at bid price : 17.02
Bid-YTW : 6.01 %
BAM.PF.F FixedReset Disc -1.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-06
Maturity Price : 16.75
Evaluated at bid price : 16.75
Bid-YTW : 6.10 %
GWO.PR.S Deemed-Retractible -1.51 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.53
Bid-YTW : 6.01 %
BAM.PR.R FixedReset Disc -1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-06
Maturity Price : 14.54
Evaluated at bid price : 14.54
Bid-YTW : 5.95 %
MFC.PR.G FixedReset Ins Non -1.32 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.96
Bid-YTW : 8.07 %
MFC.PR.M FixedReset Ins Non -1.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.60
Bid-YTW : 9.22 %
TD.PF.D FixedReset Disc -1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-06
Maturity Price : 18.50
Evaluated at bid price : 18.50
Bid-YTW : 5.36 %
IAF.PR.B Deemed-Retractible -1.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.70
Bid-YTW : 6.35 %
TD.PF.H FixedReset Disc -1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-06
Maturity Price : 23.45
Evaluated at bid price : 24.75
Bid-YTW : 5.26 %
BMO.PR.Y FixedReset Disc -1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-06
Maturity Price : 18.50
Evaluated at bid price : 18.50
Bid-YTW : 5.24 %
GWO.PR.Q Deemed-Retractible 1.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.00
Bid-YTW : 6.20 %
NA.PR.E FixedReset Disc 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-06
Maturity Price : 18.96
Evaluated at bid price : 18.96
Bid-YTW : 5.20 %
SLF.PR.E Deemed-Retractible 1.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.84
Bid-YTW : 6.75 %
CM.PR.S FixedReset Disc 1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-06
Maturity Price : 18.55
Evaluated at bid price : 18.55
Bid-YTW : 5.16 %
NA.PR.C FixedReset Disc 1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-06
Maturity Price : 20.76
Evaluated at bid price : 20.76
Bid-YTW : 5.54 %
BNS.PR.I FixedReset Disc 1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-06
Maturity Price : 20.54
Evaluated at bid price : 20.54
Bid-YTW : 4.78 %
BIP.PR.D FixedReset Disc 1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-06
Maturity Price : 22.09
Evaluated at bid price : 22.40
Bid-YTW : 5.58 %
TRP.PR.A FixedReset Disc 1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-06
Maturity Price : 13.18
Evaluated at bid price : 13.18
Bid-YTW : 5.83 %
TRP.PR.C FixedReset Disc 1.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-06
Maturity Price : 11.56
Evaluated at bid price : 11.56
Bid-YTW : 5.80 %
BIP.PR.A FixedReset Disc 1.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-06
Maturity Price : 17.75
Evaluated at bid price : 17.75
Bid-YTW : 6.63 %
TRP.PR.B FixedReset Disc 1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-06
Maturity Price : 10.96
Evaluated at bid price : 10.96
Bid-YTW : 5.51 %
GWO.PR.R Deemed-Retractible 1.60 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.20
Bid-YTW : 6.28 %
TRP.PR.F FloatingReset 1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-06
Maturity Price : 13.00
Evaluated at bid price : 13.00
Bid-YTW : 6.82 %
MFC.PR.K FixedReset Ins Non 1.75 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.45
Bid-YTW : 8.26 %
BAM.PR.C Floater 1.97 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-06
Maturity Price : 10.89
Evaluated at bid price : 10.89
Bid-YTW : 6.47 %
HSE.PR.E FixedReset Disc 2.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-06
Maturity Price : 17.85
Evaluated at bid price : 17.85
Bid-YTW : 6.61 %
TRP.PR.G FixedReset Disc 2.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-06
Maturity Price : 17.85
Evaluated at bid price : 17.85
Bid-YTW : 5.76 %
BAM.PR.K Floater 2.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-06
Maturity Price : 10.75
Evaluated at bid price : 10.75
Bid-YTW : 6.56 %
BAM.PR.B Floater 2.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-06
Maturity Price : 10.91
Evaluated at bid price : 10.91
Bid-YTW : 6.46 %
PWF.PR.P FixedReset Disc 3.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-06
Maturity Price : 13.10
Evaluated at bid price : 13.10
Bid-YTW : 5.23 %
PWF.PR.A Floater 3.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-06
Maturity Price : 11.20
Evaluated at bid price : 11.20
Bid-YTW : 6.24 %
Volume Highlights
Issue Index Shares
Traded
Notes
HSE.PR.C FixedReset Disc 224,410 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-06
Maturity Price : 16.15
Evaluated at bid price : 16.15
Bid-YTW : 6.64 %
MFC.PR.N FixedReset Ins Non 134,100 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.67
Bid-YTW : 9.10 %
TD.PF.B FixedReset Disc 117,917 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-06
Maturity Price : 17.60
Evaluated at bid price : 17.60
Bid-YTW : 5.01 %
RY.PR.M FixedReset Disc 95,800 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-06
Maturity Price : 18.06
Evaluated at bid price : 18.06
Bid-YTW : 5.24 %
TD.PF.C FixedReset Disc 59,999 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-06
Maturity Price : 16.70
Evaluated at bid price : 16.70
Bid-YTW : 5.15 %
TD.PF.K FixedReset Disc 53,739 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-06
Maturity Price : 19.91
Evaluated at bid price : 19.91
Bid-YTW : 5.05 %
There were 30 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
NA.PR.C FixedReset Disc Quote: 20.76 – 21.47
Spot Rate : 0.7100
Average : 0.4621

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-06
Maturity Price : 20.76
Evaluated at bid price : 20.76
Bid-YTW : 5.54 %

TD.PF.K FixedReset Disc Quote: 19.91 – 20.40
Spot Rate : 0.4900
Average : 0.3071

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-06
Maturity Price : 19.91
Evaluated at bid price : 19.91
Bid-YTW : 5.05 %

EMA.PR.F FixedReset Disc Quote: 16.15 – 17.00
Spot Rate : 0.8500
Average : 0.6923

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-06
Maturity Price : 16.15
Evaluated at bid price : 16.15
Bid-YTW : 5.91 %

BMO.PR.C FixedReset Disc Quote: 21.59 – 22.11
Spot Rate : 0.5200
Average : 0.3643

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-06
Maturity Price : 21.30
Evaluated at bid price : 21.59
Bid-YTW : 5.21 %

HSE.PR.A FixedReset Disc Quote: 11.09 – 11.70
Spot Rate : 0.6100
Average : 0.4564

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-06
Maturity Price : 11.09
Evaluated at bid price : 11.09
Bid-YTW : 6.38 %

MFC.PR.F FixedReset Ins Non Quote: 12.44 – 12.82
Spot Rate : 0.3800
Average : 0.2332

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.44
Bid-YTW : 10.56 %

Market Action

September 4, 2019

rainbow_190904
Click for Big

DBRS had some interesting Brexit commentary:

DBRS considers that diverging views on Brexit among citizens in the UK could inadvertently lead to the breakup of the Union. DBRS reviews the implications of no-deal scenarios and their potential impact on the unity of the United Kingdom. At one extreme is a “severe” hard Brexit whereby the UK crashes out of the EU permanently with no airbags or restraints on its impact. DBRS concludes that such a Brexit could quickly change the support for Scottish independence and even over time the support for the unification of Ireland, increasing the breakup risk of the UK. These considerations are exacerbated by a weakening economic environment that intensifies divisions within the UK.
…
Scottish independence is the most likely cause of a breakup of the UK. The Scottish government has proposed a second referendum on independence. The first referendum in September 2014 was rejected by 55.0% of voters. Reportedly, that outcome was influenced by concerns that Scotland would lose its EU membership. Should the UK leave the EU without an agreement, that consideration would no longer stand in the way. Given that almost two thirds of Scottish voters voted to remain in the Brexit referendum, the issue of Scotland remaining a member of the EU has continued to be an important component in the debate over Scottish independence. In the event that the UK leaves the EU, DBRS expects that calls for Scottish independence would become even louder, especially in a no-deal scenario.

In political developments:

Boris Johnson has faced a double defeat in the Commons after MPs turned down his motion for a general election.

Earlier, MPs backed a bill aimed at blocking a no-deal Brexit if the PM hadn’t agreed a plan with the EU ahead of the 31 October deadline.

Mr Johnson said the bill “scuppered” negotiations and the only way forward now was an election.

But Labour leader Jeremy Corbyn accused the PM of “playing a disingenuous game” to force a no-deal Brexit.

He said his party would back an election after the bill had been passed, but not before.

Both the SNP and the Liberal Democrats also criticised the prime minister’s motion as a plot to make sure the UK left the EU without a deal.

Meanwhile the the BoC stood pat:

The Bank of Canada today maintained its target for the overnight rate at 1 ¾ percent. The Bank Rate is correspondingly 2 percent and the deposit rate is 1 ½ percent.

As the US-China trade conflict has escalated, world trade has contracted and business investment has weakened. This is weighing more heavily on global economic momentum than the Bank had projected in its July Monetary Policy Report (MPR). Meanwhile, growth in the United States has moderated but remains solid, supported by consumer and government spending. Commodity prices have drifted down as concerns about global growth prospects have increased. These concerns, combined with policy responses by some central banks, have pushed bond yields to historic lows and inverted yield curves in a number of economies, including Canada.

In Canada, growth in the second quarter was strong and exceeded the Bank’s July expectation, although some of this strength is expected to be temporary. The rebound was driven by stronger energy production and robust export growth, both recovering from very weak performance in the first quarter. Housing activity has regained strength more quickly than expected as resales and housing starts catch up to underlying demand, supported by lower mortgage rates. This could add to already-high household debt levels, although mortgage underwriting rules should help to contain the buildup of vulnerabilities. Wages have picked up further, boosting labour income, yet consumption spending was unexpectedly soft in the quarter. Business investment contracted sharply after a strong first quarter, amid heightened trade uncertainty. Given this composition of growth, the Bank expects economic activity to slow in the second half of the year.

Inflation is at the 2 percent target. CPI inflation in July was stronger than expected, largely because of temporary factors. These include higher prices for air travel, mobile phones, and some food items, which are offsetting the effects of lower gasoline prices. Measures of core inflation all remain around 2 percent.

In sum, Canada’s economy is operating close to potential and inflation is on target. However, escalating trade conflicts and related uncertainty are taking a toll on the global and Canadian economies. In this context, the current degree of monetary policy stimulus remains appropriate. As the Bank works to update its projection in light of incoming data, Governing Council will pay particular attention to global developments and their impact on the outlook for Canadian growth and inflation.

Sean Kilpatrick comments in the Globe:

Heading into the rate announcement, the bank was expected to keep rates unchanged this month. However, some economists were predicting a rate cut as soon as the bank’s next decision, in late October. The Canadian dollar climbed after the statement’s release, as the bank’s tone dampened market expectations that a rate cut is on the horizon.

… and, by the time the close rolled around:

Separately, data showed Canada posted a bigger-than-expected trade deficit in July, a sign that the boost to the domestic economy from trade in the second quarter may not be repeated.
…
The Canadian dollar posted its biggest gain in seven months against the greenback on Wednesday on lowered expectations for a Bank of Canada interest rate cut in October after the central bank’s policy decision made no mention of future moves.

TXPR closed at 586.52, up 0.77% on the day. Volume was 2.36-million, about average in the context of the past thirty days.

CPD closed at 11.74, up 0.95% on the day. Volume of 155,166 was quite high but not extraordinary in the context of the past 30 days.

ZPR closed at 9.39, up 1.29% on the day. Volume of 232,279 was a little above average in the context of the past 30 days.

Five-year Canada yields were up 2bp to 1.15% today.

PerpetualDiscounts now yield 5.64%, equivalent to 7.33% interest at the standard equivalency factor of 1.3x. Long corporates now yield 3.18%, so the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) has narrowed slightly (and perhaps spuriously) to 415bp, close to the post-Credit Crunch record of 420bp set August 28. The latter value is second only to the 445bp recorded November 26, 2008, a day on which

The TXPR index was down 5.94% on the BCE news.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.0000 % 1,802.5
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.0000 % 3,307.6
Floater 6.63 % 6.72 % 67,519 12.79 4 0.0000 % 1,906.2
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0507 % 3,381.1
SplitShare 4.66 % 4.43 % 60,602 4.06 7 -0.0507 % 4,037.7
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0507 % 3,150.4
Perpetual-Premium 5.61 % -18.56 % 62,090 0.09 6 0.2283 % 2,982.5
Perpetual-Discount 5.50 % 5.64 % 67,087 14.40 28 0.3490 % 3,108.4
FixedReset Disc 5.66 % 5.33 % 179,307 14.80 73 1.4043 % 2,018.5
Deemed-Retractible 5.32 % 6.10 % 68,840 7.91 27 0.2757 % 3,092.9
FloatingReset 4.66 % 7.14 % 65,489 7.99 3 -0.0810 % 2,281.4
FixedReset Prem 5.27 % 4.21 % 138,125 1.63 14 0.3848 % 2,571.9
FixedReset Bank Non 1.98 % 4.28 % 95,153 2.33 3 -0.3338 % 2,649.9
FixedReset Ins Non 5.56 % 8.01 % 101,669 8.02 21 1.1704 % 2,072.5
Performance Highlights
Issue Index Change Notes
BNS.PR.I FixedReset Disc 1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 19.81
Evaluated at bid price : 19.81
Bid-YTW : 4.97 %
BAM.PR.M Perpetual-Discount 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 20.35
Evaluated at bid price : 20.35
Bid-YTW : 5.95 %
TD.PF.A FixedReset Disc 1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 16.50
Evaluated at bid price : 16.50
Bid-YTW : 5.19 %
TD.PF.D FixedReset Disc 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 18.24
Evaluated at bid price : 18.24
Bid-YTW : 5.43 %
RY.PR.Z FixedReset Disc 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 17.13
Evaluated at bid price : 17.13
Bid-YTW : 5.06 %
MFC.PR.C Deemed-Retractible 1.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.42
Bid-YTW : 7.02 %
GWO.PR.S Deemed-Retractible 1.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.55
Bid-YTW : 6.00 %
BIP.PR.A FixedReset Disc 1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 17.20
Evaluated at bid price : 17.20
Bid-YTW : 6.84 %
TD.PF.K FixedReset Disc 1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 19.51
Evaluated at bid price : 19.51
Bid-YTW : 5.15 %
TD.PF.C FixedReset Disc 1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 16.25
Evaluated at bid price : 16.25
Bid-YTW : 5.29 %
BNS.PR.G FixedReset Prem 1.25 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-07-25
Maturity Price : 25.00
Evaluated at bid price : 25.89
Bid-YTW : 3.87 %
CM.PR.T FixedReset Disc 1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 22.56
Evaluated at bid price : 23.50
Bid-YTW : 4.95 %
MFC.PR.R FixedReset Ins Non 1.30 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.45
Bid-YTW : 5.75 %
IFC.PR.G FixedReset Ins Non 1.30 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.70
Bid-YTW : 8.01 %
NA.PR.S FixedReset Disc 1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 16.95
Evaluated at bid price : 16.95
Bid-YTW : 5.47 %
NA.PR.C FixedReset Disc 1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 20.37
Evaluated at bid price : 20.37
Bid-YTW : 5.64 %
CM.PR.P FixedReset Disc 1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 15.70
Evaluated at bid price : 15.70
Bid-YTW : 5.47 %
GWO.PR.P Deemed-Retractible 1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.90
Bid-YTW : 5.96 %
MFC.PR.I FixedReset Ins Non 1.37 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.54
Bid-YTW : 7.81 %
BAM.PF.B FixedReset Disc 1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 16.98
Evaluated at bid price : 16.98
Bid-YTW : 5.96 %
TRP.PR.A FixedReset Disc 1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 12.55
Evaluated at bid price : 12.55
Bid-YTW : 6.12 %
TD.PF.B FixedReset Disc 1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 17.18
Evaluated at bid price : 17.18
Bid-YTW : 5.13 %
CM.PR.R FixedReset Disc 1.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 20.61
Evaluated at bid price : 20.61
Bid-YTW : 5.53 %
BMO.PR.W FixedReset Disc 1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 16.28
Evaluated at bid price : 16.28
Bid-YTW : 5.20 %
BAM.PF.A FixedReset Disc 1.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 18.48
Evaluated at bid price : 18.48
Bid-YTW : 5.93 %
RY.PR.M FixedReset Disc 1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 17.66
Evaluated at bid price : 17.66
Bid-YTW : 5.35 %
MFC.PR.H FixedReset Ins Non 1.61 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.24
Bid-YTW : 6.89 %
IAF.PR.I FixedReset Ins Non 1.63 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.70
Bid-YTW : 7.88 %
IFC.PR.C FixedReset Ins Non 1.64 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.36
Bid-YTW : 8.24 %
CM.PR.S FixedReset Disc 1.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 17.80
Evaluated at bid price : 17.80
Bid-YTW : 5.39 %
BMO.PR.F FixedReset Disc 1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 22.70
Evaluated at bid price : 23.80
Bid-YTW : 4.98 %
RY.PR.J FixedReset Disc 1.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 18.30
Evaluated at bid price : 18.30
Bid-YTW : 5.33 %
BAM.PR.T FixedReset Disc 1.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 14.12
Evaluated at bid price : 14.12
Bid-YTW : 6.24 %
PWF.PR.T FixedReset Disc 1.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 17.45
Evaluated at bid price : 17.45
Bid-YTW : 5.35 %
HSE.PR.E FixedReset Disc 1.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 17.30
Evaluated at bid price : 17.30
Bid-YTW : 6.81 %
BMO.PR.Y FixedReset Disc 1.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 18.40
Evaluated at bid price : 18.40
Bid-YTW : 5.27 %
MFC.PR.M FixedReset Ins Non 1.82 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.69
Bid-YTW : 9.14 %
GWO.PR.N FixedReset Ins Non 1.84 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.85
Bid-YTW : 9.12 %
HSE.PR.C FixedReset Disc 1.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 16.01
Evaluated at bid price : 16.01
Bid-YTW : 6.69 %
NA.PR.G FixedReset Disc 1.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 19.34
Evaluated at bid price : 19.34
Bid-YTW : 5.44 %
MFC.PR.Q FixedReset Ins Non 1.95 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.27
Bid-YTW : 8.01 %
CM.PR.O FixedReset Disc 1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 16.62
Evaluated at bid price : 16.62
Bid-YTW : 5.39 %
IAF.PR.G FixedReset Ins Non 1.98 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.50
Bid-YTW : 7.57 %
MFC.PR.G FixedReset Ins Non 1.99 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.91
Bid-YTW : 8.10 %
NA.PR.W FixedReset Disc 2.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 15.38
Evaluated at bid price : 15.38
Bid-YTW : 5.58 %
BAM.PF.E FixedReset Disc 2.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 15.50
Evaluated at bid price : 15.50
Bid-YTW : 6.14 %
TD.PF.J FixedReset Disc 2.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 20.37
Evaluated at bid price : 20.37
Bid-YTW : 4.99 %
BAM.PR.Z FixedReset Disc 2.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 17.67
Evaluated at bid price : 17.67
Bid-YTW : 6.11 %
BIP.PR.F FixedReset Disc 2.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 21.35
Evaluated at bid price : 21.65
Bid-YTW : 5.89 %
PWF.PR.P FixedReset Disc 2.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 12.50
Evaluated at bid price : 12.50
Bid-YTW : 5.48 %
MFC.PR.N FixedReset Ins Non 2.44 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.51
Bid-YTW : 9.23 %
SLF.PR.H FixedReset Ins Non 2.54 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.75
Bid-YTW : 8.67 %
BAM.PF.F FixedReset Disc 2.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 16.77
Evaluated at bid price : 16.77
Bid-YTW : 6.09 %
BMO.PR.D FixedReset Disc 2.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 20.85
Evaluated at bid price : 20.85
Bid-YTW : 5.23 %
RY.PR.S FixedReset Disc 2.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 19.62
Evaluated at bid price : 19.62
Bid-YTW : 4.92 %
BAM.PR.X FixedReset Disc 2.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 12.47
Evaluated at bid price : 12.47
Bid-YTW : 5.93 %
EMA.PR.C FixedReset Disc 2.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 17.65
Evaluated at bid price : 17.65
Bid-YTW : 5.74 %
BAM.PR.R FixedReset Disc 3.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 14.43
Evaluated at bid price : 14.43
Bid-YTW : 5.99 %
CU.PR.G Perpetual-Discount 3.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 21.25
Evaluated at bid price : 21.25
Bid-YTW : 5.33 %
CM.PR.Q FixedReset Disc 3.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 17.78
Evaluated at bid price : 17.78
Bid-YTW : 5.57 %
TD.PF.I FixedReset Disc 3.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 21.06
Evaluated at bid price : 21.06
Bid-YTW : 5.06 %
BMO.PR.T FixedReset Disc 3.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 16.82
Evaluated at bid price : 16.82
Bid-YTW : 5.06 %
BAM.PF.G FixedReset Disc 4.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 16.96
Evaluated at bid price : 16.96
Bid-YTW : 6.03 %
HSE.PR.G FixedReset Disc 4.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 17.35
Evaluated at bid price : 17.35
Bid-YTW : 6.73 %
Volume Highlights
Issue Index Shares
Traded
Notes
PWF.PR.P FixedReset Disc 119,008 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 12.50
Evaluated at bid price : 12.50
Bid-YTW : 5.48 %
TD.PF.E FixedReset Disc 103,300 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 18.50
Evaluated at bid price : 18.50
Bid-YTW : 5.46 %
MFC.PR.M FixedReset Ins Non 102,755 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.69
Bid-YTW : 9.14 %
PWF.PR.T FixedReset Disc 81,741 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 17.45
Evaluated at bid price : 17.45
Bid-YTW : 5.35 %
CM.PR.Y FixedReset Disc 74,397 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 22.95
Evaluated at bid price : 24.40
Bid-YTW : 5.02 %
TD.PF.B FixedReset Disc 57,789 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 17.18
Evaluated at bid price : 17.18
Bid-YTW : 5.13 %
There were 34 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BAM.PR.T FixedReset Disc Quote: 14.12 – 14.75
Spot Rate : 0.6300
Average : 0.4685

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 14.12
Evaluated at bid price : 14.12
Bid-YTW : 6.24 %

IFC.PR.C FixedReset Ins Non Quote: 17.36 – 17.92
Spot Rate : 0.5600
Average : 0.4241

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.36
Bid-YTW : 8.24 %

GWO.PR.F Deemed-Retractible Quote: 25.43 – 25.80
Spot Rate : 0.3700
Average : 0.2383

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2019-10-04
Maturity Price : 25.00
Evaluated at bid price : 25.43
Bid-YTW : -19.01 %

NA.PR.G FixedReset Disc Quote: 19.34 – 19.70
Spot Rate : 0.3600
Average : 0.2327

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 19.34
Evaluated at bid price : 19.34
Bid-YTW : 5.44 %

SLF.PR.J FloatingReset Quote: 12.51 – 12.89
Spot Rate : 0.3800
Average : 0.2765

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.51
Bid-YTW : 11.31 %

RY.PR.H FixedReset Disc Quote: 17.01 – 17.33
Spot Rate : 0.3200
Average : 0.2231

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-04
Maturity Price : 17.01
Evaluated at bid price : 17.01
Bid-YTW : 5.04 %

Market Action

September 3, 2019

BoJo’s Brexit plans suffered a setback:

British lawmakers on Tuesday rose up against Prime Minister Boris Johnson, moving to prevent him from taking the country out of the European Union without a formal agreement, in an epic showdown that has the country on the verge of a snap general election.
…
The lawmakers forced his hand by voting by 328 to 301 to take control of Parliament away from the government, giving themselves the authority to pass legislation that would stop the prime minister from his threat of a no-deal Brexit.
…
The extent of the Tory civil war was on full display as several Mr. Johnson’s Conservative critics, including the former chancellor of the Exchequer, Philip Hammond, lobbed hostile questions at him, making it plain that they had not been brought back into line by threats of expulsion from the party.
…
There is so little trust in British politics that Mr. Johnson’s opponents fear that he might request an election for Oct. 14 but then switch the date until after Oct. 31 as part of a move to lock in a no-deal withdrawal.

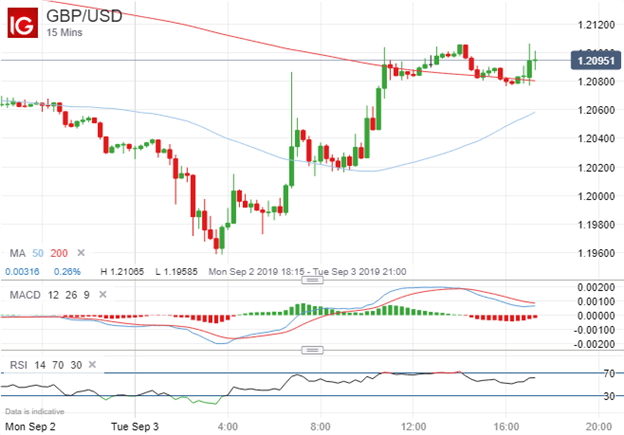
Which was good news for the GBP, anyway!

The British Pound extended its intraday rebound following the latest Brexit vote results. The Pound Sterling may continue to climb as it mirrors the fall in no-deal Brexit risks.

gbp_usd_190903
Click for Big

Meanwhile, in the Canadian preferred market … well, it’s not rallying any more.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.0240 % 1,802.5
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.0240 % 3,307.6
Floater 6.63 % 6.75 % 50,831 12.75 4 -0.0240 % 1,906.2
OpRet 0.00 % 0.00 % 0 0.00 0 0.1694 % 3,382.8
SplitShare 4.66 % 4.42 % 61,112 4.06 7 0.1694 % 4,039.8
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1694 % 3,152.0
Perpetual-Premium 5.63 % -18.07 % 63,071 0.09 6 0.1437 % 2,975.7
Perpetual-Discount 5.52 % 5.66 % 64,971 14.36 28 -0.0566 % 3,097.6
FixedReset Disc 5.74 % 5.42 % 176,225 14.70 73 -0.6777 % 1,990.5
Deemed-Retractible 5.33 % 6.18 % 66,367 7.90 27 -0.1256 % 3,084.4
FloatingReset 4.65 % 7.17 % 65,568 8.00 3 0.0405 % 2,283.2
FixedReset Prem 5.29 % 4.43 % 140,223 1.64 14 -0.1318 % 2,562.1
FixedReset Bank Non 1.98 % 4.16 % 88,103 2.34 3 0.0557 % 2,658.8
FixedReset Ins Non 5.62 % 8.18 % 100,953 7.99 21 -0.8912 % 2,048.5
Performance Highlights
Issue Index Change Notes
HSE.PR.C FixedReset Disc -3.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 15.71
Evaluated at bid price : 15.71
Bid-YTW : 6.82 %
HSE.PR.G FixedReset Disc -3.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 16.61
Evaluated at bid price : 16.61
Bid-YTW : 7.03 %
SLF.PR.G FixedReset Ins Non -2.68 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.70
Bid-YTW : 10.37 %
HSE.PR.E FixedReset Disc -2.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 6.93 %
CU.PR.G Perpetual-Discount -2.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 20.62
Evaluated at bid price : 20.62
Bid-YTW : 5.50 %
TD.PF.D FixedReset Disc -2.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 18.04
Evaluated at bid price : 18.04
Bid-YTW : 5.49 %
BAM.PR.X FixedReset Disc -2.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 12.12
Evaluated at bid price : 12.12
Bid-YTW : 6.11 %
IFC.PR.C FixedReset Ins Non -2.40 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.08
Bid-YTW : 8.44 %
SLF.PR.H FixedReset Ins Non -2.35 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.36
Bid-YTW : 8.97 %
BMO.PR.T FixedReset Disc -2.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 16.26
Evaluated at bid price : 16.26
Bid-YTW : 5.24 %
CU.PR.C FixedReset Disc -2.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 16.65
Evaluated at bid price : 16.65
Bid-YTW : 5.32 %
CM.PR.S FixedReset Disc -2.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 17.51
Evaluated at bid price : 17.51
Bid-YTW : 5.48 %
EMA.PR.C FixedReset Disc -2.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 17.15
Evaluated at bid price : 17.15
Bid-YTW : 5.91 %
MFC.PR.Q FixedReset Ins Non -2.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.92
Bid-YTW : 8.26 %
BAM.PR.T FixedReset Disc -2.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 13.88
Evaluated at bid price : 13.88
Bid-YTW : 6.35 %
BMO.PR.D FixedReset Disc -1.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 20.28
Evaluated at bid price : 20.28
Bid-YTW : 5.38 %
SLF.PR.I FixedReset Ins Non -1.93 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.76
Bid-YTW : 8.00 %
IAF.PR.I FixedReset Ins Non -1.87 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.40
Bid-YTW : 8.09 %
NA.PR.G FixedReset Disc -1.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 18.97
Evaluated at bid price : 18.97
Bid-YTW : 5.54 %
GWO.PR.N FixedReset Ins Non -1.81 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.60
Bid-YTW : 9.33 %
TRP.PR.G FixedReset Disc -1.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 16.70
Evaluated at bid price : 16.70
Bid-YTW : 6.16 %
MFC.PR.C Deemed-Retractible -1.75 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.19
Bid-YTW : 7.17 %
GWO.PR.P Deemed-Retractible -1.54 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.58
Bid-YTW : 6.14 %
RY.PR.M FixedReset Disc -1.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 17.39
Evaluated at bid price : 17.39
Bid-YTW : 5.44 %
GWO.PR.T Deemed-Retractible -1.47 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.83
Bid-YTW : 6.29 %
TD.PF.E FixedReset Disc -1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 18.38
Evaluated at bid price : 18.38
Bid-YTW : 5.50 %
NA.PR.S FixedReset Disc -1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 16.73
Evaluated at bid price : 16.73
Bid-YTW : 5.54 %
BAM.PR.Z FixedReset Disc -1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 17.27
Evaluated at bid price : 17.27
Bid-YTW : 6.26 %
MFC.PR.K FixedReset Ins Non -1.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.08
Bid-YTW : 8.52 %
MFC.PR.G FixedReset Ins Non -1.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.56
Bid-YTW : 8.35 %
PWF.PR.A Floater -1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 10.42
Evaluated at bid price : 10.42
Bid-YTW : 6.71 %
RY.PR.Z FixedReset Disc -1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 16.94
Evaluated at bid price : 16.94
Bid-YTW : 5.12 %
BAM.PF.G FixedReset Disc -1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 16.26
Evaluated at bid price : 16.26
Bid-YTW : 6.29 %
CM.PR.Q FixedReset Disc -1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 17.25
Evaluated at bid price : 17.25
Bid-YTW : 5.74 %
MFC.PR.R FixedReset Ins Non -1.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.15
Bid-YTW : 5.91 %
BIP.PR.A FixedReset Disc -1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 6.92 %
NA.PR.C FixedReset Disc -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 20.10
Evaluated at bid price : 20.10
Bid-YTW : 5.72 %
HSE.PR.A FixedReset Disc -1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 11.09
Evaluated at bid price : 11.09
Bid-YTW : 6.37 %
BAM.PR.R FixedReset Disc -1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 14.01
Evaluated at bid price : 14.01
Bid-YTW : 6.17 %
BMO.PR.Z Perpetual-Discount -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 23.93
Evaluated at bid price : 24.40
Bid-YTW : 5.14 %
RY.PR.S FixedReset Disc -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 19.07
Evaluated at bid price : 19.07
Bid-YTW : 5.07 %
BAM.PF.A FixedReset Disc -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 18.20
Evaluated at bid price : 18.20
Bid-YTW : 6.03 %
IFC.PR.G FixedReset Ins Non -1.02 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.46
Bid-YTW : 8.18 %
CM.PR.Y FixedReset Disc 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 22.93
Evaluated at bid price : 24.35
Bid-YTW : 5.03 %
BMO.PR.S FixedReset Disc 1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 5.14 %
MFC.PR.I FixedReset Ins Non 1.33 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.29
Bid-YTW : 7.98 %
BAM.PR.C Floater 1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 10.45
Evaluated at bid price : 10.45
Bid-YTW : 6.75 %
CCS.PR.C Deemed-Retractible 1.59 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.35
Bid-YTW : 5.32 %
BAM.PF.B FixedReset Disc 2.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 16.75
Evaluated at bid price : 16.75
Bid-YTW : 6.04 %
Volume Highlights
Issue Index Shares
Traded
Notes
TRP.PR.D FixedReset Disc 104,740 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 15.90
Evaluated at bid price : 15.90
Bid-YTW : 5.78 %
BAM.PF.B FixedReset Disc 64,400 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 16.75
Evaluated at bid price : 16.75
Bid-YTW : 6.04 %
TD.PF.H FixedReset Disc 52,310 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 23.37
Evaluated at bid price : 24.54
Bid-YTW : 5.31 %
TRP.PR.E FixedReset Disc 49,445 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 14.80
Evaluated at bid price : 14.80
Bid-YTW : 5.98 %
MFC.PR.C Deemed-Retractible 46,700 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.19
Bid-YTW : 7.17 %
SLF.PR.I FixedReset Ins Non 44,400 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.76
Bid-YTW : 8.00 %
There were 26 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BAM.PR.Z FixedReset Disc Quote: 17.27 – 17.99
Spot Rate : 0.7200
Average : 0.4408

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 17.27
Evaluated at bid price : 17.27
Bid-YTW : 6.26 %

CU.PR.G Perpetual-Discount Quote: 20.62 – 21.18
Spot Rate : 0.5600
Average : 0.3631

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 20.62
Evaluated at bid price : 20.62
Bid-YTW : 5.50 %

HSE.PR.E FixedReset Disc Quote: 17.00 – 17.65
Spot Rate : 0.6500
Average : 0.4667

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 6.93 %

GWO.PR.P Deemed-Retractible Quote: 23.58 – 24.07
Spot Rate : 0.4900
Average : 0.3274

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.58
Bid-YTW : 6.14 %

BNS.PR.G FixedReset Prem Quote: 25.57 – 26.03
Spot Rate : 0.4600
Average : 0.3004

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-07-25
Maturity Price : 25.00
Evaluated at bid price : 25.57
Bid-YTW : 4.57 %

BMO.PR.T FixedReset Disc Quote: 16.26 – 16.71
Spot Rate : 0.4500
Average : 0.3136

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-09-03
Maturity Price : 16.26
Evaluated at bid price : 16.26
Bid-YTW : 5.24 %

Market Action

August 30, 2019

unicorn_190830
Click for Big

TXPR closed at 584.11, up 1.25% on the day. Volume was 4.04-million, second-highest of the past 30 days, surpassed only by yesterday.

CPD closed at 11.65, up 1.13% on the day. Volume of 120,051 was above average but nothing special in the context of the past 30 days.

ZPR closed at 9.29, up 1.53% on the day. Volume of 320,323 was well above average but not extraordinary in the context of the past 30 days.

Five-year Canada yields were unchanged at 1.19% today.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 2.0538 % 1,803.0
FixedFloater 0.00 % 0.00 % 0 0.00 0 2.0538 % 3,308.4
Floater 6.62 % 6.71 % 69,249 12.81 4 2.0538 % 1,906.6
OpRet 0.00 % 0.00 % 0 0.00 0 0.1697 % 3,377.1
SplitShare 4.67 % 4.53 % 61,733 4.07 7 0.1697 % 4,032.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1697 % 3,146.6
Perpetual-Premium 5.64 % 4.21 % 64,037 0.09 9 0.0132 % 2,971.5
Perpetual-Discount 5.50 % 5.62 % 63,858 14.46 25 0.4589 % 3,099.3
FixedReset Disc 5.80 % 5.54 % 162,310 14.48 66 1.8803 % 2,004.1
Deemed-Retractible 5.33 % 6.14 % 75,671 7.91 27 0.4659 % 3,088.3
FloatingReset 4.67 % 7.13 % 68,260 8.01 3 0.3001 % 2,282.3
FixedReset Prem 5.20 % 4.86 % 179,245 1.85 21 0.2408 % 2,565.5
FixedReset Bank Non 1.98 % 4.11 % 89,488 2.34 3 -0.2083 % 2,657.3
FixedReset Ins Non 5.57 % 8.10 % 102,596 7.98 21 1.5535 % 2,066.9
Performance Highlights
Issue Index Change Notes
HSE.PR.G FixedReset Disc 1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 17.17
Evaluated at bid price : 17.17
Bid-YTW : 7.07 %
TD.PF.I FixedReset Disc 1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 20.54
Evaluated at bid price : 20.54
Bid-YTW : 5.29 %
SLF.PR.C Deemed-Retractible 1.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.25
Bid-YTW : 7.04 %
BMO.PR.Z Perpetual-Discount 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 24.18
Evaluated at bid price : 24.66
Bid-YTW : 5.08 %
TD.PF.M FixedReset Prem 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 22.87
Evaluated at bid price : 24.20
Bid-YTW : 5.08 %
TRP.PR.B FixedReset Disc 1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 10.38
Evaluated at bid price : 10.38
Bid-YTW : 6.05 %
BIP.PR.A FixedReset Disc 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 17.19
Evaluated at bid price : 17.19
Bid-YTW : 6.98 %
RY.PR.J FixedReset Disc 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 5.55 %
CM.PR.Y FixedReset Disc 1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 22.83
Evaluated at bid price : 24.10
Bid-YTW : 5.17 %
CU.PR.F Perpetual-Discount 1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 21.20
Evaluated at bid price : 21.20
Bid-YTW : 5.34 %
MFC.PR.B Deemed-Retractible 1.25 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.03
Bid-YTW : 6.81 %
TRP.PR.A FixedReset Disc 1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 12.46
Evaluated at bid price : 12.46
Bid-YTW : 6.36 %
BAM.PR.Z FixedReset Disc 1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 6.28 %
BMO.PR.C FixedReset Disc 1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 21.19
Evaluated at bid price : 21.19
Bid-YTW : 5.42 %
TRP.PR.K FixedReset Prem 1.42 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-05-31
Maturity Price : 25.00
Evaluated at bid price : 24.96
Bid-YTW : 4.99 %
PWF.PR.L Perpetual-Discount 1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 22.33
Evaluated at bid price : 22.60
Bid-YTW : 5.70 %
BAM.PR.C Floater 1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 10.29
Evaluated at bid price : 10.29
Bid-YTW : 6.85 %
MFC.PR.C Deemed-Retractible 1.53 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.55
Bid-YTW : 6.93 %
MFC.PR.Q FixedReset Ins Non 1.55 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.30
Bid-YTW : 8.05 %
TD.PF.K FixedReset Disc 1.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 19.40
Evaluated at bid price : 19.40
Bid-YTW : 5.28 %
CM.PR.Q FixedReset Disc 1.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 17.45
Evaluated at bid price : 17.45
Bid-YTW : 5.81 %
NA.PR.C FixedReset Disc 1.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 20.32
Evaluated at bid price : 20.32
Bid-YTW : 5.75 %
NA.PR.E FixedReset Disc 1.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 18.40
Evaluated at bid price : 18.40
Bid-YTW : 5.47 %
IFC.PR.G FixedReset Ins Non 1.63 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.65
Bid-YTW : 8.10 %
TRP.PR.C FixedReset Disc 1.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 11.09
Evaluated at bid price : 11.09
Bid-YTW : 6.25 %
BMO.PR.E FixedReset Disc 1.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 19.81
Evaluated at bid price : 19.81
Bid-YTW : 5.26 %
BNS.PR.I FixedReset Disc 1.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 19.45
Evaluated at bid price : 19.45
Bid-YTW : 5.16 %
IFC.PR.A FixedReset Ins Non 1.78 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.26
Bid-YTW : 10.01 %
CM.PR.O FixedReset Disc 1.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 16.32
Evaluated at bid price : 16.32
Bid-YTW : 5.59 %
TRP.PR.F FloatingReset 1.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 12.45
Evaluated at bid price : 12.45
Bid-YTW : 7.13 %
BAM.PR.B Floater 1.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 10.50
Evaluated at bid price : 10.50
Bid-YTW : 6.71 %
BIP.PR.E FixedReset Disc 1.97 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 21.21
Evaluated at bid price : 21.21
Bid-YTW : 5.90 %
EMA.PR.F FixedReset Disc 2.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 15.83
Evaluated at bid price : 15.83
Bid-YTW : 6.18 %
GWO.PR.T Deemed-Retractible 2.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.17
Bid-YTW : 6.09 %
MFC.PR.M FixedReset Ins Non 2.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.47
Bid-YTW : 9.44 %
TD.PF.C FixedReset Disc 2.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 16.20
Evaluated at bid price : 16.20
Bid-YTW : 5.46 %
TRP.PR.E FixedReset Disc 2.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 14.76
Evaluated at bid price : 14.76
Bid-YTW : 6.16 %
RY.PR.H FixedReset Disc 2.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 17.01
Evaluated at bid price : 17.01
Bid-YTW : 5.18 %
BAM.PF.F FixedReset Disc 2.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 16.50
Evaluated at bid price : 16.50
Bid-YTW : 6.34 %
MFC.PR.J FixedReset Ins Non 2.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.85
Bid-YTW : 7.69 %
TD.PF.A FixedReset Disc 2.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 16.35
Evaluated at bid price : 16.35
Bid-YTW : 5.39 %
TD.PF.E FixedReset Disc 2.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 18.65
Evaluated at bid price : 18.65
Bid-YTW : 5.54 %
BMO.PR.S FixedReset Disc 2.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 17.31
Evaluated at bid price : 17.31
Bid-YTW : 5.30 %
NA.PR.W FixedReset Disc 2.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 15.09
Evaluated at bid price : 15.09
Bid-YTW : 5.85 %
NA.PR.G FixedReset Disc 2.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 19.33
Evaluated at bid price : 19.33
Bid-YTW : 5.54 %
MFC.PR.G FixedReset Ins Non 2.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.78
Bid-YTW : 8.27 %
SLF.PR.I FixedReset Ins Non 2.61 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.11
Bid-YTW : 7.83 %
IAF.PR.I FixedReset Ins Non 2.63 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.75
Bid-YTW : 7.90 %
PWF.PR.T FixedReset Disc 2.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 17.30
Evaluated at bid price : 17.30
Bid-YTW : 5.51 %
RY.PR.M FixedReset Disc 2.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 17.66
Evaluated at bid price : 17.66
Bid-YTW : 5.48 %
MFC.PR.F FixedReset Ins Non 2.70 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.17
Bid-YTW : 10.92 %
CM.PR.R FixedReset Disc 2.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 20.50
Evaluated at bid price : 20.50
Bid-YTW : 5.65 %
TRP.PR.G FixedReset Disc 2.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 6.18 %
BAM.PF.E FixedReset Disc 2.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 15.10
Evaluated at bid price : 15.10
Bid-YTW : 6.46 %
SLF.PR.H FixedReset Ins Non 2.81 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.73
Bid-YTW : 8.77 %
RY.PR.Z FixedReset Disc 2.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 17.14
Evaluated at bid price : 17.14
Bid-YTW : 5.17 %
PWF.PR.P FixedReset Disc 2.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 12.19
Evaluated at bid price : 12.19
Bid-YTW : 5.80 %
MFC.PR.K FixedReset Ins Non 2.91 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.30
Bid-YTW : 8.41 %
IFC.PR.C FixedReset Ins Non 2.94 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.50
Bid-YTW : 8.22 %
BAM.PR.T FixedReset Disc 2.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 14.17
Evaluated at bid price : 14.17
Bid-YTW : 6.36 %
EMA.PR.C FixedReset Disc 3.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 17.52
Evaluated at bid price : 17.52
Bid-YTW : 5.89 %
TD.PF.B FixedReset Disc 3.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 5.29 %
TD.PF.D FixedReset Disc 3.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 18.50
Evaluated at bid price : 18.50
Bid-YTW : 5.48 %
TD.PF.J FixedReset Disc 3.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 5.18 %
BAM.PF.A FixedReset Disc 3.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 18.39
Evaluated at bid price : 18.39
Bid-YTW : 6.07 %
BAM.PF.G FixedReset Disc 3.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 16.45
Evaluated at bid price : 16.45
Bid-YTW : 6.36 %
BAM.PR.X FixedReset Disc 3.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 12.42
Evaluated at bid price : 12.42
Bid-YTW : 6.12 %
CU.PR.C FixedReset Disc 3.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 17.04
Evaluated at bid price : 17.04
Bid-YTW : 5.32 %
NA.PR.S FixedReset Disc 3.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 16.96
Evaluated at bid price : 16.96
Bid-YTW : 5.57 %
CM.PR.S FixedReset Disc 3.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 17.92
Evaluated at bid price : 17.92
Bid-YTW : 5.46 %
CM.PR.P FixedReset Disc 3.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 15.47
Evaluated at bid price : 15.47
Bid-YTW : 5.71 %
TRP.PR.D FixedReset Disc 3.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 15.99
Evaluated at bid price : 15.99
Bid-YTW : 5.86 %
PWF.PR.A Floater 3.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 10.55
Evaluated at bid price : 10.55
Bid-YTW : 6.62 %
SLF.PR.G FixedReset Ins Non 4.32 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.05
Bid-YTW : 10.16 %
BMO.PR.T FixedReset Disc 4.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 16.65
Evaluated at bid price : 16.65
Bid-YTW : 5.26 %
BAM.PR.R FixedReset Disc 5.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 14.16
Evaluated at bid price : 14.16
Bid-YTW : 6.26 %
BMO.PR.W FixedReset Disc 5.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 16.20
Evaluated at bid price : 16.20
Bid-YTW : 5.38 %
Volume Highlights
Issue Index Shares
Traded
Notes
TRP.PR.J FixedReset Prem 100,527 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-31
Maturity Price : 25.00
Evaluated at bid price : 25.75
Bid-YTW : 3.73 %
TD.PF.G FixedReset Prem 97,925 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 25.65
Bid-YTW : 4.15 %
RY.PR.Q FixedReset Prem 94,045 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-24
Maturity Price : 25.00
Evaluated at bid price : 25.50
Bid-YTW : 4.36 %
TRP.PR.D FixedReset Disc 91,007 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 15.99
Evaluated at bid price : 15.99
Bid-YTW : 5.86 %
MFC.PR.O FixedReset Ins Non 89,727 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-06-19
Maturity Price : 25.00
Evaluated at bid price : 25.70
Bid-YTW : 3.84 %
NA.PR.X FixedReset Prem 86,081 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-15
Maturity Price : 25.00
Evaluated at bid price : 25.56
Bid-YTW : 4.38 %
There were 54 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
HSE.PR.G FixedReset Disc Quote: 17.17 – 18.13
Spot Rate : 0.9600
Average : 0.5917

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 17.17
Evaluated at bid price : 17.17
Bid-YTW : 7.07 %

PWF.PR.P FixedReset Disc Quote: 12.19 – 13.06
Spot Rate : 0.8700
Average : 0.5745

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 12.19
Evaluated at bid price : 12.19
Bid-YTW : 5.80 %

BAM.PF.B FixedReset Disc Quote: 16.42 – 17.00
Spot Rate : 0.5800
Average : 0.3337

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 16.42
Evaluated at bid price : 16.42
Bid-YTW : 6.28 %

MFC.PR.I FixedReset Ins Non Quote: 18.05 – 18.64
Spot Rate : 0.5900
Average : 0.3629

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.05
Bid-YTW : 8.22 %

BAM.PR.K Floater Quote: 10.40 – 11.01
Spot Rate : 0.6100
Average : 0.4734

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 10.40
Evaluated at bid price : 10.40
Bid-YTW : 6.78 %

PWF.PR.A Floater Quote: 10.55 – 11.01
Spot Rate : 0.4600
Average : 0.3267

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-30
Maturity Price : 10.55
Evaluated at bid price : 10.55
Bid-YTW : 6.62 %

Market Action

August 29, 2019

unicorns_190829
Click for Big

TXPR closed at 576.90, up 1.14% on the day. Volume was 4.29-million, highest of the past 30 days, dwarfing the 3.33-million recorded on each of the next two biggest trading days August 14 and August 15.

CPD closed at 11.52, up 1.14% on the day. Volume of 102,269 was at about the median of the context of the past 30 days.

ZPR closed at 9.15, up 1.10% on the day. Volume of 225,458 well above average but nothing special in the context of the past 30 days.

Five-year Canada yields were up 1bp to 1.19% today.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 2.0459 % 1,766.7
FixedFloater 0.00 % 0.00 % 0 0.00 0 2.0459 % 3,241.8
Floater 6.76 % 6.84 % 70,035 12.64 4 2.0459 % 1,868.3
OpRet 0.00 % 0.00 % 0 0.00 0 0.0420 % 3,371.3
SplitShare 4.67 % 4.53 % 61,596 4.07 7 0.0420 % 4,026.1
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0420 % 3,141.3
Perpetual-Premium 5.64 % -1.34 % 65,129 0.09 9 0.3361 % 2,971.1
Perpetual-Discount 5.52 % 5.65 % 64,361 14.42 25 0.4358 % 3,085.2
FixedReset Disc 5.91 % 5.66 % 161,252 14.31 66 1.6048 % 1,967.1
Deemed-Retractible 5.35 % 6.24 % 67,266 7.91 27 0.3197 % 3,073.9
FloatingReset 4.67 % 7.32 % 69,071 8.00 3 2.3651 % 2,275.4
FixedReset Prem 5.21 % 5.00 % 179,279 1.85 21 0.4265 % 2,559.3
FixedReset Bank Non 1.98 % 4.11 % 89,917 2.35 3 0.2088 % 2,662.9
FixedReset Ins Non 5.66 % 8.31 % 106,812 7.96 21 2.1747 % 2,035.3
Performance Highlights
Issue Index Change Notes
NA.PR.C FixedReset Disc 1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 5.84 %
MFC.PR.R FixedReset Ins Non 1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.36
Bid-YTW : 5.86 %
SLF.PR.A Deemed-Retractible 1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.40
Bid-YTW : 6.67 %
BNS.PR.I FixedReset Disc 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 19.11
Evaluated at bid price : 19.11
Bid-YTW : 5.25 %
RY.PR.M FixedReset Disc 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 17.20
Evaluated at bid price : 17.20
Bid-YTW : 5.63 %
GWO.PR.S Deemed-Retractible 1.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.30
Bid-YTW : 6.12 %
TD.PF.B FixedReset Disc 1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 16.50
Evaluated at bid price : 16.50
Bid-YTW : 5.46 %
NA.PR.E FixedReset Disc 1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 18.11
Evaluated at bid price : 18.11
Bid-YTW : 5.56 %
CU.PR.G Perpetual-Discount 1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 21.10
Evaluated at bid price : 21.10
Bid-YTW : 5.36 %
BAM.PF.A FixedReset Disc 1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 17.82
Evaluated at bid price : 17.82
Bid-YTW : 6.27 %
BAM.PR.N Perpetual-Discount 1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 19.99
Evaluated at bid price : 19.99
Bid-YTW : 6.06 %
PWF.PR.P FixedReset Disc 1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 11.85
Evaluated at bid price : 11.85
Bid-YTW : 5.97 %
BMO.PR.S FixedReset Disc 1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 16.92
Evaluated at bid price : 16.92
Bid-YTW : 5.43 %
BIP.PR.E FixedReset Disc 1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 20.80
Evaluated at bid price : 20.80
Bid-YTW : 6.02 %
BAM.PR.M Perpetual-Discount 1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 20.02
Evaluated at bid price : 20.02
Bid-YTW : 6.05 %
IFC.PR.G FixedReset Ins Non 1.38 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.35
Bid-YTW : 8.31 %
BMO.PR.D FixedReset Disc 1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 20.55
Evaluated at bid price : 20.55
Bid-YTW : 5.40 %
TD.PF.E FixedReset Disc 1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 18.25
Evaluated at bid price : 18.25
Bid-YTW : 5.66 %
BAM.PR.C Floater 1.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 10.14
Evaluated at bid price : 10.14
Bid-YTW : 6.95 %
BAM.PF.B FixedReset Disc 1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 16.50
Evaluated at bid price : 16.50
Bid-YTW : 6.24 %
CM.PR.O FixedReset Disc 1.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 16.03
Evaluated at bid price : 16.03
Bid-YTW : 5.70 %
RY.PR.J FixedReset Disc 1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 17.80
Evaluated at bid price : 17.80
Bid-YTW : 5.62 %
BIP.PR.B FixedReset Prem 1.49 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.03
Bid-YTW : 5.06 %
NA.PR.G FixedReset Disc 1.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 18.89
Evaluated at bid price : 18.89
Bid-YTW : 5.67 %
IAF.PR.B Deemed-Retractible 1.56 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.65
Bid-YTW : 6.36 %
NA.PR.W FixedReset Disc 1.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 14.75
Evaluated at bid price : 14.75
Bid-YTW : 5.99 %
TD.PF.J FixedReset Disc 1.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 19.40
Evaluated at bid price : 19.40
Bid-YTW : 5.35 %
HSE.PR.C FixedReset Disc 1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 16.25
Evaluated at bid price : 16.25
Bid-YTW : 6.87 %
EMA.PR.F FixedReset Disc 1.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 15.51
Evaluated at bid price : 15.51
Bid-YTW : 6.31 %
TD.PF.A FixedReset Disc 1.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 16.00
Evaluated at bid price : 16.00
Bid-YTW : 5.50 %
BMO.PR.T FixedReset Disc 1.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 15.92
Evaluated at bid price : 15.92
Bid-YTW : 5.51 %
BIP.PR.D FixedReset Disc 1.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 21.40
Evaluated at bid price : 21.73
Bid-YTW : 5.76 %
RY.PR.Z FixedReset Disc 1.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 16.67
Evaluated at bid price : 16.67
Bid-YTW : 5.31 %
BAM.PF.G FixedReset Disc 1.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 15.94
Evaluated at bid price : 15.94
Bid-YTW : 6.57 %
EMA.PR.C FixedReset Disc 1.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 17.01
Evaluated at bid price : 17.01
Bid-YTW : 6.07 %
TD.PF.C FixedReset Disc 1.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 15.86
Evaluated at bid price : 15.86
Bid-YTW : 5.58 %
MFC.PR.J FixedReset Ins Non 1.93 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.45
Bid-YTW : 7.97 %
BMO.PR.C FixedReset Disc 1.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 20.90
Evaluated at bid price : 20.90
Bid-YTW : 5.49 %
MFC.PR.M FixedReset Ins Non 1.95 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.15
Bid-YTW : 9.71 %
RY.PR.H FixedReset Disc 1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 16.65
Evaluated at bid price : 16.65
Bid-YTW : 5.29 %
HSE.PR.E FixedReset Disc 2.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 17.36
Evaluated at bid price : 17.36
Bid-YTW : 7.05 %
MFC.PR.H FixedReset Ins Non 2.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.85
Bid-YTW : 7.20 %
MFC.PR.G FixedReset Ins Non 2.18 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.37
Bid-YTW : 8.57 %
IAF.PR.G FixedReset Ins Non 2.26 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.10
Bid-YTW : 7.92 %
HSE.PR.G FixedReset Disc 2.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 7.14 %
MFC.PR.Q FixedReset Ins Non 2.56 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.02
Bid-YTW : 8.24 %
BMO.PR.Y FixedReset Disc 2.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 17.96
Evaluated at bid price : 17.96
Bid-YTW : 5.53 %
IAF.PR.I FixedReset Ins Non 2.60 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.27
Bid-YTW : 8.23 %
MFC.PR.N FixedReset Ins Non 2.65 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.09
Bid-YTW : 9.69 %
IFC.PR.C FixedReset Ins Non 2.72 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.00
Bid-YTW : 8.58 %
BAM.PF.E FixedReset Disc 2.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 14.70
Evaluated at bid price : 14.70
Bid-YTW : 6.64 %
BAM.PR.X FixedReset Disc 2.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 12.03
Evaluated at bid price : 12.03
Bid-YTW : 6.32 %
BAM.PF.F FixedReset Disc 2.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 16.15
Evaluated at bid price : 16.15
Bid-YTW : 6.48 %
TD.PF.I FixedReset Disc 2.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 20.33
Evaluated at bid price : 20.33
Bid-YTW : 5.35 %
BAM.PR.T FixedReset Disc 2.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 13.76
Evaluated at bid price : 13.76
Bid-YTW : 6.55 %
IFC.PR.A FixedReset Ins Non 3.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.01
Bid-YTW : 10.24 %
SLF.PR.I FixedReset Ins Non 3.34 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.65
Bid-YTW : 8.15 %
TRP.PR.D FixedReset Disc 3.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 15.40
Evaluated at bid price : 15.40
Bid-YTW : 6.09 %
MFC.PR.K FixedReset Ins Non 3.45 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.81
Bid-YTW : 8.78 %
BAM.PR.B Floater 3.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 10.30
Evaluated at bid price : 10.30
Bid-YTW : 6.84 %
SLF.PR.G FixedReset Ins Non 3.56 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.51
Bid-YTW : 10.68 %
NA.PR.S FixedReset Disc 3.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 16.40
Evaluated at bid price : 16.40
Bid-YTW : 5.77 %
MFC.PR.I FixedReset Ins Non 3.83 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.90
Bid-YTW : 8.33 %
TRP.PR.F FloatingReset 3.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 12.37
Evaluated at bid price : 12.37
Bid-YTW : 7.32 %
BAM.PR.K Floater 4.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 10.30
Evaluated at bid price : 10.30
Bid-YTW : 6.84 %
SLF.PR.J FloatingReset 4.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.52
Bid-YTW : 11.29 %
CU.PR.C FixedReset Disc 4.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 16.48
Evaluated at bid price : 16.48
Bid-YTW : 5.50 %
TRP.PR.A FixedReset Disc 4.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 12.50
Evaluated at bid price : 12.50
Bid-YTW : 6.46 %
TRP.PR.G FixedReset Disc 4.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 16.55
Evaluated at bid price : 16.55
Bid-YTW : 6.35 %
SLF.PR.H FixedReset Ins Non 4.79 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.30
Bid-YTW : 9.11 %
TRP.PR.C FixedReset Disc 5.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 10.90
Evaluated at bid price : 10.90
Bid-YTW : 6.36 %
HSE.PR.A FixedReset Disc 5.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 11.25
Evaluated at bid price : 11.25
Bid-YTW : 6.57 %
TRP.PR.B FixedReset Disc 6.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 10.40
Evaluated at bid price : 10.40
Bid-YTW : 6.13 %
TRP.PR.E FixedReset Disc 6.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 14.45
Evaluated at bid price : 14.45
Bid-YTW : 6.30 %
Volume Highlights
Issue Index Shares
Traded
Notes
TRP.PR.B FixedReset Disc 389,564 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 10.40
Evaluated at bid price : 10.40
Bid-YTW : 6.13 %
TRP.PR.A FixedReset Disc 148,692 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 12.50
Evaluated at bid price : 12.50
Bid-YTW : 6.46 %
TD.PF.A FixedReset Disc 105,100 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 16.00
Evaluated at bid price : 16.00
Bid-YTW : 5.50 %
BAM.PF.G FixedReset Disc 92,855 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 15.94
Evaluated at bid price : 15.94
Bid-YTW : 6.57 %
PWF.PR.P FixedReset Disc 82,228 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 11.85
Evaluated at bid price : 11.85
Bid-YTW : 5.97 %
NA.PR.S FixedReset Disc 62,362 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 16.40
Evaluated at bid price : 16.40
Bid-YTW : 5.77 %
There were 62 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
PWF.PR.L Perpetual-Discount Quote: 22.28 – 22.84
Spot Rate : 0.5600
Average : 0.3616

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 22.05
Evaluated at bid price : 22.28
Bid-YTW : 5.78 %

BMO.PR.T FixedReset Disc Quote: 15.92 – 16.37
Spot Rate : 0.4500
Average : 0.2890

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 15.92
Evaluated at bid price : 15.92
Bid-YTW : 5.51 %

RY.PR.M FixedReset Disc Quote: 17.20 – 17.60
Spot Rate : 0.4000
Average : 0.2391

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 17.20
Evaluated at bid price : 17.20
Bid-YTW : 5.63 %

GWO.PR.T Deemed-Retractible Quote: 22.70 – 23.23
Spot Rate : 0.5300
Average : 0.3884

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.70
Bid-YTW : 6.35 %

CU.PR.C FixedReset Disc Quote: 16.48 – 17.00
Spot Rate : 0.5200
Average : 0.3813

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-29
Maturity Price : 16.48
Evaluated at bid price : 16.48
Bid-YTW : 5.50 %

EIT.PR.A SplitShare Quote: 25.25 – 25.64
Spot Rate : 0.3900
Average : 0.2541

YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2024-03-14
Maturity Price : 25.00
Evaluated at bid price : 25.25
Bid-YTW : 4.53 %

Market Action

August 28, 2019

What a great day! Only two of the three mainstream indicators made new lows!

TXPR closed at 570.42, up 0.02% on the day but not before touching a new 52-week low of 569.32. Volume was 2.80-million, third-highest of the past 30 days, behind only August 14 and August 15.

CPD closed at 11.39, up 0.53% on the day. Volume of 129,692 was above average but nothing special in the context of the past 30 days.

ZPR closed at 9.05, down 0.01% on the day after touching a new 52-week low of 8.98. Volume of 394,302 was second highest of the past 30 days, behind only August 13.

Five-year Canada yields were up 1bp to 1.18% today.

I note with amusement that TXPR has traced out the first part of a pretty good parabola this month:

txpr_190828
Click for Big

Doubtless there are Technical Analysts out there who will deem this very significant.

PerpetualDiscounts now yield 5.64%, equivalent to 7.33% interest at the standard equivalency factor of 1.3x. Long corporates now yield 3.15%, so the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) has widened to an eye-popping 420bp, a new post-Credit Crunch record (second only to the 445bp recorded November 26, 2008, a day on which

The TXPR index was down 5.94% on the BCE news.

) and a widening from the 410bp reported August 21.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.7795 % 1,731.3
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.7795 % 3,176.8
Floater 6.90 % 7.05 % 48,513 12.38 4 0.7795 % 1,830.8
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0903 % 3,369.9
SplitShare 4.67 % 4.48 % 61,044 4.08 7 -0.0903 % 4,024.4
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0903 % 3,140.0
Perpetual-Premium 5.66 % 3.82 % 65,649 0.09 9 -0.0575 % 2,961.1
Perpetual-Discount 5.55 % 5.64 % 65,173 14.46 25 0.1221 % 3,071.8
FixedReset Disc 6.00 % 5.71 % 158,945 14.24 66 0.0976 % 1,936.0
Deemed-Retractible 5.33 % 6.26 % 66,235 7.81 27 -0.0757 % 3,064.1
FloatingReset 4.78 % 3.98 % 29,596 2.33 3 -0.2483 % 2,222.9
FixedReset Prem 5.23 % 5.11 % 177,705 1.88 21 0.0704 % 2,548.4
FixedReset Bank Non 1.98 % 4.28 % 83,250 2.35 3 0.4474 % 2,657.3
FixedReset Ins Non 5.77 % 8.57 % 107,672 7.93 21 -0.4144 % 1,992.0
Performance Highlights
Issue Index Change Notes
HSE.PR.A FixedReset Disc -2.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-28
Maturity Price : 10.63
Evaluated at bid price : 10.63
Bid-YTW : 6.96 %
MFC.PR.K FixedReset Ins Non -2.69 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.25
Bid-YTW : 9.22 %
BIP.PR.E FixedReset Disc -1.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-28
Maturity Price : 20.75
Evaluated at bid price : 20.75
Bid-YTW : 6.14 %
IFC.PR.C FixedReset Ins Non -1.49 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.55
Bid-YTW : 8.92 %
SLF.PR.G FixedReset Ins Non -1.47 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.08
Bid-YTW : 11.11 %
CM.PR.T FixedReset Disc -1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-28
Maturity Price : 22.29
Evaluated at bid price : 23.00
Bid-YTW : 5.16 %
TD.PF.I FixedReset Disc -1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-28
Maturity Price : 19.75
Evaluated at bid price : 19.75
Bid-YTW : 5.50 %
IFC.PR.F Deemed-Retractible -1.21 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.76
Bid-YTW : 6.10 %
CCS.PR.C Deemed-Retractible -1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.18
Bid-YTW : 5.55 %
BNS.PR.I FixedReset Disc -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-28
Maturity Price : 18.90
Evaluated at bid price : 18.90
Bid-YTW : 5.31 %
IAF.PR.B Deemed-Retractible 1.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.60
Bid-YTW : 6.56 %
BMO.PR.S FixedReset Disc 1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-28
Maturity Price : 16.70
Evaluated at bid price : 16.70
Bid-YTW : 5.50 %
EMA.PR.F FixedReset Disc 1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-28
Maturity Price : 15.25
Evaluated at bid price : 15.25
Bid-YTW : 6.42 %
TRP.PR.B FixedReset Disc 1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-28
Maturity Price : 9.79
Evaluated at bid price : 9.79
Bid-YTW : 6.51 %
HSE.PR.E FixedReset Disc 1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-28
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 7.20 %
BAM.PR.C Floater 1.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-28
Maturity Price : 10.00
Evaluated at bid price : 10.00
Bid-YTW : 7.05 %
MFC.PR.J FixedReset Ins Non 1.97 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.10
Bid-YTW : 8.21 %
TRP.PR.D FixedReset Disc 2.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-28
Maturity Price : 14.90
Evaluated at bid price : 14.90
Bid-YTW : 6.29 %
Volume Highlights
Issue Index Shares
Traded
Notes
SLF.PR.I FixedReset Ins Non 160,009 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.08
Bid-YTW : 8.57 %
MFC.PR.O FixedReset Ins Non 130,605 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-06-19
Maturity Price : 25.00
Evaluated at bid price : 25.65
Bid-YTW : 3.94 %
TRP.PR.D FixedReset Disc 129,558 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-28
Maturity Price : 14.90
Evaluated at bid price : 14.90
Bid-YTW : 6.29 %
BAM.PF.B FixedReset Disc 36,716 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-28
Maturity Price : 16.27
Evaluated at bid price : 16.27
Bid-YTW : 6.33 %
CM.PR.R FixedReset Disc 35,565 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-28
Maturity Price : 19.92
Evaluated at bid price : 19.92
Bid-YTW : 5.82 %
SLF.PR.J FloatingReset 29,499 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.02
Bid-YTW : 11.81 %
There were 40 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
TRP.PR.E FixedReset Disc Quote: 13.59 – 14.10
Spot Rate : 0.5100
Average : 0.3064

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-28
Maturity Price : 13.59
Evaluated at bid price : 13.59
Bid-YTW : 6.70 %

CM.PR.Q FixedReset Disc Quote: 17.05 – 17.49
Spot Rate : 0.4400
Average : 0.2686

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-28
Maturity Price : 17.05
Evaluated at bid price : 17.05
Bid-YTW : 5.94 %

CM.PR.T FixedReset Disc Quote: 23.00 – 23.40
Spot Rate : 0.4000
Average : 0.2446

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-28
Maturity Price : 22.29
Evaluated at bid price : 23.00
Bid-YTW : 5.16 %

GWO.PR.T Deemed-Retractible Quote: 23.00 – 23.36
Spot Rate : 0.3600
Average : 0.2331

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.00
Bid-YTW : 6.36 %

CCS.PR.C Deemed-Retractible Quote: 24.18 – 24.74
Spot Rate : 0.5600
Average : 0.4372

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.18
Bid-YTW : 5.55 %

TRP.PR.B FixedReset Disc Quote: 9.79 – 10.20
Spot Rate : 0.4100
Average : 0.2873

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-28
Maturity Price : 9.79
Evaluated at bid price : 9.79
Bid-YTW : 6.51 %

Market Action

August 27, 2019

Another day, another three more 52-week lows!

TXPR closed at 570.29, down 0.35% on the day and just barely above its new 52-week low of 570.28. Volume was 2.54-million, high but not extraordinary in the context of the past thirty days.

CPD closed at 11.33, a new 52-week low and down 0.79% on the day. Volume of 110,835 was near the median in the context of the past 30 days.

ZPR closed at 9.06, down 0.66% on the day after touching a new 52-week low of 9.045. Volume of 177,769 was above average but nothing special in the context of the past 30 days.

Five-year Canada yields were down 8bp to 1.17% today.

For those who would really appreciate a bit of good news, I’ll pass along the tidbit that Queue de Cheval, my favourite steakhouse, is coming to Toronto in November.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -2.4049 % 1,717.9
FixedFloater 0.00 % 0.00 % 0 0.00 0 -2.4049 % 3,152.2
Floater 6.95 % 7.14 % 48,276 12.27 4 -2.4049 % 1,816.6
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0056 % 3,373.0
SplitShare 4.66 % 4.52 % 60,756 4.08 7 -0.0056 % 4,028.0
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0056 % 3,142.8
Perpetual-Premium 5.66 % 0.21 % 64,573 0.09 9 0.0663 % 2,962.8
Perpetual-Discount 5.56 % 5.64 % 61,638 14.43 25 -0.2579 % 3,068.1
FixedReset Disc 6.00 % 5.74 % 154,426 14.27 66 -0.3349 % 1,934.1
Deemed-Retractible 5.33 % 6.24 % 66,960 7.82 27 -0.0443 % 3,066.5
FloatingReset 4.77 % 3.98 % 30,820 2.33 3 0.0106 % 2,228.4
FixedReset Prem 5.23 % 5.07 % 176,574 1.88 21 -0.0209 % 2,546.6
FixedReset Bank Non 1.99 % 4.44 % 84,322 2.35 3 -0.0978 % 2,645.5
FixedReset Ins Non 5.75 % 8.52 % 101,963 7.93 21 -0.2057 % 2,000.3
Performance Highlights
Issue Index Change Notes
PWF.PR.A Floater -5.12 % Real enough, since the issue traded 20,050 shares today in a range of 10.21-75 before closing at 10.20-50. Fourteen of the last twenty-five trades (from 2:01pm to the close) were in the 10.21-29 range.

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-27
Maturity Price : 10.20
Evaluated at bid price : 10.20
Bid-YTW : 6.85 %

CU.PR.C FixedReset Disc -3.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-27
Maturity Price : 15.68
Evaluated at bid price : 15.68
Bid-YTW : 5.78 %
HSE.PR.E FixedReset Disc -2.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-27
Maturity Price : 16.77
Evaluated at bid price : 16.77
Bid-YTW : 7.30 %
SLF.PR.H FixedReset Ins Non -2.38 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.65
Bid-YTW : 9.64 %
MFC.PR.J FixedReset Ins Non -2.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.75
Bid-YTW : 8.46 %
BAM.PR.C Floater -1.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-27
Maturity Price : 9.83
Evaluated at bid price : 9.83
Bid-YTW : 7.17 %
TD.PF.C FixedReset Disc -1.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-27
Maturity Price : 15.42
Evaluated at bid price : 15.42
Bid-YTW : 5.73 %
CU.PR.G Perpetual-Discount -1.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-27
Maturity Price : 20.65
Evaluated at bid price : 20.65
Bid-YTW : 5.48 %
BAM.PF.D Perpetual-Discount -1.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-27
Maturity Price : 20.53
Evaluated at bid price : 20.53
Bid-YTW : 6.08 %
TRP.PR.B FixedReset Disc -1.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-27
Maturity Price : 9.66
Evaluated at bid price : 9.66
Bid-YTW : 6.60 %
BAM.PR.B Floater -1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-27
Maturity Price : 9.87
Evaluated at bid price : 9.87
Bid-YTW : 7.14 %
BAM.PR.M Perpetual-Discount -1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-27
Maturity Price : 19.62
Evaluated at bid price : 19.62
Bid-YTW : 6.17 %
CU.PR.E Perpetual-Discount -1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-27
Maturity Price : 22.10
Evaluated at bid price : 22.10
Bid-YTW : 5.58 %
BMO.PR.W FixedReset Disc -1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-27
Maturity Price : 15.30
Evaluated at bid price : 15.30
Bid-YTW : 5.70 %
CM.PR.P FixedReset Disc -1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-27
Maturity Price : 14.67
Evaluated at bid price : 14.67
Bid-YTW : 6.02 %
CM.PR.O FixedReset Disc -1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-27
Maturity Price : 15.74
Evaluated at bid price : 15.74
Bid-YTW : 5.80 %
TD.PF.L FixedReset Disc -1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-27
Maturity Price : 22.40
Evaluated at bid price : 23.18
Bid-YTW : 5.06 %
BMO.PR.Y FixedReset Disc -1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-27
Maturity Price : 17.41
Evaluated at bid price : 17.41
Bid-YTW : 5.70 %
BMO.PR.C FixedReset Disc -1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-27
Maturity Price : 20.37
Evaluated at bid price : 20.37
Bid-YTW : 5.64 %
BMO.PR.S FixedReset Disc -1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-27
Maturity Price : 16.50
Evaluated at bid price : 16.50
Bid-YTW : 5.56 %
BAM.PR.K Floater -1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-27
Maturity Price : 9.87
Evaluated at bid price : 9.87
Bid-YTW : 7.14 %
BIP.PR.C FixedReset Prem 1.01 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-09-30
Maturity Price : 25.00
Evaluated at bid price : 25.10
Bid-YTW : 5.61 %
CM.PR.S FixedReset Disc 1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-27
Maturity Price : 17.27
Evaluated at bid price : 17.27
Bid-YTW : 5.67 %
CM.PR.Y FixedReset Disc 1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-27
Maturity Price : 22.67
Evaluated at bid price : 23.75
Bid-YTW : 5.26 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.Q FixedReset Prem 169,272 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-24
Maturity Price : 25.00
Evaluated at bid price : 25.35
Bid-YTW : 4.69 %
TD.PF.M FixedReset Prem 125,300 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-27
Maturity Price : 22.69
Evaluated at bid price : 23.79
Bid-YTW : 5.18 %
GWO.PR.S Deemed-Retractible 82,300 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.41
Bid-YTW : 6.24 %
RY.PR.J FixedReset Disc 48,719 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-27
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 5.71 %
TD.PF.J FixedReset Disc 48,165 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-27
Maturity Price : 19.15
Evaluated at bid price : 19.15
Bid-YTW : 5.42 %
TRP.PR.C FixedReset Disc 44,900 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-27
Maturity Price : 10.28
Evaluated at bid price : 10.28
Bid-YTW : 6.74 %
There were 39 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
CU.PR.H Perpetual-Discount Quote: 23.76 – 24.79
Spot Rate : 1.0300
Average : 0.6324

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-27
Maturity Price : 23.30
Evaluated at bid price : 23.76
Bid-YTW : 5.53 %

CU.PR.E Perpetual-Discount Quote: 22.10 – 22.79
Spot Rate : 0.6900
Average : 0.5208

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-27
Maturity Price : 22.10
Evaluated at bid price : 22.10
Bid-YTW : 5.58 %

IAF.PR.B Deemed-Retractible Quote: 21.36 – 22.06
Spot Rate : 0.7000
Average : 0.5350

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.36
Bid-YTW : 6.70 %

BIP.PR.F FixedReset Disc Quote: 21.25 – 21.71
Spot Rate : 0.4600
Average : 0.3193

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-27
Maturity Price : 21.25
Evaluated at bid price : 21.25
Bid-YTW : 6.11 %

TD.PF.M FixedReset Prem Quote: 23.79 – 24.19
Spot Rate : 0.4000
Average : 0.2715

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-27
Maturity Price : 22.69
Evaluated at bid price : 23.79
Bid-YTW : 5.18 %

BAM.PF.E FixedReset Disc Quote: 14.22 – 14.63
Spot Rate : 0.4100
Average : 0.2846

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-27
Maturity Price : 14.22
Evaluated at bid price : 14.22
Bid-YTW : 6.87 %

Market Action

August 26, 2019

Well, we got through the G-7 meeting without any major disruptions, so let’s thank Heaven for small mercies!

In the meantime, two of the three mainstream indicators made new 52-week lows today:

TXPR closed at 572.79, a new 52-week low and down 0.12% on the day. Volume was 2.04-million, about the median for the past thirty days.

CPD closed at 11.42, down 0.52% on the day after touching a new 52-week low of 11.40. Volume of 114,368 was near the median in the context of the past 30 days.

ZPR closed at 9.12, up 0.22% on the day. Volume of 176,652 was above average but nothing special in the context of the past 30 days.

Five-year Canada yields were up 4bp to 1.25% today.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.0736 % 1,760.2
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.0736 % 3,229.9
Floater 6.79 % 7.03 % 44,892 12.40 4 -0.0736 % 1,861.4
OpRet 0.00 % 0.00 % 0 0.00 0 0.2547 % 3,373.2
SplitShare 4.66 % 4.57 % 60,763 4.08 7 0.2547 % 4,028.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.2547 % 3,143.0
Perpetual-Premium 5.66 % -3.80 % 66,147 0.09 9 -0.0265 % 2,960.9
Perpetual-Discount 5.54 % 5.64 % 61,063 14.47 25 -0.0644 % 3,076.0
FixedReset Disc 5.98 % 5.73 % 160,681 14.35 66 -0.0429 % 1,940.6
Deemed-Retractible 5.32 % 6.24 % 62,048 7.82 27 -0.0786 % 3,067.8
FloatingReset 4.75 % 3.97 % 30,075 2.34 3 -0.1235 % 2,228.2
FixedReset Prem 5.23 % 4.94 % 168,623 1.88 21 -0.0342 % 2,547.2
FixedReset Bank Non 1.99 % 4.45 % 87,412 2.35 3 0.0140 % 2,648.1
FixedReset Ins Non 5.73 % 8.45 % 99,658 7.94 21 0.1945 % 2,004.4
Performance Highlights
Issue Index Change Notes
MFC.PR.F FixedReset Ins Non -2.46 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.88
Bid-YTW : 11.21 %
SLF.PR.H FixedReset Ins Non -1.68 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.19
Bid-YTW : 9.33 %
EMA.PR.C FixedReset Disc -1.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-26
Maturity Price : 16.56
Evaluated at bid price : 16.56
Bid-YTW : 6.24 %
TD.PF.E FixedReset Disc -1.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-26
Maturity Price : 18.01
Evaluated at bid price : 18.01
Bid-YTW : 5.73 %
TD.PF.B FixedReset Disc -1.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-26
Maturity Price : 16.35
Evaluated at bid price : 16.35
Bid-YTW : 5.50 %
BAM.PF.F FixedReset Disc -1.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-26
Maturity Price : 15.51
Evaluated at bid price : 15.51
Bid-YTW : 6.74 %
SLF.PR.G FixedReset Ins Non -1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.29
Bid-YTW : 11.03 %
NA.PR.C FixedReset Disc -1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-26
Maturity Price : 19.75
Evaluated at bid price : 19.75
Bid-YTW : 5.91 %
BAM.PR.N Perpetual-Discount -1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-26
Maturity Price : 19.75
Evaluated at bid price : 19.75
Bid-YTW : 6.13 %
TD.PF.I FixedReset Disc -1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-26
Maturity Price : 20.16
Evaluated at bid price : 20.16
Bid-YTW : 5.39 %
PWF.PR.P FixedReset Disc -1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-26
Maturity Price : 11.80
Evaluated at bid price : 11.80
Bid-YTW : 5.99 %
CM.PR.R FixedReset Disc -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-26
Maturity Price : 20.18
Evaluated at bid price : 20.18
Bid-YTW : 5.74 %
CU.PR.F Perpetual-Discount -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-26
Maturity Price : 21.12
Evaluated at bid price : 21.12
Bid-YTW : 5.36 %
TRP.PR.D FixedReset Disc -1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-26
Maturity Price : 14.52
Evaluated at bid price : 14.52
Bid-YTW : 6.46 %
BAM.PR.T FixedReset Disc 1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-26
Maturity Price : 13.52
Evaluated at bid price : 13.52
Bid-YTW : 6.67 %
SLF.PR.I FixedReset Ins Non 1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.50
Bid-YTW : 8.42 %
IFC.PR.C FixedReset Ins Non 1.38 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.95
Bid-YTW : 8.61 %
BIP.PR.E FixedReset Disc 1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-26
Maturity Price : 21.05
Evaluated at bid price : 21.05
Bid-YTW : 6.05 %
PWF.PR.T FixedReset Disc 1.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-26
Maturity Price : 16.61
Evaluated at bid price : 16.61
Bid-YTW : 5.74 %
MFC.PR.G FixedReset Ins Non 1.90 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.15
Bid-YTW : 8.72 %
IFC.PR.G FixedReset Ins Non 2.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.15
Bid-YTW : 8.45 %
EMA.PR.F FixedReset Disc 2.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-26
Maturity Price : 15.11
Evaluated at bid price : 15.11
Bid-YTW : 6.47 %
HSE.PR.A FixedReset Disc 4.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-26
Maturity Price : 10.95
Evaluated at bid price : 10.95
Bid-YTW : 6.75 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PF.M FixedReset Prem 145,080 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-26
Maturity Price : 22.71
Evaluated at bid price : 23.85
Bid-YTW : 5.16 %
TD.PF.L FixedReset Disc 59,165 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-26
Maturity Price : 22.54
Evaluated at bid price : 23.45
Bid-YTW : 4.99 %
BAM.PR.T FixedReset Disc 54,700 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-26
Maturity Price : 13.52
Evaluated at bid price : 13.52
Bid-YTW : 6.67 %
TD.PF.H FixedReset Prem 45,463 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-26
Maturity Price : 23.26
Evaluated at bid price : 24.31
Bid-YTW : 5.45 %
SLF.PR.B Deemed-Retractible 45,290 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.95
Bid-YTW : 6.57 %
BMO.PR.B FixedReset Prem 33,277 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-26
Maturity Price : 23.20
Evaluated at bid price : 24.31
Bid-YTW : 5.36 %
There were 30 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BAM.PF.I FixedReset Prem Quote: 24.75 – 25.33
Spot Rate : 0.5800
Average : 0.3651

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-26
Maturity Price : 23.36
Evaluated at bid price : 24.75
Bid-YTW : 5.09 %

ELF.PR.G Perpetual-Discount Quote: 21.71 – 22.30
Spot Rate : 0.5900
Average : 0.3929

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-26
Maturity Price : 21.45
Evaluated at bid price : 21.71
Bid-YTW : 5.53 %

BAM.PF.G FixedReset Disc Quote: 15.52 – 16.05
Spot Rate : 0.5300
Average : 0.3341

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-26
Maturity Price : 15.52
Evaluated at bid price : 15.52
Bid-YTW : 6.75 %

EMA.PR.C FixedReset Disc Quote: 16.56 – 17.12
Spot Rate : 0.5600
Average : 0.3705

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-26
Maturity Price : 16.56
Evaluated at bid price : 16.56
Bid-YTW : 6.24 %

GWO.PR.M Deemed-Retractible Quote: 25.72 – 26.19
Spot Rate : 0.4700
Average : 0.3239

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2019-09-25
Maturity Price : 25.00
Evaluated at bid price : 25.72
Bid-YTW : -17.09 %

IAF.PR.B Deemed-Retractible Quote: 21.48 – 21.98
Spot Rate : 0.5000
Average : 0.3541

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.48
Bid-YTW : 6.62 %

Market Action

August 23, 2019

The Stable Genius ratcheted up the trade war today:

Hours after Beijing said it would increase tariffs on American goods in response to President Trump’s latest round of Chinese levies, the president ordered companies in the United States to stop doing business with China and warned of additional retaliation.

In a series of angry Twitter posts, Mr. Trump said “Our great American companies are hereby ordered to immediately start looking for an alternative to China, including bringing our companies HOME and making your products in the USA.”

The president also said he was ordering the United States Postal Service and private American companies like FedEx, Amazon and UPS to search packages from China for the opioid Fentanyl and refuse delivery.

Powell came perilously close to criticizing policy:

As the year has progressed, we have been monitoring three factors that are weighing on this favorable outlook: slowing global growth, trade policy uncertainty, and muted inflation. The global growth outlook has been deteriorating since the middle of last year. Trade policy uncertainty seems to be playing a role in the global slowdown and in weak manufacturing and capital spending in the United States. Inflation fell below our objective at the start of the year. It appears to be moving back up closer to our symmetric 2 percent objective, but there are concerns about a more prolonged shortfall.
…
Turning to the current context, we are carefully watching developments as we assess their implications for the U.S. outlook and the path of monetary policy. The three weeks since our July FOMC meeting have been eventful, beginning with the announcement of new tariffs on imports from China. We have seen further evidence of a global slowdown, notably in Germany and China. Geopolitical events have been much in the news, including the growing possibility of a hard Brexit, rising tensions in Hong Kong, and the dissolution of the Italian government. Financial markets have reacted strongly to this complex, turbulent picture. Equity markets have been volatile. Long-term bond rates around the world have moved down sharply to near post-crisis lows. Meanwhile, the U.S. economy has continued to perform well overall, driven by consumer spending. Job creation has slowed from last year’s pace but is still above overall labor force growth. Inflation seems to be moving up closer to 2 percent. Based on our assessment of the implications of these developments, we will act as appropriate to sustain the expansion, with a strong labor market and inflation near its symmetric 2 percent objective.

So Stable Genius had to bolster his excuses for the next recession:

Jerome H. Powell, the Federal Reserve chair, kept future interest rate cuts squarely on the table on Friday but suggested that the central bank was limited in its ability to counteract President Trump’s trade policies, which are stoking uncertainty and posing risks to the economic outlook.

Mr. Powell’s remarks drew a swift and angry reaction from Mr. Trump, who equated the Fed leader with the president’s adversary in the trade war, President Xi Jinping of China.

“My only question is, who is our bigger enemy, Jay Powell or Chairman Xi?,” Mr. Trump wrote in one of a series of Twitter posts.

The markets noticed:

The Dow Jones Industrial Average fell 622.19 points, or 2.37 per cent, to 25,630.05, the S&P 500 lost 75.7 points, or 2.59 per cent, to 2,847.25 and the Nasdaq Composite dropped 239.62 points, or 3 per cent, to 7,751.77.

In Toronto, the S&P/TSX Composite index was unofficially down 215.88 points, or 1.33 per cent, at 16,037.58.
…
The two-year/10-year yield curve inverted last week for the first time since 2007, a signal that a U.S. recession is likely in one to two years. The curve has traded in and out of inversion over the past three days.

U.S. Treasury yields fell, with 10-year notes last up 25/32 in price to yield 1.5266 per cent, from 1.61 per cent late on Thursday.

The two-year/10-year yield curve tripped to negative territory early in the session and for a third consecutive day.

The U.S. dollar fell after Powell’s comments and dropped further after Trump’s tweets.

… and, just as I go to press, I learn that Stable Genius has freaked out again:

Twelve hours after China said it would retaliate against Mr. Trump’s next round of tariffs by raising taxes on American goods, Mr. Trump said he would boost existing tariffs on $250 billion worth of Chinese goods to 30 percent from 25 percent on Oct. 1.

And he said the United States would tax another $300 billion worth of Chinese imports at a 15 percent rate, rather than the 10 percent he had initially planned. Those levies go into effect on Sept. 1.

“China should not have put new Tariffs on 75 BILLION DOLLARS of United States product (politically motivated!),” Mr. Trump tweeted. “Starting on October 1st, the 250 BILLION DOLLARS of goods and products from China, currently being taxed at 25%, will be taxed at 30%.”

I’m sure we’re all shocked that the Chinese would do something “politically motivated”.

And the preferred share market was back to normal, with all three mainstream indicators setting new lows:

TXPR closed at 573.00, down 0.48% on the day after touching a new 52-week low of 572.88. Volume was 2.71-million, third-highest of the past 30 days, behind only August 14 and August 15.

CPD closed at 11.48, down 0.35% on the day after touching a new 52-week low of 11.44. Volume of 61,338 was low in the context of the past 30 days.

ZPR closed at 9.10, down 0.55% on the day after touching a new 52-week low of 9.08. Volume of 159,026 was a little above average but nothing special in the context of the past 30 days.

Five-year Canada yields were down 12bp to 1.21% today – but even that big drop leaves us 1bp higher than last Friday’s yield.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.1958 % 1,761.5
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.1958 % 3,232.3
Floater 6.78 % 7.04 % 42,460 12.41 4 -0.1958 % 1,862.8
OpRet 0.00 % 0.00 % 0 0.00 0 0.1531 % 3,364.6
SplitShare 4.68 % 4.57 % 61,061 4.09 7 0.1531 % 4,018.0
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1531 % 3,135.0
Perpetual-Premium 5.66 % -4.36 % 66,477 0.09 9 -0.1589 % 2,961.6
Perpetual-Discount 5.54 % 5.64 % 56,583 14.47 25 -0.1644 % 3,078.0
FixedReset Disc 6.00 % 5.64 % 157,552 14.48 66 -0.6278 % 1,941.5
Deemed-Retractible 5.31 % 6.26 % 73,191 7.82 27 -0.2434 % 3,070.2
FloatingReset 4.76 % 7.61 % 58,573 7.85 3 -0.2260 % 2,230.9
FixedReset Prem 5.23 % 5.03 % 169,269 1.89 21 -0.3221 % 2,548.0
FixedReset Bank Non 1.99 % 4.43 % 88,278 2.36 3 0.1819 % 2,647.7
FixedReset Ins Non 5.74 % 8.54 % 100,812 7.93 21 -1.0464 % 2,000.5
Performance Highlights
Issue Index Change Notes
HSE.PR.A FixedReset Disc -5.49 % A nonsensical quote provided at high cost by Nonsense Central, as the issue traded 600 shares today in a range of 10.95-09 before being quoted at 10.51-22. The closing price was 10.95, reached at 2:44pm.

I have not checked whether the lamentable state of the quote is due to inadequate Toronto Stock Exchange reporting or inadequate Toronto Stock Exchange supervision of market-makers.

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-23
Maturity Price : 10.51
Evaluated at bid price : 10.51
Bid-YTW : 6.96 %

PWF.PR.T FixedReset Disc -3.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-23
Maturity Price : 16.35
Evaluated at bid price : 16.35
Bid-YTW : 5.80 %
EMA.PR.F FixedReset Disc -3.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-23
Maturity Price : 14.76
Evaluated at bid price : 14.76
Bid-YTW : 6.57 %
PWF.PR.P FixedReset Disc -3.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-23
Maturity Price : 11.94
Evaluated at bid price : 11.94
Bid-YTW : 5.86 %
MFC.PR.I FixedReset Ins Non -2.55 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.22
Bid-YTW : 8.79 %
CM.PR.P FixedReset Disc -2.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-23
Maturity Price : 14.83
Evaluated at bid price : 14.83
Bid-YTW : 5.90 %
MFC.PR.M FixedReset Ins Non -2.41 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.01
Bid-YTW : 9.76 %
IAF.PR.G FixedReset Ins Non -2.25 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.84
Bid-YTW : 8.22 %
IFC.PR.G FixedReset Ins Non -2.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.78
Bid-YTW : 8.69 %
TRP.PR.A FixedReset Disc -2.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-23
Maturity Price : 11.85
Evaluated at bid price : 11.85
Bid-YTW : 6.75 %
TD.PF.A FixedReset Disc -2.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-23
Maturity Price : 15.68
Evaluated at bid price : 15.68
Bid-YTW : 5.56 %
MFC.PR.Q FixedReset Ins Non -1.99 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.70
Bid-YTW : 8.44 %
MFC.PR.G FixedReset Ins Non -1.92 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.83
Bid-YTW : 8.93 %
MFC.PR.N FixedReset Ins Non -1.68 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.60
Bid-YTW : 10.05 %
CM.PR.Y FixedReset Disc -1.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-23
Maturity Price : 22.55
Evaluated at bid price : 23.50
Bid-YTW : 5.30 %
SLF.PR.I FixedReset Ins Non -1.65 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.31
Bid-YTW : 8.53 %
TD.PF.C FixedReset Disc -1.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-23
Maturity Price : 15.70
Evaluated at bid price : 15.70
Bid-YTW : 5.58 %
NA.PR.W FixedReset Disc -1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-23
Maturity Price : 14.62
Evaluated at bid price : 14.62
Bid-YTW : 5.98 %
HSE.PR.G FixedReset Disc -1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-23
Maturity Price : 16.55
Evaluated at bid price : 16.55
Bid-YTW : 7.28 %
IAF.PR.I FixedReset Ins Non -1.47 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.09
Bid-YTW : 8.54 %
MFC.PR.H FixedReset Ins Non -1.41 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.60
Bid-YTW : 7.32 %
TRP.PR.F FloatingReset -1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-23
Maturity Price : 11.94
Evaluated at bid price : 11.94
Bid-YTW : 7.61 %
BAM.PF.C Perpetual-Discount -1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-23
Maturity Price : 20.24
Evaluated at bid price : 20.24
Bid-YTW : 6.10 %
NA.PR.S FixedReset Disc -1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-23
Maturity Price : 15.80
Evaluated at bid price : 15.80
Bid-YTW : 5.95 %
CCS.PR.C Deemed-Retractible -1.31 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.20
Bid-YTW : 5.53 %
TRP.PR.G FixedReset Disc -1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-23
Maturity Price : 15.60
Evaluated at bid price : 15.60
Bid-YTW : 6.68 %
SLF.PR.C Deemed-Retractible -1.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.30
Bid-YTW : 7.17 %
TRP.PR.D FixedReset Disc -1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-23
Maturity Price : 14.67
Evaluated at bid price : 14.67
Bid-YTW : 6.35 %
CU.PR.H Perpetual-Discount -1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-23
Maturity Price : 23.39
Evaluated at bid price : 23.86
Bid-YTW : 5.50 %
BIP.PR.E FixedReset Disc -1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-23
Maturity Price : 20.75
Evaluated at bid price : 20.75
Bid-YTW : 6.13 %
IFC.PR.E Deemed-Retractible -1.19 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.28
Bid-YTW : 6.25 %
BAM.PR.T FixedReset Disc -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-23
Maturity Price : 13.38
Evaluated at bid price : 13.38
Bid-YTW : 6.69 %
PWF.PR.S Perpetual-Discount -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-23
Maturity Price : 21.05
Evaluated at bid price : 21.05
Bid-YTW : 5.77 %
PWF.PR.Z Perpetual-Discount 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-23
Maturity Price : 22.25
Evaluated at bid price : 22.60
Bid-YTW : 5.74 %
CU.PR.F Perpetual-Discount 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-23
Maturity Price : 21.35
Evaluated at bid price : 21.35
Bid-YTW : 5.30 %
GWO.PR.H Deemed-Retractible 1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.00
Bid-YTW : 6.59 %
PVS.PR.D SplitShare 1.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2021-10-08
Maturity Price : 25.00
Evaluated at bid price : 25.30
Bid-YTW : 3.84 %
BNS.PR.I FixedReset Disc 1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-23
Maturity Price : 19.03
Evaluated at bid price : 19.03
Bid-YTW : 5.24 %
MFC.PR.K FixedReset Ins Non 1.34 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.62
Bid-YTW : 8.89 %
PWF.PR.L Perpetual-Discount 1.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-23
Maturity Price : 22.12
Evaluated at bid price : 22.40
Bid-YTW : 5.74 %
HSE.PR.E FixedReset Disc 1.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-23
Maturity Price : 17.18
Evaluated at bid price : 17.18
Bid-YTW : 7.07 %
BAM.PF.B FixedReset Disc 1.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-23
Maturity Price : 16.30
Evaluated at bid price : 16.30
Bid-YTW : 6.28 %
Volume Highlights
Issue Index Shares
Traded
Notes
MFC.PR.N FixedReset Ins Non 200,500 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.60
Bid-YTW : 10.05 %
BMO.PR.S FixedReset Disc 184,860 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-23
Maturity Price : 16.64
Evaluated at bid price : 16.64
Bid-YTW : 5.48 %
BMO.PR.W FixedReset Disc 70,591 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-23
Maturity Price : 15.50
Evaluated at bid price : 15.50
Bid-YTW : 5.57 %
SLF.PR.E Deemed-Retractible 59,182 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.77
Bid-YTW : 6.93 %
BAM.PF.B FixedReset Disc 56,425 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-23
Maturity Price : 16.30
Evaluated at bid price : 16.30
Bid-YTW : 6.28 %
BAM.PF.A FixedReset Disc 43,157 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-23
Maturity Price : 17.75
Evaluated at bid price : 17.75
Bid-YTW : 6.25 %
There were 41 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
HSE.PR.E FixedReset Disc Quote: 17.18 – 18.29
Spot Rate : 1.1100
Average : 0.7031

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-23
Maturity Price : 17.18
Evaluated at bid price : 17.18
Bid-YTW : 7.07 %

HSE.PR.C FixedReset Disc Quote: 15.85 – 16.50
Spot Rate : 0.6500
Average : 0.4401

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-23
Maturity Price : 15.85
Evaluated at bid price : 15.85
Bid-YTW : 6.99 %

IAF.PR.G FixedReset Ins Non Quote: 17.84 – 18.40
Spot Rate : 0.5600
Average : 0.3609

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.84
Bid-YTW : 8.22 %

EMA.PR.F FixedReset Disc Quote: 14.76 – 15.44
Spot Rate : 0.6800
Average : 0.4882

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-23
Maturity Price : 14.76
Evaluated at bid price : 14.76
Bid-YTW : 6.57 %

PVS.PR.F SplitShare Quote: 25.20 – 25.79
Spot Rate : 0.5900
Average : 0.4270

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2024-09-30
Maturity Price : 25.00
Evaluated at bid price : 25.20
Bid-YTW : 4.61 %

PWF.PR.E Perpetual-Discount Quote: 23.89 – 24.47
Spot Rate : 0.5800
Average : 0.4230

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-23
Maturity Price : 23.62
Evaluated at bid price : 23.89
Bid-YTW : 5.81 %

Market Action

August 22, 2019

What a great day! Only one of the mainstream indicators made a new 52-week low!

TXPR closed at 575.74, up 0.11% on the day. Volume was 2.18-million, nothing special in the context of the past 30 days.

CPD closed at 11.52, up 0.17% on the day. Volume of 97,108 was above median but nothing special in the context of the past 30 days.

ZPR closed at 9.15, unchanged on the day after touching a new 52-week low of 9.145. Volume of 111,979 was a little above average but nothing special in the context of the past 30 days.

Five-year Canada yields were up 5bp to 1.33% today.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.2208 % 1,765.0
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.2208 % 3,238.6
Floater 6.77 % 7.03 % 41,461 12.42 4 0.2208 % 1,866.4
OpRet 0.00 % 0.00 % 0 0.00 0 -0.1528 % 3,359.4
SplitShare 4.68 % 4.56 % 60,857 4.09 7 -0.1528 % 4,011.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.1528 % 3,130.2
Perpetual-Premium 5.65 % -4.54 % 66,492 0.09 9 -0.1190 % 2,966.4
Perpetual-Discount 5.53 % 5.60 % 54,750 14.49 25 -0.3046 % 3,083.0
FixedReset Disc 5.96 % 5.58 % 153,381 14.43 66 0.3969 % 1,953.7
Deemed-Retractible 5.30 % 6.22 % 61,377 7.84 27 -0.0400 % 3,077.7
FloatingReset 4.75 % 7.50 % 60,981 7.84 3 0.1646 % 2,236.0
FixedReset Prem 5.21 % 4.87 % 170,726 1.90 21 0.0948 % 2,556.3
FixedReset Bank Non 1.99 % 4.42 % 86,289 2.37 3 0.2666 % 2,642.9
FixedReset Ins Non 5.68 % 8.34 % 100,429 7.96 21 -0.1381 % 2,021.7
Performance Highlights
Issue Index Change Notes
IFC.PR.A FixedReset Ins Non -2.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.63
Bid-YTW : 10.54 %
PWF.PR.L Perpetual-Discount -1.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-22
Maturity Price : 21.85
Evaluated at bid price : 22.09
Bid-YTW : 5.82 %
MFC.PR.B Deemed-Retractible -1.70 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.76
Bid-YTW : 6.95 %
BAM.PF.D Perpetual-Discount -1.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-22
Maturity Price : 20.68
Evaluated at bid price : 20.68
Bid-YTW : 6.03 %
BAM.PR.R FixedReset Disc -1.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-22
Maturity Price : 13.39
Evaluated at bid price : 13.39
Bid-YTW : 6.56 %
SLF.PR.I FixedReset Ins Non -1.40 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.60
Bid-YTW : 8.31 %
PWF.PR.F Perpetual-Discount -1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-22
Maturity Price : 22.69
Evaluated at bid price : 22.93
Bid-YTW : 5.77 %
MFC.PR.K FixedReset Ins Non -1.32 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.40
Bid-YTW : 9.06 %
PWF.PR.Z Perpetual-Discount -1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-22
Maturity Price : 22.02
Evaluated at bid price : 22.36
Bid-YTW : 5.80 %
PVS.PR.D SplitShare -1.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2021-10-08
Maturity Price : 25.00
Evaluated at bid price : 25.01
Bid-YTW : 4.41 %
CM.PR.T FixedReset Disc -1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-22
Maturity Price : 22.57
Evaluated at bid price : 23.52
Bid-YTW : 4.99 %
PWF.PR.K Perpetual-Discount -1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-22
Maturity Price : 21.50
Evaluated at bid price : 21.50
Bid-YTW : 5.82 %
NA.PR.W FixedReset Disc 1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-22
Maturity Price : 14.85
Evaluated at bid price : 14.85
Bid-YTW : 5.89 %
BMO.PR.Z Perpetual-Discount 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-22
Maturity Price : 23.75
Evaluated at bid price : 24.21
Bid-YTW : 5.17 %
CM.PR.P FixedReset Disc 1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-22
Maturity Price : 15.20
Evaluated at bid price : 15.20
Bid-YTW : 5.76 %
SLF.PR.B Deemed-Retractible 1.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.10
Bid-YTW : 6.48 %
RY.PR.M FixedReset Disc 1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-22
Maturity Price : 17.23
Evaluated at bid price : 17.23
Bid-YTW : 5.57 %
BMO.PR.W FixedReset Disc 1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-22
Maturity Price : 15.60
Evaluated at bid price : 15.60
Bid-YTW : 5.53 %
EMA.PR.C FixedReset Disc 1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-22
Maturity Price : 16.94
Evaluated at bid price : 16.94
Bid-YTW : 6.06 %
NA.PR.S FixedReset Disc 1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-22
Maturity Price : 16.01
Evaluated at bid price : 16.01
Bid-YTW : 5.87 %
NA.PR.G FixedReset Disc 1.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-22
Maturity Price : 18.80
Evaluated at bid price : 18.80
Bid-YTW : 5.66 %
TRP.PR.D FixedReset Disc 1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-22
Maturity Price : 14.85
Evaluated at bid price : 14.85
Bid-YTW : 6.27 %
CM.PR.O FixedReset Disc 1.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-22
Maturity Price : 16.00
Evaluated at bid price : 16.00
Bid-YTW : 5.66 %
TD.PF.C FixedReset Disc 1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-22
Maturity Price : 15.95
Evaluated at bid price : 15.95
Bid-YTW : 5.49 %
TRP.PR.G FixedReset Disc 1.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-22
Maturity Price : 15.80
Evaluated at bid price : 15.80
Bid-YTW : 6.59 %
HSE.PR.C FixedReset Disc 2.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-22
Maturity Price : 15.86
Evaluated at bid price : 15.86
Bid-YTW : 6.99 %
CCS.PR.C Deemed-Retractible 2.34 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.52
Bid-YTW : 5.37 %
TRP.PR.A FixedReset Disc 2.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-22
Maturity Price : 12.11
Evaluated at bid price : 12.11
Bid-YTW : 6.60 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PF.L FixedReset Disc 80,675 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-22
Maturity Price : 22.62
Evaluated at bid price : 23.62
Bid-YTW : 4.92 %
RY.PR.Z FixedReset Disc 80,128 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-22
Maturity Price : 16.52
Evaluated at bid price : 16.52
Bid-YTW : 5.32 %
BMO.PR.T FixedReset Disc 53,250 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-22
Maturity Price : 15.90
Evaluated at bid price : 15.90
Bid-YTW : 5.46 %
TD.PF.H FixedReset Prem 43,038 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-22
Maturity Price : 23.35
Evaluated at bid price : 24.51
Bid-YTW : 5.37 %
BAM.PF.E FixedReset Disc 38,400 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-22
Maturity Price : 14.32
Evaluated at bid price : 14.32
Bid-YTW : 6.76 %
CM.PR.P FixedReset Disc 36,800 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-22
Maturity Price : 15.20
Evaluated at bid price : 15.20
Bid-YTW : 5.76 %
There were 39 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
PWF.PR.L Perpetual-Discount Quote: 22.09 – 22.69
Spot Rate : 0.6000
Average : 0.3956

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-22
Maturity Price : 21.85
Evaluated at bid price : 22.09
Bid-YTW : 5.82 %

BAM.PF.D Perpetual-Discount Quote: 20.68 – 21.20
Spot Rate : 0.5200
Average : 0.3606

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-22
Maturity Price : 20.68
Evaluated at bid price : 20.68
Bid-YTW : 6.03 %

BIP.PR.A FixedReset Disc Quote: 17.19 – 17.60
Spot Rate : 0.4100
Average : 0.2543

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-22
Maturity Price : 17.19
Evaluated at bid price : 17.19
Bid-YTW : 7.05 %

BNS.PR.I FixedReset Disc Quote: 18.78 – 19.15
Spot Rate : 0.3700
Average : 0.2250

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-22
Maturity Price : 18.78
Evaluated at bid price : 18.78
Bid-YTW : 5.31 %

PWF.PR.K Perpetual-Discount Quote: 21.50 – 21.96
Spot Rate : 0.4600
Average : 0.3161

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-22
Maturity Price : 21.50
Evaluated at bid price : 21.50
Bid-YTW : 5.82 %

BAM.PR.X FixedReset Disc Quote: 11.79 – 12.30
Spot Rate : 0.5100
Average : 0.3717

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-08-22
Maturity Price : 11.79
Evaluated at bid price : 11.79
Bid-YTW : 6.39 %