Category: Market Action

Market Action

April 26, 2019

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.1893 % 2,098.4
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.1893 % 3,850.5
Floater 5.60 % 5.95 % 50,097 13.96 3 0.1893 % 2,219.1
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0149 % 3,282.9
SplitShare 4.88 % 4.79 % 73,541 3.79 8 -0.0149 % 3,920.5
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0149 % 3,058.9
Perpetual-Premium 5.59 % -9.33 % 94,687 0.09 10 0.0908 % 2,951.8
Perpetual-Discount 5.41 % 5.47 % 79,972 14.64 23 0.0490 % 3,107.6
FixedReset Disc 5.24 % 5.40 % 184,599 14.91 61 0.0352 % 2,197.1
Deemed-Retractible 5.22 % 5.78 % 112,016 8.11 27 0.1217 % 3,078.3
FloatingReset 4.22 % 4.38 % 51,485 2.65 5 0.6398 % 2,418.3
FixedReset Prem 5.07 % 3.69 % 284,301 2.20 23 0.0373 % 2,589.7
FixedReset Bank Non 1.97 % 3.97 % 140,544 2.67 3 0.2081 % 2,654.0
FixedReset Ins Non 4.98 % 6.65 % 102,758 8.24 22 0.3329 % 2,262.9
Performance Highlights
Issue Index Change Notes
MFC.PR.F FixedReset Ins Non -1.49 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.53
Bid-YTW : 9.04 %
BAM.PF.F FixedReset Disc -1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-26
Maturity Price : 19.52
Evaluated at bid price : 19.52
Bid-YTW : 5.81 %
TRP.PR.B FixedReset Disc -1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-26
Maturity Price : 12.37
Evaluated at bid price : 12.37
Bid-YTW : 5.83 %
NA.PR.W FixedReset Disc -1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-26
Maturity Price : 17.39
Evaluated at bid price : 17.39
Bid-YTW : 5.58 %
CM.PR.P FixedReset Disc -1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-26
Maturity Price : 17.83
Evaluated at bid price : 17.83
Bid-YTW : 5.44 %
TRP.PR.D FixedReset Disc 1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-26
Maturity Price : 17.09
Evaluated at bid price : 17.09
Bid-YTW : 5.89 %
BIP.PR.F FixedReset Disc 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-26
Maturity Price : 21.54
Evaluated at bid price : 21.85
Bid-YTW : 5.89 %
MFC.PR.K FixedReset Ins Non 1.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.70
Bid-YTW : 7.06 %
HSE.PR.E FixedReset Disc 1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-26
Maturity Price : 20.53
Evaluated at bid price : 20.53
Bid-YTW : 6.36 %
BIP.PR.D FixedReset Disc 1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-26
Maturity Price : 22.57
Evaluated at bid price : 23.20
Bid-YTW : 5.78 %
HSE.PR.G FixedReset Disc 1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-26
Maturity Price : 20.26
Evaluated at bid price : 20.26
Bid-YTW : 6.38 %
CCS.PR.C Deemed-Retractible 1.39 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.27
Bid-YTW : 5.96 %
MFC.PR.Q FixedReset Ins Non 1.42 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.65
Bid-YTW : 6.82 %
IFC.PR.G FixedReset Ins Non 1.46 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.90
Bid-YTW : 6.75 %
TRP.PR.A FixedReset Disc 1.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-26
Maturity Price : 15.06
Evaluated at bid price : 15.06
Bid-YTW : 5.93 %
MFC.PR.M FixedReset Ins Non 1.78 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.92
Bid-YTW : 7.38 %
MFC.PR.J FixedReset Ins Non 2.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.00
Bid-YTW : 6.65 %
PWF.PR.Q FloatingReset 4.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-26
Maturity Price : 14.50
Evaluated at bid price : 14.50
Bid-YTW : 5.67 %
Volume Highlights
Issue Index Shares
Traded
Notes
BMO.PR.S FixedReset Disc 114,000 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-26
Maturity Price : 19.10
Evaluated at bid price : 19.10
Bid-YTW : 5.26 %
CM.PR.R FixedReset Disc 95,900 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-26
Maturity Price : 22.19
Evaluated at bid price : 22.65
Bid-YTW : 5.39 %
BAM.PF.I FixedReset Prem 93,500 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-26
Maturity Price : 23.26
Evaluated at bid price : 24.65
Bid-YTW : 5.42 %
BAM.PF.H FixedReset Prem 80,300 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.50
Bid-YTW : 3.99 %
GWO.PR.S Deemed-Retractible 65,900 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.60
Bid-YTW : 5.53 %
CM.PR.T FixedReset Prem 65,400 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-26
Maturity Price : 23.28
Evaluated at bid price : 25.36
Bid-YTW : 4.84 %
There were 41 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
IAF.PR.I FixedReset Ins Non Quote: 22.11 – 22.59
Spot Rate : 0.4800
Average : 0.3063

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.11
Bid-YTW : 6.11 %

TD.PF.B FixedReset Disc Quote: 18.48 – 18.78
Spot Rate : 0.3000
Average : 0.2085

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-26
Maturity Price : 18.48
Evaluated at bid price : 18.48
Bid-YTW : 5.29 %

TD.PF.D FixedReset Disc Quote: 21.21 – 21.52
Spot Rate : 0.3100
Average : 0.2222

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-26
Maturity Price : 21.21
Evaluated at bid price : 21.21
Bid-YTW : 5.15 %

SLF.PR.B Deemed-Retractible Quote: 22.36 – 22.75
Spot Rate : 0.3900
Average : 0.3024

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.36
Bid-YTW : 6.24 %

MFC.PR.F FixedReset Ins Non Quote: 14.53 – 14.82
Spot Rate : 0.2900
Average : 0.2090

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.53
Bid-YTW : 9.04 %

TD.PF.J FixedReset Disc Quote: 21.60 – 21.90
Spot Rate : 0.3000
Average : 0.2214

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-26
Maturity Price : 21.31
Evaluated at bid price : 21.60
Bid-YTW : 5.11 %

Market Action

April 25, 2019

Assiduous Reader AB passes on his latest collection of derivative notes based on preferred shares:

…to which I will add

The BMO ‘Principal at Risk’ Notes page is here.

The TD Structured notes page is here. Search for the product class ‘Principal at Risk Notes’ with the keyword ZPR.

So were notes like this responsible for BMO’s buying bout of ZPR at the close today?

zpr_190425
Click for Big

I didn’t look carefully at all the details for all the notes, but I got the impression that a selling commission of 2.5% applied to these notes. Nice work, if you can get it!

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.6808 % 2,094.5
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.6808 % 3,843.3
Floater 5.61 % 5.94 % 50,751 13.97 3 0.6808 % 2,214.9
OpRet 0.00 % 0.00 % 0 0.00 0 0.0298 % 3,283.4
SplitShare 4.88 % 4.74 % 72,416 3.80 8 0.0298 % 3,921.1
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0298 % 3,059.4
Perpetual-Premium 5.60 % -9.51 % 93,881 0.09 10 -0.1262 % 2,949.1
Perpetual-Discount 5.41 % 5.48 % 79,348 14.65 23 -0.0151 % 3,106.1
FixedReset Disc 5.24 % 5.38 % 185,172 14.95 61 -0.0780 % 2,196.3
Deemed-Retractible 5.23 % 5.78 % 103,679 8.11 27 -0.0395 % 3,074.6
FloatingReset 4.25 % 4.36 % 52,182 2.66 5 -0.0759 % 2,403.0
FixedReset Prem 5.07 % 3.78 % 280,592 2.20 23 0.0627 % 2,588.7
FixedReset Bank Non 1.97 % 3.85 % 145,148 2.67 3 0.0972 % 2,648.5
FixedReset Ins Non 5.00 % 6.90 % 103,624 8.23 22 0.0959 % 2,255.4
Performance Highlights
Issue Index Change Notes
BAM.PF.G FixedReset Disc -2.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-25
Maturity Price : 19.35
Evaluated at bid price : 19.35
Bid-YTW : 5.83 %
MFC.PR.L FixedReset Ins Non -1.68 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.55
Bid-YTW : 8.06 %
BAM.PF.F FixedReset Disc -1.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-25
Maturity Price : 19.80
Evaluated at bid price : 19.80
Bid-YTW : 5.72 %
MFC.PR.M FixedReset Ins Non -1.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.59
Bid-YTW : 7.59 %
TRP.PR.C FixedReset Disc -1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-25
Maturity Price : 13.01
Evaluated at bid price : 13.01
Bid-YTW : 5.93 %
TD.PF.I FixedReset Disc -1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-25
Maturity Price : 22.09
Evaluated at bid price : 22.53
Bid-YTW : 5.11 %
CM.PR.S FixedReset Disc -1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-25
Maturity Price : 20.25
Evaluated at bid price : 20.25
Bid-YTW : 5.17 %
NA.PR.S FixedReset Disc -1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-25
Maturity Price : 18.36
Evaluated at bid price : 18.36
Bid-YTW : 5.49 %
TD.PF.A FixedReset Disc -1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-25
Maturity Price : 18.40
Evaluated at bid price : 18.40
Bid-YTW : 5.28 %
GWO.PR.N FixedReset Ins Non 1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.75
Bid-YTW : 8.79 %
TRP.PR.B FixedReset Disc 1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-25
Maturity Price : 12.53
Evaluated at bid price : 12.53
Bid-YTW : 5.75 %
BAM.PR.X FixedReset Disc 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-25
Maturity Price : 14.20
Evaluated at bid price : 14.20
Bid-YTW : 5.85 %
MFC.PR.H FixedReset Ins Non 1.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.47
Bid-YTW : 5.99 %
BAM.PR.K Floater 1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-25
Maturity Price : 11.76
Evaluated at bid price : 11.76
Bid-YTW : 5.94 %
RY.PR.J FixedReset Disc 1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-25
Maturity Price : 20.77
Evaluated at bid price : 20.77
Bid-YTW : 5.21 %
PWF.PR.K Perpetual-Discount 1.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-25
Maturity Price : 22.33
Evaluated at bid price : 22.60
Bid-YTW : 5.49 %
TD.PF.C FixedReset Disc 2.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-25
Maturity Price : 18.67
Evaluated at bid price : 18.67
Bid-YTW : 5.20 %
EMA.PR.F FixedReset Disc 3.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-25
Maturity Price : 19.30
Evaluated at bid price : 19.30
Bid-YTW : 5.61 %
Volume Highlights
Issue Index Shares
Traded
Notes
CU.PR.D Perpetual-Discount 160,500 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-25
Maturity Price : 22.31
Evaluated at bid price : 22.68
Bid-YTW : 5.47 %
BMO.PR.F FixedReset Prem 150,847 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2024-05-25
Maturity Price : 25.00
Evaluated at bid price : 25.35
Bid-YTW : 4.84 %
NA.PR.A FixedReset Prem 83,662 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-15
Maturity Price : 25.00
Evaluated at bid price : 25.81
Bid-YTW : 3.81 %
PWF.PR.L Perpetual-Discount 80,400 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-25
Maturity Price : 22.93
Evaluated at bid price : 23.20
Bid-YTW : 5.51 %
RY.PR.F Deemed-Retractible 65,100 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2019-05-25
Maturity Price : 25.00
Evaluated at bid price : 25.13
Bid-YTW : -6.07 %
GWO.PR.G Deemed-Retractible 48,500 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.01
Bid-YTW : 5.78 %
There were 37 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BMO.PR.W FixedReset Disc Quote: 18.47 – 19.02
Spot Rate : 0.5500
Average : 0.3682

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-25
Maturity Price : 18.47
Evaluated at bid price : 18.47
Bid-YTW : 5.29 %

PWF.PR.Q FloatingReset Quote: 13.90 – 14.60
Spot Rate : 0.7000
Average : 0.5759

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-25
Maturity Price : 13.90
Evaluated at bid price : 13.90
Bid-YTW : 5.92 %

TRP.PR.A FixedReset Disc Quote: 14.80 – 15.35
Spot Rate : 0.5500
Average : 0.4300

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-25
Maturity Price : 14.80
Evaluated at bid price : 14.80
Bid-YTW : 6.04 %

RY.PR.G Deemed-Retractible Quote: 25.15 – 25.42
Spot Rate : 0.2700
Average : 0.1649

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2019-05-25
Maturity Price : 25.00
Evaluated at bid price : 25.15
Bid-YTW : -7.01 %

MFC.PR.B Deemed-Retractible Quote: 21.75 – 22.10
Spot Rate : 0.3500
Average : 0.2524

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.75
Bid-YTW : 6.44 %

PWF.PR.E Perpetual-Premium Quote: 24.92 – 25.19
Spot Rate : 0.2700
Average : 0.1741

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-25
Maturity Price : 24.66
Evaluated at bid price : 24.92
Bid-YTW : 5.54 %

Market Action

April 24, 2019

The Bank of Canada rate announcement was today:

The Bank of Canada today maintained its target for the overnight rate at 1 ¾ per cent. The Bank Rate is correspondingly 2 per cent and the deposit rate is 1 ½ per cent.

Global economic growth has slowed by more than the Bank forecast in its January Monetary Policy Report (MPR). Ongoing uncertainty related to trade conflicts has undermined business sentiment and activity, contributing to a synchronous slowdown across many countries. In response, many central banks have signalled a slower pace of monetary policy normalization. Financial conditions and market sentiment have improved as a result, pushing up prices for oil and other commodities.

Global economic activity is expected to pick up during 2019 and average 3 ¼ per cent over the projection period, supported by accommodative financial conditions and as a number of temporary factors weighing on growth fade. This is roughly in line with the global economy’s potential and a modest downgrade to the Bank’s January projection.

In Canada, growth during the first half of 2019 is now expected to be slower than was anticipated in January. Last year’s oil price decline and ongoing transportation constraints have curbed investment and exports in the energy sector. Investment and exports outside the energy sector, meanwhile, have been negatively affected by trade policy uncertainty and the global slowdown. Weaker-than-anticipated housing and consumption also contributed to slower growth.

The Bank expects growth to pick up, starting in the second quarter of this year. Housing activity is expected to stabilize given continued population gains, the fading effects of past housing policy changes, and improved global financial conditions. Consumption will be underpinned by strong growth in employment income. Outside of the oil and gas sector, investment will be supported by high rates of capacity utilization and exports will expand with strengthening global demand. Meanwhile, the contribution to growth from government spending has been revised down in light of Ontario’s new budget.

Overall, the Bank projects real GDP growth of 1.2 per cent in 2019 and around 2 per cent in 2020 and 2021. This forecast implies a modest widening of the output gap, which will be absorbed over the projection period.

CPI and measures of core inflation are all close to 2 per cent. CPI inflation will likely dip in the third quarter, largely because of the dynamics of gasoline prices, before returning to about 2 per cent by year end. Taking into account the effects of the new carbon pollution charge, as well as modest excess capacity, the Bank expects inflation to remain around 2 per cent through 2020 and 2021.

Given all of these developments, Governing Council judges that an accommodative policy interest rate continues to be warranted. We will continue to evaluate the appropriate degree of monetary policy accommodation as new data arrive. In particular, we are monitoring developments in household spending, oil markets, and global trade policy to gauge the extent to which the factors weighing on growth and the inflation outlook are dissipating.

As usual, there was no reporting of the vote or of dissenting opinions because our illustrious masters do not feel any need for accountability.

The dovish stance hurt the loonie:

The Canadian dollar fell to a nearly four-month low against its broadly stronger U.S. counterpart on Wednesday, as investors raised bets on a Bank of Canada interest rate cut this year after the central bank slashed its economic growth outlook.

Canada’s central bank held its benchmark interest rate steady at 1.75 per cent as expected but removed wording about the need for future rate hikes and lowered its growth forecast for 2019 to 1.2 per cent from 1.7 per cent.
…
Chances of an interest rate cut by December rose to 65 per cent from 57 per cent before the policy announcement, data from the overnight index swaps market showed.

At 4:03 p.m., the Canadian dollar was trading 0.5 per cent lower at 1.3484 to the greenback, or 74.16 U.S. cents. The currency touched its weakest intraday level since Jan. 3 at 1.3522.

… and the GOC five-year yield dropped 7bp to 1.50%.

PerpetualDiscounts now yield 5.49%, equivalent to 7.14% interest at the standard equivalency factor of 1.3x. Long corporates now yield 3.78%, so the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) is now about 335bp, a significant widening from the 325bp reported April 17.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.2174 % 2,080.3
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.2174 % 3,817.3
Floater 5.65 % 5.97 % 51,561 13.93 3 -0.2174 % 2,199.9
OpRet 0.00 % 0.00 % 0 0.00 0 -0.2081 % 3,282.4
SplitShare 4.88 % 4.69 % 71,829 3.80 8 -0.2081 % 3,919.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.2081 % 3,058.5
Perpetual-Premium 5.59 % -11.96 % 90,832 0.09 10 0.0742 % 2,952.9
Perpetual-Discount 5.41 % 5.49 % 80,801 14.61 23 -0.0529 % 3,106.6
FixedReset Disc 5.24 % 5.38 % 184,980 14.93 61 -0.1243 % 2,198.0
Deemed-Retractible 5.23 % 5.81 % 97,161 8.11 27 0.0878 % 3,075.8
FloatingReset 4.25 % 4.36 % 54,326 2.66 5 -0.2486 % 2,404.8
FixedReset Prem 5.07 % 3.80 % 283,293 2.20 23 0.0792 % 2,587.1
FixedReset Bank Non 1.97 % 3.95 % 146,788 2.67 3 0.0278 % 2,646.0
FixedReset Ins Non 5.00 % 6.92 % 103,670 8.24 22 -0.1117 % 2,253.2
Performance Highlights
Issue Index Change Notes
TD.PF.C FixedReset Disc -2.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-24
Maturity Price : 18.23
Evaluated at bid price : 18.23
Bid-YTW : 5.33 %
BAM.PR.X FixedReset Disc -1.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-24
Maturity Price : 14.05
Evaluated at bid price : 14.05
Bid-YTW : 5.91 %
PWF.PR.Q FloatingReset -1.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-24
Maturity Price : 14.02
Evaluated at bid price : 14.02
Bid-YTW : 5.87 %
MFC.PR.F FixedReset Ins Non -1.73 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.76
Bid-YTW : 8.85 %
RY.PR.J FixedReset Disc -1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-24
Maturity Price : 20.49
Evaluated at bid price : 20.49
Bid-YTW : 5.28 %
TRP.PR.G FixedReset Disc -1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-24
Maturity Price : 19.05
Evaluated at bid price : 19.05
Bid-YTW : 6.01 %
RY.PR.M FixedReset Disc -1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-24
Maturity Price : 20.21
Evaluated at bid price : 20.21
Bid-YTW : 5.18 %
MFC.PR.J FixedReset Ins Non -1.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.54
Bid-YTW : 6.92 %
EIT.PR.A SplitShare -1.12 % YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2024-03-14
Maturity Price : 25.00
Evaluated at bid price : 24.83
Bid-YTW : 5.11 %
BAM.PR.K Floater -1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-24
Maturity Price : 11.62
Evaluated at bid price : 11.62
Bid-YTW : 6.02 %
BAM.PF.I FixedReset Prem 1.02 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-03-31
Maturity Price : 25.00
Evaluated at bid price : 24.70
Bid-YTW : 5.39 %
IFC.PR.G FixedReset Ins Non 1.18 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.55
Bid-YTW : 6.96 %
NA.PR.S FixedReset Disc 1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-24
Maturity Price : 18.57
Evaluated at bid price : 18.57
Bid-YTW : 5.43 %
NA.PR.C FixedReset Disc 1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-24
Maturity Price : 22.13
Evaluated at bid price : 22.60
Bid-YTW : 5.44 %
Volume Highlights
Issue Index Shares
Traded
Notes
BMO.PR.F FixedReset Prem 120,855 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2024-05-25
Maturity Price : 25.00
Evaluated at bid price : 25.30
Bid-YTW : 4.88 %
BMO.PR.S FixedReset Disc 102,565 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-24
Maturity Price : 19.16
Evaluated at bid price : 19.16
Bid-YTW : 5.24 %
VNR.PR.A FixedReset Prem 80,900 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-24
Maturity Price : 23.27
Evaluated at bid price : 24.89
Bid-YTW : 4.41 %
RY.PR.W Perpetual-Discount 78,171 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2019-05-24
Maturity Price : 25.00
Evaluated at bid price : 24.92
Bid-YTW : 3.94 %
SLF.PR.A Deemed-Retractible 66,336 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.13
Bid-YTW : 6.31 %
CU.PR.D Perpetual-Discount 48,300 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-24
Maturity Price : 22.38
Evaluated at bid price : 22.78
Bid-YTW : 5.44 %
There were 46 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
HSE.PR.E FixedReset Disc Quote: 20.40 – 21.04
Spot Rate : 0.6400
Average : 0.4152

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-24
Maturity Price : 20.40
Evaluated at bid price : 20.40
Bid-YTW : 6.39 %

TD.PF.C FixedReset Disc Quote: 18.23 – 18.79
Spot Rate : 0.5600
Average : 0.3695

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-24
Maturity Price : 18.23
Evaluated at bid price : 18.23
Bid-YTW : 5.33 %

HSE.PR.G FixedReset Disc Quote: 20.01 – 20.57
Spot Rate : 0.5600
Average : 0.3978

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-24
Maturity Price : 20.01
Evaluated at bid price : 20.01
Bid-YTW : 6.45 %

BIP.PR.E FixedReset Disc Quote: 21.81 – 22.35
Spot Rate : 0.5400
Average : 0.3783

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-24
Maturity Price : 21.55
Evaluated at bid price : 21.81
Bid-YTW : 5.78 %

EMA.PR.F FixedReset Disc Quote: 18.73 – 19.42
Spot Rate : 0.6900
Average : 0.5328

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-24
Maturity Price : 18.73
Evaluated at bid price : 18.73
Bid-YTW : 5.78 %

BMO.PR.Z Perpetual-Discount Quote: 25.01 – 25.40
Spot Rate : 0.3900
Average : 0.2414

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-24
Maturity Price : 24.54
Evaluated at bid price : 25.01
Bid-YTW : 5.06 %

Market Action

April 23, 2019

It was another busy day for the MOC facility, with 68 preferred share issues listed on the imbalances, many of them in lots of 5,000 shares.

MOC Devotee
Click for Big
HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.0576 % 2,084.8
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.0576 % 3,825.6
Floater 5.64 % 5.95 % 51,381 13.96 3 0.0576 % 2,204.7
OpRet 0.00 % 0.00 % 0 0.00 0 0.1389 % 3,289.3
SplitShare 4.87 % 4.69 % 72,362 3.80 8 0.1389 % 3,928.1
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1389 % 3,064.9
Perpetual-Premium 5.59 % -9.87 % 87,499 0.09 10 -0.0945 % 2,950.7
Perpetual-Discount 5.40 % 5.52 % 79,930 14.62 23 0.0733 % 3,108.2
FixedReset Disc 5.23 % 5.38 % 184,533 14.89 61 -0.2403 % 2,200.7
Deemed-Retractible 5.22 % 5.84 % 96,575 8.11 27 -0.0867 % 3,073.1
FloatingReset 4.23 % 4.32 % 54,685 2.66 5 0.0433 % 2,410.8
FixedReset Prem 5.07 % 3.81 % 283,933 2.18 23 -0.0491 % 2,585.0
FixedReset Bank Non 1.98 % 3.97 % 142,098 2.67 3 0.1252 % 2,645.2
FixedReset Ins Non 5.00 % 6.77 % 102,056 8.24 22 -0.2706 % 2,255.7
Performance Highlights
Issue Index Change Notes
TD.PF.C FixedReset Disc -2.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-23
Maturity Price : 18.75
Evaluated at bid price : 18.75
Bid-YTW : 5.18 %
EMA.PR.F FixedReset Disc -2.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-23
Maturity Price : 18.81
Evaluated at bid price : 18.81
Bid-YTW : 5.76 %
MFC.PR.Q FixedReset Ins Non -1.35 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.40
Bid-YTW : 6.96 %
MFC.PR.K FixedReset Ins Non -1.32 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.47
Bid-YTW : 7.20 %
TRP.PR.D FixedReset Disc -1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-23
Maturity Price : 16.71
Evaluated at bid price : 16.71
Bid-YTW : 6.02 %
PWF.PR.A Floater -1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-23
Maturity Price : 13.35
Evaluated at bid price : 13.35
Bid-YTW : 5.18 %
TD.PF.A FixedReset Disc -1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-23
Maturity Price : 18.70
Evaluated at bid price : 18.70
Bid-YTW : 5.19 %
CM.PR.S FixedReset Disc -1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-23
Maturity Price : 20.43
Evaluated at bid price : 20.43
Bid-YTW : 5.12 %
NA.PR.E FixedReset Disc -1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-23
Maturity Price : 19.85
Evaluated at bid price : 19.85
Bid-YTW : 5.42 %
RY.PR.Z FixedReset Disc -1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-23
Maturity Price : 18.65
Evaluated at bid price : 18.65
Bid-YTW : 5.22 %
BMO.PR.E FixedReset Disc -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-23
Maturity Price : 22.00
Evaluated at bid price : 22.51
Bid-YTW : 4.98 %
MFC.PR.N FixedReset Ins Non -1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.21
Bid-YTW : 7.76 %
BAM.PF.J FixedReset Disc -1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-23
Maturity Price : 22.75
Evaluated at bid price : 23.70
Bid-YTW : 5.00 %
GWO.PR.P Deemed-Retractible 1.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.97
Bid-YTW : 5.49 %
BAM.PR.K Floater 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-23
Maturity Price : 11.74
Evaluated at bid price : 11.74
Bid-YTW : 5.95 %
PWF.PR.P FixedReset Disc 1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-23
Maturity Price : 14.42
Evaluated at bid price : 14.42
Bid-YTW : 5.43 %
BIP.PR.D FixedReset Disc 1.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-23
Maturity Price : 22.51
Evaluated at bid price : 23.11
Bid-YTW : 5.80 %
RY.PR.M FixedReset Disc 2.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-23
Maturity Price : 20.70
Evaluated at bid price : 20.70
Bid-YTW : 5.13 %
Volume Highlights
Issue Index Shares
Traded
Notes
BAM.PF.I FixedReset Prem 157,400 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-23
Maturity Price : 23.18
Evaluated at bid price : 24.45
Bid-YTW : 5.46 %
IAF.PR.G FixedReset Ins Non 91,500 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.25
Bid-YTW : 6.22 %
BMO.PR.F FixedReset Prem 69,316 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2024-05-25
Maturity Price : 25.00
Evaluated at bid price : 25.28
Bid-YTW : 4.89 %
CM.PR.R FixedReset Disc 64,162 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-23
Maturity Price : 22.19
Evaluated at bid price : 22.65
Bid-YTW : 5.39 %
BMO.PR.E FixedReset Disc 62,800 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-23
Maturity Price : 22.00
Evaluated at bid price : 22.51
Bid-YTW : 4.98 %
BAM.PF.H FixedReset Prem 58,170 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.60
Bid-YTW : 3.72 %
There were 43 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
IFC.PR.G FixedReset Ins Non Quote: 20.31 – 21.20
Spot Rate : 0.8900
Average : 0.6060

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.31
Bid-YTW : 7.10 %

TRP.PR.C FixedReset Disc Quote: 13.15 – 13.70
Spot Rate : 0.5500
Average : 0.3398

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-23
Maturity Price : 13.15
Evaluated at bid price : 13.15
Bid-YTW : 5.87 %

NA.PR.S FixedReset Disc Quote: 18.35 – 18.79
Spot Rate : 0.4400
Average : 0.2698

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-23
Maturity Price : 18.35
Evaluated at bid price : 18.35
Bid-YTW : 5.49 %

MFC.PR.M FixedReset Ins Non Quote: 18.82 – 19.40
Spot Rate : 0.5800
Average : 0.4250

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.82
Bid-YTW : 7.44 %

PWF.PR.F Perpetual-Discount Quote: 23.61 – 24.06
Spot Rate : 0.4500
Average : 0.3130

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-23
Maturity Price : 23.33
Evaluated at bid price : 23.61
Bid-YTW : 5.57 %

IFC.PR.A FixedReset Ins Non Quote: 15.61 – 16.03
Spot Rate : 0.4200
Average : 0.2845

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.61
Bid-YTW : 8.93 %

Market Action

April 22, 2019

FAIR Canada, that superannuation scheme for tired old regulatory hacks, is in some well-deserved trouble:

The primary advocacy group for Canadian investors is losing money, looking for an executive director – and struggling to survive.
…
FAIR Canada has survived in large part in recent years on a $2-million gift from Stephen Jarislowsky, the founder of investment firm Jarislowsky Fraser Ltd., and an additional $2-million contribution from the Ontario Securities Commission, which used money collected in settlements and from fines.

Mr. Jarislowsky’s 2014 gift was conditional on FAIR finding $4-million in matching gifts, but outside of the OSC money, it has fallen far short, Mr. Pascutto said. Mr. Jarislowsky has extended a deadline for the match several times, most recently agreeing to postpone it to this coming September from March 31.
…
The Investment Industry Regulatory Organization of Canada (IIROC), which provided the initial funding for FAIR Canada, has given a total of $4.9-million over the years, including a $250,000 grant in the fall of 2018 from its restricted fund that comes from fines and settlements, spokeswoman Andrea Zviedris said in an e-mailed statement.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -1.1780 % 2,083.6
FixedFloater 0.00 % 0.00 % 0 0.00 0 -1.1780 % 3,823.4
Floater 5.62 % 6.00 % 51,942 13.89 3 -1.1780 % 2,203.4
OpRet 0.00 % 0.00 % 0 0.00 0 0.0000 % 3,284.7
SplitShare 4.87 % 4.72 % 75,126 3.80 8 0.0000 % 3,922.7
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0000 % 3,060.6
Perpetual-Premium 5.58 % -10.05 % 85,440 0.09 10 -0.0079 % 2,953.5
Perpetual-Discount 5.40 % 5.54 % 79,726 14.62 23 0.1771 % 3,105.9
FixedReset Disc 5.21 % 5.36 % 178,946 14.94 61 0.3795 % 2,206.0
Deemed-Retractible 5.22 % 5.78 % 99,734 8.12 27 0.0505 % 3,075.8
FloatingReset 4.24 % 4.36 % 55,148 2.66 5 -0.2158 % 2,409.7
FixedReset Prem 5.07 % 3.75 % 288,500 2.18 23 0.2649 % 2,586.3
FixedReset Bank Non 1.98 % 3.87 % 143,155 2.68 3 0.1951 % 2,641.9
FixedReset Ins Non 4.98 % 6.77 % 105,651 8.25 22 0.7076 % 2,261.9
Performance Highlights
Issue Index Change Notes
BAM.PR.B Floater -2.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-22
Maturity Price : 11.65
Evaluated at bid price : 11.65
Bid-YTW : 6.00 %
PWF.PR.Q FloatingReset -1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-22
Maturity Price : 14.36
Evaluated at bid price : 14.36
Bid-YTW : 5.73 %
TRP.PR.C FixedReset Disc -1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-22
Maturity Price : 13.20
Evaluated at bid price : 13.20
Bid-YTW : 5.84 %
BIP.PR.E FixedReset Disc -1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-22
Maturity Price : 21.43
Evaluated at bid price : 21.77
Bid-YTW : 5.79 %
TRP.PR.B FixedReset Disc -1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-22
Maturity Price : 12.36
Evaluated at bid price : 12.36
Bid-YTW : 5.83 %
BAM.PR.K Floater -1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-22
Maturity Price : 11.61
Evaluated at bid price : 11.61
Bid-YTW : 6.02 %
BIP.PR.C FixedReset Disc 1.02 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-09-30
Maturity Price : 25.00
Evaluated at bid price : 24.88
Bid-YTW : 5.74 %
BMO.PR.C FixedReset Disc 1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-22
Maturity Price : 22.98
Evaluated at bid price : 24.04
Bid-YTW : 5.08 %
HSE.PR.G FixedReset Disc 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-22
Maturity Price : 20.06
Evaluated at bid price : 20.06
Bid-YTW : 6.44 %
SLF.PR.J FloatingReset 1.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.93
Bid-YTW : 9.07 %
BNS.PR.I FixedReset Disc 1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-22
Maturity Price : 22.25
Evaluated at bid price : 22.93
Bid-YTW : 4.61 %
CU.PR.I FixedReset Prem 1.17 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-01
Maturity Price : 25.00
Evaluated at bid price : 25.95
Bid-YTW : 2.49 %
BNS.PR.H FixedReset Prem 1.18 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-01-26
Maturity Price : 25.00
Evaluated at bid price : 25.81
Bid-YTW : 3.60 %
SLF.PR.G FixedReset Ins Non 1.28 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.03
Bid-YTW : 8.78 %
IFC.PR.E Deemed-Retractible 1.31 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.00
Bid-YTW : 5.78 %
MFC.PR.Q FixedReset Ins Non 1.37 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.68
Bid-YTW : 6.79 %
MFC.PR.N FixedReset Ins Non 1.43 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.40
Bid-YTW : 7.63 %
EMA.PR.H FixedReset Disc 1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-22
Maturity Price : 22.71
Evaluated at bid price : 23.75
Bid-YTW : 5.19 %
BAM.PR.Z FixedReset Disc 1.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-22
Maturity Price : 20.62
Evaluated at bid price : 20.62
Bid-YTW : 5.64 %
BIP.PR.F FixedReset Disc 1.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-22
Maturity Price : 21.51
Evaluated at bid price : 21.80
Bid-YTW : 5.90 %
MFC.PR.L FixedReset Ins Non 2.34 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.90
Bid-YTW : 7.81 %
CU.PR.C FixedReset Disc 3.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-22
Maturity Price : 18.60
Evaluated at bid price : 18.60
Bid-YTW : 5.33 %
IAF.PR.G FixedReset Ins Non 5.12 % Just a reversal of Friday’s nonsense.

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.15
Bid-YTW : 6.28 %

Volume Highlights
Issue Index Shares
Traded
Notes
NA.PR.C FixedReset Disc 77,300 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-22
Maturity Price : 21.97
Evaluated at bid price : 22.36
Bid-YTW : 5.50 %
CM.PR.R FixedReset Disc 67,400 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-22
Maturity Price : 22.22
Evaluated at bid price : 22.70
Bid-YTW : 5.37 %
BMO.PR.F FixedReset Prem 56,651 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2024-05-25
Maturity Price : 25.00
Evaluated at bid price : 25.26
Bid-YTW : 4.91 %
TRP.PR.D FixedReset Disc 41,500 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-22
Maturity Price : 16.93
Evaluated at bid price : 16.93
Bid-YTW : 5.94 %
TRP.PR.K FixedReset Prem 23,236 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-05-31
Maturity Price : 25.00
Evaluated at bid price : 25.25
Bid-YTW : 4.84 %
MFC.PR.R FixedReset Ins Non 18,200 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-03-19
Maturity Price : 25.00
Evaluated at bid price : 25.18
Bid-YTW : 4.77 %
There were 5 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
SLF.PR.H FixedReset Ins Non Quote: 17.70 – 17.98
Spot Rate : 0.2800
Average : 0.2049

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.70
Bid-YTW : 7.60 %

BAM.PF.D Perpetual-Discount Quote: 21.75 – 22.20
Spot Rate : 0.4500
Average : 0.3850

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-22
Maturity Price : 21.75
Evaluated at bid price : 21.75
Bid-YTW : 5.69 %

MFC.PR.M FixedReset Ins Non Quote: 18.88 – 19.20
Spot Rate : 0.3200
Average : 0.2551

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.88
Bid-YTW : 7.39 %

BAM.PF.F FixedReset Disc Quote: 20.00 – 20.22
Spot Rate : 0.2200
Average : 0.1637

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-22
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 5.66 %

BAM.PR.N Perpetual-Discount Quote: 20.76 – 21.07
Spot Rate : 0.3100
Average : 0.2570

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-22
Maturity Price : 20.76
Evaluated at bid price : 20.76
Bid-YTW : 5.78 %

CU.PR.F Perpetual-Discount Quote: 21.22 – 21.63
Spot Rate : 0.4100
Average : 0.3655

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-22
Maturity Price : 21.22
Evaluated at bid price : 21.22
Bid-YTW : 5.39 %

Market Action

April 18, 2019

On March 28 I highlighted an issue of structured notes from TD. Assiduous Reader AB writes in and provides me with a link to the National Bank Structured Solutions Group page, who issued five separate notes “linked to a Canadian preferred share ETF” between April 10 and April 18.

There was a disorderly close in the market today, as TXPR lost 49bp in the last five minutes to close down 28bp from yesterday on high volume of over 4-million shares.

txpr_190418
Click for Big

One of the hard-working geniuses who are such a feature of Canadian investment management made extensive use of the Market-on-Close facility, which I assume helped him leave early for the long weekend.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -1.3731 % 2,108.5
FixedFloater 0.00 % 0.00 % 0 0.00 0 -1.3731 % 3,869.0
Floater 5.55 % 5.86 % 49,194 14.11 3 -1.3731 % 2,229.7
OpRet 0.00 % 0.00 % 0 0.00 0 0.0050 % 3,284.7
SplitShare 4.87 % 4.69 % 75,213 3.82 8 0.0050 % 3,922.7
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0050 % 3,060.6
Perpetual-Premium 5.58 % -8.49 % 86,667 0.09 10 -0.2043 % 2,953.7
Perpetual-Discount 5.41 % 5.52 % 80,810 14.60 23 -0.4501 % 3,100.4
FixedReset Disc 5.23 % 5.41 % 185,299 14.84 61 -0.2348 % 2,197.7
Deemed-Retractible 5.22 % 5.82 % 99,895 8.13 27 -0.2627 % 3,074.2
FloatingReset 4.23 % 4.35 % 57,414 2.67 5 -0.2798 % 2,414.9
FixedReset Prem 5.08 % 3.93 % 290,390 2.19 23 -0.4817 % 2,579.5
FixedReset Bank Non 1.98 % 4.02 % 149,013 2.69 3 0.0418 % 2,636.8
FixedReset Ins Non 5.02 % 6.89 % 109,903 8.25 22 -0.8244 % 2,246.0
Performance Highlights
Issue Index Change Notes
IAF.PR.G FixedReset Ins Non -5.54 % Not as unreasonable as it looks, as the issue traded 24,769 shares in a range of 20.42-39 before closing at 20.12-21.39. “Range” is kind of a misnomer, since the issue traded at around 21.30 for most of the day, then moved to the 20.42 MOC price with very little in between. The indicated MOC imbalance was a sell of 7,286 shares.

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.12
Bid-YTW : 6.89 %

BAM.PR.K Floater -3.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-18
Maturity Price : 11.74
Evaluated at bid price : 11.74
Bid-YTW : 5.95 %
MFC.PR.L FixedReset Ins Non -2.83 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.49
Bid-YTW : 8.11 %
TRP.PR.B FixedReset Disc -2.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-18
Maturity Price : 12.52
Evaluated at bid price : 12.52
Bid-YTW : 5.79 %
PWF.PR.Z Perpetual-Discount -2.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-18
Maturity Price : 22.96
Evaluated at bid price : 23.27
Bid-YTW : 5.54 %
PWF.PR.L Perpetual-Discount -1.97 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-18
Maturity Price : 22.59
Evaluated at bid price : 22.84
Bid-YTW : 5.59 %
MFC.PR.Q FixedReset Ins Non -1.83 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.40
Bid-YTW : 6.97 %
PWF.PR.S Perpetual-Discount -1.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-18
Maturity Price : 21.56
Evaluated at bid price : 21.56
Bid-YTW : 5.59 %
BAM.PF.I FixedReset Prem -1.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-18
Maturity Price : 23.14
Evaluated at bid price : 24.35
Bid-YTW : 5.50 %
BIP.PR.F FixedReset Disc -1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-18
Maturity Price : 21.40
Evaluated at bid price : 21.40
Bid-YTW : 6.02 %
BAM.PR.B Floater -1.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-18
Maturity Price : 11.91
Evaluated at bid price : 11.91
Bid-YTW : 5.86 %
PWF.PR.K Perpetual-Discount -1.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-18
Maturity Price : 21.76
Evaluated at bid price : 22.01
Bid-YTW : 5.63 %
BAM.PF.A FixedReset Disc -1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-18
Maturity Price : 21.00
Evaluated at bid price : 21.00
Bid-YTW : 5.62 %
BAM.PR.Z FixedReset Disc -1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-18
Maturity Price : 20.27
Evaluated at bid price : 20.27
Bid-YTW : 5.76 %
MFC.PR.B Deemed-Retractible -1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.80
Bid-YTW : 6.39 %
BAM.PR.T FixedReset Disc -1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-18
Maturity Price : 16.38
Evaluated at bid price : 16.38
Bid-YTW : 5.96 %
BNS.PR.H FixedReset Prem -1.32 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-01-26
Maturity Price : 25.00
Evaluated at bid price : 25.51
Bid-YTW : 4.04 %
GWO.PR.R Deemed-Retractible -1.30 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.80
Bid-YTW : 5.98 %
CU.PR.C FixedReset Disc -1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-18
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 5.53 %
TRP.PR.K FixedReset Prem -1.25 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-05-31
Maturity Price : 25.00
Evaluated at bid price : 25.36
Bid-YTW : 4.67 %
IFC.PR.G FixedReset Ins Non -1.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.25
Bid-YTW : 7.14 %
TRP.PR.G FixedReset Disc -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-18
Maturity Price : 19.19
Evaluated at bid price : 19.19
Bid-YTW : 5.97 %
HSE.PR.A FixedReset Disc -1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-18
Maturity Price : 12.65
Evaluated at bid price : 12.65
Bid-YTW : 6.50 %
MFC.PR.J FixedReset Ins Non -1.00 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.71
Bid-YTW : 6.82 %
CM.PR.Q FixedReset Disc 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-18
Maturity Price : 20.12
Evaluated at bid price : 20.12
Bid-YTW : 5.44 %
SLF.PR.A Deemed-Retractible 1.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.45
Bid-YTW : 6.12 %
BMO.PR.E FixedReset Disc 1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-18
Maturity Price : 22.08
Evaluated at bid price : 22.64
Bid-YTW : 4.96 %
Volume Highlights
Issue Index Shares
Traded
Notes
CM.PR.T FixedReset Prem 271,288 Indicated MOC imbalance was a buy of 61,601 shares.

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2024-04-30
Maturity Price : 25.00
Evaluated at bid price : 25.45
Bid-YTW : 4.79 %

BAM.PR.K Floater 252,100 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-18
Maturity Price : 11.74
Evaluated at bid price : 11.74
Bid-YTW : 5.95 %
CU.PR.G Perpetual-Discount 218,515 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-18
Maturity Price : 21.26
Evaluated at bid price : 21.26
Bid-YTW : 5.37 %
TD.PF.L FixedReset Prem 217,051 Indicated MOC imbalance was a buy of 3,247 shares.

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2024-04-30
Maturity Price : 25.00
Evaluated at bid price : 25.50
Bid-YTW : 4.74 %

GWO.PR.R Deemed-Retractible 140,171 Indicated MOC imbalance was a sell of 154,494 shares.

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.80
Bid-YTW : 5.98 %

VNR.PR.A FixedReset Prem 118,662 Indicated MOC imbalance was a sell of 55,262 shares.

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-18
Maturity Price : 23.26
Evaluated at bid price : 24.85
Bid-YTW : 4.43 %

BIK.PR.A FixedReset Prem 117,120 Indicated MOC imbalance was a buy of 51,183 shares.

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2024-03-31
Maturity Price : 25.00
Evaluated at bid price : 25.41
Bid-YTW : 5.57 %

BAM.PF.I FixedReset Prem 109,124 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-18
Maturity Price : 23.14
Evaluated at bid price : 24.35
Bid-YTW : 5.50 %
BMO.PR.Y FixedReset Disc 105,784 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-18
Maturity Price : 21.27
Evaluated at bid price : 21.27
Bid-YTW : 5.14 %
There were 88 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
IAF.PR.G FixedReset Ins Non Quote: 20.12 – 21.39
Spot Rate : 1.2700
Average : 0.7229

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.12
Bid-YTW : 6.89 %

IFC.PR.G FixedReset Ins Non Quote: 20.25 – 21.20
Spot Rate : 0.9500
Average : 0.5626

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.25
Bid-YTW : 7.14 %

CU.PR.I FixedReset Prem Quote: 25.65 – 26.41
Spot Rate : 0.7600
Average : 0.4676

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-01
Maturity Price : 25.00
Evaluated at bid price : 25.65
Bid-YTW : 3.22 %

PWF.PR.S Perpetual-Discount Quote: 21.56 – 22.27
Spot Rate : 0.7100
Average : 0.4296

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-18
Maturity Price : 21.56
Evaluated at bid price : 21.56
Bid-YTW : 5.59 %

MFC.PR.Q FixedReset Ins Non Quote: 20.40 – 20.90
Spot Rate : 0.5000
Average : 0.3045

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.40
Bid-YTW : 6.97 %

TD.PF.J FixedReset Disc Quote: 21.42 – 22.00
Spot Rate : 0.5800
Average : 0.3899

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-18
Maturity Price : 21.42
Evaluated at bid price : 21.42
Bid-YTW : 5.18 %

Market Action

April 17, 2019

On March 18 I reported:

Assiduous Readers will remember that Manulife was bailed out by the regulators again after a hedge fund claimed the terms of its contract with the firm allowed it to deposit unlimited funds with the firm at a guaranteed rate of up to 5%.

It turns out the bail-out was unnecessary! Manulife won the court case

‘Not so fast!’ scream the plaintiffs:

A pivotal court ruling that dismissed three lawsuits against Canadian life insurers has been formally appealed, extending a battle between the companies and three investment funds over the fine print of decades-old contracts.
…
This week the funds appealed all three cases, arguing that the core argument made by Justice Brian Scherman of the Court of Queen’s Bench for Saskatchewan when dismissing the lawsuits is incorrect. Justice Scherman ruled that the contracts were designed to be used for insurance purposes only, and that “in the some 30 years since universal life insurance policies have been sold, there is no judicial record of these policies being used in the manner proposed” by the investment funds.

In its appeal of the ruling that related to Manulife, Mosten Investment LP argued “the learned Chambers Judge erred in law in his interpretation of the contract.”

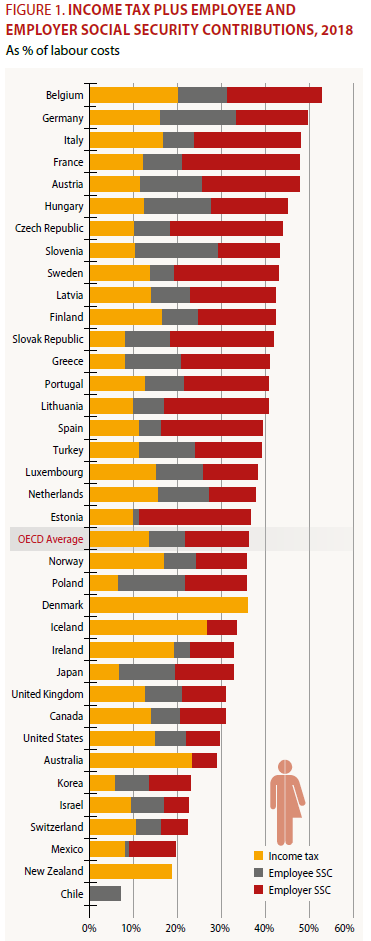
There is a fascinating chart made available in the OECD release of its publication “Taxing Wages”:

figure-1-web-full
Click for Big

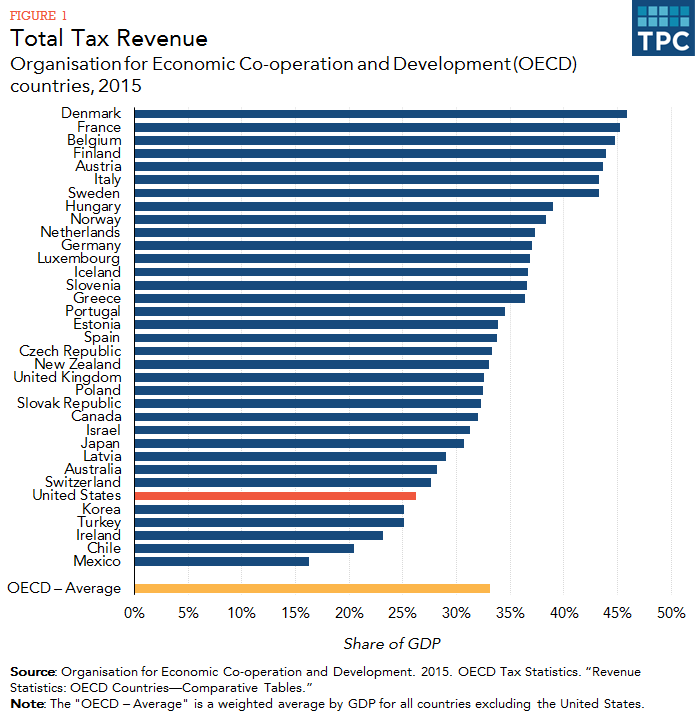
Of course, this just refers to taxes on wages; it does not include things like sales tax and property tax. In the interest of avoiding vitriolic attacks by worshippers of the Awesome and Holy United States of Free America, I will also publish a chart more favourable to that glorious nation:

3_1_4_-_figure_1
Click for Big

Of course, neither chart includes the cost of health insurance, which is a big ticket item in the Awesome and Holy United States of Free America, but that’s because health insurance is FREE ENTERPRISE, dammit, and any free citizen has a CHOICE between between buying Health Insurance, dying, or being bankrupted by medical bills.

Reasonable people can argue all day and all night regarding whether a single-payer system like Canada’s is better or worse than the US system. Each has its own advantages and disadvantages. But to take tax rates as a straight-up, single-number meaningful comparison of anything at all is simply ridiculous and annoys me.

PerpetualDiscounts now yield 5.45%, equivalent to 7.08% interest at the standard equivalency factor of 1.3x. Long corporates now yield 3.82%, so the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) is now about 325bp, unchanged from the figure reported April 10.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.4469 % 2,137.8
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.4469 % 3,922.8
Floater 5.48 % 5.76 % 45,645 14.26 3 -0.4469 % 2,260.8
OpRet 0.00 % 0.00 % 0 0.00 0 0.1292 % 3,284.6
SplitShare 4.87 % 4.61 % 75,842 3.82 8 0.1292 % 3,922.5
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1292 % 3,060.5
Perpetual-Premium 5.57 % -17.16 % 81,232 0.09 10 -0.0079 % 2,959.7
Perpetual-Discount 5.39 % 5.45 % 78,217 14.68 23 0.0019 % 3,114.4
FixedReset Disc 5.22 % 5.42 % 184,836 14.89 61 0.0987 % 2,202.9
Deemed-Retractible 5.20 % 5.80 % 99,151 8.13 27 0.0094 % 3,082.3
FloatingReset 4.22 % 4.34 % 53,154 2.68 5 0.0754 % 2,421.7
FixedReset Prem 5.06 % 3.63 % 282,841 2.19 23 0.1432 % 2,592.0
FixedReset Bank Non 1.98 % 4.02 % 145,072 2.69 3 -0.1809 % 2,635.7
FixedReset Ins Non 4.98 % 6.69 % 106,882 8.27 22 -0.0930 % 2,264.6
Performance Highlights
Issue Index Change Notes
SLF.PR.G FixedReset Ins Non -2.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.92
Bid-YTW : 8.87 %
TRP.PR.C FixedReset Disc -1.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-17
Maturity Price : 13.27
Evaluated at bid price : 13.27
Bid-YTW : 5.84 %
TRP.PR.A FixedReset Disc -1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-17
Maturity Price : 14.83
Evaluated at bid price : 14.83
Bid-YTW : 6.05 %
MFC.PR.J FixedReset Ins Non -1.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.92
Bid-YTW : 6.69 %
HSE.PR.E FixedReset Disc 1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-17
Maturity Price : 20.20
Evaluated at bid price : 20.20
Bid-YTW : 6.47 %
RY.PR.Z FixedReset Disc 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-17
Maturity Price : 18.93
Evaluated at bid price : 18.93
Bid-YTW : 5.17 %
MFC.PR.M FixedReset Ins Non 1.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.90
Bid-YTW : 7.39 %
TRP.PR.G FixedReset Disc 1.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-17
Maturity Price : 19.40
Evaluated at bid price : 19.40
Bid-YTW : 5.90 %
IAF.PR.B Deemed-Retractible 1.89 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.16
Bid-YTW : 6.11 %
TRP.PR.B FixedReset Disc 2.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-17
Maturity Price : 12.80
Evaluated at bid price : 12.80
Bid-YTW : 5.66 %
Volume Highlights
Issue Index Shares
Traded
Notes
BMO.PR.F FixedReset Prem 2,191,850 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2024-05-25
Maturity Price : 25.00
Evaluated at bid price : 25.22
Bid-YTW : 4.93 %
PWF.PR.K Perpetual-Discount 150,395 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-17
Maturity Price : 22.08
Evaluated at bid price : 22.36
Bid-YTW : 5.54 %
IFC.PR.G FixedReset Ins Non 149,035 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.50
Bid-YTW : 6.99 %
POW.PR.G Perpetual-Premium 101,854 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2019-05-17
Maturity Price : 25.50
Evaluated at bid price : 25.70
Bid-YTW : -3.64 %
PVS.PR.F SplitShare 82,900 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2024-09-30
Maturity Price : 25.00
Evaluated at bid price : 25.01
Bid-YTW : 4.93 %
TRP.PR.E FixedReset Disc 63,700 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-17
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 5.90 %
There were 31 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
ELF.PR.H Perpetual-Discount Quote: 24.95 – 25.50
Spot Rate : 0.5500
Average : 0.3163

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-17
Maturity Price : 24.41
Evaluated at bid price : 24.95
Bid-YTW : 5.52 %

TD.PF.B FixedReset Disc Quote: 18.85 – 19.24
Spot Rate : 0.3900
Average : 0.2480

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-17
Maturity Price : 18.85
Evaluated at bid price : 18.85
Bid-YTW : 5.20 %

TD.PF.D FixedReset Disc Quote: 21.03 – 21.63
Spot Rate : 0.6000
Average : 0.4699

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-17
Maturity Price : 21.03
Evaluated at bid price : 21.03
Bid-YTW : 5.21 %

IFC.PR.E Deemed-Retractible Quote: 23.86 – 24.25
Spot Rate : 0.3900
Average : 0.2818

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.86
Bid-YTW : 5.84 %

BAM.PF.D Perpetual-Discount Quote: 21.85 – 22.20
Spot Rate : 0.3500
Average : 0.2521

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-17
Maturity Price : 21.85
Evaluated at bid price : 21.85
Bid-YTW : 5.66 %

NA.PR.C FixedReset Disc Quote: 22.28 – 22.57
Spot Rate : 0.2900
Average : 0.2117

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-17
Maturity Price : 21.91
Evaluated at bid price : 22.28
Bid-YTW : 5.53 %

Market Action

April 16, 2019

I noticed another recent corporate long bond issue, this one some thirty-year notes from Pembina:

Pembina Pipeline Corporation (“Pembina” or the “Company”) (TSX: PPL; NYSE: PBA) is pleased to announce that it has closed its previously announced offering of $800 million of senior unsecured medium-term notes (the “Offering”). The Offering was conducted in two tranches consisting of $400 million in senior unsecured medium-term notes, series 12 (the “Series 12 Notes”) having a fixed coupon of 3.62% per annum, paid semi-annually, and maturing on April 3, 2029, and $400 million in senior unsecured medium-term notes, series 13 (the “Series 13 Notes”) having a fixed coupon of 4.54% per annum, paid semi-annually, and maturing on April 3, 2049.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.2622 % 2,147.4
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.2622 % 3,940.5
Floater 5.45 % 5.72 % 45,085 14.33 3 -0.2622 % 2,270.9
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0397 % 3,280.3
SplitShare 4.88 % 4.66 % 75,844 3.82 8 -0.0397 % 3,917.4
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0397 % 3,056.5
Perpetual-Premium 5.57 % -16.50 % 81,851 0.09 10 -0.0589 % 2,960.0
Perpetual-Discount 5.39 % 5.43 % 77,151 14.71 23 0.1202 % 3,114.4
FixedReset Disc 5.23 % 5.43 % 183,042 14.88 61 -0.0477 % 2,200.7
Deemed-Retractible 5.21 % 5.74 % 99,449 8.13 27 -0.0739 % 3,082.0
FloatingReset 4.22 % 4.29 % 52,991 2.68 5 0.0215 % 2,419.9
FixedReset Prem 5.06 % 3.71 % 293,626 2.20 22 0.0194 % 2,588.2
FixedReset Bank Non 1.98 % 3.95 % 146,077 2.69 3 -0.0278 % 2,640.4
FixedReset Ins Non 4.97 % 6.55 % 108,241 8.27 22 -0.0861 % 2,266.7
Performance Highlights
Issue Index Change Notes
IAF.PR.B Deemed-Retractible -1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.75
Bid-YTW : 6.34 %
BAM.PF.I FixedReset Prem -1.04 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-03-31
Maturity Price : 25.00
Evaluated at bid price : 24.66
Bid-YTW : 5.40 %
IFC.PR.C FixedReset Ins Non -1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.05
Bid-YTW : 7.31 %
TRP.PR.B FixedReset Disc -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-16
Maturity Price : 12.50
Evaluated at bid price : 12.50
Bid-YTW : 5.79 %
BAM.PF.J FixedReset Disc -1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-16
Maturity Price : 22.95
Evaluated at bid price : 24.15
Bid-YTW : 4.89 %
BMO.PR.T FixedReset Disc 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-16
Maturity Price : 18.50
Evaluated at bid price : 18.50
Bid-YTW : 5.33 %
MFC.PR.J FixedReset Ins Non 1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.15
Bid-YTW : 6.55 %
SLF.PR.H FixedReset Ins Non 1.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.90
Bid-YTW : 7.47 %
BAM.PF.C Perpetual-Discount 1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-16
Maturity Price : 21.25
Evaluated at bid price : 21.25
Bid-YTW : 5.76 %
BMO.PR.W FixedReset Disc 1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-16
Maturity Price : 18.40
Evaluated at bid price : 18.40
Bid-YTW : 5.33 %
MFC.PR.L FixedReset Ins Non 1.70 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.94
Bid-YTW : 7.79 %
BAM.PR.Z FixedReset Disc 1.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-16
Maturity Price : 20.65
Evaluated at bid price : 20.65
Bid-YTW : 5.65 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.H FixedReset Disc 116,121 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-16
Maturity Price : 19.21
Evaluated at bid price : 19.21
Bid-YTW : 5.16 %
BAM.PF.A FixedReset Disc 84,025 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-16
Maturity Price : 21.23
Evaluated at bid price : 21.23
Bid-YTW : 5.56 %
TRP.PR.E FixedReset Disc 45,090 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-16
Maturity Price : 16.92
Evaluated at bid price : 16.92
Bid-YTW : 5.93 %
BAM.PR.Z FixedReset Disc 43,519 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-16
Maturity Price : 20.65
Evaluated at bid price : 20.65
Bid-YTW : 5.65 %
TD.PF.H FixedReset Prem 43,035 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.65
Bid-YTW : 3.71 %
GWO.PR.I Deemed-Retractible 42,346 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.38
Bid-YTW : 6.44 %
There were 29 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
IAF.PR.B Deemed-Retractible Quote: 21.75 – 22.21
Spot Rate : 0.4600
Average : 0.3270

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.75
Bid-YTW : 6.34 %

BMO.PR.W FixedReset Disc Quote: 18.40 – 18.84
Spot Rate : 0.4400
Average : 0.3095

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-16
Maturity Price : 18.40
Evaluated at bid price : 18.40
Bid-YTW : 5.33 %

TRP.PR.D FixedReset Disc Quote: 17.00 – 17.39
Spot Rate : 0.3900
Average : 0.2630

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-16
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 5.94 %

BIP.PR.A FixedReset Disc Quote: 20.21 – 20.72
Spot Rate : 0.5100
Average : 0.3946

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-16
Maturity Price : 20.21
Evaluated at bid price : 20.21
Bid-YTW : 6.44 %

CCS.PR.C Deemed-Retractible Quote: 22.91 – 23.41
Spot Rate : 0.5000
Average : 0.3868

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.91
Bid-YTW : 6.13 %

CM.PR.Q FixedReset Disc Quote: 19.90 – 20.28
Spot Rate : 0.3800
Average : 0.2878

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-04-16
Maturity Price : 19.90
Evaluated at bid price : 19.90
Bid-YTW : 5.50 %

Market Action

March 29, 2019

unicorn_190329
Click for Big

TXPR closed at 627.58, up 0.57% on the day. Volume was 2.48-million, on the high side but nothing special in the context of the past thirty days.

CPD closed at 12.55, up 0.72% on the day. Volume of 94,423 was low in the context of the past thirty days.

ZPR closed at 10.12, up 0.60% on the day. Volume of 474,940 was very high in the context of the past thirty days, second only to March 13, when a stunning 1,007,639 shares changed hands.

Five-year Canada yields were up, up 6bp to 1.52% today, but that’s not sufficient to be considered a glib explanation.

So it was a fine way to close the month, but not enough to save the TXPR total return index, which saw performance of -0.46% in March but (thank heavens for small mercies) +1.11% for the quarter.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 2.7848 % 2,062.8
FixedFloater 0.00 % 0.00 % 0 0.00 0 2.7848 % 3,785.1
Floater 5.68 % 5.83 % 41,833 14.14 3 2.7848 % 2,181.4
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0645 % 3,282.6
SplitShare 4.88 % 4.50 % 77,421 3.87 8 -0.0645 % 3,920.1
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0645 % 3,058.6
Perpetual-Premium 5.67 % -9.74 % 62,689 0.09 7 0.1629 % 2,939.6
Perpetual-Discount 5.37 % 5.40 % 85,986 14.65 26 -0.0605 % 3,111.7
FixedReset Disc 5.24 % 5.22 % 193,716 15.10 64 0.8245 % 2,177.4
Deemed-Retractible 5.20 % 5.73 % 96,349 8.18 27 0.1733 % 3,082.4
FloatingReset 4.23 % 3.93 % 42,339 2.71 5 0.9318 % 2,390.5
FixedReset Prem 5.06 % 3.60 % 314,659 2.22 19 0.4293 % 2,579.1
FixedReset Bank Non 1.97 % 4.00 % 147,480 2.74 3 0.2506 % 2,636.7
FixedReset Ins Non 4.98 % 6.35 % 116,194 8.37 22 0.8645 % 2,262.2
Performance Highlights
Issue Index Change Notes
BAM.PF.F FixedReset Disc -2.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 18.81
Evaluated at bid price : 18.81
Bid-YTW : 5.78 %
BAM.PF.E FixedReset Disc -1.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 17.21
Evaluated at bid price : 17.21
Bid-YTW : 5.90 %
TD.PF.C FixedReset Disc -1.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 18.45
Evaluated at bid price : 18.45
Bid-YTW : 5.11 %
RY.PR.W Perpetual-Discount -1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 24.54
Evaluated at bid price : 24.79
Bid-YTW : 4.99 %
MFC.PR.B Deemed-Retractible -1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.93
Bid-YTW : 6.28 %
PWF.PR.T FixedReset Disc 1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 19.55
Evaluated at bid price : 19.55
Bid-YTW : 4.98 %
MFC.PR.K FixedReset Ins Non 1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.45
Bid-YTW : 7.05 %
IFC.PR.F Deemed-Retractible 1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.25
Bid-YTW : 5.71 %
BMO.PR.E FixedReset Disc 1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 22.32
Evaluated at bid price : 23.05
Bid-YTW : 4.69 %
HSE.PR.E FixedReset Disc 1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 19.55
Evaluated at bid price : 19.55
Bid-YTW : 6.44 %
TRP.PR.B FixedReset Disc 1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 11.90
Evaluated at bid price : 11.90
Bid-YTW : 5.71 %
BAM.PF.A FixedReset Disc 1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 21.15
Evaluated at bid price : 21.15
Bid-YTW : 5.40 %
TRP.PR.A FixedReset Disc 1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 14.54
Evaluated at bid price : 14.54
Bid-YTW : 5.84 %
SLF.PR.I FixedReset Ins Non 1.26 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.86
Bid-YTW : 6.22 %
W.PR.K FixedReset Prem 1.29 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-01-15
Maturity Price : 25.00
Evaluated at bid price : 25.50
Bid-YTW : 3.96 %
TD.PF.K FixedReset Disc 1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 21.53
Evaluated at bid price : 21.83
Bid-YTW : 4.90 %
GWO.PR.N FixedReset Ins Non 1.32 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.56
Bid-YTW : 8.69 %
PWF.PR.S Perpetual-Discount 1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 22.04
Evaluated at bid price : 22.40
Bid-YTW : 5.43 %
BAM.PR.K Floater 1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 11.80
Evaluated at bid price : 11.80
Bid-YTW : 5.88 %
SLF.PR.H FixedReset Ins Non 1.45 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.53
Bid-YTW : 7.51 %
IFC.PR.A FixedReset Ins Non 1.55 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.35
Bid-YTW : 8.17 %
SLF.PR.J FloatingReset 1.55 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.37
Bid-YTW : 9.44 %
PWF.PR.Q FloatingReset 1.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 14.30
Evaluated at bid price : 14.30
Bid-YTW : 5.79 %
NA.PR.S FixedReset Disc 1.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 18.75
Evaluated at bid price : 18.75
Bid-YTW : 5.22 %
TRP.PR.D FixedReset Disc 1.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 17.02
Evaluated at bid price : 17.02
Bid-YTW : 5.65 %
CU.PR.C FixedReset Disc 1.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 17.88
Evaluated at bid price : 17.88
Bid-YTW : 5.34 %
MFC.PR.L FixedReset Ins Non 1.69 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.00
Bid-YTW : 7.48 %
IFC.PR.C FixedReset Ins Non 1.76 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.07
Bid-YTW : 7.10 %
NA.PR.G FixedReset Disc 1.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 21.92
Evaluated at bid price : 22.39
Bid-YTW : 4.97 %
CM.PR.P FixedReset Disc 1.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 17.71
Evaluated at bid price : 17.71
Bid-YTW : 5.23 %
TRP.PR.C FixedReset Disc 1.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 12.77
Evaluated at bid price : 12.77
Bid-YTW : 5.73 %
TRP.PR.F FloatingReset 2.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 14.35
Evaluated at bid price : 14.35
Bid-YTW : 6.26 %
BAM.PF.G FixedReset Disc 2.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 19.10
Evaluated at bid price : 19.10
Bid-YTW : 5.68 %
BAM.PR.X FixedReset Disc 2.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 14.01
Evaluated at bid price : 14.01
Bid-YTW : 5.67 %
TRP.PR.E FixedReset Disc 2.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 16.82
Evaluated at bid price : 16.82
Bid-YTW : 5.68 %
BAM.PR.R FixedReset Disc 2.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 15.92
Evaluated at bid price : 15.92
Bid-YTW : 5.78 %
MFC.PR.N FixedReset Ins Non 2.59 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.24
Bid-YTW : 7.50 %
TD.PF.E FixedReset Disc 2.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 21.10
Evaluated at bid price : 21.10
Bid-YTW : 5.14 %
PWF.PR.A Floater 2.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 12.85
Evaluated at bid price : 12.85
Bid-YTW : 5.45 %
PWF.PR.P FixedReset Disc 2.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 14.08
Evaluated at bid price : 14.08
Bid-YTW : 5.37 %
SLF.PR.G FixedReset Ins Non 3.35 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.48
Bid-YTW : 8.96 %
NA.PR.W FixedReset Disc 3.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 5.24 %
TRP.PR.G FixedReset Disc 3.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 18.90
Evaluated at bid price : 18.90
Bid-YTW : 5.83 %
MFC.PR.F FixedReset Ins Non 3.68 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.36
Bid-YTW : 8.93 %
BAM.PR.B Floater 4.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 11.89
Evaluated at bid price : 11.89
Bid-YTW : 5.83 %
BAM.PR.T FixedReset Disc 9.87 % Just a reversal of yesterday‘s idiocy.

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 16.25
Evaluated at bid price : 16.25
Bid-YTW : 5.75 %

Volume Highlights
Issue Index Shares
Traded
Notes
BNS.PR.H FixedReset Prem 95,700 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-01-26
Maturity Price : 25.00
Evaluated at bid price : 26.06
Bid-YTW : 3.59 %
EMA.PR.H FixedReset Disc 78,000 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 22.58
Evaluated at bid price : 23.50
Bid-YTW : 5.23 %
MFC.PR.R FixedReset Ins Non 65,100 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-03-19
Maturity Price : 25.00
Evaluated at bid price : 25.11
Bid-YTW : 4.76 %
VNR.PR.A FixedReset Disc 62,300 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 23.35
Evaluated at bid price : 25.13
Bid-YTW : 4.27 %
BAM.PF.I FixedReset Prem 50,227 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-03-31
Maturity Price : 25.00
Evaluated at bid price : 25.30
Bid-YTW : 4.38 %
RY.PR.Z FixedReset Disc 41,450 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 18.40
Evaluated at bid price : 18.40
Bid-YTW : 5.05 %
There were 37 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BAM.PF.F FixedReset Disc Quote: 18.81 – 19.54
Spot Rate : 0.7300
Average : 0.4730

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 18.81
Evaluated at bid price : 18.81
Bid-YTW : 5.78 %

CM.PR.Q FixedReset Disc Quote: 19.91 – 20.54
Spot Rate : 0.6300
Average : 0.4331

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 19.91
Evaluated at bid price : 19.91
Bid-YTW : 5.27 %

TD.PF.C FixedReset Disc Quote: 18.45 – 18.99
Spot Rate : 0.5400
Average : 0.3716

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 18.45
Evaluated at bid price : 18.45
Bid-YTW : 5.11 %

TRP.PR.K FixedReset Disc Quote: 25.18 – 25.62
Spot Rate : 0.4400
Average : 0.2757

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-05-31
Maturity Price : 25.00
Evaluated at bid price : 25.18
Bid-YTW : 4.82 %

BAM.PR.Z FixedReset Disc Quote: 20.03 – 20.51
Spot Rate : 0.4800
Average : 0.3181

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 20.03
Evaluated at bid price : 20.03
Bid-YTW : 5.63 %

BAM.PF.E FixedReset Disc Quote: 17.21 – 17.80
Spot Rate : 0.5900
Average : 0.4304

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-29
Maturity Price : 17.21
Evaluated at bid price : 17.21
Bid-YTW : 5.90 %

Market Action

March 28, 2019

There was a late afternoon rally in the market yesterday which I mentioned but did not even guess at a cause. Assiduous Reader AB writes in and says:

TD issued a note tied to ZPR. They had to hedge some of their risk into the close.

He even provided a link to the product description. There’s an ongoing link to the prospectus, which states:

As of the date of this Pricing Supplement, the Bank estimates that the value of the Notes is $97.10 per $100 in principal amount.

There are a lot of moving parts in the valuation of this note and I’m not even going to try to come up with my own valuation. But the issue sold out, $20-million worth, so there’s clearly some speculative interest in buying at these levels.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -3.1071 % 2,006.9
FixedFloater 0.00 % 0.00 % 0 0.00 0 -3.1071 % 3,682.5
Floater 5.83 % 5.96 % 41,243 13.96 3 -3.1071 % 2,122.3
OpRet 0.00 % 0.00 % 0 0.00 0 0.1789 % 3,284.7
SplitShare 4.87 % 4.45 % 75,064 3.87 8 0.1789 % 3,922.7
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1789 % 3,060.6
Perpetual-Premium 5.67 % -3.59 % 61,997 0.08 7 -0.0393 % 2,934.9
Perpetual-Discount 5.36 % 5.42 % 86,145 14.64 26 -0.0043 % 3,113.6
FixedReset Disc 5.28 % 5.27 % 194,193 14.99 64 0.1287 % 2,159.6
Deemed-Retractible 5.21 % 5.74 % 100,210 8.19 27 -0.1479 % 3,077.1
FloatingReset 4.27 % 4.11 % 41,066 2.71 5 -0.2951 % 2,368.4
FixedReset Prem 5.08 % 3.83 % 314,807 2.22 19 -0.1264 % 2,568.1
FixedReset Bank Non 1.98 % 4.04 % 146,938 2.74 3 0.1255 % 2,630.1
FixedReset Ins Non 5.03 % 6.37 % 117,981 8.37 22 0.4075 % 2,242.8
Performance Highlights
Issue Index Change Notes
BAM.PR.T FixedReset Disc -7.97 % A nonsensical quote provided at high cost by Nonsense Central, as the issue traded 1400 shares today in a range of 16.00-03 before being quoted at 14.79-16.25. The closing price was 16.03.

I have not checked whether the lamentable state of the quote is due to inadequate Toronto Stock Exchange reporting or inadequate Toronto Stock Exchange supervision of market-makers.

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-28
Maturity Price : 14.79
Evaluated at bid price : 14.79
Bid-YTW : 6.32 %

BAM.PR.B Floater -5.15 % A nonsensical quote provided at high cost by Nonsense Central, as the issue traded 3212 shares today in a range of 11.99-08 before being quoted at 11.41-00. The closing price was 12.00.

I have not checked whether the lamentable state of the quote is due to inadequate Toronto Stock Exchange reporting or inadequate Toronto Stock Exchange supervision of market-makers.

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-28
Maturity Price : 11.41
Evaluated at bid price : 11.41
Bid-YTW : 6.08 %

TD.PF.E FixedReset Disc -2.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-28
Maturity Price : 20.55
Evaluated at bid price : 20.55
Bid-YTW : 5.28 %
PWF.PR.A Floater -2.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-28
Maturity Price : 12.50
Evaluated at bid price : 12.50
Bid-YTW : 5.60 %
IFC.PR.A FixedReset Ins Non -2.19 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.10
Bid-YTW : 8.36 %
BAM.PR.K Floater -2.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-28
Maturity Price : 11.64
Evaluated at bid price : 11.64
Bid-YTW : 5.96 %
CCS.PR.C Deemed-Retractible -1.95 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.65
Bid-YTW : 6.24 %
GWO.PR.S Deemed-Retractible -1.82 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.30
Bid-YTW : 5.63 %
PWF.PR.S Perpetual-Discount -1.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-28
Maturity Price : 21.82
Evaluated at bid price : 22.10
Bid-YTW : 5.51 %
PWF.PR.K Perpetual-Discount -1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-28
Maturity Price : 22.73
Evaluated at bid price : 23.02
Bid-YTW : 5.45 %
NA.PR.G FixedReset Disc -1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-28
Maturity Price : 21.65
Evaluated at bid price : 22.00
Bid-YTW : 5.07 %
BMO.PR.S FixedReset Disc -1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-28
Maturity Price : 18.75
Evaluated at bid price : 18.75
Bid-YTW : 5.12 %
HSE.PR.C FixedReset Disc -1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-28
Maturity Price : 18.15
Evaluated at bid price : 18.15
Bid-YTW : 6.36 %
PWF.PR.P FixedReset Disc -1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-28
Maturity Price : 13.68
Evaluated at bid price : 13.68
Bid-YTW : 5.53 %
BAM.PR.X FixedReset Disc -1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-28
Maturity Price : 13.70
Evaluated at bid price : 13.70
Bid-YTW : 5.80 %
PWF.PR.L Perpetual-Discount -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-28
Maturity Price : 23.25
Evaluated at bid price : 23.55
Bid-YTW : 5.49 %
RY.PR.O Perpetual-Discount 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-28
Maturity Price : 23.89
Evaluated at bid price : 24.36
Bid-YTW : 5.06 %
BAM.PF.F FixedReset Disc 1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-28
Maturity Price : 19.30
Evaluated at bid price : 19.30
Bid-YTW : 5.64 %
MFC.PR.M FixedReset Ins Non 1.31 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.62
Bid-YTW : 7.32 %
MFC.PR.I FixedReset Ins Non 1.31 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.60
Bid-YTW : 6.11 %
SLF.PR.I FixedReset Ins Non 1.33 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.60
Bid-YTW : 6.37 %
BMO.PR.E FixedReset Disc 1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-28
Maturity Price : 22.18
Evaluated at bid price : 22.80
Bid-YTW : 4.75 %
MFC.PR.G FixedReset Ins Non 1.40 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.00
Bid-YTW : 6.32 %
IAF.PR.G FixedReset Ins Non 1.47 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.70
Bid-YTW : 6.37 %
SLF.PR.H FixedReset Ins Non 1.65 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.28
Bid-YTW : 7.68 %
MFC.PR.L FixedReset Ins Non 1.67 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.70
Bid-YTW : 7.68 %
VNR.PR.A FixedReset Disc 17.60 % In response to the proposed acquisition at 25.00.

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-28
Maturity Price : 23.32
Evaluated at bid price : 25.06
Bid-YTW : 4.29 %

Volume Highlights
Issue Index Shares
Traded
Notes
VNR.PR.A FixedReset Disc 362,380 In response to the proposed acquisition at 25.00.

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-28
Maturity Price : 23.32
Evaluated at bid price : 25.06
Bid-YTW : 4.29 %

SLF.PR.D Deemed-Retractible 207,600 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.10
Bid-YTW : 6.51 %
GWO.PR.S Deemed-Retractible 89,300 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.30
Bid-YTW : 5.63 %
GWO.PR.P Deemed-Retractible 87,400 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-03-31
Maturity Price : 25.00
Evaluated at bid price : 24.98
Bid-YTW : 5.44 %
RY.PR.O Perpetual-Discount 85,600 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-28
Maturity Price : 23.89
Evaluated at bid price : 24.36
Bid-YTW : 5.06 %
RY.PR.S FixedReset Disc 82,910 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-28
Maturity Price : 21.64
Evaluated at bid price : 22.00
Bid-YTW : 4.68 %
There were 39 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
MFC.PR.G FixedReset Ins Non Quote: 21.00 – 25.00
Spot Rate : 4.0000
Average : 2.8193

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.00
Bid-YTW : 6.32 %

BAM.PR.T FixedReset Disc Quote: 14.79 – 16.25
Spot Rate : 1.4600
Average : 0.8857

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-28
Maturity Price : 14.79
Evaluated at bid price : 14.79
Bid-YTW : 6.32 %

TD.PF.B FixedReset Disc Quote: 18.55 – 19.65
Spot Rate : 1.1000
Average : 0.6569

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-28
Maturity Price : 18.55
Evaluated at bid price : 18.55
Bid-YTW : 5.11 %

IFC.PR.A FixedReset Ins Non Quote: 16.10 – 16.88
Spot Rate : 0.7800
Average : 0.4449

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2030-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.10
Bid-YTW : 8.36 %

TRP.PR.G FixedReset Disc Quote: 18.24 – 19.35
Spot Rate : 1.1100
Average : 0.8310

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-28
Maturity Price : 18.24
Evaluated at bid price : 18.24
Bid-YTW : 6.04 %

BAM.PR.B Floater Quote: 11.41 – 12.00
Spot Rate : 0.5900
Average : 0.3588

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2049-03-28
Maturity Price : 11.41
Evaluated at bid price : 11.41
Bid-YTW : 6.08 %