Category: Market Action

Market Action

March 26, 2018

Some people think the world might not end after all:

U.S. equities surged back from the biggest weekly rout in two years, with major benchmarks climbing more than 2.7 percent on signs that an escalation of trade tensions was beginning to ease.
…
The optimism toward U.S. stocks emerged after the limits of the Trump administration’s willingness to embrace protectionism came into view over the weekend. Treasury Secretary Steven Mnuchin told Fox News that he’s “cautiously hopeful” that China will reach a deal to avoid tariffs on $50 billion of U.S. exports, while European leaders demanded a permanent exclusion at the threat of retaliation and a deal was struck with South Korea.
…
The yield on 10-year Treasuries climbed four basis points to 2.85 percent.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.7296 % 3,025.6
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.7296 % 5,551.8
Floater 3.30 % 3.46 % 101,188 18.61 4 0.7296 % 3,199.6
OpRet 0.00 % 0.00 % 0 0.00 0 0.0000 % 3,167.6
SplitShare 4.69 % 4.16 % 58,167 3.25 5 0.0000 % 3,782.8
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0000 % 2,951.5
Perpetual-Premium 5.63 % 5.11 % 79,561 0.74 11 -0.1043 % 2,834.5
Perpetual-Discount 5.39 % 5.52 % 82,186 14.60 23 -0.4377 % 2,913.7
FixedReset 4.30 % 4.68 % 175,779 5.83 104 0.0904 % 2,504.7
Deemed-Retractible 5.21 % 5.84 % 90,486 5.70 28 -0.1383 % 2,900.5
FloatingReset 2.95 % 3.08 % 35,279 3.63 10 0.1064 % 2,757.5
Performance Highlights
Issue Index Change Notes
BAM.PR.M Perpetual-Discount -1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-26
Maturity Price : 20.64
Evaluated at bid price : 20.64
Bid-YTW : 5.79 %
BAM.PF.C Perpetual-Discount -1.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-26
Maturity Price : 21.15
Evaluated at bid price : 21.15
Bid-YTW : 5.77 %
BAM.PF.D Perpetual-Discount -1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-26
Maturity Price : 21.35
Evaluated at bid price : 21.35
Bid-YTW : 5.77 %
BAM.PR.N Perpetual-Discount -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-26
Maturity Price : 20.71
Evaluated at bid price : 20.71
Bid-YTW : 5.77 %
PWF.PR.E Perpetual-Discount -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-26
Maturity Price : 24.50
Evaluated at bid price : 24.75
Bid-YTW : 5.64 %
NA.PR.E FixedReset 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-26
Maturity Price : 23.04
Evaluated at bid price : 24.68
Bid-YTW : 4.66 %
TD.PF.B FixedReset 1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-26
Maturity Price : 22.67
Evaluated at bid price : 23.12
Bid-YTW : 4.68 %
PWF.PR.A Floater 1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-26
Maturity Price : 21.00
Evaluated at bid price : 21.00
Bid-YTW : 2.89 %
MFC.PR.G FixedReset 1.46 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-12-19
Maturity Price : 25.00
Evaluated at bid price : 24.31
Bid-YTW : 4.75 %
TRP.PR.C FixedReset 1.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-26
Maturity Price : 17.88
Evaluated at bid price : 17.88
Bid-YTW : 4.80 %
Volume Highlights
Issue Index Shares
Traded
Notes
BNS.PR.A FloatingReset 417,442 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-04-25
Maturity Price : 25.00
Evaluated at bid price : 25.13
Bid-YTW : -6.22 %
W.PR.M FixedReset 51,112 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-15
Maturity Price : 25.00
Evaluated at bid price : 25.82
Bid-YTW : 4.53 %
TD.PF.J FixedReset 37,250 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-26
Maturity Price : 23.18
Evaluated at bid price : 25.09
Bid-YTW : 4.64 %
TD.PF.D FixedReset 30,524 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-26
Maturity Price : 23.20
Evaluated at bid price : 24.25
Bid-YTW : 4.83 %
CM.PR.R FixedReset 27,366 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-07-31
Maturity Price : 25.00
Evaluated at bid price : 25.22
Bid-YTW : 4.37 %
BMO.PR.S FixedReset 25,986 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-26
Maturity Price : 23.06
Evaluated at bid price : 23.57
Bid-YTW : 4.65 %
There were 25 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
TRP.PR.F FloatingReset Quote: 20.18 – 21.70
Spot Rate : 1.5200
Average : 0.9710

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-26
Maturity Price : 20.18
Evaluated at bid price : 20.18
Bid-YTW : 3.71 %

EIT.PR.A SplitShare Quote: 25.55 – 26.55
Spot Rate : 1.0000
Average : 0.6456

YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2024-03-14
Maturity Price : 25.00
Evaluated at bid price : 25.55
Bid-YTW : 4.43 %

BAM.PF.E FixedReset Quote: 22.90 – 23.45
Spot Rate : 0.5500
Average : 0.4115

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-26
Maturity Price : 22.58
Evaluated at bid price : 22.90
Bid-YTW : 5.01 %

IFC.PR.E Deemed-Retractible Quote: 24.31 – 24.75
Spot Rate : 0.4400
Average : 0.3034

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.31
Bid-YTW : 5.71 %

BMO.PR.Q FixedReset Quote: 22.25 – 22.60
Spot Rate : 0.3500
Average : 0.2171

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.25
Bid-YTW : 5.22 %

TRP.PR.K FixedReset Quote: 25.55 – 25.85
Spot Rate : 0.3000
Average : 0.1801

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-05-31
Maturity Price : 25.00
Evaluated at bid price : 25.55
Bid-YTW : 4.44 %

Market Action

March 23, 2018

How about that Canadian inflation, eh?:

Canadian inflation picked up more than analysts expected in February to the fastest in more than three years as signs point to price pressures continuing to build.

Consumer prices accelerated to an annual pace of 2.2 percent in February, the most since 2014, from 1.7 percent a month earlier. Economists had anticipated a 1.9 percent increase. Core prices — which exclude more volatile items like energy and are considered a gauge of inflation pressures — inched higher for a fifth month to 2.03 percent, which is the fastest since 2012.

The budding inflation could add pressure on the Bank of Canada — which has kept the expansion going with low interest rates — to keep hiking borrowing costs to more normal levels.

All this is happening during renewed NAFTA huffing and puffing:

U.S. President Donald Trump has put new pressure on Nafta negotiations with an order saying he’ll impose steel and aluminum tariffs on Canada and Mexico on May 1 if he’s not satisfied with talks.

Trump’s presidential proclamation Thursday sets tariffs for some countries as of Friday while excluding others such as Canada and Mexico. The document specifies for the first time when those exclusions will run out, adding to pressure for a deal to be reached on the North American Free Trade Agreement around the same time.

A White House statement said Trump will decide by May 1 “whether to continue to exempt these countries from tariffs, based on the status of discussions.” Mexico has said it needs a deal by the end of April, or that talks might as well stretch past the country’s summer election, and then U.S. midterm elections this fall.

All this Trumpism is having an effect:

Spring has sprung — just not in U.S. stocks, where a harrowing week has walloped traders with echoes of February’s correction.

In the past five years, there have been only two other stretches with losses of this magnitude. The S&P 500 Index is down 6 percent. And the picture looks just as bad for the Dow Jones Industrial Average, which sank to a four-month low by the Friday close. Both indexes suffered their steepest weekly drop in more than two years.

Equities are now teetering near — and for blue chips, below — levels seen at the worst point in February’s volatility-fueled meltdown. At the epicenter this time is U.S. President Donald Trump, with his China tariffs driving Boeing Co. down more than 5 percent in a single session on Thursday and losses rippling across industries from technology to banks.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.6429 % 3,003.7
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.6429 % 5,511.6
Floater 3.32 % 3.48 % 100,759 18.58 4 -0.6429 % 3,176.4
OpRet 0.00 % 0.00 % 0 0.00 0 0.0078 % 3,167.6
SplitShare 4.69 % 4.15 % 57,540 3.26 5 0.0078 % 3,782.8
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0078 % 2,951.5
Perpetual-Premium 5.63 % 2.45 % 79,181 0.08 11 -0.0611 % 2,837.4
Perpetual-Discount 5.37 % 5.48 % 82,372 14.60 23 -0.0934 % 2,926.5
FixedReset 4.30 % 4.65 % 177,170 5.88 104 -0.2139 % 2,502.4
Deemed-Retractible 5.20 % 5.88 % 90,903 5.71 28 -0.0714 % 2,904.5
FloatingReset 2.91 % 3.04 % 34,985 3.64 10 -0.1814 % 2,754.6
Performance Highlights
Issue Index Change Notes
MFC.PR.G FixedReset -1.48 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.96
Bid-YTW : 5.08 %
TD.PF.B FixedReset -1.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-23
Maturity Price : 22.44
Evaluated at bid price : 22.86
Bid-YTW : 4.65 %
SLF.PR.G FixedReset -1.43 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.28
Bid-YTW : 7.31 %
TRP.PR.C FixedReset -1.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-23
Maturity Price : 17.60
Evaluated at bid price : 17.60
Bid-YTW : 4.78 %
MFC.PR.M FixedReset -1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.15
Bid-YTW : 5.57 %
PWF.PR.A Floater -1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-23
Maturity Price : 20.75
Evaluated at bid price : 20.75
Bid-YTW : 2.93 %
PWF.PR.F Perpetual-Discount -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-23
Maturity Price : 23.53
Evaluated at bid price : 23.80
Bid-YTW : 5.59 %
PWF.PR.T FixedReset -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-23
Maturity Price : 23.20
Evaluated at bid price : 23.80
Bid-YTW : 4.59 %
IAG.PR.G FixedReset -1.02 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.31
Bid-YTW : 5.36 %
TRP.PR.B FixedReset -1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-23
Maturity Price : 16.65
Evaluated at bid price : 16.65
Bid-YTW : 4.71 %
Volume Highlights
Issue Index Shares
Traded
Notes
MFC.PR.B Deemed-Retractible 76,624 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.54
Bid-YTW : 7.30 %
MFC.PR.C Deemed-Retractible 67,225 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.83
Bid-YTW : 7.73 %
BAM.PR.R FixedReset 47,178 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-23
Maturity Price : 20.07
Evaluated at bid price : 20.07
Bid-YTW : 5.07 %
CM.PR.R FixedReset 46,556 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-07-31
Maturity Price : 25.00
Evaluated at bid price : 25.16
Bid-YTW : 4.43 %
TD.PF.J FixedReset 40,820 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-23
Maturity Price : 23.18
Evaluated at bid price : 25.09
Bid-YTW : 4.58 %
BAM.PF.F FixedReset 34,700 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-23
Maturity Price : 23.65
Evaluated at bid price : 24.05
Bid-YTW : 5.00 %
There were 11 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
MFC.PR.G FixedReset Quote: 23.96 – 24.80
Spot Rate : 0.8400
Average : 0.4933

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.96
Bid-YTW : 5.08 %

MFC.PR.N FixedReset Quote: 22.97 – 23.70
Spot Rate : 0.7300
Average : 0.4187

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.97
Bid-YTW : 5.61 %

TRP.PR.F FloatingReset Quote: 20.22 – 20.84
Spot Rate : 0.6200
Average : 0.3690

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-23
Maturity Price : 20.22
Evaluated at bid price : 20.22
Bid-YTW : 3.66 %

PWF.PR.A Floater Quote: 20.75 – 21.34
Spot Rate : 0.5900
Average : 0.3883

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-23
Maturity Price : 20.75
Evaluated at bid price : 20.75
Bid-YTW : 2.93 %

W.PR.H Perpetual-Discount Quote: 24.75 – 25.22
Spot Rate : 0.4700
Average : 0.2810

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-23
Maturity Price : 24.50
Evaluated at bid price : 24.75
Bid-YTW : 5.65 %

RY.PR.H FixedReset Quote: 23.35 – 23.77
Spot Rate : 0.4200
Average : 0.2457

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-23
Maturity Price : 22.91
Evaluated at bid price : 23.35
Bid-YTW : 4.53 %

Market Action

March 22, 2018

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -1.8262 % 3,023.1
FixedFloater 0.00 % 0.00 % 0 0.00 0 -1.8262 % 5,547.3
Floater 3.30 % 3.46 % 101,783 18.62 4 -1.8262 % 3,196.9
OpRet 0.00 % 0.00 % 0 0.00 0 0.0157 % 3,167.4
SplitShare 4.69 % 4.18 % 58,301 3.26 5 0.0157 % 3,782.5
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0157 % 2,951.3
Perpetual-Premium 5.62 % 2.25 % 79,522 0.08 11 -0.0706 % 2,839.2
Perpetual-Discount 5.37 % 5.49 % 85,606 14.61 23 -0.2371 % 2,929.2
FixedReset 4.30 % 4.59 % 178,093 5.87 104 -0.1199 % 2,507.8
Deemed-Retractible 5.20 % 5.94 % 92,256 5.72 28 -0.3225 % 2,906.6
FloatingReset 2.91 % 3.01 % 36,229 3.65 10 0.0443 % 2,759.6
Performance Highlights
Issue Index Change Notes
PWF.PR.A Floater -2.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-22
Maturity Price : 21.00
Evaluated at bid price : 21.00
Bid-YTW : 2.89 %
BAM.PR.B Floater -1.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-22
Maturity Price : 17.32
Evaluated at bid price : 17.32
Bid-YTW : 3.48 %
BAM.PR.C Floater -1.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-22
Maturity Price : 17.42
Evaluated at bid price : 17.42
Bid-YTW : 3.46 %
BAM.PR.K Floater -1.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-22
Maturity Price : 17.37
Evaluated at bid price : 17.37
Bid-YTW : 3.47 %
BAM.PR.R FixedReset -1.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-22
Maturity Price : 20.19
Evaluated at bid price : 20.19
Bid-YTW : 5.04 %
BAM.PF.B FixedReset -1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-22
Maturity Price : 22.49
Evaluated at bid price : 23.00
Bid-YTW : 4.98 %
BAM.PF.G FixedReset -1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-22
Maturity Price : 22.95
Evaluated at bid price : 23.71
Bid-YTW : 5.02 %
SLF.PR.A Deemed-Retractible -1.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.95
Bid-YTW : 7.04 %
BAM.PF.F FixedReset -1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-22
Maturity Price : 23.58
Evaluated at bid price : 23.99
Bid-YTW : 5.01 %
TRP.PR.G FixedReset -1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-22
Maturity Price : 22.80
Evaluated at bid price : 23.56
Bid-YTW : 5.05 %
BAM.PF.A FixedReset -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-22
Maturity Price : 23.14
Evaluated at bid price : 23.90
Bid-YTW : 5.07 %
Volume Highlights
Issue Index Shares
Traded
Notes
NA.PR.C FixedReset 153,050 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-11-15
Maturity Price : 25.00
Evaluated at bid price : 25.05
Bid-YTW : 4.53 %
RY.PR.J FixedReset 71,564 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-22
Maturity Price : 23.24
Evaluated at bid price : 24.25
Bid-YTW : 4.71 %
TRP.PR.K FixedReset 56,700 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-05-31
Maturity Price : 25.00
Evaluated at bid price : 25.55
Bid-YTW : 4.43 %
RY.PR.G Deemed-Retractible 51,200 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-04-21
Maturity Price : 25.00
Evaluated at bid price : 25.19
Bid-YTW : -0.85 %
TD.PF.J FixedReset 43,770 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-22
Maturity Price : 23.17
Evaluated at bid price : 25.05
Bid-YTW : 4.59 %
CM.PR.S FixedReset 35,270 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-22
Maturity Price : 23.04
Evaluated at bid price : 24.62
Bid-YTW : 4.49 %
There were 34 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
TRP.PR.G FixedReset Quote: 23.56 – 23.99
Spot Rate : 0.4300
Average : 0.2636

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-22
Maturity Price : 22.80
Evaluated at bid price : 23.56
Bid-YTW : 5.05 %

BAM.PF.B FixedReset Quote: 23.00 – 23.43
Spot Rate : 0.4300
Average : 0.2659

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-22
Maturity Price : 22.49
Evaluated at bid price : 23.00
Bid-YTW : 4.98 %

BAM.PR.X FixedReset Quote: 17.80 – 18.10
Spot Rate : 0.3000
Average : 0.2033

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-22
Maturity Price : 17.80
Evaluated at bid price : 17.80
Bid-YTW : 4.98 %

BAM.PF.F FixedReset Quote: 23.99 – 24.26
Spot Rate : 0.2700
Average : 0.1738

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-22
Maturity Price : 23.58
Evaluated at bid price : 23.99
Bid-YTW : 5.01 %

BAM.PR.B Floater Quote: 17.32 – 17.57
Spot Rate : 0.2500
Average : 0.1649

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-22
Maturity Price : 17.32
Evaluated at bid price : 17.32
Bid-YTW : 3.48 %

PVS.PR.B SplitShare Quote: 25.20 – 25.62
Spot Rate : 0.4200
Average : 0.3427

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2019-01-10
Maturity Price : 25.00
Evaluated at bid price : 25.20
Bid-YTW : 3.56 %

Market Action

March 21, 2018

Befitting the date, today saw the FOMC spring into action:

Information received since the Federal Open Market Committee met in January indicates that the labor market has continued to strengthen and that economic activity has been rising at a moderate rate. Job gains have been strong in recent months, and the unemployment rate has stayed low. Recent data suggest that growth rates of household spending and business fixed investment have moderated from their strong fourth-quarter readings. On a 12-month basis, both overall inflation and inflation for items other than food and energy have continued to run below 2 percent. Market-based measures of inflation compensation have increased in recent months but remain low; survey-based measures of longer-term inflation expectations are little changed, on balance.

Consistent with its statutory mandate, the Committee seeks to foster maximum employment and price stability. The economic outlook has strengthened in recent months. The Committee expects that, with further gradual adjustments in the stance of monetary policy, economic activity will expand at a moderate pace in the medium term and labor market conditions will remain strong. Inflation on a 12-month basis is expected to move up in coming months and to stabilize around the Committee’s 2 percent objective over the medium term. Near-term risks to the economic outlook appear roughly balanced, but the Committee is monitoring inflation developments closely.

In view of realized and expected labor market conditions and inflation, the Committee decided to raise the target range for the federal funds rate to 1-1/2 to 1-3/4 percent.

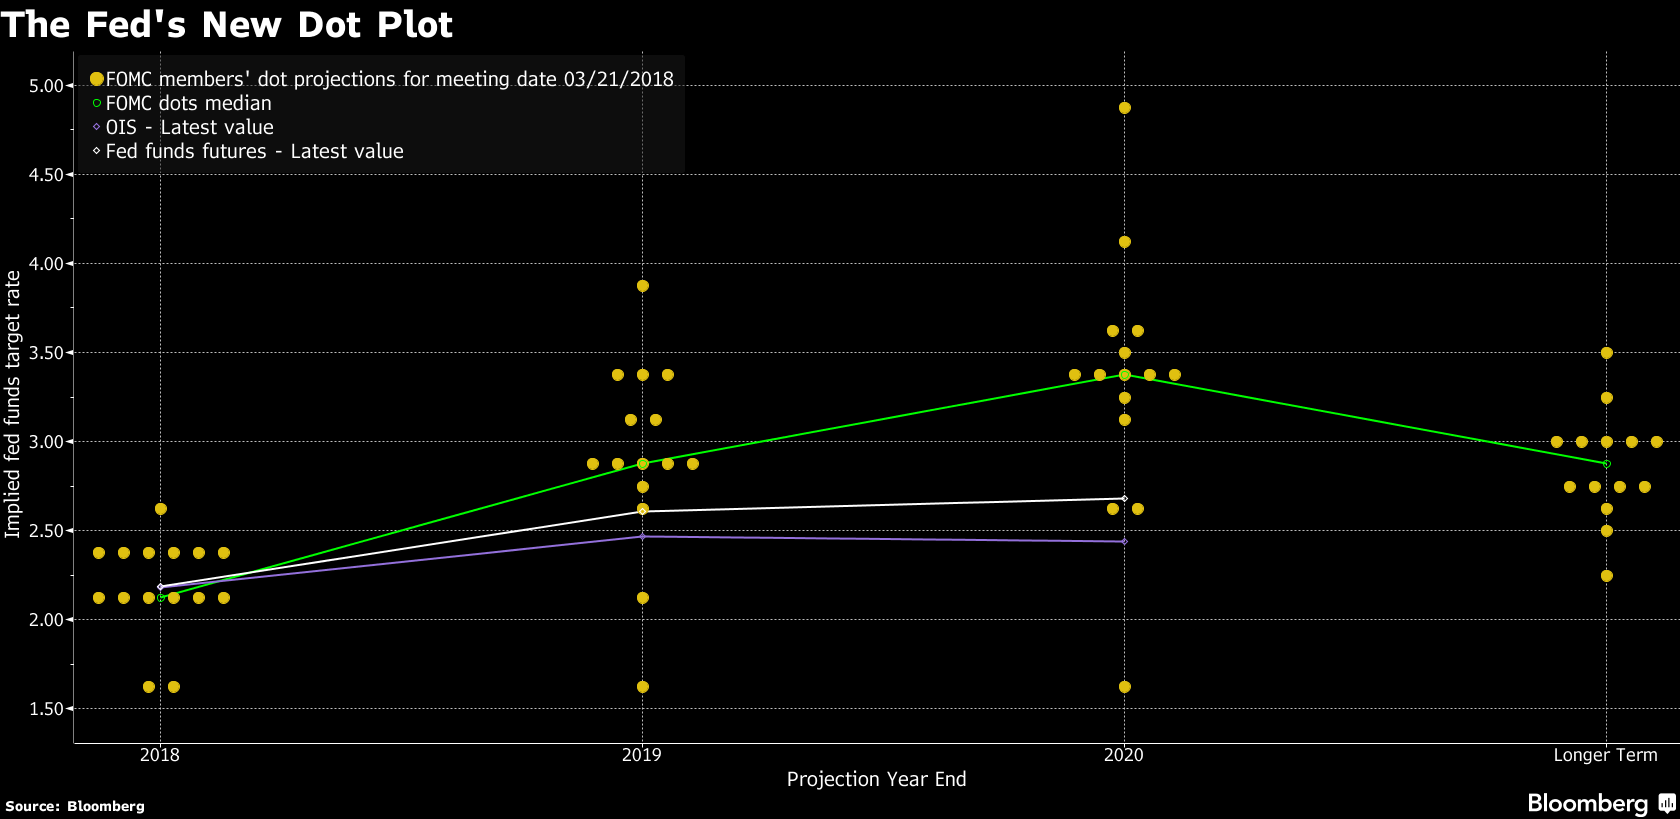
More interesting was the more hawkish dot-plot:

Federal Reserve officials, meeting for the first time under Chairman Jerome Powell, raised the benchmark lending rate a quarter-point and forecast a steeper path of hikes in 2019 and 2020, citing an improving economic outlook. Policy makers continued to project a total of three increases this year.
…
The upward revision in their rate path suggests Fed officials are looking through soft first-quarter economic reports and expect a lift this year and next from tax cuts passed by Republicans in December. Financial conditions have tightened since late January as investors look for signs that the central bank might raise rates at a faster pace, while forecasters predict stronger U.S. growth and tight labor markets.
…
In the forecasts, U.S. central bankers projected a median federal funds rate of 2.9 percent by the end of 2019, implying three rate increases next year, compared with two 2019 moves seen in the last round of forecasts in December. They saw rates at 3.4 percent in 2020, up from 3.1 percent in December, according to the median estimate.

The S&P 500 Index of U.S. stocks stayed higher after the release, while the yield on 10-year U.S. Treasury notes rose slightly, to 2.91 percent. The Bloomberg Dollar Spot Index was lower.

In another change to the statement, the Fed said inflation on an annual basis is “expected to move up in coming months,” after saying “move up this year” in the January statement. Price gains are still expected to stabilize around the Fed’s 2 percent target over the medium term, the FOMC said.

feddotplot_180321
Click for big

PerpetualDiscounts now yield 5.46%, equivalent to 7.10% interest at the standard equivalency factor of 1.3x. Long corporates now yield a little under 3.90%, so the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) is now about 320bp, a slight (and perhaps spurious) widening from the 315bp reported March 14.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.4045 % 3,079.4
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.4045 % 5,650.5
Floater 3.24 % 3.41 % 101,943 18.75 4 0.4045 % 3,256.4
OpRet 0.00 % 0.00 % 0 0.00 0 0.0705 % 3,166.9
SplitShare 4.69 % 4.20 % 56,601 3.26 5 0.0705 % 3,781.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0705 % 2,950.8
Perpetual-Premium 5.60 % 2.38 % 77,851 0.08 11 -0.1571 % 2,841.2
Perpetual-Discount 5.35 % 5.46 % 85,467 14.64 23 -0.2230 % 2,936.2
FixedReset 4.29 % 4.62 % 175,590 5.88 104 0.0133 % 2,510.8
Deemed-Retractible 5.18 % 5.76 % 91,664 5.72 28 -0.0847 % 2,916.0
FloatingReset 2.91 % 3.01 % 35,394 3.65 10 0.7941 % 2,758.4
Performance Highlights
Issue Index Change Notes
W.PR.M FixedReset -1.38 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-15
Maturity Price : 25.00
Evaluated at bid price : 25.69
Bid-YTW : 4.67 %
CU.PR.C FixedReset -1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-21
Maturity Price : 21.50
Evaluated at bid price : 21.77
Bid-YTW : 4.80 %
BAM.PR.M Perpetual-Discount -1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-21
Maturity Price : 20.95
Evaluated at bid price : 20.95
Bid-YTW : 5.70 %
SLF.PR.J FloatingReset 1.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.82
Bid-YTW : 6.18 %
HSE.PR.A FixedReset 1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-21
Maturity Price : 17.75
Evaluated at bid price : 17.75
Bid-YTW : 4.94 %
PWF.PR.P FixedReset 1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-21
Maturity Price : 19.80
Evaluated at bid price : 19.80
Bid-YTW : 4.33 %
GWO.PR.M Deemed-Retractible 1.29 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-04-30
Maturity Price : 25.25
Evaluated at bid price : 25.83
Bid-YTW : -15.92 %
PWF.PR.Q FloatingReset 9.57 % A reversal of yesterday‘s nonsense.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-21
Maturity Price : 21.42
Evaluated at bid price : 21.76
Bid-YTW : 3.02 %
BAM.PR.T FixedReset 29.98 % A reversal of yesterday‘s nonsense.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-21
Maturity Price : 20.90
Evaluated at bid price : 20.90
Bid-YTW : 4.94 %
Volume Highlights
Issue Index Shares
Traded
Notes
BAM.PR.K Floater 104,712 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-21
Maturity Price : 17.64
Evaluated at bid price : 17.64
Bid-YTW : 3.42 %
TD.PF.G FixedReset 68,469 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 26.52
Bid-YTW : 3.69 %
TRP.PR.J FixedReset 67,752 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-31
Maturity Price : 25.00
Evaluated at bid price : 26.20
Bid-YTW : 4.03 %
CM.PR.Q FixedReset 61,400 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-21
Maturity Price : 23.21
Evaluated at bid price : 24.28
Bid-YTW : 4.73 %
TD.PF.B FixedReset 57,682 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-21
Maturity Price : 22.72
Evaluated at bid price : 23.17
Bid-YTW : 4.58 %
MFC.PR.G FixedReset 56,528 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-12-19
Maturity Price : 25.00
Evaluated at bid price : 24.40
Bid-YTW : 4.62 %
There were 31 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
W.PR.M FixedReset Quote: 25.69 – 26.05
Spot Rate : 0.3600
Average : 0.2086

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-15
Maturity Price : 25.00
Evaluated at bid price : 25.69
Bid-YTW : 4.67 %

TRP.PR.E FixedReset Quote: 22.83 – 23.16
Spot Rate : 0.3300
Average : 0.2036

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-21
Maturity Price : 22.45
Evaluated at bid price : 22.83
Bid-YTW : 4.78 %

MFC.PR.M FixedReset Quote: 23.50 – 23.78
Spot Rate : 0.2800
Average : 0.1868

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.50
Bid-YTW : 5.31 %

IGM.PR.B Perpetual-Premium Quote: 25.55 – 25.80
Spot Rate : 0.2500
Average : 0.1599

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-04-20
Maturity Price : 25.25
Evaluated at bid price : 25.55
Bid-YTW : 0.71 %

TD.PF.E FixedReset Quote: 24.40 – 24.62
Spot Rate : 0.2200
Average : 0.1403

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-21
Maturity Price : 23.22
Evaluated at bid price : 24.40
Bid-YTW : 4.79 %

VNR.PR.A FixedReset Quote: 24.66 – 24.93
Spot Rate : 0.2700
Average : 0.1932

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-21
Maturity Price : 23.07
Evaluated at bid price : 24.66
Bid-YTW : 4.80 %

Market Action

March 20, 2018

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.2689 % 3,067.0
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.2689 % 5,627.7
Floater 3.26 % 3.41 % 105,079 18.73 4 -0.2689 % 3,243.3
OpRet 0.00 % 0.00 % 0 0.00 0 0.1177 % 3,164.6
SplitShare 4.69 % 4.32 % 58,729 3.26 5 0.1177 % 3,779.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1177 % 2,948.7
Perpetual-Premium 5.59 % -0.91 % 77,873 0.09 11 -0.0179 % 2,845.6
Perpetual-Discount 5.34 % 5.45 % 85,410 14.67 23 -0.0817 % 2,942.8
FixedReset 4.29 % 4.56 % 175,017 5.88 104 -0.3864 % 2,510.5
Deemed-Retractible 5.18 % 5.75 % 91,981 5.73 28 -0.2866 % 2,918.4
FloatingReset 2.93 % 3.01 % 35,919 3.65 10 -0.7219 % 2,736.7
Performance Highlights
Issue Index Change Notes
BAM.PR.T FixedReset -23.76 % Completely nonsensical, of course, but this type of thing must be expected when the financial system is controlled by a privileged oligarchy. The issue traded a whopping 4,220 shares today in a range of 21.07-23; the last trade, 100 shares at 21.07 at 3:51pm, appears to have overwhelmed the system. Perhaps the closing quote is due to unexpectedly high retail demand! I have not checked whether this lamentable state of affairs is due to inadequate Toronto Stock Exchange reporting or inadequate Toronto Stock Exchange supervision of market-makers.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-20
Maturity Price : 16.08
Evaluated at bid price : 16.08
Bid-YTW : 6.39 %
PWF.PR.Q FloatingReset -8.69 % More nonsense from Nonsense Central. The issue traded 11,800 shares in a range of 21.40-75, with the last trade of 100 shares at 21.40 coming at 3:37pm. I have not checked whether this lamentable state of affairs is due to inadequate Toronto Stock Exchange reporting or inadequate Toronto Stock Exchange supervision of market-makers.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-20
Maturity Price : 19.86
Evaluated at bid price : 19.86
Bid-YTW : 3.35 %
GWO.PR.M Deemed-Retractible -1.24 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-04-30
Maturity Price : 25.25
Evaluated at bid price : 25.50
Bid-YTW : -4.67 %
BAM.PF.E FixedReset -1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-20
Maturity Price : 22.80
Evaluated at bid price : 23.13
Bid-YTW : 4.88 %
BAM.PF.A FixedReset -1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-20
Maturity Price : 23.46
Evaluated at bid price : 24.19
Bid-YTW : 5.01 %
Volume Highlights
Issue Index Shares
Traded
Notes
CM.PR.R FixedReset 383,944 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-07-31
Maturity Price : 25.00
Evaluated at bid price : 25.19
Bid-YTW : 4.39 %
RY.PR.H FixedReset 208,200 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-20
Maturity Price : 23.00
Evaluated at bid price : 23.45
Bid-YTW : 4.51 %
TD.PF.E FixedReset 115,009 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-20
Maturity Price : 23.21
Evaluated at bid price : 24.40
Bid-YTW : 4.79 %
CM.PR.Q FixedReset 94,300 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-20
Maturity Price : 23.21
Evaluated at bid price : 24.28
Bid-YTW : 4.73 %
BAM.PF.C Perpetual-Discount 89,362 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-20
Maturity Price : 21.68
Evaluated at bid price : 21.68
Bid-YTW : 5.62 %
MFC.PR.Q FixedReset 60,400 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.80
Bid-YTW : 4.89 %
There were 27 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BAM.PR.T FixedReset Quote: 16.08 – 21.16
Spot Rate : 5.0800
Average : 2.7700

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-20
Maturity Price : 16.08
Evaluated at bid price : 16.08
Bid-YTW : 6.39 %

PWF.PR.Q FloatingReset Quote: 19.86 – 21.64
Spot Rate : 1.7800
Average : 1.0088

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-20
Maturity Price : 19.86
Evaluated at bid price : 19.86
Bid-YTW : 3.35 %

GWO.PR.M Deemed-Retractible Quote: 25.50 – 25.87
Spot Rate : 0.3700
Average : 0.2108

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-04-30
Maturity Price : 25.25
Evaluated at bid price : 25.50
Bid-YTW : -4.67 %

BMO.PR.S FixedReset Quote: 23.66 – 23.99
Spot Rate : 0.3300
Average : 0.2329

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-20
Maturity Price : 23.15
Evaluated at bid price : 23.66
Bid-YTW : 4.54 %

PVS.PR.B SplitShare Quote: 25.22 – 25.62
Spot Rate : 0.4000
Average : 0.3104

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2019-01-10
Maturity Price : 25.00
Evaluated at bid price : 25.22
Bid-YTW : 3.44 %

TD.PF.F Perpetual-Discount Quote: 24.75 – 24.99
Spot Rate : 0.2400
Average : 0.1558

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-20
Maturity Price : 24.32
Evaluated at bid price : 24.75
Bid-YTW : 5.00 %

Market Action

March 19, 2018

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.5350 % 3,075.2
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.5350 % 5,642.9
Floater 3.25 % 3.40 % 108,905 18.77 4 -0.5350 % 3,252.0
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0471 % 3,160.9
SplitShare 4.70 % 4.38 % 57,716 3.27 5 -0.0471 % 3,774.8
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0471 % 2,945.3
Perpetual-Premium 5.59 % -1.10 % 79,468 0.08 11 -0.0927 % 2,846.1
Perpetual-Discount 5.33 % 5.43 % 86,721 14.69 23 -0.2445 % 2,945.2
FixedReset 4.27 % 4.55 % 173,429 5.82 104 -0.2019 % 2,520.2
Deemed-Retractible 5.16 % 5.68 % 92,881 5.73 28 -0.1957 % 2,926.8
FloatingReset 2.91 % 3.03 % 34,370 3.65 10 -0.2342 % 2,756.6
Performance Highlights
Issue Index Change Notes
TRP.PR.D FixedReset -1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-19
Maturity Price : 22.55
Evaluated at bid price : 23.04
Bid-YTW : 4.74 %
TRP.PR.E FixedReset -1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-19
Maturity Price : 22.79
Evaluated at bid price : 23.19
Bid-YTW : 4.70 %
BAM.PR.T FixedReset -1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-19
Maturity Price : 21.09
Evaluated at bid price : 21.09
Bid-YTW : 4.89 %
BMO.PR.Q FixedReset -1.02 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.37
Bid-YTW : 5.03 %
Volume Highlights
Issue Index Shares
Traded
Notes
NA.PR.C FixedReset 129,285 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-11-15
Maturity Price : 25.00
Evaluated at bid price : 25.16
Bid-YTW : 4.42 %
MFC.PR.B Deemed-Retractible 108,215 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.95
Bid-YTW : 6.95 %
GWO.PR.G Deemed-Retractible 59,669 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.30
Bid-YTW : 5.70 %
HSE.PR.C FixedReset 56,100 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2019-12-31
Maturity Price : 25.00
Evaluated at bid price : 24.75
Bid-YTW : 5.03 %
NA.PR.S FixedReset 51,675 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-19
Maturity Price : 23.04
Evaluated at bid price : 23.55
Bid-YTW : 4.65 %
NA.PR.E FixedReset 48,100 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-19
Maturity Price : 22.99
Evaluated at bid price : 24.55
Bid-YTW : 4.63 %
There were 15 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BAM.PR.T FixedReset Quote: 21.09 – 21.44
Spot Rate : 0.3500
Average : 0.2372

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-19
Maturity Price : 21.09
Evaluated at bid price : 21.09
Bid-YTW : 4.89 %

CM.PR.O FixedReset Quote: 23.54 – 23.90
Spot Rate : 0.3600
Average : 0.2625

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-19
Maturity Price : 23.08
Evaluated at bid price : 23.54
Bid-YTW : 4.56 %

BAM.PR.R FixedReset Quote: 20.63 – 20.90
Spot Rate : 0.2700
Average : 0.1908

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-19
Maturity Price : 20.63
Evaluated at bid price : 20.63
Bid-YTW : 4.93 %

PWF.PR.F Perpetual-Discount Quote: 24.31 – 24.55
Spot Rate : 0.2400
Average : 0.1688

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-19
Maturity Price : 24.06
Evaluated at bid price : 24.31
Bid-YTW : 5.47 %

CU.PR.I FixedReset Quote: 25.81 – 26.01
Spot Rate : 0.2000
Average : 0.1324

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-01
Maturity Price : 25.00
Evaluated at bid price : 25.81
Bid-YTW : 3.33 %

CM.PR.R FixedReset Quote: 25.22 – 25.39
Spot Rate : 0.1700
Average : 0.1032

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-07-31
Maturity Price : 25.00
Evaluated at bid price : 25.22
Bid-YTW : 4.35 %

Market Action

March 16, 2018

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.1202 % 3,091.8
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.1202 % 5,673.2
Floater 3.23 % 3.38 % 109,781 18.82 4 -0.1202 % 3,269.5
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0157 % 3,162.4
SplitShare 4.70 % 4.25 % 60,005 3.28 5 -0.0157 % 3,776.6
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0157 % 2,946.6
Perpetual-Premium 5.58 % -0.72 % 77,787 0.09 11 0.1179 % 2,848.8
Perpetual-Discount 5.32 % 5.40 % 86,385 14.74 23 -0.0407 % 2,952.4
FixedReset 4.26 % 4.59 % 174,126 4.45 104 0.0464 % 2,525.3
Deemed-Retractible 5.15 % 5.61 % 93,898 5.75 28 0.1493 % 2,932.6
FloatingReset 3.00 % 3.13 % 35,688 3.66 10 0.0663 % 2,763.0
Performance Highlights
Issue Index Change Notes
EML.PR.A FixedReset 1.01 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-17
Maturity Price : 25.00
Evaluated at bid price : 26.46
Bid-YTW : 3.58 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PF.H FixedReset 191,974 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 26.15
Bid-YTW : 3.68 %
TD.PF.J FixedReset 188,613 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2023-04-30
Maturity Price : 25.00
Evaluated at bid price : 25.12
Bid-YTW : 4.62 %
TD.PF.G FixedReset 137,137 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 26.57
Bid-YTW : 3.60 %
RY.PR.H FixedReset 123,707 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-16
Maturity Price : 23.20
Evaluated at bid price : 23.64
Bid-YTW : 4.54 %
TD.PF.A FixedReset 105,753 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-16
Maturity Price : 22.96
Evaluated at bid price : 23.36
Bid-YTW : 4.59 %
TRP.PR.J FixedReset 75,100 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-31
Maturity Price : 25.00
Evaluated at bid price : 26.40
Bid-YTW : 3.75 %
There were 35 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
W.PR.H Perpetual-Discount Quote: 24.82 – 25.26
Spot Rate : 0.4400
Average : 0.2629

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-16
Maturity Price : 24.57
Evaluated at bid price : 24.82
Bid-YTW : 5.63 %

PVS.PR.B SplitShare Quote: 25.18 – 25.61
Spot Rate : 0.4300
Average : 0.3022

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2019-01-10
Maturity Price : 25.00
Evaluated at bid price : 25.18
Bid-YTW : 3.59 %

PWF.PR.A Floater Quote: 21.40 – 21.74
Spot Rate : 0.3400
Average : 0.2295

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-16
Maturity Price : 21.40
Evaluated at bid price : 21.40
Bid-YTW : 2.84 %

HSE.PR.A FixedReset Quote: 17.76 – 18.00
Spot Rate : 0.2400
Average : 0.1604

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-16
Maturity Price : 17.76
Evaluated at bid price : 17.76
Bid-YTW : 5.07 %

PVS.PR.D SplitShare Quote: 25.25 – 25.50
Spot Rate : 0.2500
Average : 0.1717

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2021-10-08
Maturity Price : 25.00
Evaluated at bid price : 25.25
Bid-YTW : 4.25 %

CM.PR.Q FixedReset Quote: 24.27 – 24.49
Spot Rate : 0.2200
Average : 0.1419

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-16
Maturity Price : 23.20
Evaluated at bid price : 24.27
Bid-YTW : 4.80 %

Market Action

March 15, 2018

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.2008 % 3,095.5
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.2008 % 5,680.1
Floater 3.23 % 3.39 % 110,297 18.80 4 0.2008 % 3,273.5
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0235 % 3,162.9
SplitShare 4.70 % 4.12 % 60,616 3.28 5 -0.0235 % 3,777.2
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0235 % 2,947.1
Perpetual-Premium 5.59 % 0.53 % 75,827 0.08 11 0.1108 % 2,845.4
Perpetual-Discount 5.32 % 5.41 % 88,387 14.73 23 0.0982 % 2,953.6
FixedReset 4.26 % 4.58 % 175,166 5.76 104 -0.0244 % 2,524.1
Deemed-Retractible 5.16 % 5.66 % 95,424 5.75 28 -0.0723 % 2,928.2
FloatingReset 3.01 % 3.13 % 35,894 3.66 10 -0.0133 % 2,761.2
Performance Highlights
Issue Index Change Notes
IFC.PR.F Deemed-Retractible -1.52 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.62
Bid-YTW : 5.56 %
MFC.PR.M FixedReset -1.30 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.49
Bid-YTW : 5.35 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.H FixedReset 212,700 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-15
Maturity Price : 23.25
Evaluated at bid price : 23.69
Bid-YTW : 4.53 %
TD.PF.J FixedReset 205,330 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2023-04-30
Maturity Price : 25.00
Evaluated at bid price : 25.12
Bid-YTW : 4.62 %
PWF.PR.K Perpetual-Discount 177,270 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-15
Maturity Price : 22.66
Evaluated at bid price : 22.90
Bid-YTW : 5.47 %
TD.PF.A FixedReset 92,268 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-15
Maturity Price : 23.13
Evaluated at bid price : 23.53
Bid-YTW : 4.55 %
GWO.PR.G Deemed-Retractible 81,406 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.34
Bid-YTW : 5.66 %
BAM.PR.M Perpetual-Discount 80,236 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-15
Maturity Price : 21.36
Evaluated at bid price : 21.36
Bid-YTW : 5.58 %
There were 30 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
IFC.PR.F Deemed-Retractible Quote: 24.62 – 25.08
Spot Rate : 0.4600
Average : 0.2880

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.62
Bid-YTW : 5.56 %

EIT.PR.A SplitShare Quote: 25.40 – 25.70
Spot Rate : 0.3000
Average : 0.2110

YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2024-03-14
Maturity Price : 25.00
Evaluated at bid price : 25.40
Bid-YTW : 4.52 %

MFC.PR.M FixedReset Quote: 23.49 – 23.74
Spot Rate : 0.2500
Average : 0.1732

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.49
Bid-YTW : 5.35 %

CCS.PR.C Deemed-Retractible Quote: 23.00 – 23.25
Spot Rate : 0.2500
Average : 0.1788

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.00
Bid-YTW : 6.45 %

VNR.PR.A FixedReset Quote: 24.65 – 24.95
Spot Rate : 0.3000
Average : 0.2340

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-15
Maturity Price : 23.07
Evaluated at bid price : 24.65
Bid-YTW : 4.85 %

MFC.PR.F FixedReset Quote: 18.84 – 19.04
Spot Rate : 0.2000
Average : 0.1346

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.84
Bid-YTW : 7.46 %

Market Action

March 14, 2018

PerpetualDiscounts now yield 5.42%, equivalent to 7.05% interest at the standard equivalency factor of 1.3x. Long corporates now yield about 3.90%, so the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) is now about 315bp, a slight (and perhaps spurious) narrowing from the 320bp reported March 7.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.1944 % 3,089.3
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.1944 % 5,668.7
Floater 3.23 % 3.40 % 111,341 18.77 4 -0.1944 % 3,266.9
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0549 % 3,163.6
SplitShare 4.69 % 4.18 % 61,594 3.28 5 -0.0549 % 3,778.1
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0549 % 2,947.8
Perpetual-Premium 5.60 % -1.11 % 77,835 0.08 11 0.1719 % 2,842.3
Perpetual-Discount 5.32 % 5.42 % 87,936 14.72 23 0.1024 % 2,950.7
FixedReset 4.26 % 4.57 % 175,822 5.82 104 0.0277 % 2,524.7
Deemed-Retractible 5.15 % 5.69 % 93,190 5.75 28 0.0582 % 2,930.3
FloatingReset 3.01 % 3.13 % 36,175 3.66 10 -0.1809 % 2,761.6
Performance Highlights
Issue Index Change Notes
IAG.PR.A Deemed-Retractible -1.35 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.00
Bid-YTW : 6.81 %
BIP.PR.B FixedReset 1.13 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-31
Maturity Price : 25.00
Evaluated at bid price : 26.00
Bid-YTW : 3.90 %
IFC.PR.E Deemed-Retractible 1.49 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.59
Bid-YTW : 5.48 %
IFC.PR.F Deemed-Retractible 1.73 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.00
Bid-YTW : 5.29 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PF.J FixedReset 605,636 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-14
Maturity Price : 23.15
Evaluated at bid price : 24.98
Bid-YTW : 4.65 %
W.PR.J Perpetual-Discount 308,900 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-14
Maturity Price : 24.49
Evaluated at bid price : 24.72
Bid-YTW : 5.76 %
BMO.PR.B FixedReset 185,072 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-02-25
Maturity Price : 25.00
Evaluated at bid price : 25.91
Bid-YTW : 3.94 %
W.PR.M FixedReset 184,131 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-15
Maturity Price : 25.00
Evaluated at bid price : 26.04
Bid-YTW : 4.22 %
POW.PR.D Perpetual-Discount 181,803 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-14
Maturity Price : 23.32
Evaluated at bid price : 23.60
Bid-YTW : 5.37 %
BAM.PF.J FixedReset 180,850 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.11
Bid-YTW : 4.62 %
BAM.PF.A FixedReset 167,506 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-14
Maturity Price : 23.85
Evaluated at bid price : 24.51
Bid-YTW : 5.02 %
IFC.PR.C FixedReset 153,573 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.37
Bid-YTW : 5.11 %
CM.PR.O FixedReset 131,067 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-14
Maturity Price : 23.44
Evaluated at bid price : 23.89
Bid-YTW : 4.56 %
NA.PR.A FixedReset 105,875 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-15
Maturity Price : 25.00
Evaluated at bid price : 26.22
Bid-YTW : 4.02 %
There were 45 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BAM.PF.C Perpetual-Discount Quote: 21.84 – 22.09
Spot Rate : 0.2500
Average : 0.1516

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-14
Maturity Price : 21.56
Evaluated at bid price : 21.84
Bid-YTW : 5.55 %

BAM.PF.H FixedReset Quote: 25.69 – 25.94
Spot Rate : 0.2500
Average : 0.1561

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.69
Bid-YTW : 3.88 %

IFC.PR.C FixedReset Quote: 23.37 – 23.58
Spot Rate : 0.2100
Average : 0.1289

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.37
Bid-YTW : 5.11 %

RY.PR.R FixedReset Quote: 26.51 – 26.72
Spot Rate : 0.2100
Average : 0.1359

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-24
Maturity Price : 25.00
Evaluated at bid price : 26.51
Bid-YTW : 3.74 %

TD.PR.Z FloatingReset Quote: 24.63 – 24.99
Spot Rate : 0.3600
Average : 0.2890

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.63
Bid-YTW : 3.15 %

RY.PR.W Perpetual-Discount Quote: 24.80 – 24.99
Spot Rate : 0.1900
Average : 0.1201

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-14
Maturity Price : 24.55
Evaluated at bid price : 24.80
Bid-YTW : 4.97 %

Market Action

March 13

Today’s gloom comes to us courtesy of Moody’s:

Canada’s mountain of consumer debt is triggering multiple alarms about the threat to the country’s banks.

Moody’s Investors Service joined the Bank for International Settlements and S&P Global Ratings which have all warned in the last month that Canada’s banking system, dominated by five giants, is facing a growing threat of souring consumer loans amid rising interest rates. The country’s ratio of household debt to disposable income reached a record 171 percent in the third quarter of last year.

The proportion of uninsured mortgages has increased to 60 percent from 50 percent five years ago, including home equity lines of credit, amid government efforts to reduce taxpayer exposure, according to the report from Moody’s on Tuesday. Canada Mortgage and Housing Corp., a government agency, insurers the bulk of mortgages in Canada.

Almost half of outstanding mortgages, many of them on fixed-rate terms, will have an interest-rate reset within the year, increasing the strain on households’ debt-servicing capacity, Moody’s said.

This looks like bad news for Aimia:

PC Optimum points will replace Aeroplan miles as the loyalty program of choice at Esso stations across the country effective June 1, as Imperial Oil Ltd. shifts its relationship to Loblaw Companies Ltd.

Aimia Inc.-operated Aeroplan notified members of the change to its 14-year partnership in an email on Tuesday.

It noted that up to 1.5 miles for every dollar spent will continue to be earned when using Aeroplan-affiliated credit cards for purchases at any retailer, including Esso.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.2254 % 3,095.3
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.2254 % 5,679.7
Floater 3.21 % 3.42 % 112,427 18.63 4 -0.2254 % 3,273.3
OpRet 0.00 % 0.00 % 0 0.00 0 0.1413 % 3,165.4
SplitShare 4.69 % 4.11 % 63,719 3.29 5 0.1413 % 3,780.1
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1413 % 2,949.4
Perpetual-Premium 5.61 % 0.13 % 79,010 0.09 11 0.1507 % 2,837.4
Perpetual-Discount 5.31 % 5.40 % 86,671 14.75 23 0.2617 % 2,947.7
FixedReset 4.25 % 4.57 % 172,268 5.82 103 0.0626 % 2,524.0
Deemed-Retractible 5.15 % 5.68 % 89,239 5.75 28 0.2961 % 2,928.6
FloatingReset 3.00 % 3.00 % 35,299 3.66 10 0.1724 % 2,766.6
Performance Highlights
Issue Index Change Notes
GWO.PR.Q Deemed-Retractible 1.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.14
Bid-YTW : 5.75 %
IAG.PR.A Deemed-Retractible 1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.30
Bid-YTW : 6.57 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PF.E FixedReset 61,925 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-10-31
Maturity Price : 25.00
Evaluated at bid price : 24.46
Bid-YTW : 4.77 %
CM.PR.R FixedReset 58,133 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-07-31
Maturity Price : 25.00
Evaluated at bid price : 25.26
Bid-YTW : 4.29 %
RY.PR.L FixedReset 29,950 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2019-02-24
Maturity Price : 25.00
Evaluated at bid price : 25.20
Bid-YTW : 3.64 %
RY.PR.Q FixedReset 27,336 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-24
Maturity Price : 25.00
Evaluated at bid price : 26.45
Bid-YTW : 3.67 %
BMO.PR.W FixedReset 23,900 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-13
Maturity Price : 22.81
Evaluated at bid price : 23.20
Bid-YTW : 4.57 %
TRP.PR.F FloatingReset 23,370 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-13
Maturity Price : 20.53
Evaluated at bid price : 20.53
Bid-YTW : 3.71 %
There were 25 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
PVS.PR.B SplitShare Quote: 25.20 – 25.61
Spot Rate : 0.4100
Average : 0.2722

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2019-01-10
Maturity Price : 25.00
Evaluated at bid price : 25.20
Bid-YTW : 3.46 %

TRP.PR.G FixedReset Quote: 24.07 – 24.38
Spot Rate : 0.3100
Average : 0.2058

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-13
Maturity Price : 23.05
Evaluated at bid price : 24.07
Bid-YTW : 4.98 %

BAM.PR.T FixedReset Quote: 21.44 – 21.78
Spot Rate : 0.3400
Average : 0.2614

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-13
Maturity Price : 21.44
Evaluated at bid price : 21.44
Bid-YTW : 4.93 %

PWF.PR.P FixedReset Quote: 19.80 – 19.99
Spot Rate : 0.1900
Average : 0.1243

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-13
Maturity Price : 19.80
Evaluated at bid price : 19.80
Bid-YTW : 4.40 %

PWF.PR.L Perpetual-Discount Quote: 23.22 – 23.50
Spot Rate : 0.2800
Average : 0.2154

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-13
Maturity Price : 22.95
Evaluated at bid price : 23.22
Bid-YTW : 5.56 %

CU.PR.G Perpetual-Discount Quote: 21.23 – 21.49
Spot Rate : 0.2600
Average : 0.1990

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-03-13
Maturity Price : 21.23
Evaluated at bid price : 21.23
Bid-YTW : 5.35 %