Category: Market Action

Market Action

January 22, 2018

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.1694 % 2,902.7
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.1694 % 5,326.3
Floater 3.42 % 3.55 % 35,475 18.40 4 -0.1694 % 3,069.6
OpRet 0.00 % 0.00 % 0 0.00 0 0.3339 % 3,168.1
SplitShare 4.63 % 4.15 % 66,251 3.39 5 0.3339 % 3,783.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.3339 % 2,951.9
Perpetual-Premium 5.37 % -0.07 % 64,785 0.09 18 0.2101 % 2,859.7
Perpetual-Discount 5.32 % 5.26 % 72,074 14.98 16 0.2342 % 2,990.8
FixedReset 4.20 % 4.46 % 144,249 3.83 100 0.0906 % 2,532.1
Deemed-Retractible 5.06 % 5.43 % 79,434 5.83 28 0.1556 % 2,946.0
FloatingReset 3.05 % 2.92 % 40,234 3.79 10 0.0261 % 2,766.5
Performance Highlights
Issue Index Change Notes
BAM.PR.B Floater -1.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-22
Maturity Price : 16.96
Evaluated at bid price : 16.96
Bid-YTW : 3.58 %
BNS.PR.Z FixedReset -1.29 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.00
Bid-YTW : 4.57 %
GWO.PR.N FixedReset 1.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.00
Bid-YTW : 7.28 %
PWF.PR.A Floater 1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-22
Maturity Price : 19.70
Evaluated at bid price : 19.70
Bid-YTW : 3.09 %
EIT.PR.A SplitShare 1.14 % YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2024-03-14
Maturity Price : 25.00
Evaluated at bid price : 25.82
Bid-YTW : 4.31 %
BAM.PR.X FixedReset 1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-22
Maturity Price : 18.21
Evaluated at bid price : 18.21
Bid-YTW : 4.94 %
PWF.PR.L Perpetual-Discount 1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-22
Maturity Price : 23.73
Evaluated at bid price : 24.04
Bid-YTW : 5.31 %
RY.PR.N Perpetual-Premium 1.31 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2024-11-24
Maturity Price : 25.00
Evaluated at bid price : 25.43
Bid-YTW : 4.77 %
PWF.PR.T FixedReset 1.63 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2019-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.01
Bid-YTW : 4.08 %
Volume Highlights
Issue Index Shares
Traded
Notes
NA.PR.E FixedReset 357,595 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-22
Maturity Price : 23.07
Evaluated at bid price : 24.78
Bid-YTW : 4.56 %
TRP.PR.K FixedReset 211,554 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-05-31
Maturity Price : 25.00
Evaluated at bid price : 26.13
Bid-YTW : 3.96 %
CM.PR.S FixedReset 136,969 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-22
Maturity Price : 23.14
Evaluated at bid price : 24.93
Bid-YTW : 4.41 %
POW.PR.G Perpetual-Premium 84,500 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-04-15
Maturity Price : 25.25
Evaluated at bid price : 25.42
Bid-YTW : 5.31 %
MFC.PR.I FixedReset 83,823 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-09-19
Maturity Price : 25.00
Evaluated at bid price : 25.19
Bid-YTW : 4.29 %
NA.PR.C FixedReset 80,195 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-11-15
Maturity Price : 25.00
Evaluated at bid price : 25.18
Bid-YTW : 4.24 %
There were 33 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
HSE.PR.G FixedReset Quote: 25.24 – 25.56
Spot Rate : 0.3200
Average : 0.2149

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-06-30
Maturity Price : 25.00
Evaluated at bid price : 25.24
Bid-YTW : 4.33 %

PVS.PR.B SplitShare Quote: 25.31 – 25.63
Spot Rate : 0.3200
Average : 0.2370

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2019-01-10
Maturity Price : 25.00
Evaluated at bid price : 25.31
Bid-YTW : 3.64 %

BAM.PR.B Floater Quote: 16.96 – 17.25
Spot Rate : 0.2900
Average : 0.2151

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-22
Maturity Price : 16.96
Evaluated at bid price : 16.96
Bid-YTW : 3.58 %

GWO.PR.R Deemed-Retractible Quote: 23.00 – 23.25
Spot Rate : 0.2500
Average : 0.1768

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.00
Bid-YTW : 6.32 %

W.PR.M FixedReset Quote: 26.15 – 26.39
Spot Rate : 0.2400
Average : 0.1674

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-15
Maturity Price : 25.00
Evaluated at bid price : 26.15
Bid-YTW : 3.92 %

TRP.PR.E FixedReset Quote: 24.03 – 24.25
Spot Rate : 0.2200
Average : 0.1505

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-22
Maturity Price : 23.68
Evaluated at bid price : 24.03
Bid-YTW : 4.54 %

Market Action

January 19, 2018

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.1414 % 2,907.6
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.1414 % 5,335.4
Floater 3.41 % 3.53 % 35,924 18.45 4 0.1414 % 3,074.8
OpRet 0.00 % 0.00 % 0 0.00 0 -0.1628 % 3,157.5
SplitShare 4.65 % 4.03 % 66,775 3.39 5 -0.1628 % 3,770.8
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.1628 % 2,942.1
Perpetual-Premium 5.38 % 0.68 % 65,028 0.09 18 -0.1268 % 2,853.7
Perpetual-Discount 5.33 % 5.28 % 72,777 14.94 16 -0.1532 % 2,983.8
FixedReset 4.20 % 4.42 % 142,604 4.05 99 0.0368 % 2,529.8
Deemed-Retractible 5.07 % 5.44 % 79,965 5.83 28 -0.0622 % 2,941.5
FloatingReset 3.04 % 2.92 % 41,876 3.80 10 -0.0391 % 2,765.8
Performance Highlights
Issue Index Change Notes
IFC.PR.C FixedReset -1.67 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.50
Bid-YTW : 5.00 %
TRP.PR.C FixedReset -1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-19
Maturity Price : 17.96
Evaluated at bid price : 17.96
Bid-YTW : 4.64 %
BNS.PR.Z FixedReset -1.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.30
Bid-YTW : 4.21 %
BAM.PF.F FixedReset -1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-19
Maturity Price : 23.53
Evaluated at bid price : 24.65
Bid-YTW : 4.85 %
TRP.PR.H FloatingReset -1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-19
Maturity Price : 17.01
Evaluated at bid price : 17.01
Bid-YTW : 3.64 %
RY.PR.N Perpetual-Premium -1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-19
Maturity Price : 24.67
Evaluated at bid price : 25.10
Bid-YTW : 4.93 %
PWF.PR.L Perpetual-Discount -1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-19
Maturity Price : 23.44
Evaluated at bid price : 23.73
Bid-YTW : 5.38 %
NA.PR.S FixedReset 1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-19
Maturity Price : 23.06
Evaluated at bid price : 23.53
Bid-YTW : 4.61 %
BAM.PR.R FixedReset 1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-19
Maturity Price : 20.75
Evaluated at bid price : 20.75
Bid-YTW : 4.91 %
SLF.PR.J FloatingReset 1.33 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.76
Bid-YTW : 6.35 %
GWO.PR.N FixedReset 1.40 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.81
Bid-YTW : 7.40 %
BAM.PR.T FixedReset 1.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-19
Maturity Price : 21.26
Evaluated at bid price : 21.26
Bid-YTW : 4.87 %
TRP.PR.G FixedReset 1.74 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-11-30
Maturity Price : 25.00
Evaluated at bid price : 24.55
Bid-YTW : 4.69 %
Volume Highlights
Issue Index Shares
Traded
Notes
BNS.PR.B FloatingReset 377,974 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.69
Bid-YTW : 3.03 %
POW.PR.G Perpetual-Premium 228,678 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-19
Maturity Price : 24.83
Evaluated at bid price : 25.17
Bid-YTW : 5.59 %
POW.PR.C Perpetual-Premium 226,257 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-02-18
Maturity Price : 25.00
Evaluated at bid price : 25.69
Bid-YTW : -24.90 %
PWF.PR.L Perpetual-Discount 209,698 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-19
Maturity Price : 23.44
Evaluated at bid price : 23.73
Bid-YTW : 5.38 %
CM.PR.S FixedReset 191,800 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-19
Maturity Price : 23.15
Evaluated at bid price : 24.96
Bid-YTW : 4.36 %
BNS.PR.Q FixedReset 141,500 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-10-25
Maturity Price : 25.00
Evaluated at bid price : 25.00
Bid-YTW : 3.54 %
TD.PR.T FloatingReset 127,183 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.70
Bid-YTW : 2.92 %
SLF.PR.J FloatingReset 125,476 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.76
Bid-YTW : 6.35 %
BNS.PR.D FloatingReset 118,802 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.79
Bid-YTW : 3.47 %
TRP.PR.K FixedReset 107,895 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-05-31
Maturity Price : 25.00
Evaluated at bid price : 26.15
Bid-YTW : 3.93 %
There were 33 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
GWO.PR.I Deemed-Retractible Quote: 21.91 – 22.32
Spot Rate : 0.4100
Average : 0.2596

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.91
Bid-YTW : 6.82 %

RY.PR.N Perpetual-Premium Quote: 25.10 – 25.50
Spot Rate : 0.4000
Average : 0.2564

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-19
Maturity Price : 24.67
Evaluated at bid price : 25.10
Bid-YTW : 4.93 %

CM.PR.O FixedReset Quote: 23.71 – 24.09
Spot Rate : 0.3800
Average : 0.2421

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-19
Maturity Price : 23.29
Evaluated at bid price : 23.71
Bid-YTW : 4.48 %

PWF.PR.T FixedReset Quote: 24.61 – 25.03
Spot Rate : 0.4200
Average : 0.2951

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-19
Maturity Price : 24.18
Evaluated at bid price : 24.61
Bid-YTW : 4.40 %

BAM.PF.F FixedReset Quote: 24.65 – 25.00
Spot Rate : 0.3500
Average : 0.2400

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-19
Maturity Price : 23.53
Evaluated at bid price : 24.65
Bid-YTW : 4.85 %

POW.PR.G Perpetual-Premium Quote: 25.17 – 25.45
Spot Rate : 0.2800
Average : 0.1766

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-19
Maturity Price : 24.83
Evaluated at bid price : 25.17
Bid-YTW : 5.59 %

Market Action

January 18, 2018

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.3405 % 2,903.5
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.3405 % 5,327.8
Floater 3.41 % 3.55 % 35,366 18.41 4 0.3405 % 3,070.5
OpRet 0.00 % 0.00 % 0 0.00 0 0.4125 % 3,162.7
SplitShare 4.64 % 4.01 % 64,907 3.40 5 0.4125 % 3,776.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.4125 % 2,946.9
Perpetual-Premium 5.37 % 1.21 % 62,859 0.09 18 0.1445 % 2,857.4
Perpetual-Discount 5.32 % 5.29 % 73,476 14.97 16 0.1589 % 2,988.4
FixedReset 4.20 % 4.44 % 142,181 4.05 99 0.1569 % 2,528.9
Deemed-Retractible 5.07 % 5.36 % 79,272 5.84 28 0.1795 % 2,943.3
FloatingReset 3.04 % 2.88 % 38,775 1.00 10 -0.0651 % 2,766.9
Performance Highlights
Issue Index Change Notes
TRP.PR.G FixedReset -1.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-18
Maturity Price : 23.05
Evaluated at bid price : 24.13
Bid-YTW : 4.93 %
TRP.PR.B FixedReset -1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-18
Maturity Price : 17.07
Evaluated at bid price : 17.07
Bid-YTW : 4.60 %
TRP.PR.C FixedReset -1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-18
Maturity Price : 18.21
Evaluated at bid price : 18.21
Bid-YTW : 4.57 %
TRP.PR.A FixedReset -1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-18
Maturity Price : 20.61
Evaluated at bid price : 20.61
Bid-YTW : 4.69 %
GWO.PR.N FixedReset -1.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.55
Bid-YTW : 7.63 %
BAM.PR.T FixedReset 1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-18
Maturity Price : 20.93
Evaluated at bid price : 20.93
Bid-YTW : 4.94 %
IFC.PR.A FixedReset 1.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.50
Bid-YTW : 6.80 %
BAM.PF.F FixedReset 1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-18
Maturity Price : 23.65
Evaluated at bid price : 24.95
Bid-YTW : 4.78 %
IFC.PR.C FixedReset 1.62 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-09-30
Maturity Price : 25.00
Evaluated at bid price : 23.90
Bid-YTW : 4.71 %
BAM.PF.I FixedReset 2.49 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-03-31
Maturity Price : 25.00
Evaluated at bid price : 25.90
Bid-YTW : 3.94 %
Volume Highlights
Issue Index Shares
Traded
Notes
CM.PR.S FixedReset 734,395 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-18
Maturity Price : 23.15
Evaluated at bid price : 24.96
Bid-YTW : 4.36 %
TRP.PR.K FixedReset 161,668 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-05-31
Maturity Price : 25.00
Evaluated at bid price : 26.15
Bid-YTW : 3.93 %
BMO.PR.R FloatingReset 152,813 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.92
Bid-YTW : 2.91 %
CU.PR.C FixedReset 57,720 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-18
Maturity Price : 21.91
Evaluated at bid price : 22.35
Bid-YTW : 4.67 %
TD.PF.H FixedReset 48,788 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 26.02
Bid-YTW : 3.66 %
TRP.PR.J FixedReset 37,520 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-31
Maturity Price : 25.00
Evaluated at bid price : 26.55
Bid-YTW : 3.78 %
There were 24 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
TRP.PR.A FixedReset Quote: 20.61 – 21.17
Spot Rate : 0.5600
Average : 0.3637

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-18
Maturity Price : 20.61
Evaluated at bid price : 20.61
Bid-YTW : 4.69 %

TRP.PR.G FixedReset Quote: 24.13 – 24.57
Spot Rate : 0.4400
Average : 0.3190

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-18
Maturity Price : 23.05
Evaluated at bid price : 24.13
Bid-YTW : 4.93 %

CU.PR.G Perpetual-Discount Quote: 21.96 – 22.28
Spot Rate : 0.3200
Average : 0.2011

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-18
Maturity Price : 21.63
Evaluated at bid price : 21.96
Bid-YTW : 5.18 %

NA.PR.S FixedReset Quote: 23.29 – 23.59
Spot Rate : 0.3000
Average : 0.1963

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-18
Maturity Price : 22.83
Evaluated at bid price : 23.29
Bid-YTW : 4.66 %

HSE.PR.E FixedReset Quote: 25.05 – 25.33
Spot Rate : 0.2800
Average : 0.1774

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-03-31
Maturity Price : 25.00
Evaluated at bid price : 25.05
Bid-YTW : 4.53 %

BMO.PR.T FixedReset Quote: 23.82 – 24.09
Spot Rate : 0.2700
Average : 0.1689

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-18
Maturity Price : 23.42
Evaluated at bid price : 23.82
Bid-YTW : 4.44 %

Market Action

January 17, 2018

PerpetualDiscounts now yield 5.30%, equivalent to 6.89% interest at the standard equivalency factor of 1.3x. Long corporates now yield about 3.85%, so the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) is now about 305bp, a significant widening from the 295bp reported January 10.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 1.5855 % 2,893.7
FixedFloater 0.00 % 0.00 % 0 0.00 0 1.5855 % 5,309.7
Floater 3.18 % 3.31 % 35,275 18.97 4 1.5855 % 3,060.0
OpRet 0.00 % 0.00 % 0 0.00 0 0.1169 % 3,149.7
SplitShare 4.66 % 4.07 % 60,088 3.40 5 0.1169 % 3,761.4
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1169 % 2,934.8
Perpetual-Premium 5.38 % 1.10 % 61,993 0.09 18 0.0701 % 2,853.3
Perpetual-Discount 5.33 % 5.30 % 74,034 14.94 16 0.1645 % 2,983.7
FixedReset 4.20 % 4.44 % 140,325 4.10 98 0.1686 % 2,524.9
Deemed-Retractible 5.08 % 5.42 % 78,611 5.84 28 0.1010 % 2,938.0
FloatingReset 3.03 % 2.87 % 40,279 1.01 10 0.3134 % 2,768.7
Performance Highlights
Issue Index Change Notes
BAM.PF.I FixedReset -3.22 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-03-31
Maturity Price : 25.00
Evaluated at bid price : 25.27
Bid-YTW : 4.60 %
RY.PR.Z FixedReset 1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-17
Maturity Price : 23.44
Evaluated at bid price : 23.89
Bid-YTW : 4.40 %
PWF.PR.P FixedReset 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-17
Maturity Price : 18.72
Evaluated at bid price : 18.72
Bid-YTW : 4.52 %
TRP.PR.A FixedReset 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-17
Maturity Price : 20.83
Evaluated at bid price : 20.83
Bid-YTW : 4.64 %
BAM.PR.B Floater 1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-17
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 3.31 %
TRP.PR.H FloatingReset 1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-17
Maturity Price : 17.11
Evaluated at bid price : 17.11
Bid-YTW : 3.62 %
RY.PR.H FixedReset 1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-17
Maturity Price : 23.66
Evaluated at bid price : 24.05
Bid-YTW : 4.41 %
PWF.PR.A Floater 1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-17
Maturity Price : 19.60
Evaluated at bid price : 19.60
Bid-YTW : 2.88 %
BAM.PR.C Floater 1.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-17
Maturity Price : 16.90
Evaluated at bid price : 16.90
Bid-YTW : 3.33 %
BAM.PR.K Floater 1.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-17
Maturity Price : 16.98
Evaluated at bid price : 16.98
Bid-YTW : 3.32 %
NA.PR.W FixedReset 1.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-17
Maturity Price : 22.76
Evaluated at bid price : 23.08
Bid-YTW : 4.53 %
TRP.PR.F FloatingReset 2.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-17
Maturity Price : 20.72
Evaluated at bid price : 20.72
Bid-YTW : 3.76 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PF.H FixedReset 140,015 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 26.01
Bid-YTW : 3.67 %
BNS.PR.B FloatingReset 133,904 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-10-25
Maturity Price : 25.00
Evaluated at bid price : 24.87
Bid-YTW : 2.57 %
BMO.PR.B FixedReset 74,522 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-02-25
Maturity Price : 25.00
Evaluated at bid price : 26.13
Bid-YTW : 3.86 %
CM.PR.O FixedReset 67,151 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-17
Maturity Price : 23.22
Evaluated at bid price : 23.64
Bid-YTW : 4.50 %
RY.PR.H FixedReset 53,876 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-17
Maturity Price : 23.66
Evaluated at bid price : 24.05
Bid-YTW : 4.41 %
TRP.PR.C FixedReset 49,136 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-17
Maturity Price : 18.42
Evaluated at bid price : 18.42
Bid-YTW : 4.52 %
There were 24 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BAM.PF.I FixedReset Quote: 25.27 – 26.15
Spot Rate : 0.8800
Average : 0.5060

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-03-31
Maturity Price : 25.00
Evaluated at bid price : 25.27
Bid-YTW : 4.60 %

IFC.PR.F Deemed-Retractible Quote: 25.01 – 25.44
Spot Rate : 0.4300
Average : 0.3232

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.01
Bid-YTW : 5.38 %

IFC.PR.A FixedReset Quote: 20.27 – 20.52
Spot Rate : 0.2500
Average : 0.1586

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.27
Bid-YTW : 6.99 %

BAM.PF.H FixedReset Quote: 26.24 – 26.55
Spot Rate : 0.3100
Average : 0.2283

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-31
Maturity Price : 25.00
Evaluated at bid price : 26.24
Bid-YTW : 3.33 %

GWO.PR.N FixedReset Quote: 18.74 – 18.94
Spot Rate : 0.2000
Average : 0.1395

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.74
Bid-YTW : 7.46 %

BAM.PR.T FixedReset Quote: 20.72 – 21.00
Spot Rate : 0.2800
Average : 0.2196

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-17
Maturity Price : 20.72
Evaluated at bid price : 20.72
Bid-YTW : 4.99 %

Market Action

January 16, 2018

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -1.9225 % 2,848.5
FixedFloater 0.00 % 0.00 % 0 0.00 0 -1.9225 % 5,226.9
Floater 3.23 % 3.35 % 35,483 18.88 4 -1.9225 % 3,012.3
OpRet 0.00 % 0.00 % 0 0.00 0 -0.2177 % 3,146.0
SplitShare 4.67 % 4.02 % 60,296 3.40 5 -0.2177 % 3,757.0
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.2177 % 2,931.4
Perpetual-Premium 5.38 % 3.37 % 61,690 0.09 18 -0.0438 % 2,851.3
Perpetual-Discount 5.34 % 5.31 % 73,693 14.91 16 -0.0647 % 2,978.8
FixedReset 4.21 % 4.47 % 140,615 4.19 98 -0.2594 % 2,520.7
Deemed-Retractible 5.08 % 5.42 % 81,505 5.84 28 -0.0757 % 2,935.1
FloatingReset 3.04 % 2.61 % 41,930 0.78 10 -0.0087 % 2,760.1
Performance Highlights
Issue Index Change Notes
BAM.PR.K Floater -2.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-16
Maturity Price : 16.67
Evaluated at bid price : 16.67
Bid-YTW : 3.38 %
BAM.PR.C Floater -2.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-16
Maturity Price : 16.61
Evaluated at bid price : 16.61
Bid-YTW : 3.39 %
NA.PR.W FixedReset -1.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-16
Maturity Price : 22.35
Evaluated at bid price : 22.65
Bid-YTW : 4.61 %
PWF.PR.A Floater -1.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-16
Maturity Price : 19.30
Evaluated at bid price : 19.30
Bid-YTW : 2.93 %
MFC.PR.M FixedReset -1.37 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.69
Bid-YTW : 5.19 %
PVS.PR.E SplitShare -1.31 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-02-15
Maturity Price : 26.00
Evaluated at bid price : 26.35
Bid-YTW : -3.96 %
BAM.PR.B Floater -1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-16
Maturity Price : 16.80
Evaluated at bid price : 16.80
Bid-YTW : 3.35 %
BMO.PR.Y FixedReset -1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-16
Maturity Price : 23.26
Evaluated at bid price : 24.51
Bid-YTW : 4.64 %
BMO.PR.S FixedReset -1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-16
Maturity Price : 23.56
Evaluated at bid price : 24.00
Bid-YTW : 4.50 %
RY.PR.H FixedReset -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-16
Maturity Price : 23.34
Evaluated at bid price : 23.74
Bid-YTW : 4.47 %
MFC.PR.N FixedReset -1.00 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.70
Bid-YTW : 5.09 %
HSE.PR.A FixedReset 2.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-16
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 4.88 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PR.T FloatingReset 205,100 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-07-31
Maturity Price : 25.00
Evaluated at bid price : 24.88
Bid-YTW : 2.21 %
RY.PR.H FixedReset 155,745 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-16
Maturity Price : 23.34
Evaluated at bid price : 23.74
Bid-YTW : 4.47 %
TD.PF.A FixedReset 140,452 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-16
Maturity Price : 23.21
Evaluated at bid price : 23.58
Bid-YTW : 4.43 %
RY.PR.I FixedReset 140,300 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2019-02-24
Maturity Price : 25.00
Evaluated at bid price : 25.17
Bid-YTW : 3.38 %
BAM.PF.A FixedReset 78,402 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-16
Maturity Price : 24.14
Evaluated at bid price : 24.67
Bid-YTW : 4.95 %
MFC.PR.R FixedReset 72,105 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-03-19
Maturity Price : 25.00
Evaluated at bid price : 25.87
Bid-YTW : 4.06 %
There were 26 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
NA.PR.W FixedReset Quote: 22.65 – 23.08
Spot Rate : 0.4300
Average : 0.2613

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-16
Maturity Price : 22.35
Evaluated at bid price : 22.65
Bid-YTW : 4.61 %

BMO.PR.Y FixedReset Quote: 24.51 – 24.92
Spot Rate : 0.4100
Average : 0.2516

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-16
Maturity Price : 23.26
Evaluated at bid price : 24.51
Bid-YTW : 4.64 %

BAM.PF.G FixedReset Quote: 24.41 – 24.83
Spot Rate : 0.4200
Average : 0.2668

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-16
Maturity Price : 23.25
Evaluated at bid price : 24.41
Bid-YTW : 4.86 %

IFC.PR.F Deemed-Retractible Quote: 25.00 – 25.30
Spot Rate : 0.3000
Average : 0.2062

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.00
Bid-YTW : 5.38 %

IFC.PR.E Deemed-Retractible Quote: 24.85 – 25.20
Spot Rate : 0.3500
Average : 0.2621

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.85
Bid-YTW : 5.38 %

CU.PR.F Perpetual-Discount Quote: 21.80 – 22.05
Spot Rate : 0.2500
Average : 0.1632

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-16
Maturity Price : 21.52
Evaluated at bid price : 21.80
Bid-YTW : 5.22 %

Market Action

January 15, 2018

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 1.2452 % 2,904.3
FixedFloater 0.00 % 0.00 % 0 0.00 0 1.2452 % 5,329.3
Floater 3.17 % 3.30 % 35,401 19.01 4 1.2452 % 3,071.3
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0932 % 3,152.9
SplitShare 4.66 % 4.08 % 62,770 3.41 5 -0.0932 % 3,765.2
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0932 % 2,937.7
Perpetual-Premium 5.38 % 3.16 % 60,023 0.09 18 -0.1137 % 2,852.5
Perpetual-Discount 5.33 % 5.30 % 72,058 14.97 16 -0.2956 % 2,980.7
FixedReset 4.20 % 4.43 % 141,012 4.06 98 -0.1085 % 2,527.2
Deemed-Retractible 5.08 % 5.44 % 82,166 5.84 28 -0.1348 % 2,937.3
FloatingReset 3.04 % 2.59 % 38,816 0.78 10 0.1220 % 2,760.3
Performance Highlights
Issue Index Change Notes
HSE.PR.A FixedReset -2.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-15
Maturity Price : 17.63
Evaluated at bid price : 17.63
Bid-YTW : 4.98 %
IFC.PR.A FixedReset -1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.35
Bid-YTW : 6.91 %
BIP.PR.A FixedReset -1.24 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-06-30
Maturity Price : 25.00
Evaluated at bid price : 24.70
Bid-YTW : 5.14 %
SLF.PR.G FixedReset -1.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.13
Bid-YTW : 7.34 %
PWF.PR.Z Perpetual-Discount -1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-15
Maturity Price : 23.94
Evaluated at bid price : 24.30
Bid-YTW : 5.30 %
TRP.PR.C FixedReset 1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-15
Maturity Price : 18.40
Evaluated at bid price : 18.40
Bid-YTW : 4.52 %
BAM.PR.K Floater 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-15
Maturity Price : 17.09
Evaluated at bid price : 17.09
Bid-YTW : 3.30 %
TRP.PR.F FloatingReset 1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-15
Maturity Price : 20.25
Evaluated at bid price : 20.25
Bid-YTW : 3.85 %
PWF.PR.A Floater 2.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-15
Maturity Price : 19.62
Evaluated at bid price : 19.62
Bid-YTW : 2.88 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.I FixedReset 101,040 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2019-02-24
Maturity Price : 25.00
Evaluated at bid price : 25.16
Bid-YTW : 3.41 %
MFC.PR.R FixedReset 67,709 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-03-19
Maturity Price : 25.00
Evaluated at bid price : 25.85
Bid-YTW : 4.07 %
BIP.PR.A FixedReset 57,258 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-06-30
Maturity Price : 25.00
Evaluated at bid price : 24.70
Bid-YTW : 5.14 %
TD.PR.S FixedReset 51,920 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-07-31
Maturity Price : 25.00
Evaluated at bid price : 24.97
Bid-YTW : 3.36 %
TRP.PR.C FixedReset 45,400 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-15
Maturity Price : 18.40
Evaluated at bid price : 18.40
Bid-YTW : 4.52 %
BMO.PR.D FixedReset 37,140 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-08-25
Maturity Price : 25.00
Evaluated at bid price : 25.30
Bid-YTW : 4.29 %
There were 24 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BAM.PF.D Perpetual-Discount Quote: 22.00 – 22.49
Spot Rate : 0.4900
Average : 0.3761

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-15
Maturity Price : 21.65
Evaluated at bid price : 22.00
Bid-YTW : 5.60 %

BAM.PR.M Perpetual-Discount Quote: 21.65 – 21.97
Spot Rate : 0.3200
Average : 0.2188

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-15
Maturity Price : 21.38
Evaluated at bid price : 21.65
Bid-YTW : 5.52 %

PWF.PR.F Perpetual-Discount Quote: 24.44 – 24.67
Spot Rate : 0.2300
Average : 0.1611

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-15
Maturity Price : 24.18
Evaluated at bid price : 24.44
Bid-YTW : 5.38 %

IFC.PR.E Deemed-Retractible Quote: 24.75 – 24.98
Spot Rate : 0.2300
Average : 0.1658

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.75
Bid-YTW : 5.44 %

BAM.PF.F FixedReset Quote: 24.56 – 24.77
Spot Rate : 0.2100
Average : 0.1618

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-15
Maturity Price : 23.49
Evaluated at bid price : 24.56
Bid-YTW : 4.87 %

BMO.PR.Q FixedReset Quote: 23.26 – 23.49
Spot Rate : 0.2300
Average : 0.1864

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.26
Bid-YTW : 3.91 %

Market Action

January 12, 2018

And now I can start on PrefLetter!

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 1.3049 % 2,868.6
FixedFloater 0.00 % 0.00 % 0 0.00 0 1.3049 % 5,263.8
Floater 3.21 % 3.33 % 35,742 18.93 4 1.3049 % 3,033.5
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0155 % 3,155.8
SplitShare 4.65 % 4.06 % 61,775 3.41 5 -0.0155 % 3,768.7
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0155 % 2,940.5
Perpetual-Premium 5.38 % -0.24 % 59,091 0.09 18 -0.1071 % 2,855.7
Perpetual-Discount 5.32 % 5.29 % 72,501 14.99 16 -0.3054 % 2,989.5
FixedReset 4.20 % 4.40 % 139,621 3.93 98 -0.1929 % 2,530.0
Deemed-Retractible 5.07 % 5.41 % 82,859 5.86 28 -0.1805 % 2,941.3
FloatingReset 3.05 % 2.51 % 39,348 0.79 10 0.0567 % 2,756.9
Performance Highlights
Issue Index Change Notes
NA.PR.S FixedReset -1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-12
Maturity Price : 23.18
Evaluated at bid price : 23.65
Bid-YTW : 4.58 %
CU.PR.C FixedReset -1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-12
Maturity Price : 21.77
Evaluated at bid price : 22.15
Bid-YTW : 4.71 %
TRP.PR.D FixedReset -1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-12
Maturity Price : 22.96
Evaluated at bid price : 23.44
Bid-YTW : 4.61 %
MFC.PR.F FixedReset -1.00 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.75
Bid-YTW : 7.42 %
BAM.PR.B Floater 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-12
Maturity Price : 16.90
Evaluated at bid price : 16.90
Bid-YTW : 3.33 %
BNS.PR.Y FixedReset 1.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.76
Bid-YTW : 3.62 %
BAM.PR.C Floater 1.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-12
Maturity Price : 16.86
Evaluated at bid price : 16.86
Bid-YTW : 3.34 %
BAM.PR.K Floater 2.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-12
Maturity Price : 16.90
Evaluated at bid price : 16.90
Bid-YTW : 3.33 %
Volume Highlights
Issue Index Shares
Traded
Notes
BAM.PF.C Perpetual-Discount 111,180 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-12
Maturity Price : 21.60
Evaluated at bid price : 21.90
Bid-YTW : 5.57 %
TRP.PR.J FixedReset 104,600 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-31
Maturity Price : 25.00
Evaluated at bid price : 26.60
Bid-YTW : 3.69 %
BNS.PR.D FloatingReset 73,000 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.75
Bid-YTW : 3.49 %
BNS.PR.Q FixedReset 62,379 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-10-25
Maturity Price : 25.00
Evaluated at bid price : 25.00
Bid-YTW : 3.45 %
NA.PR.X FixedReset 57,800 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-15
Maturity Price : 25.00
Evaluated at bid price : 26.47
Bid-YTW : 3.57 %
CM.PR.P FixedReset 54,968 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-12
Maturity Price : 23.18
Evaluated at bid price : 23.51
Bid-YTW : 4.42 %
There were 23 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
MFC.PR.N FixedReset Quote: 23.90 – 24.20
Spot Rate : 0.3000
Average : 0.2092

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.90
Bid-YTW : 4.94 %

BMO.PR.S FixedReset Quote: 24.32 – 24.60
Spot Rate : 0.2800
Average : 0.1944

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-12
Maturity Price : 23.92
Evaluated at bid price : 24.32
Bid-YTW : 4.44 %

BAM.PF.E FixedReset Quote: 23.77 – 24.06
Spot Rate : 0.2900
Average : 0.2132

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-12
Maturity Price : 22.99
Evaluated at bid price : 23.77
Bid-YTW : 4.74 %

TRP.PR.C FixedReset Quote: 18.20 – 18.47
Spot Rate : 0.2700
Average : 0.2014

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-12
Maturity Price : 18.20
Evaluated at bid price : 18.20
Bid-YTW : 4.57 %

MFC.PR.J FixedReset Quote: 24.47 – 24.67
Spot Rate : 0.2000
Average : 0.1374

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.47
Bid-YTW : 5.02 %

TRP.PR.G FixedReset Quote: 24.41 – 24.79
Spot Rate : 0.3800
Average : 0.3175

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-12
Maturity Price : 23.17
Evaluated at bid price : 24.41
Bid-YTW : 4.86 %

Market Action

January 11, 2018

Boom! The Canadian preferred share market took a whacking today; perhaps due to renewed NAFTA fears:

President Donald Trump reiterated his threat to withdraw the U.S. from Nafta while saying that gains from a new deal could be used to pay for a wall at the Mexican border.

A day after Canadian officials said they viewed the odds of withdrawal as rising, Trump repeated his threat to pull out of the North American Free Trade Agreement if it can’t be reworked in his favor, the Wall Street Journal reported Thursday, citing an interview with the president. However, Trump said he was willing to be “a little bit flexible” about the deal until after Mexico’s presidential election in July. He didn’t elaborate on what that means.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.8197 % 2,831.7
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.8197 % 5,196.0
Floater 3.25 % 3.37 % 35,831 18.85 4 -0.8197 % 2,994.5
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0621 % 3,156.3
SplitShare 4.65 % 4.01 % 58,138 3.42 5 -0.0621 % 3,769.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0621 % 2,940.9
Perpetual-Premium 5.37 % 1.93 % 59,513 0.09 18 -0.0939 % 2,858.8
Perpetual-Discount 5.30 % 5.26 % 70,980 15.03 16 0.0509 % 2,998.7
FixedReset 4.19 % 4.34 % 139,823 3.86 98 -0.4687 % 2,534.9
Deemed-Retractible 5.06 % 5.38 % 81,280 5.86 28 -0.3302 % 2,946.6
FloatingReset 2.97 % 2.71 % 37,647 1.02 10 -0.2001 % 2,755.4
Performance Highlights
Issue Index Change Notes
MFC.PR.N FixedReset -1.65 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.82
Bid-YTW : 4.99 %
BAM.PR.K Floater -1.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-11
Maturity Price : 16.48
Evaluated at bid price : 16.48
Bid-YTW : 3.42 %
MFC.PR.L FixedReset -1.48 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.37
Bid-YTW : 5.28 %
BAM.PR.T FixedReset -1.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-11
Maturity Price : 20.87
Evaluated at bid price : 20.87
Bid-YTW : 4.95 %
MFC.PR.M FixedReset -1.32 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.90
Bid-YTW : 5.03 %
CU.PR.C FixedReset -1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-11
Maturity Price : 21.96
Evaluated at bid price : 22.42
Bid-YTW : 4.65 %
SLF.PR.I FixedReset -1.25 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-12-31
Maturity Price : 25.00
Evaluated at bid price : 24.55
Bid-YTW : 4.36 %
BAM.PF.E FixedReset -1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-11
Maturity Price : 23.04
Evaluated at bid price : 23.86
Bid-YTW : 4.71 %
MFC.PR.K FixedReset -1.18 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.38
Bid-YTW : 5.35 %
MFC.PR.I FixedReset -1.18 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-09-19
Maturity Price : 25.00
Evaluated at bid price : 25.16
Bid-YTW : 4.29 %
NA.PR.X FixedReset -1.16 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-15
Maturity Price : 25.00
Evaluated at bid price : 26.45
Bid-YTW : 3.60 %
BMO.PR.W FixedReset -1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-11
Maturity Price : 23.28
Evaluated at bid price : 23.64
Bid-YTW : 4.43 %
BAM.PF.G FixedReset -1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-11
Maturity Price : 23.29
Evaluated at bid price : 24.52
Bid-YTW : 4.83 %
BAM.PF.F FixedReset -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-11
Maturity Price : 23.52
Evaluated at bid price : 24.63
Bid-YTW : 4.85 %
MFC.PR.G FixedReset -1.04 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-12-19
Maturity Price : 25.00
Evaluated at bid price : 24.74
Bid-YTW : 4.27 %
BAM.PF.D Perpetual-Discount 1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-11
Maturity Price : 21.99
Evaluated at bid price : 22.32
Bid-YTW : 5.52 %
Volume Highlights
Issue Index Shares
Traded
Notes
TRP.PR.J FixedReset 408,175 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-31
Maturity Price : 25.00
Evaluated at bid price : 26.58
Bid-YTW : 3.72 %
TRP.PR.E FixedReset 302,075 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-11
Maturity Price : 24.03
Evaluated at bid price : 24.35
Bid-YTW : 4.43 %
CM.PR.R FixedReset 186,314 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-07-31
Maturity Price : 25.00
Evaluated at bid price : 25.40
Bid-YTW : 3.98 %
BMO.PR.T FixedReset 158,425 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-11
Maturity Price : 23.61
Evaluated at bid price : 24.00
Bid-YTW : 4.40 %
TD.PF.H FixedReset 146,293 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 26.10
Bid-YTW : 3.55 %
TD.PR.S FixedReset 120,800 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-07-31
Maturity Price : 25.00
Evaluated at bid price : 24.98
Bid-YTW : 3.22 %
There were 43 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
VNR.PR.A FixedReset Quote: 25.07 – 25.36
Spot Rate : 0.2900
Average : 0.2008

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-10-15
Maturity Price : 25.00
Evaluated at bid price : 25.07
Bid-YTW : 4.57 %

PWF.PR.Z Perpetual-Discount Quote: 24.52 – 24.75
Spot Rate : 0.2300
Average : 0.1495

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-11
Maturity Price : 24.14
Evaluated at bid price : 24.52
Bid-YTW : 5.25 %

BAM.PF.C Perpetual-Discount Quote: 21.92 – 22.14
Spot Rate : 0.2200
Average : 0.1530

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-11
Maturity Price : 21.61
Evaluated at bid price : 21.92
Bid-YTW : 5.56 %

IAG.PR.G FixedReset Quote: 24.22 – 24.48
Spot Rate : 0.2600
Average : 0.1959

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-06-30
Maturity Price : 25.00
Evaluated at bid price : 24.22
Bid-YTW : 4.61 %

NA.PR.A FixedReset Quote: 26.37 – 26.55
Spot Rate : 0.1800
Average : 0.1250

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-15
Maturity Price : 25.00
Evaluated at bid price : 26.37
Bid-YTW : 3.64 %

PWF.PR.A Floater Quote: 19.20 – 19.75
Spot Rate : 0.5500
Average : 0.4995

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-11
Maturity Price : 19.20
Evaluated at bid price : 19.20
Bid-YTW : 2.94 %

Market Action

January 10, 2018

The Bay Street Boys have got all the mileage they could out of the ‘everything is rosy’ story, so now they’re shaking the other tree:

Mexico’s peso and Canada’s dollar dropped after reports the U.S. may pull out of the trillion-dollar trade pact that President Donald Trump has threatened to dump if it doesn’t favor his nation.

Both currencies pared losses after a White House official said there hasn’t been any change in Trump’s position on Nafta. The peso fell 0.5 percent to 19.3398 per dollar as of 3:33 p.m. in New York, after falling as much as 0.9 percent. The Canadian dollar slipped 0.6 percent to 1.2543 per dollar. Yields on Canadian government 2-year notes fell six basis points to 1.74 percent.

The Five-Year Canada yield declined to 1.95%.

PerpetualDiscounts now yield 5.25%, equivalent to 6.83% interest at the standard equivalency factor of 1.3x. Long corporates now yield about 3.90%, so the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) is now about 295bp, a slight (and perhaps spurious) narrowing from the 300bp reported January 3.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 1.5479 % 2,855.1
FixedFloater 0.00 % 0.00 % 0 0.00 0 1.5479 % 5,238.9
Floater 3.22 % 3.36 % 35,767 18.87 4 1.5479 % 3,019.2
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0466 % 3,158.3
SplitShare 4.65 % 4.06 % 58,758 3.42 5 -0.0466 % 3,771.6
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0466 % 2,942.8
Perpetual-Premium 5.36 % -0.57 % 55,100 0.09 18 -0.0218 % 2,861.5
Perpetual-Discount 5.30 % 5.25 % 73,936 15.06 16 -0.4881 % 2,997.2
FixedReset 4.17 % 4.15 % 139,752 3.86 98 -0.1486 % 2,546.8
Deemed-Retractible 5.04 % 5.38 % 81,297 5.86 28 -0.0545 % 2,956.3
FloatingReset 2.97 % 2.56 % 37,946 1.03 10 0.1133 % 2,760.9
Performance Highlights
Issue Index Change Notes
BAM.PF.D Perpetual-Discount -2.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-10
Maturity Price : 21.65
Evaluated at bid price : 22.00
Bid-YTW : 5.60 %
BAM.PR.M Perpetual-Discount -1.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-10
Maturity Price : 21.50
Evaluated at bid price : 21.50
Bid-YTW : 5.57 %
BAM.PR.N Perpetual-Discount -1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-10
Maturity Price : 21.45
Evaluated at bid price : 21.45
Bid-YTW : 5.59 %
CU.PR.G Perpetual-Discount -1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-10
Maturity Price : 21.67
Evaluated at bid price : 22.03
Bid-YTW : 5.15 %
CU.PR.I FixedReset -1.11 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-01
Maturity Price : 25.00
Evaluated at bid price : 25.85
Bid-YTW : 3.45 %
BIP.PR.D FixedReset -1.10 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-03-31
Maturity Price : 25.00
Evaluated at bid price : 25.24
Bid-YTW : 4.81 %
NA.PR.C FixedReset -1.06 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-11-15
Maturity Price : 25.00
Evaluated at bid price : 25.26
Bid-YTW : 4.14 %
BAM.PF.I FixedReset -1.06 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-03-31
Maturity Price : 25.00
Evaluated at bid price : 26.20
Bid-YTW : 3.62 %
NA.PR.W FixedReset -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-10
Maturity Price : 23.33
Evaluated at bid price : 23.65
Bid-YTW : 4.41 %
SLF.PR.D Deemed-Retractible -1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.80
Bid-YTW : 6.82 %
HSE.PR.A FixedReset -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-10
Maturity Price : 18.10
Evaluated at bid price : 18.10
Bid-YTW : 4.85 %
TRP.PR.A FixedReset 1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-10
Maturity Price : 21.05
Evaluated at bid price : 21.05
Bid-YTW : 4.59 %
PWF.PR.F Perpetual-Discount 1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-10
Maturity Price : 24.34
Evaluated at bid price : 24.65
Bid-YTW : 5.32 %
SLF.PR.J FloatingReset 1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.45
Bid-YTW : 6.50 %
SLF.PR.H FixedReset 1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.15
Bid-YTW : 5.43 %
BAM.PR.B Floater 1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-10
Maturity Price : 16.73
Evaluated at bid price : 16.73
Bid-YTW : 3.36 %
PWF.PR.T FixedReset 1.25 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2019-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.11
Bid-YTW : 3.56 %
IFC.PR.A FixedReset 1.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.76
Bid-YTW : 6.56 %
BAM.PR.C Floater 1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-10
Maturity Price : 16.71
Evaluated at bid price : 16.71
Bid-YTW : 3.37 %
CCS.PR.C Deemed-Retractible 1.45 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.45
Bid-YTW : 5.44 %
BAM.PR.K Floater 3.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-10
Maturity Price : 16.75
Evaluated at bid price : 16.75
Bid-YTW : 3.36 %
Volume Highlights
Issue Index Shares
Traded
Notes
CM.PR.R FixedReset 713,839 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-07-31
Maturity Price : 25.00
Evaluated at bid price : 25.38
Bid-YTW : 4.00 %
TD.PR.S FixedReset 180,700 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-07-31
Maturity Price : 25.00
Evaluated at bid price : 25.00
Bid-YTW : 3.05 %
TD.PF.C FixedReset 87,835 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-10
Maturity Price : 23.41
Evaluated at bid price : 23.73
Bid-YTW : 4.39 %
BMO.PR.D FixedReset 71,035 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-08-25
Maturity Price : 25.00
Evaluated at bid price : 25.42
Bid-YTW : 4.16 %
BMO.PR.M FixedReset 40,900 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-08-25
Maturity Price : 25.00
Evaluated at bid price : 25.08
Bid-YTW : 3.60 %
MFC.PR.J FixedReset 40,860 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.74
Bid-YTW : 4.83 %
There were 36 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
GWO.PR.M Deemed-Retractible Quote: 25.86 – 26.17
Spot Rate : 0.3100
Average : 0.1910

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-02-09
Maturity Price : 25.50
Evaluated at bid price : 25.86
Bid-YTW : -9.29 %

HSE.PR.A FixedReset Quote: 18.10 – 18.49
Spot Rate : 0.3900
Average : 0.2815

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-10
Maturity Price : 18.10
Evaluated at bid price : 18.10
Bid-YTW : 4.85 %

BAM.PF.D Perpetual-Discount Quote: 22.00 – 22.45
Spot Rate : 0.4500
Average : 0.3452

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-10
Maturity Price : 21.65
Evaluated at bid price : 22.00
Bid-YTW : 5.60 %

GWO.PR.N FixedReset Quote: 18.65 – 18.95
Spot Rate : 0.3000
Average : 0.2031

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.65
Bid-YTW : 7.51 %

BAM.PR.N Perpetual-Discount Quote: 21.45 – 21.71
Spot Rate : 0.2600
Average : 0.1713

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-10
Maturity Price : 21.45
Evaluated at bid price : 21.45
Bid-YTW : 5.59 %

BAM.PF.B FixedReset Quote: 24.30 – 24.57
Spot Rate : 0.2700
Average : 0.1843

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-10
Maturity Price : 23.86
Evaluated at bid price : 24.30
Bid-YTW : 4.73 %

Market Action

January 9, 2018

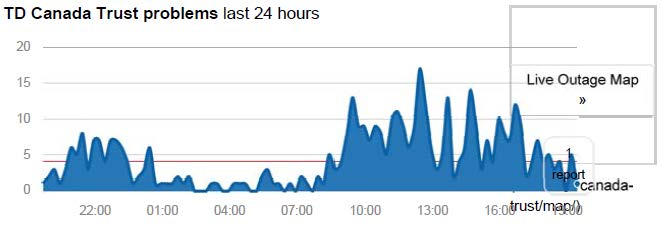
TD continues to provide cruddy service:

Been trying 5 days straight to get through to an advisor without any success. Totally, gun shy to make any risky trades after last week system issues. Why does anyone still trade with TD?.

Will TD update its customers on the outages last week? About future up trades to prevent any further issues? Compensation to investors for loses? When customers will have phone access to advisors again?

Probably no to all my questions. They don’t seem to care. I did notice their stock is the only Canadian bank stock that is trading down today.

td_outages_180109
Click for Big

The pathetic excuses for poor performance provided by Canada’s pathetic excuses for brokerage houses has really started to bother me, so I looked up the Toronto Stock Exchange Daily Trading Reports. The 2018-01-02 Report states that the TSX experienced 829,930 trades on the day (number of trades will be a better indication of retail volume than trading value), while the 2017-11-15 Report (date chosen to be reasonable recent and reasonably typical) reports 889,332 trades.

Obviously this is the smallest of all possible samples using an imperfect proxy, but this doesn’t look like an unprecedented explosion of retail activity to me! I might put a chart together at some point, or perhaps some Industrious and Assiduous Reader could do it for me. But it does seem that perhaps a few more details are required before we can understand the horrible service Canadian retail investors are getting from their beloved banks. Until we get both a convincing explanation of the problem and a reasonably well-detailed exposition of what is being done to address the problem, I suggest that retail investors not count on being able to trade during an actual market break.

However, the market was up again today, presumably due to the five-year Canada yield continuing to rise … now at 2.00%! So I’m all right, Jack.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 1.0924 % 2,811.6
FixedFloater 0.00 % 0.00 % 0 0.00 0 1.0924 % 5,159.1
Floater 3.27 % 3.41 % 33,987 18.76 4 1.0924 % 2,973.2
OpRet 0.00 % 0.00 % 0 0.00 0 0.5069 % 3,159.7
SplitShare 4.65 % 4.11 % 61,066 3.42 5 0.5069 % 3,773.4
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.5069 % 2,944.1
Perpetual-Premium 5.36 % -0.25 % 51,446 0.09 18 0.0433 % 2,862.1
Perpetual-Discount 5.28 % 5.24 % 71,755 15.10 16 -0.2390 % 3,011.9
FixedReset 4.16 % 4.07 % 140,785 3.82 98 0.4426 % 2,550.6
Deemed-Retractible 5.04 % 5.39 % 82,593 5.87 28 -0.0412 % 2,957.9
FloatingReset 2.97 % 2.50 % 39,397 0.80 10 0.4624 % 2,757.8
Performance Highlights
Issue Index Change Notes
BAM.PF.J FixedReset -2.64 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.42
Bid-YTW : 4.42 %
IFC.PR.A FixedReset -1.82 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.50
Bid-YTW : 6.77 %
BAM.PF.C Perpetual-Discount -1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-09
Maturity Price : 21.72
Evaluated at bid price : 22.06
Bid-YTW : 5.52 %
CCS.PR.C Deemed-Retractible -1.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.10
Bid-YTW : 5.68 %
BAM.PF.D Perpetual-Discount -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-09
Maturity Price : 22.22
Evaluated at bid price : 22.51
Bid-YTW : 5.47 %
MFC.PR.M FixedReset 1.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.08
Bid-YTW : 4.90 %
BAM.PF.G FixedReset 1.01 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-06-30
Maturity Price : 25.00
Evaluated at bid price : 24.91
Bid-YTW : 4.73 %
IFC.PR.C FixedReset 1.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.81
Bid-YTW : 4.77 %
MFC.PR.L FixedReset 1.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.65
Bid-YTW : 5.07 %
BNS.PR.Y FixedReset 1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.79
Bid-YTW : 3.58 %
CM.PR.O FixedReset 1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-09
Maturity Price : 23.87
Evaluated at bid price : 24.24
Bid-YTW : 4.38 %
TRP.PR.F FloatingReset 1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-09
Maturity Price : 20.17
Evaluated at bid price : 20.17
Bid-YTW : 3.78 %
TRP.PR.A FixedReset 1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-09
Maturity Price : 20.84
Evaluated at bid price : 20.84
Bid-YTW : 4.63 %
PWF.PR.T FixedReset 1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-09
Maturity Price : 24.42
Evaluated at bid price : 24.80
Bid-YTW : 4.36 %
IAG.PR.G FixedReset 1.20 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-06-30
Maturity Price : 25.00
Evaluated at bid price : 24.49
Bid-YTW : 4.33 %
BAM.PR.X FixedReset 1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-09
Maturity Price : 18.11
Evaluated at bid price : 18.11
Bid-YTW : 4.90 %
CU.PR.C FixedReset 1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-09
Maturity Price : 22.18
Evaluated at bid price : 22.78
Bid-YTW : 4.57 %
MFC.PR.K FixedReset 1.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.59
Bid-YTW : 5.19 %
BAM.PR.C Floater 1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-09
Maturity Price : 16.50
Evaluated at bid price : 16.50
Bid-YTW : 3.41 %
EIT.PR.A SplitShare 1.47 % YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2024-03-14
Maturity Price : 25.00
Evaluated at bid price : 25.49
Bid-YTW : 4.52 %
IAG.PR.A Deemed-Retractible 1.50 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.99
Bid-YTW : 6.07 %
BMO.PR.Q FixedReset 1.53 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.21
Bid-YTW : 3.95 %
BMO.PR.T FixedReset 1.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-09
Maturity Price : 23.71
Evaluated at bid price : 24.09
Bid-YTW : 4.38 %
BAM.PR.B Floater 1.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-09
Maturity Price : 16.53
Evaluated at bid price : 16.53
Bid-YTW : 3.41 %
BAM.PF.F FixedReset 1.67 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2019-09-30
Maturity Price : 25.00
Evaluated at bid price : 24.97
Bid-YTW : 4.67 %
TRP.PR.G FixedReset 1.89 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-11-30
Maturity Price : 25.00
Evaluated at bid price : 24.76
Bid-YTW : 4.32 %
TRP.PR.E FixedReset 1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-09
Maturity Price : 23.40
Evaluated at bid price : 24.42
Bid-YTW : 4.37 %
TRP.PR.D FixedReset 2.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-09
Maturity Price : 23.50
Evaluated at bid price : 23.96
Bid-YTW : 4.50 %
HSE.PR.G FixedReset 2.40 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-06-30
Maturity Price : 25.00
Evaluated at bid price : 25.63
Bid-YTW : 3.59 %
TRP.PR.B FixedReset 2.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-09
Maturity Price : 17.17
Evaluated at bid price : 17.17
Bid-YTW : 4.57 %
TRP.PR.H FloatingReset 3.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-09
Maturity Price : 16.92
Evaluated at bid price : 16.92
Bid-YTW : 3.55 %
MFC.PR.F FixedReset 3.75 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.10
Bid-YTW : 7.11 %
TRP.PR.C FixedReset 4.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-09
Maturity Price : 18.50
Evaluated at bid price : 18.50
Bid-YTW : 4.50 %
Volume Highlights
Issue Index Shares
Traded
Notes
TRP.PR.K FixedReset 314,386 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-05-31
Maturity Price : 25.00
Evaluated at bid price : 26.17
Bid-YTW : 3.88 %
RY.PR.Q FixedReset 203,403 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-24
Maturity Price : 25.00
Evaluated at bid price : 26.92
Bid-YTW : 3.31 %
BNS.PR.Q FixedReset 171,194 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-10-25
Maturity Price : 25.00
Evaluated at bid price : 25.03
Bid-YTW : 3.26 %
BNS.PR.R FixedReset 87,383 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2019-01-26
Maturity Price : 25.00
Evaluated at bid price : 25.10
Bid-YTW : 3.28 %
NA.PR.W FixedReset 86,980 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-09
Maturity Price : 23.59
Evaluated at bid price : 23.90
Bid-YTW : 4.37 %
CM.PR.P FixedReset 84,640 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-09
Maturity Price : 23.41
Evaluated at bid price : 23.73
Bid-YTW : 4.38 %
There were 46 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
TRP.PR.H FloatingReset Clearly a bogus quote (a spread of over $9 !), since the low for the day was 16.94 and the high 17.10 on what the bank-owned brokerages would possibly describe as overwhelming volume of 4,250 shares. I have not checked whether this lamentable state of affairs is due to inadequate Toronto Stock Exchange reporting or inadequate Toronto Stock Exchange supervision of market-makers.

Quote: 16.92 – 26.01
Spot Rate : 9.0900
Average : 4.9744

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-09
Maturity Price : 16.92
Evaluated at bid price : 16.92
Bid-YTW : 3.55 %

TD.PR.T FloatingReset Quote: 24.95 – 25.59
Spot Rate : 0.6400
Average : 0.3845

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-07-31
Maturity Price : 25.00
Evaluated at bid price : 24.95
Bid-YTW : 1.59 %

SLF.PR.G FixedReset Quote: 19.08 – 19.75
Spot Rate : 0.6700
Average : 0.4411

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.08
Bid-YTW : 7.36 %

IFC.PR.C FixedReset Quote: 23.81 – 24.69
Spot Rate : 0.8800
Average : 0.6887

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.81
Bid-YTW : 4.77 %

PWF.PR.F Perpetual-Discount Quote: 24.40 – 24.86
Spot Rate : 0.4600
Average : 0.2725

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-09
Maturity Price : 24.15
Evaluated at bid price : 24.40
Bid-YTW : 5.38 %

MFC.PR.G FixedReset Quote: 25.01 – 25.43
Spot Rate : 0.4200
Average : 0.2689

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-12-19
Maturity Price : 25.00
Evaluated at bid price : 25.01
Bid-YTW : 3.96 %