Category: Market Action

Market Action

January 8, 2018

TD continues to have problems:

Clearly TD Canada has sent a message to us that customer service is not a priority and is STILL not prepared to handle the growing volume of Traders out there. And so, I have begun the transfer of my funds from my Webbroker to another platform. This should be completed within the week. I have decided on Qtrade. And I will in the next while prepare for a complete withdraw of all of my money into another bank or credit union. This will need some thoughtful consideration.

I understand that Banks, like any other business, want to keep their shareholders happy. However, a complete disregard of us, the customer, this past week is quite remarkable. With the billions that this company made in its last quarter, my loss of business will not affect them at all. But I know that I am going to feel much better knowing that TD Canada will never again disrespect me this way again. Shame!

Qtrade…you’re up.
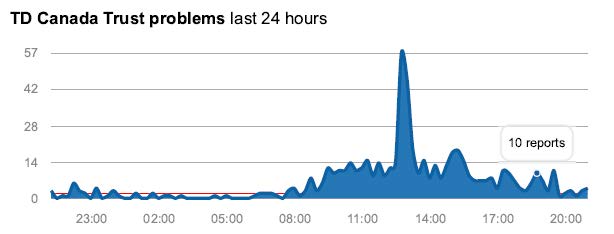
canadianoutagestd
Click for Big

The preferred share market continued to show good strength today, probably in response to continued chatter about a policy hike:

On Monday, Bank of Montreal became the last major Canadian bank to change its forecast for next week to a rate hike. That followed the release of the central bank’s latest quarterly survey, which showed a generally robust outlook for the country’s sales and businesses investment.

… and five-year Canadas now yield 1.97%!

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 3.2307 % 2,781.2
FixedFloater 0.00 % 0.00 % 0 0.00 0 3.2307 % 5,103.3
Floater 3.31 % 3.46 % 34,230 18.64 4 3.2307 % 2,941.1
OpRet 0.00 % 0.00 % 0 0.00 0 0.4229 % 3,143.8
SplitShare 4.67 % 4.10 % 60,721 3.42 5 0.4229 % 3,754.4
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.4229 % 2,929.3
Perpetual-Premium 5.34 % -2.57 % 62,932 0.09 18 0.0174 % 2,860.9
Perpetual-Discount 5.24 % 5.24 % 66,885 14.95 16 0.0133 % 3,019.1
FixedReset 4.18 % 4.23 % 140,258 3.93 98 0.4438 % 2,539.4
Deemed-Retractible 5.04 % 5.33 % 81,876 5.87 28 -0.0927 % 2,959.2
FloatingReset 2.98 % 2.61 % 38,851 0.79 10 0.4433 % 2,745.1
Performance Highlights
Issue Index Change Notes
SLF.PR.I FixedReset 1.05 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-12-31
Maturity Price : 25.00
Evaluated at bid price : 24.91
Bid-YTW : 3.95 %
BIP.PR.A FixedReset 1.08 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-06-30
Maturity Price : 25.00
Evaluated at bid price : 25.37
Bid-YTW : 3.93 %
NA.PR.S FixedReset 1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-08
Maturity Price : 23.72
Evaluated at bid price : 24.15
Bid-YTW : 4.49 %
IFC.PR.A FixedReset 1.21 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.88
Bid-YTW : 6.46 %
TD.PF.A FixedReset 1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-08
Maturity Price : 23.92
Evaluated at bid price : 24.25
Bid-YTW : 4.37 %
TRP.PR.E FixedReset 1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-08
Maturity Price : 23.60
Evaluated at bid price : 23.95
Bid-YTW : 4.50 %
NA.PR.W FixedReset 1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-08
Maturity Price : 23.41
Evaluated at bid price : 23.73
Bid-YTW : 4.40 %
MFC.PR.K FixedReset 1.30 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.30
Bid-YTW : 5.40 %
TRP.PR.F FloatingReset 1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-08
Maturity Price : 19.94
Evaluated at bid price : 19.94
Bid-YTW : 3.82 %
TRP.PR.A FixedReset 1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-08
Maturity Price : 20.60
Evaluated at bid price : 20.60
Bid-YTW : 4.69 %
TRP.PR.C FixedReset 1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-08
Maturity Price : 17.76
Evaluated at bid price : 17.76
Bid-YTW : 4.68 %
HSE.PR.C FixedReset 1.54 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2019-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.08
Bid-YTW : 4.41 %
TRP.PR.D FixedReset 1.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-08
Maturity Price : 23.02
Evaluated at bid price : 23.49
Bid-YTW : 4.59 %
BAM.PR.K Floater 1.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-08
Maturity Price : 16.05
Evaluated at bid price : 16.05
Bid-YTW : 3.51 %
MFC.PR.L FixedReset 1.96 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.40
Bid-YTW : 5.25 %
SLF.PR.H FixedReset 2.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.97
Bid-YTW : 5.56 %
PVS.PR.E SplitShare 2.06 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-02-07
Maturity Price : 26.00
Evaluated at bid price : 26.80
Bid-YTW : -24.40 %
TRP.PR.B FixedReset 2.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-08
Maturity Price : 16.75
Evaluated at bid price : 16.75
Bid-YTW : 4.68 %
HSE.PR.A FixedReset 2.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-08
Maturity Price : 18.24
Evaluated at bid price : 18.24
Bid-YTW : 4.81 %
SLF.PR.J FloatingReset 2.67 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.20
Bid-YTW : 6.70 %
BAM.PR.B Floater 3.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-08
Maturity Price : 16.26
Evaluated at bid price : 16.26
Bid-YTW : 3.46 %
PWF.PR.P FixedReset 3.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-08
Maturity Price : 18.93
Evaluated at bid price : 18.93
Bid-YTW : 4.51 %
BAM.PR.C Floater 3.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-08
Maturity Price : 16.27
Evaluated at bid price : 16.27
Bid-YTW : 3.46 %
PWF.PR.A Floater 4.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-08
Maturity Price : 19.16
Evaluated at bid price : 19.16
Bid-YTW : 2.95 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PR.Y FixedReset 110,400 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.20
Bid-YTW : 3.41 %
RY.PR.Z FixedReset 108,700 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-08
Maturity Price : 23.54
Evaluated at bid price : 23.98
Bid-YTW : 4.38 %
TRP.PR.B FixedReset 108,100 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-08
Maturity Price : 16.75
Evaluated at bid price : 16.75
Bid-YTW : 4.68 %
NA.PR.W FixedReset 104,000 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-08
Maturity Price : 23.41
Evaluated at bid price : 23.73
Bid-YTW : 4.40 %
SLF.PR.H FixedReset 103,200 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.97
Bid-YTW : 5.56 %
BNS.PR.D FloatingReset 80,500 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.65
Bid-YTW : 3.52 %
There were 38 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
IFC.PR.C FixedReset Quote: 23.56 – 24.33
Spot Rate : 0.7700
Average : 0.4790

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.56
Bid-YTW : 4.94 %

MFC.PR.F FixedReset Quote: 18.41 – 18.97
Spot Rate : 0.5600
Average : 0.3460

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.41
Bid-YTW : 7.70 %

BAM.PR.X FixedReset Quote: 17.89 – 18.40
Spot Rate : 0.5100
Average : 0.3174

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-08
Maturity Price : 17.89
Evaluated at bid price : 17.89
Bid-YTW : 4.96 %

TRP.PR.H FloatingReset Quote: 16.31 – 16.95
Spot Rate : 0.6400
Average : 0.4619

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-08
Maturity Price : 16.31
Evaluated at bid price : 16.31
Bid-YTW : 3.68 %

TRP.PR.G FixedReset Quote: 24.30 – 24.84
Spot Rate : 0.5400
Average : 0.3737

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-08
Maturity Price : 23.13
Evaluated at bid price : 24.30
Bid-YTW : 4.88 %

HSE.PR.G FixedReset Quote: 25.03 – 25.48
Spot Rate : 0.4500
Average : 0.3074

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-06-30
Maturity Price : 25.00
Evaluated at bid price : 25.03
Bid-YTW : 4.62 %

Market Action

January 5, 2018

Jobs, jobs, jobs! Not so much in the US…:

U.S. payroll gains slowed by more than forecast in December, wages picked up slightly and the jobless rate held at the lowest level since 2000, adding to signs of a full-employment economy.

Employers added 148,000 workers, compared with the 190,000 median estimate of economists surveyed by Bloomberg, held back by a drop in retail positions, a Labor Department report showed Friday. The jobless rate was at 4.1 percent for a third month, while average hourly earnings increased by 2.5 percent from a year earlier, after a 2.4 percent gain in November that was revised downward.

US markets were mildly impressed (insofar as one can assign cause and effect to market moves, which you generally can’t, but impresses the hoi polloi):

Treasuries slumped and the dollar was flat after a report showed U.S. payroll gains slowed by more than forecast in December, wages picked up slightly and the jobless rate held at the lowest level since 2000. The S&P 500 Index powered to a fresh record and registered its best week since December 2016 as investors looked past the jobs miss, speculating that Republican tax cuts will lead to higher corporate earnings. The Dow Jones Industrial Average and Nasdaq Composite Index also hit all-time highs.
…
The yield on 10-year Treasuries rose two basis points to 2.47 percent.

Meanwhile, in the frozen north:

Canada’s unemployment rate plunged to the lowest in more than 40 years, suddenly raising the odds of a Bank of Canada rate hike this month.

The jobless rate fell to 5.7 percent in December, Statistics Canada said Friday in Ottawa, the lowest in the current data series that begins in 1976. The number of jobs rose by 78,600, beating expectations and bringing the full-year employment gain to 422,500. That’s the best annual increase since 2002.

The economy showed unexpected resiliency as the year came to an end, with the figures indicating rapidly diminishing slack in the labor market that may quicken the expected pace of interest-rate increases by the Bank of Canada. Since September, Canada added 193,400 jobs — the biggest three-month gain since at least 1976.
…
Canadian bond yields and the currency soared on the surprisingly strong jobs data. The loonie strengthened to C$1.2376 per U.S. dollar, the strongest since September. The dollar buys 80.79 U.S. cents.

Bond prices plunged on expectations the jobs report may prompt the central to raise rates as early as this month. The yield on the two-year government of Canada bond jumped six basis points to 1.77 percent, close to a seven-year high. The odds of a rate hike at the Bank of Canada’s next meeting on Jan. 17 soared to 70 percent, from 40 percent yesterday, based on trading in the swaps market.

… and the banks – renowned for their forecasting prowess, provided you ignore completely random events like call volumes going up at the beginning of the year – are in a tizzy:

All but one of Canada’s six biggest commercial lenders now say the central bank will raise interest rates this month after the jobless rate dropped to its lowest in modern records.

Toronto-Dominion Bank, Bank of Nova Scotia, Royal Bank of Canada and the Canadian Imperial Bank of Commerce changed their forecasts after a Statistics Canada report Friday showed the unemployment rate unexpectedly fell to 5.7 percent in December, from 5.9 percent the previous month, on the strength of 78,600 new jobs.

At the end of the day, Perimeter reports three-month bills at 1.12% and five-year bonds at 1.96 – well above their Monday levels of 1.07% and 1.89%, respectively.

The Globe has a good story today highlighting the excellent planning and accurate forecasting of the banks’ investment industry hegemony:

But officials in the brokerage industry say the outages mostly boil down to a simple – but crucial – problem: server space. Retail demand is so unexpectedly high, particularly for stocks in the marijuana industry, that it has become overwhelming.

The brokerages won’t provide usage statistics, but according to the Investment Industry Regulatory Organization of Canada, which oversees trading activity, the volume of trades between Dec. 22 and Jan. 3 jumped 107 per cent from a year earlier. And of that surge, retail trading volumes jumped to 34 per cent of the total from 23 per cent.
…
And even when clients are not transacting, they keep logging in to watch the markets and do research. This type of activity can create just as many bandwidth problems for the servers as trading does. Demand from retail investors tends to spike at particular times – such as when the market opens and again around lunch. One day recently, one brokerage’s user activity was already near full capacity before the market even opened at 9:30 a.m.

Theoretically, banks that make a billion dollars or more every quarter should not have trouble buying servers – but the situation is more complicated than that. For one, these institutions have been cutting costs for the past few years as they got leaner, in part to take on nimble fintech startups.

Servers are also expensive assets in a world where so many firms need them, because data is a critical commodity. Until now, it didn’t seem economical for discount brokerages to have servers sitting around just in case.

This is good reporting by Kiladze and Bradshaw, but they’re too impressed by the statistic cited regarding the Dec. 22 – Jan. 3 period. This is the lightest period of the year. If volume doubles … well, nothing doubled is still nothing.

TD has some awfully angry customers:

have been trying to talk to a person at Webbroker since 7 am on Tuesday. I can only do this transaction with a person as online transaction is not allowed. (From rif to other accounts) I have called at Webbroker all hours of day and night and stayed on line for hours at a time. Last evening from 7pm until midnight and again at 4am today no response.

My local branch of TD gave me another number to call and they admitted to also knowing that it would not work, and it did not.

No one and especially an 83 year old should not have to go through a terrible experience that many or going through. It is costing many of us thousands of dollars

Some person or persons should be held accountable and they should be dismissed, and if that is the CEO great.

Seems to me that a business as rife with volume peaks as retail brokerage would design their server system so extra servers could be snapped in overnight … ‘Bob, take a truck to Future Shop and buy 1000 PCs. Fred, you and your guys don’t go home until they’re wired in.’ But what do I know?

Well, I suppose I know that when we get our next market break along the lines of late 1987, early 2001 or late 2008, retail is fucked. Let us all give thanks to the regulators for their continual efforts to place the entire industry in such good hands.

Canadian banks take full advantage of the protection from competition they enjoy and aren’t in the business of making good products. They’re in the business of making plain-vanilla, marginally acceptable products, slapping a brand-name on them and charging a premium price.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.8143 % 2,694.1
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.8143 % 4,943.6
Floater 3.41 % 3.57 % 32,704 18.39 4 0.8143 % 2,849.0
OpRet 0.00 % 0.00 % 0 0.00 0 -0.2500 % 3,130.6
SplitShare 4.69 % 4.09 % 61,102 3.43 5 -0.2500 % 3,738.5
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.2500 % 2,917.0
Perpetual-Premium 5.34 % -2.33 % 61,183 0.09 18 -0.0022 % 2,860.4
Perpetual-Discount 5.24 % 5.24 % 65,153 14.91 16 -0.1403 % 3,018.7
FixedReset 4.19 % 4.30 % 138,986 4.09 98 0.3883 % 2,528.1
Deemed-Retractible 5.03 % 5.30 % 82,401 5.88 28 0.0795 % 2,961.9
FloatingReset 2.95 % 2.78 % 38,787 3.82 10 0.6449 % 2,733.0
Performance Highlights
Issue Index Change Notes
CCS.PR.C Deemed-Retractible -1.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.20
Bid-YTW : 5.60 %
EIT.PR.A SplitShare -1.02 % YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2024-03-14
Maturity Price : 25.00
Evaluated at bid price : 25.12
Bid-YTW : 4.79 %
TRP.PR.F FloatingReset 1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-05
Maturity Price : 19.65
Evaluated at bid price : 19.65
Bid-YTW : 3.82 %
CM.PR.P FixedReset 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-05
Maturity Price : 23.18
Evaluated at bid price : 23.51
Bid-YTW : 4.33 %
HSE.PR.A FixedReset 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-05
Maturity Price : 17.80
Evaluated at bid price : 17.80
Bid-YTW : 4.82 %
TRP.PR.B FixedReset 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-05
Maturity Price : 16.38
Evaluated at bid price : 16.38
Bid-YTW : 4.67 %
IFC.PR.A FixedReset 1.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.63
Bid-YTW : 6.63 %
CM.PR.O FixedReset 1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-05
Maturity Price : 23.50
Evaluated at bid price : 23.90
Bid-YTW : 4.35 %
BAM.PR.K Floater 1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-05
Maturity Price : 15.75
Evaluated at bid price : 15.75
Bid-YTW : 3.57 %
BAM.PR.B Floater 1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-05
Maturity Price : 15.76
Evaluated at bid price : 15.76
Bid-YTW : 3.57 %
PWF.PR.T FixedReset 1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-05
Maturity Price : 24.31
Evaluated at bid price : 24.71
Bid-YTW : 4.35 %
MFC.PR.M FixedReset 1.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.75
Bid-YTW : 5.06 %
MFC.PR.N FixedReset 1.32 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.71
Bid-YTW : 4.99 %
BAM.PF.J FixedReset 1.36 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-12-31
Maturity Price : 25.00
Evaluated at bid price : 26.15
Bid-YTW : 3.77 %
BAM.PR.X FixedReset 1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-05
Maturity Price : 17.81
Evaluated at bid price : 17.81
Bid-YTW : 4.89 %
BMO.PR.T FixedReset 1.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-05
Maturity Price : 23.35
Evaluated at bid price : 23.75
Bid-YTW : 4.35 %
SLF.PR.J FloatingReset 1.91 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.70
Bid-YTW : 7.08 %
TRP.PR.C FixedReset 1.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-05
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 4.64 %
TRP.PR.E FixedReset 1.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-05
Maturity Price : 23.28
Evaluated at bid price : 23.65
Bid-YTW : 4.47 %
TRP.PR.D FixedReset 1.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-05
Maturity Price : 22.64
Evaluated at bid price : 23.09
Bid-YTW : 4.58 %
TRP.PR.A FixedReset 1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-05
Maturity Price : 20.30
Evaluated at bid price : 20.30
Bid-YTW : 4.65 %
TRP.PR.H FloatingReset 3.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-05
Maturity Price : 16.30
Evaluated at bid price : 16.30
Bid-YTW : 3.62 %
Volume Highlights
Issue Index Shares
Traded
Notes
BNS.PR.P FixedReset 181,365 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-04-25
Maturity Price : 25.00
Evaluated at bid price : 24.99
Bid-YTW : 2.82 %
MFC.PR.O FixedReset 144,344 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-06-19
Maturity Price : 25.00
Evaluated at bid price : 26.80
Bid-YTW : 3.48 %
RY.PR.I FixedReset 117,100 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2019-02-24
Maturity Price : 25.00
Evaluated at bid price : 25.12
Bid-YTW : 3.47 %
BAM.PF.A FixedReset 105,877 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-05
Maturity Price : 24.46
Evaluated at bid price : 24.90
Bid-YTW : 4.81 %
MFC.PR.K FixedReset 74,468 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.00
Bid-YTW : 5.52 %
CM.PR.Q FixedReset 72,500 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-07-31
Maturity Price : 25.00
Evaluated at bid price : 24.74
Bid-YTW : 3.95 %
There were 33 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
EIT.PR.A SplitShare Quote: 25.12 – 25.57
Spot Rate : 0.4500
Average : 0.3175

YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2024-03-14
Maturity Price : 25.00
Evaluated at bid price : 25.12
Bid-YTW : 4.79 %

PWF.PR.L Perpetual-Discount Quote: 24.50 – 24.85
Spot Rate : 0.3500
Average : 0.2315

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-05
Maturity Price : 24.21
Evaluated at bid price : 24.50
Bid-YTW : 5.28 %

SLF.PR.H FixedReset Quote: 21.53 – 21.98
Spot Rate : 0.4500
Average : 0.3361

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.53
Bid-YTW : 5.84 %

HSE.PR.C FixedReset Quote: 24.70 – 25.10
Spot Rate : 0.4000
Average : 0.3106

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-05
Maturity Price : 23.47
Evaluated at bid price : 24.70
Bid-YTW : 4.99 %

BAM.PR.K Floater Quote: 15.75 – 16.01
Spot Rate : 0.2600
Average : 0.1710

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-05
Maturity Price : 15.75
Evaluated at bid price : 15.75
Bid-YTW : 3.57 %

PWF.PR.P FixedReset Quote: 18.34 – 18.70
Spot Rate : 0.3600
Average : 0.2725

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-05
Maturity Price : 18.34
Evaluated at bid price : 18.34
Bid-YTW : 4.55 %

Market Action

January 2, 2018

The new year commenced on a positive note!

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.9349 % 2,615.3
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.9349 % 4,799.0
Floater 3.52 % 3.69 % 34,225 18.13 4 0.9349 % 2,765.7
OpRet 0.00 % 0.00 % 0 0.00 0 -0.5055 % 3,136.7
SplitShare 4.68 % 4.08 % 62,359 3.44 5 -0.5055 % 3,745.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.5055 % 2,922.7
Perpetual-Premium 5.35 % 2.70 % 45,390 0.09 18 -0.0305 % 2,852.5
Perpetual-Discount 5.26 % 5.28 % 62,802 14.91 16 0.0000 % 3,009.6
FixedReset 4.22 % 4.39 % 135,779 4.09 98 0.0408 % 2,510.1
Deemed-Retractible 5.07 % 5.38 % 78,881 5.89 28 0.0028 % 2,943.3
FloatingReset 2.97 % 2.83 % 38,368 3.84 10 0.0886 % 2,709.7
Performance Highlights
Issue Index Change Notes
PVS.PR.E SplitShare -1.91 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-02-01
Maturity Price : 26.00
Evaluated at bid price : 26.26
Bid-YTW : -2.27 %
TRP.PR.A FixedReset -1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-02
Maturity Price : 19.85
Evaluated at bid price : 19.85
Bid-YTW : 4.76 %
TD.PF.E FixedReset -1.08 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-10-31
Maturity Price : 25.00
Evaluated at bid price : 24.82
Bid-YTW : 4.23 %
TRP.PR.F FloatingReset -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-02
Maturity Price : 19.31
Evaluated at bid price : 19.31
Bid-YTW : 3.89 %
CCS.PR.C Deemed-Retractible 1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.91
Bid-YTW : 5.80 %
IAG.PR.A Deemed-Retractible 1.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.70
Bid-YTW : 6.27 %
BAM.PR.B Floater 1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-02
Maturity Price : 15.25
Evaluated at bid price : 15.25
Bid-YTW : 3.69 %
BAM.PR.C Floater 1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-02
Maturity Price : 15.25
Evaluated at bid price : 15.25
Bid-YTW : 3.69 %
BAM.PR.K Floater 1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-02
Maturity Price : 15.20
Evaluated at bid price : 15.20
Bid-YTW : 3.70 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.I FixedReset 671,300 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2019-02-24
Maturity Price : 25.00
Evaluated at bid price : 25.09
Bid-YTW : 3.55 %
BNS.PR.P FixedReset 214,500 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-04-25
Maturity Price : 25.00
Evaluated at bid price : 24.98
Bid-YTW : 2.88 %
TD.PF.C FixedReset 73,056 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-02
Maturity Price : 23.00
Evaluated at bid price : 23.33
Bid-YTW : 4.43 %
CM.PR.R FixedReset 68,920 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-07-31
Maturity Price : 25.00
Evaluated at bid price : 25.55
Bid-YTW : 3.82 %
TRP.PR.D FixedReset 65,220 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-02
Maturity Price : 21.95
Evaluated at bid price : 22.52
Bid-YTW : 4.69 %
RY.PR.J FixedReset 54,809 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-05-24
Maturity Price : 25.00
Evaluated at bid price : 24.74
Bid-YTW : 4.25 %
There were 8 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
PVS.PR.E SplitShare Quote: 26.26 – 26.92
Spot Rate : 0.6600
Average : 0.4309

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-02-01
Maturity Price : 26.00
Evaluated at bid price : 26.26
Bid-YTW : -2.27 %

TD.PR.T FloatingReset Quote: 24.92 – 25.40
Spot Rate : 0.4800
Average : 0.2839

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.92
Bid-YTW : 2.73 %

SLF.PR.D Deemed-Retractible Quote: 21.52 – 21.86
Spot Rate : 0.3400
Average : 0.2114

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.52
Bid-YTW : 7.02 %

GWO.PR.Q Deemed-Retractible Quote: 24.60 – 24.95
Spot Rate : 0.3500
Average : 0.2268

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.60
Bid-YTW : 5.46 %

CU.PR.G Perpetual-Discount Quote: 21.84 – 22.15
Spot Rate : 0.3100
Average : 0.2178

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2048-01-02
Maturity Price : 21.54
Evaluated at bid price : 21.84
Bid-YTW : 5.20 %

BMO.PR.Y FixedReset Quote: 24.75 – 25.07
Spot Rate : 0.3200
Average : 0.2280

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-08-25
Maturity Price : 25.00
Evaluated at bid price : 24.75
Bid-YTW : 4.39 %

Market Action

December 29, 2017

And that’s 2017, done and dusted! Best wishes for the new year, everybody!

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 1.4957 % 2,591.1
FixedFloater 0.00 % 0.00 % 0 0.00 0 1.4957 % 4,754.5
Floater 3.55 % 3.71 % 35,550 18.03 4 1.4957 % 2,740.0
OpRet 0.00 % 0.00 % 0 0.00 0 0.1324 % 3,152.6
SplitShare 4.66 % 4.08 % 64,503 3.45 5 0.1324 % 3,764.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1324 % 2,937.5
Perpetual-Premium 5.36 % 2.44 % 46,977 0.09 20 0.2244 % 2,853.4
Perpetual-Discount 5.23 % 5.28 % 63,343 14.92 14 0.0123 % 3,009.6
FixedReset 4.23 % 4.33 % 139,639 3.97 98 0.2673 % 2,509.0
Deemed-Retractible 5.07 % 5.19 % 82,135 5.89 30 0.1049 % 2,943.2
FloatingReset 2.83 % 2.73 % 42,418 3.85 8 0.3178 % 2,707.3
Performance Highlights
Issue Index Change Notes
GWO.PR.N FixedReset -1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.21
Bid-YTW : 7.77 %
TRP.PR.E FixedReset 1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-29
Maturity Price : 22.85
Evaluated at bid price : 23.21
Bid-YTW : 4.49 %
RY.PR.J FixedReset 1.22 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-05-24
Maturity Price : 25.00
Evaluated at bid price : 24.86
Bid-YTW : 4.02 %
RY.PR.R FixedReset 1.31 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-24
Maturity Price : 25.00
Evaluated at bid price : 27.03
Bid-YTW : 3.30 %
TRP.PR.A FixedReset 1.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-29
Maturity Price : 20.10
Evaluated at bid price : 20.10
Bid-YTW : 4.63 %
BAM.PR.R FixedReset 1.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-29
Maturity Price : 20.15
Evaluated at bid price : 20.15
Bid-YTW : 4.88 %
PWF.PR.A Floater 3.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-29
Maturity Price : 17.96
Evaluated at bid price : 17.96
Bid-YTW : 3.14 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PF.C FixedReset 17,300 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-29
Maturity Price : 22.95
Evaluated at bid price : 23.27
Bid-YTW : 4.38 %
GWO.PR.T Deemed-Retractible 17,123 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.70
Bid-YTW : 5.38 %
RY.PR.I FixedReset 17,000 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2019-02-24
Maturity Price : 25.00
Evaluated at bid price : 25.08
Bid-YTW : 3.55 %
NA.PR.S FixedReset 12,119 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-29
Maturity Price : 23.30
Evaluated at bid price : 23.75
Bid-YTW : 4.47 %
NA.PR.X FixedReset 10,900 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-15
Maturity Price : 25.00
Evaluated at bid price : 27.05
Bid-YTW : 3.25 %
There were 0 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BAM.PF.E FixedReset Quote: 23.69 – 24.01
Spot Rate : 0.3200
Average : 0.2109

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-29
Maturity Price : 22.94
Evaluated at bid price : 23.69
Bid-YTW : 4.60 %

POW.PR.G Perpetual-Premium Quote: 25.46 – 25.75
Spot Rate : 0.2900
Average : 0.1873

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-04-15
Maturity Price : 25.25
Evaluated at bid price : 25.46
Bid-YTW : 5.08 %

GWO.PR.G Deemed-Retractible Quote: 24.71 – 25.10
Spot Rate : 0.3900
Average : 0.2930

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.71
Bid-YTW : 5.43 %

GWO.PR.N FixedReset Quote: 18.21 – 18.45
Spot Rate : 0.2400
Average : 0.1597

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.21
Bid-YTW : 7.77 %

CCS.PR.C Deemed-Retractible Quote: 23.65 – 23.96
Spot Rate : 0.3100
Average : 0.2357

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.65
Bid-YTW : 5.98 %

IFC.PR.C FixedReset Quote: 23.28 – 23.64
Spot Rate : 0.3600
Average : 0.2954

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.28
Bid-YTW : 5.04 %

Market Action

December 28, 2017

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.3227 % 2,552.9
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.3227 % 4,684.5
Floater 3.60 % 3.74 % 34,030 17.97 4 0.3227 % 2,699.7
OpRet 0.00 % 0.00 % 0 0.00 0 0.0000 % 3,148.4
SplitShare 4.66 % 4.17 % 67,150 3.45 5 0.0000 % 3,759.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0000 % 2,933.6
Perpetual-Premium 5.37 % 4.83 % 47,213 2.15 20 0.0820 % 2,847.0
Perpetual-Discount 5.23 % 5.30 % 65,871 14.89 14 0.1689 % 3,009.2
FixedReset 4.24 % 4.36 % 142,332 4.16 98 0.0807 % 2,502.4
Deemed-Retractible 5.07 % 5.19 % 85,516 5.89 30 0.1451 % 2,940.1
FloatingReset 2.84 % 2.79 % 43,892 3.85 8 0.1515 % 2,698.7
Performance Highlights
Issue Index Change Notes
HSE.PR.A FixedReset -1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-28
Maturity Price : 17.05
Evaluated at bid price : 17.05
Bid-YTW : 4.94 %
RY.PR.R FixedReset -1.19 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-24
Maturity Price : 25.00
Evaluated at bid price : 26.68
Bid-YTW : 3.70 %
BAM.PR.R FixedReset 1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-28
Maturity Price : 19.83
Evaluated at bid price : 19.83
Bid-YTW : 4.96 %
BAM.PR.Z FixedReset 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-28
Maturity Price : 23.32
Evaluated at bid price : 24.56
Bid-YTW : 4.83 %
TRP.PR.F FloatingReset 1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-28
Maturity Price : 19.35
Evaluated at bid price : 19.35
Bid-YTW : 3.77 %
Volume Highlights
Issue Index Shares
Traded
Notes
W.PR.K FixedReset 50,600 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-01-15
Maturity Price : 25.00
Evaluated at bid price : 26.00
Bid-YTW : 3.79 %
RY.PR.M FixedReset 19,100 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-28
Maturity Price : 23.21
Evaluated at bid price : 24.50
Bid-YTW : 4.37 %
PVS.PR.F SplitShare 18,000 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2024-09-30
Maturity Price : 25.00
Evaluated at bid price : 25.50
Bid-YTW : 4.53 %
There were 0 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
MFC.PR.G FixedReset Quote: 24.58 – 24.99
Spot Rate : 0.4100
Average : 0.2611

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-12-19
Maturity Price : 25.00
Evaluated at bid price : 24.58
Bid-YTW : 4.40 %

TRP.PR.E FixedReset Quote: 23.25 – 23.64
Spot Rate : 0.3900
Average : 0.2515

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-28
Maturity Price : 22.89
Evaluated at bid price : 23.25
Bid-YTW : 4.55 %

VNR.PR.A FixedReset Quote: 24.95 – 25.46
Spot Rate : 0.5100
Average : 0.3777

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-28
Maturity Price : 23.16
Evaluated at bid price : 24.95
Bid-YTW : 4.62 %

W.PR.H Perpetual-Premium Quote: 24.80 – 25.25
Spot Rate : 0.4500
Average : 0.3255

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-28
Maturity Price : 24.55
Evaluated at bid price : 24.80
Bid-YTW : 5.55 %

MFC.PR.C Deemed-Retractible Quote: 21.68 – 22.00
Spot Rate : 0.3200
Average : 0.2074

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.68
Bid-YTW : 6.96 %

RY.PR.R FixedReset Quote: 26.68 – 26.97
Spot Rate : 0.2900
Average : 0.1905

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-24
Maturity Price : 25.00
Evaluated at bid price : 26.68
Bid-YTW : 3.70 %

Market Action

December 27, 2017

Well, that’s the last day of tax-loss selling, which I believe has played a role in December’s softness. Thanks to two-day settlement, tax-loss season lasted until after Christmas this year!

PerpetualDiscounts now yield 5.31%, equivalent to 6.90% interest at the standard equivalency factor of 1.3x. Long corporates now yield a little over 3.70%, so the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) is now about 320bp, a significant widening from the 310bp reported December 20.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 2.3955 % 2,544.7
FixedFloater 0.00 % 0.00 % 0 0.00 0 2.3955 % 4,669.4
Floater 3.61 % 3.76 % 35,392 17.94 4 2.3955 % 2,691.0
OpRet 0.00 % 0.00 % 0 0.00 0 0.1326 % 3,148.4
SplitShare 4.66 % 4.18 % 69,912 3.46 5 0.1326 % 3,759.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1326 % 2,933.6
Perpetual-Premium 5.36 % 4.80 % 49,161 2.15 20 0.1239 % 2,844.6
Perpetual-Discount 5.24 % 5.31 % 66,883 14.89 14 -0.0675 % 3,004.1
FixedReset 4.24 % 4.34 % 145,240 3.98 98 -0.0009 % 2,500.3
Deemed-Retractible 5.08 % 5.29 % 89,028 5.90 30 0.0041 % 2,935.8
FloatingReset 2.84 % 2.80 % 43,974 3.85 8 0.0433 % 2,694.6
Performance Highlights
Issue Index Change Notes
NA.PR.C FixedReset -1.20 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-11-15
Maturity Price : 25.00
Evaluated at bid price : 25.61
Bid-YTW : 4.03 %
HSE.PR.A FixedReset 1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-27
Maturity Price : 17.27
Evaluated at bid price : 17.27
Bid-YTW : 4.88 %
PWF.PR.A Floater 1.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-27
Maturity Price : 17.38
Evaluated at bid price : 17.38
Bid-YTW : 3.25 %
BAM.PR.B Floater 2.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-27
Maturity Price : 14.90
Evaluated at bid price : 14.90
Bid-YTW : 3.76 %
BAM.PR.K Floater 2.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-27
Maturity Price : 14.80
Evaluated at bid price : 14.80
Bid-YTW : 3.78 %
BAM.PR.C Floater 3.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-27
Maturity Price : 14.90
Evaluated at bid price : 14.90
Bid-YTW : 3.76 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.N Perpetual-Premium 40,915 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2024-11-24
Maturity Price : 25.00
Evaluated at bid price : 25.30
Bid-YTW : 4.80 %
BAM.PR.K Floater 27,100 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-27
Maturity Price : 14.80
Evaluated at bid price : 14.80
Bid-YTW : 3.78 %
PVS.PR.E SplitShare 19,141 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-01-26
Maturity Price : 26.00
Evaluated at bid price : 26.70
Bid-YTW : -22.23 %
TRP.PR.A FixedReset 15,950 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-27
Maturity Price : 19.70
Evaluated at bid price : 19.70
Bid-YTW : 4.72 %
RY.PR.M FixedReset 15,500 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-27
Maturity Price : 23.19
Evaluated at bid price : 24.45
Bid-YTW : 4.38 %
BMO.PR.Y FixedReset 15,427 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-08-25
Maturity Price : 25.00
Evaluated at bid price : 24.79
Bid-YTW : 4.29 %
There were 7 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BMO.PR.M FixedReset Quote: 25.01 – 32.95
Spot Rate : 7.9400
Average : 4.2449

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.01
Bid-YTW : 3.55 %

PWF.PR.A Floater Quote: 17.38 – 18.25
Spot Rate : 0.8700
Average : 0.5453

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-27
Maturity Price : 17.38
Evaluated at bid price : 17.38
Bid-YTW : 3.25 %

NA.PR.C FixedReset Quote: 25.61 – 25.95
Spot Rate : 0.3400
Average : 0.1987

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-11-15
Maturity Price : 25.00
Evaluated at bid price : 25.61
Bid-YTW : 4.03 %

BAM.PR.Z FixedReset Quote: 24.30 – 24.71
Spot Rate : 0.4100
Average : 0.2774

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-27
Maturity Price : 22.90
Evaluated at bid price : 24.30
Bid-YTW : 4.87 %

TRP.PR.F FloatingReset Quote: 19.12 – 19.54
Spot Rate : 0.4200
Average : 0.3134

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-27
Maturity Price : 19.12
Evaluated at bid price : 19.12
Bid-YTW : 3.82 %

MFC.PR.B Deemed-Retractible Quote: 22.40 – 22.70
Spot Rate : 0.3000
Average : 0.2033

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.40
Bid-YTW : 6.56 %

Market Action

December 22, 2017

Manulife has announced a 2.9-billion hit for 17Q4. Management must be distraught that such an important development had to be announced after the market closed for the Christmas holiday – with no time to publish a press release on their website, darn it! It only made it to Newswire – so I’ll help them out by passing along the word:

Manulife Financial Corp. is preparing to take two charges worth $2.9-billion in its fourth quarter as U.S. tax reforms and a new investment strategy reshapes the business.

The Toronto-based insurer said Friday evening that it would move to sell some private market assets, resulting in a one-time $1-billion hit to profits as the company aims to put capital toward investments that can offer higher returns.

At the same time, Manulife said that U.S. President Donald Trump’s overhaul of the U.S. tax code would result in a second $1.9-billion charge as a result of some accounting changes, but that the move would be beneficial to the company’s business south of the border over time. Both charges will be included in Manulife’s fourth-quarter results, which are set to be released on Feb. 7.
…
Over the next year and a half, Manulife plans to sell some of its alternative assets, which are long-term holdings in sectors such as timberland, farmland, infrastructure and energy. Many of these assets are located in the U.S.
…
As the alternative assets are sold, about $2-billion in regulatory capital will be freed up at Manulife. But the move will also mean that the company’s core earnings, a metric that strips out some accounting volatility, will be reduced by up to $60-million per year after tax until Manulife is able to put about $1-billion in capital to work in businesses that yield higher returns.

The second non-cash charge of $1.9-billion is an upfront hit related to major tax changes in the U.S. that are also expected to impact banks and other insurers. About one-third of Manulife’s business is in insurance and wealth-management operations in the U.S.

Readers of PrefLetter will be familiar with my long-standing qualms about Manulife’s focus on alternative assets. With respect to the $1.9-billion accounting charge, they have plenty of company:

Hours after the bill signing, announcements started to roll in from some of the world’s biggest companies — with some spectacular numbers. While the bill benefits most companies through a lower rate, it also requires them to recalculate some of the tax positions they may have been holding on their books for years.

Biotechnology company Amgen Inc. said it would take a $6 billion to $6.5 billion charge. Bank of America Corp. plans to take a $3 billion hit, and Credit Suisse Group AG will take a writedown of 2.3 billion Swiss francs ($2.32 billion).

The one-time changes are related mostly to what are known as deferred tax assets that accumulate on balance sheets when companies overpay taxes or take tax losses. On the other side of the ledger, deferred tax liabilities pile up when they’ve underpaid taxes on depreciated assets.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.8680 % 2,485.2
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.8680 % 4,560.1
Floater 3.70 % 3.83 % 32,731 17.78 4 -0.8680 % 2,628.0
OpRet 0.00 % 0.00 % 0 0.00 0 0.0000 % 3,144.3
SplitShare 4.67 % 4.16 % 72,787 3.47 5 0.0000 % 3,754.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0000 % 2,929.8
Perpetual-Premium 5.37 % 4.84 % 48,829 2.17 20 -0.0315 % 2,841.1
Perpetual-Discount 5.24 % 5.29 % 69,445 14.91 14 -0.0061 % 3,006.1
FixedReset 4.24 % 4.25 % 148,091 4.13 98 0.0668 % 2,500.4
Deemed-Retractible 5.08 % 5.27 % 88,550 5.91 30 -0.0856 % 2,935.7
FloatingReset 2.78 % 2.72 % 44,614 3.87 8 0.0325 % 2,693.5
Performance Highlights
Issue Index Change Notes
BAM.PR.C Floater -1.97 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-22
Maturity Price : 14.44
Evaluated at bid price : 14.44
Bid-YTW : 3.88 %
IFC.PR.C FixedReset 1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.40
Bid-YTW : 4.88 %
CM.PR.Q FixedReset 1.06 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-07-31
Maturity Price : 25.00
Evaluated at bid price : 24.71
Bid-YTW : 4.31 %
TRP.PR.B FixedReset 1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-22
Maturity Price : 16.24
Evaluated at bid price : 16.24
Bid-YTW : 4.42 %
CM.PR.O FixedReset 1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-22
Maturity Price : 23.44
Evaluated at bid price : 23.84
Bid-YTW : 4.22 %
IAG.PR.A Deemed-Retractible 1.39 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.54
Bid-YTW : 6.36 %
CU.PR.I FixedReset 1.39 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-01
Maturity Price : 25.00
Evaluated at bid price : 26.17
Bid-YTW : 2.94 %
Volume Highlights
Issue Index Shares
Traded
Notes
BMO.PR.B FixedReset 125,240 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-02-25
Maturity Price : 25.00
Evaluated at bid price : 26.23
Bid-YTW : 3.68 %
RY.PR.Q FixedReset 71,403 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-24
Maturity Price : 25.00
Evaluated at bid price : 26.94
Bid-YTW : 3.23 %
RY.PR.J FixedReset 56,650 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-05-24
Maturity Price : 25.00
Evaluated at bid price : 24.80
Bid-YTW : 4.09 %
BIP.PR.B FixedReset 37,800 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.75
Bid-YTW : 4.41 %
BIP.PR.D FixedReset 33,418 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-03-31
Maturity Price : 25.00
Evaluated at bid price : 25.35
Bid-YTW : 4.63 %
CM.PR.R FixedReset 14,960 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-07-31
Maturity Price : 25.00
Evaluated at bid price : 25.55
Bid-YTW : 4.05 %
There were 5 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BAM.PR.K Floater Quote: 14.44 – 15.21
Spot Rate : 0.7700
Average : 0.5435

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-22
Maturity Price : 14.44
Evaluated at bid price : 14.44
Bid-YTW : 3.88 %

BAM.PR.C Floater Quote: 14.44 – 14.92
Spot Rate : 0.4800
Average : 0.3118

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-22
Maturity Price : 14.44
Evaluated at bid price : 14.44
Bid-YTW : 3.88 %

W.PR.M FixedReset Quote: 26.36 – 26.80
Spot Rate : 0.4400
Average : 0.2926

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-15
Maturity Price : 25.00
Evaluated at bid price : 26.36
Bid-YTW : 3.95 %

IFC.PR.E Deemed-Retractible Quote: 24.91 – 25.35
Spot Rate : 0.4400
Average : 0.2990

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.91
Bid-YTW : 5.27 %

PWF.PR.R Perpetual-Premium Quote: 25.65 – 25.99
Spot Rate : 0.3400
Average : 0.2225

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-04-30
Maturity Price : 25.25
Evaluated at bid price : 25.65
Bid-YTW : 5.10 %

PWF.PR.T FixedReset Quote: 24.36 – 24.69
Spot Rate : 0.3300
Average : 0.2388

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-22
Maturity Price : 23.90
Evaluated at bid price : 24.36
Bid-YTW : 4.20 %

Market Action

December 21, 2017

Hey, how ’bout that bond market, eh?:

Benchmark bond yields are headed for the biggest weekly advance since September as investors contemplate prospects for continued economic growth and reduced central bank stimulus.
…
The yield on 10-year Treasuries slid 2 basis points Thursday, to 2.48 percent. That’s up from 2.35 percent at the end of last week.

…and Bloomberg supplies a chart of the generic 10-year Treasury yield:

10yrtreasury_171221
Click for Big

In Canada, the five-year is at 1.86% and the 3-Month Bill has breeched the point at 1.03%.

… and the BoC supplies a chart of GOC-5:

goc5_171221
Click for Big
HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.0000 % 2,506.9
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.0000 % 4,600.1
Floater 3.67 % 3.80 % 32,548 17.86 4 0.0000 % 2,651.0
OpRet 0.00 % 0.00 % 0 0.00 0 -0.1168 % 3,144.3
SplitShare 4.67 % 4.06 % 71,489 3.47 5 -0.1168 % 3,754.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.1168 % 2,929.8
Perpetual-Premium 5.37 % 4.84 % 49,707 2.17 20 0.0386 % 2,842.0
Perpetual-Discount 5.24 % 5.28 % 68,451 14.93 14 -0.0146 % 3,006.3
FixedReset 4.24 % 4.23 % 148,898 4.14 98 0.4456 % 2,498.7
Deemed-Retractible 5.07 % 5.32 % 88,845 5.92 30 -0.1985 % 2,938.2
FloatingReset 2.78 % 2.77 % 44,595 3.88 8 0.1789 % 2,692.6
Performance Highlights
Issue Index Change Notes
IAG.PR.A Deemed-Retractible -1.85 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.23
Bid-YTW : 6.59 %
BAM.PF.A FixedReset 1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-21
Maturity Price : 24.14
Evaluated at bid price : 24.65
Bid-YTW : 4.64 %
NA.PR.C FixedReset 1.09 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-11-15
Maturity Price : 25.00
Evaluated at bid price : 25.90
Bid-YTW : 3.76 %
TD.PF.D FixedReset 1.10 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-07-31
Maturity Price : 25.00
Evaluated at bid price : 24.86
Bid-YTW : 4.05 %
IFC.PR.C FixedReset 1.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.16
Bid-YTW : 5.04 %
BMO.PR.Y FixedReset 1.14 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-08-25
Maturity Price : 25.00
Evaluated at bid price : 24.83
Bid-YTW : 4.20 %
TD.PF.A FixedReset 1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-21
Maturity Price : 23.17
Evaluated at bid price : 23.53
Bid-YTW : 4.20 %
MFC.PR.H FixedReset 1.20 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-03-19
Maturity Price : 25.00
Evaluated at bid price : 25.30
Bid-YTW : 4.53 %
MFC.PR.L FixedReset 1.26 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.53
Bid-YTW : 5.59 %
BMO.PR.T FixedReset 1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-21
Maturity Price : 22.71
Evaluated at bid price : 23.10
Bid-YTW : 4.26 %
MFC.PR.M FixedReset 1.31 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.21
Bid-YTW : 5.26 %
TRP.PR.C FixedReset 1.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-21
Maturity Price : 17.25
Evaluated at bid price : 17.25
Bid-YTW : 4.50 %
NA.PR.W FixedReset 1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-21
Maturity Price : 22.69
Evaluated at bid price : 23.00
Bid-YTW : 4.30 %
IFC.PR.A FixedReset 1.57 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.06
Bid-YTW : 7.00 %
MFC.PR.N FixedReset 1.67 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.18
Bid-YTW : 5.19 %
SLF.PR.I FixedReset 1.74 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-12-31
Maturity Price : 25.00
Evaluated at bid price : 24.50
Bid-YTW : 4.34 %
Volume Highlights
Issue Index Shares
Traded
Notes
NA.PR.A FixedReset 210,180 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-15
Maturity Price : 25.00
Evaluated at bid price : 26.65
Bid-YTW : 3.64 %
TRP.PR.J FixedReset 119,680 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-31
Maturity Price : 25.00
Evaluated at bid price : 26.53
Bid-YTW : 3.71 %
CM.PR.R FixedReset 117,694 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-07-31
Maturity Price : 25.00
Evaluated at bid price : 25.75
Bid-YTW : 3.86 %
TD.PR.Z FloatingReset 100,400 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.81
Bid-YTW : 2.77 %
RY.PR.Q FixedReset 95,045 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-24
Maturity Price : 25.00
Evaluated at bid price : 27.00
Bid-YTW : 3.16 %
TD.PF.H FixedReset 92,772 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 26.22
Bid-YTW : 3.69 %
There were 41 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
SLF.PR.G FixedReset Quote: 18.11 – 18.75
Spot Rate : 0.6400
Average : 0.3913

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.11
Bid-YTW : 7.94 %

IAG.PR.A Deemed-Retractible Quote: 22.23 – 22.75
Spot Rate : 0.5200
Average : 0.3363

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.23
Bid-YTW : 6.59 %

SLF.PR.H FixedReset Quote: 21.36 – 21.79
Spot Rate : 0.4300
Average : 0.2633

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.36
Bid-YTW : 5.83 %

BAM.PR.K Floater Quote: 14.56 – 15.00
Spot Rate : 0.4400
Average : 0.2952

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-21
Maturity Price : 14.56
Evaluated at bid price : 14.56
Bid-YTW : 3.84 %

CU.PR.I FixedReset Quote: 25.81 – 26.25
Spot Rate : 0.4400
Average : 0.3196

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-01
Maturity Price : 25.00
Evaluated at bid price : 25.81
Bid-YTW : 3.44 %

CM.PR.Q FixedReset Quote: 24.45 – 24.77
Spot Rate : 0.3200
Average : 0.2136

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-21
Maturity Price : 23.24
Evaluated at bid price : 24.45
Bid-YTW : 4.42 %

Market Action

December 20, 2017

PerpetualDiscounts now yield 5.29%, equivalent to 6.88% interest at the standard equivalency factor of 1.3x. Long corporates now yield a little over 3.75%, so the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) is now about 310bp, a significant narrowing from the 320bp reported December 13.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 1.0760 % 2,506.9
FixedFloater 0.00 % 0.00 % 0 0.00 0 1.0760 % 4,600.1
Floater 3.67 % 3.80 % 32,515 17.86 4 1.0760 % 2,651.0
OpRet 0.00 % 0.00 % 0 0.00 0 0.0779 % 3,148.0
SplitShare 4.66 % 3.94 % 66,179 3.48 5 0.0779 % 3,759.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0779 % 2,933.2
Perpetual-Premium 5.35 % 4.78 % 50,404 2.14 20 0.0432 % 2,840.9
Perpetual-Discount 5.23 % 5.29 % 69,155 14.91 14 0.1227 % 3,006.8
FixedReset 4.26 % 4.30 % 149,022 4.38 98 0.1696 % 2,487.6
Deemed-Retractible 5.06 % 5.21 % 89,758 5.92 30 0.2100 % 2,944.1
FloatingReset 2.78 % 2.80 % 44,480 3.88 8 0.1358 % 2,687.8
Performance Highlights
Issue Index Change Notes
SLF.PR.I FixedReset -1.31 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.08
Bid-YTW : 4.68 %
SLF.PR.G FixedReset -1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.01
Bid-YTW : 8.03 %
PWF.PR.A Floater 1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-20
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 3.32 %
HSE.PR.A FixedReset 1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-20
Maturity Price : 16.99
Evaluated at bid price : 16.99
Bid-YTW : 4.79 %
PWF.PR.P FixedReset 1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-20
Maturity Price : 17.60
Evaluated at bid price : 17.60
Bid-YTW : 4.50 %
HSE.PR.C FixedReset 1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-20
Maturity Price : 23.34
Evaluated at bid price : 24.40
Bid-YTW : 4.86 %
BAM.PR.B Floater 1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-20
Maturity Price : 14.73
Evaluated at bid price : 14.73
Bid-YTW : 3.80 %
BAM.PR.C Floater 1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-20
Maturity Price : 14.72
Evaluated at bid price : 14.72
Bid-YTW : 3.80 %
SLF.PR.B Deemed-Retractible 1.51 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.55
Bid-YTW : 5.82 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.I FixedReset 299,875 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2019-02-24
Maturity Price : 25.00
Evaluated at bid price : 25.10
Bid-YTW : 3.41 %
RY.PR.L FixedReset 250,870 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2019-02-24
Maturity Price : 25.00
Evaluated at bid price : 25.37
Bid-YTW : 3.25 %
BMO.PR.B FixedReset 226,519 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-02-25
Maturity Price : 25.00
Evaluated at bid price : 26.10
Bid-YTW : 3.81 %
TD.PF.H FixedReset 187,539 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 26.22
Bid-YTW : 3.69 %
GWO.PR.T Deemed-Retractible 128,300 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.65
Bid-YTW : 5.40 %
BNS.PR.B FloatingReset 100,060 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.78
Bid-YTW : 2.82 %
There were 37 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
PVS.PR.E SplitShare Quote: 26.50 – 27.01
Spot Rate : 0.5100
Average : 0.3517

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-01-19
Maturity Price : 26.00
Evaluated at bid price : 26.50
Bid-YTW : -15.04 %

GWO.PR.M Deemed-Retractible Quote: 25.75 – 26.17
Spot Rate : 0.4200
Average : 0.2647

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-01-19
Maturity Price : 25.50
Evaluated at bid price : 25.75
Bid-YTW : -8.12 %

SLF.PR.I FixedReset Quote: 24.08 – 24.45
Spot Rate : 0.3700
Average : 0.2433

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.08
Bid-YTW : 4.68 %

VNR.PR.A FixedReset Quote: 24.60 – 24.90
Spot Rate : 0.3000
Average : 0.1749

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-20
Maturity Price : 23.03
Evaluated at bid price : 24.60
Bid-YTW : 4.58 %

RY.PR.D Deemed-Retractible Quote: 25.36 – 25.68
Spot Rate : 0.3200
Average : 0.1952

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-01-19
Maturity Price : 25.00
Evaluated at bid price : 25.36
Bid-YTW : -8.83 %

GWO.PR.N FixedReset Quote: 18.18 – 18.45
Spot Rate : 0.2700
Average : 0.1761

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.18
Bid-YTW : 7.67 %

Market Action

December 19, 2017

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.0663 % 2,480.2
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.0663 % 4,551.1
Floater 3.71 % 3.85 % 32,701 17.76 4 0.0663 % 2,622.8
OpRet 0.00 % 0.00 % 0 0.00 0 0.1092 % 3,145.5
SplitShare 4.67 % 3.99 % 65,090 3.48 5 0.1092 % 3,756.4
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1092 % 2,930.9
Perpetual-Premium 5.36 % 4.80 % 50,225 0.12 20 0.0000 % 2,839.7
Perpetual-Discount 5.24 % 5.31 % 69,933 14.90 14 0.0000 % 3,003.1
FixedReset 4.27 % 4.32 % 151,034 6.09 98 0.2616 % 2,483.4
Deemed-Retractible 5.07 % 5.28 % 88,878 5.92 30 -0.0925 % 2,937.9
FloatingReset 2.79 % 2.80 % 41,183 3.88 8 0.1632 % 2,684.1
Performance Highlights
Issue Index Change Notes
BAM.PR.X FixedReset 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-19
Maturity Price : 17.23
Evaluated at bid price : 17.23
Bid-YTW : 4.81 %
MFC.PR.N FixedReset 1.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.85
Bid-YTW : 5.43 %
TRP.PR.A FixedReset 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-19
Maturity Price : 19.72
Evaluated at bid price : 19.72
Bid-YTW : 4.55 %
TRP.PR.C FixedReset 1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-19
Maturity Price : 17.02
Evaluated at bid price : 17.02
Bid-YTW : 4.56 %
BAM.PR.R FixedReset 1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-19
Maturity Price : 19.70
Evaluated at bid price : 19.70
Bid-YTW : 4.85 %
IFC.PR.A FixedReset 1.81 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.70
Bid-YTW : 7.30 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.J FixedReset 105,100 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-19
Maturity Price : 23.30
Evaluated at bid price : 24.51
Bid-YTW : 4.37 %
BNS.PR.Z FixedReset 101,910 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.06
Bid-YTW : 4.46 %
CM.PR.R FixedReset 79,337 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-07-31
Maturity Price : 25.00
Evaluated at bid price : 25.60
Bid-YTW : 4.00 %
BAM.PF.J FixedReset 58,975 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.52
Bid-YTW : 4.28 %
TD.PR.Y FixedReset 57,800 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.01
Bid-YTW : 3.54 %
TD.PF.C FixedReset 47,600 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-19
Maturity Price : 22.56
Evaluated at bid price : 22.87
Bid-YTW : 4.32 %
There were 31 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
HSE.PR.A FixedReset Quote: 16.80 – 17.30
Spot Rate : 0.5000
Average : 0.3481

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-19
Maturity Price : 16.80
Evaluated at bid price : 16.80
Bid-YTW : 4.84 %

BAM.PF.E FixedReset Quote: 23.16 – 23.55
Spot Rate : 0.3900
Average : 0.2385

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-19
Maturity Price : 22.63
Evaluated at bid price : 23.16
Bid-YTW : 4.58 %

HSE.PR.E FixedReset Quote: 24.57 – 24.91
Spot Rate : 0.3400
Average : 0.2125

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-19
Maturity Price : 23.35
Evaluated at bid price : 24.57
Bid-YTW : 5.21 %

CM.PR.O FixedReset Quote: 23.42 – 23.77
Spot Rate : 0.3500
Average : 0.2446

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-19
Maturity Price : 23.01
Evaluated at bid price : 23.42
Bid-YTW : 4.30 %

W.PR.M FixedReset Quote: 26.00 – 26.35
Spot Rate : 0.3500
Average : 0.2472

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-15
Maturity Price : 25.00
Evaluated at bid price : 26.00
Bid-YTW : 4.35 %

TRP.PR.G FixedReset Quote: 24.02 – 24.49
Spot Rate : 0.4700
Average : 0.3707

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-12-19
Maturity Price : 22.99
Evaluated at bid price : 24.02
Bid-YTW : 4.67 %