Category: Market Action

Market Action

November 29, 2016

Here’s a minor milestone for US house prices:

U.S. home prices have climbed back above the record reached more than a decade ago, bringing to a close the worst period for the housing market since the Great Depression and stoking optimism for a more sustainable expansion.

The average home price for September was 0.1% above the July 2006 peak, according to the S&P CoreLogic Case-Shiller U.S. National Home Price index released Tuesday. As of the previous month’s reading of the Case-Shiller index, a widely used benchmark for U.S. housing, prices remained 0.1% below the July 2006 record.

Adjusted for inflation, the index still is about 16% below the 2006 high. Home prices jumped 5.5% over the past year.

Europe has some new refinements to the regulation of banks, including:

The new provision would create a new asset class of “non-preferred” senior debt that can be bailed in in resolution, after other capital instruments, but before other senior liabilities

Well, I suppose I sympathize with them, up to a point, for not wanting to officially call it “bail-in debt”, but “non-preferred senior debt” is not really all that good a name!

DBRS comments:

One version of this instrument is already in the final stages of legislation in France (see “DBRS: Rating the New French Senior Non-preferred Debt Instruments,” published on November 22, 2016). By introducing this instrument across Europe, the EC’s intention is to try to introduce greater harmonisation in the creditor hierarchy in Europe at a time when the regimes of different countries are diverging (e.g. the German subordination of existing traded senior debt which will be in place from January 2017).

In its recent commentary DBRS has already clarified that it intends to rate the French non-preferred senior debt instrument one notch below the bank’s Intrinsic Assessment (IA), based on the DBRS Criteria: Rating Bank Capital Securities – Subordinated, Hybrid, Preferred & Contingent Capital Securities. At the same time, DBRS currently rates existing subordinated debt at European banks generally at one notch below the IA for dated subordinated debt and cumulative junior subordinated debt, but two notches below the IA for non-cumulative junior subordinated debt. However, given the increasing likelihood that all subordinated debt will be used to absorb losses alongside equity as the implementation of BRRD (Bank Recovery and Resolution Directive) evolves, DBRS expects to see negative rating pressure on the subordinated debt that is currently rated only 1 notch below the IA, and which is at the same level as potential future issuance of nonpreferred senior debt. One possible outcome of DBRS’s deliberations is that these instruments would be downgraded to the same level as existing non-cumulative junior debt (i.e. 2 notches below the IA).

These developments are currently restricted to Europe. DBRS does not see similar rating pressure on rated subordinated in the US, Canada or Asia, given the different regulatory regimes in these countries.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.3617 % 1,748.4
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.3617 % 3,193.9
Floater 4.29 % 4.45 % 47,706 16.44 4 -0.3617 % 1,840.7
OpRet 0.00 % 0.00 % 0 0.00 0 0.1128 % 2,920.9
SplitShare 4.84 % 4.45 % 50,991 4.34 6 0.1128 % 3,488.1
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1128 % 2,721.6
Perpetual-Premium 5.44 % 5.09 % 81,987 14.46 23 0.1434 % 2,656.9
Perpetual-Discount 5.39 % 5.40 % 94,098 14.79 15 0.0953 % 2,777.6
FixedReset 4.89 % 4.63 % 208,165 6.84 96 0.1761 % 2,090.7
Deemed-Retractible 5.15 % 5.52 % 137,381 6.42 32 -0.0986 % 2,753.5
FloatingReset 2.89 % 3.89 % 43,225 4.85 12 -0.1616 % 2,301.6
Performance Highlights
Issue Index Change Notes
SLF.PR.J FloatingReset -1.67 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.57
Bid-YTW : 10.32 %
BAM.PF.E FixedReset 1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-29
Maturity Price : 19.78
Evaluated at bid price : 19.78
Bid-YTW : 4.75 %
MFC.PR.M FixedReset 1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.70
Bid-YTW : 7.80 %
SLF.PR.G FixedReset 1.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.50
Bid-YTW : 9.95 %
TRP.PR.B FixedReset 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-29
Maturity Price : 12.31
Evaluated at bid price : 12.31
Bid-YTW : 4.53 %
FTS.PR.K FixedReset 1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-29
Maturity Price : 17.43
Evaluated at bid price : 17.43
Bid-YTW : 4.52 %
BAM.PF.B FixedReset 1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-29
Maturity Price : 18.61
Evaluated at bid price : 18.61
Bid-YTW : 5.04 %
MFC.PR.F FixedReset 1.28 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.50
Bid-YTW : 10.91 %
BAM.PR.X FixedReset 1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-29
Maturity Price : 14.99
Evaluated at bid price : 14.99
Bid-YTW : 4.80 %
GWO.PR.N FixedReset 1.55 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.72
Bid-YTW : 10.74 %
FTS.PR.G FixedReset 1.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-29
Maturity Price : 17.75
Evaluated at bid price : 17.75
Bid-YTW : 4.49 %
BAM.PR.T FixedReset 3.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-29
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 4.97 %
Volume Highlights
Issue Index Shares
Traded
Notes
TRP.PR.K FixedReset 512,356 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-29
Maturity Price : 23.10
Evaluated at bid price : 24.90
Bid-YTW : 4.85 %
MFC.PR.R FixedReset 199,165 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.96
Bid-YTW : 4.90 %
BAM.PR.B Floater 125,018 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-29
Maturity Price : 10.76
Evaluated at bid price : 10.76
Bid-YTW : 4.45 %
RY.PR.L FixedReset 97,700 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.16
Bid-YTW : 3.81 %
TD.PF.H FixedReset 96,341 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.40
Bid-YTW : 4.63 %
TRP.PR.J FixedReset 94,741 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-31
Maturity Price : 25.00
Evaluated at bid price : 25.96
Bid-YTW : 4.57 %
There were 62 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
IAG.PR.G FixedReset Quote: 19.81 – 20.15
Spot Rate : 0.3400
Average : 0.2214

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.81
Bid-YTW : 7.23 %

BMO.PR.M FixedReset Quote: 23.81 – 24.09
Spot Rate : 0.2800
Average : 0.1749

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.81
Bid-YTW : 3.93 %

FTS.PR.M FixedReset Quote: 19.30 – 19.60
Spot Rate : 0.3000
Average : 0.2012

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-29
Maturity Price : 19.30
Evaluated at bid price : 19.30
Bid-YTW : 4.63 %

NA.PR.W FixedReset Quote: 18.14 – 18.45
Spot Rate : 0.3100
Average : 0.2116

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-29
Maturity Price : 18.14
Evaluated at bid price : 18.14
Bid-YTW : 4.64 %

BAM.PR.R FixedReset Quote: 16.70 – 17.00
Spot Rate : 0.3000
Average : 0.2067

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-29
Maturity Price : 16.70
Evaluated at bid price : 16.70
Bid-YTW : 4.88 %

VNR.PR.A FixedReset Quote: 18.92 – 19.20
Spot Rate : 0.2800
Average : 0.1967

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-29
Maturity Price : 18.92
Evaluated at bid price : 18.92
Bid-YTW : 5.10 %

Market Action

November 28, 2016

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.0452 % 1,754.7
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.0452 % 3,205.5
Floater 4.27 % 4.43 % 47,422 16.49 4 0.0452 % 1,847.4
OpRet 0.00 % 0.00 % 0 0.00 0 0.1090 % 2,917.6
SplitShare 4.84 % 4.40 % 51,006 2.01 6 0.1090 % 3,484.2
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1090 % 2,718.5
Perpetual-Premium 5.45 % 5.33 % 80,831 14.46 23 0.0332 % 2,653.1
Perpetual-Discount 5.40 % 5.37 % 95,655 14.80 15 0.2090 % 2,775.0
FixedReset 4.89 % 4.60 % 207,533 6.84 96 0.1017 % 2,087.1
Deemed-Retractible 5.14 % 5.52 % 137,603 6.42 32 0.2280 % 2,756.2
FloatingReset 2.88 % 3.84 % 42,302 4.85 12 0.0680 % 2,305.3
Performance Highlights
Issue Index Change Notes
GWO.PR.M Deemed-Retractible -1.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.40
Bid-YTW : 5.74 %
GWO.PR.N FixedReset -1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.51
Bid-YTW : 10.97 %
SLF.PR.E Deemed-Retractible 1.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.50
Bid-YTW : 6.73 %
SLF.PR.D Deemed-Retractible 1.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.33
Bid-YTW : 6.79 %
SLF.PR.B Deemed-Retractible 1.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.92
Bid-YTW : 6.08 %
MFC.PR.B Deemed-Retractible 1.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.26
Bid-YTW : 6.39 %
FTS.PR.M FixedReset 1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-28
Maturity Price : 19.43
Evaluated at bid price : 19.43
Bid-YTW : 4.60 %
MFC.PR.C Deemed-Retractible 1.18 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.41
Bid-YTW : 6.82 %
RY.PR.M FixedReset 1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-28
Maturity Price : 20.27
Evaluated at bid price : 20.27
Bid-YTW : 4.46 %
RY.PR.J FixedReset 1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-28
Maturity Price : 20.55
Evaluated at bid price : 20.55
Bid-YTW : 4.52 %
SLF.PR.C Deemed-Retractible 1.40 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.37
Bid-YTW : 6.76 %
SLF.PR.K FloatingReset 2.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.70
Bid-YTW : 8.33 %
Volume Highlights
Issue Index Shares
Traded
Notes
BAM.PF.I FixedReset 452,668 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-28
Maturity Price : 23.15
Evaluated at bid price : 25.04
Bid-YTW : 4.73 %
TD.PF.H FixedReset 426,019 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.43
Bid-YTW : 4.60 %
BMO.PR.B FixedReset 352,910 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-02-25
Maturity Price : 25.00
Evaluated at bid price : 25.48
Bid-YTW : 4.57 %
MFC.PR.R FixedReset 221,965 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.98
Bid-YTW : 4.89 %
TRP.PR.K FixedReset 175,465 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-28
Maturity Price : 23.10
Evaluated at bid price : 24.92
Bid-YTW : 4.84 %
CU.PR.D Perpetual-Discount 71,800 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-28
Maturity Price : 22.85
Evaluated at bid price : 23.26
Bid-YTW : 5.27 %
There were 48 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
CCS.PR.C Deemed-Retractible Quote: 23.21 – 23.90
Spot Rate : 0.6900
Average : 0.4562

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.21
Bid-YTW : 6.30 %

MFC.PR.F FixedReset Quote: 13.33 – 13.69
Spot Rate : 0.3600
Average : 0.2571

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.33
Bid-YTW : 11.09 %

RY.PR.P Perpetual-Premium Quote: 25.31 – 25.60
Spot Rate : 0.2900
Average : 0.1896

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2025-02-24
Maturity Price : 25.00
Evaluated at bid price : 25.31
Bid-YTW : 5.11 %

GWO.PR.I Deemed-Retractible Quote: 21.73 – 21.98
Spot Rate : 0.2500
Average : 0.1593

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.73
Bid-YTW : 6.76 %

CU.PR.H Perpetual-Premium Quote: 24.69 – 25.04
Spot Rate : 0.3500
Average : 0.2624

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-28
Maturity Price : 24.29
Evaluated at bid price : 24.69
Bid-YTW : 5.33 %

MFC.PR.B Deemed-Retractible Quote: 22.26 – 22.52
Spot Rate : 0.2600
Average : 0.1782

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.26
Bid-YTW : 6.39 %

Market Action

November 25, 2016

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.2267 % 1,753.9
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.2267 % 3,204.1
Floater 4.27 % 4.43 % 47,986 16.49 4 0.2267 % 1,846.5
OpRet 0.00 % 0.00 % 0 0.00 0 0.0996 % 2,914.4
SplitShare 4.84 % 4.31 % 52,796 2.02 6 0.0996 % 3,480.4
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0996 % 2,715.5
Perpetual-Premium 5.45 % 5.11 % 83,871 14.49 23 -0.0594 % 2,652.2
Perpetual-Discount 5.41 % 5.38 % 91,371 14.80 15 -0.1014 % 2,769.2
FixedReset 4.89 % 4.62 % 207,550 6.80 96 0.0876 % 2,084.9
Deemed-Retractible 5.14 % 5.27 % 136,277 4.60 32 0.0651 % 2,749.9
FloatingReset 2.88 % 3.83 % 43,998 4.86 12 -0.2541 % 2,303.7
Performance Highlights
Issue Index Change Notes
MFC.PR.F FixedReset -1.39 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.46
Bid-YTW : 10.94 %
EML.PR.A FixedReset -1.26 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-17
Maturity Price : 25.00
Evaluated at bid price : 25.83
Bid-YTW : 5.09 %
BNS.PR.C FloatingReset -1.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.25
Bid-YTW : 3.83 %
BNS.PR.B FloatingReset -1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.05
Bid-YTW : 3.83 %
BAM.PR.R FixedReset 1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-25
Maturity Price : 16.84
Evaluated at bid price : 16.84
Bid-YTW : 4.84 %
VNR.PR.A FixedReset 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-25
Maturity Price : 19.10
Evaluated at bid price : 19.10
Bid-YTW : 5.06 %
SLF.PR.J FloatingReset 1.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.05
Bid-YTW : 9.92 %
TRP.PR.C FixedReset 1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-25
Maturity Price : 13.45
Evaluated at bid price : 13.45
Bid-YTW : 4.62 %
IFC.PR.A FixedReset 1.91 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.00
Bid-YTW : 9.58 %
IFC.PR.D FloatingReset 2.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.65
Bid-YTW : 6.69 %
Volume Highlights
Issue Index Shares
Traded
Notes
TRP.PR.D FixedReset 310,900 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-25
Maturity Price : 17.98
Evaluated at bid price : 17.98
Bid-YTW : 4.84 %
TD.PF.H FixedReset 233,332 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.45
Bid-YTW : 4.57 %
TRP.PR.K FixedReset 222,465 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-25
Maturity Price : 23.11
Evaluated at bid price : 24.93
Bid-YTW : 4.84 %
RY.PR.Q FixedReset 212,864 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-24
Maturity Price : 25.00
Evaluated at bid price : 26.30
Bid-YTW : 4.25 %
RY.PR.J FixedReset 126,982 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-25
Maturity Price : 20.30
Evaluated at bid price : 20.30
Bid-YTW : 4.58 %
TRP.PR.J FixedReset 125,100 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-31
Maturity Price : 25.00
Evaluated at bid price : 26.03
Bid-YTW : 4.49 %
BAM.PF.I FixedReset 116,575 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-25
Maturity Price : 23.15
Evaluated at bid price : 25.02
Bid-YTW : 4.74 %
There were 48 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
IFC.PR.D FloatingReset Quote: 19.65 – 22.50
Spot Rate : 2.8500
Average : 2.5331

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.65
Bid-YTW : 6.69 %

SLF.PR.H FixedReset Quote: 16.92 – 17.18
Spot Rate : 0.2600
Average : 0.1759

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.92
Bid-YTW : 8.65 %

SLF.PR.A Deemed-Retractible Quote: 22.87 – 23.15
Spot Rate : 0.2800
Average : 0.2064

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.87
Bid-YTW : 6.24 %

RY.PR.J FixedReset Quote: 20.30 – 20.52
Spot Rate : 0.2200
Average : 0.1520

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-25
Maturity Price : 20.30
Evaluated at bid price : 20.30
Bid-YTW : 4.58 %

TRP.PR.G FixedReset Quote: 20.06 – 20.30
Spot Rate : 0.2400
Average : 0.1757

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-25
Maturity Price : 20.06
Evaluated at bid price : 20.06
Bid-YTW : 4.90 %

EML.PR.A FixedReset Quote: 25.83 – 26.20
Spot Rate : 0.3700
Average : 0.3069

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-17
Maturity Price : 25.00
Evaluated at bid price : 25.83
Bid-YTW : 5.09 %

Market Action

November 24, 2016

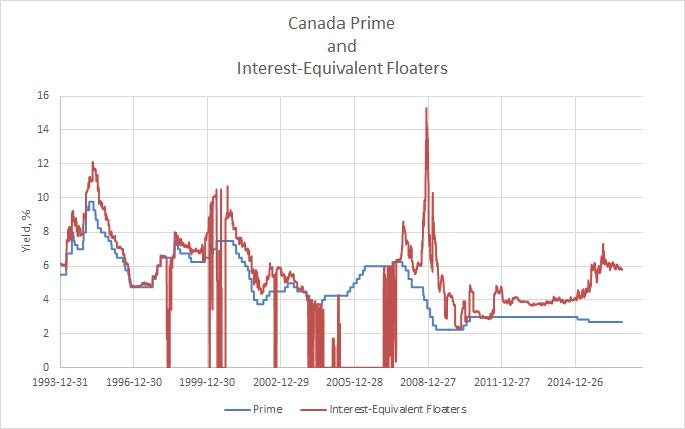
In response to overwhelming public demand (SafetyinNumbers asked me), I present a chart of Canada Prime and the interest-equivalent yield of Floaters.

PrimeAndFloaters_161124
Click for Big

There are problems with this chart:

  • Often, Floaters have traded above their contemporary call price. When this has happened I have set the interest-equivalent yield to zero.
  • In late years, the Floater index has been dominated by BAM issues, which often trade differently from the market as a whole due to credit worries and investor concentration concerns.
  • In later years, PWF.PR.A has drifted in and out of the index, relegated intermittently to Scraps on volume concerns. As PWF.PR.A has a significantly lower yield than the BAM Floaters, this creates inconsistencies when comparing one period to another.
  • At the beginning of February, 2011, I abruptly changed the interest-equivalency factor from 1.4x to 1.3x
HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.0680 % 1,750.0
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.0680 % 3,196.8
Floater 4.28 % 4.45 % 47,922 16.44 4 0.0680 % 1,842.4
OpRet 0.00 % 0.00 % 0 0.00 0 -0.2847 % 2,911.5
SplitShare 4.85 % 4.30 % 52,565 2.02 6 -0.2847 % 3,476.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.2847 % 2,712.8
Perpetual-Premium 5.45 % 5.08 % 78,671 14.41 23 -0.2058 % 2,653.8
Perpetual-Discount 5.41 % 5.37 % 91,538 14.82 15 0.0000 % 2,772.0
FixedReset 4.90 % 4.61 % 207,126 6.81 96 0.1275 % 2,083.1
Deemed-Retractible 5.14 % 5.31 % 136,327 4.51 32 -0.1664 % 2,748.1
FloatingReset 2.87 % 3.65 % 42,493 4.87 12 0.0678 % 2,309.6
Performance Highlights
Issue Index Change Notes
CCS.PR.C Deemed-Retractible -1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.21
Bid-YTW : 6.29 %
VNR.PR.A FixedReset -1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-24
Maturity Price : 18.90
Evaluated at bid price : 18.90
Bid-YTW : 5.12 %
PWF.PR.E Perpetual-Premium -1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-24
Maturity Price : 24.34
Evaluated at bid price : 24.65
Bid-YTW : 5.63 %
PWF.PR.P FixedReset -1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-24
Maturity Price : 13.62
Evaluated at bid price : 13.62
Bid-YTW : 4.67 %
TRP.PR.C FixedReset 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-24
Maturity Price : 13.29
Evaluated at bid price : 13.29
Bid-YTW : 4.68 %
BAM.PR.Z FixedReset 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-24
Maturity Price : 19.56
Evaluated at bid price : 19.56
Bid-YTW : 5.21 %
MFC.PR.F FixedReset 1.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.65
Bid-YTW : 10.73 %
TRP.PR.A FixedReset 1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-24
Maturity Price : 15.75
Evaluated at bid price : 15.75
Bid-YTW : 4.78 %
TRP.PR.F FloatingReset 1.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-24
Maturity Price : 14.95
Evaluated at bid price : 14.95
Bid-YTW : 4.11 %
TRP.PR.H FloatingReset 2.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-24
Maturity Price : 11.31
Evaluated at bid price : 11.31
Bid-YTW : 4.00 %
Volume Highlights
Issue Index Shares
Traded
Notes
TRP.PR.K FixedReset 377,038 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-24
Maturity Price : 23.10
Evaluated at bid price : 24.91
Bid-YTW : 4.84 %
TRP.PR.G FixedReset 237,996 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-24
Maturity Price : 20.21
Evaluated at bid price : 20.21
Bid-YTW : 4.86 %
MFC.PR.R FixedReset 203,300 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.99
Bid-YTW : 4.87 %
TD.PF.H FixedReset 198,328 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.52
Bid-YTW : 4.51 %
TD.PF.B FixedReset 118,600 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-24
Maturity Price : 18.60
Evaluated at bid price : 18.60
Bid-YTW : 4.52 %
TRP.PR.E FixedReset 113,321 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-24
Maturity Price : 18.35
Evaluated at bid price : 18.35
Bid-YTW : 4.79 %
There were 45 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
IFC.PR.D FloatingReset Quote: 19.25 – 22.00
Spot Rate : 2.7500
Average : 2.1856

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.25
Bid-YTW : 6.99 %

PWF.PR.E Perpetual-Premium Quote: 24.65 – 24.94
Spot Rate : 0.2900
Average : 0.1878

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-24
Maturity Price : 24.34
Evaluated at bid price : 24.65
Bid-YTW : 5.63 %

SLF.PR.C Deemed-Retractible Quote: 21.16 – 21.45
Spot Rate : 0.2900
Average : 0.1980

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.16
Bid-YTW : 7.10 %

TD.PR.Z FloatingReset Quote: 23.23 – 23.55
Spot Rate : 0.3200
Average : 0.2281

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.23
Bid-YTW : 3.64 %

TD.PR.S FixedReset Quote: 23.99 – 24.24
Spot Rate : 0.2500
Average : 0.1807

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.99
Bid-YTW : 3.77 %

TD.PR.Y FixedReset Quote: 24.16 – 24.39
Spot Rate : 0.2300
Average : 0.1638

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.16
Bid-YTW : 3.79 %

Market Action

November 23, 2016

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.2501 % 1,748.8
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.2501 % 3,194.7
Floater 4.29 % 4.46 % 48,506 16.43 4 0.2501 % 1,841.1
OpRet 0.00 % 0.00 % 0 0.00 0 0.3255 % 2,919.8
SplitShare 4.83 % 4.29 % 50,721 2.03 6 0.3255 % 3,486.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.3255 % 2,720.6
Perpetual-Premium 5.44 % 5.05 % 78,553 14.41 23 -0.0732 % 2,659.3
Perpetual-Discount 5.41 % 5.39 % 92,545 14.81 15 -0.2083 % 2,772.0
FixedReset 4.90 % 4.61 % 208,315 6.81 96 0.0479 % 2,080.5
Deemed-Retractible 5.13 % 5.30 % 138,156 4.51 32 -0.1351 % 2,752.7
FloatingReset 2.87 % 3.64 % 43,821 4.87 12 0.0424 % 2,308.0
Performance Highlights
Issue Index Change Notes
MFC.PR.B Deemed-Retractible -1.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.97
Bid-YTW : 6.57 %
FTS.PR.H FixedReset -1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-23
Maturity Price : 13.50
Evaluated at bid price : 13.50
Bid-YTW : 4.54 %
PWF.PR.P FixedReset 1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-23
Maturity Price : 13.78
Evaluated at bid price : 13.78
Bid-YTW : 4.61 %
SLF.PR.J FloatingReset 2.86 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.03
Bid-YTW : 9.94 %
Volume Highlights
Issue Index Shares
Traded
Notes
TRP.PR.K FixedReset 394,198 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-23
Maturity Price : 23.08
Evaluated at bid price : 24.85
Bid-YTW : 4.85 %
MFC.PR.R FixedReset 276,908 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.93
Bid-YTW : 4.91 %
BAM.PF.I FixedReset 131,310 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-23
Maturity Price : 23.14
Evaluated at bid price : 25.00
Bid-YTW : 4.74 %
TD.PR.Z FloatingReset 100,900 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.37
Bid-YTW : 3.52 %
CM.PR.O FixedReset 75,780 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-23
Maturity Price : 19.17
Evaluated at bid price : 19.17
Bid-YTW : 4.47 %
TD.PF.H FixedReset 72,021 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.47
Bid-YTW : 4.55 %
There were 47 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
POW.PR.C Perpetual-Premium Quote: 25.50 – 25.77
Spot Rate : 0.2700
Average : 0.1679

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-12-23
Maturity Price : 25.00
Evaluated at bid price : 25.50
Bid-YTW : -10.55 %

W.PR.K FixedReset Quote: 25.30 – 25.90
Spot Rate : 0.6000
Average : 0.5106

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-01-15
Maturity Price : 25.00
Evaluated at bid price : 25.30
Bid-YTW : 5.11 %

IGM.PR.B Perpetual-Premium Quote: 25.28 – 25.70
Spot Rate : 0.4200
Average : 0.3360

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.28
Bid-YTW : 5.55 %

BMO.PR.Y FixedReset Quote: 20.82 – 21.07
Spot Rate : 0.2500
Average : 0.1682

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-23
Maturity Price : 20.82
Evaluated at bid price : 20.82
Bid-YTW : 4.48 %

CU.PR.H Perpetual-Premium Quote: 24.73 – 25.04
Spot Rate : 0.3100
Average : 0.2346

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-23
Maturity Price : 24.33
Evaluated at bid price : 24.73
Bid-YTW : 5.31 %

TD.PF.G FixedReset Quote: 26.38 – 26.57
Spot Rate : 0.1900
Average : 0.1222

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 26.38
Bid-YTW : 4.23 %

Market Action

November 22, 2016

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.0910 % 1,744.4
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.0910 % 3,186.7
Floater 4.30 % 4.47 % 48,723 16.42 4 0.0910 % 1,836.5
OpRet 0.00 % 0.00 % 0 0.00 0 0.1197 % 2,910.3
SplitShare 4.85 % 4.27 % 49,154 2.03 6 0.1197 % 3,475.6
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1197 % 2,711.8
Perpetual-Premium 5.44 % 5.05 % 79,810 14.37 23 0.0750 % 2,661.2
Perpetual-Discount 5.39 % 5.39 % 92,001 14.82 15 -0.3115 % 2,777.8
FixedReset 4.90 % 4.63 % 209,073 6.84 96 0.2857 % 2,079.5
Deemed-Retractible 5.13 % 5.53 % 138,702 6.48 32 -0.1763 % 2,756.4
FloatingReset 2.87 % 3.59 % 40,554 4.87 12 0.0467 % 2,307.1
Performance Highlights
Issue Index Change Notes
FTS.PR.H FixedReset -1.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-22
Maturity Price : 13.65
Evaluated at bid price : 13.65
Bid-YTW : 4.49 %
MFC.PR.M FixedReset -1.29 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.43
Bid-YTW : 8.00 %
MFC.PR.N FixedReset -1.02 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.52
Bid-YTW : 7.86 %
PWF.PR.S Perpetual-Discount -1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-22
Maturity Price : 22.15
Evaluated at bid price : 22.43
Bid-YTW : 5.39 %
BAM.PF.A FixedReset 1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-22
Maturity Price : 19.46
Evaluated at bid price : 19.46
Bid-YTW : 5.15 %
BAM.PF.E FixedReset 1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-22
Maturity Price : 19.32
Evaluated at bid price : 19.32
Bid-YTW : 4.87 %
BAM.PF.F FixedReset 1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-22
Maturity Price : 20.56
Evaluated at bid price : 20.56
Bid-YTW : 4.87 %
BMO.PR.S FixedReset 1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-22
Maturity Price : 19.41
Evaluated at bid price : 19.41
Bid-YTW : 4.40 %
HSE.PR.C FixedReset 1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-22
Maturity Price : 20.19
Evaluated at bid price : 20.19
Bid-YTW : 5.26 %
BAM.PR.T FixedReset 1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-22
Maturity Price : 16.29
Evaluated at bid price : 16.29
Bid-YTW : 5.19 %
BAM.PF.B FixedReset 1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-22
Maturity Price : 18.18
Evaluated at bid price : 18.18
Bid-YTW : 5.17 %
SLF.PR.H FixedReset 1.39 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.73
Bid-YTW : 8.80 %
BAM.PF.G FixedReset 1.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-22
Maturity Price : 20.90
Evaluated at bid price : 20.90
Bid-YTW : 4.81 %
HSE.PR.E FixedReset 1.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-22
Maturity Price : 21.45
Evaluated at bid price : 21.80
Bid-YTW : 5.27 %
PVS.PR.E SplitShare 1.71 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.53
Bid-YTW : 5.07 %
SLF.PR.G FixedReset 2.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.50
Bid-YTW : 10.07 %
HSE.PR.A FixedReset 2.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-22
Maturity Price : 12.48
Evaluated at bid price : 12.48
Bid-YTW : 5.36 %
HSE.PR.G FixedReset 2.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-22
Maturity Price : 21.85
Evaluated at bid price : 22.20
Bid-YTW : 5.15 %
GWO.PR.N FixedReset 2.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.76
Bid-YTW : 10.67 %
BAM.PR.X FixedReset 2.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-22
Maturity Price : 14.58
Evaluated at bid price : 14.58
Bid-YTW : 4.95 %
BAM.PR.R FixedReset 3.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-22
Maturity Price : 16.63
Evaluated at bid price : 16.63
Bid-YTW : 4.90 %
Volume Highlights
Issue Index Shares
Traded
Notes
MFC.PR.R FixedReset 989,738 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.84
Bid-YTW : 4.96 %
TRP.PR.K FixedReset 762,444 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-22
Maturity Price : 23.07
Evaluated at bid price : 24.81
Bid-YTW : 4.86 %
BAM.PF.I FixedReset 479,900 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-22
Maturity Price : 23.12
Evaluated at bid price : 24.94
Bid-YTW : 4.75 %
TRP.PR.D FixedReset 223,212 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-22
Maturity Price : 17.87
Evaluated at bid price : 17.87
Bid-YTW : 4.87 %
TD.PF.H FixedReset 143,073 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.45
Bid-YTW : 4.56 %
BMO.PR.B FixedReset 140,258 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-02-25
Maturity Price : 25.00
Evaluated at bid price : 25.43
Bid-YTW : 4.60 %
TRP.PR.H FloatingReset 136,441 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-22
Maturity Price : 11.01
Evaluated at bid price : 11.01
Bid-YTW : 4.11 %
BAM.PF.H FixedReset 128,988 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.79
Bid-YTW : 4.37 %
There were 62 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
IFC.PR.D FloatingReset Quote: 19.30 – 22.50
Spot Rate : 3.2000
Average : 3.0654

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.30
Bid-YTW : 6.95 %

IFC.PR.A FixedReset Quote: 15.81 – 16.32
Spot Rate : 0.5100
Average : 0.3818

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.81
Bid-YTW : 9.75 %

IFC.PR.C FixedReset Quote: 19.30 – 19.60
Spot Rate : 0.3000
Average : 0.1902

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.30
Bid-YTW : 7.30 %

IGM.PR.B Perpetual-Premium Quote: 25.31 – 25.65
Spot Rate : 0.3400
Average : 0.2439

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.31
Bid-YTW : 5.48 %

NA.PR.X FixedReset Quote: 26.27 – 26.50
Spot Rate : 0.2300
Average : 0.1456

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-15
Maturity Price : 25.00
Evaluated at bid price : 26.27
Bid-YTW : 4.39 %

PVS.PR.D SplitShare Quote: 24.53 – 24.86
Spot Rate : 0.3300
Average : 0.2458

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2021-10-08
Maturity Price : 25.00
Evaluated at bid price : 24.53
Bid-YTW : 4.92 %

Market Action

November 21, 2016

I have long worried that the craze for alternative investments by pension funds and insurance companies was going to lead to trouble. Here’s an example from Dallas:

Dallas police and firefighters are withdrawing hundreds of millions from their retirement plan following a series of investment blunders, heightening the risk that a major U.S. pension fund could run out of money.

The revolt by members of the $2.27 billion Dallas Police and Fire Pension Fund offers an extreme case of what can happen when a pension wagers on lucrative returns to cover funding shortfalls.
…
A series of aggressive real-estate bets from Hawaii to Paris and a conflict over the value of those properties triggered more than $500 million in losses, leaving the fund with enough to pay just 45% of future benefits. Officials are warning the pension could go broke by 2027.
…
For 10 years, Dallas has had the highest percentage of assets in real estate of any of the about 150 plans tracked by the Public Plans Database. Pension officials traveled as far as Australia and Abu Dhabi to scope out prospective investments, according to a 2008 newsletter.

The strategy appeared to be working, with Dallas returns often beating national medians. But that success received scrutiny in 2013 when the Dallas Morning News reported that many properties hadn’t been appraised for years. Instead, certain holdings were valued based on their purchase price and in some cases by also adding development and operating expenses, said Chief Financial Officer Summer Loveland, who joined the fund in November 2013.

This revaluation loss leads one to wonder what will happen to this speculation:

While Chinese home buyers have sent prices soaring from Vancouver to Sydney, in this corner of Southeast Asia it’s China’s developers that are swamping the market, pushing prices lower with a glut of hundreds of thousands of new homes. They’re betting that the city of Johor Bahru, bordering Singapore, will eventually become the next Shenzhen.

“These Chinese players build by the thousands at one go, and they scare the hell out of everybody,” said Siva Shanker, head of investments at Axis-REIT Managers Bhd. and a former president of the Malaysian Institute of Estate Agents. “God only knows who is going to buy all these units, and when it’s completed, the bigger question is, who is going to stay in them?”
…
Developers have a pipeline of more than 350,000 private homes planned or under construction in Johor state, according to data from Malaysia’s National Property Information Centre. That’s more than all the privately built homes in Singapore. Forest City could add another 160,000 over its 30-year construction period, according to Bloomberg estimates, based on the projected population.

“Land is plentiful and cheap,” said Alan Cheong, senior director of research & consultancy at Savills Singapore. “But buyers don’t understand how real estate values play out when there is no shortage of land.”

Meanwhile, the TMX – acquired by the banks to extend their hegemony over the Canadian financial system in a transaction blessed by the regulators in exchange for extra payments to the regulators – continued to demonstrate its permanent free pass from the competition board:

The Competition Bureau has closed its investigation into TMX Group, concluding that owner of the Toronto Stock Exchange likely did not violate the Competition Act in the operation of its market data business.

Last year, TMX rival Aequitas Innovations Inc. complained to the Bureau about what it maintained was “anti-competitive conduct” from TMX Group in relation to its market data product. At the time, Aequitas was attempting to build out its own competing data product. Aequitas alleged that agreements between TMX and investment dealers prevented the sharing of private data without the consent of TMX Group.

Even though the Competition Bureau found in its investigation that this was indeed the case, there were other factors that had little to do with TMX, that made it difficult for Aequitas to launch a competing product, including dealers themselves having reservations about working with Aequitas. One such reservation was over the confidentiality of private market data, according to the Bureau’s statement.

The statement from the Bureau essentially states that it is the Bureau’s job to pick winners and they have picked their friends:

Abuse of dominance occurs when a dominant firm or group of firms in a market engages in a practice of anti-competitive acts, with the result that competition has been or is likely to be prevented or lessened substantially. The Bureau’s investigation focused on the last part of the abuse of dominance test – namely, whether the contractual clauses imposed by TMX Group were likely to substantially prevent competition in a market. Specifically, the Bureau examined whether sufficient future competition from the CMV would be likely to materialize in the absence of TMX Group’s alleged anti-competitive conduct.

Evidence obtained by the Bureau indicated that in order for the CMV to effectively compete with the current sources of indicative market data in Canada, Aequitas required a substantial volume of private market data from investment dealers. Accordingly, the Bureau considered whether there was compelling evidence that Aequitas would likely be able to obtain such a volume of private market data from investment dealers absent TMX Group’s contractual clauses. The Bureau found that:

  • •the level of interest among investment dealers in Aequitas’ proposed CMV product varied considerably;
  • •investment dealers had a number of concerns with respect to the CMV, including with respect to the confidentiality of private market data, and it was unlikely that Aequitas would be able to address these concerns within a reasonable period of time; and
  • •Aequitas had not obtained credible commitments from investment dealers to provide their private market data absent TMX Group’s contractual clauses. Moreover, it was unlikely that Aequitas would be able to obtain such commitments within a reasonable period of time given the preliminary status of negotiations between Aequitas and investment dealers.

Taken together, this evidence suggested that, even absent TMX Group’s contractual clauses, it was unlikely that Aequitas would be able to obtain a sufficient volume of private market data from investment dealers to develop a sufficiently competitive product.

It’s all very simple, isn’t it? Abuse of dominance is restraint of trade. If there’s no trade to restrain because it’s been snuffed out in the planning stages, then there can be no abuse of dominance. QED.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.2724 % 1,742.8
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.2724 % 3,183.8
Floater 4.30 % 4.49 % 48,252 16.39 4 -0.2724 % 1,834.8
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0199 % 2,906.8
SplitShare 4.86 % 4.28 % 49,387 2.03 6 -0.0199 % 3,471.4
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0199 % 2,708.5
Perpetual-Premium 5.44 % 5.06 % 79,947 14.43 23 0.1607 % 2,659.2
Perpetual-Discount 5.38 % 5.37 % 92,306 14.88 15 0.1129 % 2,786.5
FixedReset 4.92 % 4.63 % 203,842 6.82 95 0.3518 % 2,073.5
Deemed-Retractible 5.12 % 5.29 % 135,567 1.96 32 0.2443 % 2,761.3
FloatingReset 2.88 % 3.60 % 40,516 4.87 12 0.2168 % 2,306.0
Performance Highlights
Issue Index Change Notes
CU.PR.C FixedReset -2.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-21
Maturity Price : 19.05
Evaluated at bid price : 19.05
Bid-YTW : 4.47 %
W.PR.M FixedReset -1.06 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-15
Maturity Price : 25.00
Evaluated at bid price : 25.23
Bid-YTW : 5.14 %
BAM.PR.K Floater -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-21
Maturity Price : 10.59
Evaluated at bid price : 10.59
Bid-YTW : 4.52 %
FTS.PR.K FixedReset -1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-21
Maturity Price : 17.45
Evaluated at bid price : 17.45
Bid-YTW : 4.53 %
HSE.PR.E FixedReset 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-21
Maturity Price : 21.45
Evaluated at bid price : 21.45
Bid-YTW : 5.38 %
SLF.PR.H FixedReset 1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.50
Bid-YTW : 9.01 %
MFC.PR.I FixedReset 1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.35
Bid-YTW : 6.88 %
MFC.PR.B Deemed-Retractible 1.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.36
Bid-YTW : 6.30 %
MFC.PR.M FixedReset 1.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.67
Bid-YTW : 7.81 %
MFC.PR.N FixedReset 1.19 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.71
Bid-YTW : 7.70 %
GWO.PR.N FixedReset 1.28 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.47
Bid-YTW : 10.98 %
MFC.PR.C Deemed-Retractible 1.31 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.58
Bid-YTW : 6.68 %
TRP.PR.D FixedReset 1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-21
Maturity Price : 17.75
Evaluated at bid price : 17.75
Bid-YTW : 4.90 %
PWF.PR.P FixedReset 1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-21
Maturity Price : 13.71
Evaluated at bid price : 13.71
Bid-YTW : 4.63 %
RY.PR.J FixedReset 1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-21
Maturity Price : 20.32
Evaluated at bid price : 20.32
Bid-YTW : 4.57 %
TRP.PR.C FixedReset 1.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-21
Maturity Price : 13.15
Evaluated at bid price : 13.15
Bid-YTW : 4.72 %
IFC.PR.D FloatingReset 1.58 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.30
Bid-YTW : 6.95 %
HSE.PR.C FixedReset 1.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-21
Maturity Price : 19.95
Evaluated at bid price : 19.95
Bid-YTW : 5.32 %
IAG.PR.G FixedReset 1.70 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.35
Bid-YTW : 7.02 %
TRP.PR.G FixedReset 2.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-21
Maturity Price : 20.25
Evaluated at bid price : 20.25
Bid-YTW : 4.85 %
RY.PR.M FixedReset 2.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-21
Maturity Price : 19.91
Evaluated at bid price : 19.91
Bid-YTW : 4.54 %
SLF.PR.J FloatingReset 2.38 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.77
Bid-YTW : 10.20 %
Volume Highlights
Issue Index Shares
Traded
Notes
TRP.PR.K FixedReset 1,943,523 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-21
Maturity Price : 23.06
Evaluated at bid price : 24.80
Bid-YTW : 4.86 %
BAM.PF.I FixedReset 450,641 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-21
Maturity Price : 23.09
Evaluated at bid price : 24.86
Bid-YTW : 4.77 %
TD.PF.H FixedReset 303,700 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.42
Bid-YTW : 4.59 %
TRP.PR.D FixedReset 255,837 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-21
Maturity Price : 17.75
Evaluated at bid price : 17.75
Bid-YTW : 4.90 %
TRP.PR.E FixedReset 142,308 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-21
Maturity Price : 18.20
Evaluated at bid price : 18.20
Bid-YTW : 4.82 %
BNS.PR.N Deemed-Retractible 66,300 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-01-27
Maturity Price : 25.00
Evaluated at bid price : 25.19
Bid-YTW : 2.74 %
There were 41 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
W.PR.K FixedReset Quote: 25.30 – 25.99
Spot Rate : 0.6900
Average : 0.4921

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-01-15
Maturity Price : 25.00
Evaluated at bid price : 25.30
Bid-YTW : 5.10 %

PWF.PR.G Perpetual-Premium Quote: 25.41 – 25.71
Spot Rate : 0.3000
Average : 0.1901

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-12-21
Maturity Price : 25.00
Evaluated at bid price : 25.41
Bid-YTW : -9.58 %

TRP.PR.F FloatingReset Quote: 14.72 – 14.99
Spot Rate : 0.2700
Average : 0.1930

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-21
Maturity Price : 14.72
Evaluated at bid price : 14.72
Bid-YTW : 4.17 %

SLF.PR.G FixedReset Quote: 14.21 – 14.57
Spot Rate : 0.3600
Average : 0.2884

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.21
Bid-YTW : 10.36 %

PWF.PR.A Floater Quote: 12.05 – 12.35
Spot Rate : 0.3000
Average : 0.2292

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-21
Maturity Price : 12.05
Evaluated at bid price : 12.05
Bid-YTW : 3.94 %

PWF.PR.I Perpetual-Premium Quote: 25.43 – 25.67
Spot Rate : 0.2400
Average : 0.1701

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-12-21
Maturity Price : 25.00
Evaluated at bid price : 25.43
Bid-YTW : -10.33 %

Market Action

November 18, 2016

The war on banks has not been without its hilarious moments; JPMorgan provides another example:

JPMorgan Chase & Co. intern had poor grades at the Wharton School. His supervisor in Asia told colleagues that “he’s not really built” for investment banking. He had “attitude issues,” had trouble “following basic rules” and was a prolific napper. Yet in 2010 he was offered a full-time job, over the reservations of some executives.

Those details emerged on Thursday as JPMorgan agreed to pay about $264 million to settle U.S. allegations that it hired children of Chinese decision-makers to win business in violation of anti-bribery laws. Investigators described a systematic effort to curry favor with government officials and business executives.

The Wharton student’s father was an executive of a Taiwanese company offering an $800 million transaction to the bank. In an e-mail, one banker wrote, “The quid pro quo is an analyst job for his son.

The government’s 21-page agreement with JPMorgan ended an almost three-year investigation that set off a debate on Wall Street over whether U.S. business standards should be applied in foreign countries and whether favors to influential officials amounted to criminal activity.

U.S. officials said JPMorgan employees at the bank’s Hong Kong subsidiary sought to maximize profits by providing jobs and internships to children of individuals it hoped to do business with. In spite of a company policy prohibiting such quid pro quo, employees kept a spreadsheet that tracked the recruits and the revenue attributable to each one — and then doctored or altered paperwork about the hiring activity “to conceal the corrupt arrangement.” In all, the bank generated at least $35 million in profits as a result of those hires, U.S. officials said.

The WSJ has further details.

This is exactly how business is done in the West, except that we’re more adept at nodding and winking. Just ask Trust Fund Johnnie, Mayor of Toronto, about his long and arduous ascent to the executive ranks at Rogers.

I can just imagine the scenes at the prosecuting attorney’s offices … all those well paid government lackeys who got their jobs – and their entry to law school, and their partnerships at spiffy law firms – strictly on merit, dammit, strictly on merit, with just a little help from Daddykins, having apoplectic rages about horrific corruption. Of course, a lot of that is covered up by a disingenuous pleading that it’s because the hoi polloi wear brown shoes.

There’s plenty of merit in the financial services industry – more, now, with the rise of high frequency trading – but trust me, there’s no shortage of nods and winks either.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.4560 % 1,747.6
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.4560 % 3,192.5
Floater 4.29 % 4.46 % 47,153 16.44 4 0.4560 % 1,839.8
OpRet 0.00 % 0.00 % 0 0.00 0 0.4972 % 2,907.4
SplitShare 4.85 % 4.27 % 49,421 2.04 6 0.4972 % 3,472.1
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.4972 % 2,709.1
Perpetual-Premium 5.45 % 5.07 % 79,578 14.40 23 0.0682 % 2,654.9
Perpetual-Discount 5.38 % 5.38 % 93,432 14.86 15 0.1428 % 2,783.3
FixedReset 4.94 % 4.61 % 204,013 6.85 94 -0.0649 % 2,066.3
Deemed-Retractible 5.13 % 5.41 % 135,729 4.51 32 0.2959 % 2,754.6
FloatingReset 2.82 % 3.62 % 41,973 4.89 12 0.0043 % 2,301.0
Performance Highlights
Issue Index Change Notes
TRP.PR.G FixedReset -3.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-18
Maturity Price : 19.85
Evaluated at bid price : 19.85
Bid-YTW : 4.83 %
RY.PR.M FixedReset -2.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-18
Maturity Price : 19.51
Evaluated at bid price : 19.51
Bid-YTW : 4.52 %
BAM.PF.G FixedReset -1.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-18
Maturity Price : 20.63
Evaluated at bid price : 20.63
Bid-YTW : 4.76 %
CM.PR.Q FixedReset -1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-18
Maturity Price : 20.47
Evaluated at bid price : 20.47
Bid-YTW : 4.49 %
SLF.PR.H FixedReset -1.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.33
Bid-YTW : 9.10 %
HSE.PR.A FixedReset 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-18
Maturity Price : 12.11
Evaluated at bid price : 12.11
Bid-YTW : 5.34 %
SLF.PR.E Deemed-Retractible 1.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.52
Bid-YTW : 6.89 %
SLF.PR.D Deemed-Retractible 1.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.35
Bid-YTW : 6.95 %
PWF.PR.A Floater 1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-18
Maturity Price : 12.05
Evaluated at bid price : 12.05
Bid-YTW : 3.94 %
RY.PR.P Perpetual-Premium 1.36 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2025-02-24
Maturity Price : 25.00
Evaluated at bid price : 25.34
Bid-YTW : 5.07 %
IFC.PR.C FixedReset 1.58 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.30
Bid-YTW : 7.24 %
TRP.PR.B FixedReset 1.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-18
Maturity Price : 12.20
Evaluated at bid price : 12.20
Bid-YTW : 4.47 %
SLF.PR.A Deemed-Retractible 1.72 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.01
Bid-YTW : 6.14 %
Volume Highlights
Issue Index Shares
Traded
Notes
BAM.PF.I FixedReset 1,374,591 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-18
Maturity Price : 23.12
Evaluated at bid price : 24.95
Bid-YTW : 4.72 %
BNS.PR.N Deemed-Retractible 102,500 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-01-27
Maturity Price : 25.00
Evaluated at bid price : 25.21
Bid-YTW : 2.20 %
MFC.PR.O FixedReset 67,934 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-06-19
Maturity Price : 25.00
Evaluated at bid price : 25.90
Bid-YTW : 4.64 %
GWO.PR.I Deemed-Retractible 63,890 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.60
Bid-YTW : 6.83 %
BAM.PR.Z FixedReset 61,120 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-18
Maturity Price : 19.11
Evaluated at bid price : 19.11
Bid-YTW : 5.19 %
CM.PR.O FixedReset 55,900 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-18
Maturity Price : 19.10
Evaluated at bid price : 19.10
Bid-YTW : 4.36 %
There were 45 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
IFC.PR.D FloatingReset Quote: 19.00 – 22.50
Spot Rate : 3.5000
Average : 3.1566

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.00
Bid-YTW : 7.11 %

EML.PR.A FixedReset Quote: 25.90 – 26.29
Spot Rate : 0.3900
Average : 0.2437

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-17
Maturity Price : 25.00
Evaluated at bid price : 25.90
Bid-YTW : 4.99 %

IAG.PR.G FixedReset Quote: 20.01 – 20.44
Spot Rate : 0.4300
Average : 0.3057

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.01
Bid-YTW : 7.14 %

RY.PR.M FixedReset Quote: 19.51 – 19.82
Spot Rate : 0.3100
Average : 0.1997

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-18
Maturity Price : 19.51
Evaluated at bid price : 19.51
Bid-YTW : 4.52 %

BAM.PR.T FixedReset Quote: 15.96 – 16.28
Spot Rate : 0.3200
Average : 0.2158

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-18
Maturity Price : 15.96
Evaluated at bid price : 15.96
Bid-YTW : 5.13 %

HSE.PR.C FixedReset Quote: 19.63 – 19.96
Spot Rate : 0.3300
Average : 0.2440

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-18
Maturity Price : 19.63
Evaluated at bid price : 19.63
Bid-YTW : 5.30 %

Market Action

November 17, 2016

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.8740 % 1,739.7
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.8740 % 3,178.0
Floater 4.31 % 4.47 % 47,512 16.42 4 0.8740 % 1,831.5
OpRet 0.00 % 0.00 % 0 0.00 0 -0.1258 % 2,893.0
SplitShare 4.84 % 4.70 % 45,756 2.02 6 -0.1258 % 3,454.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.1258 % 2,695.7
Perpetual-Premium 5.45 % 5.13 % 82,875 14.57 23 0.5590 % 2,653.1
Perpetual-Discount 5.39 % 5.39 % 94,698 14.82 15 0.8398 % 2,779.4
FixedReset 4.93 % 4.58 % 195,501 6.78 93 -0.3137 % 2,067.6
Deemed-Retractible 5.14 % 5.44 % 132,216 4.51 32 0.6488 % 2,746.4
FloatingReset 2.82 % 3.61 % 42,192 4.89 12 -0.3094 % 2,300.9
Performance Highlights
Issue Index Change Notes
IFC.PR.D FloatingReset -2.81 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.00
Bid-YTW : 7.11 %
CU.PR.C FixedReset -2.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-17
Maturity Price : 19.40
Evaluated at bid price : 19.40
Bid-YTW : 4.24 %
BAM.PR.R FixedReset -2.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-17
Maturity Price : 16.10
Evaluated at bid price : 16.10
Bid-YTW : 4.93 %
SLF.PR.G FixedReset -1.88 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.10
Bid-YTW : 10.39 %
BAM.PR.X FixedReset -1.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-17
Maturity Price : 14.14
Evaluated at bid price : 14.14
Bid-YTW : 4.90 %
BMO.PR.M FixedReset -1.78 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.75
Bid-YTW : 3.89 %
BAM.PR.T FixedReset -1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-17
Maturity Price : 15.90
Evaluated at bid price : 15.90
Bid-YTW : 5.15 %
BAM.PR.Z FixedReset -1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-17
Maturity Price : 19.04
Evaluated at bid price : 19.04
Bid-YTW : 5.21 %
TRP.PR.G FixedReset -1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-17
Maturity Price : 20.50
Evaluated at bid price : 20.50
Bid-YTW : 4.68 %
RY.PR.J FixedReset -1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-17
Maturity Price : 20.13
Evaluated at bid price : 20.13
Bid-YTW : 4.50 %
SLF.PR.J FloatingReset -1.32 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.42
Bid-YTW : 10.48 %
CU.PR.I FixedReset -1.31 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-01
Maturity Price : 25.00
Evaluated at bid price : 25.71
Bid-YTW : 3.71 %
BMO.PR.Y FixedReset -1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-17
Maturity Price : 20.81
Evaluated at bid price : 20.81
Bid-YTW : 4.37 %
BMO.PR.Q FixedReset -1.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.93
Bid-YTW : 6.48 %
GWO.PR.N FixedReset -1.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.20
Bid-YTW : 11.20 %
BAM.PF.E FixedReset -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-17
Maturity Price : 19.22
Evaluated at bid price : 19.22
Bid-YTW : 4.77 %
FTS.PR.M FixedReset -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-17
Maturity Price : 19.30
Evaluated at bid price : 19.30
Bid-YTW : 4.51 %
GWO.PR.G Deemed-Retractible 1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.45
Bid-YTW : 5.68 %
GWO.PR.I Deemed-Retractible 1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.47
Bid-YTW : 6.92 %
VNR.PR.A FixedReset 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-17
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 4.94 %
FTS.PR.J Perpetual-Discount 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-17
Maturity Price : 22.31
Evaluated at bid price : 22.61
Bid-YTW : 5.26 %
GWO.PR.H Deemed-Retractible 1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.06
Bid-YTW : 6.21 %
BNS.PR.R FixedReset 1.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.33
Bid-YTW : 3.85 %
BAM.PR.C Floater 1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-17
Maturity Price : 10.64
Evaluated at bid price : 10.64
Bid-YTW : 4.49 %
FTS.PR.H FixedReset 1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-17
Maturity Price : 13.87
Evaluated at bid price : 13.87
Bid-YTW : 4.25 %
CU.PR.D Perpetual-Discount 1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-17
Maturity Price : 22.89
Evaluated at bid price : 23.30
Bid-YTW : 5.25 %
POW.PR.A Perpetual-Premium 1.21 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-12-17
Maturity Price : 25.00
Evaluated at bid price : 25.16
Bid-YTW : 3.97 %
CU.PR.E Perpetual-Discount 1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-17
Maturity Price : 22.84
Evaluated at bid price : 23.24
Bid-YTW : 5.27 %
CU.PR.H Perpetual-Premium 1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-17
Maturity Price : 24.45
Evaluated at bid price : 24.86
Bid-YTW : 5.28 %
IFC.PR.C FixedReset 1.33 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.00
Bid-YTW : 7.47 %
TRP.PR.H FloatingReset 1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-17
Maturity Price : 11.15
Evaluated at bid price : 11.15
Bid-YTW : 3.94 %
SLF.PR.D Deemed-Retractible 1.39 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.09
Bid-YTW : 7.14 %
PWF.PR.S Perpetual-Discount 1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-17
Maturity Price : 22.09
Evaluated at bid price : 22.35
Bid-YTW : 5.41 %
POW.PR.D Perpetual-Discount 1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-17
Maturity Price : 23.36
Evaluated at bid price : 23.65
Bid-YTW : 5.34 %
GWO.PR.Q Deemed-Retractible 1.42 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.25
Bid-YTW : 5.76 %
TRP.PR.F FloatingReset 1.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-17
Maturity Price : 14.91
Evaluated at bid price : 14.91
Bid-YTW : 4.03 %
SLF.PR.E Deemed-Retractible 1.67 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.26
Bid-YTW : 7.07 %
POW.PR.B Perpetual-Premium 1.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-17
Maturity Price : 24.51
Evaluated at bid price : 24.76
Bid-YTW : 5.46 %
IAG.PR.A Deemed-Retractible 1.82 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.40
Bid-YTW : 6.38 %
MFC.PR.C Deemed-Retractible 1.86 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.40
Bid-YTW : 6.99 %
SLF.PR.B Deemed-Retractible 1.87 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.85
Bid-YTW : 6.30 %
SLF.PR.C Deemed-Retractible 1.92 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.25
Bid-YTW : 7.02 %
MFC.PR.B Deemed-Retractible 2.29 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.30
Bid-YTW : 6.53 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PR.T FloatingReset 101,500 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.41
Bid-YTW : 3.34 %
BMO.PR.B FixedReset 98,860 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-02-25
Maturity Price : 25.00
Evaluated at bid price : 25.40
Bid-YTW : 4.61 %
NA.PR.X FixedReset 93,600 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-15
Maturity Price : 25.00
Evaluated at bid price : 26.22
Bid-YTW : 4.43 %
TD.PF.H FixedReset 88,135 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.35
Bid-YTW : 4.64 %
BNS.PR.H FixedReset 83,950 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-01-26
Maturity Price : 25.00
Evaluated at bid price : 25.60
Bid-YTW : 4.53 %
RY.PR.Q FixedReset 83,710 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-24
Maturity Price : 25.00
Evaluated at bid price : 26.01
Bid-YTW : 4.50 %
There were 84 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
IFC.PR.D FloatingReset Quote: 19.00 – 22.50
Spot Rate : 3.5000
Average : 2.7801

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.00
Bid-YTW : 7.11 %

GWO.PR.N FixedReset Quote: 13.20 – 13.62
Spot Rate : 0.4200
Average : 0.2871

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.20
Bid-YTW : 11.20 %

PWF.PR.O Perpetual-Premium Quote: 25.39 – 25.72
Spot Rate : 0.3300
Average : 0.2102

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.39
Bid-YTW : 5.13 %

BAM.PR.X FixedReset Quote: 14.14 – 14.54
Spot Rate : 0.4000
Average : 0.2867

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-17
Maturity Price : 14.14
Evaluated at bid price : 14.14
Bid-YTW : 4.90 %

PWF.PR.S Perpetual-Discount Quote: 22.35 – 22.67
Spot Rate : 0.3200
Average : 0.2133

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-17
Maturity Price : 22.09
Evaluated at bid price : 22.35
Bid-YTW : 5.41 %

SLF.PR.D Deemed-Retractible Quote: 21.09 – 21.35
Spot Rate : 0.2600
Average : 0.1609

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.09
Bid-YTW : 7.14 %

Market Action

November 16, 2016

Remember the thirty months following the dividend reset on TRP.PR.A that kicked off the bear market. Wasn’t that awful? It seems like every day the Government of Canada Five Year Yield would go down a little bit and the preferred share market would go down in sympathy.

Well, things are different now, thanks to President-elect Trump and his intended fiscal stimulus! Now the Government of Canada Five Year Yield goes up a little nearly every day and the preferred share market goes down in sympathy. Totally different environment.

PerpetualDiscounts now yield 5.39%, equivalent to 7.01% interest at the standard equivalency factor of 1.3x. Long corporates now yield just over 4.0%, so the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) is now about 300bp, a dramatic widening from the 275bp reported November 9.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.4123 % 1,724.6
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.4123 % 3,150.5
Floater 4.35 % 4.51 % 47,439 16.35 4 -0.4123 % 1,815.6
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0728 % 2,896.7
SplitShare 4.83 % 4.77 % 45,468 4.32 6 -0.0728 % 3,459.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0728 % 2,699.1
Perpetual-Premium 5.48 % 5.32 % 83,203 14.53 23 -0.8627 % 2,638.4
Perpetual-Discount 5.44 % 5.41 % 90,140 14.76 15 -0.6209 % 2,756.2
FixedReset 4.91 % 4.63 % 186,769 6.79 93 -1.2917 % 2,074.1
Deemed-Retractible 5.17 % 5.35 % 131,963 4.51 32 -0.4450 % 2,728.7
FloatingReset 2.81 % 3.54 % 42,475 4.90 12 -0.6318 % 2,308.0
Performance Highlights
Issue Index Change Notes
TRP.PR.C FixedReset -3.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 13.09
Evaluated at bid price : 13.09
Bid-YTW : 4.58 %
TRP.PR.B FixedReset -3.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 12.01
Evaluated at bid price : 12.01
Bid-YTW : 4.54 %
TRP.PR.F FloatingReset -3.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 14.70
Evaluated at bid price : 14.70
Bid-YTW : 4.09 %
TRP.PR.A FixedReset -2.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 15.28
Evaluated at bid price : 15.28
Bid-YTW : 4.78 %
RY.PR.P Perpetual-Premium -2.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 24.40
Evaluated at bid price : 24.80
Bid-YTW : 5.30 %
BAM.PF.A FixedReset -2.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 19.47
Evaluated at bid price : 19.47
Bid-YTW : 5.02 %
BAM.PF.E FixedReset -2.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 19.43
Evaluated at bid price : 19.43
Bid-YTW : 4.72 %
BAM.PF.F FixedReset -2.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 20.67
Evaluated at bid price : 20.67
Bid-YTW : 4.73 %
TRP.PR.H FloatingReset -2.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 11.00
Evaluated at bid price : 11.00
Bid-YTW : 3.99 %
RY.PR.M FixedReset -2.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 20.09
Evaluated at bid price : 20.09
Bid-YTW : 4.39 %
BAM.PR.X FixedReset -2.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 14.41
Evaluated at bid price : 14.41
Bid-YTW : 4.81 %
MFC.PR.I FixedReset -2.39 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.45
Bid-YTW : 6.88 %
BAM.PR.Z FixedReset -2.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 19.33
Evaluated at bid price : 19.33
Bid-YTW : 5.13 %
FTS.PR.H FixedReset -2.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 13.71
Evaluated at bid price : 13.71
Bid-YTW : 4.30 %
IFC.PR.C FixedReset -2.34 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.75
Bid-YTW : 7.66 %
CM.PR.P FixedReset -2.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 18.58
Evaluated at bid price : 18.58
Bid-YTW : 4.38 %
GWO.PR.N FixedReset -2.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.35
Bid-YTW : 11.03 %
FTS.PR.M FixedReset -2.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 19.51
Evaluated at bid price : 19.51
Bid-YTW : 4.46 %
HSE.PR.G FixedReset -2.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 21.47
Evaluated at bid price : 21.47
Bid-YTW : 5.24 %
VNR.PR.A FixedReset -2.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 18.80
Evaluated at bid price : 18.80
Bid-YTW : 4.99 %
MFC.PR.M FixedReset -2.18 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.82
Bid-YTW : 7.79 %
MFC.PR.N FixedReset -2.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.90
Bid-YTW : 7.65 %
HSE.PR.E FixedReset -2.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 21.18
Evaluated at bid price : 21.18
Bid-YTW : 5.34 %
CM.PR.Q FixedReset -2.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 20.76
Evaluated at bid price : 20.76
Bid-YTW : 4.43 %
RY.PR.J FixedReset -2.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 20.41
Evaluated at bid price : 20.41
Bid-YTW : 4.44 %
RY.PR.W Perpetual-Premium -2.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 24.02
Evaluated at bid price : 24.27
Bid-YTW : 5.06 %
BAM.PF.B FixedReset -2.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 18.16
Evaluated at bid price : 18.16
Bid-YTW : 5.04 %
BAM.PF.G FixedReset -2.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 21.00
Evaluated at bid price : 21.00
Bid-YTW : 4.67 %
GWO.PR.Q Deemed-Retractible -2.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.91
Bid-YTW : 5.97 %
MFC.PR.H FixedReset -2.00 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.00
Bid-YTW : 6.04 %
POW.PR.D Perpetual-Discount -1.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 23.06
Evaluated at bid price : 23.32
Bid-YTW : 5.41 %
TD.PF.F Perpetual-Premium -1.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 23.91
Evaluated at bid price : 24.29
Bid-YTW : 5.07 %
TD.PF.E FixedReset -1.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 21.25
Evaluated at bid price : 21.25
Bid-YTW : 4.43 %
MFC.PR.G FixedReset -1.84 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.76
Bid-YTW : 6.61 %
BNS.PR.R FixedReset -1.84 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.06
Bid-YTW : 4.09 %
IAG.PR.A Deemed-Retractible -1.79 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.00
Bid-YTW : 6.65 %
CM.PR.O FixedReset -1.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 19.06
Evaluated at bid price : 19.06
Bid-YTW : 4.37 %
MFC.PR.J FixedReset -1.73 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.36
Bid-YTW : 7.43 %
HSE.PR.A FixedReset -1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 12.04
Evaluated at bid price : 12.04
Bid-YTW : 5.37 %
CU.PR.I FixedReset -1.70 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-01
Maturity Price : 25.00
Evaluated at bid price : 26.05
Bid-YTW : 3.35 %
BNS.PR.Q FixedReset -1.69 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.86
Bid-YTW : 4.01 %
ELF.PR.G Perpetual-Discount -1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 21.91
Evaluated at bid price : 22.15
Bid-YTW : 5.41 %
BAM.PR.C Floater -1.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 10.52
Evaluated at bid price : 10.52
Bid-YTW : 4.54 %
MFC.PR.L FixedReset -1.67 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.28
Bid-YTW : 8.02 %
MFC.PR.K FixedReset -1.66 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.82
Bid-YTW : 8.31 %
RY.PR.O Perpetual-Premium -1.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 23.89
Evaluated at bid price : 24.26
Bid-YTW : 5.05 %
PWF.PR.T FixedReset -1.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 19.84
Evaluated at bid price : 19.84
Bid-YTW : 4.25 %
BAM.PR.T FixedReset -1.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 16.15
Evaluated at bid price : 16.15
Bid-YTW : 5.06 %
RY.PR.N Perpetual-Premium -1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 23.90
Evaluated at bid price : 24.27
Bid-YTW : 5.05 %
POW.PR.B Perpetual-Premium -1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 24.09
Evaluated at bid price : 24.35
Bid-YTW : 5.55 %
TD.PF.B FixedReset -1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 18.53
Evaluated at bid price : 18.53
Bid-YTW : 4.40 %
FTS.PR.K FixedReset -1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 17.65
Evaluated at bid price : 17.65
Bid-YTW : 4.33 %
BNS.PR.G FixedReset -1.48 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-07-25
Maturity Price : 25.00
Evaluated at bid price : 26.02
Bid-YTW : 4.63 %
RY.PR.Q FixedReset -1.44 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-24
Maturity Price : 25.00
Evaluated at bid price : 25.95
Bid-YTW : 4.56 %
TRP.PR.D FixedReset -1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 17.77
Evaluated at bid price : 17.77
Bid-YTW : 4.75 %
NA.PR.X FixedReset -1.44 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-15
Maturity Price : 25.00
Evaluated at bid price : 26.02
Bid-YTW : 4.62 %
TD.PF.G FixedReset -1.44 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 26.05
Bid-YTW : 4.53 %
TD.PF.D FixedReset -1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 20.76
Evaluated at bid price : 20.76
Bid-YTW : 4.43 %
BNS.PR.E FixedReset -1.36 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-25
Maturity Price : 25.00
Evaluated at bid price : 26.06
Bid-YTW : 4.54 %
SLF.PR.H FixedReset -1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.66
Bid-YTW : 8.79 %
MFC.PR.F FixedReset -1.32 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.42
Bid-YTW : 11.03 %
TRP.PR.E FixedReset -1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 18.16
Evaluated at bid price : 18.16
Bid-YTW : 4.70 %
PWF.PR.S Perpetual-Discount -1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 21.75
Evaluated at bid price : 22.04
Bid-YTW : 5.48 %
RY.PR.R FixedReset -1.29 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-24
Maturity Price : 25.00
Evaluated at bid price : 26.06
Bid-YTW : 4.51 %
SLF.PR.G FixedReset -1.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.37
Bid-YTW : 10.10 %
BNS.PR.Y FixedReset -1.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.65
Bid-YTW : 5.78 %
BMO.PR.S FixedReset -1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 19.30
Evaluated at bid price : 19.30
Bid-YTW : 4.30 %
POW.PR.A Perpetual-Premium -1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 24.60
Evaluated at bid price : 24.86
Bid-YTW : 5.69 %
HSE.PR.C FixedReset -1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 19.55
Evaluated at bid price : 19.55
Bid-YTW : 5.32 %
BMO.PR.Z Perpetual-Premium -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 24.11
Evaluated at bid price : 24.50
Bid-YTW : 5.10 %
RY.PR.H FixedReset -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 18.95
Evaluated at bid price : 18.95
Bid-YTW : 4.29 %
MFC.PR.C Deemed-Retractible -1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.01
Bid-YTW : 7.27 %
IGM.PR.B Perpetual-Premium -1.02 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.15
Bid-YTW : 5.76 %
GWO.PR.R Deemed-Retractible -1.02 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.40
Bid-YTW : 6.60 %
PWF.PR.L Perpetual-Premium -1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 23.44
Evaluated at bid price : 23.73
Bid-YTW : 5.41 %
Volume Highlights
Issue Index Shares
Traded
Notes
BMO.PR.B FixedReset 101,296 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-02-25
Maturity Price : 25.00
Evaluated at bid price : 25.27
Bid-YTW : 4.72 %
PWF.PR.P FixedReset 95,750 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 13.40
Evaluated at bid price : 13.40
Bid-YTW : 4.58 %
TRP.PR.H FloatingReset 86,200 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 11.00
Evaluated at bid price : 11.00
Bid-YTW : 3.99 %
BMO.PR.L Deemed-Retractible 74,568 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-05-25
Maturity Price : 25.00
Evaluated at bid price : 25.25
Bid-YTW : 3.57 %
RY.PR.A Deemed-Retractible 61,968 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-12-16
Maturity Price : 25.00
Evaluated at bid price : 25.00
Bid-YTW : 3.29 %
RY.PR.G Deemed-Retractible 61,960 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-12-16
Maturity Price : 25.00
Evaluated at bid price : 25.01
Bid-YTW : 2.83 %
There were 81 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
IFC.PR.D FloatingReset Quote: 19.55 – 22.00
Spot Rate : 2.4500
Average : 1.9908

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.55
Bid-YTW : 6.69 %

RY.PR.W Perpetual-Premium Quote: 24.27 – 24.80
Spot Rate : 0.5300
Average : 0.3263

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 24.02
Evaluated at bid price : 24.27
Bid-YTW : 5.06 %

W.PR.K FixedReset Quote: 25.28 – 25.89
Spot Rate : 0.6100
Average : 0.4140

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-01-15
Maturity Price : 25.00
Evaluated at bid price : 25.28
Bid-YTW : 5.10 %

TRP.PR.H FloatingReset Quote: 11.00 – 11.50
Spot Rate : 0.5000
Average : 0.3420

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 11.00
Evaluated at bid price : 11.00
Bid-YTW : 3.99 %

RY.PR.P Perpetual-Premium Quote: 24.80 – 25.25
Spot Rate : 0.4500
Average : 0.3066

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 24.40
Evaluated at bid price : 24.80
Bid-YTW : 5.30 %

POW.PR.A Perpetual-Premium Quote: 24.86 – 25.15
Spot Rate : 0.2900
Average : 0.1676

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-16
Maturity Price : 24.60
Evaluated at bid price : 24.86
Bid-YTW : 5.69 %