Category: Market Action

Market Action

October 3, 2016

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.2550 % 1,709.9
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.2550 % 3,123.6
Floater 4.37 % 4.54 % 40,011 16.38 4 0.2550 % 1,800.2
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0796 % 2,890.6
SplitShare 4.84 % 4.69 % 72,552 2.14 6 -0.0796 % 3,451.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0796 % 2,693.3
Perpetual-Premium 5.33 % 4.68 % 66,805 2.10 23 0.0616 % 2,690.4
Perpetual-Discount 5.10 % 5.15 % 98,314 15.15 15 -0.2022 % 2,917.6
FixedReset 4.93 % 4.27 % 148,204 6.95 92 -0.1620 % 2,055.0
Deemed-Retractible 5.02 % 2.59 % 114,307 0.32 32 -0.0381 % 2,805.1
FloatingReset 3.04 % 4.31 % 40,866 4.96 12 -0.7959 % 2,190.3
Performance Highlights
Issue Index Change Notes
IFC.PR.D FloatingReset -10.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.50
Bid-YTW : 10.05 %
SLF.PR.K FloatingReset -1.54 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.00
Bid-YTW : 8.93 %
MFC.PR.F FixedReset -1.37 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.63
Bid-YTW : 10.49 %
PWF.PR.P FixedReset -1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-03
Maturity Price : 13.20
Evaluated at bid price : 13.20
Bid-YTW : 4.29 %
BAM.PF.G FixedReset -1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-03
Maturity Price : 20.21
Evaluated at bid price : 20.21
Bid-YTW : 4.55 %
BAM.PF.B FixedReset -1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-03
Maturity Price : 17.60
Evaluated at bid price : 17.60
Bid-YTW : 4.84 %
TRP.PR.H FloatingReset -1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-03
Maturity Price : 10.58
Evaluated at bid price : 10.58
Bid-YTW : 4.28 %
SLF.PR.G FixedReset -1.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.14
Bid-YTW : 9.99 %
BAM.PF.A FixedReset -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-03
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 4.79 %
FTS.PR.K FixedReset 1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-03
Maturity Price : 17.95
Evaluated at bid price : 17.95
Bid-YTW : 3.97 %
VNR.PR.A FixedReset 1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-03
Maturity Price : 18.66
Evaluated at bid price : 18.66
Bid-YTW : 4.75 %
Volume Highlights
Issue Index Shares
Traded
Notes
TRP.PR.D FixedReset 43,200 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-03
Maturity Price : 17.92
Evaluated at bid price : 17.92
Bid-YTW : 4.36 %
TD.PR.S FixedReset 40,700 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.80
Bid-YTW : 3.76 %
TRP.PR.J FixedReset 30,247 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-31
Maturity Price : 25.00
Evaluated at bid price : 26.61
Bid-YTW : 4.11 %
RY.PR.I FixedReset 25,871 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.15
Bid-YTW : 3.79 %
TD.PF.G FixedReset 23,345 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 26.92
Bid-YTW : 3.90 %
BAM.PF.E FixedReset 23,160 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-03
Maturity Price : 18.87
Evaluated at bid price : 18.87
Bid-YTW : 4.54 %
There were 16 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
IFC.PR.D FloatingReset Quote: 15.50 – 24.00
Spot Rate : 8.5000
Average : 4.9225

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.50
Bid-YTW : 10.05 %

CGI.PR.D SplitShare Quote: 24.80 – 25.29
Spot Rate : 0.4900
Average : 0.3132

YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2023-06-14
Maturity Price : 25.00
Evaluated at bid price : 24.80
Bid-YTW : 3.94 %

SLF.PR.K FloatingReset Quote: 16.00 – 17.00
Spot Rate : 1.0000
Average : 0.8808

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.00
Bid-YTW : 8.93 %

NA.PR.S FixedReset Quote: 18.68 – 18.94
Spot Rate : 0.2600
Average : 0.1567

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-03
Maturity Price : 18.68
Evaluated at bid price : 18.68
Bid-YTW : 4.29 %

SLF.PR.G FixedReset Quote: 14.14 – 14.45
Spot Rate : 0.3100
Average : 0.2232

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.14
Bid-YTW : 9.99 %

IFC.PR.A FixedReset Quote: 15.40 – 15.75
Spot Rate : 0.3500
Average : 0.2643

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.40
Bid-YTW : 9.55 %

Market Action

September 30, 2016

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.1601 % 1,705.6
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.1601 % 3,115.7
Floater 4.85 % 4.57 % 84,784 16.27 4 0.1601 % 1,795.6
OpRet 0.00 % 0.00 % 0 0.00 0 -0.1587 % 2,892.9
SplitShare 5.06 % 4.75 % 75,123 2.15 5 -0.1587 % 3,454.7
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.1587 % 2,695.5
Perpetual-Premium 5.50 % 4.63 % 64,566 1.94 12 0.0228 % 2,688.8
Perpetual-Discount 5.12 % 5.00 % 88,673 15.04 26 0.1755 % 2,923.5
FixedReset 4.92 % 4.20 % 148,214 6.98 92 0.2689 % 2,058.4
Deemed-Retractible 5.01 % 4.79 % 111,878 1.20 32 0.1268 % 2,806.2
FloatingReset 2.84 % 4.37 % 32,078 4.98 12 0.2467 % 2,207.9
Performance Highlights
Issue Index Change Notes
RY.PR.M FixedReset 1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-30
Maturity Price : 20.17
Evaluated at bid price : 20.17
Bid-YTW : 4.12 %
TD.PR.T FloatingReset 1.02 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.82
Bid-YTW : 3.95 %
BNS.PR.Q FixedReset 1.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.97
Bid-YTW : 3.63 %
CM.PR.Q FixedReset 1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-30
Maturity Price : 20.34
Evaluated at bid price : 20.34
Bid-YTW : 4.20 %
RY.PR.J FixedReset 1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-30
Maturity Price : 20.47
Evaluated at bid price : 20.47
Bid-YTW : 4.17 %
BIP.PR.A FixedReset 1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-30
Maturity Price : 20.74
Evaluated at bid price : 20.74
Bid-YTW : 5.11 %
FTS.PR.H FixedReset 1.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-30
Maturity Price : 14.10
Evaluated at bid price : 14.10
Bid-YTW : 3.79 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PF.H FixedReset 198,923 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.75
Bid-YTW : 4.31 %
BIP.PR.C FixedReset 68,011 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-09-30
Maturity Price : 25.00
Evaluated at bid price : 25.55
Bid-YTW : 4.88 %
CM.PR.O FixedReset 53,294 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-30
Maturity Price : 18.81
Evaluated at bid price : 18.81
Bid-YTW : 4.06 %
BAM.PR.T FixedReset 42,777 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-30
Maturity Price : 15.46
Evaluated at bid price : 15.46
Bid-YTW : 4.79 %
BNS.PR.G FixedReset 42,553 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-07-25
Maturity Price : 25.00
Evaluated at bid price : 26.70
Bid-YTW : 3.87 %
BNS.PR.H FixedReset 38,985 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-01-26
Maturity Price : 25.00
Evaluated at bid price : 25.82
Bid-YTW : 4.22 %
There were 24 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
EML.PR.A FixedReset Quote: 26.31 – 26.75
Spot Rate : 0.4400
Average : 0.3145

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-17
Maturity Price : 25.00
Evaluated at bid price : 26.31
Bid-YTW : 4.43 %

VNR.PR.A FixedReset Quote: 18.43 – 18.89
Spot Rate : 0.4600
Average : 0.3435

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-30
Maturity Price : 18.43
Evaluated at bid price : 18.43
Bid-YTW : 4.77 %

IGM.PR.B Perpetual-Premium Quote: 25.30 – 25.59
Spot Rate : 0.2900
Average : 0.1968

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.30
Bid-YTW : 5.13 %

ELF.PR.F Perpetual-Discount Quote: 24.72 – 25.05
Spot Rate : 0.3300
Average : 0.2501

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-30
Maturity Price : 24.49
Evaluated at bid price : 24.72
Bid-YTW : 5.37 %

BMO.PR.R FloatingReset Quote: 22.41 – 22.70
Spot Rate : 0.2900
Average : 0.2239

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.41
Bid-YTW : 4.37 %

GWO.PR.G Deemed-Retractible Quote: 25.00 – 25.19
Spot Rate : 0.1900
Average : 0.1302

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.00
Bid-YTW : 5.23 %

Market Action

September 29, 2016

UPS is attempting to catch up in the drone wars:

UPS, despite its decades of delivery experience, is a latecomer to the drone delivery game. Drone startup Flirtey demonstrated a ship-to-shore drone delivery of medical supplies off the coast of New Jersey earlier this summer, and drone delivery company Zipline declared its intent to delivery needed blood to rural populations in Washington State’s San Juan islands.

And it’s not just startups that are already doing delivery. Amazon’s drone program is perhaps the most famous, but Europe’s own DHL delivery giant experimented with drones in difficult mountain terrain. Chinese online retailer JD.com is also exploring drone delivery in marshy and channel-crossed provinces, where flying drones can fly easily over the car-impassible waterways. That UPS is experimenting with drone technology is more a testament to the technology’s broad appeal than any particular innovation by the company itself.

On a related note, Tyler Cowen of Bloomberg claims that technology favours suburbia:

Self-driving vehicles are also likely to help the suburbs most. One of the worst things about the suburbs is the commute to the city or to other parts of the suburbs. But what if you could read, text or watch TV – safely — during that commuting time? What if you could tackle your day’s work just as you do on a train or plane? Commuting would seem a lot less painful. As driverless vehicles evolve to accommodate work and leisure uses of the automobile space, pleasure will replace commuting stress.

What about drones? They too would seem to favor remote areas where it is harder to access useful goods and services. Drones may do more for exurbs and rural areas than for the suburbs, but it seems cities will gain least. Walking or biking to nearby shops is a potential substitute for drone delivery. Rolling sidewalk drones might find it harder to negotiate crowded cities, and cities with a dense network of tall buildings may be less friendly to flying drones. Population density may increase the risk of a drone falling on someone.

Jared Dillian writes in Forbes about the message we’re sending to the Chinese:

Shockwaves reverberated through Canada last week as the government announced that negotiations would commence on an extradition treaty between Canada and China.
…
Make no mistake about it–from Canada’s perspective, this has everything to do with money laundering–and the torrid housing market. In fact, supporters of the extradition treaty directly cite the inability of middle class Canadian families to buy homes that have become prohibitively expensive, due to foreign capital pouring into the country.
…
But Canada should really reflect on whether they want a reversal of those capital flows. History has not been kind to countries that have slammed the door shut on foreign investment. And money always goes to where it is treated best. So if Canada becomes hostile to Chinese money, it will find somewhere else to go. And I’m sure lots of countries would be happy to take it.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.2307 % 1,702.8
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.2307 % 3,110.7
Floater 4.86 % 4.59 % 88,221 16.24 4 -0.2307 % 1,792.7
OpRet 0.00 % 0.00 % 0 0.00 0 0.1749 % 2,897.5
SplitShare 5.05 % 4.67 % 75,682 2.15 5 0.1749 % 3,460.2
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1749 % 2,699.8
Perpetual-Premium 5.50 % 4.63 % 64,580 1.94 12 -0.0781 % 2,688.1
Perpetual-Discount 5.13 % 5.02 % 91,923 15.08 26 0.0435 % 2,918.4
FixedReset 4.96 % 4.25 % 148,773 6.98 92 0.1850 % 2,052.8
Deemed-Retractible 5.02 % 4.52 % 111,994 1.21 32 0.0178 % 2,802.7
FloatingReset 2.84 % 4.40 % 32,262 4.97 12 0.1226 % 2,202.4
Performance Highlights
Issue Index Change Notes
ELF.PR.G Perpetual-Discount -1.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-29
Maturity Price : 22.42
Evaluated at bid price : 22.68
Bid-YTW : 5.24 %
TRP.PR.F FloatingReset -1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-29
Maturity Price : 13.95
Evaluated at bid price : 13.95
Bid-YTW : 4.40 %
PWF.PR.T FixedReset 1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-29
Maturity Price : 19.59
Evaluated at bid price : 19.59
Bid-YTW : 4.02 %
BAM.PF.G FixedReset 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-29
Maturity Price : 20.43
Evaluated at bid price : 20.43
Bid-YTW : 4.47 %
BAM.PR.R FixedReset 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-29
Maturity Price : 15.94
Evaluated at bid price : 15.94
Bid-YTW : 4.60 %
TRP.PR.C FixedReset 1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-29
Maturity Price : 13.45
Evaluated at bid price : 13.45
Bid-YTW : 4.00 %
BAM.PF.A FixedReset 1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-29
Maturity Price : 19.25
Evaluated at bid price : 19.25
Bid-YTW : 4.69 %
BAM.PF.B FixedReset 1.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-29
Maturity Price : 17.72
Evaluated at bid price : 17.72
Bid-YTW : 4.77 %
CU.PR.C FixedReset 1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-29
Maturity Price : 18.07
Evaluated at bid price : 18.07
Bid-YTW : 4.21 %
MFC.PR.F FixedReset 2.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.75
Bid-YTW : 10.33 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PF.H FixedReset 299,386 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.75
Bid-YTW : 4.30 %
BNS.PR.H FixedReset 168,425 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-01-26
Maturity Price : 25.00
Evaluated at bid price : 25.77
Bid-YTW : 4.26 %
BMO.PR.L Deemed-Retractible 69,657 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-10-29
Maturity Price : 25.25
Evaluated at bid price : 25.71
Bid-YTW : -9.38 %
BNS.PR.O Deemed-Retractible 54,300 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-10-29
Maturity Price : 25.25
Evaluated at bid price : 25.68
Bid-YTW : -4.00 %
RY.PR.R FixedReset 53,800 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-24
Maturity Price : 25.00
Evaluated at bid price : 26.85
Bid-YTW : 3.98 %
RY.PR.I FixedReset 51,750 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.15
Bid-YTW : 3.77 %
There were 35 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
IAG.PR.A Deemed-Retractible Quote: 23.06 – 23.50
Spot Rate : 0.4400
Average : 0.3330

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.06
Bid-YTW : 5.82 %

FTS.PR.F Perpetual-Discount Quote: 24.67 – 24.95
Spot Rate : 0.2800
Average : 0.1857

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-29
Maturity Price : 24.43
Evaluated at bid price : 24.67
Bid-YTW : 5.01 %

MFC.PR.O FixedReset Quote: 26.66 – 26.91
Spot Rate : 0.2500
Average : 0.1739

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-06-19
Maturity Price : 25.00
Evaluated at bid price : 26.66
Bid-YTW : 4.11 %

BNS.PR.E FixedReset Quote: 26.80 – 27.00
Spot Rate : 0.2000
Average : 0.1272

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-25
Maturity Price : 25.00
Evaluated at bid price : 26.80
Bid-YTW : 4.02 %

BNS.PR.A FloatingReset Quote: 23.11 – 23.36
Spot Rate : 0.2500
Average : 0.1789

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.11
Bid-YTW : 4.17 %

CU.PR.D Perpetual-Discount Quote: 24.56 – 24.80
Spot Rate : 0.2400
Average : 0.1739

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-29
Maturity Price : 24.08
Evaluated at bid price : 24.56
Bid-YTW : 5.02 %

Market Action

September 28, 2016

PerpetualDiscounts now yield 5.01%, equivalent to 6.51% interest at the standard equivalency factor of 1.3x. Long corporates now yield about 3.6%, so the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) is now about 290bp, unchanged from September 14.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.4995 % 1,706.8
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.4995 % 3,117.9
Floater 4.85 % 4.55 % 89,473 16.32 4 0.4995 % 1,796.9
OpRet 0.00 % 0.00 % 0 0.00 0 0.3063 % 2,892.4
SplitShare 5.06 % 4.46 % 76,540 2.16 5 0.3063 % 3,454.1
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.3063 % 2,695.1
Perpetual-Premium 5.50 % 4.64 % 65,468 1.94 12 0.1594 % 2,690.2
Perpetual-Discount 5.12 % 5.01 % 93,077 15.06 26 0.1724 % 2,917.1
FixedReset 4.97 % 4.24 % 152,550 6.98 92 0.1825 % 2,049.0
Deemed-Retractible 5.02 % 2.24 % 110,411 0.33 32 0.0827 % 2,802.2
FloatingReset 2.84 % 4.45 % 40,814 4.97 12 0.1931 % 2,199.7
Performance Highlights
Issue Index Change Notes
GRP.PR.A SplitShare 1.04 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-10-28
Maturity Price : 25.00
Evaluated at bid price : 25.35
Bid-YTW : -13.73 %
BAM.PR.R FixedReset 1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-28
Maturity Price : 15.77
Evaluated at bid price : 15.77
Bid-YTW : 4.65 %
FTS.PR.M FixedReset 1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-28
Maturity Price : 19.55
Evaluated at bid price : 19.55
Bid-YTW : 4.17 %
TRP.PR.C FixedReset 1.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-28
Maturity Price : 13.30
Evaluated at bid price : 13.30
Bid-YTW : 4.04 %
ELF.PR.G Perpetual-Discount 1.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-28
Maturity Price : 22.82
Evaluated at bid price : 23.10
Bid-YTW : 5.14 %
TRP.PR.F FloatingReset 1.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-28
Maturity Price : 14.12
Evaluated at bid price : 14.12
Bid-YTW : 4.34 %
TRP.PR.H FloatingReset 2.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-28
Maturity Price : 10.70
Evaluated at bid price : 10.70
Bid-YTW : 4.23 %
SLF.PR.G FixedReset 2.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.33
Bid-YTW : 9.76 %
Volume Highlights
Issue Index Shares
Traded
Notes
BNS.PR.N Deemed-Retractible 463,100 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-01-27
Maturity Price : 25.00
Evaluated at bid price : 25.51
Bid-YTW : 1.61 %
W.PR.J Perpetual-Discount 302,450 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-10-28
Maturity Price : 25.00
Evaluated at bid price : 25.00
Bid-YTW : 2.44 %
POW.PR.B Perpetual-Discount 235,518 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-10-28
Maturity Price : 25.00
Evaluated at bid price : 25.10
Bid-YTW : -2.53 %
GWO.PR.F Deemed-Retractible 214,389 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-10-28
Maturity Price : 25.00
Evaluated at bid price : 25.70
Bid-YTW : -26.24 %
PWF.PR.F Floater 199,860 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-28
Maturity Price : 24.68
Evaluated at bid price : 25.00
Bid-YTW : 5.32 %
PWF.PR.F Floater 199,860 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-28
Maturity Price : 24.68
Evaluated at bid price : 25.00
Bid-YTW : 5.32 %
HSB.PR.D Deemed-Retractible 177,600 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-10-28
Maturity Price : 25.00
Evaluated at bid price : 25.05
Bid-YTW : 2.24 %
BNS.PR.H FixedReset 175,110 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-01-26
Maturity Price : 25.00
Evaluated at bid price : 25.78
Bid-YTW : 4.25 %
BNS.PR.O Deemed-Retractible 140,047 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-10-28
Maturity Price : 25.25
Evaluated at bid price : 25.68
Bid-YTW : -4.18 %
TD.PF.H FixedReset 117,195 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.75
Bid-YTW : 4.30 %
TRP.PR.J FixedReset 109,369 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-31
Maturity Price : 25.00
Evaluated at bid price : 26.61
Bid-YTW : 4.10 %
FTS.PR.M FixedReset 100,235 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-28
Maturity Price : 19.55
Evaluated at bid price : 19.55
Bid-YTW : 4.17 %
There were 27 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
GRP.PR.A SplitShare Quote: 25.35 – 25.99
Spot Rate : 0.6400
Average : 0.4465

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-10-28
Maturity Price : 25.00
Evaluated at bid price : 25.35
Bid-YTW : -13.73 %

FTS.PR.G FixedReset Quote: 17.55 – 17.95
Spot Rate : 0.4000
Average : 0.2397

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-28
Maturity Price : 17.55
Evaluated at bid price : 17.55
Bid-YTW : 4.06 %

HSB.PR.D Deemed-Retractible Quote: 25.05 – 25.36
Spot Rate : 0.3100
Average : 0.1979

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-10-28
Maturity Price : 25.00
Evaluated at bid price : 25.05
Bid-YTW : 2.24 %

BNS.PR.D FloatingReset Quote: 19.54 – 19.88
Spot Rate : 0.3400
Average : 0.2304

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.54
Bid-YTW : 6.43 %

MFC.PR.H FixedReset Quote: 21.30 – 21.58
Spot Rate : 0.2800
Average : 0.1769

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.30
Bid-YTW : 6.09 %

TD.PR.Z FloatingReset Quote: 22.35 – 22.64
Spot Rate : 0.2900
Average : 0.1959

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.35
Bid-YTW : 4.46 %

Market Action

September 27, 2016

Here’s a US story we probably won’t see in Canada!

In a startling development, almost unheard of outside a recession, food prices have fallen for nine straight months in the U.S. It’s the longest streak of food deflation since 1960 — with the exception of 2009, when the financial crisis was winding down. Analysts credit low oil and grain prices, as well as cutthroat competition from discounters. Consumers are winning out; grocery chains, not so much. Their margins and, in some cases, their stock prices, are taking a hit.

Eggs and beef have have grown especially inexpensive, and it isn’t only an American phenomenon: In England, Aldi recently offered its prized 8-ounce wagyu steaks from New Zealand for about $6.50 — a little more than the price of a pint of beer.
…
[Analyst at Wolfe Research Scott] Mushkin, who researches local markets, recently found that prices of a typical basket of grocery items in Houston, had fallen almost 5 percent over the past year.

foodPrice_160927
Click for Big
HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.1429 % 1,698.3
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.1429 % 3,102.4
Floater 4.87 % 4.59 % 86,171 16.25 4 0.1429 % 1,787.9
OpRet 0.00 % 0.00 % 0 0.00 0 0.0953 % 2,883.6
SplitShare 5.05 % 4.59 % 77,227 2.16 5 0.0953 % 3,443.6
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0953 % 2,686.8
Perpetual-Premium 5.50 % 4.63 % 65,665 1.95 12 -0.0293 % 2,686.0
Perpetual-Discount 5.12 % 5.08 % 87,153 15.08 26 0.1092 % 2,912.1
FixedReset 4.98 % 4.26 % 149,058 6.98 92 -0.0016 % 2,045.3
Deemed-Retractible 5.02 % 4.85 % 111,042 0.33 32 0.0178 % 2,799.8
FloatingReset 2.85 % 4.43 % 32,492 4.97 12 0.1934 % 2,195.5
Performance Highlights
Issue Index Change Notes
BMO.PR.A FloatingReset -1.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.01
Bid-YTW : 5.13 %
TRP.PR.C FixedReset -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-27
Maturity Price : 13.24
Evaluated at bid price : 13.24
Bid-YTW : 4.12 %
W.PR.K FixedReset 1.55 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-01-15
Maturity Price : 25.00
Evaluated at bid price : 26.17
Bid-YTW : 4.34 %
Volume Highlights
Issue Index Shares
Traded
Notes
BNS.PR.H FixedReset 305,167 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-01-26
Maturity Price : 25.00
Evaluated at bid price : 25.60
Bid-YTW : 4.40 %
RY.PR.L FixedReset 92,319 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.08
Bid-YTW : 3.75 %
W.PR.M FixedReset 57,560 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-15
Maturity Price : 25.00
Evaluated at bid price : 25.85
Bid-YTW : 4.56 %
BMO.PR.S FixedReset 54,230 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-27
Maturity Price : 19.26
Evaluated at bid price : 19.26
Bid-YTW : 4.01 %
TD.PF.H FixedReset 52,355 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.52
Bid-YTW : 4.50 %
HSB.PR.C Deemed-Retractible 42,100 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-10-27
Maturity Price : 25.00
Evaluated at bid price : 24.99
Bid-YTW : 5.13 %
There were 37 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
FTS.PR.M FixedReset Quote: 19.32 – 19.65
Spot Rate : 0.3300
Average : 0.2061

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-27
Maturity Price : 19.32
Evaluated at bid price : 19.32
Bid-YTW : 4.22 %

GWO.PR.N FixedReset Quote: 14.27 – 14.58
Spot Rate : 0.3100
Average : 0.2047

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.27
Bid-YTW : 9.71 %

SLF.PR.G FixedReset Quote: 14.04 – 14.45
Spot Rate : 0.4100
Average : 0.3078

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.04
Bid-YTW : 10.05 %

BAM.PR.K Floater Quote: 10.35 – 10.60
Spot Rate : 0.2500
Average : 0.1592

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-27
Maturity Price : 10.35
Evaluated at bid price : 10.35
Bid-YTW : 4.57 %

TRP.PR.G FixedReset Quote: 20.27 – 20.65
Spot Rate : 0.3800
Average : 0.2983

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-27
Maturity Price : 20.27
Evaluated at bid price : 20.27
Bid-YTW : 4.48 %

GWO.PR.L Deemed-Retractible Quote: 25.35 – 25.64
Spot Rate : 0.2900
Average : 0.2089

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-12-31
Maturity Price : 25.25
Evaluated at bid price : 25.35
Bid-YTW : 5.27 %

Market Action

September 26, 2016

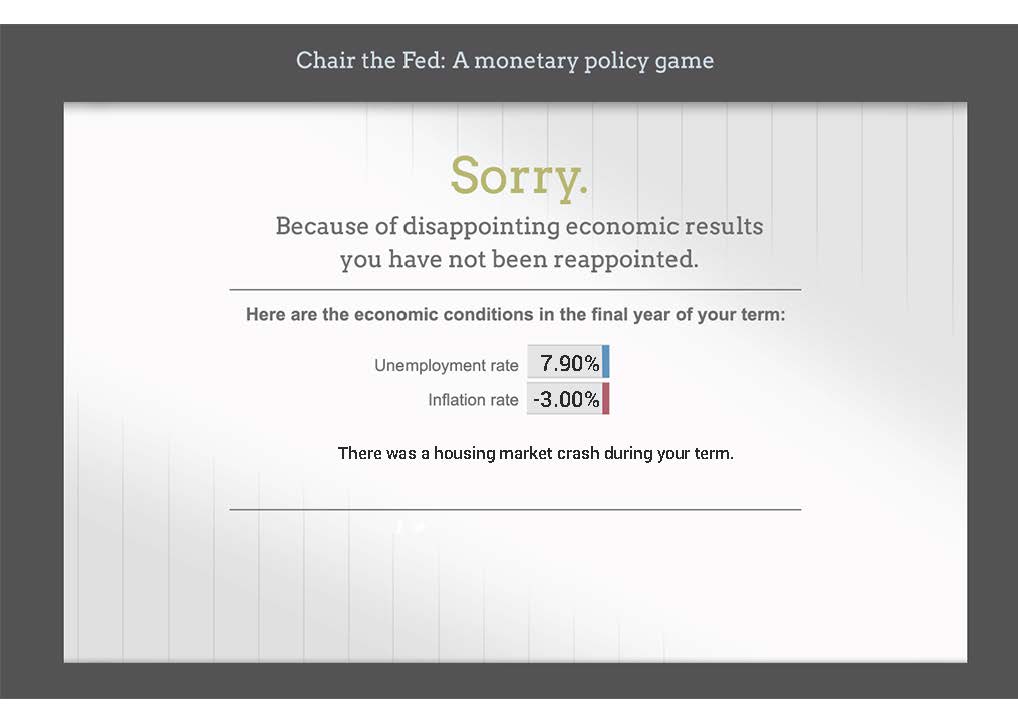
Mark Gilbert of Bloomberg writes about his experience playing a game published by the Fed:

The San Francisco branch of the Federal Reserve has a game on its website that lets you play at being Chair of the Federal Reserve. After tinkering with it, I’ve come to some conclusions: Modeling the economy is a mug’s game, short-term interest rates are a poor tool for steering the economy, and I should never be given the job of running a central bank.

The website sets out the objectives:

Your job is to set monetary policy to achieve full employment and low price inflation. Your term will last four years (16 quarters). Keep unemployment close to its natural rate of 5 percent. Keep inflation near the Fed’s 2 percent inflation target. Pay attention to the headlines for information about the economy.

Here’s how I did:

ChairtheFedGame_160926
Click for Big
HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.1783 % 1,695.9
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.1783 % 3,098.0
Floater 4.88 % 4.62 % 87,257 16.20 4 -0.1783 % 1,785.4
OpRet 0.00 % 0.00 % 0 0.00 0 0.0000 % 2,880.8
SplitShare 5.05 % 4.67 % 80,091 2.16 5 0.0000 % 3,440.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0000 % 2,684.3
Perpetual-Premium 5.50 % 4.65 % 62,963 1.95 12 0.0098 % 2,686.7
Perpetual-Discount 5.13 % 5.13 % 87,257 15.00 26 0.0934 % 2,908.9
FixedReset 4.98 % 4.27 % 148,525 6.98 92 0.1106 % 2,045.3
Deemed-Retractible 5.02 % 4.77 % 112,122 1.21 32 0.0789 % 2,799.3
FloatingReset 2.86 % 4.47 % 32,969 4.97 12 -0.1054 % 2,191.3
Performance Highlights
Issue Index Change Notes
TRP.PR.G FixedReset -1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-26
Maturity Price : 20.26
Evaluated at bid price : 20.26
Bid-YTW : 4.48 %
BAM.PR.T FixedReset -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-26
Maturity Price : 15.38
Evaluated at bid price : 15.38
Bid-YTW : 4.81 %
TRP.PR.C FixedReset 1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-26
Maturity Price : 13.38
Evaluated at bid price : 13.38
Bid-YTW : 4.08 %
NA.PR.Q FixedReset 1.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.90
Bid-YTW : 4.22 %
BMO.PR.Q FixedReset 1.46 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.15
Bid-YTW : 6.16 %
Volume Highlights
Issue Index Shares
Traded
Notes
BNS.PR.H FixedReset 233,115 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-01-26
Maturity Price : 25.00
Evaluated at bid price : 25.51
Bid-YTW : 4.47 %
MFC.PR.G FixedReset 65,768 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.76
Bid-YTW : 6.87 %
CM.PR.Q FixedReset 43,100 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-26
Maturity Price : 20.02
Evaluated at bid price : 20.02
Bid-YTW : 4.27 %
TRP.PR.E FixedReset 40,516 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-26
Maturity Price : 18.73
Evaluated at bid price : 18.73
Bid-YTW : 4.27 %
TRP.PR.J FixedReset 37,100 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-31
Maturity Price : 25.00
Evaluated at bid price : 26.59
Bid-YTW : 4.11 %
BNS.PR.O Deemed-Retractible 36,560 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-10-26
Maturity Price : 25.25
Evaluated at bid price : 25.61
Bid-YTW : -1.26 %
There were 29 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
IFC.PR.A FixedReset Quote: 15.34 – 15.63
Spot Rate : 0.2900
Average : 0.1960

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.34
Bid-YTW : 9.55 %

RY.PR.M FixedReset Quote: 20.00 – 20.26
Spot Rate : 0.2600
Average : 0.1800

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-26
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 4.15 %

HSE.PR.A FixedReset Quote: 11.88 – 12.14
Spot Rate : 0.2600
Average : 0.1946

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-26
Maturity Price : 11.88
Evaluated at bid price : 11.88
Bid-YTW : 4.94 %

POW.PR.G Perpetual-Premium Quote: 25.64 – 25.84
Spot Rate : 0.2000
Average : 0.1348

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-15
Maturity Price : 25.00
Evaluated at bid price : 25.64
Bid-YTW : 4.93 %

VNR.PR.A FixedReset Quote: 18.36 – 18.70
Spot Rate : 0.3400
Average : 0.2801

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-26
Maturity Price : 18.36
Evaluated at bid price : 18.36
Bid-YTW : 4.79 %

HSE.PR.C FixedReset Quote: 19.15 – 19.42
Spot Rate : 0.2700
Average : 0.2122

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-26
Maturity Price : 19.15
Evaluated at bid price : 19.15
Bid-YTW : 5.07 %

Market Action

September 23, 2016

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.4968 % 1,698.9
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.4968 % 3,103.5
Floater 4.87 % 4.60 % 90,578 16.24 4 -0.4968 % 1,788.6
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0159 % 2,880.8
SplitShare 5.05 % 4.73 % 81,363 2.17 5 -0.0159 % 3,440.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0159 % 2,684.3
Perpetual-Premium 5.50 % 4.61 % 66,703 1.96 12 0.0098 % 2,686.5
Perpetual-Discount 5.13 % 5.14 % 87,017 15.01 26 0.0127 % 2,906.2
FixedReset 4.98 % 4.46 % 149,265 6.94 92 0.0150 % 2,043.1
Deemed-Retractible 5.03 % 4.91 % 112,929 4.66 32 -0.0038 % 2,797.1
FloatingReset 2.85 % 4.47 % 33,004 4.98 12 -0.4024 % 2,193.6
Performance Highlights
Issue Index Change Notes
TRP.PR.F FloatingReset -2.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-23
Maturity Price : 13.71
Evaluated at bid price : 13.71
Bid-YTW : 4.47 %
TRP.PR.H FloatingReset -1.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-23
Maturity Price : 10.47
Evaluated at bid price : 10.47
Bid-YTW : 4.32 %
PWF.PR.T FixedReset -1.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-23
Maturity Price : 19.61
Evaluated at bid price : 19.61
Bid-YTW : 4.19 %
BMO.PR.A FloatingReset -1.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.25
Bid-YTW : 4.89 %
BAM.PR.B Floater -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-23
Maturity Price : 10.37
Evaluated at bid price : 10.37
Bid-YTW : 4.56 %
BIP.PR.B FixedReset 1.15 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.59
Bid-YTW : 4.89 %
VNR.PR.A FixedReset 1.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-23
Maturity Price : 18.50
Evaluated at bid price : 18.50
Bid-YTW : 4.94 %
Volume Highlights
Issue Index Shares
Traded
Notes
BNS.PR.H FixedReset 214,830 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-01-26
Maturity Price : 25.00
Evaluated at bid price : 25.48
Bid-YTW : 4.49 %
TD.PF.H FixedReset 213,511 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.45
Bid-YTW : 4.55 %
NA.PR.W FixedReset 126,350 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-23
Maturity Price : 18.20
Evaluated at bid price : 18.20
Bid-YTW : 4.37 %
RY.PR.Z FixedReset 55,250 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-23
Maturity Price : 18.90
Evaluated at bid price : 18.90
Bid-YTW : 4.12 %
PWF.PR.T FixedReset 51,950 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-23
Maturity Price : 19.61
Evaluated at bid price : 19.61
Bid-YTW : 4.19 %
BAM.PF.D Perpetual-Discount 43,000 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-23
Maturity Price : 23.01
Evaluated at bid price : 23.36
Bid-YTW : 5.25 %
There were 35 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
NA.PR.W FixedReset Quote: 18.20 – 18.48
Spot Rate : 0.2800
Average : 0.1765

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-23
Maturity Price : 18.20
Evaluated at bid price : 18.20
Bid-YTW : 4.37 %

BMO.PR.A FloatingReset Quote: 21.25 – 21.90
Spot Rate : 0.6500
Average : 0.5564

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.25
Bid-YTW : 4.89 %

GWO.PR.M Deemed-Retractible Quote: 25.92 – 26.25
Spot Rate : 0.3300
Average : 0.2479

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-10-23
Maturity Price : 25.75
Evaluated at bid price : 25.92
Bid-YTW : -3.67 %

BAM.PF.H FixedReset Quote: 26.74 – 26.99
Spot Rate : 0.2500
Average : 0.1734

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-31
Maturity Price : 25.00
Evaluated at bid price : 26.74
Bid-YTW : 3.24 %

W.PR.K FixedReset Quote: 25.69 – 26.07
Spot Rate : 0.3800
Average : 0.3048

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-01-15
Maturity Price : 25.00
Evaluated at bid price : 25.69
Bid-YTW : 4.82 %

HSE.PR.G FixedReset Quote: 21.05 – 21.33
Spot Rate : 0.2800
Average : 0.2125

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-23
Maturity Price : 21.05
Evaluated at bid price : 21.05
Bid-YTW : 5.16 %

Market Action

September 22, 2016

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.5351 % 1,707.4
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.5351 % 3,119.0
Floater 4.84 % 4.56 % 91,709 16.32 4 0.5351 % 1,797.5
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0238 % 2,881.3
SplitShare 5.05 % 4.69 % 81,472 2.17 5 -0.0238 % 3,440.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0238 % 2,684.7
Perpetual-Premium 5.50 % 4.59 % 63,232 1.06 12 0.0553 % 2,686.2
Perpetual-Discount 5.13 % 5.15 % 89,860 14.99 26 0.0285 % 2,905.9
FixedReset 4.98 % 4.43 % 146,346 6.94 92 -0.0723 % 2,042.8
Deemed-Retractible 5.03 % 4.50 % 111,455 3.20 32 0.0318 % 2,797.2
FloatingReset 2.84 % 4.37 % 33,451 4.99 12 -0.0481 % 2,202.4
Performance Highlights
Issue Index Change Notes
PWF.PR.T FixedReset -1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-22
Maturity Price : 19.90
Evaluated at bid price : 19.90
Bid-YTW : 4.12 %
PWF.PR.P FixedReset -1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-22
Maturity Price : 13.15
Evaluated at bid price : 13.15
Bid-YTW : 4.48 %
BAM.PR.T FixedReset -1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-22
Maturity Price : 15.47
Evaluated at bid price : 15.47
Bid-YTW : 5.02 %
VNR.PR.A FixedReset -1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-22
Maturity Price : 18.20
Evaluated at bid price : 18.20
Bid-YTW : 5.03 %
CM.PR.Q FixedReset -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-22
Maturity Price : 20.08
Evaluated at bid price : 20.08
Bid-YTW : 4.47 %
BAM.PR.R FixedReset -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-22
Maturity Price : 15.61
Evaluated at bid price : 15.61
Bid-YTW : 4.87 %
TRP.PR.F FloatingReset 1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-22
Maturity Price : 14.02
Evaluated at bid price : 14.02
Bid-YTW : 4.37 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PF.H FixedReset 1,021,288 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.48
Bid-YTW : 4.52 %
BNS.PR.H FixedReset 137,935 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-01-26
Maturity Price : 25.00
Evaluated at bid price : 25.47
Bid-YTW : 4.50 %
RY.PR.Z FixedReset 130,500 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-22
Maturity Price : 18.86
Evaluated at bid price : 18.86
Bid-YTW : 4.13 %
FTS.PR.J Perpetual-Discount 103,295 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-22
Maturity Price : 23.43
Evaluated at bid price : 23.90
Bid-YTW : 4.99 %
CM.PR.P FixedReset 84,200 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-22
Maturity Price : 18.42
Evaluated at bid price : 18.42
Bid-YTW : 4.30 %
SLF.PR.A Deemed-Retractible 54,213 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.97
Bid-YTW : 5.39 %
There were 33 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
VNR.PR.A FixedReset Quote: 18.20 – 18.63
Spot Rate : 0.4300
Average : 0.3181

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-22
Maturity Price : 18.20
Evaluated at bid price : 18.20
Bid-YTW : 5.03 %

BMO.PR.R FloatingReset Quote: 22.50 – 22.79
Spot Rate : 0.2900
Average : 0.1890

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.50
Bid-YTW : 4.27 %

SLF.PR.G FixedReset Quote: 14.10 – 14.36
Spot Rate : 0.2600
Average : 0.1711

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.10
Bid-YTW : 10.07 %

MFC.PR.G FixedReset Quote: 19.65 – 19.91
Spot Rate : 0.2600
Average : 0.1838

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.65
Bid-YTW : 7.12 %

TRP.PR.D FixedReset Quote: 17.90 – 18.17
Spot Rate : 0.2700
Average : 0.1943

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-22
Maturity Price : 17.90
Evaluated at bid price : 17.90
Bid-YTW : 4.59 %

PWF.PR.T FixedReset Quote: 19.90 – 20.23
Spot Rate : 0.3300
Average : 0.2603

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-22
Maturity Price : 19.90
Evaluated at bid price : 19.90
Bid-YTW : 4.12 %

Market Action

September 21, 2016

Today’s big news is the FOMC policy rate decision:

The Committee expects that, with gradual adjustments in the stance of monetary policy, economic activity will expand at a moderate pace and labor market conditions will strengthen somewhat further. Inflation is expected to remain low in the near term, in part because of earlier declines in energy prices, but to rise to 2 percent over the medium term as the transitory effects of past declines in energy and import prices dissipate and the labor market strengthens further. Near-term risks to the economic outlook appear roughly balanced. The Committee continues to closely monitor inflation indicators and global economic and financial developments.

Against this backdrop, the Committee decided to maintain the target range for the federal funds rate at 1/4 to 1/2 percent. The Committee judges that the case for an increase in the federal funds rate has strengthened but decided, for the time being, to wait for further evidence of continued progress toward its objectives. The stance of monetary policy remains accommodative, thereby supporting further improvement in labor market conditions and a return to 2 percent inflation.

In determining the timing and size of future adjustments to the target range for the federal funds rate, the Committee will assess realized and expected economic conditions relative to its objectives of maximum employment and 2 percent inflation.
…
Voting against the action were: Esther L. George, Loretta J. Mester, and Eric Rosengren, each of whom preferred at this meeting to raise the target range for the federal funds rate to 1/2 to 3/4 percent.

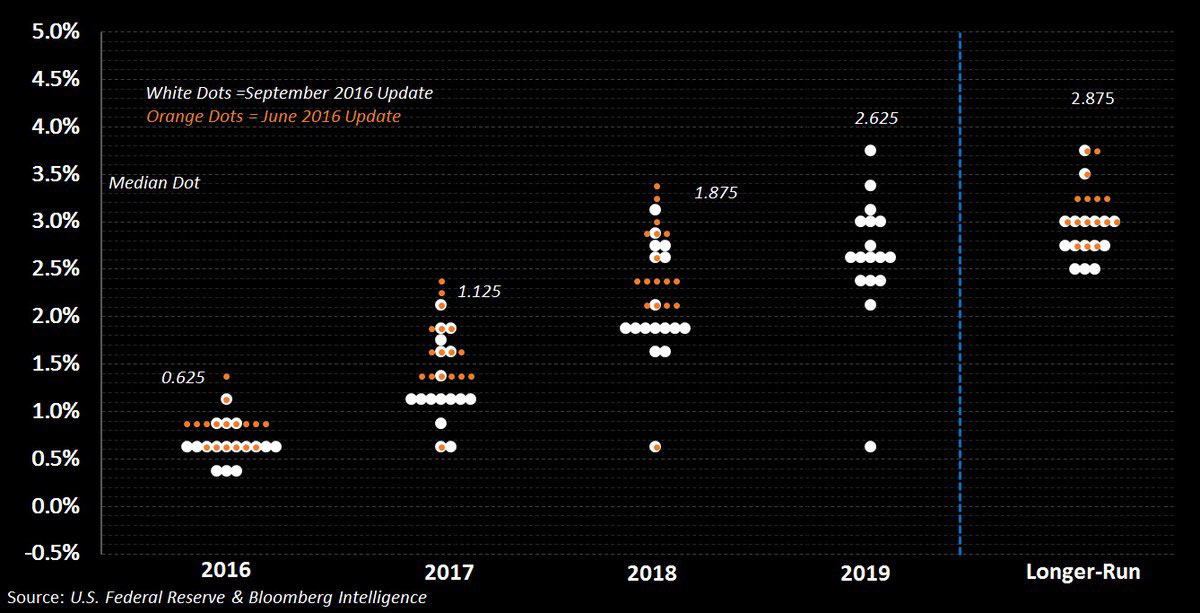
Projections for the future course of rates eased slightly but remained skewed upwards:

The central bank’s so-called “dot plot”, which it uses to signal its outlook for the path of interest rates, showed that officials expected one quarter-point rate increase this year. Three policy makers projected that keeping rates unchanged this year would be most appropriate. Officials scaled back expectations for hikes in 2017 and over the longer run.

Policy makers see two rate hikes next year, down from their June median projection of three.

FedDotPlot_160921
Click for Big

It’s interesting to see more argument that technology, not globalization, is the bug-bear of the middle class:

In the realm of international trade, it is a truism seemingly as consistent as gravity: Jobs and investment flow from north to south, while manufactured goods travel the other way around. Factories in the United States and Canada shutter as work shifts to Mexico and Central America, where human hands do it more cheaply.

So the established order of trade was by all appearances turned upside down on Tuesday, as General Motors agreed to cease manufacturing an automobile engine at a factory in Mexico while moving jobs to a plant in Canada.
…
In an era of increasingly sophisticated manufacturing that relies more on computers and robotics than low-wage hands, centers of innovation like Canada and the United States will exert a greater pull than before.
…
Given that state-of-the-art products fetch a higher price, it is presumably worth paying a premium to the limited numbers of humans involved in their creation — and especially since this buys proximity to the minds that dream up lucrative new visions. The Canadian plant getting the jobs sits near Waterloo, the birthplace of the BlackBerry, which is something like Canada’s Silicon Valley.
…
Above all, the deal underscores the potency of markets in shaping what happens in commercial life, a force far more powerful than demagogues making dubious promises about tearing up trade deals.

CalPERS, the giant pension fund that doesn’t do credit analysis, is the subject of some sharp commentary by Megan McArdle:

For example, Calpers, which uses a 7.5 percent discount rate, has a funding level of about 75 percent. It is currently contemplating lowering that discount rate all the way to 6.5 percent, but only over two decades.

It’s hard to believe that 20 years was chosen for mathematical reasons. After all, the wave of boomer retirements, which will be the greatest stressor our national retirement systems have ever seen, should be well over by 2035. Rather, one suspects it was chosen because Calpers doesn’t dare change it faster. Changing it faster would mean big increases in current contributions.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.8273 % 1,698.3
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.8273 % 3,102.4
Floater 4.87 % 4.59 % 93,930 16.27 4 0.8273 % 1,787.9
OpRet 0.00 % 0.00 % 0 0.00 0 0.0953 % 2,882.0
SplitShare 5.05 % 4.80 % 76,122 2.17 5 0.0953 % 3,441.7
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0953 % 2,685.3
Perpetual-Premium 5.50 % 4.59 % 64,217 1.96 12 0.2545 % 2,684.7
Perpetual-Discount 5.14 % 5.15 % 89,206 15.00 26 0.1231 % 2,905.0
FixedReset 4.98 % 4.44 % 147,743 6.95 92 0.2045 % 2,044.3
Deemed-Retractible 5.03 % 4.49 % 112,649 3.20 32 0.1480 % 2,796.4
FloatingReset 2.84 % 4.41 % 32,056 4.99 12 0.1840 % 2,203.5
Performance Highlights
Issue Index Change Notes
MFC.PR.H FixedReset 1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.35
Bid-YTW : 6.19 %
VNR.PR.A FixedReset 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-21
Maturity Price : 18.40
Evaluated at bid price : 18.40
Bid-YTW : 4.97 %
TRP.PR.H FloatingReset 1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-21
Maturity Price : 10.67
Evaluated at bid price : 10.67
Bid-YTW : 4.24 %
BMO.PR.A FloatingReset 1.18 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.50
Bid-YTW : 4.65 %
TRP.PR.F FloatingReset 1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-21
Maturity Price : 13.88
Evaluated at bid price : 13.88
Bid-YTW : 4.41 %
BAM.PR.S FloatingReset 1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-21
Maturity Price : 14.95
Evaluated at bid price : 14.95
Bid-YTW : 4.74 %
BAM.PR.B Floater 1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-21
Maturity Price : 10.38
Evaluated at bid price : 10.38
Bid-YTW : 4.55 %
SLF.PR.H FixedReset 1.37 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.30
Bid-YTW : 8.92 %
BAM.PR.C Floater 1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-21
Maturity Price : 10.31
Evaluated at bid price : 10.31
Bid-YTW : 4.59 %
BAM.PF.G FixedReset 1.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-21
Maturity Price : 20.35
Evaluated at bid price : 20.35
Bid-YTW : 4.64 %
BAM.PR.K Floater 2.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-21
Maturity Price : 10.40
Evaluated at bid price : 10.40
Bid-YTW : 4.55 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PF.H FixedReset 986,699 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.48
Bid-YTW : 4.52 %
BNS.PR.H FixedReset 907,815 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-01-26
Maturity Price : 25.00
Evaluated at bid price : 25.48
Bid-YTW : 4.48 %
NA.PR.A FixedReset 236,165 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-15
Maturity Price : 25.00
Evaluated at bid price : 26.45
Bid-YTW : 4.44 %
TD.PF.A FixedReset 221,900 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-21
Maturity Price : 18.80
Evaluated at bid price : 18.80
Bid-YTW : 4.21 %
RY.PR.H FixedReset 136,200 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-21
Maturity Price : 18.83
Evaluated at bid price : 18.83
Bid-YTW : 4.19 %
BAM.PR.K Floater 80,300 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-21
Maturity Price : 10.40
Evaluated at bid price : 10.40
Bid-YTW : 4.55 %
There were 21 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
MFC.PR.O FixedReset Quote: 26.62 – 26.98
Spot Rate : 0.3600
Average : 0.2211

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-06-19
Maturity Price : 25.00
Evaluated at bid price : 26.62
Bid-YTW : 4.12 %

BAM.PR.S FloatingReset Quote: 14.95 – 15.35
Spot Rate : 0.4000
Average : 0.2710

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-21
Maturity Price : 14.95
Evaluated at bid price : 14.95
Bid-YTW : 4.74 %

CU.PR.H Perpetual-Discount Quote: 25.09 – 25.50
Spot Rate : 0.4100
Average : 0.2869

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-21
Maturity Price : 24.68
Evaluated at bid price : 25.09
Bid-YTW : 5.26 %

BIP.PR.C FixedReset Quote: 25.30 – 25.53
Spot Rate : 0.2300
Average : 0.1411

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-09-30
Maturity Price : 25.00
Evaluated at bid price : 25.30
Bid-YTW : 5.08 %

TRP.PR.G FixedReset Quote: 20.32 – 20.60
Spot Rate : 0.2800
Average : 0.2027

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-21
Maturity Price : 20.32
Evaluated at bid price : 20.32
Bid-YTW : 4.61 %

CU.PR.G Perpetual-Discount Quote: 22.73 – 22.98
Spot Rate : 0.2500
Average : 0.1728

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-21
Maturity Price : 22.44
Evaluated at bid price : 22.73
Bid-YTW : 4.98 %

Market Action

September 20, 2016

A spokesman for the Minister of Finance has indicated that the long-predicted recovery may be delayed:

In our most recent Monetary Policy Report, in July, we said that our current policy rate setting of 0.5 per cent was consistent with the economy returning to full capacity toward the end of 2017 and inflation returning sustainably to its target. We’ll update our forecast next month, but in our decision on September 7, we indicated that the risks to our projected inflation profile have tilted somewhat to the downside following recent data on investment in both the United States and Canada, and the recent data on our exports. It is quite evident that our economy is still facing strong headwinds, and we need stimulative monetary policy to counteract them and move us closer to full capacity. We also need to watch the full effects of the government’s fiscal stimulus unfold.

However, the decline in the real neutral rate means that any given setting of our policy rate will be less stimulative today than it was a decade or two ago. The current policy rate, while certainly providing monetary stimulus, is not as stimulative as it would have been before the crisis.

Many will be overjoyed at this marketing scheme from Investor’s Group:

Investors Group will be discontinuing the deferred sales charge (DSC) purchase option for its mutual funds effective January 1, 2017. At the same time, fees on no-load (NL) funds will be reduced.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.2524 % 1,684.3
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.2524 % 3,077.0
Floater 4.91 % 4.65 % 86,930 16.14 4 0.2524 % 1,773.3
OpRet 0.00 % 0.00 % 0 0.00 0 0.0795 % 2,879.2
SplitShare 5.06 % 4.80 % 76,918 2.18 5 0.0795 % 3,438.4
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0795 % 2,682.8
Perpetual-Premium 5.50 % 4.62 % 68,473 1.96 12 0.1075 % 2,677.9
Perpetual-Discount 5.14 % 5.14 % 92,670 15.11 26 0.1555 % 2,901.5
FixedReset 4.99 % 4.47 % 148,293 6.94 92 0.1785 % 2,040.1
Deemed-Retractible 5.04 % 4.53 % 112,988 3.20 32 -0.0383 % 2,792.2
FloatingReset 2.84 % 4.39 % 31,234 5.00 12 -0.0175 % 2,199.4
Performance Highlights
Issue Index Change Notes
VNR.PR.A FixedReset -1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-20
Maturity Price : 18.21
Evaluated at bid price : 18.21
Bid-YTW : 5.02 %
BAM.PF.G FixedReset -1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-20
Maturity Price : 20.02
Evaluated at bid price : 20.02
Bid-YTW : 4.71 %
CCS.PR.C Deemed-Retractible -1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.06
Bid-YTW : 5.58 %
BAM.PF.H FixedReset 1.06 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-31
Maturity Price : 25.00
Evaluated at bid price : 26.78
Bid-YTW : 3.19 %
SLF.PR.I FixedReset 1.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.70
Bid-YTW : 7.65 %
TRP.PR.C FixedReset 1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-20
Maturity Price : 13.35
Evaluated at bid price : 13.35
Bid-YTW : 4.31 %
PWF.PR.P FixedReset 1.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-20
Maturity Price : 13.36
Evaluated at bid price : 13.36
Bid-YTW : 4.41 %
IFC.PR.C FixedReset 1.66 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.75
Bid-YTW : 8.29 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PF.H FixedReset 1,351,084 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.45
Bid-YTW : 4.54 %
BNS.PR.H FixedReset 278,221 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-01-26
Maturity Price : 25.00
Evaluated at bid price : 25.47
Bid-YTW : 4.49 %
TD.PF.G FixedReset 122,257 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 26.73
Bid-YTW : 4.04 %
MFC.PR.J FixedReset 90,750 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.10
Bid-YTW : 7.33 %
GWO.PR.H Deemed-Retractible 89,892 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.95
Bid-YTW : 5.50 %
BAM.PR.M Perpetual-Discount 77,305 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-20
Maturity Price : 22.47
Evaluated at bid price : 22.73
Bid-YTW : 5.23 %
There were 24 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BAM.PF.G FixedReset Quote: 20.02 – 20.47
Spot Rate : 0.4500
Average : 0.2702

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-20
Maturity Price : 20.02
Evaluated at bid price : 20.02
Bid-YTW : 4.71 %

CCS.PR.C Deemed-Retractible Quote: 24.06 – 24.59
Spot Rate : 0.5300
Average : 0.3956

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.06
Bid-YTW : 5.58 %

BNS.PR.A FloatingReset Quote: 23.10 – 23.50
Spot Rate : 0.4000
Average : 0.2677

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.10
Bid-YTW : 4.15 %

EML.PR.A FixedReset Quote: 26.15 – 26.35
Spot Rate : 0.2000
Average : 0.1449

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-17
Maturity Price : 25.00
Evaluated at bid price : 26.15
Bid-YTW : 4.55 %

TRP.PR.D FixedReset Quote: 17.85 – 18.00
Spot Rate : 0.1500
Average : 0.1017

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-20
Maturity Price : 17.85
Evaluated at bid price : 17.85
Bid-YTW : 4.60 %

NA.PR.S FixedReset Quote: 18.60 – 18.80
Spot Rate : 0.2000
Average : 0.1526

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-20
Maturity Price : 18.60
Evaluated at bid price : 18.60
Bid-YTW : 4.44 %