Category: Market Action

Market Action

February 2, 2016

There’s an interesting use of the psychology of dissent from Bridgewater hedge fund:

Along with modeling openness to criticism, [Bridgewater’s founder Ray] Dalio has fought groupthink by refusing to make decisions based on hierarchy. Rather than conducting a vote where the majority rules, or deferring to people with the most seniority or status, he strives to create an idea meritocracy where all perspectives are heard and the best argument wins.

To do that, most leaders assign a devil’s advocate. The hope is to get someone to challenge the majority’s opinion. But according to [Berkeley psychologist Charlan] Nemeth’s research and Bridgewater’s example, we’re doing it wrong.

When people are designated to dissent, they’re just playing a role. This causes two problems: They don’t argue forcefully or consistently enough for the minority viewpoint, and group members are less likely to take them seriously.

“Dissenting for the sake of dissenting is not useful. It is also not useful if it is ‘pretend dissent’ — for example, if role-played,” Nemeth explains. “It is not useful if motivated by considerations other than searching for the truth or the best solutions. But when it is authentic, it stimulates thought; it clarifies and it emboldens.”

The secret to success is sincerity, the old saying goes: Once you can fake that, you’ve got it made. In fact, it’s not easy to fake sincerity. For devil’s advocates to be maximally effective, they need to really believe in the position they’re representing — and the group needs to believe that they believe it, too.

Bond yields plummeted today:

The U.S. 10-year note yield fell one basis point as of 10:54 a.m. in Tokyo, after tumbling 10 basis points Tuesday, according to Bloomberg Bond Trader data. The price of the 2.25 percent security due in November 2025 rose 1/8, or $1.25 per $1,000 face value, to 103 23/32. The last time the yield approached the record low was in January 2015 when it dropped to 1.64 percent.

Japan’s five-year yield declined to a record low of negative 0.12 percent.

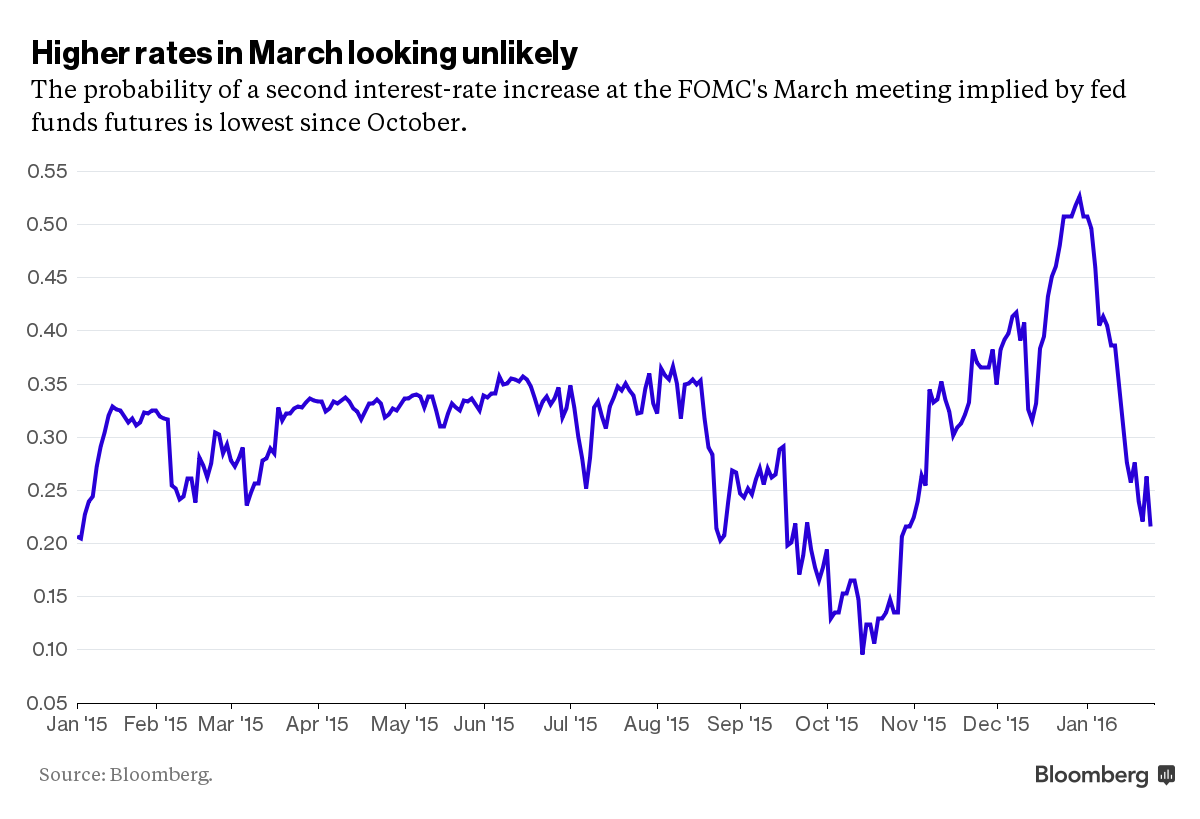
Crude oil declined to a 12-year low in January, and the MSCI All Country World Index of shares has fallen more than 7 percent this year. The odds of the Fed following its December rate increase with another in 2016 are less than 50 percent, futures contracts indicate.

Gluskin Sheff + Associates Inc.’s chief economist David Rosenberg has an interesting take on depressed markets:

Those who claim that “break-even” price levels on Middle East oil production are in single digits are only looking at covering direct production costs and are ignoring the fiscal break-even levels. As per the International Monetary Fund, the fiscal break-even oil price for Saudi Arabia is nearly $96 a barrel (hence the government seeing a 20-per-cent deficit-to-GDP ratio); $68 a barrel for the United Arab Emirates (deficit of 4 per cent of GDP); and $58 a barrel for Qatar (budget gap of 1.5 per cent of GDP).

According to estimates I have seen, as of the end of 2015, 56 per cent of the assets that sovereign wealth funds had amassed came from the oil and gas related projects and up to 10 per cent of the total money invested was in global markets.

What has happened is that many governments, especially in the Gulf region (as well as Africa and Asia), have been compelled to draw down these reserves to cover their gaping fiscal deficits.

I am seeing figures that reveal that the Saudi Arabian Monetary Agency (the kingdom’s investment arm) has withdrawn something in the order of $70-billion from external managers in just the past six months to meet its social spending requirements.

The Fed’s new stress test will doubtless cause some excited comment:

In its annual stress test for 2016, the Fed said it will assess the resilience of big banks to a number of possible situations, including one where the rate on the three-month U.S. Treasury bill stays below zero for a prolonged period.

“The severely adverse scenario is characterized by a severe global recession, accompanied by a period of heightened corporate financial stress and negative yields for short-term U.S. Treasury securities,” the central bank said in announcing the stress tests last week.

In that particular simulation, the unemployment rate doubles to 10 percent, the same level it reached in the aftermath of the last financial crisis.

Three-month bill rates have slipped slightly below zero several times in recent years, including in September after the Fed delayed rate liftoff amid global financial market turmoil, touching a low of minus 0.05 percent on Oct. 2.

But in the stress test, banks would have to handle three-month bill rates entering negative territory in the second quarter of 2016, and then falling to negative 0.5 percent and holding there through the first quarter of 2019.

And just so you don’t think I’ve forgotten about them, here’s some drone news:

Dutch police are working with a company called Guard From Above that claims to be “the first company in the world to use birds of prey to intercept hostile drones.”
…
COO and company co-founder Ben de Keijzer said that two of the most impressive characteristics of birds of prey are their speed and their power, both of which come in pretty handy when you’re knocking somebody’s Christmas toy – or a hostile attacker’s weapon – out the sky.

They are “the masters of the air,” he said, which would sound like marketing fluff speak if the video didn’t in fact show birds snapping up UAVs like so many plump chickens.

It’s an interesting idea – and the video embedded in the source is impressive – but surely it’s just a matter of time before an anti-drone drone is developed. I foresee the day when the Bad Guys send in fleets of bombers … the authorities deploy fleets of fighters to attack them … the Bad Guys deploy fighters to protect the bombers … it will be the Battle of Britain all over again!

And it was January all over again in the Canadian preferred share market, with PerpetualDiscounts off 5bp, FixedResets losing 67bp and DeemedRetractibles down 11bp. The Performance Highlights table shows a lot of churn. Volume was very low.

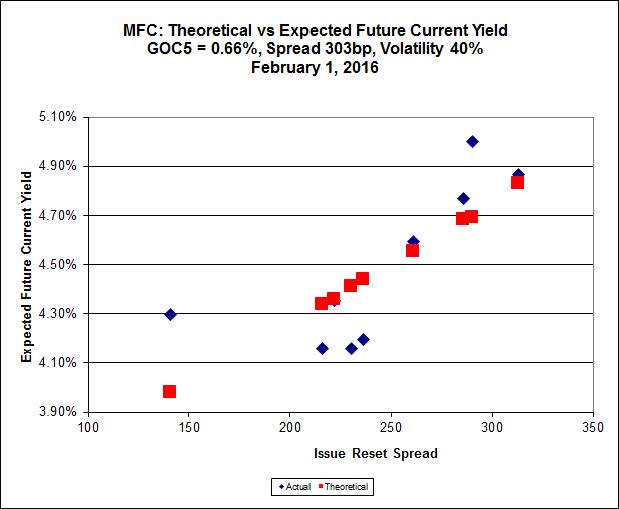
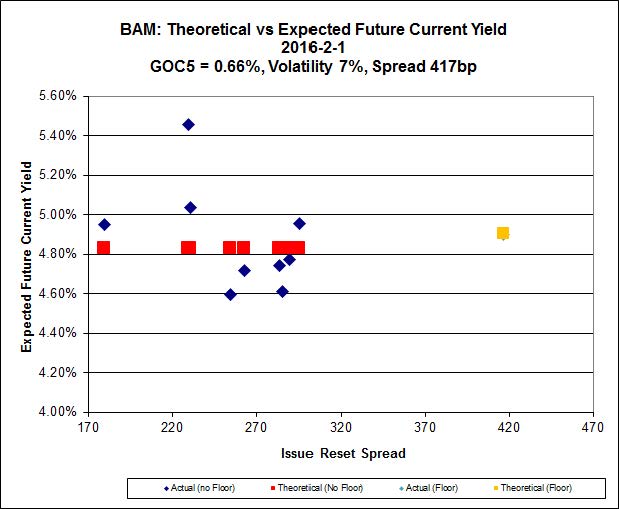
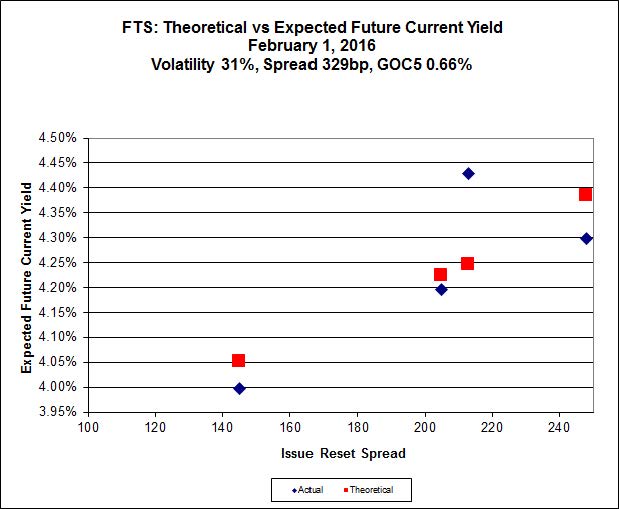
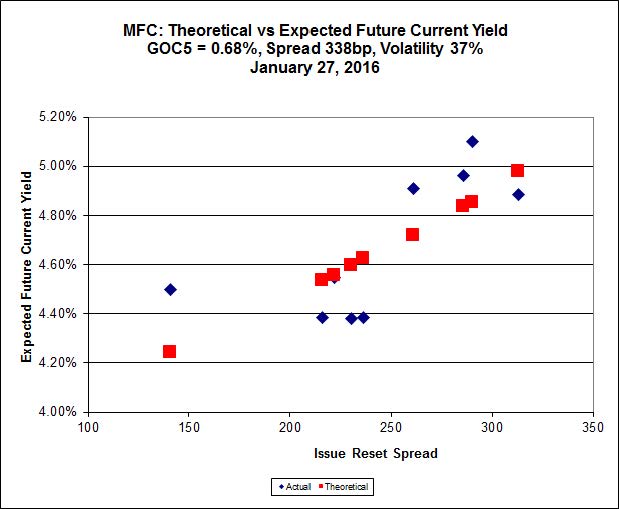
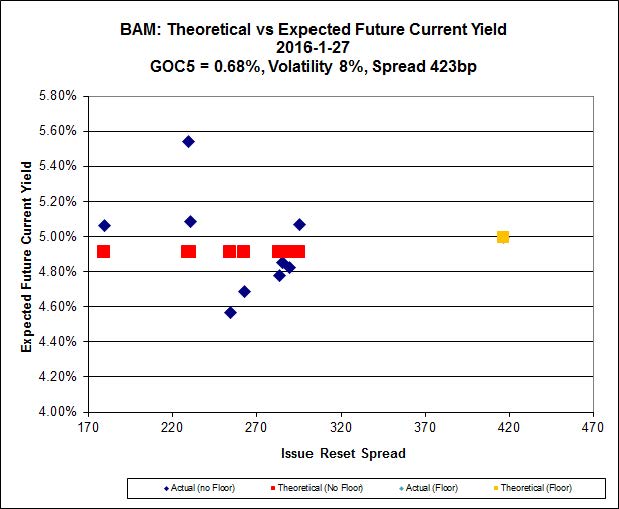
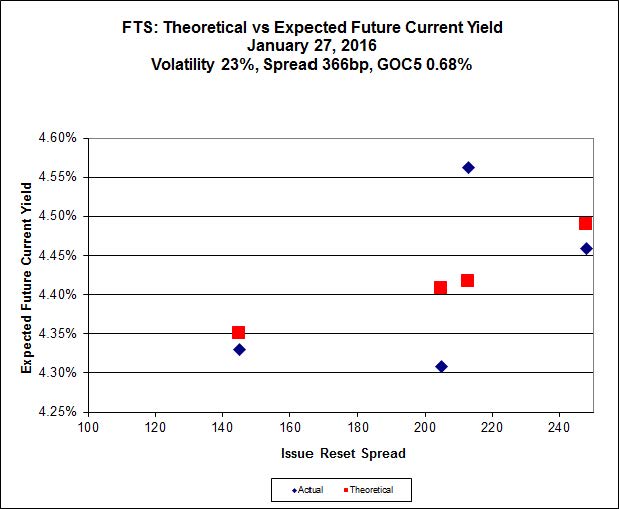
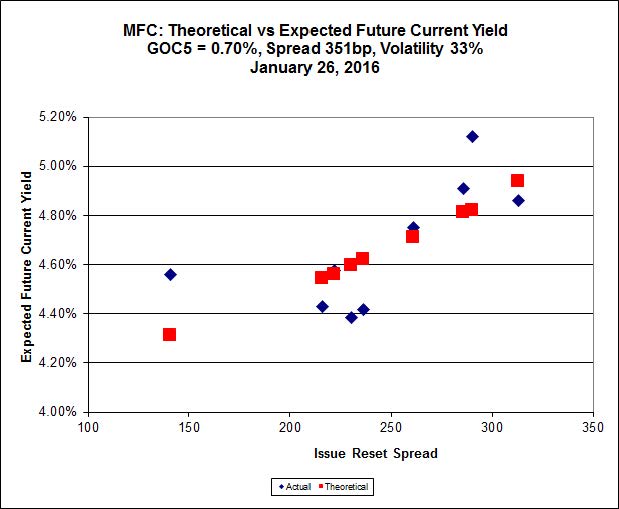
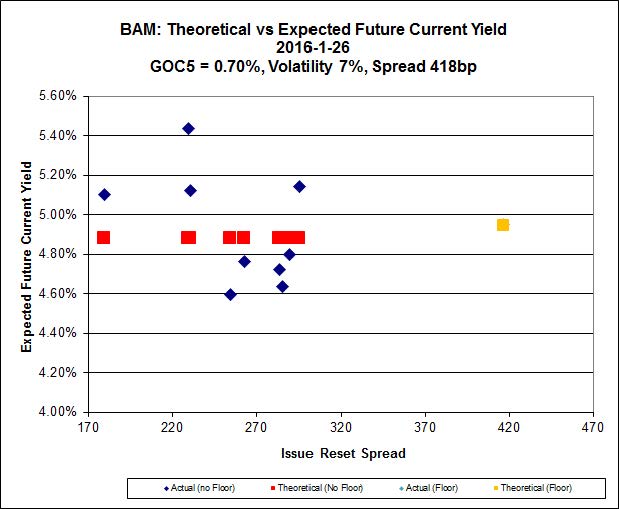
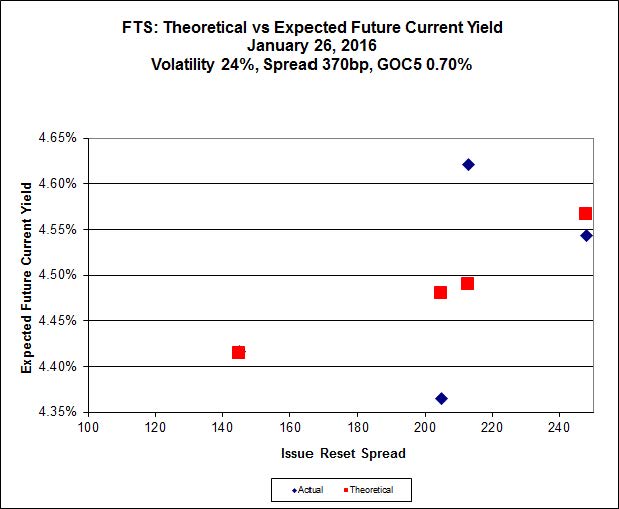
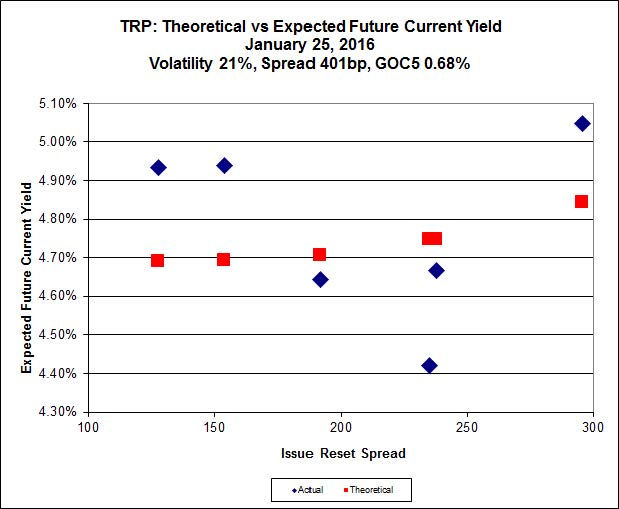
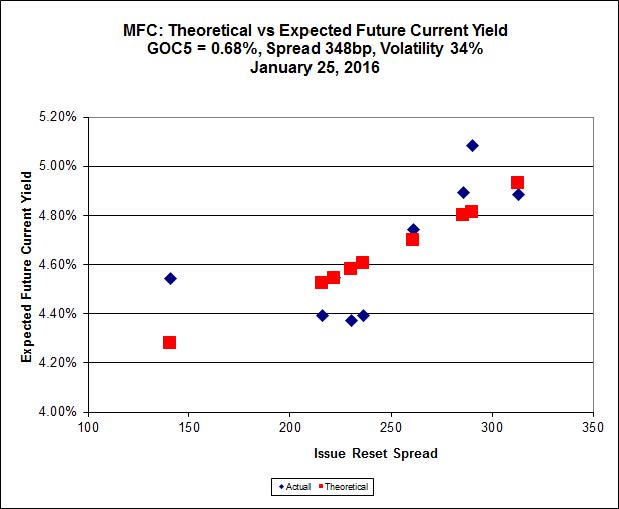
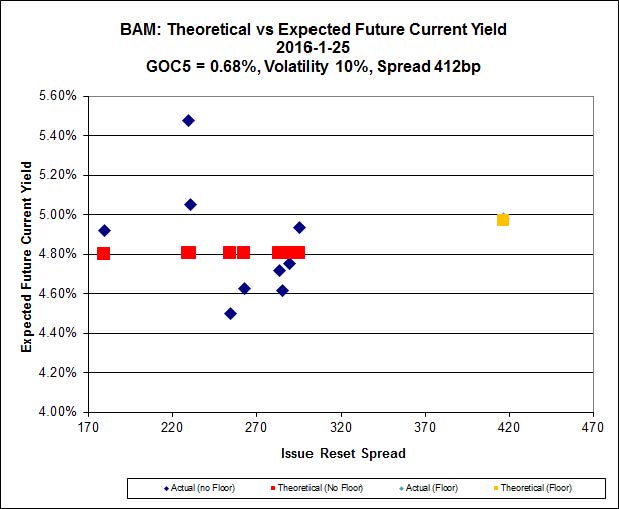
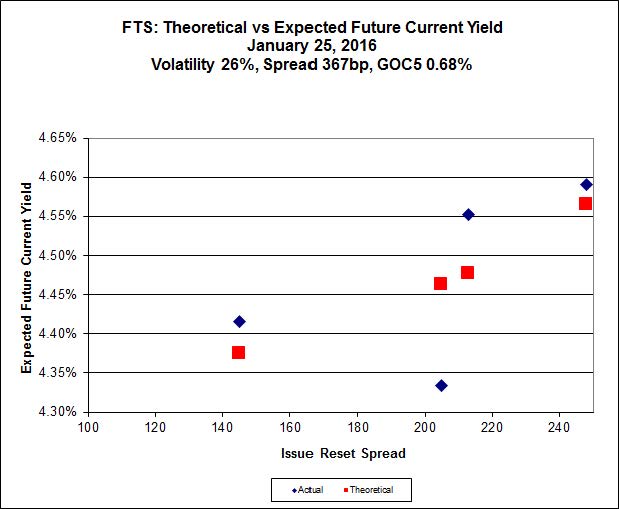
For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

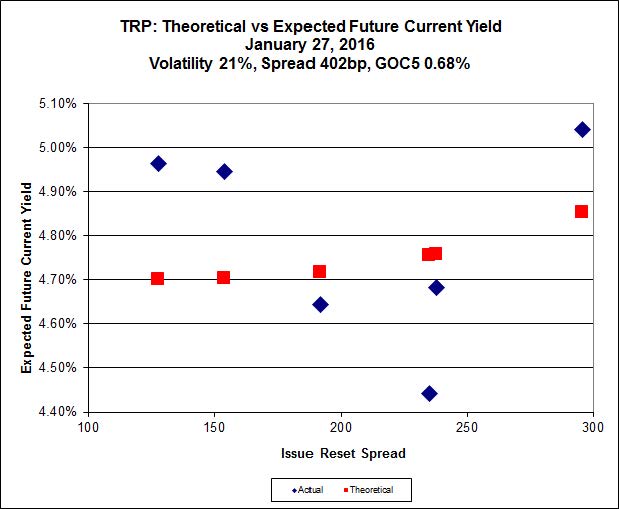
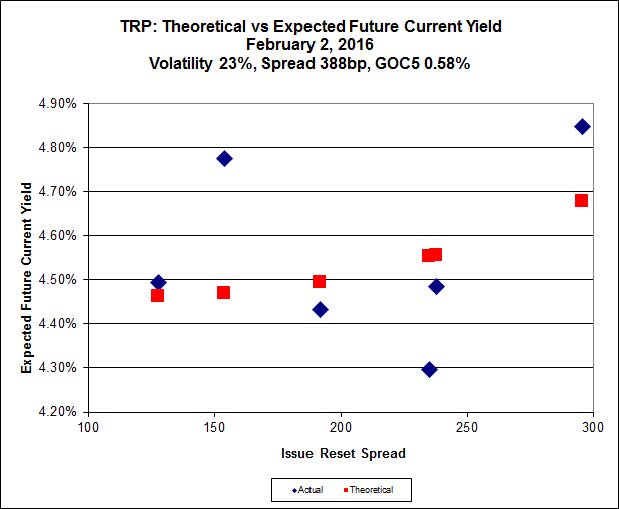
Here’s TRP:
impVol_TRP_160202
Click for Big

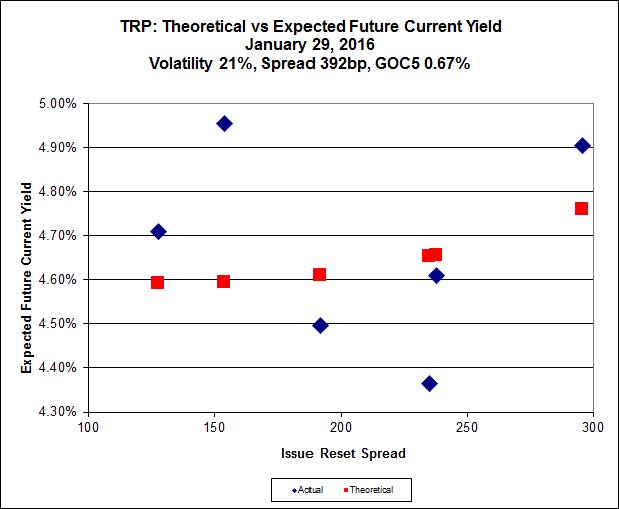
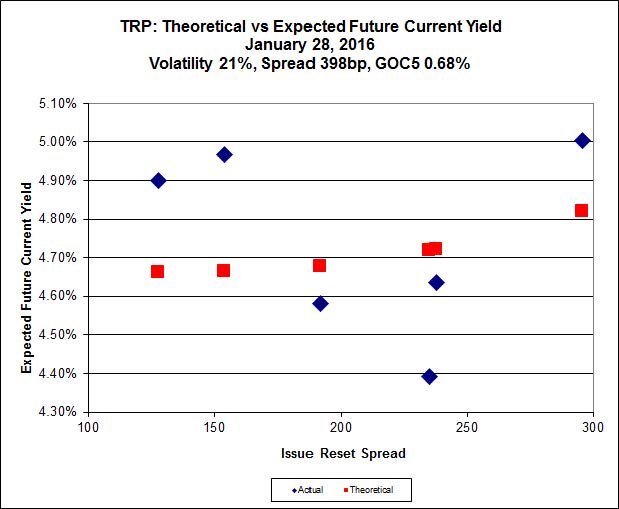
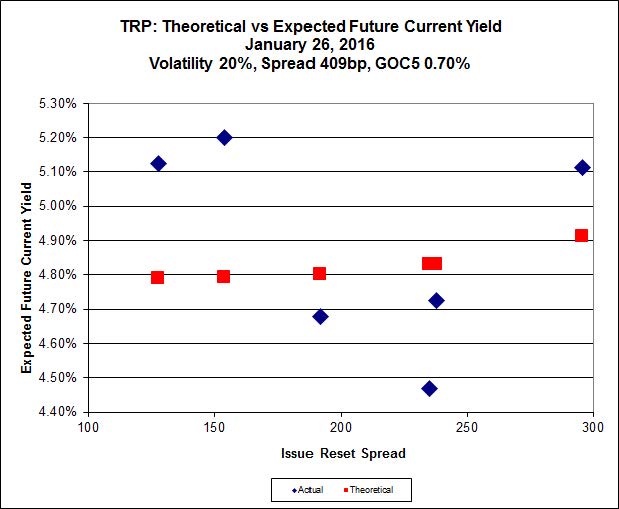
TRP.PR.E, which resets 2019-10-30 at +235, is bid at 17.05 to be $0.96 rich, while TRP.PR.C, resetting 2021-1-30 at +154, is $0.76 cheap at its bid price of 11.10.
impVol_MFC_160202
Click for Big

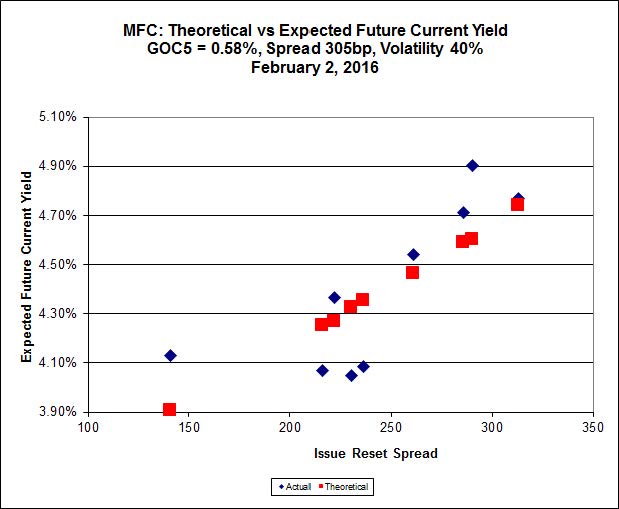
Most expensive is MFC.PR.N, resetting at +230bp on 2020-3-19, bid at 17.78 to be 1.13 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 17.75 to be 1.15 cheap.
impVol_BAM_160202
Click for Big

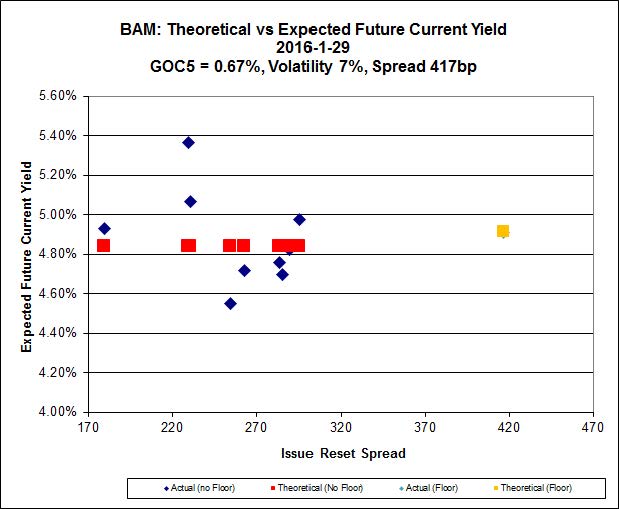
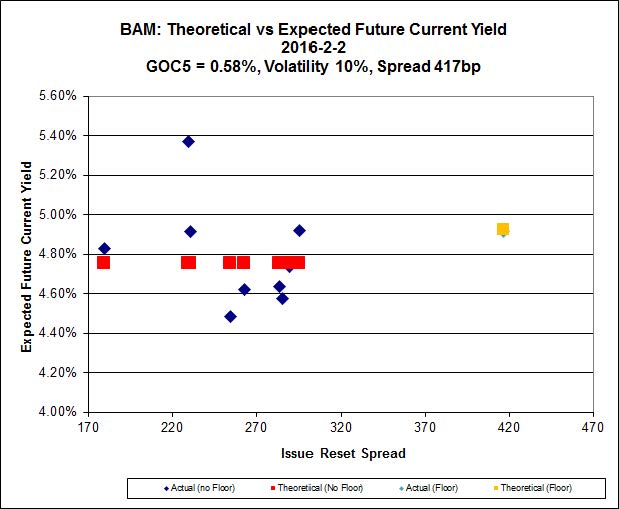
The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 13.41 to be $1.75 cheap. BAM.PF.E, resetting at +255bp on 2020-3-31 is bid at 17.46 and appears to be $0.99 rich.
impVol_FTS_160202
Click for Big

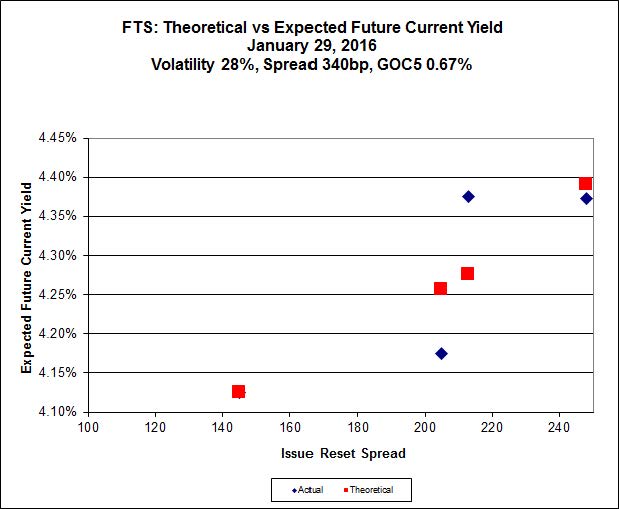
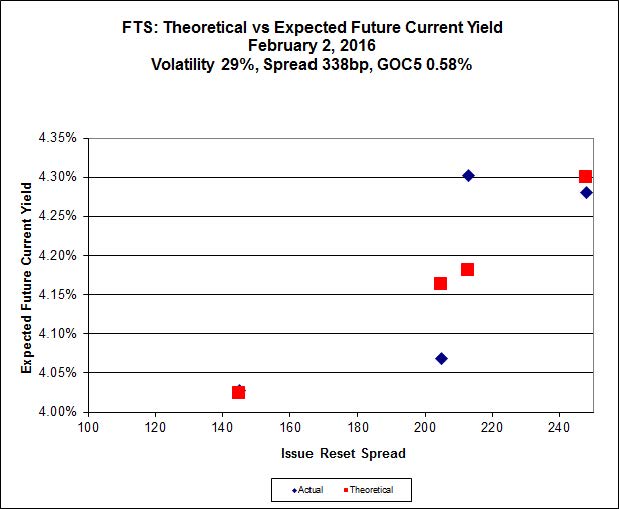
FTS.PR.K, with a spread of +205bp, and bid at 16.16, looks $0.36 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 15.75 and is $0.45 cheap.
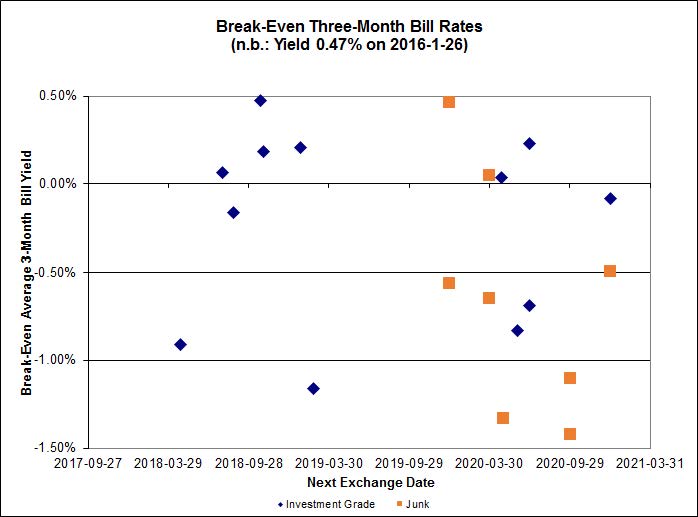
pairs_FR_160202
Click for Big

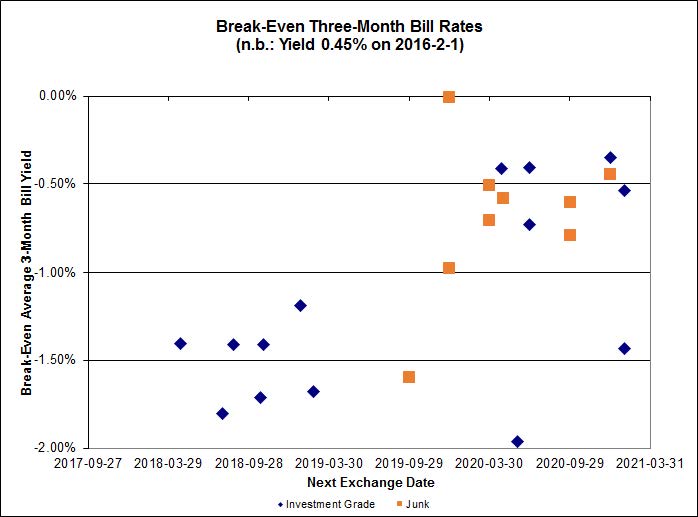
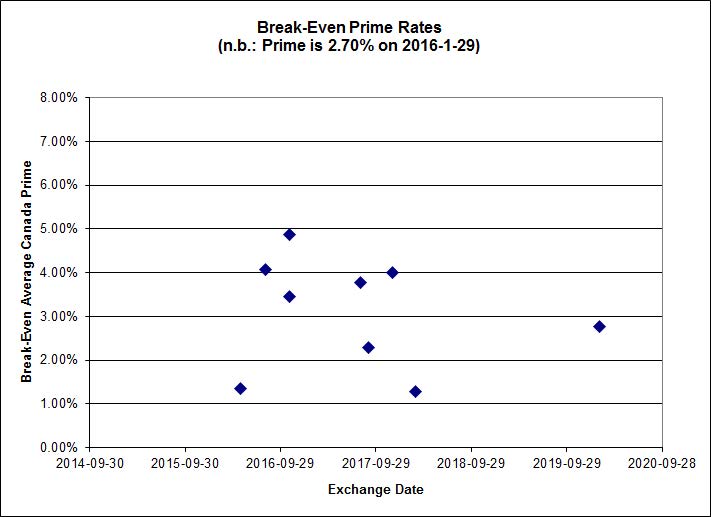
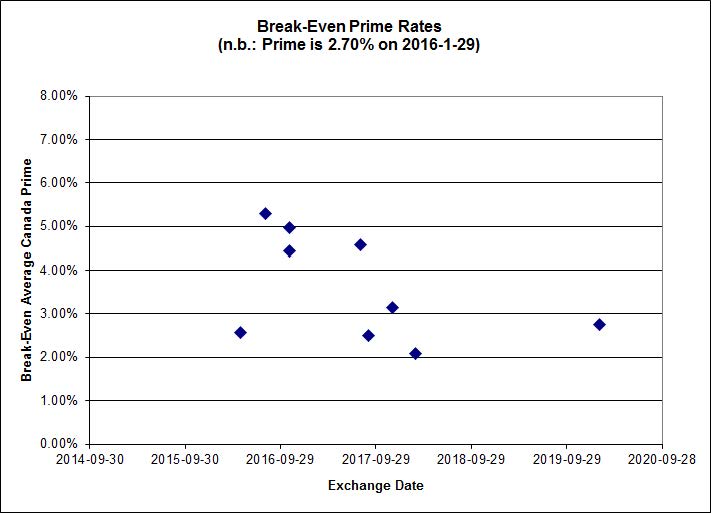
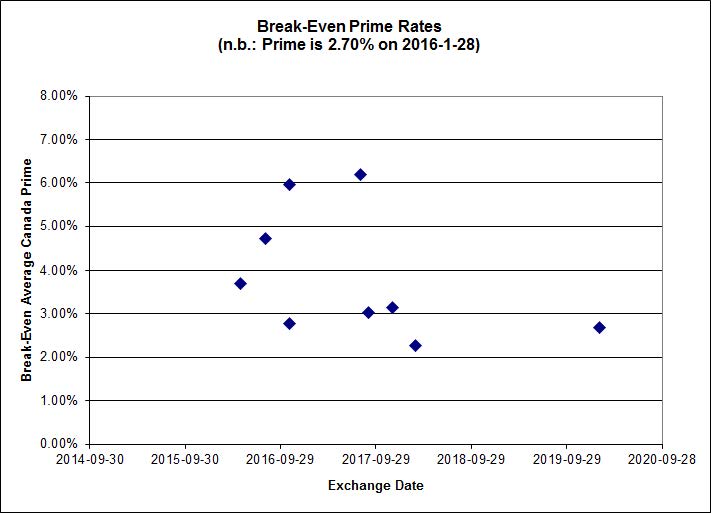
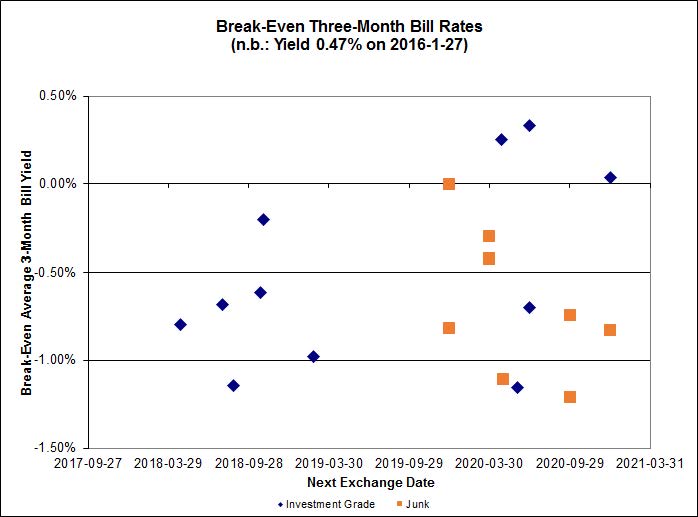
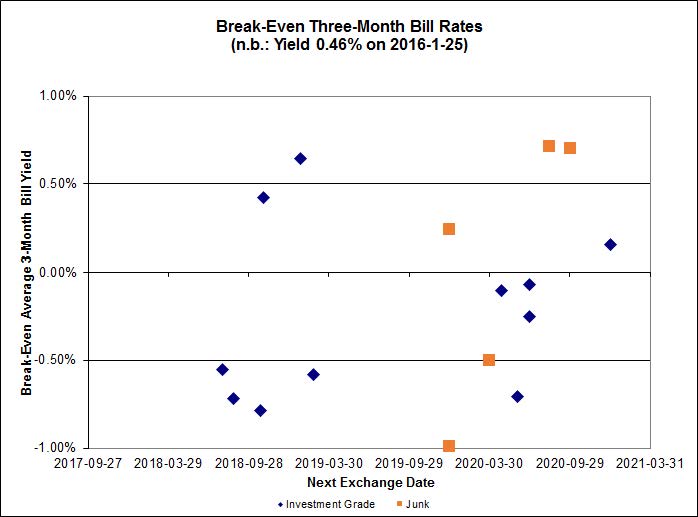
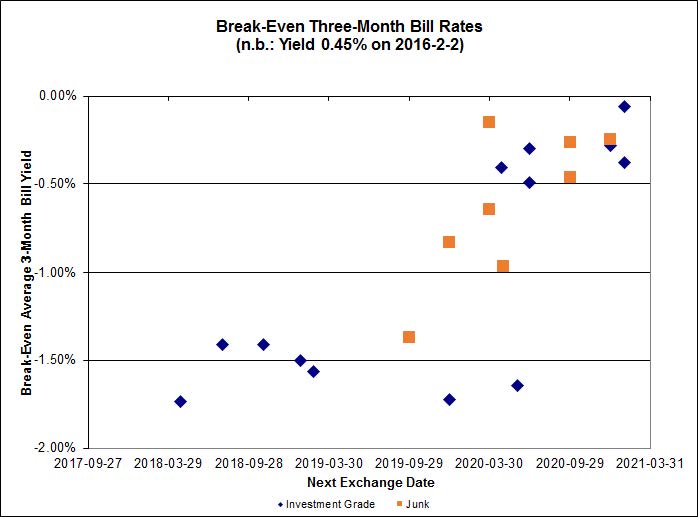
Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -1.06%, with two outliers below -2.00% and one above 0.00%. There are three junk outliers above 0.00%.
pairs_FF_160202
Click for Big

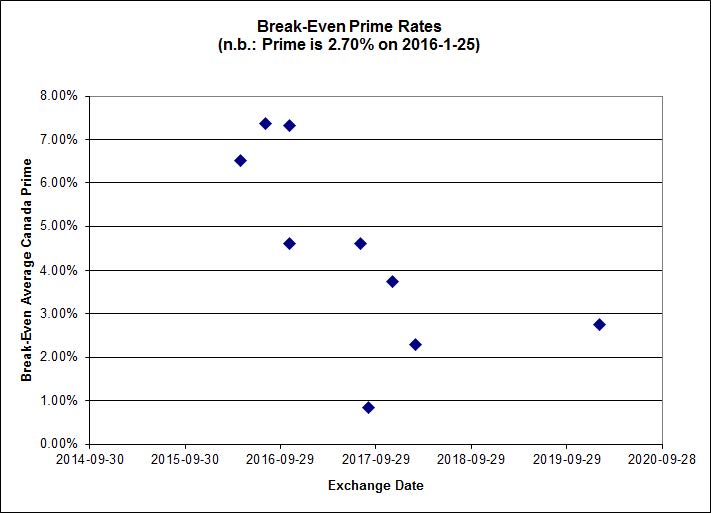
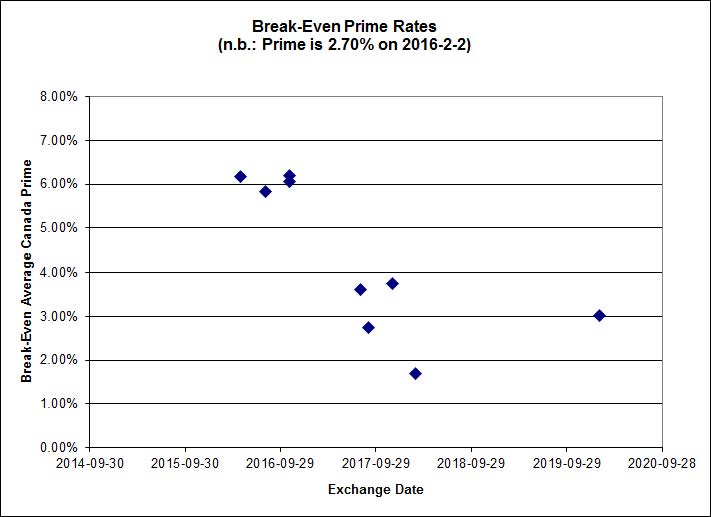
Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.29 % 6.43 % 18,792 16.16 1 0.0782 % 1,474.7
FixedFloater 7.66 % 6.69 % 28,958 15.57 1 -1.5873 % 2,595.0
Floater 4.69 % 4.90 % 75,814 15.66 4 -0.7632 % 1,635.3
OpRet 0.00 % 0.00 % 0 0.00 0 0.0069 % 2,700.8
SplitShare 4.89 % 6.30 % 81,252 2.71 6 0.0069 % 3,160.5
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0069 % 2,465.9
Perpetual-Premium 5.86 % 5.86 % 82,558 14.00 6 0.1403 % 2,517.6
Perpetual-Discount 5.80 % 5.84 % 99,234 14.11 33 -0.0487 % 2,487.0
FixedReset 5.49 % 4.97 % 224,497 14.50 84 -0.6746 % 1,836.6
Deemed-Retractible 5.27 % 5.67 % 130,702 6.95 34 -0.1110 % 2,564.1
FloatingReset 3.13 % 4.82 % 56,797 5.56 15 -0.1057 % 1,990.5
Performance Highlights
Issue Index Change Notes
FTS.PR.H FixedReset -4.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 12.60
Evaluated at bid price : 12.60
Bid-YTW : 4.47 %
SLF.PR.H FixedReset -3.62 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.10
Bid-YTW : 10.70 %
IAG.PR.G FixedReset -3.54 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.25
Bid-YTW : 8.04 %
MFC.PR.K FixedReset -3.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.03
Bid-YTW : 9.31 %
CM.PR.P FixedReset -2.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 16.70
Evaluated at bid price : 16.70
Bid-YTW : 4.68 %
FTS.PR.I FloatingReset -2.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 10.20
Evaluated at bid price : 10.20
Bid-YTW : 4.72 %
IFC.PR.A FixedReset -2.55 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.14
Bid-YTW : 10.59 %
BAM.PR.K Floater -2.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 9.75
Evaluated at bid price : 9.75
Bid-YTW : 4.90 %
HSE.PR.A FixedReset -2.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 8.50
Evaluated at bid price : 8.50
Bid-YTW : 7.21 %
BNS.PR.B FloatingReset -2.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.03
Bid-YTW : 5.21 %
CM.PR.Q FixedReset -2.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 18.60
Evaluated at bid price : 18.60
Bid-YTW : 4.74 %
FTS.PR.F Perpetual-Discount -2.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 21.37
Evaluated at bid price : 21.64
Bid-YTW : 5.75 %
SLF.PR.G FixedReset -2.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.75
Bid-YTW : 10.97 %
FTS.PR.M FixedReset -2.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 17.87
Evaluated at bid price : 17.87
Bid-YTW : 4.78 %
PWF.PR.P FixedReset -2.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 12.00
Evaluated at bid price : 12.00
Bid-YTW : 4.80 %
TRP.PR.G FixedReset -2.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 18.26
Evaluated at bid price : 18.26
Bid-YTW : 5.13 %
FTS.PR.J Perpetual-Discount -2.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 20.89
Evaluated at bid price : 20.89
Bid-YTW : 5.79 %
RY.PR.P Perpetual-Discount -2.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 23.49
Evaluated at bid price : 23.81
Bid-YTW : 5.51 %
TRP.PR.A FixedReset -1.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 14.10
Evaluated at bid price : 14.10
Bid-YTW : 4.93 %
BAM.PR.B Floater -1.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 9.73
Evaluated at bid price : 9.73
Bid-YTW : 4.91 %
BAM.PR.G FixedFloater -1.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 25.00
Evaluated at bid price : 12.40
Bid-YTW : 6.69 %
RY.PR.M FixedReset -1.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 18.11
Evaluated at bid price : 18.11
Bid-YTW : 4.67 %
BAM.PF.F FixedReset -1.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 18.80
Evaluated at bid price : 18.80
Bid-YTW : 5.03 %
BAM.PF.A FixedReset -1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 18.36
Evaluated at bid price : 18.36
Bid-YTW : 5.13 %
TD.PR.S FixedReset -1.50 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.62
Bid-YTW : 3.81 %
RY.PR.I FixedReset -1.50 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.64
Bid-YTW : 4.10 %
PWF.PR.S Perpetual-Discount -1.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 20.70
Evaluated at bid price : 20.70
Bid-YTW : 5.84 %
BAM.PR.Z FixedReset -1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 5.30 %
BNS.PR.A FloatingReset -1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.44
Bid-YTW : 4.38 %
MFC.PR.J FixedReset -1.35 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.56
Bid-YTW : 8.38 %
RY.PR.K FloatingReset -1.29 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.47
Bid-YTW : 5.06 %
W.PR.K FixedReset -1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 22.82
Evaluated at bid price : 24.10
Bid-YTW : 5.46 %
RY.PR.Z FixedReset -1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 17.34
Evaluated at bid price : 17.34
Bid-YTW : 4.45 %
NA.PR.W FixedReset -1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 16.30
Evaluated at bid price : 16.30
Bid-YTW : 4.84 %
IFC.PR.C FixedReset -1.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.40
Bid-YTW : 9.21 %
RY.PR.H FixedReset -1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 17.32
Evaluated at bid price : 17.32
Bid-YTW : 4.51 %
IAG.PR.A Deemed-Retractible -1.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.65
Bid-YTW : 7.39 %
MFC.PR.C Deemed-Retractible -1.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.61
Bid-YTW : 7.32 %
CM.PR.O FixedReset -1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 17.41
Evaluated at bid price : 17.41
Bid-YTW : 4.59 %
BAM.PR.R FixedReset -1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 13.41
Evaluated at bid price : 13.41
Bid-YTW : 5.71 %
MFC.PR.I FixedReset -1.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.25
Bid-YTW : 8.14 %
TD.PF.B FixedReset -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 17.20
Evaluated at bid price : 17.20
Bid-YTW : 4.54 %
RY.PR.F Deemed-Retractible 1.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.10
Bid-YTW : 5.13 %
TRP.PR.H FloatingReset 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 9.30
Evaluated at bid price : 9.30
Bid-YTW : 4.70 %
BMO.PR.M FixedReset 1.18 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.05
Bid-YTW : 3.48 %
TRP.PR.D FixedReset 1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 16.50
Evaluated at bid price : 16.50
Bid-YTW : 4.92 %
PWF.PR.L Perpetual-Discount 1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 21.75
Evaluated at bid price : 22.00
Bid-YTW : 5.83 %
GWO.PR.P Deemed-Retractible 1.35 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.10
Bid-YTW : 6.03 %
PWF.PR.A Floater 1.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 11.08
Evaluated at bid price : 11.08
Bid-YTW : 4.26 %
TD.PF.E FixedReset 1.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 19.73
Evaluated at bid price : 19.73
Bid-YTW : 4.57 %
HSE.PR.G FixedReset 1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 15.60
Evaluated at bid price : 15.60
Bid-YTW : 7.03 %
HSE.PR.E FixedReset 1.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 15.42
Evaluated at bid price : 15.42
Bid-YTW : 7.12 %
HSE.PR.C FixedReset 2.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 14.50
Evaluated at bid price : 14.50
Bid-YTW : 6.99 %
PWF.PR.Q FloatingReset 4.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 11.75
Evaluated at bid price : 11.75
Bid-YTW : 4.39 %
TRP.PR.I FloatingReset 11.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 10.00
Evaluated at bid price : 10.00
Bid-YTW : 5.01 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.Q FixedReset 110,167 RBC crossed 50,000 at 25.60. Scotia crossed 25,000 at the same price.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 23.31
Evaluated at bid price : 25.55
Bid-YTW : 5.13 %
BAM.PR.C Floater 99,915 Scotia crossed 92,000 at 9.80.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 9.75
Evaluated at bid price : 9.75
Bid-YTW : 4.90 %
NA.PR.X FixedReset 70,505 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 23.13
Evaluated at bid price : 24.95
Bid-YTW : 5.55 %
BNS.PR.E FixedReset 68,429 RBC crossed 25,000 at 25.72. Desjardins crossed 18,500 at 25.59.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 23.34
Evaluated at bid price : 25.62
Bid-YTW : 5.10 %
SLF.PR.D Deemed-Retractible 43,666 Scotia crossed 40,000 at 20.30.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.35
Bid-YTW : 7.42 %
TD.PF.G FixedReset 38,311 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 25.61
Bid-YTW : 5.06 %
There were 15 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
MFC.PR.K FixedReset Quote: 16.03 – 16.59
Spot Rate : 0.5600
Average : 0.3572

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.03
Bid-YTW : 9.31 %

BNS.PR.B FloatingReset Quote: 21.03 – 21.80
Spot Rate : 0.7700
Average : 0.5949

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.03
Bid-YTW : 5.21 %

BNS.PR.A FloatingReset Quote: 22.44 – 22.99
Spot Rate : 0.5500
Average : 0.3835

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.44
Bid-YTW : 4.38 %

RY.PR.P Perpetual-Discount Quote: 23.81 – 24.40
Spot Rate : 0.5900
Average : 0.4313

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-02
Maturity Price : 23.49
Evaluated at bid price : 23.81
Bid-YTW : 5.51 %

BMO.PR.R FloatingReset Quote: 21.75 – 22.50
Spot Rate : 0.7500
Average : 0.5946

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.75
Bid-YTW : 4.53 %

SLF.PR.H FixedReset Quote: 14.10 – 14.75
Spot Rate : 0.6500
Average : 0.4946

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.10
Bid-YTW : 10.70 %

Market Action

February 1, 2016

Nothing happened today. But January’s finished with – that’s enough good news for one day!

It was a mixed day for the Canadian preferred share market, with PerpetualDiscounts gaining 9bp, FixedResets up 41bp and DeemedRetractibles off 16bp. The Performance Highlights table is published (I’ve run out of things to say over the past year!). Volume was extremely low.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_160201
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 17.06 to be $0.87 rich, while TRP.PR.C, resetting 2021-1-30 at +154, is $0.80 cheap at its bid price of 11.15.

impVol_MFC_160201
Click for Big

Most expensive is MFC.PR.N, resetting at +230bp on 2020-3-19, bid at 17.79 to be 1.01 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 17.80 to be 1.18 cheap.

impVol_BAM_160201
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 13.56 to be $1.76 cheap. BAM.PF.F, resetting at +286bp on 2019-9-30 is bid at 19.09 and appears to be $0.87 rich.

impVol_FTS_160201
Click for Big

FTS.PR.M, with a spread of +248bp, and bid at 18.26, looks $0.36 expensive and resets 2019-12-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 15.75 and is $0.68 cheap.

pairs_FR_160201
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -1.24%, with one outlier below -2.00%. There are two junk outliers above 0.00%.

pairs_FF_160201
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.30 % 6.43 % 18,358 16.16 1 -0.0781 % 1,473.5
FixedFloater 7.54 % 6.59 % 27,452 15.71 1 0.0794 % 2,636.9
Floater 4.65 % 4.77 % 70,336 15.89 4 -0.1229 % 1,647.9
OpRet 0.00 % 0.00 % 0 0.00 0 0.1252 % 2,700.6
SplitShare 4.89 % 6.38 % 80,844 2.71 6 0.1252 % 3,160.2
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1252 % 2,465.7
Perpetual-Premium 5.87 % 5.87 % 81,661 14.00 6 0.0334 % 2,514.1
Perpetual-Discount 5.79 % 5.85 % 100,080 14.09 33 0.0877 % 2,488.2
FixedReset 5.49 % 4.93 % 233,222 14.35 83 0.4073 % 1,849.1
Deemed-Retractible 5.26 % 5.61 % 132,652 5.23 34 -0.1624 % 2,566.9
FloatingReset 3.12 % 4.69 % 57,344 5.57 15 -1.1631 % 1,992.6
Performance Highlights
Issue Index Change Notes
HSE.PR.A FixedReset -2.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-01
Maturity Price : 8.70
Evaluated at bid price : 8.70
Bid-YTW : 7.04 %
GWO.PR.O FloatingReset -2.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.01
Bid-YTW : 12.22 %
BAM.PR.R FixedReset -2.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-01
Maturity Price : 13.56
Evaluated at bid price : 13.56
Bid-YTW : 5.65 %
FTS.PR.I FloatingReset -1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-01
Maturity Price : 10.49
Evaluated at bid price : 10.49
Bid-YTW : 4.59 %
TD.PF.E FixedReset -1.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-01
Maturity Price : 19.39
Evaluated at bid price : 19.39
Bid-YTW : 4.65 %
FTS.PR.G FixedReset -1.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-01
Maturity Price : 15.75
Evaluated at bid price : 15.75
Bid-YTW : 4.79 %
TRP.PR.D FixedReset -1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-01
Maturity Price : 16.30
Evaluated at bid price : 16.30
Bid-YTW : 4.99 %
TRP.PR.E FixedReset -1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-01
Maturity Price : 17.06
Evaluated at bid price : 17.06
Bid-YTW : 4.84 %
BAM.PF.E FixedReset -1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-01
Maturity Price : 17.46
Evaluated at bid price : 17.46
Bid-YTW : 5.08 %
SLF.PR.E Deemed-Retractible -1.29 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.60
Bid-YTW : 7.30 %
TRP.PR.F FloatingReset -1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-01
Maturity Price : 11.57
Evaluated at bid price : 11.57
Bid-YTW : 5.18 %
HSE.PR.E FixedReset -1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-01
Maturity Price : 15.12
Evaluated at bid price : 15.12
Bid-YTW : 7.26 %
BAM.PF.D Perpetual-Discount -1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-01
Maturity Price : 19.53
Evaluated at bid price : 19.53
Bid-YTW : 6.36 %
SLF.PR.C Deemed-Retractible -1.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.58
Bid-YTW : 7.26 %
CIU.PR.C FixedReset 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-01
Maturity Price : 10.68
Evaluated at bid price : 10.68
Bid-YTW : 4.93 %
MFC.PR.I FixedReset 1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.45
Bid-YTW : 7.98 %
MFC.PR.M FixedReset 1.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.00
Bid-YTW : 8.00 %
BMO.PR.M FixedReset 1.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.77
Bid-YTW : 3.69 %
BNS.PR.Q FixedReset 1.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.75
Bid-YTW : 3.93 %
MFC.PR.K FixedReset 1.29 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.54
Bid-YTW : 8.86 %
BMO.PR.Z Perpetual-Discount 1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-01
Maturity Price : 22.64
Evaluated at bid price : 23.00
Bid-YTW : 5.43 %
FTS.PR.M FixedReset 1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-01
Maturity Price : 18.26
Evaluated at bid price : 18.26
Bid-YTW : 4.68 %
BNS.PR.R FixedReset 1.48 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.95
Bid-YTW : 4.04 %
SLF.PR.I FixedReset 1.53 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.26
Bid-YTW : 8.61 %
BAM.PF.F FixedReset 1.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-01
Maturity Price : 19.09
Evaluated at bid price : 19.09
Bid-YTW : 4.95 %
RY.PR.K FloatingReset 1.64 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.75
Bid-YTW : 4.82 %
BNS.PR.B FloatingReset 1.65 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.51
Bid-YTW : 4.79 %
TRP.PR.H FloatingReset 1.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-01
Maturity Price : 9.20
Evaluated at bid price : 9.20
Bid-YTW : 4.75 %
BNS.PR.A FloatingReset 1.84 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.75
Bid-YTW : 4.13 %
IFC.PR.C FixedReset 1.84 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.60
Bid-YTW : 9.03 %
RY.PR.I FixedReset 1.91 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.00
Bid-YTW : 3.81 %
GWO.PR.N FixedReset 1.91 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.25
Bid-YTW : 11.37 %
MFC.PR.L FixedReset 2.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.95
Bid-YTW : 8.64 %
IFC.PR.A FixedReset 2.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.51
Bid-YTW : 10.21 %
BIP.PR.B FixedReset 2.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-01
Maturity Price : 22.57
Evaluated at bid price : 23.55
Bid-YTW : 5.89 %
IAG.PR.A Deemed-Retractible 2.30 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.90
Bid-YTW : 7.21 %
BNS.PR.P FixedReset 2.42 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.15
Bid-YTW : 3.62 %
FTS.PR.H FixedReset 2.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-01
Maturity Price : 13.20
Evaluated at bid price : 13.20
Bid-YTW : 4.26 %
PWF.PR.S Perpetual-Discount 2.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-01
Maturity Price : 21.00
Evaluated at bid price : 21.00
Bid-YTW : 5.76 %
MFC.PR.J FixedReset 3.19 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.80
Bid-YTW : 8.19 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PF.B FixedReset 118,733 Nesbitt crossed blocks of 40,000 and 70,000, both at 17.45.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-01
Maturity Price : 17.38
Evaluated at bid price : 17.38
Bid-YTW : 4.50 %
NA.PR.X FixedReset 98,953 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-01
Maturity Price : 23.13
Evaluated at bid price : 24.96
Bid-YTW : 5.55 %
RY.PR.Q FixedReset 65,296 RBC crossed 25,000 at 25.75.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-01
Maturity Price : 23.34
Evaluated at bid price : 25.66
Bid-YTW : 5.10 %
BNS.PR.E FixedReset 48,206 RBC crossed 25,000 at 25.70. Desjardins crossed 10,000 at 25.72.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-25
Maturity Price : 25.00
Evaluated at bid price : 25.70
Bid-YTW : 5.07 %
BMO.PR.W FixedReset 37,655 Scotia crossed 25,300 at 16.86.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-01
Maturity Price : 16.91
Evaluated at bid price : 16.91
Bid-YTW : 4.56 %
BMO.PR.T FixedReset 30,823 Desjardins crossed 20,000 at 17.16.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-01
Maturity Price : 17.05
Evaluated at bid price : 17.05
Bid-YTW : 4.56 %
There were 11 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
GWO.PR.O FloatingReset Quote: 11.01 – 12.50
Spot Rate : 1.4900
Average : 1.1889

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.01
Bid-YTW : 12.22 %

RY.PR.K FloatingReset Quote: 21.75 – 22.58
Spot Rate : 0.8300
Average : 0.5717

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.75
Bid-YTW : 4.82 %

GWO.PR.N FixedReset Quote: 12.25 – 12.90
Spot Rate : 0.6500
Average : 0.4547

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.25
Bid-YTW : 11.37 %

TD.PF.E FixedReset Quote: 19.39 – 19.99
Spot Rate : 0.6000
Average : 0.4256

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-01
Maturity Price : 19.39
Evaluated at bid price : 19.39
Bid-YTW : 4.65 %

FTS.PR.K FixedReset Quote: 16.15 – 16.59
Spot Rate : 0.4400
Average : 0.2784

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-01
Maturity Price : 16.15
Evaluated at bid price : 16.15
Bid-YTW : 4.64 %

MFC.PR.J FixedReset Quote: 17.80 – 18.31
Spot Rate : 0.5100
Average : 0.3650

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.80
Bid-YTW : 8.19 %

Market Action

January 29, 2016

Today’s big news was the Bank of Japan moving the deposit rate to negative:

Bank of Japan Governor Haruhiko Kuroda is matching European Central Bank President Mario Draghi in pursuing negative interest rates, and even pulling ahead when it comes to driving longer-term bond yields lower.

The yen plunged more than 1 percent against the euro after Kuroda unexpectedly cut the rate on excess reserves held by financial institutions at the BOJ to minus 0.1 percent. Two-year Japanese government bond yields sank to minus 0.085 percent, closing the gap on German negative yields, while 10-year JGB yields of 0.09 percent are lower than similar-dated bunds. Kuroda said the central bank will cut the rate further if needed and that he expects to drive yields lower across the bond curve.
…
Kuroda said Friday that negative rates don’t replace quantitative easing, they simply add to the BOJ’s options. The central bank pushed back its time frame for reaching stable 2 percent inflation to around the six months starting in April 2017, the third postponement in less than a year. The bank now sees inflation rising 0.8 percent in the 12 months starting this April, down from a previous forecast of 1.4 percent.

European and Japanese policy makers have faced extra pressure to boost stimulus after the yen and euro outperformed major peers for most of this month amid demand for havens as tumbling crude oil prices and concerns China’s economy is slowing spurred a more than $6 trillion rout in global stock markets.

This had an immediate effect on US equities:

U.S. stocks joined an advance in global equities, while bonds rallied as the Bank of Japan’s unexpected monetary stimulus boosted confidence that central banks remain vigilant of slowing economic growth. The yen tumbled, while oil gained.

The Standard & Poor’s 500 Index extended gains throughout the day to post the biggest advance since Sept. 8, while the Dow Jones Industrial Average rose almost 400 points as Microsoft Corp. rallied on earnings. Yields on 10-year Treasury notes retreated, while Japanese yields fell to records after the BOJ adopted a negative interest rate. The yen weakened versus the U.S. dollar by the most in more than a year. Oil climbed for a fourth day.

… and further doubt was cast on the prospects for Fed hikes:

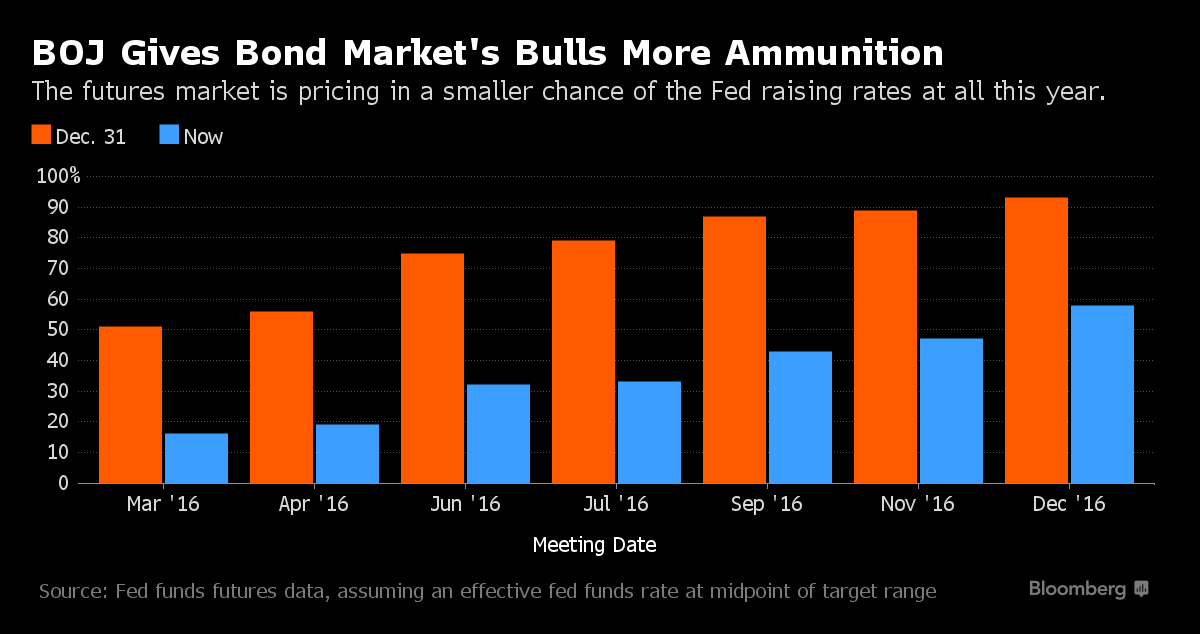
In the bond market’s view, the chance of a Federal Reserve interest-rate increase this year is practically a toss-up after the Bank of Japan’s surprise policy move.

Yields on sovereign debt fell worldwide after BOJ Governor Haruhiko Kuroda introduced negative interest rates for some bank reserves to support the world’s third-biggest economy. Derivatives traders see less than a 60 percent shot that the Fed will raise its benchmark even once this year, let alone the four quarter-point increases that policy makers projected in December.

The move from Japan is another sign of slowing global economic growth, which triggered volatility across global markets to start the year. The European Central Bank has also signaled it may add stimulus. The divergence between U.S. monetary policy and the stances in Japan and the euro region risk strengthening the greenback by driving global investors to higher-yielding American assets. That could further damp inflation in the U.S., which hasn’t reached the Fed’s 2 percent target since 2012.

FedHikeOdds
Click for Big

And the rise in oil helped out Canada’s market as well:

Canadian stocks climbed a fourth day, trimming a monthly drop that sent shares into a bear market earlier this year, as crude prices rose and data showed the resource-rich nation’s economy expanded for the first time in three months.

The Standard & Poor’s/TSX Composite Index rose 1.8 percent to 12,822.13 at 4 p.m. in Toronto. The index has rallied 8.3 percent since hitting a 2 1/2-year low on Jan. 20. While the benchmark equity gauge posted its first negative January since 2010, the late rally among energy producers has boosted the S&P/TSX’s performance to the best among developed markets this year.

Which is a good thing, because real estate is the only Canadian bright spot:

Softness in the economy has been concentrated in goods-producing sectors, which shrunk by 2.6 percent year-to-date through November. Given the carnage in commodities, the slump in construction tied to non-residential investment and mining and oil and gas extraction comes as no surprise.

Meanwhile, the services sector continues to chug along with real output up 1 percent. This suggests that the commodity collapse has yet to infect the broader economy. The bad news? The majority of that growth–53 percent–can be attributed to a single sub-sector, and one that many economists fear was cyclically overextended even before this stretch of out-performance.

realEstateGrowthProportion
Click for Big

I seem to remember a similar figure being cited for the proportion of US growth attributable to housing in the 2000-2007 period, but can’t find a citation.

But we’ll close for today with a lecture on history modification:

Oxford University’s Oriel College has decided not to tear down its statue of the British colonialist Cecil Rhodes, because of the “overwhelming message” it received that the statue should stay. The true motive appears to have been money.

The college reportedly cut short its promised six-month “listening exercise,” after it became clear that even to continue a debate on the subject could cost as much as £100 million in donations from alumni. That would catch the attention of any educational institution.
…
Chris Patten, the last British governor of Hong Kong and the University’s Chancellor, had it right when he said earlier this month that students were free to speak out against whatever they wish — Rhodes, racism or the British Empire — but not to erase history. If that’s what they need, “they should think about being educated elsewhere”:

We have to listen to those who presume that they can re-write history within the confines of their own notion of what is politically, culturally and morally correct. We do have to listen, yes – but speaking for myself, I believe it would be intellectually pusillanimous to listen for too long without saying what we think, reaffirming the values that are at the heart of Karl Popper’s ‘Open Society’ and the generosity of spirit that animated the life of Nelson Mandela. One thing we should never tolerate is intolerance. We do not want to turn our university into a drab, bland, suburb of the soul where the diet is intellectual porridge.

It was a superb day for the Canadian preferred share market, with PerpetualDiscounts winning 108bp, FixedResets up 99bp and DeemedRetractibles gaining 75bp. The lengthy Performance Highlights table shows two HSE issues at the top – even as HSE was put on Trend-Negative by DBRS. Volume was average.

But however pleasant the day might have been, it’s a big relief to have finished the month! The TXPR Total Return index is down about 10.40% on the month while TXPL is down about 14.73%. This is stunning. As discussed on January 15, the worst month recorded by the BMO-CM “50” since 1993 was November, 2008, at -10.7%, while October, 2008, will probably slip to third place with a mere 8.2% loss. It’s incredible.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_160129
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 17.30 to be $1.07 rich, while TRP.PR.C, resetting 2021-1-30 at +154, is $0.88 cheap at its bid price of 11.15.

impVol_MFC_160129
Click for Big

Most expensive is MFC.PR.N, resetting at +230bp on 2020-3-19, bid at 17.65 to be 1.04 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 17.89 to be 0.92 cheap.

impVol_BAM_160129
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 13.84 to be $1.50 cheap. BAM.PF.E, resetting at +255bp on 2020-3-31 is bid at 17.70 and appears to be $1.07 rich.

impVol_FTS_160129
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 16.29, looks $0.32 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 16.00 and is $0.37 cheap.

pairs_FR_160129
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -1.04%, with one outlier below -2.00% and one above 0.00%. There are two junk outliers above 0.00%.

pairs_FF_160129
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.29 % 6.43 % 19,060 16.17 1 0.0782 % 1,474.7
FixedFloater 7.55 % 6.59 % 27,928 15.71 1 1.5323 % 2,634.8
Floater 4.65 % 4.77 % 71,286 15.90 4 0.0984 % 1,649.9
OpRet 0.00 % 0.00 % 0 0.00 0 0.4614 % 2,697.2
SplitShare 4.90 % 6.71 % 81,879 2.72 6 0.4614 % 3,156.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.4614 % 2,462.7
Perpetual-Premium 5.87 % 5.85 % 84,063 13.94 6 0.7474 % 2,513.2
Perpetual-Discount 5.80 % 5.86 % 101,817 14.09 33 1.0802 % 2,486.0
FixedReset 5.61 % 4.96 % 236,096 14.62 83 0.9863 % 1,841.6
Deemed-Retractible 5.25 % 5.68 % 133,217 6.96 34 0.7483 % 2,571.1
FloatingReset 2.98 % 4.61 % 57,808 5.57 13 -0.0089 % 2,016.1
Performance Highlights
Issue Index Change Notes
IAG.PR.G FixedReset -2.95 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.75
Bid-YTW : 7.67 %
RY.PR.K FloatingReset -1.97 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.40
Bid-YTW : 5.12 %
PWF.PR.S Perpetual-Discount -1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 20.44
Evaluated at bid price : 20.44
Bid-YTW : 5.91 %
GWO.PR.N FixedReset 1.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.02
Bid-YTW : 11.63 %
GWO.PR.I Deemed-Retractible 1.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.92
Bid-YTW : 7.07 %
RY.PR.P Perpetual-Discount 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 23.99
Evaluated at bid price : 24.35
Bid-YTW : 5.38 %
BAM.PR.M Perpetual-Discount 1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 19.25
Evaluated at bid price : 19.25
Bid-YTW : 6.25 %
BMO.PR.Z Perpetual-Discount 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 22.39
Evaluated at bid price : 22.70
Bid-YTW : 5.50 %
ELF.PR.F Perpetual-Discount 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 22.01
Evaluated at bid price : 22.25
Bid-YTW : 6.00 %
GWO.PR.P Deemed-Retractible 1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.89
Bid-YTW : 6.15 %
BMO.PR.T FixedReset 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 17.10
Evaluated at bid price : 17.10
Bid-YTW : 4.58 %
GWO.PR.G Deemed-Retractible 1.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.08
Bid-YTW : 6.44 %
BNS.PR.M Deemed-Retractible 1.21 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.32
Bid-YTW : 5.05 %
TRP.PR.F FloatingReset 1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 11.71
Evaluated at bid price : 11.71
Bid-YTW : 5.13 %
BAM.PF.D Perpetual-Discount 1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 19.75
Evaluated at bid price : 19.75
Bid-YTW : 6.29 %
PWF.PR.K Perpetual-Discount 1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 21.38
Evaluated at bid price : 21.38
Bid-YTW : 5.83 %
MFC.PR.B Deemed-Retractible 1.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.27
Bid-YTW : 7.03 %
RY.PR.N Perpetual-Discount 1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 22.12
Evaluated at bid price : 22.46
Bid-YTW : 5.45 %
TD.PR.S FixedReset 1.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.90
Bid-YTW : 3.60 %
NA.PR.Q FixedReset 1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.16
Bid-YTW : 4.76 %
MFC.PR.G FixedReset 1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.89
Bid-YTW : 8.37 %
CU.PR.E Perpetual-Discount 1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 21.32
Evaluated at bid price : 21.32
Bid-YTW : 5.85 %
CM.PR.O FixedReset 1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 17.60
Evaluated at bid price : 17.60
Bid-YTW : 4.58 %
BAM.PR.Z FixedReset 1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 18.25
Evaluated at bid price : 18.25
Bid-YTW : 5.26 %
TD.PF.F Perpetual-Discount 1.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 22.16
Evaluated at bid price : 22.51
Bid-YTW : 5.46 %
PVS.PR.B SplitShare 1.40 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2019-01-10
Maturity Price : 25.00
Evaluated at bid price : 23.83
Bid-YTW : 6.39 %
POW.PR.G Perpetual-Discount 1.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 23.71
Evaluated at bid price : 24.16
Bid-YTW : 5.83 %
CU.PR.D Perpetual-Discount 1.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 21.27
Evaluated at bid price : 21.27
Bid-YTW : 5.87 %
RY.PR.A Deemed-Retractible 1.43 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.09
Bid-YTW : 5.13 %
RY.PR.O Perpetual-Discount 1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 22.08
Evaluated at bid price : 22.40
Bid-YTW : 5.46 %
RY.PR.G Deemed-Retractible 1.47 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.17
Bid-YTW : 5.12 %
TRP.PR.A FixedReset 1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 14.40
Evaluated at bid price : 14.40
Bid-YTW : 4.86 %
IFC.PR.A FixedReset 1.50 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.21
Bid-YTW : 10.53 %
GWO.PR.H Deemed-Retractible 1.53 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.89
Bid-YTW : 6.82 %
BAM.PR.G FixedFloater 1.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 25.00
Evaluated at bid price : 12.59
Bid-YTW : 6.59 %
ELF.PR.H Perpetual-Discount 1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 22.65
Evaluated at bid price : 23.00
Bid-YTW : 6.02 %
CU.PR.C FixedReset 1.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 17.30
Evaluated at bid price : 17.30
Bid-YTW : 4.67 %
MFC.PR.H FixedReset 1.66 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.54
Bid-YTW : 7.43 %
TRP.PR.G FixedReset 1.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 18.50
Evaluated at bid price : 18.50
Bid-YTW : 5.09 %
CIU.PR.C FixedReset 1.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 10.57
Evaluated at bid price : 10.57
Bid-YTW : 5.05 %
POW.PR.B Perpetual-Discount 1.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 22.69
Evaluated at bid price : 22.98
Bid-YTW : 5.86 %
RY.PR.W Perpetual-Discount 1.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 22.66
Evaluated at bid price : 22.90
Bid-YTW : 5.35 %
BAM.PR.X FixedReset 1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 12.53
Evaluated at bid price : 12.53
Bid-YTW : 5.41 %
CU.PR.F Perpetual-Discount 1.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 19.80
Evaluated at bid price : 19.80
Bid-YTW : 5.79 %
POW.PR.A Perpetual-Discount 1.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 23.83
Evaluated at bid price : 24.08
Bid-YTW : 5.86 %
FTS.PR.F Perpetual-Discount 2.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 21.69
Evaluated at bid price : 21.94
Bid-YTW : 5.67 %
TD.PR.Y FixedReset 2.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.83
Bid-YTW : 3.84 %
CU.PR.G Perpetual-Discount 2.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 19.60
Evaluated at bid price : 19.60
Bid-YTW : 5.85 %
MFC.PR.I FixedReset 2.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.25
Bid-YTW : 8.15 %
BAM.PR.R FixedReset 2.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 13.84
Evaluated at bid price : 13.84
Bid-YTW : 5.58 %
RY.PR.M FixedReset 2.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 18.42
Evaluated at bid price : 18.42
Bid-YTW : 4.62 %
MFC.PR.N FixedReset 2.32 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.65
Bid-YTW : 8.21 %
PWF.PR.H Perpetual-Premium 2.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 24.29
Evaluated at bid price : 24.60
Bid-YTW : 5.87 %
BIP.PR.B FixedReset 2.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 22.31
Evaluated at bid price : 23.05
Bid-YTW : 6.03 %
FTS.PR.K FixedReset 2.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 16.29
Evaluated at bid price : 16.29
Bid-YTW : 4.64 %
HSE.PR.G FixedReset 2.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 15.40
Evaluated at bid price : 15.40
Bid-YTW : 7.15 %
HSE.PR.C FixedReset 2.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 14.10
Evaluated at bid price : 14.10
Bid-YTW : 7.23 %
BNS.PR.L Deemed-Retractible 2.50 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.20
Bid-YTW : 5.15 %
MFC.PR.F FixedReset 2.64 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.05
Bid-YTW : 11.79 %
MFC.PR.M FixedReset 2.77 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.80
Bid-YTW : 8.17 %
FTS.PR.H FixedReset 2.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 12.85
Evaluated at bid price : 12.85
Bid-YTW : 4.42 %
FTS.PR.J Perpetual-Discount 2.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 21.20
Evaluated at bid price : 21.20
Bid-YTW : 5.70 %
BIP.PR.A FixedReset 2.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 17.81
Evaluated at bid price : 17.81
Bid-YTW : 6.16 %
CCS.PR.C Deemed-Retractible 3.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.71
Bid-YTW : 7.11 %
FTS.PR.G FixedReset 3.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 16.00
Evaluated at bid price : 16.00
Bid-YTW : 4.76 %
FTS.PR.M FixedReset 3.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 18.01
Evaluated at bid price : 18.01
Bid-YTW : 4.78 %
FTS.PR.I FloatingReset 3.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 10.70
Evaluated at bid price : 10.70
Bid-YTW : 4.52 %
PWF.PR.P FixedReset 3.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 12.00
Evaluated at bid price : 12.00
Bid-YTW : 4.86 %
TRP.PR.B FixedReset 3.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 10.35
Evaluated at bid price : 10.35
Bid-YTW : 4.96 %
SLF.PR.H FixedReset 3.55 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.60
Bid-YTW : 10.22 %
PWF.PR.T FixedReset 4.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 21.35
Evaluated at bid price : 21.35
Bid-YTW : 3.82 %
HSE.PR.A FixedReset 4.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 8.90
Evaluated at bid price : 8.90
Bid-YTW : 6.96 %
HSE.PR.E FixedReset 5.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 15.30
Evaluated at bid price : 15.30
Bid-YTW : 7.20 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PF.G FixedReset 177,471 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 25.61
Bid-YTW : 5.05 %
NA.PR.X FixedReset 103,750 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 23.12
Evaluated at bid price : 24.94
Bid-YTW : 5.57 %
RY.PR.M FixedReset 56,839 TD crossed 40,600 at 18.30.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 18.42
Evaluated at bid price : 18.42
Bid-YTW : 4.62 %
MFC.PR.G FixedReset 51,500 Scotia crossed 40,000 at 17.66.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.89
Bid-YTW : 8.37 %
RY.PR.Q FixedReset 50,272 Desjardins crossed 15,000 at 25.65.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 23.33
Evaluated at bid price : 25.61
Bid-YTW : 5.14 %
SLF.PR.H FixedReset 46,100 Scotia crossed 40,000 at 14.30.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.60
Bid-YTW : 10.22 %
There were 31 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BMO.PR.R FloatingReset Quote: 21.79 – 22.50
Spot Rate : 0.7100
Average : 0.5274

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.79
Bid-YTW : 4.50 %

SLF.PR.H FixedReset Quote: 14.60 – 15.10
Spot Rate : 0.5000
Average : 0.3290

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.60
Bid-YTW : 10.22 %

BMO.PR.S FixedReset Quote: 17.40 – 17.87
Spot Rate : 0.4700
Average : 0.3032

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 17.40
Evaluated at bid price : 17.40
Bid-YTW : 4.61 %

BNS.PR.P FixedReset Quote: 23.58 – 24.29
Spot Rate : 0.7100
Average : 0.5701

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.58
Bid-YTW : 4.08 %

BAM.PF.F FixedReset Quote: 18.80 – 19.60
Spot Rate : 0.8000
Average : 0.6625

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-29
Maturity Price : 18.80
Evaluated at bid price : 18.80
Bid-YTW : 5.06 %

BNS.PR.B FloatingReset Quote: 21.16 – 21.80
Spot Rate : 0.6400
Average : 0.5269

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.16
Bid-YTW : 5.09 %

Market Action

January 28, 2016

The regulatory push to move trading jobs offshore is showing signs of success:

The $13.2 trillion Treasuries market is getting pushed around more by global developments, the [JPMorgan] analysts wrote in a note titled “24 hour party people redux: Global liquidity in U.S. Treasury futures.”
…
Sleep-deprived Wall Street traders aren’t the only ones who should care. It underscores the changing structure of a market where plenty of strange distortions are happening, the analysts said.

Bond dealers’ trading books are smaller than before the financial crisis, and new regulations are making it more expensive to facilitate trades and provide some types of overnight financing. On top of that, reserve managers at global central banks sold more U.S. debt to raise cash last year, which put more pressure on the balance sheets of the dealers handling that business, the analysts said.

As a result, more trading is happening in futures relative to cash Treasuries, according to the note, since futures transactions don’t require banks to use their balance sheets. For one 10-year Treasury futures contract, about 5 percent of its volume comes around the open of trading in Tokyo and more than 25 percent is traded around the open in London, the analysts said.

To my dismay, the NYT has endorsed a Tobin Tax:

A well-designed financial transaction tax — one that applies a tiny tax rate to an array of transactions and is split between buyers and sellers — would be a progressive way to raise substantial revenue without damaging the markets. A new study by researchers at the nonpartisan Tax Policy Center has found that a 0.1 percent tax rate could bring in $66 billion a year, with 40 percent coming from the top 1 percent of income earners and 75 percent from the top 20 percent. As the rate rises, however, traders would most likely curtail their activity. The tax could bring in $76 billion a year if it was set at 0.3 percent, but above that rate, trading would probably decrease and the total revenue raised would start to fall.

The burden of this tax would be concentrated at the top, because that’s where the ownership of financial assets is concentrated.
…
Critics also contend that a financial transaction tax would have damaging effects on trade volume, volatility and the ability of markets to determine asset prices. That is debatable, and setting the tax rate low at first, and raising it gradually, would help avoid potential damage. But the possibility of unintended consequences is not the real obstacle to a broad and prudent financial transaction tax. It is that a majority of lawmakers are not willing to challenge Wall Street’s power. Imposing the tax will take leadership from the next president.

My opposition to a Tobin tax was last discussed on December 29, 2015.

A link in Ken Kivenko’s Fund Observer led me to an exhortation from the Consumers Council of Canada, which led me to an OSC-commissioned report titled Current Practices for Risk Profiling in Canada And Review of Global Best Practices, which led me to a Morningstar paper titled Variable Risk Preference Bias:

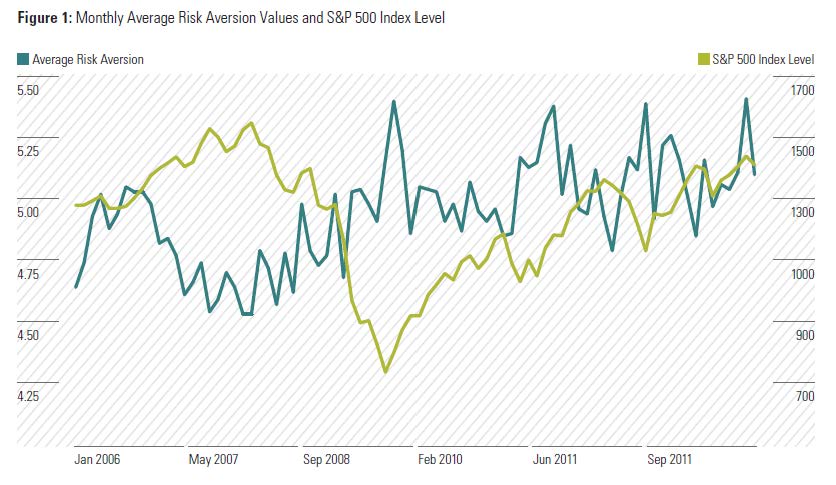
The average monthly risk aversion scores from our dataset are shown in Figure 1 along with the S&P 500 Index to illustrate the relation between stock returns and risk aversion over time.

riskAversionAndIndexLevel
Click for Big

The OSC report claims that:

Guillemette and Finke (2014) find that the correlation between a popular risk tolerance assessment score and the S&P 500 was 0.90 (or nearly perfect) during the January 2007 through March 2009 bear market, but then only 0.01 between the remainder of 2009 and April 2012. A review of scores from a 3-question risk tolerance instrument given to employees participating in Morningstar’s Managed Account program shows a similar correlation between S&P values and measured risk tolerance.

So that was kind of interesting. But what made me laugh was the paragraph in the Morningstar report that read:

Differences in the method of compensation provided through share class structure may influence whether the advisor gains from de-biasing a client who is tempted to shift his or her portfolio to safety during an equity market decline. Class A shares compensate the advisor through the payment of an upfront load. Advisors may have an incentive to encourage a client to buy a safer fund (and pay a front-end load) when they feel more risk averse and then sell them another risky fund when their risk aversion declines after prices rise. This provides a disincentive to de-bias a client. Advisors who receive compensation through higher trail commissions (C shares) have no incentive to encourage a client to shift out of risky funds during a temporary increase in risk aversion. Higher trail compensation may provide a valuable de-biasing incentive since the advisor does not need to sell a new fund to receive compensation. We hypothesize that lower 12b-1 fees lead to an incentive for advisors not to de-bias clients since their compensation is increased by catering to investor variable risk preferences by selling them new funds. For example, if the stock market falls and the client becomes more risk averse, an advisor compensated through front-end commissions has a greater incentive to move that client into bonds than an advisor who receives more commissions on a trail basis.

Granted, this is in the context of a comparison between transaction-based and asset-based fees, but it still made me laugh. I don’t think that part will be cited in an OSC report any time soon! However, the Morningstar paper also led me to a paper published by the Chicago Fed titled From the Horse’s Mouth: How do Investor Expectations of Risk and Return Vary with Economic Conditions?:

Data obtained from monthly Gallup/UBS surveys from 1998-2007 and from a special supplement to the Michigan Surveys of Consumer Attitudes, run in 22 monthly surveys between 2000-2005, are used to analyze stock market beliefs and portfolio choices of household investors. We show that the key variables found to be positive predictors of actual stock returns in the asset-pricing literature are also highly correlated with investor’s reported expected returns, but with the opposite sign. Moreover, analysis of the micro data indicates that expectations of both risk and returns on stocks are strongly influenced by perceptions of economic conditions. In particular, when investors believe macroeconomic conditions are more expansionary, they tend to expect both higher returns and lower volatility. This is difficult to reconcile with the canonical view that expected returns on stocks rise during recessions to compensate household investors for increased exposure or sensitivity to macroeconomic risks. Finally, the relevance of these investors’ reported expectations is supported by the finding of a significant link between their expectations and portfolio choices. In particular, we show that portfolio equity positions tend to be higher for those respondents that anticipate higher expected returns or lower uncertainty.

So it’s all interesting and goes a long way towards providing comfort that the ‘people are selling because the market is down’ hypothesis has at least some basis in fact.

Here’s a good illustration about how empty-headed regulatory do-goodism can reduce civil liberties while inflating university costs:

The online admissions application for Auburn University appears simple, until you get to this question on Page 7:

“Have you ever been charged with or convicted of or pled guilty or nolo contendere to a crime other than a minor traffic offense, or are there any criminal charges now pending against you?”

Those who check “yes,” even though they have never been convicted of any crime, face extra scrutiny — a follow-up call from the admissions office asking for additional information, the university says.
…
“Lots of colleges and universities don’t like the fact that they feel like they have to ask these questions,” said Michael Reilly, the executive director of the American Association of Collegiate Registrars and Admissions Officers. “But they feel like they do, just because of how prominent some of these cases are of things like sexual assault on college campuses. And they feel like they need to do what they can to screen students.”

It was a very good day for the Canadian preferred share market, with PerpetualDiscounts winning 80bp, FixedResets up 64bp and DeemedRetractibles gaining 36bp. There are lots of winners in the Performance Highlights table! Volume was average.

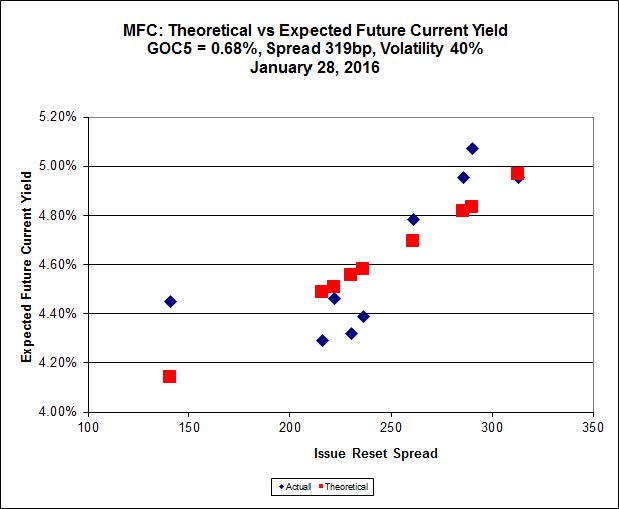
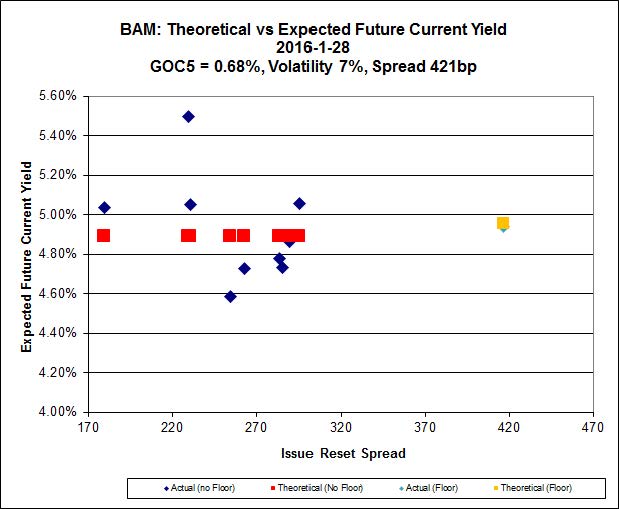
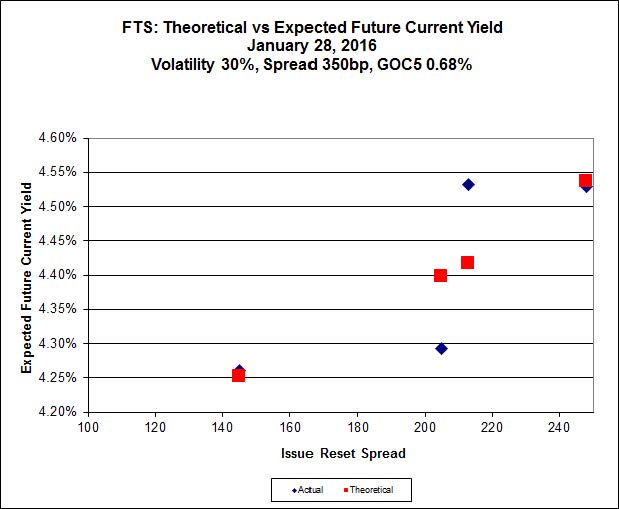
For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_160128
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 17.25 to be $1.20 rich, while TRP.PR.C, resetting 2021-1-30 at +154, is $0.73 cheap at its bid price of 11.17.

impVol_MFC_160128
Click for Big

Most expensive is MFC.PR.N, resetting at +230bp on 2020-3-19, bid at 17.25 to be 0.89 rich, while MFC.PR.F, resetting at +141bp on 2016-6-19, is bid at 11.74 to be 0.88 cheap.

impVol_BAM_160128
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 13.55 to be $1.69 cheap. BAM.PF.E, resetting at +255bp on 2020-3-31 is bid at 17.61 and appears to be $1.10 rich.

impVol_FTS_160128
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 15.90, looks $0.38 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 15.50 and is $0.41 cheap.

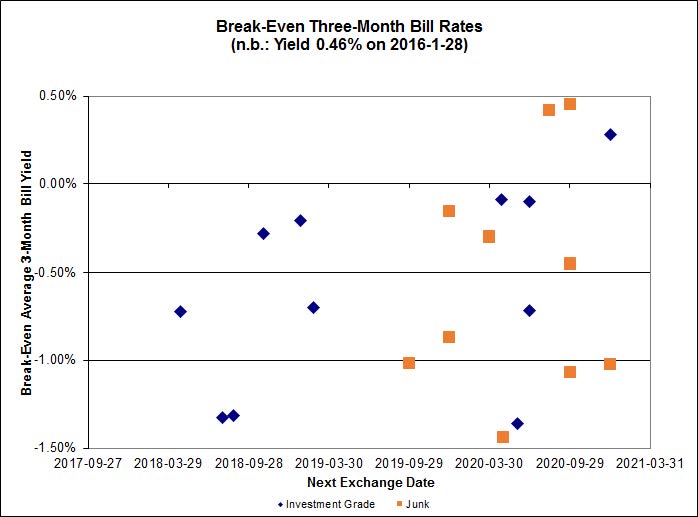
pairs_FR_160128A
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.81%, with two outliers below -1.50%. There are no junk outliers.

pairs_FF_160128
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.30 % 6.43 % 19,181 16.17 1 -1.6154 % 1,473.5
FixedFloater 7.66 % 6.69 % 28,181 15.59 1 0.6494 % 2,595.0
Floater 4.65 % 4.79 % 72,305 15.86 4 2.5492 % 1,648.3
OpRet 0.00 % 0.00 % 0 0.00 0 -0.3275 % 2,684.9
SplitShare 4.92 % 6.90 % 81,025 2.71 6 -0.3275 % 3,141.8
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.3275 % 2,451.4
Perpetual-Premium 5.92 % 5.89 % 84,349 13.87 6 0.1146 % 2,494.6
Perpetual-Discount 5.86 % 5.91 % 101,914 14.00 33 0.7968 % 2,459.4
FixedReset 5.66 % 5.05 % 237,273 14.62 83 0.6386 % 1,823.6
Deemed-Retractible 5.29 % 5.78 % 134,694 6.95 34 0.3613 % 2,552.0
FloatingReset 2.98 % 4.67 % 58,561 5.57 13 0.1107 % 2,016.2
Performance Highlights
Issue Index Change Notes
TRP.PR.H FloatingReset -2.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 9.13
Evaluated at bid price : 9.13
Bid-YTW : 4.81 %
PWF.PR.A Floater -2.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 10.90
Evaluated at bid price : 10.90
Bid-YTW : 4.33 %
CCS.PR.C Deemed-Retractible -2.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.07
Bid-YTW : 7.54 %
GWO.PR.N FixedReset -2.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.90
Bid-YTW : 11.77 %
CIU.PR.C FixedReset -1.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 10.39
Evaluated at bid price : 10.39
Bid-YTW : 5.14 %
BNS.PR.L Deemed-Retractible -1.63 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.61
Bid-YTW : 5.63 %
BAM.PR.E Ratchet -1.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 25.00
Evaluated at bid price : 12.79
Bid-YTW : 6.43 %
FTS.PR.M FixedReset -1.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 17.44
Evaluated at bid price : 17.44
Bid-YTW : 4.94 %
PWF.PR.H Perpetual-Premium -1.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 23.71
Evaluated at bid price : 24.02
Bid-YTW : 6.01 %
MFC.PR.H FixedReset -1.44 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.22
Bid-YTW : 7.66 %
PVS.PR.C SplitShare -1.38 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2017-12-10
Maturity Price : 25.00
Evaluated at bid price : 24.31
Bid-YTW : 6.89 %
CM.PR.Q FixedReset -1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 18.85
Evaluated at bid price : 18.85
Bid-YTW : 4.70 %
TD.PR.T FloatingReset -1.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.82
Bid-YTW : 4.43 %
BNS.PR.B FloatingReset -1.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.01
Bid-YTW : 5.22 %
BNS.PR.D FloatingReset -1.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.42
Bid-YTW : 6.83 %
SLF.PR.H FixedReset 1.00 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.10
Bid-YTW : 10.72 %
RY.PR.E Deemed-Retractible 1.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.00
Bid-YTW : 5.25 %
GWO.PR.I Deemed-Retractible 1.02 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.71
Bid-YTW : 7.21 %
MFC.PR.F FixedReset 1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.74
Bid-YTW : 12.15 %
RY.PR.I FixedReset 1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.41
Bid-YTW : 4.29 %
PWF.PR.E Perpetual-Discount 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 23.09
Evaluated at bid price : 23.35
Bid-YTW : 5.91 %
NA.PR.W FixedReset 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 16.51
Evaluated at bid price : 16.51
Bid-YTW : 4.81 %
RY.PR.N Perpetual-Discount 1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 21.84
Evaluated at bid price : 22.18
Bid-YTW : 5.51 %
BAM.PF.H FixedReset 1.12 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.30
Bid-YTW : 4.84 %
SLF.PR.C Deemed-Retractible 1.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.74
Bid-YTW : 7.14 %
GWO.PR.G Deemed-Retractible 1.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.82
Bid-YTW : 6.60 %
TRP.PR.E FixedReset 1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 17.25
Evaluated at bid price : 17.25
Bid-YTW : 4.82 %
TRP.PR.F FloatingReset 1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 11.57
Evaluated at bid price : 11.57
Bid-YTW : 5.20 %
BMO.PR.M FixedReset 1.25 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.48
Bid-YTW : 3.93 %
TRP.PR.B FixedReset 1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 10.00
Evaluated at bid price : 10.00
Bid-YTW : 5.13 %
TRP.PR.A FixedReset 1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 14.19
Evaluated at bid price : 14.19
Bid-YTW : 4.93 %
CU.PR.G Perpetual-Discount 1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 19.20
Evaluated at bid price : 19.20
Bid-YTW : 5.97 %
HSE.PR.E FixedReset 1.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 14.52
Evaluated at bid price : 14.52
Bid-YTW : 7.60 %
BIP.PR.A FixedReset 1.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 17.30
Evaluated at bid price : 17.30
Bid-YTW : 6.35 %
MFC.PR.N FixedReset 1.47 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.25
Bid-YTW : 8.54 %
NA.PR.S FixedReset 1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 17.06
Evaluated at bid price : 17.06
Bid-YTW : 4.83 %
HSE.PR.C FixedReset 1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 13.76
Evaluated at bid price : 13.76
Bid-YTW : 7.41 %
MFC.PR.C Deemed-Retractible 1.56 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.78
Bid-YTW : 7.19 %
CU.PR.F Perpetual-Discount 1.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 19.45
Evaluated at bid price : 19.45
Bid-YTW : 5.89 %
RY.PR.F Deemed-Retractible 1.57 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.97
Bid-YTW : 5.22 %
CU.PR.H Perpetual-Discount 1.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 22.26
Evaluated at bid price : 22.55
Bid-YTW : 5.91 %
BMO.PR.Q FixedReset 1.59 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.56
Bid-YTW : 7.39 %
CU.PR.E Perpetual-Discount 1.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 21.03
Evaluated at bid price : 21.03
Bid-YTW : 5.93 %
BAM.PR.N Perpetual-Discount 1.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 19.03
Evaluated at bid price : 19.03
Bid-YTW : 6.32 %
BNS.PR.C FloatingReset 1.61 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.07
Bid-YTW : 4.51 %
FTS.PR.H FixedReset 1.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 12.50
Evaluated at bid price : 12.50
Bid-YTW : 4.55 %
GWO.PR.Q Deemed-Retractible 1.68 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.98
Bid-YTW : 6.44 %
TD.PF.C FixedReset 1.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 17.35
Evaluated at bid price : 17.35
Bid-YTW : 4.53 %
ELF.PR.G Perpetual-Discount 1.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 20.35
Evaluated at bid price : 20.35
Bid-YTW : 5.89 %
IFC.PR.C FixedReset 1.82 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.19
Bid-YTW : 9.41 %
BAM.PF.D Perpetual-Discount 1.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 19.51
Evaluated at bid price : 19.51
Bid-YTW : 6.36 %
MFC.PR.K FixedReset 1.88 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.25
Bid-YTW : 9.13 %
RY.PR.K FloatingReset 2.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.83
Bid-YTW : 4.76 %
CU.PR.D Perpetual-Discount 2.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 20.97
Evaluated at bid price : 20.97
Bid-YTW : 5.95 %
MFC.PR.L FixedReset 2.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.55
Bid-YTW : 8.99 %
BAM.PR.M Perpetual-Discount 2.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 19.05
Evaluated at bid price : 19.05
Bid-YTW : 6.32 %
BAM.PF.F FixedReset 2.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 18.70
Evaluated at bid price : 18.70
Bid-YTW : 5.09 %
MFC.PR.J FixedReset 2.63 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.19
Bid-YTW : 8.70 %
BNS.PR.Q FixedReset 2.76 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.44
Bid-YTW : 4.19 %
NA.PR.Q FixedReset 2.93 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.85
Bid-YTW : 5.01 %
HSE.PR.A FixedReset 3.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 8.50
Evaluated at bid price : 8.50
Bid-YTW : 7.29 %
CIU.PR.A Perpetual-Discount 3.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 19.72
Evaluated at bid price : 19.72
Bid-YTW : 5.94 %
IFC.PR.A FixedReset 3.70 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.00
Bid-YTW : 10.74 %
BAM.PR.B Floater 4.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 9.93
Evaluated at bid price : 9.93
Bid-YTW : 4.80 %
BAM.PR.C Floater 4.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 9.85
Evaluated at bid price : 9.85
Bid-YTW : 4.84 %
BNS.PR.R FixedReset 4.44 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.51
Bid-YTW : 4.40 %
BAM.PR.K Floater 4.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 9.95
Evaluated at bid price : 9.95
Bid-YTW : 4.79 %
PWF.PR.P FixedReset 6.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 11.60
Evaluated at bid price : 11.60
Bid-YTW : 5.02 %
Volume Highlights
Issue Index Shares
Traded
Notes
BNS.PR.E FixedReset 112,233 Nesbitt crossed 75,000 at 25.45.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 23.28
Evaluated at bid price : 25.43
Bid-YTW : 5.16 %
TD.PF.G FixedReset 86,650 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 25.45
Bid-YTW : 5.18 %
NA.PR.X FixedReset 81,645 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 23.09
Evaluated at bid price : 24.86
Bid-YTW : 5.59 %
RY.PR.M FixedReset 78,680 Nesbitt crossed 74,500 at 18.27.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 18.03
Evaluated at bid price : 18.03
Bid-YTW : 4.72 %
BAM.PF.C Perpetual-Discount 73,400 Scotia crossed 70,000 at 19.32.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 19.32
Evaluated at bid price : 19.32
Bid-YTW : 6.36 %
BMO.PR.S FixedReset 69,756 Nesbitt crossed 56,700 at 17.20.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 17.23
Evaluated at bid price : 17.23
Bid-YTW : 4.66 %
There were 30 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BAM.PF.E FixedReset Quote: 17.61 – 18.75
Spot Rate : 1.1400
Average : 0.7170

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 17.61
Evaluated at bid price : 17.61
Bid-YTW : 5.06 %

MFC.PR.M FixedReset Quote: 17.32 – 18.37
Spot Rate : 1.0500
Average : 0.6620

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.32
Bid-YTW : 8.55 %

TRP.PR.C FixedReset Quote: 11.17 – 12.10
Spot Rate : 0.9300
Average : 0.5588

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 11.17
Evaluated at bid price : 11.17
Bid-YTW : 5.08 %

TRP.PR.B FixedReset Quote: 10.00 – 10.70
Spot Rate : 0.7000
Average : 0.4075

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 10.00
Evaluated at bid price : 10.00
Bid-YTW : 5.13 %

TRP.PR.A FixedReset Quote: 14.19 – 14.90
Spot Rate : 0.7100
Average : 0.4527

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-28
Maturity Price : 14.19
Evaluated at bid price : 14.19
Bid-YTW : 4.93 %

MFC.PR.N FixedReset Quote: 17.25 – 17.96
Spot Rate : 0.7100
Average : 0.4724

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.25
Bid-YTW : 8.54 %

Market Action

January 27, 2016

Today’s big news was the FOMC release:

Consistent with its statutory mandate, the Committee seeks to foster maximum employment and price stability. The Committee currently expects that, with gradual adjustments in the stance of monetary policy, economic activity will expand at a moderate pace and labor market indicators will continue to strengthen. Inflation is expected to remain low in the near term, in part because of the further declines in energy prices, but to rise to 2 percent over the medium term as the transitory effects of declines in energy and import prices dissipate and the labor market strengthens further. The Committee is closely monitoring global economic and financial developments and is assessing their implications for the labor market and inflation, and for the balance of risks to the outlook.

Given the economic outlook, the Committee decided to maintain the target range for the federal funds rate at 1/4 to 1/2 percent. The stance of monetary policy remains accommodative, thereby supporting further improvement in labor market conditions and a return to 2 percent inflation.

The important part was the emphasis on global conditions:

The FOMC said Wednesday it is “closely monitoring global economic and financial developments” while “assessing their implications for the labor market and inflation, and for the balance of risks to the outlook” in their statement after a two-day meeting in Washington.

That was a soft back-pedal from December when they said risks were “balanced,” and some economists said it makes an interest-rate hike at the next FOMC meeting in March less likely, while not precluding it. The FOMC left the target for their benchmark rate unchanged at 0.25 percent to 0.5 percent.

fedMarchOdds
Click for Big

… and the markets were volatile:

U.S. stocks retreated as the Federal Reserve signaled that financial-market turmoil may pose risks to its outlook for the U.S. economy, while largely maintaining its policy stance. The dollar extended losses versus the euro, while two-year Treasuries rose.

The Standard & Poor’s 500 Index sank as the Fed said it is “closely monitoring” developments from China to Europe as well as oil for any adverse impact on the U.S. economy. Apple Inc. and Boeing Co. plunged on disappointing results as the two accounted for more than half of the Dow Jones Industrial Average’s 223-point slide. Yields on two-year Treasury notes fell a third day, as the Fed kept benchmark rates unchanged and said any future hikes would be gradual. Oil rose past $32 a barrel, and gold gained.
…
The S&P 500 fell 1.1 percent to 1,882.95 as of 4 p.m. in New York, and is headed for a January loss of 7.9 percent, the most since May 2010, with anxiety over global growth wiping as much as $2.4 trillion from the value of U.S. equities this year.
…
In Canada, Bombardier Inc.’s shares fell below C$1, the latest blow for the iconic Canadian manufacturer as it buckles under $9 billion in debt. The nation’s equity benchmark advanced 0.3 percent as energy producers and banks climbed.

Treasuries recovered from their weakest levels of the day. Led by shorter maturities, yields retreated from their Wednesday highs as stocks fell following the Fed’s decision to keep its target range at 0.25 percent to 0.5 percent, as predicted by Wall Street analysts.

The Fed also emphasized that its policy on inflation is symmetrical:

As part of its annual organizational meeting actions, the Federal Open Market Committee reaffirmed its “Statement on Longer-Run Goals and Monetary Policy Strategy,” with a revision to clarify that it views its inflation objective as symmetric, and with an updated reference to participants’ estimates of the longer-run normal unemployment rate in the most recent Summary of Economic Projections (December 2015).
…
Voting against was James Bullard, who agreed the Committee’s inflation goal is symmetric, but believed the amended language is not sufficiently focused on expected future deviations of inflation from the goal.

Meanwhile, there’s a move afoot to increase the paperwork inherent in giving advice:

Canada’s mutual fund regulator is looking into whether fees charged by fund companies – such as management fees – should be included in regulatory changes that will provide investors with greater transparency concerning the cost of financial advice and of their investments.

The changes, known as the second phase of the client relationship model (CRM2), are slated for July 16, 2016, and currently do not include the costs imposed by mutual fund managers.

The focus of CRM2 is to provide disclosure of the cost of advice rather than the overall cost of an investment product. Currently – under CRM2 rules – the Mutual Fund Dealers Association will require wealth management companies to provide each investor with an annual summary of charges paid by the investor and compensation received by the firm.

Although the changes have yet to come into effect, the MFDA received feedback from financial advisers, investment dealers, fund companies and investor advocates asking to consider expanding the reporting rules to require disclosure of the other costs of owning investment funds that are not paid to the investment firm – or the financial adviser – such as management fees, fund operating costs, redemption fees and short-term trading fees.

This will help build on the biggest regulatory success story in Canadian history:

In 2000, banks controlled 23 per cent of all Canadian long-term mutual fund assets, with independents controlling 64 per cent. By the end of 2015, the banks had more than doubled their market share to nearly 50 per cent.

The banks have an enormous advantage: distribution through their branch networks. They have also been building – and buying – fund manufacturing businesses. In many cases, they now control which funds are created and where they are sold.

So buy GICs, people! They’re FREE!

Meanwhile, bond investors aren’t getting away with much:

While not as pronounced as the rout in global equity markets, losses are beginning to pile up in the bond market too. The average spread over benchmark government yields for highly rated debt has widened to 1.83 percentage points, the most in three years, from 1.18 percentage points in March, according to Bank of America Merrill Lynch indexes. Investors lost 0.2 percent on global corporate bonds in 2015, snapping a string of annual gains that averaged 7.9 percent over the previous six years, the data show.

Debt at global companies rated by Standard & Poor’s reached three times earnings before interest, tax, depreciation and amortization in 2015, the highest in data going back to 2003 and up from 2.8 times last year, according to the ratings company. Total debt at listed companies in China, the world’s second-largest economy, has climbed to the highest level in three years, according to data compiled by Bloomberg.

corporateDebtToEarnings
Click for Big

Best of all, there are high hopes that soon all those pesky non-banks will be gone:

Bombardier class B shares sank below $1 in Toronto trading Wednesday, less than half the price of its $2.21-a-share equity offering a year ago. The drop raises the possibility the company will be ejected from Canada’s main S&P/TSX stock index. To be eligible for inclusion in the index, which is reviewed quarterly, a security has to have a minimum volume-weighted average price of $1 over the past three months and must represent a minimum weight of 0.05 per cent of the index.

Tomorrow is the long awaited vote on the murky DC.PR.C Exchange Offer. One must carefully guard against human propensity to form patterns from unconnected events … but Dundee just raised a bunch of cash:

Euro Pacific Canada (“Euro Pacific”) and Dundee Securities Ltd., have entered into a definitive agreement, in which Euro Pacific will acquire Dundee Goodman Private Wealth (“DGPW”), a division of Dundee Securities Ltd. Upon completion of this transaction 78 investment advisors and related support teams will move from DGPW to Euro Pacific. Approximately $3.5 billion of investible client assets will also be transferred to Euro Pacific. Euro Pacific will also acquire Dundee Securities’ separately managed account program as well as employees related to its fixed income, foreign exchange and insurance businesses. DGPW and Euro Pacific are both members of the Investment Industry Regulatory Organization of Canada (“IIROC”) and the Canadian Investor Protection Fund (“CIPF”).

Transaction Highlights:

•Increases Euro Pacific Assets Under Management and Administration to approximately $4.2 billion;
•Euro Pacific triples in size to 100 investment advisors along with related support staff and adds offices in Toronto, Montreal, Ottawa, Calgary, Vancouver and Victoria;
•Advances Dundee’s focus of growing its alternative asset management and private investment counsel business lines;
•Dundee and Euro Pacific will enter into a distribution agreement for future differentiated products; and
•The transaction is expected to result in approximately $40 million of additional liquidity and ongoing cost savings to Dundee, which will support strategic priorities.

It was a mixed day for the Canadian preferred share market, with PerpetualDiscounts off 27bp, FixedResets up 14bp and DeemedRetractibles gaining 12bp. The Performance Highlights table is its usual jolly self. Volume was above average.

PerpetualDiscounts now yield 5.96%, equivalent to 7.75% at the standard equivalency factor of 1.3x. Long corporates now yield about 4.25% (maybe a little more) so the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) is now about 350bp, a slight (and perhaps spurious) decline from the 355bp reported January 13. Incredibly elevated!

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_160127
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 17.05 to be $1.12 rich, while TRP.PR.G, resetting 2020-11-30 at +296, is $0.70 cheap at its bid price of 18.05.

impVol_MFC_160127
Click for Big

Most expensive is MFC.PR.M, resetting at +236bp on 2019-12-19, bid at 17.33 to be 0.89 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 17.55 to be 0.90 cheap.

impVol_BAM_160127
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 13.45 to be $1.72 cheap. BAM.PF.E, resetting at +255bp on 2020-3-31 is bid at 17.69 and appears to be $1.24 rich.

impVol_FTS_160127
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 15.84, looks $0.36 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 15.40 and is $0.50 cheap.

pairs_FR_160127A
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.52%, with one outlier below -1.50% and one above +0.50%. There is one junk outlier below -1.50% and two above +0.50%.

pairs_FF_160127
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.21 % 6.33 % 20,027 16.30 1 1.6537 % 1,497.7
FixedFloater 7.71 % 6.73 % 28,687 15.54 1 -1.0442 % 2,578.3
Floater 4.77 % 5.01 % 73,237 15.47 4 1.5897 % 1,607.3
OpRet 0.00 % 0.00 % 0 0.00 0 0.3917 % 2,693.7
SplitShare 4.90 % 6.74 % 77,690 2.72 6 0.3917 % 3,152.1
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.3917 % 2,459.4
Perpetual-Premium 5.92 % 5.92 % 87,378 13.96 6 0.4741 % 2,491.7
Perpetual-Discount 5.91 % 5.96 % 102,059 13.97 33 -0.2657 % 2,440.0
FixedReset 5.69 % 5.10 % 235,170 14.64 83 0.1390 % 1,812.0
Deemed-Retractible 5.31 % 5.86 % 130,509 6.95 34 0.1222 % 2,542.8
FloatingReset 2.98 % 4.80 % 59,349 5.57 13 0.1601 % 2,014.0
Performance Highlights
Issue Index Change Notes
BAM.PF.F FixedReset -4.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 18.25
Evaluated at bid price : 18.25
Bid-YTW : 5.22 %
MFC.PR.J FixedReset -3.85 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.75
Bid-YTW : 9.06 %
BIP.PR.B FixedReset -3.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 21.85
Evaluated at bid price : 22.30
Bid-YTW : 6.25 %
BAM.PR.R FixedReset -2.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 13.45
Evaluated at bid price : 13.45
Bid-YTW : 5.74 %
CIU.PR.A Perpetual-Discount -2.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 19.10
Evaluated at bid price : 19.10
Bid-YTW : 6.14 %
BNS.PR.B FloatingReset -1.98 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.25
Bid-YTW : 5.01 %
ELF.PR.G Perpetual-Discount -1.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 5.99 %
BAM.PF.G FixedReset -1.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 18.41
Evaluated at bid price : 18.41
Bid-YTW : 5.20 %
BAM.PR.M Perpetual-Discount -1.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 18.61
Evaluated at bid price : 18.61
Bid-YTW : 6.47 %
MFC.PR.I FixedReset -1.60 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.84
Bid-YTW : 8.47 %
PWF.PR.P FixedReset -1.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 10.93
Evaluated at bid price : 10.93
Bid-YTW : 5.33 %
FTS.PR.I FloatingReset -1.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 10.34
Evaluated at bid price : 10.34
Bid-YTW : 4.68 %
TD.PF.C FixedReset -1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 17.06
Evaluated at bid price : 17.06
Bid-YTW : 4.61 %
BNS.PR.R FixedReset -1.32 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.51
Bid-YTW : 5.21 %
PWF.PR.E Perpetual-Discount -1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 22.83
Evaluated at bid price : 23.11
Bid-YTW : 5.97 %
BAM.PR.N Perpetual-Discount -1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 18.73
Evaluated at bid price : 18.73
Bid-YTW : 6.43 %
BAM.PF.D Perpetual-Discount -1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 19.16
Evaluated at bid price : 19.16
Bid-YTW : 6.48 %
GWO.PR.P Deemed-Retractible -1.18 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.50
Bid-YTW : 6.39 %
RY.PR.M FixedReset -1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 18.05
Evaluated at bid price : 18.05
Bid-YTW : 4.71 %
RY.PR.F Deemed-Retractible -1.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.60
Bid-YTW : 5.52 %
RY.PR.I FixedReset -1.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.17
Bid-YTW : 4.48 %
BAM.PR.G FixedFloater -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 25.00
Evaluated at bid price : 12.32
Bid-YTW : 6.73 %
MFC.PR.H FixedReset -1.02 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.50
Bid-YTW : 7.45 %
BAM.PF.A FixedReset -1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 18.56
Evaluated at bid price : 18.56
Bid-YTW : 5.10 %
BAM.PF.B FixedReset 1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 17.66
Evaluated at bid price : 17.66
Bid-YTW : 5.00 %
TD.PR.Y FixedReset 1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.30
Bid-YTW : 4.26 %
POW.PR.D Perpetual-Discount 1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 21.17
Evaluated at bid price : 21.17
Bid-YTW : 5.96 %
BNS.PR.Q FixedReset 1.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.81
Bid-YTW : 4.69 %
FTS.PR.H FixedReset 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 12.30
Evaluated at bid price : 12.30
Bid-YTW : 4.63 %
PWF.PR.I Perpetual-Premium 1.11 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-02-26
Maturity Price : 25.00
Evaluated at bid price : 25.40
Bid-YTW : -13.83 %
RY.PR.P Perpetual-Discount 1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 23.55
Evaluated at bid price : 23.87
Bid-YTW : 5.49 %
BMO.PR.Q FixedReset 1.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.51
Bid-YTW : 7.68 %
BAM.PR.K Floater 1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 9.51
Evaluated at bid price : 9.51
Bid-YTW : 5.02 %
TD.PR.T FloatingReset 1.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.09
Bid-YTW : 4.20 %
BNS.PR.D FloatingReset 1.25 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.63
Bid-YTW : 6.62 %
FTS.PR.M FixedReset 1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 17.72
Evaluated at bid price : 17.72
Bid-YTW : 4.86 %
SLF.PR.D Deemed-Retractible 1.29 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.43
Bid-YTW : 7.35 %
SLF.PR.B Deemed-Retractible 1.39 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.85
Bid-YTW : 6.78 %
RY.PR.L FixedReset 1.44 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.60
Bid-YTW : 4.11 %
IAG.PR.G FixedReset 1.59 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.20
Bid-YTW : 7.34 %
IFC.PR.C FixedReset 1.60 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.90
Bid-YTW : 9.67 %
BNS.PR.Z FixedReset 1.64 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.60
Bid-YTW : 7.48 %
BAM.PR.E Ratchet 1.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 25.00
Evaluated at bid price : 13.00
Bid-YTW : 6.33 %
IGM.PR.B Perpetual-Premium 1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 23.98
Evaluated at bid price : 24.44
Bid-YTW : 6.05 %
SLF.PR.I FixedReset 1.74 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.95
Bid-YTW : 8.89 %
SLF.PR.E Deemed-Retractible 1.77 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.66
Bid-YTW : 7.25 %
PWF.PR.A Floater 1.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 11.15
Evaluated at bid price : 11.15
Bid-YTW : 4.23 %
SLF.PR.A Deemed-Retractible 1.96 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.87
Bid-YTW : 6.71 %
NA.PR.W FixedReset 2.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 16.34
Evaluated at bid price : 16.34
Bid-YTW : 4.86 %
PVS.PR.B SplitShare 2.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2019-01-10
Maturity Price : 25.00
Evaluated at bid price : 23.60
Bid-YTW : 6.74 %
TRP.PR.B FixedReset 2.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 9.87
Evaluated at bid price : 9.87
Bid-YTW : 5.20 %
BAM.PR.C Floater 2.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 9.44
Evaluated at bid price : 9.44
Bid-YTW : 5.06 %
CU.PR.C FixedReset 2.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 17.05
Evaluated at bid price : 17.05
Bid-YTW : 4.73 %
BMO.PR.M FixedReset 2.77 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.40
Bid-YTW : 4.16 %
VNR.PR.A FixedReset 2.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 16.45
Evaluated at bid price : 16.45
Bid-YTW : 5.52 %
TD.PR.S FixedReset 3.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.50
Bid-YTW : 3.91 %
TRP.PR.H FloatingReset 3.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 9.39
Evaluated at bid price : 9.39
Bid-YTW : 4.68 %
TRP.PR.C FixedReset 4.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 11.22
Evaluated at bid price : 11.22
Bid-YTW : 5.06 %
PWF.PR.T FixedReset 4.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 20.45
Evaluated at bid price : 20.45
Bid-YTW : 3.99 %
Volume Highlights
Issue Index Shares
Traded
Notes
SLF.PR.A Deemed-Retractible 98,602 RBC bought 26,100 from Desjardins at 21.71 and another 10,000 from TD at 22.00.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.87
Bid-YTW : 6.71 %
NA.PR.X FixedReset 96,928 >Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 23.10
Evaluated at bid price : 24.87
Bid-YTW : 5.59 %
RY.PR.O Perpetual-Discount 78,130 TD bought three blocks of 10,000 each from RBC, all at 21.90.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 21.58
Evaluated at bid price : 21.90
Bid-YTW : 5.58 %
BMO.PR.W FixedReset 57,258 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 16.89
Evaluated at bid price : 16.89
Bid-YTW : 4.69 %
CU.PR.C FixedReset 55,539 Scotia crossed blocks of 25,000 and 16,100, both at 16.73.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 17.05
Evaluated at bid price : 17.05
Bid-YTW : 4.73 %
TD.PF.G FixedReset 48,550 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 25.45
Bid-YTW : 5.18 %
There were 40 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
CIU.PR.A Perpetual-Discount Quote: 19.10 – 20.25
Spot Rate : 1.1500
Average : 0.7867

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 19.10
Evaluated at bid price : 19.10
Bid-YTW : 6.14 %

BNS.PR.R FixedReset Quote: 22.51 – 23.80
Spot Rate : 1.2900
Average : 1.0317

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.51
Bid-YTW : 5.21 %

RY.PR.F Deemed-Retractible Quote: 23.60 – 24.20
Spot Rate : 0.6000
Average : 0.3537

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.60
Bid-YTW : 5.52 %

RY.PR.P Perpetual-Discount Quote: 23.87 – 24.65
Spot Rate : 0.7800
Average : 0.5734

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 23.55
Evaluated at bid price : 23.87
Bid-YTW : 5.49 %

BIP.PR.B FixedReset Quote: 22.30 – 22.87
Spot Rate : 0.5700
Average : 0.3806

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-27
Maturity Price : 21.85
Evaluated at bid price : 22.30
Bid-YTW : 6.25 %

SLF.PR.C Deemed-Retractible Quote: 20.51 – 21.10
Spot Rate : 0.5900
Average : 0.4012

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.51
Bid-YTW : 7.29 %

Market Action

January 26, 2016

Bloomberg published a graph showing how common negative yields have become:

negativeYields
Click for Big

There was a good chunk of pension de-risking done by Sun Life:

Two Canadian pension plans are teaming up to buy about $530-million of annuities, in a creative deal to transfer investment, longevity and inflation risk to an insurance company.

The two defined-benefit pension plans, owned by companies that did not want to be named, have struck the joint annuity agreement with Sun Life Financial Inc. despite having no other relation to each other. The advantage of banding together and doing the transaction at the same time was more than $20-million dollars in savings combined as Sun Life balanced the inflation exposure of the two plans.

Sun Life began working with both companies separately in early 2015, and the insurer noticed that they had different inflation formulas. “One plan sponsor promised to increase benefits when inflation was low. The other promised to increase benefits when inflation was high,” said Brent Simmons, senior managing director for defined-benefits at Sun Life, adding that both promises are tricky to buy proper asset management strategies for.
…
Annuities for pension plans are part of a strategy known as “pension de-risking” in industry parlance, and they are a way of reducing long-term risks and ratcheting down income volatility for defined-benefit pension plans. These sorts of transactions became commonplace in the United States several years ago, and the U.K. has also been a leader with £19-billion ($38-billion) in de-risking deals last year. Canada’s market is still developing.

Two significant de-risking annuity deals in Canada include a $150-million deal by the Canadian Wheat Board in 2013, and a $500-million deal with an unnamed Canadian company done by Industrial Alliance Insurance and Financial Services Inc. last year.

Meanwhile, Canadian retail is moving to cash:

Canadians are holding a record $75-billion in cash amid an “ocean of fear” about investing in the markets, a new study finds.

That means they could miss out on billions in payback, warns the study released today by Canadian Imperial Bank of Commerce economists Benjamin Tal and Royce Mendes.
…
And here’s a stunning figure from the report: The extra money accounts for about 10 per cent of all personal liquid assets in the country.

This angst isn’t new. It obviously came about during the 1987 crash, and again in 2001 and then again during the financial crisis.

excessCash
Click for Big
deposits
Click for Big

Sadly, it appears there will be no more entertainment from Silver Bullion Trust:

Silver Bullion Trust (“SBT” or the “Trust”) (symbol: TSX – SBT.UN (C$) and SBT.U (US$)) today announced that SBT Unitholders voted to approve amendments to SBT’s Amended and Restated Declaration of Trust dated July 9, 2009 (the “DOT”), in order to permit its conversion from a closed-end fund to a silver-bullion exchange traded fund (the “ETF Conversion”) at a special meeting of Unitholders held earlier today in Toronto.

As soon as possible, Purpose Investments Inc. will become the new manager and trustee of the Trust once the amendments to the DOT are signed and the bullion holdings will be administered by Silver Administrators Limited, SBT’s current administrator.

It was a modestly negative day for the Canadian preferred share market, with PerpetualDiscounts down 25bp, FixedResets gaining 8bp and DeemedRetractibles off 15bp. The Performance Highlights table shows a fair bit of movement below the placid surface. Volume was on the low side of average.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_160126
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 17.06 to be $1.27 rich, while TRP.PR.C, resetting 2021-1-30 at +154, is $0.92 cheap at its bid price of 10.77.

impVol_MFC_160126
Click for Big

Most expensive is MFC.PR.N, resetting at +230bp on 2020-3-19, bid at 17.10 to be 0.78 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 17.57 to be 1.11 cheap.

impVol_BAM_160126
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 13.80 to be $1.57 cheap. BAM.PF.E, resetting at +255bp on 2020-3-31 is bid at 17.69 and appears to be $1.04 rich.

impVol_FTS_160126
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 15.75, looks $0.40 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 15.31 and is $0.45 cheap.

pairs_FR_160126
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.35%, with one outlier below -1.50%. Note the range of the y-axis has changed. There is one junk outlier below -1.50% and two above +0.50%.

pairs_FF_160126
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.28 % 6.43 % 20,369 16.11 1 -1.1538 % 1,473.4
FixedFloater 7.63 % 6.66 % 28,978 15.63 1 0.7282 % 2,605.5
Floater 4.85 % 5.05 % 74,218 15.41 4 -0.3831 % 1,582.2
OpRet 0.00 % 0.00 % 0 0.00 0 -0.2094 % 2,683.2
SplitShare 4.92 % 7.12 % 78,662 2.71 6 -0.2094 % 3,139.8
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.2094 % 2,449.8
Perpetual-Premium 5.95 % 5.91 % 88,581 13.97 6 -0.1488 % 2,480.0
Perpetual-Discount 5.89 % 5.91 % 101,704 13.99 33 -0.2510 % 2,446.5
FixedReset 5.70 % 5.04 % 239,250 14.57 83 0.0787 % 1,809.5
Deemed-Retractible 5.31 % 5.86 % 127,971 6.95 34 -0.1462 % 2,539.7
FloatingReset 2.98 % 4.72 % 61,161 5.57 13 0.2497 % 2,010.8
Performance Highlights
Issue Index Change Notes
TRP.PR.C FixedReset -4.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-26
Maturity Price : 10.77
Evaluated at bid price : 10.77
Bid-YTW : 5.27 %
BAM.PR.Z FixedReset -3.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-26
Maturity Price : 17.80
Evaluated at bid price : 17.80
Bid-YTW : 5.39 %
NA.PR.W FixedReset -3.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-26
Maturity Price : 16.01
Evaluated at bid price : 16.01
Bid-YTW : 4.96 %
BAM.PR.X FixedReset -2.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-26
Maturity Price : 12.25
Evaluated at bid price : 12.25
Bid-YTW : 5.54 %
TRP.PR.B FixedReset -2.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-26
Maturity Price : 9.66
Evaluated at bid price : 9.66
Bid-YTW : 5.32 %
VNR.PR.A FixedReset -2.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-26
Maturity Price : 16.00
Evaluated at bid price : 16.00
Bid-YTW : 5.68 %
PWF.PR.T FixedReset -2.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-26
Maturity Price : 19.53
Evaluated at bid price : 19.53
Bid-YTW : 4.18 %
POW.PR.D Perpetual-Discount -2.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-26
Maturity Price : 20.95
Evaluated at bid price : 20.95
Bid-YTW : 6.02 %
BAM.PF.B FixedReset -2.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-26
Maturity Price : 17.48
Evaluated at bid price : 17.48
Bid-YTW : 5.05 %
PWF.PR.P FixedReset -2.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-26
Maturity Price : 11.10
Evaluated at bid price : 11.10
Bid-YTW : 5.25 %
GWO.PR.O FloatingReset -2.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.25
Bid-YTW : 11.91 %
IFC.PR.C FixedReset -2.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.65
Bid-YTW : 9.89 %
PVS.PR.E SplitShare -1.87 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-10-31
Maturity Price : 25.00
Evaluated at bid price : 23.11
Bid-YTW : 7.12 %
BNS.PR.Z FixedReset -1.82 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.30
Bid-YTW : 7.78 %
PWF.PR.A Floater -1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-26
Maturity Price : 10.95
Evaluated at bid price : 10.95
Bid-YTW : 4.31 %
POW.PR.A Perpetual-Discount -1.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-26
Maturity Price : 23.38
Evaluated at bid price : 23.67
Bid-YTW : 5.96 %
GWO.PR.L Deemed-Retractible -1.57 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.51
Bid-YTW : 6.03 %
TD.PR.S FixedReset -1.51 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.80
Bid-YTW : 4.47 %
BAM.PF.E FixedReset -1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-26
Maturity Price : 17.69
Evaluated at bid price : 17.69
Bid-YTW : 5.04 %
BMO.PR.M FixedReset -1.43 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.77
Bid-YTW : 4.66 %
SLF.PR.J FloatingReset -1.29 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.50
Bid-YTW : 11.80 %
CU.PR.C FixedReset -1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-26
Maturity Price : 16.60
Evaluated at bid price : 16.60
Bid-YTW : 4.86 %
POW.PR.G Perpetual-Discount -1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-26
Maturity Price : 23.36
Evaluated at bid price : 23.82
Bid-YTW : 5.91 %
POW.PR.B Perpetual-Discount -1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-26
Maturity Price : 22.41
Evaluated at bid price : 22.67
Bid-YTW : 5.94 %
TRP.PR.F FloatingReset -1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-26
Maturity Price : 11.37
Evaluated at bid price : 11.37
Bid-YTW : 5.29 %
BAM.PR.E Ratchet -1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-26
Maturity Price : 25.00
Evaluated at bid price : 12.85
Bid-YTW : 6.43 %
IFC.PR.A FixedReset -1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.40
Bid-YTW : 11.37 %
MFC.PR.H FixedReset 1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.70
Bid-YTW : 7.31 %
TD.PF.E FixedReset 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-26
Maturity Price : 19.85
Evaluated at bid price : 19.85
Bid-YTW : 4.57 %
RY.PR.H FixedReset 1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-26
Maturity Price : 17.41
Evaluated at bid price : 17.41
Bid-YTW : 4.52 %
BNS.PR.R FixedReset 1.29 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.81
Bid-YTW : 4.96 %
PVS.PR.D SplitShare 1.34 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2021-10-08
Maturity Price : 25.00
Evaluated at bid price : 22.00
Bid-YTW : 7.28 %
BAM.PR.R FixedReset 1.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-26
Maturity Price : 13.80
Evaluated at bid price : 13.80
Bid-YTW : 5.60 %
BNS.PR.A FloatingReset 1.40 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.40
Bid-YTW : 4.41 %
CCS.PR.C Deemed-Retractible 1.41 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.55
Bid-YTW : 7.20 %
BMO.PR.Y FixedReset 1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-26
Maturity Price : 19.27
Evaluated at bid price : 19.27
Bid-YTW : 4.63 %
RY.PR.M FixedReset 1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-26
Maturity Price : 18.25
Evaluated at bid price : 18.25
Bid-YTW : 4.66 %
RY.PR.I FixedReset 1.61 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.42
Bid-YTW : 4.27 %
FTS.PR.M FixedReset 1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-26
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 4.92 %
NA.PR.Q FixedReset 1.78 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.30
Bid-YTW : 5.47 %
IAG.PR.G FixedReset 1.89 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.90
Bid-YTW : 7.55 %
RY.PR.J FixedReset 1.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-26
Maturity Price : 18.52
Evaluated at bid price : 18.52
Bid-YTW : 4.71 %
RY.PR.Z FixedReset 2.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-26
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 4.44 %
SLF.PR.G FixedReset 2.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.94
Bid-YTW : 10.76 %
TD.PF.D FixedReset 2.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-26
Maturity Price : 19.01
Evaluated at bid price : 19.01
Bid-YTW : 4.66 %
HSE.PR.G FixedReset 2.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-26
Maturity Price : 15.10
Evaluated at bid price : 15.10
Bid-YTW : 7.29 %
SLF.PR.H FixedReset 2.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.10
Bid-YTW : 10.71 %
SLF.PR.I FixedReset 2.40 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.66
Bid-YTW : 9.13 %
TD.PF.A FixedReset 2.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-26
Maturity Price : 17.11
Evaluated at bid price : 17.11
Bid-YTW : 4.61 %
BNS.PR.B FloatingReset 3.19 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.68
Bid-YTW : 4.64 %
Volume Highlights
Issue Index Shares
Traded
Notes
NA.PR.X FixedReset 146,614 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-26
Maturity Price : 23.06
Evaluated at bid price : 24.77
Bid-YTW : 5.61 %
TD.PF.G FixedReset 88,726 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 25.36
Bid-YTW : 5.26 %
RY.PR.Q FixedReset 76,204 Desjardins crossed 10,700 at 25.47.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-26
Maturity Price : 23.29
Evaluated at bid price : 25.46
Bid-YTW : 5.17 %
BMO.PR.S FixedReset 70,795 Nesbitt crossed 12,500 at 17.55.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-26
Maturity Price : 17.46
Evaluated at bid price : 17.46
Bid-YTW : 4.69 %
GWO.PR.F Deemed-Retractible 68,245 Desjardins crossed 45,400 at 25.15; Nesbitt crossed 21,300 at the same price.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-02-25
Maturity Price : 25.00
Evaluated at bid price : 25.15
Bid-YTW : 3.71 %
BAM.PR.X FixedReset 67,200 TD crossed 50,000 at 12.55.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-26
Maturity Price : 12.25
Evaluated at bid price : 12.25
Bid-YTW : 5.54 %
There were 28 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
GWO.PR.O FloatingReset Quote: 11.25 – 20.25
Spot Rate : 9.0000
Average : 5.9189

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.25
Bid-YTW : 11.91 %

BNS.PR.C FloatingReset Quote: 21.65 – 22.73
Spot Rate : 1.0800
Average : 0.6508

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.65
Bid-YTW : 4.86 %

IAG.PR.G FixedReset Quote: 18.90 – 19.77
Spot Rate : 0.8700
Average : 0.6118

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.90
Bid-YTW : 7.55 %

TRP.PR.G FixedReset Quote: 17.90 – 18.65
Spot Rate : 0.7500
Average : 0.4990

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-26
Maturity Price : 17.90
Evaluated at bid price : 17.90
Bid-YTW : 5.26 %

BAM.PR.Z FixedReset Quote: 17.80 – 18.64
Spot Rate : 0.8400
Average : 0.6271

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-26
Maturity Price : 17.80
Evaluated at bid price : 17.80
Bid-YTW : 5.39 %

W.PR.H Perpetual-Discount Quote: 22.00 – 22.47
Spot Rate : 0.4700
Average : 0.3051

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-26
Maturity Price : 21.75
Evaluated at bid price : 22.00
Bid-YTW : 6.30 %

Market Action

January 25, 2016

The oil crash is being compared to subprime, in appearance if not in effect:

One year ago, analysts at Bank of America Merrill Lynch drew a parallel between the subprime mortgage crash and the disorderly fall in the price of oil.

Led by Chris Flanagan, a veteran of the securitization space, the team drew attention to Markit’s ABX Index, better known as the mother of all synthetic subprime credit indexes.
…
Fast-forward to today and the BofAML analysts provide an update to their previous thesis, which was that the downward spiral in the price of oil was shaping up to look a lot like the negative trend that engulfed the subprime space circa the year 2007.
…

Given that both housing and oil prices were fueled to spectacular heights in the two periods by massive credit expansion, it’s probably more than just coincidence that the respective “bubble” bursting patterns are so similar.
…
Lower prices beget accelerated selling, as asset owners need to raise cash. It could be margin calls or it could be producer selling needs, it doesn’t really matter: the selling becomes inevitable and turns into forced selling.

oil_subprime
Click for Big

But all that’s boring. What’s really cool is advances in 3D Printing Technology:

Orbital ATK (NYSE: OA), a global leader in aerospace and defense technologies, announced today that it has successfully tested a 3D-printed hypersonic engine combustor at NASA Langley Research Center. The combustor, produced through an additive manufacturing process known as powder bed fusion (PBF), was subjected to a variety of high-temperature hypersonic flight conditions over the course of 20 days, including one of the longest duration propulsion wind tunnel tests ever recorded for a unit of this kind. Analysis confirms the unit met or exceeded all of the test requirements.

One of the most challenging parts of the propulsion system, a scramjet combustor, houses and maintains stable combustion within an extremely volatile environment. The tests were, in part, to ensure that the PBF-produced part would be robust enough to meet mission objectives.

“Additive manufacturing opens up new possibilities for our designers and engineers,” said Pat Nolan, Vice President and General Manager of Orbital ATK’s Missile Products division of the Defense Systems Group. “This combustor is a great example of a component that was impossible to build just a few years ago. This successful test will encourage our engineers to continue to explore new designs and use these innovative tools to lower costs and decrease manufacturing time.”

The test at Langley was an important opportunity to challenge Orbital ATK’s new combustor design, made possible only through the additive manufacturing process. Complex geometries and assemblies that once required multiple components can be simplified to a single, more cost-effective assembly. However, since the components are built one layer at a time, it is now possible to design features and integrated components that could not be easily cast or otherwise machined.

And not just that … now there’s some muttering about 4-D Printing:

Now, scientists say they recently developed innovative 4D-printing methods that involve 3D-printing items that are designed to change shape after they are printed.
…
“Other active research teams exploring 4D printing require multiple materials printed together, with one material that stays rigid while another changes shape and acts like a hinge,” said study co-senior author Jennifer Lewis, a materials scientist at Harvard University.

The researchers wanted to create 4D-printed structures that were created more simply, from one kind of material instead of several. They sought inspiration from nature, looking at plants, whose tendrils, leaves and flowers can respond to environmental factors such as light and touch. For instance, “pinecones can open and close depending on their degree of hydration — how wet they are,” Lewis told Live Science.
…
Plant structures largely consist of fibers of a material known as cellulose. Lewis and her colleagues devised 3D-printed structures made of stiff cellulose fibers embedded in a soft hydrogel, the same kind of material from which soft contact lenses are made. This hydrogel swells up when immersed in water.

The researchers can control the directions in which these fibers are oriented within the printed structures. In turn, the orientations of these fibers control the way in which these structures swell when they are immersed in water, much like how cellulose fibers control the way plants flex because of pressure exerted by fluids inside them, the researchers said. In essence, the scientists can use the orientation of cellulose fibers in the structures to program how the objects change shape.

The scientists found that they could make the structures they created shift into cone, saddle, ruffle and spiral shapes minutes after they were soaked in water. They had flat sheets bend and twist into complex 3D structures resembling orchids and calla lilies.

What a completely fascinating time to be alive!

It was a good solid day for the Canadian preferred share market, with PerpetualDiscounts up 22bp, FixedResets winning 39bp and DeemedRetractibles gaining 21bp. The relatively calm numbers mask a lot of churn on the Performance Highlights table, though! Volume was well below average.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_160125
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 17.14 to be $1.18 rich, while TRP.PR.G, resetting 2020-11-30 at +296, is $0.76 cheap at its bid price of 18.03.

impVol_MFC_160125
Click for Big

Most expensive is MFC.PR.M, resetting at +236bp on 2019-12-19, bid at 17.31 to be 0.80 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 17.60 to be 1.01 cheap.

impVol_BAM_160125
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 13.61 to be $1.91 cheap. BAM.PF.E, resetting at +255bp on 2020-3-31 is bid at 17.95 and appears to be $1.13 rich.

impVol_FTS_160125
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 15.75, looks $0.46 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 15.43 and is $0.26 cheap.

pairs_FR_160125
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.43%, with two outliers below -1.00%. There are five junk outliers below -1.00%.

pairs_FF_160125
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.21 % 6.35 % 20,645 16.20 1 1.1673 % 1,490.6
FixedFloater 7.69 % 6.71 % 30,026 15.58 1 -0.7229 % 2,586.6
Floater 4.83 % 5.08 % 74,139 15.36 4 -0.1240 % 1,588.3
OpRet 0.00 % 0.00 % 0 0.00 0 -0.1464 % 2,688.8
SplitShare 4.91 % 6.77 % 78,359 2.72 6 -0.1464 % 3,146.4
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.1464 % 2,455.0
Perpetual-Premium 5.94 % 5.90 % 91,758 13.99 6 -0.2294 % 2,483.7
Perpetual-Discount 5.88 % 5.89 % 101,901 14.07 33 0.2162 % 2,452.6
FixedReset 5.71 % 5.02 % 242,324 14.71 83 0.3861 % 1,808.1
Deemed-Retractible 5.31 % 5.80 % 132,504 6.96 34 0.2115 % 2,543.5
FloatingReset 2.99 % 4.86 % 62,285 5.57 13 -0.0936 % 2,005.8
Performance Highlights
Issue Index Change Notes
GWO.PR.O FloatingReset -4.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.50
Bid-YTW : 11.62 %
SLF.PR.J FloatingReset -3.00 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.65
Bid-YTW : 11.62 %
HSE.PR.A FixedReset -2.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 8.32
Evaluated at bid price : 8.32
Bid-YTW : 7.44 %
BAM.PR.C Floater -2.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 9.20
Evaluated at bid price : 9.20
Bid-YTW : 5.19 %
SLF.PR.I FixedReset -2.46 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.27
Bid-YTW : 9.46 %
PVS.PR.D SplitShare -2.43 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2021-10-08
Maturity Price : 25.00
Evaluated at bid price : 21.71
Bid-YTW : 7.56 %
TD.PF.A FixedReset -2.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 16.62
Evaluated at bid price : 16.62
Bid-YTW : 4.75 %
BAM.PR.B Floater -2.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 9.40
Evaluated at bid price : 9.40
Bid-YTW : 5.08 %
BNS.PR.D FloatingReset -1.88 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.26
Bid-YTW : 6.98 %
BNS.PR.B FloatingReset -1.59 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.01
Bid-YTW : 5.21 %
VNR.PR.A FixedReset -1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 16.41
Evaluated at bid price : 16.41
Bid-YTW : 5.53 %
BAM.PF.F FixedReset -1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 19.18
Evaluated at bid price : 19.18
Bid-YTW : 4.95 %
PWF.PR.O Perpetual-Premium -1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 23.95
Evaluated at bid price : 24.46
Bid-YTW : 5.94 %
BNS.PR.P FixedReset -1.18 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.42
Bid-YTW : 4.20 %
CU.PR.I FixedReset -1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 23.18
Evaluated at bid price : 25.01
Bid-YTW : 4.45 %
BAM.PR.X FixedReset -1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 12.61
Evaluated at bid price : 12.61
Bid-YTW : 5.37 %
BAM.PF.G FixedReset -1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 18.66
Evaluated at bid price : 18.66
Bid-YTW : 5.13 %
GWO.PR.L Deemed-Retractible 1.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.90
Bid-YTW : 5.80 %
RY.PR.N Perpetual-Discount 1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 21.82
Evaluated at bid price : 22.15
Bid-YTW : 5.52 %
BNS.PR.A FloatingReset 1.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.09
Bid-YTW : 4.67 %
PVS.PR.C SplitShare 1.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2017-12-10
Maturity Price : 25.00
Evaluated at bid price : 24.70
Bid-YTW : 5.94 %
TD.PR.Z FloatingReset 1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.00
Bid-YTW : 4.35 %
BNS.PR.C FloatingReset 1.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.65
Bid-YTW : 4.86 %
RY.PR.W Perpetual-Discount 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 22.22
Evaluated at bid price : 22.50
Bid-YTW : 5.44 %
RY.PR.O Perpetual-Discount 1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 21.96
Evaluated at bid price : 22.24
Bid-YTW : 5.50 %
BAM.PR.E Ratchet 1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 25.00
Evaluated at bid price : 13.00
Bid-YTW : 6.35 %
NA.PR.W FixedReset 1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 16.55
Evaluated at bid price : 16.55
Bid-YTW : 4.79 %
CIU.PR.C FixedReset 1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 10.59
Evaluated at bid price : 10.59
Bid-YTW : 5.04 %
MFC.PR.H FixedReset 1.30 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.50
Bid-YTW : 7.45 %
BAM.PR.R FixedReset 1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 13.61
Evaluated at bid price : 13.61
Bid-YTW : 5.67 %
CM.PR.O FixedReset 1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 17.24
Evaluated at bid price : 17.24
Bid-YTW : 4.67 %
BAM.PF.E FixedReset 1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 17.95
Evaluated at bid price : 17.95
Bid-YTW : 4.96 %
MFC.PR.K FixedReset 1.59 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.95
Bid-YTW : 9.38 %
FTS.PR.G FixedReset 1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 15.43
Evaluated at bid price : 15.43
Bid-YTW : 4.93 %
TRP.PR.D FixedReset 1.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 16.39
Evaluated at bid price : 16.39
Bid-YTW : 4.99 %
CM.PR.Q FixedReset 1.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 19.11
Evaluated at bid price : 19.11
Bid-YTW : 4.63 %
BMO.PR.M FixedReset 2.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.10
Bid-YTW : 4.39 %
BAM.PR.K Floater 2.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 9.40
Evaluated at bid price : 9.40
Bid-YTW : 5.08 %
TD.PF.F Perpetual-Discount 2.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 21.87
Evaluated at bid price : 22.21
Bid-YTW : 5.53 %
PWF.PR.A Floater 2.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 11.15
Evaluated at bid price : 11.15
Bid-YTW : 4.23 %
TRP.PR.C FixedReset 2.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 11.24
Evaluated at bid price : 11.24
Bid-YTW : 5.05 %
BAM.PR.T FixedReset 2.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 14.80
Evaluated at bid price : 14.80
Bid-YTW : 5.32 %
TRP.PR.E FixedReset 2.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 17.14
Evaluated at bid price : 17.14
Bid-YTW : 4.84 %
BAM.PR.Z FixedReset 2.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 18.45
Evaluated at bid price : 18.45
Bid-YTW : 5.20 %
TD.PF.C FixedReset 2.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 17.30
Evaluated at bid price : 17.30
Bid-YTW : 4.54 %
PWF.PR.S Perpetual-Discount 2.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 20.65
Evaluated at bid price : 20.65
Bid-YTW : 5.85 %
RY.PR.K FloatingReset 3.31 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.55
Bid-YTW : 4.99 %
RY.PR.I FixedReset 3.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.05
Bid-YTW : 4.57 %
BIP.PR.B FixedReset 3.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 22.22
Evaluated at bid price : 22.90
Bid-YTW : 6.07 %
TRP.PR.B FixedReset 4.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 9.93
Evaluated at bid price : 9.93
Bid-YTW : 5.17 %
BAM.PF.B FixedReset 4.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 17.89
Evaluated at bid price : 17.89
Bid-YTW : 4.93 %
BAM.PF.A FixedReset 4.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 18.83
Evaluated at bid price : 18.83
Bid-YTW : 5.02 %
Volume Highlights
Issue Index Shares
Traded
Notes
NA.PR.X FixedReset 298,282 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 23.05
Evaluated at bid price : 24.72
Bid-YTW : 5.62 %
RY.PR.Q FixedReset 82,192 TD crossed 15,900 at 25.40; Scotia crossed 40,000 at the same price.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 23.25
Evaluated at bid price : 25.35
Bid-YTW : 5.20 %
BMO.PR.S FixedReset 62,563 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 17.42
Evaluated at bid price : 17.42
Bid-YTW : 4.70 %
BNS.PR.Z FixedReset 46,222 RBC crossed 40,000 at 18.65.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.64
Bid-YTW : 7.44 %
RY.PR.J FixedReset 27,691 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 18.16
Evaluated at bid price : 18.16
Bid-YTW : 4.80 %
RY.PR.Z FixedReset 27,661 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 17.15
Evaluated at bid price : 17.15
Bid-YTW : 4.53 %
There were 20 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
CCS.PR.C Deemed-Retractible Quote: 21.25 – 23.15
Spot Rate : 1.9000
Average : 1.1381

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.25
Bid-YTW : 7.41 %

TD.PF.A FixedReset Quote: 16.62 – 17.55
Spot Rate : 0.9300
Average : 0.6834

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 16.62
Evaluated at bid price : 16.62
Bid-YTW : 4.75 %

BAM.PF.F FixedReset Quote: 19.18 – 19.99
Spot Rate : 0.8100
Average : 0.6465

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-25
Maturity Price : 19.18
Evaluated at bid price : 19.18
Bid-YTW : 4.95 %

BMO.PR.Q FixedReset Quote: 18.25 – 19.00
Spot Rate : 0.7500
Average : 0.5936

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.25
Bid-YTW : 7.94 %

BNS.PR.B FloatingReset Quote: 21.01 – 21.44
Spot Rate : 0.4300
Average : 0.2771

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.01
Bid-YTW : 5.21 %

BMO.PR.M FixedReset Quote: 23.10 – 23.88
Spot Rate : 0.7800
Average : 0.6312

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.10
Bid-YTW : 4.39 %

Market Action

January 22, 2016

Yeah, so it was a Friday to be remembered:

Oil prices surged as much as 10 per cent on Friday, one of the biggest daily rallies ever, as bearish traders who had taken out record short positions scrambled to close them, betting the market’s long rout may finally be over.

The onset of a massive snowstorm on the U.S. East Coast sent heating oil up more than 10 per cent. This helped fuel a 15 per cent gain in crude prices over two days, reversing nearly half of the relentless, fund-driven selloff that had pushed crude below $30 (U.S.) a barrel for the first time in 12 years.

… and headline inflation and retail sales both rose:

Canadians are still buying new cars and vegetables even as they become more expensive, supporting the central bank’s view the economy will recover from a commodity crash without further interest-rate cuts.

December inflation climbed at the fastest pace in a year at 1.6 per cent, led by double-digit gains for fruit and vegetables and a reduced drag from gasoline, Ottawa-based Statistics Canada said Friday. The agency also reported retail sales rose 1.7 per cent in November, almost triple the highest estimate in a Bloomberg economist survey
…
Fresh fruit and vegetable prices rose 13 per cent in December from a year earlier, pushing up total food costs 3.7 per cent. Most fresh produce is imported from the U.S. or Latin America during winter. Canada’s dollar fell 16 per cent last year versus the U.S. currency.

… which made it a hot day for equities:

The Standard & Poor’s/TSX Index jumped 2.9 percent to 12,389.58 at 4 p.m. in Toronto, capping the gauge’s first weekly gain of the year. Nine of the index’s 10 main industries rose more than 1.1 percent, with energy, utility and industrial shares the biggest gainers. The S&P/TSX, which entered a bear market two weeks ago, fell on Wednesday to its lowest level since August 2012. It’s down 4.8 percent in 2016.

Canada joined a rebound among global equities sparked by speculation the European Central Bank and Bank of Japan are poised to add to stimulus at the same time China reassured investors it would do more to damp volatility. Crude oil surged 8.9 percent, bringing its two-day increase past 20 percent.
…
All but one of the 55 companies in the S&P/TSX energy index rose as the gauge climbed 5.5 percent. Baytex Energy Corp. surged 15 percent, while Paramount Resources Ltd. and Enerplus Corp. climbed at least 9.3 percent. Penn West Petroleum Ltd. rose 15 percent to the highest level in more than two weeks.

And as for preferred shares …

s_fireworks_at_the_2013_Celebration_of_Light_in_Vancouver,_BC
Click for Big

The Canadian preferred share market had a superb day today, with PerpetualDiscounts gaining 193bp, FixedResets winning 328bp and DeemedRetractibles up 223bp. The Performance Highlights table is ridiculous. Volume was very high.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_160122
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 16.72 to be $1.00 rich, while TRP.PR.B, resetting 2020-6-30 at +128, is $0.82 cheap at its bid price of 9.52.

impVol_MFC_160122
Click for Big

Most expensive is MFC.PR.N, resetting at +230bp on 2020-3-19, bid at 17.00 to be 0.81 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 17.68 to be 0.82 cheap.

impVol_BAM_160122
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 13.43 to be $1.88 cheap. BAM.PF.F, resetting at +286bp on 2019-9-30 is bid at 19.45 and appears to be $1.33 rich.

impVol_FTS_160122
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 15.75, looks $0.50 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 15.17 and is $0.48 cheap.

pairs_FR_160122
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.31%, with two outliers below -1.00%. There are five junk outliers below -1.00% and one above +1.00%

pairs_FF_160122
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.28 % 6.43 % 21,005 16.13 1 4.0486 % 1,473.4
FixedFloater 7.63 % 6.66 % 30,560 15.64 1 2.0492 % 2,605.5
Floater 4.81 % 4.96 % 75,045 15.58 4 1.6542 % 1,590.2
OpRet 0.00 % 0.00 % 0 0.00 0 0.0767 % 2,692.7
SplitShare 4.91 % 6.68 % 78,140 2.72 6 0.0767 % 3,151.0
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0767 % 2,458.5
Perpetual-Premium 5.93 % 5.88 % 92,778 13.98 6 1.3403 % 2,489.4
Perpetual-Discount 5.89 % 5.86 % 102,418 14.11 33 1.9332 % 2,447.4
FixedReset 5.73 % 4.94 % 245,812 14.89 83 3.2774 % 1,801.1
Deemed-Retractible 5.32 % 5.94 % 132,488 6.93 34 2.2257 % 2,538.1
FloatingReset 2.77 % 4.75 % 62,927 5.60 13 2.4144 % 2,007.7
Performance Highlights
Issue Index Change Notes
BIP.PR.B FixedReset 1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 21.71
Evaluated at bid price : 22.10
Bid-YTW : 6.31 %
PWF.PR.K Perpetual-Discount 1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 21.25
Evaluated at bid price : 21.25
Bid-YTW : 5.86 %
BMO.PR.L Deemed-Retractible 1.26 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-05-25
Maturity Price : 25.25
Evaluated at bid price : 25.77
Bid-YTW : 2.31 %
RY.PR.B Deemed-Retractible 1.26 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.08
Bid-YTW : 5.37 %
RY.PR.F Deemed-Retractible 1.29 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.92
Bid-YTW : 5.25 %
IGM.PR.B Perpetual-Premium 1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 23.77
Evaluated at bid price : 24.21
Bid-YTW : 6.11 %
BMO.PR.Z Perpetual-Discount 1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 22.04
Evaluated at bid price : 22.34
Bid-YTW : 5.68 %
RY.PR.A Deemed-Retractible 1.33 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.90
Bid-YTW : 5.26 %
RY.PR.O Perpetual-Discount 1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 21.70
Evaluated at bid price : 21.99
Bid-YTW : 5.56 %
PWF.PR.A Floater 1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 11.05
Evaluated at bid price : 11.05
Bid-YTW : 4.33 %
BNS.PR.O Deemed-Retractible 1.40 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-04-27
Maturity Price : 25.25
Evaluated at bid price : 25.39
Bid-YTW : 2.85 %
RY.PR.E Deemed-Retractible 1.43 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.96
Bid-YTW : 5.27 %
CU.PR.H Perpetual-Discount 1.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 21.98
Evaluated at bid price : 22.26
Bid-YTW : 5.98 %
RY.PR.C Deemed-Retractible 1.49 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.06
Bid-YTW : 5.29 %
RY.PR.D Deemed-Retractible 1.56 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.95
Bid-YTW : 5.27 %
BNS.PR.R FixedReset 1.57 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.65
Bid-YTW : 5.01 %
BMO.PR.K Deemed-Retractible 1.58 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.14
Bid-YTW : 5.34 %
TRP.PR.B FixedReset 1.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 9.52
Evaluated at bid price : 9.52
Bid-YTW : 5.09 %
GWO.PR.L Deemed-Retractible 1.61 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.65
Bid-YTW : 5.94 %
BNS.PR.B FloatingReset 1.62 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.35
Bid-YTW : 4.75 %
ELF.PR.F Perpetual-Discount 1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 21.49
Evaluated at bid price : 21.75
Bid-YTW : 6.13 %
CU.PR.D Perpetual-Discount 1.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 20.69
Evaluated at bid price : 20.69
Bid-YTW : 6.03 %
RY.PR.G Deemed-Retractible 1.68 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.98
Bid-YTW : 5.25 %
CCS.PR.C Deemed-Retractible 1.69 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.10
Bid-YTW : 7.50 %
BAM.PR.Z FixedReset 1.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 17.93
Evaluated at bid price : 17.93
Bid-YTW : 5.16 %
PWF.PR.H Perpetual-Premium 1.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 24.25
Evaluated at bid price : 24.54
Bid-YTW : 5.88 %
RY.PR.W Perpetual-Discount 1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 22.01
Evaluated at bid price : 22.25
Bid-YTW : 5.50 %
PWF.PR.O Perpetual-Premium 1.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 24.26
Evaluated at bid price : 24.76
Bid-YTW : 5.86 %
FTS.PR.F Perpetual-Discount 1.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 21.38
Evaluated at bid price : 21.38
Bid-YTW : 5.83 %
CU.PR.F Perpetual-Discount 1.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 19.10
Evaluated at bid price : 19.10
Bid-YTW : 5.99 %
RY.PR.N Perpetual-Discount 1.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 21.59
Evaluated at bid price : 21.92
Bid-YTW : 5.57 %
CU.PR.G Perpetual-Discount 1.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 19.04
Evaluated at bid price : 19.04
Bid-YTW : 6.01 %
TD.PF.C FixedReset 1.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 16.80
Evaluated at bid price : 16.80
Bid-YTW : 4.50 %
CU.PR.E Perpetual-Discount 1.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 20.70
Evaluated at bid price : 20.70
Bid-YTW : 6.02 %
W.PR.J Perpetual-Discount 1.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 22.00
Evaluated at bid price : 22.23
Bid-YTW : 6.34 %
NA.PR.Q FixedReset 1.87 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.76
Bid-YTW : 5.81 %
BNS.PR.Y FixedReset 1.92 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.13
Bid-YTW : 6.53 %
BNS.PR.C FloatingReset 1.95 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.41
Bid-YTW : 4.89 %
PWF.PR.R Perpetual-Discount 1.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 23.10
Evaluated at bid price : 23.52
Bid-YTW : 5.86 %
W.PR.H Perpetual-Discount 2.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 21.78
Evaluated at bid price : 22.02
Bid-YTW : 6.29 %
BAM.PR.G FixedFloater 2.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 25.00
Evaluated at bid price : 12.45
Bid-YTW : 6.66 %
BNS.PR.N Deemed-Retractible 2.06 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-01-27
Maturity Price : 25.00
Evaluated at bid price : 25.22
Bid-YTW : 4.24 %
BMO.PR.R FloatingReset 2.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.70
Bid-YTW : 4.50 %
BNS.PR.L Deemed-Retractible 2.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.05
Bid-YTW : 5.25 %
PWF.PR.F Perpetual-Discount 2.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 22.18
Evaluated at bid price : 22.46
Bid-YTW : 5.86 %
MFC.PR.I FixedReset 2.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.98
Bid-YTW : 8.20 %
PWF.PR.E Perpetual-Discount 2.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 23.27
Evaluated at bid price : 23.57
Bid-YTW : 5.85 %
RY.PR.L FixedReset 2.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.00
Bid-YTW : 4.49 %
TD.PR.Y FixedReset 2.25 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.70
Bid-YTW : 4.65 %
ELF.PR.G Perpetual-Discount 2.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 20.40
Evaluated at bid price : 20.40
Bid-YTW : 5.87 %
BAM.PR.C Floater 2.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 9.45
Evaluated at bid price : 9.45
Bid-YTW : 5.05 %
BNS.PR.M Deemed-Retractible 2.29 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.09
Bid-YTW : 5.22 %
FTS.PR.J Perpetual-Discount 2.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 20.65
Evaluated at bid price : 20.65
Bid-YTW : 5.85 %
BAM.PR.B Floater 2.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 9.62
Evaluated at bid price : 9.62
Bid-YTW : 4.96 %
BAM.PF.B FixedReset 2.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 17.15
Evaluated at bid price : 17.15
Bid-YTW : 4.96 %
TD.PR.Z FloatingReset 2.45 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.76
Bid-YTW : 4.39 %
POW.PR.C Perpetual-Premium 2.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 24.50
Evaluated at bid price : 24.75
Bid-YTW : 5.90 %
GWO.PR.G Deemed-Retractible 2.52 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.75
Bid-YTW : 6.63 %
CM.PR.O FixedReset 2.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 4.56 %
MFC.PR.L FixedReset 2.53 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.19
Bid-YTW : 9.18 %
TD.PR.T FloatingReset 2.54 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.80
Bid-YTW : 4.27 %
POW.PR.D Perpetual-Discount 2.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 21.28
Evaluated at bid price : 21.55
Bid-YTW : 5.83 %
PWF.PR.L Perpetual-Discount 2.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 21.55
Evaluated at bid price : 21.81
Bid-YTW : 5.86 %
POW.PR.G Perpetual-Discount 2.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 23.67
Evaluated at bid price : 24.16
Bid-YTW : 5.82 %
GWO.PR.H Deemed-Retractible 2.68 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.42
Bid-YTW : 7.11 %
CIU.PR.C FixedReset 2.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 10.46
Evaluated at bid price : 10.46
Bid-YTW : 4.74 %
BAM.PF.D Perpetual-Discount 2.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 19.42
Evaluated at bid price : 19.42
Bid-YTW : 6.39 %
BAM.PF.C Perpetual-Discount 2.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 19.25
Evaluated at bid price : 19.25
Bid-YTW : 6.38 %
POW.PR.B Perpetual-Discount 2.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 22.71
Evaluated at bid price : 23.00
Bid-YTW : 5.85 %
GWO.PR.I Deemed-Retractible 2.88 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.39
Bid-YTW : 7.42 %
MFC.PR.K FixedReset 2.88 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.70
Bid-YTW : 9.46 %
BAM.PF.E FixedReset 2.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 17.70
Evaluated at bid price : 17.70
Bid-YTW : 4.86 %
HSE.PR.C FixedReset 2.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 13.45
Evaluated at bid price : 13.45
Bid-YTW : 7.37 %
BAM.PR.R FixedReset 2.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 13.43
Evaluated at bid price : 13.43
Bid-YTW : 5.47 %
BAM.PR.N Perpetual-Discount 2.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 18.99
Evaluated at bid price : 18.99
Bid-YTW : 6.33 %
MFC.PR.H FixedReset 2.94 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.25
Bid-YTW : 7.47 %
POW.PR.A Perpetual-Discount 3.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 23.74
Evaluated at bid price : 24.05
Bid-YTW : 5.86 %
TRP.PR.C FixedReset 3.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 11.00
Evaluated at bid price : 11.00
Bid-YTW : 4.81 %
BAM.PR.M Perpetual-Discount 3.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 18.96
Evaluated at bid price : 18.96
Bid-YTW : 6.34 %
BIP.PR.A FixedReset 3.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 17.10
Evaluated at bid price : 17.10
Bid-YTW : 6.25 %
GWO.PR.S Deemed-Retractible 3.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.59
Bid-YTW : 6.16 %
BMO.PR.T FixedReset 3.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 17.28
Evaluated at bid price : 17.28
Bid-YTW : 4.43 %
NA.PR.S FixedReset 3.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 16.82
Evaluated at bid price : 16.82
Bid-YTW : 4.71 %
BMO.PR.S FixedReset 3.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 17.40
Evaluated at bid price : 17.40
Bid-YTW : 4.52 %
TD.PF.A FixedReset 3.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 17.03
Evaluated at bid price : 17.03
Bid-YTW : 4.45 %
CU.PR.I FixedReset 3.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 23.27
Evaluated at bid price : 25.30
Bid-YTW : 4.38 %
IFC.PR.A FixedReset 3.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.56
Bid-YTW : 11.01 %
BAM.PF.G FixedReset 3.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 18.85
Evaluated at bid price : 18.85
Bid-YTW : 4.91 %
GWO.PR.R Deemed-Retractible 3.29 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.35
Bid-YTW : 7.10 %
BAM.PR.X FixedReset 3.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 12.75
Evaluated at bid price : 12.75
Bid-YTW : 5.02 %
GWO.PR.Q Deemed-Retractible 3.34 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.87
Bid-YTW : 6.50 %
RY.PR.P Perpetual-Discount 3.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 23.13
Evaluated at bid price : 23.55
Bid-YTW : 5.55 %
MFC.PR.M FixedReset 3.37 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.16
Bid-YTW : 8.57 %
MFC.PR.G FixedReset 3.39 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.68
Bid-YTW : 8.35 %
PWF.PR.P FixedReset 3.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 11.45
Evaluated at bid price : 11.45
Bid-YTW : 4.75 %
RY.PR.Z FixedReset 3.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 17.22
Evaluated at bid price : 17.22
Bid-YTW : 4.33 %
BAM.PR.T FixedReset 3.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 14.48
Evaluated at bid price : 14.48
Bid-YTW : 5.19 %
RY.PR.I FixedReset 3.54 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.30
Bid-YTW : 5.11 %
GWO.PR.P Deemed-Retractible 3.58 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.01
Bid-YTW : 6.06 %
BNS.PR.Q FixedReset 3.60 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.74
Bid-YTW : 4.66 %
NA.PR.W FixedReset 3.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 16.35
Evaluated at bid price : 16.35
Bid-YTW : 4.66 %
TD.PF.B FixedReset 3.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 17.28
Evaluated at bid price : 17.28
Bid-YTW : 4.37 %
RY.PR.H FixedReset 3.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 17.30
Evaluated at bid price : 17.30
Bid-YTW : 4.36 %
TD.PR.S FixedReset 3.82 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.10
Bid-YTW : 4.13 %
MFC.PR.J FixedReset 3.83 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.34
Bid-YTW : 8.41 %
MFC.PR.C Deemed-Retractible 3.88 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.37
Bid-YTW : 7.46 %
MFC.PR.B Deemed-Retractible 3.91 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.74
Bid-YTW : 7.38 %
VNR.PR.A FixedReset 4.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 16.65
Evaluated at bid price : 16.65
Bid-YTW : 5.24 %
BAM.PR.E Ratchet 4.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 25.00
Evaluated at bid price : 12.85
Bid-YTW : 6.43 %
SLF.PR.G FixedReset 4.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.80
Bid-YTW : 10.80 %
BNS.PR.P FixedReset 4.18 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.70
Bid-YTW : 3.88 %
HSE.PR.G FixedReset 4.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 14.71
Evaluated at bid price : 14.71
Bid-YTW : 7.30 %
IFC.PR.C FixedReset 4.33 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.91
Bid-YTW : 9.45 %
SLF.PR.B Deemed-Retractible 4.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.56
Bid-YTW : 6.96 %
SLF.PR.E Deemed-Retractible 4.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.34
Bid-YTW : 7.46 %
SLF.PR.A Deemed-Retractible 4.43 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.43
Bid-YTW : 6.99 %
FTS.PR.M FixedReset 4.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 17.35
Evaluated at bid price : 17.35
Bid-YTW : 4.78 %
HSE.PR.A FixedReset 4.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 8.55
Evaluated at bid price : 8.55
Bid-YTW : 6.79 %
BMO.PR.W FixedReset 4.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 17.05
Evaluated at bid price : 17.05
Bid-YTW : 4.46 %
SLF.PR.D Deemed-Retractible 4.61 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.18
Bid-YTW : 7.51 %
SLF.PR.C Deemed-Retractible 4.62 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.38
Bid-YTW : 7.37 %
HSE.PR.E FixedReset 4.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 14.40
Evaluated at bid price : 14.40
Bid-YTW : 7.46 %
RY.PR.J FixedReset 4.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 18.10
Evaluated at bid price : 18.10
Bid-YTW : 4.65 %
RY.PR.M FixedReset 4.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 17.86
Evaluated at bid price : 17.86
Bid-YTW : 4.60 %
IAG.PR.G FixedReset 4.79 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.60
Bid-YTW : 7.62 %
TRP.PR.E FixedReset 4.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 16.72
Evaluated at bid price : 16.72
Bid-YTW : 4.78 %
GWO.PR.N FixedReset 4.98 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.23
Bid-YTW : 11.28 %
TRP.PR.F FloatingReset 5.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 11.50
Evaluated at bid price : 11.50
Bid-YTW : 4.89 %
TD.PF.D FixedReset 5.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 18.60
Evaluated at bid price : 18.60
Bid-YTW : 4.60 %
TD.PF.E FixedReset 5.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 19.60
Evaluated at bid price : 19.60
Bid-YTW : 4.48 %
FTS.PR.K FixedReset 5.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 15.75
Evaluated at bid price : 15.75
Bid-YTW : 4.59 %
CM.PR.P FixedReset 5.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 4.45 %
FTS.PR.G FixedReset 5.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 15.17
Evaluated at bid price : 15.17
Bid-YTW : 4.80 %
SLF.PR.I FixedReset 5.57 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.68
Bid-YTW : 8.92 %
SLF.PR.J FloatingReset 5.81 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.01
Bid-YTW : 10.96 %
MFC.PR.N FixedReset 5.92 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.00
Bid-YTW : 8.63 %
BMO.PR.Y FixedReset 6.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 19.08
Evaluated at bid price : 19.08
Bid-YTW : 4.53 %
CU.PR.C FixedReset 6.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 16.86
Evaluated at bid price : 16.86
Bid-YTW : 4.57 %
TRP.PR.G FixedReset 6.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 18.15
Evaluated at bid price : 18.15
Bid-YTW : 5.03 %
CM.PR.Q FixedReset 6.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 18.77
Evaluated at bid price : 18.77
Bid-YTW : 4.57 %
GWO.PR.O FloatingReset 6.67 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.00
Bid-YTW : 10.81 %
BNS.PR.D FloatingReset 6.95 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.61
Bid-YTW : 6.46 %
TRP.PR.D FixedReset 7.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 16.11
Evaluated at bid price : 16.11
Bid-YTW : 4.88 %
BAM.PF.F FixedReset 7.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 19.45
Evaluated at bid price : 19.45
Bid-YTW : 4.72 %
PWF.PR.T FixedReset 7.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 20.10
Evaluated at bid price : 20.10
Bid-YTW : 3.90 %
TRP.PR.A FixedReset 11.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 14.00
Evaluated at bid price : 14.00
Bid-YTW : 4.78 %
Volume Highlights
Issue Index Shares
Traded
Notes
NA.PR.X FixedReset 796,852 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 23.09
Evaluated at bid price : 24.84
Bid-YTW : 5.48 %
TD.PF.G FixedReset 80,725 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 23.25
Evaluated at bid price : 25.34
Bid-YTW : 5.15 %
HSE.PR.G FixedReset 75,810 RBC crossed 60,151 at 14.40.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 14.71
Evaluated at bid price : 14.71
Bid-YTW : 7.30 %
SLF.PR.H FixedReset 55,810 RBC crossed 19,000 at 13.85 and bought 11,000 from TD at 14.20.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.80
Bid-YTW : 10.79 %
TRP.PR.B FixedReset 53,570 TD crossed 31,000 at 9.65.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 9.52
Evaluated at bid price : 9.52
Bid-YTW : 5.09 %
CU.PR.H Perpetual-Discount 49,831 TD bought blocks of 10,000 shares, 20,000 and 16,300 from National, all at 22.00.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 21.98
Evaluated at bid price : 22.26
Bid-YTW : 5.98 %
There were 64 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
CM.PR.Q FixedReset Quote: 18.77 – 22.00
Spot Rate : 3.2300
Average : 1.9632

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 18.77
Evaluated at bid price : 18.77
Bid-YTW : 4.57 %

BAM.PF.A FixedReset Quote: 17.95 – 19.24
Spot Rate : 1.2900
Average : 0.8267

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 17.95
Evaluated at bid price : 17.95
Bid-YTW : 5.09 %

PWF.PR.S Perpetual-Discount Quote: 20.05 – 21.23
Spot Rate : 1.1800
Average : 0.7578

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 20.05
Evaluated at bid price : 20.05
Bid-YTW : 6.02 %

BAM.PF.B FixedReset Quote: 17.15 – 18.39
Spot Rate : 1.2400
Average : 0.8353

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-22
Maturity Price : 17.15
Evaluated at bid price : 17.15
Bid-YTW : 4.96 %

RY.PR.K FloatingReset Quote: 20.86 – 21.95
Spot Rate : 1.0900
Average : 0.7619

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.86
Bid-YTW : 5.41 %

PVS.PR.B SplitShare Quote: 23.15 – 23.88
Spot Rate : 0.7300
Average : 0.4479

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2019-01-10
Maturity Price : 25.00
Evaluated at bid price : 23.15
Bid-YTW : 7.42 %

Market Action

January 21, 2016

So much for private equity:

Henry Kravis called it private equity’s golden age. From 2005 to 2007, buyout firms paid fat prices to buy about 20 supersized companies, from Hilton Worldwide Holdings Inc. to Hertz Global Holdings Inc.

Now, a decade later, the results of that debt-fueled spree can be tabulated — and it’s hardly golden. The mega-deals produced mostly mediocre returns, falling well short of the profits that leveraged buyout shops typically seek, according to separate compilations by Bloomberg and asset manager Hamilton Lane Advisors. In more than half the deals — each valued at more than $10 billion — the firms would have been better off if they had put their investors’ money into a stock index fund.
…
The results also pale when compared with the 70 percent median return yielded by all private equity transactions during that period, the Hamilton Lane study shows. That group includes thousands of smaller deals.

On an annualized basis, the largest deals generated a median 4 percent return, according to the Hamilton Lane study, which looked at 25 transactions from the era. The Standard and Poor’s 500 Index, by comparison, returned 7.3 percent a year from the start of 2006 through 2015.

Meanwhile, players are increasing bets on a dovish Fed:

Traders have gone from betting on two Fed increases in the next year — half the pace policy makers signaled last month — to just about one, as inflation expectations have tumbled to multiyear lows and stocks worldwide have crashed. That’s comparable with the market’s predicted pace in 2013 when the Fed started talking about winding down its bond-buying program, according to a Morgan Stanley index.

Judging by futures prices, investors see the fed funds effective rate rising to 0.61 percent by year-end. That’s nearly in line with the 0.62 percent level that would signal one rate increase, assuming the Fed raises its target range by 0.25 percentage point, following liftoff from near zero last month. Futures imply a one-in-five chance the Fed will boost rates at its March meeting, and it’s not until September that the chances exceed a coin flip, data compiled by Bloomberg show.

Preferred share investors were feeling buoyant today!

buoyant
Click for Big

It was a strong day for the Canadian preferred share market, with PerpetualDiscounts gaining 39bp, FixedResets up 99bp and DeemedRetractibles winning 131bp. The Performance Highlight table was the Performance Highlights table. Volume was very high.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_160121
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 15.95 to be $1.13 rich, while TRP.PR.G, resetting 2020-11-30 at +296, is $0.44 cheap at its bid price of 17.10.

impVol_MFC_160121
Click for Big

Most expensive is MFC.PR.M, resetting at +236bp on 2019-12-19, bid at 16.60 to be 0.65 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 17.10 to be 0.79 cheap.

impVol_BAM_160121
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 13.05 to be $1.85 cheap. BAM.PF.E, resetting at +255bp on 2020-3-31 is bid at 17.20 and appears to be $1.06 rich.

impVol_FTS_160121
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 14.98, looks $0.32 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 14.42 and is $0.59 cheap.

pairs_FR_160121
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.02%, with no outliers. There are five junk outliers below -1.00%.

pairs_FF_160121
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.49 % 6.68 % 21,807 15.82 1 12.7854 % 1,416.0
FixedFloater 7.79 % 6.79 % 29,394 15.48 1 1.1609 % 2,553.1
Floater 4.88 % 5.07 % 75,453 15.38 4 0.0776 % 1,564.4
OpRet 0.00 % 0.00 % 0 0.00 0 0.1257 % 2,690.7
SplitShare 4.91 % 7.03 % 73,934 2.73 6 0.1257 % 3,148.6
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1257 % 2,456.7
Perpetual-Premium 6.01 % 5.98 % 93,006 13.94 6 0.5501 % 2,456.4
Perpetual-Discount 5.99 % 6.00 % 102,115 13.90 33 0.3852 % 2,400.9
FixedReset 5.91 % 5.09 % 241,674 14.73 82 0.9904 % 1,744.0
Deemed-Retractible 5.42 % 5.88 % 134,105 6.93 34 1.3176 % 2,482.8
FloatingReset 2.84 % 5.04 % 64,133 5.60 13 0.7810 % 1,960.3
Performance Highlights
Issue Index Change Notes
HSE.PR.E FixedReset -3.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 13.76
Evaluated at bid price : 13.76
Bid-YTW : 7.81 %
TRP.PR.B FixedReset -2.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 9.37
Evaluated at bid price : 9.37
Bid-YTW : 5.17 %
HSE.PR.C FixedReset -2.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 13.07
Evaluated at bid price : 13.07
Bid-YTW : 7.59 %
BAM.PR.X FixedReset -2.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 12.34
Evaluated at bid price : 12.34
Bid-YTW : 5.20 %
PWF.PR.A Floater -2.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 10.90
Evaluated at bid price : 10.90
Bid-YTW : 4.39 %
W.PR.H Perpetual-Discount -2.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 21.31
Evaluated at bid price : 21.58
Bid-YTW : 6.42 %
W.PR.J Perpetual-Discount -2.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 21.57
Evaluated at bid price : 21.83
Bid-YTW : 6.46 %
BAM.PR.B Floater -1.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 9.40
Evaluated at bid price : 9.40
Bid-YTW : 5.07 %
CIU.PR.C FixedReset -1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 10.18
Evaluated at bid price : 10.18
Bid-YTW : 4.87 %
PWF.PR.T FixedReset -1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 18.62
Evaluated at bid price : 18.62
Bid-YTW : 4.21 %
HSE.PR.A FixedReset -1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 8.18
Evaluated at bid price : 8.18
Bid-YTW : 7.10 %
GWO.PR.O FloatingReset -1.32 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.25
Bid-YTW : 11.66 %
PWF.PR.R Perpetual-Discount 1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 22.71
Evaluated at bid price : 23.06
Bid-YTW : 5.98 %
ELF.PR.F Perpetual-Discount 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 21.40
Evaluated at bid price : 21.40
Bid-YTW : 6.24 %
PWF.PR.H Perpetual-Premium 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 23.86
Evaluated at bid price : 24.11
Bid-YTW : 5.98 %
BNS.PR.C FloatingReset 1.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.00
Bid-YTW : 5.24 %
BAM.PR.G FixedFloater 1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 25.00
Evaluated at bid price : 12.20
Bid-YTW : 6.79 %
POW.PR.D Perpetual-Discount 1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 21.00
Evaluated at bid price : 21.00
Bid-YTW : 6.00 %
TRP.PR.D FixedReset 1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 15.03
Evaluated at bid price : 15.03
Bid-YTW : 5.24 %
MFC.PR.L FixedReset 1.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.79
Bid-YTW : 9.53 %
BMO.PR.W FixedReset 1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 16.30
Evaluated at bid price : 16.30
Bid-YTW : 4.67 %
VNR.PR.A FixedReset 1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 16.01
Evaluated at bid price : 16.01
Bid-YTW : 5.45 %
CM.PR.O FixedReset 1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 16.58
Evaluated at bid price : 16.58
Bid-YTW : 4.67 %
MFC.PR.F FixedReset 1.41 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.50
Bid-YTW : 12.17 %
IAG.PR.G FixedReset 1.43 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.75
Bid-YTW : 8.27 %
GWO.PR.S Deemed-Retractible 1.46 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.87
Bid-YTW : 6.60 %
BAM.PF.E FixedReset 1.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 17.20
Evaluated at bid price : 17.20
Bid-YTW : 5.01 %
MFC.PR.G FixedReset 1.48 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.10
Bid-YTW : 8.82 %
GWO.PR.P Deemed-Retractible 1.49 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.18
Bid-YTW : 6.57 %
PWF.PR.S Perpetual-Discount 1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 20.25
Evaluated at bid price : 20.25
Bid-YTW : 5.96 %
GWO.PR.Q Deemed-Retractible 1.51 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.13
Bid-YTW : 6.97 %
FTS.PR.J Perpetual-Discount 1.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 20.18
Evaluated at bid price : 20.18
Bid-YTW : 5.99 %
IFC.PR.C FixedReset 1.67 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.25
Bid-YTW : 10.05 %
BAM.PF.A FixedReset 1.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 17.93
Evaluated at bid price : 17.93
Bid-YTW : 5.10 %
FTS.PR.F Perpetual-Discount 1.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 21.00
Evaluated at bid price : 21.00
Bid-YTW : 5.93 %
SLF.PR.H FixedReset 1.85 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.75
Bid-YTW : 10.84 %
TD.PF.A FixedReset 1.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 16.50
Evaluated at bid price : 16.50
Bid-YTW : 4.60 %
TD.PF.C FixedReset 1.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 16.50
Evaluated at bid price : 16.50
Bid-YTW : 4.58 %
TRP.PR.F FloatingReset 1.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 10.95
Evaluated at bid price : 10.95
Bid-YTW : 5.14 %
SLF.PR.I FixedReset 1.87 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.80
Bid-YTW : 9.69 %
NA.PR.S FixedReset 1.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 16.30
Evaluated at bid price : 16.30
Bid-YTW : 4.86 %
GWO.PR.G Deemed-Retractible 1.88 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.19
Bid-YTW : 6.99 %
CCS.PR.C Deemed-Retractible 1.92 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.75
Bid-YTW : 7.74 %
CM.PR.P FixedReset 1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 16.16
Evaluated at bid price : 16.16
Bid-YTW : 4.69 %
BNS.PR.P FixedReset 1.97 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.75
Bid-YTW : 4.64 %
SLF.PR.G FixedReset 2.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.30
Bid-YTW : 11.34 %
MFC.PR.J FixedReset 2.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.70
Bid-YTW : 8.94 %
MFC.PR.M FixedReset 2.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.60
Bid-YTW : 9.04 %
RY.PR.Z FixedReset 2.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 16.89
Evaluated at bid price : 16.89
Bid-YTW : 4.50 %
TRP.PR.E FixedReset 2.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 15.95
Evaluated at bid price : 15.95
Bid-YTW : 5.02 %
GWO.PR.I Deemed-Retractible 2.32 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.82
Bid-YTW : 7.83 %
GWO.PR.L Deemed-Retractible 2.41 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.26
Bid-YTW : 6.17 %
RY.PR.H FixedReset 2.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 16.90
Evaluated at bid price : 16.90
Bid-YTW : 4.56 %
BMO.PR.T FixedReset 2.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 16.75
Evaluated at bid price : 16.75
Bid-YTW : 4.57 %
RY.PR.M FixedReset 2.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 17.26
Evaluated at bid price : 17.26
Bid-YTW : 4.85 %
GWO.PR.H Deemed-Retractible 2.71 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.86
Bid-YTW : 7.49 %
GWO.PR.R Deemed-Retractible 2.73 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.67
Bid-YTW : 7.57 %
TRP.PR.A FixedReset 2.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 12.55
Evaluated at bid price : 12.55
Bid-YTW : 5.35 %
RY.PR.J FixedReset 2.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 4.90 %
W.PR.K FixedReset 2.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 22.87
Evaluated at bid price : 24.22
Bid-YTW : 5.42 %
MFC.PR.I FixedReset 2.92 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.60
Bid-YTW : 8.50 %
TRP.PR.H FloatingReset 2.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 9.09
Evaluated at bid price : 9.09
Bid-YTW : 4.41 %
SLF.PR.B Deemed-Retractible 3.30 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.66
Bid-YTW : 7.58 %
MFC.PR.B Deemed-Retractible 3.31 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.96
Bid-YTW : 7.93 %
SLF.PR.A Deemed-Retractible 3.38 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.52
Bid-YTW : 7.62 %
TD.PF.B FixedReset 3.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 16.65
Evaluated at bid price : 16.65
Bid-YTW : 4.54 %
TD.PF.D FixedReset 3.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 17.70
Evaluated at bid price : 17.70
Bid-YTW : 4.84 %
SLF.PR.D Deemed-Retractible 3.71 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.29
Bid-YTW : 8.16 %
FTS.PR.M FixedReset 3.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 16.60
Evaluated at bid price : 16.60
Bid-YTW : 5.01 %
MFC.PR.C Deemed-Retractible 3.81 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.61
Bid-YTW : 8.01 %
BAM.PF.G FixedReset 4.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 18.25
Evaluated at bid price : 18.25
Bid-YTW : 5.08 %
SLF.PR.C Deemed-Retractible 4.51 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.48
Bid-YTW : 8.02 %
MFC.PR.H FixedReset 4.53 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.70
Bid-YTW : 7.88 %
SLF.PR.E Deemed-Retractible 4.67 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.49
Bid-YTW : 8.07 %
BAM.PR.K Floater 6.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 9.15
Evaluated at bid price : 9.15
Bid-YTW : 5.21 %
FTS.PR.H FixedReset 6.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 12.05
Evaluated at bid price : 12.05
Bid-YTW : 4.47 %
TD.PF.E FixedReset 7.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 18.65
Evaluated at bid price : 18.65
Bid-YTW : 4.71 %
SLF.PR.J FloatingReset 7.28 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.35
Bid-YTW : 11.71 %
BAM.PR.E Ratchet 12.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 25.00
Evaluated at bid price : 12.35
Bid-YTW : 6.68 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PF.G FixedReset 130,018 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 23.25
Evaluated at bid price : 25.34
Bid-YTW : 5.15 %
RY.PR.Q FixedReset 93,630 RBC crossed blocks of 29,700 and 10,000, both at 25.40.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 23.24
Evaluated at bid price : 25.30
Bid-YTW : 5.10 %
BAM.PR.X FixedReset 49,723 TD crossed 30,000 at 12.55.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 12.34
Evaluated at bid price : 12.34
Bid-YTW : 5.20 %
HSE.PR.C FixedReset 47,180 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 13.07
Evaluated at bid price : 13.07
Bid-YTW : 7.59 %
HSE.PR.E FixedReset 46,500 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 13.76
Evaluated at bid price : 13.76
Bid-YTW : 7.81 %
RY.PR.Z FixedReset 42,293 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 16.89
Evaluated at bid price : 16.89
Bid-YTW : 4.50 %
There were 60 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
GWO.PR.O FloatingReset Quote: 11.25 – 20.25
Spot Rate : 9.0000
Average : 5.5256

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.25
Bid-YTW : 11.66 %

PWF.PR.T FixedReset Quote: 18.62 – 19.98
Spot Rate : 1.3600
Average : 0.9455

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 18.62
Evaluated at bid price : 18.62
Bid-YTW : 4.21 %

GWO.PR.N FixedReset Quote: 11.65 – 12.50
Spot Rate : 0.8500
Average : 0.5500

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.65
Bid-YTW : 11.94 %

PWF.PR.P FixedReset Quote: 11.07 – 11.76
Spot Rate : 0.6900
Average : 0.4396

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-21
Maturity Price : 11.07
Evaluated at bid price : 11.07
Bid-YTW : 4.92 %

PVS.PR.C SplitShare Quote: 24.22 – 24.99
Spot Rate : 0.7700
Average : 0.5390

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2017-12-10
Maturity Price : 25.00
Evaluated at bid price : 24.22
Bid-YTW : 7.03 %

TD.PR.Y FixedReset Quote: 22.20 – 22.97
Spot Rate : 0.7700
Average : 0.5546

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.20
Bid-YTW : 5.07 %

Market Action

January 20, 2016

Today’s big news was the BoC rate announcement:

The Bank of Canada today announced that it is maintaining its target for the overnight rate at 1/2 per cent. The Bank Rate is correspondingly 3/4 per cent and the deposit rate is 1/4 per cent.

Inflation in Canada is evolving broadly as expected. Total CPI inflation remains near the bottom of the Bank’s target range as the disinflationary effects of economic slack and low consumer energy prices are only partially offset by the inflationary impact of the lower Canadian dollar on the prices of imported goods. As all of these factors dissipate, the Bank expects inflation will rise to about 2 per cent by early 2017. Measures of core inflation should remain close to 2 per cent.
….
The Bank projects Canada’s economy will grow by about 1 1/2 per cent in 2016 and 2 1/2 per cent in 2017. The complex nature of the ongoing structural adjustment makes the outlook for demand and potential output highly uncertain. The Bank’s current base case projection shows the output gap closing later than was anticipated in October, around the end of 2017. However, the Bank has not yet incorporated the positive impact of fiscal measures expected in the next federal budget.

All things considered, therefore, the risks to the profile for inflation are roughly balanced. Meanwhile, financial vulnerabilities continue to edge higher, as expected. The Bank’s Governing Council judges that the current stance of monetary policy is appropriate, and the target for the overnight rate remains at 1/2 per cent.

This was good news for some:

The loonie, as the Canadian dollar is known for the image of the aquatic bird on the C$1 coin, gained 0.7 percent to C$1.4476 per U.S. dollar at 3:30 p.m. in Toronto. One Canadian dollar buys about 69 U.S. cents. The loonie reached the cheapest since April 2003 on Wednesday before the rate announcement.

In what may be a harbinger of things to come, Pacific Exploration & Production Corp. (formerly Pacific Rubiales Energy Corp.) has run into serious trouble:

it has elected to utilize the 30 day grace period (the “Grace Period”) pursuant to the indentures governing its 5.625% notes due January 19, 2025 (the “5.625% Notes”) and its 5.375% notes due January 26, 2019 (the “5.375 Notes”, and together with the 5.625% Notes, the “Notes”) rather than make the interest payments due on January 19, 2016 and January 26, 2016, respectively, in connection with these Notes.

Specifically, the following interest payments will not be paid on the scheduled payment dates: (i) U.S.$31.3 million in the aggregate in respect of the 5.625% Notes scheduled to be paid on January 19, 2016; and (ii) U.S.$34.9 million in the aggregate in respect of the 5.375% Notes scheduled to be paid on January 26, 2016 (collectively, the “January Interest Payments”). The Company has elected to use the Grace Period to assess strategic alternatives with respect to its capital structure.

The Company’s current liquidity position is being impacted by the significantly depressed international oil prices. The Company will use the Grace Period to engage with its creditors (including its lenders and holders of each series of the Company’s notes) with a view to making its capital structure more suitable to current market conditions. The Company remains and intends to remain current with its suppliers, trade partners and contractors. Normal operations continue in Colombia and the other jurisdictions within which the Company operates.

The failure to make the January Interest Payments on the scheduled dates does not constitute an Event of Default under the indentures that govern the Notes. In each case, the Company has a 30 day period from the scheduled payment dates to cure the failure to make such payments and the Company reserves the right to make the January Interest Payments prior to the expiry of each Grace Period.

This follows some circling by the vultures:

Harbour Energy, managed by EIG Global Energy Partners (“EIG”), believes that Pacific E&P faces significant near-term insolvency concerns and requires a large infusion of new capital in order to restructure its balance sheet, avoid value-destructive asset-level reorganizations or distressed sales, and degradation of Pacific E&P’s assets through under-investment and deferred maintenance. As of September 30, 2015, Pacific E&P had approximately $5.4 billion of debt outstanding, including $4.10 billion aggregate principal amount of senior bonds that are trading at levels equivalent to approximately thirteen cents on the dollar as of January 13, 2016, indicating that no value remains in its equity. Harbour Energy and EIG are committed to investing in Pacific E&P to ensure that its operations remain intact, partnerships are maintained and, upon restructuring, Pacific E&P is once again positioned for operational excellence and growth.

… with more pressure being added today:

It appears highly unlikely that Pacific E&P will make the deferred interest payments on the 2019 Notes and the 2025 Notes nor make interest payments on the 2021 Notes or the 2023 Notes when due. However, for those that tender, because Harbour Energy’s offer includes all accrued and unpaid interest payments across all four tranches of Notes up to the end of the Company’s 30-day grace period on February 19, 2016 (assuming the company does not file for insolvency prior to that), EIG’s Tender Offer consideration of $175 per $1,000 of principal plus accrued interest is effectively $200.66 per $1,000 of principal on average across all four tranches of Notes.

“With an average effective price of approximately 20.1%, our offer represents a 100% premium over the average 10% bid price where Pacific E&P’s bonds were trading immediately before our offer was launched and when the market expected the Company to make its January interest payments. We believe the Company’s cash position is dire and that the market has underestimated the severity of the situation. …. ”

Added Mr. Thomas, “We are grateful for the bondholders who have already indicated they will tender. We believe our proposal represents the best outcome for Pacific E&P as well as the bondholders as it provides a significant premium and de-risks recovery in a comprehensive and credible way. In our view, a single voice which is prepared to support further growth of the Company in partnership with Pacific E&P’s management and other stakeholders is the only viable solution.”

Meanwhile, preferred share investors were treated to another day of watching the market:

clockworkOrange
Click for Big

It was a grim day for the Canadian preferred share market, with PerpetualDiscounts off 118bp, FixedResets losing 205bp and DeemedRetractibles down 163bp. The Performance Highlights table is ridiculous. Volume was extremely high.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_160120
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 15.61 to be $0.92 rich, while TRP.PR.A, resetting 2019-12-31 at +192, is $0.52 cheap at its bid price of 12.21.

impVol_MFC_160120
Click for Big

Most expensive is MFC.PR.L, resetting at +216bp on 2019-6-19, bid at 15.60 to be 0.73 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 16.85 to be 0.75 cheap.

impVol_BAM_160120
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 13.05 to be $1.63 cheap. BAM.PF.E, resetting at +255bp on 2020-3-31 is bid at 16.95 and appears to be $1.02 rich.

impVol_FTS_160120
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 14.89, looks $0.63 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 14.30 and is $0.34 cheap.

pairs_FR_160120
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.04%, with no outliers. There are two junk outliers below -1.00% and one above 1.00%.

pairs_FF_160120
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 6.19 % 7.49 % 22,797 14.87 1 -11.6935 % 1,255.5
FixedFloater 7.88 % 6.87 % 30,509 15.40 1 -3.5200 % 2,523.8
Floater 4.89 % 4.99 % 76,197 15.53 4 0.2074 % 1,563.1
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0837 % 2,687.3
SplitShare 4.92 % 6.83 % 68,931 2.73 6 -0.0837 % 3,144.6
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0837 % 2,453.6
Perpetual-Premium 6.04 % 6.07 % 85,813 13.81 6 -0.8657 % 2,443.0
Perpetual-Discount 6.01 % 6.06 % 101,126 13.80 33 -1.1848 % 2,391.7
FixedReset 5.97 % 5.12 % 243,510 14.59 82 -2.0519 % 1,726.9
Deemed-Retractible 5.49 % 5.94 % 132,717 6.92 34 -1.6340 % 2,450.5
FloatingReset 2.86 % 5.19 % 64,247 5.60 13 -1.4756 % 1,945.1
Performance Highlights
Issue Index Change Notes
SLF.PR.J FloatingReset -11.83 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 10.58
Bid-YTW : 12.65 %
BAM.PR.E Ratchet -11.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 25.00
Evaluated at bid price : 10.95
Bid-YTW : 7.49 %
BAM.PR.K Floater -9.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 8.60
Evaluated at bid price : 8.60
Bid-YTW : 5.55 %
FTS.PR.M FixedReset -7.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 16.00
Evaluated at bid price : 16.00
Bid-YTW : 5.20 %
FTS.PR.H FixedReset -5.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 11.28
Evaluated at bid price : 11.28
Bid-YTW : 4.79 %
HSE.PR.A FixedReset -5.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 8.30
Evaluated at bid price : 8.30
Bid-YTW : 6.99 %
TRP.PR.F FloatingReset -5.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 10.75
Evaluated at bid price : 10.75
Bid-YTW : 5.23 %
HSE.PR.G FixedReset -5.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 14.20
Evaluated at bid price : 14.20
Bid-YTW : 7.57 %
MFC.PR.K FixedReset -5.48 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.35
Bid-YTW : 9.78 %
SLF.PR.E Deemed-Retractible -5.29 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.62
Bid-YTW : 8.73 %
MFC.PR.L FixedReset -5.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.60
Bid-YTW : 9.70 %
HSE.PR.C FixedReset -4.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 13.43
Evaluated at bid price : 13.43
Bid-YTW : 7.37 %
SLF.PR.C Deemed-Retractible -4.70 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.64
Bid-YTW : 8.65 %
HSE.PR.E FixedReset -4.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 14.20
Evaluated at bid price : 14.20
Bid-YTW : 7.56 %
FTS.PR.K FixedReset -4.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 14.89
Evaluated at bid price : 14.89
Bid-YTW : 4.87 %
SLF.PR.D Deemed-Retractible -4.37 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.60
Bid-YTW : 8.68 %
SLF.PR.G FixedReset -4.37 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.05
Bid-YTW : 11.62 %
TRP.PR.A FixedReset -4.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 12.21
Evaluated at bid price : 12.21
Bid-YTW : 5.51 %
BAM.PF.G FixedReset -4.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 17.52
Evaluated at bid price : 17.52
Bid-YTW : 5.30 %
SLF.PR.A Deemed-Retractible -3.92 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.85
Bid-YTW : 8.10 %
MFC.PR.F FixedReset -3.90 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.34
Bid-YTW : 12.36 %
RY.PR.M FixedReset -3.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 16.84
Evaluated at bid price : 16.84
Bid-YTW : 4.97 %
RY.PR.J FixedReset -3.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 17.02
Evaluated at bid price : 17.02
Bid-YTW : 5.04 %
BAM.PR.R FixedReset -3.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 13.05
Evaluated at bid price : 13.05
Bid-YTW : 5.62 %
SLF.PR.B Deemed-Retractible -3.57 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.00
Bid-YTW : 8.05 %
BAM.PR.G FixedFloater -3.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 25.00
Evaluated at bid price : 12.06
Bid-YTW : 6.87 %
IAG.PR.A Deemed-Retractible -3.34 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.99
Bid-YTW : 7.82 %
BAM.PR.C Floater -3.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 9.33
Evaluated at bid price : 9.33
Bid-YTW : 5.11 %
PWF.PR.S Perpetual-Discount -3.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 19.95
Evaluated at bid price : 19.95
Bid-YTW : 6.05 %
MFC.PR.J FixedReset -3.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.35
Bid-YTW : 9.24 %
TD.PF.A FixedReset -3.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 16.20
Evaluated at bid price : 16.20
Bid-YTW : 4.68 %
TD.PR.S FixedReset -3.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.15
Bid-YTW : 4.91 %
MFC.PR.N FixedReset -2.99 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.92
Bid-YTW : 9.56 %
MFC.PR.M FixedReset -2.99 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.25
Bid-YTW : 9.34 %
BAM.PR.T FixedReset -2.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 13.99
Evaluated at bid price : 13.99
Bid-YTW : 5.37 %
BMO.PR.Y FixedReset -2.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 17.85
Evaluated at bid price : 17.85
Bid-YTW : 4.84 %
IFC.PR.C FixedReset -2.91 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.00
Bid-YTW : 10.28 %
SLF.PR.H FixedReset -2.88 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.50
Bid-YTW : 11.10 %
BIP.PR.B FixedReset -2.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 21.55
Evaluated at bid price : 21.87
Bid-YTW : 6.37 %
TD.PF.B FixedReset -2.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 16.10
Evaluated at bid price : 16.10
Bid-YTW : 4.70 %
MFC.PR.C Deemed-Retractible -2.83 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.89
Bid-YTW : 8.55 %
SLF.PR.I FixedReset -2.76 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.51
Bid-YTW : 9.95 %
FTS.PR.G FixedReset -2.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 14.30
Evaluated at bid price : 14.30
Bid-YTW : 5.10 %
TD.PR.Y FixedReset -2.69 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.40
Bid-YTW : 4.90 %
BAM.PR.X FixedReset -2.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 12.65
Evaluated at bid price : 12.65
Bid-YTW : 5.06 %
MFC.PR.B Deemed-Retractible -2.62 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.32
Bid-YTW : 8.40 %
BMO.PR.M FixedReset -2.62 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.30
Bid-YTW : 4.95 %
BAM.PF.C Perpetual-Discount -2.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 18.59
Evaluated at bid price : 18.59
Bid-YTW : 6.60 %
TRP.PR.B FixedReset -2.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 9.64
Evaluated at bid price : 9.64
Bid-YTW : 5.02 %
ELF.PR.F Perpetual-Discount -2.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 21.17
Evaluated at bid price : 21.17
Bid-YTW : 6.31 %
BAM.PF.F FixedReset -2.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 18.10
Evaluated at bid price : 18.10
Bid-YTW : 5.08 %
RY.PR.H FixedReset -2.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 16.50
Evaluated at bid price : 16.50
Bid-YTW : 4.67 %
BAM.PR.M Perpetual-Discount -2.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 18.28
Evaluated at bid price : 18.28
Bid-YTW : 6.58 %
BMO.PR.W FixedReset -2.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 16.10
Evaluated at bid price : 16.10
Bid-YTW : 4.73 %
BAM.PR.N Perpetual-Discount -2.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 18.40
Evaluated at bid price : 18.40
Bid-YTW : 6.53 %
GWO.PR.S Deemed-Retractible -2.25 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.54
Bid-YTW : 6.81 %
TD.PF.E FixedReset -2.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 17.40
Evaluated at bid price : 17.40
Bid-YTW : 5.05 %
GWO.PR.R Deemed-Retractible -2.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.12
Bid-YTW : 7.96 %
GWO.PR.H Deemed-Retractible -2.21 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.31
Bid-YTW : 7.88 %
IGM.PR.B Perpetual-Premium -2.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 23.58
Evaluated at bid price : 24.00
Bid-YTW : 6.16 %
BNS.PR.P FixedReset -2.19 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.31
Bid-YTW : 5.00 %
GWO.PR.P Deemed-Retractible -2.18 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.84
Bid-YTW : 6.78 %
TD.PF.F Perpetual-Discount -2.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 21.51
Evaluated at bid price : 21.51
Bid-YTW : 5.72 %
BAM.PF.B FixedReset -2.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 16.72
Evaluated at bid price : 16.72
Bid-YTW : 5.09 %
GWO.PR.I Deemed-Retractible -2.02 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.37
Bid-YTW : 8.15 %
TD.PF.C FixedReset -2.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 16.20
Evaluated at bid price : 16.20
Bid-YTW : 4.67 %
FTS.PR.J Perpetual-Discount -1.97 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 19.86
Evaluated at bid price : 19.86
Bid-YTW : 6.08 %
FTS.PR.F Perpetual-Discount -1.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 20.64
Evaluated at bid price : 20.64
Bid-YTW : 6.04 %
BAM.PF.A FixedReset -1.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 17.63
Evaluated at bid price : 17.63
Bid-YTW : 5.18 %
BMO.PR.Q FixedReset -1.89 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.20
Bid-YTW : 7.80 %
CCS.PR.C Deemed-Retractible -1.88 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.36
Bid-YTW : 8.02 %
BAM.PF.D Perpetual-Discount -1.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 18.84
Evaluated at bid price : 18.84
Bid-YTW : 6.58 %
PWF.PR.P FixedReset -1.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 11.05
Evaluated at bid price : 11.05
Bid-YTW : 4.92 %
POW.PR.A Perpetual-Discount -1.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 22.95
Evaluated at bid price : 23.22
Bid-YTW : 6.07 %
RY.PR.I FixedReset -1.76 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.75
Bid-YTW : 5.76 %
RY.PR.Z FixedReset -1.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 16.53
Evaluated at bid price : 16.53
Bid-YTW : 4.61 %
BMO.PR.S FixedReset -1.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 16.72
Evaluated at bid price : 16.72
Bid-YTW : 4.70 %
BAM.PF.E FixedReset -1.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 16.95
Evaluated at bid price : 16.95
Bid-YTW : 5.08 %
TD.PF.D FixedReset -1.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 17.10
Evaluated at bid price : 17.10
Bid-YTW : 5.01 %
MFC.PR.I FixedReset -1.61 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.10
Bid-YTW : 8.90 %
BNS.PR.N Deemed-Retractible -1.61 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.50
Bid-YTW : 5.65 %
TRP.PR.D FixedReset -1.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 14.85
Evaluated at bid price : 14.85
Bid-YTW : 5.31 %
RY.PR.L FixedReset -1.53 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.87
Bid-YTW : 4.80 %
TRP.PR.E FixedReset -1.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 15.61
Evaluated at bid price : 15.61
Bid-YTW : 5.14 %
POW.PR.B Perpetual-Discount -1.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 21.97
Evaluated at bid price : 22.20
Bid-YTW : 6.06 %
MFC.PR.H FixedReset -1.49 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.89
Bid-YTW : 8.50 %
RY.PR.P Perpetual-Discount -1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 22.92
Evaluated at bid price : 23.30
Bid-YTW : 5.77 %
RY.PR.K FloatingReset -1.47 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.84
Bid-YTW : 5.55 %
MFC.PR.G FixedReset -1.46 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.85
Bid-YTW : 9.02 %
TRP.PR.G FixedReset -1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 16.95
Evaluated at bid price : 16.95
Bid-YTW : 5.39 %
CIU.PR.A Perpetual-Discount -1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 19.14
Evaluated at bid price : 19.14
Bid-YTW : 6.11 %
NA.PR.Q FixedReset -1.44 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.25
Bid-YTW : 6.25 %
POW.PR.G Perpetual-Discount -1.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 22.96
Evaluated at bid price : 23.36
Bid-YTW : 6.02 %
TD.PR.Z FloatingReset -1.43 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.35
Bid-YTW : 4.73 %
BNS.PR.Q FixedReset -1.39 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.98
Bid-YTW : 5.29 %
W.PR.K FixedReset -1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 22.57
Evaluated at bid price : 23.55
Bid-YTW : 5.59 %
ELF.PR.H Perpetual-Discount -1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 21.80
Evaluated at bid price : 22.10
Bid-YTW : 6.26 %
ELF.PR.G Perpetual-Discount -1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 19.78
Evaluated at bid price : 19.78
Bid-YTW : 6.05 %
BMO.PR.T FixedReset -1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 16.35
Evaluated at bid price : 16.35
Bid-YTW : 4.69 %
CM.PR.P FixedReset -1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 15.85
Evaluated at bid price : 15.85
Bid-YTW : 4.78 %
NA.PR.S FixedReset -1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 16.00
Evaluated at bid price : 16.00
Bid-YTW : 4.96 %
RY.PR.N Perpetual-Discount -1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 21.58
Evaluated at bid price : 21.90
Bid-YTW : 5.67 %
RY.PR.W Perpetual-Discount -1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 21.76
Evaluated at bid price : 22.01
Bid-YTW : 5.65 %
BNS.PR.Y FixedReset -1.21 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.77
Bid-YTW : 6.87 %
BNS.PR.R FixedReset -1.19 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.45
Bid-YTW : 5.17 %
GWO.PR.F Deemed-Retractible -1.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.75
Bid-YTW : 6.14 %
BNS.PR.A FloatingReset -1.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.91
Bid-YTW : 4.65 %
GWO.PR.L Deemed-Retractible -1.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.69
Bid-YTW : 6.52 %
RY.PR.C Deemed-Retractible -1.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.91
Bid-YTW : 5.64 %
RY.PR.B Deemed-Retractible -1.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.92
Bid-YTW : 5.73 %
RY.PR.G Deemed-Retractible -1.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.83
Bid-YTW : 5.59 %
BNS.PR.L Deemed-Retractible -1.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.50
Bid-YTW : 5.69 %
GWO.PR.Q Deemed-Retractible -1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.80
Bid-YTW : 7.19 %
PVS.PR.E SplitShare 1.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-10-31
Maturity Price : 25.00
Evaluated at bid price : 23.45
Bid-YTW : 6.83 %
BAM.PR.B Floater 1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 9.56
Evaluated at bid price : 9.56
Bid-YTW : 4.99 %
BAM.PR.Z FixedReset 1.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 17.56
Evaluated at bid price : 17.56
Bid-YTW : 5.27 %
PWF.PR.A Floater 11.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 11.17
Evaluated at bid price : 11.17
Bid-YTW : 4.28 %
Volume Highlights
Issue Index Shares
Traded
Notes
BNS.PR.E FixedReset 171,178 TD crossed blocks of 50,000 shares, 30,000 and 10,900, all at 25.32, and another 30,000 at 25.30. CIBC sold 10,000 to anonymous at 25.28.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 23.22
Evaluated at bid price : 25.22
Bid-YTW : 5.10 %
TD.PF.G FixedReset 154,883 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 23.21
Evaluated at bid price : 25.20
Bid-YTW : 5.19 %
BMO.PR.S FixedReset 98,794 Scotia crossed 25,000 at 16.99ll Nesbitt crossed 40,000 at 17.10.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 16.72
Evaluated at bid price : 16.72
Bid-YTW : 4.70 %
RY.PR.Q FixedReset 98,273 Scotia crossed 30,000 at 25.27.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 23.21
Evaluated at bid price : 25.20
Bid-YTW : 5.12 %
BAM.PR.R FixedReset 88,196 TD crossed 10,000 at 13.25.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 13.05
Evaluated at bid price : 13.05
Bid-YTW : 5.62 %
CM.PR.O FixedReset 76,650 RBC crossed 50,000 at 16.50.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 16.36
Evaluated at bid price : 16.36
Bid-YTW : 4.74 %
There were 73 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BAM.PR.E Ratchet Quote: 10.95 – 12.91
Spot Rate : 1.9600
Average : 1.2705

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 25.00
Evaluated at bid price : 10.95
Bid-YTW : 7.49 %

BAM.PR.K Floater Quote: 8.60 – 9.80
Spot Rate : 1.2000
Average : 0.7410

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 8.60
Evaluated at bid price : 8.60
Bid-YTW : 5.55 %

SLF.PR.J FloatingReset Quote: 10.58 – 11.75
Spot Rate : 1.1700
Average : 0.7778

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 10.58
Bid-YTW : 12.65 %

FTS.PR.M FixedReset Quote: 16.00 – 17.00
Spot Rate : 1.0000
Average : 0.6606

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 16.00
Evaluated at bid price : 16.00
Bid-YTW : 5.20 %

FTS.PR.H FixedReset Quote: 11.28 – 12.10
Spot Rate : 0.8200
Average : 0.5306

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 11.28
Evaluated at bid price : 11.28
Bid-YTW : 4.79 %

TD.PF.E FixedReset Quote: 17.40 – 18.40
Spot Rate : 1.0000
Average : 0.7500

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-20
Maturity Price : 17.40
Evaluated at bid price : 17.40
Bid-YTW : 5.05 %