Category: Market Action

Market Action

October 22, 2015

Nothing happened today.

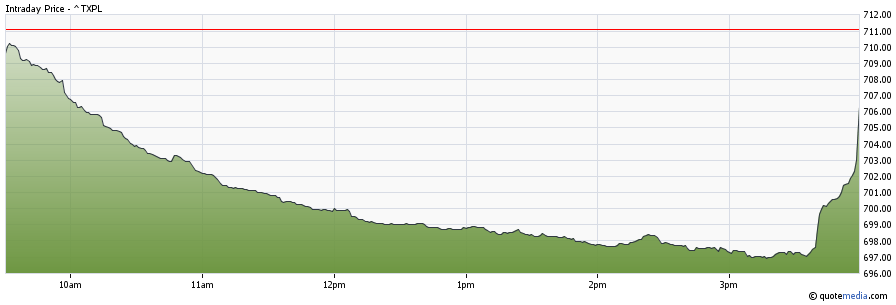
It looked for a long time as if there would be a significant pullback in the preferred share indices today, but the Forces of Goodness and Truth mounted a counterattack a little after 3:30pm that recouped a good chunk of the day’s losses:
TXPL_151022
Click for Big

TXPL closed at 706.54. You can see a tiny little sliver of green at the extreme right-hand side of the chart, showing how the index rose 3+ points in the dying seconds of the day … at 3:58pm, the index level was 702.97.

But one must remember two very important things when looking at TXPL! First, it’s a price index and therefore of highly limited informational value. All the Royal Bank issues went ex-dividend today and this caused about 5bp divergence on the day between the Total Return index and the Price Index. Additionally, TXPL is calculated on a close/close basis; while the late rally will have causes some distortion (in that the closes will be, in general, further above the bid than otherwise), there will have been even more distortion in the prior number due to yesterday‘s wild ride. In addition, TXPL is riddled with junk, which I don’t pay much attention to. What I’m trying to say is …

It was a good, albeit mixed day for the Canadian preferred share market, with PerpetualDiscounts gaining 17bp, FixedResets up 41bp and DeemedRetractibles off 27bp. The bad part of the Performance Highlights table is dominated by insurance issues; the good part is more heterogeneous. Volume was high.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

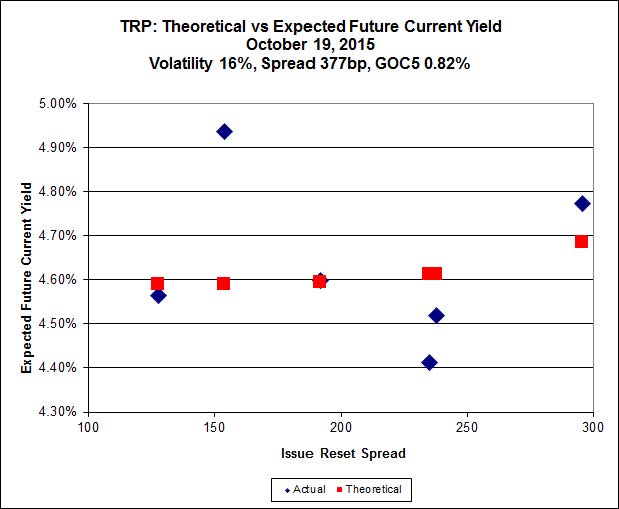
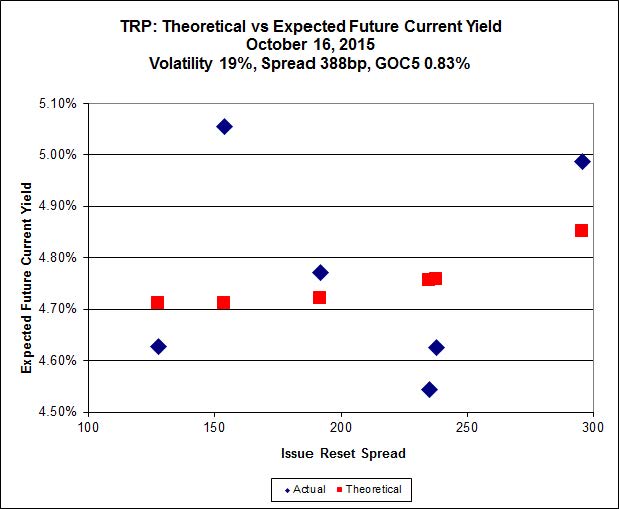
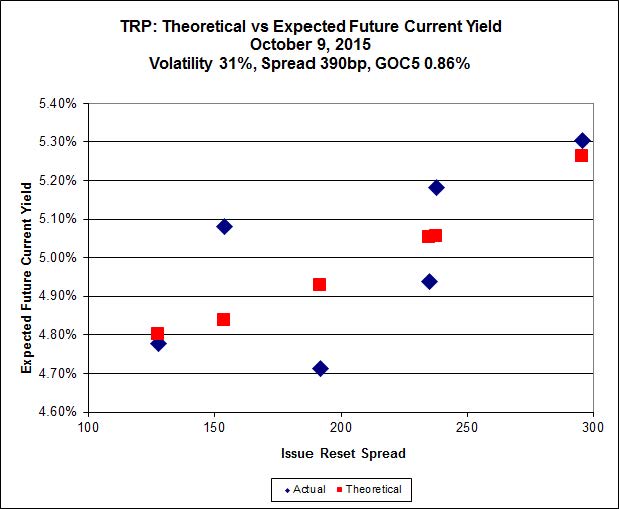
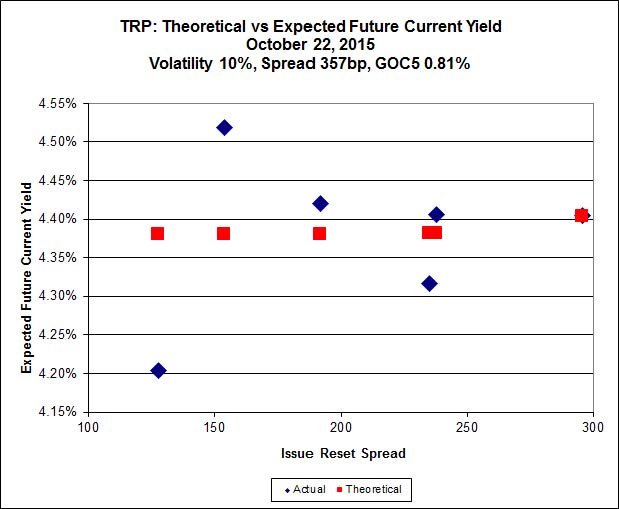
Here’s TRP:
impVol_TRP_151022
Click for Big

Implied Volatility declined to more reasonable levels today.

TRP.PR.B, which resets 2020-6-30 at +128, is bid at 12.43 to be $0.50 rich, while TRP.PR.C, resetting 2016-1-30 at +154, is $0.41 cheap at its bid price of 13.00.
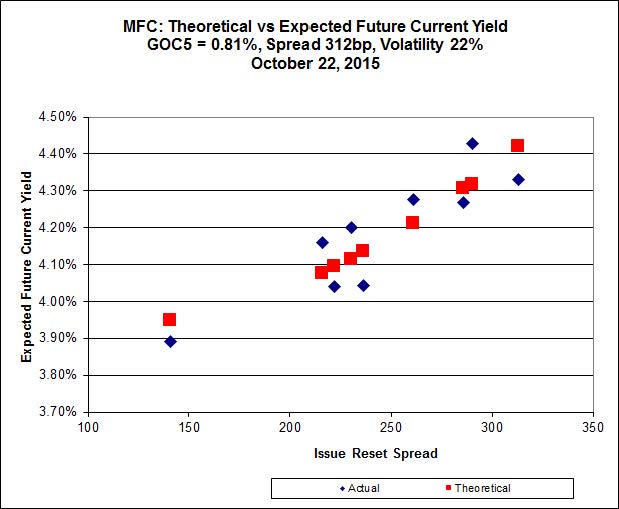
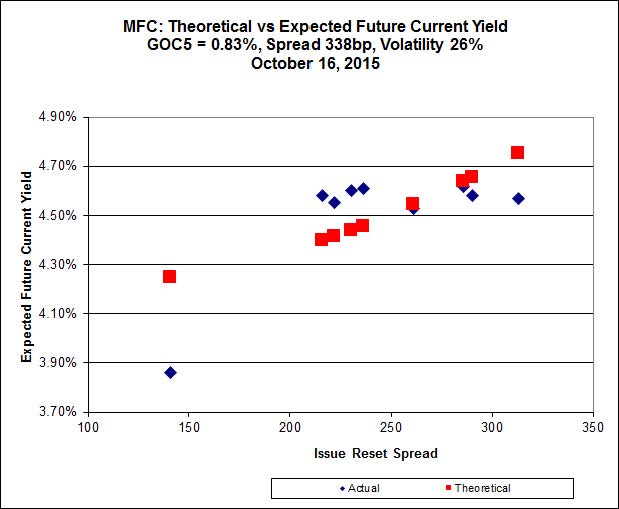
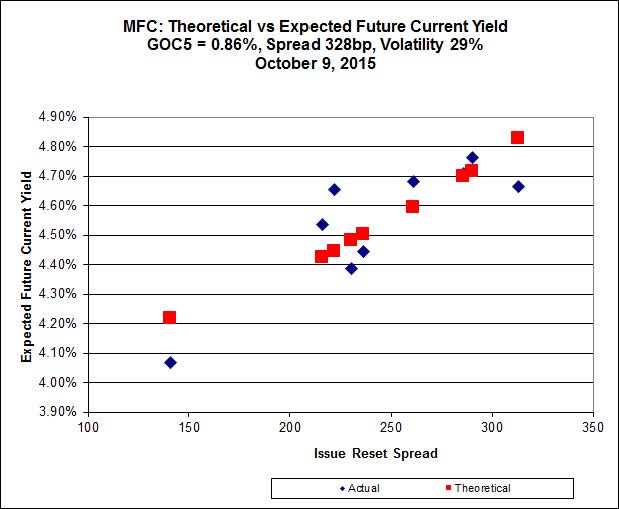
impVol_MFC_151022
Click for Big

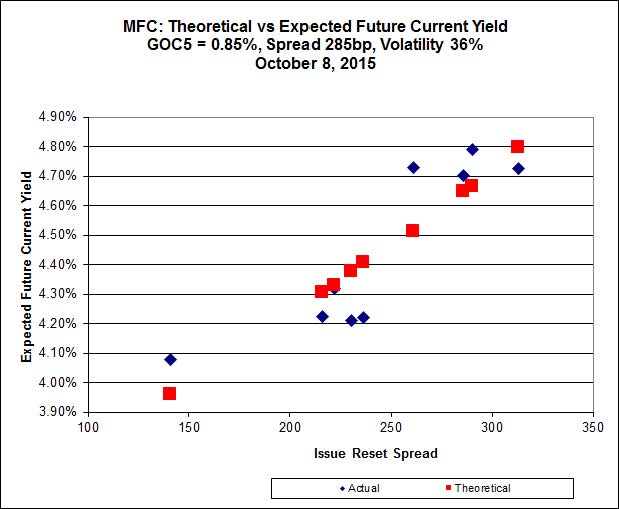
Implied Volatility declined slightly for the MFC series today.

Most expensive is MFC.PR.H, resetting at +313bp on 2017-3-19, bid at 22.75 to be 0.46 rich, while MFC.PR.G resetting at +290bp on 2016-12-19, is bid at 20.95 to be 0.54 cheap.
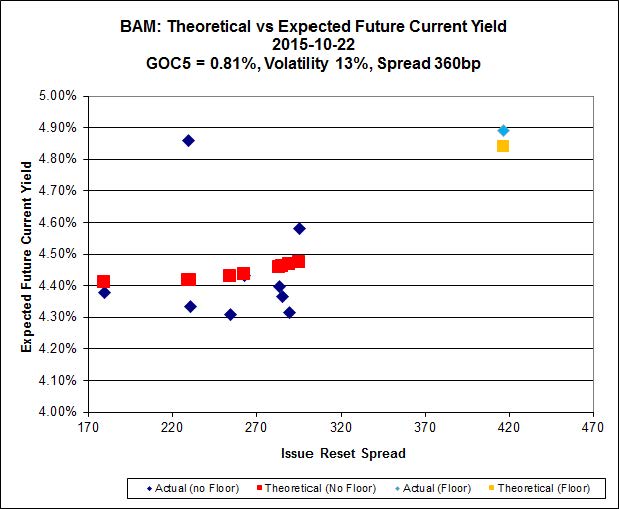
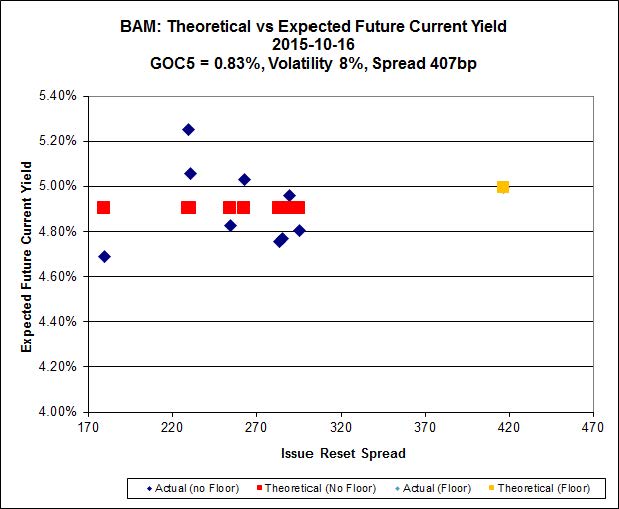
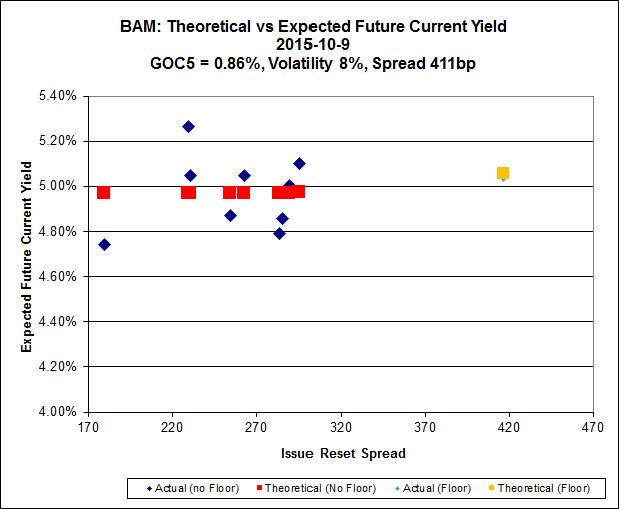
impVol_BAM_151022
Click for Big

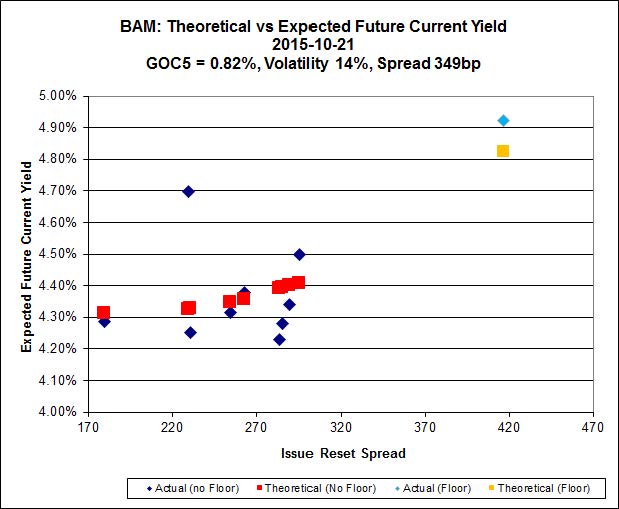
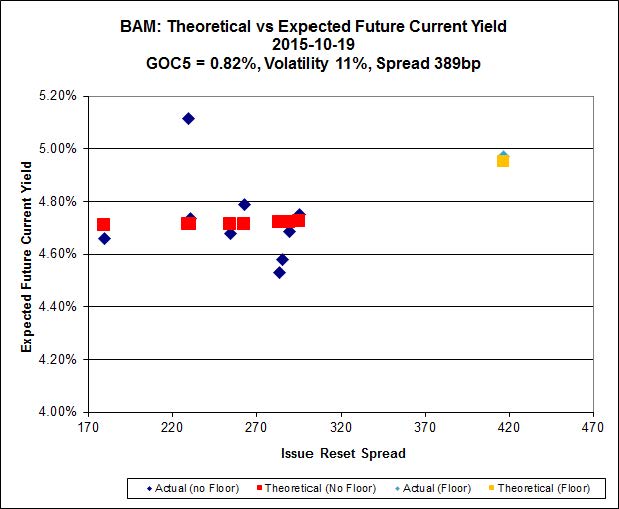
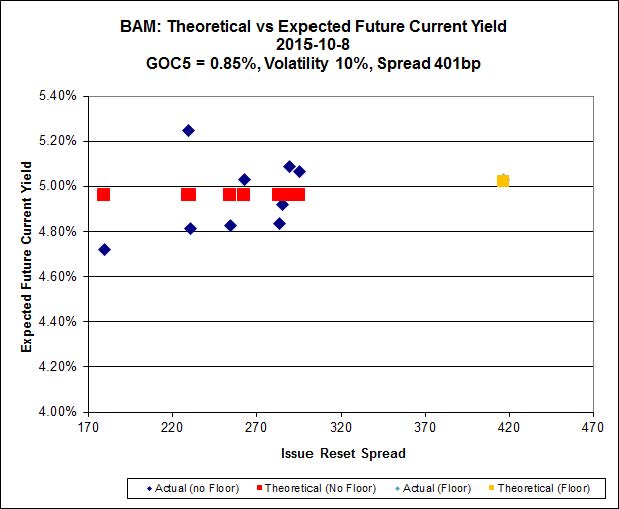
The fit on the BAM issues continues to be poor. Implied Volatility increased a little today, but this is a figure that’s very highly dependent on the performance of the high-spread issue BAM.PF.H.

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 16.00 to be $1.61 cheap. BAM.PF.A, resetting at +290bp on 2018-9-30 is bid at 21.50 and appears to be $0.74 rich.

impVol_FTS_151022
Click for Big

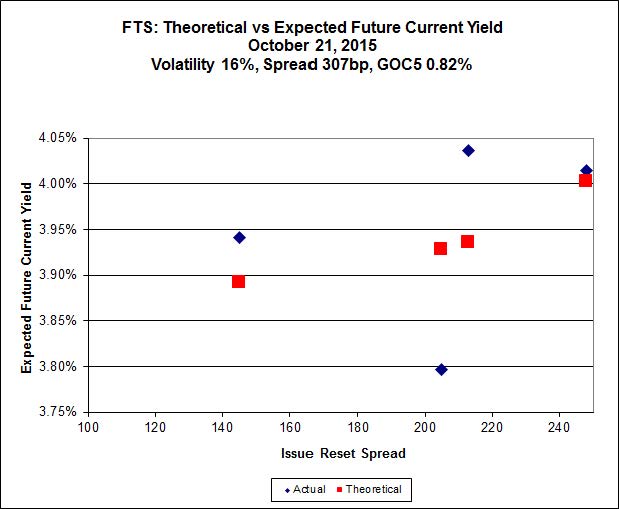
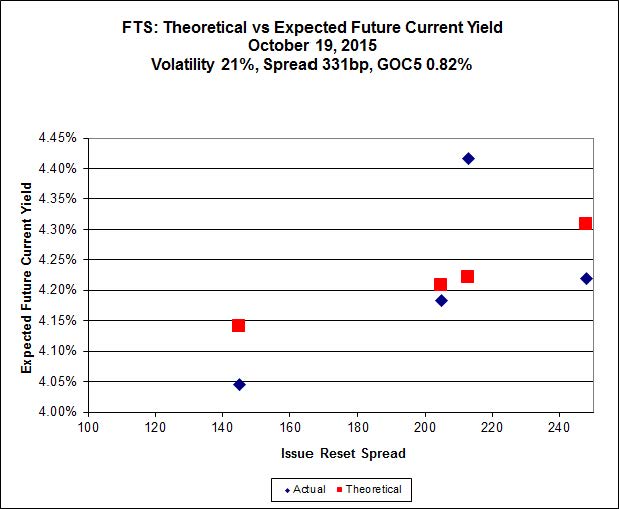
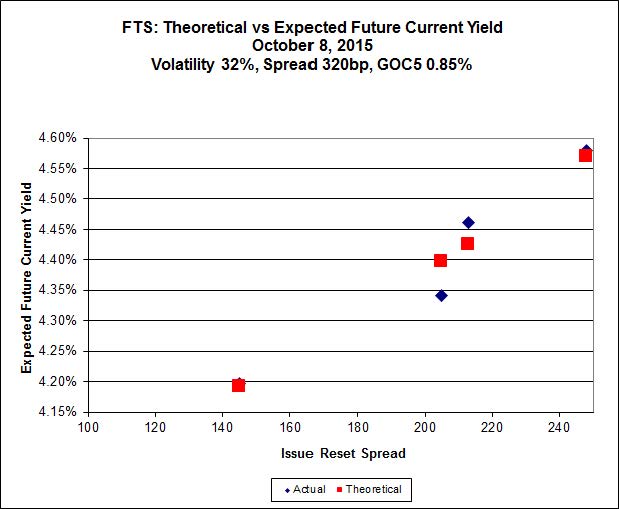
Implied Volatility remains high.

FTS.PR.K, with a spread of +205bp, and bid at 18.95, looks $1.33 expensive and resets 2019-3-1. FTS.PR.H, with a spread of +145bp and resetting 2020-6-1, is bid at 13.50 and is $0.55 cheap.
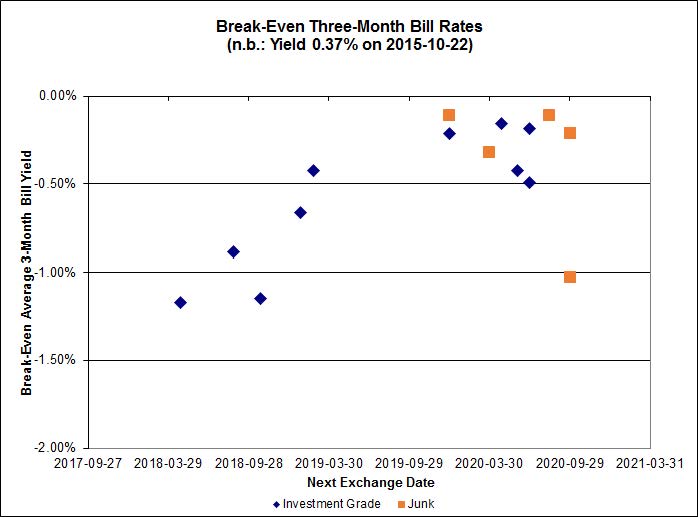
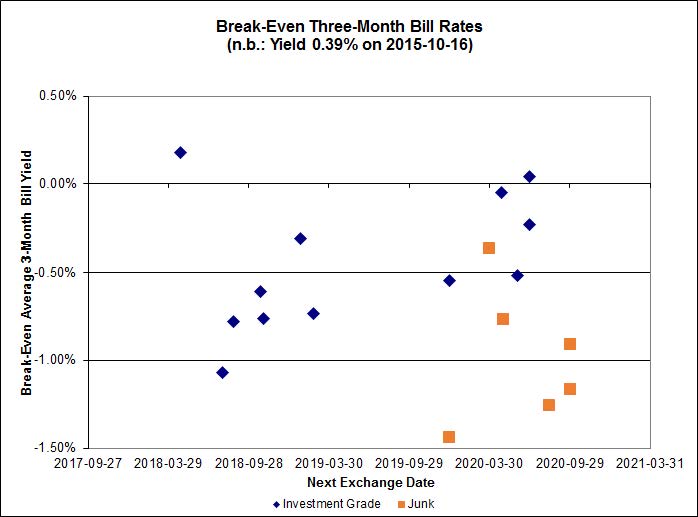
pairs_FR_151022
Click for Big

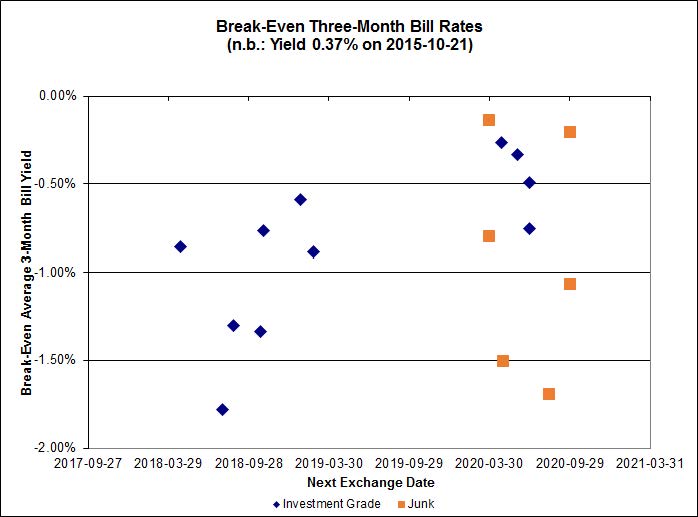
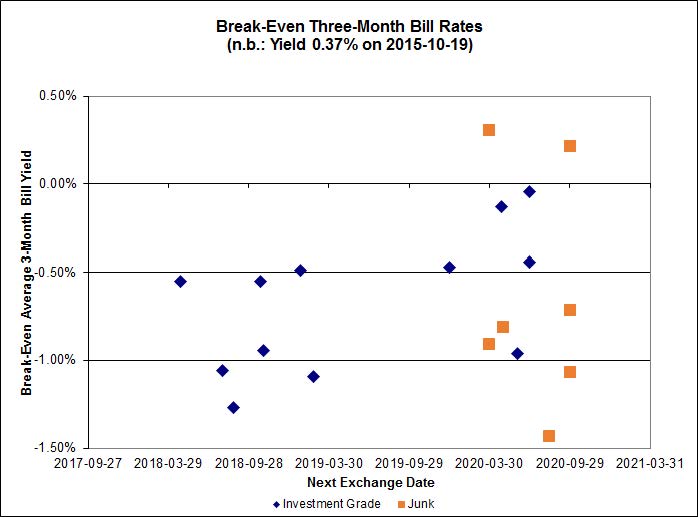
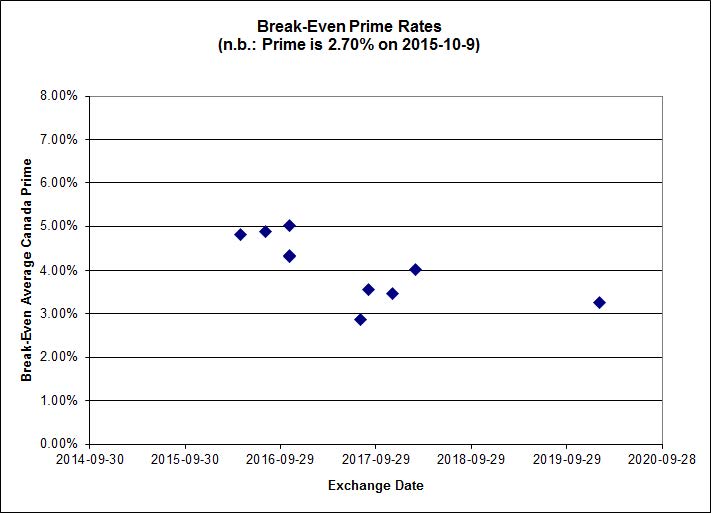
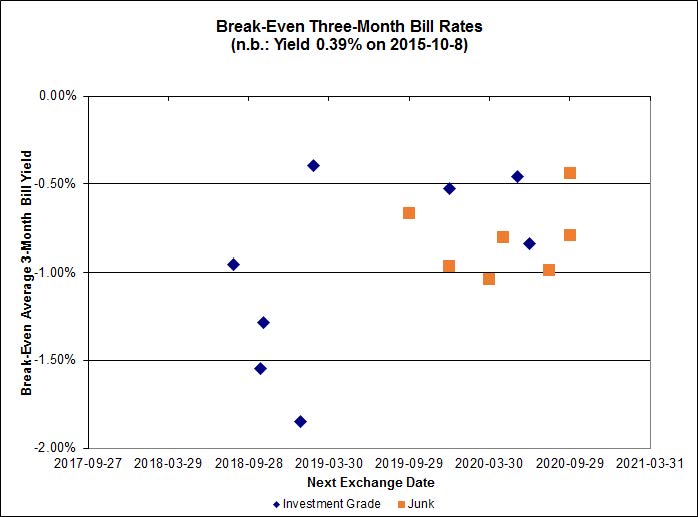
Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.88%, with two outliers below -2.00%. The distribution is bimodal, with bank NVCC non-compliant pairs averaging -1.29% and other issues averaging -0.29%. There are two junk outliers above 0.00% and three below -2.00%.
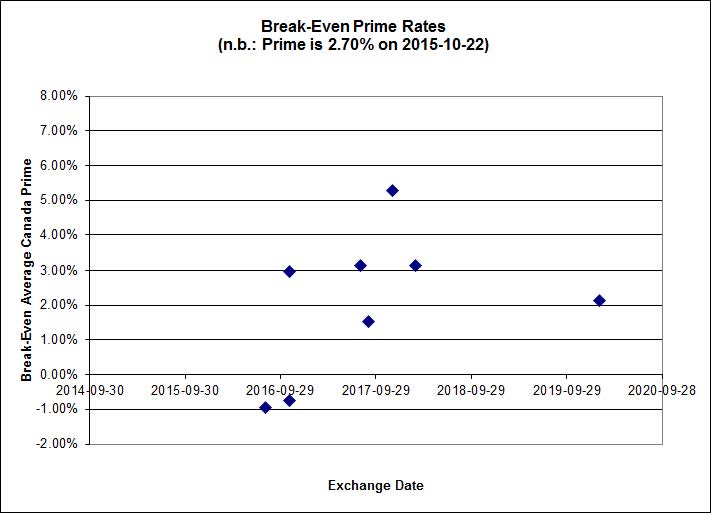
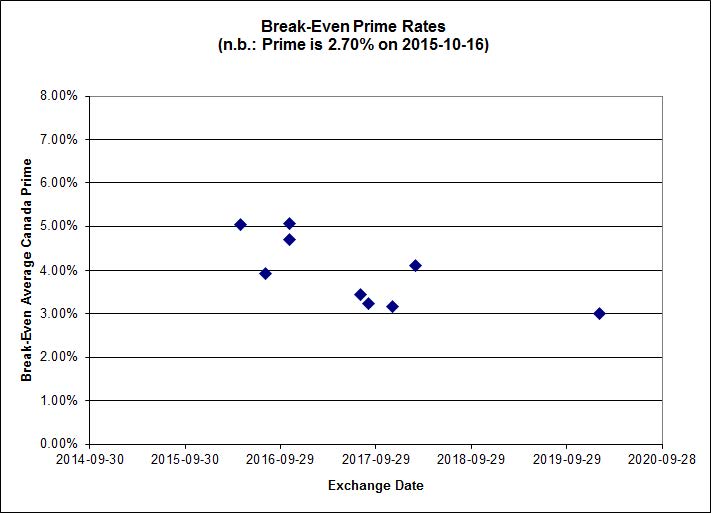
pairs_FF_151022
Click for Big

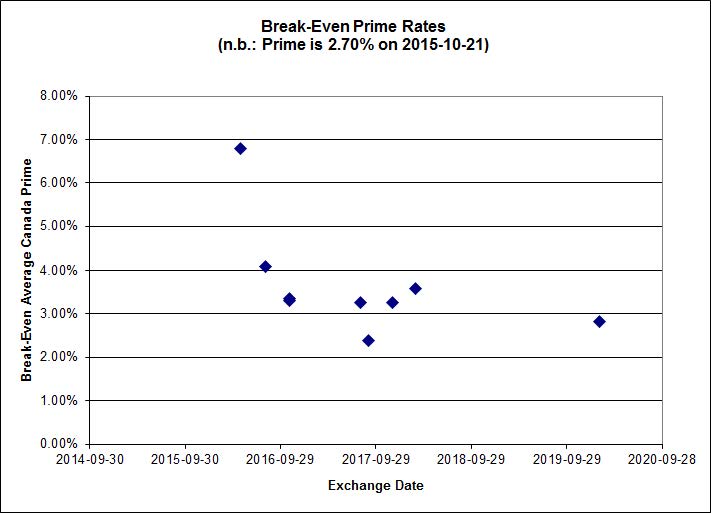
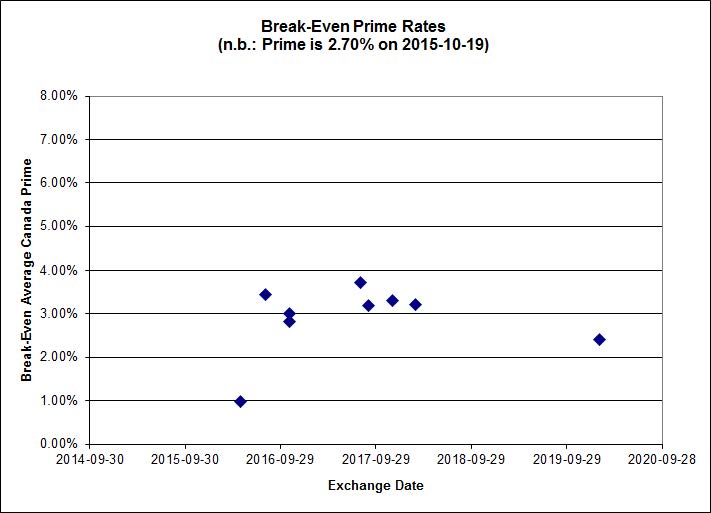
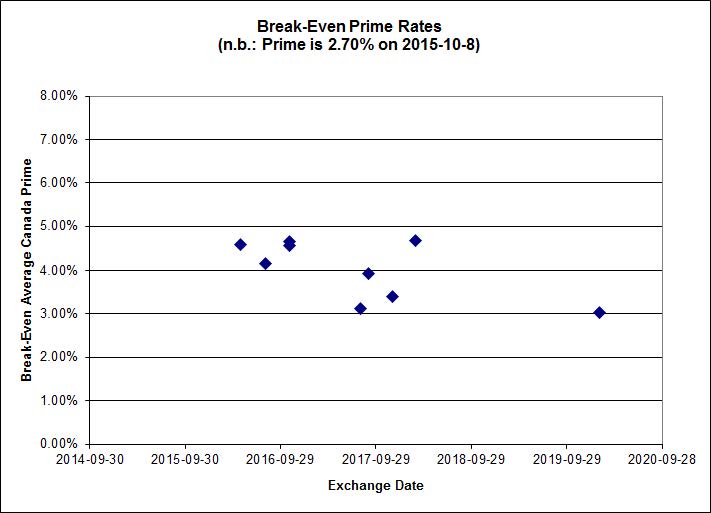
Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 1.2813 % 1,739.8
FixedFloater 0.00 % 0.00 % 0 0.00 0 1.2813 % 3,042.0
Floater 4.27 % 4.35 % 61,882 16.71 3 1.2813 % 1,849.5
OpRet 0.00 % 0.00 % 0 0.00 0 -0.2028 % 2,752.2
SplitShare 4.36 % 5.38 % 77,471 2.96 5 -0.2028 % 3,225.4
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.2028 % 2,516.6
Perpetual-Premium 5.88 % 5.83 % 67,837 14.02 5 -0.0080 % 2,476.2
Perpetual-Discount 5.67 % 5.73 % 80,908 14.23 33 0.1726 % 2,516.5
FixedReset 4.93 % 4.41 % 204,535 15.87 76 0.4051 % 2,071.0
Deemed-Retractible 5.24 % 5.05 % 106,388 5.47 33 -0.2656 % 2,547.3
FloatingReset 2.51 % 4.06 % 66,285 5.82 9 -0.1871 % 2,145.9
Performance Highlights
Issue Index Change Notes
MFC.PR.F FixedReset -3.96 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.31
Bid-YTW : 9.51 %
SLF.PR.D Deemed-Retractible -2.28 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.11
Bid-YTW : 7.49 %
MFC.PR.B Deemed-Retractible -2.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.93
Bid-YTW : 7.19 %
IFC.PR.C FixedReset -1.87 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.44
Bid-YTW : 6.92 %
SLF.PR.C Deemed-Retractible -1.84 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.22
Bid-YTW : 7.42 %
GWO.PR.R Deemed-Retractible -1.78 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.55
Bid-YTW : 6.92 %
SLF.PR.E Deemed-Retractible -1.73 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.40
Bid-YTW : 7.35 %
BNS.PR.C FloatingReset -1.63 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.37
Bid-YTW : 4.09 %
SLF.PR.J FloatingReset -1.60 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.53
Bid-YTW : 9.29 %
NA.PR.Q FixedReset -1.58 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.36
Bid-YTW : 3.88 %
SLF.PR.B Deemed-Retractible -1.55 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.66
Bid-YTW : 6.85 %
MFC.PR.N FixedReset -1.48 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.91
Bid-YTW : 6.52 %
BAM.PF.B FixedReset -1.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-22
Maturity Price : 19.41
Evaluated at bid price : 19.41
Bid-YTW : 4.69 %
SLF.PR.A Deemed-Retractible -1.37 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.61
Bid-YTW : 6.83 %
GWO.PR.N FixedReset -1.34 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.04
Bid-YTW : 9.44 %
FTS.PR.M FixedReset -1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-22
Maturity Price : 20.29
Evaluated at bid price : 20.29
Bid-YTW : 4.35 %
MFC.PR.C Deemed-Retractible -1.21 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.40
Bid-YTW : 7.38 %
SLF.PR.H FixedReset -1.19 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.39
Bid-YTW : 7.84 %
BNS.PR.R FixedReset -1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.31
Bid-YTW : 3.82 %
GWO.PR.H Deemed-Retractible -1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.92
Bid-YTW : 6.74 %
MFC.PR.M FixedReset -1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.11
Bid-YTW : 6.46 %
PWF.PR.S Perpetual-Discount -1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-22
Maturity Price : 21.38
Evaluated at bid price : 21.38
Bid-YTW : 5.64 %
RY.PR.H FixedReset 1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-22
Maturity Price : 19.09
Evaluated at bid price : 19.09
Bid-YTW : 4.25 %
RY.PR.N Perpetual-Discount 1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-22
Maturity Price : 22.37
Evaluated at bid price : 22.66
Bid-YTW : 5.39 %
BMO.PR.T FixedReset 1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-22
Maturity Price : 19.20
Evaluated at bid price : 19.20
Bid-YTW : 4.28 %
FTS.PR.K FixedReset 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-22
Maturity Price : 19.10
Evaluated at bid price : 19.10
Bid-YTW : 4.08 %
BNS.PR.O Deemed-Retractible 1.06 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2015-11-21
Maturity Price : 25.50
Evaluated at bid price : 25.77
Bid-YTW : -8.79 %
MFC.PR.I FixedReset 1.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.60
Bid-YTW : 5.86 %
BAM.PR.Z FixedReset 1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-22
Maturity Price : 21.25
Evaluated at bid price : 21.25
Bid-YTW : 4.66 %
VNR.PR.A FixedReset 1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-22
Maturity Price : 21.17
Evaluated at bid price : 21.17
Bid-YTW : 4.41 %
BMO.PR.W FixedReset 1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-22
Maturity Price : 18.85
Evaluated at bid price : 18.85
Bid-YTW : 4.33 %
CM.PR.O FixedReset 1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-22
Maturity Price : 19.47
Evaluated at bid price : 19.47
Bid-YTW : 4.26 %
TRP.PR.F FloatingReset 1.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-22
Maturity Price : 14.45
Evaluated at bid price : 14.45
Bid-YTW : 3.99 %
SLF.PR.I FixedReset 1.57 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.66
Bid-YTW : 6.23 %
GWO.PR.S Deemed-Retractible 1.67 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.80
Bid-YTW : 6.02 %
FTS.PR.F Perpetual-Discount 1.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-22
Maturity Price : 21.84
Evaluated at bid price : 22.08
Bid-YTW : 5.63 %
MFC.PR.K FixedReset 1.76 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.07
Bid-YTW : 6.91 %
RY.PR.O Perpetual-Discount 1.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-22
Maturity Price : 22.18
Evaluated at bid price : 22.53
Bid-YTW : 5.42 %
RY.PR.M FixedReset 1.97 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-22
Maturity Price : 20.23
Evaluated at bid price : 20.23
Bid-YTW : 4.31 %
BAM.PR.K Floater 2.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-22
Maturity Price : 10.94
Evaluated at bid price : 10.94
Bid-YTW : 4.35 %
TRP.PR.A FixedReset 2.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-22
Maturity Price : 15.50
Evaluated at bid price : 15.50
Bid-YTW : 4.68 %
MFC.PR.H FixedReset 2.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.43
Bid-YTW : 5.00 %
RY.PR.J FixedReset 2.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-22
Maturity Price : 20.93
Evaluated at bid price : 20.93
Bid-YTW : 4.27 %
TD.PR.Y FixedReset 3.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.54
Bid-YTW : 3.36 %
TRP.PR.G FixedReset 3.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-22
Maturity Price : 21.40
Evaluated at bid price : 21.68
Bid-YTW : 4.41 %
TD.PF.D FixedReset 3.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-22
Maturity Price : 21.15
Evaluated at bid price : 21.15
Bid-YTW : 4.29 %
MFC.PR.L FixedReset 4.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.95
Bid-YTW : 7.09 %
IFC.PR.A FixedReset 7.05 % Sort of a little bit real. The issue traded 12,581 shares today in a range of 15.60-34 before closing at 16.40-60, 14×5. The VWAP was 15.77. There were nine small trades timestamped from 3:53 to 3:58, inclusive, all executed between 15.69 and 15.74; then a trade at 16.02 for 100 shares timestamped 3:58, then 600 at 16.30 stamped 3:59. I also see 130 shares trading over 16.00 just before 3pm. So basically, this performance was running on fumes, probably from what the market-maker was smoking instead of maintaining an orderly market.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.40
Bid-YTW : 8.60 %
Volume Highlights
Issue Index Shares
Traded
Notes
CM.PR.Q FixedReset 62,228 TD sold blocks of 10,000 and 14,400 to Scotia, both at 21.50; TD crossed 12,500 at 21.49.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-22
Maturity Price : 21.40
Evaluated at bid price : 21.40
Bid-YTW : 4.24 %
CU.PR.I FixedReset 50,407 Nesbitt crossed 40,000 at 25.25.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-01
Maturity Price : 25.00
Evaluated at bid price : 25.25
Bid-YTW : 4.38 %
NA.PR.S FixedReset 49,447 TD crossed 11,500 at 20.03; Nesbitt crossed 15,500 at 19.86.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-22
Maturity Price : 19.88
Evaluated at bid price : 19.88
Bid-YTW : 4.27 %
RY.PR.L FixedReset 48,835 Desjardins crossed 39,700 at 25.10.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.97
Bid-YTW : 3.89 %
CM.PR.P FixedReset 41,280 TD crossed 17,100 at 18.99.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-22
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 4.26 %
BAM.PF.H FixedReset 36,561 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.50
Bid-YTW : 4.65 %
There were 44 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
MFC.PR.N FixedReset Quote: 19.91 – 20.67
Spot Rate : 0.7600
Average : 0.4888

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.91
Bid-YTW : 6.52 %

SLF.PR.H FixedReset Quote: 17.39 – 18.24
Spot Rate : 0.8500
Average : 0.6227

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.39
Bid-YTW : 7.84 %

BAM.PF.D Perpetual-Discount Quote: 20.77 – 21.47
Spot Rate : 0.7000
Average : 0.4786

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-22
Maturity Price : 20.77
Evaluated at bid price : 20.77
Bid-YTW : 5.97 %

BAM.PR.X FixedReset Quote: 15.27 – 15.75
Spot Rate : 0.4800
Average : 0.2807

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-22
Maturity Price : 15.27
Evaluated at bid price : 15.27
Bid-YTW : 4.64 %

FTS.PR.G FixedReset Quote: 18.35 – 18.92
Spot Rate : 0.5700
Average : 0.3890

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-22
Maturity Price : 18.35
Evaluated at bid price : 18.35
Bid-YTW : 4.29 %

BNS.PR.C FloatingReset Quote: 22.37 – 22.99
Spot Rate : 0.6200
Average : 0.4390

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.37
Bid-YTW : 4.09 %

Market Action

October 21, 2015

Top news of the day was the BoC Rate Announcement:

The Bank of Canada today announced that it is maintaining its target for the overnight rate at 1/2 per cent. The Bank Rate is correspondingly 3/4 per cent and the deposit rate is 1/4 per cent.

Inflation has evolved in line with the outlook in the Bank’s July Monetary Policy Report (MPR). Total CPI inflation remains near the bottom of the Bank’s target range, owing to declines in consumer energy prices. Core inflation is close to 2 per cent as the transitory effects of the past depreciation of the Canadian dollar are roughly offsetting disinflationary pressures from economic slack, which has increased this year. The Bank judges that the underlying trend in inflation continues to be about 1.5 to 1.7 per cent.
…
The Bank projects real GDP will grow by just over 1 per cent in 2015 before firming to about 2 per cent in 2016 and 2 1/2 per cent in 2017. The complex economic adjustments to the decline in Canada’s terms of trade will continue to play out over the projection horizon. The weaker profile for business investment suggests that, in the near term, growth in potential output is more likely to be in the lower part of the Bank’s range of estimates. Given this judgment about potential output, the Canadian economy can be expected to return to full capacity, and inflation sustainably to target, around mid-2017.

So now it’s a return to full capacity ‘around mid-2017’. In the July announcement it was ‘the first half of 2017.’ We are approaching normalcy asymptotically.

I mentioned the ‘welfare wall’ on October 14; this is the ridiculously high effective marginal tax rate on low income earners due to clawback of benefits when they’re imprudent enough to get a slightly better job or work slightly more hours. This came to mind when I read about a pending wave of closures of slum housing:

There are currently about 1.34 million units of affordable housing created by a HUD program known as Section 8 project-based rental assistance, according to a blog post published on Wednesday by Poethig and her Urban Institute colleague Reed Jordan. More than 30 percent of those units are kept affordable by contracts that are set to expire by the end of 2017.
…
Under Housing and Urban Development’s system, tenants who meet income requirements pay 30 percent of their income in rent, and HUD pays the landlord a subsidy on top of that rent. The average subsidy was $665 a month (PDF) in 2011, according to the National Low Income Housing Coalition. New York, where 33 percent of units are set to expire by 2017, has more than 123,000 units in the program; Dallas, where 47 percent of units are at risk, has about 8,800.
…
The system for preserving affordable units varies from place to place. State law gives cities in Massachusetts the right of first refusal when property owners want to let a HUD contract expire, and a number of nonprofit groups and a state-affiliated agency are devoted to preserving it. In 2013, a nonprofit called Preservation of Affordable Housing paid $234 million for about 850 apartments in Boston, Cape Cod, and elsewhere in the state to prevent the units form being converted to market rate. Washington, Chicago, and other cities require landlords to notify tenants in advance of conversions and, in some cases, give them the opportunity to buy the apartment.

So basically, given that ‘tenants … pay 30% of their income in rent’ means that the housing benefit alone is worth a 30% marginal tax rate! Overtime? A new job at $1/hour more? Are you crazy?

It’s a little difficult to put numbers on the Boston project! According to a story in the Boston Globe, basically all of the 234-million is government money, either directly or through shifting the subsidy to tax credits:

Low-income residents joined government officials and investors Thursday to celebrate the renovation of six apartment buildings, a project that totaled nearly $234 million and is being touted as the state’s largest affordable housing improvement effort.
…
They were all renovated with the help of a $168 million loan from MassHousing, the state’s affordable housing bank, almost $66 million in private investments that came from $8.9 million in tax credits provided by the Massachusetts Department of Housing and Community Development tax credits

I think the touted Preservation of Affordable Housing is just another government boondoggle, but it’s hard to say. They don’t publish their financials and their news page doesn’t provide any hints of their financing. Their news release regarding the Boston project shows the usual grab-bag of government hand-outs:

The financing package includes:
 MassHousing: $35.8 million construction and permanent loan and a $9.3 million bridge loan
 Mass Housing Investment Corp: $12.3 million federal low-income housing tax credit investment
 Two loans from the City of Cambridge /Cambridge Affordable Housing Trust: $1,852,286 and $2.4 million for a total City/Trust contribution of $4,252,286
 CEDAC: bridge loan of $3,700,000

I have sent them the following eMail:

Sirs,

I am curious regarding the incentive your beneficiaries have to improve their financial situation.

Has your organization done – or are you aware of – any research into the Effective Marginal Tax Rate (EMTR) faced by occupants of your subsidized units? By EMTR, I mean the impact of both direct taxation and reduction of benefits on additional income that could be earned by these clients.

Sincerely,

In an announcement sure to cause a fit of giggles, DBRS Confirms Advantaged Preferred Share Trust Units Stability Rating of STA-2 (middle). Stop snickering, Stability Ratings are supposed to reflect “the fund’s ability to generate sufficient cash to pay out a stable level of distributions on a per-unit basis over the longer term.” Good for snickers in the DBRS rating confirmation is the phrase:

The credit quality of the Portfolio remains strong: approximately 78% of the portfolio shares are rated at Pfd-3 (high) or higher.

Rather an unusual cut-off, wouldn’t you say? But … “Pfd-3(high)” allows them to include Enbridge. But heads will nod in agreement with:

As of Oct 14, 2015 the Trust has seen a 24% decline in Portfolio value compared to June 30, 2015 values. Such a decline is mainly explained by the negative investor sentiment regarding the overall preferred share market that translates into vast selling of preferred shares causing the supply exceeding the demand. The fund rating methodology does not directly address the potential price volatility of the Portfolio.

Until, of course, those wisely nodding heads realize that it doesn’t actually say anything. Some might wonder if this comment is the whole point of the confirmation, desperately asked for by the fund sponsors! “Please, give us something we can say to all our angry clients!”

Canadian preferred share investors have a new ride!

saturnRocketLaunch
Click for Big

It was another incredibly strong day for the Canadian preferred share market, with PerpetualDiscounts up 53bp, FixedResets winning an amazing 306bp and DeemedRetractibles gaining a mere 48bp. No less than fourteen issues, all FixedResets, gained over 5% on the day (bid/bid); this is a rather fun statistic, too bad I don’t get to use it more often! Volume was very extremely high.

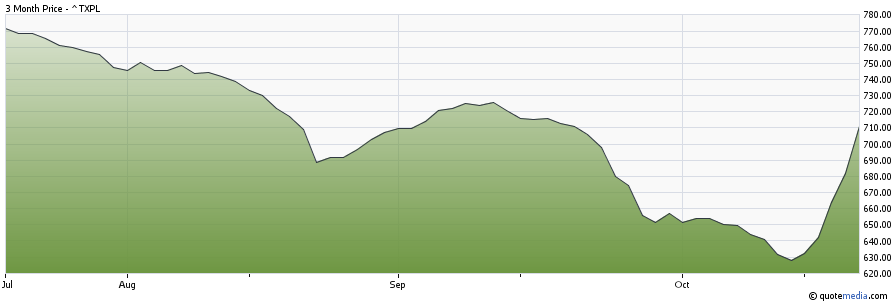
Still, let’s keep things in perspective and remember that the TXPL (price index) is still only back to where it was in mid-August. 15Q3 was a really, really, lousy quarter. On a total return basis, performance for TXPL is below zero with a start-date of August 19. So while I’m pleased to see these impressive gains, we’ll need another few weeks of them before we can call it a good year!

TXPL_151021_3Mo
Click for Big

PerpetualDiscounts now yield 5.76%, equivalent to 7.49% interest at the standard equivalency factor of 1.3x. Long corporates now yield about 4.3%, so the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) is now about 320bp, a sharp reduction from the ludicrous 340bp reported October 14.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

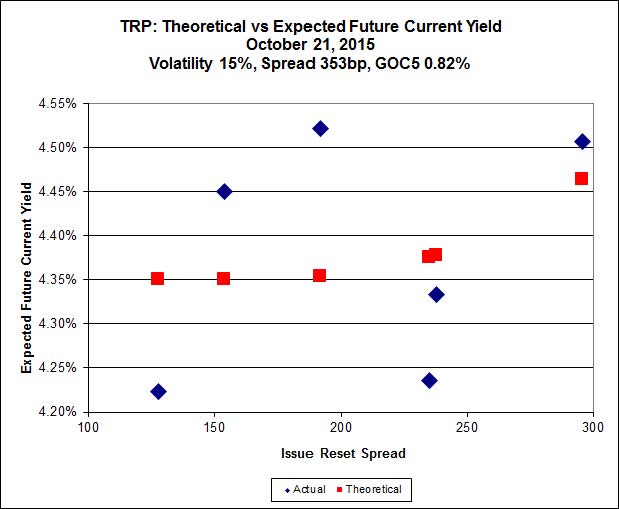
Here’s TRP:

impVol_TRP_151021
Click for Big

Implied Volatility remained constant today, above what I consider reasonable.

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 18.71 to be $0.60 rich, while TRP.PR.A, resetting 2019-12-31 at +192, is $0.58 cheap at its bid price of 15.15.

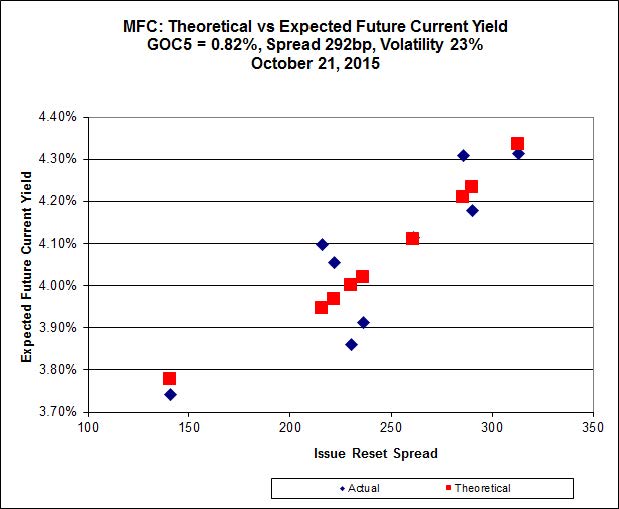
impVol_MFC_151021
Click for Big

Implied Volatility declined slightly for the MFC series today.

Most expensive is MFC.PR.N, resetting at +230bp on 2020-3-19, bid at 14.90 to be 0.71 rich, while MFC.PR.L resetting at +216bp on 2019-6-19, is bid at 18.18 to be 0.70 cheap.

impVol_BAM_151021
Click for Big

The fit on the BAM issues continues to be poor. Implied Volatility increased a little today, but this is a figure that’s very highly dependent on the performance of the high-spread issue BAM.PF.H.

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 16.60 to be $0.90 cheap. BAM.PF.G, resetting at +284bp on 2020-6-30 is bid at 21.63 and appears to be $0.69 rich.

impVol_FTS_151021
Click for Big

Implied Volatility declined again today but remains high.

FTS.PR.K, with a spread of +205bp, and bid at 18.90, looks $0.63 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 18.27 and is $0.47 cheap.

pairs_FR_151021
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.87%, with one outlier above 0.00%. The distribution is bimodal, with bank NVCC non-compliant pairs averaging -1.07% and other issues averaging -0.31%. There are two junk outliers above 0.00% and two below -2.00%.

pairs_FF_151021
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 2.3096 % 1,717.8
FixedFloater 0.00 % 0.00 % 0 0.00 0 2.3096 % 3,003.5
Floater 4.32 % 4.38 % 62,145 16.66 3 2.3096 % 1,826.1
OpRet 0.00 % 0.00 % 0 0.00 0 0.0162 % 2,757.8
SplitShare 4.35 % 5.17 % 78,063 2.97 5 0.0162 % 3,232.0
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0162 % 2,521.7
Perpetual-Premium 5.88 % 5.83 % 68,250 14.02 5 0.3135 % 2,476.4
Perpetual-Discount 5.67 % 5.76 % 80,237 14.25 33 0.5261 % 2,512.2
FixedReset 4.94 % 4.46 % 205,668 15.90 76 3.0619 % 2,062.6
Deemed-Retractible 5.22 % 5.17 % 105,739 5.44 33 0.4826 % 2,554.1
FloatingReset 2.51 % 4.02 % 68,838 5.82 9 1.7865 % 2,149.9
Performance Highlights
Issue Index Change Notes
W.PR.J Perpetual-Discount -1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 22.78
Evaluated at bid price : 23.06
Bid-YTW : 6.11 %
FTS.PR.F Perpetual-Discount -1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 21.44
Evaluated at bid price : 21.70
Bid-YTW : 5.72 %
MFC.PR.F FixedReset 1.02 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.90
Bid-YTW : 8.97 %
TD.PF.F Perpetual-Discount 1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 22.39
Evaluated at bid price : 22.69
Bid-YTW : 5.41 %
RY.PR.P Perpetual-Discount 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 23.85
Evaluated at bid price : 24.19
Bid-YTW : 5.46 %
FTS.PR.H FixedReset 1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 14.40
Evaluated at bid price : 14.40
Bid-YTW : 4.10 %
GWO.PR.H Deemed-Retractible 1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.15
Bid-YTW : 6.59 %
PWF.PR.S Perpetual-Discount 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 21.31
Evaluated at bid price : 21.60
Bid-YTW : 5.57 %
RY.PR.N Perpetual-Discount 1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 22.66
Evaluated at bid price : 23.00
Bid-YTW : 5.48 %
W.PR.H Perpetual-Discount 1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 22.80
Evaluated at bid price : 23.08
Bid-YTW : 5.99 %
GWO.PR.L Deemed-Retractible 1.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.75
Bid-YTW : 5.88 %
BNS.PR.B FloatingReset 1.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.22
Bid-YTW : 4.02 %
MFC.PR.B Deemed-Retractible 1.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.37
Bid-YTW : 6.89 %
BNS.PR.Q FixedReset 1.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.42
Bid-YTW : 3.48 %
SLF.PR.E Deemed-Retractible 1.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.76
Bid-YTW : 7.10 %
PWF.PR.E Perpetual-Discount 1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 23.68
Evaluated at bid price : 23.95
Bid-YTW : 5.76 %
GWO.PR.Q Deemed-Retractible 1.28 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.00
Bid-YTW : 6.39 %
RY.PR.L FixedReset 1.34 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.03
Bid-YTW : 4.04 %
CU.PR.H Perpetual-Discount 1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 22.79
Evaluated at bid price : 23.16
Bid-YTW : 5.77 %
BNS.PR.P FixedReset 1.38 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.30
Bid-YTW : 3.58 %
TD.PR.T FloatingReset 1.41 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.25
Bid-YTW : 3.89 %
RY.PR.W Perpetual-Discount 1.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 22.46
Evaluated at bid price : 22.72
Bid-YTW : 5.47 %
MFC.PR.C Deemed-Retractible 1.52 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.65
Bid-YTW : 7.20 %
BMO.PR.M FixedReset 1.53 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.57
Bid-YTW : 3.31 %
IFC.PR.C FixedReset 1.59 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.81
Bid-YTW : 6.66 %
SLF.PR.A Deemed-Retractible 1.67 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.91
Bid-YTW : 6.63 %
HSE.PR.G FixedReset 1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 22.71
Evaluated at bid price : 23.80
Bid-YTW : 4.61 %
SLF.PR.B Deemed-Retractible 1.76 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.00
Bid-YTW : 6.63 %
BNS.PR.A FloatingReset 1.77 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.05
Bid-YTW : 3.74 %
BAM.PF.D Perpetual-Discount 1.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 20.97
Evaluated at bid price : 20.97
Bid-YTW : 5.91 %
TRP.PR.B FixedReset 1.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 12.43
Evaluated at bid price : 12.43
Bid-YTW : 4.30 %
HSE.PR.A FixedReset 2.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 14.09
Evaluated at bid price : 14.09
Bid-YTW : 4.69 %
CM.PR.Q FixedReset 2.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 21.50
Evaluated at bid price : 21.50
Bid-YTW : 4.22 %
BMO.PR.S FixedReset 2.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 19.57
Evaluated at bid price : 19.57
Bid-YTW : 4.31 %
TD.PR.Z FloatingReset 2.37 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.00
Bid-YTW : 4.17 %
BMO.PR.Z Perpetual-Discount 2.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 23.25
Evaluated at bid price : 23.55
Bid-YTW : 5.41 %
MFC.PR.K FixedReset 2.40 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.74
Bid-YTW : 7.14 %
BAM.PR.Z FixedReset 2.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 21.00
Evaluated at bid price : 21.00
Bid-YTW : 4.72 %
VNR.PR.A FixedReset 2.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 20.92
Evaluated at bid price : 20.92
Bid-YTW : 4.46 %
TRP.PR.D FixedReset 2.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 18.46
Evaluated at bid price : 18.46
Bid-YTW : 4.57 %
TRP.PR.G FixedReset 2.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 20.97
Evaluated at bid price : 20.97
Bid-YTW : 4.59 %
BAM.PR.B Floater 2.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 11.20
Evaluated at bid price : 11.20
Bid-YTW : 4.25 %
BMO.PR.R FloatingReset 2.59 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.60
Bid-YTW : 3.76 %
TD.PR.S FixedReset 2.64 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.50
Bid-YTW : 3.21 %
HSE.PR.E FixedReset 2.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 22.63
Evaluated at bid price : 23.61
Bid-YTW : 4.67 %
BNS.PR.D FloatingReset 2.72 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.90
Bid-YTW : 6.05 %
SLF.PR.I FixedReset 2.73 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.34
Bid-YTW : 6.44 %
PWF.PR.T FixedReset 2.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 21.52
Evaluated at bid price : 21.90
Bid-YTW : 3.82 %
RY.PR.M FixedReset 2.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 20.06
Evaluated at bid price : 20.06
Bid-YTW : 4.42 %
CM.PR.O FixedReset 2.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 19.20
Evaluated at bid price : 19.20
Bid-YTW : 4.32 %
TD.PF.A FixedReset 2.97 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 19.05
Evaluated at bid price : 19.05
Bid-YTW : 4.27 %
BMO.PR.W FixedReset 3.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 18.60
Evaluated at bid price : 18.60
Bid-YTW : 4.39 %
BNS.PR.Y FixedReset 3.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.01
Bid-YTW : 5.64 %
NA.PR.Q FixedReset 3.25 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.75
Bid-YTW : 3.59 %
FTS.PR.M FixedReset 3.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 20.55
Evaluated at bid price : 20.55
Bid-YTW : 4.29 %
PWF.PR.P FixedReset 3.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 15.00
Evaluated at bid price : 15.00
Bid-YTW : 4.08 %
RY.PR.I FixedReset 3.40 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.35
Bid-YTW : 3.76 %
RY.PR.J FixedReset 3.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 20.63
Evaluated at bid price : 20.63
Bid-YTW : 4.40 %
TD.PF.B FixedReset 3.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 19.08
Evaluated at bid price : 19.08
Bid-YTW : 4.26 %
BAM.PR.C Floater 3.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 10.88
Evaluated at bid price : 10.88
Bid-YTW : 4.38 %
MFC.PR.H FixedReset 3.53 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.89
Bid-YTW : 5.31 %
NA.PR.W FixedReset 3.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 4.30 %
TRP.PR.F FloatingReset 3.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 14.24
Evaluated at bid price : 14.24
Bid-YTW : 4.05 %
RY.PR.Z FixedReset 3.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 19.34
Evaluated at bid price : 19.34
Bid-YTW : 4.23 %
BAM.PR.R FixedReset 3.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 16.60
Evaluated at bid price : 16.60
Bid-YTW : 4.87 %
BMO.PR.T FixedReset 3.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 4.33 %
BAM.PF.E FixedReset 3.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 19.52
Evaluated at bid price : 19.52
Bid-YTW : 4.70 %
RY.PR.H FixedReset 3.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 19.14
Evaluated at bid price : 19.14
Bid-YTW : 4.32 %
CM.PR.P FixedReset 4.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 18.99
Evaluated at bid price : 18.99
Bid-YTW : 4.27 %
BMO.PR.Y FixedReset 4.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 21.54
Evaluated at bid price : 21.86
Bid-YTW : 4.22 %
MFC.PR.G FixedReset 4.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.26
Bid-YTW : 5.41 %
BAM.PF.G FixedReset 4.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 21.34
Evaluated at bid price : 21.63
Bid-YTW : 4.50 %
BNS.PR.Z FixedReset 4.68 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.15
Bid-YTW : 6.06 %
BMO.PR.Q FixedReset 4.74 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.00
Bid-YTW : 5.41 %
TD.PF.C FixedReset 4.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 18.90
Evaluated at bid price : 18.90
Bid-YTW : 4.28 %
IAG.PR.G FixedReset 4.96 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.80
Bid-YTW : 5.66 %
MFC.PR.J FixedReset 4.99 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.84
Bid-YTW : 6.05 %
TD.PF.E FixedReset 5.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 21.32
Evaluated at bid price : 21.60
Bid-YTW : 4.28 %
BAM.PF.B FixedReset 5.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 19.70
Evaluated at bid price : 19.70
Bid-YTW : 4.62 %
TRP.PR.C FixedReset 5.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 13.26
Evaluated at bid price : 13.26
Bid-YTW : 4.50 %
MFC.PR.M FixedReset 5.28 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.32
Bid-YTW : 6.32 %
BAM.PF.F FixedReset 5.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 21.50
Evaluated at bid price : 21.50
Bid-YTW : 4.53 %
BIP.PR.A FixedReset 5.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 21.54
Evaluated at bid price : 21.85
Bid-YTW : 5.09 %
BAM.PF.A FixedReset 5.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 21.42
Evaluated at bid price : 21.42
Bid-YTW : 4.54 %
BAM.PR.X FixedReset 6.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 15.28
Evaluated at bid price : 15.28
Bid-YTW : 4.64 %
FTS.PR.G FixedReset 6.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 18.27
Evaluated at bid price : 18.27
Bid-YTW : 4.30 %
NA.PR.S FixedReset 6.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 19.80
Evaluated at bid price : 19.80
Bid-YTW : 4.28 %
BAM.PR.T FixedReset 7.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 18.40
Evaluated at bid price : 18.40
Bid-YTW : 4.47 %
MFC.PR.N FixedReset 7.21 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.21
Bid-YTW : 6.32 %
CU.PR.C FixedReset 7.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 21.50
Evaluated at bid price : 21.50
Bid-YTW : 3.88 %
FTS.PR.K FixedReset 7.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 18.90
Evaluated at bid price : 18.90
Bid-YTW : 4.13 %
Volume Highlights
Issue Index Shares
Traded
Notes
TRP.PR.D FixedReset 236,463 Desjardins crossed blocks of 97,000 and 104,300, both at 18.40.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 18.46
Evaluated at bid price : 18.46
Bid-YTW : 4.57 %
MFC.PR.J FixedReset 88,995 Scotia crossed 28500 at 19.90 and 40,000 at 20.00.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.84
Bid-YTW : 6.05 %
MFC.PR.M FixedReset 81,090 Scotia crossed 10,100 at 19.52 and 32,900 at 21.00. That’s one helluva difference in block prices!
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.32
Bid-YTW : 6.32 %
MFC.PR.N FixedReset 66,655 Scotia crossed 12,400 at 19.15.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.21
Bid-YTW : 6.32 %
TD.PF.E FixedReset 65,700 Scotia sold 13,800 to TD at 21.20 and bought 10,000 from RBC at 21.45.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 21.32
Evaluated at bid price : 21.60
Bid-YTW : 4.28 %
PWF.PR.P FixedReset 54,021 Nesbitt crossed 30,000 at 15.27.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 15.00
Evaluated at bid price : 15.00
Bid-YTW : 4.08 %
There were 72 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
TRP.PR.G FixedReset Quote: 20.97 – 22.39
Spot Rate : 1.4200
Average : 0.7902

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 20.97
Evaluated at bid price : 20.97
Bid-YTW : 4.59 %

MFC.PR.L FixedReset Quote: 18.18 – 19.45
Spot Rate : 1.2700
Average : 0.8489

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.18
Bid-YTW : 7.65 %

CM.PR.O FixedReset Quote: 19.20 – 20.27
Spot Rate : 1.0700
Average : 0.6604

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 19.20
Evaluated at bid price : 19.20
Bid-YTW : 4.32 %

MFC.PR.H FixedReset Quote: 22.89 – 23.99
Spot Rate : 1.1000
Average : 0.6960

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.89
Bid-YTW : 5.31 %

CM.PR.P FixedReset Quote: 18.99 – 20.00
Spot Rate : 1.0100
Average : 0.6529

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-21
Maturity Price : 18.99
Evaluated at bid price : 18.99
Bid-YTW : 4.27 %

MFC.PR.I FixedReset Quote: 21.35 – 22.10
Spot Rate : 0.7500
Average : 0.4121

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.35
Bid-YTW : 6.01 %

Market Action

October 20, 2015

Nothing happened today, other than Canadian preferred share investors checking out the current value of their portfolios:

scrooge-mcduck-swimming-in-money
Click for Big

It was another superb day for the Canadian preferred share market (boy, when things snap back, they snap back in a hurry, don’t they?) with PerpetualDiscounts up 57bp, FixedResets winning a whopping 239bp and DeemedRetractibles gaining 38bp. It will be most interesting to see in the coming weeks whether these gains continue or vanish like fairy gold! The Performance Highlights table is, of course, enormous, with no less than eight issues (all FixedResets) up more than the 5% that usually indicates a ridiculous situation with bad quotes. Volume was, again, extremely high.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_151020
Click for Big

Implied Volatility eased off again today but remains above what I consider reasonable.

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 18.56 to be $0.85 rich, while TRP.PR.C, resetting 2016-1-30 at +154, is $0.73 cheap at its bid price of 12.60.

impVol_MFC_151020
Click for Big

The MFC series has now renormalized and the fit has returned to its usual excellence.

Most expensive is MFC.PR.F, resetting at +141bp on 2016-6-19, bid at 14.75 to be 0.27 rich, while MFC.PR.J resetting at +261bp on 2018-3-19, is bid at 19.85 to be 0.31 cheap.

impVol_BAM_151020
Click for Big

The fit on the BAM issues continues to be poor.

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 16.00 to be $0.90 cheap. BAM.PF.G, resetting at +284bp on 2020-6-30 is bid at 20.75 and appears to be $0.81 rich.

impVol_FTS_151020
Click for Big

Implied Volatility declined again today but remains high.

FTS.PR.M, with a spread of +248bp, and bid at 19.90, looks $0.31 expensive and resets 2019-12-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 17.16 and is $0.67 cheap.

pairs_FR_151020
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.87%, with no outliers (although I had to change the scale again!). The distribution is slightly bimodal, with bank NVCC non-compliant pairs averaging -1.08% and other issues averaging -0.56%. There is one junk outlier above 0.00% and one below -2.00%.

pairs_FF_151020
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 2.5608 % 1,679.0
FixedFloater 0.00 % 0.00 % 0 0.00 0 2.5608 % 2,935.7
Floater 4.42 % 4.49 % 63,191 16.45 3 2.5608 % 1,784.9
OpRet 0.00 % 0.00 % 0 0.00 0 -0.2185 % 2,757.3
SplitShare 4.35 % 5.37 % 77,837 2.97 5 -0.2185 % 3,231.4
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.2185 % 2,521.3
Perpetual-Premium 5.90 % 5.86 % 68,582 14.01 5 0.4197 % 2,468.7
Perpetual-Discount 5.70 % 5.79 % 80,134 14.21 33 0.5740 % 2,499.0
FixedReset 5.10 % 4.59 % 202,460 15.59 76 2.3903 % 2,001.3
Deemed-Retractible 5.24 % 5.18 % 104,713 5.45 33 0.3775 % 2,541.8
FloatingReset 2.55 % 4.21 % 69,231 5.82 9 1.8364 % 2,112.2
Performance Highlights
Issue Index Change Notes
W.PR.H Perpetual-Discount -1.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 22.55
Evaluated at bid price : 22.81
Bid-YTW : 6.07 %
PWF.PR.S Perpetual-Discount -1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 21.36
Evaluated at bid price : 21.36
Bid-YTW : 5.64 %
GWO.PR.S Deemed-Retractible -1.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.50
Bid-YTW : 6.19 %
TRP.PR.A FixedReset 1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 15.05
Evaluated at bid price : 15.05
Bid-YTW : 4.82 %
GWO.PR.G Deemed-Retractible 1.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.95
Bid-YTW : 6.47 %
BNS.PR.Z FixedReset 1.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.25
Bid-YTW : 6.87 %
IFC.PR.A FixedReset 1.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.26
Bid-YTW : 9.60 %
GWO.PR.I Deemed-Retractible 1.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.82
Bid-YTW : 7.06 %
RY.PR.O Perpetual-Discount 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 22.25
Evaluated at bid price : 22.62
Bid-YTW : 5.52 %
IGM.PR.B Perpetual-Premium 1.17 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.00
Bid-YTW : 5.88 %
SLF.PR.E Deemed-Retractible 1.18 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.50
Bid-YTW : 7.28 %
RY.PR.L FixedReset 1.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.70
Bid-YTW : 4.28 %
RY.PR.M FixedReset 1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 19.51
Evaluated at bid price : 19.51
Bid-YTW : 4.54 %
SLF.PR.A Deemed-Retractible 1.41 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.55
Bid-YTW : 6.86 %
POW.PR.A Perpetual-Discount 1.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 24.05
Evaluated at bid price : 24.30
Bid-YTW : 5.79 %
BMO.PR.M FixedReset 1.47 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.20
Bid-YTW : 3.58 %
BIP.PR.A FixedReset 1.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 20.70
Evaluated at bid price : 20.70
Bid-YTW : 5.39 %
FTS.PR.F Perpetual-Discount 1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 21.73
Evaluated at bid price : 21.98
Bid-YTW : 5.65 %
TD.PF.E FixedReset 1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 20.55
Evaluated at bid price : 20.55
Bid-YTW : 4.52 %
SLF.PR.D Deemed-Retractible 1.49 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.41
Bid-YTW : 7.28 %
GWO.PR.P Deemed-Retractible 1.50 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.75
Bid-YTW : 6.20 %
CM.PR.O FixedReset 1.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 18.67
Evaluated at bid price : 18.67
Bid-YTW : 4.45 %
BAM.PR.K Floater 1.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 10.61
Evaluated at bid price : 10.61
Bid-YTW : 4.49 %
BAM.PF.F FixedReset 1.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 20.40
Evaluated at bid price : 20.40
Bid-YTW : 4.78 %
BMO.PR.Z Perpetual-Discount 1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 22.65
Evaluated at bid price : 23.00
Bid-YTW : 5.54 %
CU.PR.E Perpetual-Discount 1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 21.31
Evaluated at bid price : 21.59
Bid-YTW : 5.75 %
FTS.PR.H FixedReset 1.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 14.25
Evaluated at bid price : 14.25
Bid-YTW : 4.15 %
MFC.PR.F FixedReset 1.58 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.75
Bid-YTW : 9.10 %
MFC.PR.B Deemed-Retractible 1.64 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.11
Bid-YTW : 7.06 %
BMO.PR.Y FixedReset 1.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 21.00
Evaluated at bid price : 21.00
Bid-YTW : 4.42 %
CM.PR.P FixedReset 1.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 18.25
Evaluated at bid price : 18.25
Bid-YTW : 4.44 %
BNS.PR.P FixedReset 1.70 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.97
Bid-YTW : 3.82 %
BMO.PR.T FixedReset 1.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 18.31
Evaluated at bid price : 18.31
Bid-YTW : 4.50 %
TRP.PR.D FixedReset 1.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 18.01
Evaluated at bid price : 18.01
Bid-YTW : 4.68 %
FTS.PR.M FixedReset 1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 19.90
Evaluated at bid price : 19.90
Bid-YTW : 4.44 %
CU.PR.G Perpetual-Discount 1.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 20.18
Evaluated at bid price : 20.18
Bid-YTW : 5.67 %
TD.PF.D FixedReset 2.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 20.25
Evaluated at bid price : 20.25
Bid-YTW : 4.48 %
BAM.PF.A FixedReset 2.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 20.25
Evaluated at bid price : 20.25
Bid-YTW : 4.80 %
RY.PR.H FixedReset 2.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 18.43
Evaluated at bid price : 18.43
Bid-YTW : 4.49 %
BNS.PR.D FloatingReset 2.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.40
Bid-YTW : 6.51 %
CU.PR.F Perpetual-Discount 2.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 20.21
Evaluated at bid price : 20.21
Bid-YTW : 5.66 %
MFC.PR.I FixedReset 2.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.19
Bid-YTW : 6.11 %
BNS.PR.Y FixedReset 2.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.40
Bid-YTW : 6.18 %
NA.PR.S FixedReset 2.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 18.55
Evaluated at bid price : 18.55
Bid-YTW : 4.58 %
BAM.PR.X FixedReset 2.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 14.37
Evaluated at bid price : 14.37
Bid-YTW : 4.94 %
TD.PR.T FloatingReset 2.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.94
Bid-YTW : 4.13 %
FTS.PR.K FixedReset 2.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 17.54
Evaluated at bid price : 17.54
Bid-YTW : 4.46 %
TD.PR.Y FixedReset 2.28 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.76
Bid-YTW : 3.94 %
FTS.PR.J Perpetual-Discount 2.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 21.50
Evaluated at bid price : 21.50
Bid-YTW : 5.61 %
CM.PR.Q FixedReset 2.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 21.04
Evaluated at bid price : 21.04
Bid-YTW : 4.31 %
TD.PF.A FixedReset 2.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 18.50
Evaluated at bid price : 18.50
Bid-YTW : 4.40 %
NA.PR.W FixedReset 2.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 18.35
Evaluated at bid price : 18.35
Bid-YTW : 4.45 %
MFC.PR.J FixedReset 2.53 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.85
Bid-YTW : 6.70 %
MFC.PR.G FixedReset 2.54 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.38
Bid-YTW : 5.95 %
BNS.PR.B FloatingReset 2.57 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.95
Bid-YTW : 4.23 %
SLF.PR.J FloatingReset 2.61 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.75
Bid-YTW : 9.08 %
BAM.PR.C Floater 2.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 10.51
Evaluated at bid price : 10.51
Bid-YTW : 4.53 %
TD.PR.S FixedReset 2.67 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.87
Bid-YTW : 3.67 %
VNR.PR.A FixedReset 2.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 20.42
Evaluated at bid price : 20.42
Bid-YTW : 4.57 %
BAM.PF.G FixedReset 2.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 20.75
Evaluated at bid price : 20.75
Bid-YTW : 4.72 %
FTS.PR.G FixedReset 2.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 17.16
Evaluated at bid price : 17.16
Bid-YTW : 4.59 %
BNS.PR.C FloatingReset 2.77 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.60
Bid-YTW : 3.91 %
IAG.PR.G FixedReset 2.82 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.77
Bid-YTW : 6.30 %
BMO.PR.W FixedReset 2.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 18.05
Evaluated at bid price : 18.05
Bid-YTW : 4.52 %
HSE.PR.G FixedReset 2.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 22.51
Evaluated at bid price : 23.40
Bid-YTW : 4.70 %
BNS.PR.R FixedReset 2.95 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.45
Bid-YTW : 3.71 %
TRP.PR.F FloatingReset 3.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 13.75
Evaluated at bid price : 13.75
Bid-YTW : 4.19 %
BAM.PR.Z FixedReset 3.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 20.50
Evaluated at bid price : 20.50
Bid-YTW : 4.83 %
BMO.PR.Q FixedReset 3.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.05
Bid-YTW : 6.23 %
RY.PR.Z FixedReset 3.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 18.65
Evaluated at bid price : 18.65
Bid-YTW : 4.39 %
HSE.PR.C FixedReset 3.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 21.82
Evaluated at bid price : 22.20
Bid-YTW : 4.62 %
TRP.PR.G FixedReset 3.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 20.45
Evaluated at bid price : 20.45
Bid-YTW : 4.70 %
TRP.PR.E FixedReset 3.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 18.56
Evaluated at bid price : 18.56
Bid-YTW : 4.61 %
BMO.PR.S FixedReset 3.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 19.15
Evaluated at bid price : 19.15
Bid-YTW : 4.40 %
TD.PF.B FixedReset 3.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 18.45
Evaluated at bid price : 18.45
Bid-YTW : 4.40 %
BAM.PR.B Floater 3.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 10.92
Evaluated at bid price : 10.92
Bid-YTW : 4.36 %
RY.PR.J FixedReset 3.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 19.95
Evaluated at bid price : 19.95
Bid-YTW : 4.55 %
BAM.PR.T FixedReset 3.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 17.17
Evaluated at bid price : 17.17
Bid-YTW : 4.80 %
BAM.PF.B FixedReset 4.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 18.73
Evaluated at bid price : 18.73
Bid-YTW : 4.87 %
BAM.PF.E FixedReset 4.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 18.80
Evaluated at bid price : 18.80
Bid-YTW : 4.89 %
BNS.PR.Q FixedReset 4.60 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.12
Bid-YTW : 3.70 %
CU.PR.C FixedReset 4.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 20.05
Evaluated at bid price : 20.05
Bid-YTW : 4.16 %
MFC.PR.N FixedReset 4.72 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.85
Bid-YTW : 7.26 %
BAM.PR.R FixedReset 4.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 16.00
Evaluated at bid price : 16.00
Bid-YTW : 5.06 %
IFC.PR.C FixedReset 5.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.50
Bid-YTW : 6.87 %
SLF.PR.H FixedReset 5.28 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.74
Bid-YTW : 7.57 %
MFC.PR.K FixedReset 5.35 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.30
Bid-YTW : 7.46 %
TRP.PR.C FixedReset 5.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 12.60
Evaluated at bid price : 12.60
Bid-YTW : 4.73 %
SLF.PR.G FixedReset 5.44 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.50
Bid-YTW : 8.24 %
MFC.PR.M FixedReset 5.52 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.30
Bid-YTW : 7.01 %
MFC.PR.L FixedReset 5.56 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.04
Bid-YTW : 7.75 %
TRP.PR.B FixedReset 6.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 12.20
Evaluated at bid price : 12.20
Bid-YTW : 4.38 %
Volume Highlights
Issue Index Shares
Traded
Notes
TRP.PR.A FixedReset 83,070 Scotia crossed 14,200 at 15.05 and bought blocks of 23,500 and 24,200 from RBC at the same price.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 15.05
Evaluated at bid price : 15.05
Bid-YTW : 4.82 %
PWF.PR.P FixedReset 80,000 Scotia crossed blocks of 33,900 and 39,500, both at 14.94.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 14.51
Evaluated at bid price : 14.51
Bid-YTW : 4.21 %
GWO.PR.S Deemed-Retractible 65,532 TD crossed 16,900 at 23.75. RBC sold blocks of 23,200 and 11,500 to anonymous, both at 23.50.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.50
Bid-YTW : 6.19 %
TD.PF.C FixedReset 61,850 RBC crossed 12,800 at 18.05.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 18.04
Evaluated at bid price : 18.04
Bid-YTW : 4.49 %
NA.PR.S FixedReset 60,119 RBC crossed 10,000 at 18.30, then bought 29,600 from GMP at 18.40.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 18.55
Evaluated at bid price : 18.55
Bid-YTW : 4.58 %
CM.PR.O FixedReset 58,988 RBC crossed 10,000 at 18.55.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 18.67
Evaluated at bid price : 18.67
Bid-YTW : 4.45 %
There were 62 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
MFC.PR.J FixedReset Quote: 19.85 – 20.44
Spot Rate : 0.5900
Average : 0.3395

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.85
Bid-YTW : 6.70 %

W.PR.H Perpetual-Discount Quote: 22.81 – 23.51
Spot Rate : 0.7000
Average : 0.5091

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 22.55
Evaluated at bid price : 22.81
Bid-YTW : 6.07 %

FTS.PR.F Perpetual-Discount Quote: 21.98 – 22.50
Spot Rate : 0.5200
Average : 0.3400

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 21.73
Evaluated at bid price : 21.98
Bid-YTW : 5.65 %

BIP.PR.A FixedReset Quote: 20.70 – 21.15
Spot Rate : 0.4500
Average : 0.3003

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 20.70
Evaluated at bid price : 20.70
Bid-YTW : 5.39 %

GWO.PR.L Deemed-Retractible Quote: 24.45 – 24.90
Spot Rate : 0.4500
Average : 0.3194

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.45
Bid-YTW : 6.05 %

TD.PF.E FixedReset Quote: 20.55 – 21.20
Spot Rate : 0.6500
Average : 0.5248

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-20
Maturity Price : 20.55
Evaluated at bid price : 20.55
Bid-YTW : 4.52 %

Market Action

October 19, 2015

I have often railed against the useless of regulatory make-work schemes; clearly, one of the most ridiculous is the anti-money-laundering set of regulations. I’ve quoted John Allison’s observation before, but now I’ll quote it again:

And then there was the Patriot Act, which was supposed to catch terrorists. I’ve talked to many people in government and they all do this dancing act, but the fact is there has never been a single terrorist caught and convicted because of the Patriot Act. The Act cost the banking industry more than $5 billion annually, and I would argue that no one is going to be caught. If you are dumb enough to get caught under the Patriot Act, you are going to get caught anyway. The only significant conviction of the Patriot Act was Eliot Spitzer, the governor of New York, who was convicted of soliciting prostitutes under a law designed to catch terrorists.

Since he wrote that, the authorities also seem to have caught John Hastert, who needed lots of cash because he was being blackmailed as discussed on May 28, 2015; knowing that victims of blackmail can be caught and exposed more easily and righteously should certainly cause us all to sleep better at night. But the direct human effects – beyond the financial cost for this make-work – has now been written about in a Globe story about Canadian “politically exposed persons”:

Those regulations propose a vast reach: For 20 years after the politically exposed persons (PEPs) leave office, the financial institutions will need to keep their eyes on them, their family and associates. The financial institutions’ first job is to identify the PEPs; then to assess their risk; and then, if the institutions determine the PEPs are a high risk – there is little public explanation on how the banks are expected to do this – they will need to monitor the PEPs’ account activity. The institutions will need to report suspicious activity (anything they suspect is connected to terrorism or money laundering) to a federal intelligence agency known as Fintrac, which investigates and can turn over files to the Mounties or the Canada Revenue Agency.
…
Ontario sisters Catherine and Emilie Taman both said in interviews they received mysterious phone calls from their separate banks, asking intrusive questions. (Emilie Taman is running for the New Democratic Party in an Ottawa riding in the federal election.) Catherine’s banker eventually explained why: Her mother was a foreign PEP. The Taman sisters’ mother is Ms. Arbour, who apart from being a retired Supreme Court judge is also a former international war-crimes prosecutor and a former United Nations human rights commissioner. Catherine said when she refused to answer the questions (on her mother’s advice), her account was frozen, which she discovered when she tried to use her bank card in a restaurant. A letter she provided to The Globe showed her bank asking questions such as, “From whom/where are you getting money?” “How did you accumulate your wealth/net worth?”

How the banks knew the Taman sisters were Ms. Arbour’s daughters was a mystery to all three women, but experts contacted by The Globe say a small group of private companies provide lists of foreign PEPs and their families, and banks run new customers through those computerized lists, for a fee. There are similar lists for domestic PEPs.

In a commentary published in Thursday’s Globe, Ms. Arbour calls the program a “useless bureaucratic nightmare,” and says that her children should be left alone by their bankers.

The highlight of the story is a quote from one of the piggies at the trough:

“I think corruption is growing by leaps and bounds,” Garry Clement, a former national director of the RCMP’s proceeds of crime program, said in an interview. “It’s far greater than people are willing to accept.”

I have a message for Garry Clement: I don’t give a rat’s ass what you think and neither does anybody else with half a brain. Let’s see some proof. Let’s see some proof, first that corruption is growing by leaps and bounds and second that it needs to be addressed (I don’t care about corruption in Libya, the Libyans aren’t paying me anything to look after them) and third that these regulations are the best way to fight it. Proof that can stand up in court and has been used to convict real bad guys, not pathetic victims like Spitzer and Hastert.

I mentioned the folly of UK central planners with respect to buy-to-let housing on October 1. The scheme has now attracted the ire of Institute of Chartered Accountants in England & Wales:

Britain’s leading professional accounting body, the Institute of Chartered Accountants in England & Wales, has attacked the Chancellor’s controversial new tax on buy-to-let tax as “unfair and unreasonable”.

It condemns the legislation as “unthought-through” and predicts it will cause “extreme confusion”, as well as forcing some landlords out of business, distorting the market – and even making life harder for first-time buyers.

The new tax, which was not consulted upon and which The Telegraph is campaigning against, is included within the Finance Bill currently progressing through Parliament.

It will be phased in between 2017 and 2020, and effectively removes the ability of private landlords to offset the cost of their mortgage interest before arriving at a taxable profit.
…
While the proposed tax has found popularity among tenants, the ICAEW says it could exacerbate the property crisis and make it more difficult for first-time buyers.

“The interest relief restriction will favour cash buyers who want to buy to let and may increase the competition even more at the lower end of the property market, thereby increasing prices and hindering first-time buyers.”

According to the Economist, Canadian housing is grossly overvalued, tied for most in the world (with Hong Kong) with respect to rents (89% rich) and highly ranked with respect to income (34% rich). Paul Matsiras of Moody’s claims:

“The risks are less around the rapid house price appreciation per se than the fact that, relative to incomes, homes in Toronto and Vancouver are increasingly becoming unaffordable either to own or to rent,” Moody’s economist Paul Matsiras said in his report.

“Canadian household debt has risen faster than disposable income since 2011, greatly increasing the debt burden for consumers and the risks of a pullback in spending as interest rates rise.”

He warned of difficulties as the key measure of household debt to disposable income rises, now standing at almost 165 per cent.

But fear not! In future photographs of G-7 meetings, Canada will display the best hair:

The country’s three major broadcasters — CTV, CBC and Global News — have projected a Liberal majority win. The Liberals won or were leading in 183 of the 338 House of Commons seats, with the Conservatives ahead in 98 and the New Democratic Party with 30, as of 10:36 p.m. Monday in Ottawa, according to preliminary results from Elections Canada. A party needs 170 seats for a majority.
…
The Canadian dollar fell after the networks called a Liberal victory, down 0.1 percent at 10 p.m. in Toronto to C$1.3040 per U.S. dollar, dropping for a third day. The currency has depreciated 10.9 percent against the U.S. dollar this year.

I’m very glad to see the end of the Bill C-51 boys, but I wish their replacements were led by somebody with a better claim to fame than being born. But we’ll see. Maybe we can stop obsessing about how other people dress, anyway.

Yee-haw!

bullRiding
Click for Big

Canadian preferred share investors were riding the bull today in the best day I can remember off the top of my head, with PerpetualDiscounts up 76bp, FixedResets winning an incredible 304bp and DeemedRetractibles gaining 35bp. The Performance Highlights table is much as you’d expect, with no less than a dozen issues – all FixedResets – gaining more than the 5% figure that usually indicates an absurdity of some kind. Volume was very high.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_151019
Click for Big

Implied Volatility declined today but remains above what I consider reasonable.

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 17.96 to be $0.77 rich, while TRP.PR.C, resetting 2016-1-30 at +154, is $0.90 cheap at its bid price of 11.95.

impVol_MFC_151019
Click for Big

There was some normalization from Friday‘s absurd results, but MFC.PR.F is still noticeably off the line defined by the other issues.

Most expensive is MFC.PR.F, resetting at +141bp on 2016-6-19, bid at 14.52 to be 0.85 rich, while MFC.PR.L resetting at +216bp on 2019-6-19, is bid at 17.09 to be 0.51 cheap.

impVol_BAM_151019
Click for Big

The fit on the BAM issues continues to be horrible!

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 15.25 to be $0.90 cheap. BAM.PF.G, resetting at +284bp on 2020-6-30 is bid at 20.20 and appears to be $0.69 rich.

impVol_FTS_151019
Click for Big

Implied Volatility declined substantially today but remains high.

FTS.PR.M, with a spread of +248bp, and bid at 19.55, looks $0.40 expensive and resets 2019-12-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 16.70 and is $0.78 cheap.

pairs_FR_151019
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.67%, with no outliers. The distribution is only slightly bimodal, with bank NVCC non-compliant pairs averaging -0.85% and other issues averaging -0.41%. There is one junk outlier above 0.50% and one below -1.50%.

pairs_FF_151019
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.1924 % 1,637.1
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.1924 % 2,862.4
Floater 4.54 % 4.56 % 62,422 16.32 3 0.1924 % 1,740.3
OpRet 0.00 % 0.00 % 0 0.00 0 0.0648 % 2,763.4
SplitShare 4.34 % 5.16 % 77,409 2.97 5 0.0648 % 3,238.5
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0648 % 2,526.8
Perpetual-Premium 5.92 % 5.87 % 67,825 13.99 5 0.9452 % 2,458.4
Perpetual-Discount 5.74 % 5.81 % 79,938 14.16 33 0.7565 % 2,484.8
FixedReset 5.22 % 4.72 % 202,387 15.41 76 3.0427 % 1,954.6
Deemed-Retractible 5.26 % 5.22 % 103,649 5.45 33 0.3478 % 2,532.2
FloatingReset 2.60 % 4.51 % 68,564 5.81 9 1.3760 % 2,074.1
Performance Highlights
Issue Index Change Notes
BAM.PR.B Floater -1.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 10.55
Evaluated at bid price : 10.55
Bid-YTW : 4.51 %
BAM.PR.C Floater 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 10.24
Evaluated at bid price : 10.24
Bid-YTW : 4.65 %
PWF.PR.K Perpetual-Discount 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 21.51
Evaluated at bid price : 21.77
Bid-YTW : 5.70 %
CU.PR.D Perpetual-Discount 1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 21.55
Evaluated at bid price : 21.55
Bid-YTW : 5.78 %
GWO.PR.I Deemed-Retractible 1.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.59
Bid-YTW : 7.21 %
PWF.PR.L Perpetual-Discount 1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 22.06
Evaluated at bid price : 22.35
Bid-YTW : 5.71 %
BMO.PR.R FloatingReset 1.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.90
Bid-YTW : 4.31 %
POW.PR.D Perpetual-Discount 1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 21.44
Evaluated at bid price : 21.70
Bid-YTW : 5.79 %
PWF.PR.F Perpetual-Discount 1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 22.24
Evaluated at bid price : 22.51
Bid-YTW : 5.84 %
TD.PF.F Perpetual-Discount 1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 22.07
Evaluated at bid price : 22.40
Bid-YTW : 5.47 %
BAM.PR.N Perpetual-Discount 1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 20.25
Evaluated at bid price : 20.25
Bid-YTW : 5.93 %
SLF.PR.B Deemed-Retractible 1.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.43
Bid-YTW : 7.00 %
BMO.PR.Q FixedReset 1.25 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.45
Bid-YTW : 6.77 %
PWF.PR.R Perpetual-Discount 1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 23.13
Evaluated at bid price : 23.51
Bid-YTW : 5.86 %
GWO.PR.N FixedReset 1.29 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.09
Bid-YTW : 9.39 %
BNS.PR.Q FixedReset 1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.06
Bid-YTW : 4.51 %
SLF.PR.G FixedReset 1.38 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.70
Bid-YTW : 8.92 %
BAM.PR.M Perpetual-Discount 1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 20.30
Evaluated at bid price : 20.30
Bid-YTW : 5.91 %
BNS.PR.B FloatingReset 1.66 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.40
Bid-YTW : 4.67 %
GWO.PR.R Deemed-Retractible 1.67 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.90
Bid-YTW : 6.69 %
MFC.PR.B Deemed-Retractible 1.71 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.77
Bid-YTW : 7.29 %
PWF.PR.O Perpetual-Premium 1.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 24.45
Evaluated at bid price : 24.75
Bid-YTW : 5.87 %
BMO.PR.Z Perpetual-Discount 1.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 22.35
Evaluated at bid price : 22.65
Bid-YTW : 5.50 %
MFC.PR.J FixedReset 1.89 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.36
Bid-YTW : 7.04 %
PWF.PR.H Perpetual-Premium 1.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 24.29
Evaluated at bid price : 24.60
Bid-YTW : 5.86 %
TRP.PR.C FixedReset 1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 11.95
Evaluated at bid price : 11.95
Bid-YTW : 4.99 %
GWO.PR.S Deemed-Retractible 1.98 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.75
Bid-YTW : 6.04 %
TRP.PR.D FixedReset 2.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 17.70
Evaluated at bid price : 17.70
Bid-YTW : 4.76 %
BMO.PR.Y FixedReset 2.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 20.66
Evaluated at bid price : 20.66
Bid-YTW : 4.49 %
FTS.PR.H FixedReset 2.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 14.03
Evaluated at bid price : 14.03
Bid-YTW : 4.21 %
RY.PR.I FixedReset 2.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.50
Bid-YTW : 4.40 %
MFC.PR.H FixedReset 2.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.13
Bid-YTW : 5.76 %
TD.PF.E FixedReset 2.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 20.25
Evaluated at bid price : 20.25
Bid-YTW : 4.58 %
CU.PR.C FixedReset 2.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 19.15
Evaluated at bid price : 19.15
Bid-YTW : 4.36 %
PWF.PR.P FixedReset 2.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 14.44
Evaluated at bid price : 14.44
Bid-YTW : 4.23 %
BAM.PR.R FixedReset 2.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 15.25
Evaluated at bid price : 15.25
Bid-YTW : 5.31 %
BMO.PR.M FixedReset 2.45 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.85
Bid-YTW : 3.84 %
MFC.PR.G FixedReset 2.46 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.85
Bid-YTW : 6.29 %
SLF.PR.C Deemed-Retractible 2.52 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.36
Bid-YTW : 7.31 %
TRP.PR.E FixedReset 2.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 17.96
Evaluated at bid price : 17.96
Bid-YTW : 4.77 %
BNS.PR.P FixedReset 2.70 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.57
Bid-YTW : 4.12 %
NA.PR.Q FixedReset 2.72 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.15
Bid-YTW : 4.03 %
BMO.PR.T FixedReset 2.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 4.58 %
FTS.PR.G FixedReset 2.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 16.70
Evaluated at bid price : 16.70
Bid-YTW : 4.72 %
BAM.PF.E FixedReset 2.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 18.01
Evaluated at bid price : 18.01
Bid-YTW : 5.11 %
PWF.PR.S Perpetual-Discount 2.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 21.33
Evaluated at bid price : 21.62
Bid-YTW : 5.56 %
RY.PR.J FixedReset 3.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 19.23
Evaluated at bid price : 19.23
Bid-YTW : 4.72 %
IFC.PR.A FixedReset 3.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.10
Bid-YTW : 9.74 %
SLF.PR.H FixedReset 3.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.85
Bid-YTW : 8.26 %
BMO.PR.W FixedReset 3.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 17.55
Evaluated at bid price : 17.55
Bid-YTW : 4.66 %
TD.PF.B FixedReset 3.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 17.83
Evaluated at bid price : 17.83
Bid-YTW : 4.56 %
SLF.PR.I FixedReset 3.30 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.70
Bid-YTW : 6.87 %
HSE.PR.C FixedReset 3.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 21.50
Evaluated at bid price : 21.50
Bid-YTW : 4.80 %
IFC.PR.C FixedReset 3.34 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.55
Bid-YTW : 7.55 %
HSE.PR.A FixedReset 3.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 13.80
Evaluated at bid price : 13.80
Bid-YTW : 4.79 %
TRP.PR.A FixedReset 3.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 14.90
Evaluated at bid price : 14.90
Bid-YTW : 4.87 %
BMO.PR.S FixedReset 3.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 18.51
Evaluated at bid price : 18.51
Bid-YTW : 4.56 %
MFC.PR.K FixedReset 3.70 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.37
Bid-YTW : 8.17 %
BAM.PF.F FixedReset 3.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 20.09
Evaluated at bid price : 20.09
Bid-YTW : 4.85 %
MFC.PR.I FixedReset 3.90 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.76
Bid-YTW : 6.39 %
RY.PR.H FixedReset 3.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 18.06
Evaluated at bid price : 18.06
Bid-YTW : 4.58 %
BNS.PR.C FloatingReset 4.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.99
Bid-YTW : 4.38 %
TRP.PR.G FixedReset 4.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 19.80
Evaluated at bid price : 19.80
Bid-YTW : 4.86 %
TRP.PR.F FloatingReset 4.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 13.35
Evaluated at bid price : 13.35
Bid-YTW : 4.32 %
BNS.PR.R FixedReset 4.35 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.75
Bid-YTW : 4.23 %
TD.PF.D FixedReset 4.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 19.85
Evaluated at bid price : 19.85
Bid-YTW : 4.57 %
RY.PR.M FixedReset 4.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 19.25
Evaluated at bid price : 19.25
Bid-YTW : 4.60 %
RY.PR.Z FixedReset 4.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 18.08
Evaluated at bid price : 18.08
Bid-YTW : 4.53 %
FTS.PR.K FixedReset 4.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 17.15
Evaluated at bid price : 17.15
Bid-YTW : 4.56 %
CM.PR.Q FixedReset 4.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 20.56
Evaluated at bid price : 20.56
Bid-YTW : 4.41 %
VNR.PR.A FixedReset 4.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 19.88
Evaluated at bid price : 19.88
Bid-YTW : 4.70 %
BAM.PF.G FixedReset 4.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 20.20
Evaluated at bid price : 20.20
Bid-YTW : 4.85 %
CM.PR.P FixedReset 4.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 17.95
Evaluated at bid price : 17.95
Bid-YTW : 4.52 %
BAM.PF.B FixedReset 4.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 18.01
Evaluated at bid price : 18.01
Bid-YTW : 5.06 %
MFC.PR.L FixedReset 4.72 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.09
Bid-YTW : 8.50 %
TD.PF.A FixedReset 4.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 18.07
Evaluated at bid price : 18.07
Bid-YTW : 4.51 %
FTS.PR.M FixedReset 5.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 19.55
Evaluated at bid price : 19.55
Bid-YTW : 4.52 %
PWF.PR.T FixedReset 5.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 21.39
Evaluated at bid price : 21.39
Bid-YTW : 3.94 %
CM.PR.O FixedReset 5.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 18.39
Evaluated at bid price : 18.39
Bid-YTW : 4.52 %
TD.PF.C FixedReset 5.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 17.90
Evaluated at bid price : 17.90
Bid-YTW : 4.53 %
NA.PR.S FixedReset 5.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 18.16
Evaluated at bid price : 18.16
Bid-YTW : 4.68 %
BAM.PF.A FixedReset 5.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 19.85
Evaluated at bid price : 19.85
Bid-YTW : 4.90 %
MFC.PR.M FixedReset 5.66 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.29
Bid-YTW : 7.75 %
IAG.PR.G FixedReset 5.76 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.20
Bid-YTW : 6.68 %
MFC.PR.N FixedReset 5.82 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.00
Bid-YTW : 7.89 %
BIP.PR.A FixedReset 5.97 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 20.40
Evaluated at bid price : 20.40
Bid-YTW : 5.47 %
BAM.PR.T FixedReset 6.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 16.52
Evaluated at bid price : 16.52
Bid-YTW : 4.99 %
NA.PR.W FixedReset 6.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 17.90
Evaluated at bid price : 17.90
Bid-YTW : 4.57 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PF.B FixedReset 158,635 Nesbitt crossed 19,300 at 17.30; RBC crossed 107,800 at 18.00.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 17.83
Evaluated at bid price : 17.83
Bid-YTW : 4.56 %
TRP.PR.B FixedReset 139,492 Scotia crossed 58,500 at 11.40 and another 50,000 at 11.45.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 11.50
Evaluated at bid price : 11.50
Bid-YTW : 4.65 %
BMO.PR.W FixedReset 137,345 RBC crossed 110,400 at 17.50.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 17.55
Evaluated at bid price : 17.55
Bid-YTW : 4.66 %
TD.PF.A FixedReset 110,520 TD crossed 23,500 at 17.41; RBC crossed 23,800 at 17.75.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 18.07
Evaluated at bid price : 18.07
Bid-YTW : 4.51 %
RY.PR.H FixedReset 73,588 RBC crossed 30,000 at 17.86.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 18.06
Evaluated at bid price : 18.06
Bid-YTW : 4.58 %
MFC.PR.J FixedReset 72,700 Nesbitt crossed 31,000 at 19.02 and 20,000 at 19.22.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.36
Bid-YTW : 7.04 %
There were 61 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
TRP.PR.E FixedReset Quote: 17.96 – 20.00
Spot Rate : 2.0400
Average : 1.3076

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 17.96
Evaluated at bid price : 17.96
Bid-YTW : 4.77 %

HSE.PR.G FixedReset Quote: 22.75 – 23.54
Spot Rate : 0.7900
Average : 0.4964

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 22.15
Evaluated at bid price : 22.75
Bid-YTW : 4.86 %

RY.PR.N Perpetual-Discount Quote: 22.65 – 23.24
Spot Rate : 0.5900
Average : 0.3439

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 22.36
Evaluated at bid price : 22.65
Bid-YTW : 5.57 %

TRP.PR.D FixedReset Quote: 17.70 – 18.40
Spot Rate : 0.7000
Average : 0.4649

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 17.70
Evaluated at bid price : 17.70
Bid-YTW : 4.76 %

TD.PR.Z FloatingReset Quote: 21.31 – 22.00
Spot Rate : 0.6900
Average : 0.4746

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.31
Bid-YTW : 4.72 %

TD.PF.E FixedReset Quote: 20.25 – 20.85
Spot Rate : 0.6000
Average : 0.3876

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-19
Maturity Price : 20.25
Evaluated at bid price : 20.25
Bid-YTW : 4.58 %

Market Action

October 16, 2015

The Russians are bringing us new trends in financial computer hacking:

A group of Russian hackers infiltrated the servers of Dow Jones & Co., owner of the Wall Street Journal and several other news publications, and stole information to trade on before it became public, according to four people familiar with the matter.

The Federal Bureau of Investigation, Secret Service and the Securities and Exchange Commission are leading an investigation of the infiltration, according to the people. The probe began at least a year ago, one of them said.

Dow Jones, in a statement, said: “To the best of our knowledge, we have received no information from the authorities about any such alleged matter, and we are looking into whether there is any truth whatsoever to this report by a competitor news organization.”
…
Information embargoed by companies and the government for release at a later time could be valuable to traders looking to gain an edge over other market participants, as could stories being prepared on topics like mergers and acquisitions that move stock prices.
…
The hack investigation shows how quickly law enforcers are shifting to a new front in insider trading: cyberspace. Market-moving, nonpublic information used to trade hands in secret meetings. Hackers are now stealing sensitive information and selling it to traders. This new vulnerability in the financial markets is challenging law-enforcement officials who are trying to keep pace with cyber-criminals’ rapidly evolving moneymaking schemes.

For would-be inside traders, business journalists and data providers are a rich target. Potentially market-moving scoops often develop in-house for days or weeks, promising intruders a long pre-publication window to mine information and execute trades. Data being held for public release at a specified time can also be a gold mine in markets where the profitably of a trade is determined in a fraction of a second.

Life got a little better for preferred share investors today:

cat_and_butterfly-normal
Click for Big

It was a glorious day for the Canadian preferred share market, with PerpetualDiscounts gaining 32bp, FixedResets winning 142bp and DeemedRetractibles up 120bp. The Performance Highlights table is as lengthy as one might expect. Volume was extremely heavy.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_151016
Click for Big

Implied Volatility declined a lot today but remains high.

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 17.50 to be $0.78 rich, while TRP.PR.C, resetting 2016-1-30 at +154, is $0.86 cheap at its bid price of 11.72.

impVol_MFC_151016
Click for Big

There was an incredible drop in Implied Volatility today – and it would be near zero if the calculation wasn’t distorted by the MFC.PR.F outlier. Dropping the outlier results in a very good fit:

impVol_MFC_151016_adj
Click for Big

Using the all-inclusive fit, the most expensive is MFC.PR.F, resetting at +141bp on 2016-6-19, bid at 14.50 to be 1.32 rich, while MFC.PR.L resetting at +216bp on 2019-6-19, is bid at 16.32 to be 0.68 cheap.

impVol_BAM_151016
Click for Big

The fit on the BAM issues continues to be horrible!

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 14.90 to be $0.90 cheap. BAM.PF.G, resetting at +284bp on 2020-6-30 is bid at 19.30 and appears to be $0.58 rich.

impVol_FTS_151016
Click for Big

Implied Volatility declined substantially today but remains ridiculously high.

FTS.PR.M, with a spread of +248bp, and bid at 18.60, looks $0.39 expensive and resets 2019-12-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 16.24 and is $0.56 cheap.

pairs_FR_151016
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.45%, with no outliers. The distribution is only slightly bimodal, with bank NVCC non-compliant pairs averaging -0.58% and other issues averaging -0.26%. There are three junk outliers above 0.50% and one below -1.50%.

pairs_FF_151016
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 4.0721 % 1,633.9
FixedFloater 0.00 % 0.00 % 0 0.00 0 4.0721 % 2,856.9
Floater 4.55 % 4.60 % 62,771 16.24 3 4.0721 % 1,737.0
OpRet 0.00 % 0.00 % 0 0.00 0 -0.2505 % 2,761.6
SplitShare 4.34 % 5.14 % 74,724 2.98 5 -0.2505 % 3,236.4
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.2505 % 2,525.2
Perpetual-Premium 5.98 % 5.98 % 68,243 13.96 5 0.4173 % 2,435.4
Perpetual-Discount 5.78 % 5.86 % 80,238 14.10 33 0.3217 % 2,466.1
FixedReset 5.38 % 4.92 % 199,722 15.09 76 1.4250 % 1,896.9
Deemed-Retractible 5.28 % 5.22 % 103,083 5.46 33 1.1972 % 2,523.5
FloatingReset 2.66 % 4.77 % 69,057 5.81 9 0.5348 % 2,045.9
Performance Highlights
Issue Index Change Notes
BNS.PR.R FixedReset -1.51 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.76
Bid-YTW : 5.01 %
BNS.PR.D FloatingReset -1.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.02
Bid-YTW : 6.89 %
BAM.PF.B FixedReset -1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 17.20
Evaluated at bid price : 17.20
Bid-YTW : 5.34 %
GWO.PR.P Deemed-Retractible 1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.44
Bid-YTW : 6.38 %
RY.PR.Z FixedReset 1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 17.29
Evaluated at bid price : 17.29
Bid-YTW : 4.78 %
HSB.PR.C Deemed-Retractible 1.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.95
Bid-YTW : 5.21 %
IGM.PR.B Perpetual-Premium 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 24.41
Evaluated at bid price : 24.70
Bid-YTW : 5.98 %
RY.PR.G Deemed-Retractible 1.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.94
Bid-YTW : 4.69 %
RY.PR.E Deemed-Retractible 1.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.90
Bid-YTW : 4.72 %
RY.PR.C Deemed-Retractible 1.18 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.90
Bid-YTW : 4.82 %
PWF.PR.S Perpetual-Discount 1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 21.00
Evaluated at bid price : 21.00
Bid-YTW : 5.74 %
MFC.PR.N FixedReset 1.25 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.01
Bid-YTW : 8.68 %
HSB.PR.D Deemed-Retractible 1.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.81
Bid-YTW : 5.22 %
FTS.PR.G FixedReset 1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 16.24
Evaluated at bid price : 16.24
Bid-YTW : 4.90 %
GWO.PR.G Deemed-Retractible 1.35 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.56
Bid-YTW : 6.70 %
TD.PF.A FixedReset 1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 17.25
Evaluated at bid price : 17.25
Bid-YTW : 4.76 %
BAM.PR.R FixedReset 1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 14.90
Evaluated at bid price : 14.90
Bid-YTW : 5.48 %
BMO.PR.W FixedReset 1.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 4.84 %
HSE.PR.A FixedReset 1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 13.35
Evaluated at bid price : 13.35
Bid-YTW : 5.01 %
CM.PR.P FixedReset 1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 17.15
Evaluated at bid price : 17.15
Bid-YTW : 4.77 %
SLF.PR.H FixedReset 1.49 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.34
Bid-YTW : 8.70 %
TRP.PR.E FixedReset 1.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 4.93 %
BNS.PR.A FloatingReset 1.59 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.30
Bid-YTW : 4.33 %
GWO.PR.N FixedReset 1.68 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.91
Bid-YTW : 9.59 %
RY.PR.J FixedReset 1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 18.66
Evaluated at bid price : 18.66
Bid-YTW : 4.90 %
IFC.PR.C FixedReset 1.70 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.95
Bid-YTW : 8.02 %
BAM.PF.E FixedReset 1.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 17.51
Evaluated at bid price : 17.51
Bid-YTW : 5.29 %
TRP.PR.B FixedReset 1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 11.40
Evaluated at bid price : 11.40
Bid-YTW : 4.74 %
FTS.PR.K FixedReset 1.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 16.40
Evaluated at bid price : 16.40
Bid-YTW : 4.82 %
BNS.PR.M Deemed-Retractible 1.80 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.85
Bid-YTW : 4.60 %
CU.PR.C FixedReset 1.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 18.74
Evaluated at bid price : 18.74
Bid-YTW : 4.50 %
GWO.PR.H Deemed-Retractible 1.88 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.70
Bid-YTW : 6.87 %
TD.PF.D FixedReset 1.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 19.01
Evaluated at bid price : 19.01
Bid-YTW : 4.80 %
TRP.PR.F FloatingReset 1.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 12.80
Evaluated at bid price : 12.80
Bid-YTW : 4.55 %
RY.PR.H FixedReset 2.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 17.38
Evaluated at bid price : 17.38
Bid-YTW : 4.80 %
BNS.PR.L Deemed-Retractible 2.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.85
Bid-YTW : 4.60 %
BAM.PF.A FixedReset 2.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 18.80
Evaluated at bid price : 18.80
Bid-YTW : 5.21 %
BAM.PF.F FixedReset 2.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 19.35
Evaluated at bid price : 19.35
Bid-YTW : 5.07 %
TD.PF.E FixedReset 2.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 19.82
Evaluated at bid price : 19.82
Bid-YTW : 4.71 %
TRP.PR.A FixedReset 2.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 14.41
Evaluated at bid price : 14.41
Bid-YTW : 5.08 %
SLF.PR.B Deemed-Retractible 2.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.17
Bid-YTW : 7.16 %
BAM.PR.C Floater 2.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 10.13
Evaluated at bid price : 10.13
Bid-YTW : 4.70 %
GWO.PR.R Deemed-Retractible 2.33 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.54
Bid-YTW : 6.92 %
NA.PR.Q FixedReset 2.40 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.51
Bid-YTW : 4.53 %
POW.PR.G Perpetual-Discount 2.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 23.63
Evaluated at bid price : 24.09
Bid-YTW : 5.83 %
SLF.PR.D Deemed-Retractible 2.56 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.05
Bid-YTW : 7.52 %
FTS.PR.J Perpetual-Discount 2.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 20.83
Evaluated at bid price : 20.83
Bid-YTW : 5.79 %
MFC.PR.C Deemed-Retractible 2.56 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.01
Bid-YTW : 7.63 %
CM.PR.Q FixedReset 2.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 19.65
Evaluated at bid price : 19.65
Bid-YTW : 4.64 %
RY.PR.M FixedReset 2.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 18.42
Evaluated at bid price : 18.42
Bid-YTW : 4.84 %
MFC.PR.K FixedReset 2.63 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.75
Bid-YTW : 8.68 %
BAM.PR.X FixedReset 2.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 14.02
Evaluated at bid price : 14.02
Bid-YTW : 5.12 %
SLF.PR.E Deemed-Retractible 2.75 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.18
Bid-YTW : 7.49 %
SLF.PR.A Deemed-Retractible 2.76 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.21
Bid-YTW : 7.08 %
FTS.PR.M FixedReset 2.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 18.60
Evaluated at bid price : 18.60
Bid-YTW : 4.79 %
SLF.PR.C Deemed-Retractible 2.90 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.86
Bid-YTW : 7.65 %
BAM.PR.K Floater 2.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 10.35
Evaluated at bid price : 10.35
Bid-YTW : 4.60 %
TRP.PR.G FixedReset 3.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 5.09 %
MFC.PR.I FixedReset 3.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.98
Bid-YTW : 6.93 %
BAM.PR.Z FixedReset 3.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 19.72
Evaluated at bid price : 19.72
Bid-YTW : 5.06 %
MFC.PR.J FixedReset 3.26 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.00
Bid-YTW : 7.31 %
SLF.PR.G FixedReset 3.42 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.50
Bid-YTW : 9.11 %
VNR.PR.A FixedReset 3.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 4.96 %
BMO.PR.T FixedReset 3.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 17.51
Evaluated at bid price : 17.51
Bid-YTW : 4.74 %
PWF.PR.T FixedReset 4.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 20.35
Evaluated at bid price : 20.35
Bid-YTW : 4.18 %
TRP.PR.D FixedReset 4.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 17.35
Evaluated at bid price : 17.35
Bid-YTW : 4.90 %
SLF.PR.I FixedReset 4.44 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.07
Bid-YTW : 7.33 %
MFC.PR.G FixedReset 5.44 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.35
Bid-YTW : 6.64 %
MFC.PR.H FixedReset 6.28 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.67
Bid-YTW : 6.07 %
BMO.PR.Y FixedReset 6.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 20.25
Evaluated at bid price : 20.25
Bid-YTW : 4.61 %
BAM.PR.B Floater 6.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 10.70
Evaluated at bid price : 10.70
Bid-YTW : 4.45 %
Volume Highlights
Issue Index Shares
Traded
Notes
PWF.PR.F Perpetual-Discount 283,400 Nesbitt crossed blocks of 238,000 and 40,000, both at 22.40. Nice tickets!
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 22.01
Evaluated at bid price : 22.25
Bid-YTW : 5.91 %
PWF.PR.O Perpetual-Premium 190,856 Nesbitt crossed 176,700 at 24.36.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 24.03
Evaluated at bid price : 24.33
Bid-YTW : 5.97 %
BAM.PF.A FixedReset 160,376 Scotia crossed two blocks of 50,000 each, both at 18.58, and a block of 40,000 at 18.70.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 18.80
Evaluated at bid price : 18.80
Bid-YTW : 5.21 %
RY.PR.H FixedReset 125,541 Scotia crossed 42,200 at 17.25 and sold 14,100 to RBC at 17.40. RBC bought 11,900 from TD at 17.45.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 17.38
Evaluated at bid price : 17.38
Bid-YTW : 4.80 %
TRP.PR.E FixedReset 118,299 Desjardins crossed 103,400 at 17.85.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 4.93 %
RY.PR.J FixedReset 98,436 Scotia crossed 47,500 at 18.60.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 18.66
Evaluated at bid price : 18.66
Bid-YTW : 4.90 %
There were 67 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
IFC.PR.A FixedReset Quote: 14.65 – 15.98
Spot Rate : 1.3300
Average : 0.7704

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.65
Bid-YTW : 10.18 %

VNR.PR.A FixedReset Quote: 19.00 – 19.92
Spot Rate : 0.9200
Average : 0.5750

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 4.96 %

IAG.PR.G FixedReset Quote: 19.10 – 19.93
Spot Rate : 0.8300
Average : 0.5138

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.10
Bid-YTW : 7.46 %

CU.PR.C FixedReset Quote: 18.74 – 19.50
Spot Rate : 0.7600
Average : 0.4628

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 18.74
Evaluated at bid price : 18.74
Bid-YTW : 4.50 %

PWF.PR.P FixedReset Quote: 14.11 – 14.85
Spot Rate : 0.7400
Average : 0.4857

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-16
Maturity Price : 14.11
Evaluated at bid price : 14.11
Bid-YTW : 4.38 %

GWO.PR.S Deemed-Retractible Quote: 23.29 – 23.95
Spot Rate : 0.6600
Average : 0.4104

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.29
Bid-YTW : 6.31 %

Market Action

October 15, 2015

There are continued dovish expectations regarding the Fed’s next move:

The October rebound in global equities resumed, with U.S. stocks rising to a eight-week high amid bank earnings and growing speculation the Federal Reserve will delay raising interest rates until 2016. Treasuries fell and gold erased its loss for the year.
…
The probability of a Fed interest rate increase by the December policy meeting has dropped to 30 percent, down from 70 percent at the start of August, according to futures data compiled by Bloomberg. The slide worsened even after a gauge of U.S. core consumer prices advanced more than projected in September, while hiring data provided evidence of labor-market resilience.

My old buddy Doug Grieve, of long-time Nesbitt fame, mentioned on June 26 as becoming the manager of Lysander-Slater Preferred Share Dividend Fund, has now also been named as the manager of the Lysander-Slater Preferred Share ActivETF which has the awesome symbol PR.

Husky Energy, proud issuer of HSE.PR.A, HSE.PR.C, HSE.PR.E and HSE.PR.G, was confirmed at Pfd-2(low) by DBRS:

DBRS Limited (DBRS) has today confirmed the Issuer Rating and Senior Unsecured Notes and Debentures rating of Husky Energy Inc. (Husky or the Company) at A (low) as well as its Commercial Paper rating at R-1 (low) and its Preferred Shares – Cumulative rating at Pfd-2 (low), all with Stable trends. DBRS believes that Husky is in a good position to ride the challenging commodity price environment among its domestic peers given (a) Husky’s relatively low leverage; (b) reasonable liquidity and no material long-term debt refinancing risk over the next three years; (c) strong earnings and cash flow contributions from the Liwan Gas Project (Liwan) offshore China and the Company’s downstream business, which are not tied directly to oil prices; and (d) the near completion of the major capital-intensive projects – Liwan and Sunrise Energy (Sunrise) – reducing capital expenditure (capex) commitments going forward. The Stable trend incorporates DBRS’s expectation that key credit metrics will weaken materially in 2015, but will remain above average among DBRS-rated investment-grade peers in Canada; however, a negative rating action could be taken if key credit metrics remain under pressure on a sustained basis.

It was a whole new world for Canadian preferred share investors today!

the-tropical-beach
Click for Big

It was a very good day for the Canadian preferred share market, with PerpetualDiscounts gaining 28bp, FixedResets up 73bp and DeemedRetractibles winning 109bp. FixedResets dominated the nicer side of the Performance Highlights table. Volume was enormous.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_151015
Click for Big

Implied Volatility declined today but remains high.

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 17.24 to be $0.93 rich, while TRP.PR.C, resetting 2016-1-30 at +154, is $0.66 cheap at its bid price of 11.68.

impVol_MFC_151015
Click for Big

Implied Volatility remained at the highest level I am willing to consider today.

Most expensive is MFC.PR.F, resetting at +141bp on 2016-6-19, bid at 14.50 to be 0.91 rich, while MFC.PR.K resetting at +222bp on 2018-9-19, is bid at 16.32 to be 0.66 cheap.

impVol_BAM_151015
Click for Big

The fit on the BAM issues continues to be horrible!

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 14.70 to be $0.90 cheap. BAM.PF.G, resetting at +284bp on 2020-6-30 is bid at 19.30 and appears to be $0.69 rich.

impVol_FTS_151015
Click for Big

Implied Volatility edged down today but remains ridiculously high.

FTS.PR.M, with a spread of +248bp, and bid at 18.09, looks $0.34 expensive and resets 2019-12-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 16.03 and is $0.46 cheap.

pairs_FR_151015A
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.55%, with no outliers after I changed the y-axis limits. The distribution is bimodal, with bank NVCC non-compliant pairs averaging -0.85% and other issues averaging -0.14%. There are two junk outliers above 0.50%.

pairs_FF_151015
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.8932 % 1,570.0
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.8932 % 2,745.1
Floater 4.73 % 4.76 % 63,130 15.95 3 -0.8932 % 1,669.0
OpRet 0.00 % 0.00 % 0 0.00 0 0.2755 % 2,768.5
SplitShare 4.33 % 5.03 % 74,138 2.98 5 0.2755 % 3,244.6
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.2755 % 2,531.5
Perpetual-Premium 6.00 % 6.03 % 63,252 13.89 5 -0.0409 % 2,425.2
Perpetual-Discount 5.80 % 5.90 % 80,199 14.05 33 0.2827 % 2,458.2
FixedReset 5.45 % 4.96 % 197,459 14.88 76 0.7331 % 1,870.2
Deemed-Retractible 5.34 % 5.45 % 102,739 5.45 33 1.0899 % 2,493.6
FloatingReset 2.67 % 4.86 % 67,564 5.81 9 -0.0407 % 2,035.1
Performance Highlights
Issue Index Change Notes
FTS.PR.J Perpetual-Discount -2.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-15
Maturity Price : 20.31
Evaluated at bid price : 20.31
Bid-YTW : 5.94 %
RY.PR.Z FixedReset -1.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-15
Maturity Price : 17.11
Evaluated at bid price : 17.11
Bid-YTW : 4.83 %
HSE.PR.C FixedReset -1.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-15
Maturity Price : 20.77
Evaluated at bid price : 20.77
Bid-YTW : 5.00 %
BMO.PR.Q FixedReset -1.55 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.11
Bid-YTW : 7.11 %
BAM.PR.C Floater -1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-15
Maturity Price : 9.90
Evaluated at bid price : 9.90
Bid-YTW : 4.81 %
BNS.PR.D FloatingReset -1.46 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.23
Bid-YTW : 6.68 %
RY.PR.H FixedReset -1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-15
Maturity Price : 17.04
Evaluated at bid price : 17.04
Bid-YTW : 4.90 %
RY.PR.C Deemed-Retractible 1.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.61
Bid-YTW : 5.04 %
MFC.PR.C Deemed-Retractible 1.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.51
Bid-YTW : 7.98 %
RY.PR.E Deemed-Retractible 1.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.62
Bid-YTW : 4.93 %
BMO.PR.Y FixedReset 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-15
Maturity Price : 19.03
Evaluated at bid price : 19.03
Bid-YTW : 4.91 %
CU.PR.F Perpetual-Discount 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-15
Maturity Price : 19.82
Evaluated at bid price : 19.82
Bid-YTW : 5.76 %
W.PR.J Perpetual-Discount 1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-15
Maturity Price : 23.10
Evaluated at bid price : 23.36
Bid-YTW : 6.02 %
SLF.PR.J FloatingReset 1.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.30
Bid-YTW : 9.52 %
BAM.PF.B FixedReset 1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-15
Maturity Price : 17.40
Evaluated at bid price : 17.40
Bid-YTW : 5.28 %
CM.PR.O FixedReset 1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-15
Maturity Price : 17.31
Evaluated at bid price : 17.31
Bid-YTW : 4.84 %
PWF.PR.K Perpetual-Discount 1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-15
Maturity Price : 21.25
Evaluated at bid price : 21.52
Bid-YTW : 5.76 %
MFC.PR.I FixedReset 1.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.39
Bid-YTW : 7.34 %
BAM.PF.E FixedReset 1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-15
Maturity Price : 17.21
Evaluated at bid price : 17.21
Bid-YTW : 5.39 %
RY.PR.I FixedReset 1.31 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.15
Bid-YTW : 4.68 %
SLF.PR.B Deemed-Retractible 1.32 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.70
Bid-YTW : 7.47 %
BAM.PR.N Perpetual-Discount 1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-15
Maturity Price : 20.20
Evaluated at bid price : 20.20
Bid-YTW : 5.94 %
MFC.PR.M FixedReset 1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.17
Bid-YTW : 8.63 %
TD.PF.C FixedReset 1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-15
Maturity Price : 16.94
Evaluated at bid price : 16.94
Bid-YTW : 4.82 %
TD.PF.B FixedReset 1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-15
Maturity Price : 17.12
Evaluated at bid price : 17.12
Bid-YTW : 4.79 %
GWO.PR.P Deemed-Retractible 1.49 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.20
Bid-YTW : 6.52 %
CM.PR.P FixedReset 1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-15
Maturity Price : 16.90
Evaluated at bid price : 16.90
Bid-YTW : 4.84 %
RY.PR.B Deemed-Retractible 1.52 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.75
Bid-YTW : 5.04 %
SLF.PR.E Deemed-Retractible 1.60 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.64
Bid-YTW : 7.87 %
FTS.PR.M FixedReset 1.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-15
Maturity Price : 18.09
Evaluated at bid price : 18.09
Bid-YTW : 4.93 %
IAG.PR.G FixedReset 1.88 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.95
Bid-YTW : 7.57 %
TRP.PR.B FixedReset 1.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-15
Maturity Price : 11.20
Evaluated at bid price : 11.20
Bid-YTW : 4.82 %
SLF.PR.A Deemed-Retractible 1.93 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.64
Bid-YTW : 7.46 %
VNR.PR.A FixedReset 1.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-15
Maturity Price : 18.30
Evaluated at bid price : 18.30
Bid-YTW : 5.15 %
CU.PR.C FixedReset 2.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-15
Maturity Price : 18.40
Evaluated at bid price : 18.40
Bid-YTW : 4.58 %
W.PR.H Perpetual-Discount 2.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-15
Maturity Price : 22.89
Evaluated at bid price : 23.16
Bid-YTW : 5.97 %
MFC.PR.L FixedReset 2.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.20
Bid-YTW : 9.25 %
SLF.PR.D Deemed-Retractible 2.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.55
Bid-YTW : 7.87 %
SLF.PR.I FixedReset 2.41 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.26
Bid-YTW : 7.93 %
SLF.PR.H FixedReset 2.42 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.10
Bid-YTW : 8.90 %
GWO.PR.H Deemed-Retractible 2.50 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.30
Bid-YTW : 7.13 %
MFC.PR.K FixedReset 2.90 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.32
Bid-YTW : 9.04 %
MFC.PR.B Deemed-Retractible 2.95 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.25
Bid-YTW : 7.64 %
TRP.PR.G FixedReset 2.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-15
Maturity Price : 18.44
Evaluated at bid price : 18.44
Bid-YTW : 5.25 %
TRP.PR.C FixedReset 3.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-15
Maturity Price : 11.68
Evaluated at bid price : 11.68
Bid-YTW : 5.17 %
TRP.PR.D FixedReset 3.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-15
Maturity Price : 16.62
Evaluated at bid price : 16.62
Bid-YTW : 5.12 %
BAM.PR.Z FixedReset 3.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-15
Maturity Price : 19.13
Evaluated at bid price : 19.13
Bid-YTW : 5.22 %
TRP.PR.E FixedReset 4.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-15
Maturity Price : 17.24
Evaluated at bid price : 17.24
Bid-YTW : 5.01 %
PWF.PR.P FixedReset 4.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-15
Maturity Price : 14.10
Evaluated at bid price : 14.10
Bid-YTW : 4.39 %
PWF.PR.T FixedReset 6.27 % Quite real! It looks like a buy programme commenced at 2pm on the dot as the issue traded 18,033 shares in a range of 18.50-19.70. All but one of the last 25 trades were for 100 shares; all of them listed RBC as the buyer.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-15
Maturity Price : 19.50
Evaluated at bid price : 19.50
Bid-YTW : 4.37 %
HSB.PR.C Deemed-Retractible 7.91 % Simply reverses most – but not quite all! – of yesterday‘s nonsense.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.69
Bid-YTW : 5.41 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.J FixedReset 179,867 RBC crossed blocks of 47,300 and 50,300, both at 18.15. Desjardins crossed 32,800 at 18.20.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-15
Maturity Price : 18.35
Evaluated at bid price : 18.35
Bid-YTW : 4.98 %
CM.PR.O FixedReset 127,586 RBC crossed blocks of 50,000 and 24,600, both at 17.04.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-15
Maturity Price : 17.31
Evaluated at bid price : 17.31
Bid-YTW : 4.84 %
SLF.PR.I FixedReset 120,680 Desjardins crossed 81,100 at 17.95.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.26
Bid-YTW : 7.93 %
RY.PR.M FixedReset 109,938 RBC crossed 91,800 at 17.80.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-15
Maturity Price : 17.95
Evaluated at bid price : 17.95
Bid-YTW : 4.97 %
RY.PR.H FixedReset 104,375 RBC crossed 10,000 at 17.05. Nesbitt crossed blocks of 16,900 and 37,700 at the same price.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-15
Maturity Price : 17.04
Evaluated at bid price : 17.04
Bid-YTW : 4.90 %
CM.PR.P FixedReset 99,424 Nesbitt crossed 30,000 1 16.60; Scotia crossed 36,200 at 16.58.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-15
Maturity Price : 16.90
Evaluated at bid price : 16.90
Bid-YTW : 4.84 %
There were 70 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BNS.PR.Q FixedReset Quote: 22.72 – 23.67
Spot Rate : 0.9500
Average : 0.5547

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.72
Bid-YTW : 4.78 %

SLF.PR.G FixedReset Quote: 14.02 – 15.00
Spot Rate : 0.9800
Average : 0.5874

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.02
Bid-YTW : 9.55 %

IFC.PR.C FixedReset Quote: 17.65 – 18.49
Spot Rate : 0.8400
Average : 0.5483

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.65
Bid-YTW : 8.25 %

FTS.PR.M FixedReset Quote: 18.09 – 18.79
Spot Rate : 0.7000
Average : 0.4495

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-15
Maturity Price : 18.09
Evaluated at bid price : 18.09
Bid-YTW : 4.93 %

FTS.PR.J Perpetual-Discount Quote: 20.31 – 20.86
Spot Rate : 0.5500
Average : 0.3995

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-15
Maturity Price : 20.31
Evaluated at bid price : 20.31
Bid-YTW : 5.94 %

BAM.PR.M Perpetual-Discount Quote: 19.85 – 20.18
Spot Rate : 0.3300
Average : 0.2251

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-15
Maturity Price : 19.85
Evaluated at bid price : 19.85
Bid-YTW : 6.05 %

Market Action

October 14, 2015

There was an extremely benign inflation indicator in the States today:

Wholesale prices in the U.S. declined in September by the most since the start of the year as costs fell for gasoline, food and brokerage services.

The 0.5 percent decrease in the producer-price index was the biggest since January and followed no change in August, Labor Department figures showed Wednesday. The median forecast of economists surveyed by Bloomberg called for a 0.2 percent drop. Costs were down 1.1 percent over the past 12 months.
…
Energy expenses decreased 5.9 percent in September, the most since January, after falling 3.3 percent the month before. Food prices dropped 0.8 percent after a 0.3 percent gain. The costs of eggs slumped, while beef and veal prices plunged 7.9 percent, the most since January 2004.

Wholesale prices excluding these two components unexpectedly declined 0.3 percent. The median forecast in the Bloomberg survey called for a 0.1 percent gain. Those costs were up 0.8 percent from September 2014.

Goods prices, which have fallen for three straight months, slumped 1.2 percent in September. The costs of services dropped

0.4 percent, the most since February. More than a quarter of that decrease was due to slumping costs for securities brokerage, dealing and investment advice, the Labor Department said.

After eliminating food, energy and trade services to arrive at a reading that some economists prefer because it excludes one of the report’s most volatile components, wholesale costs also decreased 0.3 percent in September. That was the biggest decline since records began in 2013

“slumping costs for … investment advice”??? This isn’t a slow-down! This is a DEPRESSION!

And retail sales were sluggish:

Consumers in the U.S. tempered purchases at retailers in September, pocketing the savings from lower fuel costs and making for a weak finish to the third quarter.

The 0.1 percent gain followed little change in the prior month that was weaker than previously reported, Commerce Department figures showed Wednesday in Washington. The median forecast of 82 economists surveyed by Bloomberg called for a 0.2 percent advance. More than half of merchant categories showed decreases.

Sluggish sales may raise concern about the staying power of consumer spending, which accounts for about 70 percent of the economy, at a time overseas demand is also cooling. While job gains and cheap fuel may help to underpin purchases, a pickup in wages remains elusive as Federal Reserve policy makers are weighing whether to raise interest rates this year.

Naturally, this led the market to believe that maybe a rate hike isn’t imminent:

First Treasuries traders were banking on September for the Federal Reserve to raise interest rates. Then they turned their focus to December. Now even March is looking like a toss-up.

The drumbeat of weaker-than-forecast global economic data continued Wednesday as September U.S. retail sales fell short of analysts’ expectations. The report came after Fed Governor Daniel Tarullo, who votes on rate decisions, said Tuesday that he doesn’t currently favor an increase in 2015, even though Chair Janet Yellen has said a move would be warranted.

Traders’ bets that the Fed will lift its benchmark by year-end have dropped to less than a one-in-three chance, and aren’t much higher for January. For March, the probability has tumbled to about 50 percent, from 65 percent a month ago. The calculation is based on the assumption that the effective fed funds rate will average 0.375 percent after the first increase.

The uncertainty may be exacerbated by a disagreement regarding a basic tenet of economics:

On Monday, Governor Lael Brainard said that global risks warranted a more cautious stance from the central bank. The next day, fellow Governor Daniel Tarullo indicated that he expects it will be appropriate to keep rates on hold through year end.

The details of their dovish commentary are much more noteworthy, as both appear to disagree with Yellen’s description of what the Fed’s reaction mechanism ought to be.

At the heart of the matter is the extent to which the progress made in achieving one part of the central bank’s mandate (full employment) portends improvement in the other part (price stability, defined as an annual inflation rate of 2 percent).

The relationship between unemployment and inflation is typically understood in terms of the Phillips Curve, which holds that there is an inverse relationship between inflation and unemployment.

Yellen’s previous remarks suggest she thinks a firming labor market will indeed lead to higher levels of inflation.
…
The governors are much more skeptical.

“I do think under these circumstances it’s probably wise not to be counting so much on past correlations—things like the Phillips Curve, which really haven’t been operating very effectively for 10 years now—and instead to really look for some tangible evidence of, for example, pickups in wages or inflation that allow us to make informed decisions based on the evidence,” Tarullo said in an interview with CNBC.

Brainard issued what appeared to be an even more direct rebuttal.

“To be clear, I do not view the improvement in the labor market as a sufficient statistic for judging the outlook for inflation,” she said. “A variety of econometric estimates would suggest that the classic Phillips curve influence of resource utilization on inflation is, at best, very weak at the moment.”

Silver Bullion Trust has fired another round in its battle with Sprott (bolding from original):

Bruce Heagle, Chair of the Special Committee of the Board of Trustees of SBT stated: “Sprott’s recent claims of an “increased offer” are illusory; in reality, nothing has changed. Their supposed “premium consideration” of $0.025 per Unit is immaterial; it represents less than 0.3% of the current value of an SBT Unit, and would be more than offset by the higher annual management fees charged by Sprott. Sprott continues to offer no meaningful premium, would charge significantly higher management fees, strip Unitholders of virtually all their governance rights and expose certain U.S. Unitholders to higher tax risk. Rejecting Sprott’s self-serving, inadequate offer and retaining your SBT Units, characterized by an industry-leading expense ratio, superior bullion security and safeguards, and a sound, tax efficient structure, is the clear choice for long-term bullion investors.”

I’ll be very disappointed when the whole thing is resolved!

Element Financial, whose preferreds were recent added to the HIMIPref™ database, is shifting strategic priorities:

Element Financial Corporation (TSX:EFN) (“Element” or the “Company”), today announced that it has initiated a series of steps that will accelerate the transformation of the Company into North America’s leading fleet management and services enterprise with complementary commercial finance operations. Specifically, the Company has initiated a process to harvest capital from its Canadian commercial & vendor (“C&V”) operations for reinvestment in both organic growth and acquisition opportunities in its core fleet management business. These opportunities include the acquisition of existing fleet management businesses and portfolios as well as fleet services companies that have the potential to drive incremental service fee income for the Company. Concurrently, the Company will optimize the scale and focus of its non-fleet businesses to complement its core fleet management operations.

Some old research done for Parliament illustrates effective marginal tax rates for low income earners:

The “welfare wall” refers to the disincentives to work created by interaction between the system of social assistance and personal income taxation in Canada. Canadians who receive social assistance and subsequently accept low-paying employment face a series of consequences that could potentially make them worse off, including: higher income and payroll taxes; new work-related expenses such as transportation, clothing and childcare; reduced income support in the form of social assistance and income-tested refundable tax credits; and loss of in-kind benefits such as subsidized housing and prescription drugs.

This welfare wall can be demonstrated by estimating an individual’s effective marginal tax rate; that is, the costs associated with the next dollar of earned income. Figure 1 shows that, under the current system of social assistance and taxation in Canada, a single parent with one child who increases his/her earnings from $0 to $10,000 would lose an estimated 78 cents of every additional dollar earned. By comparison, an increase in earnings from $40,000 to $50,000 has an effective marginal tax rate of 41%.

The effective marginal tax rate of 78% on the FIRST $10,000 of earnings is, of course, ridiculous and points out the absurdity of things like the coming Toronto proposal for income-based pricing of bus passes, discussed yesterday, which will only increase the effective marginal rate by withdrawing subsidies as income increases. One suggestion that has some solid thinking behind it is for substantial refundable tax credits to replace social programmes:

The current tax system contains more than $80-billion of tax credits which are non-refundable, which means that low-income Canadians who do not have sufficient taxes owing cannot benefit from them in the same fashion as higher-income taxpayers. While tax filers will be most familiar with the basic personal amount at the top of Schedule 1 of the federal income tax form, other credits for age, eligible dependents, employment and education are also important.

Our recent research paper evaluates the effect of converting these non-refundable credits to refundable credits in the fashion of existing credits such as the Goods and Services Tax Credit and the Working Income Tax Credit and the recently replaced National Child Benefit. A refundable credit simply converts any excess between the credit and taxes owing to a refundable benefit, allowing low-income tax filers to realize the benefits of these tax credits that already accrue to higher-income tax filers.

The paper, titled THE IMPACT OF CONVERTING FEDERAL NON-REFUNDABLE TAX CREDITS INTO REFUNDABLE CREDITS by Wayne Simpson and Harvey Stevens is summarized:

With economic inequality on the rise in Canada, the federal government needs to consider innovative solutions. One possibility for improving the tax-transfer system involves refundable tax credits (RTCs). Making all tax credits refundable wouldn’t require Ottawa to introduce new tax measures; the Canadian tax system already contains a mix of RTCs and NRTCs, so the government could simply continue its practice of designing tax credit programs to be refundable.

Using Statistics Canada’s Social Policy Simulation Database and Model, this paper examines the impacts and cost of converting NRTCs to RTCs, with and without an income exemption equal to 25 percent of the before-tax low-income standard for a census family, the Census Family Low-Income Line.

Under the Option Without Exemption (OW/OE), RTC recipients are taxed at a single rate of 15 percent, regardless of family size, right up to the Line. Under the Option With Exemption (OWE), RTC recipients are taxed at zero percent up to 25 percent of the Line and at a single rate of 20 percent, regardless of family size, up to 100 percent of the Line.

The incremental cost of switching NRTCs to RTCs under the OW/OE is $6.6 billion, as additional benefits are provided to 6.4 million families — slightly less than 37 percent of all families. The cost of the OWE is $7.2 billion, as benefits flow to slightly more families — 6.45 million. However, the percentage of benefits reaching low-income families is much higher under the OWE (69 percent vs. 49 percent). Additionally, the OWE provides an average of nine percent more RTC benefits to low-income tax filers, making it clearly the superior option for poverty reduction. Moreover, the paper shows that alternative conversion schemes that set benefit reduction rates to differ by family size can further increase the benefits to low-income families at a lower overall cost.

Such changes would elicit a labour-supply response in terms of a reduction in hours worked, and while the effect is smaller under the less expensive OW/OE, the difference between the two options is slight.

This paper simulates the conversion of NRTCs to RTCs in comprehensive detail, besides providing practical advice on how such a shift would be funded. It offers valuable food for thought on an issue that is increasingly critical to Canadian society.

“Trigger warnings” have become a popular bone of contention at universities and I’ve decided to experiment with their use myself. So, before you proceed to read about the day’s market action:

exploding-head
Click for Big

It was yet another crummy day for the Canadian preferred share market, with PerpetualDiscounts and FixedResets both down 59bp and DeemedRetractibles losing 80bp. The Performance Highlights table is … well, you know. It’s the Performance Highlights table. It highlights performance. Of particular interest today though, what the amount of churn; some issues did really, really well! Volume was very extremely awfully high – this is like tax-loss selling season! And perhaps it is!

PerpetualDiscounts now yield 5.90%, equivalent to 7.67% interest at the standard equivalency factor of 1.3x. Long corporates now yield about 4.25%, so the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) is now about 340bp, a number I didn’t really expect to see ever again, a significant widening from the 330bp reported October 7.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_151014
Click for Big

Implied Volatility declined today with the normalization of the bid on TRP.PR.D, but remained ridiculously high.

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 16.50 to be $0.63 rich, while TRP.PR.C, resetting 2016-1-30 at +154, is $0.75 cheap at its bid price of 11.33.

impVol_MFC_151014A
Click for Big

Implied Volatility shot upwards today, propelled by excellent relative performance of MFC.PR.F, which is featured on the Performance Highlights table.

Most expensive is MFC.PR.F, resetting at +141bp on 2016-6-19, bid at 14.40 to be 1.04 rich, while MFC.PR.K resetting at +222bp on 2018-9-19, is bid at 15.86 to be 0.96 cheap.

impVol_BAM_151014
Click for Big

The fit on the BAM issues continues to be horrible!

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 14.60 to be $0.90 cheap. BAM.PF.G, resetting at +284bp on 2020-6-30 is bid at 19.19 and appears to be $0.86 rich.

impVol_FTS_151014
Click for Big

Implied Volatility edged up again today to the maximum level I am willing to discuss.

FTS.PR.H, with a spread of +145bp, and bid at 13.70, looks $0.16 expensive and resets 2020-6-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 16.01 and is $0.42 cheap.

pairs_FR_151014A
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.51%, with two outliers above 0.00% and none below -2.00%. The distribution is bimodal, with bank NVCC non-compliant pairs averaging -0.82% and other issues averaging -0.07%. There are three junk outliers above 0.00%.

pairs_FF_151014
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.3297 % 1,584.2
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.3297 % 2,769.8
Floater 4.69 % 4.72 % 63,238 16.02 3 -0.3297 % 1,684.1
OpRet 0.00 % 0.00 % 0 0.00 0 0.2274 % 2,760.9
SplitShare 4.34 % 5.21 % 74,179 2.99 5 0.2274 % 3,235.6
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.2274 % 2,524.6
Perpetual-Premium 6.00 % 6.04 % 61,757 13.87 5 -0.1552 % 2,426.2
Perpetual-Discount 5.81 % 5.90 % 80,200 14.06 33 -0.5894 % 2,451.3
FixedReset 5.49 % 4.97 % 197,178 14.78 76 -0.5931 % 1,856.6
Deemed-Retractible 5.40 % 6.16 % 103,151 5.45 33 -0.7991 % 2,466.7
FloatingReset 2.67 % 4.94 % 68,311 5.81 9 -0.5949 % 2,035.9
Performance Highlights
Issue Index Change Notes
HSB.PR.C Deemed-Retractible -7.44 % Not real. The issue traded a whopping 511 shares today in a range of 24.51-71. The five trades (four of which were timestamped on and after 3:58) so exhausted the market maker that the issue closed at 22.88-24.72 (!). I have not checked whether this lamentable state of affairs is due to inadequate Toronto Stock Exchange reporting or inadequate Toronto Stock Exchange supervision of market-makers.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.88
Bid-YTW : 6.86 %
TRP.PR.A FixedReset -4.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 14.15
Evaluated at bid price : 14.15
Bid-YTW : 5.17 %
BAM.PR.X FixedReset -3.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 13.52
Evaluated at bid price : 13.52
Bid-YTW : 5.31 %
BNS.PR.Q FixedReset -3.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.60
Bid-YTW : 4.88 %
RY.PR.H FixedReset -2.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 17.23
Evaluated at bid price : 17.23
Bid-YTW : 4.84 %
MFC.PR.N FixedReset -2.78 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.77
Bid-YTW : 8.87 %
PWF.PR.T FixedReset -2.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 18.35
Evaluated at bid price : 18.35
Bid-YTW : 4.65 %
IFC.PR.A FixedReset -2.53 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.65
Bid-YTW : 10.17 %
TRP.PR.F FloatingReset -2.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 12.51
Evaluated at bid price : 12.51
Bid-YTW : 4.65 %
BNS.PR.R FixedReset -2.32 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.15
Bid-YTW : 4.70 %
BAM.PR.R FixedReset -2.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 14.60
Evaluated at bid price : 14.60
Bid-YTW : 5.60 %
BAM.PR.T FixedReset -2.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 15.30
Evaluated at bid price : 15.30
Bid-YTW : 5.44 %
BMO.PR.T FixedReset -2.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 16.85
Evaluated at bid price : 16.85
Bid-YTW : 4.93 %
PWF.PR.P FixedReset -2.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 13.48
Evaluated at bid price : 13.48
Bid-YTW : 4.59 %
RY.PR.Z FixedReset -2.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 17.45
Evaluated at bid price : 17.45
Bid-YTW : 4.74 %
BNS.PR.P FixedReset -1.82 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.20
Bid-YTW : 4.41 %
FTS.PR.K FixedReset -1.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 16.21
Evaluated at bid price : 16.21
Bid-YTW : 4.87 %
BMO.PR.S FixedReset -1.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 17.69
Evaluated at bid price : 17.69
Bid-YTW : 4.81 %
W.PR.H Perpetual-Discount -1.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 22.44
Evaluated at bid price : 22.70
Bid-YTW : 6.09 %
GWO.PR.Q Deemed-Retractible -1.68 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.19
Bid-YTW : 6.88 %
TD.PF.B FixedReset -1.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 16.87
Evaluated at bid price : 16.87
Bid-YTW : 4.86 %
TD.PF.A FixedReset -1.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 16.94
Evaluated at bid price : 16.94
Bid-YTW : 4.85 %
CM.PR.O FixedReset -1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 17.11
Evaluated at bid price : 17.11
Bid-YTW : 4.89 %
CU.PR.E Perpetual-Discount -1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 21.02
Evaluated at bid price : 21.02
Bid-YTW : 5.92 %
BMO.PR.W FixedReset -1.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 16.65
Evaluated at bid price : 16.65
Bid-YTW : 4.95 %
BIP.PR.A FixedReset -1.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 19.30
Evaluated at bid price : 19.30
Bid-YTW : 5.81 %
SLF.PR.I FixedReset -1.49 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.83
Bid-YTW : 8.25 %
CU.PR.G Perpetual-Discount -1.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 19.62
Evaluated at bid price : 19.62
Bid-YTW : 5.82 %
FTS.PR.M FixedReset -1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 17.80
Evaluated at bid price : 17.80
Bid-YTW : 5.01 %
CU.PR.F Perpetual-Discount -1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 19.60
Evaluated at bid price : 19.60
Bid-YTW : 5.83 %
TRP.PR.C FixedReset -1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 11.33
Evaluated at bid price : 11.33
Bid-YTW : 5.33 %
BAM.PF.E FixedReset -1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 5.46 %
TRP.PR.B FixedReset -1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 10.99
Evaluated at bid price : 10.99
Bid-YTW : 4.92 %
BAM.PR.Z FixedReset -1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 18.51
Evaluated at bid price : 18.51
Bid-YTW : 5.40 %
TD.PF.D FixedReset -1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 18.55
Evaluated at bid price : 18.55
Bid-YTW : 4.92 %
GWO.PR.H Deemed-Retractible -1.33 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.78
Bid-YTW : 7.47 %
GWO.PR.P Deemed-Retractible -1.30 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.86
Bid-YTW : 6.73 %
IFC.PR.C FixedReset -1.28 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.79
Bid-YTW : 8.14 %
MFC.PR.C Deemed-Retractible -1.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.30
Bid-YTW : 8.13 %
CU.PR.C FixedReset -1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 18.04
Evaluated at bid price : 18.04
Bid-YTW : 4.67 %
SLF.PR.D Deemed-Retractible -1.19 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.10
Bid-YTW : 8.20 %
MFC.PR.I FixedReset -1.19 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.16
Bid-YTW : 7.50 %
POW.PR.B Perpetual-Discount -1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 22.33
Evaluated at bid price : 22.60
Bid-YTW : 5.95 %
GWO.PR.M Deemed-Retractible -1.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.51
Bid-YTW : 6.16 %
SLF.PR.J FloatingReset -1.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.15
Bid-YTW : 9.66 %
SLF.PR.E Deemed-Retractible -1.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.33
Bid-YTW : 8.09 %
TD.PF.F Perpetual-Discount -1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 21.71
Evaluated at bid price : 22.00
Bid-YTW : 5.57 %
MFC.PR.B Deemed-Retractible -1.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.67
Bid-YTW : 8.05 %
BAM.PR.M Perpetual-Discount -1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 19.82
Evaluated at bid price : 19.82
Bid-YTW : 6.05 %
SLF.PR.C Deemed-Retractible -1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.15
Bid-YTW : 8.16 %
BNS.PR.B FloatingReset -1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.08
Bid-YTW : 4.94 %
MFC.PR.J FixedReset 1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.45
Bid-YTW : 7.71 %
VNR.PR.A FixedReset 1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 17.95
Evaluated at bid price : 17.95
Bid-YTW : 5.25 %
TRP.PR.G FixedReset 1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 17.91
Evaluated at bid price : 17.91
Bid-YTW : 5.40 %
HSE.PR.E FixedReset 1.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 22.16
Evaluated at bid price : 22.75
Bid-YTW : 4.89 %
TRP.PR.D FixedReset 1.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 16.10
Evaluated at bid price : 16.10
Bid-YTW : 5.28 %
MFC.PR.H FixedReset 1.99 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.46
Bid-YTW : 6.85 %
GWO.PR.N FixedReset 3.69 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.76
Bid-YTW : 9.72 %
RY.PR.I FixedReset 4.77 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.85
Bid-YTW : 4.91 %
MFC.PR.F FixedReset 5.19 % Wow! The issue traded 26,035 shares in a range of 13.37-14.69 and closed at 14.40-69, 218×30. It caught an enormous bid after about 2:30pm.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.40
Bid-YTW : 9.44 %
Volume Highlights
Issue Index Shares
Traded
Notes
BAM.PR.N Perpetual-Discount 111,699 RBC crossed 104,800 at 19.90.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 19.93
Evaluated at bid price : 19.93
Bid-YTW : 6.02 %
RY.PR.J FixedReset 99,357 RBC crossed blocks of 14,800 shares, 32,400 and 25,000, all at 18.15.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 18.24
Evaluated at bid price : 18.24
Bid-YTW : 5.01 %
RY.PR.M FixedReset 87,709 Anonymous crossed 10,900 at 18.20; RBC crossed 52,400 at 17.85.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 17.90
Evaluated at bid price : 17.90
Bid-YTW : 4.98 %
GWO.PR.N FixedReset 66,416 Scotia crossed 21,100 at 13.55.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.76
Bid-YTW : 9.72 %
TD.PF.D FixedReset 65,381 Desjardins crossed 40,000 at 18.68.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 18.55
Evaluated at bid price : 18.55
Bid-YTW : 4.92 %
MFC.PR.H FixedReset 57,353 Nesbitt crossed 48,200 at 20.33.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.46
Bid-YTW : 6.85 %
There were 70 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
HSB.PR.C Deemed-Retractible Quote: 22.88 – 24.72
Spot Rate : 1.8400
Average : 1.0510

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.88
Bid-YTW : 6.86 %

TRP.PR.E FixedReset Quote: 16.50 – 17.95
Spot Rate : 1.4500
Average : 0.9180

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 16.50
Evaluated at bid price : 16.50
Bid-YTW : 5.24 %

MFC.PR.K FixedReset Quote: 15.86 – 16.60
Spot Rate : 0.7400
Average : 0.5186

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.86
Bid-YTW : 9.43 %

W.PR.J Perpetual-Discount Quote: 23.10 – 23.70
Spot Rate : 0.6000
Average : 0.3896

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 22.82
Evaluated at bid price : 23.10
Bid-YTW : 6.09 %

POW.PR.G Perpetual-Discount Quote: 23.50 – 24.19
Spot Rate : 0.6900
Average : 0.4919

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-14
Maturity Price : 23.12
Evaluated at bid price : 23.50
Bid-YTW : 5.98 %

TD.PR.S FixedReset Quote: 23.00 – 23.49
Spot Rate : 0.4900
Average : 0.3163

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.00
Bid-YTW : 4.34 %

Market Action

October 13, 2015

Singapore is being affected by low growth in Asia:

Singapore’s central bank eased monetary policy for the second time this year as the economy narrowly avoided a technical recession, saying weakening prospects for global growth will pose “headwinds” in the coming months.

The Monetary Authority of Singapore, which uses the currency rather than interest rates as its main policy tool, said Wednesday it will reduce “slightly” the pace of appreciation in the local dollar versus those of its trading partners. Gross domestic product unexpectedly rose an annualized 0.1 percent in the three months through September from the previous quarter, when it shrank a revised 2.5 percent, the trade ministry said in a separate statement.

“The Singapore economy is projected to expand at a modest pace in 2015 and 2016, with growth slightly weaker than earlier envisaged,” the central bank said. “The subdued global growth will exert a drag on the external-oriented sectors in Singapore in the quarters ahead.”

On a brighter note, today we learned what millennials do at the office all day, which has heretofore been very mysterious:

Last year, Playboy.com cleaned up its website to make it “safe for work,” and has since seen its monthly unique Web visitors rise fivefold. The median age of those visitors dropped to 30 years-old from 47 as a result — “an attractive demographic for advertisers,” the company said.

Of all the do-gooder strategies ever devised, there has never been anything as cruel as income-geared pricing. This mechanism traps the poor inextricably in their circumstances, since any incremental improvements they can make to income – by getting a slightly better job, or by working slightly more hours – will immediately be taxed away by reduction of benefits. So, naturally, guess what Toronto City Council is plotting?

As the TTC board contemplates another New Year’s fare increase — the seventh in as many years — there’s growing concern that the rising cost of transportation is eating through the empty pockets of its neediest riders at a disproportionate rate.

Many cities offer an income-based concession pass. Is it time for Toronto to do the same?

Still, it was nice to see Canadian preferred share investors waving the flag today:

whiteFlag
Click for Big

It was a hideous day for the Canadian preferred share market, with PerpetualDiscounts off 27bp, FixedResets losing a stunning 186bp and DeemedRetractibles down 31bp. An extraordinarily long Performance Highlights table is dominated by losing FixedResets, as might be expected. Volume was extremely high.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_151013
Click for Big

Implied Volatility remained ridiculous.

TRP.PR.A, which resets 2019-12-31 at +192, is bid at 14.83 to be $0.52 rich, while TRP.PR.D, resetting 2019-4-30 at +238, is $0.61 cheap at its bid price of 15.86.

impVol_MFC_151013
Click for Big

Implied Volatility re-established itself at higher levels today following the precipitous decline on Friday.

Most expensive is MFC.PR.F, resetting at +141bp on 2016-6-19, bid at 13.69 to be 0.59 rich, while MFC.PR.K resetting at +222bp on 2018-9-19, is bid at 16.01 to be 0.74 cheap.

impVol_BAM_151013
Click for Big

The fit on the BAM issues continues to be horrible!

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 14.92 to be $0.82 cheap. BAM.PF.G, resetting at +284bp on 2020-6-30 is bid at 19.01 and appears to be $0.69 rich.

impVol_FTS_151013
Click for Big

Implied Volatility edged up again today and is ridiculously high.

FTS.PR.K, with a spread of +205bp, and bid at 16.51, looks $0.23 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 16.16 and is $0.46 cheap.

pairs_FR_151013
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.58%, with four outliers above 0.00% and none below -2.00%. The distribution is bimodal, with bank NVCC non-compliant pairs averaging -0.90% and other issues averaging -0.13%. There are three junk outliers above 0.00%.

pairs_FF_151013
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.3640 % 1,589.4
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.3640 % 2,779.0
Floater 4.67 % 4.72 % 63,636 16.03 3 0.3640 % 1,689.6
OpRet 0.00 % 0.00 % 0 0.00 0 -0.3399 % 2,754.7
SplitShare 4.35 % 5.28 % 73,962 2.99 5 -0.3399 % 3,228.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.3399 % 2,518.8
Perpetual-Premium 5.99 % 6.03 % 59,538 13.89 5 -0.7537 % 2,430.0
Perpetual-Discount 5.78 % 5.84 % 79,185 14.12 33 -0.2720 % 2,465.8
FixedReset 5.46 % 4.97 % 195,954 14.70 76 -1.8643 % 1,867.7
Deemed-Retractible 5.36 % 5.38 % 102,075 5.46 33 -0.3074 % 2,486.6
FloatingReset 2.66 % 4.76 % 65,454 5.82 9 0.0867 % 2,048.1
Performance Highlights
Issue Index Change Notes
RY.PR.I FixedReset -6.19 % Not real. The issue traded 6,499 shares today in a range of 23.10-42 before closing at 21.81-23.42 (!). There were three trades in the last ten minutes at 23.10, totalling 2,500 shares. I have not checked whether this lamentable state of affairs is due to inadequate Toronto Stock Exchange reporting or inadequate Toronto Stock Exchange supervision of market-makers.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.81
Bid-YTW : 5.76 %
MFC.PR.H FixedReset -6.17 % Real enough! The issue traded 10,477 shares in a range of 20.01-21.68 before closing at 20.06-25. There were eleven trades in the market’s last hour, totalling 3,040 shares, in a range of 20.23-26.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.06
Bid-YTW : 7.12 %
MFC.PR.M FixedReset -5.52 % Reasonably real. The issue traded 17,011 shares today in a range of 17.26-10 before closing at 17.11-42. There were seven trades in the last ten minutes, totalling 1,300 shares, in a range of 17.26-47.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.11
Bid-YTW : 8.67 %
GWO.PR.N FixedReset -5.21 % Real! The issue traded 92,216 shares in a range of 13.30-93 before closing at 13.27-30. It looks like the market just ran of bids … there were at least eighteen trades totalling 38,800 shares timestamped between 3:35 and 3:43, then there was a pause, then seven trades totalling 2,200 shares timestamped at 3:58-3:59 in a range of 13.30-48.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.27
Bid-YTW : 10.20 %
TD.PF.C FixedReset -5.03 % Real enough! The issue traded 21,902 shares in a range of 16.55-50 before closing at 16.63-94. There were 7 trades in the last six minutes, five of them totalling 933 shares at or below 16.62, two of them totalling 200 shares at or above 16.94. On a more reasonable day for the market I would fault the market-maker for allowing a spread of almost 2%, but on a day like this … I’ll give him a pass.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 16.63
Evaluated at bid price : 16.63
Bid-YTW : 4.91 %
IAG.PR.G FixedReset -4.97 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.72
Bid-YTW : 7.73 %
CM.PR.P FixedReset -4.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 16.65
Evaluated at bid price : 16.65
Bid-YTW : 4.91 %
SLF.PR.I FixedReset -4.64 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.10
Bid-YTW : 8.04 %
MFC.PR.L FixedReset -4.32 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.93
Bid-YTW : 9.48 %
MFC.PR.N FixedReset -4.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.25
Bid-YTW : 8.47 %
NA.PR.W FixedReset -3.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 16.66
Evaluated at bid price : 16.66
Bid-YTW : 4.95 %
TD.PF.B FixedReset -3.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 17.15
Evaluated at bid price : 17.15
Bid-YTW : 4.78 %
NA.PR.S FixedReset -3.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 16.97
Evaluated at bid price : 16.97
Bid-YTW : 5.05 %
PWF.PR.T FixedReset -3.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 18.86
Evaluated at bid price : 18.86
Bid-YTW : 4.52 %
TD.PF.A FixedReset -3.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 17.21
Evaluated at bid price : 17.21
Bid-YTW : 4.77 %
CM.PR.O FixedReset -3.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 17.38
Evaluated at bid price : 17.38
Bid-YTW : 4.81 %
VNR.PR.A FixedReset -3.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 17.75
Evaluated at bid price : 17.75
Bid-YTW : 5.31 %
BMO.PR.W FixedReset -3.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 16.91
Evaluated at bid price : 16.91
Bid-YTW : 4.87 %
MFC.PR.K FixedReset -3.26 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.01
Bid-YTW : 9.30 %
TD.PR.S FixedReset -3.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.09
Bid-YTW : 4.27 %
IFC.PR.C FixedReset -3.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.02
Bid-YTW : 7.96 %
BMO.PR.Z Perpetual-Discount -2.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 22.10
Evaluated at bid price : 22.43
Bid-YTW : 5.67 %
TRP.PR.C FixedReset -2.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 11.49
Evaluated at bid price : 11.49
Bid-YTW : 5.25 %
BMO.PR.S FixedReset -2.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 18.01
Evaluated at bid price : 18.01
Bid-YTW : 4.72 %
NA.PR.Q FixedReset -2.62 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.00
Bid-YTW : 4.92 %
BIP.PR.A FixedReset -2.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 19.60
Evaluated at bid price : 19.60
Bid-YTW : 5.72 %
RY.PR.H FixedReset -2.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 17.75
Evaluated at bid price : 17.75
Bid-YTW : 4.70 %
BMO.PR.Y FixedReset -2.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 18.67
Evaluated at bid price : 18.67
Bid-YTW : 5.01 %
MFC.PR.G FixedReset -2.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.31
Bid-YTW : 7.35 %
BMO.PR.M FixedReset -2.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.51
Bid-YTW : 4.10 %
RY.PR.Z FixedReset -2.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 17.81
Evaluated at bid price : 17.81
Bid-YTW : 4.64 %
IGM.PR.B Perpetual-Premium -2.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 23.96
Evaluated at bid price : 24.25
Bid-YTW : 6.09 %
FTS.PR.G FixedReset -2.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 16.16
Evaluated at bid price : 16.16
Bid-YTW : 4.92 %
RY.PR.W Perpetual-Discount -1.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 21.98
Evaluated at bid price : 22.21
Bid-YTW : 5.59 %
TRP.PR.G FixedReset -1.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 17.67
Evaluated at bid price : 17.67
Bid-YTW : 5.48 %
MFC.PR.F FixedReset -1.86 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.69
Bid-YTW : 10.11 %
MFC.PR.I FixedReset -1.82 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.39
Bid-YTW : 7.33 %
FTS.PR.K FixedReset -1.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 16.51
Evaluated at bid price : 16.51
Bid-YTW : 4.78 %
BMO.PR.T FixedReset -1.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 17.21
Evaluated at bid price : 17.21
Bid-YTW : 4.82 %
TD.PF.E FixedReset -1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 19.20
Evaluated at bid price : 19.20
Bid-YTW : 4.86 %
BAM.PF.E FixedReset -1.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 17.24
Evaluated at bid price : 17.24
Bid-YTW : 5.38 %
MFC.PR.J FixedReset -1.51 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.25
Bid-YTW : 7.86 %
SLF.PR.A Deemed-Retractible -1.50 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.30
Bid-YTW : 7.69 %
BAM.PF.G FixedReset -1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 19.01
Evaluated at bid price : 19.01
Bid-YTW : 5.19 %
POW.PR.G Perpetual-Discount -1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 23.23
Evaluated at bid price : 23.63
Bid-YTW : 5.94 %
SLF.PR.H FixedReset -1.50 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.76
Bid-YTW : 9.18 %
MFC.PR.B Deemed-Retractible -1.44 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.89
Bid-YTW : 7.88 %
BAM.PF.B FixedReset -1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 17.05
Evaluated at bid price : 17.05
Bid-YTW : 5.39 %
RY.PR.M FixedReset -1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 18.01
Evaluated at bid price : 18.01
Bid-YTW : 4.95 %
SLF.PR.B Deemed-Retractible -1.30 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.53
Bid-YTW : 7.58 %
BAM.PF.A FixedReset -1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 18.55
Evaluated at bid price : 18.55
Bid-YTW : 5.28 %
IFC.PR.A FixedReset -1.25 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.03
Bid-YTW : 9.81 %
CU.PR.D Perpetual-Discount -1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 21.33
Evaluated at bid price : 21.33
Bid-YTW : 5.83 %
BNS.PR.D FloatingReset -1.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.61
Bid-YTW : 6.32 %
HSE.PR.A FixedReset -1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 13.15
Evaluated at bid price : 13.15
Bid-YTW : 5.08 %
TD.PF.F Perpetual-Discount -1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 21.96
Evaluated at bid price : 22.25
Bid-YTW : 5.51 %
BNS.PR.P FixedReset -1.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.63
Bid-YTW : 4.08 %
SLF.PR.D Deemed-Retractible -1.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.33
Bid-YTW : 8.03 %
RY.PR.L FixedReset -1.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.52
Bid-YTW : 4.41 %
BNS.PR.R FixedReset -1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.70
Bid-YTW : 4.27 %
CU.PR.C FixedReset -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 18.26
Evaluated at bid price : 18.26
Bid-YTW : 4.61 %
SLF.PR.C Deemed-Retractible -1.02 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.35
Bid-YTW : 8.01 %
BNS.PR.Q FixedReset -1.02 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.34
Bid-YTW : 4.29 %
MFC.PR.C Deemed-Retractible -1.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.54
Bid-YTW : 7.96 %
CU.PR.H Perpetual-Discount 1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 22.51
Evaluated at bid price : 22.83
Bid-YTW : 5.85 %
BAM.PF.D Perpetual-Discount 1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 20.49
Evaluated at bid price : 20.49
Bid-YTW : 6.04 %
TRP.PR.D FixedReset 1.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 15.86
Evaluated at bid price : 15.86
Bid-YTW : 5.37 %
HSE.PR.E FixedReset 1.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 21.96
Evaluated at bid price : 22.43
Bid-YTW : 4.97 %
SLF.PR.J FloatingReset 5.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.30
Bid-YTW : 9.51 %
Volume Highlights
Issue Index Shares
Traded
Notes
GWO.PR.N FixedReset 92,216 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.27
Bid-YTW : 10.20 %
BAM.PF.H FixedReset 70,006 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 23.14
Evaluated at bid price : 24.98
Bid-YTW : 4.96 %
CM.PR.P FixedReset 51,217 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 16.65
Evaluated at bid price : 16.65
Bid-YTW : 4.91 %
BMO.PR.Z Perpetual-Discount 48,707 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 22.10
Evaluated at bid price : 22.43
Bid-YTW : 5.67 %
CM.PR.Q FixedReset 37,747 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 19.08
Evaluated at bid price : 19.08
Bid-YTW : 4.78 %
FTS.PR.M FixedReset 35,691 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 18.06
Evaluated at bid price : 18.06
Bid-YTW : 4.93 %
There were 65 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
RY.PR.I FixedReset Quote: 21.81 – 23.00
Spot Rate : 1.1900
Average : 0.7621

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.81
Bid-YTW : 5.76 %

IAG.PR.G FixedReset Quote: 18.72 – 19.35
Spot Rate : 0.6300
Average : 0.4000

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.72
Bid-YTW : 7.73 %

CU.PR.D Perpetual-Discount Quote: 21.33 – 21.85
Spot Rate : 0.5200
Average : 0.3449

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 21.33
Evaluated at bid price : 21.33
Bid-YTW : 5.83 %

TD.PF.D FixedReset Quote: 18.80 – 19.39
Spot Rate : 0.5900
Average : 0.4502

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 18.80
Evaluated at bid price : 18.80
Bid-YTW : 4.85 %

PWF.PR.G Perpetual-Premium Quote: 24.50 – 24.94
Spot Rate : 0.4400
Average : 0.3011

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-13
Maturity Price : 24.21
Evaluated at bid price : 24.50
Bid-YTW : 6.03 %

PVS.PR.B SplitShare Quote: 24.31 – 24.74
Spot Rate : 0.4300
Average : 0.2925

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2019-01-10
Maturity Price : 25.00
Evaluated at bid price : 24.31
Bid-YTW : 5.47 %

Market Action

October 9, 2015

Margin debt in the US is declining:

NYSE margin debt surged from $182 billion to $505 billion in the six years ended in June 2015, roughly tracing the trajectory of the S&P 500, which tripled over the period. The biggest gains came in 2013, with credit rising 35 percent as U.S. stocks climbed 30 percent for the best returns in 16 years.

Since June, it’s been the other way around, with margin debt falling 6.3 percent to $473 billion at the NYSE’s last update, which covered August. The S&P 500 slid 4.4 percent at the end of that period as stocks entered a correction.

I’ll need to be convinced that this means anything as a market-timing indicator, as is often proclaimed but I’ll accept it as a rough measure of retail sentiment. It interested me due to a BIS working paper by Fernando Avalos, Ramon Moreno and Tania Romero titled Leverage on the buy side:

This paper investigates the microeconomic determinants of leverage decisions by asset managers. Investment funds (the “buy side”) have significantly increased their share of global capital flows in recent years. Unconventional monetary policies in advanced economies have squeezed returns while reducing borrowing costs, which in principle creates an incentive for asset managers to use more leverage. We start by studying the recent behaviour of fund leverage in different asset categories at an aggregate level. Leverage appears to have increased significantly in funds focused on the fixed income markets of emerging economies. Then we analyse the microeconomic factors that shape the leverage decision. In line with theory, we find that leverage rises with expected returns, and falls with market risk and borrowing costs. Transaction costs are also mentioned in the literature as another factor that should inhibit leverage. Lacking the requisite data, we introduce as proxies changes in capital controls and macroprudential policies, because they tend to affect expected returns in comparable ways. We find that tighter capital controls on inflows increase leverage rather than decrease it, but that macroprudential measures have no discernible effect. Finally, we discuss these results and their policy implications.
…
Funds dedicated to global markets or advanced economies had little debt in their capital structure, whereas debt in leveraged EME fixed income funds was close to 30 percent of AUM towards the end of our sample period. The leverage ratio of EME fixed income funds surged after 2009 before falling abruptly back in 2014, although current levels are still much higher than before the surge. The number of funds using leverage is relatively small in our sample, but their size is about three times that of their unleveraged peers. They control more than 30 percent of AUM in their sector (down from 50 percent around 2010), making them quite significant players in their target markets.

Meanwhile Fed officials seem anxious to emphasize that their hesitation in hiking rates in September due to concerns over global risks (discussed yesterday) should not be taken as an indication of what will happen in the year’s remaining two FOMC meetings:

Federal Reserve Bank of Richmond President Jeffrey Lacker said the U.S. is already at full employment and the central bank may risk overheating the economy as it attempts to drive additional job gains.

With the unemployment rate at 5.1 percent, the central bank has achieved its goal and “exhausted relevant slack in the labor market,” the Richmond Fed chief said.

“We’re there,” Lacker said in an interview in his office Thursday, referring to the central bank’s mandate to lower joblessness to the level consistent with stable price pressures. The median forecast of that rate among Fed officials is 4.9 percent, according to estimates released following last month’s meeting of the policy-making Federal Open Market Committee.

“Pushing on to wring more slack out — there is some risks associated with that,” said Lacker. Inflation pressures may emerge with a lag, but the “risks can be very real.”

The Richmond Fed chief dissented at the FOMC’s September meeting, preferring a 0.25 percentage point increase in the federal funds rate.

And Dudley of the NY Fed provided supporting fire:

Federal Reserve Bank of New York President William C. Dudley said he expects the U.S. central bank to raise interest rates by December, echoing comments by fellow regional Fed chief Dennis Lockart in Atlanta, while cautioning that this was not a pledge to action and will depend on the economy staying on track.

Dudley told CNBC television in an interview Friday that he was still in the 2015 liftoff camp.

“Based on my forecast, yes I am, but it’s a forecast. And we’re going to get a lot of data between now and December,” he said. “It’s not a commitment.”
…
Last month’s FOMC decision, and a disappointing September U.S. employment report, has sapped investors’ confidence the Fed will be able to raise rates this year, as Fed Chair Janet Yellen has said she expects will be warranted. The probability of a 2015 hike is now priced around 40 percent in federal funds futures markets, compared to above 60 percent ahead of last month’s Fed meeting, based on the assumption that the effective fed funds rate will be 0.375 percent after liftoff.

Dudley said the key to liftoff will be whether the labor market continues to improve, thereby putting more upward pressure on wages and inflation. Last month’s jobs report was “definitely weaker,” but even monthly gains of 120,000 or 150,000 are enough to continue to push the U.S. unemployment rate lower, he said.

Lockhart says the same:

Federal Reserve Bank of Atlanta President Dennis Lockhart said the first interest rate increase since 2006 will likely be warranted later this month or in December.

“The economy remains on a satisfactory track, and, speaking for myself, I see a liftoff decision later this year at the October or December FOMC meetings as likely appropriate,” Lockhart said in prepared remarks Friday in New York, referring to the Federal Open Market Committee.
…
“The ambiguity of the moment reinforces the need to closely watch the vital signs of the economy over the coming weeks to determine if the outlook has changed,” he said.

Lockhart, who has never dissented, said consumer activity will be a key signal that the U.S. economy can sustain its momentum despite the global slowdown.

“The consumer-based dimension of the economy has been robust for several months,” Lockhart said to the Society of American Business Editors and Writers, even as manufacturing and exports have been hurt by a stronger U.S. dollar.

The Atlanta Fed’s tracking estimate for the third quarter is a “relatively soft 1.1 percent,” though much of the weakness is due to a swing in inventories.

Alan Kreuger of Princeton wrote an op-ed in the NYT advocating a $12 minimum wage:

I am frequently asked, “How high can the minimum wage go without jeopardizing employment of low-wage workers? And at what level would further minimum wage increases result in more job losses than wage gains, lowering the earnings of low-wage workers as a whole?”

Although available research cannot precisely answer these questions, I am confident that a federal minimum wage that rises to around $12 an hour over the next five years or so would not have a meaningful negative effect on United States employment. One reason for this judgment is that around 140 research projects commissioned by Britain’s independent Low Pay Commission have found that the minimum wage “has led to higher than average wage increases for the lowest paid, with little evidence of adverse effects on employment or the economy.” A $12-per-hour minimum wage in the United States phased in over several years would be in the same ballpark as Britain’s minimum wage today.

But $15 an hour is beyond international experience, and could well be counterproductive. Although some high-wage cities and states could probably absorb a $15-an-hour minimum wage with little or no job loss, it is far from clear that the same could be said for every state, city and town in the United States.

I think the emphasis on the redistributive effects of the minimum wage are misguided; we should not be asking how to maximize the minimum wage subject to avoiding job losses; but rather, how to increase the minimum wage in order to force higher productivity at the low end of the job scale. I’m not suggesting that all productivity gains in the economy should be reflected in the minimum wage – that’s obviously a ridiculous argument – but some of the gains can be enforced.

Brookfield Renewable Energy Partners L.P., proud indirect issuer of BRF.PR.A, BRF.PR.B, BRF.PR.C, BRF.PR.E and BRF.PR.F, has announced:

an agreement to acquire a hydroelectric portfolio in Pennsylvania from Talen Energy for $860 million. Brookfield Renewable will acquire and fund the transaction with institutional partners and maintain an economic interest in the portfolio of approximately 40 percent. A portion of the purchase price will be funded with third party investment grade, non-recourse financing expected to close concurrently with the transaction.

The portfolio consists of two facilities, the 252 MW Holtwood station on the Susquehanna River and the 40 MW Wallenpaupack station on Lake Wallenpaupack in the Pocono Mountains, with a combined expected average annual generation of approximately 1.1 million megawatt hours. The acquisition provides a strong fit with Brookfield Renewable’s 417 MW Safe Harbor facility located eight miles upstream from Holtwood. All output is currently sold into PJM and the portfolio benefits from a diverse revenue stream including energy, capacity, renewable energy credits and ancillary services. Both Holtwood and Wallenpaupack have long-term FERC operating licenses through 2030 and 2045, respectively.

DBRS comments:

DBRS Limited (DBRS) today notes that Brookfield Renewable Energy Partners L.P. (BREP or the Company, rated BBB (high)) has announced its acquisition of a 292-megawatt (MW) hydroelectric portfolio in Pennsylvania (the Acquisition). The Acquisition is not expected to have a material impact on BREP’s rating. DBRS views the Acquisition as modestly negative to BREP’s business risk assessment (BRA), as the generation output from the acquired assets (representing approximately 4% of total pro-forma generation) is exposed to the merchant power market. However, DBRS expects BREP to prudently finance the Acquisition in order to be in line with DBRS’s 20% deconsolidated debt-to-capital threshold and to maintain a financial risk assessment (FRA) that remains supportive of the current rating.

TransCanada also announced an acquisition:

TransCanada Corporation (TSX:TRP)(NYSE:TRP) (TransCanada) today announced that it has reached an agreement to acquire the Ironwood natural gas fired, combined cycle power plant in Lebanon, Pennsylvania, with a nameplate capacity of 778 megawatts (MW), from Talen Energy Corporation (NYSE:TLN) for US$654 million. At closing, US$42 million in debt will be assumed and then repaid within 45 days of closing out of funds placed into escrow by the seller.

“This acquisition presents a unique opportunity in the current market environment and is a natural extension of our U.S. northeast power business, strengthening our overall portfolio of assets in the region,” said Russ Girling, TransCanada’s president and chief executive officer. “This relatively new and highly efficient gas-fired power plant provides us with a solid platform from which to continue to grow our already substantial wholesale, commercial and industrial customer base in this market area.”

Sure beats trying to promote Keystone! Jim Polson and Rebecca Penty of Bloomberg comment:

Companies from the Great White North are attracted by fast-growing power demand in parts of the U.S. and a regulatory model that allows bigger profits for utility monopolies. Their purchases are propping up sale values of U.S. independent producers amid a slowdown in the sector, according to UBS Securities LLC.
…
Canadian energy companies, pension funds and private equity firms are also more willing than U.S. utility owners to bank on the volatile earnings from power plants that sell into U.S. wholesale markets, said Kit Konolige, senior utility analyst for Bloomberg Intelligence. TransCanada and Brookfield bought so-called merchant plants that had been owned by PPL Corp. before it spun off Talen Energy Corp. in June to focus on more predictable utility businesses.

And it’s not just power that Canadians are after. They’re also buying up U.S. oil and natural gas properties. Canada Pension Plan Investment Board, the country’s largest pension fund, said Thursday it isn’t done shopping for energy assets after committing almost $2 billion to the industry in the last two weeks. That includes a purchase announced Thursday of oil and gas producing properties in Colorado from Encana Corp.

Talen extracted “top dollar” for its deals this week, UBS analysts led by Julien Dumoulin-Smith wrote in a note.

So there’s lots of capital leaving Canada to buy power plants in the States. One has to wonder whether a more business-friendly regulatory environment would allow further increases in electricity exports while keeping the bucks and jobs up here:

U.S. electricity trade with Canada is increasing, providing more economic and reliability benefits to both the United States and Canada. Although the amount of electricity imported over the Canadian border is a small part of the overall U.S. power supply, the transmission connections linking Canada and the United States are an important component of the electricity markets in northern states.

Overall, Canada is a net exporter of electricity to the United States, and most of its power needs are met by hydroelectricity. Large hydroelectric projects in British Columbia, Manitoba, Quebec, and Newfoundland and Labrador have significantly increased the country’s generation capacity. On a net basis, Canada exports electricity mainly to New England, New York, and the Midwest states, while the United States exports electricity primarily from the Pacific Northwest states to the Canadian province of British Columbia.

As everybody knows, my company uses proprietary software (HIMIPref™) to examine the market for trade opportunities. Recently, PrefBlog’s corporate espionage department obtained information regarding hardware used for a similar purpose by other preferred share investors:

sellDie
Click for Big

It was another hideous day for the Canadian preferred share market, with PerpetualDiscounts off 24bp, FixedResets losing 96bp and DeemedRetractibles down 29bp; the YTW on FixedResets is, incredibly, edging closer to the 5.00% mark. The Performance Highlights table is, of course, lengthy, with three MFC issues notable losers. Volume was well above average.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_151009
Click for Big

Implied Volatility remained ridiculous.

TRP.PR.A, which resets 2019-12-31 at +192, is bid at 14.75 to be $0.65 rich, while TRP.PR.C, resetting 2016-1-30 at +154, is $0.59 cheap at its bid price of 11.81.

impVol_MFC_151009
Click for Big

The fit deteriorated today for MFC, with Implied Volatility plummeting; this isn’t really surprising, given the large losses experienced by the three MFC issues at the extreme bad end of the Performance Highlights table.

Most expensive is MFC.PR.H, resetting at +313bp on 2017-3-19, bid at 21.38 to be 0.71 rich, while MFC.PR.K resetting at +222bp on 2018-9-19, is bid at 16.55 to be 0.78 cheap.

impVol_BAM_151009
Click for Big

The fit on the BAM issues continues to be horrible!

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 15.00 to be $0.90 cheap. BAM.PF.G, resetting at +284bp on 2020-6-30 is bid at 19.30 and appears to be $0.69 rich.

impVol_FTS_151009
Click for Big

Implied Volatility jumped today and is ridiculously high.

FTS.PR.K, with a spread of +205bp, and bid at 16.81, looks $0.36 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 16.49 and is $0.30 cheap.

pairs_FR_151009
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.99%, with two outliers above 0.00% and two below -2.00%. The distribution is bimodal, with bank NVCC non-compliant pairs averaging -1.51% and other issues averaging -0.26%. There are three junk outliers above 0.00%.

pairs_FF_151009
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.5992 % 1,583.6
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.5992 % 2,768.9
Floater 4.69 % 4.72 % 62,933 16.04 3 0.5992 % 1,683.5
OpRet 0.00 % 0.00 % 0 0.00 0 0.0526 % 2,764.0
SplitShare 4.34 % 5.07 % 72,442 3.00 5 0.0526 % 3,239.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0526 % 2,527.4
Perpetual-Premium 5.95 % 5.90 % 59,045 14.00 5 -0.3955 % 2,448.5
Perpetual-Discount 5.76 % 5.84 % 78,228 14.16 33 -0.2373 % 2,472.5
FixedReset 5.36 % 4.95 % 196,608 14.88 76 -0.9550 % 1,903.2
Deemed-Retractible 5.34 % 5.38 % 101,730 5.47 33 -0.2883 % 2,494.3
FloatingReset 2.66 % 4.75 % 63,342 5.83 9 0.1447 % 2,046.3
Performance Highlights
Issue Index Change Notes
MFC.PR.K FixedReset -6.87 % Not entirely real, but the issue did indeed have a bad day! It traded 33,613 shares in a range of 16.81-17.83, but it appears that the bid simply vanished shortly before the close, with 100 shares trading at 17.02 at 3:40; the next trade was 100 shares, 16.83, 3:53; and the final trade 100 shares, 16.81, 3:53. This issue also made the volume highlights, with RBC buying 19,800 from Scotia at 17.75, timestamped 11:35.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.55
Bid-YTW : 8.82 %
MFC.PR.L FixedReset -6.51 % Real enough! The issue traded 20,593 shares in a range of 16.70-17.77 before closing at 16.65-00. The day ended with two trade bursts; one set, timestamped 3:33-3:34, totalled 2900 shares in nine trades, starting at 17.00 and ending at 16.97; but 1300 of these shares traded at 16.78. The second set, timestamped 3:53-3:54, totalled 1500 shares in seven trades, starting at 16.78 and ending at 16.70.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.65
Bid-YTW : 8.85 %
MFC.PR.M FixedReset -4.78 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.11
Bid-YTW : 7.87 %
RY.PR.J FixedReset -4.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 18.42
Evaluated at bid price : 18.42
Bid-YTW : 4.96 %
BAM.PR.T FixedReset -4.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 15.70
Evaluated at bid price : 15.70
Bid-YTW : 5.29 %
PWF.PR.T FixedReset -4.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 19.60
Evaluated at bid price : 19.60
Bid-YTW : 4.34 %
MFC.PR.N FixedReset -3.74 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.01
Bid-YTW : 7.87 %
BMO.PR.T FixedReset -3.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 17.52
Evaluated at bid price : 17.52
Bid-YTW : 4.73 %
TD.PF.D FixedReset -3.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 18.73
Evaluated at bid price : 18.73
Bid-YTW : 4.86 %
RY.PR.Z FixedReset -3.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 18.18
Evaluated at bid price : 18.18
Bid-YTW : 4.53 %
SLF.PR.H FixedReset -3.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.00
Bid-YTW : 8.96 %
RY.PR.H FixedReset -2.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 18.14
Evaluated at bid price : 18.14
Bid-YTW : 4.59 %
BMO.PR.W FixedReset -2.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 17.49
Evaluated at bid price : 17.49
Bid-YTW : 4.70 %
CM.PR.Q FixedReset -2.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 19.27
Evaluated at bid price : 19.27
Bid-YTW : 4.73 %
RY.PR.M FixedReset -2.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 18.25
Evaluated at bid price : 18.25
Bid-YTW : 4.88 %
CM.PR.O FixedReset -2.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 18.02
Evaluated at bid price : 18.02
Bid-YTW : 4.64 %
TD.PF.E FixedReset -2.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 19.52
Evaluated at bid price : 19.52
Bid-YTW : 4.78 %
PWF.PR.P FixedReset -2.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 13.68
Evaluated at bid price : 13.68
Bid-YTW : 4.51 %
NA.PR.S FixedReset -2.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 17.66
Evaluated at bid price : 17.66
Bid-YTW : 4.84 %
SLF.PR.G FixedReset -2.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.20
Bid-YTW : 9.36 %
TD.PF.B FixedReset -2.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 17.85
Evaluated at bid price : 17.85
Bid-YTW : 4.58 %
CU.PR.H Perpetual-Discount -1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 22.19
Evaluated at bid price : 22.55
Bid-YTW : 5.91 %
TD.PF.A FixedReset -1.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 17.85
Evaluated at bid price : 17.85
Bid-YTW : 4.59 %
TD.PF.C FixedReset -1.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 17.51
Evaluated at bid price : 17.51
Bid-YTW : 4.66 %
RY.PR.N Perpetual-Discount -1.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 22.04
Evaluated at bid price : 22.36
Bid-YTW : 5.63 %
BMO.PR.S FixedReset -1.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 18.50
Evaluated at bid price : 18.50
Bid-YTW : 4.59 %
PWF.PR.K Perpetual-Discount -1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 21.25
Evaluated at bid price : 21.25
Bid-YTW : 5.84 %
HSE.PR.G FixedReset -1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 21.83
Evaluated at bid price : 22.26
Bid-YTW : 4.99 %
FTS.PR.G FixedReset -1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 16.49
Evaluated at bid price : 16.49
Bid-YTW : 4.81 %
CM.PR.P FixedReset -1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 4.66 %
TRP.PR.D FixedReset -1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 15.63
Evaluated at bid price : 15.63
Bid-YTW : 5.44 %
BAM.PR.N Perpetual-Discount -1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 19.88
Evaluated at bid price : 19.88
Bid-YTW : 6.03 %
BMO.PR.Y FixedReset -1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 19.08
Evaluated at bid price : 19.08
Bid-YTW : 4.90 %
GWO.PR.R Deemed-Retractible -1.19 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.80
Bid-YTW : 7.39 %
RY.PR.W Perpetual-Discount -1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 22.40
Evaluated at bid price : 22.66
Bid-YTW : 5.47 %
SLF.PR.J FloatingReset -1.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.65
Bid-YTW : 10.14 %
IFC.PR.A FixedReset -1.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.22
Bid-YTW : 9.62 %
BMO.PR.R FloatingReset -1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.50
Bid-YTW : 4.63 %
MFC.PR.B Deemed-Retractible -1.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.18
Bid-YTW : 7.67 %
RY.PR.P Perpetual-Discount -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 23.40
Evaluated at bid price : 23.70
Bid-YTW : 5.57 %
RY.PR.O Perpetual-Discount -1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 22.00
Evaluated at bid price : 22.30
Bid-YTW : 5.60 %
RY.PR.C Deemed-Retractible -1.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.55
Bid-YTW : 5.07 %
FTS.PR.H FixedReset 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 13.85
Evaluated at bid price : 13.85
Bid-YTW : 4.30 %
BAM.PF.G FixedReset 1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 19.30
Evaluated at bid price : 19.30
Bid-YTW : 5.10 %
TRP.PR.E FixedReset 1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 16.25
Evaluated at bid price : 16.25
Bid-YTW : 5.32 %
MFC.PR.J FixedReset 1.31 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.53
Bid-YTW : 7.64 %
TRP.PR.A FixedReset 1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 14.75
Evaluated at bid price : 14.75
Bid-YTW : 4.95 %
POW.PR.A Perpetual-Discount 1.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 23.59
Evaluated at bid price : 23.86
Bid-YTW : 5.89 %
MFC.PR.H FixedReset 1.57 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.38
Bid-YTW : 6.24 %
BAM.PF.F FixedReset 1.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 19.15
Evaluated at bid price : 19.15
Bid-YTW : 5.12 %
GWO.PR.N FixedReset 1.82 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.00
Bid-YTW : 9.48 %
BAM.PF.A FixedReset 2.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 18.79
Evaluated at bid price : 18.79
Bid-YTW : 5.21 %
BMO.PR.M FixedReset 2.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.00
Bid-YTW : 3.73 %
TD.PR.T FloatingReset 2.59 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.40
Bid-YTW : 4.56 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.J FixedReset 63,708 TD bought 10,900 from RBC at 19.00.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 18.42
Evaluated at bid price : 18.42
Bid-YTW : 4.96 %
BAM.PF.H FixedReset 63,340 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 23.12
Evaluated at bid price : 24.92
Bid-YTW : 4.97 %
CM.PR.Q FixedReset 46,975 TD crossed 10,000 at 19.75.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 19.27
Evaluated at bid price : 19.27
Bid-YTW : 4.73 %
BAM.PF.A FixedReset 35,504 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 18.79
Evaluated at bid price : 18.79
Bid-YTW : 5.21 %
RY.PR.P Perpetual-Discount 34,438 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 23.40
Evaluated at bid price : 23.70
Bid-YTW : 5.57 %
MFC.PR.K FixedReset 33,613 RBC bought 19,800 from Scotia at 19,800.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.55
Bid-YTW : 8.82 %
There were 45 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BAM.PR.C Floater Quote: 10.00 – 11.49
Spot Rate : 1.4900
Average : 0.8503

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 10.00
Evaluated at bid price : 10.00
Bid-YTW : 4.76 %

RY.PR.J FixedReset Quote: 18.42 – 18.90
Spot Rate : 0.4800
Average : 0.2762

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 18.42
Evaluated at bid price : 18.42
Bid-YTW : 4.96 %

MFC.PR.H FixedReset Quote: 21.38 – 21.99
Spot Rate : 0.6100
Average : 0.4179

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.38
Bid-YTW : 6.24 %

RY.PR.H FixedReset Quote: 18.14 – 18.68
Spot Rate : 0.5400
Average : 0.3497

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 18.14
Evaluated at bid price : 18.14
Bid-YTW : 4.59 %

BNS.PR.C FloatingReset Quote: 21.26 – 21.84
Spot Rate : 0.5800
Average : 0.3931

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.26
Bid-YTW : 4.97 %

TRP.PR.E FixedReset Quote: 16.25 – 17.00
Spot Rate : 0.7500
Average : 0.5922

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-09
Maturity Price : 16.25
Evaluated at bid price : 16.25
Bid-YTW : 5.32 %

Market Action

October 8, 2015

The Fed didn’t hike rates in September largely due to global risks:

Federal Reserve officials put off an interest-rate increase in September because of growing risks, mainly from China, to their outlook for economic growth and inflation even as they continued to say they were on track to raise the target later this year.

Policy makers “agreed that developments over the inter-meeting period had not materially altered the committee’s economic outlook,” according to minutes of the Sept. 16-17 session of the Federal Open Market Committee, released Thursday in Washington. Nonetheless, “the committee decided that it was prudent to wait for additional information confirming that the economic outlook had not deteriorated.”

The FOMC noted that domestic economic conditions, including data on consumer spending and housing, had continued to improve, and the labor market had reached or was close to the committee’s long-run estimates for unemployment.

Still, concerns over China and its potential spillover to other economies “were likely to depress U.S. net exports” and cause further strengthening of the dollar, which could damp inflation in the U.S.

The torrent of global money into California real estate is slowing:

International buyers are accounting for the smallest share of California home sales in at least eight years as prices climb and investors from China, the biggest source of foreign purchases, slow buying, according to the state’s Realtors group.

The share of international buyers fell this year to less than 4 percent, compared with a peak of 8 percent in 2013, the California Association of Realtors said in a report Thursday. The findings are based on a survey conducted in June of about 1,000 real estate agents. Since 2008, the first year agents were surveyed on the subject, results have shown foreigners representing at least 5 percent of transactions.

An influx of foreign money has contributed to soaring real estate prices in the largest U.S. state, particularly in coastal areas where demand is high and new inventory is limited. Buyers from mainland China, Hong Kong and Taiwan made up 43 percent of international purchases in California this year, followed by 8 percent each from Mexico and South Korea, according to the survey.
…
The median price of a California home is expected to climb 6.5 percent this year to $476,300, making it harder to find deals, according to Appleton-Young. Chinese buyers have focused their purchasing on a few areas such as the San Gabriel Valley and Irvine, outside Los Angeles, and parts of the San Francisco Bay area with reputations for quality schools.

Across the U.S., buyers from China, Hong Kong and Taiwan spent an estimated $28.6 billion on homes in the 12 months through March, the National Association of Realtors reported in June, more than double the $11.2 billion spent by No. 2 Canada. The average price was $831,800 for Chinese purchasers, compared with $499,600 for all international buyers.

California accounted for 16 percent of U.S. sales to foreign buyers, behind Florida, which had 21 percent, the national association’s report said.

Let’s hope that some of that missing money finds its way into Canada!

Hillary Clinton wrote an op-ed outlining her attack on markets:

My plan would also give regulators the authority they need to reorganize, downsize or even break apart any financial institution that is too large and risky to be managed effectively. It is a comprehensive and flexible approach. It allows regulators to adapt to changing markets and help ensure that large financial firms never pose a danger to our entire economy.

Not because they’re in trouble – because they’re too large and risky! Coming up next … jail terms for those likely to commit an offence! Matt Levine of Bloomberg opines:

And yet you can see the populist appeal. Wall Street, to a lot of people, is Wall Street, and any attack on “Wall Street” sounds good. The political desire is to have a certain quantity of “tough on Wall Street,” but what actually goes into that toughness is arbitrary and unimportant. So Clinton also wants to “reinstate the ‘swaps push-out’ rule for banks’ derivatives trading, which was repealed at the behest of the banking lobby in last year’s budget deal.” I have long thought that swaps push-out is the purest piece of symbolic emotional identification in financial regulation, and I still think that, but for precisely that reason it resonates. No one knows what it does, and no one thinks that it matters, so it is useful as a pure abstract marker of what team you’re on.

But for those of us who are more interested in finance than in politics, this just seems weird. Wall Street is not a monolith, and being “tough on Wall Street” makes no sense. Regulating the parts of Wall Street that you don’t like can help out the parts of Wall Street that you do like. Lots of hedge fund managers will be thrilled by a crackdown on high-frequency trading.15 Cracking down on small automated competitors to banks might be good for banks. There are Wall Street winners and Wall Street losers to all sorts of Wall Street regulation, and a pure quantity theory of toughness elides those differences.

Canada’s wealth management industry is asking the Ontario government for tighter regulations to restrict competition in the wealth management industry:

Canada’s wealth management industry is asking the Ontario government for tighter regulations governing financial planners and advisers.

Earlier this year, the province launched an expert committee to review the regulations, and a number of financial industry groups have responded by asking the government to enact a general legislative framework for advisers and planners.

Currently, throughout most of Canada, no general legal framework exists to regulate the activities of individuals who offer financial planning, advice and services. That means that in every province (excluding Quebec) any individual can call himself a financial planner – regardless of certification, designation or educational background.

The absence of a legal framework has raised questions within the industry about proficiency, quality standards and potential conflicts of interest.

… and competition from outfits that are not banks. That’s a real problem. However, the banks have shown their willingness in the past to pay regulators to expand their hegemony over the financial system, so guess what’s going to happen next?

Here’s a feel-good story about Canadian service sector innovation:

Like everyone, Cris Jucan has had his share of frustrating restaurant experiences. He remembers one vividly, a few years ago, when he and his friends were sitting around on a patio waiting to order drinks.

They joked that one of them should call the restaurant – on the phone – and ask that a server be sent over. That’s when the veritable light bulb went off.

Mr. Jucan, with his background in IT, wasted no time in founding Tacit Innovations, a startup that would seek to improve the restaurant experience by allowing patrons to browse menus and order meals with their phones.
…
Toronto-based Tacit Innovations, now up to 15 employees, is one of a growing number of companies tapping into the increasing tech savviness of restaurant owners and their desire to improve efficiencies, profits and customer experiences.

Veritable light bulb? I believe the writer meant “proverbial”.

But how about that preferred share market, eh? It was a walk in the park!

burning-trees
Click for Big

The Canadian preferred share market was hammered today, with PerpetualDiscounts off 45bp, FixedResets losing 169bp and DeemedRetractibles down 78bp. I cannot find sufficient superlatives to describe the Performance Highlights table. Volume was very high.

It is possible that the market was reacting to the news of the new private placement from BMO, which pays 5.85% … if this is a dividend and the bank needs the money that much, then the drop is justified. If the payments are taxed as interest, not so much. I don’t know. Or it could be the market just going down because it felt like it. I don’t know about that, either.

On a cheerier note, the increases in observed Implied Volatility suggest to me that we’re seeing some bottom feeding in the market, with the speculators (and, perhaps, long term buyers) seeking out the lowest-spread, lowest-priced issues (because then they get more leverage to future increases in GOC-5) and supporting their price relative to that of their higher-spread, higher-priced cousins. If so, it implies heightened awareness … and it is also possible that the new BMO issue represents an institutional desire to get in on the action with some serious money. This is what will eventually turn the tide, of course. But not yet!

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_151008
Click for Big

Implied Volatility rocketed upwards today and is now ridiculous.

TRP.PR.A, which resets 2019-12-31 at +192, is bid at 14.55 to be $0.49 rich, while TRP.PR.C, resetting 2016-1-30 at +154, is $0.52 cheap at its bid price of 11.83.

impVol_MFC_151008
Click for Big

Another good fit today for MFC, with Implied Volatility jumping up.

Most expensive is MFC.PR.M, resetting at +236bp on 2019-12-19, bid at 19.02 to be 0.81 rich, while MFC.PR.J resetting at +261bp on 2018-3-19, is bid at 18.29 to be 0.89 cheap.

impVol_BAM_151008
Click for Big

The fit on the BAM issues continues to be horrible, and Implied Volatility actually declined! But the relationship between the BAM FixedResets is just a mess, so I’m not taking it too seriously.

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 15.01 to be $0.87 cheap. BAM.PR.X, resetting at +180bp on 2017-6-30 is bid at 14.03 and appears to be $0.67 rich.

impVol_FTS_151008
Click for Big

Implied Volatility declined today but remains ridiculously high.

FTS.PR.K, with a spread of +205bp, and bid at 16.70, looks $0.21 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 16.70 and is $0.14 cheap.

pairs_FR_151008
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -1.00%, with two outliers above 0.00% and two below -2.00%. The distribution is bimodal, with bank NVCC non-compliant pairs averaging -1.55% and other issues averaging -0.23%. There are three junk outliers above 0.00%.

pairs_FF_151008
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.1667 % 1,574.2
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.1667 % 2,752.4
Floater 4.72 % 4.73 % 63,976 16.01 3 0.1667 % 1,673.5
OpRet 0.00 % 0.00 % 0 0.00 0 -0.2496 % 2,762.6
SplitShare 4.34 % 5.06 % 71,512 4.47 5 -0.2496 % 3,237.6
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.2496 % 2,526.1
Perpetual-Premium 5.92 % 5.87 % 57,953 14.00 5 -0.8087 % 2,458.2
Perpetual-Discount 5.75 % 5.80 % 78,691 14.19 33 -0.4507 % 2,478.4
FixedReset 5.31 % 4.85 % 196,358 14.95 76 -1.6946 % 1,921.5
Deemed-Retractible 5.32 % 5.42 % 101,858 5.47 33 -0.7806 % 2,501.5
FloatingReset 2.68 % 4.88 % 62,838 5.83 9 -0.7755 % 2,043.3
Performance Highlights
Issue Index Change Notes
MFC.PR.J FixedReset -5.53 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.29
Bid-YTW : 7.75 %
TD.PF.E FixedReset -4.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 20.01
Evaluated at bid price : 20.01
Bid-YTW : 4.59 %
MFC.PR.G FixedReset -4.82 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.57
Bid-YTW : 7.08 %
RY.PR.J FixedReset -4.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 19.29
Evaluated at bid price : 19.29
Bid-YTW : 4.66 %
TRP.PR.E FixedReset -4.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 16.04
Evaluated at bid price : 16.04
Bid-YTW : 5.30 %
TD.PF.D FixedReset -4.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 19.37
Evaluated at bid price : 19.37
Bid-YTW : 4.64 %
TRP.PR.D FixedReset -4.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 15.82
Evaluated at bid price : 15.82
Bid-YTW : 5.28 %
TRP.PR.G FixedReset -4.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 5.30 %
RY.PR.M FixedReset -3.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 18.75
Evaluated at bid price : 18.75
Bid-YTW : 4.68 %
NA.PR.W FixedReset -3.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 17.42
Evaluated at bid price : 17.42
Bid-YTW : 4.64 %
MFC.PR.I FixedReset -3.57 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.72
Bid-YTW : 7.03 %
IFC.PR.A FixedReset -3.45 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.40
Bid-YTW : 9.39 %
BMO.PR.Y FixedReset -3.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 19.31
Evaluated at bid price : 19.31
Bid-YTW : 4.77 %
HSE.PR.E FixedReset -3.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 21.66
Evaluated at bid price : 22.00
Bid-YTW : 5.01 %
TD.PR.T FloatingReset -3.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.86
Bid-YTW : 5.01 %
TD.PF.C FixedReset -3.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 17.85
Evaluated at bid price : 17.85
Bid-YTW : 4.49 %
TRP.PR.A FixedReset -3.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 14.55
Evaluated at bid price : 14.55
Bid-YTW : 4.93 %
IFC.PR.C FixedReset -2.98 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.54
Bid-YTW : 7.48 %
BAM.PR.X FixedReset -2.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 14.03
Evaluated at bid price : 14.03
Bid-YTW : 4.98 %
TD.PF.F Perpetual-Discount -2.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 22.18
Evaluated at bid price : 22.53
Bid-YTW : 5.43 %
TD.PF.A FixedReset -2.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 18.20
Evaluated at bid price : 18.20
Bid-YTW : 4.42 %
TD.PF.B FixedReset -2.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 18.22
Evaluated at bid price : 18.22
Bid-YTW : 4.41 %
NA.PR.S FixedReset -2.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 18.06
Evaluated at bid price : 18.06
Bid-YTW : 4.65 %
BMO.PR.W FixedReset -2.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 17.98
Evaluated at bid price : 17.98
Bid-YTW : 4.49 %
MFC.PR.H FixedReset -2.55 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.05
Bid-YTW : 6.38 %
SLF.PR.E Deemed-Retractible -2.54 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.60
Bid-YTW : 7.87 %
SLF.PR.C Deemed-Retractible -2.51 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.40
Bid-YTW : 7.96 %
POW.PR.A Perpetual-Discount -2.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 23.20
Evaluated at bid price : 23.50
Bid-YTW : 5.98 %
BAM.PF.G FixedReset -2.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 19.08
Evaluated at bid price : 19.08
Bid-YTW : 5.09 %
BMO.PR.T FixedReset -2.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 18.20
Evaluated at bid price : 18.20
Bid-YTW : 4.47 %
SLF.PR.G FixedReset -2.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.50
Bid-YTW : 9.04 %
RY.PR.Z FixedReset -2.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 18.80
Evaluated at bid price : 18.80
Bid-YTW : 4.30 %
SLF.PR.B Deemed-Retractible -2.32 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.66
Bid-YTW : 7.48 %
BNS.PR.C FloatingReset -2.29 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.31
Bid-YTW : 4.94 %
SLF.PR.D Deemed-Retractible -2.26 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.43
Bid-YTW : 7.94 %
SLF.PR.I FixedReset -2.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.98
Bid-YTW : 7.31 %
FTS.PR.H FixedReset -2.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 13.70
Evaluated at bid price : 13.70
Bid-YTW : 4.25 %
GWO.PR.I Deemed-Retractible -2.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.14
Bid-YTW : 7.49 %
SLF.PR.A Deemed-Retractible -2.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.60
Bid-YTW : 7.46 %
BAM.PR.R FixedReset -1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 15.01
Evaluated at bid price : 15.01
Bid-YTW : 5.32 %
GWO.PR.G Deemed-Retractible -1.94 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.27
Bid-YTW : 6.87 %
RY.PR.O Perpetual-Discount -1.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 22.18
Evaluated at bid price : 22.53
Bid-YTW : 5.53 %
CM.PR.P FixedReset -1.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 17.72
Evaluated at bid price : 17.72
Bid-YTW : 4.52 %
BAM.PF.B FixedReset -1.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 17.30
Evaluated at bid price : 17.30
Bid-YTW : 5.22 %
BAM.PF.F FixedReset -1.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 18.85
Evaluated at bid price : 18.85
Bid-YTW : 5.13 %
FTS.PR.K FixedReset -1.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 16.70
Evaluated at bid price : 16.70
Bid-YTW : 4.63 %
MFC.PR.M FixedReset -1.76 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.02
Bid-YTW : 7.16 %
CM.PR.Q FixedReset -1.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 19.80
Evaluated at bid price : 19.80
Bid-YTW : 4.54 %
PWF.PR.S Perpetual-Discount -1.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 20.53
Evaluated at bid price : 20.53
Bid-YTW : 5.86 %
GWO.PR.H Deemed-Retractible -1.63 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.16
Bid-YTW : 7.20 %
CU.PR.C FixedReset -1.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 18.40
Evaluated at bid price : 18.40
Bid-YTW : 4.48 %
MFC.PR.L FixedReset -1.60 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.81
Bid-YTW : 7.87 %
RY.PR.N Perpetual-Discount -1.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 22.44
Evaluated at bid price : 22.74
Bid-YTW : 5.53 %
RY.PR.H FixedReset -1.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 18.70
Evaluated at bid price : 18.70
Bid-YTW : 4.37 %
BMO.PR.S FixedReset -1.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 18.80
Evaluated at bid price : 18.80
Bid-YTW : 4.43 %
CM.PR.O FixedReset -1.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 18.51
Evaluated at bid price : 18.51
Bid-YTW : 4.43 %
BAM.PF.A FixedReset -1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 18.42
Evaluated at bid price : 18.42
Bid-YTW : 5.23 %
GWO.PR.R Deemed-Retractible -1.41 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.05
Bid-YTW : 7.22 %
BNS.PR.B FloatingReset -1.40 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.15
Bid-YTW : 4.88 %
GWO.PR.L Deemed-Retractible -1.38 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.26
Bid-YTW : 6.13 %
PWF.PR.T FixedReset -1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 20.43
Evaluated at bid price : 20.43
Bid-YTW : 4.08 %
MFC.PR.N FixedReset -1.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.71
Bid-YTW : 7.31 %
GWO.PR.P Deemed-Retractible -1.18 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.36
Bid-YTW : 6.41 %
PWF.PR.G Perpetual-Premium -1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 24.51
Evaluated at bid price : 24.74
Bid-YTW : 5.97 %
PWF.PR.H Perpetual-Premium -1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 24.21
Evaluated at bid price : 24.50
Bid-YTW : 5.87 %
BSC.PR.C SplitShare -1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2020-09-22
Maturity Price : 19.71
Evaluated at bid price : 19.73
Bid-YTW : 4.04 %
BNS.PR.Q FixedReset -1.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.51
Bid-YTW : 4.12 %
PWF.PR.O Perpetual-Premium -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 24.36
Evaluated at bid price : 24.66
Bid-YTW : 5.88 %
PWF.PR.L Perpetual-Discount -1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 21.98
Evaluated at bid price : 22.21
Bid-YTW : 5.74 %
BAM.PF.E FixedReset -1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 17.61
Evaluated at bid price : 17.61
Bid-YTW : 5.18 %
MFC.PR.B Deemed-Retractible -1.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.40
Bid-YTW : 7.51 %
TD.PR.Y FixedReset -1.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.32
Bid-YTW : 4.23 %
BAM.PR.Z FixedReset -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 18.81
Evaluated at bid price : 18.81
Bid-YTW : 5.22 %
FTS.PR.J Perpetual-Discount -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 21.00
Evaluated at bid price : 21.00
Bid-YTW : 5.74 %
BNS.PR.Y FixedReset -1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.31
Bid-YTW : 6.22 %
W.PR.J Perpetual-Discount 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 22.90
Evaluated at bid price : 23.17
Bid-YTW : 6.06 %
W.PR.H Perpetual-Discount 1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 22.77
Evaluated at bid price : 23.05
Bid-YTW : 5.99 %
TRP.PR.F FloatingReset 1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 12.95
Evaluated at bid price : 12.95
Bid-YTW : 4.51 %
BNS.PR.D FloatingReset 1.57 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.81
Bid-YTW : 6.13 %
Volume Highlights
Issue Index Shares
Traded
Notes
BAM.PF.H FixedReset 120,965 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 23.13
Evaluated at bid price : 24.95
Bid-YTW : 4.94 %
CU.PR.I FixedReset 100,754 Scotia crossed blocks of 35,000 and 20,000, both at 24.96.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 23.12
Evaluated at bid price : 24.91
Bid-YTW : 4.43 %
TD.PF.D FixedReset 80,593 RBC crossed 48,500 at 19.60.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 19.37
Evaluated at bid price : 19.37
Bid-YTW : 4.64 %
TRP.PR.D FixedReset 61,504 Nesbitt crossed 27,200 at 16.05.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 15.82
Evaluated at bid price : 15.82
Bid-YTW : 5.28 %
RY.PR.P Perpetual-Discount 50,315 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 23.63
Evaluated at bid price : 23.95
Bid-YTW : 5.51 %
RY.PR.J FixedReset 43,403 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 19.29
Evaluated at bid price : 19.29
Bid-YTW : 4.66 %
There were 54 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
TD.PR.T FloatingReset Quote: 20.86 – 21.68
Spot Rate : 0.8200
Average : 0.5423

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.86
Bid-YTW : 5.01 %

CU.PR.C FixedReset Quote: 18.40 – 19.30
Spot Rate : 0.9000
Average : 0.6277

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 18.40
Evaluated at bid price : 18.40
Bid-YTW : 4.48 %

TD.PF.C FixedReset Quote: 17.85 – 18.50
Spot Rate : 0.6500
Average : 0.4686

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 17.85
Evaluated at bid price : 17.85
Bid-YTW : 4.49 %

TD.PF.F Perpetual-Discount Quote: 22.53 – 22.95
Spot Rate : 0.4200
Average : 0.2636

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 22.18
Evaluated at bid price : 22.53
Bid-YTW : 5.43 %

TRP.PR.A FixedReset Quote: 14.55 – 15.27
Spot Rate : 0.7200
Average : 0.5715

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 14.55
Evaluated at bid price : 14.55
Bid-YTW : 4.93 %

W.PR.H Perpetual-Discount Quote: 23.05 – 23.70
Spot Rate : 0.6500
Average : 0.5042

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-10-08
Maturity Price : 22.77
Evaluated at bid price : 23.05
Bid-YTW : 5.99 %