Category: Market Action

Market Action

November 12, 2013

It might be a while before we see tapering:

Federal Reserve Bank of Atlanta President Dennis Lockhart, who has backed record stimulus, said he wants to see inflation accelerate toward the Fed’s 2 percent goal before the central bank reduces $85 billion in monthly bond purchases.

“I’d like to see some movement toward the target” before tapering, Lockhart said today in a Bloomberg Radio interview with Kathleen Hays. Inflation is “stable but too low” and a move up would “give me some confidence we are not dealing with some downside scenario that might develop,” said Lockhart, who doesn’t vote on policy this year.

It was another mixed day for the Canadian preferred share market, with PerpetualDiscounts down 28bp, FixedResets up 20bp and DeemedRetractibles off 5bp. In the Performance Highlights table the three losers are all PerpetualDiscounts while FixedResets dominate the winning side. Volume was above average with the highlights comprised entirely of FixedResets.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.0749 % 2,515.4
FixedFloater 4.13 % 3.41 % 30,027 18.53 1 0.8772 % 4,063.8
Floater 2.95 % 2.98 % 60,317 19.75 3 -0.0749 % 2,715.9
OpRet 4.60 % 0.88 % 70,596 0.38 3 0.1663 % 2,655.4
SplitShare 4.74 % 5.12 % 67,585 3.92 6 -0.1410 % 2,958.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1663 % 2,428.1
Perpetual-Premium 5.57 % 4.84 % 123,827 0.30 11 -0.1257 % 2,306.0
Perpetual-Discount 5.57 % 5.55 % 177,579 14.51 27 -0.2795 % 2,362.6
FixedReset 4.95 % 3.21 % 234,115 3.32 82 0.1977 % 2,484.2
Deemed-Retractible 5.08 % 3.92 % 194,404 1.47 42 -0.0532 % 2,412.3
FloatingReset 2.61 % 2.41 % 283,185 4.49 5 0.0000 % 2,456.4
Performance Highlights
Issue Index Change Notes
ELF.PR.H Perpetual-Discount -1.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-12
Maturity Price : 23.49
Evaluated at bid price : 23.85
Bid-YTW : 5.82 %
BAM.PF.D Perpetual-Discount -1.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-12
Maturity Price : 19.55
Evaluated at bid price : 19.55
Bid-YTW : 6.37 %
FTS.PR.F Perpetual-Discount -1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-12
Maturity Price : 23.01
Evaluated at bid price : 23.30
Bid-YTW : 5.35 %
IAG.PR.E Deemed-Retractible 1.05 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-12-31
Maturity Price : 25.25
Evaluated at bid price : 25.87
Bid-YTW : 5.50 %
IAG.PR.G FixedReset 1.16 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-06-30
Maturity Price : 25.00
Evaluated at bid price : 26.12
Bid-YTW : 3.15 %
BAM.PR.R FixedReset 1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-12
Maturity Price : 23.65
Evaluated at bid price : 25.62
Bid-YTW : 4.13 %
HSE.PR.A FixedReset 1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-12
Maturity Price : 22.64
Evaluated at bid price : 23.19
Bid-YTW : 3.98 %
TRP.PR.C FixedReset 1.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-12
Maturity Price : 22.40
Evaluated at bid price : 22.78
Bid-YTW : 3.83 %
CIU.PR.A Perpetual-Discount 2.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-12
Maturity Price : 21.67
Evaluated at bid price : 21.67
Bid-YTW : 5.32 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.I FixedReset 263,640 Nesbitt crossed 260,000 at 25.18.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-02-24
Maturity Price : 25.00
Evaluated at bid price : 25.17
Bid-YTW : 2.03 %
BNS.PR.Z FixedReset 168,257 Nesbitt crossed blocks of 75,000 shares, 25,000 and 50,000, all at 25.70.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.71
Bid-YTW : 4.11 %
GWO.PR.J FixedReset 53,849 Called for redemption.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.30
Bid-YTW : 2.34 %
CU.PR.C FixedReset 32,182 Nesbitt crossed 10,000 at 26.05.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-06-01
Maturity Price : 25.00
Evaluated at bid price : 26.06
Bid-YTW : 2.70 %
ENB.PR.B FixedReset 30,715 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-12
Maturity Price : 23.25
Evaluated at bid price : 24.85
Bid-YTW : 4.18 %
BAM.PF.A FixedReset 28,995 TD crossed 23,100 at 25.45.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-09-30
Maturity Price : 25.00
Evaluated at bid price : 25.45
Bid-YTW : 4.23 %
There were 43 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
FTS.PR.E OpRet Quote: 26.17 – 26.53
Spot Rate : 0.3600
Average : 0.2131

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-12-12
Maturity Price : 25.75
Evaluated at bid price : 26.17
Bid-YTW : -3.57 %

SLF.PR.I FixedReset Quote: 25.94 – 26.34
Spot Rate : 0.4000
Average : 0.2687

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.94
Bid-YTW : 3.17 %

MFC.PR.C Deemed-Retractible Quote: 21.31 – 21.80
Spot Rate : 0.4900
Average : 0.3720

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.31
Bid-YTW : 6.49 %

CU.PR.E Perpetual-Discount Quote: 23.34 – 23.68
Spot Rate : 0.3400
Average : 0.2323

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-12
Maturity Price : 23.04
Evaluated at bid price : 23.34
Bid-YTW : 5.25 %

CU.PR.F Perpetual-Discount Quote: 20.99 – 21.25
Spot Rate : 0.2600
Average : 0.1623

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-12
Maturity Price : 20.99
Evaluated at bid price : 20.99
Bid-YTW : 5.38 %

GWO.PR.I Deemed-Retractible Quote: 22.00 – 22.28
Spot Rate : 0.2800
Average : 0.1915

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.00
Bid-YTW : 6.09 %

Market Action

November 11, 2013

Nothing happened today.

It was a mixed day for the Canadian preferred share market, with PerpetualDiscounts down 8bp, FixedResets up 27bp and DeemedRetractibles off 3bp. A fairly lengthy Performance Highlights table is comprised entirely of winners, mostly FixedResets. Volume was average.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.1687 % 2,517.3
FixedFloater 4.17 % 3.45 % 28,449 18.47 1 0.0439 % 4,028.4
Floater 2.95 % 2.97 % 61,067 19.76 3 0.1687 % 2,718.0
OpRet 4.60 % 2.28 % 69,034 0.38 3 0.3336 % 2,651.0
SplitShare 4.74 % 5.10 % 68,498 3.92 6 0.0969 % 2,963.1
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.3336 % 2,424.1
Perpetual-Premium 5.57 % 4.88 % 125,785 0.28 11 -0.0036 % 2,308.9
Perpetual-Discount 5.55 % 5.55 % 178,527 14.55 27 -0.0823 % 2,369.2
FixedReset 4.96 % 3.39 % 230,889 3.32 82 0.2740 % 2,479.3
Deemed-Retractible 5.07 % 3.96 % 194,384 1.48 42 -0.0300 % 2,413.6
FloatingReset 2.61 % 2.41 % 293,489 4.50 5 -0.0079 % 2,456.4
Performance Highlights
Issue Index Change Notes
CIU.PR.A Perpetual-Discount 1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-11
Maturity Price : 21.21
Evaluated at bid price : 21.21
Bid-YTW : 5.44 %
ENB.PR.B FixedReset 1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-11
Maturity Price : 23.24
Evaluated at bid price : 24.84
Bid-YTW : 4.18 %
BMO.PR.Q FixedReset 1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.60
Bid-YTW : 3.54 %
MFC.PR.F FixedReset 1.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.30
Bid-YTW : 4.36 %
GWO.PR.N FixedReset 1.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.08
Bid-YTW : 4.68 %
IAG.PR.A Deemed-Retractible 1.18 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.34
Bid-YTW : 6.02 %
PWF.PR.L Perpetual-Discount 1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-11
Maturity Price : 23.43
Evaluated at bid price : 23.73
Bid-YTW : 5.40 %
ENB.PR.H FixedReset 1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-11
Maturity Price : 22.79
Evaluated at bid price : 24.00
Bid-YTW : 4.12 %
BAM.PR.X FixedReset 1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-11
Maturity Price : 21.94
Evaluated at bid price : 22.32
Bid-YTW : 4.31 %
CU.PR.C FixedReset 1.53 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-06-01
Maturity Price : 25.00
Evaluated at bid price : 25.90
Bid-YTW : 2.88 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.I FixedReset 168,842 Nesbitt crossed blocks of 50,000 shares, 25,000 and 40,000, all at 25.18.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-02-24
Maturity Price : 25.00
Evaluated at bid price : 25.17
Bid-YTW : 2.01 %
BNS.PR.Z FixedReset 107,130 Nesbitt crossed blocks of 50,000 and 45,000, both at 23.70.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.85
Bid-YTW : 4.03 %
GWO.PR.M Deemed-Retractible 94,538 GMP sold 21,400 to Scotia at 25.46; 12,000 to Desjardins at 25.53; and another 12,000 to Scotia again at 25.53. Desjardins crossed 12,000 at 25.53; Scotia crossed 25,000 at the same price.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.53
Bid-YTW : 5.66 %
RY.PR.D Deemed-Retractible 63,870 Nesbitt crossed blocks of 50,000 and 10,000, both at 25.45.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2015-02-24
Maturity Price : 25.25
Evaluated at bid price : 25.34
Bid-YTW : 4.07 %
IAG.PR.F Deemed-Retractible 51,700 Nesbitt crossed 50,000 at 25.50.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.50
Bid-YTW : 5.78 %
ENB.PR.Y FixedReset 36,220 Desjardins crossed 15,000 at 23.60.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-11
Maturity Price : 22.67
Evaluated at bid price : 23.84
Bid-YTW : 4.35 %
There were 31 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
TD.PR.Y FixedReset Quote: 25.01 – 25.58
Spot Rate : 0.5700
Average : 0.3269

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.01
Bid-YTW : 3.57 %

MFC.PR.K FixedReset Quote: 24.19 – 24.57
Spot Rate : 0.3800
Average : 0.2620

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.19
Bid-YTW : 4.39 %

MFC.PR.C Deemed-Retractible Quote: 21.30 – 21.65
Spot Rate : 0.3500
Average : 0.2427

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.30
Bid-YTW : 6.50 %

BAM.PR.X FixedReset Quote: 22.32 – 22.77
Spot Rate : 0.4500
Average : 0.3463

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-11
Maturity Price : 21.94
Evaluated at bid price : 22.32
Bid-YTW : 4.31 %

BMO.PR.Q FixedReset Quote: 24.60 – 24.89
Spot Rate : 0.2900
Average : 0.2053

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.60
Bid-YTW : 3.54 %

TRP.PR.A FixedReset Quote: 24.24 – 24.50
Spot Rate : 0.2600
Average : 0.1794

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-11
Maturity Price : 23.77
Evaluated at bid price : 24.24
Bid-YTW : 3.95 %

Market Action

November 8, 2013

There was a good US jobs number:

The addition of 204,000 workers followed a revised 163,000 gain in September that was larger than initially estimated, Labor Department figures showed today in Washington. The median forecast of 91 economists surveyed by Bloomberg called for an increase of 120,000. The jobless rate rose to 7.3 percent from an almost five-year low.

This didn’t help the Treasury and gold markets much:

Treasuries sank the most since July and gold slid as a bigger-than-forecast increase in American payrolls fueled speculation the Federal Reserve may trim stimulus earlier than expected. The dollar strengthened against all 16 major peers while U.S. stocks advanced.

The yield on 10-year Treasuries jumped 14 basis points to 2.74 percent at 12:58 p.m. in New York and climbed as much as 16 basis points. Gold futures dropped 1.8 percent to $1,285.00 an ounce. The Standard & Poor’s 500 Index (SPX) rebounded 0.9 percent after tumbling 1.3 percent yesterday. French bonds fell after S&P downgraded the country’s debt. The dollar climbed 0.4 percent against the euro. AT&T Inc. and BNP Paribas SA led 21 billion euros ($28 billion) of bond sales in Europe this week, the busiest in two months.

That’s right, S&P downgraded France:

  • We believe the French government’s reforms to taxation, as well as to product, services, and labor markets, will not substantially raise France’s medium-term growth prospects, and that ongoing high unemployment is weakening support for further significant fiscal and structural policy measures.
  • Furthermore, we believe lower economic growth is constraining the government’s ability to consolidate public finances.
  • We are therefore lowering our long-term foreign and local currency sovereign credit ratings on France to ‘AA’.
  • The outlook is stable, reflecting our view that the probability that we will raise or lower the rating on France over the next two years is less than one-in-three.

Angst is rising over the Fed exit from QE:

The Fed’s financial-crisis actions — from acquiring debt in the 2008 rescues of Bear Stearns Cos. and American International Group Inc. to three rounds of quantitative easing — have led so far to the record payments. Now, the prospect of a stronger economy and rising interest rates means the value of the Fed’s bond holdings will fall at the same time its funding costs climb because the central bank pays interest on the excess reserves it holds for banks.

This could cause operating losses and invite increased scrutiny from lawmakers already critical of the central bank’s policies.

That’s a risk central bankers are grappling with as they consider when to slow the $85 billion monthly pace of their government and mortgage-backed securities purchases. Federal Reserve Bank of New York President William C. Dudley said in a speech last month that the central bank’s balance-sheet expansion does “create some budget risk” that threatens the institution’s independence.

I know a number of Asset Managers read this blog. How would you guys like a quarter like these guys?

Pacific Investment Management Co., the world’s largest fixed-income manager, had $39 billion in net redemptions during the third quarter as investors fled bonds in anticipation of rising interest rates.

It was a mixed day for the Canadian preferred share market, with PerpetualDiscounts down 51bp, FixedResets up 22bp and DeemedRetractibles gaining 2bp. As might be expected, the Performance Highlights table is fairly lengthy, with the down side dominated by Perpetual Discounts and winners by FixedResets. Volume was very high.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.2058 % 2,513.0
FixedFloater 4.17 % 3.45 % 28,102 18.47 1 1.1540 % 4,026.7
Floater 2.95 % 2.98 % 62,050 19.75 3 -0.2058 % 2,713.4
OpRet 4.62 % 2.92 % 68,834 0.38 3 0.1800 % 2,642.2
SplitShare 4.74 % 5.10 % 69,402 3.93 6 0.0474 % 2,960.2
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1800 % 2,416.0
Perpetual-Premium 5.57 % 2.42 % 125,907 0.09 11 0.0809 % 2,309.0
Perpetual-Discount 5.55 % 5.53 % 177,655 14.57 27 -0.5123 % 2,371.1
FixedReset 4.98 % 3.50 % 231,640 3.32 82 0.2179 % 2,472.6
Deemed-Retractible 5.07 % 3.92 % 197,178 1.64 42 0.0242 % 2,414.3
FloatingReset 2.61 % 2.41 % 284,464 4.51 5 0.0000 % 2,456.6
Performance Highlights
Issue Index Change Notes
BAM.PF.C Perpetual-Discount -1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-08
Maturity Price : 19.81
Evaluated at bid price : 19.81
Bid-YTW : 6.22 %
ELF.PR.H Perpetual-Discount -1.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-08
Maturity Price : 23.73
Evaluated at bid price : 24.10
Bid-YTW : 5.75 %
BAM.PF.D Perpetual-Discount -1.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-08
Maturity Price : 19.87
Evaluated at bid price : 19.87
Bid-YTW : 6.26 %
FTS.PR.J Perpetual-Discount -1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-08
Maturity Price : 22.58
Evaluated at bid price : 22.95
Bid-YTW : 5.25 %
BAM.PR.M Perpetual-Discount -1.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-08
Maturity Price : 20.09
Evaluated at bid price : 20.09
Bid-YTW : 6.00 %
CU.PR.E Perpetual-Discount -1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-08
Maturity Price : 23.23
Evaluated at bid price : 23.55
Bid-YTW : 5.20 %
ELF.PR.F Perpetual-Discount -1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-08
Maturity Price : 23.09
Evaluated at bid price : 23.35
Bid-YTW : 5.72 %
BAM.PR.R FixedReset -1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-08
Maturity Price : 23.47
Evaluated at bid price : 25.07
Bid-YTW : 4.25 %
BAM.PR.N Perpetual-Discount -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-08
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 6.03 %
TRP.PR.A FixedReset 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-08
Maturity Price : 23.95
Evaluated at bid price : 24.40
Bid-YTW : 3.92 %
BAM.PR.G FixedFloater 1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-08
Maturity Price : 22.97
Evaluated at bid price : 22.79
Bid-YTW : 3.45 %
SLF.PR.G FixedReset 1.39 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.01
Bid-YTW : 3.93 %
ENB.PR.N FixedReset 1.47 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-12-01
Maturity Price : 25.00
Evaluated at bid price : 24.90
Bid-YTW : 4.28 %
IFC.PR.A FixedReset 1.93 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.76
Bid-YTW : 4.48 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.W Perpetual-Premium 113,050 RBC crossed 100,000 at 25.05.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-02-24
Maturity Price : 25.00
Evaluated at bid price : 25.00
Bid-YTW : 4.19 %
RY.PR.R FixedReset 110,268 Nesbitt bought blocks of 13,700 shares, 15,000 and 20,000 from RBC all at 25.30; then bought another 11,700 from TD at the same price.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-02-24
Maturity Price : 25.00
Evaluated at bid price : 25.22
Bid-YTW : 2.33 %
TD.PR.O Deemed-Retractible 100,818 TD crossed 99,900 at 25.40.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-12-08
Maturity Price : 25.25
Evaluated at bid price : 25.43
Bid-YTW : -2.57 %
BNS.PR.Z FixedReset 76,515 RBC bought 61,500 from Dundee at 61,500.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.75
Bid-YTW : 4.08 %
BMO.PR.J Deemed-Retractible 74,986 TD crossed 70,000 at 25.64.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-02-25
Maturity Price : 25.50
Evaluated at bid price : 25.64
Bid-YTW : 1.88 %
TD.PR.Y FixedReset 58,970 TD crossed 50,000 at 24.90.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.94
Bid-YTW : 3.60 %
There were 61 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
TRP.PR.D FixedReset Quote: 24.48 – 24.98
Spot Rate : 0.5000
Average : 0.3428

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-08
Maturity Price : 22.95
Evaluated at bid price : 24.48
Bid-YTW : 4.17 %

FTS.PR.J Perpetual-Discount Quote: 22.95 – 23.39
Spot Rate : 0.4400
Average : 0.2871

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-08
Maturity Price : 22.58
Evaluated at bid price : 22.95
Bid-YTW : 5.25 %

MFC.PR.F FixedReset Quote: 23.05 – 23.39
Spot Rate : 0.3400
Average : 0.2161

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.05
Bid-YTW : 4.48 %

IFC.PR.A FixedReset Quote: 23.76 – 24.12
Spot Rate : 0.3600
Average : 0.2377

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.76
Bid-YTW : 4.48 %

GWO.PR.N FixedReset Quote: 21.83 – 22.18
Spot Rate : 0.3500
Average : 0.2433

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.83
Bid-YTW : 4.80 %

BAM.PF.C Perpetual-Discount Quote: 19.81 – 20.05
Spot Rate : 0.2400
Average : 0.1427

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-08
Maturity Price : 19.81
Evaluated at bid price : 19.81
Bid-YTW : 6.22 %

Market Action

November 7, 2013

Maybe we will have a return to Rae Days as well!

Ontario is prepared to miss its deficit-reduction targets to avoid deep program cuts as Premier Kathleen Wynne’s government walks away from austerity.

The shift in priorities – which will effectively see the minority Liberal administration embrace deficit spending as the best way to rev up the province’s sluggish economy – will be signalled in Finance Minister Charles Sousa’s fall economic statement on Thursday, government sources told The Globe and Mail.

Policy rates were slashed in Europe:

The European Central Bank surprised the market today by cutting interest rates to a record low as falling inflation threatened its mission of keeping prices stable in the 17-country euro zone.

Wholly unexpected by the vast majority of economists, the announcement triggered an immediate fall in the euro. My mid-afternoon central European time, it was down almost 1.5 per cent against the dollar. Commodities fell while stock indexes rose.
…
ECB president Mario Draghi said he expected a “prolonged” period of low inflation but would not define that period, insisting he would have a better picture in December, when the next inflation gauge and other economic date are due. “It’s not going to be a short, short time,” he said at the ECB’s press conference in Frankfurt.

I’ve always said – they may be in trouble, they may always be in second place to the foreign flavour of the month, but it’s hard to make money betting against America:

Specialty operations are finding new opportunities because of 3-D printers, said Patrick Hunter, senior vice president of marketplace operations for MFG.com in Atlanta. The technology allows three-dimensional designs created on computers to be sent digitally to industrial machines, which put down layers of materials ranging from plastic to metal to create parts or products.

“It’s opened the doors to smaller shops because people aren’t tied to the large mass manufacturers,” said Hunter, whose company has been matching companies with parts makers for about a dozen years.

Low volume typically means runs of products of more than 1,000, which exceeds capacity of a home workshop, and less than 5,000 to 10,000, which is usually the minimum to get work done overseas at a factory in China, he said.

More than 58 percent of small shops added new machines for so-called additive technology in 2012, the third year of gains since the recession ended, according to Wohlers Report 2013, which tracks the industrial market for industrial 3-D printing technology from Fort Collins, Colorado.

I have long criticized the standard five-year term for mortgage loans in Canada – it makes no sense to finance a long-term asset exclusively with a short-term loan, although it makes all kinds of sense for lender. The US model, for all its myriad faults, at least matches financing certainty with asset life. But in Denmark the mismatch is even worse:

Danish mortgage banks have struggled to wean borrowers off loans funded by one-year bonds as deadlines near to demonstrate they can withstand a 12-month funding market freeze. Standard & Poor’s in July told lenders they risked downgrades if they don’t cut use of the securities over the next two years. The central bank has also criticized the bonds and the risks borrowers face if interest rates rise.

One-year bonds fund about 40 percent of home loans in Denmark. Borrowers have been attracted to record-low rates thanks to AAA-rated Denmark’s status as a haven from Europe’s debt crisis. Still, households have grown more exposed to interest-rate shocks as debt burdens soar to a world-record of 310 percent of disposable incomes, according to data compiled by the Organization for Economic Cooperation and Development.

Under the government’s proposed measure, short-term bonds would convert to longer-term securities if refinancing auctions fail or interest rates climb in auctions by more than 5 percentage points. Existing bonds would be excluded from the measure, which would go into effect Jan. 1 if approved by lawmakers.

The bonds convert if the auctions fail? Have the lessons of the financial crisis been forgotten so quickly?

It was a positive day for the Canadian preferred share market, with PerpetualDiscounts flat, FixedResets winning 15bp and DeemedRetractibles gaining 9bp. Volatility was average by long term standards, very low by standards of the past six months. Volume was well above average.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.0000 % 2,518.2
FixedFloater 4.22 % 3.49 % 27,201 18.38 1 0.7603 % 3,980.7
Floater 2.95 % 2.97 % 62,833 19.79 3 0.0000 % 2,719.0
OpRet 4.63 % 2.97 % 69,206 0.60 3 0.0514 % 2,637.5
SplitShare 4.74 % 5.10 % 68,680 3.94 6 -0.1383 % 2,958.8
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0514 % 2,411.7
Perpetual-Premium 5.57 % 3.22 % 126,090 0.09 11 -0.0647 % 2,307.1
Perpetual-Discount 5.52 % 5.54 % 179,211 14.57 27 0.0032 % 2,383.3
FixedReset 4.99 % 3.55 % 232,477 3.35 82 0.1526 % 2,467.2
Deemed-Retractible 5.07 % 3.97 % 197,780 1.72 42 0.0890 % 2,413.7
FloatingReset 2.62 % 2.41 % 288,613 4.51 5 0.0079 % 2,456.6
Performance Highlights
Issue Index Change Notes
HSE.PR.A FixedReset 1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-07
Maturity Price : 22.52
Evaluated at bid price : 23.01
Bid-YTW : 3.94 %
SLF.PR.G FixedReset 1.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.68
Bid-YTW : 4.01 %
MFC.PR.B Deemed-Retractible 1.38 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.06
Bid-YTW : 6.24 %
Volume Highlights
Issue Index Shares
Traded
Notes
CM.PR.K FixedReset 265,693 Nesbitt crossed two blocks of 100,000 each and one of 30,000, all at 25.51 (nice tickets!); TD crossed 30,000 at the same price.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-07-31
Maturity Price : 25.00
Evaluated at bid price : 25.53
Bid-YTW : 2.59 %
ENB.PR.T FixedReset 211,048 TD crossed 205,000 at 23.90. Another nice ticket!
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-07
Maturity Price : 22.72
Evaluated at bid price : 23.95
Bid-YTW : 4.35 %
MFC.PR.C Deemed-Retractible 188,286 RBC crossed 169,000 at 21.35.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.45
Bid-YTW : 6.40 %
RY.PR.I FixedReset 128,268 Nesbitt crossed 100,000 at 25.10; TD crossed 15,000 at the same price.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-02-24
Maturity Price : 25.00
Evaluated at bid price : 25.10
Bid-YTW : 2.88 %
RY.PR.Y FixedReset 106,296 TD crossed 99,000 at 25.95.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-11-24
Maturity Price : 25.00
Evaluated at bid price : 25.97
Bid-YTW : 2.09 %
SLF.PR.F FixedReset 80,800 TD crossed 75,000 at 25.71.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-06-30
Maturity Price : 25.00
Evaluated at bid price : 25.72
Bid-YTW : 2.50 %
There were 48 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
RY.PR.T FixedReset Quote: 25.73 – 26.24
Spot Rate : 0.5100
Average : 0.3237

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-08-24
Maturity Price : 25.00
Evaluated at bid price : 25.73
Bid-YTW : 2.20 %

CIU.PR.A Perpetual-Discount Quote: 21.00 – 21.47
Spot Rate : 0.4700
Average : 0.2954

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-07
Maturity Price : 21.00
Evaluated at bid price : 21.00
Bid-YTW : 5.49 %

HSB.PR.C Deemed-Retractible Quote: 25.12 – 25.50
Spot Rate : 0.3800
Average : 0.2272

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.12
Bid-YTW : 5.14 %

BAM.PR.K Floater Quote: 17.82 – 18.17
Spot Rate : 0.3500
Average : 0.2433

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-07
Maturity Price : 17.82
Evaluated at bid price : 17.82
Bid-YTW : 2.97 %

TRP.PR.C FixedReset Quote: 22.44 – 22.79
Spot Rate : 0.3500
Average : 0.2556

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-07
Maturity Price : 22.16
Evaluated at bid price : 22.44
Bid-YTW : 3.81 %

FTS.PR.H FixedReset Quote: 21.55 – 21.80
Spot Rate : 0.2500
Average : 0.1782

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-07
Maturity Price : 21.27
Evaluated at bid price : 21.55
Bid-YTW : 3.86 %

Market Action

November 6, 2013

US regulators are making a a big move to extend their power:

BlackRock Inc. (BLK) and Fidelity Investments will be studied by U.S. regulators who are in the early stages of reviewing whether asset managers pose a potential risk to the financial system, two people with knowledge of the matter said.

The Financial Stability Oversight Council’s discussion Oct. 31 and agreement to review New York-based BlackRock and Boston-based Fidelity don’t necessarily mean the companies will be designated systemically important by the council, according to the people, who requested anonymity because the meeting was closed to the public. The panel didn’t take any formal action regarding the companies.

FSOC’s preliminary talks may presage months of wrangling between the industry and officials charged with trying to prevent a repeat of the 2008 financial crisis. Asset managers are among non-bank financial companies that the council is empowered by law to evaluate to determine whether their failure could threaten the entire system and thus require Federal Reserve oversight. BlackRock, Fidelity and the mutual-fund industry’s trade group have said money managers aren’t a threat.

Political cover for the investigation is provided by an Office of Financial Research (who?) report titled Asset Management and Financial Stability:

Reflecting these issues, this report describes:

  • • the activities of asset management firms and the funds they manage;
  • • the key factors that make the industry vulnerable to shocks: (1) “reaching for yield” and herding behaviors; (2) redemption risk in collective investment vehicles; (3) leverage, which can amplify asset price movements and increase the potential for fire sales; and (4) firms as sources of risk;
  • • the key channels through which shocks can be transmitted: exposures across funds and firms and the impacts of fire sales; and
  • • the data available to measure those activities, vulnerabilities, and channels, and the nature of the gaps in those data.

The report does not focus on particular risks posed by money market funds. In November 2012, the Council released a detailed analysis of these funds and their risks, and the Securities and Exchange Commission (SEC) recently proposed additional reforms.2
In addition, the activities and risks posed by hedge funds, private equity, and other private funds are not addressed in detail. Additional analysis will be conducted in conjunction with further analysis of data that these funds have begun to file on Form PF. The OFR, SEC, and Commodity Futures Trading Commission (CFTC) are currently evaluating these data for monitoring purposes.

Assiduous Readers will remember that in the case of Money Market Funds, the much-needed regulatory reform was beaten back by the industry and MMFs can continue to operate as zero-capital banks. I have complete faith in the regulators to get everything backwards and regulate the hell out of asset management firms.

Here’s another region with a lousy economy:

Waning European growth and inflation will put pressure on the European Central Bank (ECB) to cut interest rates in an effort to keep the fragile recovery intact.

The autumn economic update released on Tuesday by the European Commission (EC) showed that the euro-zone economy will return to growth in 2014, after two years of recession, but at a slower pace than was forecast in the spring. Inflation in the euro zone fell to just 0.7 per cent in October, the lowest rate since 2009, when the financial crisis was at its peak.

Sometimes – not very often – there is some justice in the world:

Four Deutsche Bank AG (DBK) traders who won reinstatement of their jobs after they were dismissed following an internal probe into rate-rigging were awarded 365,474 euros ($493,370) in missed salary.

The total monthly pay of the four men, who were fired in February, ranged from 10,833 euros to 22,083 euros on average, according to the written version of the judgment made Sept. 11 and released by the Frankfurt Labor Court today. The men, whose names weren’t disclosed, returned to work on Nov. 4, according to the bank.
…
The traders said that before they were dismissed, their bonuses for 2011 were reduced as a sanction for their allegedly inappropriate behavior and that an unidentified Deutsche Bank official said they would be compensated once “the situation had calmed down,” according to the ruling.

Deutsche Bank disputes that account, the document shows. A spokesman for Deutsche Bank, Christian Streckert, declined to immediately comment when reached by phone today.

The court said the total value of the wrongful dismissal claims is 1.9 million euros. That number reflects the pay owed to the plaintiffs, including any potential future earnings under their employment contract.

The poor regulators will have to fill in the notch they made in their red pencil! Well, never mind, there are other careers to destroy and lives to ruin. And after all, the the hysteria helps balance government budgets:

A number of finance firms, including Royal Bank of Scotland and Rabobank face billions of euros in fines next month from European Union regulators for colluding on global benchmark interest rates, reinforcing Brussels’ hard line on the sector after the financial crisis.

EU antitrust chief Joaquin Almunia is set to unveil a record fine of at least €1.5-billion ($2-billion) on six banks, including Barclays and RBS, for rigging the yen Libor interest rate benchmark, a banking source said on Wednesday.

There’s a new wrinkle in the Treasury market:

The U.S. Treasury Department will sell $10 billion to $15 billion of its first floating-rate notes Jan. 29 and said a period of political wrangling over the budget requires a delay in plans to reduce coupon auctions.

The floating-rate notes will have a two-year maturity and be the Treasury’s first new security in 17 years, the department said today in its quarterly refunding announcement. Note and bond sales next week will total $70 billion, the lowest since February 2009 and less than the $72 billion auctioned last quarter, the Treasury said.
…
Floaters are securities with rates set periodically, and the Treasury’s notes will be referenced to the 13-week bill rate. They are the first new U.S. government debt securities since Treasury Inflation-Protected Securities were introduced in 1997.

It was a mildly positive day for the Canadian preferred share market, with PerpetualDiscounts winning 13bp, FixedResets up 10bp and DeemedRetractibles gaining 3bp. The Performance Highlights table is dominated by FixedResets with low Issue Reset Spreads. Volume was well above average.

PerpetualDiscounts now yield 5.54%, equivalent to 7.20% interest at the standard equivalency factor of 1.3x. Long Corporates now yield about 4.7%, so the pre-tax, interest-equivalent spread between the two is now about 250bp, a slight (and perhaps spurious, particularly given the index rebalancing as of October 31) increase from the 245bp reported October 31.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.6212 % 2,518.2
FixedFloater 4.25 % 3.52 % 27,477 18.33 1 -0.8865 % 3,950.7
Floater 2.95 % 2.96 % 63,432 19.79 3 0.6212 % 2,719.0
OpRet 4.63 % 3.11 % 68,501 0.60 3 -0.0129 % 2,636.1
SplitShare 4.74 % 5.08 % 68,938 3.66 6 -0.0014 % 2,962.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0129 % 2,410.4
Perpetual-Premium 5.57 % 2.03 % 127,777 0.09 11 0.1817 % 2,308.6
Perpetual-Discount 5.52 % 5.54 % 179,750 14.55 27 0.1287 % 2,383.3
FixedReset 5.00 % 3.57 % 231,919 3.35 82 0.1046 % 2,463.4
Deemed-Retractible 5.08 % 4.05 % 197,741 1.49 42 0.0716 % 2,411.5
FloatingReset 2.62 % 2.39 % 292,554 4.51 5 0.0159 % 2,456.4
Performance Highlights
Issue Index Change Notes
FTS.PR.H FixedReset -1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-06
Maturity Price : 21.40
Evaluated at bid price : 21.40
Bid-YTW : 3.91 %
MFC.PR.K FixedReset 1.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.00
Bid-YTW : 4.43 %
BAM.PR.X FixedReset 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-06
Maturity Price : 21.99
Evaluated at bid price : 22.40
Bid-YTW : 4.21 %
SLF.PR.G FixedReset 1.21 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.41
Bid-YTW : 4.14 %
BNS.PR.O Deemed-Retractible 1.34 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-12-06
Maturity Price : 26.00
Evaluated at bid price : 26.40
Bid-YTW : -11.78 %
TRP.PR.A FixedReset 1.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-06
Maturity Price : 23.50
Evaluated at bid price : 24.00
Bid-YTW : 3.91 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.Y FixedReset 118,962 TD crossed blocks of 50,000 and 25,000 at 25.92. RBC crossed 25,000 at the same price; Scotia crossed 12,100 at 25.95.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-11-24
Maturity Price : 25.00
Evaluated at bid price : 25.95
Bid-YTW : 2.16 %
TD.PR.Y FixedReset 104,102 TD crossed 99,900 at 24.87.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.87
Bid-YTW : 3.61 %
IAG.PR.C FixedReset 77,301 Called for redemption.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.31
Bid-YTW : 2.15 %
ENB.PR.N FixedReset 52,348 Nesbitt crossed 19,700 at 24.50 and sold 10,000 to Scotia at the same price.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-06
Maturity Price : 22.96
Evaluated at bid price : 24.46
Bid-YTW : 4.37 %
BMO.PR.J Deemed-Retractible 51,110 TD crossed 40,000 at 25.62.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-02-25
Maturity Price : 25.50
Evaluated at bid price : 25.59
Bid-YTW : 2.49 %
TD.PR.A FixedReset 46,240 RBC bought 26,500 from Scotia at 25.18.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.19
Bid-YTW : 2.11 %
There were 44 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
RY.PR.X FixedReset Quote: 25.64 – 26.10
Spot Rate : 0.4600
Average : 0.3626

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-08-24
Maturity Price : 25.00
Evaluated at bid price : 25.64
Bid-YTW : 2.65 %

BAM.PR.G FixedFloater Quote: 22.36 – 22.79
Spot Rate : 0.4300
Average : 0.3423

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-06
Maturity Price : 22.65
Evaluated at bid price : 22.36
Bid-YTW : 3.52 %

TRP.PR.D FixedReset Quote: 24.65 – 24.98
Spot Rate : 0.3300
Average : 0.2479

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-06
Maturity Price : 23.01
Evaluated at bid price : 24.65
Bid-YTW : 4.07 %

MFC.PR.B Deemed-Retractible Quote: 21.76 – 22.00
Spot Rate : 0.2400
Average : 0.1628

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.76
Bid-YTW : 6.40 %

RY.PR.C Deemed-Retractible Quote: 25.49 – 25.83
Spot Rate : 0.3400
Average : 0.2684

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-12-24
Maturity Price : 25.50
Evaluated at bid price : 25.49
Bid-YTW : 3.13 %

ELF.PR.G Perpetual-Discount Quote: 21.66 – 21.99
Spot Rate : 0.3300
Average : 0.2619

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-06
Maturity Price : 21.66
Evaluated at bid price : 21.66
Bid-YTW : 5.54 %

Market Action

November 5, 2013

OSFI has released a letter to IASB about Insurance Contracts. Their first objection is serious – very serious indeed:

We are concerned that, if the ED is finalized as proposed, OSFI would likely need to make significant adjustments to the financial statements for regulatory capital purposes.

Oh golly! They might have to change their regulatory capital calculations!

Funny, I would have thought that the sole legitimate consideration was: do the proposed changes provide a materially better reflection of reality than the prior accounting paradigm? But I suppose I am only parading my naivety.

Their second objection is equally oblivious to the issues:

Moreover, the adjustments in question may have the effect of relaxing rather than constraining the assumptions that lie behind the requirements of the standard.

Well, that’s fine – as long as the new standards reflect reality better than the old ones, who cares whether they’re relaxing or constraining?

The meat of their letter highlights some motherhood issues, but doesn’t provide any suggestions:

In our 2010 comment letter, OSFI noted the potential for significant, inappropriate volatility if short term fluctuating market rates were used to discount very long-duration liabilities. The IASB has confirmed that either a bottom-up or top-down approach could be used to determine the discount rate. However, due to the high-level nature of a principles based standard, we understand there are a wide range of views of how the top-down approach could be interpreted for the long duration discount rates as currently drafted in the ED. We are pleased that the exposure draft allows more weight to be put on long term estimates than on short-term fluctuations when forecasting unobservable discount rates for long-duration liabilities. We believe current period fluctuations should not exaggerate the volatility of very long-dated liabilities. As such, long-duration liabilities beyond the observable period where deep and liquid markets exist should grade to a slow-moving long-term rate.

When discussing Asset Liability Management, they’re a little shy about stating their concern directly:

We believe the use of OCI for insurance contract liability measurement should be optional, rather than mandatory as currently proposed in the ED.

Asset Liability Management (ALM) practices are designed to ensure that there are sufficient assets to support insurance liabilities. This is achieved by investing in various types of assets with different attributes (e.g. yield, cash flow, risk and duration) that best fulfill various insurance liabilities obligations. Accounting standards should capture economic mismatches between assets and the insurance contract liabilities they support, but standards should not create accounting mismatches on their own. We believe the mandatory use of OCI may have an unintended consequence by reflecting both economic and accounting mismatches in the financial statements, making it difficult for users to distinguish between true economic mismatches and those created by accounting standards.

In order to fulfill various types of insurance liabilities obligations, investing in assets like mortgages, equities and derivatives instead of plain vanilla bonds could be appropriate for a portfolio that is well managed and diversified. We believe the interaction between IFRS 4 and IFRS 9 needs further consideration to take into account ALM practices of life insurers and to reduce accounting mismatches.

A very bureaucratic letter! All the substance will take place behind closed doors, to ensure opacity and non-accountability.

The latest housing bubble worry emanates from Australia:

Australia, where housing accounts for about 60 percent of average household wealth compared with a global average of 45 percent, joins countries from Canada to Sweden to China seeing rapid price gains amid low borrowing costs that are sparking fears of a housing bubble. For now, constrained housing supply and demand from investors are driving prices higher, overpowering the downdraft from slower economic growth and a rising jobless rate.
…
In Sydney, the nation’s most populous city, the average home price surged 13 percent in the 10 months to Oct. 31 to a record A$718,122 according to the RP Data-Rismark home value index. That compares with $806,000 in New York as of Sept. 30, according to the Real Estate Board of New York, and 331,338 pounds ($536,237) in London, according to the Nationwide Building Society.

A report to the U.S. Treasury’s Borrowing Advisory committee titled Assessing fixed income market liquidity makes some cogent points:

  • ● Market turnover has if anything increased since the financial crisis
  • ● But liquidity is about much more than turnover
    • – Tendency to disappear abruptly when really needed
  • ● Primary liquidity not really a problem; major issues all in secondary
  • ● Neither turnover nor the street have been able to keep pace with the massive expansion in markets
  • ● Regulations have created multiple constraints likely to curtail liquidity when it is really needed:
    • – Most have pushed liquidity towards Treasuries, reducing it in risky assets:
    • • Basel risk-weightings, swaps clearing, LCR requirements
      • – Now, supplementary leverage ratios risk curtailing it even in Treasuries: dealers likely to meet requirements by reducing assets rather than raising capital
    • ● Effects of regulations to date have been offset by Fed policy pushing investors in the opposite direction:
      • – Significant demand for fixed income assets in general, and risky assets in particular
    • ● Technology and shifts in market structure have added to the appearance of liquidity, but done little to add depth
    • ● Potential for significant dislocation when investor flows reverse

    …
    Secondary trading requires risk warehouses
    …
    Capital cost under Basel 3 … 3-5x increase in charges for corporate bonds
    …
    Dealers can no longer afford to act as credit warehouses

There are a lot of great charts in those slides and I thoroughly recommend a full reading of the presentation. It strikes me that at some point, some large hedge fund – perhaps one that already acts as an intermediary for retail equity trades, standing between the brokerage house and the exchanges – will find it worth their while to make markets from their long positions. I think that – subject to regulatory bullshit, which is probably extremely bullshitty – the big Canadian funds should be doing that now. Why not?

It was a mixed day for the Canadian preferred share market, with PerpetualDiscounts up 5bp, FixedResets gaining 2bp and DeemedRetractibles off 8bp. Volatility was dominated by FixedResets. Volume was well above average.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.4919 % 2,502.7
FixedFloater 4.21 % 3.49 % 27,719 18.40 1 1.0753 % 3,986.0
Floater 2.96 % 2.99 % 64,160 19.72 3 0.4919 % 2,702.2
OpRet 4.63 % 3.16 % 67,451 0.56 3 0.1030 % 2,636.4
SplitShare 4.74 % 5.08 % 68,605 3.66 6 0.2154 % 2,962.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1030 % 2,410.8
Perpetual-Premium 5.58 % 4.35 % 126,215 0.30 11 -0.0611 % 2,304.4
Perpetual-Discount 5.51 % 5.53 % 181,283 14.56 27 0.0481 % 2,380.2
FixedReset 5.00 % 3.61 % 227,137 3.35 82 0.0158 % 2,460.8
Deemed-Retractible 5.08 % 4.08 % 193,768 1.65 42 -0.0822 % 2,409.8
FloatingReset 2.62 % 2.38 % 297,228 4.51 5 -0.0793 % 2,456.0
Performance Highlights
Issue Index Change Notes
TRP.PR.A FixedReset -1.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-05
Maturity Price : 23.05
Evaluated at bid price : 23.56
Bid-YTW : 3.98 %
FTS.PR.H FixedReset -1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-05
Maturity Price : 21.36
Evaluated at bid price : 21.66
Bid-YTW : 3.84 %
ELF.PR.G Perpetual-Discount -1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-05
Maturity Price : 21.77
Evaluated at bid price : 21.77
Bid-YTW : 5.51 %
BAM.PR.X FixedReset -1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-05
Maturity Price : 21.82
Evaluated at bid price : 22.16
Bid-YTW : 4.26 %
BAM.PR.G FixedFloater 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-05
Maturity Price : 22.80
Evaluated at bid price : 22.56
Bid-YTW : 3.49 %
SLF.PR.G FixedReset 1.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.13
Bid-YTW : 4.27 %
BAM.PR.T FixedReset 1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-05
Maturity Price : 22.83
Evaluated at bid price : 23.81
Bid-YTW : 4.34 %
Volume Highlights
Issue Index Shares
Traded
Notes
W.PR.H Perpetual-Discount 61,700 TD crossed blocks of 30,000 and 25,000, both at 24.45.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-05
Maturity Price : 24.20
Evaluated at bid price : 24.46
Bid-YTW : 5.67 %
TRP.PR.C FixedReset 57,295 Nesbitt crossed 17,700 at 22.75.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-05
Maturity Price : 22.20
Evaluated at bid price : 22.50
Bid-YTW : 3.79 %
NA.PR.L Deemed-Retractible 57,133 TD crossed blocks of 12,000 and 40,000 at 25.38.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-12-05
Maturity Price : 25.25
Evaluated at bid price : 25.27
Bid-YTW : 2.24 %
CM.PR.M FixedReset 56,870 RBC crossed 50,000 at 25.75.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-07-31
Maturity Price : 25.00
Evaluated at bid price : 25.71
Bid-YTW : 2.76 %
FTS.PR.E OpRet 53,600 RBC crossed 48,100 at 26.00.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-06-01
Maturity Price : 25.50
Evaluated at bid price : 25.96
Bid-YTW : 3.16 %
IFC.PR.C FixedReset 45,022 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-09-30
Maturity Price : 25.00
Evaluated at bid price : 25.26
Bid-YTW : 3.99 %
There were 45 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
GWO.PR.J FixedReset Quote: 25.34 – 25.97
Spot Rate : 0.6300
Average : 0.4338

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.34
Bid-YTW : 1.01 %

BAM.PR.C Floater Quote: 17.65 – 18.14
Spot Rate : 0.4900
Average : 0.3065

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-05
Maturity Price : 17.65
Evaluated at bid price : 17.65
Bid-YTW : 2.99 %

RY.PR.X FixedReset Quote: 25.65 – 26.08
Spot Rate : 0.4300
Average : 0.2558

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-08-24
Maturity Price : 25.00
Evaluated at bid price : 25.65
Bid-YTW : 2.59 %

CIU.PR.C FixedReset Quote: 21.16 – 21.93
Spot Rate : 0.7700
Average : 0.6169

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-05
Maturity Price : 21.16
Evaluated at bid price : 21.16
Bid-YTW : 3.85 %

TRP.PR.A FixedReset Quote: 23.56 – 23.99
Spot Rate : 0.4300
Average : 0.3065

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-05
Maturity Price : 23.05
Evaluated at bid price : 23.56
Bid-YTW : 3.98 %

RY.PR.C Deemed-Retractible Quote: 25.40 – 25.70
Spot Rate : 0.3000
Average : 0.1898

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2015-11-24
Maturity Price : 25.00
Evaluated at bid price : 25.40
Bid-YTW : 3.69 %

Market Action

November 4, 2013

So what happens to US banks if skyrocketting interest rates cause another housing collapse? The Fed wants to know:

The Federal Reserve said it will examine how the biggest banks might react to a jump in long-term interest rates and another housing crash as it released the next round of stress-test scenarios designed to monitor the ability of the U.S. financial system to withstand economic shocks.

The central bank mentioned that as part of two adverse scenarios it will gauge bank resilience against declines in the prices of high-risk, high-yield loans and debt and some high-priced real estate markets around the country, according to a statement released in Washington today. The central bank also inserted a test for large trading and clearing banks on counterparty default.

There’s an interesting piece on Bloomberg about local government in the rural US:

Monroe is hemorrhaging residents, like rural jurisdictions across the U.S. Yet these communities operate with the same layers of government as when horse-and-buggy travel helped determine the boundaries of the nation’s more than 3,000 counties. As population drops and infrastructure decays, officials and residents concerned about the loss of jobs and identity resist shrinking their government.

“People like that eye-to-eye contact,” said Monroe County Judge Larry Taylor, the top elected official in the county of 7,800. It has lost 44 percent of its population since 1980 as its main budget grew 9 percent, even when adjusted for inflation.
…
In North Dakota, public costs would have fallen 2.5 percent annually by combining general government, road maintenance, public safety, and health and welfare, according to a 1996 North Dakota State University analysis of a failed proposal to merge 53 counties into 15.

Rob Carrick of the Globe writes an interesting piece on BMO’s generic advisor, titled Investing advice: How adviceDirect stakes out middle ground:

In the investing business, there’s no surer validation of a new initiative than having your competitors copy you. AdviceDirect has struck out on that count. After a full year in operation, no one else has introduced a service where clients invest online while receiving a combination of Web-based and person-to-person advice.

But adviceDirect is on to something in targeting people who gravitate to DIY investing, but need help. “The discipline adviceDirect gives a do-it-yourself investor can be very attractive for people who don’t have the time, the experience or the confidence,” says Viki Lazaris, president and CEO of BMO InvestorLine.
…
BMO won’t say how many people have signed up for adviceDirect, but you get an idea of how busy things are in the fact that the advice team there comprises just eight people right now. If adviceDirect manages to build its franchise, it will be a result of the work done by these investment specialists (that’s BMO’s title for them).

I’ll suggest that a good business case for adviceDirect can be made solely on the basis of insurance … insuring BMO against the risk that mutual fund trailers will be banned (see various posts and comments commencing on December 17, 2012). In such a case, they’ll be up and running with a working model of access to small investors and that head start could be quite an advantage.

Incidentally, there was a bit of an update on that situation in June:

Indeed, according to the OSC’s transcript of the event, Greg Pollock, president and CEO of Advocis, cautioned that “financial advice would become unaffordable, and therefore
inaccessible, to the average Canadian.”

There also are fears that any move away from embedded commissions could ultimately drive many advisors out of the business. Indeed, defenders of the current system point to the U.K., which introduced new rules outlawing embedded commissions, among other reforms, on Jan. 1. It was suggested at the OSC meeting that the U.K. has lost 25% of its advisory sales force due to its ban on commissions, with several large financial services institutions dropping out of the retail investment advice business altogether.
…
According to data from London-based Matrix Solutions Inc., since the RDR took effect on Jan. 1, the number of authorized investment intermediary firms is down by about 6% as of May; the total number of registered individuals in this sector is off by 9.5%; and the ranks of so-called “customer-facing staff” is down by 12.3%.

Those figures are much lower than was suggested at the OSC’s January meeting, and it appears that the immediate effects now are being reversed a bit. In fact, the data show that the number of registered reps rose in May month-over-month, and the number of customer-facing reps rose for the second straight month.

Ontario has a message for business – Spend, spend, spend!

In a speech at Toronto’s Empire Club Monday, Finance Minister Charles Sousa took aim at so-called “dead money” – capital that corporations have been holding onto since the global recession. The federal government has already pressed companies to invest that money in the economy, and Mr. Sousa said his government would use the tax system to encourage them to do it.

These would include a tax credit for research and development spending, and an incentive for companies that buy new equipment or technology, or spend money to train employees.

Mr. Sousa said he understands why companies have been hoarding cash, but warned that doing so is holding back Canada’s economy.

Me, I’d say that what is holding back Canada’s economy is government distortion of the free markets, but I’m not the treasurer of Ontario.

Robert Shiller is warning of another housing bubble – but this one’s in Brazil:

The government increased the price limit of houses people can buy using the unemployment insurance fund on Sept. 30 after public lending for homes increased more than four times as much as private banks in the two years through June, to 202 billion reais ($90 billion), according to central bank data.

Rousseff’s homebuilding program has propelled demand as she seeks to stimulate the economy before next year’s presidential election. Robert Shiller, six weeks before winning the Nobel Prize for economics, cautioned that such demand may be fueling a bubble as home prices grow twice as fast as rent. Mortgage debt as a percentage of disposable household income has climbed to a record 15 percent, almost double the level at the start of Rousseff’s term.

It was a strong day for the Canadian preferred share market, with PerpetualDiscounts winning 27bp, FixedResets up 26bp and DeemedRetractibles gaining 16bp. FixedResets with a low Issue Reset Spread dominated the winning side of the Performance Highlights table. Volume was average.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.9935 % 2,490.4
FixedFloater 4.26 % 3.53 % 27,848 18.32 1 -1.7173 % 3,943.6
Floater 2.98 % 3.00 % 64,920 19.70 3 0.9935 % 2,689.0
OpRet 4.63 % 3.36 % 67,876 0.61 3 -0.0900 % 2,633.7
SplitShare 4.75 % 5.15 % 64,445 3.66 6 -0.0269 % 2,956.6
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0900 % 2,408.3
Perpetual-Premium 5.57 % 3.90 % 124,703 0.30 11 0.3410 % 2,305.8
Perpetual-Discount 5.52 % 5.52 % 181,505 14.56 27 0.2687 % 2,379.0
FixedReset 5.00 % 3.63 % 226,319 3.53 82 0.2576 % 2,460.5
Deemed-Retractible 5.08 % 4.07 % 192,795 1.50 42 0.0958 % 2,411.8
FloatingReset 2.62 % 2.39 % 298,417 4.52 5 0.1588 % 2,457.9
Performance Highlights
Issue Index Change Notes
BAM.PR.G FixedFloater -1.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-04
Maturity Price : 22.63
Evaluated at bid price : 22.32
Bid-YTW : 3.53 %
TRP.PR.C FixedReset -1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-04
Maturity Price : 22.05
Evaluated at bid price : 22.30
Bid-YTW : 3.83 %
IFC.PR.A FixedReset -1.30 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.55
Bid-YTW : 4.52 %
TRP.PR.B FixedReset 1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-04
Maturity Price : 20.20
Evaluated at bid price : 20.20
Bid-YTW : 3.90 %
CU.PR.G Perpetual-Discount 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-04
Maturity Price : 21.44
Evaluated at bid price : 21.44
Bid-YTW : 5.34 %
CU.PR.D Perpetual-Discount 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-04
Maturity Price : 23.38
Evaluated at bid price : 23.72
Bid-YTW : 5.24 %
BAM.PR.B Floater 1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-04
Maturity Price : 17.70
Evaluated at bid price : 17.70
Bid-YTW : 2.99 %
BAM.PR.K Floater 1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-04
Maturity Price : 17.60
Evaluated at bid price : 17.60
Bid-YTW : 3.00 %
VNR.PR.A FixedReset 1.20 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-10-15
Maturity Price : 25.00
Evaluated at bid price : 25.35
Bid-YTW : 4.05 %
FTS.PR.G FixedReset 1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-04
Maturity Price : 22.83
Evaluated at bid price : 24.10
Bid-YTW : 4.00 %
W.PR.J Perpetual-Discount 1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-04
Maturity Price : 24.51
Evaluated at bid price : 24.76
Bid-YTW : 5.70 %
ENB.PR.H FixedReset 1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-04
Maturity Price : 22.58
Evaluated at bid price : 23.55
Bid-YTW : 4.14 %
MFC.PR.F FixedReset 1.44 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.52
Bid-YTW : 4.67 %
BAM.PF.B FixedReset 1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-04
Maturity Price : 22.71
Evaluated at bid price : 23.90
Bid-YTW : 4.51 %
ENB.PR.T FixedReset 1.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-04
Maturity Price : 22.71
Evaluated at bid price : 23.91
Bid-YTW : 4.36 %
SLF.PR.G FixedReset 1.78 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.88
Bid-YTW : 4.39 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.I FixedReset 128,500 TD crossed 125,000 at 25.09.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-02-24
Maturity Price : 25.00
Evaluated at bid price : 25.07
Bid-YTW : 3.20 %
BNS.PR.R FixedReset 101,510 TD crossed 100,000 at 25.11.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.09
Bid-YTW : 3.65 %
TRP.PR.B FixedReset 69,605 Scotia crossed 40,000 at 20.15; RBC crossed 10,000 at 20.20.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-04
Maturity Price : 20.20
Evaluated at bid price : 20.20
Bid-YTW : 3.90 %
CGI.PR.D SplitShare 52,200 Desjardins crossed 51,400 at 23.90.
YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2023-06-14
Maturity Price : 25.00
Evaluated at bid price : 23.90
Bid-YTW : 4.40 %
W.PR.H Perpetual-Discount 50,676 TD crossed 50,000 at 24.45.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-04
Maturity Price : 24.15
Evaluated at bid price : 24.40
Bid-YTW : 5.68 %
HSE.PR.A FixedReset 47,318 RBC crossed 34,500 at 22.75.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-04
Maturity Price : 22.37
Evaluated at bid price : 22.77
Bid-YTW : 3.99 %
There were 30 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BAM.PR.G FixedFloater Quote: 22.32 – 22.91
Spot Rate : 0.5900
Average : 0.4174

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-04
Maturity Price : 22.63
Evaluated at bid price : 22.32
Bid-YTW : 3.53 %

GWO.PR.J FixedReset Quote: 25.23 – 25.59
Spot Rate : 0.3600
Average : 0.2188

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.23
Bid-YTW : 3.81 %

TRP.PR.C FixedReset Quote: 22.30 – 22.78
Spot Rate : 0.4800
Average : 0.3464

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-04
Maturity Price : 22.05
Evaluated at bid price : 22.30
Bid-YTW : 3.83 %

TD.PR.R Deemed-Retractible Quote: 26.17 – 26.49
Spot Rate : 0.3200
Average : 0.1972

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-12-04
Maturity Price : 26.00
Evaluated at bid price : 26.17
Bid-YTW : -1.84 %

ELF.PR.F Perpetual-Discount Quote: 23.56 – 23.90
Spot Rate : 0.3400
Average : 0.2350

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-04
Maturity Price : 23.26
Evaluated at bid price : 23.56
Bid-YTW : 5.67 %

BNS.PR.N Deemed-Retractible Quote: 25.91 – 26.24
Spot Rate : 0.3300
Average : 0.2260

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-01-29
Maturity Price : 25.75
Evaluated at bid price : 25.91
Bid-YTW : 2.69 %

Market Action

November 1, 2013

There was a little pop in bond yields today:

Treasury 10-year note yields (USGG10YR) rose to the highest levels in two weeks after a gauge of U.S. manufacturing expanded at a faster pace than forecast, weakening the case for the Federal Reserve to maintain stimulus.

The benchmark securities extended the first five-day drop in three weeks as Fed Bank of St. Louis President James Bullard said labor market gains in the past year could warrant a cut in the bond buying. Fed policy makers said Oct. 30 that the economy showed signs of “underlying strength” even as they maintained their $85 billion of monthly asset purchases.

Want a raise? Go west, young man!

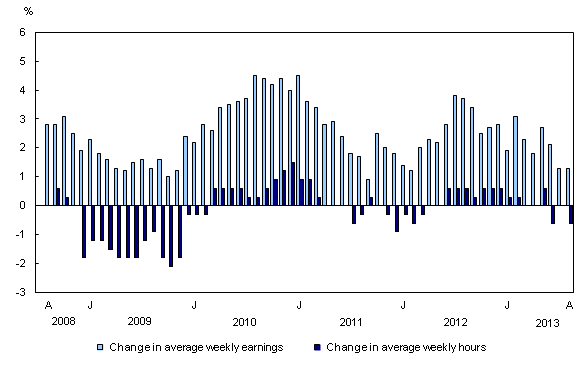
Data released yesterday by Statistics Canada showed the difference in average hourly wages in Alberta and the rest of the country, but for Saskatchewan, widened again in August.

“Note that hourly wages are now nearly $6 less in Atlantic Canada than in Alberta, the widest gap on record, a factor that has contributed to pushing more than 11,000 migrants out of the region in the past year – a major headache for housing markets, government finances, etc.,” said senior economist Robert Kavcic of BMO Nesbitt Burns.

“Even B.C. is seeing the wage gap approach $4/hour versus Alberta, and not coincidentally is also seeing a decade-high net outflow of workers.”

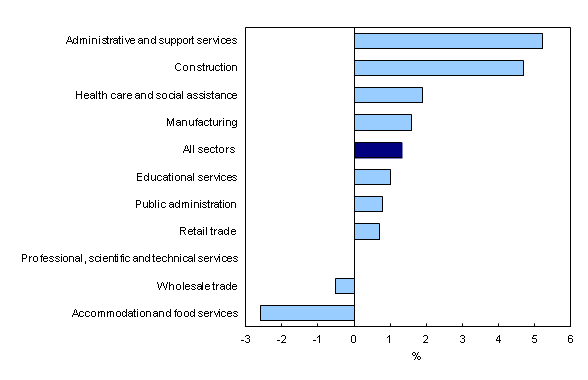
The StatsCan report indicates that a decent economy is still comfortably far away:


Click for Big

… with an implication that those who decided to earn a living filing paperwork for construction companies are getting vindicated …


Click for Big

DBRS confirmed Enbridge at Pfd-2(low):

DBRS has today confirmed the Issuer Rating of Enbridge Inc. (ENB or the Company) at A (low) and ratings on ENB’s Medium-Term Notes & Unsecured Debentures, Commercial Paper and Cumulative Redeemable Preferred Shares ratings at A (low), R-1 (low) and Pfd-2 (low), respectively, all with Stable trends. The ratings reflect (1) a relatively strong business risk profile, (2) pressure on ENB’s near-to-medium-term credit metrics and (3) results under the ten-year Competitive Tolling Settlement (CTS), effective July 1, 2011.

Enbridge is the proud issuer of ENB.PR.A, ENB.PR.B, ENB.PR.D, ENB.PR.F, ENB.PR.H, ENB.PR.N, ENB.PR.P, ENB.PR.T and ENB.PR.Y, as well as some US-Pay stuff that I don’t track.

It was a negative day for the Canadian preferred share market, with PerpetualDiscounts down 11bp, FixedResets off 3bp and DeemedRetractibles losing 18bp. The Performance Highlights table is longer than one might expect given the modest overall moves, with a preponderance of Straight losers. Volume was on the low side of average.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.2682 % 2,465.9
FixedFloater 4.18 % 3.46 % 27,003 18.46 1 0.1323 % 4,012.5
Floater 3.01 % 3.03 % 62,859 19.64 3 0.2682 % 2,662.5
OpRet 4.63 % 3.38 % 67,802 0.57 3 -0.1541 % 2,636.1
SplitShare 4.74 % 4.90 % 63,167 3.68 6 0.0202 % 2,957.4
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.1541 % 2,410.4
Perpetual-Premium 5.59 % 3.68 % 126,485 0.31 11 -0.0613 % 2,298.0
Perpetual-Discount 5.53 % 5.52 % 183,016 14.55 27 -0.1093 % 2,372.7
FixedReset 5.01 % 3.59 % 227,630 3.37 82 -0.0277 % 2,454.1
Deemed-Retractible 5.08 % 4.20 % 195,601 1.50 42 -0.1802 % 2,409.5
FloatingReset 2.62 % 2.37 % 310,113 4.53 5 -0.0317 % 2,454.0
Performance Highlights
Issue Index Change Notes
BAM.PF.B FixedReset -2.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-01
Maturity Price : 22.55
Evaluated at bid price : 23.55
Bid-YTW : 4.55 %
GWO.PR.N FixedReset -1.99 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.71
Bid-YTW : 4.75 %
MFC.PR.C Deemed-Retractible -1.66 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.30
Bid-YTW : 6.48 %
VNR.PR.A FixedReset -1.38 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-10-15
Maturity Price : 25.00
Evaluated at bid price : 25.05
Bid-YTW : 4.38 %
ELF.PR.F Perpetual-Discount -1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-01
Maturity Price : 23.22
Evaluated at bid price : 23.52
Bid-YTW : 5.67 %
BAM.PF.C Perpetual-Discount -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-01
Maturity Price : 20.01
Evaluated at bid price : 20.01
Bid-YTW : 6.14 %
SLF.PR.C Deemed-Retractible -1.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.53
Bid-YTW : 6.27 %
BAM.PR.T FixedReset 1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-01
Maturity Price : 22.57
Evaluated at bid price : 23.31
Bid-YTW : 4.42 %
TRP.PR.C FixedReset 1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-01
Maturity Price : 22.28
Evaluated at bid price : 22.61
Bid-YTW : 3.73 %
PWF.PR.L Perpetual-Discount 1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-01
Maturity Price : 23.51
Evaluated at bid price : 23.81
Bid-YTW : 5.37 %
CIU.PR.C FixedReset 2.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-01
Maturity Price : 21.09
Evaluated at bid price : 21.09
Bid-YTW : 3.82 %
Volume Highlights
Issue Index Shares
Traded
Notes
FTS.PR.J Perpetual-Discount 53,435 RBC crossed two blocks of 25,000 each, both at 23.26.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-01
Maturity Price : 22.76
Evaluated at bid price : 23.16
Bid-YTW : 5.19 %
CM.PR.G Perpetual-Premium 32,900 Desjardins crossed 21,000 at 25.03.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-05-01
Maturity Price : 25.00
Evaluated at bid price : 25.02
Bid-YTW : 5.35 %
CU.PR.C FixedReset 29,800 Scotia crossed 24,700 at 25.25.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-06-01
Maturity Price : 25.00
Evaluated at bid price : 25.25
Bid-YTW : 3.92 %
MFC.PR.C Deemed-Retractible 21,353 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.30
Bid-YTW : 6.48 %
CM.PR.E Perpetual-Premium 18,616 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-12-01
Maturity Price : 25.00
Evaluated at bid price : 25.13
Bid-YTW : -0.36 %
CM.PR.K FixedReset 18,360 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-07-31
Maturity Price : 25.00
Evaluated at bid price : 25.50
Bid-YTW : 2.70 %
There were 28 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
CIU.PR.C FixedReset Quote: 21.09 – 21.75
Spot Rate : 0.6600
Average : 0.5245

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-01
Maturity Price : 21.09
Evaluated at bid price : 21.09
Bid-YTW : 3.82 %

BNS.PR.O Deemed-Retractible Quote: 26.24 – 26.61
Spot Rate : 0.3700
Average : 0.2458

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-12-01
Maturity Price : 26.00
Evaluated at bid price : 26.24
Bid-YTW : -5.56 %

IAG.PR.G FixedReset Quote: 25.56 – 25.83
Spot Rate : 0.2700
Average : 0.1857

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-06-30
Maturity Price : 25.00
Evaluated at bid price : 25.56
Bid-YTW : 3.77 %

PWF.PR.I Perpetual-Premium Quote: 25.20 – 25.50
Spot Rate : 0.3000
Average : 0.2286

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-12-01
Maturity Price : 25.00
Evaluated at bid price : 25.20
Bid-YTW : -3.49 %

SLF.PR.G FixedReset Quote: 22.48 – 22.67
Spot Rate : 0.1900
Average : 0.1225

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.48
Bid-YTW : 4.54 %

GWO.PR.M Deemed-Retractible Quote: 25.41 – 25.58
Spot Rate : 0.1700
Average : 0.1047

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.41
Bid-YTW : 5.70 %

Market Action

October 31, 2013

Nothing happened today.

It was a mixed day for the Canadian preferred share market, with PerpetualDiscounts up 37bp, FixedResets gaining 11bp and DeemedRetractibles off 3bp. The Performance Highlights table is notable on the downside for domination by BAM Floating Rate issues, while the upside has a surprisingly large population of FixedResets. Volume was high.

PerpetualDiscounts now yield 5.49%, equivalent to 7.14% interest at the standard equivalency factor of 1.3x. Long corporates now yield about 4.7%, so the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) is now about 245bp, unchanged from October 23.

And that’s it for another month!

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.9452 % 2,459.3
FixedFloater 4.19 % 3.47 % 28,099 18.46 1 2.0702 % 4,007.2
Floater 2.75 % 3.03 % 63,356 19.65 5 -0.9452 % 2,655.4
OpRet 4.62 % 3.16 % 68,248 0.57 3 0.0900 % 2,640.2
SplitShare 4.75 % 4.90 % 63,647 3.68 6 0.1314 % 2,956.8
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0900 % 2,414.2
Perpetual-Premium 5.78 % 0.13 % 105,812 0.08 7 0.1586 % 2,299.4
Perpetual-Discount 5.49 % 5.49 % 186,112 14.46 30 0.3678 % 2,375.3
FixedReset 5.01 % 3.65 % 227,423 3.37 82 0.1110 % 2,454.8
Deemed-Retractible 5.08 % 4.15 % 195,475 1.51 43 -0.0330 % 2,413.8
FloatingReset 0.00 % 0.00 % 0 0.00 5 0.1110 % 2,454.8
Performance Highlights
Issue Index Change Notes
MFC.PR.B Deemed-Retractible -2.43 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.71
Bid-YTW : 6.41 %
BAM.PR.C Floater -1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-31
Maturity Price : 17.40
Evaluated at bid price : 17.40
Bid-YTW : 3.04 %
BAM.PR.K Floater -1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-31
Maturity Price : 17.34
Evaluated at bid price : 17.34
Bid-YTW : 3.05 %
BAM.PR.B Floater -1.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-31
Maturity Price : 17.46
Evaluated at bid price : 17.46
Bid-YTW : 3.03 %
BAM.PR.R FixedReset -1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-31
Maturity Price : 23.46
Evaluated at bid price : 25.07
Bid-YTW : 4.13 %
TRP.PR.A FixedReset -1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-31
Maturity Price : 23.63
Evaluated at bid price : 24.11
Bid-YTW : 3.84 %
PWF.PR.S Perpetual-Discount 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-31
Maturity Price : 22.60
Evaluated at bid price : 22.96
Bid-YTW : 5.24 %
GWO.PR.H Deemed-Retractible 1.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.27
Bid-YTW : 5.78 %
PWF.PR.F Perpetual-Discount 1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-31
Maturity Price : 23.70
Evaluated at bid price : 23.97
Bid-YTW : 5.50 %
VNR.PR.A FixedReset 1.20 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-10-15
Maturity Price : 25.00
Evaluated at bid price : 25.40
Bid-YTW : 3.98 %
POW.PR.D Perpetual-Discount 1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-31
Maturity Price : 22.87
Evaluated at bid price : 23.16
Bid-YTW : 5.43 %
CIU.PR.C FixedReset 1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-31
Maturity Price : 20.61
Evaluated at bid price : 20.61
Bid-YTW : 3.91 %
BAM.PR.X FixedReset 1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-31
Maturity Price : 21.96
Evaluated at bid price : 22.36
Bid-YTW : 4.18 %
ENB.PR.D FixedReset 1.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-31
Maturity Price : 22.89
Evaluated at bid price : 24.14
Bid-YTW : 4.19 %
FTS.PR.H FixedReset 1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-31
Maturity Price : 21.60
Evaluated at bid price : 22.00
Bid-YTW : 3.72 %
ENB.PR.Y FixedReset 1.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-31
Maturity Price : 22.45
Evaluated at bid price : 23.40
Bid-YTW : 4.35 %
FTS.PR.J Perpetual-Discount 1.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-31
Maturity Price : 22.75
Evaluated at bid price : 23.15
Bid-YTW : 5.19 %
ENB.PR.H FixedReset 1.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-31
Maturity Price : 22.46
Evaluated at bid price : 23.32
Bid-YTW : 4.16 %
BAM.PR.G FixedFloater 2.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-31
Maturity Price : 22.89
Evaluated at bid price : 22.68
Bid-YTW : 3.47 %
POW.PR.B Perpetual-Discount 2.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-31
Maturity Price : 23.69
Evaluated at bid price : 24.00
Bid-YTW : 5.61 %
PWF.PR.K Perpetual-Discount 2.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-31
Maturity Price : 23.04
Evaluated at bid price : 23.33
Bid-YTW : 5.32 %
TD.PR.Y FixedReset Not Calc! YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.86
Bid-YTW : 3.60 %
Volume Highlights
Issue Index Shares
Traded
Notes
SLF.PR.A Deemed-Retractible 99,266 RBC crossed 80,200 at 22.75.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.71
Bid-YTW : 5.96 %
SLF.PR.E Deemed-Retractible 97,747 RBC crossed 82,000 at 22.36.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.13
Bid-YTW : 6.00 %
CU.PR.G Perpetual-Discount 53,571 RBC crossed 24,900 at 21.39.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-31
Maturity Price : 21.30
Evaluated at bid price : 21.30
Bid-YTW : 5.38 %
GWO.PR.H Deemed-Retractible 49,176 TD crossed 30,000 at 23.38.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.27
Bid-YTW : 5.78 %
CU.PR.F Perpetual-Discount 34,460 RBC crossed 25,000 at 21.39.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-31
Maturity Price : 21.30
Evaluated at bid price : 21.30
Bid-YTW : 5.38 %
BAM.PR.M Perpetual-Discount 31,638 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-31
Maturity Price : 20.15
Evaluated at bid price : 20.15
Bid-YTW : 5.97 %
There were 51 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
MFC.PR.B Deemed-Retractible Quote: 21.71 – 22.20
Spot Rate : 0.4900
Average : 0.3070

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.71
Bid-YTW : 6.41 %

PWF.PR.L Perpetual-Discount Quote: 23.46 – 23.90
Spot Rate : 0.4400
Average : 0.3165

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-31
Maturity Price : 23.17
Evaluated at bid price : 23.46
Bid-YTW : 5.45 %

CGI.PR.D SplitShare Quote: 23.81 – 24.26
Spot Rate : 0.4500
Average : 0.3354

YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2023-06-14
Maturity Price : 25.00
Evaluated at bid price : 23.81
Bid-YTW : 4.45 %

FTS.PR.F Perpetual-Discount Quote: 23.50 – 23.89
Spot Rate : 0.3900
Average : 0.2887

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-31
Maturity Price : 23.21
Evaluated at bid price : 23.50
Bid-YTW : 5.29 %

GWO.PR.P Deemed-Retractible Quote: 24.90 – 25.24
Spot Rate : 0.3400
Average : 0.2476

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.90
Bid-YTW : 5.54 %

BAM.PR.K Floater Quote: 17.34 – 17.75
Spot Rate : 0.4100
Average : 0.3222

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-31
Maturity Price : 17.34
Evaluated at bid price : 17.34
Bid-YTW : 3.05 %

Market Action

October 30, 2013

Today’s FOMC release was ‘Steady as she goes’:

Taking into account the extent of federal fiscal retrenchment over the past year, the Committee sees the improvement in economic activity and labor market conditions since it began its asset purchase program as consistent with growing underlying strength in the broader economy. However, the Committee decided to await more evidence that progress will be sustained before adjusting the pace of its purchases. Accordingly, the Committee decided to continue purchasing additional agency mortgage-backed securities at a pace of $40 billion per month and longer-term Treasury securities at a pace of $45 billion per month. The Committee is maintaining its existing policy of reinvesting principal payments from its holdings of agency debt and agency mortgage-backed securities in agency mortgage-backed securities and of rolling over maturing Treasury securities at auction. Taken together, these actions should maintain downward pressure on longer-term interest rates, support mortgage markets, and help to make broader financial conditions more accommodative, which in turn should promote a stronger economic recovery and help to ensure that inflation, over time, is at the rate most consistent with the Committee’s dual mandate.

Joshua Zumbrun & Jeff Kearns of Bloomberg comment:

The consumer price index increased 0.2 percent after rising 0.1 percent the prior month, a Labor Department report showed today. The Fed’s preferred gauge of inflation, the personal consumption expenditures index, rose 1.2 percent in August and hasn’t breached 2 percent since March 2012.

The Fed removed a sentence from the previous statement that had said tighter financial conditions could slow the improvement in the economy.

Kansas City Fed President Esther George dissented for the seventh meeting in a row, citing the risk the Fed’s stimulus could create financial imbalances and cause long-term inflation expectations to rise.

Richard Vedder of Bloomberg rages against the cost of US universities’ hubris:

I have written before on how the expansion of federal student-loan programs has encouraged colleges to simply raise their costs. Students are left to pile up more debt while colleges indulge in their Edifice Complex — building luxury dorms and gyms and stadiums (all “sustainable,” of course) at the expense of poorer students. There is another, related government subsidy that also has perverse effects and needs reform: the tax-exempt debt binge by universities.

Schools are exuberantly borrowing, in some cases issuing 100-year (century) bonds. Some bond offerings are justified, even wise, as schools are taking advantage of low interest rates to reduce future debt-service obligations. But a lot of this activity is financing construction of high-end student housing, faddish “centers” and stadiums.

These perquisites appeal to the most affluent. For many students, however, the costs of college are rising relative to the perceived benefits, pushing them to consider lower-cost substitutes (online education, nondegree certificate programs).

Many bonds are tax-exempt. The more money borrowed, the more generous the exemption, creating in effect a taxpayer subsidy for rich universities. Should there be no cap on the tax exemptions private colleges can claim on their bond debt, and is it appropriate for the government to subsidize all types of projects at these schools?

And the argument regarding the cost of Too-Big-to-Fail rages on as well:

McCloskey’s confusion about the nature of the too-big-to-fail subsidy leads directly to another misconception: that regulatory compliance costs could somehow offset the subsidy. Compliance may or may not put a greater burden on larger banks (I suspect executives at small banks would disagree). In any case, the costs do nothing to reduce the taxpayer subsidy or the incentive to preserve it by becoming as big and systemically threatening as possible.

In other words, U.S. taxpayers are paying big banks to put the economy in danger, which is crazy. The best solution is to make banks less likely to fail by requiring that they finance themselves with more equity capital, which absorbs losses in bad times.

Regulators have taken a small step in that direction by proposing that bank holding companies have at least $5 in capital for every $100 in assets — a 5 percent leverage ratio that is a bit more than the global minimum of 3 percent. The proposal, to which banks are adamantly opposed, falls far short of the 20 percent that economists have argued would be best for the economy, but at least it’s a start. Let’s hope they stick to it.

Matt Levine writes a more sensible than usual piece about the so-call FX manipulation scandal, which I never-the-less disagree with:

There are two problems with this. One, while the bank is guaranteeing the client the WM/Reuters fix price, nobody’s guaranteeing the bank anything. The bank has to actually go trade and try to hit that price. The way the fix works is that it’s set by sampling trades over a 60-second window, so you have to have a certain amount of skill and luck to trade at (or better than) the official price. It’s risky.

Two — and this is important, too — banks are in the business of making money, and the trade they want is not “buy at WM/Reuters fix and sell at WM/Reuters fix” but rather “buy at less than WM/Reuters fix and sell at WM/Reuters fix.”
If your client tells you at 3:30 that they want to buy francs at the 4 p.m. price, there are fairly straightforward ways to try to ensure a profit. Like: If they’re buying a lot of francs, then you’d expect that to push the market for francs up. So what you could do is start buying francs at 3:30 when they’re trading at $1.1150 or whatever,**** and keep buying steadily until 4 p.m. when they’re trading at $1.1200, for an average price of like $1.1175, and then sell to the client at the 4 p.m. fix of $1.1200. You buy francs for $1.1175, you sell them for $1.1200, you make $0.0025 per franc, you do it a lot, boom, good business.
…
Also some things are right out:

In June, Bloomberg News reported that dealers pooled information about their positions through instant messages, executed their own trades before client orders and sought to manipulate the benchmark WM/Reuters rates by pushing through trades around the 60-second windows when the benchmarks are set.

The sharing client data among dealers seems self-evidently bad. The “executed their own trades before client orders and sought to manipulate the benchmark” is either bad, or just legit hedging that looks bad, or something in between, or some combination thereof, it is hard to know.

This shows a fundamental misconception of the order.

The bank has not agreed to act as agent, with fiduciary responsibility, for the client. What the bank has done is sold a very short-term (intra-day) forward contract to the client. When the dealers talk to each other, they’re not sharing information about client orders, they’re sharing information about their own orders, which they will be placing as principal in order to cover their position.

The big problem with the market is that there are too many fools and charlatans in charge of too much client money. Dealers are not your friends. Dealers are counterparties, just like Loblaws is my counterparty when I buy groceries. Loblaws and I get on well and have a mutually beneficial relationship – but they’re always trying to make it a little more beneficial for them and I’m always trying to make it a little more beneficial for me. Sadly, this fundamental truth escapes the Boo-hoo-hoo brigade.

The industry is staffed with MBAs, which stands for Minimal Brain Activity. There is nothing the dealers do that a large client – large enough to matter, large enough to be asked their intentions – cannot do himself. Trades can be sampled over a given period, whether it’s the period of the fix, or the run-up to it, or the aftermath … but, unfortunately, that involves actual work, which MBAs are fundamentally incapable of doing, or even understanding. Why, one might have to write, or commission, an algorithmic programme to buy your USD 100-million in million dollar chunks! Computer programmes? Those are for geeks! Daddy didn’t pay for a good school so I could write computer programmes! It might take more than one ‘phone call to execute the trade! More than one call? How are you going to discuss the analysis of Warren Buffet’s pronouncement on Yellen’s approach to the Fed if you have to make more than one call. Can’t be done. Call a dealer, just like Daddy calls his stockbroker.

It may be ugly and awful, but US sequestration might be working anyway:

Senator Jeff Sessions of Alabama, the top Republican on the Budget Committee, said today in an interview such an accord could be a way to replace for a year or two the automatic spending cuts, known as sequestration, that both parties decry.

“A great number of entitlement programs, mandatory programs, are not Social Security and Medicare,” Sessions said. “There are a whole bunch of programs that are mandatory in nature and have never been looked at” and weren’t in the law setting up the automatic cuts, he said, citing farm subsidies and food stamps.

Asked if such a deal is a fallback to a broader deal, he said. “I would hope so.”

BAM closed a big deal:

If you have a railroad or a port for sale, there’s a big new buyer as Brookfield Asset Management just closed a massive $7-billion (U.S.) infrastructure fund that will invest in such things as transportation and energy assets. The new money has the potential to bump up Brookfield’s fee income markedly.

Brookfield blew right through the $5-billion target. There are more than 60 investors, including sovereign wealth funds, insurers, and public and private pension plans. Brookfield is putting in $2.8-billion of its own money (through its Brookfield Infrastructure Partners and Brookfield Renewable Energy Partners LP subsidiaries), meaning $4.2-billion is coming from outside investors. Brookfield said half the investors are rookies at putting money into Brookfield funds.

The new fund will surely significantly boost Brookfield’s fee income.

At a 1.5 per cent management fee, which is in the ballpark for funds of that size, the new outside assets would represent about $63-million a year in additional income for Brookfield. That would be before any performance fees.

It’s very encouraging to see business trying to take back control of the Republican party:

The U.S. Chamber of Commerce fired an opening salvo yesterday in the battle for control of the Republican Party, endorsing a self-described “pro-business” candidate in a special U.S. House race whose opponent is backed by Tea Party groups and is vowing to “be like Ted Cruz.”

The endorsement in the Alabama contest is the chamber’s first political move since the 16-day partial U.S. government shutdown and debt-ceiling battle, which exposed a rift between the Republican establishment wing and the smaller-government movement. Cruz, a Republican senator from Texas, was the chief proponent of the ill-fated plan to link defunding Obamacare to lifting the debt ceiling and passing a government spending bill.

In reaction to the shutdown, which Standard & Poor’s estimated cost the U.S. economy $24 billion, the chamber and other business groups said they will engage in elections — including Republican primaries — to help candidates aligned with their economic goals.

It would be nice to see that in Canada, too.

It was a strong day for the Canadian preferred share market, with PerpetualDiscounts up 34bp, FixedResets gaining 10bp and DeemedRetractibles winning 59bp. The Floating Rate sector got whacked, perhaps in response to the FOMC release and those issues figured prominently on the wrong side of the Performance Highlights table. BAM issues were notable on the winning side. Volume was very high.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.6193 % 2,482.8
FixedFloater 4.28 % 3.55 % 27,931 18.30 1 -2.1145 % 3,926.0
Floater 2.73 % 2.98 % 63,138 19.77 5 -0.6193 % 2,680.7
OpRet 4.63 % 3.21 % 68,522 0.57 3 -0.0385 % 2,637.8
SplitShare 4.75 % 5.04 % 63,148 3.96 6 0.0894 % 2,952.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0385 % 2,412.0
Perpetual-Premium 5.79 % 1.39 % 105,518 0.08 7 0.2954 % 2,295.8
Perpetual-Discount 5.51 % 5.52 % 181,895 14.36 30 0.3445 % 2,366.6
FixedReset 4.92 % 3.62 % 232,654 3.55 86 0.0995 % 2,452.1
Deemed-Retractible 5.08 % 4.23 % 196,136 1.67 43 0.5898 % 2,414.6
Performance Highlights
Issue Index Change Notes
BAM.PR.G FixedFloater -2.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-30
Maturity Price : 22.56
Evaluated at bid price : 22.22
Bid-YTW : 3.55 %
PWF.PR.P FixedReset -1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-30
Maturity Price : 22.91
Evaluated at bid price : 23.62
Bid-YTW : 3.60 %
BAM.PR.K Floater -1.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-30
Maturity Price : 17.63
Evaluated at bid price : 17.63
Bid-YTW : 3.00 %
BAM.PR.B Floater -1.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-30
Maturity Price : 17.73
Evaluated at bid price : 17.73
Bid-YTW : 2.98 %
BAM.PR.C Floater -1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-30
Maturity Price : 17.70
Evaluated at bid price : 17.70
Bid-YTW : 2.98 %
BNS.PR.Z FixedReset 1.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.80
Bid-YTW : 3.95 %
MFC.PR.C Deemed-Retractible 1.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.75
Bid-YTW : 6.22 %
FTS.PR.F Perpetual-Discount 1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-30
Maturity Price : 23.06
Evaluated at bid price : 23.35
Bid-YTW : 5.32 %
GWO.PR.I Deemed-Retractible 1.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.15
Bid-YTW : 5.99 %
PWF.PR.L Perpetual-Discount 1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-30
Maturity Price : 23.13
Evaluated at bid price : 23.42
Bid-YTW : 5.46 %
BAM.PF.B FixedReset 1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-30
Maturity Price : 22.82
Evaluated at bid price : 24.15
Bid-YTW : 4.41 %
GWO.PR.R Deemed-Retractible 1.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.88
Bid-YTW : 5.93 %
TRP.PR.C FixedReset 1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-30
Maturity Price : 22.23
Evaluated at bid price : 22.54
Bid-YTW : 3.75 %
GWO.PR.H Deemed-Retractible 1.28 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.02
Bid-YTW : 5.91 %
MFC.PR.B Deemed-Retractible 1.32 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.25
Bid-YTW : 6.12 %
BAM.PR.N Perpetual-Discount 1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-30
Maturity Price : 20.35
Evaluated at bid price : 20.35
Bid-YTW : 5.91 %
BAM.PF.C Perpetual-Discount 1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-30
Maturity Price : 20.33
Evaluated at bid price : 20.33
Bid-YTW : 6.04 %
FTS.PR.H FixedReset 1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-30
Maturity Price : 21.37
Evaluated at bid price : 21.68
Bid-YTW : 3.79 %
SLF.PR.B Deemed-Retractible 1.58 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.16
Bid-YTW : 5.78 %
PWF.PR.A Floater 1.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-30
Maturity Price : 23.20
Evaluated at bid price : 23.50
Bid-YTW : 2.19 %
SLF.PR.A Deemed-Retractible 1.61 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.71
Bid-YTW : 5.96 %
GWO.PR.G Deemed-Retractible 1.67 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.40
Bid-YTW : 5.58 %
TD.PR.O Deemed-Retractible 1.90 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-11-30
Maturity Price : 25.25
Evaluated at bid price : 25.73
Bid-YTW : -16.80 %
BAM.PR.X FixedReset 2.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-30
Maturity Price : 21.74
Evaluated at bid price : 22.05
Bid-YTW : 4.25 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PR.P Deemed-Retractible 54,300 RBC crossed 49,800 at 26.00.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-12-01
Maturity Price : 25.75
Evaluated at bid price : 25.91
Bid-YTW : -2.13 %
CM.PR.M FixedReset 52,190 TD crossed 50,000 at 25.77.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-07-31
Maturity Price : 25.00
Evaluated at bid price : 25.76
Bid-YTW : 2.43 %
PWF.PR.S Perpetual-Discount 36,833 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-30
Maturity Price : 22.40
Evaluated at bid price : 22.72
Bid-YTW : 5.30 %
GWO.PR.H Deemed-Retractible 34,814 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.02
Bid-YTW : 5.91 %
POW.PR.D Perpetual-Discount 32,009 TD bought 10,000 from Scotia at 22.80.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-30
Maturity Price : 22.42
Evaluated at bid price : 22.85
Bid-YTW : 5.50 %
CU.PR.G Perpetual-Discount 31,565 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-30
Maturity Price : 21.24
Evaluated at bid price : 21.24
Bid-YTW : 5.39 %
There were 65 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BAM.PR.G FixedFloater Quote: 22.22 – 22.82
Spot Rate : 0.6000
Average : 0.4348

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-30
Maturity Price : 22.56
Evaluated at bid price : 22.22
Bid-YTW : 3.55 %

BAM.PR.K Floater Quote: 17.63 – 18.00
Spot Rate : 0.3700
Average : 0.2258

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-30
Maturity Price : 17.63
Evaluated at bid price : 17.63
Bid-YTW : 3.00 %

BNS.PR.J Deemed-Retractible Quote: 24.99 – 25.29
Spot Rate : 0.3000
Average : 0.1642

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.99
Bid-YTW : 5.29 %

FTS.PR.K FixedReset Quote: 24.41 – 24.74
Spot Rate : 0.3300
Average : 0.2168

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-30
Maturity Price : 22.93
Evaluated at bid price : 24.41
Bid-YTW : 3.87 %

BAM.PR.T FixedReset Quote: 23.10 – 23.39
Spot Rate : 0.2900
Average : 0.1834

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-30
Maturity Price : 22.45
Evaluated at bid price : 23.10
Bid-YTW : 4.46 %

PWF.PR.L Perpetual-Discount Quote: 23.42 – 23.70
Spot Rate : 0.2800
Average : 0.1811

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-30
Maturity Price : 23.13
Evaluated at bid price : 23.42
Bid-YTW : 5.46 %