Category: Market Action

Market Action

October 15, 2013

There’s an interesting comment in the BoC’s 2014–15 Debt Management Strategy Consultations:

Non-residents now hold about 28 per cent of Government of Canada marketable debt securities, approximately double the average for the five years preceding the financial crisis. Increased demand for Government of Canada securities by non-residents helps to diversify the investor base. At the same time, some market participants suggest that the growing share of securities held by foreign institutional investors, in particular, central banks and sovereign wealth funds, may be affecting the liquidity of certain sectors of the Government of Canada securities market, since some of these investors may not actively lend their securities in the repo market. Anecdotal evidence gathered by the Bank of Canada suggests that large increases in foreign official Canadian-dollar holdings have coincided with the more frequent “specials” in the Canadian debt markets. [Footnote] More research is necessary, however, to determine to what extent this relationship is causal and not explained by other factors.

Footnote reads: A security that is “on special” is an asset that is subject to elevated demand in the repo market. This causes securities borrowers in the repo market to compete for the asset by offering to lend cash below prevailing interest rates.

Specials are a wonderful opportunity for alert active portfolio managers to outperform, since the price of ‘special’ securities will rise as the shorts frantically try to square their positions. Regrettably, this may be exploited only from a ‘long-only’ perspective: shorting the temporarily expensive security carries a very high probability that all your profits from price movements will be eaten up by the cost of borrowing the security.

There is also an acknowledgment of the regulatory aspect of financial repression:

Demand for Government of Canada securities is being affected by several other important factors. Regulatory initiatives are increasing the need for high-quality collateral, which in Canada is reflected in greater demand for treasury bills and short-term bonds. In addition, the federal government and a number of provincial governments, as well as some corporations have put in place new prudential liquidity and contingency measures that have large, stable allocations to Government of Canada securities, especially treasury bills and short-term bonds. Structural changes, such as Canada’s new central counterparty for the fixed-income market and, in particular, the introduction of central clearing for blind repo trades for interdealer brokers, may also be influencing dynamics in the repo market.

One of the questions is of great interest:

In the Debt Management Strategy for 2013–14, the government announced the continuation of the temporary increase in the issuance of 10- and 30-year bonds and signalled that it would be assessing the potential benefits of issuing bonds with a maturity of 40 years or longer.

How would you characterize the demand for long-term bonds since yields began rising in May 2013 and how do you see it evolving?

All together, folks! WE WANT FORTIES! WE WANT FORTIES!

Many readers will find the following section fascinating:

Fixed-income products in Canada are typically traded over the counter (OTC), whereas equities are traded on public exchanges. Many financial institutions, institutional investors and wealth managers participate in electronic marketplaces to facilitate the trading of fixed-income securities. However, for retail investors, acquiring a position in fixed-income securities often involves buying money market and bond mutual funds or exchange-traded funds (ETFs). Wealth managers offer another avenue for retail investors to acquire fixed-income securities by leveraging institutional buying of fixed-income securities. Retail investors that prefer not to pay the asset-management fees associated with mutual funds, ETFs
and wealth managers can buy and sell fixed-income securities through an online or discount brokerage account. However, the relative opaqueness of the OTC market has led to criticism of broker compensation, transaction fees and the cost of trading from one’s own broker account. Changes implemented by the Canadian Securities Administrators to National Instrument 31-103 Registration Requirements, Exemptions and Ongoing Registrant Obligations seek to enhance registrants’ relationships with their clients (retail investors) through an expansion of cost and registrant compensation disclosure, as well as the introduction of performance reporting.

16. Of those retail investors with an online or discount brokerage account, what proportion use their account to buy fixed-income securities in general and Government of Canada securities specifically?

17. What are your views on the impact of the additional fee, commission and cost transparency required under National Instrument 31-103 for dealer and broker activities? Will these changes help to promote greater price transparency for retail investors?

18. What measures could the Government of Canada take to facilitate easier retail investor access to its debt securities?

I would be very pleased to see a Canadian programme run along the lines of Treasury Direct. On the other hand, retail is grossly over-invested in Canadas – they’re paying an enormous liquidity premium that they will never, ever need, and a smaller, but still large, regulatory premium that is simply not applicable.

Market-Timers are busily retiming the timing of their timing:

Incredibly, retail investors are now moving back into bonds. September U.S. mutual fund flow data is now out, and last month three of the four highest net inflows went into bond and credit funds, according to Morningstar. Non-traditional bonds led the way, then high yield bonds, then short-term bonds. Institutional clients don’t seem so scared either, considered how they plowed money into the Verizon Communication’s record debt offering.

Given all this data, there’s a growing counter-theory, one that hails the ‘not-so-great rotation.’ Last year Bank of America Merrill Lynch put out a report that called “The Bond Era Ends.” Morgan Stanley’s pushing back with its own report, titled “Great Rotation? Probably not.”

On the other hand, market timers are also winning the Nobel Prize, so take your pick:

Fama helped revolutionize the practice of investing by showing it was difficult to predict individual stock prices in the short run. That led to the emergence of index funds as a common investment.

Shiller showed that there’s more predictability in stock and bond markets in the long run. That encouraged the creation of institutional investors, such as hedge funds, that take bets on market trends.

In the late 1990s, Shiller said the stock market was overvalued “and lo and behold he was proven right” when the dot-com bubble burst in 2000, said Nobel committee secretary Peter Englund.

“He also predicted for a long time that the housing market was overvalued and again he was proven right,” Englund said. The U.S. property market suffered a crash in 2007 that helped fuel the global financial crisis.

Englund said he believes the three laureates agree on the findings for which they were awarded. However, Fama and Shiller have different “interpretations of the real world,” he added.

“It’s no secret that for Eugene Fama the sort of null hypothesis is that markets work well and he is willing to believe that until he is proven otherwise whereas for Robert Shiller, I think his null hypothesis is that there are periods of excessive optimism and pessimism,” Englund said.

Swiss Re may join the exodus from US life insurance:

Swiss Re Ltd. (SREN) is considering selling Aurora National Life Assurance Co. as it retreats from the U.S. life and health insurance market, people familiar with the matter said.

The world’s second-largest reinsurer is working with Barclays Plc to find buyers for Aurora National and some other U.S. assets, two people said, asking not to be identified because the matter isn’t public. The sale could fetch more than $400 million, one person said.
The deal would include about $5 billion in insurance assets, including corporate-owned and other life-insurance policies and annuities, said one person.

Corporate bond trading is entering a new era and nobody knows (or cares) where it will end:

A record share of U.S. corporate-bond trading has moved to computers as buyers who traditionally transacted over the phone seek faster ways to buy and sell in a market where Wall Street’s human traders are retreating.

Investment-grade volumes on MarketAxess Holdings Inc.’s electronic system are on pace to exceed $400 billion in 2013 after surging 45 percent to $44 billion in September from a year earlier, according to data from the company, which estimates it captures about 90 percent of electronic trades among the dollar-denominated notes. That’s equal to 14.3 percent of all market activity, including business done over the phone, up from 12.2 percent a year earlier.
…
While the dollar-denominated investment-grade bond market has increased 71 percent since 2008 to about $4.3 trillion, the size of each transaction declined to about $565,000 in the three months ended June 30, compared with about $970,000 in the first three months of 2007, according to Trace, Finra’s bond-price reporting system, which tracks both electronic transactions and those negotiated over the phone. The average investment-grade trade on MarketAxess’ system was $600,000, according to Rick McVey, the company’s chief executive officer.

“Dealers do not have the balance-sheet capacity to warehouse large block trades from investors the way they used to, so investors are breaking trades down into smaller sizes,” he said in a telephone interview.
…
The biggest U.S. banks’ fixed-income trading revenue probably fell 20 percent in the third quarter from a year earlier on lower volumes, Richard Staite, an analyst at Atlantic Equities LLP, said in a Sept. 23 report.

“It’s a reasonable-size business in terms of revenues for them, but they don’t have the balance sheet capacity to be the backstop for the market,” said Roger Rudisuli, a partner in McKinsey’s corporate and investment banking practice, speaking about dealers generally. “They cannot play this role anymore.”

Fitch placed the US on Watch-Negative:

The prolonged negotiations over raising the debt ceiling (following the episode in August 2011) risks undermining confidence in the role of the U.S. dollar as the preeminent global reserve currency, by casting doubt over the full faith and credit of the U.S. This “faith” is a key reason why the U.S. ‘AAA’ rating can tolerate a substantially higher level of public debt than other ‘AAA’ sovereigns.
…
The repeated brinkmanship over raising the debt ceiling also dents confidence in the effectiveness of the U.S. government and political institutions, and in the coherence and credibility of economic policy. It will also have some detrimental effect on the U.S. economy.
…
In the event of a deal to raise the debt ceiling and to resolve the government shutdown, which Fitch expects, the outcome of a subsequent review of the ratings would take into account the manner and duration of the agreement and the perceived risk of a similar episode occurring in the future. It would also reflect Fitch’s assessment of the following main factors:

– The impact of the debt ceiling brinkmanship and government shutdown on our assessment of the effectiveness of government and political institutions, the coherence and credibility of economic policy, the potential long-term impact on the U.S. sovereign’s cost of funding and cost of capital for the economy as a whole, and the implications for long-term growth.

– Our assessment of the prospects for further deficit-reduction measures in future years necessary to contain government deficits in the face of long-term spending pressures and place public debt on a downward path over the medium to long term.

There’s some interesting data on fast-food wage scales:

Data from the U.S. Census Bureau and public benefit programs show 52 per cent of fast-food cooks, cashiers and other “front-line” staff had relied on at least one form of public assistance, such as Medicaid, food stamps and the Earned Income Tax Credit program, between 2007 and 2011, researchers at the University of California-Berkeley and the University of Illinois said.

In a concurrent report, the pro-labor National Employment Law Project found that the 10 largest fast-food companies in the United States cost taxpayers more than $3.8 billion each year in public assistance because the workers do not make enough to pay for basic necessities themselves.
…
The Employment Policies Institute, which has opposed calls for higher fast-food wages in the past, said in a statement that the reports “ignore economic evidence that dramatic wage hikes would make fast food workers worse off” when employers “replace employees with less-costly automated alternatives.”

Replace order-takers? That’s what’s happening in Europe:

McDonalds recently went on a hiring binge in the U.S., adding 62,000 employees to its roster. The hiring picture doesn’t look quite so rosy for Europe, where the fast food chain is drafting 7,000 touch-screen kiosks to handle cashiering duties.

The move is designed to boost efficiency and make ordering more convenient for customers. In an interview with the Financial Times, McDonald’s Europe President Steve Easterbrook notes that the new system will also open up a goldmine of data. McDonald’s could potentially track every Big Mac, McNugget, and large shake you order. A calorie account tally at the end of the year could be a real shocker.

The touch screens will only accept debit or credit cards, adding to the slow death knell of cash and coins.

So we have the slightly unusual situation of Europe being ahead in automation because of low US labour costs. I suggest that this, rather than any bleeding-heartedness, is a good reason to raise the minimum wage. The burger flippers will then, perforce, find something more useful to do.

Everybody’s preparing for a US default:

A default may not disrupt markets as long as the U.S. alerted traders the night before a payment was due that it was probably going to default, giving the Federal Reserve’s Fedwire, an electronic service that transfers securities and payments, enough time to adjust its programs and allow the defaulted debt to be “transferable,” according to JPMorgan Chase & Co. That would allow them to continue to be used as collateral in repo markets.
…
The Securities Industry and Financial Markets Association, or Sifma, in a statement this month said if the Treasury were to delay payments on debt it would extend the payment date of the securities one day at a time. The Treasury Market Practice Group, an industry organization sponsored by the Federal Reserve Bank of New York that advises on transactions in U.S. securities, said last month contingency planning developed since the 2011 debt-limit crisis would mitigate yet not eliminate the operational risk posed by government-debt payment delays.

Some clearing firms are preparing for a default, with Citigroup Inc. and State Street Corp. discussing ways to limit the use of short-term Treasury bills as collateral in coming weeks, the Wall Street Journal reported on its website yesterday, citing people familiar with the matter. Citigroup told some clients it would prefer not to take U.S. government debt maturing Oct. 24 or Oct. 31 as security for transactions, the newspaper reported.

Norway has a very good Sovereign Wealth Fund policy – but even they have a problem involving politicians on one hand and a large pot of money on the other:

The Labor government, which resigned yesterday, presented what it called a “cautious” budget, saying it would use 135 billion kroner ($22 billion) of Norway’s oil wealth to plug deficits next year, equal to 5.5 percent of mainland gross domestic product. That leaves Solberg’s administration with 54 billion kroner to spend before it breaches the nation’s fiscal policy rule.
…
Solberg and her coalition partner, the Progress Party, have until early November to adjust the spending plan put forward by the outgoing administration. While she has promised to stick to the fiscal rule, which caps expenditure of Norway’s oil income at 4 percent of its wealth fund, the two parties have signaled they want to spend more on infrastructure, education and health care. Those measures will come on top of planned tax cuts.

DBRS has published its Quarterly Split Share Market Report:

DBRS has today published its quarterly surveillance report covering the Canadian split share market for Q3 2013. The report provides insight into recent market activity and summarizes the performance of split share funds rated by DBRS. Three main areas are covered in the report: equity performance, existing fund activity and new fund market activity. The appendix provides details on all of the preferred shares and securities rated by DBRS, including current ratings and recent downside protection levels.

A copy of this commentary is available by contacting us at info@dbrs.com.

It was a mixed day for the Canadian preferred share market, with PerpetualDiscounts up 7bp, FixedResets off 2bp and DeemedRetractibles gaining 1bp. The Performance Highlights table is longer than one might expect given these quiet figures, but Floaters continued to plunge. Volume was low.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -1.0948 % 2,442.9
FixedFloater 4.32 % 3.58 % 29,284 18.26 1 -0.6321 % 3,888.9
Floater 2.77 % 2.99 % 64,564 19.76 5 -1.0948 % 2,637.6
OpRet 4.62 % 2.16 % 63,641 0.45 3 -0.0897 % 2,644.6
SplitShare 4.76 % 4.99 % 63,575 4.00 6 0.1353 % 2,946.5
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0897 % 2,418.2
Perpetual-Premium 5.80 % 0.44 % 109,920 0.08 8 0.0399 % 2,279.0
Perpetual-Discount 5.58 % 5.60 % 159,991 14.44 30 0.0663 % 2,333.1
FixedReset 4.97 % 3.75 % 236,380 3.59 85 -0.0239 % 2,445.0
Deemed-Retractible 5.15 % 4.40 % 192,480 3.70 43 0.0067 % 2,373.2
Performance Highlights
Issue Index Change Notes
TRI.PR.B Floater -2.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-15
Maturity Price : 19.81
Evaluated at bid price : 19.81
Bid-YTW : 2.66 %
CIU.PR.C FixedReset -1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-15
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 4.44 %
GWO.PR.N FixedReset -1.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.76
Bid-YTW : 4.84 %
SLF.PR.A Deemed-Retractible -1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.60
Bid-YTW : 6.53 %
TRP.PR.C FixedReset -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-15
Maturity Price : 22.20
Evaluated at bid price : 22.51
Bid-YTW : 3.92 %
BAM.PR.K Floater -1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-15
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 3.02 %
TRP.PR.D FixedReset 1.22 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2019-04-30
Maturity Price : 25.00
Evaluated at bid price : 24.95
Bid-YTW : 4.03 %
IFC.PR.A FixedReset 1.71 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.36
Bid-YTW : 4.19 %
Volume Highlights
Issue Index Shares
Traded
Notes
TRP.PR.D FixedReset 182,975 Nesbitt crossed blocks of 100,000 and 30,000, both at 25.02, and bought 10,000 from TD at 25.00.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2019-04-30
Maturity Price : 25.00
Evaluated at bid price : 24.95
Bid-YTW : 4.03 %
BMO.PR.P FixedReset 86,910 RBC crossed 75,000 at 26.21.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2015-02-25
Maturity Price : 25.00
Evaluated at bid price : 26.13
Bid-YTW : 2.58 %
PWF.PR.S Perpetual-Discount 72,150 TD crossed 58,000 at 22.55.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-15
Maturity Price : 22.15
Evaluated at bid price : 22.49
Bid-YTW : 5.33 %
TD.PR.R Deemed-Retractible 51,280 RBC crossed 50,000 at 25.95.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-04-30
Maturity Price : 25.75
Evaluated at bid price : 25.95
Bid-YTW : 3.50 %
BNS.PR.N Deemed-Retractible 44,450 Nesbitt crossed 15,000 at 25.70; RBC crossed 25,000 at the same price.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-01-27
Maturity Price : 25.00
Evaluated at bid price : 25.69
Bid-YTW : 4.29 %
TD.PR.A FixedReset 38,689 Scotia bought 11,900 from Nesbitt at 25.19, then crossed 25,000 at the same price.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.19
Bid-YTW : 1.68 %
There were 22 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
HSE.PR.A FixedReset Quote: 22.65 – 23.39
Spot Rate : 0.7400
Average : 0.4209

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-15
Maturity Price : 22.28
Evaluated at bid price : 22.65
Bid-YTW : 4.12 %

TRI.PR.B Floater Quote: 19.81 – 20.49
Spot Rate : 0.6800
Average : 0.5015

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-15
Maturity Price : 19.81
Evaluated at bid price : 19.81
Bid-YTW : 2.66 %

GWO.PR.N FixedReset Quote: 21.76 – 22.29
Spot Rate : 0.5300
Average : 0.3768

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.76
Bid-YTW : 4.84 %

MFC.PR.F FixedReset Quote: 22.36 – 23.08
Spot Rate : 0.7200
Average : 0.5749

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.36
Bid-YTW : 4.82 %

CU.PR.E Perpetual-Discount Quote: 23.40 – 23.83
Spot Rate : 0.4300
Average : 0.2899

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-15
Maturity Price : 23.09
Evaluated at bid price : 23.40
Bid-YTW : 5.29 %

BNS.PR.K Deemed-Retractible Quote: 25.02 – 25.25
Spot Rate : 0.2300
Average : 0.1449

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-04-28
Maturity Price : 25.00
Evaluated at bid price : 25.02
Bid-YTW : 4.23 %

Market Action

October 11, 2013

The witch-hunt against traders continues:

The U.S. Justice Department has opened a criminal investigation of possible manipulation of the $5.3 trillion-a-day foreign exchange market, a person familiar with the matter said.

The Federal Bureau of Investigation, which is also looking into alleged rigging of interest rates associated with the London interbank offered rate, or Libor, is in the early stages of its currency market probe, said the person, who asked not to be identified because the inquiry is confidential.

The U.S. investigation comes as the U.K. Financial Conduct Authority said in June it was reviewing potential manipulation of exchange rates. That month, allegations that dealers at banks pooled information through instant messages and used client orders to move benchmark currency rates were reported by Bloomberg News. Regulators are probing the alleged abuse of financial benchmarks used in markets from oil to interest rate swaps by the firms that play a central role in setting them.

Readers will remember that the shocking allegations are that traders would position their inventories to meet known pending client orders.

You can like or dislike Obama but he’s got one thing right:

President Barack Obama knows who is the boss: the bond market.

“Ultimately, what matters is: What do the people who are buying Treasury bills think?” the president told reporters this week, when discussing measures he could take to end the threat of a historic default on the nation’s debt.

Coming up next: courses on how to cheat on personality tests:

They can drive cars, win Jeopardy and find your soon-to-be favorite song. Machines are also learning to decipher the most human qualities about you — and help businesses predict your potential to be their next star employee.

A handful of technology companies from Knack.it Corp. to Evolv Inc. are doing just that, developing video games and online questionnaires that measure personality attributes in a job applicant. Based on patterns of how a company’s best performers responded in these assessments, the software estimates a candidate’s suitability to be everything from a warehouse worker to an investment bank analyst.

Once in my twenties, when I was so desperate for work I would apply for jobs at banks and undergo the ordeal of speaking to stupid people, I was required to take a personality test. Multiple choice. Page one of the test was how you thought of yourself with respect to various attributes. Page two – cunningly designed so you couldn’t see your answsrs to page 1 when filling in page 2 – was how you thought other people perceived you with respect to those same attributes. Fortunately, I’d heard of this ridiculous piece of HR ass-covering, and knew that what you said didn’t matter much – they were interested in how closely page 1 and 2 matched. So I made the responses almost identical.

In many ways, it must be nice to be American. A constitution that actually means something, a culture that supports it and an independent judiciary that enforces it:

New York’s ban on outdoor smoking in state parks was blocked by a judge after a smokers’-rights group argued that the Office of Parks, Recreation & Historic Preservation exceeded its authority.

Supreme Court Justice George B. Ceresia Jr. in Troy, in a ruling dated Oct. 8 and made public today, permanently blocked the office from implementing or enforcing the ban and ordered it to remove any signs referring to it.

The office “extended its reach beyond interstitial rule-making and into the realm of legislating,” Ceresia wrote in his ruling, saying state law doesn’t give the parks office the right to promulgate rules “regulating conduct bearing any tenuous relationship to park patrons’ health or welfare.”

It was a mixed day for the Canadian preferred share market, with PerpetualDiscounts up 9bp, FixedResets off 3bp and DeemedRetractibles gaining 1bp. No particular patterns are observable on the moderately sized Performance Highlights table. Volume was very low.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.6320 % 2,469.9
FixedFloater 4.29 % 3.55 % 30,410 18.32 1 1.0032 % 3,913.6
Floater 2.74 % 2.97 % 62,086 19.82 5 -0.6320 % 2,666.8
OpRet 4.61 % 1.70 % 64,511 0.46 3 0.1154 % 2,647.0
SplitShare 4.77 % 5.04 % 64,312 4.01 6 0.0745 % 2,942.5
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1154 % 2,420.4
Perpetual-Premium 5.80 % 0.65 % 105,015 0.10 8 0.0924 % 2,278.1
Perpetual-Discount 5.59 % 5.58 % 165,538 14.47 30 0.0948 % 2,331.6
FixedReset 4.97 % 3.73 % 229,984 3.42 85 -0.0311 % 2,445.6
Deemed-Retractible 5.15 % 4.41 % 184,660 6.86 43 0.0115 % 2,373.0
Performance Highlights
Issue Index Change Notes
TRI.PR.B Floater -2.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-11
Maturity Price : 20.41
Evaluated at bid price : 20.41
Bid-YTW : 2.58 %
HSB.PR.D Deemed-Retractible -1.43 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.76
Bid-YTW : 5.20 %
PWF.PR.A Floater -1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-11
Maturity Price : 22.21
Evaluated at bid price : 22.48
Bid-YTW : 2.32 %
MFC.PR.K FixedReset -1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.75
Bid-YTW : 4.58 %
BAM.PR.G FixedFloater 1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-11
Maturity Price : 22.52
Evaluated at bid price : 22.15
Bid-YTW : 3.55 %
SLF.PR.H FixedReset 1.17 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-09-30
Maturity Price : 25.00
Evaluated at bid price : 24.99
Bid-YTW : 3.98 %
BAM.PF.D Perpetual-Discount 1.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-11
Maturity Price : 20.10
Evaluated at bid price : 20.10
Bid-YTW : 6.15 %
Volume Highlights
Issue Index Shares
Traded
Notes
CU.PR.D Perpetual-Discount 229,500 Nesbitt crossed blocks of 150,000 and 75,000, both at 23.45.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-11
Maturity Price : 23.14
Evaluated at bid price : 23.45
Bid-YTW : 5.28 %
SLF.PR.A Deemed-Retractible 70,782 Scotia crossed 25,000 at 21.85; Nesbitt crossed two blocks of 20,000 each, both at the same price.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.84
Bid-YTW : 6.39 %
PWF.PR.R Perpetual-Discount 68,910 Nesbitt crossed blocks of 20,000 and 40,000, both at 24.70.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-11
Maturity Price : 24.28
Evaluated at bid price : 24.69
Bid-YTW : 5.56 %
MFC.PR.E FixedReset 60,344 Nesbitt crossed 35,000 at 25.61; TD crossed 17,500 at the same price.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-09-19
Maturity Price : 25.00
Evaluated at bid price : 25.65
Bid-YTW : 3.17 %
CU.PR.E Perpetual-Discount 54,955 TD crossed 51,600 at 23.45.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-11
Maturity Price : 23.09
Evaluated at bid price : 23.40
Bid-YTW : 5.29 %
TD.PR.Y FixedReset 41,300 Will reset at 3.5595%.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.53
Bid-YTW : 3.86 %
There were 17 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
MFC.PR.F FixedReset Quote: 22.47 – 23.06
Spot Rate : 0.5900
Average : 0.4159

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.47
Bid-YTW : 4.76 %

GWO.PR.P Deemed-Retractible Quote: 24.31 – 24.67
Spot Rate : 0.3600
Average : 0.2505

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.31
Bid-YTW : 5.80 %

IAG.PR.A Deemed-Retractible Quote: 22.39 – 22.79
Spot Rate : 0.4000
Average : 0.2912

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.39
Bid-YTW : 5.93 %

TRP.PR.B FixedReset Quote: 20.18 – 20.47
Spot Rate : 0.2900
Average : 0.1824

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-11
Maturity Price : 20.18
Evaluated at bid price : 20.18
Bid-YTW : 4.04 %

PWF.PR.K Perpetual-Discount Quote: 22.17 – 22.49
Spot Rate : 0.3200
Average : 0.2177

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-11
Maturity Price : 21.83
Evaluated at bid price : 22.17
Bid-YTW : 5.58 %

ELF.PR.G Perpetual-Discount Quote: 21.10 – 21.45
Spot Rate : 0.3500
Average : 0.2503

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-11
Maturity Price : 21.10
Evaluated at bid price : 21.10
Bid-YTW : 5.66 %

Market Action

October 10, 2013

Maneuvering continues on the US debt limit:

The White House endorsed a short debt-limit increase with no policy conditions attached, signaling potential support for House Republicans’ plan for a month-long reprieve from a default.

The idea, proposed today by House Speaker John Boehner, wouldn’t end the 10-day old partial shutdown of the federal government. The plan would push the lapse of U.S. borrowing authority to Nov. 22 from Oct. 17.

It was a rather strangely mixed day on the Canadian preferred share market, with PerpetualDiscounts and DeemedRetractibles both flat, while FixedResets were down 23bp. BAM issues were notable losers on the Performance Highlights table. Volume was quite high.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.2583 % 2,485.6
FixedFloater 4.33 % 3.59 % 30,899 18.24 1 -0.1914 % 3,874.7
Floater 2.72 % 2.97 % 61,485 19.81 5 -0.2583 % 2,683.8
OpRet 4.62 % 3.18 % 61,408 0.63 3 0.2829 % 2,643.9
SplitShare 4.77 % 5.08 % 65,038 4.01 6 0.1491 % 2,940.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.2829 % 2,417.6
Perpetual-Premium 5.80 % 1.42 % 108,513 0.10 8 -0.0948 % 2,276.0
Perpetual-Discount 5.59 % 5.56 % 160,692 14.45 30 -0.0015 % 2,329.4
FixedReset 4.97 % 3.74 % 235,995 3.60 85 -0.2346 % 2,446.4
Deemed-Retractible 5.15 % 4.46 % 187,539 6.87 43 0.0000 % 2,372.7
Performance Highlights
Issue Index Change Notes
BAM.PF.D Perpetual-Discount -1.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-10
Maturity Price : 19.80
Evaluated at bid price : 19.80
Bid-YTW : 6.25 %
BAM.PR.T FixedReset -1.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-10
Maturity Price : 22.58
Evaluated at bid price : 23.33
Bid-YTW : 4.52 %
IFC.PR.A FixedReset -1.47 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.15
Bid-YTW : 4.27 %
BAM.PR.K Floater -1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-10
Maturity Price : 17.57
Evaluated at bid price : 17.57
Bid-YTW : 3.00 %
BAM.PR.X FixedReset -1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-10
Maturity Price : 21.96
Evaluated at bid price : 22.37
Bid-YTW : 4.29 %
MFC.PR.F FixedReset -1.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.42
Bid-YTW : 4.76 %
TRP.PR.C FixedReset -1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-10
Maturity Price : 22.40
Evaluated at bid price : 22.80
Bid-YTW : 3.82 %
BAM.PR.B Floater -1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-10
Maturity Price : 17.74
Evaluated at bid price : 17.74
Bid-YTW : 2.97 %
ENB.PR.H FixedReset -1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-10
Maturity Price : 22.43
Evaluated at bid price : 23.26
Bid-YTW : 4.27 %
CU.PR.F Perpetual-Discount 1.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-10
Maturity Price : 21.06
Evaluated at bid price : 21.06
Bid-YTW : 5.42 %
CU.PR.G Perpetual-Discount 1.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-10
Maturity Price : 21.05
Evaluated at bid price : 21.05
Bid-YTW : 5.42 %
PWF.PR.A Floater 2.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-10
Maturity Price : 22.49
Evaluated at bid price : 22.75
Bid-YTW : 2.30 %
Volume Highlights
Issue Index Shares
Traded
Notes
MFC.PR.A OpRet 304,000 TD crossed blocks of 199,500 and 50,000 at 25.55. RBC crossed 49,400 at the same price.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-06-19
Maturity Price : 25.25
Evaluated at bid price : 25.43
Bid-YTW : 3.39 %
MFC.PR.I FixedReset 109,600 RBC crossed two blocks of 49,400 each, both at 25.48.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-09-19
Maturity Price : 25.00
Evaluated at bid price : 25.46
Bid-YTW : 3.98 %
MFC.PR.H FixedReset 60,270 TD crossed 49,000 at 25.80.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-03-19
Maturity Price : 25.00
Evaluated at bid price : 25.75
Bid-YTW : 3.77 %
TD.PR.Y FixedReset 57,075 Maple (who?) bought 19,300 from Hampton (who?) at 19,300.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.77
Bid-YTW : 3.70 %
CU.PR.G Perpetual-Discount 54,779 Nesbitt crossed 30,000 at 21.05.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-10
Maturity Price : 21.05
Evaluated at bid price : 21.05
Bid-YTW : 5.42 %
CU.PR.F Perpetual-Discount 44,800 RBC crossed 35,000 at 21.05.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-10
Maturity Price : 21.06
Evaluated at bid price : 21.06
Bid-YTW : 5.42 %
There were 49 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
IFC.PR.A FixedReset Quote: 24.15 – 24.52
Spot Rate : 0.3700
Average : 0.2250

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.15
Bid-YTW : 4.27 %

TD.PR.S FixedReset Quote: 24.48 – 24.78
Spot Rate : 0.3000
Average : 0.1785

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.48
Bid-YTW : 3.69 %

IFC.PR.C FixedReset Quote: 25.51 – 25.79
Spot Rate : 0.2800
Average : 0.1674

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-09-30
Maturity Price : 25.00
Evaluated at bid price : 25.51
Bid-YTW : 3.53 %

TD.PR.I FixedReset Quote: 25.62 – 25.90
Spot Rate : 0.2800
Average : 0.1774

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-07-31
Maturity Price : 25.00
Evaluated at bid price : 25.62
Bid-YTW : 2.70 %

CIU.PR.C FixedReset Quote: 19.36 – 20.15
Spot Rate : 0.7900
Average : 0.6938

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-10
Maturity Price : 19.36
Evaluated at bid price : 19.36
Bid-YTW : 4.31 %

FTS.PR.J Perpetual-Discount Quote: 22.45 – 22.98
Spot Rate : 0.5300
Average : 0.4366

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-10
Maturity Price : 22.16
Evaluated at bid price : 22.45
Bid-YTW : 5.34 %

Market Action

October 9, 2013

It’s official – Yellen is the nominee for Fed governor:

President Barack Obama will nominate Janet Yellen as chairman of the Federal Reserve, which would put the world’s most powerful central bank in the hands of a key architect of its unprecedented stimulus program and the first female leader in its 100-year history.

Obama will announce the nomination at 3 p.m. today in Washington, a White House official said in an e-mailed statement. Yellen, 67, would succeed Ben S. Bernanke, whose term expires on Jan. 31.

Bernanke says:

President Obama has made an outstanding choice in nominating my colleague and friend Janet Yellen to chair the Federal Reserve Board. Janet is exceptionally well qualified for the position, with stellar academic credentials and a strong record as a leader and a policymaker.

Yellen says:

Thank you, Mr. President, I am honored and humbled by the faith you have placed in me. If confirmed by the Senate, I pledge to do my utmost to keep that trust and meet the great responsibilities that Congress has entrusted to the Federal Reserve–to promote maximum employment, stable prices, and a strong and stable financial system.

I’d also like to thank my spouse, George, and my son, Robert. I couldn’t imagine taking on this new challenge without their love and support.

The past six years have been tumultuous for the economy and challenging for many Americans. While I think we all agree, Mr. President, that more needs to be done to strengthen this recovery, particularly for those hardest hit by the Great Recession, we have made progress. The economy is stronger and the financial system sounder. As you said, Mr. President, considerable credit for that goes to Chairman Bernanke for his wise, courageous, and skillful leadership. It has been my privilege to serve with him and learn from him.

While we have made progress, we have farther to go. The mandate of the Federal Reserve is to serve all the American people, and too many Americans still can’t find a job and worry how they will pay their bills and provide for their families. The Federal Reserve can help, if it does its job effectively. We can help ensure that everyone has the opportunity to work hard and build a better life. We can ensure that inflation remains in check and doesn’t undermine the benefits of a growing economy. We can and must safeguard the financial system.

The Fed has powerful tools to influence the economy and the financial system, but I believe its greatest strength rests in its capacity to approach important decisions with expertise and objectivity, to vigorously debate diverse views, and then to unite behind its response. The Fed’s effectiveness depends on the commitment, ingenuity, and integrity of the Fed staff and my fellow policymakers. They serve America with great dedication.

Mr. President, thank you for giving me this opportunity to continue serving the Federal Reserve and carrying out its important work on behalf of the American people.

Iceland has foreign exchange problems:

Iceland’s private sector is running out of cash to repay its foreign currency debt, according to the nation’s central bank.

Non-krona debt owed by entities besides the Treasury and the central bank due through 2018 totals about 700 billion kronur ($5.8 billion), the bank said yesterday. The projected current account surpluses over the next five years aren’t estimated to reach even half of that and will equal a shortfall of about 20 percent of gross domestic product.
…
Prime Minister Sigmundur David Gunnlaugsson has said Iceland’s foreign exchange shortfall is “a matter of huge concern” as he tries to scale back currency controls in place since 2008. The government’s biggest challenge is to allow capital to flow freely without triggering a krona sell-off that would cause Iceland’s foreign debt to spike and undermine the nation’s economic recovery.

I find it hard to get excited about the US debt shennanigans and tapering … the real problem is in the real economy:

The U.S. Federal Reserve has tripled the size of its balance sheet by “printing” an ocean of money. But despite the hand-wringing of the gold bugs, recent data proves that deflation, not inflation, remains the biggest threat to the U.S. economy.

The loan-to-deposit ratio for U.S. banks explains why Fed stimulus is not translating into inflationary pressure – the added funds remain trapped in the banking system and are not reaching the real economy.
…
The intention behind the Fed’s stimulus program was that by expanding bank balance sheets, customer lending would rise, and this would create consumer and corporate demand for products and services. The loan-to-deposit ratio illustrates that the process is stalled at step two – big bank balance sheets are bloated but aggregate demand in the U.S. economy has barely improved. The output gap remains.

I suggest that investors in long-term fixed income should be cheering the dysfunction and sending large donations to the Republican Party. While long-term fixed income is priced on expected inflation, it realizes based on realized inflation. Recessions are good! Depressions are wonderful! And here’s what the OECD honcho has to say:

“We still see the probability of failing to raise the debt ceiling as low, but as the government shutdown drags on, the level of concern is ratcheting up,” said [secretary-general of the Organization for Economic Co-Operation and Development] Mr [Angel] Gurria.

“If the debt ceiling is not raised – or, better still, abolished – our calculations suggest that the OECD region as a whole will be pushed back into recession next year, and emerging economies will experience a sharp slowdown.”

The OECD projects U.S. government consumption would contract immediately by the equivalent of at least four percentage points of gross domestic product, shaving that amount from economic growth next year.

A default, of course, would be even worse, he warned, and would hit other countries hard.

Meanwhile, DBRS has put the US under Review-Negative:

This action reflects the growing risk of a selective default by the federal government on its debt securities as a result of the lack of an agreement to raise the statutory limit on federal debt (the debt ceiling). According to the U.S. Treasury, its ability to borrow will be exhausted no later than October 17, 2013, leaving a cash balance of approximately $30 billion. If the debt ceiling is not raised or eliminated by October 17, it is unclear how the Treasury would operate. While a low probability, missing payments on selected government securities cannot be ruled out. In the view of DBRS, the longer it takes for an agreement to be reached on the debt ceiling, the greater the risk of missed payments.

The review for downgrade reflects the increasing uncertainty over the debt ceiling outcome, combined with the potential lingering repercussions on both domestic and international investor sentiment, and therefore the U.S. economy and financial markets. DBRS notes that the magnitude of these repercussions could increase each day this impasse continues.

If by October 17 there is still no agreement to raise the debt ceiling and the United States subsequently misses a debt payment, DBRS would assign a Selective Default rating to the affected securities, as long as we expect the Treasury to meet its other obligations in a timely manner. If there is a full-fledged default involving a wide array of securities, the magnitude of the downgrade would be greater.

It is an article of faith that Congress’ dysfunction is due to gerrymandering and the consequent importance of primaries. There’s at least some evidence that polarization of Congress reflects polarization of the electorate – extending beyond ideology to geography:

The real reason for our increasingly divided political system is much simpler: The right wing of the Republican Party has embraced a fundamentalist version of free-market capitalism and succeeded in winning elections. (The Democrats have moved to the left, but less so.)

The Republican shift is the result of several factors. The realignment of Southern white voters into the Republican Party, the branch of conservative activism created by Barry Goldwater’s 1964 presidential campaign and the party’s increasingly firm stance on issues such as income inequality and immigration, can all be important to Republicans’ rightward shift.

The “blame it on the gerrymanders” argument mistakenly assumes that because redistricting created more comfortable seats for each party, polarization became inevitable. Our research, however, casts serious doubt on that idea.
…
Many districts are safe for one party or the other because of how Americans have sorted themselves geographically — choosing to live closer to people who are politically or culturally like-minded. In Florida, for example, Palm Beach County will be reliably Democratic and the Panhandle will consistently vote for Republicans. These geographic shifts mean that state legislatures, which approve congressional district lines, can tweak but not fundamentally alter the ideological makeup of Congress.

The research cited is a paper titled Does Gerrymandering Cause Polarization?

Arthur Heinmaa of Toron observes:

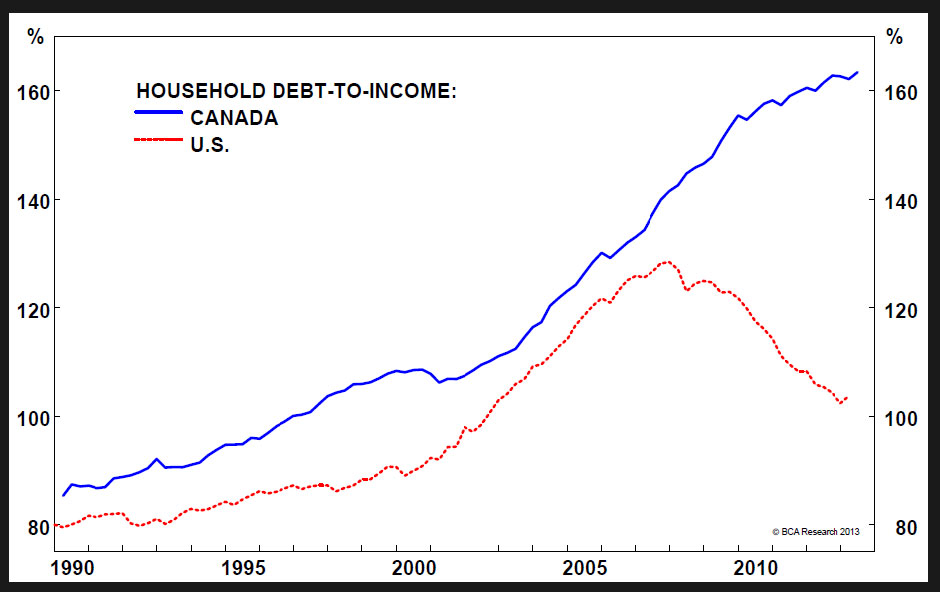
This chart continues to really worry me. There is no stopping the Canadian trend.


Click for Big

I will laugh through my tears if popping our bubble is as painful (and my guess would be more painful) than it was in America. That would put paid to the ‘Canadian financial stability due to wise regulation’ argument, which I consider ridiculous.

Louis Vachon, CEO of National Bank, the man who led the bank while it was stuffing its Money Market Fund to the nuts with ABCP issued by related companies, is now touting his Capital Markets unit:

The knock on National Bank has long been that it is too Quebec-focused, and that its capital markets earnings, which comprise 38 per cent of its net income, are inherently volatile. For these reasons, the bank trades at a lower price-earnings multiple than its Big Six peers.

Mr. Vachon is now on a crusade of sorts to “demystify” the financial markets arm. While he is realistic about his efforts – “we cannot turn lead to gold” – he argues a major point: “All we’re saying is [the unit] does not deserve the extensive discount” it receives relative to the retail operation.

Prior to 2004, he elaborates, there was never a discount for wholesale banking. And although it is understandable why the financial crisis altered that, much has changed since those tumultuous years. Any argument in favour of a discount is “passé,” he said. “If you look forward now, we’re back to more normal times and client-driven activities,” like corporate lending.

It was another negative day for the Canadian preferred share market, with PerpetualDiscounts down 24bp, FixedResets flat and DeemedRetractibles off 14bp. A lengthy Performance Highlights table is dominated by losers. Volume was low.

PerpetualDiscounts now yield 5.57%, equivalent to 7.24% interest at the standard equivalency factor of 1.3x. Long corporates continue to yield about 4.8% (OK, a smidgen more), so the pre-tax interest-equivalent spread is now about 245bp, with everything basically unchanged from the October 2 report.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -1.1845 % 2,492.0
FixedFloater 4.28 % 3.60 % 30,776 18.08 1 1.1384 % 3,882.1
Floater 2.71 % 2.94 % 63,781 19.90 5 -1.1845 % 2,690.7
OpRet 4.63 % 3.16 % 61,098 0.63 3 -0.1156 % 2,636.4
SplitShare 4.78 % 5.05 % 65,829 4.01 6 -0.3453 % 2,935.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.1156 % 2,410.8
Perpetual-Premium 5.80 % 0.26 % 105,518 0.10 8 -0.1071 % 2,278.2
Perpetual-Discount 5.59 % 5.57 % 158,188 14.46 30 -0.2430 % 2,329.4
FixedReset 4.96 % 3.71 % 234,017 3.60 85 -0.0013 % 2,452.1
Deemed-Retractible 5.15 % 4.49 % 187,711 6.83 43 -0.1358 % 2,372.7
Performance Highlights
Issue Index Change Notes
PWF.PR.A Floater -1.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-09
Maturity Price : 22.07
Evaluated at bid price : 22.30
Bid-YTW : 2.35 %
FTS.PR.J Perpetual-Discount -1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-09
Maturity Price : 22.18
Evaluated at bid price : 22.47
Bid-YTW : 5.34 %
BAM.PR.K Floater -1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-09
Maturity Price : 17.80
Evaluated at bid price : 17.80
Bid-YTW : 2.96 %
BNA.PR.E SplitShare -1.25 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2017-12-10
Maturity Price : 25.00
Evaluated at bid price : 24.45
Bid-YTW : 5.60 %
FTS.PR.F Perpetual-Discount -1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-09
Maturity Price : 22.82
Evaluated at bid price : 23.11
Bid-YTW : 5.36 %
BAM.PR.C Floater -1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-09
Maturity Price : 17.73
Evaluated at bid price : 17.73
Bid-YTW : 2.97 %
MFC.PR.B Deemed-Retractible -1.21 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.29
Bid-YTW : 6.60 %
TRP.PR.A FixedReset -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-09
Maturity Price : 23.34
Evaluated at bid price : 23.83
Bid-YTW : 4.02 %
GWO.PR.P Deemed-Retractible -1.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.40
Bid-YTW : 5.75 %
BAM.PR.G FixedFloater 1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-09
Maturity Price : 22.56
Evaluated at bid price : 22.21
Bid-YTW : 3.60 %
FTS.PR.H FixedReset 1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-09
Maturity Price : 21.03
Evaluated at bid price : 21.03
Bid-YTW : 4.08 %
Volume Highlights
Issue Index Shares
Traded
Notes
GWO.PR.L Deemed-Retractible 95,200 Nesbitt crossed blocks of 48,800 and 40,000, both at 25.10.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.90
Bid-YTW : 5.76 %
PWF.PR.R Perpetual-Discount 86,551 Nesbitt crossed two blocks of 40,000 each, both at 24.75.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-09
Maturity Price : 24.29
Evaluated at bid price : 24.70
Bid-YTW : 5.56 %
BAM.PR.B Floater 60,083 Nesbitt crossed 50,000 at 17.95.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-09
Maturity Price : 17.94
Evaluated at bid price : 17.94
Bid-YTW : 2.94 %
TD.PR.Y FixedReset 54,359 Will reset at 3.5595%.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.75
Bid-YTW : 3.71 %
BNS.PR.Q FixedReset 38,583 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.60
Bid-YTW : 3.81 %
TD.PR.C FixedReset 26,955 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.19
Bid-YTW : 2.07 %
There were 23 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
PWF.PR.A Floater Quote: 22.30 – 23.30
Spot Rate : 1.0000
Average : 0.7840

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-09
Maturity Price : 22.07
Evaluated at bid price : 22.30
Bid-YTW : 2.35 %

CU.PR.F Perpetual-Discount Quote: 20.77 – 21.21
Spot Rate : 0.4400
Average : 0.3020

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-09
Maturity Price : 20.77
Evaluated at bid price : 20.77
Bid-YTW : 5.49 %

GWO.PR.P Deemed-Retractible Quote: 24.40 – 24.67
Spot Rate : 0.2700
Average : 0.1636

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.40
Bid-YTW : 5.75 %

BNA.PR.E SplitShare Quote: 24.45 – 24.74
Spot Rate : 0.2900
Average : 0.1844

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2017-12-10
Maturity Price : 25.00
Evaluated at bid price : 24.45
Bid-YTW : 5.60 %

TD.PR.P Deemed-Retractible Quote: 25.67 – 25.92
Spot Rate : 0.2500
Average : 0.1464

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-11-01
Maturity Price : 25.00
Evaluated at bid price : 25.67
Bid-YTW : 4.22 %

MFC.PR.B Deemed-Retractible Quote: 21.29 – 21.64
Spot Rate : 0.3500
Average : 0.2512

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.29
Bid-YTW : 6.60 %

Market Action

October 8, 2013

Geez, maybe I should open a managed future fund:

Brokers have an incentive to keep clients in managed-futures funds because they receive commissions annually of up to 4 percent of assets invested, prospectuses show. Investors pay as much as 9 percent in total fees each year, including charges by general partners and fund managers.

Amazing – somebody actually took a quantitative look at the spread between downtown and suburban house prices:

No question, you’ll find house prices are cheaper outside big cities. Toronto Real Estate Board numbers suggest a spread of almost $250,000 between city homes and those in the neighbouring suburbs. But as shown in a spreadsheet created by Mr. Hughes, suburban living loses its cost advantage if you have two adults commuting by car each day. Add the effect of stress and time spent in gridlock, and suburbia looks even more costly.

It was another negative day for the Canadian preferred share market, with PerpetualDiscounts losing 28bp, FixedResets down 9bp and DeemedRetractibles off 6bp. There was a surprisingly lengthy list of losers in the Performance Highlights table. Volume was above average.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.0612 % 2,521.9
FixedFloater 4.33 % 3.65 % 31,143 17.99 1 -0.2272 % 3,838.4
Floater 2.68 % 2.92 % 65,162 19.96 5 -0.0612 % 2,723.0
OpRet 4.62 % 2.67 % 61,816 0.63 3 0.2576 % 2,639.5
SplitShare 4.76 % 5.05 % 62,160 3.73 6 0.0602 % 2,946.1
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.2576 % 2,413.5
Perpetual-Premium 5.79 % 1.04 % 106,098 0.10 8 -0.0219 % 2,280.6
Perpetual-Discount 5.58 % 5.56 % 158,413 14.51 30 -0.2845 % 2,335.1
FixedReset 4.95 % 3.69 % 235,148 3.61 85 -0.0862 % 2,452.2
Deemed-Retractible 5.14 % 4.45 % 189,415 6.87 43 -0.0554 % 2,376.0
Performance Highlights
Issue Index Change Notes
CIU.PR.C FixedReset -4.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-08
Maturity Price : 19.66
Evaluated at bid price : 19.66
Bid-YTW : 4.25 %
CU.PR.G Perpetual-Discount -1.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-08
Maturity Price : 20.75
Evaluated at bid price : 20.75
Bid-YTW : 5.50 %
BAM.PF.D Perpetual-Discount -1.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-08
Maturity Price : 20.11
Evaluated at bid price : 20.11
Bid-YTW : 6.15 %
CU.PR.F Perpetual-Discount -1.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-08
Maturity Price : 20.78
Evaluated at bid price : 20.78
Bid-YTW : 5.49 %
FTS.PR.H FixedReset -1.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-08
Maturity Price : 20.76
Evaluated at bid price : 20.76
Bid-YTW : 4.13 %
BAM.PR.Z FixedReset -1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-08
Maturity Price : 23.24
Evaluated at bid price : 25.04
Bid-YTW : 4.73 %
SLF.PR.E Deemed-Retractible -1.26 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.08
Bid-YTW : 6.53 %
SLF.PR.B Deemed-Retractible -1.21 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.13
Bid-YTW : 6.28 %
BAM.PR.M Perpetual-Discount -1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-08
Maturity Price : 19.45
Evaluated at bid price : 19.45
Bid-YTW : 6.16 %
ENB.PR.H FixedReset 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-08
Maturity Price : 22.55
Evaluated at bid price : 23.50
Bid-YTW : 4.22 %
Volume Highlights
Issue Index Shares
Traded
Notes
BNS.PR.Q FixedReset 98,437 RBC crossed 50,000 at 24.81.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.81
Bid-YTW : 3.69 %
PWF.PR.K Perpetual-Discount 40,775 National crossed 23,800 at 22.38.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-08
Maturity Price : 21.96
Evaluated at bid price : 22.31
Bid-YTW : 5.54 %
TD.PR.Y FixedReset 40,526 Will reset at 3.5595%.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.85
Bid-YTW : 3.65 %
ENB.PR.H FixedReset 35,310 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-08
Maturity Price : 22.55
Evaluated at bid price : 23.50
Bid-YTW : 4.22 %
POW.PR.D Perpetual-Discount 34,068 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-08
Maturity Price : 22.76
Evaluated at bid price : 23.00
Bid-YTW : 5.45 %
PWF.PR.S Perpetual-Discount 26,030 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-08
Maturity Price : 21.99
Evaluated at bid price : 22.28
Bid-YTW : 5.38 %
There were 41 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
CIU.PR.C FixedReset Quote: 19.66 – 20.66
Spot Rate : 1.0000
Average : 0.7071

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-08
Maturity Price : 19.66
Evaluated at bid price : 19.66
Bid-YTW : 4.25 %

CIU.PR.A Perpetual-Discount Quote: 20.42 – 21.03
Spot Rate : 0.6100
Average : 0.3766

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-08
Maturity Price : 20.42
Evaluated at bid price : 20.42
Bid-YTW : 5.71 %

IAG.PR.A Deemed-Retractible Quote: 22.62 – 22.98
Spot Rate : 0.3600
Average : 0.2535

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.62
Bid-YTW : 5.81 %

TD.PR.R Deemed-Retractible Quote: 25.85 – 26.10
Spot Rate : 0.2500
Average : 0.1520

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-04-30
Maturity Price : 25.75
Evaluated at bid price : 25.85
Bid-YTW : 4.09 %

TRP.PR.C FixedReset Quote: 23.03 – 23.54
Spot Rate : 0.5100
Average : 0.4336

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-08
Maturity Price : 22.55
Evaluated at bid price : 23.03
Bid-YTW : 3.78 %

PWF.PR.F Perpetual-Discount Quote: 23.45 – 23.68
Spot Rate : 0.2300
Average : 0.1589

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-08
Maturity Price : 23.15
Evaluated at bid price : 23.45
Bid-YTW : 5.59 %

Market Action

October 7, 2013

Lawrence Schembri, Deputy Governor of the Bank of Canada is assiduously sucking up to the politicians:

From my perspective, the FSB is a unique international organization that has certain qualities that many associate with Canadians, qualities I believe will help ensure its success in making the global financial system more resilient. A resilient global financial system is not an end in itself, but a necessary foundation for strong, sustainable and balanced global economic growth, leading to higher employment and improved living standards.

The FSB was born of necessity in the aftermath of the financial crisis. Its raison d’être stems from one overarching fact: the global financial system is highly integrated.2 Financial institutions and markets are interconnected and interdependent within and across various sectors, including banking, insurance, and pension and investment funds, and, increasingly, across national jurisdictions.

Thus, to achieve a comprehensive and coherent approach to the financial regulation and oversight necessary to attain the global public good of financial stability, coordination is essential across countries, across all of the elements of the reforms, and across many different regulators and supervisors. Failure to coordinate would lead to the fragmentation of the financial system, which would impede the global recovery. This need for effective coordination is why the G-20 established the FSB in 2009.

Can’t blame him, really – it worked for Lapdog Carney!

There’s some apocalyptic commentary on the potential for a US default:

Anyone who remembers the collapse of Lehman Brothers Holdings Inc. little more than five years ago knows what a global financial disaster is. A U.S. government default, just weeks away if Congress fails to raise the debt ceiling as it now threatens to do, will be an economic calamity like none the world has ever seen.
Failure by the world’s largest borrower to pay its debt — unprecedented in modern history — will devastate stock markets from Brazil to Zurich, halt a $5 trillion lending mechanism for investors who rely on Treasuries, blow up borrowing costs for billions of people and companies, ravage the dollar and throw the U.S. and world economies into a recession that probably would become a depression. Among the dozens of money managers, economists, bankers, traders and former government officials interviewed for this story, few view a U.S. default as anything but a financial apocalypse.
…
While none of the people interviewed for this story expect the world’s largest economy to default this time either, most say the chances of it happening now are higher than in the past.
“It would be insane to default, but it’s no longer a zero-percent probability,” said Simon Johnson, a former chief economist of the International Monetary Fund who teaches economics at the Massachusetts Institute of Technology and is a columnist for Bloomberg View.

I consider it all a little hysterical – but hey! In the financial markets, the hysterics are sometimes right!

I’ve lost a lot of business over the years by admitting there are things I don’t understand – financial guys are supposed to know just precisely how the price of eggs in Spain relates to Brazilian interest rates. But I’m in good company:

Ben S. Bernanke, the world’s most-powerful central banker, says he doesn’t understand gold prices. If his peers had paid attention, they might have stopped expanding reserves that lost $545 billion in value since bullion peaked in 2011.

Bernanke, who holds economics degrees from Harvard College and the Massachusetts Institute of Technology and led the Federal Reserve through the biggest financial disaster since the Great Depression, told the Senate Banking Committee in July that “nobody really understands gold prices and I don’t pretend to really understand them either.”

I generally have a lot of respect for the OTPP. Not this time:

The Ontario Teachers’ Pension Plan is urging the province’s securities regulator to require all public companies have at least three women on their boards, or else risk being delisted from the Toronto Stock Exchange.

Teachers outlines the proposal in a letter submitted to the Ontario Securities Commission in response to its call for comments on a possible new “comply or explain” disclosure rule to boost the number of women on boards. The OSC proposal would require companies to report annually on their efforts to improve board diversity or else explain why they have opted not to make the disclosure.

This is just political nonsense. If Teachers’ really believed that more diverse boards produced better results than less diverse boards and if they were truly interested in outperforming on behalf of their beneficiaries – they would promote a laissez faire in which there were all sorts of boards and they invested in those with more diverse boards on the grounds that these companies would kick the asses of those that were less diverse. You know, in the marketplace. I am very disappointed that Teachers’ is pursuing a political agenda.

Now that Ontario has bought up all the expensive solar panels Mexico is getting the cheap ones:

Mexico, poised to allow foreign oil extraction for the first time in 75 years, is finding its abundant natural resources also appeal to investors in a much cleaner energy: sunshine.

First Solar Inc. (FSLR) of the U.S. has bought its first projects in Mexico, while more than a dozen other developers including Germany’s Saferay GmbH and Spain’s Grupotec Tecnologia Solar SL own licenses there. Local investor Gauss Energia opened Latin America’s largest photovoltaic plant in the country last month.
…
Gauss and Portugal’s Martifer SGPS SA opened a 30-megawatt plant in La Paz, Baja California, on Sept. 12 with funding from International Finance Corp. and Nacional Financiera SNC bank. While Mexico doesn’t subsidize large solar, the $100 million project offered an economic alternative to fossil-fueled power in the area, where solar radiation exceeds the national average.

No subsidies and lots of investments! Gee, Mexico must have one of those ‘competitive advantage’ thingamajigs over Ontario when it comes to sunshine! Whoever woulda thunk it?

It was a poor day for the Canadian preferred share market, with PerpetualDiscounts down 12bp, FixedResets off 6bp and DeemedRetractibles losing 19bp. The Performance Highlights table was surprisingly short – below average even by long-term standards. Volume was average.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.2045 % 2,523.5
FixedFloater 4.32 % 3.64 % 32,450 18.01 1 0.0455 % 3,847.2
Floater 2.68 % 2.92 % 64,982 19.96 5 0.2045 % 2,724.6
OpRet 4.64 % 3.14 % 60,639 0.64 3 -0.0901 % 2,632.7
SplitShare 4.77 % 5.23 % 60,019 4.02 6 -0.2293 % 2,944.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0901 % 2,407.3
Perpetual-Premium 5.75 % 4.04 % 109,207 0.11 8 0.1883 % 2,281.1
Perpetual-Discount 5.55 % 5.56 % 157,971 14.44 30 -0.1192 % 2,341.8
FixedReset 4.95 % 3.68 % 233,882 3.61 85 -0.0580 % 2,454.3
Deemed-Retractible 5.14 % 4.49 % 191,697 6.74 43 -0.1934 % 2,377.3
Performance Highlights
Issue Index Change Notes
TRP.PR.A FixedReset -1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-07
Maturity Price : 23.53
Evaluated at bid price : 24.00
Bid-YTW : 3.99 %
CIU.PR.A Perpetual-Discount -1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-07
Maturity Price : 20.40
Evaluated at bid price : 20.40
Bid-YTW : 5.72 %
PWF.PR.O Perpetual-Premium 1.07 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.60
Bid-YTW : 5.53 %
Volume Highlights
Issue Index Shares
Traded
Notes
BNS.PR.Q FixedReset 74,616 Nesbitt crossed 28,500 at 24.83; TD crossed 20,000 at 24.82.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.82
Bid-YTW : 3.68 %
CU.PR.C FixedReset 68,605 Desjardins crossed 57,800 at 25.00.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-06-01
Maturity Price : 25.00
Evaluated at bid price : 25.01
Bid-YTW : 4.13 %
RY.PR.A Deemed-Retractible 37,805 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.11
Bid-YTW : 4.49 %
TD.PR.Y FixedReset 34,977 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.79
Bid-YTW : 3.68 %
CU.PR.E Perpetual-Discount 32,200 Nesbitt crossed 30,000 at 23.65.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-07
Maturity Price : 23.28
Evaluated at bid price : 23.60
Bid-YTW : 5.24 %
TD.PR.O Deemed-Retractible 27,134 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-10-31
Maturity Price : 25.00
Evaluated at bid price : 24.95
Bid-YTW : 4.76 %
There were 34 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
PWF.PR.O Perpetual-Premium Quote: 25.60 – 26.18
Spot Rate : 0.5800
Average : 0.3626

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.60
Bid-YTW : 5.53 %

HSE.PR.A FixedReset Quote: 22.67 – 23.13
Spot Rate : 0.4600
Average : 0.3053

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-07
Maturity Price : 22.29
Evaluated at bid price : 22.67
Bid-YTW : 4.09 %

PWF.PR.P FixedReset Quote: 24.29 – 24.75
Spot Rate : 0.4600
Average : 0.3104

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-07
Maturity Price : 23.22
Evaluated at bid price : 24.29
Bid-YTW : 3.65 %

FTS.PR.G FixedReset Quote: 23.50 – 23.89
Spot Rate : 0.3900
Average : 0.2677

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-07
Maturity Price : 22.55
Evaluated at bid price : 23.50
Bid-YTW : 4.19 %

CU.PR.G Perpetual-Discount Quote: 21.15 – 21.58
Spot Rate : 0.4300
Average : 0.3086

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-07
Maturity Price : 21.15
Evaluated at bid price : 21.15
Bid-YTW : 5.39 %

PWF.PR.M FixedReset Quote: 25.45 – 25.75
Spot Rate : 0.3000
Average : 0.1788

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.45
Bid-YTW : 3.80 %

Market Action

October 4, 2013

No jobs number today!

The absence of jobs data leaves economists and their investor clients without the month’s most important numbers on which to place bets, ranging from friendly office pools to million-dollar wagers on the health of the world’s largest economy. The Bureau of Labor Statistics, which typically issues the report on the first Friday of each month at 8:30 a.m. in Washington, yesterday said a government shutdown now in its fourth day means the latest data aren’t ready.

Shades of Enron! Investment analysis isn’t the only field where fraud flourishes in a lazy culture:

A Bangladeshi factory that produces garments for The Gap and Old Navy kept two sets of books to conceal how it is coercing employees to perform 17-hour shifts every day of the week, a new report says, underlining the inability of clothing retailers to improve working conditions among their suppliers.
…
“It is easy, because auditors and buyers never come around late at night to check these things,” the factory manager said in an interview. “Sometimes, it is the only way to meet the orders on time.”

The report said it was easy to fool retailers visiting the factory, which is located outside the capital, Dhaka, and employs 3,750 people.

Earlier this summer, the report said, “white foreigners” – buyers from Gap and Old Navy – visited the factory late in the morning of June 22.

A loudspeaker alerted the workers ahead of the visit. They were instructed to respond to questions by claiming that conditions were good and that they needed to do “just two hours of overtime a day.”

There was an interesting wrinkle in the GM bankruptcy:

In 2005, GM lost $10 billion. Researching Nova Scotia notes that year, Truong, the Fortress analyst, called the treasurer of GM Canada and learned that GM Nova Scotia Finance had made intercompany loans to its parent, Truong testified.

Such knowledge would prove useful. Under the 1900 Nova Scotia Companies Act, a company’s owner is obligated to pay the debts of all subsidiaries. Such unlimited liability companies, or ULCs, confer tax advantages on their parents.

Truong believed that GM Nova Scotia Finance’s ULC status would allow creditors to reach up to its parents to collect repayment in the event of a bankruptcy, he wrote in a Dec. 10, 2008, e-mail presented at the trial.

I find it rather odd that an oil-linked currency is a reserve currency, but perhaps that’s the whole point:

Canada now boasts the world’s fifth-largest reserve currency.

According to an International Monetary Fund report this week, central banks boosted their holdings of Canadian money to $108.9-billion in the second quarter of this year, up from $94.9-billion in the first three months of the year and $90.1-billion in the final quarter of 2012.

It was a negative day for the Canadian preferred share market, with PerpetualDiscounts down 10bp, FixedResets off 8bp and DeemedRetractibles flat. Losing FixedResets were notable in the Performance Highlights table. Volume was average.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.2855 % 2,518.3
FixedFloater 4.32 % 3.64 % 31,736 18.01 1 1.8047 % 3,845.4
Floater 2.68 % 2.92 % 65,689 19.96 5 -0.2855 % 2,719.1
OpRet 4.63 % 2.90 % 60,110 0.48 3 0.0901 % 2,635.1
SplitShare 4.75 % 5.02 % 60,706 4.03 6 0.1500 % 2,951.1
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0901 % 2,409.5
Perpetual-Premium 5.76 % 2.77 % 107,655 0.11 8 0.0000 % 2,276.8
Perpetual-Discount 5.54 % 5.56 % 146,264 14.39 30 -0.1003 % 2,344.5
FixedReset 4.94 % 3.66 % 236,746 3.62 85 -0.0845 % 2,455.7
Deemed-Retractible 5.13 % 4.41 % 192,233 6.89 43 0.0011 % 2,381.9
Performance Highlights
Issue Index Change Notes
FTS.PR.H FixedReset -1.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-04
Maturity Price : 21.00
Evaluated at bid price : 21.00
Bid-YTW : 4.09 %
HSE.PR.A FixedReset -1.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-04
Maturity Price : 22.35
Evaluated at bid price : 22.77
Bid-YTW : 4.07 %
TRP.PR.C FixedReset -1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-04
Maturity Price : 22.60
Evaluated at bid price : 23.11
Bid-YTW : 3.77 %
CU.PR.F Perpetual-Discount -1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-04
Maturity Price : 21.26
Evaluated at bid price : 21.26
Bid-YTW : 5.36 %
CIU.PR.C FixedReset -1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-04
Maturity Price : 20.52
Evaluated at bid price : 20.52
Bid-YTW : 4.07 %
BNA.PR.C SplitShare 1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2019-01-10
Maturity Price : 25.00
Evaluated at bid price : 24.35
Bid-YTW : 5.02 %
BAM.PR.G FixedFloater 1.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-04
Maturity Price : 22.42
Evaluated at bid price : 22.00
Bid-YTW : 3.64 %
Volume Highlights
Issue Index Shares
Traded
Notes
CM.PR.L FixedReset 103,537 RBC crossed blocks of 49,500 and 50,000, both at 25.53.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-04-30
Maturity Price : 25.00
Evaluated at bid price : 25.46
Bid-YTW : 2.41 %
RY.PR.X FixedReset 57,593 TD crossed 50,000 at 25.97.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-08-24
Maturity Price : 25.00
Evaluated at bid price : 25.96
Bid-YTW : 2.68 %
GWO.PR.R Deemed-Retractible 56,881 Desjardins crossed 25,000 at 22.50; TD crossed 16,900 at the same price.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.50
Bid-YTW : 6.08 %
CU.PR.C FixedReset 54,980 Desjardins crossed 49,500 at 25.00.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-06-01
Maturity Price : 25.00
Evaluated at bid price : 25.05
Bid-YTW : 4.07 %
TD.PR.K FixedReset 51,965 Desjardins crossed blocks of 30,000 and 15,000, both at 25.72.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-07-31
Maturity Price : 25.00
Evaluated at bid price : 25.67
Bid-YTW : 2.40 %
CM.PR.M FixedReset 51,232 RBC crossed 50,000 at 25.80.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-07-31
Maturity Price : 25.00
Evaluated at bid price : 25.75
Bid-YTW : 2.26 %
There were 36 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
MFC.PR.F FixedReset Quote: 22.50 – 23.39
Spot Rate : 0.8900
Average : 0.5794

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.50
Bid-YTW : 4.72 %

FTS.PR.K FixedReset Quote: 24.25 – 24.74
Spot Rate : 0.4900
Average : 0.3169

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-04
Maturity Price : 22.86
Evaluated at bid price : 24.25
Bid-YTW : 4.00 %

TD.PR.G FixedReset Quote: 25.29 – 25.59
Spot Rate : 0.3000
Average : 0.1770

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-04-30
Maturity Price : 25.00
Evaluated at bid price : 25.29
Bid-YTW : 3.33 %

BAM.PR.M Perpetual-Discount Quote: 19.80 – 20.08
Spot Rate : 0.2800
Average : 0.1871

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-04
Maturity Price : 19.80
Evaluated at bid price : 19.80
Bid-YTW : 6.05 %

BAM.PR.B Floater Quote: 18.05 – 18.32
Spot Rate : 0.2700
Average : 0.1799

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-04
Maturity Price : 18.05
Evaluated at bid price : 18.05
Bid-YTW : 2.92 %

ENB.PR.A Perpetual-Discount Quote: 25.10 – 25.40
Spot Rate : 0.3000
Average : 0.2104

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-04
Maturity Price : 24.88
Evaluated at bid price : 25.10
Bid-YTW : 5.54 %

Market Action

October 3, 2013

There is increasing awareness that the economy is not all that great:

Bank of Nova Scotia economists are now raising the possibility of no move in the Bank of Canada’s benchmark interest rate until 2016.

Other observers have speculated on late next year or early in 2015 for the first rate hike by the central bank.

But Scotiabank’s Derek Holt, Mary Webb and Dov Zigler say the Bank of Canada is now signalling a hold of more than two years, citing signs in a recent speech by senior deputy governor Tiff Macklem, among other things.
…
“The BoC probably now envisages spare capacity remaining into 2016,” the Scotiabank economists said, adding the central bank now projects hitting its 2-per-cent target for annual inflation in mid-2015.

They believe the Bank of Canada may change that forecast, to an even later date, when meets later this month and also issues its monetary policy report.

But that’s OK! We’ll all retire on the CPP:

A proposal to boost the retirement benefits for the middle class from the Canada Pension Plan through increases in contributions is rekindling momentum for pension reform ahead of a key December meeting with Finance Minister Jim Flaherty.

Prince Edward Island Finance Minister Wes Sheridan is trying to rally his colleagues around changes that would see the maximum CPP contribution rise to $4,681.20 a year from $2,356.20 starting in 2016, and the maximum annual benefit would increase to $23,400 from $12,150.

Qualifying for the maximum benefit would take an income of $102,000, up sharply from the current maximum insurable earnings cutoff of $51,000. The overall goal is to boost the savings rates of middle-income Canadians who earn less than six figures.

And – surprise! – middle-class jobs are scarce:

The top-10 list suggests there are really two sets of expanding job opportunities, at either end of the income spectrum – and not much in the middle.

If you’re entering the labour market – say you’re young, or you’re a newcomer to Canada – there are lots of points of entry at the low end of the scale. But they are not generally the types of jobs that lead you down a career path to something better, nor do these jobs fully employ many workers’ skill sets. If you are lucky enough to find full-time, full-year work in these types of jobs, paying $13 an hour or less, you would be making $26,000 a year before taxes, or less.

There is another cluster of job opportunities that pay median wages of $35 an hour or more, which translates to $70,000 a year before taxes, or more.

There are fewer opportunities in the middle, jobs that pay in the $20-something per hour range.

However, a bright note is that European distressed assets seem to have found a level:

Blackstone Group LP (BX) raised more than $4 billion in 2009 to buy European property assets anticipating that cash-strapped banks would be forced to sell as the region’s debt crisis worsened. Almost all of it sat idle for two years.

Today, the inaction has given way to a surge of deals, as lenders from Lloyds Banking Group Plc (LLOY) to Commerzbank AG (CBK) cut loose soured real estate, corporate and consumer loans. Sales of loan portfolios and other unwanted assets by European Union banks could reach 60 billion euros ($82 billion) in face value this year, according to PricewaterhouseCoopers LLP, the most since the firm began tracking data in 2010.
…
Apollo is among the most active investors, amassing loans with a face value of about 12 billion euros, including 11,000 mortgages in the U.K. Blackstone, the world’s largest alternative-asset manager, last year put $3.5 billion into distressed European mortgages and properties, the most its real estate group has plowed into the region in one year.
Investors also are buying European properties from real estate developers and taking over troubled companies or lending directly to them where banks have scaled back.
EU banks unloaded 29 billion euros of portfolio loans and assets such as mortgage-servicing units and branches in the first half of 2013, according to Richard Thompson, a partner at PwC in London. That compares with sales of 46 billion euros for all of last year, 36 billion euros in 2011 and 11 billion euros in 2010. The majority of sales have been distressed loans, Thompson said.

The arbitrary nature of corporate bond pricing (and hence the opportunity for profit) is well illustrated by this tale of woe:

Goldman Sachs Group Inc. (GS) mistakenly added about $1.5 million of interest costs to a Ford Motor Co. (F) bond sale last week by using the wrong Treasury note as a benchmark for the security, according to two people with knowledge of the transaction.
…
Typically, banks set the price of new corporate securities by using Treasury bonds with similar maturities. If the U.S. government issues notes in the middle of the week, underwriters don’t use that security as a benchmark until the following Monday.

For Dearborn, Michigan-based Ford’s Sept. 26 offering, Goldman Sachs added a 1.45 percentage-point spread to the 1.375 percent Treasury note due September 2018 that was auctioned on Sept. 25, Bloomberg data show. Instead, the bonds should have been based off the 1.5 percent security that matures in August 2018.

Matthew Klein of Bloomberg offers an excellent perspective on endowment investing:

The modern style of institutional investing can be traced to Yale University’s David Swensen, who literally wrote the book on the subject. … Three core ideas inform his thinking.

1. Savers are paid to take risk. If you want to generate big returns you have to be willing to endure large losses at any point.

2. Universities and other institutional investors have long time horizons because they expect to exist forever. This makes them different from regular people who save for retirement.

3. Contrary to standard academic theory, which suggests that savers should invest in broad indexes and avoid fees, market imperfections create opportunities for talented money managers. They can improve a portfolio’s performance through a combination of high returns and diversification benefits.
…
The potential for a mismatch between assets and liabilities is one big problem with the Yale model. Another is the focus on hunting for the best hedge funds, private-equity managers and stock pickers. This is where most of the money is made (and lost) in the endowment business. According to the Yale endowment’s most recent report, “nearly 80 percent of Yale’s outperformance relative to the average Cambridge Associates endowment was attributable to the value added by Yale’s active managers, while only 20 percent was the result of Yale’s asset allocation.” That’s great for Yale, but it’s impossible for every institution to have the best managers.

In general, I think Mr. Klein overstates the need for liquidity – it’s important, but my views are closer to precept 2 than that which he espouses.

I don’t think there’s anything wrong with the Yale model, but there are definitely problems with the implementation – as I told one guy recently, just because I believe the “Warren Buffet style” of investment CAN work, doesn’t mean I think YOU can do it.

The field is filled with ignoramuses and charlatans and institutional boards aren’t any better at picking winners than any other retail investor who handles his investments as a part-time job. Hiring a small group of specialists to farm out the work to third party firms just makes matters worse, because then allocations are made on the basis of two salesmen talking to each other.

For an institution to outperform, I believe that you have to have most, if not all, of the investment expertise in-house. ‘You don’t need to sell anything, guys, you just have to outperform on a rolling four year basis or you’re fired.’ This is the Teachers/OMERS model – and it works.

Canajans, eh? The Bank of Canada has published a working paper by Mikael Khan, Louis Morel and Patrick Sabourin titled The Common Component of CPI:An Alternative Measure of Underlying Inflation for Canada, in which the authors use factor analysis to find a common factor among 54 different components of the Consumer Price Index.


Click for Big

But, you ask, which of these 54 series was best correlated with this single underlying factor? Well, I’m glad you asked that question:

Table 2. Relationship between common component and individual components of the CPI

CPI components (y/y) Correlation % of explained variance
Alcoholic beverages served in licensed establishments 0.86 0.74

This suggests a new currency ….

It was a mixed day for the Canadian preferred share market, with PerpetualDiscounts getting whacked for 40bp, FixedResets off 3bp and DeemedRetractibles gaining 4bp. Predictably, the Performance Highlights table is heavily populated by losing PerpetualDiscounts. Volume was slightly above average.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.3151 % 2,525.5
FixedFloater 4.40 % 3.70 % 31,995 17.86 1 -1.3692 % 3,777.3
Floater 2.68 % 2.91 % 65,975 19.98 5 -0.3151 % 2,726.9
OpRet 4.64 % 2.96 % 60,751 0.48 3 -0.0901 % 2,632.7
SplitShare 4.76 % 5.07 % 60,910 4.03 6 -0.0622 % 2,946.7
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0901 % 2,407.3
Perpetual-Premium 5.76 % 1.77 % 111,776 0.12 8 -0.0644 % 2,276.8
Perpetual-Discount 5.53 % 5.56 % 147,151 14.38 30 -0.4041 % 2,346.9
FixedReset 4.93 % 3.68 % 238,684 3.62 85 -0.0261 % 2,457.8
Deemed-Retractible 5.12 % 4.43 % 197,492 6.89 43 0.0438 % 2,381.9
Performance Highlights
Issue Index Change Notes
CIU.PR.C FixedReset -3.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-03
Maturity Price : 20.74
Evaluated at bid price : 20.74
Bid-YTW : 4.03 %
BAM.PF.D Perpetual-Discount -1.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-03
Maturity Price : 20.71
Evaluated at bid price : 20.71
Bid-YTW : 5.96 %
BAM.PF.C Perpetual-Discount -1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-03
Maturity Price : 19.80
Evaluated at bid price : 19.80
Bid-YTW : 6.17 %
BAM.PR.G FixedFloater -1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-03
Maturity Price : 21.93
Evaluated at bid price : 21.61
Bid-YTW : 3.70 %
CU.PR.F Perpetual-Discount -1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-03
Maturity Price : 21.50
Evaluated at bid price : 21.50
Bid-YTW : 5.30 %
FTS.PR.F Perpetual-Discount -1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-03
Maturity Price : 23.31
Evaluated at bid price : 23.61
Bid-YTW : 5.23 %
CU.PR.G Perpetual-Discount -1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-03
Maturity Price : 21.37
Evaluated at bid price : 21.37
Bid-YTW : 5.33 %
FTS.PR.J Perpetual-Discount -1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-03
Maturity Price : 23.00
Evaluated at bid price : 23.30
Bid-YTW : 5.14 %
BAM.PR.M Perpetual-Discount -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-03
Maturity Price : 19.75
Evaluated at bid price : 19.75
Bid-YTW : 6.06 %
SLF.PR.G FixedReset 1.47 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.49
Bid-YTW : 4.15 %
Volume Highlights
Issue Index Shares
Traded
Notes
TRP.PR.D FixedReset 91,600 Nesbitt crossed 75,000 at 24.75.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-03
Maturity Price : 23.02
Evaluated at bid price : 24.70
Bid-YTW : 4.12 %
TD.PR.Y FixedReset 68,305 To reset 10/31 at 3.5595%.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.14
Bid-YTW : 3.61 %
TD.PR.T FixedReset 63,782 Scotia crossed 50,000 at 25.31.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-07-31
Maturity Price : 25.00
Evaluated at bid price : 25.32
Bid-YTW : 2.28 %
IFC.PR.A FixedReset 63,200 Scotia sold 21,600 to RBC at 24.55 and another 10,000 to Anonymous at the same price. RBC crossed 19,700 at the same price again.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.55
Bid-YTW : 4.08 %
BAM.PR.M Perpetual-Discount 39,904 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-03
Maturity Price : 19.75
Evaluated at bid price : 19.75
Bid-YTW : 6.06 %
BAM.PR.R FixedReset 39,592 Scotia crossed 25,000 at 25.20.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-03
Maturity Price : 23.50
Evaluated at bid price : 25.21
Bid-YTW : 4.21 %
There were 37 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
RY.PR.B Deemed-Retractible Quote: 25.29 – 25.77
Spot Rate : 0.4800
Average : 0.3265

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2015-08-24
Maturity Price : 25.00
Evaluated at bid price : 25.29
Bid-YTW : 4.37 %

TCA.PR.Y Perpetual-Discount Quote: 50.00 – 50.40
Spot Rate : 0.4000
Average : 0.2505

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-03-05
Maturity Price : 50.00
Evaluated at bid price : 50.00
Bid-YTW : 4.53 %

MFC.PR.G FixedReset Quote: 25.53 – 25.86
Spot Rate : 0.3300
Average : 0.2089

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-12-19
Maturity Price : 25.00
Evaluated at bid price : 25.53
Bid-YTW : 3.77 %

TRP.PR.B FixedReset Quote: 20.13 – 20.50
Spot Rate : 0.3700
Average : 0.2530

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-03
Maturity Price : 20.13
Evaluated at bid price : 20.13
Bid-YTW : 4.02 %

HSB.PR.C Deemed-Retractible Quote: 24.90 – 25.34
Spot Rate : 0.4400
Average : 0.3314

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.90
Bid-YTW : 5.20 %

GWO.PR.Q Deemed-Retractible Quote: 23.61 – 23.87
Spot Rate : 0.2600
Average : 0.1627

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.61
Bid-YTW : 5.87 %

Market Action

October 2, 2013

SEC Chair Mary Jo White gave a speech titled Focusing on Fundamentals: The Path to Address Equity Market Structure. All the usual blather, but there was one point of interest:

So, today, I am pleased to announce a new initiative we are launching that is designed to promote a fuller empirical understanding of the equity markets. SEC staff has prepared and assembled resources and data on the SEC’s web site focusing exclusively on equity market structure. The new web site should be available as early as next week and will serve as a central location for us to publicly share evolving data, research, and analysis.

Part of this initiative will be to disseminate data and related observations drawn from MIDAS that address the nature and quality of displayed liquidity across the full range of U.S.-listed equities –from the life-time of quotes, to the speed of the market, to the nature of order cancellations.
…
The new web site will also feature staff research papers based on a variety of data sources and staff reviews that identify and assemble information from the expanding economic literature on market structure topics. One paper, using order audit trail data on off-exchange trading, provides key metrics describing the underlying nature of off-exchange trading by the 44 alternative trading systems that trade equity securities. The staff’s primary observation is that ATS trading looks very similar in many respects to exchange trading.[20] Another paper summarizes current studies that address market fragmentation – both visible and dark. Additional research papers and reviews are already planned.

Maneuvering over the US debt limit continues:

Lew and President Barack Obama have said they won’t negotiate on the limit, which is tied to obligations the U.S. has already incurred. Boehner, an Ohio Republican, has issued a list of demands before he’ll support raising the ceiling. His conditions include approval of TransCanada Corp. (TRP)’s Keystone XL pipeline, major revisions to the tax code and a one-year delay of the insurance mandate in the Obama health-care law.
…
The U.S. government is already limited in action after Republicans and Democrats in Congress failed to agree on funding for the new fiscal year that began yesterday. That led to a partial shutdown of the government at midnight, forcing about 800,000 federal workers off the job. The shutdown could cost the economy as much as $10 billion a week, the White House said on its website.

DS is having a good year with US junk:

Royal Bank of Canada is on pace to join the ranks of the 10 largest underwriters of high-yield debt in the U.S. for the first time as the largest Canadian lender seeks profits abroad with issuance slowing at home.

Royal Bank’s RBC Capital Markets ranks 10th among arrangers of speculative-grade bonds at the end of the third quarter after luring bankers from firms including Deutsche Bank AG (DBK) and Credit Suisse Group AG. (CSGN) The Toronto-based firm has never been a top-10 underwriter for non-investment-grade debt in the U.S. on any given year, according to data compiled by Bloomberg.
…
While RBC expects total sales of junk bonds in the U.S. market to surpass last year’s record $353 billion, on Sept. 4 it cut its annual forecast for Canadian issuance to as little as C$4 billion ($3.9 billion) from about C$6 billion. The firm boosted the headcount in its U.S. credit team by 15 percent in the past two years, hiring almost 20 people, including 10 sales staff and eight traders. Last month Neil Yaris, who has held jobs at Credit Suisse and Bank of America Corp., joined as co-head of high-yield debt trading.
…
Royal Bank’s long-standing goal to be a Top 10 investment bank in the U.S. contrasts with retrenchment in other areas of banking. The company sold its unprofitable U.S. lender RBC Bank to PNC Financial Services Group Inc. in March 2012, ending an unsuccessful decade-long foray into U.S. retail banking.

In Canada, RBC slipped to the third spot among underwriters of high-yield debt, from No. 1 in 2012. Still, the firm has led arrangers of investment-grade company bonds in Canada for at least 14 years.

I’m in the wrong business:

Carnegie Hall employs five full-time stagehands and uses part-timers as needed, a spokeswoman, Synneve Carlino, said in an e-mail.

The full-timers earned an average of $420,000 in 2011, according to the tax return. They move equipment in and out of the building and prepare three stages for performances, while operating audiovisual and other equipment. They work on holidays and weekends.

Oh, they work on holidays and weekends. Well, I’m glad that’s cleared up.

It was a mixed day for the Canadian preferred share market, with PerpetualDiscounts down 15bp, FixedResets gaining 7bp and DeemedRetractibles off 2bp. The Performance Highlights table is average sized – by standards of the last few months – with BAM issues notable on the downside. Volume was average.

PerpetualDiscounts yield 5.56%, equivalent to 7.23% interest at the standard equivalency factor of 1.3x. Long Corporates now yield about 4.8%, so the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) is now about 245bp, a significant increase from the 235bp reported September 25, as long corporate yields have declined about 10bp on the week, while PerpetualDiscounts haven’t done much of anything.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.0508 % 2,533.5
FixedFloater 4.34 % 3.65 % 32,045 17.99 1 -1.0835 % 3,829.7
Floater 2.67 % 2.89 % 65,657 20.03 5 -0.0508 % 2,735.5
OpRet 4.63 % 2.78 % 61,624 0.49 3 -0.1028 % 2,635.1
SplitShare 4.76 % 4.97 % 60,900 4.03 6 0.1024 % 2,948.5
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.1028 % 2,409.5
Perpetual-Premium 5.76 % 3.04 % 112,395 0.12 8 -0.0520 % 2,278.3
Perpetual-Discount 5.51 % 5.56 % 145,987 14.44 30 -0.1529 % 2,356.4
FixedReset 4.93 % 3.68 % 235,270 3.65 85 0.0736 % 2,458.4
Deemed-Retractible 5.12 % 4.42 % 198,981 6.75 43 -0.0171 % 2,380.8
Performance Highlights
Issue Index Change Notes
BAM.PR.G FixedFloater -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-02
Maturity Price : 22.36
Evaluated at bid price : 21.91
Bid-YTW : 3.65 %
BAM.PF.D Perpetual-Discount -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-02
Maturity Price : 21.04
Evaluated at bid price : 21.04
Bid-YTW : 5.87 %
BAM.PR.B Floater -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-02
Maturity Price : 18.21
Evaluated at bid price : 18.21
Bid-YTW : 2.89 %
FTS.PR.G FixedReset -1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-02
Maturity Price : 22.45
Evaluated at bid price : 23.31
Bid-YTW : 4.24 %
CIU.PR.C FixedReset -1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-02
Maturity Price : 21.30
Evaluated at bid price : 21.60
Bid-YTW : 3.84 %
MFC.PR.F FixedReset 1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.58
Bid-YTW : 4.68 %
TRI.PR.B Floater 1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-02
Maturity Price : 21.35
Evaluated at bid price : 21.35
Bid-YTW : 2.47 %
HSB.PR.D Deemed-Retractible 1.62 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.05
Bid-YTW : 4.89 %
Volume Highlights
Issue Index Shares
Traded
Notes
ENB.PR.T FixedReset 87,816 TD crossed 25,000 at 24.10; Nesbitt crossed 50,000 at the same price.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-02
Maturity Price : 22.75
Evaluated at bid price : 24.01
Bid-YTW : 4.40 %
TRP.PR.D FixedReset 73,493 RBC crossed 56,500 at 24.90.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-02
Maturity Price : 23.04
Evaluated at bid price : 24.75
Bid-YTW : 4.11 %
BAM.PF.A FixedReset 58,449 Scotia crossed 45,000 at 24.75.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-02
Maturity Price : 23.11
Evaluated at bid price : 24.85
Bid-YTW : 4.65 %
HSE.PR.A FixedReset 58,356 Desjardins crossed 45,000 at 23.28.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-02
Maturity Price : 22.66
Evaluated at bid price : 23.25
Bid-YTW : 3.97 %
TD.PR.Y FixedReset 52,125 Will reset 2013-10-31 at 3.5595%.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.15
Bid-YTW : 3.61 %
TRP.PR.C FixedReset 43,235 Desjardins crossed 30,000 at 23.33.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-02
Maturity Price : 22.66
Evaluated at bid price : 23.21
Bid-YTW : 3.75 %
There were 32 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
TD.PR.T FixedReset Quote: 25.31 – 26.59
Spot Rate : 1.2800
Average : 0.7157

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-07-31
Maturity Price : 25.00
Evaluated at bid price : 25.31
Bid-YTW : 2.29 %

BAM.PR.G FixedFloater Quote: 21.91 – 23.12
Spot Rate : 1.2100
Average : 0.8050

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-02
Maturity Price : 22.36
Evaluated at bid price : 21.91
Bid-YTW : 3.65 %

TRP.PR.C FixedReset Quote: 23.21 – 23.64
Spot Rate : 0.4300
Average : 0.3076

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-02
Maturity Price : 22.66
Evaluated at bid price : 23.21
Bid-YTW : 3.75 %

ENB.PR.Y FixedReset Quote: 23.90 – 24.19
Spot Rate : 0.2900
Average : 0.1833

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-02
Maturity Price : 22.69
Evaluated at bid price : 23.90
Bid-YTW : 4.33 %

PWF.PR.K Perpetual-Discount Quote: 22.66 – 22.99
Spot Rate : 0.3300
Average : 0.2275

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-02
Maturity Price : 22.24
Evaluated at bid price : 22.66
Bid-YTW : 5.54 %

ELF.PR.G Perpetual-Discount Quote: 20.91 – 21.28
Spot Rate : 0.3700
Average : 0.2922

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-02
Maturity Price : 20.91
Evaluated at bid price : 20.91
Bid-YTW : 5.70 %

Market Action

October 1, 2013

Tiff Macklem gave a speech to the Economic Club of Canada titled Global Growth and the Prospects for Canada’s Exports – I found Chart 12 to be of great interest:

A second factor influencing our exports is competitiveness. Between 2000 and 2012, the labour cost of producing a unit of output in Canada compared with the United States, adjusted for the exchange rate, increased by 75 per cent (Chart 12). The majority of this loss of competitiveness reflects the appreciation of the Canadian dollar (shown in blue), but weak productivity growth in Canada relative to the United States also played a significant role (shown in green).


Click for Big

From the bureaucrats at the UBC Staff Pension Plan comes an excellent lesson in bafflement via bullshit:

“We have what is called a target benefit plan,” says Mr. Parker, who is executive director of the University of British Columbia’s staff pension plan.
…
In a target plan, the employer and its employees make fixed contributions, similar to a defined contribution plan. The payouts that can be expected are set as a target, which depends on projections, made by actuarial experts, of what the plan will be able to afford.

So in other words, it’s a Defined Contribution plan but they don’t want to say the words, so instead of handing over the dollar value of the account on retirement, they hand over a package of benefits, that may or may not increase or decrease and which will disappear when the beneficiary dies. Well done!

Fitch is unimpressed with the games in Washington:

The US government shutdown is not in itself a downgrade trigger for the sovereign’s ‘AAA’/Negative rating. However, it undermines confidence in both the budgetary process and critically in the prospect of the debt ceiling being raised in a timely manner to avert the risk of default on US sovereign debt obligations, says Fitch Ratings in a reiteration of its June 28 rating commentary.

A formal review of the rating with potentially negative implications would be triggered if the US government has not raised the federal debt ceiling in a timely manner prior to when the Treasury will have exhausted extraordinary measures and cash reserves. According to official comments by the US Treasury secretary, extraordinary measures could be exhausted by 17 October.

In such a scenario, the Treasury would be forced to dramatically cut back on current spending with adverse implications for the economic recovery. Even if it were to prioritise debt service – something the Treasury has repeatedly stated it has neither the legal authority nor logistical capability to do – it would likely incur arrears on a range of payment obligations and thus continue to incur debt, but in a disorderly and disruptive manner.

Even if the debt limit is not raised in a timely manner we believe there is sufficient political will and capacity to ensure that Treasury securities will continue to be honoured in full and on time. Nevertheless, investor confidence in the full faith and credit of the US would be undermined in such a scenario. This “faith” is a key underpinning of the US dollar’s global reserve currency status and reason why the US ‘AAA’ rating can tolerate a substantially higher level of public debt than other ‘AAA’ sovereigns.

Non-essential operations of the federal government will cease from today – the government shutdown – after the US House of Representatives and Senate failed to agree a continuing resolution to grant it the necessary spending authority.

Further to my rant of September 25, I was infuriated by the “Moment in Time” feature in today’s Globe (not available on-line), which claimed that “[Henry Ford] raised wages so his workers could become customers”, I looked around more carefully and found this:

It should be obvious that this story doesn’t work: Boeing would most certainly be in trouble if they had to pay their workers sufficient to afford a new jetliner. It’s also obviously true that you want every other employer to be paying their workers sufficient that they can afford your products: but that’s very much not the same as claiming that Ford should pay his workers so that they can afford Fords.
…
Ford’s turnover rate was very high. In 1913, Ford hired more than 52,000 men to keep a workforce of only 14,000.
…
Car production in the year before the pay rise was 170,000, in the year of it 202,000. As we can see above the total labour establishment was only 14,000 anyway. Even if all of his workers bought a car every year it wasn’t going to make any but a marginal difference to the sales of the firm.

We can go further too. As we’ve seen the rise in the daily wage was from $2.25 to $5 (including the bonuses etc). Say 240 working days in the year and 14,000 workers and we get a rise in the pay bill of $9 1/4 million over the year. A Model T cost between $550 and $450 (depends on which year we’re talking about). 14,000 cars sold at that price gives us $7 3/4 million to $6 1/4 million in income to the company.

It should be obvious that paying the workforce an extra $9 million so that they can then buy $7 million’s worth of company production just isn’t a way to increase your profits. It’s a great way to increase your losses though.

It was a mixed day for the Canadian preferred share market, with PerpetualDiscounts up 30bp, FixedResets off 3bp and DeemedRetractibles gaining 3bp. Not surprisingly, there’s a bit of a skew in the Performance Highlights table towards winning PerpetualDiscounts. Volume was average.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.2853 % 2,534.8
FixedFloater 4.29 % 3.61 % 31,089 18.08 1 0.7734 % 3,871.7
Floater 2.67 % 2.86 % 66,116 20.11 5 0.2853 % 2,736.9
OpRet 4.63 % 2.61 % 63,724 0.49 3 0.1674 % 2,637.8
SplitShare 4.76 % 5.03 % 60,188 4.03 6 0.1285 % 2,945.5
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1674 % 2,412.0
Perpetual-Premium 5.75 % 0.37 % 111,952 0.12 8 0.2829 % 2,279.5
Perpetual-Discount 5.50 % 5.55 % 148,220 14.46 30 0.3039 % 2,360.0
FixedReset 4.94 % 3.69 % 237,575 3.65 85 -0.0280 % 2,456.6
Deemed-Retractible 5.12 % 4.44 % 201,038 6.89 43 0.0333 % 2,381.2
Performance Highlights
Issue Index Change Notes
MFC.PR.F FixedReset -1.80 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.35
Bid-YTW : 4.79 %
HSB.PR.D Deemed-Retractible -1.40 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.65
Bid-YTW : 5.24 %
TRP.PR.A FixedReset -1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-01
Maturity Price : 23.76
Evaluated at bid price : 24.21
Bid-YTW : 3.96 %
BAM.PF.C Perpetual-Discount -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-01
Maturity Price : 20.14
Evaluated at bid price : 20.14
Bid-YTW : 6.07 %
FTS.PR.F Perpetual-Discount 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-01
Maturity Price : 23.56
Evaluated at bid price : 23.90
Bid-YTW : 5.17 %
PWF.PR.R Perpetual-Discount 1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-01
Maturity Price : 24.73
Evaluated at bid price : 25.15
Bid-YTW : 5.55 %
PWF.PR.P FixedReset 1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-01
Maturity Price : 23.19
Evaluated at bid price : 24.21
Bid-YTW : 3.67 %
W.PR.H Perpetual-Discount 1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-01
Maturity Price : 23.91
Evaluated at bid price : 24.15
Bid-YTW : 5.71 %
CGI.PR.D SplitShare 1.31 % YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2023-06-14
Maturity Price : 25.00
Evaluated at bid price : 23.91
Bid-YTW : 4.35 %
TRI.PR.B Floater 1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-01
Maturity Price : 21.10
Evaluated at bid price : 21.10
Bid-YTW : 2.50 %
FTS.PR.J Perpetual-Discount 1.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-01
Maturity Price : 23.33
Evaluated at bid price : 23.65
Bid-YTW : 5.06 %
Volume Highlights
Issue Index Shares
Traded
Notes
CU.PR.C FixedReset 104,121 Desjardins crossed 100,000 at 25.00.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-06-01
Maturity Price : 25.00
Evaluated at bid price : 25.00
Bid-YTW : 4.12 %
SLF.PR.H FixedReset 59,870 Nesbitt crossed 50,000 at 24.70.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.57
Bid-YTW : 4.21 %
BNS.PR.Q FixedReset 52,414 RBC bought 11,800 from National at 24.80.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.80
Bid-YTW : 3.69 %
MFC.PR.B Deemed-Retractible 39,809 Desjardins crossed 15,600 at 21.77, then bought 17,200 from Anonymous at 21.75.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.75
Bid-YTW : 6.33 %
BAM.PF.D Perpetual-Discount 31,981 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-01
Maturity Price : 21.26
Evaluated at bid price : 21.26
Bid-YTW : 5.80 %
BMO.PR.L Deemed-Retractible 31,541 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-05-25
Maturity Price : 25.75
Evaluated at bid price : 26.12
Bid-YTW : 4.25 %
There were 33 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
RY.PR.B Deemed-Retractible Quote: 25.49 – 25.82
Spot Rate : 0.3300
Average : 0.2109

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2015-08-24
Maturity Price : 25.00
Evaluated at bid price : 25.49
Bid-YTW : 3.92 %

BMO.PR.L Deemed-Retractible Quote: 26.12 – 26.42
Spot Rate : 0.3000
Average : 0.1916

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-05-25
Maturity Price : 25.75
Evaluated at bid price : 26.12
Bid-YTW : 4.25 %

CIU.PR.A Perpetual-Discount Quote: 20.68 – 21.42
Spot Rate : 0.7400
Average : 0.6337

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-01
Maturity Price : 20.68
Evaluated at bid price : 20.68
Bid-YTW : 5.63 %

BAM.PR.X FixedReset Quote: 22.44 – 22.88
Spot Rate : 0.4400
Average : 0.3380

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-01
Maturity Price : 22.01
Evaluated at bid price : 22.44
Bid-YTW : 4.28 %

HSB.PR.D Deemed-Retractible Quote: 24.65 – 24.99
Spot Rate : 0.3400
Average : 0.2458

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.65
Bid-YTW : 5.24 %

CIU.PR.C FixedReset Quote: 21.82 – 22.39
Spot Rate : 0.5700
Average : 0.4804

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-01
Maturity Price : 21.46
Evaluated at bid price : 21.82
Bid-YTW : 3.79 %