Category: Market Action

Market Action

June 23, 2020

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.3780 % 1,456.5
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.3780 % 2,672.5
Floater 5.38 % 5.69 % 48,122 14.39 4 0.3780 % 1,540.2
OpRet 0.00 % 0.00 % 0 0.00 0 -0.5515 % 3,421.5
SplitShare 4.91 % 5.14 % 67,109 3.83 7 -0.5515 % 4,086.0
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.5515 % 3,188.1
Perpetual-Premium 0.00 % 0.00 % 0 0.00 0 0.1882 % 3,045.0
Perpetual-Discount 5.54 % 5.71 % 76,956 14.26 35 0.1882 % 3,266.1
FixedReset Disc 6.22 % 5.11 % 153,187 14.96 83 0.1785 % 1,836.3
Deemed-Retractible 5.31 % 5.40 % 86,573 14.42 27 -0.1266 % 3,226.2
FloatingReset 4.91 % 4.94 % 46,281 15.62 3 0.6444 % 1,795.5
FixedReset Prem 0.00 % 0.00 % 0 0.00 0 0.1785 % 2,539.6
FixedReset Bank Non 1.98 % 3.31 % 121,849 1.57 2 0.1023 % 2,787.9
FixedReset Ins Non 6.43 % 5.07 % 118,758 14.92 22 0.7622 % 1,862.7
Performance Highlights
Issue Index Change Notes
TRP.PR.G FixedReset Disc -8.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 13.35
Evaluated at bid price : 13.35
Bid-YTW : 6.31 %
BIK.PR.A FixedReset Disc -7.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 22.11
Evaluated at bid price : 22.60
Bid-YTW : 6.49 %
BAM.PF.F FixedReset Disc -6.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 14.50
Evaluated at bid price : 14.50
Bid-YTW : 5.94 %
TD.PF.D FixedReset Disc -5.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 15.51
Evaluated at bid price : 15.51
Bid-YTW : 5.17 %
TRP.PR.B FixedReset Disc -3.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 7.55
Evaluated at bid price : 7.55
Bid-YTW : 5.46 %
PVS.PR.G SplitShare -2.20 % YTW SCENARIO
Maturity Type : Option Certainty
Maturity Date : 2026-02-28
Maturity Price : 25.00
Evaluated at bid price : 24.01
Bid-YTW : 5.80 %
HSE.PR.G FixedReset Disc -1.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 10.80
Evaluated at bid price : 10.80
Bid-YTW : 9.06 %
IAF.PR.B Deemed-Retractible -1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 21.40
Evaluated at bid price : 21.40
Bid-YTW : 5.40 %
PVS.PR.F SplitShare -1.59 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2024-09-30
Maturity Price : 25.00
Evaluated at bid price : 24.75
Bid-YTW : 5.14 %
TD.PF.E FixedReset Disc -1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 16.60
Evaluated at bid price : 16.60
Bid-YTW : 4.96 %
CU.PR.C FixedReset Disc -1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 14.40
Evaluated at bid price : 14.40
Bid-YTW : 4.96 %
HSE.PR.E FixedReset Disc -1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 11.75
Evaluated at bid price : 11.75
Bid-YTW : 8.96 %
PVS.PR.E SplitShare -1.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.02
Bid-YTW : 5.60 %
BAM.PF.G FixedReset Disc -1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 14.00
Evaluated at bid price : 14.00
Bid-YTW : 5.75 %
RY.PR.Z FixedReset Disc 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 15.31
Evaluated at bid price : 15.31
Bid-YTW : 4.64 %
BIP.PR.B FixedReset Disc 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 23.00
Evaluated at bid price : 23.75
Bid-YTW : 5.78 %
IFC.PR.C FixedReset Ins Non 1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 14.19
Evaluated at bid price : 14.19
Bid-YTW : 5.39 %
TD.PF.B FixedReset Disc 1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 15.30
Evaluated at bid price : 15.30
Bid-YTW : 4.78 %
SLF.PR.G FixedReset Ins Non 1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 9.16
Evaluated at bid price : 9.16
Bid-YTW : 4.86 %
CM.PR.Q FixedReset Disc 1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 15.25
Evaluated at bid price : 15.25
Bid-YTW : 5.26 %
CM.PR.O FixedReset Disc 1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 14.25
Evaluated at bid price : 14.25
Bid-YTW : 5.24 %
RY.PR.H FixedReset Disc 1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 15.63
Evaluated at bid price : 15.63
Bid-YTW : 4.61 %
NA.PR.W FixedReset Disc 1.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 14.82
Evaluated at bid price : 14.82
Bid-YTW : 5.00 %
TRP.PR.K FixedReset Disc 1.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 22.76
Evaluated at bid price : 23.10
Bid-YTW : 5.34 %
TD.PF.C FixedReset Disc 1.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 15.48
Evaluated at bid price : 15.48
Bid-YTW : 4.84 %
BMO.PR.C FixedReset Disc 1.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 18.75
Evaluated at bid price : 18.75
Bid-YTW : 5.09 %
TD.PF.I FixedReset Disc 1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 18.55
Evaluated at bid price : 18.55
Bid-YTW : 4.84 %
PWF.PR.T FixedReset Disc 1.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 14.96
Evaluated at bid price : 14.96
Bid-YTW : 5.20 %
MFC.PR.N FixedReset Ins Non 1.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 14.72
Evaluated at bid price : 14.72
Bid-YTW : 5.00 %
BMO.PR.T FixedReset Disc 1.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 14.63
Evaluated at bid price : 14.63
Bid-YTW : 4.90 %
BMO.PR.D FixedReset Disc 1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 18.25
Evaluated at bid price : 18.25
Bid-YTW : 5.04 %
NA.PR.G FixedReset Disc 2.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 17.52
Evaluated at bid price : 17.52
Bid-YTW : 5.03 %
TD.PF.M FixedReset Disc 2.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 21.64
Evaluated at bid price : 21.95
Bid-YTW : 4.84 %
RY.PR.M FixedReset Disc 2.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 15.98
Evaluated at bid price : 15.98
Bid-YTW : 4.73 %
SLF.PR.J FloatingReset 2.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 9.20
Evaluated at bid price : 9.20
Bid-YTW : 4.38 %
BMO.PR.W FixedReset Disc 2.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 15.03
Evaluated at bid price : 15.03
Bid-YTW : 4.86 %
CM.PR.R FixedReset Disc 2.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 18.77
Evaluated at bid price : 18.77
Bid-YTW : 5.19 %
NA.PR.S FixedReset Disc 2.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 15.25
Evaluated at bid price : 15.25
Bid-YTW : 5.05 %
TD.PF.L FixedReset Disc 2.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 20.50
Evaluated at bid price : 20.50
Bid-YTW : 4.92 %
PWF.PR.P FixedReset Disc 2.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 9.65
Evaluated at bid price : 9.65
Bid-YTW : 5.21 %
BIP.PR.A FixedReset Disc 2.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 15.11
Evaluated at bid price : 15.11
Bid-YTW : 6.53 %
NA.PR.C FixedReset Disc 3.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 18.90
Evaluated at bid price : 18.90
Bid-YTW : 5.20 %
MFC.PR.R FixedReset Ins Non 3.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 21.12
Evaluated at bid price : 21.12
Bid-YTW : 5.07 %
MFC.PR.G FixedReset Ins Non 3.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 16.25
Evaluated at bid price : 16.25
Bid-YTW : 5.13 %
BMO.PR.S FixedReset Disc 3.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 15.24
Evaluated at bid price : 15.24
Bid-YTW : 4.88 %
SLF.PR.I FixedReset Ins Non 3.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 16.00
Evaluated at bid price : 16.00
Bid-YTW : 4.96 %
CM.PR.P FixedReset Disc 3.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 14.98
Evaluated at bid price : 14.98
Bid-YTW : 5.01 %
Volume Highlights
Issue Index Shares
Traded
Notes
BMO.PR.S FixedReset Disc 69,256 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 15.24
Evaluated at bid price : 15.24
Bid-YTW : 4.88 %
TD.PF.E FixedReset Disc 67,813 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 16.60
Evaluated at bid price : 16.60
Bid-YTW : 4.96 %
TRP.PR.K FixedReset Disc 55,724 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 22.76
Evaluated at bid price : 23.10
Bid-YTW : 5.34 %
CU.PR.C FixedReset Disc 46,621 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 14.40
Evaluated at bid price : 14.40
Bid-YTW : 4.96 %
TRP.PR.G FixedReset Disc 44,616 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 13.35
Evaluated at bid price : 13.35
Bid-YTW : 6.31 %
TD.PF.B FixedReset Disc 40,423 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 15.30
Evaluated at bid price : 15.30
Bid-YTW : 4.78 %
There were 30 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BAM.PR.X FixedReset Disc Quote: 9.86 – 17.27
Spot Rate : 7.4100
Average : 4.2190

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 9.86
Evaluated at bid price : 9.86
Bid-YTW : 5.68 %

RY.PR.M FixedReset Disc Quote: 15.98 – 25.50
Spot Rate : 9.5200
Average : 7.4821

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 15.98
Evaluated at bid price : 15.98
Bid-YTW : 4.73 %

TRP.PR.G FixedReset Disc Quote: 13.35 – 14.60
Spot Rate : 1.2500
Average : 0.8507

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 13.35
Evaluated at bid price : 13.35
Bid-YTW : 6.31 %

TD.PF.D FixedReset Disc Quote: 15.51 – 16.60
Spot Rate : 1.0900
Average : 0.6930

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 15.51
Evaluated at bid price : 15.51
Bid-YTW : 5.17 %

BAM.PF.F FixedReset Disc Quote: 14.50 – 15.55
Spot Rate : 1.0500
Average : 0.7217

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 14.50
Evaluated at bid price : 14.50
Bid-YTW : 5.94 %

MFC.PR.I FixedReset Ins Non Quote: 15.40 – 16.96
Spot Rate : 1.5600
Average : 1.2450

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 15.40
Evaluated at bid price : 15.40
Bid-YTW : 5.50 %

Market Action

June 22, 2020

I wonder if any of the perpetuals listed today will last as long as this long bond:

YaleNews revealed that a water bond dating as far back as 1648 still contractually binds the obligated parties to pay annual interest today. Upon its discovery and subsequent analysis of its terms and agreements, reports indicate that at the time of its execution, the bond operated as a perpetual bond.

The original clauses of the agreement bound the payer to “5 percent interest in perpetuity,” a rate which was later lowered to 3.5 percent and then 2.5 percent respectively in the 1600s. At the time, physical notations of interest payments were inscribed on the bond as they were made as a means of recording them. Being of Dutch-origin and made out of goatskin, when the bond was issued, it was apparently made out to Mr. Niclaes de Meijer, a man who was ordered to pay the “sum of 1000 Carolus Guilders of 20 Stuivers a piece.”

The manuscript was filed at Yale’s Beinecke Rare Book & Manuscript Library in 2003 after Yale managed to come into possession of it. After Timothy Young, the curator of Modern Books and Manuscripts at the library, conferred with a Dutch water authority named Stichtse Rijnlanden, not only did he discover that this bond was only one of five ever found, all five of them were administered by the Hoogheemraadschap Lekdijk Bovendams.
…
In 2015, when Timothy Young returned from meeting with the relevant Dutch authority, he also brought back with him 12 years of back interest which was owed on the bond, a total which amounted to approximately 136.20 euros. Prior to 2015, the last time that the bond payments were collected was in 2003 when Yale first acquired it. At that time, as the reports states, “Geert Rouwenhorst, professor of corporate finance and deputy director of the International Center for Finance, took the bond back to the Netherlands to collect 26 years of back interest.”

Here’s a bit more sleaze from the Pace Credit Union Scandal discussed on June 18, from the extracts from the Pace Financial Offering Memorandum included in the First Report of the Liquidator obtained via the Receiver’s website:

The Issuer expects to pay fees to the Manager at standard rates common in the industry for those services – namely, asset management fees of 0.25% per month (3.0% per annum) calculated on the value of the Portfolio from time to time plus performance fees equal to 50% of profits earned provided that, in the event that the Issuer has a deficit (i.e. no profits or inadequate profits to provide for base dividends on the Preference Shares) for any particular quarter-yearly period, the asset management fees or performance fees will be reduced to the extent necessary to enable the Issuer to meet its dividend obligations, if possible, or, if not possible, waived for such period and, to those extents, will be payable in such reduced amount or will not be payable, as the case may be.

An extortionate (not “standard”!) 3% management fee per annum (the Manager is Pace Securities Corp), plus a 50% cut of profits, plus full ownership at no cost of all the common. It’s nice work, if you can get it.

It is regrettable that the Offering Memorandum is not published in its entirety; page 10 of the OM ends with:

3.1 Compensation and Securities Held
The following table provides specified information about each director, officer and promoter of the Issuer and each person who

… and pages 11 and 12 are missing. What a pity! It would have given me great pleasure to prominently display the names of the officers, directors and promoters of an issue such as this.

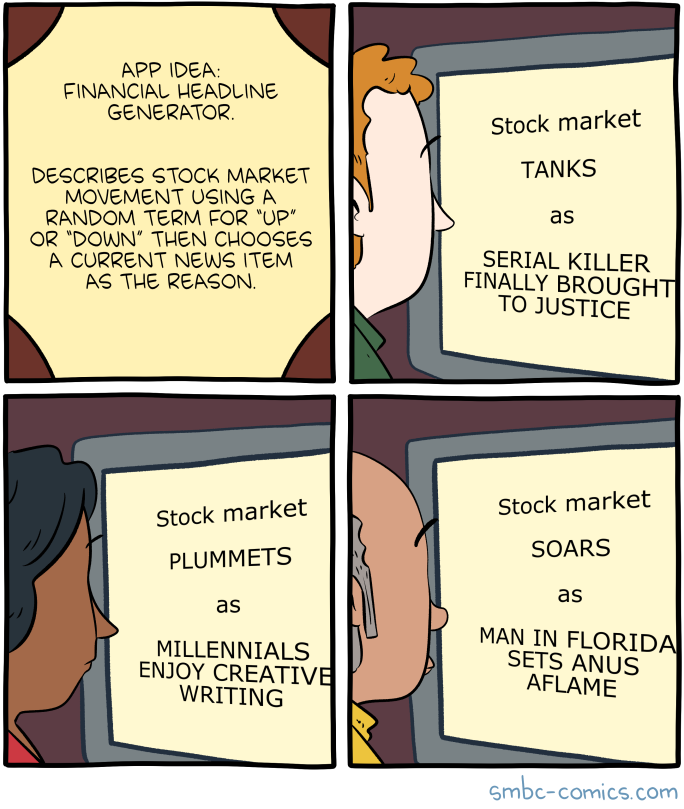
And finally, I cannot resist republishing the following comic SMBC Comics:

marketheadlinesapp
Click for Big
HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.3780 % 1,456.5
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.3780 % 2,672.5
Floater 5.38 % 5.69 % 48,122 14.39 4 0.3780 % 1,540.2
OpRet 0.00 % 0.00 % 0 0.00 0 -0.5515 % 3,421.5
SplitShare 4.91 % 5.14 % 67,109 3.83 7 -0.5515 % 4,086.0
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.5515 % 3,188.1
Perpetual-Premium 0.00 % 0.00 % 0 0.00 0 0.1882 % 3,045.0
Perpetual-Discount 5.54 % 5.71 % 76,956 14.26 35 0.1882 % 3,266.1
FixedReset Disc 6.22 % 5.11 % 153,187 14.96 83 0.1785 % 1,836.3
Deemed-Retractible 5.31 % 5.40 % 86,573 14.42 27 -0.1266 % 3,226.2
FloatingReset 4.91 % 4.94 % 46,281 15.62 3 0.6444 % 1,795.5
FixedReset Prem 0.00 % 0.00 % 0 0.00 0 0.1785 % 2,539.6
FixedReset Bank Non 1.98 % 3.31 % 121,849 1.57 2 0.1023 % 2,787.9
FixedReset Ins Non 6.43 % 5.07 % 118,758 14.92 22 0.7622 % 1,862.7
Performance Highlights
Issue Index Change Notes
TRP.PR.G FixedReset Disc -8.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 13.35
Evaluated at bid price : 13.35
Bid-YTW : 6.31 %
BIK.PR.A FixedReset Disc -7.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 22.11
Evaluated at bid price : 22.60
Bid-YTW : 6.49 %
BAM.PF.F FixedReset Disc -6.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 14.50
Evaluated at bid price : 14.50
Bid-YTW : 5.94 %
TD.PF.D FixedReset Disc -5.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 15.51
Evaluated at bid price : 15.51
Bid-YTW : 5.17 %
TRP.PR.B FixedReset Disc -3.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 7.55
Evaluated at bid price : 7.55
Bid-YTW : 5.46 %
PVS.PR.G SplitShare -2.20 % YTW SCENARIO
Maturity Type : Option Certainty
Maturity Date : 2026-02-28
Maturity Price : 25.00
Evaluated at bid price : 24.01
Bid-YTW : 5.80 %
HSE.PR.G FixedReset Disc -1.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 10.80
Evaluated at bid price : 10.80
Bid-YTW : 9.06 %
IAF.PR.B Deemed-Retractible -1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 21.40
Evaluated at bid price : 21.40
Bid-YTW : 5.40 %
PVS.PR.F SplitShare -1.59 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2024-09-30
Maturity Price : 25.00
Evaluated at bid price : 24.75
Bid-YTW : 5.14 %
TD.PF.E FixedReset Disc -1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 16.60
Evaluated at bid price : 16.60
Bid-YTW : 4.96 %
CU.PR.C FixedReset Disc -1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 14.40
Evaluated at bid price : 14.40
Bid-YTW : 4.96 %
HSE.PR.E FixedReset Disc -1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 11.75
Evaluated at bid price : 11.75
Bid-YTW : 8.96 %
PVS.PR.E SplitShare -1.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.02
Bid-YTW : 5.60 %
BAM.PF.G FixedReset Disc -1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 14.00
Evaluated at bid price : 14.00
Bid-YTW : 5.75 %
RY.PR.Z FixedReset Disc 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 15.31
Evaluated at bid price : 15.31
Bid-YTW : 4.64 %
BIP.PR.B FixedReset Disc 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 23.00
Evaluated at bid price : 23.75
Bid-YTW : 5.78 %
IFC.PR.C FixedReset Ins Non 1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 14.19
Evaluated at bid price : 14.19
Bid-YTW : 5.39 %
TD.PF.B FixedReset Disc 1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 15.30
Evaluated at bid price : 15.30
Bid-YTW : 4.78 %
SLF.PR.G FixedReset Ins Non 1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 9.16
Evaluated at bid price : 9.16
Bid-YTW : 4.86 %
CM.PR.Q FixedReset Disc 1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 15.25
Evaluated at bid price : 15.25
Bid-YTW : 5.26 %
CM.PR.O FixedReset Disc 1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 14.25
Evaluated at bid price : 14.25
Bid-YTW : 5.24 %
RY.PR.H FixedReset Disc 1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 15.63
Evaluated at bid price : 15.63
Bid-YTW : 4.61 %
NA.PR.W FixedReset Disc 1.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 14.82
Evaluated at bid price : 14.82
Bid-YTW : 5.00 %
TRP.PR.K FixedReset Disc 1.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 22.76
Evaluated at bid price : 23.10
Bid-YTW : 5.34 %
TD.PF.C FixedReset Disc 1.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 15.48
Evaluated at bid price : 15.48
Bid-YTW : 4.84 %
BMO.PR.C FixedReset Disc 1.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 18.75
Evaluated at bid price : 18.75
Bid-YTW : 5.09 %
TD.PF.I FixedReset Disc 1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 18.55
Evaluated at bid price : 18.55
Bid-YTW : 4.84 %
PWF.PR.T FixedReset Disc 1.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 14.96
Evaluated at bid price : 14.96
Bid-YTW : 5.20 %
MFC.PR.N FixedReset Ins Non 1.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 14.72
Evaluated at bid price : 14.72
Bid-YTW : 5.00 %
BMO.PR.T FixedReset Disc 1.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 14.63
Evaluated at bid price : 14.63
Bid-YTW : 4.90 %
BMO.PR.D FixedReset Disc 1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 18.25
Evaluated at bid price : 18.25
Bid-YTW : 5.04 %
NA.PR.G FixedReset Disc 2.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 17.52
Evaluated at bid price : 17.52
Bid-YTW : 5.03 %
TD.PF.M FixedReset Disc 2.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 21.64
Evaluated at bid price : 21.95
Bid-YTW : 4.84 %
RY.PR.M FixedReset Disc 2.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 15.98
Evaluated at bid price : 15.98
Bid-YTW : 4.73 %
SLF.PR.J FloatingReset 2.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 9.20
Evaluated at bid price : 9.20
Bid-YTW : 4.38 %
BMO.PR.W FixedReset Disc 2.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 15.03
Evaluated at bid price : 15.03
Bid-YTW : 4.86 %
CM.PR.R FixedReset Disc 2.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 18.77
Evaluated at bid price : 18.77
Bid-YTW : 5.19 %
NA.PR.S FixedReset Disc 2.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 15.25
Evaluated at bid price : 15.25
Bid-YTW : 5.05 %
TD.PF.L FixedReset Disc 2.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 20.50
Evaluated at bid price : 20.50
Bid-YTW : 4.92 %
PWF.PR.P FixedReset Disc 2.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 9.65
Evaluated at bid price : 9.65
Bid-YTW : 5.21 %
BIP.PR.A FixedReset Disc 2.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 15.11
Evaluated at bid price : 15.11
Bid-YTW : 6.53 %
NA.PR.C FixedReset Disc 3.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 18.90
Evaluated at bid price : 18.90
Bid-YTW : 5.20 %
MFC.PR.R FixedReset Ins Non 3.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 21.12
Evaluated at bid price : 21.12
Bid-YTW : 5.07 %
MFC.PR.G FixedReset Ins Non 3.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 16.25
Evaluated at bid price : 16.25
Bid-YTW : 5.13 %
BMO.PR.S FixedReset Disc 3.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 15.24
Evaluated at bid price : 15.24
Bid-YTW : 4.88 %
SLF.PR.I FixedReset Ins Non 3.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 16.00
Evaluated at bid price : 16.00
Bid-YTW : 4.96 %
CM.PR.P FixedReset Disc 3.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 14.98
Evaluated at bid price : 14.98
Bid-YTW : 5.01 %
Volume Highlights
Issue Index Shares
Traded
Notes
BMO.PR.S FixedReset Disc 69,256 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 15.24
Evaluated at bid price : 15.24
Bid-YTW : 4.88 %
TD.PF.E FixedReset Disc 67,813 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 16.60
Evaluated at bid price : 16.60
Bid-YTW : 4.96 %
TRP.PR.K FixedReset Disc 55,724 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 22.76
Evaluated at bid price : 23.10
Bid-YTW : 5.34 %
CU.PR.C FixedReset Disc 46,621 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 14.40
Evaluated at bid price : 14.40
Bid-YTW : 4.96 %
TRP.PR.G FixedReset Disc 44,616 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 13.35
Evaluated at bid price : 13.35
Bid-YTW : 6.31 %
TD.PF.B FixedReset Disc 40,423 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 15.30
Evaluated at bid price : 15.30
Bid-YTW : 4.78 %
There were 30 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BAM.PR.X FixedReset Disc Quote: 9.86 – 17.27
Spot Rate : 7.4100
Average : 4.2190

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 9.86
Evaluated at bid price : 9.86
Bid-YTW : 5.68 %

RY.PR.M FixedReset Disc Quote: 15.98 – 25.50
Spot Rate : 9.5200
Average : 7.4821

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 15.98
Evaluated at bid price : 15.98
Bid-YTW : 4.73 %

TRP.PR.G FixedReset Disc Quote: 13.35 – 14.60
Spot Rate : 1.2500
Average : 0.8507

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 13.35
Evaluated at bid price : 13.35
Bid-YTW : 6.31 %

TD.PF.D FixedReset Disc Quote: 15.51 – 16.60
Spot Rate : 1.0900
Average : 0.6930

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 15.51
Evaluated at bid price : 15.51
Bid-YTW : 5.17 %

BAM.PF.F FixedReset Disc Quote: 14.50 – 15.55
Spot Rate : 1.0500
Average : 0.7217

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 14.50
Evaluated at bid price : 14.50
Bid-YTW : 5.94 %

MFC.PR.I FixedReset Ins Non Quote: 15.40 – 16.96
Spot Rate : 1.5600
Average : 1.2450

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-22
Maturity Price : 15.40
Evaluated at bid price : 15.40
Bid-YTW : 5.50 %

Market Action

June 19, 2020

A bit more on the PACE Savings and Credit Union preferred share scandal, mentioned yesterday, from the IIROC Notice of Hearing and Statement of Allegations against Joseph Anthony Thomson and Gerald Douglas McRae:

14. By Confidential Offering Memorandum (the “PFL OM”) dated June 27, 2017, PFL offered Series A 5% Cumulative Redeemable Retractable Non-voting Term Preference Shares (the “PFL Preference Shares”) as an exempt distribution without a prospectus. PFL had no capital other than the proceeds of sale from the PFL Preference Shares.
…
28. FHHI’s founding capital was $10,001 and its only other assets were the proceeds of sale from the FHHI Preference Shares.
…
85. The PFL OM did not disclose the use of leverage or options. McRae signed leverage and options agreements for PFL and was aware it used those strategies, yet he never raised the issue or evidenced any supervision concerning whether their use was consistent with
the PFL OM.

86. The FHHI OMs did not disclose the use of options, other than for hedging purposes, yet McRae signed options agreements for FHHI and was aware of options use in the account. He never raised the issue or evidenced any supervision concerning whether options use was consistent with the FHHI OMs.

So, capped returns on a go-go fund, with (essentially) no junior capital to take a first loss.

Wow, looks like PACE picked some real prizewinners to run their securities subsidiary. I find it very difficult to comprehend how anybody, anywhere, could recommend these securities to anybody.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.4078 % 1,451.0
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.4078 % 2,662.5
Floater 5.40 % 5.71 % 48,264 14.35 4 -0.4078 % 1,534.4
OpRet 0.00 % 0.00 % 0 0.00 0 -0.3492 % 3,440.5
SplitShare 4.88 % 5.07 % 66,074 3.85 7 -0.3492 % 4,108.7
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.3492 % 3,205.8
Perpetual-Premium 0.00 % 0.00 % 0 0.00 0 0.1367 % 3,039.3
Perpetual-Discount 5.55 % 5.72 % 76,379 14.25 35 0.1367 % 3,260.0
FixedReset Disc 6.23 % 5.15 % 154,366 14.81 83 -0.0254 % 1,833.0
Deemed-Retractible 5.30 % 5.32 % 86,513 14.44 27 0.0705 % 3,230.2
FloatingReset 4.88 % 4.87 % 48,172 15.75 3 -0.3776 % 1,784.0
FixedReset Prem 0.00 % 0.00 % 0 0.00 0 -0.0254 % 2,535.0
FixedReset Bank Non 1.98 % 3.43 % 125,798 1.58 2 0.0000 % 2,785.0
FixedReset Ins Non 6.48 % 5.21 % 119,119 14.90 22 0.1604 % 1,848.6
Performance Highlights
Issue Index Change Notes
MFC.PR.I FixedReset Ins Non -7.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 15.40
Evaluated at bid price : 15.40
Bid-YTW : 5.52 %
TD.PF.M FixedReset Disc -3.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 21.51
Evaluated at bid price : 21.51
Bid-YTW : 4.98 %
HSE.PR.A FixedReset Disc -3.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 6.25
Evaluated at bid price : 6.25
Bid-YTW : 8.55 %
MFC.PR.G FixedReset Ins Non -3.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 15.75
Evaluated at bid price : 15.75
Bid-YTW : 5.31 %
SLF.PR.J FloatingReset -2.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 9.00
Evaluated at bid price : 9.00
Bid-YTW : 4.42 %
GWO.PR.N FixedReset Ins Non -2.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 9.40
Evaluated at bid price : 9.40
Bid-YTW : 4.50 %
BAM.PF.A FixedReset Disc -2.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 15.95
Evaluated at bid price : 15.95
Bid-YTW : 5.70 %
BAM.PR.B Floater -1.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 7.52
Evaluated at bid price : 7.52
Bid-YTW : 5.71 %
BAM.PR.R FixedReset Disc -1.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 11.85
Evaluated at bid price : 11.85
Bid-YTW : 5.70 %
PWF.PR.T FixedReset Disc -1.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 14.71
Evaluated at bid price : 14.71
Bid-YTW : 5.31 %
PVS.PR.G SplitShare -1.52 % YTW SCENARIO
Maturity Type : Option Certainty
Maturity Date : 2026-02-28
Maturity Price : 25.00
Evaluated at bid price : 24.55
Bid-YTW : 5.34 %
SLF.PR.G FixedReset Ins Non -1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 9.05
Evaluated at bid price : 9.05
Bid-YTW : 4.94 %
IFC.PR.C FixedReset Ins Non -1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 14.03
Evaluated at bid price : 14.03
Bid-YTW : 5.46 %
ELF.PR.G Perpetual-Discount -1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 21.15
Evaluated at bid price : 21.15
Bid-YTW : 5.72 %
BAM.PR.X FixedReset Disc -1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 9.89
Evaluated at bid price : 9.89
Bid-YTW : 5.68 %
BMO.PR.F FixedReset Disc -1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 21.10
Evaluated at bid price : 21.10
Bid-YTW : 4.97 %
BMO.PR.S FixedReset Disc -1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 14.77
Evaluated at bid price : 14.77
Bid-YTW : 5.05 %
CU.PR.C FixedReset Disc -1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 14.60
Evaluated at bid price : 14.60
Bid-YTW : 4.90 %
IFC.PR.I Perpetual-Discount 1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 23.71
Evaluated at bid price : 24.05
Bid-YTW : 5.62 %
BIP.PR.B FixedReset Disc 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 22.77
Evaluated at bid price : 23.50
Bid-YTW : 5.84 %
MFC.PR.F FixedReset Ins Non 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 9.30
Evaluated at bid price : 9.30
Bid-YTW : 4.87 %
IAF.PR.B Deemed-Retractible 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 21.53
Evaluated at bid price : 21.79
Bid-YTW : 5.28 %
MFC.PR.K FixedReset Ins Non 1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 14.70
Evaluated at bid price : 14.70
Bid-YTW : 5.00 %
PWF.PR.P FixedReset Disc 1.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 9.40
Evaluated at bid price : 9.40
Bid-YTW : 5.37 %
CU.PR.I FixedReset Disc 1.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 24.10
Evaluated at bid price : 24.75
Bid-YTW : 4.54 %
TD.PF.E FixedReset Disc 1.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 16.85
Evaluated at bid price : 16.85
Bid-YTW : 4.90 %
BIP.PR.C FixedReset Disc 1.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 21.93
Evaluated at bid price : 22.50
Bid-YTW : 5.94 %
TRP.PR.H FloatingReset 1.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 7.50
Evaluated at bid price : 7.50
Bid-YTW : 4.87 %
IFC.PR.A FixedReset Ins Non 1.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 11.31
Evaluated at bid price : 11.31
Bid-YTW : 5.09 %
BIP.PR.E FixedReset Disc 2.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 20.20
Evaluated at bid price : 20.20
Bid-YTW : 6.22 %
IAF.PR.G FixedReset Ins Non 2.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 15.72
Evaluated at bid price : 15.72
Bid-YTW : 5.24 %
TRP.PR.B FixedReset Disc 3.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 7.80
Evaluated at bid price : 7.80
Bid-YTW : 5.32 %
BIK.PR.A FixedReset Disc 3.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 23.08
Evaluated at bid price : 24.49
Bid-YTW : 5.93 %
BAM.PR.Z FixedReset Disc 3.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 15.54
Evaluated at bid price : 15.54
Bid-YTW : 5.74 %
MFC.PR.N FixedReset Ins Non 20.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 14.45
Evaluated at bid price : 14.45
Bid-YTW : 5.11 %
Volume Highlights
Issue Index Shares
Traded
Notes
SLF.PR.A Deemed-Retractible 95,708 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 22.34
Evaluated at bid price : 22.61
Bid-YTW : 5.26 %
BMO.PR.Q FixedReset Bank Non 77,903 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.40
Bid-YTW : 3.34 %
GWO.PR.Q Deemed-Retractible 46,904 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 22.49
Evaluated at bid price : 22.75
Bid-YTW : 5.67 %
GWO.PR.P Deemed-Retractible 40,351 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 23.36
Evaluated at bid price : 23.65
Bid-YTW : 5.72 %
CU.PR.G Perpetual-Discount 37,803 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 21.63
Evaluated at bid price : 21.63
Bid-YTW : 5.25 %
RY.PR.E Deemed-Retractible 28,979 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-07-19
Maturity Price : 25.00
Evaluated at bid price : 25.45
Bid-YTW : -12.91 %
There were 15 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
RY.PR.M FixedReset Disc Quote: 15.65 – 25.50
Spot Rate : 9.8500
Average : 5.2476

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 15.65
Evaluated at bid price : 15.65
Bid-YTW : 4.84 %

MFC.PR.I FixedReset Ins Non Quote: 15.40 – 16.85
Spot Rate : 1.4500
Average : 0.8996

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 15.40
Evaluated at bid price : 15.40
Bid-YTW : 5.52 %

RY.PR.P Perpetual-Discount Quote: 25.10 – 25.99
Spot Rate : 0.8900
Average : 0.5424

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 24.61
Evaluated at bid price : 25.10
Bid-YTW : 5.26 %

TD.PF.M FixedReset Disc Quote: 21.51 – 22.30
Spot Rate : 0.7900
Average : 0.4837

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 21.51
Evaluated at bid price : 21.51
Bid-YTW : 4.98 %

TD.PF.B FixedReset Disc Quote: 15.12 – 15.99
Spot Rate : 0.8700
Average : 0.6062

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 15.12
Evaluated at bid price : 15.12
Bid-YTW : 4.85 %

TD.PF.I FixedReset Disc Quote: 18.25 – 18.99
Spot Rate : 0.7400
Average : 0.5226

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-19
Maturity Price : 18.25
Evaluated at bid price : 18.25
Bid-YTW : 4.93 %

Market Action

June 18, 2020

There is a new data point for the collection of Seniority Spreads by Issuer! ELF came out with a new 30-year note (on June 17):

E-L Financial Corporation Limited (TSX :ELF) (TSX: ELF.PR.F) (TSX: ELF.PR.G) (TSX: ELF.PR.H) (the “Company”) announced today that it intends to issue in Canada, by way of private placement, $200 million principal amount of 4.000% senior unsecured notes due June 22, 2050 (the “Notes”).

The offering is expected to close June 22, 2020. The net proceeds of the issue will be used for general corporate purposes.

The Notes will mature on June 22, 2050 and will bear interest at an annual rate of 4.000% calculated and payable semi-annually in arrears on June 22 and December 22 of each year commencing December 22, 2020 and ending June 22, 2050. It is a condition of the closing of the offering that the Notes be assigned a rating of at least “A” by S&P Global Ratings.

The issue will be offered on an agency basis by a syndicate of dealers, co-led by Scotia Capital Inc. and CIBC World Markets Inc., and which includes BMO Nesbitt Burns Inc., National Bank Financial Inc., RBC Dominion Securities Inc. and TD Securities Inc.

ELF has three series of PerpetualDiscounts trading to yield about 5.85% as of the close June 17; equivalent to 7.60% interest, implying a Seniority Spread for this issuer of 360bp, significantly narrower than the overall average of 435bp reported June 17.

Assiduous Reader JD writes in and suggests that I write something about the PACE Savings and Credit Union preferred share scandal:

PACE Savings and Credit Union is launching an investigation into whether a subsidiary improperly sold risky investment products that lost up to 86 per cent of their value when the coronavirus pandemic upended financial markets.

The credit union, based north of Toronto, is trying to rebuild its battered reputation after allegations of fraud and self-dealing involving former top executives who have since been fired. A provincial regulator seized control of PACE in the fall of 2018 to protect its members and deposits, and has overhauled the management and board of directors.
…
The new issue became apparent when some clients received letters dated April 28, saying the value of preferred shares purchased through Pace Securities, which paid generous annual dividends of 5 per cent to 7 per cent annually, had fallen from $10 a piece to $1.62 and $1.44, respectively. Individual investments that were initially worth tens or hundreds of thousands of dollars each had been mostly wiped out, and any hope that they might recover was lost with the decision to shut down Pace Securities.
…
The preferred shares – which have characteristics of both stocks and bonds – were in two companies and sold through advisers at Pace Securities. One firm was Pace Financial Ltd., a subsidiary of the dealer, and the other was First Hamilton Holdings Inc. The CEO of Pace Securities, Joseph Thomson, was also CEO of First Hamilton, which lists former Ontario premier Ernie Eves as its chairman.
…
Pace Financial and First Hamilton both sold preferred shares to investors to raise funds, borrowed more against those funds, and invested in corporate debt to generate returns. As the pandemic crisis unfolded, and share prices plunged, the bank that had allowed Pace Financial and First Hamilton to borrow money to leverage investments through a margin account, Laurentian Bank Securities, pulled its support. That meant Pace Securities needed to raise alternate funds, but it wasn’t able to.
…
A 2018 offering memorandum describes First Hamilton’s preferred shares as “a risky investment” that is “suitable for investors … who can afford a total loss of their investment.” According to financial statements from February, 2019, obtained by The Globe, all of the bonds First Hamilton invested in were rated below investment grade. Of those, 71 per cent carried ratings that qualify them as “highly speculative,” and another 18 per cent were rated lower still.
…
Retired Toronto transit worker Elaine Gurney, 63, visited a PACE branch in Etobicoke, Ont., to reinvest $100,000 after a guaranteed investment certificate (GIC) expired. After being directed to speak with an adviser, she walked out with preferred shares in Pace Financial Ltd.

IIROC’s finally gotten involved, scheduling a disciplinary hearing:

The discipline hearing concerns allegations that:

(a) Between June 2017 and June 2019, Mr. Thomson, the Ultimate Designated Person (the “UDP”) of PSC, failed to identify and address existing and potential material conflicts of interest in a fair, equitable and transparent manner, and consistent with the best interests of PSC’s clients, contrary to Dealer Member Rule 42;

(b) Between June 2017 and June 2019, Mr. Thomson failed to ensure that investments in two proprietary products, Pace Financial Ltd. and First Hamilton Holdings Inc., for which he was the portfolio manager, were made in accordance with the objectives set out in the applicable Offering Memorandum, contrary to Consolidated Rule 1400;

(c) Between June 2017 and June 2019, Mr. Thomson, as UDP, failed to supervise the activities of PSC to ensure compliance with IIROC requirements and failed to use due diligence to ensure that orders accepted and recommendations made were suitable for clients and within the bounds of good business practice, contrary to Dealer Member Rules 38.5(c), 1300.1(a), (o), (p), (q) and (s); and

(d) Between June 2017 and June 2019, Mr. McRae, as the Chief Compliance Officer failed to monitor and assess compliance by PSC with the Dealer Member Rules and failed to adequately supervise Mr. Thomson’s securities-related activities, contrary to Dealer Member Rule 38.7.

The whole thing stinks. PACE exploited the trust that customers will normally have in their credit unions – which, I venture to speculate, will normally be even greater than that held for banks – to provide referrals to their securities subsidiary. Nothing wrong with that, or at least not much; but I am firmly in favour of total separation of deposit-taking institutions from securities dealers; and, yes, Big Banks, that includes you.

But these horrible securities that were advised! Numbers are lacking in the story, as are details of the holdings of Pace Financial, but basically at least one of the ultimate investment companies was levered up to hell ‘n’ gone to buy … junk bonds. And, I will note that I take issue with the Globe’s characterization of the dividends paid on the preferreds:

preferred shares purchased through Pace Securities, which paid generous annual dividends of 5 per cent to 7 per cent annually

As of June 30, 2017, I reported a median YTW of 5.08% on PerpetualDiscounts and 5.28% on December 29, 2017. As of June 29, 2018 I reported a median YTW of 5.48% on PerpetualDiscounts and 5.88% on December 31, 2018. The June 28, 2019 figure was 5.62%, while December 31, 2019 came in at 5.37%. And these figures are for exchange-traded issues with prospectuses; rated investment-grade by DBRS and with a (modest) minimum liquidity.

Five to seven percent, with no further upside (since they are preferred shares, not actual equity) in what appears to be an extremely aggressive and undiversified hedge fund, sold to unsophisticated grannies who wanted a GIC … well, I don’t want to make (too many!) judgments in advance of the facts. But it stinks, it stinks to high heaven.

There is a very long, very angry thread on the Canadian High Interest Savings Forum about this mess. To my surprise, Financial Wisdom Forum has only a a single bewildered and unanswered query about the matter – which to me simply supports the idea that the investors were even less sophisticated than usual.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.6854 % 1,456.9
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.6854 % 2,673.4
Floater 5.38 % 5.61 % 48,257 14.52 4 -0.6854 % 1,540.7
OpRet 0.00 % 0.00 % 0 0.00 0 0.3793 % 3,452.5
SplitShare 4.87 % 5.01 % 66,464 3.85 7 0.3793 % 4,123.1
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.3793 % 3,217.0
Perpetual-Premium 0.00 % 0.00 % 0 0.00 0 0.2556 % 3,035.2
Perpetual-Discount 5.56 % 5.68 % 76,683 14.37 35 0.2556 % 3,255.5
FixedReset Disc 6.23 % 5.13 % 160,396 14.82 83 0.0124 % 1,833.5
Deemed-Retractible 5.30 % 5.34 % 85,672 14.44 27 0.3007 % 3,228.0
FloatingReset 4.86 % 4.95 % 48,498 15.61 3 0.0000 % 1,790.8
FixedReset Prem 0.00 % 0.00 % 0 0.00 0 0.0124 % 2,535.7
FixedReset Bank Non 1.98 % 3.42 % 127,339 1.58 2 -0.3467 % 2,785.0
FixedReset Ins Non 6.49 % 5.18 % 123,948 14.91 22 -1.2148 % 1,845.6
Performance Highlights
Issue Index Change Notes
MFC.PR.N FixedReset Ins Non -18.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 12.00
Evaluated at bid price : 12.00
Bid-YTW : 6.21 %
PWF.PR.P FixedReset Disc -6.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 9.27
Evaluated at bid price : 9.27
Bid-YTW : 5.44 %
IAF.PR.G FixedReset Ins Non -4.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 15.31
Evaluated at bid price : 15.31
Bid-YTW : 5.39 %
TD.PF.L FixedReset Disc -4.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 5.06 %
IFC.PR.A FixedReset Ins Non -3.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 11.11
Evaluated at bid price : 11.11
Bid-YTW : 5.18 %
BAM.PR.Z FixedReset Disc -3.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 14.95
Evaluated at bid price : 14.95
Bid-YTW : 5.98 %
RY.PR.M FixedReset Disc -1.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 15.61
Evaluated at bid price : 15.61
Bid-YTW : 4.85 %
IFC.PR.C FixedReset Ins Non -1.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 14.21
Evaluated at bid price : 14.21
Bid-YTW : 5.39 %
BAM.PR.K Floater -1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 7.49
Evaluated at bid price : 7.49
Bid-YTW : 5.74 %
SLF.PR.H FixedReset Ins Non -1.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 12.50
Evaluated at bid price : 12.50
Bid-YTW : 5.14 %
MFC.PR.H FixedReset Ins Non -1.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 17.23
Evaluated at bid price : 17.23
Bid-YTW : 5.23 %
TD.PF.H FixedReset Disc -1.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 22.82
Evaluated at bid price : 23.27
Bid-YTW : 4.90 %
CU.PR.C FixedReset Disc -1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 14.75
Evaluated at bid price : 14.75
Bid-YTW : 4.85 %
MFC.PR.G FixedReset Ins Non -1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 16.25
Evaluated at bid price : 16.25
Bid-YTW : 5.14 %
BAM.PR.T FixedReset Disc -1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 12.20
Evaluated at bid price : 12.20
Bid-YTW : 5.71 %
SLF.PR.I FixedReset Ins Non -1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 15.50
Evaluated at bid price : 15.50
Bid-YTW : 5.13 %
HSE.PR.A FixedReset Disc -1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 6.45
Evaluated at bid price : 6.45
Bid-YTW : 8.28 %
MFC.PR.F FixedReset Ins Non -1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 9.20
Evaluated at bid price : 9.20
Bid-YTW : 4.92 %
BAM.PR.C Floater -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 7.55
Evaluated at bid price : 7.55
Bid-YTW : 5.69 %
POW.PR.G Perpetual-Discount 1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 24.31
Evaluated at bid price : 24.55
Bid-YTW : 5.80 %
BAM.PF.F FixedReset Disc 1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 15.40
Evaluated at bid price : 15.40
Bid-YTW : 5.59 %
TRP.PR.A FixedReset Disc 1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 11.65
Evaluated at bid price : 11.65
Bid-YTW : 5.64 %
EIT.PR.B SplitShare 1.31 % YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2025-03-14
Maturity Price : 25.00
Evaluated at bid price : 24.82
Bid-YTW : 5.01 %
CM.PR.Y FixedReset Disc 1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 21.50
Evaluated at bid price : 21.50
Bid-YTW : 5.05 %
BAM.PF.A FixedReset Disc 1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 16.30
Evaluated at bid price : 16.30
Bid-YTW : 5.57 %
ELF.PR.G Perpetual-Discount 1.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 21.41
Evaluated at bid price : 21.41
Bid-YTW : 5.65 %
BAM.PF.B FixedReset Disc 1.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 14.56
Evaluated at bid price : 14.56
Bid-YTW : 5.76 %
BNS.PR.H FixedReset Disc 1.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 23.60
Evaluated at bid price : 23.99
Bid-YTW : 4.83 %
BAM.PR.R FixedReset Disc 1.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 12.07
Evaluated at bid price : 12.07
Bid-YTW : 5.59 %
IAF.PR.B Deemed-Retractible 1.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 21.28
Evaluated at bid price : 21.55
Bid-YTW : 5.34 %
PWF.PR.T FixedReset Disc 2.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 14.95
Evaluated at bid price : 14.95
Bid-YTW : 5.22 %
TRP.PR.C FixedReset Disc 2.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 8.65
Evaluated at bid price : 8.65
Bid-YTW : 5.65 %
MFC.PR.J FixedReset Ins Non 3.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 16.20
Evaluated at bid price : 16.20
Bid-YTW : 5.05 %
GWO.PR.N FixedReset Ins Non 3.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 9.63
Evaluated at bid price : 9.63
Bid-YTW : 4.39 %
BAM.PF.G FixedReset Disc 7.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 14.18
Evaluated at bid price : 14.18
Bid-YTW : 5.69 %
Volume Highlights
Issue Index Shares
Traded
Notes
MFC.PR.Q FixedReset Ins Non 87,902 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 16.36
Evaluated at bid price : 16.36
Bid-YTW : 4.95 %
SLF.PR.D Deemed-Retractible 79,480 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 21.33
Evaluated at bid price : 21.33
Bid-YTW : 5.24 %
RY.PR.E Deemed-Retractible 67,602 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-07-18
Maturity Price : 25.00
Evaluated at bid price : 25.36
Bid-YTW : -8.98 %
SLF.PR.A Deemed-Retractible 59,347 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 22.36
Evaluated at bid price : 22.63
Bid-YTW : 5.25 %
GWO.PR.Q Deemed-Retractible 40,502 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 22.49
Evaluated at bid price : 22.75
Bid-YTW : 5.67 %
BAM.PR.X FixedReset Disc 40,002 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 10.01
Evaluated at bid price : 10.01
Bid-YTW : 5.61 %
There were 15 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
MFC.PR.N FixedReset Ins Non Quote: 12.00 – 14.89
Spot Rate : 2.8900
Average : 1.7035

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 12.00
Evaluated at bid price : 12.00
Bid-YTW : 6.21 %

TD.PF.L FixedReset Disc Quote: 20.00 – 21.10
Spot Rate : 1.1000
Average : 0.7442

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 5.06 %

HSE.PR.G FixedReset Disc Quote: 11.02 – 11.91
Spot Rate : 0.8900
Average : 0.5972

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 11.02
Evaluated at bid price : 11.02
Bid-YTW : 8.90 %

BAM.PR.Z FixedReset Disc Quote: 14.95 – 15.70
Spot Rate : 0.7500
Average : 0.5125

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 14.95
Evaluated at bid price : 14.95
Bid-YTW : 5.98 %

BIP.PR.E FixedReset Disc Quote: 19.80 – 20.44
Spot Rate : 0.6400
Average : 0.4551

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 19.80
Evaluated at bid price : 19.80
Bid-YTW : 6.35 %

BAM.PR.X FixedReset Disc Quote: 10.01 – 10.74
Spot Rate : 0.7300
Average : 0.5780

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-18
Maturity Price : 10.01
Evaluated at bid price : 10.01
Bid-YTW : 5.61 %

Market Action

June 17, 2020

Some of the sleazier types in this business don’t even try to look honest:

An Ontario judge has ordered a receiver to oversee Toronto’s StableView Asset Management Inc. after a regulatory probe found investors’ money had been overconcentrated in a penny stock that paid cash consulting fees of more than $100,000 to the wealth manager.

StableView, which was founded and is solely owned by Colin Fisher, manages about $30-million on behalf of 135 clients and states on its website that its “primary concern is capital preservation.” A review by the Ontario Securities Commission found that StableView poured money into a Clarocity Corp., a thinly traded real estate valuation technology company, putting StableView in breach of diversification and liquidity requirements for its funds, court records allege.

The OSC alleges that, from late 2017 to late 2018, one of the company’s funds, StableView Yield and Growth Fund, increased the concentration of its investment in Clarocity from 45 per cent of the fund’s assets to 83 per cent. Over the same period, Clarocity went from 43 per cent of the holdings in StableView’s Progressive Growth Fund to 72 per cent, court records show.

The OSC also found that StableView received fees from Clarocity in the form of cash, common shares and debentures as part of a consulting agreement. StableView received cash payments totalling $105,000 from Clarocity, which Mr. Fisher withdrew from StableView “for his own personal use,” Sherry Brown, an OSC senior forensic accountant, said in an affidavit. The OSC has alleged the fees created a conflict of interest that was not sufficiently disclosed to StableView investors.
…
In its application for the receivership, the OSC also raised doubts about how StableView valued its stake in Clarocity, much of which was in debentures. In 2018, StableView recorded the debentures at cost, despite disclosures from Clarocity that its financial position was “substantially deteriorating” – something Mr. Fisher was aware of, the OSC alleges.

But on the other hand, I don’t understand how the big guys run their businesses:

The survey of 300 global asset management firms, which was carried out by WBR Insights in the first quarter of 2020, found that controlling costs was the top priority for 87% of respondents over the next two years.
…
To that end, the survey also found that firms are looking to outsourcing and technology to help meet their goals.

For instance, Norther Trust reported that 85% of respondents have outsourced their trading desk or are considering doing so.

I don’t get it, I don’t get it at all. Trading is an absolutely integral part of portfolio management; even separating the function within the firm is a crazy thing to do. I have contempt for firms that use particular brokers in order to use their algorithms – what’s the matter, are margins on investment management so skinny you can’t afford to develop your own algorithms? Outsourcing the desk completely is totally crazy.

Fortunately, however, a firm doesn’t need too many “1%” clients to stay afloat:

The concentration of wealth among Canada’s richest 1 per cent is deeper than previously believed, according to a federal government report based on a new modelling approach.

The top one per cent of Canada’s families hold about 25.6 per cent of the wealth – roughly $3-trillion – up from 13.7 per cent estimated under previous methodology, says the report from the Office of the Parliamentary Budget Officer.
…
The amount of money held by Canadian families would total $11.7-trillion if they liquidated all assets and paid off all liabilities, about five times larger than Canada’s annual gross domestic product, the report notes.

Real estate at $5.8-trillion and mortgages at $1.5-trillion are the single largest asset and liabilities categories.

The report adds that the top 0.5 per cent of Canadian families hold 20.5 per cent or $2.4-trillion of the wealth, up from the previous estimate of 9.2 per cent.

I’ve often wondered just how stable the constitution of the “1%” (by income) is. Sure, it seems clear that the 0.5% who hold 20.5% of all Canadian wealth are always going to be part of the 1%, at least in terms of income alone before any horrifying capital losses that might get realized every now and then. But it also seems clear that since the threshold of 1% status (by employment income) was “merely” $225,409 in 2015, it seems to me that there will be plenty of people who bounce in and out of the group on a regular basis, depending on the size of their bonuses.

But yeah, these figures suggest to me that I’m on the right track when suggesting that favourable tax treatment for dividend and interest income be capped; for one thing, valuing real-estate for wealth-tax purposes is too hard; for another, somebody with $6.1-million in the kitty (according to Table 4-2 of the PBO report used as a source by the article) doesn’t really need to be incentivized to save for retirement.

PerpetualDiscounts now yield 5.74%, equivalent to 7.46% interest at the standard equivalency factor of 1.3x. Long corporates now yield 3.09%, so the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) has widened significantly to 435bp from the 415bp reported June 10.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 2.7200 % 1,467.0
FixedFloater 0.00 % 0.00 % 0 0.00 0 2.7200 % 2,691.8
Floater 5.34 % 5.61 % 46,434 14.51 4 2.7200 % 1,551.3
OpRet 0.00 % 0.00 % 0 0.00 0 0.0517 % 3,439.5
SplitShare 4.88 % 5.05 % 64,129 3.85 7 0.0517 % 4,107.5
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0517 % 3,204.8
Perpetual-Premium 0.00 % 0.00 % 0 0.00 0 0.2141 % 3,027.4
Perpetual-Discount 5.57 % 5.74 % 79,005 14.25 35 0.2141 % 3,247.2
FixedReset Disc 6.23 % 5.12 % 160,233 14.85 83 0.0282 % 1,833.3
Deemed-Retractible 5.32 % 5.46 % 85,996 14.42 27 -0.0418 % 3,218.3
FloatingReset 4.86 % 4.95 % 48,819 15.61 3 -0.0755 % 1,790.8
FixedReset Prem 0.00 % 0.00 % 0 0.00 0 0.0282 % 2,535.4
FixedReset Bank Non 1.97 % 3.26 % 127,066 1.58 2 0.0612 % 2,794.7
FixedReset Ins Non 6.41 % 5.12 % 124,968 15.02 22 -0.3480 % 1,868.3
Performance Highlights
Issue Index Change Notes
BAM.PF.G FixedReset Disc -8.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 13.20
Evaluated at bid price : 13.20
Bid-YTW : 6.12 %
TRP.PR.C FixedReset Disc -5.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 8.40
Evaluated at bid price : 8.40
Bid-YTW : 5.82 %
MFC.PR.R FixedReset Ins Non -4.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 20.55
Evaluated at bid price : 20.55
Bid-YTW : 5.22 %
HSE.PR.E FixedReset Disc -3.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 11.80
Evaluated at bid price : 11.80
Bid-YTW : 8.92 %
HSE.PR.G FixedReset Disc -3.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 11.00
Evaluated at bid price : 11.00
Bid-YTW : 8.91 %
BAM.PR.R FixedReset Disc -3.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 11.85
Evaluated at bid price : 11.85
Bid-YTW : 5.70 %
TRP.PR.B FixedReset Disc -3.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 7.55
Evaluated at bid price : 7.55
Bid-YTW : 5.49 %
BAM.PF.B FixedReset Disc -2.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 14.33
Evaluated at bid price : 14.33
Bid-YTW : 5.86 %
SLF.PR.G FixedReset Ins Non -2.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 9.18
Evaluated at bid price : 9.18
Bid-YTW : 4.87 %
HSE.PR.C FixedReset Disc -2.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 11.00
Evaluated at bid price : 11.00
Bid-YTW : 8.98 %
BAM.PR.Z FixedReset Disc -2.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 15.55
Evaluated at bid price : 15.55
Bid-YTW : 5.74 %
SLF.PR.I FixedReset Ins Non -2.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 15.70
Evaluated at bid price : 15.70
Bid-YTW : 5.06 %
MFC.PR.J FixedReset Ins Non -2.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 15.71
Evaluated at bid price : 15.71
Bid-YTW : 5.21 %
PWF.PR.T FixedReset Disc -2.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 14.55
Evaluated at bid price : 14.55
Bid-YTW : 5.37 %
IAF.PR.B Deemed-Retractible -1.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 21.15
Evaluated at bid price : 21.15
Bid-YTW : 5.46 %
TRP.PR.A FixedReset Disc -1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 11.50
Evaluated at bid price : 11.50
Bid-YTW : 5.72 %
CM.PR.P FixedReset Disc -1.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 14.45
Evaluated at bid price : 14.45
Bid-YTW : 5.22 %
EIT.PR.B SplitShare -1.41 % YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2025-03-14
Maturity Price : 25.00
Evaluated at bid price : 24.50
Bid-YTW : 5.32 %
GWO.PR.N FixedReset Ins Non -1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 9.32
Evaluated at bid price : 9.32
Bid-YTW : 4.54 %
SLF.PR.H FixedReset Ins Non -1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 12.71
Evaluated at bid price : 12.71
Bid-YTW : 5.05 %
MFC.PR.F FixedReset Ins Non -1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 9.31
Evaluated at bid price : 9.31
Bid-YTW : 4.86 %
BAM.PF.A FixedReset Disc -1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 16.08
Evaluated at bid price : 16.08
Bid-YTW : 5.64 %
RY.PR.S FixedReset Disc -1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 17.22
Evaluated at bid price : 17.22
Bid-YTW : 4.63 %
TRP.PR.E FixedReset Disc -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 12.86
Evaluated at bid price : 12.86
Bid-YTW : 5.93 %
TRP.PR.D FixedReset Disc 1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 13.05
Evaluated at bid price : 13.05
Bid-YTW : 5.89 %
BMO.PR.B FixedReset Disc 1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 22.62
Evaluated at bid price : 23.00
Bid-YTW : 4.88 %
IFC.PR.I Perpetual-Discount 1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 23.48
Evaluated at bid price : 23.80
Bid-YTW : 5.68 %
BAM.PR.T FixedReset Disc 1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 12.36
Evaluated at bid price : 12.36
Bid-YTW : 5.63 %
BAM.PR.B Floater 1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 7.65
Evaluated at bid price : 7.65
Bid-YTW : 5.61 %
BNS.PR.H FixedReset Disc 1.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 23.20
Evaluated at bid price : 23.61
Bid-YTW : 4.90 %
BIP.PR.F FixedReset Disc 1.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 20.10
Evaluated at bid price : 20.10
Bid-YTW : 6.38 %
EIT.PR.A SplitShare 1.93 % YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2024-03-14
Maturity Price : 25.00
Evaluated at bid price : 24.82
Bid-YTW : 5.05 %
BAM.PR.X FixedReset Disc 1.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 9.99
Evaluated at bid price : 9.99
Bid-YTW : 5.62 %
MFC.PR.H FixedReset Ins Non 2.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 17.51
Evaluated at bid price : 17.51
Bid-YTW : 5.14 %
BAM.PR.C Floater 2.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 7.63
Evaluated at bid price : 7.63
Bid-YTW : 5.63 %
RY.PR.H FixedReset Disc 2.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 15.40
Evaluated at bid price : 15.40
Bid-YTW : 4.69 %
TD.PF.D FixedReset Disc 2.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 16.40
Evaluated at bid price : 16.40
Bid-YTW : 4.90 %
BAM.PF.F FixedReset Disc 2.97 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 15.24
Evaluated at bid price : 15.24
Bid-YTW : 5.65 %
IAF.PR.G FixedReset Ins Non 3.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 16.01
Evaluated at bid price : 16.01
Bid-YTW : 5.15 %
TD.PF.H FixedReset Disc 3.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 23.14
Evaluated at bid price : 23.60
Bid-YTW : 4.83 %
BAM.PR.K Floater 3.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 7.62
Evaluated at bid price : 7.62
Bid-YTW : 5.64 %
PWF.PR.A Floater 3.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 9.20
Evaluated at bid price : 9.20
Bid-YTW : 4.71 %
PWF.PR.P FixedReset Disc 3.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 9.90
Evaluated at bid price : 9.90
Bid-YTW : 5.09 %
Volume Highlights
Issue Index Shares
Traded
Notes
CM.PR.S FixedReset Disc 157,151 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 15.48
Evaluated at bid price : 15.48
Bid-YTW : 5.08 %
BMO.PR.Z Perpetual-Discount 104,100 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 23.92
Evaluated at bid price : 24.20
Bid-YTW : 5.20 %
MFC.PR.B Deemed-Retractible 87,417 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 21.98
Evaluated at bid price : 22.21
Bid-YTW : 5.25 %
SLF.PR.A Deemed-Retractible 73,070 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 22.34
Evaluated at bid price : 22.61
Bid-YTW : 5.26 %
TD.PF.L FixedReset Disc 58,116 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 20.84
Evaluated at bid price : 20.84
Bid-YTW : 4.84 %
CU.PR.I FixedReset Disc 50,812 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 23.65
Evaluated at bid price : 24.40
Bid-YTW : 4.60 %
There were 23 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BAM.PF.G FixedReset Disc Quote: 13.20 – 14.69
Spot Rate : 1.4900
Average : 0.9069

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 13.20
Evaluated at bid price : 13.20
Bid-YTW : 6.12 %

MFC.PR.R FixedReset Ins Non Quote: 20.55 – 21.60
Spot Rate : 1.0500
Average : 0.7421

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 20.55
Evaluated at bid price : 20.55
Bid-YTW : 5.22 %

BIP.PR.F FixedReset Disc Quote: 20.10 – 21.00
Spot Rate : 0.9000
Average : 0.6588

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 20.10
Evaluated at bid price : 20.10
Bid-YTW : 6.38 %

GWO.PR.N FixedReset Ins Non Quote: 9.32 – 10.00
Spot Rate : 0.6800
Average : 0.4832

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 9.32
Evaluated at bid price : 9.32
Bid-YTW : 4.54 %

PWF.PR.T FixedReset Disc Quote: 14.55 – 15.25
Spot Rate : 0.7000
Average : 0.5053

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 14.55
Evaluated at bid price : 14.55
Bid-YTW : 5.37 %

BAM.PF.J FixedReset Disc Quote: 23.50 – 23.95
Spot Rate : 0.4500
Average : 0.2813

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-17
Maturity Price : 22.79
Evaluated at bid price : 23.50
Bid-YTW : 5.03 %

Market Action

June 16, 2020

unicorn_200616
Click for Big

TXPR closed at 533.62, up 1.14% on the day. Volume today was 2.27-million, near the median of the past thirty days.

CPD closed at 10.655, up 0.52% on the day. Volume was 70,852, very low in the context of the past 30 trading days.

ZPR closed at 8.31, up 0.97% on the day. Volume of 208,882 was about at the median of the past 30 trading days.

Five-year Canada yields were up 2bp at 0.38% today.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 1.0346 % 1,428.1
FixedFloater 0.00 % 0.00 % 0 0.00 0 1.0346 % 2,620.5
Floater 5.49 % 5.69 % 44,723 14.40 4 1.0346 % 1,510.2
OpRet 0.00 % 0.00 % 0 0.00 0 3.8142 % 3,437.7
SplitShare 4.89 % 4.98 % 64,254 3.85 7 3.8142 % 4,105.4
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 3.8142 % 3,203.2
Perpetual-Premium 0.00 % 0.00 % 0 0.00 0 0.7883 % 3,021.0
Perpetual-Discount 5.58 % 5.76 % 79,590 14.20 35 0.7883 % 3,240.3
FixedReset Disc 6.23 % 5.15 % 158,461 14.82 83 1.4404 % 1,832.8
Deemed-Retractible 5.32 % 5.34 % 88,916 14.40 27 0.9427 % 3,219.6
FloatingReset 4.86 % 4.90 % 48,465 15.70 3 2.9926 % 1,792.1
FixedReset Prem 0.00 % 0.00 % 0 0.00 0 1.4404 % 2,534.7
FixedReset Bank Non 1.97 % 3.06 % 98,072 1.59 2 0.5128 % 2,793.0
FixedReset Ins Non 6.38 % 5.08 % 126,542 14.96 22 1.9990 % 1,874.8
Performance Highlights
Issue Index Change Notes
RY.PR.H FixedReset Disc -1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 15.00
Evaluated at bid price : 15.00
Bid-YTW : 4.82 %
PWF.PR.S Perpetual-Discount 1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 21.13
Evaluated at bid price : 21.13
Bid-YTW : 5.77 %
NA.PR.E FixedReset Disc 1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 15.96
Evaluated at bid price : 15.96
Bid-YTW : 5.11 %
BAM.PF.D Perpetual-Discount 1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 21.83
Evaluated at bid price : 21.83
Bid-YTW : 5.64 %
TRP.PR.C FixedReset Disc 1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 8.89
Evaluated at bid price : 8.89
Bid-YTW : 5.49 %
TRP.PR.F FloatingReset 1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 9.80
Evaluated at bid price : 9.80
Bid-YTW : 5.36 %
BMO.PR.Q FixedReset Bank Non 1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.50
Bid-YTW : 3.06 %
GWO.PR.G Deemed-Retractible 1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 22.74
Evaluated at bid price : 23.03
Bid-YTW : 5.65 %
CIU.PR.A Perpetual-Discount 1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 21.10
Evaluated at bid price : 21.10
Bid-YTW : 5.50 %
GWO.PR.M Deemed-Retractible 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 24.55
Evaluated at bid price : 24.80
Bid-YTW : 5.86 %
GWO.PR.I Deemed-Retractible 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 19.95
Evaluated at bid price : 19.95
Bid-YTW : 5.66 %
GWO.PR.Q Deemed-Retractible 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 22.19
Evaluated at bid price : 22.65
Bid-YTW : 5.68 %
IFC.PR.F Deemed-Retractible 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 23.01
Evaluated at bid price : 23.35
Bid-YTW : 5.68 %
CU.PR.F Perpetual-Discount 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 21.42
Evaluated at bid price : 21.42
Bid-YTW : 5.30 %
POW.PR.D Perpetual-Discount 1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 21.83
Evaluated at bid price : 22.07
Bid-YTW : 5.76 %
BAM.PR.M Perpetual-Discount 1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 21.14
Evaluated at bid price : 21.14
Bid-YTW : 5.64 %
CU.PR.E Perpetual-Discount 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 22.59
Evaluated at bid price : 22.84
Bid-YTW : 5.40 %
GWO.PR.L Deemed-Retractible 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 24.17
Evaluated at bid price : 24.43
Bid-YTW : 5.79 %
CU.PR.H Perpetual-Discount 1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 23.97
Evaluated at bid price : 24.26
Bid-YTW : 5.45 %
PWF.PR.L Perpetual-Discount 1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 22.01
Evaluated at bid price : 22.25
Bid-YTW : 5.81 %
CM.PR.O FixedReset Disc 1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 14.08
Evaluated at bid price : 14.08
Bid-YTW : 5.32 %
PWF.PR.F Perpetual-Discount 1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 22.52
Evaluated at bid price : 22.77
Bid-YTW : 5.85 %
EML.PR.A FixedReset Ins Non 1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 23.47
Evaluated at bid price : 24.07
Bid-YTW : 5.55 %
MFC.PR.F FixedReset Ins Non 1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 9.42
Evaluated at bid price : 9.42
Bid-YTW : 4.80 %
SLF.PR.B Deemed-Retractible 1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 22.80
Evaluated at bid price : 23.08
Bid-YTW : 5.20 %
SLF.PR.A Deemed-Retractible 1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 22.31
Evaluated at bid price : 22.58
Bid-YTW : 5.26 %
BMO.PR.Y FixedReset Disc 1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 15.76
Evaluated at bid price : 15.76
Bid-YTW : 4.94 %
NA.PR.A FixedReset Disc 1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 23.24
Evaluated at bid price : 23.75
Bid-YTW : 5.36 %
BMO.PR.W FixedReset Disc 1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 14.71
Evaluated at bid price : 14.71
Bid-YTW : 4.98 %
TD.PF.K FixedReset Disc 1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 17.15
Evaluated at bid price : 17.15
Bid-YTW : 4.92 %
TD.PF.C FixedReset Disc 1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 15.30
Evaluated at bid price : 15.30
Bid-YTW : 4.90 %
CU.PR.D Perpetual-Discount 1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 22.65
Evaluated at bid price : 22.91
Bid-YTW : 5.38 %
TD.PF.A FixedReset Disc 1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 15.05
Evaluated at bid price : 15.05
Bid-YTW : 4.85 %
BNS.PR.H FixedReset Disc 1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 22.82
Evaluated at bid price : 23.22
Bid-YTW : 4.99 %
BIP.PR.D FixedReset Disc 1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 19.97
Evaluated at bid price : 19.97
Bid-YTW : 6.29 %
MFC.PR.Q FixedReset Ins Non 1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 16.20
Evaluated at bid price : 16.20
Bid-YTW : 5.00 %
IFC.PR.C FixedReset Ins Non 1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 14.40
Evaluated at bid price : 14.40
Bid-YTW : 5.32 %
PWF.PR.E Perpetual-Discount 1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 23.30
Evaluated at bid price : 23.58
Bid-YTW : 5.91 %
SLF.PR.C Deemed-Retractible 1.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 21.25
Evaluated at bid price : 21.25
Bid-YTW : 5.26 %
BIP.PR.E FixedReset Disc 1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 19.78
Evaluated at bid price : 19.78
Bid-YTW : 6.35 %
SLF.PR.E Deemed-Retractible 1.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 21.46
Evaluated at bid price : 21.46
Bid-YTW : 5.26 %
PWF.PR.Z Perpetual-Discount 1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 22.19
Evaluated at bid price : 22.55
Bid-YTW : 5.78 %
NA.PR.S FixedReset Disc 1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 14.89
Evaluated at bid price : 14.89
Bid-YTW : 5.18 %
BAM.PF.A FixedReset Disc 1.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 16.26
Evaluated at bid price : 16.26
Bid-YTW : 5.58 %
TD.PF.I FixedReset Disc 1.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 18.17
Evaluated at bid price : 18.17
Bid-YTW : 4.95 %
MFC.PR.J FixedReset Ins Non 1.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 16.05
Evaluated at bid price : 16.05
Bid-YTW : 5.09 %
BMO.PR.T FixedReset Disc 1.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 14.56
Evaluated at bid price : 14.56
Bid-YTW : 4.93 %
BAM.PF.E FixedReset Disc 1.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 13.87
Evaluated at bid price : 13.87
Bid-YTW : 5.62 %
SLF.PR.D Deemed-Retractible 1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 21.37
Evaluated at bid price : 21.37
Bid-YTW : 5.23 %
GWO.PR.N FixedReset Ins Non 1.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 9.45
Evaluated at bid price : 9.45
Bid-YTW : 4.48 %
BAM.PF.B FixedReset Disc 1.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 14.75
Evaluated at bid price : 14.75
Bid-YTW : 5.68 %
TRP.PR.A FixedReset Disc 1.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 11.70
Evaluated at bid price : 11.70
Bid-YTW : 5.62 %
CCS.PR.C Deemed-Retractible 1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 22.44
Evaluated at bid price : 22.70
Bid-YTW : 5.51 %
CU.PR.G Perpetual-Discount 1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 21.55
Evaluated at bid price : 21.55
Bid-YTW : 5.27 %
CM.PR.S FixedReset Disc 1.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 15.43
Evaluated at bid price : 15.43
Bid-YTW : 5.10 %
PWF.PR.R Perpetual-Discount 1.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 23.79
Evaluated at bid price : 24.09
Bid-YTW : 5.79 %
CM.PR.P FixedReset Disc 1.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 14.69
Evaluated at bid price : 14.69
Bid-YTW : 5.12 %
NA.PR.C FixedReset Disc 1.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 18.25
Evaluated at bid price : 18.25
Bid-YTW : 5.40 %
BAM.PR.R FixedReset Disc 1.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 12.23
Evaluated at bid price : 12.23
Bid-YTW : 5.52 %
BMO.PR.F FixedReset Disc 1.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 21.10
Evaluated at bid price : 21.10
Bid-YTW : 4.96 %
MFC.PR.L FixedReset Ins Non 1.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 13.61
Evaluated at bid price : 13.61
Bid-YTW : 5.20 %
IAF.PR.B Deemed-Retractible 2.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 21.27
Evaluated at bid price : 21.54
Bid-YTW : 5.34 %
BMO.PR.C FixedReset Disc 2.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 18.47
Evaluated at bid price : 18.47
Bid-YTW : 5.18 %
NA.PR.G FixedReset Disc 2.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 17.35
Evaluated at bid price : 17.35
Bid-YTW : 5.09 %
RY.PR.J FixedReset Disc 2.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 16.54
Evaluated at bid price : 16.54
Bid-YTW : 4.78 %
NA.PR.W FixedReset Disc 2.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 14.50
Evaluated at bid price : 14.50
Bid-YTW : 5.13 %
CM.PR.R FixedReset Disc 2.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 18.30
Evaluated at bid price : 18.30
Bid-YTW : 5.33 %
RY.PR.M FixedReset Disc 2.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 15.85
Evaluated at bid price : 15.85
Bid-YTW : 4.78 %
CU.PR.I FixedReset Disc 2.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 23.91
Evaluated at bid price : 24.60
Bid-YTW : 4.57 %
BMO.PR.D FixedReset Disc 2.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 17.80
Evaluated at bid price : 17.80
Bid-YTW : 5.18 %
MFC.PR.B Deemed-Retractible 2.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 22.00
Evaluated at bid price : 22.23
Bid-YTW : 5.25 %
TD.PF.E FixedReset Disc 2.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 16.60
Evaluated at bid price : 16.60
Bid-YTW : 4.97 %
BMO.PR.B FixedReset Disc 2.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 22.37
Evaluated at bid price : 22.72
Bid-YTW : 4.94 %
CM.PR.Q FixedReset Disc 2.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 15.10
Evaluated at bid price : 15.10
Bid-YTW : 5.33 %
PVS.PR.H SplitShare 2.70 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2027-02-28
Maturity Price : 25.00
Evaluated at bid price : 24.70
Bid-YTW : 4.96 %
MFC.PR.N FixedReset Ins Non 2.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 14.65
Evaluated at bid price : 14.65
Bid-YTW : 5.03 %
MFC.PR.K FixedReset Ins Non 2.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 14.50
Evaluated at bid price : 14.50
Bid-YTW : 5.07 %
TRP.PR.G FixedReset Disc 2.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 14.55
Evaluated at bid price : 14.55
Bid-YTW : 5.79 %
CM.PR.Y FixedReset Disc 2.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 21.08
Evaluated at bid price : 21.08
Bid-YTW : 5.15 %
CM.PR.T FixedReset Disc 2.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 19.90
Evaluated at bid price : 19.90
Bid-YTW : 5.12 %
HSE.PR.E FixedReset Disc 2.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 12.25
Evaluated at bid price : 12.25
Bid-YTW : 8.58 %
TD.PF.D FixedReset Disc 2.97 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 15.97
Evaluated at bid price : 15.97
Bid-YTW : 5.03 %
BAM.PF.G FixedReset Disc 2.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 14.47
Evaluated at bid price : 14.47
Bid-YTW : 5.58 %
TD.PF.J FixedReset Disc 3.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 17.51
Evaluated at bid price : 17.51
Bid-YTW : 4.83 %
PWF.PR.P FixedReset Disc 3.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 9.55
Evaluated at bid price : 9.55
Bid-YTW : 5.28 %
HSE.PR.G FixedReset Disc 3.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 11.36
Evaluated at bid price : 11.36
Bid-YTW : 8.62 %
BMO.PR.E FixedReset Disc 3.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 17.30
Evaluated at bid price : 17.30
Bid-YTW : 4.96 %
SLF.PR.H FixedReset Ins Non 3.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 12.87
Evaluated at bid price : 12.87
Bid-YTW : 4.99 %
MFC.PR.G FixedReset Ins Non 3.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 16.45
Evaluated at bid price : 16.45
Bid-YTW : 5.08 %
BAM.PR.K Floater 3.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 7.37
Evaluated at bid price : 7.37
Bid-YTW : 5.83 %
TD.PF.L FixedReset Disc 3.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 20.80
Evaluated at bid price : 20.80
Bid-YTW : 4.85 %
TRP.PR.B FixedReset Disc 3.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 7.79
Evaluated at bid price : 7.79
Bid-YTW : 5.32 %
CU.PR.C FixedReset Disc 4.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 15.09
Evaluated at bid price : 15.09
Bid-YTW : 4.74 %
HSE.PR.C FixedReset Disc 4.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 11.25
Evaluated at bid price : 11.25
Bid-YTW : 8.76 %
MFC.PR.R FixedReset Ins Non 4.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 21.46
Evaluated at bid price : 21.46
Bid-YTW : 4.99 %
TD.PF.M FixedReset Disc 4.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 21.74
Evaluated at bid price : 22.09
Bid-YTW : 4.81 %
MFC.PR.M FixedReset Ins Non 5.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 14.95
Evaluated at bid price : 14.95
Bid-YTW : 5.04 %
SLF.PR.G FixedReset Ins Non 5.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 9.44
Evaluated at bid price : 9.44
Bid-YTW : 4.73 %
SLF.PR.I FixedReset Ins Non 5.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 16.05
Evaluated at bid price : 16.05
Bid-YTW : 4.95 %
PVS.PR.G SplitShare 5.96 % YTW SCENARIO
Maturity Type : Option Certainty
Maturity Date : 2026-02-28
Maturity Price : 25.00
Evaluated at bid price : 24.90
Bid-YTW : 5.04 %
BAM.PR.Z FixedReset Disc 6.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 15.90
Evaluated at bid price : 15.90
Bid-YTW : 5.61 %
SLF.PR.J FloatingReset 6.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 9.25
Evaluated at bid price : 9.25
Bid-YTW : 4.30 %
EIT.PR.A SplitShare 21.14 % YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2024-03-14
Maturity Price : 25.00
Evaluated at bid price : 24.35
Bid-YTW : 5.62 %
Volume Highlights
Issue Index Shares
Traded
Notes
CM.PR.R FixedReset Disc 67,756 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 18.30
Evaluated at bid price : 18.30
Bid-YTW : 5.33 %
BAM.PF.E FixedReset Disc 66,488 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 13.87
Evaluated at bid price : 13.87
Bid-YTW : 5.62 %
BAM.PF.G FixedReset Disc 59,671 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 14.47
Evaluated at bid price : 14.47
Bid-YTW : 5.58 %
MFC.PR.R FixedReset Ins Non 54,894 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 21.46
Evaluated at bid price : 21.46
Bid-YTW : 4.99 %
BAM.PR.R FixedReset Disc 53,486 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 12.23
Evaluated at bid price : 12.23
Bid-YTW : 5.52 %
PWF.PR.P FixedReset Disc 51,684 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 9.55
Evaluated at bid price : 9.55
Bid-YTW : 5.28 %
There were 44 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
CCS.PR.C Deemed-Retractible Quote: 22.70 – 24.80
Spot Rate : 2.1000
Average : 1.6553

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 22.44
Evaluated at bid price : 22.70
Bid-YTW : 5.51 %

TD.PF.B FixedReset Disc Quote: 15.00 – 15.99
Spot Rate : 0.9900
Average : 0.6018

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 15.00
Evaluated at bid price : 15.00
Bid-YTW : 4.89 %

IAF.PR.G FixedReset Ins Non Quote: 15.50 – 16.50
Spot Rate : 1.0000
Average : 0.7054

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 15.50
Evaluated at bid price : 15.50
Bid-YTW : 5.32 %

BMO.PR.F FixedReset Disc Quote: 21.10 – 21.79
Spot Rate : 0.6900
Average : 0.4607

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 21.10
Evaluated at bid price : 21.10
Bid-YTW : 4.96 %

BAM.PR.X FixedReset Disc Quote: 9.80 – 10.74
Spot Rate : 0.9400
Average : 0.7419

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 9.80
Evaluated at bid price : 9.80
Bid-YTW : 5.73 %

BAM.PF.F FixedReset Disc Quote: 14.80 – 16.12
Spot Rate : 1.3200
Average : 1.1234

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-16
Maturity Price : 14.80
Evaluated at bid price : 14.80
Bid-YTW : 5.82 %

Market Action

June 15, 2020

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -2.4598 % 1,413.5
FixedFloater 0.00 % 0.00 % 0 0.00 0 -2.4598 % 2,593.7
Floater 5.54 % 5.67 % 42,135 14.42 4 -2.4598 % 1,494.8
OpRet 0.00 % 0.00 % 0 0.00 0 -3.8951 % 3,311.4
SplitShare 5.07 % 5.43 % 64,777 3.85 7 -3.8951 % 3,954.5
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -3.8951 % 3,085.5
Perpetual-Premium 0.00 % 0.00 % 0 0.00 0 -0.0274 % 2,997.3
Perpetual-Discount 5.63 % 5.76 % 78,638 14.21 35 -0.0274 % 3,215.0
FixedReset Disc 6.32 % 5.23 % 162,909 14.70 83 -0.2023 % 1,806.7
Deemed-Retractible 5.37 % 5.47 % 89,788 14.33 27 0.0162 % 3,189.6
FloatingReset 5.00 % 4.95 % 48,109 15.62 3 -1.6437 % 1,740.0
FixedReset Prem 0.00 % 0.00 % 0 0.00 0 -0.2023 % 2,498.7
FixedReset Bank Non 1.98 % 3.30 % 133,386 1.59 2 0.2468 % 2,778.7
FixedReset Ins Non 6.51 % 5.25 % 122,637 14.90 22 0.6900 % 1,838.1
Performance Highlights
Issue Index Change Notes
EIT.PR.A SplitShare -17.62 % YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2024-03-14
Maturity Price : 25.00
Evaluated at bid price : 20.10
Bid-YTW : 11.45 %
PVS.PR.G SplitShare -6.08 % YTW SCENARIO
Maturity Type : Option Certainty
Maturity Date : 2026-02-28
Maturity Price : 25.00
Evaluated at bid price : 23.50
Bid-YTW : 6.23 %
BAM.PR.K Floater -5.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 7.10
Evaluated at bid price : 7.10
Bid-YTW : 6.05 %
TD.PF.D FixedReset Disc -3.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 15.51
Evaluated at bid price : 15.51
Bid-YTW : 5.18 %
CU.PR.C FixedReset Disc -3.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 14.50
Evaluated at bid price : 14.50
Bid-YTW : 4.93 %
SLF.PR.J FloatingReset -3.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 8.65
Evaluated at bid price : 8.65
Bid-YTW : 4.59 %
BMO.PR.B FixedReset Disc -2.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 21.70
Evaluated at bid price : 22.15
Bid-YTW : 5.07 %
PVS.PR.H SplitShare -2.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2027-02-28
Maturity Price : 25.00
Evaluated at bid price : 24.05
Bid-YTW : 5.43 %
PWF.PR.A Floater -1.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 8.88
Evaluated at bid price : 8.88
Bid-YTW : 4.88 %
TD.PF.E FixedReset Disc -1.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 16.21
Evaluated at bid price : 16.21
Bid-YTW : 5.09 %
MFC.PR.M FixedReset Ins Non -1.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 14.20
Evaluated at bid price : 14.20
Bid-YTW : 5.32 %
CM.PR.Y FixedReset Disc -1.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 20.50
Evaluated at bid price : 20.50
Bid-YTW : 5.30 %
BAM.PR.C Floater -1.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 7.38
Evaluated at bid price : 7.38
Bid-YTW : 5.82 %
CM.PR.S FixedReset Disc -1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 15.15
Evaluated at bid price : 15.15
Bid-YTW : 5.20 %
BMO.PR.E FixedReset Disc -1.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 16.75
Evaluated at bid price : 16.75
Bid-YTW : 5.13 %
MFC.PR.G FixedReset Ins Non -1.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 15.86
Evaluated at bid price : 15.86
Bid-YTW : 5.27 %
MFC.PR.K FixedReset Ins Non -1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 14.11
Evaluated at bid price : 14.11
Bid-YTW : 5.22 %
MFC.PR.N FixedReset Ins Non -1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 14.26
Evaluated at bid price : 14.26
Bid-YTW : 5.18 %
TD.PF.M FixedReset Disc -1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 21.05
Evaluated at bid price : 21.05
Bid-YTW : 5.09 %
BMO.PR.W FixedReset Disc -1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 14.53
Evaluated at bid price : 14.53
Bid-YTW : 5.04 %
PVS.PR.E SplitShare -1.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.01
Bid-YTW : 5.57 %
BIP.PR.A FixedReset Disc -1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 14.74
Evaluated at bid price : 14.74
Bid-YTW : 6.70 %
BAM.PF.G FixedReset Disc -1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 14.05
Evaluated at bid price : 14.05
Bid-YTW : 5.74 %
BAM.PF.F FixedReset Disc -1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 14.75
Evaluated at bid price : 14.75
Bid-YTW : 5.84 %
NA.PR.X FixedReset Disc 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 23.88
Evaluated at bid price : 24.40
Bid-YTW : 5.46 %
MFC.PR.H FixedReset Ins Non 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 17.08
Evaluated at bid price : 17.08
Bid-YTW : 5.27 %
BAM.PR.X FixedReset Disc 1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 9.82
Evaluated at bid price : 9.82
Bid-YTW : 5.72 %
BIP.PR.F FixedReset Disc 1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 19.75
Evaluated at bid price : 19.75
Bid-YTW : 6.49 %
BIK.PR.A FixedReset Disc 1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 22.71
Evaluated at bid price : 23.65
Bid-YTW : 6.16 %
MFC.PR.I FixedReset Ins Non 1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 16.52
Evaluated at bid price : 16.52
Bid-YTW : 5.13 %
IFC.PR.A FixedReset Ins Non 2.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 11.64
Evaluated at bid price : 11.64
Bid-YTW : 4.93 %
GWO.PR.N FixedReset Ins Non 2.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 9.29
Evaluated at bid price : 9.29
Bid-YTW : 4.55 %
BAM.PF.E FixedReset Disc 3.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 13.65
Evaluated at bid price : 13.65
Bid-YTW : 5.72 %
NA.PR.G FixedReset Disc 3.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 5.20 %
MFC.PR.Q FixedReset Ins Non 14.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 15.98
Evaluated at bid price : 15.98
Bid-YTW : 5.07 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.M FixedReset Disc 149,439 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 15.50
Evaluated at bid price : 15.50
Bid-YTW : 4.89 %
BAM.PF.E FixedReset Disc 123,000 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 13.65
Evaluated at bid price : 13.65
Bid-YTW : 5.72 %
BAM.PF.G FixedReset Disc 122,780 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 14.05
Evaluated at bid price : 14.05
Bid-YTW : 5.74 %
TD.PF.D FixedReset Disc 42,200 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 15.51
Evaluated at bid price : 15.51
Bid-YTW : 5.18 %
NA.PR.C FixedReset Disc 39,600 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 17.91
Evaluated at bid price : 17.91
Bid-YTW : 5.50 %
MFC.PR.B Deemed-Retractible 32,800 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 21.45
Evaluated at bid price : 21.71
Bid-YTW : 5.37 %
There were 5 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
EIT.PR.A SplitShare Quote: 20.10 – 25.15
Spot Rate : 5.0500
Average : 2.9551

YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2024-03-14
Maturity Price : 25.00
Evaluated at bid price : 20.10
Bid-YTW : 11.45 %

TRP.PR.C FixedReset Disc Quote: 8.80 – 13.90
Spot Rate : 5.1000
Average : 3.6491

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 8.80
Evaluated at bid price : 8.80
Bid-YTW : 5.55 %

MFC.PR.M FixedReset Ins Non Quote: 14.20 – 16.17
Spot Rate : 1.9700
Average : 1.4104

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 14.20
Evaluated at bid price : 14.20
Bid-YTW : 5.32 %

PVS.PR.G SplitShare Quote: 23.50 – 25.25
Spot Rate : 1.7500
Average : 1.2337

YTW SCENARIO
Maturity Type : Option Certainty
Maturity Date : 2026-02-28
Maturity Price : 25.00
Evaluated at bid price : 23.50
Bid-YTW : 6.23 %

BAM.PF.F FixedReset Disc Quote: 14.75 – 16.12
Spot Rate : 1.3700
Average : 0.9078

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 14.75
Evaluated at bid price : 14.75
Bid-YTW : 5.84 %

BMO.PR.B FixedReset Disc Quote: 22.15 – 23.05
Spot Rate : 0.9000
Average : 0.6154

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-15
Maturity Price : 21.70
Evaluated at bid price : 22.15
Bid-YTW : 5.07 %

Market Action

June 12, 2020

rainbow_200612
Click for Big

TXPR closed at 528.14, up 0.82% on the day. Volume today was 1.57-million, third-lowest of the past thirty days, ahead of only May 19 and May 21.

CPD closed at 10.59, up 1.34% on the day. Volume was 157,697, above the median of the past 30 trading days.

ZPR closed at 8.22, up 0.74% on the day. Volume of 318,788 was above the median of the past 30 trading days.

Five-year Canada yields were unchanged at 0.37% today.

DBRS downgraded Cenovus:

DBRS Limited (DBRS Morningstar) downgraded Cenovus Energy Inc.’s (Cenovus or the Company) Issuer Rating and Senior Unsecured Debt rating to BBB (low) from BBB and removed the ratings from Under Review with Negative Implications, where they were placed on March 26, 2020. Both trends are Negative. On March 26, 2020, DBRS Morningstar placed Cenovus’s ratings Under Review with Negative Implications in response to the extreme price declines and heightened volatility in crude oil markets largely caused by the rapid spread of the Coronavirus Disease (COVID-19) and the concurrent crude oil-price war between OPEC (led by Saudi Arabia) and Russia. Subsequently, DBRS Morningstar revised its commodity price assumptions to factor in (1) the impact of the coronavirus pandemic on crude oil demand as lockdowns ease, (2) the significant buildup in global oil inventories, and (3) the impact of production cuts recently implemented by OPEC +. The downgrade follows DBRS Morningstar’s expectation that the Company’s key credit metrics will remain below the threshold for a BBB rating over the next three years under the revised commodity price assumptions (see DBRS Morningstar’s May 15, 2020, commentary titled “As Coronavirus Lockdowns Ease, DBRS Morningstar Resets Outlook for Oil and Natural Gas Prices”). The Negative trend reflects the dependence of the key credit metrics on higher commodity prices, especially in 2022 to support the current rating.

And now it’s time for PrefLetter!

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 1.6321 % 1,449.1
FixedFloater 0.00 % 0.00 % 0 0.00 0 1.6321 % 2,659.1
Floater 5.41 % 5.62 % 42,494 14.50 4 1.6321 % 1,532.5
OpRet 0.00 % 0.00 % 0 0.00 0 1.0434 % 3,445.6
SplitShare 4.88 % 4.93 % 64,770 3.86 7 1.0434 % 4,114.8
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 1.0434 % 3,210.5
Perpetual-Premium 0.00 % 0.00 % 0 0.00 0 0.5635 % 2,998.2
Perpetual-Discount 5.63 % 5.79 % 81,023 14.22 35 0.5635 % 3,215.8
FixedReset Disc 6.31 % 5.21 % 172,535 14.71 83 1.2042 % 1,810.4
Deemed-Retractible 5.37 % 5.58 % 90,630 14.32 27 1.2900 % 3,189.1
FloatingReset 4.92 % 4.90 % 48,150 15.71 3 1.7107 % 1,769.1
FixedReset Prem 0.00 % 0.00 % 0 0.00 0 1.2042 % 2,503.7
FixedReset Bank Non 1.99 % 3.59 % 138,729 1.60 2 0.0411 % 2,771.9
FixedReset Ins Non 6.55 % 5.22 % 123,972 14.84 22 0.9692 % 1,825.5
Performance Highlights
Issue Index Change Notes
MFC.PR.Q FixedReset Ins Non -9.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 14.01
Evaluated at bid price : 14.01
Bid-YTW : 5.82 %
BIP.PR.F FixedReset Disc -2.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 19.50
Evaluated at bid price : 19.50
Bid-YTW : 6.57 %
BIP.PR.C FixedReset Disc -1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 21.46
Evaluated at bid price : 21.80
Bid-YTW : 6.14 %
BIP.PR.D FixedReset Disc -1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 19.80
Evaluated at bid price : 19.80
Bid-YTW : 6.34 %
IAF.PR.G FixedReset Ins Non 1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 15.45
Evaluated at bid price : 15.45
Bid-YTW : 5.33 %
RY.PR.S FixedReset Disc 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 17.29
Evaluated at bid price : 17.29
Bid-YTW : 4.60 %
PWF.PR.R Perpetual-Discount 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 23.31
Evaluated at bid price : 23.60
Bid-YTW : 5.90 %
BAM.PR.N Perpetual-Discount 1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 20.90
Evaluated at bid price : 20.90
Bid-YTW : 5.70 %
SLF.PR.H FixedReset Ins Non 1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 12.39
Evaluated at bid price : 12.39
Bid-YTW : 5.18 %
BMO.PR.F FixedReset Disc 1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 20.75
Evaluated at bid price : 20.75
Bid-YTW : 5.05 %
NA.PR.A FixedReset Disc 1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 23.05
Evaluated at bid price : 23.56
Bid-YTW : 5.40 %
BAM.PF.J FixedReset Disc 1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 22.79
Evaluated at bid price : 23.50
Bid-YTW : 5.02 %
CM.PR.T FixedReset Disc 1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 19.45
Evaluated at bid price : 19.45
Bid-YTW : 5.24 %
CU.PR.E Perpetual-Discount 1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 22.12
Evaluated at bid price : 22.55
Bid-YTW : 5.45 %
CM.PR.Q FixedReset Disc 1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 14.75
Evaluated at bid price : 14.75
Bid-YTW : 5.45 %
HSE.PR.C FixedReset Disc 1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 10.84
Evaluated at bid price : 10.84
Bid-YTW : 9.11 %
CIU.PR.A Perpetual-Discount 1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 20.89
Evaluated at bid price : 20.89
Bid-YTW : 5.55 %
CM.PR.P FixedReset Disc 1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 14.45
Evaluated at bid price : 14.45
Bid-YTW : 5.21 %
MFC.PR.K FixedReset Ins Non 1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 14.30
Evaluated at bid price : 14.30
Bid-YTW : 5.14 %
RY.PR.Z FixedReset Disc 1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 15.00
Evaluated at bid price : 15.00
Bid-YTW : 4.74 %
IAF.PR.I FixedReset Ins Non 1.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 17.05
Evaluated at bid price : 17.05
Bid-YTW : 5.00 %
BMO.PR.S FixedReset Disc 1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 14.73
Evaluated at bid price : 14.73
Bid-YTW : 5.06 %
IFC.PR.C FixedReset Ins Non 1.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 14.15
Evaluated at bid price : 14.15
Bid-YTW : 5.41 %
TD.PF.J FixedReset Disc 1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 4.98 %
MFC.PR.I FixedReset Ins Non 1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 16.30
Evaluated at bid price : 16.30
Bid-YTW : 5.20 %
IFC.PR.A FixedReset Ins Non 1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 11.41
Evaluated at bid price : 11.41
Bid-YTW : 5.03 %
GWO.PR.P Deemed-Retractible 1.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 23.09
Evaluated at bid price : 23.35
Bid-YTW : 5.79 %
PWF.PR.K Perpetual-Discount 1.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 21.33
Evaluated at bid price : 21.33
Bid-YTW : 5.89 %
IFC.PR.G FixedReset Ins Non 1.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 15.50
Evaluated at bid price : 15.50
Bid-YTW : 5.28 %
MFC.PR.L FixedReset Ins Non 1.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 13.42
Evaluated at bid price : 13.42
Bid-YTW : 5.27 %
BMO.PR.W FixedReset Disc 1.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 14.70
Evaluated at bid price : 14.70
Bid-YTW : 4.98 %
BIP.PR.A FixedReset Disc 1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 14.90
Evaluated at bid price : 14.90
Bid-YTW : 6.62 %
CM.PR.Y FixedReset Disc 1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 20.85
Evaluated at bid price : 20.85
Bid-YTW : 5.21 %
TRP.PR.D FixedReset Disc 1.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 13.00
Evaluated at bid price : 13.00
Bid-YTW : 5.91 %
TD.PF.I FixedReset Disc 1.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 5.00 %
MFC.PR.M FixedReset Ins Non 1.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 14.45
Evaluated at bid price : 14.45
Bid-YTW : 5.22 %
TRP.PR.G FixedReset Disc 1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 14.25
Evaluated at bid price : 14.25
Bid-YTW : 5.91 %
CM.PR.S FixedReset Disc 1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 15.38
Evaluated at bid price : 15.38
Bid-YTW : 5.11 %
GWO.PR.I Deemed-Retractible 1.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 19.84
Evaluated at bid price : 19.84
Bid-YTW : 5.69 %
TD.PF.E FixedReset Disc 1.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 16.52
Evaluated at bid price : 16.52
Bid-YTW : 4.99 %
GWO.PR.H Deemed-Retractible 1.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 21.34
Evaluated at bid price : 21.34
Bid-YTW : 5.70 %
TD.PF.D FixedReset Disc 1.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 16.10
Evaluated at bid price : 16.10
Bid-YTW : 4.99 %
NA.PR.E FixedReset Disc 1.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 15.70
Evaluated at bid price : 15.70
Bid-YTW : 5.20 %
BAM.PR.Z FixedReset Disc 1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 14.94
Evaluated at bid price : 14.94
Bid-YTW : 5.98 %
TRP.PR.E FixedReset Disc 1.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 12.90
Evaluated at bid price : 12.90
Bid-YTW : 5.90 %
BMO.PR.B FixedReset Disc 1.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 22.35
Evaluated at bid price : 22.70
Bid-YTW : 4.94 %
TRP.PR.F FloatingReset 1.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 9.76
Evaluated at bid price : 9.76
Bid-YTW : 5.38 %
BMO.PR.T FixedReset Disc 2.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 14.30
Evaluated at bid price : 14.30
Bid-YTW : 5.02 %
BAM.PR.C Floater 2.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 7.50
Evaluated at bid price : 7.50
Bid-YTW : 5.72 %
GWO.PR.G Deemed-Retractible 2.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 22.66
Evaluated at bid price : 22.90
Bid-YTW : 5.68 %
SLF.PR.J FloatingReset 2.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 8.95
Evaluated at bid price : 8.95
Bid-YTW : 4.44 %
RY.PR.M FixedReset Disc 2.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 15.65
Evaluated at bid price : 15.65
Bid-YTW : 4.84 %
BAM.PR.K Floater 2.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 7.53
Evaluated at bid price : 7.53
Bid-YTW : 5.70 %
TD.PF.K FixedReset Disc 2.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 16.94
Evaluated at bid price : 16.94
Bid-YTW : 4.98 %
BAM.PR.B Floater 2.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 7.63
Evaluated at bid price : 7.63
Bid-YTW : 5.62 %
CCS.PR.C Deemed-Retractible 2.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 22.12
Evaluated at bid price : 22.40
Bid-YTW : 5.58 %
BAM.PR.X FixedReset Disc 2.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 9.70
Evaluated at bid price : 9.70
Bid-YTW : 5.78 %
TRP.PR.C FixedReset Disc 2.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 8.75
Evaluated at bid price : 8.75
Bid-YTW : 5.58 %
MFC.PR.C Deemed-Retractible 2.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 21.07
Evaluated at bid price : 21.07
Bid-YTW : 5.37 %
SLF.PR.B Deemed-Retractible 2.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 22.55
Evaluated at bid price : 22.81
Bid-YTW : 5.26 %
MFC.PR.B Deemed-Retractible 3.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 21.49
Evaluated at bid price : 21.75
Bid-YTW : 5.36 %
SLF.PR.C Deemed-Retractible 3.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 20.94
Evaluated at bid price : 20.94
Bid-YTW : 5.33 %
SLF.PR.E Deemed-Retractible 3.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 21.14
Evaluated at bid price : 21.14
Bid-YTW : 5.34 %
SLF.PR.A Deemed-Retractible 3.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 22.06
Evaluated at bid price : 22.29
Bid-YTW : 5.33 %
CM.PR.R FixedReset Disc 3.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 17.80
Evaluated at bid price : 17.80
Bid-YTW : 5.48 %
BAM.PF.B FixedReset Disc 3.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 14.48
Evaluated at bid price : 14.48
Bid-YTW : 5.79 %
HSE.PR.E FixedReset Disc 3.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 11.90
Evaluated at bid price : 11.90
Bid-YTW : 8.83 %
BAM.PF.F FixedReset Disc 3.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 14.90
Evaluated at bid price : 14.90
Bid-YTW : 5.78 %
HSE.PR.G FixedReset Disc 3.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 11.10
Evaluated at bid price : 11.10
Bid-YTW : 8.82 %
SLF.PR.D Deemed-Retractible 3.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 21.04
Evaluated at bid price : 21.04
Bid-YTW : 5.30 %
BAM.PF.E FixedReset Disc 4.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 13.20
Evaluated at bid price : 13.20
Bid-YTW : 5.92 %
BAM.PF.A FixedReset Disc 4.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 16.05
Evaluated at bid price : 16.05
Bid-YTW : 5.65 %
TD.PF.A FixedReset Disc 4.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 14.85
Evaluated at bid price : 14.85
Bid-YTW : 4.92 %
BAM.PR.T FixedReset Disc 4.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 12.05
Evaluated at bid price : 12.05
Bid-YTW : 5.78 %
MFC.PR.G FixedReset Ins Non 4.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 16.09
Evaluated at bid price : 16.09
Bid-YTW : 5.19 %
MFC.PR.H FixedReset Ins Non 5.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 16.89
Evaluated at bid price : 16.89
Bid-YTW : 5.33 %
MFC.PR.J FixedReset Ins Non 5.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 15.77
Evaluated at bid price : 15.77
Bid-YTW : 5.18 %
PVS.PR.G SplitShare 6.47 % YTW SCENARIO
Maturity Type : Option Certainty
Maturity Date : 2026-02-28
Maturity Price : 25.00
Evaluated at bid price : 25.02
Bid-YTW : 4.93 %
BAM.PR.R FixedReset Disc 6.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 12.08
Evaluated at bid price : 12.08
Bid-YTW : 5.58 %
BAM.PF.G FixedReset Disc 7.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 14.20
Evaluated at bid price : 14.20
Bid-YTW : 5.68 %
PWF.PR.P FixedReset Disc 13.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 9.27
Evaluated at bid price : 9.27
Bid-YTW : 5.44 %
Volume Highlights
Issue Index Shares
Traded
Notes
MFC.PR.B Deemed-Retractible 224,990 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 21.49
Evaluated at bid price : 21.75
Bid-YTW : 5.36 %
TRP.PR.E FixedReset Disc 102,400 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 12.90
Evaluated at bid price : 12.90
Bid-YTW : 5.90 %
TRP.PR.D FixedReset Disc 47,768 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 13.00
Evaluated at bid price : 13.00
Bid-YTW : 5.91 %
RY.PR.H FixedReset Disc 41,600 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 15.12
Evaluated at bid price : 15.12
Bid-YTW : 4.78 %
PWF.PR.L Perpetual-Discount 36,490 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 21.80
Evaluated at bid price : 22.04
Bid-YTW : 5.86 %
GWO.PR.G Deemed-Retractible 27,002 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 22.66
Evaluated at bid price : 22.90
Bid-YTW : 5.68 %
There were 20 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
MFC.PR.Q FixedReset Ins Non Quote: 14.01 – 15.89
Spot Rate : 1.8800
Average : 1.1974

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 14.01
Evaluated at bid price : 14.01
Bid-YTW : 5.82 %

CCS.PR.C Deemed-Retractible Quote: 22.40 – 24.80
Spot Rate : 2.4000
Average : 1.7571

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 22.12
Evaluated at bid price : 22.40
Bid-YTW : 5.58 %

MFC.PR.F FixedReset Ins Non Quote: 9.31 – 11.00
Spot Rate : 1.6900
Average : 1.0894

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 9.31
Evaluated at bid price : 9.31
Bid-YTW : 4.86 %

TRP.PR.G FixedReset Disc Quote: 14.25 – 15.50
Spot Rate : 1.2500
Average : 0.8478

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 14.25
Evaluated at bid price : 14.25
Bid-YTW : 5.91 %

NA.PR.C FixedReset Disc Quote: 17.75 – 18.64
Spot Rate : 0.8900
Average : 0.5498

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 17.75
Evaluated at bid price : 17.75
Bid-YTW : 5.55 %

NA.PR.G FixedReset Disc Quote: 16.40 – 17.18
Spot Rate : 0.7800
Average : 0.4881

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-12
Maturity Price : 16.40
Evaluated at bid price : 16.40
Bid-YTW : 5.40 %

Market Action

June 11, 2020

mushroomcloud_200611
Click for Big
coronavirus_200611
Click for Big

TXPR closed at 523.86, down 2.37% on the day. Volume today was 2.88-million, second-highest of the past thirty days, behind only June 5.

CPD closed at 10.45, down 2.06% on the day. Volume was 403,246, highest of the past 30 trading days and well ahead of second-place June 9.

ZPR closed at 8.16, down 2.16% on the day. Volume of 3,559,908 was by far the highest of the past 30 trading days, over three times the volume of second-place June 5.

Five-year Canada yields were down 2bp at 0.37% today.

Tim Shufelt comments in the Globe:

Global stock markets buckled on Thursday amid fears of a resurgence of COVID-19 infections in the United States, which could put the budding economic recovery in peril.

It was the worst day for North American stocks since the depths of the market crash in March, with the S&P/TSX Composite Index losing 4.1 per cent on the day, while the S&P 500 index dropped 5.9 per cent.

The dip followed a sobering reminder from the U.S. Federal Reserve on Wednesday about the monumental economic challenges that lie ahead, particularly as several U.S. states brace for the pandemic’s potential second wave.
…
The latest outlooks for the global economy are also distinctly negative. This week, the OECD said it expects a 6-per-cent drop in global GDP in 2020, and an 8-per-cent decline in the Canadian economy, exceeding in severity economists’ consensus for the recession on both counts.

In keeping with heightened growth fears, economically sensitive stocks were dealt a heavy blow on Thursday. The S&P/TSX Capped Energy Index dropped by 9.8 per cent, effectively wiping out the gains realized through a solid run in early June.
…
On Wednesday, the U.S. hit two million confirmed COVID-19 cases, according to Johns Hopkins University. In nearly half of U.S. states, many of which were among the earliest to reopen their economies, infections are on the rise, according to an Associated Press analysis.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -3.4157 % 1,425.9
FixedFloater 0.00 % 0.00 % 0 0.00 0 -3.4157 % 2,616.4
Floater 5.42 % 5.74 % 42,982 14.17 4 -3.4157 % 1,507.9
OpRet 0.00 % 0.00 % 0 0.00 0 -1.6756 % 3,410.0
SplitShare 4.93 % 5.13 % 65,301 3.87 7 -1.6756 % 4,072.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -1.6756 % 3,177.4
Perpetual-Premium 0.00 % 0.00 % 0 0.00 0 -1.5327 % 2,981.4
Perpetual-Discount 5.64 % 5.82 % 81,610 14.07 35 -1.5327 % 3,197.8
FixedReset Disc 6.37 % 5.41 % 171,070 14.49 83 -2.7230 % 1,788.9
Deemed-Retractible 5.43 % 5.72 % 91,946 14.22 27 -1.7488 % 3,148.4
FloatingReset 5.01 % 4.93 % 50,193 15.66 3 -2.7967 % 1,739.4
FixedReset Prem 0.00 % 0.00 % 0 0.00 0 -2.7230 % 2,473.9
FixedReset Bank Non 1.99 % 3.71 % 139,703 1.60 2 -0.1438 % 2,770.8
FixedReset Ins Non 6.60 % 5.48 % 120,504 14.44 22 -2.4012 % 1,808.0
Performance Highlights
Issue Index Change Notes
PWF.PR.P FixedReset Disc -14.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 8.15
Evaluated at bid price : 8.15
Bid-YTW : 6.56 %
BAM.PF.E FixedReset Disc -7.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 12.90
Evaluated at bid price : 12.90
Bid-YTW : 6.36 %
BAM.PF.F FixedReset Disc -7.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 14.61
Evaluated at bid price : 14.61
Bid-YTW : 6.18 %
BAM.PR.T FixedReset Disc -7.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 11.72
Evaluated at bid price : 11.72
Bid-YTW : 6.31 %
BAM.PF.G FixedReset Disc -6.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 13.45
Evaluated at bid price : 13.45
Bid-YTW : 6.34 %
BAM.PR.Z FixedReset Disc -6.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 14.94
Evaluated at bid price : 14.94
Bid-YTW : 6.30 %
PVS.PR.G SplitShare -6.56 % YTW SCENARIO
Maturity Type : Option Certainty
Maturity Date : 2026-02-28
Maturity Price : 25.00
Evaluated at bid price : 23.50
Bid-YTW : 6.21 %
TD.PF.A FixedReset Disc -6.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 14.25
Evaluated at bid price : 14.25
Bid-YTW : 5.30 %
MFC.PR.H FixedReset Ins Non -6.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 16.00
Evaluated at bid price : 16.00
Bid-YTW : 5.80 %
BAM.PF.B FixedReset Disc -6.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 14.27
Evaluated at bid price : 14.27
Bid-YTW : 6.20 %
BAM.PR.R FixedReset Disc -5.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 11.52
Evaluated at bid price : 11.52
Bid-YTW : 6.23 %
CM.PR.R FixedReset Disc -5.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 17.25
Evaluated at bid price : 17.25
Bid-YTW : 5.81 %
HSE.PR.G FixedReset Disc -5.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 10.70
Evaluated at bid price : 10.70
Bid-YTW : 9.43 %
HSE.PR.C FixedReset Disc -5.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 10.70
Evaluated at bid price : 10.70
Bid-YTW : 9.43 %
MFC.PR.M FixedReset Ins Non -5.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 14.20
Evaluated at bid price : 14.20
Bid-YTW : 5.48 %
BAM.PF.A FixedReset Disc -5.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 15.72
Evaluated at bid price : 15.72
Bid-YTW : 6.09 %
MFC.PR.G FixedReset Ins Non -5.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 15.35
Evaluated at bid price : 15.35
Bid-YTW : 5.62 %
MFC.PR.J FixedReset Ins Non -4.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 14.91
Evaluated at bid price : 14.91
Bid-YTW : 5.68 %
HSE.PR.E FixedReset Disc -4.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 11.50
Evaluated at bid price : 11.50
Bid-YTW : 9.32 %
TRP.PR.C FixedReset Disc -4.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 8.51
Evaluated at bid price : 8.51
Bid-YTW : 6.08 %
CM.PR.T FixedReset Disc -4.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 19.20
Evaluated at bid price : 19.20
Bid-YTW : 5.44 %
HSE.PR.A FixedReset Disc -4.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 6.45
Evaluated at bid price : 6.45
Bid-YTW : 8.70 %
RY.PR.M FixedReset Disc -4.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 15.30
Evaluated at bid price : 15.30
Bid-YTW : 5.14 %
BMO.PR.D FixedReset Disc -4.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 17.31
Evaluated at bid price : 17.31
Bid-YTW : 5.48 %
TRP.PR.F FloatingReset -4.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 9.57
Evaluated at bid price : 9.57
Bid-YTW : 5.49 %
BMO.PR.C FixedReset Disc -4.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 5.47 %
NA.PR.G FixedReset Disc -4.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 16.52
Evaluated at bid price : 16.52
Bid-YTW : 5.51 %
BAM.PR.B Floater -4.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 7.61
Evaluated at bid price : 7.61
Bid-YTW : 5.74 %
PWF.PR.K Perpetual-Discount -4.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 21.00
Evaluated at bid price : 21.00
Bid-YTW : 5.99 %
BAM.PR.C Floater -4.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 7.48
Evaluated at bid price : 7.48
Bid-YTW : 5.84 %
BAM.PR.K Floater -4.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 7.53
Evaluated at bid price : 7.53
Bid-YTW : 5.80 %
GWO.PR.N FixedReset Ins Non -4.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 9.00
Evaluated at bid price : 9.00
Bid-YTW : 5.02 %
BMO.PR.T FixedReset Disc -3.97 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 14.02
Evaluated at bid price : 14.02
Bid-YTW : 5.30 %
NA.PR.C FixedReset Disc -3.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 17.58
Evaluated at bid price : 17.58
Bid-YTW : 5.76 %
TD.PF.B FixedReset Disc -3.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 14.78
Evaluated at bid price : 14.78
Bid-YTW : 5.13 %
SLF.PR.D Deemed-Retractible -3.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 20.26
Evaluated at bid price : 20.26
Bid-YTW : 5.51 %
SLF.PR.A Deemed-Retractible -3.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 21.34
Evaluated at bid price : 21.61
Bid-YTW : 5.50 %
TD.PF.D FixedReset Disc -3.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 15.80
Evaluated at bid price : 15.80
Bid-YTW : 5.27 %
CM.PR.S FixedReset Disc -3.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 15.11
Evaluated at bid price : 15.11
Bid-YTW : 5.38 %
CM.PR.Y FixedReset Disc -3.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 20.50
Evaluated at bid price : 20.50
Bid-YTW : 5.42 %
BMO.PR.S FixedReset Disc -3.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 14.52
Evaluated at bid price : 14.52
Bid-YTW : 5.31 %
NA.PR.W FixedReset Disc -3.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 14.11
Evaluated at bid price : 14.11
Bid-YTW : 5.44 %
MFC.PR.I FixedReset Ins Non -3.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 16.06
Evaluated at bid price : 16.06
Bid-YTW : 5.45 %
SLF.PR.J FloatingReset -3.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 8.75
Evaluated at bid price : 8.75
Bid-YTW : 4.54 %
IFC.PR.C FixedReset Ins Non -3.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 14.15
Evaluated at bid price : 14.15
Bid-YTW : 5.71 %
SLF.PR.C Deemed-Retractible -3.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 20.31
Evaluated at bid price : 20.31
Bid-YTW : 5.50 %
CM.PR.P FixedReset Disc -3.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 14.26
Evaluated at bid price : 14.26
Bid-YTW : 5.45 %
TRP.PR.G FixedReset Disc -3.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 14.00
Evaluated at bid price : 14.00
Bid-YTW : 6.23 %
RY.PR.Z FixedReset Disc -3.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 14.80
Evaluated at bid price : 14.80
Bid-YTW : 4.98 %
RY.PR.S FixedReset Disc -3.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 17.10
Evaluated at bid price : 17.10
Bid-YTW : 4.81 %
BMO.PR.B FixedReset Disc -3.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 21.77
Evaluated at bid price : 22.26
Bid-YTW : 5.16 %
SLF.PR.E Deemed-Retractible -3.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 20.50
Evaluated at bid price : 20.50
Bid-YTW : 5.51 %
POW.PR.D Perpetual-Discount -3.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 21.48
Evaluated at bid price : 21.74
Bid-YTW : 5.84 %
EIT.PR.A SplitShare -3.10 % YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2024-03-14
Maturity Price : 25.00
Evaluated at bid price : 24.40
Bid-YTW : 5.53 %
MFC.PR.Q FixedReset Ins Non -3.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 15.46
Evaluated at bid price : 15.46
Bid-YTW : 5.41 %
NA.PR.S FixedReset Disc -3.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 14.54
Evaluated at bid price : 14.54
Bid-YTW : 5.48 %
CU.PR.E Perpetual-Discount -3.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 21.88
Evaluated at bid price : 22.26
Bid-YTW : 5.53 %
BMO.PR.F FixedReset Disc -2.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 20.50
Evaluated at bid price : 20.50
Bid-YTW : 5.23 %
RY.PR.H FixedReset Disc -2.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 15.00
Evaluated at bid price : 15.00
Bid-YTW : 4.98 %
CM.PR.Q FixedReset Disc -2.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 14.56
Evaluated at bid price : 14.56
Bid-YTW : 5.73 %
TD.PF.L FixedReset Disc -2.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 19.91
Evaluated at bid price : 19.91
Bid-YTW : 5.20 %
TD.PF.E FixedReset Disc -2.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 16.22
Evaluated at bid price : 16.22
Bid-YTW : 5.27 %
CIU.PR.A Perpetual-Discount -2.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 20.62
Evaluated at bid price : 20.62
Bid-YTW : 5.63 %
BAM.PR.X FixedReset Disc -2.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 9.60
Evaluated at bid price : 9.60
Bid-YTW : 6.26 %
CM.PR.O FixedReset Disc -2.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 13.80
Evaluated at bid price : 13.80
Bid-YTW : 5.60 %
TD.PF.M FixedReset Disc -2.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 21.10
Evaluated at bid price : 21.10
Bid-YTW : 5.18 %
CU.PR.D Perpetual-Discount -2.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 21.97
Evaluated at bid price : 22.36
Bid-YTW : 5.50 %
CU.PR.G Perpetual-Discount -2.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 20.97
Evaluated at bid price : 20.97
Bid-YTW : 5.41 %
SLF.PR.B Deemed-Retractible -2.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 21.92
Evaluated at bid price : 22.16
Bid-YTW : 5.42 %
BMO.PR.Y FixedReset Disc -2.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 15.55
Evaluated at bid price : 15.55
Bid-YTW : 5.19 %
MFC.PR.B Deemed-Retractible -2.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 21.10
Evaluated at bid price : 21.10
Bid-YTW : 5.54 %
TD.PF.K FixedReset Disc -2.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 16.55
Evaluated at bid price : 16.55
Bid-YTW : 5.26 %
RY.PR.J FixedReset Disc -2.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 16.22
Evaluated at bid price : 16.22
Bid-YTW : 5.03 %
CU.PR.I FixedReset Disc -2.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 23.27
Evaluated at bid price : 24.05
Bid-YTW : 4.66 %
SLF.PR.H FixedReset Ins Non -2.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 12.25
Evaluated at bid price : 12.25
Bid-YTW : 5.47 %
TD.PF.C FixedReset Disc -2.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 15.12
Evaluated at bid price : 15.12
Bid-YTW : 5.12 %
GWO.PR.H Deemed-Retractible -2.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 20.95
Evaluated at bid price : 20.95
Bid-YTW : 5.81 %
MFC.PR.C Deemed-Retractible -2.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 20.47
Evaluated at bid price : 20.47
Bid-YTW : 5.53 %
MFC.PR.L FixedReset Ins Non -2.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 13.21
Evaluated at bid price : 13.21
Bid-YTW : 5.55 %
CU.PR.H Perpetual-Discount -2.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 23.26
Evaluated at bid price : 23.73
Bid-YTW : 5.55 %
BIP.PR.E FixedReset Disc -2.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 19.50
Evaluated at bid price : 19.50
Bid-YTW : 6.44 %
IFC.PR.E Deemed-Retractible -2.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 22.78
Evaluated at bid price : 23.11
Bid-YTW : 5.72 %
TRP.PR.D FixedReset Disc -2.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 12.78
Evaluated at bid price : 12.78
Bid-YTW : 6.21 %
GWO.PR.S Deemed-Retractible -2.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 22.33
Evaluated at bid price : 22.57
Bid-YTW : 5.82 %
TD.PF.J FixedReset Disc -2.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 16.75
Evaluated at bid price : 16.75
Bid-YTW : 5.22 %
EIT.PR.B SplitShare -2.36 % YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2025-03-14
Maturity Price : 25.00
Evaluated at bid price : 24.80
Bid-YTW : 5.01 %
GWO.PR.R Deemed-Retractible -2.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 20.85
Evaluated at bid price : 20.85
Bid-YTW : 5.78 %
IFC.PR.G FixedReset Ins Non -2.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 15.56
Evaluated at bid price : 15.56
Bid-YTW : 5.56 %
BMO.PR.E FixedReset Disc -2.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 16.85
Evaluated at bid price : 16.85
Bid-YTW : 5.24 %
TRP.PR.E FixedReset Disc -2.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 12.65
Evaluated at bid price : 12.65
Bid-YTW : 6.21 %
TRP.PR.A FixedReset Disc -2.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 11.41
Evaluated at bid price : 11.41
Bid-YTW : 5.97 %
GWO.PR.P Deemed-Retractible -2.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 22.70
Evaluated at bid price : 22.99
Bid-YTW : 5.88 %
PWF.PR.T FixedReset Disc -2.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 14.85
Evaluated at bid price : 14.85
Bid-YTW : 5.41 %
GWO.PR.G Deemed-Retractible -2.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 22.12
Evaluated at bid price : 22.40
Bid-YTW : 5.81 %
CU.PR.F Perpetual-Discount -2.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 21.13
Evaluated at bid price : 21.13
Bid-YTW : 5.37 %
POW.PR.A Perpetual-Discount -2.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 24.06
Evaluated at bid price : 24.31
Bid-YTW : 5.85 %
GWO.PR.Q Deemed-Retractible -2.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 21.83
Evaluated at bid price : 22.22
Bid-YTW : 5.79 %
GWO.PR.I Deemed-Retractible -2.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 19.49
Evaluated at bid price : 19.49
Bid-YTW : 5.79 %
TD.PF.I FixedReset Disc -2.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 17.69
Evaluated at bid price : 17.69
Bid-YTW : 5.24 %
BIP.PR.D FixedReset Disc -1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 6.27 %
PWF.PR.R Perpetual-Discount -1.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 23.06
Evaluated at bid price : 23.34
Bid-YTW : 5.97 %
CCS.PR.C Deemed-Retractible -1.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 21.56
Evaluated at bid price : 21.82
Bid-YTW : 5.73 %
BIK.PR.A FixedReset Disc -1.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 22.53
Evaluated at bid price : 23.30
Bid-YTW : 6.26 %
SLF.PR.I FixedReset Ins Non -1.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 15.06
Evaluated at bid price : 15.06
Bid-YTW : 5.46 %
BNS.PR.H FixedReset Disc -1.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 22.48
Evaluated at bid price : 22.86
Bid-YTW : 5.19 %
BNS.PR.I FixedReset Disc -1.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 17.32
Evaluated at bid price : 17.32
Bid-YTW : 4.85 %
PWF.PR.S Perpetual-Discount -1.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 20.78
Evaluated at bid price : 20.78
Bid-YTW : 5.86 %
IFC.PR.A FixedReset Ins Non -1.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 11.45
Evaluated at bid price : 11.45
Bid-YTW : 5.38 %
CU.PR.C FixedReset Disc -1.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 15.04
Evaluated at bid price : 15.04
Bid-YTW : 4.93 %
PWF.PR.Z Perpetual-Discount -1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 21.81
Evaluated at bid price : 22.17
Bid-YTW : 5.88 %
MFC.PR.K FixedReset Ins Non -1.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 14.11
Evaluated at bid price : 14.11
Bid-YTW : 5.40 %
IFC.PR.I Perpetual-Discount -1.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 23.48
Evaluated at bid price : 23.80
Bid-YTW : 5.82 %
PVS.PR.E SplitShare -1.65 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.10
Bid-YTW : 5.38 %
PWF.PR.E Perpetual-Discount -1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 23.11
Evaluated at bid price : 23.37
Bid-YTW : 5.96 %
POW.PR.G Perpetual-Discount -1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 23.71
Evaluated at bid price : 24.00
Bid-YTW : 5.93 %
BMO.PR.W FixedReset Disc -1.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 14.46
Evaluated at bid price : 14.46
Bid-YTW : 5.23 %
GWO.PR.T Deemed-Retractible -1.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 22.03
Evaluated at bid price : 22.32
Bid-YTW : 5.77 %
PWF.PR.A Floater -1.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 9.05
Evaluated at bid price : 9.05
Bid-YTW : 4.78 %
ELF.PR.H Perpetual-Discount -1.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 23.18
Evaluated at bid price : 23.46
Bid-YTW : 5.95 %
IAF.PR.I FixedReset Ins Non -1.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 16.81
Evaluated at bid price : 16.81
Bid-YTW : 5.23 %
PWF.PR.F Perpetual-Discount -1.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 22.13
Evaluated at bid price : 22.41
Bid-YTW : 5.93 %
PWF.PR.L Perpetual-Discount -1.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 21.71
Evaluated at bid price : 21.96
Bid-YTW : 5.88 %
TD.PF.H FixedReset Disc -1.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 22.27
Evaluated at bid price : 22.67
Bid-YTW : 5.16 %
BIP.PR.C FixedReset Disc -1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 21.73
Evaluated at bid price : 22.18
Bid-YTW : 6.03 %
BAM.PF.H FixedReset Disc -1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 23.84
Evaluated at bid price : 24.50
Bid-YTW : 5.16 %
IAF.PR.B Deemed-Retractible -1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 21.05
Evaluated at bid price : 21.05
Bid-YTW : 5.48 %
BIP.PR.B FixedReset Disc -1.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 22.35
Evaluated at bid price : 23.17
Bid-YTW : 5.91 %
MFC.PR.O FixedReset Ins Non -1.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 24.22
Evaluated at bid price : 24.65
Bid-YTW : 5.55 %
ELF.PR.G Perpetual-Discount -1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 21.10
Evaluated at bid price : 21.10
Bid-YTW : 5.73 %
IAF.PR.G FixedReset Ins Non -1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 15.29
Evaluated at bid price : 15.29
Bid-YTW : 5.56 %
IFC.PR.F Deemed-Retractible -1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 23.14
Evaluated at bid price : 23.50
Bid-YTW : 5.74 %
MFC.PR.N FixedReset Ins Non -1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 14.35
Evaluated at bid price : 14.35
Bid-YTW : 5.30 %
PWF.PR.O Perpetual-Discount -1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 24.00
Evaluated at bid price : 24.25
Bid-YTW : 6.06 %
POW.PR.C Perpetual-Discount -1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 24.29
Evaluated at bid price : 24.60
Bid-YTW : 5.99 %
TRP.PR.B FixedReset Disc -1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 7.50
Evaluated at bid price : 7.50
Bid-YTW : 5.92 %
POW.PR.B Perpetual-Discount -1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 22.78
Evaluated at bid price : 23.06
Bid-YTW : 5.89 %
RY.PR.W Perpetual-Discount -1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 23.68
Evaluated at bid price : 23.95
Bid-YTW : 5.15 %
NA.PR.A FixedReset Disc -1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 22.76
Evaluated at bid price : 23.26
Bid-YTW : 5.59 %
RY.PR.Q FixedReset Disc -1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 23.78
Evaluated at bid price : 24.30
Bid-YTW : 5.21 %
BMO.PR.Z Perpetual-Discount -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 23.32
Evaluated at bid price : 23.80
Bid-YTW : 5.27 %
BAM.PF.I FixedReset Disc -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 23.70
Evaluated at bid price : 24.05
Bid-YTW : 5.06 %
MFC.PR.R FixedReset Ins Non -1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 20.56
Evaluated at bid price : 20.56
Bid-YTW : 5.34 %
PWF.PR.G Perpetual-Discount -1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 24.22
Evaluated at bid price : 24.51
Bid-YTW : 6.10 %
MFC.PR.F FixedReset Ins Non 1.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 9.32
Evaluated at bid price : 9.32
Bid-YTW : 5.16 %
SLF.PR.G FixedReset Ins Non 1.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 9.07
Evaluated at bid price : 9.07
Bid-YTW : 5.26 %
PVS.PR.H SplitShare 3.33 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2027-02-28
Maturity Price : 25.00
Evaluated at bid price : 24.80
Bid-YTW : 4.88 %
Volume Highlights
Issue Index Shares
Traded
Notes
MFC.PR.R FixedReset Ins Non 85,400 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 20.56
Evaluated at bid price : 20.56
Bid-YTW : 5.34 %
NA.PR.A FixedReset Disc 66,100 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 22.76
Evaluated at bid price : 23.26
Bid-YTW : 5.59 %
MFC.PR.B Deemed-Retractible 46,781 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 21.10
Evaluated at bid price : 21.10
Bid-YTW : 5.54 %
SLF.PR.I FixedReset Ins Non 40,716 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 15.06
Evaluated at bid price : 15.06
Bid-YTW : 5.46 %
TRP.PR.E FixedReset Disc 40,250 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 12.65
Evaluated at bid price : 12.65
Bid-YTW : 6.21 %
TD.PF.E FixedReset Disc 39,900 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 16.22
Evaluated at bid price : 16.22
Bid-YTW : 5.27 %
There were 57 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
TRP.PR.C FixedReset Disc Quote: 8.51 – 13.90
Spot Rate : 5.3900
Average : 2.9444

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 8.51
Evaluated at bid price : 8.51
Bid-YTW : 6.08 %

MFC.PR.G FixedReset Ins Non Quote: 15.35 – 19.17
Spot Rate : 3.8200
Average : 2.2497

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 15.35
Evaluated at bid price : 15.35
Bid-YTW : 5.62 %

PWF.PR.P FixedReset Disc Quote: 8.15 – 10.50
Spot Rate : 2.3500
Average : 1.5267

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 8.15
Evaluated at bid price : 8.15
Bid-YTW : 6.56 %

BAM.PF.E FixedReset Disc Quote: 12.90 – 14.41
Spot Rate : 1.5100
Average : 0.9020

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 12.90
Evaluated at bid price : 12.90
Bid-YTW : 6.36 %

PVS.PR.G SplitShare Quote: 23.50 – 25.05
Spot Rate : 1.5500
Average : 0.9830

YTW SCENARIO
Maturity Type : Option Certainty
Maturity Date : 2026-02-28
Maturity Price : 25.00
Evaluated at bid price : 23.50
Bid-YTW : 6.21 %

TD.PF.I FixedReset Disc Quote: 17.69 – 19.00
Spot Rate : 1.3100
Average : 0.8546

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-11
Maturity Price : 17.69
Evaluated at bid price : 17.69
Bid-YTW : 5.24 %

Market Action

June 10, 2020

explosion_200610
Click for Big

TXPR closed at 536.59, down 0.62% on the day. Volume today was 2.36-million, well above the median of the past thirty days

CPD closed at 10.67, down 0.56% on the day. Volume was 223,221, fourth-highest of the past 30 trading days.

ZPR closed at 8.34, down 0.83% on the day. Volume of 559,175 was second-highest of the past 30 trading days, behind only June 5.

Five-year Canada yields were down 6bp at 0.39% today.

The Fed released its FOMC Statement:

The Federal Reserve is committed to using its full range of tools to support the U.S. economy in this challenging time, thereby promoting its maximum employment and price stability goals.

The coronavirus outbreak is causing tremendous human and economic hardship across the United States and around the world. The virus and the measures taken to protect public health have induced sharp declines in economic activity and a surge in job losses. Weaker demand and significantly lower oil prices are holding down consumer price inflation. Financial conditions have improved, in part reflecting policy measures to support the economy and the flow of credit to U.S. households and businesses.

The ongoing public health crisis will weigh heavily on economic activity, employment, and inflation in the near term, and poses considerable risks to the economic outlook over the medium term. In light of these developments, the Committee decided to maintain the target range for the federal funds rate at 0 to 1/4 percent. The Committee expects to maintain this target range until it is confident that the economy has weathered recent events and is on track to achieve its maximum employment and price stability goals.

The Committee will continue to monitor the implications of incoming information for the economic outlook, including information related to public health, as well as global developments and muted inflation pressures, and will use its tools and act as appropriate to support the economy. In determining the timing and size of future adjustments to the stance of monetary policy, the Committee will assess realized and expected economic conditions relative to its maximum employment objective and its symmetric 2 percent inflation objective. This assessment will take into account a wide range of information, including measures of labor market conditions, indicators of inflation pressures and inflation expectations, and readings on financial and international developments.

To support the flow of credit to households and businesses, over coming months the Federal Reserve will increase its holdings of Treasury securities and agency residential and commercial mortgage-backed securities at least at the current pace to sustain smooth market functioning, thereby fostering effective transmission of monetary policy to broader financial conditions. In addition, the Open Market Desk will continue to offer large-scale overnight and term repurchase agreement operations. The Committee will closely monitor developments and is prepared to adjust its plans as appropriate.

Voting for the monetary policy action were Jerome H. Powell, Chair; John C. Williams, Vice Chair; Michelle W. Bowman; Lael Brainard; Richard H. Clarida; Patrick Harker; Robert S. Kaplan; Neel Kashkari; Loretta J. Mester; and Randal K. Quarles.

Of interest is the dot plot of expectations:

feddotplot_200610
Click for Big

… and the related projection of a slow recovery:

In their first economic projections this year, Fed officials indicated that they expected the unemployment rate to end 2020 at 9.3 percent and remain elevated for years, coming in at 5.5 percent in 2022, The New York Times’s Jeanna Smialek reports. Output is expected to be 6.5 percent lower at the end of this year than it was in the final quarter of 2019.

“Nearly 20 million jobs have been lost on net since February,” the Fed chair, Jerome H. Powell, said at a news conference following the release of the forecast, and noted that the figure probably understates the extent of unemployment. “The downturn has not fallen equally on all Americans.”

The new forecasts predict a much slower path back to economic strength than the Trump administration — and perhaps the stock market — seems to expect as the economy climbs out of a virus-spurred downturn. The Fed skipped its quarterly economic summary in March as the pandemic gripped the United States, sowing uncertainty as business activity came to a near standstill.

PerpetualDiscounts now yield 5.25% 5.72%, equivalent to 6.82% 7.44% interest at the standard equivalency factor of 1.3x. Long corporates now yield 3.28%, so the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) has narrowed dramatically significantly to 355bp 415bp from the 430bp reported June 3.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -1.1456 % 1,476.3
FixedFloater 0.00 % 0.00 % 0 0.00 0 -1.1456 % 2,708.9
Floater 5.23 % 5.49 % 40,576 14.56 4 -1.1456 % 1,561.2
OpRet 0.00 % 0.00 % 0 0.00 0 -0.2785 % 3,468.2
SplitShare 4.84 % 4.62 % 64,740 3.87 7 -0.2785 % 4,141.7
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.2785 % 3,231.5
Perpetual-Premium 0.00 % 0.00 % 0 0.00 0 0.0505 % 3,027.8
Perpetual-Discount 5.56 % 5.72 % 76,882 14.23 35 0.0505 % 3,247.6
FixedReset Disc 6.20 % 5.25 % 171,849 14.72 83 -0.8973 % 1,838.9
Deemed-Retractible 5.34 % 5.40 % 86,745 14.41 27 -0.2671 % 3,204.5
FloatingReset 4.87 % 4.93 % 50,265 15.66 3 -1.7453 % 1,789.4
FixedReset Prem 0.00 % 0.00 % 0 0.00 0 -0.8973 % 2,543.2
FixedReset Bank Non 1.99 % 3.66 % 141,434 1.60 2 0.0205 % 2,774.8
FixedReset Ins Non 6.44 % 5.33 % 116,753 14.69 22 -0.5369 % 1,852.5
Performance Highlights
Issue Index Change Notes
BAM.PR.X FixedReset Disc -6.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 9.88
Evaluated at bid price : 9.88
Bid-YTW : 6.08 %
NA.PR.E FixedReset Disc -4.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 15.40
Evaluated at bid price : 15.40
Bid-YTW : 5.48 %
TRP.PR.H FloatingReset -3.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 7.40
Evaluated at bid price : 7.40
Bid-YTW : 4.93 %
HSE.PR.A FixedReset Disc -3.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 6.75
Evaluated at bid price : 6.75
Bid-YTW : 8.31 %
IAF.PR.G FixedReset Ins Non -3.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 15.50
Evaluated at bid price : 15.50
Bid-YTW : 5.48 %
PVS.PR.H SplitShare -3.61 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2027-02-28
Maturity Price : 25.00
Evaluated at bid price : 24.00
Bid-YTW : 5.46 %
CU.PR.C FixedReset Disc -3.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 15.30
Evaluated at bid price : 15.30
Bid-YTW : 4.85 %
PWF.PR.P FixedReset Disc -3.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 9.52
Evaluated at bid price : 9.52
Bid-YTW : 5.60 %
MFC.PR.J FixedReset Ins Non -3.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 15.67
Evaluated at bid price : 15.67
Bid-YTW : 5.39 %
SLF.PR.G FixedReset Ins Non -3.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 8.90
Evaluated at bid price : 8.90
Bid-YTW : 5.36 %
BMO.PR.W FixedReset Disc -2.97 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 14.70
Evaluated at bid price : 14.70
Bid-YTW : 5.14 %
TRP.PR.C FixedReset Disc -2.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 8.91
Evaluated at bid price : 8.91
Bid-YTW : 5.81 %
TRP.PR.K FixedReset Disc -2.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 22.33
Evaluated at bid price : 22.64
Bid-YTW : 5.44 %
BIP.PR.F FixedReset Disc -2.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 6.40 %
RY.PR.Z FixedReset Disc -2.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 15.30
Evaluated at bid price : 15.30
Bid-YTW : 4.81 %
RY.PR.H FixedReset Disc -2.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 15.46
Evaluated at bid price : 15.46
Bid-YTW : 4.82 %
CM.PR.Q FixedReset Disc -2.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 15.00
Evaluated at bid price : 15.00
Bid-YTW : 5.56 %
TD.PF.A FixedReset Disc -1.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 15.24
Evaluated at bid price : 15.24
Bid-YTW : 4.94 %
NA.PR.G FixedReset Disc -1.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 17.25
Evaluated at bid price : 17.25
Bid-YTW : 5.27 %
MFC.PR.F FixedReset Ins Non -1.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 9.15
Evaluated at bid price : 9.15
Bid-YTW : 5.26 %
BAM.PR.C Floater -1.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 7.80
Evaluated at bid price : 7.80
Bid-YTW : 5.60 %
BAM.PR.R FixedReset Disc -1.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 12.25
Evaluated at bid price : 12.25
Bid-YTW : 5.85 %
HSE.PR.C FixedReset Disc -1.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 11.35
Evaluated at bid price : 11.35
Bid-YTW : 8.85 %
BMO.PR.E FixedReset Disc -1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 17.25
Evaluated at bid price : 17.25
Bid-YTW : 5.11 %
IFC.PR.A FixedReset Ins Non -1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 11.65
Evaluated at bid price : 11.65
Bid-YTW : 5.28 %
IFC.PR.G FixedReset Ins Non -1.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 15.93
Evaluated at bid price : 15.93
Bid-YTW : 5.43 %
SLF.PR.J FloatingReset -1.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 9.06
Evaluated at bid price : 9.06
Bid-YTW : 4.38 %
BAM.PR.K Floater -1.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 7.85
Evaluated at bid price : 7.85
Bid-YTW : 5.56 %
CM.PR.R FixedReset Disc -1.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 18.32
Evaluated at bid price : 18.32
Bid-YTW : 5.46 %
TD.PF.C FixedReset Disc -1.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 15.52
Evaluated at bid price : 15.52
Bid-YTW : 4.98 %
MFC.PR.L FixedReset Ins Non -1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 13.55
Evaluated at bid price : 13.55
Bid-YTW : 5.40 %
BMO.PR.T FixedReset Disc -1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 14.60
Evaluated at bid price : 14.60
Bid-YTW : 5.08 %
CM.PR.O FixedReset Disc -1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 14.20
Evaluated at bid price : 14.20
Bid-YTW : 5.43 %
NA.PR.A FixedReset Disc -1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 23.01
Evaluated at bid price : 23.51
Bid-YTW : 5.53 %
BAM.PR.B Floater -1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 7.94
Evaluated at bid price : 7.94
Bid-YTW : 5.49 %
PWF.PR.T FixedReset Disc -1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 15.19
Evaluated at bid price : 15.19
Bid-YTW : 5.28 %
BMO.PR.F FixedReset Disc -1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 21.13
Evaluated at bid price : 21.13
Bid-YTW : 5.07 %
NA.PR.C FixedReset Disc -1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 18.30
Evaluated at bid price : 18.30
Bid-YTW : 5.52 %
CM.PR.P FixedReset Disc -1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 14.75
Evaluated at bid price : 14.75
Bid-YTW : 5.26 %
BAM.PR.T FixedReset Disc -1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 12.61
Evaluated at bid price : 12.61
Bid-YTW : 5.85 %
BIP.PR.E FixedReset Disc -1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 6.27 %
BAM.PF.G FixedReset Disc -1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 14.41
Evaluated at bid price : 14.41
Bid-YTW : 5.91 %
W.PR.M FixedReset Disc -1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 23.71
Evaluated at bid price : 24.82
Bid-YTW : 5.26 %
BNS.PR.I FixedReset Disc -1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 17.63
Evaluated at bid price : 17.63
Bid-YTW : 4.76 %
RY.PR.S FixedReset Disc -1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 17.67
Evaluated at bid price : 17.67
Bid-YTW : 4.64 %
NA.PR.X FixedReset Disc -1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 23.78
Evaluated at bid price : 24.31
Bid-YTW : 5.59 %
BAM.PR.Z FixedReset Disc -1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 16.00
Evaluated at bid price : 16.00
Bid-YTW : 5.86 %
TD.PF.B FixedReset Disc -1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 15.37
Evaluated at bid price : 15.37
Bid-YTW : 4.92 %
GWO.PR.I Deemed-Retractible -1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 19.91
Evaluated at bid price : 19.91
Bid-YTW : 5.67 %
BIP.PR.B FixedReset Disc -1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 22.78
Evaluated at bid price : 23.50
Bid-YTW : 5.83 %
NA.PR.S FixedReset Disc -1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 15.00
Evaluated at bid price : 15.00
Bid-YTW : 5.30 %
BIK.PR.A FixedReset Disc -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 22.76
Evaluated at bid price : 23.75
Bid-YTW : 6.13 %
ELF.PR.H Perpetual-Discount 1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 23.56
Evaluated at bid price : 23.84
Bid-YTW : 5.86 %
TD.PF.J FixedReset Disc 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 17.16
Evaluated at bid price : 17.16
Bid-YTW : 5.08 %
MFC.PR.G FixedReset Ins Non 1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 16.20
Evaluated at bid price : 16.20
Bid-YTW : 5.32 %
ELF.PR.G Perpetual-Discount 1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 21.39
Evaluated at bid price : 21.39
Bid-YTW : 5.65 %
BAM.PF.B FixedReset Disc 1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 15.20
Evaluated at bid price : 15.20
Bid-YTW : 5.79 %
MFC.PR.I FixedReset Ins Non 1.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 16.64
Evaluated at bid price : 16.64
Bid-YTW : 5.25 %
MFC.PR.N FixedReset Ins Non 1.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 14.53
Evaluated at bid price : 14.53
Bid-YTW : 5.23 %
CCS.PR.C Deemed-Retractible 2.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 22.01
Evaluated at bid price : 22.25
Bid-YTW : 5.62 %
Volume Highlights
Issue Index Shares
Traded
Notes
IAF.PR.I FixedReset Ins Non 155,580 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 17.08
Evaluated at bid price : 17.08
Bid-YTW : 5.14 %
PWF.PR.P FixedReset Disc 77,629 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 9.52
Evaluated at bid price : 9.52
Bid-YTW : 5.60 %
CM.PR.R FixedReset Disc 56,101 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 18.32
Evaluated at bid price : 18.32
Bid-YTW : 5.46 %
PWF.PR.I Perpetual-Discount 53,407 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 24.64
Evaluated at bid price : 24.90
Bid-YTW : 6.11 %
BAM.PF.G FixedReset Disc 50,077 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 14.41
Evaluated at bid price : 14.41
Bid-YTW : 5.91 %
BMO.PR.S FixedReset Disc 48,982 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 15.05
Evaluated at bid price : 15.05
Bid-YTW : 5.11 %
There were 40 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
CCS.PR.C Deemed-Retractible Quote: 22.25 – 24.80
Spot Rate : 2.5500
Average : 1.7893

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 22.01
Evaluated at bid price : 22.25
Bid-YTW : 5.62 %

PVS.PR.H SplitShare Quote: 24.00 – 24.95
Spot Rate : 0.9500
Average : 0.5510

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2027-02-28
Maturity Price : 25.00
Evaluated at bid price : 24.00
Bid-YTW : 5.46 %

SLF.PR.J FloatingReset Quote: 9.06 – 10.00
Spot Rate : 0.9400
Average : 0.6318

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 9.06
Evaluated at bid price : 9.06
Bid-YTW : 4.38 %

NA.PR.E FixedReset Disc Quote: 15.40 – 16.21
Spot Rate : 0.8100
Average : 0.5324

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 15.40
Evaluated at bid price : 15.40
Bid-YTW : 5.48 %

CU.PR.I FixedReset Disc Quote: 24.70 – 25.45
Spot Rate : 0.7500
Average : 0.5168

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 24.05
Evaluated at bid price : 24.70
Bid-YTW : 4.55 %

BIP.PR.E FixedReset Disc Quote: 20.00 – 20.70
Spot Rate : 0.7000
Average : 0.4961

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2050-06-10
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 6.27 %