Category: Market Action

Market Action

September 11, 2017

The BoC has had a look at Canadian bond trading:

Technology, risk tolerance and regulation may influence dealers to reduce their trading as principals (using their own balance sheets for sales and purchases of securities) in favour of agency trading (matching client trades). A move toward agency trading would represent a change in the structure of Canadian bond markets and, in theory, could worsen some aspects of market liquidity. To assess the prevalence of agency trading in Canada, we use data from the Market Trade Reporting System to construct the first estimate of agency-based trading in Canadian bond markets. We find that agency trading is relatively uncommon across major segments of Canadian fixed-income market and that large bank broker-dealers are less likely than their smaller counterparts to trade as an agent.
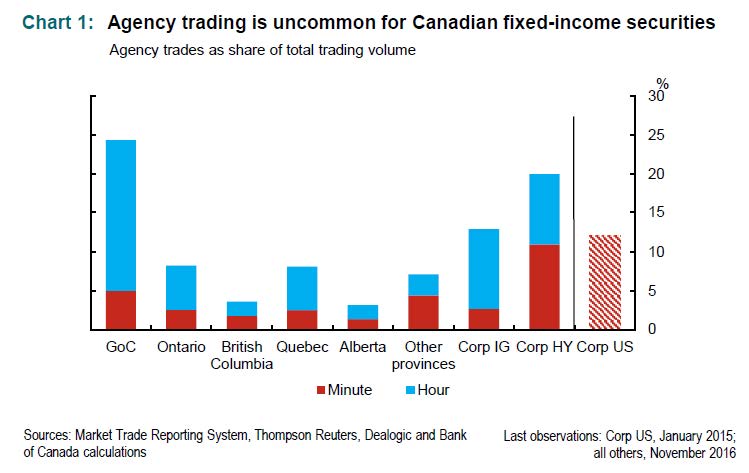
tradereversal
Click for Big

One economist has been brave enough to criticize the BoC’s communications:

The Bank of Canada didn’t give a speech or make other public comments about the strength of an economic recovery in the days before its Sept. 6 increase, a decision that Bank of Montreal Chief Economist Doug Porter called “an epic fail” in a report on Friday. The quarter-point increase to 1 percent was anticipated by six of 29 economists surveyed by Bloomberg.

Jeremy Harrison, the central bank’s chief spokesman, said in emailed comments that policy makers indicated at the last decision in July that monetary policy would be forward-looking and depend on economic data. Trading in overnight index swaps had also priced in 50-50 odds of a move this month after a strong report on second-quarter gross domestic product, which was published during a traditional blackout period in the days just before a rate meeting, Harrison said. Harrison had initially provided these comments to the Globe and Mail newspaper.

Seems to me like Porter wants his policy forecasts to be served to him on a plate, as was the case with the July increase. The major problem with the BoC’s communications is that committee votes and reasons for dissents – a normal component of the communication of a professionally run central bank – are not specified in the bank’s press releases and that the bank’s outreach is very close to being all Poloz, all the time!

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.1854 % 2,407.3
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.1854 % 4,417.3
Floater 3.90 % 3.95 % 109,308 17.44 3 -0.1854 % 2,545.7
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0950 % 3,064.1
SplitShare 4.75 % 4.53 % 65,251 3.70 5 -0.0950 % 3,659.2
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0950 % 2,855.1
Perpetual-Premium 5.43 % 4.92 % 62,749 6.13 16 -0.1999 % 2,770.8
Perpetual-Discount 5.37 % 5.43 % 66,841 14.70 19 -0.5296 % 2,880.0
FixedReset 4.36 % 4.53 % 145,685 6.26 98 -0.0149 % 2,396.5
Deemed-Retractible 5.16 % 5.74 % 96,928 6.07 31 -0.0761 % 2,840.5
FloatingReset 2.84 % 3.11 % 43,417 4.12 8 0.2209 % 2,627.3
Performance Highlights
Issue Index Change Notes
CU.PR.H Perpetual-Discount -1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-11
Maturity Price : 24.09
Evaluated at bid price : 24.50
Bid-YTW : 5.38 %
SLF.PR.H FixedReset -1.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.55
Bid-YTW : 6.33 %
HSE.PR.A FixedReset -1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-11
Maturity Price : 16.63
Evaluated at bid price : 16.63
Bid-YTW : 4.86 %
POW.PR.D Perpetual-Discount -1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-11
Maturity Price : 23.41
Evaluated at bid price : 23.70
Bid-YTW : 5.35 %
MFC.PR.B Deemed-Retractible -1.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.71
Bid-YTW : 6.98 %
BAM.PF.D Perpetual-Discount -1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-11
Maturity Price : 21.90
Evaluated at bid price : 22.22
Bid-YTW : 5.61 %
IFC.PR.A FixedReset 1.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.92
Bid-YTW : 7.26 %
VNR.PR.A FixedReset 1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-11
Maturity Price : 21.94
Evaluated at bid price : 22.45
Bid-YTW : 5.08 %
SLF.PR.J FloatingReset 1.51 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.86
Bid-YTW : 8.33 %
IFC.PR.E Deemed-Retractible 2.70 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.35
Bid-YTW : 5.94 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PF.H FixedReset 118,225 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 26.16
Bid-YTW : 3.79 %
CM.PR.R FixedReset 113,338 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-07-31
Maturity Price : 25.00
Evaluated at bid price : 25.21
Bid-YTW : 4.52 %
BAM.PF.B FixedReset 98,418 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-11
Maturity Price : 22.42
Evaluated at bid price : 22.80
Bid-YTW : 4.80 %
W.PR.K FixedReset 91,200 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-01-15
Maturity Price : 25.00
Evaluated at bid price : 26.13
Bid-YTW : 4.08 %
BMO.PR.B FixedReset 90,992 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-02-25
Maturity Price : 25.00
Evaluated at bid price : 26.16
Bid-YTW : 3.78 %
NA.PR.C FixedReset 83,425 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-11-15
Maturity Price : 25.00
Evaluated at bid price : 25.20
Bid-YTW : 4.54 %
There were 35 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
TRP.PR.G FixedReset Quote: 24.00 – 25.05
Spot Rate : 1.0500
Average : 0.6057

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-11
Maturity Price : 22.94
Evaluated at bid price : 24.00
Bid-YTW : 4.67 %

TRP.PR.A FixedReset Quote: 19.02 – 19.56
Spot Rate : 0.5400
Average : 0.3492

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-11
Maturity Price : 19.02
Evaluated at bid price : 19.02
Bid-YTW : 4.72 %

HSE.PR.C FixedReset Quote: 23.13 – 23.53
Spot Rate : 0.4000
Average : 0.2890

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-11
Maturity Price : 22.61
Evaluated at bid price : 23.13
Bid-YTW : 5.16 %

W.PR.K FixedReset Quote: 26.13 – 26.47
Spot Rate : 0.3400
Average : 0.2321

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-01-15
Maturity Price : 25.00
Evaluated at bid price : 26.13
Bid-YTW : 4.08 %

ELF.PR.G Perpetual-Discount Quote: 22.00 – 22.36
Spot Rate : 0.3600
Average : 0.2595

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-11
Maturity Price : 21.75
Evaluated at bid price : 22.00
Bid-YTW : 5.48 %

SLF.PR.E Deemed-Retractible Quote: 20.93 – 21.17
Spot Rate : 0.2400
Average : 0.1526

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.93
Bid-YTW : 7.40 %

Market Action

September 8, 2017

Drones seem to be working well in Rwanda:

The San Francisco-based robotics company is called Zipline, and it introduced a fleet of medical delivery drones into Rwanda early this year. The drones delivered blood to 21 blood transfusing facilities in western Rwanda with the government’s assistance.

The drones resemble small single prop aircraft and are designed to deliver life-saving resources to any area of Western Rwanda within 15-35 minutes, despite the remoteness of the location. So far, the operation makes about 500 deliveries a day.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.8274 % 2,411.8
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.8274 % 4,425.5
Floater 3.89 % 3.94 % 105,017 17.47 3 -0.8274 % 2,550.5
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0475 % 3,067.0
SplitShare 4.75 % 4.50 % 60,432 3.71 5 -0.0475 % 3,662.7
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0475 % 2,857.8
Perpetual-Premium 5.42 % 4.80 % 60,272 5.84 16 0.0692 % 2,776.3
Perpetual-Discount 5.34 % 5.42 % 67,705 14.72 19 -0.0568 % 2,895.3
FixedReset 4.36 % 4.52 % 146,212 6.27 98 0.0742 % 2,396.8
Deemed-Retractible 5.15 % 5.69 % 96,231 6.08 31 -0.1778 % 2,842.6
FloatingReset 2.85 % 3.22 % 44,097 4.13 8 -0.2204 % 2,621.5
Performance Highlights
Issue Index Change Notes
IFC.PR.E Deemed-Retractible -3.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.71
Bid-YTW : 6.39 %
SLF.PR.J FloatingReset -1.77 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.61
Bid-YTW : 8.55 %
SLF.PR.G FixedReset -1.73 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.00
Bid-YTW : 8.72 %
PVS.PR.E SplitShare -1.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.80
Bid-YTW : 4.83 %
BAM.PR.B Floater -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-08
Maturity Price : 14.40
Evaluated at bid price : 14.40
Bid-YTW : 3.94 %
HSE.PR.C FixedReset 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-08
Maturity Price : 22.74
Evaluated at bid price : 23.35
Bid-YTW : 5.11 %
CU.PR.C FixedReset 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-08
Maturity Price : 21.60
Evaluated at bid price : 21.60
Bid-YTW : 4.79 %
HSE.PR.A FixedReset 1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-08
Maturity Price : 16.82
Evaluated at bid price : 16.82
Bid-YTW : 4.81 %
TRP.PR.B FixedReset 1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-08
Maturity Price : 15.05
Evaluated at bid price : 15.05
Bid-YTW : 4.77 %
EIT.PR.A SplitShare 1.76 % YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2024-03-14
Maturity Price : 25.00
Evaluated at bid price : 25.44
Bid-YTW : 4.50 %
Volume Highlights
Issue Index Shares
Traded
Notes
NA.PR.A FixedReset 137,100 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-15
Maturity Price : 25.00
Evaluated at bid price : 26.25
Bid-YTW : 4.14 %
TRP.PR.B FixedReset 111,300 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-08
Maturity Price : 15.05
Evaluated at bid price : 15.05
Bid-YTW : 4.77 %
TD.PF.H FixedReset 103,513 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 26.20
Bid-YTW : 3.74 %
MFC.PR.I FixedReset 83,748 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.70
Bid-YTW : 5.44 %
NA.PR.C FixedReset 69,554 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-11-15
Maturity Price : 25.00
Evaluated at bid price : 25.22
Bid-YTW : 4.51 %
PVS.PR.D SplitShare 57,465 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2021-10-08
Maturity Price : 25.00
Evaluated at bid price : 25.00
Bid-YTW : 4.53 %
There were 23 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
IFC.PR.E Deemed-Retractible Quote: 23.71 – 24.55
Spot Rate : 0.8400
Average : 0.5159

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.71
Bid-YTW : 6.39 %

VNR.PR.A FixedReset Quote: 22.20 – 22.75
Spot Rate : 0.5500
Average : 0.3605

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-08
Maturity Price : 21.77
Evaluated at bid price : 22.20
Bid-YTW : 5.14 %

BNS.PR.D FloatingReset Quote: 22.39 – 22.79
Spot Rate : 0.4000
Average : 0.2206

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.39
Bid-YTW : 4.67 %

TRP.PR.D FixedReset Quote: 22.00 – 22.49
Spot Rate : 0.4900
Average : 0.3511

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-08
Maturity Price : 21.60
Evaluated at bid price : 22.00
Bid-YTW : 4.67 %

GWO.PR.H Deemed-Retractible Quote: 22.60 – 22.93
Spot Rate : 0.3300
Average : 0.2150

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.60
Bid-YTW : 6.49 %

CU.PR.E Perpetual-Discount Quote: 23.05 – 23.45
Spot Rate : 0.4000
Average : 0.2915

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-08
Maturity Price : 22.65
Evaluated at bid price : 23.05
Bid-YTW : 5.33 %

Market Action

September 7, 2017

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.8343 % 2,431.9
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.8343 % 4,462.5
Floater 3.86 % 3.91 % 108,884 17.53 3 0.8343 % 2,571.7
OpRet 0.00 % 0.00 % 0 0.00 0 -0.5741 % 3,068.5
SplitShare 4.75 % 4.10 % 55,969 1.30 5 -0.5741 % 3,664.4
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.5741 % 2,859.1
Perpetual-Premium 5.42 % 4.86 % 61,006 5.84 16 -0.2906 % 2,774.4
Perpetual-Discount 5.34 % 5.40 % 70,256 14.76 19 -0.6365 % 2,897.0
FixedReset 4.36 % 4.45 % 147,447 6.30 98 -0.1883 % 2,395.1
Deemed-Retractible 5.15 % 5.68 % 97,747 6.08 31 -0.4378 % 2,847.7
FloatingReset 2.72 % 3.07 % 45,372 4.14 8 0.1490 % 2,627.3
Performance Highlights
Issue Index Change Notes
TRP.PR.B FixedReset -1.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-07
Maturity Price : 14.85
Evaluated at bid price : 14.85
Bid-YTW : 4.63 %
EIT.PR.A SplitShare -1.77 % YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2024-03-14
Maturity Price : 25.00
Evaluated at bid price : 25.00
Bid-YTW : 4.81 %
CU.PR.G Perpetual-Discount -1.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-07
Maturity Price : 21.22
Evaluated at bid price : 21.22
Bid-YTW : 5.34 %
MFC.PR.F FixedReset -1.52 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.88
Bid-YTW : 8.55 %
BMO.PR.Y FixedReset -1.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-07
Maturity Price : 22.73
Evaluated at bid price : 23.51
Bid-YTW : 4.45 %
GWO.PR.T Deemed-Retractible -1.35 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.12
Bid-YTW : 5.72 %
PWF.PR.Z Perpetual-Discount -1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-07
Maturity Price : 23.83
Evaluated at bid price : 24.18
Bid-YTW : 5.44 %
SLF.PR.C Deemed-Retractible -1.28 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.77
Bid-YTW : 7.46 %
BAM.PR.X FixedReset -1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-07
Maturity Price : 17.31
Evaluated at bid price : 17.31
Bid-YTW : 4.70 %
PWF.PR.P FixedReset -1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-07
Maturity Price : 16.75
Evaluated at bid price : 16.75
Bid-YTW : 4.55 %
IAG.PR.A Deemed-Retractible -1.21 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.09
Bid-YTW : 6.60 %
SLF.PR.D Deemed-Retractible -1.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.80
Bid-YTW : 7.43 %
SLF.PR.B Deemed-Retractible -1.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.31
Bid-YTW : 6.65 %
TRP.PR.C FixedReset -1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-07
Maturity Price : 16.12
Evaluated at bid price : 16.12
Bid-YTW : 4.63 %
TRP.PR.A FixedReset -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-07
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 4.56 %
PWF.PR.K Perpetual-Discount -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-07
Maturity Price : 22.70
Evaluated at bid price : 22.94
Bid-YTW : 5.45 %
TD.PF.E FixedReset -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-07
Maturity Price : 22.99
Evaluated at bid price : 24.08
Bid-YTW : 4.46 %
GWO.PR.I Deemed-Retractible -1.02 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.33
Bid-YTW : 7.07 %
BAM.PR.B Floater 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-07
Maturity Price : 14.55
Evaluated at bid price : 14.55
Bid-YTW : 3.90 %
Volume Highlights
Issue Index Shares
Traded
Notes
BNS.PR.P FixedReset 364,100 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.99
Bid-YTW : 3.71 %
BNS.PR.H FixedReset 301,290 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-01-26
Maturity Price : 25.00
Evaluated at bid price : 26.30
Bid-YTW : 3.71 %
BNS.PR.G FixedReset 158,400 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-07-25
Maturity Price : 25.00
Evaluated at bid price : 26.96
Bid-YTW : 3.52 %
BAM.PF.G FixedReset 147,347 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-07
Maturity Price : 22.96
Evaluated at bid price : 23.90
Bid-YTW : 4.65 %
CM.PR.R FixedReset 88,987 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-07-31
Maturity Price : 25.00
Evaluated at bid price : 25.22
Bid-YTW : 4.50 %
BAM.PF.F FixedReset 86,700 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-07
Maturity Price : 23.48
Evaluated at bid price : 23.80
Bid-YTW : 4.72 %
There were 22 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
EIT.PR.A SplitShare Quote: 25.00 – 25.50
Spot Rate : 0.5000
Average : 0.3051

YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2024-03-14
Maturity Price : 25.00
Evaluated at bid price : 25.00
Bid-YTW : 4.81 %

BMO.PR.Y FixedReset Quote: 23.51 – 24.10
Spot Rate : 0.5900
Average : 0.4111

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-07
Maturity Price : 22.73
Evaluated at bid price : 23.51
Bid-YTW : 4.45 %

IAG.PR.A Deemed-Retractible Quote: 22.09 – 22.62
Spot Rate : 0.5300
Average : 0.3706

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.09
Bid-YTW : 6.60 %

GWO.PR.I Deemed-Retractible Quote: 21.33 – 21.68
Spot Rate : 0.3500
Average : 0.2201

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.33
Bid-YTW : 7.07 %

CU.PR.G Perpetual-Discount Quote: 21.22 – 21.55
Spot Rate : 0.3300
Average : 0.2049

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-07
Maturity Price : 21.22
Evaluated at bid price : 21.22
Bid-YTW : 5.34 %

PWF.PR.F Perpetual-Discount Quote: 24.55 – 24.84
Spot Rate : 0.2900
Average : 0.1907

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-07
Maturity Price : 24.25
Evaluated at bid price : 24.55
Bid-YTW : 5.40 %

Market Action

September 6, 2017

A strong day today in the wake of the BoC rate hike.

PerpetualDiscounts now yield 5.35%, equivalent to 6.96% interest at the standard equivalency factor of 1.3x. Long corporates now yield a little less than 3.95%, so the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) is now about 300bp, significantly narrower than the 310bp reported August 30.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 2.0819 % 2,411.8
FixedFloater 0.00 % 0.00 % 0 0.00 0 2.0819 % 4,425.5
Floater 3.59 % 3.63 % 109,641 18.16 3 2.0819 % 2,550.5
OpRet 0.00 % 0.00 % 0 0.00 0 0.0472 % 3,086.2
SplitShare 4.72 % 4.13 % 51,828 1.30 5 0.0472 % 3,685.6
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0472 % 2,875.6
Perpetual-Premium 5.41 % 4.79 % 58,005 5.85 16 0.0320 % 2,782.5
Perpetual-Discount 5.31 % 5.35 % 69,322 14.84 19 -0.1330 % 2,915.5
FixedReset 4.35 % 4.41 % 147,190 6.30 98 0.3864 % 2,399.6
Deemed-Retractible 5.12 % 5.51 % 99,209 6.08 31 -0.2897 % 2,860.2
FloatingReset 2.72 % 3.09 % 42,005 4.14 8 0.2379 % 2,623.4
Performance Highlights
Issue Index Change Notes
SLF.PR.A Deemed-Retractible -1.29 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.27
Bid-YTW : 6.63 %
BAM.PF.I FixedReset -1.24 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-03-31
Maturity Price : 25.00
Evaluated at bid price : 25.58
Bid-YTW : 4.48 %
PWF.PR.T FixedReset 1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-06
Maturity Price : 22.66
Evaluated at bid price : 23.10
Bid-YTW : 4.30 %
CM.PR.Q FixedReset 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-06
Maturity Price : 22.79
Evaluated at bid price : 23.59
Bid-YTW : 4.48 %
HSE.PR.C FixedReset 1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-06
Maturity Price : 22.57
Evaluated at bid price : 23.07
Bid-YTW : 5.04 %
RY.PR.M FixedReset 1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-06
Maturity Price : 22.60
Evaluated at bid price : 23.33
Bid-YTW : 4.37 %
BMO.PR.T FixedReset 1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-06
Maturity Price : 21.69
Evaluated at bid price : 22.14
Bid-YTW : 4.31 %
RY.PR.Z FixedReset 1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-06
Maturity Price : 21.60
Evaluated at bid price : 22.00
Bid-YTW : 4.32 %
TD.PF.E FixedReset 1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-06
Maturity Price : 23.10
Evaluated at bid price : 24.33
Bid-YTW : 4.40 %
PWF.PR.P FixedReset 1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-06
Maturity Price : 16.96
Evaluated at bid price : 16.96
Bid-YTW : 4.49 %
BMO.PR.Y FixedReset 1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-06
Maturity Price : 22.91
Evaluated at bid price : 23.85
Bid-YTW : 4.38 %
MFC.PR.F FixedReset 1.42 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.14
Bid-YTW : 8.31 %
TRP.PR.G FixedReset 1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-06
Maturity Price : 22.94
Evaluated at bid price : 24.00
Bid-YTW : 4.55 %
BAM.PR.B Floater 1.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-06
Maturity Price : 14.40
Evaluated at bid price : 14.40
Bid-YTW : 3.63 %
BAM.PR.K Floater 2.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-06
Maturity Price : 14.35
Evaluated at bid price : 14.35
Bid-YTW : 3.64 %
BAM.PR.C Floater 2.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-06
Maturity Price : 14.40
Evaluated at bid price : 14.40
Bid-YTW : 3.63 %
Volume Highlights
Issue Index Shares
Traded
Notes
TRP.PR.J FixedReset 242,117 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-31
Maturity Price : 25.00
Evaluated at bid price : 26.60
Bid-YTW : 3.70 %
NA.PR.C FixedReset 212,189 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-11-15
Maturity Price : 25.00
Evaluated at bid price : 25.25
Bid-YTW : 4.48 %
BMO.PR.C FixedReset 125,835 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-05-25
Maturity Price : 25.00
Evaluated at bid price : 25.40
Bid-YTW : 4.18 %
TRP.PR.K FixedReset 118,549 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-05-31
Maturity Price : 25.00
Evaluated at bid price : 26.00
Bid-YTW : 4.01 %
TRP.PR.D FixedReset 109,616 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-06
Maturity Price : 21.63
Evaluated at bid price : 22.05
Bid-YTW : 4.51 %
BAM.PR.Z FixedReset 92,600 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-06
Maturity Price : 23.14
Evaluated at bid price : 24.05
Bid-YTW : 4.74 %
There were 49 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
GWO.PR.N FixedReset Quote: 17.15 – 17.74
Spot Rate : 0.5900
Average : 0.4433

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.15
Bid-YTW : 8.25 %

CU.PR.H Perpetual-Discount Quote: 24.80 – 25.22
Spot Rate : 0.4200
Average : 0.3284

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-06
Maturity Price : 24.38
Evaluated at bid price : 24.80
Bid-YTW : 5.31 %

IFC.PR.A FixedReset Quote: 19.75 – 20.05
Spot Rate : 0.3000
Average : 0.2151

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.75
Bid-YTW : 7.23 %

W.PR.M FixedReset Quote: 26.16 – 26.40
Spot Rate : 0.2400
Average : 0.1620

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-15
Maturity Price : 25.00
Evaluated at bid price : 26.16
Bid-YTW : 4.19 %

IAG.PR.A Deemed-Retractible Quote: 22.36 – 22.63
Spot Rate : 0.2700
Average : 0.1957

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.36
Bid-YTW : 6.40 %

TRP.PR.F FloatingReset Quote: 19.20 – 19.60
Spot Rate : 0.4000
Average : 0.3264

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-06
Maturity Price : 19.20
Evaluated at bid price : 19.20
Bid-YTW : 3.58 %

Market Action

September 5, 2017

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.2125 % 2,362.6
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.2125 % 4,335.3
Floater 3.66 % 3.71 % 109,958 17.98 3 -0.2125 % 2,498.4
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0786 % 3,084.7
SplitShare 4.72 % 4.13 % 51,385 1.30 5 -0.0786 % 3,683.8
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0786 % 2,874.3
Perpetual-Premium 5.41 % 4.82 % 56,150 5.85 16 0.0000 % 2,781.6
Perpetual-Discount 5.30 % 5.33 % 70,307 14.87 19 -0.0698 % 2,919.4
FixedReset 4.37 % 4.44 % 144,827 6.29 98 -0.2285 % 2,390.3
Deemed-Retractible 5.11 % 5.52 % 98,656 6.06 31 -0.0983 % 2,868.5
FloatingReset 2.73 % 3.10 % 41,471 4.15 8 -0.2318 % 2,617.2
Performance Highlights
Issue Index Change Notes
PWF.PR.P FixedReset -1.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-05
Maturity Price : 16.75
Evaluated at bid price : 16.75
Bid-YTW : 4.55 %
TRP.PR.G FixedReset -1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-05
Maturity Price : 22.77
Evaluated at bid price : 23.65
Bid-YTW : 4.63 %
BAM.PF.G FixedReset -1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-05
Maturity Price : 22.91
Evaluated at bid price : 23.80
Bid-YTW : 4.67 %
SLF.PR.H FixedReset -1.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.83
Bid-YTW : 6.04 %
TRP.PR.F FloatingReset -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-05
Maturity Price : 19.15
Evaluated at bid price : 19.15
Bid-YTW : 3.59 %
BAM.PR.X FixedReset -1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-05
Maturity Price : 17.46
Evaluated at bid price : 17.46
Bid-YTW : 4.60 %
SLF.PR.G FixedReset 1.76 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.30
Bid-YTW : 8.34 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.R FixedReset 114,685 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-24
Maturity Price : 25.00
Evaluated at bid price : 26.78
Bid-YTW : 3.63 %
NA.PR.S FixedReset 65,625 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-05
Maturity Price : 21.75
Evaluated at bid price : 22.23
Bid-YTW : 4.48 %
SLF.PR.B Deemed-Retractible 62,505 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.77
Bid-YTW : 6.31 %
TRP.PR.K FixedReset 59,244 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-05-31
Maturity Price : 25.00
Evaluated at bid price : 25.96
Bid-YTW : 4.04 %
CM.PR.R FixedReset 55,307 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-07-31
Maturity Price : 25.00
Evaluated at bid price : 25.21
Bid-YTW : 4.09 %
TRP.PR.C FixedReset 44,150 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-05
Maturity Price : 16.30
Evaluated at bid price : 16.30
Bid-YTW : 4.58 %
There were 15 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
TD.PF.B FixedReset Quote: 21.83 – 22.14
Spot Rate : 0.3100
Average : 0.1936

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-05
Maturity Price : 21.48
Evaluated at bid price : 21.83
Bid-YTW : 4.42 %

TRP.PR.G FixedReset Quote: 23.65 – 24.00
Spot Rate : 0.3500
Average : 0.2416

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-05
Maturity Price : 22.77
Evaluated at bid price : 23.65
Bid-YTW : 4.63 %

BMO.PR.W FixedReset Quote: 21.65 – 21.89
Spot Rate : 0.2400
Average : 0.1556

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-05
Maturity Price : 21.34
Evaluated at bid price : 21.65
Bid-YTW : 4.39 %

HSE.PR.C FixedReset Quote: 22.81 – 23.25
Spot Rate : 0.4400
Average : 0.3561

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-05
Maturity Price : 22.40
Evaluated at bid price : 22.81
Bid-YTW : 5.11 %

BAM.PF.G FixedReset Quote: 23.80 – 24.06
Spot Rate : 0.2600
Average : 0.1803

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-05
Maturity Price : 22.91
Evaluated at bid price : 23.80
Bid-YTW : 4.67 %

EML.PR.A FixedReset Quote: 26.53 – 26.91
Spot Rate : 0.3800
Average : 0.3005

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-17
Maturity Price : 25.00
Evaluated at bid price : 26.53
Bid-YTW : 4.17 %

Market Action

September 1, 2017

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.2604 % 2,367.6
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.2604 % 4,344.5
Floater 3.66 % 3.69 % 114,249 18.01 3 0.2604 % 2,503.8
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0472 % 3,087.2
SplitShare 4.72 % 3.85 % 51,607 1.31 5 -0.0472 % 3,686.7
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0472 % 2,876.5
Perpetual-Premium 5.41 % 4.73 % 55,823 5.86 16 0.0172 % 2,781.6
Perpetual-Discount 5.30 % 5.34 % 73,062 14.87 19 -0.2337 % 2,921.5
FixedReset 4.36 % 4.41 % 146,813 6.33 98 0.1749 % 2,395.8
Deemed-Retractible 5.10 % 5.47 % 98,714 6.08 31 -0.1492 % 2,871.3
FloatingReset 2.57 % 2.91 % 40,974 4.17 8 0.1382 % 2,623.3
Performance Highlights
Issue Index Change Notes
PWF.PR.Z Perpetual-Discount -1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-01
Maturity Price : 24.18
Evaluated at bid price : 24.55
Bid-YTW : 5.35 %
W.PR.H Perpetual-Discount -1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-01
Maturity Price : 24.25
Evaluated at bid price : 24.55
Bid-YTW : 5.68 %
BAM.PF.G FixedReset 1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-01
Maturity Price : 23.05
Evaluated at bid price : 24.10
Bid-YTW : 4.56 %
BAM.PR.T FixedReset 1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-01
Maturity Price : 20.65
Evaluated at bid price : 20.65
Bid-YTW : 4.61 %
RY.PR.J FixedReset 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-01
Maturity Price : 22.80
Evaluated at bid price : 23.57
Bid-YTW : 4.40 %
PWF.PR.P FixedReset 1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-01
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 4.43 %
BAM.PR.X FixedReset 1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-01
Maturity Price : 17.64
Evaluated at bid price : 17.64
Bid-YTW : 4.57 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.B Deemed-Retractible 212,307 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-10-01
Maturity Price : 25.00
Evaluated at bid price : 25.08
Bid-YTW : 2.06 %
TRP.PR.J FixedReset 152,348 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-31
Maturity Price : 25.00
Evaluated at bid price : 26.70
Bid-YTW : 3.57 %
NA.PR.S FixedReset 137,706 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-01
Maturity Price : 21.81
Evaluated at bid price : 22.32
Bid-YTW : 4.42 %
RY.PR.L FixedReset 109,100 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2019-02-24
Maturity Price : 25.00
Evaluated at bid price : 25.20
Bid-YTW : 3.78 %
RY.PR.Q FixedReset 104,512 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-24
Maturity Price : 25.00
Evaluated at bid price : 26.70
Bid-YTW : 3.59 %
RY.PR.R FixedReset 102,321 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-24
Maturity Price : 25.00
Evaluated at bid price : 26.80
Bid-YTW : 3.60 %
There were 24 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
HSE.PR.G FixedReset Quote: 23.90 – 24.34
Spot Rate : 0.4400
Average : 0.3096

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-01
Maturity Price : 22.95
Evaluated at bid price : 23.90
Bid-YTW : 5.24 %

MFC.PR.M FixedReset Quote: 21.92 – 22.29
Spot Rate : 0.3700
Average : 0.2436

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.92
Bid-YTW : 5.97 %

BMO.PR.Y FixedReset Quote: 23.53 – 23.96
Spot Rate : 0.4300
Average : 0.3146

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-01
Maturity Price : 22.74
Evaluated at bid price : 23.53
Bid-YTW : 4.41 %

HSE.PR.E FixedReset Quote: 23.78 – 24.10
Spot Rate : 0.3200
Average : 0.2166

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-09-01
Maturity Price : 22.93
Evaluated at bid price : 23.78
Bid-YTW : 5.30 %

IAG.PR.G FixedReset Quote: 22.65 – 23.04
Spot Rate : 0.3900
Average : 0.2890

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.65
Bid-YTW : 5.51 %

MFC.PR.H FixedReset Quote: 24.36 – 24.67
Spot Rate : 0.3100
Average : 0.2103

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.36
Bid-YTW : 5.07 %

Market Action

August 31, 2017

Natalie Obiko Pearson of Bloomberg comes up with an explanation of housing costs that’s as good as any I’ve seen:

In the spring of 2012, Dustan Woodhouse, then a 40-year-old Vancouver mortgage broker, broke the cardinal rule of saving for retirement: he liquidated his retirement fund, took the tax hit and plowed the rest into the local real estate market.

“People told me I was crazy,” says Woodhouse, 45, whose plan is to buy and have paid off 10 such investments by his late sixties. “But that’s our pension — that’s what that property is.”
…
Woodhouse’s decision to flout traditional investment strategies has so far proved to be a winner. With the roughly C$60,000 ($47,000) he had in hand, he took out a mortgage and bought a wood-shingled townhouse near a coastal inlet east of Vancouver for C$240,000. Five years later, he figures his house has risen about 60 percent in value if sales of nearby properties are anything to go by. In the meantime, he’s accrued a nest egg of roughly C$24,000 from rental income, even after accounting for expenses, mortgage payments and taxes.
…
The price of a typical detached home in Vancouver rose 69 percent in the five years through July, compared with a return of 51 percent for the S&P/TSX Composite Index, the country’s benchmark equity index, and 7.6 percent for Canadian government bonds. Some 41 percent of baby boomers said home equity made up more than 60 percent of their household wealth, according to a survey by Manuflife Bank published in May. For 21 percent, it made up more than 80 percent.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 1.1976 % 2,361.5
FixedFloater 0.00 % 0.00 % 0 0.00 0 1.1976 % 4,333.2
Floater 3.67 % 3.70 % 115,797 17.99 3 1.1976 % 2,497.3
OpRet 0.00 % 0.00 % 0 0.00 0 0.1574 % 3,088.6
SplitShare 4.72 % 3.89 % 53,690 1.32 5 0.1574 % 3,688.5
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1574 % 2,877.9
Perpetual-Premium 5.40 % 4.84 % 55,641 6.06 17 -0.0650 % 2,781.1
Perpetual-Discount 5.31 % 5.34 % 60,821 14.87 20 0.0256 % 2,928.3
FixedReset 4.37 % 4.42 % 144,887 6.33 98 0.1589 % 2,391.6
Deemed-Retractible 5.10 % 5.41 % 101,235 6.08 31 0.0807 % 2,875.6
FloatingReset 2.63 % 3.13 % 41,034 4.17 9 0.1534 % 2,619.7
Performance Highlights
Issue Index Change Notes
BAM.PF.D Perpetual-Discount -1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-31
Maturity Price : 22.02
Evaluated at bid price : 22.39
Bid-YTW : 5.55 %
BAM.PF.B FixedReset 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-31
Maturity Price : 22.30
Evaluated at bid price : 22.67
Bid-YTW : 4.64 %
CM.PR.O FixedReset 1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-31
Maturity Price : 21.64
Evaluated at bid price : 22.07
Bid-YTW : 4.38 %
PWF.PR.Z Perpetual-Discount 1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-31
Maturity Price : 24.41
Evaluated at bid price : 24.80
Bid-YTW : 5.30 %
MFC.PR.C Deemed-Retractible 1.26 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.72
Bid-YTW : 6.78 %
MFC.PR.M FixedReset 1.34 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.86
Bid-YTW : 6.01 %
BAM.PR.B Floater 1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-31
Maturity Price : 14.11
Evaluated at bid price : 14.11
Bid-YTW : 3.70 %
SLF.PR.H FixedReset 1.40 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.99
Bid-YTW : 5.89 %
BAM.PR.C Floater 1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-31
Maturity Price : 14.09
Evaluated at bid price : 14.09
Bid-YTW : 3.70 %
SLF.PR.J FloatingReset 1.51 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.85
Bid-YTW : 7.99 %
Volume Highlights
Issue Index Shares
Traded
Notes
IFC.PR.E Deemed-Retractible 181,000 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.78
Bid-YTW : 5.62 %
CM.PR.R FixedReset 145,965 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-07-31
Maturity Price : 25.00
Evaluated at bid price : 25.14
Bid-YTW : 4.55 %
RY.PR.B Deemed-Retractible 110,442 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-09-30
Maturity Price : 25.00
Evaluated at bid price : 25.08
Bid-YTW : 1.90 %
RY.PR.R FixedReset 81,190 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-24
Maturity Price : 25.00
Evaluated at bid price : 26.80
Bid-YTW : 3.60 %
TD.PF.C FixedReset 52,400 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-31
Maturity Price : 21.42
Evaluated at bid price : 21.76
Bid-YTW : 4.36 %
TRP.PR.J FixedReset 42,875 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-31
Maturity Price : 25.00
Evaluated at bid price : 26.61
Bid-YTW : 3.67 %
There were 14 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
GWO.PR.S Deemed-Retractible Quote: 24.70 – 25.25
Spot Rate : 0.5500
Average : 0.3933

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.70
Bid-YTW : 5.41 %

BAM.PF.D Perpetual-Discount Quote: 22.39 – 22.78
Spot Rate : 0.3900
Average : 0.2682

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-31
Maturity Price : 22.02
Evaluated at bid price : 22.39
Bid-YTW : 5.55 %

BMO.PR.B FixedReset Quote: 26.13 – 26.40
Spot Rate : 0.2700
Average : 0.1559

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-02-25
Maturity Price : 25.00
Evaluated at bid price : 26.13
Bid-YTW : 3.79 %

BNS.PR.D FloatingReset Quote: 22.24 – 22.49
Spot Rate : 0.2500
Average : 0.1378

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.24
Bid-YTW : 4.53 %

TRP.PR.A FixedReset Quote: 19.26 – 19.56
Spot Rate : 0.3000
Average : 0.1962

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-31
Maturity Price : 19.26
Evaluated at bid price : 19.26
Bid-YTW : 4.45 %

RY.PR.O Perpetual-Premium Quote: 25.20 – 25.47
Spot Rate : 0.2700
Average : 0.1729

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2024-11-24
Maturity Price : 25.00
Evaluated at bid price : 25.20
Bid-YTW : 4.81 %

Market Action

August 30, 2017

PerpetualDiscounts now yield 5.35%, equivalent to 6.96% interest at the standard equivalency factor of 1.3x. Long corporates now yield a little over 3.85%, so the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) is now about 310bp, a slight (and perhaps spurious) widening from the 305bp reported August 23.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.0240 % 2,333.5
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.0240 % 4,281.9
Floater 3.71 % 3.75 % 119,603 17.89 3 0.0240 % 2,467.7
OpRet 0.00 % 0.00 % 0 0.00 0 0.1340 % 3,083.8
SplitShare 4.72 % 4.10 % 49,704 1.32 5 0.1340 % 3,682.7
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1340 % 2,873.4
Perpetual-Premium 5.40 % 4.81 % 54,898 5.87 17 0.0000 % 2,782.9
Perpetual-Discount 5.31 % 5.35 % 61,042 14.87 20 0.0341 % 2,927.6
FixedReset 4.37 % 4.43 % 147,177 6.32 98 0.1921 % 2,387.8
Deemed-Retractible 5.10 % 5.46 % 102,638 6.08 31 0.0388 % 2,873.3
FloatingReset 2.63 % 3.09 % 39,474 4.18 9 0.0205 % 2,615.6
Performance Highlights
Issue Index Change Notes
PWF.PR.Z Perpetual-Discount -1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-30
Maturity Price : 24.13
Evaluated at bid price : 24.50
Bid-YTW : 5.36 %
IFC.PR.A FixedReset 1.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.90
Bid-YTW : 7.04 %
CU.PR.C FixedReset 1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-30
Maturity Price : 21.55
Evaluated at bid price : 21.55
Bid-YTW : 4.58 %
IAG.PR.A Deemed-Retractible 1.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.66
Bid-YTW : 6.16 %
VNR.PR.A FixedReset 1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-30
Maturity Price : 21.50
Evaluated at bid price : 21.81
Bid-YTW : 5.03 %
TRP.PR.D FixedReset 1.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-30
Maturity Price : 21.72
Evaluated at bid price : 22.18
Bid-YTW : 4.43 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.B Deemed-Retractible 200,200 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-09-29
Maturity Price : 25.00
Evaluated at bid price : 25.07
Bid-YTW : 2.24 %
GWO.PR.I Deemed-Retractible 102,400 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.56
Bid-YTW : 6.87 %
TD.PF.A FixedReset 86,700 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-30
Maturity Price : 21.41
Evaluated at bid price : 21.74
Bid-YTW : 4.37 %
NA.PR.A FixedReset 41,900 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-15
Maturity Price : 25.00
Evaluated at bid price : 26.22
Bid-YTW : 4.14 %
CM.PR.R FixedReset 35,833 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-07-31
Maturity Price : 25.00
Evaluated at bid price : 25.12
Bid-YTW : 4.57 %
CU.PR.I FixedReset 31,450 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-01
Maturity Price : 25.00
Evaluated at bid price : 25.75
Bid-YTW : 3.53 %
There were 8 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
TRP.PR.G FixedReset Quote: 23.67 – 24.17
Spot Rate : 0.5000
Average : 0.3956

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-30
Maturity Price : 22.78
Evaluated at bid price : 23.67
Bid-YTW : 4.58 %

MFC.PR.M FixedReset Quote: 21.57 – 21.85
Spot Rate : 0.2800
Average : 0.1764

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.57
Bid-YTW : 6.22 %

BAM.PF.B FixedReset Quote: 22.42 – 22.70
Spot Rate : 0.2800
Average : 0.1906

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-30
Maturity Price : 21.88
Evaluated at bid price : 22.42
Bid-YTW : 4.68 %

MFC.PR.L FixedReset Quote: 20.63 – 20.94
Spot Rate : 0.3100
Average : 0.2356

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.63
Bid-YTW : 6.78 %

CU.PR.H Perpetual-Premium Quote: 24.90 – 25.25
Spot Rate : 0.3500
Average : 0.2776

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-30
Maturity Price : 24.48
Evaluated at bid price : 24.90
Bid-YTW : 5.28 %

TD.PF.E FixedReset Quote: 24.00 – 24.23
Spot Rate : 0.2300
Average : 0.1608

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-30
Maturity Price : 22.95
Evaluated at bid price : 24.00
Bid-YTW : 4.43 %

Market Action

August 29, 2017

Conversion to T+2 settlement is now underway:

The implementation of T+2 settlement formally takes place next week, on Tues. Sept. 5, but the transition effectively begins on Mon. Aug. 28.

The Canadian Capital Markets Association (CCMA) has published a support plan stressing that the move to shorter settlement cycles “is more than a one-day event.” The transition starts with the last few days of T+3 trading, it notes, and ends Sept. 8, “assuming everything goes as planned.”

The shift to T+2 involves all segments of the investment industry, including brokerage firms, investors, exchanges and other components of trading infrastructure.

It’s a good move, reducing counterparty exposure during the pre-settlement period, but doesn’t go far enough. Why isn’t T+1 standard?

The newest crypto-currency is WhopperCoins:

Fast-food chain Burger King has launched its own crypto-currency, called WhopperCoin, in Russia.

Customers will be able to claim one coin for every rouble (1.3p) they spend on the Whopper sandwich.

Russians will be able to buy a Whopper with the virtual cash, once they have amassed 1,700 whoppercoins.

The company said it would release Apple and Android apps next month so people could save, share and trade their wallet full of whoppercoins.

It’s a great idea – I don’t know what, if anything, Aimia’s doing to exploit this new technology.

The OSC Superannuation Company, which has the official name of Canadian Foundation for Advancement of Investor Rights, “FAIR Canada” for short, has appointed a new Executive Director:

Fair Canada Chair, Ermanno Pascutto, announced that Frank Allen, a seasoned securities lawyer and executive leader, has been appointed its Executive Director. Frank begins his role effective immediately.
…
Frank also acted as the General Counsel at the Ontario Securities Commission and played a leading role in the development and drafting of the OSC’s rule protecting minority security holders in related party transactions.

Mr. Allen’s tenure at the OSC was from January 1988 to January 1990, thus overlapping with FAIR’s founder and Chair Ermanno Pascutto’s tenure as OSC Executive Director from 1984-89.

Long term readers will remember that FAIR and the OSC have been in bed together for a long time – I regard FAIR as nothing more than a stalking horse for the OSC. However, there is a chance – just a chance, but it’s there! – that we will soon have seen the last of FAIR, as indicated by their Annual Report to June 30, 2016:

fairfunding
Click for Big

We’ll see what happens!

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -1.2071 % 2,333.0
FixedFloater 0.00 % 0.00 % 0 0.00 0 -1.2071 % 4,280.9
Floater 3.71 % 3.76 % 124,463 17.87 3 -1.2071 % 2,467.1
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0709 % 3,079.6
SplitShare 4.73 % 4.17 % 51,743 1.32 5 -0.0709 % 3,677.8
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0709 % 2,869.5
Perpetual-Premium 5.40 % 4.81 % 53,980 5.87 17 0.0255 % 2,782.9
Perpetual-Discount 5.31 % 5.34 % 62,043 14.87 20 0.0234 % 2,926.6
FixedReset 4.38 % 4.43 % 148,656 6.32 98 -0.5103 % 2,383.3
Deemed-Retractible 5.07 % 5.51 % 103,167 6.03 31 0.0653 % 2,872.2
FloatingReset 2.63 % 3.08 % 40,062 4.18 9 -0.2752 % 2,615.1
Performance Highlights
Issue Index Change Notes
BAM.PR.C Floater -1.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-29
Maturity Price : 13.87
Evaluated at bid price : 13.87
Bid-YTW : 3.76 %
BMO.PR.Y FixedReset -1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-29
Maturity Price : 22.65
Evaluated at bid price : 23.36
Bid-YTW : 4.44 %
IFC.PR.C FixedReset -1.56 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.05
Bid-YTW : 5.79 %
CM.PR.O FixedReset -1.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-29
Maturity Price : 21.46
Evaluated at bid price : 21.81
Bid-YTW : 4.44 %
TRP.PR.H FloatingReset -1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-29
Maturity Price : 14.90
Evaluated at bid price : 14.90
Bid-YTW : 3.31 %
PWF.PR.P FixedReset -1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-29
Maturity Price : 16.60
Evaluated at bid price : 16.60
Bid-YTW : 4.53 %
RY.PR.J FixedReset -1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-29
Maturity Price : 22.63
Evaluated at bid price : 23.26
Bid-YTW : 4.47 %
MFC.PR.G FixedReset -1.43 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.41
Bid-YTW : 5.13 %
MFC.PR.K FixedReset -1.35 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.12
Bid-YTW : 6.41 %
BAM.PF.B FixedReset -1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-29
Maturity Price : 21.92
Evaluated at bid price : 22.49
Bid-YTW : 4.66 %
TRP.PR.D FixedReset -1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-29
Maturity Price : 21.48
Evaluated at bid price : 21.83
Bid-YTW : 4.51 %
TRP.PR.C FixedReset -1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-29
Maturity Price : 16.24
Evaluated at bid price : 16.24
Bid-YTW : 4.54 %
MFC.PR.L FixedReset -1.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.65
Bid-YTW : 6.76 %
MFC.PR.F FixedReset -1.18 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.80
Bid-YTW : 8.57 %
BAM.PF.E FixedReset -1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-29
Maturity Price : 21.97
Evaluated at bid price : 22.24
Bid-YTW : 4.70 %
BMO.PR.T FixedReset -1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-29
Maturity Price : 21.34
Evaluated at bid price : 21.65
Bid-YTW : 4.37 %
BAM.PR.K Floater -1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-29
Maturity Price : 13.87
Evaluated at bid price : 13.87
Bid-YTW : 3.76 %
TRP.PR.B FixedReset -1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-29
Maturity Price : 15.10
Evaluated at bid price : 15.10
Bid-YTW : 4.50 %
TD.PF.D FixedReset -1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-29
Maturity Price : 22.79
Evaluated at bid price : 23.61
Bid-YTW : 4.44 %
EML.PR.A FixedReset -1.12 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-17
Maturity Price : 25.00
Evaluated at bid price : 26.50
Bid-YTW : 4.18 %
TD.PF.A FixedReset -1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-29
Maturity Price : 21.36
Evaluated at bid price : 21.68
Bid-YTW : 4.38 %
BAM.PR.X FixedReset -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-29
Maturity Price : 17.35
Evaluated at bid price : 17.35
Bid-YTW : 4.64 %
CU.PR.C FixedReset -1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-29
Maturity Price : 21.31
Evaluated at bid price : 21.31
Bid-YTW : 4.64 %
IFC.PR.A FixedReset -1.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.69
Bid-YTW : 7.21 %
RY.PR.Z FixedReset -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-29
Maturity Price : 21.34
Evaluated at bid price : 21.64
Bid-YTW : 4.35 %
RY.PR.M FixedReset -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-29
Maturity Price : 22.39
Evaluated at bid price : 22.96
Bid-YTW : 4.40 %
ELF.PR.G Perpetual-Discount -1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-29
Maturity Price : 22.09
Evaluated at bid price : 22.37
Bid-YTW : 5.37 %
BMO.PR.W FixedReset -1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-29
Maturity Price : 21.42
Evaluated at bid price : 21.42
Bid-YTW : 4.41 %
MFC.PR.N FixedReset -1.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.64
Bid-YTW : 6.09 %
RY.PR.H FixedReset -1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-29
Maturity Price : 21.38
Evaluated at bid price : 21.70
Bid-YTW : 4.38 %
POW.PR.D Perpetual-Discount 1.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-29
Maturity Price : 24.09
Evaluated at bid price : 24.35
Bid-YTW : 5.19 %
Volume Highlights
Issue Index Shares
Traded
Notes
TRP.PR.K FixedReset 129,575 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-05-31
Maturity Price : 25.00
Evaluated at bid price : 25.99
Bid-YTW : 4.00 %
RY.PR.B Deemed-Retractible 100,200 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-09-28
Maturity Price : 25.00
Evaluated at bid price : 25.07
Bid-YTW : 2.08 %
GWO.PR.H Deemed-Retractible 80,191 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.38
Bid-YTW : 6.12 %
IFC.PR.F Deemed-Retractible 53,392 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.79
Bid-YTW : 5.51 %
PWF.PR.T FixedReset 33,788 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-29
Maturity Price : 22.62
Evaluated at bid price : 23.05
Bid-YTW : 4.26 %
BAM.PR.K Floater 32,048 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-29
Maturity Price : 13.87
Evaluated at bid price : 13.87
Bid-YTW : 3.76 %
There were 13 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BAM.PF.E FixedReset Quote: 22.24 – 22.72
Spot Rate : 0.4800
Average : 0.3061

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-29
Maturity Price : 21.97
Evaluated at bid price : 22.24
Bid-YTW : 4.70 %

EML.PR.A FixedReset Quote: 26.50 – 26.90
Spot Rate : 0.4000
Average : 0.2517

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-17
Maturity Price : 25.00
Evaluated at bid price : 26.50
Bid-YTW : 4.18 %

TRP.PR.G FixedReset Quote: 23.79 – 24.20
Spot Rate : 0.4100
Average : 0.2811

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-29
Maturity Price : 22.84
Evaluated at bid price : 23.79
Bid-YTW : 4.55 %

TRP.PR.D FixedReset Quote: 21.83 – 22.17
Spot Rate : 0.3400
Average : 0.2118

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-29
Maturity Price : 21.48
Evaluated at bid price : 21.83
Bid-YTW : 4.51 %

BMO.PR.Y FixedReset Quote: 23.36 – 23.81
Spot Rate : 0.4500
Average : 0.3231

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-29
Maturity Price : 22.65
Evaluated at bid price : 23.36
Bid-YTW : 4.44 %

BAM.PR.R FixedReset Quote: 19.86 – 20.25
Spot Rate : 0.3900
Average : 0.2674

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-29
Maturity Price : 19.86
Evaluated at bid price : 19.86
Bid-YTW : 4.67 %

Market Action

August 28, 2017

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.6192 % 2,361.5
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.6192 % 4,333.2
Floater 3.67 % 3.70 % 118,063 18.01 3 0.6192 % 2,497.3
OpRet 0.00 % 0.00 % 0 0.00 0 0.0158 % 3,081.8
SplitShare 4.73 % 4.13 % 50,580 1.32 5 0.0158 % 3,680.4
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0158 % 2,871.6
Perpetual-Premium 5.40 % 4.77 % 55,698 5.87 17 0.0070 % 2,782.2
Perpetual-Discount 5.31 % 5.34 % 64,628 14.89 20 -0.0192 % 2,925.9
FixedReset 4.36 % 4.40 % 147,923 6.33 98 -0.1165 % 2,395.5
Deemed-Retractible 5.07 % 5.50 % 103,742 6.03 31 0.0808 % 2,870.3
FloatingReset 2.62 % 3.00 % 39,833 4.18 9 0.2182 % 2,622.3
Performance Highlights
Issue Index Change Notes
HSE.PR.G FixedReset -1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-28
Maturity Price : 22.80
Evaluated at bid price : 23.61
Bid-YTW : 5.31 %
HSE.PR.C FixedReset -1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-28
Maturity Price : 22.32
Evaluated at bid price : 22.69
Bid-YTW : 5.17 %
TRP.PR.F FloatingReset 1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-28
Maturity Price : 19.54
Evaluated at bid price : 19.54
Bid-YTW : 3.38 %
IAG.PR.A Deemed-Retractible 1.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.75
Bid-YTW : 6.30 %
TRP.PR.H FloatingReset 1.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-28
Maturity Price : 15.25
Evaluated at bid price : 15.25
Bid-YTW : 3.28 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.R FixedReset 125,400 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-24
Maturity Price : 25.00
Evaluated at bid price : 26.80
Bid-YTW : 3.59 %
RY.PR.Q FixedReset 94,200 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-24
Maturity Price : 25.00
Evaluated at bid price : 26.78
Bid-YTW : 3.49 %
RY.PR.I FixedReset 78,000 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.73
Bid-YTW : 3.77 %
CM.PR.R FixedReset 76,532 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-07-31
Maturity Price : 25.00
Evaluated at bid price : 25.13
Bid-YTW : 4.55 %
IFC.PR.F Deemed-Retractible 54,250 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.72
Bid-YTW : 5.55 %
TD.PF.A FixedReset 37,460 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-28
Maturity Price : 21.54
Evaluated at bid price : 21.92
Bid-YTW : 4.33 %
There were 19 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
POW.PR.D Perpetual-Discount Quote: 23.90 – 24.40
Spot Rate : 0.5000
Average : 0.3454

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-28
Maturity Price : 23.63
Evaluated at bid price : 23.90
Bid-YTW : 5.29 %

W.PR.H Perpetual-Discount Quote: 24.56 – 24.94
Spot Rate : 0.3800
Average : 0.2315

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2047-08-28
Maturity Price : 24.26
Evaluated at bid price : 24.56
Bid-YTW : 5.67 %

RY.PR.L FixedReset Quote: 25.25 – 25.59
Spot Rate : 0.3400
Average : 0.1945

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2019-02-24
Maturity Price : 25.00
Evaluated at bid price : 25.25
Bid-YTW : 3.61 %

SLF.PR.I FixedReset Quote: 23.18 – 23.53
Spot Rate : 0.3500
Average : 0.2066

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.18
Bid-YTW : 5.13 %

MFC.PR.C Deemed-Retractible Quote: 21.46 – 21.89
Spot Rate : 0.4300
Average : 0.2903

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.46
Bid-YTW : 6.97 %

GWO.PR.L Deemed-Retractible Quote: 25.72 – 26.18
Spot Rate : 0.4600
Average : 0.3304

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-12-31
Maturity Price : 25.25
Evaluated at bid price : 25.72
Bid-YTW : 2.76 %