Category: Market Action

Market Action

September 19, 2016

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.2159 % 1,680.1
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.2159 % 3,069.2
Floater 4.92 % 4.65 % 88,250 16.14 4 -0.2159 % 1,768.8
OpRet 0.00 % 0.00 % 0 0.00 0 -0.2222 % 2,876.9
SplitShare 5.06 % 4.80 % 75,352 2.18 5 -0.2222 % 3,435.7
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.2222 % 2,680.6
Perpetual-Premium 5.50 % 4.63 % 67,328 1.97 12 -0.0098 % 2,675.0
Perpetual-Discount 5.14 % 5.17 % 92,145 15.05 26 -0.0951 % 2,896.9
FixedReset 5.00 % 4.46 % 147,420 6.93 92 0.1545 % 2,036.4
Deemed-Retractible 5.03 % 4.68 % 114,175 3.21 32 -0.0866 % 2,793.3
FloatingReset 2.84 % 4.32 % 30,999 5.00 12 0.1359 % 2,199.8
Performance Highlights
Issue Index Change Notes
CM.PR.Q FixedReset 1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-19
Maturity Price : 20.30
Evaluated at bid price : 20.30
Bid-YTW : 4.42 %
TD.PF.E FixedReset 1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-19
Maturity Price : 20.81
Evaluated at bid price : 20.81
Bid-YTW : 4.41 %
TRP.PR.F FloatingReset 1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-19
Maturity Price : 13.66
Evaluated at bid price : 13.66
Bid-YTW : 4.49 %
BIP.PR.B FixedReset 1.70 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.70
Bid-YTW : 4.76 %
PWF.PR.T FixedReset 2.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-19
Maturity Price : 20.10
Evaluated at bid price : 20.10
Bid-YTW : 4.08 %
Volume Highlights
Issue Index Shares
Traded
Notes
BNS.PR.H FixedReset 278,740 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-01-26
Maturity Price : 25.00
Evaluated at bid price : 25.48
Bid-YTW : 4.48 %
TD.PF.H FixedReset 183,426 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.45
Bid-YTW : 4.39 %
TD.PF.G FixedReset 121,876 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 26.75
Bid-YTW : 4.02 %
GWO.PR.R Deemed-Retractible 41,720 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.67
Bid-YTW : 5.62 %
SLF.PR.A Deemed-Retractible 41,260 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.90
Bid-YTW : 5.42 %
CM.PR.O FixedReset 36,000 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-19
Maturity Price : 18.77
Evaluated at bid price : 18.77
Bid-YTW : 4.31 %
There were 15 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
HSE.PR.A FixedReset Quote: 11.85 – 12.25
Spot Rate : 0.4000
Average : 0.2562

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-19
Maturity Price : 11.85
Evaluated at bid price : 11.85
Bid-YTW : 5.18 %

IFC.PR.C FixedReset Quote: 17.46 – 17.84
Spot Rate : 0.3800
Average : 0.2549

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.46
Bid-YTW : 8.53 %

MFC.PR.B Deemed-Retractible Quote: 23.24 – 23.48
Spot Rate : 0.2400
Average : 0.1468

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.24
Bid-YTW : 5.76 %

GWO.PR.I Deemed-Retractible Quote: 22.52 – 22.77
Spot Rate : 0.2500
Average : 0.1641

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.52
Bid-YTW : 6.04 %

MFC.PR.L FixedReset Quote: 17.77 – 18.00
Spot Rate : 0.2300
Average : 0.1496

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.77
Bid-YTW : 8.14 %

CU.PR.I FixedReset Quote: 25.52 – 25.85
Spot Rate : 0.3300
Average : 0.2587

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-01
Maturity Price : 25.00
Evaluated at bid price : 25.52
Bid-YTW : 4.04 %

Market Action

September 16, 2016

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.3586 % 1,683.7
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.3586 % 3,075.8
Floater 4.91 % 4.64 % 89,675 16.17 4 -0.3586 % 1,772.6
OpRet 0.00 % 0.00 % 0 0.00 0 0.0556 % 2,883.3
SplitShare 5.05 % 4.78 % 72,373 2.19 5 0.0556 % 3,443.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0556 % 2,686.6
Perpetual-Premium 5.50 % 4.60 % 67,103 1.97 12 0.0423 % 2,675.3
Perpetual-Discount 5.14 % 5.17 % 92,170 15.00 26 0.0159 % 2,899.7
FixedReset 5.00 % 4.46 % 151,249 6.95 92 0.1109 % 2,033.3
Deemed-Retractible 5.03 % 4.49 % 116,086 3.21 32 -0.0967 % 2,795.7
FloatingReset 2.83 % 4.32 % 31,424 5.01 12 -0.3800 % 2,196.8
Performance Highlights
Issue Index Change Notes
BMO.PR.A FloatingReset -2.37 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.04
Bid-YTW : 5.06 %
CU.PR.C FixedReset -1.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-16
Maturity Price : 17.81
Evaluated at bid price : 17.81
Bid-YTW : 4.44 %
IAG.PR.A Deemed-Retractible -1.46 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.95
Bid-YTW : 5.86 %
BNS.PR.D FloatingReset -1.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.35
Bid-YTW : 6.57 %
TRP.PR.B FixedReset 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-16
Maturity Price : 11.85
Evaluated at bid price : 11.85
Bid-YTW : 4.28 %
TRP.PR.H FloatingReset 1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-16
Maturity Price : 10.41
Evaluated at bid price : 10.41
Bid-YTW : 4.32 %
NA.PR.W FixedReset 1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-16
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 4.40 %
CU.PR.H Perpetual-Discount 1.36 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2024-09-01
Maturity Price : 25.00
Evaluated at bid price : 25.35
Bid-YTW : 5.10 %
TRP.PR.C FixedReset 1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-16
Maturity Price : 13.26
Evaluated at bid price : 13.26
Bid-YTW : 4.30 %
Volume Highlights
Issue Index Shares
Traded
Notes
BNS.PR.H FixedReset 2,738,643 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-01-26
Maturity Price : 25.00
Evaluated at bid price : 25.46
Bid-YTW : 4.49 %
TD.PF.H FixedReset 401,773 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.45
Bid-YTW : 4.53 %
CM.PR.O FixedReset 213,400 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-16
Maturity Price : 18.72
Evaluated at bid price : 18.72
Bid-YTW : 4.30 %
BMO.PR.T FixedReset 104,800 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-16
Maturity Price : 18.56
Evaluated at bid price : 18.56
Bid-YTW : 4.21 %
BMO.PR.S FixedReset 59,156 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-16
Maturity Price : 18.97
Evaluated at bid price : 18.97
Bid-YTW : 4.22 %
CCS.PR.C Deemed-Retractible 54,534 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.31
Bid-YTW : 5.42 %
There were 18 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
PWF.PR.T FixedReset Quote: 19.53 – 20.22
Spot Rate : 0.6900
Average : 0.4239

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-16
Maturity Price : 19.53
Evaluated at bid price : 19.53
Bid-YTW : 4.18 %

PWF.PR.P FixedReset Quote: 13.08 – 13.60
Spot Rate : 0.5200
Average : 0.3425

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-16
Maturity Price : 13.08
Evaluated at bid price : 13.08
Bid-YTW : 4.47 %

IFC.PR.A FixedReset Quote: 15.16 – 15.60
Spot Rate : 0.4400
Average : 0.2884

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.16
Bid-YTW : 9.83 %

IAG.PR.A Deemed-Retractible Quote: 22.95 – 23.29
Spot Rate : 0.3400
Average : 0.2368

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.95
Bid-YTW : 5.86 %

BMO.PR.A FloatingReset Quote: 21.04 – 21.75
Spot Rate : 0.7100
Average : 0.6095

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.04
Bid-YTW : 5.06 %

GWO.PR.L Deemed-Retractible Quote: 25.30 – 25.68
Spot Rate : 0.3800
Average : 0.2874

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.30
Bid-YTW : 5.03 %

Market Action

September 15, 2016

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.1796 % 1,689.8
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.1796 % 3,086.9
Floater 4.89 % 4.62 % 89,967 16.22 4 0.1796 % 1,779.0
OpRet 0.00 % 0.00 % 0 0.00 0 0.0635 % 2,881.7
SplitShare 5.05 % 4.67 % 72,585 2.19 5 0.0635 % 3,441.4
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0635 % 2,685.1
Perpetual-Premium 5.51 % 4.62 % 67,607 2.12 12 0.1011 % 2,674.2
Perpetual-Discount 5.14 % 5.20 % 95,450 15.08 26 0.0667 % 2,899.2
FixedReset 5.01 % 4.47 % 153,371 6.95 91 0.1187 % 2,031.1
Deemed-Retractible 5.02 % 3.34 % 116,977 0.29 32 0.0853 % 2,798.4
FloatingReset 2.82 % 4.33 % 31,279 5.01 12 0.5358 % 2,205.2
Performance Highlights
Issue Index Change Notes
TRP.PR.H FloatingReset -1.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-15
Maturity Price : 10.29
Evaluated at bid price : 10.29
Bid-YTW : 4.37 %
BAM.PF.B FixedReset -1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-15
Maturity Price : 17.60
Evaluated at bid price : 17.60
Bid-YTW : 4.95 %
BAM.PF.G FixedReset -1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-15
Maturity Price : 20.11
Evaluated at bid price : 20.11
Bid-YTW : 4.67 %
BAM.PF.A FixedReset -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-15
Maturity Price : 18.97
Evaluated at bid price : 18.97
Bid-YTW : 4.90 %
TD.PR.Y FixedReset 1.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.95
Bid-YTW : 3.85 %
NA.PR.S FixedReset 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-15
Maturity Price : 18.50
Evaluated at bid price : 18.50
Bid-YTW : 4.44 %
MFC.PR.F FixedReset 1.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.50
Bid-YTW : 10.60 %
NA.PR.W FixedReset 1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-15
Maturity Price : 17.77
Evaluated at bid price : 17.77
Bid-YTW : 4.45 %
IAG.PR.A Deemed-Retractible 1.26 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.29
Bid-YTW : 5.64 %
CM.PR.Q FixedReset 1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-15
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 4.46 %
BNS.PR.D FloatingReset 1.72 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.57
Bid-YTW : 6.34 %
BMO.PR.A FloatingReset 6.37 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.55
Bid-YTW : 4.58 %
Volume Highlights
Issue Index Shares
Traded
Notes
BMO.PR.T FixedReset 332,050 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-15
Maturity Price : 18.51
Evaluated at bid price : 18.51
Bid-YTW : 4.22 %
TD.PF.H FixedReset 179,434 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.44
Bid-YTW : 4.54 %
TD.PF.G FixedReset 136,323 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 26.73
Bid-YTW : 4.03 %
CM.PR.O FixedReset 106,900 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-15
Maturity Price : 18.65
Evaluated at bid price : 18.65
Bid-YTW : 4.31 %
BIP.PR.C FixedReset 61,385 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-09-30
Maturity Price : 25.00
Evaluated at bid price : 25.33
Bid-YTW : 5.04 %
MFC.PR.K FixedReset 50,800 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.20
Bid-YTW : 8.48 %
There were 27 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
SLF.PR.J FloatingReset Quote: 12.76 – 13.25
Spot Rate : 0.4900
Average : 0.3107

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.76
Bid-YTW : 11.03 %

FTS.PR.M FixedReset Quote: 20.05 – 20.27
Spot Rate : 0.2200
Average : 0.1364

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-15
Maturity Price : 20.05
Evaluated at bid price : 20.05
Bid-YTW : 4.20 %

FTS.PR.H FixedReset Quote: 13.75 – 13.95
Spot Rate : 0.2000
Average : 0.1205

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-15
Maturity Price : 13.75
Evaluated at bid price : 13.75
Bid-YTW : 4.07 %

NA.PR.Q FixedReset Quote: 23.65 – 23.90
Spot Rate : 0.2500
Average : 0.1785

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.65
Bid-YTW : 4.51 %

PWF.PR.P FixedReset Quote: 13.08 – 13.29
Spot Rate : 0.2100
Average : 0.1478

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-15
Maturity Price : 13.08
Evaluated at bid price : 13.08
Bid-YTW : 4.47 %

FTS.PR.G FixedReset Quote: 17.80 – 17.99
Spot Rate : 0.1900
Average : 0.1286

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-15
Maturity Price : 17.80
Evaluated at bid price : 17.80
Bid-YTW : 4.16 %

Market Action

September 14, 2016

PerpetualDiscounts now yield 5.17%, equivalent to 6.72% interest at the standard equivalency factor of 1.3x. Long corporates now yield about 3.80%, so the pre-tax interest-equivalent spread is now about 290bp, a significant narrowing from the 305bp reported September 7.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.2151 % 1,686.8
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.2151 % 3,081.4
Floater 4.90 % 4.63 % 90,808 16.20 4 -0.2151 % 1,775.8
OpRet 0.00 % 0.00 % 0 0.00 0 0.2389 % 2,879.9
SplitShare 5.05 % 4.78 % 73,107 2.19 5 0.2389 % 3,439.2
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.2389 % 2,683.4
Perpetual-Premium 5.51 % 4.63 % 66,648 2.12 12 0.0033 % 2,671.5
Perpetual-Discount 5.14 % 5.17 % 96,219 15.11 26 0.0603 % 2,897.3
FixedReset 5.02 % 4.49 % 155,247 6.95 91 -0.0219 % 2,028.6
Deemed-Retractible 5.03 % 4.48 % 120,298 3.22 32 0.0357 % 2,796.0
FloatingReset 2.84 % 4.20 % 28,950 5.02 12 -0.4373 % 2,193.5
Performance Highlights
Issue Index Change Notes
BNS.PR.D FloatingReset -3.32 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.24
Bid-YTW : 6.68 %
TRP.PR.B FixedReset -2.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-14
Maturity Price : 11.72
Evaluated at bid price : 11.72
Bid-YTW : 4.32 %
TRP.PR.C FixedReset -1.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-14
Maturity Price : 13.06
Evaluated at bid price : 13.06
Bid-YTW : 4.37 %
TRP.PR.A FixedReset -1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-14
Maturity Price : 14.86
Evaluated at bid price : 14.86
Bid-YTW : 4.64 %
BNS.PR.A FloatingReset -1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.02
Bid-YTW : 4.20 %
SLF.PR.J FloatingReset 1.19 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.80
Bid-YTW : 10.99 %
IFC.PR.C FixedReset 1.21 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.51
Bid-YTW : 8.45 %
VNR.PR.A FixedReset 1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-14
Maturity Price : 18.48
Evaluated at bid price : 18.48
Bid-YTW : 4.91 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PF.H FixedReset 402,304 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.45
Bid-YTW : 4.53 %
TD.PF.G FixedReset 288,385 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 26.73
Bid-YTW : 4.03 %
W.PR.M FixedReset 88,668 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-15
Maturity Price : 25.00
Evaluated at bid price : 25.50
Bid-YTW : 4.83 %
TD.PF.C FixedReset 72,843 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-14
Maturity Price : 18.23
Evaluated at bid price : 18.23
Bid-YTW : 4.31 %
TD.PF.A FixedReset 63,038 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-14
Maturity Price : 18.47
Evaluated at bid price : 18.47
Bid-YTW : 4.26 %
BAM.PF.C Perpetual-Discount 55,512 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-14
Maturity Price : 22.66
Evaluated at bid price : 22.99
Bid-YTW : 5.27 %
There were 49 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
HSE.PR.A FixedReset Quote: 11.91 – 12.25
Spot Rate : 0.3400
Average : 0.2187

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-14
Maturity Price : 11.91
Evaluated at bid price : 11.91
Bid-YTW : 5.12 %

PWF.PR.S Perpetual-Discount Quote: 23.48 – 23.75
Spot Rate : 0.2700
Average : 0.1750

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-14
Maturity Price : 23.10
Evaluated at bid price : 23.48
Bid-YTW : 5.16 %

CU.PR.H Perpetual-Discount Quote: 25.01 – 25.42
Spot Rate : 0.4100
Average : 0.3154

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-14
Maturity Price : 24.60
Evaluated at bid price : 25.01
Bid-YTW : 5.27 %

BMO.PR.A FloatingReset Quote: 20.26 – 20.90
Spot Rate : 0.6400
Average : 0.5536

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.26
Bid-YTW : 5.81 %

W.PR.H Perpetual-Discount Quote: 25.10 – 25.50
Spot Rate : 0.4000
Average : 0.3180

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-14
Maturity Price : 24.88
Evaluated at bid price : 25.10
Bid-YTW : 5.57 %

GWO.PR.N FixedReset Quote: 14.05 – 14.35
Spot Rate : 0.3000
Average : 0.2192

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.05
Bid-YTW : 9.95 %

Market Action

September 13, 2016

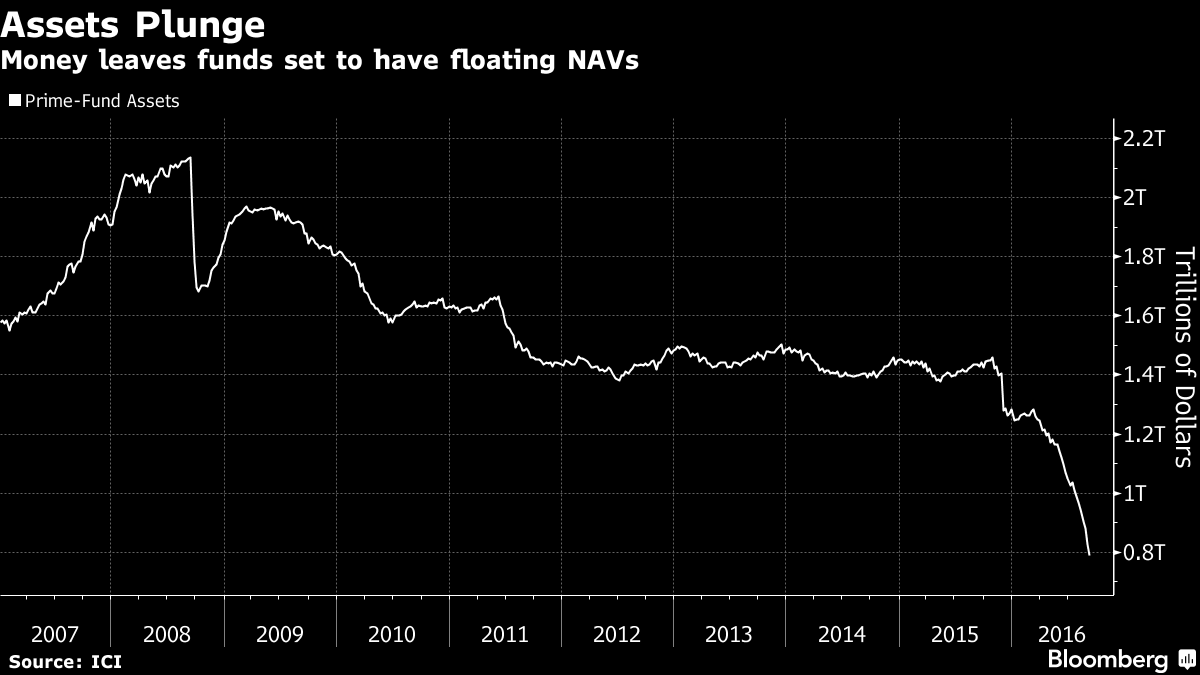
We are approaching the end-game of the US Money Market Fund re-regulation:

With a seismic overhaul of the $2.6 trillion money-market industry weeks away from kicking in, money managers are bracing for a last-minute exodus of as much as $300 billion from funds in regulators’ cross hairs.

Prime funds, which seek higher yields by buying securities like commercial paper, are at the center of the upheaval. Their assets have already plunged by almost $700 billion since the start of 2015, to $789 billion, Investment Company Institute data show. The outflow has rippled across financial markets, shattering demand for banks’ and other companies’ short-term debt and raising their funding costs.

The transformation of the money-fund industry, where investors turn to park cash, is a result of regulators’ efforts to make the financial system safer in the aftermath of the credit crisis. The key date is Oct. 14, when rules take effect mandating that institutional prime and tax-exempt funds end an over-30-year tradition of fixing shares at $1. Funds that hold only government debt will be able to maintain that level. Companies such as Federated Investors Inc. and Fidelity Investments, which have already reduced or altered prime offerings, are preparing in case investors yank more money as the new era approaches.
…
A major repercussion of the flight from prime funds is that there’s less money flowing into commercial paper and certificates of deposit, which banks depend on for funding. As a result, banks’ unsecured lending rates, such as the dollar London interbank offered rate, have soared. Three-month Libor reached about 0.86 percent Tuesday, the highest since 2009.

PrimeFundAssets_160913
Click for Big
HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.6155 % 1,690.4
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.6155 % 3,088.0
Floater 4.89 % 4.61 % 88,507 16.24 4 0.6155 % 1,779.6
OpRet 0.00 % 0.00 % 0 0.00 0 -0.1749 % 2,873.0
SplitShare 5.07 % 4.72 % 73,931 2.19 5 -0.1749 % 3,431.0
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.1749 % 2,677.0
Perpetual-Premium 5.51 % 4.64 % 68,955 1.98 12 -0.1530 % 2,671.4
Perpetual-Discount 5.15 % 5.17 % 100,156 15.09 26 -0.0359 % 2,895.6
FixedReset 5.01 % 4.50 % 153,014 6.95 91 -0.0695 % 2,029.1
Deemed-Retractible 5.03 % 4.04 % 118,542 0.37 32 -0.0673 % 2,795.0
FloatingReset 2.83 % 3.99 % 26,983 5.02 12 -0.0393 % 2,203.1
Performance Highlights
Issue Index Change Notes
TRP.PR.F FloatingReset -2.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-13
Maturity Price : 13.38
Evaluated at bid price : 13.38
Bid-YTW : 4.56 %
CU.PR.C FixedReset -2.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-13
Maturity Price : 18.07
Evaluated at bid price : 18.07
Bid-YTW : 4.37 %
PWF.PR.T FixedReset -1.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-13
Maturity Price : 19.47
Evaluated at bid price : 19.47
Bid-YTW : 4.19 %
IFC.PR.C FixedReset -1.50 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.30
Bid-YTW : 8.62 %
MFC.PR.N FixedReset -1.47 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.13
Bid-YTW : 7.97 %
VNR.PR.A FixedReset -1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-13
Maturity Price : 18.24
Evaluated at bid price : 18.24
Bid-YTW : 4.98 %
TRP.PR.G FixedReset -1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-13
Maturity Price : 20.07
Evaluated at bid price : 20.07
Bid-YTW : 4.64 %
GWO.PR.N FixedReset 1.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.17
Bid-YTW : 9.82 %
BAM.PF.F FixedReset 1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-13
Maturity Price : 19.93
Evaluated at bid price : 19.93
Bid-YTW : 4.68 %
BAM.PF.G FixedReset 1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-13
Maturity Price : 20.29
Evaluated at bid price : 20.29
Bid-YTW : 4.62 %
BAM.PR.Z FixedReset 1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-13
Maturity Price : 19.15
Evaluated at bid price : 19.15
Bid-YTW : 4.93 %
BAM.PF.A FixedReset 1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-13
Maturity Price : 19.15
Evaluated at bid price : 19.15
Bid-YTW : 4.85 %
BAM.PR.K Floater 1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-13
Maturity Price : 10.29
Evaluated at bid price : 10.29
Bid-YTW : 4.59 %
BAM.PF.E FixedReset 1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-13
Maturity Price : 18.91
Evaluated at bid price : 18.91
Bid-YTW : 4.63 %
BAM.PF.B FixedReset 1.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-13
Maturity Price : 17.94
Evaluated at bid price : 17.94
Bid-YTW : 4.85 %
BAM.PR.R FixedReset 1.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-13
Maturity Price : 15.45
Evaluated at bid price : 15.45
Bid-YTW : 4.89 %
BAM.PR.X FixedReset 2.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-13
Maturity Price : 13.50
Evaluated at bid price : 13.50
Bid-YTW : 4.79 %
BAM.PR.T FixedReset 2.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-13
Maturity Price : 15.45
Evaluated at bid price : 15.45
Bid-YTW : 4.99 %
BAM.PR.S FloatingReset 3.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-13
Maturity Price : 14.70
Evaluated at bid price : 14.70
Bid-YTW : 4.80 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PF.H FixedReset 663,207 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.47
Bid-YTW : 4.51 %
BAM.PF.C Perpetual-Discount 166,291 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-13
Maturity Price : 22.58
Evaluated at bid price : 22.90
Bid-YTW : 5.29 %
FTS.PR.H FixedReset 132,900 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-13
Maturity Price : 13.75
Evaluated at bid price : 13.75
Bid-YTW : 4.07 %
TD.PF.G FixedReset 115,200 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 26.75
Bid-YTW : 4.01 %
BMO.PR.Z Perpetual-Premium 84,833 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2024-08-25
Maturity Price : 25.00
Evaluated at bid price : 25.49
Bid-YTW : 4.77 %
TD.PF.A FixedReset 66,700 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-13
Maturity Price : 18.40
Evaluated at bid price : 18.40
Bid-YTW : 4.28 %
There were 46 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
IFC.PR.A FixedReset Quote: 15.24 – 15.75
Spot Rate : 0.5100
Average : 0.2929

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.24
Bid-YTW : 9.74 %

TRP.PR.F FloatingReset Quote: 13.38 – 13.90
Spot Rate : 0.5200
Average : 0.3269

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-13
Maturity Price : 13.38
Evaluated at bid price : 13.38
Bid-YTW : 4.56 %

TRP.PR.H FloatingReset Quote: 10.45 – 10.95
Spot Rate : 0.5000
Average : 0.3902

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-13
Maturity Price : 10.45
Evaluated at bid price : 10.45
Bid-YTW : 4.30 %

PVS.PR.B SplitShare Quote: 24.78 – 25.09
Spot Rate : 0.3100
Average : 0.2153

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2019-01-10
Maturity Price : 25.00
Evaluated at bid price : 24.78
Bid-YTW : 4.82 %

MFC.PR.F FixedReset Quote: 13.32 – 13.59
Spot Rate : 0.2700
Average : 0.1876

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.32
Bid-YTW : 10.79 %

POW.PR.B Perpetual-Discount Quote: 25.06 – 25.27
Spot Rate : 0.2100
Average : 0.1436

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-13
Maturity Price : 24.85
Evaluated at bid price : 25.06
Bid-YTW : 5.42 %

Market Action

September 12, 2016

Fed policy? Here’s the dovish view:

Federal Reserve Governor Lael Brainard counseled continued prudence in tightening monetary policy, even as she said the economy is making gradual progress toward achieving the central bank’s goals.

“The case to tighten policy preemptively is less compelling” in an environment where declining unemployment has been slow to spur faster inflation, Brainard said Monday, according to the text of her prepared remarks in Chicago. She made no reference to a specific meeting of the policy-setting Federal Open Market Committee.
…
In Monday’s speech, Brainard highlighted five major reasons for caution: inflation is less responsive to labor-market improvement than in the past, labor-market slack seems to persist, financial transmission from foreign markets is strong and poses a risk, and the interest rate where policy moves from easy to tight is lower than in the past — and is likely to stay there for some time. Her final point is that monetary policy is less able to respond to negative shocks than to a quick pickup in demand.

Despite that cautious view, Brainard also pointed to recent developments that show the economy is moving toward achieving the Fed’s goals of maximum employment and 2 percent inflation. She said the job market is making progress and getting closer to full employment and the Fed has “seen signs of progress on our inflation mandate.”

And a hawkish view:

Federal Reserve Bank of Atlanta President Dennis Lockhart repeated his call for a “serious discussion” about raising interest rates at the U.S. central bank’s meeting later this month, even after some recent disappointing economic indicators.

“Notwithstanding a few recent weak monthly reports — from the Institute for Supply Management, for example — I am satisfied at this point that conditions warrant that serious discussion,” Lockhart said Monday in Atlanta.
…
“After relatively weak growth over the first half of the year, I expect a stronger second half,” Lockhart said to the National Association for Business Economics, citing the bank’s estimate. Third-quarter growth was tracking at 3.3 percent on Friday, according to the Atlanta Fed’s tracking estimate.

The economy is “making progress” toward full employment, Lockhart said, though progress in moving inflation toward the 2 percent goal may have stalled.

“The inflation data overall have not been suggesting disinflation or deflation, but the flat trend line is enough below target that, in my opinion, the shortfall cannot be considered immaterial,” he said. “I find this to be an awkward state of affairs.”

And a market view:

U.S. stocks rebounded after the biggest rout since June wiped about $500 billion from the value of equities, the dollar fell and Treasuries erased losses as the Federal Reserve’s Lael Brainard remained dovish in her approach to tighter monetary policy. Emerging-market assets slumped.

The S&P 500 Index jumped the most in two months after sinking 2.5 percent Friday, holding gains after Brainard urged “prudence” in removing accommodation. The dollar fell for the first time in four sessions as the odds for a rate hike next week slid to 22 percent. Ten-year Treasuries remained little changed, with yields near 1.68 percent. Shares in Europe and Asia, which were closed Friday when the selloff began, dropped Monday. Emerging-market equities tumbled 2 percent, while oil rebounded past $46 a barrel.

In a sign of the times, rent control may be coming to the San Francisco bay area:

The concept of rent control, once found mostly in large cities, is spreading to the Bay Area’s suburbs, even though virtually every economist thinks it’s a bad idea.

Six Bay Area cities have measures on the November ballot that would protect existing tenants from the stratospheric rent increases that are a result of job growth far outstripping housing creation.
…
A 2012 survey by the University of Chicago’s Booth School of Business asked respected economists if they agreed that rent-control ordinances in cities such as New York and San Francisco have improved the quantity and quality of affordable rental housing over the past three decades. Eighty-one percent disagreed, 2 percent agreed and 9 percent were uncertain or had no opinion.

In 2013, Peter Tatian of the Urban Institute reviewed academic research on rent control and found “very little evidence that rent control is a good policy.” The strongest finding of one comprehensive survey was that “tenants in noncontrolled units pay higher rents than they would without the presence of rent control; one reason being that landlords need to make up the difference for lower rents in controlled units.”
…
In a report issued in February, California’s Legislative Analyst’s Office warned that rent control could encourage property owners to cut back on maintenance and repairs. “Over time, this can result in a decline in the overall quality of a community’s housing stock,” it said.

There’s a certain amount of agitation in Vancouver for more rent control:

Since 2002, British Columbia has had a two-tiered system where fixed-term renters get no protection, while those who rent month-to-month do. The legislation restricts landlords with monthly renters to a set annual increase. This year, the cap is 2.5 per cent.

Yet landlords who have the benefit of long-term tenants get the added bonus of being able to set whatever price they want when the term is up. It can lead to gouging, particularly now when the vacancy rate in Vancouver is virtually zero.

It means that renters are left with a lousy choice: Take a short-term rental and risk being asked to leave with only 30 days’ notice or sign a lease and risk having the rent skyrocket at the end of the term.

In Toronto, of course, rent control was introduced in the ’80s by Bill Davis (under election pressure from the NDP) and construction of rental apartment buildings basically halted. There have been a few buildings lately, but it’s my understanding that these developments only make sense if you can get a package of land from the city on sweetheart terms.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.3594 % 1,680.1
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.3594 % 3,069.1
Floater 4.89 % 4.67 % 88,614 16.00 4 0.3594 % 1,768.8
OpRet 0.00 % 0.00 % 0 0.00 0 -0.1904 % 2,878.1
SplitShare 5.06 % 4.68 % 76,054 2.20 5 -0.1904 % 3,437.0
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.1904 % 2,681.7
Perpetual-Premium 5.50 % 4.61 % 69,354 1.99 12 0.0130 % 2,675.5
Perpetual-Discount 5.13 % 5.17 % 99,053 14.91 26 -0.3426 % 2,896.6
FixedReset 5.00 % 4.48 % 149,903 6.96 91 -0.1558 % 2,030.5
Deemed-Retractible 5.02 % 4.84 % 118,742 3.23 32 -0.2526 % 2,796.9
FloatingReset 2.82 % 4.01 % 27,894 5.02 12 -0.0393 % 2,204.0
Performance Highlights
Issue Index Change Notes
GWO.PR.N FixedReset -1.75 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.01
Bid-YTW : 9.98 %
CCS.PR.C Deemed-Retractible -1.75 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.17
Bid-YTW : 5.50 %
MFC.PR.F FixedReset -1.33 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.31
Bid-YTW : 10.79 %
GWO.PR.I Deemed-Retractible -1.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.45
Bid-YTW : 6.07 %
BAM.PF.A FixedReset -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-12
Maturity Price : 19.17
Evaluated at bid price : 19.17
Bid-YTW : 4.94 %
FTS.PR.J Perpetual-Discount -1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-12
Maturity Price : 23.27
Evaluated at bid price : 23.71
Bid-YTW : 5.02 %
SLF.PR.J FloatingReset 1.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.74
Bid-YTW : 11.04 %
FTS.PR.H FixedReset 1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-12
Maturity Price : 13.75
Evaluated at bid price : 13.75
Bid-YTW : 4.07 %
SLF.PR.I FixedReset 2.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.29
Bid-YTW : 7.93 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PF.H FixedReset 627,315 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.48
Bid-YTW : 4.50 %
TD.PF.G FixedReset 126,300 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 26.77
Bid-YTW : 3.98 %
TRP.PR.J FixedReset 96,400 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-31
Maturity Price : 25.00
Evaluated at bid price : 26.36
Bid-YTW : 4.29 %
W.PR.M FixedReset 88,047 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-15
Maturity Price : 25.00
Evaluated at bid price : 25.50
Bid-YTW : 4.83 %
CM.PR.P FixedReset 78,030 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-12
Maturity Price : 18.30
Evaluated at bid price : 18.30
Bid-YTW : 4.30 %
NA.PR.A FixedReset 70,808 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-15
Maturity Price : 25.00
Evaluated at bid price : 26.32
Bid-YTW : 4.53 %
There were 30 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
SLF.PR.I FixedReset Quote: 18.29 – 19.16
Spot Rate : 0.8700
Average : 0.5486

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.29
Bid-YTW : 7.93 %

GWO.PR.M Deemed-Retractible Quote: 26.01 – 26.52
Spot Rate : 0.5100
Average : 0.3865

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-10-12
Maturity Price : 25.75
Evaluated at bid price : 26.01
Bid-YTW : -9.74 %

GWO.PR.N FixedReset Quote: 14.01 – 14.39
Spot Rate : 0.3800
Average : 0.2629

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.01
Bid-YTW : 9.98 %

RY.PR.W Perpetual-Discount Quote: 25.01 – 25.23
Spot Rate : 0.2200
Average : 0.1292

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-12
Maturity Price : 24.69
Evaluated at bid price : 25.01
Bid-YTW : 4.92 %

W.PR.K FixedReset Quote: 25.62 – 25.92
Spot Rate : 0.3000
Average : 0.2119

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-01-15
Maturity Price : 25.00
Evaluated at bid price : 25.62
Bid-YTW : 4.86 %

GWO.PR.I Deemed-Retractible Quote: 22.45 – 22.77
Spot Rate : 0.3200
Average : 0.2377

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.45
Bid-YTW : 6.07 %

Market Action

September 9, 2016

Common equity took a hit today:

After two months in which even a 50-point move in the Dow Jones Industrial Average was reason for excitement, investors were shaken out of their slumber as central bankers signaled reluctance to extend stimulus and sent U.S. stocks to their worst week since February.

Damage was worst in the final session, when Boston Federal Reserve President Eric Rosengren warned against waiting too long to raise interest rates. Selling built after European Central Bank President Mario Draghi downplayed the need for more measures to boost growth a day earlier. When it was over, the S&P 500 Index was down 2.3 percent to 2,127.81 on the week, with Friday’s plunge wiping out a slight gain over the first three days.

Bonds did not escape the carnage:

Draghi’s reticence accelerated a selloff in bonds that extended from Europe to the U.S. and Japan, with longer-dated securities, which have been outperforming in recent months, being the hardest hit. While yields are still low compared with historical averages, they are quickly rising from records reached earlier this year, recalling the bond rout of 2015, which saw German 10-year yields climb more than a percentage point in less than two months.

The yield on German 30-year bonds climbed 10 basis points to 0.60 percent, adding to a nine-basis-point jump the previous day. The rate on similar-maturity U.S. securities rose seven basis points to 2.38 percent.

Chances of the Fed raising rates at the September meeting climbed to 38 percent, up 16 percentage points from Wednesday, according to fed funds futures.

The U.K. and Japan, two markets which have help drive the global bond rally this year, also saw losses. The yield on 10-year gilts rose to a one-month high of 0.84 percent and the Japanese 10-year yield, which has been below zero since March, climbed to minus 0.02 percent.

Quantitative Investing is now a strategy that over-promises:

Banks and investment funds are hiring quants — people with training in physics or higher mathematics — as market intervention by central banks make it difficult to post robust profits. Money managers including UBS, Credit Suisse Group AG and GAM Holding AG are betting that the strategies widely used by the hedge-fund industry will help convince clients spooked by market volatility to invest their money instead of keeping it in cash.

The bank decided to diversify and increase the number of offerings to clients because of low interest rates, Haefele said. As part of the strategy, it raised $471 million for an oncology fund earlier this year and hired a team led by Vinay Pande from hedge fund Brevan Howard Asset Management to focus on short-term investment strategies earlier this year.

UBS manages more than $1.5 billion through quant analysis, Andreas Kessler, a spokesman for the bank, said in an e-mail. The wealth management unit started its first directly quant-based offering last year, he said.

Clients who hand over investment decisions to Haefele and his team have on average earned more on their portfolio than those who make decisions themselves, he said. That’s because they may find themselves exposed to a market downturn and fail to reinvest when things improve, he said. The bank does not disclose client returns.

Investment returns are a chaotic system; you cannot predict future absolute returns. Relative returns can be predicted a little bit, provided the two comparators are closely related. But, since UBS does not disclose client returns they’ll be able to get away with any claims they want for a long time.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.2867 % 1,674.0
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.2867 % 3,058.1
Floater 4.91 % 4.70 % 88,118 15.95 4 -0.2867 % 1,762.4
OpRet 0.00 % 0.00 % 0 0.00 0 -0.1030 % 2,883.6
SplitShare 5.05 % 4.54 % 78,770 2.21 5 -0.1030 % 3,443.6
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.1030 % 2,686.8
Perpetual-Premium 5.50 % 4.61 % 71,195 1.99 12 -0.0586 % 2,675.1
Perpetual-Discount 5.12 % 5.14 % 99,985 14.96 26 -0.0284 % 2,906.6
FixedReset 4.99 % 4.44 % 148,604 6.98 90 -0.2215 % 2,033.7
Deemed-Retractible 5.01 % 4.80 % 116,630 3.24 32 -0.1166 % 2,804.0
FloatingReset 2.82 % 3.96 % 27,763 5.03 12 -0.2135 % 2,204.8
Performance Highlights
Issue Index Change Notes
SLF.PR.J FloatingReset -2.40 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.60
Bid-YTW : 11.19 %
PWF.PR.P FixedReset -1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-09
Maturity Price : 13.15
Evaluated at bid price : 13.15
Bid-YTW : 4.44 %
MFC.PR.I FixedReset -1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.65
Bid-YTW : 7.12 %
TD.PF.D FixedReset -1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-09
Maturity Price : 19.87
Evaluated at bid price : 19.87
Bid-YTW : 4.48 %
SLF.PR.H FixedReset -1.26 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.70
Bid-YTW : 9.40 %
MFC.PR.L FixedReset -1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.98
Bid-YTW : 7.92 %
MFC.PR.F FixedReset -1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.49
Bid-YTW : 10.59 %
MFC.PR.N FixedReset -1.02 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.47
Bid-YTW : 7.68 %
FTS.PR.G FixedReset -1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-09
Maturity Price : 17.79
Evaluated at bid price : 17.79
Bid-YTW : 4.16 %
CCS.PR.C Deemed-Retractible 1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.60
Bid-YTW : 5.23 %
IFC.PR.A FixedReset 1.72 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.38
Bid-YTW : 9.84 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PF.H FixedReset 662,052 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.44
Bid-YTW : 4.52 %
RY.PR.A Deemed-Retractible 153,178 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.01
Bid-YTW : 4.51 %
TD.PF.G FixedReset 105,525 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 26.75
Bid-YTW : 3.99 %
TRP.PR.J FixedReset 91,616 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-31
Maturity Price : 25.00
Evaluated at bid price : 26.28
Bid-YTW : 4.35 %
W.PR.K FixedReset 89,924 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-01-15
Maturity Price : 25.00
Evaluated at bid price : 25.57
Bid-YTW : 4.90 %
TD.PF.A FixedReset 67,445 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-09
Maturity Price : 18.58
Evaluated at bid price : 18.58
Bid-YTW : 4.23 %
There were 21 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
TD.PF.F Perpetual-Discount Quote: 25.34 – 25.78
Spot Rate : 0.4400
Average : 0.2778

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2024-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.34
Bid-YTW : 4.80 %

GWO.PR.M Deemed-Retractible Quote: 26.16 – 26.52
Spot Rate : 0.3600
Average : 0.2511

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-10-09
Maturity Price : 25.75
Evaluated at bid price : 26.16
Bid-YTW : -16.80 %

HSE.PR.C FixedReset Quote: 19.26 – 19.65
Spot Rate : 0.3900
Average : 0.2837

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-09
Maturity Price : 19.26
Evaluated at bid price : 19.26
Bid-YTW : 5.17 %

PWF.PR.T FixedReset Quote: 19.80 – 20.16
Spot Rate : 0.3600
Average : 0.2689

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-09
Maturity Price : 19.80
Evaluated at bid price : 19.80
Bid-YTW : 4.11 %

RY.PR.Q FixedReset Quote: 26.41 – 26.63
Spot Rate : 0.2200
Average : 0.1294

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-24
Maturity Price : 25.00
Evaluated at bid price : 26.41
Bid-YTW : 4.25 %

HSE.PR.E FixedReset Quote: 20.90 – 21.20
Spot Rate : 0.3000
Average : 0.2104

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-09
Maturity Price : 20.90
Evaluated at bid price : 20.90
Bid-YTW : 5.19 %

Market Action

September 8, 2016

There is great news from the world of drones:

In what’s sure to be a college student’s dream come true, drones will soon be delivering burritos on the campus of Virginia Tech.

The experimental service, to begin this month and last just a few weeks, is a test by Project Wing, a unit of Google’s parent company Alphabet Inc. Chipotle Mexican Grill Inc. and the Blacksburg, Virginia, university have agreed to participate.
…
Project Wing will use self-guided hybrids that can fly like a plane or hover like a helicopter. They will make deliveries from a Chipotle food truck to assess the accuracy of navigation systems and how people respond.

The devices will hover overhead and lower the Chipotle edibles with a winch.

Part of the experiment will be to see how well the packaging protects the chow and keeps it warm. Food was selected as the demonstration cargo because it’s a challenge. The company is already at work on a more sophisticated second version of the aircraft that won’t be used in the tests, Vos said.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.0179 % 1,678.9
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.0179 % 3,066.9
Floater 4.89 % 4.67 % 89,168 16.00 4 -0.0179 % 1,767.5
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0554 % 2,886.5
SplitShare 5.04 % 4.38 % 81,897 2.21 5 -0.0554 % 3,447.1
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0554 % 2,689.6
Perpetual-Premium 5.50 % 3.65 % 72,300 0.14 12 0.1695 % 2,676.7
Perpetual-Discount 5.12 % 5.14 % 101,211 14.97 26 0.0632 % 2,907.4
FixedReset 4.98 % 4.38 % 149,737 6.99 90 0.5449 % 2,038.2
Deemed-Retractible 5.00 % 4.77 % 117,843 3.24 32 0.3256 % 2,807.3
FloatingReset 2.84 % 3.95 % 28,702 5.03 12 0.1702 % 2,209.5
Performance Highlights
Issue Index Change Notes
HSE.PR.A FixedReset 1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-08
Maturity Price : 12.02
Evaluated at bid price : 12.02
Bid-YTW : 5.01 %
BAM.PR.R FixedReset 1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-08
Maturity Price : 15.60
Evaluated at bid price : 15.60
Bid-YTW : 4.87 %
BMO.PR.S FixedReset 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-08
Maturity Price : 19.19
Evaluated at bid price : 19.19
Bid-YTW : 4.12 %
SLF.PR.A Deemed-Retractible 1.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.21
Bid-YTW : 5.21 %
SLF.PR.J FloatingReset 1.18 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.91
Bid-YTW : 10.87 %
BMO.PR.Q FixedReset 1.21 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.07
Bid-YTW : 6.19 %
FTS.PR.M FixedReset 1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-08
Maturity Price : 20.40
Evaluated at bid price : 20.40
Bid-YTW : 4.07 %
TRP.PR.G FixedReset 1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-08
Maturity Price : 20.60
Evaluated at bid price : 20.60
Bid-YTW : 4.48 %
FTS.PR.K FixedReset 1.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-08
Maturity Price : 18.12
Evaluated at bid price : 18.12
Bid-YTW : 3.99 %
MFC.PR.H FixedReset 1.78 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.20
Bid-YTW : 6.20 %
MFC.PR.I FixedReset 2.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.92
Bid-YTW : 6.88 %
MFC.PR.K FixedReset 2.19 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.29
Bid-YTW : 8.34 %
GWO.PR.N FixedReset 2.30 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.25
Bid-YTW : 9.70 %
MFC.PR.L FixedReset 2.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.18
Bid-YTW : 7.73 %
BAM.PR.Z FixedReset 2.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-08
Maturity Price : 19.39
Evaluated at bid price : 19.39
Bid-YTW : 4.91 %
MFC.PR.J FixedReset 2.45 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.85
Bid-YTW : 7.43 %
MFC.PR.G FixedReset 2.47 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.50
Bid-YTW : 7.12 %
BAM.PR.X FixedReset 2.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-08
Maturity Price : 13.60
Evaluated at bid price : 13.60
Bid-YTW : 4.82 %
MFC.PR.N FixedReset 2.87 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.66
Bid-YTW : 7.50 %
MFC.PR.M FixedReset 2.97 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.75
Bid-YTW : 7.49 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PF.H FixedReset 2,936,651 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.43
Bid-YTW : 4.53 %
RY.PR.J FixedReset 107,837 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-08
Maturity Price : 19.79
Evaluated at bid price : 19.79
Bid-YTW : 4.39 %
POW.PR.D Perpetual-Discount 60,364 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-08
Maturity Price : 24.29
Evaluated at bid price : 24.60
Bid-YTW : 5.15 %
PWF.PR.I Perpetual-Premium 59,533 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-10-08
Maturity Price : 25.00
Evaluated at bid price : 25.64
Bid-YTW : -16.35 %
NA.PR.A FixedReset 54,400 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-15
Maturity Price : 25.00
Evaluated at bid price : 26.30
Bid-YTW : 4.54 %
PWF.PR.L Perpetual-Discount 53,200 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-08
Maturity Price : 24.68
Evaluated at bid price : 25.00
Bid-YTW : 5.15 %
There were 51 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
MFC.PR.M FixedReset Quote: 18.75 – 19.23
Spot Rate : 0.4800
Average : 0.2947

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.75
Bid-YTW : 7.49 %

RY.PR.F Deemed-Retractible Quote: 25.20 – 25.60
Spot Rate : 0.4000
Average : 0.2379

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-10-08
Maturity Price : 25.00
Evaluated at bid price : 25.20
Bid-YTW : -3.03 %

POW.PR.G Perpetual-Premium Quote: 25.82 – 26.30
Spot Rate : 0.4800
Average : 0.3322

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-04-15
Maturity Price : 25.25
Evaluated at bid price : 25.82
Bid-YTW : 5.14 %

CCS.PR.C Deemed-Retractible Quote: 24.27 – 24.79
Spot Rate : 0.5200
Average : 0.3725

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.27
Bid-YTW : 5.43 %

RY.PR.Z FixedReset Quote: 18.70 – 19.04
Spot Rate : 0.3400
Average : 0.2162

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-08
Maturity Price : 18.70
Evaluated at bid price : 18.70
Bid-YTW : 4.09 %

FTS.PR.H FixedReset Quote: 13.60 – 13.90
Spot Rate : 0.3000
Average : 0.2035

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-08
Maturity Price : 13.60
Evaluated at bid price : 13.60
Bid-YTW : 4.05 %

Market Action

September 7, 2016

Negative interest rates have a silver lining for some firms!

It’s a sign the world is getting used to negative interest rates when what once seemed bizarre starts looking like the norm.

Consider Switzerland, where more and more companies are taking out insurance policies to protect their cash hoards from theft or damage.

“Because of the low interest rate level, we note increasing demand for insurance solutions for the storage of cash,” said Philipp Surholt at Zurich Insurance Group AG, among underwriters reporting a surge in such requests. “We’re seeing demand for coverage for sums ranging from 100 million to 500 million francs.”
…
Helvetia Holding AG said it charges about 1,000 francs ($1,020) a year to insure 1 million francs, a fraction of the 7,500 francs a company would pay to park the same amount in a bank for a year — assuming the lender passes on the full charge. But that amount doesn’t include the cost of logistics such as transport or security features like reinforced walls, guards and alarm systems.

Companies need to save a lot on bank fees for cash storage to be economical because, in addition to insurance, they have to assume the costs of managing the money, said Roberto Brunazzi, a spokesman for Baloise Holding AG. He said the company has long offered such coverage “but there has been a noticeable increase and now it’s becoming more commonplace.”

Switzerland’s continued use of high-denomination banknotes adds to the appeal of self-storage: About 1 million francs worth of 1,000-franc bills can fit in a small box.

PerpetualDiscounts now yield 5.12%, equivalent to 6.66% interest at the standard equivalency factor of 1.3x. Long corporates yield a hair over 3.60%, so the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) is now about 305bp, a slight (and perhaps spurious) widening from the 300bp reported August 31.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.5168 % 1,679.2
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.5168 % 3,067.5
Floater 4.89 % 4.67 % 82,578 16.00 4 -0.5168 % 1,767.8
OpRet 0.00 % 0.00 % 0 0.00 0 0.0634 % 2,888.1
SplitShare 5.04 % 4.38 % 85,148 2.21 5 0.0634 % 3,449.0
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0634 % 2,691.1
Perpetual-Premium 5.51 % 4.62 % 73,198 2.00 12 -0.0782 % 2,672.2
Perpetual-Discount 5.12 % 5.13 % 102,217 15.04 26 -0.0821 % 2,905.6
FixedReset 5.01 % 4.36 % 142,865 7.06 89 -0.8808 % 2,027.1
Deemed-Retractible 5.02 % 4.79 % 117,822 3.24 32 -0.0928 % 2,798.2
FloatingReset 2.85 % 3.97 % 29,679 5.03 12 -0.1960 % 2,205.8
Performance Highlights
Issue Index Change Notes
BAM.PR.X FixedReset -3.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 13.24
Evaluated at bid price : 13.24
Bid-YTW : 4.95 %
BMO.PR.Y FixedReset -2.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 20.31
Evaluated at bid price : 20.31
Bid-YTW : 4.30 %
CM.PR.Q FixedReset -2.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 19.88
Evaluated at bid price : 19.88
Bid-YTW : 4.44 %
BAM.PF.F FixedReset -2.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 20.06
Evaluated at bid price : 20.06
Bid-YTW : 4.69 %
BAM.PR.R FixedReset -2.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 15.43
Evaluated at bid price : 15.43
Bid-YTW : 4.92 %
BAM.PR.Z FixedReset -2.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 18.94
Evaluated at bid price : 18.94
Bid-YTW : 5.03 %
BAM.PF.A FixedReset -2.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 19.45
Evaluated at bid price : 19.45
Bid-YTW : 4.82 %
SLF.PR.H FixedReset -1.93 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.79
Bid-YTW : 9.26 %
MFC.PR.J FixedReset -1.92 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.40
Bid-YTW : 7.78 %
BAM.PR.T FixedReset -1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 15.40
Evaluated at bid price : 15.40
Bid-YTW : 5.05 %
BMO.PR.Q FixedReset -1.73 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.83
Bid-YTW : 6.43 %
BMO.PR.T FixedReset -1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 18.38
Evaluated at bid price : 18.38
Bid-YTW : 4.19 %
TRP.PR.D FixedReset -1.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 17.86
Evaluated at bid price : 17.86
Bid-YTW : 4.51 %
BMO.PR.W FixedReset -1.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 18.30
Evaluated at bid price : 18.30
Bid-YTW : 4.18 %
TD.PF.E FixedReset -1.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 20.81
Evaluated at bid price : 20.81
Bid-YTW : 4.34 %
RY.PR.H FixedReset -1.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 18.50
Evaluated at bid price : 18.50
Bid-YTW : 4.19 %
FTS.PR.K FixedReset -1.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 17.87
Evaluated at bid price : 17.87
Bid-YTW : 4.05 %
SLF.PR.I FixedReset -1.53 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.98
Bid-YTW : 8.12 %
BMO.PR.S FixedReset -1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 18.98
Evaluated at bid price : 18.98
Bid-YTW : 4.16 %
TD.PF.B FixedReset -1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 18.35
Evaluated at bid price : 18.35
Bid-YTW : 4.23 %
CM.PR.O FixedReset -1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 18.69
Evaluated at bid price : 18.69
Bid-YTW : 4.25 %
FTS.PR.J Perpetual-Discount -1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 23.18
Evaluated at bid price : 23.61
Bid-YTW : 5.04 %
BMO.PR.M FixedReset -1.41 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.76
Bid-YTW : 3.78 %
BAM.PF.E FixedReset -1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 19.20
Evaluated at bid price : 19.20
Bid-YTW : 4.60 %
TRP.PR.G FixedReset -1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 20.33
Evaluated at bid price : 20.33
Bid-YTW : 4.54 %
CM.PR.P FixedReset -1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 18.30
Evaluated at bid price : 18.30
Bid-YTW : 4.25 %
TD.PF.A FixedReset -1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 18.53
Evaluated at bid price : 18.53
Bid-YTW : 4.19 %
TRP.PR.B FixedReset -1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 11.90
Evaluated at bid price : 11.90
Bid-YTW : 4.19 %
HSE.PR.A FixedReset -1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 11.90
Evaluated at bid price : 11.90
Bid-YTW : 5.06 %
TD.PF.D FixedReset -1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 20.10
Evaluated at bid price : 20.10
Bid-YTW : 4.39 %
TD.PF.C FixedReset -1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 18.34
Evaluated at bid price : 18.34
Bid-YTW : 4.23 %
FTS.PR.G FixedReset -1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 17.85
Evaluated at bid price : 17.85
Bid-YTW : 4.09 %
TRP.PR.H FloatingReset -1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 10.40
Evaluated at bid price : 10.40
Bid-YTW : 4.37 %
MFC.PR.M FixedReset -1.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.21
Bid-YTW : 7.92 %
RY.PR.Z FixedReset -1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 18.64
Evaluated at bid price : 18.64
Bid-YTW : 4.10 %
RY.PR.M FixedReset -1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 19.53
Evaluated at bid price : 19.53
Bid-YTW : 4.33 %
TRP.PR.F FloatingReset -1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 13.56
Evaluated at bid price : 13.56
Bid-YTW : 4.53 %
FTS.PR.H FixedReset -1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 13.60
Evaluated at bid price : 13.60
Bid-YTW : 4.05 %
BAM.PF.G FixedReset -1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 20.62
Evaluated at bid price : 20.62
Bid-YTW : 4.59 %
MFC.PR.K FixedReset -1.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.92
Bid-YTW : 8.66 %
NA.PR.S FixedReset -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 18.85
Evaluated at bid price : 18.85
Bid-YTW : 4.30 %
IFC.PR.C FixedReset -1.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.91
Bid-YTW : 8.21 %
RY.PR.J FixedReset -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 19.90
Evaluated at bid price : 19.90
Bid-YTW : 4.36 %
MFC.PR.N FixedReset -1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.14
Bid-YTW : 7.92 %
TRP.PR.E FixedReset -1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 18.68
Evaluated at bid price : 18.68
Bid-YTW : 4.37 %
Volume Highlights
Issue Index Shares
Traded
Notes
BIP.PR.C FixedReset 288,259 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-09-30
Maturity Price : 25.00
Evaluated at bid price : 25.20
Bid-YTW : 5.13 %
FTS.PR.G FixedReset 48,589 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 17.85
Evaluated at bid price : 17.85
Bid-YTW : 4.09 %
IAG.PR.G FixedReset 40,100 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.55
Bid-YTW : 7.07 %
BAM.PR.T FixedReset 38,625 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 15.40
Evaluated at bid price : 15.40
Bid-YTW : 5.05 %
RY.PR.M FixedReset 38,575 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 19.53
Evaluated at bid price : 19.53
Bid-YTW : 4.33 %
IFC.PR.A FixedReset 36,700 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.13
Bid-YTW : 10.03 %
There were 57 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BMO.PR.Q FixedReset Quote: 19.83 – 20.25
Spot Rate : 0.4200
Average : 0.2702

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.83
Bid-YTW : 6.43 %

CU.PR.I FixedReset Quote: 25.60 – 26.08
Spot Rate : 0.4800
Average : 0.3393

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-01
Maturity Price : 25.00
Evaluated at bid price : 25.60
Bid-YTW : 3.92 %

VNR.PR.A FixedReset Quote: 18.50 – 18.80
Spot Rate : 0.3000
Average : 0.1954

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-07
Maturity Price : 18.50
Evaluated at bid price : 18.50
Bid-YTW : 4.85 %

BNS.PR.Y FixedReset Quote: 20.43 – 20.66
Spot Rate : 0.2300
Average : 0.1417

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.43
Bid-YTW : 5.82 %

PWF.PR.R Perpetual-Premium Quote: 25.44 – 25.64
Spot Rate : 0.2000
Average : 0.1267

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 25.44
Bid-YTW : 5.24 %

TRP.PR.J FixedReset Quote: 26.16 – 26.39
Spot Rate : 0.2300
Average : 0.1602

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-31
Maturity Price : 25.00
Evaluated at bid price : 26.16
Bid-YTW : 4.46 %

Market Action

September 6, 2016

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.3039 % 1,687.9
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.3039 % 3,083.4
Floater 4.87 % 4.64 % 85,976 16.07 4 0.3039 % 1,777.0
OpRet 0.00 % 0.00 % 0 0.00 0 0.1667 % 2,886.3
SplitShare 5.04 % 4.63 % 88,424 2.21 5 0.1667 % 3,446.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1667 % 2,689.4
Perpetual-Premium 5.50 % 4.04 % 74,063 0.15 12 -0.2307 % 2,674.3
Perpetual-Discount 5.11 % 5.11 % 99,865 14.99 26 0.1043 % 2,907.9
FixedReset 4.97 % 4.28 % 140,930 7.08 89 -0.5311 % 2,045.2
Deemed-Retractible 5.02 % 4.70 % 116,445 3.25 32 -0.0483 % 2,800.8
FloatingReset 2.84 % 3.97 % 30,034 5.04 12 -0.4120 % 2,210.1
Performance Highlights
Issue Index Change Notes
SLF.PR.J FloatingReset -3.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.75
Bid-YTW : 11.04 %
NA.PR.W FixedReset -1.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-06
Maturity Price : 18.23
Evaluated at bid price : 18.23
Bid-YTW : 4.28 %
MFC.PR.F FixedReset -1.81 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.60
Bid-YTW : 10.44 %
RY.PR.M FixedReset -1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-06
Maturity Price : 19.75
Evaluated at bid price : 19.75
Bid-YTW : 4.28 %
TD.PF.A FixedReset -1.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-06
Maturity Price : 18.77
Evaluated at bid price : 18.77
Bid-YTW : 4.14 %
TRP.PR.C FixedReset -1.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-06
Maturity Price : 13.22
Evaluated at bid price : 13.22
Bid-YTW : 4.25 %
TD.PF.C FixedReset -1.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-06
Maturity Price : 18.56
Evaluated at bid price : 18.56
Bid-YTW : 4.18 %
BAM.PR.Z FixedReset -1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-06
Maturity Price : 19.34
Evaluated at bid price : 19.34
Bid-YTW : 4.92 %
TD.PF.D FixedReset -1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-06
Maturity Price : 20.35
Evaluated at bid price : 20.35
Bid-YTW : 4.33 %
CM.PR.Q FixedReset -1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-06
Maturity Price : 20.32
Evaluated at bid price : 20.32
Bid-YTW : 4.34 %
BAM.PR.T FixedReset -1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-06
Maturity Price : 15.68
Evaluated at bid price : 15.68
Bid-YTW : 4.96 %
RY.PR.Z FixedReset -1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-06
Maturity Price : 18.85
Evaluated at bid price : 18.85
Bid-YTW : 4.05 %
SLF.PR.G FixedReset -1.32 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.17
Bid-YTW : 9.90 %
RY.PR.H FixedReset -1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-06
Maturity Price : 18.80
Evaluated at bid price : 18.80
Bid-YTW : 4.12 %
MFC.PR.G FixedReset -1.29 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.18
Bid-YTW : 7.35 %
TD.PF.B FixedReset -1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-06
Maturity Price : 18.63
Evaluated at bid price : 18.63
Bid-YTW : 4.17 %
MFC.PR.L FixedReset -1.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.91
Bid-YTW : 7.94 %
MFC.PR.I FixedReset -1.25 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.69
Bid-YTW : 7.04 %
RY.PR.J FixedReset -1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-06
Maturity Price : 20.11
Evaluated at bid price : 20.11
Bid-YTW : 4.32 %
TD.PF.E FixedReset -1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-06
Maturity Price : 21.15
Evaluated at bid price : 21.15
Bid-YTW : 4.27 %
BAM.PF.B FixedReset -1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-06
Maturity Price : 18.16
Evaluated at bid price : 18.16
Bid-YTW : 4.83 %
MFC.PR.H FixedReset -1.18 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.00
Bid-YTW : 6.33 %
MFC.PR.N FixedReset -1.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.33
Bid-YTW : 7.76 %
BAM.PF.A FixedReset -1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-06
Maturity Price : 19.85
Evaluated at bid price : 19.85
Bid-YTW : 4.72 %
BAM.PF.G FixedReset -1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-06
Maturity Price : 20.84
Evaluated at bid price : 20.84
Bid-YTW : 4.54 %
NA.PR.S FixedReset -1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-06
Maturity Price : 19.05
Evaluated at bid price : 19.05
Bid-YTW : 4.26 %
MFC.PR.M FixedReset -1.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.42
Bid-YTW : 7.75 %
CM.PR.P FixedReset -1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-06
Maturity Price : 18.54
Evaluated at bid price : 18.54
Bid-YTW : 4.19 %
CM.PR.O FixedReset -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-06
Maturity Price : 18.97
Evaluated at bid price : 18.97
Bid-YTW : 4.19 %
BIP.PR.A FixedReset -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-06
Maturity Price : 20.10
Evaluated at bid price : 20.10
Bid-YTW : 5.35 %
SLF.PR.I FixedReset -1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.26
Bid-YTW : 7.89 %
BAM.PR.R FixedReset -1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-06
Maturity Price : 15.76
Evaluated at bid price : 15.76
Bid-YTW : 4.74 %
PWF.PR.K Perpetual-Discount 1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-06
Maturity Price : 24.09
Evaluated at bid price : 24.35
Bid-YTW : 5.13 %
FTS.PR.H FixedReset 1.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-06
Maturity Price : 13.75
Evaluated at bid price : 13.75
Bid-YTW : 4.01 %
Volume Highlights
Issue Index Shares
Traded
Notes
BIP.PR.C FixedReset 60,790 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-09-30
Maturity Price : 25.00
Evaluated at bid price : 25.22
Bid-YTW : 5.11 %
TD.PF.C FixedReset 35,150 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-06
Maturity Price : 18.56
Evaluated at bid price : 18.56
Bid-YTW : 4.18 %
BAM.PR.K Floater 31,420 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-06
Maturity Price : 10.34
Evaluated at bid price : 10.34
Bid-YTW : 4.64 %
HSE.PR.A FixedReset 26,115 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-06
Maturity Price : 12.05
Evaluated at bid price : 12.05
Bid-YTW : 4.99 %
RY.PR.H FixedReset 25,025 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-06
Maturity Price : 18.80
Evaluated at bid price : 18.80
Bid-YTW : 4.12 %
RY.PR.M FixedReset 23,255 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-06
Maturity Price : 19.75
Evaluated at bid price : 19.75
Bid-YTW : 4.28 %
There were 27 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
GWO.PR.N FixedReset Quote: 13.98 – 14.35
Spot Rate : 0.3700
Average : 0.2677

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.98
Bid-YTW : 9.97 %

SLF.PR.G FixedReset Quote: 14.17 – 14.43
Spot Rate : 0.2600
Average : 0.1805

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.17
Bid-YTW : 9.90 %

POW.PR.C Perpetual-Premium Quote: 25.44 – 25.65
Spot Rate : 0.2100
Average : 0.1405

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-10-06
Maturity Price : 25.00
Evaluated at bid price : 25.44
Bid-YTW : -5.23 %

TRP.PR.C FixedReset Quote: 13.22 – 13.44
Spot Rate : 0.2200
Average : 0.1510

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-06
Maturity Price : 13.22
Evaluated at bid price : 13.22
Bid-YTW : 4.25 %

CU.PR.D Perpetual-Discount Quote: 24.65 – 24.83
Spot Rate : 0.1800
Average : 0.1130

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-06
Maturity Price : 24.17
Evaluated at bid price : 24.65
Bid-YTW : 4.98 %

TD.PF.D FixedReset Quote: 20.35 – 20.60
Spot Rate : 0.2500
Average : 0.1839

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-09-06
Maturity Price : 20.35
Evaluated at bid price : 20.35
Bid-YTW : 4.33 %