Category: Market Action

Market Action

March 30, 2016

It’s nice to see a little high-level push-back against civil forfeiture:

Q: What reforms would help fix the flaws in the law?

A: I’m working to draft bipartisan reforms to fix these flaws. For starters, the direct quid pro quo between asset forfeiture and funding should be eliminated. Law enforcement shouldn’t be relying on funds obtained from forfeiting the particular assets that they have seized or shift crime-fighting priorities based on financial considerations. In addition, real procedural reforms must be enacted for people whose assets are seized, including prompt timelines for government action and the ability to challenge the seizure promptly before a judge. And, individuals who cannot afford a lawyer to guide them through the system should be provided one. Part of addressing this problem lies in reversing the Supreme Court’s recent decision that allows the government to prevent people from showing that they need access to their seized funds to hire a lawyer. We also need to codify changes in the use of civil asset forfeiture in structuring cases, where small business owners like Iowa’s Carole Hinders get unfairly caught up in forfeiture for depositing money in a bank without any indication of any underlying crime. The government’s burden of proof for forfeiting assets needs to be raised.

It’s clear the current process isn’t working as Congress intended. It is time to end seizure for suspicion’s sake and enact reforms that will help restore the proper mission of asset forfeiture laws and rebuild credibility in our law enforcement agencies.

Market and Fed policy rate expectations are converging:

The Federal Reserve looks to have outsourced monetary policy to the financial markets — and that may not necessarily be bad.

Fed Chair Janet Yellen told the Economic Club of New York on Tuesday that policy makers had scaled back the number of interest rate increases they expect to carry out this year after investors did the same.

She argued that the downgrading of rate expectations in the market had led to lower bond yields, providing the economy with needed support in the face of weaker growth overseas. The Fed then followed suit this month by reducing its anticipated rate hikes in 2016 to two from four quarter-percentage point moves projected in December.
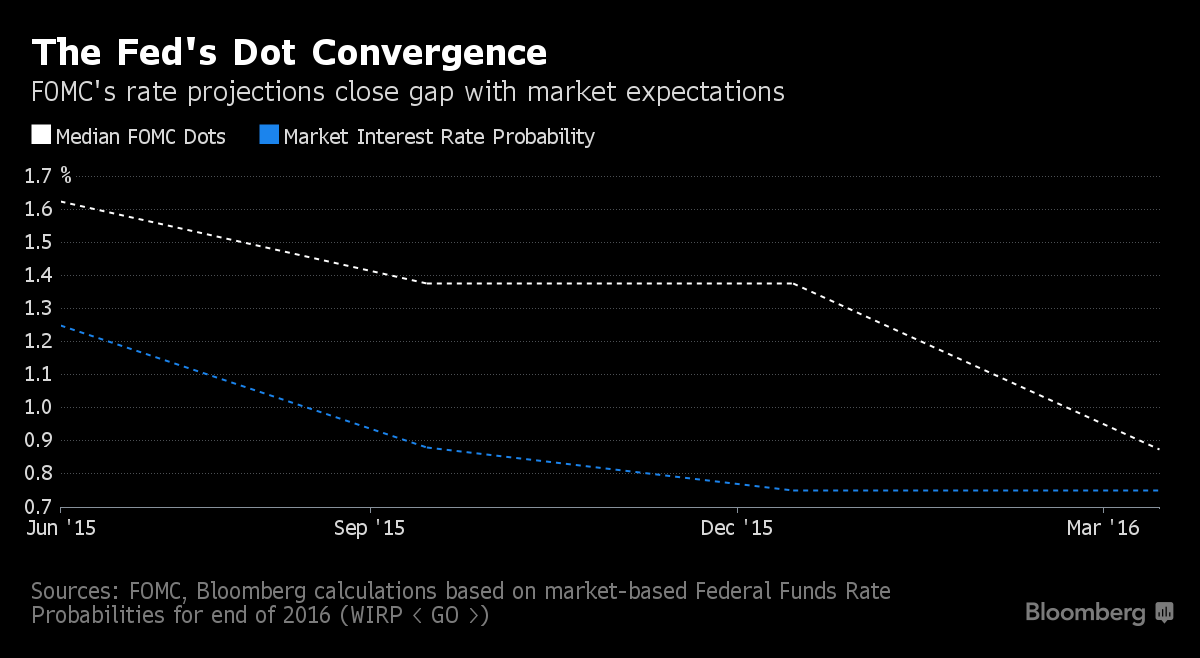
policyExpectationConvergence
Click for Big

PerpetualDiscounts now yield 5.63%, equivalent to 7.32% interest at the standard conversion factor of 1.3x. Long corporates now yield about 4.1%, so the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) is now about 320bp, unchanged from the figure reported March 23.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.00 % 6.08 % 11,039 16.60 1 1.8854 % 1,571.9
FixedFloater 6.86 % 6.03 % 24,847 16.26 1 1.0949 % 2,898.4
Floater 4.63 % 4.76 % 62,625 15.93 4 -1.3050 % 1,672.7
OpRet 0.00 % 0.00 % 0 0.00 0 0.2997 % 2,791.1
SplitShare 4.75 % 5.27 % 88,709 1.61 6 0.2997 % 3,266.1
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.2997 % 2,548.3
Perpetual-Premium 5.79 % -4.49 % 89,184 0.08 6 -0.2039 % 2,560.5
Perpetual-Discount 5.61 % 5.63 % 94,587 14.39 33 0.1798 % 2,592.5
FixedReset 5.31 % 4.81 % 184,776 13.94 87 -0.3188 % 1,921.6
Deemed-Retractible 5.20 % 5.55 % 130,740 5.08 34 0.1698 % 2,617.8
FloatingReset 3.04 % 5.04 % 37,342 5.39 16 -0.1836 % 2,018.4
Performance Highlights
Issue Index Change Notes
TRP.PR.I FloatingReset -4.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-30
Maturity Price : 11.00
Evaluated at bid price : 11.00
Bid-YTW : 4.49 %
TD.PR.S FixedReset -3.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.61
Bid-YTW : 4.78 %
TRP.PR.G FixedReset -3.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-30
Maturity Price : 18.61
Evaluated at bid price : 18.61
Bid-YTW : 5.02 %
HSE.PR.A FixedReset -2.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-30
Maturity Price : 10.35
Evaluated at bid price : 10.35
Bid-YTW : 5.93 %
TRP.PR.B FixedReset -2.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-30
Maturity Price : 10.99
Evaluated at bid price : 10.99
Bid-YTW : 4.62 %
BAM.PR.T FixedReset -1.97 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-30
Maturity Price : 15.45
Evaluated at bid price : 15.45
Bid-YTW : 5.02 %
HSE.PR.E FixedReset -1.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-30
Maturity Price : 18.41
Evaluated at bid price : 18.41
Bid-YTW : 5.91 %
TRP.PR.D FixedReset -1.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-30
Maturity Price : 16.96
Evaluated at bid price : 16.96
Bid-YTW : 4.76 %
TRP.PR.C FixedReset -1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-30
Maturity Price : 11.61
Evaluated at bid price : 11.61
Bid-YTW : 4.84 %
CIU.PR.C FixedReset -1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-30
Maturity Price : 11.06
Evaluated at bid price : 11.06
Bid-YTW : 4.71 %
TRP.PR.A FixedReset -1.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-30
Maturity Price : 15.05
Evaluated at bid price : 15.05
Bid-YTW : 4.59 %
BAM.PR.X FixedReset -1.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-30
Maturity Price : 14.00
Evaluated at bid price : 14.00
Bid-YTW : 4.73 %
IAG.PR.G FixedReset -1.57 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.85
Bid-YTW : 7.56 %
BNS.PR.Q FixedReset -1.56 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.67
Bid-YTW : 4.92 %
BAM.PR.K Floater -1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-30
Maturity Price : 9.90
Evaluated at bid price : 9.90
Bid-YTW : 4.78 %
BAM.PR.B Floater -1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-30
Maturity Price : 9.94
Evaluated at bid price : 9.94
Bid-YTW : 4.76 %
GWO.PR.N FixedReset -1.48 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.35
Bid-YTW : 10.29 %
RY.PR.I FixedReset -1.44 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.26
Bid-YTW : 4.54 %
TRP.PR.E FixedReset -1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-30
Maturity Price : 17.75
Evaluated at bid price : 17.75
Bid-YTW : 4.62 %
RY.PR.K FloatingReset -1.35 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.85
Bid-YTW : 4.87 %
PWF.PR.A Floater -1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-30
Maturity Price : 11.10
Evaluated at bid price : 11.10
Bid-YTW : 4.30 %
BIP.PR.B FixedReset -1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-30
Maturity Price : 22.86
Evaluated at bid price : 24.15
Bid-YTW : 5.66 %
NA.PR.S FixedReset -1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-30
Maturity Price : 18.15
Evaluated at bid price : 18.15
Bid-YTW : 4.57 %
MFC.PR.I FixedReset -1.21 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.83
Bid-YTW : 7.67 %
CU.PR.C FixedReset -1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-30
Maturity Price : 17.51
Evaluated at bid price : 17.51
Bid-YTW : 4.55 %
HSE.PR.G FixedReset 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-30
Maturity Price : 18.44
Evaluated at bid price : 18.44
Bid-YTW : 5.89 %
BAM.PR.G FixedFloater 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-30
Maturity Price : 25.00
Evaluated at bid price : 13.85
Bid-YTW : 6.03 %
RY.PR.F Deemed-Retractible 1.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.67
Bid-YTW : 4.82 %
BAM.PF.G FixedReset 1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-30
Maturity Price : 19.65
Evaluated at bid price : 19.65
Bid-YTW : 4.81 %
PVS.PR.D SplitShare 1.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2021-10-08
Maturity Price : 25.00
Evaluated at bid price : 23.51
Bid-YTW : 5.87 %
PWF.PR.Q FloatingReset 1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-30
Maturity Price : 11.25
Evaluated at bid price : 11.25
Bid-YTW : 4.60 %
FTS.PR.H FixedReset 1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-30
Maturity Price : 12.79
Evaluated at bid price : 12.79
Bid-YTW : 4.40 %
W.PR.K FixedReset 1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-30
Maturity Price : 23.16
Evaluated at bid price : 24.95
Bid-YTW : 5.18 %
FTS.PR.I FloatingReset 1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-30
Maturity Price : 10.50
Evaluated at bid price : 10.50
Bid-YTW : 4.54 %
MFC.PR.F FixedReset 1.46 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.21
Bid-YTW : 10.47 %
BAM.PR.E Ratchet 1.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-30
Maturity Price : 25.00
Evaluated at bid price : 13.51
Bid-YTW : 6.08 %
PWF.PR.T FixedReset 2.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-30
Maturity Price : 19.50
Evaluated at bid price : 19.50
Bid-YTW : 4.22 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.R FixedReset 87,594 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-24
Maturity Price : 25.00
Evaluated at bid price : 25.96
Bid-YTW : 4.79 %
BNS.PR.N Deemed-Retractible 67,005 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-01-27
Maturity Price : 25.00
Evaluated at bid price : 25.30
Bid-YTW : 4.86 %
RY.PR.Z FixedReset 60,289 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-30
Maturity Price : 18.51
Evaluated at bid price : 18.51
Bid-YTW : 4.22 %
RY.PR.D Deemed-Retractible 59,461 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.90
Bid-YTW : 4.69 %
TD.PF.G FixedReset 56,716 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 25.87
Bid-YTW : 5.01 %
BNS.PR.L Deemed-Retractible 39,093 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-05-27
Maturity Price : 25.00
Evaluated at bid price : 25.24
Bid-YTW : 3.14 %
There were 49 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
GWO.PR.O FloatingReset Quote: 12.01 – 14.25
Spot Rate : 2.2400
Average : 1.7176

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.01
Bid-YTW : 11.14 %

TD.PR.S FixedReset Quote: 22.61 – 23.77
Spot Rate : 1.1600
Average : 0.8311

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.61
Bid-YTW : 4.78 %

SLF.PR.J FloatingReset Quote: 12.30 – 13.00
Spot Rate : 0.7000
Average : 0.4251

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.30
Bid-YTW : 10.99 %

TD.PR.Z FloatingReset Quote: 21.32 – 22.00
Spot Rate : 0.6800
Average : 0.5336

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.32
Bid-YTW : 5.07 %

IAG.PR.G FixedReset Quote: 18.85 – 19.30
Spot Rate : 0.4500
Average : 0.3204

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.85
Bid-YTW : 7.56 %

BAM.PR.G FixedFloater Quote: 13.85 – 14.24
Spot Rate : 0.3900
Average : 0.2611

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-30
Maturity Price : 25.00
Evaluated at bid price : 13.85
Bid-YTW : 6.03 %

Market Action

March 29, 2016

My old buddy Bing Li is now the proud co-author of a book, Multi-Asset Investing: A Practitioner’s Framework:

Despite the accepted fact that a substantial part of the risk and return of any portfolio comes from asset allocation, we find today that the majority of investment professionals worldwide are focused on security selection. Multi-Asset Investing: A Practitioner’s Framework questions this basic structure of the investment process and investment industry.

  • •Who says we have to separate alpha and beta?
  • •Are the traditional definitions for risk and risk premium relevant in a multi-asset class world?
  • •Do portfolios cater for the ‘real risks’ in their investment processes?
  • •Does the whole Emerging Markets demarcation make sense for investing?
  • •Why do active Asian managers perform much poorer compared to developed market managers?
  • •Can you distinguish how much of a strategy’s performance comes from skill rather than luck?
  • •Does having a performance fee for your manager create alignment or misalignment?
  • •Why is the asset management transitioning from multi-asset strategies to multi-asset solutions?

These and many other questions are asked, and suggestions provided as potential solutions. Having worked together for fifteen years, the authors’ present implementable solutions which have helped them successfully manage large asset pools.

And Yellen has made a major speech:

Federal Reserve Chair Janet Yellen spelled out on Tuesday what she means by data dependence, asserting her leadership of the U.S. central bank with a clear message that interest rates will be raised at a cautious pace.

In one of her most detailed policy discussions this year, Yellen gave investors a list of conditions they need to watch for future rate hikes. Here they are:

  • •Foreign economies and their financial markets need to stabilize.
  • •The dollar can’t appreciate further. That would depress inflation and exports, and hurt U.S. manufacturing.
  • •Commodity prices need to stabilize to help foreign producers find a better footing for growth.
  • •The housing sector needs to make a larger contribution to U.S. output.
  • •Inflation is a two-sided risk: Yellen is skeptical that the recent rise in core inflation, which strips out food and energy, “will prove durable.” She is watching closely.

It would be interesting, to say the least, if real-estate were to become a tradeable commodity:

Canadian house prices climbed 27 per cent over the five years from February, 2011, to February, 2016, according to the Teranet-National Bank Composite House Price index. But many foreign buyers are seeing price declines, after currency conversion (see chart below).

The currencies of China, the United States and Switzerland have gained so much against the Canadian dollar that they have outrun the increase in Canadian house prices. As a result, the citizens of these countries can buy at a lower price than in 2011: For the Chinese and Americans, it is nearly 10 per cent less; for the Swiss, it is 5 per cent less.

In most other countries, currencies rose less than Canadian house prices. Some, like the

British pound, came up just a bit short – leaving a small price increase of 2.6 per cent. Others were further behind.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.10 % 6.20 % 10,953 16.46 1 1.3118 % 1,542.8
FixedFloater 6.93 % 6.10 % 24,689 16.18 1 0.3663 % 2,867.1
Floater 4.57 % 4.69 % 62,018 16.06 4 3.0378 % 1,694.8
OpRet 0.00 % 0.00 % 0 0.00 0 0.3100 % 2,782.8
SplitShare 4.76 % 5.50 % 82,133 1.61 6 0.3100 % 3,256.4
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.3100 % 2,540.7
Perpetual-Premium 5.78 % -7.00 % 84,944 0.09 6 0.2565 % 2,565.7
Perpetual-Discount 5.61 % 5.61 % 95,746 14.41 33 0.0364 % 2,587.8
FixedReset 5.30 % 4.80 % 186,095 13.85 87 0.0797 % 1,927.7
Deemed-Retractible 5.21 % 5.65 % 125,473 5.08 34 0.0475 % 2,613.3
FloatingReset 3.03 % 4.93 % 37,154 5.40 16 0.5563 % 2,022.1
Performance Highlights
Issue Index Change Notes
HSE.PR.G FixedReset -3.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-29
Maturity Price : 18.25
Evaluated at bid price : 18.25
Bid-YTW : 5.95 %
TRP.PR.D FixedReset -1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-29
Maturity Price : 17.27
Evaluated at bid price : 17.27
Bid-YTW : 4.68 %
TD.PR.Y FixedReset -1.84 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.49
Bid-YTW : 4.23 %
PWF.PR.P FixedReset -1.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-29
Maturity Price : 12.53
Evaluated at bid price : 12.53
Bid-YTW : 4.67 %
TRP.PR.G FixedReset -1.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-29
Maturity Price : 19.20
Evaluated at bid price : 19.20
Bid-YTW : 4.87 %
BNS.PR.F FloatingReset -1.28 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.77
Bid-YTW : 8.19 %
GWO.PR.M Deemed-Retractible -1.17 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-03-31
Maturity Price : 25.25
Evaluated at bid price : 25.30
Bid-YTW : 5.65 %
BAM.PF.E FixedReset -1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-29
Maturity Price : 18.31
Evaluated at bid price : 18.31
Bid-YTW : 4.81 %
SLF.PR.I FixedReset -1.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.15
Bid-YTW : 7.89 %
RY.PR.M FixedReset 1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-29
Maturity Price : 19.63
Evaluated at bid price : 19.63
Bid-YTW : 4.36 %
RY.PR.H FixedReset 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-29
Maturity Price : 18.46
Evaluated at bid price : 18.46
Bid-YTW : 4.28 %
BAM.PR.E Ratchet 1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-29
Maturity Price : 25.00
Evaluated at bid price : 13.26
Bid-YTW : 6.20 %
NA.PR.S FixedReset 1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-29
Maturity Price : 18.39
Evaluated at bid price : 18.39
Bid-YTW : 4.50 %
BMO.PR.T FixedReset 1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-29
Maturity Price : 18.38
Evaluated at bid price : 18.38
Bid-YTW : 4.28 %
MFC.PR.N FixedReset 1.60 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.40
Bid-YTW : 7.61 %
MFC.PR.M FixedReset 1.69 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.65
Bid-YTW : 7.49 %
FTS.PR.H FixedReset 1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-29
Maturity Price : 12.62
Evaluated at bid price : 12.62
Bid-YTW : 4.46 %
BNS.PR.D FloatingReset 2.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.78
Bid-YTW : 7.74 %
PWF.PR.A Floater 2.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-29
Maturity Price : 11.25
Evaluated at bid price : 11.25
Bid-YTW : 4.24 %
TRP.PR.A FixedReset 2.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-29
Maturity Price : 15.30
Evaluated at bid price : 15.30
Bid-YTW : 4.51 %
CIU.PR.C FixedReset 2.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-29
Maturity Price : 11.25
Evaluated at bid price : 11.25
Bid-YTW : 4.63 %
TRP.PR.H FloatingReset 2.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-29
Maturity Price : 9.60
Evaluated at bid price : 9.60
Bid-YTW : 4.48 %
BAM.PR.K Floater 3.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-29
Maturity Price : 10.05
Evaluated at bid price : 10.05
Bid-YTW : 4.71 %
BAM.PR.B Floater 3.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-29
Maturity Price : 10.09
Evaluated at bid price : 10.09
Bid-YTW : 4.69 %
BAM.PF.A FixedReset 3.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-29
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 4.93 %
BAM.PR.C Floater 3.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-29
Maturity Price : 9.99
Evaluated at bid price : 9.99
Bid-YTW : 4.74 %
TRP.PR.I FloatingReset 12.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-29
Maturity Price : 11.50
Evaluated at bid price : 11.50
Bid-YTW : 4.29 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.R FixedReset 162,400 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-24
Maturity Price : 25.00
Evaluated at bid price : 25.95
Bid-YTW : 4.80 %
BNS.PR.Z FixedReset 145,598 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.10
Bid-YTW : 7.16 %
MFC.PR.L FixedReset 110,500 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.65
Bid-YTW : 8.07 %
TD.PF.G FixedReset 68,810 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 25.94
Bid-YTW : 4.94 %
RY.PR.Q FixedReset 67,600 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-24
Maturity Price : 25.00
Evaluated at bid price : 26.11
Bid-YTW : 4.89 %
RY.PR.J FixedReset 59,600 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-29
Maturity Price : 19.83
Evaluated at bid price : 19.83
Bid-YTW : 4.43 %
There were 34 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
PWF.PR.T FixedReset Quote: 19.11 – 20.00
Spot Rate : 0.8900
Average : 0.6569

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-29
Maturity Price : 19.11
Evaluated at bid price : 19.11
Bid-YTW : 4.31 %

ALB.PR.C SplitShare Quote: 25.91 – 26.44
Spot Rate : 0.5300
Average : 0.3110

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-02-28
Maturity Price : 25.67
Evaluated at bid price : 25.91
Bid-YTW : 4.12 %

BMO.PR.R FloatingReset Quote: 21.65 – 22.30
Spot Rate : 0.6500
Average : 0.4322

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.65
Bid-YTW : 4.73 %

BAM.PR.E Ratchet Quote: 13.26 – 14.40
Spot Rate : 1.1400
Average : 0.9285

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-29
Maturity Price : 25.00
Evaluated at bid price : 13.26
Bid-YTW : 6.20 %

TD.PF.E FixedReset Quote: 20.40 – 21.12
Spot Rate : 0.7200
Average : 0.5244

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-29
Maturity Price : 20.40
Evaluated at bid price : 20.40
Bid-YTW : 4.48 %

PWF.PR.P FixedReset Quote: 12.53 – 12.95
Spot Rate : 0.4200
Average : 0.2799

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-29
Maturity Price : 12.53
Evaluated at bid price : 12.53
Bid-YTW : 4.67 %

Market Action

March 28, 2016

Another bare-bones report, I’m afraid! Geez, I hate the first quarter of the year!

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.14 % 6.27 % 10,200 16.30 1 0.3817 % 1,522.8
FixedFloater 6.96 % 6.12 % 24,021 16.16 1 0.7380 % 2,856.6
Floater 4.71 % 4.84 % 62,553 15.79 4 1.3629 % 1,644.8
OpRet 0.00 % 0.00 % 0 0.00 0 0.1802 % 2,774.2
SplitShare 4.80 % 5.87 % 79,195 1.62 7 0.1802 % 3,246.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1802 % 2,532.9
Perpetual-Premium 5.78 % -2.99 % 85,052 0.08 6 0.0263 % 2,559.1
Perpetual-Discount 5.61 % 5.63 % 94,578 14.39 33 0.2186 % 2,586.9
FixedReset 5.30 % 4.75 % 180,939 14.11 87 0.9345 % 1,926.2
Deemed-Retractible 5.21 % 5.45 % 126,107 5.08 34 0.7006 % 2,612.1
FloatingReset 3.05 % 4.95 % 37,253 5.40 16 0.2605 % 2,010.9
Performance Highlights
Issue Index Change Notes
PWF.PR.T FixedReset -1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 19.01
Evaluated at bid price : 19.01
Bid-YTW : 4.33 %
BNS.PR.C FloatingReset -1.02 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.33
Bid-YTW : 5.37 %
BNS.PR.Q FixedReset 1.00 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.22
Bid-YTW : 4.45 %
SLF.PR.B Deemed-Retractible 1.00 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.18
Bid-YTW : 6.53 %
SLF.PR.A Deemed-Retractible 1.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.04
Bid-YTW : 6.57 %
SLF.PR.C Deemed-Retractible 1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.55
Bid-YTW : 7.24 %
BAM.PR.K Floater 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 9.75
Evaluated at bid price : 9.75
Bid-YTW : 4.85 %
W.PR.K FixedReset 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 23.26
Evaluated at bid price : 25.26
Bid-YTW : 5.22 %
RY.PR.A Deemed-Retractible 1.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.43
Bid-YTW : 5.01 %
BIP.PR.B FixedReset 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 22.91
Evaluated at bid price : 24.28
Bid-YTW : 5.62 %
MFC.PR.F FixedReset 1.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.95
Bid-YTW : 10.74 %
PVS.PR.D SplitShare 1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2021-10-08
Maturity Price : 25.00
Evaluated at bid price : 23.05
Bid-YTW : 6.28 %
BNS.PR.Z FixedReset 1.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.06
Bid-YTW : 7.07 %
NA.PR.W FixedReset 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 17.15
Evaluated at bid price : 17.15
Bid-YTW : 4.66 %
BAM.PR.B Floater 1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 9.78
Evaluated at bid price : 9.78
Bid-YTW : 4.84 %
VNR.PR.A FixedReset 1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 5.23 %
NA.PR.S FixedReset 1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 18.15
Evaluated at bid price : 18.15
Bid-YTW : 4.57 %
GWO.PR.M Deemed-Retractible 1.19 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-03-31
Maturity Price : 25.25
Evaluated at bid price : 25.60
Bid-YTW : 5.00 %
HSB.PR.C Deemed-Retractible 1.19 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.60
Bid-YTW : 5.45 %
MFC.PR.H FixedReset 1.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.50
Bid-YTW : 6.70 %
BMO.PR.S FixedReset 1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 18.65
Evaluated at bid price : 18.65
Bid-YTW : 4.33 %
GWO.PR.G Deemed-Retractible 1.25 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.50
Bid-YTW : 6.12 %
IFC.PR.C FixedReset 1.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.52
Bid-YTW : 8.26 %
BNS.PR.Y FixedReset 1.28 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.04
Bid-YTW : 6.88 %
SLF.PR.D Deemed-Retractible 1.28 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.50
Bid-YTW : 7.28 %
BNS.PR.F FloatingReset 1.29 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.00
Bid-YTW : 7.82 %
TD.PF.C FixedReset 1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 18.65
Evaluated at bid price : 18.65
Bid-YTW : 4.23 %
RY.PR.Z FixedReset 1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 18.46
Evaluated at bid price : 18.46
Bid-YTW : 4.23 %
BAM.PR.R FixedReset 1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 15.24
Evaluated at bid price : 15.24
Bid-YTW : 4.96 %
TRP.PR.A FixedReset 1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 14.95
Evaluated at bid price : 14.95
Bid-YTW : 4.62 %
RY.PR.K FloatingReset 1.37 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.15
Bid-YTW : 4.61 %
MFC.PR.N FixedReset 1.46 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.11
Bid-YTW : 7.84 %
IAG.PR.G FixedReset 1.49 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.13
Bid-YTW : 7.35 %
MFC.PR.J FixedReset 1.50 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.22
Bid-YTW : 7.85 %
SLF.PR.H FixedReset 1.58 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.05
Bid-YTW : 8.87 %
RY.PR.I FixedReset 1.58 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.74
Bid-YTW : 4.14 %
BAM.PF.F FixedReset 1.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 19.10
Evaluated at bid price : 19.10
Bid-YTW : 4.93 %
BAM.PR.X FixedReset 1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 14.24
Evaluated at bid price : 14.24
Bid-YTW : 4.65 %
PWF.PR.P FixedReset 1.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 12.76
Evaluated at bid price : 12.76
Bid-YTW : 4.58 %
FTS.PR.M FixedReset 1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 4.72 %
BAM.PF.G FixedReset 1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 19.34
Evaluated at bid price : 19.34
Bid-YTW : 4.89 %
TRP.PR.D FixedReset 1.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 17.87
Evaluated at bid price : 17.87
Bid-YTW : 4.60 %
MFC.PR.M FixedReset 1.89 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.34
Bid-YTW : 7.73 %
BMO.PR.Q FixedReset 1.92 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.60
Bid-YTW : 7.56 %
IFC.PR.A FixedReset 1.94 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.70
Bid-YTW : 10.01 %
SLF.PR.I FixedReset 1.94 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.35
Bid-YTW : 7.73 %
BAM.PF.B FixedReset 1.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 17.81
Evaluated at bid price : 17.81
Bid-YTW : 4.90 %
TRP.PR.F FloatingReset 2.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 12.65
Evaluated at bid price : 12.65
Bid-YTW : 4.67 %
GWO.PR.N FixedReset 2.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.58
Bid-YTW : 10.05 %
TD.PR.Y FixedReset 2.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.93
Bid-YTW : 3.88 %
TRP.PR.G FixedReset 2.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 19.50
Evaluated at bid price : 19.50
Bid-YTW : 4.79 %
RY.PR.J FixedReset 2.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 19.92
Evaluated at bid price : 19.92
Bid-YTW : 4.41 %
BAM.PF.E FixedReset 2.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 18.52
Evaluated at bid price : 18.52
Bid-YTW : 4.75 %
PWF.PR.A Floater 2.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 11.00
Evaluated at bid price : 11.00
Bid-YTW : 4.34 %
CIU.PR.C FixedReset 2.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 10.96
Evaluated at bid price : 10.96
Bid-YTW : 4.75 %
BMO.PR.Y FixedReset 2.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 20.40
Evaluated at bid price : 20.40
Bid-YTW : 4.34 %
HSE.PR.A FixedReset 2.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 10.55
Evaluated at bid price : 10.55
Bid-YTW : 5.81 %
TRP.PR.B FixedReset 2.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 11.18
Evaluated at bid price : 11.18
Bid-YTW : 4.54 %
BNS.PR.L Deemed-Retractible 2.60 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-04-27
Maturity Price : 25.00
Evaluated at bid price : 25.24
Bid-YTW : 1.50 %
TD.PF.D FixedReset 2.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 19.96
Evaluated at bid price : 19.96
Bid-YTW : 4.47 %
BNS.PR.M Deemed-Retractible 2.64 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-07-27
Maturity Price : 25.00
Evaluated at bid price : 25.25
Bid-YTW : 3.65 %
BAM.PR.Z FixedReset 2.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 4.99 %
GWO.PR.O FloatingReset 3.18 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.02
Bid-YTW : 11.12 %
HSE.PR.G FixedReset 4.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 5.71 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.R FixedReset 152,079 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-24
Maturity Price : 25.00
Evaluated at bid price : 25.81
Bid-YTW : 4.91 %
BNS.PR.Z FixedReset 61,400 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.06
Bid-YTW : 7.07 %
MFC.PR.O FixedReset 54,601 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-06-19
Maturity Price : 25.00
Evaluated at bid price : 25.75
Bid-YTW : 5.08 %
W.PR.J Perpetual-Discount 43,330 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 23.23
Evaluated at bid price : 23.53
Bid-YTW : 6.07 %
TD.PF.G FixedReset 37,396 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 25.81
Bid-YTW : 4.70 %
BNS.PR.G FixedReset 34,357 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-07-25
Maturity Price : 25.00
Evaluated at bid price : 25.75
Bid-YTW : 4.93 %
There were 21 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
PWF.PR.Q FloatingReset Quote: 11.11 – 15.35
Spot Rate : 4.2400
Average : 3.4515

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 11.11
Evaluated at bid price : 11.11
Bid-YTW : 4.65 %

GWO.PR.O FloatingReset Quote: 12.02 – 14.25
Spot Rate : 2.2300
Average : 1.6327

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.02
Bid-YTW : 11.12 %

TRP.PR.E FixedReset Quote: 18.35 – 19.50
Spot Rate : 1.1500
Average : 0.7176

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 18.35
Evaluated at bid price : 18.35
Bid-YTW : 4.55 %

TRP.PR.A FixedReset Quote: 14.95 – 15.85
Spot Rate : 0.9000
Average : 0.5412

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 14.95
Evaluated at bid price : 14.95
Bid-YTW : 4.62 %

BAM.PR.E Ratchet Quote: 13.15 – 14.20
Spot Rate : 1.0500
Average : 0.6967

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 25.00
Evaluated at bid price : 13.15
Bid-YTW : 6.27 %

RY.PR.M FixedReset Quote: 19.43 – 20.20
Spot Rate : 0.7700
Average : 0.5109

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-28
Maturity Price : 19.43
Evaluated at bid price : 19.43
Bid-YTW : 4.41 %

Market Action

March 24, 2016

It’s nice to see University of Toronto as a major partner in a new advance in energy storage:

Now, a group of researchers led by Professor Ted Sargent at the University of Toronto’s Faculty of Applied Science & Engineering may have a solution inspired by nature.

The team has designed the most efficient catalyst for storing energy in chemical form, by splitting water into hydrogen and oxygen, just like plants do during photosynthesis. Oxygen is released harmlessly into the atmosphere, and hydrogen, as H2, can be converted back into energy using hydrogen fuel cells.
…
You may have seen the popular high-school science demonstration where the teacher splits water into its component elements, hydrogen and oxygen, by running electricity through it. Today this requires so much electrical input that it’s impractical to store energy this way — too great proportion of the energy generated is lost in the process of storing it.

This new catalyst facilitates the oxygen-evolution portion of the chemical reaction, making the conversion from H2O into O2 and H2 more energy-efficient than ever before. The intrinsic efficiency of the new catalyst material is over three times more efficient than the best state-of-the-art catalyst.

The new catalyst is made of abundant and low-cost metals tungsten, iron and cobalt, which are much less expensive than state-of-the-art catalysts based on precious metals. It showed no signs of degradation over more than 500 hours of continuous activity, unlike other efficient but short-lived catalysts. Their work was published online today in the leading journal Science.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.16 % 6.29 % 10,625 16.29 1 0.6918 % 1,517.0
FixedFloater 7.01 % 6.16 % 24,356 16.11 1 0.3704 % 2,835.7
Floater 4.77 % 4.89 % 62,497 15.70 4 -1.1970 % 1,622.7
OpRet 0.00 % 0.00 % 0 0.00 0 0.1521 % 2,769.2
SplitShare 4.81 % 5.71 % 77,711 1.63 7 0.1521 % 3,240.4
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1521 % 2,528.3
Perpetual-Premium 5.78 % -3.28 % 84,945 0.08 6 0.0790 % 2,558.5
Perpetual-Discount 5.62 % 5.64 % 95,385 14.41 33 -0.0418 % 2,581.2
FixedReset 5.35 % 4.91 % 185,765 13.82 87 0.1432 % 1,908.4
Deemed-Retractible 5.25 % 5.61 % 128,044 5.09 34 -0.2935 % 2,593.9
FloatingReset 3.07 % 4.93 % 37,752 5.41 16 0.1210 % 2,005.7
Performance Highlights
Issue Index Change Notes
PWF.PR.A Floater -2.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-24
Maturity Price : 10.75
Evaluated at bid price : 10.75
Bid-YTW : 4.44 %
BAM.PR.R FixedReset -1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-24
Maturity Price : 15.04
Evaluated at bid price : 15.04
Bid-YTW : 5.06 %
TD.PR.Y FixedReset -1.76 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.43
Bid-YTW : 4.28 %
IFC.PR.C FixedReset -1.70 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.30
Bid-YTW : 8.45 %
TD.PF.A FixedReset -1.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-24
Maturity Price : 18.34
Evaluated at bid price : 18.34
Bid-YTW : 4.34 %
HSB.PR.C Deemed-Retractible -1.46 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.31
Bid-YTW : 5.67 %
BAM.PR.T FixedReset -1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-24
Maturity Price : 15.64
Evaluated at bid price : 15.64
Bid-YTW : 4.99 %
CM.PR.P FixedReset -1.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-24
Maturity Price : 17.93
Evaluated at bid price : 17.93
Bid-YTW : 4.35 %
GWO.PR.G Deemed-Retractible -1.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.21
Bid-YTW : 6.29 %
SLF.PR.D Deemed-Retractible -1.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.24
Bid-YTW : 7.45 %
HSE.PR.C FixedReset -1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-24
Maturity Price : 16.60
Evaluated at bid price : 16.60
Bid-YTW : 6.06 %
SLF.PR.B Deemed-Retractible -1.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.96
Bid-YTW : 6.66 %
BAM.PR.K Floater -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-24
Maturity Price : 9.65
Evaluated at bid price : 9.65
Bid-YTW : 4.90 %
BAM.PR.B Floater -1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-24
Maturity Price : 9.67
Evaluated at bid price : 9.67
Bid-YTW : 4.89 %
PWF.PR.Q FloatingReset 1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-24
Maturity Price : 11.11
Evaluated at bid price : 11.11
Bid-YTW : 4.67 %
BMO.PR.T FixedReset 1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-24
Maturity Price : 18.18
Evaluated at bid price : 18.18
Bid-YTW : 4.35 %
TRP.PR.A FixedReset 1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-24
Maturity Price : 14.75
Evaluated at bid price : 14.75
Bid-YTW : 4.71 %
MFC.PR.I FixedReset 1.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.92
Bid-YTW : 7.60 %
SLF.PR.J FloatingReset 1.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.30
Bid-YTW : 10.98 %
MFC.PR.F FixedReset 1.26 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.81
Bid-YTW : 10.90 %
FTS.PR.H FixedReset 1.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-24
Maturity Price : 12.50
Evaluated at bid price : 12.50
Bid-YTW : 4.53 %
CM.PR.Q FixedReset 1.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-24
Maturity Price : 19.15
Evaluated at bid price : 19.15
Bid-YTW : 4.61 %
BAM.PF.G FixedReset 1.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-24
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 5.00 %
MFC.PR.M FixedReset 1.69 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.00
Bid-YTW : 7.99 %
MFC.PR.L FixedReset 1.73 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.62
Bid-YTW : 8.09 %
CIU.PR.C FixedReset 1.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-24
Maturity Price : 10.71
Evaluated at bid price : 10.71
Bid-YTW : 4.91 %
TRP.PR.C FixedReset 2.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-24
Maturity Price : 11.96
Evaluated at bid price : 11.96
Bid-YTW : 4.80 %
FTS.PR.M FixedReset 2.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-24
Maturity Price : 17.70
Evaluated at bid price : 17.70
Bid-YTW : 4.82 %
BMO.PR.Y FixedReset 2.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-24
Maturity Price : 19.90
Evaluated at bid price : 19.90
Bid-YTW : 4.46 %
PWF.PR.T FixedReset 2.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-24
Maturity Price : 19.30
Evaluated at bid price : 19.30
Bid-YTW : 4.28 %
RY.PR.J FixedReset 3.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-24
Maturity Price : 19.50
Evaluated at bid price : 19.50
Bid-YTW : 4.52 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.R FixedReset 177,897 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-24
Maturity Price : 25.00
Evaluated at bid price : 25.79
Bid-YTW : 4.92 %
RY.PR.Q FixedReset 169,826 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-24
Maturity Price : 25.00
Evaluated at bid price : 25.87
Bid-YTW : 5.08 %
BMO.PR.L Deemed-Retractible 90,419 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-05-25
Maturity Price : 25.25
Evaluated at bid price : 25.84
Bid-YTW : -5.26 %
CU.PR.I FixedReset 78,520 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-01
Maturity Price : 25.00
Evaluated at bid price : 25.40
Bid-YTW : 4.21 %
RY.PR.Z FixedReset 73,779 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-24
Maturity Price : 18.22
Evaluated at bid price : 18.22
Bid-YTW : 4.31 %
BAM.PR.M Perpetual-Discount 65,010 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-24
Maturity Price : 19.90
Evaluated at bid price : 19.90
Bid-YTW : 6.00 %
There were 39 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
PWF.PR.Q FloatingReset Quote: 11.11 – 15.35
Spot Rate : 4.2400
Average : 2.5870

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-24
Maturity Price : 11.11
Evaluated at bid price : 11.11
Bid-YTW : 4.67 %

GWO.PR.O FloatingReset Quote: 11.65 – 12.95
Spot Rate : 1.3000
Average : 0.9778

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.65
Bid-YTW : 11.54 %

PWF.PR.A Floater Quote: 10.75 – 11.38
Spot Rate : 0.6300
Average : 0.3957

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-24
Maturity Price : 10.75
Evaluated at bid price : 10.75
Bid-YTW : 4.44 %

RY.PR.K FloatingReset Quote: 21.85 – 22.46
Spot Rate : 0.6100
Average : 0.3950

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.85
Bid-YTW : 4.86 %

BNS.PR.D FloatingReset Quote: 17.42 – 18.12
Spot Rate : 0.7000
Average : 0.5054

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.42
Bid-YTW : 8.06 %

TD.PR.Y FixedReset Quote: 23.43 – 24.00
Spot Rate : 0.5700
Average : 0.3980

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.43
Bid-YTW : 4.28 %

Market Action

March 23, 2016

The US 1 year break-even inflation rate is getting reasonable:

The Treasury market is signaling inflation expectations are rising, and one metric shows traders anticipate cost increases will reach Federal Reserve Chair Janet Yellen’s 2 percent target.

The difference between yields on one-year U.S. government securities and same-maturity Treasury Inflation Protected Securities, a gauge of trader expectations for consumer prices over the life of the debt, climbed to 2.11 percentage points Tuesday. The figure was the highest in two years.

Inflation expectations for the next decade rose to 1.67 percent this week, the highest level since August.

1YrBEIR
Click for Big

‘Off-the-run’ junk names are getting harder to trade:

Traders are getting increasingly punished for trying to sell unpopular debt at the wrong time. The result has been a growing number of hedge-fund failures, increasing risk aversion by Wall Street traders and further cutbacks at big banks.

This all simply reinforces the lack of trading in less-common bonds and loans. At best, this spiral is inconvenient, especially for mutual funds and exchange-traded funds that rely on being able to sell assets to meet daily redemptions. At worst, it could set the stage for another credit seizure given the right catalyst — perhaps a sudden, unexpected corporate default or two, or the implosion of a relatively big mutual fund.

To give a feeling for just how inactive parts of the market have become, consider this: About 40 percent of the bonds in the $1.4 trillion U.S. junk-debt market didn’t trade at all in the first two months of this year, according to data compiled from Finra’s Trace and Bloomberg. While corporate-debt trading has generally increased by volume this year, more of the activity is concentrated in a fewer number of bonds.
…
“The biggest issue that the market faces is that you have an increasing amount of participants that require daily liquidity in an asset class that really doesn’t offer daily liquidity any more,” said Michael Pohly, the portfolio manager at hedge fund Kingdon Credit.

That’s a little scary. The good news so far is that these trading woes haven’t yet triggered another credit crisis. The bad news is it’s only getting harder to transact in riskier debt, making the market increasingly fragile and prone to seizures going forward.

James Bullard contributes to the discussion of the Fed’s next move, standing with the hawks:

Federal Reserve Bank of St. Louis President James Bullard said policy makers should consider raising interest rates at their next meeting amid a broadly unchanged economic outlook and prospects of inflation and unemployment exceeding targets.

“You get another strong jobs report, it looks like labor markets are improving, you could probably make a case for moving in April,” Bullard said in a Bloomberg interview in New York Wednesday, in which he criticized the Fed’s practice of publishing officials’ projections on the path of interest rates. “I think we are going to end up overshooting on inflation” and the natural rate of unemployment, he said.

David Berman of the Globe loves high-spread FixedResets:

But there’s one cash-gusher that deserves a closer look: the high-yielding preferred shares that Canada’s big banks have been issuing over the past several months without much fanfare.

It’s time to take notice. These shares yield a dazzling 5.5 per cent, an eye-popping figure in an era during which the five-year Government of Canada bond yields just 0.7 per cent.
…
Even if bond yields slide to a mere 0.2 per cent five years from now, you’ll get a 5-per-cent yield when the rate is reset. In other words, investors are insulated from low or falling interest rates, which is a nice touch when the Canadian economy is struggling and the Bank of Canada is in no hurry to raise its key rate.

There is one catch: The banks can redeem the shares after five years if they want to. Nonetheless, savvy institutional investors have been snapping up these new issues, and smaller investors can get a piece of the action as well.

While exchange-traded funds are a popular choice, direct ownership looks like a better option because it allows you to focus on the banks’ new-and-improved preferred shares and avoid the less attractive ones (and ETF fees).

National Bank has decided to guess the size of Chinese investment in Canadian real estate:

Buyers from China comprised about one-third of purchases of Vancouver’s hot housing market in 2015, according to “back of the envelope calculations” by National Bank of Canada.

Chinese investors spent about C$12.7 billion ($9.6 billion) on real estate in the western Canadian city in 2015, or 33 percent of its C$38.5 billion in total sales, according to a note by financial analyst Peter Routledge on Wednesday. In Toronto, they made up 14 percent of purchases, or about C$9 billion of the C$63 billion in deals. Routledge compiled the data by extrapolating from a Financial Times survey of 77 high-end buyers and data from the U.S. National Association of Realtors.

PerpetualDiscounts now yield 5.64%, equivalent to 7.33% interest at the standard equivalency factor of 1.3x. Long corporates now yield about 4.15%, so the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) is now about 320bp, a slight (and perhaps spurious) narrowing from the 325bp reported March 9.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.20 % 6.34 % 10,656 16.24 1 -2.9104 % 1,506.6
FixedFloater 7.04 % 6.19 % 25,342 16.09 1 0.4464 % 2,825.2
Floater 4.71 % 4.84 % 64,715 15.80 4 -0.9632 % 1,642.4
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0091 % 2,765.0
SplitShare 4.82 % 5.70 % 75,879 1.63 7 -0.0091 % 3,235.5
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0091 % 2,524.5
Perpetual-Premium 5.79 % -1.10 % 85,384 0.08 6 0.1187 % 2,556.4
Perpetual-Discount 5.62 % 5.64 % 96,683 14.43 33 0.5697 % 2,582.3
FixedReset 5.35 % 4.92 % 184,845 13.83 87 1.3903 % 1,905.6
Deemed-Retractible 5.23 % 5.64 % 129,675 5.09 34 0.3903 % 2,601.6
FloatingReset 3.07 % 4.96 % 39,306 5.41 16 0.5587 % 2,003.3
Performance Highlights
Issue Index Change Notes
BAM.PR.E Ratchet -2.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 25.00
Evaluated at bid price : 13.01
Bid-YTW : 6.34 %
PWF.PR.T FixedReset -1.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 18.78
Evaluated at bid price : 18.78
Bid-YTW : 4.41 %
BAM.PR.C Floater -1.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 9.60
Evaluated at bid price : 9.60
Bid-YTW : 4.93 %
PWF.PR.A Floater -1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 10.98
Evaluated at bid price : 10.98
Bid-YTW : 4.35 %
BMO.PR.W FixedReset 1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 17.78
Evaluated at bid price : 17.78
Bid-YTW : 4.41 %
RY.PR.G Deemed-Retractible 1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.47
Bid-YTW : 5.02 %
BNS.PR.D FloatingReset 1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.55
Bid-YTW : 7.91 %
FTS.PR.M FixedReset 1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 17.30
Evaluated at bid price : 17.30
Bid-YTW : 4.94 %
BAM.PR.N Perpetual-Discount 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 19.96
Evaluated at bid price : 19.96
Bid-YTW : 5.98 %
CU.PR.D Perpetual-Discount 1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 21.82
Evaluated at bid price : 22.14
Bid-YTW : 5.57 %
GWO.PR.R Deemed-Retractible 1.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.88
Bid-YTW : 6.71 %
MFC.PR.N FixedReset 1.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.70
Bid-YTW : 8.16 %
FTS.PR.J Perpetual-Discount 1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 21.44
Evaluated at bid price : 21.75
Bid-YTW : 5.50 %
RY.PR.W Perpetual-Discount 1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 23.48
Evaluated at bid price : 23.75
Bid-YTW : 5.20 %
FTS.PR.I FloatingReset 1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 10.13
Evaluated at bid price : 10.13
Bid-YTW : 4.73 %
NA.PR.W FixedReset 1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 4.72 %
CM.PR.O FixedReset 1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 18.37
Evaluated at bid price : 18.37
Bid-YTW : 4.35 %
CU.PR.H Perpetual-Discount 1.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 23.33
Evaluated at bid price : 23.64
Bid-YTW : 5.60 %
BIP.PR.B FixedReset 1.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 22.84
Evaluated at bid price : 24.12
Bid-YTW : 5.66 %
MFC.PR.I FixedReset 1.57 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.71
Bid-YTW : 7.76 %
TD.PR.S FixedReset 1.59 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.65
Bid-YTW : 3.91 %
MFC.PR.F FixedReset 1.61 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.65
Bid-YTW : 11.07 %
SLF.PR.H FixedReset 1.61 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.75
Bid-YTW : 9.14 %
CU.PR.F Perpetual-Discount 1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 20.48
Evaluated at bid price : 20.48
Bid-YTW : 5.55 %
BMO.PR.R FloatingReset 1.67 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.87
Bid-YTW : 4.54 %
TRP.PR.H FloatingReset 1.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 9.36
Evaluated at bid price : 9.36
Bid-YTW : 4.62 %
MFC.PR.J FixedReset 1.77 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.85
Bid-YTW : 8.14 %
RY.PR.H FixedReset 1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 18.23
Evaluated at bid price : 18.23
Bid-YTW : 4.36 %
BMO.PR.S FixedReset 1.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 18.43
Evaluated at bid price : 18.43
Bid-YTW : 4.40 %
TRP.PR.C FixedReset 1.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 11.71
Evaluated at bid price : 11.71
Bid-YTW : 4.90 %
PWF.PR.Q FloatingReset 1.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 11.00
Evaluated at bid price : 11.00
Bid-YTW : 4.72 %
TRP.PR.B FixedReset 1.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 10.85
Evaluated at bid price : 10.85
Bid-YTW : 4.71 %
W.PR.K FixedReset 1.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 23.24
Evaluated at bid price : 25.20
Bid-YTW : 5.23 %
FTS.PR.H FixedReset 1.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 12.32
Evaluated at bid price : 12.32
Bid-YTW : 4.60 %
BMO.PR.Y FixedReset 2.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 19.42
Evaluated at bid price : 19.42
Bid-YTW : 4.58 %
MFC.PR.G FixedReset 2.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.36
Bid-YTW : 7.96 %
HSE.PR.E FixedReset 2.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 18.70
Evaluated at bid price : 18.70
Bid-YTW : 5.83 %
TD.PR.Y FixedReset 2.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.85
Bid-YTW : 3.94 %
FTS.PR.K FixedReset 2.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 16.00
Evaluated at bid price : 16.00
Bid-YTW : 4.68 %
TRP.PR.D FixedReset 2.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 17.41
Evaluated at bid price : 17.41
Bid-YTW : 4.75 %
BAM.PF.F FixedReset 2.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 18.69
Evaluated at bid price : 18.69
Bid-YTW : 5.05 %
BAM.PR.Z FixedReset 2.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 18.44
Evaluated at bid price : 18.44
Bid-YTW : 5.16 %
PWF.PR.P FixedReset 2.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 12.45
Evaluated at bid price : 12.45
Bid-YTW : 4.72 %
BAM.PF.E FixedReset 2.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 18.05
Evaluated at bid price : 18.05
Bid-YTW : 4.90 %
MFC.PR.K FixedReset 2.55 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.90
Bid-YTW : 8.56 %
BAM.PF.G FixedReset 2.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 18.70
Evaluated at bid price : 18.70
Bid-YTW : 5.08 %
TRP.PR.E FixedReset 2.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 18.26
Evaluated at bid price : 18.26
Bid-YTW : 4.59 %
TRP.PR.F FloatingReset 2.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 12.32
Evaluated at bid price : 12.32
Bid-YTW : 4.81 %
GWO.PR.N FixedReset 2.68 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.40
Bid-YTW : 10.22 %
FTS.PR.G FixedReset 2.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 16.00
Evaluated at bid price : 16.00
Bid-YTW : 4.71 %
TD.PF.E FixedReset 2.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 20.14
Evaluated at bid price : 20.14
Bid-YTW : 4.55 %
BAM.PF.A FixedReset 2.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 18.45
Evaluated at bid price : 18.45
Bid-YTW : 5.10 %
RY.PR.Z FixedReset 2.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 18.25
Evaluated at bid price : 18.25
Bid-YTW : 4.30 %
BMO.PR.T FixedReset 2.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 4.39 %
CM.PR.P FixedReset 2.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 18.19
Evaluated at bid price : 18.19
Bid-YTW : 4.29 %
HSE.PR.C FixedReset 3.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 16.80
Evaluated at bid price : 16.80
Bid-YTW : 5.98 %
TD.PF.B FixedReset 3.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 18.49
Evaluated at bid price : 18.49
Bid-YTW : 4.30 %
CU.PR.C FixedReset 3.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 17.51
Evaluated at bid price : 17.51
Bid-YTW : 4.57 %
BAM.PF.B FixedReset 3.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 17.36
Evaluated at bid price : 17.36
Bid-YTW : 5.05 %
IFC.PR.C FixedReset 3.53 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.60
Bid-YTW : 8.20 %
TD.PF.A FixedReset 3.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 18.65
Evaluated at bid price : 18.65
Bid-YTW : 4.27 %
TD.PF.C FixedReset 3.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 18.56
Evaluated at bid price : 18.56
Bid-YTW : 4.27 %
IFC.PR.A FixedReset 3.67 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.42
Bid-YTW : 10.29 %
BAM.PR.X FixedReset 3.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 14.14
Evaluated at bid price : 14.14
Bid-YTW : 4.71 %
RY.PR.M FixedReset 3.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 19.15
Evaluated at bid price : 19.15
Bid-YTW : 4.49 %
TRP.PR.G FixedReset 3.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 4.93 %
BAM.PR.T FixedReset 4.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 15.87
Evaluated at bid price : 15.87
Bid-YTW : 4.91 %
BAM.PR.R FixedReset 4.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 15.34
Evaluated at bid price : 15.34
Bid-YTW : 4.96 %
Volume Highlights
Issue Index Shares
Traded
Notes
MFC.PR.O FixedReset 123,025 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-06-19
Maturity Price : 25.00
Evaluated at bid price : 25.72
Bid-YTW : 5.09 %
TD.PF.G FixedReset 110,460 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 25.81
Bid-YTW : 5.04 %
FTS.PR.M FixedReset 107,942 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 17.30
Evaluated at bid price : 17.30
Bid-YTW : 4.94 %
TRP.PR.C FixedReset 88,600 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 11.71
Evaluated at bid price : 11.71
Bid-YTW : 4.90 %
BNS.PR.N Deemed-Retractible 84,605 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-01-27
Maturity Price : 25.00
Evaluated at bid price : 25.26
Bid-YTW : 4.91 %
BNS.PR.G FixedReset 73,176 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-07-25
Maturity Price : 25.00
Evaluated at bid price : 25.71
Bid-YTW : 4.95 %
There were 45 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
RY.PR.J FixedReset Quote: 18.86 – 19.65
Spot Rate : 0.7900
Average : 0.4969

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 18.86
Evaluated at bid price : 18.86
Bid-YTW : 4.68 %

PWF.PR.Q FloatingReset Quote: 11.00 – 12.00
Spot Rate : 1.0000
Average : 0.7747

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 11.00
Evaluated at bid price : 11.00
Bid-YTW : 4.72 %

PWF.PR.T FixedReset Quote: 18.78 – 19.42
Spot Rate : 0.6400
Average : 0.4185

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 18.78
Evaluated at bid price : 18.78
Bid-YTW : 4.41 %

BMO.PR.T FixedReset Quote: 18.00 – 18.76
Spot Rate : 0.7600
Average : 0.5392

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 4.39 %

CM.PR.Q FixedReset Quote: 18.86 – 19.45
Spot Rate : 0.5900
Average : 0.3833

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 18.86
Evaluated at bid price : 18.86
Bid-YTW : 4.68 %

CU.PR.C FixedReset Quote: 17.51 – 18.02
Spot Rate : 0.5100
Average : 0.3422

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-23
Maturity Price : 17.51
Evaluated at bid price : 17.51
Bid-YTW : 4.57 %

Market Action

March 22, 2016

We’ve blown a lot of money in Ontari-ari-ari-o, but at least the Chileans know how to make solar power useful:

Valhalla Energia is seeking partners to build a 600-megawatt solar project in Chile that will incorporate hydropower to deliver energy 24 hours a day.

The company is in talks with investors to raise as much as 40 percent of the estimated $1.3 billion needed for the project — $900 million for the solar component and $400 million for a 300-megawatt hydropower system — according to Juan Andres Camus, Santiago-based Valhalla’s co-founder and chief executive officer. The rest will come from bank loans.

“We are looking for sponsors that can be part of the project as equity,” Camus said in an interview in Santiago on March 18. “We are in advanced negotiations.”

The Cielos de Tarapaca solar project aims to produce electricity around the clock, using an integrated solar and hydro system that pumps sea water uphill to a reservoir during the day and letting it flow through turbines at night.

And today’s equity tip is: sell your hypodermic syringe manufacturing stock:

A stick-on patch that tracks, and even regulates, blood sugar levels could be used by people with diabetes one day, according to a new study.

Unlike finger pricking — the traditional method of monitoring levels of the blood sugar glucose — the new patch detects the levels of glucose in a person’s sweat. Research has shown that glucose levels in sweat accurately reflect glucose levels in the blood, the researchers said.

The researchers also showed that the patch can deliver the diabetes drug metformin through the skin and that it can reduce high blood glucose levels in mice with diabetes.

Meanwhile, Fed governor Charles Evans took a dovish stance on policy rates:

Federal Reserve Bank of Chicago President Charles Evans said policy makers rightly refrained from raising interest rates this month after a rocky start to the year clouded the economic outlook.

“The rationale for no rate change in March is that economic and financial risks seem somewhat higher for 2016 than we had hoped back last December when we first began raising rates,” Evans said Tuesday in a speech in Chicago. “Most of the Federal Open Market Committee’s cautionary pause in the rate normalization path is about assessing risks and just being careful.”

There was a federal budget today, which will be discussed by many more verbose people than me. So I’ll just say it’s pretty much as expected, with some stuff that looks halfway reasonable at first sight:

The Liberals have set aside $11.9-billion for public transit, affordable housing, wastewater systems and $3.4-billion to upgrade parks, harbours, border crossings, federal airports and to clean up contaminated sites across the country.

…. but looks like a ridiculous feel-good boondoggle at second glance:

12Billion_budget2016
Click for Big

… and some stuff which will be popular among morons, but is really just an exceptionally cruel way of ensuring the next generation is brought up in an isolated environment with no jobs, no hope, no future and nothing to do except drink:

Prime Minister Justin Trudeau promised “historic investments” to First Nations and the budget followed through with $8.4-billion for education, housing and clean drinking water.

… the return of the Subsidies For Sleazebags Programme:

To facilitate access to venture capital for small and medium-sized businesses and support saving by the middle class, Budget 2016 proposes to restore the Labour-Sponsored Venture Capital Corporations (LSVCC) tax credit to 15 per cent for share purchases of provincially registered LSVCCs for 2016 and subsequent tax years. The measure will provide federal tax relief of about $815 million over the 2015–16 to 2020–21 period.

The proposed bail-in regime has been endorsed, at least in principle:

To protect Canadian taxpayers in the unlikely event of a large bank failure, the Government is proposing to implement a bail-in regime that would reinforce that bank shareholders and creditors are responsible for the bank’s risks—not taxpayers. This would allow authorities to convert eligible long-term debt of a failing systemically important bank into common shares to recapitalize the bank and allow it to remain open and operating. Such a measure is in line with international efforts to address the potential risks to the financial system and broader economy of institutions perceived as “too-big-to-fail”.

The Government is proposing to introduce framework legislation for the regime along with accompanying enhancements to Canada’s bank resolution toolkit. Regulations and guidelines setting out further features of the regime will follow. This will provide stakeholders with an additional opportunity to comment on elements of the proposed regime.

So we’ll see how it goes.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.05 % 6.15 % 10,528 16.47 1 0.0000 % 1,551.8
FixedFloater 7.07 % 6.21 % 24,391 16.05 1 0.6742 % 2,812.6
Floater 4.67 % 4.80 % 64,968 15.87 4 1.8360 % 1,658.4
OpRet 0.00 % 0.00 % 0 0.00 0 -0.1288 % 2,765.2
SplitShare 4.82 % 5.69 % 73,698 1.63 7 -0.1288 % 3,235.8
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.1288 % 2,524.7
Perpetual-Premium 5.79 % -3.66 % 86,040 0.08 6 0.1466 % 2,553.4
Perpetual-Discount 5.65 % 5.68 % 96,764 14.38 33 0.0497 % 2,567.7
FixedReset 5.43 % 5.02 % 185,513 13.84 87 0.9074 % 1,879.5
Deemed-Retractible 5.25 % 5.71 % 131,519 6.91 34 -0.0327 % 2,591.4
FloatingReset 3.09 % 4.99 % 38,627 5.42 16 0.3662 % 1,992.2
Performance Highlights
Issue Index Change Notes
BMO.PR.T FixedReset -1.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 17.49
Evaluated at bid price : 17.49
Bid-YTW : 4.52 %
CU.PR.F Perpetual-Discount -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 20.15
Evaluated at bid price : 20.15
Bid-YTW : 5.64 %
PWF.PR.P FixedReset 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 12.15
Evaluated at bid price : 12.15
Bid-YTW : 4.84 %
HSE.PR.E FixedReset 1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 18.30
Evaluated at bid price : 18.30
Bid-YTW : 5.96 %
BMO.PR.Q FixedReset 1.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.25
Bid-YTW : 7.93 %
TD.PF.B FixedReset 1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 17.91
Evaluated at bid price : 17.91
Bid-YTW : 4.44 %
TD.PF.C FixedReset 1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 17.91
Evaluated at bid price : 17.91
Bid-YTW : 4.43 %
SLF.PR.I FixedReset 1.18 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.01
Bid-YTW : 8.00 %
FTS.PR.M FixedReset 1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 17.12
Evaluated at bid price : 17.12
Bid-YTW : 4.99 %
NA.PR.Q FixedReset 1.25 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.56
Bid-YTW : 4.57 %
NA.PR.S FixedReset 1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 17.80
Evaluated at bid price : 17.80
Bid-YTW : 4.68 %
BAM.PF.G FixedReset 1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 18.23
Evaluated at bid price : 18.23
Bid-YTW : 5.22 %
SLF.PR.H FixedReset 1.31 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.50
Bid-YTW : 9.36 %
TRP.PR.E FixedReset 1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 17.80
Evaluated at bid price : 17.80
Bid-YTW : 4.71 %
BAM.PF.H FixedReset 1.37 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.85
Bid-YTW : 4.20 %
CM.PR.O FixedReset 1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 18.35
Evaluated at bid price : 18.35
Bid-YTW : 4.43 %
BAM.PR.R FixedReset 1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 14.65
Evaluated at bid price : 14.65
Bid-YTW : 5.19 %
BAM.PF.F FixedReset 1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 18.26
Evaluated at bid price : 18.26
Bid-YTW : 5.18 %
NA.PR.W FixedReset 1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 16.78
Evaluated at bid price : 16.78
Bid-YTW : 4.78 %
TD.PF.A FixedReset 1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 4.43 %
BAM.PR.Z FixedReset 1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 5.29 %
BAM.PF.A FixedReset 1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 17.95
Evaluated at bid price : 17.95
Bid-YTW : 5.24 %
FTS.PR.K FixedReset 1.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 15.65
Evaluated at bid price : 15.65
Bid-YTW : 4.79 %
TRP.PR.G FixedReset 1.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 18.30
Evaluated at bid price : 18.30
Bid-YTW : 5.12 %
TRP.PR.D FixedReset 1.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 17.01
Evaluated at bid price : 17.01
Bid-YTW : 4.86 %
TRP.PR.C FixedReset 1.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 11.50
Evaluated at bid price : 11.50
Bid-YTW : 4.99 %
MFC.PR.L FixedReset 1.78 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.20
Bid-YTW : 8.43 %
MFC.PR.H FixedReset 1.79 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.92
Bid-YTW : 7.11 %
CM.PR.Q FixedReset 1.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 19.25
Evaluated at bid price : 19.25
Bid-YTW : 4.66 %
IFC.PR.A FixedReset 1.83 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.91
Bid-YTW : 10.80 %
BAM.PF.B FixedReset 2.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 16.80
Evaluated at bid price : 16.80
Bid-YTW : 5.23 %
BAM.PR.K Floater 2.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 9.75
Evaluated at bid price : 9.75
Bid-YTW : 4.85 %
RY.PR.J FixedReset 2.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 18.71
Evaluated at bid price : 18.71
Bid-YTW : 4.72 %
BAM.PF.E FixedReset 2.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 17.61
Evaluated at bid price : 17.61
Bid-YTW : 5.02 %
BAM.PR.B Floater 2.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 9.85
Evaluated at bid price : 9.85
Bid-YTW : 4.80 %
BAM.PR.C Floater 2.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 9.75
Evaluated at bid price : 9.75
Bid-YTW : 4.85 %
RY.PR.M FixedReset 2.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 18.45
Evaluated at bid price : 18.45
Bid-YTW : 4.66 %
FTS.PR.I FloatingReset 2.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 10.00
Evaluated at bid price : 10.00
Bid-YTW : 4.79 %
TRP.PR.B FixedReset 2.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 10.65
Evaluated at bid price : 10.65
Bid-YTW : 4.80 %
TD.PF.D FixedReset 2.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 19.50
Evaluated at bid price : 19.50
Bid-YTW : 4.59 %
TRP.PR.F FloatingReset 2.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 12.00
Evaluated at bid price : 12.00
Bid-YTW : 4.94 %
IFC.PR.C FixedReset 2.84 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.00
Bid-YTW : 8.69 %
HSE.PR.A FixedReset 2.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 10.30
Evaluated at bid price : 10.30
Bid-YTW : 5.99 %
BAM.PR.X FixedReset 3.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 13.63
Evaluated at bid price : 13.63
Bid-YTW : 4.89 %
FTS.PR.H FixedReset 3.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 12.08
Evaluated at bid price : 12.08
Bid-YTW : 4.69 %
TRP.PR.A FixedReset 3.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 14.50
Evaluated at bid price : 14.50
Bid-YTW : 4.79 %
CU.PR.C FixedReset 4.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 16.96
Evaluated at bid price : 16.96
Bid-YTW : 4.72 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.R FixedReset 182,165 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-24
Maturity Price : 25.00
Evaluated at bid price : 25.60
Bid-YTW : 5.07 %
BNS.PR.Q FixedReset 179,917 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.23
Bid-YTW : 4.48 %
GWO.PR.I Deemed-Retractible 103,710 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.03
Bid-YTW : 6.95 %
BNS.PR.R FixedReset 100,685 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.64
Bid-YTW : 4.42 %
PWF.PR.F Perpetual-Discount 94,846 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 23.09
Evaluated at bid price : 23.35
Bid-YTW : 5.70 %
BNS.PR.G FixedReset 93,805 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-07-25
Maturity Price : 25.00
Evaluated at bid price : 25.59
Bid-YTW : 5.05 %
There were 44 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
FTS.PR.I FloatingReset Quote: 10.00 – 10.89
Spot Rate : 0.8900
Average : 0.5779

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 10.00
Evaluated at bid price : 10.00
Bid-YTW : 4.79 %

CU.PR.H Perpetual-Discount Quote: 23.30 – 24.00
Spot Rate : 0.7000
Average : 0.4468

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 22.89
Evaluated at bid price : 23.30
Bid-YTW : 5.67 %

FTS.PR.F Perpetual-Discount Quote: 22.15 – 22.69
Spot Rate : 0.5400
Average : 0.3560

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 21.91
Evaluated at bid price : 22.15
Bid-YTW : 5.58 %

ELF.PR.G Perpetual-Discount Quote: 20.07 – 20.52
Spot Rate : 0.4500
Average : 0.2843

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 20.07
Evaluated at bid price : 20.07
Bid-YTW : 6.04 %

BNS.PR.B FloatingReset Quote: 21.00 – 21.45
Spot Rate : 0.4500
Average : 0.3091

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.00
Bid-YTW : 5.36 %

FTS.PR.G FixedReset Quote: 15.58 – 16.03
Spot Rate : 0.4500
Average : 0.3173

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-22
Maturity Price : 15.58
Evaluated at bid price : 15.58
Bid-YTW : 4.84 %

Market Action

March 21, 2016

I mentioned Google’s proposed sale of Boston Dynamics on March 17. Jack Clark of Bloomberg has some colour commentary on the matter:

Google’s decision to try to shed its Boston Dynamics robotics group highlights a fundamental research problem: software is far easier to develop and test than hardware. That’s especially true when dealing with artificial intelligence and robotics.

Today’s industrial robots tend to be dumb machines, operating on pre-programmed routines, and are housed in metal cages to stop people walking into their zone of movement and potentially getting harmed. With Boston Dynamics, Google was working on machines that could break out of the rigid confines of the factory and perform a broader range of tasks. That requires dealing with a range of unsolved problems, requiring fundamental research.
…
Boston Dynamics’s robots need technology that doesn’t exist yet. The software to control them and give them autonomy is still a research problem being worked on by universities around the world. This is likely why Google thought it would take a decade to develop Boston Dynamics’s technology into a commercial product.

Possible acquirers include the Toyota Research Institute, a division of Toyota Motor Corp., and Amazon.com Inc., which makes robots for its fulfillment centers, according to a person familiar with Google’s plans. Toyota declined to comment, and Amazon didn’t respond to requests for comment.

It’s rare to see a company to build a product that requires such fundamental research in a number of areas, said John Schulman, a researcher with AI group OpenAI. “Having a humanoid robot that goes around and does interesting things in the real world, like maybe cleans up your house, that’s just way beyond the current state of the science.”

But on the other hand, perhaps my robotic 4am pizza delivery will arrive soon!

Domino’s Australia and Domino’s New Zealand have both released teaser videos featuring a sleek-looking new delivery robot – the Domino’s Robotic Unit (DRU). They designed the robot along with the help of Australian startup Marathon Robotics using GPS tracking and sensors to navigate around to customers’ houses.

The four-wheeled robot has multiple compartments that keeps up to 10 pizzas toastie warm, whilst a refrigerating section keeps drinks and desserts cool. The Guardian reports that customers can open the compartments by entering a security code into their smartphone when the robot arrives at their door.

There’s no word yet on when exactly Domino’s will be making the DRU a reality, though. In a statement they announced: “While he won’t be taking to the streets tomorrow, DRU is a big step forward in the work Domino’s is doing in the future commercialisation of this technology.”

And the delivery companies are lobbying for better infrastructure:

Amazon declined requests to comment for this article. But on a recent earnings call, Amazon’s chief financial officer, Brian Olsavsky, explained why Amazon wanted to move more aggressively into delivery.
…
In addition, the company’s shipping costs rose 19 percent, to $5 billion, in 2015. The millions of members of its Prime annual subscription service, Amazon’s most frequent customers, have helped feed the surge. Those customers receive free shipping for many products.
…
Already, the company’s drone push in Washington has had some success. Amazon has worked with NASA, for example, to create an air traffic system that would establish lanes in the sky for drones.

Amazon has also urged Congress to adopt rules that would allow the retailer to fly drones beyond a pilot’s line of sight, a crucial hurdle to Amazon’s goal of operating drones from its warehouses. This effort is expected to face an important test soon. This month, the Senate Transportation Committee drafted a bill that would ensure rules for delivery drones within two years.
…
Amazon is arguing for changes in many other areas, too. Already, Mr. Misener, the lead lobbyist, has called for an overhaul of an arcane system of international delivery rates that he says give foreign e-commerce rivals an unfair advantage to deliver to American homes.

He also urged the approval of legislation that aims to improve roads, bridges and railways. The bill was passed by Congress and signed into law in December.

Meanwhile, it seems to me that the homogeneity of Treasury buyers brought about by low yields is showing its downside:

The 22 primary dealers held more Treasuries last month than any time in the last two years, Federal Reserve Bank of New York data show. While at first glance that may suggest a bullish stance, the surge in holdings is more likely the result of investors including central banks dumping the debt on the firms, said JPMorgan Chase & Co. strategist Jay Barry. Foreign official accounts sold a net $105 billion of the securities in December and January, an unprecedented liquidation, Treasury Department data show.
…
As the world’s biggest bond dealers — including banks such as Bank of America Corp., Goldman Sachs Group Inc. and JPMorgan — struggled to get rid of the burgeoning pile of debt, the premium for the newest, easiest-to-trade Treasuries soared to the highest since 2011. The firms’ efforts to hedge all the Treasuries collecting on their balance sheets also roiled the futures market and a crucial corner of the financial system where traders lend and borrow securities overnight.
…
Dealers moved to minimize the risk of holding so many tough-to-unload securities by selling, or shorting, benchmark notes, said Barry of JPMorgan. They had the biggest bearish position in the newest 30-year bonds since May in the week ended March 9, according to a Credit Agricole SA analysis of New York Fed data.

Part of the fallout was seen in the $1.6 trillion market for repurchase agreements, or repos, where Wall Street goes to exchange securities for overnight cash.

The combination of dealer demand, a global government-debt rally and reduced auction sizes caused a shortage in the repo market for the securities needed to close short positions in 10-year debt. Failures to deliver 10-year notes surged in the week ended March 9 to the most since at least 2013. For all Treasuries, failures reached the highest since the financial crisis, New York Fed data show.

Demand was so great for the benchmark 10-year note that its repo rate traded at about negative 3 percent for more than a week, before an auction of the debt settled March 15 and eased the shortage. At that level, the cost of borrowing the security in the repo market was steeper than the 3 percent penalty for uncompleted trades, leading more traders to opt to let deals fail.

Two Fed governors are talking up the chances for an early hike – but, of course, this could be merely a ploy to keep the markets honest:

“There is sufficient momentum evidenced by the economic data to justify a further step at one of the coming meetings, possibly as early as the meeting scheduled for end of April,” Federal Reserve Bank of Atlanta President Dennis Lockhart said Monday in Savannah, Georgia.
…
Lockhart is a policy-centrist and doesn’t vote on the FOMC this year. His moderately upbeat assessment of the U.S. economy was shared by San Francisco Fed chief John Williams.

“All else equal, assuming everything else is basically the same and the data flow continues the way I hope and expect, then April or June would definitely be potential times to have an increase in interest rates,” he told Market News International in an interview published earlier on Monday. Williams, a former head of research for Fed Chair Janet Yellen when she ran the San Francisco Fed, also doesn’t vote on policy in 2016.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.05 % 6.15 % 10,905 16.47 1 1.5152 % 1,551.8
FixedFloater 7.12 % 6.26 % 24,724 16.01 1 -1.1843 % 2,793.8
Floater 4.75 % 4.91 % 65,837 15.68 4 -1.4378 % 1,628.5
OpRet 0.00 % 0.00 % 0 0.00 0 0.5283 % 2,768.8
SplitShare 4.81 % 5.61 % 71,630 1.64 7 0.5283 % 3,240.0
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.5283 % 2,528.0
Perpetual-Premium 5.79 % -3.85 % 87,352 0.08 6 0.1782 % 2,549.7
Perpetual-Discount 5.65 % 5.68 % 99,667 14.30 33 0.1995 % 2,566.4
FixedReset 5.48 % 5.15 % 187,524 14.30 87 0.3938 % 1,862.6
Deemed-Retractible 5.25 % 5.67 % 132,263 6.92 34 0.2132 % 2,592.3
FloatingReset 3.10 % 5.08 % 38,896 5.42 16 0.1490 % 1,984.9
Performance Highlights
Issue Index Change Notes
TRP.PR.C FixedReset -2.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-21
Maturity Price : 11.31
Evaluated at bid price : 11.31
Bid-YTW : 5.07 %
PWF.PR.A Floater -1.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-21
Maturity Price : 11.05
Evaluated at bid price : 11.05
Bid-YTW : 4.32 %
BAM.PR.B Floater -1.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-21
Maturity Price : 9.63
Evaluated at bid price : 9.63
Bid-YTW : 4.91 %
BAM.PR.C Floater -1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-21
Maturity Price : 9.53
Evaluated at bid price : 9.53
Bid-YTW : 4.96 %
BAM.PR.G FixedFloater -1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-21
Maturity Price : 25.00
Evaluated at bid price : 13.35
Bid-YTW : 6.26 %
SLF.PR.I FixedReset 1.02 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.80
Bid-YTW : 8.16 %
PVS.PR.E SplitShare 1.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-10-31
Maturity Price : 25.00
Evaluated at bid price : 23.75
Bid-YTW : 6.53 %
MFC.PR.N FixedReset 1.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.60
Bid-YTW : 8.23 %
MFC.PR.C Deemed-Retractible 1.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.72
Bid-YTW : 7.19 %
HSB.PR.D Deemed-Retractible 1.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.50
Bid-YTW : 5.40 %
FTS.PR.G FixedReset 1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-21
Maturity Price : 15.50
Evaluated at bid price : 15.50
Bid-YTW : 4.87 %
TD.PF.D FixedReset 1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-21
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 4.71 %
BNS.PR.Z FixedReset 1.39 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.97
Bid-YTW : 7.27 %
PVS.PR.D SplitShare 1.41 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2021-10-08
Maturity Price : 25.00
Evaluated at bid price : 22.97
Bid-YTW : 6.33 %
VNR.PR.A FixedReset 1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-21
Maturity Price : 17.20
Evaluated at bid price : 17.20
Bid-YTW : 5.35 %
BAM.PR.E Ratchet 1.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-21
Maturity Price : 25.00
Evaluated at bid price : 13.40
Bid-YTW : 6.15 %
MFC.PR.M FixedReset 1.67 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.70
Bid-YTW : 8.22 %
HSE.PR.E FixedReset 1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-21
Maturity Price : 18.10
Evaluated at bid price : 18.10
Bid-YTW : 6.03 %
TD.PF.E FixedReset 1.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-21
Maturity Price : 19.42
Evaluated at bid price : 19.42
Bid-YTW : 4.72 %
BMO.PR.Y FixedReset 1.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-21
Maturity Price : 18.85
Evaluated at bid price : 18.85
Bid-YTW : 4.71 %
BMO.PR.T FixedReset 1.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-21
Maturity Price : 17.75
Evaluated at bid price : 17.75
Bid-YTW : 4.45 %
MFC.PR.G FixedReset 2.21 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.06
Bid-YTW : 8.19 %
HSE.PR.G FixedReset 2.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-21
Maturity Price : 18.20
Evaluated at bid price : 18.20
Bid-YTW : 5.98 %
MFC.PR.K FixedReset 2.93 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.50
Bid-YTW : 8.89 %
MFC.PR.L FixedReset 3.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.90
Bid-YTW : 8.67 %
HSE.PR.A FixedReset 3.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-21
Maturity Price : 10.01
Evaluated at bid price : 10.01
Bid-YTW : 6.17 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.H FixedReset 128,018 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-21
Maturity Price : 17.75
Evaluated at bid price : 17.75
Bid-YTW : 4.48 %
CM.PR.P FixedReset 111,400 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-21
Maturity Price : 17.82
Evaluated at bid price : 17.82
Bid-YTW : 4.46 %
BNS.PR.O Deemed-Retractible 99,700 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-04-27
Maturity Price : 25.25
Evaluated at bid price : 25.60
Bid-YTW : -0.78 %
TD.PF.G FixedReset 91,857 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 25.66
Bid-YTW : 5.16 %
RY.PR.R FixedReset 77,555 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-24
Maturity Price : 25.00
Evaluated at bid price : 25.42
Bid-YTW : 5.22 %
BNS.PR.E FixedReset 68,909 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-21
Maturity Price : 23.37
Evaluated at bid price : 25.71
Bid-YTW : 5.15 %
There were 22 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
MFC.PR.O FixedReset Quote: 25.60 – 26.72
Spot Rate : 1.1200
Average : 0.6164

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-06-19
Maturity Price : 25.00
Evaluated at bid price : 25.60
Bid-YTW : 5.19 %

GWO.PR.O FloatingReset Quote: 11.55 – 12.95
Spot Rate : 1.4000
Average : 0.9052

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.55
Bid-YTW : 11.65 %

SLF.PR.H FixedReset Quote: 15.30 – 15.85
Spot Rate : 0.5500
Average : 0.3909

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.30
Bid-YTW : 9.54 %

BNS.PR.R FixedReset Quote: 23.51 – 23.99
Spot Rate : 0.4800
Average : 0.3508

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.51
Bid-YTW : 4.52 %

CU.PR.C FixedReset Quote: 16.30 – 16.71
Spot Rate : 0.4100
Average : 0.2877

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-21
Maturity Price : 16.30
Evaluated at bid price : 16.30
Bid-YTW : 4.92 %

FTS.PR.K FixedReset Quote: 15.40 – 15.83
Spot Rate : 0.4300
Average : 0.3097

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-21
Maturity Price : 15.40
Evaluated at bid price : 15.40
Bid-YTW : 4.87 %

Market Action

March 18, 2016

Nothing happened today.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.12 % 6.24 % 10,936 16.37 1 -1.4925 % 1,528.6
FixedFloater 7.03 % 6.18 % 24,927 16.11 1 0.0000 % 2,827.3
Floater 4.69 % 4.82 % 65,164 15.84 4 0.7996 % 1,652.2
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0659 % 2,754.2
SplitShare 4.83 % 5.68 % 71,608 1.64 7 -0.0659 % 3,223.0
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0659 % 2,514.7
Perpetual-Premium 5.80 % -2.06 % 85,687 0.08 6 0.0727 % 2,545.1
Perpetual-Discount 5.66 % 5.70 % 99,230 14.25 33 0.5198 % 2,561.3
FixedReset 5.50 % 5.22 % 189,624 14.23 87 0.0343 % 1,855.3
Deemed-Retractible 5.26 % 5.64 % 122,380 5.10 34 0.5249 % 2,586.8
FloatingReset 3.14 % 5.13 % 40,512 5.42 16 0.1684 % 1,981.9
Performance Highlights
Issue Index Change Notes
BMO.PR.Y FixedReset -1.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-18
Maturity Price : 18.50
Evaluated at bid price : 18.50
Bid-YTW : 4.89 %
BAM.PR.E Ratchet -1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-18
Maturity Price : 25.00
Evaluated at bid price : 13.20
Bid-YTW : 6.24 %
MFC.PR.M FixedReset -1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.41
Bid-YTW : 8.50 %
RY.PR.L FixedReset -1.29 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.52
Bid-YTW : 4.33 %
NA.PR.W FixedReset -1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-18
Maturity Price : 16.55
Evaluated at bid price : 16.55
Bid-YTW : 4.95 %
SLF.PR.G FixedReset -1.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.21
Bid-YTW : 10.59 %
CM.PR.Q FixedReset 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-18
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 4.79 %
CU.PR.E Perpetual-Discount 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-18
Maturity Price : 21.56
Evaluated at bid price : 21.91
Bid-YTW : 5.63 %
PWF.PR.S Perpetual-Discount 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-18
Maturity Price : 21.33
Evaluated at bid price : 21.62
Bid-YTW : 5.62 %
SLF.PR.E Deemed-Retractible 1.19 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.49
Bid-YTW : 7.31 %
MFC.PR.B Deemed-Retractible 1.25 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.05
Bid-YTW : 7.12 %
SLF.PR.D Deemed-Retractible 1.29 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.37
Bid-YTW : 7.34 %
MFC.PR.C Deemed-Retractible 1.34 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.48
Bid-YTW : 7.35 %
GWO.PR.P Deemed-Retractible 1.35 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.07
Bid-YTW : 5.95 %
CU.PR.H Perpetual-Discount 1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-18
Maturity Price : 23.17
Evaluated at bid price : 23.47
Bid-YTW : 5.63 %
GWO.PR.Q Deemed-Retractible 1.40 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.11
Bid-YTW : 6.28 %
BNS.PR.F FloatingReset 1.43 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.76
Bid-YTW : 8.19 %
GWO.PR.G Deemed-Retractible 1.43 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.33
Bid-YTW : 6.20 %
GWO.PR.R Deemed-Retractible 1.45 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.71
Bid-YTW : 6.81 %
SLF.PR.A Deemed-Retractible 1.49 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.86
Bid-YTW : 6.66 %
CU.PR.G Perpetual-Discount 1.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-18
Maturity Price : 20.22
Evaluated at bid price : 20.22
Bid-YTW : 5.62 %
HSE.PR.A FixedReset 1.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-18
Maturity Price : 9.70
Evaluated at bid price : 9.70
Bid-YTW : 6.57 %
BNS.PR.D FloatingReset 1.64 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.37
Bid-YTW : 8.11 %
SLF.PR.H FixedReset 1.67 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.25
Bid-YTW : 9.68 %
CU.PR.D Perpetual-Discount 1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-18
Maturity Price : 21.72
Evaluated at bid price : 22.00
Bid-YTW : 5.61 %
GWO.PR.H Deemed-Retractible 1.73 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.81
Bid-YTW : 6.80 %
SLF.PR.B Deemed-Retractible 1.75 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.05
Bid-YTW : 6.59 %
GWO.PR.S Deemed-Retractible 1.85 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.72
Bid-YTW : 6.01 %
GWO.PR.I Deemed-Retractible 1.90 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.97
Bid-YTW : 6.98 %
CU.PR.F Perpetual-Discount 1.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-18
Maturity Price : 20.25
Evaluated at bid price : 20.25
Bid-YTW : 5.61 %
BAM.PR.K Floater 2.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-18
Maturity Price : 9.62
Evaluated at bid price : 9.62
Bid-YTW : 4.91 %
TD.PF.A FixedReset 2.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-18
Maturity Price : 17.73
Evaluated at bid price : 17.73
Bid-YTW : 4.59 %
FTS.PR.H FixedReset 2.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-18
Maturity Price : 11.65
Evaluated at bid price : 11.65
Bid-YTW : 5.00 %
TRP.PR.C FixedReset 2.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-18
Maturity Price : 11.60
Evaluated at bid price : 11.60
Bid-YTW : 5.07 %
BAM.PR.T FixedReset 3.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-18
Maturity Price : 15.20
Evaluated at bid price : 15.20
Bid-YTW : 5.25 %
Volume Highlights
Issue Index Shares
Traded
Notes
SLF.PR.D Deemed-Retractible 130,092 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.37
Bid-YTW : 7.34 %
GWO.PR.M Deemed-Retractible 125,410 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-03-31
Maturity Price : 25.25
Evaluated at bid price : 25.40
Bid-YTW : 5.35 %
RY.PR.Q FixedReset 83,130 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-18
Maturity Price : 23.33
Evaluated at bid price : 25.58
Bid-YTW : 5.26 %
RY.PR.R FixedReset 71,182 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-24
Maturity Price : 25.00
Evaluated at bid price : 25.37
Bid-YTW : 5.25 %
SLF.PR.H FixedReset 65,305 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.25
Bid-YTW : 9.68 %
TRP.PR.C FixedReset 55,140 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-18
Maturity Price : 11.60
Evaluated at bid price : 11.60
Bid-YTW : 5.07 %
There were 35 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
PWF.PR.Q FloatingReset Quote: 10.75 – 11.75
Spot Rate : 1.0000
Average : 0.7626

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-18
Maturity Price : 10.75
Evaluated at bid price : 10.75
Bid-YTW : 4.88 %

CCS.PR.C Deemed-Retractible Quote: 21.45 – 21.99
Spot Rate : 0.5400
Average : 0.3085

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.45
Bid-YTW : 7.21 %

TD.PF.B FixedReset Quote: 17.63 – 18.13
Spot Rate : 0.5000
Average : 0.3242

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-18
Maturity Price : 17.63
Evaluated at bid price : 17.63
Bid-YTW : 4.61 %

RY.PR.L FixedReset Quote: 24.52 – 24.89
Spot Rate : 0.3700
Average : 0.2195

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.52
Bid-YTW : 4.33 %

BMO.PR.Q FixedReset Quote: 17.90 – 18.36
Spot Rate : 0.4600
Average : 0.3180

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.90
Bid-YTW : 8.37 %

BNS.PR.F FloatingReset Quote: 17.76 – 18.49
Spot Rate : 0.7300
Average : 0.6032

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.76
Bid-YTW : 8.19 %

Market Action

March 17, 2016

There is an indication that Google has become a mature company – and that’s not a good thing:

But behind the scenes a more pedestrian drama was playing out. Executives at Google parent Alphabet Inc., absorbed with making sure all the various companies under its corporate umbrella have plans to generate real revenue, concluded that Boston Dynamics isn’t likely to produce a marketable product in the next few years and have put the unit up for sale, according to two people familiar with the company’s plans.

Possible acquirers include the Toyota Research Institute, a division of Toyota Motor Corp., and Amazon.com Inc., which makes robots for its fulfillment centers, according to one person. Google and Toyota declined to comment, and Amazon didn’t respond to requests for comment.
…
Boston Dynamics, though, was never folded into Google X and was instead put up for sale. After the division’s latest robot video was posted to YouTube, in February, Google’s public-relations team expressed discomfort that Alphabet would be associated with a push into humanoid robotics. Their subsequent e-mails were also published to the internal online forum and became visible to all Google employees.

“There’s excitement from the tech press, but we’re also starting to see some negative threads about it being terrifying, ready to take humans’ jobs,” wrote Courtney Hohne, a director of communications at Google and the spokeswoman for Google X.

Hohne went on to ask her colleagues to “distance X from this video,” and wrote, “we don’t want to trigger a whole separate media cycle about where BD really is at Google.”

“We’re not going to comment on this video because there’s really not a lot we can add, and we don’t want to answer most of the Qs it triggers,” she wrote.

Demanding instant profitability … terrified of negative press … this is indicative of a company in which the careerists and managers have taken over from the innovators and visionaries. Don’t get me wrong – Google will, I am sure, continue to do excellent work. Just like Microsoft, they will be able to produce very high quality products simply by dint of their ability to spend more money on development than anybody else. But the situation with Boston Dynamics is an indication that their tenure as disruptors is over.

Pembina Pipelines has announced:

that it has entered into agreements to acquire certain sour natural gas processing assets (the “Acquired Assets”) from Paramount Resources (“Paramount”) for cash consideration of approximately $556 million, subject to customary closing adjustments (the “Transaction”).

The Acquired Assets include Paramount’s recently constructed Kakwa sour natural gas processing complex and associated infrastructure including gas gathering pipelines, sales gas pipeline and future disposal wells (the “Kakwa Assets”); and Paramount’s preliminary engineering studies, licenses and surface rights for the future construction of a sour natural gas processing facility (the “6-18 Facility”). The Transaction will add 250 million cubic feet per day (“mmcf/d”) of processing capacity in one of Pembina’s core areas. This will increase total processing capacity under Pembina’s Gas Services business to over 1.7 billion cubic feet per day (“bcf/d”), inclusive of the Musreau III and the Resthaven expansions which are expected to be on-stream by mid-2016, making Pembina one of the largest third-party gas processors serving the Western Canadian Sedimentary Basin.

They later announced:

that it has entered into an agreement with a syndicate of underwriters, co-led by Scotiabank and RBC Capital Markets, pursuant to which the underwriters have agreed to purchase from Pembina on a “bought deal” basis and sell to the public 8,825,000 common shares at a price of $34.00 per share, for gross proceeds of approximately $300 million. Pembina has also granted the underwriters an over-allotment option to purchase, on the same terms and exercisable not more than 30 days after the closing of the offering, up to an additional 1,323,750 common shares for additional gross proceeds of up to $45 million. Closing of the offering is expected to occur on or about March 29, 2016, in which case purchasers under this offering who are shareholders of record on April 25, 2016 (the “Record Date”) will be entitled to receive the Company’s monthly cash dividend payable on May 13, 2016 in respect of any common shares held on the Record Date.

Pembina intends to use the net proceeds from the offering, together with funds available under the Company’s existing credit facilities to finance the purchase price for its proposed acquisition of certain natural gas processing assets from Paramount Resources.

In response, DBRS announced that it:

notes that Pembina Pipeline Corporation (Pembina or the Company; rated BBB with a Stable trend by DBRS) has announced its agreement to acquire the Kakwa Assets and the 6-18 Facility (Acquisition Assets) from Paramount Resources, Inc. (Paramount) for total consideration of $556 million (the Acquisition). The purchase price will be funded by net proceeds from the Company’s concurrently announced $300 million bought deal common share financing and existing capacity under the $2.0 billion revolving credit facility. The Acquisition is expected to close in Q2 2016, pending approval under the Competition Act (Canada) and other customary closing conditions. Based on DBRS’s initial review of the Acquisition Assets and Pembina’s financing plan, DBRS believes that the Acquisition will not have a material impact on the Company’s credit profile.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.05 % 6.15 % 11,053 16.48 1 -0.7407 % 1,551.8
FixedFloater 7.03 % 6.18 % 24,480 16.11 1 0.0741 % 2,827.3
Floater 4.72 % 4.85 % 66,039 15.80 4 -1.3557 % 1,639.1
OpRet 0.00 % 0.00 % 0 0.00 0 -0.3745 % 2,756.0
SplitShare 4.83 % 5.62 % 71,608 1.65 7 -0.3745 % 3,225.1
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.3745 % 2,516.3
Perpetual-Premium 5.80 % -0.34 % 89,036 0.08 6 0.0859 % 2,543.3
Perpetual-Discount 5.69 % 5.74 % 100,014 14.21 33 0.2901 % 2,548.0
FixedReset 5.50 % 5.22 % 191,562 14.20 87 0.3195 % 1,854.7
Deemed-Retractible 5.29 % 5.57 % 121,422 5.11 34 0.3129 % 2,573.3
FloatingReset 3.14 % 5.16 % 40,704 5.42 16 0.0345 % 1,978.6
Performance Highlights
Issue Index Change Notes
BAM.PR.K Floater -3.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-17
Maturity Price : 9.40
Evaluated at bid price : 9.40
Bid-YTW : 5.03 %
BAM.PR.X FixedReset -2.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-17
Maturity Price : 13.00
Evaluated at bid price : 13.00
Bid-YTW : 5.28 %
CIU.PR.C FixedReset -2.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-17
Maturity Price : 10.36
Evaluated at bid price : 10.36
Bid-YTW : 5.26 %
SLF.PR.H FixedReset -1.96 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.00
Bid-YTW : 9.91 %
TRP.PR.C FixedReset -1.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-17
Maturity Price : 11.30
Evaluated at bid price : 11.30
Bid-YTW : 5.21 %
MFC.PR.F FixedReset -1.29 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.24
Bid-YTW : 11.62 %
MFC.PR.K FixedReset -1.29 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.09
Bid-YTW : 9.31 %
MFC.PR.L FixedReset -1.26 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.42
Bid-YTW : 9.13 %
TRP.PR.B FixedReset -1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-17
Maturity Price : 10.28
Evaluated at bid price : 10.28
Bid-YTW : 5.12 %
PVS.PR.D SplitShare -1.18 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2021-10-08
Maturity Price : 25.00
Evaluated at bid price : 22.65
Bid-YTW : 6.61 %
TRP.PR.F FloatingReset -1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-17
Maturity Price : 11.77
Evaluated at bid price : 11.77
Bid-YTW : 5.08 %
PWF.PR.P FixedReset -1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-17
Maturity Price : 11.89
Evaluated at bid price : 11.89
Bid-YTW : 5.06 %
GWO.PR.N FixedReset -1.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.00
Bid-YTW : 10.66 %
BNS.PR.M Deemed-Retractible 1.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.52
Bid-YTW : 5.02 %
RY.PR.E Deemed-Retractible 1.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.36
Bid-YTW : 5.09 %
TRP.PR.A FixedReset 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-17
Maturity Price : 13.95
Evaluated at bid price : 13.95
Bid-YTW : 5.10 %
TD.PF.B FixedReset 1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-17
Maturity Price : 17.70
Evaluated at bid price : 17.70
Bid-YTW : 4.59 %
SLF.PR.I FixedReset 1.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.60
Bid-YTW : 8.40 %
NA.PR.S FixedReset 1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-17
Maturity Price : 17.58
Evaluated at bid price : 17.58
Bid-YTW : 4.83 %
HSE.PR.G FixedReset 1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-17
Maturity Price : 17.85
Evaluated at bid price : 17.85
Bid-YTW : 6.18 %
BMO.PR.M FixedReset 1.21 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.47
Bid-YTW : 4.09 %
NA.PR.W FixedReset 1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-17
Maturity Price : 16.75
Evaluated at bid price : 16.75
Bid-YTW : 4.88 %
W.PR.H Perpetual-Discount 1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-17
Maturity Price : 22.91
Evaluated at bid price : 23.18
Bid-YTW : 6.03 %
MFC.PR.G FixedReset 1.37 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.80
Bid-YTW : 8.48 %
CM.PR.P FixedReset 1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-17
Maturity Price : 17.64
Evaluated at bid price : 17.64
Bid-YTW : 4.60 %
CM.PR.O FixedReset 1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-17
Maturity Price : 17.91
Evaluated at bid price : 17.91
Bid-YTW : 4.64 %
RY.PR.Z FixedReset 1.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-17
Maturity Price : 17.75
Evaluated at bid price : 17.75
Bid-YTW : 4.52 %
RY.PR.M FixedReset 1.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-17
Maturity Price : 18.13
Evaluated at bid price : 18.13
Bid-YTW : 4.83 %
MFC.PR.M FixedReset 1.55 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.65
Bid-YTW : 8.30 %
TRP.PR.E FixedReset 1.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-17
Maturity Price : 17.51
Evaluated at bid price : 17.51
Bid-YTW : 4.89 %
BMO.PR.S FixedReset 1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-17
Maturity Price : 17.85
Evaluated at bid price : 17.85
Bid-YTW : 4.64 %
FTS.PR.M FixedReset 1.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-17
Maturity Price : 16.95
Evaluated at bid price : 16.95
Bid-YTW : 5.14 %
BAM.PF.C Perpetual-Discount 1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-17
Maturity Price : 19.85
Evaluated at bid price : 19.85
Bid-YTW : 6.14 %
TD.PR.Z FloatingReset 2.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.00
Bid-YTW : 5.35 %
HSE.PR.A FixedReset 2.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-17
Maturity Price : 9.55
Evaluated at bid price : 9.55
Bid-YTW : 6.67 %
FTS.PR.H FixedReset 2.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-17
Maturity Price : 11.36
Evaluated at bid price : 11.36
Bid-YTW : 5.13 %
RY.PR.H FixedReset 2.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-17
Maturity Price : 17.70
Evaluated at bid price : 17.70
Bid-YTW : 4.58 %
TD.PF.C FixedReset 2.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-17
Maturity Price : 17.85
Evaluated at bid price : 17.85
Bid-YTW : 4.54 %
Volume Highlights
Issue Index Shares
Traded
Notes
HSE.PR.A FixedReset 251,009 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-17
Maturity Price : 9.55
Evaluated at bid price : 9.55
Bid-YTW : 6.67 %
CU.PR.E Perpetual-Discount 117,469 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-17
Maturity Price : 21.38
Evaluated at bid price : 21.67
Bid-YTW : 5.69 %
POW.PR.G Perpetual-Discount 106,700 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-17
Maturity Price : 23.91
Evaluated at bid price : 24.37
Bid-YTW : 5.83 %
BNS.PR.G FixedReset 97,990 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-07-25
Maturity Price : 25.00
Evaluated at bid price : 25.36
Bid-YTW : 5.23 %
BAM.PR.M Perpetual-Discount 96,592 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-17
Maturity Price : 19.80
Evaluated at bid price : 19.80
Bid-YTW : 6.02 %
BAM.PF.D Perpetual-Discount 95,090 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-17
Maturity Price : 20.05
Evaluated at bid price : 20.05
Bid-YTW : 6.14 %
There were 32 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BNS.PR.D FloatingReset Quote: 17.09 – 17.72
Spot Rate : 0.6300
Average : 0.4388

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.09
Bid-YTW : 8.41 %

BNS.PR.Y FixedReset Quote: 18.86 – 19.25
Spot Rate : 0.3900
Average : 0.2350

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.86
Bid-YTW : 7.06 %

POW.PR.G Perpetual-Discount Quote: 24.37 – 24.79
Spot Rate : 0.4200
Average : 0.2766

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-17
Maturity Price : 23.91
Evaluated at bid price : 24.37
Bid-YTW : 5.83 %

CU.PR.I FixedReset Quote: 25.15 – 25.50
Spot Rate : 0.3500
Average : 0.2224

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-17
Maturity Price : 23.23
Evaluated at bid price : 25.15
Bid-YTW : 4.38 %

BAM.PR.K Floater Quote: 9.40 – 9.85
Spot Rate : 0.4500
Average : 0.3278

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-17
Maturity Price : 9.40
Evaluated at bid price : 9.40
Bid-YTW : 5.03 %

PVS.PR.B SplitShare Quote: 23.83 – 24.30
Spot Rate : 0.4700
Average : 0.3491

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2019-01-10
Maturity Price : 25.00
Evaluated at bid price : 23.83
Bid-YTW : 6.27 %

Market Action

March 16, 2016

Today’s big new was the FOMC Release:

Information received since the Federal Open Market Committee met in January suggests that economic activity has been expanding at a moderate pace despite the global economic and financial developments of recent months. Household spending has been increasing at a moderate rate, and the housing sector has improved further; however, business fixed investment and net exports have been soft. A range of recent indicators, including strong job gains, points to additional strengthening of the labor market. Inflation picked up in recent months; however, it continued to run below the Committee’s 2 percent longer-run objective, partly reflecting declines in energy prices and in prices of non-energy imports. Market-based measures of inflation compensation remain low; survey-based measures of longer-term inflation expectations are little changed, on balance, in recent months.

Consistent with its statutory mandate, the Committee seeks to foster maximum employment and price stability. The Committee currently expects that, with gradual adjustments in the stance of monetary policy, economic activity will expand at a moderate pace and labor market indicators will continue to strengthen. However, global economic and financial developments continue to pose risks. Inflation is expected to remain low in the near term, in part because of earlier declines in energy prices, but to rise to 2 percent over the medium term as the transitory effects of declines in energy and import prices dissipate and the labor market strengthens further. The Committee continues to monitor inflation developments closely.

Against this backdrop, the Committee decided to maintain the target range for the federal funds rate at 1/4 to 1/2 percent. The stance of monetary policy remains accommodative, thereby supporting further improvement in labor market conditions and a return to 2 percent inflation.
…
Voting against the action was Esther L. George, who preferred at this meeting to raise the target range for the federal funds rate to 1/2 to 3/4 percent.

The press conference added a little colour:

“You have seen a shift this time, in most participants assessments of the appropriate path for policy,” Fed Chair Janet Yellen said at a press conference in Washington. “That largely reflects a somewhat slower projected path for global growth, for growth in the global economy outside the United States, and for some tightening in credit conditions in the form of an increase in spreads.”

Yields on Treasury securities fell following the Fed’s actions, with the rate on the 10-year note dropping to 1.91 percent at 4:25 p.m. in New York from 1.99 percent just before the announcement.
…
“The tone of the FOMC statement and accompanying economic projections was dovish,” Neil Dutta, head of U.S. economist at Renaissance Macro Research LLC in New York, said in a research note. The reference to global risks “pushes the Fed in the role of the world’s central bank. In this role, the Fed needs to let inflation in the U.S. surge to offset disinflation in the rest of the world.”
…
The median of Fed officials’ projections, known as the “dot plot,” saw the federal funds rate at 1.875 percent at the end of 2017, compared with 2.375 percent forecast in December. The end-2018 level fell to 3 percent, from 3.25 percent, with the longer-run projection at 3.25 percent, down from 3.5 percent.

And Brian Milner writes in the Globe:

The Fed expects the job market to continue strengthening, with unemployment sliding to 4.7 per cent by the end of this year and falling further in subsequent years. Yet, it has slightly lowered its outlook for both economic growth and inflation – expecting the latter to remain below the 2 per cent target through next year – and reduced its long-term rate forecast to 3.3 per cent from 3.5 per cent, which implies that we won’t be seeing an economic boom any time soon south of the border.

The Fed’s policy doves, led by Ms. Yellen, seem likely to hold sway, particularly now that inflation is expected to reach only 1.2 per cent this year, down from the Fed’s earlier forecast of 1.6. Gauged by Fed funds futures trading, the market is expecting the next modest hike in June and one more before the end of the year. But that is by no means a sure bet.

“Reduced uncertainty about global economic and financial developments or further meaningful gains in the labour market and core inflation, or some combination of all of these, would appear to be the necessary condition for the next normalization step,” Michael Gregory, deputy chief economist with BMO, said in a note.

It was a mixed day for the Canadian preferred share market, with PerpetualDiscounts gaining 7bp, FixedResets up 10bp and DeemedRetractibles off 9bp. The Performance Highlights table shows churn. Volume was average.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_160316
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 17.23 to be $1.09 rich, while TRP.PR.G, resetting 2020-11-30 at +296, is $0.71 cheap at its bid price of 18.18.

impVol_MFC_160316
Click for Big

Most expensive is MFC.PR.O, resetting at +497bp on 2021-6-19, bid at 25.39 to be 0.84 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 17.56 to be 1.44 cheap.

impVol_BAM_160316
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 14.25 to be $0.85 cheap. BAM.PF.E, resetting at +255 on 2020-3-31 is bid at 17.40 and appears to be $1.05 rich.

impVol_FTS_160316
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 15.42 looks $0.61 expensive and resets 2019-3-1. FTS.PR.H, with a spread of +145bp and resetting 2020-6-1, is bid at 11.12 and is $0.52 cheap.

pairs_FR_160316
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.98%, with two outliers below -2.00% and one above 0.00%. There are four junk outliers above 0.00%.

pairs_FF_160316
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.01 % 6.10 % 11,506 16.54 1 6.4669 % 1,563.4
FixedFloater 7.04 % 6.18 % 24,589 16.11 1 0.7463 % 2,825.2
Floater 4.66 % 4.82 % 66,871 15.85 4 0.6200 % 1,661.6
OpRet 0.00 % 0.00 % 0 0.00 0 0.2638 % 2,766.4
SplitShare 4.81 % 5.51 % 71,958 1.65 7 0.2638 % 3,237.2
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.2638 % 2,525.8
Perpetual-Premium 5.81 % -0.06 % 88,540 0.08 6 -0.0462 % 2,541.1
Perpetual-Discount 5.70 % 5.76 % 99,768 14.18 33 0.0685 % 2,540.7
FixedReset 5.52 % 5.23 % 192,152 14.20 87 0.1002 % 1,848.8
Deemed-Retractible 5.31 % 5.64 % 121,603 5.11 34 -0.0877 % 2,565.3
FloatingReset 3.14 % 5.14 % 40,494 5.42 16 -0.0191 % 1,977.9
Performance Highlights
Issue Index Change Notes
VNR.PR.A FixedReset -2.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-16
Maturity Price : 16.90
Evaluated at bid price : 16.90
Bid-YTW : 5.55 %
TD.PF.D FixedReset -2.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-16
Maturity Price : 18.58
Evaluated at bid price : 18.58
Bid-YTW : 4.90 %
TD.PR.Z FloatingReset -2.19 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.57
Bid-YTW : 5.73 %
BAM.PF.C Perpetual-Discount -2.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-16
Maturity Price : 19.50
Evaluated at bid price : 19.50
Bid-YTW : 6.25 %
RY.PR.M FixedReset -2.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-16
Maturity Price : 17.86
Evaluated at bid price : 17.86
Bid-YTW : 4.90 %
BMO.PR.M FixedReset -1.74 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.19
Bid-YTW : 4.31 %
RY.PR.J FixedReset -1.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-16
Maturity Price : 18.21
Evaluated at bid price : 18.21
Bid-YTW : 4.93 %
TRP.PR.E FixedReset -1.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-16
Maturity Price : 17.23
Evaluated at bid price : 17.23
Bid-YTW : 4.97 %
TRP.PR.A FixedReset -1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-16
Maturity Price : 13.80
Evaluated at bid price : 13.80
Bid-YTW : 5.15 %
RY.PR.H FixedReset -1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-16
Maturity Price : 17.27
Evaluated at bid price : 17.27
Bid-YTW : 4.70 %
FTS.PR.M FixedReset -1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-16
Maturity Price : 16.66
Evaluated at bid price : 16.66
Bid-YTW : 5.23 %
SLF.PR.J FloatingReset -1.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.10
Bid-YTW : 11.20 %
TRP.PR.G FixedReset 1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-16
Maturity Price : 18.18
Evaluated at bid price : 18.18
Bid-YTW : 5.23 %
BAM.PF.G FixedReset 1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-16
Maturity Price : 18.15
Evaluated at bid price : 18.15
Bid-YTW : 5.32 %
BAM.PR.B Floater 1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-16
Maturity Price : 9.80
Evaluated at bid price : 9.80
Bid-YTW : 4.82 %
BAM.PR.C Floater 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-16
Maturity Price : 9.70
Evaluated at bid price : 9.70
Bid-YTW : 4.87 %
FTS.PR.F Perpetual-Discount 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-16
Maturity Price : 22.00
Evaluated at bid price : 22.23
Bid-YTW : 5.55 %
TRP.PR.F FloatingReset 1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-16
Maturity Price : 11.91
Evaluated at bid price : 11.91
Bid-YTW : 5.02 %
BAM.PR.K Floater 1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-16
Maturity Price : 9.70
Evaluated at bid price : 9.70
Bid-YTW : 4.87 %
BAM.PR.R FixedReset 1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-16
Maturity Price : 14.25
Evaluated at bid price : 14.25
Bid-YTW : 5.47 %
W.PR.J Perpetual-Discount 1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-16
Maturity Price : 22.93
Evaluated at bid price : 23.20
Bid-YTW : 6.14 %
TD.PR.S FixedReset 1.25 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.54
Bid-YTW : 4.03 %
TRP.PR.D FixedReset 1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-16
Maturity Price : 16.77
Evaluated at bid price : 16.77
Bid-YTW : 5.03 %
IAG.PR.A Deemed-Retractible 1.40 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.00
Bid-YTW : 7.07 %
NA.PR.S FixedReset 1.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-16
Maturity Price : 17.38
Evaluated at bid price : 17.38
Bid-YTW : 4.89 %
TRP.PR.I FloatingReset 1.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-16
Maturity Price : 10.16
Evaluated at bid price : 10.16
Bid-YTW : 5.01 %
MFC.PR.F FixedReset 1.64 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.40
Bid-YTW : 11.44 %
NA.PR.W FixedReset 1.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-16
Maturity Price : 16.55
Evaluated at bid price : 16.55
Bid-YTW : 4.94 %
HSE.PR.G FixedReset 1.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-16
Maturity Price : 17.64
Evaluated at bid price : 17.64
Bid-YTW : 6.25 %
BAM.PR.X FixedReset 2.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-16
Maturity Price : 13.32
Evaluated at bid price : 13.32
Bid-YTW : 5.15 %
TRP.PR.B FixedReset 2.97 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-16
Maturity Price : 10.41
Evaluated at bid price : 10.41
Bid-YTW : 5.05 %
TRP.PR.C FixedReset 3.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-16
Maturity Price : 11.50
Evaluated at bid price : 11.50
Bid-YTW : 5.11 %
TRP.PR.H FloatingReset 5.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-16
Maturity Price : 9.21
Evaluated at bid price : 9.21
Bid-YTW : 4.75 %
BAM.PR.E Ratchet 6.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-16
Maturity Price : 25.00
Evaluated at bid price : 13.50
Bid-YTW : 6.10 %
Volume Highlights
Issue Index Shares
Traded
Notes
BNS.PR.G FixedReset 146,231 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-07-25
Maturity Price : 25.00
Evaluated at bid price : 25.31
Bid-YTW : 5.27 %
TRP.PR.B FixedReset 112,564 TD crossed 107,300 at 10.17.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-16
Maturity Price : 10.41
Evaluated at bid price : 10.41
Bid-YTW : 5.05 %
SLF.PR.A Deemed-Retractible 84,650 Scotia crossed 64,100 at 21.80.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.64
Bid-YTW : 6.80 %
BNS.PR.A FloatingReset 76,029 TD crossed 73,600 at 23.95.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.85
Bid-YTW : 3.36 %
GWO.PR.Q Deemed-Retractible 70,000 Nesbitt crossed 65,000 at 22.76.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.60
Bid-YTW : 6.60 %
RY.PR.Z FixedReset 65,858 RBC crossed 37,100 at 17.40, then another 20,000 at 17.50.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-16
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 4.59 %
There were 33 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
PWF.PR.O Perpetual-Premium Quote: 25.01 – 26.11
Spot Rate : 1.1000
Average : 0.6676

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-16
Maturity Price : 24.70
Evaluated at bid price : 25.01
Bid-YTW : 5.88 %

BAM.PF.C Perpetual-Discount Quote: 19.50 – 20.22
Spot Rate : 0.7200
Average : 0.4133

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-16
Maturity Price : 19.50
Evaluated at bid price : 19.50
Bid-YTW : 6.25 %

TD.PF.A FixedReset Quote: 17.30 – 18.10
Spot Rate : 0.8000
Average : 0.5117

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-16
Maturity Price : 17.30
Evaluated at bid price : 17.30
Bid-YTW : 4.71 %

TD.PR.Z FloatingReset Quote: 20.57 – 21.88
Spot Rate : 1.3100
Average : 1.0474

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.57
Bid-YTW : 5.73 %

TRP.PR.E FixedReset Quote: 17.23 – 18.00
Spot Rate : 0.7700
Average : 0.5791

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-16
Maturity Price : 17.23
Evaluated at bid price : 17.23
Bid-YTW : 4.97 %

RY.PR.J FixedReset Quote: 18.21 – 18.60
Spot Rate : 0.3900
Average : 0.2626

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-16
Maturity Price : 18.21
Evaluated at bid price : 18.21
Bid-YTW : 4.93 %