Category: Market Action

Market Action

January 19, 2016

All eyes are on the BoC policy rate meeting:

The implied odds of a rate cut according to financial markets stand at just over 50 percent, and private-sector economists are almost evenly divided on whether the nation’s central bank will cut its policy rate to a financial crisis low of 0.25 percent.
…
During the press conference that followed Stephen Poloz’s first rate decision as governor, he said that “it is the output gap which guides the pressures on inflation through time.”

In that sense, the Bank of Canada’s January 2015 interest cut was proactive, foreseeing a widening of the output gap absent the addition of monetary stimulus following the collapse in oil prices. The July reduction was of a more reactive nature, responding to a drop in activity that turned out to be larger, and ultimately long-lived, than anticipated.

This month, a blend of both dynamics is at play: sluggish fourth-quarter data suggest that there is more economic slack than the Bank of Canada envisioned in October, while declining inflation expectations and subdued hiring plans imply more weakness on the horizon.
…
Financial stability concerns are nothing new for the central bank, which maintained a tightening bias until October 2013, in part due to worries over household credit growth and elevated indebtedness. But this is the first time in recent memory that economists see threats from multiple angles.

Recently announced macro-prudential measures alleviate some of the concerns, though a rate cut would undoubtedly put downward pressure on borrowing costs, offsetting some of the forces driving borrowing rates higher.
…
The new threat to financial stability stems from the collapse in the Canadian dollar, whose 25 percent plunge over the past two years marks its worst decline for that time period on record.

The Bank of Canada could be “playing with fire” if it chose to lower rates further and “set off a freefall in the exchange rate,” said CIBC’s [chief economist Avery] Shenfeld, citing the potential negative effects on confidence and consumers’ willingness to spend. Since total spending in an economy is equal to total income, if everyone cut back on expenditures at once, Canada would be adding a household deleveraging process to its current terms of trade shock.
…
Scotia’s [Vice President of Economics Derek] Holt warns that the central bank would be stimulating unhealthy growth if it delivers a rate cut Wednesday.

“The effects of a rate cut are more likely to be reflected in interest rate sensitive sectors than the ones affected by the terms of trade shock,” he said. “[A cut] can do more to fuel financial imbalances than help the parts of the economy that are under stress.”

This potential conflict between a central bank’s most basic task–to stabilize the business cycle–and the quest to return inflation to target within a normal time frame, make the bank’s decision worth watching for market participants well beyond the nation’s borders.

Meanwhile, there is speculation that the Fed might not be as aggressive as first thought:

Less than three weeks into the new year, two of Wall Street’s biggest bond dealers are already dialing back the 2016 Treasury yield calls they made at the end of 2015.

JPMorgan Chase & Co. and Deutsche Bank AG reduced forecasts for 10-year yields at the end of last week, wagering the Federal Reserve won’t raise interest rates as many times as policy makers expect. The banks, among the 22 primary dealers that trade with the Fed, say pressures will build amid the depreciation of China’s currency, slowing global economic growth, investor flight from risky assets and a dimming inflation outlook.

Deutsche Bank predicts the 10-year yield will end the year at 1.75 percent, down from the 2.25 percent call it made in December, while JPMorgan says 10-year notes will yield 2.45 percent at year-end, down from a previous forecast of 2.75 percent.

But they’re not making much money on fixed income anyway!

Once Wall Street’s most lucrative business, fixed-income trading revenue declined for the third straight year in 2015. Net income from trading bonds, currencies, commodities and derivatives linked to them has fallen between 18 percent and 25 percent at five top banks since 2012.

Fixed-income has been in a slump with interest rates languishing near zero, oil prices falling and regulations making it tougher to place easy bets on future prices. Morgan Stanley said Tuesday that it doesn’t expect a rebound any time soon.

Which will make life interesting if downgrades pop:

More companies were at risk of having their credit ratings cut at the end of December than at the close of any other year since 2009, according to Standard & Poor’s.

The number of potential downgrades was at 655, compared with 824 reported by the finish of 2009, the rating company said in a report on Tuesday. The year-end total for 2015 was “exceptionally” higher than a yearly average of 613, it said. S&P removed 85 issuers from the list in December and added 56, of which 27 are in the U.S.

Here’s some news for the middle class:

Over five million jobs will be lost by 2020 as a result of developments in genetics, artificial intelligence, robotics and other technological change, according to World Economic Forum research.

About 7 million jobs will be lost and 2 million gained as a result of technological change in 15 major developed and emerging economies, WEF founder Klaus Schwab and managing board member Richard Samans said in “The Future of Jobs.” The findings are taken from a survey of 15 economies covering about 1.9 billion workers, or about 65 percent of the world’s total workforce.
….
To prevent a worst-case scenario — technological change accompanied by talent shortages, mass unemployment and growing inequality — reskilling and upskilling of today’s workers will be critical,” the authors said. “It is simply not possible to weather the current technological revolution by waiting for the next generation’s workforce to become better prepared.”

Administrative and office jobs will account for two-thirds of the losses, with “routine white-collar office functions at risk of being decimated,” and there will be gains in computer, mathematical, architecture and engineering-related fields. Women will be disproportionately hit by the changes because of their low participation in the STEM fields of science, technology, engineering and mathematics.

The full report is obsessed with the gender gap and gives the usual accolades to ‘reskilling and retraining’:

Responses to the Future of Jobs Survey indicate that business leaders are aware of these looming challenges but have been slow to act decisively. Just over two thirds of our respondents believe that future workforce planning and change management features as a reasonably high or very high priority on the agenda of their company’s or organization’s senior leadership, ranging from just over half in the Basic and Infrastructure sector to four out of five respondents in Energy and Healthcare. Across all industries, about two thirds of our respondents also report intentions to invest in the reskilling of current employees as part of their change management and future workforce planning efforts, making it by far the highest-ranked such strategy overall (Figure 13). However, companies that report recognizing future workforce planning as a priority are nearly 50% more likely to plan to invest in reskilling than companies who do not (61% against 39% of respondents).

Well, that might be a good enough survival tactic for individual companies, but I see very little consideration paid to the broader issues. While foretelling the future is something that is notorious for being hilarious even within twenty years, I believe we need to start addressing the topic of what the new world is going to look like.

For one thing, ‘things’ are going to become relatively cheaper and ‘entertainment’ is going to become relatively more expensive – and those are the two basic categories of things that get sold. We may have fewer doctors, as diagnosis becomes increasingly automated, but we will have more nurses, as the population ages and people in general can afford more care.

And this is the basic problem: productivity comes from leverage; you are more productive when you make widgets for ten customers as opposed to merely five. And personal services are very difficult, if not impossible to lever. So I suggest we’re going to end up with a society comprised of the ‘10%’, who have the skills to work on improving the system and the rest, who don’t. How do we address this? I never hear the politicians talking about it; they blithely assume that if we retrain a 55-year-old machine worker to become a programmer, everything will be OK.

Husky Energy, proud issuer of HSE.PR.A, HSE.PR.C, HSE.PR.E and HSE.PR.G, announced after the close today that it:

is taking additional steps to improve its resilience through the extended low commodity price environment.

“We continue to take decisive action in this period of persistent supply-demand imbalance,” said CEO Asim Ghosh. “These actions are in line with the principles we have established, namely, balancing capital spending with cash flow and maintaining a strong balance sheet. Our fundamental goal remains unchanged – the steps we are taking will see Husky emerge from this cycle as a more resilient and more profitable company.”

Updated 2016 Production and Capital Guidance

The capital plan has been revised to a range of $2.1-2.3 billion from a previous range of $2.9-3.1 billion. Savings will be achieved primarily through deferring discretionary activities in Western Canada.

The Company’s overall earnings break-even point is expected to be in the sub-$40s US WTI oil by the end of 2016. Further gains are expected to be achieved through the ongoing reduction of operating and sustaining costs.

Production is now expected to be in the range of 315,000-345,000 barrels of oil equivalent per day (boe/day), compared to the previous guidance of 330,000-360,000 boe/day.

“Within the updated capital plan, the transition into a low sustaining capital business continues unabated. Deferral of capital is in those areas that can be quickly switched on as commodity prices recover,” said Ghosh.

Dividend Update

The Company continues to triangulate its top three business priorities; a strong balance sheet, dividend and transition into a low sustaining capital business. While Husky fully recognizes the importance of the dividend, the balance sheet takes precedence in this environment.

A stock dividend was introduced in the third quarter as an interim measure in lieu of a cash dividend. Given the persistent downward pressure on oil prices and the extended lower for longer outlook, the Board of Directors has suspended the quarterly dividend. No cash or share dividend will be issued for the fourth quarter of 2015.

The Board will continue to review the dividend on a quarterly basis.

I saw some preferred share investors coming home from work tonight:

celebration
Click for Big

Those suffering from market-induced shell-shock may have trouble believing this, but it was a superb day for the Canadian preferred share market today, with PerpetualDiscounts gaining 105bp, FixedResets winning 329bp and DeemedRetractibles up 142bp. The Performance Highlights table is extraordinarily lengthy and, for a change, almost everything’s on the good side, with only one loser. Volume was very high.

So it’s clear somebody put a bit of money to work today, but we’ve been fooled on rallies before – in the second half of October and the second half of December. Will we look back on the second half of January as just another in a long series of false rallies? I don’t know – I advise everybody to invest according to the long-term properties of the asset class and leave the market timing to those who can afford the losses.

The overnight news doesn’t look too good!

U.S. index futures tumbled as the selloff in global equities intensified after oil dropped below $28 a barrel to extend a 12-year low.

Contracts on the Standard & Poor’s 500 Index due in March dropped 1.5 percent to 1,844.25 as of 7:21 a.m. in London, while Nasdaq 100 Index futures retreated 1.8 percent. West Texas Intermediate slumped 3.3 percent to $27.52 a barrel, heading for the lowest close since September 2003 and driving stock declines across Asia that sent Japanese shares into a bear market.

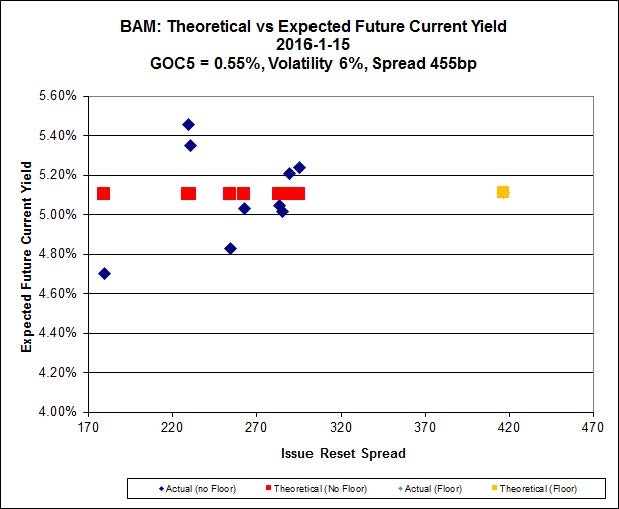
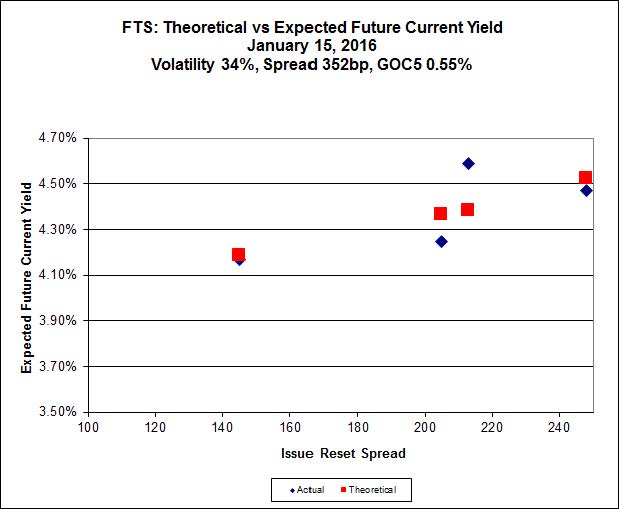
For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

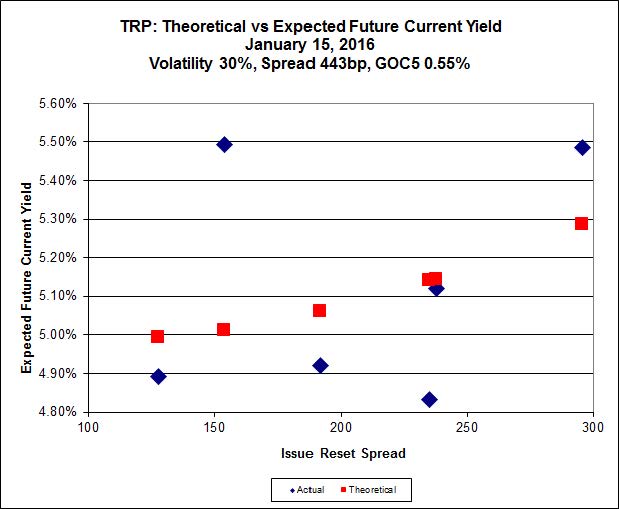
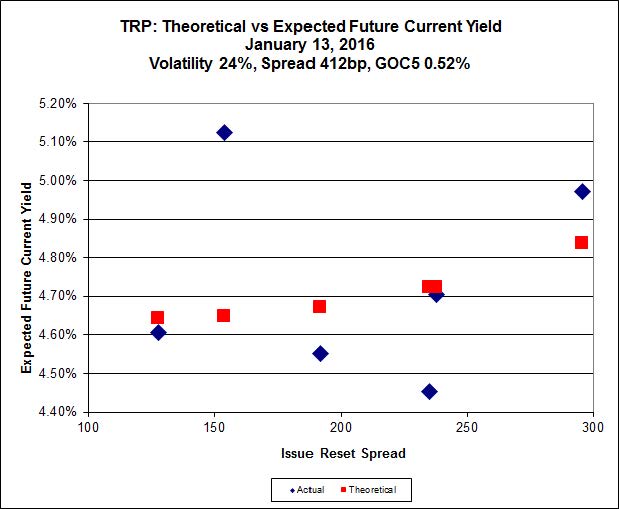
Here’s TRP:

impVol_TRP_160119
Click for Big

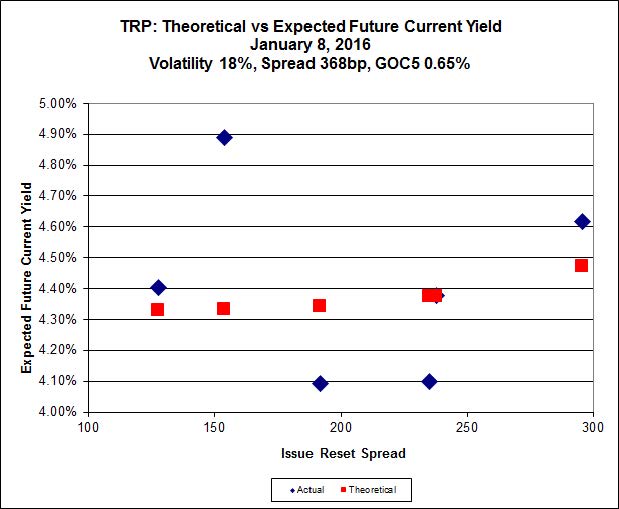
TRP.PR.E, which resets 2019-10-30 at +235, is bid at 15.85 to be $0.87 rich, while TRP.PR.C, resetting 2016-1-30 at +154, is $0.38 cheap at its bid price of 10.73.

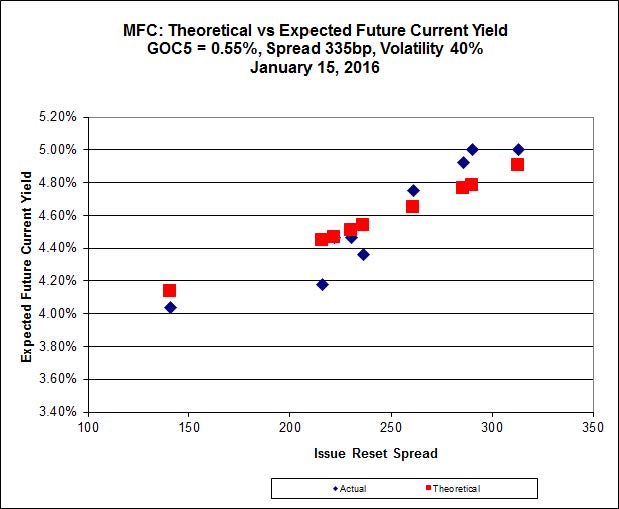
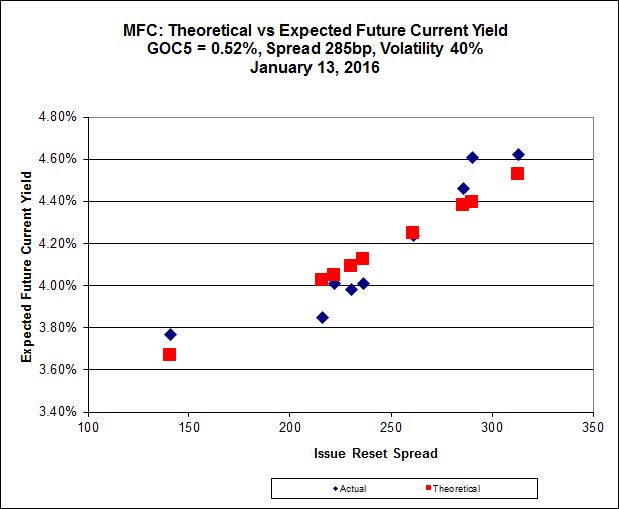
impVol_MFC_160119
Click for Big

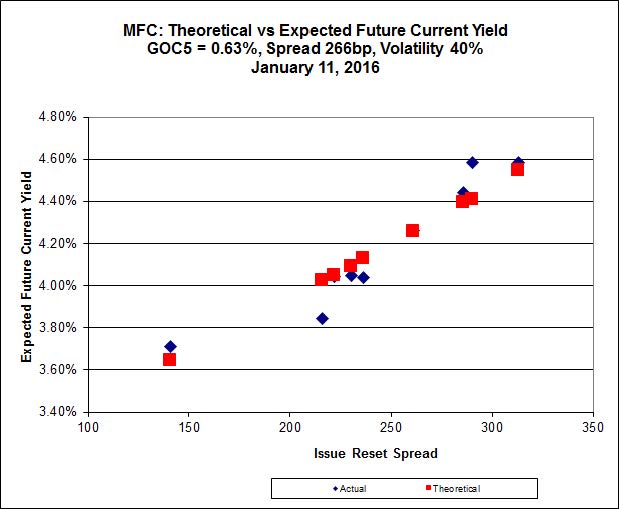
Most expensive is MFC.PR.L, resetting at +216bp on 2019-6-19, bid at 16.43 to be 1.10 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 17.10 to be 1.04 cheap.

impVol_BAM_160119
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 13.54 to be $1.41 cheap. BAM.PF.E, resetting at +255bp on 2020-3-31 is bid at 17.23 and appears to be $0.98 rich.

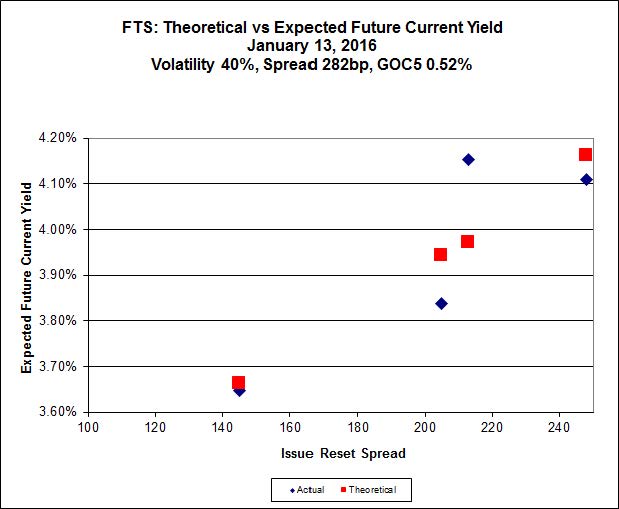
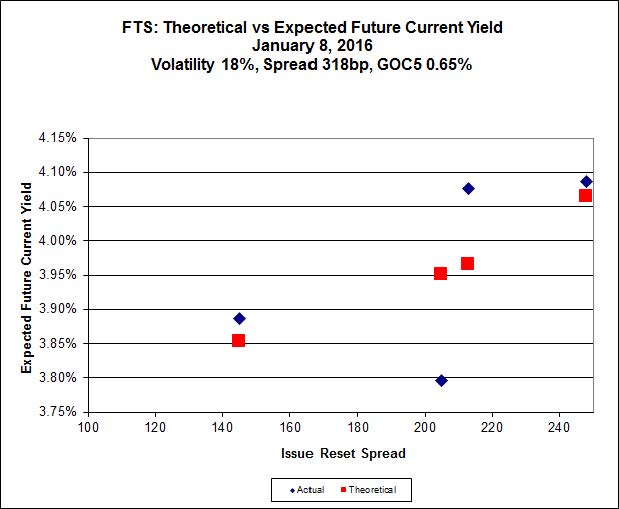
impVol_FTS_160119
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 15.59, looks $0.52 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 14.70 and is $0.79 cheap.

pairs_FR_160119
Click for Big

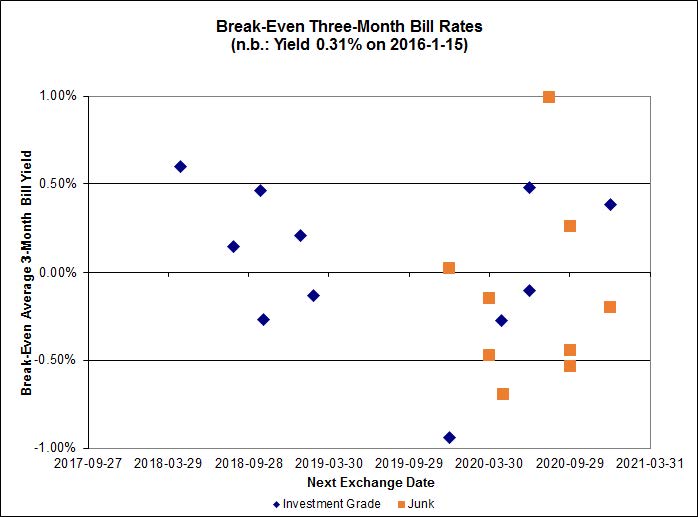
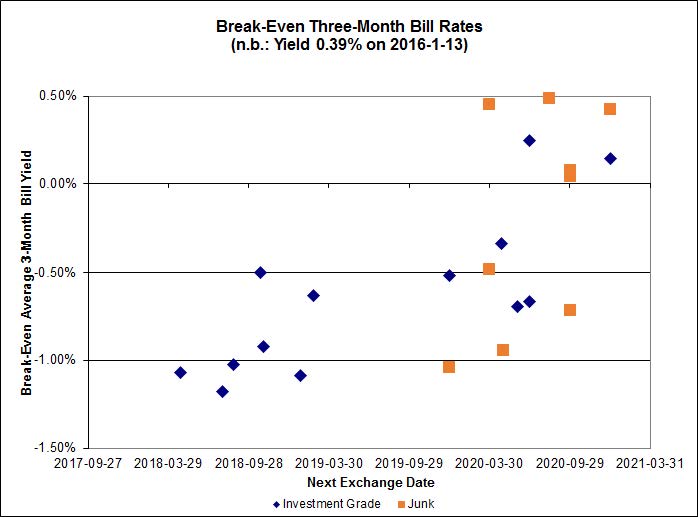
Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.35%, with two outliers above +1.00%. There is one junk outlier below -1.00% and one above 1.00%.

pairs_FF_160119
Click for Big

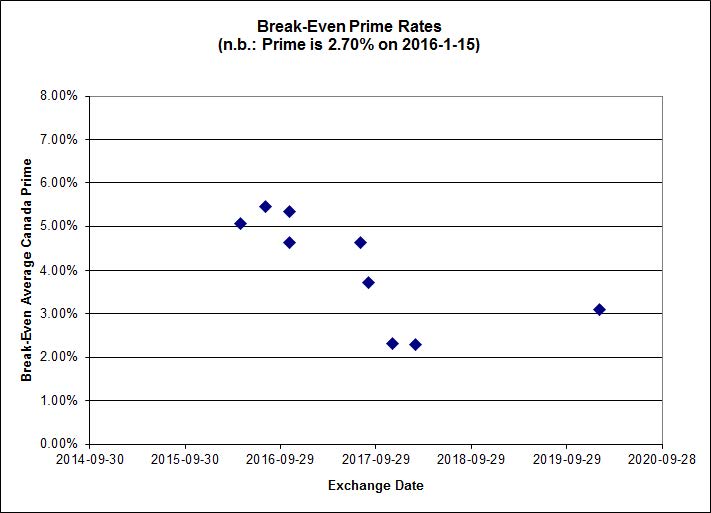
Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.47 % 6.65 % 23,899 15.86 1 0.8130 % 1,421.8
FixedFloater 7.60 % 6.63 % 30,159 15.68 1 3.9069 % 2,615.9
Floater 4.90 % 4.94 % 76,117 15.62 4 0.0000 % 1,559.9
OpRet 0.00 % 0.00 % 0 0.00 0 1.1200 % 2,689.6
SplitShare 4.91 % 7.02 % 68,197 2.74 6 1.1200 % 3,147.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 1.1200 % 2,455.6
Perpetual-Premium 5.99 % 5.99 % 85,950 13.88 6 0.9218 % 2,464.3
Perpetual-Discount 5.94 % 6.00 % 99,035 13.91 33 1.0474 % 2,420.4
FixedReset 5.85 % 5.02 % 242,960 14.79 82 3.2909 % 1,763.0
Deemed-Retractible 5.40 % 5.96 % 134,095 6.94 34 1.4195 % 2,491.2
FloatingReset 2.82 % 4.94 % 64,410 5.61 13 1.7033 % 1,974.3
Performance Highlights
Issue Index Change Notes
BAM.PR.B Floater -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 9.43
Evaluated at bid price : 9.43
Bid-YTW : 5.06 %
RY.PR.G Deemed-Retractible 1.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.09
Bid-YTW : 5.38 %
FTS.PR.G FixedReset 1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 14.70
Evaluated at bid price : 14.70
Bid-YTW : 4.95 %
BNS.PR.Z FixedReset 1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.50
Bid-YTW : 7.38 %
BAM.PF.H FixedReset 1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 23.15
Evaluated at bid price : 24.95
Bid-YTW : 4.95 %
POW.PR.C Perpetual-Premium 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 24.01
Evaluated at bid price : 24.26
Bid-YTW : 6.01 %
RY.PR.B Deemed-Retractible 1.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.19
Bid-YTW : 5.51 %
ELF.PR.G Perpetual-Discount 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 20.04
Evaluated at bid price : 20.04
Bid-YTW : 5.97 %
PWF.PR.P FixedReset 1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 11.25
Evaluated at bid price : 11.25
Bid-YTW : 4.84 %
BMO.PR.R FloatingReset 1.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.25
Bid-YTW : 4.88 %
GWO.PR.Q Deemed-Retractible 1.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.03
Bid-YTW : 7.03 %
POW.PR.G Perpetual-Discount 1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 23.26
Evaluated at bid price : 23.70
Bid-YTW : 5.93 %
IFC.PR.C FixedReset 1.31 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.45
Bid-YTW : 9.86 %
BNS.PR.Y FixedReset 1.33 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.00
Bid-YTW : 6.65 %
GWO.PR.F Deemed-Retractible 1.38 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.04
Bid-YTW : 5.96 %
GWO.PR.R Deemed-Retractible 1.38 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.58
Bid-YTW : 7.63 %
CM.PR.P FixedReset 1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 16.05
Evaluated at bid price : 16.05
Bid-YTW : 4.72 %
RY.PR.K FloatingReset 1.44 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.15
Bid-YTW : 5.27 %
ELF.PR.H Perpetual-Discount 1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 22.14
Evaluated at bid price : 22.40
Bid-YTW : 6.17 %
POW.PR.A Perpetual-Discount 1.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 23.35
Evaluated at bid price : 23.64
Bid-YTW : 5.96 %
FTS.PR.H FixedReset 1.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 11.98
Evaluated at bid price : 11.98
Bid-YTW : 4.50 %
VNR.PR.A FixedReset 1.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 15.91
Evaluated at bid price : 15.91
Bid-YTW : 5.49 %
NA.PR.Q FixedReset 1.70 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.56
Bid-YTW : 5.97 %
TD.PF.E FixedReset 1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 17.80
Evaluated at bid price : 17.80
Bid-YTW : 4.94 %
GWO.PR.H Deemed-Retractible 1.76 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.77
Bid-YTW : 7.55 %
IGM.PR.B Perpetual-Premium 1.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 24.08
Evaluated at bid price : 24.54
Bid-YTW : 6.02 %
RY.PR.I FixedReset 1.89 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.14
Bid-YTW : 5.42 %
BAM.PR.C Floater 1.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 9.65
Evaluated at bid price : 9.65
Bid-YTW : 4.94 %
POW.PR.B Perpetual-Discount 2.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 22.27
Evaluated at bid price : 22.54
Bid-YTW : 5.97 %
CU.PR.C FixedReset 2.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 16.01
Evaluated at bid price : 16.01
Bid-YTW : 4.82 %
SLF.PR.J FloatingReset 2.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.00
Bid-YTW : 10.96 %
GWO.PR.N FixedReset 2.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.80
Bid-YTW : 11.76 %
GWO.PR.I Deemed-Retractible 2.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.77
Bid-YTW : 7.86 %
BAM.PF.D Perpetual-Discount 2.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 19.20
Evaluated at bid price : 19.20
Bid-YTW : 6.46 %
TD.PF.B FixedReset 2.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 16.57
Evaluated at bid price : 16.57
Bid-YTW : 4.56 %
TD.PF.C FixedReset 2.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 16.53
Evaluated at bid price : 16.53
Bid-YTW : 4.57 %
GWO.PR.P Deemed-Retractible 2.32 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.35
Bid-YTW : 6.46 %
HSE.PR.E FixedReset 2.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 14.89
Evaluated at bid price : 14.89
Bid-YTW : 7.20 %
BMO.PR.M FixedReset 2.42 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.90
Bid-YTW : 4.45 %
PWF.PR.S Perpetual-Discount 2.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 20.62
Evaluated at bid price : 20.62
Bid-YTW : 5.85 %
BAM.PR.Z FixedReset 2.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 17.23
Evaluated at bid price : 17.23
Bid-YTW : 5.37 %
CCS.PR.C Deemed-Retractible 2.47 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.75
Bid-YTW : 7.74 %
W.PR.J Perpetual-Discount 2.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 22.05
Evaluated at bid price : 22.34
Bid-YTW : 6.31 %
PVS.PR.C SplitShare 2.50 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2017-12-10
Maturity Price : 25.00
Evaluated at bid price : 24.60
Bid-YTW : 6.12 %
BAM.PR.M Perpetual-Discount 2.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 18.72
Evaluated at bid price : 18.72
Bid-YTW : 6.42 %
MFC.PR.B Deemed-Retractible 2.59 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.84
Bid-YTW : 8.01 %
MFC.PR.C Deemed-Retractible 2.59 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.44
Bid-YTW : 8.13 %
MFC.PR.H FixedReset 2.60 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.16
Bid-YTW : 8.29 %
BAM.PR.N Perpetual-Discount 2.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 18.83
Evaluated at bid price : 18.83
Bid-YTW : 6.38 %
RY.PR.Z FixedReset 2.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 16.82
Evaluated at bid price : 16.82
Bid-YTW : 4.52 %
W.PR.H Perpetual-Discount 2.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 21.86
Evaluated at bid price : 22.10
Bid-YTW : 6.26 %
TD.PF.A FixedReset 2.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 16.72
Evaluated at bid price : 16.72
Bid-YTW : 4.53 %
BNS.PR.Q FixedReset 2.72 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.29
Bid-YTW : 5.02 %
CU.PR.I FixedReset 2.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 23.07
Evaluated at bid price : 24.70
Bid-YTW : 4.51 %
BAM.PF.C Perpetual-Discount 2.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 19.08
Evaluated at bid price : 19.08
Bid-YTW : 6.43 %
BMO.PR.W FixedReset 2.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 16.48
Evaluated at bid price : 16.48
Bid-YTW : 4.61 %
HSE.PR.C FixedReset 2.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 14.10
Evaluated at bid price : 14.10
Bid-YTW : 7.01 %
SLF.PR.G FixedReset 2.86 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.60
Bid-YTW : 11.00 %
SLF.PR.H FixedReset 2.89 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.90
Bid-YTW : 10.68 %
RY.PR.H FixedReset 3.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 16.90
Evaluated at bid price : 16.90
Bid-YTW : 4.56 %
BMO.PR.Q FixedReset 3.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.55
Bid-YTW : 7.44 %
BMO.PR.T FixedReset 3.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 16.56
Evaluated at bid price : 16.56
Bid-YTW : 4.63 %
TD.PR.Z FloatingReset 3.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.66
Bid-YTW : 4.47 %
PWF.PR.T FixedReset 3.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 18.81
Evaluated at bid price : 18.81
Bid-YTW : 4.17 %
BNS.PR.P FixedReset 3.21 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.81
Bid-YTW : 4.58 %
RY.PR.J FixedReset 3.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 17.68
Evaluated at bid price : 17.68
Bid-YTW : 4.84 %
BAM.PR.R FixedReset 3.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 13.54
Evaluated at bid price : 13.54
Bid-YTW : 5.42 %
BNS.PR.R FixedReset 3.46 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.72
Bid-YTW : 4.94 %
BAM.PR.X FixedReset 3.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 13.00
Evaluated at bid price : 13.00
Bid-YTW : 4.92 %
IAG.PR.A Deemed-Retractible 3.50 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.68
Bid-YTW : 7.33 %
PVS.PR.D SplitShare 3.50 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2021-10-08
Maturity Price : 25.00
Evaluated at bid price : 22.15
Bid-YTW : 7.11 %
IAG.PR.G FixedReset 3.52 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.35
Bid-YTW : 8.59 %
MFC.PR.L FixedReset 3.59 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.43
Bid-YTW : 8.96 %
BMO.PR.S FixedReset 3.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 4.62 %
SLF.PR.A Deemed-Retractible 3.71 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.66
Bid-YTW : 7.51 %
MFC.PR.I FixedReset 3.82 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.38
Bid-YTW : 8.67 %
SLF.PR.B Deemed-Retractible 3.86 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.74
Bid-YTW : 7.51 %
BAM.PR.G FixedFloater 3.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 25.00
Evaluated at bid price : 12.50
Bid-YTW : 6.63 %
FTS.PR.K FixedReset 3.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 15.59
Evaluated at bid price : 15.59
Bid-YTW : 4.64 %
SLF.PR.C Deemed-Retractible 3.99 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.56
Bid-YTW : 7.95 %
MFC.PR.N FixedReset 3.99 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.41
Bid-YTW : 9.12 %
SLF.PR.D Deemed-Retractible 4.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.45
Bid-YTW : 8.03 %
MFC.PR.J FixedReset 4.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.88
Bid-YTW : 8.79 %
TD.PF.D FixedReset 4.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 17.38
Evaluated at bid price : 17.38
Bid-YTW : 4.93 %
MFC.PR.G FixedReset 4.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.10
Bid-YTW : 8.81 %
SLF.PR.I FixedReset 4.25 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.95
Bid-YTW : 9.55 %
FTS.PR.M FixedReset 4.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 17.25
Evaluated at bid price : 17.25
Bid-YTW : 4.81 %
W.PR.K FixedReset 4.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 22.72
Evaluated at bid price : 23.88
Bid-YTW : 5.50 %
NA.PR.S FixedReset 4.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 16.20
Evaluated at bid price : 16.20
Bid-YTW : 4.89 %
MFC.PR.M FixedReset 4.62 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.75
Bid-YTW : 8.90 %
SLF.PR.E Deemed-Retractible 4.69 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.66
Bid-YTW : 7.94 %
MFC.PR.K FixedReset 4.77 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.24
Bid-YTW : 8.97 %
BMO.PR.Y FixedReset 4.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 18.39
Evaluated at bid price : 18.39
Bid-YTW : 4.70 %
RY.PR.M FixedReset 4.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 4.78 %
HSE.PR.G FixedReset 4.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 15.03
Evaluated at bid price : 15.03
Bid-YTW : 7.13 %
BNS.PR.B FloatingReset 5.00 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.01
Bid-YTW : 5.04 %
TD.PR.S FixedReset 5.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.85
Bid-YTW : 4.33 %
NA.PR.W FixedReset 5.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 15.76
Evaluated at bid price : 15.76
Bid-YTW : 4.84 %
TRP.PR.B FixedReset 5.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 9.89
Evaluated at bid price : 9.89
Bid-YTW : 4.89 %
TD.PR.Y FixedReset 6.33 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.02
Bid-YTW : 4.39 %
TRP.PR.A FixedReset 6.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 12.76
Evaluated at bid price : 12.76
Bid-YTW : 5.26 %
BAM.PF.A FixedReset 6.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 17.97
Evaluated at bid price : 17.97
Bid-YTW : 5.08 %
BAM.PR.T FixedReset 6.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 14.42
Evaluated at bid price : 14.42
Bid-YTW : 5.21 %
BAM.PF.B FixedReset 7.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 17.07
Evaluated at bid price : 17.07
Bid-YTW : 4.98 %
TRP.PR.D FixedReset 7.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 15.09
Evaluated at bid price : 15.09
Bid-YTW : 5.22 %
TRP.PR.E FixedReset 7.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 15.85
Evaluated at bid price : 15.85
Bid-YTW : 5.05 %
BAM.PF.G FixedReset 7.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 18.25
Evaluated at bid price : 18.25
Bid-YTW : 5.08 %
TRP.PR.F FloatingReset 8.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 11.39
Evaluated at bid price : 11.39
Bid-YTW : 4.94 %
BAM.PF.F FixedReset 8.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 18.55
Evaluated at bid price : 18.55
Bid-YTW : 4.95 %
BAM.PF.E FixedReset 9.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 17.23
Evaluated at bid price : 17.23
Bid-YTW : 4.99 %
TRP.PR.G FixedReset 10.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 17.20
Evaluated at bid price : 17.20
Bid-YTW : 5.31 %
TRP.PR.C FixedReset 14.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 10.73
Evaluated at bid price : 10.73
Bid-YTW : 4.93 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PF.G FixedReset 222,335 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 23.25
Evaluated at bid price : 25.32
Bid-YTW : 5.16 %
TRP.PR.A FixedReset 137,607 TD crossed 122,500 at 12.65.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 12.76
Evaluated at bid price : 12.76
Bid-YTW : 5.26 %
RY.PR.Q FixedReset 126,716 RBC crossed 25,000 at 25.28.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 23.25
Evaluated at bid price : 25.36
Bid-YTW : 5.08 %
BAM.PR.Z FixedReset 106,495 Scotia crossed 100,000 at 17.30.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 17.23
Evaluated at bid price : 17.23
Bid-YTW : 5.37 %
HSE.PR.C FixedReset 102,098 RBC crossed 85,000 at 14.10.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 14.10
Evaluated at bid price : 14.10
Bid-YTW : 7.01 %
MFC.PR.I FixedReset 100,510 Nesbitt crossed blocks of 30,000 and 50,000, both at 17.20.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.38
Bid-YTW : 8.67 %
There were 59 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
GWO.PR.O FloatingReset Quote: 11.40 – 14.00
Spot Rate : 2.6000
Average : 1.8433

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.40
Bid-YTW : 11.47 %

PWF.PR.T FixedReset Quote: 18.81 – 20.16
Spot Rate : 1.3500
Average : 0.9088

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 18.81
Evaluated at bid price : 18.81
Bid-YTW : 4.17 %

BNS.PR.D FloatingReset Quote: 17.52 – 18.61
Spot Rate : 1.0900
Average : 0.7587

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.52
Bid-YTW : 7.53 %

RY.PR.P Perpetual-Discount Quote: 23.65 – 24.88
Spot Rate : 1.2300
Average : 0.9068

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 23.35
Evaluated at bid price : 23.65
Bid-YTW : 5.69 %

SLF.PR.G FixedReset Quote: 12.60 – 13.52
Spot Rate : 0.9200
Average : 0.6184

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.60
Bid-YTW : 11.00 %

BAM.PR.Z FixedReset Quote: 17.23 – 18.01
Spot Rate : 0.7800
Average : 0.5046

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-19
Maturity Price : 17.23
Evaluated at bid price : 17.23
Bid-YTW : 5.37 %

Market Action

January 18, 2016

Here’s a lesson in counterparty risk management:

The demise of Invexstar Capital Management has also raised eyebrows about the ease with which a group of Italian financiers were able to trade billions of pounds of bonds with virtually no capital to back their positions.

BNP Paribas, Morgan Stanley and Nomura are among the banks to have lost at least £97 million, although the full scale of the losses is still being assessed months after the collapse.

Invexstar was a tiny broker that went under in the market meltdown that followed the spike in German government debt yields last May. The company had been set up in 2014, but, according to several sources with knowledge of its operations, the small outfit based in an office above The Daily Telegraph newspaper was able to trade billions of pounds of government and corporate bonds despite having capital of only a little over £630,000.
…
Based on the losses incurred by the banks, the size of Invexstar’s trading positions at the time of its failure would have been at least £2 billion, or more than 3,000 times the firm’s capital. Thus even a tiny movement in the value of its trading portfolio was enough to wipe out its backers’ money and leave its counterparties with huge shortfalls.

According to other traders, several banks had become suspicious about Invexstar before its failure. Lloyds Banking Group is understood to have cut its links after staff at the lender became concerned that Mr Statti repeatedly cancelled meetings to discuss the firm’s trading exposures.

In particular, suspicions had been raised at the way in which Invexstar had asked its counterparties to extend the settlement times for its trades. The settlement period is the time from when a trader places an order for some bonds to when they must pay for the securities they have agreed to purchase. While a normal settlement period in the fixed income markets is two days, Invexstar had asked for five days to pay for its trades and even as many as ten, according to sources with knowledge of the situation.

All eyes are on the potential for a BoC rate cut:

Trading in overnight index swaps currently implies the probability of a rate cut at about 60 per cent when the Bank of Canada releases its monetary policy report on Wednesday.

Economists calling for the key overnight lending rate to be maintained at 0.50 per cent say additional stimulus could test consumer sentiment. A cut to 0.25 per cent as expected by the market could bring about a “runaway exchange rate,” said Avery Shenfeld, chief economist at CIBC World Markets.
…
Over the past two years, the Canadian dollar has lost a full 25 cents in value – a downward slope unmatched in steepness, [National Bank Financial chief economist] Mr. [Stéfane] Marion said.

Certainly, a great deal of downside is to be expected considering Canada’s current economic circumstances. The precipitous decline of commodity prices has started to ripple through non-resource sectors this year, Canadian economic growth is shrinking as a result, and U.S. dollar strength has also combined to pull the loonie down forcefully.

But the losses should have been more like 10 cents, not 25 cents, Mr. Marion said. “Is the loonie out of whack with its fundamentals? We think so.”

Barclays is gung-ho:

The Bank of Canada will cut its key interest rate to at least zero this year and could move toward negative rates to offset the crude oil price slump, according to Barclays PLC.

The London-based bank expects the Bank of Canada to cut its overnight target rate 25-basis points to 0.25 per cent at its announcement on Wednesday, and a total of at least 50 basis points in 2016, Juan Prada and Andres Jaime Martinez wrote in a research note.

On a related note, S&P has Alberta on Outlook-Negative:

A second credit-rating agency has weighed in on Alberta’s debt, lowering its rating outlook to negative from stable due to the collapse in oil prices and the province’s mounting budget worries.

Moody’s Investors Service said it affirmed Alberta’s credit at triple-A, but it said the future looks riskier as world crude prices hover below $29 (U.S.) a barrel, heaping financial pressure on an energy industry that has been a major contributor to government revenues.

It is a less drastic step than a downgrade, which Standard & Poor’s did last month, lowering Alberta’s rating one notch after years of enjoying the safest category of public debt.

“While Alberta has entered the downturn in oil prices from a strong financial position, including substantial levels of cash and investments, low debt and low debt service levels, the decrease in oil prices could lead to a rapid fiscal deterioration that erodes these key supports to the triple-A rating,” Moody’s vice-president Michael Yake said in a statement.

Drones will change the world, whether we like it or not:

“Given the size, capability and versatility of drones, the risks to national security and individual privacy are high,” said Amber Dubey, head of aerospace and defense at global consultancy KPMG. “Governments should carefully strike a balance between ensuring the safety as well as not curtailing the growth of the drones and the advantages they bring.”

As countries draft new rules to respond to an explosion in sales, and a series of high-profile security concerns last year, regulators are concerned about the difficulty of enforcing regulations. Three months after the U.S. Secret Service recovered a drone on the White House grounds, Kyodo News reported in April that another was found on the roof of the Japanese prime minister’s office.

It’s only a matter of time before a drone is used to deliver a payload of explosive in a terrorist attack. I haven’t thought of a way of stopping a well-planned attack; I’m not sure if anybody has:

In an interview with the Sunday Times, Detective Chief Inspector Colin Smith, a security expert and adviser to the Home Office Centre for Applied Science and Technology, warned that small quadcopter drones could easily be used by terrorists for attacks and propaganda purposes.

Brompton Lifeco Split Corp., proud issuer of LCS and LCS.PR.A, has suspended the Capital Unit distribution:

In accordance with its articles of incorporation and the Class A Share Provisions, the regular, non-cumulative, monthly distribution for the month of January will not be paid on the class A shares of Brompton Lifeco Split Corp. The net asset value per unit as at January 14, 2016 was $14.34. Under the articles of incorporation, no cash distribution may be paid on the class A shares, if after payment of the distribution by the Fund, the net asset value per unit (consisting of one class A share and one preferred share) would be less than $15.00. The Fund will re-evaluate the payment of class A share distributions in each subsequent month with the expectation that normal monthly distributions will resume and a press release will be issued if the net asset value per unit meets this requirement.

In accordance with the Preferred Share Provisions, regular quarterly preferred share dividends will continue to be paid.

There’s a rumour that Bay Street is covered with these signs:

openManhole
Click for Big

It was a poor day for the Canadian preferred share market, all because of FixedResets: PerpetualDiscounts gained 4bp, FixedResets lost 125bp and DeemedRetractibles were off 1bp. The Performance Highlights table is its usual horrid self, but there were quite a few winners today, rebounding from last week. Volume was well above average; a bit of a surprise, given that the US was closed for MLK day.

DC.PR.C fell back to ‘retail levels’ today on volume of 7,510, closing at 16.05-39, 21×1.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_160118
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 14.75 to be $0.99 rich, while TRP.PR.C, resetting 2016-1-30 at +154, is $0.88 cheap at its bid price of 9.40.

impVol_MFC_160118
Click for Big

Most expensive is MFC.PR.L, resetting at +216bp on 2019-6-19, bid at 15.86 to be 1.08 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 16.41 to be 1.18 cheap.

impVol_BAM_160118
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 13.09 to be $0.98 cheap. BAM.PR.X, resetting at +180bp on 2017-6-30 is bid at 12.56 and appears to be $0.94 rich.

impVol_FTS_160118
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 15.00, looks $0.36 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 14.55 and is $0.46 cheap.

pairs_FR_160118
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of +0.11%, with one outlier above +1.00%. There is one junk outlier below -1.00% and two above 1.00%.

pairs_FF_160118
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.51 % 6.71 % 24,280 15.80 1 -2.3810 % 1,410.3
FixedFloater 7.90 % 6.88 % 28,947 15.38 1 -2.2746 % 2,517.6
Floater 4.90 % 4.97 % 76,939 15.56 4 -3.8624 % 1,559.9
OpRet 0.00 % 0.00 % 0 0.00 0 -1.1647 % 2,659.8
SplitShare 4.97 % 7.23 % 68,566 2.74 6 -1.1647 % 3,112.4
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -1.1647 % 2,428.4
Perpetual-Premium 6.04 % 6.07 % 84,459 13.83 6 0.0413 % 2,441.8
Perpetual-Discount 6.02 % 6.05 % 99,515 13.83 34 0.0420 % 2,395.3
FixedReset 6.04 % 5.42 % 239,689 14.16 82 -1.2484 % 1,706.9
Deemed-Retractible 5.48 % 5.96 % 133,686 6.92 34 -0.0118 % 2,456.4
FloatingReset 2.86 % 5.34 % 65,486 5.60 13 -0.6495 % 1,941.2
Performance Highlights
Issue Index Change Notes
PWF.PR.A Floater -10.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 10.00
Evaluated at bid price : 10.00
Bid-YTW : 4.79 %
MFC.PR.G FixedReset -4.87 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.41
Bid-YTW : 9.39 %
TRP.PR.A FixedReset -4.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 12.00
Evaluated at bid price : 12.00
Bid-YTW : 5.60 %
SLF.PR.G FixedReset -4.30 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.25
Bid-YTW : 11.38 %
MFC.PR.M FixedReset -4.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.01
Bid-YTW : 9.55 %
TD.PR.S FixedReset -3.97 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.75
Bid-YTW : 5.24 %
HSE.PR.C FixedReset -3.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 13.71
Evaluated at bid price : 13.71
Bid-YTW : 7.21 %
HSE.PR.G FixedReset -3.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 14.32
Evaluated at bid price : 14.32
Bid-YTW : 7.50 %
MFC.PR.H FixedReset -3.80 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.70
Bid-YTW : 8.65 %
GWO.PR.N FixedReset -3.75 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.55
Bid-YTW : 12.05 %
VNR.PR.A FixedReset -3.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 15.65
Evaluated at bid price : 15.65
Bid-YTW : 5.58 %
HSE.PR.E FixedReset -3.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 14.55
Evaluated at bid price : 14.55
Bid-YTW : 7.37 %
TD.PF.E FixedReset -3.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 5.02 %
MFC.PR.I FixedReset -3.35 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.74
Bid-YTW : 9.20 %
HSE.PR.A FixedReset -3.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 8.85
Evaluated at bid price : 8.85
Bid-YTW : 6.55 %
SLF.PR.I FixedReset -3.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.30
Bid-YTW : 10.14 %
BNS.PR.B FloatingReset -3.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.01
Bid-YTW : 5.92 %
ENB.PR.A Perpetual-Discount -3.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 20.52
Evaluated at bid price : 20.52
Bid-YTW : 6.83 %
IAG.PR.G FixedReset -2.84 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.76
Bid-YTW : 9.07 %
TRP.PR.G FixedReset -2.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 15.55
Evaluated at bid price : 15.55
Bid-YTW : 5.89 %
TD.PF.D FixedReset -2.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 16.69
Evaluated at bid price : 16.69
Bid-YTW : 5.13 %
FTS.PR.M FixedReset -2.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 16.51
Evaluated at bid price : 16.51
Bid-YTW : 5.03 %
MFC.PR.J FixedReset -2.53 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.21
Bid-YTW : 9.36 %
PVS.PR.C SplitShare -2.48 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2017-12-10
Maturity Price : 25.00
Evaluated at bid price : 24.00
Bid-YTW : 7.52 %
BAM.PR.E Ratchet -2.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 25.00
Evaluated at bid price : 12.30
Bid-YTW : 6.71 %
TRP.PR.H FloatingReset -2.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 8.79
Evaluated at bid price : 8.79
Bid-YTW : 4.56 %
BAM.PR.G FixedFloater -2.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 25.00
Evaluated at bid price : 12.03
Bid-YTW : 6.88 %
IFC.PR.A FixedReset -2.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.90
Bid-YTW : 11.72 %
TD.PR.Y FixedReset -2.26 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.65
Bid-YTW : 5.53 %
BAM.PR.K Floater -2.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 9.58
Evaluated at bid price : 9.58
Bid-YTW : 4.97 %
PWF.PR.P FixedReset -2.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 11.12
Evaluated at bid price : 11.12
Bid-YTW : 4.89 %
MFC.PR.L FixedReset -2.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.86
Bid-YTW : 9.46 %
BMO.PR.S FixedReset -2.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 16.40
Evaluated at bid price : 16.40
Bid-YTW : 4.80 %
RY.PR.I FixedReset -2.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.73
Bid-YTW : 5.77 %
CU.PR.C FixedReset -2.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 15.68
Evaluated at bid price : 15.68
Bid-YTW : 4.92 %
FTS.PR.K FixedReset -1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 15.00
Evaluated at bid price : 15.00
Bid-YTW : 4.83 %
TRP.PR.F FloatingReset -1.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 10.54
Evaluated at bid price : 10.54
Bid-YTW : 5.34 %
RY.PR.B Deemed-Retractible -1.93 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.93
Bid-YTW : 5.72 %
PVS.PR.B SplitShare -1.90 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2019-01-10
Maturity Price : 25.00
Evaluated at bid price : 23.25
Bid-YTW : 7.23 %
MFC.PR.F FixedReset -1.89 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.91
Bid-YTW : 11.68 %
TRP.PR.D FixedReset -1.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 14.05
Evaluated at bid price : 14.05
Bid-YTW : 5.62 %
BAM.PF.E FixedReset -1.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 15.76
Evaluated at bid price : 15.76
Bid-YTW : 5.49 %
NA.PR.S FixedReset -1.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 15.50
Evaluated at bid price : 15.50
Bid-YTW : 5.12 %
FTS.PR.F Perpetual-Discount -1.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 20.85
Evaluated at bid price : 20.85
Bid-YTW : 5.97 %
BNS.PR.P FixedReset -1.69 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.10
Bid-YTW : 5.17 %
ELF.PR.G Perpetual-Discount -1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 19.82
Evaluated at bid price : 19.82
Bid-YTW : 6.04 %
BNS.PR.D FloatingReset -1.69 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.50
Bid-YTW : 7.55 %
FTS.PR.H FixedReset -1.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 11.80
Evaluated at bid price : 11.80
Bid-YTW : 4.57 %
TRP.PR.E FixedReset -1.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 14.75
Evaluated at bid price : 14.75
Bid-YTW : 5.45 %
CIU.PR.C FixedReset -1.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 10.34
Evaluated at bid price : 10.34
Bid-YTW : 4.79 %
PVS.PR.D SplitShare -1.61 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2021-10-08
Maturity Price : 25.00
Evaluated at bid price : 21.40
Bid-YTW : 7.83 %
BMO.PR.R FloatingReset -1.50 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.99
Bid-YTW : 5.10 %
CM.PR.Q FixedReset -1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 17.26
Evaluated at bid price : 17.26
Bid-YTW : 4.97 %
IGM.PR.B Perpetual-Premium -1.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 23.67
Evaluated at bid price : 24.10
Bid-YTW : 6.13 %
PWF.PR.T FixedReset -1.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 18.23
Evaluated at bid price : 18.23
Bid-YTW : 4.31 %
BMO.PR.Q FixedReset -1.42 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.99
Bid-YTW : 8.01 %
BNS.PR.N Deemed-Retractible -1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.66
Bid-YTW : 5.52 %
MFC.PR.C Deemed-Retractible -1.30 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.95
Bid-YTW : 8.50 %
BNS.PR.C FloatingReset -1.28 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.76
Bid-YTW : 5.45 %
SLF.PR.J FloatingReset -1.26 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.75
Bid-YTW : 11.24 %
BMO.PR.Z Perpetual-Discount -1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 21.88
Evaluated at bid price : 22.22
Bid-YTW : 5.70 %
RY.PR.G Deemed-Retractible -1.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.85
Bid-YTW : 5.57 %
BMO.PR.Y FixedReset -1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 17.55
Evaluated at bid price : 17.55
Bid-YTW : 4.93 %
BIP.PR.A FixedReset -1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 16.80
Evaluated at bid price : 16.80
Bid-YTW : 6.36 %
GWO.PR.I Deemed-Retractible -1.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.35
Bid-YTW : 8.16 %
TRP.PR.C FixedReset -1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 9.40
Evaluated at bid price : 9.40
Bid-YTW : 5.63 %
MFC.PR.N FixedReset -1.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.78
Bid-YTW : 9.68 %
MFC.PR.B Deemed-Retractible -1.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.34
Bid-YTW : 8.38 %
ELF.PR.H Perpetual-Discount -1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 21.79
Evaluated at bid price : 22.08
Bid-YTW : 6.26 %
SLF.PR.H FixedReset -1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.51
Bid-YTW : 11.08 %
IAG.PR.A Deemed-Retractible -1.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.98
Bid-YTW : 7.82 %
FTS.PR.J Perpetual-Discount -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 20.09
Evaluated at bid price : 20.09
Bid-YTW : 6.01 %
BNS.PR.R FixedReset -1.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.96
Bid-YTW : 5.58 %
PVS.PR.E SplitShare -1.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-10-31
Maturity Price : 25.00
Evaluated at bid price : 23.00
Bid-YTW : 7.18 %
CM.PR.P FixedReset -1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 15.83
Evaluated at bid price : 15.83
Bid-YTW : 4.79 %
BNS.PR.Z FixedReset -1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.31
Bid-YTW : 7.57 %
BAM.PR.T FixedReset 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 13.51
Evaluated at bid price : 13.51
Bid-YTW : 5.57 %
GWO.PR.S Deemed-Retractible 1.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.92
Bid-YTW : 6.56 %
W.PR.J Perpetual-Discount 1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 21.54
Evaluated at bid price : 21.80
Bid-YTW : 6.46 %
POW.PR.A Perpetual-Discount 1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 23.03
Evaluated at bid price : 23.30
Bid-YTW : 6.04 %
POW.PR.C Perpetual-Premium 1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 23.69
Evaluated at bid price : 24.00
Bid-YTW : 6.08 %
SLF.PR.E Deemed-Retractible 1.51 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.78
Bid-YTW : 8.60 %
GWO.PR.H Deemed-Retractible 1.59 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.41
Bid-YTW : 7.80 %
RY.PR.L FixedReset 1.74 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.01
Bid-YTW : 4.68 %
TD.PF.A FixedReset 1.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 16.28
Evaluated at bid price : 16.28
Bid-YTW : 4.66 %
SLF.PR.A Deemed-Retractible 1.84 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.92
Bid-YTW : 8.04 %
RY.PR.E Deemed-Retractible 1.92 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.89
Bid-YTW : 5.54 %
BAM.PF.A FixedReset 1.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 16.88
Evaluated at bid price : 16.88
Bid-YTW : 5.42 %
TD.PR.T FloatingReset 1.99 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.04
Bid-YTW : 4.90 %
POW.PR.B Perpetual-Discount 2.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 21.84
Evaluated at bid price : 22.08
Bid-YTW : 6.09 %
W.PR.H Perpetual-Discount 3.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 21.26
Evaluated at bid price : 21.53
Bid-YTW : 6.43 %
FTS.PR.I FloatingReset 4.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 10.60
Evaluated at bid price : 10.60
Bid-YTW : 4.20 %
PWF.PR.L Perpetual-Discount 5.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 21.17
Evaluated at bid price : 21.17
Bid-YTW : 6.05 %
RY.PR.A Deemed-Retractible 8.25 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.87
Bid-YTW : 5.50 %
Volume Highlights
Issue Index Shares
Traded
Notes
BNS.PR.E FixedReset 260,218 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 23.20
Evaluated at bid price : 25.18
Bid-YTW : 5.11 %
BMO.PR.S FixedReset 166,227 RBC crossed 161,400 at 16.47.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 16.40
Evaluated at bid price : 16.40
Bid-YTW : 4.80 %
TD.PF.G FixedReset 151,572 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 23.23
Evaluated at bid price : 25.26
Bid-YTW : 5.17 %
BMO.PR.K Deemed-Retractible 144,371 Nesbitt crossed 125,000 at 24.75.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.76
Bid-YTW : 5.63 %
RY.PR.Q FixedReset 127,975 RBC bought 12,000 from anonymous at 25.20, and crossed 20,000 at 25.23. Desjardins crossed 50,000 at 25.23.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 23.21
Evaluated at bid price : 25.21
Bid-YTW : 5.12 %
BNS.PR.A FloatingReset 104,100 TD crossed blocks of 48,300 and 50,000, both at 22.10.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.99
Bid-YTW : 4.58 %
IGM.PR.B Perpetual-Premium 101,750 RBC crossed 100,000 at 24.20.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 23.67
Evaluated at bid price : 24.10
Bid-YTW : 6.13 %
There were 41 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
GWO.PR.O FloatingReset Quote: 11.40 – 13.00
Spot Rate : 1.6000
Average : 1.0136

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.40
Bid-YTW : 11.47 %

PWF.PR.A Floater Quote: 10.00 – 11.00
Spot Rate : 1.0000
Average : 0.6902

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 10.00
Evaluated at bid price : 10.00
Bid-YTW : 4.79 %

BNS.PR.B FloatingReset Quote: 20.01 – 20.63
Spot Rate : 0.6200
Average : 0.3975

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.01
Bid-YTW : 5.92 %

MFC.PR.M FixedReset Quote: 16.01 – 16.60
Spot Rate : 0.5900
Average : 0.3849

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.01
Bid-YTW : 9.55 %

PVS.PR.C SplitShare Quote: 24.00 – 24.50
Spot Rate : 0.5000
Average : 0.3202

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2017-12-10
Maturity Price : 25.00
Evaluated at bid price : 24.00
Bid-YTW : 7.52 %

TRP.PR.F FloatingReset Quote: 10.54 – 11.26
Spot Rate : 0.7200
Average : 0.5451

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-18
Maturity Price : 10.54
Evaluated at bid price : 10.54
Bid-YTW : 5.34 %

Market Action

January 15, 2016

Holy Smokes, that was a day and a half!

Stocks tumbled around the world, with U.S. equities sinking to their lowest levels since August, and bonds and gold jumped as oil’s plunge below $30 sent markets reeling. Treasuries extended gains as economic data and earnings added to concern that global growth is faltering.

The Dow Jones Industrial Average sank 391 points, European stocks fell into a bear market and the Shanghai Composite Index wiped out gains from an unprecedented state-rescue campaign as global equities added to the worst start to a year on record. Oil touched $29.28 a barrel before closing at a 12-year low. A measure of default risk for junk-rated U.S. companies surged to the highest in three years. Yields on 10-year Treasury notes dipped under 2 percent as doubts grow that the Federal Reserve will raise interest rates. Gold surged the most in six weeks.
…
Figures on retail sales and manufacturing Friday showed the U.S. economy ended the year on a weak note, and the start of 2016 wasn’t any better. Energy firms are laying off workers and currency markets from commodity-producing countries are in turmoil. The slump is also denting the outlook for inflation, causing traders to curb bets on how far the Fed will raise rates this year.
…
The Standard & Poor’s 500 Index plunged 2.2 percent at 4 p.m. in New York. The index fell as much as 3.3 percent before paring the slide in afternoon trading. It still capped a third weekly retreat and closed at the lowest level since Aug. 25, the day that marked the bottom of the summer selloff. U.S. equities markets are closed Monday for a federal holiday.

The gauge has lost 12 percent from its May record, leaving it well short of sliding into a bear market. It capped a third weekly decline, the longest slide since July. The Dow tumbled 2.463 points as none of its 30 members advanced, while small caps added to a bear market.
…
West Texas Intermediate crude fell as much as 6.2 percent, before settling 5.7 percent lower at $29.42 a barrel. Brent fell 5.9 percent to $29.05 a barrel. The discount on global benchmark Brent reached a five-year high as Iran moved closer to restoring exports.
…
The Bloomberg Commodity Index, which measures returns on 22 raw materials, dropped 1.4 percent to the lowest level in data going back to 1991.

Given all that, effects on Canada followed:

The country’s benchmark Standard & Poor’s/TSX Composite Index fell 2.1 percent to 12,073.46 at 4 p.m. in Toronto, undoing Thursday’s rally and resuming a sell-off that’s pulled Canada into a bear market. Stocks plunged 7.2 percent this year and are down about 23 percent from a September 2014 record. The Canadian dollar slumped to a new 13-year low and yields on five-year government bonds fell to a record low of 0.511 percent on Wednesday as speculation builds the Bank of Canada will cut interest rates next week.

Canada’s economy, heavily weighed toward resource industries such as oil and mining, has been rocked by concerns about the slowdown in China that has pushed the price of West Texas Intermediate crude below $30 for the first time since 2003. Prices for Canada’s heavy crude, which trades at a discount to the U.S. benchmark, have sunk to around $15 a barrel.

And TransAlta common got thumped:

TransAlta Corp. slumped after the Alberta electricity generator cut its dividend in preparation for a phase-out of coal power in the province.

The shares fell 9.8 per cent to $3.94 at 11:40 a.m. in Toronto. It initially dropped 14 per cent, the most on an intraday basis since 2008, to a record low.

The quarterly dividend was cut to 4 cents a share from 18 cents, the company said in a release Thursday. Calgary– based TransAlta doesn’t expect to raise equity this year as the reduced dividend will “strengthen its balance sheet.”
…
TransAlta, which has more than 70 power plants in Canada, the U.S. and Australia, said it will negotiate with the government of Alberta to “ensure the company has the certainty and capacity” to invest in clean power.
…
The falling Canadian dollar is making it more expensive to build new wind and gas-powered generators, [TransAlta CEO Dawn] Farrell said. The cost to build new projects with those technologies is more than double the current market price for power of about C$30 a megawatt hour, she said.

Well, hey, maybe the Alberta government will get some advice from Ontario, and buy that Green Power for $90/MWH!

So the SEC is now awarding prizes to short-sale analysts!

The Securities and Exchange Commission today announced a whistleblower award of more than $700,000 to a company outsider who conducted a detailed analysis that led to a successful SEC enforcement action.

“The voluntary submission of high-quality analysis by industry experts can be every bit as valuable as first-hand knowledge of wrongdoing by company insiders,” said Andrew Ceresney, Director of the SEC’s Enforcement Division. “We will continue to leverage all forms of information and analysis we receive from whistleblowers to help better detect and prosecute federal securities law violations.”

No mission creep there, nope, not a bit of it.

On such a day, it is pleasant to think about drones, instead:

In October, a Kentucky judge dismissed criminal charges against a man who had shot down a drone flying over his property. Now the drone’s owner has brought a federal civil suit against the shooter, William Merideth, arguing that the Federal Aviation Administration is in charge of all airspace and that it allows drones to fly over private property.

All this amounts to a legal mess. The law, both state and federal, is still pretty unclear about where you can fly a drone, and what you as a citizen may do if a drone — probably with a camera on board — is hovering above your home.

What’s needed is a comprehensive legal regime that integrates state and federal jurisdictions. I want to propose the outlines of such a legal model, distinguishing what should belong to the feds and what should be within the realm of the states.
…
These features give reason for states to outlaw the use of drones to observe and record people on private property without their consent. Federal control over airways shouldn’t be interpreted to displace state law regulating drones. The federal interest is in flying from place to place, not hovering to get a better view.

Protecting privacy at the state level will allow drones to fly freely without sacrificing the individual’s legitimate interest in being left alone.
…
The slogan for drone regulation should be: Feds to let them fly, states to protect what they see. The balance should let us a benefit from a new technology without sacrificing ourselves to it.

But we can reflect that comparing costs for university education is much like comparing costs for investment advice:

So since 2011, the federal government has required all schools to provide something called a net price calculator on their websites. You put in some financial data, and the calculator estimates what your actual cost would be, after any scholarships. If you aren’t among the very affluent and are applying to a private college, that net price can be tens of thousands of dollars below the list price.

Not long after the calculator became standard, a service called College Abacus emerged, allowing families to compare multiple schools at once. That spared them the laborious task of plugging the same data into multiple calculators many times over.

And how did many colleges respond? By blocking College Abacus’s access to their calculators. Imagine if Expedia or Kayak could not search for tickets on some of the most desirable airlines, and you get the idea.
…
So what’s really going on here? One strong hint comes from a letter that [College Abacus co-founder] Ms. [Abigail] Seldin received from a dean of financial aid. He wrote to her after she sent a mass note last year urging the schools that were blocking her tool to reconsider. She declined to identify him, as she still hopes to win him and others over.

“We are experiencing record student demand, engage families early in financial aid discussions and are meeting our goals,” the dean told her. “Why you think I should open myself up to a purely financial comparison when we are so much more than that, I have no idea. It is probably because you have not sat where I sit. So, kindly cease communication with me.”

However, it seems to me that the preferred share market is signalling something …

apocalypse
Click for Big

It’s ridiculous. Right now the TXPR Total Return Index Value is down about 15.2% month-to-date. Assuming that this holds through to month-end and is reflected in the BMO CM-50 index, then we can conclude that this is the worst month on record: the worst is current November, 2008, at -10.7%, and October, 2008, at -8.2%. So the violence of this drop compared to the worst part of the Credit Crunch, when there were actual Bad Things happening, should give us pause.

We may also observe that such a return would imply that the Canadian preferred share market has experienced a cumulative total return of a big fat zero since July 31, 2009; a time-span of 78 months, which is 6.5 years.

And this assumption allows us to prepare the following graph:

totalReturnHistorical
Click for Big

So … assuming there’s no recovery in the second half of the month, we’re due to record the worst 12 months in Canadian preferred market history (well … back to 1993, anyway!) and has a six-and-a-half year cumulative total return that is only a little better than the worst on record. Nice.

Update
While pondering methods of making my Assiduous Readers feel even more terrible, it occurred to me that it’s actually worse than described above. In preparing the chart above, I simply picked the most recent time that the index moved through the estimated January value, but it also broke through this barrier in November, 2005. We may observe that the index’s total cumulative return from November 30, 2005, to [estimated] January month-end, 2016, is very slightly negative (-0.27%), so holding the index for the past 10 years and two months hasn’t made you any money. The previous low for the rolling cumulative 122-month return was reached (perhaps not surprisingly) in November, 2008, when it bottomed out at +7.78%. And this is worse.

totalReturnHistorical_122
Click for Big

It was an appalling day for the Canadian preferred share market, with PerpetualDiscounts down 211bp, FixedResets losing 277bp and DeemedRetractibles off 156bp. I will not discuss the Performance Highlights table. I will not! Volume was incredibly high.

It was yet another big day for DC.PR.C, with 122,599 shares changing hands at a VWAP of 16.92. It would seem that views are being taken! I suspect that current market conditions are making it less likely for the the abusive and debatable Plan of Arrangement to succeed … investors are attempting to cash out, not in!

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_160115
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 15.00 to be $0.90 rich, while TRP.PR.C, resetting 2016-1-30 at +154, is $0.92 cheap at its bid price of 9.51.

impVol_MFC_160115
Click for Big

Most expensive is MFC.PR.L, resetting at +216bp on 2019-6-19, bid at 16.21 to be 0.98 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 17.25 to be 0.79 cheap.

impVol_BAM_160115A
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 13.06 to be $0.91 cheap. BAM.PF.E, resetting at +255bp on 2020-3-31 is bid at 16.05 and appears to be $0.85 rich.

impVol_FTS_160115
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 15.30, looks $0.41 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 14.60 and is $0.69 cheap.

pairs_FR_160115
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.17%, with two outliers below -1.00%. There is one junk outlier below -1.00% and one above 1.00%. Note that today I have shifted the vertical axis of the chart.

pairs_FF_160115
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.38 % 6.55 % 25,315 16.00 1 -3.1514 % 1,444.7
FixedFloater 7.72 % 6.73 % 29,483 15.57 1 -2.0684 % 2,576.2
Floater 4.71 % 4.86 % 77,910 15.77 4 -1.9785 % 1,622.6
OpRet 0.00 % 0.00 % 0 0.00 0 -0.1949 % 2,691.1
SplitShare 4.91 % 6.50 % 69,578 2.75 6 -0.1949 % 3,149.1
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.1949 % 2,457.1
Perpetual-Premium 6.05 % 6.03 % 85,337 13.86 6 -1.4112 % 2,440.8
Perpetual-Discount 6.03 % 6.06 % 99,102 13.81 34 -2.1090 % 2,394.3
FixedReset 5.96 % 5.41 % 240,878 14.12 82 -2.7720 % 1,728.4
Deemed-Retractible 5.48 % 6.12 % 131,708 6.94 34 -1.5601 % 2,456.7
FloatingReset 3.02 % 5.38 % 65,189 5.58 13 -2.2401 % 1,953.9
Performance Highlights
Issue Index Change Notes
RY.PR.A Deemed-Retractible -10.33 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.05
Bid-YTW : 7.05 %
FTS.PR.I FloatingReset -10.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 10.17
Evaluated at bid price : 10.17
Bid-YTW : 4.67 %
SLF.PR.H FixedReset -6.69 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.66
Bid-YTW : 11.03 %
TRP.PR.F FloatingReset -6.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 10.75
Evaluated at bid price : 10.75
Bid-YTW : 5.51 %
MFC.PR.K FixedReset -6.46 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.50
Bid-YTW : 9.70 %
HSE.PR.G FixedReset -6.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 14.90
Evaluated at bid price : 14.90
Bid-YTW : 7.30 %
HSE.PR.A FixedReset -6.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 9.15
Evaluated at bid price : 9.15
Bid-YTW : 6.58 %
MFC.PR.N FixedReset -6.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.96
Bid-YTW : 9.56 %
BAM.PF.A FixedReset -5.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 16.56
Evaluated at bid price : 16.56
Bid-YTW : 5.64 %
MFC.PR.F FixedReset -5.89 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.14
Bid-YTW : 11.54 %
PWF.PR.L Perpetual-Discount -5.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 20.13
Evaluated at bid price : 20.13
Bid-YTW : 6.36 %
W.PR.H Perpetual-Discount -5.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 20.73
Evaluated at bid price : 20.73
Bid-YTW : 6.69 %
BAM.PF.G FixedReset -5.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 16.80
Evaluated at bid price : 16.80
Bid-YTW : 5.64 %
TRP.PR.D FixedReset -5.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 14.31
Evaluated at bid price : 14.31
Bid-YTW : 5.64 %
TRP.PR.E FixedReset -5.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 15.00
Evaluated at bid price : 15.00
Bid-YTW : 5.47 %
MFC.PR.I FixedReset -5.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.32
Bid-YTW : 8.80 %
MFC.PR.J FixedReset -4.92 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.63
Bid-YTW : 9.07 %
SLF.PR.I FixedReset -4.82 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.80
Bid-YTW : 9.78 %
RY.PR.E Deemed-Retractible -4.68 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.44
Bid-YTW : 5.90 %
MFC.PR.H FixedReset -4.66 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.40
Bid-YTW : 8.18 %
BAM.PR.T FixedReset -4.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 13.36
Evaluated at bid price : 13.36
Bid-YTW : 5.79 %
BAM.PF.F FixedReset -4.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 5.53 %
BNS.PR.Q FixedReset -4.43 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.55
Bid-YTW : 5.70 %
RY.PR.J FixedReset -4.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 17.11
Evaluated at bid price : 17.11
Bid-YTW : 5.11 %
RY.PR.M FixedReset -4.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 16.73
Evaluated at bid price : 16.73
Bid-YTW : 5.10 %
BAM.PF.C Perpetual-Discount -4.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 18.48
Evaluated at bid price : 18.48
Bid-YTW : 6.64 %
NA.PR.W FixedReset -4.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 15.02
Evaluated at bid price : 15.02
Bid-YTW : 5.21 %
TD.PF.A FixedReset -4.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 16.00
Evaluated at bid price : 16.00
Bid-YTW : 4.86 %
BAM.PF.B FixedReset -4.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 15.80
Evaluated at bid price : 15.80
Bid-YTW : 5.52 %
MFC.PR.G FixedReset -4.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.25
Bid-YTW : 8.77 %
TRP.PR.B FixedReset -4.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 9.35
Evaluated at bid price : 9.35
Bid-YTW : 5.36 %
IFC.PR.C FixedReset -4.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.25
Bid-YTW : 10.14 %
BMO.PR.Y FixedReset -4.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 17.76
Evaluated at bid price : 17.76
Bid-YTW : 4.96 %
PWF.PR.P FixedReset -4.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 11.37
Evaluated at bid price : 11.37
Bid-YTW : 4.98 %
IFC.PR.A FixedReset -4.00 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.20
Bid-YTW : 11.47 %
TRP.PR.G FixedReset -3.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 16.00
Evaluated at bid price : 16.00
Bid-YTW : 5.82 %
POW.PR.B Perpetual-Discount -3.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 21.45
Evaluated at bid price : 21.45
Bid-YTW : 6.28 %
BAM.PF.D Perpetual-Discount -3.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 18.76
Evaluated at bid price : 18.76
Bid-YTW : 6.60 %
HSE.PR.E FixedReset -3.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 15.10
Evaluated at bid price : 15.10
Bid-YTW : 7.20 %
NA.PR.Q FixedReset -3.79 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.31
Bid-YTW : 6.25 %
BAM.PR.M Perpetual-Discount -3.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 18.40
Evaluated at bid price : 18.40
Bid-YTW : 6.53 %
FTS.PR.G FixedReset -3.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 14.60
Evaluated at bid price : 14.60
Bid-YTW : 5.12 %
BIP.PR.A FixedReset -3.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 6.38 %
TD.PF.D FixedReset -3.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 17.15
Evaluated at bid price : 17.15
Bid-YTW : 5.09 %
TD.PR.T FloatingReset -3.60 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.63
Bid-YTW : 5.38 %
SLF.PR.E Deemed-Retractible -3.60 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.50
Bid-YTW : 8.81 %
TRP.PR.A FixedReset -3.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 12.55
Evaluated at bid price : 12.55
Bid-YTW : 5.49 %
BNS.PR.R FixedReset -3.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.20
Bid-YTW : 5.41 %
BAM.PR.N Perpetual-Discount -3.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 18.41
Evaluated at bid price : 18.41
Bid-YTW : 6.52 %
MFC.PR.M FixedReset -3.25 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.69
Bid-YTW : 9.00 %
BMO.PR.M FixedReset -3.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.26
Bid-YTW : 5.03 %
W.PR.J Perpetual-Discount -3.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 21.25
Evaluated at bid price : 21.52
Bid-YTW : 6.54 %
FTS.PR.K FixedReset -3.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 15.30
Evaluated at bid price : 15.30
Bid-YTW : 4.85 %
TRP.PR.C FixedReset -3.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 9.51
Evaluated at bid price : 9.51
Bid-YTW : 5.80 %
BAM.PR.E Ratchet -3.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 25.00
Evaluated at bid price : 12.60
Bid-YTW : 6.55 %
MFC.PR.L FixedReset -2.99 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.21
Bid-YTW : 9.20 %
ENB.PR.A Perpetual-Discount -2.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 21.16
Evaluated at bid price : 21.16
Bid-YTW : 6.61 %
SLF.PR.A Deemed-Retractible -2.98 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.56
Bid-YTW : 8.30 %
BAM.PF.E FixedReset -2.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 16.05
Evaluated at bid price : 16.05
Bid-YTW : 5.49 %
GWO.PR.H Deemed-Retractible -2.95 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.09
Bid-YTW : 8.02 %
RY.PR.P Perpetual-Discount -2.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 23.49
Evaluated at bid price : 23.80
Bid-YTW : 5.65 %
BAM.PR.B Floater -2.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 9.59
Evaluated at bid price : 9.59
Bid-YTW : 4.97 %
HSE.PR.C FixedReset -2.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 14.27
Evaluated at bid price : 14.27
Bid-YTW : 7.04 %
POW.PR.C Perpetual-Premium -2.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 23.40
Evaluated at bid price : 23.69
Bid-YTW : 6.15 %
BAM.PR.Z FixedReset -2.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 16.75
Evaluated at bid price : 16.75
Bid-YTW : 5.65 %
RY.PR.W Perpetual-Discount -2.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 21.81
Evaluated at bid price : 22.05
Bid-YTW : 5.63 %
POW.PR.A Perpetual-Discount -2.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 22.71
Evaluated at bid price : 23.00
Bid-YTW : 6.12 %
TD.PR.Y FixedReset -2.72 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.15
Bid-YTW : 5.14 %
VNR.PR.A FixedReset -2.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 16.25
Evaluated at bid price : 16.25
Bid-YTW : 5.50 %
ELF.PR.F Perpetual-Discount -2.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 21.28
Evaluated at bid price : 21.55
Bid-YTW : 6.18 %
SLF.PR.G FixedReset -2.66 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.80
Bid-YTW : 10.83 %
BAM.PR.C Floater -2.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 9.54
Evaluated at bid price : 9.54
Bid-YTW : 4.99 %
BNS.PR.B FloatingReset -2.64 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.65
Bid-YTW : 5.47 %
PWF.PR.T FixedReset -2.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 18.50
Evaluated at bid price : 18.50
Bid-YTW : 4.34 %
SLF.PR.J FloatingReset -2.62 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.90
Bid-YTW : 11.25 %
BAM.PR.R FixedReset -2.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 13.06
Evaluated at bid price : 13.06
Bid-YTW : 5.79 %
BNS.PR.P FixedReset -2.60 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.48
Bid-YTW : 4.90 %
RY.PR.C Deemed-Retractible -2.58 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.15
Bid-YTW : 5.43 %
IAG.PR.G FixedReset -2.54 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.25
Bid-YTW : 8.75 %
ELF.PR.H Perpetual-Discount -2.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 21.97
Evaluated at bid price : 22.33
Bid-YTW : 6.18 %
RY.PR.L FixedReset -2.48 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.60
Bid-YTW : 5.05 %
GWO.PR.N FixedReset -2.44 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.00
Bid-YTW : 11.56 %
TD.PF.E FixedReset -2.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 18.15
Evaluated at bid price : 18.15
Bid-YTW : 4.93 %
RY.PR.F Deemed-Retractible -2.39 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.05
Bid-YTW : 5.35 %
PWF.PR.E Perpetual-Discount -2.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 22.54
Evaluated at bid price : 22.79
Bid-YTW : 6.05 %
RY.PR.D Deemed-Retractible -2.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.14
Bid-YTW : 5.33 %
CU.PR.F Perpetual-Discount -2.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 18.75
Evaluated at bid price : 18.75
Bid-YTW : 6.10 %
SLF.PR.C Deemed-Retractible -2.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.76
Bid-YTW : 8.54 %
BAM.PR.G FixedFloater -2.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 25.00
Evaluated at bid price : 12.31
Bid-YTW : 6.73 %
BAM.PF.H FixedReset -2.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 22.97
Evaluated at bid price : 24.45
Bid-YTW : 5.07 %
RY.PR.G Deemed-Retractible -1.95 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.15
Bid-YTW : 5.32 %
CU.PR.D Perpetual-Discount -1.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 20.18
Evaluated at bid price : 20.18
Bid-YTW : 6.17 %
BNS.PR.M Deemed-Retractible -1.94 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.80
Bid-YTW : 5.43 %
TD.PR.Z FloatingReset -1.93 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.80
Bid-YTW : 5.32 %
NA.PR.S FixedReset -1.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 15.78
Evaluated at bid price : 15.78
Bid-YTW : 5.14 %
TD.PF.B FixedReset -1.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 16.25
Evaluated at bid price : 16.25
Bid-YTW : 4.77 %
PWF.PR.F Perpetual-Discount -1.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 21.44
Evaluated at bid price : 21.70
Bid-YTW : 6.06 %
RY.PR.H FixedReset -1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 16.42
Evaluated at bid price : 16.42
Bid-YTW : 4.81 %
GWO.PR.S Deemed-Retractible -1.69 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.66
Bid-YTW : 6.72 %
SLF.PR.D Deemed-Retractible -1.68 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.71
Bid-YTW : 8.58 %
PWF.PR.A Floater -1.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 11.20
Evaluated at bid price : 11.20
Bid-YTW : 4.27 %
ELF.PR.G Perpetual-Discount -1.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 20.16
Evaluated at bid price : 20.16
Bid-YTW : 5.93 %
BNS.PR.D FloatingReset -1.66 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.80
Bid-YTW : 7.37 %
BMO.PR.Q FixedReset -1.62 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.25
Bid-YTW : 7.83 %
RY.PR.K FloatingReset -1.59 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.99
Bid-YTW : 5.54 %
BMO.PR.Z Perpetual-Discount -1.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 22.15
Evaluated at bid price : 22.50
Bid-YTW : 5.63 %
RY.PR.B Deemed-Retractible -1.57 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.40
Bid-YTW : 5.33 %
BNS.PR.Y FixedReset -1.57 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.86
Bid-YTW : 6.80 %
BMO.PR.R FloatingReset -1.52 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.31
Bid-YTW : 4.95 %
CM.PR.Q FixedReset -1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 17.52
Evaluated at bid price : 17.52
Bid-YTW : 4.99 %
IGM.PR.B Perpetual-Premium -1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 24.00
Evaluated at bid price : 24.46
Bid-YTW : 6.03 %
BNS.PR.L Deemed-Retractible -1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.90
Bid-YTW : 5.35 %
TD.PF.F Perpetual-Discount -1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 21.68
Evaluated at bid price : 21.96
Bid-YTW : 5.58 %
CU.PR.E Perpetual-Discount -1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 20.31
Evaluated at bid price : 20.31
Bid-YTW : 6.13 %
PWF.PR.I Perpetual-Premium -1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 24.44
Evaluated at bid price : 24.68
Bid-YTW : 6.09 %
POW.PR.D Perpetual-Discount -1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 20.75
Evaluated at bid price : 20.75
Bid-YTW : 6.07 %
SLF.PR.B Deemed-Retractible -1.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.00
Bid-YTW : 8.03 %
FTS.PR.H FixedReset -1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 12.00
Evaluated at bid price : 12.00
Bid-YTW : 4.63 %
GWO.PR.Q Deemed-Retractible -1.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.75
Bid-YTW : 7.21 %
RY.PR.N Perpetual-Discount -1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 21.75
Evaluated at bid price : 22.05
Bid-YTW : 5.63 %
BAM.PR.X FixedReset -1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 12.50
Evaluated at bid price : 12.50
Bid-YTW : 5.29 %
PWF.PR.H Perpetual-Premium -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 23.52
Evaluated at bid price : 23.79
Bid-YTW : 6.06 %
FTS.PR.J Perpetual-Discount -1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 20.31
Evaluated at bid price : 20.31
Bid-YTW : 5.94 %
BMO.PR.K Deemed-Retractible -1.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.01
Bid-YTW : 5.42 %
CU.PR.G Perpetual-Discount -1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 18.72
Evaluated at bid price : 18.72
Bid-YTW : 6.11 %
RY.PR.Q FixedReset -1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 23.19
Evaluated at bid price : 25.15
Bid-YTW : 5.19 %
MFC.PR.B Deemed-Retractible -1.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.56
Bid-YTW : 8.21 %
PWF.PR.G Perpetual-Premium -1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 24.25
Evaluated at bid price : 24.55
Bid-YTW : 6.02 %
CM.PR.P FixedReset 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 16.00
Evaluated at bid price : 16.00
Bid-YTW : 4.84 %
CU.PR.C FixedReset 1.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 16.00
Evaluated at bid price : 16.00
Bid-YTW : 4.95 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PF.G FixedReset 499,908 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 23.24
Evaluated at bid price : 25.29
Bid-YTW : 5.22 %
BAM.PR.K Floater 352,668 TD crossed 300,000 at 10.00, then bought 11,100 from Goldman Sachs at 9.55.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 9.80
Evaluated at bid price : 9.80
Bid-YTW : 4.86 %
RY.PR.Q FixedReset 327,782 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 23.19
Evaluated at bid price : 25.15
Bid-YTW : 5.19 %
BNS.PR.R FixedReset 188,436 RBC crossed blocks of 131,300 and 16,000, both at 22.97.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.20
Bid-YTW : 5.41 %
RY.PR.I FixedReset 104,453 Scotia crossed 96,300 at 22.10.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.18
Bid-YTW : 5.42 %
BMO.PR.S FixedReset 96,836 Scotia crossed 81,900 at 16.61.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 16.75
Evaluated at bid price : 16.75
Bid-YTW : 4.81 %
There were 89 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
RY.PR.A Deemed-Retractible Quote: 22.05 – 24.60
Spot Rate : 2.5500
Average : 1.3879

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.05
Bid-YTW : 7.05 %

PWF.PR.L Perpetual-Discount Quote: 20.13 – 21.57
Spot Rate : 1.4400
Average : 0.8962

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 20.13
Evaluated at bid price : 20.13
Bid-YTW : 6.36 %

W.PR.H Perpetual-Discount Quote: 20.73 – 22.00
Spot Rate : 1.2700
Average : 0.7651

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 20.73
Evaluated at bid price : 20.73
Bid-YTW : 6.69 %

RY.PR.E Deemed-Retractible Quote: 23.44 – 24.55
Spot Rate : 1.1100
Average : 0.6248

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.44
Bid-YTW : 5.90 %

POW.PR.C Perpetual-Premium Quote: 23.69 – 24.81
Spot Rate : 1.1200
Average : 0.6487

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-15
Maturity Price : 23.40
Evaluated at bid price : 23.69
Bid-YTW : 6.15 %

BMO.PR.Q FixedReset Quote: 18.25 – 19.25
Spot Rate : 1.0000
Average : 0.5829

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.25
Bid-YTW : 7.83 %

Market Action

January 14, 2016

Equities had a good bounce today:

U.S. stocks rallied sharply Thursday as a rebound in oil prices allowed the main indexes to claw back much of the steep fall seen in the previous session.

Gains on Wall Street were across the board, but energy shares outperformed all others as crude-oil futures CLG6, -2.44% rose 2.4% to $31.20 a barrel.

Meanwhile, St. Louis Fed President James Bullard’s comment that reaching the inflation target will take longer was said to have invigorated some of the bulls who were betting on a slower pace of interest-rate increases this year.

The S&P 500 index SPX, +1.67% closed up 31.56 points, or 1.7%, at 1,921.84. The S&P 500 energy sector soared 4.5%, while all 10 main sectors advanced. The health care and technology sectors were up 2.7% and 2% respectively.

This happened even with Bullard raising a cautious note:

Federal Reserve Bank of St. Louis President James Bullard, one of the most vocal policy makers in recent months arguing to raise interest rates, sounded a more cautious note Thursday by saying the latest decline in oil prices may delay the return of inflation to the central bank’s 2 percent target.

“With renewed declines in crude oil prices in recent weeks, the associated decline in market-based inflation expectations measures is becoming worrisome,” Bullard, who votes on policy this year, said in a speech in Memphis, Tennessee. While central bankers typically “look through” oil price changes, “one circumstance where one may be more concerned is when inflation expectations themselves begin to change due to the changes in crude oil prices,” he said.
…
Bullard told reporters after his speech that strong U.S. employment would argue that the FOMC’S median projection of rate increases totaling 1 percentage point this year is “about right,” while inflation and price expectations concerns “would tend to push off rate increases.” Bullard said he would put more weight on expectations if they continue to decline.

“Generally speaking, the markets and the committee are not thinking in terms of a January move,” Bullard said. “As far as March, we would want to get more information and see how things play out before we make a judgment.”

The U.S. economy is likely to grow 2.5 percent to 3 percent this year, and recent market volatility is no reason to revise that forecast, he told reporters.

Meanwhile, Assiduous Reader IR brings to my attention the elevated level of US credit spreads (as of January 13):

The cost to protect against defaults by North American investment-grade companies soared to a three-year high as concern lingered over falling commodity prices and financial-market turmoil triggered by China.

The Standard & Poor’s 500 Index was poised for its lowest close since September, halting a global equities rally. The Bloomberg Commodities Index on Tuesday fell to the lowest level since at least 1991 on sluggish demand from developing nations. The benchmark rebounded by 0.3 percent at 3:16 p.m. on Wednesday in New York. While Chinese exports unexpectedly expanded in December in local-currency terms, the world’s second-largest economy is expected to report the slowest annual expansion since 1990 next week.

“The recent noise from the Chinese market and continued pressure on oil has prompted investors to adjust their default expectations upward,” said Ryan Jungk, a Hartford, Connecticut-based credit analyst at Newfleet Asset Management LLC. “Investment grades are not immune from the bearish sentiment.”

The risk premium on the Markit CDX North America Investment Grade Index, which is tied to 125 equally weighted companies, rose five basis points to 103.3, according to prices compiled by Bloomberg. The measure hasn’t closed above 100 since 2012.

Which reminds me, I must thank Assiduous Reader HS for the link to the story about grocery bills and the exchange rate highlighted yesterday. I forgot yesterday – oops!

I’m wondering if this widening has anything to do with revamped bank trading-book capital rules:

Banks face tougher capital requirements on swaps, bonds and other securities that they intend to trade, as global regulators tighten market-risk rules for the second time since the financial crisis.

The Basel Committee on Banking Supervision, whose members include the U.S. Federal Reserve and the People’s Bank of China, said updated rules published on Thursday will result in a weighted mean increase of about 40 percent in trading-book capital charges. The revised framework boosts the share of banks’ risk-weighted assets produced by market risk to nearly 10 percent from about 6 percent under existing rules, the Basel group said in a statement.

The overall capital burden on banks imposed by the Fundamental Review of the Trading Book, which takes effect in 2019, is nevertheless lower than was produced by earlier proposals, the Basel Committee said. The impact on specific asset classes and business lines is likely to be uneven and could hit some banks harder than others, even making some trading desks unviable.
…
The International Swaps and Derivatives Association said in an e-mailed statement on Thursday that while the Basel Committee had amended “several areas of concern identified by the industry,” its estimate of a 40 percent increase in market-risk capital requirements “would impose a considerable burden on banks on top of the increases already introduced following the crisis, as part of Basel 2.5.”

A report last year by ISDA and other industry groups estimated the capital requirement using Basel’s new standardized approach would be 4.2 times the total market-risk capital the firms currently have.

So making it tougher for depositary banks to function as investment banks is one thing and, I think, a good thing. But I still haven’t seen anything that would indicate any thought from the regulators as to what might come next. Do they want to make it easier for non-banks to become market-makers? I have often suggested that it would make sense hedge funds – already acting as market makers for equities – to hire bond desks and start trading corporate bonds vigorously. But there’s nothing. If anybody has seen any regulatory musing about where the risk will go after its presence in the banking sector has been reduced, let me know!

US authorities have gleefully announced another successful shake-down:

Goldman Sachs Group Inc. said it agreed to settle a U.S. probe into its handling of mortgage-backed securities for about $5.1 billion, cutting fourth-quarter profit by about $1.5 billion and closing out a year of record legal and litigation costs.

The proposed deal, which the bank announced in a statement Thursday, would be the latest multibillion-dollar settlement resulting from the government’s push to hold Wall Street firms to account for creating and selling subprime mortgage bonds that helped spur the 2008 financial crisis.
…
The government’s mortgage-backed security resolutions stem from a working group of prosecutors and other officials that President Barack Obama ordered up in 2012 to punish Wall Street for fueling the financial crisis with bonds linked to souring mortgages. Until then, the Justice Department had been pilloried for years for not having brought significant cases against banks and their executives.

Hey – it’s easier than raising taxes, or running for political office on the basis of policy!

And the SEC reminds us of how business gets done:

Washington D.C., Jan. 14, 2016 — The Securities and Exchange Commission today announced that State Street Bank and Trust Company agreed to pay $12 million to settle charges that it conducted a pay-to-play scheme through its then-senior vice president and a hired lobbyist to win contracts to service Ohio pension funds.

An SEC investigation found that Vincent DeBaggis, who headed State Street’s public funds group responsible for serving as custodians or sub-custodians to public retirement funds, entered into an agreement with Ohio’s then-deputy treasurer to make illicit cash payments and political campaign contributions. In exchange, State Street received three lucrative sub-custodian contracts to safeguard certain funds’ investment assets and effect the settlement of their securities transactions.

The market is also feeling sour about the Canadian economy:

Canadian benchmark bond yields fell to a new record low on Thursday, as the market increasingly bets on a rate cut to insulate the domestic economy from the oil crash.

With yields around the world declining this year as investors forsake riskier assets in favour of safe havens such as government bonds, Canadian 10-year government yields touched a record low of 1.192 per cent on Thursday.

The Canadian five-year benchmark yield marked its own new low point a day earlier, opening up a spread against its U.S. equivalent reminiscent of some dire economic episodes in Canada’s past, said Mark Chandler, head of fixed income research at Royal Bank of Canada.

“We’re at a point where it’s almost unprecedented,” he said. “If you think about market sentiment right now, it’s almost like Canada’s not going to live through this.”

The short year so far has seen market losses pile up in Canada at an alarming pace.

The Canadian dollar dipped to a new 13-year low of $0.6946 against the U.S. dollar on Thursday.

Oil sank below $30 (U.S.) a barrel on Tuesday for the first time since 2003, before rebounding modestly.

Meanwhile, the S&P/TSX composite index dipped to its lowest intraday level since July, 2013, in morning trading on Thursday before rebounding, as longer-term bond yields fell.

A thin majority of economists now expect the deteriorating conditions will compel Bank of Canada Governor Stephen Poloz to cut the overnight lending rate by 25 basis points to 0.25 per cent next week. The key policy rate has not been set that low since the depths of the financial crisis in late 2009 and early 2010.

But I think I’ve found another book about Canadian preferred shares:

torment
Click for Big

It was another utterly appalling day for the Canadian preferred share market, with PerpetualDiscounts down 95bp, FixedResets losing 265bp and DeemedRetractibles off 53bp. The Performance Highlights table is headed by some incredible losses, virtually all of which are entirely genuine, albeit on markets that I would not feel comfortable characterizing as “orderly”. [I did write commentary on the worst ones; then clicked the wrong button when typing and lost it all. Damn.] Volume was extremely high.

It was another big day for DC.PR.C, with 119,915 shares changing hands at a VWAP of 17.00. It would seem that views are being taken! The current price of 17.00 corresponds to a yield of 9.20% to the extended retraction date of 2019-6-30, given a coupon of 7.50%, all of which assumes that the abusive and debatable Plan of Arrangement succeeds.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 16.11 to be $0.91 rich, while TRP.PR.C, resetting 2016-1-30 at +154, is $1.03 cheap at its bid price of 10.05.

Click for Big

Most expensive is MFC.PR.L, resetting at +216bp on 2019-6-19, bid at 17.40 to be 0.75 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 18.55 to be 0.92 cheap.

Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 13.75 to be $1.09 cheap. BAM.PF.E, resetting at +255bp on 2020-3-31 is bid at 16.83 and appears to be $0.67 rich.

Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 16.74, looks $0.45 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 15.95 and is $0.73 cheap.

Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.63%, with no outliers. There is one junk outlier below -1.50% and one above 0.50%.

Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.21 % 6.34 % 25,694 16.24 1 -1.8113 % 1,491.7
FixedFloater 7.56 % 6.59 % 29,756 15.74 1 -0.7893 % 2,630.6
Floater 4.62 % 4.82 % 77,185 15.84 4 -2.6860 % 1,655.3
OpRet 0.00 % 0.00 % 0 0.00 0 -0.9464 % 2,696.4
SplitShare 4.90 % 6.48 % 70,422 2.76 6 -0.9464 % 3,155.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.9464 % 2,461.9
Perpetual-Premium 5.96 % 5.96 % 86,337 13.97 6 -0.5801 % 2,475.8
Perpetual-Discount 5.90 % 5.97 % 98,417 13.95 34 -0.9528 % 2,445.9
FixedReset 5.80 % 5.21 % 240,007 14.43 82 -2.6460 % 1,777.7
Deemed-Retractible 5.39 % 5.95 % 126,298 6.94 34 -0.5335 % 2,495.6
FloatingReset 2.96 % 4.98 % 64,189 5.59 13 -1.1404 % 1,998.7
Performance Highlights
Issue Index Change Notes
FTS.PR.H FixedReset -10.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 12.15
Evaluated at bid price : 12.15
Bid-YTW : 4.58 %
HSE.PR.C FixedReset -8.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 14.70
Evaluated at bid price : 14.70
Bid-YTW : 6.82 %
CIU.PR.C FixedReset -6.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 10.50
Evaluated at bid price : 10.50
Bid-YTW : 4.93 %
FTS.PR.M FixedReset -6.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 17.11
Evaluated at bid price : 17.11
Bid-YTW : 4.95 %
PWF.PR.T FixedReset -6.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 4.23 %
FTS.PR.K FixedReset -5.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 15.80
Evaluated at bid price : 15.80
Bid-YTW : 4.69 %
MFC.PR.J FixedReset -5.25 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.49
Bid-YTW : 8.35 %
FTS.PR.I FloatingReset -5.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 11.30
Evaluated at bid price : 11.30
Bid-YTW : 4.20 %
NA.PR.Q FixedReset -5.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.15
Bid-YTW : 5.51 %
IFC.PR.C FixedReset -4.90 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.90
Bid-YTW : 9.54 %
FTS.PR.G FixedReset -4.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 15.17
Evaluated at bid price : 15.17
Bid-YTW : 4.92 %
CCS.PR.C Deemed-Retractible -4.84 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.25
Bid-YTW : 8.08 %
IAG.PR.G FixedReset -4.84 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.70
Bid-YTW : 8.38 %
TRP.PR.G FixedReset -4.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 16.66
Evaluated at bid price : 16.66
Bid-YTW : 5.58 %
HSE.PR.G FixedReset -4.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 15.90
Evaluated at bid price : 15.90
Bid-YTW : 6.83 %
GWO.PR.O FloatingReset -4.60 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.40
Bid-YTW : 11.64 %
W.PR.K FixedReset -4.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 22.16
Evaluated at bid price : 22.80
Bid-YTW : 5.80 %
RY.PR.I FixedReset -4.31 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.20
Bid-YTW : 5.40 %
HSE.PR.E FixedReset -4.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 15.70
Evaluated at bid price : 15.70
Bid-YTW : 6.92 %
NA.PR.W FixedReset -4.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 15.70
Evaluated at bid price : 15.70
Bid-YTW : 4.97 %
SLF.PR.I FixedReset -4.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.60
Bid-YTW : 9.07 %
SLF.PR.G FixedReset -4.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.15
Bid-YTW : 10.46 %
IFC.PR.A FixedReset -3.98 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.75
Bid-YTW : 10.88 %
MFC.PR.L FixedReset -3.97 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.71
Bid-YTW : 8.77 %
MFC.PR.M FixedReset -3.90 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.25
Bid-YTW : 8.53 %
MFC.PR.N FixedReset -3.90 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.01
Bid-YTW : 8.65 %
NA.PR.S FixedReset -3.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 16.08
Evaluated at bid price : 16.08
Bid-YTW : 5.04 %
BMO.PR.T FixedReset -3.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 16.20
Evaluated at bid price : 16.20
Bid-YTW : 4.85 %
RY.PR.Z FixedReset -3.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 16.50
Evaluated at bid price : 16.50
Bid-YTW : 4.73 %
HSE.PR.A FixedReset -3.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 9.76
Evaluated at bid price : 9.76
Bid-YTW : 6.16 %
BAM.PF.F FixedReset -3.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 17.80
Evaluated at bid price : 17.80
Bid-YTW : 5.27 %
MFC.PR.I FixedReset -3.43 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.30
Bid-YTW : 8.01 %
TRP.PR.F FloatingReset -3.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 11.52
Evaluated at bid price : 11.52
Bid-YTW : 5.14 %
CM.PR.Q FixedReset -3.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 17.77
Evaluated at bid price : 17.77
Bid-YTW : 4.91 %
CU.PR.C FixedReset -3.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 15.75
Evaluated at bid price : 15.75
Bid-YTW : 5.03 %
GWO.PR.N FixedReset -3.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.30
Bid-YTW : 11.22 %
PWF.PR.A Floater -3.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 11.39
Evaluated at bid price : 11.39
Bid-YTW : 4.20 %
BIP.PR.A FixedReset -3.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 17.65
Evaluated at bid price : 17.65
Bid-YTW : 6.14 %
SLF.PR.H FixedReset -3.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.64
Bid-YTW : 10.05 %
MFC.PR.K FixedReset -2.99 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.57
Bid-YTW : 8.75 %
TRP.PR.A FixedReset -2.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 13.00
Evaluated at bid price : 13.00
Bid-YTW : 5.29 %
TD.PF.C FixedReset -2.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 16.40
Evaluated at bid price : 16.40
Bid-YTW : 4.71 %
MFC.PR.G FixedReset -2.91 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.01
Bid-YTW : 8.16 %
BMO.PR.S FixedReset -2.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 16.80
Evaluated at bid price : 16.80
Bid-YTW : 4.79 %
CU.PR.H Perpetual-Discount -2.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 22.04
Evaluated at bid price : 22.35
Bid-YTW : 5.95 %
BAM.PR.K Floater -2.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 9.87
Evaluated at bid price : 9.87
Bid-YTW : 4.82 %
TD.PF.D FixedReset -2.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 17.80
Evaluated at bid price : 17.80
Bid-YTW : 4.90 %
BAM.PR.B Floater -2.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 9.88
Evaluated at bid price : 9.88
Bid-YTW : 4.82 %
BNS.PR.R FixedReset -2.63 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.95
Bid-YTW : 4.79 %
W.PR.J Perpetual-Discount -2.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 22.00
Evaluated at bid price : 22.23
Bid-YTW : 6.33 %
BMO.PR.W FixedReset -2.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 16.20
Evaluated at bid price : 16.20
Bid-YTW : 4.81 %
TD.PR.S FixedReset -2.58 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.70
Bid-YTW : 4.49 %
TD.PF.B FixedReset -2.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 16.55
Evaluated at bid price : 16.55
Bid-YTW : 4.68 %
PVS.PR.E SplitShare -2.52 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-10-31
Maturity Price : 25.00
Evaluated at bid price : 23.25
Bid-YTW : 6.96 %
CIU.PR.A Perpetual-Discount -2.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 19.41
Evaluated at bid price : 19.41
Bid-YTW : 6.02 %
BAM.PR.R FixedReset -2.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 13.41
Evaluated at bid price : 13.41
Bid-YTW : 5.63 %
W.PR.H Perpetual-Discount -2.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 21.75
Evaluated at bid price : 22.00
Bid-YTW : 6.28 %
TD.PF.A FixedReset -2.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 16.72
Evaluated at bid price : 16.72
Bid-YTW : 4.64 %
BMO.PR.Z Perpetual-Discount -2.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 22.52
Evaluated at bid price : 22.86
Bid-YTW : 5.54 %
TRP.PR.C FixedReset -2.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 9.82
Evaluated at bid price : 9.82
Bid-YTW : 5.61 %
TRP.PR.H FloatingReset -2.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 9.00
Evaluated at bid price : 9.00
Bid-YTW : 4.79 %
MFC.PR.H FixedReset -2.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.30
Bid-YTW : 7.50 %
TD.PF.E FixedReset -2.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 18.60
Evaluated at bid price : 18.60
Bid-YTW : 4.81 %
BAM.PR.C Floater -2.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 9.80
Evaluated at bid price : 9.80
Bid-YTW : 4.86 %
CM.PR.O FixedReset -2.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 16.50
Evaluated at bid price : 16.50
Bid-YTW : 4.80 %
BAM.PF.G FixedReset -1.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 17.79
Evaluated at bid price : 17.79
Bid-YTW : 5.31 %
RY.PR.H FixedReset -1.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 16.72
Evaluated at bid price : 16.72
Bid-YTW : 4.72 %
BAM.PR.E Ratchet -1.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 25.00
Evaluated at bid price : 13.01
Bid-YTW : 6.34 %
PVS.PR.D SplitShare -1.79 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2021-10-08
Maturity Price : 25.00
Evaluated at bid price : 21.95
Bid-YTW : 7.28 %
FTS.PR.J Perpetual-Discount -1.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 20.53
Evaluated at bid price : 20.53
Bid-YTW : 5.88 %
BAM.PF.E FixedReset -1.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 16.54
Evaluated at bid price : 16.54
Bid-YTW : 5.32 %
CU.PR.G Perpetual-Discount -1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 18.92
Evaluated at bid price : 18.92
Bid-YTW : 6.04 %
FTS.PR.F Perpetual-Discount -1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 21.30
Evaluated at bid price : 21.30
Bid-YTW : 5.84 %
TRP.PR.D FixedReset -1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 15.15
Evaluated at bid price : 15.15
Bid-YTW : 5.32 %
CM.PR.P FixedReset -1.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 15.83
Evaluated at bid price : 15.83
Bid-YTW : 4.90 %
TRP.PR.E FixedReset -1.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 15.85
Evaluated at bid price : 15.85
Bid-YTW : 5.17 %
BMO.PR.Y FixedReset -1.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 18.51
Evaluated at bid price : 18.51
Bid-YTW : 4.76 %
POW.PR.D Perpetual-Discount -1.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 21.01
Evaluated at bid price : 21.01
Bid-YTW : 5.99 %
BIP.PR.B FixedReset -1.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 22.14
Evaluated at bid price : 22.76
Bid-YTW : 6.10 %
ELF.PR.G Perpetual-Discount -1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 20.50
Evaluated at bid price : 20.50
Bid-YTW : 5.83 %
RY.PR.K FloatingReset -1.48 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.33
Bid-YTW : 5.24 %
BNS.PR.C FloatingReset -1.44 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.21
Bid-YTW : 5.17 %
GWO.PR.F Deemed-Retractible -1.44 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.70
Bid-YTW : 6.15 %
PWF.PR.K Perpetual-Discount -1.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 20.70
Evaluated at bid price : 20.70
Bid-YTW : 6.00 %
BAM.PR.Z FixedReset -1.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 17.25
Evaluated at bid price : 17.25
Bid-YTW : 5.48 %
SLF.PR.A Deemed-Retractible -1.42 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.16
Bid-YTW : 7.85 %
RY.PR.M FixedReset -1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 4.87 %
BAM.PF.B FixedReset -1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 16.50
Evaluated at bid price : 16.50
Bid-YTW : 5.27 %
ENB.PR.A Perpetual-Discount -1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 21.55
Evaluated at bid price : 21.81
Bid-YTW : 6.40 %
CU.PR.E Perpetual-Discount -1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 20.57
Evaluated at bid price : 20.57
Bid-YTW : 6.05 %
PWF.PR.P FixedReset -1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 11.85
Evaluated at bid price : 11.85
Bid-YTW : 4.78 %
POW.PR.B Perpetual-Discount -1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 22.10
Evaluated at bid price : 22.32
Bid-YTW : 6.02 %
SLF.PR.E Deemed-Retractible -1.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.19
Bid-YTW : 8.27 %
RY.PR.L FixedReset -1.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.20
Bid-YTW : 4.57 %
PVS.PR.B SplitShare -1.21 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2019-01-10
Maturity Price : 25.00
Evaluated at bid price : 23.71
Bid-YTW : 6.48 %
BNS.PR.Q FixedReset -1.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.55
Bid-YTW : 4.84 %
SLF.PR.B Deemed-Retractible -1.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.25
Bid-YTW : 7.85 %
TD.PR.Y FixedReset -1.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.77
Bid-YTW : 4.63 %
CU.PR.F Perpetual-Discount -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 19.15
Evaluated at bid price : 19.15
Bid-YTW : 5.97 %
BMO.PR.M FixedReset -1.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.00
Bid-YTW : 4.41 %
MFC.PR.B Deemed-Retractible -1.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.76
Bid-YTW : 8.05 %
BNS.PR.L Deemed-Retractible -1.02 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.23
Bid-YTW : 5.08 %
BAM.PF.A FixedReset -1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 17.61
Evaluated at bid price : 17.61
Bid-YTW : 5.30 %
ELF.PR.H Perpetual-Discount 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 22.57
Evaluated at bid price : 22.90
Bid-YTW : 6.03 %
VNR.PR.A FixedReset 3.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 16.70
Evaluated at bid price : 16.70
Bid-YTW : 5.35 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PF.G FixedReset 2,212,913 New issue settled today.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 23.25
Evaluated at bid price : 25.34
Bid-YTW : 5.21 %
RY.PR.Q FixedReset 402,847 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 23.27
Evaluated at bid price : 25.41
Bid-YTW : 5.13 %
TD.PR.T FloatingReset 88,325 Scotia crossed 79,200 at 21.60.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.40
Bid-YTW : 4.71 %
BAM.PR.K Floater 85,700 Nesbitt crossed 75,000 at 10.00.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 9.87
Evaluated at bid price : 9.87
Bid-YTW : 4.82 %
RY.PR.L FixedReset 81,370 TD crossed blocks of 12,000 at 24.50 and 63,300 at 24.36.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.20
Bid-YTW : 4.57 %
IFC.PR.A FixedReset 78,400 Scotia crossed two blocks of 25,000 each at 14.32 and 10,200 at 14.20.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.75
Bid-YTW : 10.88 %
There were 60 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BNS.PR.R FixedReset Quote: 22.95 – 23.79
Spot Rate : 0.8400
Average : 0.5294

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.95
Bid-YTW : 4.79 %

SLF.PR.I FixedReset Quote: 16.60 – 17.40
Spot Rate : 0.8000
Average : 0.5117

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.60
Bid-YTW : 9.07 %

W.PR.K FixedReset Quote: 22.80 – 23.55
Spot Rate : 0.7500
Average : 0.4672

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 22.16
Evaluated at bid price : 22.80
Bid-YTW : 5.80 %

IFC.PR.A FixedReset Quote: 13.75 – 14.50
Spot Rate : 0.7500
Average : 0.4759

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.75
Bid-YTW : 10.88 %

RY.PR.K FloatingReset Quote: 21.33 – 22.36
Spot Rate : 1.0300
Average : 0.7583

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.33
Bid-YTW : 5.24 %

FTS.PR.I FloatingReset Quote: 11.30 – 12.22
Spot Rate : 0.9200
Average : 0.6609

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-14
Maturity Price : 11.30
Evaluated at bid price : 11.30
Bid-YTW : 4.20 %

Market Action

January 13, 2016

The low dollar is attracting some notice:

On Tuesday, the Canadian dollar, commonly known as the loonie, broke below 70 U.S. cents for the first time since May 1, 2003.

For America’s northern neighbor, which imports about 80 percent of the fresh fruits and vegetables its citizens consume, this entails a sharp rise in prices for these goods. With lower-income households tending to spend a larger portion of income on food, this side effect of a soft currency brings them the most acute stress.
…
From coast-to-coast-to-coast, Canadians have taken to social media to express displeasure with soaring produce prices:

Bombardier is desperately reinventing its business model:

Bombardier Inc. scrapped $1.75 billion of business-aircraft orders, saying it anticipates making more money by reselling them directly to customers.

The Canadian planemaker also said it was ending a four-decade relationship with distributor TAG Aeronautics as part of a change in its sales strategy. Bombardier will book a $278 million pretax charge in the fourth quarter due to its moves to cut out the middleman standing between itself and aircraft buyers.

Bombardier is revamping its business-jet sales effort as the company’s finances have been strained by its $5.4 billion program for C Series commercial planes. The development of its largest-ever model is more than two years late and at least $2 billion over budget, and Bombardier has been seeking more government aid to right itself.

If it doesn’t work, they can always get another government cheque!

I’m not sure whether it’s a genuine attempt to track down laundered money or the misuse of government powers to follow a populist agenda, but I am sure we’ll hear calls for this in Canada!

Concerned about illicit money flowing into luxury real estate, the Treasury Department said Wednesday that it would begin identifying and tracking secret buyers of high-end properties.

The initiative will start in two of the nation’s major destinations for global wealth: Manhattan and Miami-Dade County. It will shine a light on the darkest corner of the real estate market: all-cash purchases made by shell companies that often shield purchasers’ identities.

It is the first time the federal government has required real estate companies to disclose names behind all-cash transactions, and it is likely to send shudders through the real estate industry, which has benefited enormously in recent years from a building boom increasingly dependent on wealthy, secretive buyers.

The initiative is part of a broader federal effort to increase the focus on money laundering in real estate. Treasury and federal law enforcement officials said they were putting greater resources into investigating luxury real estate sales that involve shell companies like limited liability companies, often known as L.L.C.s; partnerships; and other entities.

There will be ceaseless debate over the next twelve months regarding the advisability of Fed hikes … Larry Summers has fired the opening volley:

Policy makers need to heed the message from global commodity and stock markets that “risks are substantially tilted to the downside,” former U.S. Treasury Secretary Lawrence Summers said Wednesday.

Given the weakness in prices and growth, it’ll be hard for the world to take in stride four interest-rate increases that forecasters are penciling in from the Federal Reserve this year, Summers said in a Bloomberg TV interview.

“I would be surprised if the world economy could comfortably withstand four hikes, and I think that basically the markets agree with me,” he said, adding that’s why it’s important to prepare for a range of possibilities. “Really, what policy makers need to think about is, it is insurance against the more negative scenarios.”

It was another crummy day for equities:

U.S. stocks tumbled, with the Dow Jones Industrial Average plunging more than 370 points and small caps entering a bear market, as oil’s failure to maintain a 4 percent rally rekindled a flight from risk assets. Treasuries surged amid signs that demand for the relative safety of bonds is rising.

The Standard & Poor’s 500 Index fell past 1,900, a level it’s closed below only five times in the past 14 months. The Nasdaq 100 Index had its worst day since Aug. 24, as selling was heaviest in technology and consumer shares. The Russell 2000 Index capped a 22 percent slide from its June record. Brent crude dipped below $30 for the first time since 2004. The yield on the 10-year Treasury note fell to 2.04 percent, after an auction of $21 billion of 10-year notes was deemed ‘outstanding.’ Gold traded above $1,090 an ounce.
…
Treasuries rallied after investors flocked to a $21 billion auction of 10-year notes at the lowest yields since October amid concern that global growth is slowing. A class of investors that includes foreign central banks and mutual funds bought 71 percent of the sale, the second-highest amount on record.

Meanwhile, at time of writing, Chinese equities have bounced back a little … but nobody knows how much of that is manipulation:

The Shanghai Composite Index gained 2 percent to 3,007.65 at the close, reversing a loss of as much as 2.8 percent and sending a gauge of volatility to the highest levels since September. The ChiNext small-caps index surged the most in two months after 28 listed companies vowed to take action to stabilize the market, with some pledging not to sell shares over the next six months. State funds may have entered to buy stocks after the Shanghai index fell below the lowest levels reached in last year’s rout, according to Galaxy Securities Co.
…
The Shanghai gauge earlier dropped below the low of 2,927.29 set in August, when a summer rout wiped out $5 trillion and spurred the government to impose emergency rescue measures. The index, the worst performer among 93 global benchmark measures tracked by Bloomberg this year, fell as much as 20 percent from the December high before paring losses.

The question of trailer fees and the regulatory banishment thereof has been discussed many times on PrefBlog – a CSA request for comment was mentioned on December 13, 2012, for instance, which was clarified on December 18, 2012, with more discussion December 27, 2012. Assiduous Readers with good memories will remember that I have argued that the only problem with the Platonic ideals espoused by regulatory dreamers is that they won’t work in the real world (much like the regulatory dreamers themselves): Joe Lunchbucket does not want to pay a fee to his advisor unless the advisor trades a lot; this goes double if he’s just lost money in the market. So instead of buying an equity mutual fund like he should, he’ll go down to the bank and put his money into a GIC and every step in the process will be approved by the bank’s compliance department, stuffed to the gills with ex-regulators on fat salaries.

I was only one of many holding this view:

From now on, financial advisers will have to charge upfront fees to their customers rather than receive commission from companies supplying financial products. The move by the Financial Services Authority under its retail distribution review (RDR) includes pensions, Isas and unit trusts, and is designed to be more transparent and to reduce the risk of mis-selling.

It means that consumers will see clearly the cost of financial advice which may previously have appeared to be free since the charges were part of the commission payments made to the adviser. But some analysts believe that spelling out the costs, even though these can be spread over a number of years, could put many customers off seeking advice.

A recent survey by Rostrum Research found that nine out of 10 consumers would only pay up to £25 for an hour’s financial advice, compared with the mooted £50-£250 an hour fee range expected in the review.

I have been criticized for this view, but it appears that two years after banning producer payments to intermediaries, it is becoming clear that Joe Lunchbucket does not want to pay for advice:

An influential panel of experts appointed by the Government as part of the Financial Advice Market Review is considering radical reforms to regulation which would roll back key aspects of the RDR to boost access to advice, Money Marketing understands.

The FAMR, jointly led by the Treasury and the FCA, is assessing barriers to the provision of financial advice following the pensions overhaul introduced last April. In particular, the review is looking to tackle the advice gap for people with smaller pots to invest.
…
Sources close to the panel say a number of radical ideas have been seriously discussed during the three sessions held in the second half of last year. These include creating a new basic tier of advice with a lower qualification requirement for simple accumulation products, developing a new charging structure similar to commission and banning regulated advisers from selling unregulated products.
…

A separate source says allowing firms to receive commission on simple accumulation product sales is also under consideration.

The source says: “The panel have discussed putting forward an alternative commercial model for advice that would allow a fee to be built into the product. So today you might pay 1 per cent and it is normally paid by selling units in funds but it has to be agreed as part of your service agreement with the adviser. What is being discussed is more like commission.

“So you could invest in an Isa or a pension and the adviser receives a fee on completion of the transaction direct from the provider.”

Panel members have also discussed the possibility of banning regulated advisers from selling unregulated products.

No agreement has been reached on taking these proposals to the Government.

However, the very fact they are being discussed suggests the FAMR could fundamentally redraw the advice landscape yet again.

Shaw Communications, proud issuer of SJR.PR.A, will finance the acquisition of Wind Mobile by selling media assets to the related Corus Entertainment:

Corus Entertainment Inc. has agreed to pay $2.65-billion to acquire Shaw Media Inc. from Shaw Communications Inc., bulking up to compete in a shifting television landscape.

The price will be paid through a combination of $1.85-billion in cash and 71 million Corus class B shares at $11.21 per share. Both companies are ultimately controlled by the Shaw family of Alberta, but are separately listed on the Toronto Stock Exchange.
…
It also removes any doubt about how Shaw will pay for its $1.6-billion acquisition of Wind Mobile Corp., which it announced in December. There had been some speculation that it could sell its U.S. data centre business ViaWest or issue equity.

Instead, Shaw made it clear it intends to use the cash from the sale of Shaw Media to fund the Wind purchase.

Shaw expects its acquisition of Wind to close in the third quarter of its fiscal year, which is the three-month period ending May 31, and said Wednesday if that transaction closes earlier, it will rely on bridge financing to fund the deal.

DBRS comments:

Following the divestiture, DBRS notes that the loss of Shaw Media’s operating income and substantial cash generating capacity, in conjunction with the inclusion of the negative free cash flow wireless and existing business infrastructure services segments, will result in free cash flow (after cash dividend payments) turning negative until F2018. This signals a meaningful, albeit temporary, loss in financial flexibility and places greater reliance on growth in operating income to achieve stated financial leverage targets.

In its review, DBRS will focus on (1) assessing the business risk profile of the new entity, including organic growth prospects in the remaining segments and risks associated with integration of WIND; (2) the Company’s longer-term business strategy; (3) financial management intentions of the new entity going forward and its free cash flow trajectory profile; and (4) the Company’s liquidity profile over the near to medium term.

The proposed asset sale and the WIND acquisition are proceeding through customary regulatory, concurrently, and are both expected to close by Q3 F2016. As previously announced, the Company has secured a $1.7 billion bridge facility, which would allow it to complete the WIND acquisition in the event of a delay in completing the proposed divestiture. The Company would then repay the bridge upon receipt of proceeds from the Shaw Media divestiture.

The previously instated Under Review with Negative Implications rating action will be resolved once DBRS becomes confident that the proposed transaction will close under the current terms, at which point DBRS will likely downgrade Shaw’s ratings by one notch, to the BBB (low) rating category.

This follows prior news that SJR: Credit Agencies Nervous About Wind Acquisition.

GMP, proud issuer of GMP.PR.B, has swallowed hard and acknowledged hard times:

GMP Capital Inc.’s radical restructuring, which involves shutting down its United Kingdom and Australian operations as well as eliminating its dividend, is also hitting senior staff at home.

In total, seventy-three jobs are being axed in a new round of cuts announced Wednesday, affecting investment bankers, research analysts and employees in sales and trading. Twenty-nine positions are being eliminated in Canada, 22 in the U.K., 12 in Australia and 10 in the U.S. GMP said 97 positions – a quarter of its work force – have now been eliminated since the end of the third quarter.
…
GMP has lost money in three of the past four quarters. In the third quarter of 2015, revenue from the company’s energy sector investment banking cratered 87 per cent from a year ago.

The brokerage was founded in 1995 and went public in December, 2003. GMP was immensely profitable during the great bull run in resources and some of its proprietary traders, such as Michael Wekerle, were among the best paid people on Bay Street. In mid-2006, GMP’s share price peaked at $28. It closed Tuesday at $3.92 – not far from an all-time low.

I have not seen any reaction from the Credit Rating Agencies yet.

I came across the following on the Internet … I think it might be a book about Canadian preferred shares …

preferredShareBook
Click for Big

It was another horrible day for the Canadian preferred share market, with PerpetualDiscounts down 44bp, FixedResets losing 133bp and DeemedRetractibles off 29bp. The Performance Highlights table is as lengthy as one might expect, but on the bright side there were a few winners today! Volume was well below average.

It was a big day for DC.PR.C, which Assiduous Readers will remember is the target of an abusive Exchange Offer via a Plan of Arrangement which has been the subject of widespread interest. The issue traded 732,460 shares today in a range of 16.70-00, including a monster-block of 555,600, crossed by GMP shortly before the close at 17.00. When one considers that there are only 6-million shares out, one gets even more impressed! The stock was up sharply on the day. If we assume this is an actual arm’s-length cross (and not an internal cross between two accounts of the same manager), then it looks like somebody has started to feel good about the deal … all the more so since the record date to vote on the Plan of Arrangement has long since passed.

PerpetualDiscounts now yield 5.93%, equivalent to 7.71% interest at the standard equivalency factor of 1.3x. Long corporates now yield about 4.15%, so the pre-tax interest-equivalent spread is now about 355bp, a stunning increase from the 330bp that I should have reported last week. This is an incredible number, surpassed only for a month or so during the credit crunch … and this is happening without any significant credit worries!

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_160113
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 16.11 to be $0.91 rich, while TRP.PR.C, resetting 2016-1-30 at +154, is $1.03 cheap at its bid price of 10.05.

impVol_MFC_160113
Click for Big

Most expensive is MFC.PR.L, resetting at +216bp on 2019-6-19, bid at 17.40 to be 0.75 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 18.55 to be 0.92 cheap.

impVol_BAM_160113
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 13.75 to be $1.09 cheap. BAM.PF.E, resetting at +255bp on 2020-3-31 is bid at 16.83 and appears to be $0.67 rich.

impVol_FTS_160113
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 16.74, looks $0.45 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 15.95 and is $0.73 cheap.

pairs_FR_160113
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.63%, with no outliers. There is one junk outlier below -1.50% and one above 0.50%.

pairs_FF_160113
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.12 % 6.23 % 26,781 16.38 1 -4.2630 % 1,519.2
FixedFloater 7.50 % 6.54 % 31,078 15.80 1 0.0581 % 2,651.5
Floater 4.49 % 4.69 % 78,248 16.08 4 0.5017 % 1,701.0
OpRet 0.00 % 0.00 % 0 0.00 0 0.0019 % 2,722.1
SplitShare 4.85 % 6.03 % 67,583 2.76 6 0.0019 % 3,185.4
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0019 % 2,485.4
Perpetual-Premium 5.93 % 5.82 % 85,246 2.71 6 -0.1684 % 2,490.2
Perpetual-Discount 5.84 % 5.93 % 93,623 14.03 34 -0.4432 % 2,469.4
FixedReset 5.65 % 5.08 % 238,260 14.57 81 -1.3328 % 1,826.0
Deemed-Retractible 5.36 % 5.59 % 121,511 5.27 34 -0.2872 % 2,509.0
FloatingReset 2.92 % 4.91 % 63,358 5.59 13 0.3148 % 2,021.7
Performance Highlights
Issue Index Change Notes
VNR.PR.A FixedReset -7.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 16.17
Evaluated at bid price : 16.17
Bid-YTW : 5.52 %
HSE.PR.E FixedReset -5.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 16.38
Evaluated at bid price : 16.38
Bid-YTW : 6.63 %
MFC.PR.F FixedReset -5.54 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.80
Bid-YTW : 10.81 %
CU.PR.C FixedReset -4.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 16.27
Evaluated at bid price : 16.27
Bid-YTW : 4.87 %
BAM.PR.E Ratchet -4.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 25.00
Evaluated at bid price : 13.25
Bid-YTW : 6.23 %
FTS.PR.G FixedReset -4.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 15.95
Evaluated at bid price : 15.95
Bid-YTW : 4.67 %
FTS.PR.K FixedReset -3.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 16.74
Evaluated at bid price : 16.74
Bid-YTW : 4.42 %
MFC.PR.H FixedReset -3.47 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.74
Bid-YTW : 7.18 %
NA.PR.S FixedReset -3.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 16.73
Evaluated at bid price : 16.73
Bid-YTW : 4.84 %
TRP.PR.G FixedReset -2.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 5.31 %
IFC.PR.C FixedReset -2.79 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.72
Bid-YTW : 8.83 %
BAM.PR.T FixedReset -2.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 14.00
Evaluated at bid price : 14.00
Bid-YTW : 5.52 %
CM.PR.P FixedReset -2.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 16.10
Evaluated at bid price : 16.10
Bid-YTW : 4.81 %
NA.PR.W FixedReset -2.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 16.38
Evaluated at bid price : 16.38
Bid-YTW : 4.76 %
CM.PR.O FixedReset -2.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 16.85
Evaluated at bid price : 16.85
Bid-YTW : 4.70 %
TRP.PR.D FixedReset -2.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 15.41
Evaluated at bid price : 15.41
Bid-YTW : 5.22 %
BAM.PF.A FixedReset -2.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 17.79
Evaluated at bid price : 17.79
Bid-YTW : 5.24 %
BMO.PR.W FixedReset -2.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 16.63
Evaluated at bid price : 16.63
Bid-YTW : 4.68 %
TRP.PR.C FixedReset -2.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 10.05
Evaluated at bid price : 10.05
Bid-YTW : 5.48 %
HSE.PR.C FixedReset -2.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 16.10
Evaluated at bid price : 16.10
Bid-YTW : 6.21 %
BAM.PR.X FixedReset -2.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 12.69
Evaluated at bid price : 12.69
Bid-YTW : 5.21 %
BMO.PR.S FixedReset -2.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 17.30
Evaluated at bid price : 17.30
Bid-YTW : 4.65 %
TD.PF.E FixedReset -2.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 4.70 %
TRP.PR.F FloatingReset -2.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 11.91
Evaluated at bid price : 11.91
Bid-YTW : 4.97 %
IFC.PR.A FixedReset -2.25 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.32
Bid-YTW : 10.29 %
CU.PR.I FixedReset -2.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 22.95
Evaluated at bid price : 24.40
Bid-YTW : 4.58 %
BAM.PF.D Perpetual-Discount -2.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 19.64
Evaluated at bid price : 19.64
Bid-YTW : 6.30 %
HSE.PR.G FixedReset -2.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 16.68
Evaluated at bid price : 16.68
Bid-YTW : 6.50 %
BAM.PF.F FixedReset -1.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 18.45
Evaluated at bid price : 18.45
Bid-YTW : 5.08 %
TRP.PR.B FixedReset -1.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 9.77
Evaluated at bid price : 9.77
Bid-YTW : 5.12 %
SLF.PR.G FixedReset -1.86 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.70
Bid-YTW : 9.90 %
RY.PR.H FixedReset -1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 17.03
Evaluated at bid price : 17.03
Bid-YTW : 4.63 %
BAM.PF.C Perpetual-Discount -1.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 19.44
Evaluated at bid price : 19.44
Bid-YTW : 6.30 %
ELF.PR.H Perpetual-Discount -1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 22.36
Evaluated at bid price : 22.66
Bid-YTW : 6.09 %
BAM.PR.N Perpetual-Discount -1.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 19.10
Evaluated at bid price : 19.10
Bid-YTW : 6.28 %
SLF.PR.I FixedReset -1.65 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.31
Bid-YTW : 8.47 %
TD.PF.B FixedReset -1.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 16.98
Evaluated at bid price : 16.98
Bid-YTW : 4.55 %
NA.PR.Q FixedReset -1.60 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.33
Bid-YTW : 4.54 %
SLF.PR.D Deemed-Retractible -1.54 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.20
Bid-YTW : 8.20 %
BIP.PR.A FixedReset -1.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 18.22
Evaluated at bid price : 18.22
Bid-YTW : 5.94 %
MFC.PR.M FixedReset -1.48 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.95
Bid-YTW : 7.96 %
RY.PR.J FixedReset -1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 4.85 %
IAG.PR.A Deemed-Retractible -1.47 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.06
Bid-YTW : 7.75 %
RY.PR.M FixedReset -1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 17.75
Evaluated at bid price : 17.75
Bid-YTW : 4.80 %
BAM.PR.Z FixedReset -1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 5.40 %
MFC.PR.N FixedReset -1.39 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.70
Bid-YTW : 8.09 %
RY.PR.Z FixedReset -1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 17.11
Evaluated at bid price : 17.11
Bid-YTW : 4.55 %
SLF.PR.C Deemed-Retractible -1.38 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.35
Bid-YTW : 8.09 %
FTS.PR.M FixedReset -1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 18.25
Evaluated at bid price : 18.25
Bid-YTW : 4.63 %
BAM.PR.M Perpetual-Discount -1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 19.10
Evaluated at bid price : 19.10
Bid-YTW : 6.28 %
IAG.PR.G FixedReset -1.33 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.60
Bid-YTW : 7.68 %
TRP.PR.A FixedReset -1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 13.40
Evaluated at bid price : 13.40
Bid-YTW : 5.13 %
MFC.PR.I FixedReset -1.30 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.95
Bid-YTW : 7.52 %
BAM.PF.B FixedReset -1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 16.73
Evaluated at bid price : 16.73
Bid-YTW : 5.20 %
MFC.PR.J FixedReset -1.28 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.46
Bid-YTW : 7.59 %
MFC.PR.K FixedReset -1.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.08
Bid-YTW : 8.32 %
CU.PR.D Perpetual-Discount -1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 20.77
Evaluated at bid price : 20.77
Bid-YTW : 5.99 %
W.PR.H Perpetual-Discount -1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 22.27
Evaluated at bid price : 22.54
Bid-YTW : 6.13 %
SLF.PR.E Deemed-Retractible -1.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.43
Bid-YTW : 8.09 %
PWF.PR.T FixedReset -1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 20.25
Evaluated at bid price : 20.25
Bid-YTW : 3.96 %
TRP.PR.E FixedReset -1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 16.11
Evaluated at bid price : 16.11
Bid-YTW : 5.08 %
TD.PF.D FixedReset -1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 18.29
Evaluated at bid price : 18.29
Bid-YTW : 4.77 %
BAM.PF.G FixedReset -1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 18.15
Evaluated at bid price : 18.15
Bid-YTW : 5.20 %
BAM.PR.R FixedReset -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 13.75
Evaluated at bid price : 13.75
Bid-YTW : 5.49 %
BMO.PR.Y FixedReset -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 18.81
Evaluated at bid price : 18.81
Bid-YTW : 4.68 %
MFC.PR.B Deemed-Retractible -1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.97
Bid-YTW : 7.90 %
TD.PF.A FixedReset -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 17.12
Evaluated at bid price : 17.12
Bid-YTW : 4.53 %
CM.PR.Q FixedReset -1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 18.37
Evaluated at bid price : 18.37
Bid-YTW : 4.75 %
BAM.PF.E FixedReset -1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 16.83
Evaluated at bid price : 16.83
Bid-YTW : 5.22 %
TD.PR.Y FixedReset 1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.02
Bid-YTW : 4.42 %
RY.PR.K FloatingReset 1.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.65
Bid-YTW : 4.96 %
POW.PR.C Perpetual-Premium 1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 24.30
Evaluated at bid price : 24.61
Bid-YTW : 5.92 %
BAM.PF.H FixedReset 1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 23.20
Evaluated at bid price : 25.10
Bid-YTW : 4.91 %
BNS.PR.Q FixedReset 1.38 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.81
Bid-YTW : 4.63 %
PWF.PR.P FixedReset 1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 12.00
Evaluated at bid price : 12.00
Bid-YTW : 4.71 %
MFC.PR.G FixedReset 1.64 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.55
Bid-YTW : 7.74 %
BAM.PR.K Floater 2.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 10.15
Evaluated at bid price : 10.15
Bid-YTW : 4.69 %
BNS.PR.R FixedReset 2.61 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.57
Bid-YTW : 4.28 %
CCS.PR.C Deemed-Retractible 2.70 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.28
Bid-YTW : 7.35 %
BNS.PR.D FloatingReset 3.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.08
Bid-YTW : 7.08 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.Q FixedReset 288,467 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 23.28
Evaluated at bid price : 25.46
Bid-YTW : 5.11 %
BNS.PR.E FixedReset 158,036 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 23.29
Evaluated at bid price : 25.47
Bid-YTW : 5.10 %
NA.PR.S FixedReset 108,125 TD crossed 98,800 at 16.90.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 16.73
Evaluated at bid price : 16.73
Bid-YTW : 4.84 %
TD.PR.T FloatingReset 65,152 Scotia crossed 63,200 at 21.65.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.58
Bid-YTW : 4.56 %
RY.PR.I FixedReset 43,400 Nesbitt crossed 35,000 at 23.21.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.20
Bid-YTW : 4.57 %
BNS.PR.L Deemed-Retractible 39,064 RBC crossed 35,300 at 24.48.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.48
Bid-YTW : 4.88 %
There were 20 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
GWO.PR.O FloatingReset Quote: 11.95 – 13.75
Spot Rate : 1.8000
Average : 1.4048

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.95
Bid-YTW : 11.01 %

VNR.PR.A FixedReset Quote: 16.17 – 17.11
Spot Rate : 0.9400
Average : 0.7033

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 16.17
Evaluated at bid price : 16.17
Bid-YTW : 5.52 %

FTS.PR.M FixedReset Quote: 18.25 – 18.87
Spot Rate : 0.6200
Average : 0.4595

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 18.25
Evaluated at bid price : 18.25
Bid-YTW : 4.63 %

FTS.PR.H FixedReset Quote: 13.50 – 13.99
Spot Rate : 0.4900
Average : 0.3545

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 13.50
Evaluated at bid price : 13.50
Bid-YTW : 4.11 %

HSE.PR.G FixedReset Quote: 16.68 – 17.29
Spot Rate : 0.6100
Average : 0.4813

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-13
Maturity Price : 16.68
Evaluated at bid price : 16.68
Bid-YTW : 6.50 %

GWO.PR.L Deemed-Retractible Quote: 23.90 – 24.36
Spot Rate : 0.4600
Average : 0.3511

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.90
Bid-YTW : 6.37 %

Market Action

January 12, 2016

The big news of the day was the diving of the loonie:

The currency fell as much as 0.6 percent to 69.90 U.S. cents Tuesday in Toronto,, the first time it touched that level since May 2003, as crude oil fell to a 12-year low of $29.93 per barrel in New York. The first time the Canadian dollar weakened below 70 U.S. cents was 1997, before the country’s oil industry took off and when its government was wrestling with a budget deficit.

It mostly traded below 70 U.S. cents between 1997 and 2003, a period when manufacturing made up a larger part of exports than oil. It’s all-time low was 61.76 U.S. cents in 2002.
…
Even though [Macquarie Group forecaster David] Doyle predicted Canada’s central bank will cut its benchmark rate to a record low 0.25 percent on Jan. 20, a weakened manufacturing sector and more competition from Mexico in the U.S. market, Canada’s largest trading partner, mean it will take longer for the country to see an economic benefit with oil prices still depressed.

Once the loonie, as the currency is called for the aquatic bird on the C$1 coin, reaches its record low, it will stay depressed through the end of 2018, Doyle said.

“Manufacturing and non-energy exports have far less ability to propel the economic outlook than they have in the past,” Doyle said. “Many of our oil and oil-related sectors have grown, and a lot of our manufacturing sectors have not grown and remained low.”

Meanwhile, it appears that insurance and SIFI regulation is having some of its intended effect:

MetLife joins General Electric Co.’s finance unit in seeking to simplify operations after being designated by a U.S. panel as a non-bank systemically important financial institution, a tag that can lead to stricter limits on the balance sheet. [MetLife CEO Steve] Kandarian has sought to reverse that designation in court.

The retail business, as part of a SIFI, faces “higher capital requirements that could put it at a significant competitive disadvantage,” Kandarian said in the statement. “Even though we are appealing our SIFI designation in court and do not believe any part of MetLife is systemic, this risk of increased capital requirements contributed to our decision to pursue the separation.”
…
The retail unit slated for separation is a provider of variable annuities, where results can be tied to fluctuations in stock markets and interest rates. The new company would also include life insurance entities. MetLife didn’t outline a timetable for the plan, saying the completion of a transaction could depend on market conditions, and also regulatory approvals.
…
MetLife is among four non-bank companies that were named SIFIs by the Financial Stability Oversight Council. That panel was created by the 2010 Dodd-Frank law and charged with monitoring potential threats to the financial system after the near collapse in 2008 of companies including insurer American International Group Inc., which required a U.S. bailout.

GE has been divesting finance operations and has said it will apply to drop its tag as a SIFI. Prudential Financial Inc., the second-largest U.S. life insurer, in 2013 opted against filing a lawsuit to overturn its SIFI status.

AIG, also a SIFI, has been facing pressure from activist investor Carl Icahn to break up into three separate businesses — one offering property-casualty coverage, another selling life insurance and a third backing mortgages. Icahn has said the risk tag is intended to be a tax on size and AIG’s businesses would be worth more to shareholders if they’re not part of a systemically important company.

So, up to a point, I approve of this. Huge financial empires can lead to trouble. My problem with the implementation, however, is that too much is left to opinion and there is too sharp a break between SIFI and non-SIFI status. I would prefer to see a surcharge on risk-weighted assets so that companies can find their optimal size, without the inevitable games-playing that is intrinsic to the current solution; for more discussion, see my post Capital Surcharges for Globally Important Investment Banks.

Assiduous Reader JP brings to my attention new rules on lease reporting:

The International Accounting Standards Board (IASB) published a new rule on Wednesday requiring leases of more than a year to be placed on balance sheets from January 2019.

“It’s a major change and will affect around half of all companies, especially airlines, shipping and retail. They will have significantly different financial statements,” IASB Chairman Hans Hoogervorst told Reuters.

Some defunct retailers have surprised investors by disclosing that off-balance sheet leases were almost 66 times the value of on-balance sheet debt, the IASB said.
…
Hoogervorst’s predecessor, David Tweedie, kicked off the reform two decades ago and annoyed leasing companies by saying he wanted to fly the Atlantic in a plane that was on the airline’s balance sheet.

“It will change balance sheets massively,” Tweedie told Reuters. “You can’t be paying rent for an aeroplane you have to stick in the Arizona desert and pretend it’s not a liability.”

I have often thought that the main value of ‘green’ legislation is that it forces a certain amount of thinking about why we do things the way we do. Humans are intrinsically lazy, and will seek to apply cookie-cutter solutions that have worked out reasonably well in the past instead of redesigning everything from scratch. Most of the time, that’s the proper thing to do, of course; but every now and then a fresh look makes the light-bulb spring to life:

The clinical white beam of LEDs and frustrating time-delay of ‘green’ lighting has left many hankering after the instant, bright warm glow of traditional filament bulbs.

But now scientists in the US believe they have come up with a solution which could see a reprieve for incandescent bulbs.

Researchers at MIT have shown that by surrounding the filament with a special crystal structure in the glass they can bounce back the energy which is usually lost in heat, while still allowing the light through.

They refer to the technique as ‘recycling light’ because the energy which would usually escape into the air is redirected back to the filament where it can create new light.
…
Usually traditional light bulbs are only about five per cent efficient, with 95 per cent of the energy being lost to the atmosphere. In comparison LED or florescent bulbs manage around 14 per cent efficiency. But the scientists believe that the new bulb could reach efficiency levels of 40 per cent.

And it shows colours far more naturally than modern energy-efficient bulbs. Traditional incandescent bulbs have a ‘colour rendering index’ rating of 100, because they match the hue of objects seen in natural daylight. However even ‘warm’ finish LED or florescent bulbs can only manage an index rating of 80 and most are far less.

“This experimental device is a proof-of-concept, at the low end of performance that could be ultimately achieved by this approach,” said principal research scientist Ivan Celanovic.

Meanwhile, Lockhart points out that the financial system does not perfectly reflect the real economy:

Federal Reserve Bank of Atlanta President Dennis Lockhart said he favors continued tightening of monetary policy this year, and a global selloff in stock markets is unlikely to affect the U.S. economy.

“When such volatility develops, I think it’s helpful to look at the real economy of the United States as opposed to the financial economy and ask if something is fundamentally wrong,” Lockhart said in a speech Monday in Atlanta. “Are there serious imbalances that make the broad economy vulnerable to foreign shocks? I don’t see that kind of connection in current circumstances. ”

Lockhart told reporters after his speech the persistence of turmoil such as what occurred starting in August might change that view.

“If the volatility continues for several weeks, I may have to revise my view that I don’t now see a connection between financial markets abroad and the real economy,” Lockhart said. “It is a matter of how long it lasts.”

Failed politicians and backscratchers are getting very excited about the creation of a brand new regulated business:

Liberal MP Bill Blair wants to make it clear the growth and sale of legal marijuana in Canada will not be a free-for-all.

In an interview, the chief architect of the country’s new marijuana regime frequently used such words as “control” and “strict regulation” as he discussed the federal government’s options.
…
“There is a need for some control,” he said. “Our intent is to legalize, regulate and restrict. There needs to be reasonable restrictions on making sure that we keep it away from kids, because I think that is very much in the public interest. We also have to ensure that the social and the health harms are properly managed and mitigated, and that can be done through regulation.”

Illegal pot dispensaries are appearing in greater numbers across the country. In addition, some advocates of legalization say that the Trudeau government’s promise to make pot legal means police should immediately stop charging people for possessing marijuana.

On the other hand, some people in the marijuana industry say only licensed and regulated operators should be able to grow and sell the drug. In particular, a number of investors in the medical marijuana business, which was heavily regulated by the Conservative government, want similar rules and restrictions for recreational pot.

Yes, it is only through restriction of competition that hopelessly incompetent ex-politicians like George ‘e-Health’ Smitherman will be able to make a living:

A former high-ranking colleague and friend of MP Bill Blair, the Liberal government’s point man on marijuana legalization, will lobby the ex-Toronto police chief in hopes of ensuring a tightly controlled system in which only licensed firms are allowed to grow the lucrative drug.

Kim Derry, a deputy chief of the Toronto Police Service under Mr. Blair, is a promoter of marijuana facility THC Meds Ontario Inc., along with George Smitherman, a former Ontario Liberal deputy premier. Mr. Blair, put in charge of the marijuana file last week, will play a key role in determining who gets to grow the product once it is legalized.

While some growers want loosely regulated production across the country, the operators of companies such as THC Meds say production licences should be limited to professional operations.

In an interview, Mr. Derry said the government should aim to “get rid of the goons” who are currently in the marijuana business, calling for tight regulations on who can grow and sell the product.

There is a reasonably good book excerpt about annuities in the Globe:

One of the signs will be when the gap between the yields on long-term government bonds and inflation is relatively high–that is to say, when the real yield on long-term bonds is high.

You might wonder what long-term bonds have to do with annuities. The interest rate that determines the cost of annuities is never advertised by the insurer but it happens to be closely tied to the yield on long-term government bonds, which is readily available. The gap between long-term bond yields and inflation is currently rather small, even though inflation is low which means that now might not be the best time to buy an annuity. Note that the nominal yield on bonds is not important, just the real yield. Hence, you are better off buying an annuity when long-term bond yields are 4 per cent and inflation is 2 per cent than when long-term bond yields and inflation are both 5 per cent.

It’s nice to see some rational discussion of annuity pricing in the popular press, but I must say I find great fault with the author’s arguments on market timing. Dammit, it can’t be done! And it is unbelievably reckless to indulge in timing when making a significant, irreversible decision to annuitize, even if it’s with only a portion of the nest egg.

As I have discussed in PrefLetter (and in one free article, for you cheapskates) annuities are lousy investments, but they are great insurance. Any retiree who is encroaching on his capital to fund his living expenses should very carefully consider buying an annuity of sufficient size that he becomes cash-flow neutral, i.e., that all normal living expenses are covered by the annuity payments and the income from the remaining investment portfolio. That way, you’ve got the encroachment on capital done all at once and have considerably less worry about what happens when there’s no more capital to be encroached upon.

At time of writing there is some hope that markets might not go down tomorrow:

Asian stocks rallied from a three-year low, tracking a rebound in the U.S. amid speculation a selloff that erased more than $5 trillion from global equity values this year had gone too far. Oil rose for the first time this year and the offshore yuan strengthened for a fifth day.

The MSCI Asia-Pacific Index climbed the most in four weeks as benchmark share indexes rallied across the region. U.S. index futures gained after the Standard & Poor’s 500 Index advanced for a second day. Treasuries took back some of the last session’s gains, which were spurred by crude’s decline to below $30 for the first time in 12 years. The more positive sentiment diminished the appeal of haven currencies, with the yen retreating as Australia’s dollar appreciated.

On the other hand the Royal Bank of Scotland issued some cheery advice:

Investors face a “cataclysmic year” where stock markets could fall by up to 20% and oil could slump to $16 a barrel, economists at the Royal Bank of Scotland have warned.

In a note to its clients the bank said: “Sell everything except high quality bonds. This is about return of capital, not return on capital. In a crowded hall, exit doors are small.” It said the current situation was reminiscent of 2008, when the collapse of the Lehman Brothers investment bank led to the global financial crisis. This time China could be the crisis point.
…
RBS is not the only negative voice at the moment. Analysts at JP Morgan have advised clients to sell stocks on any bounce.

Morgan Stanley has said oil could fall to $20 a barrel, while Standard Chartered has predicted an even bigger slide, to as low as $10. Standard said: “Given that no fundamental relationship is currently driving the oil market towards any equilibrium, prices are being moved almost entirely by financial flows caused by fluctuations in other asset prices, including the US dollar and equity markets.

“We think prices could fall as low as $10 a barrel before most of the money managers in the market conceded that matters had gone too far.”

But in the meantime, Canadian preferred share investors are looking at their account balances:

horror
Click for Big

It was an incredibly horrible day for the Canadian preferred share market, with PerpetualDiscounts down 92bp, FixedResets losing 243bp and DeemedRetractibles off 58bp. The Performance Highlights table is immense, of course, with not a single winner. Volume was extremely high.

All I can think of by way of explanation is that with the dollar down so much due to oil and speculation of a Bank of Canada policy cut in the future, people are getting ever more gloomy about the prospect of five year Canadas ever yielding more than one percent – yields dropped precipitously today to 0.57%, which is below the all-time low (based on BoC weekly data) of 0.62%, reached 2015-2-4. One wonders how many people lost their houses in the tightening of the early eighties and are now getting crushed by loosening in their retirement accounts.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_160112
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 16.30 to be $0.79 rich, while TRP.PR.C, resetting 2016-1-30 at +154, is $0.99 cheap at its bid price of 10.30.

impVol_MFC_160112
Click for Big

Most expensive is MFC.PR.L, resetting at +216bp on 2019-6-19, bid at 17.50 to be 0.55 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 18.25 to be 1.49 cheap.

impVol_BAM_160112
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 13.90 to be $1.17 cheap. BAM.PF.F, resetting at +286bp on 2019-9-30 is bid at 18.81 and appears to be $0.80 rich.

impVol_FTS_160112
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 17.37, looks $0.68 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 16.64 and is $0.46 cheap.

pairs_FR_160112
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.62%, with no outliers; note that the vertical axis has been shifted upwards today. There is one junk outlier below -1.50% and one above 0.50%.

pairs_FF_160112
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 4.90 % 5.95 % 26,900 16.71 1 -4.2215 % 1,586.9
FixedFloater 7.36 % 6.54 % 32,338 15.52 1 -3.0075 % 2,650.0
Floater 4.52 % 4.69 % 79,057 16.08 4 -3.1467 % 1,692.5
OpRet 0.00 % 0.00 % 0 0.00 0 -0.5113 % 2,722.1
SplitShare 4.85 % 6.02 % 68,527 2.77 6 -0.5113 % 3,185.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.5113 % 2,485.3
Perpetual-Premium 5.92 % 5.74 % 86,220 2.71 6 -0.2887 % 2,494.4
Perpetual-Discount 5.82 % 5.91 % 94,766 14.06 34 -0.9198 % 2,480.4
FixedReset 5.58 % 5.02 % 239,105 14.81 81 -2.4289 % 1,850.7
Deemed-Retractible 5.35 % 5.25 % 121,610 5.27 34 -0.5837 % 2,516.2
FloatingReset 2.93 % 4.91 % 65,755 5.60 13 -1.4163 % 2,015.4
Performance Highlights
Issue Index Change Notes
PWF.PR.P FixedReset -7.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 11.83
Evaluated at bid price : 11.83
Bid-YTW : 4.78 %
TRP.PR.E FixedReset -6.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 16.30
Evaluated at bid price : 16.30
Bid-YTW : 5.02 %
TRP.PR.A FixedReset -6.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 13.58
Evaluated at bid price : 13.58
Bid-YTW : 5.06 %
TRP.PR.B FixedReset -6.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 9.96
Evaluated at bid price : 9.96
Bid-YTW : 5.02 %
CCS.PR.C Deemed-Retractible -5.60 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.72
Bid-YTW : 7.74 %
HSE.PR.A FixedReset -5.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 10.22
Evaluated at bid price : 10.22
Bid-YTW : 5.88 %
HSE.PR.G FixedReset -5.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 17.02
Evaluated at bid price : 17.02
Bid-YTW : 6.36 %
TRP.PR.G FixedReset -5.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 18.03
Evaluated at bid price : 18.03
Bid-YTW : 5.15 %
MFC.PR.G FixedReset -5.19 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.25
Bid-YTW : 7.97 %
TRP.PR.D FixedReset -5.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 15.80
Evaluated at bid price : 15.80
Bid-YTW : 5.09 %
BAM.PR.Z FixedReset -5.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 17.75
Evaluated at bid price : 17.75
Bid-YTW : 5.32 %
TRP.PR.C FixedReset -5.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 10.30
Evaluated at bid price : 10.30
Bid-YTW : 5.35 %
BAM.PR.X FixedReset -4.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 13.00
Evaluated at bid price : 13.00
Bid-YTW : 5.08 %
BAM.PR.R FixedReset -4.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 13.90
Evaluated at bid price : 13.90
Bid-YTW : 5.43 %
BAM.PR.T FixedReset -4.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 14.40
Evaluated at bid price : 14.40
Bid-YTW : 5.36 %
PWF.PR.A Floater -4.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 11.75
Evaluated at bid price : 11.75
Bid-YTW : 4.07 %
BMO.PR.T FixedReset -4.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 16.75
Evaluated at bid price : 16.75
Bid-YTW : 4.68 %
RY.PR.M FixedReset -4.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 18.01
Evaluated at bid price : 18.01
Bid-YTW : 4.73 %
BAM.PR.E Ratchet -4.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 25.00
Evaluated at bid price : 13.84
Bid-YTW : 5.95 %
CM.PR.P FixedReset -4.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 16.56
Evaluated at bid price : 16.56
Bid-YTW : 4.67 %
TRP.PR.F FloatingReset -4.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 12.19
Evaluated at bid price : 12.19
Bid-YTW : 4.86 %
SLF.PR.J FloatingReset -3.92 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.25
Bid-YTW : 10.85 %
IFC.PR.C FixedReset -3.91 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.20
Bid-YTW : 8.43 %
CM.PR.O FixedReset -3.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 17.30
Evaluated at bid price : 17.30
Bid-YTW : 4.57 %
FTS.PR.I FloatingReset -3.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 11.92
Evaluated at bid price : 11.92
Bid-YTW : 3.98 %
HSE.PR.E FixedReset -3.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 17.40
Evaluated at bid price : 17.40
Bid-YTW : 6.23 %
BNS.PR.D FloatingReset -3.63 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.54
Bid-YTW : 7.63 %
MFC.PR.L FixedReset -3.58 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.50
Bid-YTW : 8.11 %
RY.PR.J FixedReset -3.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 18.27
Evaluated at bid price : 18.27
Bid-YTW : 4.78 %
IAG.PR.G FixedReset -3.33 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.85
Bid-YTW : 7.49 %
BAM.PR.B Floater -3.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 10.15
Evaluated at bid price : 10.15
Bid-YTW : 4.69 %
SLF.PR.H FixedReset -3.32 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.13
Bid-YTW : 9.58 %
VNR.PR.A FixedReset -3.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 17.56
Evaluated at bid price : 17.56
Bid-YTW : 5.08 %
RY.PR.Z FixedReset -3.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 17.35
Evaluated at bid price : 17.35
Bid-YTW : 4.48 %
BAM.PF.B FixedReset -3.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 16.95
Evaluated at bid price : 16.95
Bid-YTW : 5.13 %
TD.PR.Y FixedReset -3.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.77
Bid-YTW : 4.62 %
NA.PR.S FixedReset -3.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 17.25
Evaluated at bid price : 17.25
Bid-YTW : 4.69 %
BAM.PR.G FixedFloater -3.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 25.00
Evaluated at bid price : 12.90
Bid-YTW : 6.54 %
ENB.PR.A Perpetual-Discount -2.97 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 21.97
Evaluated at bid price : 22.20
Bid-YTW : 6.28 %
RY.PR.H FixedReset -2.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 17.34
Evaluated at bid price : 17.34
Bid-YTW : 4.54 %
PWF.PR.T FixedReset -2.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 20.50
Evaluated at bid price : 20.50
Bid-YTW : 3.91 %
SLF.PR.I FixedReset -2.82 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.60
Bid-YTW : 8.24 %
BMO.PR.W FixedReset -2.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 17.05
Evaluated at bid price : 17.05
Bid-YTW : 4.56 %
BAM.PF.G FixedReset -2.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 18.35
Evaluated at bid price : 18.35
Bid-YTW : 5.14 %
TD.PF.A FixedReset -2.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 17.30
Evaluated at bid price : 17.30
Bid-YTW : 4.48 %
GWO.PR.L Deemed-Retractible -2.67 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.10
Bid-YTW : 6.25 %
CIU.PR.C FixedReset -2.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 11.35
Evaluated at bid price : 11.35
Bid-YTW : 4.55 %
TD.PF.E FixedReset -2.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 19.45
Evaluated at bid price : 19.45
Bid-YTW : 4.59 %
GWO.PR.O FloatingReset -2.45 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.95
Bid-YTW : 11.01 %
BAM.PR.C Floater -2.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 10.05
Evaluated at bid price : 10.05
Bid-YTW : 4.74 %
BMO.PR.Q FixedReset -2.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.65
Bid-YTW : 7.42 %
BNS.PR.Q FixedReset -2.34 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.50
Bid-YTW : 4.88 %
BNS.PR.R FixedReset -2.34 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.97
Bid-YTW : 4.76 %
MFC.PR.I FixedReset -2.29 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.20
Bid-YTW : 7.33 %
TD.PF.B FixedReset -2.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 17.26
Evaluated at bid price : 17.26
Bid-YTW : 4.48 %
BAM.PR.N Perpetual-Discount -2.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 19.42
Evaluated at bid price : 19.42
Bid-YTW : 6.18 %
BIP.PR.B FixedReset -2.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 22.37
Evaluated at bid price : 23.16
Bid-YTW : 5.98 %
BAM.PR.K Floater -2.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 9.91
Evaluated at bid price : 9.91
Bid-YTW : 4.80 %
CU.PR.G Perpetual-Discount -2.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 19.35
Evaluated at bid price : 19.35
Bid-YTW : 5.90 %
BAM.PF.E FixedReset -2.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 5.17 %
BAM.PF.A FixedReset -1.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 18.24
Evaluated at bid price : 18.24
Bid-YTW : 5.11 %
MFC.PR.K FixedReset -1.87 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.30
Bid-YTW : 8.14 %
TD.PF.D FixedReset -1.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 18.50
Evaluated at bid price : 18.50
Bid-YTW : 4.71 %
BMO.PR.S FixedReset -1.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 17.72
Evaluated at bid price : 17.72
Bid-YTW : 4.53 %
NA.PR.W FixedReset -1.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 16.82
Evaluated at bid price : 16.82
Bid-YTW : 4.63 %
HSE.PR.C FixedReset -1.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 16.50
Evaluated at bid price : 16.50
Bid-YTW : 6.05 %
BAM.PR.M Perpetual-Discount -1.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 19.36
Evaluated at bid price : 19.36
Bid-YTW : 6.20 %
CU.PR.H Perpetual-Discount -1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 22.64
Evaluated at bid price : 23.00
Bid-YTW : 5.77 %
RY.PR.L FixedReset -1.65 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.50
Bid-YTW : 4.33 %
RY.PR.K FloatingReset -1.61 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.40
Bid-YTW : 5.17 %
BIP.PR.A FixedReset -1.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 18.50
Evaluated at bid price : 18.50
Bid-YTW : 5.85 %
BNS.PR.Z FixedReset -1.59 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.55
Bid-YTW : 7.41 %
MFC.PR.J FixedReset -1.58 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.70
Bid-YTW : 7.41 %
POW.PR.B Perpetual-Discount -1.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 22.22
Evaluated at bid price : 22.50
Bid-YTW : 5.97 %
GWO.PR.M Deemed-Retractible -1.54 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.91
Bid-YTW : 5.92 %
MFC.PR.M FixedReset -1.51 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.22
Bid-YTW : 7.75 %
BMO.PR.Y FixedReset -1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 19.01
Evaluated at bid price : 19.01
Bid-YTW : 4.63 %
GWO.PR.I Deemed-Retractible -1.50 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.70
Bid-YTW : 7.89 %
PVS.PR.E SplitShare -1.49 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-10-31
Maturity Price : 25.00
Evaluated at bid price : 23.85
Bid-YTW : 6.49 %
GWO.PR.G Deemed-Retractible -1.47 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.12
Bid-YTW : 7.01 %
MFC.PR.F FixedReset -1.45 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.55
Bid-YTW : 10.03 %
W.PR.H Perpetual-Discount -1.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 22.56
Evaluated at bid price : 22.82
Bid-YTW : 6.05 %
FTS.PR.K FixedReset -1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 17.37
Evaluated at bid price : 17.37
Bid-YTW : 4.25 %
CU.PR.D Perpetual-Discount -1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 21.03
Evaluated at bid price : 21.03
Bid-YTW : 5.92 %
FTS.PR.F Perpetual-Discount -1.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 21.53
Evaluated at bid price : 21.79
Bid-YTW : 5.69 %
FTS.PR.M FixedReset -1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 18.50
Evaluated at bid price : 18.50
Bid-YTW : 4.56 %
ELF.PR.G Perpetual-Discount -1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 20.71
Evaluated at bid price : 20.71
Bid-YTW : 5.77 %
BAM.PF.D Perpetual-Discount -1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 20.05
Evaluated at bid price : 20.05
Bid-YTW : 6.17 %
W.PR.K FixedReset -1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 22.64
Evaluated at bid price : 23.70
Bid-YTW : 5.55 %
BNS.PR.P FixedReset -1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.26
Bid-YTW : 4.26 %
GWO.PR.S Deemed-Retractible -1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.26
Bid-YTW : 6.34 %
POW.PR.D Perpetual-Discount -1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 21.30
Evaluated at bid price : 21.30
Bid-YTW : 5.91 %
POW.PR.C Perpetual-Premium -1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 24.05
Evaluated at bid price : 24.30
Bid-YTW : 6.00 %
PWF.PR.K Perpetual-Discount -1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 20.90
Evaluated at bid price : 20.90
Bid-YTW : 5.94 %
TD.PF.C FixedReset -1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 17.05
Evaluated at bid price : 17.05
Bid-YTW : 4.53 %
GWO.PR.N FixedReset -1.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.75
Bid-YTW : 10.73 %
BAM.PF.H FixedReset -1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 23.09
Evaluated at bid price : 24.78
Bid-YTW : 4.99 %
NA.PR.Q FixedReset -1.21 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.71
Bid-YTW : 4.24 %
TD.PR.Z FloatingReset -1.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.15
Bid-YTW : 5.01 %
POW.PR.G Perpetual-Discount -1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 23.29
Evaluated at bid price : 23.73
Bid-YTW : 5.92 %
GWO.PR.Q Deemed-Retractible -1.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.18
Bid-YTW : 6.91 %
BAM.PF.F FixedReset -1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 18.81
Evaluated at bid price : 18.81
Bid-YTW : 4.98 %
GWO.PR.H Deemed-Retractible -1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.77
Bid-YTW : 7.53 %
W.PR.J Perpetual-Discount -1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 22.77
Evaluated at bid price : 23.05
Bid-YTW : 6.10 %
IFC.PR.A FixedReset -1.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.65
Bid-YTW : 9.97 %
CM.PR.Q FixedReset -1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 18.56
Evaluated at bid price : 18.56
Bid-YTW : 4.70 %
PWF.PR.O Perpetual-Premium -1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 24.01
Evaluated at bid price : 24.50
Bid-YTW : 5.92 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PR.T FloatingReset 300,555 Scotia crossed 300,000 at 21.60.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.55
Bid-YTW : 4.58 %
RY.PR.I FixedReset 232,300 Nesbitt crossed 76,800 at 23.30; RBC crossed 149,900 at the same price.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.20
Bid-YTW : 4.56 %
RY.PR.Q FixedReset 219,115 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 23.30
Evaluated at bid price : 25.50
Bid-YTW : 5.10 %
IFC.PR.A FixedReset 131,050 Desjardins crossed 107,000 at 14.85; Nesbitt crossed 15,700 at the same price.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.65
Bid-YTW : 9.97 %
BNS.PR.L Deemed-Retractible 108,575 RBC crossed 71,200 at 24.54.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.41
Bid-YTW : 4.94 %
BAM.PF.H FixedReset 98,870 Desjardins crossed 71,600 at 25.00.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 23.09
Evaluated at bid price : 24.78
Bid-YTW : 4.99 %
There were 57 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
IFC.PR.C FixedReset Quote: 17.20 – 18.99
Spot Rate : 1.7900
Average : 1.0550

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.20
Bid-YTW : 8.43 %

HSE.PR.C FixedReset Quote: 16.50 – 18.31
Spot Rate : 1.8100
Average : 1.1658

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 16.50
Evaluated at bid price : 16.50
Bid-YTW : 6.05 %

PWF.PR.A Floater Quote: 11.75 – 13.25
Spot Rate : 1.5000
Average : 0.8901

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 11.75
Evaluated at bid price : 11.75
Bid-YTW : 4.07 %

CCS.PR.C Deemed-Retractible Quote: 20.72 – 22.00
Spot Rate : 1.2800
Average : 0.9257

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.72
Bid-YTW : 7.74 %

PWF.PR.P FixedReset Quote: 11.83 – 12.81
Spot Rate : 0.9800
Average : 0.6258

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-12
Maturity Price : 11.83
Evaluated at bid price : 11.83
Bid-YTW : 4.78 %

BNS.PR.A FloatingReset Quote: 22.00 – 22.99
Spot Rate : 0.9900
Average : 0.6437

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.00
Bid-YTW : 4.68 %

Market Action

January 11, 2016

While preparing PrefLetter I came across this interesting chart, from a presentation by BoC Deputy Governor Lynn Patterson:

counterfeitingCanada
Click for Big

Speaking of the BoC, the Business Outlook Survey is spreading gloom:

The quarterly survey of business executives, published by the central bank Monday, showed that the prolonged oil slump is taking a deepening toll on the mood of the country’s corporate leaders. It also shows that, increasingly, the negative impact and mounting pessimism are infecting parts of the economy beyond the resource sector.

What’s more, the details press on many of the hot buttons for the bank’s decision on interest rates, the next of which comes only days from now (Jan. 20). Spending intentions for new capacity and hiring are at their lowest since the Great Recession; businesses still have ample excess capacity; already-tepid inflation expectations are declining.
…
Neither the bond market nor the majority of economists expect a cut next week, but the Business Outlook Survey has made a cut look like a serious possibility at some point in the next few months. At least one prominent central-bank watcher – Merrill Lynch economist Emanuella Enenajor – is convinced that the survey seals the deal on a quarter-point rate cut next week.

It’s not getting any better! Oil and copper got crushed today:

Oil plunged to its lowest point since 2003 on Monday, as West Texas intermediate (WTI), the North American benchmark, declined to $31.12 (U.S.) a barrel. It has lost 15 per cent of its value in the first few days of 2016.

Copper, meanwhile, tumbled to a six-year low of $1.97 a pound. The metal, used for a wide variety of industrial and construction applications, is down more than 9 per cent in January.

… which is putting the banks under pressure:

Consider the urgency: The price of oil – exploring 12-year lows – is fast-approaching worst-case hypothetical scenarios used in bank stress tests in 2015, raising concerns about whether loan losses will spike as energy companies fail to meet their debt obligations. Big Six loans to the oil and gas sector total nearly $113-billion.
…
The lower prices are nearing, or passing through, some significant thresholds. Canadian Imperial Bank of Commerce used $30 oil in its stress tests a year ago; Bank of Montreal stress-tested its loan portfolio at $35 a barrel in 2015, and assumed that oil would recover to $50 a barrel this year.

Financial 15 Split Corp., proud issuer of FTN.PR.A, has been confirmed at Pfd-4(high) by DBRS:

DBRS Limited (DBRS) has today confirmed the rating of the Preferred Shares (the Preferred Shares) issued by Financial 15 Split Corp. (the Company) at Pfd-4 (high).
…
During 2015, the NAV of the Company has experienced some fluctuation due to volatility in the markets. Downside protection available to holders of the Preferred Shares is 40.7% as of December 15, 2015. The dividend coverage ratio has risen to 0.6 times over the past year. Regular monthly Class A Share distributions will result in an average grind of approximately 3.5% over the next five years.

Happy preferred share investors held a parade in honour of the market today!

funeralProcession
Click for Big

It was yet another grim day for the Canadian preferred share market today, with PerpetualDiscounts off 68bp, FixedResets losing a stunning 199bp and DeemedRetractibles down 84bp. The Performance Highlights table is, of course, ridiculous. Volume was well above average.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_160111
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 17.51 to be $1.03 rich, while TRP.PR.C, resetting 2016-1-30 at +154, is $1.23 cheap at its bid price of 10.85.

impVol_MFC_160111
Click for Big

Most expensive is MFC.PR.L, resetting at +216bp on 2019-6-19, bid at 18.15 to be 0.82 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 19.25 to be 0.77 cheap.

impVol_BAM_160111
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 14.60 to be $0.99 cheap. BAM.PR.X, resetting at +180bp on 2017-6-30 is bid at 13.67 and appears to be $0.74 rich.

impVol_FTS_160111
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 17.62, looks $0.84 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 16.51 and is $0.70 cheap.

pairs_FR_160111
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.78%, with one outlier above 0.00%. There is one junk outlier below -2.00% and four above 0.00%.

pairs_FF_160111
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 4.70 % 5.69 % 27,014 17.02 1 1.4035 % 1,656.8
FixedFloater 7.14 % 6.34 % 32,242 15.77 1 2.4653 % 2,732.1
Floater 4.37 % 4.53 % 79,818 16.38 4 -1.9065 % 1,747.5
OpRet 0.00 % 0.00 % 0 0.00 0 0.0137 % 2,736.1
SplitShare 4.83 % 5.79 % 70,997 1.80 6 0.0137 % 3,201.7
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0137 % 2,498.1
Perpetual-Premium 5.90 % 5.81 % 85,367 2.72 6 -0.5476 % 2,501.6
Perpetual-Discount 5.76 % 5.85 % 94,429 14.14 34 -0.6755 % 2,503.4
FixedReset 5.44 % 4.82 % 237,193 15.07 81 -1.9911 % 1,896.8
Deemed-Retractible 5.32 % 5.20 % 122,011 5.27 34 -0.8429 % 2,531.0
FloatingReset 2.89 % 4.79 % 62,006 5.60 13 -0.6169 % 2,044.3
Performance Highlights
Issue Index Change Notes
TRP.PR.A FixedReset -7.26 % Not real. The issue traded 5,880 shares today in a range of 15.18-84 before closing at 14.56-24, 1×1. The last trade of the day was at 2:17pm, at 15.18. I have not checked whether this lamentable state of affairs is due to inadequate Toronto Stock Exchange reporting or inadequate Toronto Stock Exchange supervision of market-makers.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 14.56
Evaluated at bid price : 14.56
Bid-YTW : 4.70 %
BAM.PF.E FixedReset -5.34 % Sort of real. The issue traded 10,590 shares today in a range of 17.36-33 before closing at 17.36-60, 4×1. The VWAP was 17.68. We’ll give the Exchange and the market maker a pass on this one, largely because I’m such a nice guy.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 17.36
Evaluated at bid price : 17.36
Bid-YTW : 5.05 %
TRP.PR.H FloatingReset -5.23 % Reasonably real. The issue traded 8,659 shares in a range of 9.26-80 before closing at 9.25-75, 4×1. VWAP was 9.68. But really, guys a 5%+ quote spread? I have not checked whether this lamentable state of affairs is due to inadequate Toronto Stock Exchange reporting or inadequate Toronto Stock Exchange supervision of market-makers.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 9.25
Evaluated at bid price : 9.25
Bid-YTW : 4.65 %
HSE.PR.C FixedReset -5.14 % Exaggerated. The issue traded 9,300 shares in a range of 16.62-17.95 before closing at 16.79-50, 2×30. VWAP was 17.28; the last trade was at 17.02 for 100 shares, timestamped 2:50pm. I have not checked whether this lamentable state of affairs is due to inadequate Toronto Stock Exchange reporting or inadequate Toronto Stock Exchange supervision of market-makers.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 16.79
Evaluated at bid price : 16.79
Bid-YTW : 5.94 %
BAM.PR.T FixedReset -5.09 % Well, OK. The issue traded 13,600 shares today in a range of 15.01-91 before closing at 15.11-30, 5×2. VWAP was 15.49; the last trade was for 500 shares at 15.12 timestamped 3:48.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 15.11
Evaluated at bid price : 15.11
Bid-YTW : 5.10 %
BAM.PF.A FixedReset -4.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 18.60
Evaluated at bid price : 18.60
Bid-YTW : 5.00 %
BAM.PR.K Floater -4.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 10.12
Evaluated at bid price : 10.12
Bid-YTW : 4.70 %
BAM.PF.F FixedReset -4.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 19.02
Evaluated at bid price : 19.02
Bid-YTW : 4.92 %
TRP.PR.E FixedReset -4.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 17.51
Evaluated at bid price : 17.51
Bid-YTW : 4.65 %
HSE.PR.G FixedReset -4.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 6.01 %
BAM.PR.R FixedReset -3.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 14.60
Evaluated at bid price : 14.60
Bid-YTW : 5.16 %
TRP.PR.D FixedReset -3.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 16.65
Evaluated at bid price : 16.65
Bid-YTW : 4.82 %
BAM.PR.X FixedReset -3.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 13.67
Evaluated at bid price : 13.67
Bid-YTW : 4.82 %
MFC.PR.H FixedReset -3.53 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.50
Bid-YTW : 6.65 %
PWF.PR.P FixedReset -3.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 12.81
Evaluated at bid price : 12.81
Bid-YTW : 4.41 %
BAM.PF.G FixedReset -3.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 18.86
Evaluated at bid price : 18.86
Bid-YTW : 4.99 %
BAM.PF.B FixedReset -3.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 4.96 %
IFC.PR.A FixedReset -3.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.80
Bid-YTW : 9.82 %
BMO.PR.M FixedReset -3.25 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.25
Bid-YTW : 4.21 %
FTS.PR.G FixedReset -3.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 16.51
Evaluated at bid price : 16.51
Bid-YTW : 4.51 %
SLF.PR.H FixedReset -3.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.65
Bid-YTW : 9.11 %
TRP.PR.C FixedReset -3.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 10.85
Evaluated at bid price : 10.85
Bid-YTW : 5.07 %
CM.PR.Q FixedReset -2.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 18.75
Evaluated at bid price : 18.75
Bid-YTW : 4.65 %
GWO.PR.N FixedReset -2.93 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.91
Bid-YTW : 10.56 %
HSE.PR.A FixedReset -2.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 10.81
Evaluated at bid price : 10.81
Bid-YTW : 5.56 %
MFC.PR.N FixedReset -2.74 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.10
Bid-YTW : 7.77 %
SLF.PR.B Deemed-Retractible -2.74 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.59
Bid-YTW : 7.60 %
TRP.PR.B FixedReset -2.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 10.66
Evaluated at bid price : 10.66
Bid-YTW : 4.69 %
FTS.PR.J Perpetual-Discount -2.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 21.21
Evaluated at bid price : 21.21
Bid-YTW : 5.68 %
SLF.PR.C Deemed-Retractible -2.69 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.50
Bid-YTW : 7.97 %
TRP.PR.G FixedReset -2.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 19.03
Evaluated at bid price : 19.03
Bid-YTW : 4.87 %
SLF.PR.A Deemed-Retractible -2.64 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.62
Bid-YTW : 7.52 %
PWF.PR.S Perpetual-Discount -2.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 20.40
Evaluated at bid price : 20.40
Bid-YTW : 5.90 %
BMO.PR.Q FixedReset -2.60 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.10
Bid-YTW : 6.97 %
BNS.PR.P FixedReset -2.56 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.58
Bid-YTW : 4.01 %
MFC.PR.M FixedReset -2.53 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.50
Bid-YTW : 7.54 %
BMO.PR.S FixedReset -2.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 18.05
Evaluated at bid price : 18.05
Bid-YTW : 4.44 %
MFC.PR.C Deemed-Retractible -2.42 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.76
Bid-YTW : 7.87 %
BAM.PR.Z FixedReset -2.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 18.70
Evaluated at bid price : 18.70
Bid-YTW : 5.04 %
SLF.PR.E Deemed-Retractible -2.33 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.68
Bid-YTW : 7.90 %
MFC.PR.J FixedReset -2.31 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.00
Bid-YTW : 7.19 %
BNS.PR.Q FixedReset -2.29 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.04
Bid-YTW : 4.44 %
BNS.PR.R FixedReset -2.29 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.52
Bid-YTW : 4.32 %
TD.PF.D FixedReset -2.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 18.85
Evaluated at bid price : 18.85
Bid-YTW : 4.62 %
GWO.PR.S Deemed-Retractible -2.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.58
Bid-YTW : 6.14 %
SLF.PR.I FixedReset -2.21 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.11
Bid-YTW : 7.84 %
CM.PR.P FixedReset -2.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 17.28
Evaluated at bid price : 17.28
Bid-YTW : 4.47 %
IFC.PR.C FixedReset -2.19 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.90
Bid-YTW : 7.88 %
CIU.PR.C FixedReset -2.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 11.65
Evaluated at bid price : 11.65
Bid-YTW : 4.43 %
TD.PR.S FixedReset -2.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.50
Bid-YTW : 3.85 %
MFC.PR.I FixedReset -2.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.65
Bid-YTW : 7.00 %
CU.PR.F Perpetual-Discount -2.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 19.66
Evaluated at bid price : 19.66
Bid-YTW : 5.81 %
MFC.PR.B Deemed-Retractible -2.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.13
Bid-YTW : 7.78 %
FTS.PR.M FixedReset -2.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 18.76
Evaluated at bid price : 18.76
Bid-YTW : 4.50 %
TD.PF.C FixedReset -1.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 17.27
Evaluated at bid price : 17.27
Bid-YTW : 4.47 %
SLF.PR.G FixedReset -1.96 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.02
Bid-YTW : 9.58 %
BMO.PR.W FixedReset -1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 17.53
Evaluated at bid price : 17.53
Bid-YTW : 4.43 %
IAG.PR.A Deemed-Retractible -1.92 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.40
Bid-YTW : 7.50 %
PWF.PR.H Perpetual-Premium -1.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 23.89
Evaluated at bid price : 24.14
Bid-YTW : 5.96 %
BAM.PR.C Floater -1.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 10.30
Evaluated at bid price : 10.30
Bid-YTW : 4.62 %
GWO.PR.P Deemed-Retractible -1.73 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.29
Bid-YTW : 6.48 %
TD.PF.B FixedReset -1.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 17.65
Evaluated at bid price : 17.65
Bid-YTW : 4.37 %
CM.PR.O FixedReset -1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 4.39 %
SLF.PR.D Deemed-Retractible -1.62 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.48
Bid-YTW : 7.98 %
RY.PR.I FixedReset -1.61 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.27
Bid-YTW : 4.51 %
CU.PR.G Perpetual-Discount -1.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 19.76
Evaluated at bid price : 19.76
Bid-YTW : 5.78 %
BMO.PR.Y FixedReset -1.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 19.30
Evaluated at bid price : 19.30
Bid-YTW : 4.55 %
HSE.PR.E FixedReset -1.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 18.10
Evaluated at bid price : 18.10
Bid-YTW : 5.98 %
GWO.PR.R Deemed-Retractible -1.47 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.80
Bid-YTW : 7.45 %
RY.PR.J FixedReset -1.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 18.94
Evaluated at bid price : 18.94
Bid-YTW : 4.60 %
BIP.PR.B FixedReset -1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 22.62
Evaluated at bid price : 23.66
Bid-YTW : 5.84 %
CU.PR.E Perpetual-Discount -1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 21.23
Evaluated at bid price : 21.23
Bid-YTW : 5.86 %
TD.PR.T FloatingReset -1.38 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.40
Bid-YTW : 4.71 %
FTS.PR.F Perpetual-Discount -1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 21.86
Evaluated at bid price : 22.10
Bid-YTW : 5.61 %
IAG.PR.G FixedReset -1.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.50
Bid-YTW : 7.02 %
GWO.PR.H Deemed-Retractible -1.18 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.00
Bid-YTW : 7.37 %
TD.PF.A FixedReset -1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 17.78
Evaluated at bid price : 17.78
Bid-YTW : 4.35 %
SLF.PR.J FloatingReset -1.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.75
Bid-YTW : 10.32 %
BMO.PR.T FixedReset -1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 17.51
Evaluated at bid price : 17.51
Bid-YTW : 4.47 %
BNS.PR.Z FixedReset -1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.85
Bid-YTW : 7.11 %
BMO.PR.R FloatingReset -1.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.76
Bid-YTW : 4.56 %
BAM.PF.C Perpetual-Discount -1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 19.98
Evaluated at bid price : 19.98
Bid-YTW : 6.13 %
GWO.PR.I Deemed-Retractible -1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.00
Bid-YTW : 7.67 %
CU.PR.D Perpetual-Discount -1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 21.33
Evaluated at bid price : 21.33
Bid-YTW : 5.83 %
GWO.PR.G Deemed-Retractible -1.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.45
Bid-YTW : 6.79 %
POW.PR.D Perpetual-Discount -1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 21.32
Evaluated at bid price : 21.59
Bid-YTW : 5.81 %
RY.PR.M FixedReset -1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 18.81
Evaluated at bid price : 18.81
Bid-YTW : 4.52 %
GWO.PR.F Deemed-Retractible 1.11 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-02-10
Maturity Price : 25.00
Evaluated at bid price : 25.40
Bid-YTW : -10.98 %
BAM.PR.E Ratchet 1.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 25.00
Evaluated at bid price : 14.45
Bid-YTW : 5.69 %
RY.PR.K FloatingReset 1.87 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.75
Bid-YTW : 4.87 %
BAM.PR.G FixedFloater 2.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 25.00
Evaluated at bid price : 13.30
Bid-YTW : 6.34 %
Volume Highlights
Issue Index Shares
Traded
Notes
BNS.PR.Z FixedReset 218,179 Scotia crossed 100,000 at 19.06. RBC crossed 50,000 at the same price.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.85
Bid-YTW : 7.11 %
BNS.PR.L Deemed-Retractible 209,671 RBC crossed 192,000 at 24.54.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.46
Bid-YTW : 4.90 %
MFC.PR.I FixedReset 103,000 Nesbitt crossed 100,000 at 19.93.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.65
Bid-YTW : 7.00 %
RY.PR.C Deemed-Retractible 73,612 RBC crossed 50,000 at 24.89, then bought 13,900 at the same price from TD.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.83
Bid-YTW : 4.87 %
TD.PF.C FixedReset 55,135 Scotia crossed 40,000 at 17.50.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 17.27
Evaluated at bid price : 17.27
Bid-YTW : 4.47 %
BMO.PR.T FixedReset 51,827 TD crossed 25,700 at 17.80.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 17.51
Evaluated at bid price : 17.51
Bid-YTW : 4.47 %
There were 42 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BNS.PR.R FixedReset Quote: 23.52 – 24.49
Spot Rate : 0.9700
Average : 0.5572

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.52
Bid-YTW : 4.32 %

BMO.PR.M FixedReset Quote: 23.25 – 24.00
Spot Rate : 0.7500
Average : 0.4770

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.25
Bid-YTW : 4.21 %

CIU.PR.C FixedReset Quote: 11.65 – 12.90
Spot Rate : 1.2500
Average : 0.9946

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 11.65
Evaluated at bid price : 11.65
Bid-YTW : 4.43 %

TRP.PR.A FixedReset Quote: 14.56 – 15.24
Spot Rate : 0.6800
Average : 0.4286

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 14.56
Evaluated at bid price : 14.56
Bid-YTW : 4.70 %

HSE.PR.C FixedReset Quote: 16.79 – 17.50
Spot Rate : 0.7100
Average : 0.4596

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-11
Maturity Price : 16.79
Evaluated at bid price : 16.79
Bid-YTW : 5.94 %

TD.PR.T FloatingReset Quote: 21.40 – 22.04
Spot Rate : 0.6400
Average : 0.4292

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.40
Bid-YTW : 4.71 %

Market Action

January 8, 2016

Jobs, jobs, jobs!

Employers in December added 292,000 workers, exceeding the highest estimate in a Bloomberg survey, and payrolls for the previous two months were revised higher, a Labor Department report showed on Friday. The jobless rate held at 5 percent as people entering the labor force found work. At the same time, worker pay disappointed, rising less than forecast from a year earlier.
…
Labor Department revisions to prior reports added a total of 50,000 jobs to payrolls in November and October. For all of 2015, employment climbed by 2.65 million after a 3.1 million gain in 2014, for the best back-to-back years since 1998-99.
…
While employers continue to aggressively add to headcounts, worker pay has yet to show a sustainable pickup. Average hourly earnings in December were unchanged from the prior month and increased 2.5 percent from a year earlier. The median forecast called for a 2.7 percent year-over-year gain.
…
Among measures of labor-market slack, the number of Americans who are working part time though would rather have a full time position, or the measure known as part-time for economic reasons, eased to 6.02 million from 6.09 million.

The underemployment rate — which includes part-time workers who’d prefer a full-time position and people who want to work but have given up looking — held at 9.9 percent.
…
Hiring gains last month were broad-based, with construction adding 45,000 jobs, health-care providers taking on 52,600 and temporary help services boosting headcounts by 34,400. Factories even added the most jobs — 8,000 — in five months.

There will even be job openings for Secret Policemen and government propagandists!

The Obama administration on Friday asked some of the nation’s biggest technology companies for help in the fight against terrorism as it announced steps to thwart the recruitment and radicalization of extremists.

Top administration officials met in San Jose, California with representatives of Twitter Inc., Apple Inc., Facebook Inc. and other Silicon Valley companies. In a seven-page memo sent in advance, the companies were asked for ideas on how extremist content online can be identified and removed, as well as help creating alternative messages, according to excerpts of the document obtained and described to Bloomberg News.

“We are interested in exploring all options with you for how to deal with the growing threat of terrorists and other malicious actors using technology,” the memo said. “Are there high-level principles we could agree on for working through these problems together? And are there technologies that could make it harder for terrorists to use the Internet to mobilize, facilitate, and operationalize?”

Meanwhile, Canadians got government work:

Canada added 23,000 jobs in December, surpassing expectations due to gains in self-employment, health care and education.

December’s gains helped reverse huge election-related job declines in November and capped a tumultuous year for job creation. The country added a total of 158,000 jobs in 2015, an increase of 0.9 per cent over the previous year, despite mass layoffs in the energy sector.
…
Hiring in the private sector was flat compared with the previous year while the public sector added 41,000 new jobs, an increase of 1.1 per cent, and self-employment grew by 92,000 jobs, or 3.4 per cent.

But soon we’ll be able to beg tourists for American dollars!

Toronto has made it onto the New York Times’s list of 52 top global tourist destinations for 2016, at No. 7.

I want to see the sights of 10-15 years ago again … walk around downtown, see a tour bus on every corner, theatre industry booming … who knows, maybe they’ll even start up a Toronto-Rochester catamaran!

But anyway, despite the encouraging job news, equities fell:

U.S. stocks tumbled in a late-afternoon selloff that sent major equity indexes to their worst weekly declines in more than four years, as investors found little relief in moves by China to restore calm to its sinking markets and data that showed resilience in the U.S labor market.
…
The S&P 500 dropped 1.1 percent to 1,922.03 at 4 p.m. in New York, and fell 6 percent for the week. The Dow Jones Industrial Average sank 167.65 points, or 1 percent, to 16,346.45. The index lost more than 1,000 points this week in its worst opening five-days to a year ever. The Nasdaq Composite Index declined 1 percent, stretching its losing streak to seven days, the longest since 2011.
…
The S&P 500 has fallen 7.3 percent since the Federal Reserve raised interest rates last month for the first time in nearly a decade. The central bank balked at boosting borrowing costs in September in part due to turbulence sparked by China’s August currency devaluation. The poor start to 2016 has left the benchmark index 9.8 percent below its all-time high set in May after coming within 1 percent of the record as recently as November. It’s 2.9 percent above the August bottom.

And now there are calls for fiscal stimulus:

[Central Banks] have only themselves to blame for becoming agents of volatility, according to Christopher Walen, senior managing director at Kroll Bond Rating Agency Inc.

He told Bloomberg Television this week that officials’ willingness to keep interest rates near zero and repeatedly buy bonds and other assets meant they became “way too involved in the global economy” and should have left more of the lifting work to governments.

The handover to looser fiscal policy now needs to happen if economic growth and inflation are to get the spur they need, said Martin Malone, global macro policy strategist at London-based brokerage Mint Partners.

“Major economies have exhausted monetary and foreign-exchange policies,” he said. “Government action must take over from central-bank policies, triggering more confident private-sector investment and spending.”

The influence of central bankers was underscored by a report this week from currency strategists at HSBC Holdings Plc, which calculated foreign-exchange markets are more sensitive to interest-rate decision-making than at any time in the last 15 years.

But it will take a long time for the Fed to shrink its balance sheet:

It will take the U.S. central bank at least six years to reduce its bloated balance sheet back to more a normal size, San Francisco Federal Reserve Bank President John Williamssaid, as officials take a gradual approach to withdrawing crisis-level stimulus.

“Our plan is to shrink the balance sheet ‘organically,’ if you will, through the maturation of the assets,” Williams said in the text of remarks Friday in Santa Barbara, California. “It’s likely going to take at least six years to get the balance sheet back to normal, which is in keeping with the overall approach to removing accommodation gradually.”

The Federal Reserve is slowly weaning the economy off of ultra-easy monetary policy that saw it hold interest rates near zero for seven years and balloon the balance sheet to around $4.5 trillion through three rounds of buying mainly Treasuries and mortgage-backed securities. Officials took a major step in December, raising interest rates for the first time since 2006, and said they’ll wait until the process of policy normalization is well under way before beginning to allow excess balance-sheet holdings to roll off.

“The Fed has started the process of raising interest rates, but the path to normal will be gradual,” Williams said Friday.

Dividend Split Corp. II, proud issuer of DF.PR.A has been confirmed at Pfd-3(Low) by DBRS:

DBRS Limited (DBRS) has today confirmed the rating of the Preferred Shares issued by Dividend 15 Split Corp. II (the Company) at Pfd-3 (low). In November and December of 2006, the Company issued 5.6 million Preferred Shares (at $10.00 each) and an equal number of Class A Shares (at $15.00 each). The final redemption date for both classes of shares issued is December 1, 2019 (extended from December 1, 2014, at a special meeting of shareholders on June 3, 2013).
…
Holders of the Class A Shares receive regular monthly cash dividends targeted to be $0.10 per Class A Share to yield 8% per annum on the issue price of $15.00. No monthly distributions to the Class A Shares are made if the dividends of the Preferred Shares are in arrears or the NAV of the Company falls below 1.5 times the principal amount of the outstanding Preferred Shares. Furthermore, no special distributions are made if the NAV of the Company is below $25.00. The NAV as of December 15, 2015, was $14.52, resulting in no distributions paid to the Class A Shares for December 31, 2015. On maturity, the holders of the Preferred Shares will be entitled to the value of the Company, up to the face value of the Preferred Shares, in priority to the holders of the Class A Shares. Holders of the Class A Shares will receive all remaining value of the Company.

The confirmation of the Pfd-3 (low) rating of the Preferred Shares is based primarily on the downside protection available and the additional protection provided by the asset coverage test, which does not permit any distributions to holders of the Class A Shares if the NAV of the Company falls below $15.00.

The year-end NAVPU for DF.PR.A was 14.51; the sort-of comparable, XDV is down about 4% since then.

But for now, Canadian preferred share investors can look forward to two days with no losses!

Mr__Miserable
Click for Big

It was another horrid day for Canadian preferred share investors, with PerpetualDiscounts down 32bp, FixedResets losing 84bp and DeemedRetractibles off 27bp. The Performance Highlights table is lengthy. Volume was very low.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_160108
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 18.30 to be $1.15 rich, while TRP.PR.C, resetting 2016-1-30 at +154, is $1.44 cheap at its bid price of 11.20.

impVol_MFC_160108
Click for Big

Most expensive is MFC.PR.M, resetting at +236bp on 2019-12-19, bid at 18.98 to be 0.56 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 19.34 to be 1.03 cheap.

impVol_BAM_160108
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 15.18 to be $1.10 cheap. BAM.PF.E, resetting at +255bp on 2020-3-31 is bid at 18.34 and appears to be $0.69 rich.

impVol_FTS_160108
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 17.78, looks $0.69 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 17.05 and is $0.48 cheap.

pairs_FR_160108
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -1.27%, with three outliers below -2.00%. There is one junk outlier below -2.00% and three above 0.00%.

pairs_FF_160108
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

But now … on to PrefLetter.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 4.76 % 5.77 % 26,798 16.93 1 1.7857 % 1,633.9
FixedFloater 7.32 % 6.50 % 32,713 15.58 1 -6.7529 % 2,666.4
Floater 4.29 % 4.49 % 80,694 16.47 4 0.0454 % 1,781.5
OpRet 0.00 % 0.00 % 0 0.00 0 0.0069 % 2,735.7
SplitShare 4.83 % 5.77 % 71,882 1.81 6 0.0069 % 3,201.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0069 % 2,497.8
Perpetual-Premium 5.87 % 5.66 % 86,132 2.73 6 -0.0067 % 2,515.4
Perpetual-Discount 5.72 % 5.79 % 94,230 14.23 34 -0.3168 % 2,520.5
FixedReset 5.33 % 4.63 % 239,519 14.87 81 -0.8361 % 1,935.3
Deemed-Retractible 5.27 % 5.15 % 121,027 5.28 34 -0.2747 % 2,552.5
FloatingReset 2.87 % 4.64 % 63,131 5.62 13 -1.3458 % 2,057.0
Performance Highlights
Issue Index Change Notes
BAM.PR.G FixedFloater -6.75 % Just more nonsense from Nonsense Central. The issue traded 2,000 shares in a range of 13.75-35 before closing at 12.98-14.35, 3×4; this is particularly ridiculous in light of the fact that according to TMX figures, BAM.PR.E, this issue’s Strong Pair, had a very good day. I have not checked whether this lamentable state of affairs is due to inadequate Toronto Stock Exchange reporting or inadequate Toronto Stock Exchange supervision of market-makers.

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 25.00
Evaluated at bid price : 12.98
Bid-YTW : 6.50 %

BAM.PF.G FixedReset -4.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 19.52
Evaluated at bid price : 19.52
Bid-YTW : 4.82 %
RY.PR.K FloatingReset -4.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.35
Bid-YTW : 5.21 %
MFC.PR.G FixedReset -3.78 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.34
Bid-YTW : 7.15 %
TRP.PR.F FloatingReset -3.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 12.75
Evaluated at bid price : 12.75
Bid-YTW : 4.64 %
CIU.PR.C FixedReset -3.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 11.91
Evaluated at bid price : 11.91
Bid-YTW : 4.33 %
CU.PR.C FixedReset -3.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 17.25
Evaluated at bid price : 17.25
Bid-YTW : 4.58 %
BAM.PF.B FixedReset -3.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 18.10
Evaluated at bid price : 18.10
Bid-YTW : 4.79 %
BMO.PR.T FixedReset -2.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 17.71
Evaluated at bid price : 17.71
Bid-YTW : 4.41 %
SLF.PR.I FixedReset -2.58 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.52
Bid-YTW : 7.52 %
BAM.PF.A FixedReset -2.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 19.50
Evaluated at bid price : 19.50
Bid-YTW : 4.76 %
MFC.PR.N FixedReset -2.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.61
Bid-YTW : 7.38 %
MFC.PR.M FixedReset -2.32 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.98
Bid-YTW : 7.17 %
BAM.PR.Z FixedReset -2.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 19.16
Evaluated at bid price : 19.16
Bid-YTW : 4.91 %
FTS.PR.H FixedReset -2.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 13.51
Evaluated at bid price : 13.51
Bid-YTW : 4.10 %
MFC.PR.I FixedReset -2.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.07
Bid-YTW : 6.70 %
PWF.PR.L Perpetual-Discount -1.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 21.48
Evaluated at bid price : 21.74
Bid-YTW : 5.87 %
BAM.PF.E FixedReset -1.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 18.34
Evaluated at bid price : 18.34
Bid-YTW : 4.77 %
BIP.PR.A FixedReset -1.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 18.88
Evaluated at bid price : 18.88
Bid-YTW : 5.72 %
SLF.PR.J FloatingReset -1.90 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.90
Bid-YTW : 10.15 %
CIU.PR.A Perpetual-Discount -1.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 20.29
Evaluated at bid price : 20.29
Bid-YTW : 5.75 %
BAM.PF.F FixedReset -1.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 19.88
Evaluated at bid price : 19.88
Bid-YTW : 4.70 %
PWF.PR.A Floater -1.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 12.38
Evaluated at bid price : 12.38
Bid-YTW : 3.86 %
BAM.PR.T FixedReset -1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 15.92
Evaluated at bid price : 15.92
Bid-YTW : 4.83 %
TD.PF.C FixedReset -1.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 17.62
Evaluated at bid price : 17.62
Bid-YTW : 4.37 %
HSE.PR.A FixedReset -1.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 11.12
Evaluated at bid price : 11.12
Bid-YTW : 5.40 %
TD.PF.E FixedReset -1.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 20.12
Evaluated at bid price : 20.12
Bid-YTW : 4.44 %
IAG.PR.G FixedReset -1.55 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.74
Bid-YTW : 6.84 %
BNS.PR.Q FixedReset -1.50 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.58
Bid-YTW : 4.00 %
TRP.PR.C FixedReset -1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 11.20
Evaluated at bid price : 11.20
Bid-YTW : 4.91 %
SLF.PR.H FixedReset -1.46 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.16
Bid-YTW : 8.66 %
TRP.PR.B FixedReset -1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 10.96
Evaluated at bid price : 10.96
Bid-YTW : 4.55 %
TRP.PR.D FixedReset -1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 17.31
Evaluated at bid price : 17.31
Bid-YTW : 4.63 %
GWO.PR.Q Deemed-Retractible -1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.50
Bid-YTW : 6.70 %
GWO.PR.R Deemed-Retractible -1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.11
Bid-YTW : 7.23 %
BNS.PR.R FixedReset -1.35 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.07
Bid-YTW : 3.88 %
SLF.PR.D Deemed-Retractible -1.35 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.80
Bid-YTW : 7.74 %
IAG.PR.A Deemed-Retractible -1.33 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.80
Bid-YTW : 7.21 %
TD.PF.A FixedReset -1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 17.99
Evaluated at bid price : 17.99
Bid-YTW : 4.30 %
BNS.PR.A FloatingReset -1.30 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.10
Bid-YTW : 4.59 %
POW.PR.B Perpetual-Discount -1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 22.66
Evaluated at bid price : 22.90
Bid-YTW : 5.86 %
TRP.PR.A FixedReset -1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 15.70
Evaluated at bid price : 15.70
Bid-YTW : 4.35 %
CU.PR.E Perpetual-Discount -1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 21.53
Evaluated at bid price : 21.53
Bid-YTW : 5.77 %
GWO.PR.I Deemed-Retractible -1.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.21
Bid-YTW : 7.51 %
RY.PR.M FixedReset -1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 4.47 %
BNS.PR.C FloatingReset -1.18 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.75
Bid-YTW : 4.70 %
CM.PR.P FixedReset -1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 17.67
Evaluated at bid price : 17.67
Bid-YTW : 4.37 %
TD.PR.T FloatingReset -1.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.70
Bid-YTW : 4.45 %
TRP.PR.E FixedReset -1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 18.30
Evaluated at bid price : 18.30
Bid-YTW : 4.44 %
TD.PF.D FixedReset -1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 19.29
Evaluated at bid price : 19.29
Bid-YTW : 4.52 %
BAM.PR.R FixedReset -1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 15.18
Evaluated at bid price : 15.18
Bid-YTW : 4.96 %
TD.PR.Z FloatingReset -1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.60
Bid-YTW : 4.62 %
SLF.PR.C Deemed-Retractible -1.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.04
Bid-YTW : 7.57 %
GWO.PR.P Deemed-Retractible -1.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.70
Bid-YTW : 6.22 %
SLF.PR.B Deemed-Retractible -1.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.17
Bid-YTW : 7.19 %
SLF.PR.A Deemed-Retractible -1.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.18
Bid-YTW : 7.12 %
PWF.PR.E Perpetual-Discount -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 23.17
Evaluated at bid price : 23.47
Bid-YTW : 5.86 %
TRP.PR.G FixedReset -1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 19.55
Evaluated at bid price : 19.55
Bid-YTW : 4.74 %
CU.PR.D Perpetual-Discount -1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 21.55
Evaluated at bid price : 21.55
Bid-YTW : 5.77 %
HSE.PR.C FixedReset -1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 17.70
Evaluated at bid price : 17.70
Bid-YTW : 5.62 %
PWF.PR.T FixedReset 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 21.25
Evaluated at bid price : 21.25
Bid-YTW : 3.76 %
IFC.PR.C FixedReset 1.44 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.30
Bid-YTW : 7.56 %
BNS.PR.N Deemed-Retractible 1.52 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-02-26
Maturity Price : 25.25
Evaluated at bid price : 25.45
Bid-YTW : -3.21 %
BAM.PR.E Ratchet 1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 25.00
Evaluated at bid price : 14.25
Bid-YTW : 5.77 %
VNR.PR.A FixedReset 3.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 18.15
Evaluated at bid price : 18.15
Bid-YTW : 4.91 %
Volume Highlights
Issue Index Shares
Traded
Notes
BNS.PR.M Deemed-Retractible 115,800 RBC crossed 98,000 at 24.60.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.50
Bid-YTW : 4.86 %
RY.PR.Q FixedReset 84,345 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-24
Maturity Price : 25.00
Evaluated at bid price : 25.65
Bid-YTW : 5.04 %
BNS.PR.L Deemed-Retractible 74,544 RBC bought 20,000 from Nesbitt at 24.50, then another 27,500 at 24.52.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.50
Bid-YTW : 4.86 %
NA.PR.Q FixedReset 65,285 RBC crossed 40,000 at 24.23.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.03
Bid-YTW : 3.98 %
FTS.PR.J Perpetual-Discount 44,500 Desjardins crossed 40,000 at 21.80.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 21.47
Evaluated at bid price : 21.80
Bid-YTW : 5.50 %
TD.PF.B FixedReset 38,613 Scotia crossed 25,000 at 18.25.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 17.95
Evaluated at bid price : 17.95
Bid-YTW : 4.30 %
There were 14 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BAM.PR.G FixedFloater Quote: 12.98 – 14.35
Spot Rate : 1.3700
Average : 0.8740

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 25.00
Evaluated at bid price : 12.98
Bid-YTW : 6.50 %

TRP.PR.F FloatingReset Quote: 12.75 – 13.59
Spot Rate : 0.8400
Average : 0.5329

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 12.75
Evaluated at bid price : 12.75
Bid-YTW : 4.64 %

FTS.PR.M FixedReset Quote: 19.15 – 19.97
Spot Rate : 0.8200
Average : 0.5229

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 19.15
Evaluated at bid price : 19.15
Bid-YTW : 4.40 %

RY.PR.K FloatingReset Quote: 21.35 – 22.13
Spot Rate : 0.7800
Average : 0.5004

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.35
Bid-YTW : 5.21 %

MFC.PR.G FixedReset Quote: 19.34 – 19.90
Spot Rate : 0.5600
Average : 0.3467

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.34
Bid-YTW : 7.15 %

CIU.PR.C FixedReset Quote: 11.91 – 12.82
Spot Rate : 0.9100
Average : 0.7146

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-08
Maturity Price : 11.91
Evaluated at bid price : 11.91
Bid-YTW : 4.33 %

Market Action

January 7, 2016

Here’s to the new feds, just like the old feds:

If you closed your eyes, you could almost imagine Stephen Harper is still prime minister.

Progressive voters who hoped Justin Trudeau would abruptly shift the federal government to the left once he became Prime Minister must be in despair as the new regime announces one conservative-friendly policy after another – further proof that when it comes to the really big decisions, the imperative of protecting jobs and the economy trumps human rights, the environment and other concerns in these difficult days.

For the umpteenth time, the Liberals campaigned from the left and now are governing from the centre-right. Only those born yesterday will be surprised by this.
…
The Liberals have taken a few token progressive steps: appointing women to half the posts in cabinet, restoring the long-form census, cancelling an ugly and intrusive monument to the victims of communism – that sort of on-the-margins thing. But on the big stuff, everyone is a Conservative, especially the Liberals.

It is my theory that on big, highly visible policy issues, you are actually more likely to get the right thing done if you have a government that – in theory – opposes the policy. For instance, consider the nineties when Chretien and Martin hacked away the deficit and got federal finances on an even keel. They did the right thing; many of their supporters criticized them harshly for this, but I suggest that a Conservative government at that time would not have been anywhere near so decisive.

If the Conservatives had done it, it would have reinforced every stereotype in the book; they would have cemented a reputation as the heartless party of Big Business only and would still be feeling that pain … in much the same way as the Ontario Progressive Conservatives are still losing votes because of Mike Harris’ ‘Common Sense Revolution’.

But when the Liberals do it … people first think that what the government is doing is awful … then they remember that it goes against party stereotypes to some degree … and then they decide that the situation must be really serious and the actions really necessary if the party is going against the grain. The Liberals have more political room to impose austerity; the Conservatives have more political room to run deficits totalling $127-billion.

And in the last campaign, the NDP couldn’t promise deficit-financed infrastructure spending; that would have reinforced their stereotype. The Liberals could.

So anyway, it was a cruddy day for equities:

The Standard & Poor’s 500 Index capped its worst-ever four-day start to a year, while gold rallied with the yen as turmoil in China spread around the world and billionaire George Soros warned that a larger crisis may be brewing.

The U.S. equities benchmark ended the first four days of 2016 lower by 4.9 percent, while the Dow Jones Industrial Average has erased more than 900 points so far this year. A measure of global shares wrapped up a four-day slide of 5.2 percent, its worst start in records back to 1998. Selling in global equities began in China after the central bank weakened the yuan an eighth day. Crude settled at a 12-year low, and copper dipped below $2 for the first time since 2009. The yen reached a four-month high.
…
The Standard & Poor’s 500 Index slid 2.4 percent at 4:15 p.m in New York. The index is down 4.9 percent this year, its worst start in data going back to 1928. The MSCI All-Country World Index fell for a fourth day, bringing its slide this year to 5.2 percent.

And pundits are dividing blame between Chinese retail investors …:

The globe-spanning stampede is vast and complicated, as hedge-fund managers, currency specialists and oil traders from Bangkok to Frankfurt weigh everything from rising U.S. interest rates to overflowing crude-oil storage tanks and a rising belief that China’s economic slowdown is more severe than once thought, and getting worse.

But at the head of the stampede is a cavalcade of largely unsophisticated Chinese investors who live in a country that has made gambling illegal but turned its stock markets into the world’s largest casino. This is not a small group, numbering nearly three times the population of Canada, but they are among the most active retail traders on Earth – and they’re playing roulette at a table where everyone is whispering that it’s time to bet on red.

… and ham-fisted Chinese regulators:

After watching a stock-market collapse wipe out $5 trillion of wealth in less than three months last year, Chinese authorities hatched a plan to stem the pain: circuit breakers that would be triggered by daily declines of 5 percent.

The new system went into effect Jan. 4. It lasted all of four days. After two harrowing sessions — on Monday and Thursday — that tripped the breaker repeatedly and convulsed global markets, officials suspended the rule, saying it was only exacerbating declines. While that acknowledgment addresses critics’ concerns, the flip-flop at the same time only adds to the sentiment among global investors that authorities are improvising — and improvising poorly — as they try to stabilize markets and shore up the economy.
…
On the currency front, policy makers have pledged to keep the yuan stable, drawing down a record $108 billion from foreign reserves last month to prop it up. At the same time, the People’s Bank of China set its reference rate at unexpectedly weak levels this week, raising speculation that it’s more tolerant of depreciation to spur exports.

“The more alarming thing is that they weakened the currency after saying they wouldn’t,” said Patrick Chovanec, New York-based chief strategist at Silvercrest Asset Management Group. “So that raises all these issues of mixed signals, confusion. It is very unclear what the policy is, whether they know what the policy is, whether they know how to implement the policy.”
…
Chinese regulators moved to control the damage earlier Thursday, imposing a new limit on the amount of stock that major corporate shareholders can sell. That followed intervention by government funds to prop up shares on Tuesday, according to people familiar with the matter.

The Chinese circuit-breakers have attracted high-level criticism:

“They’re just on the wrong track,” said Nicholas Brady, 85, the former U.S. Treasury secretary who ran a committee that recommended the curbs on equity trading after the 1987 crash. “They need a set of circuit breakers that appropriately reflects their market.”

Brady spoke Thursday after Chinese regulators suspended their newly introduced program that ends stock trading for the entire day after a 7 percent plunge. The halt was set off twice in its first week of operation, bolstering speculation China set its threshold too low.
…
“I don’t think this is an exact science,” said Sang Lee, an analyst at financial-markets researcher Aite Group. With circuit breakers, “If you set these too low, instead of easing volatility it may increase volatility.”

That echoes the view of Brady, who was chairman of Wall Street powerhouse Dillon Read & Co. when President Ronald Reagan asked him to figure out what happened during the 1987 crash and propose solutions.

Meanwhile, Adam Haigh on Bloomberg reminds us there’s still lots of arbitrary rules to restrict Chinese markets:

A 10 percent daily limit on single stock moves and a rule preventing investors from buying and selling the same shares in a day remain in force. Volume in what was once the world’s most active index futures market is minimal after authorities curtailed trading amid a summer rout, making it more difficult to implement hedging strategies. Officials unveiled curbs Thursday on share sales by major stockholders just a day before an existing ban was due to expire. And the activity of foreign investors is limited by quotas, given either to asset managers or to users of the Hong Kong-Shanghai exchange link.
…
There’s also the prospect that regulators and executives will dust off last year’s playbook as they seek to stem losses. At the height of the summer rout, about half of China’s listed companies were halted, while officials investigated trading strategies, made it harder for investors to borrow money to buy equities and vowed to “purify” the market.

Meanwhile, Poloz has a new script from his new masters:

Bank of Canada governor Stephen Poloz is encouraging the Liberal government to act on promised infrastructure spending, acknowledging there are limits to what monetary policy can do to boost Canada’s sluggish economy.

Officials with Canada’s central bank are currently working with the Finance Department on economic models aimed at measuring the likely impact of promised government spending on infrastructure, as well as tax cuts that took effect this year.
…
Speaking to reporters in Ottawa, Mr. Poloz said the cheaper dollar alone is not enough to counter the shock from the commodities price slump. And he said the economy would benefit from some government fiscal policy.

“Infrastructure is an ingredient to economic growth. It’s sort of the enabler of economic growth,” he said.

Speaking of the Canadian dollar, I ran across the publication A History of the Canadian Dollar by James Powell and published by the Bank of Canada today. It’s ten years old now … it might need a new chapter! I’m too young to remember the hey-day of:

diefenbuck
Click for Big

… so I’ll have to find solace in boring the whippersnappers with tales of:

truedough
Click for Big

There’s a chance that PrefBlog won’t have John Nagel to kick around any more:

John Nagel, a fixture in the preferred share market for more than three decades, has retired from his post at Desjardins Securities.

But it’s not clear at this stage, whether Nagel who spent the past 13 plus years at Desjardins, has retired from the investment industry.

In a note to clients, Nagel – who first traded preferred shares while at Gardiner Watson in the mid-1980s – noted the firm had achieved a “great deal” since he arrived in June 2002. For instance the firm “established and earned a significant improvement in its syndication positions,” as well as hiring and training assistants and analysts “many of whom have continued on successfully in the financial services field.” In addition, Nagel’s team, that produced market commentary and market, improved the firm’s preferred trading and sales activities.
…
With Nagel’s retirement, the preferred share department will report to Mark Lucey, a managing director and head of equities and capital markets. Previously it reported to fixed income. Julian Pope, David Paul and Alex Somjen will now man the firm’s pref share group.

Meanwhile, in the Canadian preferred share market:

MarketSignal
Click for Big

It was an appalling day for the Canadian preferred share market, with PerpetualDiscounts down 101bp, FixedResets losing 136bp and DeemedRetractibles off 63bp. The Performance Highlights table is about as long as one might expect. Volume was well below average.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 4.85 % 5.88 % 27,752 16.80 1 -1.7544 % 1,605.2
FixedFloater 6.82 % 6.05 % 32,894 16.14 1 0.0000 % 2,859.5
Floater 4.29 % 4.53 % 81,017 16.40 4 -2.4801 % 1,780.7
OpRet 0.00 % 0.00 % 0 0.00 0 -0.3178 % 2,735.5
SplitShare 4.83 % 5.76 % 74,846 1.82 6 -0.3178 % 3,201.0
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.3178 % 2,497.6
Perpetual-Premium 5.87 % 3.79 % 84,250 0.09 6 -0.5644 % 2,515.6
Perpetual-Discount 5.71 % 5.75 % 94,652 14.31 34 -1.0117 % 2,528.5
FixedReset 5.29 % 4.64 % 243,586 14.80 81 -1.3646 % 1,951.6
Deemed-Retractible 5.26 % 5.23 % 121,283 5.28 34 -0.6262 % 2,559.5
FloatingReset 2.89 % 4.49 % 62,948 5.62 13 -0.5922 % 2,085.1
Performance Highlights
Issue Index Change Notes
VNR.PR.A FixedReset -7.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 17.62
Evaluated at bid price : 17.62
Bid-YTW : 5.13 %
PWF.PR.T FixedReset -5.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 21.02
Evaluated at bid price : 21.02
Bid-YTW : 3.87 %
HSE.PR.A FixedReset -4.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 11.31
Evaluated at bid price : 11.31
Bid-YTW : 5.44 %
SLF.PR.H FixedReset -4.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.40
Bid-YTW : 8.53 %
CCS.PR.C Deemed-Retractible -4.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.02
Bid-YTW : 6.84 %
BAM.PR.T FixedReset -3.97 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 16.21
Evaluated at bid price : 16.21
Bid-YTW : 4.83 %
BAM.PF.E FixedReset -3.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 18.70
Evaluated at bid price : 18.70
Bid-YTW : 4.74 %
BAM.PR.B Floater -3.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 10.50
Evaluated at bid price : 10.50
Bid-YTW : 4.53 %
BMO.PR.Q FixedReset -3.47 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.50
Bid-YTW : 6.64 %
MFC.PR.F FixedReset -3.43 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.78
Bid-YTW : 9.87 %
SLF.PR.J FloatingReset -3.31 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.15
Bid-YTW : 9.96 %
BAM.PR.X FixedReset -3.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 14.32
Evaluated at bid price : 14.32
Bid-YTW : 4.69 %
NA.PR.W FixedReset -3.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 17.40
Evaluated at bid price : 17.40
Bid-YTW : 4.54 %
FTS.PR.K FixedReset -3.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 17.79
Evaluated at bid price : 17.79
Bid-YTW : 4.21 %
BMO.PR.Y FixedReset -3.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 19.76
Evaluated at bid price : 19.76
Bid-YTW : 4.50 %
BAM.PR.C Floater -2.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 10.43
Evaluated at bid price : 10.43
Bid-YTW : 4.56 %
RY.PR.M FixedReset -2.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 19.23
Evaluated at bid price : 19.23
Bid-YTW : 4.48 %
BAM.PR.K Floater -2.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 10.50
Evaluated at bid price : 10.50
Bid-YTW : 4.53 %
BAM.PF.B FixedReset -2.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 18.66
Evaluated at bid price : 18.66
Bid-YTW : 4.71 %
MFC.PR.L FixedReset -2.53 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.12
Bid-YTW : 7.65 %
W.PR.J Perpetual-Discount -2.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 22.88
Evaluated at bid price : 23.15
Bid-YTW : 6.07 %
CM.PR.Q FixedReset -2.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 19.35
Evaluated at bid price : 19.35
Bid-YTW : 4.56 %
MFC.PR.K FixedReset -2.52 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.82
Bid-YTW : 7.77 %
BNS.PR.Z FixedReset -2.46 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.02
Bid-YTW : 7.00 %
FTS.PR.H FixedReset -2.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 13.81
Evaluated at bid price : 13.81
Bid-YTW : 4.09 %
RY.PR.J FixedReset -2.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 19.41
Evaluated at bid price : 19.41
Bid-YTW : 4.55 %
POW.PR.D Perpetual-Discount -2.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 21.66
Evaluated at bid price : 21.91
Bid-YTW : 5.72 %
POW.PR.G Perpetual-Discount -2.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 23.53
Evaluated at bid price : 24.00
Bid-YTW : 5.84 %
BAM.PF.G FixedReset -2.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 20.35
Evaluated at bid price : 20.35
Bid-YTW : 4.67 %
MFC.PR.I FixedReset -2.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.50
Bid-YTW : 6.46 %
MFC.PR.H FixedReset -2.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.35
Bid-YTW : 6.14 %
NA.PR.S FixedReset -1.97 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 17.95
Evaluated at bid price : 17.95
Bid-YTW : 4.57 %
BAM.PF.A FixedReset -1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 4.71 %
TRP.PR.D FixedReset -1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 17.55
Evaluated at bid price : 17.55
Bid-YTW : 4.64 %
BAM.PR.R FixedReset -1.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 15.35
Evaluated at bid price : 15.35
Bid-YTW : 5.00 %
PWF.PR.R Perpetual-Discount -1.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 23.17
Evaluated at bid price : 23.60
Bid-YTW : 5.82 %
MFC.PR.G FixedReset -1.86 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.10
Bid-YTW : 6.68 %
TRP.PR.F FloatingReset -1.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 13.25
Evaluated at bid price : 13.25
Bid-YTW : 4.54 %
SLF.PR.G FixedReset -1.78 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.36
Bid-YTW : 9.29 %
GWO.PR.N FixedReset -1.77 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.31
Bid-YTW : 10.16 %
MFC.PR.J FixedReset -1.77 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.45
Bid-YTW : 6.91 %
BAM.PR.E Ratchet -1.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 25.00
Evaluated at bid price : 14.00
Bid-YTW : 5.88 %
MFC.PR.C Deemed-Retractible -1.70 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.25
Bid-YTW : 7.50 %
PWF.PR.K Perpetual-Discount -1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 21.49
Evaluated at bid price : 21.49
Bid-YTW : 5.77 %
PWF.PR.H Perpetual-Premium -1.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 24.22
Evaluated at bid price : 24.51
Bid-YTW : 5.87 %
W.PR.H Perpetual-Discount -1.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 22.71
Evaluated at bid price : 23.00
Bid-YTW : 6.00 %
BNS.PR.N Deemed-Retractible -1.53 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-01-27
Maturity Price : 25.00
Evaluated at bid price : 25.07
Bid-YTW : 4.66 %
MFC.PR.B Deemed-Retractible -1.52 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.75
Bid-YTW : 7.33 %
BAM.PF.F FixedReset -1.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 20.25
Evaluated at bid price : 20.25
Bid-YTW : 4.67 %
SLF.PR.I FixedReset -1.50 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.01
Bid-YTW : 7.22 %
TD.PF.E FixedReset -1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 20.45
Evaluated at bid price : 20.45
Bid-YTW : 4.42 %
BMO.PR.Z Perpetual-Discount -1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 22.84
Evaluated at bid price : 23.23
Bid-YTW : 5.44 %
PWF.PR.P FixedReset -1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 13.30
Evaluated at bid price : 13.30
Bid-YTW : 4.36 %
CM.PR.O FixedReset -1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 18.35
Evaluated at bid price : 18.35
Bid-YTW : 4.37 %
TD.PF.D FixedReset -1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 19.51
Evaluated at bid price : 19.51
Bid-YTW : 4.52 %
CU.PR.G Perpetual-Discount -1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 20.25
Evaluated at bid price : 20.25
Bid-YTW : 5.63 %
FTS.PR.G FixedReset -1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 17.06
Evaluated at bid price : 17.06
Bid-YTW : 4.43 %
ELF.PR.F Perpetual-Discount -1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 22.44
Evaluated at bid price : 22.70
Bid-YTW : 5.85 %
TD.PR.Y FixedReset -1.33 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.68
Bid-YTW : 3.92 %
TRP.PR.H FloatingReset -1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 9.71
Evaluated at bid price : 9.71
Bid-YTW : 4.53 %
SLF.PR.E Deemed-Retractible -1.32 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.26
Bid-YTW : 7.47 %
MFC.PR.N FixedReset -1.29 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.06
Bid-YTW : 7.08 %
FTS.PR.M FixedReset -1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 19.15
Evaluated at bid price : 19.15
Bid-YTW : 4.46 %
IFC.PR.A FixedReset -1.29 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.35
Bid-YTW : 9.35 %
MFC.PR.M FixedReset -1.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.43
Bid-YTW : 6.88 %
ELF.PR.G Perpetual-Discount -1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 21.00
Evaluated at bid price : 21.00
Bid-YTW : 5.68 %
CU.PR.F Perpetual-Discount -1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 20.25
Evaluated at bid price : 20.25
Bid-YTW : 5.63 %
CM.PR.P FixedReset -1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 17.88
Evaluated at bid price : 17.88
Bid-YTW : 4.38 %
BNS.PR.C FloatingReset -1.21 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.01
Bid-YTW : 4.52 %
RY.PR.H FixedReset -1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 18.16
Evaluated at bid price : 18.16
Bid-YTW : 4.39 %
RY.PR.I FixedReset -1.18 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.44
Bid-YTW : 4.39 %
BAM.PR.Z FixedReset -1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 19.61
Evaluated at bid price : 19.61
Bid-YTW : 4.87 %
CU.PR.D Perpetual-Discount -1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 21.45
Evaluated at bid price : 21.77
Bid-YTW : 5.69 %
GWO.PR.S Deemed-Retractible -1.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.12
Bid-YTW : 5.81 %
CU.PR.H Perpetual-Discount -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 23.15
Evaluated at bid price : 23.45
Bid-YTW : 5.66 %
POW.PR.A Perpetual-Discount -1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 23.96
Evaluated at bid price : 24.21
Bid-YTW : 5.80 %
PWF.PR.A Floater -1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 12.61
Evaluated at bid price : 12.61
Bid-YTW : 3.78 %
FTS.PR.J Perpetual-Discount -1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 21.45
Evaluated at bid price : 21.78
Bid-YTW : 5.51 %
HSE.PR.C FixedReset 1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 17.88
Evaluated at bid price : 17.88
Bid-YTW : 5.63 %
BNS.PR.D FloatingReset 1.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.24
Bid-YTW : 6.95 %
HSE.PR.G FixedReset 1.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 18.70
Evaluated at bid price : 18.70
Bid-YTW : 5.84 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.Q FixedReset 162,764 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-24
Maturity Price : 25.00
Evaluated at bid price : 25.64
Bid-YTW : 5.05 %
TRP.PR.H FloatingReset 110,400 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 9.71
Evaluated at bid price : 9.71
Bid-YTW : 4.53 %
TRP.PR.F FloatingReset 106,435 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 13.25
Evaluated at bid price : 13.25
Bid-YTW : 4.54 %
MFC.PR.F FixedReset 105,420 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.78
Bid-YTW : 9.87 %
BNS.PR.E FixedReset 102,593 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-25
Maturity Price : 25.00
Evaluated at bid price : 25.72
Bid-YTW : 4.97 %
SLF.PR.I FixedReset 74,345 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.01
Bid-YTW : 7.22 %
There were 21 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
VNR.PR.A FixedReset Quote: 17.62 – 18.91
Spot Rate : 1.2900
Average : 0.8588

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 17.62
Evaluated at bid price : 17.62
Bid-YTW : 5.13 %

CCS.PR.C Deemed-Retractible Quote: 22.02 – 22.75
Spot Rate : 0.7300
Average : 0.4943

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.02
Bid-YTW : 6.84 %

POW.PR.G Perpetual-Discount Quote: 24.00 – 24.50
Spot Rate : 0.5000
Average : 0.3265

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 23.53
Evaluated at bid price : 24.00
Bid-YTW : 5.84 %

PWF.PR.T FixedReset Quote: 21.02 – 22.00
Spot Rate : 0.9800
Average : 0.8083

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 21.02
Evaluated at bid price : 21.02
Bid-YTW : 3.87 %

CU.PR.G Perpetual-Discount Quote: 20.25 – 20.70
Spot Rate : 0.4500
Average : 0.2944

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 20.25
Evaluated at bid price : 20.25
Bid-YTW : 5.63 %

RY.PR.O Perpetual-Discount Quote: 22.60 – 22.97
Spot Rate : 0.3700
Average : 0.2234

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-07
Maturity Price : 22.31
Evaluated at bid price : 22.60
Bid-YTW : 5.48 %

Market Action

January 6, 2016

Well, it was a pretty lousy day for equities:

Global equities capped their worst start to a year since 2000, with the Dow Jones Industrial Average sliding more than 250 points, as China unexpectedly weakening its currency fueled fresh concern over the strength of the world economy. Bonds gained.

The MSCI All-Country World Index ended the first three days of 2016 down by 3.3 percent, as U.S. stocks fell to a three-month low and emerging-market shares dropped to their cheapest level since 2009. Brent crude plunged to its lowest point since 2004, while U.S. oil spiked below $34 a barrel as supplies at a hub rose to a record. The dollar pared gains after minutes of the Federal Reserve’s last meeting were released. Treasuries jumped, with yields on 10-year notes dropping seven basis points to 2.17 percent.
…
China’s growing tolerance for a weaker yuan signaled the government is struggling in its efforts to shore up economic growth and rekindled concern last seen in August, when U.S. stocks entered their first correction in four years amid anxiety the slowdown in China would hamper global growth. U.S. crude’s plunge toward $34 a barrel heightened disinflation fears as investors assess the ability of central banks to meet policy goals. The World Bank cut its global growth forecasts for this year and next as markets closed.

… and this had an effect on the loonie …

But on Wednesday, Canada’s benchmark heavy crude price was hit hard again, falling below $20 (U.S.) a barrel for the first time since record-keeping for that grade began seven years ago. It fell in concert with global crude prices such as the international benchmark Brent, which sank to its lowest since 2004.

That helped pull the loonie down half a cent to less than 71 cents. The Canadian currency has been hit by the oil shock, poor prospects for domestic economic growth and the different paths on interest rates being taken by the U.S. Federal Reserve Board and the Bank of Canada.

The Canadian dollar, which sank 16 per cent last year, has now reached depths last seen in August, 2003, and further weakening is possible. That spells more worries for importers as well as travellers heading to the United States.

Meanwhile, the S&P/TSX composite index skidded 193 points to 12,726.80 in its third straight session of losses, pulled lower by energy shares such as Encana Corp. and Paramount Resources Ltd.

… and given the state of overnight markets:

The worst start for Chinese markets in two decades showed no signs of letting up after the central bank cut its yuan reference rate by the most since August, sparking a selloff in stocks that forced the $6.6 trillion market to shut early.

China’s CSI 300 Index plunged 7.2 percent before bourses were halted by circuit breakers in the first half hour of trading, while the onshore yuan weakened 0.6 percent versus the dollar to a five-year low. The People’s Bank of China cut its reference rate on Thursday for an eighth straight day, fueling concern that tepid economic growth is prompting authorities to guide the currency lower.

… it looks like tomorrow might be worse:

U.S. index futures sank after China’s weaker yuan fix spurred a rout in the nation’s equities that triggered a market-wide halt for the second time this week.

Contracts on the Standard & Poor’s 500 Index slid 1.7 percent to 1,953 as of 2:40 p.m. in Hong Kong. Those on the Dow Jones Industrial Average lost 1.6 percent after the gauge capped its worst three-day start to a year since 2008. Chinese stock exchanges closed less than half an hour after they opened as the CSI 300 Index plunged more than 7 percent, setting off a circuit-breaker mechanism.

Meanwhile Fischer is indicating a steady policy of Fed hikes:

Federal Reserve Vice Chairman Stanley Fischer said policy makers’ forecasts predicting four interest-rate increases in 2016 were “in the ballpark,” though China’s slowing economy and other sources of uncertainty make it difficult to predict the path of policy.

“The reason we meet eight times a year is because things happen, and as they happen you want to adjust your policy,” Fischer said in an interview Wednesday on CNBC.

Fischer’s remarks come three weeks after the Fed raised interest rates for the first time in almost a decade. Policy makers said at the time they would continue to monitor real and expected progress on inflation, which remains below their 2 percent target, as they contemplate when to raise again.

And a modest rise in Canadian mortgage rates has the chatteratti going wild!

There’s just one reason for the strength of Canada’s housing market – low, stable mortgage rates.

Rates are still low, but the stable part is in question after Royal Bank of Canada announced a small but still significant round of mortgage rate increases that will take effect Friday. Other banks will likely adjust rates as well, after a brief period of letting RBC draw fire as the first to move.

RBC will increase borrowing costs on special offers for fixed-rate mortgages with terms of two to five years by 0.1 of a percentage point.
…
Lenders are facing higher costs for financing mortgages as a result of new mortgage market rules introduced last year by federal regulators. As well, unsettled financial market conditions are forcing lenders to pay higher rates on the money they raise to lend out as mortgages.

Has anybody seen a lift in GIC rates lately?

TransCanada Corporation, proud issuer of TRP.PR.A, TRP.PR.B, TRP.PR.C, TRP.PR.D, TRP.PR.E, TRP.PR.F, TRP.PR.G and TRP.PR.H, has announced a NAFTA claim regarding the Keystone XL refusal:

TransCanada Corporation (TSX:TRP) (NYSE:TRP) (TransCanada) announced today it has filed a Notice of Intent to initiate a claim under Chapter 11 of the North American Free Trade Agreement (NAFTA) in response to the U.S. Administration’s decision to deny a Presidential Permit for the Keystone XL Pipeline on the basis that the denial was arbitrary and unjustified.

TransCanada also has filed a lawsuit in the U.S. Federal Court in Houston, Texas, asserting that the President’s decision to deny construction of Keystone XL exceeded his power under the U.S. Constitution.

Further, as a result of the permit denial, TransCanada is reviewing the approximate $4.3 billion (US$3.1 billion) carrying value invested in the project and related assets and expects that an estimated $2.5 to $2.9 billion after-tax write-down will be recorded in the company’s fourth quarter results.

DBRS says ‘no big deal’:

DBRS Limited (DBRS) notes that TransCanada Corporation (TCC, or the Company) announced today that it has filed a Notice of Intent to initiate a claim under Chapter 11 of the North American Free Trade Agreement (NAFTA) in response to the U.S. Administration’s decision to deny a Presidential border crossing permit for the Keystone XL pipeline project (KXL) on the basis that the denial was arbitrary and unjustified. Through the NAFTA claim, TCC will be seeking to recover more than USD 15 billion in costs and damages suffered by the Company as a result of the U.S. Administration’s breach of its NAFTA obligations. Concurrently, TCC has filed a lawsuit in the U.S. Federal Court in Houston, Texas, asserting that the President’s decision to deny construction of KXL exceeded his power under the U.S. Constitution.
…
Overall, DBRS views the impact of TCC’s legal actions to be credit neutral. DBRS had previously commented (Press release dated November 6, 2015) that it viewed the denial of the KXL permit as having no impact on the credit ratings of TCC, and its wholly owned subsidiaries (TransCanada PipeLines Limited and Nova Gas Transmission Limited). Today’s announcement does not impact the Company’s business risk profile as the current ratings reflect environmental, regulatory and political risks with respect to several of the Company’s development projects, including KXL. Furthermore, TCC expects the support for this energy infrastructure project from shippers, underpinned by long-term contracts, to continue through the remedial process. DBRS has modeled the impact of the $2.9 billion writedown (maximum of the range) together with TCC’s recent approximately $300 million share buyback (December 2015), and the USD 654 million acquisition of Ironwood Power Plant (October 2015; 100% debt financed, expected to close Q1 2016) on the Company’s credit metrics on a pro forma basis, and has concluded that the writedown does not have an impact on the Company’s financial risk profile as key credit metrics are expected to remain reasonable for the current rating of A (low), with a Stable trend.

It was another awful day for the Canadian preferred share market, with PerpetualDiscounts off 17bp, FixedResets losing 58bp and DeemedRetractibles down 26bp. The Performance Highlights table is again very lengthy. Volume was well below average.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_160106
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 18.50 to be $1.04 rich, while TRP.PR.C, resetting 2016-1-30 at +154, is $1.46 cheap at its bid price of 11.45.

impVol_MFC_160106
Click for Big

Most expensive is MFC.PR.M, resetting at +236bp on 2019-12-19, bid at 19.68 to be 0.61 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 20.48 to be 0.62 cheap.

impVol_BAM_160106
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 15.65 to be $1.51 cheap. BAM.PF.E, resetting at +255bp on 2020-3-31 is bid at 19.45 and appears to be $0.93 rich.

impVol_FTS_160106
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 18.38, looks $0.85 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 17.30 and is $0.66 cheap.

pairs_FR_160106
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -1.00%, with one outlier below -2.00%. There is one junk outlier below -2.00% and three above 0.00%.

pairs_FF_160106
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 4.76 % 5.77 % 28,945 16.94 1 1.7857 % 1,633.9
FixedFloater 6.82 % 6.05 % 33,401 16.14 1 0.0000 % 2,859.5
Floater 4.19 % 4.37 % 82,161 16.71 4 0.6687 % 1,826.0
OpRet 0.00 % 0.00 % 0 0.00 0 0.0000 % 2,744.2
SplitShare 4.81 % 5.61 % 77,849 2.79 6 0.0000 % 3,211.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0000 % 2,505.5
Perpetual-Premium 5.83 % -0.81 % 90,248 0.09 6 0.1618 % 2,529.8
Perpetual-Discount 5.65 % 5.67 % 97,982 14.40 34 -0.1724 % 2,554.3
FixedReset 5.22 % 4.54 % 246,690 15.61 81 -0.5771 % 1,978.6
Deemed-Retractible 5.23 % 5.05 % 123,119 5.29 34 -0.2673 % 2,575.7
FloatingReset 2.87 % 4.37 % 63,812 5.62 13 -0.0815 % 2,097.5
Performance Highlights
Issue Index Change Notes
BNS.PR.D FloatingReset -5.16 % The closing bid of 18.02 is actually pretty reasonable – the issue traded 6,232 shares today in a range of 18.10-95 before closing at 18.02-29, 1×1. The execution prices nosedived from 18.67 at 3:21pm to 18.10 at 3:53pm on twelve trades out of CIBC totalling 2500 shares. YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.02
Bid-YTW : 7.17 %
IFC.PR.C FixedReset -4.62 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.17
Bid-YTW : 7.72 %
CU.PR.C FixedReset -3.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-06
Maturity Price : 17.90
Evaluated at bid price : 17.90
Bid-YTW : 4.49 %
HSE.PR.A FixedReset -3.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-06
Maturity Price : 11.85
Evaluated at bid price : 11.85
Bid-YTW : 5.19 %
TRP.PR.C FixedReset -3.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-06
Maturity Price : 11.45
Evaluated at bid price : 11.45
Bid-YTW : 4.93 %
TRP.PR.B FixedReset -2.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-06
Maturity Price : 11.10
Evaluated at bid price : 11.10
Bid-YTW : 4.60 %
TRP.PR.D FixedReset -2.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-06
Maturity Price : 17.90
Evaluated at bid price : 17.90
Bid-YTW : 4.54 %
SLF.PR.I FixedReset -2.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.30
Bid-YTW : 7.01 %
IAG.PR.G FixedReset -2.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.25
Bid-YTW : 6.54 %
FTS.PR.F Perpetual-Discount -1.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-06
Maturity Price : 22.34
Evaluated at bid price : 22.61
Bid-YTW : 5.48 %
TRP.PR.H FloatingReset -1.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-06
Maturity Price : 9.84
Evaluated at bid price : 9.84
Bid-YTW : 4.47 %
W.PR.K FixedReset -1.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-06
Maturity Price : 22.86
Evaluated at bid price : 24.20
Bid-YTW : 5.41 %
BAM.PR.Z FixedReset -1.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-06
Maturity Price : 19.84
Evaluated at bid price : 19.84
Bid-YTW : 4.81 %
NA.PR.Q FixedReset -1.71 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.08
Bid-YTW : 3.98 %
GWO.PR.O FloatingReset -1.67 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.35
Bid-YTW : 10.61 %
HSE.PR.C FixedReset -1.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-06
Maturity Price : 17.70
Evaluated at bid price : 17.70
Bid-YTW : 5.69 %
FTS.PR.J Perpetual-Discount -1.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-06
Maturity Price : 21.70
Evaluated at bid price : 22.00
Bid-YTW : 5.45 %
MFC.PR.I FixedReset -1.50 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.95
Bid-YTW : 6.16 %
MFC.PR.J FixedReset -1.49 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.80
Bid-YTW : 6.66 %
BNS.PR.Y FixedReset -1.47 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.38
Bid-YTW : 6.29 %
BAM.PR.R FixedReset -1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-06
Maturity Price : 15.65
Evaluated at bid price : 15.65
Bid-YTW : 4.90 %
MFC.PR.F FixedReset -1.31 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.27
Bid-YTW : 9.40 %
BNS.PR.Z FixedReset -1.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.50
Bid-YTW : 6.54 %
BAM.PF.H FixedReset -1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-06
Maturity Price : 23.21
Evaluated at bid price : 25.15
Bid-YTW : 4.89 %
BAM.PF.B FixedReset -1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-06
Maturity Price : 19.15
Evaluated at bid price : 19.15
Bid-YTW : 4.58 %
FTS.PR.G FixedReset -1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-06
Maturity Price : 17.30
Evaluated at bid price : 17.30
Bid-YTW : 4.37 %
BAM.PR.X FixedReset -1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-06
Maturity Price : 14.80
Evaluated at bid price : 14.80
Bid-YTW : 4.53 %
RY.PR.K FloatingReset -1.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.25
Bid-YTW : 4.49 %
BIP.PR.A FixedReset -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-06
Maturity Price : 19.30
Evaluated at bid price : 19.30
Bid-YTW : 5.65 %
PWF.PR.T FixedReset -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-06
Maturity Price : 21.93
Evaluated at bid price : 22.25
Bid-YTW : 3.62 %
GWO.PR.N FixedReset -1.02 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.55
Bid-YTW : 9.92 %
PWF.PR.A Floater 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-06
Maturity Price : 12.74
Evaluated at bid price : 12.74
Bid-YTW : 3.75 %
MFC.PR.N FixedReset 1.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.31
Bid-YTW : 6.90 %
ELF.PR.G Perpetual-Discount 1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-06
Maturity Price : 21.26
Evaluated at bid price : 21.26
Bid-YTW : 5.61 %
CCS.PR.C Deemed-Retractible 1.55 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.95
Bid-YTW : 6.25 %
BAM.PR.E Ratchet 1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-06
Maturity Price : 25.00
Evaluated at bid price : 14.25
Bid-YTW : 5.77 %
HSE.PR.E FixedReset 1.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-06
Maturity Price : 18.55
Evaluated at bid price : 18.55
Bid-YTW : 5.89 %
TRP.PR.F FloatingReset 2.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-06
Maturity Price : 13.50
Evaluated at bid price : 13.50
Bid-YTW : 4.45 %
BNS.PR.C FloatingReset 2.63 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.28
Bid-YTW : 4.30 %
BAM.PR.K Floater 2.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-06
Maturity Price : 10.78
Evaluated at bid price : 10.78
Bid-YTW : 4.41 %
Volume Highlights
Issue Index Shares
Traded
Notes
BMO.PR.Q FixedReset 102,737 TD crossed 50,000 at 20.29; RBC crossed 46,700 at the same price.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.20
Bid-YTW : 5.99 %
RY.PR.Q FixedReset 99,011 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-24
Maturity Price : 25.00
Evaluated at bid price : 25.61
Bid-YTW : 5.07 %
CU.PR.C FixedReset 48,687 Scotia crossed 40,700 at 18.55.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-06
Maturity Price : 17.90
Evaluated at bid price : 17.90
Bid-YTW : 4.49 %
BAM.PF.H FixedReset 32,965 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-06
Maturity Price : 23.21
Evaluated at bid price : 25.15
Bid-YTW : 4.89 %
BNS.PR.E FixedReset 32,874 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-25
Maturity Price : 25.00
Evaluated at bid price : 25.60
Bid-YTW : 5.07 %
MFC.PR.M FixedReset 32,247 Scotia crossed 27,500 at 19.80.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.68
Bid-YTW : 6.70 %
There were 21 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
GWO.PR.O FloatingReset This quote is particularly ridiculous in light of the fact that the issue traded 8,965 shares today. Thank you, Nonsense Central! I have not checked whether this lamentable state of affairs is due to inadequate Toronto Stock Exchange reporting or inadequate Toronto Stock Exchange supervision of market-makers.

Quote: 12.35 – 20.25
Spot Rate : 7.9000
Average : 6.5170

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.35
Bid-YTW : 10.61 %

TD.PR.Y FixedReset Quote: 24.00 – 24.50
Spot Rate : 0.5000
Average : 0.3425

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.00
Bid-YTW : 3.67 %

CM.PR.Q FixedReset Quote: 19.85 – 20.25
Spot Rate : 0.4000
Average : 0.2534

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-06
Maturity Price : 19.85
Evaluated at bid price : 19.85
Bid-YTW : 4.45 %

BMO.PR.Z Perpetual-Discount Quote: 23.58 – 23.99
Spot Rate : 0.4100
Average : 0.2893

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-06
Maturity Price : 23.27
Evaluated at bid price : 23.58
Bid-YTW : 5.36 %

SLF.PR.J FloatingReset Quote: 13.60 – 13.98
Spot Rate : 0.3800
Average : 0.2751

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.60
Bid-YTW : 9.51 %

TRP.PR.H FloatingReset Quote: 9.84 – 10.25
Spot Rate : 0.4100
Average : 0.3063

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-06
Maturity Price : 9.84
Evaluated at bid price : 9.84
Bid-YTW : 4.47 %