Category: Market Action

Market Action

December 17, 2015

The Fed’s implementation of new policy tools to raise the overnight rate went smoothly:

The Federal Reserve succeeded in nudging borrowing costs higher Thursday after its first interest-rate increase since 2006, and policy makers only needed to siphon $105 billion from money-market funds to achieve their goal.

Led by Chair Janet Yellen, the Fed lifted the federal funds rate from near zero, where it had been since the financial crisis unfolded in 2008. Thursday, the quarter-point rate boost rippled through money markets that are awash in nearly $3 trillion in excess cash that the Fed injected through bond purchases.

For all the talk of the challenge facing officials as they orchestrate higher rates with so much money sloshing around, Thursday’s market operations weren’t much different in scale than previous days. And the benchmark rate rose 0.2 percentage point, or 20 basis points — practically to the middle of the Fed’s intended range.
…
While the Fed is sticking to the funds rate as its main method of communicating its policy stance, the burden of lifting rates fell elsewhere. That’s because with so much cash in the system, interbank lending has fallen almost 90 percent since 2008.

interbankLending_151217
Click for Big

It looks as if somebody was either naughty or careless at Octagon:

Octagon Capital Corp. has been declared bankrupt, its chief financial officer has been fired and the brokerage is facing a shortfall of as much as $6.1-million.

The Canadian Investor Protection Fund (CIPF) paid out millions of dollars to investors after the small Toronto-based investment firm was unable to meet obligations to clients when it entered bankruptcy proceedings earlier this month. The Investment Industry Regulatory Organization of Canada (IIROC) discovered the deficiency in late November after a routine audit, according to court documents filed by Octagon’s bankruptcy trustee, Ernst and Young Inc. reason for the shortfall is unknown and an investigation continues.

“I am co-operating fully with the trustee,” John Palumbo, Octagon Capital’s chief executive officer, said in an e-mail. “I can say that [the $6.1-million shortfall] represents an accounting amount which is in dispute, and I believe the total is much less.”

On the same day the shortfall was revealed, Octagon notified the IIROC that its chief financial officer, Christopher Everest, “was unable to return to work and was being removed from Octagon’s accounts, e-mail and payroll systems,” according to court documents.

“He was terminated for cause,” Mr. Palumbo said on Thursday.

The banks are claiming they are forced to publish shoddy analysis:

In a world where market news zips around at lightning speed with a click or a tweet, there is at least one anachronism: The delay in analyst research on companies that have just completed an IPO. Analysts who work for the investment firms that have taken the companies public have been blocked from issuing reports for 40 full days after the stock’s debut.

Regulators have now moved to shorten that period. FINRA, the U.S. body that governs its investment dealers, cut the IPO “quiet period” to 10 days this fall. And IIROC, the Investment Industry Regulatory Organization of Canada, followed quickly with a rule that harmonized the Canadian rules with the U.S. so as not to disadvantage this country’s investment dealers.

The biggest Canadian investment banks have now responded to this liberalization with a universal position: We want no part of this. Instead, they say, they want the quiet period extended to a full 25 days.
…
With a new publication schedule of 10 days post-IPO, analysts won’t have enough time to meet with management and produce a robust report, the firms argue.

If firms compete to be first to market with their reports, just 10 days after the IPO, “a likely outcome is a dilution in the quality of research being produced,” Quentin Broad, the head of equity research at CIBC World Markets Inc., said in that firm’s comment letter to IIROC. And the most likely investor to be harmed, Mr. Broad says, are retail investors who “may consume a single research product without conducting or having access to any additional research of their own.”

Does it really make any difference? Sell-side analysis is excellent for data, pretty good for generating ideas regarding analytical techniques … but as far as actual actionable investment recommendations are concerned? Entertainment value only.

As part of what appears to be a global redefinition of what the word “Conservative” means in politics, the UK wants all businesses and the self-employed to file four tax returns every year:

Tax returns will have to be filed four times a year as part of a “digital revolution” at HMRC, George Osborne has indicated

Business and self-employed workers will be expected to file their tax returns online from 2020 using free apps on their smartphones and HMRC’s website.

The Government estimates that the move will raise an additional £600million a year by the end of this Parliament because it will help the taxman keep a better track of people’s income. It has insisted that the new digital service will make it easier to file tax returns.
…
A spokeswoman for the ICAEW group of Chartered Accountants said: “This is an additional burden for small businesses especially at a time when they are already struggling with changes such as auto-enrollment. It is already a significant burden for people to file it once a year.”

Earlier this year it MPs condemned the “abysmal” customer service at HMRC after it emerged that half of all calls to the taxman go unanswered.

This has provoked howls of anguish:

Self-employed workers, landlords and small business owners currently have to submit their figures just once every 12 months.

Switching them to quarterly returns will bring them into line with big corporations. But financial experts say the move will simply add to the reams of red tape already strangling small firms.

‘These changes are going to be very onerous,’ said Chas Roy-Chowdhury, of the Association of Chartered Certified Accountants.

‘It is not just about filling in a form, it is going to be a real burden.

‘Workers will have to make sure their books and records are up to date at least four times a year in case the taxman decides something is amiss and investigates them.’

Initially workers will not have to pay tax four times a year. But accountants suspect quarterly returns are a step toward this.

The plans were slipped out in the small print of George Osborne’s autumn statement. Around four million people will be affected: the self employed, small business owners and landlords who make more than £10,000 a year profit.

Industrial Alliance Insurance and Financial Services Inc., proud issuer of IAG.PR.A and IAG.PR.G, was confirmed at Pfd-2(high) by DBRS:

The Company has strong capitalization as illustrated by (1) its financial leverage ratio of 24.5% at Q3 2015, significantly reduced from a high of 35.2% at year-end 2012; (2) the improvement in the EBIT fixed-charge coverage ratio to 6.8x at Q3 2015, compared with 5.6x at Q3 2014; and (3) the minimum continuing capital and surplus requirement (MCCSR) of 225% at Q3 2015, an improvement of ten percentage points from Q3 2014.

The Stable trends on IAG’s credit ratings take into account the Company’s conservative risk management, good financial metrics and capital levels coupled with low volatility. Negative ratings pressure could arise if IAG experiences a sustained erosion of market share in key segments, a negative impact on its earnings because of lower interest rates, equity market declines or adverse policyholder behaviour, or acquisitions of risky businesses. Positive pressure on IAG’s ratings could emerge if underperforming businesses become profitable, if there is a reduction in exposure to interest rate and stock market value fluctuations, and if there is a significant increase in market share without cutting premium rates.

There has been a massive amount of issue news today, so for convenience I will list the posts here:

It was a mixed day for the Canadian preferred share market, with PerpetualDiscounts gaining 28bp, FixedResets off 22bp and DeemedRetractibles up 43bp. The Performance Highlights table has shortened to a more manageable length. Volume was extremely high, though off the peaks of the past few days.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 4.98 % 6.06 % 33,112 16.57 1 -0.3650 % 1,558.0
FixedFloater 7.25 % 6.43 % 35,636 15.72 1 -0.0763 % 2,691.0
Floater 4.34 % 4.46 % 83,721 16.52 4 -0.6391 % 1,760.0
OpRet 4.87 % 4.24 % 25,393 0.69 1 0.0397 % 2,735.4
SplitShare 4.87 % 6.04 % 82,279 1.87 6 -0.0968 % 3,172.7
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0968 % 2,475.4
Perpetual-Premium 5.82 % 5.89 % 97,851 13.96 7 0.4765 % 2,489.7
Perpetual-Discount 5.77 % 5.84 % 102,586 14.08 33 0.2777 % 2,484.3
FixedReset 5.24 % 4.68 % 271,798 14.86 81 -0.2172 % 1,972.7
Deemed-Retractible 5.22 % 4.88 % 139,760 5.31 33 0.4316 % 2,567.1
FloatingReset 2.79 % 4.26 % 68,255 5.68 11 0.4952 % 2,113.9
Performance Highlights
Issue Index Change Notes
HSE.PR.E FixedReset -6.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 17.84
Evaluated at bid price : 17.84
Bid-YTW : 6.15 %
HSE.PR.G FixedReset -4.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 18.10
Evaluated at bid price : 18.10
Bid-YTW : 6.05 %
IAG.PR.A Deemed-Retractible -4.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.71
Bid-YTW : 7.92 %
HSE.PR.C FixedReset -3.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 17.11
Evaluated at bid price : 17.11
Bid-YTW : 5.91 %
FTS.PR.H FixedReset -3.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 14.20
Evaluated at bid price : 14.20
Bid-YTW : 4.02 %
CIU.PR.C FixedReset -2.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 13.23
Evaluated at bid price : 13.23
Bid-YTW : 4.07 %
TD.PF.D FixedReset -2.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 19.50
Evaluated at bid price : 19.50
Bid-YTW : 4.62 %
SLF.PR.I FixedReset -2.41 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.86
Bid-YTW : 6.61 %
BAM.PR.C Floater -2.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 10.45
Evaluated at bid price : 10.45
Bid-YTW : 4.52 %
BAM.PR.X FixedReset -2.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 14.05
Evaluated at bid price : 14.05
Bid-YTW : 4.84 %
CIU.PR.A Perpetual-Discount -2.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 19.83
Evaluated at bid price : 19.83
Bid-YTW : 5.86 %
BAM.PR.B Floater -2.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 10.60
Evaluated at bid price : 10.60
Bid-YTW : 4.46 %
MFC.PR.I FixedReset -2.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.65
Bid-YTW : 5.70 %
TRP.PR.A FixedReset -2.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 15.36
Evaluated at bid price : 15.36
Bid-YTW : 4.57 %
IAG.PR.G FixedReset -2.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.80
Bid-YTW : 6.17 %
TRP.PR.B FixedReset -2.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 11.20
Evaluated at bid price : 11.20
Bid-YTW : 4.61 %
MFC.PR.J FixedReset -1.94 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.25
Bid-YTW : 6.34 %
TRP.PR.G FixedReset -1.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 19.50
Evaluated at bid price : 19.50
Bid-YTW : 4.83 %
PWF.PR.P FixedReset -1.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 14.05
Evaluated at bid price : 14.05
Bid-YTW : 4.24 %
SLF.PR.J FloatingReset -1.69 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.83
Bid-YTW : 10.16 %
BMO.PR.Q FixedReset -1.66 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.20
Bid-YTW : 5.97 %
FTS.PR.I FloatingReset -1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 11.64
Evaluated at bid price : 11.64
Bid-YTW : 4.09 %
MFC.PR.G FixedReset -1.26 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.09
Bid-YTW : 6.01 %
BNS.PR.Q FixedReset -1.25 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.76
Bid-YTW : 4.05 %
BAM.PR.K Floater -1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 10.40
Evaluated at bid price : 10.40
Bid-YTW : 4.54 %
BNS.PR.Z FixedReset -1.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.15
Bid-YTW : 7.07 %
FTS.PR.G FixedReset -1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 17.23
Evaluated at bid price : 17.23
Bid-YTW : 4.42 %
SLF.PR.G FixedReset 1.00 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.15
Bid-YTW : 8.54 %
BNS.PR.O Deemed-Retractible 1.02 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-01-16
Maturity Price : 25.50
Evaluated at bid price : 25.83
Bid-YTW : -1.64 %
GWO.PR.I Deemed-Retractible 1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.62
Bid-YTW : 7.16 %
BAM.PF.H FixedReset 1.07 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.47
Bid-YTW : 4.56 %
FTS.PR.M FixedReset 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 20.75
Evaluated at bid price : 20.75
Bid-YTW : 4.13 %
MFC.PR.C Deemed-Retractible 1.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.53
Bid-YTW : 7.25 %
TRP.PR.D FixedReset 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 18.08
Evaluated at bid price : 18.08
Bid-YTW : 4.61 %
TD.PR.T FloatingReset 1.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.50
Bid-YTW : 3.87 %
HSB.PR.C Deemed-Retractible 1.13 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-01-16
Maturity Price : 25.00
Evaluated at bid price : 25.03
Bid-YTW : 1.26 %
NA.PR.Q FixedReset 1.18 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.91
Bid-YTW : 3.52 %
ELF.PR.F Perpetual-Discount 1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 22.38
Evaluated at bid price : 22.64
Bid-YTW : 5.95 %
NA.PR.W FixedReset 1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 17.25
Evaluated at bid price : 17.25
Bid-YTW : 4.70 %
ELF.PR.G Perpetual-Discount 1.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 20.77
Evaluated at bid price : 20.77
Bid-YTW : 5.83 %
MFC.PR.M FixedReset 1.52 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.10
Bid-YTW : 6.39 %
BNS.PR.Y FixedReset 1.53 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.85
Bid-YTW : 5.92 %
BNS.PR.N Deemed-Retractible 1.63 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-01-27
Maturity Price : 25.25
Evaluated at bid price : 25.55
Bid-YTW : 0.57 %
TD.PR.S FixedReset 1.68 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.20
Bid-YTW : 3.48 %
ENB.PR.A Perpetual-Discount 1.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 22.66
Evaluated at bid price : 22.90
Bid-YTW : 6.06 %
TD.PR.Z FloatingReset 1.81 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.55
Bid-YTW : 3.92 %
TD.PF.E FixedReset 1.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 20.88
Evaluated at bid price : 20.88
Bid-YTW : 4.42 %
GWO.PR.H Deemed-Retractible 1.97 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.70
Bid-YTW : 6.83 %
BIP.PR.B FixedReset 2.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 22.46
Evaluated at bid price : 23.35
Bid-YTW : 5.89 %
PWF.PR.T FixedReset 2.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 22.27
Evaluated at bid price : 22.75
Bid-YTW : 3.62 %
BNS.PR.D FloatingReset 2.44 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.90
Bid-YTW : 6.30 %
BIP.PR.A FixedReset 2.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 19.70
Evaluated at bid price : 19.70
Bid-YTW : 5.56 %
TRP.PR.F FloatingReset 2.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 13.25
Evaluated at bid price : 13.25
Bid-YTW : 4.45 %
PWF.PR.A Floater 2.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 12.08
Evaluated at bid price : 12.08
Bid-YTW : 3.94 %
CM.PR.P FixedReset 3.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 17.56
Evaluated at bid price : 17.56
Bid-YTW : 4.58 %
VNR.PR.A FixedReset 3.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 19.75
Evaluated at bid price : 19.75
Bid-YTW : 4.69 %
Volume Highlights
Issue Index Shares
Traded
Notes
BNS.PR.E FixedReset 1,123,441 New issue settled today.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-25
Maturity Price : 25.00
Evaluated at bid price : 25.20
Bid-YTW : 5.36 %
RY.PR.Q FixedReset 297,994 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 23.17
Evaluated at bid price : 25.12
Bid-YTW : 5.25 %
CU.PR.I FixedReset 163,858 Nesbitt crossed 133,200 at 25.10.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 23.13
Evaluated at bid price : 24.89
Bid-YTW : 4.44 %
RY.PR.H FixedReset 132,160 Desjardins crossed 100,000 at 18.40
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 18.19
Evaluated at bid price : 18.19
Bid-YTW : 4.42 %
NA.PR.S FixedReset 69,879 Nesbitt crossed 21,000 at 18.05; Desjardins crossed 36,400 at 17.80.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 17.75
Evaluated at bid price : 17.75
Bid-YTW : 4.74 %
BNS.PR.A FloatingReset 65,000 RBC crossed 55,200 at 22.50.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.61
Bid-YTW : 4.26 %
There were 72 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
GWO.PR.F Deemed-Retractible Quote: 25.09 – 25.99
Spot Rate : 0.9000
Average : 0.5544

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-01-16
Maturity Price : 25.00
Evaluated at bid price : 25.09
Bid-YTW : -1.23 %

TRP.PR.G FixedReset Quote: 19.50 – 20.40
Spot Rate : 0.9000
Average : 0.5610

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 19.50
Evaluated at bid price : 19.50
Bid-YTW : 4.83 %

CIU.PR.C FixedReset Quote: 13.23 – 14.33
Spot Rate : 1.1000
Average : 0.8335

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 13.23
Evaluated at bid price : 13.23
Bid-YTW : 4.07 %

BNS.PR.B FloatingReset Quote: 21.85 – 22.40
Spot Rate : 0.5500
Average : 0.3408

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.85
Bid-YTW : 4.50 %

NA.PR.W FixedReset Quote: 17.25 – 18.00
Spot Rate : 0.7500
Average : 0.5431

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-17
Maturity Price : 17.25
Evaluated at bid price : 17.25
Bid-YTW : 4.70 %

BNS.PR.C FloatingReset Quote: 22.09 – 22.73
Spot Rate : 0.6400
Average : 0.4564

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.09
Bid-YTW : 4.50 %

Market Action

December 16, 2015

The hot news of the day is the FOMC Statement:

Information received since the Federal Open Market Committee met in October suggests that economic activity has been expanding at a moderate pace. Household spending and business fixed investment have been increasing at solid rates in recent months, and the housing sector has improved further; however, net exports have been soft. A range of recent labor market indicators, including ongoing job gains and declining unemployment, shows further improvement and confirms that underutilization of labor resources has diminished appreciably since early this year. Inflation has continued to run below the Committee’s 2 percent longer-run objective, partly reflecting declines in energy prices and in prices of non-energy imports. Market-based measures of inflation compensation remain low; some survey-based measures of longer-term inflation expectations have edged down.
…
Overall, taking into account domestic and international developments, the Committee sees the risks to the outlook for both economic activity and the labor market as balanced. Inflation is expected to rise to 2 percent over the medium term as the transitory effects of declines in energy and import prices dissipate and the labor market strengthens further. The Committee continues to monitor inflation developments closely.

The Committee judges that there has been considerable improvement in labor market conditions this year, and it is reasonably confident that inflation will rise, over the medium term, to its 2 percent objective. Given the economic outlook, and recognizing the time it takes for policy actions to affect future economic outcomes, the Committee decided to raise the target range for the federal funds rate to 1/4 to 1/2 percent. The stance of monetary policy remains accommodative after this increase, thereby supporting further improvement in labor market conditions and a return to 2 percent inflation.
…
The Committee expects that economic conditions will evolve in a manner that will warrant only gradual increases in the federal funds rate; the federal funds rate is likely to remain, for some time, below levels that are expected to prevail in the longer run. However, the actual path of the federal funds rate will depend on the economic outlook as informed by incoming data.

There were no dissents. The move was met with cheers:

“Americans should realize that the Fed’s decision today reflects our confidence in the U.S. economy,” Yellen said. “While things may be uneven across regions of the country and different industrial sectors, we see an economy that is on a path of sustainable improvement.”

Equity prices rallied in response, with the Standard & Poor’s 500 Index of U.S. stocks rising 1.5 percent to 2,073.07 in New York. Bond prices fell on the prospects of higher short-term interest rates, though yields on the benchmark 10-year Treasury note remained below levels seen last month.
…
Policy makers forecast that the short-term policy rate will rise to 1.375 percent at the end of 2016, implying four quarter-point increases in the target range next year, based on the median number from 17 officials.

“I do want to emphasize that while we have said gradual, gradual does not mean mechanical — evenly timed, equally sized, interest-rate changes,” she said. “As the outlook evolves, we’ll respond appropriately. I strongly doubt that it will mean equally spaced hikes,” she added.

The Fed will be able to take such an approach because inflation is so far below its 2 percent goal. As measured by the personal consumption expenditure price index, it rose by 0.2 percent in the 12 months through October.

The telecoms are changing:

Shaw Communications Inc. is finally poised to enter the wireless business, with a $1.6-billion deal to buy Toronto startup carrier Wind Mobile Corp.

Calgary-based cable operator Shaw announced the transaction on Wednesday evening, noting that while the deal still requires approval from the federal government and the Competition Bureau, it expects it to close during the third quarter of fiscal 2016 (the first half of the calendar year).

Wind, which operates in urban areas in Ontario, British Columbia and Alberta, has 940,000 subscribers, and Shaw said the small carrier is expected to generate $485-million in revenue and $65-million in earnings before interest, taxes, depreciation and amortization (EBITDA) in 2015.
…
Wind has provided a lower-priced alternative to Canada’s Big Three carriers – Telus, BCE Inc. and Rogers Communications Inc. – and consumers will be wondering whether that will evaporate with this sale.

[Shaw CEO] Mr. [Brad] Shaw said as the wireless company improves its coverage and upgrades to LTE (fourth-generation), “I see pricing somewhat discounted, but probably closer to the incumbents as we go forward, which allows us to increase ARPU [average revenue per user]. But listen, growth is very important to us and that’s going to be a key driver, as well as making sure consumers feel there’s value.”

HSBC Bank Canada, proud issuer of HSB.PR.C and HSB.PR.D, has been confirmed at Pfd-2 by DBRS:

DBRS Limited (DBRS) has today confirmed all the ratings of HSBC Bank Canada (HSBC Canada or the Bank) including the Bank’s Long-Term Deposits and Senior Debt at A (high) and the Short-Term Instruments at R-1 (middle). All trends are Stable. Additionally, DBRS discontinued the rating of HSBC Canada Asset Trust (HaTS HSBC Bank Canada’s innovative Tier 1 capital instruments) following repayment of the final instrument.

Earlier this year, on September 29, 2015, DBRS downgraded the Long-Term Deposits and Senior Debt, and Subordinated Debt ratings of HSBC Canada following the conclusion of a review of government support at HSBC Holdings plc, the indirect parent entity of HSBC Canada. The changes reflect DBRS’s view that developments in European regulation and legislation mean that there is less certainty about the likelihood of timely systemic support. Given HSBC Canada’s position in the global franchise of HSBC Group (the Group), DBRS has assigned an SA1 designation to the bank under “DBRS Criteria: Support Assessments for Banks and Banking Organisations,” which implies strong and predictable support from the Group, should it be required. As a result, HSBC Canada’s rating generally moves in tandem with HSBC Holdings plc’s rating. Accordingly, HSBC Canada’s senior debt rating is notched down by one notch from HSBC Holdings plc’s rating of AA (low).
…
Some factors that may improve HSBC Canada’s overall credit strength include reductions in geographic and/or sector loan concentrations, or a successful growth of retail wealth management. On the other hand, any significant increase in provisions (particularly related to energy sector lending), evidence of compliance failings or a change in DBRS’s assessment of likely support from the HSBC Group could put negative pressure on the rating assessment.

The trouble nowadays, though, is that when people refer to “lift-off”, I don’t know whether they’re talking about the Fed rate increase or the Canadian preferred share market!

NASA's Orion Spacecraft Launches Unmanned Test Flight
Click for Big

The Canadian preferred share market was on fire again today, with PerpetualDiscounts up 102bp, FixedResets winning 336bp and DeemedRetractibles gaining 59bp. The Performance Highlights table is ridiculously long again, of course, with no less than fifteen issues returning more than 5.00% on the day. Volume was again very, very heavy.

PerpetualDiscounts now yield 5.86%, equivalent to 7.62% interest at the standard equivalency factor of 1.3x. Long corporates now yield a little over 4.2%, so the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) is now about 340bp, down only slightly (and perhaps spuriously) from the 345bp reported December 9

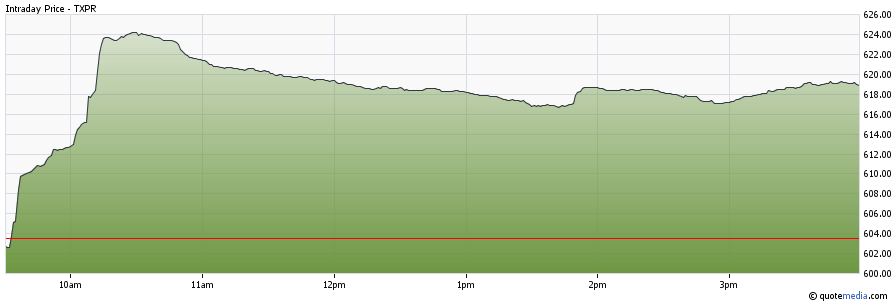
At time of writing the TMXMoney website doesn’t have the Total Return Index Value for TXPL, but I guess it’s about maybe 1,256.41, which would put the index down 3.22% on the month-to-date, but 6.36% above the December 14 low.

TXPR_151216
Click for Big

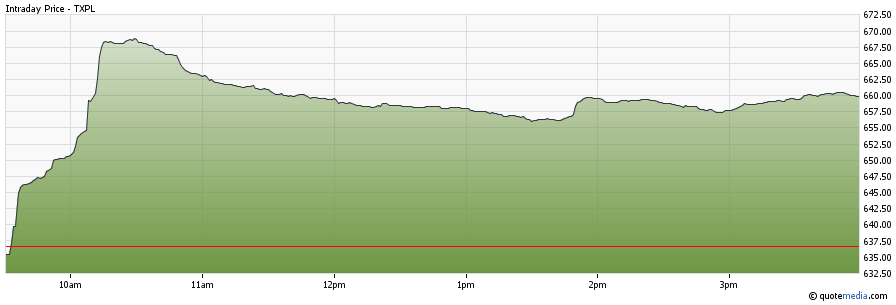
Similarly, TXPL is somewhere close to 773.32, down 3.68% on the month-to-date but 9.08% above the December 14 low.

TXPL_151216
Click for Big

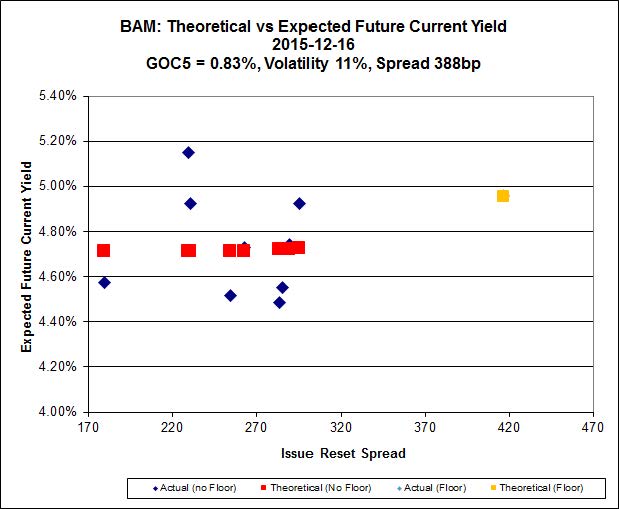
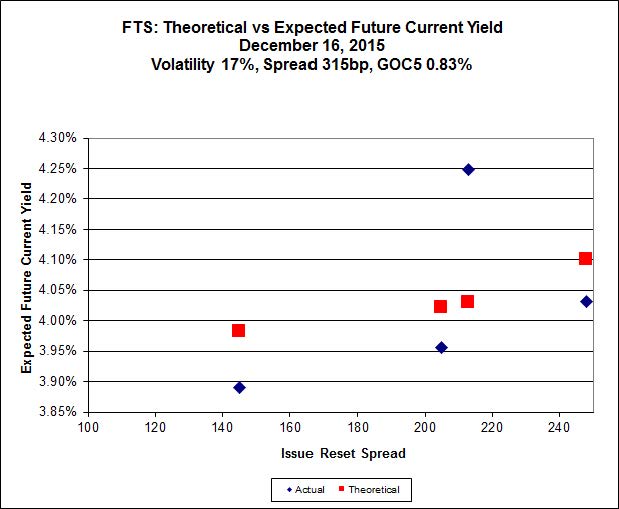
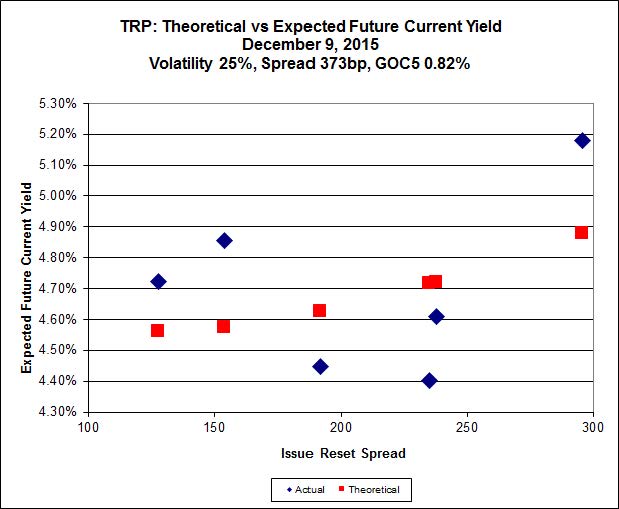
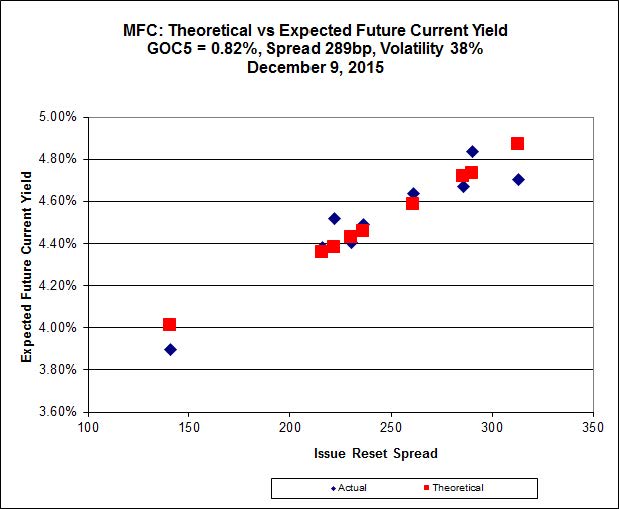
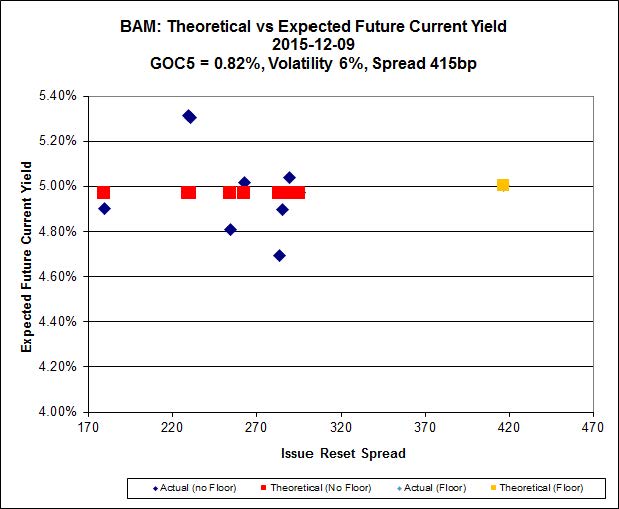
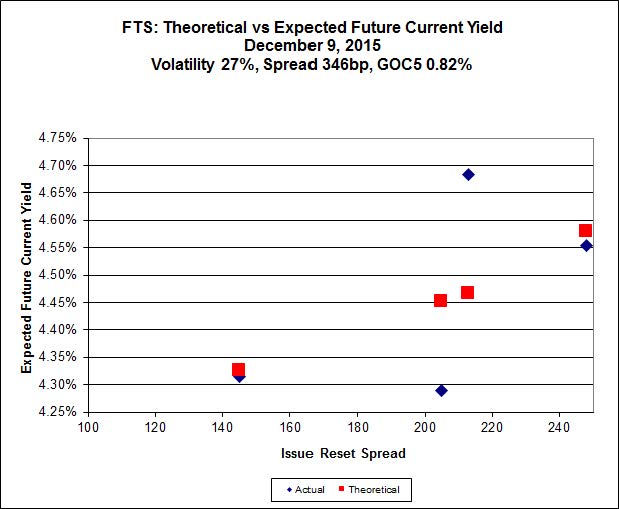
For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

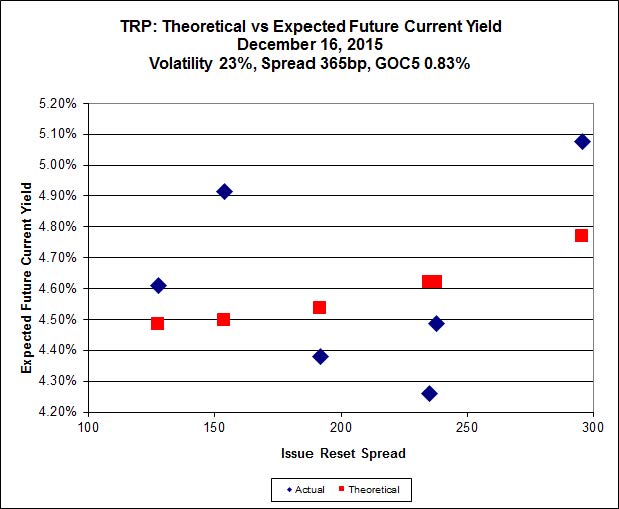
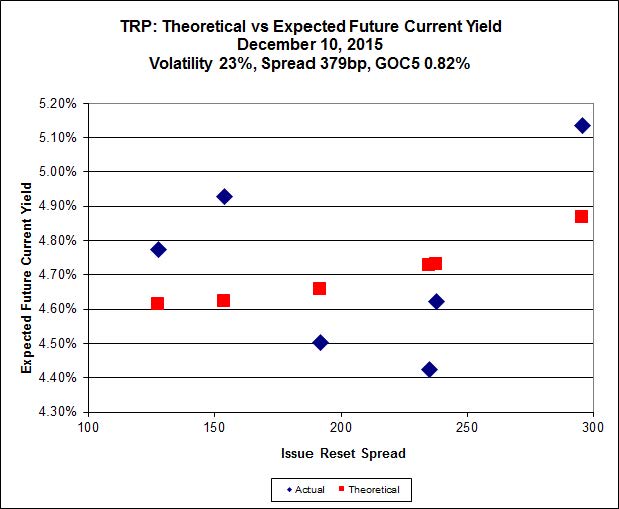
Here’s TRP:

impVol_TRP_151216
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 18.66 to be $1.45 rich, while TRP.PR.C, resetting 2016-1-30 at +154, is $1.12 cheap at its bid price of 12.06.

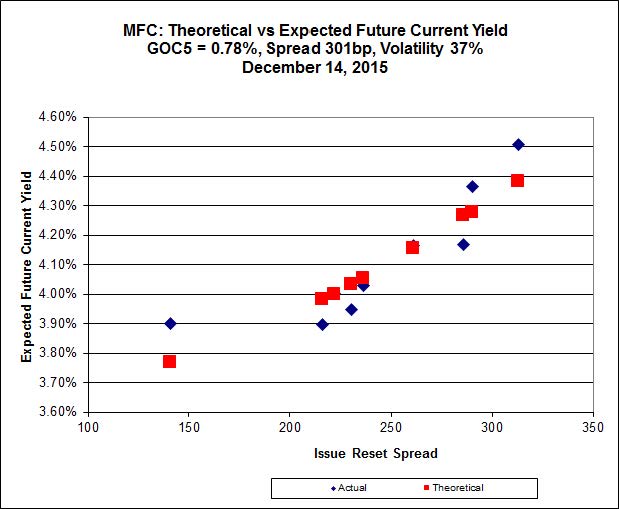
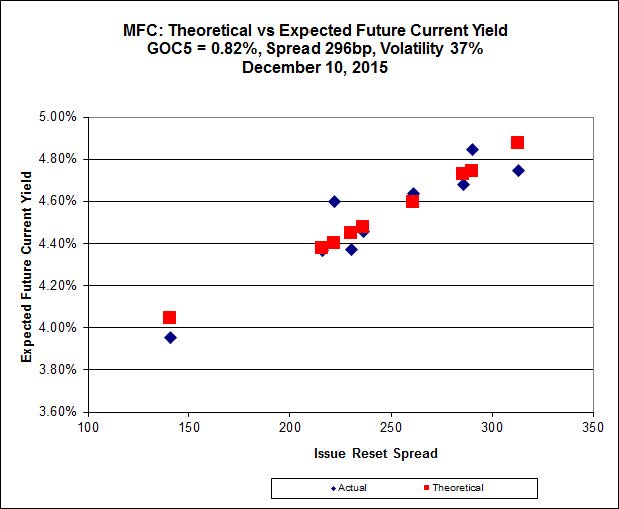
impVol_MFC_151216
Click for Big

Most expensive is MFC.PR.H, resetting at +313bp on 2017-3-19, bid at 21.96 to be 0.64 cheap, while MFC.PR.I, resetting at +286bp on 2017-9-19, is bid at 22.13 to be 0.51 rich.

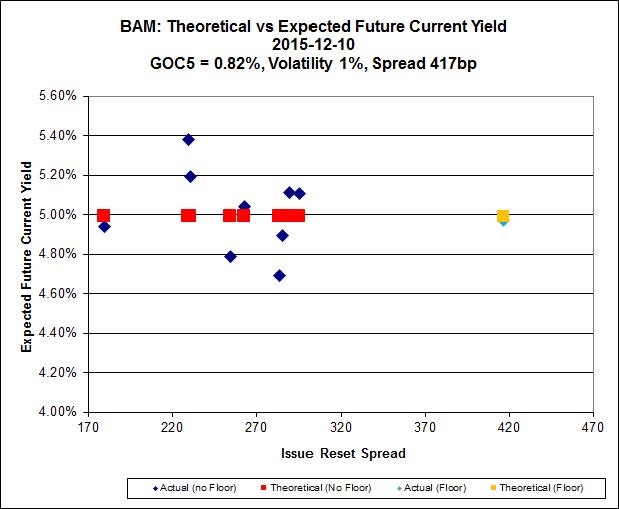
impVol_BAM_151216
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 15.20 to be $1.41 cheap. BAM.PF.G, resetting at +284bp on 2020-6-30 is bid at 20.45 and appears to be $1.01 rich.

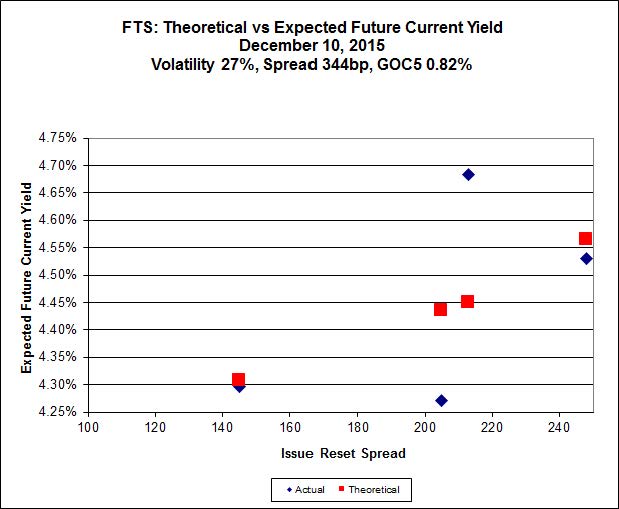
impVol_FTS_151216
Click for Big

FTS.PR.M, with a spread of +248bp, and bid at 20.53, looks $0.35 expensive and resets 2019-12-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 17.42 and is $0.94 cheap.

pairs_FR_151216
Click for Big

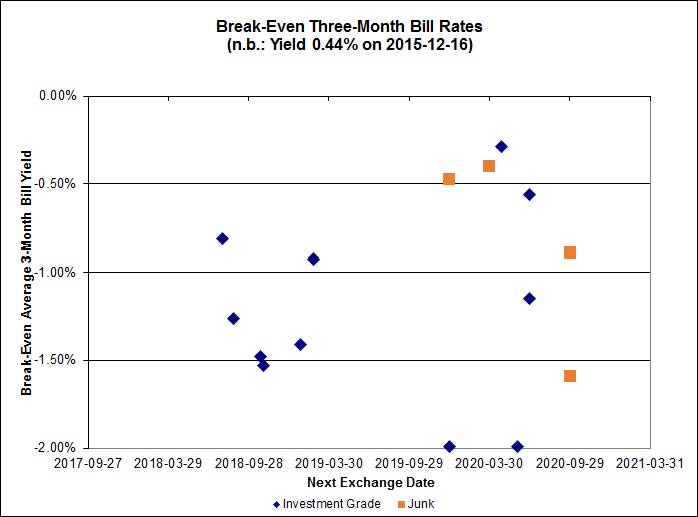
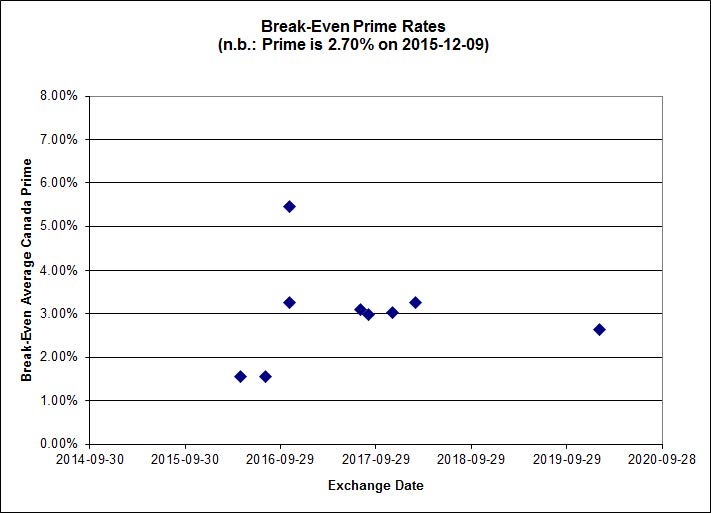
Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -1.33%, with one outlier below -2.00%. There are two junk outliers below -2.00% and four above 0.00%. Note the vertical axis of this graph has been changed.

pairs_FF_151216
Click for Big

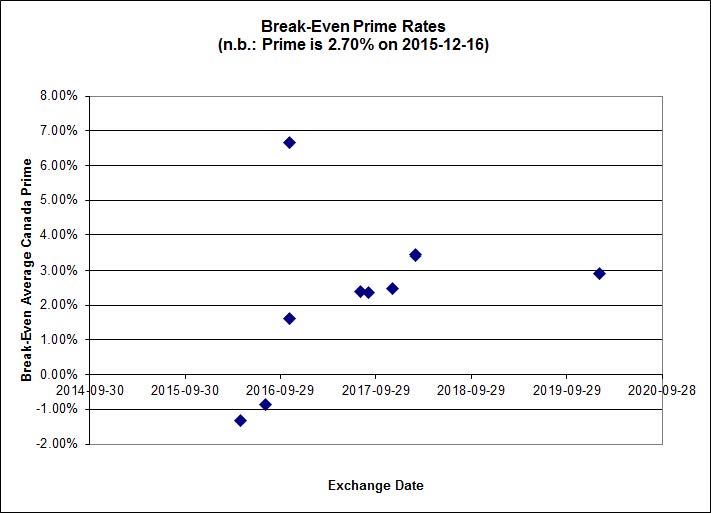
Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 4.96 % 6.03 % 33,638 16.60 1 0.3663 % 1,563.8
FixedFloater 7.25 % 6.42 % 35,518 15.72 1 1.9440 % 2,693.1
Floater 4.31 % 4.36 % 84,444 16.72 4 0.5739 % 1,771.4
OpRet 4.87 % 4.28 % 26,297 0.69 1 0.0000 % 2,734.3
SplitShare 4.87 % 5.81 % 82,956 1.87 6 0.0415 % 3,175.7
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0415 % 2,477.8
Perpetual-Premium 5.85 % 5.91 % 98,476 13.90 7 0.5310 % 2,477.8
Perpetual-Discount 5.78 % 5.86 % 104,697 14.05 33 1.0227 % 2,477.5
FixedReset 5.22 % 4.72 % 265,864 15.31 80 3.3632 % 1,977.0
Deemed-Retractible 5.25 % 5.30 % 135,940 5.31 33 0.5933 % 2,556.1
FloatingReset 2.81 % 4.27 % 68,373 5.67 11 1.9011 % 2,103.5
Performance Highlights
Issue Index Change Notes
PVS.PR.E SplitShare -1.98 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-10-31
Maturity Price : 25.00
Evaluated at bid price : 23.82
Bid-YTW : 6.43 %
BAM.PR.K Floater -1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 10.52
Evaluated at bid price : 10.52
Bid-YTW : 4.49 %
BAM.PF.H FixedReset 1.00 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.20
Bid-YTW : 4.80 %
CU.PR.I FixedReset 1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 23.13
Evaluated at bid price : 24.90
Bid-YTW : 4.44 %
RY.PR.B Deemed-Retractible 1.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.97
Bid-YTW : 4.80 %
RY.PR.D Deemed-Retractible 1.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.88
Bid-YTW : 4.67 %
MFC.PR.C Deemed-Retractible 1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.31
Bid-YTW : 7.40 %
IFC.PR.C FixedReset 1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.26
Bid-YTW : 6.91 %
PWF.PR.H Perpetual-Premium 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 24.43
Evaluated at bid price : 24.67
Bid-YTW : 5.91 %
FTS.PR.K FixedReset 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 18.20
Evaluated at bid price : 18.20
Bid-YTW : 4.15 %
SLF.PR.C Deemed-Retractible 1.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.32
Bid-YTW : 7.31 %
CU.PR.D Perpetual-Discount 1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 21.19
Evaluated at bid price : 21.19
Bid-YTW : 5.84 %
PWF.PR.L Perpetual-Discount 1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 21.82
Evaluated at bid price : 22.06
Bid-YTW : 5.86 %
POW.PR.A Perpetual-Discount 1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 23.99
Evaluated at bid price : 24.24
Bid-YTW : 5.87 %
GWO.PR.P Deemed-Retractible 1.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.96
Bid-YTW : 6.01 %
TRP.PR.B FixedReset 1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 11.44
Evaluated at bid price : 11.44
Bid-YTW : 4.51 %
SLF.PR.D Deemed-Retractible 1.25 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.21
Bid-YTW : 7.38 %
ELF.PR.F Perpetual-Discount 1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 22.06
Evaluated at bid price : 22.35
Bid-YTW : 6.03 %
TRP.PR.E FixedReset 1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 18.66
Evaluated at bid price : 18.66
Bid-YTW : 4.54 %
BAM.PR.B Floater 1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 10.84
Evaluated at bid price : 10.84
Bid-YTW : 4.36 %
BIP.PR.A FixedReset 1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 19.22
Evaluated at bid price : 19.22
Bid-YTW : 5.70 %
PWF.PR.F Perpetual-Discount 1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 22.29
Evaluated at bid price : 22.56
Bid-YTW : 5.90 %
PVS.PR.D SplitShare 1.38 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2021-10-08
Maturity Price : 25.00
Evaluated at bid price : 22.06
Bid-YTW : 7.06 %
IAG.PR.A Deemed-Retractible 1.38 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.55
Bid-YTW : 7.32 %
BAM.PR.T FixedReset 1.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 15.95
Evaluated at bid price : 15.95
Bid-YTW : 4.96 %
FTS.PR.J Perpetual-Discount 1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 21.55
Evaluated at bid price : 21.55
Bid-YTW : 5.56 %
TD.PR.T FloatingReset 1.51 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.25
Bid-YTW : 4.07 %
CU.PR.E Perpetual-Discount 1.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 21.25
Evaluated at bid price : 21.25
Bid-YTW : 5.82 %
ELF.PR.G Perpetual-Discount 1.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 20.46
Evaluated at bid price : 20.46
Bid-YTW : 5.91 %
CU.PR.F Perpetual-Discount 1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 19.70
Evaluated at bid price : 19.70
Bid-YTW : 5.77 %
PWF.PR.E Perpetual-Discount 1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 23.33
Evaluated at bid price : 23.61
Bid-YTW : 5.90 %
MFC.PR.B Deemed-Retractible 1.56 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.88
Bid-YTW : 7.18 %
CM.PR.Q FixedReset 1.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 19.40
Evaluated at bid price : 19.40
Bid-YTW : 4.64 %
TD.PF.A FixedReset 1.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 18.07
Evaluated at bid price : 18.07
Bid-YTW : 4.46 %
CU.PR.H Perpetual-Discount 1.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 22.15
Evaluated at bid price : 22.50
Bid-YTW : 5.87 %
BIP.PR.B FixedReset 1.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 22.20
Evaluated at bid price : 22.87
Bid-YTW : 6.03 %
PWF.PR.K Perpetual-Discount 1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 21.42
Evaluated at bid price : 21.68
Bid-YTW : 5.78 %
CM.PR.P FixedReset 1.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 17.03
Evaluated at bid price : 17.03
Bid-YTW : 4.72 %
BAM.PR.R FixedReset 1.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 15.20
Evaluated at bid price : 15.20
Bid-YTW : 5.11 %
TRP.PR.H FloatingReset 1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 10.10
Evaluated at bid price : 10.10
Bid-YTW : 4.25 %
ENB.PR.A Perpetual-Discount 1.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 22.22
Evaluated at bid price : 22.50
Bid-YTW : 6.16 %
TD.PR.Z FloatingReset 1.75 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.15
Bid-YTW : 4.23 %
TRP.PR.D FixedReset 1.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 17.88
Evaluated at bid price : 17.88
Bid-YTW : 4.67 %
VNR.PR.A FixedReset 1.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 4.88 %
BAM.PR.Z FixedReset 1.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 19.25
Evaluated at bid price : 19.25
Bid-YTW : 4.99 %
SLF.PR.J FloatingReset 1.87 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.05
Bid-YTW : 9.93 %
BAM.PR.C Floater 1.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 10.70
Evaluated at bid price : 10.70
Bid-YTW : 4.41 %
RY.PR.I FixedReset 1.91 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.00
Bid-YTW : 3.93 %
CU.PR.G Perpetual-Discount 1.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 19.70
Evaluated at bid price : 19.70
Bid-YTW : 5.77 %
BAM.PR.G FixedFloater 1.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 25.00
Evaluated at bid price : 13.11
Bid-YTW : 6.42 %
CIU.PR.C FixedReset 2.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 13.60
Evaluated at bid price : 13.60
Bid-YTW : 3.95 %
BNS.PR.R FixedReset 2.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.33
Bid-YTW : 3.87 %
TD.PF.B FixedReset 2.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 17.83
Evaluated at bid price : 17.83
Bid-YTW : 4.51 %
BNS.PR.C FloatingReset 2.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.00
Bid-YTW : 4.57 %
PWF.PR.T FixedReset 2.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 21.93
Evaluated at bid price : 22.25
Bid-YTW : 3.71 %
BNS.PR.B FloatingReset 2.29 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.87
Bid-YTW : 4.48 %
BNS.PR.D FloatingReset 2.50 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.45
Bid-YTW : 6.73 %
NA.PR.Q FixedReset 2.54 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.62
Bid-YTW : 3.74 %
W.PR.J Perpetual-Discount 2.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 22.93
Evaluated at bid price : 23.21
Bid-YTW : 6.14 %
W.PR.H Perpetual-Discount 2.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 22.71
Evaluated at bid price : 23.00
Bid-YTW : 6.08 %
BNS.PR.Z FixedReset 2.81 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.37
Bid-YTW : 6.86 %
MFC.PR.H FixedReset 2.86 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.96
Bid-YTW : 5.74 %
RY.PR.M FixedReset 2.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 18.86
Evaluated at bid price : 18.86
Bid-YTW : 4.59 %
BNS.PR.Y FixedReset 2.89 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.55
Bid-YTW : 6.19 %
TRP.PR.G FixedReset 2.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 19.86
Evaluated at bid price : 19.86
Bid-YTW : 4.74 %
BMO.PR.S FixedReset 2.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 18.42
Evaluated at bid price : 18.42
Bid-YTW : 4.45 %
MFC.PR.F FixedReset 2.94 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.36
Bid-YTW : 9.30 %
TRP.PR.C FixedReset 3.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 12.06
Evaluated at bid price : 12.06
Bid-YTW : 4.82 %
NA.PR.W FixedReset 3.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 17.02
Evaluated at bid price : 17.02
Bid-YTW : 4.76 %
TD.PR.S FixedReset 3.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.80
Bid-YTW : 3.79 %
FTS.PR.H FixedReset 3.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 14.65
Evaluated at bid price : 14.65
Bid-YTW : 3.90 %
MFC.PR.J FixedReset 3.25 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.65
Bid-YTW : 6.07 %
HSE.PR.E FixedReset 3.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 5.77 %
NA.PR.S FixedReset 3.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 17.68
Evaluated at bid price : 17.68
Bid-YTW : 4.76 %
BMO.PR.W FixedReset 3.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 17.60
Evaluated at bid price : 17.60
Bid-YTW : 4.51 %
BMO.PR.R FloatingReset 3.41 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.75
Bid-YTW : 3.72 %
SLF.PR.G FixedReset 3.45 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.00
Bid-YTW : 8.67 %
BMO.PR.M FixedReset 3.49 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.60
Bid-YTW : 3.18 %
RY.PR.J FixedReset 3.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 19.20
Evaluated at bid price : 19.20
Bid-YTW : 4.62 %
BAM.PF.B FixedReset 3.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 18.29
Evaluated at bid price : 18.29
Bid-YTW : 4.84 %
TD.PF.C FixedReset 3.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 18.01
Evaluated at bid price : 18.01
Bid-YTW : 4.45 %
TD.PF.D FixedReset 3.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 19.99
Evaluated at bid price : 19.99
Bid-YTW : 4.50 %
TD.PF.E FixedReset 3.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 20.50
Evaluated at bid price : 20.50
Bid-YTW : 4.50 %
BMO.PR.T FixedReset 3.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 17.71
Evaluated at bid price : 17.71
Bid-YTW : 4.51 %
IFC.PR.A FixedReset 3.84 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.24
Bid-YTW : 8.54 %
MFC.PR.L FixedReset 3.84 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.18
Bid-YTW : 6.84 %
BNS.PR.P FixedReset 3.87 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.68
Bid-YTW : 3.34 %
IAG.PR.G FixedReset 3.91 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.25
Bid-YTW : 5.88 %
FTS.PR.I FloatingReset 3.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 11.80
Evaluated at bid price : 11.80
Bid-YTW : 4.03 %
RY.PR.H FixedReset 3.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 18.25
Evaluated at bid price : 18.25
Bid-YTW : 4.40 %
RY.PR.Z FixedReset 4.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 18.21
Evaluated at bid price : 18.21
Bid-YTW : 4.36 %
CM.PR.O FixedReset 4.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 17.91
Evaluated at bid price : 17.91
Bid-YTW : 4.59 %
MFC.PR.G FixedReset 4.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.36
Bid-YTW : 5.84 %
HSE.PR.C FixedReset 4.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 17.71
Evaluated at bid price : 17.71
Bid-YTW : 5.71 %
BMO.PR.Q FixedReset 4.37 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.54
Bid-YTW : 5.66 %
MFC.PR.K FixedReset 4.38 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.05
Bid-YTW : 6.83 %
BNS.PR.Q FixedReset 4.43 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.06
Bid-YTW : 3.81 %
FTS.PR.M FixedReset 4.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 20.53
Evaluated at bid price : 20.53
Bid-YTW : 4.18 %
TRP.PR.A FixedReset 4.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 15.70
Evaluated at bid price : 15.70
Bid-YTW : 4.47 %
HSE.PR.G FixedReset 4.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 5.76 %
GWO.PR.N FixedReset 5.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.76
Bid-YTW : 9.56 %
CU.PR.C FixedReset 5.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 18.92
Evaluated at bid price : 18.92
Bid-YTW : 4.28 %
MFC.PR.N FixedReset 5.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.82
Bid-YTW : 6.51 %
MFC.PR.I FixedReset 5.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.13
Bid-YTW : 5.41 %
FTS.PR.G FixedReset 5.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 17.42
Evaluated at bid price : 17.42
Bid-YTW : 4.37 %
MFC.PR.M FixedReset 5.60 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.80
Bid-YTW : 6.59 %
SLF.PR.I FixedReset 5.71 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.35
Bid-YTW : 6.28 %
TD.PR.Y FixedReset 5.82 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.37
Bid-YTW : 3.54 %
BAM.PF.A FixedReset 6.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 19.67
Evaluated at bid price : 19.67
Bid-YTW : 4.82 %
BAM.PF.G FixedReset 6.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 20.45
Evaluated at bid price : 20.45
Bid-YTW : 4.67 %
BAM.PF.F FixedReset 6.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 20.26
Evaluated at bid price : 20.26
Bid-YTW : 4.69 %
SLF.PR.H FixedReset 6.99 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.60
Bid-YTW : 7.56 %
BAM.PR.X FixedReset 7.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 14.38
Evaluated at bid price : 14.38
Bid-YTW : 4.73 %
BAM.PF.E FixedReset 7.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 18.71
Evaluated at bid price : 18.71
Bid-YTW : 4.76 %
PWF.PR.P FixedReset 9.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 14.30
Evaluated at bid price : 14.30
Bid-YTW : 4.17 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.Q FixedReset 1,558,368 New issue settled today.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 23.17
Evaluated at bid price : 25.10
Bid-YTW : 5.25 %
IFC.PR.A FixedReset 135,504 Desjardins crossed blocks of 39,600 and 58,100, both at 16.20.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.24
Bid-YTW : 8.54 %
W.PR.K FixedReset 102,801 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 22.89
Evaluated at bid price : 24.28
Bid-YTW : 5.36 %
RY.PR.W Perpetual-Discount 92,464 Nesbitt crossed 75,000 at 21.87.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 21.69
Evaluated at bid price : 21.94
Bid-YTW : 5.63 %
HSE.PR.G FixedReset 87,537 Scotia crossed 65,600 at 18.72.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 5.76 %
RY.PR.N Perpetual-Discount 86,776 Nesbitt crossed 75,000 at 22.05.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 21.79
Evaluated at bid price : 22.11
Bid-YTW : 5.58 %
There were 93 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BAM.PR.E Ratchet Quote: 13.70 – 15.50
Spot Rate : 1.8000
Average : 1.3113

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 25.00
Evaluated at bid price : 13.70
Bid-YTW : 6.03 %

TD.PR.T FloatingReset Quote: 22.25 – 23.35
Spot Rate : 1.1000
Average : 0.6731

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.25
Bid-YTW : 4.07 %

PWF.PR.A Floater Quote: 11.75 – 12.75
Spot Rate : 1.0000
Average : 0.6683

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 11.75
Evaluated at bid price : 11.75
Bid-YTW : 4.05 %

IGM.PR.B Perpetual-Premium Quote: 24.99 – 25.74
Spot Rate : 0.7500
Average : 0.4456

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 24.70
Evaluated at bid price : 24.99
Bid-YTW : 5.98 %

TD.PR.Z FloatingReset Quote: 22.15 – 22.97
Spot Rate : 0.8200
Average : 0.5641

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.15
Bid-YTW : 4.23 %

VNR.PR.A FixedReset Quote: 19.00 – 19.66
Spot Rate : 0.6600
Average : 0.4336

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-16
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 4.88 %

Market Action

December 15, 2015

The equities markets did well today:

The Standard & Poor’s 500 Index capped its first back-to-back gains in more than a month as energy companies led a rally with crude oil, while Federal Reserve officials started a two-day meeting at which they’re widely expected to raise interest rates for the first time since 2006.
…
The S&P 500 climbed 1.1 percent to 2,043.41 at 4 p.m. in New York, marking its first consecutive increases since Nov. 3. The Dow Jones Industrial Average rose 156.41 points, or 0.9 percent, to 17,524.91, even as 3M’s retreat amounted to about 63 points off the index. The Nasdaq Composite Index rallied 0.9 percent. About 8.1 billion shares traded hands on U.S. exchanges, 12 percent above the three-month average.
…
Fed officials announce their rate decision tomorrow at 2 p.m. in Washington, and traders are pricing in a 78 percent chance of a liftoff. Data today reinforced expectations for a gradual increase in rates, with the cost of living holding steady in November, underscoring scant inflation that is well below the Fed’s goal. Among the other few economic cues before the rate announcement are reports on housing starts and industrial production Wednesday.

And the junk market is hearing some whispering from bottom feeders:

Amid an almost 6 percent selloff in high-yield debt this year, speculative-grade credit is yielding 3.52 percentage points more than stocks in the Standard & Poor’s 500 Index are earning — the widest spread since 2010, according to data compiled by Bloomberg. Since the start of the 6 1/2-year bull market, junk securities have held an advantage of less than half that — 1.36 percent — over equity counterparts, the data show.

junkEquitySpread_151215
Click for Big

Tracy Alloway of Bloomberg points out that regulations affecting repos indirectly affect corporate bond liquidity:

While the focus, when it comes to a lack of liquidity in the bond market, has often been placed squarely on the shrinking amount of bonds on dealer-bank balance sheets, a further change to the banking business is arguably exacerbating the recent downward spiral in debt. That change is the shrinking of the repo business, which involves banks lending their balance sheets to clients and is often described as the great lubricator for financial markets.

The business has been shrinking in recent years. A huge regulatory overhaul has made repo more expensive in the face of various new mandates, including the leverage ratio and the net stable funding ratio, encouraging banks to pull back on their repo business and helping to push repo rates higher.

generalCollateral_151215
Click for Big

Barrick announced pricing for its debt tender deal.

Dominion and Anglo Investment Corporation Limited, which is a major vehicle of the Jackman family, has tightened control of E-L Financial, proud issuer of ELF.PR.F, ELF.PR.G and ELF.PR.H:

Dominion and Anglo Investment Corporation Limited (“Dominion and Anglo”) announces that it acquired a further 80,000 Common Shares of E-L Financial Corporation Limited (“E-L Financial”) (TSX:ELF) (TSX:ELF.PR.F) (TSX:ELF.PR.G) (TSX:ELF.PR.H), increasing its ownership from 1,302,323 (32.4%) of the Common Shares to 1,382,323 (34.39%) of the Common Shares. Dominion and Anglo has an informal understanding with other shareholders of E-L Financial under which they act in concert with respect to the voting of securities of E-L Financial held by them. The purchase increases the ownership of Dominion and Anglo and these other shareholders from 2,748,329 (68.38%) of the Common Shares to 2,828,329 (70.37%) of the Common Shares. The purchase was effected through the facilities of the Toronto Stock Exchange for consideration of $680.00 per share.

But guess what, preferred share fans? Santa came early!

santaCash
Click for Big

It was an extremely strong day for the Canadian preferred share market … I suspect some major player decided to get in now rather than wait for the end of tax-loss selling season, when every other potential buyer will be in the market while the tax-loss sellers enjoy the holidays. PerpetualDiscounts gained 68bp, FixedResets won 430bp and DeemedRetractibles were up 81bp. The Performance Highlights table is, of course, immense, with no less than 31 issues exceeding the 5% change level that is normally indicative of some kind of problem; there were no losers. Volume continued to be extremely heavy.

For those keeping score, TXPR is now down 5.65% on the month to date, but 3.68% above its low of yesterday.

TXPR_151215
Click for Big

TXPL is down 7.07% on the month to date, but 5.24% above its low of yesterday.

TXPL_151215
Click for Big
HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 4.98 % 6.06 % 35,128 16.58 1 3.0189 % 1,558.0
FixedFloater 7.39 % 6.54 % 36,155 15.57 1 0.7048 % 2,641.7
Floater 4.34 % 4.41 % 84,987 16.61 4 3.5910 % 1,761.3
OpRet 4.87 % 4.27 % 27,384 0.70 1 0.0000 % 2,734.3
SplitShare 4.87 % 5.85 % 83,582 1.87 6 0.2237 % 3,174.4
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.2237 % 2,476.8
Perpetual-Premium 5.88 % 5.97 % 91,219 13.86 7 0.0866 % 2,464.8
Perpetual-Discount 5.84 % 5.91 % 103,412 13.96 33 0.6836 % 2,452.4
FixedReset 5.40 % 4.88 % 260,807 15.12 79 4.2975 % 1,912.7
Deemed-Retractible 5.28 % 5.33 % 135,712 5.31 33 0.8071 % 2,541.0
FloatingReset 2.86 % 4.53 % 67,455 5.67 11 0.7549 % 2,064.3
Performance Highlights
Issue Index Change Notes
BAM.PR.N Perpetual-Discount 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 19.14
Evaluated at bid price : 19.14
Bid-YTW : 6.23 %
SLF.PR.B Deemed-Retractible 1.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.37
Bid-YTW : 6.99 %
GWO.PR.G Deemed-Retractible 1.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.55
Bid-YTW : 6.66 %
GWO.PR.F Deemed-Retractible 1.21 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-01-14
Maturity Price : 25.00
Evaluated at bid price : 25.10
Bid-YTW : -2.10 %
BAM.PF.H FixedReset 1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 23.14
Evaluated at bid price : 24.95
Bid-YTW : 4.92 %
CM.PR.O FixedReset 1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 17.21
Evaluated at bid price : 17.21
Bid-YTW : 4.78 %
PWF.PR.R Perpetual-Discount 1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 23.20
Evaluated at bid price : 23.60
Bid-YTW : 5.90 %
TD.PR.Z FloatingReset 1.35 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.77
Bid-YTW : 4.54 %
BMO.PR.R FloatingReset 1.38 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.00
Bid-YTW : 4.32 %
SLF.PR.E Deemed-Retractible 1.40 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.23
Bid-YTW : 7.42 %
ELF.PR.G Perpetual-Discount 1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 20.15
Evaluated at bid price : 20.15
Bid-YTW : 6.01 %
SLF.PR.C Deemed-Retractible 1.41 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.09
Bid-YTW : 7.47 %
SLF.PR.D Deemed-Retractible 1.42 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.96
Bid-YTW : 7.56 %
TD.PR.S FixedReset 1.45 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.08
Bid-YTW : 4.35 %
PVS.PR.E SplitShare 1.46 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-10-31
Maturity Price : 25.00
Evaluated at bid price : 24.30
Bid-YTW : 6.07 %
HSB.PR.D Deemed-Retractible 1.46 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-01-14
Maturity Price : 25.00
Evaluated at bid price : 24.95
Bid-YTW : 4.83 %
BNS.PR.B FloatingReset 1.52 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.38
Bid-YTW : 4.89 %
ELF.PR.H Perpetual-Discount 1.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 22.67
Evaluated at bid price : 23.02
Bid-YTW : 6.07 %
BNS.PR.Y FixedReset 1.60 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.00
Bid-YTW : 6.70 %
CU.PR.I FixedReset 1.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 23.04
Evaluated at bid price : 24.65
Bid-YTW : 4.50 %
GWO.PR.H Deemed-Retractible 1.71 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.41
Bid-YTW : 7.02 %
NA.PR.Q FixedReset 1.74 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.01
Bid-YTW : 4.20 %
SLF.PR.G FixedReset 1.75 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.50
Bid-YTW : 9.11 %
BAM.PF.E FixedReset 1.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 17.38
Evaluated at bid price : 17.38
Bid-YTW : 5.14 %
TRP.PR.F FloatingReset 1.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 13.02
Evaluated at bid price : 13.02
Bid-YTW : 4.53 %
CM.PR.P FixedReset 1.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 16.75
Evaluated at bid price : 16.75
Bid-YTW : 4.80 %
W.PR.H Perpetual-Discount 1.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 22.14
Evaluated at bid price : 22.42
Bid-YTW : 6.24 %
NA.PR.W FixedReset 1.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 16.51
Evaluated at bid price : 16.51
Bid-YTW : 4.91 %
BMO.PR.Z Perpetual-Discount 1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 22.52
Evaluated at bid price : 22.85
Bid-YTW : 5.51 %
NA.PR.S FixedReset 2.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 17.10
Evaluated at bid price : 17.10
Bid-YTW : 4.93 %
GWO.PR.I Deemed-Retractible 2.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.38
Bid-YTW : 7.32 %
W.PR.J Perpetual-Discount 2.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 22.36
Evaluated at bid price : 22.63
Bid-YTW : 6.30 %
RY.PR.Z FixedReset 2.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 4.54 %
MFC.PR.H FixedReset 2.40 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.35
Bid-YTW : 6.12 %
BMO.PR.T FixedReset 2.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 17.07
Evaluated at bid price : 17.07
Bid-YTW : 4.69 %
RY.PR.H FixedReset 2.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 17.55
Evaluated at bid price : 17.55
Bid-YTW : 4.58 %
BNS.PR.P FixedReset 2.50 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.76
Bid-YTW : 4.04 %
CIU.PR.C FixedReset 2.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 13.33
Evaluated at bid price : 13.33
Bid-YTW : 4.03 %
TRP.PR.H FloatingReset 2.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 9.93
Evaluated at bid price : 9.93
Bid-YTW : 4.33 %
MFC.PR.F FixedReset 2.72 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.95
Bid-YTW : 9.68 %
TRP.PR.A FixedReset 2.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 15.00
Evaluated at bid price : 15.00
Bid-YTW : 4.68 %
TD.PF.B FixedReset 2.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 17.45
Evaluated at bid price : 17.45
Bid-YTW : 4.61 %
BAM.PF.F FixedReset 2.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 5.01 %
BAM.PR.E Ratchet 3.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 25.00
Evaluated at bid price : 13.65
Bid-YTW : 6.06 %
BMO.PR.W FixedReset 3.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 17.02
Evaluated at bid price : 17.02
Bid-YTW : 4.66 %
BIP.PR.A FixedReset 3.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 18.97
Evaluated at bid price : 18.97
Bid-YTW : 5.77 %
BNS.PR.Q FixedReset 3.18 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.04
Bid-YTW : 4.61 %
RY.PR.M FixedReset 3.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 18.33
Evaluated at bid price : 18.33
Bid-YTW : 4.72 %
TRP.PR.G FixedReset 3.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 19.30
Evaluated at bid price : 19.30
Bid-YTW : 4.88 %
PWF.PR.T FixedReset 3.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 21.42
Evaluated at bid price : 21.76
Bid-YTW : 3.80 %
BMO.PR.Q FixedReset 3.31 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.68
Bid-YTW : 6.44 %
RY.PR.J FixedReset 3.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 18.55
Evaluated at bid price : 18.55
Bid-YTW : 4.78 %
BAM.PF.G FixedReset 3.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 19.25
Evaluated at bid price : 19.25
Bid-YTW : 4.97 %
BNS.PR.Z FixedReset 3.52 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.84
Bid-YTW : 7.36 %
HSE.PR.G FixedReset 3.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 18.15
Evaluated at bid price : 18.15
Bid-YTW : 6.03 %
TD.PF.A FixedReset 3.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 17.79
Evaluated at bid price : 17.79
Bid-YTW : 4.53 %
CU.PR.C FixedReset 3.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 18.01
Evaluated at bid price : 18.01
Bid-YTW : 4.50 %
HSE.PR.E FixedReset 3.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 18.40
Evaluated at bid price : 18.40
Bid-YTW : 5.96 %
TD.PF.C FixedReset 3.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 17.39
Evaluated at bid price : 17.39
Bid-YTW : 4.62 %
RY.PR.L FixedReset 3.98 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.80
Bid-YTW : 4.08 %
TD.PF.E FixedReset 4.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 19.76
Evaluated at bid price : 19.76
Bid-YTW : 4.67 %
HSE.PR.C FixedReset 4.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 5.95 %
BAM.PR.B Floater 4.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 10.70
Evaluated at bid price : 10.70
Bid-YTW : 4.41 %
BAM.PR.C Floater 4.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 10.50
Evaluated at bid price : 10.50
Bid-YTW : 4.50 %
BAM.PR.X FixedReset 4.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 13.36
Evaluated at bid price : 13.36
Bid-YTW : 5.10 %
GWO.PR.N FixedReset 4.63 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.10
Bid-YTW : 10.21 %
TRP.PR.E FixedReset 4.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 18.42
Evaluated at bid price : 18.42
Bid-YTW : 4.60 %
RY.PR.I FixedReset 4.67 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.55
Bid-YTW : 4.27 %
FTS.PR.G FixedReset 4.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 16.50
Evaluated at bid price : 16.50
Bid-YTW : 4.62 %
BAM.PF.A FixedReset 4.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 18.55
Evaluated at bid price : 18.55
Bid-YTW : 5.11 %
BAM.PF.B FixedReset 5.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 17.67
Evaluated at bid price : 17.67
Bid-YTW : 5.01 %
VNR.PR.A FixedReset 5.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 18.66
Evaluated at bid price : 18.66
Bid-YTW : 4.97 %
BMO.PR.Y FixedReset 5.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 19.55
Evaluated at bid price : 19.55
Bid-YTW : 4.57 %
TRP.PR.C FixedReset 5.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 11.70
Evaluated at bid price : 11.70
Bid-YTW : 4.97 %
SLF.PR.I FixedReset 5.42 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.25
Bid-YTW : 7.03 %
BMO.PR.M FixedReset 5.64 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.77
Bid-YTW : 3.80 %
BNS.PR.R FixedReset 5.73 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.82
Bid-YTW : 4.26 %
TD.PF.D FixedReset 5.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 19.28
Evaluated at bid price : 19.28
Bid-YTW : 4.67 %
BAM.PR.R FixedReset 5.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 14.95
Evaluated at bid price : 14.95
Bid-YTW : 5.19 %
SLF.PR.H FixedReset 5.92 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.45
Bid-YTW : 8.47 %
BAM.PR.T FixedReset 5.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 15.73
Evaluated at bid price : 15.73
Bid-YTW : 5.03 %
TRP.PR.D FixedReset 6.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 17.57
Evaluated at bid price : 17.57
Bid-YTW : 4.75 %
FTS.PR.K FixedReset 6.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 4.19 %
BAM.PR.K Floater 6.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 10.66
Evaluated at bid price : 10.66
Bid-YTW : 4.43 %
MFC.PR.K FixedReset 6.73 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.25
Bid-YTW : 7.41 %
BMO.PR.S FixedReset 6.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 17.90
Evaluated at bid price : 17.90
Bid-YTW : 4.58 %
BAM.PR.Z FixedReset 7.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 18.90
Evaluated at bid price : 18.90
Bid-YTW : 5.09 %
FTS.PR.M FixedReset 7.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 19.62
Evaluated at bid price : 19.62
Bid-YTW : 4.38 %
CM.PR.Q FixedReset 7.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 19.10
Evaluated at bid price : 19.10
Bid-YTW : 4.72 %
MFC.PR.L FixedReset 7.32 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.47
Bid-YTW : 7.35 %
TRP.PR.B FixedReset 7.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 11.30
Evaluated at bid price : 11.30
Bid-YTW : 4.57 %
IAG.PR.G FixedReset 7.63 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.45
Bid-YTW : 6.39 %
MFC.PR.M FixedReset 7.88 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.75
Bid-YTW : 7.34 %
MFC.PR.J FixedReset 8.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.00
Bid-YTW : 6.50 %
HSE.PR.A FixedReset 8.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 11.50
Evaluated at bid price : 11.50
Bid-YTW : 5.42 %
IFC.PR.C FixedReset 8.86 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.05
Bid-YTW : 7.06 %
MFC.PR.N FixedReset 8.90 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.85
Bid-YTW : 7.19 %
MFC.PR.G FixedReset 9.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.52
Bid-YTW : 6.38 %
IFC.PR.A FixedReset 9.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.64
Bid-YTW : 9.05 %
MFC.PR.I FixedReset 9.70 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.03
Bid-YTW : 6.09 %
FTS.PR.H FixedReset 11.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 14.20
Evaluated at bid price : 14.20
Bid-YTW : 4.02 %
Volume Highlights
Issue Index Shares
Traded
Notes
W.PR.K FixedReset 241,305 New issue settled today.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 22.81
Evaluated at bid price : 24.10
Bid-YTW : 5.41 %
GWO.PR.N FixedReset 119,159 Scotia crossed 10,000 at 12.67. RBC sold blocks of 58,700 and 20,000 to anonymous, both at 13.05.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.10
Bid-YTW : 10.21 %
BAM.PF.A FixedReset 77,694 Scotia crossed 30,000 at 18.10.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 18.55
Evaluated at bid price : 18.55
Bid-YTW : 5.11 %
MFC.PR.F FixedReset 72,914 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.95
Bid-YTW : 9.68 %
CM.PR.O FixedReset 69,950 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 17.21
Evaluated at bid price : 17.21
Bid-YTW : 4.78 %
BAM.PR.R FixedReset 63,185 Scotia crossed 22,300 at 14.76.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 14.95
Evaluated at bid price : 14.95
Bid-YTW : 5.19 %
There were 87 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BAM.PR.G FixedFloater Quote: 12.86 – 14.50
Spot Rate : 1.6400
Average : 0.9694

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 25.00
Evaluated at bid price : 12.86
Bid-YTW : 6.54 %

MFC.PR.H FixedReset Quote: 21.35 – 22.33
Spot Rate : 0.9800
Average : 0.5651

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.35
Bid-YTW : 6.12 %

PWF.PR.P FixedReset Quote: 13.01 – 13.75
Spot Rate : 0.7400
Average : 0.4394

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-15
Maturity Price : 13.01
Evaluated at bid price : 13.01
Bid-YTW : 4.58 %

MFC.PR.M FixedReset Quote: 18.75 – 19.61
Spot Rate : 0.8600
Average : 0.5880

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.75
Bid-YTW : 7.34 %

SLF.PR.I FixedReset Quote: 19.25 – 20.00
Spot Rate : 0.7500
Average : 0.4837

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.25
Bid-YTW : 7.03 %

BNS.PR.P FixedReset Quote: 23.76 – 24.48
Spot Rate : 0.7200
Average : 0.4757

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.76
Bid-YTW : 4.04 %

Market Action

December 14, 2015

Mohamed A. El-Erian commented on the Third Avenue fund closure:

The scale of the accident increases significantly if individual managers within the asset class have ventured to more exotic and less liquid securities in search of returns. I don’t mean to say that it isn’t worthwhile to pursue such investments, especially when underpinned by solid credit research. It is, but in the proper context and size. Such investments can be particularly dangerous to an open-fund structure during periods of market dislocations if a significant part of the investor base acts on the belief that daily liquidity for exit is available at a decent valuation.
…
Depending on how far the situation deteriorates, price overshoots can take valuations well beyond what is warranted by credit and economic fundamentals, as well as fuel contagion within the asset class. Then, investor outflows are likely to accelerate further, putting pressure on both liquid and illiquid names. And even though the turmoil can create attractive investment opportunities, fresh cash takes time to engage.

The greater the dislocation of the asset class, the higher the risk of spillovers to other types of investments, starting with the asset classes that share the same characteristics of credit, default and liquidity risks.

Broker-dealers will be less willing and able to act as stabilizers by stepping up with their own balance sheets. Both regulatory and market forces have limited their appetite for this countercyclical role. In addition, their willingness to accumulate such inventory decreases as we get closer to the close of their fiscal year (which, for many, is December).

There’s one casualty already:

Third Avenue Management is parting ways with Chief Executive Officer David M. Barse after he announced plans last week to freeze redemptions in its troubled high-yield mutual fund, the Wall Street Journal reported, citing unidentified people familiar with the matter.

Barse was let go and isn’t allowed back in the building, the newspaper said, citing a security guard at the firm’s New York headquarters. Daniel Gagnier, a spokesman for Third Avenue, declined to comment when reached by Bloomberg. Barse didn’t respond to messages left at his home over the weekend.

A C.D.Howe paper by Craig Alexander and Paul Jacobson titled Mortgaged to the Hilt: Risks From The Distribution of Household Mortgage Debt has some interesting things to say:

The National Balance Sheet Accounts show the dramatic rise of household mortgage debt growth since 1999, jumping from $375 billion to $1.16 trillion in 2014. The increasing size of mortgages was clearly tied to rising demand and soaring cost for residential real estate. From 1999 to 2014, national average resale home prices soared by 158 percent, requiring larger mortgages for many buyers.
…
According to the national average data from the National Balance Sheet Accounts, mortgage debt as a share of disposable income climbed from 66 percent in 1999 to 99 percent in 2012 and reached 104 percent in 2014. But, these economy-wide averages understate the degree of financial risk for those that carried mortgages because they divide the value of mortgages across the income of households with and without mortgages.

The SFS data show that primary mortgages have increased significantly. The primary mortgage debt-to-disposable income ratio has climbed from 144 percent of income in 1999 to 204 percent in 2012. However, this also understates the degree of financial risk for a significant minority of households. The share of exceptionally high mortgage-leverage households has increased. This can be seen in the ratio of primary residence mortgage debt to after-tax income across mortgaged households. In 1999, 12.6 percent of households had mortgages that exceeded 300 percent of disposable income (Figure 1). By 2012, the share had reached 27.4 percent. And, the share of households with mortgages at 500 percent or more of disposable income has climbed from 3.4 percent in 1999 to 10.8 percent in 2012. The underlying story is that as older, smaller mortgages were paid off, they were replaced by larger new mortgages reflecting the increase in home prices that has far outpaced household income growth.

And it looks like OSFI’s contemplating making mortgage applications even more of a paperwork nightmare than they are already:

Canada’s banking and insurance regulator highlighted fraudulent mortgage practices as a key threat to the country’s financial system, prompting consultations with lenders over how to ensure that the system can withstand a severe housing market downturn.

“It has come to light that institutions have been, I would say inadvertently, making mortgages to people whose income has been falsified,” said Jeremy Rudin, superintendent of financial institutions.

“One of things we’ve been doing is encouraging sound risk management. And as we set out in our guideline on mortgage underwriting, income verification – checking to make sure the borrower has the ability to carry the loan – is an important part of sound underwriting.”

Decisions, decisions…:

As the Treasury Department ponders which American woman should be featured on the $10 bill, an abundance of ideas is delaying the decision until next year.

The department is taking additional time to consider a range of options after receiving more suggestions than originally expected, the Treasury said Friday in an e-mailed statement. Secretary Jacob Lew is now expected to announce the choice in 2016.

I vote for Scarlett Johansson, nude.

But such happy thoughts are interrupted by warning stickers that might be put on preferred share buy confirmations soon:

cliffWarning
Click for Big

It was an utterly appalling day for the Canadian preferred share market, with PerpetualDiscounts down 84bp, FixedResets losing 194bp and DeemedRetractibles off 44bp. What can I say about the Performance Highlights table. “It is long”? How does that sound? Volume was enormous again.

For those keeping score, TXPR is now down 9.00% on the month to date and is now 1.07% below the low of October 14.

TXPR_151214
Click for Big

TXPL is down about 11.70% on the month to date and is 2.50% below the low the October 14.

TXPL_151214
Click for Big

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_151214
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 17.60 to be $1.26 rich, while TRP.PR.C, resetting 2016-1-30 at +154, is $1.08 cheap at its bid price of 11.10.

impVol_MFC_151214
Click for Big

Most expensive is MFC.PR.H, resetting at +313bp on 2017-3-19, bid at 20.85 to be 0.73 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 18.81 to be 0.68 cheap.

impVol_BAM_151214
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 14.12 to be $1.04 cheap. BAM.PF.G, resetting at +284bp on 2020-6-30 is bid at 18.60 and appears to be $0.79 rich.

impVol_FTS_151214
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 16.93, looks $0.82 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 15.75 and is $0.79 cheap.

pairs_FR_151214
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.09%, with no outliers. There is one junk outlier below -1.00% and one above +1.00%. Note the vertical axis of this graph has been changed.

pairs_FF_151214
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.13 % 6.24 % 33,251 16.36 1 -0.3759 % 1,512.4
FixedFloater 7.44 % 6.59 % 33,611 15.52 1 -0.6226 % 2,623.3
Floater 4.49 % 4.61 % 85,427 16.24 4 -0.9656 % 1,700.2
OpRet 4.87 % 4.25 % 28,516 0.70 1 0.0000 % 2,734.3
SplitShare 4.88 % 5.85 % 84,172 1.88 6 -0.5928 % 3,167.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.5928 % 2,471.3
Perpetual-Premium 5.88 % 5.95 % 91,987 13.85 7 -0.0750 % 2,462.6
Perpetual-Discount 5.88 % 5.96 % 102,618 13.90 33 -0.8390 % 2,435.7
FixedReset 5.63 % 5.06 % 254,121 14.65 78 -1.9400 % 1,833.9
Deemed-Retractible 5.32 % 5.88 % 135,492 7.03 33 -0.4371 % 2,520.7
FloatingReset 2.88 % 4.62 % 64,478 5.67 11 -1.0367 % 2,048.8
Performance Highlights
Issue Index Change Notes
GWO.PR.N FixedReset -7.26 % A little bit real, but not quite as bad as it looks. The issue traded 32,758 shares in a range of 12.87-77 before closing at 12.52-75, 2×3 … so while the bid is reasonable compared to the offer, the offer is below the low for the day, which is less reasonable. The last trade of the day was at 13.04, timestamped 3:58, for 100 shares. VWAP was 13.23.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.52
Bid-YTW : 10.80 %
HSE.PR.A FixedReset -6.68 % Quite real enough! The issue traded 19,609 shares today in a range of 10.61-40 before closing at 10.61-02, 2×4. There were six trades totalling 900 shares timestamped 3:59 done at 10.61. VWAP was 10.99.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 10.61
Evaluated at bid price : 10.61
Bid-YTW : 5.88 %
W.PR.J Perpetual-Discount -6.54 % Not real. The issue traded 1,100 shares today in a range of 23.10-26 before closing at 22.16-08, 6×6. The last trade of the day was for 100 shares at 23.10, timestamped 3:47. VWAP was 23.22. I have not checked whether this lamentable state of affairs is due to inadequate Toronto Stock Exchange reporting or inadequate Toronto Stock Exchange supervision of market-makers.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 21.92
Evaluated at bid price : 22.16
Bid-YTW : 6.43 %
W.PR.H Perpetual-Discount -6.46 % Not real, as the issue traded 1,335 shares in a range of 22.92-50 before closing at 22.56-80, 12×10. It will be noted that here I am reporting a 22.56 closing bid and using a 22.00 bid for calculation purposes. Well, all I can say is that the 22.00 is what I have bought from the Toronto Exchange at great expense, and the 22.56 is what they report on their website. I suppose the National Best Bid was on another exchange.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 21.75
Evaluated at bid price : 22.00
Bid-YTW : 6.36 %
TRP.PR.C FixedReset -6.01 % It looks like this issue was targeted by the seller who took the market down late in the day, as the last twenty-four trades all list “anonymous” as the seller. These trades started at 3:51 at a price of 11.13 and lasted until 3:59 at 11.12 – most of the trades were executed above these levels. These trades totalled 3,000 shares, vs. 28,104 on the day. The day’s VWAP was 11.53.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 11.10
Evaluated at bid price : 11.10
Bid-YTW : 5.24 %
BIP.PR.B FixedReset -4.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 21.91
Evaluated at bid price : 22.40
Bid-YTW : 6.17 %
PWF.PR.P FixedReset -4.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 12.90
Evaluated at bid price : 12.90
Bid-YTW : 4.62 %
TRP.PR.D FixedReset -4.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 16.54
Evaluated at bid price : 16.54
Bid-YTW : 5.06 %
CIU.PR.C FixedReset -4.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 13.00
Evaluated at bid price : 13.00
Bid-YTW : 4.14 %
BMO.PR.S FixedReset -4.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 16.77
Evaluated at bid price : 16.77
Bid-YTW : 4.90 %
BNS.PR.Z FixedReset -4.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.20
Bid-YTW : 7.99 %
HSE.PR.C FixedReset -4.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 16.32
Evaluated at bid price : 16.32
Bid-YTW : 6.20 %
PWF.PR.T FixedReset -3.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 21.07
Evaluated at bid price : 21.07
Bid-YTW : 3.96 %
TRP.PR.A FixedReset -3.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 14.59
Evaluated at bid price : 14.59
Bid-YTW : 4.81 %
MFC.PR.F FixedReset -3.69 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.58
Bid-YTW : 10.04 %
IFC.PR.A FixedReset -3.57 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.32
Bid-YTW : 10.28 %
MFC.PR.I FixedReset -3.43 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.17
Bid-YTW : 7.36 %
TRP.PR.B FixedReset -3.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 10.50
Evaluated at bid price : 10.50
Bid-YTW : 4.92 %
BNS.PR.R FixedReset -3.30 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.53
Bid-YTW : 5.30 %
MFC.PR.G FixedReset -3.19 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.81
Bid-YTW : 7.57 %
BAM.PR.R FixedReset -2.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 14.12
Evaluated at bid price : 14.12
Bid-YTW : 5.50 %
BNS.PR.Y FixedReset -2.65 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.70
Bid-YTW : 6.98 %
BMO.PR.Y FixedReset -2.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 18.56
Evaluated at bid price : 18.56
Bid-YTW : 4.82 %
PVS.PR.D SplitShare -2.54 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2021-10-08
Maturity Price : 25.00
Evaluated at bid price : 21.85
Bid-YTW : 7.25 %
BMO.PR.T FixedReset -2.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 16.67
Evaluated at bid price : 16.67
Bid-YTW : 4.80 %
BMO.PR.W FixedReset -2.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 16.52
Evaluated at bid price : 16.52
Bid-YTW : 4.81 %
CU.PR.C FixedReset -2.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 17.36
Evaluated at bid price : 17.36
Bid-YTW : 4.67 %
CM.PR.P FixedReset -2.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 16.44
Evaluated at bid price : 16.44
Bid-YTW : 4.90 %
RY.PR.I FixedReset -2.39 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.50
Bid-YTW : 5.11 %
FTS.PR.H FixedReset -2.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 12.77
Evaluated at bid price : 12.77
Bid-YTW : 4.48 %
CM.PR.Q FixedReset -2.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 17.81
Evaluated at bid price : 17.81
Bid-YTW : 5.06 %
CU.PR.I FixedReset -2.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 22.89
Evaluated at bid price : 24.25
Bid-YTW : 4.59 %
BMO.PR.M FixedReset -2.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.50
Bid-YTW : 4.81 %
NA.PR.W FixedReset -2.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 16.20
Evaluated at bid price : 16.20
Bid-YTW : 5.01 %
TRP.PR.E FixedReset -2.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 17.60
Evaluated at bid price : 17.60
Bid-YTW : 4.82 %
PWF.PR.A Floater -2.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 11.75
Evaluated at bid price : 11.75
Bid-YTW : 4.05 %
RY.PR.L FixedReset -2.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.85
Bid-YTW : 4.82 %
NA.PR.Q FixedReset -2.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.60
Bid-YTW : 4.52 %
SLF.PR.H FixedReset -2.02 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.53
Bid-YTW : 9.25 %
TD.PF.E FixedReset -1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 4.86 %
RY.PR.M FixedReset -1.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 17.76
Evaluated at bid price : 17.76
Bid-YTW : 4.88 %
BNS.PR.Q FixedReset -1.93 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.33
Bid-YTW : 5.19 %
RY.PR.J FixedReset -1.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 17.95
Evaluated at bid price : 17.95
Bid-YTW : 4.94 %
BMO.PR.Z Perpetual-Discount -1.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 22.09
Evaluated at bid price : 22.41
Bid-YTW : 5.62 %
TD.PR.Z FloatingReset -1.87 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.48
Bid-YTW : 4.78 %
MFC.PR.N FixedReset -1.87 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.31
Bid-YTW : 8.37 %
MFC.PR.J FixedReset -1.86 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.50
Bid-YTW : 7.57 %
CM.PR.O FixedReset -1.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 4.85 %
RY.PR.A Deemed-Retractible -1.75 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.21
Bid-YTW : 5.13 %
TRP.PR.F FloatingReset -1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 12.78
Evaluated at bid price : 12.78
Bid-YTW : 4.62 %
HSE.PR.G FixedReset -1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 6.26 %
BAM.PR.Z FixedReset -1.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 17.65
Evaluated at bid price : 17.65
Bid-YTW : 5.45 %
BIP.PR.A FixedReset -1.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 18.40
Evaluated at bid price : 18.40
Bid-YTW : 5.95 %
FTS.PR.G FixedReset -1.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 15.75
Evaluated at bid price : 15.75
Bid-YTW : 4.85 %
IAG.PR.G FixedReset -1.55 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.00
Bid-YTW : 7.40 %
SLF.PR.J FloatingReset -1.55 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.72
Bid-YTW : 10.26 %
TRP.PR.H FloatingReset -1.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 9.68
Evaluated at bid price : 9.68
Bid-YTW : 4.44 %
TD.PF.B FixedReset -1.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 16.95
Evaluated at bid price : 16.95
Bid-YTW : 4.75 %
TD.PF.C FixedReset -1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 16.73
Evaluated at bid price : 16.73
Bid-YTW : 4.80 %
ELF.PR.H Perpetual-Discount -1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 22.37
Evaluated at bid price : 22.66
Bid-YTW : 6.17 %
GWO.PR.F Deemed-Retractible -1.39 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.80
Bid-YTW : 6.02 %
BAM.PR.X FixedReset -1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 12.78
Evaluated at bid price : 12.78
Bid-YTW : 5.34 %
PVS.PR.C SplitShare -1.37 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2017-12-10
Maturity Price : 25.00
Evaluated at bid price : 24.41
Bid-YTW : 6.21 %
NA.PR.S FixedReset -1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 16.75
Evaluated at bid price : 16.75
Bid-YTW : 5.03 %
BNS.PR.P FixedReset -1.32 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.18
Bid-YTW : 4.49 %
FTS.PR.I FloatingReset -1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 11.40
Evaluated at bid price : 11.40
Bid-YTW : 4.17 %
CIU.PR.A Perpetual-Discount -1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 20.10
Evaluated at bid price : 20.10
Bid-YTW : 5.78 %
RY.PR.O Perpetual-Discount -1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 21.50
Evaluated at bid price : 21.80
Bid-YTW : 5.66 %
TD.PR.Y FixedReset -1.25 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.00
Bid-YTW : 4.60 %
GWO.PR.G Deemed-Retractible -1.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.30
Bid-YTW : 6.81 %
TD.PF.F Perpetual-Discount -1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 21.60
Evaluated at bid price : 21.93
Bid-YTW : 5.65 %
BAM.PF.H FixedReset -1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 23.04
Evaluated at bid price : 24.65
Bid-YTW : 4.99 %
MFC.PR.M FixedReset -1.19 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.38
Bid-YTW : 8.39 %
BNS.PR.D FloatingReset -1.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.86
Bid-YTW : 7.30 %
TD.PF.A FixedReset -1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 17.15
Evaluated at bid price : 17.15
Bid-YTW : 4.70 %
BMO.PR.R FloatingReset -1.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.70
Bid-YTW : 4.56 %
BAM.PF.A FixedReset -1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 17.70
Evaluated at bid price : 17.70
Bid-YTW : 5.36 %
GWO.PR.I Deemed-Retractible -1.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.96
Bid-YTW : 7.61 %
FTS.PR.J Perpetual-Discount -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 21.07
Evaluated at bid price : 21.07
Bid-YTW : 5.69 %
RY.PR.F Deemed-Retractible -1.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.30
Bid-YTW : 5.06 %
IFC.PR.C FixedReset 1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.50
Bid-YTW : 8.22 %
RY.PR.P Perpetual-Discount 1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 24.04
Evaluated at bid price : 24.40
Bid-YTW : 5.47 %
MFC.PR.K FixedReset 1.79 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.10
Bid-YTW : 8.30 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.Z FixedReset 94,695 GMP bought blocks of 18,400 and 16,900 from National at 17.25.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 17.10
Evaluated at bid price : 17.10
Bid-YTW : 4.65 %
TRP.PR.A FixedReset 69,180 RBC crossed 50,400 at 15.25.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 14.59
Evaluated at bid price : 14.59
Bid-YTW : 4.81 %
TRP.PR.F FloatingReset 59,315 RBC crossed 53,000 at 12.60.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 12.78
Evaluated at bid price : 12.78
Bid-YTW : 4.62 %
TRP.PR.D FixedReset 56,782 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 16.54
Evaluated at bid price : 16.54
Bid-YTW : 5.06 %
BAM.PF.H FixedReset 54,415 Nesbitt crossed 25,000 at 24.85.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 23.04
Evaluated at bid price : 24.65
Bid-YTW : 4.99 %
NA.PR.S FixedReset 53,016 Nesbitt crossed 29,000 at 16.90.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 16.75
Evaluated at bid price : 16.75
Bid-YTW : 5.03 %
There were 82 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BIP.PR.B FixedReset Quote: 22.40 – 23.40
Spot Rate : 1.0000
Average : 0.5767

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 21.91
Evaluated at bid price : 22.40
Bid-YTW : 6.17 %

W.PR.J Perpetual-Discount Quote: 22.16 – 23.08
Spot Rate : 0.9200
Average : 0.5539

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 21.92
Evaluated at bid price : 22.16
Bid-YTW : 6.43 %

W.PR.H Perpetual-Discount Quote: 22.00 – 22.80
Spot Rate : 0.8000
Average : 0.4906

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 21.75
Evaluated at bid price : 22.00
Bid-YTW : 6.36 %

BMO.PR.S FixedReset Quote: 16.77 – 17.30
Spot Rate : 0.5300
Average : 0.3183

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 16.77
Evaluated at bid price : 16.77
Bid-YTW : 4.90 %

CIU.PR.C FixedReset Quote: 13.00 – 13.79
Spot Rate : 0.7900
Average : 0.5804

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 13.00
Evaluated at bid price : 13.00
Bid-YTW : 4.14 %

CM.PR.Q FixedReset Quote: 17.81 – 18.46
Spot Rate : 0.6500
Average : 0.4432

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-14
Maturity Price : 17.81
Evaluated at bid price : 17.81
Bid-YTW : 5.06 %

Market Action

December 11, 2015

We have a new government, but the same old central planners:

Finance Minister Bill Morneau today announced changes to the rules for government-backed mortgage insurance to contain risks in the housing market, reduce taxpayer exposure and support long-term stability. Effective February 15, 2016, the minimum down payment for new insured mortgages will increase from 5 per cent to 10 per cent for the portion of the house price above $500,000. The 5 per cent minimum down payment for properties up to $500,000 remains unchanged.

Today’s announcement represents a graduated approach to increasing the down payment requirement proportionally to the cost of a home. Canadians who already hold mortgages will not be affected by this announcement.

The Government continuously monitors the housing market and is committed to implementing policy measures that maintain a healthy, competitive and stable housing market. Higher homeowner equity plays a key role in maintaining a stable and secure housing market.

The backgrounder reveals nothing relevant:

The Bank Act requires federally regulated lenders to obtain mortgage default insurance (“mortgage insurance”) for homebuyers who make a down payment of less than 20 per cent of the property purchase price. The homebuyer pays the premium for this insurance, which protects the lender against mortgage loan losses if the homebuyer defaults.

By reducing risk to lenders, mortgage insurance enables consumers to purchase homes with a down payment as low as 5 per cent of the property value and at lower mortgage interest rates that are comparable to those received by homebuyers with higher down payments.
…
The Government guarantee of mortgage insurance is intended to support access to homeownership for creditworthy buyers and promote stability in the housing market, financial system and economy. As part of its role to promote stability, and to protect taxpayers from potential mortgage loan losses, the Government sets the eligibility rules for new government-backed insured mortgages.

Between 2008 and 2012, four rounds of changes were made to the eligibility rules, aimed at encouraging insured borrowers to build and retain housing equity and take on mortgage debt that they are able to service over the economic cycle.

And the FAQs are puerile:

Why is the Government making this change at this time?

The Government continuously monitors the housing market and is prepared to implement policy measures to maintain a healthy, competitive and stable housing market. The new measure reduces housing market risks by increasing borrower equity. This protects the stability of the housing market and the economy as a whole, as well as the interests of taxpayers who ultimately back government-guaranteed mortgage insurance.

What will be the impact of the higher down payment requirement on the Canadian economy?

Higher homeowner equity will help maintain a stable and secure housing market and balanced economic growth over the long-term. In the short term, this targeted measure will dampen somewhat the pace of housing activity over the next year, as some prospective homebuyers save for the increased minimum down payment.

There is no meat on these bones at all. There is nothing to quantify any improvement in government policy objectives that is served by this policy. It’s just another randomly chosen measure that will be touted as an indication to those who are unable to compete for housing that Your Government Is Doing Something.

But the cheerleaders were out in force:

Some new buyers in Toronto and Vancouver will be knocked out of the market temporarily.

But that’s a fair price for bringing some stability to a housing market where prices in many cities have for years risen far in excess of incomes.
…
Boomers in particular are living in homes that have increased many times in value. A big decline in house prices would be a shocking setback to these people and could negatively affect their financial health in retirement.

Mild as it is, the new down payment rule could only momentarily slow hot markets. But at least the new Liberal government has shown that it’s monitoring housing and ready to act to keep it in line. For homeowners, that’s far better news than another month of big price gains.

As I have noted before, the fact that people are taking advantage of low interest rate to load up on non-productive housing assets instead of productive capital assets is a genuine concern for the western world. There was a story illustrating the process the other day:

It was after losing a huge chunk of money in the stock market, twice, that Ottawa couple Denise and Stuart MacPherson decided they needed to find a new way to save for retirement.

The first bath they took was during the dot-com bust at the start of the century, after getting caught up in the hype around technology stocks. The second was the global financial crisis in 2008, when they watched half of their investments go down the drain.

“That was a very hard lesson to learn, mostly because we didn’t really understand what we were investing in,” says Ms. MacPherson, 61. “It was a wake-up call for us.”

Instead of jumping back into the market, the couple, working then as civil servants, decided to start investing in something they could see and understand.

“That’s when we started looking at real estate,” Ms. MacPherson says.

I suggest that from a policy perspective, what we need is more housing price volatility, not less. Let’s wipe out a swath of real-estate entrepreneurs – as happened in the early eighties and again in the early nineties – pour encourager les autres. Trying to turn the housing market into a 5% GIC – as the repeated lauding of ‘stability’ implies – will have quite the opposite effect from that which is intended. The trouble is, of course, that the central planners and regulators want to turn everything into a 5% GIC, since they run into less criticism that way.

I was more impressed with OSFI’s note titled Updating capital requirements for residential mortgages:

OSFI is planning to update the regulatory capital requirements for loans secured by residential real estate properties (i.e. residential mortgages).
…
The purpose of OSFI’s regulatory capital framework is to ensure, as much as possible, that federally regulated financial institutions can absorb severe but plausible losses. The potential severity of loss scenarios in the residential mortgage market depends crucially on price developments. In particular, potential losses become more severe during extended periods where house prices have recently risen rapidly and/or are high relative to borrower incomes. As a result, the potential severity of losses may vary across Canada.

Accordingly, for banks using internal models, OSFI will propose a risk-sensitive floor for one of the model inputs (losses in the event of default) that will be tied to increases in local property prices and/or to house prices that are high relative to borrower incomes. This will ensure a level of consistency and conservatism in the protection provided to depositors and unsecured creditors.

For federally regulated private mortgage insurers, we will introduce a new standardized approach that updates the capital requirements for mortgage guarantee insurance risk. It will require more capital when house prices are high relative to borrower incomes. This will ensure a level of conservatism in the protection provided to policyholders and unsecured creditors.

The part of this policy that looks back at past prices to determine risk is – in broad outlines – something I’ve been advocating for years, most recently on November 30:

There are two approaches that can be taken: the first is to insist that for risk-management purposes, the loan-to-value ratio of a mortgage be calculated not according to the sale price or to the appraised value, but to an estimate of what this would have been five or ten years ago, adjusted for inflation. So, for instance, if we have a house that sold in 2014 for $567,000 and has a mortgage of $400,000, we would now currently say the LTV is 71%. I suggest that for regulatory risk purposes we use the 2009 price of $395,000, add on 10% to reflect plain vanilla inflation for a notional value of $435,000, and say OK, you’ve got to put up capital reflecting this notional LTV of 92%, which is a different kettle of fish altogether.

The second approach would simply say … 40% of your balance sheet is now mortgages, the average over the last ten years is 30%, the difference is 10% and 10% of that is 1%, so there’s a countercyclical capital surcharge of 1% that will be applied to your risk weighted assets. A solution would need to be more detailed, with meaningful categorizations of bank assets and threshold values for surcharges so that slow change is not discouraged, but that’s the general idea.

Such broad-brush changes are strongly preferable to the micro-management of the economy implicit in down-payment rules.

Meanwhile Third Avenue Management rocked the junk market by liquidating its junk fund:

I am writing to inform you that the Board of Trustees of the Third Avenue Trust has adopted a Plan of Liquidation for the Third Avenue Focused Credit Fund (“FCF”). Pursuant to this Plan, on or about December 16, 2015, there will be a distribution to all FCF shareholders of the Fund’s cash assets not required for the expenses of the Fund and its liquidation. The remaining assets have been placed into a liquidating trust (the “Liquidating Trust”) and interests in that trust will also be distributed to FCF shareholders on or about December 16, 2015. These two distributions will constitute the full redemption for all shares of FCF and existing FCF shareholders will all become beneficiaries of the Liquidating Trust, which will make periodic distributions as cash is received for the remaining investments. The record date for these distributions is December 9, 2015, so no further subscriptions or redemptions will be accepted. Interests in the Liquidating Trust will not trade and will, in general, be transferable only by operation of law.
…
In line with its investment approach, FCF has some investments in companies that have undergone restructurings in the last eighteen months, and while we believe that these investments are likely to generate positive returns for shareholders over time, if FCF were forced to sell those investments immediately, it would only realize a portion of those investments’ fair value given current market conditions. We believe that doing so would be contrary to the interests of all of our shareholders, which is why we have taken steps to protect shareholder value by returning cash and implementing the Liquidating Trust to seek maximum value for these investments.

The past performance of this fund – which I have not examined in any detail at all – makes it seem like just another go-go fund:

In 2010, it earned 15.63%, according to Morningstar MORN +0.00%, outperforming the Barclays Aggregate Bond Index by over 900 basis points. That out-performance turned in 2011 when bond markets were spooked by the government’s near-breach of a debt limit, but it returned the following year. In 2013, the Third Avenue Credit Fund was the top fund in its category, according to Morningstar, returning 16.8%, outperforming its index by a whopping 1,800 basis points.

Over the past 24-months, Third Avenue’s performance turned sharply negative, testing investors’ patience. Part of the fund’s troubles come from owning debts in some of the largest leveraged buyouts that remain in the coffers of private equity firms, or stumbled in their return to public markets.

But, as a chart prepared by the WSJ indicates, go-go investing works really well for managers!

thirdAvenueCash
Click for Big

Look at all that money chasing performance! But all good things come to an end:

The fund, which had $3.5 billion in assets as recently as July of last year, suffered almost $1 billion in redemptions this year through November. The Third Avenue fund lost 13 percent in the past month and is down 27 percent this year, according to data compiled by Bloomberg. Assets have declined to $788 million as of Dec. 8 as clients pulled an estimated $979 million this year through November, according to Morningstar Inc.

“It’s significantly bad news for the market, and another straw on the camel’s back,” said Martin Fridson, a money manager at Lehmann Livian Fridson Advisors LLC. “It’s not typical, but it raises the question: Can this happen to the next-worst fund? You just don’t know. It certainly doesn’t encourage people to put money in, and that just exacerbates the liquidity problem there.”

The weakness in the market comes as credit quality in speculative-grade debt is falling. For every junk-bond issuer that had its rating boosted this year, two have been downgraded, a ratio not seen since 2009, according to data compiled by Bloomberg.

And companies are increasingly defaulting on their debt. Swift Energy Co.’s failure to make an $8.9 million interest payment last week raised the global tally of defaults to 102 issuers, a figure last exceeded in 2009, according to Standard & Poor’s.

And there is some credibility to the claim that the fund fell into a shark tank:

Mutual funds that own hard-to-trade debt are gunning for an advantage when it comes to returns, but they can face a big disadvantage when it comes time to sell.

They are often the weakest hand in a market of hungry experienced traders simply by virtue of their structure. They must publicly report their holdings, albeit on a delayed basis, and disclose information about investor inflows and outflows. Hedge funds, on the other hand, do not have to disclose nearly as much.

That’s like putting a huge “kick me” sign on these mutual funds when investors start asking for their money back. Because the debt these funds own may only trade a few times a year, prices are as reliant on supply and demand as the actual fundamentals of a given company.
…
Exhibit A of this phenomenon is Third Avenue Management. After it decided to liquidate its $788 million mutual fund that focuses on highly distressed debt — and to gate in remaining investors to avoid a fire sale of the remaining assets — its chief executive hinted that the fund was a victim of just such behavior.

“Our portfolio was well known, it’s almost like we were targeted,” CEO David Barse said, according to the Wall Street Journal.

But misery loves company, and fund holders had that, all right:

Global financial markets turned gloomy as the prospects for a Federal Reserve interest-rate increase next week and a drop in oil helped spark a selloff in riskier assets, from equities to commodities to high-yield debt.

U.S. stocks tumbled to a two-month low, with the Dow Jones Industrial Average dropping more than 300 points, while shares in developing nations extended the longest slump since June. Oil plunged below $36 a barrel to cap its worst week in a year, and junk bonds had their worst day since December 2012. Treasuries rallied with the yen on haven demand.
…
The Standard & Poor’s 500 Index slumped 1.9 percent to 2,012.37 at 4 p.m. in New York, to the lowest level since Oct. 14. The gauge sank 3.8 percent in the week. That’s the most since Aug. 21, when signs of slowing growth from China to Europe rekindled concern that weakness could spread to America.
…
The iShares iBoxx $ High Yield Corporate Bond exchange-traded fund, known by its ticker of HYG, tumbled 2.7 percent as oil extended its loss. Trading in the high-yield ETF options surged as billionaire investor Carl Icahnsaid more pain is coming. “The meltdown in High Yield is just beginning,” he wrote on his verified Twitter account Friday.
…
Traders are pricing in a 72 percent chance that the Fed will raise rates at its Dec. 16 meeting, with data out of the U.S. Friday showing growth in retail sales and producer prices for November. That’s down from 80 percent earlier this week, amid the turmoil on financial markets.
…
The Stoxx Europe 600 Index tumbled 2 percent, taking its weekly loss to 4 percent. The regional benchmark fell to its lowest level since October and has sunk 7.7 in December amid a rout in commodity companies and disappointment over the European Central Bank’s last meeting.
…
The risk premium on the Markit CDX North American High Yield Index, a credit-default swaps benchmark tied to the debt of 100 speculative-grade companies, rose 36 basis points to 514.52 basis points, the highest since December 2012. BlackRock’s iShares iBoxx High Yield Corporate Bond ETF, the largest fund of its kind, fell to the lowest levels since 2009.

U.S. 10-year yields fell nine basis points to 2.13 percent on Friday, compared with 2.17 percent on Dec. 31, 2014. The yield on similar-maturity German bunds was at 0.54 percent.
…
Oil declined to the lowest level since 2008 in London amid estimates that OPEC’s decision to scrap production limits will keep the market oversupplied. West Texas Intermediate for January delivery slipped to $35.62 a barrel for the lowest settlement since 2009.

Crude capped its worst week in a year. The global oil surplus will persist at least until late 2016 as demand growth slows and OPEC shows “renewed determination” to maximize output, the International Energy Agency said in a report released Friday.

I ran across an interesting blog post today – CBO: Tangled Web of Welfare Programs Creates High Tax Rates on Participants, which included this chart:

cbo_tableau_marginal
Click for Big

… and this map of US federal programmes:

house_human_resources_welfare_chart
Click for Big

Despite all this there are still many people willing to snare people in the poverty trap; if this requires intellectual dishonesty when discussing a universal refundable tax credit, so what?

E-L Financial, proud issuer of ELF.PR.F, ELF.PR.G and ELF.PR.H, has Solidified its Long-term Interest in Empire Life:

Financial Corporation Limited (E-L Financial) (TSX:ELF) (TSX:ELF.PR.F) (TSX:ELF.PR.G) (TSX:ELF.PR.H) has agreed to purchase Guardian Assurance Limited’s (Guardian) 19% share of holding company E-L Financial Services Limited (ELFS). As a result of this agreement, E-L Financial will own 100% of ELFS, which owns 98.3% of The Empire Life Insurance Company (Empire Life).

The transaction will close next week, at a purchase price of approximately book value, or $200 million (CDN).

“For years, Empire Life has been an important long-term investment for E-L Financial,” said Mr. Duncan Jackman, Chairman and Chief Executive Officer of E-L Financial, “We are very excited about being able to increase our stake in this great company and reinforce our continued commitment to its ongoing success.” Mr. Jackman also acknowledged Guardian’s strong contribution to Empire Life.

It was a mixed day for the Canadian preferred share market, with PerpetualDiscounts gaining 33bp, FixedResets off 15bp and DeemedRetractibles up 41bp. Today’s big move in government rates took the YTW of FixedResets below 5%. The Performance Highlights table continues to show a lot of churn. Volume was extremely high by all standards save those of the last few days.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_151211
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 17.99 to be $1.14 rich, while TRP.PR.C, resetting 2016-1-30 at +154, is $0.89 cheap at its bid price of 11.81.

impVol_MFC_151211
Click for Big

Mostexpensive is MFC.PR.H, resetting at +313bp on 2017-3-19, bid at 21.00 to be 0.57 rich, while MFC.PR.K, resetting at +222bp on 2018-9-19, is bid at 16.80 to be 0.59 cheap.

impVol_BAM_151211
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 14.51 to be $0.83 cheap. BAM.PF.G, resetting at +284bp on 2020-6-30 is bid at 19.50 and appears to be $1.44 rich.

impVol_FTS_151211
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 17.00, looks $0.75 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 16.00 and is $0.75 cheap.

pairs_FR_151211A
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.40%, with no outliers. There is one junk outlier below -1.50%.

pairs_FF_151211A
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.11 % 6.21 % 33,729 16.39 1 1.0638 % 1,518.1
FixedFloater 7.39 % 6.55 % 33,493 15.58 1 -2.5038 % 2,639.7
Floater 4.45 % 4.63 % 86,239 16.21 4 -1.5309 % 1,716.8
OpRet 4.87 % 4.20 % 28,843 0.71 1 0.0000 % 2,734.3
SplitShare 4.85 % 5.62 % 84,680 1.89 6 -0.5335 % 3,186.2
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.5335 % 2,486.0
Perpetual-Premium 5.88 % 5.94 % 93,087 13.89 7 0.2430 % 2,464.5
Perpetual-Discount 5.83 % 5.91 % 102,793 13.96 33 0.3315 % 2,456.3
FixedReset 5.52 % 4.90 % 258,329 14.80 78 -0.1508 % 1,870.1
Deemed-Retractible 5.30 % 5.46 % 136,053 5.32 33 0.4072 % 2,531.7
FloatingReset 2.85 % 4.44 % 64,555 5.68 11 -0.4301 % 2,070.3
Performance Highlights
Issue Index Change Notes
BIP.PR.B FixedReset -3.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 22.56
Evaluated at bid price : 23.55
Bid-YTW : 5.83 %
HSE.PR.A FixedReset -2.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 11.37
Evaluated at bid price : 11.37
Bid-YTW : 5.48 %
HSE.PR.G FixedReset -2.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 17.80
Evaluated at bid price : 17.80
Bid-YTW : 6.15 %
BAM.PR.K Floater -2.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 10.10
Evaluated at bid price : 10.10
Bid-YTW : 4.68 %
BAM.PR.G FixedFloater -2.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 25.00
Evaluated at bid price : 12.85
Bid-YTW : 6.55 %
BAM.PR.C Floater -2.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 10.15
Evaluated at bid price : 10.15
Bid-YTW : 4.65 %
RY.PR.L FixedReset -2.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.37
Bid-YTW : 4.40 %
BNS.PR.B FloatingReset -1.90 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.15
Bid-YTW : 5.07 %
BAM.PR.B Floater -1.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 10.20
Evaluated at bid price : 10.20
Bid-YTW : 4.63 %
BNS.PR.R FixedReset -1.69 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.30
Bid-YTW : 4.66 %
BIP.PR.A FixedReset -1.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 18.70
Evaluated at bid price : 18.70
Bid-YTW : 5.85 %
BNS.PR.Q FixedReset -1.56 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.77
Bid-YTW : 4.82 %
BNS.PR.D FloatingReset -1.53 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.07
Bid-YTW : 7.08 %
CM.PR.Q FixedReset -1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 18.24
Evaluated at bid price : 18.24
Bid-YTW : 4.94 %
BAM.PR.Z FixedReset -1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 17.95
Evaluated at bid price : 17.95
Bid-YTW : 5.36 %
MFC.PR.M FixedReset -1.35 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.59
Bid-YTW : 8.21 %
TRP.PR.C FixedReset -1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 11.81
Evaluated at bid price : 11.81
Bid-YTW : 4.92 %
FTS.PR.I FloatingReset -1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 11.55
Evaluated at bid price : 11.55
Bid-YTW : 4.12 %
NA.PR.S FixedReset -1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 16.98
Evaluated at bid price : 16.98
Bid-YTW : 4.96 %
TRP.PR.B FixedReset -1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 10.86
Evaluated at bid price : 10.86
Bid-YTW : 4.75 %
PVS.PR.E SplitShare -1.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-10-31
Maturity Price : 25.00
Evaluated at bid price : 23.90
Bid-YTW : 6.35 %
PVS.PR.D SplitShare -1.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2021-10-08
Maturity Price : 25.00
Evaluated at bid price : 22.42
Bid-YTW : 6.72 %
BMO.PR.S FixedReset -1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 4.68 %
MFC.PR.N FixedReset -1.18 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.64
Bid-YTW : 8.10 %
HSE.PR.C FixedReset -1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 5.95 %
TD.PR.S FixedReset -1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.91
Bid-YTW : 4.47 %
PVS.PR.B SplitShare -1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2019-01-10
Maturity Price : 25.00
Evaluated at bid price : 24.00
Bid-YTW : 5.83 %
SLF.PR.D Deemed-Retractible 1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.64
Bid-YTW : 7.77 %
CU.PR.F Perpetual-Discount 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 19.40
Evaluated at bid price : 19.40
Bid-YTW : 5.85 %
BAM.PR.E Ratchet 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 25.00
Evaluated at bid price : 13.30
Bid-YTW : 6.21 %
BMO.PR.Z Perpetual-Discount 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 22.51
Evaluated at bid price : 22.84
Bid-YTW : 5.51 %
GWO.PR.S Deemed-Retractible 1.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.12
Bid-YTW : 5.75 %
GWO.PR.I Deemed-Retractible 1.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.18
Bid-YTW : 7.45 %
SLF.PR.A Deemed-Retractible 1.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.94
Bid-YTW : 7.21 %
GWO.PR.Q Deemed-Retractible 1.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.55
Bid-YTW : 6.59 %
FTS.PR.K FixedReset 1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 4.45 %
MFC.PR.G FixedReset 1.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.43
Bid-YTW : 7.12 %
GWO.PR.R Deemed-Retractible 1.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.01
Bid-YTW : 7.22 %
POW.PR.A Perpetual-Discount 1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 23.74
Evaluated at bid price : 24.05
Bid-YTW : 5.91 %
IFC.PR.A FixedReset 1.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.85
Bid-YTW : 9.76 %
TRP.PR.H FloatingReset 1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 9.83
Evaluated at bid price : 9.83
Bid-YTW : 4.37 %
FTS.PR.J Perpetual-Discount 1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 21.30
Evaluated at bid price : 21.30
Bid-YTW : 5.62 %
GWO.PR.P Deemed-Retractible 1.37 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.65
Bid-YTW : 6.18 %
IFC.PR.C FixedReset 1.58 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.31
Bid-YTW : 8.36 %
FTS.PR.G FixedReset 1.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 16.00
Evaluated at bid price : 16.00
Bid-YTW : 4.77 %
MFC.PR.K FixedReset 1.63 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.80
Bid-YTW : 8.53 %
SLF.PR.C Deemed-Retractible 1.65 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.74
Bid-YTW : 7.70 %
MFC.PR.L FixedReset 1.70 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.35
Bid-YTW : 8.20 %
SLF.PR.J FloatingReset 1.73 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.92
Bid-YTW : 10.05 %
MFC.PR.J FixedReset 1.89 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.85
Bid-YTW : 7.30 %
TRP.PR.G FixedReset 1.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 18.75
Evaluated at bid price : 18.75
Bid-YTW : 5.02 %
SLF.PR.H FixedReset 1.93 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.85
Bid-YTW : 8.96 %
BAM.PR.R FixedReset 2.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 14.51
Evaluated at bid price : 14.51
Bid-YTW : 5.35 %
CU.PR.C FixedReset 4.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 17.80
Evaluated at bid price : 17.80
Bid-YTW : 4.55 %
Volume Highlights
Issue Index Shares
Traded
Notes
BNS.PR.A FloatingReset 378,986 TD crossed blocks of 80,476 and 284,943, both at 22.82.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.83
Bid-YTW : 4.07 %
PWF.PR.K Perpetual-Discount 305,430 Nesbitt crossed 300,000 at 21.46.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 21.44
Evaluated at bid price : 21.44
Bid-YTW : 5.86 %
PWF.PR.E Perpetual-Discount 301,700 Nesbitt crossed 300,000 at 23.36.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 23.10
Evaluated at bid price : 23.36
Bid-YTW : 5.96 %
PWF.PR.S Perpetual-Discount 213,165 Nesbitt crossed 200,000 at 20.82.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 20.60
Evaluated at bid price : 20.60
Bid-YTW : 5.91 %
BAM.PR.K Floater 211,400 TD crossed 200,000 at 10.20.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 10.10
Evaluated at bid price : 10.10
Bid-YTW : 4.68 %
BAM.PR.C Floater 207,699 TD crossed 200,000 at 10.20.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 10.15
Evaluated at bid price : 10.15
Bid-YTW : 4.65 %
PWF.PR.L Perpetual-Discount 203,425 Nesbitt crossed 200,000 at 21.82.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 21.57
Evaluated at bid price : 21.83
Bid-YTW : 5.91 %
CU.PR.I FixedReset 149,244 Desardins crossed 50,000 at 24.90. Scotia crossed blocks of 25,000 and 50,000 at the same price.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 23.09
Evaluated at bid price : 24.80
Bid-YTW : 4.46 %
TD.PF.B FixedReset 109,519 Nesbitt crossed 65,700 at 17.20.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 17.21
Evaluated at bid price : 17.21
Bid-YTW : 4.67 %
FTS.PR.E OpRet 100,400 Scotia crossed 100,000 at 25.22.
YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2016-08-31
Maturity Price : 25.00
Evaluated at bid price : 25.16
Bid-YTW : 4.20 %
There were 77 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
RY.PR.L FixedReset Quote: 24.37 – 25.00
Spot Rate : 0.6300
Average : 0.3805

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.37
Bid-YTW : 4.40 %

CIU.PR.A Perpetual-Discount Quote: 20.36 – 21.19
Spot Rate : 0.8300
Average : 0.6453

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 20.36
Evaluated at bid price : 20.36
Bid-YTW : 5.70 %

HSE.PR.C FixedReset Quote: 17.00 – 17.50
Spot Rate : 0.5000
Average : 0.3312

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 5.95 %

GWO.PR.M Deemed-Retractible Quote: 24.81 – 25.26
Spot Rate : 0.4500
Average : 0.2836

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.81
Bid-YTW : 5.90 %

TD.PF.E FixedReset Quote: 19.38 – 19.90
Spot Rate : 0.5200
Average : 0.3627

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-11
Maturity Price : 19.38
Evaluated at bid price : 19.38
Bid-YTW : 4.76 %

MFC.PR.G FixedReset Quote: 19.43 – 19.97
Spot Rate : 0.5400
Average : 0.4013

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.43
Bid-YTW : 7.12 %

Market Action

December 10, 2015

On November 24 I mentioned the tender offer for a big chunk of Talisman’s debt securities. Today they announced the pricing:

Talisman Energy Inc. (the “Offeror”) announced today the pricing of its previously announced tender offer (the “Offer”) to purchase for cash up to $1,524,531,000 aggregate principal amount (the “Maximum Tender Amount”) of the 5.85% Senior Notes due 2037 (CUSIP No. 87425E AJ2), 5.50% Senior Notes due 2042 (CUSIP No. 87425E AN3), 6.25% Senior Notes due 2038 (CUSIP No. 87425E AK9), 7.25% Debentures due 2027 (CUSIP No. 87425E AE3) and 5.75% Senior Notes due 2035 (CUSIP No. 87425E AH6) issued by the Offeror (collectively, the “Securities”).
…
The Offeror has accepted for purchase on the Early Settlement Date Securities having an aggregate principal amount equal to the Maximum Tender Amount that were validly tendered and not validly withdrawn on or before the Early Tender Date (as defined below). Settlement for Securities validly tendered on or prior to the Early Tender Date and accepted for purchase pursuant to the Offer is expected to occur on December 11, 2015.

The Offer is being made upon the terms and subject to the general conditions set forth in the Offer to Purchase, as amended by the Offeror’s press release dated December 9, 2015 announcing an increase in the Maximum Tender Amount to $1,524,531,000. The Offer will expire at 12:00 midnight, New York City time, on December 22, 2015 (one minute after 11:59 p.m., New York City time, on December 22, 2015), unless extended or earlier terminated by the Offeror (as it may be extended or earlier terminated, the “Expiration Date”). The deadline to validly withdraw tenders of Securities was 5:00 p.m., New York City time, on December 8, 2015; therefore, Securities that have been tendered and not validly withdrawn, and Securities tendered after that date, may not be withdrawn unless otherwise required by applicable law.

Seems to me they just about nailed the pricing of this, which was about 420bp over comparable Treasuries, give or take a few beeps dependent on the issue. They got all they wanted, with no more than 80% take-up for any of the five issues.

The bureaucrats will be happy today! The ‘guilty until proven innocent’ aspect of anti-corruption laws has permitted them to exercise a certain level of direction and control over SNC Lavalin:

The previous Conservative government softened its tough anti-corruption rules for companies doing business with Ottawa last July in the face of intense criticism from business groups. The most contentious part of the rules was an inflexible 10-year contracting ban on companies charged with a long list of offences anywhere in the world, which was softened to five years. Under the new rules, the government could also immediately suspend any company charged.

That last change was of particular concern to SNC, given that it was charged in February with fraud and corruption related to its business in Libya and does significant business with the federal government. The company wanted to be sure it wouldn’t be suspended so entered into talks on an administrative agreement, said SNC spokesman Louis-Antoine Paquin.

The SNC-Lavalin agreement is the first reached under the new regime, and allows the company to continue with existing contracts and any future work with the federal government. As part of the deal, it agreed to strict conditions and third-party oversight of its business practices. The specific terms are confidential, Mr. Paquin said.

And soon life may get even better for the central planners, when everybody’s a Secret Policeman:

A pledge of allegiance to the Islamic State (IS) – otherwise known as Daesh – that might have been posted to Facebook by suspected terrorist Tashfeen Malik has prompted US lawmakers to revive a bill that would require technology companies such as Facebook and Twitter to report suspected online terror activity.

Sen. Dianne Feinstein, a Democrat from California, is sponsoring the legislation along with Sen. Richard Burr, a Republican from North Carolina.

From her statement:

We’re in a new age where terrorist groups like [Islamic State of Iraq and the Levant, or ISIL] are using social media to reinvent how they recruit and plot attacks.

That information can be the key to identifying and stopping terrorist recruitment or a terrorist attack, but we need help from technology companies.

Feinstein said that under the legislation, companies wouldn’t have to go out of their way to uncover terrorist activity. But if they do happen upon it, they’d be required to report it to law enforcement.

Laurentian Bank, proud issuer of LB.PR.F and LB.PR.H, got a vote of confidence from DBRS:

DBRS Limited (DBRS) notes that yesterday Laurentian Bank of Canada (Laurentian or the Bank) (Deposits and Senior Debt, rated A (low)) launched a $65 million common share offering to strengthen its capital ratios after reporting a net loss for Q4 2015 of $18.7 million due to impairment and restructuring charges totalling $61.7 million after tax. Excluding these charges and other adjustments, Laurentian announced good core net earnings of $44.1 million for Q4 2015 and $172.2 million for the full year ended October 31, 2015. The Bank’s year-end CET1 capital ratio of 7.6% would instead be 8.0% pro forma the common share issue. With good underlying results and a net impact-to-capital ratio of only 7 basis points (bps) due to the charges, there is no impact to DBRS current ratings for Laurentian at this time.
…
DBRS does view positively Laurentian’s decision to issue common shares in order to improve the buffer it has relative to regulatory minimums. However, DBRS also reiterates its observation from its November 6, 2015, rating report that, even after the common share issuance, Laurentian’s capitalization levels are closer to regulatory minimums than its peers. Although the Bank has indicated it is raising the capital in order to strengthen its flexibility, including being able to proceed with opportunistic acquisitions consistent with its growth objectives, if they were to present themselves (there are none on the immediate horizon), DBRS believes the Bank will still have a limited buffer to withstand a major problem and continues to have limited financial flexibility.

It was – wait for it – a mixed day for the Canadian preferred share market, with PerpetualDiscounts down 27bp, FixedResets off 9bp and DeemedRetractibles gaining 22bp. The Performance Highlights table continues to reveal a lot of churn. Volume is still enormously high.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_151210
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 17.91 to be $1.15 rich, while TRP.PR.G, resetting 2020-11-30 at +154, is $1.02 cheap at its bid price of 18.40.

impVol_MFC_151210
Click for Big

Most expensive is MFC.PR.H, resetting at +313bp on 2017-3-19, bid at 20.80 to be 0.54 rich, while MFC.PR.K, resetting at +222bp on 2018-9-19, is bid at 16.53 to be 0.75 cheap.

impVol_BAM_151210
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 14.50 to be $1.13 cheap. BAM.PF.G, resetting at +284bp on 2020-6-30 is bid at 19.50 and appears to be $1.16 rich.

impVol_FTS_151210
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 16.80, looks $0.62 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 15.75 and is $0.83 cheap.

pairs_FR_151210
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.41%, with one outlier below -1.50%. There is one junk outlier below -1.50%.

pairs_FF_151210
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.17 % 6.28 % 33,816 16.31 1 -3.5897 % 1,502.1
FixedFloater 7.21 % 6.38 % 33,212 15.78 1 -0.9023 % 2,707.5
Floater 4.34 % 4.56 % 80,043 16.21 4 -3.2889 % 1,743.5
OpRet 4.87 % 4.18 % 26,709 0.71 1 0.0000 % 2,734.3
SplitShare 4.82 % 5.46 % 83,698 2.86 6 0.0342 % 3,203.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0342 % 2,499.3
Perpetual-Premium 5.89 % 5.96 % 95,099 13.84 7 -0.1387 % 2,458.5
Perpetual-Discount 5.84 % 5.94 % 100,369 13.95 33 -0.2700 % 2,448.2
FixedReset 5.50 % 5.04 % 259,405 14.40 78 -0.0913 % 1,873.0
Deemed-Retractible 5.31 % 5.48 % 137,966 5.32 33 0.2263 % 2,521.5
FloatingReset 2.83 % 4.33 % 66,482 5.69 11 -0.8330 % 2,079.2
Performance Highlights
Issue Index Change Notes
HSE.PR.A FixedReset -3.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 11.69
Evaluated at bid price : 11.69
Bid-YTW : 5.63 %
BAM.PR.E Ratchet -3.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 25.00
Evaluated at bid price : 13.16
Bid-YTW : 6.28 %
BAM.PR.K Floater -3.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 10.51
Evaluated at bid price : 10.51
Bid-YTW : 4.56 %
BAM.PR.B Floater -3.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 10.51
Evaluated at bid price : 10.51
Bid-YTW : 4.56 %
PWF.PR.A Floater -3.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 12.00
Evaluated at bid price : 12.00
Bid-YTW : 3.97 %
BNS.PR.D FloatingReset -2.96 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.35
Bid-YTW : 6.79 %
BAM.PR.C Floater -2.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 10.50
Evaluated at bid price : 10.50
Bid-YTW : 4.56 %
HSE.PR.C FixedReset -2.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 17.20
Evaluated at bid price : 17.20
Bid-YTW : 6.03 %
BAM.PR.Z FixedReset -2.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 18.50
Evaluated at bid price : 18.50
Bid-YTW : 5.48 %
BNS.PR.Y FixedReset -2.18 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.26
Bid-YTW : 6.48 %
BNS.PR.B FloatingReset -2.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.56
Bid-YTW : 4.72 %
BNS.PR.Z FixedReset -1.95 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.10
Bid-YTW : 7.25 %
SLF.PR.J FloatingReset -1.93 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.70
Bid-YTW : 10.25 %
CU.PR.F Perpetual-Discount -1.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 19.20
Evaluated at bid price : 19.20
Bid-YTW : 5.91 %
ENB.PR.A Perpetual-Discount -1.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 22.01
Evaluated at bid price : 22.25
Bid-YTW : 6.23 %
MFC.PR.K FixedReset -1.72 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.53
Bid-YTW : 8.87 %
BNS.PR.C FloatingReset -1.67 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.73
Bid-YTW : 4.77 %
IAG.PR.G FixedReset -1.52 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.43
Bid-YTW : 7.21 %
TD.PR.S FixedReset -1.49 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.15
Bid-YTW : 4.36 %
TRP.PR.C FixedReset -1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 11.97
Evaluated at bid price : 11.97
Bid-YTW : 5.15 %
BAM.PF.A FixedReset -1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 18.20
Evaluated at bid price : 18.20
Bid-YTW : 5.48 %
MFC.PR.F FixedReset -1.40 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.10
Bid-YTW : 9.71 %
PWF.PR.R Perpetual-Discount -1.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 22.93
Evaluated at bid price : 23.32
Bid-YTW : 5.96 %
TD.PF.E FixedReset -1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 19.30
Evaluated at bid price : 19.30
Bid-YTW : 4.91 %
CU.PR.E Perpetual-Discount -1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 20.73
Evaluated at bid price : 20.73
Bid-YTW : 5.96 %
CU.PR.D Perpetual-Discount -1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 20.86
Evaluated at bid price : 20.86
Bid-YTW : 5.93 %
TD.PF.F Perpetual-Discount -1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 21.86
Evaluated at bid price : 22.20
Bid-YTW : 5.58 %
ELF.PR.G Perpetual-Discount -1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 19.95
Evaluated at bid price : 19.95
Bid-YTW : 6.06 %
TRP.PR.A FixedReset -1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 15.21
Evaluated at bid price : 15.21
Bid-YTW : 4.79 %
BAM.PR.R FixedReset -1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 14.50
Evaluated at bid price : 14.50
Bid-YTW : 5.76 %
CIU.PR.A Perpetual-Discount -1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 20.50
Evaluated at bid price : 20.50
Bid-YTW : 5.66 %
BMO.PR.Z Perpetual-Discount -1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 22.30
Evaluated at bid price : 22.59
Bid-YTW : 5.57 %
TRP.PR.B FixedReset -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 11.00
Evaluated at bid price : 11.00
Bid-YTW : 4.93 %
PWF.PR.O Perpetual-Premium -1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 23.99
Evaluated at bid price : 24.46
Bid-YTW : 5.99 %
BMO.PR.W FixedReset 1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 16.88
Evaluated at bid price : 16.88
Bid-YTW : 4.87 %
RY.PR.B Deemed-Retractible 1.02 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.81
Bid-YTW : 4.91 %
TD.PF.C FixedReset 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 17.03
Evaluated at bid price : 17.03
Bid-YTW : 4.88 %
GWO.PR.H Deemed-Retractible 1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.05
Bid-YTW : 7.24 %
FTS.PR.J Perpetual-Discount 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 21.03
Evaluated at bid price : 21.03
Bid-YTW : 5.70 %
RY.PR.H FixedReset 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 17.29
Evaluated at bid price : 17.29
Bid-YTW : 4.82 %
RY.PR.W Perpetual-Discount 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 21.50
Evaluated at bid price : 21.76
Bid-YTW : 5.67 %
NA.PR.W FixedReset 1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 16.54
Evaluated at bid price : 16.54
Bid-YTW : 5.07 %
RY.PR.J FixedReset 1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 18.28
Evaluated at bid price : 18.28
Bid-YTW : 5.00 %
BAM.PR.N Perpetual-Discount 1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 19.16
Evaluated at bid price : 19.16
Bid-YTW : 6.34 %
FTS.PR.F Perpetual-Discount 1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 21.59
Evaluated at bid price : 21.85
Bid-YTW : 5.64 %
RY.PR.Z FixedReset 1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 17.28
Evaluated at bid price : 17.28
Bid-YTW : 4.77 %
IAG.PR.A Deemed-Retractible 1.49 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.50
Bid-YTW : 7.34 %
BMO.PR.S FixedReset 1.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 17.71
Evaluated at bid price : 17.71
Bid-YTW : 4.79 %
BAM.PR.T FixedReset 2.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 15.07
Evaluated at bid price : 15.07
Bid-YTW : 5.60 %
BIP.PR.A FixedReset 4.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 19.01
Evaluated at bid price : 19.01
Bid-YTW : 5.89 %
Volume Highlights
Issue Index Shares
Traded
Notes
BNS.PR.C FloatingReset 184,623 TD crossed 182,600 shares at 21.80.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.73
Bid-YTW : 4.77 %
PWF.PR.H Perpetual-Premium 106,684 RBC crossed 97,900 at 24.46.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 24.02
Evaluated at bid price : 24.27
Bid-YTW : 6.00 %
TD.PR.T FloatingReset 105,364 TD crossed 100,000 at 22.15.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.15
Bid-YTW : 4.13 %
RY.PR.Z FixedReset 90,536 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 17.28
Evaluated at bid price : 17.28
Bid-YTW : 4.77 %
FTS.PR.M FixedReset 76,669 Nesbitt crossed 50,000 at 18.10.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 18.21
Evaluated at bid price : 18.21
Bid-YTW : 4.88 %
RY.PR.J FixedReset 70,415 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 18.28
Evaluated at bid price : 18.28
Bid-YTW : 5.00 %
There were 86 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BAM.PR.K Floater Quote: 10.51 – 11.30
Spot Rate : 0.7900
Average : 0.5157

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 10.51
Evaluated at bid price : 10.51
Bid-YTW : 4.56 %

BAM.PR.E Ratchet Quote: 13.16 – 14.00
Spot Rate : 0.8400
Average : 0.6874

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 25.00
Evaluated at bid price : 13.16
Bid-YTW : 6.28 %

MFC.PR.N FixedReset Quote: 17.85 – 18.40
Spot Rate : 0.5500
Average : 0.4130

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.85
Bid-YTW : 8.01 %

PWF.PR.A Floater Quote: 12.00 – 12.74
Spot Rate : 0.7400
Average : 0.6068

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 12.00
Evaluated at bid price : 12.00
Bid-YTW : 3.97 %

PWF.PR.R Perpetual-Discount Quote: 23.32 – 23.81
Spot Rate : 0.4900
Average : 0.3569

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 22.93
Evaluated at bid price : 23.32
Bid-YTW : 5.96 %

TRP.PR.H FloatingReset Quote: 9.71 – 10.17
Spot Rate : 0.4600
Average : 0.3278

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-10
Maturity Price : 9.71
Evaluated at bid price : 9.71
Bid-YTW : 4.40 %

Market Action

December 9, 2015

Well, it looks like one source of PrefBlog entertainment is coming to an end … Sprott is on the verge of winning the battle for Gold Trust:

Sprott Asset Management LP (“Sprott” or “Sprott Asset Management”), together with Sprott Physical Gold Trust (NYSE:PHYS) (TSX:PHY.U) and Sprott Physical Silver Trust (NYSE:PSLV) (TSX:PHS.U), today announced that a majority of Central GoldTrust (“GTU”) (TSX:GTU.UN) (TSX:GTU.U) (NYSEMKT:GTU) unitholders have tendered into the Sprott offer for GTU, and as a result Sprott, on behalf of tendering GTU unitholders and as described in Sprott’s November 20, 2015 Notice of Extension and Variation, has removed Brian Felske, Glenn Fox, Bruce Heagle, Ian McAvity, Michael Parente and Jason Schwandt as GTU trustees and appointed Marc Faber, James Fox, Sharon Ranson, John Wilson and Rosemary Zigrossi as new trustees of GTU. Stefan Spicer remains a trustee of GTU.

Following the replacement of GTU’s trustees, Sprott, also on behalf of tendering GTU unitholders, submitted a unitholder meeting requisition to the reconstituted GTU board proposing that the Merger transaction forming part of the Sprott offer for GTU be considered at a special meeting of GTU unitholders.

Sprott has extended the expiry times of the Sprott offers for GTU and for Silver Bullion Trust (“SBT”) (TSX:SBT.UN) (TSX:SBT.U) (collectively, the “Sprott offers”) to 5:00 p.m. (Toronto time) on January 12, 2016. Notices of extension will be filed shortly.

As of 5:00 p.m. (Toronto time) on December 7, 2015, there were 10,641,033 GTU units (55.14% of all outstanding GTU units) and 2,294,963 SBT units (41.98% of all outstanding SBT units) tendered to the respective Sprott offers.

Fortunately, the battle for Silver Trust still rages and incumbent management had this to say:

Silver Bullion Trust (“SBT”) (TSX:SBT.UN) (C$) and (TSX:SBT.U) (US$) confirmed today that the unsolicited offer by Sprott Asset Management LP and Sprott Physical Silver Trust (“Sprott PSLV”; and collectively, “Sprott”) for all of the outstanding units of SBT has once again failed to achieve sufficient acceptance to satisfy the required minimum tender condition. As a result, Sprott has yet again, for the 8th time, extended the expiry date of their offer, which is now set to expire on January 12, 2016.

Bruce Heagle, Chair of the Special Committee of the Board of Trustees, stated: “Yet again, Sprott’s inadequate offer has failed to achieve sufficient support from SBT unitholders. We expect that unitholder support for Sprott’s offer will erode further and support for the proposed conversion (the “ETF Conversion”) of SBT into a silver bullion exchange-traded fund will gain momentum as unitholders review the Trustees’ Information Circular (the “Circular”), which describes the benefits of the ETF Conversion for all unitholders and its clear advantages relative to Sprott’s offer. We are confident that unitholders will reach the same conclusion as the Independent Trustees have; that the proposed ETF Conversion is a superior alternative to Sprott’s inadequate offer.”

Gold Trust, regrettably, was silent.

I understand there will be a new publication devoted to the Canadian preferred share market:

Haunt of Fear 021 (EC) 11
Click for Big

It was another appalling day for the Canadian preferred share market, with PerpetualDiscounts down 3bp, FixedResets losing 133bp and DeemedRetractibles off 45bp. FixedReset yields have now broken through the 5.00% barrier. The Performance Highlights table is its usual ridiculous self. Volume was, again, incredibly high.

PerpetualDiscounts now yield 5.91%, equivalent to 7.68% interest at the standard equivalency factor of 1.3x. Long corporates now yield a little over 4.2%, so the pre-tax interest-equivalent spread [in this context, the “Seniority Spread”] is now about 345bp, an incredibly high number, representing an explosive widening from the 310bp reported December 2.

For those keeping score, TXPR is now down about 7.16% on the month to date and is now only 0.93% above the low of October 14.

TXPR_151209
Click for Big

TXPL is down about 8.76% on the month to date and is 0.74% above the October 14 low.

TXPL_151209
Click for Big

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_151209
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 18.00 to be $1.20 rich, while TRP.PR.G, resetting 2020-11-30 at +154, is $1.13 cheap at its bid price of 18.25.

impVol_MFC_151209
Click for Big

Most expensive is MFC.PR.H, resetting at +313bp on 2017-3-19, bid at 21.00 to be 0.72 rich, while MFC.PR.K, resetting at +222bp on 2018-9-19, is bid at 16.82 to be 0.52 cheap.

impVol_BAM_151209
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 14.68 to be $1.01 cheap. BAM.PF.G, resetting at +284bp on 2020-6-30 is bid at 19.50 and appears to be $1.09 rich.

impVol_FTS_151209
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 16.73, looks $0.61 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 15.75 and is $0.76 cheap.

pairs_FR_151209
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.41%, with one outlier below -1.50%. There is one junk outlier below -1.50%.

pairs_FF_151209
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 4.98 % 6.05 % 34,207 16.59 1 1.1111 % 1,558.0
FixedFloater 7.14 % 6.32 % 32,909 15.86 1 -1.4815 % 2,732.1
Floater 4.20 % 4.39 % 75,601 16.53 4 1.5801 % 1,802.8
OpRet 4.87 % 4.17 % 27,812 0.71 1 0.0000 % 2,734.3
SplitShare 4.82 % 5.25 % 84,704 2.86 6 0.3504 % 3,202.2
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.3504 % 2,498.5
Perpetual-Premium 5.89 % 5.96 % 95,692 13.88 7 -0.4143 % 2,461.9
Perpetual-Discount 5.83 % 5.91 % 99,616 14.00 33 -0.9342 % 2,454.8
FixedReset 5.49 % 5.06 % 253,245 14.45 78 -1.3343 % 1,874.7
Deemed-Retractible 5.33 % 5.51 % 133,768 5.33 33 -0.4532 % 2,515.8
FloatingReset 2.80 % 4.29 % 64,866 5.69 11 -0.6531 % 2,096.7
Performance Highlights
Issue Index Change Notes
HSE.PR.E FixedReset -7.36 % Not real, as the issue traded 32,700 shares in a range of 18.47-19.60 before closing at 17.88-19.00, 12×4. Almost all of the last 25 trades were at 19.00, with a few dipping as low as 18.87. I have not checked whether this lamentable state of affairs is due to inadequate Toronto Stock Exchange reporting or inadequate Toronto Stock Exchange supervision of market-makers.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 17.88
Evaluated at bid price : 17.88
Bid-YTW : 6.27 %
HSE.PR.G FixedReset -5.64 % Real enough, as the issue traded 14,921 shares in a range of 18.10-19.60 before closing at 18.40-00, 1×1. Only two of the last twenty-five trades were executed below 18.80 and most were comfortably above 19.00. However, there were trades [for 100 shares apiece] at 18.55 and 18.45, timestamped 3:36, so I guess we can call this one “real enough”, while faulting the market maker for an unnecessarily volatile market.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 18.40
Evaluated at bid price : 18.40
Bid-YTW : 6.08 %
BIP.PR.A FixedReset -5.35 % This is real, as the issue traded 11,461 shares in a range of 18.21-20 before closing at 18.22-45, 3×2. The trade price slipped below 18.40 at 3:01 and remained there for the day’s last sixteen trades.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 18.22
Evaluated at bid price : 18.22
Bid-YTW : 6.14 %
MFC.PR.M FixedReset -4.48 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.70
Bid-YTW : 8.20 %
BAM.PR.X FixedReset -3.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 13.36
Evaluated at bid price : 13.36
Bid-YTW : 5.50 %
SLF.PR.H FixedReset -3.60 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.53
Bid-YTW : 9.40 %
MFC.PR.K FixedReset -3.56 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.82
Bid-YTW : 8.63 %
TD.PF.D FixedReset -3.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 18.31
Evaluated at bid price : 18.31
Bid-YTW : 5.06 %
MFC.PR.N FixedReset -3.33 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.70
Bid-YTW : 8.12 %
ENB.PR.A Perpetual-Discount -3.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 22.39
Evaluated at bid price : 22.65
Bid-YTW : 6.11 %
TD.PR.Y FixedReset -3.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.26
Bid-YTW : 4.46 %
MFC.PR.L FixedReset -2.91 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.01
Bid-YTW : 8.57 %
NA.PR.W FixedReset -2.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 16.35
Evaluated at bid price : 16.35
Bid-YTW : 5.13 %
BMO.PR.Q FixedReset -2.50 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.50
Bid-YTW : 6.73 %
BAM.PR.N Perpetual-Discount -2.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 18.91
Evaluated at bid price : 18.91
Bid-YTW : 6.42 %
BAM.PF.C Perpetual-Discount -2.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 19.12
Evaluated at bid price : 19.12
Bid-YTW : 6.48 %
BAM.PR.T FixedReset -2.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 14.75
Evaluated at bid price : 14.75
Bid-YTW : 5.73 %
RY.PR.H FixedReset -2.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 17.10
Evaluated at bid price : 17.10
Bid-YTW : 4.87 %
TD.PF.C FixedReset -2.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 16.85
Evaluated at bid price : 16.85
Bid-YTW : 4.93 %
BMO.PR.Y FixedReset -2.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 19.15
Evaluated at bid price : 19.15
Bid-YTW : 4.81 %
TRP.PR.F FloatingReset -2.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 12.96
Evaluated at bid price : 12.96
Bid-YTW : 4.53 %
CU.PR.G Perpetual-Discount -2.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 19.55
Evaluated at bid price : 19.55
Bid-YTW : 5.80 %
RY.PR.J FixedReset -2.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 18.05
Evaluated at bid price : 18.05
Bid-YTW : 5.06 %
BNS.PR.Z FixedReset -2.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.48
Bid-YTW : 6.88 %
CU.PR.E Perpetual-Discount -2.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 21.02
Evaluated at bid price : 21.02
Bid-YTW : 5.88 %
BAM.PR.R FixedReset -2.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 14.68
Evaluated at bid price : 14.68
Bid-YTW : 5.68 %
NA.PR.S FixedReset -2.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 17.05
Evaluated at bid price : 17.05
Bid-YTW : 5.11 %
RY.PR.Z FixedReset -2.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 17.04
Evaluated at bid price : 17.04
Bid-YTW : 4.84 %
BNS.PR.Y FixedReset -2.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.69
Bid-YTW : 6.08 %
HSE.PR.A FixedReset -1.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 12.14
Evaluated at bid price : 12.14
Bid-YTW : 5.42 %
POW.PR.C Perpetual-Premium -1.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 24.23
Evaluated at bid price : 24.53
Bid-YTW : 6.00 %
BNS.PR.R FixedReset -1.86 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.75
Bid-YTW : 4.37 %
TD.PF.A FixedReset -1.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 17.15
Evaluated at bid price : 17.15
Bid-YTW : 4.87 %
BNS.PR.Q FixedReset -1.82 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.25
Bid-YTW : 4.50 %
BAM.PF.D Perpetual-Discount -1.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 19.47
Evaluated at bid price : 19.47
Bid-YTW : 6.43 %
BAM.PF.E FixedReset -1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 17.52
Evaluated at bid price : 17.52
Bid-YTW : 5.36 %
FTS.PR.K FixedReset -1.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 16.73
Evaluated at bid price : 16.73
Bid-YTW : 4.70 %
RY.PR.W Perpetual-Discount -1.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 21.25
Evaluated at bid price : 21.52
Bid-YTW : 5.73 %
FTS.PR.J Perpetual-Discount -1.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 20.80
Evaluated at bid price : 20.80
Bid-YTW : 5.76 %
TD.PF.E FixedReset -1.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 19.57
Evaluated at bid price : 19.57
Bid-YTW : 4.84 %
BMO.PR.W FixedReset -1.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 16.71
Evaluated at bid price : 16.71
Bid-YTW : 4.92 %
BAM.PR.M Perpetual-Discount -1.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 18.96
Evaluated at bid price : 18.96
Bid-YTW : 6.40 %
MFC.PR.F FixedReset -1.58 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.30
Bid-YTW : 9.52 %
BMO.PR.S FixedReset -1.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 17.43
Evaluated at bid price : 17.43
Bid-YTW : 4.87 %
CU.PR.D Perpetual-Discount -1.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 21.15
Evaluated at bid price : 21.15
Bid-YTW : 5.84 %
TRP.PR.H FloatingReset -1.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 9.71
Evaluated at bid price : 9.71
Bid-YTW : 4.40 %
CU.PR.F Perpetual-Discount -1.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 19.57
Evaluated at bid price : 19.57
Bid-YTW : 5.80 %
BAM.PR.G FixedFloater -1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 25.00
Evaluated at bid price : 13.30
Bid-YTW : 6.32 %
TD.PF.B FixedReset -1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 17.10
Evaluated at bid price : 17.10
Bid-YTW : 4.87 %
GWO.PR.I Deemed-Retractible -1.39 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.92
Bid-YTW : 7.63 %
RY.PR.M FixedReset -1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 17.95
Evaluated at bid price : 17.95
Bid-YTW : 4.97 %
BMO.PR.Z Perpetual-Discount -1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 22.52
Evaluated at bid price : 22.85
Bid-YTW : 5.50 %
POW.PR.B Perpetual-Discount -1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 22.40
Evaluated at bid price : 22.66
Bid-YTW : 6.00 %
CM.PR.Q FixedReset -1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 18.37
Evaluated at bid price : 18.37
Bid-YTW : 5.04 %
BMO.PR.T FixedReset -1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 16.90
Evaluated at bid price : 16.90
Bid-YTW : 4.90 %
BNS.PR.P FixedReset -1.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.72
Bid-YTW : 4.14 %
PWF.PR.K Perpetual-Discount -1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 21.25
Evaluated at bid price : 21.25
Bid-YTW : 5.91 %
SLF.PR.J FloatingReset -1.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.95
Bid-YTW : 10.00 %
FTS.PR.I FloatingReset -1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 11.70
Evaluated at bid price : 11.70
Bid-YTW : 4.04 %
MFC.PR.J FixedReset -1.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.49
Bid-YTW : 7.68 %
GWO.PR.Q Deemed-Retractible -1.02 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.22
Bid-YTW : 6.80 %
BNS.PR.O Deemed-Retractible -1.02 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-04-26
Maturity Price : 25.00
Evaluated at bid price : 25.28
Bid-YTW : 5.21 %
FTS.PR.M FixedReset 1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 18.12
Evaluated at bid price : 18.12
Bid-YTW : 4.90 %
BAM.PR.E Ratchet 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 25.00
Evaluated at bid price : 13.65
Bid-YTW : 6.05 %
BAM.PR.C Floater 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 10.80
Evaluated at bid price : 10.80
Bid-YTW : 4.44 %
HSE.PR.C FixedReset 1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 17.68
Evaluated at bid price : 17.68
Bid-YTW : 5.86 %
PWF.PR.A Floater 1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 12.40
Evaluated at bid price : 12.40
Bid-YTW : 3.84 %
BAM.PR.K Floater 2.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 10.90
Evaluated at bid price : 10.90
Bid-YTW : 4.39 %
PVS.PR.D SplitShare 3.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2021-10-08
Maturity Price : 25.00
Evaluated at bid price : 22.68
Bid-YTW : 6.48 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.I FixedReset 203,946 Nesbitt crossed 100,000 at 23.10 and 99,800 at 23.20.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.16
Bid-YTW : 4.63 %
FTS.PR.M FixedReset 154,838 Scotia crossed blocks of 48,500 and 70,000, both at 18.10.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 18.12
Evaluated at bid price : 18.12
Bid-YTW : 4.90 %
TD.PF.A FixedReset 84,381 Nesbitt crossed 50,400 at 17.20.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 17.15
Evaluated at bid price : 17.15
Bid-YTW : 4.87 %
RY.PR.Z FixedReset 75,757 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 17.04
Evaluated at bid price : 17.04
Bid-YTW : 4.84 %
RY.PR.J FixedReset 73,576 Scotia crossed 40,000 at 18.50.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 18.05
Evaluated at bid price : 18.05
Bid-YTW : 5.06 %
TRP.PR.D FixedReset 73,240 RBC crossed 25,000 at 17.40.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 17.35
Evaluated at bid price : 17.35
Bid-YTW : 4.98 %
There were 88 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
TD.PR.Y FixedReset Quote: 23.26 – 23.99
Spot Rate : 0.7300
Average : 0.4573

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.26
Bid-YTW : 4.46 %

HSE.PR.E FixedReset Quote: 17.88 – 19.00
Spot Rate : 1.1200
Average : 0.8576

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 17.88
Evaluated at bid price : 17.88
Bid-YTW : 6.27 %

BAM.PR.X FixedReset Quote: 13.36 – 13.96
Spot Rate : 0.6000
Average : 0.3915

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 13.36
Evaluated at bid price : 13.36
Bid-YTW : 5.50 %

SLF.PR.H FixedReset Quote: 15.53 – 16.10
Spot Rate : 0.5700
Average : 0.3677

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.53
Bid-YTW : 9.40 %

RY.PR.N Perpetual-Discount Quote: 22.05 – 22.50
Spot Rate : 0.4500
Average : 0.2914

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 21.75
Evaluated at bid price : 22.05
Bid-YTW : 5.59 %

POW.PR.C Perpetual-Premium Quote: 24.53 – 25.00
Spot Rate : 0.4700
Average : 0.3137

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-09
Maturity Price : 24.23
Evaluated at bid price : 24.53
Bid-YTW : 6.00 %

Market Action

December 8, 2015

Good news! Litvak’s won his appeal!

In a ruling that will shape how the U.S. Justice Department and Securities and Exchange Commission pursue several similar cases already in the pipeline, a federal appeals court threw out Jesse Litvak’s March 2014 conviction for defrauding the U.S. Troubled Asset Relief Program and making false statements to the government. Prosecutors will retry charges of lying to buyers and sellers of mortgage-backed securities.

Tuesday’s decision forces the U.S. to bolster its case that traders who lie to customers are committing fraud. In it, the appeals court faulted the judge for excluding some defense evidence, saying the accused must be allowed to show that his actions were in keeping with how Wall Street does business.
…
A central issue in the Litvak case is whether it’s important for the buyer of a bond to know how much a trader paid for it. Prosecutors argued that Litvak’s lies about how much he paid constituted fraud. Litvak’s team compared their client to used-car salesman who isn’t expected to be honest about what he paid for a car: If a sophisticated bond-buyer agrees the price is fair, they argued, it doesn’t matter what the dealer originally paid.

Litvak’s case was last discussed on PrefBlog on August 13.

The Bank of Canada has acknowledged that its policy options have been widened:

Policy makers still have firepower to spur growth even with borrowing costs near zero, Bank of Canada Governor Stephen Poloz said, citing unconventional policies and fiscal stimulus.

While the central bank doesn’t expect another crisis that will force it to resort to such policies, a number of tools are still available, including charging banks for deposits, forward guidance and asset purchases, Poloz said. Fiscal stimulus could be even more effective than monetary policy in extreme circumstances, he said.

“I certainly hope we won’t ever have to use these tools,” Poloz said Tuesday during a speech in Toronto. “However, in an uncertain world, a central bank has to be prepared for all eventualities.”

While Poloz sought to highlight the hypothetical nature of his comments, the speech comes amid growing concern for Canada’s economy as fresh signs of weakness in China and growing concerns about a global oil glut damp the outlook for commodity-producing nations.

Swaps trading suggests investors are pricing in a 25 percent chance of another rate cut by May, following two reductions this year that brought the benchmark rate to 0.5 percent.

I’m not reading much into this. The central banks just want to make their toolbox transparent, so that during the next crisis there will be fewer surprises to worry about. During the Credit Crunch you could almost see the Fed moving down the list … ‘do this, tick the box, see if it’s enough ….’

Meanwhile the central planners are touting micro-management of the economy:

“There are significant pockets of vulnerability created by the growth in mortgage debt in recent years,” according to Craig Alexander, a C.D. Howe researcher and former chief economist at Toronto Dominion Bank, and Paul Jacobson, president of the Canadian Association for Business Economics. “The majority of Canadians have been responsible in their borrowing, but the sustained low interest rate environment has encouraged a significant minority to take on considerably more mortgage debt relative to after-tax income.”

New Finance Minister Bill Morneau, who was chairman of C.D. Howe before entering politics, has said housing is one of the first briefings he took from his officials. Canada has long faced international warnings about the need to head off a housing crash like those seen in the U.S., the U.K. and Spain, and former Finance Minister Jim Flaherty acted several times to tighten lending rules.

Putting in new restrictions is difficult because those past changes have already slowed credit growth, and because the risks now are in a few segments of the market that make using a “blunt tool” approach counter-productive, the authors said.

Policy makers could set tougher underwriting rules on criteria such as credit scores and debt-service ratios, or raise the interest rate that tests a borrower’s ability to pay up later, Alexander and Jacobson wrote.

One tool to target Vancouver and Toronto would be raising the down payment requirement on more expensive homes, the report said. That echoes a proposal the finance department has been making this year, according to people familiar with those talks.

OSFI’s Deputy Superintendent Mark Zelmer gave a speech to the C.D. Howe Institute, Toronto, Ontario, December 8, 2015 titled Asset Managers and Global Financial Stability:

Liquidity mismatches could potentially contribute to instability in important financial markets

The first topic I would like to address relates to liquidity mismatches. Combining less liquid investments with short-notice redemption features for fund units gives rise to a potential misalignment between the redeemability of investment fund units versus the actual liquidity of their underlying investments. This mismatch may result in fragile demand for those investments if investors think they are more liquid than they really are. When times are good, everyone benefits. But if prospects dim and investors suddenly decide to rush to the exit gates, it could prove very disruptive for the markets in question, particularly if a fund has to quickly liquidate large blocks of securities to meet the redemption requests.
…
While most funds are well positioned to cope with normal redemption flows, their ability to cope with an unexpectedly large surge in redemption requests merits further exploration. As we shine light down this corridor, however, we should resist the temptation to treat investment fund liquidity management practices as a macro-prudential tool for cushioning markets from the actions of end-investors. Taken to extremes, that would slow markets’ processing of new information, which could give rise to some easy arbitrage opportunities. I do not think we need to give more sophisticated and nimble market participants new ways to profit at the expense of everyone else.

Leverage comes in many forms
…
Investment funds of all types also make use of financial derivatives to hedge risks and as a cheap way to establish investment positions. The latter is often prevalent in situations where cash markets are less liquid and positions can be established at lower cost through derivatives markets. This can, however, result in the creation of leverage within a fund when the values of the derivatives’ exposures change over the life of the contracts.

As was shown by the failure of Long-term Capital Management in 1998, global financial stability concerns can emerge in situations where banks supply the financing for these investment funds or serve as the principal counterparties for investment fund derivatives transactions. Of course, much has changed since then. There have been advances in asset manager and bank risk management practices, plus a number of regulatory measures to contain the amount of leverage in the global financial system.

Transferring investment mandates may not be as easy as some people think

The third potential vulnerability I want to highlight focuses on the challenges of replacing asset managers. Now, let me stress at the outset that the asset management industry has plenty of experience in transferring investment mandates from one asset manager to another, with no disruptions to markets or other parts of the financial system. A lot of credit is due to the asset managers in question, their advisers, custodians and the firms that specialize in providing transition services. But, if you take a snapshot of the global asset management sector at any point in time, you will see a small group of asset managers that clearly stands out from the rest in terms of the amount of assets they have under management. This begs the question of how easy would it be to transfer their investment mandates to other asset managers on short notice, especially if the need arose in a period when markets are under stress.

Presumably, such an event is most likely to arise in a situation where a very large asset manager is experiencing operational difficulties or challenges that inhibit its ability to deliver services as per investor expectations. If the issues are serious enough and the disruptions sufficiently prolonged, it is conceivable that investors could lose confidence in the funds offered by the asset manager and seek to either move their funds or accounts to another manager, or even liquidate their investments and re-establish them with another manager. Similar issues could also arise from a reputational risk perspective.
…
Nevertheless, it does beg the issue of what steps could be taken to quickly transfer investment mandates from one manager to another in a smooth fashion, so as to minimise the need for any actual redemptions of fund units by end-investors that would then trigger transactions in financial markets. As I noted at the outset, the asset management industry argues that such processes operate fairly smoothly in practice, given the role that transition managers and custodians play in facilitating transfers of funds and investor accounts from one manager to another. The industry is also quick to cite the recent PIMCO experience as a good example to that effect. And, certainly, that has been the experience to date. But, one cannot help but wonder whether the PIMCO episode would have played out so smoothly had it happened say, in the autumn of 2008, when the global financial system as a whole was in the midst of trying to cope with a major crisis.

Huh. That last point could be laying the ground for expropriation of investment management contracts.

On another note, it appears that nowadays even your car will rat you out:

“Attention!” the automated call from the black Ford Escort’s vehicle emergency system had said after detecting a crash and calling emergency number 911.

“A crash has occurred in a Ford vehicle. Press 1 at any time for location information or press 0 to speak with vehicle occupants.”

A recording of the call obtained by local station WPBF features Bernstein, a 57-year-old from Port Lucie, Florida, telling the dispatcher (repeatedly) that there hadn’t been any accident and that no, she hadn’t been drinking.
…
Although Bernstein initially denied it, there had, in fact, been two accidents.

The first was a hit-and-run on Monday afternoon last week (30 November).

The victim, Anna Preston, said she was struck from behind by a black vehicle that took off.

As the New York Daily News reports, after her car ratted her out, police went by Bernstein’s house to have a chat with her.

There, they saw the black Ford with a wrecked front-end, with silver paint from Preston’s car still on it.

So I understand they’re making a movie based on the Canadian preferred share market:

the-night-the-world-exploded
Click for Big

It was an incredibly awful day for the Canadian preferred share market, with PerpetualDiscounts off 82bp, FixedResets losing an awesome 261bp and DeemedRetractibles down 97bp. The yield-to-worst on the HIMIPref™ FixedReset subindex is now 4.99% – a level not seen since late May, 2009. The Performance Highlights table is, of course, ridiculous, with bank issues being more prominent at the extreme bad end than usual. Volume was enormous – I’m not sure whether it is unprecedentedly enormous or not, but it’s certainly among the historic highs.

For those keeping score, TXPR is now down about 5.69% on the month to date and is now down to October 16 levels – about 2.53% above the low of October 14.

TXPL is down about 6.88% on the month to date and is also down to October 16 levels – about 2.81% above the October 14 low.

But take heart! There was a late day rally in TXPR:

TXPR_151208
Click for Big

… and in TXPL:

TXPL_151208
Click for Big
HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.04 % 6.12 % 34,818 16.51 1 0.0000 % 1,540.9
FixedFloater 7.04 % 6.23 % 33,377 15.97 1 -2.5271 % 2,773.2
Floater 4.27 % 4.44 % 75,276 16.45 4 0.7276 % 1,774.7
OpRet 4.87 % 4.15 % 28,961 0.71 1 -0.0794 % 2,734.3
SplitShare 4.84 % 5.52 % 85,404 2.87 6 -0.6620 % 3,191.0
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.6620 % 2,489.8
Perpetual-Premium 5.86 % 5.91 % 94,764 13.90 7 -0.8445 % 2,472.2
Perpetual-Discount 5.77 % 5.88 % 99,912 14.05 33 -0.8221 % 2,478.0
FixedReset 5.42 % 4.99 % 244,070 14.51 78 -2.6133 % 1,900.0
Deemed-Retractible 5.30 % 5.43 % 130,510 5.33 33 -0.9703 % 2,527.2
FloatingReset 2.79 % 4.21 % 62,913 5.69 11 -1.3815 % 2,110.5
Performance Highlights
Issue Index Change Notes
RY.PR.M FixedReset -6.91 % Reasonable enough, as the issue traded 66,593 shares in a range of 18.01-19.55 before closing at 18.20-60, 2×9. Most of the trades in the last half hour were closer to the closing ask, but there was some activity at 18.25 at 3:32pm. The VWAP was 18.74.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 18.20
Evaluated at bid price : 18.20
Bid-YTW : 4.90 %
HSE.PR.C FixedReset -6.84 % Reasonable, as the issue traded 39,786 shares in a range of 17.40-18.70 before closing at 17.42-74, 5×1. Most trades in the last two minutes were below 17.50. VWAP was 17.79.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 17.42
Evaluated at bid price : 17.42
Bid-YTW : 5.95 %
CM.PR.Q FixedReset -6.77 % Quite reasonable, as the issue traded 60,797 shares in a range of 18.51-19.70 before closing at 18.60-23, 5×5. Twenty of the last twenty-five trades were below 18.70. VWAP was 18.98.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 18.60
Evaluated at bid price : 18.60
Bid-YTW : 4.98 %
RY.PR.J FixedReset -6.58 % Quite reasonable, as the issue traded 71,991 shares in a range of 18.30-19.75 before closing at 18.45-60, 1×7. Twenty-three of the last twenty-five trades were at or below 18.50. VWAP was 18.78.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 18.45
Evaluated at bid price : 18.45
Bid-YTW : 4.95 %
HSE.PR.G FixedReset -6.25 % Reasonable enough, as the issue traded 17,404 shares in a range of 19.36-91 before closing at 19.50-79, 7×10. Twenty-two of the last twenty-five trades were at or above 19.70. VWAP was 19.66.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 19.50
Evaluated at bid price : 19.50
Bid-YTW : 5.73 %
TD.PF.D FixedReset -6.04 % Reasonable enough, as the issue traded 58,173 shares in a range of 18.73-20.18 before closing at 18.98-20, 6×100. Eighteen of the last twenty-five trades were below 19.00. VWAP was 19.27.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 18.98
Evaluated at bid price : 18.98
Bid-YTW : 4.88 %
BMO.PR.S FixedReset -5.55 % Quite reasonable, as the issue traded 251,922 shares in a range of 17.40-18.72 before closing at 17.71-83, 4×12. Twenty-one of the last twenty-five trades were at or below 17.80. VWAP was 17.93.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 17.71
Evaluated at bid price : 17.71
Bid-YTW : 4.79 %
BMO.PR.T FixedReset -5.31 % Reasonable, as the issue traded 32,668 shares in a range of 16.92-18.05 before closing at 17.11-39, 1×2. Twenty-one of the last twenty-five trades were at or below 17.20. VWAP was 17.48.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 17.11
Evaluated at bid price : 17.11
Bid-YTW : 4.84 %
BMO.PR.W FixedReset -4.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 16.99
Evaluated at bid price : 16.99
Bid-YTW : 4.83 %
CM.PR.O FixedReset -4.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 17.45
Evaluated at bid price : 17.45
Bid-YTW : 4.88 %
PVS.PR.D SplitShare -4.43 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2021-10-08
Maturity Price : 25.00
Evaluated at bid price : 22.01
Bid-YTW : 7.08 %
TD.PF.B FixedReset -4.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 17.35
Evaluated at bid price : 17.35
Bid-YTW : 4.80 %
TD.PF.C FixedReset -4.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 17.26
Evaluated at bid price : 17.26
Bid-YTW : 4.81 %
BAM.PF.F FixedReset -4.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 18.77
Evaluated at bid price : 18.77
Bid-YTW : 5.32 %
RY.PR.I FixedReset -4.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.12
Bid-YTW : 4.66 %
HSE.PR.E FixedReset -4.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 19.30
Evaluated at bid price : 19.30
Bid-YTW : 5.81 %
SLF.PR.I FixedReset -4.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.50
Bid-YTW : 7.70 %
RY.PR.Z FixedReset -4.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 17.40
Evaluated at bid price : 17.40
Bid-YTW : 4.73 %
MFC.PR.J FixedReset -4.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.69
Bid-YTW : 7.53 %
BAM.PF.B FixedReset -3.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 17.25
Evaluated at bid price : 17.25
Bid-YTW : 5.40 %
TD.PF.E FixedReset -3.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 19.90
Evaluated at bid price : 19.90
Bid-YTW : 4.76 %
CM.PR.P FixedReset -3.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 16.75
Evaluated at bid price : 16.75
Bid-YTW : 4.96 %
BMO.PR.Y FixedReset -3.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 19.60
Evaluated at bid price : 19.60
Bid-YTW : 4.69 %
BMO.PR.M FixedReset -3.58 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.15
Bid-YTW : 4.35 %
BAM.PF.A FixedReset -3.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 18.42
Evaluated at bid price : 18.42
Bid-YTW : 5.41 %
MFC.PR.G FixedReset -3.48 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.40
Bid-YTW : 7.27 %
BAM.PF.G FixedReset -3.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 18.85
Evaluated at bid price : 18.85
Bid-YTW : 5.32 %
RY.PR.H FixedReset -3.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 17.52
Evaluated at bid price : 17.52
Bid-YTW : 4.75 %
TD.PF.A FixedReset -3.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 17.47
Evaluated at bid price : 17.47
Bid-YTW : 4.77 %
IAG.PR.G FixedReset -3.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.73
Bid-YTW : 7.00 %
TD.PR.S FixedReset -3.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.51
Bid-YTW : 4.07 %
BAM.PF.E FixedReset -2.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 17.84
Evaluated at bid price : 17.84
Bid-YTW : 5.26 %
BAM.PR.Z FixedReset -2.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 5.33 %
NA.PR.S FixedReset -2.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 17.42
Evaluated at bid price : 17.42
Bid-YTW : 5.00 %
MFC.PR.C Deemed-Retractible -2.81 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.68
Bid-YTW : 7.82 %
BMO.PR.Z Perpetual-Discount -2.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 22.77
Evaluated at bid price : 23.15
Bid-YTW : 5.43 %
MFC.PR.I FixedReset -2.72 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.65
Bid-YTW : 7.13 %
NA.PR.W FixedReset -2.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 16.80
Evaluated at bid price : 16.80
Bid-YTW : 4.99 %
FTS.PR.F Perpetual-Discount -2.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 21.40
Evaluated at bid price : 21.67
Bid-YTW : 5.68 %
BAM.PF.H FixedReset -2.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 23.13
Evaluated at bid price : 24.91
Bid-YTW : 5.05 %
BIP.PR.A FixedReset -2.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 19.25
Evaluated at bid price : 19.25
Bid-YTW : 5.81 %
BNS.PR.C FloatingReset -2.54 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.24
Bid-YTW : 4.35 %
BAM.PR.G FixedFloater -2.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 25.00
Evaluated at bid price : 13.50
Bid-YTW : 6.23 %
RY.PR.P Perpetual-Discount -2.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 23.86
Evaluated at bid price : 24.20
Bid-YTW : 5.51 %
BMO.PR.R FloatingReset -2.34 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.10
Bid-YTW : 4.21 %
CU.PR.C FixedReset -2.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 17.14
Evaluated at bid price : 17.14
Bid-YTW : 4.91 %
CU.PR.I FixedReset -2.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 23.13
Evaluated at bid price : 24.90
Bid-YTW : 4.49 %
NA.PR.Q FixedReset -2.31 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.09
Bid-YTW : 4.22 %
BNS.PR.R FixedReset -2.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.20
Bid-YTW : 4.02 %
PWF.PR.H Perpetual-Premium -2.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 24.10
Evaluated at bid price : 24.36
Bid-YTW : 5.98 %
FTS.PR.H FixedReset -2.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 13.25
Evaluated at bid price : 13.25
Bid-YTW : 4.52 %
RY.PR.O Perpetual-Discount -2.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 21.82
Evaluated at bid price : 22.15
Bid-YTW : 5.56 %
TRP.PR.G FixedReset -2.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 18.30
Evaluated at bid price : 18.30
Bid-YTW : 5.28 %
SLF.PR.H FixedReset -1.95 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.11
Bid-YTW : 8.90 %
RY.PR.W Perpetual-Discount -1.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 21.65
Evaluated at bid price : 21.90
Bid-YTW : 5.63 %
BNS.PR.P FixedReset -1.92 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.00
Bid-YTW : 3.92 %
FTS.PR.G FixedReset -1.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 15.75
Evaluated at bid price : 15.75
Bid-YTW : 5.04 %
RY.PR.N Perpetual-Discount -1.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 21.97
Evaluated at bid price : 22.26
Bid-YTW : 5.54 %
POW.PR.G Perpetual-Premium -1.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 23.49
Evaluated at bid price : 23.95
Bid-YTW : 5.93 %
PWF.PR.P FixedReset -1.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 13.65
Evaluated at bid price : 13.65
Bid-YTW : 4.62 %
GWO.PR.G Deemed-Retractible -1.76 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.30
Bid-YTW : 6.80 %
GWO.PR.I Deemed-Retractible -1.75 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.20
Bid-YTW : 7.43 %
IAG.PR.A Deemed-Retractible -1.69 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.40
Bid-YTW : 7.40 %
GWO.PR.R Deemed-Retractible -1.65 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.81
Bid-YTW : 7.34 %
BNS.PR.B FloatingReset -1.60 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.10
Bid-YTW : 4.27 %
MFC.PR.B Deemed-Retractible -1.59 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.39
Bid-YTW : 7.49 %
PWF.PR.T FixedReset -1.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 21.81
Evaluated at bid price : 22.09
Bid-YTW : 3.88 %
BNS.PR.Z FixedReset -1.53 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.91
Bid-YTW : 6.48 %
BNS.PR.N Deemed-Retractible -1.52 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-01-27
Maturity Price : 25.00
Evaluated at bid price : 25.23
Bid-YTW : 4.92 %
PWF.PR.S Perpetual-Discount -1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 20.70
Evaluated at bid price : 20.70
Bid-YTW : 5.88 %
ENB.PR.A Perpetual-Discount -1.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 23.14
Evaluated at bid price : 23.40
Bid-YTW : 5.91 %
SLF.PR.D Deemed-Retractible -1.42 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.42
Bid-YTW : 7.93 %
BNS.PR.Q FixedReset -1.42 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.68
Bid-YTW : 4.16 %
TRP.PR.F FloatingReset -1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 13.26
Evaluated at bid price : 13.26
Bid-YTW : 4.42 %
TRP.PR.H FloatingReset -1.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 9.86
Evaluated at bid price : 9.86
Bid-YTW : 4.33 %
IFC.PR.C FixedReset -1.39 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.07
Bid-YTW : 8.92 %
BMO.PR.Q FixedReset -1.38 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.00
Bid-YTW : 6.27 %
GWO.PR.H Deemed-Retractible -1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.00
Bid-YTW : 7.27 %
BNS.PR.D FloatingReset -1.35 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.00
Bid-YTW : 6.17 %
BNS.PR.A FloatingReset -1.35 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.69
Bid-YTW : 4.17 %
TD.PR.T FloatingReset -1.33 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.20
Bid-YTW : 4.08 %
PWF.PR.E Perpetual-Discount -1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 23.13
Evaluated at bid price : 23.39
Bid-YTW : 5.95 %
BNS.PR.M Deemed-Retractible -1.28 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.69
Bid-YTW : 4.85 %
ELF.PR.G Perpetual-Discount -1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 20.20
Evaluated at bid price : 20.20
Bid-YTW : 5.98 %
MFC.PR.N FixedReset -1.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.31
Bid-YTW : 7.65 %
SLF.PR.C Deemed-Retractible -1.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.45
Bid-YTW : 7.90 %
BNS.PR.L Deemed-Retractible -1.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.71
Bid-YTW : 4.83 %
BAM.PR.T FixedReset -1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 15.12
Evaluated at bid price : 15.12
Bid-YTW : 5.58 %
TD.PR.Z FloatingReset -1.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.21
Bid-YTW : 4.16 %
SLF.PR.E Deemed-Retractible -1.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.66
Bid-YTW : 7.81 %
GWO.PR.P Deemed-Retractible -1.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.29
Bid-YTW : 6.39 %
CU.PR.F Perpetual-Discount -1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 19.87
Evaluated at bid price : 19.87
Bid-YTW : 5.71 %
FTS.PR.J Perpetual-Discount -1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 21.16
Evaluated at bid price : 21.16
Bid-YTW : 5.66 %
TD.PF.F Perpetual-Discount -1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 22.10
Evaluated at bid price : 22.44
Bid-YTW : 5.51 %
BAM.PF.D Perpetual-Discount -1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 19.83
Evaluated at bid price : 19.83
Bid-YTW : 6.31 %
GWO.PR.L Deemed-Retractible -1.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.43
Bid-YTW : 5.97 %
MFC.PR.H FixedReset -1.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.00
Bid-YTW : 6.47 %
PWF.PR.L Perpetual-Discount -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 21.78
Evaluated at bid price : 22.02
Bid-YTW : 5.86 %
TD.PR.Y FixedReset -1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.02
Bid-YTW : 3.86 %
BAM.PR.M Perpetual-Discount -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 19.27
Evaluated at bid price : 19.27
Bid-YTW : 6.30 %
MFC.PR.K FixedReset 1.40 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.44
Bid-YTW : 8.12 %
BAM.PR.B Floater 1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 10.80
Evaluated at bid price : 10.80
Bid-YTW : 4.44 %
BAM.PR.C Floater 1.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 10.68
Evaluated at bid price : 10.68
Bid-YTW : 4.49 %
SLF.PR.J FloatingReset 1.55 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.10
Bid-YTW : 9.84 %
ELF.PR.H Perpetual-Discount 4.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 22.66
Evaluated at bid price : 23.00
Bid-YTW : 6.07 %
Volume Highlights
Issue Index Shares
Traded
Notes
CM.PR.O FixedReset 287,269 Desjardins crossed 248,400 at 17.20.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 17.45
Evaluated at bid price : 17.45
Bid-YTW : 4.88 %
BMO.PR.S FixedReset 251,922 RBC crossed 203,800 at 17.40.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 17.71
Evaluated at bid price : 17.71
Bid-YTW : 4.79 %
BAM.PF.H FixedReset 166,439 TD bought 40,500 from National at 24.85.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 23.13
Evaluated at bid price : 24.91
Bid-YTW : 5.05 %
RY.PR.L FixedReset 150,200 TD sold 39,500 to CIBC at 25.00, and another 40,000 to RBC at the same price.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.85
Bid-YTW : 4.10 %
BIP.PR.B FixedReset 113,268 New issue settled today.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 22.92
Evaluated at bid price : 24.35
Bid-YTW : 5.61 %
BNS.PR.M Deemed-Retractible 80,383 CIBC bought 50,000 from TD at 25.00.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.69
Bid-YTW : 4.85 %
There were 94 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
TRP.PR.A FixedReset Quote: 15.51 – 17.50
Spot Rate : 1.9900
Average : 1.1428

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 15.51
Evaluated at bid price : 15.51
Bid-YTW : 4.70 %

ELF.PR.G Perpetual-Discount Quote: 20.20 – 20.84
Spot Rate : 0.6400
Average : 0.3954

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 20.20
Evaluated at bid price : 20.20
Bid-YTW : 5.98 %

RY.PR.I FixedReset Quote: 23.12 – 23.78
Spot Rate : 0.6600
Average : 0.4338

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.12
Bid-YTW : 4.66 %

PWF.PR.H Perpetual-Premium Quote: 24.36 – 24.99
Spot Rate : 0.6300
Average : 0.4160

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 24.10
Evaluated at bid price : 24.36
Bid-YTW : 5.98 %

FTS.PR.F Perpetual-Discount Quote: 21.67 – 22.29
Spot Rate : 0.6200
Average : 0.4179

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-08
Maturity Price : 21.40
Evaluated at bid price : 21.67
Bid-YTW : 5.68 %

TD.PR.S FixedReset Quote: 23.51 – 24.03
Spot Rate : 0.5200
Average : 0.3354

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.51
Bid-YTW : 4.07 %

Market Action

December 7, 2015

Oil got whacked today:

Oil fell to the lowest level in more than six years amid speculation that a record global glut will be prolonged after OPEC effectively abandoned its longtime strategy of limiting output to control prices.
…
West Texas Intermediate for January delivery sank $2.32, or 5.8 percent, to settle at $37.65 a barrel on the New York Mercantile Exchange, the lowest close since February 2009. The volume of all futures traded was 63 percent above the 100-day average at 2:40 p.m.
…
Tumbling oil helped spur a rout in energy stocks, which were the worst performers on the Standard & Poor’s 500 Index. Williams Cos., a pipeline company, dropped 17 percent, making it the worst performer on the S&P 500 Monday. Exxon Mobil Corp. and Chevron Corp., the biggest U.S. energy producers, fell 2.9 percent and 2.6 percent, respectively. The pain wasn’t limited to the U.S., as BP Plc slipped 3.4 percent and Royal Dutch Shell Plc decreased 4.2 percent.

Other places, too!

Oil’s struggles mean more suffering for the Canadian dollar. It fell .84 of a cent to 74 cents (U.S.) on Monday, its lowest since June of 2004. Energy products represented roughly a quarter of Canada’s exports last year, and oil’s slump has been the key factor in the loonie’s 21-per-cent nosedive against its U.S. counterpart since the middle of 2014.
…
The Toronto Stock Exchange’s oil and gas index tumbled 6 per cent, the main factor in a 2.4-per-cent slide in the S&P/TSX composite index. Energy stocks make up nearly a fifth of the composite index. Companies with the highest debt levels and focus on oil took the biggest hits. Penn West Petroleum Ltd. sank nearly18 per cent, and Baytex Energy Corp. fell 17 per cent.

Things may seem bleak, but take heart! There’s some more drone news today:

The ranks of older and frail adults are growing rapidly in the developed world, raising alarms about how society is going to help them take care of themselves in their own homes.

Naira Hovakimyan has an idea: drones.

The University of Illinois roboticist recently received a $1.5 million grant from the National Science Foundation to explore the idea of designing small autonomous drones to perform simple household chores, like retrieving a bottle of medicine from another room. Dr. Hovakimyan acknowledged that the idea might seem off-putting to many, but she believes that drones not only will be safe, but will become an everyday fixture in elder care within a decade or two.

And for preferred share investors …

00GasExplosionOilField
Click for Big

It was a horrible day for the Canadian preferred share market, with PerpetualDiscounts losing 124bp, FixedResets down 99bp and DeemedRetractibles off 9bp. Let’s just not talk about the Performance Highlights table, OK? Volume was very, very extremely much huge, enlivened by a stack of after-hours contingent crosses by Nesbitt.

For those keeping score, TXPR is now down about 4.12% on the month to date and is now down to October 19 levels – about 4.23% above the low of October 14.

TXPL is down about 5.33% on the month to date and is also down to October 19 levels – about 4.52% above the October 14 low.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.04 % 6.12 % 35,311 16.51 1 -9.0909 % 1,540.9
FixedFloater 6.86 % 6.07 % 31,670 16.18 1 -4.6143 % 2,845.1
Floater 4.30 % 4.50 % 74,465 16.34 4 -1.2573 % 1,761.9
OpRet 4.86 % 4.02 % 29,400 0.72 1 -0.0397 % 2,736.5
SplitShare 4.80 % 5.50 % 85,917 2.87 6 -0.1839 % 3,212.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.1839 % 2,506.4
Perpetual-Premium 5.81 % 5.84 % 88,033 14.00 7 -0.3412 % 2,493.2
Perpetual-Discount 5.73 % 5.81 % 99,680 14.15 33 -1.2382 % 2,498.5
FixedReset 5.28 % 4.85 % 232,665 14.77 77 -0.9915 % 1,951.0
Deemed-Retractible 5.25 % 5.34 % 130,657 5.34 33 -0.0855 % 2,552.0
FloatingReset 2.75 % 3.95 % 62,476 5.71 11 -0.5768 % 2,140.0
Performance Highlights
Issue Index Change Notes
BAM.PR.E Ratchet -9.09 % Sort-of reasonable, as the issue traded 4,600 shares in a range of 13.35-14.50 before closing at 13.50-14.59, 3×5. There were only five trades after 2:30pm, totaling 1400 shares, commencing with a trade at 14.10 and sporadically declining to 13.35. The VWAP was 14.21. I have not checked whether this lamentable state of affairs is due to inadequate Toronto Stock Exchange reporting or inadequate Toronto Stock Exchange supervision of market-makers.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 25.00
Evaluated at bid price : 13.50
Bid-YTW : 6.12 %
MFC.PR.L FixedReset -6.65 % Not entirely unreasonable, since the issue traded 18,101 shares in a range of 17.40-18.64 before closing at 17.42-74, 3×1. VWAP was 17.96.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.42
Bid-YTW : 8.23 %
ELF.PR.H Perpetual-Discount -6.26 % Ridiculous, as the issue traded 6,528 shares in a range of 23.25-97 before closing at 22.03-00, 5×3. VWAP was 23.47. I have not checked whether this lamentable state of affairs is due to inadequate Toronto Stock Exchange reporting or inadequate Toronto Stock Exchange supervision of market-makers.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 21.74
Evaluated at bid price : 22.03
Bid-YTW : 6.34 %
HSE.PR.C FixedReset -5.79 % Entirely reasonable, as the issue traded 19,063 shares in a range of 18.57-19.86 before closing at 18.70-26, 1×1. VWAP was 19.17; There were quite a few trades below the closing bid after 3:30pm.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 18.70
Evaluated at bid price : 18.70
Bid-YTW : 5.54 %
BAM.PR.G FixedFloater -4.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 25.00
Evaluated at bid price : 13.85
Bid-YTW : 6.07 %
SLF.PR.I FixedReset -4.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.30
Bid-YTW : 7.12 %
TRP.PR.G FixedReset -4.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 18.68
Evaluated at bid price : 18.68
Bid-YTW : 5.17 %
MFC.PR.N FixedReset -3.94 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.54
Bid-YTW : 7.48 %
MFC.PR.M FixedReset -3.88 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.60
Bid-YTW : 7.51 %
IFC.PR.A FixedReset -3.77 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.06
Bid-YTW : 9.94 %
ELF.PR.F Perpetual-Discount -3.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 21.91
Evaluated at bid price : 22.15
Bid-YTW : 6.07 %
HSE.PR.E FixedReset -2.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 20.15
Evaluated at bid price : 20.15
Bid-YTW : 5.56 %
FTS.PR.M FixedReset -2.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 18.12
Evaluated at bid price : 18.12
Bid-YTW : 4.90 %
CU.PR.H Perpetual-Discount -2.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 22.08
Evaluated at bid price : 22.41
Bid-YTW : 5.89 %
MFC.PR.I FixedReset -2.74 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.20
Bid-YTW : 6.75 %
VNR.PR.A FixedReset -2.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 18.01
Evaluated at bid price : 18.01
Bid-YTW : 5.32 %
TD.PF.E FixedReset -2.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 20.69
Evaluated at bid price : 20.69
Bid-YTW : 4.58 %
TRP.PR.H FloatingReset -2.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 10.00
Evaluated at bid price : 10.00
Bid-YTW : 4.27 %
SLF.PR.H FixedReset -2.49 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.43
Bid-YTW : 8.62 %
HSE.PR.G FixedReset -2.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 20.80
Evaluated at bid price : 20.80
Bid-YTW : 5.37 %
MFC.PR.G FixedReset -2.28 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.10
Bid-YTW : 6.78 %
BAM.PR.N Perpetual-Discount -2.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 19.37
Evaluated at bid price : 19.37
Bid-YTW : 6.26 %
PWF.PR.A Floater -2.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 12.25
Evaluated at bid price : 12.25
Bid-YTW : 3.88 %
IAG.PR.A Deemed-Retractible -1.98 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.75
Bid-YTW : 7.16 %
BAM.PF.C Perpetual-Discount -1.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 19.68
Evaluated at bid price : 19.68
Bid-YTW : 6.29 %
BIP.PR.A FixedReset -1.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 19.76
Evaluated at bid price : 19.76
Bid-YTW : 5.66 %
PWF.PR.R Perpetual-Discount -1.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 23.27
Evaluated at bid price : 23.70
Bid-YTW : 5.86 %
TRP.PR.E FixedReset -1.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 18.11
Evaluated at bid price : 18.11
Bid-YTW : 4.83 %
BAM.PR.X FixedReset -1.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 13.86
Evaluated at bid price : 13.86
Bid-YTW : 5.29 %
CU.PR.C FixedReset -1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 17.55
Evaluated at bid price : 17.55
Bid-YTW : 4.80 %
MFC.PR.H FixedReset -1.76 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.23
Bid-YTW : 6.31 %
POW.PR.D Perpetual-Discount -1.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 21.56
Evaluated at bid price : 21.82
Bid-YTW : 5.81 %
FTS.PR.K FixedReset -1.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 4.62 %
BAM.PR.M Perpetual-Discount -1.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 19.47
Evaluated at bid price : 19.47
Bid-YTW : 6.23 %
BAM.PF.D Perpetual-Discount -1.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 20.05
Evaluated at bid price : 20.05
Bid-YTW : 6.24 %
BAM.PR.C Floater -1.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 10.52
Evaluated at bid price : 10.52
Bid-YTW : 4.55 %
TRP.PR.B FixedReset -1.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 11.22
Evaluated at bid price : 11.22
Bid-YTW : 4.83 %
IFC.PR.C FixedReset -1.65 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.31
Bid-YTW : 8.72 %
CU.PR.D Perpetual-Discount -1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 21.31
Evaluated at bid price : 21.58
Bid-YTW : 5.71 %
FTS.PR.H FixedReset -1.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 13.54
Evaluated at bid price : 13.54
Bid-YTW : 4.42 %
SLF.PR.G FixedReset -1.58 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.36
Bid-YTW : 9.29 %
PWF.PR.L Perpetual-Discount -1.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 22.03
Evaluated at bid price : 22.26
Bid-YTW : 5.80 %
MFC.PR.F FixedReset -1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.46
Bid-YTW : 9.37 %
IAG.PR.G FixedReset -1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.37
Bid-YTW : 6.56 %
HSE.PR.A FixedReset -1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 12.38
Evaluated at bid price : 12.38
Bid-YTW : 5.31 %
PWF.PR.E Perpetual-Discount -1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 23.41
Evaluated at bid price : 23.70
Bid-YTW : 5.87 %
PWF.PR.F Perpetual-Discount -1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 22.28
Evaluated at bid price : 22.55
Bid-YTW : 5.89 %
CM.PR.P FixedReset -1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 17.40
Evaluated at bid price : 17.40
Bid-YTW : 4.77 %
TRP.PR.D FixedReset -1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 17.35
Evaluated at bid price : 17.35
Bid-YTW : 4.98 %
SLF.PR.C Deemed-Retractible -1.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.69
Bid-YTW : 7.73 %
CU.PR.E Perpetual-Discount -1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 21.55
Evaluated at bid price : 21.55
Bid-YTW : 5.73 %
W.PR.J Perpetual-Discount -1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 23.56
Evaluated at bid price : 23.83
Bid-YTW : 5.96 %
BNS.PR.A FloatingReset -1.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.00
Bid-YTW : 3.92 %
BAM.PF.G FixedReset -1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 19.53
Evaluated at bid price : 19.53
Bid-YTW : 5.13 %
SLF.PR.E Deemed-Retractible -1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.89
Bid-YTW : 7.64 %
ENB.PR.A Perpetual-Discount -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 23.48
Evaluated at bid price : 23.75
Bid-YTW : 5.82 %
POW.PR.A Perpetual-Discount -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 23.74
Evaluated at bid price : 24.05
Bid-YTW : 5.91 %
BAM.PF.H FixedReset 1.07 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.57
Bid-YTW : 4.72 %
NA.PR.S FixedReset 1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 17.93
Evaluated at bid price : 17.93
Bid-YTW : 4.85 %
MFC.PR.B Deemed-Retractible 1.67 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.72
Bid-YTW : 7.26 %
GWO.PR.N FixedReset 1.96 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.51
Bid-YTW : 9.97 %
TRP.PR.C FixedReset 2.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 12.30
Evaluated at bid price : 12.30
Bid-YTW : 5.01 %
GWO.PR.S Deemed-Retractible 5.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.26
Bid-YTW : 5.66 %
Volume Highlights
Issue Index Shares
Traded
Notes
BMO.PR.S FixedReset 313,635 Nesbitt crossed 293,800 at 18.82 after hours as a contingent cross.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 18.75
Evaluated at bid price : 18.75
Bid-YTW : 4.52 %
MFC.PR.M FixedReset 292,516 Nesbitt crossed 274,100 at 18.60 after hours as a contingent cross.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.60
Bid-YTW : 7.51 %
BAM.PF.G FixedReset 271,995 Nesbitt crossed 251,200 at 19.58 after hours as a contingent cross.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 19.53
Evaluated at bid price : 19.53
Bid-YTW : 5.13 %
BAM.PF.F FixedReset 265,625 Nesbitt crossed 260,000 at 19.65 after hours as a contingent cross.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 19.60
Evaluated at bid price : 19.60
Bid-YTW : 5.09 %
RY.PR.J FixedReset 255,232 Nesbitt crossed 228,400 at 19.83 after hours as a contingent cross.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 19.75
Evaluated at bid price : 19.75
Bid-YTW : 4.62 %
FTS.PR.M FixedReset 203,405 Nesbitt crossed 184,800 at 18.40 after hours as a contingent cross.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 18.12
Evaluated at bid price : 18.12
Bid-YTW : 4.90 %
BAM.PR.T FixedReset 185,974 Nesbitt crossed 166,400 at 15.43 after hours as a contingent cross.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 15.30
Evaluated at bid price : 15.30
Bid-YTW : 5.51 %
POW.PR.G Perpetual-Premium 184,737 Nesbitt crossed 178,700 at 24.40 after hours as a contingent cross.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 23.90
Evaluated at bid price : 24.39
Bid-YTW : 5.81 %
HSE.PR.E FixedReset 171,252 Nesbitt crossed 159,900 at 20.31 after hours as a contingent cross.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 20.15
Evaluated at bid price : 20.15
Bid-YTW : 5.56 %
BAM.PR.N Perpetual-Discount 168,241 Nesbitt crossed 152,100 at 19.50 after hours as a contingent cross.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 19.37
Evaluated at bid price : 19.37
Bid-YTW : 6.26 %
TRP.PR.D FixedReset 154,478 RBC crossed 14,100 at 17.55. Desjardins crossed 101,600 at 17.29.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 17.35
Evaluated at bid price : 17.35
Bid-YTW : 4.98 %
CU.PR.H Perpetual-Discount 150,827 Nesbitt crossed 141,600 at 22.41 after hours as a contingent cross.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 22.08
Evaluated at bid price : 22.41
Bid-YTW : 5.89 %
RY.PR.P Perpetual-Discount 138,408 Nesbitt crossed 137,000 at 24.79 after hours as a contingent cross.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 24.41
Evaluated at bid price : 24.79
Bid-YTW : 5.37 %
BNS.PR.M Deemed-Retractible 138,241 Nesbitt crossed 126,500 at 25.01 after hours as a contingent cross.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.01
Bid-YTW : 4.60 %
BNS.PR.L Deemed-Retractible 135,762 Nesbitt crossed 127,900 at 25.02 after hours as a contingent cross.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.01
Bid-YTW : 4.60 %
RY.PR.F Deemed-Retractible 124,132 RBC crossed 49,400 at 24.82. Nesbitt crossed 61,700 at 24.78 after hours as a contingent cross.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.77
Bid-YTW : 4.68 %
BAM.PF.E FixedReset 117,469 Nesbitt crossed 102,700 at 18.74 after hours as a contingent cross.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 18.37
Evaluated at bid price : 18.37
Bid-YTW : 5.10 %
TD.PF.F Perpetual-Discount 117,273 Nesbitt crossed 114,200 at 22.72 after hours as a contingent cross.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 22.39
Evaluated at bid price : 22.69
Bid-YTW : 5.45 %
BAM.PR.Z FixedReset 116,350 Nesbitt crossed 89,700 at 19.72 after hours as a contingent cross.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 19.56
Evaluated at bid price : 19.56
Bid-YTW : 5.17 %
GWO.PR.M Deemed-Retractible 114,826 Nesbitt crossed 106,200 at 25.20 after hours as a contingent cross.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.20
Bid-YTW : 5.67 %
TRP.PR.E FixedReset 112,153 Desjardins crossed 91,400 at 18.53.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 18.11
Evaluated at bid price : 18.11
Bid-YTW : 4.83 %
IGM.PR.B Perpetual-Premium 110,292 Nesbitt crossed 108,400 at 25.28 after hours as a contingent cross.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 24.93
Evaluated at bid price : 25.28
Bid-YTW : 5.90 %
PWF.PR.G Perpetual-Premium 109,903 Nesbitt crossed 100,200 at 25.34 after hours as a contingent cross.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-01-06
Maturity Price : 25.00
Evaluated at bid price : 25.30
Bid-YTW : -1.41 %
BMO.PR.Z Perpetual-Discount 109,414 Nesbitt crossed 102,700 at 23.85 after hours as a contingent cross.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 23.48
Evaluated at bid price : 23.80
Bid-YTW : 5.28 %
SLF.PR.B Deemed-Retractible 108,170 Nesbitt crossed 99,500 at 21.21 after hours as a contingent cross.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.12
Bid-YTW : 7.13 %
MFC.PR.B Deemed-Retractible 104,967 Nesbitt crossed 99,100 at 20.75 after hours as a contingent cross.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.72
Bid-YTW : 7.26 %
PWF.PR.K Perpetual-Discount 104,603 Nesbitt crossed 101,100 at 21.87 after hours as a contingent cross.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 21.34
Evaluated at bid price : 21.61
Bid-YTW : 5.79 %
There were 68 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
VNR.PR.A FixedReset Quote: 18.01 – 19.00
Spot Rate : 0.9900
Average : 0.6495

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 18.01
Evaluated at bid price : 18.01
Bid-YTW : 5.32 %

ELF.PR.H Perpetual-Discount Quote: 22.03 – 23.00
Spot Rate : 0.9700
Average : 0.6410

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 21.74
Evaluated at bid price : 22.03
Bid-YTW : 6.34 %

HSE.PR.E FixedReset Quote: 20.15 – 20.98
Spot Rate : 0.8300
Average : 0.6028

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 20.15
Evaluated at bid price : 20.15
Bid-YTW : 5.56 %

TD.PF.E FixedReset Quote: 20.69 – 21.35
Spot Rate : 0.6600
Average : 0.4349

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 20.69
Evaluated at bid price : 20.69
Bid-YTW : 4.58 %

GWO.PR.M Deemed-Retractible Quote: 25.20 – 25.91
Spot Rate : 0.7100
Average : 0.5014

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.20
Bid-YTW : 5.67 %

BAM.PR.E Ratchet Quote: 13.50 – 14.59
Spot Rate : 1.0900
Average : 0.8896

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-07
Maturity Price : 25.00
Evaluated at bid price : 13.50
Bid-YTW : 6.12 %

Market Action

December 4, 2015

Jobs, jobs, jobs!

Employers added more jobs than forecast in November, underscoring Federal Reserve Chair Janet Yellen’s confidence that the U.S. economy is strong enough to withstand higher borrowing costs.

The 211,000 increase in payrolls followed a 298,000 gain in October that was bigger than previously estimated, a Labor Department report showed Friday. The median forecast called for a 200,000 advance. The jobless rate held at a more than seven-year low of 5 percent.
…
Employee pay increased at a steady pace last month. Average hourly earnings at private employers rose 0.2 percent in November after a 0.4 percent gain. Year-over-year hourly pay rose 2.3 percent after a 2.5 percent gain a month earlier.

Employment in November was spurred by the biggest increase in construction hiring since January 2014. Retailers, health-care providers and leisure and hospitality companies added jobs at a healthy, but slower pace than in October.

Meanwhile in Canada:

Canada’s trade deficit unexpectedly jumped to $2.76-billion in October as exports to the crucial U.S. market dropped by the most in almost two-and-a-half years, Statistics Canada data showed on Friday.

October marked the 14th consecutive monthly trade deficit, reflecting Canadian exporters’ continuing struggles amid a sharp fall in oil prices. Analysts polled by Reuters had forecast a shortfall of $1.70-billion.

… and nothing good is forecast for oil:

OPEC’s refusal to rein in production spells extended pain for Canada’s oil patch, setting the stage for deeper cutbacks as a worldwide glut of crude keeps pressure on U.S. and global prices.

West Texas intermediate oil sank below $40 (U.S.) a barrel on Friday after the Organization of the Petroleum Exporting Countries failed to agree on production limits, effectively maintaining a Saudi Arabia-led policy of pumping record volumes to defend market share.
…
The Bank of Canada has estimated that overall capital spending in the industry will fall by 20 per cent in 2016 following a 40-per-cent drop this year.

Remember the Enbridge dropdown that was viewed so unfavourably by S&P, Moody’s and DBRS? It’s an ill wind that blows nobody any good:

Enbridge Inc. (“Enbridge” or “the Company”) (TSX:ENB) (NYSE:ENB) today announced that its Board of Directors has declared a quarterly dividend of $0.53 per common share, payable on March 1, 2016 to shareholders of record on February 16, 2016. The dividend reflects a 14 percent increase from the prior quarterly rate, marking the twenty-first consecutive year of increased dividends for the Company.

“The core of our shareholder value proposition is our reliable business model, which continues to deliver strong and predictable results and dividend growth,” said Al Monaco, President and Chief Executive Officer. “The 14 percent dividend increase reflects the confidence we have in our outlook, underpinned by the strength of our businesses, an industry leading growth program and our sound financial position. Over the last two years, we have increased our dividend by over 50 percent while maintaining strong available cash flow coverage.”

Enbridge also announced a guidance range for 2016 available cash flow from operations (“ACFFO”) per share of $3.80 to $4.50. The growth in the Company’s ACFFO per share guidance range for 2016 reflects growth from its existing businesses and the successful execution of its capital program.

Assiduous Readers will remember my post of June 26,2014, in which I advocated paying cash – always! Now we have more reason to use cash in Canada:

Users beware: The banks are spying on you! It recently emerged that deep inside a TD Canada Trust Visa cardholders agreement are embedded a couple of troubling lines giving the bank the legal right to collect data on everything a person does online.

The scope of these provisions, revealed last week by the CBC, is expansive. They basically give the bank the right to view the content of Google searches, the sort of online videos a cardholder watches, their social media activity and much, much more.

The bank can learn a lot from this information. Are you searching for legal advice on defaulting from a loan? Are you thinking of moving or getting married? Are you straight or gay? Do you prefer cats or dogs?

It was another crummy day for the Canadian preferred share market, with PerpetualDiscounts down 53bp, FixedResets off 44bp, and DeemedRetractibles losing 54bp. The Performance Highlights table is, of course, ridiculous, but at least there were a few winners today! Volume was extremely high.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_151204
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 18.45 to be $1.20 rich, while TRP.PR.C, resetting 2016-1-30 at +154, is $1.08 cheap at its bid price of 12.00.

impVol_MFC_151204
Click for Big

Most expensive is MFC.PR.N, resetting at +230bp on 2020-3-19, bid at 19.30 to be 0.62 rich, while MFC.PR.K, resetting at +222bp on 2018-9-19, is bid at 17.32 to be 1.11 cheap.

impVol_BAM_151204
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 15.02 to be $1.26 cheap. BAM.PF.E, resetting at +255bp on 2020-3-31 is bid at 18.54 and appears to be $0.99 rich.

impVol_FTS_151204
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 17.30, looks $0.70 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 15.95 and is $1.05 cheap.

pairs_FR_151204
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.69%, with no outliers. There is one junk outlier below -1.50% and one above +0.50%.

pairs_FF_151204
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 4.58 % 5.54 % 34,691 17.21 1 6.5280 % 1,695.0
FixedFloater 6.54 % 5.77 % 30,193 16.55 1 0.0689 % 2,982.7
Floater 4.43 % 4.48 % 90,617 16.38 3 0.3761 % 1,784.3
OpRet 4.86 % 3.92 % 30,588 0.73 1 0.0397 % 2,737.6
SplitShare 4.76 % 5.50 % 127,573 4.31 5 0.0878 % 3,218.2
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0878 % 2,511.0
Perpetual-Premium 5.81 % 5.81 % 90,824 14.01 6 -0.5065 % 2,501.7
Perpetual-Discount 5.66 % 5.75 % 93,452 14.25 33 -0.5335 % 2,529.9
FixedReset 5.21 % 4.95 % 228,176 14.81 76 -0.4448 % 1,970.6
Deemed-Retractible 5.25 % 5.43 % 127,180 5.35 33 -0.5389 % 2,554.2
FloatingReset 2.68 % 3.86 % 63,057 5.71 10 -0.7167 % 2,152.4
Performance Highlights
Issue Index Change Notes
GWO.PR.S Deemed-Retractible -5.84 % More nonsense from Nonsense Central, as the issue traded 4,100 shares in a range of 24.02-50 before closing at 23.07-24.53, 11×1. The last trade of the day, at the low, was timestamped 3:18pm. I have not checked whether this lamentable state of affairs is due to inadequate Toronto Stock Exchange reporting or inadequate Toronto Stock Exchange supervision of market-makers.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.07
Bid-YTW : 6.36 %
IFC.PR.C FixedReset -4.35 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.60
Bid-YTW : 8.51 %
MFC.PR.K FixedReset -4.31 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.32
Bid-YTW : 8.23 %
SLF.PR.H FixedReset -4.26 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.85
Bid-YTW : 8.31 %
MFC.PR.H FixedReset -3.96 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.61
Bid-YTW : 6.09 %
CU.PR.C FixedReset -3.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-04
Maturity Price : 17.87
Evaluated at bid price : 17.87
Bid-YTW : 4.75 %
FTS.PR.G FixedReset -3.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-04
Maturity Price : 15.95
Evaluated at bid price : 15.95
Bid-YTW : 5.01 %
MFC.PR.B Deemed-Retractible -3.00 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.38
Bid-YTW : 7.49 %
FTS.PR.K FixedReset -2.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-04
Maturity Price : 17.30
Evaluated at bid price : 17.30
Bid-YTW : 4.57 %
MFC.PR.G FixedReset -2.74 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.57
Bid-YTW : 6.49 %
VNR.PR.A FixedReset -2.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-04
Maturity Price : 18.50
Evaluated at bid price : 18.50
Bid-YTW : 5.21 %
BAM.PR.X FixedReset -2.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-04
Maturity Price : 14.12
Evaluated at bid price : 14.12
Bid-YTW : 5.23 %
MFC.PR.I FixedReset -2.58 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.77
Bid-YTW : 6.39 %
ELF.PR.H Perpetual-Discount -2.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-04
Maturity Price : 23.09
Evaluated at bid price : 23.50
Bid-YTW : 5.93 %
TRP.PR.B FixedReset -2.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-04
Maturity Price : 11.41
Evaluated at bid price : 11.41
Bid-YTW : 4.80 %
SLF.PR.I FixedReset -2.00 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.12
Bid-YTW : 6.58 %
BMO.PR.R FloatingReset -1.99 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.61
Bid-YTW : 3.82 %
CU.PR.H Perpetual-Discount -1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-04
Maturity Price : 22.69
Evaluated at bid price : 23.05
Bid-YTW : 5.72 %
IAG.PR.G FixedReset -1.90 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.65
Bid-YTW : 6.39 %
BAM.PR.T FixedReset -1.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-04
Maturity Price : 15.27
Evaluated at bid price : 15.27
Bid-YTW : 5.60 %
CM.PR.Q FixedReset -1.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-04
Maturity Price : 19.94
Evaluated at bid price : 19.94
Bid-YTW : 4.67 %
GWO.PR.Q Deemed-Retractible -1.66 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.52
Bid-YTW : 6.60 %
NA.PR.W FixedReset -1.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-04
Maturity Price : 17.24
Evaluated at bid price : 17.24
Bid-YTW : 4.89 %
FTS.PR.M FixedReset -1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-04
Maturity Price : 18.65
Evaluated at bid price : 18.65
Bid-YTW : 4.79 %
MFC.PR.J FixedReset -1.61 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.53
Bid-YTW : 6.94 %
HSE.PR.E FixedReset -1.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-04
Maturity Price : 20.76
Evaluated at bid price : 20.76
Bid-YTW : 5.42 %
HSE.PR.A FixedReset -1.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-04
Maturity Price : 12.55
Evaluated at bid price : 12.55
Bid-YTW : 5.30 %
MFC.PR.M FixedReset -1.53 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.35
Bid-YTW : 6.98 %
IFC.PR.A FixedReset -1.45 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.65
Bid-YTW : 9.49 %
POW.PR.G Perpetual-Discount -1.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-04
Maturity Price : 24.14
Evaluated at bid price : 24.60
Bid-YTW : 5.76 %
GWO.PR.I Deemed-Retractible -1.39 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.50
Bid-YTW : 7.21 %
FTS.PR.H FixedReset -1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-04
Maturity Price : 13.76
Evaluated at bid price : 13.76
Bid-YTW : 4.39 %
POW.PR.B Perpetual-Discount -1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-04
Maturity Price : 22.98
Evaluated at bid price : 23.25
Bid-YTW : 5.83 %
POW.PR.D Perpetual-Discount -1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-04
Maturity Price : 21.98
Evaluated at bid price : 22.21
Bid-YTW : 5.71 %
GWO.PR.P Deemed-Retractible -1.33 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.71
Bid-YTW : 6.13 %
NA.PR.S FixedReset -1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-04
Maturity Price : 17.70
Evaluated at bid price : 17.70
Bid-YTW : 4.95 %
BAM.PF.B FixedReset -1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-04
Maturity Price : 17.87
Evaluated at bid price : 17.87
Bid-YTW : 5.25 %
PWF.PR.O Perpetual-Premium -1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-04
Maturity Price : 24.77
Evaluated at bid price : 25.06
Bid-YTW : 5.85 %
PWF.PR.K Perpetual-Discount -1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-04
Maturity Price : 21.54
Evaluated at bid price : 21.80
Bid-YTW : 5.74 %
BNS.PR.B FloatingReset -1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.45
Bid-YTW : 4.00 %
SLF.PR.D Deemed-Retractible -1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.87
Bid-YTW : 7.59 %
CU.PR.G Perpetual-Discount -1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-04
Maturity Price : 20.05
Evaluated at bid price : 20.05
Bid-YTW : 5.65 %
TRP.PR.H FloatingReset -1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-04
Maturity Price : 10.26
Evaluated at bid price : 10.26
Bid-YTW : 4.21 %
RY.PR.H FixedReset -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-04
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 4.65 %
GWO.PR.R Deemed-Retractible -1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.22
Bid-YTW : 7.06 %
TRP.PR.D FixedReset -1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-04
Maturity Price : 17.57
Evaluated at bid price : 17.57
Bid-YTW : 4.95 %
BAM.PR.C Floater 1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-04
Maturity Price : 10.70
Evaluated at bid price : 10.70
Bid-YTW : 4.48 %
HSE.PR.C FixedReset 2.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-04
Maturity Price : 19.85
Evaluated at bid price : 19.85
Bid-YTW : 5.24 %
BAM.PR.E Ratchet 6.53 % Just a reversal of yesterday‘s nonsense.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-04
Maturity Price : 25.00
Evaluated at bid price : 14.85
Bid-YTW : 5.54 %
BAM.PF.G FixedReset 33.00 % Don’t get excited! It’s just a reversal of yesterday‘s nonsense.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-04
Maturity Price : 19.75
Evaluated at bid price : 19.75
Bid-YTW : 5.09 %
Volume Highlights
Issue Index Shares
Traded
Notes
BAM.PR.B Floater 192,246 Desjardins sold six blocks to anonymous, totalling 132,400 shares, all at 10.85.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-04
Maturity Price : 10.70
Evaluated at bid price : 10.70
Bid-YTW : 4.48 %
BAM.PR.K Floater 136,450 TD crossed 127,200 at 10.85.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-04
Maturity Price : 10.63
Evaluated at bid price : 10.63
Bid-YTW : 4.51 %
BNS.PR.R FixedReset 102,400 RBC crossed 50,000 at 24.80; TD crossed 25,000 at the same price.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.75
Bid-YTW : 3.61 %
RY.PR.J FixedReset 83,101 TD crossed blocks of 50,000 and 18,400, both at 19.80.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-04
Maturity Price : 19.75
Evaluated at bid price : 19.75
Bid-YTW : 4.65 %
BNS.PR.P FixedReset 70,470 Nesbitt crossed 50,000 at 24.50.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.50
Bid-YTW : 3.56 %
RY.PR.I FixedReset 50,000 Scotia crossed blocks of 22,500 and 11,400, both at 24.35.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.35
Bid-YTW : 3.72 %
There were 64 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
GWO.PR.S Deemed-Retractible Quote: 23.07 – 24.53
Spot Rate : 1.4600
Average : 0.8676

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.07
Bid-YTW : 6.36 %

MFC.PR.K FixedReset Quote: 17.32 – 18.70
Spot Rate : 1.3800
Average : 0.9731

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.32
Bid-YTW : 8.23 %

MFC.PR.B Deemed-Retractible Quote: 20.38 – 21.07
Spot Rate : 0.6900
Average : 0.4580

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.38
Bid-YTW : 7.49 %

IAG.PR.G FixedReset Quote: 20.65 – 21.44
Spot Rate : 0.7900
Average : 0.5751

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.65
Bid-YTW : 6.39 %

HSE.PR.A FixedReset Quote: 12.55 – 12.99
Spot Rate : 0.4400
Average : 0.2845

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-04
Maturity Price : 12.55
Evaluated at bid price : 12.55
Bid-YTW : 5.30 %

ELF.PR.H Perpetual-Discount Quote: 23.50 – 23.92
Spot Rate : 0.4200
Average : 0.2803

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-04
Maturity Price : 23.09
Evaluated at bid price : 23.50
Bid-YTW : 5.93 %