Category: Market Action

Market Action

May 14, 2015

The Bank of Canada published the Bank of Canada Review – Spring 2015, which is a bust as far as capital markets articles are concerned. Articles are:

  • Inflation Dynamics in the Post-Crisis Period
  • The Slowdown in Global Trade
  • Improving the Foundation of Canada’s Payments System
  • The “Bank” at the Bank of Canada
  • The Use of Cash in Canada

Some investors thought they heard opportunity knock today … but only the ding-dongs:

Fooling investors is surprisingly easy. You can even do it on the government’s official site for company filings.

The latest reminder unspooled within a few minutes Thursday when a notice came out that a purported private-equity firm made a bid to buy Avon Products Inc. In a market where computers scrape filings and trade automatically on news headlines, the stock shot up 20 percent before the company said it was a hoax.

The notice, submitted by a firm registered at an empty office, was filed on the Securities and Exchange Commission’s Edgar system, which houses more than 20 million company filings for investors to peruse. Already more than 4,700 filings have been submitted today.

The SEC doesn’t verify whether entities using its filing systems “are real or have money,” said James Maloney, a former SEC official now at law firm Gibson Dunn & Crutcher. Getting access to Edgar “is no more complicated than signing up for an e-mail account,” he said.
…
Should the SEC vet Edgar filings before they go out? Maloney says no.

“It would be the equivalent of saying don’t let anyone have e-mail or Twitter because they might use it for bad purposes,” he said.

Live by the sword, die by the sword. Good riddance.

Still, it was a pretty good day, all in:

The Standard & Poor’s 500 Index closed at an all-time high, halting a three-session slide, as Microsoft Corp. and Apple Inc. led a rally in technology shares and the weaker dollar spurred gains in multi-national companies.

It looks like infrastructure investors have another target:

Greece will continue with efforts to privatize the country’s largest port and regional airports as it seeks ways to attract investment for other state assets, Economy Minister George Stathakis said, in a government concession in talks with its creditors.

The privatization process that is already underway for the Piraeus Port Authority SA, operator of Greece’s largest harbor, and for 14 regional airports will continue, Stathakis said today in an interview in Tbilisi, Georgia. “We’re trying to revise some elements of these privatizations in order to improve them and I think we’ll get a sensible agreement for both.”

A sale of the Piraeus Port would be a reversal on the part of Greece’s Syriza party-led government, which had earlier pledged to block such moves. As part of ongoing negotiations to unlock aid to Europe’s most-indebted nation, Greek’s European creditors have asked for more specific policy proposals in areas including labor market deregulation, a pension-system overhaul, sales tax reform and privatization of state-held assets. Still, Stathakis said the government doesn’t plan to sell other assets at the moment.

Fed hikes? What Fed hikes?

The longer U.S. central bankers wait to initiate their tightening cycle, the more traders push back their expectations for when borrowing costs will start rising. On Thursday, futures contracts were implying that traders saw the fed funds rate at about 0.3 percent rate by December. That’s the lowest estimate of the year, and about half the forecast for the overnight lending benchmark that the Fed gave in March.

The market is essentially calling the Fed’s bluff. Traders are betting that policy makers won’t be able to raise rates this year without disrupting stocks and bonds, something that they’d really rather not do. So either U.S. policy makers will have to risk another market-wide tantrum, or they’ll give in to traders who embrace the idea of these historically low borrowing costs sticking around for longer.

I’m not going to try and guess whether hikes will come this year, next year, or not until after my retirement. But my fears of a disorderly return to normal are growing.

It was a mixed day for the Canadian preferred share market today, with PerpetualDiscounts off 7bp, FixedResets up 4bp and DeemedRetractibles gaining 1bp. The Performance Highlights table is shorter than it has been of late, but still much longer than the 2014 average. Volume was very low.

PerpetualDiscounts now yield 5.06%, equivalent to 6.58% interest at the standard equivalency factor of 1.3x. Long corporates now yield about 4.05%, so the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) is now about 255bp, a slight (and perhaps spurious) widening from the 250bp reported May 6.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

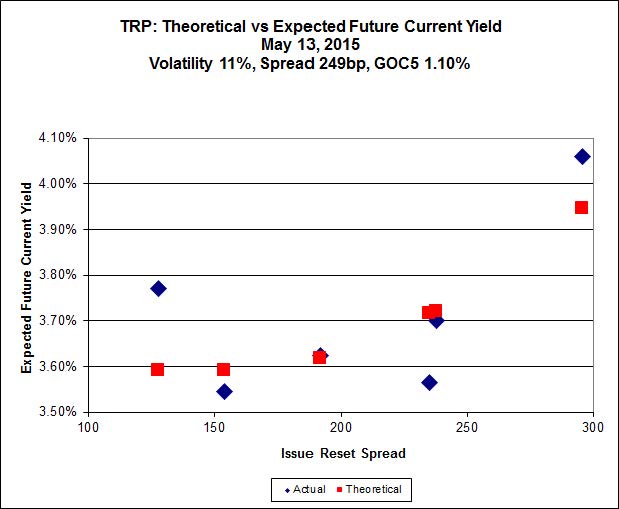
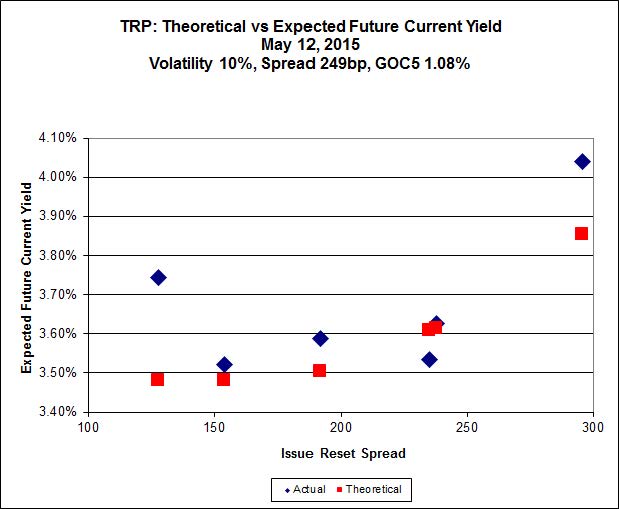
Here’s TRP:
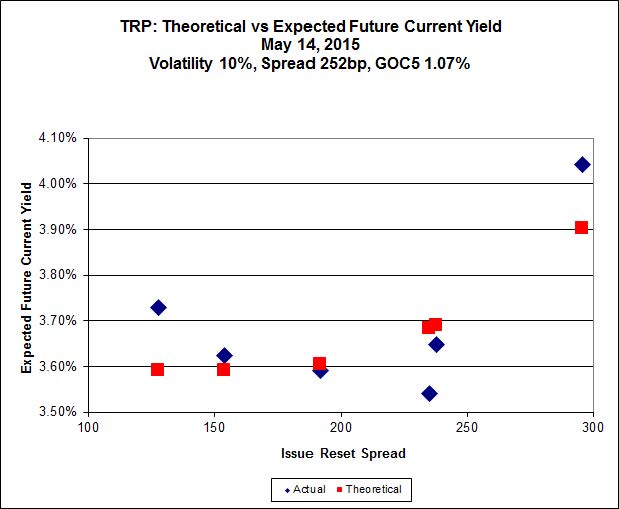
impVol_TRP_150514
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 24.15 to be $0.94 rich, while TRP.PR.G, resetting 2020-11-30 at +296, is $0.79 cheap at its bid price of 24.92.

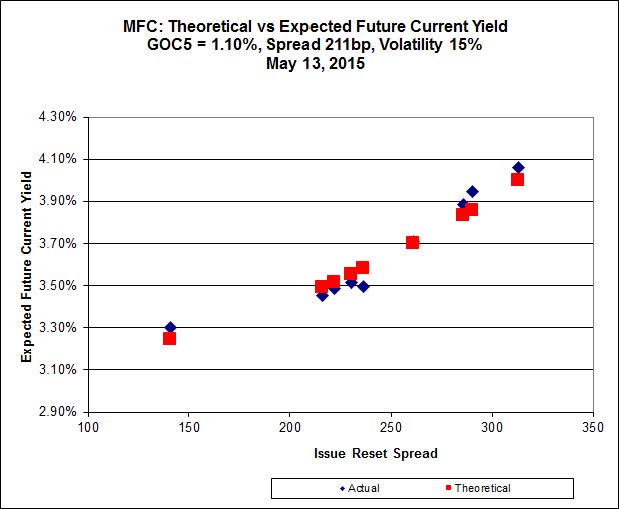
impVol_MFC_150514
Click for Big

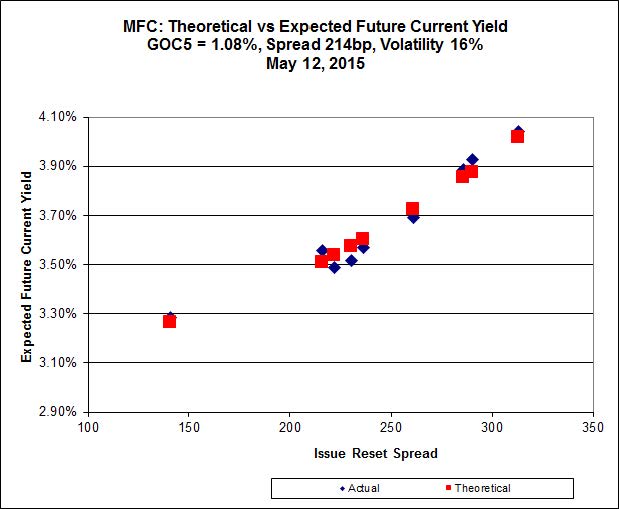
Another excellent fit, but the numbers are perplexing. Implied Volatility for MFC continues to be a conundrum. It is still too high if we consider that NVCC rules will never apply to these issues; it is still too low if we consider them to be NVCC non-compliant issues (and therefore with Deemed Maturities in the call schedule).

Most expensive is MFC.PR.M, resetting at +236 on 2019-12-19, bid at 24.75 to be $0.51 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 25.35 to be $0.65 cheap.
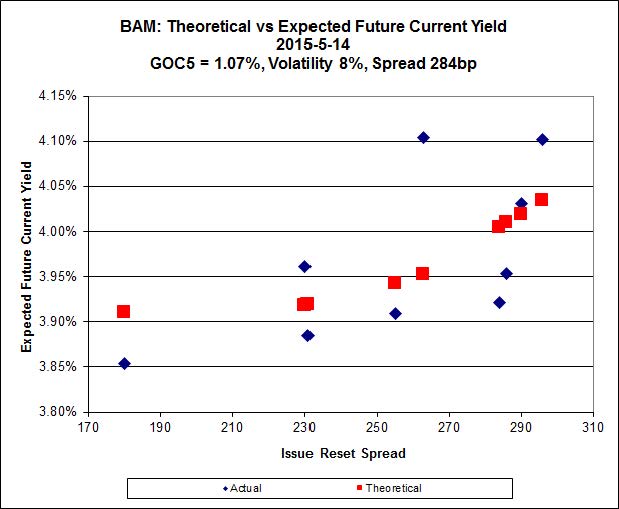
impVol_BAM_150514
Click for Big

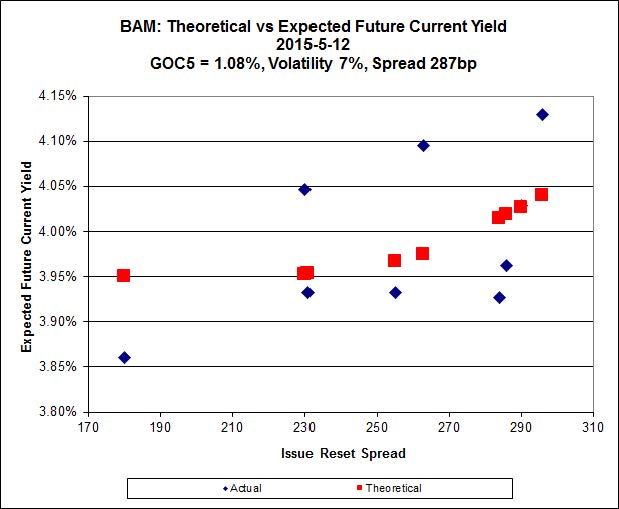
The cheapest issue relative to its peers is BAM.PF.B, resetting at +263bp on 2019-3-31, bid at 22.54 to be $0.86 cheap. BAM.PF.G, resetting at +284bp 2020-6-30 is bid at 24.93 and appears to be $0.52 rich.

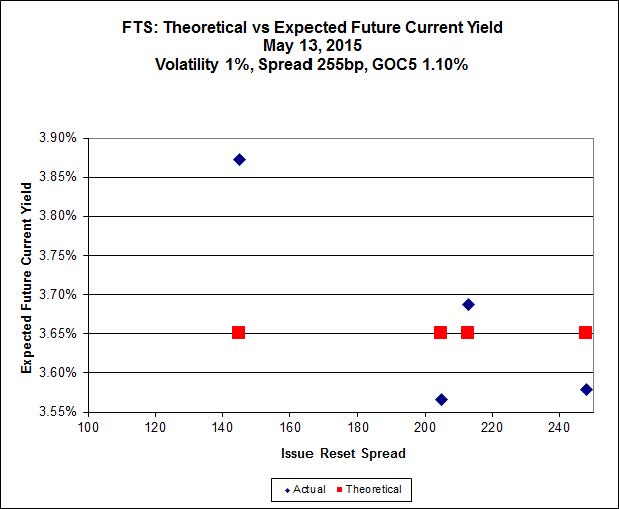
impVol_FTS_150514
Click for Big

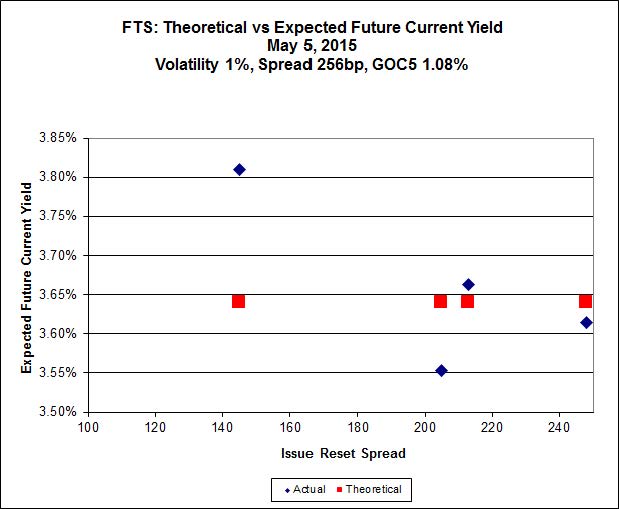
FTS.PR.H, with a spread of +145bp, and bid at 16.33, looks $0.98 cheap and resets 2015-6-1. FTS.PR.K, with a spread of +205bp and resetting 2019-3-1, is bid at 22.00 and is $0.57 rich.
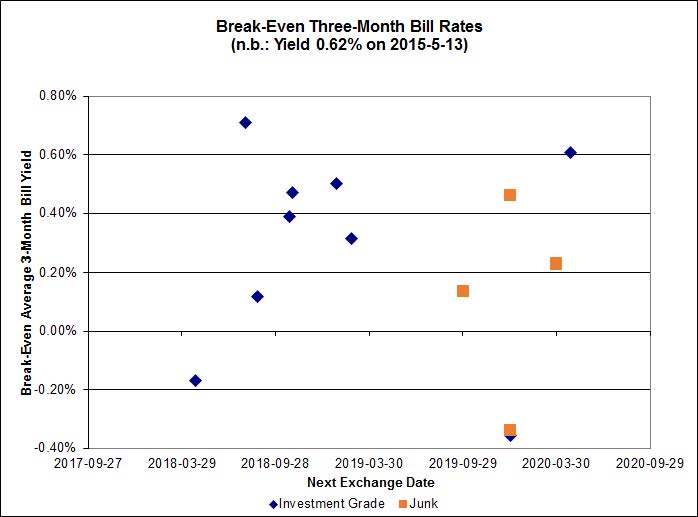
pairs_FR_150514
Click for Big

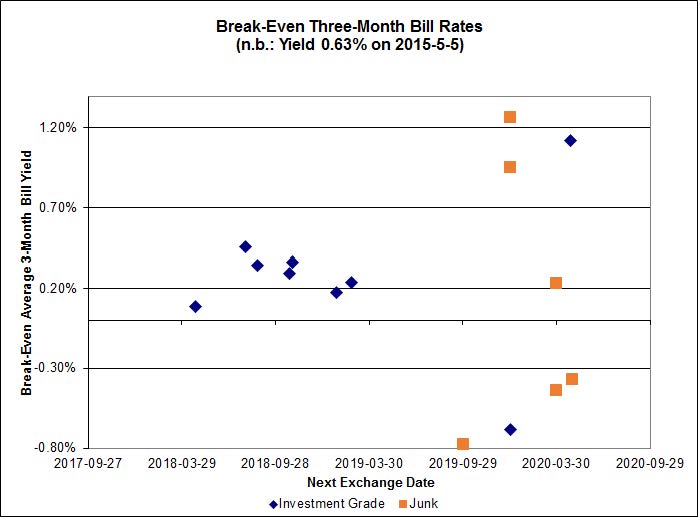
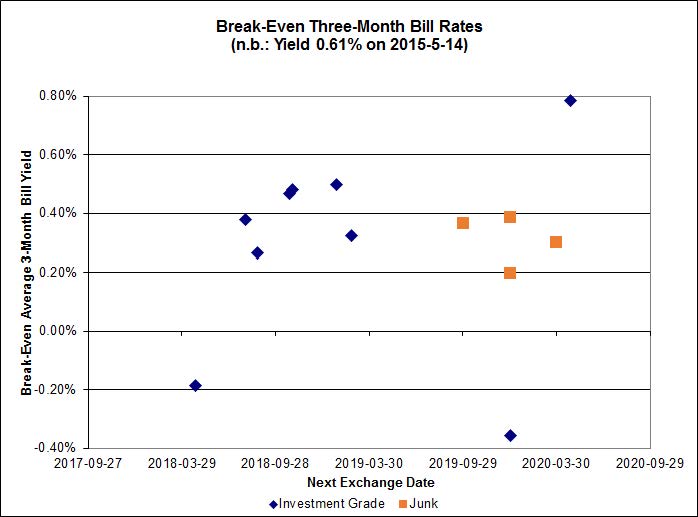
Investment-grade pairs predict an average over the next five-odd years of about 0.30%, including the TRP.PR.A / TRP.PR.F at -0.36% and the BNS.PR.Y / BNS.PR.D pair at +0.78. On the junk side, the FFH.PR.E / FFH.PR.F pair is at -0.85%, while BRF.PR.A / BRF.PR.B is at -1.05%.
pairs_FF_150514
Click for Big

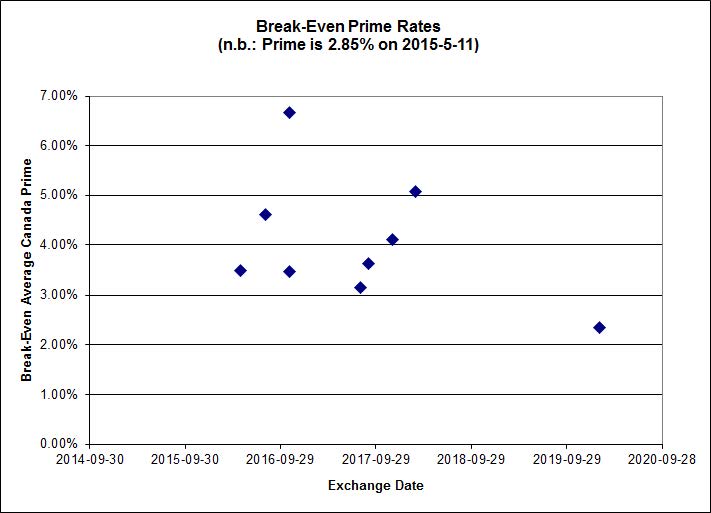
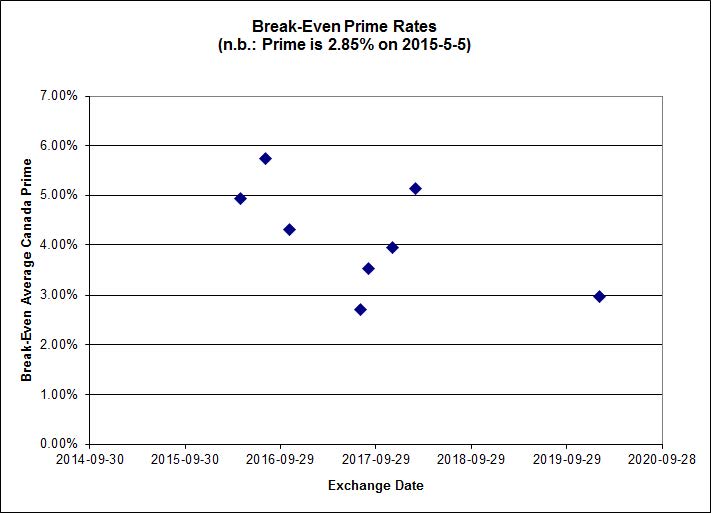
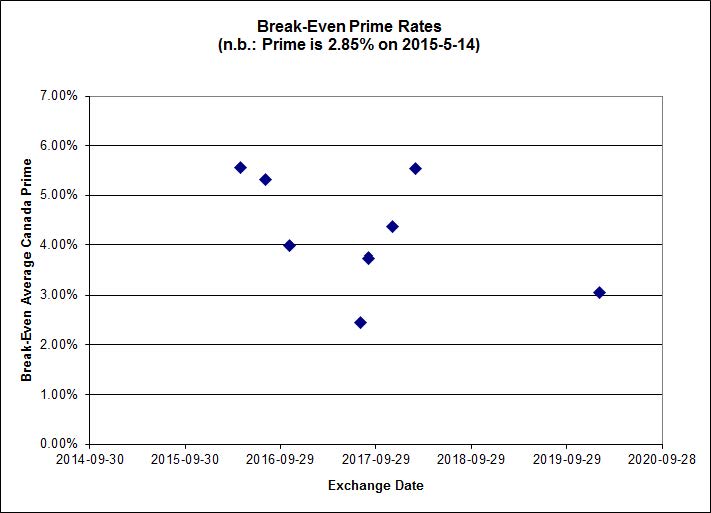
Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.3167 % 2,305.4
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.3167 % 4,031.0
Floater 3.15 % 3.30 % 53,697 18.96 4 0.3167 % 2,450.8
OpRet 4.43 % -4.72 % 38,605 0.13 2 0.0123 % 2,774.9
SplitShare 4.57 % 4.80 % 60,523 3.34 3 -0.0267 % 3,223.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0123 % 2,537.4
Perpetual-Premium 5.46 % 2.09 % 63,637 0.08 18 -0.0283 % 2,520.6
Perpetual-Discount 5.05 % 5.06 % 120,016 15.38 15 -0.0687 % 2,787.0
FixedReset 4.39 % 3.73 % 271,447 16.57 86 0.0412 % 2,425.1
Deemed-Retractible 4.92 % 3.35 % 111,028 0.62 35 0.0137 % 2,644.0
FloatingReset 2.59 % 2.89 % 61,323 6.18 7 -0.1154 % 2,333.7
Performance Highlights
Issue Index Change Notes
TRP.PR.C FixedReset -3.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-14
Maturity Price : 18.01
Evaluated at bid price : 18.01
Bid-YTW : 3.63 %
RY.PR.Z FixedReset -1.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-14
Maturity Price : 23.00
Evaluated at bid price : 24.34
Bid-YTW : 3.36 %
CU.PR.E Perpetual-Discount -1.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-14
Maturity Price : 24.30
Evaluated at bid price : 24.76
Bid-YTW : 4.93 %
CU.PR.D Perpetual-Discount -1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-14
Maturity Price : 24.73
Evaluated at bid price : 25.20
Bid-YTW : 4.85 %
GWO.PR.N FixedReset -1.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.15
Bid-YTW : 6.27 %
ENB.PR.T FixedReset 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-14
Maturity Price : 19.90
Evaluated at bid price : 19.90
Bid-YTW : 4.55 %
PWF.PR.A Floater 1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-14
Maturity Price : 17.90
Evaluated at bid price : 17.90
Bid-YTW : 2.78 %
MFC.PR.K FixedReset 1.18 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.10
Bid-YTW : 3.98 %
BAM.PR.R FixedReset 1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-14
Maturity Price : 21.27
Evaluated at bid price : 21.27
Bid-YTW : 4.08 %
IFC.PR.A FixedReset 1.30 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.05
Bid-YTW : 5.37 %
Volume Highlights
Issue Index Shares
Traded
Notes
PWF.PR.T FixedReset 159,112 RBC crossed 108,600 at 25.29. TD bought blocks of 10,000 and 30,000 from Scotia, both at 25.20.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-14
Maturity Price : 23.35
Evaluated at bid price : 25.20
Bid-YTW : 3.38 %
PWF.PR.P FixedReset 130,633 Nesbitt sold 23,800 to RBC at 18.65 and another 16,200 to TD at 18.60, then crossed 90,000 at 18.65.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-14
Maturity Price : 18.57
Evaluated at bid price : 18.57
Bid-YTW : 3.64 %
BMO.PR.T FixedReset 53,326 RBC crossed 50,000 at 24.50.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-14
Maturity Price : 23.00
Evaluated at bid price : 24.40
Bid-YTW : 3.36 %
BAM.PR.Z FixedReset 52,397 Nesbitt crossed 44,700 at 24.50.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-14
Maturity Price : 23.28
Evaluated at bid price : 24.56
Bid-YTW : 4.12 %
ENB.PR.T FixedReset 45,126 RBC crossed 34,200 at 20.20.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-14
Maturity Price : 19.90
Evaluated at bid price : 19.90
Bid-YTW : 4.55 %
BMO.PR.L Deemed-Retractible 38,400 RBC crossed two blocks of 19,100 each, both at 25.70.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2015-06-24
Maturity Price : 25.50
Evaluated at bid price : 25.71
Bid-YTW : -3.13 %
There were 18 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
TD.PR.T FloatingReset Quote: 24.10 – 24.54
Spot Rate : 0.4400
Average : 0.2733

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.10
Bid-YTW : 2.85 %

HSE.PR.C FixedReset Quote: 25.00 – 25.40
Spot Rate : 0.4000
Average : 0.2404

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-14
Maturity Price : 23.19
Evaluated at bid price : 25.00
Bid-YTW : 4.15 %

PWF.PR.P FixedReset Quote: 18.57 – 19.06
Spot Rate : 0.4900
Average : 0.3676

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-14
Maturity Price : 18.57
Evaluated at bid price : 18.57
Bid-YTW : 3.64 %

RY.PR.Z FixedReset Quote: 24.34 – 24.78
Spot Rate : 0.4400
Average : 0.3358

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-14
Maturity Price : 23.00
Evaluated at bid price : 24.34
Bid-YTW : 3.36 %

PWF.PR.A Floater Quote: 17.90 – 18.35
Spot Rate : 0.4500
Average : 0.3746

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-14
Maturity Price : 17.90
Evaluated at bid price : 17.90
Bid-YTW : 2.78 %

GWO.PR.N FixedReset Quote: 18.15 – 18.40
Spot Rate : 0.2500
Average : 0.1807

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.15
Bid-YTW : 6.27 %

Market Action

May 13, 2015

On April 30, S&P published its 2014 Annual Global Corporate Default Study And Rating Transitions:

In a year marked by considerable geopolitical turmoil, the ending of the Federal Reserve’s monthly asset purchases, and the steep decline in the price of oil, corporate borrowers fared very well by historical standards. In the full year, 60 global corporate issuers defaulted, considerably lower than the 81 last year and the lowest total since 2011 (see table 1). These 60 defaulted issuers accounted for a total of $91.6 billion in debt, down from $97.3 billion in 2013.

Overall, credit quality and rating stability remained high in 2014 (see table 6). The ratio of downgrades to upgrades increased marginally relative to 2013, but the rate of upgrades still outpaced that of downgrades. Overall, the percentage of rating actions decreased, and the magnitude of individual rating changes remained muted. This pushed the average number of notches recorded among downgrades to 1.36 from 1.38 in 2013. Meanwhile, the average number of notches for upgrades remained nearly unchanged, at 1.16 versus 1.15 in 2013 (see chart 13). (Watch the related CreditMatters TV segment titled, “Standard & Poor’s Global Corporate Default And Rating Transitions Study,” dated April 30, 2015.)

Overview

  • •The number of global defaults in 2014 declined to 60 from 81 in 2013. This helped push the global speculative-grade default rate down to 1.42% from 2.28% at the end of 2013. Similar to 2013, this decline is a result of both a smaller number of defaults and an increase in the number of speculative-grade issuers in 2014–up to 3,163 from 2,804 a year earlier.
  • •The one-year global Gini ratio rose to 93 in 2014, which is the second highest in 34 years. This is largely attributable to the roughly 91% of the rated defaulters in 2014 beginning the year with ratings of ‘B-‘ or lower.
  • •The overall rate of rating actions decreased in 2014. The downgrade rate decreased to 8.4% from 9.4% in 2013, while the upgrade rate declined to 9.3% from 11.4%. Ratings stability increased, with the rate of unchanged ratings hitting a 10-year high of 74.5%.
  • •Consistent with past years, the U.S. continues to account for the majority of defaults globally in 2014, at 55%. However, this is the lowest percentage in the past 34 years. Following the U.S., emerging markets accounted for just over 25% of the remaining defaulters.

They have also published a bit more commentary:

U.S. corporate credit performed exceptionally well in 2014 as the number of rated companies defaulting declined to its lowest number since 2007. While the Federal Reserve completed its round of tapering, winding down its monthly large-scale asset purchases, interest rates for highly rated credits fell from already low levels. Corporate bond issuance surpassed $1 trillion for a third consecutive year, and investment-grade and Treasury bond yields fell. As the speculative-grade market faced rising volatility during the year brought about by falling oil prices and rising geopolitical strains, the speculative-grade default rate fell to below 2%, less than one half of its long-term average. Slow but steady economic growth continued to support business conditions, and the upgrade to downgrade ratio improved as more U.S. companies were upgraded than downgraded in 2014. The number of U.S. corporate defaulters fell to 33 from 45 in 2013. The defaulting companies were either unrated or were rated ‘B-‘ and lower as of the beginning of 2014, consistent with our findings that Standard & Poor’s Ratings Services’ U.S. corporate credit ratings continue to serve as effective indicators of relative credit risk. (Watch the related CreditMatters TV segment titled, “Standard & Poor’s U.S. Corporate Default And Rating Transitions Study,” dated May 11, 2015.)

Overview

  • •In 2014, 33 U.S. companies with $82 billion in outstanding debt defaulted; by comparison, 45 U.S. corporates defaulted with $64.9 billion of outstanding debt in 2013.
  • •The U.S. speculative-grade (‘BB+’ and lower) corporate default rate fell to 1.59% as of year-end 2014 from 2.16% as of year-end 2013. Of the companies that defaulted in 2014, the highest rated was ‘B-‘.
  • •Companies in the lowest rating categories had the highest default rates: 25% of the companies rated ‘CCC’/’C’ at the beginning of the year had defaulted by the end of the year.
  • •The one-year Gini ratio for Standard & Poor’s 2014 ratings’ performance climbed to a new high of 96.1%. This is the highest one-year Gini recorded for U.S. corporates in our data going back to 1981.
  • •Overall, ratings were more stable in 2014 than in 2013: Nearly 76% of ratings were unchanged in 2014, up from 72% the prior year.

SEC Chair Mary Jo White gave a speech lauding the opportunities that market complexity gives for regulatory employment, and the fine job the SEC is doing, titled Optimizing Our Equity Market Structure. These were Opening Remarks at the Inaugural Meeting of the Equity Market Structure Advisory Committee:

It is fitting that today we are starting our market structure discussion with an assessment of Rule 611 of Regulation NMS — the order protection rule. The selection of this rule for the inaugural meeting is reflective of how important it is to examine the fundamentals of our current market and regulatory structure, to explore their impact and assess their continued utility. This is not done just for an interesting discussion — although I am sure it will be that. Rather, we are about the serious business of optimizing the structure of our equity markets through a careful, data-driven assessment where no issue is off limits or any assumption unquestioned. And Rule 611 is most certainly a rule that features prominently in the discussion of market structure, with different views of its various impacts, including critiques that it has: (1) contributed to excessive fragmentation; (2) led to increased off-exchange trading; (3) harmed institutional investors; and (4) failed to achieve the objective of enhancing displayed liquidity. The Division of Trading and Markets has prepared and posted on our website a memorandum that is intended to help explore the extent to which these claims may or may not be accurate. Addressing Rule 611 will no doubt serve to highlight the other forces that have shaped our market structure, whether they be regulatory, competitive, or technological.

Rule 611 is part of Regulation NMS:

Regulation NMS includes new substantive rules that are designed to modernize and strengthen the regulatory structure of the U.S. equity markets. First, the “Order Protection Rule” requires trading centers to establish, maintain, and enforce written policies and procedures reasonably designed to prevent the execution of trades at prices inferior to protected quotations displayed by other trading centers, subject to an applicable exception. To be protected, a quotation must be immediately and automatically accessible. Second, the “Access Rule” requires fair and non-discriminatory access to quotations, establishes a limit on access fees to harmonize the pricing of quotations across different trading centers, and requires each national securities exchange and national securities association to adopt, maintain, and enforce written rules that prohibit their members from engaging in a pattern or practice of displaying quotations that lock or cross automated quotations. Third, the “Sub-Penny Rule” prohibits market participants from accepting, ranking, or displaying orders, quotations, or indications of interest in a pricing increment smaller than a penny, except for orders, quotations, or indications of interest that are priced at less than $1.00 per share. Finally, the Commission is adopting amendments to the “Market Data Rules” that update the requirements for consolidating, distributing, and displaying market information, as well as amendments to the joint industry plans for disseminating market information that modify the formulas for allocating plan revenues (“Allocation Amendment”) and broaden participation in plan governance (“Governance Amendment”).

After all the garbage coming from the regulators, it’s nice to see that someone gets it:

An ex-Jefferies & Co. trader convicted last year of lying to buyers and sellers of mortgage-backed bonds may have done nothing worse in one judge’s view than what a homeowner does when selling a house.

There’s a “certain amount of license and puffery” that goes on in the bond market, especially with “big boys” “who are capable of very sophisticated analysis,” U.S. Circuit Judge Barrington D. Parker said Wednesday during the appeal of Jesse Litvak’s conviction. “This kind of thing goes on all the time.”

Litvak, 40, was found guilty by a federal jury in New Haven, Connecticut, in March 2014, becoming the first person convicted of fraud tied to the Troubled Asset Relief Program set up by the U.S. amid the 2008 financial crisis. On appeal, Litvak says the case would make crimes out of statements in everyday negotiations such as car sales and that his lies weren’t material to the bond transactions.

Parker, one of three judges hearing the case in the U.S. Court of Appeals in New York, may agree. He asked Assistant U.S. Attorney Jonathan Francis if a real estate broker would be making a material misrepresentation by falsely telling a home buyer that a seller wouldn’t accept a lower offer.

Francis said the rules are different in the securities industry and that a higher standard is needed to discourage deceit and ensure that markets are fair and that investors won’t be ripped off.

Mr. Francis’ position is, of course, bullshit. The reason there is more regulation in the securities industry than in real-estate is because there are more layers of middlemen in securities transactions and these middlemen are giant corporations who pay regulatory fees as a part of doing business and pass them on to clients without itemization. If clients knew how much regulation was costing them, directly and indirectly, there would be a lot less regulation.

It was a mixed day for the Canadian preferred share market, with PerpetualDiscounts gaining 24bp, FixedResets off 3bp and DeemedRetractibles down 7bp. The performance highlights table shows volatility remains a big factor, with Enbridge issues prominent on the bad side. Volume was on the low side of average.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_150513
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 24.20 to be $0.99 rich, while TRP.PR.B, resetting 2015-6-30 at +128, is $0.79 cheap at its bid price of 15.78.

impVol_MFC_150513
Click for Big

Another excellent fit, but the numbers are perplexing. Implied Volatility for MFC continues to be a conundrum. It is still too high if we consider that NVCC rules will never apply to these issues; it is still too low if we consider them to be NVCC non-compliant issues (and therefore with Deemed Maturities in the call schedule).

Most expensive is MFC.PR.M, resetting at +236 on 2019-12-19, bid at 24.75 to be $0.60 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 25.33 to be $0.61 cheap.

impVol_BAM_150513
Click for Big

The cheapest issue relative to its peers is BAM.PF.B, resetting at +263bp on 2019-3-31, bid at 22.52 to be $0.83 cheap. BAM.PF.G, resetting at +284bp 2020-6-30 is bid at 24.97 and appears to be $0.56 rich.

impVol_FTS_150513
Click for Big

FTS.PR.H, with a spread of +145bp, and bid at 16.46, looks $1.01 cheap and resets 2015-6-1. FTS.PR.K, with a spread of +205bp and resetting 2019-3-1, is bid at 22.08 and is $0.50 rich.

pairs_FR_150513
Click for Big

Investment-grade pairs predict an average over the next five-odd years of about 0.30%, including the TRP.PR.A / TRP.PR.F at -0.36%. On the junk side, the FFH.PR.E / FFH.PR.F pair is at -1.06%, while BRF.PR.A / BRF.PR.B is at -1.36%.

pairs_FF_150513
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.4728 % 2,298.2
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.4728 % 4,018.3
Floater 3.16 % 3.30 % 54,370 18.96 4 -0.4728 % 2,443.1
OpRet 4.41 % -4.13 % 38,819 0.13 2 0.0980 % 2,774.6
SplitShare 4.57 % 4.81 % 59,198 3.34 3 0.0802 % 3,224.1
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0980 % 2,537.1
Perpetual-Premium 5.46 % 2.38 % 63,834 0.08 18 0.0052 % 2,521.3
Perpetual-Discount 5.04 % 5.04 % 121,767 15.29 15 0.2370 % 2,788.9
FixedReset 4.39 % 3.76 % 272,135 16.42 86 -0.0255 % 2,424.1
Deemed-Retractible 4.92 % 3.24 % 110,399 0.62 35 -0.0696 % 2,643.6
FloatingReset 2.58 % 2.92 % 61,974 6.18 7 -0.0729 % 2,336.4
Performance Highlights
Issue Index Change Notes
ENB.PR.N FixedReset -2.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-13
Maturity Price : 20.35
Evaluated at bid price : 20.35
Bid-YTW : 4.59 %
ENB.PR.Y FixedReset -1.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-13
Maturity Price : 19.25
Evaluated at bid price : 19.25
Bid-YTW : 4.59 %
HSE.PR.A FixedReset -1.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-13
Maturity Price : 17.48
Evaluated at bid price : 17.48
Bid-YTW : 4.07 %
ENB.PR.P FixedReset -1.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-13
Maturity Price : 20.01
Evaluated at bid price : 20.01
Bid-YTW : 4.52 %
ENB.PR.F FixedReset -1.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-13
Maturity Price : 19.55
Evaluated at bid price : 19.55
Bid-YTW : 4.61 %
TRP.PR.D FixedReset -1.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-13
Maturity Price : 22.62
Evaluated at bid price : 23.51
Bid-YTW : 3.68 %
ENB.PR.D FixedReset -1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-13
Maturity Price : 19.50
Evaluated at bid price : 19.50
Bid-YTW : 4.46 %
ENB.PR.T FixedReset -1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-13
Maturity Price : 19.68
Evaluated at bid price : 19.68
Bid-YTW : 4.60 %
ENB.PR.B FixedReset -1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-13
Maturity Price : 19.45
Evaluated at bid price : 19.45
Bid-YTW : 4.47 %
ELF.PR.H Perpetual-Premium -1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-13
Maturity Price : 24.72
Evaluated at bid price : 25.20
Bid-YTW : 5.49 %
ELF.PR.G Perpetual-Discount -1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-13
Maturity Price : 23.11
Evaluated at bid price : 23.40
Bid-YTW : 5.11 %
ENB.PR.A Perpetual-Premium 1.04 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2015-06-12
Maturity Price : 25.00
Evaluated at bid price : 25.35
Bid-YTW : -14.37 %
RY.PR.Z FixedReset 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-13
Maturity Price : 23.15
Evaluated at bid price : 24.72
Bid-YTW : 3.29 %
SLF.PR.H FixedReset 1.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.95
Bid-YTW : 4.96 %
CM.PR.P FixedReset 1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-13
Maturity Price : 23.00
Evaluated at bid price : 24.50
Bid-YTW : 3.34 %
CU.PR.D Perpetual-Discount 1.23 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-09-01
Maturity Price : 25.25
Evaluated at bid price : 25.50
Bid-YTW : 4.61 %
CIU.PR.C FixedReset 1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-13
Maturity Price : 16.20
Evaluated at bid price : 16.20
Bid-YTW : 3.76 %
PWF.PR.S Perpetual-Discount 1.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-13
Maturity Price : 24.33
Evaluated at bid price : 24.75
Bid-YTW : 4.86 %
MFC.PR.M FixedReset 2.74 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.75
Bid-YTW : 3.85 %
MFC.PR.L FixedReset 3.65 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.59
Bid-YTW : 4.31 %
Volume Highlights
Issue Index Shares
Traded
Notes
ENB.PR.H FixedReset 121,407 Nesbitt crossed 100,000 at 18.60.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-13
Maturity Price : 18.37
Evaluated at bid price : 18.37
Bid-YTW : 4.47 %
MFC.PR.A OpRet 89,420 Called for redemption June 19.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2015-06-19
Maturity Price : 25.00
Evaluated at bid price : 25.25
Bid-YTW : 0.32 %
BAM.PF.G FixedReset 44,659 Desjardins crossed 40,000 at 24.85.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-13
Maturity Price : 23.14
Evaluated at bid price : 24.97
Bid-YTW : 3.94 %
SLF.PR.H FixedReset 41,221 Nesbitt crossed 38,300 at 21.90.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.95
Bid-YTW : 4.96 %
ENB.PR.P FixedReset 27,576 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-13
Maturity Price : 20.01
Evaluated at bid price : 20.01
Bid-YTW : 4.52 %
RY.PR.H FixedReset 24,106 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-13
Maturity Price : 23.07
Evaluated at bid price : 24.59
Bid-YTW : 3.34 %
There were 29 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
MFC.PR.K FixedReset Quote: 23.82 – 24.50
Spot Rate : 0.6800
Average : 0.4164

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.82
Bid-YTW : 4.12 %

ELF.PR.H Perpetual-Premium Quote: 25.20 – 25.65
Spot Rate : 0.4500
Average : 0.3273

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-13
Maturity Price : 24.72
Evaluated at bid price : 25.20
Bid-YTW : 5.49 %

ENB.PR.N FixedReset Quote: 20.35 – 20.73
Spot Rate : 0.3800
Average : 0.2644

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-13
Maturity Price : 20.35
Evaluated at bid price : 20.35
Bid-YTW : 4.59 %

ENB.PR.F FixedReset Quote: 19.55 – 19.87
Spot Rate : 0.3200
Average : 0.2273

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-13
Maturity Price : 19.55
Evaluated at bid price : 19.55
Bid-YTW : 4.61 %

MFC.PR.I FixedReset Quote: 25.48 – 25.73
Spot Rate : 0.2500
Average : 0.1654

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-09-19
Maturity Price : 25.00
Evaluated at bid price : 25.48
Bid-YTW : 3.85 %

IFC.PR.A FixedReset Quote: 20.78 – 21.15
Spot Rate : 0.3700
Average : 0.2903

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.78
Bid-YTW : 5.53 %

Market Action

May 12, 2015

For those who missed it, Bloomberg has an admirable piece on the some explanations of the global bond rout:

Between the ECB’s bond buying and the threat of deflation, yields across Europe started to go negative this year, meaning investors were essentially paying for the privilege to lend their money out. That created a spill over effect into bond markets in the rest of the world as investors went in search of a better deal, pulling yields down in those markets too. The average yield across all Germany’s debt went negative about three weeks ago. That seems to have been the straw that broke the camel’s back. Since then that average yield has climbed to the highest level this year. Yields on about $2 trillion of bonds across 12 countries still linger below zero.

The US Department of So-Called Justice has decided a little more regulatory extortion is never a bad thing:

The U.S. Justice Department is set to rip up its agreement not to prosecute UBS Group AG for rigging benchmark interest rates, according to a person familiar with the matter, taking a new step to hold banks accountable for repeat offenses.

The move by the U.S. would be a first for the industry, making good on a March threat by a senior Justice Department official to revoke such agreements and putting banks on notice that these accords can be unwound if misconduct continues.
…
UBS’s cooperation in the currency probe may help shield it from antitrust charges in that matter. However, the bank is still exposed to fraud charges in that case, and any admission of wrongdoing could also put it in violation of an earlier deal the Zurich-based bank struck with the Justice Department.

In a December 2012 non-prosecution agreement with the U.S. to resolve a worldwide investigation into the manipulation of the London interbank offered rate, or Libor, UBS promised not to commit crimes for two years.

Don’t bet your bottom dollar on Chicago, Chicago:

Chicago had its credit rating cut to junk by Moody’s Investors Service after the Illinois Supreme Court’s rejection of a state pension-overhaul plan reduced the city’s options for fixing its own underfunded system.

The two-level downgrade to Ba1 affects $8.1 billion of general obligations, which were already the lowest-rated among the 90 biggest U.S. cities, excluding Detroit. The outlook is still negative. Moody’s has dropped the city seven levels since July 2013.
…
The deterioration in the credit standing of the third-most-populous U.S. city underscores how pension promises are squeezing the finances of states and localities nationwide. Moody’s downgrade compounds Chicago’s fiscal struggles: its counterparties can immediately demand as much as $2.2 billion in accelerated principal, accrued interest and termination fees, New York-based Moody’s said in the report.

There’s an interesting piece on Bloomberg about using technology to compete with cheap labour:

A few years ago, in an effort to diversify his company’s offerings, Pomini teamed up with Selvaggia Armani, an artist and designer. The two began working on a series of lamps designed by Armani and manufactured to order on Pomini’s 3D printers. The pieces—some of which include intricate meshwork or interlocking chains that would be difficult to produce using traditional methods—take shape slowly, each layer fused from powdered nylon by a high-power laser. The project was a surprising success: Pomini now works with more than a dozen designers; he introduced 3D­printed jewelry in 2012. “This is the beauty of this technology,” says Armani, 47. “You can build things that are impossible.”
…
Armani have helped turn northeastern Italy into an unlikely hothouse of innovation. Last year growth in the region was positive for the first time since 2007, at 0.5 percent. Exports rose by 3.5 percent in 2014 and are expected to keep climbing. In the province of Trento, for instance, the public and private sectors together invest some 2 percent of gross domestic product in research and development. At the Centro Moda Canossa—a trade school in Trento for children age 14 to 18 specializing in fashion design and tailoring—the faculty recently added a class in which students incorporate 3D printing, laser cutting, and microcontroller chips into their designs. “You can’t offer a job from the past. Nobody will come,” says Michele Bommassar, 36, the school’s vice director. “You have to offer the jobs of the future.”

Is anybody in Canada listening? No? OK, go back to sleep, then. You’ll want to be rested for the anti-globalization demo.

In other news, Hydro One, having achieved the pinnacle of operating efficiency, has decided to join the Junior Justice League:

A Hydro One employee will be fired following an incident on Sunday when a female television reporter was harassed by Toronto FC fans hurling obscenities while she was doing a live hit.

“Hydro One is taking steps to terminate the employee for violating our Code of Conduct,” Hydro One spokesman Daffyd Roderick said in a statement.

“Respect for all people is ingrained in the code and our values. We are committed to a work environment where discrimination or harassment of any type is met with zero tolerance.”

So now, not only will universities like Dalhousie be able to administer the extra-judicial flavour of the month (as discussed on January 6) but any two-bit corporation will be able to do the same. So we are beginning to see a reversion to the good old days, when your employer had the ability to regulate every aspect of your life … it will be interesting to learn when unions become popular again, which will happen as soon as enough people get fed up with the abuse and fearful of its consequences – especially when it results from an essentially random occurance of internet pile-on.

It was a negative day for the Canadian preferred share market, with PerpetualDiscounts losing 26bp, FixedResets off 4bp and DeemedRetractibles down 8bp. FixedResets dominated both ends of the Performance Highlights table. Volume was extremely high.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_150512
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 24.26 to be $0.49 rich, while TRP.PR.G, resetting 2020-11-30 at +296, is $1.21 cheap at its bid price of 25.00.

impVol_MFC_150512
Click for Big

Another excellent fit, but the numbers are perplexing. Implied Volatility for MFC continues to be a conundrum. It is still too high if we consider that NVCC rules will never apply to these issues; it is still too low if we consider them to be NVCC non-compliant issues (and therefore with Deemed Maturities in the call schedule).

Most expensive is MFC.PR.N, resetting at +230 on 2020-3-19, bid at 24.04 to be $0.40 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 25.33 to be $0.35 cheap.

impVol_BAM_150512
Click for Big

The cheapest issue relative to its peers is BAM.PF.B, resetting at +263bp on 2019-3-31, bid at 22.65 to be $0.69 cheap. BAM.PF.G, resetting at +284bp 2020-6-30 is bid at 24.96 and appears to be $0.55 rich.

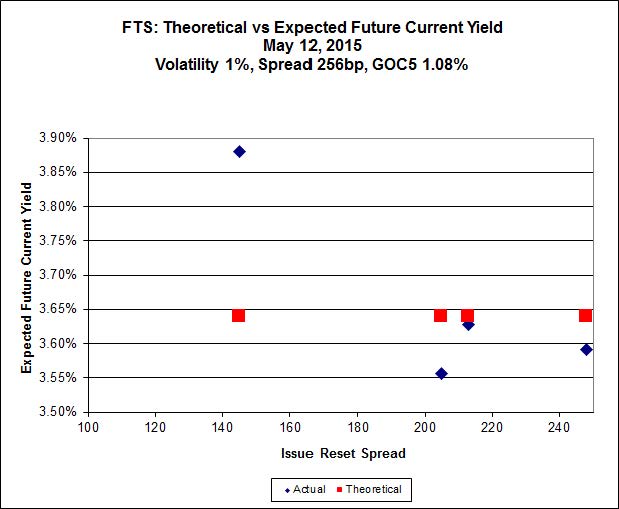
impVol_FTS_150512
Click for Big

FTS.PR.H, with a spread of +145bp, and bid at 16.30, looks $1.08 cheap and resets 2015-6-1. FTS.PR.K, with a spread of +205bp and resetting 2019-3-1, is bid at 22.00 and is $0.50 rich.

pairs_FR_150512
Click for Big

Investment-grade pairs predict an average over the next five-odd years of about 0.40%, but TRP.PR.A / TRP.PR.F remains an outlier at -0.39%. On the junk side, the FFH.PR.E / FFH.PR.F pair is at -1.12%.

pairs_FF_150512
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.1104 % 2,309.1
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.1104 % 4,037.3
Floater 3.14 % 3.27 % 54,838 19.02 4 0.1104 % 2,454.7
OpRet 4.41 % -2.65 % 39,132 0.14 2 0.1178 % 2,771.8
SplitShare 4.58 % 4.80 % 59,082 3.34 3 -0.3594 % 3,221.6
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1178 % 2,534.6
Perpetual-Premium 5.45 % 2.18 % 66,363 0.08 18 0.0283 % 2,521.2
Perpetual-Discount 5.05 % 5.07 % 119,922 15.35 15 -0.2559 % 2,782.3
FixedReset 4.38 % 3.73 % 273,092 16.33 86 -0.0363 % 2,424.7
Deemed-Retractible 4.91 % 3.51 % 110,294 0.78 35 -0.0752 % 2,645.4
FloatingReset 2.58 % 2.91 % 62,405 6.19 7 -0.0243 % 2,338.1
Performance Highlights
Issue Index Change Notes
MFC.PR.L FixedReset -3.76 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.76
Bid-YTW : 4.76 %
SLF.PR.H FixedReset -3.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.70
Bid-YTW : 5.10 %
FTS.PR.H FixedReset -2.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-12
Maturity Price : 16.30
Evaluated at bid price : 16.30
Bid-YTW : 3.84 %
FTS.PR.K FixedReset -1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-12
Maturity Price : 21.70
Evaluated at bid price : 22.00
Bid-YTW : 3.72 %
ENB.PR.T FixedReset -1.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-12
Maturity Price : 20.20
Evaluated at bid price : 20.20
Bid-YTW : 4.56 %
PWF.PR.P FixedReset -1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-12
Maturity Price : 18.75
Evaluated at bid price : 18.75
Bid-YTW : 3.60 %
IFC.PR.A FixedReset -1.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.80
Bid-YTW : 5.51 %
PWF.PR.S Perpetual-Discount -1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-12
Maturity Price : 23.92
Evaluated at bid price : 24.32
Bid-YTW : 4.95 %
GWO.PR.I Deemed-Retractible -1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.75
Bid-YTW : 5.26 %
MFC.PR.H FixedReset 1.01 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-03-19
Maturity Price : 25.00
Evaluated at bid price : 26.05
Bid-YTW : 2.64 %
BMO.PR.T FixedReset 1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-12
Maturity Price : 23.06
Evaluated at bid price : 24.55
Bid-YTW : 3.33 %
BAM.PR.R FixedReset 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-12
Maturity Price : 20.88
Evaluated at bid price : 20.88
Bid-YTW : 4.16 %
BAM.PR.X FixedReset 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-12
Maturity Price : 18.65
Evaluated at bid price : 18.65
Bid-YTW : 4.08 %
GWO.PR.N FixedReset 1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.35
Bid-YTW : 6.13 %
NA.PR.W FixedReset 1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-12
Maturity Price : 23.00
Evaluated at bid price : 24.50
Bid-YTW : 3.37 %
TRP.PR.C FixedReset 1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-12
Maturity Price : 18.60
Evaluated at bid price : 18.60
Bid-YTW : 3.52 %
BMO.PR.S FixedReset 1.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-12
Maturity Price : 23.22
Evaluated at bid price : 24.92
Bid-YTW : 3.35 %
BAM.PR.T FixedReset 2.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-12
Maturity Price : 21.27
Evaluated at bid price : 21.55
Bid-YTW : 4.01 %
Volume Highlights
Issue Index Shares
Traded
Notes
BAM.PF.F FixedReset 127,583 Desjardins crossed 100,000 at 24.85; TD crossed 25,000 at the same price.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-12
Maturity Price : 23.16
Evaluated at bid price : 24.86
Bid-YTW : 3.96 %
CM.PR.Q FixedReset 115,410 Nesbitt crossed 76,800 at 25.00; TD crossed 25,000 at 24.97.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-12
Maturity Price : 23.10
Evaluated at bid price : 24.85
Bid-YTW : 3.69 %
RY.PR.H FixedReset 82,086 Desjardins crossed 20,000 at 24.62; RBC crossed 40,400 at the same price.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-12
Maturity Price : 23.08
Evaluated at bid price : 24.61
Bid-YTW : 3.34 %
ENB.PR.H FixedReset 63,230 RBC crossed blocks of 23,600 and 26,400, both at 18.86.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-12
Maturity Price : 18.75
Evaluated at bid price : 18.75
Bid-YTW : 4.46 %
RY.PR.C Deemed-Retractible 59,095 Nesbitt crossed 50,000 at 25.25.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2015-11-24
Maturity Price : 25.00
Evaluated at bid price : 25.18
Bid-YTW : 2.95 %
ENB.PR.T FixedReset 51,581 RBC crossed 40,000 at 20.45.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-12
Maturity Price : 20.20
Evaluated at bid price : 20.20
Bid-YTW : 4.56 %
There were 52 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
MFC.PR.M FixedReset Quote: 24.09 – 24.97
Spot Rate : 0.8800
Average : 0.5983

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.09
Bid-YTW : 4.19 %

IAG.PR.G FixedReset Quote: 25.95 – 26.50
Spot Rate : 0.5500
Average : 0.4134

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-06-30
Maturity Price : 25.00
Evaluated at bid price : 25.95
Bid-YTW : 2.70 %

RY.PR.Z FixedReset Quote: 24.46 – 24.94
Spot Rate : 0.4800
Average : 0.3657

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-12
Maturity Price : 23.05
Evaluated at bid price : 24.46
Bid-YTW : 3.34 %

PWF.PR.F Perpetual-Discount Quote: 25.01 – 25.29
Spot Rate : 0.2800
Average : 0.1688

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-12
Maturity Price : 24.69
Evaluated at bid price : 25.01
Bid-YTW : 5.28 %

GWO.PR.F Deemed-Retractible Quote: 25.61 – 25.98
Spot Rate : 0.3700
Average : 0.2603

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2015-06-11
Maturity Price : 25.00
Evaluated at bid price : 25.61
Bid-YTW : -14.88 %

BAM.PF.B FixedReset Quote: 22.65 – 22.99
Spot Rate : 0.3400
Average : 0.2306

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-12
Maturity Price : 22.14
Evaluated at bid price : 22.65
Bid-YTW : 4.15 %

Market Action

May 11, 2015

Markets are forecasting no changes in the Canadian policy rate:

The bond market is starting to believe Bank of Canada Governor Stephen Poloz’s newfound optimism in the Canadian economy, resetting borrowing costs back to the day of his shock rate cut.

Traders have almost completely priced out another rate cut in banker’s acceptances contracts, a predictor of interest rates. Contracts due December, 2015, reached 1 per cent this month for the first time since Jan. 21, the day the Bank of Canada lowered its overnight rate to 0.75 per cent to contend with the collapse in the price of oil, the nation’s biggest export.

So-called Bax contracts have settled about 20 basis points above the central bank’s target rate on average since 1992, data compiled by Bloomberg show. The yield has averaged 0.91 per cent this year.

It was another violently mixed day for the Canadian preferred share market, with PerpetualDiscounts down 58bp, FixedResets gaining 18bp and DeemedRetractibles off 6bp. A lengthy Performance Highlights table is dominated by FixedResets, particularly on the good side. Volume was average.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_150511
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 24.24 to be $0.98 rich, while TRP.PR.G, resetting 2020-11-30 at +296, is $0.90 cheap at its bid price of 24.95.

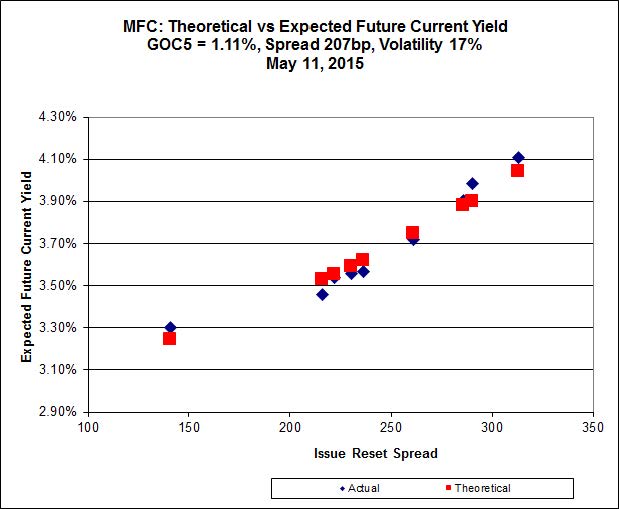
impVol_MFC_150511
Click for Big

Another excellent fit, but the numbers are perplexing. Implied Volatility for MFC continues to be a conundrum. It is still too high if we consider that NVCC rules will never apply to these issues; it is still too low if we consider them to be NVCC non-compliant issues (and therefore with Deemed Maturities in the call schedule).

Most expensive is MFC.PR.L, resetting at +216 on 2019-6-19, bid at 23.65 to be $0.49 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 25.16 to be $0.55 cheap.

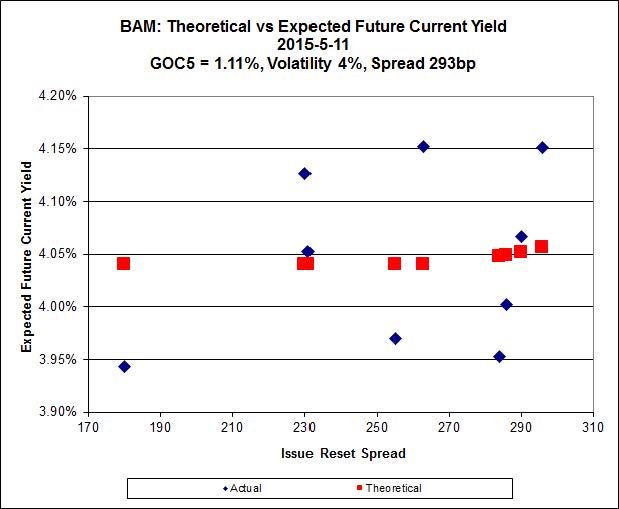
impVol_BAM_150511
Click for Big

The cheapest issue relative to its peers is BAM.PF.B, resetting at +263bp on 2019-3-31, bid at 22.52 to be $0.62 cheap. BAM.PF.G, resetting at +284bp 2020-6-30 is bid at 24.98 and appears to be $0.58 rich.

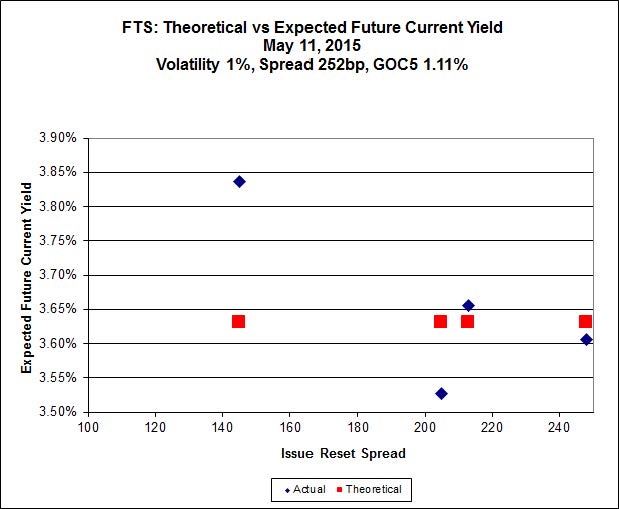
impVol_FTS_150511
Click for Big

FTS.PR.H, with a spread of +145bp, and bid at 16.68, looks $0.95 cheap and resets 2015-6-1. FTS.PR.K, with a spread of +205bp and resetting 2019-3-1, is bid at 22.40 and is $0.64 rich.

pairs_FR_150511
Click for Big

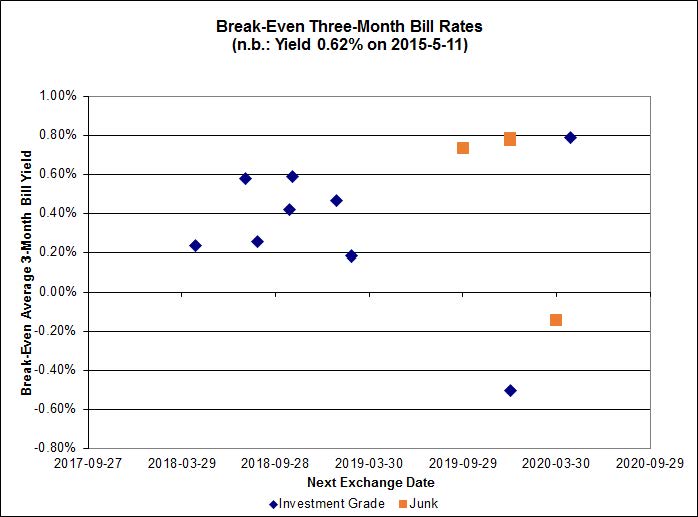
Investment-grade pairs now predict an average over the next five years of about 0.40%, but TRP.PR.A / TRP.PR.F is an outlier at -0.51% and BNS.PR.Y / BNS.PR.D is at +0.78%. On the junk side, the FFH.PR.E / FFH.PR.F pair is at -1.03% while BRF.PR.A / BRF.PR.B is at +1.03%.

pairs_FF_150511
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.9378 % 2,306.5
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.9378 % 4,032.9
Floater 3.15 % 3.26 % 55,736 19.05 4 -0.9378 % 2,452.0
OpRet 4.42 % -2.04 % 38,273 0.14 2 -0.0785 % 2,768.6
SplitShare 4.56 % 4.66 % 59,622 3.35 3 0.1600 % 3,233.2
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0785 % 2,531.6
Perpetual-Premium 5.45 % 2.00 % 66,427 0.08 18 -0.0697 % 2,520.5
Perpetual-Discount 5.04 % 5.03 % 119,119 15.36 15 -0.5779 % 2,789.5
FixedReset 4.38 % 3.72 % 270,070 16.39 86 0.1805 % 2,425.6
Deemed-Retractible 4.91 % 3.22 % 110,721 0.53 35 -0.0569 % 2,647.4
FloatingReset 2.58 % 2.92 % 62,894 6.19 7 0.2251 % 2,338.7
Performance Highlights
Issue Index Change Notes
BAM.PR.C Floater -1.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-11
Maturity Price : 15.10
Evaluated at bid price : 15.10
Bid-YTW : 3.33 %
CU.PR.F Perpetual-Discount -1.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-11
Maturity Price : 22.46
Evaluated at bid price : 22.85
Bid-YTW : 4.91 %
CIU.PR.C FixedReset -1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-11
Maturity Price : 16.02
Evaluated at bid price : 16.02
Bid-YTW : 3.80 %
RY.PR.Z FixedReset -1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-11
Maturity Price : 23.08
Evaluated at bid price : 24.54
Bid-YTW : 3.32 %
TRP.PR.D FixedReset -1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-11
Maturity Price : 22.71
Evaluated at bid price : 23.69
Bid-YTW : 3.65 %
PWF.PR.S Perpetual-Discount -1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-11
Maturity Price : 24.21
Evaluated at bid price : 24.62
Bid-YTW : 4.89 %
TRP.PR.A FixedReset -1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-11
Maturity Price : 20.88
Evaluated at bid price : 20.88
Bid-YTW : 3.64 %
CU.PR.G Perpetual-Discount -1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-11
Maturity Price : 22.55
Evaluated at bid price : 22.95
Bid-YTW : 4.89 %
BAM.PR.B Floater -1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-11
Maturity Price : 15.41
Evaluated at bid price : 15.41
Bid-YTW : 3.26 %
ENB.PR.F FixedReset -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-11
Maturity Price : 20.23
Evaluated at bid price : 20.23
Bid-YTW : 4.53 %
FTS.PR.M FixedReset -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-11
Maturity Price : 23.16
Evaluated at bid price : 24.89
Bid-YTW : 3.57 %
BMO.PR.T FixedReset 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-11
Maturity Price : 22.96
Evaluated at bid price : 24.30
Bid-YTW : 3.38 %
MFC.PR.N FixedReset 1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.96
Bid-YTW : 4.18 %
FTS.PR.K FixedReset 1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-11
Maturity Price : 21.98
Evaluated at bid price : 22.40
Bid-YTW : 3.64 %
MFC.PR.M FixedReset 1.29 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.31
Bid-YTW : 4.07 %
BNS.PR.Z FixedReset 1.51 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.60
Bid-YTW : 3.48 %
TRP.PR.C FixedReset 1.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-11
Maturity Price : 18.30
Evaluated at bid price : 18.30
Bid-YTW : 3.57 %
GWO.PR.N FixedReset 1.97 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.15
Bid-YTW : 6.27 %
SLF.PR.G FixedReset 2.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.03
Bid-YTW : 6.38 %
FTS.PR.G FixedReset 2.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-11
Maturity Price : 21.85
Evaluated at bid price : 22.16
Bid-YTW : 3.72 %
RY.PR.H FixedReset 2.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-11
Maturity Price : 23.11
Evaluated at bid price : 24.70
Bid-YTW : 3.32 %
MFC.PR.L FixedReset 2.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.65
Bid-YTW : 4.28 %
TD.PF.B FixedReset 2.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-11
Maturity Price : 23.12
Evaluated at bid price : 24.69
Bid-YTW : 3.33 %
HSE.PR.A FixedReset 2.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-11
Maturity Price : 17.92
Evaluated at bid price : 17.92
Bid-YTW : 3.97 %
Volume Highlights
Issue Index Shares
Traded
Notes
TRP.PR.B FixedReset 122,714 TD crossed four blocks: 35,000 shares, 17,500 shares, 30,000 and 29,500, all at 15.91.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-11
Maturity Price : 15.80
Evaluated at bid price : 15.80
Bid-YTW : 3.67 %
RY.PR.I FixedReset 85,880 Nesbitt crossed two blocks of 35,000 each and one of 15,000, all at 25.35.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.41
Bid-YTW : 2.99 %
TRP.PR.G FixedReset 68,982 TD crossed 20,000 at 25.07.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-11
Maturity Price : 23.11
Evaluated at bid price : 24.95
Bid-YTW : 3.81 %
BNS.PR.O Deemed-Retractible 63,250 RBC crossed 61,100 at 26.00.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2015-06-10
Maturity Price : 25.50
Evaluated at bid price : 25.82
Bid-YTW : -7.56 %
TRP.PR.A FixedReset 58,801 TD crossed 35,000 at 21.40 and 15,000 at 21.20.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-11
Maturity Price : 20.88
Evaluated at bid price : 20.88
Bid-YTW : 3.64 %
BMO.PR.M FixedReset 45,800 RBC crossed 45,200 at 25.23.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.25
Bid-YTW : 2.85 %
There were 31 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
FTS.PR.K FixedReset Quote: 22.40 – 22.98
Spot Rate : 0.5800
Average : 0.3664

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-11
Maturity Price : 21.98
Evaluated at bid price : 22.40
Bid-YTW : 3.64 %

MFC.PR.H FixedReset Quote: 25.79 – 26.24
Spot Rate : 0.4500
Average : 0.2931

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-03-19
Maturity Price : 25.00
Evaluated at bid price : 25.79
Bid-YTW : 3.21 %

RY.PR.Z FixedReset Quote: 24.54 – 24.88
Spot Rate : 0.3400
Average : 0.2403

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-11
Maturity Price : 23.08
Evaluated at bid price : 24.54
Bid-YTW : 3.32 %

MFC.PR.C Deemed-Retractible Quote: 23.78 – 24.05
Spot Rate : 0.2700
Average : 0.1733

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.78
Bid-YTW : 5.26 %

IAG.PR.A Deemed-Retractible Quote: 23.99 – 24.31
Spot Rate : 0.3200
Average : 0.2254

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.99
Bid-YTW : 5.23 %

BMO.PR.K Deemed-Retractible Quote: 25.60 – 25.84
Spot Rate : 0.2400
Average : 0.1504

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2015-06-10
Maturity Price : 25.50
Evaluated at bid price : 25.60
Bid-YTW : -2.01 %

Market Action

May 8, 2015

Jobs, jobs, jobs!

April’s job-creation score was better, March was worse, and the U.S. jobless rate crept closer to the Federal Reserve’s moving target for full employment.

The 223,000 increase in payrolls last month followed a revised 85,000 gain in March that was the smallest since June 2012, figures from the Labor Department showed Friday in Washington. The jobless rate fell to 5.4 percent, the lowest since May 2008, from 5.5 percent.
…
Wage growth remained limited, with average hourly earnings rising 0.1 percent in April after a revised 0.2 percent March gain that was weaker than initially reported. The median forecast in a Bloomberg survey projected a 0.2 percent increase for last month.

Compared with a year earlier, hourly pay was up 2.2 percent last month, holding within the narrow range tracked over the past four years.
…
The report also included positive news on the size of the labor force. The participation rate, which indicates the share of working-age people who are employed or looking for work, increased to 62.8 percent from 62.7 percent in March, which matched the lowest since 1978. The gain was paced by 45-to-64 year-old Americans.
…
The Fed now defines full employment as between 5 percent and 5.2 percent, according to projections released after their March 17-18 meeting. The range was lowered from 5.2 percent to 5.5 percent after the jobless rate reached the top of the scale in February.

In Canada, not so much:

The Target effect is denting Canada’s jobs numbers.

Employers shed a total of 19,700 jobs last month, according to Statistics Canada, the most since August, as retailers eliminated thousands of sales, cashiers and clerks positions.

The numbers show the impact of a raft of store closings amid upheaval in the sector, including Target Canada, Best Buy, Mexx, Smart Set, Indigo Books and Sony. The sector may be in flux, but it remains the largest source of employment in the country.
…
The retail sector posted a loss of 20,500 workers, Statscan said Friday, leaving employment levels flat from a year earlier. Monthly jobs numbers can be volatile, but separate payrolls data show the retail sector has contracted for four months in a row.

In January, Target said it was pulling out of Canada, an abrupt move that spelled job losses for 17,600 of its workers over the ensuing months and put pressure on hundreds of firms that served the chain, forcing some of them to lay off staff, too.

Across Canada, the jobless rate stayed at 6.8 per cent as fewer people looked for work.

Monthly numbers can swing up and down, but smoothed-out averages show employment has grown by just 2,600 jobs on average per month in the past half-year. Year-over-year employment growth has been stuck below 1 per cent for the past 13 months.

Other sectors shed workers as well last month, in construction and information services. Natural resources were little changed in the month, but are down 6.6 per cent from a year earlier, reflecting the oil price slide.

On the other hand, it’s my understanding that in Toronto, house flippers have basically been priced out of the market by eager-to-buy veterans of too many bidding wars. In the States, not so much:

Real estate buyers seeking money to renovate and flip U.S. houses are getting help from some of the world’s biggest investment firms.

Colony Capital Inc., Blackstone Group LP and Cerberus Capital Management are among the companies that have started making bridge loans to investors who buy homes to sell them quickly for a profit. Borrowing costs — traditionally the highest in residential lending — are tumbling as the firms compete for customers.

The foray represents a deepening bet on the housing market by Wall Street-backed companies, many of which have built rental-home empires during the past three years and started specialty-lending businesses to finance smaller investors. Big firms with deep pockets and access to cheap capital may have an edge over local private lenders that have dominated flipper financing.
…
Home flippers are benefiting from rising prices, limited new construction and a shortage of inventory on the market. While quick resales have decreased from the start of the housing market’s rebound, when investors snapped up discounted distressed homes, profits are getting bigger.

The average gross profit for completed flips in the first quarter was $72,450, up from $61,684 a year earlier and the highest in records dating to 2011, according to a report Thursday from RealtyTrac, a real estate data firm. Markets with the highest average gross return on investment included Baltimore, central Florida and Detroit.

‘Who will watch the watchers?’ query the wise men in Congress. Watcher watchers!

Senate Banking Committee Chairman Richard Shelby is putting the finishing touches on a bill that could give Congress more power over the New York Fed and create a commission with authority to propose sweeping reforms of the entire Fed system.

Other senators want to curb the Fed’s ability to bail out banks during a financial meltdown and increase transparency of its regulation.

“Shelby wants to do something with the Fed,” said Ed Mills, a financial-policy analyst at FBR & Co. in Arlington, Virginia, and a former adviser to Democrats in the House and Senate. “It seems as if they’re going to have something in here that is additional oversight of the Fed or rebalancing some of the power internally at the Fed, whether staff resources or more transparency.”

There’s really only one structural problem with the Fed: it has responsibility for both bank supervision and monetary policy. While there are good arguments to be made in favour of combining the mandates, as has been discussed previously on PrefBlog (see, for example, September 10, 2008 and Willem Buiter’s Prescription), I continue to think that puts just too much power in the hands of one institution.

As far as ‘Fed bailouts of Wall Street Banks’ are concerned – well, for the most part that’s a canard. The explicit bail-outs were done by the Treasury with the authority of congress. The Fed simply lent to solvent banks against adequate collateral … which is what Central Banks are supposed to do during a liquidity crisis. They can, however, be criticized for not ensuring that these loans were not made at penalty rates:

The Fed didn’t tell anyone which banks were in trouble so deep they required a combined $1.2 trillion on Dec. 5, 2008, their single neediest day. Bankers didn’t mention that they took tens of billions of dollars in emergency loans at the same time they were assuring investors their firms were healthy. And no one calculated until now that banks reaped an estimated $13 billion of income by taking advantage of the Fed’s below-market rates, Bloomberg Markets magazine reports in its January issue.

Brookfield Investments Corporation, proud issuer of BRN.PR.A (which is not tracked by HIMIPref™) has been confirmed at Pfd-2(low) by DBRS:

DBRS Limited (DBRS) has today confirmed the rating of Pfd-2 (low) with a Stable trend for the Senior Preferred Shares of Brookfield Investments Corporation (Brookfield Investments or the Company). The rating continues to be based on the strength of Brookfield Investments’ owner (Brookfield Asset Management Inc. or BAM; rated A (low), Stable trend by DBRS), as well as the Company’s relatively stable portfolio of real estate and asset management investments, with strong asset and dividend coverage. The rating remains limited by Brookfield Investments’ exposure to the volatility of overall capital markets, concentration of investments in the real estate sector, lack of investment restrictions and the relative illiquidity of unlisted investments.

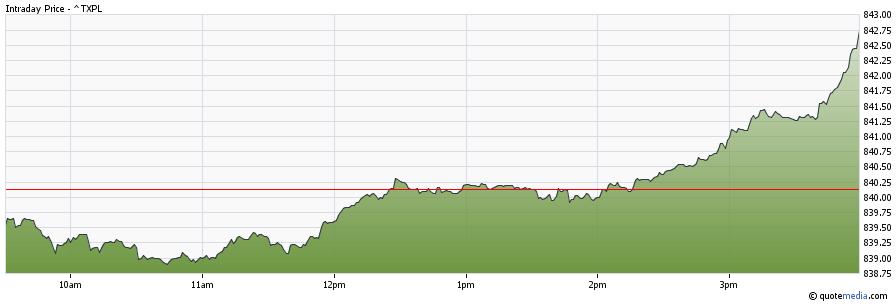
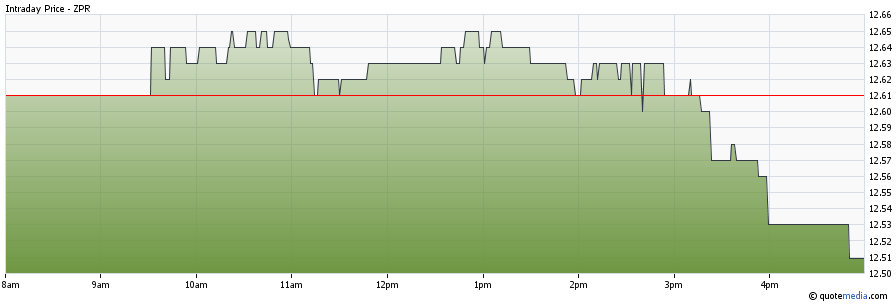
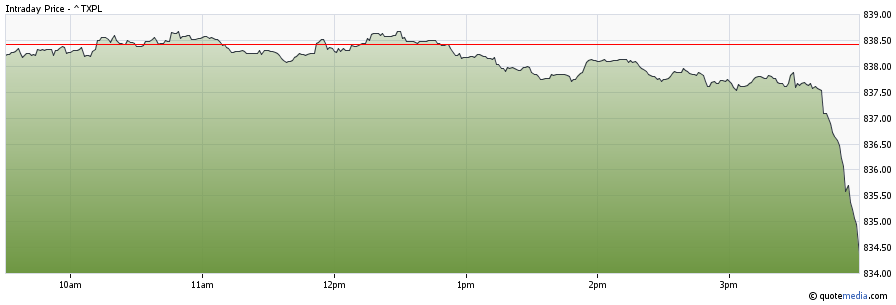
It was another strong-mixed day for the Canadian preferred share market, with PerpetualDiscounts gaining 19bp, FixedResets up 33bp and DeemedRetractibles off 2bp. The strength in FixedResets came at the end of the day:

TXPL
TXPL_150508
Click for Big

A Performance Highlights table of unsurprising size was unsurprisingly dominated by winning FixedResets, but there were a few losers in the mix. Volume was quite high.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

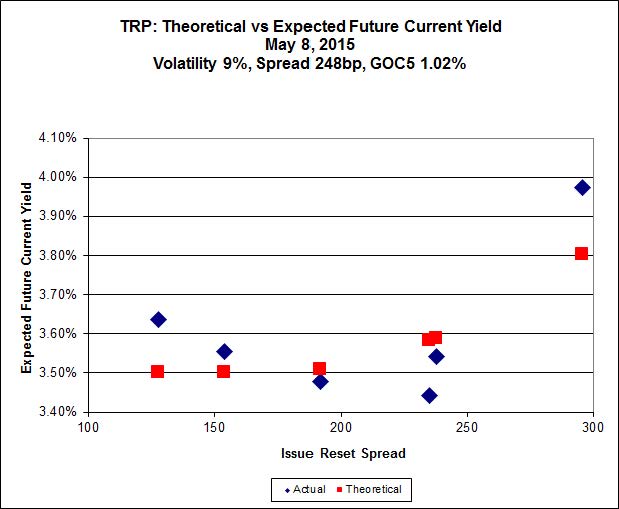
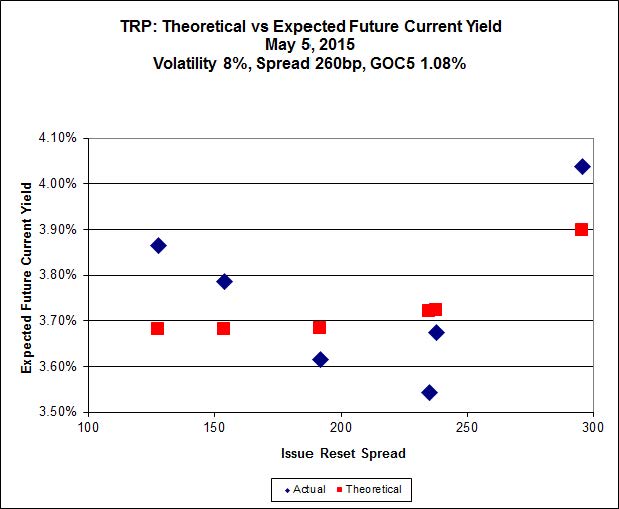
Here’s TRP:

impVol_TRP_150508
Click for Big

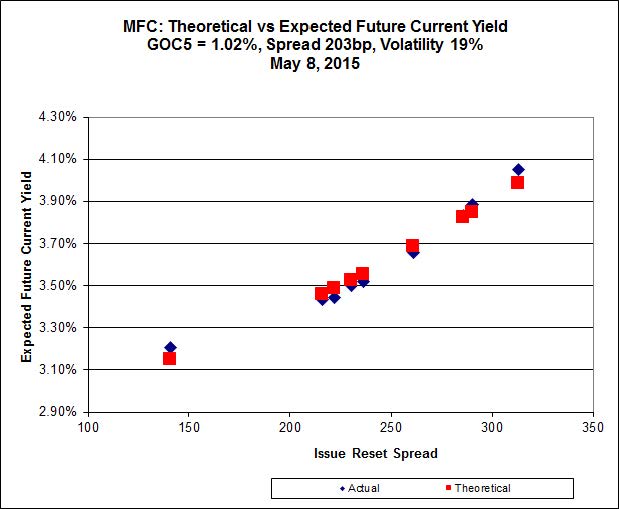
TRP.PR.E, which resets 2019-10-30 at +235, is bid at 24.48 to be $0.96 rich, while TRP.PR.G, resetting 2020-11-30 at +296, is $1.12 cheap at its bid price of 25.04.

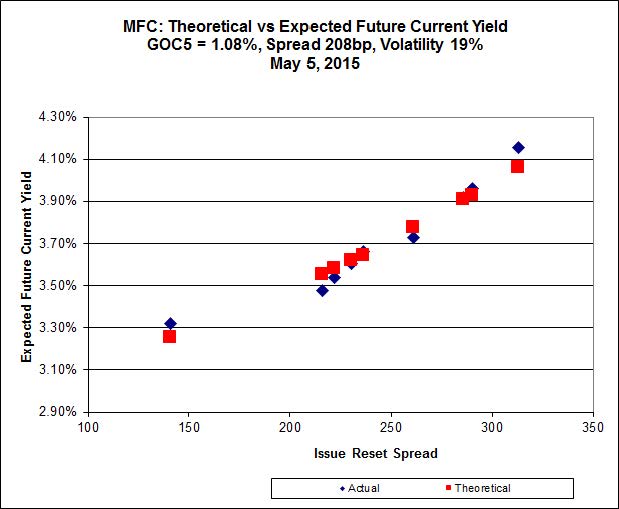
impVol_MFC_150508
Click for Big

Another excellent fit, but the numbers are perplexing. Implied Volatility for MFC continues to be a conundrum. It is still too high if we consider that NVCC rules will never apply to these issues; it is still too low if we consider them to be NVCC non-compliant issues (and therefore with Deemed Maturities in the call schedule).

Most expensive is MFC.PR.K, resetting at +222 on 2018-9-19, bid at 23.52 to be $0.28 rich, while MFC.PR.H, resetting at +313bp on 2017-3-19, is bid at 25.61 to be $0.43 cheap.

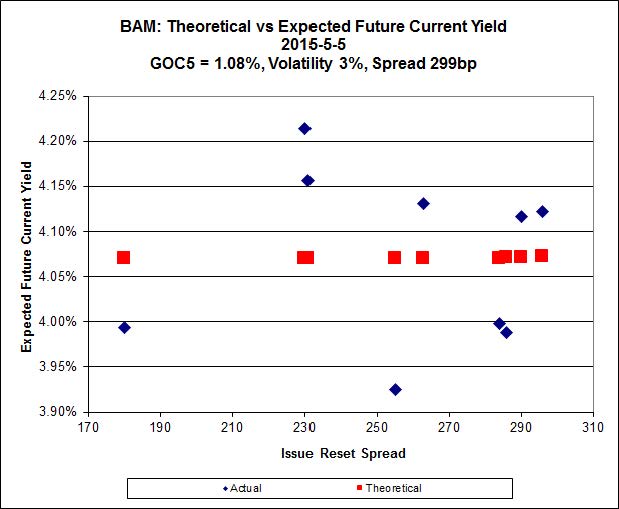
impVol_BAM_150508
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 20.52 to be $0.60 cheap. BAM.PR.X, resetting at +180bp 2017-6-30 is bid at 18.51 and appears to be $0.57 rich.

impVol_FTS_150508
Click for Big

FTS.PR.H, with a spread of +145bp, and bid at 16.63, looks $0.76 cheap and resets 2015-6-1. FTS.PR.K, with a spread of +205bp and resetting 2019-3-1, is bid at 22.14 and is $0.52 rich.

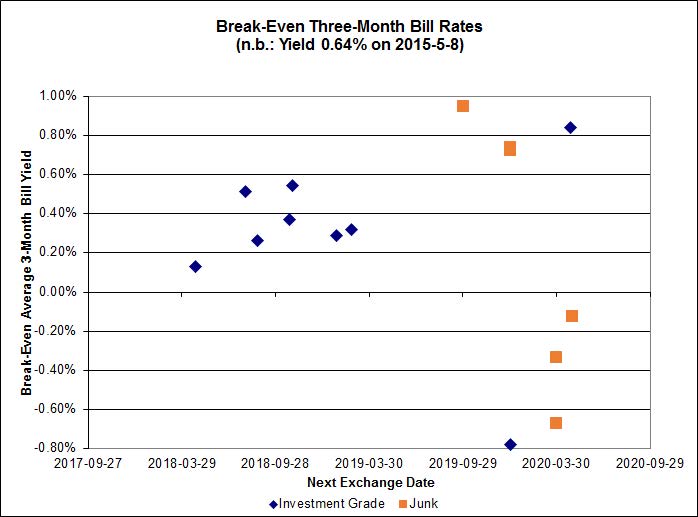
pairs_FR_150508
Click for Big

Investment-grade pairs now predict an average over the next five years of about 0.35%, but TRP.PR.A / TRP.PR.F is an outlier at -0.78% and BNS.PR.Y / BNS.PR.D is at +0.84%. On the junk side, the FFH.PR.E / FFH.PR.F pair is at -0.68% while DC.PR.B / DC.PR.D is now at 0.95%.

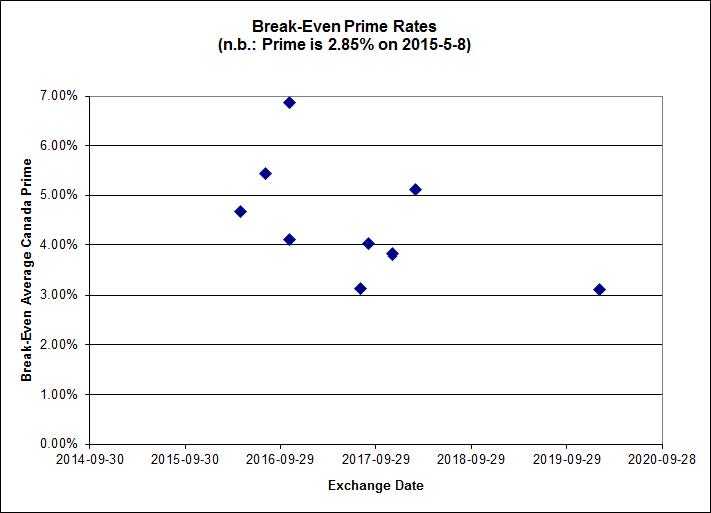
pairs_FF_150508
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.4202 % 2,328.4
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.4202 % 4,071.1
Floater 3.12 % 3.22 % 55,010 19.15 4 -0.4202 % 2,475.2
OpRet 4.41 % -1.93 % 38,432 0.15 2 -0.0196 % 2,770.8
SplitShare 4.57 % 4.78 % 61,960 3.36 3 0.0267 % 3,228.0
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0196 % 2,533.6
Perpetual-Premium 5.45 % 1.43 % 67,136 0.08 18 0.0763 % 2,522.3
Perpetual-Discount 5.01 % 5.00 % 120,224 15.42 15 0.1884 % 2,805.7
FixedReset 4.38 % 3.73 % 274,342 16.32 86 0.3291 % 2,421.2
Deemed-Retractible 4.92 % 3.04 % 110,198 0.22 36 -0.0243 % 2,648.9
FloatingReset 2.59 % 2.93 % 65,325 6.20 7 -0.1033 % 2,333.4
Performance Highlights
Issue Index Change Notes
PWF.PR.P FixedReset -1.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-08
Maturity Price : 18.87
Evaluated at bid price : 18.87
Bid-YTW : 3.57 %
GWO.PR.N FixedReset -1.66 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.80
Bid-YTW : 6.50 %
FTS.PR.G FixedReset -1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-08
Maturity Price : 21.39
Evaluated at bid price : 21.71
Bid-YTW : 3.79 %
BAM.PR.K Floater -1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-08
Maturity Price : 15.30
Evaluated at bid price : 15.30
Bid-YTW : 3.28 %
MFC.PR.N FixedReset -1.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.70
Bid-YTW : 4.32 %
BAM.PF.F FixedReset 1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-08
Maturity Price : 23.14
Evaluated at bid price : 24.80
Bid-YTW : 3.97 %
HSE.PR.A FixedReset 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-08
Maturity Price : 17.45
Evaluated at bid price : 17.45
Bid-YTW : 4.08 %
NA.PR.S FixedReset 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-08
Maturity Price : 23.29
Evaluated at bid price : 25.12
Bid-YTW : 3.39 %
MFC.PR.K FixedReset 1.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.52
Bid-YTW : 4.28 %
CU.PR.D Perpetual-Discount 1.16 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-09-01
Maturity Price : 25.25
Evaluated at bid price : 25.25
Bid-YTW : 4.81 %
MFC.PR.L FixedReset 1.18 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.14
Bid-YTW : 4.55 %
BAM.PF.G FixedReset 1.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-08
Maturity Price : 23.14
Evaluated at bid price : 24.96
Bid-YTW : 3.94 %
FTS.PR.M FixedReset 1.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-08
Maturity Price : 23.24
Evaluated at bid price : 25.15
Bid-YTW : 3.51 %
TD.PF.C FixedReset 1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-08
Maturity Price : 22.89
Evaluated at bid price : 24.22
Bid-YTW : 3.39 %
BAM.PR.T FixedReset 1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-08
Maturity Price : 21.10
Evaluated at bid price : 21.10
Bid-YTW : 4.12 %
BAM.PR.X FixedReset 1.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-08
Maturity Price : 18.51
Evaluated at bid price : 18.51
Bid-YTW : 4.11 %
BAM.PF.A FixedReset 2.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-08
Maturity Price : 23.24
Evaluated at bid price : 24.76
Bid-YTW : 3.99 %
TRP.PR.C FixedReset 2.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-08
Maturity Price : 18.01
Evaluated at bid price : 18.01
Bid-YTW : 3.63 %
CIU.PR.C FixedReset 2.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-08
Maturity Price : 16.26
Evaluated at bid price : 16.26
Bid-YTW : 3.74 %
Volume Highlights
Issue Index Shares
Traded
Notes
CU.PR.F Perpetual-Discount 125,058 TD crossed 72,500 at 23.35; RBC crossed 52,000 at the same price.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-08
Maturity Price : 22.94
Evaluated at bid price : 23.25
Bid-YTW : 4.83 %
RY.PR.M FixedReset 102,306 RBC bought blocks of 10,000 and 20,000 from TD, both at 24.84, then crossed 24,000 at the same price.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-08
Maturity Price : 23.05
Evaluated at bid price : 24.76
Bid-YTW : 3.57 %
BAM.PF.D Perpetual-Discount 96,307 RBC crossed blocks of 25,000 and 60,600 at 23.45.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-08
Maturity Price : 23.15
Evaluated at bid price : 23.47
Bid-YTW : 5.27 %
FTS.PR.M FixedReset 86,240 Desjardins crossed 75,000 at 25.09.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-08
Maturity Price : 23.24
Evaluated at bid price : 25.15
Bid-YTW : 3.51 %
TRP.PR.F FloatingReset 55,200 RBC crossed 40,000 at 18.97.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-08
Maturity Price : 19.04
Evaluated at bid price : 19.04
Bid-YTW : 3.39 %
SLF.PR.A Deemed-Retractible 54,594 Scotia crossed 40,000 at 24.75.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.71
Bid-YTW : 4.99 %
There were 48 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
RY.PR.H FixedReset Quote: 24.17 – 24.75
Spot Rate : 0.5800
Average : 0.3928

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-08
Maturity Price : 22.90
Evaluated at bid price : 24.17
Bid-YTW : 3.42 %

ENB.PR.D FixedReset Quote: 20.00 – 20.45
Spot Rate : 0.4500
Average : 0.2761

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-08
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 4.42 %

BMO.PR.T FixedReset Quote: 24.05 – 24.60
Spot Rate : 0.5500
Average : 0.3993

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-08
Maturity Price : 22.85
Evaluated at bid price : 24.05
Bid-YTW : 3.42 %

BMO.PR.W FixedReset Quote: 24.01 – 24.37
Spot Rate : 0.3600
Average : 0.2258

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-08
Maturity Price : 22.81
Evaluated at bid price : 24.01
Bid-YTW : 3.40 %

BMO.PR.S FixedReset Quote: 24.46 – 24.88
Spot Rate : 0.4200
Average : 0.3022

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-08
Maturity Price : 23.04
Evaluated at bid price : 24.46
Bid-YTW : 3.44 %

BAM.PR.K Floater Quote: 15.30 – 15.67
Spot Rate : 0.3700
Average : 0.2589

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-08
Maturity Price : 15.30
Evaluated at bid price : 15.30
Bid-YTW : 3.28 %

Market Action

May 7, 2015

I hear there’s a bit of backlash against the lawyers, accountants and stockbrokers crossing the Alberta-Saskatchewan border in search of a better life:

albertaExodus
Click for Big

The Swiss central bank accumulated a lot of foreign currency as it attempted to defend the indefensible CHF / EUR peg. Guess what they’ve done with all that cash!

The Swiss National Bank had a rough quarter in Q1 as the decision to abandon the increasingly unsustainable EURCHF floor (an event which marked an implicit admission that central banks are not all-powerful after all) blew a $32 billion hole in the central bank’s euro reserves. That, however, wasn’t the most remarkable takeaway from the SNB’s quarterly report.

More interesting than the massive loss was the line item in the SNB’s balance sheet which shows that 18% of the bank’s assets are held in foreign stocks.

By “blew a hole”, he must be referring to the P&L – the balance sheet bloated, of course.

SNBStocks
Click for Big

Liquidity problems continue to attract attention:

As bonds tumbled across Europe, the bid-ask spread, a gauge of the market’s depth derived from the difference in prices or yields between buyers and sellers, widened. It reached 0.27 basis point for German 10-year bunds on Thursday, up from as low as 0.1 in March and an average of 0.2 this year, data compiled by Bloomberg show.

That means sellers may be getting squeezed by a shortage of buyers. Adding to the risk of holding bonds, implied option volatility on German 10-year bund futures contracts surged in the past week to the highest since August 2012.
…
Bonds have sold off in a global rout that wiped more than $430 billion from the market in the past week. A capitulation on long positions, or bets that prices will rise, was triggered by a shift in sentiment as improving economic data and rising oil prices prompted investors to revolt against record-low yields.

Yet the magnitude of the decline wasn’t justified by those economic numbers, none of which points to a big jump in inflation or interest rates, according to Rabobank’s McGuire.

The yield on Germany’s 10-year bund, the benchmark euro-zone security, has surged 43 basis points since the start of last week to a high for 2015. A basis point is 0.01 percentage point.

The jump suggests that increased regulation may be hampering dealers’ ability to make markets and that bond-purchase programs such as the European Central Bank’s quantitative-easing plan have cut the amount of securities in circulation.

The Canadian preferred share market was on fire today, albeit very unevenly. Can I call this “on mixed fire”? PerpetualDiscounts gained 43bp, FixedResets were up 62bp, while DeemedRetractibles were off 6bp. The volume highlights table is, predictably, both lengthy and dominated by FixedResets. Volume was very high.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_150507
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 24.24 to be $0.95 rich, while TRP.PR.G, resetting 2020-11-30 at +296, is $0.86 cheap at its bid price of 25.11.

impVol_MFC_150507

Click for Big

Another excellent fit, but the numbers are perplexing. Implied Volatility for MFC continues to be a conundrum. It is still too high if we consider that NVCC rules will never apply to these issues; it is still too low if we consider them to be NVCC non-compliant issues (and therefore with Deemed Maturities in the call schedule).

Most expensive is MFC.PR.N, resetting at +230 on 2020-3-19, bid at 23.97 to be $0.51 rich, while MFC.PR.H, resetting at +313bp on 2017-3-19, is bid at 25.52 to be $0.47 cheap.

impVol_BAM_150507
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 20.34 to be $0.56 cheap. BAM.PF.E, resetting at +255bp 2020-3-31 is bid at 23.16 and appears to be $0.72 rich.

impVol_FTS_150507
Click for Big

FTS.PR.H, with a spread of +145bp, and bid at 16.70, looks $0.73 cheap and resets 2015-6-1. FTS.PR.K, with a spread of +205bp and resetting 2019-3-1, is bid at 22.10 and is $0.50 rich.

pairs_FR_150507
Click for Big

Investment-grade pairs now predict an average over the next five years of about 0.40%, but TRP.PR.A / TRP.PR.F is an outlier at -0.77% and BNS.PR.Y / BNS.PR.D is at +0.70%. On the junk side, the BRF.PR.A / BRF.PR.B pair is at -0.72% while FFH.PR.C / FFH.PR.D is at +1.20%.

pairs_FF_150507
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.0000 % 2,338.2
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.0000 % 4,088.2
Floater 3.11 % 3.21 % 55,369 19.19 4 0.0000 % 2,485.7
OpRet 4.41 % -2.41 % 38,332 0.15 2 0.1571 % 2,771.3
SplitShare 4.57 % 4.76 % 64,240 3.36 3 -0.0933 % 3,227.2
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1571 % 2,534.1
Perpetual-Premium 5.45 % 1.73 % 68,137 0.08 18 -0.0501 % 2,520.3
Perpetual-Discount 5.02 % 5.00 % 121,959 15.42 15 0.4341 % 2,800.4
FixedReset 4.40 % 3.81 % 277,275 16.21 86 0.6169 % 2,413.3
Deemed-Retractible 4.92 % 3.42 % 114,117 0.30 36 -0.0564 % 2,649.6
FloatingReset 2.59 % 2.96 % 64,301 6.20 7 0.5561 % 2,335.9
Performance Highlights
Issue Index Change Notes
SLF.PR.G FixedReset -1.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.60
Bid-YTW : 6.75 %
NA.PR.S FixedReset 1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-07
Maturity Price : 23.19
Evaluated at bid price : 24.85
Bid-YTW : 3.50 %
ENB.PR.B FixedReset 1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-07
Maturity Price : 19.76
Evaluated at bid price : 19.76
Bid-YTW : 4.56 %
BAM.PR.T FixedReset 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-07
Maturity Price : 20.75
Evaluated at bid price : 20.75
Bid-YTW : 4.27 %
CU.PR.G Perpetual-Discount 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-07
Maturity Price : 23.04
Evaluated at bid price : 23.35
Bid-YTW : 4.81 %
ENB.PF.E FixedReset 1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-07
Maturity Price : 21.91
Evaluated at bid price : 22.40
Bid-YTW : 4.41 %
ENB.PF.C FixedReset 1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-07
Maturity Price : 21.82
Evaluated at bid price : 22.25
Bid-YTW : 4.42 %
TRP.PR.D FixedReset 1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-07
Maturity Price : 22.78
Evaluated at bid price : 23.83
Bid-YTW : 3.68 %
BAM.PF.G FixedReset 1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-07
Maturity Price : 23.01
Evaluated at bid price : 24.60
Bid-YTW : 4.07 %
BMO.PR.W FixedReset 1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-07
Maturity Price : 22.78
Evaluated at bid price : 23.94
Bid-YTW : 3.47 %
BAM.PR.X FixedReset 1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-07
Maturity Price : 18.15
Evaluated at bid price : 18.15
Bid-YTW : 4.29 %
BAM.PF.D Perpetual-Discount 1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-07
Maturity Price : 23.07
Evaluated at bid price : 23.39
Bid-YTW : 5.29 %
BAM.PF.A FixedReset 1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-07
Maturity Price : 23.03
Evaluated at bid price : 24.25
Bid-YTW : 4.16 %
TRP.PR.F FloatingReset 1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-07
Maturity Price : 19.02
Evaluated at bid price : 19.02
Bid-YTW : 3.40 %
ENB.PR.T FixedReset 1.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-07
Maturity Price : 20.59
Evaluated at bid price : 20.59
Bid-YTW : 4.54 %
BAM.PF.C Perpetual-Discount 1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-07
Maturity Price : 22.76
Evaluated at bid price : 23.06
Bid-YTW : 5.31 %
NA.PR.W FixedReset 1.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-07
Maturity Price : 22.94
Evaluated at bid price : 24.35
Bid-YTW : 3.45 %
ENB.PR.J FixedReset 1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-07
Maturity Price : 21.65
Evaluated at bid price : 21.94
Bid-YTW : 4.39 %
TRP.PR.A FixedReset 1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-07
Maturity Price : 21.11
Evaluated at bid price : 21.11
Bid-YTW : 3.66 %
ENB.PR.F FixedReset 1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-07
Maturity Price : 20.40
Evaluated at bid price : 20.40
Bid-YTW : 4.56 %
IAG.PR.G FixedReset 1.51 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-06-30
Maturity Price : 25.00
Evaluated at bid price : 25.51
Bid-YTW : 3.53 %
ENB.PR.Y FixedReset 1.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-07
Maturity Price : 20.03
Evaluated at bid price : 20.03
Bid-YTW : 4.55 %
BNS.PR.Y FixedReset 1.59 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.05
Bid-YTW : 3.19 %
ENB.PR.P FixedReset 1.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-07
Maturity Price : 20.91
Evaluated at bid price : 20.91
Bid-YTW : 4.46 %
TD.PF.B FixedReset 1.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-07
Maturity Price : 22.96
Evaluated at bid price : 24.30
Bid-YTW : 3.46 %
PWF.PR.P FixedReset 1.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-07
Maturity Price : 19.21
Evaluated at bid price : 19.21
Bid-YTW : 3.60 %
BAM.PF.E FixedReset 1.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-07
Maturity Price : 22.37
Evaluated at bid price : 23.16
Bid-YTW : 4.11 %
RY.PR.Z FixedReset 2.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-07
Maturity Price : 23.14
Evaluated at bid price : 24.70
Bid-YTW : 3.35 %
MFC.PR.N FixedReset 2.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.97
Bid-YTW : 4.21 %
MFC.PR.M FixedReset 2.43 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.00
Bid-YTW : 4.26 %
TRP.PR.B FixedReset 2.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-07
Maturity Price : 15.68
Evaluated at bid price : 15.68
Bid-YTW : 3.81 %
TRP.PR.C FixedReset 2.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-07
Maturity Price : 17.58
Evaluated at bid price : 17.58
Bid-YTW : 3.82 %
IFC.PR.A FixedReset 3.70 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.00
Bid-YTW : 5.44 %
Volume Highlights
Issue Index Shares
Traded
Notes
BNS.PR.M Deemed-Retractible 80,747 Scotia crossed 75,000 at 25.36.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2015-07-27
Maturity Price : 25.25
Evaluated at bid price : 25.33
Bid-YTW : 3.42 %
TRP.PR.E FixedReset 43,201 Desjardins crossed 15,800 at 24.23.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-07
Maturity Price : 22.92
Evaluated at bid price : 24.24
Bid-YTW : 3.64 %
TD.PF.C FixedReset 42,757 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-07
Maturity Price : 22.73
Evaluated at bid price : 23.85
Bid-YTW : 3.52 %
ENB.PR.B FixedReset 37,690 Desjardins crossed 10,000 at 19.60.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-07
Maturity Price : 19.76
Evaluated at bid price : 19.76
Bid-YTW : 4.56 %
CM.PR.O FixedReset 37,659 TD crossed 17,300 at 24.51.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-07
Maturity Price : 23.05
Evaluated at bid price : 24.51
Bid-YTW : 3.48 %
RY.PR.H FixedReset 34,819 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-07
Maturity Price : 22.93
Evaluated at bid price : 24.23
Bid-YTW : 3.47 %
There were 53 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
MFC.PR.L FixedReset Quote: 22.87 – 23.64
Spot Rate : 0.7700
Average : 0.5104

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.87
Bid-YTW : 4.73 %

TD.PF.B FixedReset Quote: 24.30 – 25.00
Spot Rate : 0.7000
Average : 0.4812

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-07
Maturity Price : 22.96
Evaluated at bid price : 24.30
Bid-YTW : 3.46 %

CIU.PR.C FixedReset Quote: 15.81 – 17.50
Spot Rate : 1.6900
Average : 1.4748

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-07
Maturity Price : 15.81
Evaluated at bid price : 15.81
Bid-YTW : 3.96 %

BNS.PR.Z FixedReset Quote: 23.25 – 23.73
Spot Rate : 0.4800
Average : 0.3096

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.25
Bid-YTW : 3.79 %

BNS.PR.O Deemed-Retractible Quote: 25.68 – 26.08
Spot Rate : 0.4000
Average : 0.2443

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2015-06-06
Maturity Price : 25.50
Evaluated at bid price : 25.68
Bid-YTW : -1.80 %

FTS.PR.M FixedReset Quote: 24.77 – 25.25
Spot Rate : 0.4800
Average : 0.3304

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-07
Maturity Price : 23.11
Evaluated at bid price : 24.77
Bid-YTW : 3.65 %

Market Action

May 6, 2015

Here’s bit of an update on the persecution of Navinder Singh Sarao:

Sarao’s lawyer, James Lewis, disclosed the existence of a worldwide freezing order on his client’s assets that precludes him from raising the 5 million-pound ($7.6 million) bail.

Sarao has been “languishing on remand unable to meet” the bail conditions, and it’s “impossible to supply the security,” because of the freezing order, Lewis said. He also unsuccessfully applied to have a blanket ban on Internet use amended to only restrict him from trading, arguing a complete prohibition was “manifestly disproportionate.”

Sarao has been in custody since April 21, when he was arrested at the house he shares with his parents near Heathrow airport. He is being held at Wandsworth prison in London while fighting extradition to the U.S.

Roscoe rejected a request to release Sarao solely on a 50,000 pound-security put up by his parents, saying the bail amount had to satisfy her that he isn’t a flight risk.

Yep, that’s the way to do it! Set bail to a ludicrously high amount, then freeze the guy’s assets so he can’t possibly put up the money! As noted on May 1, the most recent penalty for spoofing was a sixty day trading suspension. But Sarao’s offence was blatant? Yeah, right, that’s why it took five years to find it, and why it got no mention whatsoever in the SEC report.

Selective enforcement is an affront to justice, and the anti-spoofing laws are ridiculous and unenforceable in the first place.

Fitch Ratings thinks the Canadian economy is vulnerable to condos:

There are more than 80,000 condo units under construction across Ontario, most of them in the Greater Toronto Area. That’s 50 per cent higher than just four years ago, although the number of new housing starts has fallen from its peak in 2012, Fitch said. In the face of so much supply, condo prices have remained flat across the province.

Therein lies the problem, according to Fitch.

“As a large number of units come on line, prices may soften, which could reverberate throughout the Canadian economy,” Fitch director Stefan Hilts wrote. “Lower prices would reduce the incentives to build further units, which could hit employment in the construction sector that has been buoyed by continuing price growth. This in turn could lead to more significant downside exposure.”

Yellen is trying to talk down the market (without saying “irrational exuberance”):

Federal Reserve Chair Janet Yellen, surveying the financial landscape for signs of bubbles after more than six years of near-zero rates, warned that both stocks and bonds are richly valued.

“I would highlight that equity-market valuations at this point generally are quite high,” Yellen said in Washington on Wednesday in response to a question at a forum on finance. “Now, they’re not so high when you compare the returns on equities to the returns on safe assets like bonds, which are also very low, but there are potential dangers there.”

Yellen said bond yields “could see a sharp jump” when the Fed raises its benchmark interest rate. Most Fed officials predict that will happen this year for the first time since 2006.

She highlighted the term premium:

“Long-term interest rates are at very low levels, and that would appear to embody low term premiums, which can move, and can move very rapidly,” Yellen said after a speech in Washington. “We need to be attentive, and are to the possibility that when the Fed decides it’s time to begin raising rates, these term premiums could move up, and we could see a sharp jump in long-term rates.”

And the “global bond rout” has spread to Japan:

Japan’s government bonds joined a worldwide rout in sovereign debt as investors in Tokyo returned from a three-day national holiday.
…
The yield on the 10-year bond jumped seven basis points to 0.43 percent as of 8:52 a.m. in Tokyo from May 1, according to Japan Bond Trading Co., the nation’s largest inter-dealer debt broker. The price of the 0.4 percent debt due March 2025 fell 0.665 yen to 99.716. A basis point is 0.01 percentage point.

Meanwhile in the real economy (remember that?) productivity is falling:

Productivity over the past six months fell by the most in more than two decades, leading to increases in U.S. labor costs that threaten corporate profits.

The measure of employee output per hour decreased at a 1.9 percent annualized rate after a revised 2.1 percent drop in the prior three months, a Labor Department report showed Wednesday in Washington. The decline on average over the past two quarters was the biggest since the first six months of 1993. Expenses per worker increased more than projected at the start of the year.

A lack of business investment in new technology may mean productivity will continue to languish and limit the economic expansion’s potential. Rising labor costs without offsetting increases in efficiency would also hurt business earnings, and in turn restrain the hiring that would propel consumer spending.

But it’s an ill wind that doesn’t blow the banks any good:

The chart watchers in the stock market would like to draw your attention to notable recent moves by some large U.S. banks. JPMorgan Chase & Co.’s shares, for example, on Monday reached the highest level in 15 years. Goldman Sachs Group Inc. touched the highest price since 2008 last month and the SPDR S&P Bank ETF reached a 13-month high this week.

One obvious reason for the recent strength is a strong earnings season. The 24 companies in the KBW Bank Index posted profit growth of 8.8 percent and beat analysts’ estimates by almost 10 percent. Another reason, however, is a bit more slippery: the recent spike higher in interest rates on longer-term Treasuries. The subsequent steepening of the yield curve, it stands to reason, should be good for banks because they borrow at short-term rates and lend at long-term rates.

The sell-side old boys’ club in the States has approved an increase in tick size for smaller company shares, as a way of chipping away against hedge-fund friendly maker-taker fees:

The U.S. Securities and Exchange Commission approved a two-year program designed to test ways to boost investors’ interest in smaller stocks.

The trading experiment, championed by small-business advocates and opposed by big investors such as Fidelity Investments and D.E. Shaw & Co., will widen the minimum price at which stocks for small companies are quoted on exchanges, the SEC said Wednesday in a statement. The program would reward brokers for making markets in less-liquid stocks by widening the amount they earn when buying and selling shares.

Exchanges must start the pilot program by May 6, 2016, the SEC said. It will apply to shares of 1,400 companies with market values under $3 billion and average daily trading volume of less than 1 million shares, the SEC said.
…
Asset managers such as Fidelity opposed the program because they’re concerned it will raise transaction costs and probably won’t foster more initial public offerings.

Naturally, it did not occur to anybody at the SEC or the Dodd-Frank crowd in congress to do something about the ridiculous cost of going public and being a public company.

It was a mixed day for the Canadian preferred share market, with PerpetualDiscounts up 22bp, FixedResets off 14bp and DeemedRetractibles gaining 4bp. The Performance Highlights table is dominated by losing FixedResets. Volume was average.

PerpetualDiscounts now yield 5.02%, equivalent to 6.53% interest at the standard equivalency factor of 1.3x. Long corporates now yield about 4.05% so the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) is not now about 250bp, a very sharp narrowing from the 295bp reported April 22.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_150506
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 24.19 to be $1.17 rich, while TRP.PR.B, resetting 2015-6-30 at +128, is $0.91 cheap at its bid price of 25.01.

impVol_MFC_150506
Click for Big

Another excellent fit, but the numbers are perplexing. Implied Volatility for MFC continues to be a conundrum. It is still too high if we consider that NVCC rules will never apply to these issues; it is still too low if we consider them to be NVCC non-compliant issues (and therefore with Deemed Maturities in the call schedule).

Most expensive is MFC.PR.K, resetting at +222 on 2018-9-19, bid at 23.33 to be $0.30 rich, while MFC.PR.H, resetting at +313bp on 2017-3-19, is bid at 25.35 to be $0.55 cheap.

impVol_BAM_150506
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 20.18 to be $0.53 cheap. BAM.PF.E, resetting at +255bp 2020-3-31 is bid at 22.72 and appears to be $0.50 rich.

impVol_FTS_150506
Click for Big

FTS.PR.H, with a spread of +145bp, and bid at 16.60, looks $0.83 cheap and resets 2015-6-1. FTS.PR.K, with a spread of +205bp and resetting 2019-3-1, is bid at 21.90 and is $0.41 rich.

pairs_FR_150506
Click for Big

Investment-grade pairs now predict an average over the next five years of about 0.30%, but TRP.PR.A / TRP.PR.F is an outlier at -0.73% and BNS.PR.Y / BNS.PR.D is at +0.96%. On the junk side, the DC.PR.B / DC.PR.D pair is at -0.78% while FFH.PR.C / FFH.PR.D is at +1.22%.

pairs_FF_150506
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.5320 % 2,338.2
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.5320 % 4,088.2
Floater 3.11 % 3.19 % 53,826 19.23 4 0.5320 % 2,485.7
OpRet 4.42 % -1.10 % 36,036 0.15 2 0.0000 % 2,767.0
SplitShare 4.56 % 4.70 % 64,901 3.36 3 -0.1729 % 3,230.2
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0000 % 2,530.1
Perpetual-Premium 5.45 % 1.07 % 68,493 0.08 18 0.0153 % 2,521.6
Perpetual-Discount 5.04 % 5.02 % 122,804 15.44 15 0.2231 % 2,788.3
FixedReset 4.42 % 3.92 % 279,074 16.11 86 -0.1417 % 2,398.5
Deemed-Retractible 4.92 % 3.08 % 114,001 0.55 36 0.0443 % 2,651.1
FloatingReset 2.61 % 2.99 % 66,459 6.20 7 0.0611 % 2,322.9
Performance Highlights
Issue Index Change Notes
CIU.PR.C FixedReset -6.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-06
Maturity Price : 15.90
Evaluated at bid price : 15.90
Bid-YTW : 3.94 %
SLF.PR.G FixedReset -1.93 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.80
Bid-YTW : 6.61 %
BAM.PF.E FixedReset -1.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-06
Maturity Price : 22.12
Evaluated at bid price : 22.72
Bid-YTW : 4.21 %
TD.PF.B FixedReset -1.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-06
Maturity Price : 22.77
Evaluated at bid price : 23.86
Bid-YTW : 3.54 %
MFC.PR.L FixedReset -1.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.01
Bid-YTW : 4.65 %
IFC.PR.A FixedReset -1.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.25
Bid-YTW : 5.90 %
TD.PF.C FixedReset -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-06
Maturity Price : 22.71
Evaluated at bid price : 23.81
Bid-YTW : 3.53 %
TRP.PR.C FixedReset -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-06
Maturity Price : 17.12
Evaluated at bid price : 17.12
Bid-YTW : 3.92 %
BAM.PF.A FixedReset -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-06
Maturity Price : 22.88
Evaluated at bid price : 23.92
Bid-YTW : 4.23 %
VNR.PR.A FixedReset -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-06
Maturity Price : 23.07
Evaluated at bid price : 24.00
Bid-YTW : 4.08 %
HSE.PR.E FixedReset 1.03 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-03-31
Maturity Price : 25.00
Evaluated at bid price : 25.62
Bid-YTW : 4.11 %
FTS.PR.J Perpetual-Discount 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-06
Maturity Price : 24.08
Evaluated at bid price : 24.50
Bid-YTW : 4.91 %
BAM.PR.K Floater 1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-06
Maturity Price : 15.50
Evaluated at bid price : 15.50
Bid-YTW : 3.24 %
MFC.PR.F FixedReset 1.33 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.00
Bid-YTW : 6.10 %
ENB.PR.B FixedReset 1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-06
Maturity Price : 19.56
Evaluated at bid price : 19.56
Bid-YTW : 4.60 %
ENB.PF.G FixedReset 1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-06
Maturity Price : 21.92
Evaluated at bid price : 22.44
Bid-YTW : 4.42 %
CU.PR.E Perpetual-Discount 1.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-06
Maturity Price : 24.31
Evaluated at bid price : 24.77
Bid-YTW : 4.93 %
SLF.PR.H FixedReset 1.81 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.50
Bid-YTW : 4.71 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.Z FixedReset 86,137 RBC crossed 69,000 at 24.10.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-06
Maturity Price : 22.93
Evaluated at bid price : 24.18
Bid-YTW : 3.45 %
TD.PF.C FixedReset 81,580 RBC sold 15,700 to TD at 23.82, then crossed 44,200 at 23.80.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-06
Maturity Price : 22.71
Evaluated at bid price : 23.81
Bid-YTW : 3.53 %
RY.PR.J FixedReset 77,339 RBC crossed 46,000 at 24.89.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-06
Maturity Price : 23.11
Evaluated at bid price : 24.86
Bid-YTW : 3.66 %
NA.PR.S FixedReset 55,180 RBC crossed 43,100 at 24.60.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-06
Maturity Price : 23.10
Evaluated at bid price : 24.60
Bid-YTW : 3.55 %
CM.PR.Q FixedReset 46,600 RBC crossed 42,500 at 24.85.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-06
Maturity Price : 23.10
Evaluated at bid price : 24.86
Bid-YTW : 3.74 %
GWO.PR.R Deemed-Retractible 43,388 Scotia bought 10,000 from National at 24.90.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.93
Bid-YTW : 4.92 %
There were 30 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
CIU.PR.C FixedReset Quote: 15.90 – 17.49
Spot Rate : 1.5900
Average : 1.2387

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-06
Maturity Price : 15.90
Evaluated at bid price : 15.90
Bid-YTW : 3.94 %

BNS.PR.Y FixedReset Quote: 22.69 – 23.25
Spot Rate : 0.5600
Average : 0.3622

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.69
Bid-YTW : 3.44 %

BAM.PF.E FixedReset Quote: 22.72 – 23.20
Spot Rate : 0.4800
Average : 0.3082

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-06
Maturity Price : 22.12
Evaluated at bid price : 22.72
Bid-YTW : 4.21 %

TD.PF.B FixedReset Quote: 23.86 – 24.25
Spot Rate : 0.3900
Average : 0.2414

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-06
Maturity Price : 22.77
Evaluated at bid price : 23.86
Bid-YTW : 3.54 %

BAM.PF.F FixedReset Quote: 24.51 – 24.85
Spot Rate : 0.3400
Average : 0.2019

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-06
Maturity Price : 23.03
Evaluated at bid price : 24.51
Bid-YTW : 4.09 %

MFC.PR.N FixedReset Quote: 23.45 – 23.75
Spot Rate : 0.3000
Average : 0.1993

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.45
Bid-YTW : 4.48 %

Market Action

May 5, 2015

After years of pretending that their resource-funded low taxes meant that they were some kind of conservatives, Albertans have finally admitted they’re actually a pack of socialists:

Albertans have chosen a new political path with the stunning election of a majority New Democratic government, ending a Progressive Conservative dynasty in power for more than four decades.

The NDP, leading in the polls for much of the campaign, becomes only the third party to govern the province since 1935. Heading a new government, Leader Rachel Notley will now have a mandate to take the province in a new direction but will also inherit tough economic challenges.

Solidarity, comrades!

Australia cut policy rates and market rates rose:

Australia cut interest rates to a fresh record low and said there are signs of improving household spending, sending the currency and bond yields higher as markets bet policy makers won’t ease further.

The central bank lowered the key rate to 2 percent from 2.25 percent Tuesday, as predicted by traders and economists. Governor Glenn Stevens said in an accompanying statement “the inflation outlook provided the opportunity for monetary policy to be eased further, so as to reinforce recent encouraging trends in household demand.”

While weaker business investment and subdued spending by the government is weighing on the economy, encouraging the RBA to cut, there are signs that low borrowing costs are starting to spur stronger demand from households. Stevens cited a better jobs market and gave no indication the central bank was considering a further easing.

But bonds fell everywhere:

Treasuries fell with European bonds as oil’s rally above $60 a barrel added to signs of incipient inflation, while concern rose that Greece won’t be able to resolve its debt crisis. U.S. stocks tumbled the most in more than a month amid a retreat in global equities.

Yields on 10-year Treasury notes rose four basis points to 2.19 percent by 5 p.m. in New York, extending an eight-week high as U.S. crude jumped 2.5 percent to $60.40 a barrel. German bonds resumed losses, while Spanish debt tumbled with Greek stocks. The Standard & Poor’s 500 Index lost 1.2 percent, the steepest drop since March 25. European equities slid to the lowest level since March 10. Copper entered a bull market.

The exodus from sovereign-debt markets is accelerating as investors question the sustainability of rallies that pushed yields to record lows. Data Tuesday showed U.S. services growth accelerated more than forecast last month as the Federal Reserve considers raising interest rates. Crude traded in New York topped $60 for the first time this year on speculation the biggest supply glut in 85 years will ease.
…
Ten-year Treasury yields have increased 28 basis points, or 0.28 percentage point, since April 24 and earlier on Tuesday touched the highest level since March 6. German 10-year yields rose six basis points to 0.52 percent, for a seventh straight gain to the highest level since January. Spain’s 10-year rate jumped the most since June 2013.

There are rumblings of an increase in inflation targets:

A quarter of a century since New Zealand opened the era of inflation targeting, policy makers from the U.S., euro area, U.K. and Japan are all undershooting their consumer-price goals. Of the Group of Seven, only Canada is currently meeting its mandate.

Rather than lowering their sights to make things easier, the misses are fanning calls for targets to be increased from the 2 percent most aim for to perhaps as high as 4 percent.

While a similar idea was pitched five years ago by International Monetary Fund economists led by Olivier Blanchard, and endorsed by Nobel laureate Paul Krugman, this time around it may be the central-banking community itself proposing a rethink.

Former Federal Reserve Chair Ben S. Bernanke last month suggested he would be open to an increase in the U.S. Federal Reserve’s 2 percent goal, saying there is nothing “magical” about that number.

Fed Bank of Boston President Eric Rosengren said the same month it could be the case “inflation targets have been set too low.” His colleague from San Francisco, John Williams, told the New York Times that if the future is one of weaker growth because of demographics and productivity then it’s worth asking “is the 2 percent inflation goal sufficiently high in that kind of world?”

But if they can’t hit 2 percent, why lift the targets?

Doing so may ignite current inflation expectations, lowering so-called real interest rates and giving economic growth an extra spur, according to Jeremy Lawson, chief economist at Standard Life Investments Ltd.

And today’s drone news is about privacy:

Conflict is on the rise. A New Jersey man last year shot down a drone flying over his neighborhood. Last June, a woman in Connecticut was arrested after she was accused of assaulting a young man flying a helicopter drone over a public beach.

In the past two years, at least seven states have outlawed the use of drones to violate privacy, according to the National Conference of State Legislatures. California is considering a bill that would expand trespassing laws to include piloting a drone within 350 feet above private property without permission.
…
States already protect citizens against Peeping Toms regardless of the technology involved, said Brendan Schulman, an attorney who specializes in drones at Kramer Levin Naftalis and Frankel in New York.

“Many of these state law proposals are an overreaction, because existing state privacy laws already cover the types of misconduct that people are most concerned about,” he said. “It shouldn’t matter if you use a tripod or a zoom lens or a hidden camera placed in a tree. If you’re invading someone’s privacy, it’s the misconduct that should be illegal, and not the technology.”

PrefBlog’s “Things That Make You Go ‘Hmmm'” department presents, for your delectation and amusement, charts of the TXPL FixedReset index and of ZPR, the ETF based on that index, for today:

ZPR
ZPR_150505
Click for Big
TXPL
TXPL_150505
Click for Big

So it looks like there was mild weakness in TXPL commencing at about 1pm, which had no effect on ZPR until about 3pm, when ZPR started collapsing, which in turn led to a rapid collapse just before the bell in TXPL. ZPR had volume for the day of 895,012 which, by standards of the past month, is above average but not spectacular. Total returns for the day for the two measures were roughly equal. It would be most interesting to learn just what is going on; if the liquidity pundits are correct – and I think they are – we may see more of this type of loose-linkage-fast-collapse behaviour in the future, should a general rise in bond yields become disorderly.

It was a mixed day for the Canadian preferred share market, with PerpetualDiscounts off 29bp, FixedResets down 47bp and DeemedRetractibles gaining 6bp. ENB FixedResets dominate the bad part of the Performance Highlights table. Volume was well above average.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_150505
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 24.20 to be $1.15 rich, while TRP.PR.G, resetting 2020-11-30 at +296, is $0.91 cheap at its bid price of 25.01.

impVol_MFC_150505
Click for Big

Another excellent fit, but the numbers are perplexing. Implied Volatility for MFC continues to be a conundrum. It is still too high if we consider that NVCC rules will never apply to these issues; it is still too low if we consider them to be NVCC non-compliant issues (and therefore with Deemed Maturities in the call schedule).

Most expensive is MFC.PR.L, resetting at +216 on 2019-6-19, bid at 23.30 to be $0.51 rich, while MFC.PR.H, resetting at +313bp on 2017-3-19, is bid at 25.34 to be $0.58 cheap.

impVol_BAM_150505
Click for Big

The cheapest issue relative to its peers is BAM.PF.R, resetting at +230bp on 2016-6-30, bid at 20.05 to be $0.71 cheap. BAM.PF.E, resetting at +255bp 2020-3-31 is bid at 23.12 and appears to be $0.82 rich.

impVol_FTS_150505
Click for Big

FTS.PR.H, with a spread of +145bp, and bid at 16.60, looks $0.78 cheap and resets 2015-6-1. FTS.PR.K, with a spread of +205bp and resetting 2019-3-1, is bid at 22.02 and is $0.52 rich.

pairs_FR_150505A
Click for Big

Investment-grade pairs now predict an average over the next five years of about 0.30%, but TRP.PR.A / TRP.PR.F is an outlier at -0.69%. The DC.PR.B / DC.PR.D pair retains its customary outlier status, with a breakeven rate of -0.78%, but has now managed to edge its way into the graph area while the new data point for BRF.PR.A / BRF.PR.B is at -1.22% and BRF.PR.B lost its virginity with a whopping 600 shares traded.

pairs_FF_150505
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 1.2035 % 2,325.8
FixedFloater 0.00 % 0.00 % 0 0.00 0 1.2035 % 4,066.6
Floater 3.12 % 3.21 % 53,444 19.19 4 1.2035 % 2,472.5
OpRet 4.42 % -1.08 % 36,619 0.16 2 -0.0196 % 2,767.0
SplitShare 4.56 % 4.77 % 67,067 3.36 3 0.4006 % 3,235.8
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0196 % 2,530.1
Perpetual-Premium 5.45 % 1.35 % 68,942 0.08 18 -0.0523 % 2,521.2
Perpetual-Discount 5.05 % 5.00 % 115,691 15.45 15 -0.2869 % 2,782.1
FixedReset 4.42 % 3.90 % 272,866 16.19 86 -0.4716 % 2,401.9
Deemed-Retractible 4.92 % 3.19 % 112,578 0.30 36 0.0565 % 2,649.9
FloatingReset 2.61 % 2.99 % 68,831 6.20 7 0.0367 % 2,321.5
Performance Highlights
Issue Index Change Notes
ENB.PR.B FixedReset -4.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-05
Maturity Price : 19.28
Evaluated at bid price : 19.28
Bid-YTW : 4.67 %
BAM.PR.T FixedReset -2.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-05
Maturity Price : 20.39
Evaluated at bid price : 20.39
Bid-YTW : 4.34 %
FTS.PR.J Perpetual-Discount -2.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-05
Maturity Price : 23.83
Evaluated at bid price : 24.24
Bid-YTW : 4.96 %
BAM.PR.X FixedReset -2.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-05
Maturity Price : 18.03
Evaluated at bid price : 18.03
Bid-YTW : 4.31 %
ENB.PR.F FixedReset -2.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-05
Maturity Price : 20.20
Evaluated at bid price : 20.20
Bid-YTW : 4.61 %
ENB.PR.D FixedReset -2.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-05
Maturity Price : 19.92
Evaluated at bid price : 19.92
Bid-YTW : 4.51 %
ENB.PF.G FixedReset -1.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-05
Maturity Price : 21.70
Evaluated at bid price : 22.11
Bid-YTW : 4.50 %
BAM.PR.R FixedReset -1.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-05
Maturity Price : 20.05
Evaluated at bid price : 20.05
Bid-YTW : 4.41 %
IFC.PR.C FixedReset -1.78 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.21
Bid-YTW : 4.28 %
ENB.PR.J FixedReset -1.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-05
Maturity Price : 21.55
Evaluated at bid price : 21.81
Bid-YTW : 4.41 %
ENB.PF.E FixedReset -1.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-05
Maturity Price : 21.63
Evaluated at bid price : 21.99
Bid-YTW : 4.50 %
ENB.PF.C FixedReset -1.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-05
Maturity Price : 21.60
Evaluated at bid price : 21.93
Bid-YTW : 4.49 %
ENB.PR.T FixedReset -1.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-05
Maturity Price : 20.43
Evaluated at bid price : 20.43
Bid-YTW : 4.57 %
BNS.PR.Y FixedReset -1.30 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.82
Bid-YTW : 3.35 %
NA.PR.S FixedReset -1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-05
Maturity Price : 23.07
Evaluated at bid price : 24.52
Bid-YTW : 3.57 %
ENB.PR.N FixedReset -1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-05
Maturity Price : 21.15
Evaluated at bid price : 21.15
Bid-YTW : 4.55 %
ENB.PR.Y FixedReset -1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-05
Maturity Price : 19.83
Evaluated at bid price : 19.83
Bid-YTW : 4.60 %
TRP.PR.D FixedReset -1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-05
Maturity Price : 22.64
Evaluated at bid price : 23.54
Bid-YTW : 3.74 %
ENB.PR.P FixedReset -1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-05
Maturity Price : 20.66
Evaluated at bid price : 20.66
Bid-YTW : 4.51 %
CU.PR.E Perpetual-Discount -1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-05
Maturity Price : 23.98
Evaluated at bid price : 24.40
Bid-YTW : 5.00 %
MFC.PR.F FixedReset -1.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.75
Bid-YTW : 6.26 %
BAM.PR.K Floater 1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-05
Maturity Price : 15.30
Evaluated at bid price : 15.30
Bid-YTW : 3.28 %
CIU.PR.C FixedReset 1.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-05
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 3.68 %
BAM.PR.C Floater 1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-05
Maturity Price : 15.39
Evaluated at bid price : 15.39
Bid-YTW : 3.26 %
HSE.PR.A FixedReset 2.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-05
Maturity Price : 17.17
Evaluated at bid price : 17.17
Bid-YTW : 4.24 %
BAM.PR.B Floater 2.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-05
Maturity Price : 15.65
Evaluated at bid price : 15.65
Bid-YTW : 3.21 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PF.C FixedReset 63,365 TD bought 10,000 from RBC at 24.09, then crossed 20,000 at the same price.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-05
Maturity Price : 22.82
Evaluated at bid price : 24.07
Bid-YTW : 3.48 %
ENB.PR.D FixedReset 63,180 TD crossed 40,000 at 20.00.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-05
Maturity Price : 19.92
Evaluated at bid price : 19.92
Bid-YTW : 4.51 %
TRP.PR.G FixedReset 50,330 RBC crossed 17,500 at 25.20.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-05
Maturity Price : 23.13
Evaluated at bid price : 25.01
Bid-YTW : 3.90 %
RY.PR.H FixedReset 47,655 TD crossed 25,000 at 24.22.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-05
Maturity Price : 22.89
Evaluated at bid price : 24.15
Bid-YTW : 3.48 %
CM.PR.Q FixedReset 46,260 Scotia crossed 40,000 at 24.95.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-05
Maturity Price : 23.02
Evaluated at bid price : 24.65
Bid-YTW : 3.78 %
PWF.PR.P FixedReset 45,955 Scotia bought 21,300 from RBC at 18.60.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-05
Maturity Price : 18.70
Evaluated at bid price : 18.70
Bid-YTW : 3.70 %
There were 41 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
ENB.PR.B FixedReset Quote: 19.28 – 19.93
Spot Rate : 0.6500
Average : 0.3703

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-05
Maturity Price : 19.28
Evaluated at bid price : 19.28
Bid-YTW : 4.67 %

FTS.PR.J Perpetual-Discount Quote: 24.24 – 24.90
Spot Rate : 0.6600
Average : 0.4218

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-05
Maturity Price : 23.83
Evaluated at bid price : 24.24
Bid-YTW : 4.96 %

BMO.PR.T FixedReset Quote: 24.05 – 24.60
Spot Rate : 0.5500
Average : 0.3169

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-05
Maturity Price : 22.85
Evaluated at bid price : 24.05
Bid-YTW : 3.48 %

NA.PR.S FixedReset Quote: 24.52 – 25.00
Spot Rate : 0.4800
Average : 0.2874

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-05
Maturity Price : 23.07
Evaluated at bid price : 24.52
Bid-YTW : 3.57 %

IFC.PR.C FixedReset Quote: 24.21 – 24.69
Spot Rate : 0.4800
Average : 0.3131

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.21
Bid-YTW : 4.28 %

CU.PR.E Perpetual-Discount Quote: 24.40 – 24.89
Spot Rate : 0.4900
Average : 0.3266

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-05
Maturity Price : 23.98
Evaluated at bid price : 24.40
Bid-YTW : 5.00 %

Market Action

May 4, 2015

Canadian banks do not own hedge funds, so the TMX announced reductions in maker-taker fees:

TMX Group Ltd., the owner of the Toronto Stock Exchange and other Canadian markets, said Monday that it will cut rebates it pays traders who provide liquidity by an average of 31 percent and trading fees by 26 percent on average.

The rebate-and-fee system — called maker-taker and also deployed by American exchanges — is blamed by critics for skewing incentives for brokers and encouraging needless trading meant to simply collect the rebates. While the New York Stock Exchange’s owner last year talked about changing the system in the U.S., TMX’s statement Monday included concrete plans that are poised to be implemented.

“The maker-taker model has been controversial for a long time,” Kevan Cowan, president of TSX Markets and group head of equities, said in a phone interview from Toronto. “It’s closely linked to issues around electronic trading. We felt, based on primarily customer feedback but also what’s going on in the regulatory and competitive landscape, that now was a good time for us to take a leadership position.”

It will be noted that the banks clear-cut the competitive landscape by buying the Toronto Exchange. This move was permitted by the regulators on the grounds that the banks would pay the regulators extra money.

Treasuries took another hit today:

The 30-year bond yield rose five basis points, or 0.05 percentage point, to 2.88 percent at 5 p.m. New York time. The price of the 2.5 percent security maturing in February 2045 fell 30/32, or $9.38 per $1,000 face amount, to 92 1/2, according to Bloomberg Bond Trader prices. The yield reached the highest level since Dec. 24.

Benchmark 10-year yields rose 21 basis points last week, nearly matching the 22 basis point move in German bunds of comparable maturity, the most since January 2013.
…
The gap between yields on Treasuries maturing in five- and 30-years, known as the yield curve, widened to 1.37 percentage points, the most since December.

The 5-30 spread is – or at least should be! – important for FixedReset pricing. Steepening should(!) imply poor performance by FixedResets.

I found this piece on youthful environment interesting:

Male children who are raised in below-median income families in Baltimore earn 1.4 percent less in adult family income for each year that they’re exposed to the neighborhood. That means a man who spent his entire childhood — 20 years — in Baltimore would earn about 28 percent less relative to the national average as an adult.

That gives Baltimore the worst ranking among the 100 largest counties in the U.S. While a penalty exists for girls, too, it’s less substantial, amounting to 0.3 percent in lost earnings per childhood year.

There are pockets across the U.S. “which seem to produce especially poor outcomes for boys,” Harvard economists Raj Chetty and Nathaniel Hendren wrote in a new study. “Areas with high degrees of segregation and sprawl generate particularly negative outcomes for boys relative to girls.”

The abstract of the paper, The Impacts of Neighborhoods on Intergenerational Mobility: Childhood Exposure Effects and County-Level Estimates, by Raj Chetty and Nathaniel Hendren, reads:

We characterize the effects of neighborhoods on children’s earnings and other outcomes in adulthood by studying more than five million families who move across counties in the U.S. Our analysis consists of two parts. In the first part, we present quasi-experimental evidence that neighborhoods affect intergenerational mobility through childhood exposure effects. In particular, the outcomes of children whose families move to a better neighborhood – as measured by the outcomes of children already living there – improve linearly in proportion to the time they spend growing up in that area. We distinguish the causal effects of neighborhoods from confounding factors by comparing the outcomes of siblings within families, studying moves triggered by displacement shocks, and exploiting sharp variation in predicted place effects across birth cohorts, genders, and quantiles. We also document analogous childhood exposure effects for college attendance, teenage birth rates, and marriage rates. In the second part of the paper, we identify the causal effect of growing up in every county in the U.S. by estimating a fixed effects model identified from families who move across counties with children of different ages. We use these estimates to decompose observed intergenerational mobility into a causal and sorting component in each county. For children growing up in families at the 25th percentile of the income distribution, each year of childhood exposure to a one standard deviation (SD) better county increases income in adulthood by 0.5%. Hence, growing up in a one SD better county from birth increases a child’s income by approximately 10%. Low-income children are most likely to succeed in counties that have less concentrated poverty, less income inequality, better schools, a larger share of two-parent families, and lower crime rates. Boys’ outcomes vary more across areas than girls, and boys have especially poor outcomes in highly-segregated areas. In urban areas, better areas have higher house prices, but our analysis uncovers significant variation in neighborhood quality even conditional on prices.

Fortis still hasn’t announced a reset rate for FTS.PR.H yet, despite the fact that it must have been calculated:

“Fixed Rate Calculation Date” means, for any Subsequent Fixed Rate Period, the 30th day prior to the first day of such Subsequent Fixed Rate Period.
…
“Subsequent Fixed Rate Period” means, for the initial Subsequent Fixed Rate Period, the period commencing on June 1, 2015 to, but excluding, June 1, 2020 and, for each succeeding Subsequent Fixed Rate Period, the period commencing on the first day of June immediately following the end of the immediately preceding Subsequent Fixed Rate Period to, but excluding, June 1 in the fifth year thereafter.
…
The Annual Fixed Dividend Rate applicable to a Subsequent Fixed Rate Period will be determined by the Corporation on the Fixed Rate Calculation Date. Such determination will, in the absence of manifest error, be final and binding upon the Corporation and upon all holders of the Series H First Preference Shares. The Corporation will, on the Fixed Rate Calculation Date, give written notice of the Annual Fixed Dividend Rate for the ensuing Subsequent Fixed Rate Period to the registered holders of the then outstanding Series H First Preference Shares.

I assume this figure will be released tomorrow morning:

Fortis Inc. (“Fortis” or the “Corporation”) (TSX:FTS) will release its first quarter 2015 results on Tuesday, May 5, 2015. A teleconference and webcast will be held the same day at 10:00 a.m. (Eastern). Barry Perry, President and Chief Executive Officer, Fortis, and Karl Smith, Executive Vice President, Chief Financial Officer, Fortis, will discuss the Corporation’s first quarter 2015 results.

Analysts, members of the media and other interested parties in North America are invited to participate by calling 1.877.223.4471. International participants may participate by calling 647.788.4922. Please dial in 10 minutes prior to the start of the call. No pass code is required.

It was a positive day for the Canadian preferred share market, with PerpetualDiscounts up 17bp, FixedResets winning 17bp and DeemedRetractibles gaining 1bp. The Performance Highlights table calmed down a bit, but is still dominated by winning FixedResets. Volume was below average.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_150504
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 24.32 to be $1.21 rich, while TRP.PR.G, resetting 2020-11-30 at +296, is $0.96 cheap at its bid price of 25.00.

impVol_MFC_150504
Click for Big

Another excellent fit, but the numbers are perplexing. Implied Volatility for MFC continues to be a conundrum. It is still too high if we consider that NVCC rules will never apply to these issues; it is still too low if we consider them to be NVCC non-compliant issues (and therefore with Deemed Maturities in the call schedule).

Most expensive is MFC.PR.L, resetting at +216 on 2019-6-19, bid at 23.31 to be $0.40 rich, while MFC.PR.H, resetting at +313bp on 2017-3-19, is bid at 25.48 to be $0.50 cheap.

impVol_BAM_150504
Click for Big

The cheapest issue relative to its peers is BAM.PF.R, resetting at +230bp on 2016-6-30, bid at 20.43 to be $0.60 cheap. BAM.PF.E, resetting at +255bp 2020-3-31 is bid at 23.16 and appears to be $0.61 rich.

impVol_FTS_150504
Click for Big

FTS.PR.H, with a spread of +145bp, and bid at 16.75, looks $0.65 cheap and resets 2015-6-1. FTS.PR.K, with a spread of +205bp and resetting 2019-3-1, is bid at 22.03 and is $0.52 rich.

pairs_FR_150504
Click for Big

Investment-grade pairs now predict an average over the next five years of about 0.25%, but TRP.PR.A / TRP.PR.F is an outlier at -0.62%. The DC.PR.B / DC.PR.D pair retains its customary outlier status, with a breakeven rate of -1.39%, while the new data point for BRF.PR.A / BRF.PR.B is at -1.22% … but there has still been no trading yet for BRF.PR.B.

pairs_FF_150504
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.0792 % 2,298.2
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.0792 % 4,018.3
Floater 3.16 % 3.28 % 53,773 19.02 4 0.0792 % 2,443.1
OpRet 4.42 % -1.06 % 38,133 0.16 2 0.0786 % 2,767.5
SplitShare 4.57 % 4.90 % 68,087 3.37 3 -0.0134 % 3,222.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0786 % 2,530.6
Perpetual-Premium 5.45 % 0.70 % 68,360 0.08 18 0.0959 % 2,522.5
Perpetual-Discount 5.02 % 4.98 % 114,596 15.44 15 0.1499 % 2,790.1
FixedReset 4.40 % 3.86 % 273,131 16.35 86 0.1686 % 2,413.2
Deemed-Retractible 4.93 % 2.98 % 113,370 0.30 36 0.0111 % 2,648.4
FloatingReset 2.61 % 2.99 % 69,505 6.20 7 0.0184 % 2,320.7
Performance Highlights
Issue Index Change Notes
IFC.PR.A FixedReset -1.52 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.68
Bid-YTW : 5.63 %
MFC.PR.M FixedReset -1.46 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.65
Bid-YTW : 4.45 %
BAM.PR.X FixedReset -1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-04
Maturity Price : 18.52
Evaluated at bid price : 18.52
Bid-YTW : 4.19 %
FTS.PR.H FixedReset 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-04
Maturity Price : 16.75
Evaluated at bid price : 16.75
Bid-YTW : 3.84 %
PWF.PR.P FixedReset 1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-04
Maturity Price : 18.75
Evaluated at bid price : 18.75
Bid-YTW : 3.69 %
MFC.PR.K FixedReset 1.38 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.44
Bid-YTW : 4.36 %
GWO.PR.N FixedReset 1.44 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.36
Bid-YTW : 6.19 %
ENB.PR.F FixedReset 1.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-04
Maturity Price : 20.69
Evaluated at bid price : 20.69
Bid-YTW : 4.49 %
PWF.PR.A Floater 2.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-04
Maturity Price : 17.60
Evaluated at bid price : 17.60
Bid-YTW : 2.83 %
SLF.PR.G FixedReset 2.54 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.20
Bid-YTW : 6.33 %
CIU.PR.C FixedReset 3.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-04
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 3.76 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PF.E FixedReset 52,830 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.05
Bid-YTW : 3.69 %
GWO.PR.R Deemed-Retractible 37,100 TD crossed 30,000 at 25.03.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.00
Bid-YTW : 4.88 %
SLF.PR.H FixedReset 36,246 RBC crossed 30,000 at 22.07.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.25
Bid-YTW : 4.84 %
CM.PR.Q FixedReset 31,504 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-04
Maturity Price : 23.08
Evaluated at bid price : 24.82
Bid-YTW : 3.75 %
TD.PF.B FixedReset 30,413 TD crossed 25,000 at 24.28.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-04
Maturity Price : 22.95
Evaluated at bid price : 24.28
Bid-YTW : 3.46 %
TRP.PR.G FixedReset 29,900 RBC crossed 17,500 at 25.10.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-11-30
Maturity Price : 25.00
Evaluated at bid price : 25.00
Bid-YTW : 3.76 %
There were 26 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
VNR.PR.A FixedReset Quote: 24.13 – 24.83
Spot Rate : 0.7000
Average : 0.4552

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-04
Maturity Price : 23.13
Evaluated at bid price : 24.13
Bid-YTW : 4.05 %

IFC.PR.A FixedReset Quote: 20.68 – 21.26
Spot Rate : 0.5800
Average : 0.4049

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.68
Bid-YTW : 5.63 %

RY.PR.H FixedReset Quote: 24.08 – 24.45
Spot Rate : 0.3700
Average : 0.2201

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-04
Maturity Price : 22.86
Evaluated at bid price : 24.08
Bid-YTW : 3.49 %

BAM.PR.Z FixedReset Quote: 24.41 – 24.84
Spot Rate : 0.4300
Average : 0.3154

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-04
Maturity Price : 23.21
Evaluated at bid price : 24.41
Bid-YTW : 4.21 %

SLF.PR.G FixedReset Quote: 18.20 – 18.50
Spot Rate : 0.3000
Average : 0.1925

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.20
Bid-YTW : 6.33 %

PWF.PR.T FixedReset Quote: 24.86 – 25.25
Spot Rate : 0.3900
Average : 0.2836

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-04
Maturity Price : 23.23
Evaluated at bid price : 24.86
Bid-YTW : 3.50 %

Market Action

May 1, 2015

The CME’s Department of Selective Enforcement has decided to make a sudden fuss about spoofing and two guys have been scapegoated:

CME Group Inc. said it suspended two traders for placing manipulative trades similar to the ones that catapulted Navinder Singh Sarao into headlines around the world last week.

Heet Khara and Nasim Salim engaged in a practice called “layering,” in which orders are placed with no intention of following through on them, according to CME, the owner of the futures exchange where the two gold and silver traders did business. Khara and Salim are barred from trading on CME markets for 60 days.

However, the trivial nature of the transgression is illustrated by the fact that they only face a 60 day trading ban. Have a nice holiday guys … unless, of course, you hire somebody else to push the buttons with the assistance of your advice. The ZeroHedge blog considers the affair to be scapegoating and window-dressing with a hint of racism.

Anti-Spoofing regulations are unenforceable and spoofing does no direct harm to the interests of fundamental traders (indirect harm, through a thinning of the markets, is possible but I have not seen evidence of this). Anti-spoofing regulations should be repealed; I suspect that consequent private sector development of counter-spoofing tactics will be far more effective than any amount of regulation could ever possibly be.

Holy smokaramaville, but it’s been a week and half for the fixed income markets! Bloomberg notes that it’s been the worst week in almost two months (put that way, it sounds pretty routine, doesn’t it?):

The worst week for U.S. 10-year notes in almost two months got even bleaker as a rout in European bonds continued to diminish investor appetite for relatively higher U.S. yields. The notes also extended an April decline after a report showed U.S. consumer confidence rose last month.
…
Treasury 10-year yields rose eight basis points, or 0.08 percentage point, to 2.11 percent as of 5 p.m. New York time. It touched 2.12 percent, the highest since March 13, based on Bloomberg Bond Trader data. The benchmark 2 percent note due in February 2025 fell 23/32, or $7.19 per $1,000 face amount, to 99.
…
Ten-year yields climbed 20 basis points this week, the most since the week ending March 6, and are up from 1.92 percent at the start of April.

U.S. debt extended losses after the University of Michigan said Friday that its final consumer-confidence index for April increased to 95.9 from 93 in March. The median projection in a Bloomberg survey of economists was for 96.

That followed a series of weak first-quarter economic readings that the Fed this week blamed on “transitory” factors including brutal winter weather in much of the U.S. Fed Chair Janet Yellen and her colleagues reiterated in a statement on April 29 after a two-day meeting that they believe growth will pick up to a “moderate pace”.
…
Euro-area debt started selling off early in the week and reached a peak on April 29, when 55 billion euros ($62 billion) was wiped off the value of the region’s government bonds on the day.

The extra yield that investors get for holding Treasury 10-year notes instead of similar-maturity German bunds narrowed to 167 basis points on Thursday, the least on a closing basis since April 3.

… and the chart:

1200x-1
Click for Big

This is despite the moderating influence of hedge fund activity:

They don’t think it will last.

Hedge-fund managers and other large speculators who saw the start or this week’s bond rout nevertheless moved in the opposite direction, trimming bearish bets on 10-year notes to the lowest level in 10 weeks.

Net shorts on the securities totaled 98,565 contracts as of April 28, down from 153,366 the week before, according to Commodity Futures Trading Commission data.

It would be most interesting to learn whether hedge-fund activity is generally counterflow. I suspect it is, given that reversion is what quants do best, but I am not aware of any research on this.

And all this affected Canada. According to the BoC, five-year Canadas were trading at 0.71% last Friday, and according to Perimeter they ended this week at 1.04%. That’s a hell of a move for a five year sovereign – although not quite so fast as the descent in January when the overnight rate got cut.

What’s driving it, I think, is that as discussed yesterday, the previously announced European deflation has been cancelled. So markets which were expecting low rates forever are now expecting high rates forever … and this has certainly had an effect in the preferred share market, as previous panic over continued reductions in FixedReset dividends on reset have, at the very least, been moderated.

But we’ll see what next week brings. The market does what it wants to do when it wants to do it. For what it’s worth, I believe that the current situation of 5-year governments trading below inflation to be unsustainable, a very useful word for financial analysis since it doesn’t mean anything. I will opine that I believe the paradox will be resolved by an increase in sovereign yields (rather than a decline in inflation), but I would not dream of predicting just exactly when this might occur.

Still, the violent change in sentiment made it a wild month for FixedResets!

FR_TRIV_150501
Click for Big

Look at all the fun you had in April and it didn’t cost you anything!

It was an unevenly strong day for the Canadian preferred share market, with PerpetualDiscounts up 30bp, FixedResets winning 64bp and DeemedRetractibles gaining 3bp. The Performance Highlights table is, as one might expect, dominated by winning FixedResets. Volume was below average.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_150501
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 24.15 to be $1.11 rich, while TRP.PR.G, resetting 2020-11-30 at +296, is $0.88 cheap at its bid price of 25.05.

impVol_MFC_150501
Click for Big

Another excellent fit, but the numbers are perplexing. Implied Volatility for MFC continues to be a conundrum. It is still too high if we consider that NVCC rules will never apply to these issues; it is still too low if we consider them to be NVCC non-compliant issues (and therefore with Deemed Maturities in the call schedule).

Most expensive is MFC.PR.L, resetting at +216 on 2019-6-19, bid at 23.30 to be $0.40 rich, while MFC.PR.H, resetting at +313bp on 2017-3-19, is bid at 25.41 to be $0.53 cheap.

impVol_BAM_150501
Click for Big

The cheapest issue relative to its peers is BAM.PF.B, resetting at +263bp on 2019-3-31, bid at 22.45 to be $0.61 cheap. BAM.PR.X, resetting at +180bp 2017-6-30 is bid at 18.75 and appears to be $0.82 rich.

impVol_FTS_150501
Click for Big

FTS.PR.H, with a spread of +145bp, and bid at 16.57, looks $0.82 cheap and resets 2015-6-1. FTS.PR.K, with a spread of +205bp and resetting 2019-3-1, is bid at 22.22 and is $0.64 rich.

pairs_FR_150501
Click for Big

Investment-grade pairs now predict an average over the next five years of about 0.25%, but TRP.PR.A / TRP.PR.F is an outlier at -0.33%. The DC.PR.B / DC.PR.D pair retains its customary outlier status, with a breakeven rate of -1.27%. The new data point for BRF.PR.A / BRF.PR.B cannot be considered reliable.

pairs_FF_150501
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.9600 % 2,296.3
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.9600 % 4,015.1
Floater 3.16 % 3.25 % 54,172 19.09 4 0.9600 % 2,441.2
OpRet 4.42 % -4.62 % 37,871 0.09 2 -0.0197 % 2,765.3
SplitShare 4.57 % 4.76 % 68,324 3.37 3 -0.2663 % 3,223.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0197 % 2,528.6
Perpetual-Premium 5.45 % -0.79 % 68,911 0.08 18 0.0676 % 2,520.1
Perpetual-Discount 5.03 % 4.99 % 115,903 15.41 15 0.3046 % 2,785.9
FixedReset 4.40 % 3.73 % 276,479 16.74 86 0.6384 % 2,409.2
Deemed-Retractible 4.93 % 2.99 % 112,826 0.24 36 0.0343 % 2,648.1
FloatingReset 2.59 % 2.96 % 71,981 6.21 7 -0.1222 % 2,320.2
Performance Highlights
Issue Index Change Notes
BAM.PF.B FixedReset -1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-01
Maturity Price : 22.00
Evaluated at bid price : 22.45
Bid-YTW : 4.07 %
FTS.PR.K FixedReset 1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-01
Maturity Price : 21.85
Evaluated at bid price : 22.22
Bid-YTW : 3.54 %
ENB.PR.Y FixedReset 1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-01
Maturity Price : 20.14
Evaluated at bid price : 20.14
Bid-YTW : 4.32 %
RY.PR.L FixedReset 1.01 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2019-02-24
Maturity Price : 25.00
Evaluated at bid price : 25.90
Bid-YTW : 3.19 %
TRP.PR.D FixedReset 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-01
Maturity Price : 22.74
Evaluated at bid price : 23.75
Bid-YTW : 3.51 %
ENB.PF.A FixedReset 1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-01
Maturity Price : 21.75
Evaluated at bid price : 22.14
Bid-YTW : 4.27 %
MFC.PR.J FixedReset 1.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.52
Bid-YTW : 3.97 %
NA.PR.W FixedReset 1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-01
Maturity Price : 22.83
Evaluated at bid price : 24.10
Bid-YTW : 3.33 %
MFC.PR.N FixedReset 1.28 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.70
Bid-YTW : 4.24 %
IAG.PR.G FixedReset 1.29 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.20
Bid-YTW : 3.82 %
BAM.PR.B Floater 1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-01
Maturity Price : 15.44
Evaluated at bid price : 15.44
Bid-YTW : 3.25 %
BNS.PR.R FixedReset 1.31 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.47
Bid-YTW : 3.04 %
ENB.PF.G FixedReset 1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-01
Maturity Price : 22.02
Evaluated at bid price : 22.60
Bid-YTW : 4.22 %
PWF.PR.P FixedReset 1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-01
Maturity Price : 18.50
Evaluated at bid price : 18.50
Bid-YTW : 3.47 %
BNS.PR.Z FixedReset 1.39 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.30
Bid-YTW : 3.55 %
TD.PF.C FixedReset 1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-01
Maturity Price : 22.82
Evaluated at bid price : 24.06
Bid-YTW : 3.31 %
FTS.PR.F Perpetual-Discount 1.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-01
Maturity Price : 24.57
Evaluated at bid price : 24.80
Bid-YTW : 5.01 %
ENB.PR.N FixedReset 1.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-01
Maturity Price : 21.45
Evaluated at bid price : 21.45
Bid-YTW : 4.28 %
BAM.PR.K Floater 1.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-01
Maturity Price : 15.16
Evaluated at bid price : 15.16
Bid-YTW : 3.31 %
ENB.PR.H FixedReset 1.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-01
Maturity Price : 18.76
Evaluated at bid price : 18.76
Bid-YTW : 4.30 %
BAM.PR.X FixedReset 1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-01
Maturity Price : 18.75
Evaluated at bid price : 18.75
Bid-YTW : 3.89 %
BAM.PF.E FixedReset 1.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-01
Maturity Price : 22.35
Evaluated at bid price : 23.13
Bid-YTW : 3.94 %
BAM.PR.R FixedReset 1.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-01
Maturity Price : 20.55
Evaluated at bid price : 20.55
Bid-YTW : 4.06 %
MFC.PR.M FixedReset 2.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.00
Bid-YTW : 4.15 %
BAM.PR.T FixedReset 2.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-01
Maturity Price : 20.80
Evaluated at bid price : 20.80
Bid-YTW : 4.03 %
ENB.PR.D FixedReset 2.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-01
Maturity Price : 20.35
Evaluated at bid price : 20.35
Bid-YTW : 4.20 %
CIU.PR.C FixedReset 2.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-01
Maturity Price : 16.43
Evaluated at bid price : 16.43
Bid-YTW : 3.59 %
HSE.PR.A FixedReset 2.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-01
Maturity Price : 16.75
Evaluated at bid price : 16.75
Bid-YTW : 4.05 %
MFC.PR.L FixedReset 3.56 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.30
Bid-YTW : 4.37 %
ENB.PR.B FixedReset 3.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-01
Maturity Price : 20.20
Evaluated at bid price : 20.20
Bid-YTW : 4.22 %
SLF.PR.G FixedReset 3.98 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.75
Bid-YTW : 6.39 %
Volume Highlights
Issue Index Shares
Traded
Notes
SLF.PR.G FixedReset 94,480 RBC bought two blocks from Nesbitt: 16,700 at 17.00 and 22,600 at 17.20.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.75
Bid-YTW : 6.39 %
ENB.PR.B FixedReset 80,049 RBC crossed 19,300 at 19.45.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-01
Maturity Price : 20.20
Evaluated at bid price : 20.20
Bid-YTW : 4.22 %
BMO.PR.J Deemed-Retractible 78,100 Called for redemption.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2015-05-31
Maturity Price : 25.25
Evaluated at bid price : 25.22
Bid-YTW : 2.35 %
TD.PF.C FixedReset 59,208 Desjardins crossed 38,200 at 24.04.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-01
Maturity Price : 22.82
Evaluated at bid price : 24.06
Bid-YTW : 3.31 %
RY.PR.C Deemed-Retractible 41,600 Nesbitt bought four blocks of 10,000 each from anonymous, all at 25.16.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2015-11-24
Maturity Price : 25.00
Evaluated at bid price : 25.12
Bid-YTW : 3.22 %
CM.PR.Q FixedReset 31,700 Nesbitt crossed 25,000 at 25.00.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-01
Maturity Price : 23.09
Evaluated at bid price : 24.85
Bid-YTW : 3.59 %
There were 23 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
CIU.PR.C FixedReset Quote: 16.43 – 17.25
Spot Rate : 0.8200
Average : 0.6700

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-01
Maturity Price : 16.43
Evaluated at bid price : 16.43
Bid-YTW : 3.59 %

CU.PR.D Perpetual-Discount Quote: 24.86 – 25.25
Spot Rate : 0.3900
Average : 0.2449

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-01
Maturity Price : 24.40
Evaluated at bid price : 24.86
Bid-YTW : 4.98 %

ENB.PR.P FixedReset Quote: 20.73 – 21.09
Spot Rate : 0.3600
Average : 0.2225

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-01
Maturity Price : 20.73
Evaluated at bid price : 20.73
Bid-YTW : 4.29 %

ENB.PR.T FixedReset Quote: 20.61 – 20.94
Spot Rate : 0.3300
Average : 0.2032

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-01
Maturity Price : 20.61
Evaluated at bid price : 20.61
Bid-YTW : 4.33 %

ENB.PF.E FixedReset Quote: 22.15 – 22.43
Spot Rate : 0.2800
Average : 0.1814

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-05-01
Maturity Price : 21.74
Evaluated at bid price : 22.15
Bid-YTW : 4.29 %

GWO.PR.H Deemed-Retractible Quote: 24.63 – 24.90
Spot Rate : 0.2700
Average : 0.1749

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.63
Bid-YTW : 5.13 %