Category: Market Action

Market Action

October 29, 2013

Nothing happened today.

It was a good strong day for the Canadian preferred share market, with PerpetualDiscounts up 17bp, FixedResets gaining 10bp and DeemedRetractibles winning 39bp. The Performance Highlights table is dominated by winning insurance-sector DeemedRetractibles. Volume was very high.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.1344 % 2,498.3
FixedFloater 4.19 % 3.46 % 26,336 18.47 1 0.3981 % 4,010.8
Floater 2.71 % 2.93 % 63,693 19.90 5 0.1344 % 2,697.4
OpRet 4.63 % 3.19 % 69,595 0.58 3 0.1673 % 2,638.8
SplitShare 4.76 % 5.07 % 65,679 3.96 6 0.1013 % 2,950.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1673 % 2,412.9
Perpetual-Premium 5.81 % 3.16 % 107,015 0.08 7 0.1422 % 2,289.0
Perpetual-Discount 5.52 % 5.55 % 178,054 14.46 30 0.1675 % 2,358.4
FixedReset 4.92 % 3.59 % 233,753 3.75 86 0.1017 % 2,449.7
Deemed-Retractible 5.10 % 4.31 % 195,076 2.81 43 0.3892 % 2,400.5
Performance Highlights
Issue Index Change Notes
TRP.PR.C FixedReset -1.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-29
Maturity Price : 22.02
Evaluated at bid price : 22.26
Bid-YTW : 3.80 %
TRI.PR.B Floater -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-29
Maturity Price : 19.89
Evaluated at bid price : 19.89
Bid-YTW : 2.65 %
FTS.PR.G FixedReset -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-29
Maturity Price : 22.70
Evaluated at bid price : 23.80
Bid-YTW : 4.03 %
BNS.PR.Y FixedReset -1.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.53
Bid-YTW : 3.79 %
SLF.PR.E Deemed-Retractible 1.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.98
Bid-YTW : 6.08 %
ENB.PR.Y FixedReset 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-29
Maturity Price : 22.20
Evaluated at bid price : 22.92
Bid-YTW : 4.46 %
PWF.PR.K Perpetual-Discount 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-29
Maturity Price : 22.25
Evaluated at bid price : 22.65
Bid-YTW : 5.47 %
PWF.PR.L Perpetual-Discount 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-29
Maturity Price : 22.86
Evaluated at bid price : 23.15
Bid-YTW : 5.53 %
TRP.PR.B FixedReset 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-29
Maturity Price : 20.33
Evaluated at bid price : 20.33
Bid-YTW : 3.83 %
MFC.PR.C Deemed-Retractible 1.46 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.51
Bid-YTW : 6.35 %
SLF.PR.B Deemed-Retractible 1.56 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.80
Bid-YTW : 5.97 %
SLF.PR.D Deemed-Retractible 1.78 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.68
Bid-YTW : 6.18 %
GWO.PR.H Deemed-Retractible 1.93 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.73
Bid-YTW : 6.06 %
MFC.PR.B Deemed-Retractible 2.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.96
Bid-YTW : 6.27 %
FTS.PR.H FixedReset 2.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-29
Maturity Price : 21.35
Evaluated at bid price : 21.35
Bid-YTW : 3.87 %
GWO.PR.I Deemed-Retractible 2.77 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.90
Bid-YTW : 6.12 %
Volume Highlights
Issue Index Shares
Traded
Notes
ENB.PR.N FixedReset 110,636 Scotia crossed 100,000 at 24.25.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-29
Maturity Price : 22.91
Evaluated at bid price : 24.33
Bid-YTW : 4.36 %
FTS.PR.E OpRet 102,500 RBC crossed 100,000 at 26.00.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-06-01
Maturity Price : 25.50
Evaluated at bid price : 25.92
Bid-YTW : 3.33 %
BNS.PR.X FixedReset 76,621 Nesbitt crossed 75,000 at 25.45.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-04-25
Maturity Price : 25.00
Evaluated at bid price : 25.45
Bid-YTW : 2.40 %
SLF.PR.E Deemed-Retractible 63,683 TD crossed 50,000 at 21.88.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.98
Bid-YTW : 6.08 %
SLF.PR.F FixedReset 58,913 TD crossed 50,000 at 25.70.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-06-30
Maturity Price : 25.00
Evaluated at bid price : 25.66
Bid-YTW : 2.77 %
MFC.PR.B Deemed-Retractible 56,854 Nesbitt crossed 46,400 at 21.65.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.96
Bid-YTW : 6.27 %
There were 62 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
TRP.PR.C FixedReset Quote: 22.26 – 22.78
Spot Rate : 0.5200
Average : 0.3910

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-29
Maturity Price : 22.02
Evaluated at bid price : 22.26
Bid-YTW : 3.80 %

SLF.PR.A Deemed-Retractible Quote: 22.35 – 22.69
Spot Rate : 0.3400
Average : 0.2340

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.35
Bid-YTW : 6.15 %

BAM.PF.C Perpetual-Discount Quote: 20.04 – 20.27
Spot Rate : 0.2300
Average : 0.1414

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-29
Maturity Price : 20.04
Evaluated at bid price : 20.04
Bid-YTW : 6.13 %

TD.PR.O Deemed-Retractible Quote: 25.25 – 25.50
Spot Rate : 0.2500
Average : 0.1679

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.25
Bid-YTW : 3.82 %

CU.PR.F Perpetual-Discount Quote: 21.29 – 21.56
Spot Rate : 0.2700
Average : 0.1905

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-29
Maturity Price : 21.29
Evaluated at bid price : 21.29
Bid-YTW : 5.38 %

BNS.PR.Y FixedReset Quote: 23.53 – 23.79
Spot Rate : 0.2600
Average : 0.1868

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.53
Bid-YTW : 3.79 %

Market Action

October 28, 2013

Singapore is is seeking to encourage HFT:

Singapore Exchange Ltd. (SGX), Southeast Asia’s biggest bourse operator, wants to lure more high-speed traders onto its stock market as it grapples with lower volume.

Computerized trading firms, which execute transactions in fractions of a second, account for a negligible share of volume on Singapore Exchange’s cash equities market, according to bourse spokeswoman Loh Wei Ling, while they contribute 30 percent of revenue from derivatives. Singapore Exchange will seek to change that once it introduces safeguards, Chief Executive Officer Magnus Bocker said at a briefing this month.

“We will pursue high-frequency trading once we have circuit breakers and other policies in place,” he said. “That will enhance the liquidity and quality of the Singapore market.”

It’s nice to know that they’re not beholden to the Old Boys Club.

I understand that the SplitShare new issue, Prime US Banking Sector Split Corp. discussed on October 2, has been withdrawn. However, there is no confirmation of this as yet on the Quadravest website, the fund’s website or SEDAR. It’s a shame – new issues of this nature that get so far can cost the sponsor a great deal of money.

A gushing article about Raymond James brokerage makes a good point about the effects of bank regulation in Canada:

For instance, Raymond is looking to expand its corporate lending arm after acquiring the Canadian assets of Allied Irish Banks in 2011, and lending spreads are much more attractive here because there is less competition for loans. South of the border, everyone from banks to shadow banks to hedge funds are willing to lend money, and that hurts loan margins and covenant quality.

The Bank of Canada is very frightened of shadow banking, as are other regulators who want to work for banks eventually.

Seth Carpenter, Jane Ihrig, Elizabeth Klee, Daniel Quinn, and Alexander Boote of the Federal Reserve have written a paper titled The Federal Reserve’s Balance Sheet and Earnings: A primer and projections:

Over the past few years, the Federal Reserve’s use of unconventional monetary policy tools has received a vast amount of public attention, from discussing how these asset purchases have put downward pressure on longer-term interest rates and thus supported economic activity to evaluating the implications for Federal Reserve remittances to the Treasury and the effect on monetary and fiscal policy. As the economic recovery has gained some momentum of late, the focus has turned to issues associated with the normalization of monetary policy. In this paper, we consider a variety of scenarios consistent with statements by Federal Reserve officials about how the FOMC will normalize policy, including whether to sell mortgage-backed securities and the timing of lifting the federal funds rate off from the zero lower bound. In addition, we analyze the potential costs associated with using reserve-draining tools, which could become an important expense during the years of normalization. In each of these scenarios, we discuss the implications of these normalization policies on the size and composition of Federal Reserve asset holdings, which provides some indicate the length of time unconventional monetary policy will be in place, and on remittances of earnings to the Treasury, which capture the interest rate risk of these normalization policies.

What I find of interest is that Treasury remittances are affected only by realized capital losses on the sales – unrealized capital losses are a mere bagatelle, as higlighted by Joshua Zumbrun of Bloomberg. Mark-to-market is for suckers, losers and the private sector regulated by the Fed.

James Hamilton of Econbrowser comments:

The hot debate among Fed watchers– when will the Fed announce a “tapering” of its large-scale purchases– concerns a change in the stock of Treasuries and mortgage-backed securities that the Fed ends up holding that comes to only a fraction of that $600 B reference point. For example, I noted earlier that if the Fed had (as some market observers once anticipated) announced at its September FOMC meeting that it would begin to reduce its net purchases of Treasury securities by $2.5 B per month beginning in October, the result as of the end of 2014 would be that the Fed would be holding about $100 B less in Treasury securities by the end of 2014 than if it waits to begin tapering until January. Using the above table as a guide, that suggests a difference of perhaps 2.5-5 basis points (that is, less than 0.05 percentage points difference in the annual yield) on a 10-year Treasury. Even if you double or triple that by adding in the consequences of MBS purchases, it’s hard to see this as the #1 news event with which financial markets should be gripped.

Matthew Klein of Bloomberg has some interesting commentary on cat bonds:

While we shouldn’t cry for the reinsurers just yet, some pension funds may end up buying these high-yielding assets before they fully understand how to model their risks, just as some loaded up on subprime mortgage securities during the mid-2000s. (On the bright side, investors won’t have to worry about fraud when calculating the probability of another Hurricane Sandy.)

Initially, this would depress the cost of disaster insurance, which might lead to overbuilding in risky areas and laxer enforcement of building safety codes. It could also push the insurers and reinsurers to underwrite new risks they are less familiar with in an effort to prop up margins, a danger that was highlighted by the UK’s Prudential Regulation Authority last month. The Bank for International Settlements, based in Basel, Switzerland, has also been looking into the impact of the reinsurance business on financial stability.

In the event of disaster, outside investors who didn’t appreciate what they had been buying might get so spooked by losses that they would cut their allocation to the entire sector. Small shifts from the perspective of pensions could have big effects on insurers’ ability to protect against future catastrophes. The result would be much greater volatility in the cost of insurance, to say nothing of the impact on pension beneficiaries. Plan sponsors and regulators should be careful.

It was a positive day for the Canadian preferred share market, with PerpetualDiscounts gaining 2bp, FixedResets winning 16bp and DeemedRetractibles up 10bp. A surprisingly lengthy Performance Highlights table is dominated by winners. Volume was above average.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.5195 % 2,494.9
FixedFloater 4.20 % 3.48 % 26,588 18.44 1 1.8010 % 3,994.9
Floater 2.71 % 2.95 % 63,934 19.85 5 0.5195 % 2,693.8
OpRet 4.63 % 3.45 % 72,249 0.58 3 -0.1157 % 2,634.4
SplitShare 4.76 % 5.23 % 68,408 3.96 6 0.0352 % 2,947.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.1157 % 2,408.9
Perpetual-Premium 5.82 % 5.65 % 108,388 4.33 7 -0.0341 % 2,285.8
Perpetual-Discount 5.53 % 5.58 % 177,333 14.46 30 0.0231 % 2,354.5
FixedReset 4.93 % 3.62 % 236,046 3.99 86 0.1572 % 2,447.2
Deemed-Retractible 5.12 % 4.34 % 193,949 2.81 43 0.0972 % 2,391.2
Performance Highlights
Issue Index Change Notes
GWO.PR.N FixedReset -1.57 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.91
Bid-YTW : 4.64 %
CIU.PR.A Perpetual-Discount -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-28
Maturity Price : 21.02
Evaluated at bid price : 21.02
Bid-YTW : 5.57 %
BAM.PF.B FixedReset 1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-28
Maturity Price : 22.73
Evaluated at bid price : 23.95
Bid-YTW : 4.46 %
TD.PR.Q Deemed-Retractible 1.12 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-11-27
Maturity Price : 26.00
Evaluated at bid price : 26.20
Bid-YTW : -4.44 %
TRP.PR.A FixedReset 1.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-28
Maturity Price : 23.90
Evaluated at bid price : 24.35
Bid-YTW : 3.81 %
BNS.PR.Y FixedReset 1.54 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.77
Bid-YTW : 3.65 %
BAM.PR.G FixedFloater 1.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-28
Maturity Price : 22.84
Evaluated at bid price : 22.61
Bid-YTW : 3.48 %
TRI.PR.B Floater 2.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-28
Maturity Price : 20.10
Evaluated at bid price : 20.10
Bid-YTW : 2.63 %
TRP.PR.C FixedReset 2.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-28
Maturity Price : 22.30
Evaluated at bid price : 22.65
Bid-YTW : 3.73 %
Volume Highlights
Issue Index Shares
Traded
Notes
BNS.PR.Y FixedReset 66,455 Scotia crossed 56,400 at 23.60.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.77
Bid-YTW : 3.65 %
RY.PR.X FixedReset 59,983 TD crossed 50,000 at 25.60.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-08-24
Maturity Price : 25.00
Evaluated at bid price : 25.61
Bid-YTW : 2.71 %
ENB.PR.T FixedReset 57,092 RBC crossed 50,000 at 23.40.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-28
Maturity Price : 22.47
Evaluated at bid price : 23.41
Bid-YTW : 4.44 %
CIU.PR.A Perpetual-Discount 51,500 Scotia crossed 47,300 at 21.20.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-28
Maturity Price : 21.02
Evaluated at bid price : 21.02
Bid-YTW : 5.57 %
CM.PR.M FixedReset 51,416 RBC crossed 50,000 at 25.80.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-07-31
Maturity Price : 25.00
Evaluated at bid price : 25.76
Bid-YTW : 2.41 %
CM.PR.E Perpetual-Discount 36,802 RBC crossed 28,500 at 25.12.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-11-27
Maturity Price : 25.00
Evaluated at bid price : 25.09
Bid-YTW : 0.84 %
There were 40 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
CIU.PR.A Perpetual-Discount Quote: 21.02 – 21.65
Spot Rate : 0.6300
Average : 0.4446

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-28
Maturity Price : 21.02
Evaluated at bid price : 21.02
Bid-YTW : 5.57 %

BAM.PR.R FixedReset Quote: 25.14 – 25.64
Spot Rate : 0.5000
Average : 0.3349

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-28
Maturity Price : 23.49
Evaluated at bid price : 25.14
Bid-YTW : 4.11 %

FTS.PR.J Perpetual-Discount Quote: 22.61 – 22.98
Spot Rate : 0.3700
Average : 0.2510

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-28
Maturity Price : 22.29
Evaluated at bid price : 22.61
Bid-YTW : 5.32 %

GWO.PR.N FixedReset Quote: 21.91 – 22.30
Spot Rate : 0.3900
Average : 0.2867

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.91
Bid-YTW : 4.64 %

MFC.PR.K FixedReset Quote: 23.51 – 23.87
Spot Rate : 0.3600
Average : 0.2624

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.51
Bid-YTW : 4.63 %

ENB.PR.B FixedReset Quote: 23.78 – 24.14
Spot Rate : 0.3600
Average : 0.2722

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-28
Maturity Price : 22.79
Evaluated at bid price : 23.78
Bid-YTW : 4.30 %

Market Action

October 25, 2013

The BoC has released a paper by Bo Young Chang and Bruno Feunou titled Measuring Uncertainty in Monetary Policy Using Implied Volatility and Realized Volatility:

We measure uncertainty surrounding the central bank’s future policy rates using implied volatility computed from interest rate option prices and realized volatility computed from intraday prices of interest rate futures. Both volatility measures show that uncertainty decreased following the most important policy actions taken by the Bank of Canada as a response to the financial crisis of 2007–08, such as the conditional commitment of 2009–10, the unscheduled cut in the target rate coordinated with other major central banks, and the introduction of term purchase and resale agreements. We also find that, on average, uncertainty decreases following the Bank of Canada’s policy rate announcements. Furthermore, our measures of policy rate uncertainty improve the estimation of policy rate expectations from overnight index swap (OIS) rates by predicting the risk premium in the OIS market.

It was a mixed day for the Canadian preferred share market, with PerpetualDiscounts off 1bp, FixedResets down 5bp and DeemedRetractibles gaining 9bp. Volatility was high, but without obvious patterns. Volume was high.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.7425 % 2,482.0
FixedFloater 4.28 % 3.55 % 26,961 18.31 1 -0.6708 % 3,924.2
Floater 2.73 % 2.96 % 62,882 19.82 5 -0.7425 % 2,679.9
OpRet 4.63 % 3.29 % 71,364 0.59 3 -0.0899 % 2,637.5
SplitShare 4.76 % 5.30 % 68,533 3.97 6 0.2763 % 2,946.2
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0899 % 2,411.7
Perpetual-Premium 5.81 % 2.78 % 108,979 0.08 7 -0.0455 % 2,286.5
Perpetual-Discount 5.53 % 5.56 % 178,700 14.40 30 -0.0130 % 2,354.0
FixedReset 4.96 % 3.66 % 243,609 3.38 85 -0.0517 % 2,443.3
Deemed-Retractible 5.13 % 4.37 % 192,696 2.82 43 0.0915 % 2,388.9
Performance Highlights
Issue Index Change Notes
TRI.PR.B Floater -3.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-25
Maturity Price : 19.70
Evaluated at bid price : 19.70
Bid-YTW : 2.68 %
FTS.PR.H FixedReset -1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-25
Maturity Price : 20.71
Evaluated at bid price : 20.71
Bid-YTW : 4.14 %
MFC.PR.B Deemed-Retractible -1.66 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.39
Bid-YTW : 6.58 %
SLF.PR.G FixedReset -1.43 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.70
Bid-YTW : 4.54 %
W.PR.J Perpetual-Discount -1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-25
Maturity Price : 24.21
Evaluated at bid price : 24.47
Bid-YTW : 5.76 %
SLF.PR.B Deemed-Retractible 1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.49
Bid-YTW : 6.12 %
GWO.PR.N FixedReset 1.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.26
Bid-YTW : 4.57 %
BNA.PR.E SplitShare 1.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2017-12-10
Maturity Price : 25.00
Evaluated at bid price : 24.75
Bid-YTW : 5.33 %
SLF.PR.D Deemed-Retractible 1.38 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.35
Bid-YTW : 6.36 %
CIU.PR.A Perpetual-Discount 2.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-25
Maturity Price : 21.24
Evaluated at bid price : 21.24
Bid-YTW : 5.51 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.L FixedReset 390,080 RBC crossed 382,000 at 25.12. Nice ticket!
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-02-24
Maturity Price : 25.00
Evaluated at bid price : 25.14
Bid-YTW : 2.54 %
MFC.PR.F FixedReset 201,629 RBC crossed 193,700 at 22.00.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.08
Bid-YTW : 4.95 %
BNS.PR.K Deemed-Retractible 122,597 Nesbitt crossed blocks of 58,700 and 59,100, both at 25.07.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-04-28
Maturity Price : 25.00
Evaluated at bid price : 25.07
Bid-YTW : 4.06 %
TD.PR.C FixedReset 107,119 Nesbitt crossed 50,000 at 25.19; TD crossed 50,000 at 25.18.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.18
Bid-YTW : 2.56 %
BAM.PR.R FixedReset 47,650 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-25
Maturity Price : 23.44
Evaluated at bid price : 25.00
Bid-YTW : 4.26 %
GWO.PR.H Deemed-Retractible 46,697 TD crossed 30,000 at 22.30.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.30
Bid-YTW : 6.28 %
There were 55 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
MFC.PR.B Deemed-Retractible Quote: 21.39 – 21.91
Spot Rate : 0.5200
Average : 0.3279

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.39
Bid-YTW : 6.58 %

RY.PR.R FixedReset Quote: 25.15 – 25.52
Spot Rate : 0.3700
Average : 0.2253

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-02-24
Maturity Price : 25.00
Evaluated at bid price : 25.15
Bid-YTW : 2.91 %

VNR.PR.A FixedReset Quote: 24.91 – 25.28
Spot Rate : 0.3700
Average : 0.2317

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-10-15
Maturity Price : 25.00
Evaluated at bid price : 24.91
Bid-YTW : 4.51 %

BAM.PR.G FixedFloater Quote: 22.21 – 22.67
Spot Rate : 0.4600
Average : 0.3492

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-25
Maturity Price : 22.55
Evaluated at bid price : 22.21
Bid-YTW : 3.55 %

IFC.PR.C FixedReset Quote: 25.12 – 25.47
Spot Rate : 0.3500
Average : 0.2404

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-09-30
Maturity Price : 25.00
Evaluated at bid price : 25.12
Bid-YTW : 4.15 %

GWO.PR.P Deemed-Retractible Quote: 24.60 – 24.92
Spot Rate : 0.3200
Average : 0.2306

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.60
Bid-YTW : 5.68 %

Market Action

October 24, 2013

There are so many investors buying US real estate that there is chatter that end-users are being squeezed out of the market:

Home purchases by institutional buyers reached a record high in September and all-cash buyers accounted for almost half of sales as investors responded to rising demand from renters.

Institutional purchases accounted for 14 percent of sales, according to a report today from RealtyTrac. That was the highest share since the real estate data firm began in 2011 to track transactions by that group, which it defines as buyers of 10 or more homes a year. All-cash sales rose to 49 percent from 40 percent in August and 30 percent a year earlier, a sign that rising mortgage rates since May have kept some people out of the market and that smaller investors are stepping up purchases.

“Both investors and traditional buyers are trying to snap up cheap homes before prices go higher, but the investors have the advantage of paying cash and not having to go through a convoluted mortgage process,” said Michael Hanson, a former Federal Reserve economist now working for Bank of America Corp. in New York. “People are being bid out of some markets because of investor demand.”

High-end real-estate in the Hamptons is surging:

Josh Guberman paid $3.4 million in 2011 for a house that had lingered on the market in New York’s Hamptons for almost a year. He knew what it was missing.

Guberman tripled the size of the 3,400-square-foot (316-square-meter) property in Southampton, creating nine bedrooms, a wine cellar and zen garden, before putting it on the market again. In July, a buyer paid $8.8 million, $50,000 more than the asking price.
…
In Suffolk County, home to the Hamptons, 188 residential properties priced at at least $750,000 changed hands within a year of the previous purchase, according to third-quarter data from RealtyTrac. That’s up from 22 such high-end flips at the same time in 2012, the Irvine, California-based firm said.

Treasuries are responding to the wider economy:

Treasury 10-year note yields traded at almost a three-month low as signs of a loss of momentum in global economic growth stoked bets the Federal Reserve will delay slowing its stimulus program until next year.

U.S. government debt was poised for a weekly gain as more Americans than forecast filed applications for jobless benefits last week and the trade deficit was little changed in August as imports and exports stalled. Treasury Inflation Protected Securities headed for the biggest two-month increase in more than a year as a sale of $7 billion of 30-year TIPS drew strong demand in the first auction since lawmakers voted to raise the debt ceiling. The U.S. will sell $96 billion in notes next week.

Liquidity rules in the US are being used as an instrument of financial repression:

The biggest U.S. banks would be required to hold enough easily sold assets to survive a 30-day credit drought under Federal Reserve liquidity rules that exceed international standards adopted earlier this year.

The Fed liquidity coverage ratio proposal approved unanimously today at a meeting in Washington continues the U.S. trend of pushing further than Basel III accords, calling for earlier execution than in the European Union. The U.S. plan, most stringent for banks with more than $250 billion in assets or substantial international reach, seeks implementation by 2017 — two years ahead of the Basel deadline set in January.
…
The banks can use an unlimited amount of cash, Treasuries and central-bank reserves to fulfill the requirement and can also keep 40 percent of it in less liquid assets.

Those other assets can include sovereign debt with a 20 percent risk weight and debt from Fannie Mae and Freddie Mac (FMCC) — subject to a 15 percent haircut. A narrower 15 percent of the liquidity can be in investment-grade corporate debt and publicly traded company stock, with a 50 percent haircut.

Equities as part of a liquidity reserve, even with a 50% haircut? One wonders at the dealmaking process that produced that decision.

David Parkinson of the Globe remarks:

And what happened when the Fed decided at its mid-September policy meeting not to begin tapering after all? Since then, the U.S. 10-year yield has backtracked 35 basis points – and Canada’s 10-year yield has matched it point-for-point.

There’s another ridiculous article on Canadian mortgages:

It was expected that higher interest rates would do the rest of the work. But that’s now in question, after the Bank of Canada pushed out the timeline for raising short-term rates.
…
There are some minor moves that Ottawa is already planning that could have a bit of a cooling impact on the market. Sources say the Department of Finance has circulated a discussion paper on portfolio insurance. It proposes some changes such as limiting portfolio insurance to terms, such as five years, rather than having it be for the full life of the mortgages, and taking away the ability of banks to substitute one mortgage for another within a portfolio. Changes such as these would further reduce Ottawa’s exposure to the housing market.

Of course, selling less mortgage insurance would also reduce Ottawa’s exposure to the housing market. And charging more for it would certainly mitigate and probably reduce Ottawa’s exposure to the housing market. Why isn’t Spend-Every-Penny’s recklessness in fuelling the housing boom ever addressed?

It was a good day for the Canadian preferred share market, with PerpetualDiscounts winning 18bp, FixedResets up 9bp and DeemedRetractibles gaining 6bp. A surprisingly lengthy Performance Highlights table shows no clear patterns. Volume was very high.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.1860 % 2,500.6
FixedFloater 4.25 % 3.52 % 26,899 18.36 1 0.5848 % 3,950.7
Floater 2.71 % 2.96 % 62,860 19.81 5 0.1860 % 2,699.9
OpRet 4.62 % 2.79 % 66,089 0.43 3 -0.0385 % 2,639.8
SplitShare 4.78 % 5.31 % 68,759 3.97 6 0.0389 % 2,938.1
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0385 % 2,413.9
Perpetual-Premium 5.81 % 3.66 % 106,889 0.08 7 0.0341 % 2,287.6
Perpetual-Discount 5.53 % 5.58 % 166,896 14.38 30 0.1816 % 2,354.3
FixedReset 4.98 % 3.68 % 230,541 3.56 85 0.0930 % 2,444.6
Deemed-Retractible 5.13 % 4.36 % 188,247 6.72 43 0.0620 % 2,386.7
Performance Highlights
Issue Index Change Notes
IAG.PR.A Deemed-Retractible -3.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.66
Bid-YTW : 6.35 %
IFC.PR.A FixedReset -1.73 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.86
Bid-YTW : 4.41 %
BNS.PR.Y FixedReset -1.43 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.41
Bid-YTW : 3.96 %
MFC.PR.F FixedReset -1.42 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.14
Bid-YTW : 4.92 %
POW.PR.B Perpetual-Discount 1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-24
Maturity Price : 23.32
Evaluated at bid price : 23.60
Bid-YTW : 5.70 %
CIU.PR.C FixedReset 1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-24
Maturity Price : 20.21
Evaluated at bid price : 20.21
Bid-YTW : 4.13 %
SLF.PR.E Deemed-Retractible 1.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.55
Bid-YTW : 6.30 %
TRI.PR.B Floater 1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-24
Maturity Price : 20.45
Evaluated at bid price : 20.45
Bid-YTW : 2.58 %
BAM.PF.B FixedReset 1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-24
Maturity Price : 22.66
Evaluated at bid price : 23.80
Bid-YTW : 4.59 %
BAM.PF.A FixedReset 1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-24
Maturity Price : 23.14
Evaluated at bid price : 24.93
Bid-YTW : 4.63 %
MFC.PR.B Deemed-Retractible 1.68 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.75
Bid-YTW : 6.38 %
TRP.PR.A FixedReset 2.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-24
Maturity Price : 23.57
Evaluated at bid price : 24.05
Bid-YTW : 3.98 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.E Deemed-Retractible 105,725 RBC crossed 60,000 at 25.18; TD crossed 25,000 at the same price.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-02-24
Maturity Price : 25.00
Evaluated at bid price : 25.19
Bid-YTW : 4.01 %
CM.PR.L FixedReset 87,416 TD sold 10,000 to Nesbitt at 25.49, then crossed 75,000 at 25.50.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-04-30
Maturity Price : 25.00
Evaluated at bid price : 25.48
Bid-YTW : 2.51 %
SLF.PR.F FixedReset 67,457 Scotia crossed 25,000 at 25.57; RBC crossed 25,000 at the same price.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-06-30
Maturity Price : 25.00
Evaluated at bid price : 25.57
Bid-YTW : 3.24 %
CU.PR.D Perpetual-Discount 67,000 Nesbitt crossed blocks of 25,000 and 40,000, both at 23.50.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-24
Maturity Price : 23.18
Evaluated at bid price : 23.50
Bid-YTW : 5.28 %
RY.PR.N FixedReset 64,123 RBC crossed 60,000 at 25.19.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-02-24
Maturity Price : 25.00
Evaluated at bid price : 25.16
Bid-YTW : 2.76 %
GWO.PR.M Deemed-Retractible 63,525 TD crossed 50,000 at 25.45.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.41
Bid-YTW : 5.69 %
There were 58 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
MFC.PR.F FixedReset Quote: 22.14 – 22.78
Spot Rate : 0.6400
Average : 0.4204

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.14
Bid-YTW : 4.92 %

CIU.PR.A Perpetual-Discount Quote: 20.81 – 21.26
Spot Rate : 0.4500
Average : 0.2756

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-24
Maturity Price : 20.81
Evaluated at bid price : 20.81
Bid-YTW : 5.62 %

IAG.PR.A Deemed-Retractible Quote: 21.66 – 22.28
Spot Rate : 0.6200
Average : 0.4724

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.66
Bid-YTW : 6.35 %

TRI.PR.B Floater Quote: 20.45 – 21.09
Spot Rate : 0.6400
Average : 0.4968

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-24
Maturity Price : 20.45
Evaluated at bid price : 20.45
Bid-YTW : 2.58 %

HSB.PR.C Deemed-Retractible Quote: 24.97 – 25.29
Spot Rate : 0.3200
Average : 0.2055

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.97
Bid-YTW : 5.20 %

BNS.PR.L Deemed-Retractible Quote: 25.18 – 25.46
Spot Rate : 0.2800
Average : 0.1796

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.18
Bid-YTW : 4.41 %

Market Action

October 23, 2013

You’ve got to go a long way to find inflation but there is some:

Australia’s consumer prices gained more than economists forecast last quarter, sending the local currency higher as money markets pared bets the central bank will extend its two-year easing of monetary policy this year.

The trimmed mean gauge of core prices rose 0.7 percent from the previous quarter, the Bureau of Statistics said in Sydney today, compared with the median forecast of 25 economists for a 0.6 percent gain. The consumer price index gained 1.2 percent from the previous three months, compared with economists forecast for a 0.8 percent increase.

Reserve Bank of Australia Governor Glenn Stevens reduced borrowing costs eight times — for a total of 2.25 percentage points — from November 2011 to a record low 2.5 percent in August. With annual price rises within its 2 percent to 3 percent target, he’s seeking to boost job-intensive industries such as construction as a mining investment boom crests.

You won’t find much in Canada!

Inflation in Canada has remained low in recent months, reflecting the significant slack in the economy, heightened competition in the retail sector, and other sector-specific factors. With larger and more persistent excess supply in the economy, both total CPI and core inflation are expected to return more gradually to 2 per cent, around the end of 2015.

Although the Bank considers the risks around its projected inflation path to be balanced, the fact that inflation has been persistently below target means that downside risks to inflation assume increasing importance. However, the Bank must also take into consideration the risk of exacerbating already-elevated household imbalances. Weighing these considerations, the Bank judges that the substantial monetary policy stimulus currently in place remains appropriate and therefore has decided to maintain the target for the overnight rate at 1 per cent.

Michael Babad of the Globe emphasizes the ‘household imbalances’ risk:

It’s not that things aren’t necessarily going as expected, it’s the tweaks to the language. In September, for example, the central bank said in its policy announcement that housing had been “slightly stronger than anticipated,”

The central bank’s comments today underscore the angst surrounding Canada’s housing market and record high debt burdens among consumers.

The housing market slumped in the summer of 2012 after Finance Minister Jim Flaherty moved to cool it off with another round of mortgage restrictions.

Of course, Spend-Every-Penny continues to pump up the housing market with reckless provisions of guarantees by the CMHC. These have the ultimate effect of funding mortgage loans much cheaper for the banks than business loans.

The “crowdfunding” idea continues to move ahead slowly:

Entrepreneurs and start-up companies looking for backing will be able to solicit small investments over the Internet from the general public under a new proposal unveiled by U.S. regulators on Wednesday.
…
The crowdfunding rule would let small businesses raise more than $1-million a year by tapping unaccredited investors.

Companies could sell stakes to mom-and-pop investors without registering the securities with the SEC, a move designed to make it cheaper and less cumbersome for struggling startups trying to get their businesses off the ground.

They would still be required to raise the money through regulated broker-dealers such as CircleUp or through crowdfunding portals.

How many entities might register as crowdfunding portals is still unknown, as many are holding off making any decisions until they see how the SEC’s rules shape up.

Under the proposal, crowdfunding portals would be required to provide investors with educational materials and take certain steps to reduce the risk of fraud.

SEC Commissioner Michael S. Piwowar is supportive:

Still, the worthy goals of crowdfunding do not alter the fact that this new mechanism for raising capital presents a number of challenges. The JOBS Act not only requires the Commission to develop a completely new regulatory framework that promotes capital formation for startup companies, but also to implement this innovative framework in a way that protects investors from fraud.

Despite these challenges, crowdfunding presents a number of opportunities. Small businesses – the engines of innovation, economic growth, and job creation – will have the opportunity to access capital from sources that have been previously unavailable. All investors – not just the so-called “accredited investors” – will have the opportunity to invest in entrepreneurs and their ideas at an earlier stage than ever before. The concept of the “wisdom of the crowd,” which has proven to be useful in other areas, will now be unleashed to allocate capital to more productive uses.

Not surprisingly, SEC Commissioner Luis A. Aguilar supports less regulation as long as it is replaced with new regulation:

The use of crowdfunding to reach potentially vulnerable segments of society is a particular concern. Many of the SEC’s enforcement cases arise from “affinity frauds” that exploit the trust and friendship that often exists among members of any ethnic, religious, or other community.[Footnote] Given the possibility that crowdfunding may facilitate affinity fraud by making it easier to identify and target vulnerable groups, I would urge the Commission’s enforcement staff and state securities regulators to take a proactive approach to monitor the crowdfunding space for potential problems. In that regard, I am pleased to note that the North American Securities Administrators Association announced the formation of a task force on Internet fraud investigations shortly after the enactment of the JOBS Act.[Footnote]
…
It is therefore essential that the Commission work to establish this new financing technique in a responsible manner. Because of the importance of small business funding, I support the issuance of this proposal. However, I recognize that crowdfunding may entail substantial risks. I look forward to public comments, particularly from investors and investor advocates, as to how the rules can be improved. I also note that Title III of the JOBS Act expressly requires that, in carrying out the rulemaking required to implement the crowdfunding exemption, the Commission shall consult with the state securities commissions.[Footnote] To that end, I look forward to hearing from state regulators.

SEC Commissioner Kara M. Stein wants to ensure there are lots of jobs created handling the red-tape:

First, there is ambiguity in the statute about how much any single investor should be permitted to invest. There are essentially two tests: one based on the income of the investor, and another based on the net worth of the investor. However, it’s not clear from the statute which test should apply and when. One approach is to separately look at both the investor’s income and net worth, and allow the investor to invest up to the maximum amount allowed by the test permitting the greater investment amount. That is the approach taken in the proposed rule. The proposed rule also excludes from the calculation of net worth an individual’s primary residence. No senior citizen living off of a modest, fixed income should be at risk of losing her home to a crowdfunding venture. But even with primary residences excluded from the calculation, I remain concerned that taking the “greater than” approach may expose seniors or others to risks and losses they cannot afford. Another approach could be to limit the investor to the lower investment amount dictated by either the annual income or net worth tests. The release requests comment on which approach is appropriate, and I look forward to hearing from commenters on all sides of this fundamental issue.

The second area I’d like to highlight is whether we should permit funding portals not based in the United States to register and operate in the United States. The release proposes to allow non-U.S. funding portals to register as long as they meet certain requirements, including the portal’s ability to submit to an on-site examination. Given the complexities currently surrounding compliance and enforcement with respect to non-U.S. entities, I believe we need to hear from all parties on this issue and make certain, at a minimum, that all funding portals are fully within our examination and enforcement jurisdiction. I look forward to hearing commenters’ perspectives on this aspect of the proposal.

Third, there is substantial discussion in the release with respect to an issuer’s responsibility to keep complete and accurate records of its securityholders. I believe this is a critically important issue that could have far-reaching implications for the marketplace. A business simply must be able to track who its owners are. While I understand that requiring a registered transfer agent would increase the costs to an issuer, I would like to hear from commenters about possible third-party, cost-effective solutions to help crowdfunding issuers manage their recordkeeping responsibilities.

SEC Commissioner Daniel M. Gallagher is too shy to reveal his views:

The JOBs Act has provided for many investor protections in Title III, including disclosure requirements and the mandatory use of intermediaries called funding portals, and I believe our proposal is generally careful to not add additional, unnecessary frictions into this marketplace. That said, the proof is in the pudding and I look forward to hearing from commenters on whether the balance of investor protection and innovation we are seeking is appropriate.

And to be sure, there is a lot to comment on. In addition to the substantive rule proposal reflected in the proposed rule text and related release language, there are 295 questions in the release. On the actual rule proposal as well as the questions, I especially want to hear from both the small business entrepreneurs we seek to assist, and those investors who look forward to supporting them.

The full release is over 400 pages long. For those with less patience, the press release states:

Consistent with the JOBS Act, the proposed rules would among other things permit individuals to invest subject to certain thresholds, limit the amount of money a company can raise, require companies to disclose certain information about their offers, and create a regulatory framework for the intermediaries that would facilitate the crowdfunding transactions.

Under the proposed rules:

A company would be able to raise a maximum aggregate amount of $1 million through crowdfunding offerings in a 12-month period.
Investors, over the course of a 12-month period, would be permitted to invest up to:

  • $2,000 or 5 percent of their annual income or net worth, whichever is greater, if both their annual income and net worth are less than $100,000.
  • 10 percent of their annual income or net worth, whichever is greater, if either their annual income or net worth is equal to or more than $100,000. During the 12-month period, these investors would not be able to purchase more than $100,000 of securities through crowdfunding.

Certain companies would not be eligible to use the crowdfunding exemption. Ineligible companies include non-U.S. companies, companies that already are SEC reporting companies, certain investment companies, companies that are disqualified under the proposed disqualification rules, companies that have failed to comply with the annual reporting requirements in the proposed rules, and companies that have no specific business plan or have indicated their business plan is to engage in a merger or acquisition with an unidentified company or companies.

As mandated by Title III of the JOBS Act, securities purchased in a crowdfunding transaction could not be resold for a period of one year. Holders of these securities would not count toward the threshold that requires a company to register with the SEC under Section 12(g) of the Exchange Act.

Enforcing the limits per investor sounds like a job and a half! So fear not! There will be plenty of work for the regulators!

Interestingly, Canada Post no longer wants its debt rated by S&P:

  • We are affirming our ‘AAA’ long-term issuer credit and senior unsecured debt ratings and ‘A-1+’ short-term rating on Canada Post Corp. (CPC).
  • We have revised our assessment of CPC’s role with and link to the Canadian federal government to “critical” and “integral’ from “very important” and “very strong”, respectively, under our government-related entities criteria.
  • Accordingly, we have revised the company’s likelihood of receiving extraordinary government support to “almost certain” from “very high”.
  • We are withdrawing our ratings at CPC’s request.

I’m not quite sure what to make of that, particularly in light of Royal Mail’s IPO success:

Forget Twitter. The hottest stock offering of the year is the Royal Mail.

Shares in Britain’s 500-year-old postal service soared as high as 50 per cent over their initial offering price in the days after being listed this month, proving that a very mature business can still excite investors.

That has triggered a sense of postal envy in Ottawa. This could have been Canada Post’s big payday.
…
If nothing is done to fix its broken business model Canada Post says it will be losing nearly $1-billion a year by 2020.
…
None of the proposed options for fixing the post office are very palatable. They include moving all Canadians to community mailboxes, going to three-day-a week delivery from the current five, franchising more post offices, raising stamp prices and slowing mail delivery, according to a recent Conference Board of Canada report commissioned by the post office.

I don’t understand why the reporter thinks three-day-a-week delivery is unpalatable. What comes in the mail? Magazines and bills. Twice a week is fine for residential service. Maybe more often in high-volume areas, like downtown Toronto.

DBRS updated its report on Veresen, proud issuer of VSN.PR.A and VSN.PR.C:

Veresen continues to pursue its growth and diversification initiatives. In May 2013, the Company filed an application with the Federal Energy Regulatory Commission (FERC) to construct and operate an LNG export facility and related power and pipeline infrastructure at Coos Bay, Oregon (Jordan Cove Energy Project, or the Project). The estimated cost of the Project is $7.5 billion, with an expected in-service date of 2018. DBRS recognizes that the Project is significant and transformative, as it adds growth and diversification to Veresen’s business, and expects that its success will have a positive impact on the Company’s business risk profile. However, the Project is much larger than those undertaken by the Company in the past and entails significant execution risks. The underpinning of firm long-term anchor shipping contracts will be critical to financing the Project in the market, and DBRS expects the Project to be syndicated, due to its relative size and complexity. DBRS will continue to monitor the developments on the Project to assess any impact on the Company’s financial profile.

It was a mixed day for the Canadian preferred share market, with PerpetualDiscounts off 1bp, FixedResets down 6bp and DeemedRetractibles gaining 3bp. Volatility was at normal levels. Volume was high.

PerpetualDiscounts now yield 5.58%, equivalent to 7.25% interest at the standard equivalency factor of 1.3x. Long corporates now yield about 4.8%, so the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) is now about 245bp, unchanged from October 9.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.9281 % 2,495.9
FixedFloater 4.27 % 3.54 % 27,149 18.32 1 0.0450 % 3,927.7
Floater 2.71 % 2.96 % 63,110 19.83 5 0.9281 % 2,694.9
OpRet 4.62 % 2.84 % 64,791 0.59 3 -0.0898 % 2,640.8
SplitShare 4.78 % 5.28 % 67,507 3.98 6 -0.2004 % 2,937.0
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0898 % 2,414.8
Perpetual-Premium 5.81 % 4.45 % 108,272 0.08 7 -0.0057 % 2,286.8
Perpetual-Discount 5.54 % 5.58 % 166,215 14.37 30 -0.0072 % 2,350.0
FixedReset 4.98 % 3.72 % 232,432 3.57 85 -0.0637 % 2,442.3
Deemed-Retractible 5.13 % 4.32 % 189,771 2.22 43 0.0267 % 2,385.2
Performance Highlights
Issue Index Change Notes
TRP.PR.C FixedReset -1.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-23
Maturity Price : 21.61
Evaluated at bid price : 22.03
Bid-YTW : 3.96 %
BAM.PR.X FixedReset -1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-23
Maturity Price : 21.35
Evaluated at bid price : 21.66
Bid-YTW : 4.45 %
IFC.PR.C FixedReset -1.44 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-09-30
Maturity Price : 25.00
Evaluated at bid price : 25.29
Bid-YTW : 3.90 %
BAM.PR.K Floater 1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-23
Maturity Price : 17.82
Evaluated at bid price : 17.82
Bid-YTW : 2.96 %
BAM.PR.C Floater 1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-23
Maturity Price : 17.80
Evaluated at bid price : 17.80
Bid-YTW : 2.97 %
CIU.PR.C FixedReset 2.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-23
Maturity Price : 19.99
Evaluated at bid price : 19.99
Bid-YTW : 4.17 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PR.T FixedReset 128,118 Scotia crossed blocks of 25,000 and 18,600, both at 25.20. RBC crossed 25,000 and 44,400, both at the same price.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-07-31
Maturity Price : 25.00
Evaluated at bid price : 25.16
Bid-YTW : 2.25 %
RY.PR.P FixedReset 79,146 Nesbitt crossed 75,000 at 25.18.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-02-24
Maturity Price : 25.00
Evaluated at bid price : 25.15
Bid-YTW : 2.86 %
GWO.PR.R Deemed-Retractible 57,297 Desjardins crossed 26,400 at 22.40.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.30
Bid-YTW : 6.22 %
GWO.PR.J FixedReset 55,601 Desjardins crossed 50,000 at 25.19.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.16
Bid-YTW : 4.64 %
IAG.PR.G FixedReset 54,505 RBC crossed 44,000 at 25.45.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-06-30
Maturity Price : 25.00
Evaluated at bid price : 25.37
Bid-YTW : 3.97 %
IAG.PR.C FixedReset 51,751 Desjardins crossed 50,000 at 25.22.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.20
Bid-YTW : 4.05 %
There were 46 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
PWF.PR.A Floater Quote: 23.11 – 23.99
Spot Rate : 0.8800
Average : 0.6371

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-23
Maturity Price : 22.83
Evaluated at bid price : 23.11
Bid-YTW : 2.23 %

SLF.PR.G FixedReset Quote: 22.86 – 23.24
Spot Rate : 0.3800
Average : 0.2341

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.86
Bid-YTW : 4.46 %

GWO.PR.N FixedReset Quote: 21.81 – 22.29
Spot Rate : 0.4800
Average : 0.3403

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.81
Bid-YTW : 4.80 %

BAM.PR.G FixedFloater Quote: 22.23 – 22.72
Spot Rate : 0.4900
Average : 0.3566

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-23
Maturity Price : 22.57
Evaluated at bid price : 22.23
Bid-YTW : 3.54 %

FTS.PR.F Perpetual-Discount Quote: 23.03 – 23.41
Spot Rate : 0.3800
Average : 0.2509

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-23
Maturity Price : 22.74
Evaluated at bid price : 23.03
Bid-YTW : 5.39 %

CIU.PR.C FixedReset Quote: 19.99 – 20.49
Spot Rate : 0.5000
Average : 0.3853

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-23
Maturity Price : 19.99
Evaluated at bid price : 19.99
Bid-YTW : 4.17 %

Market Action

October 22, 2013

Buffet is discussing regulation again following the latest round of regulatory extortion:

Warren Buffett, the billionaire chairman of Berkshire Hathaway Inc. (BRK/A), said JPMorgan Chase & Co. (JPM) Chief Executive Officer Jamie Dimon has little room to bargain as regulators probe the sale of faulty mortgage bonds.

“If you’re a financial institution and you’re threatened with criminal prosecution, you have no ability to negotiate,” Buffett told Bloomberg Television’s Betty Liu in an interview today. “Basically, you’ve got to be like a wolf that bares its throat, you know, when it gets to the end. You cannot win.”

Dimon reached a tentative $13 billion settlement to resolve civil disputes between JPMorgan and the U.S. government. The bank won’t be released from criminal liabilities, according to a person familiar with the talks who asked not to be identified because they were private. Some of the practices under the probe relate to Bear Stearns Cos. and Washington Mutual, which JPMorgan bought in 2008 as the housing bubble burst.

The delayed September jobs number was anemic:

Employers in the U.S. added fewer workers to payrolls than projected in September, indicating the world’s largest economy had little momentum leading up to the federal government shutdown.

The addition of 148,000 workers followed a revised 193,000 gain in August that was larger than initially estimated, Labor Department figures showed today in Washington. The median forecast of 93 economists surveyed by Bloomberg called for a 180,000 advance. Unemployment fell to 7.2 percent, the lowest level since November 2008.

Stocks and Treasuries climbed as the report supported expectations that the Federal Reserve won’t hurry to reduce the monthly bond purchases aimed at spurring growth and employment. Progress in the labor market depends on how quickly the economy can bounce back from the loss of business and confidence caused by the budget battles in Washington.

Mark Zelmer of OSFI gave a speech titled Simplicity and Supervision: Rules are not enough in New York today. Not very interesting; there may be some nuances about modelling that will be of interest to specialists. It will be remembered that OSFI has no expertise in critiquing models whatsoever. Tim Kiladze of the Globe claims it’s a regulatory scuffle:

Canada’s top banking watchdog is pushing back against a growing chorus of global regulators who want to simplify the way that banks calculate their capital cushions.
…
Now the Basel Committee is considering proposals to monitor simple metrics such as non-performing assets to total assets, historical profit volatility and the leverage ratio. But while OSFI, the top Canadian regulator, agrees that it can be hard to compare risk models across banks, it is strongly urging its peers not to undo a good chunk of the past five years of work. “Simplifying the rule book will not change the game,” deputy superintendent Mark Zelmer said at a conference Tuesday.
…
The regulator may have been keeping mum on the issue because Canada’s banks capital levels arguably don’t look as strong under the leverage ratio. Now that other major countries, like the United States, are floating ideas to surpass the Basel III minimums under the leverage ratio, OSFI is speaking up in favour of its preferred method of regulation

There is muttering about a possible Global Housing Bubble Redux:

In Germany, the Bundesbank has warned about rising prices that are “difficult to justify based on fundamental factors,” like demographics or economic expansion. The central bank observed that apartment prices in key urban centres have jumped by more than 25 per cent in the past three years – and a whopping 80 per cent in Berlin – which could spark “fears of a broad-based property price boom.”
…
In China, concerted government efforts to take the air out of the bubble have largely been ineffective, as witnessed by the 9.1 per cent rise in new home prices, the biggest jump in three years. In the largest cities, the increases were in the double digits.

In Britain, which is still digging its way out of recession, average prices climbed the most in three years, as mortgage lending reached levels not seen in five years. But there was Jon Cunliffe, newly appointed deputy governor of the Bank of England, telling a parliamentary committee not to worry that the government’s popular Help to Buy mortgage loan scheme might inflate a bubble.

The problem is that so many people consider housing investment to be the sure ticket to riches – and stock market investment to be the road to ruin. Here in Canada, the feds pour fuel on the fire with there reckless expansion of CHMC insurance.

Part of the solution is to make it easier to go public, with the object of allowing people to buy pieces of local business that they recognize; that means decreasing regulation.

Of course, in some cases it’s a simple case of supply and demand:

The number of new homes sold in September in the Greater Toronto Area was up four per cent from the same month last year, but 2013 is shaping up to be the weakest year in a decade, according to industry figures.

In the first nine months of this year, there were 19,327 new homes sold in the GTA – 44 per cent below the 10-year average, according RealNet Canada figures released by the Building Industry and Land Development Association.

BILD attributes the weak sales activity to a significant reduction in the supply of land for building, which has pushed up prices.

And I don’t see much hope any time soon for decreased regulation, as extra-judicial punishments increase in popularity:

The yakuza, Japan’s organized-crime syndicates that have reaped billions from activities ranging from extortion to human trafficking, are finding their ranks decimated by authorities employing methods similar to those used to jail Al Capone: going after their money.

Japan’s Financial Services Agency delivered the latest blow, last month ordering Mizuho Financial Group Inc. (8411) to improve compliance and then demanding that top executives report by Oct. 28 what they knew and when about a consumer-credit affiliate found making loans to crime groups.
…
While the gangs themselves aren’t illegal in Japan, violating the exclusion ordinances — which also require customers seeking financial and other services to attest to non-association with a criminal enterprise — could come with a fine of 500,000 yen ($5,080) or a year in jail.

It was a good day for the Canadian preferred share market, with PerpetualDiscounts up 21bp, FixedResets gaining 7bp and DeemedRetractibles winning 24bp. A fairly lengthy performance highlights table is dominated by winners. Volume was above average.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.7449 % 2,473.0
FixedFloater 4.28 % 3.55 % 26,818 18.32 1 0.2708 % 3,926.0
Floater 2.73 % 2.97 % 63,787 19.79 5 0.7449 % 2,670.1
OpRet 4.62 % 2.34 % 64,854 0.43 3 0.0000 % 2,643.2
SplitShare 4.77 % 5.25 % 66,127 3.98 6 0.0206 % 2,942.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0000 % 2,417.0
Perpetual-Premium 5.81 % 3.76 % 108,652 0.08 7 0.1594 % 2,286.9
Perpetual-Discount 5.54 % 5.58 % 167,442 14.36 30 0.2074 % 2,350.2
FixedReset 4.98 % 3.66 % 231,275 3.39 85 0.0697 % 2,443.9
Deemed-Retractible 5.14 % 4.36 % 188,983 6.70 43 0.2350 % 2,384.6
Performance Highlights
Issue Index Change Notes
FTS.PR.H FixedReset -1.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-22
Maturity Price : 20.86
Evaluated at bid price : 20.86
Bid-YTW : 4.11 %
GWO.PR.N FixedReset -1.48 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.90
Bid-YTW : 4.75 %
MFC.PR.B Deemed-Retractible 1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.50
Bid-YTW : 6.51 %
PWF.PR.K Perpetual-Discount 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-22
Maturity Price : 22.03
Evaluated at bid price : 22.39
Bid-YTW : 5.53 %
RY.PR.F Deemed-Retractible 1.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.15
Bid-YTW : 4.33 %
TRI.PR.B Floater 1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-22
Maturity Price : 20.05
Evaluated at bid price : 20.05
Bid-YTW : 2.63 %
SLF.PR.E Deemed-Retractible 1.38 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.30
Bid-YTW : 6.44 %
MFC.PR.F FixedReset 1.58 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.49
Bid-YTW : 4.74 %
CIU.PR.C FixedReset 1.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-22
Maturity Price : 19.45
Evaluated at bid price : 19.45
Bid-YTW : 4.29 %
Volume Highlights
Issue Index Shares
Traded
Notes
PWF.PR.L Perpetual-Discount 90,279 Desjardins bought blocks of 17,200 and 54,400 from National, both at 22.65.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-22
Maturity Price : 22.39
Evaluated at bid price : 22.68
Bid-YTW : 5.63 %
ENB.PR.T FixedReset 70,418 RBC crossed 50,000 at 23.40.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-22
Maturity Price : 22.43
Evaluated at bid price : 23.33
Bid-YTW : 4.55 %
PWF.PR.O Perpetual-Premium 67,469 Scotia crossed 60,000 at 25.35.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.32
Bid-YTW : 5.51 %
MFC.PR.E FixedReset 64,475 Nesbitt crossed two blocks of 25,000 each, both at 25.60.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-09-19
Maturity Price : 25.00
Evaluated at bid price : 25.60
Bid-YTW : 3.50 %
TD.PR.R Deemed-Retractible 55,033 Nesbitt crossed two blocks of 25,000 each, both at 26.05.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-11-21
Maturity Price : 26.00
Evaluated at bid price : 26.08
Bid-YTW : 0.02 %
SLF.PR.D Deemed-Retractible 44,206 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.95
Bid-YTW : 6.58 %
There were 43 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
FTS.PR.H FixedReset Quote: 20.86 – 21.30
Spot Rate : 0.4400
Average : 0.2844

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-22
Maturity Price : 20.86
Evaluated at bid price : 20.86
Bid-YTW : 4.11 %

TRP.PR.B FixedReset Quote: 20.13 – 20.51
Spot Rate : 0.3800
Average : 0.2459

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-22
Maturity Price : 20.13
Evaluated at bid price : 20.13
Bid-YTW : 4.01 %

IAG.PR.E Deemed-Retractible Quote: 25.38 – 25.74
Spot Rate : 0.3600
Average : 0.2751

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.38
Bid-YTW : 5.90 %

CIU.PR.C FixedReset Quote: 19.45 – 19.79
Spot Rate : 0.3400
Average : 0.2595

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-22
Maturity Price : 19.45
Evaluated at bid price : 19.45
Bid-YTW : 4.29 %

BMO.PR.K Deemed-Retractible Quote: 25.98 – 26.20
Spot Rate : 0.2200
Average : 0.1516

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-11-25
Maturity Price : 25.50
Evaluated at bid price : 25.98
Bid-YTW : 4.17 %

RY.PR.B Deemed-Retractible Quote: 25.23 – 25.42
Spot Rate : 0.1900
Average : 0.1264

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2015-08-24
Maturity Price : 25.00
Evaluated at bid price : 25.23
Bid-YTW : 3.97 %

Market Action

October 21, 2013

There’s an interesting battle shaping up for control of the Republican party:

A battle for control of the Republican Party has erupted as an emboldened Tea Party moved to oust senators who voted to reopen the government while business groups mobilized to defeat allies of the small-government movement.

“We are going to get engaged,” said Scott Reed, senior political strategist for the U.S. Chamber of Commerce. “The need is now more than ever to elect people who understand the free market and not silliness.” The chamber spent $35.7 million on federal elections in 2012, according to the Center for Responsive Politics, a Washington-based group that tracks campaign spending.

I remain a conservative, but I ended my involvement with the Conservative party when it became apparent that it was no longer the party of fiscal restraint and realism, but had morphed into a Junior Republican party.

Brian Milner of the Globe reminds us that, for all the talk of rising interest rates, the economy really needs stimulus rather than restraint:

The latest Canadian inflation figures inspire descriptions like benign, subdued, tepid and tame. Consumer price inflation remained steady in September at an annual rate of 1.1 per cent. The core price index, which excludes more volatile food and energy costs, also didn’t budge from the previous level of 1.3 per cent. With inflation essentially a non-factor, the conventional wisdom is that the Bank of Canada can afford to leave monetary policy untouched.
…
Right now, although prices have been rising slightly in most categories (led by booze and tobacco), the inflation rate sits perilously close to the bottom end of the bank’s target range of 1 to 3 per cent, well below the mid-point of 2 per cent the bank and its counterparts in other developed countries regard as ideal. Now, 1 per cent would be welcomed in deflation-ravaged Japan, which hasn’t posted a level that high since 2008. But it ought to be setting off warning bells here.

Isn’t market timing wonderful?

Hedge-fund manager John Paulson’s PFR Gold Fund fell 16 percent in September after bullion and related stocks declined, according to a report to investors obtained by Bloomberg News.
Last month’s loss brings the 2013 decline in the $350 million fund, which invests in gold stocks and derivatives, to 62 percent, according to the report. Bullion producers fell 9.4 percent and the metal dropped 5 percent in September after a Federal Reserve policy maker said a small reduction in bond purchases may occur in October and the threat of a U.S. attack on Syria eased.

Paulson, 57, is known for making $15 billion for his investors in 2007 by betting against subprime mortgages before the housing collapse.

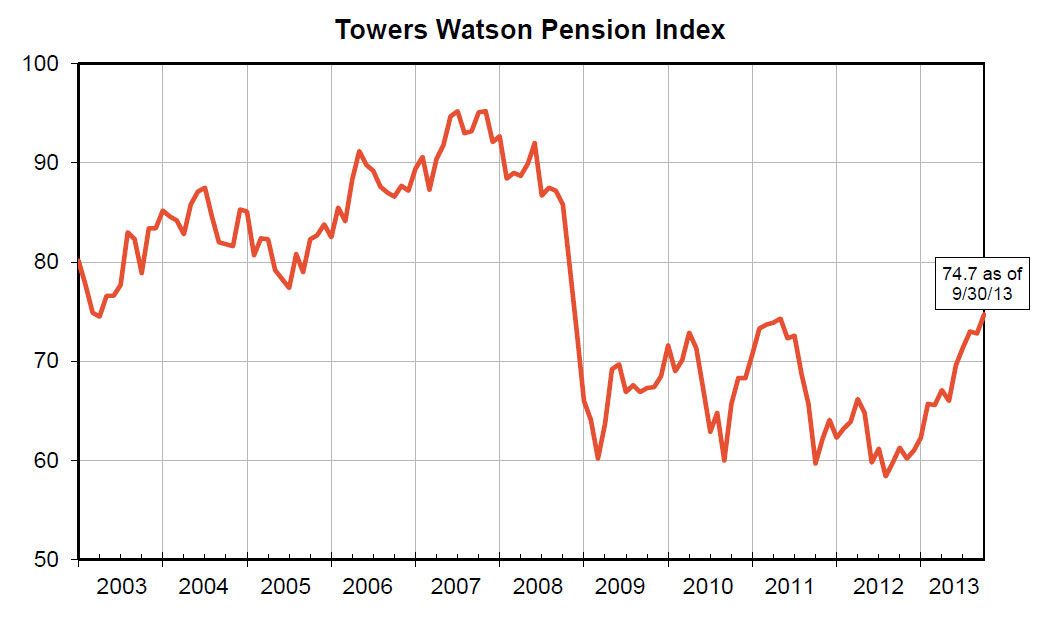
Towers Perrin reports:

A strong equity market drove September financial results. The benchmark asset portfolio earned almost 3% for the month, driving the Towers Watson Pension Index up 2.6% to 74.7. With this increase the index is now up almost 20% for the year.


Click for Big

It was a slightly positive day for the Canadian preferred share market, with PerpetualDiscounts gaining 6bp, FixedResets up 7bp and DeemedRetractibles flat. The Performance Highlights Table is surprisingly lengthy considering the modest overall changes and is dominated by winners. Volume was above average; block trading data is not available.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.5804 % 2,454.7
FixedFloater 4.29 % 3.56 % 27,926 18.30 1 0.2715 % 3,915.4
Floater 2.75 % 3.00 % 63,507 19.73 5 0.5804 % 2,650.4
OpRet 4.62 % 2.33 % 65,123 0.44 3 0.0642 % 2,643.2
SplitShare 4.77 % 5.25 % 63,297 3.98 6 -0.0718 % 2,942.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0642 % 2,417.0
Perpetual-Premium 5.82 % 4.96 % 108,543 0.08 7 -0.0797 % 2,283.3
Perpetual-Discount 5.55 % 5.59 % 166,612 14.37 30 0.0623 % 2,345.3
FixedReset 4.97 % 3.70 % 232,582 3.57 85 0.0695 % 2,442.2
Deemed-Retractible 5.14 % 4.44 % 188,641 6.84 43 0.0000 % 2,379.0
Performance Highlights
Issue Index Change Notes
ENB.PR.P FixedReset -1.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-21
Maturity Price : 22.33
Evaluated at bid price : 23.12
Bid-YTW : 4.61 %
CIU.PR.C FixedReset -1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-21
Maturity Price : 19.10
Evaluated at bid price : 19.10
Bid-YTW : 4.37 %
ENB.PR.Y FixedReset 1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-21
Maturity Price : 22.27
Evaluated at bid price : 23.05
Bid-YTW : 4.52 %
BAM.PR.C Floater 1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-21
Maturity Price : 17.55
Evaluated at bid price : 17.55
Bid-YTW : 3.01 %
ENB.PR.N FixedReset 1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-21
Maturity Price : 22.92
Evaluated at bid price : 24.35
Bid-YTW : 4.45 %
BMO.PR.Q FixedReset 1.19 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.58
Bid-YTW : 3.67 %
BAM.PR.M Perpetual-Discount 1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-21
Maturity Price : 19.95
Evaluated at bid price : 19.95
Bid-YTW : 6.02 %
BAM.PF.C Perpetual-Discount 1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-21
Maturity Price : 19.92
Evaluated at bid price : 19.92
Bid-YTW : 6.16 %
BNS.PR.Y FixedReset 1.46 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.69
Bid-YTW : 3.79 %
TRP.PR.C FixedReset 1.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-21
Maturity Price : 22.09
Evaluated at bid price : 22.36
Bid-YTW : 3.91 %
IFC.PR.A FixedReset 1.62 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.49
Bid-YTW : 4.12 %
Volume Highlights
Issue Index Shares
Traded
Notes
CIU.PR.B FixedReset 169,394 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-06-01
Maturity Price : 25.00
Evaluated at bid price : 25.71
Bid-YTW : 3.56 %
TD.PR.S FixedReset 157,774 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.52
Bid-YTW : 3.67 %
BMO.PR.M FixedReset 69,493 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.62
Bid-YTW : 3.74 %
BNS.PR.P FixedReset 64,837 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-04-25
Maturity Price : 25.00
Evaluated at bid price : 24.64
Bid-YTW : 3.69 %
CU.PR.C FixedReset 46,756 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-06-01
Maturity Price : 25.00
Evaluated at bid price : 25.32
Bid-YTW : 3.80 %
BMO.PR.R FixedReset 33,910 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-08-25
Maturity Price : 25.00
Evaluated at bid price : 25.11
Bid-YTW : 2.49 %
There were 42 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
TRI.PR.B Floater Quote: 19.80 – 20.23
Spot Rate : 0.4300
Average : 0.3135

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-21
Maturity Price : 19.80
Evaluated at bid price : 19.80
Bid-YTW : 2.66 %

TD.PR.R Deemed-Retractible Quote: 26.06 – 26.33
Spot Rate : 0.2700
Average : 0.1539

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-11-20
Maturity Price : 26.00
Evaluated at bid price : 26.06
Bid-YTW : 0.78 %

IAG.PR.G FixedReset Quote: 25.55 – 25.90
Spot Rate : 0.3500
Average : 0.2363

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-06-30
Maturity Price : 25.00
Evaluated at bid price : 25.55
Bid-YTW : 3.75 %

MFC.PR.K FixedReset Quote: 23.45 – 23.90
Spot Rate : 0.4500
Average : 0.3517

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.45
Bid-YTW : 4.72 %

CU.PR.F Perpetual-Discount Quote: 21.26 – 21.59
Spot Rate : 0.3300
Average : 0.2363

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-21
Maturity Price : 21.26
Evaluated at bid price : 21.26
Bid-YTW : 5.38 %

ENB.PR.F FixedReset Quote: 23.37 – 23.70
Spot Rate : 0.3300
Average : 0.2374

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-21
Maturity Price : 22.50
Evaluated at bid price : 23.37
Bid-YTW : 4.57 %

Market Action

October 18, 2013

The New York Times touts an online personal finance video series:

After all, there are few entirely conflict-free places where investors can educate themselves on the topic, and there’s little to no money-related guidance offered within the public school system, which is where the financial groundwork should really be laid.

Joshua Rauh, a finance professor at the Stanford Graduate School of Business, is acutely aware of that. And it’s why he felt compelled to open his graduate-level course on the finance of retirement and pensions to the masses. “My goal is to try to empower people to make better decisions about their finances with an eye toward retirement and for retirees who are thinking about managing their money,” Professor Rauh said, “whether it is buying an annuity or having a spending rule.”

The course, which is offered free online, begins on Monday. I sat for nearly half of his online video lectures — on topics like “saving for retirement” and “making smart decisions as a stock market investor” — earlier this week. Watching remotely means you won’t be party to the discussion that will emerge from the Socratic method Professor Rauh uses in his traditional classroom on campus. And there are already 13,000 students, so it’s hard to expect any personal attention.

DBRS confirmed Advantaged Preferred Share Trust at STA-2 (middle):

Since October 2012, the performance of the Portfolio has been fairly stable. The weighted-average yield of the Portfolio is approximately 5.18%, as of September 30, 2013. The Trust’s current net income (including a regular additional payment under the forward agreement to offset operating expenses) covers the full distribution paid out to Unitholders. As a result, the rating of STA-2 (middle) on the Units has been confirmed. The main constraints to the rating are the interest rate risk of the Portfolio and the potential for capital losses and reductions in income resulting from underlying securities being called for redemption by their respective issuers.

DBRS confirmed TDS.PR.C at Pfd-2:

On October 18, 2012, DBRS upgraded the ratings on the Class C Preferred Shares to Pfd-2 from Pfd-2 (low), due to a steady increase in downside protection in the months leading up to the rating action, as well as a greatly improved dividend coverage ratio. Since then, performance has been generally positive, with the net asset value (NAV) of the Company fluctuating around $30.00 before increasing to $33.51 as of October 10, 2013. Downside protection available to holders of the Class C Preferred Shares increased to 70.2% as of October 2013, compared with 66.1% in October 2012. As a result, the rating of the Class C Preferred Shares has been confirmed at Pfd-2.

It was a mixed day for the Canadian preferred share market, with PerpetualDiscounts gaining 6bp, FixedResets off 7bp and DeemedRetractibles up 8bp. A surprisingly lengthy performance highlights table was dominated by FixedResets, both winners and losers. Volume was enormous.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.3470 % 2,440.5
FixedFloater 4.30 % 3.57 % 28,862 18.28 1 0.0000 % 3,904.8
Floater 2.77 % 3.02 % 64,031 19.68 5 -0.3470 % 2,635.1
OpRet 4.62 % 2.72 % 64,291 0.60 3 0.0257 % 2,641.5
SplitShare 4.77 % 5.23 % 63,249 3.99 6 0.2071 % 2,944.4
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0257 % 2,415.4
Perpetual-Premium 5.82 % -0.07 % 108,543 0.08 7 0.2167 % 2,285.1
Perpetual-Discount 5.56 % 5.57 % 168,410 14.47 30 0.0624 % 2,343.8
FixedReset 4.98 % 3.78 % 235,758 3.40 85 -0.0656 % 2,440.5
Deemed-Retractible 5.14 % 4.40 % 187,794 6.85 43 0.0822 % 2,379.0
Performance Highlights
Issue Index Change Notes
ENB.PR.D FixedReset -1.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-18
Maturity Price : 22.44
Evaluated at bid price : 23.22
Bid-YTW : 4.53 %
BNS.PR.Y FixedReset -1.35 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.35
Bid-YTW : 4.02 %
TRP.PR.A FixedReset -1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-18
Maturity Price : 22.97
Evaluated at bid price : 23.47
Bid-YTW : 4.11 %
BAM.PR.K Floater -1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-18
Maturity Price : 17.33
Evaluated at bid price : 17.33
Bid-YTW : 3.05 %
BAM.PR.B Floater -1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-18
Maturity Price : 17.48
Evaluated at bid price : 17.48
Bid-YTW : 3.02 %
MFC.PR.F FixedReset -1.21 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.02
Bid-YTW : 5.00 %
HSB.PR.D Deemed-Retractible 1.00 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.25
Bid-YTW : 4.38 %
PWF.PR.A Floater 1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-18
Maturity Price : 22.50
Evaluated at bid price : 22.76
Bid-YTW : 2.30 %
IFC.PR.C FixedReset 1.02 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-09-30
Maturity Price : 25.00
Evaluated at bid price : 25.71
Bid-YTW : 3.28 %
SLF.PR.G FixedReset 1.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.15
Bid-YTW : 4.35 %
FTS.PR.H FixedReset 1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-18
Maturity Price : 21.20
Evaluated at bid price : 21.20
Bid-YTW : 4.08 %
CU.PR.C FixedReset 1.39 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-06-01
Maturity Price : 25.00
Evaluated at bid price : 25.48
Bid-YTW : 3.60 %
BAM.PR.X FixedReset 1.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-18
Maturity Price : 21.67
Evaluated at bid price : 21.96
Bid-YTW : 4.42 %
Volume Highlights
Issue Index Shares
Traded
Notes
CIU.PR.B FixedReset 193,575 Deleted from TXPR.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-06-01
Maturity Price : 25.00
Evaluated at bid price : 25.71
Bid-YTW : 3.52 %
TD.PR.S FixedReset 168,183 I assume the index weight changed, due to partial conversion to TD.PR.T, which has been added to TXPR.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.52
Bid-YTW : 3.69 %
W.PR.H Perpetual-Discount 166,758 Added to TXPR.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-18
Maturity Price : 24.19
Evaluated at bid price : 24.45
Bid-YTW : 5.65 %
BMO.PR.R FixedReset 147,381 Added to TXPR.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-08-25
Maturity Price : 25.00
Evaluated at bid price : 25.10
Bid-YTW : 2.48 %
FTS.PR.K FixedReset 130,701 Added to TXPR.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-18
Maturity Price : 22.99
Evaluated at bid price : 24.58
Bid-YTW : 3.96 %
PWF.PR.L Perpetual-Discount 124,494 National sold 10,000 to TD at 22.70, then crossed 12,300 at 22.65. Anonymous crossed 10,000 at 22.66, then sold 45,000 to Desjardins at the same price and 15,000 to National at the same price again.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-18
Maturity Price : 22.37
Evaluated at bid price : 22.66
Bid-YTW : 5.64 %
BMO.PR.M FixedReset 122,454 TD crossed blocks of 44,800 and 20,000 at 24.58. Nesbitt crossed 50,000 at 24.57.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.57
Bid-YTW : 3.78 %
CM.PR.M FixedReset 101,430 RBC crossed two blocks of 50,000 each, both at 25.82.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-07-31
Maturity Price : 25.00
Evaluated at bid price : 25.70
Bid-YTW : 2.63 %
There were 77 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
ENB.PR.Y FixedReset Quote: 22.80 – 23.14
Spot Rate : 0.3400
Average : 0.1960

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-18
Maturity Price : 22.13
Evaluated at bid price : 22.80
Bid-YTW : 4.61 %

BAM.PR.C Floater Quote: 17.35 – 17.75
Spot Rate : 0.4000
Average : 0.2707

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-18
Maturity Price : 17.35
Evaluated at bid price : 17.35
Bid-YTW : 3.04 %

BNA.PR.C SplitShare Quote: 24.16 – 24.46
Spot Rate : 0.3000
Average : 0.1902

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2019-01-10
Maturity Price : 25.00
Evaluated at bid price : 24.16
Bid-YTW : 5.23 %

BNS.PR.Y FixedReset Quote: 23.35 – 23.62
Spot Rate : 0.2700
Average : 0.1673

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.35
Bid-YTW : 4.02 %

CU.PR.G Perpetual-Discount Quote: 21.10 – 21.49
Spot Rate : 0.3900
Average : 0.2927

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-18
Maturity Price : 21.10
Evaluated at bid price : 21.10
Bid-YTW : 5.41 %

CGI.PR.D SplitShare Quote: 23.80 – 24.07
Spot Rate : 0.2700
Average : 0.1899

YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2023-06-14
Maturity Price : 25.00
Evaluated at bid price : 23.80
Bid-YTW : 4.43 %

Market Action

October 17, 2013

It appears that some people are ecstatic that Armageddon has been delayed by three months:

U.S. stocks rose, sending the Standard & Poor’s 500 Index to a record, as speculation grew that the Federal Reserve will maintain the pace of stimulus after Congress ended the budget standoff.
…
The S&P 500 rose 0.7 percent to 1,733.15 at 4 p.m. in New York, surpassing the previous record of 1,725.52 from Sept. 18. The Dow Jones Industrial Average fell 2.18 points to 15,371.65, held down by IBM and Goldman Sachs. About 6.6 billion shares changed hands on U.S. exchanges, 12 percent above the three-month average.

“The taper seems a little bit further out, certainly than anybody expected eight weeks ago and maybe even just a couple of weeks ago,” Walter Todd, chief investment officer at Greenwood Capital Inc., said in a phone interview from Greenwood, South Carolina. He helps manage $950 million. “It keeps a lid on rates and provides more liquidity for risk assets like stocks. People are back to focusing on the individual company dynamics that occur during earnings season.”

The S&P 500 gained 2.4 percent during the 16-day government closure that ended yesterday after President Barack Obama signed a bill to fund the government through Jan. 15 and extend the borrowing authority through Feb. 7.

My favourite Fed President, Richard Fisher, has some interesting views on US housing:

A top Federal Reserve official said on Thursday he is seeing fresh signs of a U.S. “housing bubble” and warned about the central bank’s ongoing purchases of mortgage-based bonds.

“I’m beginning to see signs not just in my district but across the country that we are entering, once again, a housing bubble,” Dallas Fed President Richard Fisher told reporters after a speech in New York. “So that leads me … to be very cautious about our mortgage-backed securities purchase program.”
…
Fisher, a vocal hawk on monetary policy, repeated he would not support a reduction in the quantitative easing (QE) program at a Fed meeting later this month in large part because of the fiscal “mess” in Washington.

But citing rising year-on-year house prices in Texas cities, and elsewhere in the country, he warned that the central bank’s hyper-accommodative policies could be inflating dangerous asset price bubbles.

It was a fine day for the Canadian preferred share market, with PerpetualDiscounts winning 42bp, FixedResets gaining 5bp and DeemedRetractibles up 20bp. The Performance Highlights table is heavily skewed towards the two better classes. Volume was high, with the Volume Highlights table comprised entirely of FixedResets.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.1896 % 2,449.0
FixedFloater 4.30 % 3.57 % 27,863 18.29 1 0.4089 % 3,904.8
Floater 2.76 % 2.98 % 64,182 19.78 5 0.1896 % 2,644.3
OpRet 4.62 % 2.59 % 65,012 0.61 3 -0.0642 % 2,640.8
SplitShare 4.78 % 5.28 % 61,734 3.99 6 -0.3308 % 2,938.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0642 % 2,414.8
Perpetual-Premium 5.83 % 4.16 % 108,489 0.08 7 -0.0228 % 2,280.2
Perpetual-Discount 5.56 % 5.59 % 158,504 14.46 30 0.4166 % 2,342.4
FixedReset 4.97 % 3.79 % 233,547 3.41 85 0.0460 % 2,442.1
Deemed-Retractible 5.14 % 4.45 % 190,418 6.85 43 0.1963 % 2,377.0
Performance Highlights
Issue Index Change Notes
IAG.PR.E Deemed-Retractible -1.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.37
Bid-YTW : 5.90 %
FTS.PR.J Perpetual-Discount 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-17
Maturity Price : 22.33
Evaluated at bid price : 22.65
Bid-YTW : 5.30 %
CIU.PR.C FixedReset 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-17
Maturity Price : 19.55
Evaluated at bid price : 19.55
Bid-YTW : 4.31 %
SLF.PR.G FixedReset 1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.90
Bid-YTW : 4.47 %
CU.PR.F Perpetual-Discount 1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-17
Maturity Price : 21.35
Evaluated at bid price : 21.35
Bid-YTW : 5.35 %
TRP.PR.A FixedReset 1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-17
Maturity Price : 23.27
Evaluated at bid price : 23.77
Bid-YTW : 4.06 %
SLF.PR.B Deemed-Retractible 1.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.05
Bid-YTW : 6.35 %
CIU.PR.A Perpetual-Discount 1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-17
Maturity Price : 20.65
Evaluated at bid price : 20.65
Bid-YTW : 5.66 %
SLF.PR.A Deemed-Retractible 1.30 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.85
Bid-YTW : 6.40 %
BAM.PF.D Perpetual-Discount 1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-17
Maturity Price : 20.26
Evaluated at bid price : 20.26
Bid-YTW : 6.11 %
BAM.PR.N Perpetual-Discount 1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-17
Maturity Price : 19.80
Evaluated at bid price : 19.80
Bid-YTW : 6.06 %
Volume Highlights
Issue Index Shares
Traded
Notes
TRP.PR.D FixedReset 107,851 Scotia crossed 100,000 at 24.87.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-17
Maturity Price : 23.03
Evaluated at bid price : 24.71
Bid-YTW : 4.14 %
TD.PR.S FixedReset 106,062 Scotia crossed 37,300 at 24.50; Nesbitt crossed 63,800 at 24.50.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.47
Bid-YTW : 3.71 %
BMO.PR.M FixedReset 93,020 Nesbitt crossed blocks of 25,000 and 50,000, both at 24.58. According to TMXMoney, anyway. The Financial Post report is difficult to make out.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.55
Bid-YTW : 3.79 %
MFC.PR.J FixedReset 73,976 Scotia crossed 70,500 at 25.17.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-03-19
Maturity Price : 25.00
Evaluated at bid price : 25.03
Bid-YTW : 4.07 %
IAG.PR.G FixedReset 63,749 Scotia crossed 56,500 at 25.60.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-06-30
Maturity Price : 25.00
Evaluated at bid price : 25.51
Bid-YTW : 3.79 %
BAM.PF.A FixedReset 63,545 Scotia crossed 50,000 at 24.33.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-17
Maturity Price : 22.89
Evaluated at bid price : 24.25
Bid-YTW : 4.82 %
There were 48 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BNA.PR.E SplitShare Quote: 24.47 – 24.87
Spot Rate : 0.4000
Average : 0.2807

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2017-12-10
Maturity Price : 25.00
Evaluated at bid price : 24.47
Bid-YTW : 5.61 %

GCS.PR.A SplitShare Quote: 24.73 – 25.00
Spot Rate : 0.2700
Average : 0.1632

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2019-07-31
Maturity Price : 25.00
Evaluated at bid price : 24.73
Bid-YTW : 4.24 %

MFC.PR.K FixedReset Quote: 23.45 – 23.85
Spot Rate : 0.4000
Average : 0.3032

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.45
Bid-YTW : 4.73 %

BAM.PR.M Perpetual-Discount Quote: 19.65 – 19.92
Spot Rate : 0.2700
Average : 0.1842

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-17
Maturity Price : 19.65
Evaluated at bid price : 19.65
Bid-YTW : 6.11 %

TRP.PR.C FixedReset Quote: 22.01 – 22.34
Spot Rate : 0.3300
Average : 0.2478

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-17
Maturity Price : 21.60
Evaluated at bid price : 22.01
Bid-YTW : 4.00 %

W.PR.J Perpetual-Discount Quote: 24.71 – 24.98
Spot Rate : 0.2700
Average : 0.1894

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-17
Maturity Price : 24.47
Evaluated at bid price : 24.71
Bid-YTW : 5.70 %

Market Action

October 16, 2013

The GSE debate is resurfacing, just like all the other Hallowe’en zombies:

President Barack Obama and lawmakers from both parties have called for the two mortgage-finance companies to be replaced by a new U.S. housing system. While the official position hasn’t changed, a bipartisan group of U.S. senators writing legislation is grappling with how to ensure that changes to Fannie Mae and Freddie Mac don’t disrupt the recovering housing market.

Some Democrats said they are leery of engineering a switch that would liquidate the government-sponsored enterprises, or GSEs, leaving it to private entities to risk their own capital on home loans.
…
Since they nearly collapsed during the 2008 credit crisis, the two companies have drawn $187.5 billion from taxpayers and have been considered too politically toxic to be preserved. While the U.S. holds controlling stakes, the outcome will affect private investors including hedge funds Perry Capital and Paulson and Co., which have accumulated preferred shares and have spent months lobbying for Fannie Mae and Freddie Mac to be recapitalized.
…
Driving investor hopes and the change in tone are the record profits Fannie Mae and Freddie Mac (FMCC) have been posting as the housing market rebounds from the worst recession since the 1930s. The companies are required to send almost all of those profits back to the Treasury. So far, they’ve remitted about $146 billion, which under terms of the bailout counts as a return on the U.S. investment rather than a repayment.

Shareholders including Perry Capital and Fairholme Funds Inc. have sued the U.S., charging that Treasury is expropriating the value of its investors’ preferred shares in Fannie Mae and Freddie Mac. Those suits are adding urgency to lawmakers’ efforts.

James Hamilton of Econbrowser commented in August:

I have not seen the details of the specific proposals favored by Senators Corker and Warner or President Obama. If the suggestion is to return Fannie and Freddie to the status of supposedly non-governmental entities, insisting that this time the government really, truly would not bail them out if they get into trouble, I would not support the plan. We tried that idea, and it’s just not operational. The notion that a truly private company could plausibly earn its profit by guaranteeing trillions of dollars in mortgages is on its face implausible, because there is no private strategy that could truly diversify or hedge away the risk associated with major aggregate disruptions. What Fannie or Freddie really did was “guarantee” the loans as long as times were good, and count on federal assistance when times were bad.

If instead the proposal is to keep Fannie and Freddie in government receivership, and with that authority gradually slow and eventually stop the GSEs’ issuance of new debt and guarantees, then I am all on board.

The Tea Party is in a tizzy about China:

The U.S. must “shoulder its responsibility” as the world’s biggest economy and holder of the main reserve currency and “take concrete measures before Oct. 17 to avoid a default,” Deputy Finance Minister Zhu Guangyao said at a briefing with reporters yesterday in Beijing in which he referred to “the attitude of the Tea Party.”

Lawmakers tied to the Tea Party didn’t appreciate the advice, even from a nation that holds almost a quarter of foreign-owned Treasuries — $1.28 trillion as of July.

“They need to stay out of our politics,” Representative Blake Farenthold, a Tea Party-backed Texas Republican, said in an interview. China’s criticism “almost sounds like a threat,” said Representative Ted Yoho, a Florida Republican. “For them to say something derogatory about the Tea Party, I take offense to that.”

It would appear that the Tea Party needs remedial education about the relationship between “paying the piper” and “calling the tune”. But they may have actually gone too far this time:

But some of them had to be queasy when they saw an NBC News-Wall Street Journal poll last week: Only 24 percent of Americans had a favorable view of the Republican Party, the lowest ever. By eight points, the public said it preferred a Congress controlled by the Democrats over one in Republican hands. Positive feelings toward the Tea Party fell to an all-time low.

Meanwhile, fear is taking its toll:

Investors pulled $41.6 billion from U.S. money-market mutual funds in the past week, or 1.6 percent of total assets, as concern grew over lawmakers’ inability to strike a budget deal that would avert a default on Treasury securities.

The exodus in the seven days through yesterday was punctuated by the withdrawal of $21.6 billion on Oct. 11, according to research firm Crane Data LLC in Westborough, Massachusetts. Investors pulled $15.7 billion in the preceeding seven days.

While the spike appeared connected to the approaching debt ceiling, it was exacerbated by companies moving cash to make bi-monthly payroll and meet a quarterly tax payment deadline on the next business day, Peter Crane, president of Crane Data, said in an interview.

The capitalist folk hero has commented on US bank regulation:

Billionaire investor Warren Buffett said JPMorgan Chase & Co. (JPM) Chief Executive Officer Jamie Dimon will withstand litigation and legal probes that led his bank to take a $7.2 billion charge in the third quarter.

“If a cop follows you for 500 miles (800 kilometers), you’re going to get a ticket,” Buffett, the chairman and CEO of Berkshire Hathaway Inc. (BRK/A), said today in an interview on CNBC. “And believe me, you’ve had a lot of cops that have been following a long time, and they’re going to write some tickets.”
…
Banks rely on so many licenses that the threat of criminal charges can undermine their business, Buffett said. The billionaire served as interim chairman and CEO of Salomon Inc. in 1991 and 1992 as the company sought to recover from involvement in a Treasury debt auction scandal.

“A large financial institution just can’t take that,” he said. “You are in a terrible negotiating position, and I’ve been in that position. If they want to take a pound of flesh, they can take a pound of flesh. But if they want to take a ton of flesh, they can take that, too.”

The Feds have succeeded in driving away foreign capital:

Egyptian telecom investor Naguib Sawiris vows to never again consider investing in Canada after the federal government’s decision to block a $520-million bid for Manitoba Telecom Services Inc.’s Allstream division, according to a published report.

“I am finished with Canada, I tell you,” Mr. Sawiris is quoted in a lengthy article in Ahram Online, the English-language website of Egyptian news organization Al-Ahram.

I was very pleased to learn of a proposal to mitigate the effects of the dairy monopoly:

The Canadian government has struck a tentative trade deal with the European Union but is now seeking the consent of all the provinces before agreeing to the accord, sources say.
…
The development comes after a breakthrough in long-running talks where Ottawa agreed to more than double the amount of European cheese that can enter this country without facing steep protectionist tariffs.

Getting unanimous provincial consent sounds like a job and a half, but perhaps somebody will convince Marois that Muslims don’t eat dairy products. Regrettably:

NDP Leader Thomas Mulcair signalled he’s girding to fight the deal on the grounds it would allow in more than 13,500 additional tonnes of European cheese each year, a development that threatens to crowd out Canadian product.

I have sent the following eMail to my NDP MP:

I was very disappointed to learn ([LINK]) that the NDP intends to oppose an increase in the amount of European cheese that can enter this country without facing steep protectionist tariffs.

Why does the NDP favour charging single mums and kids extortionate rates for their dairy products in order to prop up a grossly inefficient industry that has as its main purpose the subsidization of bucolic lifestyles for the favoured few?

Why are you making it more difficult for working Canadians to provide nutritious food to their families?

But don’t worry, Big Government fans! There are plenty of little piggies waiting for their turn at the trough:

Newspaper publisher turned wannabe oilman David Black says he’s looking for $8-billion in loan guarantees from Ottawa to help cover the costs of his planned $26-billion oil refinery project. Mr. Black argues the undertaking is crucial to the country’s economy, and could even help build the energy partnership between Alberta and British Columbia.

It’s a black day for the professionalism of the Canadian investment management industry, such as it is. It looks like the OTPP’s foray into politics (sneered at on October 7) comes straight from the top:

Ontario’s proposal to create a voluntary disclosure rule to boost women on boards is unlikely to cause much improvement and will likely have to be turned into a quota, warns the head of Ontario Teachers’ Pension Plan.

Speaking at a public forum Wednesday hosted by the Ontario Securities Commission, Jim Leech said Canada has a smaller proportion of women on corporate boards than countries like Turkey and Poland. He said voluntary disclosure rules can be tried for three or four years, but will probably end up being rejected as inadequate.

“Let’s skip this intermediate step we don’t think is going to work,” Mr. Leech proposed.

Teachers has urged regulators to instead require all public company boards to have at least three women directors.

Maybe Leech is sucking political arse in hopes of a position with the proposed Ontario Pension Plan.

Ottawa’s busy with another idiotic throne speech:

“Our government will introduce balanced-budget legislation,” the speech, read by Governor-General David Johnston Wednesday, said.
…
There are loopholes in the balanced-budget legislation if the economic turns sour. “It will require balanced budgets during normal economic times and [set] concrete timelines for returning to balance in the event of an economic crisis,” the Throne Speech said.

Balanced-budget legislation has been criticized as gimmicky because a future government could simply pass a bill repealing it.

So Spend-Every-Penny is up to his usual tricks – claiming that a balanced budget is a major accomplishment, while doing absolutely nothing to run a surplus in good times.

There’s an interesting trend on Wall Street:

Inside One Equity Partners are as many as eight Olympians and even more of their world- or Olympic gold medals, said managing partner Dick Cashin, who competed internationally as a rower and now hires former college athletes while recommending others do the same.

“Everybody thinks sports is about winning,” says the 60-year-old Cashin, who didn’t earn a medal as a member of the 1972 U.S. Olympic team. “For me, it’s more about losing and then figuring out a way to win. It’s those things that make working with athletes and hiring former athletes a reasonable thing to consider.”

I don’t have the experience to endorse the idea – and, more importantly, I don’t have the experience for you guys to accept any endorsement of mine as meaning anything – but there is a similarity to my favouring of science grads. Science grads make great analytical employees because they have the attitude that for every question, there is exactly one right answer. We can’t get there, but we can get close, and the closer your answer is to the Platonic ideal, the better it is. An athlete’s win/loss mentality is similar. Leave second place to the Arts students.

DBRS has confirmed LB.PR.E (PerpetualDiscount) and LB.PR.F (FixedReset) at Pfd-3(low) with a Positive Trend:

Laurentian’s improved earnings profile has contributed to its ability to sustain profitability from core businesses, despite a slowing Québec economy. Segment and geographic diversification continues to improve with the growth of B2B Bank (organically and through acquisitions). Notwithstanding, geographic concentration continues to be a challenge, with 62% of the loans based in Québec at the end of Q3 2013. The Bank has been able to generate consistently respectable levels of profitability in the face of maintaining conservative credit and financial risk profiles. There have been some gains made in Laurentian’s expense ratio from 2012 to the first nine months of 2013, but the cost structure remains high.

DBRS has confirmed CWB.PR.A at Pfd-3(high) [Stable]:

CWB’s most important strengths are its strong asset quality as evidenced by its very long history of low write-off rates, its proven niche strategy using relationship-based lending, its low cost base (partially due to business mix) and its strong internal capital generation. Additionally, funding diversification has improved over the past several years. CWB recently recorded its 101st consecutive profitable quarter.

Challenges remain, including concentration in the loan book, both geographically (Alberta and British Columbia) and by industry (commercial, construction and real estate lending), although the secured nature of the loan book and low write-off rates suggest this issue has been well managed throughout the Bank’s history.

It was a mildly negative day for the Canadian preferred share market, with PerpetualDiscounts off 2bp, FixedResets losing 17bp and DeemedRetractibles down 3bp. Given such lack of movement the Performance Highlights table is surprisingly lengthy, featuring losing FixedResets. Volume was above average.

Update: US uncertainty resolved… for a while:

The U.S. Congress voted to halt the 16-day government shutdown and raise the U.S. debt limit, ending the nation’s fiscal impasse.

The House of Representatives voted 285-144 to clear a measure that now heads to President Barack Obama for his signature. The House vote was less than three hours after the Senate passed the bill, 81-18.
…
The agreement negotiated by Senate Majority Leader Harry Reid and Minority Leader Mitch McConnell will fund the government at Republican-backed spending levels through Jan. 15, 2014, and suspend the debt limit through Feb. 7, setting up another round of confrontations then.

All of the votes against the proposal in the Senate were from Republicans. One senator, Republican James Inhofe of Oklahoma, was absent.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.0633 % 2,444.4
FixedFloater 4.32 % 3.58 % 28,972 18.26 1 0.0000 % 3,888.9
Floater 2.77 % 2.98 % 63,588 19.78 5 0.0633 % 2,639.3
OpRet 4.62 % 2.77 % 63,971 0.45 3 -0.0769 % 2,642.5
SplitShare 4.76 % 5.10 % 64,290 3.99 6 0.0540 % 2,948.0
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0769 % 2,416.3
Perpetual-Premium 5.83 % 3.96 % 108,961 0.08 7 0.0725 % 2,280.7
Perpetual-Discount 5.58 % 5.61 % 159,522 14.44 30 -0.0204 % 2,332.7
FixedReset 4.98 % 3.77 % 230,721 3.41 85 -0.1669 % 2,441.0
Deemed-Retractible 5.15 % 4.42 % 191,828 6.85 43 -0.0345 % 2,372.4
Performance Highlights
Issue Index Change Notes
BAM.PR.X FixedReset -2.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-16
Maturity Price : 21.28
Evaluated at bid price : 21.56
Bid-YTW : 4.50 %
TRP.PR.C FixedReset -1.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-16
Maturity Price : 21.67
Evaluated at bid price : 22.11
Bid-YTW : 3.98 %
IFC.PR.A FixedReset -1.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.05
Bid-YTW : 4.34 %
MFC.PR.K FixedReset -1.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.39
Bid-YTW : 4.76 %
TRP.PR.A FixedReset -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-16
Maturity Price : 23.00
Evaluated at bid price : 23.50
Bid-YTW : 4.11 %
SLF.PR.H FixedReset -1.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.61
Bid-YTW : 4.23 %
CGI.PR.D SplitShare 1.28 % YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2023-06-14
Maturity Price : 25.00
Evaluated at bid price : 23.80
Bid-YTW : 4.43 %
CIU.PR.C FixedReset 1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-16
Maturity Price : 19.34
Evaluated at bid price : 19.34
Bid-YTW : 4.36 %
GWO.PR.N FixedReset 1.88 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.17
Bid-YTW : 4.64 %
Volume Highlights
Issue Index Shares
Traded
Notes
BMO.PR.P FixedReset 102,522 RBC crossed 100,000 at 26.17.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2015-02-25
Maturity Price : 25.00
Evaluated at bid price : 26.13
Bid-YTW : 2.59 %
BAM.PF.C Perpetual-Discount 50,267 TD crossed 17,000 at 19.55.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-16
Maturity Price : 19.55
Evaluated at bid price : 19.55
Bid-YTW : 6.27 %
GWO.PR.I Deemed-Retractible 30,513 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.18
Bid-YTW : 6.49 %
BMO.PR.M FixedReset 29,113 RBC crossed 15,100 at 24.64.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.59
Bid-YTW : 3.76 %
BAM.PF.D Perpetual-Discount 27,075 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-16
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 6.19 %
TD.PR.R Deemed-Retractible 25,444 TD crossed 25,000 at 25.97.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-04-30
Maturity Price : 25.75
Evaluated at bid price : 25.96
Bid-YTW : 3.45 %
There were 42 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
PWF.PR.A Floater Quote: 22.31 – 23.29
Spot Rate : 0.9800
Average : 0.6621

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-16
Maturity Price : 22.08
Evaluated at bid price : 22.31
Bid-YTW : 2.35 %

TRI.PR.B Floater Quote: 19.75 – 20.49
Spot Rate : 0.7400
Average : 0.6263

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-16
Maturity Price : 19.75
Evaluated at bid price : 19.75
Bid-YTW : 2.67 %

MFC.PR.K FixedReset Quote: 23.39 – 23.70
Spot Rate : 0.3100
Average : 0.1971

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.39
Bid-YTW : 4.76 %

FTS.PR.J Perpetual-Discount Quote: 22.41 – 22.89
Spot Rate : 0.4800
Average : 0.3750

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-16
Maturity Price : 22.10
Evaluated at bid price : 22.41
Bid-YTW : 5.36 %

BAM.PR.G FixedFloater Quote: 22.01 – 22.53
Spot Rate : 0.5200
Average : 0.4284

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-16
Maturity Price : 22.42
Evaluated at bid price : 22.01
Bid-YTW : 3.58 %

TRP.PR.B FixedReset Quote: 20.16 – 20.49
Spot Rate : 0.3300
Average : 0.2540

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-10-16
Maturity Price : 20.16
Evaluated at bid price : 20.16
Bid-YTW : 4.05 %