Category: Market Action

Market Action

August 24, 2010

The Bank of Canada has released a discussion paper by Zhongfang He titled Evaluating the Effect of the Bank of Canada’s Conditional Commitment Policy:

The author evaluates the effect of the Bank of Canada’s conditional commitment regarding the target overnight rate on longer-term market interest rates by taking into account the relationship between interest rates, inflation, and unemployment rates. By using vector autoregressive models of monthly interest rates, month-over-month inflation, and unemployment rates for Canada and the United States, the author finds that the Canadian 1-year treasury bill rates and 1-year forward 3-month rates have generally been lower than their model-implied values since April 2009, while the difference between the U.S. realized rates and their model-implied values has been much smaller. The author also studies the effect of the conditional commitment on longer-term government bond yields with maturities of 2, 5, and 10 years, and finds lower actual Canadian longer-term interest rates than their model-implied values, though their difference diminishes as the maturities become longer. The evidence appears to suggest that the Bank of Canada’s conditional commitment likely has produced a persistent effect in lowering Canadian interest rates relative to what their historical relationship with inflation and unemployment rates would imply. However, this finding is not statistically strong and is subject to caveats such as possible in-sample model instability and the dependence of the results on the choice of inflation variable.

Ontario will tinker with pension guarantees:

The fund, which provides pensioners with up to $1,000 a month if their private-sector plan fails to provide its full benefit, has been an albatross for the governing Liberals, who have repeatedly warned that it hasn’t been funded properly since its inception 30 years ago.

That looming threat came to a head last year during the global recession, when the government was faced with a fund that didn’t have enough cash to help thousands of workers at corporate giants like General Motors of Canada Ltd. and Nortel Networks Corp. that were poised to collapse into bankruptcy.
…
“These rules will help reduce – hopefully eliminate – the kind of moral hazard that I would associate with companies and employee groups agreeing to benefits without properly funding them.”

Mr. Duncan is also proposing some temporary relief for certain pension plans in the broader public sector by offering them more time to pay down solvency deficits, as long as they meet certain conditions, and a review of the pension system every five years.

This may be related politically to Nortel’s pension status:

On Sept. 30, 2010, the Nortel Defined Benefit Pension Plans will become orphans. The Financial Services Commission of Ontario (FSCO) will then take over as required by current law.

Unless the Ontario government takes prompt action, Nortel’s pensioners will then lose 36% of their pensions and possibly even more. A major part of their loss occurs because, under current regulations, FSCO will simply wind-up the pension funds by converting them to annuities. This forever locks-in the existing pension deficit and it adds major penalties, because the cost of annuities is presently at the worst they have even been in 25 years with no relief in sight.

In 2001 Nortel’s plan went from half a billion surplus to one billion deficit; to $1.8-billion in 2002 …

Manulife common (MFC-TO) got hammered today:

Manulife Financial Corp., North America’s third-largest insurer, decreased 5.4 percent to a 17-month low of $11.71. Bank of America Corp. analyst Steve Theriault yesterday increased his third-quarter loss estimate for the company to 94 cents a share from 37 cents a share, excluding certain items. Sun Life Financial Inc., Canada’s third-biggest insurance company, dropped 4.3 percent to C$24.17.

Fitch affirmed MFC:

Fitch Ratings has assigned an ‘A-‘ rating to Manulife Financial Corporations (MFC’s) recently issued C$900 million 4.079% medium-term notes due Aug. 20, 2015. At the same time Fitch affirmed all of MFC’s existing ratings. (A full list of rating actions follows at the end of this release.) The Rating Outlook is Stable.
…
Within Fitch’s rating rationale are multiple considerations. If MFC were to materially deviate from any of these items, especially for an extended period, the ratings could be impacted. Included within these key rating rationale factors are the following:

–The annual 3Q’10 actuarial experience and methods adjustments of at least C$1 billion;
–MFC adjusted earnings of C$3 billion a year;
–Operating company Minimum Continuing Capital and Surplus Requirements (MCCSR) ratio above 190%;
–Holding company financial leverage not exceeding 20% on Fitch’s equity adjusted leverage basis;
–Current sensitivity to equity markets;
–Current volatility in earnings

…
–C$$350 million 4.1% class A, series 1, preferred stock at ‘BBB’;
–C$350 million 4.65% class A, series 2, preferred stock at ‘BBB’;
–C$300 million 4.5% class A, series 3, preferred stock at ‘BBB’;
–C$450 million 6.6% non-cumulative, preferred class A, series 4 stock at ‘BBB’;
–C$350 million 5.60% non-cumulative rate reset, preferred class 1, series 1 stock at ‘BBB’.

S&P says Ireland needs a little more green:

Ireland’s long-term sovereign credit rating was cut one step to AA- from AA by Standard & Poor’s, which cited the projected cost of supporting the nation’s financial sector.

“The negative outlook reflects our view that a further downgrade is possible if the fiscal cost of supporting the banking sector rises further, or if other adverse economic developments weaken the government’s ability to meet its medium- term fiscal objectives,” S&P said today in a statement.

S&P said its new projections suggest that Ireland’s net general government debt will rise toward 113 percent of gross domestic product in 2012. That’s more than 1.5 times the median for the average of euro zone sovereign nations, and “well above” the debt burdens the New York-based firm said it projects for similarly rated countries in the region such as Belgium at 98 percent and Spain at 65 percent.

The Canadian preferred share market edged a little higher today, with PerpetualDiscounts up 6bp and FixedResets gaining 10bp. Volume was above average. MFC’s preferreds were not immune to the woes of the common, with two issues figuring in the performance highlights – which were all losses today.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.3305 % 2,048.7
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.3305 % 3,103.6
Floater 2.55 % 2.17 % 36,162 21.92 4 -0.3305 % 2,212.1
OpRet 4.91 % 4.11 % 97,880 0.90 9 -0.3526 % 2,343.2
SplitShare 6.05 % -32.87 % 67,451 0.09 2 0.1044 % 2,328.2
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.3526 % 2,142.7
Perpetual-Premium 5.76 % 5.22 % 101,904 1.75 7 0.0450 % 1,963.0
Perpetual-Discount 5.72 % 5.77 % 186,794 14.11 71 0.0585 % 1,896.7
FixedReset 5.28 % 3.24 % 274,303 3.37 47 0.0975 % 2,245.9
Performance Highlights
Issue Index Change Notes
BAM.PR.O OpRet -1.53 % YTW SCENARIO
Maturity Type : Option Certainty
Maturity Date : 2013-06-30
Maturity Price : 25.00
Evaluated at bid price : 25.80
Bid-YTW : 4.11 %
BAM.PR.K Floater -1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-24
Maturity Price : 14.89
Evaluated at bid price : 14.89
Bid-YTW : 3.26 %
MFC.PR.D FixedReset -1.25 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-07-19
Maturity Price : 25.00
Evaluated at bid price : 26.76
Bid-YTW : 4.52 %
BAM.PR.I OpRet -1.04 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2011-07-30
Maturity Price : 25.25
Evaluated at bid price : 25.63
Bid-YTW : 4.72 %
MFC.PR.B Perpetual-Discount -1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-24
Maturity Price : 18.76
Evaluated at bid price : 18.76
Bid-YTW : 6.21 %
Volume Highlights
Issue Index Shares
Traded
Notes
MFC.PR.B Perpetual-Discount 169,174 Nesbitt crossed 75,000 at 19.00; RBC crossed 45,000 at the same price.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-24
Maturity Price : 18.76
Evaluated at bid price : 18.76
Bid-YTW : 6.21 %
CM.PR.D Perpetual-Discount 166,030 TD crossed blocks of 29,900 and 30,000, both at 25.20. Nesbitt crossed 100,000 at 25.21.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2012-05-30
Maturity Price : 25.00
Evaluated at bid price : 25.17
Bid-YTW : 5.60 %
BNS.PR.J Perpetual-Discount 91,861 RBC crossed 84,100 at 24.07.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-24
Maturity Price : 22.96
Evaluated at bid price : 24.05
Bid-YTW : 5.46 %
MFC.PR.E FixedReset 85,029 Nesbitt crossed 10,000 at 25.85; RBC crossed 50,000 at 25.82.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-10-19
Maturity Price : 25.00
Evaluated at bid price : 25.91
Bid-YTW : 4.54 %
BMO.PR.P FixedReset 83,911 RBC crossed blocks of 37,700 and 40,000, both at 27.25.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2015-03-27
Maturity Price : 25.00
Evaluated at bid price : 27.26
Bid-YTW : 3.23 %
SLF.PR.E Perpetual-Discount 74,040 RBC crossed 69,100 at 19.00.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-24
Maturity Price : 18.93
Evaluated at bid price : 18.93
Bid-YTW : 5.94 %
There were 45 other index-included issues trading in excess of 10,000 shares.
Market Action

August 23, 2010

I should have mentioned this earlier … but it just seemed so trivial! S&P has announced:

the S&P/TSX North American Preferred Stock Index. The Index seeks to provide investors with the opportunity to achieve broad diversification and exposure to North American preferred stocks.

Preferred stocks are a class of securities that combine the characteristics of debt and common stocks. Their returns have low correlations with common stock returns and with bond returns, making them good diversifiers. While their expected volatility and returns lie between those of common stocks and bonds, their yields are typically higher than that of common stock, the bond market and the money market.
“Preferred stocks are attractive to investors in today’s low interest rate environment, due to their higher yields,” says Steve Rive, Managing Director at S&P Indices. “The S&P/TSX North American Preferred Stock Index will provide investors with a diversified and broadly representative exposure to this important segment of the market.”

The S&P/TSX North American Preferred Stock Index is comprised of a 50% equal weighting in the S&P/TSX Preferred Share Index and S&P U.S. Preferred Stock Index. The S&P/TSX Preferred Share Index is comprised of preferred stocks trading on the Toronto Stock Exchange that meet criteria relating to minimum size, liquidity, issuer rating, and exchange listing. The S&P U.S. Preferred Stock Index measures the yield and price performance of preferred stocks in the U.S. equity universe by using a rules-driven methodology. It is comprised of preferred stocks issued by U.S. entities that meet a set of defined criteria.

I don’t see the point of this. The US and Canadian preferred share markets are very different animals, with very different taxation profiles. My guess is that there will be an ETF announcement in the very near future. Thanks to Assiduous Readers MP and like_to_retire for reminding me that I’m supposed to report EVERYTHING about Canadian preferred shares, not just the news that investors might consider interesting or useful.

The FRBNY has released a staff report about a fascinating idea by Marco Del Negro, Fabrizio Perri, and Fabiano Schivardi titled Tax Buyouts:

The paper studies a fiscal policy instrument that can reduce fiscal distortions, without affecting revenues, in a politically viable way. The instrument is a private contract (tax buyout), offered by the government to each individual citizen, whereby the citizen can choose to pay a fixed price up front in exchange for a given reduction in her tax rate for a prespecified period of time. We consider a dynamic overlapping-generations economy, calibrated to match several features of the U.S. income and wealth distribution, and show that, under simple pricing, the introduction of the buyout is revenue neutral and at the same time can benefit a significant fraction of the population and lead to sizable increases in labor supply, income, consumption, and welfare.
…
The baseline buyout we consider is a reduction in the marginal tax rate of at most 5% offered at a price of roughly $4500, which ensures revenue neutrality.

The FRBNY also released a staff report by James Vickery and Joshua Wright titled TBA Trading and Liquidity in the Agency MBS Market:

Most mortgages in the United States are securitized through the agency mortgage-backedsecurities (MBS) market. These securities are generally traded on a “to-be-announced,” or TBA, basis. This trading convention significantly improves agency MBS liquidity, leading to lower borrowing costs for households. Evaluation of potential reforms to the U.S. housing finance system should take into account the effects of those reforms on the operation of the TBA market.
…
Consistent with the view that liquidity effects were important during this period, the timing of the increase in the jumbo-conforming spread corresponds closely to the collapse in non-agency MBS liquidity and mortgage securitization during the second half of 2007. Furthermore, this spread remains significantly elevated even today, despite normalization in many measures of credit risk premia.

I know a man who considers one thing to be an infallible contrarian indicator: when the little guy gets in … :

The amount of money flowing into bond funds is poised to exceed the cash that went into stock funds during the internet bubble, stoking concern that fixed- income markets are headed for a fall.

Investors poured $480.2 billion into mutual funds that focus on debt in the two years ending June, compared with the $496.9 billion received by equity funds from 1999 to 2000, according to data compiled by Bloomberg and the Washington-based Investment Company Institute.

Concern that the global economic recovery is faltering, with the U.S. growing at a slower-than-forecast 2.4 percent pace in the second quarter, is prompting investors to pile into fixed-income securities of all types even with some yields at record lows. The new cash has helped fuel a rally and drove yields on investment-grade U.S. corporate debt down to a record 3.79 percent last week, while two-year U.S. Treasury yields fell to an all-time low of less than 0.5 percent.

There’s increased chatter about century bonds:

“With credit spreads rallying, it’s the perfect environment for issuers to get away with 100-year bonds,” said one banker who has been selectively pitching the idea to institutional investors. “There is a natural trend to go long, so the obvious extension of that is to move past the 30-year bucket.”

As investors move “out on the curve” to longer-dated issues, the amount of three-year corporate debt offerings has fallen by 50% compared to 2009. The pace of 30-year issuance has risen by 30%, according to Dealogic.

New York State may be reducing return assumptions for its pension funds:

New York state’s $132.6 billion pension fund, the nation’s third-largest, will cut the assumed rate of return on its investments to less than the 8 percent it has used for a decade.

A reduction to 7.5 percent or 7.75 percent is likely, said Robert Whalen, a spokesman for Comptroller Thomas DiNapoli. The move “will increase the required contributions from the state and local governments but will keep the fund as strong as it is now,” Whalen said.

The plan, which covers 1 million current and retired workers, had assets equal to about 107 percent of its future liabilities, according to the fund. New York was one of only four states with pension systems in 2008 that fully funded their future obligations, according to a study by the Washington-based Pew Center on the States.

By way of comparison, the Ontario Teachers’ Pension Plan states:

A typical teacher retiring in 2009 has 26 years of pension credit and is expected to receive a pension for 30 years, plus a survivor may be paid after that. Working teachers can expect to collect their pensions for longer than they contributed to the plan.
…

FUNDING VALUATION ASSUMPTIONS (percent)
  2009 Filed 2009 Preliminary
Rate of return 5.00 4.90
Inflation rate 1.35 1.35
Real rate of return 3.65 3.55

The assumptions for 2010 are nominal 5.5% less inflation 2.55% equals real 2.95%. Since:

The OTF and the Ontario government adopted a Funding Management Policy in 2003. Under the policy:

  • If assets are equal to or up to 10% greater than liabilities, the plan is in balance and no change is required.
  • If assets are more than 10% greater than liabilities, the plan has a surplus that can be used to reduce contribution rates or improve benefits.
  • If liabilities are greater than assets, the plan has a shortfall. The OTF and the government can address a shortfall by increasing contributions, invoking conditional inflation protection for pension credit earned after 2009, changing other benefits members will earn in the future, or adopting a combination of these measures.

… one cannot help but wonder if the relatively low return assumptions are simply yet another way of back-dooring some extra benefits to the plan members.

BIS has commenced publishing property price statistics. Oddly, there are no data available for Canada.

The Bank of Canada has released a working paper by Hajime Tomura titled Liquidity Transformation and Bank Capital Requirements:

This paper presents a dynamic general equilibrium model where asymmetric information about asset quality leads to asset illiquidity. Banking arises endogenously in this environment as banks can pool illiquid assets to average out their idiosyncratic qualities and issue liquid liabilities backed by pooled assets whose total quality is public information. Moreover, the liquidity mismatch in banks’ balance sheets leads to endogenous bank capital (outside equity) requirements for preventing bank runs. The model indicates that banking has both positive and negative effects on long-run economic growth and that business-cycle dynamics of asset prices, asset illiquidity and bank capital requirements are interconnected.
…
The model, however, also shows that if a deterioration in asymmetric information in the asset market increases the illiquidity of bank assets significantly, then banks need to raise more bank capital during the liquidity crisis to prevent self-fulfilling bank runs. This result implies that the counter-cyclical capital buffer will not help to free up bank capital as designed in a liquidity crisis.

The (alleged) G-20 protesters had their day in court today:

Over 300 people facing G20-related charges appeared at a Toronto courthouse Monday, a legal tidal wave resulting from the largest mass arrests in Canadian history.

The court’s hallways are only designed to hold 176 people. Officers have been tasked with regulating the intake of defendants to ensure the building doesn’t break fire code. The court’s legal aid office brought in extra staff, including French-speakers.

I don’t know the name of the petty, vindictive ratshit who decided to make the scheduling an extra-judicial punishment … but I have a message for him: You have held the courts in contempt, and you have done more damage to the rule of law than any of those charged. Asshole.

It was a mixed day on good volume for the Canadian preferred share market, with PerpetualDiscounts gaining 23bp and FixedResets losing 5bp; the change narrowed the Bozo Spread (Current Yield PerpetualDiscounts less Current Yield FixedResets) slightly to 44bp.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.1059 % 2,055.5
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.1059 % 3,113.8
Floater 2.54 % 2.17 % 36,708 21.93 4 0.1059 % 2,219.4
OpRet 4.90 % -1.52 % 99,311 0.19 9 0.0301 % 2,351.5
SplitShare 6.05 % -30.77 % 68,049 0.09 2 -0.3121 % 2,325.8
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0301 % 2,150.2
Perpetual-Premium 5.77 % 5.20 % 100,766 5.57 7 0.1351 % 1,962.1
Perpetual-Discount 5.73 % 5.78 % 185,006 14.13 71 0.2302 % 1,895.6
FixedReset 5.29 % 3.28 % 278,289 3.37 47 -0.0537 % 2,243.7
Performance Highlights
Issue Index Change Notes
BNA.PR.C SplitShare -1.45 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2019-01-10
Maturity Price : 25.00
Evaluated at bid price : 21.11
Bid-YTW : 6.83 %
CM.PR.K FixedReset -1.07 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-08-30
Maturity Price : 25.00
Evaluated at bid price : 26.71
Bid-YTW : 3.56 %
POW.PR.D Perpetual-Discount 1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-23
Maturity Price : 21.49
Evaluated at bid price : 21.76
Bid-YTW : 5.81 %
Volume Highlights
Issue Index Shares
Traded
Notes
MFC.PR.B Perpetual-Discount 86,943 Nesbitt crossed blocks of 12,000 and 40,000, both at 19.00.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-23
Maturity Price : 18.95
Evaluated at bid price : 18.95
Bid-YTW : 6.15 %
TD.PR.M OpRet 80,435 TD crossed 19,800 at 26.18. RBC crossed blocks of 25,000 and 20,000, both at 26.05.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2010-09-22
Maturity Price : 25.75
Evaluated at bid price : 26.15
Bid-YTW : -10.45 %
RY.PR.I FixedReset 51,115 RBC crossed 44,700 at 26.45.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-03-26
Maturity Price : 25.00
Evaluated at bid price : 26.45
Bid-YTW : 3.22 %
RY.PR.G Perpetual-Discount 49,890 TD crossed 30,000 at 20.75.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-23
Maturity Price : 20.70
Evaluated at bid price : 20.70
Bid-YTW : 5.47 %
BNS.PR.P FixedReset 46,055 RBC crossed 30,100 at 26.25.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-05-25
Maturity Price : 25.00
Evaluated at bid price : 26.26
Bid-YTW : 3.15 %
RY.PR.W Perpetual-Discount 43,575 RBC crossed blocks of 21,900 and 11,600, both at 22.48.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-23
Maturity Price : 22.24
Evaluated at bid price : 22.40
Bid-YTW : 5.49 %
There were 36 other index-included issues trading in excess of 10,000 shares.
Market Action

August 20, 2010

Was the Panic of 2007 bogus? I have previously highlighted doubts about the ABX index validity (as has, famously, Fabulous Fab) … Richard Stanton and Nancy Wallace supply another interesting paper, The Bear’s Lair: Indexed Credit Default Swaps and the Subprime Mortgage Crisis:

ABX.HE indexed credit default swaps on baskets of mortgage-backed securities are now the main benchmark used by financial institutions to mark their subprime mortgage portfolios to market. However, we find that current prices for the ABX.HE indices are inconsistent with any finite assumption for mortgage default rates, and that ABX.HE price changes are uncorrelated with changes in the credit performance of the underlying loans. These results cast serious doubt on the suitability of the ABX.HE indices as valuation benchmarks. We also find that ABX.HE price changes are significantly related to short-sale activity in the option and equity markets of the publicly traded builders, the commercial banks, the investment banks and the government sponsored enterprises (GSEs). This suggests that capital constraints, limiting the supply of ABS insurance, may be playing a role here similar to that identified by Froot (2001) in the market for catastrophe insurance.
…
We collect detailed credit and prepayment histories from 2006{2008 for all of the roughly 360,000 individual loans underlying the ABX.HE indices, and use these data, plus current prices, to infer the market’s expectations for future defaults. Using both a simple, “back-of-the-envelope” model (in which all defaults and insurance payments occur instantaneously) and a full CDS valuation model calibrated to the historical loan-level performance data, we find that recent price levels for ABX.HE index CDS are inconsistent with any reasonable forecast for the future default performance of the underlying loans. For example, assuming a recovery rate of 21%, the AAA ABX.HE prices on June 30, 2009 imply default rates of 100% on the underlying loans. In other words, if recovery rates exceed 21% (a value well below anything ever observed in U.S. mortgage markets), there is no default rate high enough to support observed prices. We also find that changes in the credit performance of the underlying loans explain almost none of the observed price changes in the ABX.HE indices. These results cast serious doubt on the use of the ABX.HE indices for marking mortgage portfolios to market.

The Canadian preferred share market advanced modestly on good volume today, with PerpetualDiscounts gaining 2bp and FixedResets up 7bp.

MFC issues maintained their presence in the volume highlights; probably continuing portfolio rebalancing after the DBRS downgrade.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.4480 % 2,053.3
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.4480 % 3,110.6
Floater 2.55 % 2.17 % 36,998 21.93 4 -0.4480 % 2,217.1
OpRet 4.90 % -2.64 % 102,983 0.19 9 0.1249 % 2,350.8
SplitShare 6.03 % -25.10 % 67,997 0.09 2 0.1459 % 2,333.1
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1249 % 2,149.6
Perpetual-Premium 5.77 % 5.49 % 101,002 5.58 7 -0.1405 % 1,959.4
Perpetual-Discount 5.74 % 5.78 % 183,793 14.07 71 0.0161 % 1,891.3
FixedReset 5.28 % 3.28 % 287,612 3.38 47 0.0676 % 2,244.9
Performance Highlights
Issue Index Change Notes
TRI.PR.B Floater -1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-20
Maturity Price : 23.09
Evaluated at bid price : 23.35
Bid-YTW : 2.05 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.G Perpetual-Discount 210,890 TD crossed 187,800 at 20.60.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-20
Maturity Price : 20.63
Evaluated at bid price : 20.63
Bid-YTW : 5.49 %
TRP.PR.B FixedReset 77,674 Scotia crossed 11,000 at 24.97; Nesbitt crossed 50,000 at the same price.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-20
Maturity Price : 24.92
Evaluated at bid price : 24.97
Bid-YTW : 3.63 %
MFC.PR.B Perpetual-Discount 49,579 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-20
Maturity Price : 18.90
Evaluated at bid price : 18.90
Bid-YTW : 6.16 %
TD.PR.O Perpetual-Discount 43,971 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-20
Maturity Price : 22.25
Evaluated at bid price : 22.40
Bid-YTW : 5.46 %
SLF.PR.A Perpetual-Discount 42,436 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-20
Maturity Price : 20.03
Evaluated at bid price : 20.03
Bid-YTW : 6.03 %
MFC.PR.E FixedReset 37,773 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-10-19
Maturity Price : 25.00
Evaluated at bid price : 26.00
Bid-YTW : 4.44 %
There were 36 other index-included issues trading in excess of 10,000 shares.
Market Action

August 19, 2010

Econbrowser‘s James Hamilton sounds a gloomy note in his post Will the Fed Do More?:

Certainly Federal Reserve Bank of St. Louis President James Bullard is trying to communicate that the Fed needs to respond more if disinflation continues:

There has been disinflation. It has been at the low end of where I’d like to see it. For that reason I think we should supplement our quantitative easing program if we get further developments on that front. We should have a plan in place to take action if it moves lower.

My expectation is that Hoenig’s forecast will prove optimistic, and that last week’s modest easing is not the last we’re going to hear from the Fed.

Not to be out-done, Econbrowser‘s Menzie Chinn writes a post Financing US Debt which presents highlights of a recent paper:

We use the CBO assessment of the President’s budget, and a key estimated relationship between the ten year – three month spread and the unemployment gap, inflation, structural budget deficits, and foreign official purchase of Treasury securities. Note that we presume that, contrary to some people’s assertions, deficits matter. Actually, we estimate the relationship, and find that each percentage point of the structural, or cyclically adjusted, budget deficit raises the spread by 27 basis points. The fit is displayed in Chart 5.

The Canadian preferred share market rocketted ahead on good volume today, with PerpetualDiscounts up 26bp and FixedResets up 16bp. FixedResets set a new all-time low median average yield-to-worst at 3.26%. Interestingly, the Bozo Spread (Current Yield PerpetualDiscounts less Current Yield FixedResets) has narrowed very slightly to 45bp.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.2112 % 2,062.6
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.2112 % 3,124.5
Floater 2.54 % 2.16 % 37,323 21.95 4 0.2112 % 2,227.0
OpRet 4.90 % 0.55 % 103,677 0.20 9 0.0862 % 2,347.9
SplitShare 6.04 % -24.10 % 70,236 0.09 2 0.2297 % 2,329.7
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0862 % 2,146.9
Perpetual-Premium 5.77 % 5.32 % 98,815 1.76 7 0.0562 % 1,962.2
Perpetual-Discount 5.74 % 5.77 % 183,740 14.12 71 0.2558 % 1,891.0
FixedReset 5.29 % 3.26 % 291,604 3.38 47 0.1550 % 2,243.4
Performance Highlights
Issue Index Change Notes
TRI.PR.B Floater 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-19
Maturity Price : 23.32
Evaluated at bid price : 23.60
Bid-YTW : 2.02 %
CM.PR.M FixedReset 1.08 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-08-30
Maturity Price : 25.00
Evaluated at bid price : 28.17
Bid-YTW : 3.23 %
W.PR.J Perpetual-Discount 1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-19
Maturity Price : 23.88
Evaluated at bid price : 24.13
Bid-YTW : 5.87 %
SLF.PR.F FixedReset 4.00 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-07-30
Maturity Price : 25.00
Evaluated at bid price : 27.85
Bid-YTW : 3.15 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PR.O Perpetual-Discount 57,244 Desjardins crossed two blocks of 20,000 each, both at 22.35.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-19
Maturity Price : 22.16
Evaluated at bid price : 22.31
Bid-YTW : 5.48 %
RY.PR.L FixedReset 38,400 Anonymous crossed 37,800 at 27.25.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-03-26
Maturity Price : 25.00
Evaluated at bid price : 27.30
Bid-YTW : 2.83 %
BNS.PR.N Perpetual-Discount 37,490 Nesbitt crossed 30,000 at 23.97.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-19
Maturity Price : 23.65
Evaluated at bid price : 23.85
Bid-YTW : 5.55 %
BMO.PR.L Perpetual-Premium 33,514 Desjardins crossed 30,000 at 26.00.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-06-24
Maturity Price : 25.00
Evaluated at bid price : 25.76
Bid-YTW : 5.29 %
TRP.PR.C FixedReset 32,155 Nesbitt crossed 18,000 at 25.50.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-19
Maturity Price : 23.27
Evaluated at bid price : 25.45
Bid-YTW : 3.71 %
PWF.PR.L Perpetual-Discount 31,803 Desjardins crossed 30,000 at 21.75.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-19
Maturity Price : 21.46
Evaluated at bid price : 21.77
Bid-YTW : 5.90 %
There were 36 other index-included issues trading in excess of 10,000 shares.
Market Action

August 18, 2010

The Barclays settlement of allegations they did business with bad people and covered it up was criticized here yesterday. I am pleased to see it has hit a roadblock:

A federal judge refused to endorse a settlement between the U.S. and a bank for a third time in a year, calling a proposed $298 million fine of Barclays Plc for trading with Iran, Cuba and Sudan “a sweetheart deal.”

U.S. District Judge Emmet Sullivan in Washington scheduled a hearing for today to address the question he asked prosecutors yesterday: “Why isn’t the government getting tough with the banks?” U.S. District Judge Ellen Huvelle in Washington on Aug. 16 likewise held up a $75 million settlement between the Securities and Exchange Commission and Citigroup Inc., lawyers in the case said.
…
“Courts are wrestling with what they see as a disparity between the way in which the conduct is being characterized as serious and the penalties that are being imposed,” said James Doty, former SEC general counsel who is now a partner at Baker Botts LLP in Washington.

U.S. agencies and prosecutors, taking note of the decisions, will begin trying harder to deliver the executives responsible for misconduct, Doty said.

I’ll believe it when I see it. Imposing fines on the shareholders is an accepted part of the game, but going after individuals will be a threat to the regulators’ club membership.

And at the same time, New Jersey is in the spotlight:

New Jersey settled claims that it misled investors in $26 billion of municipal bonds by masking underfunding of its two biggest pension plans, in the first Securities and Exchange Commission case to target a state.
…
New Jersey agreed to settle the SEC case without admitting or denying the agency’s findings. The state consented to a cease-and-desist order, and wasn’t required to pay any civil fines or penalties.

So what did happen? The SEC explains:

The SEC’s order requires the State of New Jersey to cease and desist from committing or causing any violations and any future violations of Sections 17(a)(2) and 17(a)(3) of the Securities Act of 1933. New Jersey consented to the issuance of the order without admitting or denying the findings. In determining to accept New Jersey’s offer to settle this matter, the Commission considered the cooperation afforded the SEC’s staff during the investigation and certain remedial acts taken by the state.

So basically it was a bureaucrats cuddle-fest. Fabulous Fabio … eat your heart out.

Inflationistas will be pleased to see that UK inflation exceeded 3.1% in July, which the BoE attributes to tax increases, oil prices and the decline of Sterling. HM Treasury has promised to tighten the fiscal screws further. The BoE’s views on inflation were last discussed August 11.

There was continued heavy volume in the Canadian preferred share market today, with PerpetualDiscounts gaining 34bp, while FixedResets lost 4bp.

PerpetualDiscounts now yield 5.79%, equivalent to 8.11% interest at the standard conversion factor of 1.4x. Long Corporates are now pretty close to 5.35%, so the pre-tax interest equivalent spread (also called the Seniority Spread) is about 270bp, down marginally – and perhaps spuriously – from the 275bp reported August 11.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.1057 % 2,058.2
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.1057 % 3,118.0
Floater 2.54 % 2.16 % 36,886 21.96 4 0.1057 % 2,222.3
OpRet 4.91 % 0.54 % 107,960 0.20 9 -0.2365 % 2,345.8
SplitShare 6.06 % -21.87 % 69,600 0.09 2 0.9031 % 2,324.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.2365 % 2,145.1
Perpetual-Premium 5.77 % 5.23 % 92,482 5.58 7 0.3045 % 1,961.1
Perpetual-Discount 5.75 % 5.79 % 185,976 14.08 71 0.3352 % 1,886.2
FixedReset 5.30 % 3.32 % 295,966 3.38 47 -0.0362 % 2,239.9
Performance Highlights
Issue Index Change Notes
SLF.PR.F FixedReset -3.70 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-07-30
Maturity Price : 25.00
Evaluated at bid price : 26.78
Bid-YTW : 4.27 %
BAM.PR.O OpRet -2.13 % YTW SCENARIO
Maturity Type : Option Certainty
Maturity Date : 2013-06-30
Maturity Price : 25.00
Evaluated at bid price : 25.70
Bid-YTW : 4.23 %
HSB.PR.D Perpetual-Discount 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-18
Maturity Price : 21.57
Evaluated at bid price : 21.87
Bid-YTW : 5.79 %
BNS.PR.M Perpetual-Discount 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-18
Maturity Price : 20.65
Evaluated at bid price : 20.65
Bid-YTW : 5.51 %
RY.PR.B Perpetual-Discount 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-18
Maturity Price : 21.45
Evaluated at bid price : 21.45
Bid-YTW : 5.51 %
BNA.PR.D SplitShare 1.25 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2010-09-17
Maturity Price : 26.00
Evaluated at bid price : 26.55
Bid-YTW : -21.87 %
BMO.PR.L Perpetual-Premium 1.25 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-06-24
Maturity Price : 25.00
Evaluated at bid price : 25.90
Bid-YTW : 5.19 %
RY.PR.F Perpetual-Discount 1.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-18
Maturity Price : 20.50
Evaluated at bid price : 20.50
Bid-YTW : 5.46 %
MFC.PR.B Perpetual-Discount 1.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-18
Maturity Price : 18.80
Evaluated at bid price : 18.80
Bid-YTW : 6.19 %
NA.PR.L Perpetual-Discount 1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-18
Maturity Price : 21.71
Evaluated at bid price : 21.71
Bid-YTW : 5.63 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.Y FixedReset 81,526 TD crossed blocks of 30,000 and 40,000, both at 27.95.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-12-24
Maturity Price : 25.00
Evaluated at bid price : 27.93
Bid-YTW : 3.20 %
BAM.PR.J OpRet 70,300 Nesbitt crossed blocks of 40,000 and 27,300, both at 26.15.
YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2018-03-30
Maturity Price : 25.00
Evaluated at bid price : 26.05
Bid-YTW : 4.88 %
BMO.PR.M FixedReset 56,245 Nesbitt crossed 19,800 at 26.60. TD crossed two blocks of 10,000 each at the same price.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-09-24
Maturity Price : 25.00
Evaluated at bid price : 26.60
Bid-YTW : 2.73 %
HSB.PR.E FixedReset 54,579 TD crossed 40,000 at 27.98.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-07-30
Maturity Price : 25.00
Evaluated at bid price : 27.94
Bid-YTW : 3.67 %
CM.PR.H Perpetual-Discount 51,766 RBC crossed 24,000 at 21.13.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-18
Maturity Price : 21.17
Evaluated at bid price : 21.17
Bid-YTW : 5.73 %
MFC.PR.C Perpetual-Discount 45,093 TD crossed 15,300 at 18.15.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-18
Maturity Price : 18.15
Evaluated at bid price : 18.15
Bid-YTW : 6.21 %
There were 57 other index-included issues trading in excess of 10,000 shares.
Market Action

August 17, 2010

The Nanex explanation of the Flash Crash was discussed on August 9. It now appears that the mechanism is considered plausible by the CFTC:

What this delay means is that, hypothetically, at the same real time, there could be two different price quotes: the real time NYSE price quote feed that had most stocks falling rapidly and the delayed consolidated price quote feed where the prices had not yet fully reflected the downward movement. Therefore, an algorithmic computer program, which would use high-frequency or flash trading and is written to sense price differences, could submit buy and sell orders to arbitrage between the two prices. The algo program could buy at the lower price from the NYSE feed and immediately sell on another exchange portal using the delayed consolidated price quote feed. This could be done is large quantities, repeatedly. Here is what we know: there was a delay between the premium and the consolidated price quote feeds. What we do not know yet is if some algorithmic trading took advantage of that situation.

We had our Technology Advisory Committee in this room last month and I asked the experts if this type of thing was possible or if it was just a conspiracy theory. Four of the panelists assured me that this could take place. In fact, they even acknowledged that some algorithmic programs were geared to not only take advantage of market circumstances, but could be used to instigate certain market conditions in order to then initiate their own program of buying or selling.

Therefore, I urge the staffs of the CFTC and the SEC to not leave this and any other stones unturned as they continue to investigate the flash crash. Did algo price pirates seek false profits on May 6th? Inquiring minds want to know.

Pirates? Sounds like he’s got a solution and is just waiting for a plausible problem.

A Barclay’s settlement illustrates all I find confusing about financial regulation:

Barclays PLC agreed to pay $298 million to settle charges by U.S. and New York prosecutors that the U.K. bank altered financial records for more than a decade to hide hundreds of millions of dollars in payments flowing into the U.S. from Cuba, Libya, Iran and other sanctioned countries.

The bank plans to pay $298 million to settle claims by U.S. prosecutors that it altered financial records for more than a decade to hide hundreds of millions of dollars that flowed to the U.S. from nations like Cuba, Libya and Iran.
…
A federal court filing said Barclays “accepts and acknowledges responsibility for its conduct and that of its employees.” U.S. officials said the bank altered payment messages or deleted information about sanctioned countries.

In other cases, Barclays returned payments out of fear they would be detected by U.S. officials, sending fax cover sheets that said: “Payments to U.S.A. must NOT contain the word listed below.” Prosecutors said payments often were re-sent after references to the sanctioned countries, which included Sudan and Myanmar, were omitted.

OK, so they pay a fine. Good. But it doesn’t say anywhere that anyone’s been banned from the industry. They altered records! They had a protocol for hiding transfers! That shows deliberate intent to break the law, with a policy set somewhere by somebody who thought about it … and nobody’s been banned from the industry? And yet they’re going after a dumbass salesman at Goldman who did his job and did it well? I don’t get it.

It was a good day on the Canadian preferred share market, with PerpetualDiscounts up 24bp and FixedResets gaining 3bp on high volume. Sadly, FixedResets did not set a new yield low today – in fact, the median weighte average YTW actually increased fractionally.

MFC issues continue to be prominent in the highlights.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.0661 % 2,056.0
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.0661 % 3,114.7
Floater 2.54 % 2.16 % 38,385 21.96 4 0.0661 % 2,220.0
OpRet 4.90 % -1.58 % 99,970 0.20 9 -0.0301 % 2,351.4
SplitShare 6.02 % -7.77 % 64,403 0.08 2 0.4379 % 2,303.5
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0301 % 2,150.1
Perpetual-Premium 5.79 % 5.41 % 92,663 5.59 7 0.3963 % 1,955.1
Perpetual-Discount 5.77 % 5.84 % 183,119 14.07 71 0.2395 % 1,879.8
FixedReset 5.29 % 3.32 % 274,579 3.39 47 0.0346 % 2,240.7
Performance Highlights
Issue Index Change Notes
MFC.PR.C Perpetual-Discount -1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-17
Maturity Price : 18.06
Evaluated at bid price : 18.06
Bid-YTW : 6.24 %
MFC.PR.B Perpetual-Discount -1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-17
Maturity Price : 18.50
Evaluated at bid price : 18.50
Bid-YTW : 6.29 %
RY.PR.A Perpetual-Discount 1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-17
Maturity Price : 20.56
Evaluated at bid price : 20.56
Bid-YTW : 5.44 %
RY.PR.H Perpetual-Premium 1.04 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-06-23
Maturity Price : 25.00
Evaluated at bid price : 25.35
Bid-YTW : 5.42 %
BMO.PR.K Perpetual-Discount 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-17
Maturity Price : 23.56
Evaluated at bid price : 23.76
Bid-YTW : 5.54 %
BAM.PR.M Perpetual-Discount 1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-17
Maturity Price : 19.41
Evaluated at bid price : 19.41
Bid-YTW : 6.22 %
POW.PR.D Perpetual-Discount 1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-17
Maturity Price : 21.52
Evaluated at bid price : 21.52
Bid-YTW : 5.89 %
TD.PR.C FixedReset 1.33 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-03-02
Maturity Price : 25.00
Evaluated at bid price : 27.36
Bid-YTW : 2.82 %
Volume Highlights
Issue Index Shares
Traded
Notes
MFC.PR.B Perpetual-Discount 114,947 RBC bought 11,500 from Nesbitt at 18.50; TD crosed 40,000 at 18.60. RBC crossed 13,200 at 18.69.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-17
Maturity Price : 18.50
Evaluated at bid price : 18.50
Bid-YTW : 6.29 %
BMO.PR.P FixedReset 60,781 RBC crossed blocks of 17,000 and 33,000 at 27.25.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2015-03-27
Maturity Price : 25.00
Evaluated at bid price : 27.20
Bid-YTW : 3.28 %
MFC.PR.E FixedReset 59,063 RBC crossed 15,200 at 26.25.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-10-19
Maturity Price : 25.00
Evaluated at bid price : 26.15
Bid-YTW : 4.27 %
RY.PR.I FixedReset 56,912 National bought 10,700 from anonymous at 26.45; RBC crossed 24,300 at 26.36.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-03-26
Maturity Price : 25.00
Evaluated at bid price : 26.30
Bid-YTW : 3.38 %
CM.PR.H Perpetual-Discount 55,141 RBC crossed 24,000 at 21.05.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-17
Maturity Price : 21.06
Evaluated at bid price : 21.06
Bid-YTW : 5.76 %
GWO.PR.G Perpetual-Discount 52,786 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-17
Maturity Price : 21.87
Evaluated at bid price : 22.21
Bid-YTW : 5.93 %
There were 55 other index-included issues trading in excess of 10,000 shares.
Market Action

August 16, 2010

The FDIC is looking for comments:

The FDIC and the other federal banking agencies are requesting comment on alternative standards of creditworthiness to replace the use of credit ratings in the risk-based capital requirements. The comment period for the attached Advance Notice of Proposed Rulemaking (ANPR) will be 60 days after its publication in the Federal Register.

They’ll get a lot of comments … but I don’t know how many useful ones!

Fans of Judge Jed Rakoff can add another bubble-gum card to their collection – Judge Ellen Segal Huvelle:

A federal judge refused to approve the Securities and Exchange Commission’s $75 million settlement with Citigroup Inc. over the bank’s disclosure of subprime-mortgage problems, saying she is “baffled” by the proposed pact.

The move by U.S. District Judge Ellen Segal Huvelle represents another challenge for the SEC as it tries to punish financial institutions blamed for the financial crisis.

Judge Ellen Segal Huvelle said she didn’t have “sufficient information.”

The judge, striking a frustrated tone, fired several questions at the SEC, among them why it pursued only two individuals in the case and why Citigroup shareholders should have to pay for the alleged sins of bank executives.

“I look at this and say, ‘Why would I find this fair and reasonable?'” the judge told both sides at a 90-minute hearing. “You expect the court to rubber-stamp, but we can’t.”

Part of freedom is an independent judiciary – which is why politicians and bureaucrats avoid them whenever possible.

New York Congressman Peter King stated on the weekend that he agrees with Sarah Palin, Newt Gingrich, other Republicans and Al-Qaeda that there is some kind of religious war going on:

“President Obama is wrong,” said King in an e-mailed statement. “The right and moral thing for President Obama to have done was to urge Muslim leaders to respect the families of those who died and move their mosque away from Ground Zero.”

I hadn’t realized there was a religious crusade going on; I thought it was simply some harrassment of the civilized world by a rag-tag pack of psychopaths. But it’s nice to see the US Republicans agree with Al-Qaeda on something; it gives hope for the brotherhood of man.

There was good volume in the Canadian preferred share market today as PerpetualDiscounts gained 9bp and FixedResets were up 9bp. The win by FixedResets took their median weighted average yield down to 3.318%, just a hair off the all-time low of 3.314% set on March 26.

MFC was again prominent on the highlight reel.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.0000 % 2,054.7
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.0000 % 3,112.6
Floater 2.55 % 2.16 % 38,454 21.97 4 0.0000 % 2,218.5
OpRet 4.90 % -1.56 % 99,153 0.20 9 -0.3000 % 2,352.1
SplitShare 6.05 % -2.62 % 64,157 0.08 2 0.2299 % 2,293.5
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.3000 % 2,150.8
Perpetual-Premium 5.81 % 5.55 % 93,684 5.65 7 -0.1301 % 1,947.4
Perpetual-Discount 5.78 % 5.83 % 180,241 14.07 71 0.0865 % 1,875.4
FixedReset 5.30 % 3.32 % 272,788 3.39 47 0.0921 % 2,239.9
Performance Highlights
Issue Index Change Notes
MFC.PR.D FixedReset -1.25 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-07-19
Maturity Price : 25.00
Evaluated at bid price : 26.91
Bid-YTW : 4.34 %
MFC.PR.A OpRet -1.18 % YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2015-12-18
Maturity Price : 25.00
Evaluated at bid price : 25.03
Bid-YTW : 4.02 %
RY.PR.T FixedReset 1.05 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-09-23
Maturity Price : 25.00
Evaluated at bid price : 27.84
Bid-YTW : 3.26 %
Volume Highlights
Issue Index Shares
Traded
Notes
TRP.PR.A FixedReset 155,470 RBC crossed blocks of 100,000 and 40,000 at 26.05.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2015-01-30
Maturity Price : 25.00
Evaluated at bid price : 26.02
Bid-YTW : 3.76 %
MFC.PR.B Perpetual-Discount 85,589 Nesbitt crossed blocks of 20,000 and 40,000 at 18.80.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-16
Maturity Price : 18.70
Evaluated at bid price : 18.70
Bid-YTW : 6.22 %
TD.PR.R Perpetual-Discount 60,830 Desjardins crossed 15,400 at 24.75; CIBC bought 13,000 from National at 24.78.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-16
Maturity Price : 24.52
Evaluated at bid price : 24.75
Bid-YTW : 5.70 %
TRP.PR.C FixedReset 55,030 RBC crossed 49,100 at 25.35.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-16
Maturity Price : 23.22
Evaluated at bid price : 25.30
Bid-YTW : 3.74 %
GWO.PR.H Perpetual-Discount 54,800 Desjardins crossed 25,000 at 20.85; Nesbitt crossed 25,000 at 20.86.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-16
Maturity Price : 20.85
Evaluated at bid price : 20.85
Bid-YTW : 5.91 %
TRP.PR.B FixedReset 39,241 Nesbitt crossed 25,000 at 25.05.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-16
Maturity Price : 24.97
Evaluated at bid price : 25.02
Bid-YTW : 3.62 %
There were 35 other index-included issues trading in excess of 10,000 shares.
Market Action

August 13, 2010

Nothing happened today. BOR-RING!

It was a relatively quiet day in the Canadian preferred share market as well, where volume was below average. PerpetualDiscounts were about as flat as you can get, despite dominating the (reasonably short) performance table, which was in turn comprised entirely of losers. The Manulife PerpetualDiscounts, MFC.PR.B and MFC.PR.C had a horrible day; it appears that a number of holders wanted to sell after last week’s earnings release, but wanted to earn just one more dividend before getting out. Both issues made it onto the volume table as well.

It was left to FixedResets to provide the day’s entertainment and they managed to gain 5bp on the day, taking the median weighted average yield down to 3.35% – the second lowest on record, beaten only by March 26 … which, as many will know, marked the beginning of a severe slump in prices that lasted until the end of April.

I asked a Technical Analyst if 3.30% marked a Resistance Point, but after talking for half an hour he realized that not only was his chart upside down, but that the kids had been using it for tick tac toe. I’ll call him again next year and learn why it is now totally obvious that the market is currently about to … er … do whatever it’s going to do.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.5786 % 2,054.7
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.5786 % 3,112.6
Floater 2.55 % 2.15 % 35,602 21.94 4 -0.5786 % 2,218.5
OpRet 4.88 % -1.50 % 100,455 0.21 9 0.0155 % 2,359.2
SplitShare 6.06 % -1.01 % 64,763 0.08 2 0.1675 % 2,288.2
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0155 % 2,157.3
Perpetual-Premium 5.80 % 5.57 % 94,556 5.60 7 0.1813 % 1,950.0
Perpetual-Discount 5.79 % 5.87 % 172,772 14.03 71 -0.0002 % 1,873.7
FixedReset 5.30 % 3.35 % 275,212 3.40 47 0.0490 % 2,237.9
Performance Highlights
Issue Index Change Notes
MFC.PR.B Perpetual-Discount -2.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-13
Maturity Price : 18.70
Evaluated at bid price : 18.70
Bid-YTW : 6.22 %
MFC.PR.C Perpetual-Discount -2.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-13
Maturity Price : 18.31
Evaluated at bid price : 18.31
Bid-YTW : 6.15 %
GWO.PR.J FixedReset -1.58 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-01-30
Maturity Price : 25.00
Evaluated at bid price : 27.35
Bid-YTW : 3.35 %
HSB.PR.D Perpetual-Discount -1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-13
Maturity Price : 21.54
Evaluated at bid price : 21.54
Bid-YTW : 5.89 %
BAM.PR.K Floater -1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-13
Maturity Price : 15.05
Evaluated at bid price : 15.05
Bid-YTW : 3.22 %
ELF.PR.G Perpetual-Discount -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-13
Maturity Price : 19.15
Evaluated at bid price : 19.15
Bid-YTW : 6.28 %
Volume Highlights
Issue Index Shares
Traded
Notes
MFC.PR.B Perpetual-Discount 34,882 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-13
Maturity Price : 18.70
Evaluated at bid price : 18.70
Bid-YTW : 6.22 %
RY.PR.X FixedReset 26,733 TD crossed 20,000 at 27.80.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-09-23
Maturity Price : 25.00
Evaluated at bid price : 27.82
Bid-YTW : 3.29 %
ELF.PR.G Perpetual-Discount 25,975 Nesbitt crossed 20,400 at 19.10.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-13
Maturity Price : 19.15
Evaluated at bid price : 19.15
Bid-YTW : 6.28 %
MFC.PR.E FixedReset 25,200 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-10-19
Maturity Price : 25.00
Evaluated at bid price : 26.36
Bid-YTW : 4.04 %
BMO.PR.P FixedReset 23,735 TD crossed 17,200 at 27.35.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2015-03-27
Maturity Price : 25.00
Evaluated at bid price : 27.30
Bid-YTW : 3.18 %
MFC.PR.C Perpetual-Discount 22,305 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-13
Maturity Price : 18.31
Evaluated at bid price : 18.31
Bid-YTW : 6.15 %
There were 17 other index-included issues trading in excess of 10,000 shares.
Market Action

August 12, 2010

Jump on the long corporate express!

Johnson & Johnson sold $1.1 billion of bonds at the lowest interest rates on record for 10-year and 30-year securities amid surging investor demand for the highest- rated corporate debt.

The drugmaker, in the first offering by a nonfinancial AAA rated company in 15 months, sold $550 million of 2.95 percent, 10-year notes and the same amount of 4.5 percent, 30-year bonds, according to data compiled by Bloomberg. That’s the lowest coupons for those maturities on record, according to Citigroup Inc. data going back to 1981.
…
The company’s 10-year debt yields 43 basis points more than similar-maturity Treasuries, and the 30-year bonds pay a spread of 68 basis points, Bloomberg data show. A basis point is 0.01 percentage point.

Greece isn’t having much fun:

Greece’s recession deepened in the second quarter, according to official estimates released Thursday, as the country felt the painful consequences of the government’s drive to reduce its debt load with aggressive austerity cuts.

Gross domestic product declined by 1.5 per cent from the previous quarter as the government reduced spending. The unemployment rate, meanwhile, rose to 12 per cent in May from 11.9 per cent, the statistics agency said.

Manulife common took another hit today:

Worries about deteriorating economic conditions pushed the TSX financial sector down 1.56 per cent as TD Bank (TSX:TD) fell 90 cents to $70.82. Manulife Financial was down 62 cents or 4.62 per cent at $12.79 in heavy trading. Its stock has plunged 20 per cent since surprising investors with a $2.4-billion quarterly loss last week, followed by a downgrade by DBRS.

The PerpetualDiscount preferreds, MFC.PR.B and MFC.PR.C have underperformed their index sharply, but not ridiculously, since August 4, the day before the earnings announcement: -1.67% and -1.71% vs. +0.41%. However, they go ex-Dividend tomorrow and we may well see a rush for the exits.

The Canadian preferred share market was strong today on average volume, with PerpetualDiscounts up 10bp and FixedResets up 15bp. The win by the FixedResets took their yield to the sixth-lowest of all time, just a hair higher than the recent low set on August 4.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.2361 % 2,066.6
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.2361 % 3,130.7
Floater 2.53 % 2.14 % 37,065 21.97 4 -0.2361 % 2,231.4
OpRet 4.88 % 1.41 % 104,205 0.21 9 0.0986 % 2,358.8
SplitShare 6.07 % -1.70 % 66,993 0.08 2 0.8870 % 2,284.4
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0986 % 2,156.9
Perpetual-Premium 5.81 % 5.54 % 97,808 5.66 7 -0.1584 % 1,946.4
Perpetual-Discount 5.79 % 5.81 % 174,581 14.04 71 0.0992 % 1,873.7
FixedReset 5.30 % 3.39 % 278,778 3.40 47 0.1498 % 2,236.8
Performance Highlights
Issue Index Change Notes
BMO.PR.H Perpetual-Discount 1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-12
Maturity Price : 22.97
Evaluated at bid price : 23.86
Bid-YTW : 5.53 %
NA.PR.L Perpetual-Discount 1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-12
Maturity Price : 21.55
Evaluated at bid price : 21.55
Bid-YTW : 5.66 %
TD.PR.O Perpetual-Discount 1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-12
Maturity Price : 22.07
Evaluated at bid price : 22.21
Bid-YTW : 5.50 %
GWO.PR.J FixedReset 1.61 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-01-30
Maturity Price : 25.00
Evaluated at bid price : 27.79
Bid-YTW : 2.83 %
BNA.PR.C SplitShare 1.97 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2019-01-10
Maturity Price : 25.00
Evaluated at bid price : 21.26
Bid-YTW : 6.88 %
Volume Highlights
Issue Index Shares
Traded
Notes
TRP.PR.B FixedReset 50,800 RBC crossed 25,000 at 25.01.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-12
Maturity Price : 24.95
Evaluated at bid price : 25.00
Bid-YTW : 3.68 %
RY.PR.B Perpetual-Discount 37,618 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-12
Maturity Price : 21.01
Evaluated at bid price : 21.01
Bid-YTW : 5.62 %
RY.PR.I FixedReset 36,890 Nesbitt crossed 35,200 at 26.35.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-03-26
Maturity Price : 25.00
Evaluated at bid price : 26.33
Bid-YTW : 3.34 %
BNS.PR.Y FixedReset 27,420 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-12
Maturity Price : 24.85
Evaluated at bid price : 24.90
Bid-YTW : 3.41 %
TRP.PR.C FixedReset 26,100 Desjardins crossed 10,000 at 25.26.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-12
Maturity Price : 23.20
Evaluated at bid price : 25.23
Bid-YTW : 3.82 %
CM.PR.H Perpetual-Discount 24,850 Nesbitt crossed 10,500 at 21.00.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-12
Maturity Price : 20.98
Evaluated at bid price : 20.98
Bid-YTW : 5.77 %
There were 25 other index-included issues trading in excess of 10,000 shares.
Market Action

August 11, 2010

The FOMC was gloomy yesterday; the BoE is gloomy today:

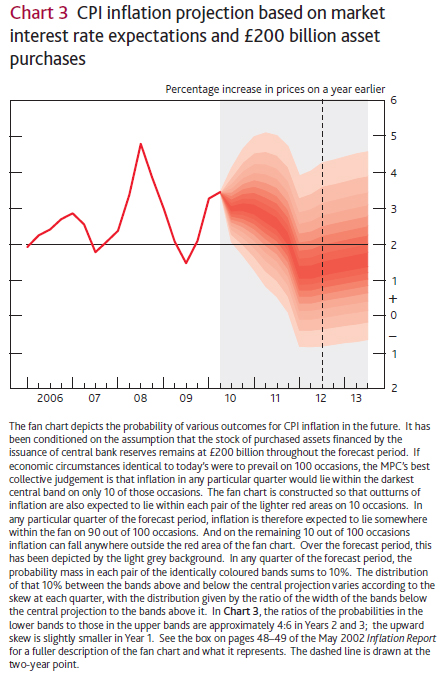
Bank of England Governor Mervyn King said inflation will probably slow below the bank’s target in 2012 and growth will be weaker than previously forecast, signaling the U.K. economy may need more emergency stimulus.

Inflation will be about 1.5 percent in two years, below the 2 percent goal, the central bank said in its quarterly Inflation Report today. Inflation will undershoot the target even if the bank keeps its benchmark interest rate at the current 0.5 percent, the forecasts show. Growth may peak at a 3 percent annual pace instead of the 3.6 percent rate forecast in May.

The full inflation report uses the highly-touted fan charts that were recommended for central bank communications a few years back.


Click for big

An Assiduous Reader draws my attention to the 3Q10 Report of the Treasury Borrowing Advisory Committee:

The bulk of the reduction in coupon issuance should continue to be in the two-year, three-year, five-year and seven-year maturities. Although this is broadly consistent with the Committee’s desire to increase the average maturity of the outstanding debt, some felt that given the meaningful progress thus far, reductions in ten-year notes and thirty-year bonds could be justified.
…
Finally, the Committee felt that growing TIPS from roughly $80 billion gross issuance in fiscal year 2010, to over $100 billion in fiscal year 2011, was still appropriate.
…
The presentation (see attached) highlights that municipal bonds outstanding rose over the last decade by $1 trillion to $2.8 trillion. Despite some of the recent headline risks and the challenging economic outlook, the member concluded the municipal market appears to be in reasonably good condition. Broadly, municipalities still have a low probability of default, historically high recoveries, low absolute cost of funds, access to a broader investor base via the Build America Bonds program, and a largely unlevered existing retail investor base. Implicit in this analysis is the Federal government’s willingness to intervene in the event the municipal market ceases to function.
…
…the presentation (see attached) highlights the absence of mortgage hedging needs as a stabilizing force underpinning long term yields. In addition, the member referenced the secular increase in demand for long duration assets from asset managers, insurance companies, and pension funds. Furthermore, cyclically, the member showed that investor confidence in the path of central bank policy rates tends to anchor long term yields.

The seeds of something very interesting may have been planted in Greece:

Slovakia’s parliament rejected the nation’s participation in a loan for Greece after the month-old government overturned the previous Cabinet’s policy and said poor countries shouldn’t pay for the profligacy of richer peers.

Of the 84 lawmakers present in the Bratislava-based assembly, one voted in favor while 69 were against and 14 abstained, reversing a decision by the previous Cabinet to lend Greece 816 million euros ($1.1 billion). The funds were to be part of a loan package pledged by the European Union to help Greece avoid a default. The current Slovak government of Iveta Radicova, which took office last month, is against the aid.

The vote breaks the euro region’s unity in handling the sovereign-debt crisis, though the decision won’t prevent Greece from drawing the loan.

Assiduous Readers will remember the whispers that Lehman failed in part because its peers wouldn’t give it emergency relief, which in turn was because it did not participate in the Long Term Capital Management bail-out of 1998. Now, I like to think that the full story is a little more hard-nosed and a little less school-girlish than that … but I will agree it may have had some influence.

The SEC/CFTC inquiry into the Flash Crash is continuing:

As part of the SEC and CFTC review of market events on May 6, we are pursuing two related courses of inquiry. The first is empirical and data driven. SEC staff have been reviewing raw transaction and order data, order book “snapshots,” trade summaries, information about broken trades, and information related to initiation of LRPs and self-help. The second is focused on extensive interviews with market participants — their first-hand accounts of what occurred on May 6 and their responses to those events. These efforts will culminate in an SEC-CFTC joint report that will be presented to this Committee for its consideration next month and, of course, shared with the public, as well.We are considering, as well, whether other steps are appropriate to reduce the risk of sudden disruptions and clearly erroneous trades, including deterring or prohibiting the use of “stub” quotes by market makers.

The comments have been published. BlackRock wants:

We believe those reforms should include:

  • Uniform “circuit breakers” for stocks and ETFs across all exchanges;
  • Making exchange trade error cancellation rules less arbitrary and more transparent in a manner that does not discourage liquidity providers from providing liquidity at times of market stress
  • Clearer guidelines for inter-market order routing rules
  • Replacing “stop loss” orders with “stop loss limit” orders to specify a limit price; and
  • Expanding the role of lead market makers to ensure orderly market functioning.

TD Ameritrade makes the startling revelation:

The firm has noted previously that the May 6th market event demonstrated that today’s markets contain many players who use their liquidity opportunistically – applying it when in their favor, but pulling it during times of market duress.

… and defends stop orders without any quantification:

Finally, as to the specific allegation that retail market orders and stop orders contributed to the downturn, I can tell you from TD Ameritrade’s perspective, such orders are important to our clients, and looking at our own data, we do not believe there is any factual basis to assert that these types of orders contributed to the problem. In fact, TD Ameritrade clients’ market and stop orders were within average daily volume, on a percentage basis. Prohibiting market and stop orders would be a significantly adverse, misguided, and unnecessary over-reaction to the underlying causes of the May 6th market event, which would unduly deny to retail investors the access to the markets that they enjoy today.

Knight Capital, on the other hand, highlights stop orders:

When the S&P 500 traded at 1120, stop orders were triggered and the market traded lower. When the market did not promptly bounce back, buyers became sellers and the market traded down another 5% -6%. During this period, the NYSE triggered its liquidity refreshment points (LRPs) in a number of securities. Orders were then routed away from the NYSE to other destinations where liquidity in certain stocks was thinner and prices wider.

Invesco has a different view:

As an institution, we have long understood the significant risk of using market orders particularly as the market has become more fragmented. We abandoned their use many years ago in favor of marketable limit and limit orders. In light of the events of May 6 and the continuing issues small market orders have had in the market (i.e., electing newly imposed single-stock circuit breakers on WPO, CSCO, C, APC), Invesco strongly supports the examination of the current practices surrounding the use of market orders, particularly the use of “stop loss” orders. We would recommend at the very least that exchanges or broker dealers who continue to use market orders do so using collars on the market orders they submit. A collared market order should only allow execution of the order within a certain percentage of the reference price (i.e., 3% from the last sale). This would give their clients some level of protection from the impact market orders can have in the current environment and would likely reduce or altogether eliminate the issue of small share amounts triggering circuit breakers.

Invesco also wants examination of HFT:

Additionally, regulators should act to address the increasing number of order cancellations in the securities markets. It has been theorized that as many as 95% of all orders entered by high frequency traders are subsequently cancelled. Incentives that currently exist for market participants to route orders to particular venues, such as liquidity rebates, and any related conflicts of interest that may arise due to these incentives also need to be examined.

Dow Jones has a report focussing on market-making obligations titled DJ New Obligations For Market Liquidity Providers Questioned:

Getco LLC, Virtu Financial LLC and Knight Capital Group Inc. (KCG) have proposed to the SEC a range of new rules for market makers. The rules under consideration could include a requirement for market makers to provide quotes to buy or sell a stock no more than 10% above or below the current price.

Mendelson said new market making obligations would increase costs for retail and institutional investors. “On those rare occasions when markets are severely disrupted, market-maker obligations will accomplish nothing,” he said. “Let’s not do it here. It will just add a burden for investors.”

Me, I think the whole concept of allowing special privileges to market makers in exchange for obligations of any type really needs to be examined. It is at least generally accepted as ludicrous that the obligations can be met with a stub-quote.

But to get total insanity, you need a politician and Senator Charles Schumer fills the void:

Many institutional investors and trading firms left the market that day as volatility peaked during the session, according to an SEC investigation detailed Wednesday during a joint hearing held by the SEC and the Commodity Futures Trading Commission. A final report on the flash crash is due in September.

Sen. Schumer said in his letter that any trader or firm making markets in 25 or more stocks or exchange-traded funds ought to bear trading obligations, according to a draft seen by Dow Jones Newswires.

His recommendations for market makers closely align with several proposals made last month by trading firms Knight Capital Group Inc., Getco LLC and Virtu Financial LLC.

Market makers are traders who stand ready to take the other side of an incoming order. The evolution of markets has seen the practice evolve into a competitive industry dominated by computer-driven trading systems.

The SEC must update its definition of market makers to account for this shift, Sen. Schumer said. He proposed requiring such participants to quote prices between the highest bid and lowest offer for a certain period of the trading day, depending on the stock.

I don’t see anything remotely like this proposal in the Knight Capital letter on the Flash Crash, it’s in another letter entirely, Comment Letter on File No. S7-02-10, which is the Concept Release on Equity Market Structure. I wish journalists would realize that their beloved quill pen era has gone for good, and start footnoting their damn stories.

I’ve suggested Dubai on occasion as an alternative financial centre for hedge funds et al. Well, they’ll have to reform their justice system a little:

In all, about 40 percent of the 1,200 people in Dubai Central Prison have been convicted of defaulting on bank loans, Human Rights Watch said in a report in January. Even after completing their sentences, the New York-based group said, prisoners are likely to remain in jail until their debt is paid off, unlike in the U.S. or the U.K., where debtors’ prisons were abolished in the 19th century.

Over-lengthy sentences and insufficiently developed laws for prosecuting financial crime threaten to discourage investment in Dubai, said Habib al-Mulla, the former chairman of the Dubai Financial Services Authority, an industry regulator. The U.S. State Department said in a March report that while the country’s constitution guarantees an independent judiciary, the U.A.E. court system remains “subject to review by the political leadership.” Defendants can spend months without being charged and are often unfairly denied bail, according to lawyers.

The European sovereign debt crisis is bad enough for Spain, but the regions are being hit worse:

Catalonia, which accounts for a fifth of Spanish gross domestic product, has been shut out of public bond markets since March and the extra yield it pays over national government debt has almost tripled this year. Galicia, in the northwest, has asked to freeze payments of debt it owes the central government and the Madrid region postponed a bond sale last month.

Spain’s regions, which borrowed at similar rates to the central government before the global credit crisis started in 2007, are key players in Zapatero’s drive to get his budget in order and push down the country’s borrowing costs. They control around twice as much spending as the state, employ more than half of all public workers and piled on debt during the recession.
…
The yield on 10-year Spanish government bonds has dropped 78 basis points to 4.102 percent since June 16. The extra return investors demand to hold the debt rather than German equivalents was at 168 basis points yesterday, down from a euro-era high of 221 points two months ago.

Banks are nevertheless charging Catalonia more for loans than the building companies stung by Spain’s construction slump.

The region, which attracts more tourists than any other in Spain, paid 300 basis points more than three-month Euribor for 1 billion euros of four-year bank loans last month, a spokesman said. Fomento de Construcciones & Contratas SA, Spain’s fourth- largest builder, said on Aug. 2 it agreed to pay a 260-basis point spread to extend 1.1 billion euros of loans until 2014.

The Canadian preferred share market edged higher on good volume today, with PerpetualDiscounts gaining 9bp and FixedResets up 6bp.

PerpetualDiscounts now yield 5.82%, equivalent to 8.15% at the standard equivalency factor of 1.4x. Long Corporates now yield about 5.4% (!) so the pre-tax interest-equivalent spread (also called the Seniority Spread) now stands at about 275bp, a small (and perhaps meaningless) widening from the 270bp reported August 4.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.1833 % 2,071.5
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.1833 % 3,138.1
Floater 2.53 % 2.14 % 38,588 21.99 4 -0.1833 % 2,236.7
OpRet 4.88 % -1.47 % 105,764 0.22 9 -0.0857 % 2,356.5
SplitShare 6.12 % -1.47 % 67,917 0.08 2 -0.1897 % 2,264.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0857 % 2,154.8
Perpetual-Premium 5.80 % 5.50 % 98,183 5.66 7 0.1927 % 1,949.5
Perpetual-Discount 5.79 % 5.82 % 175,951 14.05 71 0.0868 % 1,871.9
FixedReset 5.31 % 3.41 % 281,088 3.40 47 0.0623 % 2,233.4
Performance Highlights
Issue Index Change Notes
PWF.PR.P FixedReset 1.25 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-03-01
Maturity Price : 25.00
Evaluated at bid price : 25.87
Bid-YTW : 3.80 %
GWO.PR.L Perpetual-Discount 1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-11
Maturity Price : 23.92
Evaluated at bid price : 24.11
Bid-YTW : 5.94 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.G Perpetual-Discount 89,915 RBC crossed blocks of 23,700 and 50,000, both at 20.25.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-11
Maturity Price : 20.21
Evaluated at bid price : 20.21
Bid-YTW : 5.59 %
IAG.PR.C FixedReset 49,512 Desjardins crossed 16,500 at 27.35; RBC crossed 30,000 at the same price.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-01-30
Maturity Price : 25.00
Evaluated at bid price : 27.20
Bid-YTW : 3.72 %
BMO.PR.P FixedReset 40,210 RBC crossed 29,900 at 27.12.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2015-03-27
Maturity Price : 25.00
Evaluated at bid price : 27.13
Bid-YTW : 3.33 %
TRP.PR.A FixedReset 37,565 TD crossed 25,000 at 25.92.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2015-01-30
Maturity Price : 25.00
Evaluated at bid price : 25.92
Bid-YTW : 3.85 %
CM.PR.H Perpetual-Discount 35,725 Nesbitt crossed 10,000 at 20.96.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-11
Maturity Price : 20.95
Evaluated at bid price : 20.95
Bid-YTW : 5.78 %
GWO.PR.I Perpetual-Discount 31,150 TD crossed 21,600 at 19.33.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2040-08-11
Maturity Price : 19.39
Evaluated at bid price : 19.39
Bid-YTW : 5.89 %
There were 32 other index-included issues trading in excess of 10,000 shares.