The FOMC tightened today:
The Federal Open Market Committee approved the following statement for release by a 12 – 0 vote:
The Committee decided to raise the target range for the federal funds rate by 1/4 percentage point to 3-3/4 to 4 percent, in support of the Federal Reserve’s dual mandate. The Committee is continuing its policy of maintaining ample reserves in the banking system.
Economic activity is expanding at a solid pace. While uncertainty remains elevated owing, in part, to geopolitical developments, domestic spending has been resilient. Productivity growth is strong, and capital investment is robust. Job gains have kept pace with the workforce, and the unemployment rate has changed little.
Inflation remains elevated. Today’s policy action will support a timelier return to the Committee’s 2 percent goal. The Committee will deliver price stability.
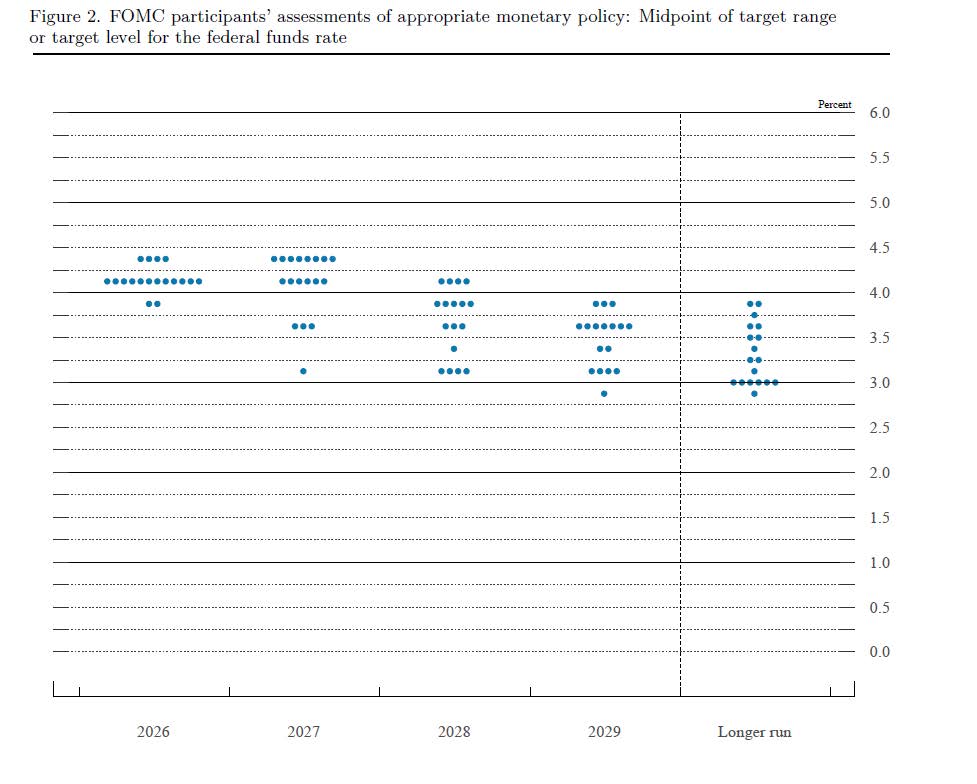
… and the dot plot suggests there will be more to come … and not just for a little while:
Equities didn’t like it:
Before the Fed’s announcement, the three major U.S. stock indexes had been gaining ground, with a chips rebound, giving the tech-heavy Nasdaq the edge. Earlier in the session, robust U.S. retail sales data suggested consumers were still spending, despite an affordability squeeze due to rising prices, particularly at the gasoline pump.
The war in the Middle East expanded as Saudi warplanes pounded Yemen while Iran-backed Houthi fighters launched drones and missiles at Saudi cities in a signal of Iran’s extended reach in the widening conflict.
Even so, oil prices dipped after reports that Saudi Arabia was offering additional crude cargoes via Oman eased concerns about supply disruptions. Crude is up over 20% in the last 2-1/2 weeks. Front-month WTI settled down 3.2% and Brent crude settled down 2.7%.
The Dow Jones Industrial Average fell 631.33 points, or 1.21%, to 51,461.78, the S&P 500 lost 33.59 points, or 0.44%, to 7,552.14 and the Nasdaq Composite lost 3.15 points, or 0.01%, to 25,978.43.
The S&P/TSX Composite Index ended down 90.8 points, or 0.3%, at 35,491.27, its lowest closing level since July 31.
…
Six of the 10 major TSX sectors notched gains, led by a 1.9% advance for utilities as yields on long-dated bonds eased. Short-term U.S. bond yields, however, did rise following the Fed announcement and press conference, signaling a market pricing in more rate hikes ahead. Fed policy decisions having a greater immediate impact on the shorter end of the bond curve.
| HIMIPref™ Preferred Indices These values reflect the December 2008 revision of the HIMIPref™ Indices Values are provisional and are finalized monthly |
|||||||
| Index | Mean Current Yield (at bid) |
Median YTW |
Median Average Trading Value |
Median Mod Dur (YTW) |
Issues | Day’s Perf. | Index Value |
| Ratchet | 0.00 % | 0.00 % | 0 | 0.00 | 0 | 0.0221 % | 2,794.3 |
| FixedFloater | 0.00 % | 0.00 % | 0 | 0.00 | 0 | 0.0221 % | 5,262.1 |
| Floater | 5.17 % | 5.20 % | 31,084 | 15.23 | 3 | 0.0221 % | 3,032.6 |
| OpRet | 0.00 % | 0.00 % | 0 | 0.00 | 0 | 0.1494 % | 3,632.5 |
| SplitShare | 4.65 % | 4.41 % | 55,993 | 2.53 | 4 | 0.1494 % | 4,337.9 |
| Interest-Bearing | 0.00 % | 0.00 % | 0 | 0.00 | 0 | 0.1494 % | 3,384.6 |
| Perpetual-Premium | 5.75 % | 5.83 % | 75,010 | 14.03 | 9 | -0.0715 % | 3,018.7 |
| Perpetual-Discount | 5.72 % | 5.82 % | 42,482 | 14.12 | 21 | 0.0843 % | 3,305.0 |
| FixedReset Disc | 5.63 % | 6.28 % | 84,664 | 13.43 | 21 | -0.2115 % | 3,385.3 |
| Insurance Straight | 5.65 % | 5.65 % | 49,519 | 14.37 | 19 | -0.4814 % | 3,185.0 |
| FloatingReset | 0.00 % | 0.00 % | 0 | 0.00 | 0 | -0.2115 % | 4,133.4 |
| FixedReset Prem | 5.96 % | 4.66 % | 82,110 | 2.03 | 27 | -0.1404 % | 2,648.9 |
| FixedReset Bank Non | 0.00 % | 0.00 % | 0 | 0.00 | 0 | -0.2115 % | 3,460.4 |
| FixedReset Ins Non | 5.24 % | 5.50 % | 55,349 | 1.88 | 14 | -0.5306 % | 3,256.7 |
| Performance Highlights | |||
| Issue | Index | Change | Notes |
| GWO.PR.Y | Insurance Straight | -5.47 % | YTW SCENARIO Maturity Type : Limit Maturity Maturity Date : 2056-09-16 Maturity Price : 19.00 Evaluated at bid price : 19.00 Bid-YTW : 5.95 % |
| BN.PR.T | FixedReset Disc | -5.39 % | YTW SCENARIO Maturity Type : Limit Maturity Maturity Date : 2056-09-16 Maturity Price : 22.14 Evaluated at bid price : 22.80 Bid-YTW : 6.42 % |
| MFC.PR.L | FixedReset Ins Non | -3.33 % | YTW SCENARIO Maturity Type : Limit Maturity Maturity Date : 2056-09-16 Maturity Price : 23.29 Evaluated at bid price : 24.65 Bid-YTW : 5.83 % |
| BN.PR.B | Floater | -2.48 % | YTW SCENARIO Maturity Type : Limit Maturity Maturity Date : 2056-09-16 Maturity Price : 14.53 Evaluated at bid price : 14.53 Bid-YTW : 5.38 % |
| MFC.PR.Q | FixedReset Ins Non | -2.26 % | YTW SCENARIO Maturity Type : Call Maturity Date : 2028-06-19 Maturity Price : 25.00 Evaluated at bid price : 25.12 Bid-YTW : 5.67 % |
| BN.PR.M | Perpetual-Discount | -2.22 % | YTW SCENARIO Maturity Type : Limit Maturity Maturity Date : 2056-09-16 Maturity Price : 20.24 Evaluated at bid price : 20.24 Bid-YTW : 5.89 % |
| GWO.PR.Q | Insurance Straight | -1.55 % | YTW SCENARIO Maturity Type : Limit Maturity Maturity Date : 2056-09-16 Maturity Price : 21.97 Evaluated at bid price : 22.20 Bid-YTW : 5.81 % |
| ENB.PR.D | FixedReset Disc | -1.47 % | YTW SCENARIO Maturity Type : Limit Maturity Maturity Date : 2056-09-16 Maturity Price : 23.06 Evaluated at bid price : 23.50 Bid-YTW : 6.36 % |
| GWO.PR.N | FixedReset Ins Non | -1.44 % | YTW SCENARIO Maturity Type : Limit Maturity Maturity Date : 2056-09-16 Maturity Price : 20.60 Evaluated at bid price : 20.60 Bid-YTW : 5.73 % |
| NA.PR.G | FixedReset Prem | -1.31 % | YTW SCENARIO Maturity Type : Call Maturity Date : 2028-11-16 Maturity Price : 25.00 Evaluated at bid price : 26.40 Bid-YTW : 4.63 % |
| ENB.PR.Y | FixedReset Disc | -1.29 % | YTW SCENARIO Maturity Type : Limit Maturity Maturity Date : 2056-09-16 Maturity Price : 22.44 Evaluated at bid price : 23.00 Bid-YTW : 6.41 % |
| SLF.PR.C | Insurance Straight | -1.25 % | YTW SCENARIO Maturity Type : Limit Maturity Maturity Date : 2056-09-16 Maturity Price : 20.59 Evaluated at bid price : 20.59 Bid-YTW : 5.43 % |
| GWO.PR.G | Insurance Straight | -1.17 % | YTW SCENARIO Maturity Type : Limit Maturity Maturity Date : 2056-09-16 Maturity Price : 22.49 Evaluated at bid price : 22.75 Bid-YTW : 5.73 % |
| BN.PF.B | FixedReset Prem | -1.10 % | YTW SCENARIO Maturity Type : Call Maturity Date : 2029-04-01 Maturity Price : 25.00 Evaluated at bid price : 25.22 Bid-YTW : 5.71 % |
| SLF.PR.D | Insurance Straight | -1.06 % | YTW SCENARIO Maturity Type : Limit Maturity Maturity Date : 2056-09-16 Maturity Price : 20.48 Evaluated at bid price : 20.48 Bid-YTW : 5.46 % |
| PWF.PF.A | Perpetual-Discount | -1.05 % | YTW SCENARIO Maturity Type : Limit Maturity Maturity Date : 2056-09-16 Maturity Price : 19.76 Evaluated at bid price : 19.76 Bid-YTW : 5.78 % |
| GWO.PR.I | Insurance Straight | -1.04 % | YTW SCENARIO Maturity Type : Limit Maturity Maturity Date : 2056-09-16 Maturity Price : 20.00 Evaluated at bid price : 20.00 Bid-YTW : 5.65 % |
| BN.PF.A | FixedReset Prem | 1.17 % | YTW SCENARIO Maturity Type : Call Maturity Date : 2028-09-30 Maturity Price : 25.00 Evaluated at bid price : 25.85 Bid-YTW : 4.88 % |
| BN.PR.K | Floater | 1.21 % | YTW SCENARIO Maturity Type : Limit Maturity Maturity Date : 2056-09-16 Maturity Price : 15.04 Evaluated at bid price : 15.04 Bid-YTW : 5.20 % |
| PWF.PR.A | Floater | 1.30 % | YTW SCENARIO Maturity Type : Limit Maturity Maturity Date : 2056-09-16 Maturity Price : 15.60 Evaluated at bid price : 15.60 Bid-YTW : 5.05 % |
| BN.PF.M | FixedReset Prem | 1.39 % | YTW SCENARIO Maturity Type : Call Maturity Date : 2031-01-01 Maturity Price : 25.00 Evaluated at bid price : 25.60 Bid-YTW : 5.00 % |
| GWO.PR.S | Insurance Straight | 2.69 % | YTW SCENARIO Maturity Type : Limit Maturity Maturity Date : 2056-09-16 Maturity Price : 22.66 Evaluated at bid price : 22.90 Bid-YTW : 5.74 % |
| GWO.PR.R | Insurance Straight | 2.90 % | YTW SCENARIO Maturity Type : Limit Maturity Maturity Date : 2056-09-16 Maturity Price : 20.95 Evaluated at bid price : 20.95 Bid-YTW : 5.75 % |
| CU.PR.J | Perpetual-Discount | 6.14 % | YTW SCENARIO Maturity Type : Limit Maturity Maturity Date : 2056-09-16 Maturity Price : 20.91 Evaluated at bid price : 20.91 Bid-YTW : 5.74 % |
| BN.PR.Z | FixedReset Disc | 8.94 % | YTW SCENARIO Maturity Type : Call Maturity Date : 2027-12-31 Maturity Price : 25.00 Evaluated at bid price : 25.60 Bid-YTW : 4.00 % |
| Volume Highlights | |||
| Issue | Index | Shares Traded |
Notes |
| ENB.PR.B | FixedReset Disc | 34,140 | YTW SCENARIO Maturity Type : Limit Maturity Maturity Date : 2056-09-16 Maturity Price : 23.08 Evaluated at bid price : 23.75 Bid-YTW : 6.33 % |
| FTS.PR.M | FixedReset Prem | 28,000 | YTW SCENARIO Maturity Type : Call Maturity Date : 2029-12-01 Maturity Price : 25.00 Evaluated at bid price : 25.10 Bid-YTW : 5.47 % |
| BILP.PR.A | FixedReset Prem | 26,975 | YTW SCENARIO Maturity Type : Call Maturity Date : 2031-10-01 Maturity Price : 25.00 Evaluated at bid price : 25.20 Bid-YTW : 5.55 % |
| GWO.PF.A | Perpetual-Premium | 17,505 | YTW SCENARIO Maturity Type : Limit Maturity Maturity Date : 2056-09-16 Maturity Price : 24.45 Evaluated at bid price : 24.84 Bid-YTW : 5.74 % |
| SLF.PR.D | Insurance Straight | 10,925 | YTW SCENARIO Maturity Type : Limit Maturity Maturity Date : 2056-09-16 Maturity Price : 20.48 Evaluated at bid price : 20.48 Bid-YTW : 5.46 % |
| GWO.PR.R | Insurance Straight | 10,500 | YTW SCENARIO Maturity Type : Limit Maturity Maturity Date : 2056-09-16 Maturity Price : 20.95 Evaluated at bid price : 20.95 Bid-YTW : 5.75 % |
| There were 0 other index-included issues trading in excess of 10,000 shares. | |||
| Wide Spread Highlights | ||
| See TMX DataLinx: ‘Last’ != ‘Close’ and the posts linked therein for an idea of why these quotes are so horrible. | ||
| Issue | Index | Quote Data and Yield Notes |
| GWO.PR.Y | Insurance Straight | Quote: 19.00 – 20.50 Spot Rate : 1.5000 Average : 1.0009 YTW SCENARIO |
| BN.PR.T | FixedReset Disc | Quote: 22.80 – 24.20 Spot Rate : 1.4000 Average : 0.9151 YTW SCENARIO |
| MFC.PR.L | FixedReset Ins Non | Quote: 24.65 – 25.65 Spot Rate : 1.0000 Average : 0.6614 YTW SCENARIO |
| ENB.PF.E | FixedReset Disc | Quote: 23.91 – 24.50 Spot Rate : 0.5900 Average : 0.3485 YTW SCENARIO |
| MFC.PR.B | Insurance Straight | Quote: 20.88 – 21.88 Spot Rate : 1.0000 Average : 0.7685 YTW SCENARIO |
| NA.PR.G | FixedReset Prem | Quote: 26.40 – 27.28 Spot Rate : 0.8800 Average : 0.6651 YTW SCENARIO |