Category: Market Action

Market Action

June 22, 2026

Canadian inflation stepped on the gas!

Canada’s annual inflation rate in May accelerated more than expected to 3.2 per cent, a 29-month high, data showed on Monday, as the impact of higher crude oil prices due to the Iran conflict continued to filter through gasoline costs.

Analysts polled by Reuters had estimated the annual inflation rate to touch 3 per cent in May, up from 2.8 per cent in April.
…
Gasoline prices in May rose by 33.2 per cent on a year-over-year basis. Consumers in May shelled out more for gasoline than from its previous peak four years ago when Russia invaded Ukraine, Statscan said.

This led to an increase in the cost of transportation, which accounts for almost 18.5 per cent of the CPI basket, posting a 9-per-cent annual increase last month.
…
Cost of food, which also contributes around 17 per cent of the CPI basket, rose 3.8 per cent in May from 3.5 per cent in April, Statscan said, adding that this was fuelled by an increase in prices of fresh fruits and vegetables which rose by 5.3 per cent and 9 per cent respectively in May.

The impact of higher transportation and food prices were largely offset by shelter costs, the biggest contributor to the CPI basket at close to 30 per cent. Shelter costs rose by 1.7 per cent in May following a 1.8-per-cent increase in April, data showed, especially led by a reduction in mortgage costs which shrunk by 0.2 per cent last month.
…
CPI-median, the centremost component of the CPI basket, was at 2.1 per cent, while CPI-trim, which excludes the most extreme price changes, was at 2 per cent.

The day was enlivened by the closing of the GWO.PF.A Straight 5.7% issue.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.64 % 6.04 % 23,224 14.78 1 -0.5705 % 2,600.6
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.8704 % 4,909.1
Floater 5.54 % 5.65 % 39,731 14.48 3 -0.8704 % 2,829.1
OpRet 0.00 % 0.00 % 0 0.00 0 0.1031 % 3,634.2
SplitShare 4.79 % 4.48 % 52,390 2.74 5 0.1031 % 4,340.0
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1031 % 3,386.2
Perpetual-Premium 5.70 % 5.73 % 70,548 14.01 7 -0.0964 % 3,064.2
Perpetual-Discount 5.59 % 5.68 % 40,404 14.31 29 0.0770 % 3,377.9
FixedReset Disc 5.67 % 5.99 % 117,076 13.80 19 -0.4626 % 3,281.5
Insurance Straight 5.51 % 5.56 % 46,259 14.55 22 -0.4723 % 3,268.3
FloatingReset 4.70 % 4.73 % 19,448 16.06 1 0.0000 % 4,023.4
FixedReset Prem 5.93 % 4.58 % 82,430 2.33 29 0.0000 % 2,649.0
FixedReset Bank Non 0.00 % 0.00 % 0 0.00 0 -0.4626 % 3,354.4
FixedReset Ins Non 5.15 % 5.33 % 67,623 14.59 14 0.0389 % 3,210.2
Performance Highlights
Issue Index Change Notes
IFC.PR.E Insurance Straight -8.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-22
Maturity Price : 21.30
Evaluated at bid price : 21.57
Bid-YTW : 6.05 %
BN.PR.T FixedReset Disc -2.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-22
Maturity Price : 21.58
Evaluated at bid price : 21.95
Bid-YTW : 6.06 %
PWF.PR.A Floater -1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-22
Maturity Price : 14.46
Evaluated at bid price : 14.46
Bid-YTW : 5.46 %
NA.PR.K FixedReset Prem -1.18 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2029-05-01
Maturity Price : 25.00
Evaluated at bid price : 27.67
Bid-YTW : 4.10 %
IFC.PR.M Perpetual-Premium -1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-22
Maturity Price : 24.26
Evaluated at bid price : 24.65
Bid-YTW : 5.59 %
BN.PR.R FixedReset Disc -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-22
Maturity Price : 22.37
Evaluated at bid price : 23.17
Bid-YTW : 5.79 %
MFC.PR.B Insurance Straight 1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-22
Maturity Price : 22.21
Evaluated at bid price : 22.48
Bid-YTW : 5.19 %
CIU.PR.A Perpetual-Discount 1.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-22
Maturity Price : 20.82
Evaluated at bid price : 20.82
Bid-YTW : 5.58 %
MFC.PR.J FixedReset Ins Non 1.89 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2028-03-19
Maturity Price : 25.00
Evaluated at bid price : 25.29
Bid-YTW : 5.53 %
PWF.PR.S Perpetual-Discount 1.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-22
Maturity Price : 21.39
Evaluated at bid price : 21.66
Bid-YTW : 5.62 %
Volume Highlights
Issue Index Shares
Traded
Notes
GWO.PF.A Perpetual-Discount 509,000 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-22
Maturity Price : 24.46
Evaluated at bid price : 24.85
Bid-YTW : 5.76 %
SLF.PR.H FixedReset Ins Non 54,600 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-22
Maturity Price : 23.25
Evaluated at bid price : 24.20
Bid-YTW : 5.36 %
PWF.PR.A Floater 30,900 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-22
Maturity Price : 14.46
Evaluated at bid price : 14.46
Bid-YTW : 5.46 %
TD.PF.I FixedReset Prem 20,200 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2027-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.99
Bid-YTW : 3.99 %
IFC.PR.I Insurance Straight 16,100 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-22
Maturity Price : 24.21
Evaluated at bid price : 24.71
Bid-YTW : 5.46 %
IFC.PR.K Insurance Straight 10,100 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-22
Maturity Price : 23.40
Evaluated at bid price : 23.85
Bid-YTW : 5.51 %
There were 0 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
See TMX DataLinx: ‘Last’ != ‘Close’ and the posts linked therein for an idea of why these quotes are so horrible.
Issue Index Quote Data and Yield Notes
IFC.PR.E Insurance Straight Quote: 21.57 – 23.88
Spot Rate : 2.3100
Average : 1.3132

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-22
Maturity Price : 21.30
Evaluated at bid price : 21.57
Bid-YTW : 6.05 %

GWO.PR.Y Insurance Straight Quote: 20.86 – 22.22
Spot Rate : 1.3600
Average : 0.8685

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-22
Maturity Price : 20.86
Evaluated at bid price : 20.86
Bid-YTW : 5.42 %

PWF.PR.P FixedReset Disc Quote: 20.36 – 21.50
Spot Rate : 1.1400
Average : 0.6924

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-22
Maturity Price : 20.36
Evaluated at bid price : 20.36
Bid-YTW : 5.81 %

NA.PR.C FixedReset Prem Quote: 26.44 – 27.44
Spot Rate : 1.0000
Average : 0.6003

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2027-11-15
Maturity Price : 25.00
Evaluated at bid price : 26.44
Bid-YTW : 3.33 %

BN.PR.T FixedReset Disc Quote: 21.95 – 23.55
Spot Rate : 1.6000
Average : 1.2138

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-22
Maturity Price : 21.58
Evaluated at bid price : 21.95
Bid-YTW : 6.06 %

IFC.PR.M Perpetual-Premium Quote: 24.65 – 25.45
Spot Rate : 0.8000
Average : 0.4779

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-22
Maturity Price : 24.26
Evaluated at bid price : 24.65
Bid-YTW : 5.59 %

Market Action

June 19, 2026

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.61 % 6.00 % 24,172 14.83 1 0.1714 % 2,615.5
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.6869 % 4,952.2
Floater 5.50 % 5.61 % 40,349 14.56 3 0.6869 % 2,854.0
OpRet 0.00 % 0.00 % 0 0.00 0 0.0397 % 3,630.4
SplitShare 4.80 % 4.83 % 52,635 2.74 5 0.0397 % 4,335.5
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0397 % 3,382.7
Perpetual-Premium 5.69 % 5.73 % 71,636 14.03 7 0.0284 % 3,067.1
Perpetual-Discount 5.59 % 5.67 % 40,136 14.32 28 0.0724 % 3,375.3
FixedReset Disc 5.64 % 5.88 % 118,599 13.87 19 0.1438 % 3,296.8
Insurance Straight 5.49 % 5.51 % 46,176 14.58 22 -0.0079 % 3,283.8
FloatingReset 4.72 % 4.74 % 20,241 16.04 1 0.0000 % 4,023.4
FixedReset Prem 5.93 % 4.66 % 85,576 2.24 29 0.2187 % 2,649.0
FixedReset Bank Non 0.00 % 0.00 % 0 0.00 0 0.1438 % 3,370.0
FixedReset Ins Non 5.15 % 5.28 % 68,340 14.64 14 0.2579 % 3,209.0
Performance Highlights
Issue Index Change Notes
CIU.PR.A Perpetual-Discount -1.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-19
Maturity Price : 20.50
Evaluated at bid price : 20.50
Bid-YTW : 5.67 %
MFC.PR.J FixedReset Ins Non -1.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-19
Maturity Price : 23.58
Evaluated at bid price : 24.82
Bid-YTW : 5.74 %
ENB.PR.F FixedReset Disc -1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-19
Maturity Price : 22.86
Evaluated at bid price : 23.20
Bid-YTW : 6.05 %
MFC.PR.C Insurance Straight -1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-19
Maturity Price : 21.28
Evaluated at bid price : 21.55
Bid-YTW : 5.24 %
GWO.PR.T Insurance Straight -1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-19
Maturity Price : 22.22
Evaluated at bid price : 22.50
Bid-YTW : 5.73 %
MFC.PR.N FixedReset Ins Non 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-19
Maturity Price : 23.26
Evaluated at bid price : 24.94
Bid-YTW : 5.27 %
MFC.PR.M FixedReset Ins Non 1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-19
Maturity Price : 23.35
Evaluated at bid price : 25.12
Bid-YTW : 5.36 %
BN.PR.R FixedReset Disc 1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-19
Maturity Price : 22.50
Evaluated at bid price : 23.41
Bid-YTW : 5.70 %
BN.PF.A FixedReset Prem 1.52 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2028-09-30
Maturity Price : 25.00
Evaluated at bid price : 25.99
Bid-YTW : 4.83 %
BN.PF.F FixedReset Prem 1.53 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2029-10-01
Maturity Price : 25.00
Evaluated at bid price : 25.20
Bid-YTW : 5.54 %
ENB.PF.A FixedReset Disc 1.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-19
Maturity Price : 22.78
Evaluated at bid price : 23.72
Bid-YTW : 6.03 %
GWO.PR.N FixedReset Ins Non 2.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-19
Maturity Price : 19.40
Evaluated at bid price : 19.40
Bid-YTW : 5.55 %
BN.PR.K Floater 2.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-19
Maturity Price : 13.95
Evaluated at bid price : 13.95
Bid-YTW : 5.61 %
Volume Highlights
Issue Index Shares
Traded
Notes
PWF.PR.T FixedReset Prem 72,200 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-19
Maturity Price : 23.48
Evaluated at bid price : 25.09
Bid-YTW : 5.44 %
ENB.PR.Y FixedReset Disc 29,300 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-19
Maturity Price : 22.17
Evaluated at bid price : 22.61
Bid-YTW : 6.02 %
There were 0 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
See TMX DataLinx: ‘Last’ != ‘Close’ and the posts linked therein for an idea of why these quotes are so horrible.
Issue Index Quote Data and Yield Notes
MFC.PR.J FixedReset Ins Non Quote: 24.82 – 25.99
Spot Rate : 1.1700
Average : 0.7160

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-19
Maturity Price : 23.58
Evaluated at bid price : 24.82
Bid-YTW : 5.74 %

CIU.PR.A Perpetual-Discount Quote: 20.50 – 21.13
Spot Rate : 0.6300
Average : 0.3940

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-19
Maturity Price : 20.50
Evaluated at bid price : 20.50
Bid-YTW : 5.67 %

PWF.PR.S Perpetual-Discount Quote: 21.25 – 21.93
Spot Rate : 0.6800
Average : 0.5257

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-19
Maturity Price : 21.25
Evaluated at bid price : 21.25
Bid-YTW : 5.74 %

BN.PR.T FixedReset Disc Quote: 22.61 – 23.55
Spot Rate : 0.9400
Average : 0.7904

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-19
Maturity Price : 22.02
Evaluated at bid price : 22.61
Bid-YTW : 5.85 %

MFC.PR.B Insurance Straight Quote: 22.18 – 22.67
Spot Rate : 0.4900
Average : 0.3714

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-19
Maturity Price : 21.94
Evaluated at bid price : 22.18
Bid-YTW : 5.26 %

PWF.PR.T FixedReset Prem Quote: 25.09 – 26.09
Spot Rate : 1.0000
Average : 0.8924

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-19
Maturity Price : 23.48
Evaluated at bid price : 25.09
Bid-YTW : 5.44 %

Market Action

June 18, 2026

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.62 % 6.01 % 24,161 14.82 1 0.0000 % 2,611.0
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.3327 % 4,918.4
Floater 5.53 % 5.59 % 40,885 14.58 3 0.3327 % 2,834.5
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0397 % 3,629.0
SplitShare 4.80 % 4.57 % 54,706 2.75 5 -0.0397 % 4,333.8
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0397 % 3,381.4
Perpetual-Premium 5.69 % 5.73 % 72,083 14.02 7 0.0567 % 3,066.3
Perpetual-Discount 5.59 % 5.67 % 40,569 14.31 28 -0.1602 % 3,372.8
FixedReset Disc 5.65 % 5.88 % 123,438 13.88 19 -0.3502 % 3,292.0
Insurance Straight 5.49 % 5.51 % 46,886 14.61 22 0.0993 % 3,284.1
FloatingReset 4.72 % 4.73 % 21,067 16.04 1 -1.7043 % 4,023.4
FixedReset Prem 5.94 % 4.68 % 86,854 2.35 29 -0.1487 % 2,643.2
FixedReset Bank Non 0.00 % 0.00 % 0 0.00 0 -0.3502 % 3,365.1
FixedReset Ins Non 5.16 % 5.32 % 69,016 14.56 14 -0.1915 % 3,200.7
Performance Highlights
Issue Index Change Notes
ENB.PF.A FixedReset Disc -2.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-18
Maturity Price : 22.56
Evaluated at bid price : 23.30
Bid-YTW : 6.15 %
SLF.PR.J FloatingReset -1.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-18
Maturity Price : 19.61
Evaluated at bid price : 19.61
Bid-YTW : 4.73 %
GWO.PR.N FixedReset Ins Non -1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-18
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 5.67 %
PWF.PR.S Perpetual-Discount -1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-18
Maturity Price : 21.25
Evaluated at bid price : 21.25
Bid-YTW : 5.74 %
CU.PR.E Perpetual-Discount -1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-18
Maturity Price : 21.75
Evaluated at bid price : 22.00
Bid-YTW : 5.61 %
CU.PR.D Perpetual-Discount -1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-18
Maturity Price : 21.76
Evaluated at bid price : 22.01
Bid-YTW : 5.61 %
BN.PF.F FixedReset Prem -1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-18
Maturity Price : 23.27
Evaluated at bid price : 24.82
Bid-YTW : 5.90 %
BN.PF.A FixedReset Prem -1.16 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2028-09-30
Maturity Price : 25.00
Evaluated at bid price : 25.60
Bid-YTW : 5.54 %
ENB.PR.Y FixedReset Disc -1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-18
Maturity Price : 22.09
Evaluated at bid price : 22.50
Bid-YTW : 6.05 %
ENB.PF.E FixedReset Disc -1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-18
Maturity Price : 22.51
Evaluated at bid price : 23.30
Bid-YTW : 6.07 %
BN.PR.B Floater 1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-18
Maturity Price : 13.99
Evaluated at bid price : 13.99
Bid-YTW : 5.59 %
MFC.PR.C Insurance Straight 1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-18
Maturity Price : 21.57
Evaluated at bid price : 21.83
Bid-YTW : 5.17 %
GWO.PR.H Insurance Straight 3.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-18
Maturity Price : 21.38
Evaluated at bid price : 21.65
Bid-YTW : 5.61 %
Volume Highlights
Issue Index Shares
Traded
Notes
PVS.PR.H SplitShare 95,075 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2026-07-18
Maturity Price : 25.00
Evaluated at bid price : 25.08
Bid-YTW : 2.53 %
PVS.PR.K SplitShare 43,200 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2029-05-31
Maturity Price : 25.00
Evaluated at bid price : 24.97
Bid-YTW : 4.57 %
NA.PR.S FixedReset Prem 36,100 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2029-05-15
Maturity Price : 25.00
Evaluated at bid price : 26.19
Bid-YTW : 4.67 %
PWF.PR.A Floater 31,700 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-18
Maturity Price : 14.64
Evaluated at bid price : 14.64
Bid-YTW : 5.39 %
PWF.PR.Z Perpetual-Discount 27,800 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-18
Maturity Price : 22.77
Evaluated at bid price : 23.05
Bid-YTW : 5.66 %
TD.PF.I FixedReset Prem 14,069 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2027-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.85
Bid-YTW : 4.38 %
There were 8 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
See TMX DataLinx: ‘Last’ != ‘Close’ and the posts linked therein for an idea of why these quotes are so horrible.
Issue Index Quote Data and Yield Notes
BN.PR.T FixedReset Disc Quote: 22.61 – 23.55
Spot Rate : 0.9400
Average : 0.6263

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-18
Maturity Price : 22.02
Evaluated at bid price : 22.61
Bid-YTW : 5.85 %

MFC.PR.N FixedReset Ins Non Quote: 24.67 – 25.50
Spot Rate : 0.8300
Average : 0.5211

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-18
Maturity Price : 23.16
Evaluated at bid price : 24.67
Bid-YTW : 5.34 %

ENB.PF.A FixedReset Disc Quote: 23.30 – 24.05
Spot Rate : 0.7500
Average : 0.4657

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-18
Maturity Price : 22.56
Evaluated at bid price : 23.30
Bid-YTW : 6.15 %

PWF.PR.T FixedReset Prem Quote: 25.09 – 26.09
Spot Rate : 1.0000
Average : 0.7744

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-18
Maturity Price : 23.48
Evaluated at bid price : 25.09
Bid-YTW : 5.44 %

PWF.PR.R Perpetual-Discount Quote: 24.40 – 25.00
Spot Rate : 0.6000
Average : 0.3775

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-18
Maturity Price : 24.15
Evaluated at bid price : 24.40
Bid-YTW : 5.71 %

MFC.PR.M FixedReset Ins Non Quote: 24.80 – 25.45
Spot Rate : 0.6500
Average : 0.4302

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-18
Maturity Price : 23.24
Evaluated at bid price : 24.80
Bid-YTW : 5.44 %

Market Action

June 17, 2026

The FOMC stood pat today:

The Federal Open Market Committee approved the following statement for release by a 12 – 0 vote:

The Committee decided to maintain the target range for the federal funds rate at 3-1/2 to 3-3/4 percent, in support of the Federal Reserve’s dual mandate. The Committee reaffirmed its policy of maintaining ample reserves in the banking system.

Economic activity is expanding at a solid pace despite elevated uncertainty that owes, in part, to the conflict in the Middle East. Productivity growth and capital investment are strong. Job gains have kept pace with the workforce, and the unemployment rate has changed little.

Inflation remains elevated relative to the Committee’s 2 percent goal, in part reflecting supply shocks that have driven price increases in certain sectors, including energy. The Committee will deliver price stability.

“The committee will deliver price stability”? That sounds more like a Republican talking point than a central bank pronouncement … well, we’ll see. And there’s a lot less economic substance in this release than I like to see. Nevertheless, it carried unanimously, as was so eagerly trumpetted in the first line, which surprises me. Maybe Trump-toadyism has taken over. Maybe everybody just wants to be nice to Warsh at his first meeting. I certainly don’t know.

But the opacity continued into the press conference:

But as determined as Warsh said the Fed was to modernizing and fixing the economy’s problems, Warsh was noticeably less willing to provide detailed answers about the Fed’s decision-making process or thoughts on broader economic topics than Powell. Warsh often referred back to the Fed’s brief statement about the economy rather than expounding upon it.

In an answer that Warsh acknowledged was purposefully “curt,” he said: “I’ve got nothing more to say than the statement itself.” In another, he noted, “I can’t do much better than the committee just did. So let me restate it.”

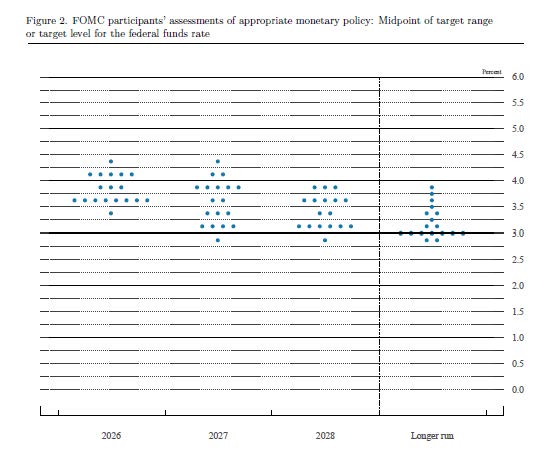
The Fed’s economic projections still include the dot-plot:

Ben Werschkul comments:

The Federal Reserve’s latest “dot plot,” outlining policymakers’ interest rate projections, revealed a sharp shift in central bankers’ expectations.

Not only are rate cuts almost surely off the table for the rest of the year, but there is also a sharply higher chance of a hike before the end of 2026.

Nine policymakers who participated in the exercise projected at least one hike, with six even suggesting multiple hikes could be in the offing.
…
The median forecast for interest rates at the end of 2027 remains unchanged at the current rate of 3.50% to 3.75%.

The projection is a sharp change from the outlook released in March, which had maintained a median forecast for one rate cut in 2026 and two in total by the end of 2027.

The equity markets responded poorly:

Major North American stock indexes immediately turned lower after the U.S. Federal Reserve kept interest rates unchanged as investors interpreted the accompanying details as being hawkish.

Short-term bonds yields spiked, as did the U.S. dollar against major currencies. The Canadian dollar traded at its lowest since 2025, at just above the 71 cents US level, down about a third of a cent for the session.

The U.S. two-year bond yield rocketed 9 basis points higher, a large one-day move. Short-term ​U.S. interest-rate ‌futures are now pricing in a ⁠bigger ​chance that the Federal Reserve will deliver ​a ‌rate hike by September than opt to ‌keep ​rates where they ‌are.

The ​shift in market-based ⁠rate-path expectations ⁠comes after the ​Fed said it would leave the policy rate in its ⁠current 3.50%-3.75% range at this time, but a ⁠near-majority of policymakers ​penciled a ⁠rate hike by the ‌end of 2026 ​to combat higher inflation.

PerpetualDiscounts now yield 5.66%, equivalent to 7.36% interest at the standard conversion factor of 1.3x. Long corporates yielded 4.89% on 2026-06-17. Therefore the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) has widened to 245bp from the 235bp reported June 10.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.62 % 6.01 % 24,221 14.82 1 0.0000 % 2,611.0
FixedFloater 0.00 % 0.00 % 0 0.00 0 1.4220 % 4,902.1
Floater 5.55 % 5.65 % 40,972 14.50 3 1.4220 % 2,825.1
OpRet 0.00 % 0.00 % 0 0.00 0 -0.1742 % 3,630.4
SplitShare 4.80 % 4.50 % 50,660 2.75 5 -0.1742 % 4,335.5
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.1742 % 3,382.7
Perpetual-Premium 5.70 % 5.74 % 73,099 14.10 7 -0.0851 % 3,064.5
Perpetual-Discount 5.58 % 5.66 % 40,906 14.34 28 0.2125 % 3,378.3
FixedReset Disc 5.63 % 5.86 % 125,180 13.92 19 0.0159 % 3,303.6
Insurance Straight 5.49 % 5.50 % 47,154 14.63 22 -0.2160 % 3,280.8
FloatingReset 4.64 % 4.65 % 21,926 16.20 1 0.0000 % 4,093.2
FixedReset Prem 5.94 % 4.57 % 90,437 2.35 29 0.1744 % 2,647.2
FixedReset Bank Non 0.00 % 0.00 % 0 0.00 0 0.0159 % 3,377.0
FixedReset Ins Non 5.15 % 5.27 % 69,882 14.60 14 0.1649 % 3,206.9
Performance Highlights
Issue Index Change Notes
GWO.PR.H Insurance Straight -3.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-17
Maturity Price : 20.99
Evaluated at bid price : 20.99
Bid-YTW : 5.80 %
FTS.PR.F Perpetual-Discount -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-17
Maturity Price : 22.71
Evaluated at bid price : 23.00
Bid-YTW : 5.36 %
ENB.PR.H FixedReset Disc -1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-17
Maturity Price : 23.19
Evaluated at bid price : 23.50
Bid-YTW : 5.69 %
ENB.PF.E FixedReset Disc 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-17
Maturity Price : 22.64
Evaluated at bid price : 23.55
Bid-YTW : 6.00 %
BN.PF.A FixedReset Prem 1.17 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2028-09-30
Maturity Price : 25.00
Evaluated at bid price : 25.90
Bid-YTW : 4.98 %
GWO.PR.T Insurance Straight 1.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-17
Maturity Price : 22.66
Evaluated at bid price : 22.90
Bid-YTW : 5.63 %
PWF.PR.Z Perpetual-Discount 3.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-17
Maturity Price : 22.74
Evaluated at bid price : 23.03
Bid-YTW : 5.66 %
PWF.PR.A Floater 3.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-17
Maturity Price : 14.64
Evaluated at bid price : 14.64
Bid-YTW : 5.39 %
Volume Highlights
Issue Index Shares
Traded
Notes
BN.PF.I FixedReset Prem 43,700 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2027-03-31
Maturity Price : 25.00
Evaluated at bid price : 25.27
Bid-YTW : 3.75 %
PWF.PR.P FixedReset Disc 37,500 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-17
Maturity Price : 20.56
Evaluated at bid price : 20.56
Bid-YTW : 5.73 %
IFC.PR.C FixedReset Ins Non 35,000 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2026-09-30
Maturity Price : 25.00
Evaluated at bid price : 25.03
Bid-YTW : 2.59 %
ENB.PR.P FixedReset Disc 26,700 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-17
Maturity Price : 23.03
Evaluated at bid price : 24.03
Bid-YTW : 5.86 %
PWF.PR.T FixedReset Prem 25,100 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-17
Maturity Price : 23.48
Evaluated at bid price : 25.08
Bid-YTW : 5.44 %
POW.PR.I Perpetual-Premium 15,100 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-17
Maturity Price : 24.61
Evaluated at bid price : 25.01
Bid-YTW : 5.74 %
There were 3 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
See TMX DataLinx: ‘Last’ != ‘Close’ and the posts linked therein for an idea of why these quotes are so horrible.
Issue Index Quote Data and Yield Notes
IFC.PR.A FixedReset Ins Non Quote: 22.00 – 23.34
Spot Rate : 1.3400
Average : 1.0033

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-17
Maturity Price : 21.60
Evaluated at bid price : 22.00
Bid-YTW : 5.44 %

GWO.PR.H Insurance Straight Quote: 20.99 – 21.78
Spot Rate : 0.7900
Average : 0.4762

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-17
Maturity Price : 20.99
Evaluated at bid price : 20.99
Bid-YTW : 5.80 %

BN.PF.M FixedReset Prem Quote: 25.75 – 26.62
Spot Rate : 0.8700
Average : 0.7404

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2031-01-01
Maturity Price : 25.00
Evaluated at bid price : 25.75
Bid-YTW : 4.88 %

ENB.PF.K FixedReset Prem Quote: 25.46 – 25.85
Spot Rate : 0.3900
Average : 0.2664

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2028-03-01
Maturity Price : 25.00
Evaluated at bid price : 25.46
Bid-YTW : 5.28 %

CU.PR.J Perpetual-Discount Quote: 21.66 – 22.18
Spot Rate : 0.5200
Average : 0.4139

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-17
Maturity Price : 21.66
Evaluated at bid price : 21.66
Bid-YTW : 5.54 %

IFC.PR.K Insurance Straight Quote: 23.85 – 24.90
Spot Rate : 1.0500
Average : 0.9491

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-17
Maturity Price : 23.40
Evaluated at bid price : 23.85
Bid-YTW : 5.50 %

Market Action

June 16, 2026

The SSL situation has been resolved, I think. If anybody’s still getting a ‘certificate problem’ or other peculiar behaviour, please let me know at jiHymas@himivest.com.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.62 % 6.01 % 25,205 14.82 1 0.5169 % 2,611.0
FixedFloater 0.00 % 0.00 % 0 0.00 0 -2.3075 % 4,833.4
Floater 5.63 % 5.70 % 40,481 14.42 3 -2.3075 % 2,785.5
OpRet 0.00 % 0.00 % 0 0.00 0 0.2302 % 3,636.8
SplitShare 4.79 % 4.30 % 50,061 2.75 5 0.2302 % 4,343.1
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.2302 % 3,388.6
Perpetual-Premium 5.69 % 5.73 % 70,934 14.02 7 0.0000 % 3,067.1
Perpetual-Discount 5.59 % 5.67 % 41,449 14.32 28 0.1766 % 3,371.1
FixedReset Disc 5.63 % 5.86 % 130,276 13.92 19 0.1732 % 3,303.1
Insurance Straight 5.48 % 5.53 % 46,334 14.63 22 0.0258 % 3,287.9
FloatingReset 4.64 % 4.65 % 22,808 16.20 1 0.0000 % 4,093.2
FixedReset Prem 5.95 % 4.66 % 90,026 2.25 29 0.0524 % 2,642.5
FixedReset Bank Non 0.00 % 0.00 % 0 0.00 0 0.1732 % 3,376.4
FixedReset Ins Non 5.16 % 5.32 % 70,372 14.57 14 -0.4892 % 3,201.6
Performance Highlights
Issue Index Change Notes
PWF.PR.A Floater -3.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-16
Maturity Price : 14.17
Evaluated at bid price : 14.17
Bid-YTW : 5.57 %
BN.PR.K Floater -2.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-16
Maturity Price : 13.59
Evaluated at bid price : 13.59
Bid-YTW : 5.76 %
PWF.PR.Z Perpetual-Discount -2.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-16
Maturity Price : 22.07
Evaluated at bid price : 22.30
Bid-YTW : 5.86 %
IFC.PR.A FixedReset Ins Non -2.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-16
Maturity Price : 21.60
Evaluated at bid price : 22.00
Bid-YTW : 5.44 %
GWO.PR.N FixedReset Ins Non -1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-16
Maturity Price : 19.22
Evaluated at bid price : 19.22
Bid-YTW : 5.60 %
ENB.PF.E FixedReset Disc -1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-16
Maturity Price : 22.51
Evaluated at bid price : 23.30
Bid-YTW : 6.07 %
GWO.PR.Q Insurance Straight 1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-16
Maturity Price : 22.74
Evaluated at bid price : 23.03
Bid-YTW : 5.60 %
ENB.PR.D FixedReset Disc 1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-16
Maturity Price : 22.31
Evaluated at bid price : 22.66
Bid-YTW : 6.03 %
IFC.PR.E Insurance Straight 1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-16
Maturity Price : 23.36
Evaluated at bid price : 23.65
Bid-YTW : 5.50 %
PWF.PF.A Perpetual-Discount 1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-16
Maturity Price : 20.38
Evaluated at bid price : 20.38
Bid-YTW : 5.61 %
PWF.PR.F Perpetual-Discount 1.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-16
Maturity Price : 23.15
Evaluated at bid price : 23.45
Bid-YTW : 5.67 %
BN.PF.D Perpetual-Discount 2.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-16
Maturity Price : 21.24
Evaluated at bid price : 21.24
Bid-YTW : 5.79 %
CU.PR.E Perpetual-Discount 2.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-16
Maturity Price : 22.01
Evaluated at bid price : 22.25
Bid-YTW : 5.54 %
Volume Highlights
Issue Index Shares
Traded
Notes
ENB.PR.B FixedReset Disc 25,576 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-16
Maturity Price : 22.09
Evaluated at bid price : 22.75
Bid-YTW : 6.01 %
BN.PR.R FixedReset Disc 20,527 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-16
Maturity Price : 22.33
Evaluated at bid price : 23.09
Bid-YTW : 5.79 %
MFC.PR.F FixedReset Ins Non 19,400 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-16
Maturity Price : 21.01
Evaluated at bid price : 21.01
Bid-YTW : 5.35 %
BN.PF.M FixedReset Prem 18,300 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2031-01-01
Maturity Price : 25.00
Evaluated at bid price : 25.76
Bid-YTW : 4.87 %
PWF.PR.E Perpetual-Discount 17,350 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-16
Maturity Price : 24.09
Evaluated at bid price : 24.35
Bid-YTW : 5.72 %
POW.PR.I Perpetual-Premium 16,339 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-16
Maturity Price : 24.61
Evaluated at bid price : 25.01
Bid-YTW : 5.73 %
There were 5 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
See TMX DataLinx: ‘Last’ != ‘Close’ and the posts linked therein for an idea of why these quotes are so horrible.
Issue Index Quote Data and Yield Notes
IFC.PR.K Insurance Straight Quote: 23.65 – 24.90
Spot Rate : 1.2500
Average : 0.8385

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-16
Maturity Price : 23.19
Evaluated at bid price : 23.65
Bid-YTW : 5.55 %

TD.PF.A FixedReset Prem Quote: 25.45 – 26.20
Spot Rate : 0.7500
Average : 0.4464

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2029-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.45
Bid-YTW : 4.62 %

BN.PF.M FixedReset Prem Quote: 25.76 – 26.62
Spot Rate : 0.8600
Average : 0.5982

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2031-01-01
Maturity Price : 25.00
Evaluated at bid price : 25.76
Bid-YTW : 4.87 %

PWF.PR.Z Perpetual-Discount Quote: 22.30 – 23.11
Spot Rate : 0.8100
Average : 0.5889

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-16
Maturity Price : 22.07
Evaluated at bid price : 22.30
Bid-YTW : 5.86 %

IFC.PR.A FixedReset Ins Non Quote: 22.00 – 22.81
Spot Rate : 0.8100
Average : 0.6341

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-16
Maturity Price : 21.60
Evaluated at bid price : 22.00
Bid-YTW : 5.44 %

SLF.PR.E Insurance Straight Quote: 21.65 – 22.32
Spot Rate : 0.6700
Average : 0.5049

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-16
Maturity Price : 21.38
Evaluated at bid price : 21.65
Bid-YTW : 5.20 %

Market Action

June 15, 2026

Sorry about the expired SSL certificate. I have a guy working on it – the problem should be fixed very soon.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.65 % 6.04 % 25,564 14.79 1 -1.3598 % 2,597.6
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.0000 % 4,947.5
Floater 5.50 % 5.60 % 40,699 14.58 3 0.0000 % 2,851.3
OpRet 0.00 % 0.00 % 0 0.00 0 0.0556 % 3,628.4
SplitShare 4.80 % 4.48 % 49,443 2.76 5 0.0556 % 4,333.1
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0556 % 3,380.9
Perpetual-Premium 5.69 % 5.72 % 73,550 13.98 7 0.2159 % 3,067.1
Perpetual-Discount 5.60 % 5.68 % 41,395 14.30 28 -0.0678 % 3,365.1
FixedReset Disc 5.64 % 5.88 % 129,196 13.90 19 -0.0751 % 3,297.4
Insurance Straight 5.48 % 5.57 % 45,752 14.51 22 -0.4381 % 3,287.1
FloatingReset 4.64 % 4.65 % 23,725 16.20 1 0.0000 % 4,093.2
FixedReset Prem 5.95 % 4.68 % 89,444 2.25 29 -0.3198 % 2,641.2
FixedReset Bank Non 0.00 % 0.00 % 0 0.00 0 -0.0751 % 3,370.6
FixedReset Ins Non 5.14 % 5.30 % 71,021 14.59 14 0.0060 % 3,217.3
Performance Highlights
Issue Index Change Notes
GWO.PR.T Insurance Straight -4.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-15
Maturity Price : 22.22
Evaluated at bid price : 22.50
Bid-YTW : 5.73 %
CU.PR.E Perpetual-Discount -2.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-15
Maturity Price : 21.44
Evaluated at bid price : 21.70
Bid-YTW : 5.68 %
PWF.PF.A Perpetual-Discount -1.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-15
Maturity Price : 20.10
Evaluated at bid price : 20.10
Bid-YTW : 5.69 %
GWO.PR.Q Insurance Straight -1.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-15
Maturity Price : 22.55
Evaluated at bid price : 22.80
Bid-YTW : 5.66 %
PWF.PR.A Floater -1.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-15
Maturity Price : 14.65
Evaluated at bid price : 14.65
Bid-YTW : 5.38 %
BN.PF.K Ratchet -1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-15
Maturity Price : 22.00
Evaluated at bid price : 17.41
Bid-YTW : 6.04 %
ENB.PR.D FixedReset Disc -1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-15
Maturity Price : 21.86
Evaluated at bid price : 22.40
Bid-YTW : 6.09 %
GWO.PR.N FixedReset Ins Non -1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-15
Maturity Price : 19.50
Evaluated at bid price : 19.50
Bid-YTW : 5.52 %
NA.PR.C FixedReset Prem -1.07 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2027-11-15
Maturity Price : 25.00
Evaluated at bid price : 26.00
Bid-YTW : 4.54 %
CCS.PR.C Insurance Straight 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-15
Maturity Price : 22.48
Evaluated at bid price : 22.74
Bid-YTW : 5.50 %
FTS.PR.J Perpetual-Discount 1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-15
Maturity Price : 22.40
Evaluated at bid price : 22.66
Bid-YTW : 5.27 %
BN.PF.M FixedReset Prem 1.67 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2031-01-01
Maturity Price : 25.00
Evaluated at bid price : 25.85
Bid-YTW : 4.78 %
CU.PR.G Perpetual-Discount 1.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-15
Maturity Price : 20.65
Evaluated at bid price : 20.65
Bid-YTW : 5.50 %
IFC.PR.M Perpetual-Premium 1.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-15
Maturity Price : 24.69
Evaluated at bid price : 25.10
Bid-YTW : 5.57 %
CU.PR.H Perpetual-Discount 1.97 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-15
Maturity Price : 24.06
Evaluated at bid price : 24.32
Bid-YTW : 5.43 %
FTS.PR.F Perpetual-Discount 2.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-15
Maturity Price : 22.73
Evaluated at bid price : 23.02
Bid-YTW : 5.35 %
ENB.PF.A FixedReset Disc 2.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-15
Maturity Price : 22.87
Evaluated at bid price : 23.90
Bid-YTW : 5.98 %
PWF.PR.Z Perpetual-Discount 2.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-15
Maturity Price : 22.65
Evaluated at bid price : 22.90
Bid-YTW : 5.70 %
BN.PR.K Floater 4.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-15
Maturity Price : 13.97
Evaluated at bid price : 13.97
Bid-YTW : 5.60 %
Volume Highlights
Issue Index Shares
Traded
Notes
ENB.PF.K FixedReset Prem 123,000 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2028-03-01
Maturity Price : 25.00
Evaluated at bid price : 25.57
Bid-YTW : 4.99 %
ENB.PR.B FixedReset Disc 26,300 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-15
Maturity Price : 22.06
Evaluated at bid price : 22.69
Bid-YTW : 6.02 %
CU.PR.C FixedReset Prem 25,400 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2027-06-01
Maturity Price : 25.00
Evaluated at bid price : 25.20
Bid-YTW : 4.58 %
GWO.PR.Z Insurance Straight 20,400 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-15
Maturity Price : 24.47
Evaluated at bid price : 24.87
Bid-YTW : 5.73 %
ENB.PR.T FixedReset Disc 16,700 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-15
Maturity Price : 23.27
Evaluated at bid price : 24.67
Bid-YTW : 5.76 %
ENB.PR.D FixedReset Disc 13,400 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-15
Maturity Price : 21.86
Evaluated at bid price : 22.40
Bid-YTW : 6.09 %
There were 4 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
See TMX DataLinx: ‘Last’ != ‘Close’ and the posts linked therein for an idea of why these quotes are so horrible.
Issue Index Quote Data and Yield Notes
GWO.PR.Y Insurance Straight Quote: 20.76 – 22.22
Spot Rate : 1.4600
Average : 0.9899

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-15
Maturity Price : 20.76
Evaluated at bid price : 20.76
Bid-YTW : 5.44 %

GWO.PR.T Insurance Straight Quote: 22.50 – 23.75
Spot Rate : 1.2500
Average : 0.9121

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-15
Maturity Price : 22.22
Evaluated at bid price : 22.50
Bid-YTW : 5.73 %

CU.PR.E Perpetual-Discount Quote: 21.70 – 22.40
Spot Rate : 0.7000
Average : 0.4195

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-15
Maturity Price : 21.44
Evaluated at bid price : 21.70
Bid-YTW : 5.68 %

MFC.PR.M FixedReset Ins Non Quote: 24.88 – 25.45
Spot Rate : 0.5700
Average : 0.3471

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-15
Maturity Price : 23.26
Evaluated at bid price : 24.88
Bid-YTW : 5.42 %

MFC.PR.C Insurance Straight Quote: 21.45 – 22.25
Spot Rate : 0.8000
Average : 0.5979

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-15
Maturity Price : 21.45
Evaluated at bid price : 21.45
Bid-YTW : 5.27 %

BN.PF.G FixedReset Prem Quote: 24.58 – 25.25
Spot Rate : 0.6700
Average : 0.4729

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-15
Maturity Price : 23.09
Evaluated at bid price : 24.58
Bid-YTW : 5.89 %

Market Action

June 12, 2026

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.57 % 5.77 % 25,725 14.71 1 -0.2825 % 2,633.4
FixedFloater 0.00 % 0.00 % 0 0.00 0 -1.4388 % 4,947.5
Floater 5.50 % 5.69 % 39,394 14.29 3 -1.4388 % 2,851.3
OpRet 0.00 % 0.00 % 0 0.00 0 -0.3640 % 3,626.4
SplitShare 4.80 % 4.56 % 49,381 2.76 5 -0.3640 % 4,330.7
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.3640 % 3,379.0
Perpetual-Premium 5.70 % 5.70 % 73,894 14.01 7 -0.4919 % 3,060.5
Perpetual-Discount 5.60 % 5.68 % 40,729 14.32 28 -0.3236 % 3,367.4
FixedReset Disc 5.64 % 5.90 % 128,562 13.89 19 -0.0637 % 3,299.9
Insurance Straight 5.46 % 5.53 % 46,373 14.58 22 0.0059 % 3,301.5
FloatingReset 4.64 % 4.65 % 24,678 16.21 1 -0.2500 % 4,093.2
FixedReset Prem 5.93 % 4.88 % 90,208 2.26 29 0.0174 % 2,649.6
FixedReset Bank Non 0.00 % 0.00 % 0 0.00 0 -0.0637 % 3,373.1
FixedReset Ins Non 5.14 % 5.32 % 70,437 14.60 14 0.1045 % 3,217.1
Performance Highlights
Issue Index Change Notes
PWF.PR.Z Perpetual-Discount -3.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-12
Maturity Price : 22.08
Evaluated at bid price : 22.30
Bid-YTW : 5.85 %
BN.PR.K Floater -2.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-12
Maturity Price : 13.59
Evaluated at bid price : 13.59
Bid-YTW : 5.85 %
ENB.PF.A FixedReset Disc -2.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-12
Maturity Price : 22.56
Evaluated at bid price : 23.30
Bid-YTW : 6.15 %
PWF.PR.F Perpetual-Discount -2.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-12
Maturity Price : 22.84
Evaluated at bid price : 23.12
Bid-YTW : 5.75 %
IFC.PR.M Perpetual-Premium -1.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-12
Maturity Price : 24.26
Evaluated at bid price : 24.65
Bid-YTW : 5.68 %
PWF.PR.S Perpetual-Discount -1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-12
Maturity Price : 21.25
Evaluated at bid price : 21.25
Bid-YTW : 5.73 %
SLF.PR.E Insurance Straight -1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-12
Maturity Price : 21.32
Evaluated at bid price : 21.59
Bid-YTW : 5.21 %
PWF.PR.P FixedReset Disc -1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-12
Maturity Price : 20.56
Evaluated at bid price : 20.56
Bid-YTW : 5.73 %
CCS.PR.C Insurance Straight -1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-12
Maturity Price : 22.22
Evaluated at bid price : 22.50
Bid-YTW : 5.56 %
SLF.PR.C Insurance Straight -1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-12
Maturity Price : 21.30
Evaluated at bid price : 21.57
Bid-YTW : 5.16 %
SLF.PR.D Insurance Straight -1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-12
Maturity Price : 21.35
Evaluated at bid price : 21.62
Bid-YTW : 5.14 %
MFC.PR.B Insurance Straight 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-12
Maturity Price : 22.33
Evaluated at bid price : 22.60
Bid-YTW : 5.15 %
GWO.PR.I Insurance Straight 1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-12
Maturity Price : 20.97
Evaluated at bid price : 20.97
Bid-YTW : 5.38 %
GWO.PR.N FixedReset Ins Non 1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-12
Maturity Price : 19.75
Evaluated at bid price : 19.75
Bid-YTW : 5.45 %
GWO.PR.T Insurance Straight 1.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-12
Maturity Price : 23.25
Evaluated at bid price : 23.55
Bid-YTW : 5.47 %
Volume Highlights
Issue Index Shares
Traded
Notes
BN.PF.D Perpetual-Discount 21,559 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-12
Maturity Price : 21.28
Evaluated at bid price : 21.28
Bid-YTW : 5.88 %
BN.PR.M Perpetual-Discount 21,200 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-12
Maturity Price : 20.76
Evaluated at bid price : 20.76
Bid-YTW : 5.84 %
ENB.PR.D FixedReset Disc 16,500 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-12
Maturity Price : 22.35
Evaluated at bid price : 22.70
Bid-YTW : 6.02 %
TD.PF.I FixedReset Prem 13,500 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2027-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.78
Bid-YTW : 4.53 %
ENB.PR.B FixedReset Disc 11,080 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-12
Maturity Price : 22.09
Evaluated at bid price : 22.75
Bid-YTW : 6.00 %
ENB.PR.P FixedReset Disc 10,500 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-12
Maturity Price : 22.96
Evaluated at bid price : 23.87
Bid-YTW : 5.90 %
There were 0 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
See TMX DataLinx: ‘Last’ != ‘Close’ and the posts linked therein for an idea of why these quotes are so horrible.
Issue Index Quote Data and Yield Notes
PWF.PR.T FixedReset Prem Quote: 25.01 – 26.01
Spot Rate : 1.0000
Average : 0.5945

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-12
Maturity Price : 23.45
Evaluated at bid price : 25.01
Bid-YTW : 5.45 %

SLF.PR.G FixedReset Ins Non Quote: 20.80 – 21.80
Spot Rate : 1.0000
Average : 0.6173

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-12
Maturity Price : 20.80
Evaluated at bid price : 20.80
Bid-YTW : 5.32 %

PWF.PR.P FixedReset Disc Quote: 20.56 – 21.50
Spot Rate : 0.9400
Average : 0.5775

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-12
Maturity Price : 20.56
Evaluated at bid price : 20.56
Bid-YTW : 5.73 %

PWF.PR.Z Perpetual-Discount Quote: 22.30 – 23.24
Spot Rate : 0.9400
Average : 0.5838

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-12
Maturity Price : 22.08
Evaluated at bid price : 22.30
Bid-YTW : 5.85 %

MFC.PR.K FixedReset Ins Non Quote: 25.40 – 26.14
Spot Rate : 0.7400
Average : 0.4642

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-12
Maturity Price : 23.66
Evaluated at bid price : 25.40
Bid-YTW : 5.28 %

MFC.PR.F FixedReset Ins Non Quote: 21.09 – 22.00
Spot Rate : 0.9100
Average : 0.6531

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-12
Maturity Price : 21.09
Evaluated at bid price : 21.09
Bid-YTW : 5.33 %

Market Action

June 11, 2026

US wholesale inflation ticked up:

The Producer Price Index, a closely watched gauge of wholesale inflation, rose 1.1% in May, lifting the annual rate to 6.5%, its highest since November 2022, according to Bureau of Labor Statistics data released Thursday.
…
Excluding food and energy prices, a core measurement of PPI rose 0.4% from April, holding at 4.9% annually.

When also stripping out the price changes for “trade services” – a volatile category that measures profit margins for wholesalers and retailers – in addition to energy and food, that index rose 0.8% in May (a four-year high) and 5.1% annually, the largest rise since October 2022.

And the European Central Bank hiked its policy rate:

The European Central Bank on Thursday became the first major central bank to raise interest rates in response to the Iran war as policy makers around the world, including new U.S. Federal Reserve Chair Kevin Warsh, wrestle with how to confront the inflation fed by sharply higher oil prices.

The ECB’s rate-setting council raised its benchmark rate to 2.25 per cent from 2 per cent, where it had been for a year. The move comes ahead of rate-setting meetings next week at the Fed, the Bank of Japan and the Bank of England.
…
The bank’s future decisions depend to a great extent on how long energy prices remain elevated and how high they go, ECB President Christine Lagarde said at a post-decision news conference. She said the bank was “well positioned to navigate the uncertainty caused by the war” and would “closely monitor the situation and follow a data-dependent and meeting-by-meeting approach.” She said the bank was “not pre-committing to a particular rate path.”

She said oil prices were expected to “lift inflation further over the summer” and that inflation was expected to remain “well above target” into the first half of next year. The Strait of Hormuz has been closed to most ship traffic for 103 days now.

Central banks in Australia and the Philippines have raises rates since the start of the war, and attention is focusing now on decisions in larger economies. For its part, the U.S. Federal Reserve is expected to keep its key interest rate unchanged when it meets next week with new chair Warsh, appointed earlier this year by President Donald Trump.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.55 % 5.74 % 25,843 14.73 1 2.0173 % 2,640.8
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.6776 % 5,019.8
Floater 5.42 % 5.64 % 38,728 14.37 3 0.6776 % 2,892.9
OpRet 0.00 % 0.00 % 0 0.00 0 0.0396 % 3,639.7
SplitShare 4.79 % 4.35 % 49,209 2.77 5 0.0396 % 4,346.5
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0396 % 3,391.3
Perpetual-Premium 5.68 % 5.56 % 75,055 6.54 7 -0.0678 % 3,075.7
Perpetual-Discount 5.58 % 5.64 % 41,212 14.38 28 0.0330 % 3,378.4
FixedReset Disc 5.63 % 5.98 % 128,444 13.79 19 0.0205 % 3,302.0
Insurance Straight 5.46 % 5.55 % 46,877 14.60 22 0.1601 % 3,301.3
FloatingReset 4.64 % 4.65 % 25,669 16.21 1 -1.2346 % 4,103.5
FixedReset Prem 5.93 % 4.70 % 90,812 2.26 29 -0.0308 % 2,649.2
FixedReset Bank Non 0.00 % 0.00 % 0 0.00 0 0.0205 % 3,375.3
FixedReset Ins Non 5.14 % 5.40 % 71,236 14.48 14 0.0090 % 3,213.8
Performance Highlights
Issue Index Change Notes
SLF.PR.H FixedReset Ins Non -1.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-11
Maturity Price : 23.24
Evaluated at bid price : 24.16
Bid-YTW : 5.43 %
FTS.PR.F Perpetual-Discount -1.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-11
Maturity Price : 22.25
Evaluated at bid price : 22.52
Bid-YTW : 5.47 %
SLF.PR.J FloatingReset -1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-11
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 4.65 %
CU.PR.G Perpetual-Discount -1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-11
Maturity Price : 20.30
Evaluated at bid price : 20.30
Bid-YTW : 5.59 %
FTS.PR.M FixedReset Prem -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-11
Maturity Price : 23.26
Evaluated at bid price : 24.85
Bid-YTW : 5.60 %
SLF.PR.E Insurance Straight 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-11
Maturity Price : 21.64
Evaluated at bid price : 21.89
Bid-YTW : 5.14 %
GWO.PR.R Insurance Straight 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-11
Maturity Price : 21.36
Evaluated at bid price : 21.63
Bid-YTW : 5.55 %
SLF.PR.D Insurance Straight 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-11
Maturity Price : 21.58
Evaluated at bid price : 21.84
Bid-YTW : 5.09 %
GWO.PR.Q Insurance Straight 1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-11
Maturity Price : 22.82
Evaluated at bid price : 23.10
Bid-YTW : 5.58 %
BN.PR.B Floater 1.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-11
Maturity Price : 14.09
Evaluated at bid price : 14.09
Bid-YTW : 5.64 %
BN.PF.K Ratchet 2.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-11
Maturity Price : 19.39
Evaluated at bid price : 17.70
Bid-YTW : 5.74 %
GWO.PR.N FixedReset Ins Non 2.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-11
Maturity Price : 19.48
Evaluated at bid price : 19.48
Bid-YTW : 5.60 %
Volume Highlights
Issue Index Shares
Traded
Notes
SLF.PR.J FloatingReset 125,700 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-11
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 4.65 %
ENB.PR.J FixedReset Disc 35,100 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-11
Maturity Price : 22.95
Evaluated at bid price : 23.86
Bid-YTW : 6.05 %
FFH.PR.K FixedReset Prem 30,660 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2027-03-31
Maturity Price : 25.00
Evaluated at bid price : 25.36
Bid-YTW : 4.50 %
ENB.PF.A FixedReset Disc 25,178 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-11
Maturity Price : 22.84
Evaluated at bid price : 23.85
Bid-YTW : 6.06 %
SLF.PR.C Insurance Straight 18,500 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-11
Maturity Price : 21.56
Evaluated at bid price : 21.82
Bid-YTW : 5.10 %
ENB.PR.P FixedReset Disc 18,300 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-11
Maturity Price : 22.95
Evaluated at bid price : 23.87
Bid-YTW : 5.98 %
There were 4 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
See TMX DataLinx: ‘Last’ != ‘Close’ and the posts linked therein for an idea of why these quotes are so horrible.
Issue Index Quote Data and Yield Notes
ENB.PF.E FixedReset Disc Quote: 23.28 – 24.70
Spot Rate : 1.4200
Average : 0.9927

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-11
Maturity Price : 22.50
Evaluated at bid price : 23.28
Bid-YTW : 6.14 %

CU.PR.J Perpetual-Discount Quote: 21.66 – 23.00
Spot Rate : 1.3400
Average : 0.9657

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-11
Maturity Price : 21.66
Evaluated at bid price : 21.66
Bid-YTW : 5.53 %

BN.PR.B Floater Quote: 14.09 – 15.17
Spot Rate : 1.0800
Average : 0.8295

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-11
Maturity Price : 14.09
Evaluated at bid price : 14.09
Bid-YTW : 5.64 %

ENB.PR.H FixedReset Disc Quote: 23.70 – 24.50
Spot Rate : 0.8000
Average : 0.5576

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-11
Maturity Price : 22.95
Evaluated at bid price : 23.70
Bid-YTW : 5.70 %

CU.PR.G Perpetual-Discount Quote: 20.30 – 20.80
Spot Rate : 0.5000
Average : 0.3248

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-11
Maturity Price : 20.30
Evaluated at bid price : 20.30
Bid-YTW : 5.59 %

ENB.PF.K FixedReset Prem Quote: 25.50 – 25.85
Spot Rate : 0.3500
Average : 0.2188

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2028-03-01
Maturity Price : 25.00
Evaluated at bid price : 25.50
Bid-YTW : 5.13 %

Market Action

June 10, 2026

The Bank of Canada kept things steady today:

The Bank of Canada today held its target for the overnight rate at 2.25%, with the Bank Rate at 2.5% and the deposit rate at 2.20%.

The conflict in the Middle East is now in its fourth month. The resulting increases in energy prices and disruptions in global supply chains are weighing on global economic growth and pushing up inflation. At the same time, the US administration continues to propose new tariffs and trade policy uncertainty remains elevated.

In the United States, economic growth remains solid, supported by consumption and AI‑related investment. In the euro area, growth is subdued, with higher energy prices weighing on activity. China’s economic growth continues to be supported by strong exports.

Canadian financial conditions have loosened since the April Monetary Policy Report. Global equity markets have been buoyant and bond yields remain volatile. The Canadian dollar has weakened against the US dollar and other currencies.

In Canada, GDP edged down by 0.1% in the first quarter, weaker than expected at the time of the April MPR. Consumer spending grew 1.4% but government spending unexpectedly declined. Housing activity also declined and business investment remained weak. Exports fell while imports rose strongly as inventories were rebuilt. Employment was up in May, but looking through monthly volatility, employment in Canada is little changed since the start of the year. The unemployment rate continues to fluctuate in the 6 ½%-7% range with the most recent reading at 6.6% in May.

Recent data suggests that growth will resume in the second quarter but, even with some rebound, the economy is expected to remain in excess supply.

As expected, CPI inflation rose in April, reaching 2.8%. The increase reflects energy prices, both higher oil prices and the impact of the elimination of the consumer carbon tax falling out of the 12-month rate of inflation. So far, there has been limited evidence of broad-based pass-through of higher energy prices to other consumer prices. Measures of core inflation have moved down to around 2% and the share of CPI components growing above 3% is close to its historical average. Food price inflation moderated but remains high, and shelter inflation continued to slow. With global oil prices still elevated—roughly $10 a barrel above our April MPR assumptions—total inflation is expected to hover around 3% in the near term before easing gradually towards 2%.

Against this overall backdrop, Governing Council decided to maintain the policy rate at 2.25%. Economic activity in Canada has been weak and uncertainty about US trade policy persists. The conflict in the Middle East is ongoing and oil prices remain elevated. Governing Council is continuing to look through the war’s near-term impact on headline inflation, but will not let higher energy prices become persistent inflation. As the outlook evolves, we stand ready to respond as needed. The Bank is committed to maintaining Canadians’ confidence in price stability through this period of global upheaval.

Inflation in the US ticked up:

Annual inflation rose to a three-year-high of 4.2% in May, underscoring how elevated energy prices are rippling through the US economy, according to new data from the Bureau of Labor Statistics.

Prices rose 0.5% on a monthly basis, driven higher by the US-Israeli war with Iran, the latest Consumer Price Index shows. The higher cost of energy accounted for 60% of the monthly increase.

Overall food prices and grocery prices didn’t rise as fast as they did in April, increasing 0.2% and 0.1%, respectively, versus 0.5% and 0.7%.
…
The underlying inflation trends are running more muted. The closely watched “core” CPI gauge that strips out food and energy rose a slower-than-expected 0.2% from April, bringing the annual rate to 2.9%.

PerpetualDiscounts now yield 5.65%, equivalent to 7.34% interest at the standard conversion factor of 1.3x. Long corporates yielded 4.97% on 2026-06-9, but the closing price did not change from the 9th to the 10th, so we’ll overlook the date mismatch. Therefore the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) has narrowed sharply to 235bp from the 250bp reported June 3.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.67 % 6.06 % 26,870 14.78 1 0.0000 % 2,588.6
FixedFloater 0.00 % 0.00 % 0 0.00 0 1.4218 % 4,986.0
Floater 5.46 % 5.70 % 38,447 14.28 3 1.4218 % 2,873.4
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0475 % 3,638.2
SplitShare 4.79 % 4.34 % 51,236 2.77 5 -0.0475 % 4,344.8
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0475 % 3,390.0
Perpetual-Premium 5.67 % 5.53 % 77,933 6.54 7 -0.0226 % 3,077.7
Perpetual-Discount 5.58 % 5.65 % 41,418 14.37 28 -0.0958 % 3,377.2
FixedReset Disc 5.64 % 5.95 % 129,873 13.80 19 -0.0114 % 3,301.3
Insurance Straight 5.47 % 5.51 % 48,700 14.57 22 0.0376 % 3,296.1
FloatingReset 4.58 % 4.59 % 23,740 16.32 1 1.4529 % 4,154.8
FixedReset Prem 5.93 % 4.69 % 84,635 2.26 29 0.0736 % 2,650.0
FixedReset Bank Non 0.00 % 0.00 % 0 0.00 0 -0.0114 % 3,374.6
FixedReset Ins Non 5.14 % 5.38 % 71,289 14.49 14 -0.0239 % 3,213.5
Performance Highlights
Issue Index Change Notes
CU.PR.H Perpetual-Discount -2.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-10
Maturity Price : 23.58
Evaluated at bid price : 23.85
Bid-YTW : 5.53 %
PWF.PR.P FixedReset Disc -1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-10
Maturity Price : 20.76
Evaluated at bid price : 20.76
Bid-YTW : 5.75 %
ENB.PR.B FixedReset Disc -1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-10
Maturity Price : 21.94
Evaluated at bid price : 22.50
Bid-YTW : 6.17 %
BN.PR.K Floater 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-10
Maturity Price : 13.95
Evaluated at bid price : 13.95
Bid-YTW : 5.70 %
SLF.PR.J FloatingReset 1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-10
Maturity Price : 20.25
Evaluated at bid price : 20.25
Bid-YTW : 4.59 %
FTS.PR.F Perpetual-Discount 1.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-10
Maturity Price : 22.59
Evaluated at bid price : 22.84
Bid-YTW : 5.39 %
ENB.PF.C FixedReset Disc 1.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-10
Maturity Price : 22.59
Evaluated at bid price : 23.40
Bid-YTW : 6.12 %
PWF.PR.A Floater 2.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-10
Maturity Price : 15.00
Evaluated at bid price : 15.00
Bid-YTW : 5.25 %
Volume Highlights
Issue Index Shares
Traded
Notes
NA.PR.E FixedReset Prem 26,353 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2028-05-15
Maturity Price : 25.00
Evaluated at bid price : 25.69
Bid-YTW : 4.56 %
ENB.PR.J FixedReset Disc 23,933 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-10
Maturity Price : 22.92
Evaluated at bid price : 23.80
Bid-YTW : 6.07 %
ENB.PR.T FixedReset Disc 21,706 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-10
Maturity Price : 23.22
Evaluated at bid price : 24.55
Bid-YTW : 5.87 %
FFH.PR.K FixedReset Prem 18,918 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2027-03-31
Maturity Price : 25.00
Evaluated at bid price : 25.37
Bid-YTW : 4.44 %
There were 0 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
See TMX DataLinx: ‘Last’ != ‘Close’ and the posts linked therein for an idea of why these quotes are so horrible.
Issue Index Quote Data and Yield Notes
GWO.PR.Y Insurance Straight Quote: 20.76 – 22.22
Spot Rate : 1.4600
Average : 0.8372

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-10
Maturity Price : 20.76
Evaluated at bid price : 20.76
Bid-YTW : 5.44 %

CU.PR.J Perpetual-Discount Quote: 21.62 – 22.50
Spot Rate : 0.8800
Average : 0.5554

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-10
Maturity Price : 21.62
Evaluated at bid price : 21.62
Bid-YTW : 5.54 %

GWO.PR.Q Insurance Straight Quote: 22.80 – 23.85
Spot Rate : 1.0500
Average : 0.8202

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-10
Maturity Price : 22.55
Evaluated at bid price : 22.80
Bid-YTW : 5.65 %

GWO.PR.N FixedReset Ins Non Quote: 19.00 – 20.50
Spot Rate : 1.5000
Average : 1.2897

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-10
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 5.74 %

ENB.PR.J FixedReset Disc Quote: 23.80 – 24.50
Spot Rate : 0.7000
Average : 0.5371

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-10
Maturity Price : 22.92
Evaluated at bid price : 23.80
Bid-YTW : 6.07 %

CU.PR.H Perpetual-Discount Quote: 23.85 – 24.68
Spot Rate : 0.8300
Average : 0.6672

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-10
Maturity Price : 23.58
Evaluated at bid price : 23.85
Bid-YTW : 5.53 %

Market Action

June 9, 2026

The American indifference to the problems at Social Security continue to be ignored:

Tens of millions of retirees and other Americans could see smaller monthly Social Security checks in six years if lawmakers don’t act to shore up the program’s finances, according to an annual report released Tuesday by Social Security’s trustees.

Social Security’s retirement trust fund — which helps support payments to senior citizens, their dependents and survivors of deceased workers — is expected to be exhausted in late 2032, which is one quarter earlier than previously forecast, according to the trustees. At that time, payroll tax revenue and other income sources will be able to cover only 78% of benefits owed.

That means the next president could be faced with having to address Social Security’s shaky finances, which have long been considered a third rail in American politics. The issue could play a more prominent role in the 2028 presidential campaign if the projected expected insolvency date remains only a few years away.

The combined Social Security’s retirement and disability trust funds — are expected to be exhausted in 2034, the same as last year’s forecast, according to the trustees. At that time, payroll tax revenue and other income sources will be able to cover only 83% of benefits owed.

I don’t understand why this isn’t a huge issue in American politics. We addressed our problem with CPP back in the ’90’s – about thirty years ago. Since then, administrations of both stripes have ignored the issue, which is looming, obvious and public knowledge: Clinton, Bush, Obama, Trump #1, Biden, Trump #2 . ‘Low taxes, low taxes’ the chant goes … never mind that taxes (local + regional + federal + deficits) are basically the sme in the US and Canada, as far as I’ve ever been able to tell, as long as you don’t count medical expenses as a tax because, you know, insurance covers it.

I suspect that this is because America’s billionaires basically run the show down there; they couldn’t care less about Social Security.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.67 % 6.06 % 27,894 14.78 1 0.0000 % 2,588.6
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.0711 % 4,916.1
Floater 5.54 % 5.76 % 38,673 14.18 3 0.0711 % 2,833.2
OpRet 0.00 % 0.00 % 0 0.00 0 0.6850 % 3,639.9
SplitShare 4.79 % 4.34 % 50,745 2.77 5 0.6850 % 4,346.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.6850 % 3,391.6
Perpetual-Premium 5.67 % 5.53 % 78,074 6.55 7 0.2662 % 3,078.4
Perpetual-Discount 5.58 % 5.63 % 42,936 14.40 28 0.3608 % 3,380.5
FixedReset Disc 5.63 % 5.94 % 130,992 13.82 19 -0.3921 % 3,301.7
Insurance Straight 5.47 % 5.52 % 46,846 14.58 22 0.2379 % 3,294.8
FloatingReset 4.65 % 4.66 % 24,601 16.20 1 0.0000 % 4,095.3
FixedReset Prem 5.93 % 4.70 % 81,708 2.27 29 -0.1177 % 2,648.0
FixedReset Bank Non 0.00 % 0.00 % 0 0.00 0 -0.3921 % 3,375.0
FixedReset Ins Non 5.14 % 5.36 % 72,339 14.50 14 -0.3392 % 3,214.2
Performance Highlights
Issue Index Change Notes
GWO.PR.N FixedReset Ins Non -4.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-09
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 5.74 %
ENB.PF.C FixedReset Disc -2.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-09
Maturity Price : 22.36
Evaluated at bid price : 23.00
Bid-YTW : 6.24 %
ENB.PF.E FixedReset Disc -2.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-09
Maturity Price : 22.37
Evaluated at bid price : 23.05
Bid-YTW : 6.21 %
BN.PR.X FixedReset Disc -2.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-09
Maturity Price : 21.30
Evaluated at bid price : 21.30
Bid-YTW : 5.90 %
PWF.PR.A Floater -1.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-09
Maturity Price : 14.60
Evaluated at bid price : 14.60
Bid-YTW : 5.39 %
ENB.PR.J FixedReset Disc -1.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-09
Maturity Price : 22.87
Evaluated at bid price : 23.70
Bid-YTW : 6.10 %
GWO.PR.R Insurance Straight -1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-09
Maturity Price : 21.40
Evaluated at bid price : 21.40
Bid-YTW : 5.62 %
GWO.PR.Q Insurance Straight -1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-09
Maturity Price : 22.55
Evaluated at bid price : 22.80
Bid-YTW : 5.65 %
MFC.PR.K FixedReset Ins Non -1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-09
Maturity Price : 23.64
Evaluated at bid price : 25.37
Bid-YTW : 5.36 %
BN.PF.A FixedReset Prem -1.04 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2028-09-30
Maturity Price : 25.00
Evaluated at bid price : 25.78
Bid-YTW : 5.93 %
ENB.PR.B FixedReset Disc 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-09
Maturity Price : 22.09
Evaluated at bid price : 22.75
Bid-YTW : 6.09 %
PWF.PR.P FixedReset Disc 1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-09
Maturity Price : 21.00
Evaluated at bid price : 21.00
Bid-YTW : 5.68 %
ENB.PR.Y FixedReset Disc 1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-09
Maturity Price : 22.17
Evaluated at bid price : 22.62
Bid-YTW : 6.09 %
PWF.PR.L Perpetual-Discount 1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-09
Maturity Price : 22.71
Evaluated at bid price : 23.00
Bid-YTW : 5.61 %
PWF.PR.K Perpetual-Discount 1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-09
Maturity Price : 22.10
Evaluated at bid price : 22.32
Bid-YTW : 5.61 %
POW.PR.B Perpetual-Discount 1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-09
Maturity Price : 23.69
Evaluated at bid price : 24.00
Bid-YTW : 5.65 %
BN.PR.K Floater 1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-09
Maturity Price : 13.80
Evaluated at bid price : 13.80
Bid-YTW : 5.76 %
PWF.PR.S Perpetual-Discount 1.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-09
Maturity Price : 21.37
Evaluated at bid price : 21.64
Bid-YTW : 5.61 %
PVS.PR.M SplitShare 2.58 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2031-03-31
Maturity Price : 25.00
Evaluated at bid price : 25.43
Bid-YTW : 4.78 %
CU.PR.H Perpetual-Discount 2.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-09
Maturity Price : 24.21
Evaluated at bid price : 24.50
Bid-YTW : 5.38 %
IFC.PR.F Insurance Straight 4.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-09
Maturity Price : 23.73
Evaluated at bid price : 24.00
Bid-YTW : 5.62 %
Volume Highlights
Issue Index Shares
Traded
Notes
ENB.PR.P FixedReset Disc 62,400 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-09
Maturity Price : 23.02
Evaluated at bid price : 24.00
Bid-YTW : 5.94 %
ENB.PR.T FixedReset Disc 28,900 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-09
Maturity Price : 23.26
Evaluated at bid price : 24.65
Bid-YTW : 5.84 %
ENB.PF.C FixedReset Disc 13,500 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-09
Maturity Price : 22.36
Evaluated at bid price : 23.00
Bid-YTW : 6.24 %
There were 0 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
See TMX DataLinx: ‘Last’ != ‘Close’ and the posts linked therein for an idea of why these quotes are so horrible.
Issue Index Quote Data and Yield Notes
GWO.PR.N FixedReset Ins Non Quote: 19.00 – 20.50
Spot Rate : 1.5000
Average : 1.0592

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-09
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 5.74 %

ENB.PF.C FixedReset Disc Quote: 23.00 – 24.00
Spot Rate : 1.0000
Average : 0.6069

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-09
Maturity Price : 22.36
Evaluated at bid price : 23.00
Bid-YTW : 6.24 %

GWO.PR.T Insurance Straight Quote: 23.20 – 25.00
Spot Rate : 1.8000
Average : 1.5339

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-09
Maturity Price : 22.93
Evaluated at bid price : 23.20
Bid-YTW : 5.55 %

BN.PR.T FixedReset Disc Quote: 22.90 – 23.55
Spot Rate : 0.6500
Average : 0.4094

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-09
Maturity Price : 22.19
Evaluated at bid price : 22.90
Bid-YTW : 5.92 %

GWO.PR.Q Insurance Straight Quote: 22.80 – 23.55
Spot Rate : 0.7500
Average : 0.5682

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-09
Maturity Price : 22.55
Evaluated at bid price : 22.80
Bid-YTW : 5.65 %

IFC.PR.K Insurance Straight Quote: 23.90 – 25.10
Spot Rate : 1.2000
Average : 1.0496

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-06-09
Maturity Price : 23.45
Evaluated at bid price : 23.90
Bid-YTW : 5.58 %