Category: Market Action

Market Action

June 9, 2016

Janus Capital introduced a new batch of ETFs today … some old guys might want to overweight them:

It’s easy to imagine the slapping sounds of high-fives when Janus executives conjured up these ticker symbols: SLIM, for the Obesity ETF; OLD, for the Long-Term Care ETF; FITS, for the Health and Fitness ETF; and ORG, for the Organics ETF. Each started trading on Thursday, representing the fund manager’s second set of original equity ETF offerings after entering the space in 2014 with the purchase of VelocityShares.

Assiduous Reader JR reminds me I haven’t posted any drone news in a while … so how about a passenger drone?

Ehang CEO Huazhi Hu began designing the one-seater electric drone a couple of years ago, after two of his pilot friends were killed in plane crashes. He decided that people needed a form of short-to-medium-distance personal air transport that didn’t require them to have a pilot’s license, and that took much of the danger out of low-altitude flight.

The idea behind the Chinese-built 184 is that users will simply get in, power it up, select their destination using a 12-inch touchscreen tablet display, then press the “take-off” button. The drone’s automated flight systems will take over from there, managing tasks such as communication with air traffic control and other aircraft, obstacle avoidance, and of course navigation – it will always choose the fastest yet safest route between its present location and its destination.

Failsafe systems will reportedly take over in the event of malfunctions, plus passengers can get the drone to stop and hover in place if needed.

The company is hoping to start testing this year.

DBRS confirmed Brookfield Office Properties at Pfd-3:

DBRS Limited (DBRS) has confirmed the rating of Brookfield Office Properties Inc.’s (Brookfield or the Company) Senior Unsecured Notes at BBB and its Cumulative Redeemable Preferred Shares, Class AAA at Pfd-3, both with Stable trends. The confirmation acknowledges DBRS’s previous expectation that Brookfield’s coverage ratios would remain at aggressive levels for the current rating category during the re-leasing transition period (2015–2016) at BPNY. The confirmation reflects DBRS’s expectation for a gradual improvement in coverage ratios in 2016, driven by income contributions from leases at BPNY, and that Brookfield will use asset disposition proceeds to reduce debt.
…
If Brookfield achieves weaker operating income and/or increased leverage such that the Company fails to meet DBRS’s expectations of EBITDA interest coverage (including capitalized interest) increasing to 1.70x within a year, a negative rating action could occur. Although highly unlikely, a positive rating action would require Brookfield to demonstrate meaningful improvement in operating income and significant deleveraging of its balance sheet.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.7957 % 1,695.9
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.7957 % 3,098.1
Floater 4.48 % 4.56 % 65,400 16.21 3 0.7957 % 1,785.5
OpRet 4.87 % -1.09 % 42,779 0.08 1 0.0000 % 2,831.3
SplitShare 4.87 % 4.70 % 86,984 4.69 7 0.0689 % 3,343.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0689 % 2,609.0
Perpetual-Premium 5.60 % -1.16 % 75,250 0.09 9 -0.0911 % 2,623.3
Perpetual-Discount 5.37 % 5.46 % 106,183 14.66 28 0.0184 % 2,730.5
FixedReset 5.05 % 4.48 % 160,995 7.44 87 0.3550 % 2,020.6
Deemed-Retractible 5.11 % 5.30 % 128,332 4.96 33 0.0579 % 2,706.8
FloatingReset 3.09 % 4.92 % 26,999 5.23 17 0.2775 % 2,125.8
Performance Highlights
Issue Index Change Notes
BAM.PR.X FixedReset -1.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-09
Maturity Price : 14.17
Evaluated at bid price : 14.17
Bid-YTW : 4.61 %
POW.PR.D Perpetual-Discount -1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-09
Maturity Price : 22.70
Evaluated at bid price : 22.94
Bid-YTW : 5.53 %
PWF.PR.Q FloatingReset -1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-09
Maturity Price : 12.50
Evaluated at bid price : 12.50
Bid-YTW : 4.26 %
GWO.PR.O FloatingReset -1.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.00
Bid-YTW : 10.33 %
BAM.PR.R FixedReset -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-09
Maturity Price : 15.20
Evaluated at bid price : 15.20
Bid-YTW : 4.92 %
TRP.PR.G FixedReset 1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-09
Maturity Price : 19.91
Evaluated at bid price : 19.91
Bid-YTW : 4.60 %
BAM.PR.B Floater 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-09
Maturity Price : 10.67
Evaluated at bid price : 10.67
Bid-YTW : 4.49 %
BNS.PR.P FixedReset 1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.22
Bid-YTW : 3.59 %
BNS.PR.Q FixedReset 1.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.22
Bid-YTW : 4.38 %
TD.PR.S FixedReset 1.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.22
Bid-YTW : 4.21 %
CM.PR.Q FixedReset 1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-09
Maturity Price : 20.39
Evaluated at bid price : 20.39
Bid-YTW : 4.29 %
RY.PR.M FixedReset 1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-09
Maturity Price : 19.66
Evaluated at bid price : 19.66
Bid-YTW : 4.27 %
NA.PR.S FixedReset 1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-09
Maturity Price : 18.68
Evaluated at bid price : 18.68
Bid-YTW : 4.32 %
TRP.PR.E FixedReset 1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-09
Maturity Price : 18.69
Evaluated at bid price : 18.69
Bid-YTW : 4.35 %
FTS.PR.K FixedReset 1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-09
Maturity Price : 17.71
Evaluated at bid price : 17.71
Bid-YTW : 4.06 %
TRP.PR.I FloatingReset 1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-09
Maturity Price : 11.50
Evaluated at bid price : 11.50
Bid-YTW : 4.50 %
BMO.PR.R FloatingReset 1.33 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.14
Bid-YTW : 4.44 %
TRP.PR.D FixedReset 1.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-09
Maturity Price : 17.98
Evaluated at bid price : 17.98
Bid-YTW : 4.46 %
CCS.PR.C Deemed-Retractible 1.84 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.25
Bid-YTW : 6.05 %
HSE.PR.A FixedReset 2.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-09
Maturity Price : 12.14
Evaluated at bid price : 12.14
Bid-YTW : 4.90 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PF.G FixedReset 121,992 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 26.33
Bid-YTW : 4.44 %
TD.PF.C FixedReset 85,406 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-09
Maturity Price : 18.66
Evaluated at bid price : 18.66
Bid-YTW : 4.14 %
BMO.PR.W FixedReset 58,823 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-09
Maturity Price : 18.71
Evaluated at bid price : 18.71
Bid-YTW : 4.06 %
RY.PR.Z FixedReset 48,654 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-09
Maturity Price : 18.72
Evaluated at bid price : 18.72
Bid-YTW : 4.06 %
GWO.PR.P Deemed-Retractible 36,800 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.90
Bid-YTW : 5.45 %
MFC.PR.L FixedReset 33,907 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.39
Bid-YTW : 6.70 %
There were 16 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
GWO.PR.O FloatingReset Quote: 13.00 – 15.46
Spot Rate : 2.4600
Average : 1.5029

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.00
Bid-YTW : 10.33 %

ALB.PR.C SplitShare Quote: 26.02 – 27.00
Spot Rate : 0.9800
Average : 0.7113

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-02-28
Maturity Price : 25.67
Evaluated at bid price : 26.02
Bid-YTW : 2.99 %

RY.PR.I FixedReset Quote: 23.16 – 23.60
Spot Rate : 0.4400
Average : 0.3004

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.16
Bid-YTW : 4.58 %

POW.PR.D Perpetual-Discount Quote: 22.94 – 23.27
Spot Rate : 0.3300
Average : 0.1956

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-09
Maturity Price : 22.70
Evaluated at bid price : 22.94
Bid-YTW : 5.53 %

BAM.PR.Z FixedReset Quote: 19.52 – 19.77
Spot Rate : 0.2500
Average : 0.1787

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-09
Maturity Price : 19.52
Evaluated at bid price : 19.52
Bid-YTW : 4.85 %

TD.PF.F Perpetual-Discount Quote: 24.68 – 24.89
Spot Rate : 0.2100
Average : 0.1401

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-09
Maturity Price : 24.29
Evaluated at bid price : 24.68
Bid-YTW : 5.01 %

Market Action

June 8, 2016

PerpetualDiscounts now have a yield of 5.38%, equivalent to 6.99% interest at the standard equivalency factor of 1.3x. Long corporates now yield 3.9%, so the pre-tax interest-equivalent spread is now about 310bp, narrowing from the 320bp reported June 1.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.4155 % 1,682.6
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.4155 % 3,073.7
Floater 4.51 % 4.58 % 66,142 16.17 3 0.4155 % 1,771.4
OpRet 4.87 % -1.25 % 42,959 0.08 1 0.0796 % 2,831.3
SplitShare 4.88 % 4.71 % 86,961 4.69 7 0.2938 % 3,341.6
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.2938 % 2,607.2
Perpetual-Premium 5.60 % -1.34 % 75,481 0.09 9 0.2131 % 2,625.7
Perpetual-Discount 5.37 % 5.38 % 107,687 14.66 28 0.1639 % 2,730.0
FixedReset 5.07 % 4.53 % 163,198 14.58 87 0.2324 % 2,013.4
Deemed-Retractible 5.11 % 5.35 % 131,433 4.96 33 0.0832 % 2,705.2
FloatingReset 3.10 % 5.00 % 26,842 5.23 17 0.1911 % 2,119.9
Performance Highlights
Issue Index Change Notes
BMO.PR.Q FixedReset -3.65 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.51
Bid-YTW : 6.58 %
MFC.PR.F FixedReset -2.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.58
Bid-YTW : 10.13 %
SLF.PR.H FixedReset -2.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.36
Bid-YTW : 8.54 %
EML.PR.A FixedReset -1.53 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-17
Maturity Price : 25.00
Evaluated at bid price : 25.80
Bid-YTW : 5.22 %
CU.PR.C FixedReset -1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-08
Maturity Price : 17.71
Evaluated at bid price : 17.71
Bid-YTW : 4.37 %
GWO.PR.N FixedReset -1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.30
Bid-YTW : 9.44 %
TD.PF.D FixedReset 1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-08
Maturity Price : 20.20
Evaluated at bid price : 20.20
Bid-YTW : 4.33 %
FTS.PR.K FixedReset 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-08
Maturity Price : 17.48
Evaluated at bid price : 17.48
Bid-YTW : 4.12 %
TRP.PR.E FixedReset 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-08
Maturity Price : 18.45
Evaluated at bid price : 18.45
Bid-YTW : 4.40 %
CCS.PR.C Deemed-Retractible 1.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.83
Bid-YTW : 6.31 %
FTS.PR.H FixedReset 1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-08
Maturity Price : 13.91
Evaluated at bid price : 13.91
Bid-YTW : 3.91 %
FTS.PR.G FixedReset 1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-08
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 4.27 %
RY.PR.M FixedReset 1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-08
Maturity Price : 19.42
Evaluated at bid price : 19.42
Bid-YTW : 4.32 %
FTS.PR.I FloatingReset 1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-08
Maturity Price : 12.05
Evaluated at bid price : 12.05
Bid-YTW : 4.09 %
HSE.PR.G FixedReset 1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-08
Maturity Price : 20.65
Evaluated at bid price : 20.65
Bid-YTW : 5.16 %
RY.PR.J FixedReset 1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-08
Maturity Price : 19.81
Evaluated at bid price : 19.81
Bid-YTW : 4.35 %
CM.PR.Q FixedReset 1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-08
Maturity Price : 20.15
Evaluated at bid price : 20.15
Bid-YTW : 4.35 %
NA.PR.S FixedReset 1.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-08
Maturity Price : 18.45
Evaluated at bid price : 18.45
Bid-YTW : 4.37 %
MFC.PR.J FixedReset 1.49 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.40
Bid-YTW : 6.20 %
TRP.PR.F FloatingReset 1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-08
Maturity Price : 14.58
Evaluated at bid price : 14.58
Bid-YTW : 4.16 %
HSE.PR.E FixedReset 1.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-08
Maturity Price : 20.60
Evaluated at bid price : 20.60
Bid-YTW : 5.19 %
NA.PR.W FixedReset 2.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-08
Maturity Price : 17.96
Evaluated at bid price : 17.96
Bid-YTW : 4.32 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PF.G FixedReset 137,715 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 26.31
Bid-YTW : 4.46 %
TD.PF.C FixedReset 74,900 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-08
Maturity Price : 18.63
Evaluated at bid price : 18.63
Bid-YTW : 4.15 %
RY.PR.R FixedReset 72,100 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-24
Maturity Price : 25.00
Evaluated at bid price : 26.45
Bid-YTW : 4.57 %
NA.PR.S FixedReset 72,025 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-08
Maturity Price : 18.45
Evaluated at bid price : 18.45
Bid-YTW : 4.37 %
RY.PR.H FixedReset 58,978 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-08
Maturity Price : 18.76
Evaluated at bid price : 18.76
Bid-YTW : 4.10 %
TRP.PR.D FixedReset 54,863 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-08
Maturity Price : 17.71
Evaluated at bid price : 17.71
Bid-YTW : 4.52 %
There were 41 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
SLF.PR.H FixedReset Quote: 16.36 – 16.74
Spot Rate : 0.3800
Average : 0.2566

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.36
Bid-YTW : 8.54 %

ALB.PR.C SplitShare Quote: 26.02 – 26.55
Spot Rate : 0.5300
Average : 0.4167

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-02-28
Maturity Price : 25.67
Evaluated at bid price : 26.02
Bid-YTW : 2.97 %

IAG.PR.A Deemed-Retractible Quote: 22.03 – 22.45
Spot Rate : 0.4200
Average : 0.3214

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.03
Bid-YTW : 6.40 %

BMO.PR.R FloatingReset Quote: 21.85 – 22.25
Spot Rate : 0.4000
Average : 0.3033

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.85
Bid-YTW : 4.69 %

TRP.PR.I FloatingReset Quote: 11.35 – 12.00
Spot Rate : 0.6500
Average : 0.5567

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-08
Maturity Price : 11.35
Evaluated at bid price : 11.35
Bid-YTW : 4.56 %

FTS.PR.I FloatingReset Quote: 12.05 – 12.53
Spot Rate : 0.4800
Average : 0.3869

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-08
Maturity Price : 12.05
Evaluated at bid price : 12.05
Bid-YTW : 4.09 %

Market Action

June 7, 2016

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.4771 % 1,675.6
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.4771 % 3,061.0
Floater 4.53 % 4.60 % 68,276 16.13 3 -0.4771 % 1,764.1
OpRet 4.87 % -0.45 % 44,728 0.08 1 0.0000 % 2,829.0
SplitShare 4.89 % 4.88 % 87,932 4.69 7 0.0458 % 3,331.8
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0458 % 2,599.6
Perpetual-Premium 5.61 % 1.36 % 78,469 0.09 9 0.0696 % 2,620.1
Perpetual-Discount 5.38 % 5.40 % 106,985 14.67 28 0.1365 % 2,725.5
FixedReset 5.08 % 4.56 % 162,755 14.58 87 0.1826 % 2,008.8
Deemed-Retractible 5.12 % 5.33 % 131,440 4.96 33 0.0883 % 2,703.0
FloatingReset 3.10 % 5.06 % 25,950 5.23 17 0.1496 % 2,115.8
Performance Highlights
Issue Index Change Notes
BMO.PR.Q FixedReset -1.89 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.25
Bid-YTW : 5.86 %
HSE.PR.A FixedReset -1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-07
Maturity Price : 11.76
Evaluated at bid price : 11.76
Bid-YTW : 5.05 %
BMO.PR.M FixedReset -1.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.10
Bid-YTW : 4.30 %
HSE.PR.G FixedReset 1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-07
Maturity Price : 20.38
Evaluated at bid price : 20.38
Bid-YTW : 5.23 %
HSE.PR.E FixedReset 1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-07
Maturity Price : 20.20
Evaluated at bid price : 20.20
Bid-YTW : 5.29 %
BAM.PR.R FixedReset 1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-07
Maturity Price : 15.28
Evaluated at bid price : 15.28
Bid-YTW : 4.89 %
SLF.PR.H FixedReset 1.21 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.70
Bid-YTW : 8.25 %
MFC.PR.F FixedReset 1.39 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.89
Bid-YTW : 9.81 %
BAM.PR.Z FixedReset 1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-07
Maturity Price : 19.68
Evaluated at bid price : 19.68
Bid-YTW : 4.81 %
TRP.PR.D FixedReset 1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-07
Maturity Price : 17.80
Evaluated at bid price : 17.80
Bid-YTW : 4.50 %
BAM.PR.T FixedReset 1.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-07
Maturity Price : 15.79
Evaluated at bid price : 15.79
Bid-YTW : 4.90 %
PWF.PR.P FixedReset 2.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-07
Maturity Price : 13.60
Evaluated at bid price : 13.60
Bid-YTW : 4.18 %
HSE.PR.C FixedReset 2.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-07
Maturity Price : 18.40
Evaluated at bid price : 18.40
Bid-YTW : 5.34 %
Volume Highlights
Issue Index Shares
Traded
Notes
TRP.PR.J FixedReset 163,400 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-31
Maturity Price : 25.00
Evaluated at bid price : 25.73
Bid-YTW : 4.89 %
TD.PF.G FixedReset 93,643 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 26.29
Bid-YTW : 4.47 %
BNS.PR.G FixedReset 85,475 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-07-25
Maturity Price : 25.00
Evaluated at bid price : 26.29
Bid-YTW : 4.67 %
TRP.PR.D FixedReset 76,878 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-07
Maturity Price : 17.80
Evaluated at bid price : 17.80
Bid-YTW : 4.50 %
RY.PR.B Deemed-Retractible 58,046 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-07-07
Maturity Price : 25.00
Evaluated at bid price : 25.13
Bid-YTW : 0.56 %
BAM.PR.T FixedReset 44,078 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-07
Maturity Price : 15.79
Evaluated at bid price : 15.79
Bid-YTW : 4.90 %
There were 24 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
TRP.PR.A FixedReset Quote: 15.15 – 16.20
Spot Rate : 1.0500
Average : 0.6223

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-07
Maturity Price : 15.15
Evaluated at bid price : 15.15
Bid-YTW : 4.45 %

BNS.PR.B FloatingReset Quote: 21.48 – 21.99
Spot Rate : 0.5100
Average : 0.3222

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.48
Bid-YTW : 5.18 %

POW.PR.G Perpetual-Premium Quote: 25.54 – 25.95
Spot Rate : 0.4100
Average : 0.2500

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-15
Maturity Price : 25.00
Evaluated at bid price : 25.54
Bid-YTW : 5.32 %

MFC.PR.J FixedReset Quote: 20.10 – 20.62
Spot Rate : 0.5200
Average : 0.3724

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.10
Bid-YTW : 6.41 %

MFC.PR.I FixedReset Quote: 21.05 – 21.43
Spot Rate : 0.3800
Average : 0.2556

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.05
Bid-YTW : 6.01 %

GWO.PR.L Deemed-Retractible Quote: 25.50 – 25.86
Spot Rate : 0.3600
Average : 0.2544

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-12-31
Maturity Price : 25.25
Evaluated at bid price : 25.50
Bid-YTW : 4.73 %

Market Action

June 6, 2016

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.6080 % 1,683.6
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.6080 % 3,075.6
Floater 4.51 % 4.57 % 64,076 16.19 3 0.6080 % 1,772.5
OpRet 4.87 % -0.61 % 44,718 0.08 1 0.0398 % 2,829.0
SplitShare 4.89 % 4.94 % 82,623 4.69 7 0.1674 % 3,330.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1674 % 2,598.4
Perpetual-Premium 5.61 % 0.21 % 78,710 0.09 9 0.0610 % 2,618.3
Perpetual-Discount 5.38 % 5.40 % 107,590 14.63 28 0.0906 % 2,721.8
FixedReset 5.09 % 4.57 % 162,543 14.48 87 0.1035 % 2,005.1
Deemed-Retractible 5.12 % 5.31 % 127,582 4.96 33 0.0404 % 2,700.6
FloatingReset 3.11 % 5.13 % 26,271 5.23 17 1.5443 % 2,112.7
Performance Highlights
Issue Index Change Notes
CCS.PR.C Deemed-Retractible -1.61 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.55
Bid-YTW : 6.49 %
IFC.PR.C FixedReset -1.41 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.14
Bid-YTW : 7.90 %
GWO.PR.N FixedReset 1.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.50
Bid-YTW : 9.24 %
CGI.PR.D SplitShare 1.17 % YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2023-06-14
Maturity Price : 25.00
Evaluated at bid price : 25.00
Bid-YTW : 3.75 %
BAM.PF.E FixedReset 1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-06
Maturity Price : 19.10
Evaluated at bid price : 19.10
Bid-YTW : 4.60 %
TRP.PR.G FixedReset 1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-06
Maturity Price : 19.40
Evaluated at bid price : 19.40
Bid-YTW : 4.72 %
FTS.PR.H FixedReset 1.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-06
Maturity Price : 13.74
Evaluated at bid price : 13.74
Bid-YTW : 3.96 %
TRP.PR.F FloatingReset 2.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-06
Maturity Price : 14.30
Evaluated at bid price : 14.30
Bid-YTW : 4.24 %
HSE.PR.A FixedReset 3.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-06
Maturity Price : 11.89
Evaluated at bid price : 11.89
Bid-YTW : 5.00 %
TRP.PR.H FloatingReset 9.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-06
Maturity Price : 10.21
Evaluated at bid price : 10.21
Bid-YTW : 4.38 %
PWF.PR.Q FloatingReset 34.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-06
Maturity Price : 12.50
Evaluated at bid price : 12.50
Bid-YTW : 4.26 %
Volume Highlights
Issue Index Shares
Traded
Notes
MFC.PR.F FixedReset 93,583 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.70
Bid-YTW : 10.00 %
MFC.PR.O FixedReset 61,885 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-06-19
Maturity Price : 25.00
Evaluated at bid price : 26.20
Bid-YTW : 4.51 %
TRP.PR.J FixedReset 53,930 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-31
Maturity Price : 25.00
Evaluated at bid price : 25.72
Bid-YTW : 4.89 %
BNS.PR.G FixedReset 33,300 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-07-25
Maturity Price : 25.00
Evaluated at bid price : 26.37
Bid-YTW : 4.60 %
TD.PF.B FixedReset 24,008 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-06
Maturity Price : 18.68
Evaluated at bid price : 18.68
Bid-YTW : 4.14 %
HSE.PR.A FixedReset 21,975 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-06
Maturity Price : 11.89
Evaluated at bid price : 11.89
Bid-YTW : 5.00 %
There were 12 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
HSE.PR.C FixedReset Quote: 17.91 – 18.66
Spot Rate : 0.7500
Average : 0.5378

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-06
Maturity Price : 17.91
Evaluated at bid price : 17.91
Bid-YTW : 5.49 %

PWF.PR.P FixedReset Quote: 13.30 – 13.75
Spot Rate : 0.4500
Average : 0.3074

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-06
Maturity Price : 13.30
Evaluated at bid price : 13.30
Bid-YTW : 4.28 %

HSE.PR.E FixedReset Quote: 19.97 – 20.46
Spot Rate : 0.4900
Average : 0.3524

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-06
Maturity Price : 19.97
Evaluated at bid price : 19.97
Bid-YTW : 5.36 %

HSE.PR.A FixedReset Quote: 11.89 – 12.33
Spot Rate : 0.4400
Average : 0.3090

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-06
Maturity Price : 11.89
Evaluated at bid price : 11.89
Bid-YTW : 5.00 %

CM.PR.O FixedReset Quote: 19.00 – 19.34
Spot Rate : 0.3400
Average : 0.2395

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-06
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 4.15 %

SLF.PR.H FixedReset Quote: 16.50 – 16.79
Spot Rate : 0.2900
Average : 0.1993

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.50
Bid-YTW : 8.42 %

Market Action

June 3, 2016

Jobs, jobs … whoopsy!

The U.S. economy looks to be in danger of losing its main pillar as employers throttled back hiring in May to the lowest level in almost six years.

The slowdown — payrolls rose by 38,000 after a downwardly revised 123,000 in April — raised questions about the ability of consumers to keep spending at a good clip. It also cast doubts on Federal Reserve policy makers’ intentions to raise interest rates soon.
…
The deceleration in the labor market was widespread, with industries from construction and manufacturing to temporary-help services cutting workers.
…
Unemployment did drop, to an almost nine-year low of 4.7 percent last month from 5 percent in April. But even that was bad news as the decline was mainly because more Americans dropped out of the labor force rather than from an increase in employment.

In a sign that the jobs market may remain weak, the Institute for Supply Management reported that American service providers expanded in May at the slowest pace in more than two years. Its measure of services employment dropped to its lowest since February 2014.
…
About the only bright spot in the report was worker pay. Average hourly earnings, rose by 0.2 percent in May after a 0.4 percent gain in April that was a bit stronger than initially reported. Pay increased 2.5 percent over the 12 months ended in May.

This, naturally enough, dampens expectations for a Fed hike:

The argument for a June interest-rate hike from the Federal Reserve has evaporated.

Economists and investors largely agreed that a disappointing employment report for May — the U.S. economy added just 38,000 new jobs — all but eliminated the chance that Fed officials would tighten policy when they meet June 14-15 in Washington, and may make it difficult for them to raise in July.
…
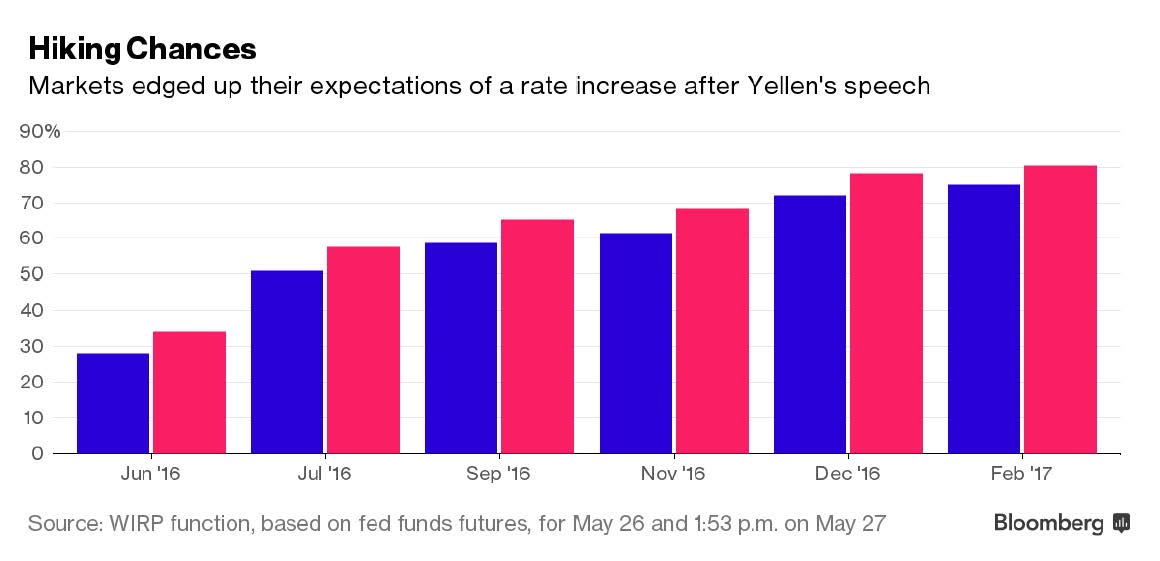
Odds of a June hike implied by futures trading, which had risen as high as 34 percent in late May as Fed officials hinted at their eagerness to raise rates, tumbled to just 4 percent following the employment report. The odds are based on prices in federal funds futures contracts.

And, perhaps on a related note, the amount of negative yield debt is increasing:

Negative-yielding government debt has risen above $10tn for the first time, enveloping an increasingly large part of the financial markets after being fuelled by central bank stimulus and a voracious investor appetite for sovereign paper.

The amount of sovereign debt trading with a sub-zero yield climbed 5 per cent in May from a month earlier to $10.4tn, buoyed by rising bond prices in Italy, Japan, Germany and France, according to rating agency Fitch. Yields fall as the price of the underlying bonds climbs.

The ascent of the negative yield, which first affected only the shortest maturing notes from highly rated sovereigns, has encompassed seven-year German Bunds and 10-year Japanese government bonds as both the European Central Bank and Bank of Japan have cut benchmark interest rates and launched bond-buying programmes.

On Wednesday the ECB left its main deposit rate for bank reserves unchanged at minus 0.4 per cent.

Unwinding this easy-money is going to be interesting:

Lurking in the bond market is a $1 trillion reason for the Federal Reserve to go slow on interest-rate increases.

That’s how much bondholders stand to lose if Treasury yields rise unexpectedly by 1 percentage point, according to a Goldman Sachs Group Inc. estimate. A hit of that magnitude would exceed the realized losses since the financial crisis on mortgage bonds without government backing, Goldman Sachs analysts Marty Young and Charles Himmelberg wrote in a note published today.

There’s been some loss of face for the US government’s regulatory extortion squad:

The U.S. government has been made several of these unusual repayments in the aftermath of its historic pursuit of insider trading, which led to 80 convictions, brought down at least five hedge funds and resulted in more than $2 billion in payments from defendants.

Fourteen of those convictions have now been overturned — including two that were struck down by an appeals court in 2014, opening the door for the victors and others to claw back penalties and fines from the Justice Department and the U.S. Securities and Exchange Commission. The government has now handed back more than $40 million in all, including to three individuals whose convictions were overturned and two of the hedge funds where they worked.
…
The refunds are among several setbacks for the government recently in its insider-trading crackdown. Earlier this year, an appeals court temporarily released convicted stock trader Douglas Whitman from a California halfway house after he argued that his conduct may not have been illegal, depending on how the U.S. Supreme Court rules in another pending insider-trading case.

Five others convicted of insider trading, including former Goldman Sachs Group Inc. director Rajat Gupta, have sought reviews of their cases.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.0320 % 1,673.5
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.0320 % 3,057.1
Floater 4.54 % 4.61 % 64,181 16.14 3 -0.0320 % 1,761.8
OpRet 4.88 % -0.61 % 46,540 0.08 1 -0.2779 % 2,827.9
SplitShare 4.90 % 5.14 % 81,368 4.70 7 -0.0231 % 3,324.7
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0231 % 2,594.1
Perpetual-Premium 5.62 % 3.54 % 79,812 0.09 9 0.2007 % 2,616.7
Perpetual-Discount 5.39 % 5.50 % 110,101 14.62 28 0.2864 % 2,719.4
FixedReset 5.10 % 4.66 % 163,460 14.32 87 -0.0451 % 2,003.0
Deemed-Retractible 5.12 % 5.36 % 128,646 4.97 33 -0.0240 % 2,699.5
FloatingReset 3.20 % 5.25 % 26,200 5.24 17 -1.9133 % 2,080.5
Performance Highlights
Issue Index Change Notes
PWF.PR.Q FloatingReset -28.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-03
Maturity Price : 9.32
Evaluated at bid price : 9.32
Bid-YTW : 5.81 %
TRP.PR.H FloatingReset -10.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-03
Maturity Price : 9.35
Evaluated at bid price : 9.35
Bid-YTW : 4.86 %
TRP.PR.I FloatingReset -3.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-03
Maturity Price : 11.20
Evaluated at bid price : 11.20
Bid-YTW : 4.69 %
IAG.PR.G FixedReset -2.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.99
Bid-YTW : 6.81 %
TRP.PR.G FixedReset -1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-03
Maturity Price : 19.15
Evaluated at bid price : 19.15
Bid-YTW : 4.94 %
BNS.PR.Y FixedReset -1.47 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.11
Bid-YTW : 5.98 %
BMO.PR.Q FixedReset -1.44 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.50
Bid-YTW : 5.79 %
HSE.PR.A FixedReset -1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-03
Maturity Price : 11.46
Evaluated at bid price : 11.46
Bid-YTW : 5.43 %
TRP.PR.A FixedReset -1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-03
Maturity Price : 15.00
Evaluated at bid price : 15.00
Bid-YTW : 4.71 %
TRP.PR.F FloatingReset -1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-03
Maturity Price : 13.90
Evaluated at bid price : 13.90
Bid-YTW : 4.42 %
BNS.PR.Z FixedReset -1.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.10
Bid-YTW : 6.30 %
CU.PR.C FixedReset -1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-03
Maturity Price : 17.75
Evaluated at bid price : 17.75
Bid-YTW : 4.57 %
BAM.PR.Z FixedReset -1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-03
Maturity Price : 19.50
Evaluated at bid price : 19.50
Bid-YTW : 5.02 %
TD.PF.E FixedReset -1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-03
Maturity Price : 20.71
Evaluated at bid price : 20.71
Bid-YTW : 4.48 %
W.PR.H Perpetual-Discount 1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-03
Maturity Price : 23.91
Evaluated at bid price : 24.15
Bid-YTW : 5.78 %
BAM.PR.X FixedReset 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-03
Maturity Price : 14.30
Evaluated at bid price : 14.30
Bid-YTW : 4.83 %
HSE.PR.E FixedReset 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-03
Maturity Price : 19.86
Evaluated at bid price : 19.86
Bid-YTW : 5.54 %
BAM.PF.G FixedReset 1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-03
Maturity Price : 20.50
Evaluated at bid price : 20.50
Bid-YTW : 4.75 %
FTS.PR.H FixedReset 1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-03
Maturity Price : 13.52
Evaluated at bid price : 13.52
Bid-YTW : 4.26 %
FTS.PR.J Perpetual-Discount 1.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-03
Maturity Price : 22.58
Evaluated at bid price : 22.90
Bid-YTW : 5.20 %
BAM.PR.T FixedReset 1.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-03
Maturity Price : 15.60
Evaluated at bid price : 15.60
Bid-YTW : 5.17 %
GWO.PR.N FixedReset 1.63 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.34
Bid-YTW : 9.46 %
FTS.PR.F Perpetual-Discount 2.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-03
Maturity Price : 23.32
Evaluated at bid price : 23.60
Bid-YTW : 5.21 %
HSE.PR.G FixedReset 2.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-03
Maturity Price : 19.99
Evaluated at bid price : 19.99
Bid-YTW : 5.48 %
Volume Highlights
Issue Index Shares
Traded
Notes
CU.PR.E Perpetual-Discount 142,332 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-03
Maturity Price : 22.48
Evaluated at bid price : 22.79
Bid-YTW : 5.39 %
BAM.PR.C Floater 100,891 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-03
Maturity Price : 10.36
Evaluated at bid price : 10.36
Bid-YTW : 4.62 %
CU.PR.D Perpetual-Discount 94,671 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-03
Maturity Price : 22.45
Evaluated at bid price : 22.76
Bid-YTW : 5.40 %
MFC.PR.F FixedReset 94,281 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.71
Bid-YTW : 10.20 %
RY.PR.H FixedReset 80,961 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-03
Maturity Price : 18.61
Evaluated at bid price : 18.61
Bid-YTW : 4.32 %
BNS.PR.A FloatingReset 72,063 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.85
Bid-YTW : 4.38 %
There were 33 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
PWF.PR.Q FloatingReset Quote: 9.32 – 13.00
Spot Rate : 3.6800
Average : 2.0883

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-03
Maturity Price : 9.32
Evaluated at bid price : 9.32
Bid-YTW : 5.81 %

TRP.PR.F FloatingReset Quote: 13.90 – 14.90
Spot Rate : 1.0000
Average : 0.6346

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-03
Maturity Price : 13.90
Evaluated at bid price : 13.90
Bid-YTW : 4.42 %

HSE.PR.G FixedReset Quote: 19.99 – 21.00
Spot Rate : 1.0100
Average : 0.7024

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-03
Maturity Price : 19.99
Evaluated at bid price : 19.99
Bid-YTW : 5.48 %

TRP.PR.H FloatingReset Quote: 9.35 – 10.47
Spot Rate : 1.1200
Average : 0.8416

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-03
Maturity Price : 9.35
Evaluated at bid price : 9.35
Bid-YTW : 4.86 %

TRP.PR.G FixedReset Quote: 19.15 – 19.71
Spot Rate : 0.5600
Average : 0.3927

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-03
Maturity Price : 19.15
Evaluated at bid price : 19.15
Bid-YTW : 4.94 %

CGI.PR.D SplitShare Quote: 24.71 – 25.23
Spot Rate : 0.5200
Average : 0.3727

YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2023-06-14
Maturity Price : 25.00
Evaluated at bid price : 24.71
Bid-YTW : 3.94 %

Market Action

June 2, 2016

There is growing fear that Canadian housing is a momentum play:

The Bank of Canada is concerned that the acceleration in housing prices in Toronto and Vancouver may be partly due to purchases based solely on the expectation that prices will keep going up, Deputy Governor Lawrence Schembri said on Thursday.

Schembri said that Canadians moving away from resource-producing regions to the major cities of Toronto and Vancouver in order to find jobs has created a huge demand for housing in those cities, driving prices up as supply remains relatively limited.

But he expressed concern that such fundamentals are not the only reason for rising prices.

“The concern that we have at the Bank of Canada is these price increases may reflect in part the fact that certain people (are) buying housing on (speculation), expecting this price increase to continue,” said Schembri.

“People should not be buying housing based on the expectation these prices are going to continue” as the demand from the influx of workers into those regions will not continue at the same rate, Schembri said.

He was speaking during a question-and-answer session following a presentation on the outlook for the economy.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -1.1698 % 1,674.0
FixedFloater 0.00 % 0.00 % 0 0.00 0 -1.1698 % 3,058.0
Floater 4.53 % 4.59 % 61,290 16.17 3 -1.1698 % 1,762.4
OpRet 4.86 % -4.12 % 46,260 0.08 1 0.0000 % 2,835.8
SplitShare 4.90 % 5.02 % 82,104 4.70 7 0.2140 % 3,325.5
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.2140 % 2,594.7
Perpetual-Premium 5.63 % 4.83 % 80,753 0.09 9 -0.0436 % 2,611.4
Perpetual-Discount 5.40 % 5.51 % 110,887 14.60 28 -0.0169 % 2,711.6
FixedReset 5.09 % 4.65 % 162,745 7.44 87 -0.3804 % 2,003.9
Deemed-Retractible 5.12 % 5.31 % 129,686 4.98 33 0.0454 % 2,700.1
FloatingReset 3.14 % 5.02 % 23,834 5.24 17 0.2978 % 2,121.1
Performance Highlights
Issue Index Change Notes
BAM.PR.T FixedReset -2.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-02
Maturity Price : 15.35
Evaluated at bid price : 15.35
Bid-YTW : 5.26 %
TRP.PR.D FixedReset -2.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-02
Maturity Price : 17.68
Evaluated at bid price : 17.68
Bid-YTW : 4.73 %
IFC.PR.A FixedReset -2.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.81
Bid-YTW : 9.30 %
BAM.PR.R FixedReset -2.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-02
Maturity Price : 15.08
Evaluated at bid price : 15.08
Bid-YTW : 5.22 %
NA.PR.Q FixedReset -2.02 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.81
Bid-YTW : 4.39 %
NA.PR.S FixedReset -1.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-02
Maturity Price : 18.14
Evaluated at bid price : 18.14
Bid-YTW : 4.64 %
FTS.PR.F Perpetual-Discount -1.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-02
Maturity Price : 22.79
Evaluated at bid price : 23.07
Bid-YTW : 5.33 %
BAM.PF.G FixedReset -1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-02
Maturity Price : 20.27
Evaluated at bid price : 20.27
Bid-YTW : 4.80 %
BNS.PR.Z FixedReset -1.79 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.33
Bid-YTW : 6.08 %
RY.PR.J FixedReset -1.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-02
Maturity Price : 19.58
Evaluated at bid price : 19.58
Bid-YTW : 4.56 %
CU.PR.C FixedReset -1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-02
Maturity Price : 17.95
Evaluated at bid price : 17.95
Bid-YTW : 4.52 %
BAM.PR.C Floater -1.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-02
Maturity Price : 10.34
Evaluated at bid price : 10.34
Bid-YTW : 4.63 %
TRP.PR.C FixedReset -1.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-02
Maturity Price : 12.35
Evaluated at bid price : 12.35
Bid-YTW : 4.74 %
CM.PR.Q FixedReset -1.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-02
Maturity Price : 20.10
Evaluated at bid price : 20.10
Bid-YTW : 4.51 %
NA.PR.W FixedReset -1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-02
Maturity Price : 17.54
Evaluated at bid price : 17.54
Bid-YTW : 4.62 %
BAM.PR.B Floater -1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-02
Maturity Price : 10.48
Evaluated at bid price : 10.48
Bid-YTW : 4.57 %
FTS.PR.G FixedReset -1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-02
Maturity Price : 16.76
Evaluated at bid price : 16.76
Bid-YTW : 4.55 %
TRP.PR.E FixedReset -1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-02
Maturity Price : 18.30
Evaluated at bid price : 18.30
Bid-YTW : 4.62 %
FTS.PR.J Perpetual-Discount -1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-02
Maturity Price : 22.24
Evaluated at bid price : 22.56
Bid-YTW : 5.28 %
MFC.PR.M FixedReset -1.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.00
Bid-YTW : 6.56 %
BNS.PR.Y FixedReset -1.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.41
Bid-YTW : 5.69 %
BAM.PF.F FixedReset -1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-02
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 4.85 %
HSE.PR.C FixedReset 1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-02
Maturity Price : 17.90
Evaluated at bid price : 17.90
Bid-YTW : 5.66 %
TRP.PR.A FixedReset 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-02
Maturity Price : 15.20
Evaluated at bid price : 15.20
Bid-YTW : 4.65 %
BMO.PR.R FloatingReset 1.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.25
Bid-YTW : 4.36 %
FTS.PR.H FixedReset 1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-02
Maturity Price : 13.35
Evaluated at bid price : 13.35
Bid-YTW : 4.32 %
TRP.PR.H FloatingReset 1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-02
Maturity Price : 10.45
Evaluated at bid price : 10.45
Bid-YTW : 4.35 %
FTS.PR.M FixedReset 1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-02
Maturity Price : 19.30
Evaluated at bid price : 19.30
Bid-YTW : 4.46 %
HSE.PR.B FloatingReset 1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-02
Maturity Price : 10.57
Evaluated at bid price : 10.57
Bid-YTW : 5.36 %
TRP.PR.I FloatingReset 1.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-02
Maturity Price : 11.65
Evaluated at bid price : 11.65
Bid-YTW : 4.51 %
HSE.PR.A FixedReset 1.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-02
Maturity Price : 11.62
Evaluated at bid price : 11.62
Bid-YTW : 5.36 %
TRP.PR.F FloatingReset 1.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-02
Maturity Price : 14.06
Evaluated at bid price : 14.06
Bid-YTW : 4.37 %
Volume Highlights
Issue Index Shares
Traded
Notes
NA.PR.S FixedReset 226,216 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-02
Maturity Price : 18.14
Evaluated at bid price : 18.14
Bid-YTW : 4.64 %
NA.PR.X FixedReset 130,483 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-15
Maturity Price : 25.00
Evaluated at bid price : 25.96
Bid-YTW : 4.81 %
RY.PR.A Deemed-Retractible 102,800 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.00
Bid-YTW : 4.49 %
BNS.PR.G FixedReset 74,200 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-07-25
Maturity Price : 25.00
Evaluated at bid price : 26.30
Bid-YTW : 4.65 %
TRP.PR.J FixedReset 70,531 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-31
Maturity Price : 25.00
Evaluated at bid price : 25.71
Bid-YTW : 4.89 %
CU.PR.C FixedReset 58,795 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-02
Maturity Price : 17.95
Evaluated at bid price : 17.95
Bid-YTW : 4.52 %
There were 27 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
NA.PR.Q FixedReset Quote: 23.81 – 24.39
Spot Rate : 0.5800
Average : 0.3808

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.81
Bid-YTW : 4.39 %

BAM.PR.T FixedReset Quote: 15.35 – 15.91
Spot Rate : 0.5600
Average : 0.3752

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-02
Maturity Price : 15.35
Evaluated at bid price : 15.35
Bid-YTW : 5.26 %

GWO.PR.O FloatingReset Quote: 13.10 – 13.95
Spot Rate : 0.8500
Average : 0.6814

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.10
Bid-YTW : 10.24 %

FTS.PR.F Perpetual-Discount Quote: 23.07 – 23.49
Spot Rate : 0.4200
Average : 0.2575

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-02
Maturity Price : 22.79
Evaluated at bid price : 23.07
Bid-YTW : 5.33 %

HSE.PR.G FixedReset Quote: 19.50 – 20.00
Spot Rate : 0.5000
Average : 0.3652

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-02
Maturity Price : 19.50
Evaluated at bid price : 19.50
Bid-YTW : 5.62 %

BAM.PF.G FixedReset Quote: 20.27 – 20.65
Spot Rate : 0.3800
Average : 0.2690

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-02
Maturity Price : 20.27
Evaluated at bid price : 20.27
Bid-YTW : 4.80 %

Market Action

June 1, 2016

There are some that now believe the US has lost ground as a competitive economy:

The United States was knocked out of the top spot in this year’s ranking of the world’s most competitive countries, a position it had held since 2013.

This according to the annual evaluation by the International Institute for Management Development (IMD), a Switzerland-based private business school whose World Competitiveness Center research group has ranked nations on their competitiveness on the global business stage since 1989.
…
The United States fell two positions on the annual ranking, supplanted by Hong Kong and Switzerland. Hong Kong’s role as the gateway to the economic might of the Chinese Mainland (which ranked 25 on the list), as well as the rest of Asia, gives it fuel for its economic machine. At the same time it is diversified and therefore safer from economic shocks within the region. But there are other factors at play, says Professor Arturo Bris, director of the IMD World Competitiveness Center.

“Hong Kong has an amazing regulatory system,” Bris told Forbes. “Business-friendly, promoting competition, and at the same time investing in public education. It has built an amazing public sector – which, of course is easy to do in a small economy – but Hong Kong is extremely efficient.”
…
Switzerland, which jumped two places to settle at No. 2 this year, withstood currency depreciation to surge in 2016. “Exports have increased and capital influx has increased as well and the GDP has grown,” explained Bris. “The Swiss economy has performed well, despite these monetary imbalances.”
…
. Hungary, for example, has given fiscal incentives to the IT business community, says Bris. “In Hungary, if you are an IT professional, you don’t pay income taxes—same thing in Estonia or Lithuania.” Professionals in Eastern European nations, he added, have played a role in innovations by companies like WhatsApp and Spotify.

The problems with risk-assessment are apparent in fields other than investment:

Millions of Americans are missing out on a chance to avoid debilitating fractures from weakened bones, researchers say, because they are terrified of exceedingly rare side effects from drugs that can help them.

Reports of the drugs’ causing jawbones to rot and thighbones to snap in two have shaken many osteoporosis patients so much that they say they would rather take their chances with the disease. Use of the most commonly prescribed osteoporosis drugs fell by 50 percent from 2008 to 2012, according to a recent paper, and doctors say the trend is continuing.
…

There is little question that fractures caused by fragile bones are a real problem, particularly for women. A 50-year-old woman has a 50 percent chance of having an osteoporotic fracture in her remaining years. The drugs, meant to be started when bone density falls very low and the chance of a fracture soars, can reduce that risk by half, studies show.

But to many, it matters little that the drugs’ frightening side effects are extremely rare. Estimates are that 10 to 40 in 100,000 osteoporosis patients taking the drugs — including alendronate, ibandronate, risedronate and zoledronate — have sustained broken thighbones. Fewer than one in 100,000 have had the jawbone problem.

“You only need to treat 50 people to prevent a fracture, but you need to treat 40,000 to see an atypical fracture,” said Dr. Clifford J. Rosen, a professor of medicine at Tufts University who has no association with the makers of the drugs.

PerpetualDiscounts now yield 5.50%, equivalent to 7.15% interest at the standard equivalency factor of 1.3x. Long corporates now yield about 3.95%, so the pre-tax interest-equivalent spread is now about 320bp, unchanged from the value reported May 25.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.3780 % 1,693.8
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.3780 % 3,094.2
Floater 4.48 % 4.56 % 63,305 16.24 3 -0.3780 % 1,783.2
OpRet 0.00 % 0.00 % 0 0.00 1 -0.0116 % 2,835.8
SplitShare 4.91 % 5.18 % 82,151 4.70 7 -0.0116 % 3,318.4
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0116 % 2,589.1
Perpetual-Premium 5.63 % 1.21 % 81,870 0.09 9 -0.0305 % 2,612.6
Perpetual-Discount 5.40 % 5.50 % 111,619 14.61 28 0.2377 % 2,712.0
FixedReset 5.07 % 4.60 % 161,720 7.43 87 0.7153 % 2,011.6
Deemed-Retractible 5.12 % 5.34 % 131,192 4.98 33 0.0732 % 2,698.9
FloatingReset 3.15 % 4.98 % 23,748 5.24 17 0.1287 % 2,114.8
Performance Highlights
Issue Index Change Notes
TRP.PR.B FixedReset -1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-01
Maturity Price : 11.80
Evaluated at bid price : 11.80
Bid-YTW : 4.43 %
FTS.PR.I FloatingReset 1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-01
Maturity Price : 12.10
Evaluated at bid price : 12.10
Bid-YTW : 4.11 %
TD.PF.E FixedReset 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-01
Maturity Price : 20.97
Evaluated at bid price : 20.97
Bid-YTW : 4.42 %
SLF.PR.I FixedReset 1.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.97
Bid-YTW : 6.66 %
TD.PF.B FixedReset 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-01
Maturity Price : 18.60
Evaluated at bid price : 18.60
Bid-YTW : 4.34 %
BAM.PF.E FixedReset 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-01
Maturity Price : 18.99
Evaluated at bid price : 18.99
Bid-YTW : 4.78 %
HSE.PR.C FixedReset 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-01
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 5.74 %
MFC.PR.K FixedReset 1.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.68
Bid-YTW : 7.23 %
SLF.PR.J FloatingReset 1.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.10
Bid-YTW : 10.40 %
BNS.PR.P FixedReset 1.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.13
Bid-YTW : 3.76 %
BAM.PF.G FixedReset 1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-01
Maturity Price : 20.64
Evaluated at bid price : 20.64
Bid-YTW : 4.71 %
RY.PR.H FixedReset 1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-01
Maturity Price : 18.62
Evaluated at bid price : 18.62
Bid-YTW : 4.31 %
BAM.PF.B FixedReset 1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-01
Maturity Price : 18.35
Evaluated at bid price : 18.35
Bid-YTW : 4.92 %
CM.PR.O FixedReset 1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-01
Maturity Price : 18.85
Evaluated at bid price : 18.85
Bid-YTW : 4.36 %
SLF.PR.G FixedReset 1.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.68
Bid-YTW : 9.27 %
MFC.PR.F FixedReset 1.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.85
Bid-YTW : 10.06 %
BMO.PR.Q FixedReset 1.26 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.86
Bid-YTW : 5.45 %
TRP.PR.H FloatingReset 1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-01
Maturity Price : 10.33
Evaluated at bid price : 10.33
Bid-YTW : 4.40 %
HSE.PR.E FixedReset 1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-01
Maturity Price : 19.85
Evaluated at bid price : 19.85
Bid-YTW : 5.64 %
HSE.PR.A FixedReset 1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-01
Maturity Price : 11.56
Evaluated at bid price : 11.56
Bid-YTW : 5.47 %
BAM.PR.R FixedReset 1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-01
Maturity Price : 15.40
Evaluated at bid price : 15.40
Bid-YTW : 5.11 %
BAM.PR.Z FixedReset 1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-01
Maturity Price : 19.86
Evaluated at bid price : 19.86
Bid-YTW : 4.93 %
FTS.PR.G FixedReset 1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-01
Maturity Price : 16.98
Evaluated at bid price : 16.98
Bid-YTW : 4.49 %
CU.PR.C FixedReset 1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-01
Maturity Price : 18.25
Evaluated at bid price : 18.25
Bid-YTW : 4.45 %
CM.PR.Q FixedReset 1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-01
Maturity Price : 20.40
Evaluated at bid price : 20.40
Bid-YTW : 4.44 %
TRP.PR.I FloatingReset 1.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-01
Maturity Price : 11.45
Evaluated at bid price : 11.45
Bid-YTW : 4.59 %
TRP.PR.E FixedReset 1.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-01
Maturity Price : 18.54
Evaluated at bid price : 18.54
Bid-YTW : 4.56 %
IAG.PR.G FixedReset 1.67 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.64
Bid-YTW : 6.35 %
FTS.PR.M FixedReset 1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-01
Maturity Price : 19.07
Evaluated at bid price : 19.07
Bid-YTW : 4.52 %
RY.PR.J FixedReset 1.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-01
Maturity Price : 19.91
Evaluated at bid price : 19.91
Bid-YTW : 4.48 %
BAM.PR.T FixedReset 1.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-01
Maturity Price : 15.80
Evaluated at bid price : 15.80
Bid-YTW : 5.10 %
IFC.PR.A FixedReset 1.96 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.16
Bid-YTW : 8.98 %
MFC.PR.I FixedReset 2.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.34
Bid-YTW : 5.95 %
MFC.PR.L FixedReset 2.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.30
Bid-YTW : 6.86 %
TRP.PR.G FixedReset 2.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-01
Maturity Price : 19.67
Evaluated at bid price : 19.67
Bid-YTW : 4.81 %
TRP.PR.A FixedReset 2.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-01
Maturity Price : 15.04
Evaluated at bid price : 15.04
Bid-YTW : 4.70 %
TRP.PR.D FixedReset 3.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-01
Maturity Price : 18.15
Evaluated at bid price : 18.15
Bid-YTW : 4.60 %
Volume Highlights
Issue Index Shares
Traded
Notes
TRP.PR.J FixedReset 355,584 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-31
Maturity Price : 25.00
Evaluated at bid price : 25.70
Bid-YTW : 4.90 %
TD.PF.G FixedReset 255,403 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 26.11
Bid-YTW : 4.62 %
RY.PR.R FixedReset 184,693 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-24
Maturity Price : 25.00
Evaluated at bid price : 26.39
Bid-YTW : 4.60 %
BNS.PR.G FixedReset 163,173 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-07-25
Maturity Price : 25.00
Evaluated at bid price : 26.22
Bid-YTW : 4.72 %
HSE.PR.A FixedReset 110,600 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-01
Maturity Price : 11.56
Evaluated at bid price : 11.56
Bid-YTW : 5.47 %
POW.PR.G Perpetual-Premium 107,180 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-15
Maturity Price : 25.00
Evaluated at bid price : 25.43
Bid-YTW : 5.40 %
There were 40 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
GWO.PR.N FixedReset Quote: 14.00 – 14.74
Spot Rate : 0.7400
Average : 0.5557

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.00
Bid-YTW : 9.79 %

TD.PR.Z FloatingReset Quote: 21.37 – 21.87
Spot Rate : 0.5000
Average : 0.3366

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.37
Bid-YTW : 5.27 %

TRP.PR.H FloatingReset Quote: 10.33 – 11.00
Spot Rate : 0.6700
Average : 0.5214

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-01
Maturity Price : 10.33
Evaluated at bid price : 10.33
Bid-YTW : 4.40 %

HSE.PR.C FixedReset Quote: 18.00 – 18.40
Spot Rate : 0.4000
Average : 0.2822

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-01
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 5.74 %

ELF.PR.H Perpetual-Discount Quote: 24.30 – 24.65
Spot Rate : 0.3500
Average : 0.2354

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-01
Maturity Price : 23.83
Evaluated at bid price : 24.30
Bid-YTW : 5.72 %

FTS.PR.K FixedReset Quote: 17.31 – 17.65
Spot Rate : 0.3400
Average : 0.2287

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-06-01
Maturity Price : 17.31
Evaluated at bid price : 17.31
Bid-YTW : 4.37 %

Market Action

May 31, 2016

Weakness in the Canadian economy late in first quarter is stoking fears of contraction:

Despite the solid growth, the first-quarter result was well below the 2.8 per cent average estimate of economists, and a far cry from forecasts of more than 3 per cent from just a few weeks ago, testament to the disappointingly weak finish to the quarter. March’s real GDP was down 0.2 per cent month over month, even worse than the 0.1-per-cent decline economists had anticipated, marking the second straight month of contraction after a booming start to the year.
…
In March, the big drag on growth was from the beleaguered energy sector, which slumped 1.5 per cent month over month. A sharp drop in drilling activity sent oil and gas support services down 14 per cent in the month, while oil and gas extraction fell 0.8 per cent. The manufacturing sector dipped 0.2 per cent in March, adding to its 0.9-per-cent slowdown in February. And retail sales fell 1.3 per cent, reversing course after two straight months of gains.

Overall, output from goods-producing industries slumped 0.8 per cent in March, their worst performance in six months. Services-producing industries were flat for the second straight month.

I confess that I’m surprised to see EU boffins say something sensible about the new economy:

European Union governments should not ban services like home-rental site Airbnb or ride-hailing app Uber except as a last resort, the EU says in new guidelines, seeking to rein in a crackdown on the “sharing economy”.

In guidelines seen by Reuters, the European Commission said any restrictions by EU member states on these new online services should be justified and proportionate to the public interest at stake.

“Total bans of an activity constitute a measure of last resort that should be applied only if and where no less restrictive requirements to attain a public interest can be used,” the draft document says.

In the case of room-renting sites like Airbnb, the Commission said banning short-term lets of apartments “appears difficult to justify” when limits on the maximum number of days apartments can be rented out would be more appropriate.

The guidelines will come as good news for the likes of Uber and Airbnb, which have faced outright bans or restrictions in some cities as established industry players complain of unfair competition.

There is fierce competition in the drones market to make the transition from toys to tools:

So Shenzhen-based DJI is pouring money into its development kit, which allows software developers to write their own applications for specific tasks, similar to the way Apple Inc. does for its iPhones.

Up for grabs is a market for aerial mining surveys, pipeline inspection, search and rescue, crop spraying and hundreds of other commercial tasks that’s expected to reach $127 billion by 2020.
…
Farmers were some of the earliest civil adopters, using drones to identify differences in crop conditions. Yamaha Motor Co. has been dusting crops in Japan with UAVs for more than two decades. With the cost dropping for cargo-carrying drones, DJI and others are building crop-spraying and remote sensing vehicles that can help reduce chemical use and improve yields. It has been estimated that precision agriculture will account for about 80 percent of the U.S. market for commercial UAVs.
…
The Rwandan government partnered with San Francisco-based Zipline to fly blood bags at 100 kilometers per hour to remote hospitals. Other to watch are Matternet in Menlo Park, California, and startup Flirtey, which said it made the first FAA-approved urban drone delivery of an emergency kit in the U.S. this year.

Steve Denning of Forbes comes up with a provocative but plausible explanation of US malaise:

• A study published in December 2015 by the National Bureau of Economic Research (NBER) shows that start-up activity has been slowing down in the United States for about three decades, dropping sharply over the past 10 years. New firms accounted for about 13% of all companies in the late 1980s, but only about 8% two decades later. In the 1980s and 1990s, small number of young, innovative, and dynamic companies grew at very high rates. But in the post-2000 period, startups contributed less to U.S. job creation than they did in earlier decades.

• The Kauffman Foundation reports that the percentage of adults owning a business has been declining since the 1990s, when the foundation first began to track that number.

• A study by the Brookings Institution found that the start-up rate (the number of new companies as a percentage of all firms) has fallen by nearly half since 1978.
…
A rather more obvious suspect [for the cause of declining entrepreneurship] is the burden of Americans’ $1.2 trillion in student loan debt.
…
A 2013 report by the think tank Demos found that student debt has a negative effect on income, by making borrowers more risk-averse and discouraging them from moving to another city or taking gambles on new jobs or launching a new business. Even more seriously, student loan borrowers save less early on in their lives, and they tend to be more conservative with their investments, due to constraints on income and credit. When even investing in a home seems too risky, launching a new business is even less likely.
…
The student debt crisis is transforming the saving, spending and investment behavior of an entire generation, and is transforming the economy along with it. The trend is not a good one.

Through a set of collective missteps, America has opted to put a crushing debt burden on the segment of society that can least afford it and the group that has the most to contribute the future. This is not just a question of social justice: it is nothing less than an issue of national economic survival.

Unless lawmakers across the country take radical action to address the skyrocketing cost of college, and attendant student debt burden, we can expect U.S. entrepreneurship to continue its frightening decline.

Assiduous Readers who are amused at the emergence of Donald Trump and the Angry White Boys in the US should take a look at the Globe & Mail comments section any time there is a story on Vancouver real-estate. There is a huge population of old-stock Canadians who are entitled to a good career and a detached house in Vancouver. Now that the former is getting more elusive and the latter has roared out of reach for most, they are incensed at the crooks from China who have taken it all away from them; I wouldn’t be surprised to see a fringe party emerge in British Columbia in the next little while.

And finally, for your month-end interest and delectation, is the Official TSX Quote for HSE.PR.B:

HSEPRBquote_160531
Click for Big

Yes, you read that right, 10.55-22.00, 1×5. I have not checked whether this lamentable state of affairs is due to inadequate Toronto Stock Exchange reporting or inadequate Toronto Stock Exchange supervision of market-makers.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 4.66 % 5.65 % 10,803 17.12 1 1.7544 % 1,700.2
FixedFloater 6.51 % 5.65 % 17,398 16.88 1 1.7422 % 3,106.0
Floater 4.34 % 4.49 % 44,162 16.37 4 -0.6838 % 1,790.0
OpRet 0.00 % 0.00 % 0 0.00 0 0.0346 % 2,836.1
SplitShare 4.93 % 5.00 % 81,673 3.91 7 0.0346 % 3,318.8
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0346 % 2,589.4
Perpetual-Premium 5.73 % -15.97 % 84,703 0.09 6 0.1895 % 2,613.4
Perpetual-Discount 5.42 % 5.45 % 104,971 14.57 33 0.0364 % 2,705.6
FixedReset 5.13 % 4.64 % 159,555 7.43 88 0.0614 % 1,997.3
Deemed-Retractible 5.13 % 5.31 % 132,378 4.98 33 -0.0237 % 2,696.9
FloatingReset 3.15 % 5.01 % 23,896 5.25 17 0.2960 % 2,112.1
Performance Highlights
Issue Index Change Notes
TRP.PR.H FloatingReset -3.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-31
Maturity Price : 10.20
Evaluated at bid price : 10.20
Bid-YTW : 4.45 %
BAM.PR.T FixedReset -2.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-31
Maturity Price : 15.51
Evaluated at bid price : 15.51
Bid-YTW : 5.20 %
BAM.PR.R FixedReset -1.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-31
Maturity Price : 15.20
Evaluated at bid price : 15.20
Bid-YTW : 5.18 %
BMO.PR.Y FixedReset -1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-31
Maturity Price : 20.40
Evaluated at bid price : 20.40
Bid-YTW : 4.40 %
BAM.PR.C Floater -1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-31
Maturity Price : 10.50
Evaluated at bid price : 10.50
Bid-YTW : 4.56 %
TRP.PR.G FixedReset -1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-31
Maturity Price : 19.14
Evaluated at bid price : 19.14
Bid-YTW : 4.94 %
MFC.PR.F FixedReset -1.30 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.68
Bid-YTW : 10.22 %
BMO.PR.M FixedReset -1.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.30
Bid-YTW : 4.21 %
BAM.PR.B Floater -1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-31
Maturity Price : 10.67
Evaluated at bid price : 10.67
Bid-YTW : 4.49 %
W.PR.J Perpetual-Discount -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-31
Maturity Price : 23.88
Evaluated at bid price : 24.13
Bid-YTW : 5.88 %
BAM.PF.A FixedReset 1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-31
Maturity Price : 19.61
Evaluated at bid price : 19.61
Bid-YTW : 4.93 %
BAM.PR.X FixedReset 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-31
Maturity Price : 14.10
Evaluated at bid price : 14.10
Bid-YTW : 4.90 %
BIP.PR.A FixedReset 1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-31
Maturity Price : 19.26
Evaluated at bid price : 19.26
Bid-YTW : 5.70 %
MFC.PR.N FixedReset 1.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.00
Bid-YTW : 6.49 %
FTS.PR.K FixedReset 1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-31
Maturity Price : 17.38
Evaluated at bid price : 17.38
Bid-YTW : 4.35 %
TRP.PR.C FixedReset 1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-31
Maturity Price : 12.54
Evaluated at bid price : 12.54
Bid-YTW : 4.66 %
SLF.PR.G FixedReset 1.40 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.50
Bid-YTW : 9.44 %
GWO.PR.O FloatingReset 1.60 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.10
Bid-YTW : 10.24 %
BAM.PR.G FixedFloater 1.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-31
Maturity Price : 25.00
Evaluated at bid price : 14.60
Bid-YTW : 5.65 %
BAM.PR.E Ratchet 1.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-31
Maturity Price : 25.00
Evaluated at bid price : 14.50
Bid-YTW : 5.65 %
TRP.PR.F FloatingReset 1.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-31
Maturity Price : 13.85
Evaluated at bid price : 13.85
Bid-YTW : 4.43 %
CIU.PR.C FixedReset 2.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-31
Maturity Price : 12.25
Evaluated at bid price : 12.25
Bid-YTW : 4.42 %
BMO.PR.Q FixedReset 2.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.60
Bid-YTW : 5.69 %
PWF.PR.Q FloatingReset 3.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-31
Maturity Price : 12.90
Evaluated at bid price : 12.90
Bid-YTW : 4.18 %
FTS.PR.I FloatingReset 4.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-31
Maturity Price : 11.98
Evaluated at bid price : 11.98
Bid-YTW : 4.16 %
Volume Highlights
Issue Index Shares
Traded
Notes
TRP.PR.J FixedReset 114,764 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-31
Maturity Price : 25.00
Evaluated at bid price : 25.70
Bid-YTW : 4.89 %
IFC.PR.A FixedReset 72,625 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.85
Bid-YTW : 9.26 %
TD.PF.G FixedReset 63,670 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 26.13
Bid-YTW : 4.60 %
BNS.PR.G FixedReset 53,485 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-07-25
Maturity Price : 25.00
Evaluated at bid price : 26.18
Bid-YTW : 4.75 %
TD.PR.Y FixedReset 39,900 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.25
Bid-YTW : 4.46 %
RY.PR.H FixedReset 38,232 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-31
Maturity Price : 18.40
Evaluated at bid price : 18.40
Bid-YTW : 4.37 %
There were 30 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
HSE.PR.B FloatingReset Quote: 10.55 – 12.55
Spot Rate : 2.0000
Average : 1.3418

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-31
Maturity Price : 10.55
Evaluated at bid price : 10.55
Bid-YTW : 5.46 %

TRP.PR.B FixedReset Quote: 11.95 – 12.55
Spot Rate : 0.6000
Average : 0.3769

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-31
Maturity Price : 11.95
Evaluated at bid price : 11.95
Bid-YTW : 4.37 %

RY.PR.M FixedReset Quote: 19.30 – 19.77
Spot Rate : 0.4700
Average : 0.2957

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-31
Maturity Price : 19.30
Evaluated at bid price : 19.30
Bid-YTW : 4.50 %

TD.PF.F Perpetual-Discount Quote: 24.40 – 24.78
Spot Rate : 0.3800
Average : 0.2370

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-31
Maturity Price : 24.03
Evaluated at bid price : 24.40
Bid-YTW : 5.06 %

GWO.PR.F Deemed-Retractible Quote: 25.55 – 25.99
Spot Rate : 0.4400
Average : 0.2992

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-06-30
Maturity Price : 25.00
Evaluated at bid price : 25.55
Bid-YTW : -24.81 %

PWF.PR.P FixedReset Quote: 13.32 – 13.76
Spot Rate : 0.4400
Average : 0.3099

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-31
Maturity Price : 13.32
Evaluated at bid price : 13.32
Bid-YTW : 4.49 %

Market Action

May 30, 2016

Treasury markets, such as they were, were weak today:

Ten-year Treasury futures contracts for September delivery slid 14/32, or $4.38 per $1,000 face amount, to 129 9/32 as of 11:07 a.m. in New York, based on electronic trading at the Chicago Board of Trade. It was the biggest decline since May 18.
…
The odds of a rate increase in June implied by federal funds futures climbed to 34 percent from 30 percent on May 27. They rise to 80 percent by year-end, up from 74 percent three days previously

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 4.74 % 5.75 % 10,670 17.00 1 -2.0619 % 1,670.9
FixedFloater 6.62 % 5.75 % 17,193 16.75 1 -1.7123 % 3,052.8
Floater 4.31 % 4.43 % 42,538 16.47 4 0.6423 % 1,802.3
OpRet 0.00 % 0.00 % 0 0.00 0 0.0809 % 2,835.1
SplitShare 4.94 % 5.17 % 80,249 3.92 7 0.0809 % 3,317.6
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0809 % 2,588.5
Perpetual-Premium 5.74 % -14.66 % 85,844 0.09 6 0.0458 % 2,608.4
Perpetual-Discount 5.42 % 5.46 % 105,283 14.57 33 0.2753 % 2,704.6
FixedReset 5.13 % 4.65 % 164,119 7.41 88 0.3287 % 1,996.1
Deemed-Retractible 5.10 % 5.43 % 131,832 4.86 33 0.2356 % 2,697.6
FloatingReset 3.16 % 5.00 % 25,401 5.25 17 -0.1061 % 2,105.9
Performance Highlights
Issue Index Change Notes
BAM.PR.E Ratchet -2.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-30
Maturity Price : 25.00
Evaluated at bid price : 14.25
Bid-YTW : 5.75 %
BAM.PR.G FixedFloater -1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-30
Maturity Price : 25.00
Evaluated at bid price : 14.35
Bid-YTW : 5.75 %
TRP.PR.I FloatingReset -1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-30
Maturity Price : 11.25
Evaluated at bid price : 11.25
Bid-YTW : 4.67 %
FTS.PR.I FloatingReset -1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-30
Maturity Price : 11.50
Evaluated at bid price : 11.50
Bid-YTW : 4.33 %
SLF.PR.H FixedReset 1.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.49
Bid-YTW : 8.61 %
BAM.PF.E FixedReset 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-30
Maturity Price : 18.72
Evaluated at bid price : 18.72
Bid-YTW : 4.85 %
IAG.PR.A Deemed-Retractible 1.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.85
Bid-YTW : 6.50 %
GWO.PR.I Deemed-Retractible 1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.10
Bid-YTW : 6.41 %
CU.PR.C FixedReset 1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-30
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 4.51 %
FTS.PR.J Perpetual-Discount 1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-30
Maturity Price : 22.37
Evaluated at bid price : 22.66
Bid-YTW : 5.25 %
FTS.PR.F Perpetual-Discount 1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-30
Maturity Price : 23.03
Evaluated at bid price : 23.30
Bid-YTW : 5.27 %
CCS.PR.C Deemed-Retractible 1.41 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.86
Bid-YTW : 6.27 %
TRP.PR.H FloatingReset 1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-30
Maturity Price : 10.60
Evaluated at bid price : 10.60
Bid-YTW : 4.28 %
MFC.PR.G FixedReset 1.46 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.15
Bid-YTW : 6.71 %
MFC.PR.N FixedReset 1.54 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.75
Bid-YTW : 6.66 %
TRP.PR.C FixedReset 1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-30
Maturity Price : 12.38
Evaluated at bid price : 12.38
Bid-YTW : 4.72 %
BAM.PF.G FixedReset 1.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-30
Maturity Price : 20.34
Evaluated at bid price : 20.34
Bid-YTW : 4.78 %
BAM.PF.B FixedReset 1.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-30
Maturity Price : 18.15
Evaluated at bid price : 18.15
Bid-YTW : 4.97 %
TRP.PR.B FixedReset 1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-30
Maturity Price : 11.90
Evaluated at bid price : 11.90
Bid-YTW : 4.39 %
BMO.PR.T FixedReset 1.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-30
Maturity Price : 18.34
Evaluated at bid price : 18.34
Bid-YTW : 4.36 %
MFC.PR.M FixedReset 2.00 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.90
Bid-YTW : 6.62 %
Volume Highlights
Issue Index Shares
Traded
Notes
TRP.PR.D FixedReset 230,297 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-30
Maturity Price : 17.60
Evaluated at bid price : 17.60
Bid-YTW : 4.75 %
CU.PR.C FixedReset 125,286 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-30
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 4.51 %
POW.PR.D Perpetual-Discount 105,800 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-30
Maturity Price : 22.70
Evaluated at bid price : 22.94
Bid-YTW : 5.52 %
TD.PF.G FixedReset 48,720 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 26.15
Bid-YTW : 4.58 %
BMO.PR.K Deemed-Retractible 31,000 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-06-29
Maturity Price : 25.25
Evaluated at bid price : 25.60
Bid-YTW : -10.43 %
RY.PR.C Deemed-Retractible 30,706 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-06-29
Maturity Price : 25.00
Evaluated at bid price : 25.20
Bid-YTW : -4.15 %
There were 12 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
POW.PR.G Perpetual-Discount Quote: 25.39 – 26.50
Spot Rate : 1.1100
Average : 0.6385

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-15
Maturity Price : 25.00
Evaluated at bid price : 25.39
Bid-YTW : 5.43 %

BAM.PR.E Ratchet Quote: 14.25 – 15.14
Spot Rate : 0.8900
Average : 0.6597

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-30
Maturity Price : 25.00
Evaluated at bid price : 14.25
Bid-YTW : 5.75 %

SLF.PR.G FixedReset Quote: 14.30 – 14.80
Spot Rate : 0.5000
Average : 0.3335

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.30
Bid-YTW : 9.62 %

TD.PF.A FixedReset Quote: 18.51 – 18.98
Spot Rate : 0.4700
Average : 0.3117

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-30
Maturity Price : 18.51
Evaluated at bid price : 18.51
Bid-YTW : 4.37 %

GWO.PR.O FloatingReset Quote: 13.00 – 13.95
Spot Rate : 0.9500
Average : 0.8241

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.00
Bid-YTW : 10.46 %

GWO.PR.N FixedReset Quote: 14.06 – 14.50
Spot Rate : 0.4400
Average : 0.3246

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.06
Bid-YTW : 9.85 %

Market Action

May 27, 2017

Janet Yellen did some modest sabre-rattling:

Federal Reserve Chair Janet Yellen said the ongoing improvement in the U.S. economy would warrant another interest rate increase “in the coming months,” stopping short of giving an explicit hint that the central bank would act in June.

“It’s appropriate — and I’ve said this in the past — for the Fed to gradually and cautiously increase our overnight interest rate over time,” Yellen said Friday during remarks at Harvard University in Cambridge, Massachusetts. “Probably in the coming months such a move would be appropriate.”
…
“The economy is continuing to improve,” she said in a discussion with Harvard economics professor Gregory Mankiw. She added that she expects “inflation will move up over the next couple of years to our 2 percent objective,” provided headwinds holding down price pressures, including energy prices and a stronger dollar, stabilize alongside an improving labor market.

Several regional Fed presidents, ranging from Boston Fed President Eric Rosengren to San Francisco’s John Williams, have in recent weeks urged financial market participants to take more seriously the chances of a rate hike in the next two months, pointing to continued signs of steady if unspectacular growth in the U.S. economy and the waning of risks posed by global economic and financial conditions.

hikeChance_160527
Click for Big
HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 4.64 % 5.62 % 10,825 17.16 1 0.7328 % 1,706.1
FixedFloater 6.51 % 5.65 % 17,890 16.89 1 3.5461 % 3,106.0
Floater 4.34 % 4.46 % 42,921 16.43 4 1.6321 % 1,790.8
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0489 % 2,832.8
SplitShare 4.94 % 5.18 % 80,930 3.92 7 -0.0489 % 3,314.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0489 % 2,586.4
Perpetual-Premium 5.74 % -14.32 % 86,088 0.09 6 0.1375 % 2,607.2
Perpetual-Discount 5.44 % 5.54 % 106,458 14.53 33 0.2040 % 2,697.2
FixedReset 5.15 % 4.65 % 165,326 7.42 88 0.4436 % 1,989.5
Deemed-Retractible 5.10 % 5.61 % 129,747 4.99 33 0.1107 % 2,691.2
FloatingReset 3.17 % 4.99 % 25,906 5.26 17 0.0215 % 2,108.1
Performance Highlights
Issue Index Change Notes
PWF.PR.Q FloatingReset -3.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-27
Maturity Price : 12.52
Evaluated at bid price : 12.52
Bid-YTW : 4.33 %
IAG.PR.A Deemed-Retractible -1.79 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.90
Bid-YTW : 6.65 %
HSE.PR.B FloatingReset -1.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-27
Maturity Price : 10.60
Evaluated at bid price : 10.60
Bid-YTW : 5.46 %
BMO.PR.T FixedReset -1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-27
Maturity Price : 18.01
Evaluated at bid price : 18.01
Bid-YTW : 4.41 %
BNS.PR.R FixedReset -1.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.35
Bid-YTW : 4.60 %
CIU.PR.C FixedReset -1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-27
Maturity Price : 12.00
Evaluated at bid price : 12.00
Bid-YTW : 4.47 %
MFC.PR.M FixedReset -1.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.51
Bid-YTW : 6.88 %
BAM.PF.G FixedReset 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-27
Maturity Price : 20.01
Evaluated at bid price : 20.01
Bid-YTW : 4.84 %
TRP.PR.F FloatingReset 1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-27
Maturity Price : 13.61
Evaluated at bid price : 13.61
Bid-YTW : 4.53 %
BAM.PF.E FixedReset 1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-27
Maturity Price : 18.52
Evaluated at bid price : 18.52
Bid-YTW : 4.88 %
BAM.PR.X FixedReset 1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-27
Maturity Price : 14.02
Evaluated at bid price : 14.02
Bid-YTW : 4.89 %
BAM.PF.A FixedReset 1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-27
Maturity Price : 19.29
Evaluated at bid price : 19.29
Bid-YTW : 4.98 %
BMO.PR.Q FixedReset 1.30 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.26
Bid-YTW : 5.98 %
TRP.PR.G FixedReset 1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-27
Maturity Price : 19.30
Evaluated at bid price : 19.30
Bid-YTW : 4.88 %
TRP.PR.H FloatingReset 1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-27
Maturity Price : 10.45
Evaluated at bid price : 10.45
Bid-YTW : 4.37 %
BAM.PF.B FixedReset 1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-27
Maturity Price : 17.85
Evaluated at bid price : 17.85
Bid-YTW : 5.03 %
TD.PF.D FixedReset 1.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-27
Maturity Price : 20.10
Evaluated at bid price : 20.10
Bid-YTW : 4.48 %
NA.PR.Q FixedReset 1.47 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.15
Bid-YTW : 4.08 %
BAM.PR.B Floater 1.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-27
Maturity Price : 10.73
Evaluated at bid price : 10.73
Bid-YTW : 4.46 %
BAM.PR.K Floater 1.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-27
Maturity Price : 10.61
Evaluated at bid price : 10.61
Bid-YTW : 4.51 %
HSE.PR.E FixedReset 1.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-27
Maturity Price : 19.62
Evaluated at bid price : 19.62
Bid-YTW : 5.68 %
BAM.PF.F FixedReset 1.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-27
Maturity Price : 19.95
Evaluated at bid price : 19.95
Bid-YTW : 4.83 %
BIP.PR.B FixedReset 2.30 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.19
Bid-YTW : 5.22 %
IFC.PR.A FixedReset 2.58 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.91
Bid-YTW : 9.16 %
BNS.PR.Y FixedReset 2.60 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.51
Bid-YTW : 5.58 %
BNS.PR.Z FixedReset 2.72 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.41
Bid-YTW : 5.98 %
BAM.PR.Z FixedReset 3.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-27
Maturity Price : 19.50
Evaluated at bid price : 19.50
Bid-YTW : 4.99 %
BAM.PR.T FixedReset 3.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-27
Maturity Price : 15.75
Evaluated at bid price : 15.75
Bid-YTW : 5.08 %
BAM.PR.G FixedFloater 3.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-27
Maturity Price : 25.00
Evaluated at bid price : 14.60
Bid-YTW : 5.65 %
BAM.PR.C Floater 3.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-27
Maturity Price : 10.60
Evaluated at bid price : 10.60
Bid-YTW : 4.51 %
Volume Highlights
Issue Index Shares
Traded
Notes
TRP.PR.J FixedReset 91,027 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-31
Maturity Price : 25.00
Evaluated at bid price : 25.70
Bid-YTW : 4.88 %
TD.PF.G FixedReset 86,663 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 26.12
Bid-YTW : 4.59 %
BNS.PR.G FixedReset 58,250 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-07-25
Maturity Price : 25.00
Evaluated at bid price : 26.15
Bid-YTW : 4.76 %
BAM.PF.H FixedReset 57,633 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-31
Maturity Price : 25.00
Evaluated at bid price : 26.07
Bid-YTW : 4.18 %
BAM.PR.M Perpetual-Discount 43,100 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-27
Maturity Price : 20.83
Evaluated at bid price : 20.83
Bid-YTW : 5.80 %
MFC.PR.F FixedReset 41,095 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.85
Bid-YTW : 10.01 %
There were 23 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
GWO.PR.M Deemed-Retractible Believe it or not, the actual quote for GWO.PR.M, sold to me at an enormous price by the Exchange, was 25.55-55.13, 8×2. See the picture below for proof! I have not checked whether this lamentable state of affairs is due to inadequate Toronto Stock Exchange reporting or inadequate Toronto Stock Exchange supervision of market-makers.

Quote: 25.55 – 27.55
Spot Rate : 2.0000
Average : 1.1139

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-03-31
Maturity Price : 25.25
Evaluated at bid price : 25.55
Bid-YTW : 5.62 %

PWF.PR.T FixedReset Quote: 21.56 – 22.67
Spot Rate : 1.1100
Average : 0.6563

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-27
Maturity Price : 21.27
Evaluated at bid price : 21.56
Bid-YTW : 3.83 %

BAM.PF.G FixedReset Quote: 20.01 – 20.87
Spot Rate : 0.8600
Average : 0.5903

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-27
Maturity Price : 20.01
Evaluated at bid price : 20.01
Bid-YTW : 4.84 %

CM.PR.Q FixedReset Quote: 20.06 – 20.65
Spot Rate : 0.5900
Average : 0.3605

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-27
Maturity Price : 20.06
Evaluated at bid price : 20.06
Bid-YTW : 4.49 %

PWF.PR.Q FloatingReset Quote: 12.52 – 13.39
Spot Rate : 0.8700
Average : 0.6542

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-27
Maturity Price : 12.52
Evaluated at bid price : 12.52
Bid-YTW : 4.33 %

BAM.PR.Z FixedReset Quote: 19.50 – 19.95
Spot Rate : 0.4500
Average : 0.3057

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-27
Maturity Price : 19.50
Evaluated at bid price : 19.50
Bid-YTW : 4.99 %

GWOPRM_160527
Click for Big