Category: Market Action

Market Action

February 17, 2015

Equities popped today on the back of oil:

The Standard & Poor’s 500 Index rose 1.7 percent to 1,926.82 at 4 p.m. in New York, capping its first three-day advance this year and closing at a two-week high. The Dow climbed 257.42 points, or 1.6 percent, to 16,453.83. The Nasdaq Composite Index gained 2.2 percent. About 9.2 billion shares traded hands on U.S. exchanges, 14 percent above the three-month average.
…
Equity gains are coming virtually as fast as the losses that sent the S&P 500 to its worst start to any year, with almost half of 2016’s decline made up in three days. The rally today occurred as oil climbed more than 5 percent, Federal Reserve officials expressed caution on the economy and data on manufacturing was better than forecast.

On the other hand, Japan auctioned 5-year bonds with a negative yield:

Japan’s government got paid to borrow at a five-year note auction for the first time on Thursday after the central bank adopted a negative interest-rate policy on Jan. 29. The sale drew an average yield of minus 0.138 percent. Japan is following Germany, Switzerland and Denmark in being able to attract buyers even as yields fall below zero.

One of the many benefits of High Frequency Trading may be the arbitrage between the cash and futures markets:

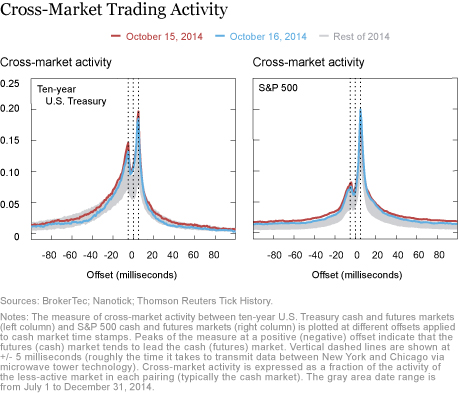
The close relationship between market volatility and trading activity is a long-established fact in financial markets. In recent years, much of the trading in U.S. Treasury and equity markets has been associated with nearly simultaneous trading between the leading cash and futures platforms. The striking cross-activity patterns that arise in both high-frequency cross-market trading and related cross-market order book changes in U.S. Treasury markets are also witnessed in other asset classes and naturally lead to the question that we investigate in this post of how the cross-market component of overall trading activity is related to volatility.

The chart below displays a measure of cross-market activity for the ten-year Treasury note cash and futures markets (left column) and the S&P 500 cash and futures markets (right column) across different millisecond offsets. Of note is the pronounced asymmetry of the spike in the measure at +5 milliseconds for the S&P 500 compared with the ten-year U.S. Treasury. The much higher spike for the positive 5 millisecond offset is consistent with the often-cited dominant role played by the S&P futures market in price discovery. Leaving this asymmetry aside, the spikes in cross-market activity on October 15 and 16, 2014, stand out as being well-aligned with the heightened volatility and trading observed on those days. Cross-market trading and quoting activity thus appears to be related to variations in market volatility, which can create (short-lived) dislocations in relative valuations as market participants respond to news about fundamentals or market activity itself.
crossMarketActivity
Click for Big

It was a superb day for the Canadian preferred share market, with PerpetualDiscounts up 19bp, FixedResets winning 142bp and DeemedRetractibles gaining 12bp. Unsurprisingly, the Performance Highlights table is both enormous and dominated by FixedReset winners, with many issues gaining over 5%. Volume was very high.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

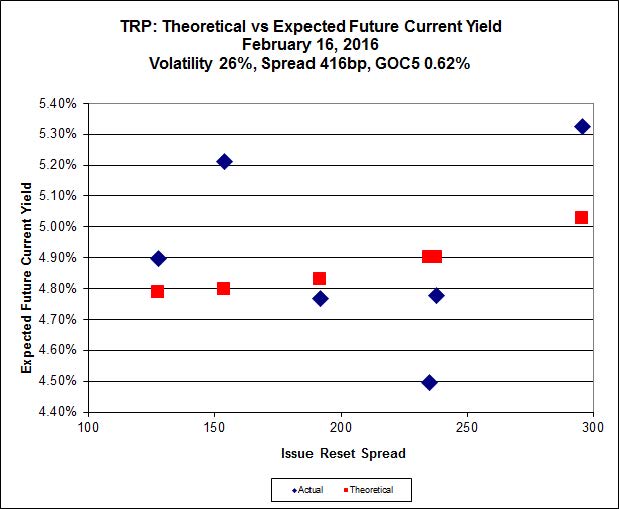
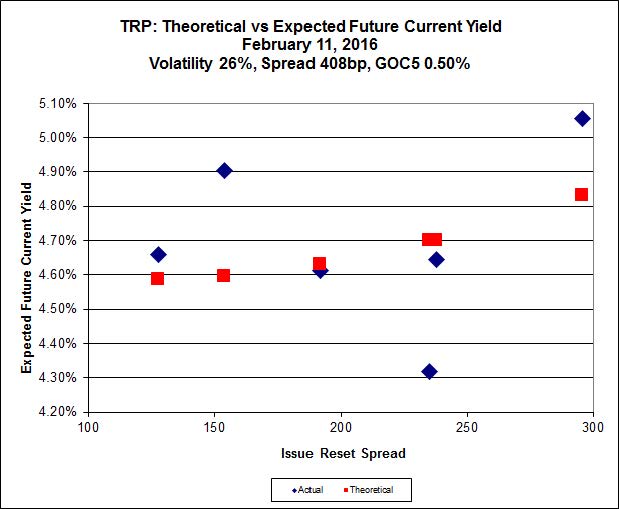
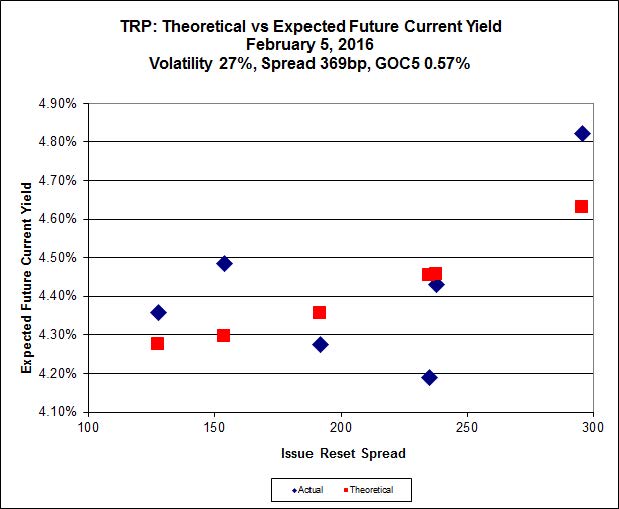
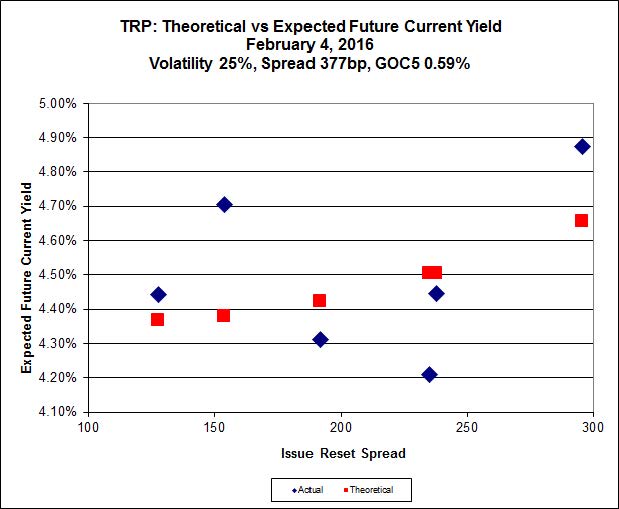
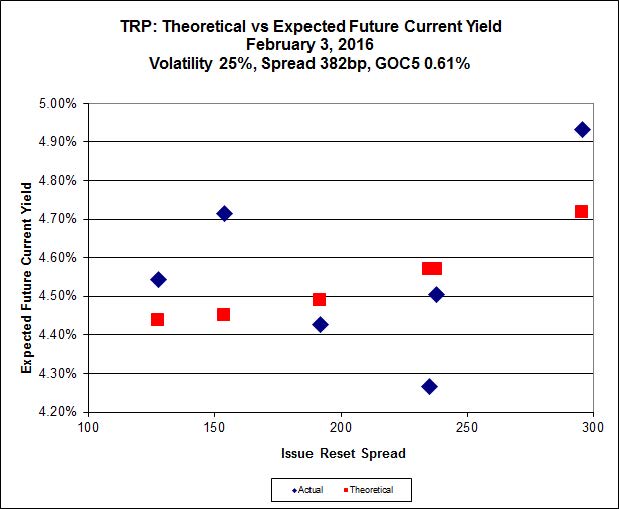
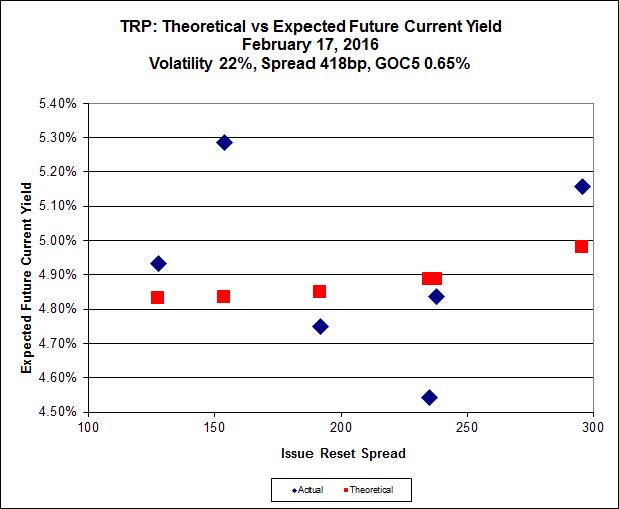
Here’s TRP:
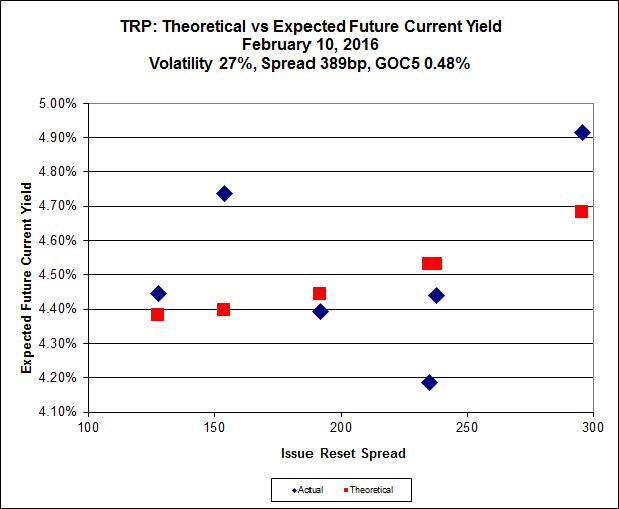
impVol_TRP_160217
Click for Big

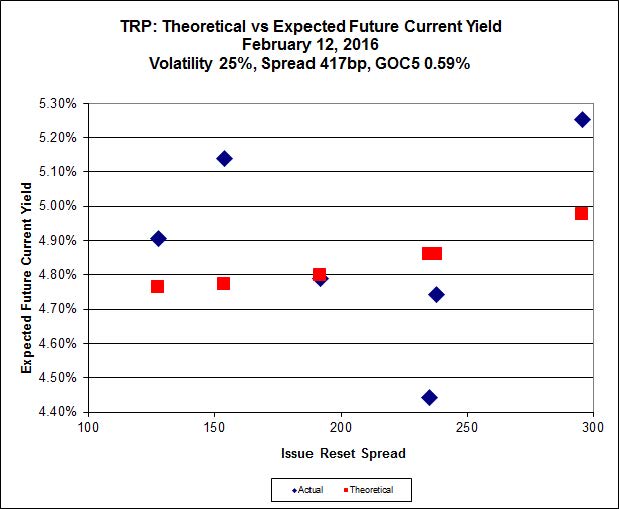
TRP.PR.E, which resets 2019-10-30 at +235, is bid at 16.51 to be $1.16 rich, while TRP.PR.C, resetting 2021-1-30 at +154, is $0.97 cheap at its bid price of 10.36.
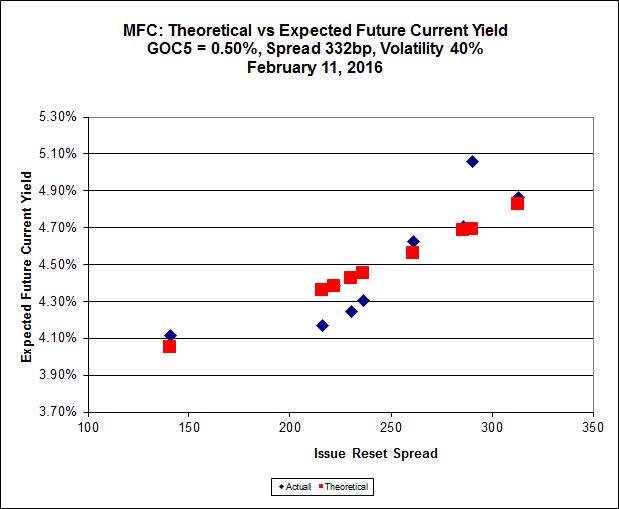
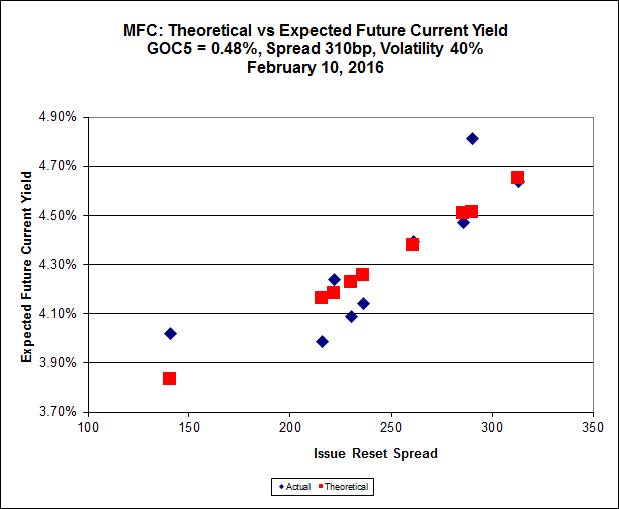
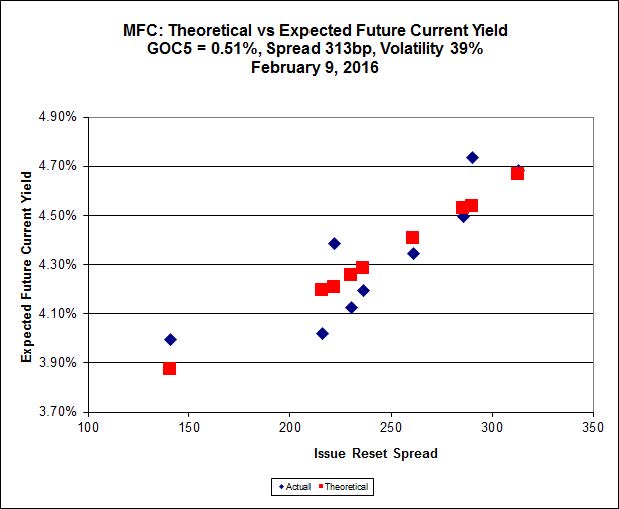
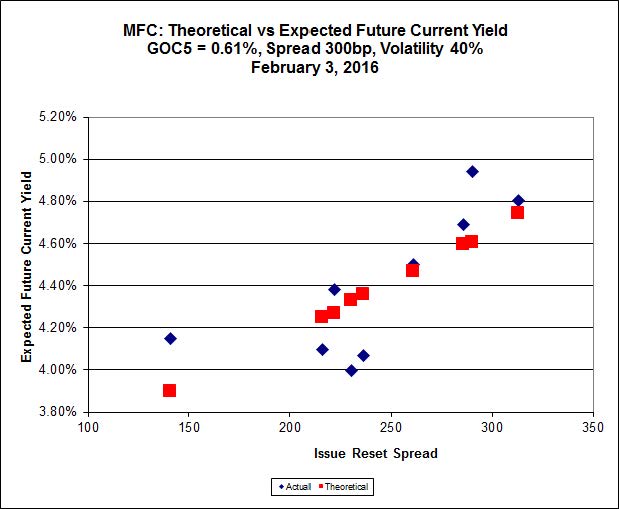
impVol_MFC_160217
Click for Big

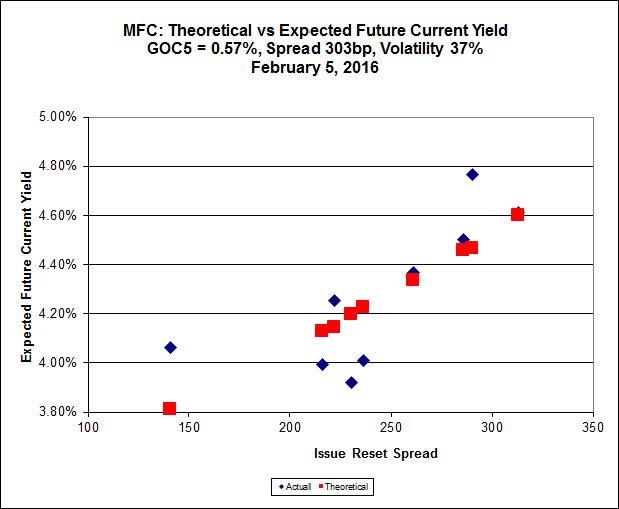
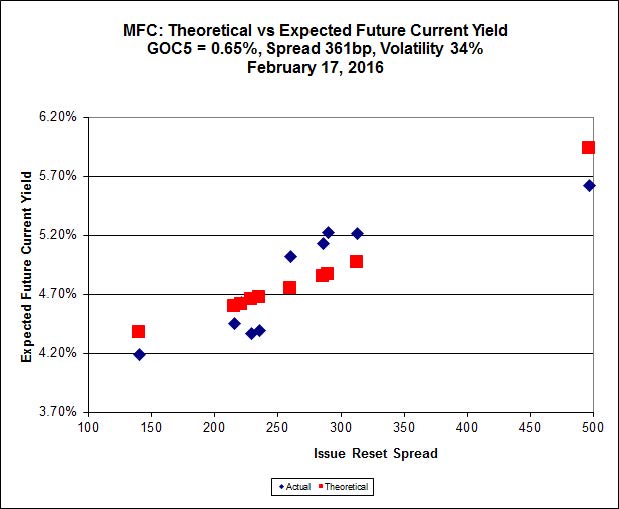
This analysis includes the new issue with a deemed price of 25.00.

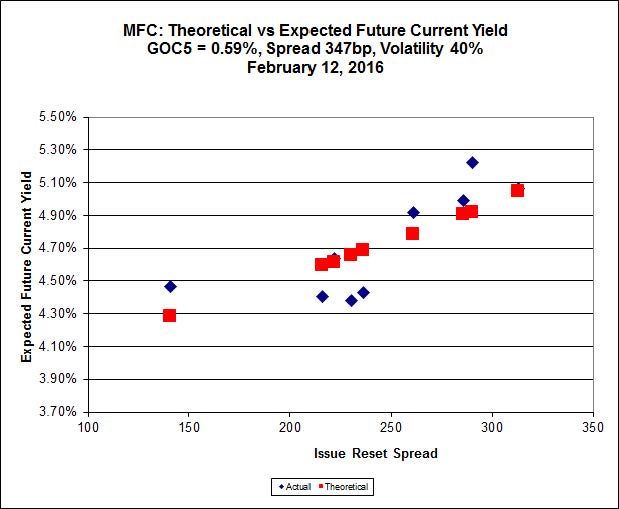
Most expensive is the new issue, resetting at +497bp on 2021-6-19, deemed at 25.00 to be 1.32 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 16.99 to be 1.25 cheap.
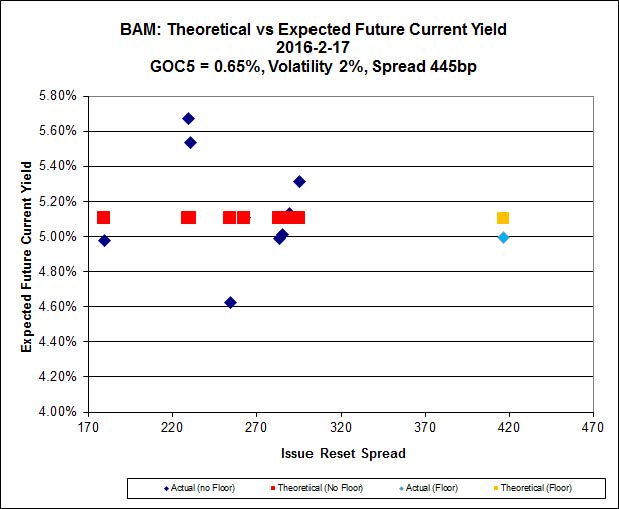
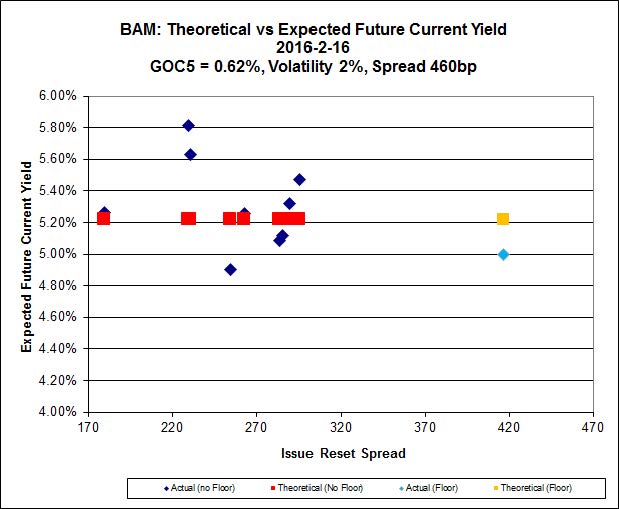
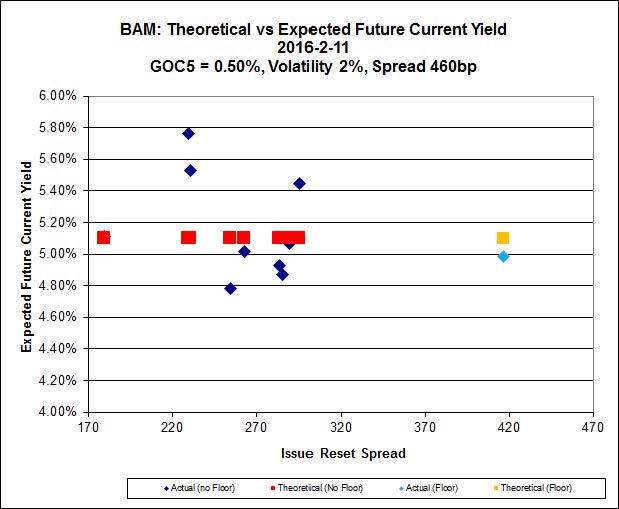
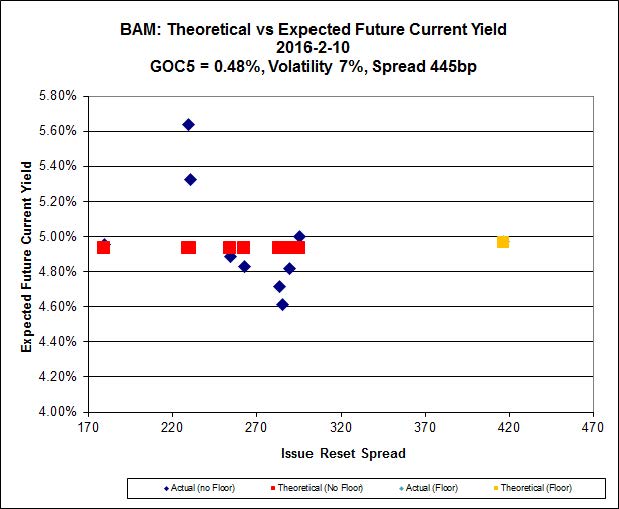
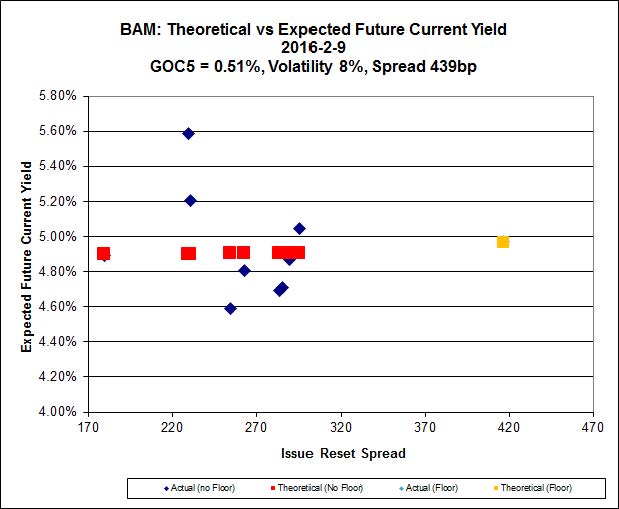
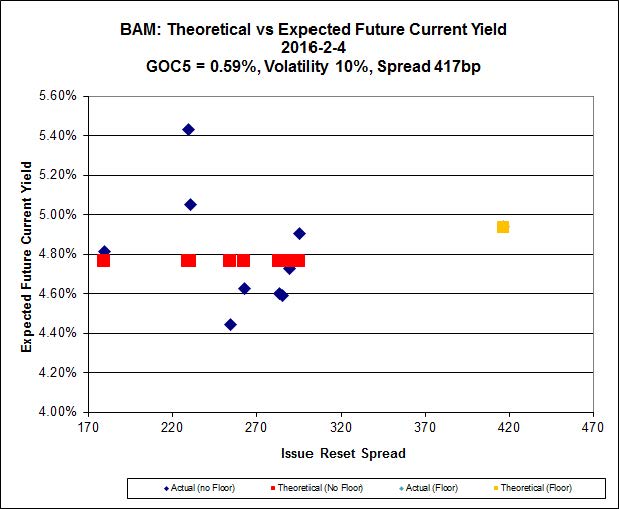
impVol_BAM_160217
Click for Big

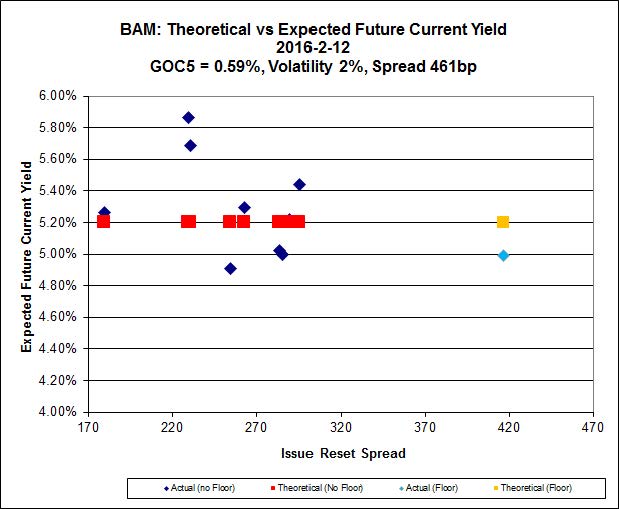
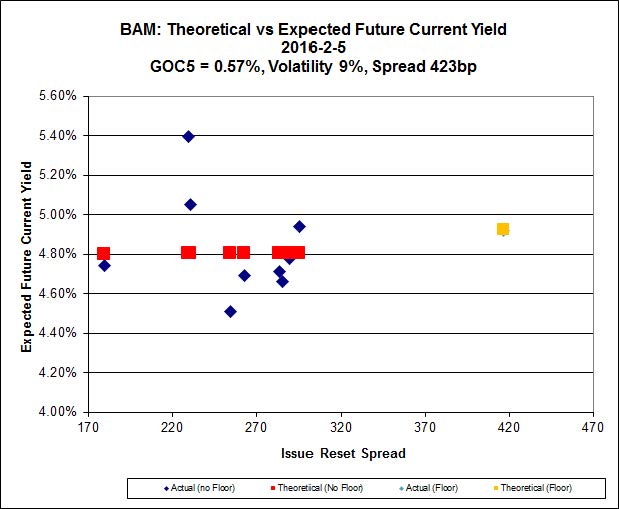
The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 13.00 to be $1.46 cheap. BAM.PF.E, resetting at +255bp on 2020-3-31 is bid at 17.31 and appears to be $1.62 rich.

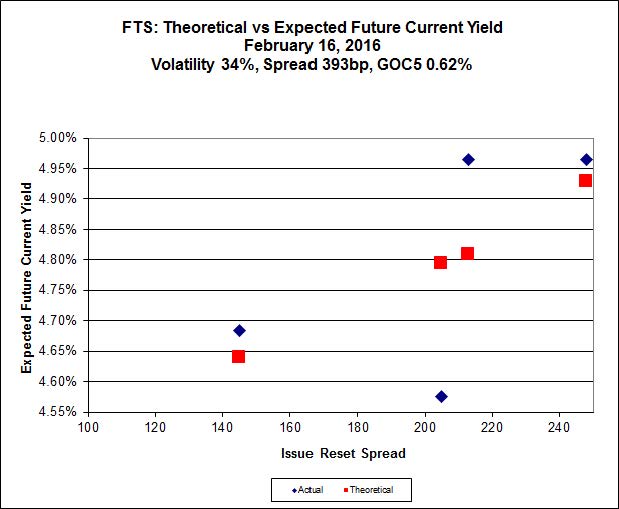
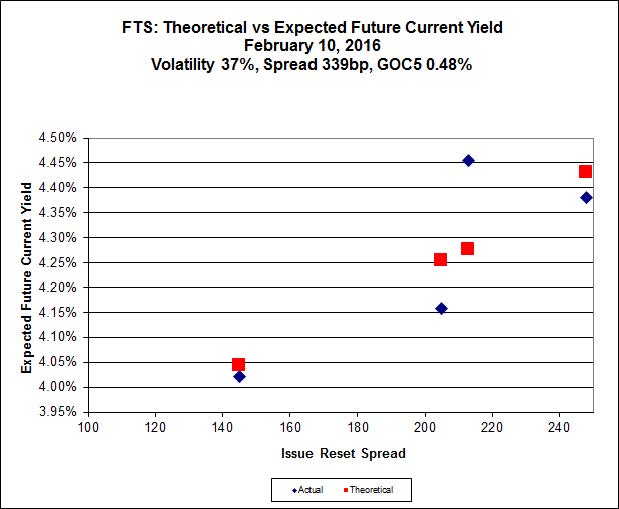
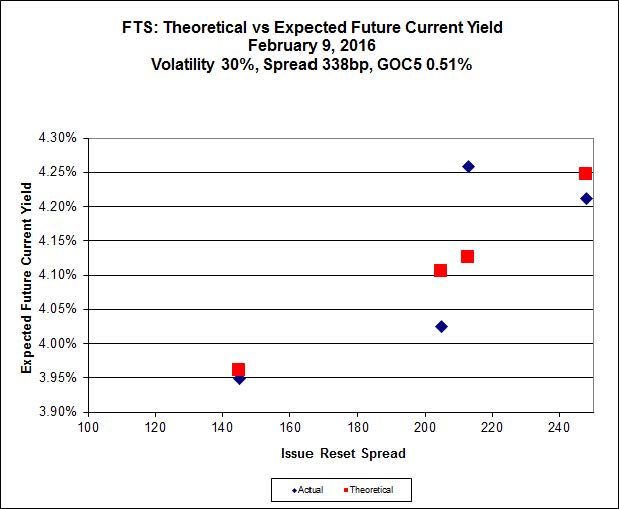
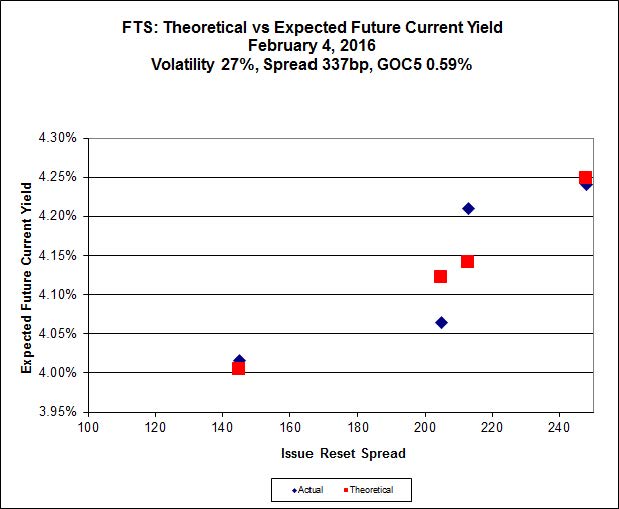
impVol_FTS_160217
Click for Big

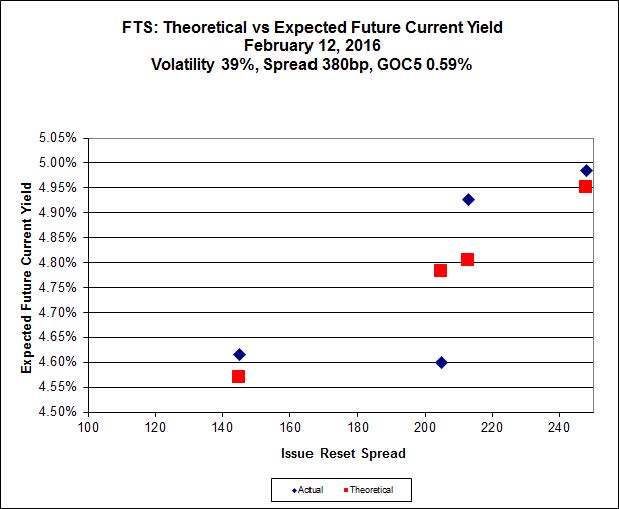
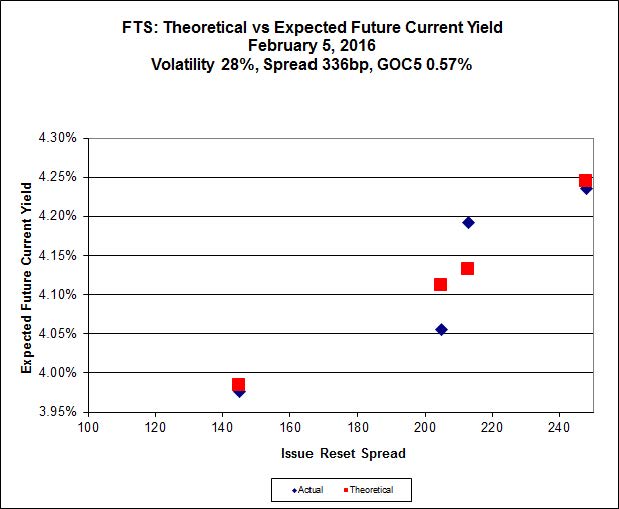
FTS.PR.K, with a spread of +205bp, and bid at 15.00, looks $0.81 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 14.00 and is $0.58 cheap.
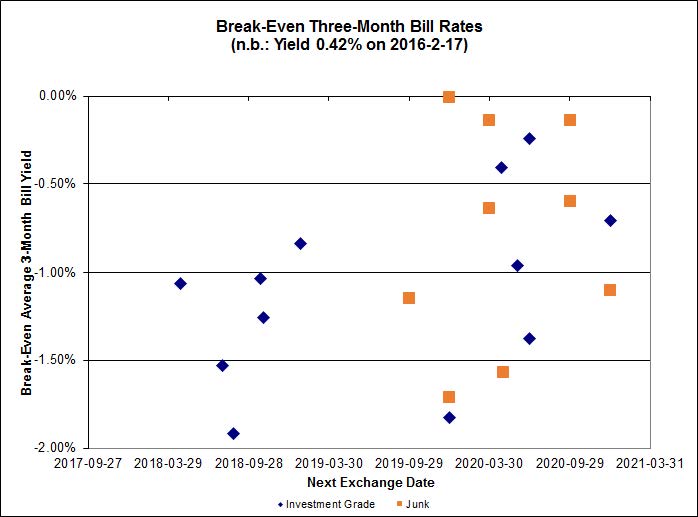
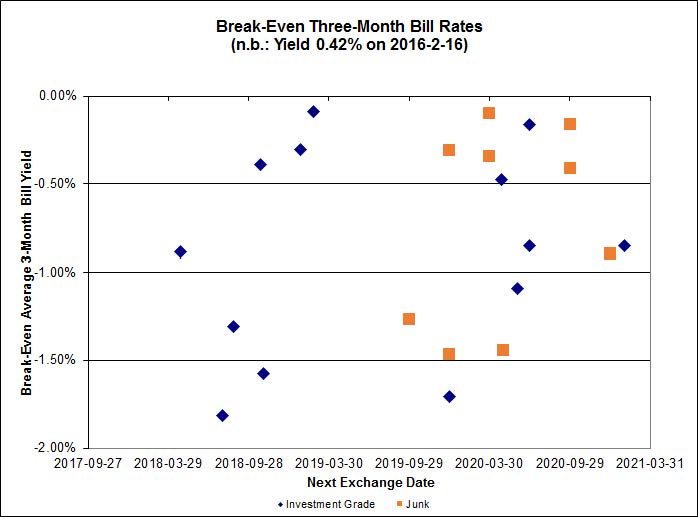
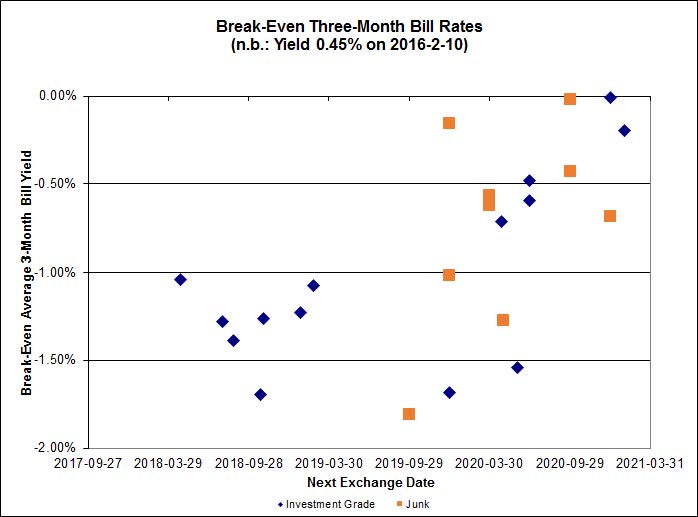
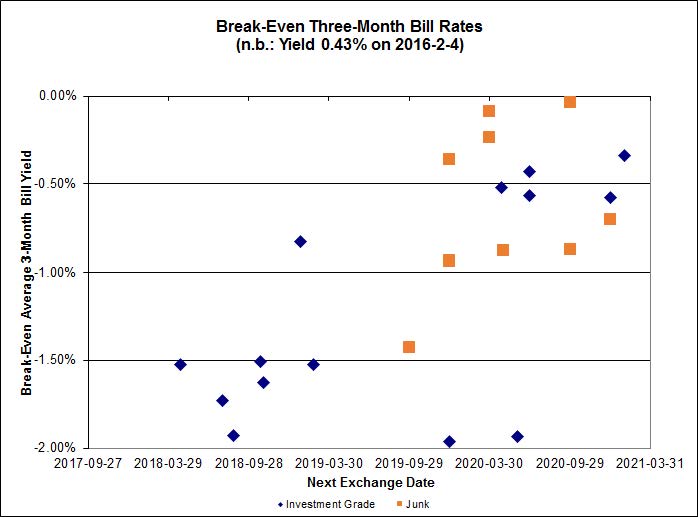
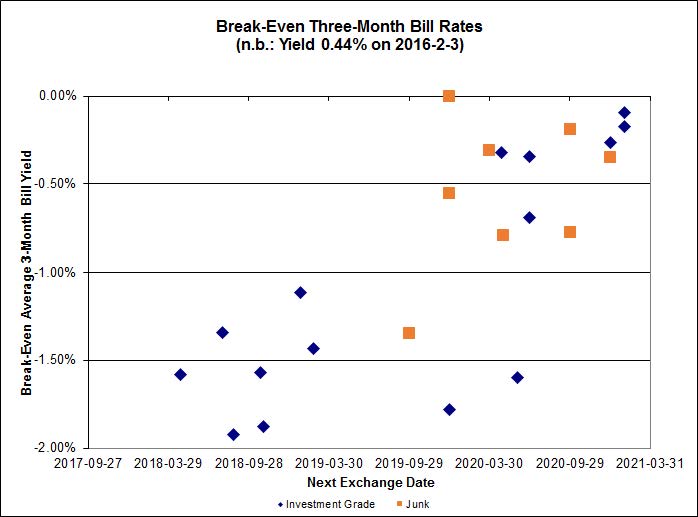
pairs_FR_160217
Click for Big

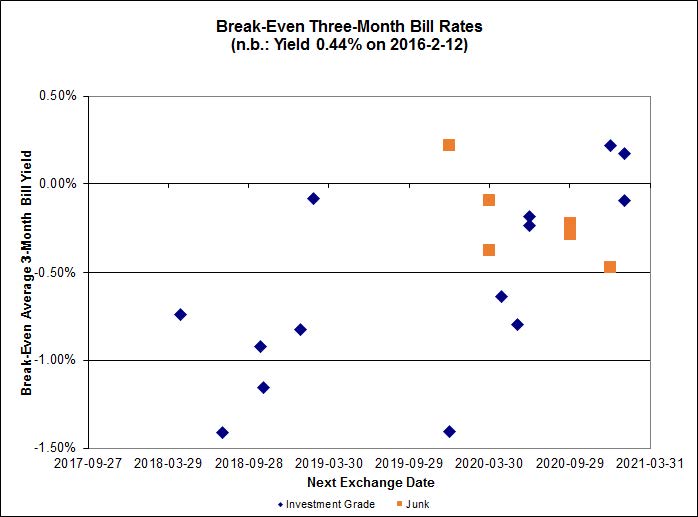
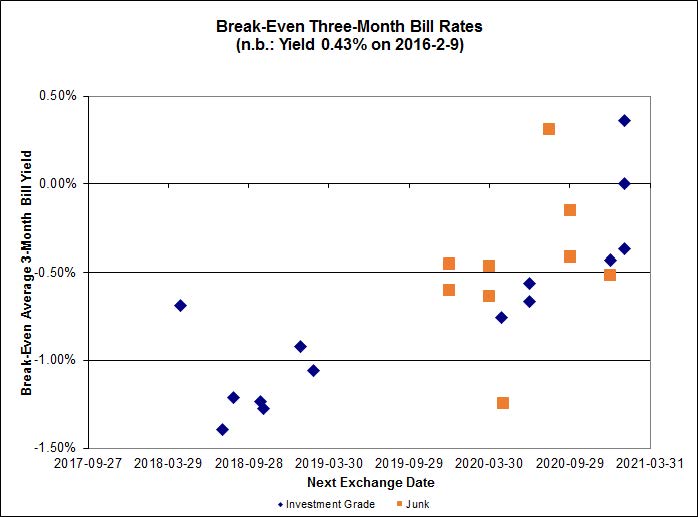
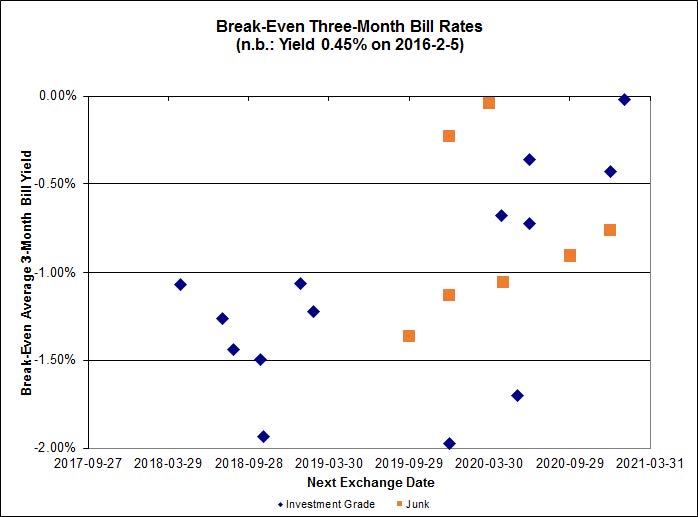
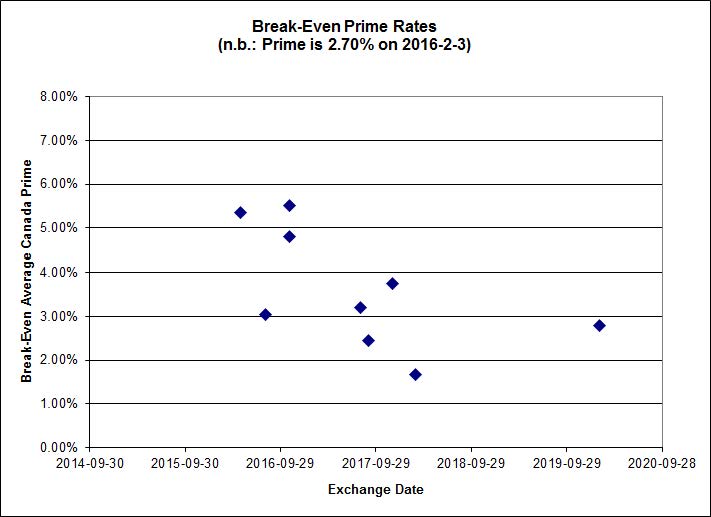
Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.72%, with four outliers above 0.00%. There are two junk outliers above 0.00%.

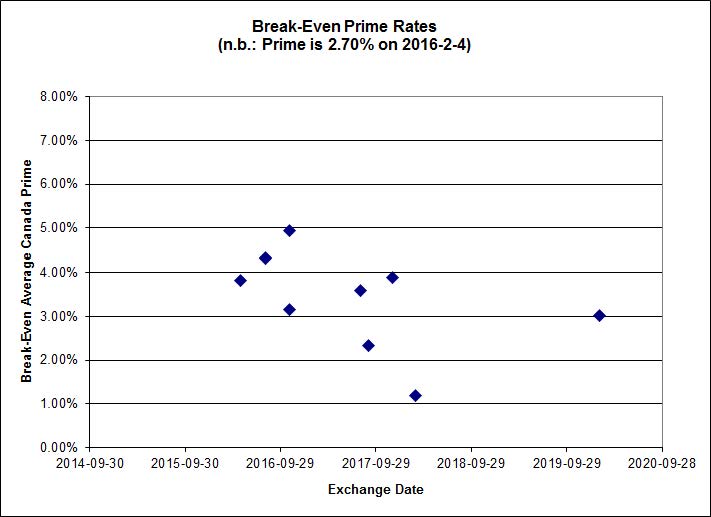
pairs_FF_160217
Click for Big

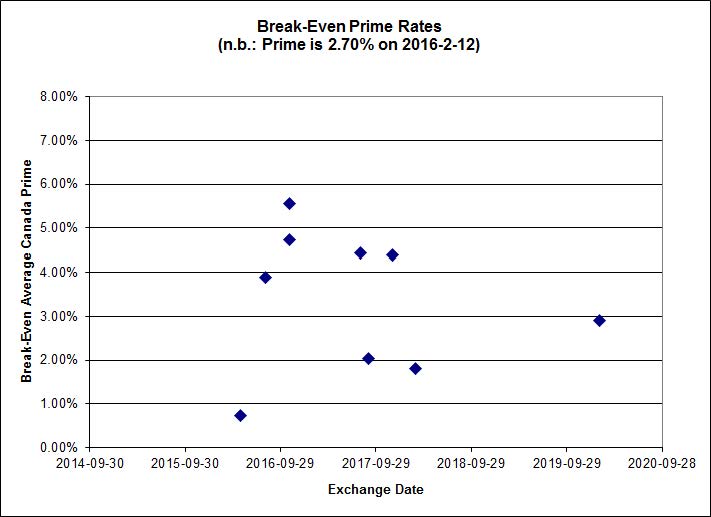
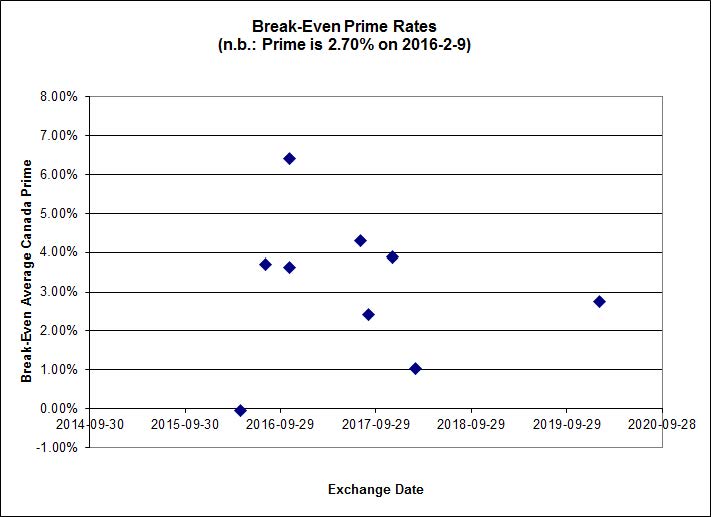
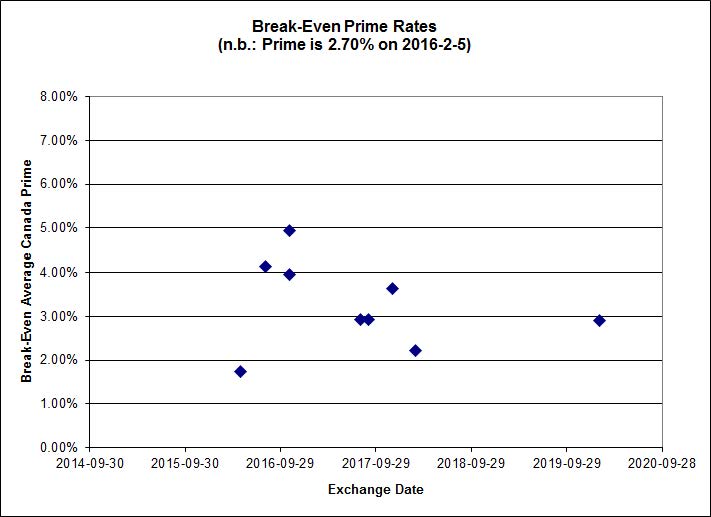
Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.71 % 6.94 % 15,457 15.53 1 1.2810 % 1,366.4
FixedFloater 7.88 % 6.89 % 24,873 15.30 1 1.7722 % 2,523.8
Floater 5.20 % 5.41 % 81,003 14.76 4 3.2983 % 1,473.9
OpRet 0.00 % 0.00 % 0 0.00 0 0.3516 % 2,746.5
SplitShare 4.81 % 5.75 % 74,386 2.67 6 0.3516 % 3,213.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.3516 % 2,507.6
Perpetual-Premium 5.85 % 5.82 % 83,019 13.87 6 0.1000 % 2,522.5
Perpetual-Discount 5.80 % 5.84 % 99,678 14.13 33 0.1897 % 2,493.1
FixedReset 5.74 % 5.11 % 211,852 14.43 84 1.4227 % 1,768.5
Deemed-Retractible 5.34 % 5.81 % 123,857 6.89 34 0.1153 % 2,529.7
FloatingReset 3.11 % 5.02 % 49,790 5.51 16 0.4631 % 1,967.6
Performance Highlights
Issue Index Change Notes
BNS.PR.B FloatingReset -1.50 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.08
Bid-YTW : 5.19 %
GWO.PR.O FloatingReset -1.33 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.15
Bid-YTW : 12.10 %
BNS.PR.C FloatingReset -1.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.50
Bid-YTW : 5.02 %
TD.PR.Y FixedReset -1.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.32
Bid-YTW : 4.22 %
TRP.PR.F FloatingReset 1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 11.04
Evaluated at bid price : 11.04
Bid-YTW : 5.42 %
TD.PF.B FixedReset 1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 16.70
Evaluated at bid price : 16.70
Bid-YTW : 4.58 %
PWF.PR.K Perpetual-Discount 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 21.47
Evaluated at bid price : 21.73
Bid-YTW : 5.74 %
FTS.PR.G FixedReset 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 14.00
Evaluated at bid price : 14.00
Bid-YTW : 5.17 %
MFC.PR.G FixedReset 1.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.99
Bid-YTW : 9.04 %
RY.PR.J FixedReset 1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 17.40
Evaluated at bid price : 17.40
Bid-YTW : 4.90 %
CM.PR.Q FixedReset 1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 17.91
Evaluated at bid price : 17.91
Bid-YTW : 4.84 %
SLF.PR.I FixedReset 1.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.50
Bid-YTW : 9.20 %
TD.PF.E FixedReset 1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 18.30
Evaluated at bid price : 18.30
Bid-YTW : 4.85 %
BAM.PR.E Ratchet 1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 25.00
Evaluated at bid price : 11.86
Bid-YTW : 6.94 %
BNS.PR.Y FixedReset 1.30 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.75
Bid-YTW : 7.00 %
BMO.PR.M FixedReset 1.30 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.31
Bid-YTW : 4.03 %
RY.PR.W Perpetual-Discount 1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 22.88
Evaluated at bid price : 23.15
Bid-YTW : 5.30 %
POW.PR.D Perpetual-Discount 1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 21.33
Evaluated at bid price : 21.60
Bid-YTW : 5.85 %
RY.PR.M FixedReset 1.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 17.07
Evaluated at bid price : 17.07
Bid-YTW : 4.87 %
W.PR.K FixedReset 1.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 22.83
Evaluated at bid price : 24.10
Bid-YTW : 5.48 %
TRP.PR.A FixedReset 1.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 13.53
Evaluated at bid price : 13.53
Bid-YTW : 5.02 %
CM.PR.P FixedReset 1.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 16.00
Evaluated at bid price : 16.00
Bid-YTW : 4.79 %
BNS.PR.D FloatingReset 1.74 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.58
Bid-YTW : 7.73 %
PVS.PR.D SplitShare 1.75 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2021-10-08
Maturity Price : 25.00
Evaluated at bid price : 23.30
Bid-YTW : 6.17 %
BAM.PR.G FixedFloater 1.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 25.00
Evaluated at bid price : 12.06
Bid-YTW : 6.89 %
TD.PF.F Perpetual-Discount 1.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 22.12
Evaluated at bid price : 22.46
Bid-YTW : 5.49 %
BMO.PR.T FixedReset 1.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 16.52
Evaluated at bid price : 16.52
Bid-YTW : 4.61 %
HSE.PR.A FixedReset 2.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 8.35
Evaluated at bid price : 8.35
Bid-YTW : 7.09 %
NA.PR.Q FixedReset 2.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.63
Bid-YTW : 5.16 %
FTS.PR.I FloatingReset 2.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 9.42
Evaluated at bid price : 9.42
Bid-YTW : 5.02 %
FTS.PR.M FixedReset 2.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 16.00
Evaluated at bid price : 16.00
Bid-YTW : 5.16 %
PWF.PR.T FixedReset 2.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 19.53
Evaluated at bid price : 19.53
Bid-YTW : 4.06 %
BAM.PR.T FixedReset 2.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 13.37
Evaluated at bid price : 13.37
Bid-YTW : 5.72 %
SLF.PR.J FloatingReset 2.78 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.45
Bid-YTW : 11.92 %
MFC.PR.L FixedReset 2.80 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.78
Bid-YTW : 9.66 %
FTS.PR.K FixedReset 2.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 15.00
Evaluated at bid price : 15.00
Bid-YTW : 4.79 %
BAM.PF.G FixedReset 2.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 5.37 %
BAM.PF.F FixedReset 3.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 17.51
Evaluated at bid price : 17.51
Bid-YTW : 5.33 %
HSE.PR.E FixedReset 3.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 15.10
Evaluated at bid price : 15.10
Bid-YTW : 7.18 %
BAM.PR.R FixedReset 3.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 13.00
Evaluated at bid price : 13.00
Bid-YTW : 5.74 %
BAM.PF.B FixedReset 3.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 16.06
Evaluated at bid price : 16.06
Bid-YTW : 5.38 %
BAM.PR.Z FixedReset 3.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 16.99
Evaluated at bid price : 16.99
Bid-YTW : 5.52 %
CM.PR.O FixedReset 4.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 16.65
Evaluated at bid price : 16.65
Bid-YTW : 4.71 %
TRP.PR.G FixedReset 4.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 5.28 %
MFC.PR.N FixedReset 4.19 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.90
Bid-YTW : 8.82 %
BAM.PR.K Floater 4.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 8.86
Evaluated at bid price : 8.86
Bid-YTW : 5.41 %
MFC.PR.M FixedReset 4.45 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.13
Bid-YTW : 8.70 %
BAM.PR.C Floater 4.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 8.67
Evaluated at bid price : 8.67
Bid-YTW : 5.53 %
HSE.PR.G FixedReset 4.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 15.26
Evaluated at bid price : 15.26
Bid-YTW : 7.10 %
BAM.PF.A FixedReset 4.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 17.30
Evaluated at bid price : 17.30
Bid-YTW : 5.35 %
SLF.PR.H FixedReset 4.96 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.60
Bid-YTW : 10.14 %
GWO.PR.N FixedReset 5.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.75
Bid-YTW : 10.83 %
MFC.PR.K FixedReset 5.44 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.50
Bid-YTW : 9.77 %
MFC.PR.F FixedReset 5.48 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.31
Bid-YTW : 11.39 %
BAM.PR.B Floater 5.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 8.80
Evaluated at bid price : 8.80
Bid-YTW : 5.44 %
SLF.PR.G FixedReset 6.37 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.52
Bid-YTW : 10.17 %
BAM.PR.X FixedReset 7.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 12.31
Evaluated at bid price : 12.31
Bid-YTW : 5.30 %
BAM.PF.E FixedReset 7.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 17.31
Evaluated at bid price : 17.31
Bid-YTW : 5.03 %
PWF.PR.Q FloatingReset 8.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 10.85
Evaluated at bid price : 10.85
Bid-YTW : 4.74 %
Volume Highlights
Issue Index Shares
Traded
Notes
FTS.PR.M FixedReset 155,067 TD crossed 21,000 at 15.90, followed by blocks of 100,000 and 19,000, both at 16.00.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 16.00
Evaluated at bid price : 16.00
Bid-YTW : 5.16 %
FTS.PR.H FixedReset 151,934 Scotia crossed blocks of 52,800 and 95,400, both at 11.20.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 11.16
Evaluated at bid price : 11.16
Bid-YTW : 4.83 %
BAM.PR.K Floater 114,575 TD crossed 100,000 at 8.70.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 8.86
Evaluated at bid price : 8.86
Bid-YTW : 5.41 %
TD.PF.G FixedReset 95,049 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 23.25
Evaluated at bid price : 25.31
Bid-YTW : 5.21 %
BMO.PR.Y FixedReset 90,020 Scotia crossed blocks of 50,000 and 25,000, both at 18.25.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 18.23
Evaluated at bid price : 18.23
Bid-YTW : 4.71 %
RY.PR.Q FixedReset 83,277 RBC crossed 10,000 at 25.40.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 23.28
Evaluated at bid price : 25.44
Bid-YTW : 5.11 %
There were 56 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
FTS.PR.H FixedReset Quote: 11.16 – 12.35
Spot Rate : 1.1900
Average : 0.7183

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 11.16
Evaluated at bid price : 11.16
Bid-YTW : 4.83 %

MFC.PR.H FixedReset Quote: 18.12 – 19.12
Spot Rate : 1.0000
Average : 0.6328

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.12
Bid-YTW : 8.44 %

CIU.PR.C FixedReset Quote: 9.82 – 10.57
Spot Rate : 0.7500
Average : 0.4374

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 9.82
Evaluated at bid price : 9.82
Bid-YTW : 5.00 %

FTS.PR.G FixedReset Quote: 14.00 – 15.00
Spot Rate : 1.0000
Average : 0.6993

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 14.00
Evaluated at bid price : 14.00
Bid-YTW : 5.17 %

TRP.PR.I FloatingReset Quote: 10.75 – 12.00
Spot Rate : 1.2500
Average : 1.0157

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 10.75
Evaluated at bid price : 10.75
Bid-YTW : 4.64 %

TRP.PR.A FixedReset Quote: 13.53 – 14.19
Spot Rate : 0.6600
Average : 0.4437

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-17
Maturity Price : 13.53
Evaluated at bid price : 13.53
Bid-YTW : 5.02 %

Market Action

February 16, 2016

I have no idea how important this service really is … but certainly my projections of sixteen years ago (that the Internet would promote a meritocracy and decrease the importance of brand names) are seeing some acceptance:

Joshua Young started his hedge fund less than a year ago. Last month, he caught a break when a university endowment handed him $20 million, quintupling his assets under management.

How did an obscure Houston fund called Bison Interests land such a big fish?

Young, all of 32, had set up a profile on SumZero, a website that started out as a repository for buy-side research and has more recently morphed into a mashup of LinkedIn and Match.com where institutional investors can find up-and-coming fund managers and choose them based on the quality of their analysis. Using SumZero, Young bypassed an old-boy network that prizes relationships, credentials and word-of-mouth referrals. The company says it has helped generate hundreds of introductions between the more than 12,000 fund managers with SumZero profiles and the 270 institutional investors now using the site, which include the family offices of several big tech executives.
…
Multiple studies have shown that smaller funds tend to do better than larger ones, some of which have performed poorly during the recent market rout. But herd mentality and risk-avoidance prompts many institutional investors to steer their money to big, entrenched players. Firms with more than $5 billion under management represent just 6 percent of all hedge funds but manage about 70 percent of the invested capital, according to Hedge Fund Research.

This trend, if it is a trend, ties in with the Death of a Salesman meme:

Banks are taking a hatchet to their bond-trading businesses and the biggest casualties are proving to be the people with the most experience.

About 70 percent of credit traders cut in London last year at the 12 largest investment banks had worked in the financial industry for more than 10 years, according to data compiled by headhunters Michelangelo Search, which specializes in sales, trading and research roles. That’s increasingly leaving trading desks manned by more junior colleagues.

Experienced, better-compensated staff are falling victim to banks’ efforts to reduce costs as they try to generate profit within constraints imposed by regulators and central banks since the global financial crisis. There’s more to come as banks from Bank of America Corp. to Goldman Sachs Group Inc. consider cuts as soon as this quarter.

“I’ve been in the fixed income business for 35 years but most of my cohort is now missing in action,” said Tim Skeet, who has worked in bond-market roles since 1981, and is currently looking for a new position in the industry. “There’s a ‘juniorization’ of the workplace underway in London as banks focus more on costs than revenues.”

Understanding the connection requires a little explanation. The Masters of the Universe, the fixed income traders/salesmen who pulled down megabucks during the boom, do not achieve that status by being red-hot super-sharp analysts. What they got – and still get – paid for is bringing in business and keeping that inventory turning over while making the full spread (or more!) every time.

You don’t need any understanding of the bond market to do that. In my experience, that doesn’t even help. What you need is a deep voice, a firm handshake, a little charisma, and a great big expense account so entertain the clients. Contacts from prep school or Daddy’s friends are good things to have as well. And presto! You’re a trader!

Old bond traders didn’t make the big bucks for analysis, or helping clients achieve outperformance. As my Assiduous Readers will remember, the average Portfolio Manager has about enough brains to use the right fork when taking clients out to lunch, but that’s about where it ends and that’s all that’s necessary. So they rely extensively on their salesman’s advice. On occasion, that salesman will be the de facto portfolio manager, because the PM of record is a rubber stamp. And once the PM finds a guy he thinks he can trust, that salesman will get a lot of business from him; and that business will follow the salesman if he changes firms. And the bosses know that, so the salesman gets considerable incentive to stay on board and keep producing those lovely, lovely spreads of pure profit.

In Canada, the model started dying, as far as I can tell, some time in the mid-2000s. The banks don’t like having employees who make good money, so they started bringing in high-school students to act as salesmen (well, they sounded like high school students to me!). The selling template went from ‘I can make you look good’ to ‘We’re a bank!’.

And, I think, the same thing is starting to play out globally, helped along by a bit more transparency (even in 1990-odd, Bloomberg took all the fun out of the Eurobond market), a little less influence of the old-boy network when hiring portfolio managers (they’re all bank drones nowadays, too!) and, of course, all the scandals.

Maybe. It would take a team of sociologists to prove I’m right … but it would take the same team to prove I’m wrong! So I’ve said something provocative that is not susceptible to disproof, which is the holy grail of investment writing.

Meanwhile in Canada, the central planners are hard at work:

Canadians looking to buy homes between $500,000 and $1-million will have to put down larger down payments as new federal rules took effect Monday.

Under the changes, home buyers must now put at least 10 per cent down on the portion of a home that costs more than $500,000.

Buyers can still put down five per cent on the first $500,000 of a home purchase. Homes that cost more than $1-million still require a 20 per cent down payment.

Phil Soper, president and CEO of Royal LePage, says the new rules aim to slow the breakneck pace of price growth in the red-hot markets of Toronto and Vancouver without affecting markets that are lagging, such as those in oil-dependent provinces.

“The problem with monetary policy is that it impacts the struggling Calgary market or the just fine Winnipeg market and the overheated Vancouver market in equal amounts,” Soper said.

And in BC, there’s more welfare:

Hours after the Canadian Real Estate Association reported that Greater Vancouver housing prices led the country in growth, climbing on average by more than 20 per cent over the past year, Finance Minister Mike de Jong rose in the legislature to lay out a fiscal plan that he said will help more people realize the dream of owning a house.

In the first major overhaul of the Property Transfer Tax since its inception in 1988, Mr. de Jong has raised the exemption threshold – solely on new houses – to $750,000. The new tax break, available only to Canadian citizens and permanent residents, could mean savings of up to $13,000 on a house.

Element Financial, proud issuer of EFN.PR.A, EFN.PR.C, EFN.PR.E and EFN.PR.G, has announced:

that following the completion of a strategic review of each of the Company’s business units that it initiated in October of last year, the Board of Directors has approved plans to proceed with a transaction that will result in the separation of the current business into two publicly traded companies – a $19.5 billion world class fleet management company (Element Fleet Management) to be led by Bradley Nullmeyer and a $7.0 billion North American commercial finance company (Element Commercial Asset Management) to be led by Steven Hudson.
…
The Company is currently analyzing the most efficient method to implement the separation of the two businesses and further details will be provided to the market as Element completes this analysis with its advisors. The separation transaction that will split the Company into these two publicly traded entities is expected to be completed on a tax free basis before the end of 2016. The allocation of the assets, liabilities and capital structure of the Company, as well as the structure of the Board and the deployment of current corporate services staff between the two new entities will be determined as the details of this separation transaction are determined.

We’ll see what happens as details emerge, but I have a hard time envisaging this as being credit-positive for the preferreds!

It was a relatively quiet day overall for the Canadian preferred share market, with PerpetualDiscounts gaining 5bp, FixedResets off 10bp and DeemedRetractibles flat. The overall calm masked significant churn, as shown in the Performance Highlights table. Volume was high.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_160216
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 16.52 to be $1.37 rich, while TRP.PR.G, resetting 2020-11-30 at +296, is $1.00 cheap at its bid price of 16.81.

impVol_MFC_160216
Click for Big

This analysis includes the new issue with a deemed price of 25.00.

Most expensive is the new issue, resetting at +497bp on 2021-6-19, deemed at 25.00 to be 1.08 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 16.80 to be 1.13 cheap.

impVol_BAM_160216
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 12.56 to be $1.42 cheap. BAM.PF.H, resetting at +417M500bp on 2020-12-31 is bid at 25.03 and appears to be $1.08 rich.

impVol_FTS_160216
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 14.59, looks $0.67 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 13.85 and is $0.44 cheap.

pairs_FR_160216
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.62%, with three outliers above 0.50%. Note that the range of the y-axis has been changed. There are two junk outliers above 0.00%.

pairs_FF_160216
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.78 % 7.02 % 16,155 15.43 1 -3.6214 % 1,349.1
FixedFloater 8.02 % 7.00 % 25,969 15.17 1 0.0000 % 2,479.9
Floater 5.37 % 5.64 % 77,140 14.39 4 -0.3400 % 1,426.8
OpRet 0.00 % 0.00 % 0 0.00 0 0.3717 % 2,736.8
SplitShare 4.83 % 5.91 % 74,395 2.68 6 0.3717 % 3,202.6
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.3717 % 2,498.8
Perpetual-Premium 5.86 % 5.83 % 84,124 13.88 6 0.4957 % 2,519.9
Perpetual-Discount 5.81 % 5.83 % 98,483 14.10 33 0.0488 % 2,488.4
FixedReset 5.82 % 5.12 % 210,031 14.13 84 -0.1013 % 1,743.7
Deemed-Retractible 5.34 % 5.89 % 123,748 6.89 34 0.0000 % 2,526.8
FloatingReset 3.12 % 4.91 % 49,989 5.51 16 -0.4494 % 1,958.6
Performance Highlights
Issue Index Change Notes
PWF.PR.Q FloatingReset -6.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 10.00
Evaluated at bid price : 10.00
Bid-YTW : 5.15 %
BAM.PR.E Ratchet -3.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 25.00
Evaluated at bid price : 11.71
Bid-YTW : 7.02 %
TD.PF.E FixedReset -3.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 18.07
Evaluated at bid price : 18.07
Bid-YTW : 4.92 %
CM.PR.O FixedReset -3.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 16.00
Evaluated at bid price : 16.00
Bid-YTW : 4.91 %
MFC.PR.K FixedReset -2.97 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.70
Bid-YTW : 10.54 %
FTS.PR.I FloatingReset -2.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 9.20
Evaluated at bid price : 9.20
Bid-YTW : 5.14 %
NA.PR.S FixedReset -2.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 16.05
Evaluated at bid price : 16.05
Bid-YTW : 5.00 %
PWF.PR.T FixedReset -1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 19.02
Evaluated at bid price : 19.02
Bid-YTW : 4.17 %
TD.PF.F Perpetual-Discount -1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 21.76
Evaluated at bid price : 22.06
Bid-YTW : 5.59 %
RY.PR.M FixedReset -1.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 16.83
Evaluated at bid price : 16.83
Bid-YTW : 4.94 %
NA.PR.Q FixedReset -1.77 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.15
Bid-YTW : 5.56 %
MFC.PR.N FixedReset -1.70 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.22
Bid-YTW : 9.41 %
MFC.PR.L FixedReset -1.60 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.35
Bid-YTW : 10.06 %
BAM.PR.B Floater -1.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 8.32
Evaluated at bid price : 8.32
Bid-YTW : 5.76 %
BMO.PR.Y FixedReset -1.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 18.12
Evaluated at bid price : 18.12
Bid-YTW : 4.74 %
BAM.PF.F FixedReset -1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 5.49 %
MFC.PR.M FixedReset -1.44 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.40
Bid-YTW : 9.33 %
TD.PF.D FixedReset -1.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 17.55
Evaluated at bid price : 17.55
Bid-YTW : 4.93 %
MFC.PR.I FixedReset -1.33 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.05
Bid-YTW : 9.07 %
BMO.PR.T FixedReset -1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 16.20
Evaluated at bid price : 16.20
Bid-YTW : 4.70 %
BNS.PR.R FixedReset -1.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.23
Bid-YTW : 4.61 %
BNS.PR.Q FixedReset -1.26 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.80
Bid-YTW : 4.68 %
MFC.PR.H FixedReset -1.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.15
Bid-YTW : 8.42 %
BAM.PR.K Floater -1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 8.50
Evaluated at bid price : 8.50
Bid-YTW : 5.64 %
TD.PR.Z FloatingReset -1.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.45
Bid-YTW : 4.85 %
BAM.PR.C Floater -1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 8.30
Evaluated at bid price : 8.30
Bid-YTW : 5.78 %
TD.PR.T FloatingReset -1.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.28
Bid-YTW : 4.91 %
BMO.PR.M FixedReset -1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.01
Bid-YTW : 4.27 %
HSE.PR.G FixedReset -1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 14.60
Evaluated at bid price : 14.60
Bid-YTW : 7.44 %
RY.PR.A Deemed-Retractible -1.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.56
Bid-YTW : 5.61 %
BAM.PF.E FixedReset 1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 16.16
Evaluated at bid price : 16.16
Bid-YTW : 5.41 %
TD.PF.A FixedReset 1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 16.65
Evaluated at bid price : 16.65
Bid-YTW : 4.61 %
NA.PR.W FixedReset 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 15.27
Evaluated at bid price : 15.27
Bid-YTW : 5.07 %
BIP.PR.B FixedReset 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 22.72
Evaluated at bid price : 23.85
Bid-YTW : 5.82 %
PVS.PR.D SplitShare 1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2021-10-08
Maturity Price : 25.00
Evaluated at bid price : 22.90
Bid-YTW : 6.53 %
TD.PF.C FixedReset 1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 16.61
Evaluated at bid price : 16.61
Bid-YTW : 4.60 %
BMO.PR.K Deemed-Retractible 1.21 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-11-25
Maturity Price : 25.00
Evaluated at bid price : 25.15
Bid-YTW : 4.32 %
SLF.PR.J FloatingReset 1.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.14
Bid-YTW : 12.29 %
BAM.PR.X FixedReset 1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 11.50
Evaluated at bid price : 11.50
Bid-YTW : 5.69 %
PWF.PR.O Perpetual-Premium 1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 24.49
Evaluated at bid price : 25.00
Bid-YTW : 5.83 %
GWO.PR.N FixedReset 1.34 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.12
Bid-YTW : 11.53 %
FTS.PR.M FixedReset 1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 15.61
Evaluated at bid price : 15.61
Bid-YTW : 5.29 %
HSE.PR.A FixedReset 1.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 8.18
Evaluated at bid price : 8.18
Bid-YTW : 7.24 %
FTS.PR.K FixedReset 1.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 14.59
Evaluated at bid price : 14.59
Bid-YTW : 4.93 %
TRP.PR.A FixedReset 1.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 13.32
Evaluated at bid price : 13.32
Bid-YTW : 5.10 %
BAM.PF.B FixedReset 1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 15.46
Evaluated at bid price : 15.46
Bid-YTW : 5.60 %
TRP.PR.B FixedReset 1.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 9.70
Evaluated at bid price : 9.70
Bid-YTW : 5.07 %
BAM.PR.R FixedReset 1.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 12.56
Evaluated at bid price : 12.56
Bid-YTW : 5.94 %
PWF.PR.A Floater 2.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 10.05
Evaluated at bid price : 10.05
Bid-YTW : 4.73 %
HSE.PR.C FixedReset 2.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 13.54
Evaluated at bid price : 13.54
Bid-YTW : 7.40 %
BAM.PR.T FixedReset 2.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 13.01
Evaluated at bid price : 13.01
Bid-YTW : 5.88 %
IAG.PR.A Deemed-Retractible 2.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.00
Bid-YTW : 7.18 %
TRP.PR.H FloatingReset 2.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 8.79
Evaluated at bid price : 8.79
Bid-YTW : 4.95 %
SLF.PR.I FixedReset 2.52 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.30
Bid-YTW : 9.37 %
SLF.PR.H FixedReset 3.42 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.91
Bid-YTW : 10.82 %
MFC.PR.F FixedReset 4.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.67
Bid-YTW : 12.13 %
SLF.PR.G FixedReset 5.92 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.71
Bid-YTW : 11.01 %
Volume Highlights
Issue Index Shares
Traded
Notes
EML.PR.A FixedReset 351,820 New issue settled today.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.73
Bid-YTW : 5.88 %
BMO.PR.Q FixedReset 234,685 Desjardins crossed blocks of 200,000 and 19,900, both at 17.85.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.85
Bid-YTW : 8.05 %
PWF.PR.L Perpetual-Discount 206,022 Nesbitt and TD crossed 100,000 shares each, both at 22.05.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 21.81
Evaluated at bid price : 22.05
Bid-YTW : 5.83 %
TD.PF.G FixedReset 110,273 RBC crossed 10,000 at 25.40.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 23.26
Evaluated at bid price : 25.35
Bid-YTW : 5.20 %
PWF.PR.K Perpetual-Discount 101,110 Nesbitt crossed 100,000 at 21.40.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 21.50
Evaluated at bid price : 21.50
Bid-YTW : 5.82 %
RY.PR.Q FixedReset 86,662 TD crossed 11,500 at 25.41. RBC crossed 10,000 at 25.42.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 23.27
Evaluated at bid price : 25.40
Bid-YTW : 5.12 %
There were 44 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
NA.PR.Q FixedReset Quote: 22.15 – 22.98
Spot Rate : 0.8300
Average : 0.5693

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.15
Bid-YTW : 5.56 %

HSE.PR.G FixedReset Quote: 14.60 – 15.50
Spot Rate : 0.9000
Average : 0.6424

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 14.60
Evaluated at bid price : 14.60
Bid-YTW : 7.44 %

TD.PF.F Perpetual-Discount Quote: 22.06 – 22.67
Spot Rate : 0.6100
Average : 0.3760

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 21.76
Evaluated at bid price : 22.06
Bid-YTW : 5.59 %

TD.PR.Z FloatingReset Quote: 21.45 – 22.17
Spot Rate : 0.7200
Average : 0.5311

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.45
Bid-YTW : 4.85 %

PWF.PR.Q FloatingReset Quote: 10.00 – 11.90
Spot Rate : 1.9000
Average : 1.7164

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-16
Maturity Price : 10.00
Evaluated at bid price : 10.00
Bid-YTW : 5.15 %

TD.PR.T FloatingReset Quote: 21.28 – 21.88
Spot Rate : 0.6000
Average : 0.4366

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.28
Bid-YTW : 4.91 %

Market Action

February 12, 2016

I’m pleased to see that the fed’s are asking Bombardier questions before cutting the inevitable cheque:

Prime Minister Justin Trudeau will have a hard time saying no to Bombardier Inc.’s request for aid to complete the troubled C Series aircraft because of the company’s deep political and economic roots in Canada.
…
Here are six things former officials and analysts say Trudeau is looking at:1. Viability Does the C Series have a bright future?
…
2. Efficacy Why hasn’t past aid worked?
…
3. Impact Bombardier now has Canada’s top corporate research budget at C$2 billion, more than double that of struggling smartphone-maker BlackBerry Ltd., according to Research Infosource Inc.
…
4. Competition Aerospace is supported by state funding elsewhere. Officials briefing Trudeau said it “is often seen as a ‘pay to play’ industry,” and the C Series will compete with aircraft made by Airbus Group SE, Boeing and Embraer SA. Sergio Marchi, a former Liberal trade minister and Canadian ambassador to the World Trade Organization, cited a past dispute with Brazil’s support for Embraer as an example of the risks to Canada of not backing Bombardier. “We need to find creative ways to sustain our global players, because other governments did,” he said in an interview last week.

5. Governance There are concerns with the way the company is run. Bombardier is controlled by its namesake family through shares with extra voting rights, and officials familiar with the government’s plans have said the company’s current governance structure is a barrier to federal aid.
…
6. Politics

Trudeau is from Bombardier’s hometown and 40 of his 184 Liberal lawmakers are from Quebec, Canada’s second-most populous province. Spurning Bombardier means the prime minister would have to explain why one of Quebec’s biggest employers can’t have a fraction of the C$9.15 billion bailout offered to Ontario’s General Motors Co. and Chrysler factories in 2009.

The cheque will inevitably come. The last time a Canadian Prime Minister told the Gee-Whiz boys that the Federal Money Fountain was being turned off, the political liability lasted over fifty years.

Dudley was dovish on rates today and nonplussed at premature talk of negative US policy rates:

The U.S. economy has the momentum to help weather stormy global financial markets and policy makers have many other options before they would consider driving borrowing costs below zero if they need to protect growth, Federal Reserve Bank of New York President William Dudley said.

“I just find that an extraordinarily premature conversation to be having,” Dudley said at a press briefing Friday in New York. “There are a lot of things that we would do long before we would really think about moving to negative interest rates.”

Financial markets have been routed in recent weeks by concerns over the global economic outlook. Dudley said the Fed was “definitely aware of what’s going on internationally” and would take that into account when the policy-setting Federal Open Market Committee meets on March 15-16.

In a remark that will probably reinforce views among investors that the Fed will not hike interest rates next month, Dudley said that the outlook for how quickly inflation would rise has been dimmed by recent financial-market developments.

“Inflation is probably going to take a little bit longer to get back to our 2 percent objective, everything equal, than maybe what you thought a few months ago,” he said.

But it’s not stopping the NYT from musing over possible consequences:

So what are some of the weird things that could happen in a world in which negative rates become routine?

The policies in Europe and Japan are still relatively new and involve rates only slightly below zero. But if the policies become long-lasting, or negative rates go much lower, there are a lot of mind-bending ways it could affect routine transactions.

For example, would people start prepaying years’ worth of cable bills to avoid having money tied up in a money-losing bank account? How about property taxes? Would companies and governments put in place new policies prohibiting people from paying their bills too early?

Or consider this: Many commercial transactions now take place with some short-term credit attached — for example, a company that gets a 60-day grace period to pay bills from its suppliers. Would that flip, and suddenly suppliers would prohibit upfront payment and insist that their customers wait 60 days to pay?

Might new businesses sprout up that allow people to securely store thousands of dollars in bundles of $100 bills, or could people buy physical objects as stores of value that the banks can’t charge a negative interest rate on?

“Negative interest rates in Japan is blowing my mind,” said Jose Canseco, the provocative retired baseball player not normally known for his economic musings, on Twitter. And the truth is, he’s not the only one.

And it’s not stopping the bond market worrying!

As worries about European banks’ credit pushed global stocks into a bear market, demand for U.S. debt heated up, driving benchmark 10-year yields toward record lows.

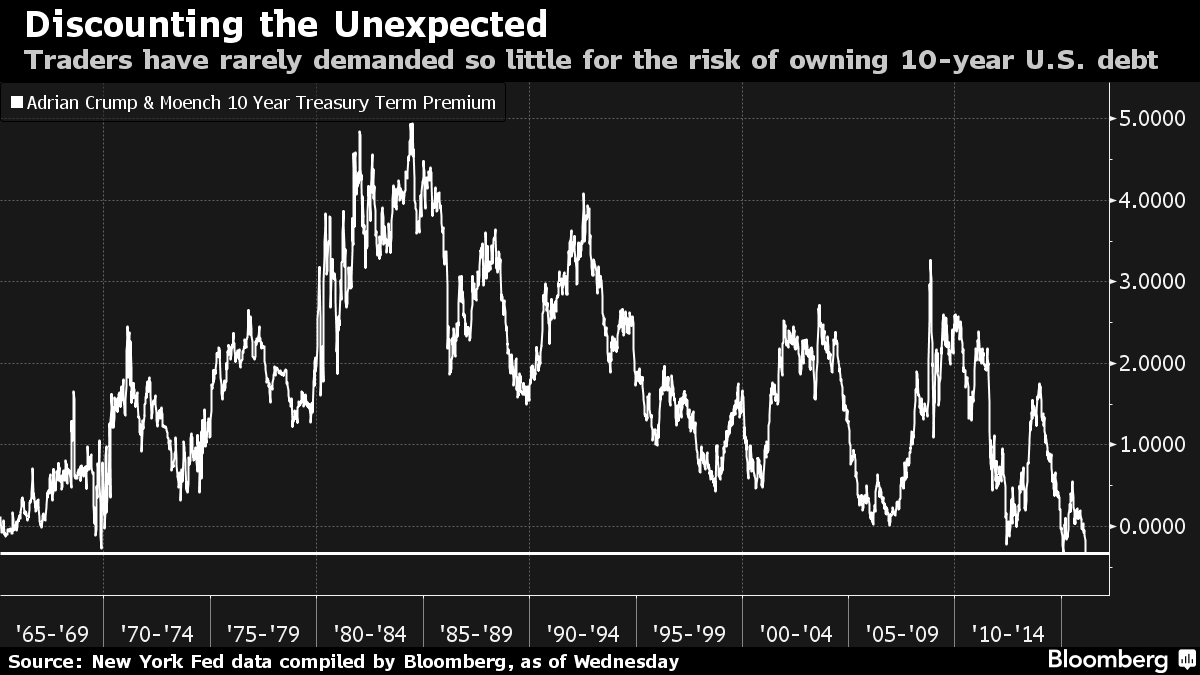
During the Treasuries rally, investors discounted the risk of any surprise jump in interest rates or inflation by the most since January 2015, according to a gauge known as the term premium. The measure of how much extra return investors demand against unexpected developments over the life of the security approached the 45-year low set during last year’s global deflation scare, going by the Federal Reserve Bank of New York’s favored formula.
…
By the close of trading Friday, the market-implied chances of a rate cut by the end of 2016 had fallen to about one percent. Traders assign a 30 percent chance of a quarter-point increase by the end of 2016, down from a 93 percent probability seen at the end of last year.

Signs of distress were also evident in the Treasuries yield curve. It has yet to flash the traditional recession signal — short-term yields climbing above long-term yields. But that difference has shriveled. The gap between three-month and 10-year yields, which the Cleveland Fed uses as a growth indicator, narrowed to the smallest since 2012. The spread between two- and 10-year yields shrank to the slimmest since 2007.

termPremium
Click for Big

It was a mixed day for the Canadian preferred share market, with PerpetualDiscounts gaining 15bp, FixedResets off 72bp and DeemedRetractibles up 36bp. The Performance Highlights table was produced on schedule. Volume was average.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_160212
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 16.55 to be $1.42 rich, while TRP.PR.G, resetting 2020-11-30 at +296, is $0.94 cheap at its bid price of 16.90.

impVol_MFC_160212
Click for Big

Most expensive is MFC.PR.N, resetting at +230bp on 2020-3-19, bid at 16.50 to be 0.99 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 16.70 to be 1.05 cheap.

impVol_BAM_160212
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 12.32 to be $1.57 cheap. BAM.PF.H, resetting at +417M500bp on 2020-12-31 is bid at 25.04 and appears to be $1.00 rich.

impVol_FTS_160212
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 14.35, looks $0.55 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 13.80 and is $0.35 cheap.

pairs_FR_160212
Click for Big

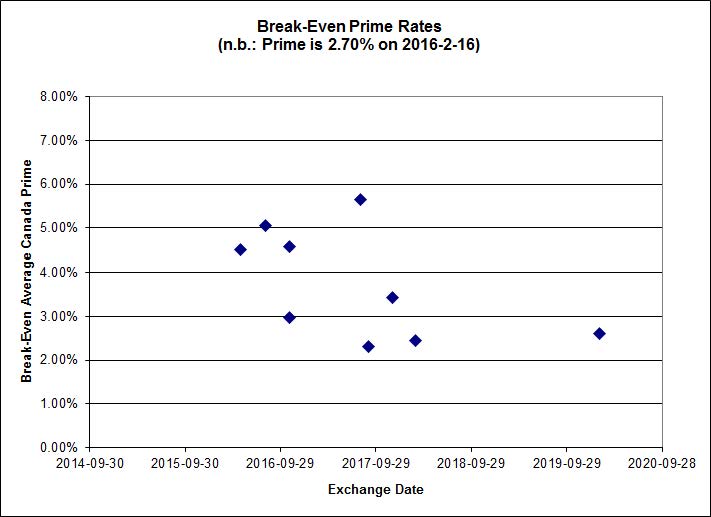
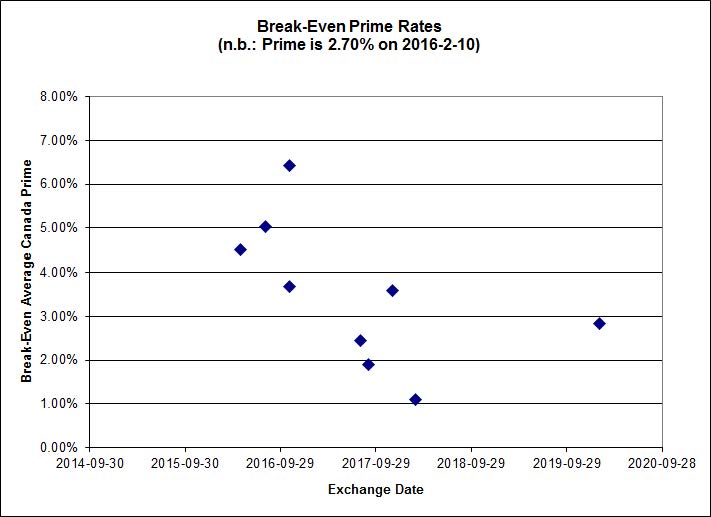
Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.53%, with one outlier above 0.50% and one below -1.50%. Note that the range of the y-axis has been changed. There are two junk outliers above 0.50% and three below -1.50%.

pairs_FF_160212
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.57 % 6.77 % 16,440 15.73 1 4.6512 % 1,399.8
FixedFloater 8.02 % 7.00 % 25,643 15.18 1 -1.2500 % 2,479.9
Floater 5.36 % 5.57 % 71,806 14.51 4 -0.5355 % 1,431.7
OpRet 0.00 % 0.00 % 0 0.00 0 0.4077 % 2,726.7
SplitShare 4.84 % 5.82 % 73,447 2.69 6 0.4077 % 3,190.8
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.4077 % 2,489.6
Perpetual-Premium 5.89 % 5.85 % 82,283 13.85 6 -0.2272 % 2,507.5
Perpetual-Discount 5.82 % 5.85 % 97,920 14.08 33 0.1471 % 2,487.2
FixedReset 5.82 % 5.16 % 212,416 14.23 83 -0.7230 % 1,745.5
Deemed-Retractible 5.34 % 5.75 % 125,241 5.19 34 0.3587 % 2,526.8
FloatingReset 3.11 % 4.84 % 50,367 5.53 16 -0.3591 % 1,967.4
Performance Highlights
Issue Index Change Notes
FTS.PR.H FixedReset -4.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 11.05
Evaluated at bid price : 11.05
Bid-YTW : 4.87 %
SLF.PR.G FixedReset -3.85 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.00
Bid-YTW : 11.79 %
BAM.PR.C Floater -3.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 8.39
Evaluated at bid price : 8.39
Bid-YTW : 5.71 %
BAM.PR.B Floater -3.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 8.45
Evaluated at bid price : 8.45
Bid-YTW : 5.67 %
MFC.PR.F FixedReset -3.45 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.20
Bid-YTW : 12.69 %
CM.PR.Q FixedReset -3.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 17.53
Evaluated at bid price : 17.53
Bid-YTW : 4.94 %
MFC.PR.J FixedReset -3.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.27
Bid-YTW : 9.42 %
MFC.PR.I FixedReset -3.19 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.28
Bid-YTW : 8.86 %
RY.PR.J FixedReset -3.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 17.29
Evaluated at bid price : 17.29
Bid-YTW : 4.93 %
GWO.PR.N FixedReset -2.92 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.96
Bid-YTW : 11.69 %
NA.PR.W FixedReset -2.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 15.11
Evaluated at bid price : 15.11
Bid-YTW : 5.12 %
IFC.PR.A FixedReset -2.69 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.00
Bid-YTW : 11.75 %
TRP.PR.F FloatingReset -2.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 10.95
Evaluated at bid price : 10.95
Bid-YTW : 5.46 %
BAM.PF.B FixedReset -2.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 15.20
Evaluated at bid price : 15.20
Bid-YTW : 5.69 %
IAG.PR.G FixedReset -2.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.76
Bid-YTW : 9.19 %
MFC.PR.K FixedReset -2.26 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.15
Bid-YTW : 10.08 %
SLF.PR.J FloatingReset -2.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.00
Bid-YTW : 12.45 %
MFC.PR.L FixedReset -2.19 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.60
Bid-YTW : 9.81 %
NA.PR.S FixedReset -2.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 16.39
Evaluated at bid price : 16.39
Bid-YTW : 4.89 %
CM.PR.P FixedReset -2.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 15.86
Evaluated at bid price : 15.86
Bid-YTW : 4.83 %
HSE.PR.C FixedReset -2.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 13.27
Evaluated at bid price : 13.27
Bid-YTW : 7.55 %
HSE.PR.G FixedReset -2.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 14.75
Evaluated at bid price : 14.75
Bid-YTW : 7.35 %
CM.PR.O FixedReset -1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 16.50
Evaluated at bid price : 16.50
Bid-YTW : 4.75 %
RY.PR.M FixedReset -1.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 17.14
Evaluated at bid price : 17.14
Bid-YTW : 4.85 %
RY.PR.H FixedReset -1.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 16.61
Evaluated at bid price : 16.61
Bid-YTW : 4.60 %
TRP.PR.H FloatingReset -1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 8.60
Evaluated at bid price : 8.60
Bid-YTW : 5.06 %
BMO.PR.S FixedReset -1.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 16.68
Evaluated at bid price : 16.68
Bid-YTW : 4.68 %
MFC.PR.H FixedReset -1.50 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.37
Bid-YTW : 8.23 %
PWF.PR.A Floater -1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 9.85
Evaluated at bid price : 9.85
Bid-YTW : 4.81 %
FTS.PR.G FixedReset -1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 13.80
Evaluated at bid price : 13.80
Bid-YTW : 5.24 %
TD.PF.E FixedReset -1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 18.73
Evaluated at bid price : 18.73
Bid-YTW : 4.74 %
HSE.PR.E FixedReset -1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 14.60
Evaluated at bid price : 14.60
Bid-YTW : 7.43 %
FTS.PR.K FixedReset -1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 14.35
Evaluated at bid price : 14.35
Bid-YTW : 5.01 %
TD.PF.A FixedReset -1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 16.48
Evaluated at bid price : 16.48
Bid-YTW : 4.65 %
BAM.PR.G FixedFloater -1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 25.00
Evaluated at bid price : 11.85
Bid-YTW : 7.00 %
RY.PR.Z FixedReset -1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 16.71
Evaluated at bid price : 16.71
Bid-YTW : 4.52 %
TRP.PR.G FixedReset -1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 16.90
Evaluated at bid price : 16.90
Bid-YTW : 5.47 %
FTS.PR.M FixedReset -1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 15.40
Evaluated at bid price : 15.40
Bid-YTW : 5.36 %
TD.PF.D FixedReset -1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 17.80
Evaluated at bid price : 17.80
Bid-YTW : 4.86 %
TD.PF.C FixedReset -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 16.42
Evaluated at bid price : 16.42
Bid-YTW : 4.65 %
BMO.PR.Y FixedReset -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 18.40
Evaluated at bid price : 18.40
Bid-YTW : 4.66 %
BNS.PR.D FloatingReset -1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.24
Bid-YTW : 8.07 %
CIU.PR.C FixedReset -1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 9.80
Evaluated at bid price : 9.80
Bid-YTW : 5.00 %
NA.PR.Q FixedReset 1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.55
Bid-YTW : 5.21 %
TRP.PR.D FixedReset 1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 15.66
Evaluated at bid price : 15.66
Bid-YTW : 5.08 %
SLF.PR.D Deemed-Retractible 1.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.99
Bid-YTW : 7.71 %
SLF.PR.H FixedReset 1.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.45
Bid-YTW : 11.29 %
BAM.PR.R FixedReset 1.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 12.32
Evaluated at bid price : 12.32
Bid-YTW : 6.06 %
PVS.PR.B SplitShare 1.46 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2019-01-10
Maturity Price : 25.00
Evaluated at bid price : 24.40
Bid-YTW : 5.59 %
PWF.PR.S Perpetual-Discount 1.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 20.90
Evaluated at bid price : 20.90
Bid-YTW : 5.80 %
GWO.PR.I Deemed-Retractible 1.70 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.39
Bid-YTW : 7.48 %
BAM.PR.Z FixedReset 2.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 16.32
Evaluated at bid price : 16.32
Bid-YTW : 5.75 %
BAM.PR.E Ratchet 4.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 25.00
Evaluated at bid price : 12.15
Bid-YTW : 6.77 %
BAM.PR.K Floater 7.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 8.60
Evaluated at bid price : 8.60
Bid-YTW : 5.57 %
Volume Highlights
Issue Index Shares
Traded
Notes
BAM.PR.X FixedReset 149,544 Desjardins crossed blocks of 103,000 and 40,000, both at 11.30.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 11.35
Evaluated at bid price : 11.35
Bid-YTW : 5.77 %
BAM.PF.E FixedReset 118,920 Desjardins crossed 109,000 at 16.00.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 16.00
Evaluated at bid price : 16.00
Bid-YTW : 5.46 %
PWF.PR.P FixedReset 81,969 Desjardins crossed blocks of 22,600 and 50,000, both at 11.68.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 11.55
Evaluated at bid price : 11.55
Bid-YTW : 4.85 %
BNS.PR.Z FixedReset 58,615 TD crossed 49,700 at 18.30.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.50
Bid-YTW : 7.57 %
RY.PR.Q FixedReset 46,900 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 23.26
Evaluated at bid price : 25.37
Bid-YTW : 5.12 %
NA.PR.X FixedReset 32,554 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 23.11
Evaluated at bid price : 24.90
Bid-YTW : 5.51 %
There were 33 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BAM.PF.E FixedReset Quote: 16.00 – 18.48
Spot Rate : 2.4800
Average : 1.5742

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 16.00
Evaluated at bid price : 16.00
Bid-YTW : 5.46 %

ELF.PR.F Perpetual-Discount Quote: 21.95 – 22.42
Spot Rate : 0.4700
Average : 0.3193

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 21.70
Evaluated at bid price : 21.95
Bid-YTW : 6.10 %

TD.PR.S FixedReset Quote: 23.31 – 23.80
Spot Rate : 0.4900
Average : 0.3540

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.31
Bid-YTW : 4.03 %

BMO.PR.T FixedReset Quote: 16.41 – 16.93
Spot Rate : 0.5200
Average : 0.3849

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 16.41
Evaluated at bid price : 16.41
Bid-YTW : 4.64 %

ELF.PR.H Perpetual-Discount Quote: 22.61 – 23.03
Spot Rate : 0.4200
Average : 0.2890

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 22.32
Evaluated at bid price : 22.61
Bid-YTW : 6.14 %

BAM.PR.X FixedReset Quote: 11.35 – 11.78
Spot Rate : 0.4300
Average : 0.3003

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-12
Maturity Price : 11.35
Evaluated at bid price : 11.35
Bid-YTW : 5.77 %

Market Action

February 11, 2016

Assiduous Reader prefobsessed sent me a link to a Barry Critchley piece titled Behind RioCan’s decision to redeem its first-of-its-kind rate reset preferreds. I have updated the post that reported REI.PR.A to be Redeemed.

Meanwhile, Sweden’s gone more deeply negative:

Sweden’s central bank lowered its key interest rate even further below zero and said it’s prepared to use its full toolbox of measures as it battles to revive inflation and keep the krona from appreciating.

The repo rate was reduced to minus 0.50 percent from minus 0.35 percent, the Stockholm-based bank said. A cut was predicted by 10 of the 18 analysts surveyed by Bloomberg, though only three had anticipated this magnitude. The bank said government bond purchases will continue as planned for the first six months of 2016 and that it “will reinvest maturities and coupons from the government bond portfolio until further notice.”

“Uncertainty regarding global developments is still high, with low inflation and several central banks pursuing more expansionary monetary policy,” the Riksbank said. “Swedish monetary policy must relate to this. Otherwise the krona exchange rate is at risk of strengthening at a faster rate than in the forecast, which would make it harder to push up inflation and stabilize it around 2 percent.”

There are fears that this policy will inflate a housing bubble:

HSBC economist James Pomeroy wrote in a recent note:

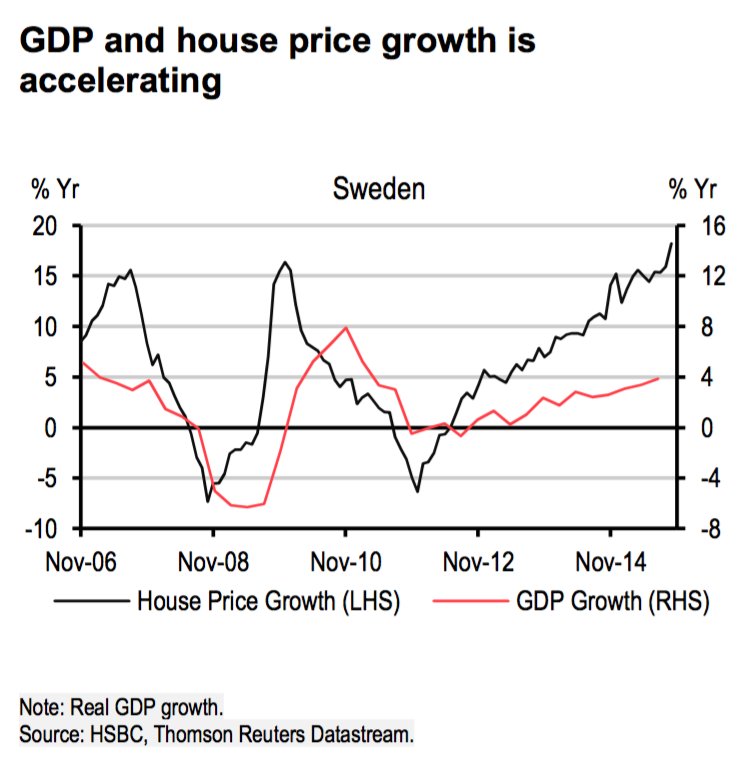
We’ve long argued that the Swedish economy does not warrant further stimulus, but that the Riksbank would continue to ease given the low inflation rate. The economy is the fastest growing in the developed world (3.9% y-o-y in Q3) and house prices continue to accelerate and are now up 18% y-o-y across the country. Under normal circumstances, one might expect the Riksbank to be hiking rates but – given ultra-loose ECB policy – rates are being kept much lower.

As positive as the story appears for early 2016, there are plenty of reasons to be concerned about the medium term. The pace of acceleration in the housing market points to a bubble.
…
… The housing market continues to pose significant risks for the Swedish economy. With prices now up 18% on the year and no sign of macroprudential measures coming into force, we worry that this is not sustainable. Should the housing market roll over at any point in 2016 (or 2017) the impact on the economy would be severe. Estimates from the National Institute of Economic Research suggest that a 20% fall in house prices would lead to a recession-like impact on consumption and unemployment, with a smaller fall still having severe economic consequences.

swedishHousing
Click for Big

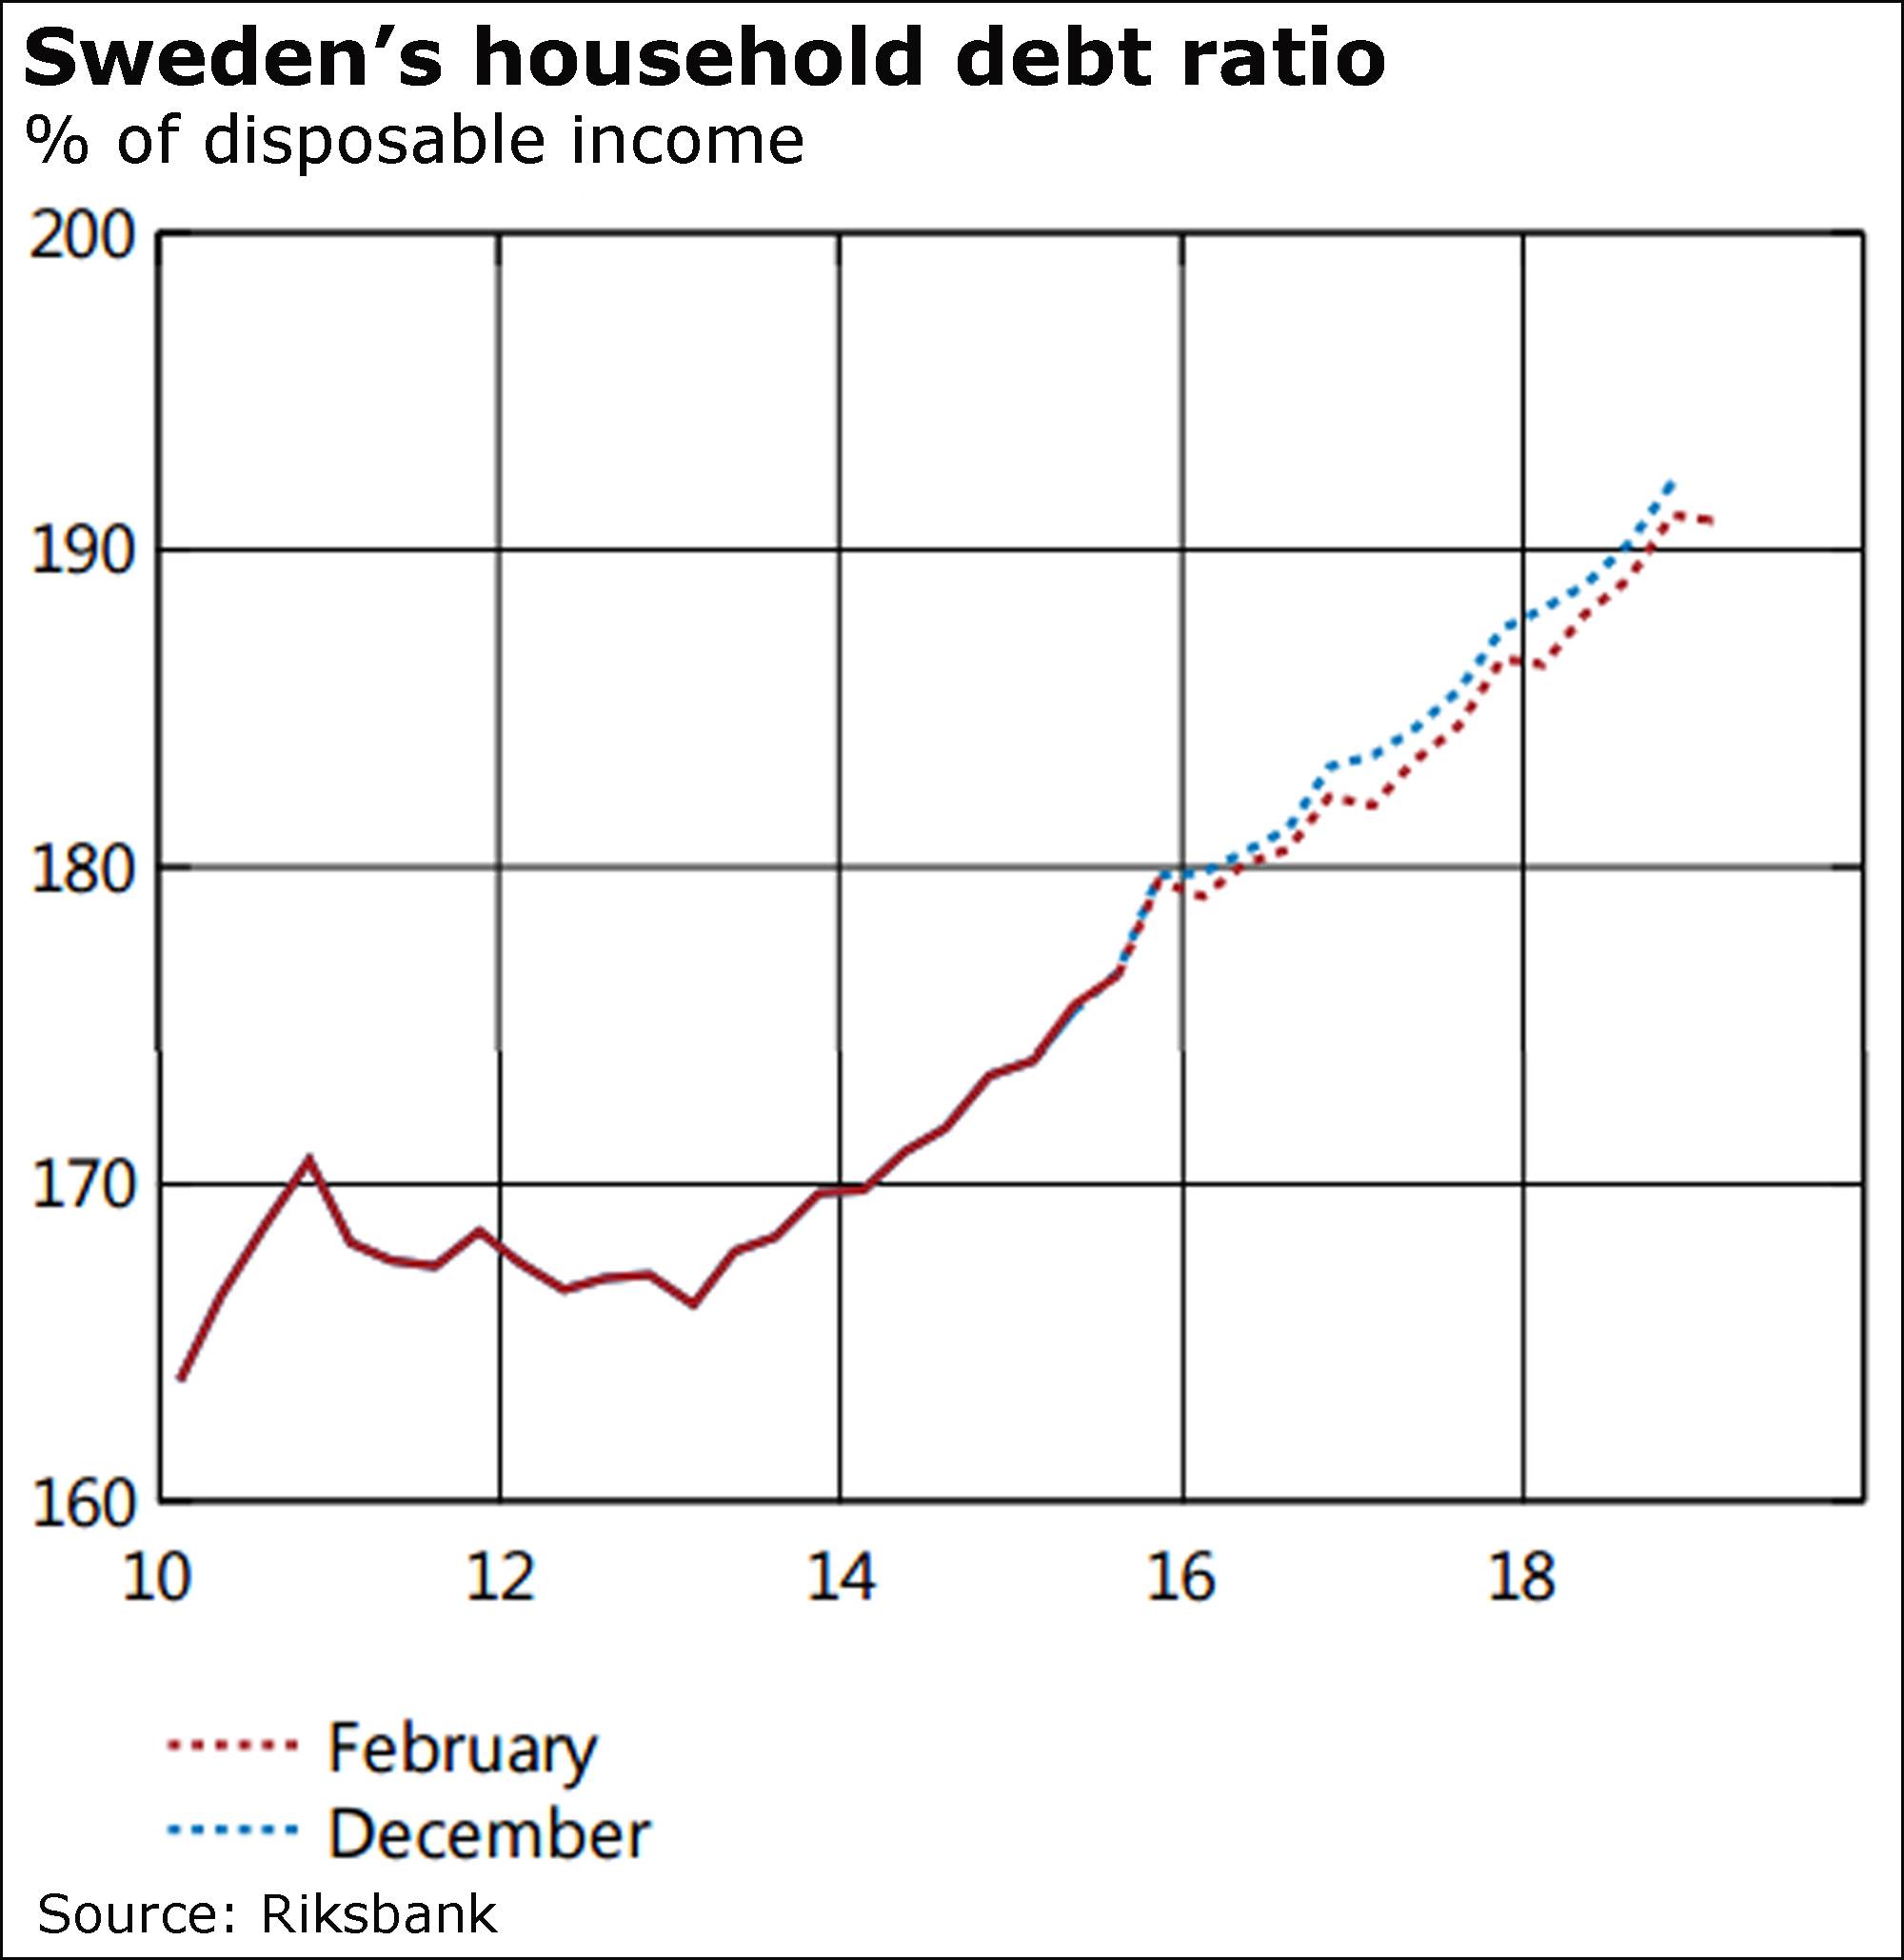
And Michael Babad of the Globe supplies another chart:

swedendebt
Click for Big

The Swedish action has been fingered as one of the triggers for today’s debacle:

The latest culprits picked out of the police lineup: The Swedish central bank’s bigger bet on negative interest rates; Fed chief Janet Yellen’s testimony before largely clueless U.S. legislators; and bearish hedge-fund manager Kyle Bass’s assertion that Chinese banks are facing huge losses that dwarf those of the U.S. financial system in the 2008 crash.

All are fanning fears that another U.S. and global recession looms, that central banks have run out of ammunition to fight it the way they did during the previous financial crisis and that more than a few of the world’s major banks aren’t in good enough shape to withstand the ensuing fallout.

… and what a debacle it was!

Fearful investors have turned to the health of the global banking system as the latest fixation in a market frenzy that continues to escalate.

Bank equities were trounced worldwide on Thursday, leading the way for an all-consuming stock market selloff that spared no major benchmark.

An overwhelming demand for safety dominated investor attitudes, as the ability of central banks to fend off economic threats seems increasingly doubtful.

While crude oil has been at the crux of the recent outburst of market volatility, bank valuations have now begun to reflect a grim assessment of the global economy.
…
Withering risk appetite gripped equities on Thursday, as major Asian and European indexes fell by between 2 per cent and 6 per cent, adding to global equity losses in excess of $15-trillion (U.S.) this year.

In North America, the S&P 500 index dipped to a new two-year low before a late afternoon rally pared back the losses to end the day down by 1.2 per cent. The Nasdaq composite index meanwhile flirted with a 20-per-cent decline conventionally signifying bear market territory. That’s where the S&P/TSX composite index already resides, with Thursday’s 100-point drop adding to a total decline of 23 per cent since September, 2014.

Overnight markets, at time of writing, seem to be getting worse:

The global equity bear market deepened in Asian trading, with Japanese stocks headed for their worst week since 2008 amid anxiety over central banks’ ability to revive the world economy. U.S. crude rose from a 12-year low.

The Topix index slumped 4.1 percent in Tokyo as traders returned from holiday, pushing the regional Asian benchmark toward its steepest weekly drop since gyrations in Chinese assets at the start of the year. The index pared some of its losses as the yen weakened for the first time this week. U.S. index futures indicated gains after losses there helped the MSCI All-Country Index cap a 20 percent slide from its May record.

…and in Korea:

Trading in South Korea’s Kosdaq exchange for smaller stocks was temporarily halted after the benchmark gauge plunged more than 8 percent on concern valuations were excessive relative to earnings prospects.

Trading was suspended for 20 minutes at 11:55 a.m. in Seoul after the measure dropped 8.2 percent. The index pared declines to 6.1 percent at the close. Celltrion Inc. was the biggest drag on the small-cap measure after the stock almost tripled in the past 12 months. The Kospi gauge of larger companies closed at its lowest level since August.

The Kosdaq index of more than 1,100 companies jumped 26 percent to outperform the large-cap gauge last year as investors piled into biotech shares and other smaller companies in search of earnings growth as smokestack industries stagnated. Celltrion, which developed an arthritis medicine, trades at 42 times projected 12 month profits, four times the Kospi’s 10.5 times.

And there are, as I always like to point out … unintended consequences:

It seemed like a good idea at the time: Cut interest rates below zero to revive growth.

But as policy makers from Tokyo to Stockholm embrace the notion, investors are close to panic mode. Far from buoying financial markets this year, negative rates have helped to put global stocks on the brink of a bear market, sent the cost of protection against corporate defaults soaring and driven investors to havens such as U.S. Treasury bonds and gold.

Fueling the turmoil is fear that negative rates will slam the world’s banks. In theory, negative rates could be the panacea to cure sluggish global growth: by charging lenders fees for parking money at central banks, policy makers hope banks will use that cash to make loans, jump-starting their economies. In practice, investors worry it may squeeze bank profits and rattle money markets.

“We’re here in an environment where central banks have to learn one message, and that is that negative interest rates are not desirable and they are not workable,” Hans Redeker, head of global foreign-exchange strategy at Morgan Stanley in London, said in a Bloomberg Television interview. “When you cut into negative interest rates you have to think about the profitability of the banking sector.”

About a quarter of the world economy is now in negative-rate territory with more than $7 trillion of government debt offering yields less than zero.

Last October, BIS published a working paper by Claudio Borio, Leonardo Gambacorta and Boris Hofmann titled The influence of monetary policy on bank profitability:

This paper investigates how monetary policy affects bank profitability. We use data for 109 large international banks headquartered in 14 major advanced economies for the period 1995–2012. Overall, we find a positive relationship between the level of short-term rates and the slope of the yield curve (the “interest rate structure”, for short), on the one hand, and bank profitability – return on assets – on the other. This suggests that the positive impact of the interest rate structure on net interest income dominates the negative one on loan loss provisions and on non-interest income. We also find that the effect is stronger when the interest rate level is lower and the slope less steep, ie that non-linearities are present. All this suggests that, over time, unusually low interest rates and an unusually flat term structure erode bank profitability.
…
Abstracting from macroeconomic effects, our findings help shed light on the impact of monetary policy on bank profitability after the crisis. Taking our results at face value, we find that the impact, on balance, was positive in the first two years post-crisis (2009–10) but turned negative in the following four years (2011–14). In the first two years, ROA was boosted by an estimated cumulative 0.3 percentage points: the negative effect on bank profitability linked to the decrease in the short-term rate was more than compensated for by the positive one deriving from the increase in the yield curve slope. In contrast, in the following four years, the further decrease in short-term rates and flattening of the yield curve cut ROA by an estimated cumulative 0.6 percentage points. With an average annual ROA of 0.64 over the sample period (1995-2012, Table 1), this means that over 2011–14, the average bank in the sample lost one year of profits as a consequence of low interest rates and compressed yield spreads.

Anybody who finds all this depressing should relax; read a nice book instead:

EndOfTheWorldNews
Click for Big

It was a horrible day for the Canadian preferred share market, horribler for some sectors than for others, with PerpetualDiscounts off 25bp, FixedResets losing 234bp and DeemedRetractibles down 65bp. Floaters got destroyed. Volume was high.

For those keeping track of Floaters, the all-time low closing bid for BAM.PR.B was 5.90 on 2008-12-19; for BAM.PR.C it was 6.06 on 2008-12-22; and for BAM.PR.K, 6.40 ON 2018-12-18. So we’re still a way off from my positive comments during the Credit Crunch. But some people, I’m sure, are just discovering the answer to the question: Are Floating Prefs Money Market Vehicles?.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_160211
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 16.50 to be $1.34 rich, while TRP.PR.G, resetting 2020-11-30 at +296, is $0.80 cheap at its bid price of 17.11.

impVol_MFC_160211
Click for Big

Most expensive is MFC.PR.L, resetting at +216bp on 2019-6-19, bid at 15.95 to be 0.70 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 16.80 to be 1.33 cheap.

impVol_BAM_160211
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 12.15 to be $1.58 cheap. BAM.PF.E, resetting at +255bp on 2020-3-31 is bid at 15.95 and appears to be $1.00 rich.

impVol_FTS_160211
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 14.80, looks $0.49 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 14.25 and is $0.43 cheap.

pairs_FR_160211A
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.56%, with two outliers above 0.00%. There are four junk outliers above 0.00% and one below -2.00%.

pairs_FF_160211
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.83 % 7.07 % 17,116 15.38 1 -9.2969 % 1,337.6
FixedFloater 7.92 % 6.91 % 24,790 15.28 1 -2.8340 % 2,511.3
Floater 5.33 % 5.46 % 72,273 14.68 4 -11.9821 % 1,439.4
OpRet 0.00 % 0.00 % 0 0.00 0 0.0484 % 2,715.6
SplitShare 4.86 % 6.13 % 74,068 2.68 6 0.0484 % 3,177.8
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0484 % 2,479.5
Perpetual-Premium 5.87 % 5.85 % 85,307 13.97 6 0.3488 % 2,513.2
Perpetual-Discount 5.82 % 5.86 % 100,435 14.08 33 -0.2549 % 2,483.5
FixedReset 5.77 % 5.07 % 214,342 14.37 83 -2.3397 % 1,758.2
Deemed-Retractible 5.36 % 5.89 % 125,449 5.19 34 -0.6488 % 2,517.8
FloatingReset 3.08 % 4.83 % 50,523 5.53 16 0.3917 % 1,974.5
Performance Highlights
Issue Index Change Notes
BAM.PR.K Floater -18.37 % Only half real, but many will consider half to be rather more than enough! The issue traded 9,000 shares in a range of 8.99-85 before closing at 8.00-9.01, 5×1. The day’s low had been 9.58 until five trades totalling 600 shares took the price down to the day’s low in the last ten minutes of the day. It’s a good thing there was a market maker on duty to maintain an orderly market, eh? I have not checked whether this lamentable state of affairs is due to inadequate Toronto Stock Exchange reporting or inadequate Toronto Stock Exchange supervision of market-makers.

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 8.00
Evaluated at bid price : 8.00
Bid-YTW : 5.99 %

BAM.PR.B Floater -11.52 % Entirely real. The issue traded 10,420 shares in a range of 9.00-73 before closing at 8.76-00, 1×252. Not a typo! There were 25,200 shares being offered at 9.00 at the close!

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 8.76
Evaluated at bid price : 8.76
Bid-YTW : 5.46 %

BAM.PR.C Floater -10.66 % Totally real. The issue traded 8,990 shares in a range of 8.85-9.65 before closing at 8.72-85, 2×504. Yup … 504. There were 50,400 shares offered at 8.85 at the close.

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 8.72
Evaluated at bid price : 8.72
Bid-YTW : 5.49 %

BAM.PR.E Ratchet -9.30 % Not really all that real, since the issue traded 1,675 shares in a range of 12.40-80 before closing at 11.61-12.86 (!) 12×3. However, the bid probably dropped in sympathy with BAM’s floaters, above.

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 25.00
Evaluated at bid price : 11.61
Bid-YTW : 7.07 %

PWF.PR.A Floater -7.83 % Not real, since the issue traded 1,966 shares in a range of 10.19-86 before closing at 10.00-45, 1×1. As above, however, it’s reasonable to assume that bidders backed off when they saw what was happening to BAM’s floaters.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 10.00
Evaluated at bid price : 10.00
Bid-YTW : 4.73 %
BAM.PR.Z FixedReset -7.62 % Not real. The issue traded 7,410 shares in a range of 16.45-34 before closing at 15.89-16.90 (!) 8×5. I have not checked whether this lamentable state of affairs is due to inadequate Toronto Stock Exchange reporting or inadequate Toronto Stock Exchange supervision of market-makers.

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 15.89
Evaluated at bid price : 15.89
Bid-YTW : 5.79 %

SLF.PR.H FixedReset -6.73 % Not real. The issue traded 11,590 shares in a range of 13.75-10 before closing at 13.30-92, 5×6. I have not checked whether this lamentable state of affairs is due to inadequate Toronto Stock Exchange reporting or inadequate Toronto Stock Exchange supervision of market-makers.

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.30
Bid-YTW : 11.33 %

FTS.PR.M FixedReset -6.16 % Real enough, as the issue traded 13,016 shares in a range of 15.80-05 before closing at 15.85-25, 2×10.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 15.85
Evaluated at bid price : 15.85
Bid-YTW : 5.21 %
SLF.PR.I FixedReset -5.37 % Real enough, since the issue traded 3,392 shares in a range of 15.76-58 before closing at 15.85-29, 5×4.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.85
Bid-YTW : 9.66 %
BAM.PF.F FixedReset -4.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 17.25
Evaluated at bid price : 17.25
Bid-YTW : 5.31 %
MFC.PR.I FixedReset -4.44 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.85
Bid-YTW : 8.31 %
BAM.PF.A FixedReset -4.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 16.78
Evaluated at bid price : 16.78
Bid-YTW : 5.41 %
MFC.PR.J FixedReset -4.38 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.82
Bid-YTW : 8.87 %
IFC.PR.C FixedReset -4.38 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.30
Bid-YTW : 10.02 %
MFC.PR.G FixedReset -4.33 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.80
Bid-YTW : 9.08 %
MFC.PR.H FixedReset -4.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.65
Bid-YTW : 7.92 %
TRP.PR.A FixedReset -3.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 13.12
Evaluated at bid price : 13.12
Bid-YTW : 5.05 %
IFC.PR.A FixedReset -3.88 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.36
Bid-YTW : 11.26 %
TRP.PR.D FixedReset -3.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 15.50
Evaluated at bid price : 15.50
Bid-YTW : 5.02 %
TD.PF.D FixedReset -3.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 4.72 %
BAM.PF.G FixedReset -3.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 16.95
Evaluated at bid price : 16.95
Bid-YTW : 5.45 %
MFC.PR.L FixedReset -3.63 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.95
Bid-YTW : 9.43 %
TRP.PR.B FixedReset -3.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 9.55
Evaluated at bid price : 9.55
Bid-YTW : 4.99 %
HSE.PR.A FixedReset -3.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 8.01
Evaluated at bid price : 8.01
Bid-YTW : 7.13 %
IAG.PR.G FixedReset -3.49 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.15
Bid-YTW : 8.77 %
NA.PR.Q FixedReset -3.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.32
Bid-YTW : 5.34 %
MFC.PR.M FixedReset -3.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.61
Bid-YTW : 9.07 %
BAM.PF.B FixedReset -3.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 15.60
Evaluated at bid price : 15.60
Bid-YTW : 5.43 %
TD.PF.E FixedReset -3.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 4.59 %
BAM.PR.T FixedReset -3.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 12.70
Evaluated at bid price : 12.70
Bid-YTW : 5.87 %
HSE.PR.G FixedReset -3.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 15.06
Evaluated at bid price : 15.06
Bid-YTW : 7.09 %
NA.PR.S FixedReset -3.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 16.75
Evaluated at bid price : 16.75
Bid-YTW : 4.68 %
RY.PR.M FixedReset -2.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 17.45
Evaluated at bid price : 17.45
Bid-YTW : 4.67 %
MFC.PR.N FixedReset -2.94 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.50
Bid-YTW : 9.10 %
BNS.PR.Y FixedReset -2.90 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.75
Bid-YTW : 6.95 %
SLF.PR.G FixedReset -2.88 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.48
Bid-YTW : 11.19 %
NA.PR.W FixedReset -2.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 15.55
Evaluated at bid price : 15.55
Bid-YTW : 4.87 %
BAM.PR.G FixedFloater -2.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 25.00
Evaluated at bid price : 12.00
Bid-YTW : 6.91 %
FTS.PR.G FixedReset -2.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 14.25
Evaluated at bid price : 14.25
Bid-YTW : 5.06 %
MFC.PR.K FixedReset -2.70 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.50
Bid-YTW : 9.68 %
BNS.PR.Z FixedReset -2.70 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.40
Bid-YTW : 7.66 %
HSE.PR.E FixedReset -2.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 14.80
Evaluated at bid price : 14.80
Bid-YTW : 7.22 %
FTS.PR.K FixedReset -2.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 14.80
Evaluated at bid price : 14.80
Bid-YTW : 4.85 %
BMO.PR.T FixedReset -2.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 16.51
Evaluated at bid price : 16.51
Bid-YTW : 4.50 %
CU.PR.C FixedReset -2.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 15.30
Evaluated at bid price : 15.30
Bid-YTW : 4.88 %
FTS.PR.H FixedReset -2.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 11.70
Evaluated at bid price : 11.70
Bid-YTW : 4.54 %
TRP.PR.C FixedReset -2.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 10.40
Evaluated at bid price : 10.40
Bid-YTW : 5.11 %
PWF.PR.T FixedReset -2.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 19.45
Evaluated at bid price : 19.45
Bid-YTW : 3.98 %
HSE.PR.C FixedReset -2.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 13.55
Evaluated at bid price : 13.55
Bid-YTW : 7.27 %
TRP.PR.E FixedReset -2.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 16.50
Evaluated at bid price : 16.50
Bid-YTW : 4.80 %
BNS.PR.D FloatingReset -2.35 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.42
Bid-YTW : 7.87 %
TD.PF.A FixedReset -2.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 16.70
Evaluated at bid price : 16.70
Bid-YTW : 4.49 %
CM.PR.Q FixedReset -2.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 18.13
Evaluated at bid price : 18.13
Bid-YTW : 4.69 %
SLF.PR.J FloatingReset -2.26 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.25
Bid-YTW : 12.12 %
TRP.PR.G FixedReset -2.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 17.11
Evaluated at bid price : 17.11
Bid-YTW : 5.31 %
BAM.PR.X FixedReset -2.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 11.25
Evaluated at bid price : 11.25
Bid-YTW : 5.64 %
BIP.PR.A FixedReset -2.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 17.27
Evaluated at bid price : 17.27
Bid-YTW : 6.16 %
BMO.PR.W FixedReset -2.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 16.41
Evaluated at bid price : 16.41
Bid-YTW : 4.50 %
RY.PR.I FixedReset -2.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.30
Bid-YTW : 4.30 %
GWO.PR.H Deemed-Retractible -2.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.15
Bid-YTW : 7.35 %
TD.PF.B FixedReset -2.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 16.61
Evaluated at bid price : 16.61
Bid-YTW : 4.50 %
CM.PR.O FixedReset -2.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 16.80
Evaluated at bid price : 16.80
Bid-YTW : 4.56 %
BMO.PR.Q FixedReset -1.92 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.85
Bid-YTW : 7.94 %
BNS.PR.Q FixedReset -1.88 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.02
Bid-YTW : 4.45 %
BNS.PR.P FixedReset -1.88 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.55
Bid-YTW : 4.01 %
BMO.PR.R FloatingReset -1.83 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.40
Bid-YTW : 4.83 %
FTS.PR.I FloatingReset -1.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 9.55
Evaluated at bid price : 9.55
Bid-YTW : 5.00 %
RY.PR.H FixedReset -1.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 16.90
Evaluated at bid price : 16.90
Bid-YTW : 4.42 %
RY.PR.J FixedReset -1.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 17.85
Evaluated at bid price : 17.85
Bid-YTW : 4.68 %
CM.PR.P FixedReset -1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 16.20
Evaluated at bid price : 16.20
Bid-YTW : 4.63 %
GWO.PR.Q Deemed-Retractible -1.63 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.31
Bid-YTW : 6.91 %
RY.PR.Z FixedReset -1.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 16.92
Evaluated at bid price : 16.92
Bid-YTW : 4.36 %
PWF.PR.P FixedReset -1.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 11.51
Evaluated at bid price : 11.51
Bid-YTW : 4.74 %
SLF.PR.E Deemed-Retractible -1.58 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.98
Bid-YTW : 7.77 %
BMO.PR.M FixedReset -1.57 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.25
Bid-YTW : 4.02 %
BAM.PR.R FixedReset -1.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 12.15
Evaluated at bid price : 12.15
Bid-YTW : 5.98 %
SLF.PR.D Deemed-Retractible -1.44 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.78
Bid-YTW : 7.86 %
BMO.PR.S FixedReset -1.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 16.95
Evaluated at bid price : 16.95
Bid-YTW : 4.50 %
TD.PR.T FloatingReset -1.38 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.50
Bid-YTW : 4.69 %
MFC.PR.F FixedReset -1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.60
Bid-YTW : 12.07 %
GWO.PR.I Deemed-Retractible -1.33 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.05
Bid-YTW : 7.72 %
BMO.PR.Y FixedReset -1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 18.60
Evaluated at bid price : 18.60
Bid-YTW : 4.53 %
SLF.PR.C Deemed-Retractible -1.28 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.04
Bid-YTW : 7.67 %
TD.PR.Y FixedReset -1.26 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.55
Bid-YTW : 3.98 %
SLF.PR.A Deemed-Retractible -1.25 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.25
Bid-YTW : 7.17 %
ELF.PR.H Perpetual-Discount -1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 22.28
Evaluated at bid price : 22.57
Bid-YTW : 6.15 %
CCS.PR.C Deemed-Retractible -1.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.11
Bid-YTW : 7.55 %
TD.PF.C FixedReset -1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 16.60
Evaluated at bid price : 16.60
Bid-YTW : 4.50 %
RY.PR.L FixedReset -1.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.51
Bid-YTW : 4.11 %
GWO.PR.R Deemed-Retractible -1.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.00
Bid-YTW : 7.40 %
BAM.PR.N Perpetual-Discount -1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 19.27
Evaluated at bid price : 19.27
Bid-YTW : 6.26 %
BNS.PR.N Deemed-Retractible -1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.85
Bid-YTW : 5.43 %
SLF.PR.B Deemed-Retractible -1.02 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.40
Bid-YTW : 7.12 %
CIU.PR.C FixedReset -1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 9.90
Evaluated at bid price : 9.90
Bid-YTW : 4.75 %
PWF.PR.O Perpetual-Premium 1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 24.40
Evaluated at bid price : 24.91
Bid-YTW : 5.85 %
PWF.PR.H Perpetual-Premium 1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 24.57
Evaluated at bid price : 24.82
Bid-YTW : 5.83 %
GWO.PR.N FixedReset 1.40 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.32
Bid-YTW : 11.24 %
RY.PR.W Perpetual-Discount 1.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 22.66
Evaluated at bid price : 22.90
Bid-YTW : 5.36 %
BAM.PF.E FixedReset 2.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 15.95
Evaluated at bid price : 15.95
Bid-YTW : 5.38 %
PWF.PR.Q FloatingReset 32.39 % Just a pullback from yesterday‘s nonsense.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 10.75
Evaluated at bid price : 10.75
Bid-YTW : 4.76 %
Volume Highlights
Issue Index Shares
Traded
Notes
NA.PR.X FixedReset 167,480 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 23.08
Evaluated at bid price : 24.81
Bid-YTW : 5.47 %
RY.PR.Q FixedReset 167,128 Scotia crossed blocks of 20,000 and 91,500, both at 25.42.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 23.26
Evaluated at bid price : 25.35
Bid-YTW : 5.07 %
TD.PF.G FixedReset 94,653 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 23.26
Evaluated at bid price : 25.35
Bid-YTW : 5.13 %
POW.PR.C Perpetual-Premium 78,100 TD crossed 67,800 at 24.80.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 24.50
Evaluated at bid price : 24.75
Bid-YTW : 5.92 %
BMO.PR.R FloatingReset 61,900 Scotia crossed blocks of 20,000 and 40,000, both at 21.50.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.40
Bid-YTW : 4.83 %
BNS.PR.E FixedReset 50,782 Scotia crossed 29,000 at 25.45.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 23.24
Evaluated at bid price : 25.27
Bid-YTW : 5.07 %
There were 47 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BAM.PR.E Ratchet Quote: 11.61 – 12.86
Spot Rate : 1.2500
Average : 0.6887

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 25.00
Evaluated at bid price : 11.61
Bid-YTW : 7.07 %

BAM.PR.K Floater Quote: 8.00 – 9.01
Spot Rate : 1.0100
Average : 0.6016

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 8.00
Evaluated at bid price : 8.00
Bid-YTW : 5.99 %

BAM.PF.G FixedReset Quote: 16.95 – 18.00
Spot Rate : 1.0500
Average : 0.6512

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 16.95
Evaluated at bid price : 16.95
Bid-YTW : 5.45 %

RY.PR.K FloatingReset Quote: 22.00 – 22.83
Spot Rate : 0.8300
Average : 0.5400

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.00
Bid-YTW : 4.62 %

BAM.PR.Z FixedReset Quote: 15.89 – 16.90
Spot Rate : 1.0100
Average : 0.7364

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 15.89
Evaluated at bid price : 15.89
Bid-YTW : 5.79 %

FTS.PR.K FixedReset Quote: 14.80 – 15.50
Spot Rate : 0.7000
Average : 0.4491

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-11
Maturity Price : 14.80
Evaluated at bid price : 14.80
Bid-YTW : 4.85 %

Market Action

February 10, 2016

Treasuries continued to climb today:

Treasury 10-year notes gained, pushing yields near a one-year low, as Federal Reserve Chair Janet Yellen stuck to her call for gradual interest-rate increases.

Government bonds are surging this year as turmoil in equity and commodity markets boosts demand for fixed-income assets amid concern that global growth is slowing. Declining inflation expectations have supported longer-dated Treasuries, with the gap between yields on two-year notes and 10-year securities falling to the lowest in more than eight years. An auction of 10-year notes drew the lowest yield since 2012.

Yellen emphasized the Fed’s intent to hike rates; the schedule is up in the air:

In presenting the Fed’s semi-annual economic report to Congress, Yellen said the turbulence had “significantly” tightened financial conditions by pushing down stock prices, pushing up the dollar and raising some borrowing costs.

“These developments, if they prove persistent, could weigh on the outlook for economic activity and the labor market,” she told the House Financial Services Committee.

Yellen though made clear that the policy-setting Federal Open Market Committee remains committed to gradually raising rates, after increasing them in December for the first time in nine years.

“I do not expect the FOMC is going to be soon in a situation where it’s necessary to cut rates,” she added.

… and she suggested laws need to be clarified to allow for negative rates:

The Federal Reserve has not yet determined whether it would be able to legally implement negative interest rates in the U.S., Chair Janet Yellen said.

“I would say that remains a question that we still would need to investigate more thoroughly,” Yellen said Wednesday in response to questions from the House Financial Services Committee in Washington. “I am not aware of anything that would prevent us from doing it, but I’m saying we have not fully investigated the legal issues — that still needs to be done.”

A 2010 staff memo posted on the central bank’s website late last month cast doubt on whether the law that authorized the Fed to pay interest on excess reserves, or IOER, also would grant it the authority to charge interest.

DBRS put Algonquin Power & Utilities Corp. on Review-Developing; I have updated the post regarding S&P’s negative outlook.

It was a mixed day for the Canadian preferred share market, with PerpetualDiscounts gaining 16bp, FixedResets off 79bp and DeemedRetractibles up 38bp. The Performance Highlights table highlights very poor performance from the FTS issues, presumably as a result of worries regarding their credit quality. Volume was slightly below average.

PerpetualDiscounts now yield 5.85%, equivalent to 7.60% interest at the standard equivalency factor of 1.3x. Long corporates now yield about 4.1% (maybe a little more) so the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) is now about 350bp, a significant increase from the 335bp reported February 3.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_160210
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 16.90 to be $1.28 rich, while TRP.PR.G, resetting 2020-11-30 at +296, is $0.87 cheap at its bid price of 17.50.

impVol_MFC_160210
Click for Big

Most expensive is MFC.PR.L, resetting at +216bp on 2019-6-19, bid at 16.55 to be 0.69 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 17.56 to be 1.18 cheap.

impVol_BAM_160210
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 12.33 to be $1.77 cheap. BAM.PF.F, resetting at +286bp on 2019-9-30 is bid at 18.10 and appears to be $1.16 rich.

impVol_FTS_160210
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 15.21, looks $0.34 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 14.65 and is $0.61 cheap.

pairs_FR_160210
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -1.01%, with one outlier below -2.00% and one above 0.00%. Note that the range of the y-axis has changed. There are two junk outliers above 0.00%.

pairs_FF_160210
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.29 % 6.43 % 17,068 16.14 1 0.0000 % 1,474.7
FixedFloater 7.69 % 6.72 % 24,685 15.52 1 0.0000 % 2,584.5
Floater 4.69 % 4.83 % 72,175 15.77 4 0.4736 % 1,635.3
OpRet 0.00 % 0.00 % 0 0.00 0 0.1177 % 2,714.3
SplitShare 4.87 % 6.18 % 76,727 2.69 6 0.1177 % 3,176.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1177 % 2,478.3
Perpetual-Premium 5.89 % 5.90 % 85,981 13.96 6 -0.2742 % 2,504.5
Perpetual-Discount 5.80 % 5.85 % 98,174 14.06 33 0.1618 % 2,489.9
FixedReset 5.64 % 4.92 % 215,194 14.51 83 -0.7949 % 1,800.3
Deemed-Retractible 5.33 % 5.82 % 126,305 6.90 34 0.3756 % 2,534.2
FloatingReset 3.09 % 4.86 % 49,092 5.54 16 -1.3974 % 1,966.8
Performance Highlights
Issue Index Change Notes
PWF.PR.Q FloatingReset -24.47 % Not real; there was no trading today. Not a single share. In fact, the issue hasn’t traded since February 5, so maybe the market maker took the day off. But I have not checked whether this lamentable state of affairs is due to inadequate Toronto Stock Exchange reporting or inadequate Toronto Stock Exchange supervision of market-makers.

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 8.12
Evaluated at bid price : 8.12
Bid-YTW : 6.31 %

BAM.PF.E FixedReset -6.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 15.50
Evaluated at bid price : 15.50
Bid-YTW : 5.54 %
FTS.PR.G FixedReset -5.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 14.65
Evaluated at bid price : 14.65
Bid-YTW : 4.92 %
FTS.PR.M FixedReset -4.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 16.89
Evaluated at bid price : 16.89
Bid-YTW : 4.87 %
FTS.PR.K FixedReset -4.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 15.21
Evaluated at bid price : 15.21
Bid-YTW : 4.71 %
TRP.PR.C FixedReset -4.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 10.66
Evaluated at bid price : 10.66
Bid-YTW : 4.98 %
TRP.PR.A FixedReset -3.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 13.66
Evaluated at bid price : 13.66
Bid-YTW : 4.84 %
TRP.PR.B FixedReset -3.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 9.90
Evaluated at bid price : 9.90
Bid-YTW : 4.80 %
TRP.PR.E FixedReset -3.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 16.90
Evaluated at bid price : 16.90
Bid-YTW : 4.68 %
CU.PR.C FixedReset -3.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 15.70
Evaluated at bid price : 15.70
Bid-YTW : 4.76 %
TRP.PR.G FixedReset -3.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 5.19 %
TRP.PR.H FloatingReset -3.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 8.70
Evaluated at bid price : 8.70
Bid-YTW : 4.97 %
BAM.PR.T FixedReset -3.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 13.10
Evaluated at bid price : 13.10
Bid-YTW : 5.68 %
FTS.PR.H FixedReset -3.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 12.00
Evaluated at bid price : 12.00
Bid-YTW : 4.42 %
GWO.PR.N FixedReset -3.26 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.15
Bid-YTW : 11.42 %
FTS.PR.I FloatingReset -2.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 9.72
Evaluated at bid price : 9.72
Bid-YTW : 4.91 %
SLF.PR.I FixedReset -2.79 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.75
Bid-YTW : 8.87 %
TRP.PR.D FixedReset -2.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 16.11
Evaluated at bid price : 16.11
Bid-YTW : 4.82 %
BAM.PR.X FixedReset -2.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 11.50
Evaluated at bid price : 11.50
Bid-YTW : 5.51 %
HSE.PR.C FixedReset -2.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 13.88
Evaluated at bid price : 13.88
Bid-YTW : 7.09 %
MFC.PR.G FixedReset -2.44 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.56
Bid-YTW : 8.45 %
MFC.PR.F FixedReset -2.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.76
Bid-YTW : 11.87 %
MFC.PR.J FixedReset -2.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.59
Bid-YTW : 8.23 %
CIU.PR.C FixedReset -1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 10.00
Evaluated at bid price : 10.00
Bid-YTW : 4.70 %
BAM.PR.R FixedReset -1.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 12.33
Evaluated at bid price : 12.33
Bid-YTW : 5.88 %
BAM.PF.B FixedReset -1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 16.10
Evaluated at bid price : 16.10
Bid-YTW : 5.25 %
VNR.PR.A FixedReset -1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 16.47
Evaluated at bid price : 16.47
Bid-YTW : 5.25 %
RY.PR.J FixedReset -1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 18.15
Evaluated at bid price : 18.15
Bid-YTW : 4.60 %
BAM.PF.G FixedReset -1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 17.60
Evaluated at bid price : 17.60
Bid-YTW : 5.24 %
BAM.PR.K Floater -1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 9.80
Evaluated at bid price : 9.80
Bid-YTW : 4.88 %
PWF.PR.P FixedReset -1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 11.70
Evaluated at bid price : 11.70
Bid-YTW : 4.66 %
IFC.PR.C FixedReset -1.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.00
Bid-YTW : 9.38 %
SLF.PR.G FixedReset -1.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.85
Bid-YTW : 10.79 %
W.PR.K FixedReset -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 22.78
Evaluated at bid price : 24.00
Bid-YTW : 5.50 %
BMO.PR.S FixedReset 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 17.19
Evaluated at bid price : 17.19
Bid-YTW : 4.43 %
CIU.PR.A Perpetual-Discount 1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 19.40
Evaluated at bid price : 19.40
Bid-YTW : 5.95 %
BAM.PF.F FixedReset 1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 18.10
Evaluated at bid price : 18.10
Bid-YTW : 5.05 %
SLF.PR.B Deemed-Retractible 1.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.62
Bid-YTW : 6.97 %
RY.PR.L FixedReset 1.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.80
Bid-YTW : 3.88 %
SLF.PR.A Deemed-Retractible 1.32 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.52
Bid-YTW : 6.98 %
FTS.PR.F Perpetual-Discount 1.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 21.54
Evaluated at bid price : 21.80
Bid-YTW : 5.72 %
SLF.PR.C Deemed-Retractible 1.40 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.30
Bid-YTW : 7.48 %
GWO.PR.R Deemed-Retractible 1.63 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.24
Bid-YTW : 7.23 %
FTS.PR.J Perpetual-Discount 1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 21.10
Evaluated at bid price : 21.10
Bid-YTW : 5.75 %
GWO.PR.Q Deemed-Retractible 1.89 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.68
Bid-YTW : 6.67 %
BMO.PR.T FixedReset 2.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 16.95
Evaluated at bid price : 16.95
Bid-YTW : 4.38 %
TD.PF.A FixedReset 2.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 17.10
Evaluated at bid price : 17.10
Bid-YTW : 4.38 %
GWO.PR.H Deemed-Retractible 2.18 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.60
Bid-YTW : 7.04 %
MFC.PR.K FixedReset 2.31 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.93
Bid-YTW : 9.28 %
PWF.PR.A Floater 3.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 10.85
Evaluated at bid price : 10.85
Bid-YTW : 4.36 %
Volume Highlights
Issue Index Shares
Traded
Notes
HSE.PR.A FixedReset 270,860 RBC crossed 256,900 at 8.25. Nice ticket! At just under one-third of par value!
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 8.30
Evaluated at bid price : 8.30
Bid-YTW : 6.87 %
FTS.PR.M FixedReset 146,598 Scotia crossed 20,000 at 17.56 and 111,000 at 17.45.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 16.89
Evaluated at bid price : 16.89
Bid-YTW : 4.87 %
BMO.PR.Z Perpetual-Discount 106,708 Nesbitt crossed 50,000 at 22.45; Scotia crossed 47,700 at the same price.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 22.09
Evaluated at bid price : 22.41
Bid-YTW : 5.58 %
NA.PR.X FixedReset 102,491 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 23.10
Evaluated at bid price : 24.88
Bid-YTW : 5.45 %
BMO.PR.Q FixedReset 101,900 Scotia crossed 91,300 at 18.45.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.20
Bid-YTW : 7.58 %
BNS.PR.E FixedReset 60,415 TD crossed 23,000 at 25.48; RBC crossed 25,000 at the same price.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 23.28
Evaluated at bid price : 25.43
Bid-YTW : 5.03 %
There were 28 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
PWF.PR.Q FloatingReset Quote: 8.12 – 11.75
Spot Rate : 3.6300
Average : 2.7545

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 8.12
Evaluated at bid price : 8.12
Bid-YTW : 6.31 %

BAM.PF.E FixedReset Quote: 15.50 – 16.67
Spot Rate : 1.1700
Average : 0.7248

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 15.50
Evaluated at bid price : 15.50
Bid-YTW : 5.54 %

TRP.PR.G FixedReset Quote: 17.50 – 18.18
Spot Rate : 0.6800
Average : 0.5011

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 5.19 %

RY.PR.P Perpetual-Discount Quote: 24.25 – 24.74
Spot Rate : 0.4900
Average : 0.3127

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 23.90
Evaluated at bid price : 24.25
Bid-YTW : 5.42 %

PWF.PR.E Perpetual-Discount Quote: 23.33 – 23.89
Spot Rate : 0.5600
Average : 0.3847

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 23.07
Evaluated at bid price : 23.33
Bid-YTW : 5.94 %

RY.PR.W Perpetual-Discount Quote: 22.50 – 22.98
Spot Rate : 0.4800
Average : 0.3272

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-10
Maturity Price : 22.22
Evaluated at bid price : 22.50
Bid-YTW : 5.45 %

Market Action

February 9, 2016

So it was another crummy day for equities:

Canadian bank stocks were down more than 3.5 per cent during the day, marking the biggest decline for the group since August, 2009, when stock markets were emerging fitfully from the global financial crisis.

Stocks recovered some lost ground later in the day, but over all, Canadian bank stocks have tumbled more than 7 per cent this year.

While that is relatively mild next to the double-digit declines among U.S. and European bank stocks, Tuesday’s downturn suggests investors are starting to lump the big banks together with their global peers.
…
The backdrop to the day’s market turbulence certainly pointed to indiscriminate alarm among investors. European stocks fell 1.8 per cent and Japanese stocks fell 5.4 per cent. The Toronto Stock Exchange tumbled 2 per cent.

And the Canadian short-term yield curve inverted:

The Canadian yield curve was briefly inverted out to five years on Tuesday before recovering to roughly flat levels. This is bad news for domestic investors. Just how bad things will get depends on how much faith remains in central bank monetary policy and the extent to which “it’s different this time.”

Supported by Federal Reserve research studies, inverted yield curves are a widely accepted, long-standing indicator of economic recessions. In Canada, the last time the yield curve was inverted out to five years (the five-year Government of Canada bond yielded less than the three-month T-bill yield) was in January, 2015, just as the domestic technical recession began.

… and oil’s in the tank:

Crude tumbled the most in five months in London as price volatility climbed to a seven-year high and Goldman Sachs Group Inc. warned of wider swings to come.

Brent futures fell 7.8 percent as global equities neared a bear market. Volatility is set to “spike” as prices seek an equilibrium, which could drag oil below $20 a barrel, Goldman Sachs said. The CBOE Crude Oil Volatility Index, which measures expectations of price swings, rose as high as 73.52, almost the highest since 2009. The world oil surplus will be bigger in the first half of this year than previously estimated, according to the International Energy Agency.

… and overnight markets are grim:

Japanese stocks extended losses and Singaporean shares tumbled following a two-day break, as persistent concern over market volatility helped the yen solidify its ascent. Oil climbed back above $28 a barrel before an update on U.S. stockpiles.

The Topix index headed for the biggest two-day drop since the aftermath of the March 2011 earthquake in Tokyo as a gauge of Japanese equity volatility soared. The Straits Times Index in Singapore sank the most in three weeks while the yen strengthened a third day and gold resumed its advance. U.S. index futures reversed some early gains as Vermont Senator Bernie Sanders defeated Hillary Clinton in the New Hampshire Democratic Primary, while Donald Trump prevailed over a crowded Republican field.

But cheer up! The regulators are making investing safer!

New proposals from the U.S. securities watchdog aimed at reducing risks in exchange-traded funds (ETFs) may end up being the best thing that ever happened to rival exchange-traded notes (ETNs).

ETFs holding some $225 billion worth of assets are likely to violate the new rules suggested by the Securities and Exchange Commission (SEC), and could ironically spark a mass migration of investors into riskier products.
…
The first rule proposal attempts to address liquidity concerns by requiring that no more than 15 percent of a fund’s holdings take longer than seven days to liquidate without moving the market. This effectively means that “every broad corporate and high-yield bond fund and every broad emerging markets fund would be in trouble,” according to Nadig, who ran the numbers using his own trading estimates of how many ETFs would be in violation.
…
The other proposal attempts to address derivatives usage by limiting the leverage in 40 Act funds to 150 percent. That puts a majority of the two-times and three-times levered ETFs in violation. While the issuers may be able to find clever workarounds to get to the two- and three-times exposure while still remaining in compliance, it does put another $25 billion at risk of being in violation, leaving many investors searching to find other ways to get this exposure, such as ETNs.

Unlike ETFs, exchange-traded notes involve investors taking on significant credit risk to the ETN’s issuers.

ETNs are unsecured debt obligations regulated under the less-stringent Securities Act of 1933, and are not required to physically hold anything. As such, there is a risk that the issuer could default and investors would lose some or all of their investment. This is very different to the structure of a high-yield bond ETF or even a leveraged ETF, both of which physically hold the securities or derivatives involved. Shareholders have ownership of those assets even if the issuer goes out of business.

I continue to feel that the best option is to allow for staggered redemptions, so that ETF (and mutual fund) investors get a break on fees if they agree to a delayed redemption schedule; e.g., you have to give 20 trading day’s notice of redemption and your cash redemption value is based on the equally weighted mean average of the redemption prices on each of those days. Perhaps a third class of share would not be redeemable or exchangeable at all; at the core of an ETF would be a CEF.

But really, requiring that 85% of ETF holdings have a reasonable probability of being liquidated in seven days with ABSOLUTELY ZERO MARKET IMPACT is going way too far. But how else can the public be forced to buy government bonds at yields below the inflation rate?

It’s also going to force people into direct corporate bond holdings, as well. Just wait until Joe Lunchbucket finds that one of his five holdings has gone bust!

I really suggest that preferred share investors relax a little. Maybe watch a nice movie:

apocalypsenow
Click for Big

It was a horrible day for the Canadian preferred share market, with PerpetualDiscounts off 89bp, FixedResets down 150bp and DeemedRetractibles losing 151bp. The Performance highlights table is, of course, ridiculous; all four of the FTS FixedResets are down over 150bp on the day in the wake of the company’s ambitious takeover announcement. Volume was average.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_160209
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 17.55 to be $1.36 rich, while TRP.PR.G, resetting 2020-11-30 at +296, is $0.85 cheap at its bid price of 18.15.

impVol_MFC_160209
Click for Big

Most expensive is MFC.PR.L, resetting at +216bp on 2019-6-19, bid at 16.60 to be 0.68 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 18.00 to be 0.79 cheap.

impVol_BAM_160209
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 12.57 to be $1.77 cheap. BAM.PF.E, resetting at +255bp on 2020-3-31 is bid at 16.66 and appears to be $1.05 rich.

impVol_FTS_160209
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 15.90, looks $0.31 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 15.50 and is $0.50 cheap.

pairs_FR_160209
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.95%, with two outliers below -1.50%. There is one junk outlier below -1.50% and one above +0.50%.

pairs_FF_160209
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.29 % 6.43 % 17,696 16.14 1 -0.6982 % 1,474.7
FixedFloater 7.69 % 6.72 % 25,764 15.52 1 -1.2000 % 2,584.5
Floater 4.71 % 4.81 % 74,939 15.81 4 -0.0249 % 1,627.6
OpRet 0.00 % 0.00 % 0 0.00 0 0.2220 % 2,711.1
SplitShare 4.87 % 6.27 % 77,398 2.69 6 0.2220 % 3,172.5
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.2220 % 2,475.3
Perpetual-Premium 5.88 % 5.88 % 83,066 13.94 6 -0.1603 % 2,511.4
Perpetual-Discount 5.81 % 5.85 % 99,218 14.07 33 -0.8904 % 2,485.8
FixedReset 5.59 % 4.78 % 215,725 14.59 83 -1.3007 % 1,814.7
Deemed-Retractible 5.35 % 5.55 % 127,752 5.20 34 -1.5051 % 2,524.7
FloatingReset 3.05 % 4.69 % 49,492 5.55 16 -0.9230 % 1,994.7
Performance Highlights
Issue Index Change Notes
PWF.PR.Q FloatingReset -6.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 10.75
Evaluated at bid price : 10.75
Bid-YTW : 4.76 %
BAM.PR.R FixedReset -4.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 12.57
Evaluated at bid price : 12.57
Bid-YTW : 5.77 %
BMO.PR.S FixedReset -4.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 17.01
Evaluated at bid price : 17.01
Bid-YTW : 4.48 %
TRP.PR.F FloatingReset -4.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 11.27
Evaluated at bid price : 11.27
Bid-YTW : 5.28 %
BAM.PR.X FixedReset -4.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 11.80
Evaluated at bid price : 11.80
Bid-YTW : 5.37 %
FTS.PR.J Perpetual-Discount -3.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 20.76
Evaluated at bid price : 20.76
Bid-YTW : 5.84 %
CM.PR.O FixedReset -3.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 17.01
Evaluated at bid price : 17.01
Bid-YTW : 4.50 %
HSE.PR.C FixedReset -3.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 14.23
Evaluated at bid price : 14.23
Bid-YTW : 6.90 %
BMO.PR.T FixedReset -3.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 16.61
Evaluated at bid price : 16.61
Bid-YTW : 4.47 %
MFC.PR.N FixedReset -3.51 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.03
Bid-YTW : 8.64 %
MFC.PR.K FixedReset -3.41 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.57
Bid-YTW : 9.60 %
CM.PR.P FixedReset -3.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 16.50
Evaluated at bid price : 16.50
Bid-YTW : 4.54 %
PWF.PR.T FixedReset -3.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 20.01
Evaluated at bid price : 20.01
Bid-YTW : 3.86 %
FTS.PR.F Perpetual-Discount -3.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 21.50
Evaluated at bid price : 21.50
Bid-YTW : 5.82 %
CU.PR.C FixedReset -3.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 16.30
Evaluated at bid price : 16.30
Bid-YTW : 4.58 %
GWO.PR.R Deemed-Retractible -3.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.90
Bid-YTW : 7.46 %
BNS.PR.F FloatingReset -3.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.83
Bid-YTW : 7.92 %
RY.PR.M FixedReset -3.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 4.53 %
TD.PF.A FixedReset -3.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 16.75
Evaluated at bid price : 16.75
Bid-YTW : 4.47 %
GWO.PR.H Deemed-Retractible -2.98 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.14
Bid-YTW : 7.35 %
SLF.PR.B Deemed-Retractible -2.95 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.36
Bid-YTW : 7.15 %
HSE.PR.E FixedReset -2.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 15.30
Evaluated at bid price : 15.30
Bid-YTW : 6.98 %
GWO.PR.Q Deemed-Retractible -2.88 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.26
Bid-YTW : 6.94 %
PWF.PR.A Floater -2.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 10.50
Evaluated at bid price : 10.50
Bid-YTW : 4.50 %
GWO.PR.L Deemed-Retractible -2.82 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.10
Bid-YTW : 6.31 %
SLF.PR.C Deemed-Retractible -2.77 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.02
Bid-YTW : 7.68 %
FTS.PR.I FloatingReset -2.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 10.02
Evaluated at bid price : 10.02
Bid-YTW : 4.76 %
SLF.PR.D Deemed-Retractible -2.69 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.88
Bid-YTW : 7.78 %
SLF.PR.A Deemed-Retractible -2.66 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.24
Bid-YTW : 7.17 %
RY.PR.J FixedReset -2.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 18.40
Evaluated at bid price : 18.40
Bid-YTW : 4.54 %
BAM.PF.E FixedReset -2.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 16.66
Evaluated at bid price : 16.66
Bid-YTW : 5.14 %
MFC.PR.H FixedReset -2.61 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.43
Bid-YTW : 7.34 %
MFC.PR.B Deemed-Retractible -2.57 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.51
Bid-YTW : 7.59 %
BIP.PR.A FixedReset -2.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 17.66
Evaluated at bid price : 17.66
Bid-YTW : 6.02 %
NA.PR.W FixedReset -2.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 15.95
Evaluated at bid price : 15.95
Bid-YTW : 4.74 %
BAM.PR.Z FixedReset -2.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 17.20
Evaluated at bid price : 17.20
Bid-YTW : 5.33 %
HSE.PR.G FixedReset -2.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 15.62
Evaluated at bid price : 15.62
Bid-YTW : 6.83 %
TD.PF.B FixedReset -2.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 16.86
Evaluated at bid price : 16.86
Bid-YTW : 4.43 %
MFC.PR.C Deemed-Retractible -2.37 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.15
Bid-YTW : 7.67 %
NA.PR.S FixedReset -2.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 17.29
Evaluated at bid price : 17.29
Bid-YTW : 4.53 %
RY.PR.H FixedReset -2.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 17.13
Evaluated at bid price : 17.13
Bid-YTW : 4.36 %
RY.PR.Z FixedReset -2.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 17.07
Evaluated at bid price : 17.07
Bid-YTW : 4.32 %
BAM.PF.B FixedReset -2.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 16.33
Evaluated at bid price : 16.33
Bid-YTW : 5.17 %
GWO.PR.I Deemed-Retractible -2.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.25
Bid-YTW : 7.57 %
GWO.PR.G Deemed-Retractible -2.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.58
Bid-YTW : 6.78 %
ELF.PR.G Perpetual-Discount -2.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 20.35
Evaluated at bid price : 20.35
Bid-YTW : 5.90 %
GWO.PR.P Deemed-Retractible -2.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.47
Bid-YTW : 6.44 %
HSE.PR.A FixedReset -2.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 8.32
Evaluated at bid price : 8.32
Bid-YTW : 6.85 %
SLF.PR.E Deemed-Retractible -2.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.10
Bid-YTW : 7.68 %
TD.PF.D FixedReset -2.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 18.85
Evaluated at bid price : 18.85
Bid-YTW : 4.50 %
CM.PR.Q FixedReset -2.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 18.71
Evaluated at bid price : 18.71
Bid-YTW : 4.54 %
BMO.PR.Y FixedReset -2.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 18.91
Evaluated at bid price : 18.91
Bid-YTW : 4.45 %
MFC.PR.M FixedReset -1.95 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.11
Bid-YTW : 8.64 %
BMO.PR.Z Perpetual-Discount -1.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 22.09
Evaluated at bid price : 22.41
Bid-YTW : 5.58 %
SLF.PR.H FixedReset -1.86 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.28
Bid-YTW : 10.32 %
BAM.PF.A FixedReset -1.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 17.52
Evaluated at bid price : 17.52
Bid-YTW : 5.18 %
CU.PR.F Perpetual-Discount -1.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 19.48
Evaluated at bid price : 19.48
Bid-YTW : 5.79 %
BMO.PR.W FixedReset -1.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 16.80
Evaluated at bid price : 16.80
Bid-YTW : 4.39 %
TD.PR.S FixedReset -1.58 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.60
Bid-YTW : 3.74 %
IFC.PR.A FixedReset -1.55 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.94
Bid-YTW : 10.64 %
SLF.PR.I FixedReset -1.54 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.23
Bid-YTW : 8.47 %
TRP.PR.H FloatingReset -1.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 9.01
Evaluated at bid price : 9.01
Bid-YTW : 4.80 %
POW.PR.B Perpetual-Discount -1.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 22.54
Evaluated at bid price : 22.79
Bid-YTW : 5.93 %
FTS.PR.H FixedReset -1.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 12.41
Evaluated at bid price : 12.41
Bid-YTW : 4.27 %
CU.PR.E Perpetual-Discount -1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 21.08
Evaluated at bid price : 21.08
Bid-YTW : 5.83 %
TD.PF.C FixedReset -1.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 16.91
Evaluated at bid price : 16.91
Bid-YTW : 4.41 %
BNS.PR.M Deemed-Retractible -1.44 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.91
Bid-YTW : 5.41 %
CIU.PR.A Perpetual-Discount -1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 19.18
Evaluated at bid price : 19.18
Bid-YTW : 6.02 %
BAM.PF.G FixedReset -1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 17.84
Evaluated at bid price : 17.84
Bid-YTW : 5.17 %
MFC.PR.F FixedReset -1.40 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.01
Bid-YTW : 11.58 %
FTS.PR.M FixedReset -1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 17.75
Evaluated at bid price : 17.75
Bid-YTW : 4.63 %
TRP.PR.A FixedReset -1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 14.20
Evaluated at bid price : 14.20
Bid-YTW : 4.65 %
RY.PR.E Deemed-Retractible -1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.92
Bid-YTW : 5.35 %
RY.PR.W Perpetual-Discount -1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 22.43
Evaluated at bid price : 22.69
Bid-YTW : 5.41 %
CCS.PR.C Deemed-Retractible -1.28 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.57
Bid-YTW : 7.23 %
TD.PF.E FixedReset -1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 19.45
Evaluated at bid price : 19.45
Bid-YTW : 4.48 %
TD.PF.F Perpetual-Discount -1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 22.00
Evaluated at bid price : 22.30
Bid-YTW : 5.52 %
FTS.PR.G FixedReset -1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 15.50
Evaluated at bid price : 15.50
Bid-YTW : 4.63 %
RY.PR.A Deemed-Retractible -1.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.80
Bid-YTW : 5.40 %
BAM.PR.G FixedFloater -1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 25.00
Evaluated at bid price : 12.35
Bid-YTW : 6.72 %
RY.PR.L FixedReset -1.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.50
Bid-YTW : 4.11 %
CU.PR.D Perpetual-Discount -1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 21.15
Evaluated at bid price : 21.15
Bid-YTW : 5.81 %
RY.PR.B Deemed-Retractible -1.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.29
Bid-YTW : 5.25 %
MFC.PR.L FixedReset -1.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.60
Bid-YTW : 8.84 %
BNS.PR.L Deemed-Retractible -1.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.88
Bid-YTW : 5.44 %
RY.PR.O Perpetual-Discount -1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 21.82
Evaluated at bid price : 22.15
Bid-YTW : 5.53 %
MFC.PR.I FixedReset -1.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.74
Bid-YTW : 7.61 %
MFC.PR.G FixedReset -1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.00
Bid-YTW : 8.09 %
RY.PR.G Deemed-Retractible -1.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.85
Bid-YTW : 5.41 %
BNS.PR.B FloatingReset -1.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.42
Bid-YTW : 4.86 %
BAM.PF.F FixedReset -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 17.89
Evaluated at bid price : 17.89
Bid-YTW : 5.11 %
RY.PR.F Deemed-Retractible -1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.84
Bid-YTW : 5.36 %
PVS.PR.D SplitShare 1.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2021-10-08
Maturity Price : 25.00
Evaluated at bid price : 22.50
Bid-YTW : 6.87 %
BAM.PR.K Floater 1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 9.93
Evaluated at bid price : 9.93
Bid-YTW : 4.81 %
BNS.PR.D FloatingReset 1.71 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.80
Bid-YTW : 7.46 %
BAM.PR.B Floater 1.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 9.94
Evaluated at bid price : 9.94
Bid-YTW : 4.81 %
TRP.PR.D FixedReset 3.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 16.56
Evaluated at bid price : 16.56
Bid-YTW : 4.69 %
BMO.PR.Q FixedReset 4.69 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.32
Bid-YTW : 7.45 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.H FixedReset 132,012 Desjardins crossed 126,200 at 17.15.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 17.13
Evaluated at bid price : 17.13
Bid-YTW : 4.36 %
NA.PR.X FixedReset 111,975 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 23.13
Evaluated at bid price : 24.96
Bid-YTW : 5.43 %
PWF.PR.A Floater 100,508 Desjardins bought 96,500 from anonymous at 10.45.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 10.50
Evaluated at bid price : 10.50
Bid-YTW : 4.50 %
BMO.PR.Q FixedReset 78,800 TD crossed 50,000 at 18.35; Scotia crossed 25,000 at the same price.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.32
Bid-YTW : 7.45 %
TD.PF.G FixedReset 76,371 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 23.27
Evaluated at bid price : 25.40
Bid-YTW : 5.12 %
BNS.PR.E FixedReset 65,032 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 23.28
Evaluated at bid price : 25.42
Bid-YTW : 5.03 %
There were 30 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
GWO.PR.L Deemed-Retractible Quote: 24.10 – 24.82
Spot Rate : 0.7200
Average : 0.4782

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.10
Bid-YTW : 6.31 %

TD.PF.F Perpetual-Discount Quote: 22.30 – 22.85
Spot Rate : 0.5500
Average : 0.3472

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 22.00
Evaluated at bid price : 22.30
Bid-YTW : 5.52 %

RY.PR.J FixedReset Quote: 18.40 – 18.93
Spot Rate : 0.5300
Average : 0.3313

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 18.40
Evaluated at bid price : 18.40
Bid-YTW : 4.54 %

BMO.PR.T FixedReset Quote: 16.61 – 17.15
Spot Rate : 0.5400
Average : 0.3477

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-09
Maturity Price : 16.61
Evaluated at bid price : 16.61
Bid-YTW : 4.47 %

TD.PR.Z FloatingReset Quote: 21.95 – 22.60
Spot Rate : 0.6500
Average : 0.4773

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.95
Bid-YTW : 4.40 %

GWO.PR.O FloatingReset Quote: 11.24 – 13.25
Spot Rate : 2.0100
Average : 1.8387

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.24
Bid-YTW : 11.94 %

Market Action

February 8, 2016

There is speculation regarding negative US rates:

If the world’s biggest economy weakens enough that traditional policy measures don’t help, the Fed may consider pushing rates below zero, according to Bank of America Corp. and JPMorgan Chase & Co.

That step would broaden the Fed’s toolkit beyond what was available during the financial crisis, when it slashed its overnight benchmark near zero and bought bonds to stimulate the economy. In 2012, New York Fed researchers said negative rates could prompt individuals to avoid depositing money in banks, potentially weakening the financial system.

“They’re still concerned, but not as much as they once were,” said Mark Cabana, a New York-based interest-rate strategist at Bank of America. “They’ve seen how successful they were in other countries, where there haven’t been adverse impacts on market functioning.”

Traders may be getting on board with the possibility too. The implied probability of U.S. rates sinking below zero by the end of 2017 has jumped to roughly 13 percent, the highest since at least July, data compiled by Bloomberg show. The wagers are tied to the London interbank offered rate, which partly reflects expectations for Fed rates.

negRatesProb
Click for Big

And 10-Year JGBs are at zero:

The yield on Japan’s benchmark 10-year government bonds fell to zero for the first time, an unprecedented low for a Group-of-Seven economy, as global financial turmoil and the Bank of Japan’s adoption of negative interest rates drive demand for the notes.

The 10-year yield has tumbled from 0.22 percent before the BOJ surprised markets with the decision on Jan. 29 to introduce a minus 0.1 percent rate on some of the reserves financial institutions park at the central bank. It fell four basis points to zero percent as of 10:17 a.m. in Tokyo.

Japanese bonds are also climbing as sovereign securities rally worldwide. Global stocks have dropped almost 10 percent this year on concern growth is slowing in China, and as slumping oil prices undermine policy makers efforts to revive inflation. About 29 percent of the outstanding debt in the Bloomberg Global Sovereign Bond index was yielding less than zero as of 5 p.m. in New York on Monday. Swiss 3 percent notes due in 2018 were offering the lowest yield in the index, according to data compiled by Bloomberg.

Deutsche Bank might have trouble paying coupons on its CoCos:

Deutsche Bank AG may struggle to pay coupons on its riskiest bonds next year if operating results disappoint or litigation costs are higher than expected, according to analysts at CreditSights Inc.

Bonds and stock of Germany’s largest bank have plunged this year, with the shares shedding 39 percent of their value and its contingent convertible bonds — known as CoCos, or additional Tier 1 securities — turning in a similar performance. The cost of protecting the company’s subordinated debt from default for five years using credit-default swaps has more than doubled since the end of 2015, rising to 438 basis points, a four-year high, from 187.
…
The question for CoCo investors and holders of trust preferred securities is whether Deutsche Bank has sufficient “available distributable items,” a measure based on audited unconsolidated accounts calculated under German accounting principles, to make the payments, according to [CreditSights analyst Simon] Adamson. Given that there are reserves available to make up any shortfall that might prevent payouts, “we would be surprised” if Deutsche Bank didn’t pay coupons on its CoCos this year, which are determined by its 2015 performance, he said.

At the end of 2014, the latest figure available, Deutsche Bank had 2.87 billion euros ($3.2 billion) of ADIs, according to a presentation. The company also has 2.93 billion euros in a general reserve that could be used to top up ADI, as well as a 5.5 billion-euro “blocked amount” that was excluded from the ADI calculation and could probably be unblocked if necessary, according to CreditSights.

DBYields
Click for Big

UK authorities have done much to cement perception of regulators as Keystone Kops:

The first signs of trouble for prosecutors came about three weeks into the trial. Their witness was a government investigator called to lay out details of the probe into the alleged rigging of a key interest rate by a group of brokers who faced up to 20 years in prison.

But as the investigator went through a calendar his agency had compiled listing days the rates had allegedly been manipulated, his team admitted they had some of the dates wrong. Waving the schedule as he spoke, defense lawyer Philip Hackett asked if the prosecution was “making this up as they go along.”
….
The case against the brokers looked like a slam-dunk for [Serious Fraud Office chief prosecutor Mukul] Chawla. To begin with, [Tom] Hayes [now serving an 11-year sentence] had admitted conspiring with the six men to rig the rate to boost his trading profits. Reams of e-mail and instant-message evidence showed the defendants discussing the alleged crimes with Hayes. Two of the firms they worked for — ICAP and RP Martin — had already been fined $90 million by U.K. and U.S. regulators for failing to curb the brokers’ behavior.
…
But as Chawla laid out his case, even some of his own witnesses seemed to undermine it. In the second week, the prosecutor called John Ewan, a former director of the British Bankers’ Association, the trade body that officially oversaw Libor until 2013, in an effort to explain how the system was supposed to work when it wasn’t being rigged.

Instead of upstanding, Ewan came off as evasive. At one point, he claimed he had no idea the rate was being manipulated, despite written evidence that traders had told him.
…
The following week, Chawla called Paul Chadwick, the SFO investigator. It should have been a routine discussion on how the evidence was compiled, but descended into an argument when it emerged that the SFO had changed the dates it claimed rigging took place. The initial version had some defendants accused of manipulation on days when they’d been on vacation. Hackett, a defense counsel, would later denounce the SFO’s handling of the probe as an “utter shambles.”

However, the best line I’ve seem coming out of a courtroom in recent memory comes from one of the defendants:

Former Tullett Prebon broker Noel Cryan, for example, had exchanged dozens of instant messages with Hayes over a 10-month period in 2009 in which he pledged to help manipulate the rate.

Prosecutors argued the communications proved Cryan’s guilt. But he testified that it had all been a ruse. He’d never actually followed through on Hayes’s requests, he said, but only deceived him to allow his firm to pocket the more than 200,000 pounds commissions Hayes’s bank paid as rewards.

When Chawla asked Cryan how he justified lying to one of his best and longest-standing customers, Cryan cracked a wide smile. “It’s called broking Mr. Chawla,” he said.

Members of the jury rolled their eyes when defense counsel revealed that the SFO didn’t have any proof that Cryan had actually passed on Hayes’s requests to Tullett Prebon’s cash brokers to carry them out.

Meanwhile, Timothy Lane, Deputy Governor of the BoC, has implied he not only has a crystal ball but is much wiser than investor-scum:

Macroprudential tools can be used in two ways. One is to foster a more resilient financial system on an ongoing basis. To give just one example, regulators can establish ceilings on mortgage loan-to-value ratios on an ongoing basis, so that any correction in housing prices is less likely to create stress for the financial system. With a more resilient system, all of the financial stability concerns I have been discussing become more manageable.

Authorities could also, in principle, adjust macroprudential tools to dampen financial cycles—tightening them when leverage is building up and risk taking is increasing, and easing those requirements when that cycle turns. For example, regulators can lower loan-to-value ratios in response to indications of rising household sector vulnerabilities. Another example is the countercyclical capital buffer introduced as part of the Basel III reform of bank capital requirements.

Such countercyclical measures are designed, in part, to weaken the feedback loop between asset prices and credit growth that can lead to the kind of financial excesses that set the stage for a crisis. The track record of countercyclical measures in leaning against a financial cycle is not yet nearly sufficient to form a definite view of their practical effectiveness, however.

“Not yet nearly sufficient”? There’s complete negative evidence, more like. The Fed never saw the US housing bubble and has produced convincing evidence that there was no reason for them to see it.

Central bankers are about bright and wise enough to change policy rates when inflation changes and sometimes miss that boat completely as well. Once they are permitted to apply “macro-prudential tools” (the new euphemism for Soviet-style central planning) we’ll all be worse off.

There are some things I support that might be considered “macro-prudential”, but which fall far short of Mr. Lane’s winner-picking and crony-capitalism. I think, for instance, that given that 40% of Canadian bank assets are mortgages, compared to a 30% historical rate, it would be entirely proper to apply a surcharge to the risk weights of this asset class – as well as, potentially, other balloons. But I do not suggest this because I’m the smartest guy in the room and my uncle once dated the sister of a cabinet minister; I suggest this simply because it is a large change and it behooves us to behave with caution when things are changing. When things get significantly out of whack with historical averages, lean against them; but do not attempt to pick winners and over-ride the judgement of the guy on the ground who figures he can handle a 95% LTV mortgage; or the guy in the bank who figures he’s right. To do so is intellectual narcissism.

But on a bright note, there’s another currency-driven takeover:

Reno, Nevada-based Tahoe agreed to acquire Lake Shore on Monday in an all-stock deal valued at C$945 million ($678 million). From the perspective of Tahoe, which has mines in Latin America, the advantages are twofold, according to Barry Allan, a Toronto-based senior vice president at Mackie Research Capital Corp.

“It’s political diversification for these Tahoe shareholders,” Allan said by phone. “You’ve got stable Canada, thank you very much, an attractive currency. It’s just an insurance policy.”
…
In the deal, Lake Shore investors will get 0.1467 of a Tahoe share for every share they own, the companies said Monday in a statement. The ratio implies C$1.71 per Lake Shore common share, based on Tahoe’s closing on Friday, representing a premium of about 15 percent to Lake Shore’s closing price that day, the companies said.

It was a horrible day for the Canadian preferred share market, with PerpetualDiscounts off 35bp, FixedResets losing 98bp and DeemedRetractibles down 56bp. The Performance Highlights table is lengthy. Volume was well below average.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_160208
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 17.60 to be $1.43 rich, while TRP.PR.C, resetting 2021-1-30 at +154, is $0.78 cheap at its bid price of 11.11.

impVol_MFC_160208
Click for Big

Most expensive is MFC.PR.N, resetting at +230bp on 2020-3-19, bid at 17.65 to be 0.83 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 18.20 to be 0.95 cheap.

impVol_BAM_160208
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 13.15 to be $1.52 cheap. BAM.PF.E, resetting at +255bp on 2020-3-31 is bid at 17.11 and appears to be $1.13 rich.

impVol_FTS_160208
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 16.03, looks $0.24 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 15.69 and is $0.51 cheap.

pairs_FR_160208
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.84%, with three outliers below -1.50%. Note the x-axis has been shifted today. There are two junk outliers below -1.50% and one above +0.50%.

pairs_FF_160208
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.26 % 6.39 % 17,413 16.20 1 0.7031 % 1,485.0
FixedFloater 7.60 % 6.64 % 25,967 15.62 1 -0.7937 % 2,615.9
Floater 4.71 % 4.87 % 75,285 15.70 4 -2.9035 % 1,628.0
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0970 % 2,705.1
SplitShare 4.88 % 6.26 % 78,533 2.69 6 -0.0970 % 3,165.5
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0970 % 2,469.9
Perpetual-Premium 5.87 % 5.85 % 82,389 13.95 6 -0.7292 % 2,515.4
Perpetual-Discount 5.76 % 5.81 % 97,861 14.17 33 -0.3513 % 2,508.2
FixedReset 5.52 % 4.84 % 217,721 14.78 83 -0.9831 % 1,838.7
Deemed-Retractible 5.27 % 5.81 % 128,170 6.92 34 -0.5625 % 2,563.3
FloatingReset 3.02 % 4.55 % 49,522 5.55 16 -0.4445 % 2,013.3
Performance Highlights
Issue Index Change Notes
BMO.PR.Q FixedReset -6.42 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.50
Bid-YTW : 8.30 %
TRP.PR.C FixedReset -5.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 11.11
Evaluated at bid price : 11.11
Bid-YTW : 4.78 %
MFC.PR.M FixedReset -4.44 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.45
Bid-YTW : 8.35 %
BAM.PR.T FixedReset -4.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 13.65
Evaluated at bid price : 13.65
Bid-YTW : 5.45 %
TRP.PR.B FixedReset -3.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 10.20
Evaluated at bid price : 10.20
Bid-YTW : 4.66 %
MFC.PR.N FixedReset -3.55 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.65
Bid-YTW : 8.12 %
TRP.PR.D FixedReset -3.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 16.06
Evaluated at bid price : 16.06
Bid-YTW : 4.84 %
IAG.PR.G FixedReset -3.50 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.91
Bid-YTW : 8.15 %
BAM.PR.B Floater -3.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 9.76
Evaluated at bid price : 9.76
Bid-YTW : 4.90 %
PWF.PR.A Floater -3.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 10.81
Evaluated at bid price : 10.81
Bid-YTW : 4.37 %
TRP.PR.I FloatingReset -2.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 10.85
Evaluated at bid price : 10.85
Bid-YTW : 4.57 %
BNS.PR.D FloatingReset -2.83 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.50
Bid-YTW : 7.77 %
BAM.PR.K Floater -2.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 9.81
Evaluated at bid price : 9.81
Bid-YTW : 4.87 %
FTS.PR.G FixedReset -2.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 15.69
Evaluated at bid price : 15.69
Bid-YTW : 4.57 %
BAM.PR.C Floater -2.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 9.75
Evaluated at bid price : 9.75
Bid-YTW : 4.90 %
GWO.PR.S Deemed-Retractible -2.40 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.55
Bid-YTW : 6.22 %
CIU.PR.C FixedReset -2.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 10.21
Evaluated at bid price : 10.21
Bid-YTW : 4.60 %
CCS.PR.C Deemed-Retractible -2.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.85
Bid-YTW : 7.04 %
PWF.PR.Q FloatingReset -2.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 11.50
Evaluated at bid price : 11.50
Bid-YTW : 4.44 %
HSE.PR.C FixedReset -2.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 14.76
Evaluated at bid price : 14.76
Bid-YTW : 6.64 %
BAM.PF.B FixedReset -2.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 16.70
Evaluated at bid price : 16.70
Bid-YTW : 5.05 %
PWF.PR.T FixedReset -2.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 20.70
Evaluated at bid price : 20.70
Bid-YTW : 3.73 %
IFC.PR.C FixedReset -1.94 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.21
Bid-YTW : 9.18 %
TD.PR.Y FixedReset -1.78 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.79
Bid-YTW : 3.79 %
MFC.PR.L FixedReset -1.76 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.79
Bid-YTW : 8.68 %
BAM.PF.F FixedReset -1.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 18.08
Evaluated at bid price : 18.08
Bid-YTW : 5.05 %
CIU.PR.A Perpetual-Discount -1.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 19.46
Evaluated at bid price : 19.46
Bid-YTW : 5.93 %
MFC.PR.K FixedReset -1.71 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.12
Bid-YTW : 9.11 %
TD.PF.C FixedReset -1.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 17.16
Evaluated at bid price : 17.16
Bid-YTW : 4.35 %
BAM.PF.A FixedReset -1.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 17.85
Evaluated at bid price : 17.85
Bid-YTW : 5.08 %
BAM.PR.X FixedReset -1.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 12.30
Evaluated at bid price : 12.30
Bid-YTW : 5.13 %
PWF.PR.O Perpetual-Premium -1.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 24.14
Evaluated at bid price : 24.66
Bid-YTW : 5.91 %
NA.PR.W FixedReset -1.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 16.35
Evaluated at bid price : 16.35
Bid-YTW : 4.62 %
IGM.PR.B Perpetual-Premium -1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 24.62
Evaluated at bid price : 24.92
Bid-YTW : 5.96 %
HSE.PR.E FixedReset -1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 15.76
Evaluated at bid price : 15.76
Bid-YTW : 6.76 %
SLF.PR.H FixedReset -1.49 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.55
Bid-YTW : 10.05 %
SLF.PR.J FloatingReset -1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.58
Bid-YTW : 11.71 %
BAM.PR.Z FixedReset -1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 17.63
Evaluated at bid price : 17.63
Bid-YTW : 5.20 %
RY.PR.J FixedReset -1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 18.90
Evaluated at bid price : 18.90
Bid-YTW : 4.42 %
MFC.PR.C Deemed-Retractible -1.29 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.64
Bid-YTW : 7.32 %
POW.PR.D Perpetual-Discount -1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 21.25
Evaluated at bid price : 21.52
Bid-YTW : 5.86 %
HSE.PR.A FixedReset -1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 8.50
Evaluated at bid price : 8.50
Bid-YTW : 6.70 %
HSE.PR.G FixedReset -1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 16.00
Evaluated at bid price : 16.00
Bid-YTW : 6.66 %
BNS.PR.L Deemed-Retractible -1.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.15
Bid-YTW : 5.22 %
TRP.PR.F FloatingReset -1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 11.76
Evaluated at bid price : 11.76
Bid-YTW : 5.05 %
RY.PR.M FixedReset -1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 18.58
Evaluated at bid price : 18.58
Bid-YTW : 4.38 %
PWF.PR.E Perpetual-Discount -1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 23.14
Evaluated at bid price : 23.44
Bid-YTW : 5.90 %
BAM.PR.R FixedReset -1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 13.15
Evaluated at bid price : 13.15
Bid-YTW : 5.51 %
RY.PR.G Deemed-Retractible -1.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.11
Bid-YTW : 5.19 %
MFC.PR.J FixedReset -1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.00
Bid-YTW : 7.90 %
TRP.PR.A FixedReset -1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 14.40
Evaluated at bid price : 14.40
Bid-YTW : 4.58 %
BAM.PF.E FixedReset -1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 17.11
Evaluated at bid price : 17.11
Bid-YTW : 4.99 %
BNS.PR.R FixedReset -1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.76
Bid-YTW : 4.12 %
TD.PF.B FixedReset -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 17.27
Evaluated at bid price : 17.27
Bid-YTW : 4.32 %
BNS.PR.Q FixedReset -1.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.51
Bid-YTW : 4.04 %
BIP.PR.B FixedReset -1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 22.60
Evaluated at bid price : 23.61
Bid-YTW : 5.88 %
SLF.PR.G FixedReset 1.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.00
Bid-YTW : 10.62 %
TD.PR.S FixedReset 1.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.98
Bid-YTW : 3.44 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.Q FixedReset 147,180 Nesbitt sold 19,600 to CIBC at 25.50, then crossed 100,000 at the same price.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 23.29
Evaluated at bid price : 25.46
Bid-YTW : 5.04 %
BMO.PR.Q FixedReset 80,983 GMP sold 71,900 to National at 18.55.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.50
Bid-YTW : 8.30 %
NA.PR.X FixedReset 54,570 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 23.13
Evaluated at bid price : 24.96
Bid-YTW : 5.43 %
TRP.PR.E FixedReset 42,600 Nesbitt crossed 31,100 at 17.65.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 17.60
Evaluated at bid price : 17.60
Bid-YTW : 4.48 %
BNS.PR.E FixedReset 40,805 RBC crossed 25,000 at 25.55.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 23.30
Evaluated at bid price : 25.49
Bid-YTW : 5.01 %
MFC.PR.G FixedReset 37,700 TD crossed 19,500 at 18.25.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.20
Bid-YTW : 7.93 %
There were 23 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BMO.PR.Q FixedReset Quote: 17.50 – 18.55
Spot Rate : 1.0500
Average : 0.6840

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.50
Bid-YTW : 8.30 %

GWO.PR.S Deemed-Retractible Quote: 23.55 – 24.36
Spot Rate : 0.8100
Average : 0.4600

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.55
Bid-YTW : 6.22 %

TRP.PR.B FixedReset Quote: 10.20 – 10.94
Spot Rate : 0.7400
Average : 0.4421

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 10.20
Evaluated at bid price : 10.20
Bid-YTW : 4.66 %

TRP.PR.D FixedReset Quote: 16.06 – 16.89
Spot Rate : 0.8300
Average : 0.5336

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 16.06
Evaluated at bid price : 16.06
Bid-YTW : 4.84 %

BAM.PR.T FixedReset Quote: 13.65 – 14.30
Spot Rate : 0.6500
Average : 0.4236

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-08
Maturity Price : 13.65
Evaluated at bid price : 13.65
Bid-YTW : 5.45 %

MFC.PR.M FixedReset Quote: 17.45 – 18.15
Spot Rate : 0.7000
Average : 0.4835

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.45
Bid-YTW : 8.35 %

Market Action

February 5, 2016

Jobs, jobs, … well, a few jobs, anyway:

Job growth settled into a more sustainable pace in January and the unemployment rate dropped to an almost eight-year low of 4.9 percent, signs of a resilient labor market that’s causing wage growth to stir.

The 151,000 advance in payrolls, while less than forecast, largely reflected payback for a seasonal hiring pickup in the final two months of 2015, Labor Department figures showed Friday. The jobless rate fell to the lowest level since February 2008. Hourly earnings rose more than estimated after climbing in the year to December by the most since July 2009.
…
Friday’s data showed a much-awaited pickup in wage growth is starting to manifest itself. Average hourly earnings rose 0.5 percent from a month earlier to $25.39. The year-over-year increase of 2.5 percent followed a 2.7 percent jump in the 12 months ended in December, which was the biggest advance since mid-2009.

All in all, the report was somewhat hawkish for the Fed:

Most obviously, the jobless rate dropped in January to 4.9 percent, matching the Fed’s median forecast for the long-run sustainable level of unemployment — or “full employment” — and continuing the most impressive trend in U.S. economic data.

USUnemployment
Click for Big

Perhaps even more encouraging was the move in the labor force participation rate. The share of the working-age population that was either employed or looking for a job ticked up to 62.7 percent in January from 62.6 percent the month before. From a year earlier, some 1.31 million people have entered the labor force.

USParticipationRate
Click for Big

Average hourly earnings rose by a more-than-expected 2.5 percent in January from the year before. Wages for the year through December were revised upward to 2.7 percent, the highest level since July 2009.

USWageGrowth
Click for Big

Meanwhile, back in the frozen North:

Over all, Canada shed 5,700 jobs in January, pushing the jobless rate up by 0.1 percentage point and missing analyst expectations as energy-related declines offset a spurt in public sector employment.
…
Ontario was the only province to see job expansion, with 20,000 new positions created last month, according to Statscan. Most of the increases were in trade, education, and accommodation and food services.

But we can hope for higher unemployment amongst stock brokers!

Banks are watching wealthy clients flirt with robo-advisers, and that’s one reason the lenders are racing to release their own versions of the automated investing technology this year, according to a consultant.

Millennials and small investors aren’t the only ones using robo-advisers, a group that includes pioneers Wealthfront Inc. and Betterment LLC and services provided by mutual-fund giants, said Kendra Thompson, an Accenture Plc managing director. At Charles Schwab Corp., about 15 percent of those in automated portfolios have at least $1 million at the company.

“It’s real money moving,” Thompson said in an interview. “You’re seeing experimentation from people with much larger portfolios, where they’re taking a portion of their money and putting them in these offerings to try them out.”

… despite the best efforts of their future colleagues:

OSC Notice 33-745 also provided some commentary on what would be expected of a registered advising representative (AR) in the context of an online advisory business:

“The online advice model that we have considered acceptable involves an interactive website used to collect KYC information, which will be reviewed by a registered AR. The AR will communicate with the client by telephone, video link, email or internet chats. The AR must ensure that sufficient KYC information has been gathered to support the PM firm’s obligation to make suitability determinations for the client.

Each of the firms that we have registered to provide online advice operates on a discretionary managed account basis, using portfolios of unleveraged exchange traded funds (ETFs) or low cost mutual funds. In most cases, these are model portfolios which are selected for a client based on a profile generated by the KYC collection process. An AR will review and approve the suitability of the portfolio for the client. The client’s account is periodically rebalanced to the parameters set for their portfolio.

This is not the so-called “robo-advice” model seen in the United States, where online advice has seen rapid growth in the last few years. The online advisers operating in Ontario are offering hybrid services that utilize an online platform for the efficiencies it offers, while ARs remain actively involved in decision making.”

It was a good day for the Canadian preferred share market, with PerpetualDiscounts winning 62bp, FixedResets up 54bp and DeemedRetractibles gaining 8bp. The Performance Highlights table is lengthy. Volume was well below average.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_160205
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 17.43 to be $1.04 rich, while TRP.PR.G, resetting 2020-11-30 at +296, is $0.76 cheap at its bid price of 18.30.

impVol_MFC_160205
Click for Big

Most expensive is MFC.PR.N, resetting at +230bp on 2020-3-19, bid at 18.30 to be 1.21 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 18.20 to be 1.23 cheap.

impVol_BAM_160205
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 13.30 to be $1.65 cheap. BAM.PF.E, resetting at +255bp on 2020-3-31 is bid at 17.30 and appears to be $1.05 rich.

impVol_FTS_160205
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 16.15, looks $0.22 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 16.10 and is $0.24 cheap.

pairs_FR_160205
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.92%, with two outliers above 0.00%. There are four junk outliers above 0.00%.

pairs_FF_160205
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.29 % 6.43 % 17,535 16.15 1 0.0000 % 1,474.7
FixedFloater 7.54 % 6.59 % 26,260 15.69 1 0.0000 % 2,636.9
Floater 4.57 % 4.73 % 76,154 15.97 4 0.5841 % 1,676.7
OpRet 0.00 % 0.00 % 0 0.00 0 0.1458 % 2,707.8
SplitShare 4.88 % 6.35 % 81,687 2.70 6 0.1458 % 3,168.6
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1458 % 2,472.3
Perpetual-Premium 5.83 % 5.52 % 82,594 2.51 6 0.1461 % 2,533.9
Perpetual-Discount 5.74 % 5.77 % 98,625 14.25 33 0.2292 % 2,517.0
FixedReset 5.46 % 4.80 % 221,263 14.54 83 0.0119 % 1,856.9
Deemed-Retractible 5.24 % 5.56 % 130,758 5.22 34 0.0540 % 2,577.8
FloatingReset 3.04 % 4.65 % 50,430 5.56 16 0.1946 % 2,022.2
Performance Highlights
Issue Index Change Notes
TRP.PR.I FloatingReset -3.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-05
Maturity Price : 11.17
Evaluated at bid price : 11.17
Bid-YTW : 4.48 %
BAM.PF.G FixedReset -2.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-05
Maturity Price : 18.10
Evaluated at bid price : 18.10
Bid-YTW : 5.27 %
BAM.PF.F FixedReset -2.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-05
Maturity Price : 18.40
Evaluated at bid price : 18.40
Bid-YTW : 5.15 %
HSE.PR.A FixedReset -2.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-05
Maturity Price : 8.61
Evaluated at bid price : 8.61
Bid-YTW : 7.12 %
BAM.PF.E FixedReset -2.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-05
Maturity Price : 17.30
Evaluated at bid price : 17.30
Bid-YTW : 5.13 %
BAM.PF.B FixedReset -2.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-05
Maturity Price : 17.05
Evaluated at bid price : 17.05
Bid-YTW : 5.16 %
TRP.PR.H FloatingReset -1.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-05
Maturity Price : 9.17
Evaluated at bid price : 9.17
Bid-YTW : 4.77 %
BAM.PF.A FixedReset -1.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-05
Maturity Price : 18.15
Evaluated at bid price : 18.15
Bid-YTW : 5.19 %
BMO.PR.Z Perpetual-Discount -1.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-05
Maturity Price : 22.41
Evaluated at bid price : 22.73
Bid-YTW : 5.50 %
VNR.PR.A FixedReset -1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-05
Maturity Price : 16.77
Evaluated at bid price : 16.77
Bid-YTW : 5.38 %
BAM.PR.Z FixedReset -1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-05
Maturity Price : 17.87
Evaluated at bid price : 17.87
Bid-YTW : 5.34 %
SLF.PR.G FixedReset -1.00 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.87
Bid-YTW : 10.85 %
BAM.PR.B Floater 1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-05
Maturity Price : 10.10
Evaluated at bid price : 10.10
Bid-YTW : 4.73 %
MFC.PR.L FixedReset 1.00 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.09
Bid-YTW : 8.54 %
W.PR.H Perpetual-Discount 1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-05
Maturity Price : 22.70
Evaluated at bid price : 22.99
Bid-YTW : 6.04 %
ELF.PR.F Perpetual-Discount 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-05
Maturity Price : 22.10
Evaluated at bid price : 22.32
Bid-YTW : 5.99 %
TD.PF.E FixedReset 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-05
Maturity Price : 19.77
Evaluated at bid price : 19.77
Bid-YTW : 4.57 %
HSE.PR.C FixedReset 1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-05
Maturity Price : 15.07
Evaluated at bid price : 15.07
Bid-YTW : 6.72 %
MFC.PR.H FixedReset 1.21 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.05
Bid-YTW : 7.05 %
PWF.PR.K Perpetual-Discount 1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-05
Maturity Price : 21.37
Evaluated at bid price : 21.64
Bid-YTW : 5.75 %
RY.PR.J FixedReset 1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-05
Maturity Price : 19.15
Evaluated at bid price : 19.15
Bid-YTW : 4.53 %
MFC.PR.F FixedReset 1.33 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.18
Bid-YTW : 11.63 %
CCS.PR.C Deemed-Retractible 1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.35
Bid-YTW : 6.70 %
W.PR.J Perpetual-Discount 1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-05
Maturity Price : 22.93
Evaluated at bid price : 23.20
Bid-YTW : 6.09 %
HSE.PR.E FixedReset 1.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-05
Maturity Price : 16.00
Evaluated at bid price : 16.00
Bid-YTW : 6.86 %
CIU.PR.C FixedReset 1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-05
Maturity Price : 10.45
Evaluated at bid price : 10.45
Bid-YTW : 4.90 %
PWF.PR.T FixedReset 1.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-05
Maturity Price : 21.13
Evaluated at bid price : 21.13
Bid-YTW : 3.83 %
HSE.PR.G FixedReset 1.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-05
Maturity Price : 16.20
Evaluated at bid price : 16.20
Bid-YTW : 6.76 %
W.PR.K FixedReset 1.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-05
Maturity Price : 22.89
Evaluated at bid price : 24.25
Bid-YTW : 5.42 %
GWO.PR.O FloatingReset 1.99 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.25
Bid-YTW : 11.94 %
FTS.PR.I FloatingReset 2.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-05
Maturity Price : 10.25
Evaluated at bid price : 10.25
Bid-YTW : 4.70 %
BNS.PR.F FloatingReset 2.76 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.26
Bid-YTW : 7.48 %
TRP.PR.C FixedReset 3.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-05
Maturity Price : 11.76
Evaluated at bid price : 11.76
Bid-YTW : 4.78 %
Volume Highlights
Issue Index Shares
Traded
Notes
BAM.PR.T FixedReset 83,306 TD crossed 80,000 at 14.45.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-05
Maturity Price : 14.25
Evaluated at bid price : 14.25
Bid-YTW : 5.50 %
NA.PR.X FixedReset 66,528 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-05
Maturity Price : 23.14
Evaluated at bid price : 24.98
Bid-YTW : 5.55 %
RY.PR.H FixedReset 65,145 Desjardins crossed 50,000 at 17.58.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-05
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 4.47 %
TD.PF.G FixedReset 54,500 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 25.48
Bid-YTW : 5.18 %
MFC.PR.J FixedReset 52,368 Desjardins crossed 50,000 at 18.15.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.20
Bid-YTW : 7.88 %
TRP.PR.G FixedReset 45,354 Desjardins bought 20,700 from National at 18.25.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-05
Maturity Price : 18.30
Evaluated at bid price : 18.30
Bid-YTW : 5.13 %
There were 22 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
HSE.PR.C FixedReset Quote: 15.07 – 18.50
Spot Rate : 3.4300
Average : 1.8786

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-05
Maturity Price : 15.07
Evaluated at bid price : 15.07
Bid-YTW : 6.72 %

GWO.PR.O FloatingReset Quote: 11.25 – 13.50
Spot Rate : 2.2500
Average : 1.5421

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.25
Bid-YTW : 11.94 %

SLF.PR.J FloatingReset Quote: 11.74 – 12.55
Spot Rate : 0.8100
Average : 0.5388

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.74
Bid-YTW : 11.55 %

CU.PR.C FixedReset Quote: 17.00 – 17.50
Spot Rate : 0.5000
Average : 0.3251

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-05
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 4.62 %

RY.PR.M FixedReset Quote: 18.80 – 19.39
Spot Rate : 0.5900
Average : 0.4292

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-05
Maturity Price : 18.80
Evaluated at bid price : 18.80
Bid-YTW : 4.50 %

TD.PR.Z FloatingReset Quote: 21.85 – 22.45
Spot Rate : 0.6000
Average : 0.4393

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.85
Bid-YTW : 4.49 %

Market Action

February 4, 2016

There are mutterings about increasing foreign holdings of Canada bonds:

The Canadian fixed-income market is exposed to foreign investors like never before, said Warren Lovely, head of public-sector research at National Bank. And with Canada’s once-superior economic stature having slouched under the weight of the commodity shock, the appeal of Canadian bonds to global investors could fade, he said.

“If not a full-blown systemic risk, Canada’s leverage to foreign portfolio investors is a notable vulnerability for the country’s capital markets and debt issuers,” he said.

GOCForeignHeld
Click for Big

Morgan Stanley has prepared some interesting charts on global monetary policy:

The Bank of England voted unanimously not to raise interest rates Thursday, as the sole dissenter on the Monetary Policy Committee abandoned his recent calls to tighten policy. The European Commission also slashed its inflation forecasts, all but guaranteeing more quantitative easing when the European Central Bank next meets in March. Now, given the world’s deteriorating economic backdrop, that December rate increase from the Federal Reserve looks increasingly anachronistic.

monthsToUKHike
Click for Big
chanceOfUKCut
Click for Big
chanceOfFedHikeMarch
Click for Big

S&P published a review article titled Negative Interest Rates: Why Central Banks Can Defy “Time Preference”. It’s mainly about the BoJ move to negative policy rates, but concluded:

Since the Global Financial Crisis erupted in 2008 and triggered the Great Recession and ushered in a period of secular macro deleveraging, the major central banks of the world have progressively implemented all manner of “unconventional” monetary policy measures. There are now five major central banks implementing some form of negative interest rate policy. Two of those central banks are also implementing full-fledged QE. The Federal Reserve has made one interest rate hike, but it continues to have a balance sheet with a stock of QE on it to the tune of more than $3 trillion. Similarly the Bank of England, while not having raised interest rates yet, maintains a much enlarged balance sheet, thanks to its earlier five rounds of QE. Several major central banks have experimented with various forms of forward guidance too.

When future historians look back on this period, they will likely describe a world in which the major central banks all experimented with new forms of monetary policy easing and learned from one another in the process, as one central bank after another pioneered new policy innovations and others adopted and adapted them, some rapidly, others with long lags. Disentangling cause and effect in the process of cross-fertilization and adaptation will be no simple feat.

There is nothing new in this of course: The 20 years or so preceding the financial crisis were ones in which similar cross-fertilization of ideas and practice occurred, as what become known as “flexible inflation targeting” became the orthodoxy of central banking, before it was confronted by the ghost of Hyman Minsky (14).

It is my compelling sense that this process of cross-pollination of policy learning and institutional evolution is far from over. The journey into uncharted monetary waters continues.

It was a good day for the Canadian preferred share market, with PerpetualDiscounts winning 62bp, FixedResets up 54bp and DeemedRetractibles gaining 8bp. The Performance Highlights table is lengthy. Volume was average.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_160204
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 17.46 to be $1.14 rich, while TRP.PR.G, resetting 2020-11-30 at +296, is $0.86 cheap at its bid price of 18.21.

impVol_MFC_160204
Click for Big

Most expensive is MFC.PR.N, resetting at +230bp on 2020-3-19, bid at 18.35 to be 1.36 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 18.15 to be 1.20 cheap.

impVol_BAM_160204
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 13.30 to be $1.88 cheap. BAM.PF.E, resetting at +255bp on 2020-3-31 is bid at 17.66 and appears to be $1.17 rich.

impVol_FTS_160204
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 16.24, looks $0.23 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 16.15 and is $0.27 cheap.

pairs_FR_160204
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.98%, with two outliers above 0.00%. There are two junk outliers above 0.00%.

pairs_FF_160204
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.29 % 6.43 % 17,743 16.16 1 0.0000 % 1,474.7
FixedFloater 7.54 % 6.59 % 27,398 15.69 1 0.8000 % 2,636.9
Floater 4.60 % 4.74 % 73,652 15.95 4 1.0079 % 1,667.0
OpRet 0.00 % 0.00 % 0 0.00 0 0.1181 % 2,703.8
SplitShare 4.88 % 6.33 % 80,663 2.70 6 0.1181 % 3,164.0
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1181 % 2,468.7
Perpetual-Premium 5.83 % 5.83 % 81,018 13.99 6 0.3798 % 2,530.2
Perpetual-Discount 5.76 % 5.80 % 99,183 14.18 33 0.6211 % 2,511.3
FixedReset 5.46 % 4.86 % 225,799 14.39 83 0.5445 % 1,856.7
Deemed-Retractible 5.24 % 5.75 % 131,429 6.94 34 0.0779 % 2,576.4
FloatingReset 3.04 % 4.54 % 52,268 5.56 16 0.3644 % 2,018.3
Performance Highlights
Issue Index Change Notes
FTS.PR.I FloatingReset -2.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 10.04
Evaluated at bid price : 10.04
Bid-YTW : 4.80 %
CIU.PR.C FixedReset -1.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 10.29
Evaluated at bid price : 10.29
Bid-YTW : 4.97 %
TD.PF.E FixedReset -1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 19.56
Evaluated at bid price : 19.56
Bid-YTW : 4.61 %
HSE.PR.C FixedReset -1.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 14.90
Evaluated at bid price : 14.90
Bid-YTW : 6.80 %
BNS.PR.D FloatingReset -1.32 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.01
Bid-YTW : 7.25 %
HSE.PR.G FixedReset -1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 15.90
Evaluated at bid price : 15.90
Bid-YTW : 6.89 %
BNS.PR.F FloatingReset -1.28 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.77
Bid-YTW : 7.98 %
MFC.PR.F FixedReset -1.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.02
Bid-YTW : 11.81 %
PWF.PR.T FixedReset -1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 20.78
Evaluated at bid price : 20.78
Bid-YTW : 3.89 %
W.PR.K FixedReset -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 22.69
Evaluated at bid price : 23.80
Bid-YTW : 5.54 %
BAM.PF.C Perpetual-Discount 1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 19.72
Evaluated at bid price : 19.72
Bid-YTW : 6.24 %
RY.PR.N Perpetual-Discount 1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 22.35
Evaluated at bid price : 22.65
Bid-YTW : 5.41 %
BNS.PR.P FixedReset 1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.26
Bid-YTW : 3.55 %
FTS.PR.M FixedReset 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 18.10
Evaluated at bid price : 18.10
Bid-YTW : 4.72 %
CIU.PR.A Perpetual-Discount 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 19.71
Evaluated at bid price : 19.71
Bid-YTW : 5.85 %
BMO.PR.Z Perpetual-Discount 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 22.73
Evaluated at bid price : 23.10
Bid-YTW : 5.41 %
BMO.PR.W FixedReset 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 17.22
Evaluated at bid price : 17.22
Bid-YTW : 4.48 %
CU.PR.F Perpetual-Discount 1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 19.68
Evaluated at bid price : 19.68
Bid-YTW : 5.73 %
CM.PR.O FixedReset 1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 17.80
Evaluated at bid price : 17.80
Bid-YTW : 4.49 %
BAM.PF.A FixedReset 1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 18.46
Evaluated at bid price : 18.46
Bid-YTW : 5.10 %
TRP.PR.B FixedReset 1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 10.52
Evaluated at bid price : 10.52
Bid-YTW : 4.83 %
BAM.PR.C Floater 1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 9.96
Evaluated at bid price : 9.96
Bid-YTW : 4.79 %
BNS.PR.A FloatingReset 1.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.80
Bid-YTW : 4.10 %
BIP.PR.B FixedReset 1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 22.70
Evaluated at bid price : 23.81
Bid-YTW : 5.82 %
RY.PR.M FixedReset 1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 18.70
Evaluated at bid price : 18.70
Bid-YTW : 4.52 %
VNR.PR.A FixedReset 1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 5.31 %
CM.PR.Q FixedReset 1.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 19.03
Evaluated at bid price : 19.03
Bid-YTW : 4.63 %
BAM.PF.D Perpetual-Discount 1.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 19.99
Evaluated at bid price : 19.99
Bid-YTW : 6.22 %
BAM.PR.M Perpetual-Discount 1.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 19.52
Evaluated at bid price : 19.52
Bid-YTW : 6.17 %
MFC.PR.H FixedReset 1.80 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.81
Bid-YTW : 7.22 %
BAM.PR.K Floater 1.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 10.08
Evaluated at bid price : 10.08
Bid-YTW : 4.74 %
TRP.PR.A FixedReset 1.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 14.55
Evaluated at bid price : 14.55
Bid-YTW : 4.77 %
BAM.PR.N Perpetual-Discount 1.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 19.58
Evaluated at bid price : 19.58
Bid-YTW : 6.15 %
MFC.PR.J FixedReset 1.84 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.22
Bid-YTW : 7.87 %
IAG.PR.G FixedReset 1.93 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.51
Bid-YTW : 7.84 %
NA.PR.W FixedReset 1.97 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 16.56
Evaluated at bid price : 16.56
Bid-YTW : 4.76 %
HSE.PR.A FixedReset 1.97 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 8.79
Evaluated at bid price : 8.79
Bid-YTW : 6.97 %
W.PR.J Perpetual-Discount 2.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 22.62
Evaluated at bid price : 22.87
Bid-YTW : 6.18 %
MFC.PR.I FixedReset 2.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.90
Bid-YTW : 7.64 %
MFC.PR.G FixedReset 2.25 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.15
Bid-YTW : 8.15 %
GWO.PR.N FixedReset 2.46 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.50
Bid-YTW : 11.10 %
W.PR.H Perpetual-Discount 2.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 22.50
Evaluated at bid price : 22.76
Bid-YTW : 6.10 %
BAM.PF.E FixedReset 3.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 17.66
Evaluated at bid price : 17.66
Bid-YTW : 5.02 %
BAM.PF.G FixedReset 3.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 18.65
Evaluated at bid price : 18.65
Bid-YTW : 5.11 %
FTS.PR.G FixedReset 4.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 16.15
Evaluated at bid price : 16.15
Bid-YTW : 4.67 %
BAM.PF.B FixedReset 5.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 17.40
Evaluated at bid price : 17.40
Bid-YTW : 5.05 %
TRP.PR.I FloatingReset 9.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 11.52
Evaluated at bid price : 11.52
Bid-YTW : 4.35 %
Volume Highlights
Issue Index Shares
Traded
Notes
NA.PR.X FixedReset 372,600 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 23.14
Evaluated at bid price : 24.98
Bid-YTW : 5.54 %
TD.PF.G FixedReset 127,910 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 25.52
Bid-YTW : 5.14 %
BNS.PR.Z FixedReset 127,490 Desjardins crossed blocks of 40,000 and 29,100, both at 18.82. TD crossed 50,000 at 18.85.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.94
Bid-YTW : 7.12 %
RY.PR.Q FixedReset 117,729 RBC crossed two blocks of 25,000 each and one of 30,000, all at 25.63.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 23.32
Evaluated at bid price : 25.56
Bid-YTW : 5.13 %
HSB.PR.D Deemed-Retractible 101,940 Nesbitt crossed 99,700 at 24.90.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.85
Bid-YTW : 5.24 %
NA.PR.W FixedReset 85,609 Scotia crossed blocks of 32,200 and 40,000, both at 16.30.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 16.56
Evaluated at bid price : 16.56
Bid-YTW : 4.76 %
There were 35 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BAM.PF.F FixedReset Quote: 18.80 – 20.00
Spot Rate : 1.2000
Average : 0.9477

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 18.80
Evaluated at bid price : 18.80
Bid-YTW : 5.03 %

W.PR.K FixedReset Quote: 23.80 – 24.49
Spot Rate : 0.6900
Average : 0.4580

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 22.69
Evaluated at bid price : 23.80
Bid-YTW : 5.54 %

VNR.PR.A FixedReset Quote: 17.00 – 17.64
Spot Rate : 0.6400
Average : 0.4179

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 5.31 %

W.PR.J Perpetual-Discount Quote: 22.87 – 23.40
Spot Rate : 0.5300
Average : 0.3652

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 22.62
Evaluated at bid price : 22.87
Bid-YTW : 6.18 %

FTS.PR.I FloatingReset Quote: 10.04 – 10.57
Spot Rate : 0.5300
Average : 0.3980

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 10.04
Evaluated at bid price : 10.04
Bid-YTW : 4.80 %

BAM.PR.N Perpetual-Discount Quote: 19.58 – 19.98
Spot Rate : 0.4000
Average : 0.2794

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-04
Maturity Price : 19.58
Evaluated at bid price : 19.58
Bid-YTW : 6.15 %

Market Action

February 3, 2016

I mentioned yesterday the thesis that depressed markets are due to SWFs cashing out (although whenever I read that acronym, my first thought is “Single White Female”. Blush, blush.) Charles Stein of Bloomberg adds a bit more colour to that idea:

Money managers are having trouble hanging on to money.

Franklin Resources Inc. said Wednesday that investors withdrew $20.6 billion in the fourth quarter, the latest asset manager to highlight the issue of redemptions. Affiliated Mangers Group Inc. said on Tuesday that it had outflows of $6.8 billion, while Waddell & Reed saw $5 billion in withdrawals, contributing to the biggest drop in its stock since the financial crisis of 2008.

Money managers are hurt by slumping stock markets worldwide, which have prompted investors to dump anything perceived as risky. The firms are getting squeezed by sovereign wealth funds in need of cash after oil prices plunged, and the shift by investors from active funds to cheaper ones that track indexes. The preference for passive products and exchange-traded funds has created winners, including Vanguard Group Inc. and BlackRock Inc.
…
Aberdeen Asset Managment Plc last month cited the cash needs of sovereign wealth funds as one of the reasons the firm experienced 9.1 billion pounds ($13.2 billion) of withdrawals in the fourth quarter. The wealth funds from oil-producing nations, which boosted their investments when energy prices were high, are taking money back to fill the budget shortfalls created by cheap oil.

“Sovereign wealth funds were set up for a rainy day and that rainy day has arrived,” Aberdeen CEO Martin Gilbert said on a conference call in January. Gilbert in November said that 2016 would be a tough one for the asset management business if oil remained at $45 to $50 a barrel. It sells today for about $30.

Phillips of Casey Quirk estimated that about 70 percent of net global flows in 2015 went into passive products, a business dominated by a small number of players. Vanguard, known for its low-cost index funds and exchange-traded funds, collected a record $236 billion in deposits last year, including more than $58 billion in the fourth quarter.

cashFlows
Click for Big

But what the hell. Every day there’s an announcement of astonishing technological progress:

Scientists at the Max Planck Institute in Germany have successfully conducted a revolutionary nuclear fusion experiment. Using their experimental reactor, the Wendelstein 7-X (W7X) stellarator, they have managed to sustain a hydrogen plasma – a key step on the path to creating workable nuclear fusion. The German chancellor Angela Merkel, who herself has a doctorate in physics, switched on the device at 2:35 p.m. GMT (9:35 a.m. EST).

As a clean, near-limitless source of energy, it’s no understatement to say that controlled nuclear fusion (replicating the process that powers the Sun) would change the world, and several nations are striving to make breakthroughs in this field. Germany is undoubtedly the frontrunner in one respect: This is the second time that it’s successfully fired up its experimental fusion reactor.

So this is just one element in the thesis that technological progress has become so swift that disruptions in the market have become so frequent and fundamental that low growth – at least in the developed world – is virtually inevitable. Disruption is good in the long run, but bad in the short run … it took a long time for stenographers to re-train as administrative assistants, and a long time for companies to realize they needed them! It would be ideal if disruptions were maintained at a constant low level to allow for adjustment without broader-based recessions … but those darned engineers and scientists refuse to cooperate!

It was a good day for the Canadian preferred share market, with PerpetualDiscounts gaining 35bp, FixedResets winning 55bp and DeemedRetractibles up 40bp. The Performance Highlights table is lengthy. Volume was a little below average.

PerpetualDiscounts now yield 5.82%, equivalent to 7.57% interest at the standard equivalency factor of 1.3x. Long corporates continue to yield 4.2%, so the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) is now about 335bp, a significant decline from the 350bp reported January 27.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_160203
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 17.35 to be $1.15 rich, while TRP.PR.G, resetting 2020-11-30 at +296, is $0.82 cheap at its bid price of 18.10.

impVol_MFC_160203
Click for Big

Most expensive is MFC.PR.N, resetting at +230bp on 2020-3-19, bid at 18.20 to be 1.39 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 17.75 to be 1.31 cheap.

impVol_BAM_160203
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 13.35 to be $1.59 cheap. BAM.PF.F, resetting at +286bp on 2019-9-30 is bid at 18.80 and appears to be $0.99 rich.

impVol_FTS_160203
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 16.23, looks $0.49 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 15.50 and is $0.65 cheap.

pairs_FR_160203
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.98%, with one outlier above 0.00%. There are three junk outliers above 0.00%.

pairs_FF_160203
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.29 % 6.43 % 18,511 16.16 1 0.0000 % 1,474.7
FixedFloater 7.60 % 6.64 % 28,586 15.63 1 0.8065 % 2,615.9
Floater 4.65 % 4.82 % 74,649 15.80 4 0.9179 % 1,650.3
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0069 % 2,700.6
SplitShare 4.89 % 6.26 % 80,714 2.71 6 -0.0069 % 3,160.2
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0069 % 2,465.7
Perpetual-Premium 5.86 % 5.83 % 81,596 14.00 6 0.1201 % 2,520.6
Perpetual-Discount 5.79 % 5.82 % 98,399 14.14 33 0.3534 % 2,495.8
FixedReset 5.49 % 4.89 % 226,762 14.48 83 0.5471 % 1,846.6
Deemed-Retractible 5.25 % 5.69 % 131,408 6.94 34 0.4027 % 2,574.4
FloatingReset 3.05 % 4.68 % 52,853 5.56 16 1.0284 % 2,011.0
Performance Highlights
Issue Index Change Notes
BAM.PF.B FixedReset -5.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 16.46
Evaluated at bid price : 16.46
Bid-YTW : 5.35 %
BAM.PF.G FixedReset -2.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 17.98
Evaluated at bid price : 17.98
Bid-YTW : 5.31 %
PWF.PR.T FixedReset -2.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 21.01
Evaluated at bid price : 21.01
Bid-YTW : 3.85 %
BAM.PR.T FixedReset -2.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 14.40
Evaluated at bid price : 14.40
Bid-YTW : 5.44 %
BAM.PF.E FixedReset -1.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 17.13
Evaluated at bid price : 17.13
Bid-YTW : 5.18 %
FTS.PR.G FixedReset -1.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 15.50
Evaluated at bid price : 15.50
Bid-YTW : 4.88 %
BNS.PR.N Deemed-Retractible -1.10 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-01-27
Maturity Price : 25.00
Evaluated at bid price : 25.15
Bid-YTW : 4.68 %
BMO.PR.W FixedReset 1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 17.03
Evaluated at bid price : 17.03
Bid-YTW : 4.53 %
CIU.PR.C FixedReset 1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 10.47
Evaluated at bid price : 10.47
Bid-YTW : 4.89 %
RY.PR.F Deemed-Retractible 1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.35
Bid-YTW : 4.94 %
BMO.PR.Y FixedReset 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 19.35
Evaluated at bid price : 19.35
Bid-YTW : 4.52 %
RY.PR.P Perpetual-Discount 1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 23.72
Evaluated at bid price : 24.06
Bid-YTW : 5.45 %
CM.PR.O FixedReset 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 17.60
Evaluated at bid price : 17.60
Bid-YTW : 4.54 %
RY.PR.I FixedReset 1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.90
Bid-YTW : 3.90 %
TD.PF.B FixedReset 1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 17.39
Evaluated at bid price : 17.39
Bid-YTW : 4.49 %
SLF.PR.I FixedReset 1.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.45
Bid-YTW : 8.46 %
CU.PR.C FixedReset 1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 17.20
Evaluated at bid price : 17.20
Bid-YTW : 4.56 %
CU.PR.H Perpetual-Discount 1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 22.35
Evaluated at bid price : 22.66
Bid-YTW : 5.79 %
TRP.PR.F FloatingReset 1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 11.79
Evaluated at bid price : 11.79
Bid-YTW : 5.08 %
VNR.PR.A FixedReset 1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 16.75
Evaluated at bid price : 16.75
Bid-YTW : 5.39 %
TRP.PR.A FixedReset 1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 14.29
Evaluated at bid price : 14.29
Bid-YTW : 4.86 %
MFC.PR.I FixedReset 1.37 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.50
Bid-YTW : 7.94 %
NA.PR.S FixedReset 1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 17.56
Evaluated at bid price : 17.56
Bid-YTW : 4.66 %
RY.PR.L FixedReset 1.39 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.85
Bid-YTW : 3.91 %
SLF.PR.J FloatingReset 1.39 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.66
Bid-YTW : 11.63 %
BIP.PR.A FixedReset 1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 6.07 %
HSE.PR.A FixedReset 1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 8.62
Evaluated at bid price : 8.62
Bid-YTW : 7.11 %
MFC.PR.M FixedReset 1.44 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.26
Bid-YTW : 7.80 %
BAM.PR.K Floater 1.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 9.90
Evaluated at bid price : 9.90
Bid-YTW : 4.82 %
CCS.PR.C Deemed-Retractible 1.57 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.05
Bid-YTW : 6.89 %
BNS.PR.F FloatingReset 1.58 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.00
Bid-YTW : 7.74 %
RY.PR.K FloatingReset 1.63 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.82
Bid-YTW : 4.77 %
TD.PF.C FixedReset 1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 17.40
Evaluated at bid price : 17.40
Bid-YTW : 4.48 %
PWF.PR.S Perpetual-Discount 1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 21.05
Evaluated at bid price : 21.05
Bid-YTW : 5.74 %
BNS.PR.Z FixedReset 1.72 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.90
Bid-YTW : 7.16 %
TRP.PR.E FixedReset 1.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 17.35
Evaluated at bid price : 17.35
Bid-YTW : 4.75 %
BNS.PR.L Deemed-Retractible 1.79 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.48
Bid-YTW : 4.94 %
BAM.PR.B Floater 1.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 9.91
Evaluated at bid price : 9.91
Bid-YTW : 4.82 %
RY.PR.M FixedReset 1.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 18.45
Evaluated at bid price : 18.45
Bid-YTW : 4.58 %
MFC.PR.J FixedReset 1.88 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.89
Bid-YTW : 8.12 %
BNS.PR.C FloatingReset 2.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.16
Bid-YTW : 4.44 %
MFC.PR.N FixedReset 2.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.20
Bid-YTW : 7.78 %
FTS.PR.F Perpetual-Discount 2.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 21.95
Evaluated at bid price : 22.19
Bid-YTW : 5.61 %
TRP.PR.C FixedReset 2.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 11.40
Evaluated at bid price : 11.40
Bid-YTW : 4.93 %
SLF.PR.G FixedReset 2.75 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.10
Bid-YTW : 10.60 %
HSE.PR.E FixedReset 2.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 15.85
Evaluated at bid price : 15.85
Bid-YTW : 6.92 %
BNS.PR.B FloatingReset 2.95 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.65
Bid-YTW : 4.68 %
CM.PR.P FixedReset 3.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 17.21
Evaluated at bid price : 17.21
Bid-YTW : 4.54 %
FTS.PR.J Perpetual-Discount 3.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 21.55
Evaluated at bid price : 21.55
Bid-YTW : 5.62 %
HSE.PR.G FixedReset 3.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 16.11
Evaluated at bid price : 16.11
Bid-YTW : 6.80 %
SLF.PR.H FixedReset 4.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.68
Bid-YTW : 10.13 %
HSE.PR.C FixedReset 4.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 15.15
Evaluated at bid price : 15.15
Bid-YTW : 6.68 %
TRP.PR.I FloatingReset 5.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 10.50
Evaluated at bid price : 10.50
Bid-YTW : 4.77 %
Volume Highlights
Issue Index Shares
Traded
Notes
NA.PR.X FixedReset 144,750 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 23.13
Evaluated at bid price : 24.97
Bid-YTW : 5.55 %
RY.PR.Q FixedReset 144,512 Nesbitt crossed blocks of 50,000 and 59,000, both at 25.62.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 23.32
Evaluated at bid price : 25.59
Bid-YTW : 5.12 %
BNS.PR.E FixedReset 111,649 RBC crossed 25,000 at 25.63. Scotia crossed blocks of 40,000 and 20,000, both at the same price.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 23.33
Evaluated at bid price : 25.58
Bid-YTW : 5.11 %
BMO.PR.W FixedReset 59,769 Nesbitt crossed 25,100 at 17.00. Desjardins crossed 16,500 at the same price.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 17.03
Evaluated at bid price : 17.03
Bid-YTW : 4.53 %
TD.PF.G FixedReset 47,207 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 25.60
Bid-YTW : 5.07 %
BMO.PR.T FixedReset 37,422 Scotia crossed 25,000 at 17.22.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 17.22
Evaluated at bid price : 17.22
Bid-YTW : 4.51 %
There were 28 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BAM.PF.B FixedReset Quote: 16.46 – 17.43
Spot Rate : 0.9700
Average : 0.6121

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 16.46
Evaluated at bid price : 16.46
Bid-YTW : 5.35 %

NA.PR.W FixedReset Quote: 16.24 – 17.01
Spot Rate : 0.7700
Average : 0.4632

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 16.24
Evaluated at bid price : 16.24
Bid-YTW : 4.86 %

RY.PR.K FloatingReset Quote: 21.82 – 22.83
Spot Rate : 1.0100
Average : 0.7406

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.82
Bid-YTW : 4.77 %

FTS.PR.G FixedReset Quote: 15.50 – 16.11
Spot Rate : 0.6100
Average : 0.3914

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 15.50
Evaluated at bid price : 15.50
Bid-YTW : 4.88 %

PWF.PR.T FixedReset Quote: 21.01 – 21.70
Spot Rate : 0.6900
Average : 0.4862

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 21.01
Evaluated at bid price : 21.01
Bid-YTW : 3.85 %

CIU.PR.A Perpetual-Discount Quote: 19.50 – 20.18
Spot Rate : 0.6800
Average : 0.4980

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-02-03
Maturity Price : 19.50
Evaluated at bid price : 19.50
Bid-YTW : 5.91 %