Category: Market Action

Market Action

July 18, 2013

Detroit’s gone bust:

Detroit (9845MF) became the most populous U.S. city to file for bankruptcy, seeking court protection from creditors while it tries to eliminate a budget deficit and cut long-term debt.
…
Michigan’s largest city has seen its population decline to 707,000, down 7 percent since 2010, according to U.S. Census data. Median household income was less than $28,000, compared with $49,000 statewide, and more than 36 percent of residents lived in poverty as of 2011, Census data show. The median home value of $71,000 was barely half the $137,000 value statewide.

The city listed assets and debt of more than $1 billion in a Chapter 9 petition filed today in court in Detroit. Chapter 9 of the U.S. Bankruptcy Code is reserved for municipalities and differs from the rules used by bankrupt companies in Chapter 11.
…
Among the biggest drains on the city’s general fund, which pays for police, fire and other basic services, are health benefits paid to 18,500 retired city workers, mostly former police and firefighters, according to Orr’s May report. Without changes, the city will pay $163 million for retiree health-care costs in the next fiscal year, which starts July 1, the report found.

The Globe has more colour:

Among the points [Michigan Governor Rick Snyder] cited:

  • Citizens wait an average 58 minutes for police to respond, and just 8.7 per cent of cases are solved. “The city’s police cars, fire trucks and ambulances are so old that breakdowns make it impossible to keep up the fleet or properly carry out their roles.”
  • Only one-third of the city’s ambulances were in service in the first quarter.
  • Some 40 per cent of the street lights were dead in the first three months of the year.
  • “Large swathes of largely abandoned structures,” some 78,000, are creating public safety problems.
  • The city has more than $18-billion in financial obligations, and even if it could raise taxes, the people can’t afford to pay them.

Big news! The new regime for insurers is on its way!

Global insurers identified as too big to fail will have to hold higher reserves and draw up recovery and resolution plans to limit the economic fallout should they go bust, the industry’s watchdog said.

The International Association of Insurance Supervisors, which collected data from 50 insurers in 14 jurisdictions, including the U.S., to help the Financial Stability Board draw up a list of systemically important firms, released its assessment methodology and policy measures today. The list of insurers will be announced by the Basel, Switzerland-based FSB in coming days.
…
“Since the financial crisis, supervisors across the sector have worked diligently to address risks to the global financial system from systemically important financial institutions,” Peter Braumueller, chair of the IAIS executive committee, said in a statement. “The measures and framework put forward by the IAIS today complete a major piece of this reform in a manner specifically designed for the insurance sector.”

The companies on the FSB insurer list will be included based on criteria such as size, global activity and the amount of non-insurance businesses they have. The designation of systemically important means the failure of the company could threaten the financial system.

The IAIS would impose tougher capital standards on the systemically important insurers to increase their capacity to absorb losses and require them to design recovery and resolution plans to meet cases of severe financial distress. The FSB said in June it will follow up next year with a list of too-big-to-fail reinsurers.
…
The IAIS said non-traditional activities, including alternative risk transfers such as insurance-linked securities and financial guarantee insurance, as well as capital-markets businesses, banking, third-party asset management and industrial activities, are deemed the most risky and are the most important categories for assessing the systemic importance of an insurer. The firm’s interconnectedness was the next most significant consideration, the watchdog said.

The IAIS has said that traditional insurance and reinsurance are unlikely to cause or amplify systemic risk.

The list of GSIIs has been released:

Allianz SE
American International Group, Inc.
Assicurazioni Generali S.p.A.
Aviva plc
Axa S.A.
MetLife, Inc.
Ping An Insurance (Group) Company of China, Ltd.
Prudential Financial, Inc.
Prudential plc

It was a down day for the Canadian preferred share market, with PerpetualDiscounts losing 14bp, FixedResets off 1bp and DeemedRetractibles down 8bp. Volatility was low. Volume was high.

PerpetualDiscounts now yield 5.34%, equivalent to 6.94% interest at the standard equivalency factor of 1.3x. Long Corporates now yield about 4.6%, so the pre-tax interest-equivalent spread is now about 235bp, a small (and perhaps spurious) narrowing from the 240bp reported July 10.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.2329 % 2,577.0
FixedFloater 4.16 % 3.44 % 39,520 18.51 1 0.8830 % 3,994.0
Floater 2.72 % 2.91 % 87,859 19.95 4 -0.2329 % 2,782.4
OpRet 4.59 % 2.75 % 74,239 0.69 3 0.1148 % 2,631.1
SplitShare 4.66 % 4.41 % 59,450 3.93 6 -0.0331 % 2,972.6
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1148 % 2,405.9
Perpetual-Premium 5.59 % 4.31 % 101,411 0.59 12 0.1485 % 2,293.7
Perpetual-Discount 5.32 % 5.34 % 139,036 14.83 26 -0.1418 % 2,420.1
FixedReset 4.95 % 3.55 % 238,138 3.86 84 -0.0114 % 2,482.0
Deemed-Retractible 5.05 % 4.48 % 194,944 6.89 43 -0.0750 % 2,389.8
Performance Highlights
Issue Index Change Notes
W.PR.J Perpetual-Discount -1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-18
Maturity Price : 24.25
Evaluated at bid price : 24.55
Bid-YTW : 5.73 %
TRP.PR.B FixedReset 1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-18
Maturity Price : 23.30
Evaluated at bid price : 23.64
Bid-YTW : 3.26 %
Volume Highlights
Issue Index Shares
Traded
Notes
FTS.PR.K FixedReset 334,167 New issue settled today.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-18
Maturity Price : 23.14
Evaluated at bid price : 25.03
Bid-YTW : 3.71 %
SLF.PR.H FixedReset 191,001 Scotia sold 59,800 to National at 25.20, then crossed two blocks of 60,000 each at the same price.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-09-30
Maturity Price : 25.00
Evaluated at bid price : 25.12
Bid-YTW : 3.82 %
RY.PR.X FixedReset 130,203 Scotia crossed blocks of 100,000 and 23,600, both at 26.31.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-08-24
Maturity Price : 25.00
Evaluated at bid price : 26.27
Bid-YTW : 2.44 %
BAM.PF.D Perpetual-Discount 98,950 Added to TXPR.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-18
Maturity Price : 22.80
Evaluated at bid price : 23.16
Bid-YTW : 5.34 %
BMO.PR.J Deemed-Retractible 72,037 RBC crossed blocks of 35,300 and 15,000, both at 25.30.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.25
Bid-YTW : 4.48 %
RY.PR.D Deemed-Retractible 62,820 Added to TXPR.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.35
Bid-YTW : 4.42 %
There were 58 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BNS.PR.A FixedReset Quote: 26.12 – 26.48
Spot Rate : 0.3600
Average : 0.2250

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-08-17
Maturity Price : 25.50
Evaluated at bid price : 26.12
Bid-YTW : -27.21 %

FTS.PR.J Perpetual-Discount Quote: 23.34 – 23.68
Spot Rate : 0.3400
Average : 0.2411

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-18
Maturity Price : 22.92
Evaluated at bid price : 23.34
Bid-YTW : 5.14 %

PWF.PR.R Perpetual-Discount Quote: 25.10 – 25.39
Spot Rate : 0.2900
Average : 0.2032

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 25.10
Bid-YTW : 5.44 %

ELF.PR.G Perpetual-Discount Quote: 22.54 – 22.80
Spot Rate : 0.2600
Average : 0.1918

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-18
Maturity Price : 22.23
Evaluated at bid price : 22.54
Bid-YTW : 5.28 %

SLF.PR.G FixedReset Quote: 24.25 – 24.42
Spot Rate : 0.1700
Average : 0.1073

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.25
Bid-YTW : 3.71 %

IGM.PR.B Perpetual-Premium Quote: 25.38 – 25.59
Spot Rate : 0.2100
Average : 0.1501

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-12-31
Maturity Price : 25.25
Evaluated at bid price : 25.38
Bid-YTW : 5.69 %

Market Action

July 17, 2013

Bernanke used his Monetary Policy Report to clarify his ‘tapering’ comments:

I emphasize that, because our asset purchases depend on economic and financial developments, they are by no means on a preset course. On the one hand, if economic conditions were to improve faster than expected, and inflation appeared to be rising decisively back toward our objective, the pace of asset purchases could be reduced somewhat more quickly. On the other hand, if the outlook for employment were to become relatively less favorable, if inflation did not appear to be moving back toward 2 percent, or if financial conditions–which have tightened recently–were judged to be insufficiently accommodative to allow us to attain our mandated objectives, the current pace of purchases could be maintained for longer. Indeed, if needed, the Committee would be prepared to employ all of its tools, including an increase the pace of purchases for a time, to promote a return to maximum employment in a context of price stability.

Industrial Alliance is buying a conglomerator:

Consistent with its strategy to beef up its asset management arm, insurer Industrial Alliance is scooping up Jovian Capital, a holding company that owns stakes in a number of small asset managers, for $94-million. The deal adds roughly $7-billion of assets to the insurer’s existing $45-billion portfolio.
…
At first glance, Jovian may seem like a bit of an odd choice. The company hasn’t produced positive cash flow in the past few years, and it posted a $7.5-million loss from continuing operations in 2012.

Plus, last year some shareholders were outraged after Jovian’s management team cut themselves a $12-million compensation cheque amidst the weak performance. Shareholders wanted this cash for themselves.

Jovian is the sponsor of Jov Leon Frazer Preferred Equity fund, which has struggled since inception.

The Bank of Canada is maintaining the overnight rate at 1%:

Inflation has been low in recent months and is expected to remain subdued in the near term. The weakness in core inflation reflects persistent material excess capacity, heightened competitive pressures on retailers, relatively subdued wage increases, and some temporary sector-specific factors. Total CPI inflation has also been restrained by declining mortgage interest costs. As the economy gradually returns to full capacity and with inflation expectations well-anchored, both core and total CPI inflation are expected to return to 2 per cent around mid-2015.

Against this backdrop, the Bank has decided to maintain the target for the overnight rate at 1 per cent. As long as there is significant slack in the Canadian economy, the inflation outlook remains muted, and imbalances in the household sector continue to evolve constructively, the considerable monetary policy stimulus currently in place will remain appropriate. Over time, as the normalization of these conditions unfolds, a gradual normalization of policy interest rates can also be expected, consistent with achieving the 2 per cent inflation target.

TransAlta is taking drastic action:

TransAlta Corp., the worst-performing power generation stock in North America the past year, is betting a spinoff of its wind and hydroelectric power plants will increase the company’s value and help reverse two years of losses.

Canada’s largest publicly traded electricity generator gained 9.7 percent since the company said on June 26 it plans an initial public offering of some renewable energy assets. TransAlta has expanded its wind and hydro power capacity to about 25 percent from 15 percent in 2008 with developments in eastern Canada and parts of the U.S., even as power prices in its main markets of Alberta and Washington State declined.

“Investors are willing to pay more for renewables,” Jeremy Rosenfield, an analyst at Dejardins Capital Markets in Montreal, said by phone July 4.

The spinoff could help boost TransAlta’s shares to C$15.50 from C$14.54 at 4:05 p.m. in Toronto today, said Benjamin Pham, a BMO Capital Markets analyst, in a June 27 note. TransAlta’s renewable portfolio has been undervalued for years, he said.

“The structure of the spinoff is designed to permit TransAlta to retain control of its renewable energy fleet while unlocking value to the benefit of shareholders and to accelerate development and acquisition opportunities,” he said.

TransAlta is expected to raise C$200 million ($190 million) to C$250 million in the IPO when it closes in August, the company said in a statement. It will retain an 80 percent to 85 percent stake in the unit.

It hasn’t done their preferreds much good – TA.PR.D, TA.PR.F and TA.PR.H got whacked today. I have no idea why.

It looks like Parakeet Poluz has been given his script:

Stephen Poloz has spelled out what he expects to see from the economy before the Bank of Canada hikes interest rates, and the timeline appears to be a long one.

The new central bank governor sees holding the benchmark overnight rate at its current low level as long as there is significant excess capacity in the economy, the outlook for inflation remains muted, and households continue to get a better handle on their personal debts.

Also, the Conservatives have to get re-elected. That’s very important.

Interesting piece on the decline of the work ethic:

“Absenteeism is often explained around levels in workplace stress,” says Wolfgang Lehmann, a professor of sociology at the University of Western Ontario.

He partly attributes the rise in absenteeism, which has increased from 8 days lost per worker in 2000 to 9.3 days in 2011, to the stressful impact of layoffs, as well as the strain of caring for both children and elderly parents.

But that’s only part of a complex web of factors, and while it might seem obvious that sunny skies tempt workers to shirk their duties, it’s just another small piece of a puzzle that includes an employee’s gender, education level, and personal happiness.
…
Regardless of occupation or demographics, two factors that drive absenteeism are good benefits and bad management, according to Howard Seiden, an expert on workplace absenteeism at the University of Toronto.

“It’s not just a gender thing, or an age thing – it’s an unhappiness thing,” Dr. Seiden says. “People who aren’t happy and don’t like their jobs look for reasons not to come to work.”

It was another mixed day for the Canadian preferred share market, with PerpetualDiscounts up 23bp, FixedResets off 4bp and DeemedRetractibles down 9bp. Volatility was average – CU issues did well. Volume was high.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.0647 % 2,583.0
FixedFloater 4.19 % 3.48 % 39,412 18.44 1 0.1769 % 3,959.1
Floater 2.72 % 2.91 % 89,085 19.96 4 0.0647 % 2,788.9
OpRet 4.59 % 0.89 % 73,082 0.69 3 0.4097 % 2,628.1
SplitShare 4.66 % 4.40 % 61,243 3.93 6 0.0860 % 2,973.5
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.4097 % 2,403.1
Perpetual-Premium 5.60 % 4.45 % 99,746 0.77 12 -0.1417 % 2,290.3
Perpetual-Discount 5.31 % 5.30 % 138,701 14.84 26 0.2278 % 2,423.5
FixedReset 4.96 % 3.52 % 237,115 3.62 83 -0.0357 % 2,482.3
Deemed-Retractible 5.04 % 4.48 % 189,468 6.90 43 -0.0852 % 2,391.6
Performance Highlights
Issue Index Change Notes
ELF.PR.H Perpetual-Premium -1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-17
Maturity Price : 24.49
Evaluated at bid price : 24.90
Bid-YTW : 5.54 %
TRP.PR.B FixedReset -1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-17
Maturity Price : 22.94
Evaluated at bid price : 23.29
Bid-YTW : 3.31 %
CU.PR.F Perpetual-Discount 1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-17
Maturity Price : 22.86
Evaluated at bid price : 23.25
Bid-YTW : 4.88 %
CIU.PR.A Perpetual-Discount 1.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-17
Maturity Price : 22.61
Evaluated at bid price : 22.91
Bid-YTW : 5.07 %
CU.PR.G Perpetual-Discount 2.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-17
Maturity Price : 23.05
Evaluated at bid price : 23.46
Bid-YTW : 4.85 %
Volume Highlights
Issue Index Shares
Traded
Notes
BAM.PR.R FixedReset 203,755 Added to TXPR.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-17
Maturity Price : 23.71
Evaluated at bid price : 26.05
Bid-YTW : 3.92 %
BNS.PR.P FixedReset 176,332 It’s Strong Pair, BNS.PR.A, was added to TXPR, but it’s difficult to rationalize causation.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-04-25
Maturity Price : 25.00
Evaluated at bid price : 24.64
Bid-YTW : 3.66 %
BAM.PR.M Perpetual-Discount 111,870 Added to TXPR.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-17
Maturity Price : 22.08
Evaluated at bid price : 22.08
Bid-YTW : 5.43 %
SLF.PR.I FixedReset 82,590 Scotia crossed blocks of 36,000 and 25,000, both at 25.65.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.62
Bid-YTW : 3.56 %
TD.PR.P Deemed-Retractible 81,378 Added to TXPR.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-08-16
Maturity Price : 26.00
Evaluated at bid price : 26.06
Bid-YTW : -0.12 %
CM.PR.M FixedReset 76,209 Added to TXPR.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-07-31
Maturity Price : 25.00
Evaluated at bid price : 26.04
Bid-YTW : 2.22 %
There were 56 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
TRI.PR.B Floater Quote: 23.50 – 24.50
Spot Rate : 1.0000
Average : 0.6312

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-17
Maturity Price : 23.20
Evaluated at bid price : 23.50
Bid-YTW : 2.21 %

GWO.PR.R Deemed-Retractible Quote: 23.97 – 24.28
Spot Rate : 0.3100
Average : 0.1881

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.97
Bid-YTW : 5.34 %

BNS.PR.O Deemed-Retractible Quote: 25.76 – 26.14
Spot Rate : 0.3800
Average : 0.2752

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-04-26
Maturity Price : 25.00
Evaluated at bid price : 25.76
Bid-YTW : 4.67 %

FTS.PR.E OpRet Quote: 25.90 – 26.30
Spot Rate : 0.4000
Average : 0.3241

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-06-01
Maturity Price : 25.50
Evaluated at bid price : 25.90
Bid-YTW : 3.71 %

CIU.PR.C FixedReset Quote: 24.36 – 24.87
Spot Rate : 0.5100
Average : 0.4409

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-17
Maturity Price : 23.15
Evaluated at bid price : 24.36
Bid-YTW : 3.20 %

IAG.PR.F Deemed-Retractible Quote: 25.80 – 26.09
Spot Rate : 0.2900
Average : 0.2288

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2019-03-31
Maturity Price : 25.00
Evaluated at bid price : 25.80
Bid-YTW : 5.34 %

Market Action

July 16, 2013

Nothing happened today.

It was another mixed day for the Canadian preferred share market, with PerpetualDiscounts up 15bp, FixedResets down 9bp and DeemedRetractibles gaining 1bp. Volatility was average – by long-term standards! – but comprised entirely of losers. Volume was average.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.0259 % 2,581.3
FixedFloater 4.20 % 3.49 % 39,724 18.43 1 0.0000 % 3,952.1
Floater 2.72 % 2.92 % 89,985 19.95 4 0.0259 % 2,787.1
OpRet 4.61 % 3.29 % 73,721 0.85 3 -0.1023 % 2,617.4
SplitShare 4.67 % 4.50 % 63,775 3.93 6 -0.0132 % 2,971.0
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.1023 % 2,393.3
Perpetual-Premium 5.59 % 4.17 % 99,112 0.77 12 0.0692 % 2,293.6
Perpetual-Discount 5.33 % 5.25 % 138,113 14.81 26 0.1488 % 2,418.0
FixedReset 4.96 % 3.46 % 231,600 3.56 83 -0.0918 % 2,483.2
Deemed-Retractible 5.04 % 4.47 % 186,565 7.00 43 0.0141 % 2,393.7
Performance Highlights
Issue Index Change Notes
CIU.PR.A Perpetual-Discount -1.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-16
Maturity Price : 22.14
Evaluated at bid price : 22.52
Bid-YTW : 5.16 %
SLF.PR.G FixedReset -1.38 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.21
Bid-YTW : 3.73 %
MFC.PR.F FixedReset -1.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.70
Bid-YTW : 3.60 %
FTS.PR.J Perpetual-Discount -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-16
Maturity Price : 23.15
Evaluated at bid price : 23.45
Bid-YTW : 5.12 %
Volume Highlights
Issue Index Shares
Traded
Notes
GWO.PR.H Deemed-Retractible 149,231 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.77
Bid-YTW : 5.49 %
SLF.PR.H FixedReset 61,540 National crossed 40,000 at 25.15.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-09-30
Maturity Price : 25.00
Evaluated at bid price : 25.15
Bid-YTW : 3.77 %
TRP.PR.D FixedReset 55,933 TD crossed 28,000 at 25.30.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-16
Maturity Price : 23.17
Evaluated at bid price : 25.15
Bid-YTW : 3.98 %
GWO.PR.Q Deemed-Retractible 55,660 Scotia crossed 52,800 at 24.75.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.78
Bid-YTW : 5.31 %
CM.PR.M FixedReset 51,675 Nesbitt crossed 50,000 at 26.05.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-07-31
Maturity Price : 25.00
Evaluated at bid price : 26.00
Bid-YTW : 2.37 %
MFC.PR.K FixedReset 47,363 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-09-19
Maturity Price : 25.00
Evaluated at bid price : 25.19
Bid-YTW : 3.71 %
There were 35 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
CU.PR.G Perpetual-Discount Quote: 23.00 – 23.24
Spot Rate : 0.2400
Average : 0.1582

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-16
Maturity Price : 22.66
Evaluated at bid price : 23.00
Bid-YTW : 4.95 %

MFC.PR.C Deemed-Retractible Quote: 22.50 – 22.79
Spot Rate : 0.2900
Average : 0.2113

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.50
Bid-YTW : 5.77 %

BNS.PR.K Deemed-Retractible Quote: 25.06 – 25.29
Spot Rate : 0.2300
Average : 0.1682

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-04-28
Maturity Price : 25.00
Evaluated at bid price : 25.06
Bid-YTW : 4.21 %

MFC.PR.F FixedReset Quote: 24.70 – 24.95
Spot Rate : 0.2500
Average : 0.1889

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.70
Bid-YTW : 3.60 %

BNS.PR.O Deemed-Retractible Quote: 25.91 – 26.13
Spot Rate : 0.2200
Average : 0.1603

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-04-28
Maturity Price : 25.75
Evaluated at bid price : 25.91
Bid-YTW : 4.31 %

CIU.PR.A Perpetual-Discount Quote: 22.52 – 22.90
Spot Rate : 0.3800
Average : 0.3253

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-16
Maturity Price : 22.14
Evaluated at bid price : 22.52
Bid-YTW : 5.16 %

Market Action

July 15, 2013

Are the bond vigilantes hanging up their spurs?

U.S. fixed-income mutual funds attracted investor deposits last week, rebounding from redemptions spurred by speculation that the Federal Reserve would scale back its unprecedented stimulus, while bond exchange-traded funds had withdrawals.

Investors put $219 million into U.S. taxable-bond mutual funds while pulling $456 million from bond ETFs in the week ended July 10, Denver-based research firm Lipper said yesterday in an e-mailed statement. They deposited more than $3 billion in bond mutual funds and ETFs combined during the week ended July 3, the first week of net deposits in five weeks. U.S. bond funds had withdrawals of $23.7 billion in the four weeks ended June 26, the most since October 2008, Lipper said.

“Taxable-bond fund investors were of two minds,” Lipper said in the statement. “Neither amount reflected a strong opinion on bonds.”

It’s always nice to see big banks hurt by negative convexity:

JPMorgan Chase & Co (JPM). Chief Executive Officer Jamie Dimon warned investors that higher interest rates could lead to a “dramatic reduction” in the bank’s profits by eroding demand for mortgage refinancing.

The surge in 30-year home-loan rates to 4.46 percent at the end of June from 3.51 percent in mid-May caused second-quarter mortgage-fee revenue to decline 20 percent, the New York-based bank reported today. Refinancing volume could fall as much as 40 percent in the second half if rates remain elevated, Chief Financial Officer Marianne Lake told analysts on a call today.
…
Refinancings, which accounted for 76 percent of the industry’s $1.75 trillion in loan originations last year, slumped after 30-year rates surged in May and June, data compiled by Freddie Mac show. Applications to refinance loans fell 42 percent across the industry from May 17 to July 5, according to Joel Kan, an economist at the Mortgage Bankers Association, a Washington-based trade group.

Fortunately for Canadian banks, there is no real competition in Canada so we don’t have thirty-year open mortgages.

Electrical Engineering Professor Reza Iravani of the University of Toronto has come up with a a revolutionary idea for electricity delivery in Toronto:

“The delivery system has to be reinforced so even if you lose a station, the rest of the system can maintain operation without a major blackout,” he said.

Amazing. A system with some redundancy to make it more robust to single-point failure. Give the man a Nobel Prize – and, while you’re at it, a consulting contract to help the Bank of Canada with their Centralized Counterparty idea.

Investors in US Municipals have another thing to worry about:

Detroit bondholders may have a new worry after a judge ruled that Jefferson County, Alabama, could have paid legal bills for its bankruptcy from cash that was going to pay warrant holders owed $3 billion.

The ruling should concern bond investors whose revenue was previously protected from use by municipalities, said R. Dale Ginter, a bankruptcy lawyer at Downey Brand LLP in Sacramento, California. It may force those bondholders to reconsider waging an extensive legal fight to protect their interests, said Ginter, who represented retirees in the bankruptcy of Vallejo, California.
…
The ruling could apply to any municipal bankruptcy with debt being paid by pledged revenues such as parking fees, airport lease payments or water and sewer charges, Ginter said. Detroit is in talks to get bondholders and current and former city workers to accept $2 billion in exchange for wiping out the $11.5 billion they may be owed. Kevyn Orr, Detroit’s emergency financial manager, said he may put the city into bankruptcy if they can’t strike a deal.

It was a mixed day for the Canadian preferred share market, with PerpetualDiscounts up 20bp, FixedResets off 2bp and DeemedRetractibles flat. Volatility was lower than normal – especially when compared with recent times – but what there was was all positive. Volume was a little below average.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.2336 % 2,580.6
FixedFloater 4.20 % 3.49 % 41,381 18.43 1 0.4889 % 3,952.1
Floater 2.72 % 2.91 % 86,966 19.96 4 0.2336 % 2,786.4
OpRet 4.60 % 2.27 % 73,962 0.70 3 -0.0895 % 2,620.1
SplitShare 4.66 % 4.47 % 66,412 3.93 6 0.0217 % 2,971.4
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0895 % 2,395.8
Perpetual-Premium 5.60 % 4.11 % 99,741 0.78 12 0.0726 % 2,292.0
Perpetual-Discount 5.33 % 5.34 % 138,163 14.81 26 0.2034 % 2,414.4
FixedReset 4.95 % 3.41 % 232,126 3.56 83 -0.0233 % 2,485.4
Deemed-Retractible 5.04 % 4.49 % 187,830 7.00 43 -0.0009 % 2,393.3
Performance Highlights
Issue Index Change Notes
BAM.PR.N Perpetual-Discount 1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-15
Maturity Price : 21.65
Evaluated at bid price : 21.65
Bid-YTW : 5.54 %
ELF.PR.G Perpetual-Discount 1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-15
Maturity Price : 22.23
Evaluated at bid price : 22.55
Bid-YTW : 5.28 %
Volume Highlights
Issue Index Shares
Traded
Notes
BNS.PR.O Deemed-Retractible 105,100 RBC crossed 103,000 at 26.00.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-08-14
Maturity Price : 26.00
Evaluated at bid price : 26.00
Bid-YTW : 2.53 %
CU.PR.F Perpetual-Discount 65,010 Scotia crossed 56,000 at 22.65.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-15
Maturity Price : 22.44
Evaluated at bid price : 22.75
Bid-YTW : 4.99 %
ENB.PR.Y FixedReset 61,028 National bought 34,500 from Scotia at 25.00.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-15
Maturity Price : 23.09
Evaluated at bid price : 24.96
Bid-YTW : 3.99 %
CM.PR.K FixedReset 45,804 Nesbitt crossed 25,000 at 25.73.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-07-31
Maturity Price : 25.00
Evaluated at bid price : 25.70
Bid-YTW : 2.42 %
MFC.PR.K FixedReset 44,285 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-09-19
Maturity Price : 25.00
Evaluated at bid price : 25.22
Bid-YTW : 3.68 %
CM.PR.G Perpetual-Premium 35,542 Scotia crossed 24,800 at 25.25.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-05-01
Maturity Price : 25.00
Evaluated at bid price : 25.20
Bid-YTW : 4.11 %
There were 27 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
IAG.PR.G FixedReset Quote: 25.70 – 26.23
Spot Rate : 0.5300
Average : 0.3718

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-06-30
Maturity Price : 25.00
Evaluated at bid price : 25.70
Bid-YTW : 3.60 %

CU.PR.F Perpetual-Discount Quote: 22.75 – 23.20
Spot Rate : 0.4500
Average : 0.2929

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-15
Maturity Price : 22.44
Evaluated at bid price : 22.75
Bid-YTW : 4.99 %

BAM.PR.G FixedFloater Quote: 22.61 – 23.23
Spot Rate : 0.6200
Average : 0.4981

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-15
Maturity Price : 22.89
Evaluated at bid price : 22.61
Bid-YTW : 3.49 %

GWO.PR.M Deemed-Retractible Quote: 26.15 – 26.45
Spot Rate : 0.3000
Average : 0.2191

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2019-03-31
Maturity Price : 25.00
Evaluated at bid price : 26.15
Bid-YTW : 4.95 %

PWF.PR.R Perpetual-Discount Quote: 25.25 – 25.48
Spot Rate : 0.2300
Average : 0.1695

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 25.25
Bid-YTW : 5.34 %

TD.PR.K FixedReset Quote: 25.90 – 26.04
Spot Rate : 0.1400
Average : 0.0809

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-07-31
Maturity Price : 25.00
Evaluated at bid price : 25.90
Bid-YTW : 2.48 %

Market Action

July 12, 2013

Nothing happened today.

It was another day of solid recovery for the Canadian preferred share market, with PerpetualDiscounts winning 26bp, FixedResets gaining 10bp and DeemedRetractibles up 15bp. The Performance Highlights table is suitably bulky, comprised entirely of winners. Volume was above average.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.3909 % 2,574.6
FixedFloater 4.22 % 3.50 % 41,237 18.40 1 1.1236 % 3,932.8
Floater 2.73 % 2.93 % 86,335 19.93 4 0.3909 % 2,779.9
OpRet 4.60 % 1.79 % 75,091 0.71 3 0.2049 % 2,622.4
SplitShare 4.67 % 4.14 % 67,124 3.94 6 0.0383 % 2,970.7
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.2049 % 2,397.9
Perpetual-Premium 5.60 % 4.06 % 100,281 0.78 12 0.2813 % 2,290.3
Perpetual-Discount 5.35 % 5.25 % 139,247 14.78 26 0.2609 % 2,409.5
FixedReset 4.95 % 3.40 % 235,243 3.58 83 0.1004 % 2,486.0
Deemed-Retractible 5.04 % 4.50 % 185,094 6.91 43 0.1558 % 2,393.3
Performance Highlights
Issue Index Change Notes
GWO.PR.M Deemed-Retractible 1.01 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2019-03-31
Maturity Price : 25.00
Evaluated at bid price : 26.10
Bid-YTW : 4.98 %
TRI.PR.B Floater 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-12
Maturity Price : 23.20
Evaluated at bid price : 23.50
Bid-YTW : 2.21 %
BAM.PR.G FixedFloater 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-12
Maturity Price : 22.81
Evaluated at bid price : 22.50
Bid-YTW : 3.50 %
GWO.PR.G Deemed-Retractible 1.18 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.90
Bid-YTW : 5.30 %
GWO.PR.P Deemed-Retractible 1.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.30
Bid-YTW : 5.31 %
ELF.PR.H Perpetual-Premium 1.29 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-17
Maturity Price : 25.00
Evaluated at bid price : 25.22
Bid-YTW : 5.38 %
MFC.PR.F FixedReset 2.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.00
Bid-YTW : 3.47 %
Volume Highlights
Issue Index Shares
Traded
Notes
BNS.PR.P FixedReset 79,800 TD crossed 49,500 at 24.75; National crossed 25,000 at the same price.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-04-25
Maturity Price : 25.00
Evaluated at bid price : 24.61
Bid-YTW : 3.68 %
BNS.PR.N Deemed-Retractible 52,750 TD crossed 50,000 at 25.71.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-01-27
Maturity Price : 25.00
Evaluated at bid price : 25.68
Bid-YTW : 4.35 %
ENB.PR.F FixedReset 45,721 TD crossed 30,300 at 24.95.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-12
Maturity Price : 23.15
Evaluated at bid price : 24.95
Bid-YTW : 4.11 %
MFC.PR.I FixedReset 43,983 Desjardins crossed 30,000 at 25.95.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-09-19
Maturity Price : 25.00
Evaluated at bid price : 25.95
Bid-YTW : 3.51 %
ENB.PR.Y FixedReset 40,680 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-12
Maturity Price : 23.08
Evaluated at bid price : 24.93
Bid-YTW : 3.99 %
MFC.PR.K FixedReset 36,325 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-09-19
Maturity Price : 25.00
Evaluated at bid price : 25.15
Bid-YTW : 3.74 %
There were 37 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BAM.PR.G FixedFloater Quote: 22.50 – 22.95
Spot Rate : 0.4500
Average : 0.3645

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-12
Maturity Price : 22.81
Evaluated at bid price : 22.50
Bid-YTW : 3.50 %

CIU.PR.C FixedReset Quote: 24.51 – 24.96
Spot Rate : 0.4500
Average : 0.3676

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-12
Maturity Price : 23.21
Evaluated at bid price : 24.51
Bid-YTW : 3.17 %

RY.PR.W Perpetual-Premium Quote: 25.05 – 25.25
Spot Rate : 0.2000
Average : 0.1242

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-12
Maturity Price : 24.79
Evaluated at bid price : 25.05
Bid-YTW : 4.95 %

MFC.PR.H FixedReset Quote: 25.98 – 26.20
Spot Rate : 0.2200
Average : 0.1479

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-03-19
Maturity Price : 25.00
Evaluated at bid price : 25.98
Bid-YTW : 3.56 %

FTS.PR.J Perpetual-Discount Quote: 23.60 – 23.99
Spot Rate : 0.3900
Average : 0.3184

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-12
Maturity Price : 23.29
Evaluated at bid price : 23.60
Bid-YTW : 5.08 %

BMO.PR.J Deemed-Retractible Quote: 25.25 – 25.50
Spot Rate : 0.2500
Average : 0.1853

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.25
Bid-YTW : 4.46 %

Market Action

July 11, 2013

Sorry this is so late, folks! Summertime and the living is easy!

More Fed-watching!

Federal Reserve Chairman Ben S. Bernanke called for maintaining accommodation even as the minutes of policy makers’ June meeting showed them debating whether to stop bond buying by the Fed in 2013.

“Highly accommodative monetary policy for the foreseeable future is what’s needed in the U.S. economy,” Bernanke said yesterday in response to a question after a speech in Cambridge, Massachusetts.

The Fed chairman spoke just three hours after the central bank released minutes of the June 18-19 gathering showing that about half of the 19 participants in the Federal Open Market Committee wanted to halt $85 billion in monthly bond purchases by year end. At the same time, the minutes showed many Fed officials wanted to see more signs employment is improving before backing a trim to bond purchases known as quantitative easing.

The debate underscores Bernanke’s challenge in affirming that, even after starting to reduce monthly bond buying, policy makers plan to maintain unprecedented stimulus with a record-high balance sheet and near-zero target interest rate.

The persecution of Fabulous Fab for doing his job is entering a new stage:

After the allegations, he kept his head down. He testified succinctly before Congress, left his job to enroll in a doctoral program, and popped up in Africa doing charity work.

This is the new Fabrice Tourre who will walk into Manhattan federal court July 15.
…
In 2010, the Securities and Exchange Commission sued New York-based Goldman Sachs and Tourre for fraud for concealing the role of the hedge fund Paulson & Co., founded by billionaire John Paulson, in selecting the assets inside the Abacus portfolio — assets Paulson wanted to fail.

Goldman Sachs paid a then-record $550 million fine to settle the allegations. Tourre chose to fight them. U.S. District Judge Katherine Forrest, who will oversee the trial, summed up the SEC’s case like this: “Tourre handed Little Red Riding Hood an invitation to grandmother’s house while concealing the fact that it was written by the Big Bad Wolf.”
…
Tourre’s court date threatens to undo some of the progress Goldman Sachs has made in rehabilitating its image. In the lead-up to his trial, the bank and its former employee have exhibited an awkward arm’s-length relationship. Goldman Sachs is paying for Tourre’s defense and for the use of a sophisticated public-relations team from Sard Verbinnen & Co., but the bank is limited by the terms of its SEC settlement in what it can say publicly about the Abacus deal.
…
“This is so clearly a case of scapegoating,” said Dennis Kelleher, CEO of Better Markets, an advocacy group that has lobbied for the overhaul of financial regulations. “It’s one of the most egregious misuses of SEC power I’ve ever seen.”

If he loses – and he could go to jail over this – one lesson must be learned by all fund sponsors: it must be stated in the offering materials, in big bright red letters, that all the assets of the fund were bought from somebody else. Somebody who will not, presumably, be too upset if they subsequently decline in value.

As an aside, the HR departments are taking over:

Valerie Thompson went from a childhood hawking fish, fruit and vegetables in London’s run-down East End to a Eurobond star at Salomon Brothers Inc. when it was the world’s biggest trading firm. Like the successful trader she was, she got out at the top.

Eurobonds, international securities with untaxed interest payments, were only a decade old in 1973 when Thompson, who left school at age 15, landed a clerical job typing orders into a telex machine. She prospered as the market surged and was running new-issue strategy and managing the risk generated on London’s biggest bond trading floor when she left, just before the 1987 stock crash and as market returns began to diminish.

For all her acumen, Thompson, 57, says someone with her background couldn’t get a job in today’s financial industry.
“They closed the door,” she said in a lunchtime interview at Coya, the Peruvian restaurant on London’s Piccadilly, last month. “And they said, ‘You know what? To work in the City now you need three degrees.’ I find it downright wrong.”

When I got into this industry in 1986, I was working for Merrill Lynch as a temp; I applied for one of the posted jobs. HR told me they weren’t hiring … a chemistry degree? Why would we hire somebody with a chemistry degree? I don’t see any beakers around here, do you, Edna? My manager kicked ass and I got a new call offering me my pick of all the jobs in operations.

Tim Kiladze of the Globe has a very good article on the Canadian implications of the Basel 3 leverage ratio, titled How Canada’s banks benefit from OSFI’s leverage ratio:

While that might be a problem outside Canada, the Big Six argue that they already comply with OSFI’s asset-to-capital multiple, which limits a bank’s assets to 20 times their capital. Reverse that equation, and you get a 5-per-cent leverage ratio.

In other words, they should already exceed the coming 3-per-cent minimum, and even would be close to the 5- and 6-per-cent levels the U.S. just proposed for its own banks, depending on their size.

But it isn’t that easy. The way OSFI calculates leverage and capital differs from the new Basel standards. If you update OSFI’s model to abide by the new rules, our banks aren’t as well off.

The key difference, according to analyst Brad Smith at Stonecap Securities, is rooted in how you classify capital. Under OSFI’s model, Tier 1 and Tier 11 capital are included, whereas the Basel model has much stricter definitions. (Explaining these nuances gets incredibly wonky, but the main message is that OSFI is more lenient.)

By including Tier 2 capital, OSFI offers the Big Six a 26-per-cent leverage benefit – meaning their total capital jumps to $178-billion from just $141-billion of straightforward Tier 1 capital.

Mr. Smith also noted that OSFI’s calculation strips $167-billion of estimated securitized mortgages out of the Big Six’s asset exposure, lowering their asset total.

Removes these benefits and Mr. Smith calculates that Canadian banks would still meet the new Basel leverage requirements, but “fall well below” the proposed U.S. measure.

In order to meet a 5-per-cent minimum, “domestic banks would either have to reduce on-balance sheet exposure by over $700-billion (20 per cent) or add additional Tier 1 capital of approximately $35-billion even before considering the impact of off-balance sheet exposure levels,” Mr. Smith noted.

It may actually be worse than that. As I frequently complain, OSFI can boost the allowable leverage to 23x, and neither OSFI nor the bank benefitting has to give any explanation at all for the increased ceiling. I suspect it’s all just arranged over a friendly lunch.

A very nice day for the Canadian preferred share market, with PerpetualDiscounts winning 59bp, FixedResets gaining 9bp and DeemedRetractibles up 19bp. The Performance Highlights table is comprised entirely of winners, dominated by PerpetualDiscounts and PerpetualPremiums. Volume was above average.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.1044 % 2,564.6
FixedFloater 4.27 % 3.55 % 41,853 18.31 1 0.2117 % 3,889.1
Floater 2.74 % 2.92 % 86,387 19.94 4 0.1044 % 2,769.1
OpRet 4.61 % 2.04 % 74,273 0.71 3 0.0335 % 2,617.1
SplitShare 4.67 % 4.33 % 69,829 3.95 6 0.0042 % 2,969.6
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0335 % 2,393.0
Perpetual-Premium 5.62 % 4.30 % 101,098 0.79 12 0.2721 % 2,283.9
Perpetual-Discount 5.36 % 5.35 % 140,889 14.77 26 0.5984 % 2,403.2
FixedReset 4.96 % 3.48 % 236,060 3.57 83 0.0929 % 2,483.5
Deemed-Retractible 5.05 % 4.52 % 187,306 7.03 43 0.1937 % 2,389.6
Performance Highlights
Issue Index Change Notes
BAM.PR.Z FixedReset 1.09 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.88
Bid-YTW : 3.99 %
PWF.PR.K Perpetual-Discount 1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-11
Maturity Price : 23.28
Evaluated at bid price : 23.54
Bid-YTW : 5.26 %
PWF.PR.L Perpetual-Discount 1.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-11
Maturity Price : 23.50
Evaluated at bid price : 23.83
Bid-YTW : 5.35 %
MFC.PR.F FixedReset 1.41 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.50
Bid-YTW : 3.77 %
FTS.PR.J Perpetual-Discount 1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-11
Maturity Price : 23.42
Evaluated at bid price : 23.75
Bid-YTW : 5.05 %
CIU.PR.A Perpetual-Discount 1.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-11
Maturity Price : 22.64
Evaluated at bid price : 22.96
Bid-YTW : 5.06 %
ELF.PR.H Perpetual-Premium 1.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-11
Maturity Price : 24.49
Evaluated at bid price : 24.90
Bid-YTW : 5.53 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.E Deemed-Retractible 115,298 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.20
Bid-YTW : 4.49 %
RY.PR.C Deemed-Retractible 107,266 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.29
Bid-YTW : 4.54 %
RY.PR.B Deemed-Retractible 84,844 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2015-08-24
Maturity Price : 25.00
Evaluated at bid price : 25.30
Bid-YTW : 4.44 %
RY.PR.F Deemed-Retractible 79,654 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.16
Bid-YTW : 4.46 %
ENB.PR.H FixedReset 73,840 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-11
Maturity Price : 22.89
Evaluated at bid price : 24.30
Bid-YTW : 4.02 %
BNS.PR.A FixedReset 64,326 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-08-10
Maturity Price : 25.50
Evaluated at bid price : 25.95
Bid-YTW : -20.20 %
There were 37 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
ELF.PR.H Perpetual-Premium Quote: 24.90 – 25.49
Spot Rate : 0.5900
Average : 0.4098

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-11
Maturity Price : 24.49
Evaluated at bid price : 24.90
Bid-YTW : 5.53 %

BAM.PF.A FixedReset Quote: 25.34 – 25.69
Spot Rate : 0.3500
Average : 0.2021

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-09-30
Maturity Price : 25.00
Evaluated at bid price : 25.34
Bid-YTW : 4.26 %

CU.PR.C FixedReset Quote: 25.62 – 25.97
Spot Rate : 0.3500
Average : 0.2559

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-06-01
Maturity Price : 25.00
Evaluated at bid price : 25.62
Bid-YTW : 3.45 %

BAM.PR.X FixedReset Quote: 24.25 – 24.47
Spot Rate : 0.2200
Average : 0.1301

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-11
Maturity Price : 22.97
Evaluated at bid price : 24.25
Bid-YTW : 3.87 %

PWF.PR.E Perpetual-Discount Quote: 24.75 – 24.99
Spot Rate : 0.2400
Average : 0.1594

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-11
Maturity Price : 24.50
Evaluated at bid price : 24.75
Bid-YTW : 5.56 %

MFC.PR.I FixedReset Quote: 25.81 – 26.10
Spot Rate : 0.2900
Average : 0.2154

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-09-19
Maturity Price : 25.00
Evaluated at bid price : 25.81
Bid-YTW : 3.65 %

Market Action

July 10, 2013

It’s a Fed-Watching Frenzy!

“The minutes largely reiterated what the chairman said in June,” Ryan Larson, the Chicago-based head of U.S. equity trading at RBC Global Asset Management (U.S.) Inc., said by e-mail. His firm oversees $290 billion. “Tapering, whether it will be this year or next, is inevitable. The market was initially encouraged that the Fed is waiting on additional data, but possibly taken aback by the fact that about half the participants indicated that asset purchases should end later this year.”

Minutes from the central bank’s June 18-19 meeting, released today in Washington, showed that while several members judged that a reduction in asset purchases “would likely soon be warranted,” many officials want to see more signs employment is picking up before they’ll begin slowing the pace of $85 billion in monthly bond purchases.

The Globe was a bit more colourful:

The minutes show there was an intense debate about how to communicate the Fed’s intentions. A minority of policy makers are worried that the Fed’s policies are too aggressive, risking inflation and asset-price bubbles, and should be reversed as soon as possible. And among the supporters of more QE, there was a feeling that the central bank should nonetheless send the message that economic conditions were improving, heralding an eventual end to the bond-buying program.

It was decided that Mr. Bernanke should attempt to lay out a path for QE at the press conference that followed the meeting. That’s when he told reporters that if the economic outlook held, the Fed likely would slow its bond purchases later in 2014 and end the program in the middle of 2015, when the unemployment rate likely will have fallen to about 7 per cent.

Stock markets plunged immediately, as traders the world over largely disregarded Mr. Bernanke’s insistence that the Fed also could boost asset purchases if the economy failed to unfold as expected.

BIS has published a paper titled Analysis of risk-weighted assets for credit risk in the banking book:

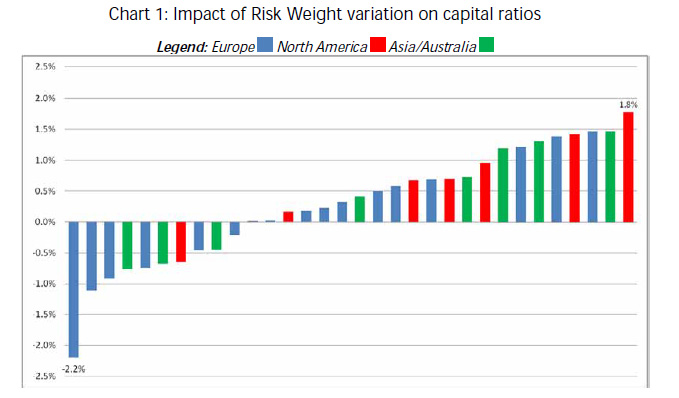
The bottom-up portfolio benchmarking exercise (the hypothetical portfolio exercise, or HPE), under which banks were asked to evaluate the risk of a common set of (largely low-default) wholesale obligors and exposures, revealed notable dispersion in the estimates of PD and LGD assigned to the same exposures. The three wholesale asset classes covered by the HPE analysis (sovereign, bank, and corporate) account on average for about 40% of participating banks’ total credit RWAs. A rough translation of the implied risk weight variations into potential impact on banks’ capital ratios suggests that the impact could be material; at the extremes, capital ratios could vary by as much as 1.5 to 2 percentage points (or 15 to 20% in relative terms) in either direction around the 10% benchmark used for this study. However, most of the banks (22 of the 32 participating banks) lie within one percentage point of that benchmark (see Chart 1 below).


Click for Big
Change from 10% capital ratio if individual bank risk weights from the HPE are adjusted to the median from the sample. Each bar represents one bank. The chart is based on the assumption that variations observed at each bank for the hypothetical portfolios are representative for the entire sovereign, bank, and corporate portfolios of the bank and are adjusted accordingly. No other adjustments are made to RWA or capital.

A reader brings to my attention a debunking of green disinformation:

  • The “Gas Town Steam Clock” is not powered by steam
  • The iconic wind turbine at Grouse Mountain is an energy sink
  • BC Hydro’s emissions reporting is highly misleading
  • Vancouver is nowhere as near as green as it likes to thing it is

I left this one out yesterday: DBRS confirmed RY at Pfd-1(low), although its NVCC-compliant RY.PR.W is still under Review-Negative:

RBC’s diversified business model and geographic profile have provided the Bank with consistently strong profitability and return on equity throughout various business and credit cycles. RBC is the largest retail bank in Canada and currently holds first or second-ranking positions in each business it participates in domestically, with an objective to become the leader in every business. The Bank continues to build on its leading market positions within Canada and is expanding its presence globally, particularly in wealth management and capital markets, where the Bank has been increasing its market share among the top global banks.

Despite strong performance in recent years, continued long-term domestic growth within Canada is expected to be a challenge given the Bank’s significant market share positions, the mature Canadian banking industry and the competitive landscape. Domestically, RBC and its large competitors have little room to grow beyond market growth rates, which have been strong in recent years. Additionally, foreign banks that previously exited the domestic market during the crisis have re-emerged as competitors.

DBRS does not expect potential house price depreciation in Canada to result in material losses from the Bank’s real estate secured lending portfolio, notwithstanding the high indebtedness of the average Canadian consumer and significant increases in housing prices in certain sectors of the Canadian real estate market.

The rating on the Non-Cumulative First Preferred Shares, Series W remains Under Review with Negative Implications. DBRS hopes to resolve this rating in the near future after the publication of the results from DBRS’s recent Request for Comments on Rating Subordinated, Hybrids and Preferred Bank Capital Securities

It was another day of retreat for the Canadian preferred share market, with PerpetualDiscounts losing 24bp, FixedResets off 8bp and DeemedRetractibles down 13bp. The Performance Highlights table was at average length – it hasn’t been average for a while!

PerpetualDiscounts now yield 5.41%, equivalent to 7.03% interest at the standard equivalency factor of 1.3x. Long corporates now yield about 4.65%, so the pre-tax interest-equivalent spread (in this context, the Seniority Spread) is now about 240bp, unchanged from the figure reported July 3.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.5062 % 2,561.9
FixedFloater 4.23 % 3.57 % 41,662 18.12 1 -0.1779 % 3,880.9
Floater 2.74 % 2.94 % 84,173 19.90 4 -0.5062 % 2,766.2
OpRet 4.81 % 2.08 % 77,228 0.71 4 0.0097 % 2,616.2
SplitShare 4.67 % 4.28 % 70,619 3.95 6 -0.1368 % 2,969.5
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0097 % 2,392.2
Perpetual-Premium 5.63 % 4.60 % 102,398 0.79 12 -0.0928 % 2,277.7
Perpetual-Discount 5.39 % 5.41 % 142,637 14.77 26 -0.2398 % 2,389.0
FixedReset 4.96 % 3.50 % 237,865 3.38 83 -0.0814 % 2,481.2
Deemed-Retractible 5.06 % 4.53 % 178,192 7.03 43 -0.1258 % 2,385.0
Performance Highlights
Issue Index Change Notes
FTS.PR.F Perpetual-Discount -1.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-10
Maturity Price : 23.05
Evaluated at bid price : 23.46
Bid-YTW : 5.27 %
ELF.PR.H Perpetual-Premium -1.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-10
Maturity Price : 24.05
Evaluated at bid price : 24.44
Bid-YTW : 5.64 %
BAM.PR.B Floater -1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-10
Maturity Price : 17.94
Evaluated at bid price : 17.94
Bid-YTW : 2.94 %
SLF.PR.G FixedReset -1.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.46
Bid-YTW : 3.70 %
Volume Highlights
Issue Index Shares
Traded
Notes
GWO.PR.H Deemed-Retractible 305,615 TD crossed blocks of 250,000 and 48,600, both at 23.80. Nice tickets!
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.72
Bid-YTW : 5.50 %
BNS.PR.Q FixedReset 160,395 RBC crossed blocks of 50,000 and 100,000, both at 25.00.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.95
Bid-YTW : 3.58 %
BAM.PR.N Perpetual-Discount 143,422 Desjardins crossed blocks of 50,000 and 83,300, both at 21.30.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-10
Maturity Price : 21.24
Evaluated at bid price : 21.24
Bid-YTW : 5.64 %
RY.PR.X FixedReset 139,715 RBC crossed 40,000 and 59,600, both at 26.23.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-08-24
Maturity Price : 25.00
Evaluated at bid price : 26.24
Bid-YTW : 2.49 %
TD.PR.S FixedReset 137,785 Reset rate announced.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.76
Bid-YTW : 3.59 %
ENB.PR.F FixedReset 56,221 National crossed 24,700 at 24.90.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-10
Maturity Price : 23.12
Evaluated at bid price : 24.86
Bid-YTW : 4.21 %
There were 64 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
GWO.PR.F Deemed-Retractible Quote: 25.30 – 25.59
Spot Rate : 0.2900
Average : 0.1902

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-08-09
Maturity Price : 25.00
Evaluated at bid price : 25.30
Bid-YTW : -6.57 %

TCA.PR.X Perpetual-Discount Quote: 49.70 – 50.00
Spot Rate : 0.3000
Average : 0.2132

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-10
Maturity Price : 49.24
Evaluated at bid price : 49.70
Bid-YTW : 5.64 %

PWF.PR.O Perpetual-Premium Quote: 25.45 – 25.78
Spot Rate : 0.3300
Average : 0.2453

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-10-31
Maturity Price : 25.25
Evaluated at bid price : 25.45
Bid-YTW : 5.48 %

BNA.PR.E SplitShare Quote: 25.70 – 26.00
Spot Rate : 0.3000
Average : 0.2182

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2017-12-10
Maturity Price : 25.00
Evaluated at bid price : 25.70
Bid-YTW : 4.28 %

SLF.PR.A Deemed-Retractible Quote: 23.13 – 23.39
Spot Rate : 0.2600
Average : 0.1798

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.13
Bid-YTW : 5.69 %

MFC.PR.F FixedReset Quote: 24.16 – 24.55
Spot Rate : 0.3900
Average : 0.3101

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.16
Bid-YTW : 3.92 %

Market Action

July 9, 2013

The US is taking effective action on bank capital ratios:

Capital standards at the biggest U.S. lenders would rise to 5 percent of assets for parent companies and 6 percent for their banking units under a plan proposed today by federal regulators.

The Office of the Comptroller of the Currency proposed a leverage ratio that’s 2 percentage points more than the 3 percent international minimum for holding companies, the agency said in a statement. Capital at U.S.-backed deposit and lending units must be twice the global standard at 6 percent, according to the OCC. The Federal Deposit Insurance Corp. is set to vote on the proposal later today.
…
The changes would affect the eight U.S. institutions already tagged as globally important, according to the Federal Reserve. The Financial Stability Board, a group of international central bankers that coordinates financial rules, identified them as JPMorgan (JPM) Chase & Co., Citigroup Inc. (C), Wells Fargo & Co. (WFC), Goldman Sachs Group Inc., Bank of America Corp. (BAC), Morgan Stanley (MS), State Street Corp. (STT) and Bank of New York Mellon Corp.

Based on the largest banks’ September data, the holding companies fell short of the new leverage requirement by $63 billion, FDIC staff said in a meeting with reporters today. The insured lending units would need $89 billion more in capital.

Banks would have until Jan. 1, 2018 to comply, according to today’s statement. The proposal faces a 60-day public comment period and needs final approvals from the three agencies.

The NYSE is taking over LIBOR:

NYSE Euronext (NYX) will replace the British Bankers’ Association as Libor’s administrator in early 2014, the London-based lobby group that started the benchmark more than two decades ago said in a statement today. The U.K.’s Financial Conduct Authority began regulating Libor, the benchmark for more than $300 trillion of securities, in April as part of the overhaul.

The New York-based purchaser already operates Liffe, Europe’s second-largest derivatives exchange, which offers derivatives based on Libor. A government review recommended last year that the BBA should be stripped of responsibility for Libor after regulators found banks had tried to manipulate it to profit from bets on derivatives.

“The fact they are handing this to a derivatives exchange is a surprise,” Peter Lenardos, a financials and exchange analyst at RBC Capital Markets in London, said by telephone today. “It just doesn’t seem independent enough. They are taking the setting of Libor from the banks and giving it to an exchange not known as a benchmark provider.”

Americans, unlike everybody else on earth, are well known for meticulous attention to routine government bullshit:

Anthony J. Domico, a former contractor hired to check the backgrounds of U.S. government workers, filed a 2006 report with the results of an investigation.

There was just one snag: A person he claimed to have interviewed had been dead for more than a decade. Domico, who had worked for contractors CACI International Inc. (CACI) and Systems Application & Technologies Inc., found himself the subject of a federal probe.

Domico is among 20 investigators who have pleaded guilty or have been convicted of falsifying such reports since 2006. Half of them worked for companies such as Altegrity Inc., which performed a background check on national-security contractor Edward Snowden. The cases may represent a fraction of the fabrications in a government vetting process with little oversight, according to lawmakers and U.S. watchdog officials.

Hats off to the NYSE for its eagerness to feast at the government trough!

The IMF is full of cheer:

World economic growth will struggle to accelerate this year as a U.S. expansion weakens, China’s economy levels off and Europe’s recession deepens, the International Monetary Fund said.

Global growth will be 3.1 percent this year, unchanged from the 2012 rate, and less than the 3.3 percent forecast in April, the Washington-based fund said today, trimming its prediction for this year a fifth consecutive time. The IMF reduced its 2013 projection for the U.S. to 1.7 percent growth from 1.9 percent in April, while next year’s outlook was trimmed to 2.7 percent from 3 percent initially reported in April.

So there continues to be a tug of war in the Fixed Income markets between the presumed tapering of Quantitative Easing and a really lousy global economy.

BNS was confirmed at Pfd-1(low) by DBRS:

Scotiabank continues to expand its footprint, both geographically and within business lines, by leveraging organic growth opportunities while still favouring an acquisition-oriented strategy. The Bank has made over 30 acquisitions since 2007, including sizable acquisitions, most notably the acquisition of ING Bank of Canada (ING) in August 2012 and the addition of a 51% stake in Colombian-based Banco Colpatria in January 2012. As a result of the aforementioned acquisitions, as well as organic growth, Scotiabank has grown in size at a more rapid pace than its Canadian banking peers. While offering greater growth opportunities and potentially higher returns, Scotiabank’s investments in the Caribbean, Central America, South America and Asia have inherently higher risk profiles relative to developed markets, resulting in additional political, economic, currency and operational risks.

The asset quality profile of the Bank remains good with particular strength in the Canadian market, although provisions in Latin America increased, in line with portfolio growth and a shift in portfolio mix. In May 2013, Scotiabank announced an upcoming leadership change: Rick Waugh will retire as CEO on November 1, 2013, and Brian Porter, the Bank’s current president, will assume the CEO role. Mr. Porter has extensive experience with the Bank and has held a number of high-level roles across several of its operating units; a smooth transition is expected, with no shift in strategic direction anticipated as a result of the change.

DBRS does not expect potential house price depreciation in Canada to result in material losses from the Bank’s real estate secured lending portfolio, notwithstanding the high indebtedness of the average Canadian consumer and significant increases in housing prices in certain sectors of the Canadian real estate market.

DBRS confirmed CM at Pfd-1(low), with the NVCC-compliant issues still under review-negative:

CIBC has one of the larger multi-pronged distribution networks in Canada to service its retail customers. The Bank also has one of the largest wealth management platforms in Canada relative to its large Canadian peers, positioning CIBC to benefit from longer-term demographic shifts as the domestic population ages. DBRS believes that CIBC’s Canadian retail markets strategy – to increase product penetration using a relationship-based approach – will be challenging given the Bank’s below-average customer satisfaction scores. CIBC continues to have the lowest customer satisfaction index ranking among the five largest Canadian banks, according to J.D. Power and Associates’ 2012 Canadian Retail Banking Customer Satisfaction Study.

It has been almost a year since CIBC ceased mortgage originations from its FirstLine broker channel on July 31, 2012. CIBC has focused its efforts on transitioning FirstLine customers to branch-based mortgages where the Bank benefits from higher margins and deeper client relationships, offering cross-sell opportunities. Thus far, the Bank has successfully executed on its retention of FirstLine clients, exceeding the initial 25% customer retention target.

CIBC remains engaged in discussions with Aimia Inc. (Aimia), the parent company of Aeroplan, regarding negotiations over the contract renewal of Aeroplan co-branded credit cards. It remains unclear whether CIBC will choose to renew its contract with Aimia, as The Toronto-Dominion Bank has put forth a competitive bid for the contract, which CIBC has the right of first refusal to match. CIBC has been extensively evaluating the prospect of developing its own loyalty travel card, which it is prepared to invest heavily in. The Bank’s ability to create an in-house credit card offering as compelling as the Aeroplan co-branded card remains unclear, although its intention is to leverage customer information to provide an industry-leading travel rewards card.

DBRS does not expect potential house price depreciation in Canada to result in material losses from the Bank’s real estate secured lending portfolio, notwithstanding the high indebtedness of the average Canadian consumer and significant increases in housing prices in certain sectors of the Canadian real estate market.

The ratings on the Non-Cumulative Class A Preferred Shares, Series 26, 27 and 29 remain Under Review with Negative Implications. DBRS hopes to resolve this rating in the near future after the publication of the results from DBRS’s recent Request for Comments on Rating Subordinated, Hybrids and Preferred Bank Capital Securities.

DBRS confirmed BMO at Pfd-1(low):

BMO’s integration of its 2011 acquisition of Marshall and Ilsley Corporation (M&I) has thus far proved successful, with the Bank achieving a large portion of the forecasted synergies. The strong credit performance of the acquired portfolio has led to substantial recoveries over the past two years. DBRS notes that while the acquisition of M&I materially increased the scale of BMO’s U.S. operation, it further exposes the Bank to the U.S. economy, real estate market, and interest rate and regulatory environments.

In the current environment of high consumer leverage, BMO has chosen to key in on products that, in management’s opinion, offer good risk-return tradeoffs, and reduced exposure in areas with less attractive risk-adjusted returns. As a result, BMO actively promoted a specific residential mortgage product – a five-year term 25-year amortization fixed-rate mortgage – that it believes has attractive fundamentals and low credit risk. At the same time, the Bank pulled back slightly on unsecured lending, which would likely be the first product to suffer delinquencies if consumer leverage stresses were to materialize, as well as on commercial real estate lending, where BMO has continued to limit the amount of its exposure in this highly competitive market.

DBRS does not expect potential house price depreciation in Canada to result in material losses from the Bank’s real estate secured lending portfolio, notwithstanding the high indebtedness of the average Canadian consumer and significant increases in housing prices in certain sectors of the Canadian real estate market.

DBRS confirmed NA at Pfd-2:

National continues to maintain its strong regional franchise in Québec, with particular emphasis on its retail, small business and commercial banking units as well as its wealth management business and national financial markets franchise. While strong market shares in the home province remain a key strength of the Bank, the ratings reflect the Bank’s regional concentration in Québec.

National delivered strong earnings growth in its Wealth Management and Financial Markets units in the first six months of 2013, as the Bank has begun to reap the benefits of a greater national presence outside of its core Québec market. National is leveraging the interprovincial acquisitions it has made over the past few years to establish a broader domestic presence in Wealth Management and Financial Markets.

National’s efficiency ratio (operating expenses over operating revenue) continues to sit above the average of its peer group, partly as a result of the high cost structure in the Bank’s Wealth Management segment. Given the number of acquisitions undertaken in Wealth Management over the past five years, most recently the acquisitions in 2012 of HSBC Securities (Canada) Inc. and Wellington West Holdings Inc., the Bank will now have to focus on aligning the different pieces of the business unit. The broader domestic presence of the Wealth Management segment and the alignment of the different pieces of the business should create the potential for the Bank to lower the expense base of the operating segment.

DBRS does not expect potential house price depreciation in Canada to result in material losses from the Bank’s real estate secured lending portfolio, notwithstanding the high indebtedness of the average Canadian consumer and significant increases in housing prices in certain sectors of the Canadian real estate market.

DBRS confirmed TD at Pfd-1(low):

Given revenue headwinds posed by the low interest rate environment and global uncertainty, TD, like its Canadian banking peers, has looked to expense management as a core focus of earnings growth. Contributions from Canadian personal banking will likely moderate as revenue growth slows, with households limiting new borrowing, and as the federal government’s tightening of mortgage rules continues to weigh on residential mortgage activity. TD continues to see earnings growth from its U.S. Personal and Commercial Banking (P&C) unit in 2013, supported by strong organic loan growth in personal and business lending relative to the prior year period (excluding the acquisition of Target Corporation’s U.S. credit card portfolio).

TD has created a retail banking north-south corridor in the eastern United States as a result of acquisitions and organic growth across its expanding network, providing the Bank with scale advantages. However, the U.S. P&C unit will be challenged by regulatory headwinds, margin pressures and the still-recovering economy within the United States.

In April of 2013, TD announced that its long-standing CEO, Ed Clark, will be stepping down in late 2014 and that Bharat Masrani, who leads the Bank’s U.S. P&C group, will assume the role of CEO. The long transition period for Masrani provides ample time for a smooth transition; no change in strategy or culture is anticipated. Additionally, TD closed two transactions in the second quarter of 2013, Target Corporation’s U.S. credit card portfolio and Epoch Holding Corporation, and entered into an agreement to acquire HSBC Retail Services Limited’s private label credit card portfolio. All transactions are consistent with the Bank’s strategy to grow assets within the United States.

DBRS does not expect potential house price depreciation in Canada to result in material losses from the Bank’s real estate secured lending portfolio, notwithstanding the high indebtedness of the average Canadian consumer and significant increases in housing prices in certain sectors of the Canadian real estate market.

It was a poor day for the Canadian preferred share market, with PerpetualDiscounts losing 40bp, FixedResets off 10bp and DeemedRetractibles down 18bp. The larger-than-average Performance Highlights table is, unsurprisingly enough, dominated by PerpetualDiscount losers. Volume was quite high.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.0519 % 2,575.0
FixedFloater 4.23 % 3.56 % 43,424 18.13 1 0.2229 % 3,887.8
Floater 2.73 % 2.91 % 77,941 19.99 4 -0.0519 % 2,780.2
OpRet 4.81 % 2.02 % 75,264 0.71 4 -0.1355 % 2,615.9
SplitShare 4.66 % 4.21 % 65,402 3.96 6 0.0614 % 2,973.5
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.1355 % 2,392.0
Perpetual-Premium 5.63 % 4.58 % 102,312 0.79 12 -0.0795 % 2,279.8
Perpetual-Discount 5.38 % 5.37 % 139,102 14.81 26 -0.3956 % 2,394.7
FixedReset 4.96 % 3.40 % 239,511 3.39 83 -0.0966 % 2,483.2
Deemed-Retractible 5.05 % 4.51 % 175,564 6.92 43 -0.1790 % 2,388.0
Performance Highlights
Issue Index Change Notes
FTS.PR.J Perpetual-Discount -3.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-09
Maturity Price : 23.24
Evaluated at bid price : 23.55
Bid-YTW : 5.09 %
CU.PR.D Perpetual-Discount -1.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-09
Maturity Price : 23.42
Evaluated at bid price : 23.75
Bid-YTW : 5.21 %
PWF.PR.L Perpetual-Discount -1.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-09
Maturity Price : 23.13
Evaluated at bid price : 23.60
Bid-YTW : 5.39 %
PWF.PR.K Perpetual-Discount -1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-09
Maturity Price : 22.84
Evaluated at bid price : 23.25
Bid-YTW : 5.31 %
HSE.PR.A FixedReset -1.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-09
Maturity Price : 23.07
Evaluated at bid price : 24.11
Bid-YTW : 3.77 %
CU.PR.E Perpetual-Discount -1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-09
Maturity Price : 23.42
Evaluated at bid price : 23.75
Bid-YTW : 5.21 %
MFC.PR.F FixedReset -1.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.34
Bid-YTW : 3.84 %
BAM.PF.C Perpetual-Discount 1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-09
Maturity Price : 21.31
Evaluated at bid price : 21.60
Bid-YTW : 5.64 %
Volume Highlights
Issue Index Shares
Traded
Notes
W.PR.H Perpetual-Discount 132,112 Nesbitt crossed 125,000 at 24.65.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-09
Maturity Price : 24.16
Evaluated at bid price : 24.42
Bid-YTW : 5.65 %
MFC.PR.D FixedReset 96,846 Nesbitt crossed 85,000 at 25.93.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-06-19
Maturity Price : 25.00
Evaluated at bid price : 25.91
Bid-YTW : 3.09 %
POW.PR.G Perpetual-Premium 61,395 RBC crossed 48,700 at 25.35.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-15
Maturity Price : 25.00
Evaluated at bid price : 25.20
Bid-YTW : 5.49 %
POW.PR.D Perpetual-Discount 61,235 RBC crossed 49,000 at 23.90.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-09
Maturity Price : 23.43
Evaluated at bid price : 23.69
Bid-YTW : 5.29 %
PWF.PR.S Perpetual-Discount 60,601 TD crossed 25,000 at 23.60.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-09
Maturity Price : 23.01
Evaluated at bid price : 23.42
Bid-YTW : 5.11 %
TD.PR.S FixedReset 52,246 Reset rate recently reported.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.86
Bid-YTW : 3.53 %
There were 52 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
HSE.PR.A FixedReset Quote: 24.11 – 24.62
Spot Rate : 0.5100
Average : 0.3687

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-09
Maturity Price : 23.07
Evaluated at bid price : 24.11
Bid-YTW : 3.77 %

GWO.PR.L Deemed-Retractible Quote: 25.45 – 25.95
Spot Rate : 0.5000
Average : 0.3913

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.45
Bid-YTW : 5.33 %

BAM.PR.G FixedFloater Quote: 22.48 – 22.86
Spot Rate : 0.3800
Average : 0.2752

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-09
Maturity Price : 22.79
Evaluated at bid price : 22.48
Bid-YTW : 3.56 %

FTS.PR.J Perpetual-Discount Quote: 23.55 – 23.91
Spot Rate : 0.3600
Average : 0.2647

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-09
Maturity Price : 23.24
Evaluated at bid price : 23.55
Bid-YTW : 5.09 %

FTS.PR.F Perpetual-Discount Quote: 23.92 – 24.34
Spot Rate : 0.4200
Average : 0.3394

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-09
Maturity Price : 23.59
Evaluated at bid price : 23.92
Bid-YTW : 5.17 %

BMO.PR.L Deemed-Retractible Quote: 26.18 – 26.44
Spot Rate : 0.2600
Average : 0.1884

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-05-25
Maturity Price : 25.75
Evaluated at bid price : 26.18
Bid-YTW : 4.48 %

Market Action

July 8, 2013

You think you’ve had a bad time in the markets for the past year? Here’s a guy who’s had a bad time in the markets for the past year:

Brazilian billionaire Eike Batista lost more than a quarter of his net worth after the state development bank said he offered personal guarantees for 2.3 billion reais ($1 billion) in loans and a rout of his publicly traded companies deepened.

Batista is now worth $2.9 billion, down from $4.1 billion at the close of trading July 2, according to the Bloomberg Billionaires Index. The loans are part of the 10.4 billion reais that Batista’s companies contracted with the state-run lender, known as BNDES, since 2007. BNDES provided the tally of the loans and their respective guarantees in response to a request by Bloomberg under Brazil’s freedom of information law. The bank didn’t say how much is outstanding.

Batista’s fortune has plunged from a peak of $34.5 billion last year after he repeatedly failed to meet targets he had set for his startup companies. The latest disappointment came when his flagship OGX Petroleo & Gas Participacoes SA (OGXP3) said July 1 that it may shut down its only producing oil field, prompting a selloff that’s since erased $1 billion in market value from his six publicly traded units.
…
The information provided by BNDES follows a July 1 report from Bank of America Corp. that estimated that the Rio de Janeiro-based lender was the most exposed of Brazil’s banks to Batista’s companies, having lent 4.9 billion reais, or 5.8 percent of the bank’s regulatory capital.

The best thing about bond ETFs is that they provide liquidity. The worst thing about them is that they provide liquidity:

Investors who sought exchange-traded funds as a faster way to trade corporate bonds are finding that they can be as expensive to trade as the underlying debt.

As trading in the three-biggest credit ETFs surged to unprecedented levels last month amid the market’s biggest losses since 2008, the funds’ shares dropped as much as 1.1 percentage points more than the net value of the less-traded securities they hold. The two largest high-yield bond ETFs have lost about 6 percent since reaching a five-year high May 8. That’s about 2 percentage points more than the loss for the Bank of America Merrill Lynch U.S. High Yield Index.

The gap reflects the extra charge investors paid for a speedier exit in a declining market by using ETFs that trade like stocks rather than buying and selling the less-liquid debt. Investors yanked about $1.83 billion of shares from the two-biggest junk ETFs last month, forcing sales of their holdings at a time when demand was evaporating.
…
Shares of BlackRock Inc.’s $13.7 billion iShares iBoxx $ High Yield Corporate Bond ETF, the biggest of its kind, plummeted 4.3 percent in the six days ended June 24, while the net value of its assets dropped 3 percent, data compiled by Bloomberg show. The fund’s share price fell to the lowest level in 12 months on June 24, to $89.04. The lowest value last month for the underlying assets was $89.66, the data show.

“The price reflects where you can exchange risk,” said Matt Tucker, head of iShares fixed-income strategy at BlackRock, the biggest ETF provider. “It’s the correct price. The reality is the majority of the high-yield market doesn’t trade every day.”

Nature abhors a vacuum:

Blackstone Group LP (BX), the private-equity firm that has spent $5 billion on more than 30,000 distressed houses, is preparing to expand its bet on the housing recovery by lending to other landlords.

The firm, which already owns more rental homes than any other investor, has set up B2R Finance LP to offer loans starting at $10 million, according to four people who reviewed the terms. B2R is reaching out to landlords with portfolios of properties seeking to grow in the burgeoning industry for single-family homes to rent, said the people, who asked not to be identified because the discussions are private.

The world’s largest private-equity firm said last month that it was entering the later stages of its buying spree after leading a group of institutional investors who’ve spent at least $17 billion on more than 100,000 homes over two years, helping fuel the fastest price gains since 2006. By increasing its stake in the rebound through lending, New York-based Blackstone could benefit from smaller landlords already investing in what Goldman Sachs Group Inc. estimates to be a $2.8 trillion market.

Live by market-timing, die by market timing:

John Paulson, the billionaire hedge-fund manager seeking to rebound from losses tied to bullion, posted a 23 percent decline in his PFR Gold Fund last month, according to a letter to investors.

The drop brings losses in the strategy, formerly known as the Paulson Gold Fund, to 65 percent since the start of the year, the firm said in the July 3 letter, a copy of which was obtained by Bloomberg News.

This report was delayed due to the incompetence of Toronto Hydro.

It was a day of modest recovery for the Canadian preferred share market; more modest than many recent days, but still a recovery! PerpetualDiscounts and DeemedRetractibles were both up 8bp, while FixedResets won 12bp. Volatility was more than one could generally expect on such a day; volume was average.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.3645 % 2,576.3
FixedFloater 4.24 % 3.57 % 43,975 18.12 1 -0.3554 % 3,879.2
Floater 2.72 % 2.90 % 78,760 20.00 4 0.3645 % 2,781.7
OpRet 4.84 % 3.37 % 61,750 0.15 5 0.0156 % 2,619.5
SplitShare 4.66 % 4.28 % 66,464 3.96 6 0.1618 % 2,971.7
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0156 % 2,395.2
Perpetual-Premium 5.62 % 3.99 % 102,674 0.08 12 0.1306 % 2,281.6
Perpetual-Discount 5.36 % 5.33 % 138,830 14.76 26 0.0849 % 2,404.2
FixedReset 4.95 % 3.41 % 239,169 3.59 83 0.1166 % 2,485.6
Deemed-Retractible 5.05 % 4.49 % 177,810 6.90 44 0.0760 % 2,392.3
Performance Highlights
Issue Index Change Notes
CU.PR.E Perpetual-Discount -1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-08
Maturity Price : 23.69
Evaluated at bid price : 24.04
Bid-YTW : 5.14 %
HSB.PR.C Deemed-Retractible -1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.98
Bid-YTW : 5.16 %
SLF.PR.H FixedReset 1.11 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-09-30
Maturity Price : 25.00
Evaluated at bid price : 25.57
Bid-YTW : 3.19 %
GCS.PR.A SplitShare 1.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2019-07-31
Maturity Price : 25.00
Evaluated at bid price : 25.00
Bid-YTW : 4.01 %
TRP.PR.B FixedReset 1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-08
Maturity Price : 23.16
Evaluated at bid price : 23.50
Bid-YTW : 3.38 %
FTS.PR.J Perpetual-Discount 1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-08
Maturity Price : 23.98
Evaluated at bid price : 24.35
Bid-YTW : 4.92 %
PWF.PR.L Perpetual-Discount 1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-08
Maturity Price : 23.71
Evaluated at bid price : 24.05
Bid-YTW : 5.29 %
BAM.PR.K Floater 1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-08
Maturity Price : 17.83
Evaluated at bid price : 17.83
Bid-YTW : 2.96 %
Volume Highlights
Issue Index Shares
Traded
Notes
BNS.PR.R FixedReset 59,400 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.09
Bid-YTW : 3.72 %
CM.PR.G Perpetual-Premium 51,917 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-08-07
Maturity Price : 25.25
Evaluated at bid price : 25.20
Bid-YTW : 3.88 %
PWF.PR.G Perpetual-Premium 44,100 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-08-07
Maturity Price : 25.00
Evaluated at bid price : 24.98
Bid-YTW : 2.36 %
TCA.PR.Y Perpetual-Discount 43,343 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-03-05
Maturity Price : 50.00
Evaluated at bid price : 50.01
Bid-YTW : 5.00 %
TD.PR.S FixedReset 34,966 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.84
Bid-YTW : 3.54 %
MFC.PR.K FixedReset 34,400 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-09-19
Maturity Price : 25.00
Evaluated at bid price : 25.01
Bid-YTW : 3.85 %
There were 34 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
ENB.PR.H FixedReset Quote: 24.40 – 24.79
Spot Rate : 0.3900
Average : 0.2611

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-08
Maturity Price : 22.93
Evaluated at bid price : 24.40
Bid-YTW : 4.00 %

GWO.PR.L Deemed-Retractible Quote: 25.40 – 25.79
Spot Rate : 0.3900
Average : 0.2721

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-12-31
Maturity Price : 25.25
Evaluated at bid price : 25.40
Bid-YTW : 5.51 %

CU.PR.C FixedReset Quote: 25.72 – 26.09
Spot Rate : 0.3700
Average : 0.2688

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-06-01
Maturity Price : 25.00
Evaluated at bid price : 25.72
Bid-YTW : 3.34 %

MFC.PR.F FixedReset Quote: 24.60 – 24.97
Spot Rate : 0.3700
Average : 0.2689

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.60
Bid-YTW : 3.72 %

CM.PR.K FixedReset Quote: 25.58 – 25.90
Spot Rate : 0.3200
Average : 0.2267

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-07-31
Maturity Price : 25.00
Evaluated at bid price : 25.58
Bid-YTW : 2.83 %

W.PR.J Perpetual-Discount Quote: 24.57 – 24.84
Spot Rate : 0.2700
Average : 0.1881

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-08
Maturity Price : 24.27
Evaluated at bid price : 24.57
Bid-YTW : 5.71 %

Market Action

July 5, 2013

Nice article on pension derisking:

Such pension “derisking” approaches include lump-sum payouts to vested, terminated employees; liability-driven investment (LDI) strategies that match up plan assets with pension liabilities by moving from equities to long-term bonds; and the one currently making headlines — annuitization, the transfer of a sizable percentage of pension obligations to an insurance company for a paid premium. These tactics join more-traditional approaches, such as freezing and closing pension plans. Taken together, they constitute a sea change in pension-plan treatment.

A good US jobs number had the market in a tizzy:

Employment roared ahead in June, indicating the U.S. economy is poised for faster growth as it shakes off the impact of tax increases and budget cuts.

Payrolls rose by 195,000 workers for a second month, the Labor Department reported today in Washington, exceeding the 165,000 gain projected by economists in a Bloomberg survey. The jobless rate stayed at 7.6 percent, close to a four-year low.

Hourly earnings in the year ended in June advanced by the most since July 2011, giving Americans already buoyed by higher home prices more reason to boost household spending, which accounts for 70 percent of the economy. Stocks climbed, while the yield on 10-year Treasuries rose to the highest in almost two years on expectations the Federal Reserve will start trimming $85 billion in monthly bond purchases in September.

The Canadian preferred share market got knocked back, with PerpetualDiscounts losing 51bp, FixedResets off 20bp and DeemedRetractibles down 35bp. The Performance Highlights table was suitably dismal: very lengthy with only one winner; Brookfield issues led the way downwards. Interestingly, the Volume Highlights table is comprised entirely of Royal Bank issues, led by DeemedRetractibles; volume was above average.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.7751 % 2,566.9
FixedFloater 4.22 % 3.56 % 44,070 18.15 1 -2.1304 % 3,893.0
Floater 2.73 % 2.90 % 79,674 20.02 4 -0.7751 % 2,771.6
OpRet 4.84 % 3.30 % 63,983 0.15 5 0.1483 % 2,619.1
SplitShare 4.67 % 4.27 % 69,221 3.96 6 -0.2030 % 2,966.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1483 % 2,394.9
Perpetual-Premium 5.60 % 4.12 % 102,524 0.09 12 -0.2568 % 2,278.7
Perpetual-Discount 5.35 % 5.38 % 141,102 14.74 26 -0.5064 % 2,402.2
FixedReset 4.96 % 3.44 % 241,676 3.60 83 -0.2027 % 2,482.7
Deemed-Retractible 5.06 % 4.49 % 178,207 4.87 44 -0.3485 % 2,390.5
Performance Highlights
Issue Index Change Notes
BAM.PR.G FixedFloater -2.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-05
Maturity Price : 22.82
Evaluated at bid price : 22.51
Bid-YTW : 3.56 %
BAM.PR.M Perpetual-Discount -1.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-05
Maturity Price : 21.29
Evaluated at bid price : 21.29
Bid-YTW : 5.62 %
BAM.PR.N Perpetual-Discount -1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-05
Maturity Price : 21.27
Evaluated at bid price : 21.27
Bid-YTW : 5.63 %
FTS.PR.F Perpetual-Discount -1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-05
Maturity Price : 23.86
Evaluated at bid price : 24.20
Bid-YTW : 5.10 %
BAM.PF.C Perpetual-Discount -1.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-05
Maturity Price : 21.50
Evaluated at bid price : 21.50
Bid-YTW : 5.68 %
CU.PR.G Perpetual-Discount -1.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-05
Maturity Price : 22.20
Evaluated at bid price : 22.55
Bid-YTW : 5.04 %
TRI.PR.B Floater -1.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-05
Maturity Price : 22.98
Evaluated at bid price : 23.25
Bid-YTW : 2.24 %
CU.PR.F Perpetual-Discount -1.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-05
Maturity Price : 22.04
Evaluated at bid price : 22.35
Bid-YTW : 5.08 %
BAM.PR.K Floater -1.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-05
Maturity Price : 17.57
Evaluated at bid price : 17.57
Bid-YTW : 3.00 %
SLF.PR.B Deemed-Retractible -1.40 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.28
Bid-YTW : 5.66 %
BAM.PF.B FixedReset -1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-05
Maturity Price : 23.04
Evaluated at bid price : 24.76
Bid-YTW : 4.29 %
ELF.PR.H Perpetual-Premium -1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-05
Maturity Price : 24.49
Evaluated at bid price : 24.90
Bid-YTW : 5.53 %
IFC.PR.A FixedReset -1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.35
Bid-YTW : 3.68 %
ELF.PR.G Perpetual-Discount -1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-05
Maturity Price : 22.15
Evaluated at bid price : 22.15
Bid-YTW : 5.38 %
MFC.PR.B Deemed-Retractible -1.33 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.08
Bid-YTW : 5.62 %
BAM.PR.Z FixedReset -1.31 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.66
Bid-YTW : 4.19 %
IFC.PR.C FixedReset -1.28 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-09-30
Maturity Price : 25.00
Evaluated at bid price : 25.52
Bid-YTW : 3.55 %
MFC.PR.C Deemed-Retractible -1.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.51
Bid-YTW : 5.74 %
GWO.PR.I Deemed-Retractible -1.26 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.65
Bid-YTW : 5.66 %
GWO.PR.P Deemed-Retractible -1.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.01
Bid-YTW : 5.44 %
GWO.PR.R Deemed-Retractible -1.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.15
Bid-YTW : 5.23 %
CU.PR.C FixedReset -1.11 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-06-01
Maturity Price : 25.00
Evaluated at bid price : 25.72
Bid-YTW : 3.33 %
SLF.PR.D Deemed-Retractible -1.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.26
Bid-YTW : 5.80 %
BAM.PF.D Perpetual-Discount -1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-05
Maturity Price : 22.45
Evaluated at bid price : 22.75
Bid-YTW : 5.42 %
IAG.PR.A Deemed-Retractible -1.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.51
Bid-YTW : 5.33 %
HSE.PR.A FixedReset -1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-05
Maturity Price : 23.24
Evaluated at bid price : 24.50
Bid-YTW : 3.63 %
PWF.PR.F Perpetual-Discount 1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-05
Maturity Price : 24.51
Evaluated at bid price : 24.76
Bid-YTW : 5.39 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.D Deemed-Retractible 167,769 Nesbitt crossed 150,000 at 25.20.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.21
Bid-YTW : 4.48 %
RY.PR.B Deemed-Retractible 162,337 Nesbitt crossed 155,000 at 25.40.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2015-08-24
Maturity Price : 25.00
Evaluated at bid price : 25.32
Bid-YTW : 4.36 %
RY.PR.G Deemed-Retractible 138,040 Nesbitt crossed 130,000 at 25.20.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.15
Bid-YTW : 4.51 %
RY.PR.C Deemed-Retractible 137,600 Nesbitt crossed 130,000 at 25.30.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.31
Bid-YTW : 4.52 %
RY.PR.T FixedReset 104,233 Nesbitt crossed 50,000 at 26.30; RBC crossed 48,900 at the same price.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-08-24
Maturity Price : 25.00
Evaluated at bid price : 26.25
Bid-YTW : 2.43 %
RY.PR.I FixedReset 67,566 RBC crossed blocks of 12,500 and 50,000, both at 25.40.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-02-24
Maturity Price : 25.00
Evaluated at bid price : 25.38
Bid-YTW : 3.49 %
There were 38 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
PWF.PR.K Perpetual-Discount Quote: 23.80 – 24.19
Spot Rate : 0.3900
Average : 0.2633

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-05
Maturity Price : 23.53
Evaluated at bid price : 23.80
Bid-YTW : 5.28 %

POW.PR.A Perpetual-Discount Quote: 24.71 – 25.05
Spot Rate : 0.3400
Average : 0.2366

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-05
Maturity Price : 24.47
Evaluated at bid price : 24.71
Bid-YTW : 5.68 %

BAM.PR.K Floater Quote: 17.57 – 17.90
Spot Rate : 0.3300
Average : 0.2270

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-07-05
Maturity Price : 17.57
Evaluated at bid price : 17.57
Bid-YTW : 3.00 %

BMO.PR.J Deemed-Retractible Quote: 25.30 – 25.59
Spot Rate : 0.2900
Average : 0.1923

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.30
Bid-YTW : 4.42 %

FTS.PR.E OpRet Quote: 26.08 – 26.51
Spot Rate : 0.4300
Average : 0.3346

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-08-04
Maturity Price : 25.75
Evaluated at bid price : 26.08
Bid-YTW : -5.33 %

RY.PR.P FixedReset Quote: 25.60 – 25.85
Spot Rate : 0.2500
Average : 0.1638

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-02-24
Maturity Price : 25.00
Evaluated at bid price : 25.60
Bid-YTW : 3.56 %