Canadian inflation softened a little:
The annual rate of inflation remained steady at 3.1 per cent in October as higher prices for gas, groceries and clothes were subdued by cheaper cellphone plans and slower rent price growth, Statistics Canada said Monday.
…
Excluding energy, inflation edged down to 2 per cent in October from 2.1 per cent the month before.
Meanwhile, Tiff Macklem will not seek a second term as BoC Governor:
The Bank of Canada is officially launching its search for a new governor, with Tiff Macklem confirming on Monday that he will not seek a second term when his seven-year appointment ends next June.
The bank’s 12 independent directors have formed a search committee to select the next governor, and the recruitment process is expected to be completed by spring 2027, the bank said in a news release.
…
The Globe and Mail spoke to nine leading economists and former central bankers to get a read on the field of potential candidates.The odds-on favourite is Jean Boivin, the head of the BlackRock Investment Institute and a former Bank of Canada deputy governor during Mr. Carney’s term at the bank. The two other most commonly mentioned names are former senior deputy governor Carolyn Wilkins and current deputy governor Nicolas Vincent.
And there is some concern that insurers’ exposure to AI debt is too high:
The amount of A.I. debt being held by insurance companies has soared this year. U.S. life insurers, including some of the largest like Athene and Corebridge Financial, held $85.2 billion in A.I. debt as of June 30, up 24 percent from six months prior, according to Moody’s.
While this accounts for just 2.1 percent of life insurers’ total debt, their exposure is expected to grow quickly. Life insurers could hold up to $185 billion of A.I. investments by the end of next year, according to Moody’s.
Life insurers owned about 15 percent of A.I. data center debt as of June 30, according to a recent estimate by Barclay’s.
…
One of the lenders loudly voicing concerns is Ares Management, one of the largest private credit firms with $691 billion in assets.In a recent newsletter, Ares argues that tech giants have found ways to bring insurers into risky debt deals with “two-faced transactions.” The tech companies are creating complex financial entities that are being assigned nearly the same secure credit ratings as the tech companies themselves. But, Ares said, there are fewer guarantees that these entities will repay the debt than if the tech giants had borrowed the money directly.
“Sometimes structural complexity and financial engineering are not used to improve risk, but to hide it,” the firm wrote in the newsletter.
Ares cites Meta’s data center in Richland Parish, La., as a prime example.
Rather than owning the project outright, Meta took only a 20 percent stake while the investment firm Blue Owl owns the rest.
Yet, S&P Global was comfortable enough to rate the project’s $27 billion in debt just one notch below Meta’s strong corporate rating because of guarantees the tech company provided. Those included a $28 billion lease guarantee over 20 years or to find a tenant if Meta walked away.
That rating helped open the door for life insurers, which, according to Moodys, funded $3.4 billion of the deal.
But Meta is not promising to repay the project’s debt investors. In a statement, a Meta spokesperson wrote that “Meta has not guaranteed repayment of the bonds.”
The linked newsletter is interesting. There’s a graphic, summarizing their analysis of one deal:
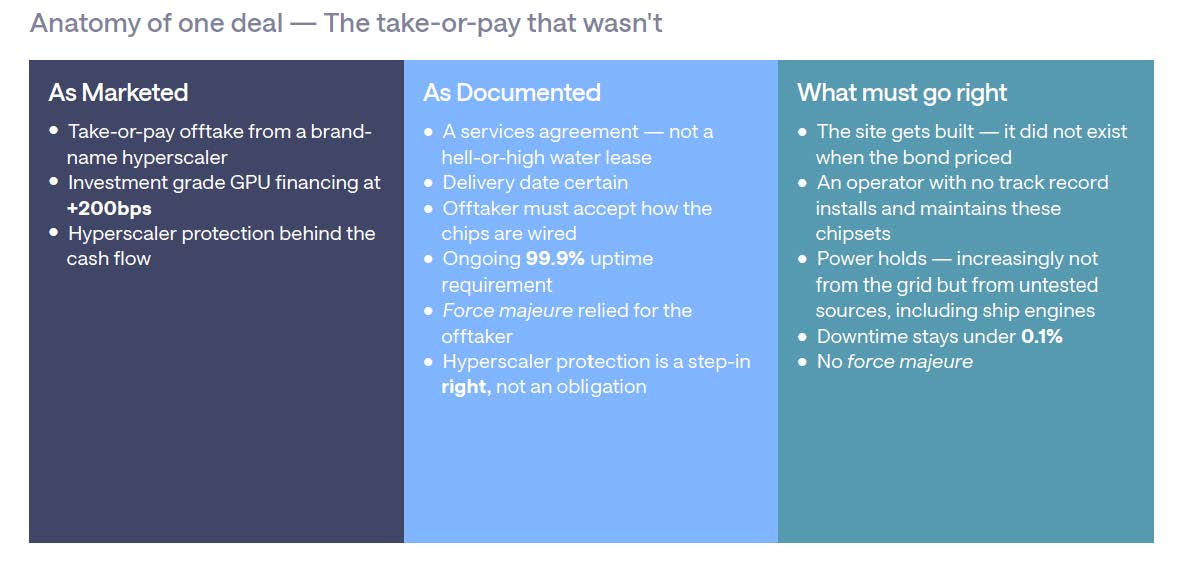
… with some explanation:
THE NOT SO FINE PRINT
In one recent transaction, a freshly-minted “AI cloud provider” – a former bitcoin miner – financed a fleet of Nvidia’s GPUs at a spread of just 200bps, solely on the strength of a hyperscaler’s offtake. The offtake agreement was marketed as take-or-pay. It was not, as the table above illustrates. Miss any item in that third column and the end customer, on which the entire transaction rests, does not have to pay. We wish we could say this was the craziest thing we’ve seen; alas, we cannot.
In other news, Enbridge will issue 1.1-billion in sub-debt:
DBRS Limited (Morningstar DBRS) also assigns a rating of BBB with a Stable Trend to the following Fixed-to-Fixed Rate Subordinated Notes.
— USD 550 million 6.700% Series A Fixed-to-Fixed Rate Subordinated Notes due May 15, 2057
— USD 550 million 6.875% Series B Fixed-to-Fixed Rate Subordinated Notes due May 15, 2057Enbridge intends to use the net proceeds of the issuance to repay existing indebtedness, capital expenditures or for other general corporate purposes.
… but there are no details on the Enbridge website.
| HIMIPref™ Preferred Indices These values reflect the December 2008 revision of the HIMIPref™ Indices Values are provisional and are finalized monthly |
|||||||
| Index | Mean Current Yield (at bid) |
Median YTW |
Median Average Trading Value |
Median Mod Dur (YTW) |
Issues | Day’s Perf. | Index Value |
| Ratchet | 0.00 % | 0.00 % | 0 | 0.00 | 0 | 0.0000 % | 2,750.9 |
| FixedFloater | 0.00 % | 0.00 % | 0 | 0.00 | 0 | 0.0000 % | 5,180.4 |
| Floater | 5.63 % | 5.72 % | 42,128 | 14.28 | 1 | 0.0000 % | 2,985.5 |
| OpRet | 0.00 % | 0.00 % | 0 | 0.00 | 0 | 0.1196 % | 3,625.3 |
| SplitShare | 4.89 % | 5.33 % | 50,086 | 3.23 | 6 | 0.1196 % | 4,329.4 |
| Interest-Bearing | 0.00 % | 0.00 % | 0 | 0.00 | 0 | 0.1196 % | 3,377.9 |
| Perpetual-Premium | 5.74 % | -0.19 % | 40,838 | 0.08 | 1 | 0.0000 % | 3,056.2 |
| Perpetual-Discount | 5.74 % | 5.82 % | 43,320 | 14.09 | 33 | -0.0147 % | 3,282.1 |
| FixedReset Disc | 5.81 % | 6.28 % | 85,540 | 13.46 | 22 | -1.3751 % | 3,291.1 |
| Insurance Straight | 5.65 % | 5.75 % | 56,011 | 14.19 | 20 | -0.0541 % | 3,187.1 |
| FloatingReset | 0.00 % | 0.00 % | 0 | 0.00 | 0 | -1.3751 % | 4,018.5 |
| FixedReset Prem | 6.00 % | 5.34 % | 68,063 | 1.90 | 28 | 0.0491 % | 2,611.3 |
| FixedReset Bank Non | 0.00 % | 0.00 % | 0 | 0.00 | 0 | -1.3751 % | 3,364.2 |
| FixedReset Ins Non | 5.64 % | 5.84 % | 48,560 | 13.93 | 13 | 0.0579 % | 3,227.6 |
| Performance Highlights | |||
| Issue | Index | Change | Notes |
| BN.PR.X | FixedReset Disc | -29.35 % | YTW SCENARIO Maturity Type : Limit Maturity Maturity Date : 2056-11-16 Maturity Price : 15.00 Evaluated at bid price : 15.00 Bid-YTW : 9.12 % |
| POW.PR.B | Perpetual-Discount | -5.47 % | YTW SCENARIO Maturity Type : Limit Maturity Maturity Date : 2056-11-16 Maturity Price : 21.88 Evaluated at bid price : 22.12 Bid-YTW : 6.12 % |
| ENB.PF.C | FixedReset Disc | -4.51 % | YTW SCENARIO Maturity Type : Limit Maturity Maturity Date : 2056-11-16 Maturity Price : 22.19 Evaluated at bid price : 22.65 Bid-YTW : 6.71 % |
| GWO.PR.R | Insurance Straight | -3.37 % | YTW SCENARIO Maturity Type : Limit Maturity Maturity Date : 2056-11-16 Maturity Price : 20.35 Evaluated at bid price : 20.35 Bid-YTW : 6.00 % |
| CU.PR.F | Perpetual-Discount | -2.65 % | YTW SCENARIO Maturity Type : Limit Maturity Maturity Date : 2056-11-16 Maturity Price : 20.20 Evaluated at bid price : 20.20 Bid-YTW : 5.59 % |
| POW.PR.I | Perpetual-Discount | -1.51 % | YTW SCENARIO Maturity Type : Limit Maturity Maturity Date : 2056-11-16 Maturity Price : 23.77 Evaluated at bid price : 24.13 Bid-YTW : 5.91 % |
| ENB.PR.H | FixedReset Disc | -1.03 % | YTW SCENARIO Maturity Type : Limit Maturity Maturity Date : 2056-11-16 Maturity Price : 23.65 Evaluated at bid price : 24.00 Bid-YTW : 6.02 % |
| ENB.PR.P | FixedReset Disc | 1.38 % | YTW SCENARIO Maturity Type : Limit Maturity Maturity Date : 2056-11-16 Maturity Price : 23.17 Evaluated at bid price : 24.16 Bid-YTW : 6.27 % |
| FTS.PR.H | FixedReset Disc | 1.50 % | YTW SCENARIO Maturity Type : Limit Maturity Maturity Date : 2056-11-16 Maturity Price : 20.35 Evaluated at bid price : 20.35 Bid-YTW : 6.08 % |
| CU.PR.D | Perpetual-Discount | 1.55 % | YTW SCENARIO Maturity Type : Limit Maturity Maturity Date : 2056-11-16 Maturity Price : 22.66 Evaluated at bid price : 22.90 Bid-YTW : 5.36 % |
| CU.PR.J | Perpetual-Discount | 1.85 % | YTW SCENARIO Maturity Type : Limit Maturity Maturity Date : 2056-11-16 Maturity Price : 21.71 Evaluated at bid price : 22.05 Bid-YTW : 5.39 % |
| CU.PR.E | Perpetual-Discount | 2.72 % | YTW SCENARIO Maturity Type : Limit Maturity Maturity Date : 2056-11-16 Maturity Price : 22.77 Evaluated at bid price : 23.05 Bid-YTW : 5.32 % |
| Volume Highlights | |||
| Issue | Index | Shares Traded |
Notes |
| TD.PF.I | FixedReset Prem | 44,900 | YTW SCENARIO Maturity Type : Call Maturity Date : 2027-10-31 Maturity Price : 25.00 Evaluated at bid price : 25.55 Bid-YTW : 4.26 % |
| BN.PF.N | FixedReset Disc | 37,900 | YTW SCENARIO Maturity Type : Limit Maturity Maturity Date : 2056-11-16 Maturity Price : 23.15 Evaluated at bid price : 24.99 Bid-YTW : 5.69 % |
| BILP.PR.A | FixedReset Prem | 31,300 | YTW SCENARIO Maturity Type : Call Maturity Date : 2031-10-01 Maturity Price : 25.00 Evaluated at bid price : 25.20 Bid-YTW : 5.77 % |
| BN.PF.G | FixedReset Disc | 20,800 | YTW SCENARIO Maturity Type : Call Maturity Date : 2030-07-01 Maturity Price : 25.00 Evaluated at bid price : 24.79 Bid-YTW : 6.19 % |
| BMO.PR.E | FixedReset Prem | 20,800 | YTW SCENARIO Maturity Type : Call Maturity Date : 2028-11-25 Maturity Price : 25.00 Evaluated at bid price : 26.15 Bid-YTW : 4.36 % |
| CU.PR.E | Perpetual-Discount | 20,600 | YTW SCENARIO Maturity Type : Limit Maturity Maturity Date : 2056-11-16 Maturity Price : 22.77 Evaluated at bid price : 23.05 Bid-YTW : 5.32 % |
| There were 3 other index-included issues trading in excess of 10,000 shares. | |||
| Wide Spread Highlights | ||
| See TMX DataLinx: ‘Last’ != ‘Close’ and the posts linked therein for an idea of why these quotes are so horrible. | ||
| Issue | Index | Quote Data and Yield Notes |
| BN.PR.X | FixedReset Disc | Quote: 15.00 – 21.55 Spot Rate : 6.5500 Average : 3.5713 YTW SCENARIO |
| POW.PR.B | Perpetual-Discount | Quote: 22.12 – 23.50 Spot Rate : 1.3800 Average : 0.8144 YTW SCENARIO |
| GWO.PR.S | Insurance Straight | Quote: 22.95 – 24.90 Spot Rate : 1.9500 Average : 1.4606 YTW SCENARIO |
| MIC.PR.A | Perpetual-Discount | Quote: 22.06 – 23.06 Spot Rate : 1.0000 Average : 0.6150 YTW SCENARIO |
| GWO.PR.R | Insurance Straight | Quote: 20.35 – 21.20 Spot Rate : 0.8500 Average : 0.5216 YTW SCENARIO |
| ENB.PF.C | FixedReset Disc | Quote: 22.65 – 23.75 Spot Rate : 1.1000 Average : 0.8012 YTW SCENARIO |