Category: Market Action

Market Action

September 23, 2015

It looks like we have a few more weeks of the entertaining Sprott-Spicer battle to look forward to, as Silver Bullion Trust points out (bolding from original):

Silver Bullion Trust (“SBT”) (symbol: TSX – SBT.UN (C$) SBT.U (US$)) today noted that Sprott Asset Management LP and Sprott Physical Silver Trust (collectively, “Sprott”) have failed by a substantial margin to achieve sufficient support from SBT Unitholders to complete their offer. As a result, Sprott has yet again extended their inadequate, hostile offer to acquire all of the outstanding Units of SBT. They have made no improvement to the terms of their offer, which is now set to expire on October 9, 2015.

Since May 27th, Sprott has harassed SBT Unitholders and their intermediaries with misleading information about Sprott’s offer and defamatory comments about SBT, its Trustees and its administrator. The majority of SBT Unitholders have consistently said “NO” to Sprott’s offer and have clearly expressed the view that they wish to continue to remain SBT Unitholders.

SBT is concerned that some brokers may have misled their Unitholder clients into believing that they must choose one of the two tendering options, and could not “do nothing” in response to Sprott’s offer. SBT Unitholders are reminded that they are NOT REQUIRED to tender their Units to Sprott, regardless of what brokers may say. If instructed by a broker that tendering is required or that Unitholders cannot “do nothing,” please call D.F. King & Co at 1-800-398-2816 for assistance.
…
Unitholders who have refused to tender are urged to retain their SBT Units and not tender to Sprott’s offer. Sprott’s offer cannot succeed unless 662/3% of the Units are actually tendered, which has not been achieved.

During the Credit Crunch there was a notable amount of “jingle-mail” in the States – that being the sobriquet for the act of abandoning your house and sending the keys to the (underwater) mortgage servicer. I advocated – and continue to advocate – for a mortgage system in which the standard is ‘with recourse’ to the homeowner, i.e., that the homeowner is on the hook for the entire amount and that if the house doesn’t cover his balance due, that’s his tough luck.

But the Mayor of Barcelona points out that this can lead to social unrest in a broad market decline:

Under Spanish law, when a bank forecloses on a mortgage and seizes a house or apartment, only part of the debt is wiped out. The rest remains on the books, and the owner isn’t able to declare bankruptcy to escape the debt. The bank has claim to all assets, not just the house.

“The president of the government had explicitly told the population, ‘You have to buy a house because it’s the most secure investment, the best thing for your country,’ ” says Colau. “Millions of people who weren’t trying to speculate, or to be rich, but who thought they were doing the most responsible thing, the safest thing, discovered that they had done the worst thing in their lives, and that there was no way to escape.”

In 2009, Colau and a handful of other activists formed a grassroots organization called the Platform for People Affected by Mortgages—known by its Spanish acronym PAH. “She’s a natural leader,” says Lucía Martín, one of the group’s founders. “It’s not that she says, ‘OK, I’m going to be the leader.’ It’s that everybody looks around and says, ‘Yes. Her. She looks like she can do it.’ It became really obvious.”

One of the first people PAH assisted was Matías González Barquero, who had taken out a mortgage on his home to soundproof his bar at the request of the municipality. González was forced to close the bar in 2009 after a partner died and another fell sick. As a small-business owner, he was ineligible for unemployment, and soon he couldn’t pay his mortgage.

When he attended his first PAH meeting in 2010, his apartment had already been put up for auction, but it had failed to sell, and he hadn’t moved out. When González was scheduled to be evicted by police in March 2010, the group obtained a period of leniency from a judge. Over the next year and a half, PAH blocked two other eviction attempts, mobilizing some 300 people to block the entrance to his apartment. Colau was with González in his house, coordinating the protest from behind locked doors. “She said, ‘You keep calm, we’re going to make it,’ ” recalls González. “When she was facing the banks, she was very tough. But with me, she was a very close person.”

In other geopolitical news (since preferred shares are, you know, kinda boring) it looks like the group that takes decisive action against ISIS will be one with interests that are almost as antithetical to ours:

President Vladimir Putin, determined to strengthen Russia’s only military outpost in the Middle East, is preparing to launch unilateral airstrikes against Islamic State from inside Syria if the U.S. rejects his proposal to join forces, two people familiar with the matter said.

Putin’s preferred course of action, though, is for America and its allies to agree to coordinate their campaign against the terrorist group with Russia, Iran and the Syrian army, which the Obama administration has so far resisted, according to a person close to the Kremlin and an adviser to the Defense Ministry in Moscow.

Russian diplomacy has shifted into overdrive as Putin seeks to avoid the collapse of the embattled regime of Bashar al-Assad, a longtime ally who’s fighting both a 4 1/2 year civil war and Sunni extremists under the banner of Islamic State. Israeli Prime Minister Benjamin Netanyahu flew to Moscow for talks with Putin on Monday, followed by Turkish President Recep Tayyip Erdogan on Tuesday.

Stop dilly-dallying! Smash ISIS now!

There was carnage for the Canadian preferred share market today, with PerpetualDiscounts down 61bp, FixedResets losing 70bp and DeemedRetractibles off 16bp. As one might expect, the Performance Highlights table is both enormous and dominated by losing FixedResets. Volume was very low.

PerpetualDiscounts now yield 5.61%, equivalent to 7.29% interest at the standard equivalency factor of 1.3x. Long corporates now yield a hair under 4.2%, so the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) is now about 310bp, a significant rise from the 300bp reported September 9.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

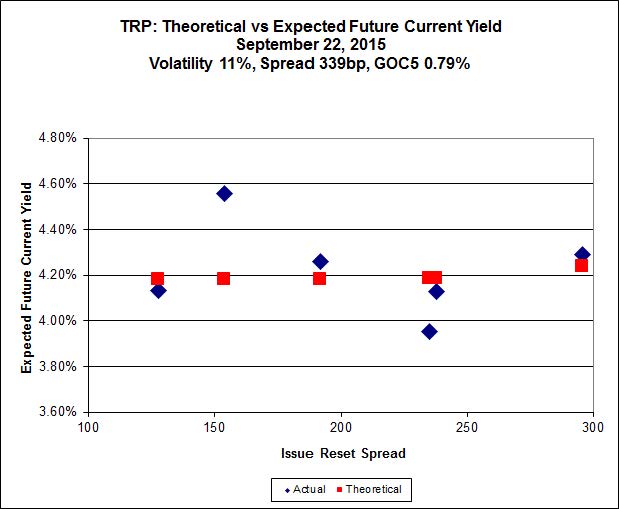
Here’s TRP:

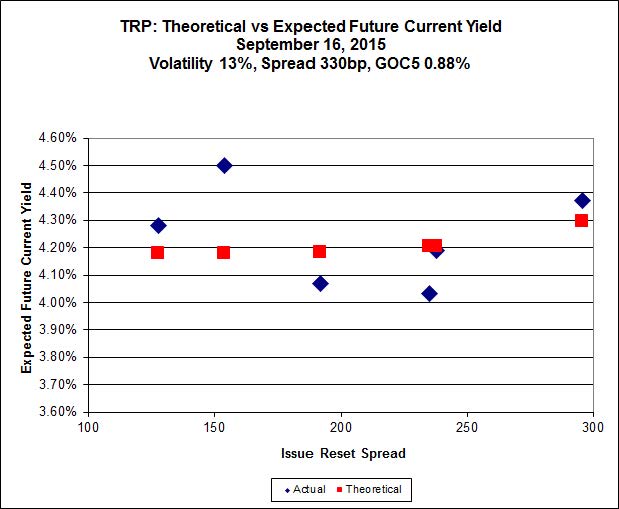
impVol_TRP_150923
Click for Big

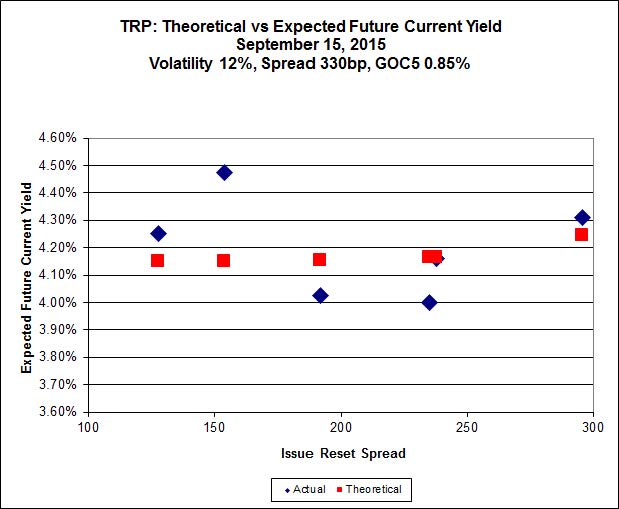
TRP.PR.E, which resets 2019-10-30 at +235, is bid at 19.86 to be $1.21 rich, while TRP.PR.C, resetting 2016-1-30 at +164, is $1.29 cheap at its bid price of 12.60.

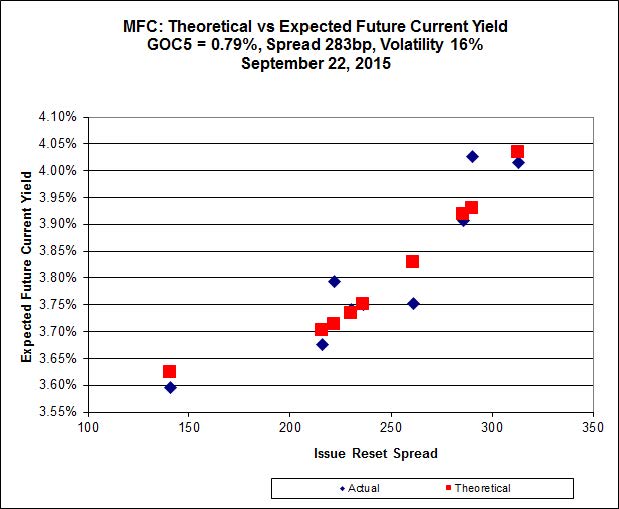
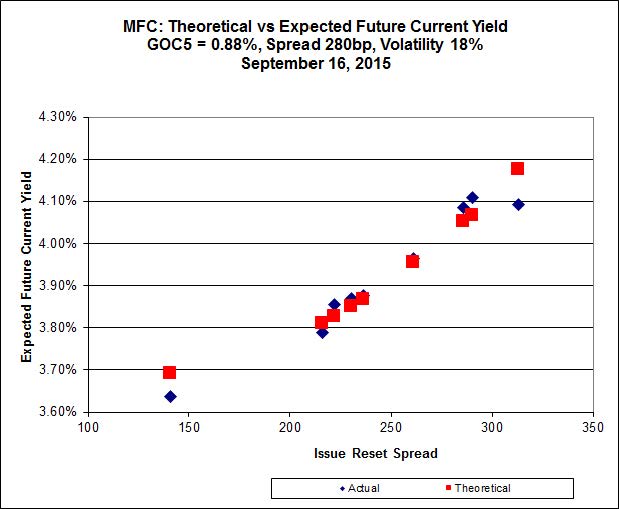
impVol_MFC_150923
Click for Big

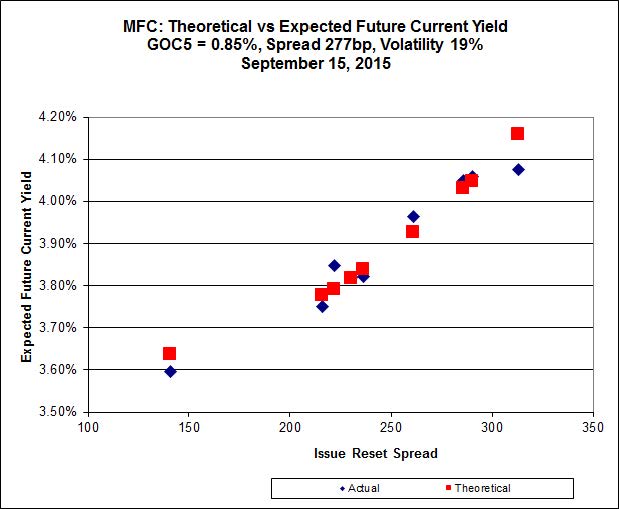
Another good fit today for MFC, with Implied Volatility unchanged today.

Most expensive is MFC.PR.J, resetting at +261bp on 2018-3-19, bid at 22.60 to be 0.52 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 22.80 to be 0.57 cheap.

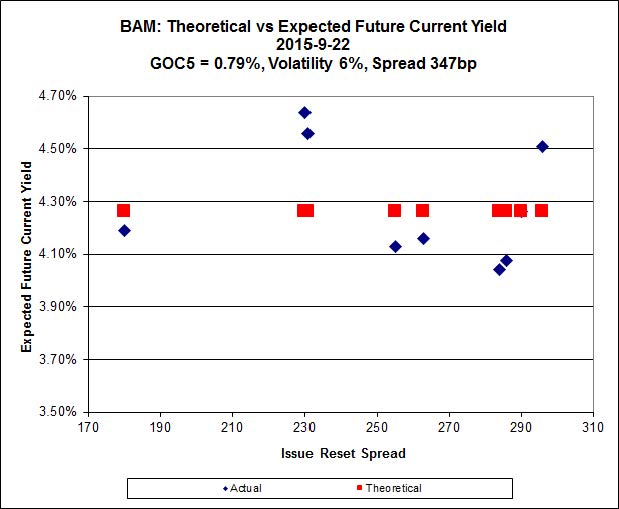
impVol_BAM_150923
Click for Big

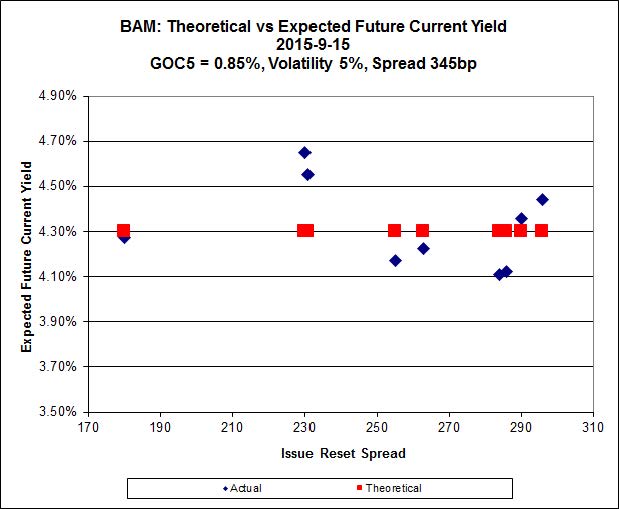
The fit on the BAM issues continues to be horrible.

The cheapest issue relative to its peers is BAM.PR.Z (with a lousy bid, discussed in the Performance Highlights table), resetting at +296bp on 2017-12-31, bid at 19.40 to be $2.26 cheap. BAM.PF.G, resetting at +284bp on 2020-6-30 is bid at 22.40 and appears to be $1.47 rich.

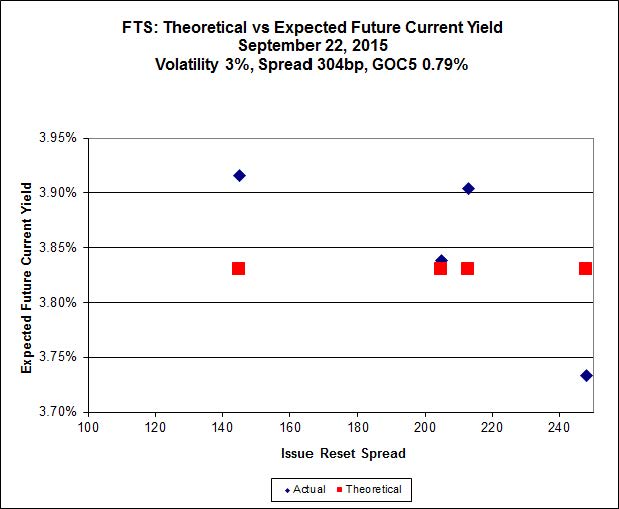
impVol_FTS_150923
Click for Big

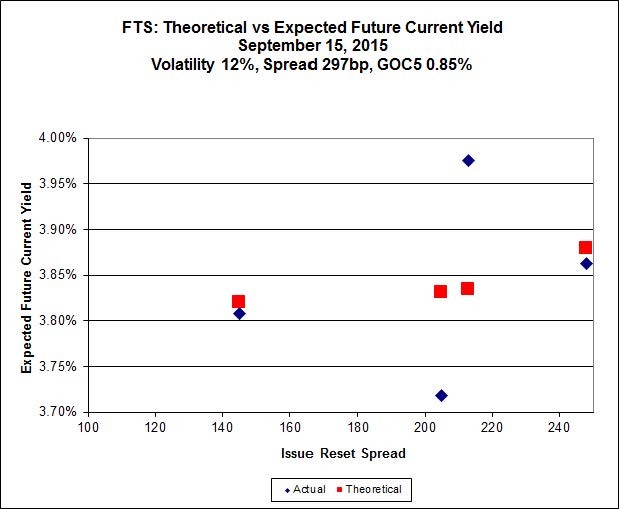
FTS.PR.M, with a spread of +248bp, and bid at 21.70, looks $0.77 expensive and resets 2019-12-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 18.30 and is $0.40 cheap.

pairs_FR_150923
Click for Big

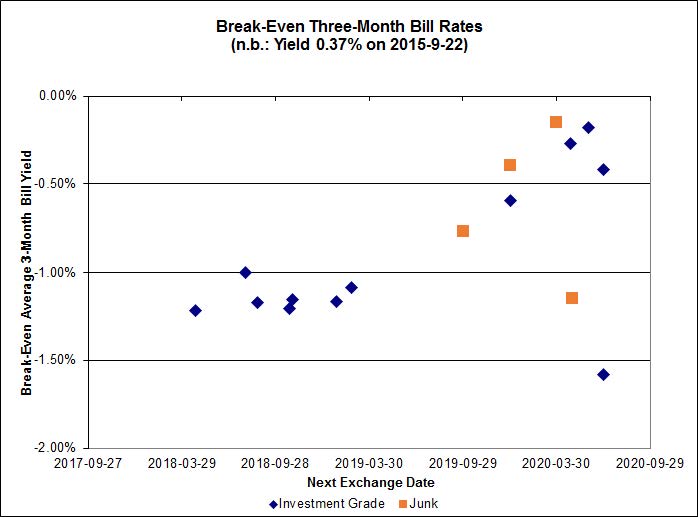
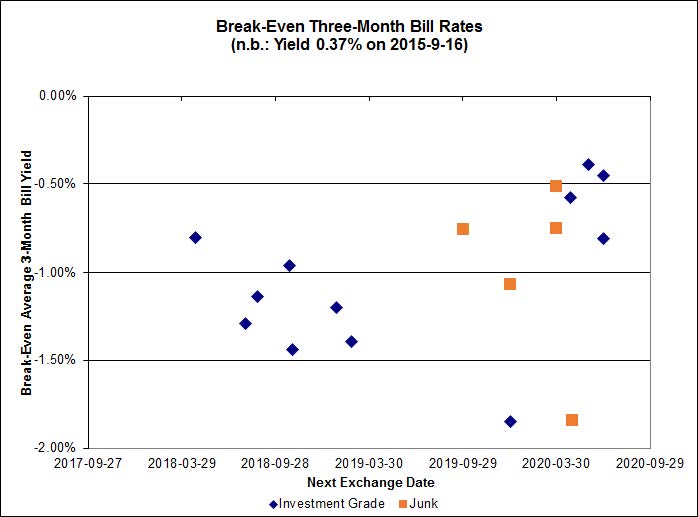
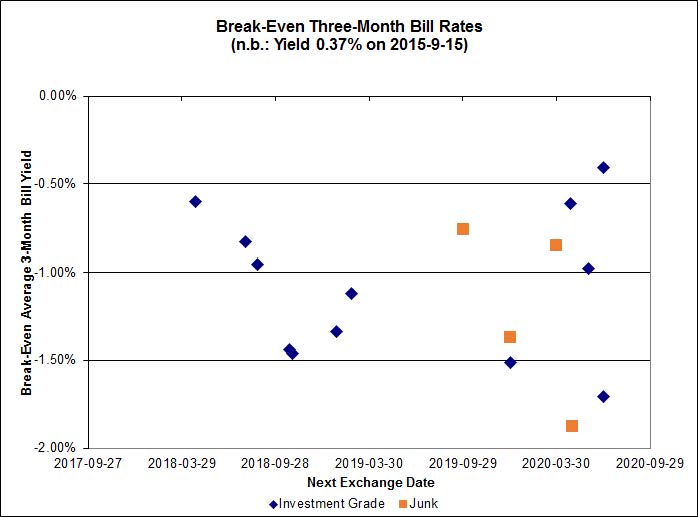
Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.87%, with no outliers. The distribution’s bimodality has returned, with bank NVCC non-compliant pairs averaging -1.06% and other issues averaging -0.59%. There are two junk outliers above 0.00%.

pairs_FF_150923
Click for Big

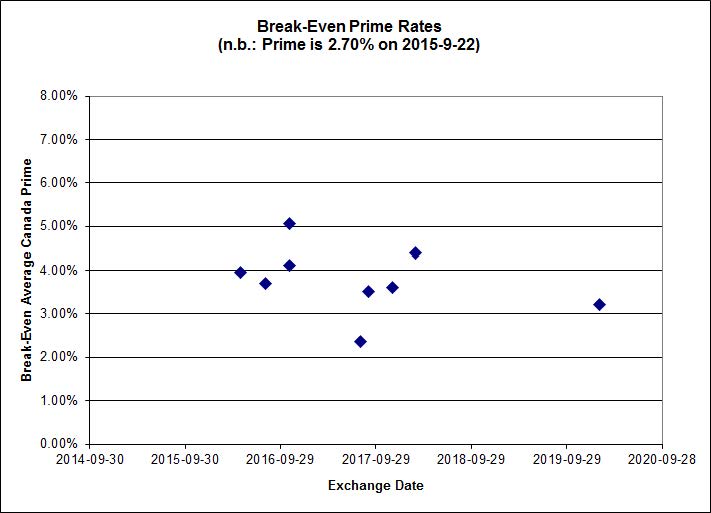
Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.7949 % 1,635.0
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.7949 % 2,858.7
Floater 4.54 % 4.55 % 60,472 16.34 3 -0.7949 % 1,738.1
OpRet 0.00 % 0.00 % 0 0.00 0 0.0386 % 2,770.9
SplitShare 4.48 % 4.88 % 62,106 2.08 4 0.0386 % 3,247.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0386 % 2,533.7
Perpetual-Premium 5.73 % 1.47 % 57,128 0.08 8 -0.1733 % 2,494.1
Perpetual-Discount 5.50 % 5.61 % 66,431 14.46 30 -0.6118 % 2,577.6
FixedReset 4.81 % 4.29 % 171,798 15.69 74 -0.6967 % 2,115.2
Deemed-Retractible 5.17 % 4.75 % 91,626 5.47 33 -0.1643 % 2,572.0
FloatingReset 2.52 % 4.16 % 55,150 5.88 9 -0.0720 % 2,124.1
Performance Highlights
Issue Index Change Notes
BAM.PR.Z FixedReset -6.97 % Some might call this technically real since the issue traded 7,542 shares in a range of 19.00-20.82, but the trade at 19.00 was for 600 shares and occurred at 3:54pm, the same timestamp as the trade preceding it, 800 shares at 20.25. The VWAP was 20.52, while the closing quote was 19.35-15. I’m willing to listen to stories, but for now I’m going to mark this down as an example of shoddy market-making.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 19.35
Evaluated at bid price : 19.35
Bid-YTW : 5.08 %
FTS.PR.K FixedReset -3.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 17.87
Evaluated at bid price : 17.87
Bid-YTW : 4.33 %
FTS.PR.J Perpetual-Discount -3.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 21.32
Evaluated at bid price : 21.60
Bid-YTW : 5.54 %
TRP.PR.F FloatingReset -3.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 13.75
Evaluated at bid price : 13.75
Bid-YTW : 4.16 %
BAM.PR.T FixedReset -2.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 16.51
Evaluated at bid price : 16.51
Bid-YTW : 4.95 %
BAM.PR.R FixedReset -2.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 16.23
Evaluated at bid price : 16.23
Bid-YTW : 4.94 %
FTS.PR.F Perpetual-Discount -2.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 21.70
Evaluated at bid price : 21.95
Bid-YTW : 5.63 %
IFC.PR.C FixedReset -2.39 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.22
Bid-YTW : 6.98 %
PWF.PR.P FixedReset -2.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 15.25
Evaluated at bid price : 15.25
Bid-YTW : 4.06 %
FTS.PR.G FixedReset -2.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 18.30
Evaluated at bid price : 18.30
Bid-YTW : 4.25 %
MFC.PR.F FixedReset -2.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.98
Bid-YTW : 8.79 %
CU.PR.F Perpetual-Discount -1.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 20.20
Evaluated at bid price : 20.20
Bid-YTW : 5.63 %
TD.PF.C FixedReset -1.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 20.61
Evaluated at bid price : 20.61
Bid-YTW : 3.95 %
BAM.PR.M Perpetual-Discount -1.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 20.81
Evaluated at bid price : 20.81
Bid-YTW : 5.74 %
NA.PR.W FixedReset -1.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 20.62
Evaluated at bid price : 20.62
Bid-YTW : 3.98 %
TD.PF.B FixedReset -1.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 20.85
Evaluated at bid price : 20.85
Bid-YTW : 3.92 %
BAM.PF.C Perpetual-Discount -1.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 21.07
Evaluated at bid price : 21.07
Bid-YTW : 5.79 %
BNS.PR.Z FixedReset -1.52 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.77
Bid-YTW : 5.62 %
GWO.PR.I Deemed-Retractible -1.51 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.53
Bid-YTW : 6.53 %
MFC.PR.C Deemed-Retractible -1.46 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.89
Bid-YTW : 6.97 %
MFC.PR.I FixedReset -1.46 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.01
Bid-YTW : 4.94 %
BAM.PR.C Floater -1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 10.30
Evaluated at bid price : 10.30
Bid-YTW : 4.59 %
TRP.PR.C FixedReset -1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 12.60
Evaluated at bid price : 12.60
Bid-YTW : 4.81 %
PWF.PR.K Perpetual-Discount -1.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 22.27
Evaluated at bid price : 22.54
Bid-YTW : 5.57 %
POW.PR.D Perpetual-Discount -1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 22.25
Evaluated at bid price : 22.52
Bid-YTW : 5.55 %
GWO.PR.R Deemed-Retractible -1.31 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.86
Bid-YTW : 6.65 %
BMO.PR.S FixedReset -1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 21.35
Evaluated at bid price : 21.35
Bid-YTW : 3.90 %
RY.PR.H FixedReset -1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 20.93
Evaluated at bid price : 20.93
Bid-YTW : 3.90 %
RY.PR.Z FixedReset -1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 20.84
Evaluated at bid price : 20.84
Bid-YTW : 3.88 %
BAM.PF.B FixedReset -1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 20.30
Evaluated at bid price : 20.30
Bid-YTW : 4.44 %
BNS.PR.Y FixedReset -1.19 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.75
Bid-YTW : 5.04 %
SLF.PR.I FixedReset -1.19 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.81
Bid-YTW : 6.05 %
TD.PF.A FixedReset -1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 20.86
Evaluated at bid price : 20.86
Bid-YTW : 3.92 %
CM.PR.P FixedReset -1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 20.37
Evaluated at bid price : 20.37
Bid-YTW : 4.00 %
HSE.PR.A FixedReset -1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 13.40
Evaluated at bid price : 13.40
Bid-YTW : 4.89 %
BMO.PR.W FixedReset -1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 20.55
Evaluated at bid price : 20.55
Bid-YTW : 3.92 %
SLF.PR.H FixedReset -1.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.51
Bid-YTW : 7.65 %
RY.PR.M FixedReset -1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 21.97
Evaluated at bid price : 22.50
Bid-YTW : 3.85 %
PWF.PR.T FixedReset 1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 22.31
Evaluated at bid price : 22.85
Bid-YTW : 3.67 %
TD.PF.D FixedReset 1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 22.60
Evaluated at bid price : 23.60
Bid-YTW : 3.79 %
BAM.PR.X FixedReset 1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 15.65
Evaluated at bid price : 15.65
Bid-YTW : 4.48 %
BMO.PR.T FixedReset 1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 20.83
Evaluated at bid price : 20.83
Bid-YTW : 3.90 %
SLF.PR.J FloatingReset 1.80 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.98
Bid-YTW : 9.73 %
Volume Highlights
Issue Index Shares
Traded
Notes
TRP.PR.E FixedReset 34,835 Desjardins crossed 11,700 at 19.90.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 19.86
Evaluated at bid price : 19.86
Bid-YTW : 4.34 %
BAM.PR.B Floater 33,881 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 10.50
Evaluated at bid price : 10.50
Bid-YTW : 4.50 %
SLF.PR.J FloatingReset 29,899 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.98
Bid-YTW : 9.73 %
TRP.PR.F FloatingReset 29,350 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 13.75
Evaluated at bid price : 13.75
Bid-YTW : 4.16 %
BAM.PF.A FixedReset 21,150 RBC crossed 17,000 at 21.55.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 21.45
Evaluated at bid price : 21.45
Bid-YTW : 4.49 %
TRP.PR.A FixedReset 20,887 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 15.75
Evaluated at bid price : 15.75
Bid-YTW : 4.56 %
There were 16 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
MFC.PR.L FixedReset Quote: 20.00 – 22.25
Spot Rate : 2.2500
Average : 1.2387

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.00
Bid-YTW : 6.28 %

BAM.PR.Z FixedReset Quote: 19.35 – 20.15
Spot Rate : 0.8000
Average : 0.4722

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 19.35
Evaluated at bid price : 19.35
Bid-YTW : 5.08 %

BAM.PR.X FixedReset Quote: 15.65 – 16.18
Spot Rate : 0.5300
Average : 0.3553

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 15.65
Evaluated at bid price : 15.65
Bid-YTW : 4.48 %

SLF.PR.H FixedReset Quote: 17.51 – 18.00
Spot Rate : 0.4900
Average : 0.3488

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.51
Bid-YTW : 7.65 %

BAM.PR.M Perpetual-Discount Quote: 20.81 – 21.25
Spot Rate : 0.4400
Average : 0.3199

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 20.81
Evaluated at bid price : 20.81
Bid-YTW : 5.74 %

FTS.PR.G FixedReset Quote: 18.30 – 18.70
Spot Rate : 0.4000
Average : 0.2891

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-23
Maturity Price : 18.30
Evaluated at bid price : 18.30
Bid-YTW : 4.25 %

Market Action

September 22, 2015

Well, here’s another nail in Keystone’s coffin:

Ending years of declining to take a side on the issue because of her role in the Obama administration, Hillary Clinton on Tuesday announced her opposition to the construction of the Keystone XL oil pipeline.

“I don’t think we need to have a pipeline bringing very dirty oil, exploiting the tar sands in western Canada, across our border,” she told the Des Moines Register’s editorial board.

At a town hall in Des Moines beforehand, she expressed an eagerness to end the debate over Keystone, which had become a “distraction” from the broader fight against climate change. “I don’t think it’s in the best interest of what we need to do to combat climate change, ” she said in response to a question from a Drake University student.

Power Corporation, proud issuer of myriad preferred shares issues, has been confirmed at Pfd-2(high) by DBRS:

DBRS Limited (DBRS) has today confirmed the Senior Debt as well as the Non-Cumulative First Preferred Shares and Cumulative Redeemable First Preferred Shares, 1986 Series ratings of Power Corporation of Canada (POW or the Company) at A (high) and Pfd-2 (high), respectively. The trend on the ratings remains Stable. The credit strength of POW is directly tied to its 65.6% equity interest in Power Financial Corporation (PWF), which represents a substantial majority of the Company’s earnings and cash flow as well as the vast majority of the Company’s estimated net asset value. The Senior Debt rating of the Company is A (high) or one notch below the AA (low) rating on the Senior Debentures of PWF, reflecting the structural subordination of the holding company’s obligations.

Should PWF be upgraded, then POW could also benefit. Conversely, a shift in the Company’s risk profile resulting from a major divestiture or acquisition, a material increase in financial leverage or increased adoption of double leverage, deteriorating earnings and prolonged distress at the major operating subsidiaries, a downgrade of the rating of Great-West Lifeco Inc. (GWO) or PWF, or evidence of governance and control difficulties could have negative rating implications.

Similarly, Power Financial Corporation, issuer of myriad preferred share issues of its own, was confirmed at Pfd-1(low) by DBRS:

DBRS Limited (DBRS) has today confirmed the Issuer Rating and Senior Debentures rating of Power Financial Corporation (PWF or the Company) at AA (low), along with the Non-Cumulative First Preferred Shares and Cumulative First Preferred Shares (Series A) ratings at Pfd-1 (low). All trends remain Stable. The Company’s ratings are largely derived from its controlling interests in two of Canada’s leading financial service providers: Great-West Lifeco Inc. (GWO; Senior Debt rated AA (low) by DBRS), one of the three largest life insurance concerns in Canada, and IGM Financial Inc. (IGM; Senior Debt rated A (high) by DBRS), one of the largest mutual fund complexes in Canada as measured by long-term assets under management (AUM).

These two interests, accounting for more than 90% of the Company’s earnings, dividends and asset value, are a source of stable recurring earnings and cash flow. Under the strategic leadership of the Company, both GWO and IGM have become increasingly diversified as they have grown, both organically and by acquisition. The Company has correspondingly increased its exposure to the wealth management business in all of its chosen geographies. Both of these subsidiaries in turn benefit from the Company’s hands-on governance and risk-averse culture.

PWF’s ratings currently reflect the ratings of its most highly rated subsidiary, GWO. Should GWO be upgraded, PWF could also benefit. Conversely, a material increase in unconsolidated financial leverage giving rise to deterioration in coverage ratios; any deterioration in the creditworthiness of a major operating subsidiary, particularly a downgrade of the rating of GWO; a shift in the Company’s risk profile resulting from a major divestiture or acquisition; or evidence of governance and control difficulties could have negative rating implications.

It was a poor day for the Canadian preferred share market, with PerpetualDiscounts down 27bp, FixedResets losing 57bp and DeemedRetractibles off 10bp. The Performance Highlights table is very long, dominated by losing FixedResets, with only one winner amongst the carnage. Volume was slightly below average.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_150922
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 19.85 to be $1.10 rich, while TRP.PR.C, resetting 2016-1-30 at +164, is $1.16 cheap at its bid price of 12.78.

impVol_MFC_150922
Click for Big

Another good fit today for MFC, with Implied Volatility falling significantly today.

Most expensive is MFC.PR.J, resetting at +261bp on 2018-3-19, bid at 22.65 to be 0.45 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 22.91 to be 0.57 cheap.

impVol_BAM_150922
Click for Big

The fit on the BAM issues continues to be horrible.

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 16.70 to be $1.47 cheap. BAM.PF.G, resetting at +284bp on 2020-6-30 is bid at 22.45 and appears to be $1.15 rich.

impVol_FTS_150922
Click for Big

FTS.PR.M, with a spread of +248bp, and bid at 21.90, looks $0.56 expensive and resets 2019-12-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 18.70 and is $0.36 cheap.

pairs_FR_150922
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.92%, with no outliers. The distribution’s bimodality has returned, with bank NVCC non-compliant pairs averaging -1.14% and other issues averaging -0.61%. There are two junk outliers above 0.00%.

pairs_FF_150922
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.0636 % 1,648.1
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.0636 % 2,881.6
Floater 4.51 % 4.52 % 60,202 16.38 3 0.0636 % 1,752.0
OpRet 0.00 % 0.00 % 0 0.00 0 0.0742 % 2,769.8
SplitShare 4.48 % 4.83 % 62,815 3.05 4 0.0742 % 3,246.1
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0742 % 2,532.7
Perpetual-Premium 5.72 % 0.80 % 57,832 0.08 8 0.0901 % 2,498.4
Perpetual-Discount 5.47 % 5.57 % 66,407 14.52 30 -0.2677 % 2,593.5
FixedReset 4.78 % 4.27 % 178,259 15.80 74 -0.5695 % 2,130.0
Deemed-Retractible 5.16 % 4.54 % 92,174 5.48 33 -0.0997 % 2,576.3
FloatingReset 2.52 % 4.03 % 51,264 5.88 9 -1.0569 % 2,125.6
Performance Highlights
Issue Index Change Notes
SLF.PR.J FloatingReset -3.77 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.75
Bid-YTW : 9.95 %
TRP.PR.F FloatingReset -3.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-22
Maturity Price : 14.20
Evaluated at bid price : 14.20
Bid-YTW : 4.03 %
TRP.PR.A FixedReset -3.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-22
Maturity Price : 15.90
Evaluated at bid price : 15.90
Bid-YTW : 4.51 %
GWO.PR.S Deemed-Retractible -2.80 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.60
Bid-YTW : 6.07 %
FTS.PR.H FixedReset -2.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-22
Maturity Price : 14.30
Evaluated at bid price : 14.30
Bid-YTW : 4.08 %
BMO.PR.T FixedReset -2.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-22
Maturity Price : 20.55
Evaluated at bid price : 20.55
Bid-YTW : 3.95 %
IFC.PR.A FixedReset -2.26 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.00
Bid-YTW : 8.83 %
BNS.PR.D FloatingReset -2.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.86
Bid-YTW : 5.21 %
BAM.PF.D Perpetual-Discount -2.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-22
Maturity Price : 21.26
Evaluated at bid price : 21.54
Bid-YTW : 5.70 %
BAM.PR.N Perpetual-Discount -1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-22
Maturity Price : 21.00
Evaluated at bid price : 21.00
Bid-YTW : 5.69 %
CM.PR.P FixedReset -1.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-22
Maturity Price : 20.60
Evaluated at bid price : 20.60
Bid-YTW : 3.95 %
FTS.PR.K FixedReset -1.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-22
Maturity Price : 18.50
Evaluated at bid price : 18.50
Bid-YTW : 4.17 %
MFC.PR.K FixedReset -1.73 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.84
Bid-YTW : 6.29 %
TRP.PR.C FixedReset -1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-22
Maturity Price : 12.78
Evaluated at bid price : 12.78
Bid-YTW : 4.74 %
VNR.PR.A FixedReset -1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-22
Maturity Price : 19.81
Evaluated at bid price : 19.81
Bid-YTW : 4.76 %
BNS.PR.Z FixedReset -1.68 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.09
Bid-YTW : 5.35 %
CM.PR.O FixedReset -1.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-22
Maturity Price : 21.36
Evaluated at bid price : 21.36
Bid-YTW : 3.90 %
GWO.PR.N FixedReset -1.57 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.45
Bid-YTW : 8.95 %
BNS.PR.C FloatingReset -1.52 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.01
Bid-YTW : 4.42 %
BNS.PR.Y FixedReset -1.41 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.00
Bid-YTW : 4.83 %
SLF.PR.I FixedReset -1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.06
Bid-YTW : 5.89 %
HSE.PR.A FixedReset -1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-22
Maturity Price : 13.55
Evaluated at bid price : 13.55
Bid-YTW : 4.83 %
BAM.PR.T FixedReset -1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-22
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 4.80 %
TD.PF.E FixedReset -1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-22
Maturity Price : 22.78
Evaluated at bid price : 24.02
Bid-YTW : 3.79 %
POW.PR.B Perpetual-Discount -1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-22
Maturity Price : 23.58
Evaluated at bid price : 23.85
Bid-YTW : 5.61 %
FTS.PR.M FixedReset -1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-22
Maturity Price : 21.60
Evaluated at bid price : 21.90
Bid-YTW : 3.96 %
BNS.PR.A FloatingReset -1.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.90
Bid-YTW : 3.91 %
TD.PF.C FixedReset -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-22
Maturity Price : 21.00
Evaluated at bid price : 21.00
Bid-YTW : 3.87 %
BIP.PR.A FixedReset -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-22
Maturity Price : 21.48
Evaluated at bid price : 21.77
Bid-YTW : 5.06 %
TD.PF.A FixedReset -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-22
Maturity Price : 21.11
Evaluated at bid price : 21.11
Bid-YTW : 3.87 %
TRP.PR.B FixedReset -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-22
Maturity Price : 12.53
Evaluated at bid price : 12.53
Bid-YTW : 4.22 %
IAG.PR.G FixedReset 1.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.54
Bid-YTW : 5.14 %
Volume Highlights
Issue Index Shares
Traded
Notes
BSC.PR.C SplitShare 65,570 New issue settled today.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2020-09-22
Maturity Price : 19.71
Evaluated at bid price : 19.69
Bid-YTW : 4.04 %
TRP.PR.E FixedReset 50,191 RBC bought 10,000 from TD at 20.00. Desjardins crossed 14,700 at 19.85.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-22
Maturity Price : 19.85
Evaluated at bid price : 19.85
Bid-YTW : 4.34 %
NA.PR.S FixedReset 42,908 TD crossed 29,100 at 21.70.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-22
Maturity Price : 21.31
Evaluated at bid price : 21.60
Bid-YTW : 3.92 %
FTS.PR.K FixedReset 40,000 Nesbitt crossed 30,900 at 18.60.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-22
Maturity Price : 18.50
Evaluated at bid price : 18.50
Bid-YTW : 4.17 %
FTS.PR.F Perpetual-Discount 33,050 RBC crossed 19,800 at 22.52.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-22
Maturity Price : 22.23
Evaluated at bid price : 22.50
Bid-YTW : 5.49 %
BNS.PR.P FixedReset 31,300 RBC crossed 25,000 at 24.47.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.40
Bid-YTW : 3.59 %
There were 27 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
RY.PR.Z FixedReset Quote: 21.10 – 21.82
Spot Rate : 0.7200
Average : 0.4419

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-22
Maturity Price : 21.10
Evaluated at bid price : 21.10
Bid-YTW : 3.83 %

MFC.PR.G FixedReset Quote: 22.91 – 23.51
Spot Rate : 0.6000
Average : 0.3788

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.91
Bid-YTW : 4.96 %

BAM.PF.D Perpetual-Discount Quote: 21.54 – 22.05
Spot Rate : 0.5100
Average : 0.3289

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-22
Maturity Price : 21.26
Evaluated at bid price : 21.54
Bid-YTW : 5.70 %

TD.PR.Z FloatingReset Quote: 22.43 – 22.98
Spot Rate : 0.5500
Average : 0.3939

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.43
Bid-YTW : 3.88 %

BMO.PR.T FixedReset Quote: 20.55 – 21.05
Spot Rate : 0.5000
Average : 0.3618

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-22
Maturity Price : 20.55
Evaluated at bid price : 20.55
Bid-YTW : 3.95 %

BAM.PR.N Perpetual-Discount Quote: 21.00 – 21.40
Spot Rate : 0.4000
Average : 0.2829

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-22
Maturity Price : 21.00
Evaluated at bid price : 21.00
Bid-YTW : 5.69 %

Market Action

September 21, 2015

Fed officials are busily warning against complacency:

Federal Reserve officials argued that an interest-rate increase is still warranted this year, laying out the case for liftoff in remarks over the weekend that counter bets by traders that the central bank will stay on hold until 2016.

Three policy makers separately explained their rationale for enacting a rate increase at one of the Fed’s two remaining meetings of 2015, citing declines in unemployment and other gains in the U.S. economy that should outweigh headwinds from slower growth abroad and turbulent financial markets.

San Francisco Fed President John Williams, a policy centrist who has worked closely with Chair Janet Yellen, said Sunday that “in my mind, it was a close call” to delay a rate rise at last week’s Federal Open Market Committee meeting.

Williams’ comments on Fox News Channel’s “Sunday Morning Futures with Maria Bartiromo” echoed remarks he made the day before, and chimed with the reasoning of St. Louis Fed President James Bullard and Richmond Fed President Jeffrey Lacker. Both weighed in on Saturday over the FOMC’s vote to leave rates near zero.

Non-voting FOMC members are also weighing in:

Federal Reserve Bank of St. Louis President James Bullard said he pushed against the central bank’s decision this week to delay an interest rate increase, because the economy has more or less fulfilled policy makers’ goals.

“The case for policy normalization is quite strong, since Committee objectives have essentially been met,” Bullard said in slides prepared for a speech in Nashville, Tennessee. “I argued against the decision at the FOMC meeting.”

Bullard is not a voting member of the policy-setting Federal Open Market Committee in 2015, but will vote in 2016.

I’ve said it before, I’ll say it again – I’m sure that most, if not all, of these public statements are deliberately orchestrated by the FOMC as a whole. ‘You made some good points in the meeting, guys. You should speak up in public.’ In that way, the market learns a bit more about the decision than is available in the simple ternary result (up, unchanged, down) and about what elements of the data are considered important and on the cusp of change. It’s a lot better system than the Canadian one, in which (since Dodge retired) Moses descends from the mountain with the Finance Minister’s decision.

I’ve heard a rumour that Volkswagen has a new motto – “Don’t help me!”:

Discrepancies in the European tests on the diesel models of the VW Passat, the VW Jetta and the BMW X5 last year gave Peter Mock an idea.

Mock, European managing director of a little-known clean-air group, suggested replicating the tests in the U.S. The U.S. has higher emissions standards than the rest of the world and a history of enforcing them, so Mock and his American counterpart, John German, were sure the U.S. versions of the vehicles would pass the emissions tests, German said. That way, they reasoned, they could show Europeans it was possible for diesel cars to run clean.

“We had no cause for suspicion,” German, U.S. co-lead of the International Council on Clean Transportation, said in an interview. “We thought the vehicles would be clean.”

So began a series of events that resulted in Volkswagen AG admitting that it built “defeat device” software into a half-million of its diesel cars from 2009 to 2015 that automatically cheated on U.S. air-pollution tests. The world’s second-biggest carmaker now faces billions in fines, possible jail time for its executives and the undoing of its U.S. expansion plans.

Hat tip to Assiduous Reader JP, who brought this to my attention.

It didn’t do their stock price much good:

Volkswagen AG dropped 15 percent, the most in almost six years, after it admitted to cheating on U.S. air pollution tests for years.

The shares declined as much as 23.80 euros and were down 14 percent at 140 euros as of 9:03 a.m. in Frankfurt. The drop extends the fall for the year to 24 percent, valuing the Wolfsburg, Germany-based company at 66.2 billion euros ($74.9 billion).

Volkswagen Chief Executive Officer Martin Winterkorn said on Sunday that the company is cooperating with regulatory investigators and ordered its own external investigation into the issue. The CEO said he was “deeply sorry” for breaking the public’s trust.

Public trust is right!

John Decker bought his 2013 Volkswagen Jetta diesel thinking he was doing his part to improve the environment and reduce his carbon footprint.

Now that the German automaker has admitted its claims about the model’s performance were false, he just wants the company to buy it back from him.

“I feel completely deceived by Volkswagen,” Decker, of Sacramento, California, said in an interview. “I’m extremely upset about it. I feel defrauded.”
…
Decker wants Volkswagen to compensate him for the purchase. He said he has been in contact with the law firm of Hagens Berman Sobol Shapiro LLP in Seattle, which announced Sept. 18 that it was filing a federal lawsuit against Volkswagen. The firm estimates that some consumers paid as much as $7,000 more for a diesel model.

“I don’t want my car anymore, frankly,” Decker said. “I’d like Volkswagen to buy it back from me. I really don’t want it. I don’t want to drive it. I don’t want anything to do with Volkswagen.”

Assiduous Reader JP – who has been very industriously outperforming you other bums who never send me anything – also alerts me to the denouement of a Dutch takeover defence initiated last spring:

Israel’s Teva Pharmaceutical Industries Ltd. said Tuesday it is bidding $40 billion for Mylan NV, a drug company with headquarters in Canonsburg, Pa., but incorporated in the Netherlands. In early April, moving preemptively to thwart such an offer, a Dutch law firm submitted paperwork on Mylan’s behalf to the Netherlands trade registry to create an obscure but powerful legal vehicle called a “stichting.”

The entity, named Stichting Preferred Shares Mylan, is essentially an empty shell. But it possesses special powers, thanks to a shareholder-approved provision tucked into the paperwork for a previous Mylan acquisition: If Mylan ever receives an unsolicited takeover bid, the stichting can get veto rights over any takeover.

Stichtings, which mean “foundations” in Dutch, have been around for hundreds of years, primarily used by Dutch charities. During the World War II, Dutch companies transferred their ownership to stichtings based in the Dutch Antilles in the Caribbean to protect assets from the German occupiers, experts say.
…
Their key attribute is that stichtings, often referred to as orphan foundations, don’t have any legal owners. That means they can be used to put money or other assets outside the reach of government authorities, competitors or shareholders. The stichting’s purpose and the responsibilities of its board of directors can be tailored to the vehicle’s needs.

But management has decided it is sufficiently entrenched:

Mylan said Monday that it has moved to cancel the preferred shares issued to the entity in July, as the threats to the company “have been sufficiently addressed.”

In a bit of fun news that shows Natural Philosophy as a hobby is not yet dead, World Bank economist Kaushik Basu has proved the Pythagorean Theorem. I don’t know if there’s any listing of proofs that might be considered authoritative, but here’s one site with 111 versions. Keep them coming, boys! Should we ever meet aliens, it will be most interesting to learn how many proofs they have and which ones they consider standard.

Meanwhile Russians are voting with their feet:

Official statistics show the number of Russian citizens leaving permanently or for more than nine months reached 53,235 in 2014, up 11 percent and the highest in nine years. Germany, the U.S. and Israel all report increases in the numbers of applications for immigration visas from Russia.

russianEmmigration
Click for Big

Parakeet Poluz made a good point about Malthusian forecasts and Club of Rome projections:

But history has repeatedly shown that new technologies can quickly upend assumptions about future demand and supply.

For example, back in the 1970s, there were predictions that the world would run out of copper by the end of the century. The people who made that forecast did not foresee that copper wire, long a staple of communications infrastructure, would be replaced by fibre-optic cable, with its glass threads made from silica. This technology helped reduce the demand for copper, in essence extending its supply.

Similarly, digital photography had a dramatic impact on the photo-processing industry. Twenty years ago, the idea that everyone would carry around telephones that were also good-quality cameras was ridiculous. People took pictures with cameras that were loaded with film and took the film to a developer. The processing consumed a lot of silver. Back then, if you didn’t anticipate the emergence of digital photography, you might have expected this source of demand would continue indefinitely. Instead, according to the Washington-based Silver Institute, the use of silver in photography peaked in 1999 and has fallen by almost 80 per cent since.

It would appear that he fulfilled his cheerleading mandate in the question and answer period:

“In terms of being excessively dependent, I don’t buy that. Twenty per cent of our economy is the resource economy. That’s very important; it’s our backbone. It’s always been our history, and the rest is in some way dependent on that continuing to perform,” Mr Poloz told a business audience in Calgary, where the collapse in oil prices has led to deep cuts in spending and thousands of layoffs in the energy sector.

“We’re a highly diversified economy, and we should be thankful that we’ve got resources as part of our diversification, whereas lots of other countries don’t have that.”

During the federal election campaign, there has been considerable debate about the growing emphasis on energy-sector expansion under Conservative Leader Stephen Harper and, subsequently, the broad economic consequences of the industry’s downturn.

Excessively dependent? Bank of Canada research has noted:

Two aspects of the recent monetary history of Canada, Australia, and New Zealand stand out: the sensitivity of their dollars to prices of resource-based commodities, and inflation targeting.

… while less authoritative but still credible research asserts:

In the last ten years, over half of Canada’s total exports consisted of energy and non-energy commodities. Because the Canadian dollar is often called a “commodity currency”, this paper seeks to test the relevance of commodity prices in explaining the variation in the Canadian real exchange rate against the US dollar, the UK pound, and the Japanese yen. The currencies of these countries are chosen for the analysis because of Canada’s strong trade relationships with the United States, the United Kingdom, and Japan. The dynamic empirical model in this research demonstrates that the proportion of the variation in Canada’s real exchange rate that is attributable to a volatile commodity price shock differs depending on the currency pairing. The results also suggest that the relationship between commodity prices and the Canadian dollar has strengthened over the last two decades.

Sounds excessive to me! Meanwhile, Werner Antweiler of UBC has gone so far as to say:

Is the Canadian Dollar a petrodollar? If you had asked me this question in the 1990s, I would have said “only a little”. At the time, commodity prices were not generally thought to be primary drivers of the exchange rate. During that decade, oil prices were relatively flat and thus the observable variation in the exchange rate was driven by other factors. Most international economists, including those at the Bank of Canada who have a professional interest in this question, were indeed puzzled to find that the CAD/USD exchange rate was difficult to predict based on fundamental factors.

While I was researching oil prices for another issue, I had another look at the relationship between oil prices and the CAD/USD exchange rate, and was indeed a bit surprised how much the oil price matters for determining the value of the Canadian Dollar. As two diagrams show below, there can be little question that during the last fifteen years the Canadian Dollar has morphed into a “petrocurrency”.

In simple terms, a petrocurrency is a currency of an oil-producing country—such as Canada—whose oil exports as a share of total exports are sufficiently large that the value of that country’s currency rises and falls along with the price of oil. In other words, a petrocurrency appreciates when the oil price rises and depreciates when the oil price falls.

Perhaps Mr. Poluz will explain how a deeply rooted manufacturing complex is supposed to survive, when our currency fluctuates so much against our number one trading partner with such alarming amplitude?

One of the more entertaining corporate battles of recent times may have ended in a draw:

Sprott Asset Management LP (“Sprott” or “Sprott Asset Management”), together with Sprott Physical Gold Trust (NYSE:PHYS) (TSX:PHY.U) and Sprott Physical Silver Trust (NYSE:PSLV) (TSX:PHS.U), today announced that it has filed notices of extension in connection with the offers by Sprott Asset Management Gold Bid LP and Sprott Asset Management Silver Bid LP to acquire all of the outstanding units of Central GoldTrust (“GTU”) (TSX: GTU.UN) (TSX:GTU.U) (NYSEMKT:GTU) and Silver Bullion Trust (“SBT”) (TSX:SBT.UN) (TSX:SBT.U), respectively, for units of Sprott Physical Gold Trust and units of Sprott Physical Silver Trust, in each case on a net asset value (NAV) to NAV exchange basis (collectively, the “Sprott offers”). The notices of extension extend the expiry time of the Sprott offers to 5 p.m. (Toronto time) on October 9, 2015.
…
As of 5:00 p.m. (Toronto time) on September 18, 2015, there were 9,928,736 GTU units (51.45% of all outstanding units) and 2,065,574 SBT units (37.78% of all outstanding units) tendered into the respective Sprott offers.

IGM Financial, proud issuer of IGM.PR.B, has been confirmed at Pfd-2(high) by DBRS:

DBRS Limited (DBRS) has today confirmed the Issuer Rating and Unsecured Debentures rating of IGM Financial Inc. (IGM or the Company) at A (high) and the First Preferred Shares rating at Pfd-2 (high). The trends are Stable.
…
In addition to strong profitability, the Company’s credit rating also benefits from strong cash flows (which comfortably cover the upfront distribution costs of mutual fund sales), strong liquidity and a conservative financial profile. The Company’s ratio of debt plus preferred shares-to-total capitalization remains appropriate for the rating.

As a member of the Power Financial Corporation (Power) group of companies, IGM benefits from the additional financial flexibility of having a strategic shareholder and the associated strong governance and risk avoidance management model that is typical of Power subsidiaries.

It was a day of little overall movement for the Canadian preferred share market, with PerpetualDiscounts and DeemedRetractibles both off 6bp, while FixedResets gained 4bp. The placidity of the indices masked a lot of churn, though, as reported on the Performance Highlights table. Volume was very low.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_150921
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 20.00 to be $1.04 rich, while TRP.PR.C, resetting 2016-1-30 at +164, is $1.17 cheap at its bid price of 13.00.

impVol_MFC_150921
Click for Big

Another good fit today for MFC, with Implied Volatility falling a bit today.

Most expensive is MFC.PR.J, resetting at +261bp on 2018-3-19, bid at 22.65 to be 0.44 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 23.03 to be 0.44 cheap.

impVol_BAM_150921
Click for Big

The fit on the BAM issues continues to be horrible.

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 16.50 to be $1.63 cheap. BAM.PF.G, resetting at +284bp on 2020-6-30 is bid at 22.60 and appears to be $1.31 rich.

impVol_FTS_150921
Click for Big

FTS.PR.M, with a spread of +248bp, and bid at 22.15, looks $0.54 expensive and resets 2019-12-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 18.79 and is $0.53 cheap.

pairs_FR_150921
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.93%, with no outliers. The distribution’s bimodality has returned, with bank NVCC non-compliant pairs averaging -1.08% and other issues averaging -0.71%. There are two junk outliers above 0.00%.

pairs_FF_150921
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.0954 % 1,647.0
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.0954 % 2,879.8
Floater 4.51 % 4.54 % 59,940 16.36 3 -0.0954 % 1,750.9
OpRet 0.00 % 0.00 % 0 0.00 0 -0.3382 % 2,767.8
SplitShare 4.65 % 5.03 % 63,501 3.05 3 -0.3382 % 3,243.7
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.3382 % 2,530.8
Perpetual-Premium 5.71 % 1.09 % 53,552 0.08 8 0.0840 % 2,496.2
Perpetual-Discount 5.45 % 5.55 % 67,270 14.55 30 -0.0619 % 2,600.4
FixedReset 4.75 % 4.24 % 180,340 15.86 74 0.0365 % 2,142.2
Deemed-Retractible 5.15 % 4.68 % 91,108 5.49 33 -0.0606 % 2,578.9
FloatingReset 2.49 % 4.12 % 49,353 5.88 9 0.1700 % 2,148.3
Performance Highlights
Issue Index Change Notes
BIP.PR.A FixedReset -2.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-21
Maturity Price : 21.65
Evaluated at bid price : 22.00
Bid-YTW : 5.00 %
GWO.PR.N FixedReset -2.46 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.68
Bid-YTW : 8.74 %
MFC.PR.F FixedReset -1.81 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.22
Bid-YTW : 8.58 %
TRP.PR.A FixedReset -1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-21
Maturity Price : 16.45
Evaluated at bid price : 16.45
Bid-YTW : 4.36 %
IFC.PR.C FixedReset -1.55 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.69
Bid-YTW : 6.65 %
BMO.PR.R FloatingReset -1.47 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.07
Bid-YTW : 4.12 %
BNS.PR.Y FixedReset -1.39 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.30
Bid-YTW : 4.58 %
BAM.PR.R FixedReset -1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-21
Maturity Price : 16.53
Evaluated at bid price : 16.53
Bid-YTW : 4.84 %
CU.PR.C FixedReset -1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-21
Maturity Price : 20.70
Evaluated at bid price : 20.70
Bid-YTW : 3.99 %
PWF.PR.F Perpetual-Discount -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-21
Maturity Price : 23.63
Evaluated at bid price : 23.90
Bid-YTW : 5.57 %
BMO.PR.Y FixedReset 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-21
Maturity Price : 22.47
Evaluated at bid price : 23.35
Bid-YTW : 3.86 %
MFC.PR.N FixedReset 1.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.78
Bid-YTW : 5.87 %
MFC.PR.J FixedReset 1.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.65
Bid-YTW : 4.88 %
TRP.PR.B FixedReset 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-21
Maturity Price : 12.66
Evaluated at bid price : 12.66
Bid-YTW : 4.17 %
VNR.PR.A FixedReset 1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-21
Maturity Price : 20.15
Evaluated at bid price : 20.15
Bid-YTW : 4.68 %
MFC.PR.I FixedReset 1.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.19
Bid-YTW : 4.84 %
BAM.PR.X FixedReset 1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-21
Maturity Price : 15.50
Evaluated at bid price : 15.50
Bid-YTW : 4.52 %
HSE.PR.G FixedReset 1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-21
Maturity Price : 22.08
Evaluated at bid price : 22.65
Bid-YTW : 4.84 %
SLF.PR.H FixedReset 1.43 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.75
Bid-YTW : 7.46 %
BNS.PR.D FloatingReset 1.45 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.30
Bid-YTW : 4.83 %
BMO.PR.M FixedReset 1.47 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.15
Bid-YTW : 3.56 %
TRP.PR.C FixedReset 1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-21
Maturity Price : 13.00
Evaluated at bid price : 13.00
Bid-YTW : 4.65 %
BNS.PR.P FixedReset 1.57 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.52
Bid-YTW : 3.51 %
SLF.PR.J FloatingReset 1.69 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.25
Bid-YTW : 9.46 %
FTS.PR.K FixedReset 1.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-21
Maturity Price : 18.85
Evaluated at bid price : 18.85
Bid-YTW : 4.09 %
TRP.PR.F FloatingReset 2.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-21
Maturity Price : 14.70
Evaluated at bid price : 14.70
Bid-YTW : 3.89 %
PWF.PR.P FixedReset 2.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-21
Maturity Price : 15.62
Evaluated at bid price : 15.62
Bid-YTW : 3.96 %
Volume Highlights
Issue Index Shares
Traded
Notes
FTS.PR.K FixedReset 112,520 Desjardins crossed blocks of 85,200 and 10,000, both at 18.95.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-21
Maturity Price : 18.85
Evaluated at bid price : 18.85
Bid-YTW : 4.09 %
TRP.PR.E FixedReset 59,776 TD crossed blocks of 17,000 and 20,000, both at 20.05.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-21
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 4.31 %
RY.PR.J FixedReset 36,284 TD crossed 17,000 at 22.62.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-21
Maturity Price : 22.49
Evaluated at bid price : 23.36
Bid-YTW : 3.78 %
RY.PR.I FixedReset 33,900 Desjardins crossed blocks of 15,400 and 15,000, both at 24.80.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.62
Bid-YTW : 3.50 %
MFC.PR.G FixedReset 32,593 Nesbitt crossed 30,000 at 23.20.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.03
Bid-YTW : 4.89 %
TRP.PR.D FixedReset 28,912 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-21
Maturity Price : 19.29
Evaluated at bid price : 19.29
Bid-YTW : 4.40 %
There were 16 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
MFC.PR.M FixedReset Quote: 21.10 – 21.85
Spot Rate : 0.7500
Average : 0.5086

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.10
Bid-YTW : 5.74 %

IFC.PR.C FixedReset Quote: 19.69 – 20.15
Spot Rate : 0.4600
Average : 0.3114

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.69
Bid-YTW : 6.65 %

GWO.PR.R Deemed-Retractible Quote: 22.25 – 22.60
Spot Rate : 0.3500
Average : 0.2038

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.25
Bid-YTW : 6.40 %

TD.PR.Z FloatingReset Quote: 22.40 – 22.74
Spot Rate : 0.3400
Average : 0.2227

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.40
Bid-YTW : 3.90 %

GWO.PR.L Deemed-Retractible Quote: 25.15 – 25.50
Spot Rate : 0.3500
Average : 0.2367

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.15
Bid-YTW : 5.59 %

BMO.PR.R FloatingReset Quote: 22.07 – 22.50
Spot Rate : 0.4300
Average : 0.3167

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.07
Bid-YTW : 4.12 %

Market Action

September 18, 2015

Nothing happened today, except that bonds had a good day:

The S&P 500 retreated 1.6 percent at 4 p.m. in New York, erasing its gain for the week. The gauge ended lower yesterday by 0.4 percent, erasing a gain of as much as 1.3 percent after Yellen indicated that global developments overshadowed signs of strength in America.
…
U.S. two-year Treasuries extended their biggest one-day rally since 2009, while Pacific Investment Management Co. said policy makers may wait until next year before raising rates. JPMorgan Asset Management said the Fed’s statement was good for bonds and they still like debt due between seven and 10 years.

Bonds gained from Australia to Germany, while Treasuries added to an advance from Thursday. The yield on 10-year German bunds, the euro region’s benchmark sovereign securities, dropped 12 basis points to 0.66 percent, set for its biggest decline since July 7, on prospects for further easing by the European Central Bank.

Rates on similar-maturity Italian bonds fell 14 basis points to 1.76 percent, while those on Spain’s declined 15 basis points to 1.94 percent. The yield on U.S. 10-year Treasuries fell six basis points to 2.13 percent on Friday, after sliding 10 basis points the previous day.

It was yet another negative day for the Canadian preferred share market, with PerpetualDiscounts gaining 5bp, FixedResets down 48bp and DeemedRetractibles off 6bp. The Performance Highlights table is comprised entirely of losers, mostly FixedResets. Volume was extremely low.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_150918
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 20.06 to be $1.05 rich, while TRP.PR.C, resetting 2016-1-30 at +164, is $1.32 cheap at its bid price of 12.81.

impVol_MFC_150918
Click for Big

Another good fit today for MFC, with Implied Volatility falling a bit today.

Most expensive is MFC.PR.H, resetting at +313bp on 2017-3-19, bid at 24.41 to be 0.32 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 23.03 to be 0.30 cheap.

impVol_BAM_150918
Click for Big

The fit on the BAM issues continues to be horrible.

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 16.80 to be $1.42 cheap. BAM.PF.G, resetting at +284bp on 2020-6-30 is bid at 22.54 and appears to be $1.17 rich.

impVol_FTS_150918
Click for Big

FTS.PR.M, with a spread of +248bp, and bid at 22.20, looks $0.66 expensive and resets 2019-12-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 18.79 and is $0.43 cheap.

pairs_FR_150918
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.87%, with no outliers. The distribution’s bimodality has vanished. There are two junk outliers above 0.00%.

pairs_FR_150918
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -1.1003 % 1,648.6
FixedFloater 0.00 % 0.00 % 0 0.00 0 -1.1003 % 2,882.5
Floater 4.51 % 4.54 % 58,288 16.37 3 -1.1003 % 1,752.6
OpRet 0.00 % 0.00 % 0 0.00 0 0.0812 % 2,777.2
SplitShare 4.63 % 4.95 % 61,117 3.06 3 0.0812 % 3,254.7
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0812 % 2,539.4
Perpetual-Premium 5.71 % 2.95 % 53,691 0.08 8 0.1138 % 2,494.1
Perpetual-Discount 5.45 % 5.52 % 66,304 14.59 30 0.0476 % 2,602.0
FixedReset 4.75 % 4.21 % 178,672 15.99 74 -0.4801 % 2,141.4
Deemed-Retractible 5.15 % 4.75 % 91,336 5.50 33 -0.0580 % 2,580.4
FloatingReset 2.49 % 3.96 % 49,480 5.90 9 -0.5021 % 2,144.7
Performance Highlights
Issue Index Change Notes
TRP.PR.C FixedReset -4.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-18
Maturity Price : 12.81
Evaluated at bid price : 12.81
Bid-YTW : 4.62 %
HSE.PR.A FixedReset -2.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-18
Maturity Price : 13.80
Evaluated at bid price : 13.80
Bid-YTW : 4.65 %
TRP.PR.A FixedReset -2.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-18
Maturity Price : 16.75
Evaluated at bid price : 16.75
Bid-YTW : 4.22 %
SLF.PR.J FloatingReset -2.40 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.03
Bid-YTW : 9.65 %
TRP.PR.F FloatingReset -2.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-18
Maturity Price : 14.40
Evaluated at bid price : 14.40
Bid-YTW : 3.96 %
SLF.PR.H FixedReset -1.96 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.50
Bid-YTW : 7.59 %
MFC.PR.F FixedReset -1.96 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.50
Bid-YTW : 8.27 %
BAM.PR.K Floater -1.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-18
Maturity Price : 10.42
Evaluated at bid price : 10.42
Bid-YTW : 4.54 %
SLF.PR.G FixedReset -1.73 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.35
Bid-YTW : 8.23 %
TD.PR.S FixedReset -1.56 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.97
Bid-YTW : 3.66 %
VNR.PR.A FixedReset -1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-18
Maturity Price : 19.90
Evaluated at bid price : 19.90
Bid-YTW : 4.68 %
BAM.PR.Z FixedReset -1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-18
Maturity Price : 21.00
Evaluated at bid price : 21.00
Bid-YTW : 4.62 %
TRP.PR.B FixedReset -1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-18
Maturity Price : 12.52
Evaluated at bid price : 12.52
Bid-YTW : 4.14 %
BMO.PR.T FixedReset -1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-18
Maturity Price : 20.94
Evaluated at bid price : 20.94
Bid-YTW : 3.82 %
PWF.PR.T FixedReset -1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-18
Maturity Price : 22.21
Evaluated at bid price : 22.70
Bid-YTW : 3.65 %
IFC.PR.C FixedReset -1.38 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.00
Bid-YTW : 6.39 %
IAG.PR.G FixedReset -1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.50
Bid-YTW : 5.11 %
FTS.PR.K FixedReset -1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-18
Maturity Price : 18.50
Evaluated at bid price : 18.50
Bid-YTW : 4.11 %
GWO.PR.N FixedReset -1.31 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.05
Bid-YTW : 8.35 %
BAM.PR.R FixedReset -1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-18
Maturity Price : 16.75
Evaluated at bid price : 16.75
Bid-YTW : 4.70 %
HSE.PR.G FixedReset -1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-18
Maturity Price : 21.89
Evaluated at bid price : 22.35
Bid-YTW : 4.87 %
MFC.PR.I FixedReset -1.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.90
Bid-YTW : 4.96 %
FTS.PR.F Perpetual-Discount -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-18
Maturity Price : 22.24
Evaluated at bid price : 22.51
Bid-YTW : 5.48 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PF.F Perpetual-Discount 65,100 RBC crossed 48,200 at 24.35.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-18
Maturity Price : 24.03
Evaluated at bid price : 24.39
Bid-YTW : 5.09 %
NA.PR.S FixedReset 52,575 TD crossed 46,700 at 21.75.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-18
Maturity Price : 21.31
Evaluated at bid price : 21.60
Bid-YTW : 3.87 %
MFC.PR.G FixedReset 36,160 Nesbitt crossed 34,600 at 23.20.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.03
Bid-YTW : 4.84 %
GWO.PR.N FixedReset 32,586 Nesbitt crossed 28,700 at 15.30.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.05
Bid-YTW : 8.35 %
BNS.PR.Q FixedReset 27,200 RBC crossed 25,000 at 24.32.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.29
Bid-YTW : 3.65 %
SLF.PR.J FloatingReset 27,038 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.03
Bid-YTW : 9.65 %
There were 12 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
RY.PR.J FixedReset Quote: 23.35 – 24.00
Spot Rate : 0.6500
Average : 0.4263

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-18
Maturity Price : 22.49
Evaluated at bid price : 23.35
Bid-YTW : 3.74 %

TRP.PR.F FloatingReset Quote: 14.40 – 15.20
Spot Rate : 0.8000
Average : 0.5885

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-18
Maturity Price : 14.40
Evaluated at bid price : 14.40
Bid-YTW : 3.96 %

HSE.PR.G FixedReset Quote: 22.35 – 22.99
Spot Rate : 0.6400
Average : 0.4319

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-18
Maturity Price : 21.89
Evaluated at bid price : 22.35
Bid-YTW : 4.87 %

MFC.PR.N FixedReset Quote: 20.56 – 21.18
Spot Rate : 0.6200
Average : 0.4233

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.56
Bid-YTW : 5.98 %

TD.PR.S FixedReset Quote: 23.97 – 24.55
Spot Rate : 0.5800
Average : 0.3843

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.97
Bid-YTW : 3.66 %

TRP.PR.C FixedReset Quote: 12.81 – 13.30
Spot Rate : 0.4900
Average : 0.2972

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-18
Maturity Price : 12.81
Evaluated at bid price : 12.81
Bid-YTW : 4.62 %

Market Action

September 17, 2015

Today’s big news was the FOMC release:

Information received since the Federal Open Market Committee met in July suggests that economic activity is expanding at a moderate pace. Household spending and business fixed investment have been increasing moderately, and the housing sector has improved further; however, net exports have been soft. The labor market continued to improve, with solid job gains and declining unemployment. On balance, labor market indicators show that underutilization of labor resources has diminished since early this year. Inflation has continued to run below the Committee’s longer-run objective, partly reflecting declines in energy prices and in prices of non-energy imports. Market-based measures of inflation compensation moved lower; survey-based measures of longer-term inflation expectations have remained stable.
…
To support continued progress toward maximum employment and price stability, the Committee today reaffirmed its view that the current 0 to 1/4 percent target range for the federal funds rate remains appropriate. In determining how long to maintain this target range, the Committee will assess progress–both realized and expected–toward its objectives of maximum employment and 2 percent inflation. This assessment will take into account a wide range of information, including measures of labor market conditions, indicators of inflation pressures and inflation expectations, and readings on financial and international developments. The Committee anticipates that it will be appropriate to raise the target range for the federal funds rate when it has seen some further improvement in the labor market and is reasonably confident that inflation will move back to its 2 percent objective over the medium term.
…
The Committee currently anticipates that, even after employment and inflation are near mandate-consistent levels, economic conditions may, for some time, warrant keeping the target federal funds rate below levels the Committee views as normal in the longer run.
…
Voting against the action was Jeffrey M. Lacker, who preferred to raise the target range for the federal funds rate by 25 basis points at this meeting.

Meanwhile, in Canada:

The number of EI beneficiaries rose 2 per cent to 545,200 in July from a month earlier, Statistics Canada said Thursday, led by increases in British Columbia, Ontario and Alberta. That level is 7.1 per cent higher than a year ago.

In Alberta, the province most exposed to lower oil prices, the number of EI beneficiaries climbed for the ninth straight month. EI numbers rose 1.8 per cent from a month earlier – a slower pace than in previous months – and are 72.2 per cent higher than in July of last year.

British Columbia and Ontario saw the biggest monthly percentage increases while Quebec and Saskatchewan also registered gains. Numbers fell in Manitoba and Newfoundland.

It was a mildly negative day for the Canadian preferred share market, with PerpetualDiscounts gaining 5bp, FixedResets off 8bp and DeemedRetractibles down 19bp. The Performance Highlights table is reasonably balanced. Volume was low.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_150917
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 20.00 to be $0.81 rich, while TRP.PR.C, resetting 2016-1-30 at +164, is $1.04 cheap at its bid price of 13.39.

impVol_MFC_150917
Click for Big

Another good fit today for MFC, with Implied Volatility falling a bit today.

Most expensive is MFC.PR.H, resetting at +313bp on 2017-3-19, bid at 24.36 to be 0.25 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 23.07 to be 0.28 cheap.

impVol_BAM_150917
Click for Big

The fit on the BAM issues continues to be horrible.

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 17.00 to be $1.30 cheap. BAM.PF.G, resetting at +284bp on 2020-6-30 is bid at 22.48 and appears to be $1.06 rich.

impVol_FTS_150917
Click for Big

FTS.PR.M, with a spread of +248bp, and bid at 22.20, looks $0.61 expensive and resets 2019-12-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 18.79 and is $0.50 cheap.

pairs_FR_150917
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.89%, with no outliers. The distribution’s bimodality has vanished. There are two junk outliers above 0.00%.

pairs_FF_150917
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.0944 % 1,666.9
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.0944 % 2,914.6
Floater 4.46 % 4.45 % 57,298 16.54 3 0.0944 % 1,772.1
OpRet 0.00 % 0.00 % 0 0.00 0 -0.2970 % 2,774.9
SplitShare 4.64 % 4.94 % 60,339 3.06 3 -0.2970 % 3,252.0
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.2970 % 2,537.4
Perpetual-Premium 5.72 % 4.73 % 54,130 0.08 8 -0.1087 % 2,491.2
Perpetual-Discount 5.45 % 5.53 % 67,104 14.59 30 0.0511 % 2,600.8
FixedReset 4.73 % 4.10 % 173,820 16.12 74 -0.0843 % 2,151.7
Deemed-Retractible 5.15 % 5.08 % 93,885 5.50 33 -0.1926 % 2,581.9
FloatingReset 2.47 % 3.88 % 49,687 5.91 9 -0.0764 % 2,155.5
Performance Highlights
Issue Index Change Notes
SLF.PR.J FloatingReset -2.84 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.35
Bid-YTW : 9.34 %
IFC.PR.A FixedReset -1.80 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.34
Bid-YTW : 8.48 %
IAG.PR.G FixedReset -1.64 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.81
Bid-YTW : 4.93 %
PWF.PR.T FixedReset -1.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-17
Maturity Price : 22.41
Evaluated at bid price : 23.02
Bid-YTW : 3.59 %
SLF.PR.B Deemed-Retractible -1.48 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.02
Bid-YTW : 6.54 %
FTS.PR.K FixedReset -1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-17
Maturity Price : 18.75
Evaluated at bid price : 18.75
Bid-YTW : 4.06 %
HSE.PR.E FixedReset -1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-17
Maturity Price : 22.06
Evaluated at bid price : 22.60
Bid-YTW : 4.82 %
PWF.PR.S Perpetual-Discount -1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-17
Maturity Price : 21.99
Evaluated at bid price : 22.31
Bid-YTW : 5.44 %
BMO.PR.M FixedReset -1.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.01
Bid-YTW : 3.63 %
BNS.PR.P FixedReset -1.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.05
Bid-YTW : 3.81 %
NA.PR.S FixedReset -1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-17
Maturity Price : 21.52
Evaluated at bid price : 21.52
Bid-YTW : 3.91 %
RY.PR.I FixedReset -1.21 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.50
Bid-YTW : 3.56 %
TD.PF.F Perpetual-Discount -1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-17
Maturity Price : 23.83
Evaluated at bid price : 24.17
Bid-YTW : 5.13 %
PVS.PR.D SplitShare -1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2021-10-08
Maturity Price : 25.00
Evaluated at bid price : 24.05
Bid-YTW : 5.29 %
TD.PF.D FixedReset -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-17
Maturity Price : 22.37
Evaluated at bid price : 23.16
Bid-YTW : 3.83 %
GWO.PR.S Deemed-Retractible -1.02 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.25
Bid-YTW : 5.68 %
MFC.PR.N FixedReset 1.02 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.76
Bid-YTW : 5.85 %
MFC.PR.J FixedReset 1.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.25
Bid-YTW : 5.06 %
SLF.PR.G FixedReset 1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.62
Bid-YTW : 8.01 %
MFC.PR.I FixedReset 1.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.15
Bid-YTW : 4.81 %
HSE.PR.C FixedReset 1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-17
Maturity Price : 20.75
Evaluated at bid price : 20.75
Bid-YTW : 4.89 %
SLF.PR.H FixedReset 1.31 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.85
Bid-YTW : 7.32 %
GWO.PR.N FixedReset 1.40 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.25
Bid-YTW : 8.18 %
FTS.PR.M FixedReset 1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-17
Maturity Price : 21.82
Evaluated at bid price : 22.20
Bid-YTW : 3.85 %
MFC.PR.M FixedReset 1.44 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.20
Bid-YTW : 5.64 %
POW.PR.B Perpetual-Discount 1.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-17
Maturity Price : 23.88
Evaluated at bid price : 24.13
Bid-YTW : 5.54 %
TRP.PR.F FloatingReset 2.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-17
Maturity Price : 14.70
Evaluated at bid price : 14.70
Bid-YTW : 3.87 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.L FixedReset 45,613 RBC crossed 38,000 at 25.65.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.49
Bid-YTW : 3.61 %
TD.PF.F Perpetual-Discount 41,450 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-17
Maturity Price : 23.83
Evaluated at bid price : 24.17
Bid-YTW : 5.13 %
FTS.PR.G FixedReset 40,390 Scotia crossed 40,000 at 18.90.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-17
Maturity Price : 18.79
Evaluated at bid price : 18.79
Bid-YTW : 4.07 %
BAM.PR.B Floater 36,847 Nesbitt crossed 25,000 at 10.70.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-17
Maturity Price : 10.71
Evaluated at bid price : 10.71
Bid-YTW : 4.41 %
PWF.PR.P FixedReset 31,282 Scotia crossed 22,800 at 15.40.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-17
Maturity Price : 15.36
Evaluated at bid price : 15.36
Bid-YTW : 3.94 %
BAM.PF.A FixedReset 31,000 RBC crossed 24,400 at 21.72.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-17
Maturity Price : 21.32
Evaluated at bid price : 21.62
Bid-YTW : 4.38 %
There were 17 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
FTS.PR.K FixedReset Quote: 18.75 – 19.59
Spot Rate : 0.8400
Average : 0.6315

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-17
Maturity Price : 18.75
Evaluated at bid price : 18.75
Bid-YTW : 4.06 %

BNS.PR.P FixedReset Quote: 24.05 – 24.47
Spot Rate : 0.4200
Average : 0.2499

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.05
Bid-YTW : 3.81 %

SLF.PR.B Deemed-Retractible Quote: 22.02 – 22.45
Spot Rate : 0.4300
Average : 0.2965

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.02
Bid-YTW : 6.54 %

FTS.PR.G FixedReset Quote: 18.79 – 19.25
Spot Rate : 0.4600
Average : 0.3417

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-17
Maturity Price : 18.79
Evaluated at bid price : 18.79
Bid-YTW : 4.07 %

MFC.PR.C Deemed-Retractible Quote: 21.18 – 21.62
Spot Rate : 0.4400
Average : 0.3260

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.18
Bid-YTW : 6.76 %

PVS.PR.D SplitShare Quote: 24.05 – 24.40
Spot Rate : 0.3500
Average : 0.2443

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2021-10-08
Maturity Price : 25.00
Evaluated at bid price : 24.05
Bid-YTW : 5.29 %

Market Action

September 16, 2015

The OECD is not impressed with Canada’s growth:

In the quarterly update of its global outlook, the Organization for Economic Co-operation and Development cut its forecast for Canadian gross domestic product growth to 1.1 per cent this year, down from 1.5 per cent in its June outlook. For 2016, it reduced its GDP growth projection to 2.1 per cent from 2.3 per cent.

The OECD report underlines Canada’s underperformance this year relative to other major world economies, even as its neighbour and biggest trading partner, the United States, continues to gain momentum. The OECD upgraded its projection for U.S. GDP growth this year to 2.4 per cent, up from 2 per cent in its June report. Among the G7 major industrialized countries, Canada’s forecast 2015 growth is in the middle of the pack, ahead of Japan (0.6 per cent), Italy (0.7 per cent) and France (1.0 per cent). But Canada’s slowdown this year is the worst in G7, and the cut in its OECD forecast is the largest in the group.

Meanwhile, US inflation is moderate:

Prices paid by American households declined in August as cheaper gasoline helped keep inflation below the objective of Federal Reserve policy makers.

The consumer-price index fell 0.1 percent, the first decrease since January, after a 0.1 percent gain in July, Labor Department figures showed Wednesday. The so-called core measure, which strips out often-volatile fuel and food costs, rose 0.1 percent for a second month. Goods prices declined, while services barely rose.
…
The consumer price gauge increased 0.2 percent in the 12 months ended in August, the same as in July.

The core CPI measure, which excludes volatile food and fuel costs, rose 1.8 percent from August 2014, matching the prior month’s year-over-year gain.

In the comments to yesterday’s post, Assiduous Reader gimlimike brings to my attention a perpetual Dutch bond issued in 1648. I love perpetuals! If I’m reading the Dutch in the photograph correctly, the bond pays 25 guilders annually on an initial investment of 1,000 guilders, or 2.5%.

A similar bond was auctioned by Christies in 2000 with some interesting historical notes:

The Lekdijk Bovendams was incorporated in 1971 into a larger municipal organization, the Waterschap Kromme Rijn, which took over the payment of annual interest on the handful of extant original bonds. According to a 1978 report of the Waterschap’s Secretary, the corporation had issued a total of 48 bonds in the 17th and 18th century; their denominations ranged from 400 to 8,000 Guilders. Only 4 bonds were issued in the amount of 1200 Guilders. In 1978, only 22 of the 48 issued were still traceable (most in the hands of banks and other institutions, a few in private hands). According to a recent communication from C. Vanema, Archivist of the Streekarchief “Rijnstreek,” where the papers of the Waterschaap are deposited, there are today only five of these early bonds still active. Only one, issued in 1624 and owned since 1938 by the New York Stock Exchange, pre-dates the present bond, and only two of bonds issued in the 17th century are still active.

The good effects of centuries of such care may be observed via Google Maps. Given that one Guilder is 0.453780 Euros, the bond pays 11.34 Euros per year; given that Yale paid 24,000 Euros for it in 2003, the yield is 0.05% and the duration is therefore 2,000.

Yet another candidate has been dropped from the ballot over past indiscretions, and rewarded for his willingness to serve by being publicly vilified. At some point, we’re going to have to learn that not everybody has been a saint since birth; and that those who have been may not necessarily make the best legislators. But it makes us feel better about ourselves to scapegoat those unlucky enough to have been caught … meanwhile, I will continue to quite adequately represented provincially by Cheri DiNovo, who doubtless wouldn’t even be called for an interview in these puritanical times.

It was a negative day for the Canadian preferred share market, with PerpetualDiscounts off 5bp, FixedResets losing 25bp and DeemedRetractibles down 9bp. The Performance Highlights table is dominated by losing FixedResets, mostly of the low-spread variety. Volume was well below average.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_150916
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 20.02 to be $0.89 rich, while TRP.PR.C, resetting 2016-1-30 at +164, is $1.02 cheap at its bid price of 13.45.

impVol_MFC_150916
Click for Big

Another good fit today for MFC, with Implied Volatility falling a bit today.

Most expensive is MFC.PR.H, resetting at +313bp on 2017-3-19, bid at 24.49 to be 0.49 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 23.00 to be 0.23 cheap.

impVol_BAM_150916
Click for Big

The fit on the BAM issues continues to be horrible.

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 16.80 to be $1.48 cheap. BAM.PF.G, resetting at +284bp on 2020-6-30 is bid at 22.33 and appears to be $0.95 rich.

impVol_FTS_150916
Click for Big

FTS.PR.M, with a spread of +248bp, and bid at 21.89, looks $0.41 expensive and resets 2019-12-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 18.73 and is $0.52 cheap.

pairs_FR_150916
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -1.03%, with no outliers. The distribution has become bimodal again, with bank NVCC non-compliant issues averaging -1.17% and other issues averaging -0.82%. There are no junk outliers below -2.00%, but one above 0.00%.

pairs_FF_150916
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.1260 % 1,665.4
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.1260 % 2,911.8
Floater 4.46 % 4.46 % 57,556 16.52 3 0.1260 % 1,770.4
OpRet 0.00 % 0.00 % 0 0.00 0 0.0135 % 2,783.2
SplitShare 4.62 % 4.99 % 62,832 3.07 3 0.0135 % 3,261.7
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0135 % 2,544.9
Perpetual-Premium 5.71 % 2.47 % 54,398 0.08 8 0.0494 % 2,494.0
Perpetual-Discount 5.45 % 5.55 % 69,525 14.53 30 -0.0504 % 2,599.5
FixedReset 4.73 % 4.11 % 180,377 16.10 74 -0.2528 % 2,153.6
Deemed-Retractible 5.14 % 4.76 % 94,987 5.50 33 -0.0931 % 2,586.9
FloatingReset 2.47 % 3.97 % 50,398 5.91 9 -0.1851 % 2,157.1
Performance Highlights
Issue Index Change Notes
FTS.PR.H FixedReset -3.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-16
Maturity Price : 14.61
Evaluated at bid price : 14.61
Bid-YTW : 3.93 %
SLF.PR.G FixedReset -3.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.45
Bid-YTW : 8.14 %
FTS.PR.K FixedReset -2.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-16
Maturity Price : 19.01
Evaluated at bid price : 19.01
Bid-YTW : 4.00 %
SLF.PR.H FixedReset -2.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.62
Bid-YTW : 7.49 %
TRP.PR.F FloatingReset -1.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-16
Maturity Price : 14.36
Evaluated at bid price : 14.36
Bid-YTW : 3.97 %
IFC.PR.C FixedReset -1.84 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.25
Bid-YTW : 6.22 %
BMO.PR.Y FixedReset -1.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-16
Maturity Price : 22.34
Evaluated at bid price : 23.10
Bid-YTW : 3.87 %
BNS.PR.Q FixedReset -1.58 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.31
Bid-YTW : 3.63 %
W.PR.H Perpetual-Discount -1.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-16
Maturity Price : 23.59
Evaluated at bid price : 23.86
Bid-YTW : 5.86 %
BNS.PR.R FixedReset -1.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.64
Bid-YTW : 3.65 %
TD.PF.A FixedReset -1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-16
Maturity Price : 21.24
Evaluated at bid price : 21.24
Bid-YTW : 3.80 %
BMO.PR.T FixedReset -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-16
Maturity Price : 21.10
Evaluated at bid price : 21.10
Bid-YTW : 3.79 %
TD.PR.S FixedReset 1.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.50
Bid-YTW : 3.27 %
FTS.PR.M FixedReset 1.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-16
Maturity Price : 21.59
Evaluated at bid price : 21.89
Bid-YTW : 3.91 %
VNR.PR.A FixedReset 1.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-16
Maturity Price : 20.21
Evaluated at bid price : 20.21
Bid-YTW : 4.60 %
SLF.PR.J FloatingReset 3.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.74
Bid-YTW : 8.97 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PF.E FixedReset 31,255 Scotia crossed 24,000 at 24.15.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-16
Maturity Price : 22.85
Evaluated at bid price : 24.20
Bid-YTW : 3.71 %
BAM.PR.B Floater 26,982 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-16
Maturity Price : 10.71
Evaluated at bid price : 10.71
Bid-YTW : 4.41 %
MFC.PR.J FixedReset 23,798 RBC crossed 21,000 at 22.04.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.01
Bid-YTW : 5.20 %
BNS.PR.Q FixedReset 22,175 RBC crossed 20,300 at 24.32.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.31
Bid-YTW : 3.63 %
BNS.PR.Y FixedReset 21,745 Desjardins crossed 18,200 at 21.75.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.72
Bid-YTW : 4.22 %
PVS.PR.D SplitShare 21,130 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2021-10-08
Maturity Price : 25.00
Evaluated at bid price : 24.30
Bid-YTW : 5.09 %
There were 20 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
FTS.PR.K FixedReset Quote: 19.01 – 19.59
Spot Rate : 0.5800
Average : 0.4029

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-16
Maturity Price : 19.01
Evaluated at bid price : 19.01
Bid-YTW : 4.00 %

BMO.PR.Y FixedReset Quote: 23.10 – 23.55
Spot Rate : 0.4500
Average : 0.2895

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-16
Maturity Price : 22.34
Evaluated at bid price : 23.10
Bid-YTW : 3.87 %

IAG.PR.G FixedReset Quote: 23.19 – 23.60
Spot Rate : 0.4100
Average : 0.2640

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.19
Bid-YTW : 4.71 %

BNS.PR.R FixedReset Quote: 24.64 – 25.00
Spot Rate : 0.3600
Average : 0.2261

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.64
Bid-YTW : 3.65 %

TD.PF.D FixedReset Quote: 23.40 – 23.79
Spot Rate : 0.3900
Average : 0.2660

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-16
Maturity Price : 22.50
Evaluated at bid price : 23.40
Bid-YTW : 3.78 %

TD.PF.A FixedReset Quote: 21.24 – 21.64
Spot Rate : 0.4000
Average : 0.2827

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-16
Maturity Price : 21.24
Evaluated at bid price : 21.24
Bid-YTW : 3.80 %

Market Action

September 15, 2015

“Markets, schmarkets!” says the US consumer, “Where can I spend what I just saved on gas?“:

Retail sales in the U.S. climbed for a second straight month, a sign consumers may be looking past recent volatility in financial markets.

The 0.2 percent increase in August followed a 0.7 percent gain in July that was larger than previously reported, Commerce Department figures showed Tuesday in Washington. The median forecast of 84 economists surveyed by Bloomberg called for a 0.3 percent advance.

Although confidence has taken a hit from stock-market turmoil and global-growth concerns, the data show households are still putting their savings from cheap energy to work. More jobs and higher pay would go a long way in supporting household spending, which Federal Reserve policy makers are watching as they consider raising interest rates as soon as this week.

The news whacked Treasuries:

Treasuries tumbled, lifting the two-year note yield to the highest since April 2011, as gains in U.S. retail sales prompted investors to retreat from the securities that would be most affected if the Federal Reserve raises interest rates.

Sell orders in two- and five-year Treasury futures helped accelerate the move higher in yields amid investors’ concern that the Fed may raise rates as soon as Thursday for the first time since 2006. Yields rose the most in almost three weeks after data showed retail sales increased 0.2 percent in August while July’s gain was larger than previously reported. The figures signal consumers may be looking past recent financial-market volatility.
…
Treasury two-year note yields rose eight basis points, or 0.08 percentage point, to 0.80 percent as of 5 p.m. in New York, based on Bloomberg Bond Trader data. The price of the 0.625 percent security due in August 2017 fell 5/32, or $1.56 per $1,000 face amount, to 99 21/32.

Benchmark 10-year note yields rose 10 basis points to 2.29 percent.

Futures contracts show a 28 percent probability that the Fed will boost rates when it meets Sept. 16-17, according to data compiled by Bloomberg.The calculation is based on the assumption that the effective fed funds rate will average 0.375 percent after the first increase, versus the current target of zero to 0.25 percent.

It was a mostly lousy day for the Canadian preferred share market, with PerpetualDiscounts gaining 1bp, FixedResets down 58bp and DeemedRetractibles off 14bp. The Performance Highlights table is comprised almost entirely of losers. Volume was below average.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_150915
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 20.00 to be $0.79 rich, while TRP.PR.C, resetting 2016-1-30 at +164, is $1.05 cheap at its bid price of 13.35.

impVol_MFC_150915
Click for Big

Another good fit today for MFC, with Implied Volatility falling a bit today.

Most expensive is MFC.PR.H, resetting at +313bp on 2017-3-19, bid at 24.41 to be 0.48 rich, while MFC.PR.K, resetting at +222bp on 2018-9-19, is bid at 19.95 to be 0.29 cheap.

impVol_BAM_150915
Click for Big

The fit on the BAM issues continues to be horrible.

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 16.90 to be $1.37 cheap. BAM.PF.G, resetting at +284bp on 2020-6-30 is bid at 22.44 and appears to be $0.99 rich.

impVol_FTS_150915
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 19.50, looks $0.57 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 18.74 and is $0.69 cheap.

pairs_FR_150915
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -1.08%, with no outliers. The distribution is no longer bimodal. There are no junk outliers below -2.00%, but two above 0.00%.

pairs_FF_150915
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.0315 % 1,663.3
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.0315 % 2,908.2
Floater 4.47 % 4.46 % 56,225 16.53 3 0.0315 % 1,768.2
OpRet 0.00 % 0.00 % 0 0.00 0 0.2572 % 2,782.8
SplitShare 4.62 % 5.03 % 63,003 3.07 3 0.2572 % 3,261.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.2572 % 2,544.6
Perpetual-Premium 5.72 % 3.85 % 54,940 0.08 8 0.0198 % 2,492.7
Perpetual-Discount 5.45 % 5.55 % 69,845 14.55 30 0.0130 % 2,600.8
FixedReset 4.72 % 4.14 % 176,254 16.16 74 -0.5779 % 2,159.0
Deemed-Retractible 5.13 % 5.08 % 94,906 5.50 33 -0.1431 % 2,589.3
FloatingReset 2.47 % 3.89 % 50,759 5.91 9 -0.5791 % 2,161.1
Performance Highlights
Issue Index Change Notes
TRP.PR.G FixedReset -2.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-15
Maturity Price : 21.70
Evaluated at bid price : 22.10
Bid-YTW : 4.23 %
MFC.PR.N FixedReset -2.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.62
Bid-YTW : 5.94 %
TD.PR.S FixedReset -2.26 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.21
Bid-YTW : 3.48 %
NA.PR.S FixedReset -2.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-15
Maturity Price : 21.42
Evaluated at bid price : 21.75
Bid-YTW : 3.84 %
SLF.PR.C Deemed-Retractible -2.00 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.07
Bid-YTW : 6.75 %
BNS.PR.P FixedReset -1.98 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.30
Bid-YTW : 3.63 %
FTS.PR.H FixedReset -1.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-15
Maturity Price : 15.10
Evaluated at bid price : 15.10
Bid-YTW : 3.80 %
IAG.PR.G FixedReset -1.94 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.30
Bid-YTW : 4.65 %
MFC.PR.F FixedReset -1.94 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.71
Bid-YTW : 8.09 %
HSE.PR.G FixedReset -1.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-15
Maturity Price : 21.95
Evaluated at bid price : 22.45
Bid-YTW : 4.84 %
MFC.PR.M FixedReset -1.73 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.00
Bid-YTW : 5.76 %
TRP.PR.F FloatingReset -1.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-15
Maturity Price : 14.65
Evaluated at bid price : 14.65
Bid-YTW : 3.89 %
HSE.PR.C FixedReset -1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-15
Maturity Price : 20.45
Evaluated at bid price : 20.45
Bid-YTW : 4.96 %
SLF.PR.D Deemed-Retractible -1.63 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.10
Bid-YTW : 6.73 %
BAM.PR.T FixedReset -1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-15
Maturity Price : 17.36
Evaluated at bid price : 17.36
Bid-YTW : 4.63 %
MFC.PR.G FixedReset -1.32 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.10
Bid-YTW : 4.80 %
NA.PR.W FixedReset -1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-15
Maturity Price : 21.37
Evaluated at bid price : 21.37
Bid-YTW : 3.78 %
SLF.PR.H FixedReset -1.26 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.02
Bid-YTW : 7.19 %
BMO.PR.M FixedReset -1.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.30
Bid-YTW : 3.41 %
BNS.PR.D FloatingReset -1.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.21
Bid-YTW : 4.88 %
PWF.PR.F Perpetual-Discount -1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-15
Maturity Price : 23.67
Evaluated at bid price : 23.94
Bid-YTW : 5.55 %
TRP.PR.C FixedReset -1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-15
Maturity Price : 13.35
Evaluated at bid price : 13.35
Bid-YTW : 4.43 %
BMO.PR.S FixedReset -1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-15
Maturity Price : 21.39
Evaluated at bid price : 21.71
Bid-YTW : 3.75 %
BNS.PR.A FloatingReset -1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.16
Bid-YTW : 3.69 %
GWO.PR.N FixedReset 1.21 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.10
Bid-YTW : 8.30 %
BAM.PF.D Perpetual-Discount 1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-15
Maturity Price : 21.43
Evaluated at bid price : 21.77
Bid-YTW : 5.63 %
Volume Highlights
Issue Index Shares
Traded
Notes
NA.PR.M Deemed-Retractible 95,150 Called for redemption.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2015-10-15
Maturity Price : 25.50
Evaluated at bid price : 25.79
Bid-YTW : -1.86 %
FTS.PR.G FixedReset 86,685 Scotia crossed 25,000 at 18.90. Nesbitt crossed 25,000 at the same price.; RBC crossed 29,000 at the same price again.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-15
Maturity Price : 18.74
Evaluated at bid price : 18.74
Bid-YTW : 4.08 %
BMO.PR.T FixedReset 71,390 Scotia crossed 60,000 at 21.50.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-15
Maturity Price : 21.32
Evaluated at bid price : 21.32
Bid-YTW : 3.75 %
BMO.PR.Q FixedReset 51,048 RBC crossed 45,000 at 21.50.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.30
Bid-YTW : 5.00 %
BNS.PR.O Deemed-Retractible 50,768 Nesbitt crossed 50,000 at 25.65.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-04-27
Maturity Price : 25.25
Evaluated at bid price : 25.65
Bid-YTW : 4.04 %
BAM.PR.R FixedReset 39,990 RBC crossed 30,800 at 16.99.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-15
Maturity Price : 16.94
Evaluated at bid price : 16.94
Bid-YTW : 4.65 %
There were 27 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
VNR.PR.A FixedReset Quote: 19.89 – 20.95
Spot Rate : 1.0600
Average : 0.6101

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-15
Maturity Price : 19.89
Evaluated at bid price : 19.89
Bid-YTW : 4.68 %

MFC.PR.M FixedReset Quote: 21.00 – 21.90
Spot Rate : 0.9000
Average : 0.6707

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.00
Bid-YTW : 5.76 %

SLF.PR.H FixedReset Quote: 18.02 – 18.55
Spot Rate : 0.5300
Average : 0.3767

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.02
Bid-YTW : 7.19 %

TD.PR.S FixedReset Quote: 24.21 – 24.64
Spot Rate : 0.4300
Average : 0.2794

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.21
Bid-YTW : 3.48 %

BNS.PR.D FloatingReset Quote: 20.21 – 20.65
Spot Rate : 0.4400
Average : 0.2898

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.21
Bid-YTW : 4.88 %

BAM.PF.G FixedReset Quote: 22.44 – 22.81
Spot Rate : 0.3700
Average : 0.2284

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-15
Maturity Price : 21.95
Evaluated at bid price : 22.44
Bid-YTW : 4.23 %

Market Action

September 14, 2015

It’s nice to see an intelligently run bond ETF:

The Market Vectors Fallen Angel High Yield Bond ETF (ANGL) is up 28 percent since its April 2012 inception, which is double the performance of the SPDR Barclays High Yield Bond ETF (JNK) and the iShares iBoxx $ Investment Grade Corporate Bond ETF (LQD), as seen in the chart below.
…
Generally speaking, it really comes down to a value factor in bonds that ANGL has tapped into. When these bonds — typically issued by large companies such as Alcoa, Sprint, and Nokia — get downgraded from investment grade to high-yield, they tend to get oversold leading up to the downgrade. Much of this selling is from active managers and institutions getting rid of these bonds that they owned to keep up with their investment-grade benchmarks. This means extra selling pressure.

It was a poor day for the Canadian preferred share market today, with PerpetualDiscounts down 24bp, FixedResets losing 43bp and DeemedRetractibles off 1bp. There is a fairly long Performance Highlights table dominated by losing FixedResets, but three TRP issues did well. Volume was below average.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_150914
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 20.05 to be $0.61 rich, while TRP.PR.C, resetting 2016-1-30 at +164, is $0.91 cheap at its bid price of 13.50.

impVol_MFC_150914
Click for Big

Another good fit today for MFC, with Implied Volatility falling a bit today.

Most expensive is MFC.PR.H, resetting at +313bp on 2017-3-19, bid at 24.36 to be 0.34 rich, while MFC.PR.K, resetting at +222bp on 2018-9-19, is bid at 19.83 to be 0.63 cheap.

impVol_BAM_150914
Click for Big

The fit on the BAM issues continues to be horrible.

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 16.90 to be $1.40 cheap. BAM.PF.G, resetting at +284bp on 2020-6-30 is bid at 22.64 and appears to be $1.11 rich.

impVol_FTS_150914
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 19.48, looks $0.41 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 18.75 and is $0.80 cheap.

pairs_FR_150914
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -1.14%, with no outliers. Note that the distribution is bimodal, with NVCC non-compliant bank issues averaging -1.28% and the unregulated issues averaging -0.95%. There are no junk outliers below -2.00%, but two above 0.00%.

pairs_FF_150914
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.1895 % 1,662.8
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.1895 % 2,907.3
Floater 4.47 % 4.43 % 56,826 16.58 3 0.1895 % 1,767.6
OpRet 0.00 % 0.00 % 0 0.00 0 -0.2431 % 2,775.7
SplitShare 4.64 % 5.08 % 63,895 3.07 3 -0.2431 % 3,252.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.2431 % 2,538.1
Perpetual-Premium 5.72 % 2.56 % 55,347 0.08 8 -0.0544 % 2,492.2
Perpetual-Discount 5.45 % 5.51 % 70,806 14.60 30 -0.2400 % 2,600.4
FixedReset 4.69 % 4.09 % 174,744 16.16 74 -0.4339 % 2,171.6
Deemed-Retractible 5.13 % 4.73 % 93,237 5.49 33 -0.0100 % 2,593.0
FloatingReset 2.45 % 3.81 % 50,703 5.91 9 -0.3237 % 2,173.7
Performance Highlights
Issue Index Change Notes
IFC.PR.A FixedReset -3.47 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.70
Bid-YTW : 8.18 %
SLF.PR.J FloatingReset -3.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.34
Bid-YTW : 9.34 %
MFC.PR.K FixedReset -2.60 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.83
Bid-YTW : 6.24 %
CU.PR.C FixedReset -2.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-14
Maturity Price : 20.89
Evaluated at bid price : 20.89
Bid-YTW : 3.89 %
TRP.PR.D FixedReset -2.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-14
Maturity Price : 19.49
Evaluated at bid price : 19.49
Bid-YTW : 4.29 %
IFC.PR.C FixedReset -2.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.63
Bid-YTW : 5.97 %
SLF.PR.H FixedReset -1.99 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.25
Bid-YTW : 7.02 %
BAM.PF.D Perpetual-Discount -1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-14
Maturity Price : 21.51
Evaluated at bid price : 21.51
Bid-YTW : 5.72 %
MFC.PR.L FixedReset -1.96 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.05
Bid-YTW : 6.20 %
FTS.PR.K FixedReset -1.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-14
Maturity Price : 19.48
Evaluated at bid price : 19.48
Bid-YTW : 3.90 %
ENB.PR.A Perpetual-Discount -1.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-14
Maturity Price : 23.95
Evaluated at bid price : 24.20
Bid-YTW : 5.72 %
PWF.PR.P FixedReset -1.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-14
Maturity Price : 15.50
Evaluated at bid price : 15.50
Bid-YTW : 3.90 %
MFC.PR.M FixedReset -1.75 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.37
Bid-YTW : 5.53 %
GWO.PR.N FixedReset -1.52 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.92
Bid-YTW : 8.45 %
BAM.PR.T FixedReset -1.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-14
Maturity Price : 17.60
Evaluated at bid price : 17.60
Bid-YTW : 4.56 %
MFC.PR.I FixedReset -1.42 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.98
Bid-YTW : 4.90 %
SLF.PR.G FixedReset -1.42 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.02
Bid-YTW : 7.68 %
MFC.PR.F FixedReset -1.42 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.02
Bid-YTW : 7.83 %
CU.PR.G Perpetual-Discount -1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-14
Maturity Price : 20.71
Evaluated at bid price : 20.71
Bid-YTW : 5.48 %
TD.PF.E FixedReset -1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-14
Maturity Price : 22.83
Evaluated at bid price : 24.15
Bid-YTW : 3.72 %
CM.PR.P FixedReset -1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-14
Maturity Price : 21.03
Evaluated at bid price : 21.03
Bid-YTW : 3.82 %
MFC.PR.N FixedReset -1.26 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.10
Bid-YTW : 5.63 %
CU.PR.F Perpetual-Discount -1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-14
Maturity Price : 20.60
Evaluated at bid price : 20.60
Bid-YTW : 5.51 %
TRP.PR.E FixedReset -1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-14
Maturity Price : 20.05
Evaluated at bid price : 20.05
Bid-YTW : 4.24 %
FTS.PR.G FixedReset -1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-14
Maturity Price : 18.75
Evaluated at bid price : 18.75
Bid-YTW : 4.08 %
RY.PR.M FixedReset -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-14
Maturity Price : 22.27
Evaluated at bid price : 23.00
Bid-YTW : 3.70 %
BAM.PR.R FixedReset -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-14
Maturity Price : 16.90
Evaluated at bid price : 16.90
Bid-YTW : 4.66 %
CU.PR.E Perpetual-Discount -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-14
Maturity Price : 21.78
Evaluated at bid price : 22.12
Bid-YTW : 5.57 %
MFC.PR.G FixedReset 1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.41
Bid-YTW : 4.62 %
TRP.PR.B FixedReset 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-14
Maturity Price : 12.60
Evaluated at bid price : 12.60
Bid-YTW : 4.11 %
TRP.PR.C FixedReset 2.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-14
Maturity Price : 13.50
Evaluated at bid price : 13.50
Bid-YTW : 4.38 %
TRP.PR.G FixedReset 3.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-14
Maturity Price : 22.12
Evaluated at bid price : 22.75
Bid-YTW : 4.09 %
Volume Highlights
Issue Index Shares
Traded
Notes
TRP.PR.E FixedReset 153,763 RBC crossed 150,000 at 20.43.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-14
Maturity Price : 20.05
Evaluated at bid price : 20.05
Bid-YTW : 4.24 %
IFC.PR.A FixedReset 96,384 Desjardins crossed 88,000 at 17.35.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.70
Bid-YTW : 8.18 %
SLF.PR.G FixedReset 72,600 Scotia crossed 50,000 at 16.25.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.02
Bid-YTW : 7.68 %
BNS.PR.A FloatingReset 68,150 Desjardins crossed 65,900 at 23.36.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.40
Bid-YTW : 3.51 %
TD.PF.A FixedReset 67,350 RBC crossed 48,100 at 21.70.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-14
Maturity Price : 21.27
Evaluated at bid price : 21.55
Bid-YTW : 3.71 %
BMO.PR.K Deemed-Retractible 60,864 TD crossed blocks of 45,900 and 10,500, both at 25.50.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2015-11-25
Maturity Price : 25.25
Evaluated at bid price : 25.46
Bid-YTW : 2.41 %
There were 25 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
IFC.PR.A FixedReset Quote: 16.70 – 17.68
Spot Rate : 0.9800
Average : 0.6067

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.70
Bid-YTW : 8.18 %

FTS.PR.F Perpetual-Discount Quote: 22.75 – 23.49
Spot Rate : 0.7400
Average : 0.4915

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-14
Maturity Price : 22.49
Evaluated at bid price : 22.75
Bid-YTW : 5.42 %

BAM.PF.D Perpetual-Discount Quote: 21.51 – 22.05
Spot Rate : 0.5400
Average : 0.3461

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-14
Maturity Price : 21.51
Evaluated at bid price : 21.51
Bid-YTW : 5.72 %

GWO.PR.N FixedReset Quote: 14.92 – 15.39
Spot Rate : 0.4700
Average : 0.3020

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.92
Bid-YTW : 8.45 %

MFC.PR.M FixedReset Quote: 21.37 – 21.95
Spot Rate : 0.5800
Average : 0.4193

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.37
Bid-YTW : 5.53 %

HSE.PR.E FixedReset Quote: 22.85 – 23.40
Spot Rate : 0.5500
Average : 0.3911

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-14
Maturity Price : 22.22
Evaluated at bid price : 22.85
Bid-YTW : 4.76 %

Market Action

September 11, 2015

Civil Forfeiture writ large! There can no longer be any doubt but that the War On Banks is nothing more than a populist tax-grab:

The Manhattan district attorney is sending $38 million taken in civil forfeiture from international banks in New York to cities and counties across the country to pay for testing 56,000 rape kits that have been collecting dust in police storage rooms for years.
…
The money comes from large settlements Mr. Vance’s office reached with international banks charged with violating United States sanctions, among them BNP Paribas, HSBC and Standard Chartered Bank. The office has amassed more than $800 million from these settlements, and Mr. Vance so far has used about $240 million to pay for local criminal justice programs, like providing computerized tablets to police officers and upgrading security in housing projects.

I’m pleased to learn that TSFA limits are becoming a campaign issue:

Just how much Canadians should be allowed to stash in their tax-free savings accounts is expected to become an election issue, after NDP Leader Tom Mulcair and Liberal Leader Justin Trudeau repeated promises this week to roll back a Conservative budget measure that nearly doubled the contribution limit on such accounts.

In interviews with CBC’s Peter Mansbridge broadcast this week, both opposition leaders confirmed they would scrap the Conservative move, unveiled in this year’s federal budget, to increase the limit for a tax-free savings account (TFSA) from $5,500 to $10,000.

“The doubling of it is irresponsible,” Mr. Trudeau said. “It’s only the wealthiest Canadians who have $10,000 laying around at the end of the year that they can put into that.”

I just wish our economically illiterate chatteratti had a more coherent plan than ‘soak the rich’, but if we insist on enthroning politicians whose greatest achievement in life was being born, then we have to take what we get.

I have long been of the view that contribution limits are ridiculously high; the lifetime limit for all tax-advantaged savings should be set so that an annuity purchased at age 65 will replace 75% of the median Canadian family income of about $75,000. So that’s an income requirement of about $56,000, which requires about $1.1-million in capital right now, which implies annual contributions totalling about $23,000 with a constant 3% real growth rate over thirty years. And all this includes CPP!

If you don’t like those numbers, suggest your own and we can talk. But I see no reason why somebody with expectations exceeding these levels should be subsidized.

And, just as some light relief, here’s the latest installment of Spy vs. Spy:

When the Justice Department arrested the chairman of Temple University’s physics department this spring and accused him of sharing sensitive American-made technology with China, prosecutors had what seemed like a damning piece of evidence: schematics of sophisticated laboratory equipment sent by the professor, Xi Xiaoxing, to scientists in China.

The schematics, prosecutors said, revealed the design of a device known as a pocket heater. The equipment is used in semiconductor research, and Dr. Xi had signed an agreement promising to keep its design a secret.

But months later, long after federal agents had led Dr. Xi away in handcuffs, independent experts discovered something wrong with the evidence at the heart of the Justice Department’s case: The blueprints were not for a pocket heater.

It was a reasonably good day for the Canadian preferred share market, with PerpetualDiscounts off 3bp, FixedResets up 46bp and DeemedRetractibles gaining 31bp. MFC FixedResets were notable on the good side of a relatively subdued Performance Highlights table. Volume was below average.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_150911
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 20.30 to be $0.89 rich, while TRP.PR.C, resetting 2016-1-30 at +164, is $1.36 cheap at its bid price of 13.15.

impVol_MFC_150911
Click for Big

Another good fit today for MFC, with Implied Volatility edging up a bit today.

Most expensive is MFC.PR.M, resetting at +236bp on 2019-12-19, bid at 21.75 to be 0.42 rich, while MFC.PR.J, resetting at +261bp on 2018-3-19, is bid at 22.00 to be 0.38 cheap.

impVol_BAM_150911
Click for Big

The fit on the BAM issues continues to be horrible.

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 17.08 to be $1.24 cheap. BAM.PF.G, resetting at +284bp on 2020-6-30 is bid at 22.50 and appears to be $0.96 rich.

impVol_FTS_150911
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 19.85, looks $0.59 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 18.98 and is $0.76 cheap.

pairs_FR_150911
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -1.11%, with no outliers. Note that the distribution is bimodal, with NVCC non-compliant bank issues averaging -1.26% and the unregulated issues averaging -0.90%. There is one junk outlier below -2.00% and two above 0.00%.

pairs_FF_150911
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 1.5962 % 1,659.6
FixedFloater 0.00 % 0.00 % 0 0.00 0 1.5962 % 2,901.8
Floater 4.48 % 4.45 % 57,633 16.54 3 1.5962 % 1,764.3
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0135 % 2,782.4
SplitShare 4.63 % 4.92 % 63,045 3.08 3 -0.0135 % 3,260.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0135 % 2,544.2
Perpetual-Premium 5.72 % 5.50 % 57,276 1.99 8 0.0940 % 2,493.6
Perpetual-Discount 5.43 % 5.50 % 70,742 14.59 30 -0.0311 % 2,606.7
FixedReset 4.67 % 4.16 % 177,528 16.22 74 0.4648 % 2,181.0
Deemed-Retractible 5.13 % 4.46 % 93,582 0.85 33 0.3059 % 2,593.3
FloatingReset 2.93 % 4.29 % 52,847 5.84 9 0.4498 % 2,180.8
Performance Highlights
Issue Index Change Notes
SLF.PR.H FixedReset -3.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.62
Bid-YTW : 6.76 %
GWO.PR.N FixedReset -2.38 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.15
Bid-YTW : 8.24 %
PWF.PR.P FixedReset -1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-11
Maturity Price : 15.78
Evaluated at bid price : 15.78
Bid-YTW : 3.83 %
SLF.PR.J FloatingReset -1.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.77
Bid-YTW : 9.50 %
MFC.PR.K FixedReset 1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.36
Bid-YTW : 5.89 %
TD.PF.D FixedReset 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-11
Maturity Price : 22.62
Evaluated at bid price : 23.65
Bid-YTW : 3.73 %
BAM.PF.B FixedReset 1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-11
Maturity Price : 20.45
Evaluated at bid price : 20.45
Bid-YTW : 4.35 %
BAM.PR.T FixedReset 1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-11
Maturity Price : 17.86
Evaluated at bid price : 17.86
Bid-YTW : 4.49 %
IFC.PR.A FixedReset 1.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.30
Bid-YTW : 7.69 %
MFC.PR.F FixedReset 1.44 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.25
Bid-YTW : 7.64 %
HSE.PR.E FixedReset 1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-11
Maturity Price : 22.09
Evaluated at bid price : 22.65
Bid-YTW : 4.80 %
GWO.PR.I Deemed-Retractible 1.58 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.92
Bid-YTW : 6.26 %
TRP.PR.A FixedReset 1.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-11
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 4.03 %
MFC.PR.G FixedReset 1.80 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.17
Bid-YTW : 4.75 %
BAM.PR.B Floater 1.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-11
Maturity Price : 10.67
Evaluated at bid price : 10.67
Bid-YTW : 4.42 %
TRP.PR.D FixedReset 1.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-11
Maturity Price : 19.95
Evaluated at bid price : 19.95
Bid-YTW : 4.19 %
BIP.PR.A FixedReset 1.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-11
Maturity Price : 21.79
Evaluated at bid price : 22.20
Bid-YTW : 4.90 %
BAM.PR.K Floater 2.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-11
Maturity Price : 10.60
Evaluated at bid price : 10.60
Bid-YTW : 4.45 %
TRP.PR.F FloatingReset 2.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-11
Maturity Price : 14.90
Evaluated at bid price : 14.90
Bid-YTW : 4.49 %
BAM.PR.R FixedReset 2.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-11
Maturity Price : 17.08
Evaluated at bid price : 17.08
Bid-YTW : 4.61 %
IFC.PR.C FixedReset 2.86 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.08
Bid-YTW : 5.68 %
MFC.PR.L FixedReset 3.02 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.45
Bid-YTW : 5.93 %
BAM.PR.X FixedReset 3.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-11
Maturity Price : 15.47
Evaluated at bid price : 15.47
Bid-YTW : 4.45 %
MFC.PR.M FixedReset 3.52 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.75
Bid-YTW : 5.30 %
MFC.PR.N FixedReset 3.59 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.37
Bid-YTW : 5.46 %
Volume Highlights
Issue Index Shares
Traded
Notes
CM.PR.P FixedReset 59,490 TD crossed 25,000 at 21.30.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-11
Maturity Price : 21.30
Evaluated at bid price : 21.30
Bid-YTW : 3.77 %
BAM.PF.G FixedReset 51,095 RBC bought 37,500 from TD at 22.30.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-11
Maturity Price : 21.99
Evaluated at bid price : 22.50
Bid-YTW : 4.21 %
TD.PF.A FixedReset 49,308 TD crossed 10,000 at 21.74.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-11
Maturity Price : 21.37
Evaluated at bid price : 21.68
Bid-YTW : 3.69 %
RY.PR.I FixedReset 44,646 Desjardins crossed 39,700 at 24.82.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.80
Bid-YTW : 3.33 %
BAM.PF.E FixedReset 37,762 National bought 28,900 from Scotia at 20.32.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-11
Maturity Price : 20.37
Evaluated at bid price : 20.37
Bid-YTW : 4.40 %
BMO.PR.T FixedReset 37,720 Scotia crossed 30,000 at 21.75.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-11
Maturity Price : 21.51
Evaluated at bid price : 21.51
Bid-YTW : 3.72 %
There were 24 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
MFC.PR.G FixedReset Quote: 23.17 – 23.79
Spot Rate : 0.6200
Average : 0.3989

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.17
Bid-YTW : 4.75 %

TRP.PR.G FixedReset Quote: 22.00 – 22.95
Spot Rate : 0.9500
Average : 0.7555

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-11
Maturity Price : 21.63
Evaluated at bid price : 22.00
Bid-YTW : 4.25 %

HSE.PR.G FixedReset Quote: 22.85 – 23.50
Spot Rate : 0.6500
Average : 0.4699

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-11
Maturity Price : 22.20
Evaluated at bid price : 22.85
Bid-YTW : 4.74 %

IGM.PR.B Perpetual-Premium Quote: 25.40 – 26.06
Spot Rate : 0.6600
Average : 0.4890

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-11
Maturity Price : 25.08
Evaluated at bid price : 25.40
Bid-YTW : 5.88 %

SLF.PR.H FixedReset Quote: 18.62 – 19.05
Spot Rate : 0.4300
Average : 0.2731

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.62
Bid-YTW : 6.76 %

MFC.PR.L FixedReset Quote: 20.45 – 20.95
Spot Rate : 0.5000
Average : 0.3640

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.45
Bid-YTW : 5.93 %

Market Action

September 10, 2015

CP Rail sold a century bond!

The railroad’s $900 million [USD] 100-year bond, sold with a coupon of 6.125 percent, shows how the once-troubled company has won over investor hearts and minds under new Chief Executive Officer Hunter Harrison, even as it embarks on a share-repurchase plan that would boost its debt load.
…
The century bond sale was the biggest by CP Rail since 1986. The company also issued $300 million in 20-year bonds with a 4.8 percent coupon. The average maturity on the Bank of America Merrill Lynch 15+ Year BBB US Corporate Index is 25 years with a yield of 5.5 percent, according to Bank of America Merrill Lynch data. The last century bond was issued by Brazil’s Petrobras Global Finance in June with a 6.85 percent coupon, according to data compiled by Bloomberg. Calgary-based Enbridge Inc., a pipeline operator, issued C$100 million ($76 million) of century bonds in Canada in 2012.

BMO has announced a major acquisition:

Bank of Montreal, Canada’s fourth-largest lender, agreed to buy General Electric Co.’s transportation finance business in the U.S. and Canada.

The unit had net earning assets of about C$11.5 billion ($8.7 billion) as of June 30, the Toronto-based bank said Thursday in a statement that didn’t disclose terms. The GE unit’s management team and about 600 employees will join Bank of Montreal, according to a presentation on the bank’s website.

Bank of Montreal’s agreement is the latest in a U.S. expansion that began in 1984 with its purchase of Chicago-based Harris Bank. The lender’s last major U.S. deal was its July 2011 takeover of Milwaukee-based Marshall & Ilsley Corp., which doubled deposits and branches and strengthened its commercial lending focus across the U.S. Midwest.

The relationship between ETFs, funds and crisis liquidity has been a hot issue. Barclays weighs in with some musings on ‘first-mover’ advantage:

Illiquidity in corporate bonds would in theory spell bad news for bond funds that promise investors the ability to immediately get out of their positions. The concern here is that once investors get a whiff of an impending mass selloff in bonds, they could potentially rush for the exits to try to get ahead of it.

With liquidity already low, that could put massive pressure on debt prices. Those who manage to squeeze through the keyhole first get rewarded for their speed but end up exacerbating this downward spiral. The slowest investors, meanwhile, get left with a portfolio of bonds that’s potentially much reduced in price.

By how much, you ask? Barclays estimates about 2 percent for funds that hold junk-rated corporate debt (boldface ours):

Mutual fund investors are, thus, faced with a first mover’s advantage to redeem in large selloff days because of a combination of inflated pricing and potential rebalancing costs. The magnitude of this advantage can be very meaningful economically. Assuming a 10 percent market shock leads to 10 percent outflows, we estimate that the first mover advantage is as much as 1.78 percent, or 1.61 percent from [net asset value] inflation and 0.17 percent from rebalancing costs.The benefit to early redeemers is effectively a tax on investors who remain invested through big downturns and ironically encourages demanding more liquidity.

They suggest a ‘scaled exit fee’:

“An “exit fee” that charges investors to withdraw their money from bond funds could arguably help slow theoretical outflows. (There is, of course, a converse argument that says such a fee would merely exacerbate the rush to the exit.) Barclays argues for a more refined approach that involves scaled fees:

Redemption fees are relatively straightforward and could be set such that they exactly neutralize the advantage of redeeming first in a down market. In our worst-case scenario, a redemption fee on the order of 2.0% would do the trick. That said, redemption fees are a somewhat blunt instrument. They penalize anyone withdrawing funds equally, regardless of how much liquidity the investor is demanding. Indeed, penalizing every investor based on a worst-case scenario may not be necessary. We believe a more nuanced approach would be to enforce minimum redemption fees according to a settlement schedule, with the minimum fee declining to zero as the investor allows settlement time to increase.

We wonder what the bond fund managers would say.

Well, PrefBlog says that, as stated, the idea is moronic, a typical product of a trading house that knows all about trading and nothing about investing.

What price will the redemption be at? Say you’ve got a million bucks in the fund and give me thirty days notice that you want out. So, notice period be damned, the price you’ll get is the day of actual redemption, thirty days hence. So should I sell securities now to raise the cash? Then I’ve got cash in the fund, which is kind of not the point of a fund (although the concept of fund investment is being increasingly circumscribed by liquidity rules and policies, as discussed on June 12). And I have to hold that cash in the fund for thirty days, reducing my duration and watching the market go up (because it always goes up in situations like this). So, nope, I’m not going to do it. I’m going to sell when I can get prices that will reasonably approximate the prices I use for determining the redemption value, which is to say, maybe half an hour prior to the close on the redemption date. So thirty day’s notice hasn’t done me a lot of good, has it?

The idea can be rescued by paying a blended price. Never mind “thirty day’s” notice, give me “twenty trading day’s” notice and agreed to get paid a blended price comprised of the NAV at the end of every equally weighted trading day. Then I can confidently sell 5% of your redemption value every day without screwing my other clients. There could be problems with this; if, for instance, a very large fund was to have a commitment to sell $10-million in preferreds for cash every day for the next twenty and this information becomes public … well, there won’t be much buying interest from other players for the next 15 trading days! So that’s got to be top-secret information … and in this business, ain’t nuthin’ top-secret.

A battle is brewing in the States over the right to bear screwdrivers:

Apple doesn’t publish repair manuals or sell parts to customers, and its warranty doesn’t apply if unauthorized repair damages its device. Samsung wouldn’t say why it doesn’t share repair information, though it makes some parts available to shops. Even John Deere gives only approved technicians access to the embedded software that controls systems in its machines. The manufacturers argue these limitations keep products working safely, and that copyright law lets them protect their intellectual property so it isn’t pirated.

“Bulls–t,” says Gay Gordon-Byrne, executive director of the Digital Right to Repair Coalition, based in North Haledon, N.J. “Repair is a profit center for a lot of companies, and sometimes it is more profitable than selling hardware.” Maintaining “repair monopolies,” she says, pushes up costs and makes customers more likely to simply junk old models for new ones. Apple charges $79 to replace an iPhone 4 battery. Repair website IFixit charges $20 for a battery and DIY kit for the same job.

Gordon-Byrne’s organization and advocates such as the Electronic Frontier Foundation are supporting bills introduced this year in Massachusetts, Minnesota, and New York that would require manufacturers to sell parts and provide manuals to hardware owners and independent repair shops. Separate efforts in Congress would amend the federal Digital Millennium Copyright Act by giving explicit permission for consumers to circumvent a manufacturer’s digital lock on its software for a lawful reason such as repair.

Times are tough in the dairy business:

Record prices last year primed farmers to bolster output in the U.S., where milk production in 2015 will reach 208.7 billion pounds—the fifth consecutive record-setting year. In April the EU, seeking to liberalize trade, removed quotas that had been in place for the past 30 years, leading to increased production from Ireland, the Netherlands, and the U.K. China is producing more milk thanks to investments such as a $140 million, 20,000-cow facility that China Modern Dairy Holdings, partly owned by private equity firm KKR, unveiled in 2013. The Chinese are also consuming stockpiled milk powder and importing less. Global milk supply grew 3.7 percent last year, almost triple the growth rate of 2013, the USDA says.
…
Overcapacity “is a long-term problem that a short-term fix won’t address,” says Robbie Turner, head of European markets at Rice Dairy International.

Nope, the only fix is to squeeze out the high-cost producers during times of oversupply, giving low-cost producers room to expand during times of undersupply. It’s called “economics”, though some prefer “competition”.

It was a mixed day in the Canadian preferred share market, with PerpetualDiscounts gaining 1bp, FixedResets off 9bp and DeemedRetractibles up 2bp. FixedResets comprised the entire good side of the Performance Highlights table. Volume was very, awfully, miserably, disgustingly, quietly low.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_150910
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 20.15 to be $0.94 rich, while TRP.PR.C, resetting 2016-1-30 at +164, is $1.21 cheap at its bid price of 13.15.

impVol_MFC_150910
Click for Big

Another good fit today for MFC, with Implied Volatility falling a bit today.

Most expensive is MFC.PR.H, resetting at +313bp on 2017-3-19, bid at 24.26 to be 0.44 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 22.76 to be 0.36 cheap.

impVol_BAM_150910
Click for Big

The fit on the BAM issues continues to be horrible.

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 17.01 to be $1.41 cheap. BAM.PF.F, resetting at +286bp on 2019-9-30 is bid at 22.70 and appears to be $0.93 rich.

impVol_FTS_150910
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 19.73, looks $0.45 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 19.13 and is $0.62 cheap.

pairs_FR_150910
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -1.17%, with no outliers. Note that the distribution is bimodal, with NVCC non-compliant bank issues averaging -1.32% and the unregulated issues averaging -0.94%. There are two junk outliers below -2.00% and one above 0.00%.

pairs_FF_150910
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -1.8657 % 1,633.5
FixedFloater 0.00 % 0.00 % 0 0.00 0 -1.8657 % 2,856.2
Floater 4.49 % 4.57 % 58,488 16.20 3 -1.8657 % 1,736.6
OpRet 0.00 % 0.00 % 0 0.00 0 0.3523 % 2,782.8
SplitShare 4.62 % 4.92 % 63,980 3.08 3 0.3523 % 3,261.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.3523 % 2,544.6
Perpetual-Premium 5.72 % 2.89 % 56,870 0.08 8 0.0693 % 2,491.2
Perpetual-Discount 5.42 % 5.50 % 71,363 14.59 30 0.0129 % 2,607.5
FixedReset 4.68 % 4.12 % 172,457 15.92 74 -0.0872 % 2,170.9
Deemed-Retractible 5.14 % 5.21 % 94,479 5.38 33 0.0189 % 2,585.4
FloatingReset 2.44 % 3.89 % 54,843 5.93 9 -0.2756 % 2,171.0
Performance Highlights
Issue Index Change Notes
TRP.PR.B FixedReset -2.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-10
Maturity Price : 12.47
Evaluated at bid price : 12.47
Bid-YTW : 4.18 %
BAM.PR.K Floater -2.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-10
Maturity Price : 10.50
Evaluated at bid price : 10.50
Bid-YTW : 4.57 %
HSE.PR.E FixedReset -2.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-10
Maturity Price : 21.88
Evaluated at bid price : 22.32
Bid-YTW : 4.90 %
TRP.PR.F FloatingReset -1.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-10
Maturity Price : 14.56
Evaluated at bid price : 14.56
Bid-YTW : 3.89 %
BAM.PR.B Floater -1.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-10
Maturity Price : 10.61
Evaluated at bid price : 10.61
Bid-YTW : 4.52 %
BAM.PR.R FixedReset -1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-10
Maturity Price : 17.01
Evaluated at bid price : 17.01
Bid-YTW : 4.78 %
HSE.PR.C FixedReset -1.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-10
Maturity Price : 20.85
Evaluated at bid price : 20.85
Bid-YTW : 4.87 %
TD.PF.D FixedReset -1.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-10
Maturity Price : 22.50
Evaluated at bid price : 23.40
Bid-YTW : 3.79 %
MFC.PR.F FixedReset -1.42 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.02
Bid-YTW : 7.84 %
BAM.PR.C Floater -1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-10
Maturity Price : 10.45
Evaluated at bid price : 10.45
Bid-YTW : 4.59 %
NA.PR.S FixedReset -1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-10
Maturity Price : 21.70
Evaluated at bid price : 22.00
Bid-YTW : 3.81 %
TD.PF.B FixedReset -1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-10
Maturity Price : 21.30
Evaluated at bid price : 21.59
Bid-YTW : 3.72 %
CM.PR.Q FixedReset -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-10
Maturity Price : 22.52
Evaluated at bid price : 23.45
Bid-YTW : 3.79 %
TRP.PR.C FixedReset -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-10
Maturity Price : 13.15
Evaluated at bid price : 13.15
Bid-YTW : 4.53 %
HSE.PR.A FixedReset -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-10
Maturity Price : 14.15
Evaluated at bid price : 14.15
Bid-YTW : 4.56 %
TRP.PR.A FixedReset -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-10
Maturity Price : 17.22
Evaluated at bid price : 17.22
Bid-YTW : 4.12 %
GWO.PR.I Deemed-Retractible -1.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.58
Bid-YTW : 6.47 %
RY.PR.Z FixedReset -1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-10
Maturity Price : 21.29
Evaluated at bid price : 21.58
Bid-YTW : 3.68 %
MFC.PR.H FixedReset 1.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.27
Bid-YTW : 4.42 %
TRP.PR.E FixedReset 1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-10
Maturity Price : 20.15
Evaluated at bid price : 20.15
Bid-YTW : 4.23 %
FTS.PR.H FixedReset 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-10
Maturity Price : 15.52
Evaluated at bid price : 15.52
Bid-YTW : 3.71 %
MFC.PR.K FixedReset 1.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.15
Bid-YTW : 6.04 %
SLF.PR.H FixedReset 1.21 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.25
Bid-YTW : 6.34 %
BAM.PR.X FixedReset 1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-10
Maturity Price : 15.25
Evaluated at bid price : 15.25
Bid-YTW : 4.66 %
TRP.PR.G FixedReset 1.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-10
Maturity Price : 21.56
Evaluated at bid price : 21.90
Bid-YTW : 4.29 %
FTS.PR.K FixedReset 2.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-10
Maturity Price : 19.73
Evaluated at bid price : 19.73
Bid-YTW : 3.86 %
FTS.PR.G FixedReset 2.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-10
Maturity Price : 19.13
Evaluated at bid price : 19.13
Bid-YTW : 4.02 %
IFC.PR.A FixedReset 2.54 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.35
Bid-YTW : 7.87 %
Volume Highlights
Issue Index Shares
Traded
Notes
FTS.PR.M FixedReset 40,520 RBC crossed 10,000 at 21.68; Scotia crossed 20,200 at 21.66.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-10
Maturity Price : 21.35
Evaluated at bid price : 21.65
Bid-YTW : 3.97 %
BAM.PR.R FixedReset 20,486 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-10
Maturity Price : 17.01
Evaluated at bid price : 17.01
Bid-YTW : 4.78 %
TRP.PR.D FixedReset 16,684 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-10
Maturity Price : 19.57
Evaluated at bid price : 19.57
Bid-YTW : 4.29 %
RY.PR.Z FixedReset 16,140 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-10
Maturity Price : 21.29
Evaluated at bid price : 21.58
Bid-YTW : 3.68 %
BAM.PR.B Floater 16,089 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-10
Maturity Price : 10.61
Evaluated at bid price : 10.61
Bid-YTW : 4.52 %
BAM.PF.D Perpetual-Discount 15,985 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-10
Maturity Price : 21.86
Evaluated at bid price : 22.15
Bid-YTW : 5.63 %
There were 6 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
IFC.PR.C FixedReset Quote: 20.75 – 21.60
Spot Rate : 0.8500
Average : 0.6733

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.75
Bid-YTW : 6.07 %

TRP.PR.F FloatingReset Quote: 14.56 – 15.24
Spot Rate : 0.6800
Average : 0.5079

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-10
Maturity Price : 14.56
Evaluated at bid price : 14.56
Bid-YTW : 3.89 %

ELF.PR.F Perpetual-Discount Quote: 23.02 – 23.51
Spot Rate : 0.4900
Average : 0.3381

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-09-10
Maturity Price : 22.73
Evaluated at bid price : 23.02
Bid-YTW : 5.84 %

MFC.PR.M FixedReset Quote: 21.01 – 21.49
Spot Rate : 0.4800
Average : 0.3450

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.01
Bid-YTW : 5.76 %

GWO.PR.H Deemed-Retractible Quote: 22.45 – 22.95
Spot Rate : 0.5000
Average : 0.3764

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.45
Bid-YTW : 6.31 %

MFC.PR.N FixedReset Quote: 20.63 – 21.45
Spot Rate : 0.8200
Average : 0.6975

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.63
Bid-YTW : 5.93 %