Category: Market Action

Market Action

November 1, 2016

Today’s top news story is that people lash out when disturbed by change:

In this western Wisconsin enclave and other pockets of the rural Midwest, Mr. Trump’s pledge to build a wall along the Mexican border and prioritize jobs for American workers has struck a chord with some whites uneasy over rapidly changing demographics. They said they are worried illegal immigrants are crowding schools and unfairly tapping public assistance, problems they believe Mr. Trump would fix.

The Journal identified the epicenter of this shift using the diversity index, a tool often used by social scientists and economists. It measures the chance that any two people in a county will have a different race or ethnicity. In 244 counties, that diversity index at least doubled between 2000 and 2015, and more than half those counties were in the cluster of five Midwestern states. The analysis excludes tiny counties that produce numeric aberrations.

Traditional immigrant gateways like Los Angeles, Miami and Queens, N.Y., draw a far greater number of Latino and other minority residents, but because they have long been melting pots, their diversity has barely changed over the past 15 years.

In 88% of the rapidly diversifying counties, Latino population growth was the main driver. In about two-thirds of counties, newcomers helped expand the overall population. In the remaining third, the population fell despite an influx of new arrivals, which magnified the shift for locals as their peers died or moved away.

diversityChanges
Click for Big
diversityEffects
Click for Big
HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.0231 % 1,714.7
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.0231 % 3,132.4
Floater 4.37 % 4.53 % 42,743 16.33 4 0.0231 % 1,805.2
OpRet 0.00 % 0.00 % 0 0.00 0 0.1057 % 2,906.3
SplitShare 4.82 % 4.67 % 41,885 2.06 6 0.1057 % 3,470.7
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1057 % 2,708.0
Perpetual-Premium 5.35 % 4.65 % 72,266 0.40 23 -0.0326 % 2,702.7
Perpetual-Discount 5.10 % 5.11 % 92,398 15.29 15 -0.0084 % 2,925.7
FixedReset 4.83 % 4.24 % 180,649 6.88 93 0.0052 % 2,106.9
Deemed-Retractible 5.03 % 4.66 % 117,303 1.12 32 -0.2417 % 2,804.6
FloatingReset 2.86 % 3.49 % 40,906 4.93 12 0.2742 % 2,289.9
Performance Highlights
Issue Index Change Notes
TRP.PR.C FixedReset -2.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-01
Maturity Price : 13.25
Evaluated at bid price : 13.25
Bid-YTW : 4.27 %
TRP.PR.B FixedReset -1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-01
Maturity Price : 11.95
Evaluated at bid price : 11.95
Bid-YTW : 4.27 %
TRP.PR.D FixedReset -1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-01
Maturity Price : 18.13
Evaluated at bid price : 18.13
Bid-YTW : 4.45 %
PWF.PR.P FixedReset -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-01
Maturity Price : 13.51
Evaluated at bid price : 13.51
Bid-YTW : 4.30 %
HSE.PR.G FixedReset 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-01
Maturity Price : 21.70
Evaluated at bid price : 22.00
Bid-YTW : 4.93 %
IFC.PR.A FixedReset 1.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.95
Bid-YTW : 9.24 %
HSE.PR.A FixedReset 1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-01
Maturity Price : 12.27
Evaluated at bid price : 12.27
Bid-YTW : 5.01 %
HSE.PR.C FixedReset 1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-01
Maturity Price : 19.82
Evaluated at bid price : 19.82
Bid-YTW : 5.07 %
HSE.PR.E FixedReset 1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-01
Maturity Price : 21.44
Evaluated at bid price : 21.78
Bid-YTW : 5.00 %
IFC.PR.D FloatingReset 1.60 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.05
Bid-YTW : 7.05 %
Volume Highlights
Issue Index Shares
Traded
Notes
BMO.PR.B FixedReset 1,463,200 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-02-25
Maturity Price : 25.00
Evaluated at bid price : 25.76
Bid-YTW : 4.26 %
TD.PF.H FixedReset 170,496 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.75
Bid-YTW : 4.24 %
NA.PR.X FixedReset 131,398 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-15
Maturity Price : 25.00
Evaluated at bid price : 26.68
Bid-YTW : 3.94 %
RY.PR.Q FixedReset 112,295 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-24
Maturity Price : 25.00
Evaluated at bid price : 26.65
Bid-YTW : 3.85 %
CM.PR.P FixedReset 102,160 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-01
Maturity Price : 18.92
Evaluated at bid price : 18.92
Bid-YTW : 4.11 %
TD.PF.B FixedReset 91,096 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-01
Maturity Price : 18.82
Evaluated at bid price : 18.82
Bid-YTW : 4.13 %
There were 41 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
SLF.PR.K FloatingReset Quote: 16.35 – 17.00
Spot Rate : 0.6500
Average : 0.5307

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.35
Bid-YTW : 8.66 %

GWO.PR.P Deemed-Retractible Quote: 25.15 – 25.43
Spot Rate : 0.2800
Average : 0.1796

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.15
Bid-YTW : 5.42 %

TRP.PR.F FloatingReset Quote: 14.39 – 14.70
Spot Rate : 0.3100
Average : 0.2218

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-01
Maturity Price : 14.39
Evaluated at bid price : 14.39
Bid-YTW : 4.21 %

TRP.PR.C FixedReset Quote: 13.25 – 13.51
Spot Rate : 0.2600
Average : 0.1767

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-01
Maturity Price : 13.25
Evaluated at bid price : 13.25
Bid-YTW : 4.27 %

NA.PR.Q FixedReset Quote: 24.52 – 24.75
Spot Rate : 0.2300
Average : 0.1598

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.52
Bid-YTW : 3.66 %

PWF.PR.P FixedReset Quote: 13.51 – 13.75
Spot Rate : 0.2400
Average : 0.1714

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-11-01
Maturity Price : 13.51
Evaluated at bid price : 13.51
Bid-YTW : 4.30 %

Market Action

October 31, 2016

More on my speculation on small-batch craftsmanship as the future of employment:

Today, smaller plants are particularly important to job creation in factory work, said Scott Paul, president of the Alliance for American Manufacturing. “Megafactories are the exception today,” Mr. Paul said. “Small manufacturing is holding its own — and you are seeing some interesting developments in urban centers.”

Out of 252,000 manufacturing companies in the United States, only 3,700 had more than 500 workers. The vast majority employ fewer than 20

While they may not rival the scale of 1950s assembly lines, these smaller craft-type producers hold out hope for cities, Mr. Paul said, particularly as some companies look to move jobs back from overseas to be closer to customers and more nimble to supply customized, small-batch orders.

What is more, these jobs pay people more. According to the Bureau of Labor Statistics, manufacturing workers typically earn just over $26 an hour. By contrast, medical orderlies and nurse’s assistants (a growing field) earn half as much. And fast food, a mainstay for Americans with a high school diploma or less, has a median hourly wage of $9.11.

It’s also support for my other thesis: don’t bet against America! That bet’s been a losing game since 1850!

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.2087 % 1,714.3
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.2087 % 3,131.6
Floater 4.37 % 4.52 % 42,928 16.36 4 0.2087 % 1,804.8
OpRet 0.00 % 0.00 % 0 0.00 0 0.1191 % 2,903.2
SplitShare 4.82 % 4.69 % 42,352 2.07 6 0.1191 % 3,467.1
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1191 % 2,705.1
Perpetual-Premium 5.35 % 4.16 % 73,222 0.09 23 -0.0377 % 2,703.6
Perpetual-Discount 5.09 % 5.10 % 93,918 15.30 15 0.1605 % 2,925.9
FixedReset 4.83 % 4.22 % 177,718 6.89 93 0.1763 % 2,106.8
Deemed-Retractible 5.02 % 4.64 % 116,325 1.12 32 -0.0496 % 2,811.4
FloatingReset 2.87 % 3.56 % 40,172 4.93 12 0.2104 % 2,283.6
Performance Highlights
Issue Index Change Notes
GWO.PR.N FixedReset -1.42 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.90
Bid-YTW : 10.29 %
VNR.PR.A FixedReset -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-31
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 4.72 %
TRP.PR.D FixedReset 1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-31
Maturity Price : 18.35
Evaluated at bid price : 18.35
Bid-YTW : 4.40 %
IFC.PR.D FloatingReset 1.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.75
Bid-YTW : 7.28 %
IFC.PR.A FixedReset 1.61 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.78
Bid-YTW : 9.40 %
SLF.PR.J FloatingReset 1.92 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.25
Bid-YTW : 10.63 %
Volume Highlights
Issue Index Shares
Traded
Notes
BMO.PR.B FixedReset 1,173,708 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-02-25
Maturity Price : 25.00
Evaluated at bid price : 25.72
Bid-YTW : 4.29 %
BNS.PR.H FixedReset 95,800 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-01-26
Maturity Price : 25.00
Evaluated at bid price : 25.90
Bid-YTW : 4.23 %
RY.PR.Z FixedReset 68,313 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-31
Maturity Price : 19.15
Evaluated at bid price : 19.15
Bid-YTW : 3.99 %
BAM.PF.F FixedReset 63,200 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-31
Maturity Price : 20.89
Evaluated at bid price : 20.89
Bid-YTW : 4.50 %
BMO.PR.T FixedReset 60,760 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-31
Maturity Price : 18.99
Evaluated at bid price : 18.99
Bid-YTW : 4.06 %
GWO.PR.P Deemed-Retractible 53,917 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.40
Bid-YTW : 5.26 %
There were 35 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
VNR.PR.A FixedReset Quote: 19.00 – 19.50
Spot Rate : 0.5000
Average : 0.3467

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-31
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 4.72 %

GWO.PR.N FixedReset Quote: 13.90 – 14.25
Spot Rate : 0.3500
Average : 0.2297

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.90
Bid-YTW : 10.29 %

BAM.PF.G FixedReset Quote: 21.15 – 21.47
Spot Rate : 0.3200
Average : 0.2043

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-31
Maturity Price : 21.15
Evaluated at bid price : 21.15
Bid-YTW : 4.46 %

IFC.PR.A FixedReset Quote: 15.78 – 16.05
Spot Rate : 0.2700
Average : 0.1610

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.78
Bid-YTW : 9.40 %

W.PR.M FixedReset Quote: 26.05 – 26.39
Spot Rate : 0.3400
Average : 0.2378

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-15
Maturity Price : 25.00
Evaluated at bid price : 26.05
Bid-YTW : 4.33 %

HSE.PR.A FixedReset Quote: 12.12 – 12.40
Spot Rate : 0.2800
Average : 0.1861

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-31
Maturity Price : 12.12
Evaluated at bid price : 12.12
Bid-YTW : 5.07 %

Market Action

October 28, 2016

The financial services prep-school boys are hurting:

This is Wall Street’s new tech meritocracy. Financial institutions traditionally coveted graduates from Stanford and other big-name schools and people already working in Silicon Valley. But that system tends to overlook good programmers from other schools or gifted dropouts, according to recruiters. And besides, banks need to fill so many programming jobs that elite schools can’t possibly pump out enough candidates.

So the industry is looking in places it never did, turning to outside firms to evaluate prospective programmers based on objective measurements, not their pedigree. The idea is that people lacking a computer science degree — art majors, graphic designers and chemistry graduates from the University of Delaware like Furlong — can still make the leap to well-paid careers in technology. By using algorithms to spot talented coders, HackerRank and competitors with names like Codility claim they’ve essentially increased the world’s supply of developers.

There are some who think that the fixed income tide has turned:

Bonds worldwide have lost 2.9 percent in October, according to the Bloomberg Barclays Global Aggregate Index, which tracks everything from sovereign obligations to mortgage-backed debt to corporate borrowings. The last time the bond world was dealt such a blow was May 2013, when then-Federal Reserve Chairman Ben S. Bernanke signaled the central bank might slow its unprecedented bond buying.

Europe led the losses that reverberated worldwide this week as signs of accelerating inflation and economic growth spurred speculation that the European Central Bank and its major counterparts are moving closer to curbing monetary stimulus, including asset purchases. The result is that investors are abandoning one of the year’s biggest trades — a bet on higher-yielding, long-term bonds — as they wake up to the limits of central-bank demand that drove bond yields to record lows as recently as July.
…
Yields on 10-year gilts reached 1.31 percent, the highest since June 23, the day of the U.K. vote to leave the European Union. Similar-maturity German bonds were set for their worst month since 2013, pushing yields to 0.217 percent, a level last seen in May. U.S. 10-year Treasury yields touched about 1.88 percent, the highest since May.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.0232 % 1,710.7
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.0232 % 3,125.1
Floater 4.38 % 4.53 % 43,057 16.35 4 -0.0232 % 1,801.0
OpRet 0.00 % 0.00 % 0 0.00 0 0.0331 % 2,899.8
SplitShare 4.83 % 4.67 % 42,709 2.07 6 0.0331 % 3,462.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0331 % 2,701.9
Perpetual-Premium 5.35 % 2.31 % 74,092 0.09 23 0.1411 % 2,704.6
Perpetual-Discount 5.10 % 5.11 % 95,295 15.30 15 0.2653 % 2,921.2
FixedReset 4.84 % 4.17 % 180,097 6.90 93 0.2020 % 2,103.1
Deemed-Retractible 5.02 % 3.28 % 110,647 0.41 32 0.2242 % 2,812.8
FloatingReset 2.86 % 3.52 % 40,718 4.94 12 0.5215 % 2,278.8
Performance Highlights
Issue Index Change Notes
VNR.PR.A FixedReset -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-28
Maturity Price : 19.20
Evaluated at bid price : 19.20
Bid-YTW : 4.61 %
TD.PF.D FixedReset 1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-28
Maturity Price : 21.19
Evaluated at bid price : 21.19
Bid-YTW : 4.12 %
MFC.PR.O FixedReset 1.12 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-06-19
Maturity Price : 25.00
Evaluated at bid price : 27.10
Bid-YTW : 3.78 %
TRP.PR.H FloatingReset 1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-28
Maturity Price : 10.81
Evaluated at bid price : 10.81
Bid-YTW : 4.08 %
TRP.PR.F FloatingReset 2.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-28
Maturity Price : 14.59
Evaluated at bid price : 14.59
Bid-YTW : 4.13 %
GWO.PR.N FixedReset 2.25 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.10
Bid-YTW : 10.04 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.I FixedReset 264,077 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.34
Bid-YTW : 3.52 %
BNS.PR.R FixedReset 107,646 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.71
Bid-YTW : 3.36 %
TRP.PR.F FloatingReset 105,900 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-28
Maturity Price : 14.59
Evaluated at bid price : 14.59
Bid-YTW : 4.13 %
PWF.PR.L Perpetual-Premium 90,290 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-11-27
Maturity Price : 25.00
Evaluated at bid price : 25.05
Bid-YTW : 2.16 %
TRP.PR.H FloatingReset 81,000 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-28
Maturity Price : 10.81
Evaluated at bid price : 10.81
Bid-YTW : 4.08 %
W.PR.J Perpetual-Premium 59,250 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-11-27
Maturity Price : 25.00
Evaluated at bid price : 25.44
Bid-YTW : -12.81 %
There were 35 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
PWF.PR.A Floater Quote: 11.65 – 12.05
Spot Rate : 0.4000
Average : 0.2881

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-28
Maturity Price : 11.65
Evaluated at bid price : 11.65
Bid-YTW : 4.05 %

TRP.PR.G FixedReset Quote: 20.67 – 20.97
Spot Rate : 0.3000
Average : 0.1988

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-28
Maturity Price : 20.67
Evaluated at bid price : 20.67
Bid-YTW : 4.49 %

CCS.PR.C Deemed-Retractible Quote: 24.40 – 24.73
Spot Rate : 0.3300
Average : 0.2421

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.40
Bid-YTW : 5.46 %

RY.PR.I FixedReset Quote: 24.34 – 24.59
Spot Rate : 0.2500
Average : 0.1784

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.34
Bid-YTW : 3.52 %

PVS.PR.C SplitShare Quote: 25.15 – 25.39
Spot Rate : 0.2400
Average : 0.1705

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2017-12-10
Maturity Price : 25.00
Evaluated at bid price : 25.15
Bid-YTW : 4.96 %

CU.PR.H Perpetual-Premium Quote: 25.70 – 25.90
Spot Rate : 0.2000
Average : 0.1384

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2024-09-01
Maturity Price : 25.00
Evaluated at bid price : 25.70
Bid-YTW : 4.98 %

Market Action

October 27, 2016

Assiduous Reader MichaelA brings to my attention a wonderful, lengthy article on practical robotics research titled Pizza, the unsung agent of the robot revolution:

It’s often been said that without the online adult entertainment industry driving innovation on the Internet, the e-commerce and video streaming platforms that we take for granted today would never have matured so rapidly.

In years to come, will we be saying the same about pizza’s role in accelerating retail delivery technologies?

Pizza and porn, driving technological progress! You see, girls, us guys really do serve a higher purpose!

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.5533 % 1,711.1
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.5533 % 3,125.8
Floater 4.38 % 4.53 % 43,315 16.36 4 -0.5533 % 1,801.4
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0066 % 2,898.8
SplitShare 4.83 % 4.67 % 41,414 2.08 6 -0.0066 % 3,461.8
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0066 % 2,701.0
Perpetual-Premium 5.35 % 4.59 % 77,139 0.09 23 0.0652 % 2,700.8
Perpetual-Discount 5.12 % 5.10 % 95,259 15.29 15 0.2888 % 2,913.5
FixedReset 4.85 % 4.21 % 178,263 6.91 93 0.0870 % 2,098.8
Deemed-Retractible 5.03 % 3.21 % 110,537 0.42 32 -0.0407 % 2,806.5
FloatingReset 2.87 % 3.63 % 40,463 4.93 12 0.1901 % 2,267.0
Performance Highlights
Issue Index Change Notes
PWF.PR.A Floater -1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-27
Maturity Price : 11.60
Evaluated at bid price : 11.60
Bid-YTW : 4.07 %
Volume Highlights
Issue Index Shares
Traded
Notes
BMO.PR.B FixedReset 340,735 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-02-25
Maturity Price : 25.00
Evaluated at bid price : 25.70
Bid-YTW : 4.30 %
GWO.PR.N FixedReset 255,500 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.79
Bid-YTW : 10.36 %
RY.PR.Q FixedReset 224,651 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-24
Maturity Price : 25.00
Evaluated at bid price : 26.65
Bid-YTW : 3.84 %
TRP.PR.J FixedReset 154,271 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-31
Maturity Price : 25.00
Evaluated at bid price : 26.56
Bid-YTW : 4.23 %
BNS.PR.R FixedReset 152,724 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.67
Bid-YTW : 3.40 %
RY.PR.R FixedReset 113,522 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-24
Maturity Price : 25.00
Evaluated at bid price : 26.74
Bid-YTW : 3.84 %
BNS.PR.H FixedReset 111,873 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-01-26
Maturity Price : 25.00
Evaluated at bid price : 25.93
Bid-YTW : 4.20 %
There were 29 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
PWF.PR.T FixedReset Quote: 20.10 – 20.55
Spot Rate : 0.4500
Average : 0.2955

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-27
Maturity Price : 20.10
Evaluated at bid price : 20.10
Bid-YTW : 3.95 %

IAG.PR.A Deemed-Retractible Quote: 23.30 – 23.79
Spot Rate : 0.4900
Average : 0.3429

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.30
Bid-YTW : 5.73 %

W.PR.K FixedReset Quote: 26.01 – 26.30
Spot Rate : 0.2900
Average : 0.2116

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-01-15
Maturity Price : 25.00
Evaluated at bid price : 26.01
Bid-YTW : 4.27 %

BNS.PR.R FixedReset Quote: 24.67 – 24.86
Spot Rate : 0.1900
Average : 0.1251

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.67
Bid-YTW : 3.40 %

GWO.PR.F Deemed-Retractible Quote: 25.64 – 25.95
Spot Rate : 0.3100
Average : 0.2467

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-11-26
Maturity Price : 25.00
Evaluated at bid price : 25.64
Bid-YTW : -18.69 %

FTS.PR.J Perpetual-Discount Quote: 23.74 – 23.95
Spot Rate : 0.2100
Average : 0.1536

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-27
Maturity Price : 23.29
Evaluated at bid price : 23.74
Bid-YTW : 5.06 %

Market Action

October 26, 2016

I am among many people who like to ponder the future of employment amidst all the automation nowadays. Not with any apocalyptic bias – it is self-evident that the cost of everything is, ultimately, a labour cost and therefore labour income – but with what I hope is a less jaundiced eye.

I think we may be entering a new era of craftsmanship, in which we have Big Business producing commodities for the masses and small, internet-enabled businesses taking a more careful and individualistic approach. I may be biased in this, because that’s the business model of Hymas Investment Management Inc., but there’s other evidence we’re heading that way.

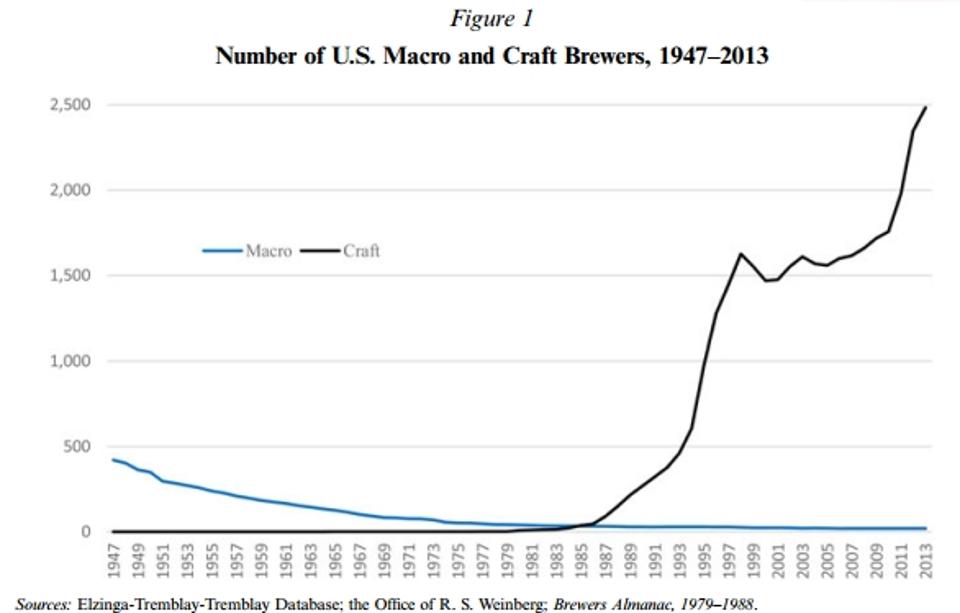
Consider craft beer:

But it wasn’t too long ago that American beer drinkers were largely limited to what beer buffs call MillCoorWeiser beer—the mass produced American lager most prominently sold under the Budweiser, Miller, and Coors brand names. In their 2015 article, Economists Kenneth G. Elzinga, Carol Tremblay and Victor J. Tremblay (Elzinga et al.) report that prior to 1970 over 99% of the beer consumed in the U.S. was the traditional lager beer produced by the large domestic breweries. Needless to say, it was a bland time for American beer.

Then in 1965, entrepreneur and innovator Fritz Maytag purchased the failing Anchor Brewing Company, located in San Francisco, and the revival of craft beer was under way. Maytag revived the brewery, and according to Elzinga et al. his operation inspired other entrepreneurs to join him in the craft beer renaissance.

num-macro-and-craft-brewers
Click for Big

And in Toronto:

The number of manufacturing firms has increased in recent years. “We attribute the growth to a lot more micro-manufacturing, as well as the ‘maker movement’” of independent inventors, designers and tinkerers, as well as tech hardware companies, says [manager of entrepreneurship services for Toronto] Mr. [Chris] Rickett.

“Part of making sure manufacturing continues to exist is making sure that people know it is this very creative job opportunity. It needs rebranding, and the maker movement is really good at that.”

What’s more, he says, new tech tools are making it a lot easier to open a manufacturing business.

“It used to be if you wanted to make a product, the process of prototyping that and getting it to market was very long,” he explains. “Now you can prototype it down at the library, using their MakerBot [3-D printer], then put that prototype on Kickstarter and presell the product.”

The upshot is that the timelines and barriers to starting a manufacturing company have been drastically reduced.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 1.1660 % 1,720.6
FixedFloater 0.00 % 0.00 % 0 0.00 0 1.1660 % 3,143.2
Floater 4.36 % 4.51 % 42,876 16.38 4 1.1660 % 1,811.5
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0331 % 2,899.0
SplitShare 4.83 % 4.62 % 41,728 2.08 6 -0.0331 % 3,462.0
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0331 % 2,701.2
Perpetual-Premium 5.35 % 4.69 % 76,982 0.18 23 -0.0977 % 2,699.0
Perpetual-Discount 5.13 % 5.14 % 96,311 15.24 15 -0.2936 % 2,905.1
FixedReset 4.85 % 4.20 % 164,894 6.90 93 0.2227 % 2,097.0
Deemed-Retractible 5.02 % 3.50 % 110,901 0.42 32 -0.0420 % 2,807.6
FloatingReset 2.88 % 3.72 % 42,037 4.93 12 0.1688 % 2,262.7
Performance Highlights
Issue Index Change Notes
FTS.PR.F Perpetual-Discount -1.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-26
Maturity Price : 23.91
Evaluated at bid price : 24.15
Bid-YTW : 5.14 %
W.PR.H Perpetual-Premium -1.14 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-11-25
Maturity Price : 25.00
Evaluated at bid price : 25.22
Bid-YTW : -3.15 %
FTS.PR.J Perpetual-Discount -1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-26
Maturity Price : 23.18
Evaluated at bid price : 23.62
Bid-YTW : 5.08 %
W.PR.J Perpetual-Premium -1.05 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-11-25
Maturity Price : 25.00
Evaluated at bid price : 25.36
Bid-YTW : -9.55 %
SLF.PR.J FloatingReset 1.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.98
Bid-YTW : 10.89 %
FTS.PR.M FixedReset 1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-26
Maturity Price : 19.60
Evaluated at bid price : 19.60
Bid-YTW : 4.27 %
BMO.PR.S FixedReset 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-26
Maturity Price : 19.71
Evaluated at bid price : 19.71
Bid-YTW : 4.03 %
BAM.PR.X FixedReset 1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-26
Maturity Price : 14.61
Evaluated at bid price : 14.61
Bid-YTW : 4.36 %
TRP.PR.H FloatingReset 1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-26
Maturity Price : 10.73
Evaluated at bid price : 10.73
Bid-YTW : 4.11 %
BAM.PR.C Floater 1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-26
Maturity Price : 10.50
Evaluated at bid price : 10.50
Bid-YTW : 4.54 %
PWF.PR.T FixedReset 1.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-26
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 3.97 %
PWF.PR.A Floater 2.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-26
Maturity Price : 11.80
Evaluated at bid price : 11.80
Bid-YTW : 4.00 %
Volume Highlights
Issue Index Shares
Traded
Notes
BMO.PR.B FixedReset 438,604 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-02-25
Maturity Price : 25.00
Evaluated at bid price : 25.73
Bid-YTW : 4.27 %
BIP.PR.B FixedReset 256,100 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.68
Bid-YTW : 4.91 %
RY.PR.E Deemed-Retractible 231,800 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-11-25
Maturity Price : 25.00
Evaluated at bid price : 25.05
Bid-YTW : -2.27 %
TRP.PR.B FixedReset 117,950 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-26
Maturity Price : 12.14
Evaluated at bid price : 12.14
Bid-YTW : 4.12 %
TD.PF.H FixedReset 110,954 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.71
Bid-YTW : 4.26 %
BIP.PR.C FixedReset 95,278 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-09-30
Maturity Price : 25.00
Evaluated at bid price : 25.72
Bid-YTW : 4.81 %
There were 38 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
TD.PF.E FixedReset Quote: 21.46 – 21.89
Spot Rate : 0.4300
Average : 0.2658

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-26
Maturity Price : 21.46
Evaluated at bid price : 21.46
Bid-YTW : 4.17 %

TRP.PR.A FixedReset Quote: 15.51 – 15.93
Spot Rate : 0.4200
Average : 0.2825

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-26
Maturity Price : 15.51
Evaluated at bid price : 15.51
Bid-YTW : 4.40 %

SLF.PR.K FloatingReset Quote: 16.25 – 16.75
Spot Rate : 0.5000
Average : 0.3997

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.25
Bid-YTW : 8.72 %

IAG.PR.G FixedReset Quote: 20.30 – 20.59
Spot Rate : 0.2900
Average : 0.2007

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.30
Bid-YTW : 6.64 %

TD.PF.D FixedReset Quote: 20.97 – 21.20
Spot Rate : 0.2300
Average : 0.1489

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-26
Maturity Price : 20.97
Evaluated at bid price : 20.97
Bid-YTW : 4.17 %

MFC.PR.J FixedReset Quote: 19.77 – 20.00
Spot Rate : 0.2300
Average : 0.1559

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.77
Bid-YTW : 6.86 %

Market Action

October 25, 2016

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.2791 % 1,700.8
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.2791 % 3,107.0
Floater 4.41 % 4.54 % 42,393 16.34 4 -0.2791 % 1,790.6
OpRet 0.00 % 0.00 % 0 0.00 0 -0.1453 % 2,899.9
SplitShare 4.83 % 4.62 % 41,790 2.08 6 -0.1453 % 3,463.2
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.1453 % 2,702.1
Perpetual-Premium 5.35 % 4.67 % 74,273 0.98 23 -0.1507 % 2,701.7
Perpetual-Discount 5.12 % 5.08 % 96,878 15.26 15 0.1668 % 2,913.7
FixedReset 4.86 % 4.24 % 165,911 6.90 93 -0.1011 % 2,092.4
Deemed-Retractible 5.02 % 3.35 % 111,775 0.42 32 -0.0102 % 2,808.8
FloatingReset 2.88 % 3.75 % 42,306 4.93 12 -0.3665 % 2,258.9
Performance Highlights
Issue Index Change Notes
SLF.PR.K FloatingReset -2.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.25
Bid-YTW : 8.72 %
SLF.PR.J FloatingReset -1.53 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.85
Bid-YTW : 11.03 %
TRP.PR.D FixedReset -1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-25
Maturity Price : 18.01
Evaluated at bid price : 18.01
Bid-YTW : 4.42 %
TRP.PR.E FixedReset -1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-25
Maturity Price : 18.45
Evaluated at bid price : 18.45
Bid-YTW : 4.36 %
VNR.PR.A FixedReset -1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-25
Maturity Price : 19.32
Evaluated at bid price : 19.32
Bid-YTW : 4.57 %
TRP.PR.G FixedReset -1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-25
Maturity Price : 20.60
Evaluated at bid price : 20.60
Bid-YTW : 4.51 %
BNS.PR.D FloatingReset -1.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.38
Bid-YTW : 6.53 %
IAG.PR.G FixedReset 1.00 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.20
Bid-YTW : 6.71 %
FTS.PR.K FixedReset 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-25
Maturity Price : 17.89
Evaluated at bid price : 17.89
Bid-YTW : 4.07 %
FTS.PR.F Perpetual-Discount 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-25
Maturity Price : 24.28
Evaluated at bid price : 24.58
Bid-YTW : 5.05 %
HSE.PR.E FixedReset 1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-25
Maturity Price : 21.38
Evaluated at bid price : 21.70
Bid-YTW : 4.97 %
FTS.PR.M FixedReset 1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-25
Maturity Price : 19.40
Evaluated at bid price : 19.40
Bid-YTW : 4.32 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.Q FixedReset 316,230 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-24
Maturity Price : 25.00
Evaluated at bid price : 26.61
Bid-YTW : 3.87 %
BMO.PR.B FixedReset 277,250 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-02-25
Maturity Price : 25.00
Evaluated at bid price : 25.72
Bid-YTW : 4.28 %
NA.PR.X FixedReset 191,190 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-15
Maturity Price : 25.00
Evaluated at bid price : 26.65
Bid-YTW : 3.95 %
RY.PR.L FixedReset 132,544 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.25
Bid-YTW : 3.48 %
RY.PR.R FixedReset 119,945 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-24
Maturity Price : 25.00
Evaluated at bid price : 26.68
Bid-YTW : 3.89 %
NA.PR.S FixedReset 109,308 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-25
Maturity Price : 18.95
Evaluated at bid price : 18.95
Bid-YTW : 4.22 %
There were 46 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
SLF.PR.K FloatingReset Quote: 16.25 – 16.75
Spot Rate : 0.5000
Average : 0.2897

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.25
Bid-YTW : 8.72 %

TRP.PR.D FixedReset Quote: 18.01 – 18.31
Spot Rate : 0.3000
Average : 0.1963

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-25
Maturity Price : 18.01
Evaluated at bid price : 18.01
Bid-YTW : 4.42 %

BMO.PR.S FixedReset Quote: 19.50 – 19.75
Spot Rate : 0.2500
Average : 0.1591

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-25
Maturity Price : 19.50
Evaluated at bid price : 19.50
Bid-YTW : 4.07 %

W.PR.H Perpetual-Premium Quote: 25.51 – 25.79
Spot Rate : 0.2800
Average : 0.1955

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-11-24
Maturity Price : 25.00
Evaluated at bid price : 25.51
Bid-YTW : -16.55 %

IFC.PR.D FloatingReset Quote: 18.55 – 23.00
Spot Rate : 4.4500
Average : 4.3744

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.55
Bid-YTW : 7.41 %

GRP.PR.A SplitShare Quote: 25.67 – 26.00
Spot Rate : 0.3300
Average : 0.2559

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-11-24
Maturity Price : 25.00
Evaluated at bid price : 25.67
Bid-YTW : -22.52 %

Market Action

October 24, 2016

Another shot has been fired in the minimum wage battles:

Just around the corner from Google’s GOOGL +0.26% main campus in Mountain View, California sits a nondescript concrete building. Inside the building, the future of fast food is being developed and refined. This is the headquarters of Zume. Founded by former Zynga Studio head Alex Garden, Zume wants to revolutionize the $9.7 billion pizza delivery world. Their plan is simple; no humans, all robots. From the production line assembly of the pizza to the eventual delivery, robots are the primary labor ingredient.

The process is not completely human free at this point, with humans adding the cheese and toppings, but it is only a matter of time before robots are able to take over that process as well. Currently the robots add sauce to the dough (the sauce robot is named “Marta”) which travels on a conveyor belt to humans who add toppings and cheese. Bruno the robot then places the pizzas in an oven. A couple of Fiats driven by humans (for now) deliver the pizzas locally.

Here’s an interesting piece on drone taxis:

Mass transit, the lifeblood of cities worldwide, is under threat from the biggest innovation in automotive technology since Henry Ford’s assembly line first flooded streets with cars.

The self-driving vehicles being pioneered by Tesla Motors Inc., Alphabet Inc.’s Google and others are poised to dramatically lower the cost of taxis, potentially making them cheaper than buses or subways, according to a joint report by Bloomberg New Energy Finance and McKinsey & Co. Having no driver to pay could reduce taxi prices to 67 cents a mile by 2025, less than a quarter of the cost in Manhattan today, the report found.

It’s a change with the potential to reshape commuting patterns, transforming urban life. As prices fall, the challenge for cities is that the cars may become too popular. Instead of complementing public transit, they may lure commuters away from buses and trains, inundating streets with drone cars.

I find it very worrisome that US tribalism is increasing:

The divisions over Peter Thiel and his support for Donald Trump are deepening in Silicon Valley.

Dismay over the billionaire venture capitalist’s stance on the Republican candidate has been showing up all across the technology landscape — from a startup founder saying he regrets taking a Trump backer’s money to a prominent diversity group refusing to work with any company associated with Thiel. In one recent case, it also throttled the flow of cash into a fledgling VC fund.

Arlan Hamilton, managing partner at Backstage Capital, said she rejected a potential investor because the person refused to disavow and sever ties with Thiel, a co-founder of PayPal and Palantir Technologies Inc. She declined to name the investor, saying the person offered to put $500,000 in her Los Angeles-based technology seed fund.

While the amount is tiny by industry standards, it is significant to Hamilton’s year-old seed fund, which has about $5 million in commitments, according to a report by Inc. The stymied deal reflects the growing divisiveness in the run up to the U.S. presidential election, which is spilling into everyday business. Hamilton took to Twitter to air her political protest.

“Because of my Peter Thiel stance, my company just lost half a million $ in new funding,” Hamilton wrote on Twitter. “Couldn’t have Thiel money flowing through our company. Hard problem. Easy decision.”

The market report will be delayed.

Update, 2016-10-26:

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.9673 % 1,705.6
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.9673 % 3,115.7
Floater 4.40 % 4.53 % 41,928 16.36 4 -0.9673 % 1,795.6
OpRet 0.00 % 0.00 % 0 0.00 0 0.0330 % 2,904.2
SplitShare 4.82 % 4.55 % 38,680 2.09 6 0.0330 % 3,468.2
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0330 % 2,706.0
Perpetual-Premium 5.34 % 3.47 % 73,104 0.10 23 -0.0142 % 2,705.8
Perpetual-Discount 5.12 % 5.12 % 97,730 15.24 15 -0.0170 % 2,908.8
FixedReset 4.86 % 4.25 % 165,450 6.90 93 -0.1057 % 2,094.5
Deemed-Retractible 5.02 % 2.96 % 111,585 0.43 32 -0.1506 % 2,809.1
FloatingReset 2.87 % 3.79 % 42,403 4.95 12 0.0302 % 2,267.2
Performance Highlights
Issue Index Change Notes
TRP.PR.H FloatingReset -2.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-24
Maturity Price : 10.68
Evaluated at bid price : 10.68
Bid-YTW : 4.13 %
BIP.PR.A FixedReset -1.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-24
Maturity Price : 21.39
Evaluated at bid price : 21.71
Bid-YTW : 4.96 %
BAM.PR.B Floater -1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-24
Maturity Price : 10.52
Evaluated at bid price : 10.52
Bid-YTW : 4.53 %
IFC.PR.A FixedReset -1.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.42
Bid-YTW : 9.66 %
MFC.PR.L FixedReset -1.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.52
Bid-YTW : 7.58 %
MFC.PR.J FixedReset -1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.77
Bid-YTW : 6.85 %
SLF.PR.G FixedReset -1.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.15
Bid-YTW : 10.09 %
BAM.PR.C Floater -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-24
Maturity Price : 10.41
Evaluated at bid price : 10.41
Bid-YTW : 4.58 %
MFC.PR.O FixedReset 1.01 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-06-19
Maturity Price : 25.00
Evaluated at bid price : 26.88
Bid-YTW : 3.97 %
BAM.PF.A FixedReset 1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-24
Maturity Price : 19.75
Evaluated at bid price : 19.75
Bid-YTW : 4.68 %
Volume Highlights
Issue Index Shares
Traded
Notes
BMO.PR.B FixedReset 529,555 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-02-25
Maturity Price : 25.00
Evaluated at bid price : 25.71
Bid-YTW : 4.29 %
TD.PF.H FixedReset 461,080 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.70
Bid-YTW : 4.26 %
RY.PR.L FixedReset 417,634 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.20
Bid-YTW : 3.52 %
BNS.PR.H FixedReset 357,756 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-01-26
Maturity Price : 25.00
Evaluated at bid price : 25.86
Bid-YTW : 4.25 %
RY.PR.J FixedReset 198,575 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-24
Maturity Price : 20.95
Evaluated at bid price : 20.95
Bid-YTW : 4.10 %
TRP.PR.D FixedReset 168,236 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-24
Maturity Price : 18.25
Evaluated at bid price : 18.25
Bid-YTW : 4.36 %
GWO.PR.Q Deemed-Retractible 111,700 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.03
Bid-YTW : 5.22 %
There were 34 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
IFC.PR.D FloatingReset Quote: 18.55 – 23.00
Spot Rate : 4.4500
Average : 4.2914

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.55
Bid-YTW : 7.40 %

TRP.PR.H FloatingReset Quote: 10.68 – 11.14
Spot Rate : 0.4600
Average : 0.3224

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-24
Maturity Price : 10.68
Evaluated at bid price : 10.68
Bid-YTW : 4.13 %

GWO.PR.N FixedReset Quote: 13.77 – 14.17
Spot Rate : 0.4000
Average : 0.2774

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.77
Bid-YTW : 10.37 %

RY.PR.P Perpetual-Premium Quote: 25.95 – 26.14
Spot Rate : 0.1900
Average : 0.1325

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2025-02-24
Maturity Price : 25.00
Evaluated at bid price : 25.95
Bid-YTW : 4.66 %

TRP.PR.B FixedReset Quote: 12.09 – 12.28
Spot Rate : 0.1900
Average : 0.1339

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-24
Maturity Price : 12.09
Evaluated at bid price : 12.09
Bid-YTW : 4.13 %

ELF.PR.G Perpetual-Discount Quote: 22.87 – 23.11
Spot Rate : 0.2400
Average : 0.1842

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-24
Maturity Price : 22.62
Evaluated at bid price : 22.87
Bid-YTW : 5.22 %

Market Action

October 21, 2016

Here’s some drone news with a sting in its tail!

The day when police zap suspects from the sky with drones carrying stun guns may be nearing.

Taser International Inc., known for its stun guns and body cameras, is exploring the concept of a drone armed with a stun gun for use by police. This week, the company held discussions with police officials about such a device during a law-enforcement conference here.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.5338 % 1,722.2
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.5338 % 3,146.1
Floater 4.35 % 4.46 % 42,139 16.50 4 0.5338 % 1,813.1
OpRet 0.00 % 0.00 % 0 0.00 0 0.0000 % 2,903.2
SplitShare 4.82 % 4.53 % 38,933 2.09 6 0.0000 % 3,467.1
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0000 % 2,705.1
Perpetual-Premium 5.33 % 2.93 % 72,573 0.11 23 0.4841 % 2,706.2
Perpetual-Discount 5.12 % 5.11 % 98,896 15.26 15 -0.0847 % 2,909.3
FixedReset 4.85 % 4.29 % 167,659 6.89 93 -0.2855 % 2,096.7
Deemed-Retractible 5.00 % 3.16 % 111,639 0.43 32 0.2350 % 2,813.3
FloatingReset 2.96 % 3.93 % 40,831 4.95 12 -0.0991 % 2,266.5
Performance Highlights
Issue Index Change Notes
BAM.PF.A FixedReset -2.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-21
Maturity Price : 19.51
Evaluated at bid price : 19.51
Bid-YTW : 4.85 %
SLF.PR.J FloatingReset -1.89 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.00
Bid-YTW : 10.95 %
SLF.PR.G FixedReset -1.79 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.30
Bid-YTW : 10.00 %
BAM.PF.B FixedReset -1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-21
Maturity Price : 18.47
Evaluated at bid price : 18.47
Bid-YTW : 4.80 %
IAG.PR.G FixedReset -1.47 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.11
Bid-YTW : 6.87 %
MFC.PR.O FixedReset -1.44 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-06-19
Maturity Price : 25.00
Evaluated at bid price : 26.61
Bid-YTW : 4.21 %
TRP.PR.A FixedReset -1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-21
Maturity Price : 15.64
Evaluated at bid price : 15.64
Bid-YTW : 4.50 %
BAM.PF.G FixedReset -1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-21
Maturity Price : 21.18
Evaluated at bid price : 21.18
Bid-YTW : 4.50 %
BAM.PF.E FixedReset -1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-21
Maturity Price : 19.60
Evaluated at bid price : 19.60
Bid-YTW : 4.54 %
HSE.PR.C FixedReset -1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-21
Maturity Price : 19.53
Evaluated at bid price : 19.53
Bid-YTW : 5.19 %
TRP.PR.C FixedReset -1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-21
Maturity Price : 13.57
Evaluated at bid price : 13.57
Bid-YTW : 4.24 %
BAM.PR.Z FixedReset -1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-21
Maturity Price : 19.79
Evaluated at bid price : 19.79
Bid-YTW : 4.85 %
BAM.PR.B Floater 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-21
Maturity Price : 10.68
Evaluated at bid price : 10.68
Bid-YTW : 4.46 %
RY.PR.I FixedReset 1.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.80
Bid-YTW : 3.36 %
MFC.PR.B Deemed-Retractible 1.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.75
Bid-YTW : 5.50 %
SLF.PR.C Deemed-Retractible 1.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.58
Bid-YTW : 6.03 %
W.PR.J Perpetual-Premium 2.63 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-11-20
Maturity Price : 25.00
Evaluated at bid price : 25.77
Bid-YTW : -28.06 %
W.PR.H Perpetual-Premium 2.78 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-11-20
Maturity Price : 25.00
Evaluated at bid price : 25.86
Bid-YTW : -31.77 %
Volume Highlights
Issue Index Shares
Traded
Notes
BMO.PR.B FixedReset 4,330,078 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-02-25
Maturity Price : 25.00
Evaluated at bid price : 25.69
Bid-YTW : 4.29 %
TD.PF.H FixedReset 895,400 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.83
Bid-YTW : 4.14 %
BNS.PR.H FixedReset 185,571 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-01-26
Maturity Price : 25.00
Evaluated at bid price : 25.88
Bid-YTW : 4.22 %
GWO.PR.Q Deemed-Retractible 144,439 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.04
Bid-YTW : 5.20 %
GWO.PR.N FixedReset 112,243 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.78
Bid-YTW : 10.40 %
GWO.PR.L Deemed-Retractible 106,489 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-12-31
Maturity Price : 25.50
Evaluated at bid price : 25.70
Bid-YTW : 3.16 %
There were 51 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
IFC.PR.D FloatingReset Quote: 18.55 – 23.00
Spot Rate : 4.4500
Average : 4.1175

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.55
Bid-YTW : 7.48 %

BAM.PF.A FixedReset Quote: 19.51 – 19.99
Spot Rate : 0.4800
Average : 0.3282

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-21
Maturity Price : 19.51
Evaluated at bid price : 19.51
Bid-YTW : 4.85 %

SLF.PR.G FixedReset Quote: 14.30 – 14.72
Spot Rate : 0.4200
Average : 0.3106

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.30
Bid-YTW : 10.00 %

BMO.PR.Q FixedReset Quote: 20.35 – 20.65
Spot Rate : 0.3000
Average : 0.1956

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.35
Bid-YTW : 6.06 %

GWO.PR.S Deemed-Retractible Quote: 25.66 – 25.91
Spot Rate : 0.2500
Average : 0.1633

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.66
Bid-YTW : 4.94 %

MFC.PR.O FixedReset Quote: 26.61 – 26.90
Spot Rate : 0.2900
Average : 0.2071

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-06-19
Maturity Price : 25.00
Evaluated at bid price : 26.61
Bid-YTW : 4.21 %

Market Action

October 20, 2016

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.4824 % 1,713.1
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.4824 % 3,129.4
Floater 4.36 % 4.51 % 43,750 16.41 4 -0.4824 % 1,803.5
OpRet 0.00 % 0.00 % 0 0.00 0 0.0463 % 2,903.2
SplitShare 4.82 % 4.49 % 40,515 2.10 6 0.0463 % 3,467.1
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0463 % 2,705.1
Perpetual-Premium 5.35 % 4.74 % 70,934 0.11 23 0.0103 % 2,693.1
Perpetual-Discount 5.12 % 5.09 % 98,669 15.32 15 -0.0790 % 2,911.8
FixedReset 4.83 % 4.26 % 161,549 6.90 92 0.1781 % 2,102.7
Deemed-Retractible 5.01 % 3.25 % 112,064 0.44 32 0.0508 % 2,806.8
FloatingReset 2.96 % 3.99 % 40,897 4.95 12 0.3763 % 2,268.7
Performance Highlights
Issue Index Change Notes
FTS.PR.M FixedReset -2.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-20
Maturity Price : 19.33
Evaluated at bid price : 19.33
Bid-YTW : 4.44 %
FTS.PR.G FixedReset -2.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-20
Maturity Price : 18.01
Evaluated at bid price : 18.01
Bid-YTW : 4.20 %
FTS.PR.H FixedReset -2.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-20
Maturity Price : 13.95
Evaluated at bid price : 13.95
Bid-YTW : 4.11 %
FTS.PR.K FixedReset -2.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-20
Maturity Price : 17.87
Evaluated at bid price : 17.87
Bid-YTW : 4.20 %
FTS.PR.F Perpetual-Discount -1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-20
Maturity Price : 24.09
Evaluated at bid price : 24.35
Bid-YTW : 5.09 %
CU.PR.I FixedReset -1.33 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-01
Maturity Price : 25.00
Evaluated at bid price : 26.05
Bid-YTW : 3.57 %
TRP.PR.G FixedReset -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-20
Maturity Price : 21.03
Evaluated at bid price : 21.03
Bid-YTW : 4.50 %
BAM.PF.G FixedReset 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-20
Maturity Price : 21.45
Evaluated at bid price : 21.45
Bid-YTW : 4.44 %
SLF.PR.J FloatingReset 1.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.25
Bid-YTW : 10.67 %
HSE.PR.C FixedReset 1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-20
Maturity Price : 19.74
Evaluated at bid price : 19.74
Bid-YTW : 5.13 %
MFC.PR.J FixedReset 1.41 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.09
Bid-YTW : 6.70 %
TRP.PR.H FloatingReset 1.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-20
Maturity Price : 11.00
Evaluated at bid price : 11.00
Bid-YTW : 4.17 %
BIP.PR.A FixedReset 2.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-20
Maturity Price : 21.72
Evaluated at bid price : 22.03
Bid-YTW : 4.97 %
Volume Highlights
Issue Index Shares
Traded
Notes
BNS.PR.H FixedReset 820,915 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-01-26
Maturity Price : 25.00
Evaluated at bid price : 25.91
Bid-YTW : 4.20 %
RY.PR.C Deemed-Retractible 103,500 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-11-19
Maturity Price : 25.00
Evaluated at bid price : 25.35
Bid-YTW : -3.63 %
POW.PR.D Perpetual-Discount 102,800 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-20
Maturity Price : 24.61
Evaluated at bid price : 24.87
Bid-YTW : 5.05 %
TD.PF.H FixedReset 85,853 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.78
Bid-YTW : 4.18 %
TRP.PR.D FixedReset 77,265 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-20
Maturity Price : 18.40
Evaluated at bid price : 18.40
Bid-YTW : 4.44 %
BNS.PR.G FixedReset 63,087 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-07-25
Maturity Price : 25.00
Evaluated at bid price : 26.79
Bid-YTW : 3.84 %
There were 57 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
IFC.PR.D FloatingReset Quote: 18.55 – 23.00
Spot Rate : 4.4500
Average : 3.7530

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.55
Bid-YTW : 7.47 %

TRP.PR.F FloatingReset Quote: 14.59 – 14.90
Spot Rate : 0.3100
Average : 0.2017

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-20
Maturity Price : 14.59
Evaluated at bid price : 14.59
Bid-YTW : 4.25 %

CU.PR.I FixedReset Quote: 26.05 – 26.45
Spot Rate : 0.4000
Average : 0.2926

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-01
Maturity Price : 25.00
Evaluated at bid price : 26.05
Bid-YTW : 3.57 %

BMO.PR.W FixedReset Quote: 19.05 – 19.34
Spot Rate : 0.2900
Average : 0.1899

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-20
Maturity Price : 19.05
Evaluated at bid price : 19.05
Bid-YTW : 4.15 %

IFC.PR.A FixedReset Quote: 15.63 – 15.85
Spot Rate : 0.2200
Average : 0.1433

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.63
Bid-YTW : 9.56 %

FTS.PR.F Perpetual-Discount Quote: 24.35 – 24.65
Spot Rate : 0.3000
Average : 0.2238

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-20
Maturity Price : 24.09
Evaluated at bid price : 24.35
Bid-YTW : 5.09 %

Market Action

October 19, 2016

Happy Anniversary, market crash of 1987!

The Bank of Canada gloomily maintained its policy yields today:

The Bank of Canada today announced that it is maintaining its target for the overnight rate at 1/2 per cent. The Bank Rate is correspondingly 3/4 per cent and the deposit rate is 1/4 per cent.
…
Looking through the choppiness of recent data, the profile for growth in Canada is now lower than projected in July’s Monetary Policy Report (MPR). This is due in large part to slower near-term housing resale activity and a lower trajectory for exports. The federal government’s new measures to promote stability in Canada’s housing market are likely to restrain residential investment while dampening household vulnerabilities. Recent export data are improving but are not strong enough to make up for ground lost during the first half of 2016, despite the effects of the Canadian dollar’s past depreciation. Growth in exports over 2017 and 2018 are projected to be slower than previously forecast, due to lower estimates of global demand, a composition of US growth that appears less favourable to Canadian exports, and ongoing competitiveness challenges for Canadian firms.
…
The Bank expects Canada’s real GDP to grow by 1.1 per cent in 2016 and about 2 per cent in both 2017 and 2018. This projection implies that the economy returns to full capacity around mid-2018, materially later than the Bank had anticipated in July.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.9040 % 1,721.4
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.9040 % 3,144.6
Floater 4.34 % 4.50 % 43,688 16.43 4 0.9040 % 1,812.2
OpRet 0.00 % 0.00 % 0 0.00 0 0.1522 % 2,901.9
SplitShare 4.82 % 4.52 % 42,056 2.10 6 0.1522 % 3,465.4
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1522 % 2,703.9
Perpetual-Premium 5.35 % 4.71 % 71,650 0.20 23 0.0086 % 2,692.8
Perpetual-Discount 5.12 % 5.07 % 98,605 15.32 15 0.0904 % 2,914.1
FixedReset 4.84 % 4.27 % 162,634 6.90 92 0.5493 % 2,099.0
Deemed-Retractible 5.02 % 4.06 % 112,730 0.27 32 0.1043 % 2,805.3
FloatingReset 2.97 % 4.03 % 40,333 4.95 12 -0.0173 % 2,260.2
Performance Highlights
Issue Index Change Notes
HSE.PR.E FixedReset 1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-19
Maturity Price : 21.50
Evaluated at bid price : 21.50
Bid-YTW : 5.13 %
RY.PR.J FixedReset 1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-19
Maturity Price : 21.16
Evaluated at bid price : 21.16
Bid-YTW : 4.22 %
MFC.PR.M FixedReset 1.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.00
Bid-YTW : 7.48 %
BAM.PF.G FixedReset 1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-19
Maturity Price : 21.23
Evaluated at bid price : 21.23
Bid-YTW : 4.49 %
RY.PR.M FixedReset 1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-19
Maturity Price : 20.77
Evaluated at bid price : 20.77
Bid-YTW : 4.18 %
TD.PF.D FixedReset 1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-19
Maturity Price : 20.81
Evaluated at bid price : 20.81
Bid-YTW : 4.29 %
BAM.PF.A FixedReset 1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-19
Maturity Price : 19.95
Evaluated at bid price : 19.95
Bid-YTW : 4.74 %
TRP.PR.E FixedReset 1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-19
Maturity Price : 18.97
Evaluated at bid price : 18.97
Bid-YTW : 4.35 %
GWO.PR.N FixedReset 1.38 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.94
Bid-YTW : 10.22 %
HSE.PR.A FixedReset 1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-19
Maturity Price : 12.15
Evaluated at bid price : 12.15
Bid-YTW : 5.13 %
BAM.PR.C Floater 1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-19
Maturity Price : 10.55
Evaluated at bid price : 10.55
Bid-YTW : 4.51 %
MFC.PR.J FixedReset 1.49 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.81
Bid-YTW : 6.90 %
CU.PR.C FixedReset 1.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-19
Maturity Price : 19.55
Evaluated at bid price : 19.55
Bid-YTW : 4.13 %
VNR.PR.A FixedReset 1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-19
Maturity Price : 19.60
Evaluated at bid price : 19.60
Bid-YTW : 4.63 %
BAM.PF.B FixedReset 1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-19
Maturity Price : 18.61
Evaluated at bid price : 18.61
Bid-YTW : 4.76 %
BAM.PR.Z FixedReset 1.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-19
Maturity Price : 20.03
Evaluated at bid price : 20.03
Bid-YTW : 4.79 %
FTS.PR.K FixedReset 1.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-19
Maturity Price : 18.24
Evaluated at bid price : 18.24
Bid-YTW : 4.11 %
BAM.PF.F FixedReset 1.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-19
Maturity Price : 20.92
Evaluated at bid price : 20.92
Bid-YTW : 4.53 %
MFC.PR.I FixedReset 1.86 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.85
Bid-YTW : 6.41 %
BAM.PR.R FixedReset 1.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-19
Maturity Price : 16.37
Evaluated at bid price : 16.37
Bid-YTW : 4.70 %
BAM.PR.X FixedReset 2.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-19
Maturity Price : 14.30
Evaluated at bid price : 14.30
Bid-YTW : 4.63 %
FTS.PR.G FixedReset 2.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-19
Maturity Price : 18.42
Evaluated at bid price : 18.42
Bid-YTW : 4.11 %
SLF.PR.G FixedReset 2.33 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.50
Bid-YTW : 9.79 %
Volume Highlights
Issue Index Shares
Traded
Notes
NA.PR.A FixedReset 120,529 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-15
Maturity Price : 25.00
Evaluated at bid price : 25.96
Bid-YTW : 4.45 %
TD.PF.H FixedReset 89,670 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.78
Bid-YTW : 4.18 %
BNS.PR.H FixedReset 84,325 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2022-01-26
Maturity Price : 25.00
Evaluated at bid price : 25.94
Bid-YTW : 4.17 %
TD.PR.Y FixedReset 83,525 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.22
Bid-YTW : 3.53 %
NA.PR.X FixedReset 81,738 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-15
Maturity Price : 25.00
Evaluated at bid price : 26.44
Bid-YTW : 4.13 %
TD.PR.T FloatingReset 75,300 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.03
Bid-YTW : 3.70 %
There were 44 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
IFC.PR.D FloatingReset Quote: 18.55 – 23.00
Spot Rate : 4.4500
Average : 2.9888

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.55
Bid-YTW : 7.47 %

GWO.PR.F Deemed-Retractible Quote: 25.71 – 26.23
Spot Rate : 0.5200
Average : 0.3343

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-11-18
Maturity Price : 25.00
Evaluated at bid price : 25.71
Bid-YTW : -23.06 %

BIP.PR.A FixedReset Quote: 21.58 – 21.95
Spot Rate : 0.3700
Average : 0.2223

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-10-19
Maturity Price : 21.29
Evaluated at bid price : 21.58
Bid-YTW : 5.08 %

NA.PR.Q FixedReset Quote: 24.07 – 24.40
Spot Rate : 0.3300
Average : 0.2631

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.07
Bid-YTW : 4.06 %

MFC.PR.F FixedReset Quote: 13.94 – 14.17
Spot Rate : 0.2300
Average : 0.1665

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.94
Bid-YTW : 10.30 %

TD.PR.Y FixedReset Quote: 24.22 – 24.40
Spot Rate : 0.1800
Average : 0.1187

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.22
Bid-YTW : 3.53 %