Category: Market Action

Market Action

May 26, 2016

An interesting proposal for the stored-energy problem:

But there is another gravity-based energy storage system that does not need any water, and is even less energy and materials intensive. It’s called Advanced Rail Energy Storage (ARES).

Reminiscent of King Sisyphus of Greek mythology, ARES will use surplus wind and solar energy to move millions of pounds of rock uphill in special electric rail cars, converting thousands of megawatt-hours (MWh) to potential energy, enough to power a medium-sized city for several hours. It can sit there storing this energy as long as one wants. When needed, the rail cars roll back downhill, converting this gravitational potential energy to electricity that goes out onto the grid.
…
ARES bridges the power gap between large scale battery and flywheel installations and the far larger pumped-hydro. With about an 80% efficiency, somewhat greater than pumped-hydro, ARES has a lower life-cycle cost than batteries, a higher energy-to-power ratio than flywheels and a greater efficiency and far faster ramp-rate than pumped-hydro or compressed air.

Too bad this wasn’t developed in Ontario – but we blew the budget on cheap crap.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 4.66 % 5.67 % 10,847 17.04 1 0.6944 % 1,693.7
FixedFloater 6.74 % 5.86 % 17,921 16.63 1 -1.0526 % 2,999.6
Floater 4.41 % 4.53 % 42,997 16.30 4 0.4450 % 1,762.0
OpRet 0.00 % 0.00 % 0 0.00 0 0.1288 % 2,834.2
SplitShare 4.94 % 4.98 % 79,976 3.93 7 0.1288 % 3,316.6
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1288 % 2,587.7
Perpetual-Premium 5.75 % -12.44 % 85,883 0.09 6 0.0458 % 2,603.6
Perpetual-Discount 5.45 % 5.54 % 106,796 14.53 33 0.2911 % 2,691.7
FixedReset 5.16 % 4.68 % 164,545 13.82 88 0.5245 % 1,980.7
Deemed-Retractible 5.11 % 5.57 % 130,078 5.00 33 0.1273 % 2,688.3
FloatingReset 3.17 % 4.92 % 26,090 5.26 17 0.5812 % 2,107.7
Performance Highlights
Issue Index Change Notes
HSE.PR.A FixedReset -2.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-26
Maturity Price : 11.23
Evaluated at bid price : 11.23
Bid-YTW : 5.60 %
BAM.PR.G FixedFloater -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-26
Maturity Price : 25.00
Evaluated at bid price : 14.10
Bid-YTW : 5.86 %
TRP.PR.B FixedReset 1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-26
Maturity Price : 11.77
Evaluated at bid price : 11.77
Bid-YTW : 4.47 %
TD.PF.A FixedReset 1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-26
Maturity Price : 18.56
Evaluated at bid price : 18.56
Bid-YTW : 4.33 %
TRP.PR.A FixedReset 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-26
Maturity Price : 14.60
Evaluated at bid price : 14.60
Bid-YTW : 4.90 %
BAM.PR.K Floater 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-26
Maturity Price : 10.41
Evaluated at bid price : 10.41
Bid-YTW : 4.60 %
BMO.PR.S FixedReset 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-26
Maturity Price : 18.77
Evaluated at bid price : 18.77
Bid-YTW : 4.34 %
IAG.PR.A Deemed-Retractible 1.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.30
Bid-YTW : 6.38 %
BAM.PR.X FixedReset 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-26
Maturity Price : 13.85
Evaluated at bid price : 13.85
Bid-YTW : 4.95 %
MFC.PR.I FixedReset 1.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.66
Bid-YTW : 6.38 %
RY.PR.H FixedReset 1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-26
Maturity Price : 18.43
Evaluated at bid price : 18.43
Bid-YTW : 4.33 %
CM.PR.P FixedReset 1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-26
Maturity Price : 18.22
Evaluated at bid price : 18.22
Bid-YTW : 4.38 %
BMO.PR.T FixedReset 1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-26
Maturity Price : 18.26
Evaluated at bid price : 18.26
Bid-YTW : 4.35 %
TD.PF.C FixedReset 1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-26
Maturity Price : 18.25
Evaluated at bid price : 18.25
Bid-YTW : 4.39 %
BNS.PR.Q FixedReset 1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.12
Bid-YTW : 4.52 %
MFC.PR.K FixedReset 1.37 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.45
Bid-YTW : 7.37 %
BAM.PF.E FixedReset 1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-26
Maturity Price : 18.30
Evaluated at bid price : 18.30
Bid-YTW : 4.94 %
PWF.PR.P FixedReset 1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-26
Maturity Price : 13.30
Evaluated at bid price : 13.30
Bid-YTW : 4.47 %
BMO.PR.Q FixedReset 1.47 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.00
Bid-YTW : 6.22 %
MFC.PR.G FixedReset 1.48 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.83
Bid-YTW : 6.90 %
BNS.PR.Y FixedReset 1.63 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.99
Bid-YTW : 6.07 %
CM.PR.Q FixedReset 1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-26
Maturity Price : 19.88
Evaluated at bid price : 19.88
Bid-YTW : 4.53 %
W.PR.H Perpetual-Discount 1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-26
Maturity Price : 23.85
Evaluated at bid price : 24.10
Bid-YTW : 5.78 %
TRP.PR.C FixedReset 1.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-26
Maturity Price : 12.30
Evaluated at bid price : 12.30
Bid-YTW : 4.72 %
MFC.PR.N FixedReset 1.71 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.58
Bid-YTW : 6.76 %
BMO.PR.R FloatingReset 1.78 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.30
Bid-YTW : 4.31 %
BAM.PR.B Floater 1.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-26
Maturity Price : 10.57
Evaluated at bid price : 10.57
Bid-YTW : 4.53 %
BMO.PR.Y FixedReset 1.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-26
Maturity Price : 20.45
Evaluated at bid price : 20.45
Bid-YTW : 4.36 %
FTS.PR.I FloatingReset 2.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-26
Maturity Price : 11.70
Evaluated at bid price : 11.70
Bid-YTW : 4.28 %
MFC.PR.M FixedReset 2.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.75
Bid-YTW : 6.70 %
IFC.PR.C FixedReset 2.43 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.11
Bid-YTW : 8.06 %
CIU.PR.C FixedReset 3.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-26
Maturity Price : 12.15
Evaluated at bid price : 12.15
Bid-YTW : 4.42 %
PWF.PR.Q FloatingReset 4.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-26
Maturity Price : 13.00
Evaluated at bid price : 13.00
Bid-YTW : 4.17 %
Volume Highlights
Issue Index Shares
Traded
Notes
FTS.PR.M FixedReset 216,343 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-26
Maturity Price : 18.70
Evaluated at bid price : 18.70
Bid-YTW : 4.58 %
TD.PF.G FixedReset 163,679 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 26.11
Bid-YTW : 4.60 %
MFC.PR.O FixedReset 123,846 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-06-19
Maturity Price : 25.00
Evaluated at bid price : 26.04
Bid-YTW : 4.62 %
RY.PR.R FixedReset 118,271 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-24
Maturity Price : 25.00
Evaluated at bid price : 26.18
Bid-YTW : 4.77 %
TRP.PR.J FixedReset 113,227 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-31
Maturity Price : 25.00
Evaluated at bid price : 25.70
Bid-YTW : 4.88 %
RY.PR.J FixedReset 67,600 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-26
Maturity Price : 19.50
Evaluated at bid price : 19.50
Bid-YTW : 4.55 %
There were 34 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
ALB.PR.C SplitShare Quote: 26.00 – 27.00
Spot Rate : 1.0000
Average : 0.7390

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-02-28
Maturity Price : 25.67
Evaluated at bid price : 26.00
Bid-YTW : 2.94 %

TRP.PR.H FloatingReset Quote: 10.43 – 11.00
Spot Rate : 0.5700
Average : 0.3821

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-26
Maturity Price : 10.43
Evaluated at bid price : 10.43
Bid-YTW : 4.44 %

BNS.PR.B FloatingReset Quote: 21.38 – 21.81
Spot Rate : 0.4300
Average : 0.2655

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.38
Bid-YTW : 5.28 %

BAM.PR.C Floater Quote: 10.21 – 10.58
Spot Rate : 0.3700
Average : 0.2178

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-26
Maturity Price : 10.21
Evaluated at bid price : 10.21
Bid-YTW : 4.69 %

IFC.PR.A FixedReset Quote: 15.51 – 15.98
Spot Rate : 0.4700
Average : 0.3178

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.51
Bid-YTW : 9.53 %

BAM.PR.E Ratchet Quote: 14.50 – 15.00
Spot Rate : 0.5000
Average : 0.3603

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-26
Maturity Price : 25.00
Evaluated at bid price : 14.50
Bid-YTW : 5.67 %

Market Action

May 25, 2016

Today’s news is that the BOC Policy Rate remains unchanged:

The Bank of Canada today announced that it is maintaining its target for the overnight rate at 1/2 per cent. The Bank Rate is correspondingly 3/4 per cent and the deposit rate is 1/4 per cent.

The global economy is evolving largely as the Bank projected in its April Monetary Policy Report (MPR). In the United States, despite weakness in the first quarter, a number of indicators, including employment, point to a return to solid growth in 2016. Financial conditions remain accommodative, with ongoing geopolitical factors contributing to fragile market sentiment. Oil prices are higher, in part because of short-term supply disruptions.

In Canada, the economy’s structural adjustment to the oil price shock continues, but is proving to be uneven. Growth in the first quarter of 2016 appears to be in line with the Bank’s April projection, although business investment and intentions remain disappointing. The second quarter will be much weaker than predicted because of the devastating Alberta wildfires. The Bank’s preliminary assessment is that fire-related destruction and the associated halt to oil production will cut about 1 1/4 percentage points off real GDP growth in the second quarter. The economy is expected to rebound in the third quarter, as oil production resumes and reconstruction begins. While the Canadian dollar has been fluctuating in response to shifting expectations of US monetary policy and higher oil prices, it is now close to the level assumed in April.

Inflation is roughly in line with the Bank’s expectations. Total CPI inflation has risen recently, largely due to movements in gasoline prices, but remains slightly below the 2 per cent target. Measures of core inflation remain close to 2 per cent, reflecting the offsetting influences of past exchange rate depreciation and excess capacity.

Canada’s housing market continues to display strong regional divergences, reinforced by the complex adjustment underway in the economy. In this context, household vulnerabilities have moved higher. Meanwhile, the risks to the Bank’s inflation projection remain roughly balanced. Therefore, the Bank’s Governing Council judges that the current stance of monetary policy is still appropriate, and the target for the overnight rate remains at 1/2 per cent.

The Globe’s David Parkinson longs for more detail:

Beyond that, though, the Bank of Canada had surprisingly little to say. Even by the typically parsimonious standards of Bank of Canada rate statements, this one was on the short side. The bank squeezed in a very brief description of the current state of the country’s economy, without clarifying many of the most burning questions.

Most crucially, while the bank said it expects that the economy will “rebound” from the wildfire-related second-quarter slump, it stopped short of discussing the likelihood that this rebound will be enough to keep overall 2016 growth on track for the 1.7 per cent it forecast in April.

Does this delay the economy’s return to full capacity, the most critical variable in charting the Bank of Canada’s interest-rate path? Is that a significant risk that has emerged to the central bank’s outlook? If it is, the bank isn’t saying so.

One thing I really like to see when wandering around and looking at things is evidence that somebody has actually thought about something. There are so many details in life we do most of our activities on auto-pilot, but it is in business that I really like to see a bit of attention to detail. For instance, there’s a restaurant on Yonge Street that has chairs with racks underneath them. It makes all kinds of sense – the restaurant is close to Ryerson, popular with the kids there and one can well imagine that, particularly in winter, the floor’s going to get somewhat wet and dirty and the kids would really like to put their books and backpacks somewhere else. So the owner put in chairs with racks underneath, so this could be accommodated without losing a chair that could be used by another customer.

Yes, it’s a small thing. By itself it’s not going to make or break the business. But it indicates to me that when the owner went out on his chair-buying expedition, he thought about what would be useful and maybe even spent a little extra money addressing the issue. A small thing, but how often do you see it?

Which brings me to Personal Capital Corporation, which I mentioned on May 20 when news broke that IGM had put a chunk of money into the robo-advisor. It was just a short mention, but it did attract some attention … from Personal Capital Corporation, via eMail:

Good morning,

I’m [redacted] with Personal Capital, and I just wanted to thank you for writing that informative article covering IGM Financial’s investment in us!

For something like this where you mention us, would you be able to add a wealth management page link for “wealth management” in the paragraph over the Preferred Indices table? Here’s the URL to make things easier: https://www.personalcapital.com/wealth-management

Thanks so much for your time!

How about that, eh? Clearly, PCC has some kind of web-search robot that sends a list of mentions to somebody and that somebody tries to keep the buzz going in a useful manner … even when the mention is on an obscure specialist blog like this one. I’ve mentioned thousands of companies on this blog over the years and this is the very first time I’ve received an eMail like this. Good for PCC! I have no idea about the quality of their product or much else about them apart from what I’ve said … but if I was looking for a robo-advisor, either for myself or to recommend to friends or clients, Personal Capital Corporation would be on the long-list, for this reason alone.

So, new reader MA, “Content and Social Media” contact at PCC … this one’s for you: Personal Capital Corporation Wealth Management.

Speaking of robo-advisors, PWF’s venture, WealthSimple, is attempting to enter partnerships with advisors:

Toronto-based robo-advisor Wealthsimple Financial Inc. officially launched its platform specifically for financial advisors, dubbed Wealthsimple for Advisors, on Tuesday.

The platform, originally offered earlier this year as a pilot project for 50 advisors, is mainly intended for advisors who have clients with small accounts that don’t meet minimum account requirements, but that advisors don’t want to sever that relationship. Such an example would be a client’s child.

This platform allows advisors to maintain a relationship with those smaller account clients without spending time on the day-to-day management of the account, says Jason Goldlist, chief marketing officer with Wealthsimple. Instead, advisors can focus on accounts that better fit their business and minimum requirements.
…
Advisors interested in working with the robo-advisor can invite clients via email to sign up for a Wealthsimple account. Wealthsimple then handles the investment management of those accounts. Advisors cannot create their own investment portfolios for clients on the platform or recommend their own products.

And I mentioned the automaker and mobility provider jostling yesterday – this also caught the attention of Bloomberg’s Justin Fox:

During a visit to Bloomberg last year, Renault and Nissan Chief Executive Officer Carlos Ghosn grumbled that Alphabet’s (at that point it was still Google’s) self-driving car was a “box” devoid of “seduction and attractiveness,” and said “the car industry will do everything it can to make sure that the product does not become a commodity.”

But auto executives are also familiar with Harvard Business School professor Clayton M. Christensen’s argument that if an innovation comes along that disrupts your way of doing business, there’s often not a whole lot you can do to stop it. The automakers cutting deals with ride-hailing companies are hoping that they can figure out an on-demand business model if it turns out they need to.

Can they? Tom Bartman, a senior researcher at Christensen’s Forum for Growth and Innovation at HBS, is dubious. “Business models can’t change,” he says. Once a business learns how to make money one way, it’s almost impossible to shift gears. Still, there is one slender reed of hope: “While businesses can’t change, corporations can.”

Assiduous Reader BarleyandHops provides two very good links in the comments to May 24. The first of these discusses massive factory automation in China:

One factory has “reduced employee strength from 110,000 to 50,000 thanks to the introduction of robots”, a government official told the South China Morning Post.

Xu Yulian, head of publicity for the Kunshan region, added: “More companies are likely to follow suit.”

China is investing heavily in a robot workforce.

In a statement to the BBC, Foxconn Technology Group confirmed that it was automating “many of the manufacturing tasks associated with our operations” but denied that it meant long-term job losses.
…
Former McDonald’s chief executive Ed Rensi recently told the US’s Fox Business programme a minimum-wage increase to $15 an hour would make companies consider robot workers.

“It’s cheaper to buy a $35,000 robotic arm than it is to hire an employee who is inefficient, making $15 an hour bagging French fries,” he said.

And fast-food is indeed being robotically served up in innovation-crazy Japan:

But Pizza Hut in Japan will be the first major chain to utilize robots to actually serve customers in its pilot program later this year.

According to the Wall Street Journal, the company has ordered several models of Pepper, a humanoid robot that is also being tested in the cruise and airline industries, to take orders and accept payment. The program will be tested in select Japanese franchise locations by the end of the year. It’s powered by MasterPass, MasterCard’s digital wallet and mobile payment platform.

To place an order, customers can simply say hello to Pepper to begin the process. They can either tap an icon within the MasterPass digital wallet app through their phone or scan a QR code on a tablet the robot holds. As the customer orders, the robot responds by lighting up and using hand gestures– just like a real human.

An article in the Globe unabashedly discloses the actual reason for Proportional Representation’s popularity amongst certain members of the elite: backroom deals can be cut allowing the top end of the parties’ lists to be populated by those who are otherwise unelectable. They seem quite proud of this end-run around democracy. So … start hob-nobbing and donating now!

“We definitely want any reform that will increase our ability to affect who is being [elected] and to make sure we choose people who will actually promote women’s rights and other oppressed groups’ rights,” said Hilla Kerner, spokeswoman for the Vancouver Rape Relief and Women’s Shelter.
…
Some European countries with proportional representation systems, for example, have more women in their legislatures than Canada. Ms. Blomme, a political scientist with the Broadbent Institute, said academic studies have shown that the system increases by up to 8 per cent the proportion of women in legislatures.

8%? In Canada, that’s about 27 seats … get those chequebooks ready!

PerpetualDiscounts now yield 5.56%, equivalent to 7.23% interest at the standard equivalency factor of 1.3x. Long corporates now yield about 4.00% – OK, maybe just a smidge over – so the pre-tax interest-equivalent spread is now about 320bp, a slight (and perhaps spurious) narrowing from the 325bp reported May 18.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 4.69 % 5.71 % 11,226 17.00 1 1.0526 % 1,682.0
FixedFloater 6.67 % 5.79 % 17,998 16.71 1 0.0000 % 3,031.5
Floater 4.43 % 4.61 % 43,592 16.15 4 2.1287 % 1,754.2
OpRet 0.00 % 0.00 % 0 0.00 0 0.2202 % 2,830.6
SplitShare 4.94 % 5.14 % 83,039 3.93 7 0.2202 % 3,312.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.2202 % 2,584.4
Perpetual-Premium 5.75 % -12.62 % 85,249 0.09 6 -0.0327 % 2,602.5
Perpetual-Discount 5.47 % 5.56 % 104,733 14.51 33 0.0380 % 2,683.9
FixedReset 5.19 % 4.65 % 163,096 13.77 88 0.1143 % 1,970.4
Deemed-Retractible 5.12 % 5.56 % 129,910 5.00 33 0.1009 % 2,684.8
FloatingReset 3.19 % 5.05 % 25,836 5.26 17 -0.0385 % 2,095.5
Performance Highlights
Issue Index Change Notes
FTS.PR.I FloatingReset -1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-25
Maturity Price : 11.47
Evaluated at bid price : 11.47
Bid-YTW : 4.36 %
BAM.PR.X FixedReset -1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-25
Maturity Price : 13.70
Evaluated at bid price : 13.70
Bid-YTW : 5.01 %
BAM.PR.E Ratchet 1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-25
Maturity Price : 25.00
Evaluated at bid price : 14.40
Bid-YTW : 5.71 %
MFC.PR.B Deemed-Retractible 1.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.48
Bid-YTW : 6.15 %
FTS.PR.K FixedReset 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-25
Maturity Price : 17.10
Evaluated at bid price : 17.10
Bid-YTW : 4.39 %
PWF.PR.A Floater 1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-25
Maturity Price : 11.75
Evaluated at bid price : 11.75
Bid-YTW : 4.05 %
TD.PF.B FixedReset 1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-25
Maturity Price : 18.27
Evaluated at bid price : 18.27
Bid-YTW : 4.39 %
NA.PR.S FixedReset 1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-25
Maturity Price : 18.35
Evaluated at bid price : 18.35
Bid-YTW : 4.55 %
VNR.PR.A FixedReset 1.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-25
Maturity Price : 18.45
Evaluated at bid price : 18.45
Bid-YTW : 5.00 %
PWF.PR.T FixedReset 1.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-25
Maturity Price : 21.35
Evaluated at bid price : 21.35
Bid-YTW : 3.89 %
BNS.PR.R FixedReset 1.87 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.43
Bid-YTW : 4.53 %
TRP.PR.B FixedReset 2.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-25
Maturity Price : 11.65
Evaluated at bid price : 11.65
Bid-YTW : 4.51 %
GWO.PR.N FixedReset 2.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.05
Bid-YTW : 9.83 %
BAM.PR.K Floater 2.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-25
Maturity Price : 10.30
Evaluated at bid price : 10.30
Bid-YTW : 4.65 %
BAM.PR.C Floater 2.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-25
Maturity Price : 10.27
Evaluated at bid price : 10.27
Bid-YTW : 4.66 %
BAM.PR.B Floater 2.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-25
Maturity Price : 10.38
Evaluated at bid price : 10.38
Bid-YTW : 4.61 %
Volume Highlights
Issue Index Shares
Traded
Notes
BAM.PR.K Floater 154,476 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-25
Maturity Price : 10.30
Evaluated at bid price : 10.30
Bid-YTW : 4.65 %
PWF.PR.E Perpetual-Discount 150,869 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-25
Maturity Price : 24.55
Evaluated at bid price : 24.80
Bid-YTW : 5.60 %
PWF.PR.L Perpetual-Discount 128,169 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-25
Maturity Price : 22.93
Evaluated at bid price : 23.20
Bid-YTW : 5.54 %
TD.PF.C FixedReset 113,877 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-25
Maturity Price : 18.02
Evaluated at bid price : 18.02
Bid-YTW : 4.44 %
MFC.PR.M FixedReset 95,379 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.35
Bid-YTW : 6.99 %
RY.PR.R FixedReset 66,192 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-24
Maturity Price : 25.00
Evaluated at bid price : 26.25
Bid-YTW : 4.70 %
There were 62 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
CIU.PR.C FixedReset Quote: 11.72 – 12.44
Spot Rate : 0.7200
Average : 0.5454

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-25
Maturity Price : 11.72
Evaluated at bid price : 11.72
Bid-YTW : 4.58 %

MFC.PR.H FixedReset Quote: 21.50 – 21.92
Spot Rate : 0.4200
Average : 0.2565

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.50
Bid-YTW : 6.04 %

GWO.PR.F Deemed-Retractible Quote: 25.70 – 26.12
Spot Rate : 0.4200
Average : 0.2734

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-06-24
Maturity Price : 25.00
Evaluated at bid price : 25.70
Bid-YTW : -16.50 %

MFC.PR.K FixedReset Quote: 18.20 – 18.59
Spot Rate : 0.3900
Average : 0.2615

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.20
Bid-YTW : 7.56 %

GWO.PR.O FloatingReset Quote: 13.01 – 13.79
Spot Rate : 0.7800
Average : 0.6515

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.01
Bid-YTW : 10.44 %

BAM.PF.E FixedReset Quote: 18.05 – 18.40
Spot Rate : 0.3500
Average : 0.2323

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-25
Maturity Price : 18.05
Evaluated at bid price : 18.05
Bid-YTW : 5.01 %

Market Action

May 24, 2016

Hurray! Food delivery robots!

When the staff at Starship Technologies in Tallinn, Estonia are ready for lunch, they’ll order a few pizzas just like any other office. But they don’t have a human do the pickup or delivery. Instead, a two-foot high, forty-pound, self-driving robot on wheels will get the job.

The staff made up of engineers and project managers sometimes use a credit line with the local pizzeria. Or they’ll just put cash inside the robot itself. The machine is covered with carefully concealed sensors and nine cameras, so that on a bank of screens in the office, they can get a first-person view of its journey from a couple feet off the ground, traversing pavements and passing by pedestrians to pick up their order. Once they see the robot is in the pizzeria, they’ll hit a button to unlock the hatch so the restaurant can get the cash and put in the hot pizzas.

This is the future of delivery, according to Starship, whose robots are 90-99% automated, according to its CFO, Allan Martinson.

A fascinating example of technological disruption is blockchains in finance:

The risk posed by fraud in the $4 trillion trade-financing industry has prompted banks to start exploring distributed-ledger technology like the one that underpins bitcoin.

Standard Chartered Plc, which lost almost $200 million from a fraud at China’s Qingdao port two years ago, has teamed up with DBS Group Holdings Ltd. to develop an electronic ledger of invoices that uses a parallel platform to the blockchain employed in bitcoin transactions. Lenders such as Bank of America Corp. and HSBC Holdings Plc say they’re looking at blockchain for trade finance and other banking applications.

Blockchain proponents argue that the technology will change the face of banking, helping lenders cut billions of dollars in costs. Trade financing, a centuries-old banking mainstay, may become ground zero for blockchain adoption because it promises to do away with paper invoices and the fraud that accompanies them — if banks can come together around a joint platform.

There was a nice article on Bloomberg about Treasury duration management:

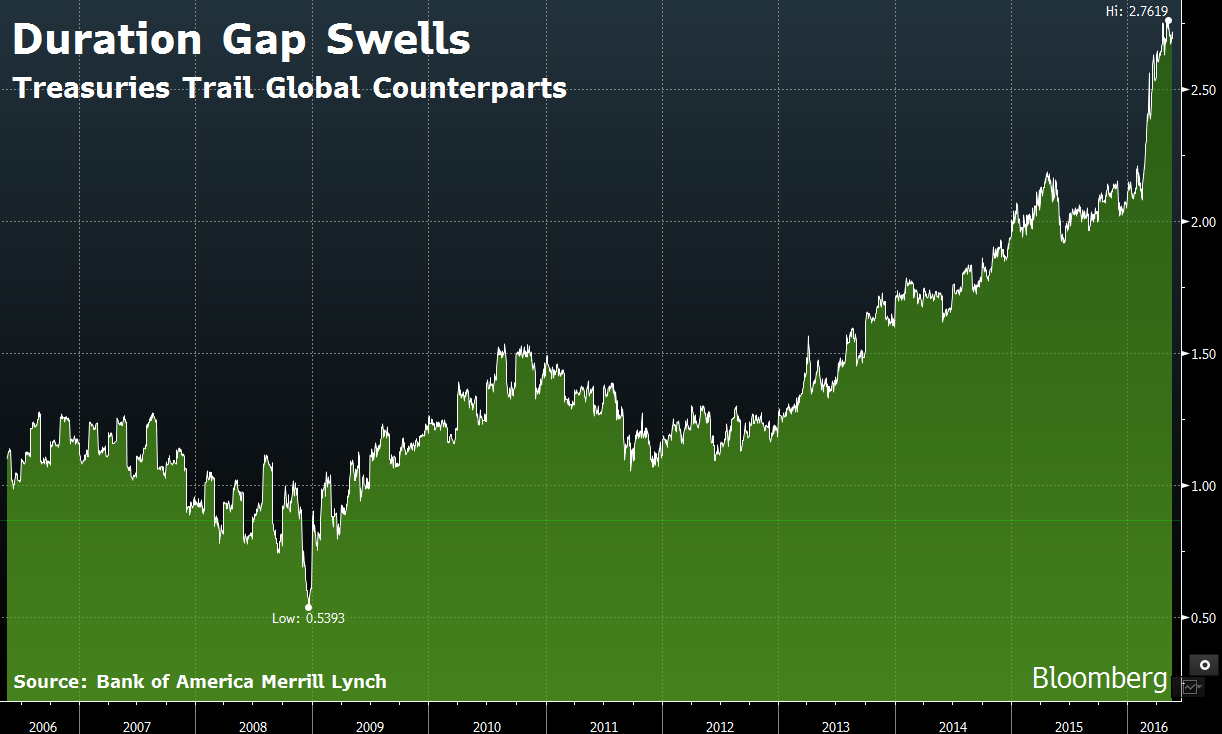
To lock in historically low interest rates, Belgium, Canada, France, Mexico, Spain, Switzerland and the U.K. have all sold debt maturing in 40 to 100 years since 2014, even if infrequently. Not the U.S., which in the interest of keeping sales regular has stuck to securities of three decades or less. That policy has made the globe’s biggest debtor a laggard in a key bond-market metric related to the average maturity of its securities. By this measure, the gap between the U.S. and its peers has never been wider.
…
Yet by a gauge known as modified duration, a measure of debt’s price sensitivity to interest-rate changes that rises with maturity, it’s still trailing global peers. Typically, bonds with longer duration gain more when rates fall, and suffer steeper losses when rates rise.

For Treasuries, the figure is 6.2, compared with 8.9 for an index that tracks the sovereign securities of more than 20 other nations, Bank of America Merrill Lynch data show. This month, the gap between the two reached the widest since at least 2006. One of the starkest contrasts is with the U.K., which issues long-dated bonds for pensions and insurers. Its debt has a duration above 10, Bank of America data show.

sovereignDurationGap
Click for Big

“The Treasury likes to see large, liquid markets, and something like a 50-year bond is not going to be particularly liquid,” said James Moore, head of investment solutions in Newport Beach, California, at Pacific Investment Management Co., which oversees about $1.5 trillion. “The Treasury is thinking about and balancing a multiplicity of objectives when they consider issuance, and liquidity and depth are some of them.”

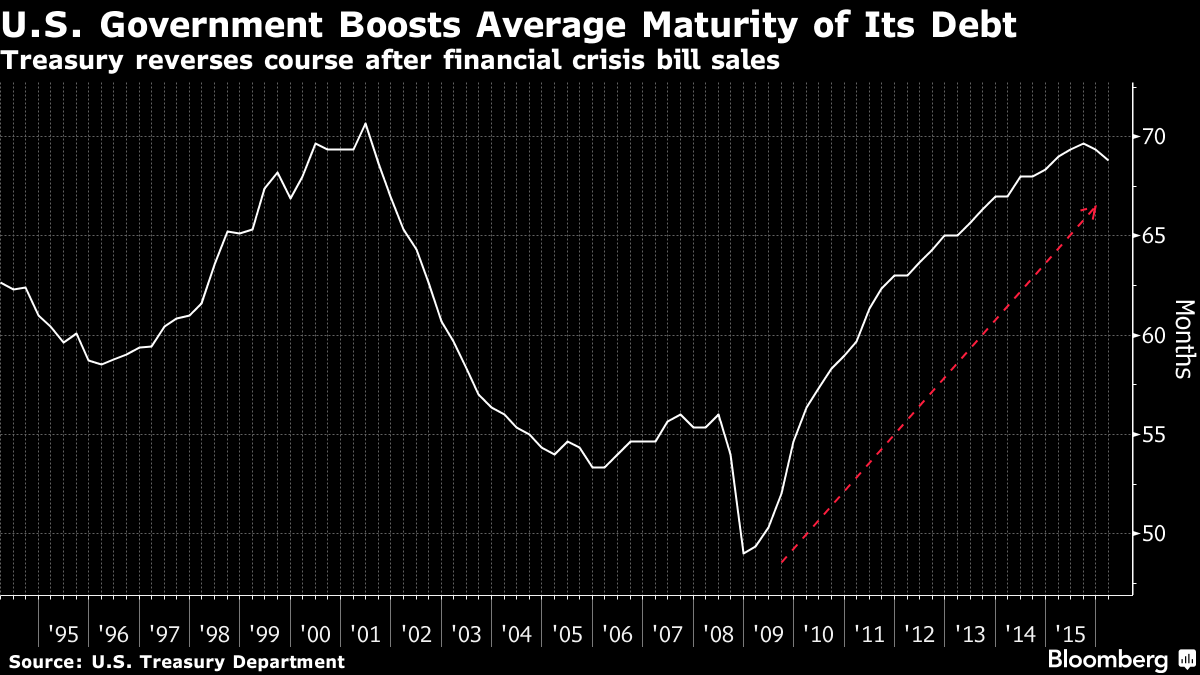
The U.S. hasn’t exactly stood still. The average lifespan of the government’s debt is now about 69 months, up from 49 in December 2008, when it was ramping up short-term bill issuance as part of emergency spending during the financial crisis, Treasury data show.

treasuryAverageTerm
Click for Big

The Treasury’s Borrowing Advisory Committee, which includes some dealers, voiced concern over that risk in 2011, when the department last asked the group to consider ultra-long bonds. The topic has been discussed several times at quarterly gatherings since.

The primary buyers of very long-dated debt — pensions and insurers — tend to prefer higher-yielding corporate bonds. Microsoft’s 40-year bond last year was priced to yield 1.8 percentage points above 30-year Treasuries. And other investors may deem ultra-long debt too perilous because of the steep losses they’d incur should yields rise.

It’s interesting to see the car manufacturers jockeying for the new opportunities in fleet management – first, there’s Gett and Volkswagen:

Gett Inc., a taxi-ordering application that competes with Uber Technologies Inc., raised $300 million in a strategic investment from German carmaker Volkswagen AG to fund its growth in Europe and New York City.

Gett, based in Tel Aviv, Israel, has offered rides for as low as $1 and expanded its services to include deliveries of goods. The company hired Wells Fargo & Co. to find investors for the round, people familiar with the matter said in February. Volkswagen’s contribution brings total funds raised by Gett to more than $520 million, the taxi service said Tuesday in an e-mailed statement.

Volkswagen made the investment as part of a push to boost digital offerings and move beyond its diesel-engine manipulation scandal. Mobility services promise strong growth prospects and earnings potential in coming years, VW said Tuesday in a statement.
…
With operations in over 60 cities worldwide, including London, Moscow and New York, Gett is a major ride-hailing provider and services will be expanded further as part of the alliance with VW. Last month, it completed its bid to buy London’s Radio Taxis in a move that brought Gett’s car fleet in the city to 11,500, a number the company says amounts to half of all licensed taxis in the city.
…
Expanding digital services in connected cars is a cornerstone of VW’s strategy through 2025, which will be presented in mid-June. More than 250 employees are developing the plan, which will comprise eight key initiatives across the group, Mueller said last week at an internal management meeting at the carmaker’s Wolfsburg, Germany, headquarters.

Volkswagen is not the first car manufacturer to get involved in the ride-hailing business. General Motors Co. bought a 9 percent stake in Lyft for $500 million in January and Apple Inc. made a $1 billion investment in China’s Didi this month.

And, of course, Car2Go is a subsidiary of Daimler, while Zipcar is, perhaps more logically, subsidiary of the old-line car rental company Avis Budget, while Hertz is trying to develop the business as a sideline. Meanwhile, Toyota is investing in Uber:

Toyota Motor Corp. said it is making a strategic investment in Uber Technologies Inc. and will offer auto leases to the ride-hailing company’s drivers.

Uber declined to disclose the size of the investment. Toyota wasn’t immediately available for comment. By leasing Toyota cars, Uber will expand its existing program, which also includes Enterprise Holdings Inc.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 4.74 % 5.77 % 11,622 16.92 1 -1.7241 % 1,664.5
FixedFloater 6.67 % 5.79 % 18,730 16.72 1 1.0638 % 3,031.5
Floater 4.52 % 4.74 % 44,034 15.91 4 -0.1671 % 1,717.7
OpRet 0.00 % 0.00 % 0 0.00 0 0.2113 % 2,824.3
SplitShare 4.96 % 5.17 % 79,136 3.93 7 0.2113 % 3,305.0
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.2113 % 2,578.7
Perpetual-Premium 5.75 % -11.46 % 78,921 0.09 6 0.1180 % 2,603.3
Perpetual-Discount 5.47 % 5.57 % 101,783 14.51 33 0.1485 % 2,682.9
FixedReset 5.20 % 4.68 % 164,828 13.81 88 0.2169 % 1,968.2
Deemed-Retractible 5.12 % 5.57 % 133,036 6.75 33 0.0745 % 2,682.1
FloatingReset 3.19 % 5.00 % 26,062 5.26 17 0.3195 % 2,096.3
Performance Highlights
Issue Index Change Notes
GWO.PR.O FloatingReset -3.70 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.00
Bid-YTW : 10.45 %
BAM.PR.E Ratchet -1.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-24
Maturity Price : 25.00
Evaluated at bid price : 14.25
Bid-YTW : 5.77 %
CU.PR.C FixedReset -1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-24
Maturity Price : 17.75
Evaluated at bid price : 17.75
Bid-YTW : 4.54 %
BAM.PR.X FixedReset 1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-24
Maturity Price : 13.89
Evaluated at bid price : 13.89
Bid-YTW : 4.93 %
BAM.PR.G FixedFloater 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-24
Maturity Price : 25.00
Evaluated at bid price : 14.25
Bid-YTW : 5.79 %
TD.PF.F Perpetual-Discount 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-24
Maturity Price : 24.16
Evaluated at bid price : 24.54
Bid-YTW : 5.02 %
TRP.PR.F FloatingReset 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-24
Maturity Price : 13.50
Evaluated at bid price : 13.50
Bid-YTW : 4.63 %
SLF.PR.H FixedReset 1.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.47
Bid-YTW : 8.79 %
RY.PR.M FixedReset 1.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-24
Maturity Price : 19.12
Evaluated at bid price : 19.12
Bid-YTW : 4.52 %
CM.PR.Q FixedReset 1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-24
Maturity Price : 19.71
Evaluated at bid price : 19.71
Bid-YTW : 4.57 %
BMO.PR.Y FixedReset 1.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-24
Maturity Price : 20.15
Evaluated at bid price : 20.15
Bid-YTW : 4.43 %
FTS.PR.H FixedReset 2.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-24
Maturity Price : 13.20
Evaluated at bid price : 13.20
Bid-YTW : 4.33 %
TRP.PR.I FloatingReset 2.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-24
Maturity Price : 11.25
Evaluated at bid price : 11.25
Bid-YTW : 4.69 %
FTS.PR.I FloatingReset 2.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-24
Maturity Price : 11.67
Evaluated at bid price : 11.67
Bid-YTW : 4.29 %
HSE.PR.B FloatingReset 3.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-24
Maturity Price : 10.70
Evaluated at bid price : 10.70
Bid-YTW : 5.40 %
Volume Highlights
Issue Index Shares
Traded
Notes
TRP.PR.J FixedReset 51,779 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-31
Maturity Price : 25.00
Evaluated at bid price : 25.73
Bid-YTW : 4.85 %
RY.PR.Q FixedReset 38,165 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-24
Maturity Price : 25.00
Evaluated at bid price : 26.16
Bid-YTW : 4.48 %
SLF.PR.I FixedReset 36,900 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.60
Bid-YTW : 7.07 %
RY.PR.W Perpetual-Discount 33,222 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-24
Maturity Price : 24.23
Evaluated at bid price : 24.53
Bid-YTW : 5.01 %
RY.PR.R FixedReset 30,239 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-24
Maturity Price : 25.00
Evaluated at bid price : 26.26
Bid-YTW : 4.69 %
RY.PR.M FixedReset 26,200 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-24
Maturity Price : 19.12
Evaluated at bid price : 19.12
Bid-YTW : 4.52 %
There were 14 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
GWO.PR.O FloatingReset Quote: 13.00 – 13.79
Spot Rate : 0.7900
Average : 0.5107

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.00
Bid-YTW : 10.45 %

TRP.PR.D FixedReset Quote: 17.36 – 17.75
Spot Rate : 0.3900
Average : 0.2476

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-24
Maturity Price : 17.36
Evaluated at bid price : 17.36
Bid-YTW : 4.78 %

BAM.PR.E Ratchet Quote: 14.25 – 14.75
Spot Rate : 0.5000
Average : 0.3795

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-24
Maturity Price : 25.00
Evaluated at bid price : 14.25
Bid-YTW : 5.77 %

TD.PF.B FixedReset Quote: 18.03 – 18.38
Spot Rate : 0.3500
Average : 0.2378

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-24
Maturity Price : 18.03
Evaluated at bid price : 18.03
Bid-YTW : 4.45 %

TD.PR.S FixedReset Quote: 22.75 – 23.24
Spot Rate : 0.4900
Average : 0.3841

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.75
Bid-YTW : 4.67 %

ELF.PR.G Perpetual-Discount Quote: 21.10 – 21.50
Spot Rate : 0.4000
Average : 0.2985

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-24
Maturity Price : 21.10
Evaluated at bid price : 21.10
Bid-YTW : 5.71 %

Market Action

May 20, 2016

EMA wants to issue new preferreds; Barry Critchley points out they’ll have to pay up relative to their last round:

This week Emera took another step on the way to rounding up the cash need to fund the US$10.4 billion acquisition of TECO Energy.

Emera, which expects to close the acquisition by mid-year, raised $544 million from the sale of most of its stake in Algonquin Power & Utilities Corp. After the share sale, Emera — which is expected to receive the second instalment of a $2.185 billion offering of convertible debentures when the TECO deal gets the final green light — will own about five per cent of Algonquin.

But lots of capital still needs to be raised — even if it seems that all the common equity has been obtained. In a presentation unveiled this week, Emera indicated it is seeking between US$3.4 billion and US$3.8 billion of debt (the US$10.4 billion acquisition cost includes US$3.9 billion of assumed debt). It is also after US$0.8 billion to US$1.2 billion in either preferred equity or hybrid securities.
…
Emera last issued rate reset preferred shares in May 2014 when it raised $200 million at a yield of 4.25 per cent. At 4.25 per cent, the coupon represented a spread of 263 basis points above comparable five-year Canada bonds.

Next time out Emera will find that the preferred share market has changed in two ways.

IGM Financial has bought a piece of a robo-advisor:

IGM Financial Inc. has closed a $50 million (U.S.) investment in Personal Capital Corporation, a market-leading digital wealth advisor based in the U.S., with an agreement to invest an additional $25 million (U.S.) in the next year for a total of $75 million (U.S.). This would result in an initial 10% ownership stake increasing to 15% within 12 months, with the remaining interest owned by Personal Capital’s management team and existing investors.

Personal Capital’s approach to wealth management – combining dedicated financial advisors with innovative customer-facing technology – is unique in the industry. Led by a market-leading and experienced team with a long track record in financial services, Personal Capital has been growing rapidly in the mass affluent and high net worth investor segments of the market, offering a unique, compelling and valuable proposition for its clients.

This is kind of interesting, since IGM’s parent, PWF, already has a piece of WealthSimple, as discussed April 9, 2015.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 4.66 % 5.66 % 11,568 17.06 1 0.6944 % 1,693.7
FixedFloater 6.74 % 5.85 % 18,988 16.65 1 -2.7586 % 2,999.6
Floater 4.51 % 4.72 % 44,505 15.95 4 0.4317 % 1,720.6
OpRet 0.00 % 0.00 % 0 0.00 0 -0.2390 % 2,818.4
SplitShare 4.97 % 5.28 % 80,228 3.94 7 -0.2390 % 3,298.0
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.2390 % 2,573.3
Perpetual-Premium 5.76 % -9.92 % 78,517 0.09 6 0.0853 % 2,600.2
Perpetual-Discount 5.48 % 5.57 % 102,014 14.50 33 0.1460 % 2,678.9
FixedReset 5.21 % 4.64 % 166,452 13.84 88 0.3126 % 1,963.9
Deemed-Retractible 5.12 % 5.47 % 132,034 5.01 33 0.1175 % 2,680.1
FloatingReset 3.20 % 5.00 % 26,016 5.27 17 0.0351 % 2,089.6
Performance Highlights
Issue Index Change Notes
TRP.PR.I FloatingReset -4.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-20
Maturity Price : 11.00
Evaluated at bid price : 11.00
Bid-YTW : 4.79 %
BAM.PR.G FixedFloater -2.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-20
Maturity Price : 25.00
Evaluated at bid price : 14.10
Bid-YTW : 5.85 %
SLF.PR.H FixedReset -1.99 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.27
Bid-YTW : 8.94 %
ALB.PR.C SplitShare -1.11 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-02-28
Maturity Price : 25.67
Evaluated at bid price : 25.76
Bid-YTW : 4.10 %
TRP.PR.E FixedReset 1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-20
Maturity Price : 17.98
Evaluated at bid price : 17.98
Bid-YTW : 4.67 %
TD.PR.S FixedReset 1.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.95
Bid-YTW : 4.48 %
BAM.PF.B FixedReset 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-20
Maturity Price : 17.48
Evaluated at bid price : 17.48
Bid-YTW : 5.13 %
NA.PR.S FixedReset 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-20
Maturity Price : 18.01
Evaluated at bid price : 18.01
Bid-YTW : 4.64 %
TD.PR.Y FixedReset 1.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.25
Bid-YTW : 4.42 %
BAM.PF.F FixedReset 1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-20
Maturity Price : 19.62
Evaluated at bid price : 19.62
Bid-YTW : 4.91 %
BAM.PF.E FixedReset 1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-20
Maturity Price : 18.16
Evaluated at bid price : 18.16
Bid-YTW : 4.97 %
FTS.PR.K FixedReset 1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-20
Maturity Price : 16.86
Evaluated at bid price : 16.86
Bid-YTW : 4.45 %
HSE.PR.C FixedReset 1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-20
Maturity Price : 17.54
Evaluated at bid price : 17.54
Bid-YTW : 5.85 %
FTS.PR.M FixedReset 1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-20
Maturity Price : 18.46
Evaluated at bid price : 18.46
Bid-YTW : 4.64 %
BAM.PR.X FixedReset 1.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-20
Maturity Price : 13.75
Evaluated at bid price : 13.75
Bid-YTW : 4.98 %
BAM.PR.T FixedReset 1.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-20
Maturity Price : 15.35
Evaluated at bid price : 15.35
Bid-YTW : 5.21 %
BAM.PF.A FixedReset 1.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-20
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 5.06 %
TRP.PR.A FixedReset 2.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-20
Maturity Price : 14.31
Evaluated at bid price : 14.31
Bid-YTW : 5.00 %
GWO.PR.O FloatingReset 3.85 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.50
Bid-YTW : 9.92 %
Volume Highlights
Issue Index Shares
Traded
Notes
TRP.PR.J FixedReset 112,180 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-31
Maturity Price : 25.00
Evaluated at bid price : 25.76
Bid-YTW : 4.81 %
FTS.PR.K FixedReset 28,368 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-20
Maturity Price : 16.86
Evaluated at bid price : 16.86
Bid-YTW : 4.45 %
TD.PF.C FixedReset 25,223 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-20
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 4.44 %
NA.PR.X FixedReset 23,346 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-15
Maturity Price : 25.00
Evaluated at bid price : 26.10
Bid-YTW : 4.64 %
TD.PF.G FixedReset 17,988 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 26.12
Bid-YTW : 4.57 %
TRP.PR.A FixedReset 17,950 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-20
Maturity Price : 14.31
Evaluated at bid price : 14.31
Bid-YTW : 5.00 %
There were 22 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BAM.PR.G FixedFloater Quote: 14.10 – 14.85
Spot Rate : 0.7500
Average : 0.4749

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-20
Maturity Price : 25.00
Evaluated at bid price : 14.10
Bid-YTW : 5.85 %

EML.PR.A FixedReset Quote: 25.82 – 26.58
Spot Rate : 0.7600
Average : 0.4894

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-17
Maturity Price : 25.00
Evaluated at bid price : 25.82
Bid-YTW : 5.14 %

HSE.PR.B FloatingReset Quote: 10.35 – 11.28
Spot Rate : 0.9300
Average : 0.7073

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-20
Maturity Price : 10.35
Evaluated at bid price : 10.35
Bid-YTW : 5.58 %

ALB.PR.C SplitShare Quote: 25.76 – 26.50
Spot Rate : 0.7400
Average : 0.5897

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-02-28
Maturity Price : 25.67
Evaluated at bid price : 25.76
Bid-YTW : 4.10 %

SLF.PR.J FloatingReset Quote: 13.00 – 13.45
Spot Rate : 0.4500
Average : 0.3312

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.00
Bid-YTW : 10.60 %

SLF.PR.I FixedReset Quote: 19.43 – 19.94
Spot Rate : 0.5100
Average : 0.3929

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.43
Bid-YTW : 7.15 %

Market Action

May 19, 2016

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 4.69 % 5.70 % 12,032 17.02 1 -0.4838 % 1,682.0
FixedFloater 6.55 % 5.68 % 19,121 16.86 1 1.0453 % 3,084.7
Floater 4.53 % 4.75 % 44,776 15.90 4 0.2163 % 1,713.2
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0348 % 2,825.1
SplitShare 4.95 % 5.09 % 83,077 3.95 7 -0.0348 % 3,305.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0348 % 2,579.4
Perpetual-Premium 5.76 % -11.01 % 78,310 0.09 6 0.0000 % 2,598.0
Perpetual-Discount 5.48 % 5.57 % 103,339 14.52 33 -0.0145 % 2,675.0
FixedReset 5.22 % 4.63 % 164,900 13.82 88 -0.1938 % 1,957.8
Deemed-Retractible 5.13 % 5.53 % 131,576 5.01 33 0.4175 % 2,677.0
FloatingReset 3.15 % 5.01 % 25,656 5.28 17 0.3984 % 2,088.9
Performance Highlights
Issue Index Change Notes
PWF.PR.Q FloatingReset -2.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-19
Maturity Price : 12.51
Evaluated at bid price : 12.51
Bid-YTW : 4.27 %
NA.PR.S FixedReset -2.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-19
Maturity Price : 17.82
Evaluated at bid price : 17.82
Bid-YTW : 4.59 %
TRP.PR.A FixedReset -1.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-19
Maturity Price : 14.00
Evaluated at bid price : 14.00
Bid-YTW : 4.99 %
CU.PR.C FixedReset -1.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-19
Maturity Price : 17.78
Evaluated at bid price : 17.78
Bid-YTW : 4.42 %
SLF.PR.G FixedReset -1.63 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.46
Bid-YTW : 9.50 %
BMO.PR.W FixedReset -1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-19
Maturity Price : 17.79
Evaluated at bid price : 17.79
Bid-YTW : 4.34 %
BMO.PR.T FixedReset -1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-19
Maturity Price : 17.85
Evaluated at bid price : 17.85
Bid-YTW : 4.35 %
TD.PF.A FixedReset -1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-19
Maturity Price : 18.30
Evaluated at bid price : 18.30
Bid-YTW : 4.29 %
RY.PR.Z FixedReset -1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-19
Maturity Price : 18.15
Evaluated at bid price : 18.15
Bid-YTW : 4.25 %
NA.PR.W FixedReset -1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-19
Maturity Price : 17.57
Evaluated at bid price : 17.57
Bid-YTW : 4.48 %
BAM.PR.G FixedFloater 1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-19
Maturity Price : 25.00
Evaluated at bid price : 14.50
Bid-YTW : 5.68 %
IAG.PR.G FixedReset 1.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.12
Bid-YTW : 6.77 %
BAM.PR.R FixedReset 1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-19
Maturity Price : 15.05
Evaluated at bid price : 15.05
Bid-YTW : 5.05 %
BAM.PR.T FixedReset 1.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-19
Maturity Price : 15.07
Evaluated at bid price : 15.07
Bid-YTW : 5.18 %
SLF.PR.J FloatingReset 2.19 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.05
Bid-YTW : 10.50 %
FTS.PR.I FloatingReset 2.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-19
Maturity Price : 11.51
Evaluated at bid price : 11.51
Bid-YTW : 4.28 %
TRP.PR.I FloatingReset 7.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-19
Maturity Price : 11.55
Evaluated at bid price : 11.55
Bid-YTW : 4.49 %
Volume Highlights
Issue Index Shares
Traded
Notes
BNS.PR.O Deemed-Retractible 115,600 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-06-18
Maturity Price : 25.25
Evaluated at bid price : 25.43
Bid-YTW : 0.37 %
BAM.PF.G FixedReset 49,242 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-19
Maturity Price : 19.73
Evaluated at bid price : 19.73
Bid-YTW : 4.82 %
MFC.PR.M FixedReset 45,000 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.20
Bid-YTW : 7.03 %
PWF.PR.H Perpetual-Premium 35,243 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-06-18
Maturity Price : 25.00
Evaluated at bid price : 25.17
Bid-YTW : 1.11 %
TD.PF.B FixedReset 34,440 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-19
Maturity Price : 18.15
Evaluated at bid price : 18.15
Bid-YTW : 4.32 %
RY.PR.H FixedReset 30,250 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-19
Maturity Price : 18.10
Evaluated at bid price : 18.10
Bid-YTW : 4.32 %
There were 36 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BNS.PR.P FixedReset Quote: 23.85 – 24.49
Spot Rate : 0.6400
Average : 0.3617

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.85
Bid-YTW : 3.89 %

VNR.PR.A FixedReset Quote: 18.00 – 18.49
Spot Rate : 0.4900
Average : 0.3211

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-19
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 5.02 %

PWF.PR.Q FloatingReset Quote: 12.51 – 13.39
Spot Rate : 0.8800
Average : 0.7541

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-19
Maturity Price : 12.51
Evaluated at bid price : 12.51
Bid-YTW : 4.27 %

BNS.PR.R FixedReset Quote: 22.76 – 23.35
Spot Rate : 0.5900
Average : 0.4850

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.76
Bid-YTW : 5.04 %

BNS.PR.D FloatingReset Quote: 18.51 – 18.74
Spot Rate : 0.2300
Average : 0.1434

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.51
Bid-YTW : 7.18 %

IFC.PR.C FixedReset Quote: 17.58 – 17.89
Spot Rate : 0.3100
Average : 0.2240

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.58
Bid-YTW : 8.36 %

Market Action

May 18, 2016

PerpetualDiscounts now yield 5.59%, equivalent to 7.27% interest at the standard equivalency factor of 1.3x. Long corporates now yield 4.00%, so the pre-tax interest-equivalent spread is now about 325bp, a slight (and perhaps spurious) narrowing from the 330bp reported May 11.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 4.67 % 5.68 % 11,772 17.05 1 0.1384 % 1,690.2
FixedFloater 6.62 % 5.74 % 18,540 16.79 1 0.0000 % 3,052.8
Floater 4.54 % 4.75 % 44,961 15.89 4 -0.7395 % 1,709.5
OpRet 0.00 % 0.00 % 0 0.00 0 0.2191 % 2,826.1
SplitShare 4.95 % 5.05 % 82,785 2.49 7 0.2191 % 3,307.1
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.2191 % 2,580.3
Perpetual-Premium 5.76 % -9.37 % 74,272 0.09 6 0.0000 % 2,598.0
Perpetual-Discount 5.48 % 5.59 % 103,383 14.50 33 -0.2022 % 2,675.4
FixedReset 5.21 % 4.69 % 166,294 13.81 88 -0.1286 % 1,961.6
Deemed-Retractible 5.15 % 5.56 % 131,545 6.76 33 -0.0773 % 2,665.9
FloatingReset 3.16 % 5.00 % 26,458 5.28 17 -0.2111 % 2,080.6
Performance Highlights
Issue Index Change Notes
TRP.PR.A FixedReset -2.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-18
Maturity Price : 14.27
Evaluated at bid price : 14.27
Bid-YTW : 4.88 %
TD.PF.E FixedReset -2.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-18
Maturity Price : 20.24
Evaluated at bid price : 20.24
Bid-YTW : 4.48 %
PWF.PR.A Floater -2.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-18
Maturity Price : 11.51
Evaluated at bid price : 11.51
Bid-YTW : 4.13 %
FTS.PR.I FloatingReset -1.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-18
Maturity Price : 11.22
Evaluated at bid price : 11.22
Bid-YTW : 4.39 %
FTS.PR.J Perpetual-Discount -1.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-18
Maturity Price : 22.09
Evaluated at bid price : 22.36
Bid-YTW : 5.32 %
TRP.PR.G FixedReset -1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-18
Maturity Price : 19.02
Evaluated at bid price : 19.02
Bid-YTW : 4.86 %
MFC.PR.F FixedReset -1.45 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.56
Bid-YTW : 10.15 %
FTS.PR.F Perpetual-Discount -1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-18
Maturity Price : 22.77
Evaluated at bid price : 23.05
Bid-YTW : 5.32 %
TRP.PR.E FixedReset -1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-18
Maturity Price : 17.91
Evaluated at bid price : 17.91
Bid-YTW : 4.60 %
CU.PR.G Perpetual-Discount -1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-18
Maturity Price : 20.78
Evaluated at bid price : 20.78
Bid-YTW : 5.44 %
CM.PR.P FixedReset -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-18
Maturity Price : 18.14
Evaluated at bid price : 18.14
Bid-YTW : 4.31 %
NA.PR.W FixedReset -1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-18
Maturity Price : 17.75
Evaluated at bid price : 17.75
Bid-YTW : 4.43 %
CU.PR.I FixedReset 1.02 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-01
Maturity Price : 25.00
Evaluated at bid price : 25.70
Bid-YTW : 3.80 %
FTS.PR.H FixedReset 1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-18
Maturity Price : 12.90
Evaluated at bid price : 12.90
Bid-YTW : 4.31 %
MFC.PR.J FixedReset 1.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.80
Bid-YTW : 6.62 %
SLF.PR.G FixedReset 1.31 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.70
Bid-YTW : 9.27 %
BIP.PR.A FixedReset 1.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-18
Maturity Price : 19.15
Evaluated at bid price : 19.15
Bid-YTW : 5.72 %
PWF.PR.Q FloatingReset 1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-18
Maturity Price : 12.85
Evaluated at bid price : 12.85
Bid-YTW : 4.15 %
FTS.PR.M FixedReset 1.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-18
Maturity Price : 18.25
Evaluated at bid price : 18.25
Bid-YTW : 4.60 %
SLF.PR.H FixedReset 1.97 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.57
Bid-YTW : 8.58 %
Volume Highlights
Issue Index Shares
Traded
Notes
BNS.PR.O Deemed-Retractible 30,900 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-06-17
Maturity Price : 25.25
Evaluated at bid price : 25.40
Bid-YTW : 1.63 %
RY.PR.R FixedReset 24,063 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-24
Maturity Price : 25.00
Evaluated at bid price : 26.30
Bid-YTW : 4.64 %
BAM.PF.D Perpetual-Discount 22,186 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-18
Maturity Price : 21.01
Evaluated at bid price : 21.01
Bid-YTW : 5.93 %
BAM.PF.C Perpetual-Discount 18,250 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-18
Maturity Price : 20.86
Evaluated at bid price : 20.86
Bid-YTW : 5.91 %
EML.PR.A FixedReset 17,080 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-17
Maturity Price : 25.00
Evaluated at bid price : 25.80
Bid-YTW : 5.15 %
TD.PF.G FixedReset 15,297 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 26.13
Bid-YTW : 4.56 %
There were 16 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
FTS.PR.I FloatingReset Quote: 11.22 – 11.85
Spot Rate : 0.6300
Average : 0.4375

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-18
Maturity Price : 11.22
Evaluated at bid price : 11.22
Bid-YTW : 4.39 %

SLF.PR.J FloatingReset Quote: 12.77 – 13.25
Spot Rate : 0.4800
Average : 0.3117

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.77
Bid-YTW : 10.80 %

EML.PR.A FixedReset Quote: 25.80 – 26.25
Spot Rate : 0.4500
Average : 0.2942

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-17
Maturity Price : 25.00
Evaluated at bid price : 25.80
Bid-YTW : 5.15 %

TRP.PR.A FixedReset Quote: 14.27 – 14.82
Spot Rate : 0.5500
Average : 0.4110

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-18
Maturity Price : 14.27
Evaluated at bid price : 14.27
Bid-YTW : 4.88 %

BAM.PF.B FixedReset Quote: 17.30 – 17.77
Spot Rate : 0.4700
Average : 0.3421

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-18
Maturity Price : 17.30
Evaluated at bid price : 17.30
Bid-YTW : 5.08 %

NA.PR.W FixedReset Quote: 17.75 – 18.09
Spot Rate : 0.3400
Average : 0.2418

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-18
Maturity Price : 17.75
Evaluated at bid price : 17.75
Bid-YTW : 4.43 %

Market Action

May 17, 2016

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 4.68 % 5.68 % 11,857 17.05 1 -0.2761 % 1,687.8
FixedFloater 6.62 % 5.74 % 18,761 16.79 1 0.0000 % 3,052.8
Floater 4.51 % 4.73 % 44,248 15.94 4 0.3111 % 1,722.2
OpRet 0.00 % 0.00 % 0 0.00 0 0.0173 % 2,819.9
SplitShare 4.93 % 5.24 % 81,579 2.46 7 0.0173 % 3,299.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0173 % 2,574.7
Perpetual-Premium 5.76 % -10.92 % 75,343 0.08 6 0.0788 % 2,598.0
Perpetual-Discount 5.47 % 5.57 % 103,302 14.48 33 0.1130 % 2,680.8
FixedReset 5.21 % 4.65 % 166,708 7.48 88 -0.0473 % 1,964.1
Deemed-Retractible 5.15 % 5.58 % 130,646 6.76 33 0.1549 % 2,667.9
FloatingReset 3.16 % 4.91 % 27,100 5.29 17 0.0916 % 2,085.0
Performance Highlights
Issue Index Change Notes
FTS.PR.G FixedReset -2.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-17
Maturity Price : 16.14
Evaluated at bid price : 16.14
Bid-YTW : 4.58 %
BAM.PR.X FixedReset -2.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-17
Maturity Price : 13.43
Evaluated at bid price : 13.43
Bid-YTW : 4.96 %
FTS.PR.I FloatingReset -2.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-17
Maturity Price : 11.44
Evaluated at bid price : 11.44
Bid-YTW : 4.30 %
FTS.PR.M FixedReset -1.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-17
Maturity Price : 17.96
Evaluated at bid price : 17.96
Bid-YTW : 4.67 %
FTS.PR.H FixedReset -1.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-17
Maturity Price : 12.75
Evaluated at bid price : 12.75
Bid-YTW : 4.36 %
GWO.PR.N FixedReset -1.44 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.65
Bid-YTW : 10.16 %
RY.PR.J FixedReset -1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-17
Maturity Price : 19.27
Evaluated at bid price : 19.27
Bid-YTW : 4.52 %
SLF.PR.J FloatingReset -1.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.86
Bid-YTW : 10.69 %
FTS.PR.K FixedReset -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-17
Maturity Price : 16.54
Evaluated at bid price : 16.54
Bid-YTW : 4.43 %
BAM.PR.Z FixedReset 1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-17
Maturity Price : 18.60
Evaluated at bid price : 18.60
Bid-YTW : 5.13 %
NA.PR.Q FixedReset 1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.39
Bid-YTW : 4.62 %
TD.PR.T FloatingReset 1.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.60
Bid-YTW : 4.91 %
HSE.PR.G FixedReset 1.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-17
Maturity Price : 19.20
Evaluated at bid price : 19.20
Bid-YTW : 5.70 %
TRP.PR.E FixedReset 1.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-17
Maturity Price : 18.15
Evaluated at bid price : 18.15
Bid-YTW : 4.53 %
HSE.PR.E FixedReset 1.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-17
Maturity Price : 19.45
Evaluated at bid price : 19.45
Bid-YTW : 5.64 %
CM.PR.Q FixedReset 2.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-17
Maturity Price : 19.45
Evaluated at bid price : 19.45
Bid-YTW : 4.55 %
Volume Highlights
Issue Index Shares
Traded
Notes
TRP.PR.J FixedReset 41,513 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-31
Maturity Price : 25.00
Evaluated at bid price : 25.76
Bid-YTW : 4.80 %
MFC.PR.O FixedReset 37,692 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-06-19
Maturity Price : 25.00
Evaluated at bid price : 26.15
Bid-YTW : 4.50 %
RY.PR.R FixedReset 30,738 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-24
Maturity Price : 25.00
Evaluated at bid price : 26.35
Bid-YTW : 4.60 %
BIP.PR.B FixedReset 27,942 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-17
Maturity Price : 23.20
Evaluated at bid price : 25.02
Bid-YTW : 5.48 %
RY.PR.Z FixedReset 25,505 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-17
Maturity Price : 18.40
Evaluated at bid price : 18.40
Bid-YTW : 4.19 %
PVS.PR.E SplitShare 19,025 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-10-31
Maturity Price : 25.00
Evaluated at bid price : 24.47
Bid-YTW : 6.15 %
There were 14 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
PWF.PR.Q FloatingReset Quote: 12.66 – 13.48
Spot Rate : 0.8200
Average : 0.6006

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-17
Maturity Price : 12.66
Evaluated at bid price : 12.66
Bid-YTW : 4.22 %

HSE.PR.G FixedReset Quote: 19.20 – 19.60
Spot Rate : 0.4000
Average : 0.2847

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-17
Maturity Price : 19.20
Evaluated at bid price : 19.20
Bid-YTW : 5.70 %

HSE.PR.C FixedReset Quote: 17.31 – 17.59
Spot Rate : 0.2800
Average : 0.1929

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-17
Maturity Price : 17.31
Evaluated at bid price : 17.31
Bid-YTW : 5.83 %

BAM.PR.R FixedReset Quote: 14.85 – 15.08
Spot Rate : 0.2300
Average : 0.1479

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-17
Maturity Price : 14.85
Evaluated at bid price : 14.85
Bid-YTW : 5.11 %

BAM.PR.X FixedReset Quote: 13.43 – 13.75
Spot Rate : 0.3200
Average : 0.2400

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-17
Maturity Price : 13.43
Evaluated at bid price : 13.43
Bid-YTW : 4.96 %

BAM.PF.E FixedReset Quote: 17.90 – 18.10
Spot Rate : 0.2000
Average : 0.1470

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-17
Maturity Price : 17.90
Evaluated at bid price : 17.90
Bid-YTW : 4.95 %

Market Action

May 16, 2016

The BoC has released the Bank of Canada Review – Spring 2016.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 4.66 % 5.67 % 12,333 17.07 1 0.6250 % 1,692.5
FixedFloater 6.62 % 5.74 % 18,307 16.79 1 0.0000 % 3,052.8
Floater 4.52 % 4.75 % 43,664 15.90 4 -0.1911 % 1,716.9
OpRet 0.00 % 0.00 % 0 0.00 0 0.1906 % 2,819.5
SplitShare 4.93 % 5.47 % 82,625 2.46 7 0.1906 % 3,299.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1906 % 2,574.2
Perpetual-Premium 5.77 % -10.51 % 78,439 0.08 6 0.0394 % 2,596.0
Perpetual-Discount 5.48 % 5.59 % 102,937 14.49 33 0.2506 % 2,677.8
FixedReset 5.21 % 4.74 % 168,276 7.48 88 -0.1845 % 1,965.0
Deemed-Retractible 5.16 % 5.67 % 131,472 6.77 33 0.1590 % 2,663.8
FloatingReset 3.16 % 5.15 % 25,182 5.29 17 0.1732 % 2,083.1
Performance Highlights
Issue Index Change Notes
CM.PR.Q FixedReset -3.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-16
Maturity Price : 18.93
Evaluated at bid price : 18.93
Bid-YTW : 4.67 %
BIP.PR.A FixedReset -2.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-16
Maturity Price : 18.89
Evaluated at bid price : 18.89
Bid-YTW : 5.80 %
IFC.PR.C FixedReset -2.19 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.90
Bid-YTW : 8.10 %
BMO.PR.Y FixedReset -1.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-16
Maturity Price : 19.75
Evaluated at bid price : 19.75
Bid-YTW : 4.43 %
CU.PR.C FixedReset -1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-16
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 4.36 %
TD.PF.E FixedReset -1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-16
Maturity Price : 20.67
Evaluated at bid price : 20.67
Bid-YTW : 4.38 %
IFC.PR.A FixedReset -1.29 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.31
Bid-YTW : 9.60 %
NA.PR.S FixedReset -1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-16
Maturity Price : 18.46
Evaluated at bid price : 18.46
Bid-YTW : 4.42 %
CIU.PR.A Perpetual-Discount 1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-16
Maturity Price : 21.25
Evaluated at bid price : 21.25
Bid-YTW : 5.43 %
FTS.PR.I FloatingReset 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-16
Maturity Price : 11.70
Evaluated at bid price : 11.70
Bid-YTW : 4.21 %
SLF.PR.J FloatingReset 1.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.00
Bid-YTW : 10.54 %
HSE.PR.B FloatingReset 1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-16
Maturity Price : 10.35
Evaluated at bid price : 10.35
Bid-YTW : 5.51 %
FTS.PR.G FixedReset 1.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-16
Maturity Price : 16.61
Evaluated at bid price : 16.61
Bid-YTW : 4.45 %
GWO.PR.N FixedReset 1.47 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.85
Bid-YTW : 9.95 %
GWO.PR.O FloatingReset 1.56 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.00
Bid-YTW : 10.37 %
HSE.PR.A FixedReset 3.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-16
Maturity Price : 11.65
Evaluated at bid price : 11.65
Bid-YTW : 5.26 %
Volume Highlights
Issue Index Shares
Traded
Notes
BAM.PR.K Floater 69,200 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-16
Maturity Price : 10.06
Evaluated at bid price : 10.06
Bid-YTW : 4.75 %
BAM.PF.H FixedReset 49,818 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-31
Maturity Price : 25.00
Evaluated at bid price : 26.02
Bid-YTW : 4.19 %
NA.PR.X FixedReset 49,091 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-15
Maturity Price : 25.00
Evaluated at bid price : 26.20
Bid-YTW : 4.54 %
MFC.PR.O FixedReset 44,088 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-06-19
Maturity Price : 25.00
Evaluated at bid price : 26.00
Bid-YTW : 4.63 %
BAM.PR.R FixedReset 39,594 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-16
Maturity Price : 14.95
Evaluated at bid price : 14.95
Bid-YTW : 5.08 %
BAM.PF.B FixedReset 32,625 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-16
Maturity Price : 17.55
Evaluated at bid price : 17.55
Bid-YTW : 5.01 %
There were 40 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
CM.PR.Q FixedReset Quote: 18.93 – 19.50
Spot Rate : 0.5700
Average : 0.3855

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-16
Maturity Price : 18.93
Evaluated at bid price : 18.93
Bid-YTW : 4.67 %

ALB.PR.C SplitShare Quote: 26.05 – 26.88
Spot Rate : 0.8300
Average : 0.6523

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-02-28
Maturity Price : 25.67
Evaluated at bid price : 26.05
Bid-YTW : 2.58 %

CU.PR.C FixedReset Quote: 18.00 – 18.43
Spot Rate : 0.4300
Average : 0.2878

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-16
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 4.36 %

CU.PR.I FixedReset Quote: 25.45 – 25.93
Spot Rate : 0.4800
Average : 0.3824

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-01
Maturity Price : 25.00
Evaluated at bid price : 25.45
Bid-YTW : 4.04 %

SLF.PR.H FixedReset Quote: 16.12 – 16.69
Spot Rate : 0.5700
Average : 0.4754

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.12
Bid-YTW : 8.96 %

TRP.PR.I FloatingReset Quote: 10.75 – 12.28
Spot Rate : 1.5300
Average : 1.4562

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-16
Maturity Price : 10.75
Evaluated at bid price : 10.75
Bid-YTW : 4.83 %

Market Action

May 13, 2016

Assiduous Readers will remember my interest in the minimum wage debate and my position that an increase in the minimum wage is desirable, not because of any bleating about fairness, but because this will help to increase productivity as lower-skill jobs are automated. This automation is well-illustrated by McDonalds self-ordering kiosks in Europe; the issue was further discussed on August 6, 2015. We now have another data point – the hamburger chain Wendy’s is bringing in more self-ordering kiosks to reduce labour costs:

Wendy’s (WEN) said that self-service ordering kiosks will be made available across its 6,000-plus restaurants in the second half of the year as minimum wage hikes and a tight labor market push up wages.

It will be up to franchisees whether to deploy the labor-saving technology, but Wendy’s President Todd Penegor did note that some franchise locations have been raising prices to offset wage hikes.

McDonald’s (MCD) has been testing self-service kiosks. But Wendy’s, which has been vocal about embracing labor-saving technology, is launching the biggest potential expansion.

Wendy’s Penegor said company-operated stores, only about 10% of the total, are seeing wage inflation of 5% to 6%, driven both by the minimum wage and some by the need to offer a competitive wage “to access good labor.”
…
In addition to self-order kiosks, the company is also getting ready to move beyond the testing phase with labor-saving mobile ordering and mobile payment available systemwide by the end of the year. Yum Brands and McDonald’s already have mobile ordering apps.

… and Assiduous Reader SM draws my attention to drone racing:

With the drone industry charged, Mountain Dew® and DR1 Racing, announced a global partnership full of industry firsts. Featuring the top drone racing pilots in the world, this newly formed drone racing series marks the first branded partnership and national broadcast for this burgeoning sport. Headlining the series, the DR1 Invitational presented by Mountain Dew will air this August in a one-hour broadcast special. DR1 will also be the first truly live drone series to stream globally on Twitch, the world’s leading social video platform and community for gamers.
…
The DR1 Invitational presented by Mountain Dew will showcase 12 of the top drone racing pilots in the world as they compete for the title at the iconic Sepulveda Dam in Los Angeles this summer. Pilots, who control drones from the top of the dam, will face down a gauntlet of environmental and man-made obstacles as they fly their drones at speeds of more than 80 MPH while spectators watch on from above.

Sounds great, but best of all would be a demolition derby! Have a field – say the size of a football field – with a large hoop at each end. Go through the hoops alternately. Most hoop passages in twenty minutes wins. I’d buy tickets for that!

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 4.69 % 5.70 % 11,720 17.03 1 0.0000 % 1,682.0
FixedFloater 6.62 % 5.74 % 18,930 16.80 1 -0.4854 % 3,052.8
Floater 4.51 % 4.73 % 43,819 15.94 4 0.0717 % 1,720.1
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0589 % 2,814.1
SplitShare 4.94 % 5.47 % 80,008 3.96 7 -0.0589 % 3,293.0
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0589 % 2,569.3
Perpetual-Premium 5.77 % -10.28 % 79,408 0.08 6 -0.0066 % 2,595.0
Perpetual-Discount 5.49 % 5.58 % 102,536 14.51 33 0.1860 % 2,671.1
FixedReset 5.19 % 4.70 % 168,453 7.42 88 -0.1390 % 1,968.7
Deemed-Retractible 5.16 % 5.66 % 129,257 6.77 33 -0.0013 % 2,659.6
FloatingReset 3.16 % 5.19 % 23,705 5.29 17 0.1802 % 2,079.5
Performance Highlights
Issue Index Change Notes
HSE.PR.G FixedReset -3.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-13
Maturity Price : 18.75
Evaluated at bid price : 18.75
Bid-YTW : 5.83 %
NA.PR.Q FixedReset -1.57 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.13
Bid-YTW : 4.83 %
HSE.PR.C FixedReset -1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-13
Maturity Price : 17.10
Evaluated at bid price : 17.10
Bid-YTW : 5.90 %
TD.PR.T FloatingReset -1.48 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.28
Bid-YTW : 5.19 %
FTS.PR.H FixedReset -1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-13
Maturity Price : 13.02
Evaluated at bid price : 13.02
Bid-YTW : 4.34 %
MFC.PR.C Deemed-Retractible -1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.01
Bid-YTW : 7.13 %
MFC.PR.K FixedReset -1.34 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.45
Bid-YTW : 7.44 %
TD.PR.S FixedReset -1.31 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.56
Bid-YTW : 4.75 %
HSE.PR.E FixedReset -1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-13
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 5.77 %
TRP.PR.G FixedReset -1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-13
Maturity Price : 19.35
Evaluated at bid price : 19.35
Bid-YTW : 4.86 %
MFC.PR.L FixedReset -1.26 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.76
Bid-YTW : 7.32 %
MFC.PR.H FixedReset -1.25 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.25
Bid-YTW : 6.29 %
MFC.PR.I FixedReset -1.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.37
Bid-YTW : 6.66 %
MFC.PR.M FixedReset -1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.20
Bid-YTW : 7.20 %
TRP.PR.C FixedReset 1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-13
Maturity Price : 12.00
Evaluated at bid price : 12.00
Bid-YTW : 4.70 %
CU.PR.F Perpetual-Discount 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-13
Maturity Price : 20.92
Evaluated at bid price : 20.92
Bid-YTW : 5.39 %
TRP.PR.B FixedReset 1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-13
Maturity Price : 11.50
Evaluated at bid price : 11.50
Bid-YTW : 4.42 %
BAM.PR.X FixedReset 1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-13
Maturity Price : 13.71
Evaluated at bid price : 13.71
Bid-YTW : 4.85 %
TD.PF.F Perpetual-Discount 1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-13
Maturity Price : 24.12
Evaluated at bid price : 24.50
Bid-YTW : 5.02 %
PWF.PR.Q FloatingReset 2.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-13
Maturity Price : 12.57
Evaluated at bid price : 12.57
Bid-YTW : 4.25 %
TRP.PR.A FixedReset 3.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-13
Maturity Price : 14.59
Evaluated at bid price : 14.59
Bid-YTW : 4.76 %
SLF.PR.J FloatingReset 4.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.85
Bid-YTW : 10.69 %
BIP.PR.A FixedReset 8.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-13
Maturity Price : 19.40
Evaluated at bid price : 19.40
Bid-YTW : 5.64 %
Volume Highlights
Issue Index Shares
Traded
Notes
FTS.PR.H FixedReset 233,200 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-13
Maturity Price : 13.02
Evaluated at bid price : 13.02
Bid-YTW : 4.34 %
TRP.PR.J FixedReset 60,016 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-31
Maturity Price : 25.00
Evaluated at bid price : 25.75
Bid-YTW : 4.80 %
NA.PR.X FixedReset 55,941 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-15
Maturity Price : 25.00
Evaluated at bid price : 26.22
Bid-YTW : 4.52 %
TRP.PR.C FixedReset 54,200 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-13
Maturity Price : 12.00
Evaluated at bid price : 12.00
Bid-YTW : 4.70 %
RY.PR.Q FixedReset 52,106 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-24
Maturity Price : 25.00
Evaluated at bid price : 26.13
Bid-YTW : 4.47 %
TD.PF.F Perpetual-Discount 32,220 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-13
Maturity Price : 24.12
Evaluated at bid price : 24.50
Bid-YTW : 5.02 %
There were 24 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
POW.PR.B Perpetual-Discount Quote: 23.82 – 24.28
Spot Rate : 0.4600
Average : 0.3133

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-13
Maturity Price : 23.55
Evaluated at bid price : 23.82
Bid-YTW : 5.67 %

IAG.PR.A Deemed-Retractible Quote: 21.68 – 22.20
Spot Rate : 0.5200
Average : 0.3885

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.68
Bid-YTW : 6.76 %

RY.PR.J FixedReset Quote: 19.39 – 19.99
Spot Rate : 0.6000
Average : 0.4712

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-13
Maturity Price : 19.39
Evaluated at bid price : 19.39
Bid-YTW : 4.48 %

BNS.PR.F FloatingReset Quote: 18.51 – 19.55
Spot Rate : 1.0400
Average : 0.9120

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.51
Bid-YTW : 7.57 %

PWF.PR.L Perpetual-Discount Quote: 22.90 – 23.23
Spot Rate : 0.3300
Average : 0.2070

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-13
Maturity Price : 22.66
Evaluated at bid price : 22.90
Bid-YTW : 5.61 %

MFC.PR.I FixedReset Quote: 20.37 – 20.73
Spot Rate : 0.3600
Average : 0.2443

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.37
Bid-YTW : 6.66 %

Market Action

May 12, 2016

Remember the peculiar redemption of REI.PR.A? Assiduous Reader HS draws my attention to a peculiar redemption of UBS-D in the States:

  • •The redemption of UBS-D caused a 52% jump in its value yesterday.
  • •The issue had a 1% yield. There is no financial logic for it to be called.
  • •UBS wasted millions of dollars without explanation

…
UBS-D is not strictly a preferred stock, but a trust preferred security, which gives the parent company some tax advantages. The floating rate was 0.7% above the one-month LIBOR, making the yield at redemption a measly 1.13%.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 4.69 % 5.70 % 12,191 17.03 1 0.0000 % 1,682.0
FixedFloater 6.59 % 5.71 % 19,692 16.84 1 3.0000 % 3,067.7
Floater 4.52 % 4.72 % 45,345 15.97 4 0.0239 % 1,718.9
OpRet 0.00 % 0.00 % 0 0.00 0 -0.1809 % 2,815.7
SplitShare 4.94 % 5.33 % 80,778 1.50 7 -0.1809 % 3,295.0
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.1809 % 2,570.9
Perpetual-Premium 5.77 % -12.02 % 80,632 0.09 6 -0.0591 % 2,595.1
Perpetual-Discount 5.50 % 5.57 % 101,484 14.53 33 -0.0303 % 2,666.1
FixedReset 5.18 % 4.67 % 169,857 13.56 88 -0.2183 % 1,971.4
Deemed-Retractible 5.16 % 5.68 % 129,459 6.78 33 -0.0699 % 2,659.6
FloatingReset 3.13 % 4.87 % 23,740 5.31 17 -0.7851 % 2,075.7
Performance Highlights
Issue Index Change Notes
BIP.PR.A FixedReset -7.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-12
Maturity Price : 17.83
Evaluated at bid price : 17.83
Bid-YTW : 6.13 %
SLF.PR.J FloatingReset -4.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.33
Bid-YTW : 11.21 %
TRP.PR.I FloatingReset -4.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-12
Maturity Price : 10.75
Evaluated at bid price : 10.75
Bid-YTW : 4.76 %
PWF.PR.Q FloatingReset -3.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-12
Maturity Price : 12.28
Evaluated at bid price : 12.28
Bid-YTW : 4.28 %
BNS.PR.F FloatingReset -2.63 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.51
Bid-YTW : 7.53 %
TD.PF.D FixedReset -2.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-12
Maturity Price : 20.15
Evaluated at bid price : 20.15
Bid-YTW : 4.37 %
TRP.PR.A FixedReset -2.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-12
Maturity Price : 14.12
Evaluated at bid price : 14.12
Bid-YTW : 4.91 %
BAM.PF.F FixedReset -2.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-12
Maturity Price : 19.35
Evaluated at bid price : 19.35
Bid-YTW : 4.87 %
BNS.PR.Y FixedReset -1.59 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.77
Bid-YTW : 6.20 %
BAM.PF.G FixedReset -1.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-12
Maturity Price : 19.94
Evaluated at bid price : 19.94
Bid-YTW : 4.75 %
SLF.PR.G FixedReset -1.51 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.33
Bid-YTW : 9.59 %
BAM.PF.A FixedReset -1.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-12
Maturity Price : 18.76
Evaluated at bid price : 18.76
Bid-YTW : 5.01 %
RY.PR.M FixedReset -1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-12
Maturity Price : 19.28
Evaluated at bid price : 19.28
Bid-YTW : 4.38 %
RY.PR.J FixedReset -1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-12
Maturity Price : 19.52
Evaluated at bid price : 19.52
Bid-YTW : 4.44 %
TRP.PR.C FixedReset -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-12
Maturity Price : 11.87
Evaluated at bid price : 11.87
Bid-YTW : 4.74 %
BNS.PR.Z FixedReset -1.00 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.80
Bid-YTW : 6.50 %
IAG.PR.G FixedReset 1.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.95
Bid-YTW : 6.86 %
BMO.PR.S FixedReset 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-12
Maturity Price : 18.78
Evaluated at bid price : 18.78
Bid-YTW : 4.22 %
RY.PR.H FixedReset 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-12
Maturity Price : 18.65
Evaluated at bid price : 18.65
Bid-YTW : 4.17 %
CM.PR.P FixedReset 1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-12
Maturity Price : 18.60
Evaluated at bid price : 18.60
Bid-YTW : 4.18 %
TD.PF.F Perpetual-Discount 1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-12
Maturity Price : 23.79
Evaluated at bid price : 24.15
Bid-YTW : 5.09 %
TRP.PR.F FloatingReset 1.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-12
Maturity Price : 13.30
Evaluated at bid price : 13.30
Bid-YTW : 4.58 %
IFC.PR.A FixedReset 1.56 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.64
Bid-YTW : 9.26 %
BAM.PR.G FixedFloater 3.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-12
Maturity Price : 25.00
Evaluated at bid price : 14.42
Bid-YTW : 5.71 %
Volume Highlights
Issue Index Shares
Traded
Notes
TRP.PR.J FixedReset 105,935 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-31
Maturity Price : 25.00
Evaluated at bid price : 25.77
Bid-YTW : 4.77 %
BMO.PR.Y FixedReset 104,410 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-12
Maturity Price : 20.35
Evaluated at bid price : 20.35
Bid-YTW : 4.29 %
MFC.PR.O FixedReset 53,600 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-06-19
Maturity Price : 25.00
Evaluated at bid price : 26.32
Bid-YTW : 4.72 %
BAM.PR.T FixedReset 34,950 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-12
Maturity Price : 14.90
Evaluated at bid price : 14.90
Bid-YTW : 5.21 %
TRP.PR.D FixedReset 33,500 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-12
Maturity Price : 17.20
Evaluated at bid price : 17.20
Bid-YTW : 4.70 %
SLF.PR.G FixedReset 30,319 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.33
Bid-YTW : 9.59 %
There were 48 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BIP.PR.A FixedReset Quote: 17.83 – 19.00
Spot Rate : 1.1700
Average : 0.7524

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-12
Maturity Price : 17.83
Evaluated at bid price : 17.83
Bid-YTW : 6.13 %

BNS.PR.F FloatingReset Quote: 18.51 – 19.55
Spot Rate : 1.0400
Average : 0.7716

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.51
Bid-YTW : 7.53 %

TRP.PR.I FloatingReset Quote: 10.75 – 12.28
Spot Rate : 1.5300
Average : 1.3264

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-12
Maturity Price : 10.75
Evaluated at bid price : 10.75
Bid-YTW : 4.76 %

TD.PR.T FloatingReset Quote: 21.60 – 22.00
Spot Rate : 0.4000
Average : 0.2402

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.60
Bid-YTW : 4.87 %

PWF.PR.Q FloatingReset Quote: 12.28 – 12.90
Spot Rate : 0.6200
Average : 0.4624

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-05-12
Maturity Price : 12.28
Evaluated at bid price : 12.28
Bid-YTW : 4.28 %

SLF.PR.J FloatingReset Quote: 12.33 – 12.84
Spot Rate : 0.5100
Average : 0.3543

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.33
Bid-YTW : 11.21 %