Category: Market Action

Market Action

March 15, 2016

Bloomberg reminds us that forecasting is hard:

FedForecastMarch16
Click for Big

First National Financial Corporation, proud issuer of FN.PR.A, has been confirmed at Pfd-3 by DBRS:

DBRS Limited (DBRS) has today confirmed the Issuer Rating of First National Financial LP (FNFLP) at BBB, and the ratings for the Senior Unsecured Debt and Class A Preference Shares of First National Financial Corporation (FNFC; DBRS refers to FNFLP and FNFC together as First National or the Company) at BBB (low) and Pfd-3, respectively. The trend on these ratings is Stable. The rating actions follow a detailed review of the Company’s operating results, financial fundamentals and future prospects.
…
DBRS considers First National’s low risk balance sheet as a key factor supporting the ratings. DBRS notes that the Company’s direct credit exposure is limited to a $246 million mortgage investment portfolio (0.9% of total assets as of YE15) it holds on its balance sheet, mostly in commercial bridge lending. Historically, mortgages originated by First National have outperformed the industry with very low delinquency rates. DBRS sees sustaining this performance as critical to the Company’s business model and franchise. While low energy prices continue to be a headwind for the Canadian economy, the impact on the Canadian housing market has largely been regional to date, with some weakening of credit metrics in the western provinces.

DBRS considers First National’s liquidity and funding to be appropriately managed and aligned with its assets. First National funds most of its MUA either through sales to institutional investors (63%) or by securitization (26%), with the remaining MUA mostly warehoused temporarily, awaiting sale or securitization. However, FNF does have some concentration risk, with 13.7% of placement fees and mortgage income being originated from one Canadian financial institution in 2015.
…
DBRS considers First National’s capital levels to be acceptable given the relatively low level of credit risk. At December 31, 2015, the Company’s tangible partner equity-to-tangible assets (excluding securitized mortgages) was 8.8%. However, given the high dividend payout ratio, organic capital generation has been constrained. DBRS would view improved capital retention favourably.

It was a modestly positive day for the Canadian preferred share market, with PerpetualDiscounts gaining 1bp, FixedResets up 11bp and DeemedRetractibles winning 18bp. The Performance Highlights table shows a fair amount of underlying churn. While overall volume was average, there was a lot of volume in the top issues.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

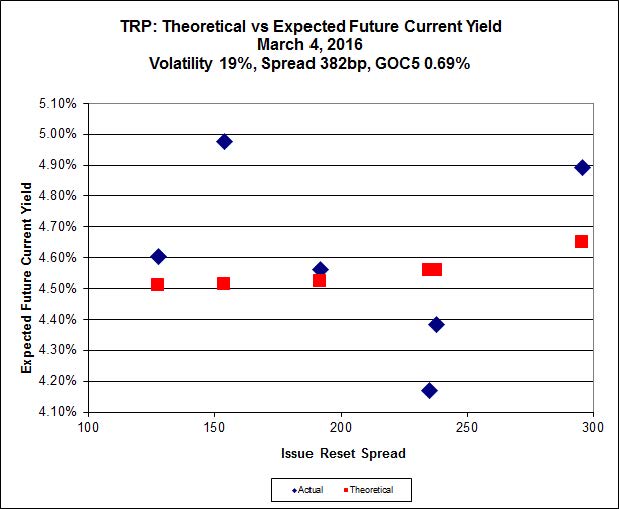
Here’s TRP:

impVol_TRP_160315
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 17.50 to be $1.47 rich, while TRP.PR.G, resetting 2020-11-30 at +296, is $0.84 cheap at its bid price of 18.00.

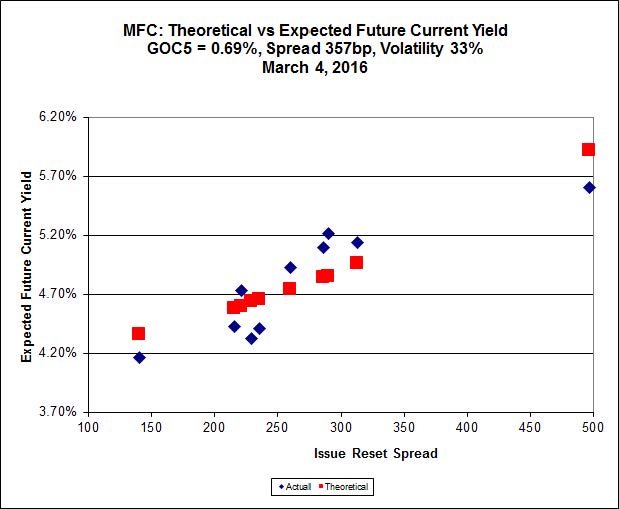
impVol_MFC_160315
Click for Big

Most expensive is MFC.PR.N, resetting at +230bp on 2020-3-19, bid at 17.28 to be 0.78 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 17.61 to be 1.38 cheap.

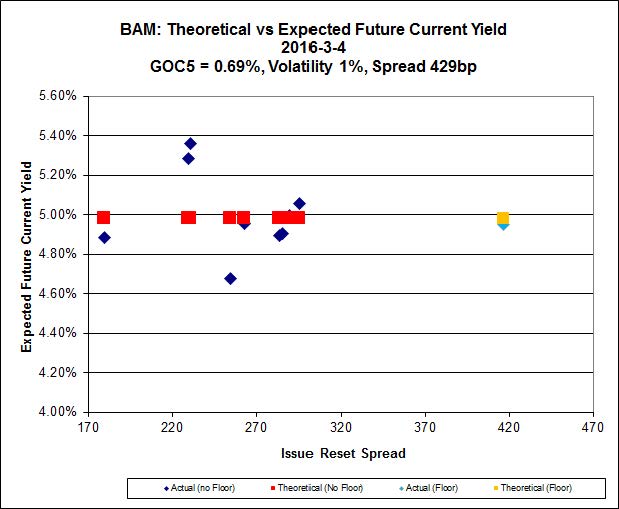
impVol_BAM_160315
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 14.08 to be $1.00 cheap. BAM.PF.E, resetting at +255 on 2020-3-31 is bid at 17.40 and appears to be $1.04 rich.

impVol_FTS_160315
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 15.30 looks $0.48 expensive and resets 2019-3-1. FTS.PR.H, with a spread of +145bp and resetting 2020-6-1, is bid at 11.15 and is $0.53 cheap.

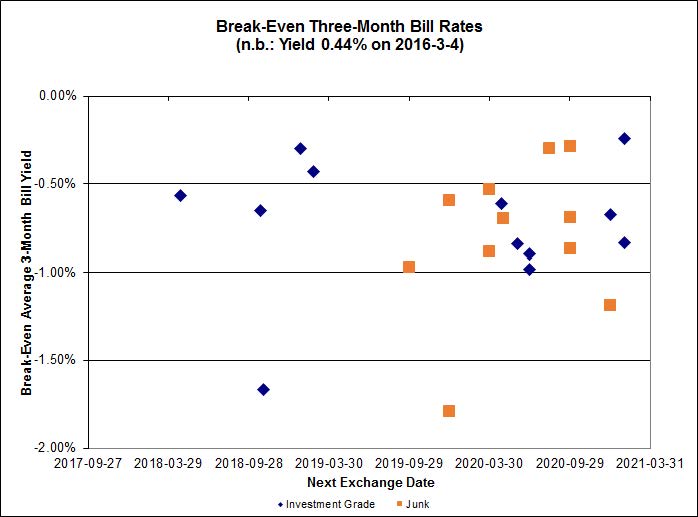
pairs_FR_160315
Click for Big

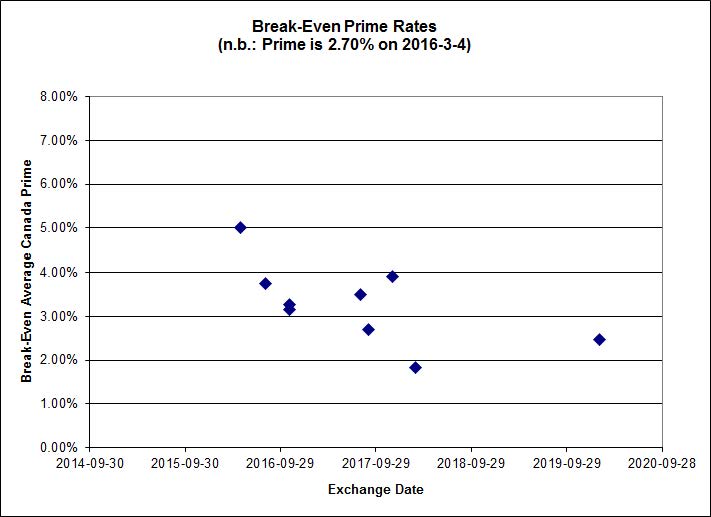
Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.93%, with two outliers below -2.00% and one above 0.00%. There is one junk outlier above 0.00%.

pairs_FF_160315
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.33 % 6.50 % 11,976 16.07 1 -2.4615 % 1,468.4
FixedFloater 7.09 % 6.23 % 24,953 16.05 1 0.0000 % 2,804.3
Floater 4.69 % 4.87 % 67,495 15.76 4 -1.7065 % 1,651.4
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0453 % 2,759.1
SplitShare 4.83 % 5.80 % 71,928 1.65 7 -0.0453 % 3,228.7
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0453 % 2,519.2
Perpetual-Premium 5.81 % -0.25 % 89,056 0.08 6 0.1323 % 2,542.3
Perpetual-Discount 5.71 % 5.75 % 99,684 14.24 33 0.0055 % 2,538.9
FixedReset 5.52 % 5.23 % 195,099 14.20 87 0.1115 % 1,846.9
Deemed-Retractible 5.30 % 5.49 % 116,808 5.11 34 0.1846 % 2,567.5
FloatingReset 3.14 % 5.14 % 38,499 5.43 16 -0.2368 % 1,978.3
Performance Highlights
Issue Index Change Notes
TRP.PR.H FloatingReset -4.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-15
Maturity Price : 8.77
Evaluated at bid price : 8.77
Bid-YTW : 4.99 %
BAM.PR.K Floater -3.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-15
Maturity Price : 9.59
Evaluated at bid price : 9.59
Bid-YTW : 4.93 %
TRP.PR.B FixedReset -2.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-15
Maturity Price : 10.11
Evaluated at bid price : 10.11
Bid-YTW : 5.20 %
BAM.PR.E Ratchet -2.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-15
Maturity Price : 25.00
Evaluated at bid price : 12.68
Bid-YTW : 6.50 %
BAM.PR.B Floater -1.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-15
Maturity Price : 9.70
Evaluated at bid price : 9.70
Bid-YTW : 4.87 %
W.PR.J Perpetual-Discount -1.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-15
Maturity Price : 22.68
Evaluated at bid price : 22.92
Bid-YTW : 6.22 %
PWF.PR.T FixedReset -1.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-15
Maturity Price : 19.06
Evaluated at bid price : 19.06
Bid-YTW : 4.43 %
SLF.PR.H FixedReset -1.55 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.26
Bid-YTW : 9.66 %
MFC.PR.L FixedReset -1.49 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.50
Bid-YTW : 9.06 %
BAM.PR.C Floater -1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-15
Maturity Price : 9.60
Evaluated at bid price : 9.60
Bid-YTW : 4.92 %
BAM.PF.G FixedReset -1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-15
Maturity Price : 17.97
Evaluated at bid price : 17.97
Bid-YTW : 5.37 %
TRP.PR.G FixedReset -1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-15
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 5.29 %
BAM.PF.F FixedReset -1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-15
Maturity Price : 17.99
Evaluated at bid price : 17.99
Bid-YTW : 5.34 %
HSE.PR.G FixedReset -1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-15
Maturity Price : 17.32
Evaluated at bid price : 17.32
Bid-YTW : 6.37 %
BNS.PR.F FloatingReset -1.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.51
Bid-YTW : 8.45 %
W.PR.H Perpetual-Discount -1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-15
Maturity Price : 22.64
Evaluated at bid price : 22.89
Bid-YTW : 6.11 %
RY.PR.W Perpetual-Discount -1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-15
Maturity Price : 23.04
Evaluated at bid price : 23.31
Bid-YTW : 5.29 %
NA.PR.S FixedReset -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-15
Maturity Price : 17.12
Evaluated at bid price : 17.12
Bid-YTW : 4.96 %
TRP.PR.D FixedReset -1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-15
Maturity Price : 16.55
Evaluated at bid price : 16.55
Bid-YTW : 5.10 %
BMO.PR.R FloatingReset -1.00 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.70
Bid-YTW : 4.69 %
MFC.PR.M FixedReset 1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.52
Bid-YTW : 8.40 %
SLF.PR.C Deemed-Retractible 1.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.34
Bid-YTW : 7.35 %
RY.PR.P Perpetual-Discount 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-15
Maturity Price : 24.20
Evaluated at bid price : 24.57
Bid-YTW : 5.38 %
PWF.PR.L Perpetual-Discount 1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-15
Maturity Price : 22.29
Evaluated at bid price : 22.56
Bid-YTW : 5.72 %
SLF.PR.D Deemed-Retractible 1.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.27
Bid-YTW : 7.40 %
PWF.PR.K Perpetual-Discount 1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-15
Maturity Price : 21.66
Evaluated at bid price : 21.91
Bid-YTW : 5.72 %
BAM.PR.T FixedReset 1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-15
Maturity Price : 14.69
Evaluated at bid price : 14.69
Bid-YTW : 5.44 %
FTS.PR.G FixedReset 1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-15
Maturity Price : 15.35
Evaluated at bid price : 15.35
Bid-YTW : 5.03 %
SLF.PR.G FixedReset 1.52 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.40
Bid-YTW : 10.38 %
CM.PR.O FixedReset 1.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-15
Maturity Price : 17.79
Evaluated at bid price : 17.79
Bid-YTW : 4.67 %
BNS.PR.A FloatingReset 1.71 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.76
Bid-YTW : 3.43 %
TD.PF.D FixedReset 1.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-15
Maturity Price : 19.05
Evaluated at bid price : 19.05
Bid-YTW : 4.78 %
VNR.PR.A FixedReset 2.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-15
Maturity Price : 17.40
Evaluated at bid price : 17.40
Bid-YTW : 5.39 %
BAM.PF.B FixedReset 11.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-15
Maturity Price : 16.65
Evaluated at bid price : 16.65
Bid-YTW : 5.37 %
Volume Highlights
Issue Index Shares
Traded
Notes
BNS.PR.G FixedReset 216,325 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-07-25
Maturity Price : 25.00
Evaluated at bid price : 25.26
Bid-YTW : 5.31 %
FTS.PR.H FixedReset 138,200 TD crossed 133,200 at 11.10.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-15
Maturity Price : 11.15
Evaluated at bid price : 11.15
Bid-YTW : 5.22 %
RY.PR.A Deemed-Retractible 135,534 RBC crossed 129,500 at 24.00.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.04
Bid-YTW : 5.30 %
TRP.PR.E FixedReset 121,488 Scotia crossed blocks of 100,000 and 17,800, both at 17.65.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-15
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 4.89 %
POW.PR.G Perpetual-Discount 117,124 Nesbitt crossed 106,100 at 24.40.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-15
Maturity Price : 23.95
Evaluated at bid price : 24.42
Bid-YTW : 5.82 %
GWO.PR.P Deemed-Retractible 113,121 Nesbitt crossed 107,700 at 23.68.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.67
Bid-YTW : 6.19 %
RY.PR.R FixedReset 112,597 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-24
Maturity Price : 25.00
Evaluated at bid price : 25.38
Bid-YTW : 5.24 %
BMO.PR.S FixedReset 112,126 RBC crossed blocks of 55,700 and 53,800, both at 17.60.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-15
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 4.73 %
PWF.PR.P FixedReset 110,715 Nesbitt crossed 104,700 at 12.04.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-15
Maturity Price : 12.00
Evaluated at bid price : 12.00
Bid-YTW : 5.01 %
RY.PR.L FixedReset 110,546 RBC crossed 107,100 at 24.67.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.62
Bid-YTW : 4.24 %
RY.PR.H FixedReset 105,658 RBC crossed 37,100 at 17.47 and 45,000 at 17.40.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-15
Maturity Price : 17.47
Evaluated at bid price : 17.47
Bid-YTW : 4.65 %
There were 32 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
TD.PR.Z FloatingReset Quote: 21.03 – 22.01
Spot Rate : 0.9800
Average : 0.7594

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.03
Bid-YTW : 5.32 %

BAM.PF.F FixedReset Quote: 17.99 – 18.60
Spot Rate : 0.6100
Average : 0.4247

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-15
Maturity Price : 17.99
Evaluated at bid price : 17.99
Bid-YTW : 5.34 %

TRP.PR.I FloatingReset Quote: 10.00 – 11.65
Spot Rate : 1.6500
Average : 1.4798

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-15
Maturity Price : 10.00
Evaluated at bid price : 10.00
Bid-YTW : 5.09 %

TRP.PR.H FloatingReset Quote: 8.77 – 9.29
Spot Rate : 0.5200
Average : 0.3800

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-15
Maturity Price : 8.77
Evaluated at bid price : 8.77
Bid-YTW : 4.99 %

RY.PR.W Perpetual-Discount Quote: 23.31 – 23.77
Spot Rate : 0.4600
Average : 0.3477

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-15
Maturity Price : 23.04
Evaluated at bid price : 23.31
Bid-YTW : 5.29 %

BAM.PR.E Ratchet Quote: 12.68 – 13.90
Spot Rate : 1.2200
Average : 1.1266

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-15
Maturity Price : 25.00
Evaluated at bid price : 12.68
Bid-YTW : 6.50 %

Market Action

March 14, 2016

Nothing happened today.

Wait, I’m wrong. China is drafting a Tobin Tax:

China’s central bank has drafted rules for a tax on foreign-exchange transactions that would help curb currency speculation, according to people with knowledge of the matter.

The initial rate of the so-called Tobin tax may be kept at zero to allow authorities time to refine the rules, said the people, who asked not to be identified as the discussions are private. The tax is not designed to disrupt hedging and other foreign-exchange transactions undertaken by companies, they said.

Imposing a levy on foreign-exchange trading would be the most extreme step yet by policy makers to prevent speculative bets against the Chinese currency, after state-run banks repeatedly intervened to support the yuan and the government intensified a crackdown on capital outflows. A Tobin tax would complicate plans by China to create an international reserve currency and could undermine the leadership’s pledge to increase the role of market forces in the world’s second-largest economy.

It was a mixed day for the Canadian preferred share market, with PerpetualDiscounts down 11bp, FixedResets gaining 10bp and DeemedRetractibles off 7bp. The Performance Highlights table shows highlights of performance. Volume was well below average.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_160314
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 17.55 to be $1.38 rich, while TRP.PR.C, resetting 2021-1-30 at +296, is $0.88 cheap at its bid price of 11.22.

impVol_BAM_160314
Click for Big

Most expensive is MFC.PR.L, resetting at +216bp on 2019-6-19, bid at 16.75 to be 0.82 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 17.73 to be 1.25 cheap.

impVol_BAM_160314
Click for Big

The cheapest issue relative to its peers is BAM.PF.B, resetting at +263bp on 2019-3-31, bid at 14.90 to be $1.72 cheap. BAM.PF.E, resetting at +255 on 2020-3-31 is bid at 17.40 and appears to be $1.12 rich.

impVol_FTS_160314
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 15.45 looks $0.64 expensive and resets 2019-3-1. FTS.PR.H, with a spread of +145bp and resetting 2020-6-1, is bid at 11.20 and is $0.49 cheap.

pairs_FR_160314
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.89%, with one outlier below -2.00%. There are three junk outliers above 0.00% and one below -2.00%.

pairs_FF_160314
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.20 % 6.34 % 11,989 16.26 1 -1.8868 % 1,505.5
FixedFloater 7.09 % 6.23 % 24,465 16.06 1 0.0000 % 2,804.3
Floater 4.61 % 4.76 % 68,643 15.97 4 -0.1946 % 1,680.1
OpRet 0.00 % 0.00 % 0 0.00 0 0.0352 % 2,760.4
SplitShare 4.82 % 5.67 % 72,309 1.65 7 0.0352 % 3,230.2
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0352 % 2,520.3
Perpetual-Premium 5.81 % 3.93 % 82,451 0.08 6 -0.0198 % 2,538.9
Perpetual-Discount 5.71 % 5.79 % 96,248 14.14 33 -0.1149 % 2,538.8
FixedReset 5.53 % 5.23 % 197,117 14.18 87 0.0956 % 1,844.8
Deemed-Retractible 5.31 % 5.52 % 114,690 5.11 34 -0.0687 % 2,562.8
FloatingReset 3.14 % 5.14 % 39,169 5.43 16 -0.2248 % 1,983.0
Performance Highlights
Issue Index Change Notes
BAM.PF.B FixedReset -10.89 % Nonsensical, as the issue traded a whopping 325 shares today in a range of 16.96-97 before closing at 14.90-16.98 (way to go on the $2 spreads, guys!) 5×1. BAM.PF.B was also ludicrous on March 10, so these guys are doing really well! I have not checked whether this lamentable state of affairs is due to inadequate Toronto Stock Exchange reporting or inadequate Toronto Stock Exchange supervision of market-makers.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-14
Maturity Price : 14.90
Evaluated at bid price : 14.90
Bid-YTW : 6.02 %
TRP.PR.I FloatingReset -8.26 % Even a blind squirrel can sometimes find a nut, and sometimes even quotes from the TSX will bear resemblance to reality! The issue traded 200 shares, all at 10.05.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-14
Maturity Price : 10.00
Evaluated at bid price : 10.00
Bid-YTW : 5.09 %
MFC.PR.F FixedReset -2.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.25
Bid-YTW : 11.60 %
BAM.PR.E Ratchet -1.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-14
Maturity Price : 25.00
Evaluated at bid price : 13.00
Bid-YTW : 6.34 %
VNR.PR.A FixedReset -1.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-14
Maturity Price : 16.90
Evaluated at bid price : 16.90
Bid-YTW : 5.55 %
BAM.PF.A FixedReset -1.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-14
Maturity Price : 17.74
Evaluated at bid price : 17.74
Bid-YTW : 5.40 %
BNS.PR.F FloatingReset -1.67 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.71
Bid-YTW : 8.23 %
BNS.PR.D FloatingReset -1.54 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.21
Bid-YTW : 8.27 %
GWO.PR.N FixedReset -1.52 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.00
Bid-YTW : 10.64 %
CIU.PR.C FixedReset -1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-14
Maturity Price : 10.59
Evaluated at bid price : 10.59
Bid-YTW : 5.15 %
CU.PR.F Perpetual-Discount -1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-14
Maturity Price : 19.85
Evaluated at bid price : 19.85
Bid-YTW : 5.72 %
BNS.PR.Z FixedReset -1.43 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.66
Bid-YTW : 7.57 %
CU.PR.E Perpetual-Discount -1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-14
Maturity Price : 21.50
Evaluated at bid price : 21.50
Bid-YTW : 5.75 %
TD.PR.T FloatingReset -1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.08
Bid-YTW : 5.18 %
BAM.PR.T FixedReset -1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-14
Maturity Price : 14.50
Evaluated at bid price : 14.50
Bid-YTW : 5.51 %
BAM.PF.F FixedReset -1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-14
Maturity Price : 18.22
Evaluated at bid price : 18.22
Bid-YTW : 5.27 %
CU.PR.G Perpetual-Discount -1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-14
Maturity Price : 19.85
Evaluated at bid price : 19.85
Bid-YTW : 5.72 %
CU.PR.D Perpetual-Discount -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-14
Maturity Price : 21.33
Evaluated at bid price : 21.60
Bid-YTW : 5.71 %
TD.PR.S FixedReset -1.02 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.27
Bid-YTW : 4.25 %
BNS.PR.P FixedReset 1.00 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.14
Bid-YTW : 3.79 %
CM.PR.Q FixedReset 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-14
Maturity Price : 18.76
Evaluated at bid price : 18.76
Bid-YTW : 4.85 %
TRP.PR.C FixedReset 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-14
Maturity Price : 11.22
Evaluated at bid price : 11.22
Bid-YTW : 5.24 %
BNS.PR.C FloatingReset 1.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.47
Bid-YTW : 5.14 %
BNS.PR.B FloatingReset 1.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.15
Bid-YTW : 5.23 %
CM.PR.O FixedReset 1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-14
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 4.75 %
FTS.PR.K FixedReset 1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-14
Maturity Price : 15.45
Evaluated at bid price : 15.45
Bid-YTW : 4.96 %
CM.PR.P FixedReset 1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-14
Maturity Price : 17.30
Evaluated at bid price : 17.30
Bid-YTW : 4.69 %
TRP.PR.D FixedReset 1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-14
Maturity Price : 16.72
Evaluated at bid price : 16.72
Bid-YTW : 5.04 %
TRP.PR.E FixedReset 1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-14
Maturity Price : 17.55
Evaluated at bid price : 17.55
Bid-YTW : 4.87 %
BNS.PR.A FloatingReset 1.52 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.36
Bid-YTW : 3.74 %
BNS.PR.R FixedReset 1.66 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.28
Bid-YTW : 4.74 %
HSE.PR.A FixedReset 1.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-14
Maturity Price : 9.39
Evaluated at bid price : 9.39
Bid-YTW : 6.78 %
NA.PR.W FixedReset 1.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-14
Maturity Price : 16.40
Evaluated at bid price : 16.40
Bid-YTW : 4.99 %
TRP.PR.G FixedReset 1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-14
Maturity Price : 18.24
Evaluated at bid price : 18.24
Bid-YTW : 5.22 %
BAM.PR.Z FixedReset 1.97 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-14
Maturity Price : 17.63
Evaluated at bid price : 17.63
Bid-YTW : 5.50 %
NA.PR.S FixedReset 2.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-14
Maturity Price : 17.30
Evaluated at bid price : 17.30
Bid-YTW : 4.91 %
BNS.PR.Q FixedReset 2.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.98
Bid-YTW : 4.72 %
BAM.PR.X FixedReset 2.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-14
Maturity Price : 13.11
Evaluated at bid price : 13.11
Bid-YTW : 5.23 %
SLF.PR.J FloatingReset 2.52 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.20
Bid-YTW : 11.08 %
Volume Highlights
Issue Index Shares
Traded
Notes
BNS.PR.G FixedReset 955,584 New issue settled today.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-07-25
Maturity Price : 25.00
Evaluated at bid price : 25.26
Bid-YTW : 5.31 %
PWF.PR.O Perpetual-Premium 101,800 Nesbitt crossed 100,000 at 25.15.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-14
Maturity Price : 24.69
Evaluated at bid price : 25.00
Bid-YTW : 5.88 %
RY.PR.R FixedReset 86,663 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-24
Maturity Price : 25.00
Evaluated at bid price : 25.38
Bid-YTW : 5.23 %
TRP.PR.C FixedReset 59,200 TD crossed 49,800 at 11.35.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-14
Maturity Price : 11.22
Evaluated at bid price : 11.22
Bid-YTW : 5.24 %
PWF.PR.H Perpetual-Premium 53,300 Scotia crossed 50,000 at 25.12.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-14
Maturity Price : 24.84
Evaluated at bid price : 25.07
Bid-YTW : 5.81 %
MFC.PR.G FixedReset 48,575 Scotia crossed 35,000 at 17.78.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.73
Bid-YTW : 8.53 %
There were 23 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BAM.PF.B FixedReset Quote: 14.90 – 16.98
Spot Rate : 2.0800
Average : 1.3764

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-14
Maturity Price : 14.90
Evaluated at bid price : 14.90
Bid-YTW : 6.02 %

TRP.PR.I FloatingReset Quote: 10.00 – 11.65
Spot Rate : 1.6500
Average : 1.2932

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-14
Maturity Price : 10.00
Evaluated at bid price : 10.00
Bid-YTW : 5.09 %

GWO.PR.O FloatingReset Quote: 11.51 – 12.95
Spot Rate : 1.4400
Average : 1.1309

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.51
Bid-YTW : 11.70 %

BAM.PR.E Ratchet Quote: 13.00 – 14.33
Spot Rate : 1.3300
Average : 1.0242

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-14
Maturity Price : 25.00
Evaluated at bid price : 13.00
Bid-YTW : 6.34 %

CM.PR.O FixedReset Quote: 17.50 – 18.18
Spot Rate : 0.6800
Average : 0.4539

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-14
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 4.75 %

VNR.PR.A FixedReset Quote: 16.90 – 17.50
Spot Rate : 0.6000
Average : 0.4105

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-14
Maturity Price : 16.90
Evaluated at bid price : 16.90
Bid-YTW : 5.55 %

Market Action

March 11, 2016

There’s a horrible jobs market in Canada:

Canada’s jobless rate unexpectedly rose to 7.3 per cent in February, the highest level in nearly three years as the hard-hit resources sector shed another round of jobs.

Over all, the country missed analyst forecasts and shed 2,300 positions. This marked the third month the unemployment rate increased, according to Statistics Canada monthly labour report.
…
Nearly 9,000 people lost work in the natural resources sector last month, adding to the tens of thousands of positions that have vanished since oil started plunging mid-2014. Husky Energy Inc. and Cenovus Energy Inc. were among those in the energy sector slashing jobs.
…
Alberta’s jobless rate jumped to 7.9 per cent from 7.4 per cent in January, as more Albertans hunted for work.

But it wasn’t just the oil rich province that bore the brunt of the pain. Saskatchewan lost 7,800 jobs, the most of any of the resource dependent provinces. Ontario also shed 11,000 positions.

British Columbia, which along with Ontario is expected to grow more than the national average, was the only region to significantly add new jobs. Employment in the western province grew by 14,000 due to an increase in trade.
…
Full-time employment fell by 52,000 positions while part time rose by 49,500 spots. Employment in the services-producing sector fell by 44,500 positions, with losses in accommodation and food services.

And this is happening while the chances of a Fed hike are rising:

The bond market is boosting its bets on a Federal Reserve interest-rate increase in June as stocks and oil rally.

As Treasuries head toward a third straight weekly decline, traders now see the probability of a June rate hike as slightly better than a coin flip, according to futures data compiled by Bloomberg. That’s up from a 45 percent chance assigned Thursday and odds below 10 percent seen a month ago. Since 1994, the Fed hasn’t raised rates unless the futures market had priced in at least 60 percent of the move the day before, Bank of America interest-rate strategist Mark Cabana wrote in a March 11 note.
…
There’s almost no market expectation for the Fed to raise rates at its next policy-setting meeting March 15-16, with the futures market implying a 4 percent chance, assuming the fed funds effective rate averages 0.625 percent after the next hike. For the central bank’s June meeting, though, the market-implied probability rose to 51 percent Friday as gains in stocks and crude prices dented demand for Treasuries and other havens.

George Weston Limited has been confirmed at Pfd-3 by DBRS:

DBRS Limited (DBRS) has today confirmed the Issuer Rating and Notes & Debentures rating of George Weston Limited (GWL or the Company) at BBB as well as its Short-Term Issuer Rating at R-2 (high) and its Preferred Shares rating at Pfd-3. All trends are Stable. DBRS notes that, on March xx, 2016, DBRS confirmed the ratings of Loblaw Companies Limited (Loblaw) and changed the trend to Positive from Stable (see separate press release).
…
GWL’s financial profile should remain stable based on its relatively stable balance-sheet debt, sizable cash balance and cash-generating capacity. Capital expenditures (capex) at Weston Foods are expected to remain elevated in the $300 million range in 2016 and to moderate somewhat going forward as the Company continues to invest new capacity, primarily in the United States, as well as replacement of end-of-life assets with more efficient alternatives. As a result, Weston Foods is likely to generate free cash flow deficits in the next one to two years. GWL is no longer committed to maintaining at least $1.0 billion of cash on hand as Loblaw completed its debt repayment plans in F2015. Over the near to medium term, DBRS expects that the Company will use any free cash flow (including dividends and distributions received) as well as cash on hand to continue to invest in growth (organic through Weston Foods capex or through acquisition) as well as to further increase returns to shareholders. DBRS notes that any rating upgrade on Loblaw to BBB (high) will not likely result in a corresponding rating action on the ratings of GWL.

It was a strong day for the Canadian preferred share market, with PerpetualDiscounts up 54bp, FixedResets winning 85bp and DeemedRetractibles gaining 45bp. The Performance Highlights table is lengthy. Volume was average.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_160311
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 17.31 to be $1.36 rich, while TRP.PR.C, resetting 2021-1-30 at +296, is $0.88 cheap at its bid price of 11.10.

impVol_MFC_160311
Click for Big

Most expensive is MFC.PR.O, resetting at +497bp on 2021-6-19, bid at 25.33 to be 0.78 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 17.80 to be 1.16 cheap.

impVol_BAM_160311
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 13.90 to be $1.30 cheap. BAM.PF.E, resetting at +255 on 2020-3-31 is bid at 17.45 and appears to be $1.03 rich.

impVol_FTS_160311
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 15.27 looks $0.49 expensive and resets 2019-3-1. FTS.PR.H, with a spread of +145bp and resetting 2020-6-1, is bid at 11.13 and is $0.54 cheap.

pairs_FR_160311
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.79%, with two outliers below -2.00% and one above 0.00%. Note that the range of the y-axis has changed today. There are two junk outliers above 0.00%.

pairs_FF_160311
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.11 % 6.21 % 12,104 16.41 1 0.0000 % 1,534.4
FixedFloater 7.09 % 6.22 % 24,711 16.07 1 1.3616 % 2,804.3
Floater 4.60 % 4.77 % 69,288 15.95 4 -0.0873 % 1,683.3
OpRet 0.00 % 0.00 % 0 0.00 0 0.1185 % 2,759.4
SplitShare 4.83 % 5.64 % 71,649 1.66 7 0.1185 % 3,229.0
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1185 % 2,519.4
Perpetual-Premium 5.81 % 1.38 % 76,345 0.08 6 -0.0661 % 2,539.4
Perpetual-Discount 5.70 % 5.76 % 96,638 14.19 33 0.5414 % 2,541.7
FixedReset 5.53 % 5.23 % 200,115 14.37 86 0.8486 % 1,843.1
Deemed-Retractible 5.31 % 5.51 % 115,679 5.12 34 0.4522 % 2,564.5
FloatingReset 3.13 % 5.10 % 39,734 5.44 16 0.1450 % 1,987.5
Performance Highlights
Issue Index Change Notes
TRP.PR.G FixedReset -1.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 17.89
Evaluated at bid price : 17.89
Bid-YTW : 5.32 %
TD.PR.Z FloatingReset -1.65 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.90
Bid-YTW : 5.42 %
BNS.PR.A FloatingReset -1.54 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.01
Bid-YTW : 4.02 %
MFC.PR.N FixedReset -1.31 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.27
Bid-YTW : 8.52 %
W.PR.H Perpetual-Discount -1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 22.71
Evaluated at bid price : 23.00
Bid-YTW : 6.07 %
BMO.PR.Q FixedReset -1.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.70
Bid-YTW : 8.55 %
NA.PR.Q FixedReset -1.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.05
Bid-YTW : 5.02 %
NA.PR.W FixedReset 1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 16.12
Evaluated at bid price : 16.12
Bid-YTW : 5.08 %
HSE.PR.E FixedReset 1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 17.60
Evaluated at bid price : 17.60
Bid-YTW : 6.28 %
BMO.PR.R FloatingReset 1.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.10
Bid-YTW : 4.34 %
CU.PR.G Perpetual-Discount 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 20.10
Evaluated at bid price : 20.10
Bid-YTW : 5.65 %
ELF.PR.H Perpetual-Discount 1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 22.65
Evaluated at bid price : 23.00
Bid-YTW : 6.07 %
SLF.PR.B Deemed-Retractible 1.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.67
Bid-YTW : 6.82 %
CU.PR.D Perpetual-Discount 1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 21.50
Evaluated at bid price : 21.83
Bid-YTW : 5.64 %
CM.PR.O FixedReset 1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 17.30
Evaluated at bid price : 17.30
Bid-YTW : 4.80 %
TD.PF.A FixedReset 1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 17.20
Evaluated at bid price : 17.20
Bid-YTW : 4.73 %
CU.PR.C FixedReset 1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 16.15
Evaluated at bid price : 16.15
Bid-YTW : 5.07 %
BAM.PR.T FixedReset 1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 14.69
Evaluated at bid price : 14.69
Bid-YTW : 5.43 %
TD.PF.B FixedReset 1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 17.30
Evaluated at bid price : 17.30
Bid-YTW : 4.69 %
BNS.PR.M Deemed-Retractible 1.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.40
Bid-YTW : 5.10 %
BMO.PR.S FixedReset 1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 4.73 %
SLF.PR.I FixedReset 1.28 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.46
Bid-YTW : 8.50 %
RY.PR.W Perpetual-Discount 1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 23.32
Evaluated at bid price : 23.60
Bid-YTW : 5.22 %
CU.PR.E Perpetual-Discount 1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 21.49
Evaluated at bid price : 21.81
Bid-YTW : 5.65 %
BAM.PR.G FixedFloater 1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 25.00
Evaluated at bid price : 13.40
Bid-YTW : 6.22 %
BAM.PF.C Perpetual-Discount 1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 6.08 %
ELF.PR.F Perpetual-Discount 1.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 22.06
Evaluated at bid price : 22.29
Bid-YTW : 6.04 %
MFC.PR.J FixedReset 1.47 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.30
Bid-YTW : 8.62 %
FTS.PR.G FixedReset 1.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 15.15
Evaluated at bid price : 15.15
Bid-YTW : 5.09 %
BAM.PR.M Perpetual-Discount 1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 19.80
Evaluated at bid price : 19.80
Bid-YTW : 6.02 %
BAM.PF.G FixedReset 1.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 18.25
Evaluated at bid price : 18.25
Bid-YTW : 5.28 %
TRP.PR.F FloatingReset 1.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 11.71
Evaluated at bid price : 11.71
Bid-YTW : 5.10 %
RY.PR.H FixedReset 1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 17.45
Evaluated at bid price : 17.45
Bid-YTW : 4.65 %
BAM.PF.D Perpetual-Discount 1.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 20.20
Evaluated at bid price : 20.20
Bid-YTW : 6.09 %
BMO.PR.W FixedReset 1.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 17.16
Evaluated at bid price : 17.16
Bid-YTW : 4.67 %
BAM.PR.N Perpetual-Discount 1.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 19.84
Evaluated at bid price : 19.84
Bid-YTW : 6.01 %
BIP.PR.A FixedReset 1.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 19.05
Evaluated at bid price : 19.05
Bid-YTW : 5.79 %
VNR.PR.A FixedReset 2.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 17.21
Evaluated at bid price : 17.21
Bid-YTW : 5.44 %
FTS.PR.M FixedReset 2.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 16.95
Evaluated at bid price : 16.95
Bid-YTW : 5.13 %
BAM.PR.R FixedReset 2.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 13.90
Evaluated at bid price : 13.90
Bid-YTW : 5.60 %
CM.PR.P FixedReset 2.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 17.08
Evaluated at bid price : 17.08
Bid-YTW : 4.75 %
BAM.PF.E FixedReset 2.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 17.45
Evaluated at bid price : 17.45
Bid-YTW : 5.15 %
MFC.PR.M FixedReset 2.18 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.32
Bid-YTW : 8.55 %
RY.PR.Z FixedReset 2.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 17.49
Evaluated at bid price : 17.49
Bid-YTW : 4.58 %
SLF.PR.H FixedReset 2.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.54
Bid-YTW : 9.39 %
TRP.PR.D FixedReset 2.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 16.50
Evaluated at bid price : 16.50
Bid-YTW : 5.11 %
RY.PR.M FixedReset 2.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 18.22
Evaluated at bid price : 18.22
Bid-YTW : 4.80 %
GWO.PR.O FloatingReset 2.59 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.50
Bid-YTW : 11.70 %
BAM.PF.A FixedReset 2.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 18.05
Evaluated at bid price : 18.05
Bid-YTW : 5.30 %
BMO.PR.T FixedReset 2.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 17.38
Evaluated at bid price : 17.38
Bid-YTW : 4.64 %
BAM.PF.F FixedReset 2.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 18.45
Evaluated at bid price : 18.45
Bid-YTW : 5.20 %
BAM.PR.X FixedReset 3.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 12.81
Evaluated at bid price : 12.81
Bid-YTW : 5.35 %
HSE.PR.C FixedReset 3.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 15.80
Evaluated at bid price : 15.80
Bid-YTW : 6.46 %
HSE.PR.A FixedReset 4.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 9.23
Evaluated at bid price : 9.23
Bid-YTW : 6.89 %
PWF.PR.Q FloatingReset 4.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 10.75
Evaluated at bid price : 10.75
Bid-YTW : 4.87 %
TD.PF.C FixedReset 5.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 17.10
Evaluated at bid price : 17.10
Bid-YTW : 4.74 %
BAM.PF.B FixedReset 5.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 16.72
Evaluated at bid price : 16.72
Bid-YTW : 5.34 %
Volume Highlights
Issue Index Shares
Traded
Notes
BAM.PR.R FixedReset 132,627 TD crossed 50,000 at 13.87. Scotia crossed 71,600 at the same price.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 13.90
Evaluated at bid price : 13.90
Bid-YTW : 5.60 %
MFC.PR.G FixedReset 124,982 Scotia crossed 115,000 at 17.78.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.80
Bid-YTW : 8.46 %
RY.PR.R FixedReset 99,975 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-24
Maturity Price : 25.00
Evaluated at bid price : 25.34
Bid-YTW : 5.26 %
TD.PF.G FixedReset 76,250 Scotia crossed 25,000 at 25.50. RBC crossed 29,100 at the same price.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 25.49
Bid-YTW : 5.29 %
RY.PR.L FixedReset 53,400 RBC crossed 50,000 at 24.70.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.65
Bid-YTW : 4.21 %
W.PR.H Perpetual-Discount 51,490 Nesbitt crossed 50,000 at 23.20.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 22.71
Evaluated at bid price : 23.00
Bid-YTW : 6.07 %
There were 33 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BAM.PR.E Ratchet Quote: 13.25 – 14.18
Spot Rate : 0.9300
Average : 0.6889

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 25.00
Evaluated at bid price : 13.25
Bid-YTW : 6.21 %

PWF.PR.T FixedReset Quote: 19.26 – 19.79
Spot Rate : 0.5300
Average : 0.3503

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 19.26
Evaluated at bid price : 19.26
Bid-YTW : 4.37 %

BNS.PR.R FixedReset Quote: 22.90 – 23.49
Spot Rate : 0.5900
Average : 0.4379

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.90
Bid-YTW : 5.05 %

W.PR.H Perpetual-Discount Quote: 23.00 – 23.49
Spot Rate : 0.4900
Average : 0.3390

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 22.71
Evaluated at bid price : 23.00
Bid-YTW : 6.07 %

TRP.PR.F FloatingReset Quote: 11.71 – 12.30
Spot Rate : 0.5900
Average : 0.4399

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-11
Maturity Price : 11.71
Evaluated at bid price : 11.71
Bid-YTW : 5.10 %

TD.PR.Y FixedReset Quote: 23.29 – 23.85
Spot Rate : 0.5600
Average : 0.4173

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.29
Bid-YTW : 4.41 %

Market Action

March 10, 2016

Europe continues to ease monetary policy:

In the face of a global debate on whether monetary policy has lost its effectiveness and is even planting the seeds of the next crisis, the ECB has delivered a solid defense of the right and power of central banks to boost growth and inflation at will. The best that can be said for euro-area fiscal policy is that it’s not hampering the recovery, so Draghi has underlined that he won’t wait for others to act.
…
The president announced cuts to all three of the ECB’s rates, bringing the deposit rate to minus 0.4 percent, and a 20 billion-euro ($22 billion) expansion of quantitative easing that for the first time opens the door to purchases of corporate bonds. On top of that, he announced a new four-year loan program that potentially allows banks to be remunerated for taking the ECB’s money if they expand credit to the real economy, in a quartet of operations stretching to 2021.

Draghi’s policy arc has been in defiance of warnings by monetary conservatives, including those in Germany’s Bundesbank since the beginning of his term, up to more recent calls by the Group of 20 nations to shift the burden of growth generation away from monetary policy and toward structural policies or more government investment.

Instead, Draghi sounded resigned when asked about euro-area fiscal policy. That domain spans countries including Spain, France and Italy that are close to their legal deficit limits, and nations that can afford to spend more — read Germany — that have promised voters they won’t do so.

Certainly the OSC is working hard to spark inflation:

The Ontario Securities Commission says its revenues will rise almost 14 per cent in its current fiscal year, leaving the regulator with a surplus of $6.6-million for the year.

The commission published details of its financial outlook Thursday for the fiscal year ending March 31, saying revenue has climbed due to fee changes introduced last year. Those fee adjustments, as well as fee increases introduced in 2013, have returned the commission to strong profitability after it recorded deficits from 2009 to 2013.

The OSC said it expects to take in revenue of $115.8-million in fiscal 2016, a 14-per-cent increase from $101.6-million in fiscal 2015. Expenses are expected to climb sharply to $109-million in the current year from $96.9-million in fiscal 2015, leaving the OSC with an anticipated surplus of $6.6-million this year, up from $4.7-million last year.

Market participants – including listed companies, investment firms and other registrants – pay participation and activity fees to the OSC, which account for more than 99 per cent of its revenue. The OSC adjusted its fee structure last year to base its participation fees on a firm’s most recent annual financial results so they closely track current market conditions.

Perhaps they now have enough to cut another cheque to their good buddies at FAIR Canada!

Canada is now a net creditor of the US – but I would really like to see some currency-adjusted figures!:

Canada is now a creditor to the U.S. for the first time on record, government data show, reflecting the northern nation’s love affair with assets south of the border.

The stock of U.S. assets held by Canadians in the fourth quarter of 2015 — everything from corporate acquisitions to portfolio investments — exceeded assets held by Americans in Canada for the first time since at least 1990, according to quarterly data published Thursday by Statistics Canada.

Easy credit, strong balance sheets, and lack of investing opportunities at home have been the main factors driving Canadian money managers and companies on a shopping spree south of the border. The value of those investments has jumped over the last couple of years as the U.S. dollar has strengthened. U.S. investors, meanwhile, haven’t been reciprocating.
…
Canada’s total net asset position with all countries rose to C$472 billion in the fourth quarter. That’s good news from a creditworthiness point of view. The more indebted a country is to foreigners the more vulnerable it is to financial shocks and Canada’s creditor status helps in times like this when financial markets are volatile, commodity prices are falling and the country is running large current account deficits.

The US is moving to get some more work out of its foreign graduates:

The federal government will publish the rule on Friday, saying that international students earning degrees in science, technology, engineering and mathematics fields in the United States will now be eligible to stay for three years of on-the-job training. This is seven months longer than under the 2008 rule it replaces for the STEM Optional Practical Training program, known as OPT. The new rule will take effect on May 10.
…
This rule is yet another flash point in the controversy over immigration reform. Industry leaders who say they are desperate for skilled talent and those defending the rights of American workers see the training program’s extension as an end-around to stalled reform. But that is all they agree upon.

“It’s an ongoing assault on American workers,” said John Miano, a lawyer for a technology workers’ union in Washington State, whose lawsuit last summer was what forced the government to vacate the previous rule and create a new one, this time for public comment.

There is speculation that TransCanada is contemplating a large acquisition:

TransCanada Corp. would snap up a big chunk of the natural gas business that’s given it the most troublesome competition if it completes a speculated U.S. takeover worth more than $9-billion (U.S.).

TransCanada said on Thursday that it was in talks with a third party, but did not name it or provide any guarantees that it would clinch a deal.

The company is in talks with Houston-based Columbia Pipeline Group Inc., according to the Wall Street Journal, which cited anonymous sources. Columbia is best known for its extensive pipeline network in the Marcellus and Utica natural gas regions in the U.S. Northeast.

Merrill Lynch has come up with some interesting figures on Canadian housing turnover:

Here are three key numbers to keep in mind when you’re talking about Canada’s housing markets: 24, 17 and 10.

Those, according to research from Bank of America Merrill Lynch, highlight the frothy nature of real estate in British Columbia and Ontario, compared with the rest of the country.

They’re the number of existing home sales per 1,000 people.

In B.C., home to Canada’s hottest market, the ratio is 24 per 1,000 in Vancouver. In Ontario, where Toronto is also a hotbed, it’s 17. And in the rest of Canada, it’s just 10, according to the bank’s North America economist, Emanuella Enenajor.

“Although Canada’s housing market may not be in a bubble, the B.C. (British Columbia) market likely is,” Ms. Enenajor said in her report.

It was an off day for the Canadian preferred share market, with PerpetualDiscounts and DeemedRetractibles both off 21bp and FixedResets down 39bp. The Performance Highlights table continues to show a lot of churn. Volume was well below average.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_160310
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 17.25 to be $1.27 rich, while TRP.PR.C, resetting 2021-1-30 at +296, is $0.84 cheap at its bid price of 11.06.

impVol_MFC_160310
Click for Big

Most expensive is MFC.PR.N, resetting at +230bp on 2020-3-19, bid at 17.50 to be 1.01 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 17.78 to be 1.11 cheap.

impVol_BAM_160310
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 13.94 to be $1.11 cheap. BAM.PF.E, resetting at +255 on 2020-3-31 is bid at 17.35 and appears to be $1.06 rich.

impVol_FTS_160310
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 15.12 looks $0.52 expensive and resets 2019-3-1. FTS.PR.H, with a spread of +145bp and resetting 2020-6-1, is bid at 11.09 and is $0.39 cheap.

pairs_FR_160310
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.73%, with three outliers below -1.50% and one above +0.50%. Note that the range of the y-axis has changed today. There are two junk outliers below -1.50%.

pairs_FF_160310
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.11 % 6.21 % 12,271 16.42 1 0.0000 % 1,534.4
FixedFloater 7.19 % 6.31 % 24,098 15.96 1 0.1515 % 2,766.6
Floater 4.55 % 4.77 % 71,868 15.82 4 -0.7646 % 1,684.8
OpRet 0.00 % 0.00 % 0 0.00 0 0.1939 % 2,756.1
SplitShare 4.82 % 5.48 % 70,996 2.64 7 0.1939 % 3,225.2
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1939 % 2,516.4
Perpetual-Premium 5.81 % -0.61 % 74,756 0.08 6 0.0794 % 2,541.1
Perpetual-Discount 5.72 % 5.77 % 96,300 14.18 33 -0.2096 % 2,528.0
FixedReset 5.57 % 5.19 % 201,732 14.28 86 -0.3913 % 1,827.6
Deemed-Retractible 5.33 % 5.66 % 114,768 5.12 34 -0.2115 % 2,553.0
FloatingReset 3.09 % 5.08 % 40,146 5.45 16 0.1835 % 1,984.6
Performance Highlights
Issue Index Change Notes
BAM.PF.B FixedReset -5.59 % Nonsensical, as the issue traded 4,725 shares in a range of 16.75-00 before closing at 16.05-17.19, 8×1. VWAP was 16.89. I have not checked whether this lamentable state of affairs is due to inadequate Toronto Stock Exchange reporting or inadequate Toronto Stock Exchange supervision of market-makers.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-10
Maturity Price : 16.05
Evaluated at bid price : 16.05
Bid-YTW : 5.57 %
TD.PF.C FixedReset -4.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-10
Maturity Price : 16.23
Evaluated at bid price : 16.23
Bid-YTW : 4.89 %
TRP.PR.D FixedReset -4.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-10
Maturity Price : 16.12
Evaluated at bid price : 16.12
Bid-YTW : 5.12 %
MFC.PR.M FixedReset -3.97 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.95
Bid-YTW : 8.80 %
BAM.PR.X FixedReset -3.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-10
Maturity Price : 12.70
Evaluated at bid price : 12.70
Bid-YTW : 5.39 %
TRP.PR.C FixedReset -2.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-10
Maturity Price : 11.06
Evaluated at bid price : 11.06
Bid-YTW : 5.16 %
FTS.PR.H FixedReset -2.97 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-10
Maturity Price : 11.09
Evaluated at bid price : 11.09
Bid-YTW : 5.09 %
TRP.PR.F FloatingReset -2.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-10
Maturity Price : 11.52
Evaluated at bid price : 11.52
Bid-YTW : 5.12 %
HSE.PR.A FixedReset -2.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-10
Maturity Price : 9.14
Evaluated at bid price : 9.14
Bid-YTW : 6.84 %
PWF.PR.T FixedReset -2.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-10
Maturity Price : 19.10
Evaluated at bid price : 19.10
Bid-YTW : 4.31 %
TRP.PR.H FloatingReset -2.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-10
Maturity Price : 9.03
Evaluated at bid price : 9.03
Bid-YTW : 4.76 %
TD.PR.Y FixedReset -2.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.28
Bid-YTW : 4.37 %
FTS.PR.M FixedReset -2.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-10
Maturity Price : 16.60
Evaluated at bid price : 16.60
Bid-YTW : 5.13 %
BMO.PR.Q FixedReset -2.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.90
Bid-YTW : 8.23 %
FTS.PR.K FixedReset -1.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-10
Maturity Price : 15.12
Evaluated at bid price : 15.12
Bid-YTW : 4.94 %
TRP.PR.A FixedReset -1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-10
Maturity Price : 14.00
Evaluated at bid price : 14.00
Bid-YTW : 4.94 %
TRP.PR.G FixedReset -1.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-10
Maturity Price : 18.24
Evaluated at bid price : 18.24
Bid-YTW : 5.12 %
BNS.PR.Z FixedReset -1.57 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.79
Bid-YTW : 7.40 %
RY.PR.Z FixedReset -1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-10
Maturity Price : 17.11
Evaluated at bid price : 17.11
Bid-YTW : 4.57 %
TD.PR.Z FloatingReset -1.53 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.25
Bid-YTW : 5.08 %
BAM.PR.R FixedReset -1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-10
Maturity Price : 13.94
Evaluated at bid price : 13.94
Bid-YTW : 5.59 %
PWF.PR.A Floater -1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-10
Maturity Price : 11.50
Evaluated at bid price : 11.50
Bid-YTW : 4.14 %
BAM.PR.B Floater -1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-10
Maturity Price : 10.06
Evaluated at bid price : 10.06
Bid-YTW : 4.77 %
HSE.PR.C FixedReset -1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-10
Maturity Price : 15.51
Evaluated at bid price : 15.51
Bid-YTW : 6.61 %
MFC.PR.J FixedReset -1.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.05
Bid-YTW : 8.74 %
BAM.PF.E FixedReset -1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-10
Maturity Price : 17.35
Evaluated at bid price : 17.35
Bid-YTW : 5.19 %
BAM.PR.Z FixedReset -1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-10
Maturity Price : 17.52
Evaluated at bid price : 17.52
Bid-YTW : 5.53 %
PWF.PR.P FixedReset 1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-10
Maturity Price : 12.00
Evaluated at bid price : 12.00
Bid-YTW : 4.87 %
GWO.PR.N FixedReset 1.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.22
Bid-YTW : 10.35 %
MFC.PR.G FixedReset 1.31 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.78
Bid-YTW : 8.37 %
BNS.PR.B FloatingReset 1.31 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.87
Bid-YTW : 5.43 %
BMO.PR.R FloatingReset 1.53 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.87
Bid-YTW : 4.50 %
MFC.PR.H FixedReset 1.83 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.50
Bid-YTW : 7.37 %
BNS.PR.A FloatingReset 1.83 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.37
Bid-YTW : 3.70 %
CIU.PR.C FixedReset 2.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-10
Maturity Price : 10.75
Evaluated at bid price : 10.75
Bid-YTW : 4.85 %
MFC.PR.K FixedReset 2.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.05
Bid-YTW : 9.24 %
MFC.PR.F FixedReset 2.37 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.55
Bid-YTW : 11.11 %
IAG.PR.G FixedReset 2.75 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.70
Bid-YTW : 7.63 %
TD.PF.D FixedReset 7.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-10
Maturity Price : 18.54
Evaluated at bid price : 18.54
Bid-YTW : 4.81 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PF.G FixedReset 126,731 RBC sold 19,100 to anonymous at 25.50. Scotai crossed 50,500 at the same price. TD crossed 25,000 at the same price again.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-10
Maturity Price : 23.31
Evaluated at bid price : 25.50
Bid-YTW : 5.27 %
RY.PR.R FixedReset 113,582 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-24
Maturity Price : 25.00
Evaluated at bid price : 25.32
Bid-YTW : 5.27 %
FTS.PR.M FixedReset 106,150 Scotia crossed 99,400 at 17.15.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-10
Maturity Price : 16.60
Evaluated at bid price : 16.60
Bid-YTW : 5.13 %
MFC.PR.M FixedReset 83,179 Scotia crossed 74,800 at 17.80.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.95
Bid-YTW : 8.80 %
RY.PR.Q FixedReset 68,036 Scotia crossed 50,000 at 25.50.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-10
Maturity Price : 23.31
Evaluated at bid price : 25.51
Bid-YTW : 5.20 %
TRP.PR.D FixedReset 66,637 Desjardins crossed 50,000 at 16.90.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-10
Maturity Price : 16.12
Evaluated at bid price : 16.12
Bid-YTW : 5.12 %
There were 22 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
GWO.PR.O FloatingReset Quote: 11.21 – 12.94
Spot Rate : 1.7300
Average : 1.2767

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.21
Bid-YTW : 11.99 %

BAM.PF.B FixedReset Quote: 16.05 – 17.19
Spot Rate : 1.1400
Average : 0.7419

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-10
Maturity Price : 16.05
Evaluated at bid price : 16.05
Bid-YTW : 5.57 %

TD.PF.C FixedReset Quote: 16.23 – 17.14
Spot Rate : 0.9100
Average : 0.5976

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-10
Maturity Price : 16.23
Evaluated at bid price : 16.23
Bid-YTW : 4.89 %

CM.PR.Q FixedReset Quote: 18.57 – 19.30
Spot Rate : 0.7300
Average : 0.4861

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-10
Maturity Price : 18.57
Evaluated at bid price : 18.57
Bid-YTW : 4.81 %

MFC.PR.M FixedReset Quote: 16.95 – 17.59
Spot Rate : 0.6400
Average : 0.3982

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.95
Bid-YTW : 8.80 %

BNS.PR.Z FixedReset Quote: 18.79 – 19.33
Spot Rate : 0.5400
Average : 0.3473

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.79
Bid-YTW : 7.40 %

Market Action

March 9, 2016

Today’s big news was the BoC announcement:

The Bank of Canada today announced that it is maintaining its target for the overnight rate at 1/2 per cent. The Bank Rate is correspondingly 3/4 per cent and the deposit rate is 1/4 per cent.

The global economy is progressing largely as the Bank anticipated in its January Monetary Policy Report (MPR). Financial market volatility, reflecting heightened concerns about economic momentum, appears to be abating. Although downside risks remain, the Bank still expects global growth to strengthen this year and next. Recent data indicate that the U.S. expansion remains broadly on track. At the same time, the low level of oil prices will continue to dampen growth in Canada and other energy-producing countries.

Prices of oil and other commodities have rebounded in recent weeks. In this context, and in light of shifting expectations for monetary policy in Canada and the United States, the Canadian dollar has appreciated from its recent lows. With these movements, both the price of oil and the exchange rate have averaged close to levels assumed in the January MPR.

Canada’s GDP growth in the fourth quarter was not as weak as expected, but the near-term outlook for the economy remains broadly the same as in January. National employment has held up despite job losses in resource-intensive regions, and household spending continues to underpin domestic demand. Non-energy exports are gathering momentum, particularly in sectors that are sensitive to exchange rate movements. However, overall business investment remains very weak due to retrenchment in the resource sector.

Inflation in Canada is evolving broadly as anticipated. The factors that pushed total CPI inflation up to 2 per cent will likely unwind in the months ahead. Measures of core inflation are at or just below 2 per cent, boosted by the temporary effects of past exchange rate depreciation. Material excess capacity in the Canadian economy will continue to dampen inflation.

An assessment of the impact of the upcoming federal budget’s fiscal measures will be incorporated into the Bank’s April projection. All things considered, the risks to the profile for inflation are roughly balanced. Meanwhile, financial vulnerabilities continue to edge higher, in part due to regional shifts in activity associated with the structural adjustment underway in Canada’s economy. The Bank’s Governing Council judges that the overall balance of risks remains within the zone for which the current stance of monetary policy is appropriate, and the target for the overnight rate remains at 1/2 per cent.

Meanwhile, there is a larger than usual international influence on Fed policy:

Investors are betting that the Fed will hold interest rates steady at its March 15-16 meeting as it assess the impact of a shaky global economy and jittery financial markets. A rise in the dollar triggered by easier policy from the ECB and perhaps the BOJ would support a go-slow strategy to raising rates in the U.S.

Asked how the U.S. central bank would respond if the ECB pushed rates further into negative territory, Fed Governor Lael Brainard told CNBC television on March 7 that she was focused on developments in the U.S. She quickly added though that the economy was being buffeted by “powerful cross currents” from abroad and that a further rise in the dollar would hit manufacturing-industry exports.
…
Fed Vice Chairman Stanley Fischer alluded to the central bank’s dollar dilemma when he spoke to the American Economic Association’s annual meeting in San Francisco on Jan. 3.

While policy makers in general recognize the benefits of floating currency rates in redistributing demand throughout the world economy, “they’re not so happy” when they’re the ones “giving up some growth, for instance, by having their exchange rate appreciate,” he said.

And New Zealand has cut its policy rate:

New Zealand’s central bank unexpectedly cut interest rates to a fresh record low and signaled further easing may be needed, saying it’s concerned by a slump in inflation expectations. The kiwi plunged by more than one U.S. cent.

Reserve Bank Governor Graeme Wheeler lowered the official cash rate by a quarter point to 2.25 percent, a move predicted by just two of 17 economists surveyed by Bloomberg. The remainder tipped no change. “Further policy easing may be required to ensure that future average inflation settles near the middle of the target range,” Wheeler said Thursday in Wellington.

Wheeler has resumed easing monetary policy as a stubbornly firm New Zealand dollar, weaker commodity prices and falling price expectations keep inflation beneath his 1-3 percent target. The central bank’s forecasts suggest one further reduction in borrowing costs this year to underpin economic growth and return inflation to its 2 percent target midpoint by early 2018.
…
The New Zealand dollar plunged after the statement, buying 66.58 U.S. cents at 9:38 a.m. in Wellington from 67.80 before the decision. The currency has climbed since late January, muting price pressures, and “a decline would be appropriate given the weakness in export prices,” Wheeler said today.

CalPers, the $284.56-billion dollar pension fund that doesn’t do its own credit analysis, has managed to shake down Moody’s:

Moody’s Investors Service Inc. agreed to pay $130 million to settle claims by the California Public Employee Retirement System over allegedly inflated ratings on residential-mortgage bond deals.

The largest U.S. state pension fund’s accord with Moody’s follows the February 2015 announcement that McGraw Hill Financial Inc.’s Standard & Poor’s would pay $125 million to settle claims by Calpers over grades on subprime mortgages during the run-up to the 2008 financial crisis.
…
McGraw Hill’s pact with Calpers was part of a $1.5 billion settlement to resolve similar allegations from the U.S. Justice Department and more than a dozen states.

Calpers sued the companies along with Fitch Ratings Ltd. in 2009 alleging it sustained losses of as much as $1 billion from “wildly inaccurate” risk assessments. Calpers said it put $1.3 billion into three investment vehicles backed by subprime mortgages in 2006 and 2007. The investments crumbled amid the housing crisis. The pension fund claimed the ratings companies helped fuel the investments and bent rules to give them the highest ratings to boost their profits from issuers, Calpers alleged.

They’d be better off checking their assumptions:

The economic assumptions include an assumed inflation assumption of 2.75 percent compounded annually. The inflation assumption is a component of assumed investment return, assumed wage growth, and assumed future post-retirement cost-of-living increases.

Based upon the asset allocation of the Public Employees’ Retirement Fund (PERF), the assumed investment return (net of administrative and investment expenses) is 7.5 percent per year, compounded annually.

On a positive note, the settlement will provide funds for senior management to give to their buddies, similarly to the scam discussed on April 23, 2012.

The Saudis are looking for a bank loan:

Saudi Arabia is seeking a bank loan of between $6-billion (U.S.) and $8-billion, sources familiar with the matter told Reuters, in what would be the first significant foreign borrowing by the kingdom’s government for over a decade.

Riyadh has asked lenders to submit proposals to extend it a five-year U.S. dollar loan of that size, with an option to increase it, the sources said, to help plug a record budget deficit caused by low oil prices.
…
The kingdom’s budget deficit reached nearly $100-billion last year. The government is currently bridging the gap by drawing down its massive store of foreign assets and issuing domestic bonds. But the assets will only last a few more years at their current rate of decline, while the bond issues have started to strain liquidity in the banking system.

Comic book fans and supporters of civil forfeiture will be pleased to learn that the Junior Justice League has another member:

The NHL ruled that an off-season rape allegation made against Patrick Kane was unfounded in determining that the Chicago Blackhawks star forward will not face any league disciplinary action.

The decision was issued on Wednesday, when the league issued a one-paragraph statement announcing it had completed its independent review of the allegations against Kane. The final step of the investigation occurred on Monday, when Kane met with NHL Commissioner Gary Bettman in New York.

Barry Critchley has enthusiastically endorsed the quixotic bid to get RON.PR.A taken out at par. I have updated the PrefBlog report on this week’s development.

It was a mixed day for the Canadian preferred share market, with PerpetualDiscounts gaining 2bp, FixedResets up 37bp and DeemedRetractibles off 26bp. The Performance Highlights table is lengthy, with numerous TRP and HSE issues at the top of the list. Volume was below average.

PerpetualDiscounts now yield 5.76%, equivalent to 7.49% interest at the standard equivalency factor of 1.3x. Long corporates now yield about 4.25%, so the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) is now about 325bp, equal to the spread reported on March 2.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_160309
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 17.30 to be $0.99 rich, while TRP.PR.C, resetting 2021-1-30 at +296, is $0.69 cheap at its bid price of 11.40.

impVol_MFC_160309
Click for Big

Most expensive is MFC.PR.N, resetting at +230bp on 2020-3-19, bid at 17.50 to be 1.08 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 17.55 to be 1.32 cheap.

impVol_BAM_160309
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 13.77 to be $1.29 cheap. BAM.PF.E, resetting at +255 on 2020-3-31 is bid at 17.55 and appears to be $1.15 rich.

impVol_FTS_160309
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 15.40 looks $0.53 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 15.05 and is $0.24 cheap.

pairs_FR_160309
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.95%, with one outlier below -2.00%. There is one junk outlier above 0.00%.

pairs_FF_160309
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.11 % 6.21 % 12,116 16.42 1 0.0000 % 1,534.4
FixedFloater 7.20 % 6.32 % 24,080 15.95 1 0.9946 % 2,762.4
Floater 4.52 % 4.71 % 73,033 15.94 4 0.8191 % 1,697.8
OpRet 0.00 % 0.00 % 0 0.00 0 0.0730 % 2,750.8
SplitShare 4.83 % 5.82 % 71,615 2.64 7 0.0730 % 3,219.0
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0730 % 2,511.6
Perpetual-Premium 5.81 % -0.80 % 77,419 0.08 6 0.1259 % 2,539.1
Perpetual-Discount 5.71 % 5.76 % 98,605 14.20 33 0.0219 % 2,533.3
FixedReset 5.54 % 5.19 % 205,975 14.53 86 0.3709 % 1,834.8
Deemed-Retractible 5.32 % 5.54 % 115,745 5.12 34 -0.2631 % 2,558.4
FloatingReset 3.09 % 4.98 % 40,623 5.45 16 0.5651 % 1,981.0
Performance Highlights
Issue Index Change Notes
TD.PF.D FixedReset -8.12 % Completely nonsensical, as the issue traded 6,646 shares today in a range of 18.50-17 before closing at 17.32-19.30. VWAP was 18.87. Way to go with the $1.98 spreads there, guys! I have not checked whether this lamentable state of affairs is due to inadequate Toronto Stock Exchange reporting or inadequate Toronto Stock Exchange supervision of market-makers.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 17.32
Evaluated at bid price : 17.32
Bid-YTW : 5.16 %
TRP.PR.E FixedReset -3.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 17.30
Evaluated at bid price : 17.30
Bid-YTW : 4.83 %
CIU.PR.C FixedReset -2.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 10.52
Evaluated at bid price : 10.52
Bid-YTW : 4.96 %
TRP.PR.B FixedReset -2.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 10.31
Evaluated at bid price : 10.31
Bid-YTW : 4.93 %
BAM.PF.F FixedReset -1.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 18.36
Evaluated at bid price : 18.36
Bid-YTW : 5.23 %
TRP.PR.D FixedReset -1.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 16.80
Evaluated at bid price : 16.80
Bid-YTW : 4.90 %
BNS.PR.L Deemed-Retractible -1.68 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.04
Bid-YTW : 5.39 %
BAM.PR.N Perpetual-Discount -1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 19.75
Evaluated at bid price : 19.75
Bid-YTW : 6.14 %
BNS.PR.R FixedReset -1.40 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.55
Bid-YTW : 5.30 %
MFC.PR.F FixedReset -1.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.26
Bid-YTW : 11.43 %
BAM.PF.E FixedReset -1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 17.55
Evaluated at bid price : 17.55
Bid-YTW : 5.12 %
GWO.PR.I Deemed-Retractible -1.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.40
Bid-YTW : 7.35 %
VNR.PR.A FixedReset 1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 16.84
Evaluated at bid price : 16.84
Bid-YTW : 5.44 %
MFC.PR.K FixedReset 1.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.68
Bid-YTW : 9.57 %
RY.PR.Z FixedReset 1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 17.38
Evaluated at bid price : 17.38
Bid-YTW : 4.50 %
SLF.PR.I FixedReset 1.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.30
Bid-YTW : 8.52 %
RY.PR.M FixedReset 1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 17.91
Evaluated at bid price : 17.91
Bid-YTW : 4.78 %
IFC.PR.C FixedReset 1.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.40
Bid-YTW : 9.37 %
GWO.PR.O FloatingReset 1.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.20
Bid-YTW : 12.00 %
TD.PF.A FixedReset 1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 17.02
Evaluated at bid price : 17.02
Bid-YTW : 4.67 %
FTS.PR.M FixedReset 1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 16.98
Evaluated at bid price : 16.98
Bid-YTW : 5.01 %
MFC.PR.J FixedReset 1.47 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.25
Bid-YTW : 8.57 %
GWO.PR.N FixedReset 1.48 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.07
Bid-YTW : 10.50 %
BNS.PR.Z FixedReset 1.54 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.09
Bid-YTW : 7.10 %
BMO.PR.Q FixedReset 1.56 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.28
Bid-YTW : 7.83 %
CM.PR.P FixedReset 1.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 16.86
Evaluated at bid price : 16.86
Bid-YTW : 4.70 %
CM.PR.O FixedReset 1.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 17.25
Evaluated at bid price : 17.25
Bid-YTW : 4.70 %
BAM.PR.X FixedReset 1.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 13.16
Evaluated at bid price : 13.16
Bid-YTW : 5.19 %
BAM.PR.Z FixedReset 1.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 17.70
Evaluated at bid price : 17.70
Bid-YTW : 5.47 %
TRP.PR.F FloatingReset 1.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 11.85
Evaluated at bid price : 11.85
Bid-YTW : 4.98 %
FTS.PR.H FixedReset 2.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 11.43
Evaluated at bid price : 11.43
Bid-YTW : 4.93 %
SLF.PR.J FloatingReset 2.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.75
Bid-YTW : 11.52 %
PWF.PR.A Floater 2.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 11.65
Evaluated at bid price : 11.65
Bid-YTW : 4.09 %
IAG.PR.G FixedReset 2.25 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.20
Bid-YTW : 8.01 %
HSE.PR.C FixedReset 2.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 15.70
Evaluated at bid price : 15.70
Bid-YTW : 6.52 %
RY.PR.J FixedReset 2.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 18.44
Evaluated at bid price : 18.44
Bid-YTW : 4.76 %
BIP.PR.A FixedReset 2.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 18.70
Evaluated at bid price : 18.70
Bid-YTW : 5.80 %
BAM.PR.R FixedReset 2.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 14.15
Evaluated at bid price : 14.15
Bid-YTW : 5.51 %
TRP.PR.H FloatingReset 2.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 9.25
Evaluated at bid price : 9.25
Bid-YTW : 4.64 %
TRP.PR.C FixedReset 2.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 11.40
Evaluated at bid price : 11.40
Bid-YTW : 5.01 %
HSE.PR.G FixedReset 3.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 17.69
Evaluated at bid price : 17.69
Bid-YTW : 6.25 %
TRP.PR.I FloatingReset 3.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 10.90
Evaluated at bid price : 10.90
Bid-YTW : 4.59 %
HSE.PR.E FixedReset 3.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 17.69
Evaluated at bid price : 17.69
Bid-YTW : 6.26 %
HSE.PR.A FixedReset 4.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 9.40
Evaluated at bid price : 9.40
Bid-YTW : 6.65 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.R FixedReset 255,385 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-24
Maturity Price : 25.00
Evaluated at bid price : 25.31
Bid-YTW : 5.28 %
RY.PR.H FixedReset 60,655 RBC crossed 40,000 at 17.35.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 17.25
Evaluated at bid price : 17.25
Bid-YTW : 4.59 %
RY.PR.Q FixedReset 60,473 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 23.31
Evaluated at bid price : 25.53
Bid-YTW : 5.20 %
SLF.PR.E Deemed-Retractible 60,419 Desjardins crossed 50,000 at 20.01.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.00
Bid-YTW : 7.64 %
TD.PF.G FixedReset 51,152 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 23.31
Evaluated at bid price : 25.49
Bid-YTW : 5.27 %
FTS.PR.J Perpetual-Discount 46,730 Scotia crossed 20,600 at 21.22. CIBC bought 20,000 from TD at 21.45.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 21.22
Evaluated at bid price : 21.22
Bid-YTW : 5.64 %
There were 26 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
TD.PF.D FixedReset Quote: 17.32 – 19.30
Spot Rate : 1.9800
Average : 1.1657

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 17.32
Evaluated at bid price : 17.32
Bid-YTW : 5.16 %

BAM.PR.G FixedFloater Quote: 13.20 – 14.50
Spot Rate : 1.3000
Average : 0.8361

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 25.00
Evaluated at bid price : 13.20
Bid-YTW : 6.32 %

TRP.PR.E FixedReset Quote: 17.30 – 18.40
Spot Rate : 1.1000
Average : 0.6668

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 17.30
Evaluated at bid price : 17.30
Bid-YTW : 4.83 %

MFC.PR.L FixedReset Quote: 16.32 – 17.27
Spot Rate : 0.9500
Average : 0.6609

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.32
Bid-YTW : 9.12 %

TRP.PR.B FixedReset Quote: 10.31 – 10.95
Spot Rate : 0.6400
Average : 0.4377

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-09
Maturity Price : 10.31
Evaluated at bid price : 10.31
Bid-YTW : 4.93 %

PVS.PR.D SplitShare Quote: 22.71 – 23.24
Spot Rate : 0.5300
Average : 0.3465

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2021-10-08
Maturity Price : 25.00
Evaluated at bid price : 22.71
Bid-YTW : 6.52 %

Market Action

March 8, 2016

Assiduous Readers will remember covered bonds – issues that are guaranteed both by the issuing bank and by a mortgage pool. This results in high ratings – for instance Royal Bank’s covered bonds are rated AAA by DBRS. So … having sovereign-style credit ratings leads to sovereign-style prices:

The first non-government issuer just got paid to borrow in euros.

Berlin Hyp AG sold 500 million euros ($550 million) of three-year covered bonds priced to yield minus 0.162 percent on Tuesday, according to data compiled by Bloomberg. The sale followed the euro area’s first zero-coupon covered bond, sold last month by another German issuer, Landesbank Hessen-Thueringen Girozentrale.
…
In the secondary market, almost 70 percent of German covered bonds have yields of less than zero, according to HSBC data tracking issues of at least 500 million euros. Issuers have extended maturities in the last month to avoid selling bonds with negative yields, said Matthias Melms, an analyst at NordLB.

“There seems too little concern that the market has become more and more distorted or even impaired,” said Bernd Volk, head of European covered and agency bond research at Deutsche Bank AG.

Berlin Hyp is majority-owned by Germany’s savings banks, which are supported by the nation’s states and municipalities.

Assiduous Reader AP writes in with a link to a piece about robot (and drone!) law:

OK, let’s say there’s no hack, but a self-driving car still crashes. What’s the driver’s responsibility?

On the self-driving cars that are being tested right now, the carmakers want the driver paying attention—and right now, they’re not doing it. They’re playing cards. That’s a little scary. And even if driver is well-intentioned, sitting there alert, it’s hard to stay alert for a long drive if you have nothing to do. This is the problem of “unintentional inattention,” and it goes well beyond cars.

Imagine you’ve got robot mall cops. There’s eight of them running around the mall and one guy in a room someplace looking at eight TV screens. He’s bored out of his mind, falling asleep. Then something happens, and it’s his fault because he’s asleep at the switch. Sometimes this is called the “human in the loop” problem. Autonomy seems dangerous, so you put a human in the loop. But that person’s job is very passive. It’s tough to do, and it may be a low-wage, low-status job. Then you blame the person who fails to monitor, even though the system sets them up for the fall. That’s not a good design, but I don’t know what the answer is.

It was a poor day for the Canadian preferred share market, with PerpetualDiscounts off 25bp, FixedResets losing 101bp and DeemedRetractibles down 80b. The Performance Highlights table is predictably lengthy. Volume was well above average.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_160308
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 18.00 to be $1.54 rich, while TRP.PR.C, resetting 2021-1-30 at +296, is $1.11 cheap at its bid price of 11.07.

impVol_MFC_160308
Click for Big

Most expensive is MFC.PR.N, resetting at +230bp on 2020-3-19, bid at 17.50 to be 1.14 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 17.49 to be 1.33 cheap.

impVol_BAM_160308
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 13.77 to be $1.29 cheap. BAM.PF.E, resetting at +255 on 2020-3-31 is bid at 17.75 and appears to be $1.41 rich.

impVol_FTS_160308
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 15.32 looks $0.58 expensive and resets 2019-3-1. FTS.PR.H, with a spread of +145bp and resetting 2020-6-1, is bid at 11.20 and is $0.31 cheap.

pairs_FR_160308
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -1.02%, with one outlier below -2.00% and two above 0.00%. There are no junk outliers.

pairs_FF_160308
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.11 % 6.21 % 12,617 16.42 1 2.9526 % 1,534.4
FixedFloater 7.27 % 6.38 % 24,247 15.88 1 2.1094 % 2,735.2
Floater 4.55 % 4.75 % 74,148 15.86 4 -1.2372 % 1,684.0
OpRet 0.00 % 0.00 % 0 0.00 0 0.0471 % 2,748.8
SplitShare 4.84 % 5.73 % 73,249 2.64 7 0.0471 % 3,216.6
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0471 % 2,509.7
Perpetual-Premium 5.82 % 0.80 % 75,293 0.08 6 -0.1521 % 2,535.9
Perpetual-Discount 5.71 % 5.78 % 100,198 14.13 33 -0.2542 % 2,532.8
FixedReset 5.56 % 5.10 % 208,689 14.46 86 -1.0052 % 1,828.0
Deemed-Retractible 5.30 % 5.60 % 115,808 5.13 34 -0.8018 % 2,565.1
FloatingReset 3.11 % 4.89 % 40,945 5.46 16 -0.9745 % 1,969.8
Performance Highlights
Issue Index Change Notes
BAM.PR.Z FixedReset -5.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 17.41
Evaluated at bid price : 17.41
Bid-YTW : 5.57 %
FTS.PR.G FixedReset -4.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 15.02
Evaluated at bid price : 15.02
Bid-YTW : 5.00 %
FTS.PR.H FixedReset -4.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 11.20
Evaluated at bid price : 11.20
Bid-YTW : 5.04 %
TRP.PR.I FloatingReset -4.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 10.51
Evaluated at bid price : 10.51
Bid-YTW : 4.76 %
BAM.PR.R FixedReset -4.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 13.77
Evaluated at bid price : 13.77
Bid-YTW : 5.66 %
TRP.PR.H FloatingReset -4.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 9.00
Evaluated at bid price : 9.00
Bid-YTW : 4.77 %
HSE.PR.A FixedReset -3.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 9.00
Evaluated at bid price : 9.00
Bid-YTW : 6.95 %
BAM.PR.X FixedReset -3.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 12.95
Evaluated at bid price : 12.95
Bid-YTW : 5.27 %
CU.PR.C FixedReset -3.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 15.95
Evaluated at bid price : 15.95
Bid-YTW : 5.00 %
HSE.PR.E FixedReset -3.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 17.04
Evaluated at bid price : 17.04
Bid-YTW : 6.51 %
TRP.PR.B FixedReset -3.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 10.52
Evaluated at bid price : 10.52
Bid-YTW : 4.83 %
TD.PF.A FixedReset -2.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 16.80
Evaluated at bid price : 16.80
Bid-YTW : 4.73 %
NA.PR.W FixedReset -2.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 15.86
Evaluated at bid price : 15.86
Bid-YTW : 5.04 %
VNR.PR.A FixedReset -2.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 16.67
Evaluated at bid price : 16.67
Bid-YTW : 5.49 %
MFC.PR.J FixedReset -2.58 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.00
Bid-YTW : 8.78 %
HSE.PR.C FixedReset -2.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 15.35
Evaluated at bid price : 15.35
Bid-YTW : 6.68 %
BMO.PR.Q FixedReset -2.44 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.00
Bid-YTW : 8.12 %
RY.PR.J FixedReset -2.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 18.01
Evaluated at bid price : 18.01
Bid-YTW : 4.88 %
BNS.PR.B FloatingReset -2.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.50
Bid-YTW : 5.76 %
FTS.PR.K FixedReset -2.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 15.32
Evaluated at bid price : 15.32
Bid-YTW : 4.87 %
TRP.PR.C FixedReset -2.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 11.07
Evaluated at bid price : 11.07
Bid-YTW : 5.16 %
TRP.PR.G FixedReset -2.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 18.40
Evaluated at bid price : 18.40
Bid-YTW : 5.07 %
PWF.PR.A Floater -2.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 11.40
Evaluated at bid price : 11.40
Bid-YTW : 4.18 %
BMO.PR.T FixedReset -2.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 16.91
Evaluated at bid price : 16.91
Bid-YTW : 4.66 %
MFC.PR.B Deemed-Retractible -1.96 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.56
Bid-YTW : 7.43 %
RY.PR.H FixedReset -1.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 17.11
Evaluated at bid price : 17.11
Bid-YTW : 4.63 %
SLF.PR.A Deemed-Retractible -1.89 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.27
Bid-YTW : 7.03 %
RY.PR.M FixedReset -1.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 17.70
Evaluated at bid price : 17.70
Bid-YTW : 4.84 %
NA.PR.S FixedReset -1.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 16.90
Evaluated at bid price : 16.90
Bid-YTW : 4.91 %
MFC.PR.C Deemed-Retractible -1.86 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.07
Bid-YTW : 7.61 %
TRP.PR.D FixedReset -1.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 17.10
Evaluated at bid price : 17.10
Bid-YTW : 4.81 %
PWF.PR.P FixedReset -1.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 11.98
Evaluated at bid price : 11.98
Bid-YTW : 4.88 %
BNS.PR.Z FixedReset -1.78 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.80
Bid-YTW : 7.39 %
MFC.PR.K FixedReset -1.77 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.50
Bid-YTW : 9.73 %
SLF.PR.C Deemed-Retractible -1.76 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.07
Bid-YTW : 7.53 %
TRP.PR.F FloatingReset -1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 11.65
Evaluated at bid price : 11.65
Bid-YTW : 5.06 %
SLF.PR.E Deemed-Retractible -1.67 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.05
Bid-YTW : 7.60 %
BAM.PF.A FixedReset -1.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 17.75
Evaluated at bid price : 17.75
Bid-YTW : 5.38 %
SLF.PR.B Deemed-Retractible -1.60 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.54
Bid-YTW : 6.90 %
SLF.PR.D Deemed-Retractible -1.57 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.01
Bid-YTW : 7.57 %
BNS.PR.F FloatingReset -1.57 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.17
Bid-YTW : 7.68 %
MFC.PR.N FixedReset -1.46 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.50
Bid-YTW : 8.27 %
BMO.PR.S FixedReset -1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 17.09
Evaluated at bid price : 17.09
Bid-YTW : 4.73 %
HSE.PR.G FixedReset -1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 17.15
Evaluated at bid price : 17.15
Bid-YTW : 6.46 %
FTS.PR.M FixedReset -1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 16.75
Evaluated at bid price : 16.75
Bid-YTW : 5.08 %
CM.PR.O FixedReset -1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 16.98
Evaluated at bid price : 16.98
Bid-YTW : 4.78 %
BNS.PR.C FloatingReset -1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.98
Bid-YTW : 5.53 %
FTS.PR.J Perpetual-Discount -1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 21.16
Evaluated at bid price : 21.16
Bid-YTW : 5.66 %
GWO.PR.R Deemed-Retractible -1.34 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.32
Bid-YTW : 7.05 %
CM.PR.P FixedReset -1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 16.60
Evaluated at bid price : 16.60
Bid-YTW : 4.78 %
PWF.PR.L Perpetual-Discount -1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 21.95
Evaluated at bid price : 22.19
Bid-YTW : 5.81 %
SLF.PR.J FloatingReset -1.29 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.50
Bid-YTW : 11.81 %
MFC.PR.M FixedReset -1.29 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.65
Bid-YTW : 8.22 %
RY.PR.Z FixedReset -1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 17.18
Evaluated at bid price : 17.18
Bid-YTW : 4.55 %
GWO.PR.O FloatingReset -1.25 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.06
Bid-YTW : 12.16 %
GWO.PR.P Deemed-Retractible -1.25 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.73
Bid-YTW : 6.14 %
BIP.PR.A FixedReset -1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 18.22
Evaluated at bid price : 18.22
Bid-YTW : 5.96 %
RY.PR.W Perpetual-Discount -1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 22.71
Evaluated at bid price : 23.00
Bid-YTW : 5.36 %
IFC.PR.C FixedReset -1.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.20
Bid-YTW : 9.55 %
TRP.PR.E FixedReset -1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 4.63 %
GWO.PR.H Deemed-Retractible -1.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.49
Bid-YTW : 6.99 %
MFC.PR.H FixedReset -1.19 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.15
Bid-YTW : 7.62 %
MFC.PR.G FixedReset -1.19 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.49
Bid-YTW : 8.60 %
BAM.PR.K Floater -1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 10.01
Evaluated at bid price : 10.01
Bid-YTW : 4.79 %
FTS.PR.F Perpetual-Discount -1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 21.65
Evaluated at bid price : 21.90
Bid-YTW : 5.62 %
BMO.PR.W FixedReset -1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 16.81
Evaluated at bid price : 16.81
Bid-YTW : 4.65 %
BNS.PR.Y FixedReset -1.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.81
Bid-YTW : 7.05 %
BAM.PR.T FixedReset -1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 14.75
Evaluated at bid price : 14.75
Bid-YTW : 5.39 %
BMO.PR.M FixedReset 1.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.50
Bid-YTW : 3.99 %
CIU.PR.A Perpetual-Discount 1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 20.38
Evaluated at bid price : 20.38
Bid-YTW : 5.69 %
TD.PR.Y FixedReset 1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.80
Bid-YTW : 3.94 %
TD.PF.C FixedReset 1.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 16.91
Evaluated at bid price : 16.91
Bid-YTW : 4.68 %
TD.PF.E FixedReset 2.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 19.40
Evaluated at bid price : 19.40
Bid-YTW : 4.71 %
BAM.PR.G FixedFloater 2.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 25.00
Evaluated at bid price : 13.07
Bid-YTW : 6.38 %
BAM.PR.E Ratchet 2.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 25.00
Evaluated at bid price : 13.25
Bid-YTW : 6.21 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.R FixedReset 451,304 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-24
Maturity Price : 25.00
Evaluated at bid price : 25.22
Bid-YTW : 5.35 %
TD.PF.A FixedReset 131,588 RBC crossed 10,000 at 17.15. Desjardins crossed blocks of 16,800 and 100,000 at the same price.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 16.80
Evaluated at bid price : 16.80
Bid-YTW : 4.73 %
RY.PR.Q FixedReset 120,522 TD crossed two blocks of 39,000 each, both at 25.50.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 23.29
Evaluated at bid price : 25.45
Bid-YTW : 5.21 %
NA.PR.S FixedReset 120,516 Nesbitt crossed blocks of 50,000 and 61,600, both at 17.00.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 16.90
Evaluated at bid price : 16.90
Bid-YTW : 4.91 %
CU.PR.I FixedReset 67,932 RBC crossed 50,000 at 25.20.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 23.23
Evaluated at bid price : 25.15
Bid-YTW : 4.38 %
TD.PF.G FixedReset 64,167 TD crossed 39,000 at 25.50.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 23.30
Evaluated at bid price : 25.46
Bid-YTW : 5.28 %
There were 45 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
TD.PR.T FloatingReset Quote: 21.36 – 22.22
Spot Rate : 0.8600
Average : 0.5746

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.36
Bid-YTW : 4.89 %

TRP.PR.H FloatingReset Quote: 9.00 – 9.74
Spot Rate : 0.7400
Average : 0.4833

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 9.00
Evaluated at bid price : 9.00
Bid-YTW : 4.77 %

TD.PF.A FixedReset Quote: 16.80 – 17.39
Spot Rate : 0.5900
Average : 0.3668

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 16.80
Evaluated at bid price : 16.80
Bid-YTW : 4.73 %

BAM.PR.Z FixedReset Quote: 17.41 – 17.99
Spot Rate : 0.5800
Average : 0.3890

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 17.41
Evaluated at bid price : 17.41
Bid-YTW : 5.57 %

GWO.PR.O FloatingReset Quote: 11.06 – 12.00
Spot Rate : 0.9400
Average : 0.7574

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.06
Bid-YTW : 12.16 %

FTS.PR.M FixedReset Quote: 16.75 – 17.30
Spot Rate : 0.5500
Average : 0.3753

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-08
Maturity Price : 16.75
Evaluated at bid price : 16.75
Bid-YTW : 5.08 %

Market Action

March 7, 2015

There’s an interesting story on Bloomberg about the invention of the ETF:

Yet, as [Nathan] Most and [Steven] Bloom were discovering at AMEX in 1988, the SEC had essentially requested the ETF’s very creation. “The theory presented was that it would be possible to create baskets of key stocks available for sale,” says David Ruder, a professor of law at Northwestern University who was SEC chairman from 1987 to 1989. “Those baskets would then be able to be sold without causing the whole market to collapse.” It was just a suggestion, Ruder says, and one the SEC didn’t expect anybody to act on. Bloom remembers another detail he and Most latched onto: He recalls the SEC indicating that if someone wanted to engineer such a product, the agency might grant approval quickly.

The AMEX team dropped everything else and dove in. “We were essentially reverse-engineering what the SEC called for in their report,” Bloom says. “We viewed it as a product proposal being made by the regulators.”
…
Most, who studied physics at the University of California at Los Angeles before serving as a Navy submarine engineer during World War II, ultimately found inspiration from his time in commodities—first as a trader for Pacific Vegetable Oil, then as president of the Pacific Commodities Exchange. As Most knew, commodities are typically stored in warehouses, which issue ­receipts that can then be traded. “You store a commodity and you get a warehouse receipt,” Most later recounted for ETF.com founder Jim Wiandt. “You can sell it; do a lot of things with it. Because you don’t want to be moving the merchandise back and forth all the time, so you keep it in place and you simply transfer the warehouse receipt.”

He and Bloom wondered why that same concept couldn’t be applied to a basket of equities.

It was a superb day for the Canadian preferred share market, with PerpetualDiscounts gaining 40bp, FixedResets winning 155bp and DeemedRetractibles up 51bp. The Performance Highlights table is lengthy. Volume was average.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.26 % 6.39 % 12,740 16.20 1 1.6588 % 1,490.4
FixedFloater 7.42 % 6.51 % 24,637 15.72 1 0.3135 % 2,678.7
Floater 4.50 % 4.71 % 75,114 15.94 4 1.7676 % 1,705.1
OpRet 0.00 % 0.00 % 0 0.00 0 0.0781 % 2,747.5
SplitShare 4.84 % 5.90 % 76,050 2.64 7 0.0781 % 3,215.1
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0781 % 2,508.6
Perpetual-Premium 5.81 % 0.60 % 75,710 0.08 6 -0.0463 % 2,539.8
Perpetual-Discount 5.70 % 5.75 % 100,640 14.24 33 0.4035 % 2,539.2
FixedReset 5.51 % 5.01 % 196,550 14.32 86 1.5516 % 1,846.5
Deemed-Retractible 5.26 % 5.51 % 113,021 5.14 34 0.5145 % 2,585.9
FloatingReset 3.08 % 4.85 % 41,543 5.46 16 1.2605 % 1,989.2
Performance Highlights
Issue Index Change Notes
PWF.PR.Q FloatingReset -2.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 10.25
Evaluated at bid price : 10.25
Bid-YTW : 5.03 %
TD.PF.C FixedReset -1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 16.62
Evaluated at bid price : 16.62
Bid-YTW : 4.76 %
BNS.PR.R FixedReset 1.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.90
Bid-YTW : 4.99 %
HSB.PR.C Deemed-Retractible 1.02 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.76
Bid-YTW : 5.51 %
CM.PR.P FixedReset 1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 16.82
Evaluated at bid price : 16.82
Bid-YTW : 4.71 %
NA.PR.Q FixedReset 1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.49
Bid-YTW : 4.58 %
TRP.PR.C FixedReset 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 11.32
Evaluated at bid price : 11.32
Bid-YTW : 4.96 %
PWF.PR.L Perpetual-Discount 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 22.21
Evaluated at bid price : 22.48
Bid-YTW : 5.74 %
BNS.PR.F FloatingReset 1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.46
Bid-YTW : 7.38 %
BAM.PR.N Perpetual-Discount 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 20.05
Evaluated at bid price : 20.05
Bid-YTW : 6.05 %
BAM.PF.C Perpetual-Discount 1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 20.22
Evaluated at bid price : 20.22
Bid-YTW : 6.12 %
PWF.PR.S Perpetual-Discount 1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 21.40
Evaluated at bid price : 21.40
Bid-YTW : 5.69 %
BMO.PR.Y FixedReset 1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 18.52
Evaluated at bid price : 18.52
Bid-YTW : 4.78 %
BNS.PR.P FixedReset 1.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.09
Bid-YTW : 3.76 %
HSB.PR.D Deemed-Retractible 1.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.61
Bid-YTW : 5.53 %
TD.PF.B FixedReset 1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 17.14
Evaluated at bid price : 17.14
Bid-YTW : 4.62 %
CM.PR.O FixedReset 1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 17.22
Evaluated at bid price : 17.22
Bid-YTW : 4.71 %
BAM.PR.K Floater 1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 10.13
Evaluated at bid price : 10.13
Bid-YTW : 4.73 %
BMO.PR.W FixedReset 1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 16.99
Evaluated at bid price : 16.99
Bid-YTW : 4.60 %
MFC.PR.C Deemed-Retractible 1.39 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.45
Bid-YTW : 7.34 %
TRP.PR.B FixedReset 1.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 10.85
Evaluated at bid price : 10.85
Bid-YTW : 4.68 %
TD.PR.T FloatingReset 1.41 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.55
Bid-YTW : 4.72 %
PWF.PR.P FixedReset 1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 12.20
Evaluated at bid price : 12.20
Bid-YTW : 4.79 %
SLF.PR.I FixedReset 1.42 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.14
Bid-YTW : 8.64 %
TD.PR.Y FixedReset 1.43 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.48
Bid-YTW : 4.20 %
MFC.PR.B Deemed-Retractible 1.50 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.97
Bid-YTW : 7.14 %
CIU.PR.C FixedReset 1.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 10.76
Evaluated at bid price : 10.76
Bid-YTW : 4.84 %
BAM.PR.M Perpetual-Discount 1.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 20.08
Evaluated at bid price : 20.08
Bid-YTW : 6.04 %
BMO.PR.S FixedReset 1.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 17.34
Evaluated at bid price : 17.34
Bid-YTW : 4.66 %
BMO.PR.T FixedReset 1.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 17.26
Evaluated at bid price : 17.26
Bid-YTW : 4.56 %
IFC.PR.A FixedReset 1.54 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.83
Bid-YTW : 11.09 %
SLF.PR.D Deemed-Retractible 1.55 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.33
Bid-YTW : 7.34 %
SLF.PR.C Deemed-Retractible 1.59 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.43
Bid-YTW : 7.27 %
SLF.PR.E Deemed-Retractible 1.59 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.39
Bid-YTW : 7.35 %
SLF.PR.A Deemed-Retractible 1.64 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.68
Bid-YTW : 6.75 %
BAM.PR.E Ratchet 1.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 25.00
Evaluated at bid price : 12.87
Bid-YTW : 6.39 %
SLF.PR.B Deemed-Retractible 1.77 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.89
Bid-YTW : 6.66 %
BAM.PR.R FixedReset 1.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 14.40
Evaluated at bid price : 14.40
Bid-YTW : 5.41 %
BAM.PR.C Floater 1.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 10.08
Evaluated at bid price : 10.08
Bid-YTW : 4.76 %
GWO.PR.O FloatingReset 1.82 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.20
Bid-YTW : 11.99 %
VNR.PR.A FixedReset 1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 17.13
Evaluated at bid price : 17.13
Bid-YTW : 5.34 %
RY.PR.H FixedReset 1.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 17.44
Evaluated at bid price : 17.44
Bid-YTW : 4.54 %
TD.PF.D FixedReset 2.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 18.75
Evaluated at bid price : 18.75
Bid-YTW : 4.76 %
TD.PF.A FixedReset 2.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 17.30
Evaluated at bid price : 17.30
Bid-YTW : 4.59 %
TRP.PR.F FloatingReset 2.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 11.85
Evaluated at bid price : 11.85
Bid-YTW : 4.97 %
BAM.PR.Z FixedReset 2.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 18.45
Evaluated at bid price : 18.45
Bid-YTW : 5.24 %
SLF.PR.H FixedReset 2.35 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.24
Bid-YTW : 9.53 %
TD.PR.Z FloatingReset 2.43 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.52
Bid-YTW : 4.83 %
BIP.PR.A FixedReset 2.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 18.45
Evaluated at bid price : 18.45
Bid-YTW : 5.88 %
BAM.PF.E FixedReset 2.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 17.77
Evaluated at bid price : 17.77
Bid-YTW : 5.05 %
CM.PR.Q FixedReset 2.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 18.62
Evaluated at bid price : 18.62
Bid-YTW : 4.79 %
MFC.PR.I FixedReset 2.64 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.87
Bid-YTW : 8.36 %
FTS.PR.M FixedReset 2.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 16.99
Evaluated at bid price : 16.99
Bid-YTW : 5.01 %
MFC.PR.N FixedReset 2.66 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.76
Bid-YTW : 8.05 %
MFC.PR.K FixedReset 2.67 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.78
Bid-YTW : 9.47 %
NA.PR.S FixedReset 2.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 17.22
Evaluated at bid price : 17.22
Bid-YTW : 4.81 %
GWO.PR.N FixedReset 2.79 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.90
Bid-YTW : 10.67 %
BMO.PR.R FloatingReset 2.82 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.50
Bid-YTW : 4.81 %
MFC.PR.G FixedReset 2.85 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.70
Bid-YTW : 8.42 %
IFC.PR.C FixedReset 2.89 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.40
Bid-YTW : 9.37 %
PWF.PR.A Floater 3.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 11.64
Evaluated at bid price : 11.64
Bid-YTW : 4.09 %
FTS.PR.I FloatingReset 3.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 9.80
Evaluated at bid price : 9.80
Bid-YTW : 4.85 %
IAG.PR.G FixedReset 3.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.95
Bid-YTW : 8.20 %
NA.PR.W FixedReset 3.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 16.30
Evaluated at bid price : 16.30
Bid-YTW : 4.90 %
BAM.PF.F FixedReset 3.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 18.71
Evaluated at bid price : 18.71
Bid-YTW : 5.12 %
MFC.PR.M FixedReset 3.41 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.88
Bid-YTW : 8.03 %
HSE.PR.C FixedReset 3.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 15.75
Evaluated at bid price : 15.75
Bid-YTW : 6.50 %
TRP.PR.H FloatingReset 3.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 9.40
Evaluated at bid price : 9.40
Bid-YTW : 4.57 %
MFC.PR.J FixedReset 4.18 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.45
Bid-YTW : 8.40 %
MFC.PR.H FixedReset 4.19 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.38
Bid-YTW : 7.45 %
FTS.PR.K FixedReset 4.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 15.67
Evaluated at bid price : 15.67
Bid-YTW : 4.75 %
HSE.PR.E FixedReset 4.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 17.60
Evaluated at bid price : 17.60
Bid-YTW : 6.29 %
CU.PR.C FixedReset 4.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 16.55
Evaluated at bid price : 16.55
Bid-YTW : 4.81 %
HSE.PR.G FixedReset 4.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 17.40
Evaluated at bid price : 17.40
Bid-YTW : 6.36 %
FTS.PR.G FixedReset 5.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 15.77
Evaluated at bid price : 15.77
Bid-YTW : 4.75 %
BAM.PR.X FixedReset 5.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 13.45
Evaluated at bid price : 13.45
Bid-YTW : 5.07 %
FTS.PR.H FixedReset 5.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 11.75
Evaluated at bid price : 11.75
Bid-YTW : 4.79 %
BAM.PR.T FixedReset 6.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 14.90
Evaluated at bid price : 14.90
Bid-YTW : 5.33 %
HSE.PR.A FixedReset 6.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 9.35
Evaluated at bid price : 9.35
Bid-YTW : 6.68 %
TRP.PR.I FloatingReset 7.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 11.00
Evaluated at bid price : 11.00
Bid-YTW : 4.48 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.R FixedReset 1,482,632 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-08-24
Maturity Price : 25.00
Evaluated at bid price : 25.23
Bid-YTW : 5.34 %
TRP.PR.C FixedReset 196,412 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 11.32
Evaluated at bid price : 11.32
Bid-YTW : 4.96 %
MFC.PR.O FixedReset 83,165 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-06-19
Maturity Price : 25.00
Evaluated at bid price : 25.25
Bid-YTW : 5.46 %
TD.PF.G FixedReset 82,880 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-30
Maturity Price : 25.00
Evaluated at bid price : 25.52
Bid-YTW : 5.24 %
RY.PR.Q FixedReset 80,143 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 23.31
Evaluated at bid price : 25.52
Bid-YTW : 5.20 %
CCS.PR.C Deemed-Retractible 71,767 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.07
Bid-YTW : 7.44 %
There were 33 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
PWF.PR.Q FloatingReset Quote: 10.25 – 15.39
Spot Rate : 5.1400
Average : 3.3735

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 10.25
Evaluated at bid price : 10.25
Bid-YTW : 5.03 %

BAM.PR.E Ratchet Quote: 12.87 – 14.40
Spot Rate : 1.5300
Average : 0.9047

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 25.00
Evaluated at bid price : 12.87
Bid-YTW : 6.39 %

TD.PF.C FixedReset Quote: 16.62 – 17.47
Spot Rate : 0.8500
Average : 0.5167

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 16.62
Evaluated at bid price : 16.62
Bid-YTW : 4.76 %

TRP.PR.A FixedReset Quote: 14.33 – 15.60
Spot Rate : 1.2700
Average : 0.9390

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 14.33
Evaluated at bid price : 14.33
Bid-YTW : 4.82 %

MFC.PR.I FixedReset Quote: 17.87 – 18.45
Spot Rate : 0.5800
Average : 0.3556

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.87
Bid-YTW : 8.36 %

BMO.PR.T FixedReset Quote: 17.26 – 18.03
Spot Rate : 0.7700
Average : 0.5690

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-07
Maturity Price : 17.26
Evaluated at bid price : 17.26
Bid-YTW : 4.56 %

Market Action

March 4, 2016

Jobs, jobs, jobs!

Employers added more workers in February than projected but wages unexpectedly declined, dashing hopes that reduced slack in the labor market was starting to benefit all Americans.

The 242,000 gain followed a 172,000 rise in January that was larger than previously estimated, a Labor Department report showed Friday. The jobless rate held at 4.9 percent as people entered the labor force and found work. Average hourly earnings dropped, the first monthly decline in more than a year, and workers put in fewer hours.
…
Average hourly earnings dropped by 0.1 percent from the prior month, the first decline since December 2014, the Labor Department’s figures showed. Worker pay increased 2.2 percent over the 12 months ended in February, less than the 2.5 percent forecast in the Bloomberg survey. Wage growth has been hovering just above 2 percent year-over-year on average since the current expansion began in mid-2009.
…
Payrolls at retailers climbed about 55,000 in February after a 62,000 advance a month earlier, while health care employment increased 57,400.

Payrolls at factories declined by 16,000 after a 23,000 gain and construction companies added 19,000 workers.

The participation rate, which shows the share of working-age people in the labor force, jumped to 62.9 percent, the highest since January 2015.

An otherwise interesting article quantifying projected investor losses from negative yields was spoilt by a misconception about the bond market:

As central bankers in Europe and Japan experiment with negative-rate policies to ignite their economies, investors are essentially being charged a fee to own about $7.7 trillion of sovereign debt.

How big of a tax is this on bond buyers? Well, here’s one way to get a sense of it: Investors would lose about 71 billion euros ($78 billion) if they were to buy all of Germany’s negative-yielding bonds coming due in more than two years and held them to maturity, according to calculations by Bloomberg Intelligence analyst David Powell.
…
Of course, this is an entirely hypothetical exercise. Many investors aren’t planning to hold this debt until maturity. Some are counting on yields to go even more negative, meaning that prices would increase, allowing them to get out without losses or even a profit if and when they want to.

It’s the last paragraph, of course, that is complete bullshit. This stuff is Fixed Income. It has a fixed coupon (mostly!) and a fixed maturity date and a fixed redemption price.

Therefore, the loss from today’s price to maturity is fixed. OK, so some investors are hoping prices will increase between now and maturity, if only a little bit and if only for a short while. So what? If current investors in German bonds should be so lucky as to unload their stakes with a 71-billion euro profit (from today’s prices) instead of an equally sized loss, all that means is that the buyers will, between transaction date and maturity, realize a 142-billion euro loss.

Because, you see, this stuff is fixed income.

Quibbling that the central banks / government treasuries could be the buyer is meaningless. In that case the central banks and government treasuries are taking the loss, even if they wish to cast it as a redemption.

There has been some philosophizing over productivity:

It’s a paradox that’s been puzzling economists for a while. How can U.S. productivity growth be slowing down at the same time that innovation in everything from smartphones to 3D printing seems to be speeding up?

A trio of economists from the Federal Reserve and the International Monetary Fund think they have the answer and it’s not particularly pretty. They argue in a new paper that the down-shift in productivity is for real. It’s not a mirage of mis-measurement by government statisticians unable to keep up with rapidly changing technology.
…
The authors — David Byrne from the Fed in Washington, John Fernald from the San Francisco Fed and Marshall Reinsdorf from the International Monetary Fund — also don’t deny that IT has made Americans’ lives easier and more enjoyable in many ways, from calling up directions on Google Maps to trading cat videos on Facebook.

But that doesn’t translate into more economic output. The researchers compare such online services to an old economy innovation: television. It too enhanced Americans’ leisure time but didn’t make them more productive.

There are lots of available critiques of GDP; perhaps the productivity problem is just another one of them.

Matt Levine writes an entertaining piece on the valuation of private equities:

Today’s Wall Street Journal has a terrific story about how mutual funds that bought stakes in large closely held technology companies are now writing down some of those stakes:

BlackRock Inc., Fidelity Investments, T. Rowe Price Group Inc. and Wellington Management run or advise mutual funds that own shares in at least 40 closely held startups valued at $1 billion or more apiece, according to securities filings analyzed by The Wall Street Journal.

For 13 of the startups, at least one mutual-fund firm values its investment at less than what it paid, the Journal’s analysis shows. Those firms are valuing the 13 companies at an average of 28% below their original purchase price.

…
You know what I think! Private markets are the new public markets, and if you want to run a giant company with hundreds of employees, a multibillion-dollar valuation, and millions of dollars raised from public mutual funds, while still calling it a “startup,” you can do that now. (You can even call it a “unicorn,” if “startup” seems a little low-rent.) But what this means is that private companies are the new public companies, and sometimes public companies’ stocks go down. In a world where venture-funded startups exist in a sort of trial-and-error, proof-of-concept phase, and go public when it turns out the concept works, private valuations shouldn’t fluctuate unpredictably: You raise money, your thing works, you raise more money at a higher valuation, your thing scales a bit, and you go public at a yet higher valuation. (Or: You raise money, your thing fails, you send your venture capitalists a note with your condolences, and that is that.) The problems of running an operating business for the long term, with revenue fluctuations and competitive pressures and changing market conditions, get worked out in your stock price as a public company. Sometimes it goes down!

In a world where venture-funded startups are also mutual-fund-funded multibillion-dollar companies with massive established businesses used by millions of people, that’s not the model any more.
…
They [privately held companies] can even avoid the discipline of fluctuating stock prices. Just don’t sell to mutual funds! It is an obvious answer, and private companies have noticed:

Some venture capitalists anticipate further markdowns by mutual funds. That could make some startups more reluctant to seek mutual-fund money, since public disclosure of their valuations is watched so closely.

Assiduous Readers will remember that I expect that sooner or later we’re going to see a gigantic juicy private equity valuation scandal … and then we’ll learn which pension funds and which public investment companies (such as insurers) have been naughty.

It was another superb day for the Canadian preferred share market, with PerpetualDiscounts up 51bp, FixedResets winning 75bp and DeemedRetractibles up 36bp. The Performance Highlights table has only three losers. Volume was well below average.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_160304
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 18.22 to be $1.54 rich, while TRP.PR.C, resetting 2021-1-30 at +296, is $1.16 cheap at its bid price of 11.20.

impVol_MFC_160304
Click for Big

Most expensive is MFC.PR.O, resetting at +497bp on 2021-6-19, bid at 25.25 to be 1.32 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 17.21 to be 1.30 cheap.

impVol_BAM_160304
Click for Big

The cheapest issue relative to its peers is BAM.PR.T, resetting at +231bp on 2017-3-31, bid at 14.00 to be $1.06 cheap. BAM.PF.E, resetting at +255 on 2020-3-31 is bid at 17.33 and appears to be $1.06 rich.

impVol_FTS_160304
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 15.02 looks $0.44 expensive and resets 2019-3-1. FTS.PR.H, with a spread of +145bp and resetting 2020-6-1, is bid at 11.12 and is $0.31 cheap.

pairs_FR_160304
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.96%, with three outliers below -2.00% and one above 0.00%. There are no junk outliers.

pairs_FF_160304
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.34 % 6.49 % 12,958 16.09 1 -0.3150 % 1,466.1
FixedFloater 7.45 % 6.53 % 23,749 15.70 1 -0.0783 % 2,670.3
Floater 4.58 % 4.74 % 77,562 15.88 4 0.5600 % 1,675.5
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0338 % 2,745.4
SplitShare 4.84 % 5.87 % 77,232 2.65 7 -0.0338 % 3,212.6
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0338 % 2,506.6
Perpetual-Premium 5.81 % 0.98 % 76,539 0.08 6 0.0662 % 2,540.9
Perpetual-Discount 5.72 % 5.77 % 101,095 14.15 33 0.5145 % 2,529.0
FixedReset 5.59 % 5.13 % 196,630 14.49 85 0.7490 % 1,818.3
Deemed-Retractible 5.29 % 5.71 % 113,059 5.14 34 0.3586 % 2,572.6
FloatingReset 3.10 % 5.26 % 41,029 5.46 16 0.5543 % 1,964.5
Performance Highlights
Issue Index Change Notes
BAM.PR.T FixedReset -3.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 14.00
Evaluated at bid price : 14.00
Bid-YTW : 5.60 %
HSE.PR.G FixedReset -1.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 16.60
Evaluated at bid price : 16.60
Bid-YTW : 6.61 %
BMO.PR.Q FixedReset -1.39 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.39
Bid-YTW : 7.64 %
RY.PR.I FixedReset 1.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.15
Bid-YTW : 4.55 %
FTS.PR.I FloatingReset 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 9.50
Evaluated at bid price : 9.50
Bid-YTW : 4.98 %
IFC.PR.C FixedReset 1.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.94
Bid-YTW : 9.70 %
BMO.PR.W FixedReset 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 16.77
Evaluated at bid price : 16.77
Bid-YTW : 4.60 %
ELF.PR.G Perpetual-Discount 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 20.08
Evaluated at bid price : 20.08
Bid-YTW : 6.01 %
RY.PR.H FixedReset 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 17.10
Evaluated at bid price : 17.10
Bid-YTW : 4.57 %
VNR.PR.A FixedReset 1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 16.80
Evaluated at bid price : 16.80
Bid-YTW : 5.37 %
SLF.PR.J FloatingReset 1.21 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.69
Bid-YTW : 11.56 %
CU.PR.C FixedReset 1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 15.85
Evaluated at bid price : 15.85
Bid-YTW : 4.95 %
MFC.PR.G FixedReset 1.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.21
Bid-YTW : 8.76 %
TD.PR.Z FloatingReset 1.25 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.01
Bid-YTW : 5.26 %
CU.PR.H Perpetual-Discount 1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 22.94
Evaluated at bid price : 23.35
Bid-YTW : 5.64 %
BAM.PF.C Perpetual-Discount 1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 19.99
Evaluated at bid price : 19.99
Bid-YTW : 6.19 %
TD.PR.S FixedReset 1.42 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.53
Bid-YTW : 3.93 %
MFC.PR.J FixedReset 1.45 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.75
Bid-YTW : 8.93 %
IAG.PR.G FixedReset 1.46 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.40
Bid-YTW : 8.58 %
BIP.PR.A FixedReset 1.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 18.01
Evaluated at bid price : 18.01
Bid-YTW : 5.97 %
MFC.PR.M FixedReset 1.47 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.29
Bid-YTW : 8.46 %
RY.PR.Z FixedReset 1.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 17.25
Evaluated at bid price : 17.25
Bid-YTW : 4.47 %
TRP.PR.E FixedReset 1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 18.22
Evaluated at bid price : 18.22
Bid-YTW : 4.52 %
BAM.PR.M Perpetual-Discount 1.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 19.78
Evaluated at bid price : 19.78
Bid-YTW : 6.13 %
BMO.PR.Y FixedReset 1.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 18.30
Evaluated at bid price : 18.30
Bid-YTW : 4.78 %
BAM.PF.A FixedReset 1.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 17.96
Evaluated at bid price : 17.96
Bid-YTW : 5.25 %
CM.PR.Q FixedReset 1.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 18.15
Evaluated at bid price : 18.15
Bid-YTW : 4.86 %
FTS.PR.F Perpetual-Discount 1.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 21.94
Evaluated at bid price : 22.18
Bid-YTW : 5.55 %
FTS.PR.J Perpetual-Discount 1.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 21.42
Evaluated at bid price : 21.42
Bid-YTW : 5.58 %
BAM.PF.D Perpetual-Discount 1.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 20.15
Evaluated at bid price : 20.15
Bid-YTW : 6.20 %
BAM.PR.N Perpetual-Discount 1.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 19.83
Evaluated at bid price : 19.83
Bid-YTW : 6.11 %
MFC.PR.I FixedReset 1.81 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.41
Bid-YTW : 8.67 %
HSE.PR.A FixedReset 1.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 8.76
Evaluated at bid price : 8.76
Bid-YTW : 6.99 %
BMO.PR.M FixedReset 1.89 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.20
Bid-YTW : 4.20 %
IFC.PR.A FixedReset 2.02 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.62
Bid-YTW : 11.24 %
MFC.PR.L FixedReset 2.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.10
Bid-YTW : 9.26 %
TD.PF.D FixedReset 2.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 18.37
Evaluated at bid price : 18.37
Bid-YTW : 4.80 %
PWF.PR.T FixedReset 2.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 19.70
Evaluated at bid price : 19.70
Bid-YTW : 4.11 %
BNS.PR.C FloatingReset 2.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.22
Bid-YTW : 5.29 %
BAM.PR.Z FixedReset 2.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 18.05
Evaluated at bid price : 18.05
Bid-YTW : 5.29 %
MFC.PR.N FixedReset 2.37 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.30
Bid-YTW : 8.39 %
BAM.PF.F FixedReset 2.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 18.10
Evaluated at bid price : 18.10
Bid-YTW : 5.24 %
TD.PF.E FixedReset 2.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 4.76 %
NA.PR.S FixedReset 2.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 16.76
Evaluated at bid price : 16.76
Bid-YTW : 4.88 %
NA.PR.W FixedReset 2.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 15.80
Evaluated at bid price : 15.80
Bid-YTW : 5.00 %
PWF.PR.A Floater 2.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 11.30
Evaluated at bid price : 11.30
Bid-YTW : 4.21 %
TRP.PR.D FixedReset 3.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 17.51
Evaluated at bid price : 17.51
Bid-YTW : 4.63 %
SLF.PR.H FixedReset 3.19 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.89
Bid-YTW : 9.78 %
FTS.PR.G FixedReset 3.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 15.00
Evaluated at bid price : 15.00
Bid-YTW : 4.93 %
TRP.PR.F FloatingReset 3.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 11.60
Evaluated at bid price : 11.60
Bid-YTW : 5.06 %
CIU.PR.C FixedReset 3.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 10.60
Evaluated at bid price : 10.60
Bid-YTW : 4.80 %
Volume Highlights
Issue Index Shares
Traded
Notes
SLF.PR.H FixedReset 161,200 Scotia crossed 160,000 at 14.52.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.89
Bid-YTW : 9.78 %
RY.PR.Q FixedReset 38,817 RBC crossed 15,000 at 25.52.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 23.29
Evaluated at bid price : 25.45
Bid-YTW : 5.17 %
TD.PF.G FixedReset 35,839 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 23.31
Evaluated at bid price : 25.50
Bid-YTW : 5.23 %
MFC.PR.O FixedReset 35,385 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-06-19
Maturity Price : 25.00
Evaluated at bid price : 25.25
Bid-YTW : 5.45 %
HSE.PR.A FixedReset 34,260 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 8.76
Evaluated at bid price : 8.76
Bid-YTW : 6.99 %
SLF.PR.G FixedReset 32,056 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.30
Bid-YTW : 10.35 %
There were 21 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
HSE.PR.C FixedReset Quote: 15.17 – 18.00
Spot Rate : 2.8300
Average : 1.5785

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 15.17
Evaluated at bid price : 15.17
Bid-YTW : 6.69 %

TD.PR.Z FloatingReset Quote: 21.01 – 22.75
Spot Rate : 1.7400
Average : 1.3684

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.01
Bid-YTW : 5.26 %

TRP.PR.I FloatingReset Quote: 10.25 – 11.99
Spot Rate : 1.7400
Average : 1.4284

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 10.25
Evaluated at bid price : 10.25
Bid-YTW : 4.86 %

BMO.PR.M FixedReset Quote: 23.20 – 23.90
Spot Rate : 0.7000
Average : 0.4183

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.20
Bid-YTW : 4.20 %

FTS.PR.G FixedReset Quote: 15.00 – 15.78
Spot Rate : 0.7800
Average : 0.5113

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 15.00
Evaluated at bid price : 15.00
Bid-YTW : 4.93 %

FTS.PR.H FixedReset Quote: 11.12 – 11.78
Spot Rate : 0.6600
Average : 0.4031

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-04
Maturity Price : 11.12
Evaluated at bid price : 11.12
Bid-YTW : 4.98 %

Market Action

March 3, 2016

It seems there’s another way to increase low-end salaries:

Costco Wholesale Corp. will lift its minimum wage for the first time in nine years, by a $1.50 an hour, as the labor market tightens and competitors start giving workers a raise.

The second-largest U.S. retailer will start paying at least $13-to-$13.50 an hour, up from $11.50-to-$12 an hour, the company said Thursday in a conference call with analysts. The increase will cut its earnings per share in the next three months by 1 cent, and by 2 cents in the following three quarters, the Issaquah, Washington-based company said.

Retailers are under pressure to boost wages as unemployment falls below 5 percent and 14 states have raised their minimum wage this year. Wal-Mart Stores Inc., which operates the Sam’s Club warehouse-style chain, a Costco competitor, lifted its pay floor to $10 an hour this year and gave an increase to more than 1 million workers. Costco didn’t say how many of its 117,000 employees would get a raise.

But some might not sign up with Costco – because the fearmongers are winning:

The declining level of trust among Americans may have contributed to reduced flexibility in the U.S. labor market over the last several decades, according to a Federal Reserve working paper.

In the paper, Fed economists Raven Molloy, Christopher Smith and Riccardo Trezzi, along with University of Notre Dame professor Abigail Wozniak, identify a 10 percent to 15 percent decline in U.S. labor market fluidity — a measure that encompasses workers switching jobs and moving states as well as employers creating or cutting positions — since the early 1980s.

In U.S. states where the share of people who said their trust in strangers fell more steeply, labor mobility registered greater declines, according to the paper. The drop in social trust “may have increased the cost of job search or made both parties in the hiring process more risk averse,” it said.

“Regardless of the cause, less fluidity in the labor market leads to fewer opportunities for workers to renegotiate their current employment arrangements using outside options as leverage or to change jobs,” the authors wrote. That means less scope for wage growth, and that U.S. workers may be more reluctant to quit their jobs, “leading to ‘precautionary’ job holding and again an increase in the likelihood that the unemployed are there involuntarily.”

The paper by Raven S. Molloy, Christopher L. Smith, Riccardo Trezzi, and Abigail Wozniak is titled Understanding Declining Fluidity in the U.S. Labor Market. I would quote from it, but there appears to be some kind of incompatible font problem which gives rise to strange effects when copied.

BMO has redeemed a chunk of sub-debt on its pretend-maturity:

Bank of Montreal (TSX:BMO)(NYSE:BMO) today announced its intention to redeem all of its $700,000,000 Series D Medium-Term Notes First Tranche (the “Notes”) on April 21, 2016. The Notes are redeemable at par together with accrued and unpaid interest to, but excluding, the redemption date.

These notes were issued in 2006.

It was a superb day for the Canadian preferred share market, with PerpetualDiscounts gaining 22bp, FixedResets winning 117bp and DeemedRetractibles up 53bp. The Performance Highlights table is, predictably enough, dominated by winning FixedResets, with issues from TRP and BAM leading the pack. Volume was average.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_160303
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 17.95 to be $1.47 rich, while TRP.PR.C, resetting 2021-1-30 at +296, is $1.00 cheap at its bid price of 11.22.

impVol_MFC_160303
Click for Big

Most expensive is MFC.PR.O, resetting at +497bp on 2021-6-19, bid at 25.20 to be 1.41 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 17.00 to be 1.34 cheap.

impVol_BAM_160303
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 14.23 to be $0.70 cheap. BAM.PF.E, resetting at +255 on 2020-3-31 is bid at 17.25 and appears to be $1.07 rich.

impVol_FTS_160303
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 15.02 looks $0.57 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 14.50 and is $0.37 cheap.

pairs_FR_160303
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.99%, with two outliers below -2.00%. Note that the range of the y-axis has changed today. There are no junk outliers.

pairs_FF_160303
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.33 % 6.47 % 12,259 16.12 1 1.6000 % 1,470.7
FixedFloater 7.44 % 6.53 % 23,056 15.71 1 2.1600 % 2,672.4
Floater 4.60 % 4.76 % 78,482 15.84 4 1.5328 % 1,666.1
OpRet 0.00 % 0.00 % 0 0.00 0 0.3572 % 2,746.3
SplitShare 4.84 % 5.69 % 78,466 2.66 7 0.3572 % 3,213.7
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.3572 % 2,507.4
Perpetual-Premium 5.81 % 4.21 % 77,077 0.08 6 0.1789 % 2,539.3
Perpetual-Discount 5.75 % 5.79 % 102,111 14.15 33 0.2184 % 2,516.1
FixedReset 5.64 % 5.14 % 198,742 14.54 85 1.1679 % 1,804.8
Deemed-Retractible 5.31 % 5.87 % 116,364 5.14 34 0.5280 % 2,563.5
FloatingReset 3.12 % 5.31 % 42,581 5.46 16 0.3813 % 1,953.6
Performance Highlights
Issue Index Change Notes
PWF.PR.Q FloatingReset -3.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 10.50
Evaluated at bid price : 10.50
Bid-YTW : 4.89 %
GWO.PR.O FloatingReset -2.31 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.00
Bid-YTW : 12.20 %
GWO.PR.N FixedReset -1.26 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.54
Bid-YTW : 11.01 %
RY.PR.H FixedReset 1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 16.91
Evaluated at bid price : 16.91
Bid-YTW : 4.62 %
RY.PR.D Deemed-Retractible 1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.18
Bid-YTW : 5.20 %
RY.PR.I FixedReset 1.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.91
Bid-YTW : 4.75 %
RY.PR.A Deemed-Retractible 1.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.11
Bid-YTW : 5.21 %
CM.PR.P FixedReset 1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 16.58
Evaluated at bid price : 16.58
Bid-YTW : 4.72 %
GWO.PR.L Deemed-Retractible 1.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.47
Bid-YTW : 5.94 %
GWO.PR.I Deemed-Retractible 1.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.75
Bid-YTW : 7.09 %
TD.PF.A FixedReset 1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 16.89
Evaluated at bid price : 16.89
Bid-YTW : 4.64 %
IAG.PR.G FixedReset 1.18 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.15
Bid-YTW : 8.78 %
BMO.PR.T FixedReset 1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 16.85
Evaluated at bid price : 16.85
Bid-YTW : 4.61 %
BNS.PR.M Deemed-Retractible 1.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.37
Bid-YTW : 5.10 %
BAM.PR.R FixedReset 1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 14.23
Evaluated at bid price : 14.23
Bid-YTW : 5.38 %
MFC.PR.I FixedReset 1.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.10
Bid-YTW : 8.92 %
TD.PF.E FixedReset 1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 18.55
Evaluated at bid price : 18.55
Bid-YTW : 4.87 %
VNR.PR.A FixedReset 1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 16.61
Evaluated at bid price : 16.61
Bid-YTW : 5.44 %
MFC.PR.L FixedReset 1.28 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.78
Bid-YTW : 9.55 %
CU.PR.C FixedReset 1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 15.66
Evaluated at bid price : 15.66
Bid-YTW : 5.01 %
PVS.PR.D SplitShare 1.39 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2021-10-08
Maturity Price : 25.00
Evaluated at bid price : 22.56
Bid-YTW : 6.64 %
BMO.PR.M FixedReset 1.43 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.77
Bid-YTW : 4.55 %
W.PR.K FixedReset 1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 23.03
Evaluated at bid price : 24.60
Bid-YTW : 5.36 %
RY.PR.Z FixedReset 1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 17.00
Evaluated at bid price : 17.00
Bid-YTW : 4.54 %
SLF.PR.I FixedReset 1.51 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.80
Bid-YTW : 8.85 %
TD.PF.C FixedReset 1.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 16.85
Evaluated at bid price : 16.85
Bid-YTW : 4.63 %
BAM.PR.E Ratchet 1.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 25.00
Evaluated at bid price : 12.70
Bid-YTW : 6.47 %
FTS.PR.I FloatingReset 1.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 9.40
Evaluated at bid price : 9.40
Bid-YTW : 5.03 %
TD.PF.B FixedReset 1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 16.84
Evaluated at bid price : 16.84
Bid-YTW : 4.64 %
BAM.PF.G FixedReset 1.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 17.95
Evaluated at bid price : 17.95
Bid-YTW : 5.32 %
FTS.PR.M FixedReset 1.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 16.60
Evaluated at bid price : 16.60
Bid-YTW : 5.06 %
MFC.PR.K FixedReset 1.85 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.39
Bid-YTW : 9.77 %
MFC.PR.F FixedReset 1.86 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.62
Bid-YTW : 10.93 %
MFC.PR.J FixedReset 1.91 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.51
Bid-YTW : 9.13 %
HSE.PR.G FixedReset 1.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 16.88
Evaluated at bid price : 16.88
Bid-YTW : 6.50 %
BAM.PR.B Floater 2.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 10.05
Evaluated at bid price : 10.05
Bid-YTW : 4.77 %
BAM.PR.C Floater 2.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 9.95
Evaluated at bid price : 9.95
Bid-YTW : 4.82 %
BAM.PF.E FixedReset 2.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 17.25
Evaluated at bid price : 17.25
Bid-YTW : 5.15 %
BAM.PR.G FixedFloater 2.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 25.00
Evaluated at bid price : 12.77
Bid-YTW : 6.53 %
HSE.PR.E FixedReset 2.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 16.79
Evaluated at bid price : 16.79
Bid-YTW : 6.54 %
BAM.PF.F FixedReset 2.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 17.68
Evaluated at bid price : 17.68
Bid-YTW : 5.37 %
RY.PR.M FixedReset 2.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 17.87
Evaluated at bid price : 17.87
Bid-YTW : 4.74 %
BAM.PR.Z FixedReset 2.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 17.65
Evaluated at bid price : 17.65
Bid-YTW : 5.42 %
TRP.PR.B FixedReset 2.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 10.70
Evaluated at bid price : 10.70
Bid-YTW : 4.65 %
BIP.PR.A FixedReset 2.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 17.75
Evaluated at bid price : 17.75
Bid-YTW : 6.06 %
HSE.PR.C FixedReset 2.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 15.10
Evaluated at bid price : 15.10
Bid-YTW : 6.72 %
CM.PR.O FixedReset 3.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 17.11
Evaluated at bid price : 17.11
Bid-YTW : 4.68 %
MFC.PR.G FixedReset 3.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.00
Bid-YTW : 8.93 %
BAM.PR.K Floater 3.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 10.06
Evaluated at bid price : 10.06
Bid-YTW : 4.76 %
RY.PR.J FixedReset 3.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 18.13
Evaluated at bid price : 18.13
Bid-YTW : 4.79 %
BMO.PR.Q FixedReset 3.32 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.65
Bid-YTW : 7.37 %
TRP.PR.C FixedReset 3.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 11.22
Evaluated at bid price : 11.22
Bid-YTW : 5.00 %
TRP.PR.F FloatingReset 3.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 11.21
Evaluated at bid price : 11.21
Bid-YTW : 5.24 %
TRP.PR.E FixedReset 3.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 17.95
Evaluated at bid price : 17.95
Bid-YTW : 4.59 %
TRP.PR.A FixedReset 3.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 14.20
Evaluated at bid price : 14.20
Bid-YTW : 4.79 %
BAM.PR.T FixedReset 3.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 14.50
Evaluated at bid price : 14.50
Bid-YTW : 5.39 %
BAM.PF.B FixedReset 4.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 16.71
Evaluated at bid price : 16.71
Bid-YTW : 5.27 %
BAM.PF.A FixedReset 4.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 17.66
Evaluated at bid price : 17.66
Bid-YTW : 5.34 %
TRP.PR.D FixedReset 4.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 16.98
Evaluated at bid price : 16.98
Bid-YTW : 4.78 %
TRP.PR.G FixedReset 5.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 18.60
Evaluated at bid price : 18.60
Bid-YTW : 4.96 %
TRP.PR.I FloatingReset 7.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 10.25
Evaluated at bid price : 10.25
Bid-YTW : 4.86 %
Volume Highlights
Issue Index Shares
Traded
Notes
BMO.PR.W FixedReset 99,180 RBC crossed 68,000 at 16.45.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 16.59
Evaluated at bid price : 16.59
Bid-YTW : 4.65 %
TD.PF.G FixedReset 86,302 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 23.28
Evaluated at bid price : 25.41
Bid-YTW : 5.25 %
BNS.PR.E FixedReset 73,858 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 23.27
Evaluated at bid price : 25.37
Bid-YTW : 5.18 %
NA.PR.X FixedReset 72,223 Nesbitt crossed 39,000 at 25.17.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 23.20
Evaluated at bid price : 25.17
Bid-YTW : 5.51 %
MFC.PR.O FixedReset 66,145 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-06-19
Maturity Price : 25.00
Evaluated at bid price : 25.20
Bid-YTW : 5.49 %
HSE.PR.A FixedReset 56,150 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 8.60
Evaluated at bid price : 8.60
Bid-YTW : 7.12 %
There were 30 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
HSE.PR.G FixedReset Quote: 16.88 – 24.50
Spot Rate : 7.6200
Average : 4.2889

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 16.88
Evaluated at bid price : 16.88
Bid-YTW : 6.50 %

PWF.PR.Q FloatingReset Quote: 10.50 – 12.05
Spot Rate : 1.5500
Average : 1.3123

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 10.50
Evaluated at bid price : 10.50
Bid-YTW : 4.89 %

CM.PR.Q FixedReset Quote: 17.84 – 18.50
Spot Rate : 0.6600
Average : 0.4432

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-03
Maturity Price : 17.84
Evaluated at bid price : 17.84
Bid-YTW : 4.95 %

MFC.PR.L FixedReset Quote: 15.78 – 16.39
Spot Rate : 0.6100
Average : 0.4169

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.78
Bid-YTW : 9.55 %

MFC.PR.K FixedReset Quote: 15.39 – 16.01
Spot Rate : 0.6200
Average : 0.4367

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.39
Bid-YTW : 9.77 %

BNS.PR.C FloatingReset Quote: 20.77 – 21.59
Spot Rate : 0.8200
Average : 0.6386

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.77
Bid-YTW : 5.69 %

Market Action

March 2, 2016

American shoppers are loading up on the blue-light special:

The Canadian dollar — the loonie — has fallen about 18 percent against its U.S. counterpart over the past two years after flirting with parity several times in the last decade. At the same time, spending by U.S. shoppers using PayPal on Canadian websites jumped 20 percent in 2015 from the year before.

“The recent drop in the Canadian dollar presents an exciting export opportunity for Canadian businesses selling to American buyers,” Cameron Schmidt, PayPal Inc.’s Canadian general manager, said in an e-mail.

As the energy and mining industries struggle under the collapse of a decade-long bull market for commodities, Canada is turning to exports and tourism for growth. The expansion of online shopping allows that to happen without requiring Americans to dig out their passports.
…
“Across our customer base, Canadian businesses saw strong growth among U.S. shoppers in 2015,” Brent Bellm, chief executive officer of Austin, Texas-based Bigcommerce, said in an e-mail. Sales at Canadian Bigcommerce stores during the holiday shopping season rose 39 percent from the same period a year earlier, while the number of actual stores only went up 2.9 percent, he said.

Not just retail, but retailers:

U.S. health-care-services giant McKesson Corp. is taking on the heavyweights of Canada’s drugstore industry with a $3-billion deal for the Rexall pharmacy chain and related companies.

McKesson of San Francisco, which already owns smaller drugstores in Canada and supplies drugs to Rexall and other pharmacies, is adding to its size and buying power by acquiring the 470 Rexall stores. It gives Rexall more heft in its fight with industry leader Shoppers Drug Mart, which was acquired by grocery titan Loblaw Cos. Ltd. for $12.4-billion two years ago.

Zachary Tracer of Bloomberg adds:

The deal is the drug distributor’s latest in a series of efforts to expand geographically and deepen its offerings. In 2014, it announced it would buy 10 drugstores from Loblaw Cos., and last year it announced an agreement to buy a drug distribution business in Belgium. Its biggest recent deal was a $1.2 billion acquisition of two oncology businesses, Vantage Oncology LLC and Biologics Inc., which included 50 cancer treatment centers in 13 states.

There will, of course, be the usual whining from the usual crowd who don’t realize that the capital doesn’t just disappear:

Famously publicity shy, Mr. Katz gave little in the way of specifics Wednesday about what he will do with the proceeds of the sale of Rexall Health to the United States-based McKesson Corp.

In a news release on Wednesday, the billionaire said going forward, his privately held Katz Group will continue to invest in its three other lines of business – real estate, sports and entertainment, and private and public investments.

But Mr. Katz, 54, has made no secret that his current focus is far away from the world of neighbourhood drugstores and Medicentres, and is laser-trained on the building of Canada’s largest mixed-use sports and entertainment district.
…
The price tag will be hefty, even for someone of Mr. Katz’s considerable means. The development is a joint project with WAM Development Group, but Mr. Katz holds a 90-per-cent stake. The first 25-acre phases of the project will cost $2.5-billion, but the final tally, once the planned second phase is built, could reach $6-billion. The budget for the steel-topped arena itself – being jointly funded by the city, and set to open this fall – is $606.5-million.

There are other, more modest, sales – probably also given something of a boost by an influx of foreign capital:

Her strata council’s sale of their 21-unit building to Concert Properties for $5-million – about 65 per cent more than the assessed value of all the units – will close this May, as well as a recent sale of a group of owners in the West End to Bosa Properties, are the first two major deals such as this in the Lower Mainland.

Until now, strata buyouts have mainly been duplexes, triplexes or very small complexes with a handful of owners, said Tony Gioventu, president of the Condominium Home Owners Association.

But condo experts such as Mr. Gioventu, real estate lawyers, and residents say it’s just the beginning.

More than a million people in British Columbia live in strata-titled housing in the hundreds of buildings that have been constructed since the province’s first strata act in 1966 made them legally possible.

Buildings are getting old. Developers are hungry for any new site in the land-squeezed Lower Mainland.

And city governments have been identifying new areas of density, which is fresh bait for redevelopment.

The wave is especially likely to grow because British Columbia is about to enact a new piece of legislation this spring so that strata councils no longer have to get 100-per-cent agreement among owners to sell, but only 80 per cent.

That will open the door for many more strata councils to force a sale on holdout owners, of which there is generally at least one in any building.

Geez, it seems like only yesterday that I was talking about squeeze-outs and eminent domain laws! So here’s another attempt at a Solomonic decision regarding minority ownership rights!

It looks like the Fairfax underwriters bit off more than they chew:

Fairfax Financial Holdings Ltd.’s latest financing didn’t sell as planned, forcing the underwriters to absorb millions of dollars in potential losses from unsold shares.

The $735-million financing was sold by way of a bought deal, which means the underwriters paid Fairfax the money up front and absorbed the risk of re-selling the shares to the market. Many investors balked at the terms, with only about 50 per cent of the transaction sold, according to people familiar with it, so advisers are currently holding the remaining portion. The deal was originally priced at $735 a share, a 3.9-per-cent discount to the market price. Fairfax’s shares currently trade for $709 apiece, having fallen 7 per cent since the deal was announced.

At the moment, the underwriters are collectively breaking even on the deal – after accounting for the 4-per-cent, or $29-million, commission, they earn. However, they are expected to launch what is known as a “clean-up” trade, in which the unsold shares will be unloaded at a bigger discount. Depending on this final price, there is a chance the underwriters eke out a small profit on the deal – but they could also be on the hook for millions of dollars.

Looks like the OSC will soon be publishing mutual fund research:

Regulators are taking a closer look at actively managed funds to determine if portfolio managers are fulfilling their duty – or simply hugging an index.

The Ontario Securities Commission wants to know whether funds that are advertised as actively managed are in fact living up to their name, or whether they are exhibiting a close tracking of their benchmark index, such as the S&P 500 or the S&P/TSX composite index.
…
About 37 per cent of the assets in equity mutual funds sold in this country are in closet indexers, according to research by Martijn Cremers of the University of Notre Dame, Miguel Ferreira of the Nova School of Business and Economics, Pedro Matos of the University of Virginia and Laura Starks of the University of Texas.

By comparison, only 15 per cent of the net assets in equity mutual funds sold in the United States are in closet indexers. The level of closet indexing in Canada is the highest among the 20 countries covered in the paper when it is calculated as a percentage of equity funds sold in each country.

A recent report by the OSC stated that it had “commenced a targeted review of conventional mutual funds that disclose in their prospectus and marketing materials that they pursue active management strategies … Among other data, we considered the funds’ active share (a measure of the percentage of a fund’s portfolio holdings that differs from the composition of its benchmark index) to assess the extent of active management.”

The OSC is currently seeking additional information from portfolio managers, including how the securities are selected for their funds.

This story comes from the 2015 – Summary Report for Investment Fund and Structured Product Issuers.

Forbes published two pretty compelling charts about American universities:

educationInflation
Click for Big
administrativeBloat
Click for Big

RONA has filed its management circular for the proposed dual Plans of Arrangement with Lowe’s. I have updated the post regarding the announcement of the proposed Arrangement.

It was a superb day for the Canadian preferred share market, with PerpetualDiscounts gaining 41bp, FixedResets winning 160bp and DeemedRetractibles up 63bp. There is not a single loser in the Performance Highlights table, which is suitably dominated by winning FixedResets. Floaters did very well. Volume was above average.

PerpetualDiscounts now yield 5.79%, equivalent to 7.53% interest at the standard equivalency factor of 1.3x. Long Corporates now yield about 4.3%, so the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) is now about 325bp, a significant narrowing from the 340bp reported February 24.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_160302
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 17.32 to be $1.51 rich, while TRP.PR.C, resetting 2021-1-30 at +296, is $0.93 cheap at its bid price of 10.85.

impVol_MFC_160302
Click for Big

Most expensive is MFC.PR.O, resetting at +497bp on 2021-6-19, bid at 25.18 to be 1.28 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 16.49 to be 1.71 cheap.

impVol_BAM_160302
Click for Big

The cheapest issue relative to its peers is BAM.PR.T, resetting at +231bp on 2017-3-31, bid at 14.00 to be $0.72 cheap. BAM.PF.E, resetting at +255 on 2020-3-31 is bid at 16.90 and appears to be $1.04 rich.

impVol_FTS_160302
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 14.90, looks $0.57 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 14.47 and is $0.26 cheap.

pairs_FR_160302
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.90%, with three outliers below -1.50%. Note that the range of the y-axis has changed today. There are two junk outliers below -1.50%.

pairs_FF_160302
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.41 % 6.57 % 12,782 16.00 1 2.4590 % 1,447.6
FixedFloater 7.60 % 6.66 % 22,025 15.55 1 2.8807 % 2,615.9
Floater 4.67 % 4.87 % 79,560 15.66 4 4.2257 % 1,641.0
OpRet 0.00 % 0.00 % 0 0.00 0 0.1610 % 2,736.5
SplitShare 4.86 % 5.90 % 79,272 2.66 7 0.1610 % 3,202.2
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1610 % 2,498.5
Perpetual-Premium 5.82 % -0.37 % 79,836 0.08 6 0.1061 % 2,534.7
Perpetual-Discount 5.76 % 5.79 % 102,804 14.11 33 0.4081 % 2,510.6
FixedReset 5.70 % 5.17 % 200,099 14.27 85 1.6000 % 1,784.0
Deemed-Retractible 5.33 % 5.94 % 117,576 5.14 34 0.6252 % 2,550.0
FloatingReset 3.13 % 5.46 % 44,355 5.46 16 1.6693 % 1,946.2
Performance Highlights
Issue Index Change Notes
ELF.PR.G Perpetual-Discount 1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 6.04 %
BAM.PF.C Perpetual-Discount 1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 19.67
Evaluated at bid price : 19.67
Bid-YTW : 6.29 %
BNS.PR.A FloatingReset 1.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.04
Bid-YTW : 3.94 %
GWO.PR.Q Deemed-Retractible 1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.95
Bid-YTW : 6.35 %
SLF.PR.I FixedReset 1.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.55
Bid-YTW : 9.06 %
GWO.PR.M Deemed-Retractible 1.20 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-03-31
Maturity Price : 25.25
Evaluated at bid price : 25.25
Bid-YTW : 5.54 %
RY.PR.I FixedReset 1.21 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.67
Bid-YTW : 4.95 %
BAM.PR.T FixedReset 1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 13.97
Evaluated at bid price : 13.97
Bid-YTW : 5.61 %
ELF.PR.F Perpetual-Discount 1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 21.91
Evaluated at bid price : 22.15
Bid-YTW : 6.07 %
HSE.PR.A FixedReset 1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 8.58
Evaluated at bid price : 8.58
Bid-YTW : 7.13 %
BMO.PR.W FixedReset 1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 16.51
Evaluated at bid price : 16.51
Bid-YTW : 4.67 %
PWF.PR.P FixedReset 1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 12.15
Evaluated at bid price : 12.15
Bid-YTW : 4.73 %
GWO.PR.O FloatingReset 1.44 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.26
Bid-YTW : 11.88 %
GWO.PR.I Deemed-Retractible 1.58 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.52
Bid-YTW : 7.25 %
FTS.PR.I FloatingReset 1.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 9.25
Evaluated at bid price : 9.25
Bid-YTW : 5.11 %
BNS.PR.Y FixedReset 1.66 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.99
Bid-YTW : 6.83 %
BMO.PR.Q FixedReset 1.69 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.05
Bid-YTW : 7.98 %
CM.PR.Q FixedReset 1.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 17.75
Evaluated at bid price : 17.75
Bid-YTW : 4.97 %
CCS.PR.C Deemed-Retractible 1.74 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.06
Bid-YTW : 7.43 %
SLF.PR.H FixedReset 1.75 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.50
Bid-YTW : 10.15 %
TD.PF.A FixedReset 1.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 16.70
Evaluated at bid price : 16.70
Bid-YTW : 4.69 %
CM.PR.P FixedReset 1.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 16.40
Evaluated at bid price : 16.40
Bid-YTW : 4.77 %
BMO.PR.Y FixedReset 1.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 17.84
Evaluated at bid price : 17.84
Bid-YTW : 4.90 %
CU.PR.C FixedReset 1.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 15.45
Evaluated at bid price : 15.45
Bid-YTW : 5.08 %
RY.PR.Z FixedReset 2.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 16.75
Evaluated at bid price : 16.75
Bid-YTW : 4.61 %
IAG.PR.G FixedReset 2.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.95
Bid-YTW : 8.95 %
TD.PF.E FixedReset 2.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 18.32
Evaluated at bid price : 18.32
Bid-YTW : 4.93 %
FTS.PR.G FixedReset 2.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 14.47
Evaluated at bid price : 14.47
Bid-YTW : 5.11 %
BNS.PR.D FloatingReset 2.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.63
Bid-YTW : 7.72 %
SLF.PR.J FloatingReset 2.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 11.50
Bid-YTW : 11.77 %
FTS.PR.M FixedReset 2.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 16.31
Evaluated at bid price : 16.31
Bid-YTW : 5.15 %
MFC.PR.K FixedReset 2.44 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.11
Bid-YTW : 10.03 %
BAM.PR.E Ratchet 2.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 25.00
Evaluated at bid price : 12.50
Bid-YTW : 6.57 %
NA.PR.W FixedReset 2.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 15.27
Evaluated at bid price : 15.27
Bid-YTW : 5.17 %
BAM.PF.G FixedReset 2.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 17.65
Evaluated at bid price : 17.65
Bid-YTW : 5.42 %
BAM.PF.F FixedReset 2.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 17.25
Evaluated at bid price : 17.25
Bid-YTW : 5.51 %
BAM.PF.B FixedReset 2.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 16.05
Evaluated at bid price : 16.05
Bid-YTW : 5.49 %
TD.PR.Y FixedReset 2.80 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.13
Bid-YTW : 4.45 %
BAM.PR.G FixedFloater 2.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 25.00
Evaluated at bid price : 12.50
Bid-YTW : 6.66 %
TRP.PR.F FloatingReset 3.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 10.82
Evaluated at bid price : 10.82
Bid-YTW : 5.42 %
BAM.PF.E FixedReset 3.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 16.90
Evaluated at bid price : 16.90
Bid-YTW : 5.26 %
HSE.PR.G FixedReset 3.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 16.55
Evaluated at bid price : 16.55
Bid-YTW : 6.63 %
BAM.PR.K Floater 3.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 9.75
Evaluated at bid price : 9.75
Bid-YTW : 4.92 %
RY.PR.J FixedReset 3.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 17.56
Evaluated at bid price : 17.56
Bid-YTW : 4.94 %
RY.PR.M FixedReset 3.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 17.40
Evaluated at bid price : 17.40
Bid-YTW : 4.87 %
TD.PF.D FixedReset 3.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 17.93
Evaluated at bid price : 17.93
Bid-YTW : 4.92 %
BAM.PR.R FixedReset 3.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 14.06
Evaluated at bid price : 14.06
Bid-YTW : 5.44 %
MFC.PR.L FixedReset 3.32 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.58
Bid-YTW : 9.73 %
NA.PR.S FixedReset 3.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 16.19
Evaluated at bid price : 16.19
Bid-YTW : 5.06 %
FTS.PR.K FixedReset 3.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 14.90
Evaluated at bid price : 14.90
Bid-YTW : 4.93 %
CIU.PR.C FixedReset 3.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 10.23
Evaluated at bid price : 10.23
Bid-YTW : 4.97 %
BAM.PR.X FixedReset 3.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 12.76
Evaluated at bid price : 12.76
Bid-YTW : 5.25 %
HSE.PR.C FixedReset 3.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 14.67
Evaluated at bid price : 14.67
Bid-YTW : 6.92 %
MFC.PR.N FixedReset 3.69 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.85
Bid-YTW : 8.75 %
MFC.PR.M FixedReset 3.72 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.00
Bid-YTW : 8.70 %
BAM.PR.Z FixedReset 3.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 17.17
Evaluated at bid price : 17.17
Bid-YTW : 5.57 %
TRP.PR.G FixedReset 4.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 17.70
Evaluated at bid price : 17.70
Bid-YTW : 5.22 %
BAM.PR.C Floater 4.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 9.75
Evaluated at bid price : 9.75
Bid-YTW : 4.92 %
TRP.PR.H FloatingReset 4.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 9.00
Evaluated at bid price : 9.00
Bid-YTW : 4.74 %
TRP.PR.C FixedReset 4.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 10.85
Evaluated at bid price : 10.85
Bid-YTW : 5.17 %
TD.PR.T FloatingReset 4.37 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.25
Bid-YTW : 4.96 %
TRP.PR.B FixedReset 4.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 10.40
Evaluated at bid price : 10.40
Bid-YTW : 4.78 %
HSE.PR.E FixedReset 4.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 16.42
Evaluated at bid price : 16.42
Bid-YTW : 6.69 %
PWF.PR.A Floater 4.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 11.10
Evaluated at bid price : 11.10
Bid-YTW : 4.29 %
BAM.PR.B Floater 4.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 9.85
Evaluated at bid price : 9.85
Bid-YTW : 4.87 %
TRP.PR.D FixedReset 5.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 16.20
Evaluated at bid price : 16.20
Bid-YTW : 5.02 %
TRP.PR.A FixedReset 5.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 13.70
Evaluated at bid price : 13.70
Bid-YTW : 4.97 %
TRP.PR.E FixedReset 5.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 17.32
Evaluated at bid price : 17.32
Bid-YTW : 4.76 %
PWF.PR.Q FloatingReset 6.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 10.85
Evaluated at bid price : 10.85
Bid-YTW : 4.73 %
Volume Highlights
Issue Index Shares
Traded
Notes
NA.PR.Q FixedReset 116,330 GMC sold 20,700 to Scotia, 15,200 to TD and crossed 40,000, all at 23.00. Scotia bought 24,100 from TD at the same price.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.90
Bid-YTW : 5.02 %
FTS.PR.M FixedReset 106,660 Nesbitt crossed 100,000 at 16.50.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 16.31
Evaluated at bid price : 16.31
Bid-YTW : 5.15 %
BAM.PR.Z FixedReset 75,746 Scotia crossed blocks of 40,000 and 25,000, both at 17.20.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 17.17
Evaluated at bid price : 17.17
Bid-YTW : 5.57 %
POW.PR.C Perpetual-Premium 72,300 Nesbitt crossed 68,900 at 25.32.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-04-01
Maturity Price : 25.00
Evaluated at bid price : 25.32
Bid-YTW : -0.69 %
MFC.PR.O FixedReset 63,534 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-06-19
Maturity Price : 25.00
Evaluated at bid price : 25.18
Bid-YTW : 5.50 %
IAG.PR.G FixedReset 62,495 RBC crossed 25,000 at 16.55, then another 28,400 at 16.65.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.95
Bid-YTW : 8.95 %
There were 40 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
TD.PR.Z FloatingReset Quote: 20.78 – 22.75
Spot Rate : 1.9700
Average : 1.3020

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.78
Bid-YTW : 5.46 %

HSE.PR.E FixedReset Quote: 16.42 – 17.40
Spot Rate : 0.9800
Average : 0.6866

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 16.42
Evaluated at bid price : 16.42
Bid-YTW : 6.69 %

BAM.PF.A FixedReset Quote: 16.95 – 17.61
Spot Rate : 0.6600
Average : 0.3940

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 16.95
Evaluated at bid price : 16.95
Bid-YTW : 5.58 %

BAM.PF.F FixedReset Quote: 17.25 – 17.92
Spot Rate : 0.6700
Average : 0.4523

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 17.25
Evaluated at bid price : 17.25
Bid-YTW : 5.51 %

PWF.PR.T FixedReset Quote: 19.16 – 19.80
Spot Rate : 0.6400
Average : 0.4418

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-03-02
Maturity Price : 19.16
Evaluated at bid price : 19.16
Bid-YTW : 4.23 %

BNS.PR.R FixedReset Quote: 22.83 – 23.40
Spot Rate : 0.5700
Average : 0.3943

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.83
Bid-YTW : 5.01 %