Category: Market Action

Market Action

January 5, 2016

Nothing happened today, although at time of writing Asian markets are getting hit again:

Asian stocks slumped along with U.S. index futures after China weakened the yuan, underscoring concern the world’s second-largest economy is struggling. The won fell with shares in Seoul after North Korea conducted its fourth nuclear test.

Japanese equities dropped and contracts on the Standard & Poor’s 500 Indexslid 0.9 percent as of 2:22 p.m. in Tokyo. Kim Jong Un’s regime detonated a hydrogen device at an underground test site in the far northeast, the official Korean Central News Agency said. The yen advanced to a more than two-month high amid demand for safer assets, as Australian government bonds extended their climb and Treasuries advanced for a fifth session. Gold held gains, while zinc led industrial metals lower in London and Shanghai on concerns demand is ebbing in China.
…
The Bloomberg-JPMorgan Asia Dollar Index fell to the lowest level since April 2009 as China’s central bank weakened the yuan’s reference rate for the seventh day in a row, heightening the risk of a currency war. The gap between the yuan rate inside China and that for the currency traded offshore expanded, underscoring speculation the government faces pressure to devalue its currency to aid the economy. China’s CSI 300 Index rose 0.4 percent, gaining for a second session after Monday’s 7 percent rout.

The Globe’s Rob Carrick touts preferred shares:

Avoid preferred shares then? Not necessarily. In fact, now may be the time to start buying. In a recent note to clients, the independent analyst Harry Levant of IncomeResearch.ca argues that the preferred market may have bottomed late in 2015. His suggestion for locking in a solid yield and possibly profiting from a rebound in prices is to buy an exchange-traded fund called the iShares Preferred Share Index ETF (CPD-T).
…
Mr. Levant notes that CPD wasn’t a great choice last year because its portfolio weights rate resets more heavily than the fixed-rate preferred shares that held up comparatively well. With rate resets looking like they may have hit bottom, CPD becomes more attractive.

The distribution yield for CPD in early January was 4.95 per cent. That’s 4.5 per cent on an after-fee basis, which is roughly double the yield on a 30-year Government of Canada bond. Safe, preferred shares are most assuredly not. But they do have rebound potential now, and a pretty fine yield as well.

I’ll note that the distribution yield of 4.95% (or 4.5% after fees) quoted in the article will be as difficult to really understand as anything else with preferred shares these days. On a cash basis, it will overestimate sustainable yield, because there are still a LOT of dividend cuts yet to come although [given a constant GOC-5 yield] we have just about finished with the 40%+ cuts. On the other hand, the calculation of Distribution Yield will not take any account of the special case of insurance company NVCC non-compliant issues – that is, the probability assigned to an extension of the NVCC rules is zero. So prospective buyers should ensure they understand how the quoted yield may change in the future given various interest-rate and regulatory scenarios.

It looked like it was going to be another horrific day for Canadian preferred shares, but a late afternoon rally upgraded the status to merely appalling.

Here’s TXPR:

TXPR_160105
Click for Big
TXPL_160105
Click for Big

So preferred share investors partied in the streets!

bringOutYourDead
Click for Big

It was an appalling day for the Canadian preferred share market, with PerpetualDiscounts gaining 7bp, FixedResets down 207bp and DeemedRetractibles off 10bp. As might be expected, the Performance Highlights table is an almost solid wall of FixedReset losers, but there were a few winners bouncing back from yesterday. Volume picked up to just a little below average.

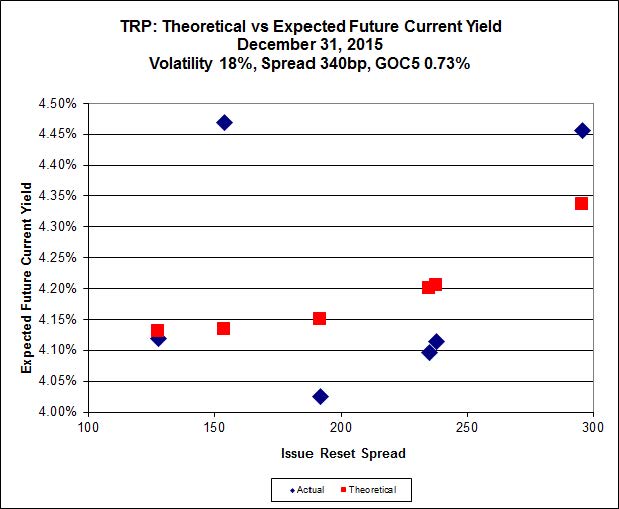
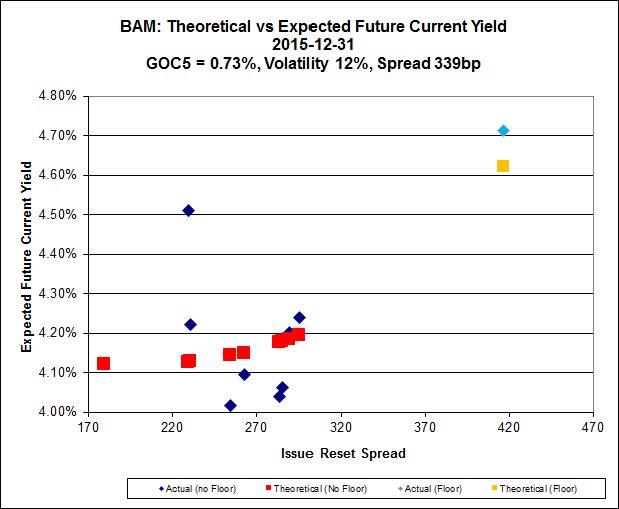
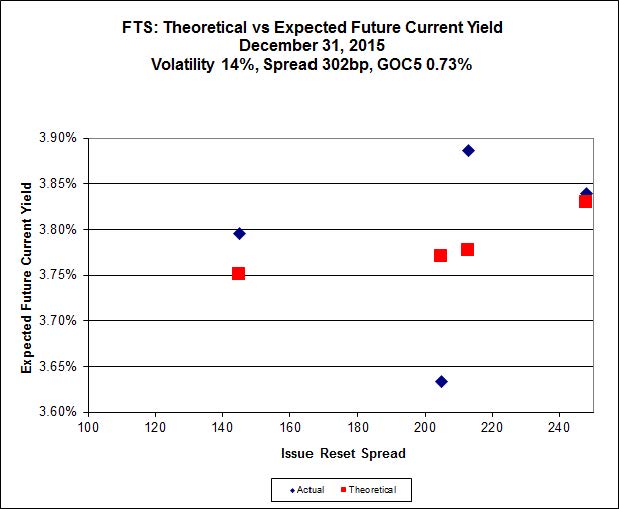
For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

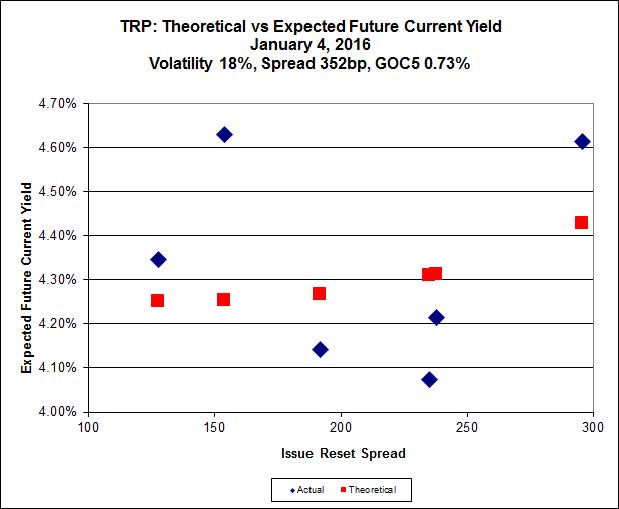
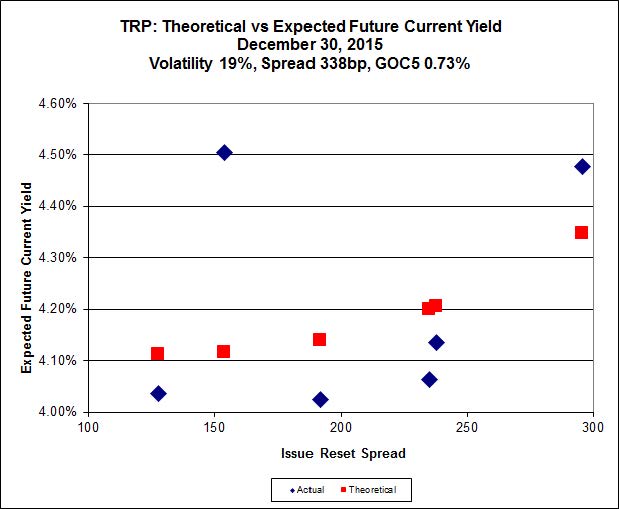
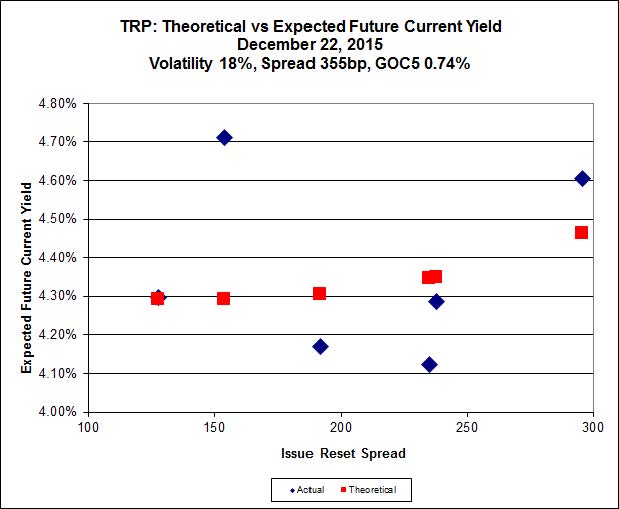
Here’s TRP:

impVol_TRP_160105
Click for Big

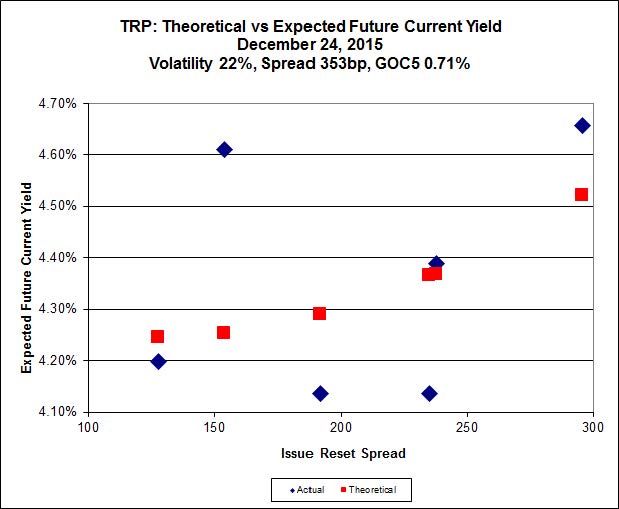
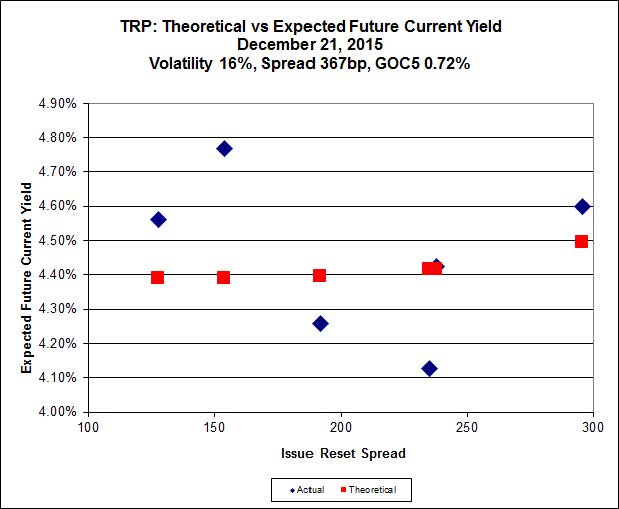
TRP.PR.E, which resets 2019-10-30 at +235, is bid at 18.65 to be $1.00 rich, while TRP.PR.C, resetting 2016-1-30 at +154, is $1.36 cheap at its bid price of 11.81.

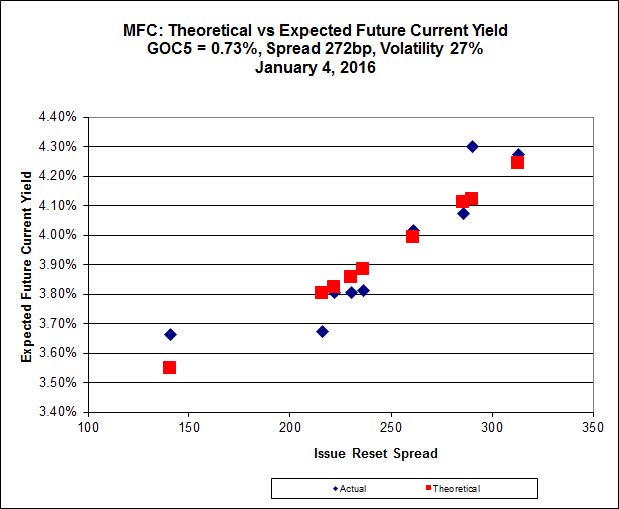
impVol_MFC_160105
Click for Big

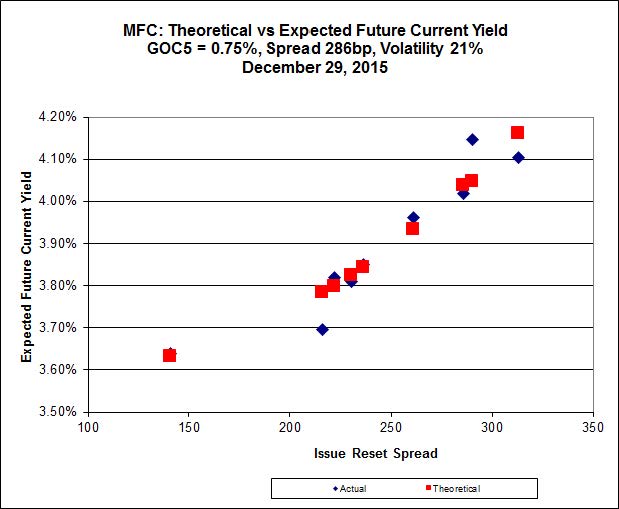
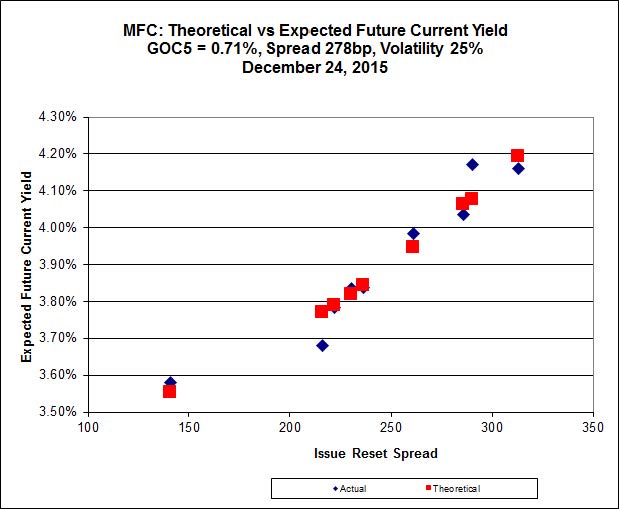
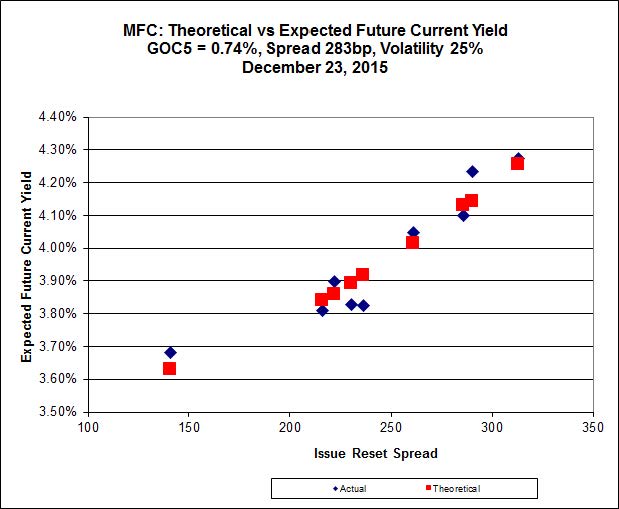
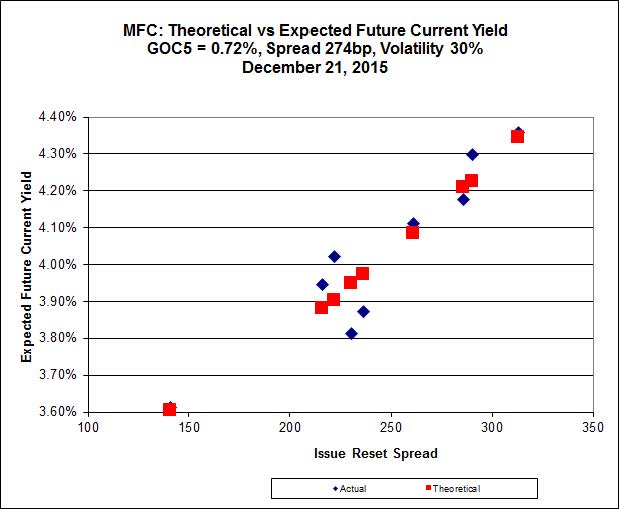
A big jump in Implied Volatility today, as is usually the case when there is a dramatically poor day. Given this, and the high levels of Implied Volatility generally, I suspect that this means there is something else going on. Low-Spread FixedResets have a higher degree of leverage to future changes in the GOC-5 yield; I think that this is what is being paid for.

Most expensive is MFC.PR.L, resetting at +216bp on 2019-6-19, bid at 18.70 to be 0.35 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 20.66 to be 0.58 cheap.

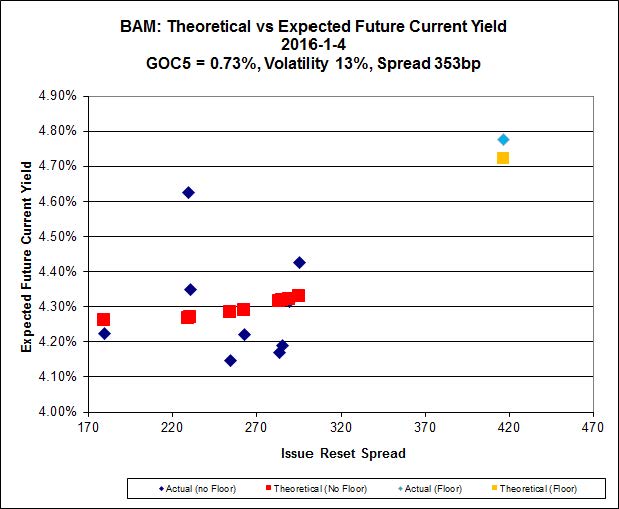
impVol_BAM_160105
Click for Big

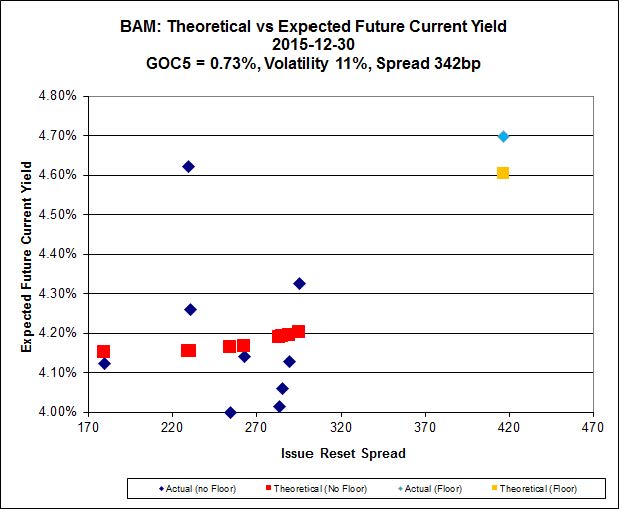
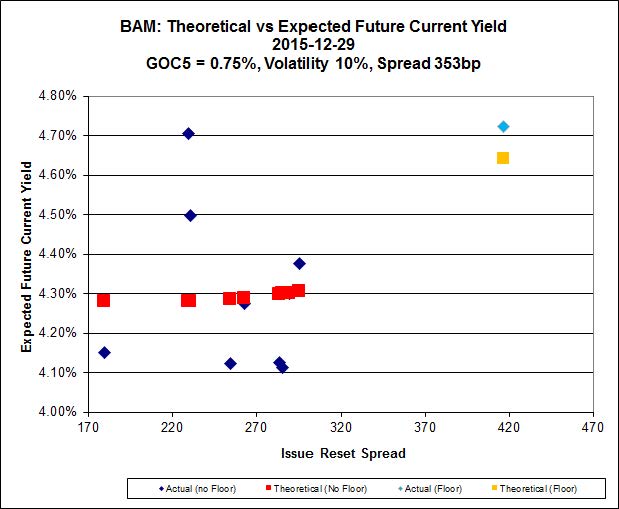
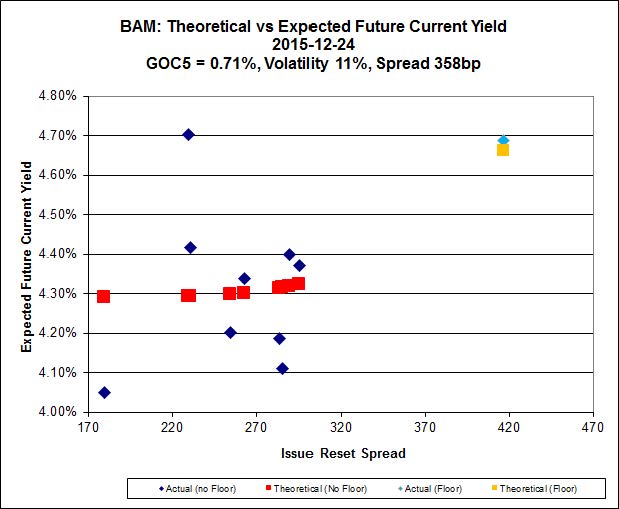
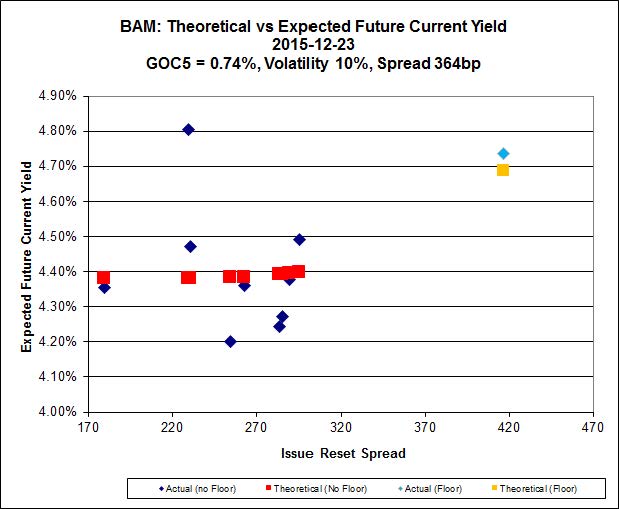
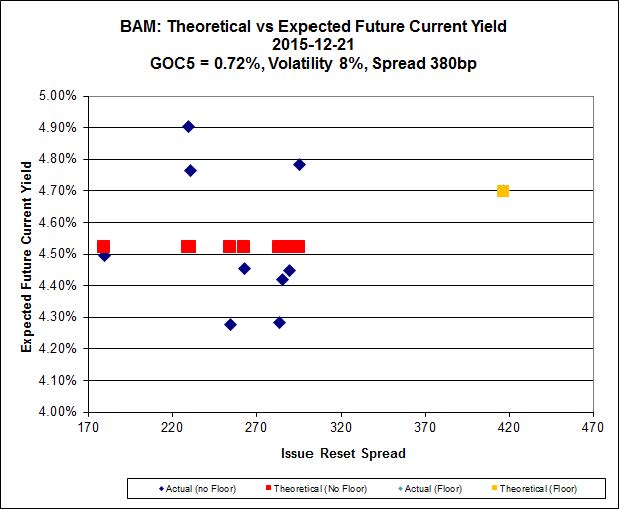
The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 15.86 to be $1.40 cheap. BAM.PF.E, resetting at +255bp on 2020-3-31 is bid at 19.50 and appears to be $0.85 rich.

impVol_FTS_160105
Click for Big

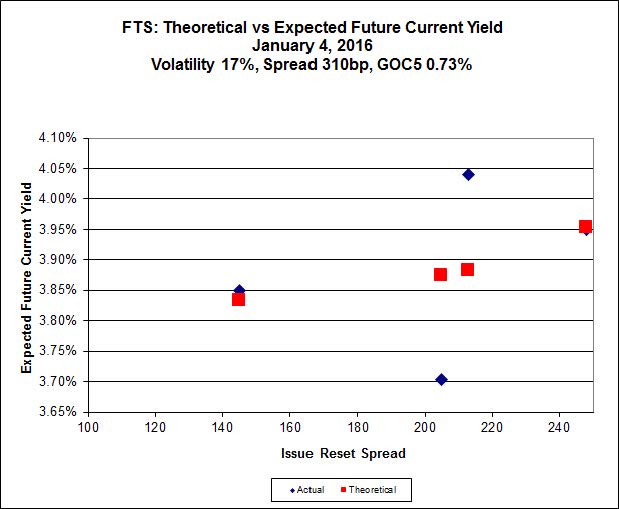
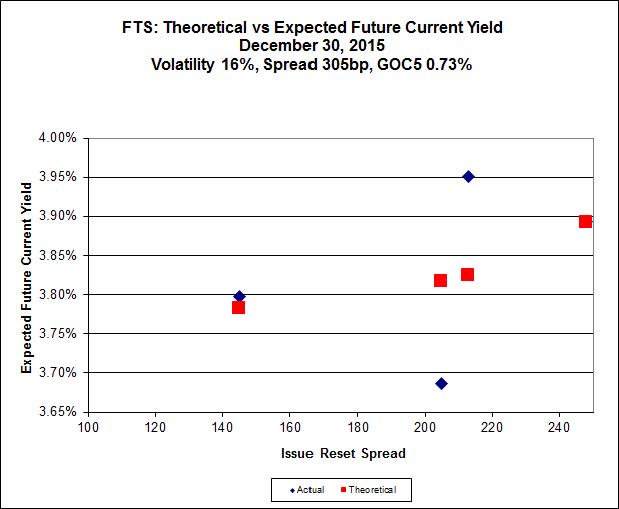
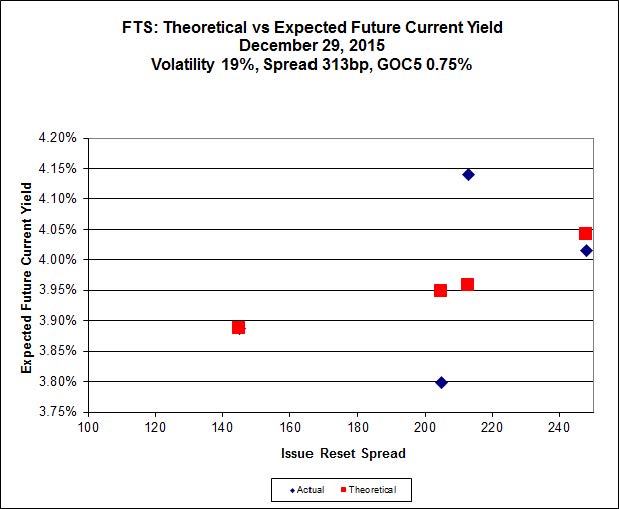
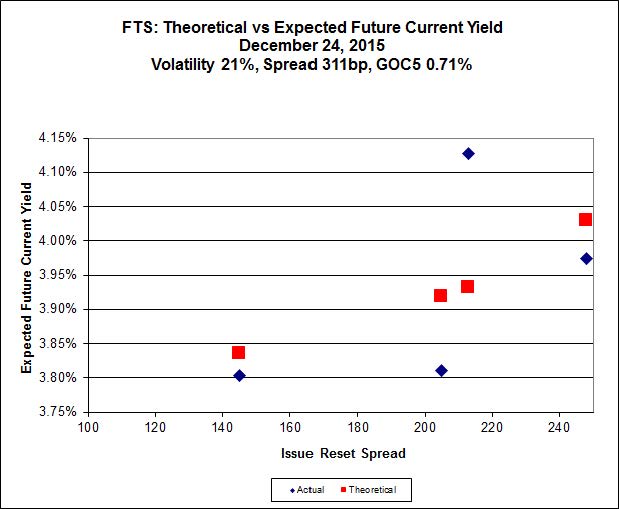
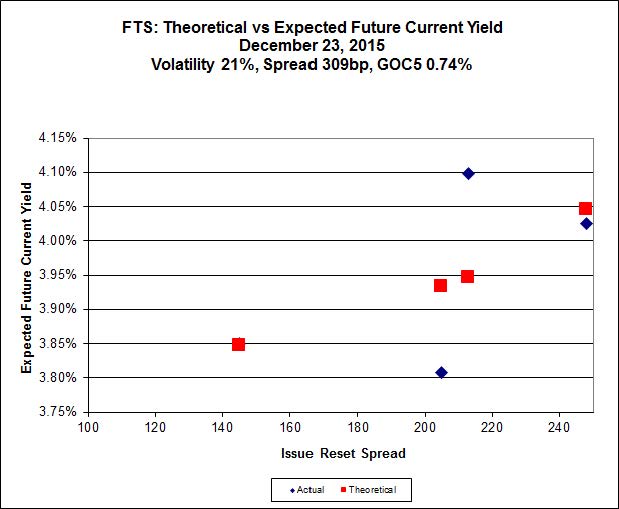
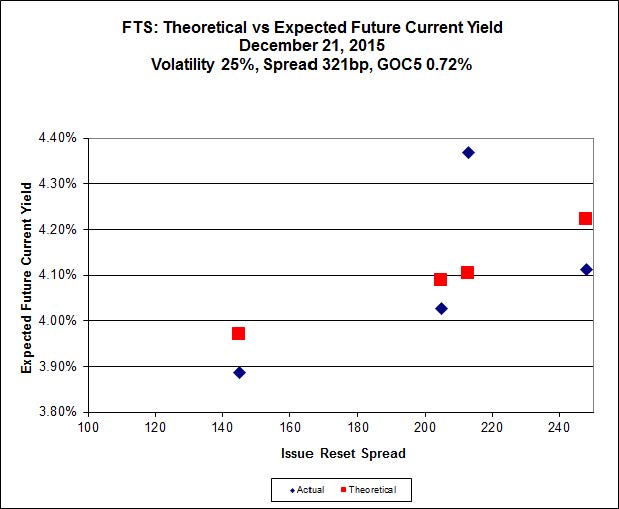
FTS.PR.K, with a spread of +205bp, and bid at 18.24, looks $0.65 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 17.50 and is $0.51 cheap.

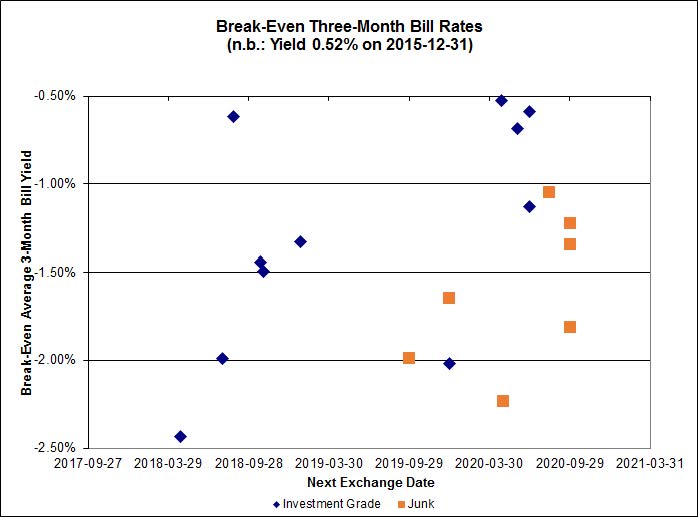
pairs_FR_160105
Click for Big

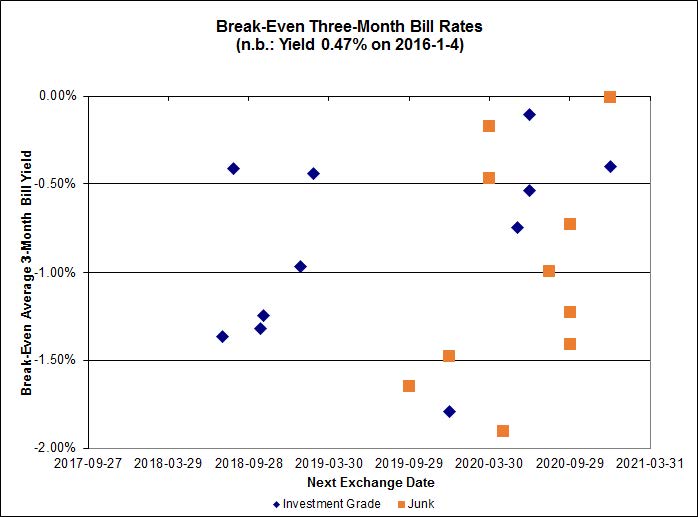
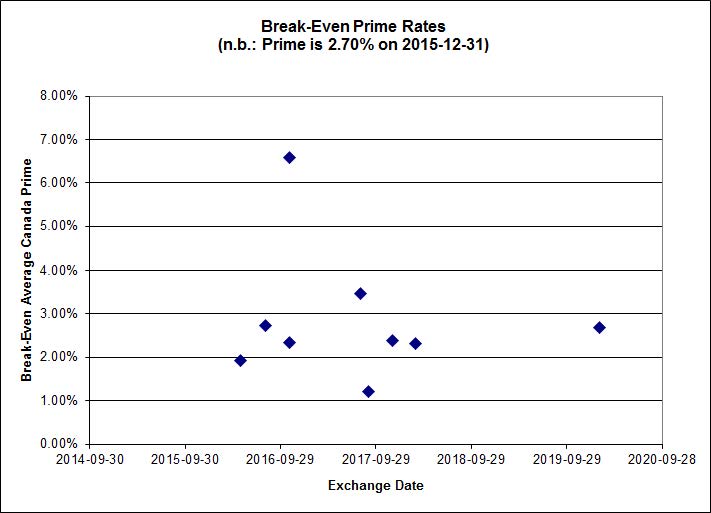
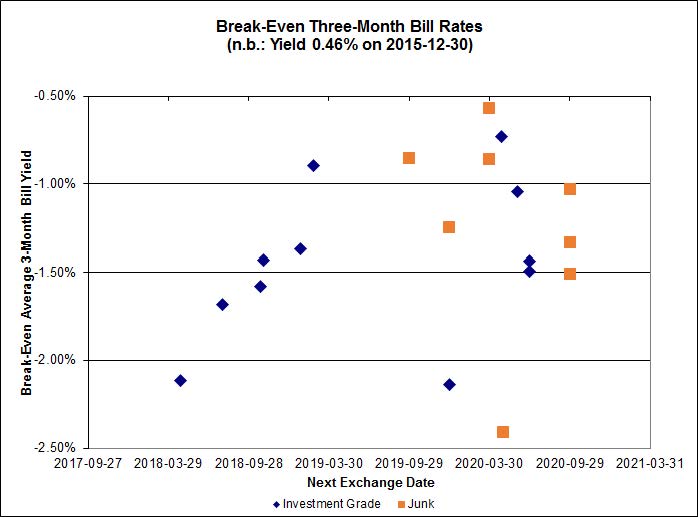
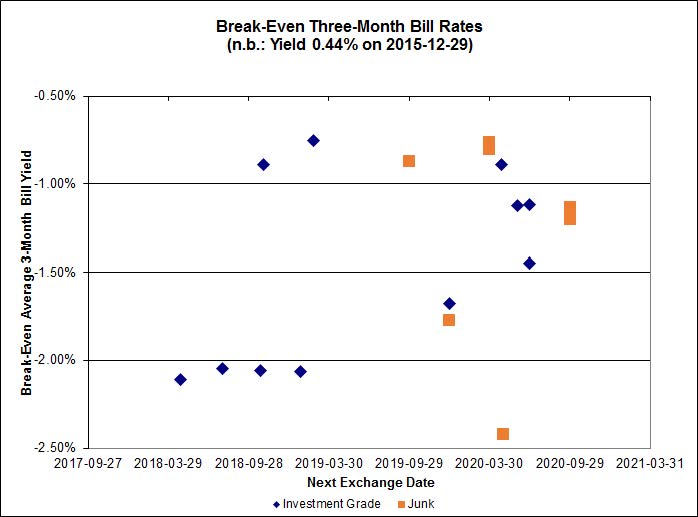
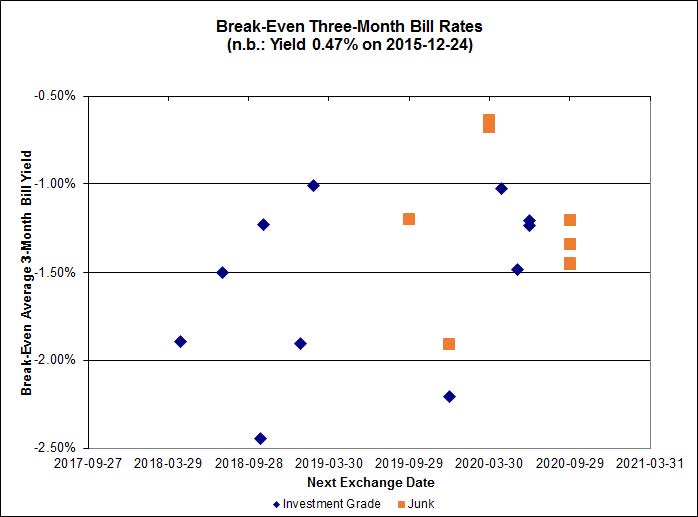
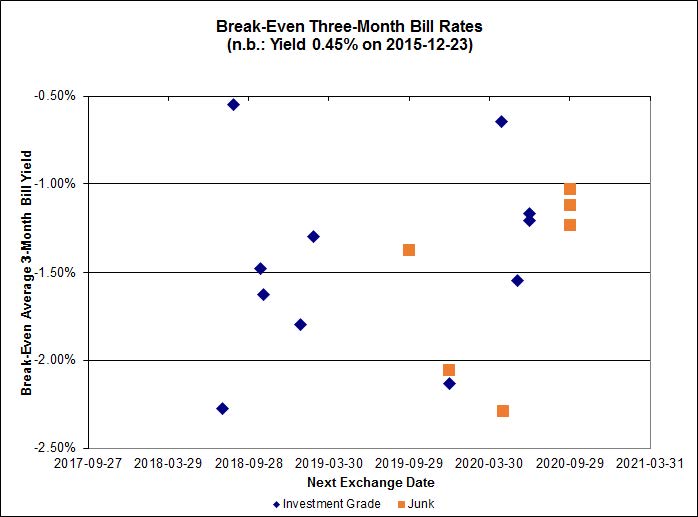
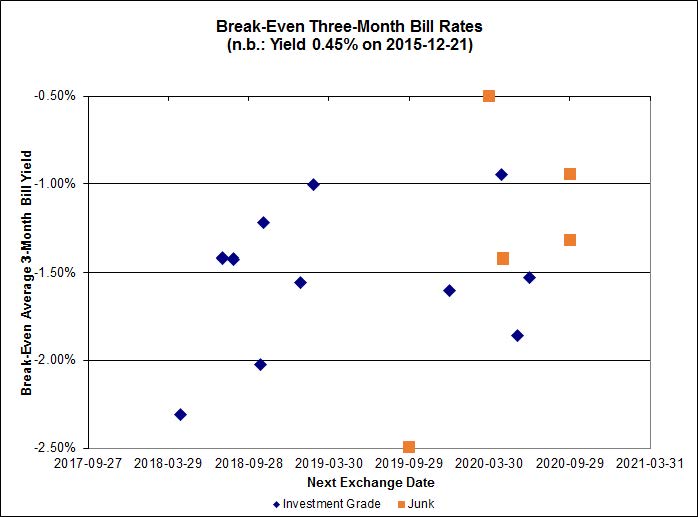
Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -1.06%, with one outlier above 0.00%, and two below -2.00%. There is one junk outlier below -2.00% and two above 0.00%.

pairs_FF_160105
Click for Big

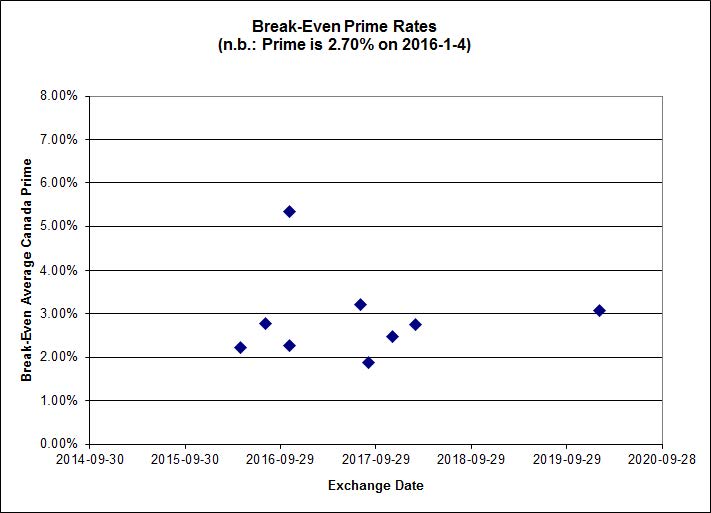
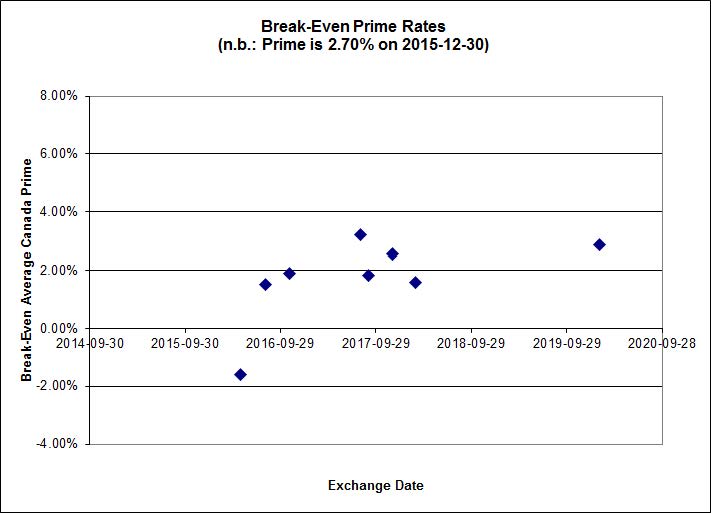
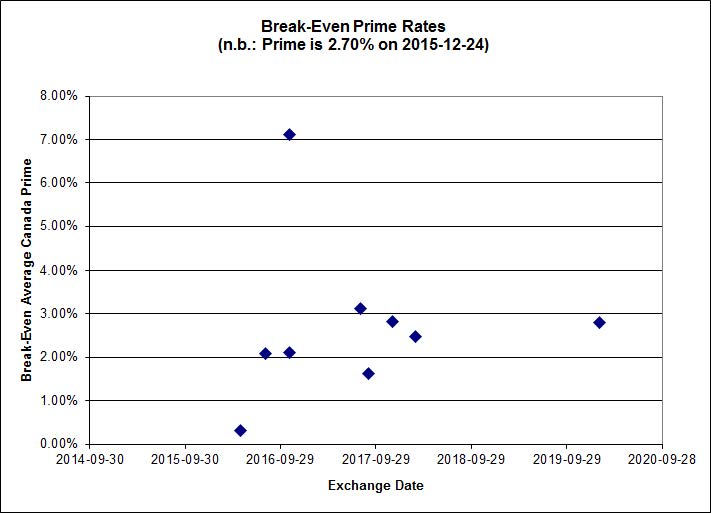
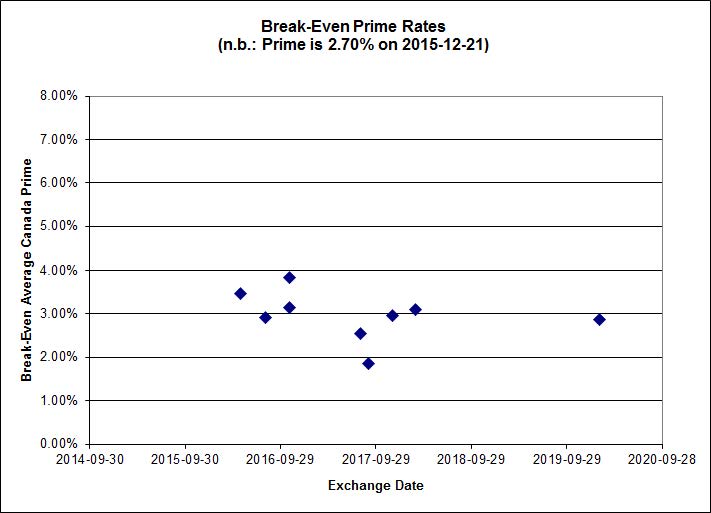
Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 4.85 % 5.88 % 28,780 16.81 1 -1.5471 % 1,605.2
FixedFloater 6.82 % 6.05 % 34,824 16.14 1 0.0000 % 2,859.5
Floater 4.21 % 4.35 % 79,991 16.74 4 -0.4439 % 1,813.8
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0795 % 2,744.2
SplitShare 4.81 % 5.75 % 78,083 1.82 6 -0.0795 % 3,211.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0795 % 2,505.5
Perpetual-Premium 5.79 % -1.96 % 90,870 0.08 6 0.0659 % 2,525.8
Perpetual-Discount 5.62 % 5.67 % 98,669 14.37 34 0.0706 % 2,558.7
FixedReset 5.18 % 4.51 % 252,463 14.84 81 -2.0716 % 1,990.1
Deemed-Retractible 5.21 % 5.11 % 123,037 5.30 34 -0.0986 % 2,582.6
FloatingReset 2.87 % 4.47 % 66,091 5.61 13 -1.4372 % 2,099.2
Performance Highlights
Issue Index Change Notes
MFC.PR.K FixedReset -5.67 % Reasonably real, as the issue traded 5,022 shares in a range of 18.36-22 before closing at 18.29-82, 1×2. VWAP was 18.62; the last trade of the day was at 2:45pm. We’ll give the market maker a pass on this, even though the closing spread is ridiculous.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.29
Bid-YTW : 7.40 %
MFC.PR.L FixedReset -4.93 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.70
Bid-YTW : 7.21 %
IFC.PR.C FixedReset -4.75 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.05
Bid-YTW : 7.07 %
SLF.PR.H FixedReset -4.71 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.01
Bid-YTW : 8.03 %
CM.PR.P FixedReset -4.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 18.05
Evaluated at bid price : 18.05
Bid-YTW : 4.34 %
CM.PR.O FixedReset -4.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 18.55
Evaluated at bid price : 18.55
Bid-YTW : 4.32 %
TD.PF.E FixedReset -4.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 20.92
Evaluated at bid price : 20.92
Bid-YTW : 4.38 %
HSE.PR.A FixedReset -4.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 12.23
Evaluated at bid price : 12.23
Bid-YTW : 5.02 %
MFC.PR.N FixedReset -4.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.09
Bid-YTW : 7.05 %
BAM.PF.F FixedReset -4.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 20.57
Evaluated at bid price : 20.57
Bid-YTW : 4.59 %
FTS.PR.M FixedReset -3.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 19.51
Evaluated at bid price : 19.51
Bid-YTW : 4.38 %
TD.PF.A FixedReset -3.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 18.55
Evaluated at bid price : 18.55
Bid-YTW : 4.31 %
TD.PF.B FixedReset -3.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 18.41
Evaluated at bid price : 18.41
Bid-YTW : 4.33 %
PWF.PR.P FixedReset -3.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 13.85
Evaluated at bid price : 13.85
Bid-YTW : 4.25 %
MFC.PR.M FixedReset -3.75 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.51
Bid-YTW : 6.82 %
TD.PF.D FixedReset -3.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 19.84
Evaluated at bid price : 19.84
Bid-YTW : 4.51 %
TRP.PR.C FixedReset -3.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 11.81
Evaluated at bid price : 11.81
Bid-YTW : 4.78 %
MFC.PR.I FixedReset -3.45 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.27
Bid-YTW : 5.95 %
NA.PR.S FixedReset -3.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 18.35
Evaluated at bid price : 18.35
Bid-YTW : 4.46 %
BMO.PR.T FixedReset -3.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 18.40
Evaluated at bid price : 18.40
Bid-YTW : 4.31 %
SLF.PR.I FixedReset -3.38 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.72
Bid-YTW : 6.71 %
MFC.PR.J FixedReset -3.37 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.10
Bid-YTW : 6.45 %
IAG.PR.G FixedReset -3.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.68
Bid-YTW : 6.25 %
BMO.PR.W FixedReset -3.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 18.35
Evaluated at bid price : 18.35
Bid-YTW : 4.29 %
BAM.PR.R FixedReset -3.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 15.86
Evaluated at bid price : 15.86
Bid-YTW : 4.84 %
TD.PF.C FixedReset -3.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 18.35
Evaluated at bid price : 18.35
Bid-YTW : 4.34 %
BAM.PR.Z FixedReset -3.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 20.19
Evaluated at bid price : 20.19
Bid-YTW : 4.72 %
BNS.PR.D FloatingReset -3.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.00
Bid-YTW : 6.21 %
BMO.PR.S FixedReset -3.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 18.86
Evaluated at bid price : 18.86
Bid-YTW : 4.31 %
BAM.PR.K Floater -2.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 10.49
Evaluated at bid price : 10.49
Bid-YTW : 4.53 %
CU.PR.C FixedReset -2.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 18.51
Evaluated at bid price : 18.51
Bid-YTW : 4.34 %
RY.PR.H FixedReset -2.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 18.45
Evaluated at bid price : 18.45
Bid-YTW : 4.32 %
NA.PR.W FixedReset -2.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 17.86
Evaluated at bid price : 17.86
Bid-YTW : 4.41 %
RY.PR.Z FixedReset -2.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 18.41
Evaluated at bid price : 18.41
Bid-YTW : 4.28 %
MFC.PR.H FixedReset -2.83 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.95
Bid-YTW : 5.75 %
FTS.PR.K FixedReset -2.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 18.24
Evaluated at bid price : 18.24
Bid-YTW : 4.11 %
BAM.PF.G FixedReset -2.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 20.80
Evaluated at bid price : 20.80
Bid-YTW : 4.57 %
BNS.PR.C FloatingReset -2.73 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.71
Bid-YTW : 4.77 %
BAM.PR.T FixedReset -2.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 17.01
Evaluated at bid price : 17.01
Bid-YTW : 4.60 %
BAM.PF.B FixedReset -2.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 19.38
Evaluated at bid price : 19.38
Bid-YTW : 4.53 %
RY.PR.J FixedReset -2.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 19.84
Evaluated at bid price : 19.84
Bid-YTW : 4.45 %
BAM.PF.A FixedReset -2.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 20.56
Evaluated at bid price : 20.56
Bid-YTW : 4.58 %
RY.PR.M FixedReset -2.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 19.75
Evaluated at bid price : 19.75
Bid-YTW : 4.36 %
BNS.PR.Z FixedReset -2.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.75
Bid-YTW : 6.31 %
BMO.PR.R FloatingReset -2.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.20
Bid-YTW : 4.23 %
BMO.PR.Y FixedReset -2.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 20.35
Evaluated at bid price : 20.35
Bid-YTW : 4.37 %
TRP.PR.H FloatingReset -2.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 10.03
Evaluated at bid price : 10.03
Bid-YTW : 4.39 %
BNS.PR.Y FixedReset -2.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.67
Bid-YTW : 6.02 %
MFC.PR.G FixedReset -2.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.66
Bid-YTW : 6.30 %
TD.PR.T FloatingReset -2.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.90
Bid-YTW : 4.43 %
TD.PR.Z FloatingReset -2.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.95
Bid-YTW : 4.47 %
NA.PR.Q FixedReset -2.00 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.50
Bid-YTW : 3.66 %
BNS.PR.B FloatingReset -1.99 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.62
Bid-YTW : 4.66 %
IFC.PR.A FixedReset -1.90 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.50
Bid-YTW : 9.21 %
CM.PR.Q FixedReset -1.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 19.85
Evaluated at bid price : 19.85
Bid-YTW : 4.45 %
BAM.PR.E Ratchet -1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 25.00
Evaluated at bid price : 14.00
Bid-YTW : 5.88 %
TRP.PR.F FloatingReset -1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 13.20
Evaluated at bid price : 13.20
Bid-YTW : 4.55 %
TD.PR.Y FixedReset -1.43 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.05
Bid-YTW : 3.80 %
BAM.PF.E FixedReset -1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 19.50
Evaluated at bid price : 19.50
Bid-YTW : 4.53 %
TRP.PR.B FixedReset -1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 11.40
Evaluated at bid price : 11.40
Bid-YTW : 4.48 %
RY.PR.I FixedReset -1.33 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.72
Bid-YTW : 4.16 %
BNS.PR.Q FixedReset -1.33 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.79
Bid-YTW : 3.86 %
TRP.PR.E FixedReset -1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 18.65
Evaluated at bid price : 18.65
Bid-YTW : 4.42 %
HSE.PR.E FixedReset -1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 18.20
Evaluated at bid price : 18.20
Bid-YTW : 6.01 %
FTS.PR.J Perpetual-Discount -1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 22.07
Evaluated at bid price : 22.36
Bid-YTW : 5.36 %
BNS.PR.E FixedReset -1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 23.29
Evaluated at bid price : 25.47
Bid-YTW : 5.13 %
BMO.PR.Z Perpetual-Discount -1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 23.29
Evaluated at bid price : 23.60
Bid-YTW : 5.35 %
TRP.PR.G FixedReset -1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 19.76
Evaluated at bid price : 19.76
Bid-YTW : 4.74 %
RY.PR.L FixedReset -1.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.83
Bid-YTW : 4.09 %
FTS.PR.G FixedReset -1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 17.50
Evaluated at bid price : 17.50
Bid-YTW : 4.32 %
HSE.PR.G FixedReset -1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 18.30
Evaluated at bid price : 18.30
Bid-YTW : 5.96 %
CU.PR.I FixedReset -1.05 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-01
Maturity Price : 25.00
Evaluated at bid price : 25.33
Bid-YTW : 4.32 %
BSC.PR.C SplitShare -1.05 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-09-22
Maturity Price : 19.71
Evaluated at bid price : 19.74
Bid-YTW : 4.01 %
GWO.PR.S Deemed-Retractible -1.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.59
Bid-YTW : 5.53 %
ENB.PR.A Perpetual-Discount -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 22.72
Evaluated at bid price : 23.01
Bid-YTW : 6.05 %
CU.PR.G Perpetual-Discount 1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 20.53
Evaluated at bid price : 20.53
Bid-YTW : 5.55 %
ELF.PR.G Perpetual-Discount 1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 21.01
Evaluated at bid price : 21.01
Bid-YTW : 5.68 %
GWO.PR.O FloatingReset 1.95 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.56
Bid-YTW : 10.38 %
HSE.PR.C FixedReset 2.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 5.59 %
VNR.PR.A FixedReset 4.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 19.31
Evaluated at bid price : 19.31
Bid-YTW : 4.77 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.Q FixedReset 647,883 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-24
Maturity Price : 25.00
Evaluated at bid price : 25.67
Bid-YTW : 5.02 %
BNS.PR.E FixedReset 353,322 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 23.29
Evaluated at bid price : 25.47
Bid-YTW : 5.13 %
BIP.PR.A FixedReset 52,230 Nesbitt crossed 50,000 at 19.75.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 19.51
Evaluated at bid price : 19.51
Bid-YTW : 5.59 %
TD.PF.C FixedReset 26,660 Desjardins bought 14,000 from National at 18.20.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 18.35
Evaluated at bid price : 18.35
Bid-YTW : 4.34 %
RY.PR.Z FixedReset 25,416 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 18.41
Evaluated at bid price : 18.41
Bid-YTW : 4.28 %
BNS.PR.R FixedReset 24,926 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.27
Bid-YTW : 3.75 %
There were 28 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BNS.PR.Z FixedReset Quote: 19.75 – 20.39
Spot Rate : 0.6400
Average : 0.3788

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.75
Bid-YTW : 6.31 %

BMO.PR.R FloatingReset Quote: 22.20 – 22.83
Spot Rate : 0.6300
Average : 0.4149

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.20
Bid-YTW : 4.23 %

BAM.PR.Z FixedReset Quote: 20.19 – 20.83
Spot Rate : 0.6400
Average : 0.4388

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 20.19
Evaluated at bid price : 20.19
Bid-YTW : 4.72 %

IFC.PR.C FixedReset Quote: 19.05 – 19.70
Spot Rate : 0.6500
Average : 0.4595

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.05
Bid-YTW : 7.07 %

PWF.PR.T FixedReset Quote: 22.75 – 23.96
Spot Rate : 1.2100
Average : 1.0259

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-05
Maturity Price : 22.27
Evaluated at bid price : 22.75
Bid-YTW : 3.59 %

SLF.PR.H FixedReset Quote: 17.01 – 17.85
Spot Rate : 0.8400
Average : 0.6588

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.01
Bid-YTW : 8.03 %

Market Action

January 4, 2016

For many, the new year started with a hangover:

As losses snowballed in U.S. stocks around midday, the best thing U.S. bulls had to say about the worst start to a year since 2001 was that there are 248 more trading days to make it up.
…
Taking a break and breathing helped: the Dow added almost 150 points in the last 30 minutes to pare its loss to 276 points. Still, investors returning to work from holidays were greeted by the sixth-worst start to a year since 1927 for the Standard & Poor’s 500 Index, which plunged 1.5 percent to erase $289 billion in market value as weak Chinese manufacturing data unnerved equity markets.

The selloff started in China and persisted thanks to a flareup in tension between Saudi Arabia and Iran. A report in the U.S. showed manufacturing contracted at the fastest pace in more than six years added to concerns that growth is slowing.

The rout appears to have paused, due in part to decisive action from the Chinese securities regulator:

Asian stocks erased losses as a selloff in China abated after the regulator sought to reassure investors following Monday’s plunge. Oil and industrial metals rose.

The regional share gauge erased what would have been a second day of declines as Korean and Japanese equities rose. The Shanghai Composite Index wiped out an initial slump of more than 3 percent as China’s central bank injected cash into the banking system and the securities regulator pledged to keep improving its circuit-breaker system that saw stock trading halted amid Monday’s rout. West Texas Intermediate crude rose 0.6 percent.
…
A 7 percent slump in mainland China shares triggered a trading halt there on the first day of business in 2016. The rout, which spread throughout Asia, Europe and the U.S., was sparked by weak factory data in China and exacerbated by a slide in American manufacturing. China Securities Regulatory Commission said it’s studying measures to limit the pace of stock sales by major shareholders, while the central bank Monday conducted the biggest reverse-repurchase operations since September.

Good stuff! If the market’s going down due to selling pressure, make it illegal to sell! That will fix everything!

Meanwhile Federal Reserve Vice Chairman Stanley Fischer has given a boost to the central planners and micro-managers:

He told the American Economic Association on Sunday that the Fed is not as well-equipped with regulatory powers to rein in housing and other asset bubbles as some other central banks. And he questioned whether Congress had gone too far in limiting the Fed’s ability to intervene if a crisis erupted and threatened the financial system.

“We won’t know until it’s very late” whether the Fed has been constrained too much, Fischer said at the AEA’s annual meeting in San Francisco. That’s something “we have to worry about a great deal.”

Fischer’s comments suggest that the central bank may need to rely more on monetary policy to restrain financial excesses than it has in the past. In fact, he told the conference that it might be necessary for the Fed to increase interest rates if financial markets were overheating, though the first line of defense should be the use of regulatory measures to head off bubbles.

In arguing that the Fed has less leeway to restrain speculative excesses than other central banks, Fischer pointed in particular to the property market, the epicenter of the last financial crisis. Faced with run-away real estate prices, many other countries have tightened loan-to-value or debt-to-income ratios to curb borrowing.

“In the United States, responding to such problems with these tools would require inter-agency coordination” between the Fed and other government regulators, he said. That “could make their use cumbersome at critical moments.”

On Dec. 18 the Fed and other agencies issued a thinly veiled warning to banks in which it “reminded” them about “existing regulatory guidance on prudent risk management practices for commercial real estate lending.”

But when discussing Fischer we must remember that he’s basically sound:

Lesson T4: The lender of last resort, TBTF, and moral hazard.9 The role of the central bank as lender of last resort is a central theme in Walter Bagehot’s 1873 classic on central banking, Lombard Street. The case for the central bank to be the lender of last resort is clear in the case of a liquidity crisis–one that arises from a temporary shortage of liquidity, typically in a financial panic–but less so in the case of solvency crises.10

In principle the distinction between liquidity and solvency problems should guide the actions of the central bank and the government in a financial crisis. But in a crisis, the distinction between illiquidity and insolvency is rarely clear-cut–and whether a company goes bankrupt will depend on how the authorities respond to the crisis.

Further, one has to be clear about which aspects of government actions are critical in this regard. If a firm is bankrupt, it may well be optimal for the firm to continue to operate while being reorganized, as typically happens in bankruptcies. In such a case, in which the firm’s capital is negative, the ownership of the bankrupt firm should be changed–unless the owners succeed in mobilizing more capital, in which case the company was probably not bankrupt.

And this isn’t exactly drone news – which I am confident will be prominent on this blog in 2016, if not dominant – but close enough for Government Motors work:

General Motors Co. will invest $500 million in Lyft Inc., giving the ride-hailing startup a valuation of $5.5 billion and a major ally in the global battle against Uber Technologies Inc.

The investment, part of a $1 billion financing round for Lyft, is the biggest move by an automaker to date when it comes to grappling with the meteoric rise of the ride-hailing industry.

GM and Lyft said they will work together to develop a network of self-driving cars that riders can call up on-demand, a vision of the future shared by the likes of Uber Chief Executive Officer Travis Kalanick and Google-parent Alphabet Inc. More immediately, America’s largest automaker will offer Lyft drivers vehicles for short-term rent through various hubs in U.S. cities, the companies said in separate statements on Monday.

John Shmuel of the Financial Post recently touted the interest of institutional investors in the preferred market:

There are also signs that institutional players are taking notice of the market after the recent discounts. Retail investors are usually the biggest buyers of preferred shares, with institutional investors representing only 20 per cent of the buyers of an average issuance.

But that has changed with recent issues. In September, for example, Canadian Utilities Ltd. raised $250 million by offering a rate reset preferred share at a yield of 4.5 per cent, and 70 per cent of the buyers were institutional investors.

The issue also included a new minimum yield feature, offering investors a floor that will prevent the yield from going below what it was issued at.

More recently, Royal Bank of Canada came to market with one of the biggest preferred share issuances ever in Canada, offering investors a rate of 5.5 per cent, which will reset every five years at 4.53 per cent above the government five-year bond yield.

Institutional investors were again the biggest buyers in this issue, scooping up two-thirds of the shares.

Now, this is a little peculiar; something I would want to be asking questions about. As all Assiduous Readers know, new issues are generally deprecated on PrefBlog because they have a very high negative convexity. Sometimes – rarely – the concession makes them worth-while, but in general, the fact that long-term potential capital gains are tightly constrained and that potential capital losses are not make them poor investments. I will certainly agree that a market outlook of unchanging yields can make them more attractive, especially if there is a nice new-issue concession offered; and I will also agree that in an environment of rising yields there is a certain amount of loss-mitigation due to the erosion of the premium for the embedded call; but the article is touting the potential for capital gains, in which case deeply discounted issues are the way to go. It would be interesting to have an honest heart-to-heart with the players who scooped up these new issues … but an outsider will never get that!

Assiduous Reader SafetyinNumbers brings to my attention a Normal Course Issuer Bid for AZP.PR.A, AZP.PR.B and AZP.PR.C:

Atlantic Power Corporation (TSX: ATP) (NYSE: AT) (the “Company” or “Atlantic Power”) and Atlantic Power Preferred Equity Ltd (“APPEL”) announced today that Atlantic Power intends to make a normal course issuer bid (“NCIB”) for each of the following series of the Company’s convertible unsecured subordinated debentures and its common shares and that APPEL intends to make an NCIB for each of the following series of its preferred shares (collectively, the “Public Securities”):
…
Under its previous NCIB, Atlantic Power purchased Cdn$150,000 of its 6.25% debentures at an average price of Cdn$87.12; Cdn$4,661,000 of its 5.6% debentures at an average price of Cdn$91.71; US$13,000,000 of its 5.75% debentures at an average price of US$80.80; and Cdn$10,000,000 of its 6.0% debentures at an average price of Cdn$82.19.

It’s nice to see the company delivering, given its poor credit, but I suspect that prudence will dictate that the company only buys back the debentures.

In the week following Christmas, preferred share investors enjoyed fireworks. Now they get:

fireworksDebris
Click for Big

It was a horrible start to the year for the Canadian preferred share market, with PerpetualDiscounts off 41bp, FixedResets losing an incredible 297bp and DeemedRetractibles down 56bp. The Performance Highlights table is just silly, of course, with only one winner. Volume was very low – in fact, by my ‘breadth’ measure it wasn’t much more than we saw during the dead week of Christmas to New Year’s,

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_160104
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 18.90 to be $1.03 rich, while TRP.PR.C, resetting 2016-1-30 at +154, is $1.09 cheap at its bid price of 12.26.

impVol_MFC_160104
Click for Big

Most expensive is MFC.PR.L, resetting at +216bp on 2019-6-19, bid at 19.67 to be 0.66 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 21.11 to be 0.92 0cheap.

impVol_BAM_160104
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 16.38 to be $1.37 cheap. BAM.PF.G, resetting at +284bp on 2020-6-30 is bid at 21.40 and appears to be $0.71 rich.

impVol_FTS_160104
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 18.77, looks $0.83 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 17.70 and is $0.72 cheap.

pairs_FR_160104
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -0.89%, with one outliers above 0.00%, and one below -2.00%. Note the scale of the y-axis has changed. There is one junk outlier above 0.00%.

pairs_FF_160104
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 4.77 % 5.79 % 29,266 16.92 1 -1.9310 % 1,630.4
FixedFloater 6.82 % 6.05 % 36,225 16.14 1 -0.2151 % 2,859.5
Floater 4.19 % 4.38 % 78,915 16.69 4 -0.3538 % 1,821.9
OpRet 0.00 % 0.00 % 0 0.00 0 -0.1132 % 2,746.4
SplitShare 4.81 % 5.78 % 80,711 1.82 6 -0.1132 % 3,213.8
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.1132 % 2,507.5
Perpetual-Premium 5.79 % 3.20 % 91,891 0.09 6 -0.4462 % 2,524.1
Perpetual-Discount 5.63 % 5.68 % 102,372 14.36 34 -0.4139 % 2,556.9
FixedReset 5.07 % 4.40 % 255,333 14.78 81 -2.9709 % 2,032.2
Deemed-Retractible 5.21 % 5.17 % 125,066 5.30 34 -0.5584 % 2,585.1
FloatingReset 2.82 % 4.27 % 65,184 5.62 13 -1.3557 % 2,129.8
Performance Highlights
Issue Index Change Notes
VNR.PR.A FixedReset -7.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 18.47
Evaluated at bid price : 18.47
Bid-YTW : 4.99 %
MFC.PR.G FixedReset -6.55 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.11
Bid-YTW : 6.00 %
BMO.PR.Q FixedReset -6.44 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.21
Bid-YTW : 5.97 %
MFC.PR.H FixedReset -6.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.59
Bid-YTW : 5.36 %
GWO.PR.O FloatingReset -5.95 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.32
Bid-YTW : 10.63 %
BAM.PR.X FixedReset -5.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 14.98
Evaluated at bid price : 14.98
Bid-YTW : 4.47 %
SLF.PR.H FixedReset -5.61 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.85
Bid-YTW : 7.37 %
CU.PR.C FixedReset -5.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 19.07
Evaluated at bid price : 19.07
Bid-YTW : 4.21 %
TRP.PR.B FixedReset -5.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 11.56
Evaluated at bid price : 11.56
Bid-YTW : 4.41 %
MFC.PR.J FixedReset -5.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.80
Bid-YTW : 5.98 %
IFC.PR.A FixedReset -5.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.80
Bid-YTW : 8.94 %
MFC.PR.N FixedReset -5.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.90
Bid-YTW : 6.48 %
MFC.PR.K FixedReset -4.95 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.39
Bid-YTW : 6.60 %
SLF.PR.G FixedReset -4.87 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.65
Bid-YTW : 9.01 %
HSE.PR.E FixedReset -4.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 18.44
Evaluated at bid price : 18.44
Bid-YTW : 5.93 %
MFC.PR.I FixedReset -4.84 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.03
Bid-YTW : 5.47 %
HSE.PR.C FixedReset -4.82 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 17.58
Evaluated at bid price : 17.58
Bid-YTW : 5.72 %
HSE.PR.G FixedReset -4.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 18.50
Evaluated at bid price : 18.50
Bid-YTW : 5.90 %
BIP.PR.A FixedReset -4.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 19.55
Evaluated at bid price : 19.55
Bid-YTW : 5.58 %
SLF.PR.I FixedReset -4.40 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.41
Bid-YTW : 6.24 %
CM.PR.P FixedReset -4.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 18.92
Evaluated at bid price : 18.92
Bid-YTW : 4.13 %
MFC.PR.M FixedReset -4.30 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.27
Bid-YTW : 6.29 %
NA.PR.W FixedReset -4.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 18.39
Evaluated at bid price : 18.39
Bid-YTW : 4.28 %
BAM.PR.Z FixedReset -4.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 20.85
Evaluated at bid price : 20.85
Bid-YTW : 4.57 %
IFC.PR.C FixedReset -4.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.00
Bid-YTW : 6.41 %
FTS.PR.G FixedReset -3.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 17.70
Evaluated at bid price : 17.70
Bid-YTW : 4.26 %
RY.PR.K FloatingReset -3.79 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.61
Bid-YTW : 4.20 %
IAG.PR.G FixedReset -3.69 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.40
Bid-YTW : 5.78 %
MFC.PR.L FixedReset -3.67 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.67
Bid-YTW : 6.51 %
PWF.PR.T FixedReset -3.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 22.36
Evaluated at bid price : 22.89
Bid-YTW : 3.56 %
BMO.PR.S FixedReset -3.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 19.47
Evaluated at bid price : 19.47
Bid-YTW : 4.17 %
CM.PR.O FixedReset -3.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 19.39
Evaluated at bid price : 19.39
Bid-YTW : 4.13 %
TRP.PR.C FixedReset -3.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 12.26
Evaluated at bid price : 12.26
Bid-YTW : 4.61 %
BNS.PR.Z FixedReset -3.40 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.20
Bid-YTW : 5.90 %
TRP.PR.G FixedReset -3.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 4.68 %
BNS.PR.Y FixedReset -3.32 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.10
Bid-YTW : 5.63 %
BMO.PR.T FixedReset -3.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 19.05
Evaluated at bid price : 19.05
Bid-YTW : 4.16 %
BMO.PR.Y FixedReset -3.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 20.80
Evaluated at bid price : 20.80
Bid-YTW : 4.27 %
BAM.PF.G FixedReset -3.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 21.40
Evaluated at bid price : 21.40
Bid-YTW : 4.43 %
BAM.PF.E FixedReset -3.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 19.78
Evaluated at bid price : 19.78
Bid-YTW : 4.47 %
RY.PR.H FixedReset -3.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 4.19 %
BAM.PF.F FixedReset -3.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 21.43
Evaluated at bid price : 21.43
Bid-YTW : 4.40 %
BAM.PF.B FixedReset -2.97 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 19.90
Evaluated at bid price : 19.90
Bid-YTW : 4.40 %
BAM.PR.T FixedReset -2.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 17.47
Evaluated at bid price : 17.47
Bid-YTW : 4.47 %
RY.PR.Z FixedReset -2.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 18.95
Evaluated at bid price : 18.95
Bid-YTW : 4.15 %
TRP.PR.A FixedReset -2.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 16.00
Evaluated at bid price : 16.00
Bid-YTW : 4.34 %
FTS.PR.M FixedReset -2.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 20.32
Evaluated at bid price : 20.32
Bid-YTW : 4.20 %
BMO.PR.W FixedReset -2.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 18.98
Evaluated at bid price : 18.98
Bid-YTW : 4.14 %
HSE.PR.A FixedReset -2.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 12.75
Evaluated at bid price : 12.75
Bid-YTW : 4.82 %
BAM.PF.A FixedReset -2.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 21.03
Evaluated at bid price : 21.03
Bid-YTW : 4.47 %
TD.PF.A FixedReset -2.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 19.32
Evaluated at bid price : 19.32
Bid-YTW : 4.13 %
TD.PF.C FixedReset -2.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 18.95
Evaluated at bid price : 18.95
Bid-YTW : 4.20 %
MFC.PR.F FixedReset -2.60 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.60
Bid-YTW : 9.09 %
BAM.PR.R FixedReset -2.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 16.38
Evaluated at bid price : 16.38
Bid-YTW : 4.68 %
TD.PF.B FixedReset -2.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 19.15
Evaluated at bid price : 19.15
Bid-YTW : 4.16 %
GWO.PR.N FixedReset -2.43 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.65
Bid-YTW : 9.82 %
TRP.PR.D FixedReset -2.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 18.45
Evaluated at bid price : 18.45
Bid-YTW : 4.40 %
CIU.PR.C FixedReset -2.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 12.40
Evaluated at bid price : 12.40
Bid-YTW : 4.28 %
CM.PR.Q FixedReset -2.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 20.20
Evaluated at bid price : 20.20
Bid-YTW : 4.37 %
SLF.PR.A Deemed-Retractible -2.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.41
Bid-YTW : 6.96 %
BMO.PR.M FixedReset -2.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.00
Bid-YTW : 3.64 %
MFC.PR.C Deemed-Retractible -2.18 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.62
Bid-YTW : 7.24 %
TD.PF.D FixedReset -2.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 20.61
Evaluated at bid price : 20.61
Bid-YTW : 4.34 %
SLF.PR.J FloatingReset -2.00 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.72
Bid-YTW : 9.39 %
FTS.PR.I FloatingReset -1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 12.50
Evaluated at bid price : 12.50
Bid-YTW : 3.87 %
MFC.PR.B Deemed-Retractible -1.95 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.13
Bid-YTW : 7.06 %
BAM.PR.E Ratchet -1.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 25.00
Evaluated at bid price : 14.22
Bid-YTW : 5.79 %
BNS.PR.A FloatingReset -1.93 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.41
Bid-YTW : 4.37 %
RY.PR.I FixedReset -1.92 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.04
Bid-YTW : 3.91 %
CU.PR.G Perpetual-Discount -1.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 20.26
Evaluated at bid price : 20.26
Bid-YTW : 5.63 %
FTS.PR.K FixedReset -1.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 18.77
Evaluated at bid price : 18.77
Bid-YTW : 3.98 %
TRP.PR.F FloatingReset -1.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 13.40
Evaluated at bid price : 13.40
Bid-YTW : 4.49 %
BMO.PR.R FloatingReset -1.77 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.70
Bid-YTW : 3.83 %
RY.PR.J FixedReset -1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 20.34
Evaluated at bid price : 20.34
Bid-YTW : 4.33 %
CU.PR.F Perpetual-Discount -1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 20.35
Evaluated at bid price : 20.35
Bid-YTW : 5.60 %
BAM.PF.C Perpetual-Discount -1.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 20.07
Evaluated at bid price : 20.07
Bid-YTW : 6.09 %
SLF.PR.C Deemed-Retractible -1.59 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.36
Bid-YTW : 7.33 %
BNS.PR.P FixedReset -1.57 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.47
Bid-YTW : 3.35 %
CU.PR.E Perpetual-Discount -1.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 21.64
Evaluated at bid price : 21.91
Bid-YTW : 5.65 %
POW.PR.D Perpetual-Discount -1.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 21.98
Evaluated at bid price : 22.21
Bid-YTW : 5.64 %
TD.PF.E FixedReset -1.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 21.53
Evaluated at bid price : 21.84
Bid-YTW : 4.17 %
FTS.PR.H FixedReset -1.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 14.16
Evaluated at bid price : 14.16
Bid-YTW : 3.99 %
SLF.PR.B Deemed-Retractible -1.37 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.60
Bid-YTW : 6.89 %
SLF.PR.D Deemed-Retractible -1.36 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.27
Bid-YTW : 7.40 %
BAM.PF.H FixedReset -1.35 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.65
Bid-YTW : 4.45 %
CU.PR.D Perpetual-Discount -1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 21.66
Evaluated at bid price : 21.94
Bid-YTW : 5.64 %
TD.PR.S FixedReset -1.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.20
Bid-YTW : 3.49 %
CIU.PR.A Perpetual-Discount -1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 20.50
Evaluated at bid price : 20.50
Bid-YTW : 5.69 %
NA.PR.S FixedReset -1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 4.31 %
IGM.PR.B Perpetual-Premium -1.07 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.03
Bid-YTW : 5.74 %
RY.PR.M FixedReset -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 20.20
Evaluated at bid price : 20.20
Bid-YTW : 4.26 %
ENB.PR.A Perpetual-Discount 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 22.98
Evaluated at bid price : 23.25
Bid-YTW : 5.98 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.Q FixedReset 190,141 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-24
Maturity Price : 25.00
Evaluated at bid price : 25.66
Bid-YTW : 5.02 %
NA.PR.S FixedReset 137,370 TD crossed 130,000 at 19.00.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 4.31 %
GWO.PR.N FixedReset 56,825 Scotia crossed 45,000 at 13.90.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.65
Bid-YTW : 9.82 %
FTS.PR.M FixedReset 52,750 Desjardins crossed 50,000 at 20.45.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 20.32
Evaluated at bid price : 20.32
Bid-YTW : 4.20 %
BIP.PR.B FixedReset 34,721 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 22.78
Evaluated at bid price : 24.00
Bid-YTW : 5.73 %
CM.PR.O FixedReset 32,000 RBC crossed 25,000 at 19.62.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 19.39
Evaluated at bid price : 19.39
Bid-YTW : 4.13 %
There were 11 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
VNR.PR.A FixedReset Quote: 18.47 – 20.00
Spot Rate : 1.5300
Average : 0.8870

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 18.47
Evaluated at bid price : 18.47
Bid-YTW : 4.99 %

BMO.PR.Q FixedReset Quote: 20.21 – 21.27
Spot Rate : 1.0600
Average : 0.6874

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.21
Bid-YTW : 5.97 %

SLF.PR.I FixedReset Quote: 20.41 – 21.20
Spot Rate : 0.7900
Average : 0.5261

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.41
Bid-YTW : 6.24 %

MFC.PR.J FixedReset Quote: 20.80 – 21.50
Spot Rate : 0.7000
Average : 0.4445

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.80
Bid-YTW : 5.98 %

SLF.PR.H FixedReset Quote: 17.85 – 18.56
Spot Rate : 0.7100
Average : 0.4601

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.85
Bid-YTW : 7.37 %

PWF.PR.T FixedReset Quote: 22.89 – 23.95
Spot Rate : 1.0600
Average : 0.8240

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2046-01-04
Maturity Price : 22.36
Evaluated at bid price : 22.89
Bid-YTW : 3.56 %

Market Action

December 31, 2015

The federal Competition Bureau has heretofore been best known for its decision, reported July 4, 2012, to allow the banks to reduce competition in the Canadian financial market, provided extra payments were made to their buddies at the OSC. It would seem that the Bureau has been very impressed by the OSC’s ability to fund puppet groups providing employment for their buddies at taxpayer expense and have decided that this is just too good a deal to turn down:

As part of a consent agreement with the Competition Bureau, Telus will issue rebates of up to $7.34 million to certain current and former wireless customers after the Bureau concluded that Telus made, or permitted to be made, false or misleading representations in advertisements for premium text messages in pop‑up ads, apps and on social media.
…
Telus will also donate a total of $250,000 to the Ryerson University Privacy and Big Data Institute; Éducaloi, a non‑profit organization dedicated to helping the public understand their rights and responsibilities under the law; and the Centre de recherche en droit public de l’Université de Montréal.

It’s nice work, if you can get it!

Canadian preferred share investors celebrated the first calendar week of No More Tax Loss Selling!

party
Click for Big

It was an excellent day overall for the Canadian preferred share market, although DeemedRetractibles provided a reminder of what 2015 was like, with PerpetualDiscounts gaining 63bp, FixedResets up 93bp and DeemedRetractibles off 18bp. The Performance Highlights table continues to show lots of churn. Volume was virtually non-existent.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_151231
Click for Big

TRP.PR.A, which resets 2019-12-31 at +192, is bid at 16.46 to be $0.50 rich, while TRP.PR.C, resetting 2016-1-30 at +154, is $1.03 cheap at its bid price of 12.70.

impVol_MFC_151231
Click for Big

Most expensive is MFC.PR.L, resetting at +216bp on 2019-6-19, bid at 20.42 to be 0.47 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 22.59 to be 0.66 cheap.

impVol_BAM_151231
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 16.80 to be $1.56 cheap. BAM.PF.G, resetting at +284bp on 2020-6-30 is bid at 22.10 and appears to be $0.73 rich.

impVol_FTS_151231
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 19.13, looks $0.70 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 18.40 and is $0.53 cheap.

pairs_FR_151231A
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -1.09%, with two outliers above -0.50%, including the newly created GWO.PR.N / GWO.PR.O pair. There are four junk outliers above -0.50%, including the newly created FFH.PR.I / FFH.PR.J pair.

pairs_FF_151231
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 4.68 % 5.67 % 29,722 17.08 1 0.6944 % 1,662.5
FixedFloater 6.81 % 6.03 % 37,769 16.17 1 3.7175 % 2,865.7
Floater 4.18 % 4.32 % 79,998 16.76 4 -0.3306 % 1,828.4
OpRet 4.84 % 3.69 % 24,986 0.65 1 0.3172 % 2,749.5
SplitShare 4.80 % 5.55 % 83,852 1.83 6 0.1454 % 3,217.5
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1454 % 2,510.4
Perpetual-Premium 5.75 % 2.81 % 91,918 0.08 7 0.1017 % 2,535.4
Perpetual-Discount 5.60 % 5.66 % 104,639 14.38 33 0.6347 % 2,567.6
FixedReset 4.92 % 4.26 % 259,128 14.92 81 0.9296 % 2,094.4
Deemed-Retractible 5.17 % 5.09 % 128,555 5.31 33 -0.1768 % 2,599.6
FloatingReset 2.80 % 4.15 % 68,430 5.64 12 0.1337 % 2,159.1
Performance Highlights
Issue Index Change Notes
TRP.PR.B FixedReset -2.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 12.20
Evaluated at bid price : 12.20
Bid-YTW : 4.18 %
IAG.PR.A Deemed-Retractible -1.85 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.25
Bid-YTW : 6.89 %
BAM.PF.A FixedReset -1.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 21.30
Evaluated at bid price : 21.60
Bid-YTW : 4.33 %
SLF.PR.G FixedReset -1.53 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.40
Bid-YTW : 8.34 %
SLF.PR.D Deemed-Retractible -1.39 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.55
Bid-YTW : 7.19 %
SLF.PR.C Deemed-Retractible -1.00 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.69
Bid-YTW : 7.09 %
IAG.PR.G FixedReset 1.00 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.22
Bid-YTW : 5.27 %
BAM.PR.N Perpetual-Discount 1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 20.01
Evaluated at bid price : 20.01
Bid-YTW : 5.98 %
MFC.PR.F FixedReset 1.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.99
Bid-YTW : 8.73 %
BAM.PF.B FixedReset 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 20.51
Evaluated at bid price : 20.51
Bid-YTW : 4.27 %
TD.PF.C FixedReset 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 19.46
Evaluated at bid price : 19.46
Bid-YTW : 4.08 %
ELF.PR.G Perpetual-Discount 1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 20.89
Evaluated at bid price : 20.89
Bid-YTW : 5.71 %
MFC.PR.G FixedReset 1.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.59
Bid-YTW : 5.07 %
TD.PF.D FixedReset 1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 21.05
Evaluated at bid price : 21.05
Bid-YTW : 4.25 %
BMO.PR.S FixedReset 1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 20.20
Evaluated at bid price : 20.20
Bid-YTW : 4.01 %
CU.PR.C FixedReset 1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 20.17
Evaluated at bid price : 20.17
Bid-YTW : 3.97 %
MFC.PR.I FixedReset 1.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.15
Bid-YTW : 4.79 %
RY.PR.H FixedReset 1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 19.60
Evaluated at bid price : 19.60
Bid-YTW : 4.06 %
RY.PR.Z FixedReset 1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 19.51
Evaluated at bid price : 19.51
Bid-YTW : 4.03 %
MFC.PR.J FixedReset 1.34 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.95
Bid-YTW : 5.25 %
W.PR.H Perpetual-Discount 1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 23.25
Evaluated at bid price : 23.55
Bid-YTW : 5.85 %
FTS.PR.M FixedReset 1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 20.90
Evaluated at bid price : 20.90
Bid-YTW : 4.07 %
BMO.PR.Y FixedReset 1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 21.50
Evaluated at bid price : 21.50
Bid-YTW : 4.13 %
BNS.PR.D FloatingReset 1.48 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.46
Bid-YTW : 5.76 %
FTS.PR.K FixedReset 1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 19.13
Evaluated at bid price : 19.13
Bid-YTW : 3.90 %
RY.PR.M FixedReset 1.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 20.41
Evaluated at bid price : 20.41
Bid-YTW : 4.21 %
MFC.PR.M FixedReset 1.58 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.18
Bid-YTW : 5.69 %
IFC.PR.A FixedReset 1.59 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.66
Bid-YTW : 8.20 %
MFC.PR.N FixedReset 1.65 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.95
Bid-YTW : 5.77 %
FTS.PR.G FixedReset 1.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 18.40
Evaluated at bid price : 18.40
Bid-YTW : 4.09 %
BMO.PR.W FixedReset 1.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 19.51
Evaluated at bid price : 19.51
Bid-YTW : 4.02 %
PWF.PR.T FixedReset 1.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 22.84
Evaluated at bid price : 23.75
Bid-YTW : 3.39 %
HSE.PR.G FixedReset 1.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 19.43
Evaluated at bid price : 19.43
Bid-YTW : 5.61 %
TD.PF.B FixedReset 1.97 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 19.64
Evaluated at bid price : 19.64
Bid-YTW : 4.05 %
BAM.PR.Z FixedReset 2.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 21.42
Evaluated at bid price : 21.76
Bid-YTW : 4.35 %
BMO.PR.T FixedReset 2.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 19.70
Evaluated at bid price : 19.70
Bid-YTW : 4.01 %
CIU.PR.A Perpetual-Discount 2.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 20.74
Evaluated at bid price : 20.74
Bid-YTW : 5.62 %
SLF.PR.H FixedReset 2.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.91
Bid-YTW : 6.59 %
BAM.PR.R FixedReset 2.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 16.80
Evaluated at bid price : 16.80
Bid-YTW : 4.57 %
TD.PF.A FixedReset 2.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 19.84
Evaluated at bid price : 19.84
Bid-YTW : 4.02 %
FTS.PR.F Perpetual-Discount 2.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 22.97
Evaluated at bid price : 23.24
Bid-YTW : 5.32 %
FTS.PR.I FloatingReset 2.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 12.75
Evaluated at bid price : 12.75
Bid-YTW : 3.77 %
BAM.PF.D Perpetual-Discount 2.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 20.50
Evaluated at bid price : 20.50
Bid-YTW : 6.02 %
CM.PR.O FixedReset 2.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 20.11
Evaluated at bid price : 20.11
Bid-YTW : 3.97 %
CIU.PR.C FixedReset 2.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 12.70
Evaluated at bid price : 12.70
Bid-YTW : 4.17 %
CU.PR.F Perpetual-Discount 3.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 20.69
Evaluated at bid price : 20.69
Bid-YTW : 5.51 %
HSE.PR.E FixedReset 3.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 19.38
Evaluated at bid price : 19.38
Bid-YTW : 5.63 %
CM.PR.P FixedReset 3.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 19.77
Evaluated at bid price : 19.77
Bid-YTW : 3.95 %
HSE.PR.A FixedReset 3.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 13.10
Evaluated at bid price : 13.10
Bid-YTW : 4.70 %
BAM.PR.G FixedFloater 3.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 25.00
Evaluated at bid price : 13.95
Bid-YTW : 6.03 %
BAM.PR.X FixedReset 3.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 15.92
Evaluated at bid price : 15.92
Bid-YTW : 4.21 %
NA.PR.W FixedReset 3.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 19.20
Evaluated at bid price : 19.20
Bid-YTW : 4.17 %
MFC.PR.K FixedReset 3.98 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.40
Bid-YTW : 5.91 %
IFC.PR.C FixedReset 4.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.85
Bid-YTW : 5.84 %
SLF.PR.J FloatingReset 4.40 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.00
Bid-YTW : 9.10 %
HSE.PR.C FixedReset 5.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 18.47
Evaluated at bid price : 18.47
Bid-YTW : 5.44 %
Volume Highlights
Issue Index Shares
Traded
Notes
MFC.PR.F FixedReset 44,160 RBC crossed 34,300 at 15.00.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.99
Bid-YTW : 8.73 %
BAM.PR.R FixedReset 21,263 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 16.80
Evaluated at bid price : 16.80
Bid-YTW : 4.57 %
CM.PR.P FixedReset 18,500 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 19.77
Evaluated at bid price : 19.77
Bid-YTW : 3.95 %
MFC.PR.I FixedReset 12,950 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.15
Bid-YTW : 4.79 %
HSE.PR.A FixedReset 12,929 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 13.10
Evaluated at bid price : 13.10
Bid-YTW : 4.70 %
SLF.PR.J FloatingReset 12,700 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.00
Bid-YTW : 9.10 %
There were 3 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
TRP.PR.E FixedReset Quote: 18.80 – 20.00
Spot Rate : 1.2000
Average : 0.8799

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 18.80
Evaluated at bid price : 18.80
Bid-YTW : 4.38 %

HSE.PR.G FixedReset Quote: 19.43 – 20.07
Spot Rate : 0.6400
Average : 0.3922

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 19.43
Evaluated at bid price : 19.43
Bid-YTW : 5.61 %

W.PR.J Perpetual-Discount Quote: 23.89 – 24.42
Spot Rate : 0.5300
Average : 0.3703

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-31
Maturity Price : 23.62
Evaluated at bid price : 23.89
Bid-YTW : 5.87 %

BNS.PR.C FloatingReset Quote: 22.29 – 22.99
Spot Rate : 0.7000
Average : 0.5610

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.29
Bid-YTW : 4.27 %

SLF.PR.G FixedReset Quote: 15.40 – 16.00
Spot Rate : 0.6000
Average : 0.4723

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.40
Bid-YTW : 8.34 %

IGM.PR.B Perpetual-Premium Quote: 25.30 – 25.70
Spot Rate : 0.4000
Average : 0.2982

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-12-31
Maturity Price : 25.25
Evaluated at bid price : 25.30
Bid-YTW : 5.51 %

Market Action

December 30, 2015

New Year’s is prediction season!

Bond returns will probably be ho-hum next year — just as they have been in 2015 — according to the biggest investors.

JPMorgan Chase & Co., Fidelity Investments, Pacific Investment Management Co. and Goldman Sachs Group Inc. are all cautioning investors not to be too optimistic. Goldman Sachs predicts benchmark U.S. 10-year yields will climb to 3 percent by the end of 2016 from 2.30 percent Wednesday.
…
The odds of at least one more increase in 2016 are 94 percent, futures contracts indicate, threatening to push bond yields higher worldwide.
…
An investor would lose 3.2 percent if Goldman Sachs’s yield forecast proves to be accurate, data compiled by Bloomberg show.

There is another interesting column on risk in Bloomberg, penned by Justin Fox:

Twenty years ago, Dutch journalist Sheila Sitalsing sat down with a demographer at the country’s statistics office to talk about how aging would change the Netherlands. His prediction, she recounts in a column that’s the most-read thing on the website of the Dutch newspaper de Volkskrant, was that aging would “change the atmosphere and the mentality of the country.” For example:

Things that come with being young — taking risks, seizing opportunities, daring to do things, diving into the deep end without thought and without water wings, doing drugs, making noise, calling after girls on the street corner, embracing the strange and the new — would become less common. The atmosphere would be determined by the concerns of the old: avoiding risk, being careful, preserving what you have, saying goodbye, keeping quiet, suspicion of the foreign, avoiding fuss and noise — absolutely no fuss and noise! — and seizing every possible occasion to complain at length about alleged fuss and noise.

Among other things, I was impressed that (in Holland, twenty years ago) it was possible to say anything about cat-calling girls in terms other than the deepest deprecation, and still get published!

It was a superb no-more-tax-loss-selling day for the Canadian preferred share market today, with PerpetualDiscounts up 111bp, FixedResets winning 169bp and DeemedRetractibles gaining 37bp. The Performance Highlights table is as ridiculously long as you might expect, with only a single loser. Volume was, again, pathetically low.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_151230
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 18.95 to be $0.62 rich, while TRP.PR.C, resetting 2016-1-30 at +154, is $1.19 cheap at its bid price of 12.60.

impVol_MFC_151230
Click for Big

Most expensive is MFC.PR.L, resetting at +216bp on 2019-6-19, bid at 20.25 to be 0.60 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 22.33 to be 0.67 cheap.

impVol_BAM_151230
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 16.39 to be $1.85 cheap. BAM.PF.E, resetting at +255bp on 2020-3-31 is bid at 20.50 and appears to be $0.80 rich.

impVol_FTS_151230
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 18.85, looks $0.64 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 18.10 and is $0.59 cheap.

pairs_FR_151230
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -1.35%, with one outlier above -0.50%. There are two junk outliers above -0.50%.

pairs_FF_151230
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 4.72 % 5.71 % 30,975 17.03 1 4.0462 % 1,651.1
FixedFloater 7.06 % 6.26 % 37,792 15.89 1 0.5232 % 2,762.9
Floater 4.17 % 4.31 % 81,306 16.79 4 2.7633 % 1,834.4
OpRet 4.86 % 4.17 % 25,341 0.65 1 0.0000 % 2,740.8
SplitShare 4.81 % 5.72 % 84,029 1.84 6 0.3252 % 3,212.8
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.3252 % 2,506.7
Perpetual-Premium 5.76 % 5.52 % 91,945 1.89 7 0.5855 % 2,532.8
Perpetual-Discount 5.64 % 5.71 % 103,697 14.36 33 1.1113 % 2,551.4
FixedReset 4.99 % 4.30 % 267,776 14.97 81 1.6856 % 2,075.1
Deemed-Retractible 5.15 % 4.78 % 133,114 5.28 33 0.3729 % 2,604.2
FloatingReset 2.77 % 4.07 % 69,458 5.63 11 0.9955 % 2,156.2
Performance Highlights
Issue Index Change Notes
BAM.PF.D Perpetual-Discount -1.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 19.94
Evaluated at bid price : 19.94
Bid-YTW : 6.19 %
BNS.PR.Z FixedReset 1.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.99
Bid-YTW : 5.39 %
POW.PR.A Perpetual-Discount 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 24.25
Evaluated at bid price : 24.55
Bid-YTW : 5.71 %
POW.PR.B Perpetual-Discount 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 23.15
Evaluated at bid price : 23.45
Bid-YTW : 5.71 %
SLF.PR.I FixedReset 1.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.24
Bid-YTW : 5.69 %
BAM.PR.R FixedReset 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 16.39
Evaluated at bid price : 16.39
Bid-YTW : 4.69 %
RY.PR.O Perpetual-Discount 1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 22.46
Evaluated at bid price : 22.78
Bid-YTW : 5.43 %
MFC.PR.C Deemed-Retractible 1.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.00
Bid-YTW : 6.96 %
PVS.PR.D SplitShare 1.16 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2021-10-08
Maturity Price : 25.00
Evaluated at bid price : 22.71
Bid-YTW : 6.52 %
TD.PR.Y FixedReset 1.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.55
Bid-YTW : 3.41 %
PWF.PR.R Perpetual-Discount 1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 23.95
Evaluated at bid price : 24.40
Bid-YTW : 5.71 %
PWF.PR.S Perpetual-Discount 1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 21.57
Evaluated at bid price : 21.85
Bid-YTW : 5.57 %
RY.PR.N Perpetual-Discount 1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 22.42
Evaluated at bid price : 22.73
Bid-YTW : 5.44 %
GWO.PR.H Deemed-Retractible 1.28 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.16
Bid-YTW : 6.57 %
CM.PR.Q FixedReset 1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 20.55
Evaluated at bid price : 20.55
Bid-YTW : 4.29 %
SLF.PR.E Deemed-Retractible 1.30 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.06
Bid-YTW : 6.90 %
PWF.PR.L Perpetual-Discount 1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 22.34
Evaluated at bid price : 22.61
Bid-YTW : 5.73 %
POW.PR.D Perpetual-Discount 1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 22.22
Evaluated at bid price : 22.50
Bid-YTW : 5.56 %
W.PR.H Perpetual-Discount 1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 22.96
Evaluated at bid price : 23.23
Bid-YTW : 5.93 %
ENB.PR.A Perpetual-Discount 1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 22.82
Evaluated at bid price : 23.10
Bid-YTW : 6.02 %
BMO.PR.Z Perpetual-Discount 1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 23.42
Evaluated at bid price : 23.74
Bid-YTW : 5.31 %
CU.PR.C FixedReset 1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 19.92
Evaluated at bid price : 19.92
Bid-YTW : 4.02 %
RY.PR.W Perpetual-Discount 1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 22.44
Evaluated at bid price : 22.70
Bid-YTW : 5.45 %
FTS.PR.H FixedReset 1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 14.35
Evaluated at bid price : 14.35
Bid-YTW : 3.93 %
TD.PF.D FixedReset 1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 20.79
Evaluated at bid price : 20.79
Bid-YTW : 4.30 %
BIP.PR.A FixedReset 1.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 20.61
Evaluated at bid price : 20.61
Bid-YTW : 5.28 %
MFC.PR.H FixedReset 1.44 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.98
Bid-YTW : 4.54 %
SLF.PR.C Deemed-Retractible 1.46 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.90
Bid-YTW : 6.95 %
TD.PF.F Perpetual-Discount 1.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 22.55
Evaluated at bid price : 22.88
Bid-YTW : 5.43 %
MFC.PR.G FixedReset 1.50 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.33
Bid-YTW : 5.23 %
PWF.PR.T FixedReset 1.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 22.60
Evaluated at bid price : 23.30
Bid-YTW : 3.48 %
POW.PR.G Perpetual-Premium 1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 24.39
Evaluated at bid price : 24.86
Bid-YTW : 5.63 %
SLF.PR.J FloatingReset 1.59 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.41
Bid-YTW : 9.66 %
TD.PF.E FixedReset 1.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 21.72
Evaluated at bid price : 22.10
Bid-YTW : 4.11 %
IFC.PR.A FixedReset 1.61 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.40
Bid-YTW : 8.41 %
IAG.PR.A Deemed-Retractible 1.64 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.65
Bid-YTW : 6.62 %
ELF.PR.F Perpetual-Discount 1.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 22.53
Evaluated at bid price : 22.78
Bid-YTW : 5.82 %
TRP.PR.G FixedReset 1.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 20.60
Evaluated at bid price : 20.60
Bid-YTW : 4.54 %
BNS.PR.B FloatingReset 1.68 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.38
Bid-YTW : 4.12 %
SLF.PR.A Deemed-Retractible 1.70 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.09
Bid-YTW : 6.50 %
MFC.PR.I FixedReset 1.78 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.86
Bid-YTW : 4.96 %
W.PR.J Perpetual-Discount 1.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 23.49
Evaluated at bid price : 23.76
Bid-YTW : 5.90 %
PWF.PR.A Floater 1.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 12.63
Evaluated at bid price : 12.63
Bid-YTW : 3.78 %
NA.PR.S FixedReset 1.86 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 19.15
Evaluated at bid price : 19.15
Bid-YTW : 4.35 %
BAM.PR.C Floater 1.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 10.90
Evaluated at bid price : 10.90
Bid-YTW : 4.34 %
RY.PR.H FixedReset 1.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 19.35
Evaluated at bid price : 19.35
Bid-YTW : 4.11 %
BNS.PR.D FloatingReset 1.90 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.27
Bid-YTW : 6.02 %
BNS.PR.C FloatingReset 1.91 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.45
Bid-YTW : 4.26 %
RY.PR.M FixedReset 1.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 20.10
Evaluated at bid price : 20.10
Bid-YTW : 4.27 %
VNR.PR.A FixedReset 2.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 19.75
Evaluated at bid price : 19.75
Bid-YTW : 4.65 %
CU.PR.D Perpetual-Discount 2.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 21.77
Evaluated at bid price : 22.08
Bid-YTW : 5.60 %
IAG.PR.G FixedReset 2.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.00
Bid-YTW : 5.40 %
SLF.PR.D Deemed-Retractible 2.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.84
Bid-YTW : 6.99 %
TRP.PR.A FixedReset 2.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 16.46
Evaluated at bid price : 16.46
Bid-YTW : 4.22 %
TD.PF.B FixedReset 2.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 19.26
Evaluated at bid price : 19.26
Bid-YTW : 4.13 %
MFC.PR.J FixedReset 2.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.66
Bid-YTW : 5.42 %
CU.PR.E Perpetual-Discount 2.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 21.80
Evaluated at bid price : 22.13
Bid-YTW : 5.58 %
BAM.PR.B Floater 2.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 10.98
Evaluated at bid price : 10.98
Bid-YTW : 4.31 %
FTS.PR.J Perpetual-Discount 2.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 22.15
Evaluated at bid price : 22.48
Bid-YTW : 5.33 %
BAM.PF.G FixedReset 2.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 21.83
Evaluated at bid price : 22.24
Bid-YTW : 4.23 %
FTS.PR.I FloatingReset 2.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 12.41
Evaluated at bid price : 12.41
Bid-YTW : 3.88 %
FTS.PR.K FixedReset 2.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 18.85
Evaluated at bid price : 18.85
Bid-YTW : 3.96 %
IFC.PR.C FixedReset 2.35 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.01
Bid-YTW : 6.39 %
TD.PF.C FixedReset 2.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 19.25
Evaluated at bid price : 19.25
Bid-YTW : 4.12 %
TD.PF.A FixedReset 2.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 19.35
Evaluated at bid price : 19.35
Bid-YTW : 4.12 %
TRP.PR.C FixedReset 2.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 12.60
Evaluated at bid price : 12.60
Bid-YTW : 4.48 %
BAM.PF.E FixedReset 2.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 20.50
Evaluated at bid price : 20.50
Bid-YTW : 4.31 %
PWF.PR.P FixedReset 2.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 14.50
Evaluated at bid price : 14.50
Bid-YTW : 4.05 %
FTS.PR.M FixedReset 2.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 20.61
Evaluated at bid price : 20.61
Bid-YTW : 4.13 %
CU.PR.H Perpetual-Discount 2.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 23.33
Evaluated at bid price : 23.64
Bid-YTW : 5.60 %
CU.PR.G Perpetual-Discount 2.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 20.65
Evaluated at bid price : 20.65
Bid-YTW : 5.51 %
ELF.PR.H Perpetual-Discount 2.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 23.16
Evaluated at bid price : 23.59
Bid-YTW : 5.83 %
BAM.PF.B FixedReset 2.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 20.29
Evaluated at bid price : 20.29
Bid-YTW : 4.32 %
BMO.PR.Y FixedReset 2.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 21.20
Evaluated at bid price : 21.20
Bid-YTW : 4.19 %
NA.PR.W FixedReset 2.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 18.50
Evaluated at bid price : 18.50
Bid-YTW : 4.33 %
RY.PR.J FixedReset 2.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 20.49
Evaluated at bid price : 20.49
Bid-YTW : 4.30 %
RY.PR.Z FixedReset 2.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 19.26
Evaluated at bid price : 19.26
Bid-YTW : 4.08 %
SLF.PR.H FixedReset 2.72 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.50
Bid-YTW : 6.88 %
HSE.PR.G FixedReset 2.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 19.06
Evaluated at bid price : 19.06
Bid-YTW : 5.72 %
TRP.PR.B FixedReset 2.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 12.45
Evaluated at bid price : 12.45
Bid-YTW : 4.09 %
MFC.PR.L FixedReset 2.90 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.25
Bid-YTW : 6.11 %
MFC.PR.N FixedReset 3.00 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.61
Bid-YTW : 5.99 %
BMO.PR.W FixedReset 3.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 19.16
Evaluated at bid price : 19.16
Bid-YTW : 4.09 %
TRP.PR.H FloatingReset 3.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 10.22
Evaluated at bid price : 10.22
Bid-YTW : 4.26 %
BMO.PR.T FixedReset 3.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 19.30
Evaluated at bid price : 19.30
Bid-YTW : 4.10 %
MFC.PR.M FixedReset 3.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.85
Bid-YTW : 5.90 %
TRP.PR.D FixedReset 3.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 18.80
Evaluated at bid price : 18.80
Bid-YTW : 4.31 %
CM.PR.O FixedReset 3.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 19.55
Evaluated at bid price : 19.55
Bid-YTW : 4.09 %
SLF.PR.G FixedReset 3.51 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.64
Bid-YTW : 8.14 %
HSE.PR.C FixedReset 3.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 17.56
Evaluated at bid price : 17.56
Bid-YTW : 5.73 %
BMO.PR.S FixedReset 3.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 19.95
Evaluated at bid price : 19.95
Bid-YTW : 4.06 %
BAM.PF.A FixedReset 3.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 21.58
Evaluated at bid price : 21.99
Bid-YTW : 4.24 %
HSE.PR.E FixedReset 3.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 18.80
Evaluated at bid price : 18.80
Bid-YTW : 5.81 %
BAM.PR.E Ratchet 4.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 25.00
Evaluated at bid price : 14.40
Bid-YTW : 5.71 %
FTS.PR.G FixedReset 4.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 18.10
Evaluated at bid price : 18.10
Bid-YTW : 4.16 %
HSE.PR.A FixedReset 4.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 12.65
Evaluated at bid price : 12.65
Bid-YTW : 4.87 %
BAM.PR.T FixedReset 4.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 17.84
Evaluated at bid price : 17.84
Bid-YTW : 4.38 %
BAM.PR.K Floater 5.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 10.86
Evaluated at bid price : 10.86
Bid-YTW : 4.36 %
CM.PR.P FixedReset 5.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 19.15
Evaluated at bid price : 19.15
Bid-YTW : 4.08 %
Volume Highlights
Issue Index Shares
Traded
Notes
BAM.PR.R FixedReset 52,000 Desjardins crossed 20,000 at 16.34 and another 20,000 at 16.35.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 16.39
Evaluated at bid price : 16.39
Bid-YTW : 4.69 %
RY.PR.Q FixedReset 35,037 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-24
Maturity Price : 25.00
Evaluated at bid price : 25.75
Bid-YTW : 4.93 %
BNS.PR.E FixedReset 18,145 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-25
Maturity Price : 25.00
Evaluated at bid price : 25.77
Bid-YTW : 4.91 %
TRP.PR.C FixedReset 14,950 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 12.60
Evaluated at bid price : 12.60
Bid-YTW : 4.48 %
RY.PR.H FixedReset 14,361 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 19.35
Evaluated at bid price : 19.35
Bid-YTW : 4.11 %
TD.PF.A FixedReset 14,200 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 19.35
Evaluated at bid price : 19.35
Bid-YTW : 4.12 %
There were 5 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
TD.PF.E FixedReset Quote: 22.10 – 25.00
Spot Rate : 2.9000
Average : 1.6647

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 21.72
Evaluated at bid price : 22.10
Bid-YTW : 4.11 %

CIU.PR.A Perpetual-Discount Quote: 20.30 – 21.25
Spot Rate : 0.9500
Average : 0.6063

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 20.30
Evaluated at bid price : 20.30
Bid-YTW : 5.74 %

BAM.PF.D Perpetual-Discount Quote: 19.94 – 20.66
Spot Rate : 0.7200
Average : 0.4296

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 19.94
Evaluated at bid price : 19.94
Bid-YTW : 6.19 %

FTS.PR.F Perpetual-Discount Quote: 22.66 – 23.54
Spot Rate : 0.8800
Average : 0.5934

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 22.40
Evaluated at bid price : 22.66
Bid-YTW : 5.46 %

MFC.PR.K FixedReset Quote: 19.62 – 20.50
Spot Rate : 0.8800
Average : 0.6176

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.62
Bid-YTW : 6.43 %

TRP.PR.E FixedReset Quote: 18.95 – 19.69
Spot Rate : 0.7400
Average : 0.5290

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-30
Maturity Price : 18.95
Evaluated at bid price : 18.95
Bid-YTW : 4.35 %

Market Action

December 29, 2015

Looks like we may be looking at a Tobin Tax:

Chinese securities regulators are preparing some of the world’s strictest regulations on a trading practice at the heart of the global debate over high-speed computerized markets.

The draft rules are designed to prevent traders from flooding exchanges with orders they don’t fill by charging market participants fees for habitual cancellations. The proposal, which could come into force next year, echoes a plan by U.S. presidential hopeful Hillary Clinton to discourage high-speed trading strategies that she says could destabilize markets.

As regulators around the world grapple with the most effective ways to police computer-driven markets, they have focused on how to stop traders from using bogus orders to unfairly move prices in their favor. Critics contend that the tactic makes markets less fair and enables some traders to engage in a manipulative practice known as spoofing. Opponents of the proposed taxes on canceled orders say they would harm legitimate market makers and raise costs for the average investor.
…
China’s proposals on algorithmic trading, revealed around the same time in October as Clinton’s, state that “frequently placing and withdrawing orders where the ratio of trades concluded is abnormally low” would be prohibited, according to a translation by law firm Linklaters LLP. Traders who cancel more than 40 percent of their submitted orders in any given day would be charged a fee of 2 yuan (31 cents) per transaction.
…
Other measures suggested by the CSRC include forcing traders who use automated orders to provide a detailed description of their strategies to regulators and wait for a review before they’re allowed to execute trades. That proposal has raised concern among some international investors who don’t want to disclose their proprietary trading algorithms, according to Calvin Tai, the head of global clearing at Hong Kong’s stock exchange.

Clinton, the front-runner to win the Democratic nomination for president, called for a fee on canceled orders in October and explicitly linked the idea to curbing high-frequency traders. Her plan is designed to target “harmful” high-frequency trading that makes markets “less stable and less fair,” Clinton’s campaign said at the time.

There is nothing intrinsically wrong with an exchange fee for cancelled orders. A 96% cancellation rate will obviously strain the system more than will a lower rate and require increased investment by all serious participants, in bandwidth and a ticker-plant. However, when charges such as China’s $0.31/transaction become exorbitant it becomes clear that this is just a revenue grab that will lead to migration of the markets to more trader-friendly nations, as well as having all the usual effects of ‘stamp charges’ on market liquidity. Compare the $0.31/transaction fee to the Toronto Stock Exchange’s Maker-Taker fees, which net out to $0.0004 / share. [I’ll save you the trouble: that means the Exchange would charge as much for a cancelled order as for an execution of 775 shares].

As I stated on April 3, 2014:

However, it is quite apparent that Tobin taxes harm market quality. One possibility where the AR PL and I might have a meeting of minds is the potential for an exchange to impose a fee for the placement of an order – generally, once you’re permitted to place orders on the exchange, the only fees remaining are charged for executed transactions.

Schwab is upset about the number of orders:

High-frequency trading pumped out over 300,000 trade inquiries each second last year, up from just 50,000 only seven years earlier. Yet actual trade volume on the exchanges has remained relatively flat over that period. It’s an explosion of head-fake ephemeral orders – not to lock in real trades, but to skim pennies off the public markets by the billions.
…
Added systems burdens, costs and distortions of rapid-fire quote activity: Ephemeral quotes, also called “quote stuffing,” that are cancelled and reposted in milliseconds distort the tape and present risk to the resiliency and integrity of critical market data and trading infrastructure. The tremendous added costs associated with the expanded capacity and bandwidth necessary to support this added data traffic is ultimately borne in part by individual investors.

There are solutions. Today there is no restriction to pumping out millions of orders in a matter of seconds, only to reverse the majority of them. It’s the life-blood of high-frequency trading. A simple solution would be to establish cancellation fees to discourage the practice of quote stuffing. The SEC and CFTC floated the idea last year. It has great merit. Make the fees high enough and they will eliminate high-frequency trading entirely.

However, I would support a charge for order entry (or simply order cancellation, assuming that executed orders get charged by other means) only to the extent that it is imposed by the exchanges to recover costs or as a source of competitive advantage. If, once you count amortization of all the required infrastructure, it costs $1 to process 1,000,000 orders, then by all means, charge $0.000001 to process an order. If you want to make a profit and the market will bear it, then by all means, charge $0.000002 to process an order. If your customers complain that they have to process all these orders too, then by all means offer them a kiddie feed at reduced price, transmitting orders only when they have been extant for 10 milliseconds.

But don’t start imposing fees with grandiose visions of Better Living Through Higher Taxation. We all know where that ends up.

Fortis Inc., proud issuer of FTS.PR.E, FTS.PR.F, FTS.PR.G, FTS.PR.H, FTS.PR.I, FTS.PR.J, FTS.PR.K and FTS.PR.M, was confirmed at Pfd-2(low) by DBRS:

DBRS Limited (DBRS) has today confirmed the A (low) Issuer Rating, A (low) Unsecured Debentures rating and Pfd-2 (low) Preferred Shares rating of Fortis Inc. (Fortis, the Parent or the Company) with Stable trends. This action is based on DBRS’s view of the Company’s financial performance to date in 2015 (YTD 2015). The confirmations reflect Fortis’ improved business risk profile following the completion of the Waneta Expansion hydro generation project (Waneta Expansion), no material changes in its regulated subsidiaries and its reasonable consolidated and non-consolidated financial profiles.
…
Fortis maintained reasonable consolidated and non-consolidated ratios in YTD 2015 and remained consistent with the current rating. These ratios are expected to improve by the end of 2015 and in the medium term since (i) $230 million non-consolidated debt was reduced after September 30, 2015, with proceeds from the sale of Fortis Properties; (ii) all regulated utilities are expected to maintain their leverage in line with the regulatory capital structure in their respective jurisdictions; and (iii) Fortis’ equity injection to its utilities is expected to be modest and manageable over the next few years.

The cessation of tax-loss selling pressure led to a superb day for the Canadian preferred share market, with PerpetualDiscounts up 94bp, FixedResets winning 121bp and DeemedRetractibles gaining 87bp. The Performance Highlights table is enormous, naturally enough, with only one loser. Volume was very extremely awfully low.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_151229
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 18.86 to be $0.91 rich, while TRP.PR.C, resetting 2016-1-30 at +154, is $1.19 cheap at its bid price of 12.30.

impVol_MFC_151229
Click for Big

Most expensive is MFC.PR.L, resetting at +216bp on 2019-6-19, bid at 19.68 to be 0.45 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 22.00 to be 0.54 cheap.

impVol_BAM_151229
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 16.21 to be $1.60 cheap. BAM.PF.F, resetting at +286bp on 2019-9-30 is bid at 21.95 and appears to be $0.96 rich.

impVol_FTS_151229
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 18.43, looks $0.70 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 17.39 and is $0.80 cheap.

pairs_FR_151229
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -1.37%, with one outlier above -0.50%. There are two junk outliers above -0.50%.

pairs_FF_151229
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 4.91 % 5.95 % 32,165 16.74 1 0.0180 % 1,586.9
FixedFloater 7.10 % 6.30 % 39,441 15.85 1 1.1338 % 2,748.6
Floater 4.28 % 4.40 % 82,517 16.61 4 2.8658 % 1,785.1
OpRet 4.86 % 4.15 % 26,388 0.66 1 0.0794 % 2,740.8
SplitShare 4.83 % 5.42 % 84,274 1.84 6 0.3027 % 3,202.4
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.3027 % 2,498.6
Perpetual-Premium 5.79 % 5.45 % 91,663 2.58 7 0.8523 % 2,518.1
Perpetual-Discount 5.69 % 5.75 % 105,325 14.27 33 0.9418 % 2,523.3
FixedReset 5.07 % 4.37 % 270,601 14.85 81 1.2111 % 2,040.7
Deemed-Retractible 5.17 % 4.79 % 134,552 5.27 33 0.8682 % 2,594.6
FloatingReset 2.79 % 4.12 % 70,258 5.63 11 1.1263 % 2,135.0
Performance Highlights
Issue Index Change Notes
NA.PR.W FixedReset -1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 18.02
Evaluated at bid price : 18.02
Bid-YTW : 4.45 %
MFC.PR.M FixedReset 1.00 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.20
Bid-YTW : 6.33 %
BAM.PR.Z FixedReset 1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 21.20
Evaluated at bid price : 21.20
Bid-YTW : 4.49 %
GWO.PR.S Deemed-Retractible 1.02 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.75
Bid-YTW : 5.42 %
SLF.PR.A Deemed-Retractible 1.02 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.72
Bid-YTW : 6.74 %
TD.PF.F Perpetual-Discount 1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 22.19
Evaluated at bid price : 22.55
Bid-YTW : 5.51 %
RY.PR.O Perpetual-Discount 1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 22.16
Evaluated at bid price : 22.52
Bid-YTW : 5.49 %
TD.PR.Z FloatingReset 1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.48
Bid-YTW : 4.02 %
BAM.PF.F FixedReset 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 21.66
Evaluated at bid price : 21.95
Bid-YTW : 4.27 %
PWF.PR.O Perpetual-Premium 1.08 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.34
Bid-YTW : 5.67 %
FTS.PR.G FixedReset 1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 17.39
Evaluated at bid price : 17.39
Bid-YTW : 4.34 %
BAM.PR.G FixedFloater 1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 25.00
Evaluated at bid price : 13.38
Bid-YTW : 6.30 %
TD.PF.D FixedReset 1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 20.50
Evaluated at bid price : 20.50
Bid-YTW : 4.36 %
POW.PR.B Perpetual-Discount 1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 22.93
Evaluated at bid price : 23.20
Bid-YTW : 5.77 %
BNS.PR.P FixedReset 1.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.95
Bid-YTW : 3.14 %
HSE.PR.A FixedReset 1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 12.15
Evaluated at bid price : 12.15
Bid-YTW : 5.07 %
PVS.PR.B SplitShare 1.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2019-01-10
Maturity Price : 25.00
Evaluated at bid price : 24.00
Bid-YTW : 5.94 %
IGM.PR.B Perpetual-Premium 1.27 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.20
Bid-YTW : 5.45 %
BAM.PR.K Floater 1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 10.30
Evaluated at bid price : 10.30
Bid-YTW : 4.59 %
RY.PR.H FixedReset 1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 18.99
Evaluated at bid price : 18.99
Bid-YTW : 4.19 %
FTS.PR.F Perpetual-Discount 1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 22.35
Evaluated at bid price : 22.62
Bid-YTW : 5.46 %
VNR.PR.A FixedReset 1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 19.35
Evaluated at bid price : 19.35
Bid-YTW : 4.75 %
BAM.PR.R FixedReset 1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 16.21
Evaluated at bid price : 16.21
Bid-YTW : 4.74 %
TD.PR.S FixedReset 1.32 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.52
Bid-YTW : 3.24 %
SLF.PR.D Deemed-Retractible 1.34 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.41
Bid-YTW : 7.28 %
TD.PF.B FixedReset 1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 18.86
Evaluated at bid price : 18.86
Bid-YTW : 4.22 %
ELF.PR.G Perpetual-Discount 1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 20.78
Evaluated at bid price : 20.78
Bid-YTW : 5.84 %
PWF.PR.H Perpetual-Premium 1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 24.69
Evaluated at bid price : 25.01
Bid-YTW : 5.84 %
SLF.PR.J FloatingReset 1.38 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.20
Bid-YTW : 9.86 %
ELF.PR.F Perpetual-Discount 1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 22.47
Evaluated at bid price : 22.73
Bid-YTW : 5.94 %
TRP.PR.A FixedReset 1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 16.12
Evaluated at bid price : 16.12
Bid-YTW : 4.31 %
BMO.PR.Z Perpetual-Discount 1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 23.01
Evaluated at bid price : 23.43
Bid-YTW : 5.38 %
BNS.PR.B FloatingReset 1.43 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.01
Bid-YTW : 4.42 %
GWO.PR.G Deemed-Retractible 1.44 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.24
Bid-YTW : 6.26 %
BMO.PR.S FixedReset 1.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 19.26
Evaluated at bid price : 19.26
Bid-YTW : 4.21 %
SLF.PR.B Deemed-Retractible 1.54 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.80
Bid-YTW : 6.74 %
MFC.PR.I FixedReset 1.54 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.46
Bid-YTW : 5.20 %
W.PR.K FixedReset 1.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 23.09
Evaluated at bid price : 24.79
Bid-YTW : 5.25 %
TD.PF.C FixedReset 1.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 18.80
Evaluated at bid price : 18.80
Bid-YTW : 4.23 %
GWO.PR.H Deemed-Retractible 1.63 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.88
Bid-YTW : 6.74 %
GWO.PR.Q Deemed-Retractible 1.63 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.10
Bid-YTW : 6.30 %
SLF.PR.C Deemed-Retractible 1.63 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.60
Bid-YTW : 7.15 %
BMO.PR.W FixedReset 1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 18.60
Evaluated at bid price : 18.60
Bid-YTW : 4.22 %
HSE.PR.G FixedReset 1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 18.55
Evaluated at bid price : 18.55
Bid-YTW : 5.87 %
SLF.PR.E Deemed-Retractible 1.66 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.79
Bid-YTW : 7.08 %
FTS.PR.J Perpetual-Discount 1.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 21.70
Evaluated at bid price : 22.00
Bid-YTW : 5.44 %
SLF.PR.H FixedReset 1.69 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.01
Bid-YTW : 7.24 %
MFC.PR.G FixedReset 1.71 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.00
Bid-YTW : 5.43 %
BMO.PR.Y FixedReset 1.72 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 20.65
Evaluated at bid price : 20.65
Bid-YTW : 4.30 %
FTS.PR.K FixedReset 1.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 18.43
Evaluated at bid price : 18.43
Bid-YTW : 4.06 %
GWO.PR.I Deemed-Retractible 1.81 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.84
Bid-YTW : 7.04 %
MFC.PR.J FixedReset 1.82 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.21
Bid-YTW : 5.71 %
BNS.PR.D FloatingReset 1.83 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.91
Bid-YTW : 6.35 %
IAG.PR.G FixedReset 1.89 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.55
Bid-YTW : 5.68 %
NA.PR.Q FixedReset 1.92 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-11-15
Maturity Price : 25.00
Evaluated at bid price : 25.50
Bid-YTW : 2.97 %
MFC.PR.N FixedReset 1.99 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.01
Bid-YTW : 6.39 %
MFC.PR.C Deemed-Retractible 2.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.76
Bid-YTW : 7.12 %
MFC.PR.B Deemed-Retractible 2.02 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.20
Bid-YTW : 7.00 %
NA.PR.S FixedReset 2.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 18.80
Evaluated at bid price : 18.80
Bid-YTW : 4.43 %
RY.PR.L FixedReset 2.08 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.56
Bid-YTW : 3.53 %
TRP.PR.B FixedReset 2.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 12.10
Evaluated at bid price : 12.10
Bid-YTW : 4.21 %
BIP.PR.A FixedReset 2.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 20.32
Evaluated at bid price : 20.32
Bid-YTW : 5.36 %
GWO.PR.M Deemed-Retractible 2.15 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2019-03-31
Maturity Price : 25.00
Evaluated at bid price : 25.69
Bid-YTW : 4.89 %
IFC.PR.A FixedReset 2.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 16.14
Bid-YTW : 8.63 %
GWO.PR.P Deemed-Retractible 2.31 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.41
Bid-YTW : 5.77 %
CM.PR.Q FixedReset 2.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 20.29
Evaluated at bid price : 20.29
Bid-YTW : 4.34 %
FTS.PR.I FloatingReset 2.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 12.14
Evaluated at bid price : 12.14
Bid-YTW : 3.96 %
CIU.PR.A Perpetual-Discount 2.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 20.40
Evaluated at bid price : 20.40
Bid-YTW : 5.71 %
MFC.PR.H FixedReset 2.47 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.64
Bid-YTW : 4.73 %
HSE.PR.C FixedReset 2.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 16.96
Evaluated at bid price : 16.96
Bid-YTW : 5.94 %
GWO.PR.R Deemed-Retractible 2.49 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.79
Bid-YTW : 6.75 %
BAM.PF.G FixedReset 2.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 21.48
Evaluated at bid price : 21.76
Bid-YTW : 4.34 %
CM.PR.O FixedReset 2.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 18.89
Evaluated at bid price : 18.89
Bid-YTW : 4.23 %
BAM.PF.B FixedReset 2.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 19.77
Evaluated at bid price : 19.77
Bid-YTW : 4.43 %
TRP.PR.G FixedReset 2.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 20.26
Evaluated at bid price : 20.26
Bid-YTW : 4.62 %
PWF.PR.T FixedReset 2.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 22.40
Evaluated at bid price : 22.95
Bid-YTW : 3.55 %
RY.PR.M FixedReset 2.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 19.72
Evaluated at bid price : 19.72
Bid-YTW : 4.36 %
W.PR.H Perpetual-Discount 2.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 22.69
Evaluated at bid price : 22.93
Bid-YTW : 6.01 %
TRP.PR.C FixedReset 3.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 12.30
Evaluated at bid price : 12.30
Bid-YTW : 4.58 %
BAM.PF.E FixedReset 3.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 20.01
Evaluated at bid price : 20.01
Bid-YTW : 4.41 %
TRP.PR.E FixedReset 3.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 18.86
Evaluated at bid price : 18.86
Bid-YTW : 4.37 %
W.PR.J Perpetual-Discount 3.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 23.07
Evaluated at bid price : 23.33
Bid-YTW : 6.01 %
BAM.PF.A FixedReset 3.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 21.22
Evaluated at bid price : 21.22
Bid-YTW : 4.43 %
BAM.PR.C Floater 4.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 10.70
Evaluated at bid price : 10.70
Bid-YTW : 4.42 %
TRP.PR.D FixedReset 4.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 18.20
Evaluated at bid price : 18.20
Bid-YTW : 4.46 %
TRP.PR.F FloatingReset 5.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 13.60
Evaluated at bid price : 13.60
Bid-YTW : 4.38 %
BAM.PR.B Floater 5.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 10.75
Evaluated at bid price : 10.75
Bid-YTW : 4.40 %
Volume Highlights
Issue Index Shares
Traded
Notes
BIP.PR.B FixedReset 54,030 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 22.74
Evaluated at bid price : 23.91
Bid-YTW : 5.75 %
RY.PR.Z FixedReset 45,450 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 18.75
Evaluated at bid price : 18.75
Bid-YTW : 4.20 %
RY.PR.Q FixedReset 25,850 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-24
Maturity Price : 25.00
Evaluated at bid price : 25.70
Bid-YTW : 4.97 %
CM.PR.O FixedReset 21,434 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 18.89
Evaluated at bid price : 18.89
Bid-YTW : 4.23 %
RY.PR.H FixedReset 17,941 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 18.99
Evaluated at bid price : 18.99
Bid-YTW : 4.19 %
MFC.PR.G FixedReset 16,000 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.00
Bid-YTW : 5.43 %
There were 3 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
PWF.PR.T FixedReset Quote: 22.95 – 24.99
Spot Rate : 2.0400
Average : 1.4856

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 22.40
Evaluated at bid price : 22.95
Bid-YTW : 3.55 %

NA.PR.W FixedReset Quote: 18.02 – 18.70
Spot Rate : 0.6800
Average : 0.4352

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 18.02
Evaluated at bid price : 18.02
Bid-YTW : 4.45 %

CIU.PR.C FixedReset Quote: 12.33 – 13.46
Spot Rate : 1.1300
Average : 0.8966

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 12.33
Evaluated at bid price : 12.33
Bid-YTW : 4.30 %

SLF.PR.J FloatingReset Quote: 13.20 – 13.80
Spot Rate : 0.6000
Average : 0.3849

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.20
Bid-YTW : 9.86 %

HSE.PR.A FixedReset Quote: 12.15 – 12.68
Spot Rate : 0.5300
Average : 0.3188

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 12.15
Evaluated at bid price : 12.15
Bid-YTW : 5.07 %

TRP.PR.B FixedReset Quote: 12.10 – 12.60
Spot Rate : 0.5000
Average : 0.3208

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-29
Maturity Price : 12.10
Evaluated at bid price : 12.10
Bid-YTW : 4.21 %

Market Action

December 24, 2015

Nothing happened today.

The last day of tax-loss selling season was mixed for the Canadian preferred share market, with PerpetualDiscounts off 5bp, FixedResets gaining 22bp and DeemedRetractibles down 11bp. A lot of churn is still revealed by the Performance Highlights table. Volume was, somewhat surprisingly, above average even though the trading day was foreshortened due to the desire of the most highly paid professionals on earth to get away early.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_151224
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 18.50 to be $0.97 rich, while TRP.PR.C, resetting 2016-1-30 at +154, is $1.03 cheap at its bid price of 12.20.

impVol_MFC_151224
Click for Big

Most expensive is MFC.PR.L, resetting at +216bp on 2019-6-19, bid at 19.50 to be 0.47 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 21.63 to be 0.52 cheap.

impVol_BAM_151224
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 16.00 to be $1.54 cheap. BAM.PF.F, resetting at +286bp on 2019-9-30 is bid at 21.72 and appears to be $1.04 rich.

impVol_FTS_151224
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 18.11, looks $0.50 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 17.20 and is $0.86 cheap.

pairs_FR_151224
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -1.45%, with one outlier above -0.50%. There are two junk outliers above -0.50% and one below -2.50%.

pairs_FF_151224
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 4.89 % 5.95 % 33,564 16.69 1 -0.7143 % 1,586.6
FixedFloater 7.18 % 6.37 % 41,170 15.78 1 0.2273 % 2,717.8
Floater 4.40 % 4.61 % 83,713 16.21 4 -0.8776 % 1,735.4
OpRet 4.86 % 4.18 % 26,414 0.67 1 0.0000 % 2,738.6
SplitShare 4.84 % 5.94 % 84,686 1.86 6 -0.2694 % 3,192.7
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.2694 % 2,491.1
Perpetual-Premium 5.83 % 5.80 % 94,481 13.90 7 -0.1713 % 2,496.8
Perpetual-Discount 5.74 % 5.79 % 106,793 14.18 33 -0.0537 % 2,499.8
FixedReset 5.13 % 4.48 % 274,689 14.73 81 0.2177 % 2,016.3
Deemed-Retractible 5.21 % 4.81 % 135,489 5.29 33 -0.1081 % 2,572.2
FloatingReset 2.81 % 4.18 % 69,695 5.65 11 -0.5551 % 2,111.2
Performance Highlights
Issue Index Change Notes
TRP.PR.D FixedReset -3.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-24
Maturity Price : 17.60
Evaluated at bid price : 17.60
Bid-YTW : 4.71 %
BNS.PR.B FloatingReset -3.00 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.70
Bid-YTW : 4.65 %
HSE.PR.G FixedReset -2.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-24
Maturity Price : 18.25
Evaluated at bid price : 18.25
Bid-YTW : 5.98 %
RY.PR.M FixedReset -2.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-24
Maturity Price : 19.17
Evaluated at bid price : 19.17
Bid-YTW : 4.49 %
BAM.PR.B Floater -2.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-24
Maturity Price : 10.20
Evaluated at bid price : 10.20
Bid-YTW : 4.64 %
BNS.PR.D FloatingReset -2.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.57
Bid-YTW : 6.65 %
PWF.PR.T FixedReset -2.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-24
Maturity Price : 21.97
Evaluated at bid price : 22.31
Bid-YTW : 3.68 %
TD.PR.Y FixedReset -2.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.26
Bid-YTW : 3.62 %
TD.PR.S FixedReset -1.98 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.20
Bid-YTW : 3.48 %
CM.PR.O FixedReset -1.97 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-24
Maturity Price : 18.40
Evaluated at bid price : 18.40
Bid-YTW : 4.36 %
TRP.PR.G FixedReset -1.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-24
Maturity Price : 19.70
Evaluated at bid price : 19.70
Bid-YTW : 4.76 %
BMO.PR.Y FixedReset -1.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-24
Maturity Price : 20.30
Evaluated at bid price : 20.30
Bid-YTW : 4.38 %
FTS.PR.G FixedReset -1.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-24
Maturity Price : 17.20
Evaluated at bid price : 17.20
Bid-YTW : 4.40 %
PVS.PR.D SplitShare -1.45 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2021-10-08
Maturity Price : 25.00
Evaluated at bid price : 22.45
Bid-YTW : 6.74 %
NA.PR.S FixedReset -1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-24
Maturity Price : 18.42
Evaluated at bid price : 18.42
Bid-YTW : 4.53 %
BAM.PF.A FixedReset -1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-24
Maturity Price : 20.52
Evaluated at bid price : 20.52
Bid-YTW : 4.59 %
MFC.PR.M FixedReset -1.28 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.00
Bid-YTW : 6.46 %
BAM.PR.K Floater -1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-24
Maturity Price : 10.17
Evaluated at bid price : 10.17
Bid-YTW : 4.65 %
GWO.PR.M Deemed-Retractible -1.26 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.15
Bid-YTW : 5.74 %
TRP.PR.E FixedReset -1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-24
Maturity Price : 18.50
Evaluated at bid price : 18.50
Bid-YTW : 4.55 %
MFC.PR.N FixedReset -1.21 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.62
Bid-YTW : 6.65 %
FTS.PR.K FixedReset -1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-24
Maturity Price : 18.11
Evaluated at bid price : 18.11
Bid-YTW : 4.14 %
GWO.PR.I Deemed-Retractible -1.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.47
Bid-YTW : 7.28 %
TD.PR.Z FloatingReset -1.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.25
Bid-YTW : 4.18 %
RY.PR.I FixedReset -1.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.35
Bid-YTW : 3.66 %
BNS.PR.C FloatingReset -1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.00
Bid-YTW : 4.60 %
BMO.PR.Z Perpetual-Discount -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-24
Maturity Price : 22.74
Evaluated at bid price : 23.11
Bid-YTW : 5.45 %
GWO.PR.R Deemed-Retractible -1.02 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.26
Bid-YTW : 7.08 %
TRP.PR.H FloatingReset 1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-24
Maturity Price : 9.90
Evaluated at bid price : 9.90
Bid-YTW : 4.37 %
BNS.PR.A FloatingReset 1.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.92
Bid-YTW : 4.04 %
BAM.PR.R FixedReset 1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-24
Maturity Price : 16.00
Evaluated at bid price : 16.00
Bid-YTW : 4.81 %
CU.PR.I FixedReset 1.17 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-01
Maturity Price : 25.00
Evaluated at bid price : 26.00
Bid-YTW : 3.69 %
IFC.PR.C FixedReset 1.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.36
Bid-YTW : 6.83 %
TD.PF.D FixedReset 1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-24
Maturity Price : 20.27
Evaluated at bid price : 20.27
Bid-YTW : 4.42 %
SLF.PR.J FloatingReset 1.32 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.02
Bid-YTW : 10.01 %
VNR.PR.A FixedReset 1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-24
Maturity Price : 19.10
Evaluated at bid price : 19.10
Bid-YTW : 4.82 %
MFC.PR.F FixedReset 1.37 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.80
Bid-YTW : 8.89 %
BIP.PR.A FixedReset 1.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-24
Maturity Price : 19.90
Evaluated at bid price : 19.90
Bid-YTW : 5.48 %
SLF.PR.G FixedReset 1.62 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.05
Bid-YTW : 8.63 %
TD.PF.E FixedReset 1.83 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-24
Maturity Price : 21.36
Evaluated at bid price : 21.65
Bid-YTW : 4.21 %
MFC.PR.H FixedReset 1.90 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.07
Bid-YTW : 5.06 %
BAM.PR.Z FixedReset 1.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-24
Maturity Price : 20.99
Evaluated at bid price : 20.99
Bid-YTW : 4.54 %
MFC.PR.K FixedReset 1.95 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.36
Bid-YTW : 6.61 %
CU.PR.C FixedReset 2.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-24
Maturity Price : 19.50
Evaluated at bid price : 19.50
Bid-YTW : 4.12 %
SLF.PR.H FixedReset 2.37 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.71
Bid-YTW : 7.46 %
MFC.PR.L FixedReset 2.47 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.50
Bid-YTW : 6.61 %
BAM.PF.F FixedReset 3.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-24
Maturity Price : 21.40
Evaluated at bid price : 21.72
Bid-YTW : 4.32 %
BNS.PR.Z FixedReset 3.29 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.72
Bid-YTW : 5.62 %
HSE.PR.A FixedReset 3.54 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-24
Maturity Price : 12.00
Evaluated at bid price : 12.00
Bid-YTW : 5.14 %
GWO.PR.N FixedReset 3.60 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.80
Bid-YTW : 9.51 %
SLF.PR.I FixedReset 5.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.85
Bid-YTW : 5.94 %
IAG.PR.G FixedReset 5.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.15
Bid-YTW : 5.93 %
BAM.PR.X FixedReset 6.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-24
Maturity Price : 15.50
Evaluated at bid price : 15.50
Bid-YTW : 4.34 %
Volume Highlights
Issue Index Shares
Traded
Notes
MFC.PR.G FixedReset 64,200 RBC crossed 50,000 at 21.75.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.63
Bid-YTW : 5.66 %
TRP.PR.C FixedReset 34,558 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-24
Maturity Price : 12.20
Evaluated at bid price : 12.20
Bid-YTW : 4.71 %
TRP.PR.D FixedReset 29,210 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-24
Maturity Price : 17.60
Evaluated at bid price : 17.60
Bid-YTW : 4.71 %
RY.PR.Q FixedReset 26,664 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-24
Maturity Price : 25.00
Evaluated at bid price : 25.82
Bid-YTW : 4.86 %
TD.PF.B FixedReset 25,565 Scotia crossed 10,000 at 18.72.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-24
Maturity Price : 18.61
Evaluated at bid price : 18.61
Bid-YTW : 4.29 %
RY.PR.H FixedReset 25,197 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-24
Maturity Price : 18.75
Evaluated at bid price : 18.75
Bid-YTW : 4.25 %
There were 37 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BAM.PF.F FixedReset Quote: 21.72 – 23.00
Spot Rate : 1.2800
Average : 0.7552

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-24
Maturity Price : 21.40
Evaluated at bid price : 21.72
Bid-YTW : 4.32 %

NA.PR.Q FixedReset Quote: 25.02 – 25.93
Spot Rate : 0.9100
Average : 0.5755

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.02
Bid-YTW : 3.43 %

VNR.PR.A FixedReset Quote: 19.10 – 20.00
Spot Rate : 0.9000
Average : 0.5849

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-24
Maturity Price : 19.10
Evaluated at bid price : 19.10
Bid-YTW : 4.82 %

BAM.PF.A FixedReset Quote: 20.52 – 21.23
Spot Rate : 0.7100
Average : 0.4419

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-24
Maturity Price : 20.52
Evaluated at bid price : 20.52
Bid-YTW : 4.59 %

TD.PF.E FixedReset Quote: 21.65 – 22.40
Spot Rate : 0.7500
Average : 0.4968

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-24
Maturity Price : 21.36
Evaluated at bid price : 21.65
Bid-YTW : 4.21 %

W.PR.K FixedReset Quote: 24.40 – 24.95
Spot Rate : 0.5500
Average : 0.3051

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-24
Maturity Price : 22.94
Evaluated at bid price : 24.40
Bid-YTW : 5.34 %

Market Action

December 23, 2015

Canadian preferred shares appear to have been hit over the past few months by tax loss selling, but we’re not the only targets:

Investors pulled more money from U.S. mutual funds last week than they have in any seven-day period in the past two and a half years.

Net redemptions reached $28.6 billion in the week ended Dec. 16, according to a statement from the Investment Company Institute, a trade group. It was the biggest weekly outflow since June 2013, ICI data show.

Some of the redemptions might reflect year-end tax-loss selling, which are sales made for tax purposes, ICI Senior Economist Shelly Antoniewicz said in the statement.

Investors withdrew $11.1 billion from stock funds, $12 billion from bond funds and $5.6 billion from funds that buy a mix of stocks and bonds. Municipal bond funds attracted $647 million, the only category that saw inflows.

Mutual funds have experienced net redemptions every month since July, according to ICI data. In each of the first six months of the year, funds gathered money.

On September 21 I discussed the characterization of the Canadian dollar as a petrodollar. Now it turns out that, as far as one measure is concerned, we’re the petrodollariest in the world!

No other major currency is as closely tied to the value of its key commodity export as the loonie is to crude right now. The correlation between the Canadian dollar and the benchmark West Texas Intermediate oil price is about 0.56, meaning the two have a strong positive relationship. That’s the closest association among 16 of the world’s most-traded currencies including the Australian and New Zealand dollars, Norway’s krone and Brazil’s real.

With oil futures trading below $45 a barrel through 2016, the loonie may continue to struggle. The currency has declined 16 per cent over the past year, touching an 11-year low of $1.4001 per U.S. dollar last week. The drop comes as the price of WTI fell to the lowest since 2009 after the Organization of Petroleum Exporting Countries announced this month it was abandoning production limits, and with U.S. crude stockpiles forecast to climb to the highest since 1930.
…
The 120-day correlation coefficient between 16 major currencies tracked by Bloomberg and their country’s main export commodity — based on 2014 World Bank data — show that the Mexican peso and oil had the second strongest correlation, at 0.41. The correlation between the Australian dollar and iron ore was 0.13, while the link between New Zealand’s currency and whole milk powder was 0.11. A reading of 1 means that gauges move in lockstep; minus 1 means they move in opposite directions.

Crude fell below $34 a barrel on Dec. 21. WTI futures for delivery in March are trading at about $37, compared to $39 for those settling in June.

The Canadian dollar has already fallen below Scotiabank’s 2016 target of $1.39 and there is “clear risk of an overshoot” toward $1.42-$1.43 through the first quarter, [chief foreign-exchange strategist for Bank of Nova Scotia] Mr. [Shaun] Osborne said.

There’s an interesting piece on the bond market, examined through the lens of the Litvak case:

Earlier this year, Sally Yates, the agency’s No. 2 official, ordered policy changes to push prosecutors to bring criminal charges against company executives suspected of financial wrongdoing. Her memo almost admitted that the U.S. Department of Justice had lapsed in its duty to put criminals behind bars. In a September speech, Yates said: “This memo is designed to ensure that all attorneys across the department are consistent in our best efforts to hold to account the individuals responsible for illegal corporate conduct. It’s the only way to truly deter corporate wrongdoing.”

The case against Litvak was supposed to be the opening salvo against dishonest conduct among bond traders. The Justice Department and U.S. Securities and Exchange Commission have built more than a dozen other cases using the one against Litvak as a model.

The cases won’t be easy victories for the government. Lying doesn’t necessarily violate securities law. It’s only fraud when that deception is considered important to a buyer. The question becomes: Is it important that the buyer knew how much Litvak paid for bonds he later sold? “The government may not like how these markets work, and it may look bad from the outside looking in, but it is how they do work,” says Charles Geisst, a Wall Street historian at Manhattan College in New York.
…
As the SEC sees it, just because something is common practice on Wall Street doesn’t mean it conforms to securities laws. The agency has built its own algorithms to comb through trading data to look for red flags instead of waiting for complaints. The SEC has uncovered brokers charging buyers higher fees, traders hiding their positions, and dealers running deceptive auctions. “We’ve identified billions of dollars of potentially problematic trades,” says Michael Osnato Jr., head of the regulator’s Complex Financial Instruments unit. “We have opened promising investigations thus far based on these efforts and expect more to follow soon.”

The Litvak ruling will shape how the SEC pursues some of these violations. The intensive monitoring of debt backed by mortgages and other assets represents a first for the agency. Before the credit crisis, the SEC viewed the market participants as sophisticated investors who didn’t need close supervision. That assumption came undone when plummeting prices in the debt markets kicked off the crisis. “The government’s new interest is reflective of the fact that they’ve had very little interest in this market historically,” says James Cox, a professor at Duke University School of Law. “They just hadn’t looked at it.”

The SEC doesn’t understand any markets, really, other than bank accounts that accrue interest daily. But hey! Markets went down, therefore nefarious activity was behind it, therefore somebody’s got to go to jail – it doesn’t matter who, really. The persecution of Litvak has been discussed on PrefBlog many times before, most recently on December 8.

Speaking of the way the market operates, I see there’s a dust-up with Dominion Diamond Corp. I have no knowledge of this company, but one part of the article drew my attention as a possible winner of “2015 Statements Best Illustrating Intellectual Bankruptcy of Equities Markets”:

Dominion enjoys considerable financial flexibility, according to Edward Sterck, a London-based analyst with Bank of Montreal’s investment arm. The miner has amassed net cash of $284-million (U.S.), equal to about 40 per cent of its market capitalization, he wrote in a research note.

He said that while Dominion’s near-term mine plan has been subject to frequent changes, its longer-term outlook has remained consistently positive.

Mr. Sterck projects an attractive bump in free cash flow over the years to come as new production comes into play, but added that “the problem is that the increased cash flows do not really begin in earnest until mid-2016, so why should investors hold the stock now?”

Ummmm … because increased cash flows begin in earnest in mid-2016?

Meanwhile, there has been a sudden change in the living rooms of preferred share investors … they now look like this:

mountainPresents
Click for Big

It was a strong day for the Canadian preferred share market, with PerpetualDiscounts gaining 30bp, FixedResets winning 166bp and DeemedRetractibles up 37bp … it appears that bargain hunters have decided not to wait until the precise end of tax-loss selling season after all! The performance highlights table is as lengthy as one might guess from the raw numbers. Volume continued to be enormously high … which leads to interesting speculation as to what might happen when tax-loss selling season ends.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_151223
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 18.73 to be $0.96 rich, while TRP.PR.C, resetting 2016-1-30 at +154, is $1.18 cheap at its bid price of 12.10.

impVol_MFC_151223
Click for Big

Most expensive is MFC.PR.M, resetting at +236bp on 2019-12-19, bid at 20.26 to be 0.48 rich, while MFC.PR.G, resetting at +290bp on 2016-12-19, is bid at 21.50 to be 0.48 cheap.

impVol_BAM_151223
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 15.82 to be $1.53 cheap. BAM.PF.E, resetting at +255bp on 2020-3-31 is bid at 19.58 and appears to be $0.81 rich.

impVol_FTS_151223
Click for Big

FTS.PR.K, with a spread of +205bp, and bid at 18.32, looks $0.59 expensive and resets 2019-3-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 17.51 and is $0.67 cheap.

pairs_FR_151223
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -1.52%, with one outlier below -2.50%. There are four junk outliers above -0.50%.

pairs_FF_151223
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 4.85 % 5.90 % 35,026 16.75 1 0.0000 % 1,598.0
FixedFloater 7.20 % 6.38 % 41,323 15.76 1 -0.4525 % 2,711.6
Floater 4.36 % 4.54 % 84,982 16.36 4 -1.3667 % 1,750.7
OpRet 4.86 % 4.17 % 27,412 0.67 1 0.0000 % 2,738.6
SplitShare 4.83 % 5.87 % 84,887 1.86 6 0.0293 % 3,201.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0293 % 2,497.8
Perpetual-Premium 5.82 % 5.87 % 97,659 13.91 7 0.2347 % 2,501.1
Perpetual-Discount 5.74 % 5.80 % 107,756 14.19 33 0.3040 % 2,501.1
FixedReset 5.14 % 4.48 % 278,104 14.72 81 1.6599 % 2,011.9
Deemed-Retractible 5.21 % 4.80 % 139,962 5.29 33 0.3745 % 2,575.0
FloatingReset 2.80 % 4.10 % 70,387 5.65 11 1.8268 % 2,123.0
Performance Highlights
Issue Index Change Notes
MFC.PR.F FixedReset -4.45 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.60
Bid-YTW : 9.06 %
BAM.PR.B Floater -2.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 10.42
Evaluated at bid price : 10.42
Bid-YTW : 4.54 %
BAM.PR.K Floater -2.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 10.30
Evaluated at bid price : 10.30
Bid-YTW : 4.59 %
PWF.PR.P FixedReset -1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 14.00
Evaluated at bid price : 14.00
Bid-YTW : 4.21 %
PVS.PR.B SplitShare -1.26 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2019-01-10
Maturity Price : 25.00
Evaluated at bid price : 23.60
Bid-YTW : 6.51 %
GWO.PR.N FixedReset -1.19 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.32
Bid-YTW : 9.97 %
ENB.PR.A Perpetual-Discount -1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 22.41
Evaluated at bid price : 22.67
Bid-YTW : 6.12 %
POW.PR.C Perpetual-Premium 1.01 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-01-22
Maturity Price : 25.00
Evaluated at bid price : 25.00
Bid-YTW : 1.36 %
BAM.PR.R FixedReset 1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 15.82
Evaluated at bid price : 15.82
Bid-YTW : 4.87 %
RY.PR.L FixedReset 1.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.04
Bid-YTW : 3.91 %
BAM.PF.G FixedReset 1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 21.09
Evaluated at bid price : 21.09
Bid-YTW : 4.50 %
TRP.PR.A FixedReset 1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 15.95
Evaluated at bid price : 15.95
Bid-YTW : 4.36 %
CIU.PR.A Perpetual-Discount 1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 20.03
Evaluated at bid price : 20.03
Bid-YTW : 5.81 %
BAM.PR.M Perpetual-Discount 1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 19.56
Evaluated at bid price : 19.56
Bid-YTW : 6.11 %
MFC.PR.G FixedReset 1.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.50
Bid-YTW : 5.73 %
BNS.PR.Y FixedReset 1.34 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.42
Bid-YTW : 5.42 %
RY.PR.O Perpetual-Discount 1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 22.08
Evaluated at bid price : 22.41
Bid-YTW : 5.51 %
TD.PF.D FixedReset 1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 20.02
Evaluated at bid price : 20.02
Bid-YTW : 4.47 %
TRP.PR.E FixedReset 1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 18.73
Evaluated at bid price : 18.73
Bid-YTW : 4.49 %
TRP.PR.G FixedReset 1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 20.09
Evaluated at bid price : 20.09
Bid-YTW : 4.66 %
TD.PF.B FixedReset 1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 18.61
Evaluated at bid price : 18.61
Bid-YTW : 4.29 %
BAM.PF.H FixedReset 1.45 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.91
Bid-YTW : 4.19 %
FTS.PR.H FixedReset 1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 14.22
Evaluated at bid price : 14.22
Bid-YTW : 3.98 %
MFC.PR.I FixedReset 1.57 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.95
Bid-YTW : 5.50 %
BNS.PR.A FloatingReset 1.61 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.68
Bid-YTW : 4.23 %
SLF.PR.I FixedReset 1.64 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.83
Bid-YTW : 6.62 %
IAG.PR.A Deemed-Retractible 1.67 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.35
Bid-YTW : 6.80 %
TD.PR.Y FixedReset 1.68 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.77
Bid-YTW : 3.24 %
IFC.PR.C FixedReset 1.70 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.13
Bid-YTW : 6.99 %
SLF.PR.H FixedReset 1.70 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.30
Bid-YTW : 7.77 %
MFC.PR.L FixedReset 1.76 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.03
Bid-YTW : 6.94 %
HSE.PR.C FixedReset 1.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 16.55
Evaluated at bid price : 16.55
Bid-YTW : 6.09 %
MFC.PR.N FixedReset 1.79 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.86
Bid-YTW : 6.48 %
VNR.PR.A FixedReset 1.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 18.85
Evaluated at bid price : 18.85
Bid-YTW : 4.89 %
TD.PF.A FixedReset 1.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 18.81
Evaluated at bid price : 18.81
Bid-YTW : 4.25 %
BAM.PF.E FixedReset 1.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 19.58
Evaluated at bid price : 19.58
Bid-YTW : 4.52 %
TD.PR.S FixedReset 1.98 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.69
Bid-YTW : 3.11 %
CM.PR.O FixedReset 2.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 18.77
Evaluated at bid price : 18.77
Bid-YTW : 4.27 %
BNS.PR.R FixedReset 2.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.82
Bid-YTW : 3.50 %
RY.PR.H FixedReset 2.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 18.80
Evaluated at bid price : 18.80
Bid-YTW : 4.24 %
HSE.PR.G FixedReset 2.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 18.80
Evaluated at bid price : 18.80
Bid-YTW : 5.80 %
CM.PR.P FixedReset 2.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 18.25
Evaluated at bid price : 18.25
Bid-YTW : 4.29 %
TD.PF.E FixedReset 2.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 21.26
Evaluated at bid price : 21.26
Bid-YTW : 4.31 %
NA.PR.W FixedReset 2.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 18.25
Evaluated at bid price : 18.25
Bid-YTW : 4.40 %
CU.PR.C FixedReset 2.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 19.06
Evaluated at bid price : 19.06
Bid-YTW : 4.21 %
MFC.PR.M FixedReset 2.32 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.26
Bid-YTW : 6.28 %
MFC.PR.J FixedReset 2.38 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.69
Bid-YTW : 6.04 %
BNS.PR.Q FixedReset 2.46 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.55
Bid-YTW : 3.44 %
BMO.PR.Q FixedReset 2.51 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.65
Bid-YTW : 4.70 %
FTS.PR.M FixedReset 2.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 4.27 %
MFC.PR.K FixedReset 2.54 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.99
Bid-YTW : 6.86 %
TD.PF.C FixedReset 2.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 18.50
Evaluated at bid price : 18.50
Bid-YTW : 4.30 %
TRP.PR.B FixedReset 2.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 11.75
Evaluated at bid price : 11.75
Bid-YTW : 4.35 %
CM.PR.Q FixedReset 2.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 19.75
Evaluated at bid price : 19.75
Bid-YTW : 4.47 %
RY.PR.Z FixedReset 2.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 18.80
Evaluated at bid price : 18.80
Bid-YTW : 4.19 %
TRP.PR.D FixedReset 2.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 18.20
Evaluated at bid price : 18.20
Bid-YTW : 4.55 %
BAM.PF.A FixedReset 2.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 20.79
Evaluated at bid price : 20.79
Bid-YTW : 4.53 %
NA.PR.S FixedReset 2.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 18.69
Evaluated at bid price : 18.69
Bid-YTW : 4.47 %
TRP.PR.C FixedReset 2.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 12.10
Evaluated at bid price : 12.10
Bid-YTW : 4.75 %
BAM.PF.F FixedReset 2.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 21.07
Evaluated at bid price : 21.07
Bid-YTW : 4.48 %
BMO.PR.R FloatingReset 3.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.25
Bid-YTW : 3.36 %
BMO.PR.T FixedReset 3.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 18.60
Evaluated at bid price : 18.60
Bid-YTW : 4.26 %
FTS.PR.K FixedReset 3.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 18.32
Evaluated at bid price : 18.32
Bid-YTW : 4.09 %
PWF.PR.T FixedReset 3.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 22.29
Evaluated at bid price : 22.78
Bid-YTW : 3.58 %
HSE.PR.A FixedReset 3.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 11.59
Evaluated at bid price : 11.59
Bid-YTW : 5.33 %
BAM.PR.Z FixedReset 3.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 20.59
Evaluated at bid price : 20.59
Bid-YTW : 4.63 %
BNS.PR.B FloatingReset 3.95 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.37
Bid-YTW : 4.10 %
BAM.PR.T FixedReset 4.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 17.05
Evaluated at bid price : 17.05
Bid-YTW : 4.60 %
FTS.PR.G FixedReset 4.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 17.51
Evaluated at bid price : 17.51
Bid-YTW : 4.32 %
BNS.PR.Z FixedReset 4.75 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.06
Bid-YTW : 6.21 %
BMO.PR.Y FixedReset 6.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 20.67
Evaluated at bid price : 20.67
Bid-YTW : 4.30 %
BNS.PR.D FloatingReset 7.11 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.97
Bid-YTW : 6.27 %
Volume Highlights
Issue Index Shares
Traded
Notes
CU.PR.I FixedReset 82,237 Scotia crossed 75,000 at 25.75.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-01
Maturity Price : 25.00
Evaluated at bid price : 25.70
Bid-YTW : 3.95 %
RY.PR.Q FixedReset 79,291 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-24
Maturity Price : 25.00
Evaluated at bid price : 25.73
Bid-YTW : 4.93 %
SLF.PR.C Deemed-Retractible 69,404 Desjardins crossed 51,900 at 20.40.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.32
Bid-YTW : 7.33 %
RY.PR.J FixedReset 58,200 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 19.75
Evaluated at bid price : 19.75
Bid-YTW : 4.47 %
TRP.PR.D FixedReset 51,563 National crossed 11,900 at 18.20.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 18.20
Evaluated at bid price : 18.20
Bid-YTW : 4.55 %
BNS.PR.E FixedReset 50,490 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-25
Maturity Price : 25.00
Evaluated at bid price : 25.89
Bid-YTW : 4.78 %
There were 81 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
TRP.PR.E FixedReset Quote: 18.73 – 19.30
Spot Rate : 0.5700
Average : 0.3645

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 18.73
Evaluated at bid price : 18.73
Bid-YTW : 4.49 %

RY.PR.L FixedReset Quote: 25.04 – 25.69
Spot Rate : 0.6500
Average : 0.4498

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.04
Bid-YTW : 3.91 %

CM.PR.Q FixedReset Quote: 19.75 – 20.49
Spot Rate : 0.7400
Average : 0.5464

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-23
Maturity Price : 19.75
Evaluated at bid price : 19.75
Bid-YTW : 4.47 %

IAG.PR.A Deemed-Retractible Quote: 21.35 – 22.00
Spot Rate : 0.6500
Average : 0.4633

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.35
Bid-YTW : 6.80 %

GWO.PR.S Deemed-Retractible Quote: 24.31 – 24.76
Spot Rate : 0.4500
Average : 0.3057

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.31
Bid-YTW : 5.66 %

MFC.PR.L FixedReset Quote: 19.03 – 19.49
Spot Rate : 0.4600
Average : 0.3198

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.03
Bid-YTW : 6.94 %

Market Action

December 22, 2015

Nothing much happened today.

Neil Irwin of the NYT makes a good point in his review of The Big Short (movie to be released Wednesday 23rd):

A lot of people thought a decade ago that there might be a housing bubble. Few of them understood the connections between housing prices and poor lending practices; the connection from poor lending practices to complex, highly rated securities; the connection between those securities to the balance sheets of major banks; and the peril to the economy if just a few of them faltered.

At each link in that chain, there were people aware that something was wrong, but who lacked the ability to put those pieces together and connect bad lending in Florida suburbs with the existential risk being taken by companies like Bear Stearns and Lehman Brothers.

The impossible job for the regulators (and journalists, and credit rating agencies) of the future is to better understand how the pieces within the infinitely complex economy and financial system connect with one another.

“The Big Short” is a powerful reminder of how hard that will be.

It was really just another example of the Law of Unintended Consequences, writ large.

Brookfield Investments Corporation, proud issuer of BRN.PR.A, was confirmed at Pfd-2(low) by DBRS:

DBRS Limited (DBRS) today confirms Brookfield Investments Corporation’s (BIC or the Company) Senior Preferred Shares rating at Pfd-2 (low) with a Stable trend. The confirmation follows the announcement that (1) Brookfield Asset Management (BAM or the Guarantor), BIC’s 100% shareholder, will provide a full and unconditional subordinated guarantee on BIC’s outstanding Senior Preferred Shares, and (2) BIC will rely on continuous disclosure exemption and no longer file its financial statements. DBRS understands that the guarantee will apply to all BIC’s Preferred Shares outstanding other than those held by BAM and its affiliates. Claims under the guarantee will be subordinated to all outstanding senior indebtedness of BAM and will effectively rank pari passu with Preferred Shares issued by BAM.
…
The proposed change will result in BIC’s discontinuing any public disclosure of its financial performance and investment composition. DBRS understands that BAM and BIC intend to maintain similar asset size, composition and financing sources in the foreseeable future. In view of this and so long as BAM’s guarantee remains valid, DBRS will no longer issue separate rating reports on BAM and will report the rating of BIC’s Preferred Shares as a guaranteed issue in future BAM rating reports.

Faircourt Split Trust, proud issuer of FCS.PR.C, has been confirmed at Pfd-3(low) by DBRS:

Based on yields of underlying securities as of December 15, 2015, the Portfolio currently receives dividends to cover 14% of Preferred Security distributions. As of December 14, 2015, downside protection available to holders of the Preferred Securities was 30.2%.
…
The asset coverage test does not permit any cash distributions to the [Capital] unitholders if, after giving effect to the proposed distribution, the total assets of the Portfolio would be less than 1.4 times the outstanding principal amount of the Preferred Securities.

The Preferred Share distributions will result in an average annual grind on the net asset value (NAV) of 4.4% in the next 3.5 years.
…
According to the terms of the Trust’s Declaration of Trust, the Trust has the ability to borrow up to 10% of Total Assets (as defined in the Declaration of Trust) under a loan facility in order to meet its investment objectives. Under the terms of the Company’s Trust Indenture, the loan facility is considered Senior Indebtedness, and all amounts owing under the loan facility will be paid in priority to the 6.00% Preferred Securities. There is currently no loan facility in place and, therefore, there are currently no amounts owing under a loan facility; however, to the extent that the Trust borrows under a loan facility, the rating on the 6.00% Preferred Securities could be negatively affected. DBRS will continue to monitor the situation in connection with the ongoing surveillance of the rating on the 6.00% Preferred Securities, and will take appropriate ratings action as necessary.

It was a good day for the Canadian preferred share market, with PerpetualDiscounts winning 70bp, FixedResets up 67bp and DeemedRetractibles gaining 37bp. The Performance Highlights table continues to show a lot of churn. Volume remained extremely high.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 4.85 % 5.90 % 33,806 16.75 1 5.5807 % 1,598.0
FixedFloater 7.16 % 6.35 % 39,135 15.80 1 0.0755 % 2,723.9
Floater 4.31 % 4.41 % 83,448 16.60 4 -2.2707 % 1,775.0
OpRet 4.86 % 4.15 % 28,440 0.68 1 0.0000 % 2,738.6
SplitShare 4.83 % 5.81 % 83,800 1.86 6 0.0156 % 3,200.4
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0156 % 2,497.1
Perpetual-Premium 5.83 % 5.86 % 99,151 13.93 7 0.3447 % 2,495.2
Perpetual-Discount 5.75 % 5.83 % 107,469 14.11 33 0.6970 % 2,493.5
FixedReset 5.22 % 4.59 % 274,045 14.70 81 0.6674 % 1,979.1
Deemed-Retractible 5.23 % 4.88 % 141,741 5.29 33 0.3733 % 2,565.4
FloatingReset 2.85 % 4.52 % 70,566 5.65 11 -0.0908 % 2,084.9
Performance Highlights
Issue Index Change Notes
BAM.PR.C Floater -4.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 10.36
Evaluated at bid price : 10.36
Bid-YTW : 4.56 %
BNS.PR.D FloatingReset -4.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.71
Bid-YTW : 7.49 %
BAM.PR.B Floater -2.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 10.71
Evaluated at bid price : 10.71
Bid-YTW : 4.41 %
CIU.PR.C FixedReset -2.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 12.51
Evaluated at bid price : 12.51
Bid-YTW : 4.25 %
SLF.PR.H FixedReset -2.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.01
Bid-YTW : 8.00 %
BAM.PR.K Floater -2.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 10.58
Evaluated at bid price : 10.58
Bid-YTW : 4.47 %
IFC.PR.C FixedReset -2.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.81
Bid-YTW : 7.22 %
BAM.PF.H FixedReset -1.77 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.54
Bid-YTW : 4.51 %
BIP.PR.A FixedReset -1.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 19.45
Evaluated at bid price : 19.45
Bid-YTW : 5.60 %
RY.PR.P Perpetual-Discount -1.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 24.06
Evaluated at bid price : 24.42
Bid-YTW : 5.47 %
MFC.PR.N FixedReset -1.46 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.51
Bid-YTW : 6.72 %
BNS.PR.A FloatingReset -1.28 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.32
Bid-YTW : 4.52 %
SLF.PR.J FloatingReset 1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 12.80
Bid-YTW : 10.22 %
BMO.PR.Y FixedReset 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 19.50
Evaluated at bid price : 19.50
Bid-YTW : 4.56 %
BAM.PF.F FixedReset 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 20.46
Evaluated at bid price : 20.46
Bid-YTW : 4.62 %
VNR.PR.A FixedReset 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 18.50
Evaluated at bid price : 18.50
Bid-YTW : 4.98 %
TRP.PR.D FixedReset 1.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 17.71
Evaluated at bid price : 17.71
Bid-YTW : 4.68 %
PWF.PR.E Perpetual-Discount 1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 23.51
Evaluated at bid price : 23.78
Bid-YTW : 5.87 %
RY.PR.I FixedReset 1.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.37
Bid-YTW : 3.64 %
IFC.PR.A FixedReset 1.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.80
Bid-YTW : 8.91 %
BNS.PR.C FloatingReset 1.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.05
Bid-YTW : 4.55 %
HSB.PR.C Deemed-Retractible 1.29 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-01-21
Maturity Price : 25.00
Evaluated at bid price : 25.04
Bid-YTW : 1.62 %
MFC.PR.K FixedReset 1.31 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.52
Bid-YTW : 7.20 %
GWO.PR.N FixedReset 1.35 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.48
Bid-YTW : 9.81 %
GWO.PR.G Deemed-Retractible 1.43 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.76
Bid-YTW : 6.54 %
CU.PR.C FixedReset 1.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 18.63
Evaluated at bid price : 18.63
Bid-YTW : 4.31 %
BAM.PR.R FixedReset 1.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 15.65
Evaluated at bid price : 15.65
Bid-YTW : 4.92 %
NA.PR.S FixedReset 1.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 18.16
Evaluated at bid price : 18.16
Bid-YTW : 4.60 %
TD.PF.D FixedReset 1.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 19.75
Evaluated at bid price : 19.75
Bid-YTW : 4.53 %
TRP.PR.A FixedReset 1.74 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 15.77
Evaluated at bid price : 15.77
Bid-YTW : 4.41 %
POW.PR.D Perpetual-Discount 1.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 21.91
Evaluated at bid price : 22.15
Bid-YTW : 5.64 %
BMO.PR.Q FixedReset 1.78 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.12
Bid-YTW : 5.15 %
BAM.PF.B FixedReset 1.81 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 19.14
Evaluated at bid price : 19.14
Bid-YTW : 4.59 %
CU.PR.D Perpetual-Discount 1.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 21.50
Evaluated at bid price : 21.50
Bid-YTW : 5.76 %
MFC.PR.H FixedReset 1.90 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.50
Bid-YTW : 5.39 %
CU.PR.F Perpetual-Discount 1.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 20.01
Evaluated at bid price : 20.01
Bid-YTW : 5.68 %
BAM.PF.C Perpetual-Discount 1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 19.73
Evaluated at bid price : 19.73
Bid-YTW : 6.18 %
RY.PR.M FixedReset 2.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 19.52
Evaluated at bid price : 19.52
Bid-YTW : 4.41 %
CU.PR.G Perpetual-Discount 2.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 20.02
Evaluated at bid price : 20.02
Bid-YTW : 5.68 %
BMO.PR.S FixedReset 2.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 19.05
Evaluated at bid price : 19.05
Bid-YTW : 4.27 %
MFC.PR.L FixedReset 2.47 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.70
Bid-YTW : 7.18 %
FTS.PR.K FixedReset 2.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 17.67
Evaluated at bid price : 17.67
Bid-YTW : 4.24 %
PWF.PR.S Perpetual-Discount 2.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 21.51
Evaluated at bid price : 21.51
Bid-YTW : 5.67 %
FTS.PR.G FixedReset 2.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 16.79
Evaluated at bid price : 16.79
Bid-YTW : 4.51 %
BAM.PR.Z FixedReset 2.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 19.81
Evaluated at bid price : 19.81
Bid-YTW : 4.82 %
BAM.PR.T FixedReset 3.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 16.39
Evaluated at bid price : 16.39
Bid-YTW : 4.79 %
GWO.PR.L Deemed-Retractible 3.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.13
Bid-YTW : 5.59 %
IAG.PR.G FixedReset 3.35 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.05
Bid-YTW : 6.65 %
MFC.PR.F FixedReset 3.66 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.28
Bid-YTW : 8.46 %
BAM.PR.X FixedReset 4.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 14.57
Evaluated at bid price : 14.57
Bid-YTW : 4.62 %
NA.PR.W FixedReset 4.08 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 17.85
Evaluated at bid price : 17.85
Bid-YTW : 4.50 %
TRP.PR.B FixedReset 4.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 11.45
Evaluated at bid price : 11.45
Bid-YTW : 4.46 %
FTS.PR.I FloatingReset 4.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 11.80
Evaluated at bid price : 11.80
Bid-YTW : 4.06 %
PWF.PR.P FixedReset 5.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 14.20
Evaluated at bid price : 14.20
Bid-YTW : 4.15 %
BAM.PR.E Ratchet 5.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 25.00
Evaluated at bid price : 14.00
Bid-YTW : 5.90 %
Volume Highlights
Issue Index Shares
Traded
Notes
MFC.PR.C Deemed-Retractible 183,101 YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.38
Bid-YTW : 7.37 %
RY.PR.Q FixedReset 131,502 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-24
Maturity Price : 25.00
Evaluated at bid price : 25.65
Bid-YTW : 4.99 %
NA.PR.S FixedReset 120,129 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 18.16
Evaluated at bid price : 18.16
Bid-YTW : 4.60 %
BAM.PR.B Floater 119,356 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 10.71
Evaluated at bid price : 10.71
Bid-YTW : 4.41 %
HSE.PR.G FixedReset 87,850 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 18.40
Evaluated at bid price : 18.40
Bid-YTW : 5.93 %
BAM.PR.K Floater 79,527 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 10.58
Evaluated at bid price : 10.58
Bid-YTW : 4.47 %
There were 74 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
PWF.PR.T FixedReset Quote: 21.95 – 24.52
Spot Rate : 2.5700
Average : 1.5060

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 21.56
Evaluated at bid price : 21.95
Bid-YTW : 3.73 %

BAM.PR.E Ratchet Quote: 14.00 – 15.84
Spot Rate : 1.8400
Average : 1.1711

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 25.00
Evaluated at bid price : 14.00
Bid-YTW : 5.90 %

BNS.PR.D FloatingReset Quote: 17.71 – 18.60
Spot Rate : 0.8900
Average : 0.5109

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.71
Bid-YTW : 7.49 %

BAM.PR.T FixedReset Quote: 16.39 – 17.40
Spot Rate : 1.0100
Average : 0.6437

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 16.39
Evaluated at bid price : 16.39
Bid-YTW : 4.79 %

BMO.PR.T FixedReset Quote: 17.95 – 18.85
Spot Rate : 0.9000
Average : 0.6190

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-22
Maturity Price : 17.95
Evaluated at bid price : 17.95
Bid-YTW : 4.42 %

BNS.PR.A FloatingReset Quote: 22.32 – 22.99
Spot Rate : 0.6700
Average : 0.4431

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.32
Bid-YTW : 4.52 %

Market Action

December 21, 2021

Nothing much happened today in the financial world, although what with the solstice and all, a few preferred share new issue salesmen may have been sacrificed by their clients.

In the real world, though there was marvellous news regarding private space ventures:

Elon Musk’s SpaceX showcased his dream of reusable spacecraft by making a Falcon 9 booster the first piece of an orbital rocket to land back on Earth, minutes after lofting satellites toward orbit.

Space Exploration Technologies Corp. pulled off the soft, vertical touchdown after the two-stage rocket propelled its payload of 11 Orbcomm Inc. satellites aloft. It was the company’s first flight since a fiery blast destroyed a Falcon 9 rocket in June, minutes after lift off.

“Welcome back, baby!” Musk wrote in a Twitter post on his way to the landing zone.

Monday’s mission helped validate Musk’s vision for lower-cost spaceflight and provides SpaceX a boost in his race with fellow billionaire Jeff Bezos to develop craft that can survive fiery blasts and return to Earth to be reused. Instead of ditching the booster, SpaceX used thrusters and sophisticated navigation to steer it from space to Landing Zone 1, a former U.S. Air Force rocket and missile testing range.

Scotia announced the redemption of sub-debt on its pretend-maturity:

Scotiabank (TSX: BNS) (NYSE: BNS) today announced that the Bank intends to redeem all outstanding 6.65% debentures due January 22, 2021 for 100% of their principal amount plus accrued interest to the redemption date. The redemption will occur on January 22, 2016. Formal notice will be delivered to the debenture holders in accordance with the terms and conditions set forth in the related trust indenture.

The redemption has been approved by the Office of the Superintendent of Financial Institutions and will be financed out of the general funds of Scotiabank.

This will assist new issue salesmen to sell ten-year sub-debt as if it should have a spread off five-year Canadas, although from what I understand this doesn’t work as well as it used to:

Investors who leaped into Basel-compliant bonds issued by Canadian banks to great fanfare are likely regretting their haste. A year on, the reward for taking on the risk of bailing out a bank has become much richer.

Relative yields of the bonds have widened 25 basis points this year, the worst performance among Canadian five-year corporate bonds, according to RBC Dominion Securities research. The debt is designed to convert to equity if a bank gets into financial distress, in line with new Basel rules to prevent another financial crisis. The first issue of the debt, called contingent capital bonds, in Canada was by Royal Bank of Canada in July, 2014.

RioCan REIT, proud issuer of REI.PR.A and REI.PR.C, was confirmed at Pfd-3(high) by DBRS:

DBRS Limited (DBRS) has today confirmed RioCan Real Estate Investment Trust’s (RioCan or the Trust) Senior Unsecured Debentures rating and Senior Unsecured Debentures, Series I rating at BBB (high) and its Preferred Trust Units rating at Pfd-3 (high), all with Stable trends. The confirmations reflect RioCan’s near-term enhanced financial flexibility to fund its development pipeline and DBRS’s expectation that financial metrics will return to BBB (high) levels. The confirmations follow RioCan’s announcement to sell its U.S. portfolio of 49 retail properties located in the Northeastern United States and Texas for a total sale price of USD 1.9 billion or $2.7 billion to Blackstone Real Estate Partners VIII (Blackstone; the Transaction).
…
DBRS notes that a positive rating action could occur should RioCan increase the size of its portfolio and reduce its geographic concentration while maintaining EBITDA interest coverage (including capitalized interest) above 3.0 times, such that it is more consistent with the A (low) rating category.

Valener Inc., proud issuer of VNR.PR.A, was confirmed at Pfd-2(low) by DBRS:

DBRS Limited (DBRS) has today confirmed Valener Inc.’s (Valener or the Company) Cumulative Rate Reset Preferred Shares, Series A rating at Pfd-2 (low) with a Stable trend. Valener’s preferred share rating is based on the credit quality of Gaz Métro Limited Partnership (the Partnership), which guarantees the First Mortgage Bonds and Senior Secured Notes (rated “A”) of Gaz Métro inc. The one-notch differential in the ratings of Valener and the Partnership reflects the structural subordination at Valener.
…
As the Company has no bonds/debentures issued, and is not expected to issue any long-term debt in the foreseeable future, its leverage solely consists of its credit facility outstanding. As at September 30, 2015, Valener utilized approximately $120 million of the $200 million credit facility which matures on September 30, 2020. Valener’s debt-to-capital ratio was reasonable at approximately 14.3% as at September 30, 2015. Valener is expected to fund future growth investments in a prudent manner to maintain leverage within the 20% threshold. If Valener is unable to do so on a sustained basis, this could result in a negative rating action. Other key non-consolidated credit metrics have also remained supportive of the current rating category, including cash flow-to-interest at 38.8 times, cash-flow fixed coverage at 10.4 times and cash flow-to-debt at 49.7% in F2015.

It was a modestly negative day for the Canadian preferred share market, with PerpetualDiscounts off 7bp, FixedResets down 9bp and DeemedRetractibles losing 36bp. The Performance Highlights table is very long considering the placid overall numbers. Volume was very high.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_151221
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 18.60 to be $1.22 rich, while TRP.PR.C, resetting 2016-1-30 at +154, is $1.02 cheap at its bid price of 11.85.

impVol_MFC_151221
Click for Big

Most expensive is MFC.PR.N, resetting at +230bp on 2020-3-19, bid at 19.80 to be 0.68 rich, while MFC.PR.K, resetting at +222bp on 2018-9-19, is bid at 18.28 to be 0.55 cheap.

impVol_BAM_151221
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 15.40 to be $1.30 cheap. BAM.PF.G, resetting at +284bp on 2020-6-30 is bid at 20.78 and appears to be $1.09 rich.

impVol_FTS_151221
Click for Big

FTS.PR.M, with a spread of +248bp, and bid at 19.48, looks $0.51 expensive and resets 2019-12-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 16.31 and is $1.05 cheap.

pairs_FR_151221
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -1.44%, with one outlier above -0.50%. There are five junk outliers above -0.50%.

pairs_FF_151221
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 5.12 % 6.24 % 34,043 16.35 1 -3.5636 % 1,513.5
FixedFloater 7.17 % 6.35 % 38,939 15.79 1 0.3788 % 2,721.9
Floater 4.21 % 4.31 % 83,269 16.81 4 0.6949 % 1,816.2
OpRet 4.86 % 4.13 % 26,335 0.68 1 0.1192 % 2,738.6
SplitShare 4.83 % 6.01 % 84,147 1.86 6 -0.0361 % 3,199.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0361 % 2,496.7
Perpetual-Premium 5.83 % 5.90 % 97,956 13.93 7 -0.0686 % 2,486.7
Perpetual-Discount 5.79 % 5.87 % 105,174 14.05 33 -0.0666 % 2,476.3
FixedReset 5.26 % 4.64 % 273,504 14.67 81 -0.0881 % 1,966.0
Deemed-Retractible 5.25 % 5.32 % 139,767 5.29 33 -0.3552 % 2,555.9
FloatingReset 2.84 % 4.28 % 68,806 5.66 11 -0.9637 % 2,086.8
Performance Highlights
Issue Index Change Notes
VNR.PR.A FixedReset -5.37 % Not real. The issue traded 6,560 shares today in a range of 18.64-20.12 before closing at 18.31-09, 2×2. VWAP was 19.42. I have not checked whether this lamentable state of affairs is due to inadequate Toronto Stock Exchange reporting or inadequate Toronto Stock Exchange supervision of market-makers.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 18.31
Evaluated at bid price : 18.31
Bid-YTW : 5.03 %
FTS.PR.M FixedReset -4.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 19.46
Evaluated at bid price : 19.46
Bid-YTW : 4.39 %
CIU.PR.C FixedReset -4.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 12.81
Evaluated at bid price : 12.81
Bid-YTW : 4.15 %
IAG.PR.G FixedReset -4.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.40
Bid-YTW : 7.10 %
BNS.PR.B FloatingReset -3.93 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.50
Bid-YTW : 4.81 %
BAM.PR.E Ratchet -3.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 25.00
Evaluated at bid price : 13.26
Bid-YTW : 6.24 %
FTS.PR.G FixedReset -3.43 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 16.31
Evaluated at bid price : 16.31
Bid-YTW : 4.64 %
FTS.PR.K FixedReset -2.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 17.20
Evaluated at bid price : 17.20
Bid-YTW : 4.36 %
MFC.PR.L FixedReset -2.51 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.25
Bid-YTW : 7.51 %
HSE.PR.C FixedReset -2.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 16.35
Evaluated at bid price : 16.35
Bid-YTW : 6.17 %
CU.PR.C FixedReset -2.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 18.36
Evaluated at bid price : 18.36
Bid-YTW : 4.37 %
HSE.PR.E FixedReset -2.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 17.95
Evaluated at bid price : 17.95
Bid-YTW : 6.08 %
BNS.PR.D FloatingReset -2.12 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.45
Bid-YTW : 6.76 %
PWF.PR.A Floater -1.98 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 12.35
Evaluated at bid price : 12.35
Bid-YTW : 3.86 %
BAM.PF.E FixedReset -1.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 19.12
Evaluated at bid price : 19.12
Bid-YTW : 4.63 %
BAM.PR.T FixedReset -1.85 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 15.90
Evaluated at bid price : 15.90
Bid-YTW : 4.94 %
ENB.PR.A Perpetual-Discount -1.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 22.61
Evaluated at bid price : 22.86
Bid-YTW : 6.07 %
PWF.PR.T FixedReset -1.56 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 21.82
Evaluated at bid price : 22.10
Bid-YTW : 3.72 %
BNS.PR.C FloatingReset -1.40 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.78
Bid-YTW : 4.78 %
CM.PR.Q FixedReset -1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 19.30
Evaluated at bid price : 19.30
Bid-YTW : 4.64 %
PWF.PR.K Perpetual-Discount -1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 21.45
Evaluated at bid price : 21.45
Bid-YTW : 5.87 %
MFC.PR.K FixedReset -1.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.28
Bid-YTW : 7.38 %
PVS.PR.B SplitShare -1.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2019-01-10
Maturity Price : 25.00
Evaluated at bid price : 23.90
Bid-YTW : 6.04 %
MFC.PR.J FixedReset -1.22 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.25
Bid-YTW : 6.32 %
BAM.PF.F FixedReset -1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 20.25
Evaluated at bid price : 20.25
Bid-YTW : 4.67 %
RY.PR.F Deemed-Retractible -1.21 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.46
Bid-YTW : 4.95 %
MFC.PR.G FixedReset -1.17 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.05
Bid-YTW : 6.02 %
PWF.PR.P FixedReset -1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 13.50
Evaluated at bid price : 13.50
Bid-YTW : 4.36 %
MFC.PR.I FixedReset -1.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.43
Bid-YTW : 5.83 %
GWO.PR.Q Deemed-Retractible -1.10 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.50
Bid-YTW : 6.65 %
BNS.PR.L Deemed-Retractible -1.04 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.70
Bid-YTW : 4.87 %
BAM.PF.D Perpetual-Discount 1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 19.85
Evaluated at bid price : 19.85
Bid-YTW : 6.21 %
BMO.PR.Z Perpetual-Discount 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 22.86
Evaluated at bid price : 23.25
Bid-YTW : 5.41 %
RY.PR.I FixedReset 1.05 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.10
Bid-YTW : 3.84 %
BMO.PR.T FixedReset 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 17.98
Evaluated at bid price : 17.98
Bid-YTW : 4.41 %
BNS.PR.A FloatingReset 1.07 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.61
Bid-YTW : 4.28 %
BAM.PF.G FixedReset 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 20.78
Evaluated at bid price : 20.78
Bid-YTW : 4.57 %
CIU.PR.A Perpetual-Discount 1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 19.82
Evaluated at bid price : 19.82
Bid-YTW : 5.87 %
SLF.PR.G FixedReset 1.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.98
Bid-YTW : 8.68 %
BAM.PF.H FixedReset 1.17 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-31
Maturity Price : 25.00
Evaluated at bid price : 26.00
Bid-YTW : 4.10 %
BAM.PR.N Perpetual-Discount 1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 19.37
Evaluated at bid price : 19.37
Bid-YTW : 6.17 %
RY.PR.J FixedReset 1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 19.41
Evaluated at bid price : 19.41
Bid-YTW : 4.54 %
PVS.PR.D SplitShare 1.39 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2021-10-08
Maturity Price : 25.00
Evaluated at bid price : 22.65
Bid-YTW : 6.55 %
RY.PR.Q FixedReset 1.43 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-24
Maturity Price : 25.00
Evaluated at bid price : 25.58
Bid-YTW : 5.05 %
TRP.PR.B FixedReset 1.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 10.96
Evaluated at bid price : 10.96
Bid-YTW : 4.66 %
BIP.PR.A FixedReset 1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 19.80
Evaluated at bid price : 19.80
Bid-YTW : 5.50 %
BNS.PR.Y FixedReset 1.51 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.20
Bid-YTW : 5.61 %
BMO.PR.W FixedReset 1.52 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 18.03
Evaluated at bid price : 18.03
Bid-YTW : 4.36 %
CU.PR.I FixedReset 1.56 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2020-12-01
Maturity Price : 25.00
Evaluated at bid price : 25.42
Bid-YTW : 4.20 %
BAM.PR.B Floater 1.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 10.97
Evaluated at bid price : 10.97
Bid-YTW : 4.31 %
BAM.PF.A FixedReset 1.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 20.35
Evaluated at bid price : 20.35
Bid-YTW : 4.63 %
NA.PR.Q FixedReset 1.75 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.95
Bid-YTW : 3.48 %
BMO.PR.S FixedReset 1.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 18.60
Evaluated at bid price : 18.60
Bid-YTW : 4.37 %
CM.PR.O FixedReset 1.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 18.47
Evaluated at bid price : 18.47
Bid-YTW : 4.42 %
CM.PR.P FixedReset 2.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 18.00
Evaluated at bid price : 18.00
Bid-YTW : 4.43 %
BMO.PR.Q FixedReset 2.47 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.75
Bid-YTW : 5.46 %
BAM.PR.K Floater 2.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 10.80
Evaluated at bid price : 10.80
Bid-YTW : 4.38 %
MFC.PR.F FixedReset 3.73 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.74
Bid-YTW : 8.93 %
TRP.PR.A FixedReset 4.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 15.50
Evaluated at bid price : 15.50
Bid-YTW : 4.49 %
Volume Highlights
Issue Index Shares
Traded
Notes
FTS.PR.E OpRet 222,000 Nesbitt crossed blocks of 200,000 and 20,000, both at 25.22.
YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2016-08-31
Maturity Price : 25.00
Evaluated at bid price : 25.20
Bid-YTW : 4.13 %
RY.PR.Q FixedReset 205,155 National bought 13,500 from anonymous at 25.50; Desjardins sold 10,000 to RBC and another 10,600 to National, both at 25.60.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-05-24
Maturity Price : 25.00
Evaluated at bid price : 25.58
Bid-YTW : 5.05 %
RY.PR.J FixedReset 131,479 Scotia crossed 100,000 at 19.35.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 19.41
Evaluated at bid price : 19.41
Bid-YTW : 4.54 %
RY.PR.D Deemed-Retractible 102,550 RBC crossed 100,000 at 24.80.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.62
Bid-YTW : 4.88 %
BNS.PR.E FixedReset 70,870 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-25
Maturity Price : 25.00
Evaluated at bid price : 25.65
Bid-YTW : 4.98 %
TD.PF.B FixedReset 55,622 TD crossed 31,000 at 18.12.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 18.17
Evaluated at bid price : 18.17
Bid-YTW : 4.39 %
There were 72 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
ENB.PR.A Perpetual-Discount Quote: 22.86 – 23.50
Spot Rate : 0.6400
Average : 0.4216

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 22.61
Evaluated at bid price : 22.86
Bid-YTW : 6.07 %

ELF.PR.H Perpetual-Discount Quote: 23.03 – 23.67
Spot Rate : 0.6400
Average : 0.4305

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 22.68
Evaluated at bid price : 23.03
Bid-YTW : 6.07 %

BNS.PR.B FloatingReset Quote: 21.50 – 22.13
Spot Rate : 0.6300
Average : 0.4220

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.50
Bid-YTW : 4.81 %

BAM.PF.D Perpetual-Discount Quote: 19.85 – 20.41
Spot Rate : 0.5600
Average : 0.3747

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 19.85
Evaluated at bid price : 19.85
Bid-YTW : 6.21 %

FTS.PR.I FloatingReset Quote: 11.26 – 11.92
Spot Rate : 0.6600
Average : 0.4953

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-21
Maturity Price : 11.26
Evaluated at bid price : 11.26
Bid-YTW : 4.25 %

RY.PR.D Deemed-Retractible Quote: 24.62 – 25.09
Spot Rate : 0.4700
Average : 0.3102

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.62
Bid-YTW : 4.88 %

Market Action

December 18, 2015

Amidst all the snivelling from old-stock Canadians unable to compete in the Vancouver housing market it’s nice to see a major move in the other direction:

President Barack Obama signed into law a measure easing a 35-year-old tax on foreign investment in U.S. real estate, potentially opening the door to greater purchases by overseas investors, a major source of capital since the financial crisis.

Contained in the $1.1 trillion spending measure that was passed to avoid a government shutdown is a provision that treats foreign pension funds the same as their U.S. counterparts for real estate investments. The provision waives the tax imposed on such investors under the 1980 Foreign Investment in Real Property Tax Act, known as FIRPTA.

“FIRPTA has historically made direct investment in U.S. property a non-starter for trillions of dollars worth of foreign pensions,” said James Corl, a managing director at private equity firm Siguler Guff & Co. “This tax-law modification is a game changer” that could result in hundreds of billions of new capital flows into U.S. real estate.

S&P has downgraded Alberta:

We are lowering our long-term issuer credit and senior unsecured debt ratings on the Province of Alberta to ‘AA+’ from ‘AAA’. We are also lowering our ‘AAA’ senior unsecured debt rating on Alberta Capital Finance Authority to ‘AA+’ from ‘AAA’.

The downgrade reflects our view of Alberta’s projected oil price-driven weak budgetary performances in the next two years; moderate, but rapidly rising, tax-supported debt burden; and now-average economic prospects. The stable outlook reflects our expectations that the province’s liquidity will continue to be exceptional in the next two years, real GDP growth will be positive in 2016 and 2017, and that the debt burden will remain moderate despite large deficit-driven increases in fiscal years 2016-2018.
…
We assess the provincial economy as strong despite the plunge in oil prices and declining real GDP that we expect for 2015. The concentration in the oil and gas industry tempers our assessment of the provincial economy. In 2014, the industry, which includes supporting activities, represented about 27% of real GDP and about 6% of employment. This exposure brings economic and fiscal volatility as oil and gas prices move, as the decline in oil prices indicates. Furthermore, the prospects for energy prices have caused us to reassess Alberta’s growth prospects as average, from above-average previously. We estimate the provincial GDP per capita to be about US$80,800 (2012-2014), which we consider to be high compared with that of peers. Real and nominal GDP growth in 2014 was what we consider very strong despite the fall in oil prices in the second half of the year. Real GDP rose 4.5% (5.1% in 2014): nominal GDP increased 9.1%, compared with 10.2%. Labor force results were also strong, in our opinion. Employment grew 2.2% (2.5% in 2013) and the unemployment rate was 4.7%, up only slightly from 2013. For 2015, the province expects real and nominal GDP to decline 1.0% and 9.4%, respectively. In 2016, we believe real and nominal GDP should rebound, with about 1.0% and 4.0% growth, respectively.

Alberta’s financial management is very strong, in our view. Budget information is comprehensive and detailed. The province produces a five-year capital plan annually. The level of transparency and disclosure in financial statements is high. The independent auditor-general, who reports to the legislature, audits financial statements. Debt and liquidity management and related policies and practices are prudent and risk-averse. A capable and experienced administration supports the recently elected governing party.

I mentioned the Capital Power debt reorganization on November 19 and November 20; now it has come to fruition:

Capital Power Corporation (“Capital Power”) (TSX: CPX) and Capital Power L.P. (“CPLP”) announced today the completion of a previously announced transaction to exchange all outstanding CPLP medium term notes (“CPLP Notes”) for newly issued Capital Power medium term notes (“Capital Power Notes”) that have the same financial and other terms as the CPLP Notes and that are unconditionally guaranteed by CPLP (“Note Exchange”).

The Note Exchange transaction received strong support and was approved by more than 87% of the votes cast at the December 17, 2015 meeting of holders of CPLP Notes, voting as a single class.

As a result of the Note Exchange, the CPLP Notes have been cancelled and the following Capital Power Notes were issued in exchange for them:
◦4.85% Medium Term Notes of Capital Power due February 21, 2019, Series 1
◦5.276% Medium Term Notes of Capital Power due November 16, 2020, Series 2

The Note Exchange and additional steps to reorganize CPLP’s capital structure were undertaken to simplify the organizational structure and reduce reporting obligations. The cessation of CPLP as a reporting issuer and transition of long-term credit ratings to only Capital Power will result in efficiencies for Capital Power while providing noteholders with better liquidity over time and structural enhancement. The timing of the Note Exchange follows the exchange of all remaining Exchangeable Common Limited Partnership Units of CPLP for shares of Capital Power by EPCOR Power Development Corporation on April 2, 2015.

RBC Capital Markets acted as the Solicitation Agent for the Note Exchange transaction

So, what’s done is done. RBC got paid and their counsel got paid:

The Solicitation Agent will be entitled to receive a fee for its services and be reimbursed for certain reasonable out-of-pocket expenses, including fees of legal counsel, and will be indemnified against certain liabilities and expenses in connection with the solicitation of votes in favour of the Note Exchange Resolution.

… and Kingsdale got paid:

CPLP has retained Kingsdale Shareholder Services to act as information agent in connection with the Note Exchange Transaction. The Information Agent will receive reasonable and customary compensation from CPLP for its services in connection with the Note Exchange Transaction, will be reimbursed for certain out-of-pocket expenses and will be indemnified against certain liabilities and expenses in connection with the Note Exchange Transaction.

… and I’m sure lots of other people got paid, but the Noteholders didn’t get paid, not a penny. And they voted in favour anyway! Like I always say, there’s one born every minute!

It was a modestly negative day for the Canadian preferred share market, with PerpetualDiscounts losing 26bp, FixedResets down 25bp and DeemedRetractibles off 8bp. The Performance Highlights table continues to be enormous, though, indicating a lot of churn under the placid surface. Volume was extremely high.

For as long as the FixedReset market is so violently unsettled, I’ll keep publishing updates of the more interesting and meaningful series of FixedResets’ Implied Volatilities. This doesn’t include Enbridge because although Enbridge has a large number of issues outstanding, all of which are quite liquid, the range of Issue Reset Spreads is too small for decent conclusions. The low is 212bp (ENB.PR.H; second-lowest is ENB.PR.D at 237bp) and the high is a mere 268 for ENB.PF.G.

Remember that all rich /cheap assessments are:
» based on Implied Volatility Theory only
» are relative only to other FixedResets from the same issuer
» assume constant GOC-5 yield
» assume constant Implied Volatility
» assume constant spread

Here’s TRP:

impVol_TRP_151218A
Click for Big

TRP.PR.E, which resets 2019-10-30 at +235, is bid at 18.50 to be $1.26 rich, while TRP.PR.C, resetting 2016-1-30 at +154, is $0.84 cheap at its bid price of 11.91.

impVol_MFC_151218
Click for Big

Most expensive is MFC.PR.G, resetting at +290bp on 2016-12-19, bid at 21.30 to be 0.37 cheap, while MFC.PR.N, resetting at +230bp on 2020-3-19, is bid at 19.75 to be 0.57 rich.

impVol_BAM_151218
Click for Big

The cheapest issue relative to its peers is BAM.PR.R, resetting at +230bp on 2016-6-30, bid at 15.41 to be $1.35 cheap. BAM.PF.E, resetting at +255bp on 2020-3-31 is bid at 19.50 and appears to be $1.36 rich.

impVol_FTS_151218
Click for Big

FTS.PR.M, with a spread of +248bp, and bid at 20.39, looks $0.33 expensive and resets 2019-12-1. FTS.PR.G, with a spread of +213bp and resetting 2018-9-1, is bid at 16.89 and is $0.98 cheap.

pairs_FR_151218
Click for Big

Investment-grade pairs predict an average three-month bill yield over the next five-odd years of -1.03%, with one outlier below -2.00%. There is one junk outlier below -2.00% and four above 0.00%.

pairs_FF_151218
Click for Big

Shall we just say that this exhibits a high level of confidence in the continued rapacity of Canadian banks?

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 4.94 % 6.01 % 33,464 16.63 1 0.7326 % 1,569.5
FixedFloater 7.20 % 6.38 % 36,162 15.77 1 0.7634 % 2,711.6
Floater 4.24 % 4.37 % 83,977 16.68 4 2.4810 % 1,803.7
OpRet 4.87 % 4.26 % 24,386 0.69 1 0.0000 % 2,735.4
SplitShare 4.83 % 5.58 % 81,423 1.87 6 0.8948 % 3,201.0
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.8948 % 2,497.6
Perpetual-Premium 5.82 % 5.90 % 97,893 13.95 7 -0.0514 % 2,488.4
Perpetual-Discount 5.78 % 5.86 % 102,834 14.04 33 -0.2576 % 2,477.9
FixedReset 5.25 % 4.65 % 272,003 14.77 81 -0.2534 % 1,967.7
Deemed-Retractible 5.23 % 5.37 % 135,266 5.31 33 -0.0839 % 2,565.0
FloatingReset 2.80 % 4.19 % 67,614 5.67 11 -0.3235 % 2,107.1
Performance Highlights
Issue Index Change Notes
IFC.PR.A FixedReset -4.44 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.50
Bid-YTW : 9.19 %
TRP.PR.A FixedReset -3.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 14.79
Evaluated at bid price : 14.79
Bid-YTW : 4.75 %
TRP.PR.H FloatingReset -3.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 9.80
Evaluated at bid price : 9.80
Bid-YTW : 4.39 %
MFC.PR.K FixedReset -3.59 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.51
Bid-YTW : 7.22 %
TRP.PR.B FixedReset -3.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 10.80
Evaluated at bid price : 10.80
Bid-YTW : 4.79 %
PWF.PR.P FixedReset -2.78 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 13.66
Evaluated at bid price : 13.66
Bid-YTW : 4.37 %
MFC.PR.L FixedReset -2.70 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 18.72
Bid-YTW : 7.17 %
IAG.PR.G FixedReset -2.60 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.26
Bid-YTW : 6.53 %
FTS.PR.I FloatingReset -2.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 11.35
Evaluated at bid price : 11.35
Bid-YTW : 4.19 %
GWO.PR.N FixedReset -2.42 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 13.33
Bid-YTW : 9.99 %
HSE.PR.A FixedReset -2.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 11.20
Evaluated at bid price : 11.20
Bid-YTW : 5.57 %
TRP.PR.D FixedReset -2.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 17.67
Evaluated at bid price : 17.67
Bid-YTW : 4.73 %
SLF.PR.G FixedReset -2.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.81
Bid-YTW : 8.84 %
HSE.PR.C FixedReset -2.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 16.75
Evaluated at bid price : 16.75
Bid-YTW : 6.05 %
VNR.PR.A FixedReset -2.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 19.35
Evaluated at bid price : 19.35
Bid-YTW : 4.79 %
RY.PR.L FixedReset -2.00 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.55
Bid-YTW : 4.28 %
FTS.PR.K FixedReset -1.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 17.69
Evaluated at bid price : 17.69
Bid-YTW : 4.27 %
FTS.PR.G FixedReset -1.97 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 16.89
Evaluated at bid price : 16.89
Bid-YTW : 4.51 %
FTS.PR.H FixedReset -1.76 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 13.95
Evaluated at bid price : 13.95
Bid-YTW : 4.10 %
FTS.PR.M FixedReset -1.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 20.39
Evaluated at bid price : 20.39
Bid-YTW : 4.21 %
NA.PR.Q FixedReset -1.57 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.52
Bid-YTW : 3.81 %
HSB.PR.C Deemed-Retractible -1.52 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.65
Bid-YTW : 5.37 %
TRP.PR.F FloatingReset -1.51 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 13.05
Evaluated at bid price : 13.05
Bid-YTW : 4.52 %
MFC.PR.M FixedReset -1.49 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 19.80
Bid-YTW : 6.60 %
TRP.PR.E FixedReset -1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 18.50
Evaluated at bid price : 18.50
Bid-YTW : 4.58 %
W.PR.J Perpetual-Discount -1.41 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 22.72
Evaluated at bid price : 23.01
Bid-YTW : 6.19 %
MFC.PR.F FixedReset -1.39 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 14.21
Bid-YTW : 9.45 %
TRP.PR.C FixedReset -1.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 11.91
Evaluated at bid price : 11.91
Bid-YTW : 4.88 %
PWF.PR.T FixedReset -1.32 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 22.07
Evaluated at bid price : 22.45
Bid-YTW : 3.68 %
W.PR.H Perpetual-Discount -1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 22.53
Evaluated at bid price : 22.78
Bid-YTW : 6.15 %
ELF.PR.G Perpetual-Discount -1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 20.52
Evaluated at bid price : 20.52
Bid-YTW : 5.90 %
SLF.PR.H FixedReset -1.20 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 17.30
Bid-YTW : 7.79 %
CIU.PR.A Perpetual-Discount -1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 19.60
Evaluated at bid price : 19.60
Bid-YTW : 5.93 %
HSB.PR.D Deemed-Retractible -1.15 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.82
Bid-YTW : 5.13 %
BNS.PR.A FloatingReset -1.06 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.37
Bid-YTW : 4.46 %
ELF.PR.F Perpetual-Discount -1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 22.12
Evaluated at bid price : 22.40
Bid-YTW : 6.02 %
TD.PF.E FixedReset -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 20.66
Evaluated at bid price : 20.66
Bid-YTW : 4.46 %
CU.PR.C FixedReset -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 18.80
Evaluated at bid price : 18.80
Bid-YTW : 4.31 %
BMO.PR.Y FixedReset -1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 19.35
Evaluated at bid price : 19.35
Bid-YTW : 4.62 %
RY.PR.A Deemed-Retractible -1.01 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.47
Bid-YTW : 4.94 %
PVS.PR.C SplitShare 1.02 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2017-12-10
Maturity Price : 25.00
Evaluated at bid price : 24.75
Bid-YTW : 5.50 %
BAM.PR.K Floater 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 10.51
Evaluated at bid price : 10.51
Bid-YTW : 4.50 %
PVS.PR.D SplitShare 1.09 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2021-10-08
Maturity Price : 25.00
Evaluated at bid price : 22.34
Bid-YTW : 6.81 %
BNS.PR.L Deemed-Retractible 1.13 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.96
Bid-YTW : 4.67 %
MFC.PR.J FixedReset 1.23 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.50
Bid-YTW : 6.17 %
BAM.PR.T FixedReset 1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 16.20
Evaluated at bid price : 16.20
Bid-YTW : 4.88 %
BNS.PR.E FixedReset 1.27 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-25
Maturity Price : 25.00
Evaluated at bid price : 25.52
Bid-YTW : 5.09 %
CIU.PR.C FixedReset 1.28 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 13.40
Evaluated at bid price : 13.40
Bid-YTW : 4.01 %
BAM.PF.F FixedReset 1.38 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 20.50
Evaluated at bid price : 20.50
Bid-YTW : 4.64 %
ENB.PR.A Perpetual-Discount 1.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 22.98
Evaluated at bid price : 23.25
Bid-YTW : 5.96 %
RY.PR.M FixedReset 1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 4.56 %
HSE.PR.G FixedReset 1.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 18.40
Evaluated at bid price : 18.40
Bid-YTW : 5.95 %
BAM.PF.A FixedReset 1.68 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 4.74 %
MFC.PR.H FixedReset 1.79 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.15
Bid-YTW : 5.63 %
BAM.PR.B Floater 1.89 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 10.80
Evaluated at bid price : 10.80
Bid-YTW : 4.37 %
BAM.PR.R FixedReset 2.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 15.41
Evaluated at bid price : 15.41
Bid-YTW : 5.04 %
BAM.PF.B FixedReset 2.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 18.65
Evaluated at bid price : 18.65
Bid-YTW : 4.74 %
TRP.PR.G FixedReset 2.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 19.95
Evaluated at bid price : 19.95
Bid-YTW : 4.72 %
BAM.PR.C Floater 2.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 10.70
Evaluated at bid price : 10.70
Bid-YTW : 4.42 %
BNS.PR.B FloatingReset 2.43 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.38
Bid-YTW : 4.08 %
HSE.PR.E FixedReset 2.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 18.34
Evaluated at bid price : 18.34
Bid-YTW : 5.98 %
PVS.PR.E SplitShare 3.56 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-10-31
Maturity Price : 25.00
Evaluated at bid price : 24.45
Bid-YTW : 5.96 %
BAM.PF.E FixedReset 4.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 19.50
Evaluated at bid price : 19.50
Bid-YTW : 4.57 %
PWF.PR.A Floater 4.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 12.60
Evaluated at bid price : 12.60
Bid-YTW : 3.78 %
IAG.PR.A Deemed-Retractible 4.77 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 20.65
Bid-YTW : 7.26 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.Q FixedReset 356,269 Recent new issue.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 23.21
Evaluated at bid price : 25.22
Bid-YTW : 5.22 %
BNS.PR.E FixedReset 167,063 Recent new issue.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2021-04-25
Maturity Price : 25.00
Evaluated at bid price : 25.52
Bid-YTW : 5.09 %
BAM.PF.B FixedReset 113,133 Scotia crossed blocks of 37,600 and 54,000, both at 18.35.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 18.65
Evaluated at bid price : 18.65
Bid-YTW : 4.74 %
POW.PR.C Perpetual-Premium 104,835 Nesbitt crossed blocks of 51,400 and 50,000, both at 25.05.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 24.81
Evaluated at bid price : 25.03
Bid-YTW : 5.90 %
BIP.PR.B FixedReset 47,175 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 22.57
Evaluated at bid price : 23.56
Bid-YTW : 5.84 %
HSE.PR.E FixedReset 46,986 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 18.34
Evaluated at bid price : 18.34
Bid-YTW : 5.98 %
There were 73 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
RY.PR.L FixedReset Quote: 24.55 – 25.13
Spot Rate : 0.5800
Average : 0.3617

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.55
Bid-YTW : 4.28 %

VNR.PR.A FixedReset Quote: 19.35 – 20.07
Spot Rate : 0.7200
Average : 0.5351

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 19.35
Evaluated at bid price : 19.35
Bid-YTW : 4.79 %

IFC.PR.A FixedReset Quote: 15.50 – 16.09
Spot Rate : 0.5900
Average : 0.4132

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 15.50
Bid-YTW : 9.19 %

BMO.PR.Y FixedReset Quote: 19.35 – 19.77
Spot Rate : 0.4200
Average : 0.2835

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 19.35
Evaluated at bid price : 19.35
Bid-YTW : 4.62 %

FTS.PR.I FloatingReset Quote: 11.35 – 11.79
Spot Rate : 0.4400
Average : 0.3146

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 11.35
Evaluated at bid price : 11.35
Bid-YTW : 4.19 %

BAM.PF.A FixedReset Quote: 20.00 – 20.40
Spot Rate : 0.4000
Average : 0.2885

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2045-12-18
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 4.74 %