Category: Market Action

Market Action

November 26, 2013

Still trying to Import material from the old site. Still having problems. Still feeling homicidal about poorly designed software.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.3909 % 2,521.0
FixedFloater 4.24 % 3.53 % 30,053 18.29 1 0.7201 % 3,954.2
Floater 2.94 % 2.97 % 61,568 19.76 3 -0.3909 % 2,722.0
OpRet 4.62 % -4.72 % 75,914 0.08 3 0.0514 % 2,660.3
SplitShare 4.74 % 4.16 % 68,962 3.65 6 -0.0188 % 2,984.0
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0514 % 2,432.6
Perpetual-Premium 5.56 % 4.92 % 125,285 0.27 11 0.0700 % 2,313.4
Perpetual-Discount 5.57 % 5.54 % 165,007 14.53 27 -0.0826 % 2,363.6
FixedReset 4.96 % 3.25 % 226,254 3.27 82 0.1104 % 2,486.8
Deemed-Retractible 5.06 % 3.94 % 195,087 1.36 42 -0.0664 % 2,425.7
FloatingReset 2.65 % 2.34 % 291,893 4.45 5 0.1505 % 2,463.8
Performance Highlights
Issue Index Change Notes
CU.PR.E Perpetual-Discount -1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-26
Maturity Price : 22.60
Evaluated at bid price : 22.99
Bid-YTW : 5.34 %
ENB.PR.Y FixedReset 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-26
Maturity Price : 22.69
Evaluated at bid price : 23.90
Bid-YTW : 4.22 %
TRP.PR.A FixedReset 1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-26
Maturity Price : 24.17
Evaluated at bid price : 24.59
Bid-YTW : 3.81 %
HSB.PR.D Deemed-Retractible 1.23 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.46
Bid-YTW : 4.03 %
Volume Highlights
Issue Index Shares
Traded
Notes
MFC.PR.D FixedReset 104,377 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-06-19
Maturity Price : 25.00
Evaluated at bid price : 25.53
Bid-YTW : 2.09 %
TRP.PR.D FixedReset 95,197 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-26
Maturity Price : 23.15
Evaluated at bid price : 25.05
Bid-YTW : 4.00 %
GWO.PR.J FixedReset 51,369 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.31
Bid-YTW : 2.64 %
ENB.PR.Y FixedReset 48,240 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-26
Maturity Price : 22.69
Evaluated at bid price : 23.90
Bid-YTW : 4.22 %
TRP.PR.C FixedReset 36,927 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-26
Maturity Price : 22.46
Evaluated at bid price : 22.75
Bid-YTW : 3.77 %
FTS.PR.H FixedReset 28,010 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-26
Maturity Price : 20.98
Evaluated at bid price : 20.98
Bid-YTW : 3.93 %
There were 44 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BNA.PR.E SplitShare Quote: 24.95 – 25.49
Spot Rate : 0.5400
Average : 0.3749

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2017-12-10
Maturity Price : 25.00
Evaluated at bid price : 24.95
Bid-YTW : 4.90 %

CU.PR.E Perpetual-Discount Quote: 22.99 – 23.43
Spot Rate : 0.4400
Average : 0.3130

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-26
Maturity Price : 22.60
Evaluated at bid price : 22.99
Bid-YTW : 5.34 %

VNR.PR.A FixedReset Quote: 25.40 – 25.69
Spot Rate : 0.2900
Average : 0.1918

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-10-15
Maturity Price : 25.00
Evaluated at bid price : 25.40
Bid-YTW : 4.06 %

TRP.PR.B FixedReset Quote: 20.91 – 21.18
Spot Rate : 0.2700
Average : 0.1776

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-26
Maturity Price : 20.91
Evaluated at bid price : 20.91
Bid-YTW : 3.78 %

BNS.PR.Z FixedReset Quote: 24.00 – 24.25
Spot Rate : 0.2500
Average : 0.1624

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.00
Bid-YTW : 3.90 %

RY.PR.D Deemed-Retractible Quote: 25.43 – 25.71
Spot Rate : 0.2800
Average : 0.1947

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2015-02-24
Maturity Price : 25.25
Evaluated at bid price : 25.43
Bid-YTW : 3.91 %

Market Action

November 25, 2013

I’m having lots of fun importing the old PrefBlog into the new PrefBlog. It’s all tick-a-box software. ‘We need this feature! It doesn’t matter if it only works in ideal conditions – just tick the box!’

There are some things I can try tomorrow. Right now I’m too irritated.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.0932 % 2,530.9
FixedFloater 4.28 % 3.56 % 30,205 18.23 1 0.4067 % 3,926.0
Floater 2.93 % 2.96 % 62,119 19.78 3 0.0932 % 2,732.7
OpRet 4.62 % -4.63 % 75,695 0.08 3 -0.1283 % 2,658.9
SplitShare 4.74 % 4.14 % 68,806 3.65 6 -0.0559 % 2,984.6
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.1283 % 2,431.3
Perpetual-Premium 5.57 % 4.37 % 122,755 0.09 11 0.1565 % 2,311.8
Perpetual-Discount 5.57 % 5.56 % 180,287 14.51 27 -0.1730 % 2,365.5
FixedReset 4.97 % 3.30 % 228,106 3.27 82 0.0136 % 2,484.0
Deemed-Retractible 5.06 % 3.96 % 195,191 1.44 42 0.1015 % 2,427.3
FloatingReset 2.65 % 2.39 % 300,867 4.46 5 0.0238 % 2,460.1
Performance Highlights
Issue Index Change Notes
MFC.PR.F FixedReset -1.37 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.31
Bid-YTW : 4.67 %
CU.PR.D Perpetual-Discount -1.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-25
Maturity Price : 22.99
Evaluated at bid price : 23.29
Bid-YTW : 5.27 %
PWF.PR.S Perpetual-Discount -1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-25
Maturity Price : 22.09
Evaluated at bid price : 22.40
Bid-YTW : 5.40 %
Volume Highlights
Issue Index Shares
Traded
Notes
BNS.PR.T FixedReset 277,277 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-04-25
Maturity Price : 25.00
Evaluated at bid price : 25.55
Bid-YTW : 1.87 %
BNS.PR.B FloatingReset 267,900 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-10-25
Maturity Price : 25.00
Evaluated at bid price : 25.04
Bid-YTW : 2.54 %
BMO.PR.R FloatingReset 81,460 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-08-25
Maturity Price : 25.00
Evaluated at bid price : 25.09
Bid-YTW : 2.39 %
BAM.PF.D Perpetual-Discount 32,648 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-25
Maturity Price : 19.94
Evaluated at bid price : 19.94
Bid-YTW : 6.26 %
RY.PR.P FixedReset 30,966 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-02-24
Maturity Price : 25.00
Evaluated at bid price : 25.23
Bid-YTW : 2.61 %
FTS.PR.H FixedReset 24,111 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-25
Maturity Price : 20.89
Evaluated at bid price : 20.89
Bid-YTW : 3.95 %
There were 36 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
MFC.PR.J FixedReset Quote: 25.29 – 25.77
Spot Rate : 0.4800
Average : 0.2776

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-03-19
Maturity Price : 25.00
Evaluated at bid price : 25.29
Bid-YTW : 3.66 %

CIU.PR.C FixedReset Quote: 21.19 – 21.72
Spot Rate : 0.5300
Average : 0.3892

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-25
Maturity Price : 21.19
Evaluated at bid price : 21.19
Bid-YTW : 3.80 %

ENB.PR.N FixedReset Quote: 24.53 – 24.84
Spot Rate : 0.3100
Average : 0.1995

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-25
Maturity Price : 22.99
Evaluated at bid price : 24.53
Bid-YTW : 4.30 %

TD.PR.P Deemed-Retractible Quote: 26.09 – 26.47
Spot Rate : 0.3800
Average : 0.2818

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-12-25
Maturity Price : 25.75
Evaluated at bid price : 26.09
Bid-YTW : -6.55 %

MFC.PR.B Deemed-Retractible Quote: 21.85 – 22.21
Spot Rate : 0.3600
Average : 0.2654

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.85
Bid-YTW : 6.23 %

BAM.PR.C Floater Quote: 17.89 – 18.15
Spot Rate : 0.2600
Average : 0.1924

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-25
Maturity Price : 17.89
Evaluated at bid price : 17.89
Bid-YTW : 2.96 %

Market Action

November 22, 2013

Nothing happened today, except for more server-fiddling.

It was another mixed day for the Canadian preferred share market, with PerpetualDiscounts down 10bp, FixedResets up 13bp and DeemedRetractibles off 2bp. Volatility was low. Volume was above average, led by two FloatingReset issues.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.1117 % 2,528.6
FixedFloater 4.29 % 3.57 % 30,007 18.21 1 -0.3602 % 3,910.1
Floater 2.93 % 2.96 % 63,114 19.77 3 -0.1117 % 2,730.2
OpRet 4.62 % -4.78 % 72,755 0.08 3 -0.1537 % 2,662.3
SplitShare 4.74 % 4.14 % 68,459 3.66 6 0.0198 % 2,986.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.1537 % 2,434.4
Perpetual-Premium 5.58 % 3.88 % 123,557 0.09 11 -0.0054 % 2,308.1
Perpetual-Discount 5.56 % 5.55 % 181,561 14.50 27 -0.1050 % 2,369.6
FixedReset 4.97 % 3.26 % 230,360 3.28 82 0.1313 % 2,483.7
Deemed-Retractible 5.05 % 4.00 % 191,190 1.45 42 -0.0183 % 2,424.9
FloatingReset 2.65 % 2.42 % 305,032 4.46 5 -0.0475 % 2,459.5
Performance Highlights
Issue Index Change Notes
CIU.PR.A Perpetual-Discount -1.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-22
Maturity Price : 21.07
Evaluated at bid price : 21.07
Bid-YTW : 5.49 %
IFC.PR.A FixedReset -1.03 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.91
Bid-YTW : 4.38 %
BAM.PF.B FixedReset 1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-22
Maturity Price : 23.02
Evaluated at bid price : 24.65
Bid-YTW : 4.36 %
Volume Highlights
Issue Index Shares
Traded
Notes
BMO.PR.R FloatingReset 277,640 Scotia crossed blocks of 200,000 and 66,600, both at 25.06. Nice tickets!
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-08-25
Maturity Price : 25.00
Evaluated at bid price : 25.05
Bid-YTW : 2.42 %
TD.PR.Z FloatingReset 242,000 Scotia crossed blocks of 188,200 and 50,000, both at 25.03. More nice tickets!
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.04
Bid-YTW : 2.50 %
CM.PR.L FixedReset 60,408 RBC crossed 25,000 at 25.63.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-04-30
Maturity Price : 25.00
Evaluated at bid price : 25.60
Bid-YTW : 1.87 %
BAM.PF.D Perpetual-Discount 50,775 RBC crossed 12,400 at 19.85.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-22
Maturity Price : 19.95
Evaluated at bid price : 19.95
Bid-YTW : 6.25 %
BNS.PR.X FixedReset 47,000 RBC crossed 30,000 at 25.58.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-04-25
Maturity Price : 25.00
Evaluated at bid price : 25.55
Bid-YTW : 1.83 %
BNS.PR.T FixedReset 42,575 RBC crossed 38,200 at 25.58.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-04-25
Maturity Price : 25.00
Evaluated at bid price : 25.55
Bid-YTW : 1.83 %
There were 40 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
BNS.PR.P FixedReset Quote: 25.10 – 25.43
Spot Rate : 0.3300
Average : 0.2118

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-04-25
Maturity Price : 25.00
Evaluated at bid price : 25.10
Bid-YTW : 3.31 %

GWO.PR.R Deemed-Retractible Quote: 23.01 – 23.27
Spot Rate : 0.2600
Average : 0.1615

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.01
Bid-YTW : 5.90 %

W.PR.H Perpetual-Discount Quote: 24.45 – 24.73
Spot Rate : 0.2800
Average : 0.2045

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-22
Maturity Price : 24.19
Evaluated at bid price : 24.45
Bid-YTW : 5.69 %

FTS.PR.F Perpetual-Discount Quote: 23.25 – 23.47
Spot Rate : 0.2200
Average : 0.1545

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-22
Maturity Price : 22.96
Evaluated at bid price : 23.25
Bid-YTW : 5.28 %

BAM.PR.Z FixedReset Quote: 25.80 – 26.00
Spot Rate : 0.2000
Average : 0.1401

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.80
Bid-YTW : 4.16 %

BNS.PR.O Deemed-Retractible Quote: 26.45 – 26.80
Spot Rate : 0.3500
Average : 0.2903

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-12-22
Maturity Price : 26.00
Evaluated at bid price : 26.45
Bid-YTW : -11.26 %

Market Action

November 21, 2013

Deflation fears?

Wholesale prices in the U.S. fell in October for a second month, reflecting cheaper energy costs.

The 0.2 percent drop in the producer-price index followed a 0.1 percent decline the prior month, a Labor Department report showed today in Washington. The decrease matched the median estimate in a Bloomberg survey of 75 economists. The so-called core measure, which excludes food and energy, increased 0.2 percent as the cost of cars jumped by the most in four years.

Server fiddling continues. PrefInfo.com has been moved to the new server and works fine! PrefShares.com has also been moved; the DNS change should be propogated across the Internet by 6pm Friday 22.

It was a mixed day for the Canadian preferred share market, with PerpetualDiscounts up 24bp, FixedResets gaining 3bp and DeemedRetractibles off 3bp. BAM issues were conspicuous in the Performance Highlights, with Floaters down and PerpetualDiscounts up. Volume was well above average.

PerpetualDiscounts now yield 5.57%, equivalent to 7.24% interest at the standard equivalency factor of 1.3x. Long corporates now yield about 4.8%, so the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) is now about 245bp, a slight (and perhaps spurious) decline from the 250bp reported November 6.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -1.1953 % 2,531.4
FixedFloater 4.28 % 3.56 % 31,164 18.24 1 0.0000 % 3,924.2
Floater 2.93 % 2.96 % 58,595 19.79 3 -1.1953 % 2,733.2
OpRet 4.61 % -6.76 % 71,484 0.08 3 0.1026 % 2,666.4
SplitShare 4.74 % 4.14 % 67,901 3.66 6 0.2372 % 2,985.7
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1026 % 2,438.2
Perpetual-Premium 5.58 % 4.35 % 123,349 0.28 11 0.0666 % 2,308.3
Perpetual-Discount 5.55 % 5.57 % 178,648 14.50 27 0.2445 % 2,372.1
FixedReset 4.97 % 3.38 % 225,655 3.32 82 0.0261 % 2,480.4
Deemed-Retractible 5.05 % 3.87 % 191,361 1.45 42 -0.0298 % 2,425.3
FloatingReset 2.65 % 2.41 % 308,165 4.47 5 0.0396 % 2,460.7
Performance Highlights
Issue Index Change Notes
BAM.PR.K Floater -1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-21
Maturity Price : 17.84
Evaluated at bid price : 17.84
Bid-YTW : 2.97 %
BAM.PR.B Floater -1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-21
Maturity Price : 17.99
Evaluated at bid price : 17.99
Bid-YTW : 2.94 %
MFC.PR.K FixedReset -1.14 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.22
Bid-YTW : 4.24 %
BNS.PR.K Deemed-Retractible 1.03 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-12-21
Maturity Price : 25.25
Evaluated at bid price : 25.47
Bid-YTW : -2.49 %
HSE.PR.A FixedReset 1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-21
Maturity Price : 22.98
Evaluated at bid price : 23.79
Bid-YTW : 3.79 %
BAM.PF.C Perpetual-Discount 2.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-21
Maturity Price : 19.89
Evaluated at bid price : 19.89
Bid-YTW : 6.21 %
BAM.PF.D Perpetual-Discount 2.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-21
Maturity Price : 20.08
Evaluated at bid price : 20.08
Bid-YTW : 6.21 %
Volume Highlights
Issue Index Shares
Traded
Notes
TRP.PR.C FixedReset 164,084 Scotia crossed 20,000 at 22.72 and 131,400 at 22.70. Nice tickets!
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-21
Maturity Price : 22.30
Evaluated at bid price : 22.63
Bid-YTW : 3.79 %
RY.PR.W Perpetual-Premium 84,583 RBC crossed 74,700 at 25.00.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-21
Maturity Price : 24.75
Evaluated at bid price : 24.99
Bid-YTW : 4.91 %
SLF.PR.D Deemed-Retractible 61,779 Scotia crossed 39,500 at 21.80.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.82
Bid-YTW : 6.15 %
SLF.PR.E Deemed-Retractible 58,650 Scotia crossed 45,100 at 22.15.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.16
Bid-YTW : 6.02 %
TD.PR.K FixedReset 58,646 Scotia crossed 53,400 at 25.80.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-07-31
Maturity Price : 25.00
Evaluated at bid price : 25.71
Bid-YTW : 2.63 %
BMO.PR.N FixedReset 58,320 Nesbitt crossed 50,000 at 25.28.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-02-25
Maturity Price : 25.00
Evaluated at bid price : 25.25
Bid-YTW : 2.41 %
There were 43 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
CIU.PR.A Perpetual-Discount Quote: 21.41 – 21.84
Spot Rate : 0.4300
Average : 0.3278

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-21
Maturity Price : 21.41
Evaluated at bid price : 21.41
Bid-YTW : 5.40 %

CIU.PR.B FixedReset Quote: 25.55 – 25.78
Spot Rate : 0.2300
Average : 0.1438

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-06-01
Maturity Price : 25.00
Evaluated at bid price : 25.55
Bid-YTW : 2.18 %

FTS.PR.K FixedReset Quote: 24.11 – 24.39
Spot Rate : 0.2800
Average : 0.2003

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-21
Maturity Price : 22.81
Evaluated at bid price : 24.11
Bid-YTW : 3.93 %

POW.PR.D Perpetual-Discount Quote: 22.80 – 23.08
Spot Rate : 0.2800
Average : 0.2041

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-21
Maturity Price : 22.39
Evaluated at bid price : 22.80
Bid-YTW : 5.53 %

IAG.PR.F Deemed-Retractible Quote: 25.90 – 26.30
Spot Rate : 0.4000
Average : 0.3266

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2019-03-31
Maturity Price : 25.00
Evaluated at bid price : 25.90
Bid-YTW : 5.34 %

BAM.PR.K Floater Quote: 17.84 – 18.02
Spot Rate : 0.1800
Average : 0.1249

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-21
Maturity Price : 17.84
Evaluated at bid price : 17.84
Bid-YTW : 2.97 %

Market Action

November 20, 2013

A tale of two economies! Europe contemplates easing:

The European Central Bank is considering a smaller-than-normal cut in the deposit rate if officials decide to take it negative for the first time, according to two people with knowledge of the debate.

Policy makers would reduce the rate for commercial lenders who park excess cash at the ECB to minus 0.1 percent from zero, said the people who asked not to be identified because the talks aren’t public. It would be the first time the central bank has adjusted interest rates by less than a quarter of a percentage point. The concept, which has been discussed by Governing Council members, doesn’t yet have a consensus, the people said.

Members of the council, which is holding a mid-month meeting in Frankfurt this week, have said that a negative deposit rate is a potential tool for warding off deflation. They’ve also cautioned that the consequences of such an unprecedented measure aren’t clear. The central bank this month refrained from cutting the deposit rate even as it reduced its benchmark lending rate to a record low of 0.25 percent, and Governing Council member Jens Weidmann has warned against further loosening of monetary policy.

… while the US contemplates less easing:

The U.S. Federal Reserve is getting closer to curbing its experiment in buying financial assets – but is still a long way from ending the age of easy money.

Recent communications by the central bank show that policy makers are poised to reduce, or “taper,” their monthly bond-buying program. Minutes of the Fed’s October policy meeting, released Wednesday after the customary three-week delay, state that “some” officials believed the pace of purchases could be slowed at “one of the next few meetings,” so long as key indicators continue to show the U.S. economy gaining strength.
…
But the Fed minutes also make it clear that policy makers will slow the bond-buying program because they are nervous about unintended future outcomes – not because they think the economy is ready for higher short-term rates. The majority of the Fed’s leaders favour leaving its benchmark rate near zero for a period that most likely will be measured in years rather than months.

It was a mixed day for the Canadian preferred share market, with PerpetualDiscounts off 9bp, FixedResets up 7bp and DeemedRetractibles gaining 6bp. The Performance Highlights table is dominated by losers. Volume was well above average.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.3321 % 2,562.0
FixedFloater 4.28 % 3.56 % 31,672 18.24 1 -0.0900 % 3,924.2
Floater 2.90 % 2.92 % 58,835 19.88 3 0.3321 % 2,766.3
OpRet 4.62 % -0.82 % 72,566 0.08 3 0.0256 % 2,663.7
SplitShare 4.74 % 4.19 % 68,414 3.90 6 0.1312 % 2,978.6
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0256 % 2,435.7
Perpetual-Premium 5.58 % 4.92 % 124,143 0.28 11 -0.0540 % 2,306.7
Perpetual-Discount 5.57 % 5.56 % 165,987 14.53 27 -0.0906 % 2,366.3
FixedReset 4.97 % 3.33 % 225,015 3.29 82 0.0694 % 2,479.8
Deemed-Retractible 5.05 % 3.92 % 192,794 1.45 42 0.0578 % 2,426.0
FloatingReset 2.65 % 2.42 % 310,988 4.47 5 0.0158 % 2,459.7
Performance Highlights
Issue Index Change Notes
BAM.PR.T FixedReset -1.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-20
Maturity Price : 23.04
Evaluated at bid price : 24.25
Bid-YTW : 4.26 %
MFC.PR.F FixedReset -1.35 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.69
Bid-YTW : 4.48 %
PWF.PR.S Perpetual-Discount -1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-20
Maturity Price : 22.24
Evaluated at bid price : 22.54
Bid-YTW : 5.36 %
BAM.PF.C Perpetual-Discount -1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-20
Maturity Price : 19.45
Evaluated at bid price : 19.45
Bid-YTW : 6.35 %
IAG.PR.G FixedReset 1.51 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-06-30
Maturity Price : 25.00
Evaluated at bid price : 26.18
Bid-YTW : 3.11 %
Volume Highlights
Issue Index Shares
Traded
Notes
RY.PR.W Perpetual-Premium 174,215 Desjardins crossed blocks of 40,000 and 46,200, both at 25.00. RBC crossed 20,000 at the same price.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-20
Maturity Price : 24.74
Evaluated at bid price : 24.98
Bid-YTW : 4.92 %
RY.PR.R FixedReset 105,388 Nesbitt crossed 100,000 at 25.24.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-02-24
Maturity Price : 25.00
Evaluated at bid price : 25.22
Bid-YTW : 2.63 %
RY.PR.N FixedReset 104,663 Nesbitt crossed 100,000 at 25.24.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-02-24
Maturity Price : 25.00
Evaluated at bid price : 25.21
Bid-YTW : 2.78 %
BNS.PR.O Deemed-Retractible 58,780 RBC crossed 38,800 and 19,000, both at 26.59.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-12-20
Maturity Price : 26.00
Evaluated at bid price : 26.45
Bid-YTW : -11.60 %
MFC.PR.K FixedReset 51,732 Nesbitt crossed 40,000 at 24.55.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.50
Bid-YTW : 4.11 %
HSE.PR.A FixedReset 46,320 RBC crossed 19,800 at 23.70.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-20
Maturity Price : 22.76
Evaluated at bid price : 23.39
Bid-YTW : 3.88 %
There were 43 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
RY.PR.G Deemed-Retractible Quote: 25.43 – 25.84
Spot Rate : 0.4100
Average : 0.2341

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2015-05-24
Maturity Price : 25.25
Evaluated at bid price : 25.43
Bid-YTW : 3.95 %

PWF.PR.S Perpetual-Discount Quote: 22.54 – 22.92
Spot Rate : 0.3800
Average : 0.2549

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-20
Maturity Price : 22.24
Evaluated at bid price : 22.54
Bid-YTW : 5.36 %

MFC.PR.H FixedReset Quote: 26.07 – 26.44
Spot Rate : 0.3700
Average : 0.2596

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-03-19
Maturity Price : 25.00
Evaluated at bid price : 26.07
Bid-YTW : 3.14 %

BAM.PR.X FixedReset Quote: 22.36 – 22.63
Spot Rate : 0.2700
Average : 0.1749

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-20
Maturity Price : 21.97
Evaluated at bid price : 22.36
Bid-YTW : 4.24 %

TCA.PR.Y Perpetual-Premium Quote: 50.17 – 50.40
Spot Rate : 0.2300
Average : 0.1541

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-03-05
Maturity Price : 50.00
Evaluated at bid price : 50.17
Bid-YTW : 5.43 %

ELF.PR.G Perpetual-Discount Quote: 21.57 – 21.97
Spot Rate : 0.4000
Average : 0.3289

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-20
Maturity Price : 21.57
Evaluated at bid price : 21.57
Bid-YTW : 5.58 %

Market Action

November 19, 2013

Nothing happened today, as the world waits with bated breath for me to finish server-fiddling.

It was a mixed day for the Canadian preferred share market, with PerpetualDiscounts and FixedResets both down 9bp, while DeemedRetractibles were up 18bp. Volatility was long-term normal. Volume was average.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.1848 % 2,553.5
FixedFloater 4.27 % 3.55 % 31,624 18.25 1 0.0450 % 3,927.7
Floater 2.91 % 2.93 % 59,023 19.87 3 0.1848 % 2,757.1
OpRet 4.62 % -6.46 % 71,956 0.08 3 0.5026 % 2,663.0
SplitShare 4.72 % 5.15 % 66,921 3.90 6 0.1418 % 2,974.7
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.5026 % 2,435.1
Perpetual-Premium 5.58 % 4.30 % 124,961 0.29 11 0.1315 % 2,308.0
Perpetual-Discount 5.56 % 5.56 % 182,699 14.54 27 -0.0857 % 2,368.5
FixedReset 4.98 % 3.41 % 227,582 3.32 82 -0.0890 % 2,478.1
Deemed-Retractible 5.05 % 3.93 % 194,529 1.45 42 0.1774 % 2,424.6
FloatingReset 2.65 % 2.41 % 313,698 4.47 5 0.0238 % 2,459.3
Performance Highlights
Issue Index Change Notes
CIU.PR.C FixedReset -1.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-19
Maturity Price : 21.15
Evaluated at bid price : 21.15
Bid-YTW : 3.81 %
GWO.PR.N FixedReset -1.50 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.31
Bid-YTW : 4.52 %
CGI.PR.D SplitShare 1.03 % YTW SCENARIO
Maturity Type : Soft Maturity
Maturity Date : 2023-06-14
Maturity Price : 25.00
Evaluated at bid price : 24.45
Bid-YTW : 4.14 %
Volume Highlights
Issue Index Shares
Traded
Notes
TRP.PR.C FixedReset 181,003 Desjardins crossed blocks of 77,400 and 80,000, both at 22.75. Nesbitt crossed 12,000 at 22.95.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-19
Maturity Price : 22.38
Evaluated at bid price : 22.75
Bid-YTW : 3.77 %
HSE.PR.A FixedReset 75,652 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-19
Maturity Price : 22.67
Evaluated at bid price : 23.24
Bid-YTW : 3.91 %
BMO.PR.L Deemed-Retractible 69,450 RBC crossed 64,300 at 26.60.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-12-19
Maturity Price : 26.00
Evaluated at bid price : 26.55
Bid-YTW : -19.96 %
SLF.PR.A Deemed-Retractible 60,216 RBC crossed 49,600 at 22.75.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.83
Bid-YTW : 5.94 %
RY.PR.Y FixedReset 49,202 RBC crossed 48,700 at 26.10.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-11-24
Maturity Price : 25.00
Evaluated at bid price : 26.02
Bid-YTW : 1.96 %
TRP.PR.B FixedReset 46,549 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-19
Maturity Price : 20.80
Evaluated at bid price : 20.80
Bid-YTW : 3.81 %
There were 35 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
GWO.PR.N FixedReset Quote: 22.31 – 22.89
Spot Rate : 0.5800
Average : 0.4312

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.31
Bid-YTW : 4.52 %

CIU.PR.C FixedReset Quote: 21.15 – 21.68
Spot Rate : 0.5300
Average : 0.4010

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-19
Maturity Price : 21.15
Evaluated at bid price : 21.15
Bid-YTW : 3.81 %

BNA.PR.E SplitShare Quote: 25.00 – 25.32
Spot Rate : 0.3200
Average : 0.2138

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2017-12-10
Maturity Price : 25.00
Evaluated at bid price : 25.00
Bid-YTW : 5.15 %

TD.PR.P Deemed-Retractible Quote: 26.05 – 26.51
Spot Rate : 0.4600
Average : 0.3553

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-12-19
Maturity Price : 25.75
Evaluated at bid price : 26.05
Bid-YTW : -5.72 %

BNS.PR.Y FixedReset Quote: 23.61 – 24.04
Spot Rate : 0.4300
Average : 0.3342

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.61
Bid-YTW : 3.82 %

HSE.PR.A FixedReset Quote: 23.24 – 23.70
Spot Rate : 0.4600
Average : 0.3651

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-19
Maturity Price : 22.67
Evaluated at bid price : 23.24
Bid-YTW : 3.91 %

Market Action

November 18, 2013

Nothing happened today.

However, I am having server problems. After having given sterling service on the farm for many years, IBM informs me that my server is getting unreliable. Rather than refurbish the old server, I have rented a new one and am in the process of copying files and installing software and, when that nightmare is over, will be changing the DNS. Ideally, this will be invisible to Assiduous Readers.

It was a modestly good day for the Canadian preferred share market, with PerpetualDiscounts winning 14bp, FixedResets gaining 1bp and DeemedRetractibles up 10bp. There was a relatively lengthy Performance Highlights table, with FixedResets scattered around like straws in the wind. Volume was average.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.6137 % 2,548.8
FixedFloater 4.28 % 3.56 % 32,844 18.25 1 -1.6379 % 3,926.0
Floater 2.91 % 2.93 % 59,640 19.86 3 0.6137 % 2,752.0
OpRet 4.64 % 2.13 % 72,900 0.36 3 -0.0644 % 2,649.7
SplitShare 4.72 % 5.09 % 67,054 3.90 6 0.0928 % 2,970.5
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0644 % 2,422.9
Perpetual-Premium 5.58 % 4.72 % 125,539 0.29 11 -0.1241 % 2,305.0
Perpetual-Discount 5.56 % 5.58 % 180,403 14.51 27 0.1392 % 2,370.5
FixedReset 4.97 % 3.47 % 230,181 3.32 82 0.0103 % 2,480.3
Deemed-Retractible 5.06 % 3.96 % 193,651 1.39 42 0.1014 % 2,420.3
FloatingReset 2.65 % 2.42 % 317,392 4.47 5 0.0555 % 2,458.7
Performance Highlights
Issue Index Change Notes
HSE.PR.A FixedReset -2.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-18
Maturity Price : 22.57
Evaluated at bid price : 23.07
Bid-YTW : 3.94 %
BAM.PR.G FixedFloater -1.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-18
Maturity Price : 22.55
Evaluated at bid price : 22.22
Bid-YTW : 3.56 %
MFC.PR.G FixedReset -1.31 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-12-19
Maturity Price : 25.00
Evaluated at bid price : 25.56
Bid-YTW : 3.52 %
CIU.PR.A Perpetual-Discount -1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-18
Maturity Price : 21.36
Evaluated at bid price : 21.36
Bid-YTW : 5.41 %
BAM.PR.T FixedReset 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-18
Maturity Price : 23.18
Evaluated at bid price : 24.60
Bid-YTW : 4.19 %
PWF.PR.L Perpetual-Discount 1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-18
Maturity Price : 23.36
Evaluated at bid price : 23.80
Bid-YTW : 5.38 %
CU.PR.E Perpetual-Discount 1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-18
Maturity Price : 23.41
Evaluated at bid price : 23.75
Bid-YTW : 5.16 %
TRP.PR.C FixedReset 1.24 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-18
Maturity Price : 22.51
Evaluated at bid price : 22.80
Bid-YTW : 3.76 %
GWO.PR.N FixedReset 1.57 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.65
Bid-YTW : 4.35 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PR.Z FloatingReset 182,050 Nesbitt crossed blocks of 25,000 and 153,400, both at 25.01.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.01
Bid-YTW : 2.57 %
BMO.PR.L Deemed-Retractible 172,710 RBC crossed blocks of 100,000 shares, 20,000 and 30,000, all at 26.60.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-12-18
Maturity Price : 26.00
Evaluated at bid price : 26.52
Bid-YTW : -18.89 %
RY.PR.Y FixedReset 82,285 TD crossed 71,100 at 26.00.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-11-24
Maturity Price : 25.00
Evaluated at bid price : 26.01
Bid-YTW : 1.99 %
RY.PR.I FixedReset 44,870 Nesbitt crossed 40,000 at 25.18.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-02-24
Maturity Price : 25.00
Evaluated at bid price : 25.18
Bid-YTW : 2.00 %
BNS.PR.Z FixedReset 41,299 RBC crossed 23,300 at 23.70.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.70
Bid-YTW : 4.08 %
BAM.PF.D Perpetual-Discount 37,520 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-18
Maturity Price : 19.73
Evaluated at bid price : 19.73
Bid-YTW : 6.32 %
There were 30 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
MFC.PR.G FixedReset Quote: 25.56 – 26.19
Spot Rate : 0.6300
Average : 0.3605

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2016-12-19
Maturity Price : 25.00
Evaluated at bid price : 25.56
Bid-YTW : 3.52 %

BAM.PR.G FixedFloater Quote: 22.22 – 22.75
Spot Rate : 0.5300
Average : 0.3672

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-18
Maturity Price : 22.55
Evaluated at bid price : 22.22
Bid-YTW : 3.56 %

HSE.PR.A FixedReset Quote: 23.07 – 23.48
Spot Rate : 0.4100
Average : 0.2610

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-18
Maturity Price : 22.57
Evaluated at bid price : 23.07
Bid-YTW : 3.94 %

TD.PR.P Deemed-Retractible Quote: 26.02 – 26.39
Spot Rate : 0.3700
Average : 0.2405

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-12-18
Maturity Price : 25.75
Evaluated at bid price : 26.02
Bid-YTW : -4.52 %

FTS.PR.E OpRet Quote: 25.84 – 26.19
Spot Rate : 0.3500
Average : 0.2232

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-12-18
Maturity Price : 25.75
Evaluated at bid price : 25.84
Bid-YTW : -1.55 %

BMO.PR.P FixedReset Quote: 26.09 – 26.44
Spot Rate : 0.3500
Average : 0.2294

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2015-02-25
Maturity Price : 25.00
Evaluated at bid price : 26.09
Bid-YTW : 1.84 %

Market Action

November 15, 2013

Nothing happened today, except web server problems for me. Joy!

It was a mixed day for the Canadian preferred share market, with PerpetualDiscounts off 4bp, FixedResets down 39bp and DeemedRetractibles gaining 5bp. The Performance Highlights table was dominated by losing low-Spread FixedResets. Volume was well above average.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.0000 % 2,533.3
FixedFloater 4.21 % 3.49 % 32,975 18.39 1 -0.9211 % 3,991.3
Floater 2.93 % 2.95 % 60,221 19.80 3 0.0000 % 2,735.3
OpRet 4.64 % 1.86 % 69,234 0.08 3 -0.0048 % 2,651.4
SplitShare 4.73 % 5.14 % 66,568 3.91 6 -0.0198 % 2,967.7
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0048 % 2,424.4
Perpetual-Premium 5.58 % 4.26 % 125,632 0.09 11 -0.0539 % 2,307.8
Perpetual-Discount 5.56 % 5.57 % 176,840 14.50 27 -0.0437 % 2,367.2
FixedReset 4.97 % 3.39 % 229,648 3.33 82 -0.3938 % 2,480.0
Deemed-Retractible 5.07 % 3.97 % 193,754 1.46 42 0.0455 % 2,417.9
FloatingReset 2.61 % 2.39 % 322,012 4.49 5 -0.0871 % 2,457.3
Performance Highlights
Issue Index Change Notes
TRP.PR.A FixedReset -1.94 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-15
Maturity Price : 23.78
Evaluated at bid price : 24.25
Bid-YTW : 3.95 %
IAG.PR.G FixedReset -1.79 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-06-30
Maturity Price : 25.00
Evaluated at bid price : 25.75
Bid-YTW : 3.59 %
ENB.PR.T FixedReset -1.46 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-15
Maturity Price : 22.59
Evaluated at bid price : 23.65
Bid-YTW : 4.43 %
ENB.PR.F FixedReset -1.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-15
Maturity Price : 22.94
Evaluated at bid price : 24.30
Bid-YTW : 4.31 %
TRP.PR.C FixedReset -1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-15
Maturity Price : 22.22
Evaluated at bid price : 22.52
Bid-YTW : 3.88 %
BNS.PR.Y FixedReset -1.24 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.90
Bid-YTW : 3.70 %
ELF.PR.H Perpetual-Discount -1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-15
Maturity Price : 23.55
Evaluated at bid price : 23.91
Bid-YTW : 5.80 %
ENB.PR.Y FixedReset -1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-15
Maturity Price : 22.45
Evaluated at bid price : 23.38
Bid-YTW : 4.39 %
ENB.PR.P FixedReset -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-15
Maturity Price : 22.65
Evaluated at bid price : 23.76
Bid-YTW : 4.41 %
MFC.PR.I FixedReset -1.01 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-09-19
Maturity Price : 25.00
Evaluated at bid price : 25.71
Bid-YTW : 3.51 %
PWF.PR.S Perpetual-Discount 1.15 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-15
Maturity Price : 22.51
Evaluated at bid price : 22.85
Bid-YTW : 5.28 %
CIU.PR.A Perpetual-Discount 1.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-15
Maturity Price : 21.60
Evaluated at bid price : 21.60
Bid-YTW : 5.34 %
Volume Highlights
Issue Index Shares
Traded
Notes
BNS.PR.Z FixedReset 403,746 Nesbitt crossed blocks of 170,000 and 20,000, both at 23.70. RBC crossed 205,000 at the same price. Nice tickets!
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.75
Bid-YTW : 4.09 %
CU.PR.C FixedReset 225,730 RBC crossed blocks of 100,000 and 20,000, both at 25.60. Nesbitt crossed 100,000 at the same price.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-06-01
Maturity Price : 25.00
Evaluated at bid price : 25.48
Bid-YTW : 3.39 %
BNS.PR.B FloatingReset 108,500 Scotia crossed blocks of 50,000 shares, 23,100 and 30,000, all at 25.03.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-10-25
Maturity Price : 25.00
Evaluated at bid price : 25.01
Bid-YTW : 2.51 %
TD.PR.Z FloatingReset 102,000 Scotia crossed 100,000 at 25.03.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.01
Bid-YTW : 2.53 %
RY.PR.T FixedReset 62,115 TD crossed 47,800 at 25.71.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-08-24
Maturity Price : 25.00
Evaluated at bid price : 25.74
Bid-YTW : 2.21 %
FTS.PR.H FixedReset 60,550 RBC crossed 24,500 at 21.10.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-15
Maturity Price : 20.95
Evaluated at bid price : 20.95
Bid-YTW : 4.02 %
There were 47 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
TRP.PR.A FixedReset Quote: 24.25 – 24.75
Spot Rate : 0.5000
Average : 0.2904

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-15
Maturity Price : 23.78
Evaluated at bid price : 24.25
Bid-YTW : 3.95 %

TRP.PR.C FixedReset Quote: 22.52 – 23.09
Spot Rate : 0.5700
Average : 0.3670

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-15
Maturity Price : 22.22
Evaluated at bid price : 22.52
Bid-YTW : 3.88 %

MFC.PR.H FixedReset Quote: 26.08 – 26.45
Spot Rate : 0.3700
Average : 0.2333

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-03-19
Maturity Price : 25.00
Evaluated at bid price : 26.08
Bid-YTW : 3.11 %

TRP.PR.B FixedReset Quote: 20.70 – 21.00
Spot Rate : 0.3000
Average : 0.1930

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-15
Maturity Price : 20.70
Evaluated at bid price : 20.70
Bid-YTW : 3.90 %

HSB.PR.C Deemed-Retractible Quote: 25.18 – 25.46
Spot Rate : 0.2800
Average : 0.1758

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-06-30
Maturity Price : 25.00
Evaluated at bid price : 25.18
Bid-YTW : 5.04 %

FTS.PR.J Perpetual-Discount Quote: 22.63 – 23.07
Spot Rate : 0.4400
Average : 0.3399

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-15
Maturity Price : 22.31
Evaluated at bid price : 22.63
Bid-YTW : 5.25 %

Market Action

November 14, 2013

The Beaudoin-Bombardier family is doing what it does best:

Bombardier Inc.’s Beaudoin-Bombardier family owns a controlling stake in McInnis Cement, a Quebec company that is in talks with the provincial government over financial backing for its proposed $1-billion cement plant in Port-Daniel-Gascons, Que.

As Assiduous Reader Nestor said in the comments, tapering is a long long way off:

Janet Yellen, nominated to be the next chairman of the Federal Reserve, signaled she will carry on the central bank’s unprecedented stimulus until she sees improvement in an economy that’s operating well below potential.

“A strong recovery will ultimately enable the Fed to reduce its monetary accommodation and reliance on unconventional policy tools such as asset purchases,” Yellen said in testimony for her nomination hearing before the Senate Banking Committee today in Washington. “Supporting the recovery today is the surest path to returning to a more normal approach to monetary policy.”

The Ban-the-Bond movement is having an effect:

Moody’s Investors Service cut its ratings on four of the biggest U.S. banks after deciding the government would be less likely to help them repay creditors in a crisis.

Morgan Stanley (MS), Goldman Sachs Group Inc. (GS), JPMorgan Chase & Co. (JPM) and Bank of New York Mellon Corp. had their senior holding company ratings lowered one level yesterday after Moody’s concluded a review of eight U.S. banks that began in August. Spokesmen for the four companies declined to comment.

U.S. banking regulators have been preparing rules and procedures that seek to allow the government to wind down even the largest financial companies without providing taxpayer assistance. The plans would require investors to accept losses and could require bonds to be converted into equity capital.

“We believe that U.S. bank regulators have made substantive progress in establishing a credible framework to resolve a large, failing bank,” Robert Young, a managing director at Moody’s, said in a statement. “Rather than relying on public funds to bail out one of these institutions, we expect that bank holding company creditors will be bailed-in and thereby shoulder much of the burden to help recapitalize a failing bank.”

Premier Wynne is terribly, terribly concerned about Rob Ford. In less important news:

Heinz said it is closing its plant in Leamington, Ont., in mid-2014, a move that will cost 740 jobs and end almost a century of ketchup making in the southern Ontario town.
…
Other Canadian food plants slated to close include:

– Lance Canada Ltd.’s bakery in Cambridge, which employs 130 people. It will close in May, the company’s North Carolina parent said.

– Canada Bread’s snack cake plant in Shawinigan, Que., is scheduled to close in May.

– Kraft Canada’s coffee plant in Oakville, Ont., is expected to close this year.

It was a positive day for the Canadian preferred share market, with PerpetualDiscounts up 14bp, FixedResets winning 18bp and DeemedRetractibles up 12bp. A modest – by recent standards – Performance Highlights table is comprised entirely of winners and dominated by FixedResets. Volume was average.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.4483 % 2,533.3
FixedFloater 4.17 % 3.45 % 31,508 18.46 1 -0.1314 % 4,028.4
Floater 2.93 % 2.95 % 59,641 19.81 3 0.4483 % 2,735.3
OpRet 4.62 % 2.80 % 70,110 0.37 3 -0.3327 % 2,651.5
SplitShare 4.73 % 5.11 % 65,462 3.92 6 0.2374 % 2,968.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.3327 % 2,424.6
Perpetual-Premium 5.57 % 2.59 % 124,988 0.09 11 0.0036 % 2,309.1
Perpetual-Discount 5.56 % 5.55 % 178,777 14.55 27 0.1393 % 2,368.2
FixedReset 4.95 % 3.22 % 231,469 3.30 82 0.1750 % 2,489.8
Deemed-Retractible 5.07 % 4.00 % 194,505 1.47 42 0.1198 % 2,416.8
FloatingReset 2.61 % 2.35 % 301,675 4.49 5 0.0317 % 2,459.5
Performance Highlights
Issue Index Change Notes
ELF.PR.H Perpetual-Discount 1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-14
Maturity Price : 23.82
Evaluated at bid price : 24.20
Bid-YTW : 5.73 %
CU.PR.E Perpetual-Discount 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-14
Maturity Price : 23.29
Evaluated at bid price : 23.62
Bid-YTW : 5.19 %
HSE.PR.A FixedReset 1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-14
Maturity Price : 22.87
Evaluated at bid price : 23.60
Bid-YTW : 3.90 %
VNR.PR.A FixedReset 1.11 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-10-15
Maturity Price : 25.00
Evaluated at bid price : 25.58
Bid-YTW : 3.83 %
MFC.PR.K FixedReset 1.27 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.70
Bid-YTW : 4.16 %
BAM.PF.B FixedReset 1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-14
Maturity Price : 22.80
Evaluated at bid price : 24.10
Bid-YTW : 4.53 %
Volume Highlights
Issue Index Shares
Traded
Notes
BMO.PR.J Deemed-Retractible 59,335 RBC crossed 50,000 at 25.60.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-02-25
Maturity Price : 25.50
Evaluated at bid price : 25.59
Bid-YTW : 2.69 %
TRP.PR.B FixedReset 58,878 Desjardins crossed blocks of 18,200 and 11,800, both at 20.70. RBC crossed 13,400 at 20.80.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-14
Maturity Price : 20.85
Evaluated at bid price : 20.85
Bid-YTW : 3.87 %
FTS.PR.H FixedReset 58,008 RBC crossed 42,400 at 21.12.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-14
Maturity Price : 21.12
Evaluated at bid price : 21.12
Bid-YTW : 3.99 %
BMO.PR.R FloatingReset 55,200 Scotia bought 48,600 from RBC at 25.05.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-08-25
Maturity Price : 25.00
Evaluated at bid price : 25.07
Bid-YTW : 2.35 %
BAM.PF.C Perpetual-Discount 36,922 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-14
Maturity Price : 19.61
Evaluated at bid price : 19.61
Bid-YTW : 6.29 %
CM.PR.M FixedReset 30,400 Scotia bought 19,700 from RBC at 25.80.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-07-31
Maturity Price : 25.00
Evaluated at bid price : 25.80
Bid-YTW : 2.35 %
There were 35 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
PWF.PR.F Perpetual-Discount Quote: 23.80 – 24.07
Spot Rate : 0.2700
Average : 0.1724

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-14
Maturity Price : 23.53
Evaluated at bid price : 23.80
Bid-YTW : 5.55 %

ELF.PR.G Perpetual-Discount Quote: 21.61 – 21.95
Spot Rate : 0.3400
Average : 0.2482

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-14
Maturity Price : 21.61
Evaluated at bid price : 21.61
Bid-YTW : 5.56 %

TD.PR.O Deemed-Retractible Quote: 25.25 – 25.49
Spot Rate : 0.2400
Average : 0.1584

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2014-10-31
Maturity Price : 25.00
Evaluated at bid price : 25.25
Bid-YTW : 4.00 %

BNS.PR.Y FixedReset Quote: 24.20 – 24.49
Spot Rate : 0.2900
Average : 0.2270

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 24.20
Bid-YTW : 3.52 %

CU.PR.C FixedReset Quote: 25.55 – 25.85
Spot Rate : 0.3000
Average : 0.2382

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-06-01
Maturity Price : 25.00
Evaluated at bid price : 25.55
Bid-YTW : 3.30 %

ENB.PR.A Perpetual-Premium Quote: 25.02 – 25.27
Spot Rate : 0.2500
Average : 0.1913

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2013-12-14
Maturity Price : 25.00
Evaluated at bid price : 25.02
Bid-YTW : 1.41 %

Market Action

November 12, 2013

Good times to be in corporate finance:

Canadian companies are borrowing more than ever, breaking records for selling new debt in a push to lock in low interest rates before borrowing costs rise.

Corporations and financial institutions have set a new mark for fixed-income sales this year by issuing more than $100-billion in debt, higher than the full-year record set in 2012.
…
As usual, Canadian banks dominate bond sales this year, raising $47-billion, up 23 per cent from 2012, according to CIBC. However, non-bank borrowers have increased their game, raising an usually large amount of debt, helping to push total issuance to sky-high levels.

ETFs and mutual funds have the great virtue of increasing liquidity for retail investors – I often recommend bond ETFs to clients. But the mismatch between retail liquidity and underlying liquidity is getting worrisome:

A recent presentation by Citi’s Matt King, includes a chart entitled “Entrance with No Exit” that has been costing me sleep. Mr. King’s chart asserts that if and when a significant percentage of the holders of almost $900-billion (U.S.) invested in U.S. corporate debt mutual funds and ETFs (investment grade plus high yield debt) want to sell, there may not be anyone to bid for them.

In the past, large banks carried enormous portfolios of both investment grade and high yield debt issues and provided liquidity to the market – buying bonds when the market was weak and selling when it was strong.

Since the financial crisis, however, U.S. banks have responded to regulatory pressure over proprietary trading and capital requirements by drastically reducing their holdings – from about $300-billion to less than $100-billion – while mutual fund and ETF fixed income assets have almost doubled from just under $500-billion.

There’s $900-billion in corporate debt funds and ETFs and a tenth of that in the banking system so, there is no way the banks can offset a buyers strike in bond funds if it occurs.
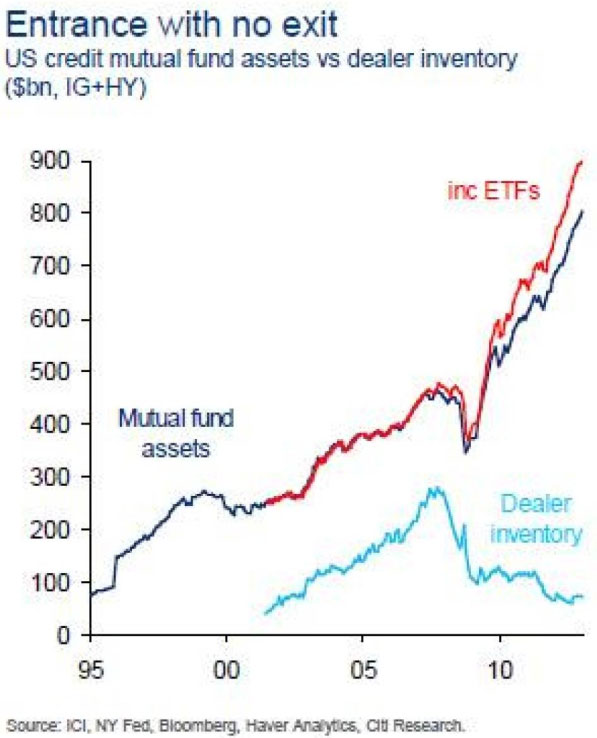

Click for Big

If an apocalypse happens due to this, it will be bargain season for long term investors, but those who need the cash – or even the margin – might find themselves a little embarrassed.

Decreased liquidity in corporate bonds was discussed on November 5, while US regulatory moves to extend their power over asset managers was discussed November 6. Does anybody else see a pattern here? Mark my words, there will be enforced ‘gating’ of mutual fund and ETF redemptions soon (ETF redemptions coming in big blocks from arbitrageurs). All that power has to go somewhere! We will then see ETFs trading at a discount to NAV, and a lot of very unhappy mutual fund fund clients.

So what’s the solution? As far as I can tell, there ain’t one. Companies will have to keep a little extra cash on hand in case the markets decide to shut down for a while; investors will have to keep a little more cash on hand than otherwise for the same reason. Ultimately, the benefits of allowing retail decent access to the corporate bond markets outweighs the harms … but you can bet the regulators won’t see it that way. Nobody must be hurt! If anybody is ever hurt by anything, it’s because of a Wall Street conspiracy!

It was a day of small gains for the Canadian preferred share market, with PerpetualDiscounts winning 10bp, FixedResets gaining 5bp and DeemedRetractibles up 7bp. Surprisingly, the Performance Highlights table is relatively lengthy. FloatingResets traded up a storm today on big blocks through Nesbitt, with an assist from Scotia, although there is no way of telling whether or not they were ‘real’ crosses or internal crosses; volume was above average.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.2622 % 2,522.0
FixedFloater 4.16 % 3.44 % 30,800 18.47 1 -0.7391 % 4,033.7
Floater 2.94 % 2.97 % 59,658 19.78 3 0.2622 % 2,723.0
OpRet 4.61 % 1.19 % 67,910 0.37 3 0.1868 % 2,660.4
SplitShare 4.74 % 5.13 % 65,290 3.92 6 0.0807 % 2,961.3
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1868 % 2,432.7
Perpetual-Premium 5.57 % 3.88 % 124,296 0.09 11 0.1290 % 2,309.0
Perpetual-Discount 5.57 % 5.55 % 176,877 14.51 27 0.1010 % 2,364.9
FixedReset 4.96 % 3.33 % 231,281 3.31 82 0.0504 % 2,485.5
Deemed-Retractible 5.07 % 4.02 % 189,766 1.47 42 0.0677 % 2,413.9
FloatingReset 2.61 % 2.38 % 305,823 4.49 5 0.0952 % 2,458.7
Performance Highlights
Issue Index Change Notes
CIU.PR.A Perpetual-Discount -2.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-13
Maturity Price : 21.20
Evaluated at bid price : 21.20
Bid-YTW : 5.44 %
BAM.PR.X FixedReset -1.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-13
Maturity Price : 21.79
Evaluated at bid price : 22.12
Bid-YTW : 4.36 %
CU.PR.C FixedReset -1.34 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-06-01
Maturity Price : 25.00
Evaluated at bid price : 25.71
Bid-YTW : 3.11 %
FTS.PR.G FixedReset 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-13
Maturity Price : 22.77
Evaluated at bid price : 23.96
Bid-YTW : 4.04 %
FTS.PR.F Perpetual-Discount 1.10 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-13
Maturity Price : 22.96
Evaluated at bid price : 23.25
Bid-YTW : 5.27 %
IAG.PR.A Deemed-Retractible 1.62 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 22.56
Bid-YTW : 5.90 %
MFC.PR.C Deemed-Retractible 1.78 % YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 21.69
Bid-YTW : 6.28 %
TRP.PR.B FixedReset 1.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-13
Maturity Price : 20.81
Evaluated at bid price : 20.81
Bid-YTW : 3.88 %
Volume Highlights
Issue Index Shares
Traded
Notes
TD.PR.Z FloatingReset 256,885 Nesbitt crossed 200,000 at 25.00; Scotia crossed 50,000 at 25.03.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.03
Bid-YTW : 2.52 %
BMO.PR.R FloatingReset 251,600 Nesbitt crossed 200,000 at 25.03; Scotia crossed 50,000 at the same price.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-08-25
Maturity Price : 25.00
Evaluated at bid price : 25.04
Bid-YTW : 2.38 %
TD.PR.T FloatingReset 208,816 Nesbitt crossed 200,000 at 25.10.
YTW SCENARIO
Maturity Type : Call
Maturity Date : 2018-07-31
Maturity Price : 25.00
Evaluated at bid price : 25.16
Bid-YTW : 2.26 %
BNS.PR.B FloatingReset 207,987 Nesbitt crossed 200,000 at 25.02.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.03
Bid-YTW : 2.54 %
BNS.PR.Z FixedReset 115,587 Nesbitt crossed 100,000 at 23.70.
YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2022-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.66
Bid-YTW : 4.15 %
TRP.PR.C FixedReset 44,454 Desjardins crossed 30,000 at 22.80.
YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-13
Maturity Price : 22.37
Evaluated at bid price : 22.74
Bid-YTW : 3.83 %
There were 42 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
Issue Index Quote Data and Yield Notes
CU.PR.E Perpetual-Discount Quote: 23.37 – 23.82
Spot Rate : 0.4500
Average : 0.3462

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-13
Maturity Price : 23.06
Evaluated at bid price : 23.37
Bid-YTW : 5.24 %

BAM.PF.D Perpetual-Discount Quote: 19.69 – 19.96
Spot Rate : 0.2700
Average : 0.1909

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2043-11-13
Maturity Price : 19.69
Evaluated at bid price : 19.69
Bid-YTW : 6.33 %

MFC.PR.F FixedReset Quote: 23.30 – 23.49
Spot Rate : 0.1900
Average : 0.1302

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2025-01-31
Maturity Price : 25.00
Evaluated at bid price : 23.30
Bid-YTW : 4.36 %

CU.PR.C FixedReset Quote: 25.71 – 25.94
Spot Rate : 0.2300
Average : 0.1704

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-06-01
Maturity Price : 25.00
Evaluated at bid price : 25.71
Bid-YTW : 3.11 %

MFC.PR.I FixedReset Quote: 26.07 – 26.28
Spot Rate : 0.2100
Average : 0.1516

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2017-09-19
Maturity Price : 25.00
Evaluated at bid price : 26.07
Bid-YTW : 3.41 %

BNA.PR.C SplitShare Quote: 24.26 – 24.43
Spot Rate : 0.1700
Average : 0.1177

YTW SCENARIO
Maturity Type : Hard Maturity
Maturity Date : 2019-01-10
Maturity Price : 25.00
Evaluated at bid price : 24.26
Bid-YTW : 5.22 %